Magnetite Mines Ltd. · ASX:MGT
Magnetite Mines — Royal Resources — Shareholder Meeting (November 2013)
23 slides from Magnetite Mines's shareholder meeting presentation, Nov 28, 2013
Slide 1: 2013 AGM Presentation: Summary of activities
RESOURCES LIMITED 2013 AGM Presentation Summary of activities Marcus Flis, MD 28 November, 2013
Slide 2: Disclaimer and Competent Person's Statement
DISCLAIMER AND COMPETENT PERSON’S STATEMENT This presentation has been prepared by Royal Resources Limited (ABN 34 108 102 432) (“Royal”) based on information available to it. No representation or warranty, express or implied, is made as to the fairness, accuracy, completeness or correctness of the
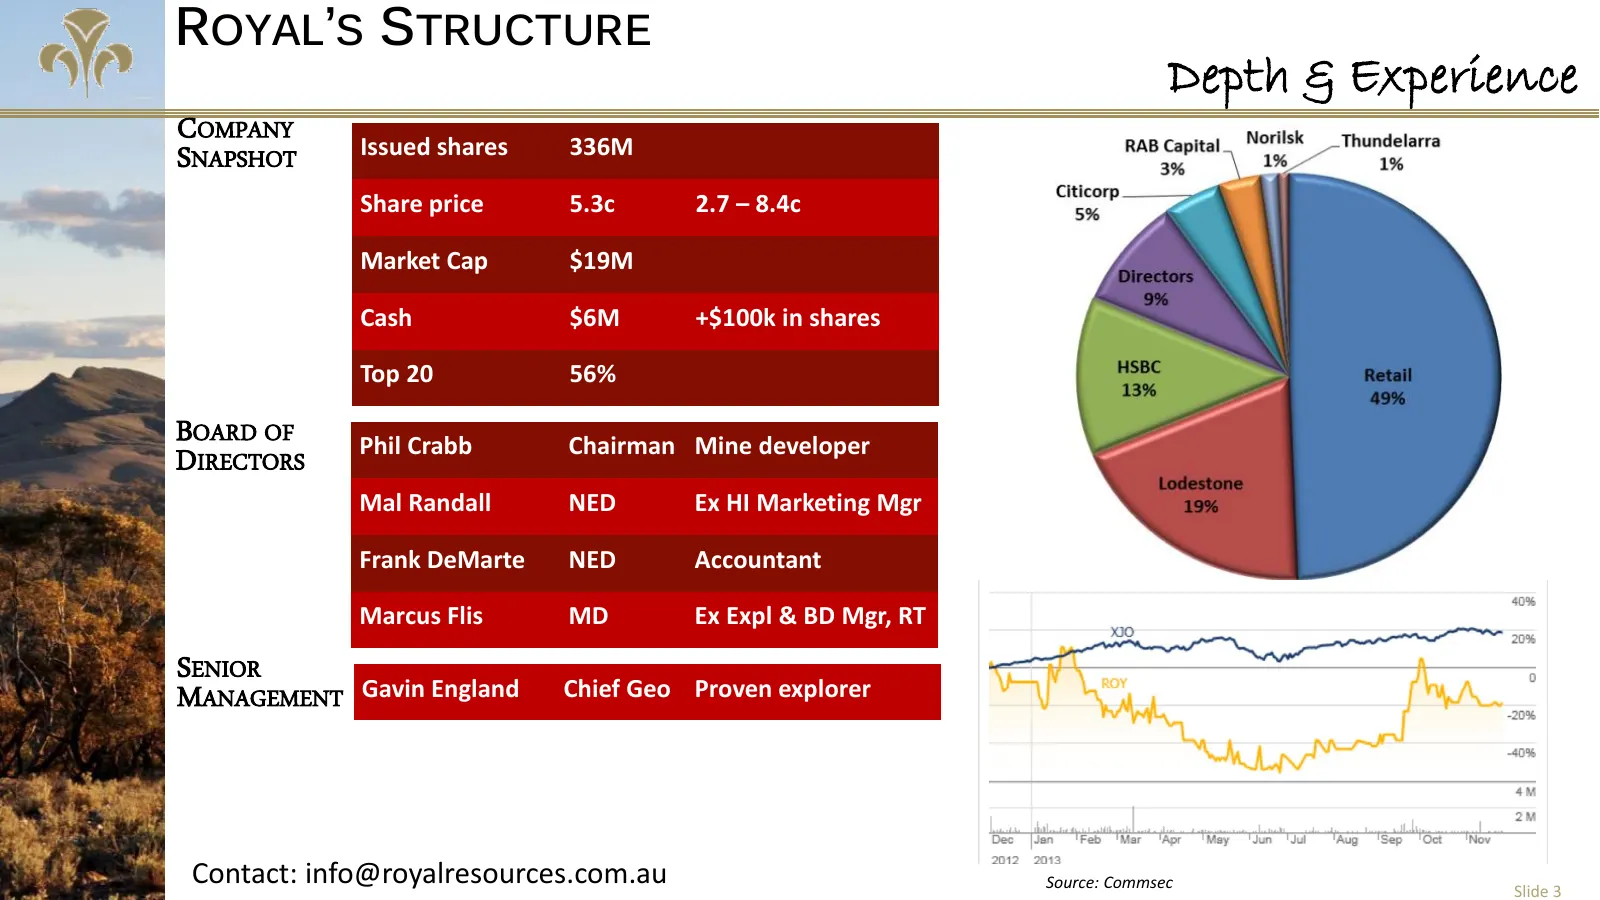
Slide 3: Royal's Structure: Depth & Experience
ROYAL’S STRUCTURE Depth & Experience COMPANY Issued shares 336M SNAPSHOT Share price 5.3c 2.7 – 8.4c Market Cap $19M Cash $6M +$100k in shares Top 20 56% BOARD OF Phil Crabb Chairman Mine developer DIRECTORS Mal Randall NED Ex HI Marketing Mgr Frank DeMarte NED Accountant Marcus Flis MD Ex Expl & BD
Slide 4: Royal's Strategy: Measured growth
ROYAL’S STRATEGY Measured growth Philosophy: Define and develop a company-making project that maximises shareholder value Focus: The Red Dragon Venture in the emerging Braemar Iron Formation, SA Commodities: The “convex” metals: Iron, Copper, Gold, Nickel sulphides, Tin, Manganese, Lead/Zinc Resourc
Slide 5: Royal's Ability to Monetise
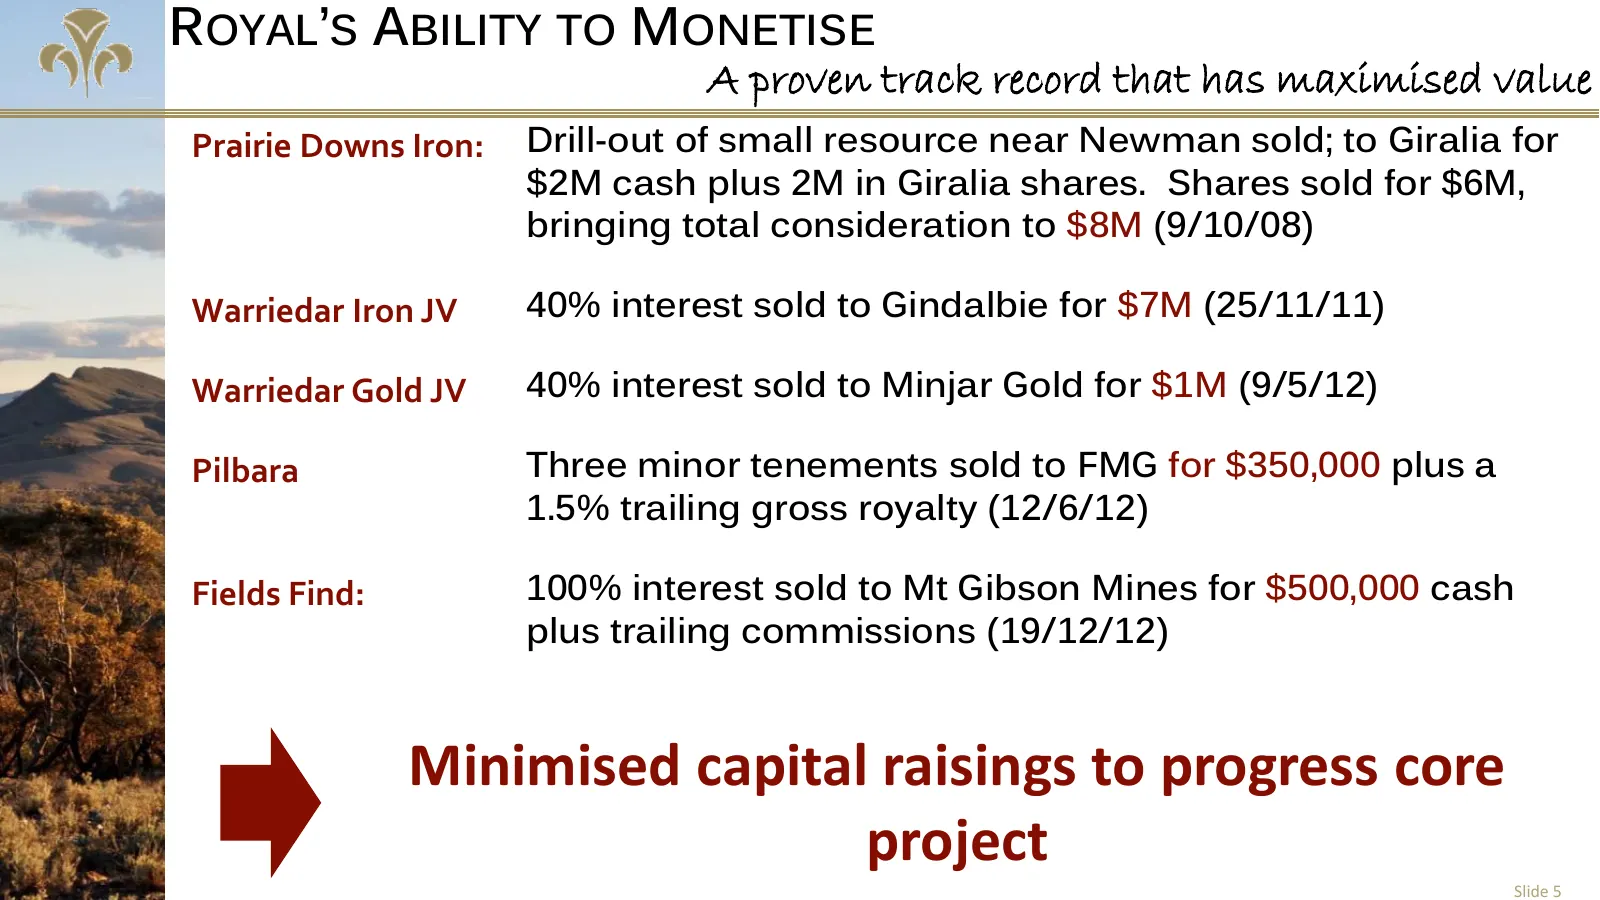
ROYAL’S ABILITY TO MONETISE A proven track record that has maximised value Prairie Downs Iron: Drill-out of small resource near Newman sold; to Giralia for $2M cash plus 2M in Giralia shares. Shares sold for $6M, bringing total consideration to $8M (9/10/08) Warriedar Iron JV 40% interest sold to Gi
Slide 6: Royal's Ability to Attract Cornerstone Investors
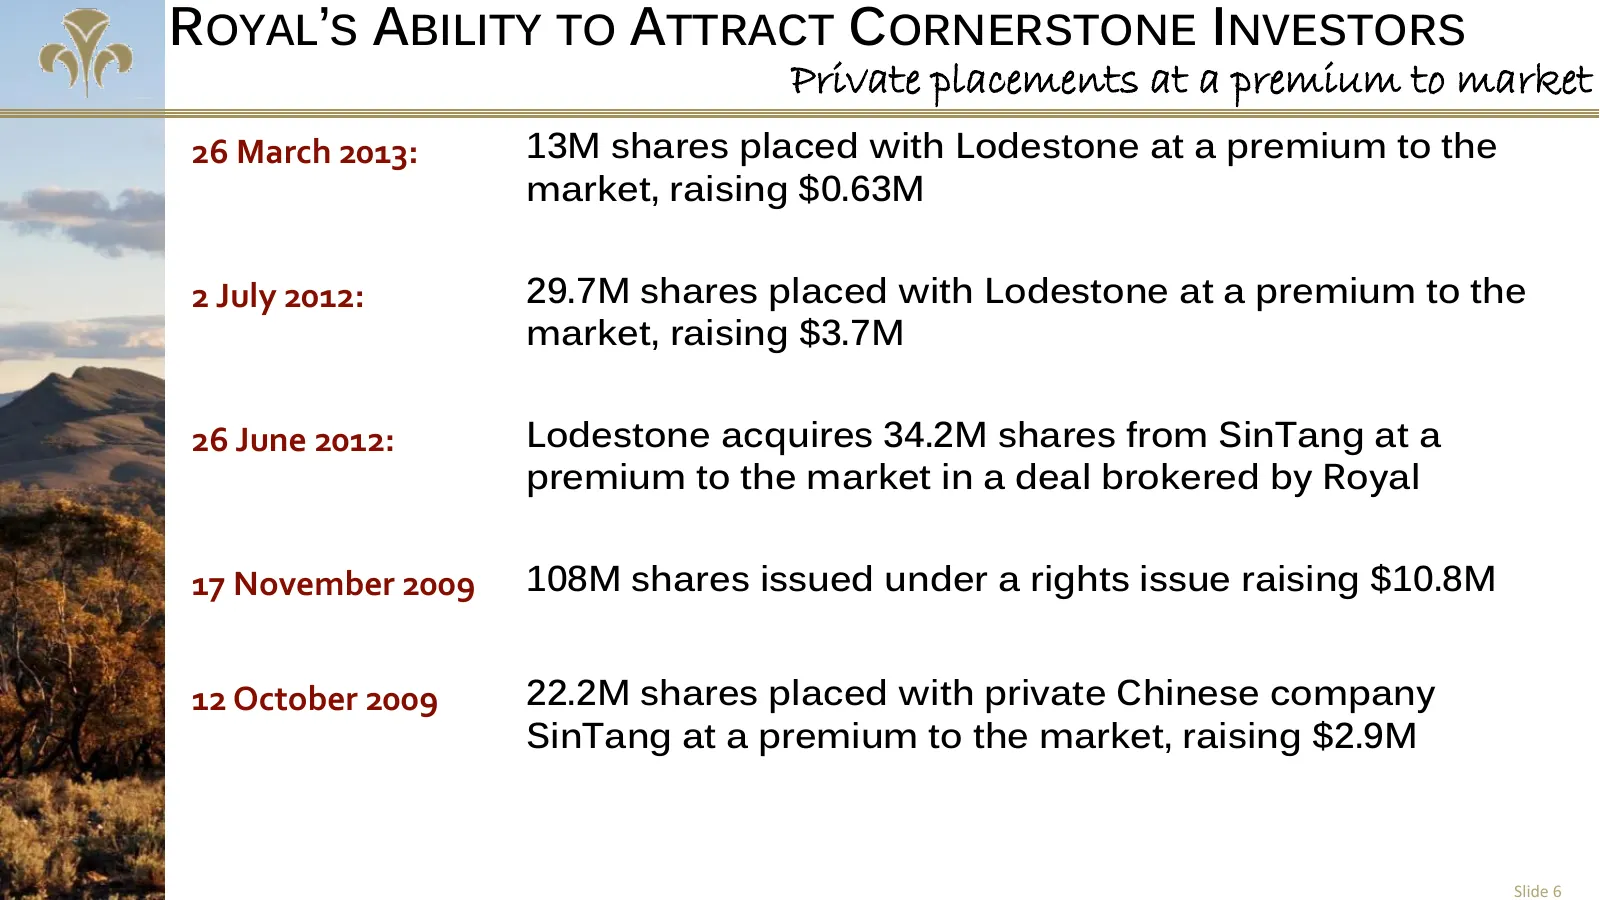
ROYAL’S ABILITY TO ATTRACT CORNERSTONE INVESTORS Private placements at a premium to market 26 March 2013: 13M shares placed with Lodestone at a premium to the market, raising $0.63M 2 July 2012: 29.7M shares placed with Lodestone at a premium to the market, raising $3.7M 26 June 2012: Lodestone acqu
Slide 7: Royal: An Industry-Recognised Explorer
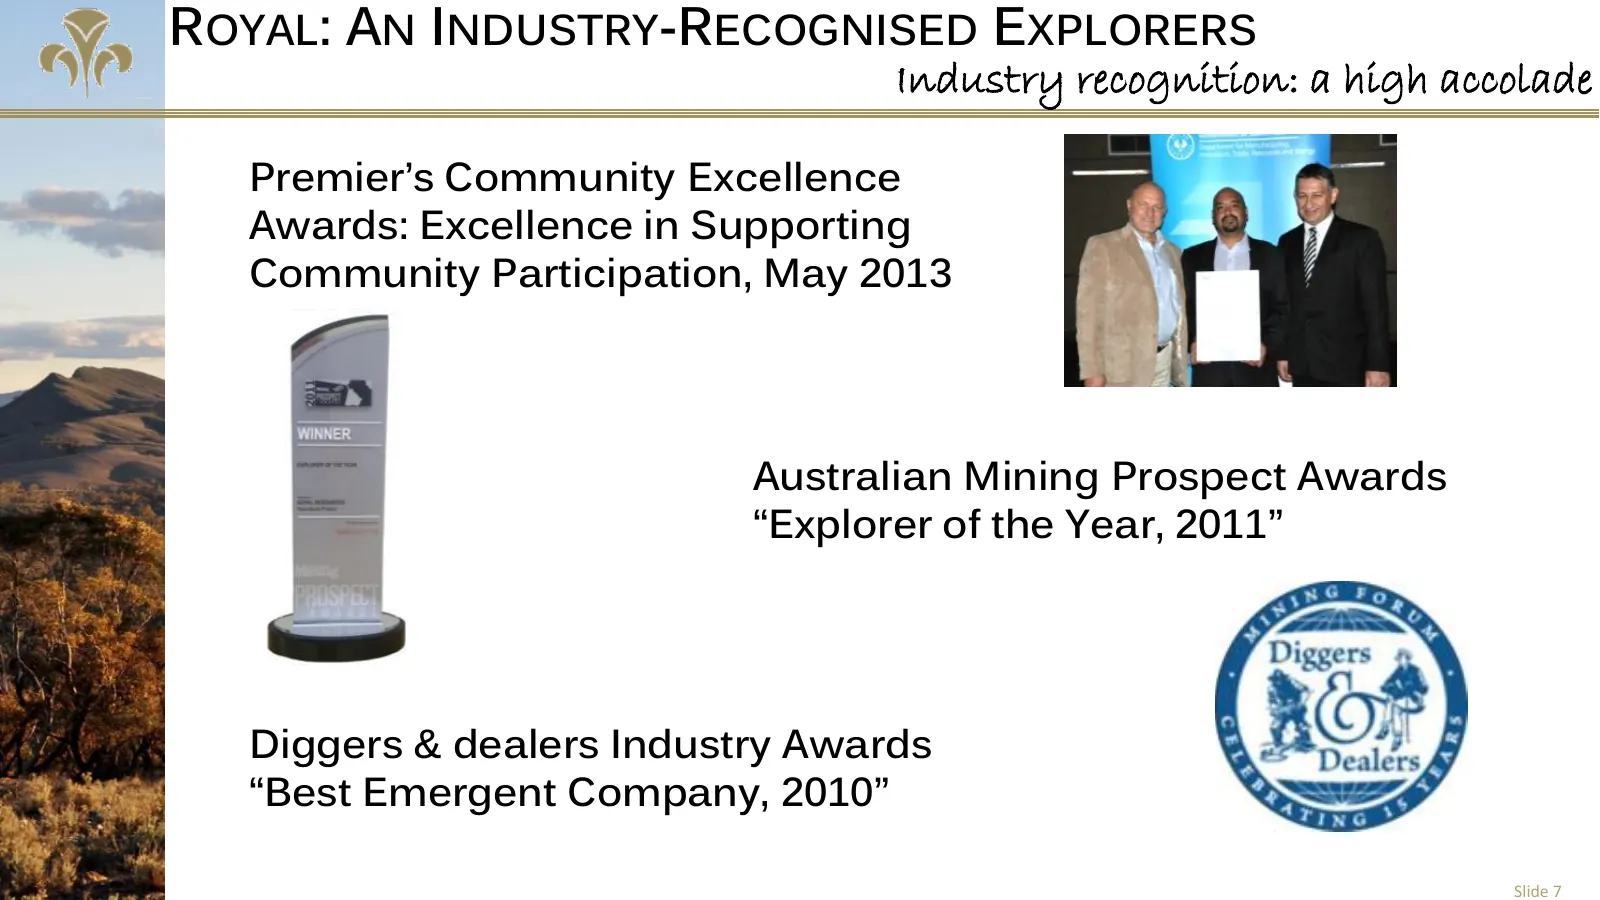
ROYAL: AN INDUSTRY-RECOGNISED EXPLORERS Industry recognition: a high accolade Premier’s Community Excellence Awards: Excellence in Supporting Community Participation, May 2013 Australian Mining Prospect Awards “Explorer of the Year, 2011” Diggers & dealers Industry Awards “Best Emergent Company, 201
Slide 8: Significant Events Over the Past Year
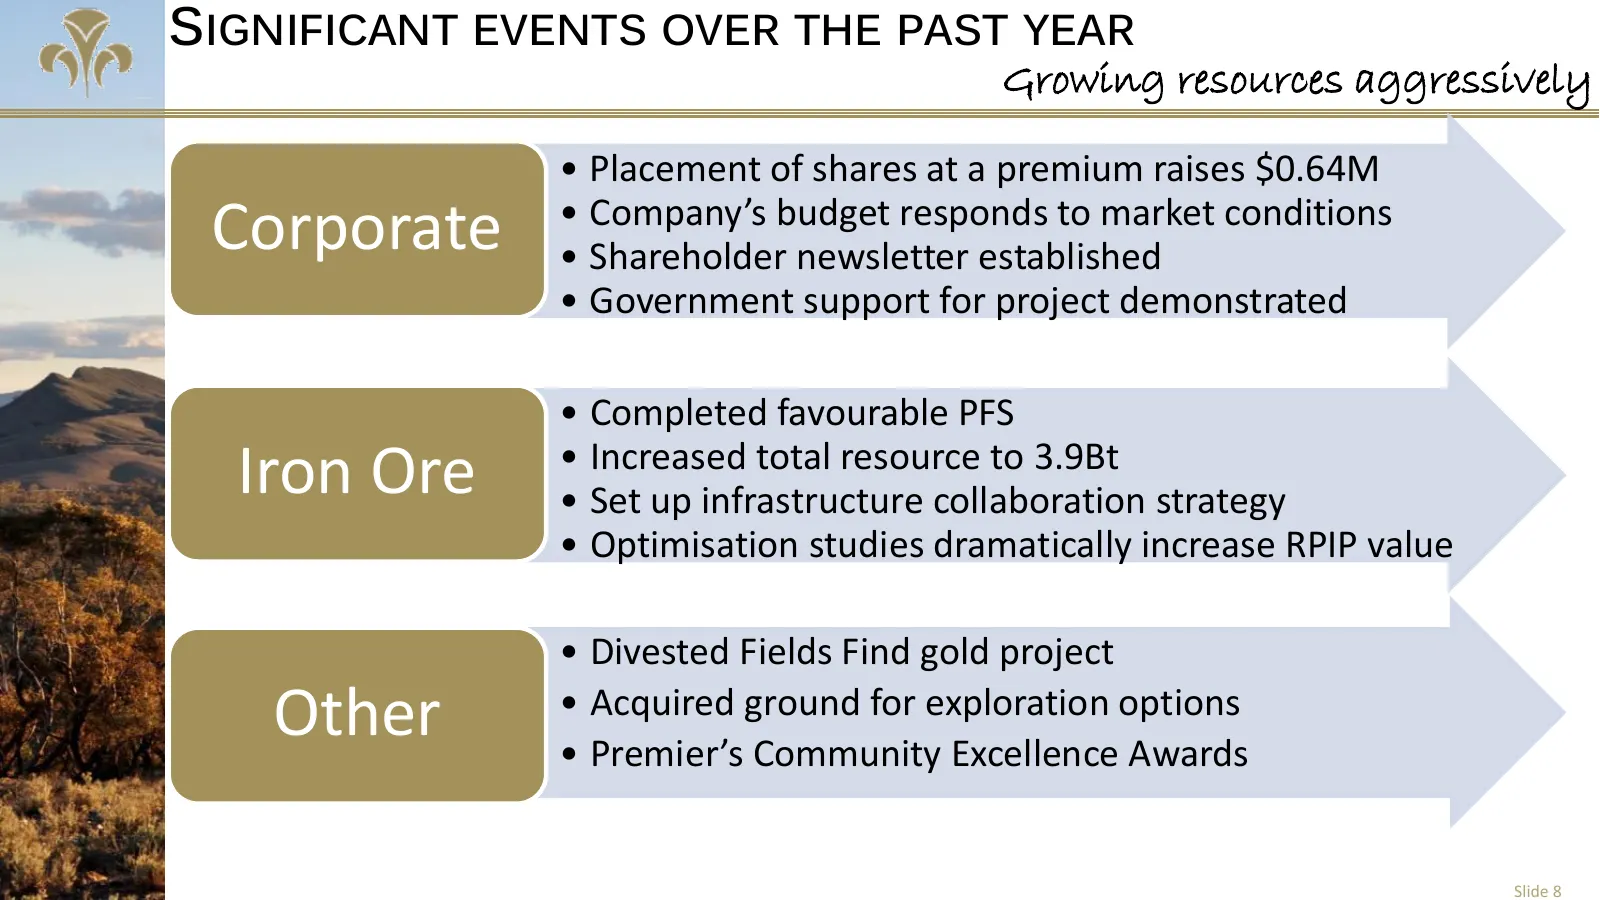
SIGNIFICANT EVENTS OVER THE PAST YEAR Growing resources aggressively • Placement of shares at a premium raises $0.64M • Company’s budget responds to market conditions Corporate • Shareholder newsletter established • Government support for project demonstrated • Completed favourable PFS • Increased t
Slide 9: Red Dragon Venture – 100% Royal Owned
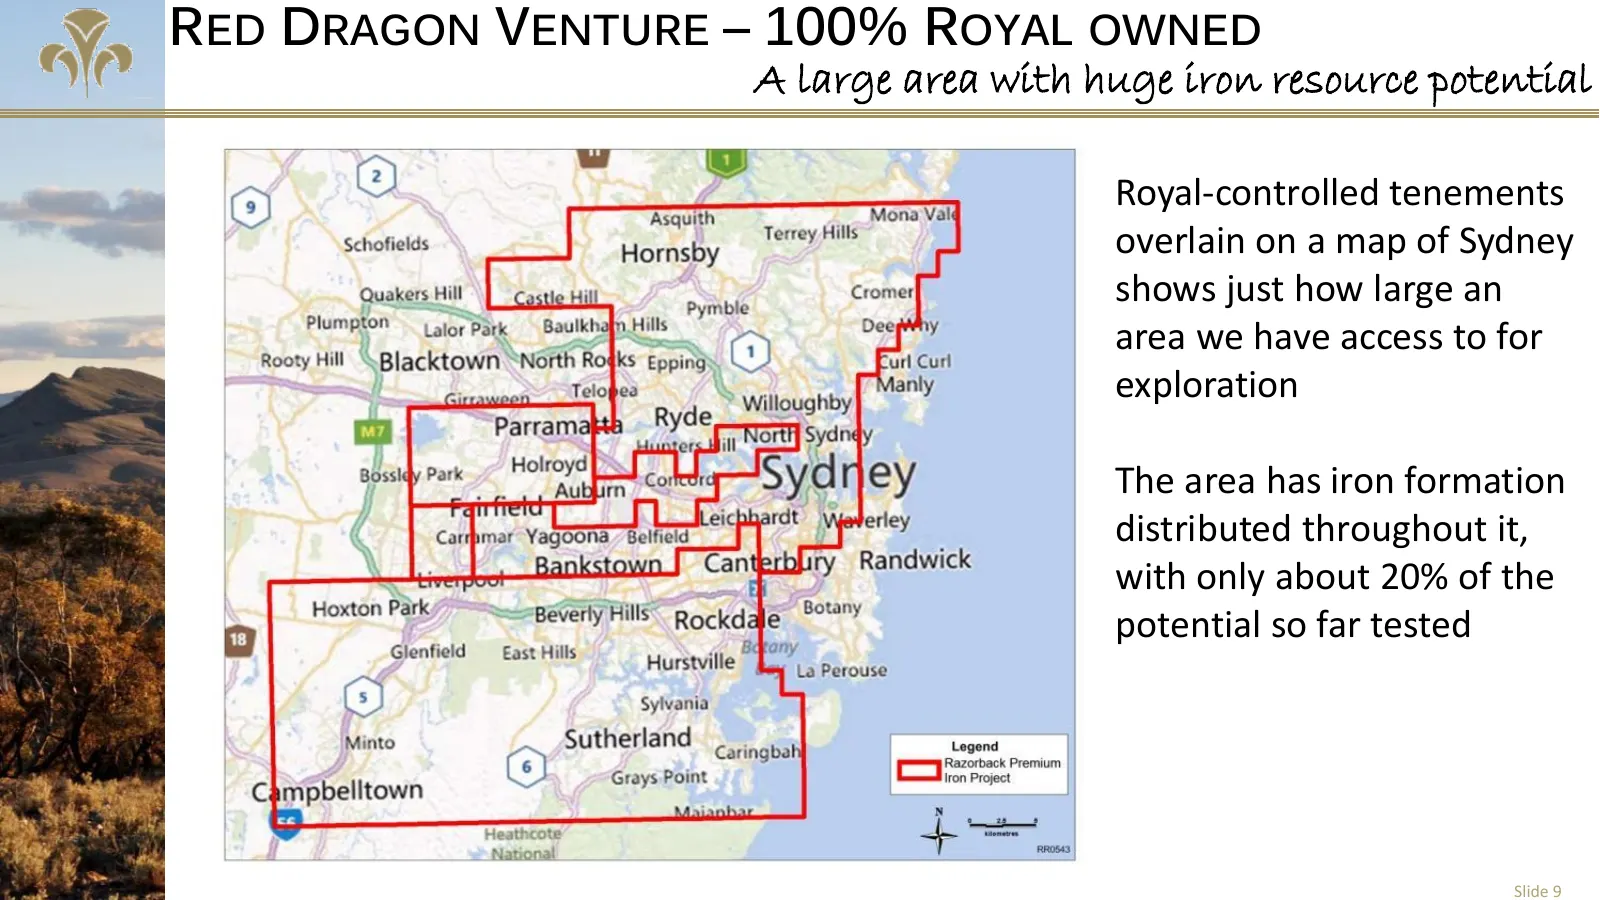
RED DRAGON VENTURE – 100% ROYAL OWNED A large area with huge iron resource potential Royal-controlled tenements overlain on a map of Sydney shows just how large an area we have access to for exploration The area has iron formation distributed throughout it, with only about 20% of the potential so fa
Slide 10: Red Dragon Venture – 3.92 Billion Tonnes
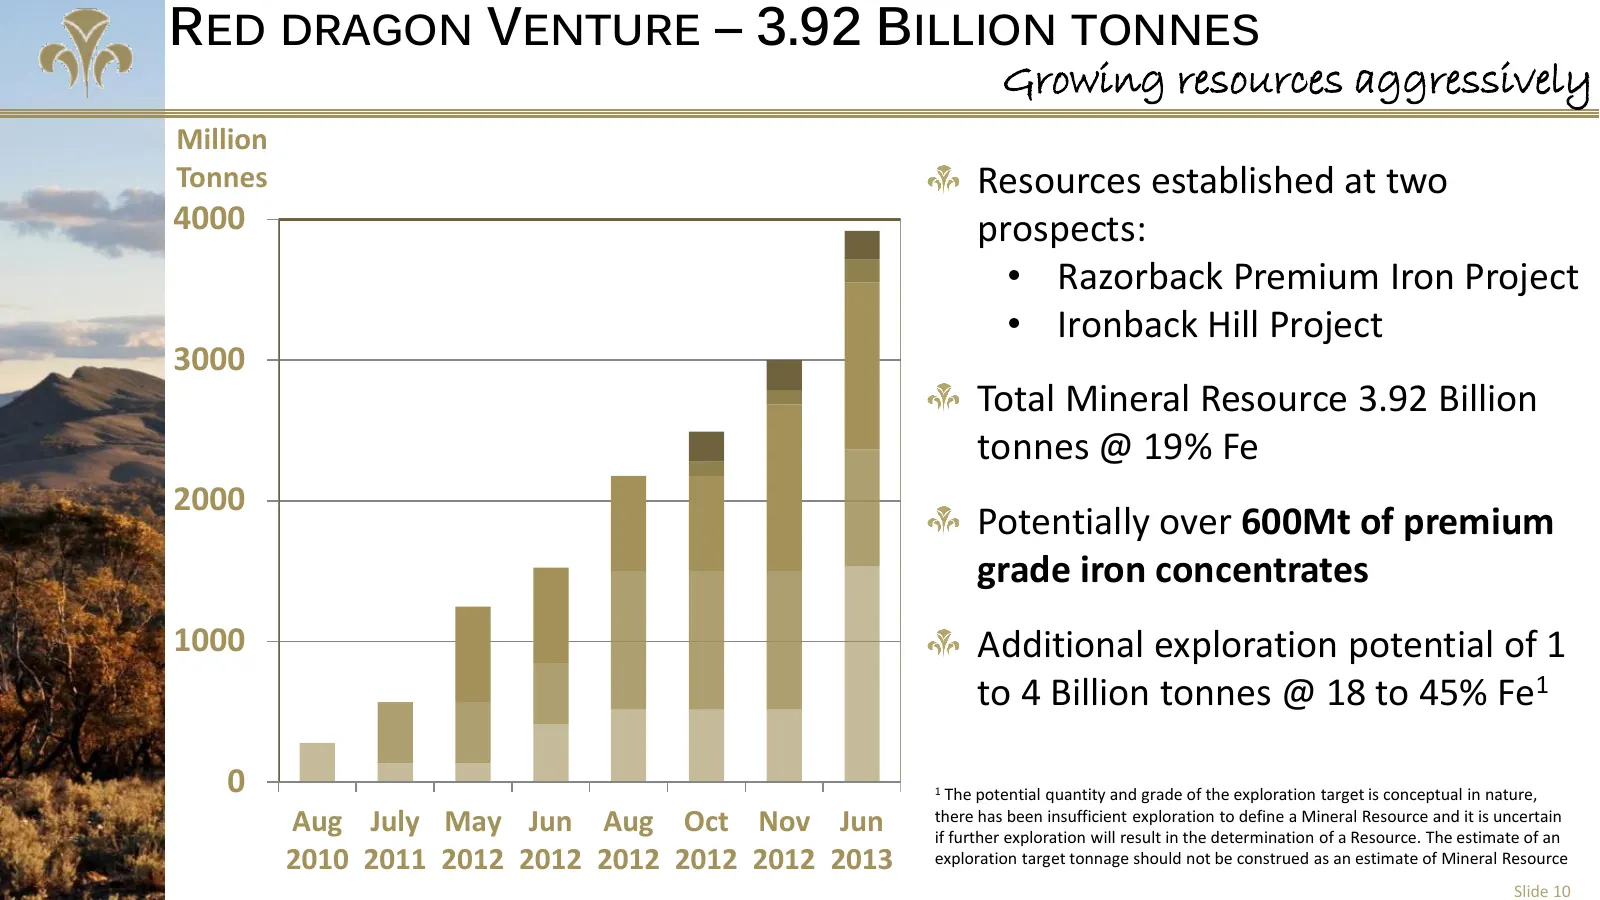
RED DRAGON VENTURE – 3.92 BILLION TONNES Growing resources aggressively Million Tonnes Resources established at two 4000 prospects: • Razorback Premium Iron Project • Ironback Hill Project 3000 Total Mineral Resource 3.92 Billion tonnes @ 19% Fe 2000 Potentially over 600Mt of premium grade iron conc
Slide 11: Razorback Premium Iron Project: Feeding an aggressive time line
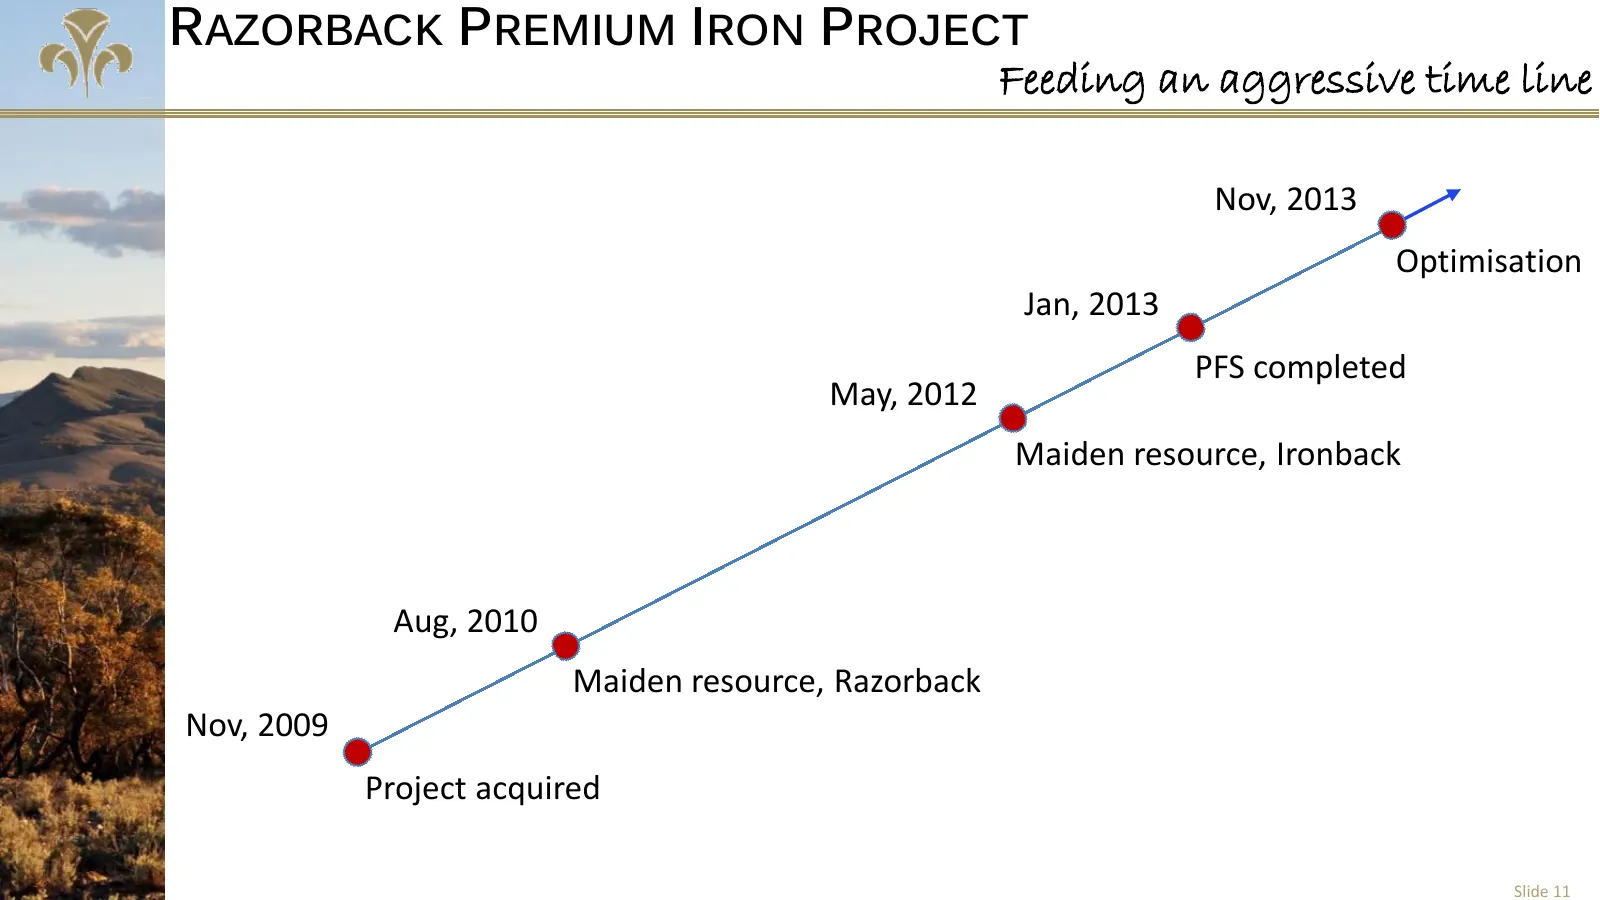
RAZORBACK PREMIUM IRON PROJECT Feeding an aggressive time line Nov, 2013 Optimisation Jan, 2013 PFS completed May, 2012 Maiden resource, Ironback Aug, 2010 Maiden resource, Razorback Nov, 2009 Project acquired Slide 11
Slide 12: Optimisation Study Outcomes
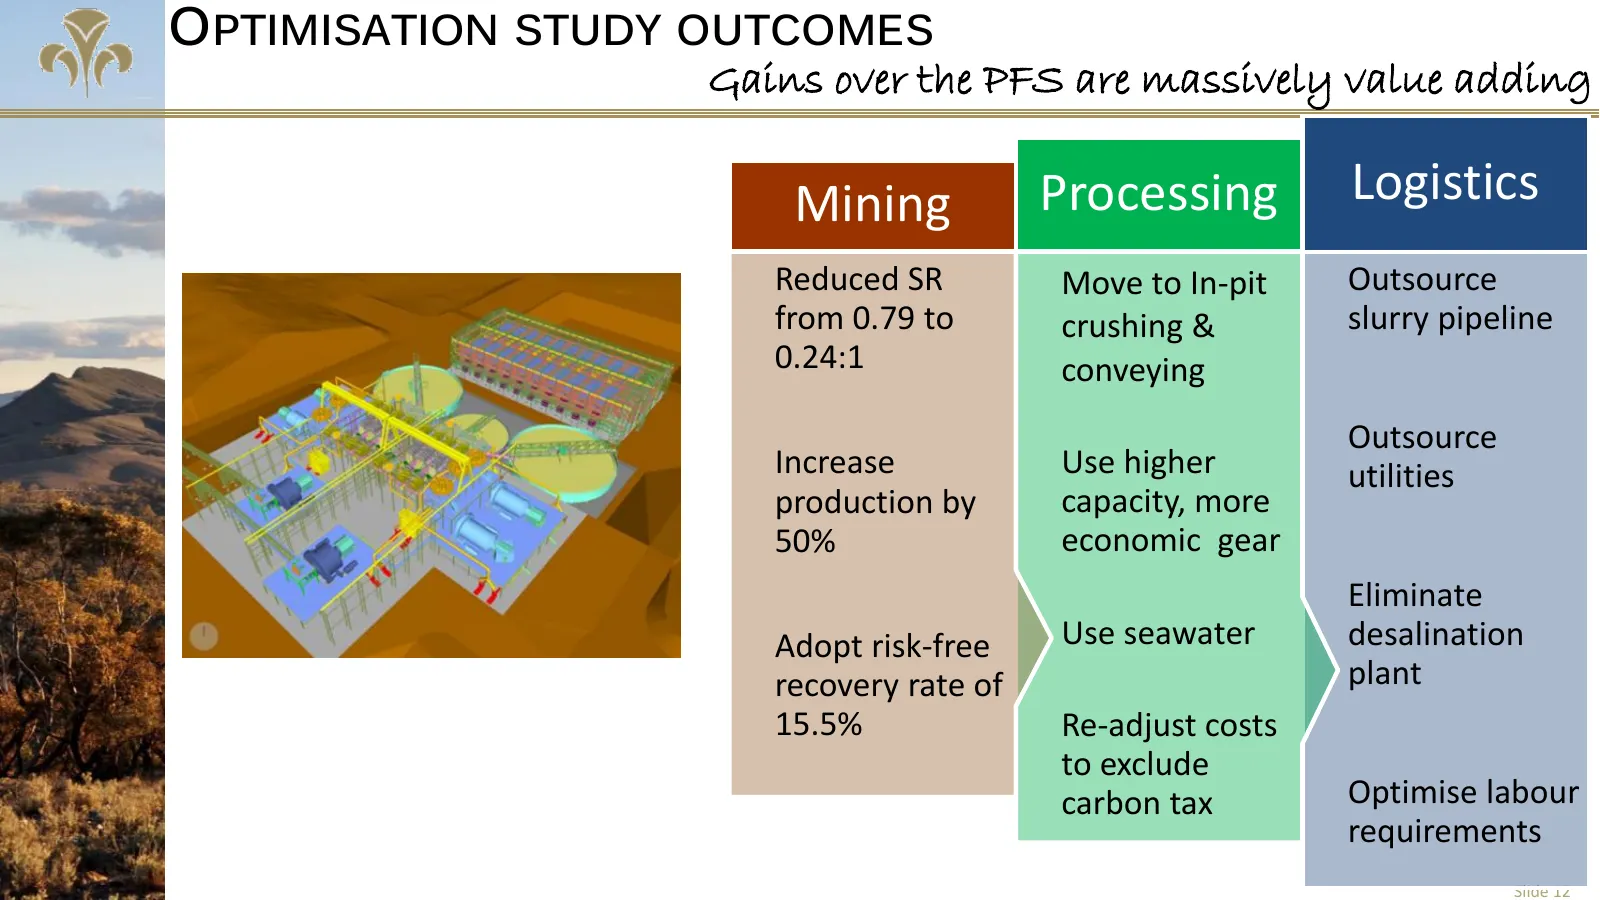
OPTIMISATION STUDY OUTCOMES Gains over the PFS are massively value adding Mining Processing Logistics Reduced SR Move to In-pit Outsource from 0.79 to crushing & slurry pipeline 0.24:1 conveying Outsource Increase Use higher utilities production by capacity, more 50% economic gear Eliminate Adopt ri
Slide 13: Mining Operation
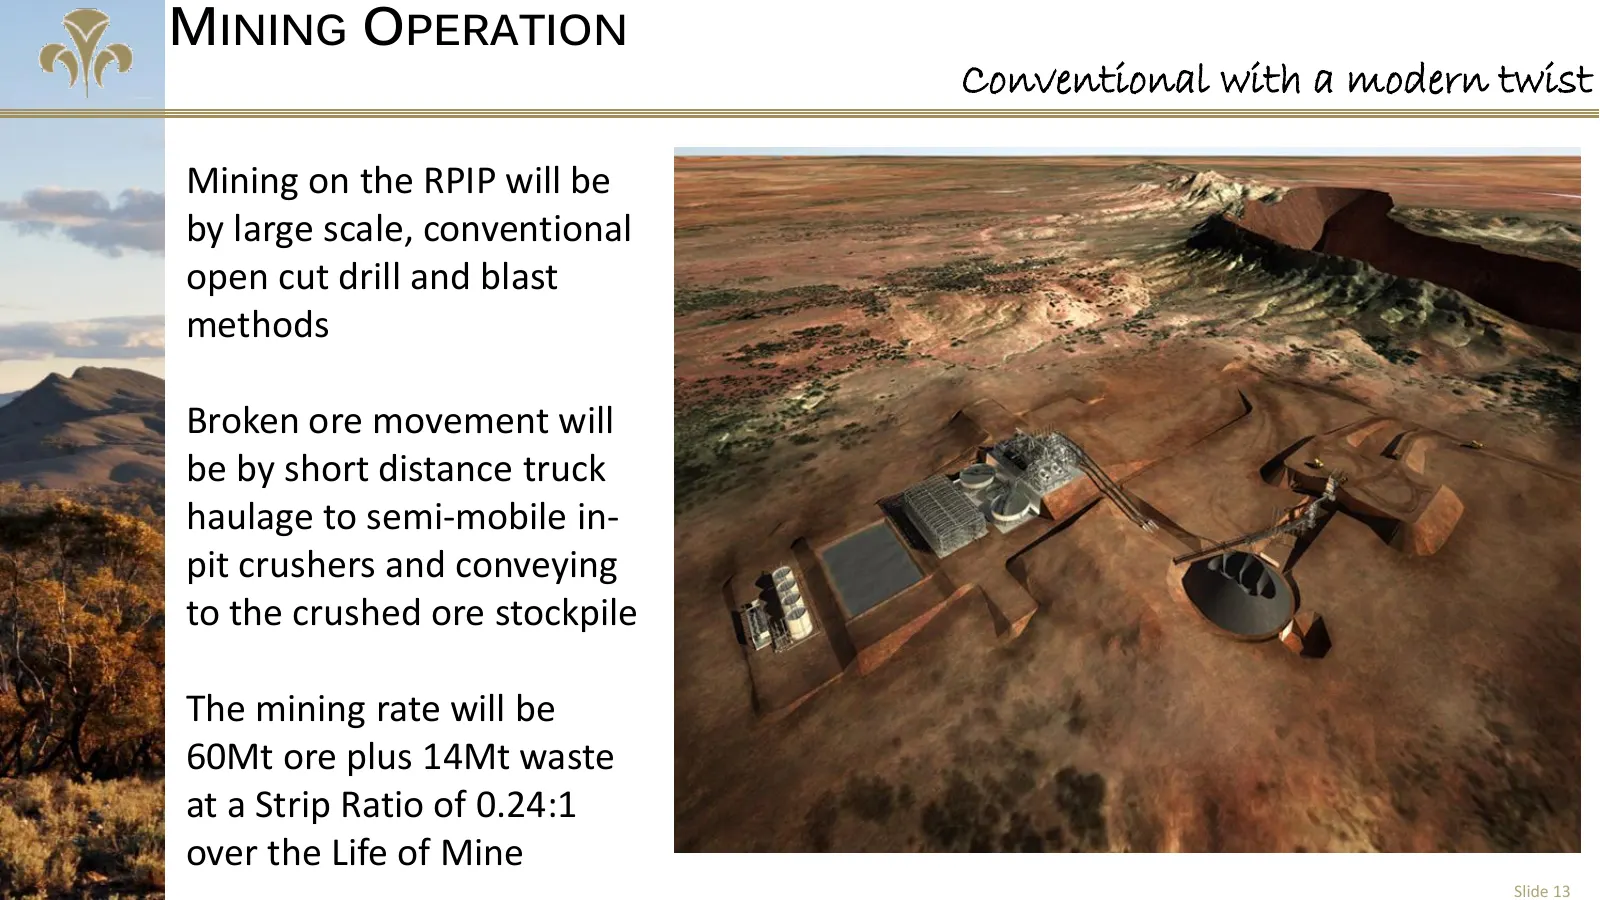
MINING OPERATION Conventional with a modern twist Mining on the RPIP will be by large scale, conventional open cut drill and blast methods Broken ore movement will be by short distance truck haulage to semi-mobile in- pit crushers and conveying to the crushed ore stockpile The mining rate will be 60
Slide 14: Ore Processing
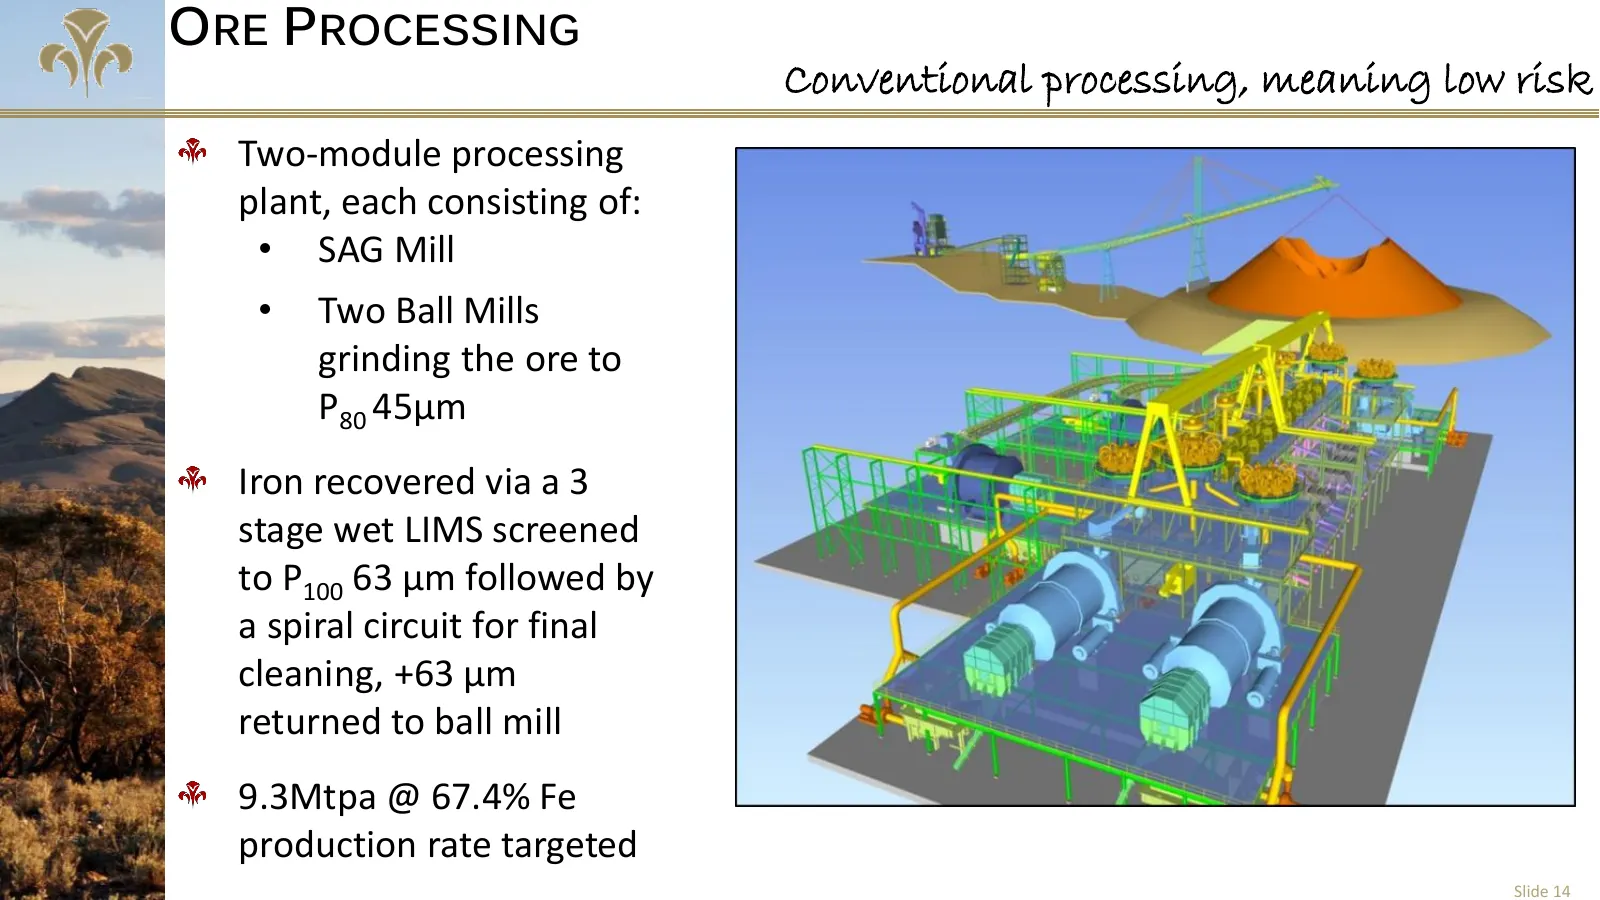
ORE PROCESSING Conventional processing, meaning low risk Two-module processing plant, each consisting of: • SAG Mill • Two Ball Mills grinding the ore to P80 45µm Iron recovered via a 3 stage wet LIMS screened to P100 63 µm followed by a spiral circuit for final cleaning, +63 µm returned to ball mil
Slide 15: Infrastructure & Utilities
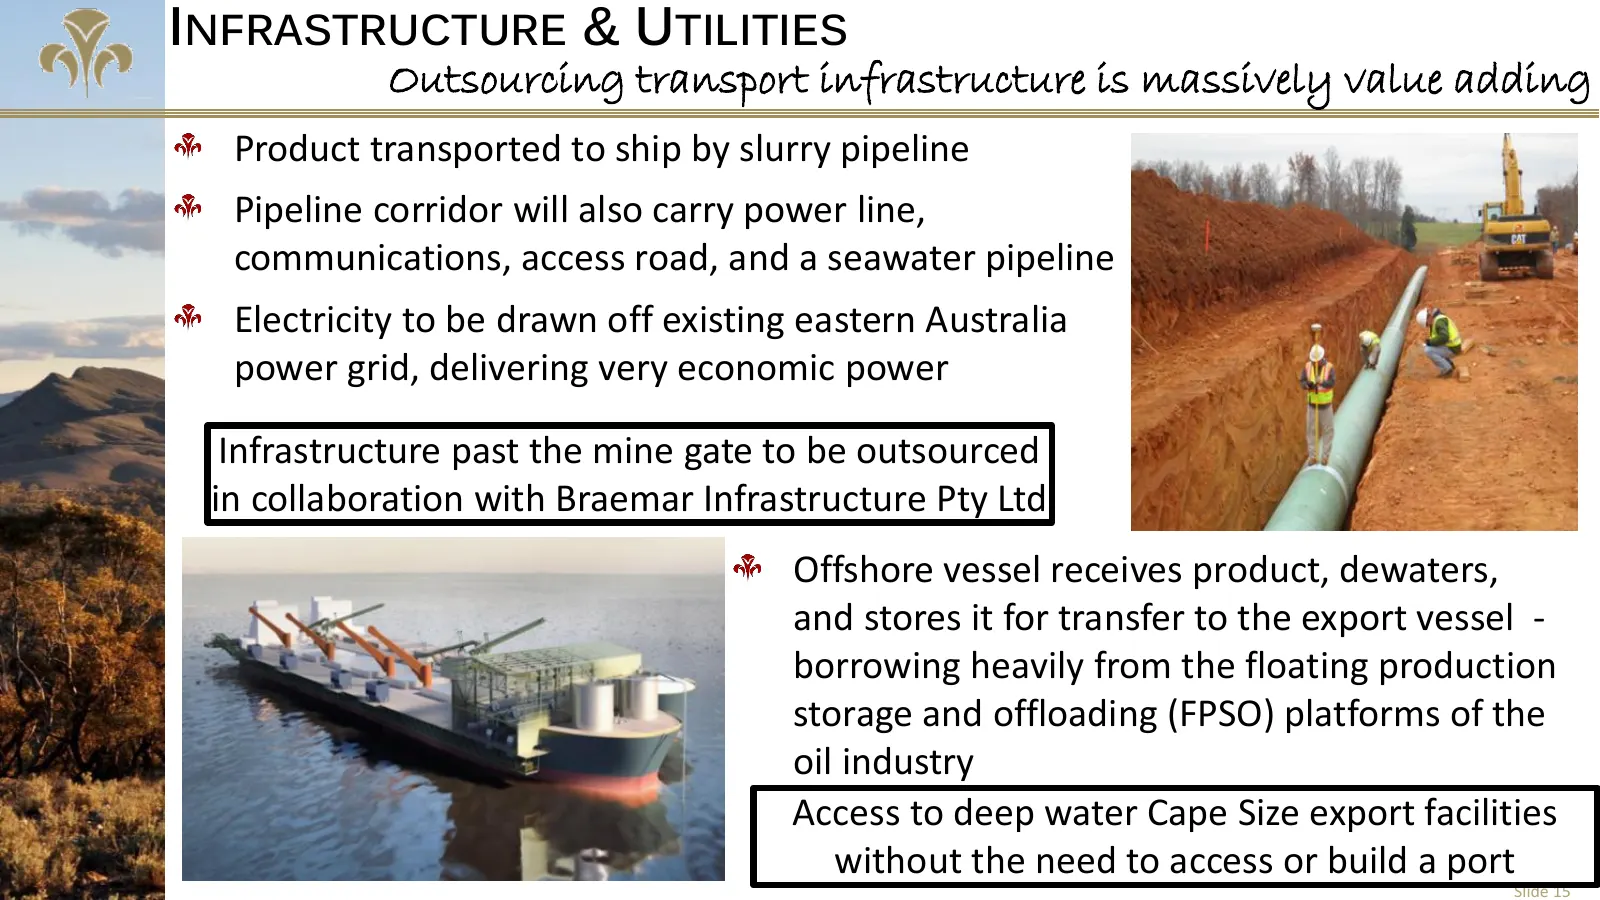
INFRASTRUCTURE & UTILITIES Outsourcing transport infrastructure is massively value adding Product transported to ship by slurry pipeline Pipeline corridor will also carry power line, communications, access road, and a seawater pipeline Electricity to be drawn off existing eastern Australia power gri
Slide 16: Razorback Premium Iron Project: Key Facts
RAZORBACK PREMIUM IRON PROJECT Royal’s flagship iron project KEY FACTS Resource: 2.7 Billion tonnes for 418 Million tonnes of 67.4% Fe concentrate Production rate: 9.3 Million tonnes per year target Mining rate: 60 Million tonnes per year target Infrastructure: Power, water, pipeline, roads, dormito
Slide 17: Key Advantages of Razorback
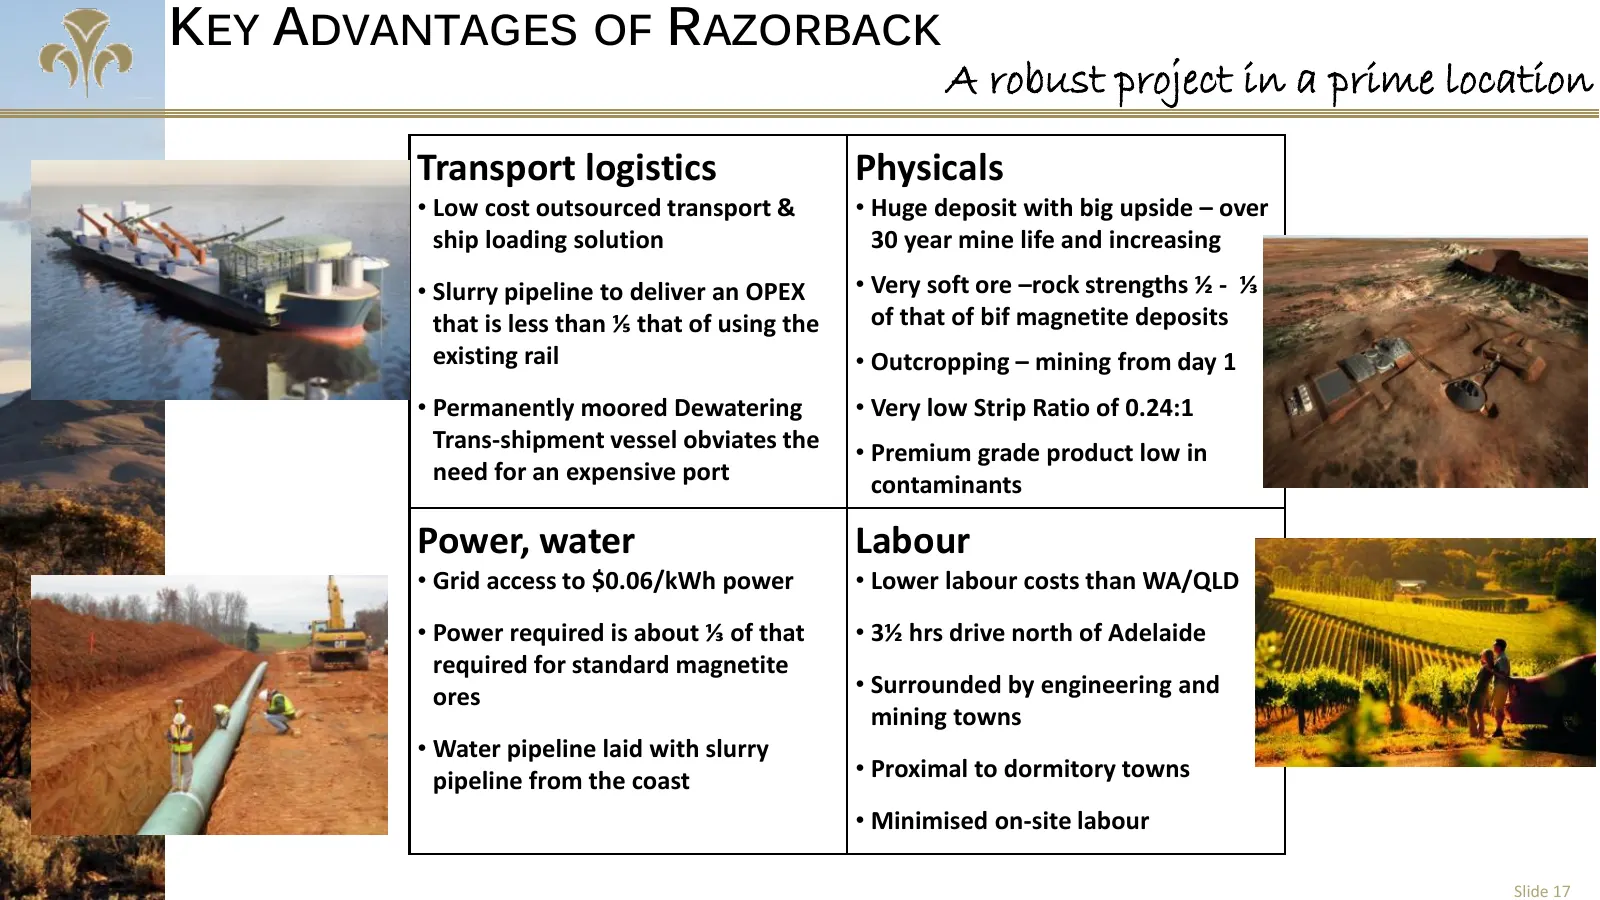
KEY ADVANTAGES OF RAZORBACK A robust project in a prime location Transport logistics Physicals • Low cost outsourced transport & • Huge deposit with big upside – over ship loading solution 30 year mine life and increasing • Slurry pipeline to deliver an OPEX • Very soft ore –rock strengths ½ - ⅓ tha
Slide 18: BIPL Engagement: A game changer for RPIP's Capital Intensity
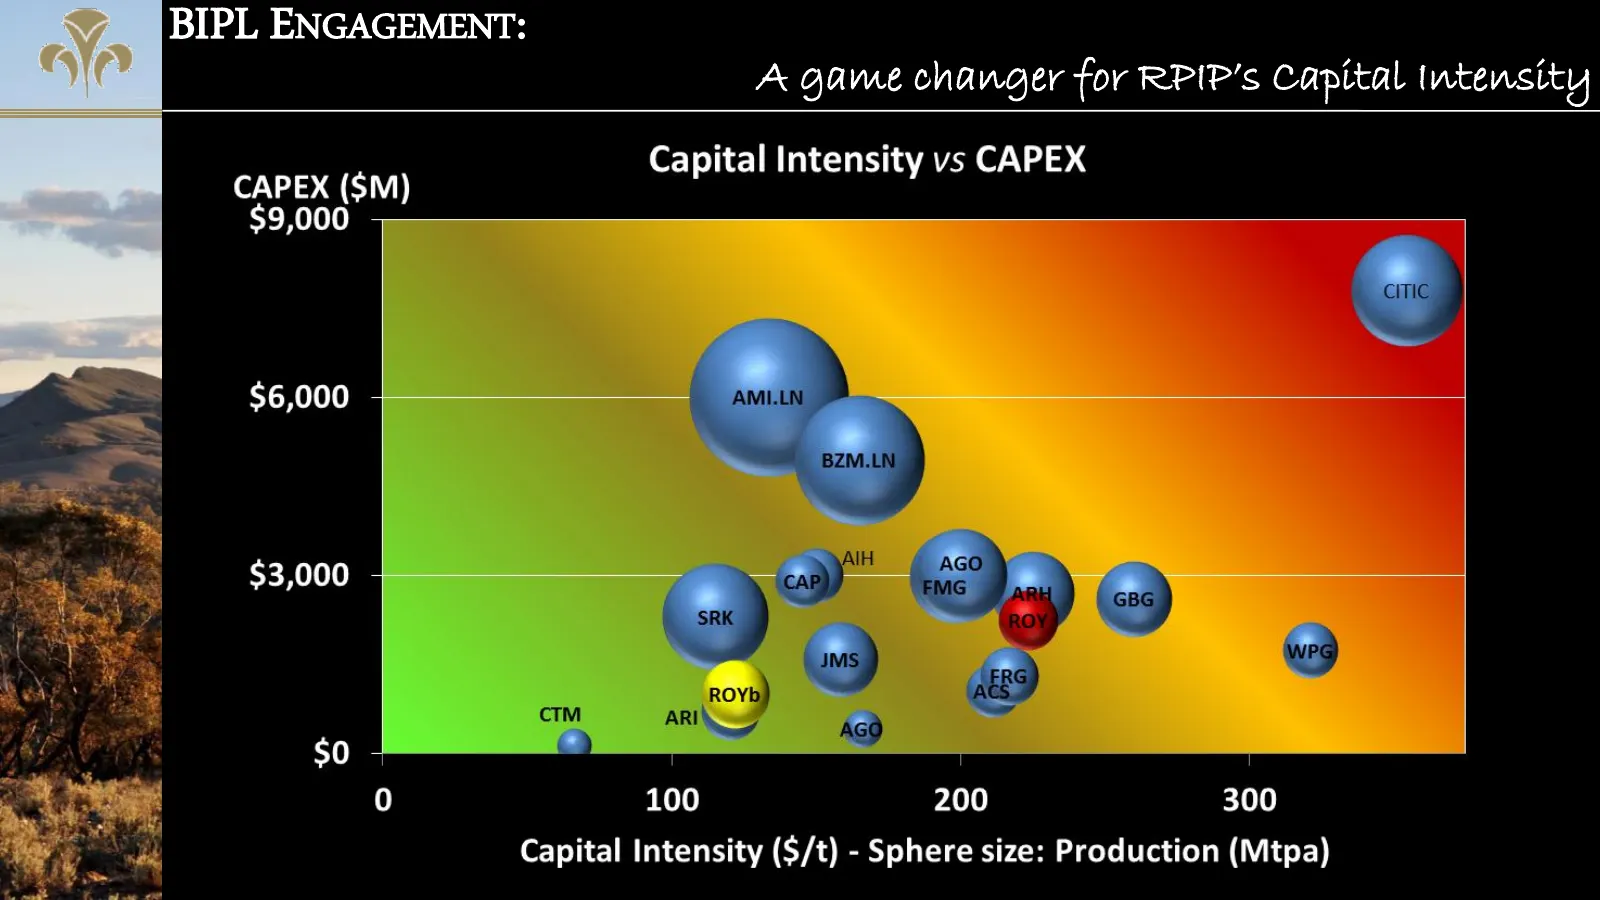
BIPL ENGAGEMENT: A game changer for RPIP’s Capital Intensity Slide 18
Slide 19: A Premium Product Attracting a Premium Price
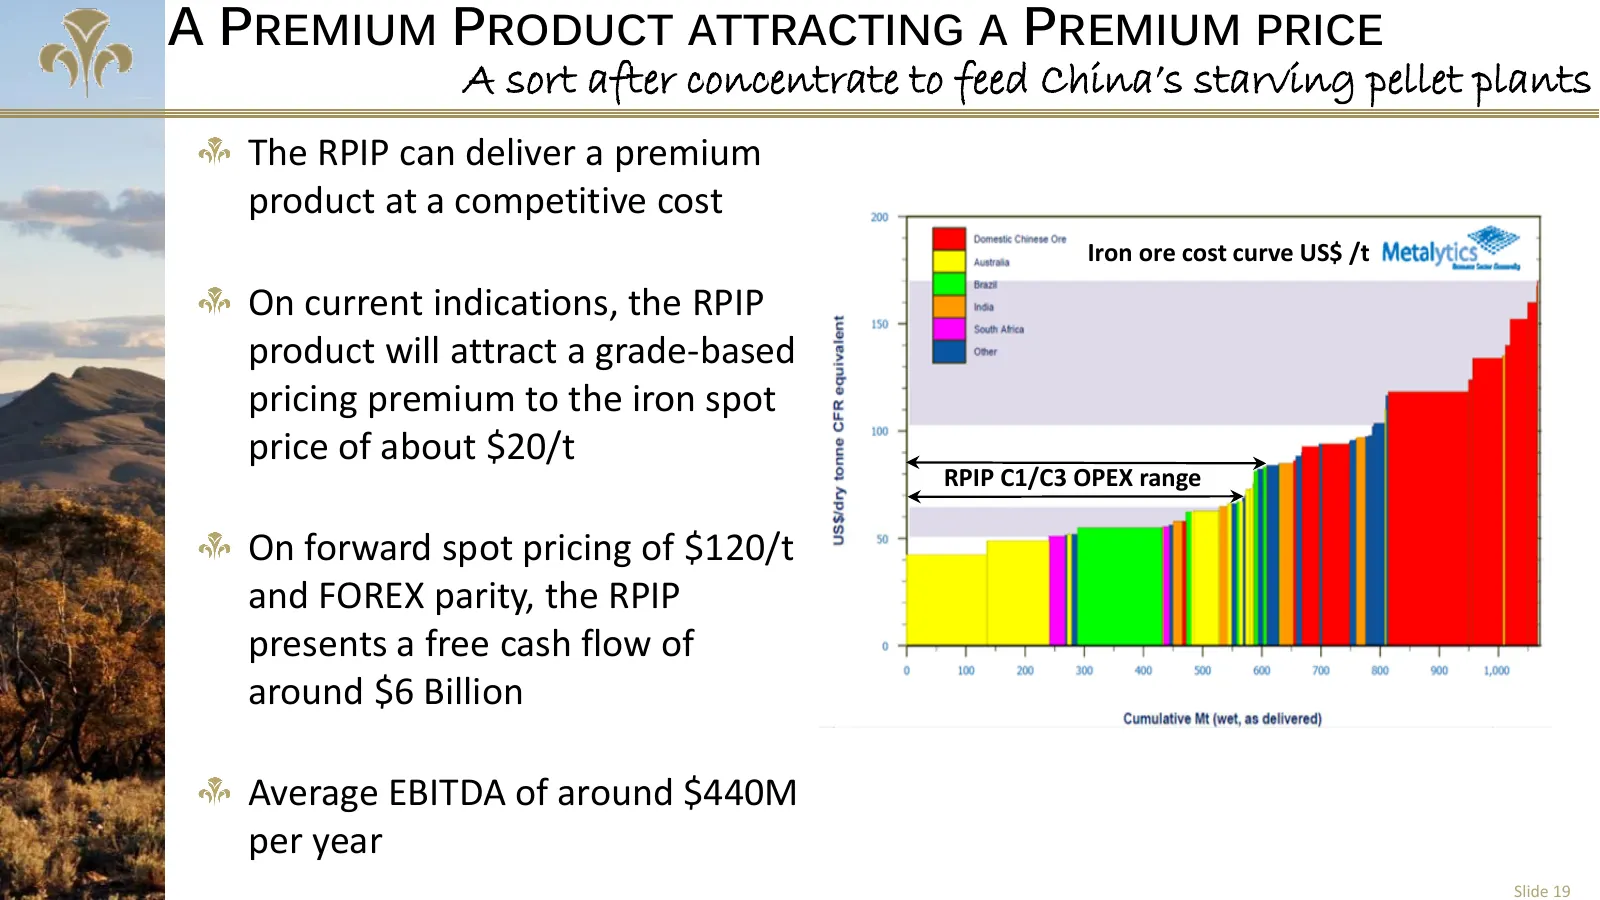
A PREMIUM PRODUCT ATTRACTING A PREMIUM PRICE A sort after concentrate to feed China’s starving pellet plants The RPIP can deliver a premium product at a competitive cost Iron ore cost curve US$ /t On current indications, the RPIP product will attract a grade-based pricing premium to the iron spot pr
Slide 20: Iron: Resilient and Growing Demand
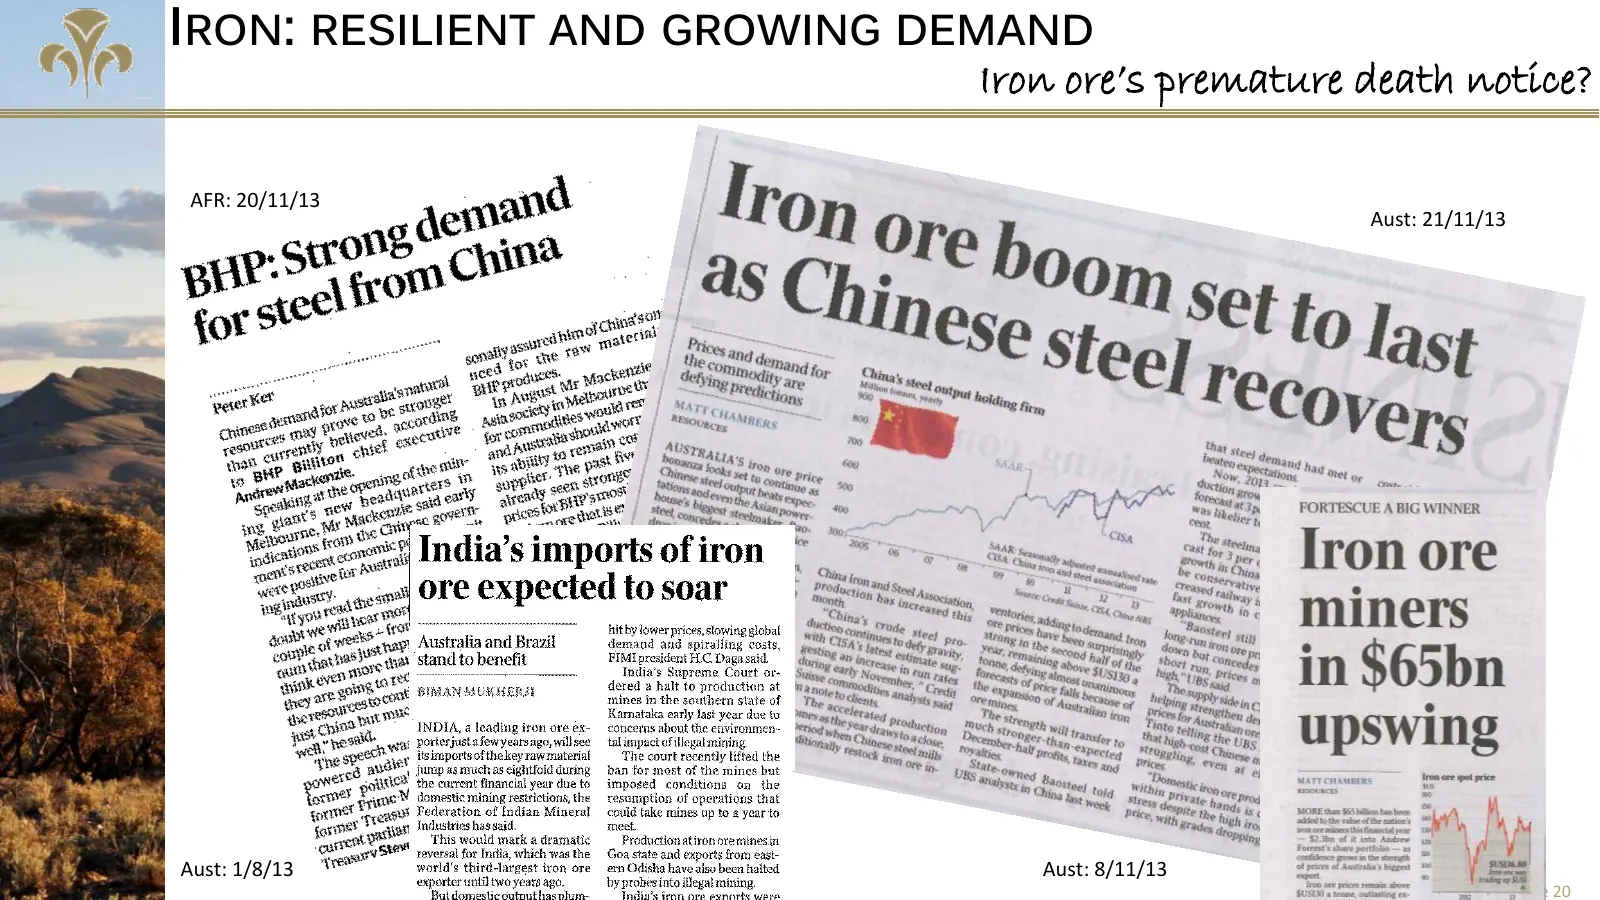
IRON: RESILIENT AND GROWING DEMAND Iron ore’s premature death notice? AFR: 20/11/13 Aust: 21/11/13 Aust: 1/8/13 Aust: 8/11/13 Slide 20
Slide 21: Iron: Not Such a Resilient and Growing Supply?
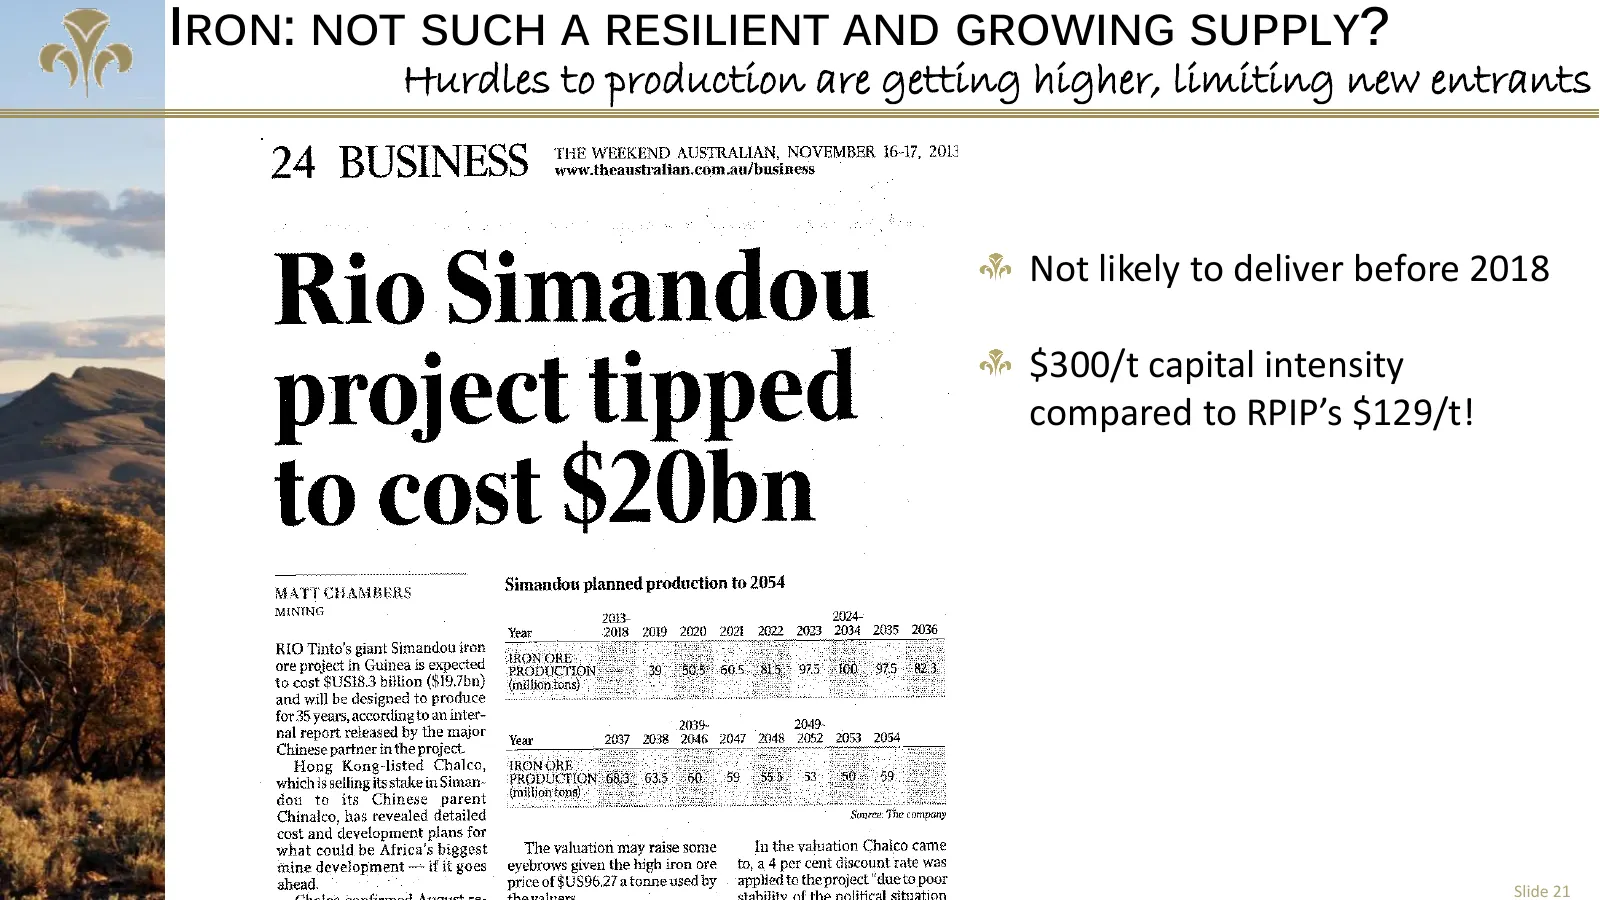
IRON: NOT SUCH A RESILIENT AND GROWING SUPPLY? Hurdles to production are getting higher, limiting new entrants Not likely to deliver before 2018 $300/t capital intensity compared to RPIP’s $129/t! Slide 21
Slide 22: Huge Blue Sky Potential
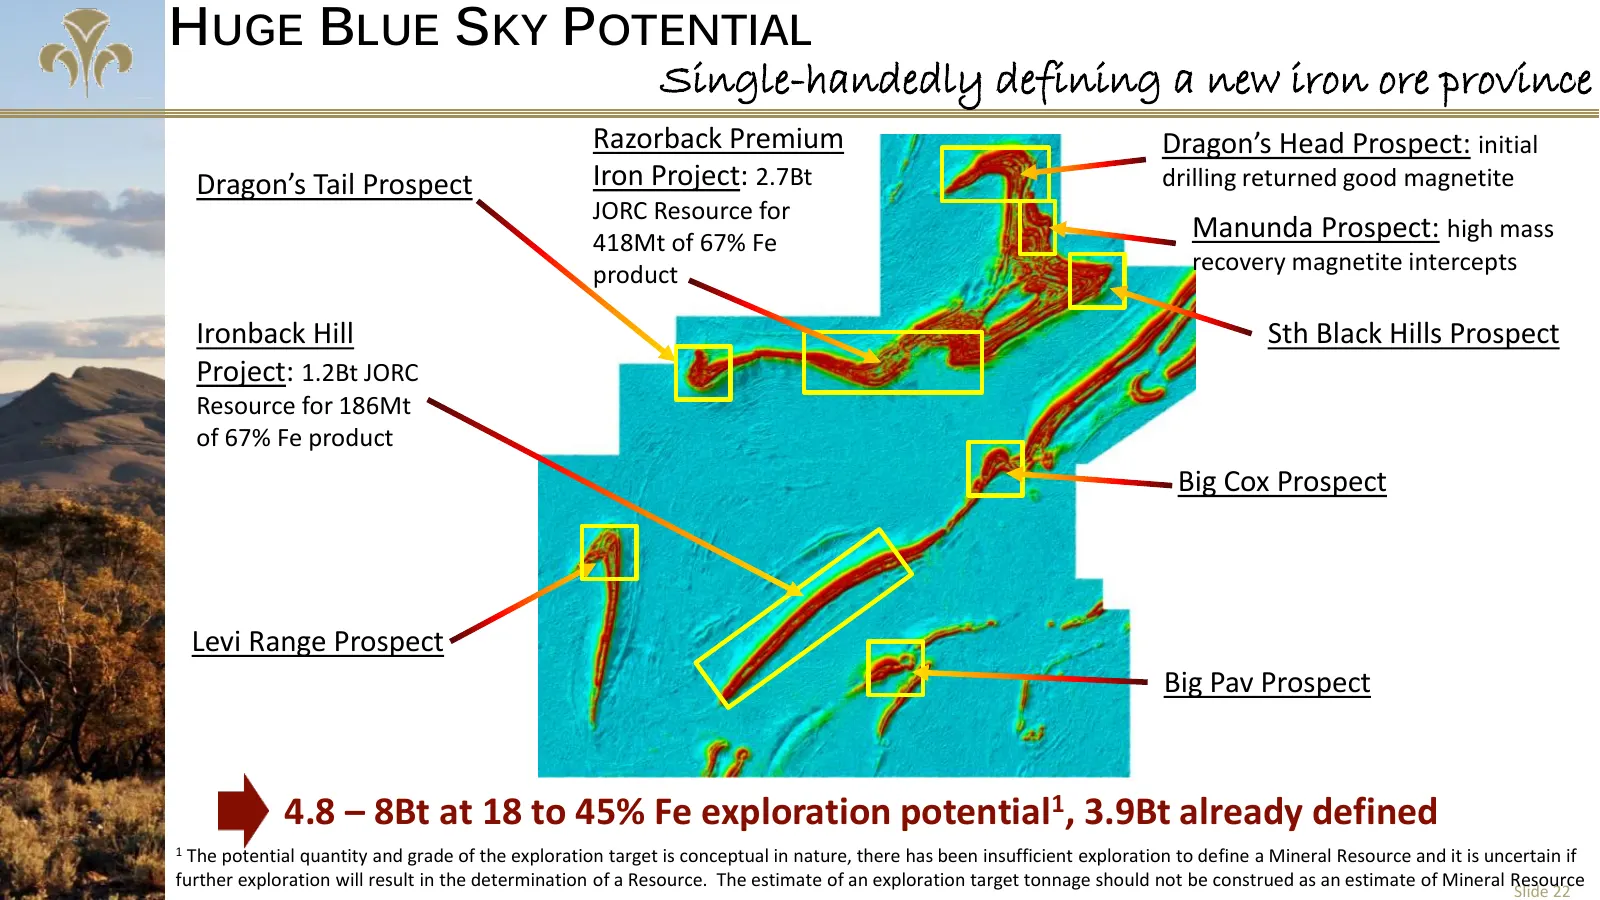
HUGE BLUE SKY POTENTIAL Single-handedly defining a new iron ore province Razorback Premium Dragon’s Head Prospect: initial Dragon’s Tail Prospect Iron Project: 2.7Bt drilling returned good magnetite JORC Resource for 418Mt of 67% Fe Manunda Prospect: high mass product recovery magnetite intercepts I
Slide 23: Thank you, Questions?
RESOURCES LIMITED Thank you, Questions?
Source: Internet Archive copy of magnetitemines.com
More decks from Magnetite Mines Ltd.
 Investor Presentation (September 2026)41 slides · September 2026
 Investor Presentation (March 2026)22 slides · Mar 10, 2026
 Shareholder Meeting (November 2025)18 slides · Nov 26, 2025
 Investor Presentation (August 2025)22 slides · Aug 8, 2025
 TACTIC Conference 202516 slides · Jul 30, 2025
 The Australian Green Iron & Steel Forum 202519 slides · Mar 26, 2025