Dot Hill Systems — Sidoti & Company's Semi-Annual Microcap Conference (June 2013)
36 slides from Dot Hill Systems's conference presentation, Jun 7, 2013
Slide 1: Driving Growth – Sidoti Microcap Conference
DRIVING GROWTH NASDAQ: HILL June 7, 2013 Sidoti & Company’s Semi-Annual Microcap Conference Dot Hill Systems Corp.
Slide 2: Safe Harbor
Safe Harbor Statements contained in this presentation regarding matters that are not historical facts are “forward- looking statements” within the meaning of the Private Securities Litigation Reform Act. Because such statements are subject to risks and uncertainties, actual results may differ materi
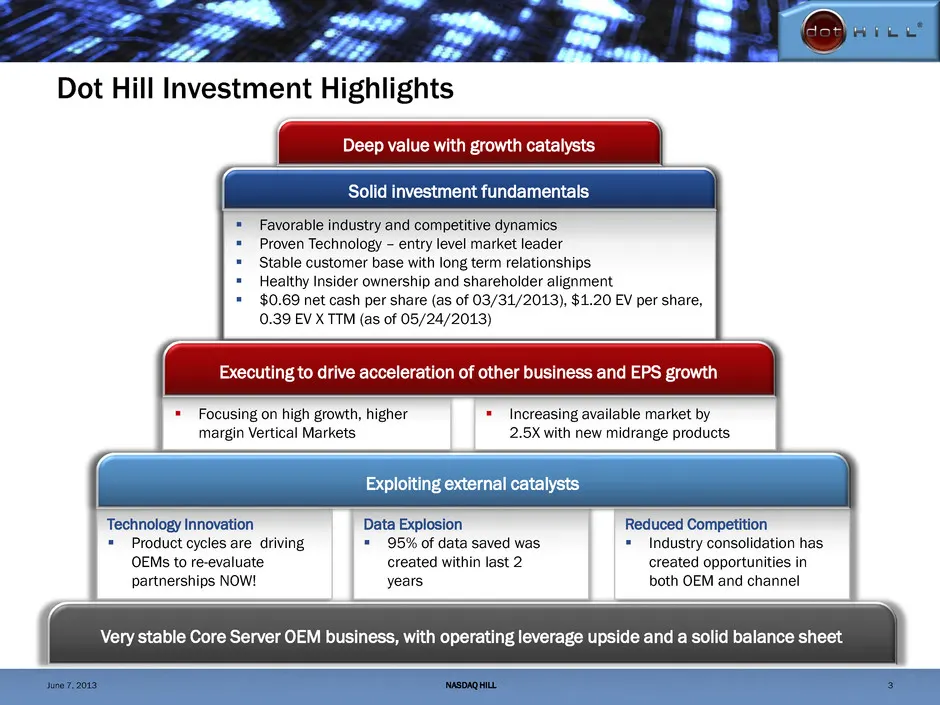
Slide 3: Dot Hill Investment Highlights
Dot Hill Investment Highlights Very stable Core Server OEM business, with operating leverage upside and a solid balance sheet Solid investment fundamentals Favorable industry and competitive dynamics Proven Technology – entry level market leader Stable customer base with long term relationship
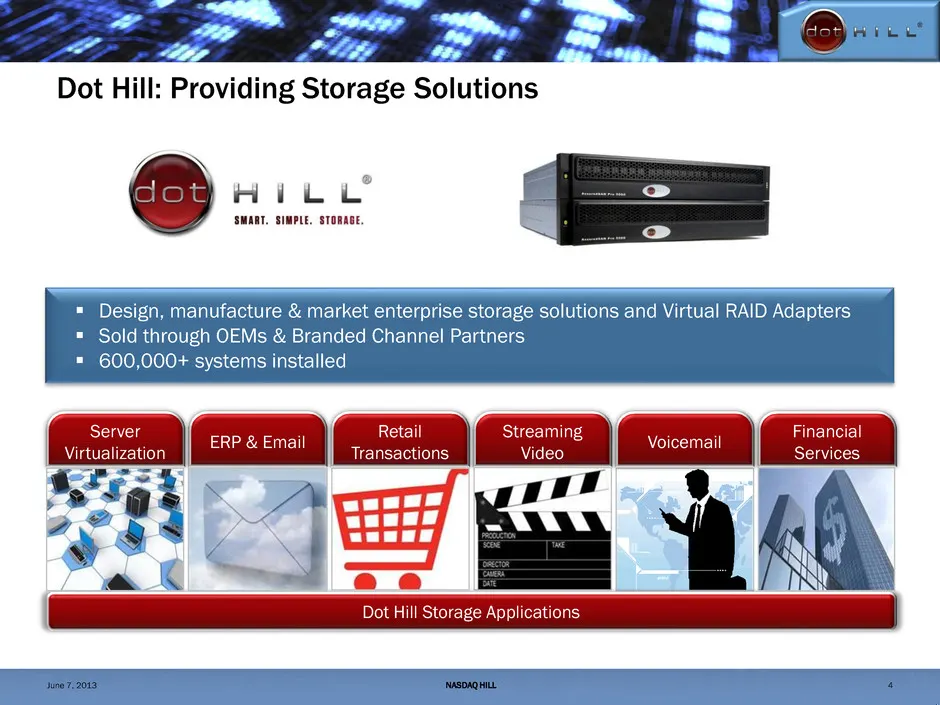
Slide 4: Dot Hill: Providing Storage Solutions
Dot Hill: Providing Storage Solutions Financial Services Streaming Video Retail Transactions ERP & Email Voicemail Dot Hill Storage Applications Server Virtualization Design, manufacture & market enterprise storage solutions and Virtual RAID Adapters Sold through OEMs & Branded Channel Partners
Slide 5: Dot Hill Routes to Market
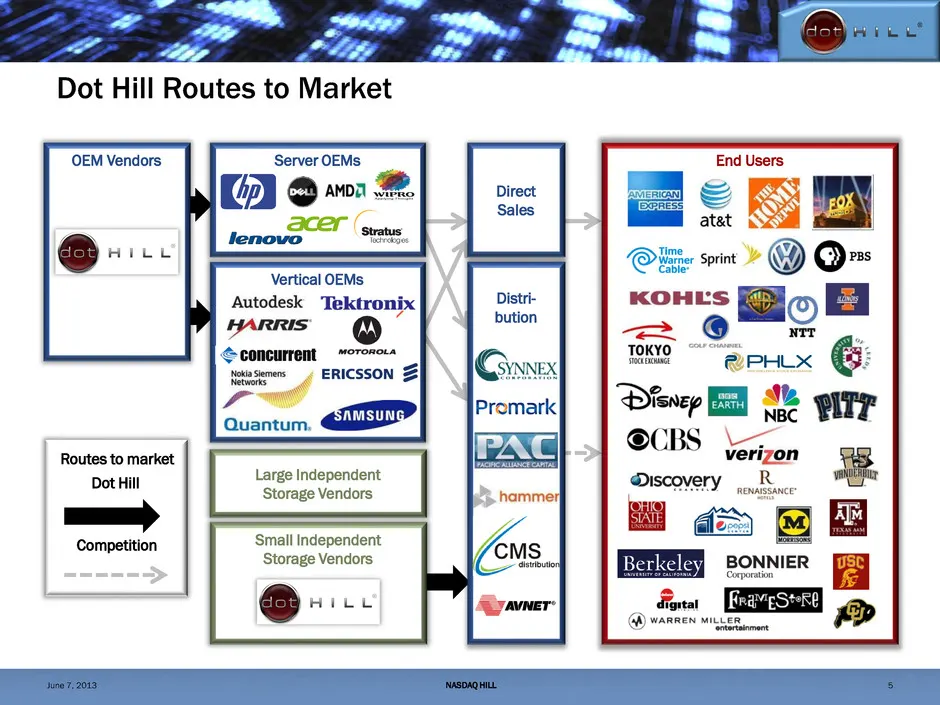
Dot Hill Routes to Market Small Independent Storage Vendors OEM Vendors Server OEMs Vertical OEMs Large Independent Storage Vendors Direct Sales End Users Distri- bution Routes to market Dot Hill Competition NASDAQ HILL 5 June 7, 2013
Slide 6: WW Storage Market 2011-2016
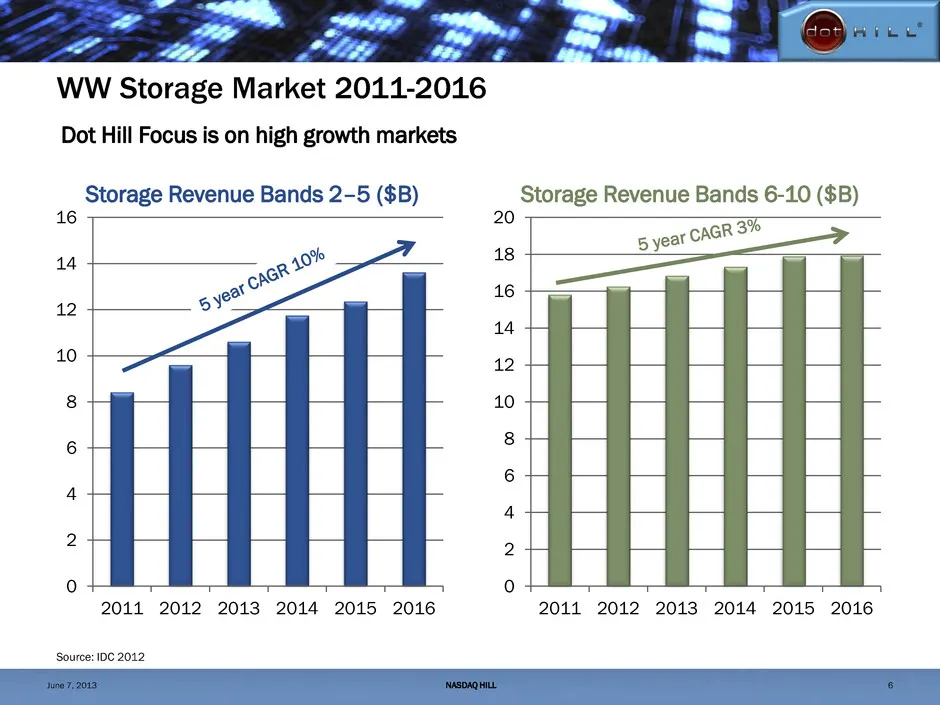
WW Storage Market 2011-2016 0 2 4 6 8 10 12 14 16 2011 2012 2013 2014 2015 2016 Source: IDC 2012 Storage Revenue Bands 2–5 ($B) 0 2 4 6 8 10 12 14 16 18 20 2011 2012 2013 2014 2015 2016 Storage Revenue Bands 6-10 ($B) NASDAQ HILL 6 Dot Hill Focus is on high growth markets June 7, 2013
Slide 7: Dot Hill: Leader in the IP Landscape
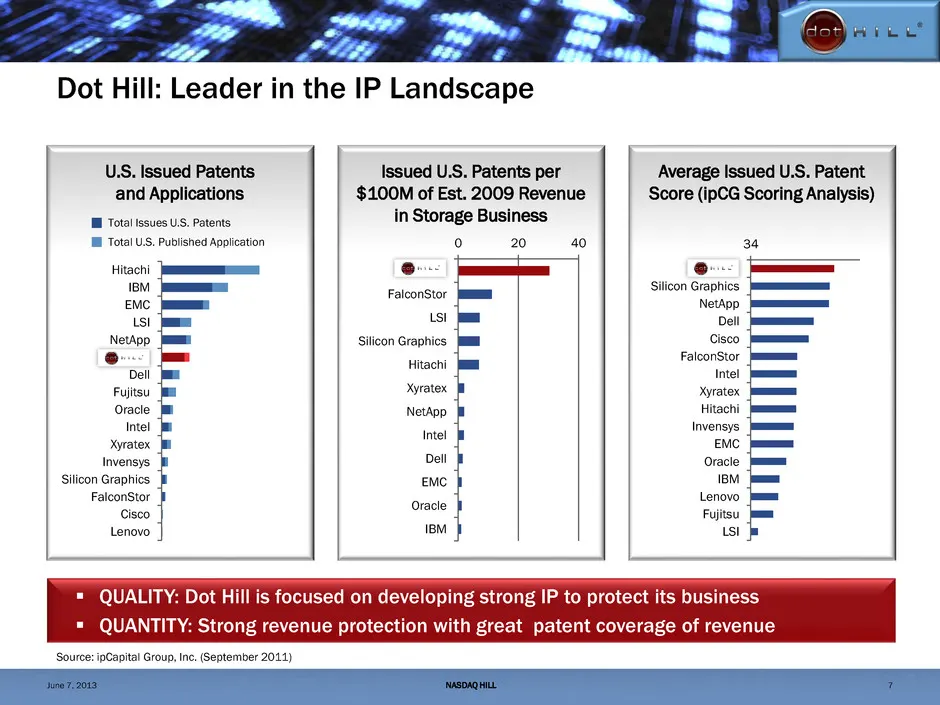
Dot Hill: Leader in the IP Landscape Source: ipCapital Group, Inc. (September 2011) QUALITY: Dot Hill is focused on developing strong IP to protect its business QUANTITY: Strong revenue protection with great patent coverage of revenue U.S. Issued Patents and Applications Issued U.S. Patents per
Slide 8: Dot Hill's Server OEM Foundation
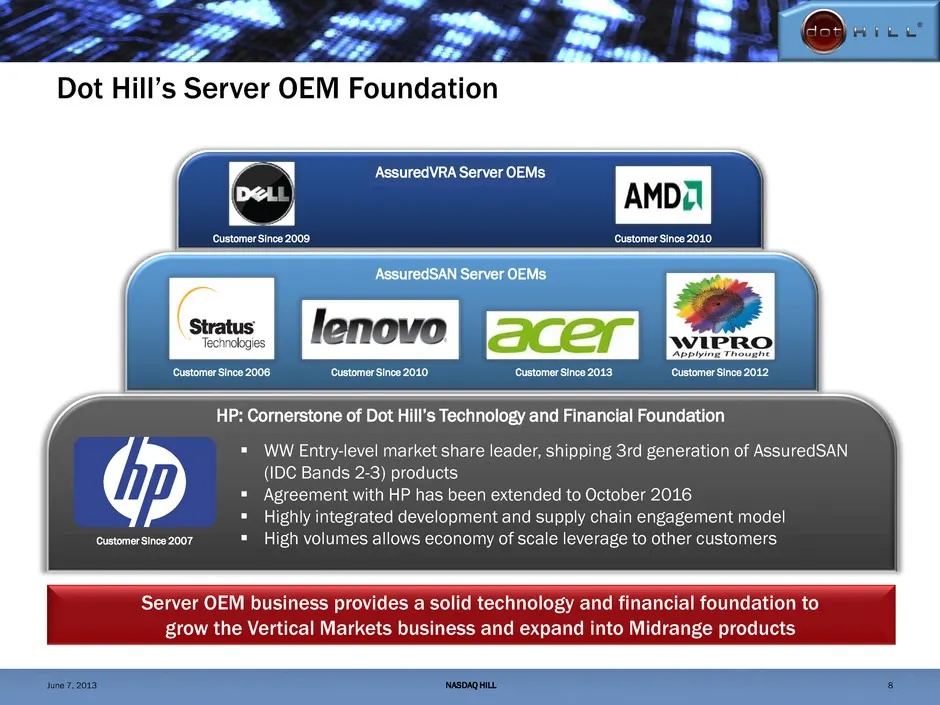
Dot Hill’s Server OEM Foundation AssuredVRA Server OEMs Customer Since 2009 Customer Since 2010 Server OEM business provides a solid technology and financial foundation to grow the Vertical Markets business and expand into Midrange products Customer Since 2007 HP: Cornerstone of Dot Hill’s Technolog
Slide 9: Look Back to 2010 / 2013 Strategic Initiatives
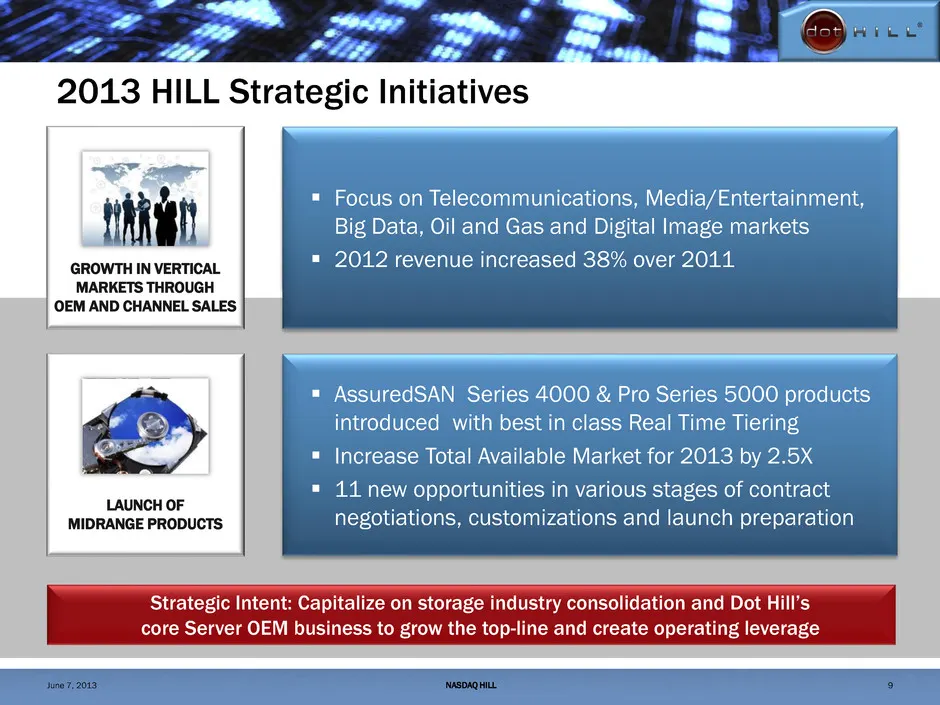
Look Back to 2010 HILL Strategic Initiatives CHANNELS SOFTWARE SYSTEMS Channels GOAL: Diversify revenues at higher margins Smoother revenue stream from more customers Add-on Professional Services Focus on Telecommunications, Media/Entertainment, Big Data, Oil and Gas and Digital Image markets
Slide 10: Vertical Markets Focus to Drive Growth
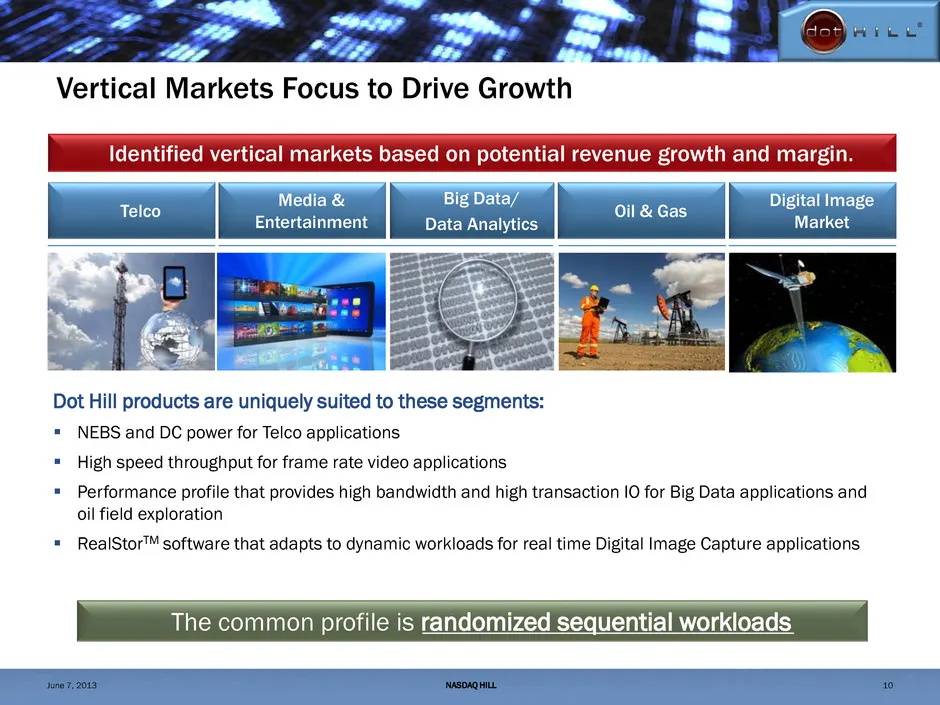
Identified vertical markets based on potential revenue growth and margin. Vertical Markets Focus to Drive Growth Telco Media & Entertainment Big Data/ Data Analytics Oil & Gas Digital Image Market Dot Hill products are uniquely suited to these segments: NEBS and DC power for Telco applications H
Slide 11: Vertical Markets: Annual Revenue
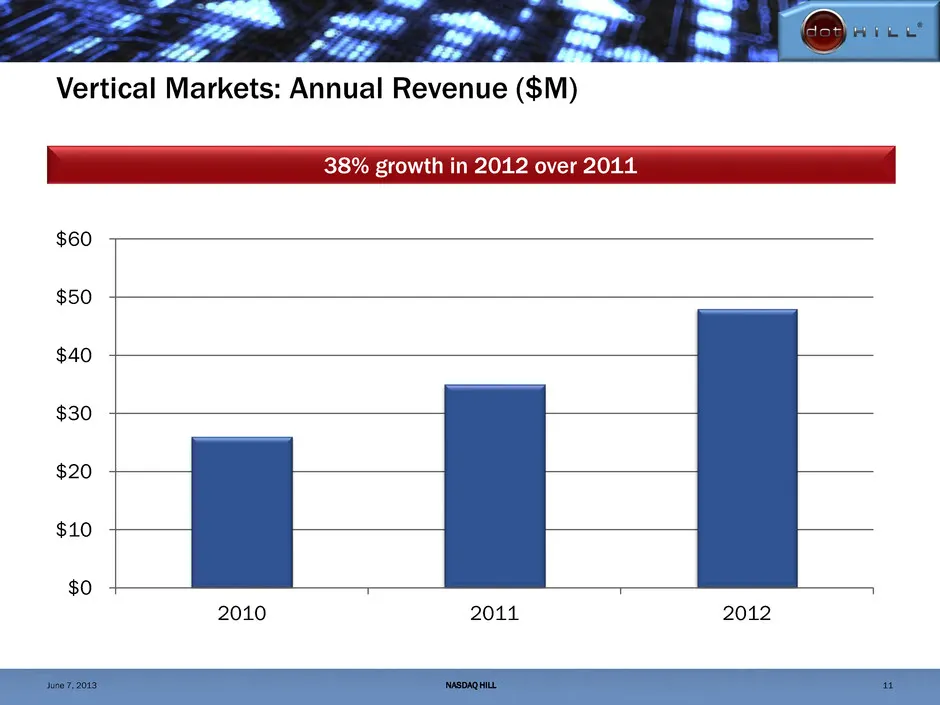
Vertical Markets: Annual Revenue ($M) $0 $10 $20 $30 $40 $50 $60 2010 2011 2012 38% growth in 2012 over 2011 NASDAQ HILL 11 June 7, 2013
Slide 12: AssuredSAN Midrange Product Positioning
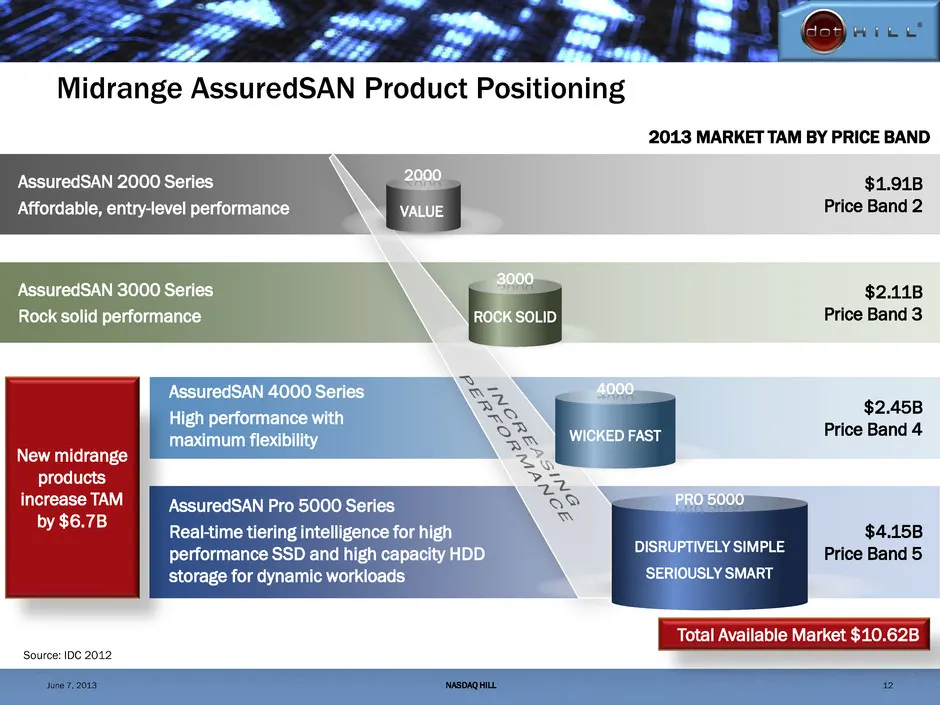
AssuredSAN Pro 5000 Series Real-time tiering intelligence for high performance SSD and high capacity HDD storage for dynamic workloads $4.15B Price Band 5 AssuredSAN 4000 Series High performance with maximum flexibility $2.45B Price Band 4 AssuredSAN 3000 Series Rock solid performance $2.11B Price B
Slide 13: The Business Value of RealStor Software
The Business Value of RealStor Software Run your business in real time. RealStor. Accelerate your data with real time tiering Pay less now. Spend time using your system, not managing it. Peace of mind knowing your data is secure. NASDAQ HILL 13 June 7, 2013
Slide 14: A History of Industry Consolidation
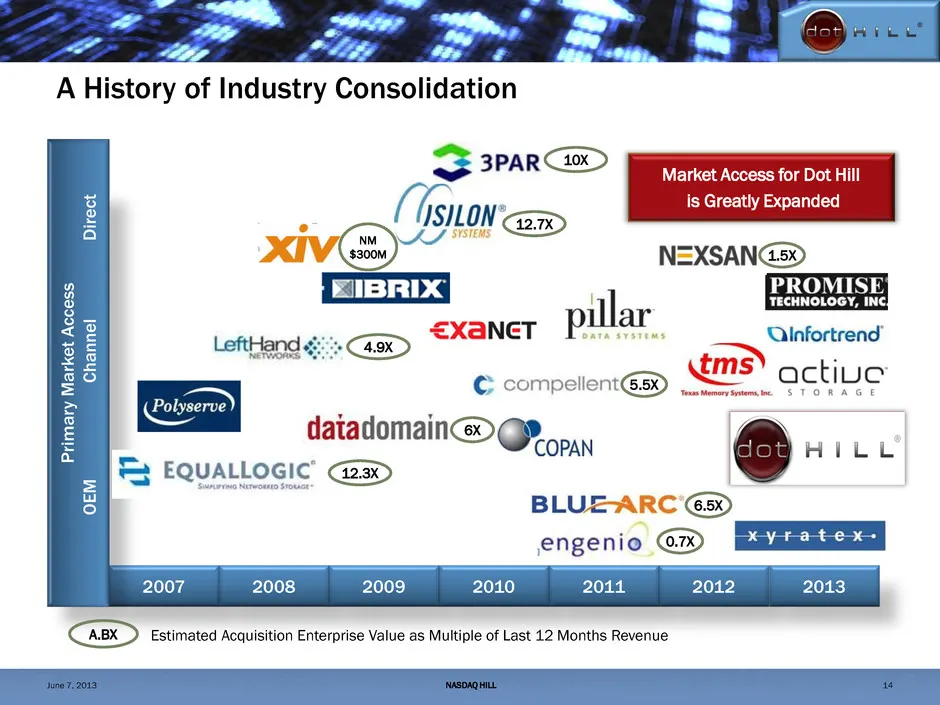
A History of Industry Consolidation 2007 2008 2009 2010 2011 2012 2013 Pr ima ry Ma rk e t A cc e ss OEM Ch a n n el D ir ec t Market Access for Dot Hill is Greatly Expanded Estimated Acquisition Enterprise Value as Multiple of Last 12 Months Revenue A.BX 12.3X 4.9X 10X 12.7X 6X 5.5X 6.5X 0.7X 1.5X
Slide 15: Typical OEM Sales Cycle
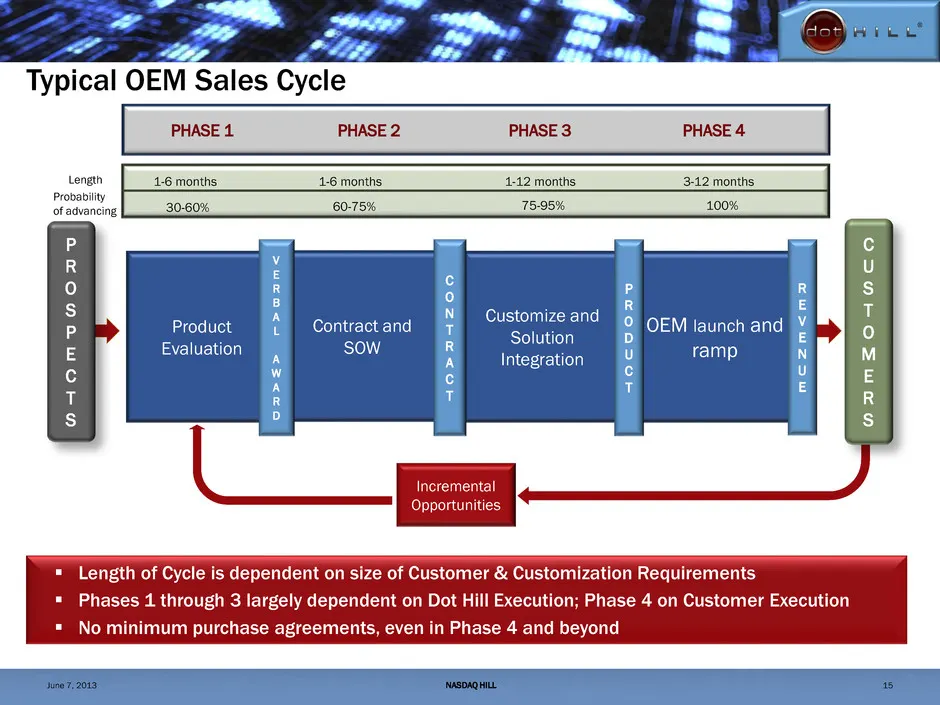
Typical OEM Sales Cycle Length of Cycle is dependent on size of Customer & Customization Requirements Phases 1 through 3 largely dependent on Dot Hill Execution; Phase 4 on Customer Execution No minimum purchase agreements, even in Phase 4 and beyond Incremental Opportunities PHASE 1 PHASE 2 P
Slide 16: Incremental Opportunities – New OEMs in the Pipeline (4/8/13)
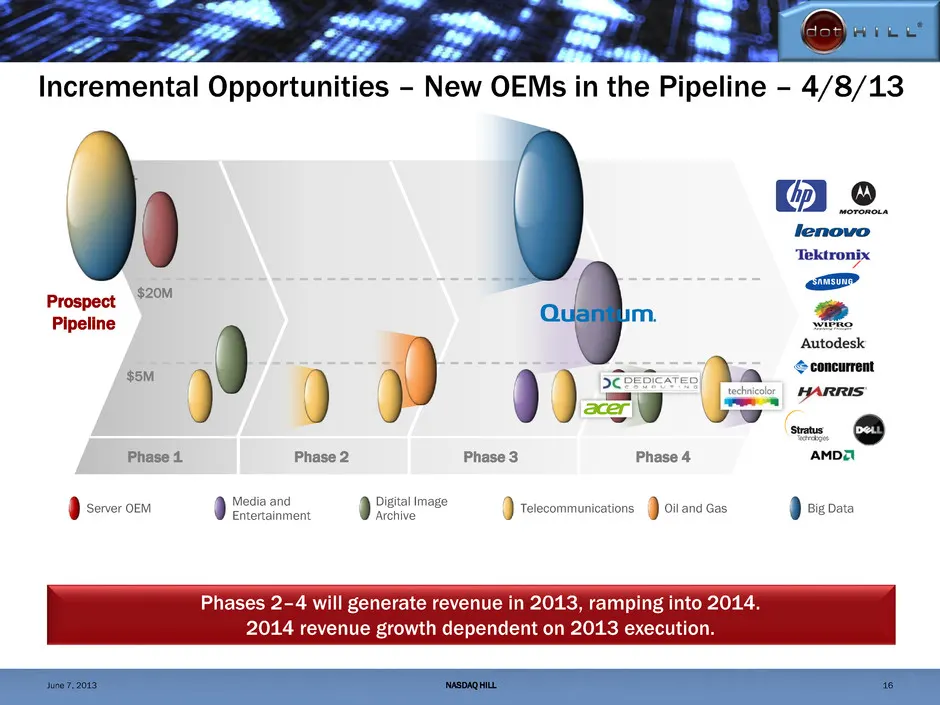
Incremental Opportunities – New OEMs in the Pipeline – 4/8/13 Prospect Pipeline $50M+ $5M $20M Server OEM Digital Image Archive Media and Entertainment Telecommunications Oil and Gas Big Data Phase 1 Phase 4 Phase 2 Phase 3 Phases 2–4 will generate revenue in 2013, ramping into 2014. 2014 revenue gr
Slide 17: Incremental Opportunities – New OEMs in the Pipeline (5/9/13)
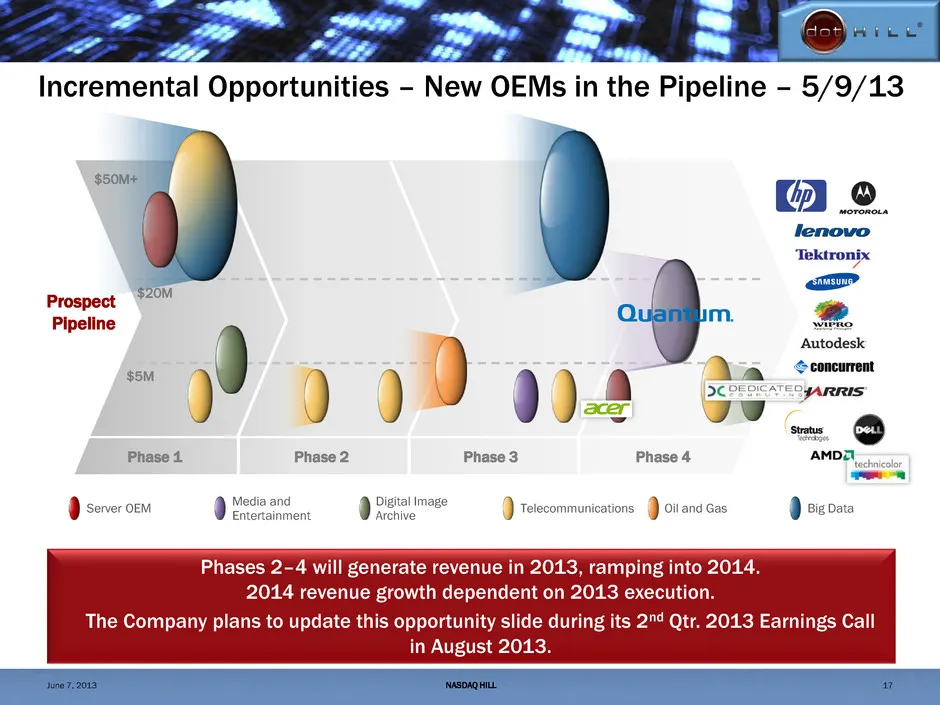
Incremental Opportunities – New OEMs in the Pipeline – 5/9/13 Prospect Pipeline $50M+ $5M $20M Server OEM Digital Image Archive Media and Entertainment Telecommunications Oil and Gas Big Data Phase 1 Phase 4 Phase 2 Phase 3 Phases 2–4 will generate revenue in 2013, ramping into 2014. 2014 revenue gr
Slide 18: Financials and Business Model
DRIVING GROWTH NASDAQ: HILL June 7, 2013 Financials and Business Model A STRONG FOUNDATION FOR
Slide 19: About Non-GAAP Financial Measures
About Non-GAAP Financial Measures In 2012 and/or 2013, the Company’s non-GAAP financial measures exclude the impact of stock-based compensation expense, legal settlements and associated expenses, intangible asset amortization, restructuring and severance charges, charges or credits for contingent co
Slide 20: Creating Operating Leverage (Non-GAAP)
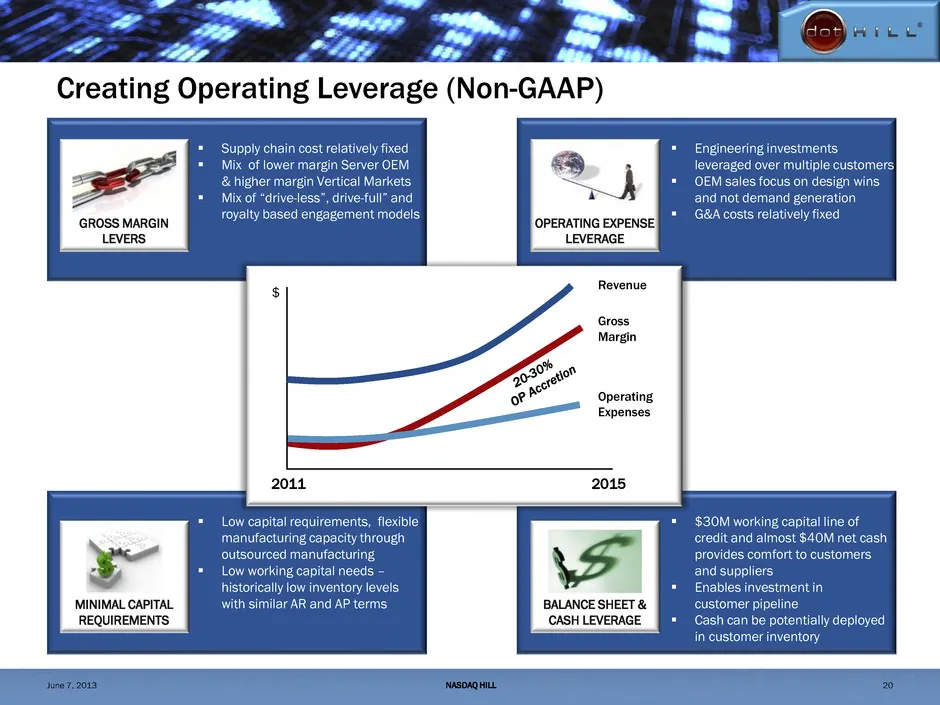
Creating Operating Leverage (Non-GAAP) Revenue Gross Margin Operating Expenses 2011 2015 $ Supply chain cost relatively fixed Mix of lower margin Server OEM & higher margin Vertical Markets Mix of “drive-less”, drive-full” and royalty based engagement models Engineering investments leveraged
Slide 21: Incremental Opportunities – 2013 & 2014 Revenue Potential
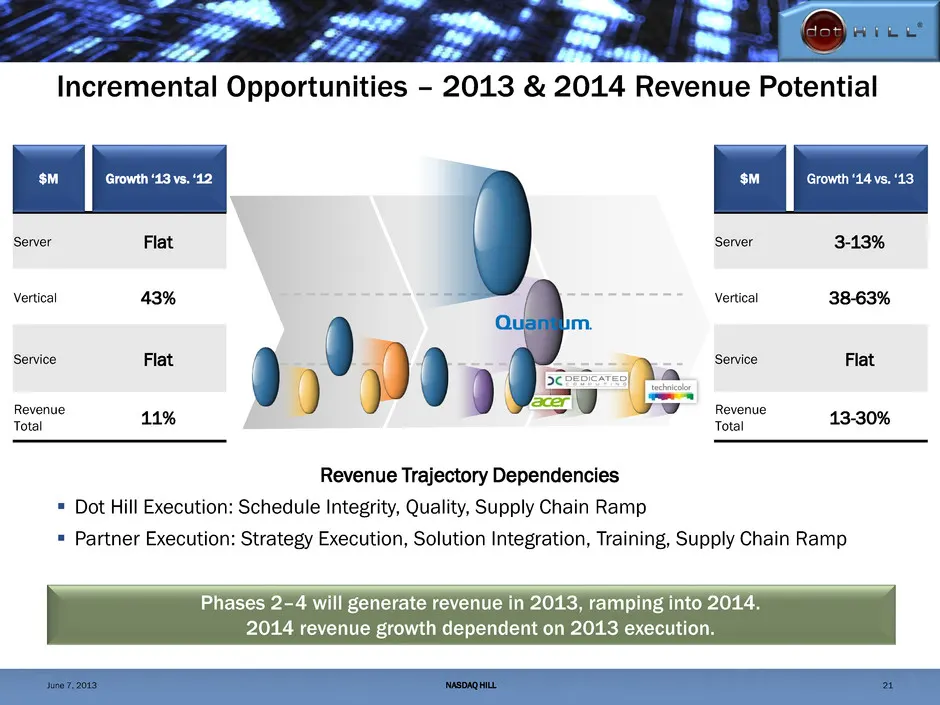
Incremental Opportunities – 2013 & 2014 Revenue Potential Phases 2–4 will generate revenue in 2013, ramping into 2014. 2014 revenue growth dependent on 2013 execution. Server OEM 141 141 Vertical Mkts 48 69 Service 7 7 Revenue Total 197 216 2012 Actuals 2013 Midpoint $M Server OEM 141 145-160 Vertic
Slide 22: Target Non-GAAP Operating Model
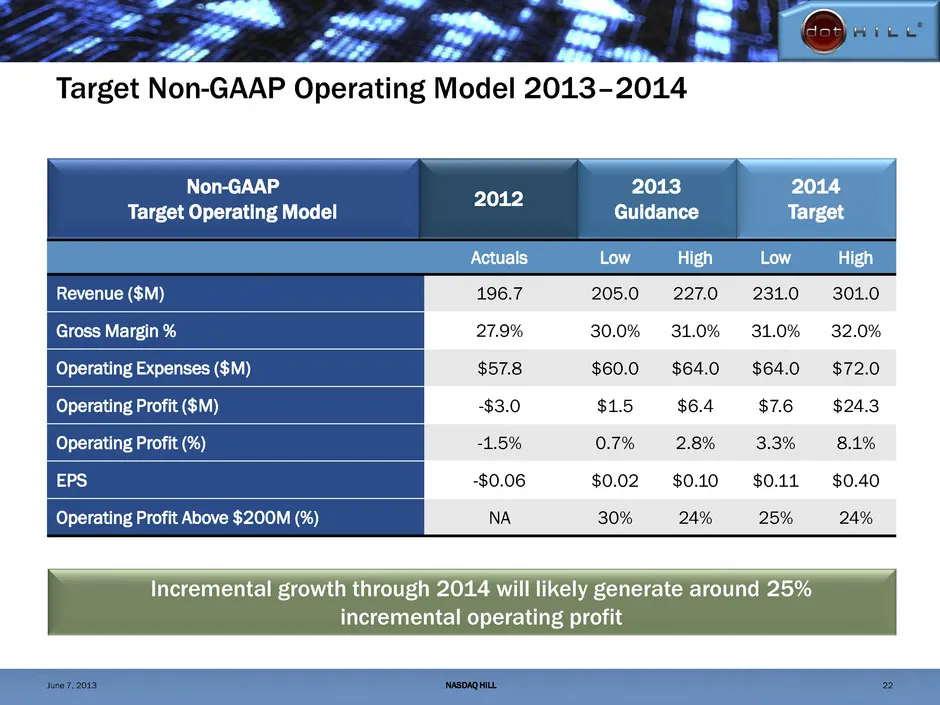
Target Non-GAAP Operating Model 2013–2014 Actuals Revenue ($M) 196.7 Gross Margin % 27.9% Operating Expenses ($M) $57.8 Operating Profit ($M) -$3.0 Operating Profit (%) -1.5% EPS -$0.06 Operating Profit Above $200M (%) NA 2012 Non-GAAP Target Operating Model Incremental growth through 2014 will like
Slide 23: Why Dot Hill?
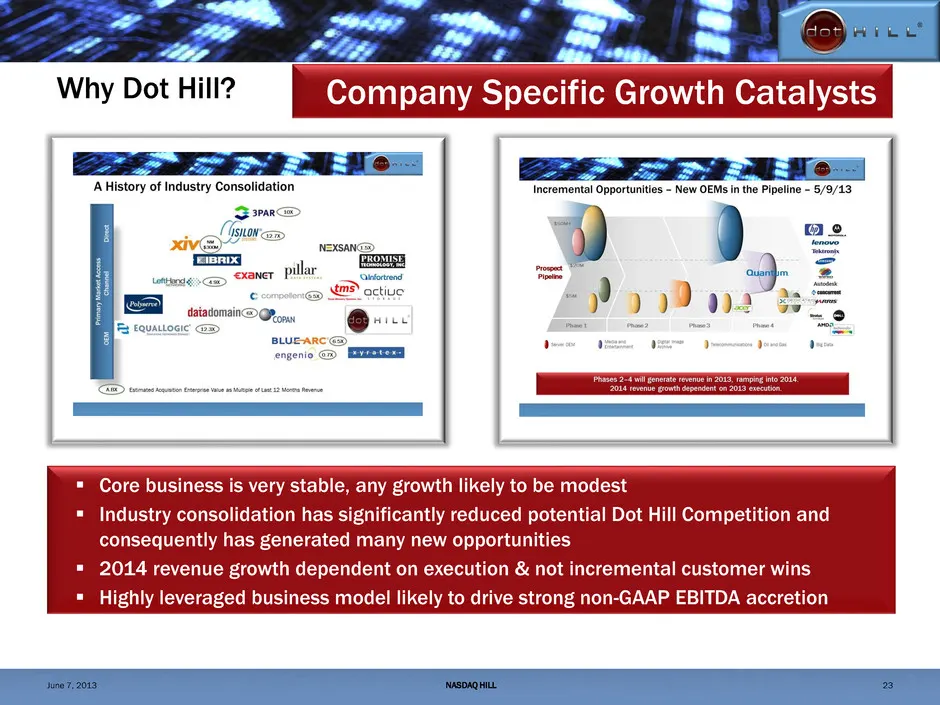
Why Dot Hill? Core business is very stable, any growth likely to be modest Industry consolidation has significantly reduced potential Dot Hill Competition and consequently has generated many new opportunities 2014 revenue growth dependent on execution & not incremental customer wins Highly l
Slide 24: Appendix I: Select Financial Results, Q2 and 2013 Guidance
DRIVING GROWTH NASDAQ: HILL June 7, 2013 Appendix I: Select Financial Results, Q2 and 2013 Guidance A STRONG FOUNDATION FOR
Slide 25: 2012 Non-GAAP Financial Recap
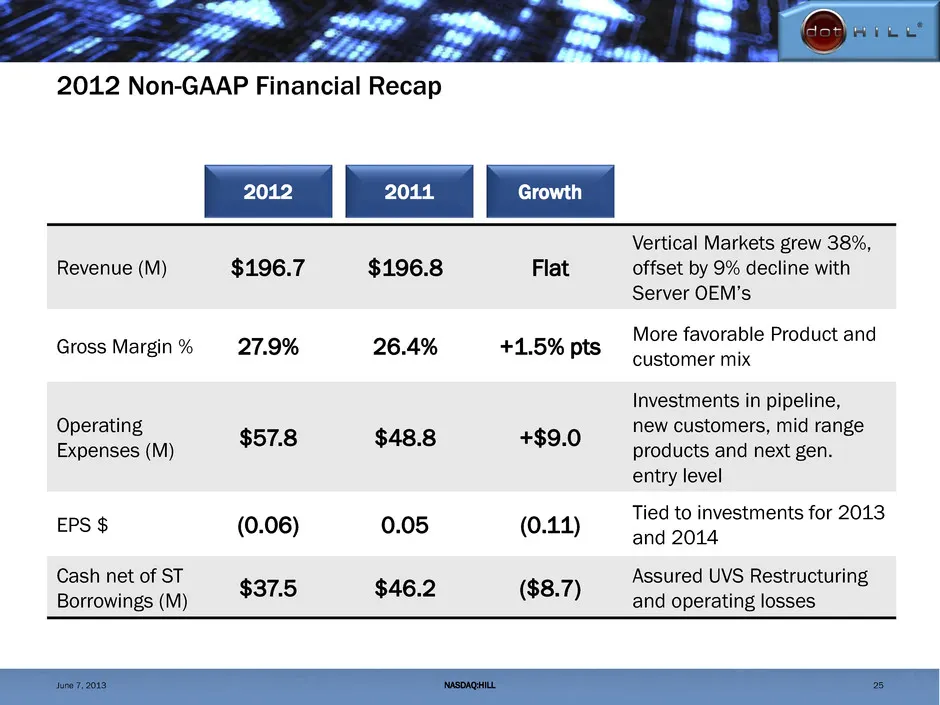
2012 Non-GAAP Financial Recap 25 Revenue (M) $196.7 $196.8 Flat Vertical Markets grew 38%, offset by 9% decline with Server OEM’s Gross Margin % 27.9% 26.4% +1.5% pts More favorable Product and customer mix Operating Expenses (M) $57.8 $48.8 +$9.0 Investments in pipeline, new customers, mid range pr
Slide 26: Q1'13 Non-GAAP Financial Metrics
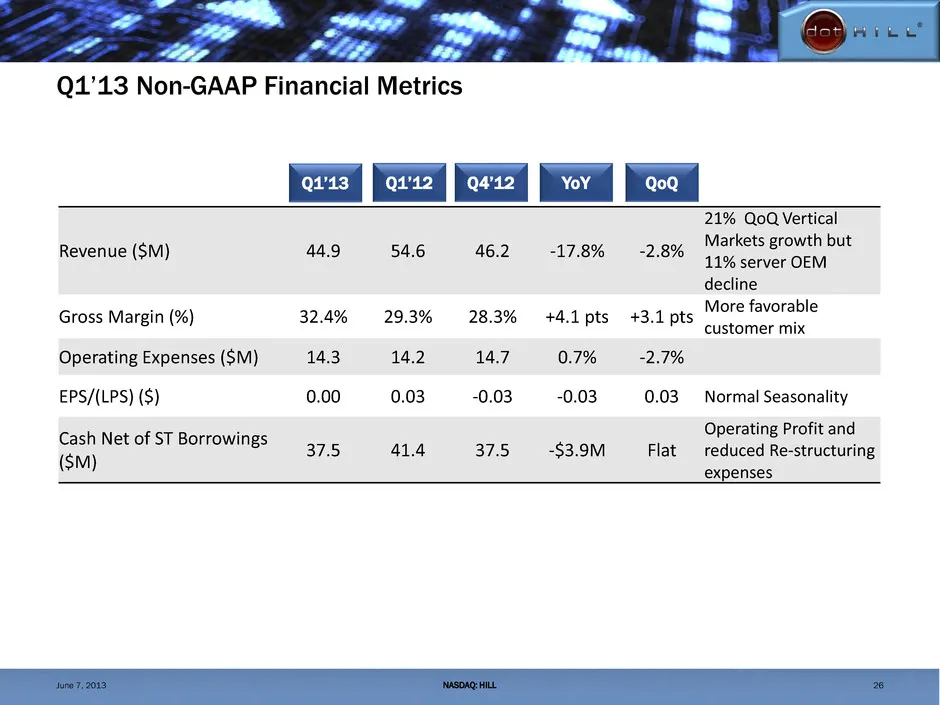
Q1’13 Non-GAAP Financial Metrics NASDAQ: HILL 26 Revenue ($M) 44.9 54.6 46.2 -17.8% -2.8% 21% QoQ Vertical Markets growth but 11% server OEM decline Gross Margin (%) 32.4% 29.3% 28.3% +4.1 pts +3.1 pts More favorable customer mix Operating Expenses ($M) 14.3 14.2 14.7 0.7% -2.7% EPS/(LPS) ($) 0.00 0
Slide 27: Q2'13 and Full Year 2013 Non-GAAP Guidance
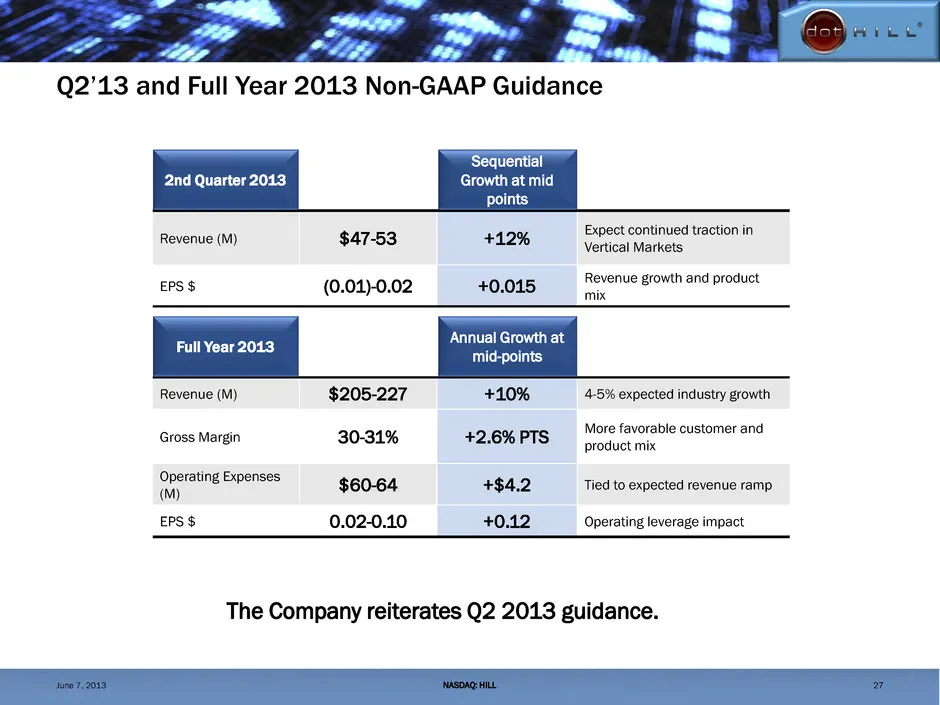
Q2’13 and Full Year 2013 Non-GAAP Guidance 27 Revenue (M) $47-53 +12% Expect continued traction in Vertical Markets EPS $ (0.01)-0.02 +0.015 Revenue growth and product mix 2nd Quarter 2013 Sequential Growth at mid points Revenue (M) $205-227 +10% 4-5% expected industry growth Gross Margin 30-31% +2.
Slide 28: Key Financial Metrics
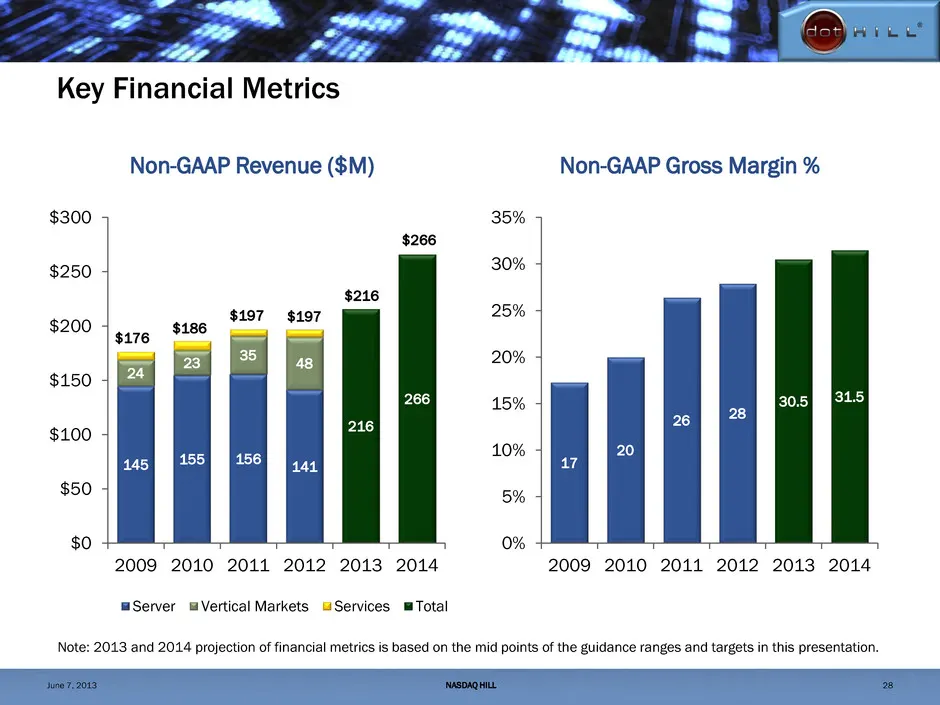
Key Financial Metrics 145 155 156 141 24 23 35 48 216 266 $0 $50 $100 $150 $200 $250 $300 2009 2010 2011 2012 2013 2014 Server Vertical Markets Services Total Non-GAAP Revenue ($M) Non-GAAP Gross Margin % Note: 2013 and 2014 projection of financial metrics is based on the mid points of the guidance
Slide 29: Key Financial Metrics (Cont'd)
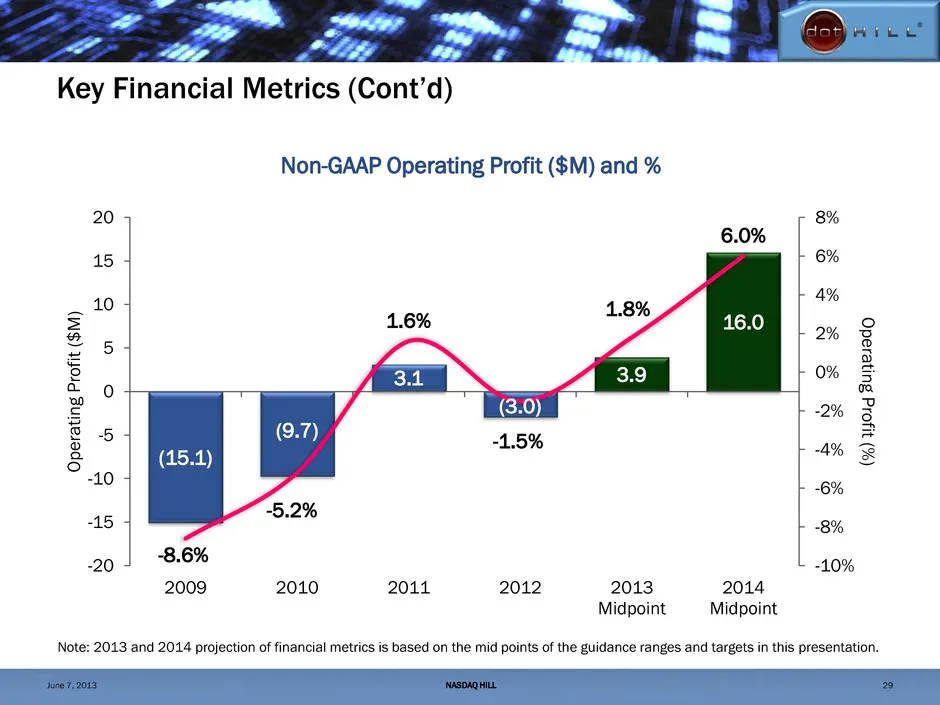
Key Financial Metrics (Cont’d) (15.1) (9.7) 3.1 (3.0) 3.9 16.0 -8.6% -5.2% 1.6% -1.5% 1.8% 6.0% -10% -8% -6% -4% -2% 0% 2% 4% 6% 8% -20 -15 -10 -5 0 5 10 15 20 2009 2010 2011 2012 2013 Midpoint 2014 Midpoint O p e ratin g P ro fit (% ) Operat in g P ro fit ($ M ) Non-GAAP Operating Profit ($M) and %
Slide 30: Appendix II: Reconciliation of GAAP to Non-GAAP Financial Measures
DRIVING GROWTH NASDAQ: HILL June 7, 2013 Appendix II: Reconciliation of GAAP to Non-GAAP Financial Measures A STRONG FOUNDATION FOR
Slide 31: Q1'13 GAAP to Non-GAAP Revenue Reconciliation
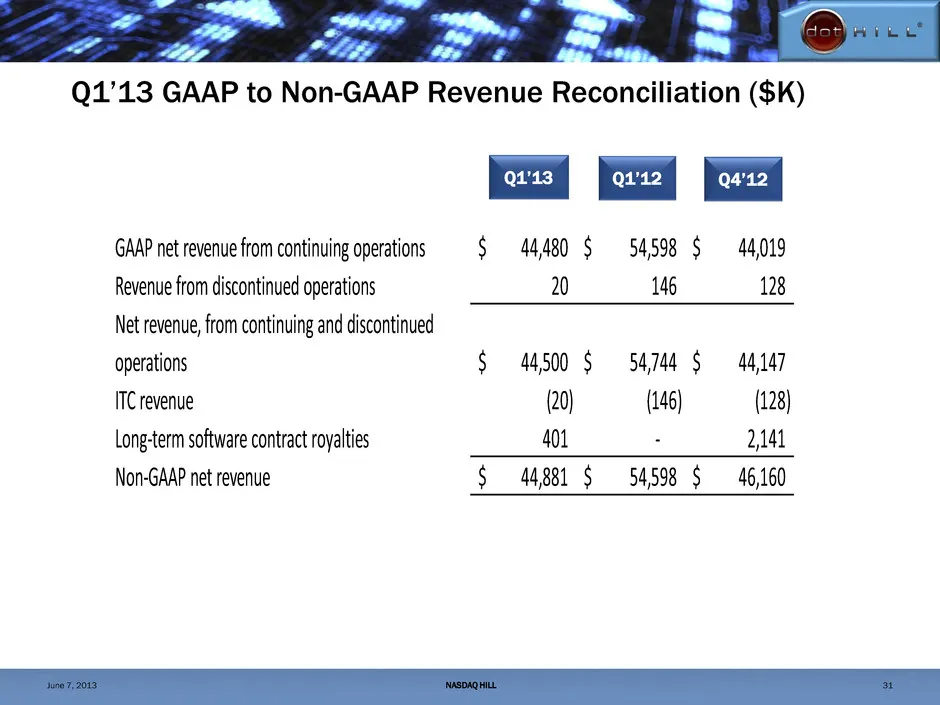
Q1’13 GAAP to Non-GAAP Revenue Reconciliation ($K) Q1’13 Q1’12 Q4’12 GAAP net revenue from continuing operations 44,480$ 54,598$ 44,019$ Revenue from discontinued operations 20 146 128 Net revenue, from continuing and discontinued operations 44,500$ 54,744$ 44,147$ ITC revenue (20) (146) (128) Long-
Slide 32: Q1'13 GAAP to Non-GAAP Gross Profit Reconciliation
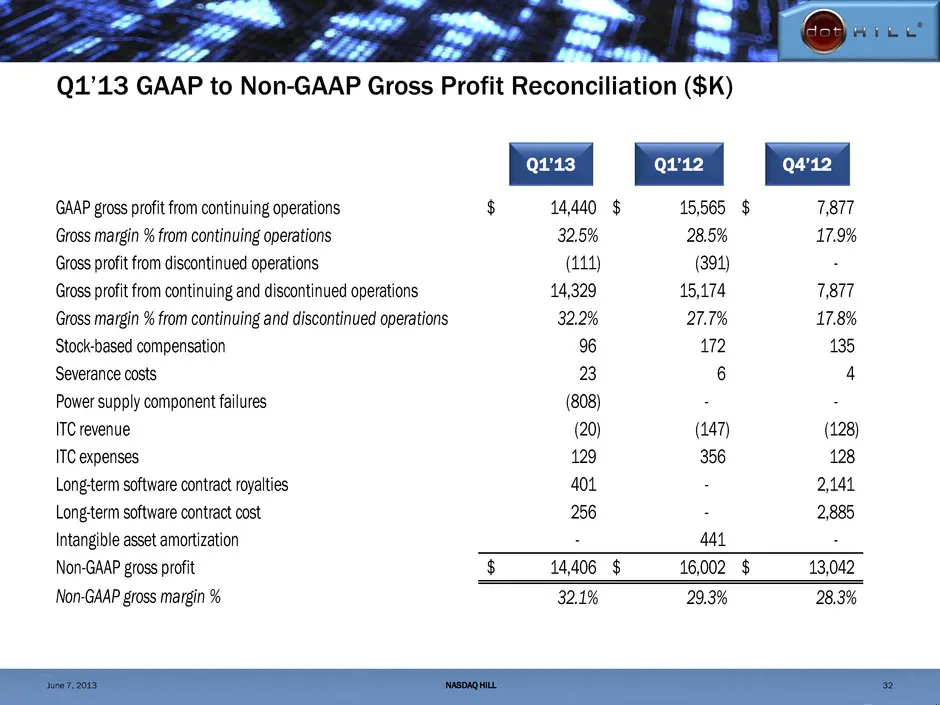
Q1’13 GAAP to Non-GAAP Gross Profit Reconciliation ($K) Q1’13 Q1’12 Q4’12 GAAP gross profit from continuing operations 14,440$ 15,565$ 7,877$ Gross margin % from continuing operations 32.5% 28.5% 17.9% Gross profit from discontinued operations (111) (391) - Gross profit from continuing and discontin
Slide 33: Q1'13 GAAP to Non-GAAP Operating Expenses Reconciliation
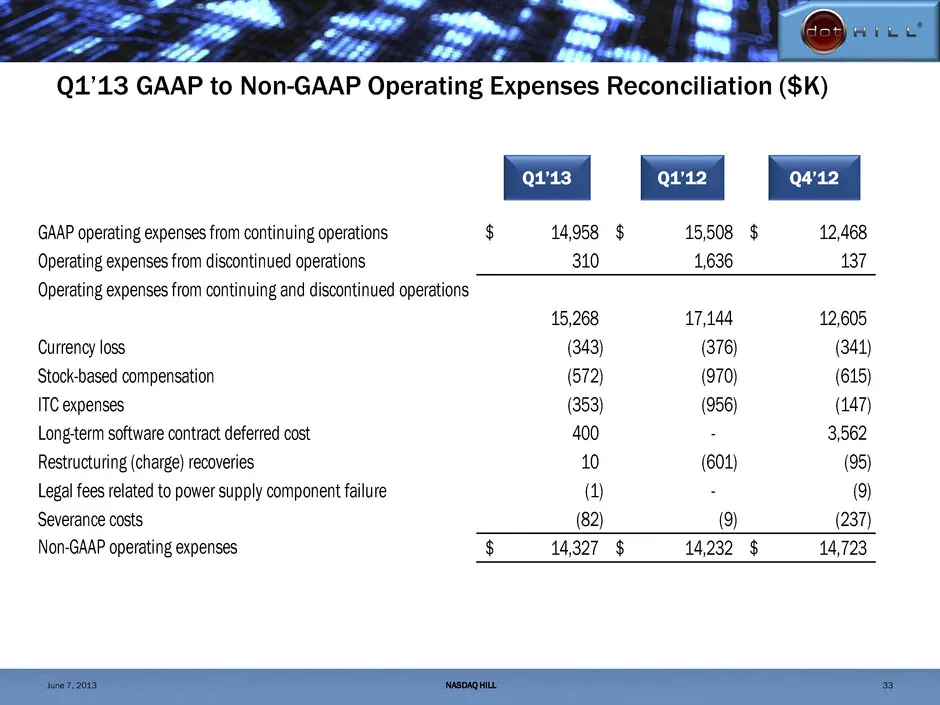
Q1’13 GAAP to Non-GAAP Operating Expenses Reconciliation ($K) Q1’13 Q1’12 Q4’12 GAAP operating expenses from continuing operations 14,958$ 15,508$ 12,468$ Operating expenses from discontinued operations 310 1,636 137 Operating expenses from continuing and discontinued operations 15,268 17,144 12,605
Slide 34: Q1'13 GAAP to Non-GAAP Net Income (Loss) Reconciliation
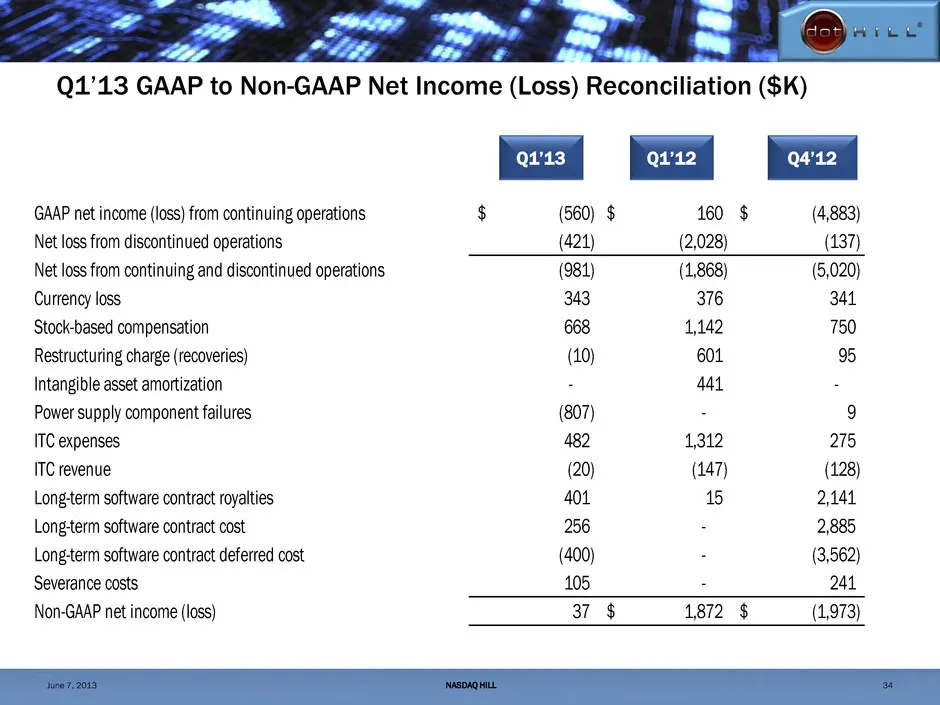
Q1’13 GAAP to Non-GAAP Net Income (Loss) Reconciliation ($K) Q1’13 Q1’12 Q4’12 GAAP net income (loss) from continuing operations (560)$ 160$ (4,883)$ Net loss from discontinued operations (421) (2,028) (137) Net loss from continuing and discontinued operations (981) (1,868) (5,020) Currency loss 343
Slide 35: Q1'13 GAAP to Non-GAAP EPS (LPS) Reconciliation
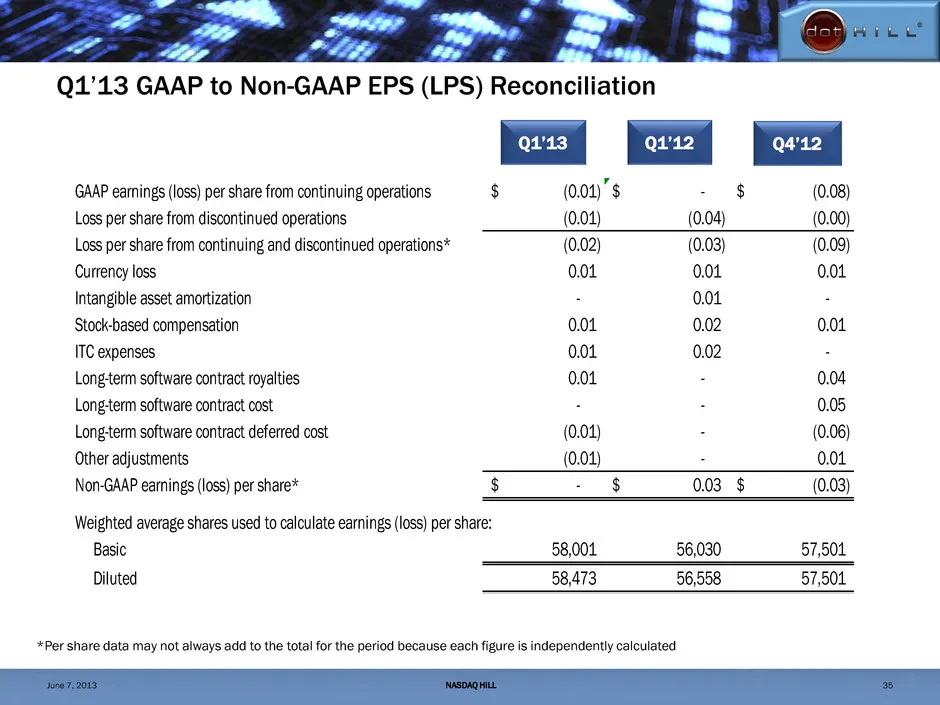
Q1’13 GAAP to Non-GAAP EPS (LPS) Reconciliation Q1’13 Q1’12 Q4’12 GAAP earnings (loss) per share from continuing operations (0.01)$ -$ (0.08)$ Loss per share from discontinued operations (0.01) (0.04) (0.00) Loss per share from continuing and discontinued operations* (0.02) (0.03) (0.09) Currency lo
Slide 36: Q1'13 Cash Reconciliation
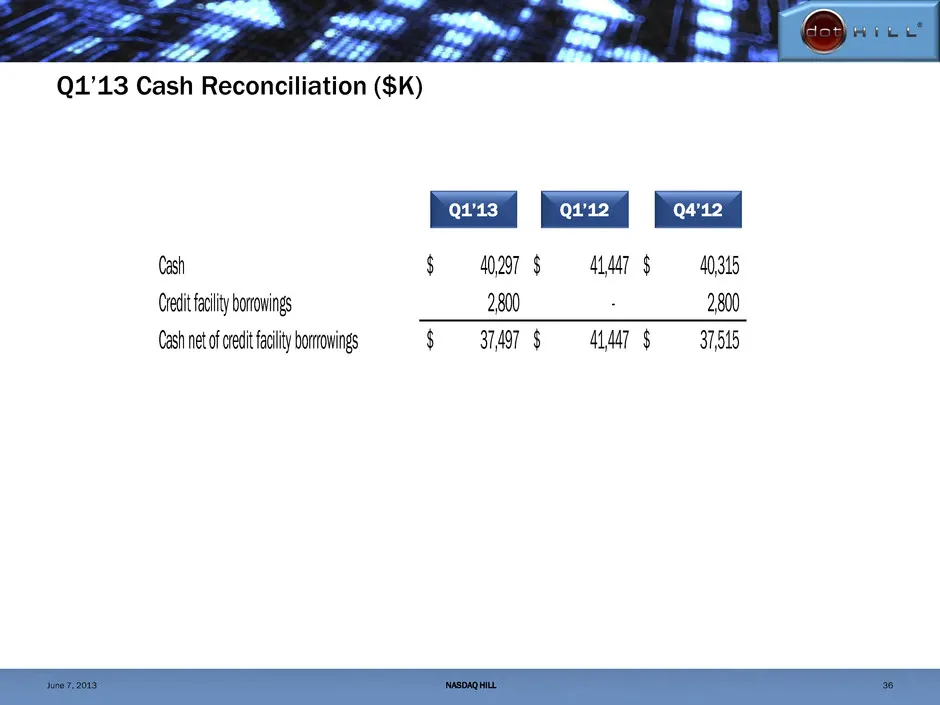
Q1’13 Cash Reconciliation ($K) Q1’13 Q1’12 Q4’12 Cash 40,297$ 41,447$ 40,315$ Credit facility borrowings 2,800 - 2,800 Cash net of credit facility borrrowings 37,497$ 41,447$ 37,515$ NASDAQ HILL 36 June 7, 2013
Source: SEC EDGAR · 8-K filed Jun 7, 2013
More decks from Dot Hill Systems Corp
 Q2 2015 Earnings Presentation27 slides · Aug 6, 2015
 Investor Presentation (May 2015)58 slides · May 12, 2015
 Q1 2015 Earnings Presentation13 slides · May 7, 2015
 Investor Presentation (March 2015)15 slides · Mar 5, 2015
 Investor Presentation (January 2015)49 slides · Jan 12, 2015
 Investor Presentation (November 2014)47 slides · Nov 10, 2014