SKF AB Class A · OMXSTO:SKF_A
SKF AB Class A — Investor Day (2018)
17 slides from SKF AB Class A's investor day presentation, 2018
Slide 1: SKF Capital Markets Day 2018
SKF Capital Markets Day 2018 Christian Johansson, Senior Vice President & CFO
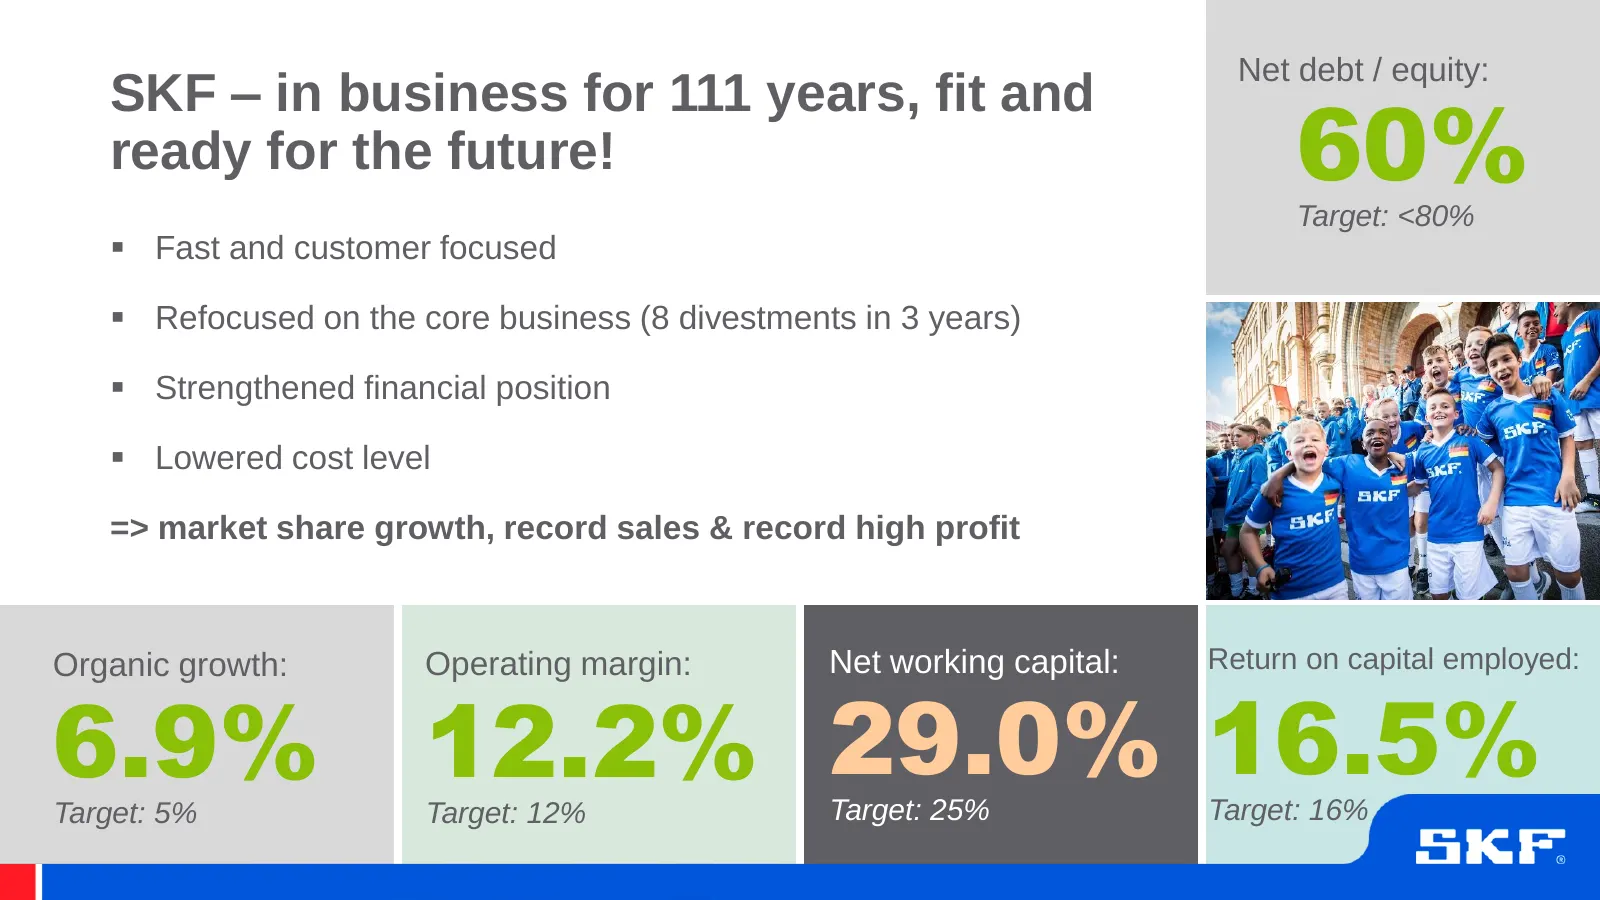
Slide 2: SKF – in business for 111 years, fit and ready for the future
Net debt / equity: SKF – in business for 111 years, fit and ready for the future! 60% Target: <80% ▪ Fast and customer focused ▪ Refocused on the core business (8 divestments in 3 years) ▪ Strengthened financial position ▪ Lowered cost level => market share growth, record sales & record high profit
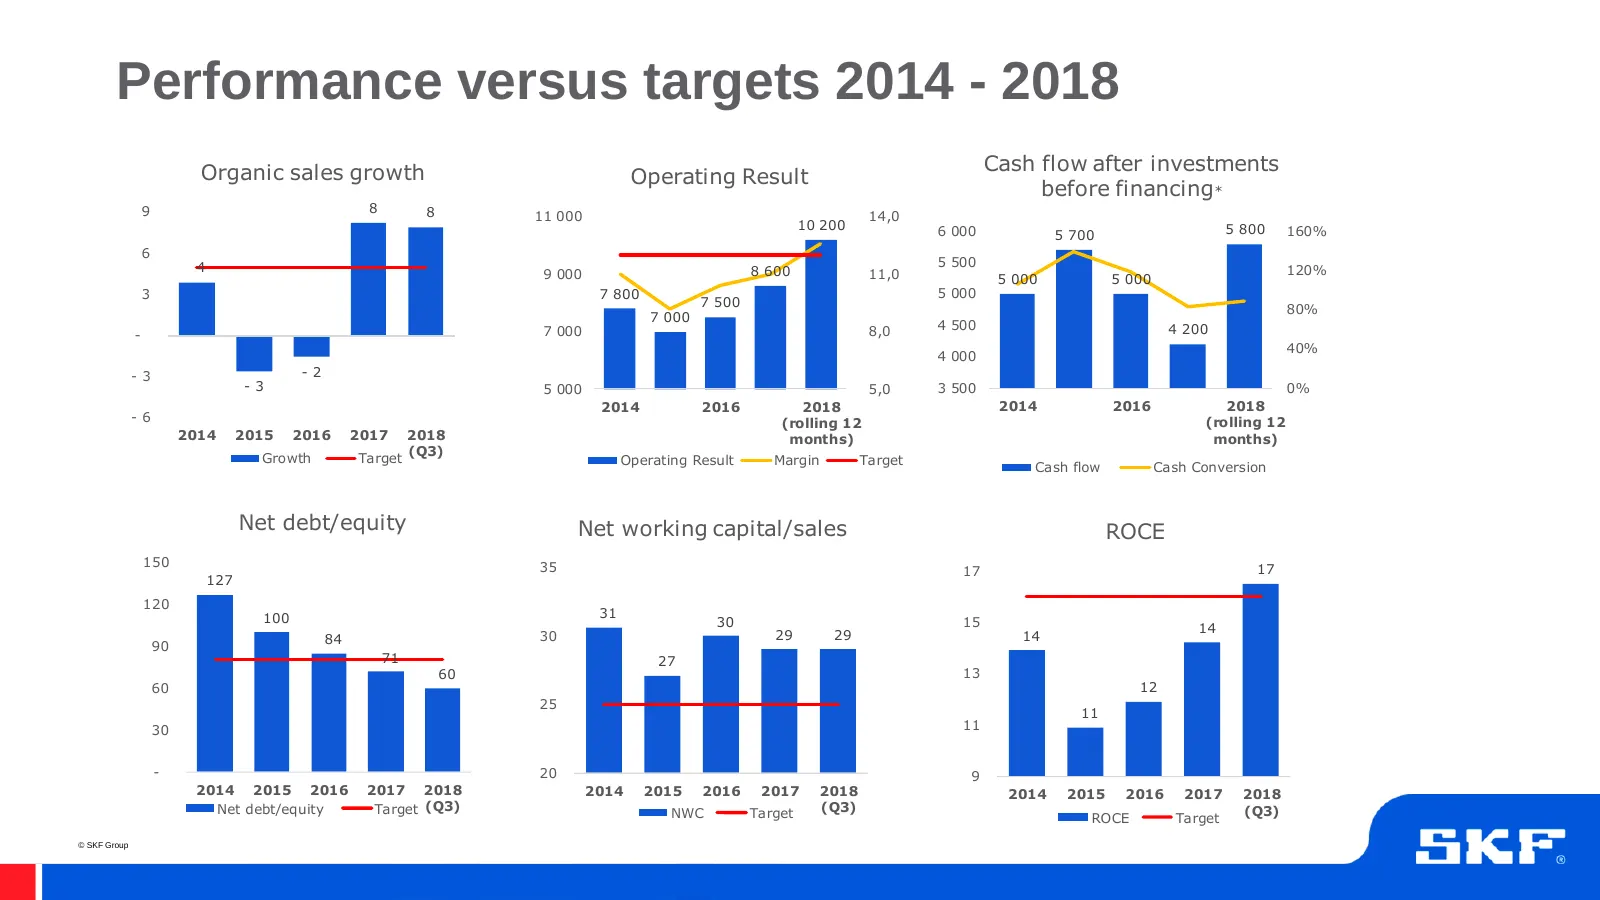
Slide 3: Performance versus targets 2014 - 2018
Performance versus targets 2014 - 2018 Organic sales growth Cash flow after investments Operating Result before financing* 9 8 8 11 000 14,0 10 200 6 000 5 800 160% 5 700 6 4 5 500 9 000 8 600 11,0 120% 5 000 5 000 3 7 800 5 000 7 500 80% 7 000 7 000 8,0 4 500 4 200 - 40% 4 000 -3 -2 -3 5 000 5,0 3
Slide 4: Accelerating for the future within tight frames
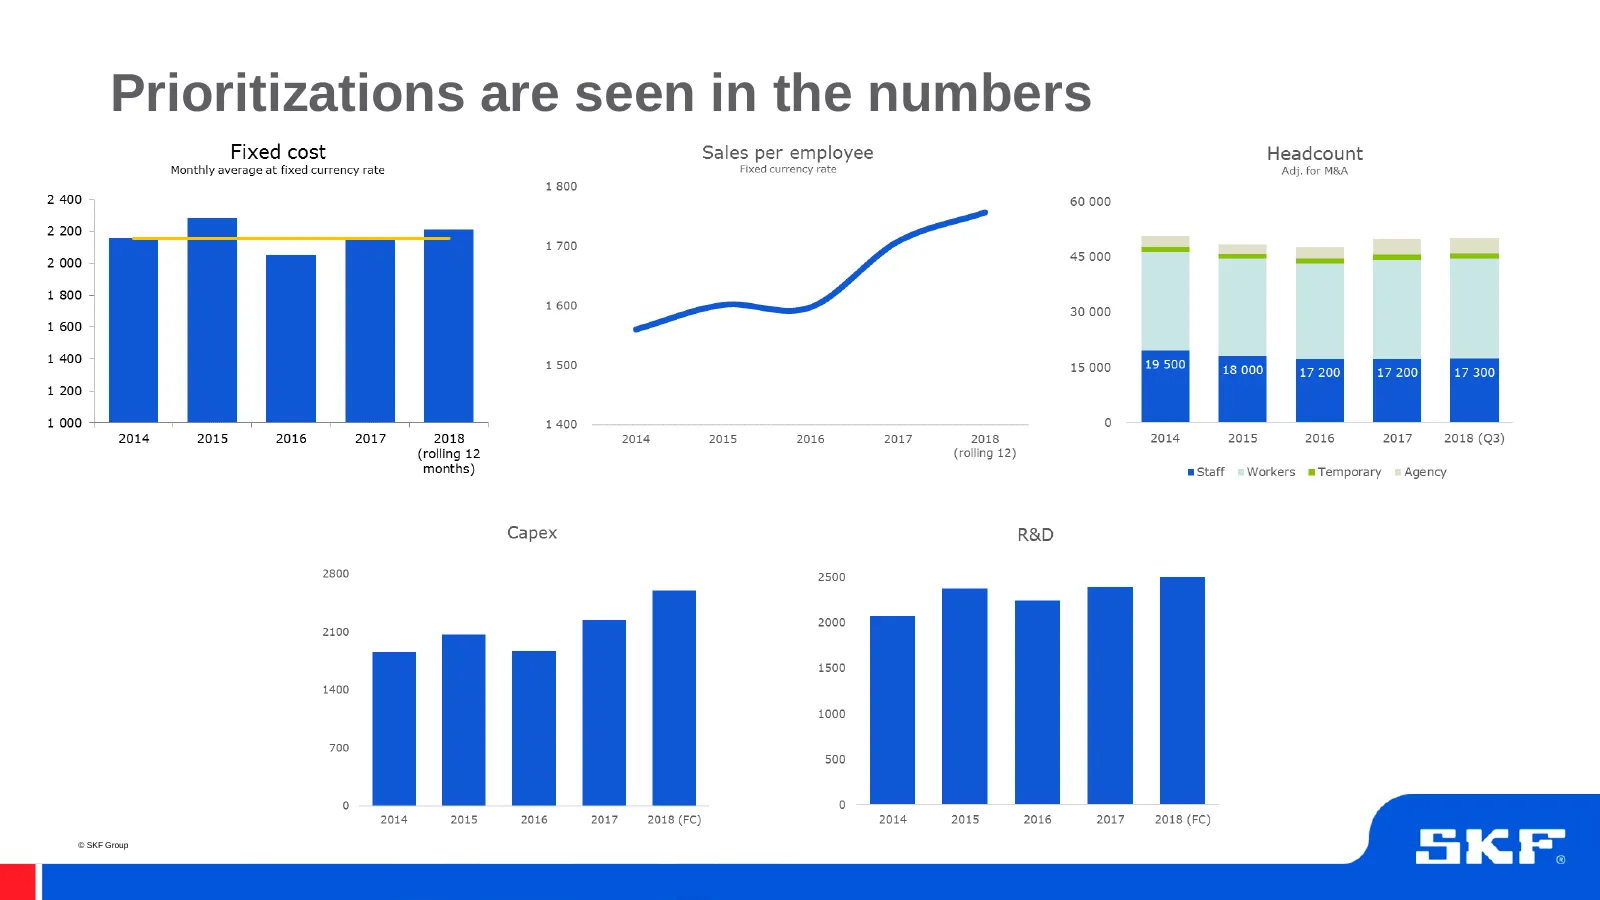
Accelerating for the future within tight frames We have increased our efforts on: While: ▪ Research and development Kept fixed costs unchanged ▪ IT Reduced the number of employees ▪ Capital expenditures Reduced debt by more than 11 billion Prioritizations based on a clear and agreed direction © SK
Slide 5: Prioritizations are seen in the numbers
Prioritizations are seen in the numbers © SKF Group
Slide 6: Strategic IT initiatives @ SKF – an overview
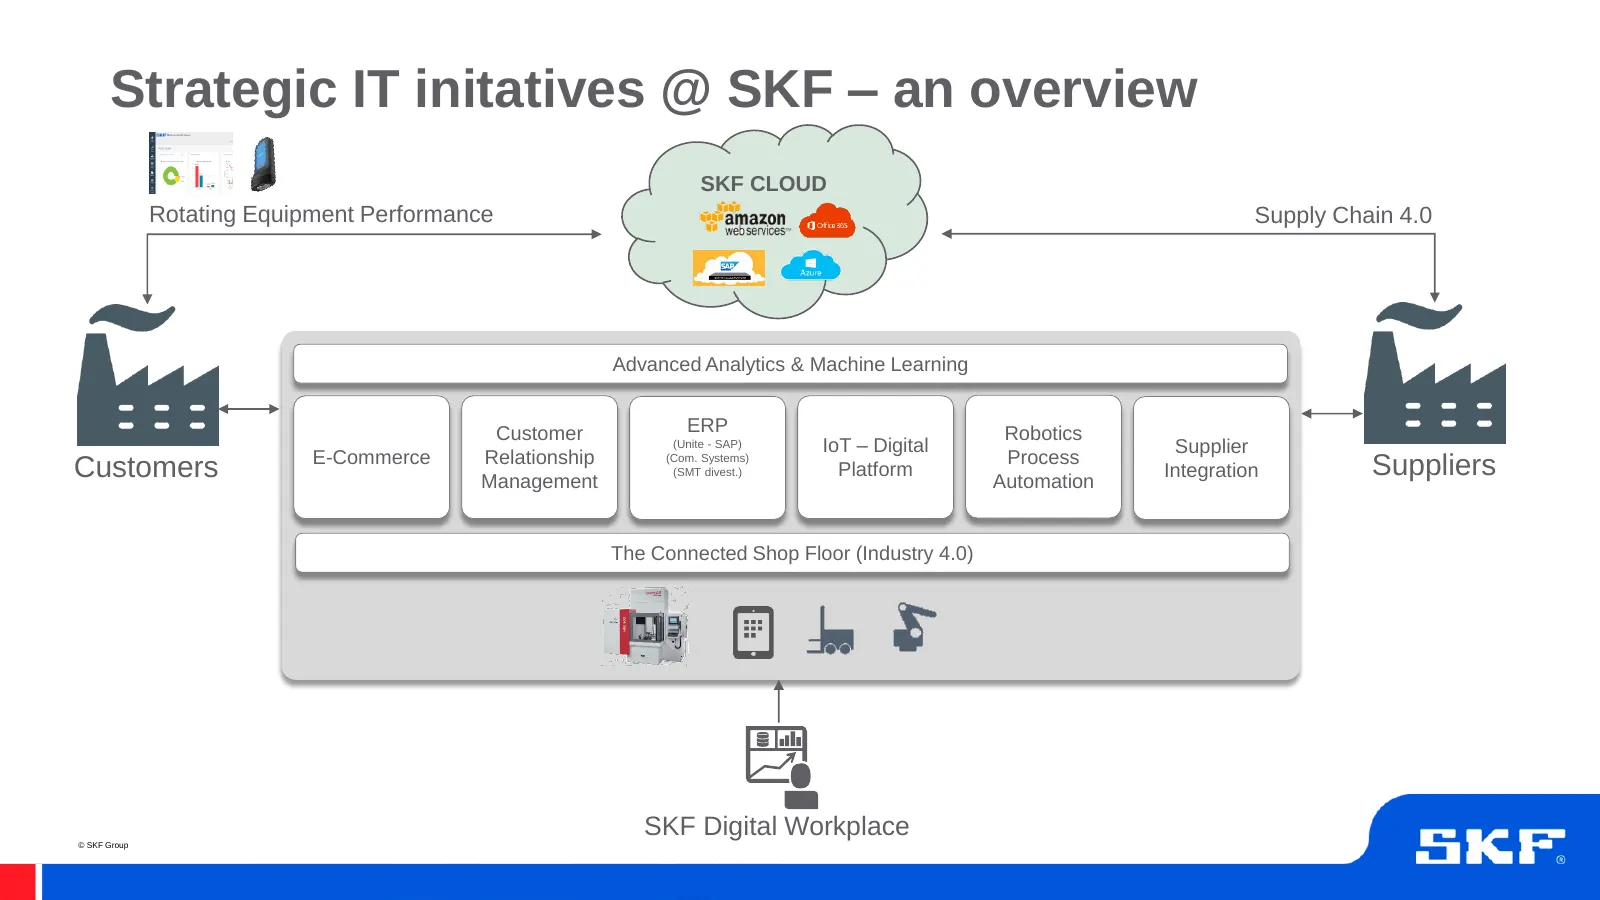
Strategic IT initatives @ SKF – an overview SKF CLOUD Rotating Equipment Performance Supply Chain 4.0 Advanced Analytics & Machine Learning Customer ERP Robotics (Unite - SAP) IoT – Digital Supplier E-Commerce Relationship (Com. Systems) Process Customers Management (SMT divest.) Platform Automation
Slide 7: R&D footprint – moving testing closer to customer
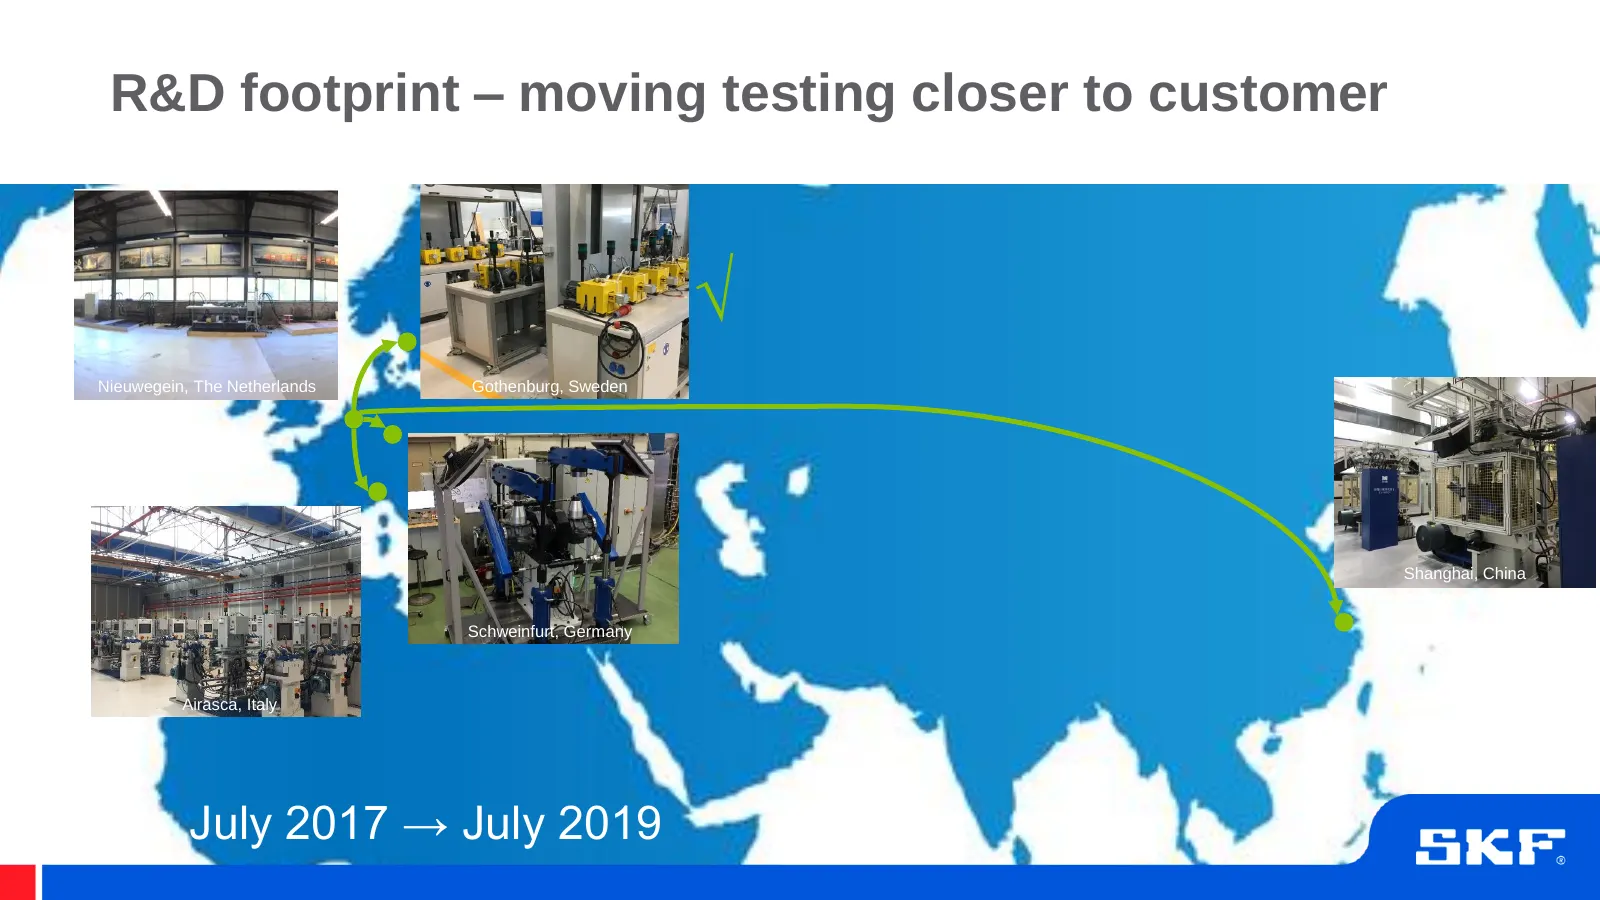
R&D footprint – moving testing closer to customer √ Nieuwegein, The Netherlands Gothenburg, Sweden Shanghai, China Schweinfurt, Germany Airasca, Italy July 2017 → July 2019
Slide 8: New market offers for products and REP
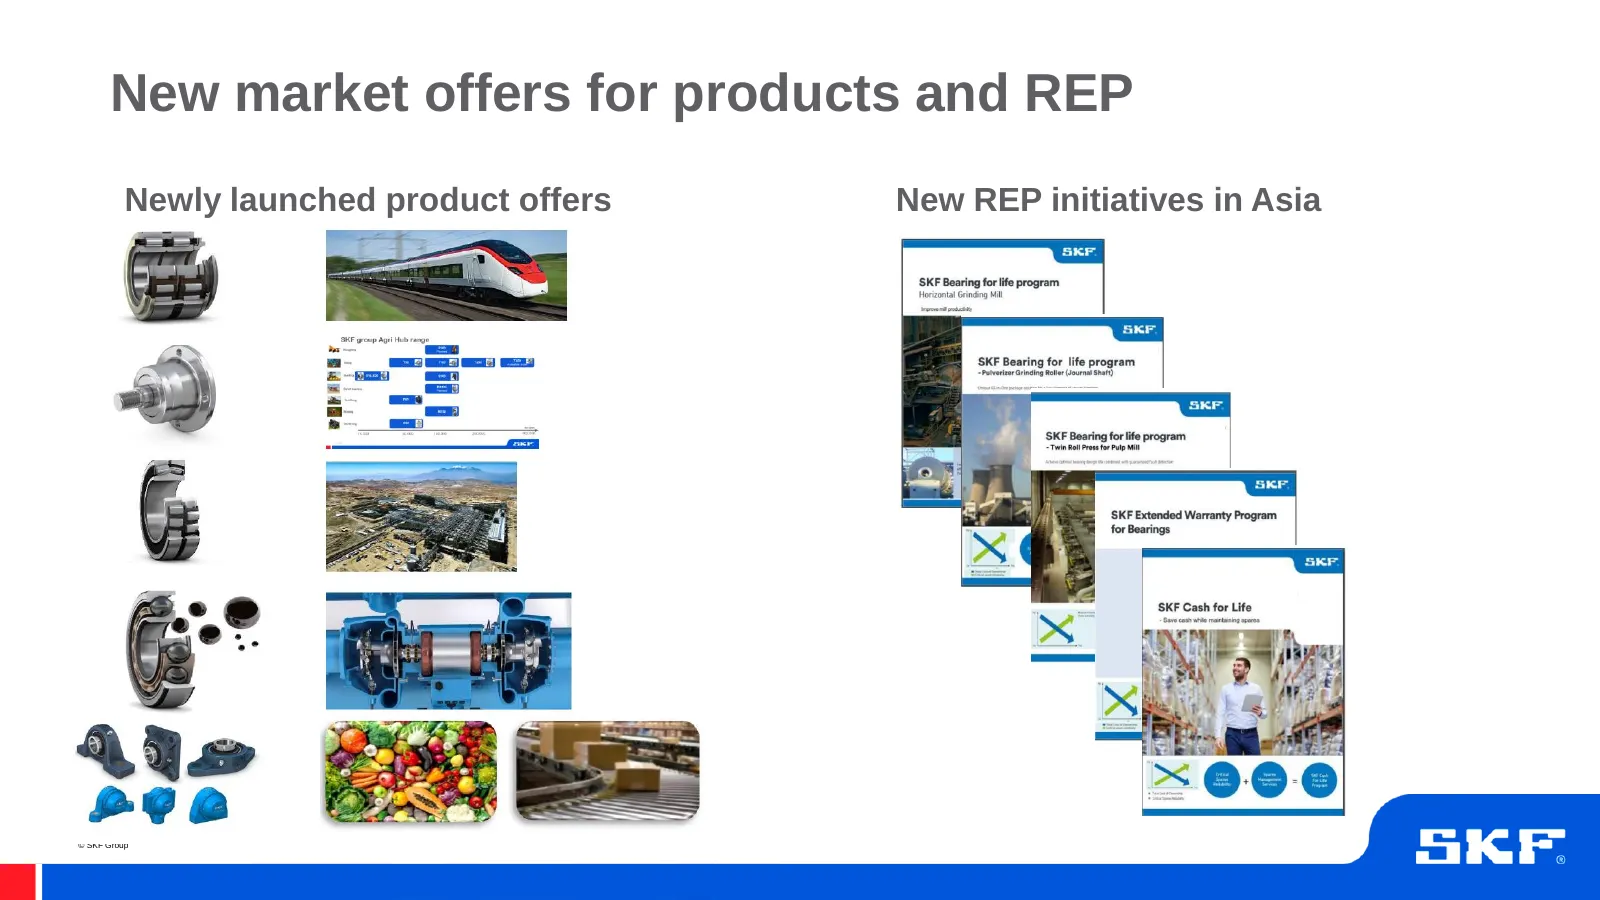
New market offers for products and REP Newly launched product offers New REP initiatives in Asia © SKF Group
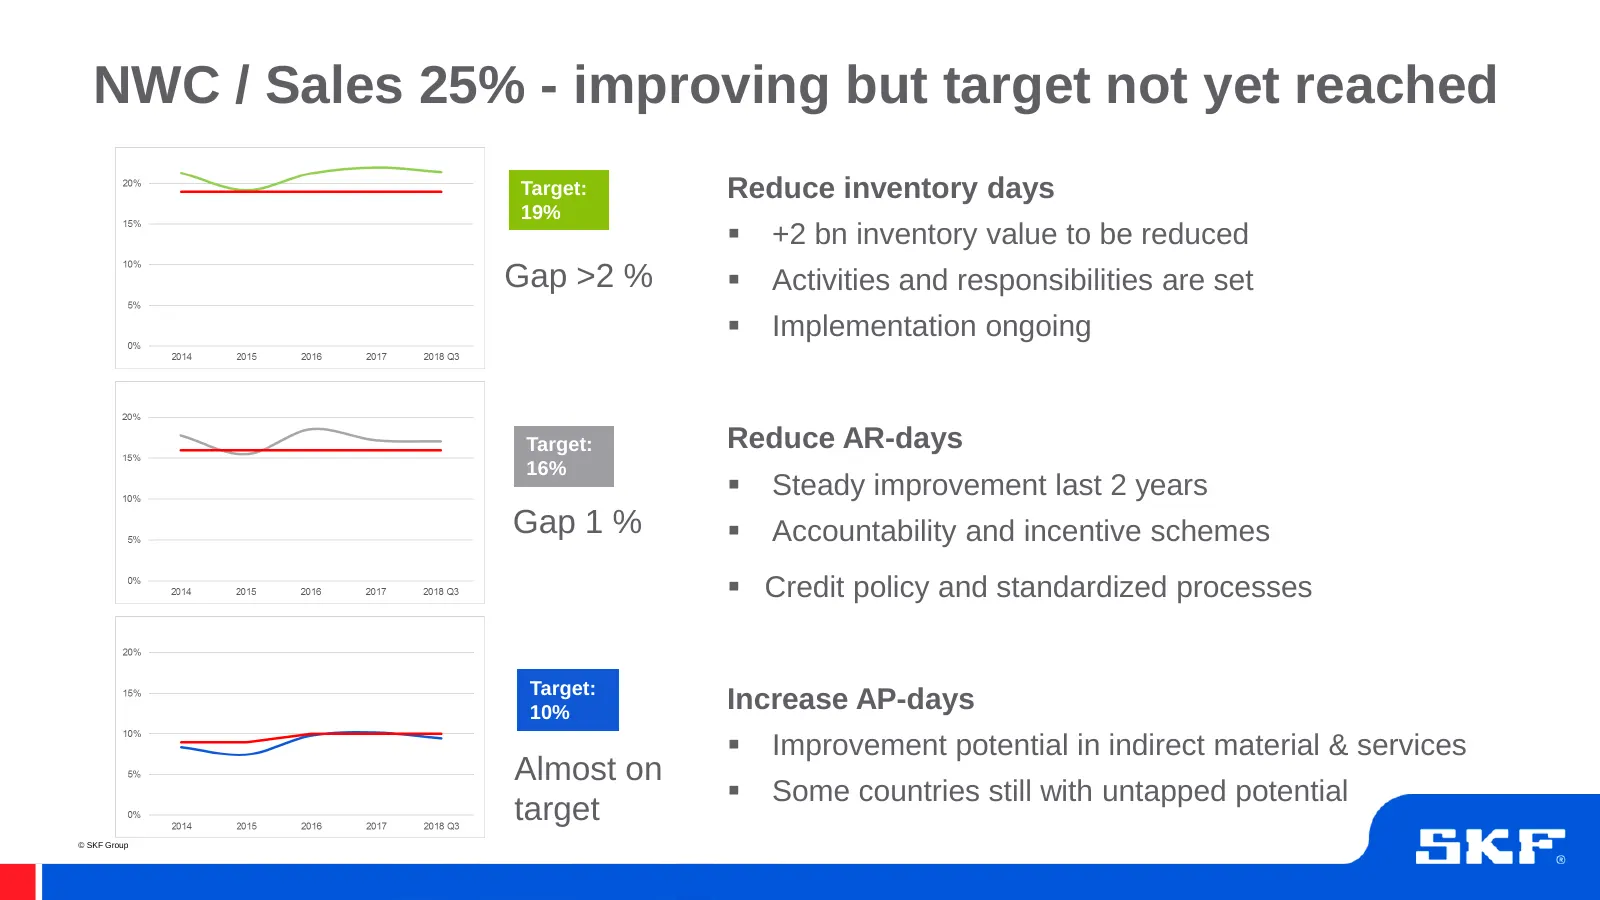
Slide 9: NWC / Sales 25% - improving but target not yet reached
NWC / Sales 25% - improving but target not yet reached Target: Reduce inventory days 19% ▪ +2 bn inventory value to be reduced Gap >2 % ▪ Activities and responsibilities are set ▪ Implementation ongoing Target: Reduce AR-days 16% ▪ Steady improvement last 2 years Gap 1 % ▪ Accountability and incenti
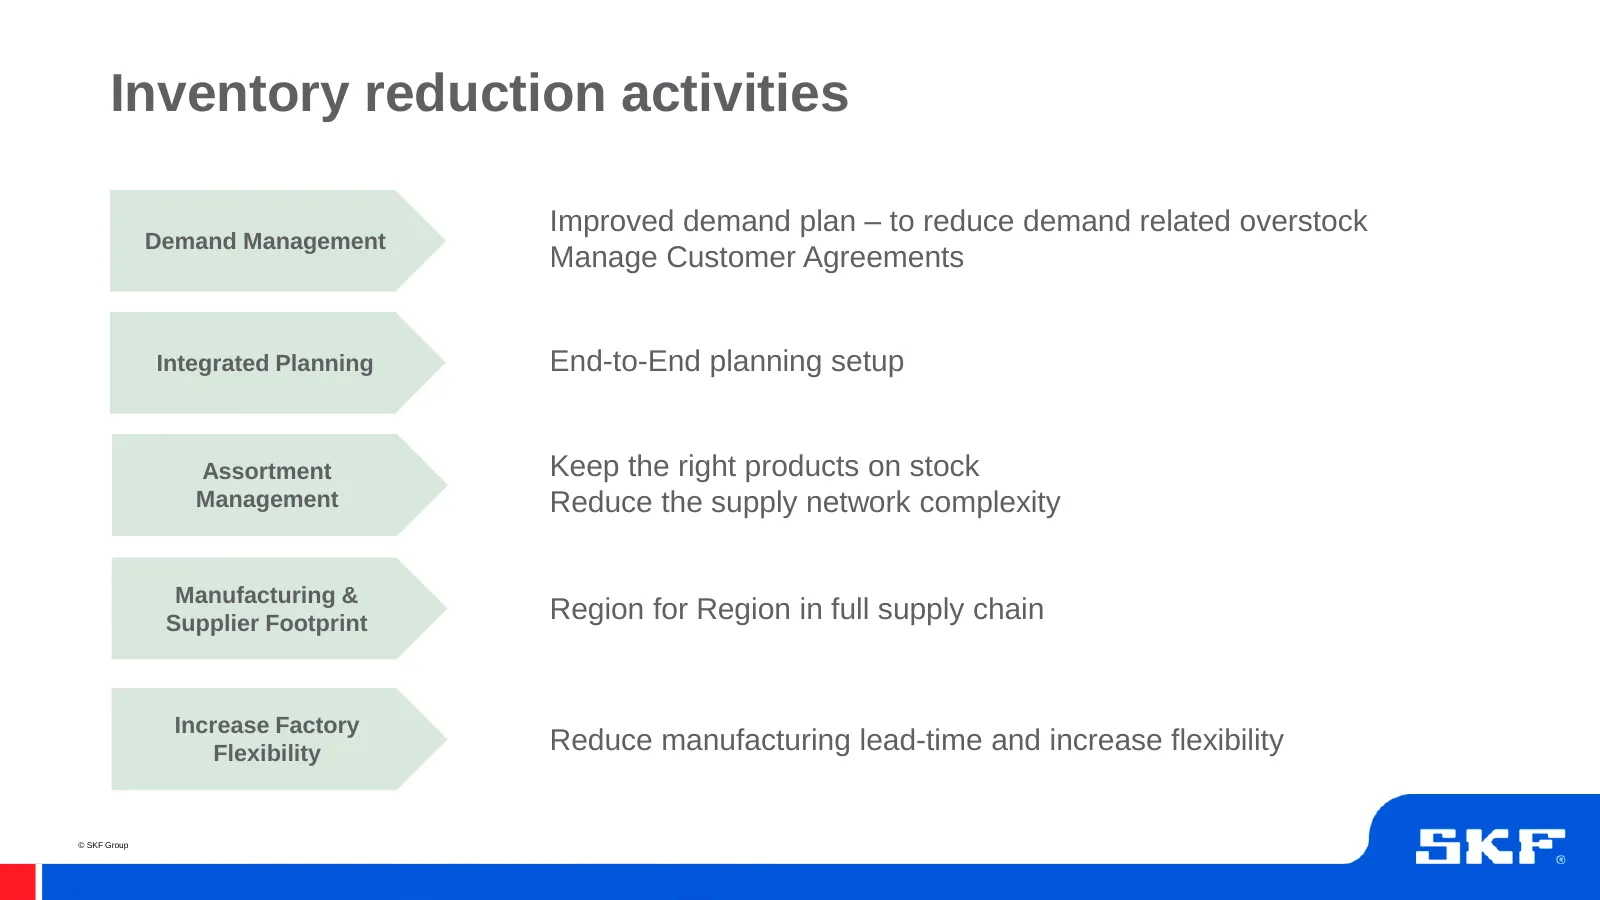
Slide 10: Inventory reduction activities
Inventory reduction activities Improved demand plan – to reduce demand related overstock Demand Management Manage Customer Agreements Integrated Planning End-to-End planning setup Assortment Keep the right products on stock Management Reduce the supply network complexity Manufacturing & Supplier Foo
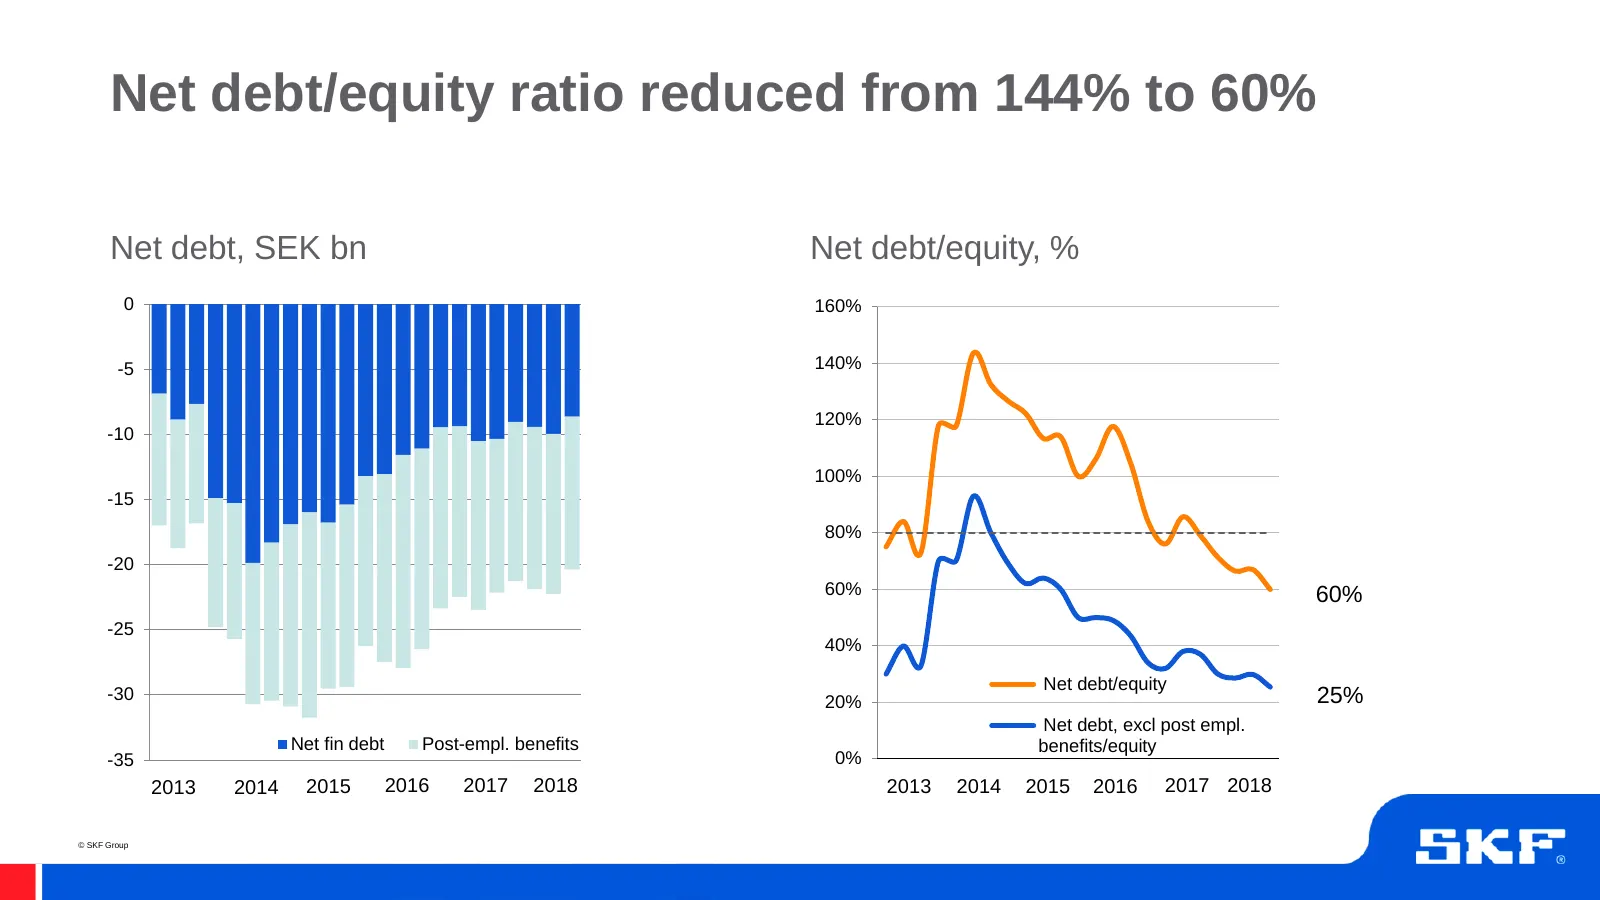
Slide 11: Net debt/equity ratio reduced from 144% to 60%
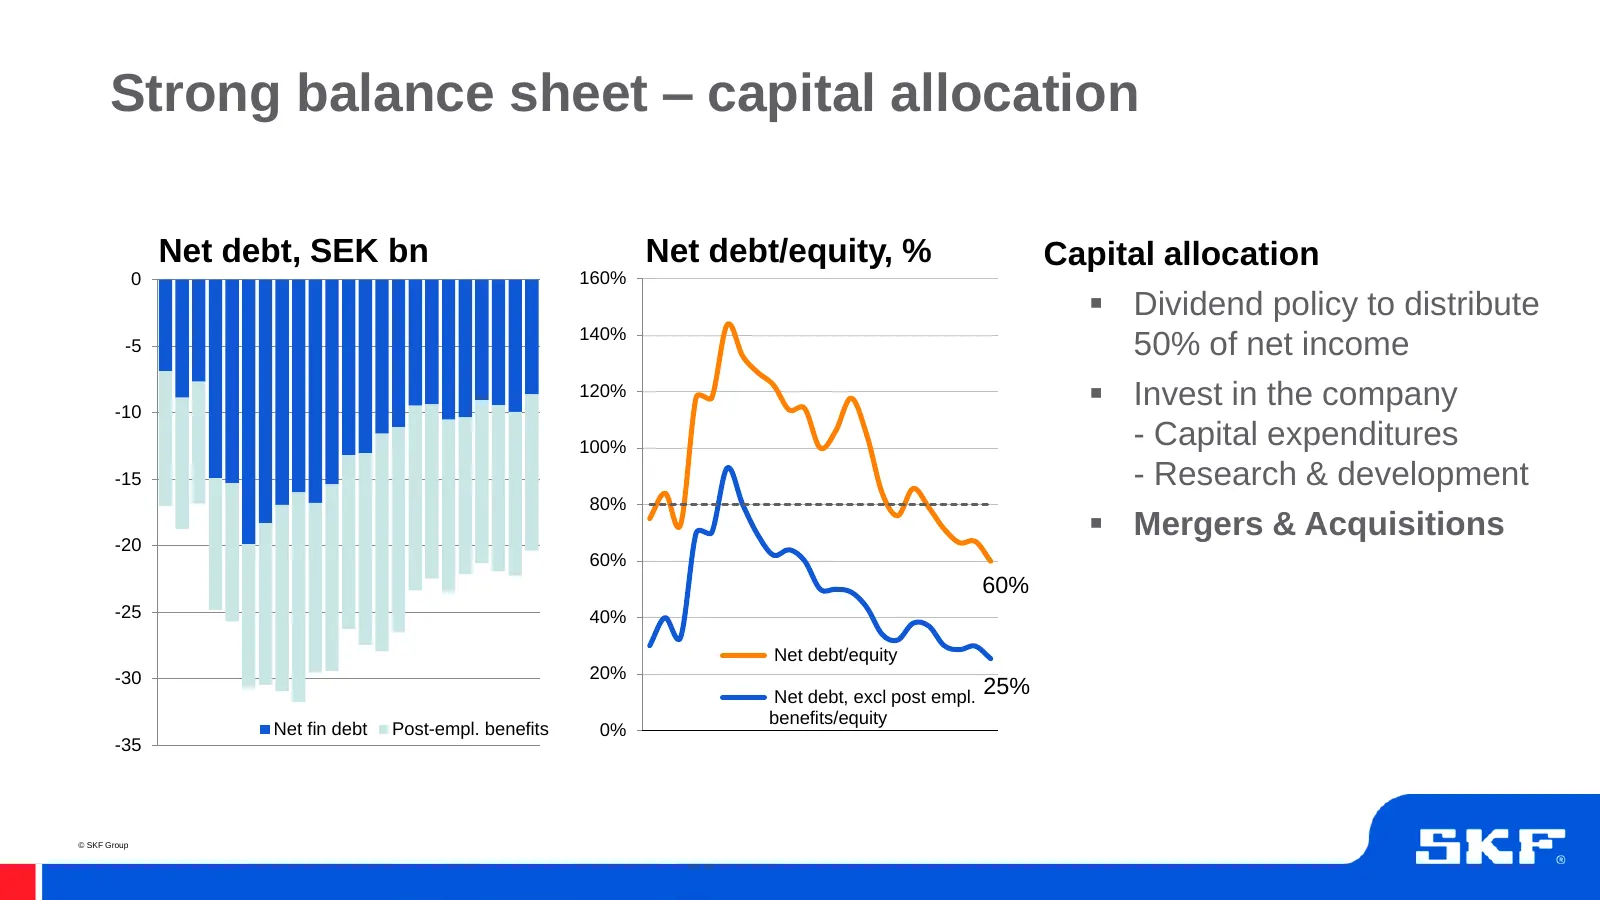
Net debt/equity ratio reduced from 144% to 60% Net debt, SEK bn Net debt/equity, % 0 160% -5 140% 120% -10 100% -15 80% -20 60% 60% -25 40% Net debt/equity -30 20% 25% Net debt, excl post empl. Net fin debt Post-empl. benefits benefits/equity -35 0% 2013 2014 2015 2016 2017 2018 2013 2014 2015 2016
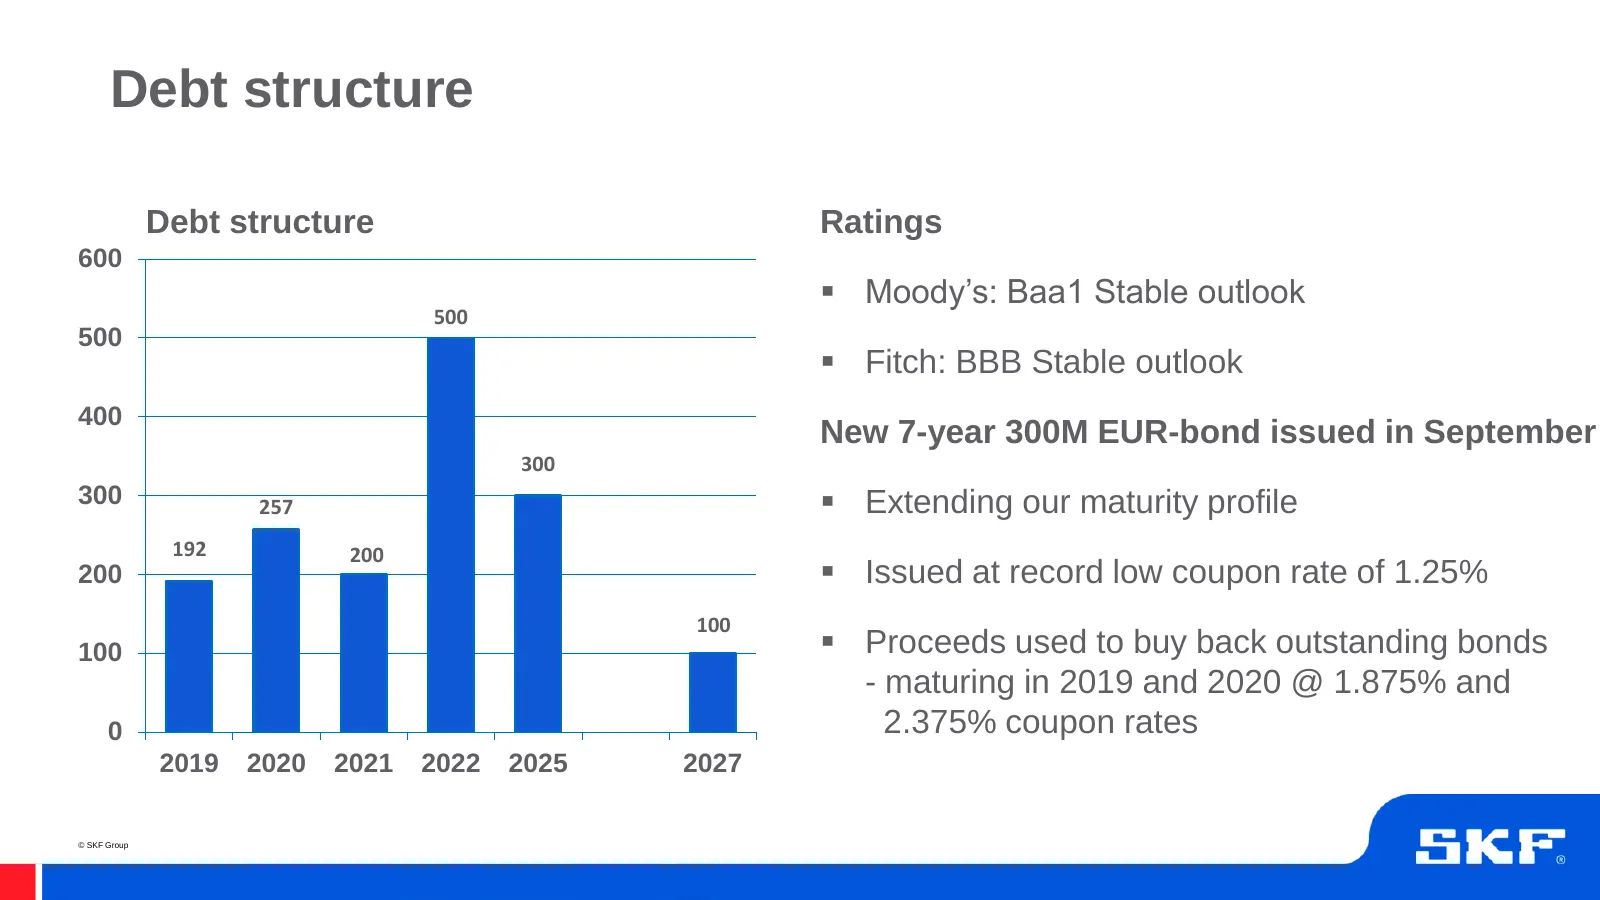
Slide 12: Debt structure
Debt structure Debt structure Ratings 600 ▪ Moody’s: Baa1 Stable outlook 500 500 ▪ Fitch: BBB Stable outlook 400 New 7-year 300M EUR-bond issued in September 300 300 257 ▪ Extending our maturity profile 192 200 200 ▪ Issued at record low coupon rate of 1.25% 100 100 ▪ Proceeds used to buy back outst
Slide 13: Strong balance sheet – capital allocation
Strong balance sheet – capital allocation Net debt, SEK bn Net debt/equity, % Capital allocation 0 160% ▪ Dividend policy to distribute 140% -5 50% of net income -10 120% ▪ Invest in the company 100% - Capital expenditures -15 - Research & development 80% -20 ▪ Mergers & Acquisitions 60% 60% -25 40%
Slide 14: Active portfolio management
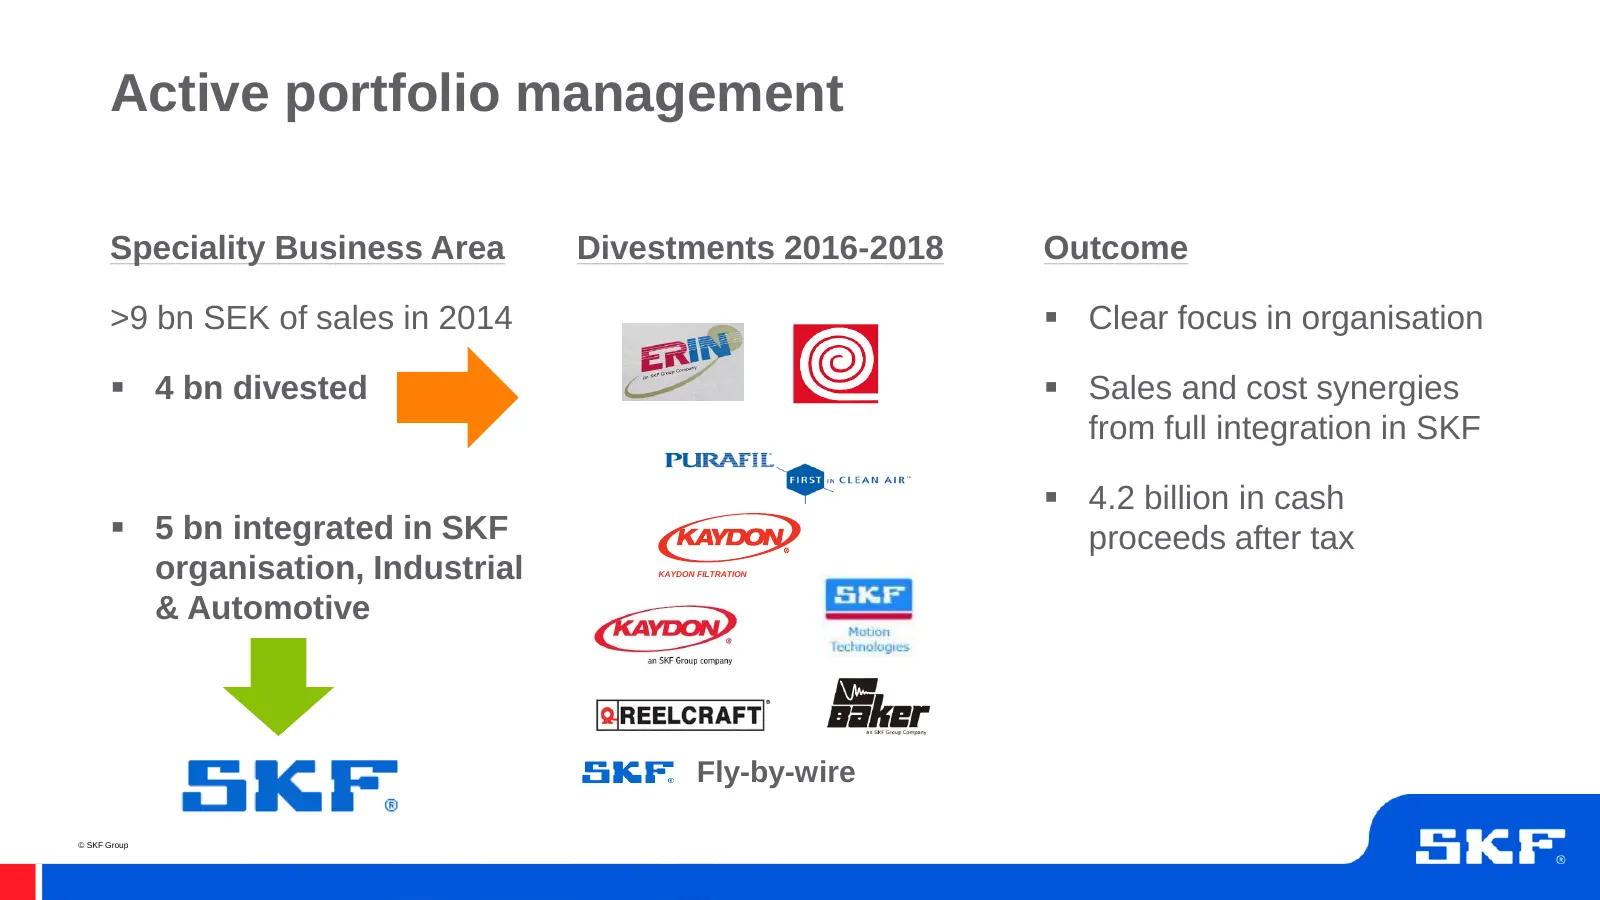
Active portfolio management Speciality Business Area Divestments 2016-2018 Outcome >9 bn SEK of sales in 2014 ▪ Clear focus in organisation ▪ 4 bn divested ▪ Sales and cost synergies from full integration in SKF ▪ 4.2 billion in cash ▪ 5 bn integrated in SKF proceeds after tax organisation, Industri
Slide 15: Strong balance sheet create gunpowder for acquisitions
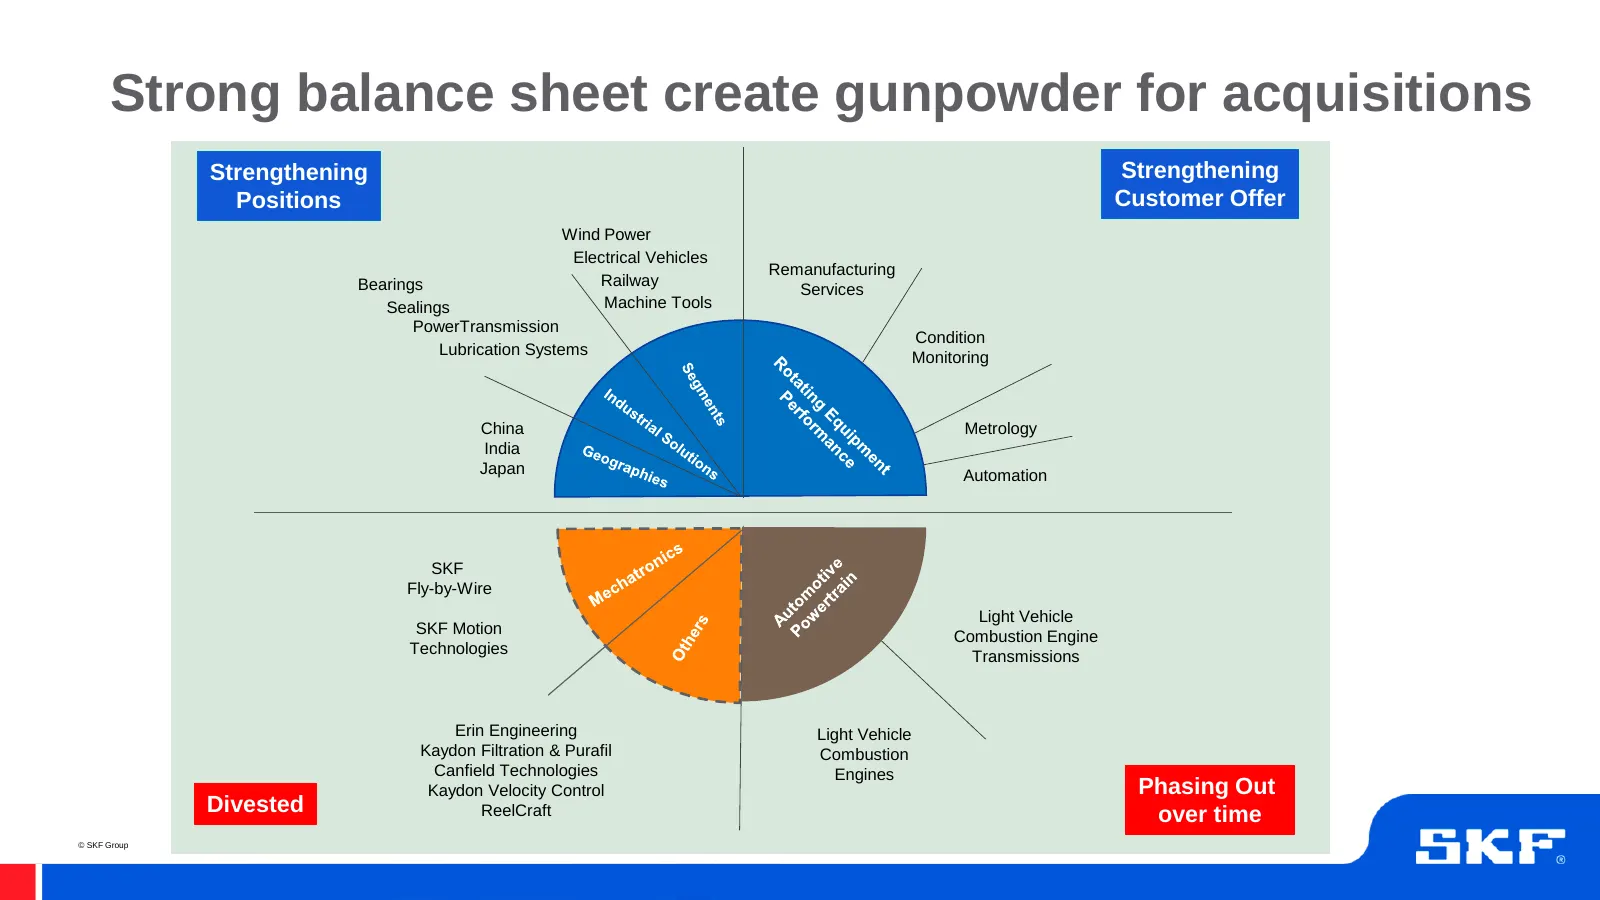
Strong balance sheet create gunpowder for acquisitions Strengthening Strengthening Positions Customer Offer Wind Power Electrical Vehicles Remanufacturing Bearings Railway Services Sealings Machine Tools PowerTransmission Condition Lubrication Systems Monitoring China Metrology India Japan Automatio
Slide 16: Business cycle management
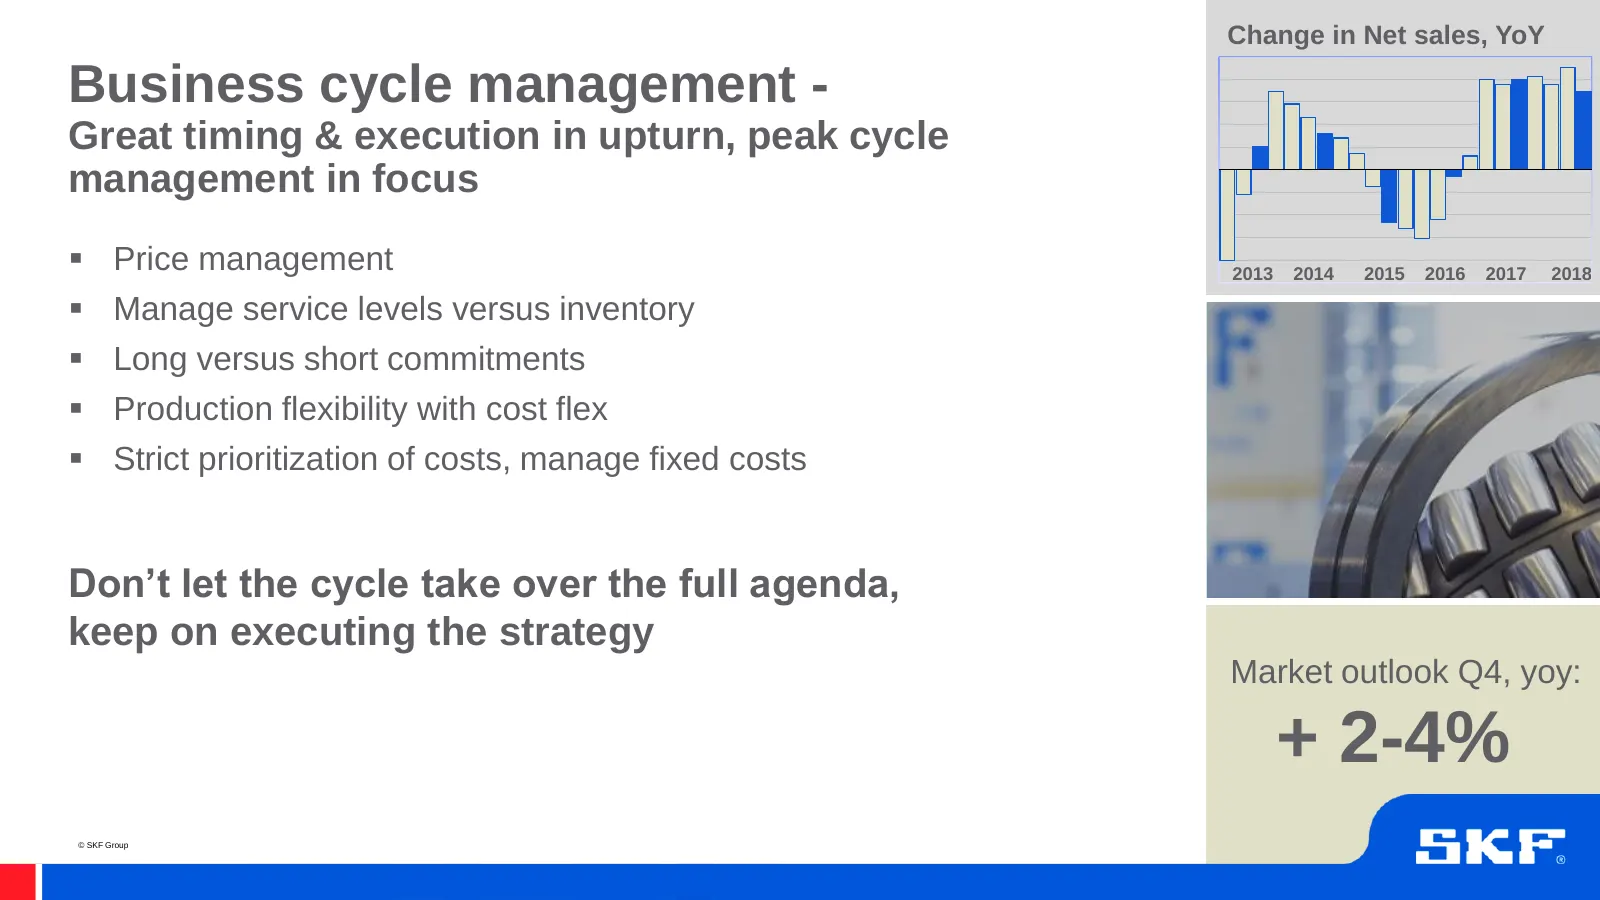
Change in Net sales, YoY Business cycle management - Great timing & execution in upturn, peak cycle management in focus ▪ Price management 2013 2014 2015 2016 2017 2018 ▪ Manage service levels versus inventory ▪ Long versus short commitments ▪ Production flexibility with cost flex ▪ Strict prioritiz
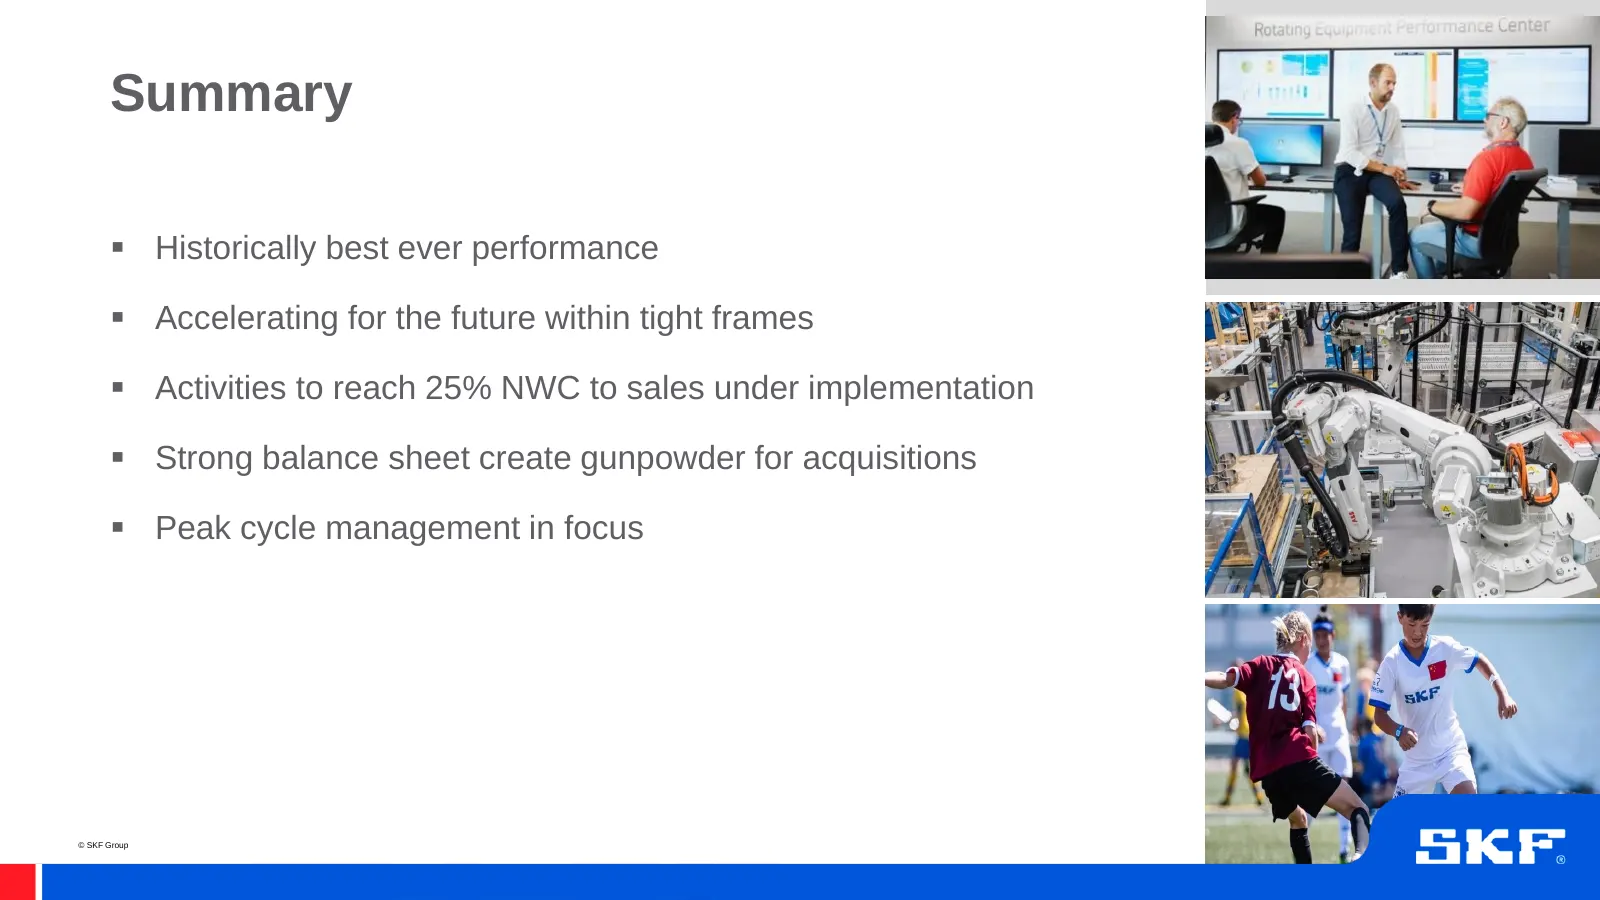
Slide 17: Summary
Summary ▪ Historically best ever performance ▪ Accelerating for the future within tight frames ▪ Activities to reach 25% NWC to sales under implementation ▪ Strong balance sheet create gunpowder for acquisitions ▪ Peak cycle management in focus © SKF Group
Source: Internet Archive copy of investors.skf.com
More decks from SKF AB Class A
 Q3 2026 Earnings Presentation20 slides · Oct 21, 2026
 SKF India — Q1 FY2026-27 Earnings Presentation20 slides · Aug 17, 2026
 Q2 2026 Earnings Presentation21 slides · Jul 17, 2026
 SKF India (Industrial) — Q4 FY2026 Earnings Presentation20 slides · May 13, 2026
 Q1 2026 Earnings Presentation22 slides · Apr 21, 2026
 Q4 2025 Earnings Presentation19 slides · Jan 30, 2026