Bay Bancorp — Shareholder Meeting (May 2014)
33 slides from Bay Bancorp's shareholder meeting presentation, May 14, 2014
Slide 1: Annual Shareholders Meeting Year-End Presentation
Bay Bancorp, Inc. Annual Shareholders Meeting Year-End Presentation Kevin B. Cashen - CEO May 14, 2014 _
Slide 2: Disclosure
Disclosure gQ BayBank This presentation contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and the Private Securities Litigation Reform Act of 1995 concerning Bay Bancorp Inc’s plans, strategies, objectives, expectations, intentions, financia
Slide 3: Agenda
Agenda gQ BayBank I. Overview of the Company Il. Market Update Ill. Bay Bancorp, Inc. 2013 Performance IV. Strategic Plan V. Summary
Slide 4: Overview of the Company
Agenda gQ BayBank 1. Overview of the Company
Slide 5: History of Bay Bank
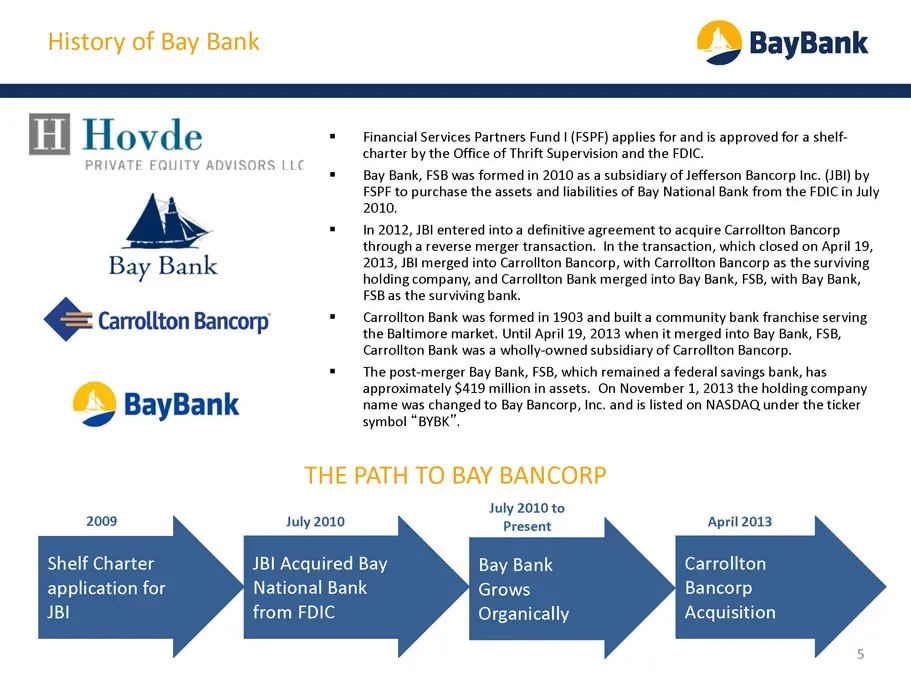
History of Bay Bank gQ BayBank Hovde = Financial Services Partners Fund | (FSPF) applies for and is approved for a shelf- Sai ive: CoLiiry anvisoeeure charter by the Office of Thrift Supervision and the FDIC. aia Bay Bank, FSB was formed in 2010 as a subsidiary of Jefferson Bancorp Inc. (JBI) by FSP
Slide 6: Management Team
Management Team gQ BayBank Kevin Cashen, CEO and President - Baltimore native with over 30 years of experience in community banking in Virginia and Maryland including Loyola Federal S&L, Signet Bank and Chevy Chase Bank. H. King Corbett, Chief Lending Officer - Baltimore native with over 35 years of
Slide 7: Board of Directors
Board of Directors Joseph J. Thomas, Executive Chairman Bay Bancorp and Bay Bank - Managing Director of Hovde Private Equity Advisors LLC, where he is responsible for the day-to-day operations of the fund. Mr. Thomas offers nearly 30 years of financial services experience and previously Head of Fina
Slide 8: Deposit Market Share & Branch Footprint
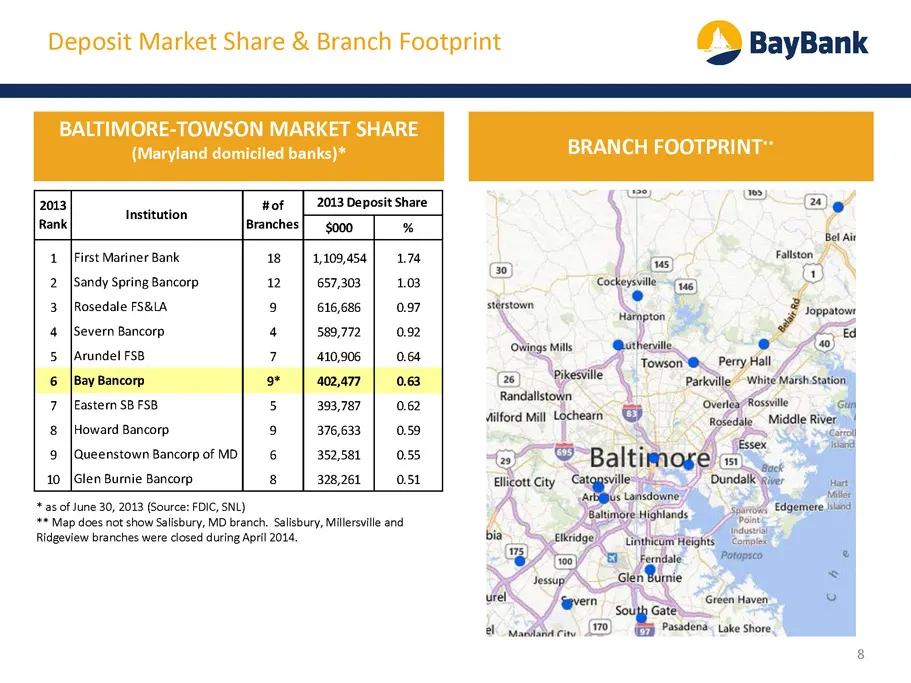
Deposit Market Share & Branch Footprint BALTIMORE-TOWSON MARKET SHARE (Maryland domiciled banks)* 218 of | 2013 Deposit Share Rank neiutton: Branches! $000 % 1. [First Mariner Bank 1s | 1109454] 1.74 2. |sandy Spring Bancorp 12 | 657,303 | 108, 3. [Rosedale FS&LA 9 | 616686 | 097 4. [Severn Bancorp
Slide 9: Comprehensive and Diverse Business Units
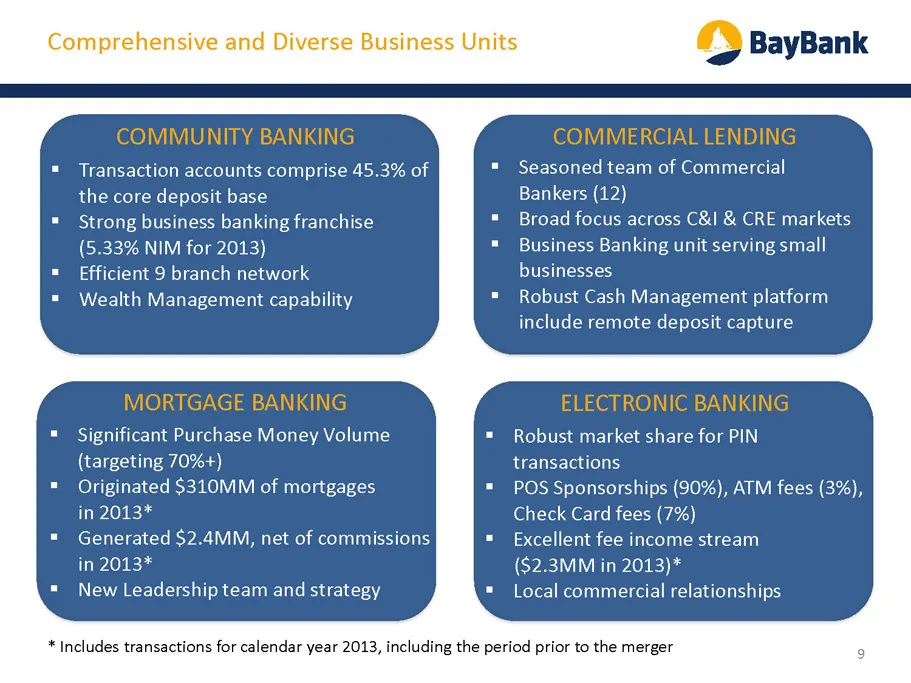
Comprehensive and Diverse Business Units Transaction accounts comprise 45.3% of the core deposit base Strong business banking franchise (5.33% NIM for 2013) Efficient 9 branch network Wealth Management capability Significant Purchase Money Volume (targeting 70%+) Originated $310MM of mortgages in 20
Slide 10: Security and Trading Overview
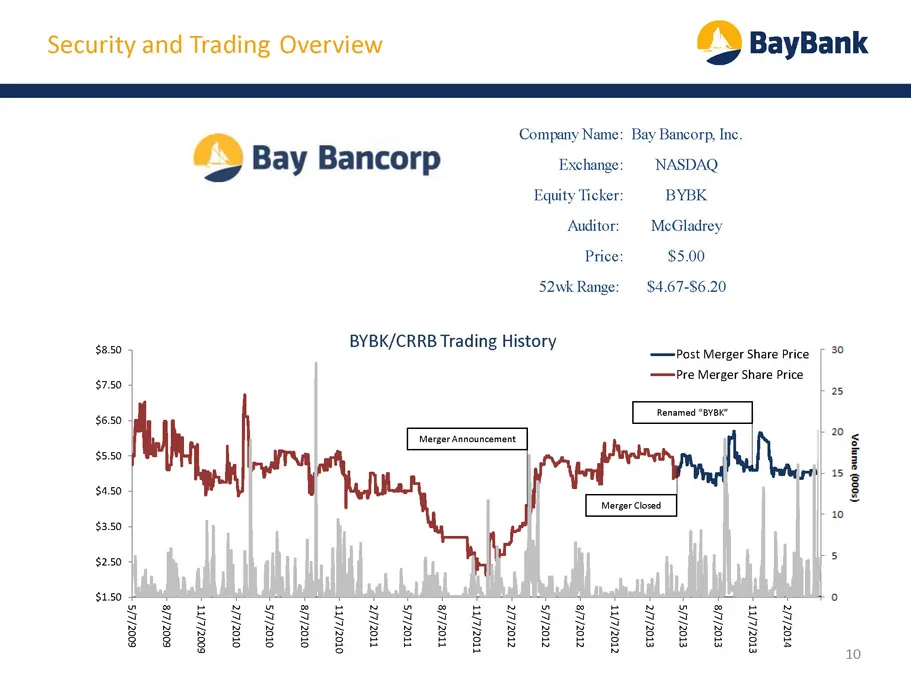
Security and Trading Overview gQ BayBank Company Name: Bay Bancorp, Inc. g Bay Bancorp Exchange: NASDAQ Ticker: BYBK Auditor: McGladrey Price: $5.00 S2wk Range: — $4.67-S6.20 a= BYBK/CRRB Trading History —snsceig ae riks —Pre Merger Share Price $750 4 S650 | [ese] w= ML Man i ' : wie annus eu one vr
Slide 11: Market Update
Agenda gQ BayBank Il. Market Update
Slide 12: Baltimore Rationale
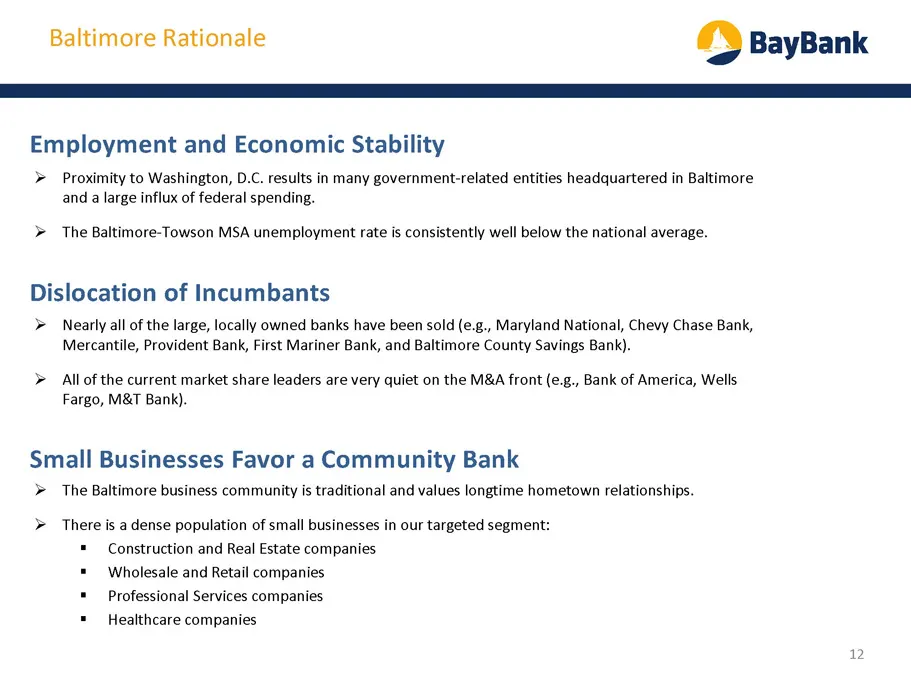
Baltimore Rationale gQ BayBank Employment and Economic Stability > Proximity to Washington, D.C. results in many government-related entities headquartered in Baltimore and a large influx of federal spending. > The Baltimore-Towson MSA unemployment rate is consistently well below the national average
Slide 13: Favorable Demographics
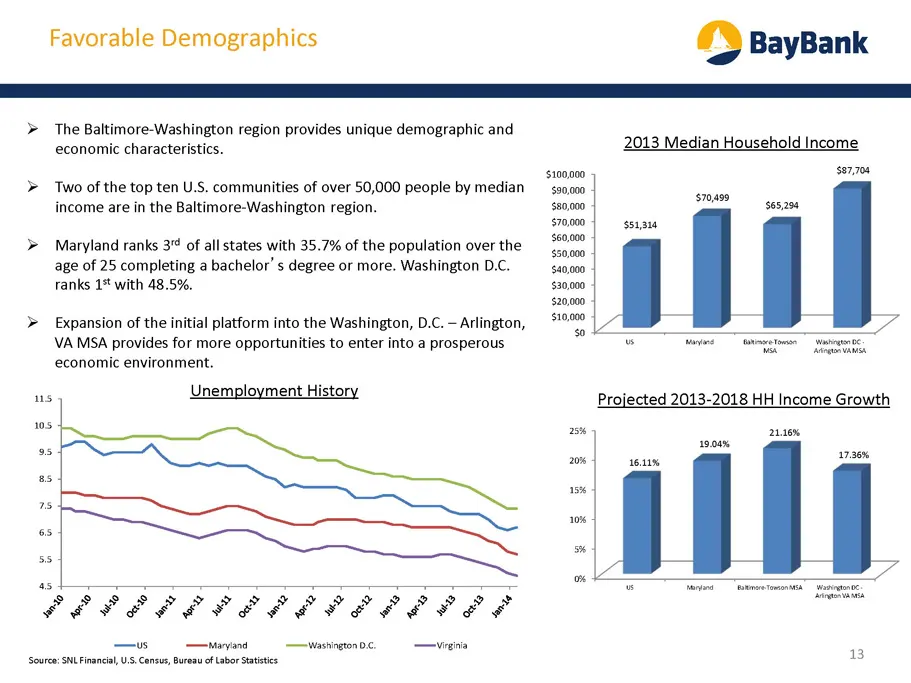
Favorable Demographics » The Baltimore-Washington region provides unique demographic and economic characteristics. > Two of the top ten U.S. communities of over 50,000 people by median income are in the Baltimore-Washington region. > Maryland ranks 3"¢ of all states with 35.7% of the population over
Slide 14: Dynamic Employment Base
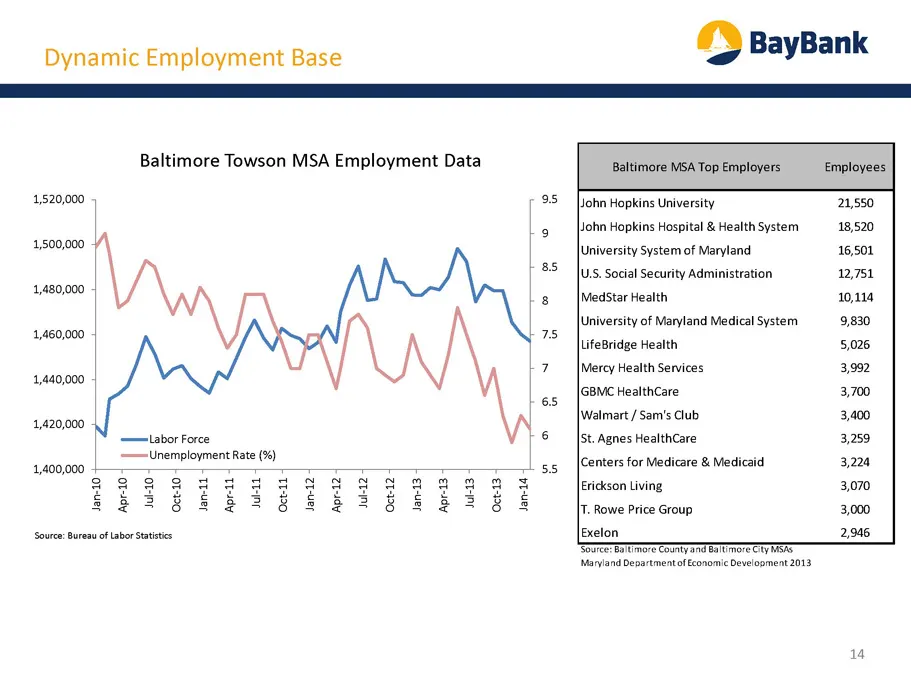
Dynamic Employment Base Baltimore Towson MSA Employment Data 1,520,000 1,500,000 4,480,000 4,460,000 1,440,000 1,420,000 —Labor Force 6 Unemployment Rate (%) 2,400,000 4 5s eee 3 33399999999 9 5 S228 82 28 S228 8228 5 Source: Bure of Labor Statistic gQ BayBank Baltimore MSA Top Employers Employees L
Slide 15: Lack of Local Leading Bank
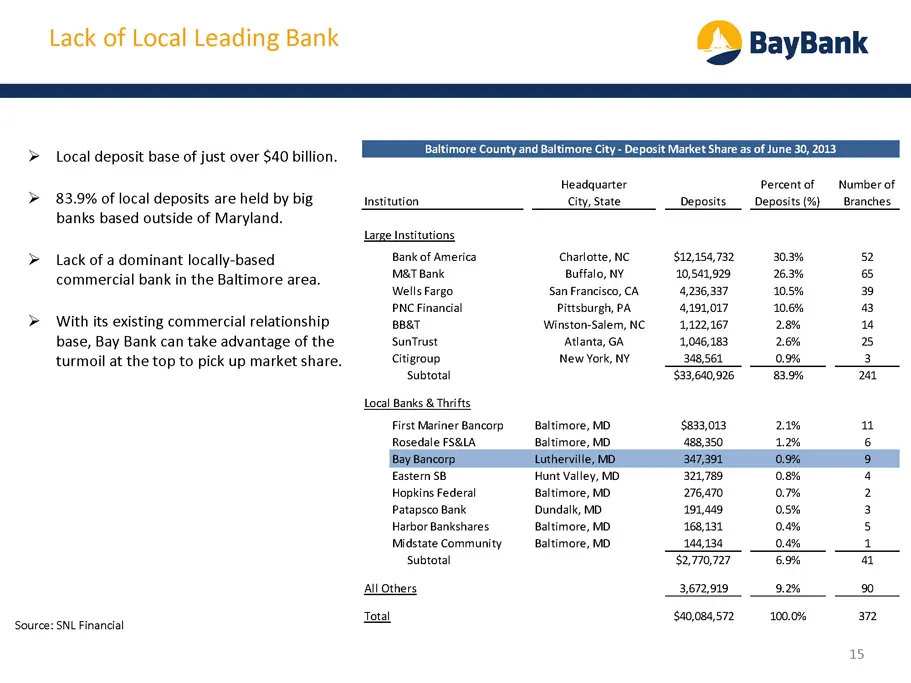
Lack of Local Leading Bank gQ BayBank Baltimore County and Baltimore City - Deposit Market Share as of June 30, 2013 > Local deposit base of just over $40 billion. A : | Headquarter Percentof Number of > 83.9% of local deposits are held by big. Institution City, State Deposits __Deposits (%} __ Bran
Slide 16: Bay Bancorp, Inc. / Bay Bank 2013 Performance
Agenda gQ BayBank Ill. Bay Bancorp, Inc. / Bay Bank 2013 Performance
Slide 17: Annual Financial Summary
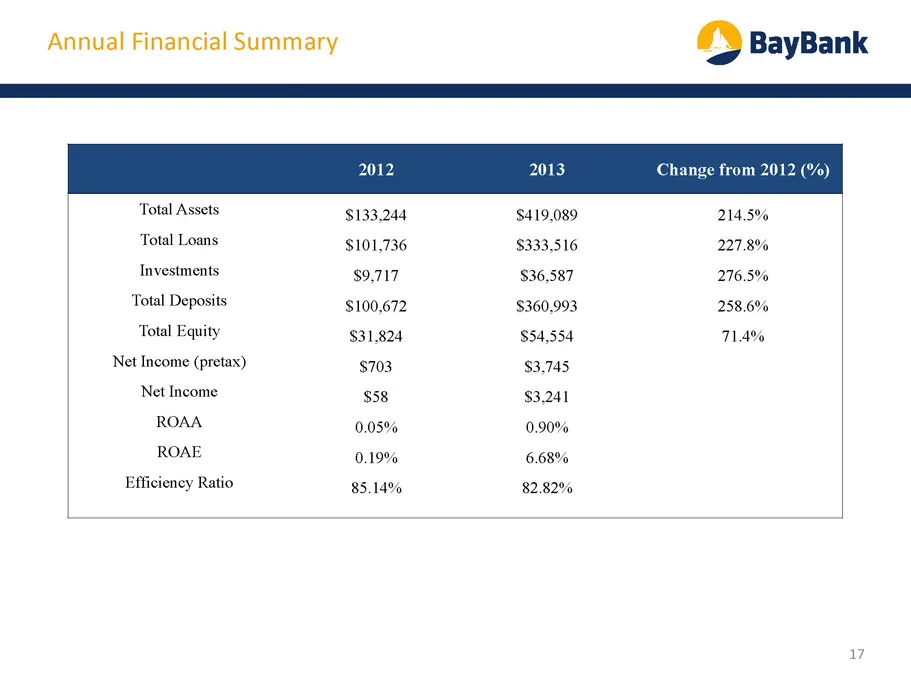
Annual Financial Summary Total Assets Total Loans Investments Total Deposits Total Equity Net Income (pretax) Net Income ROAA ROAE Efficiency Ratio $133,244 $101,736 $9,717 $100,672 $31,824 $703 $58 0.05% 0.19% 85.14% $419,089 $333,516 $36,587 $360,993 $54,554 $3,745, $3,241 0.90% 6.68% 82.82% 214.5
Slide 18: Highlights of 2013 Performance
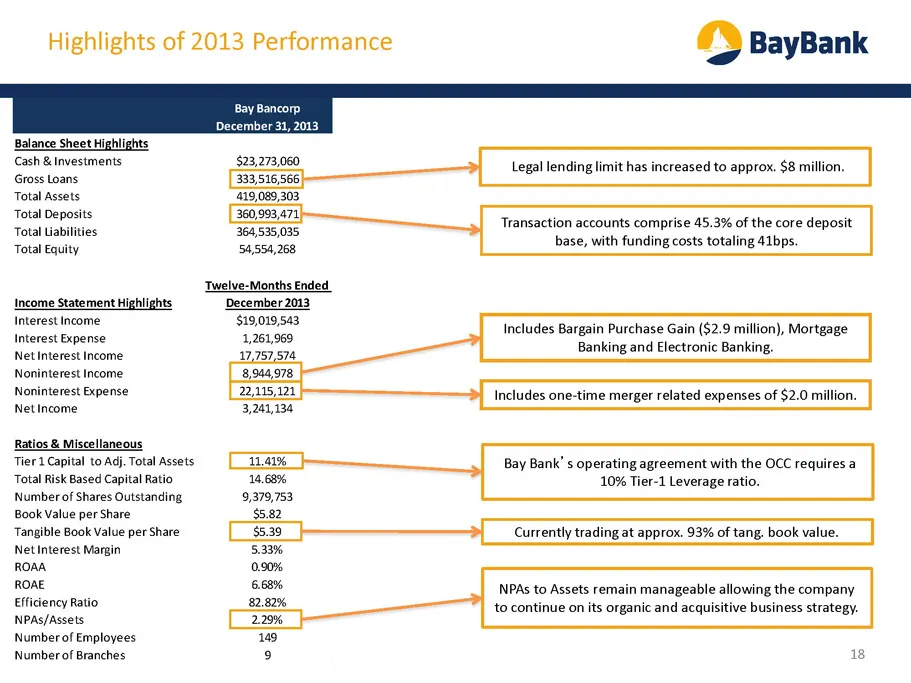
Highlights of 2013 Performance gQ BayBank Bay Bancorp December 31, 2013 Balance Sheet Highlights Cosh G bvectienis $23,273,060 Legal lending limit has increased to approx. $8 million. | Gross Loans 333,516,566) ee 8 PP Total Assets 419,089,303 Total Deposits 360,993,474 Transaction accounts comprise
Slide 19: Composition of Revenue
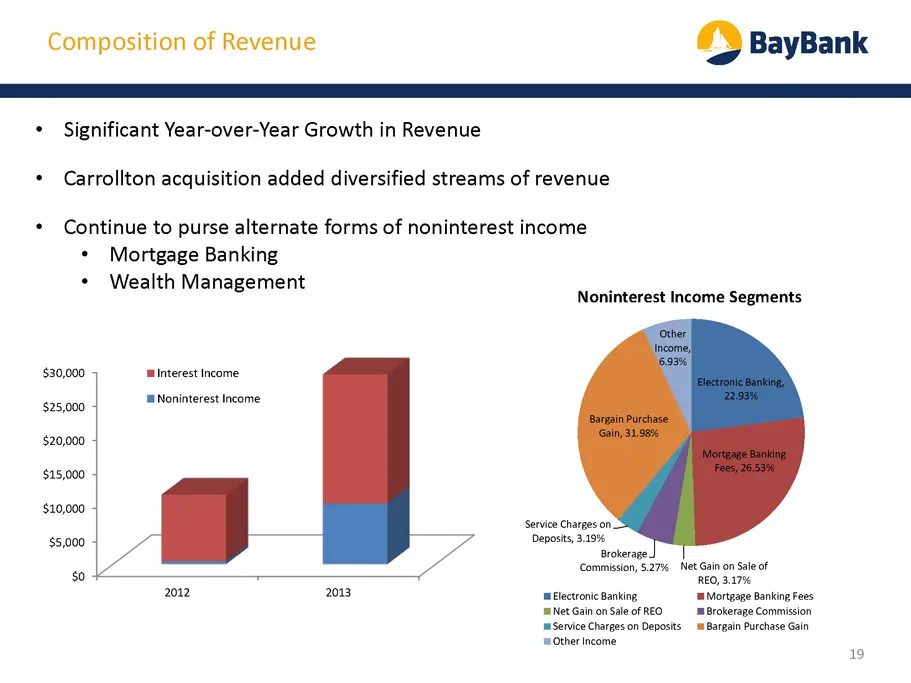
Composition of Revenue gQ BayBank * Significant Year-over-Year Growth in Revenue * Carrollton acquisition added diversified streams of revenue * Continue to purse alternate forms of noninterest income * Mortgage Banking * Wealth Management Noninterest Income Segments $30,000 interest Income 25080 mN
Slide 20: December 31, 2013 Loan & Deposit Composition
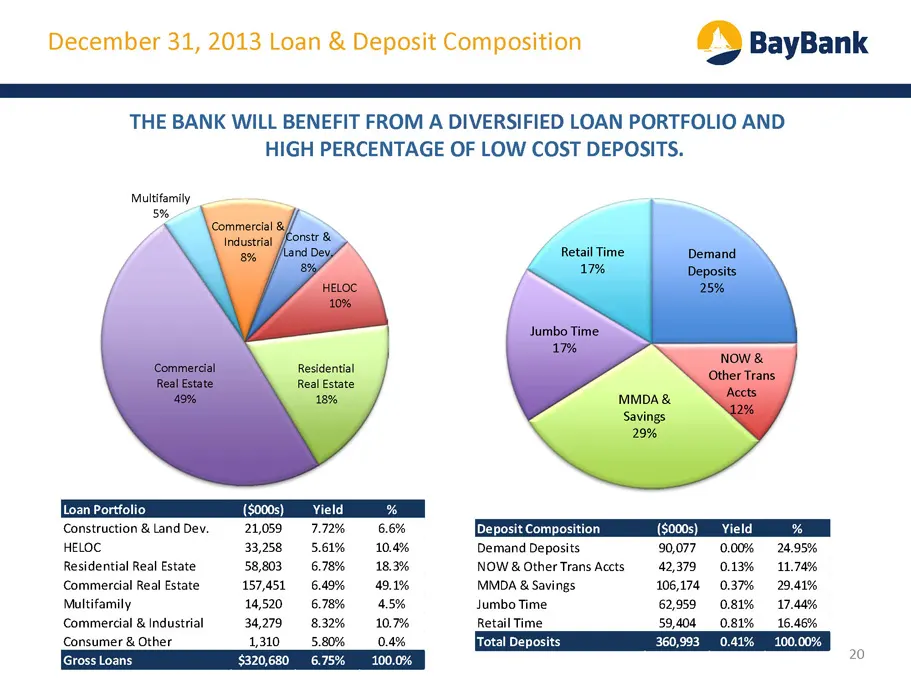
December 31, 2013 Loan & Deposit Composition gQ BayBank THE BANK WILL BENEFIT FROM A DIVERSIFIED LOAN PORTFOLIO AND HIGH PERCENTAGE OF LOW COST DEPOSITS. Multifamily 5% Loan Portfolio ($000s)__Yield Construction & Land Dev. 21,059 7.72% HELOC 33,258 5.61% Demand Deposits 90,077 0.00% 24.95% Resident
Slide 21: Loan Overview
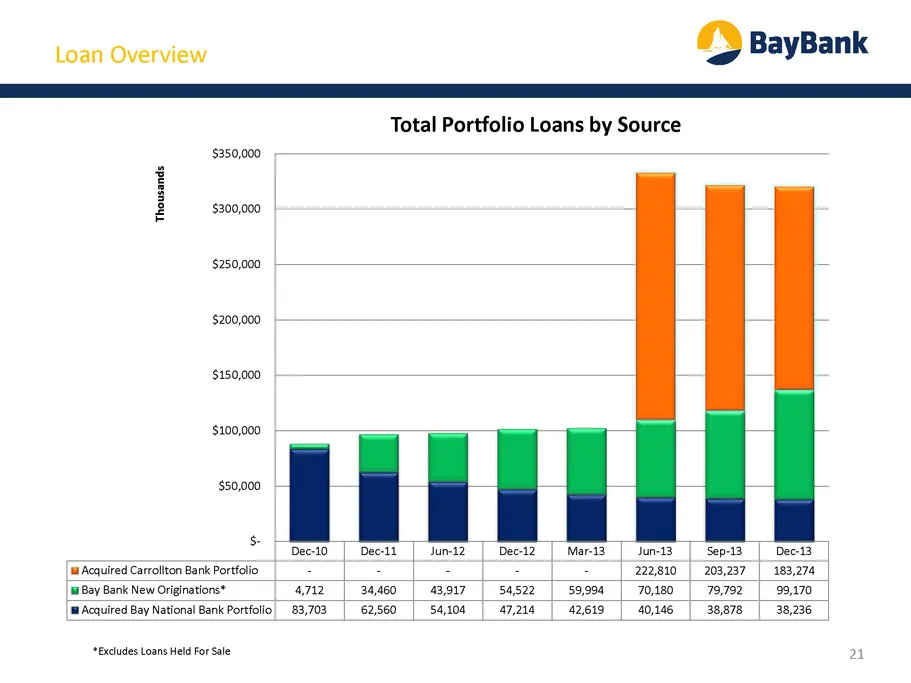
Loan Overview gQ BayBank Total Portfolio Loans by Source $350,000 $300,000 Thousands $250,000 $200,000 $150,000 Dec-it | _Junei2 T Jun-13 | Sep-t3_ | Deee3 ‘Whcquired Carroliten BarkPortolio | - = ~ | 222.10 | 203237 | 183,274 Bay Bank New Orginations™ a7 | 34460 | 43917 | 54522 | 59.998 | 70,180 |
Slide 22: Proven Asset Quality Resolution
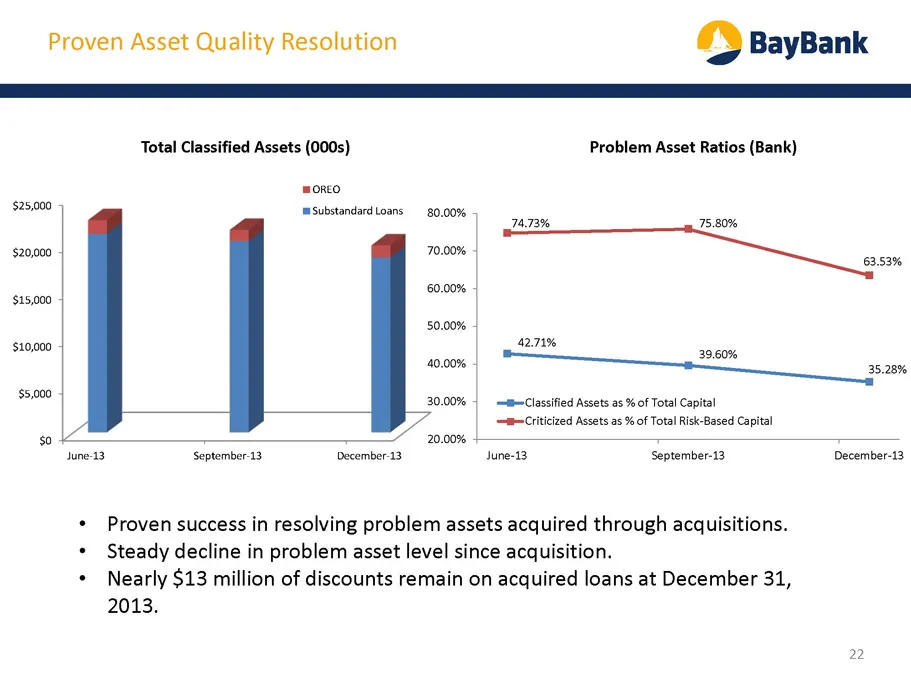
Proven Asset Quality Resolution gQ BayBank Total Classified Assets (000s) Problem Asset Ratios (Bank) moReO $25,000 Substandard Loans 80.00% + 747% 75.80% 70.00% _ ie. 60.00% + $15,000 50.00% | 30.00% | —meClassified Assets as % of Total Capital ‘e-Criticized Assets as % of Total Risk-Based Capital
Slide 23: Deposit & Funding Analysis
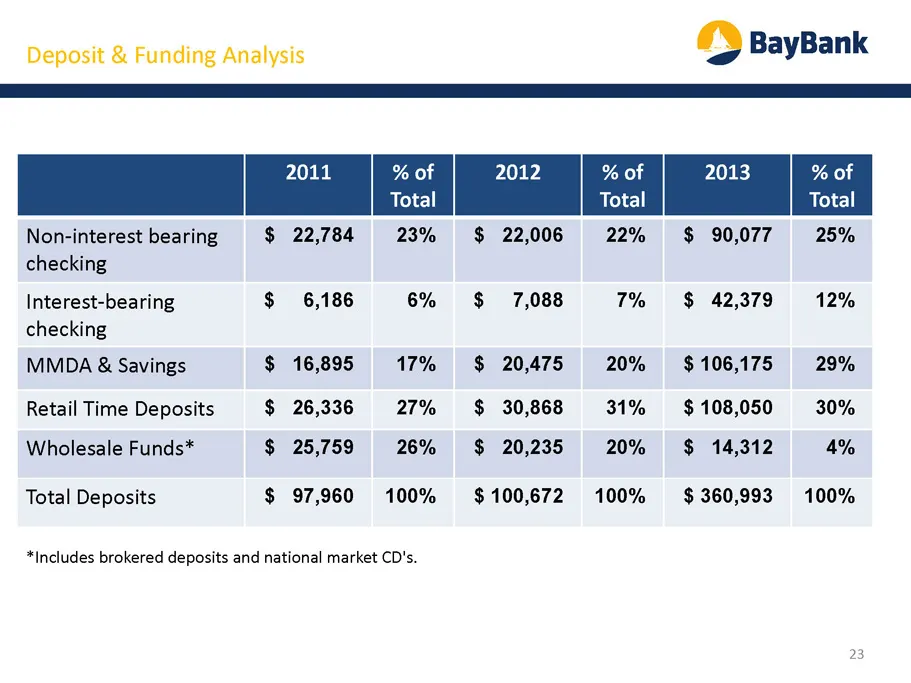
Deposit & Funding Analysis gQ BayBank 2011 % of of 2013 % of Total Total Total Non-interest bearing 22,784 23% $ 22,006 22% $ 90,077 25% checking Interest-bearing $ 6,186 6% $ 7,088 7% $ 42,379 12% checking MMDA & Savings $ 16,895 17% $ 20,475 20% $106,175 29% Retail Time Deposits $ 26,336 27% $ 30,
Slide 24: BYBK Peer Analysis
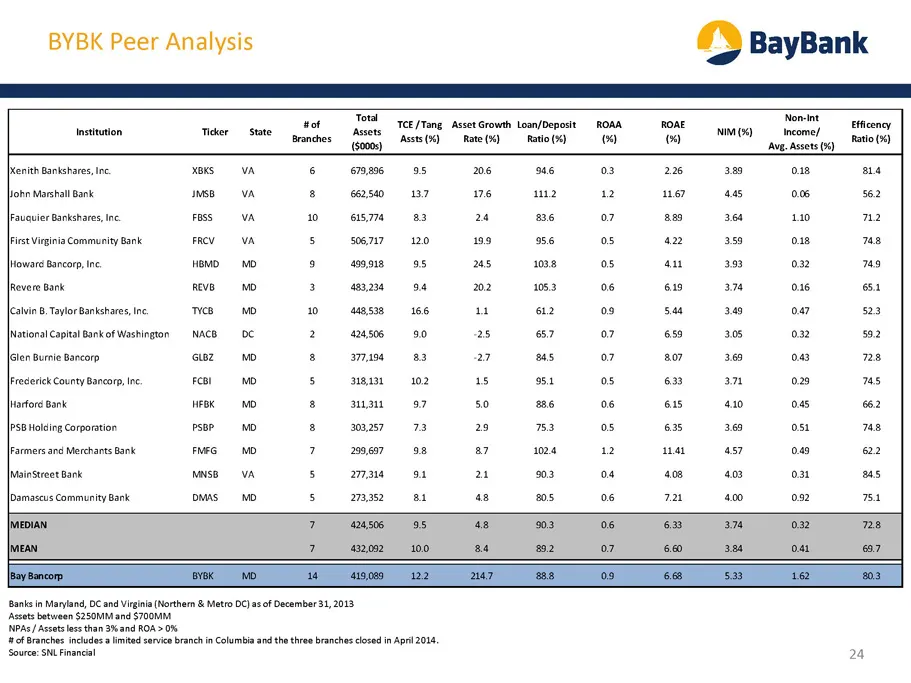
BYBK Peer Analysis gQ BayBank Hof Total TCE /Tang Asset Growth Loan/Deposit ROAA ROAE Lica Efficenc mse rier oe gS eee TE Manco est fk EAE dele a 22 ee re ‘Banks in Maryland, OC and Viegiia (Norther & Metro OC) as of December, 2013 Assets between $250MM and $700MNI "NPAs / Asstslass than 3% and ROA>
Slide 25: Strategic Plan for Bay Bancorp, Inc. / Bay Bank
Agenda gQ BayBank IV. Strategic Plan for Bay Bancorp, Inc. / Bay Bank 25
Slide 26: Strategic Vision
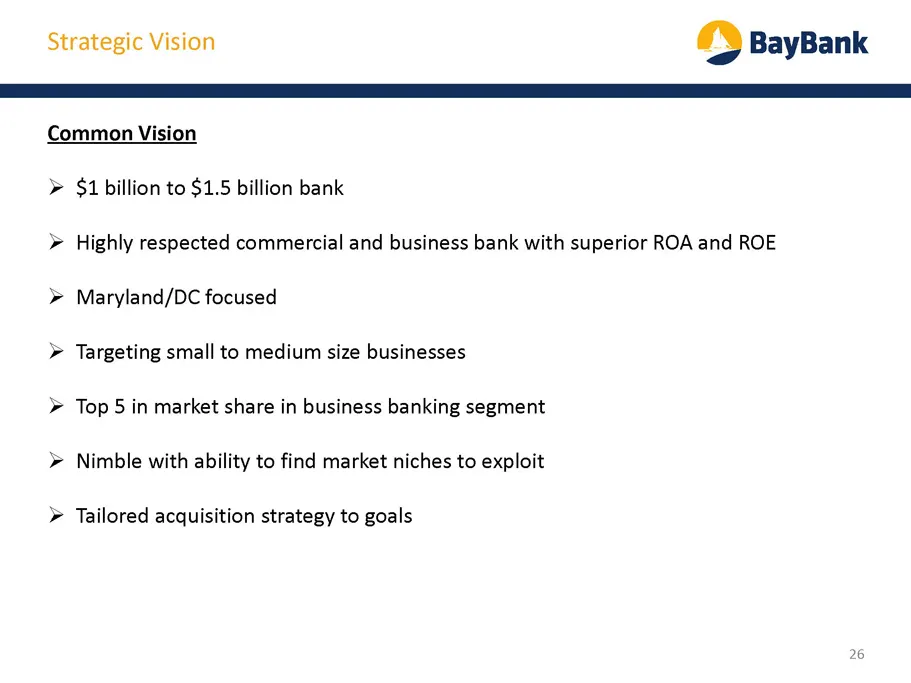
Strategic Vision gQ BayBank Common Vision > $1 billion to $1.5 billion bank Highly respected commercial and business bank with superior ROA and ROE Vv » Maryland/DC focused > Targeting small to medium size businesses Top 5 in market share in business banking segment Vv >» Nimble with ability to find
Slide 27: High Quality Employees / Financial Stewardship
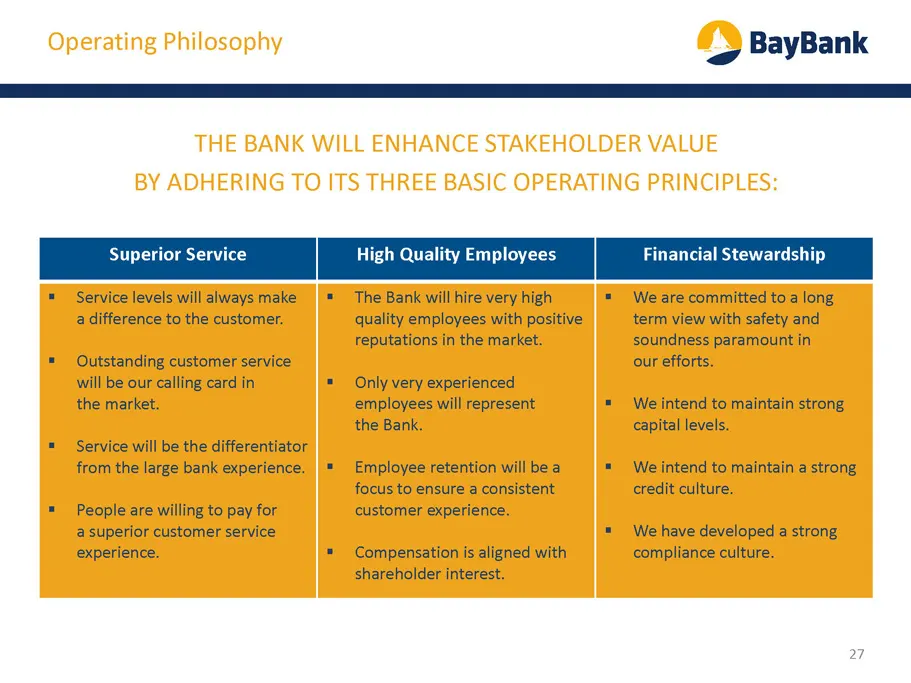
“> BayBank High Quality Employees Financial Stewardship Service levels will always make a difference to the customer. Outstanding customer service will be our calling card in the market. Service will be the differentiator from the large bank experience. People are willing to pay for a superior custo
Slide 28: Improving Profitability - Initiatives for 2014
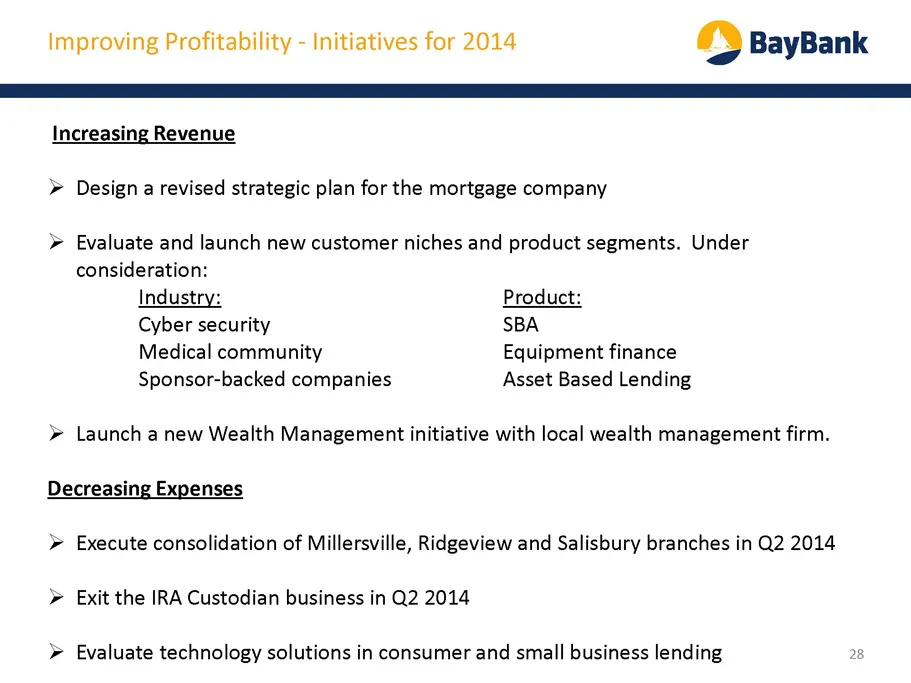
Improving Profitability - Initiatives for 2014 gQ BayBank Increasing Revenue > Design a revised strategic plan for the mortgage company > Evaluate and launch new customer niches and product segments. Under consideration: Industry: Product: Cyber security SBA Medical community Equipment finance Spons
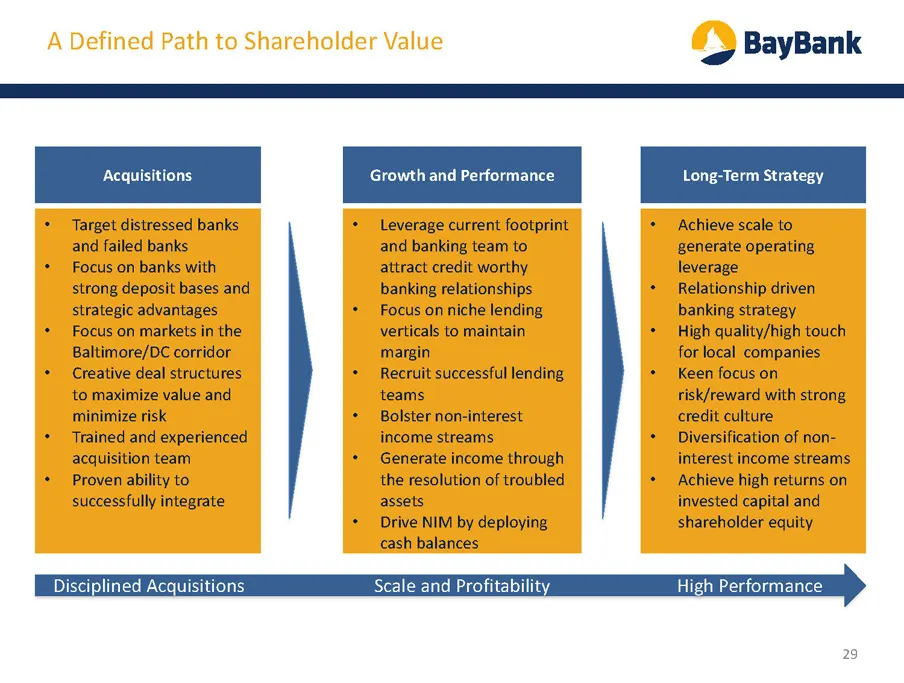
Slide 29: Growth Strategy: Acquisitions, Organic Growth, Scale
_o BayBank eet metres ee eee + Target distressed banks + Leverage current footprint + Achieve scale to and failed banks and banking team to generate operating * Focus on banks with attract credit worthy leverage strong deposit bases and banking relationships + Relationship driven strategic advantage
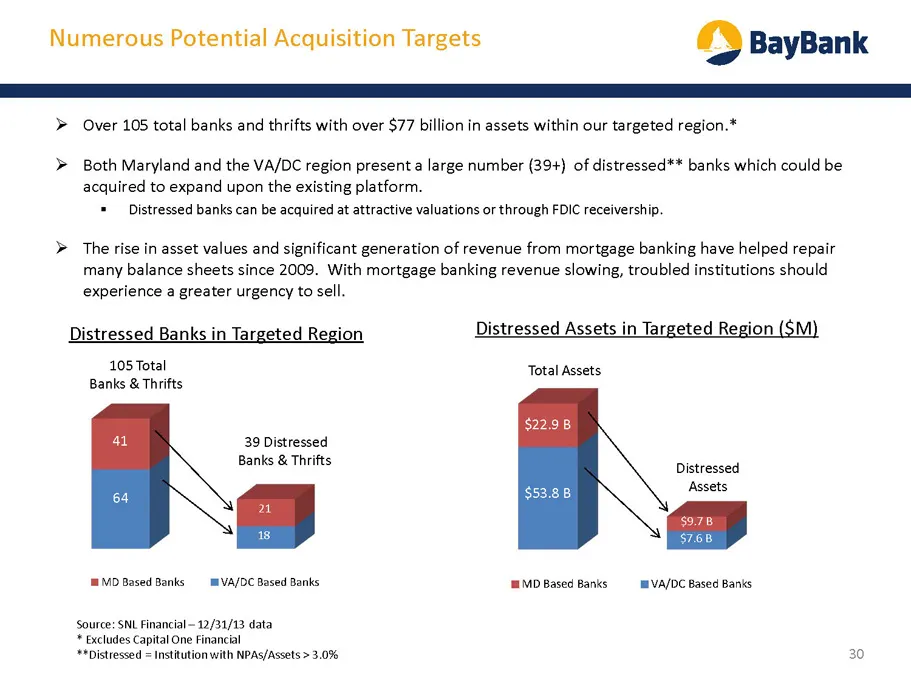
Slide 30: Numerous Potential Acquisition Targets
Numerous Potential Acquisition Targets gQ BayBank » Over 105 total banks and thrifts with over $77 billion in assets within our targeted region.* > Both Maryland and the VA/DC region present a large number (39+) of distressed** banks which could be acquired to expand upon the existing platform. = Di
Slide 31: Summary
Agenda gQ BayBank Vv. Summary 31
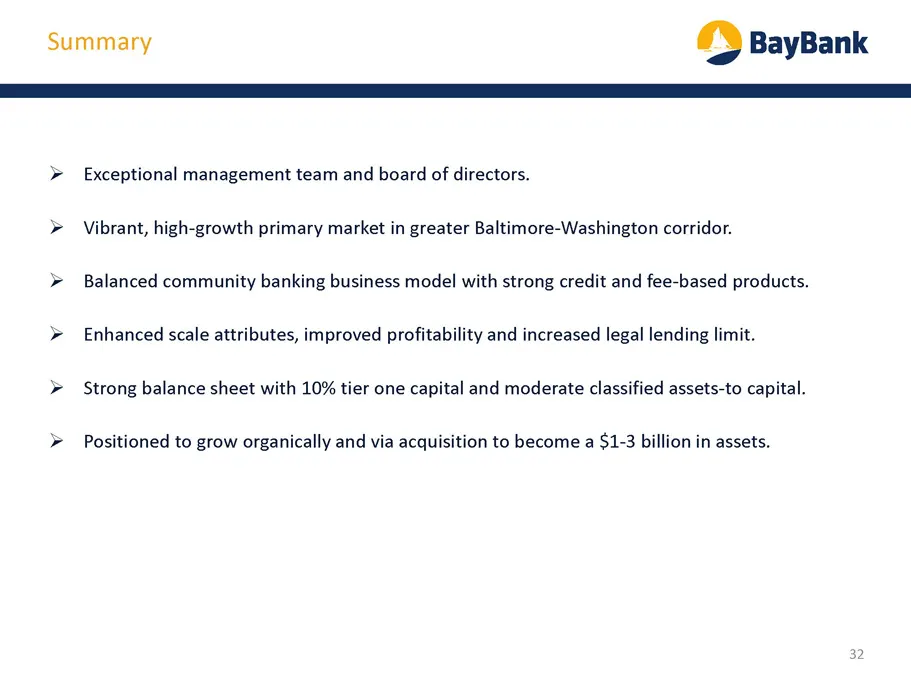
Slide 32: Summary
Summary gQ BayBank > Exceptional management team and board of directors. > Vibrant, high-growth primary market in greater Baltimore-Washington corridor. > Balanced community banking business model with strong credit and fee-based products. > Enhanced scale attributes, improved profitability and incr
Slide 33: Contact Information
Contact Information g Bay Bancorp Joseph J. Thomas Executive Chairman (410) 536-7336 jthomas@baybankmd.com 7151 Columbia Gateway Drive, Suite A Columbia, MD 21046 Kevin B. Cashen Chief Executive Officer 410-427-3707 kcashen@baybankmd.com 2328 West Joppa Road Suite 325 Lutherville, MD 21093 gQ BayBan
Source: SEC EDGAR · 8-K filed May 14, 2014
More decks from Bay Bancorp Inc
 FIG Partners Community Bank Forum 201735 slides · Jun 26, 2017
 Shareholder Meeting (May 2017)18 slides · May 24, 2017
 Investor Presentation (February 2017)37 slides · Feb 7, 2017
 Shareholder Meeting (May 2016)47 slides · May 25, 2016
 Merger or Acquisition (January 2016)15 slides · Jan 27, 2016
 FIG Partners Bank CEO Forum (September 2015)41 slides · Sep 29, 2015