Crystal River Capital — Investor Presentation (November 2007)
23 slides from Crystal River Capital's investor presentation, Nov 15, 2007
Slide 1: Investor Presentation November 2007
Investor Presentation November 2007
Slide 2: Forward Looking Statement
2 Forward Looking Statement Some of the statements contained in this presentation are “forward looking statements” within the meaning of Section 21E of the Securities Exchange Act of 1934 and Section 27A of the Securities Act of 1933 that involve risks, uncertainties and assumptions with respect to
Slide 3: Agenda
3 Agenda Company overview Compelling business model Portfolio and growth strategy
Slide 4: At A Glance
4 At A Glance Specialty finance REIT invests in debt or debt-like instruments across the real estate spectrum NYSE: CRZ market cap ~$420M (1) total assets: $2.9B (1) 7% owned by parent company / management / directors (1) As of September 30, 2007
Slide 5: A Company on the Move
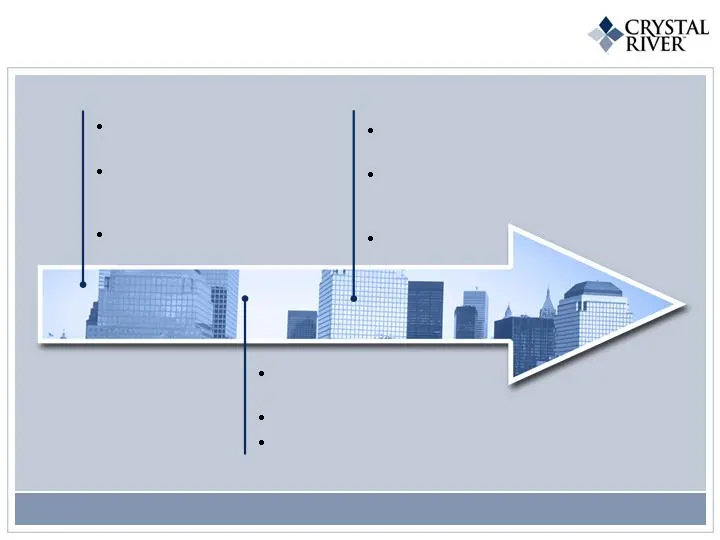
5 A Company on the Move Private offering raised $406M First CDO financing $378M (ratings affirmed by Fitch in Aug 2007) Paid 3 dividends 2005 Second CDO financing $390M Solid performance despite market volatility Stable dividends 2007 August IPO raised $159M Paid 4 dividends Assets increased 41% 200
Slide 6: A Dynamic, Flexible Investment Strategy
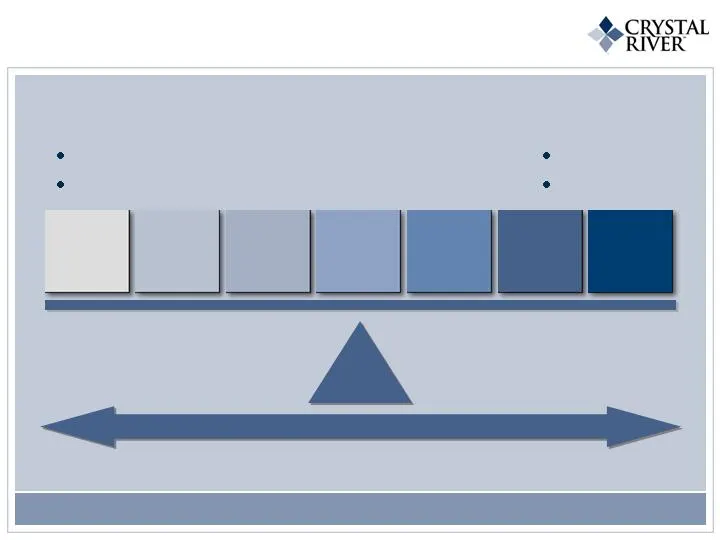
B-Notes/ Mezzanine CRE debt Real Estate Equity Alternative Real Estate Assets 6 A Dynamic, Flexible Investment Strategy High grade High leverage High yield Low leverage Agency MBS Non-Agency MBS Other ABS CMBS
Slide 7: Partnered with Leading Investment Managers
7 Partnered with Leading Investment Managers Externally managed by subsidiaries of Brookfield Asset Management (NYSE: BAM) $80B AUM, 50 offices and 300 investment professionals worldwide * superior track record $23B in CMBS, RMBS and ABS for major pension plans, national banks and insurance companie
Slide 8: Agenda
8 Agenda Company overview Portfolio and growth strategy Compelling business model
Slide 9: Our Cornerstone: Relative Value Approach
9 Our Cornerstone: Relative Value Approach = Best investment opportunities Macroeconomic analysis Sector level Security level Relative value among issuers Relative value between fixed income sectors Long-term macro- economic trends
Slide 10: Powerful Proprietary and External Analytical Platform
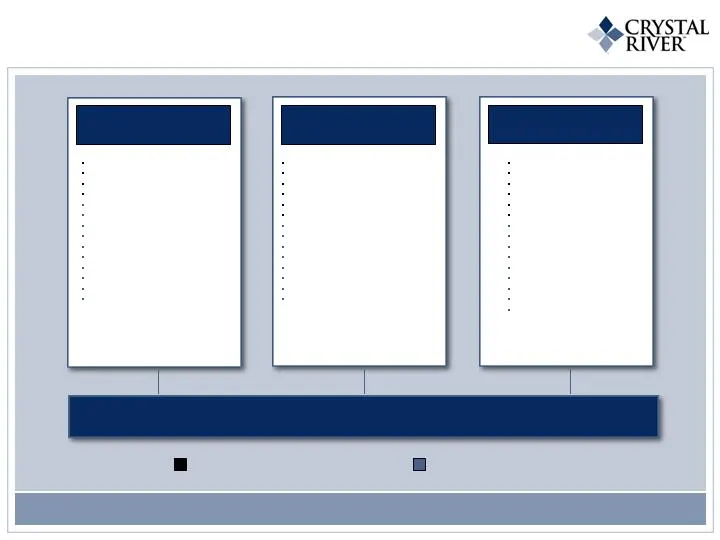
Analytical Platform CMBS Residential MBS / ABS Corporate Credit 10 Powerful Proprietary and External Analytical Platform Shortfall Model Surveillance Scoring Model Loan Level Default / Loss Model Tenant Credit Scoring System Realpoint Trepp Intex PolyPaths REIS Co-Star Shopping Center Directory Wach
Slide 11: Experienced Investment Management Team
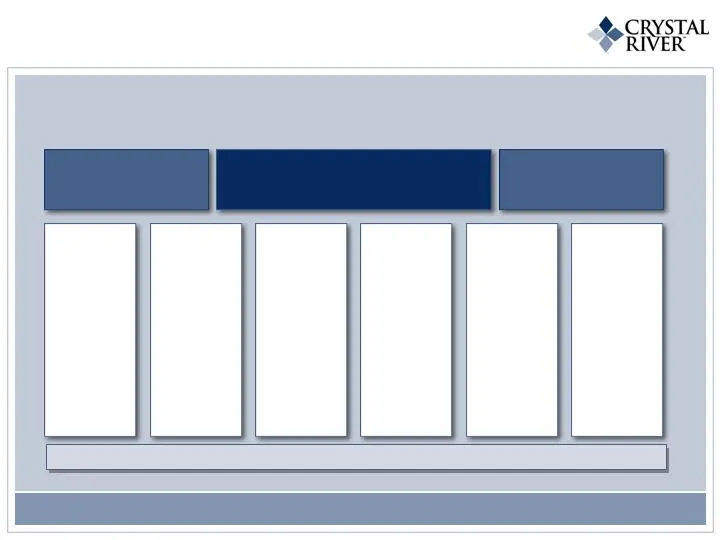
Clifford Lai, President & CEO Jon Tyras, General Counsel/ Corp. Secretary Craig Laurie, Chief Financial Officer 11 Experienced Investment Management Team CMBS and CRE Management (10) RMBS Management (15) Agency MBS & Cash Management CDO Management (2) Finance & Accounting (5) Investor Relations (1)
Slide 12: Efficient Financing Strategy
12 Efficient Financing Strategy Match-fund assets and liabilities Leverage targets for each asset class Strong relationships with banks short term: repurchase agreements, warehouse facilities, bank facilities long term: CDOs, bank term funding Closed second CDO in Q1 2007 for $390M attractive, cost-
Slide 13: Our Assets Are Well Financed
(As of September 30, 2007) ($ in millions) Asset Carrying Value CDO Debt (1) Funding Facilities (2) Repurchase Agreements Other Term Debt 13 Our Assets Are Well Financed (1) CDO debt has been allocated based upon the asset mix within the Company’s CDOs (2) Related party repurchase agreement of $37.3
Slide 14: Stable Dividends, Attractive Yield
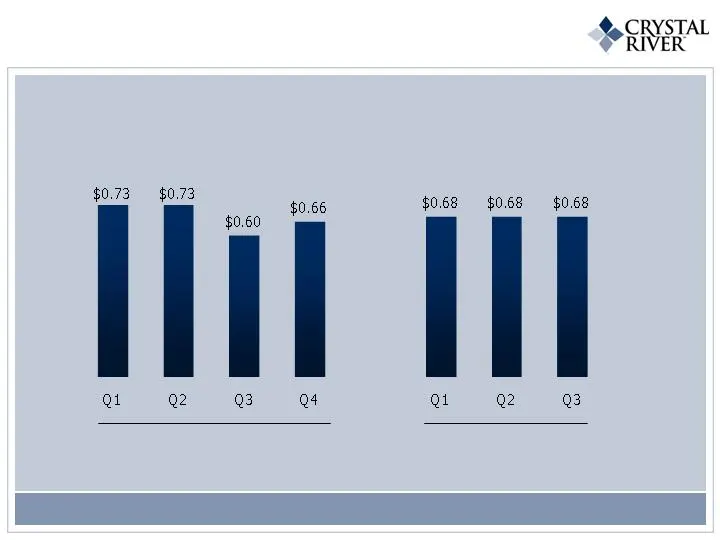
14 Stable Dividends, Attractive Yield Quarterly Dividend 2006 2007
Slide 15: Agenda
15 Agenda Company overview Compelling business model Portfolio and growth strategy
Slide 16: Sector Comment / Outlook Current Asset Allocation
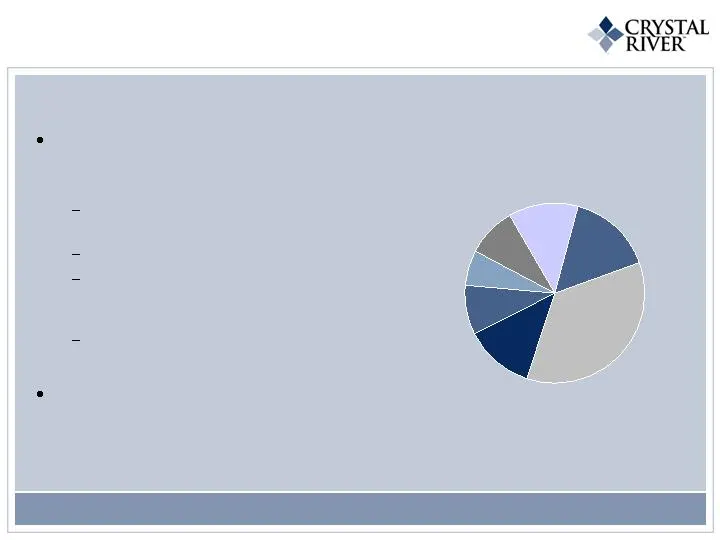
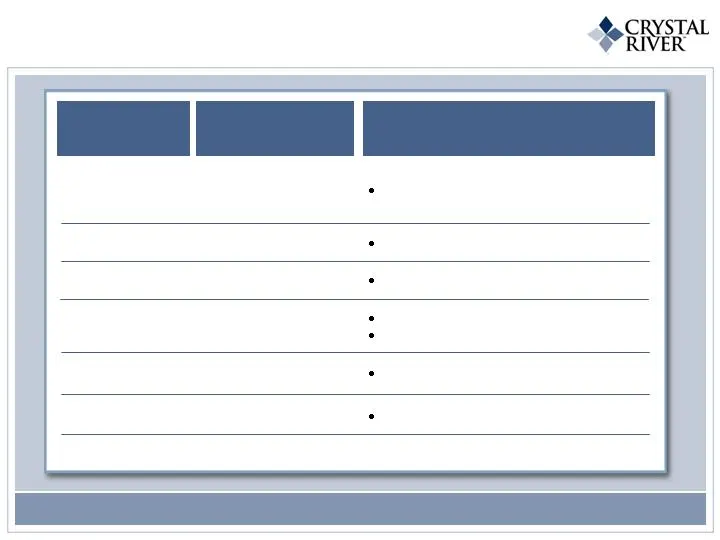
Sector Comment / Outlook Current Asset Allocation 16 CRE debt & equity 18% Continued focus, strong fundamentals Portfolio Snapshot (1) Agency MBS 54% Reduced position to reinvest from lower- yielding into higher-yielding assets CMBS 18% Continued focus, strong fundamentals Non-Agency RMBS 8% Only $7
Slide 17: Target Asset Classes – Commercial Real Estate
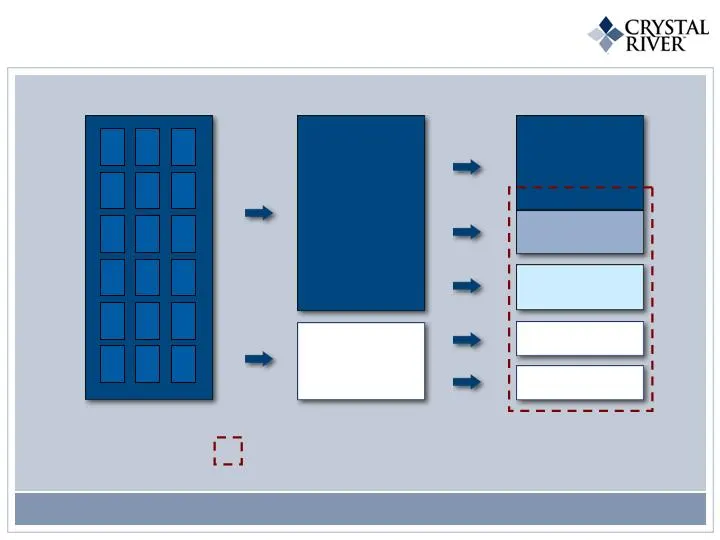
$400 Million Large Loan Investment- Grade CMBS $500 Million Office Tower 17 Target Asset Classes – Commercial Real Estate $100 Million Equity (Real estate company owns or controls the property) $25 Million Mezzanine Loan $75 Million Equity* Subordinated CMBS or “B-Pieces” $50 Million B-Note Targeted
Slide 18: Target Asset Classes – Residential Real Estate
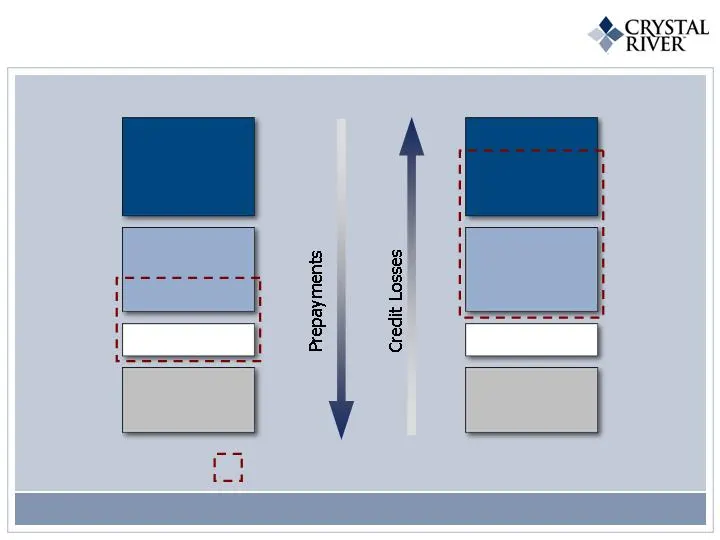
AAA AAA 18 Target Asset Classes – Residential Real Estate Prime RMBS Sub-Prime RMBS AA - BBB BB – First-Loss Homeowner Equity AA - BBB BB – First-Loss Homeowner Equity Targeted Crystal River Investments
Slide 19: Our Portfolio "Dashboard"
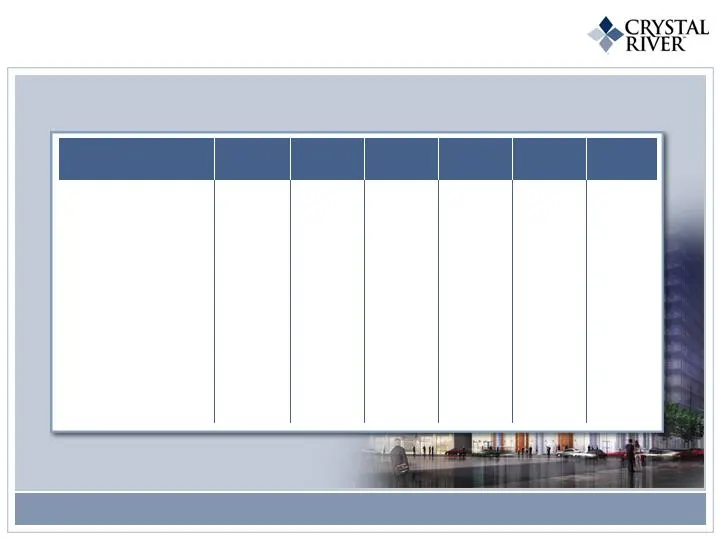
Agency MBS RMBS CMBS CRE Debt & Equity Alternatives / ABS Blended 19 Our Portfolio “Dashboard” Assumptions based on current market conditions and may change based on future developments Equity Allocation (%) 20-25 20 -25 20 - 25 20 - 25 0 - 5 Asset Allocation (%) 45-50 5 -10 20 - 25 10 - 15 1 - 5 As
Slide 20: Well Positioned in Current Market Environment
$160M 2M shares 91% 3% $40M 20 Well Positioned in Current Market Environment (1) Unencumbered assets to provide potential liquidity Stock repurchase approved August 2007 (1) As of September 30, 2007 Term financing of non “Agency MBS” assets Percent of portfolio in sub-prime RMBS Strong cash position
Slide 21: Portfolio Strategy
Long-term Short-term 21 Portfolio Strategy Until debt & equity markets return: Reallocate from lower-yielding to higher- yielding assets Repurchase shares at attractive levels Focus on adding attractive commercial real estate equity opportunities Manage liquidity Provide stable dividend for investor
Slide 22: Why Invest in Crystal River
22 Why Invest in Crystal River Compelling business model leading investment managers, dynamic multi-sector approach Strong backing through the Brookfield platform proprietary deals, sharing of expertise Well-financed portfolio with attractive ROEs Match-term funding, niche sectors
Slide 23: Investor Presentation
Investor Presentation November 2007
Source: SEC EDGAR · 8-K filed Nov 15, 2007