Nedbank Group · JSE:NED
Nedbank — Investor Day (November 2013)
91 slides from Nedbank's investor day presentation, November 2013
Slide 1: Charting a new path to sustainable, profitable growth: Strategy update on progress & prospects
Nedbank Retail Charting a new path to sustainable, profitable growth: Strategy update on progress & prospects Retail Investor Day, November 2013
Slide 2: Make things happen
MAKE (©) THINGS HAPPEN NEDBANK
Slide 3: Repositioning Retail – presentation topics
Repositioning Retail – presentation topics ▪ Executive Summary ▪ What we set out to do in 2010 ▪ Progress to date ▪ How we achieved it ▪ Future trends & prospects 3
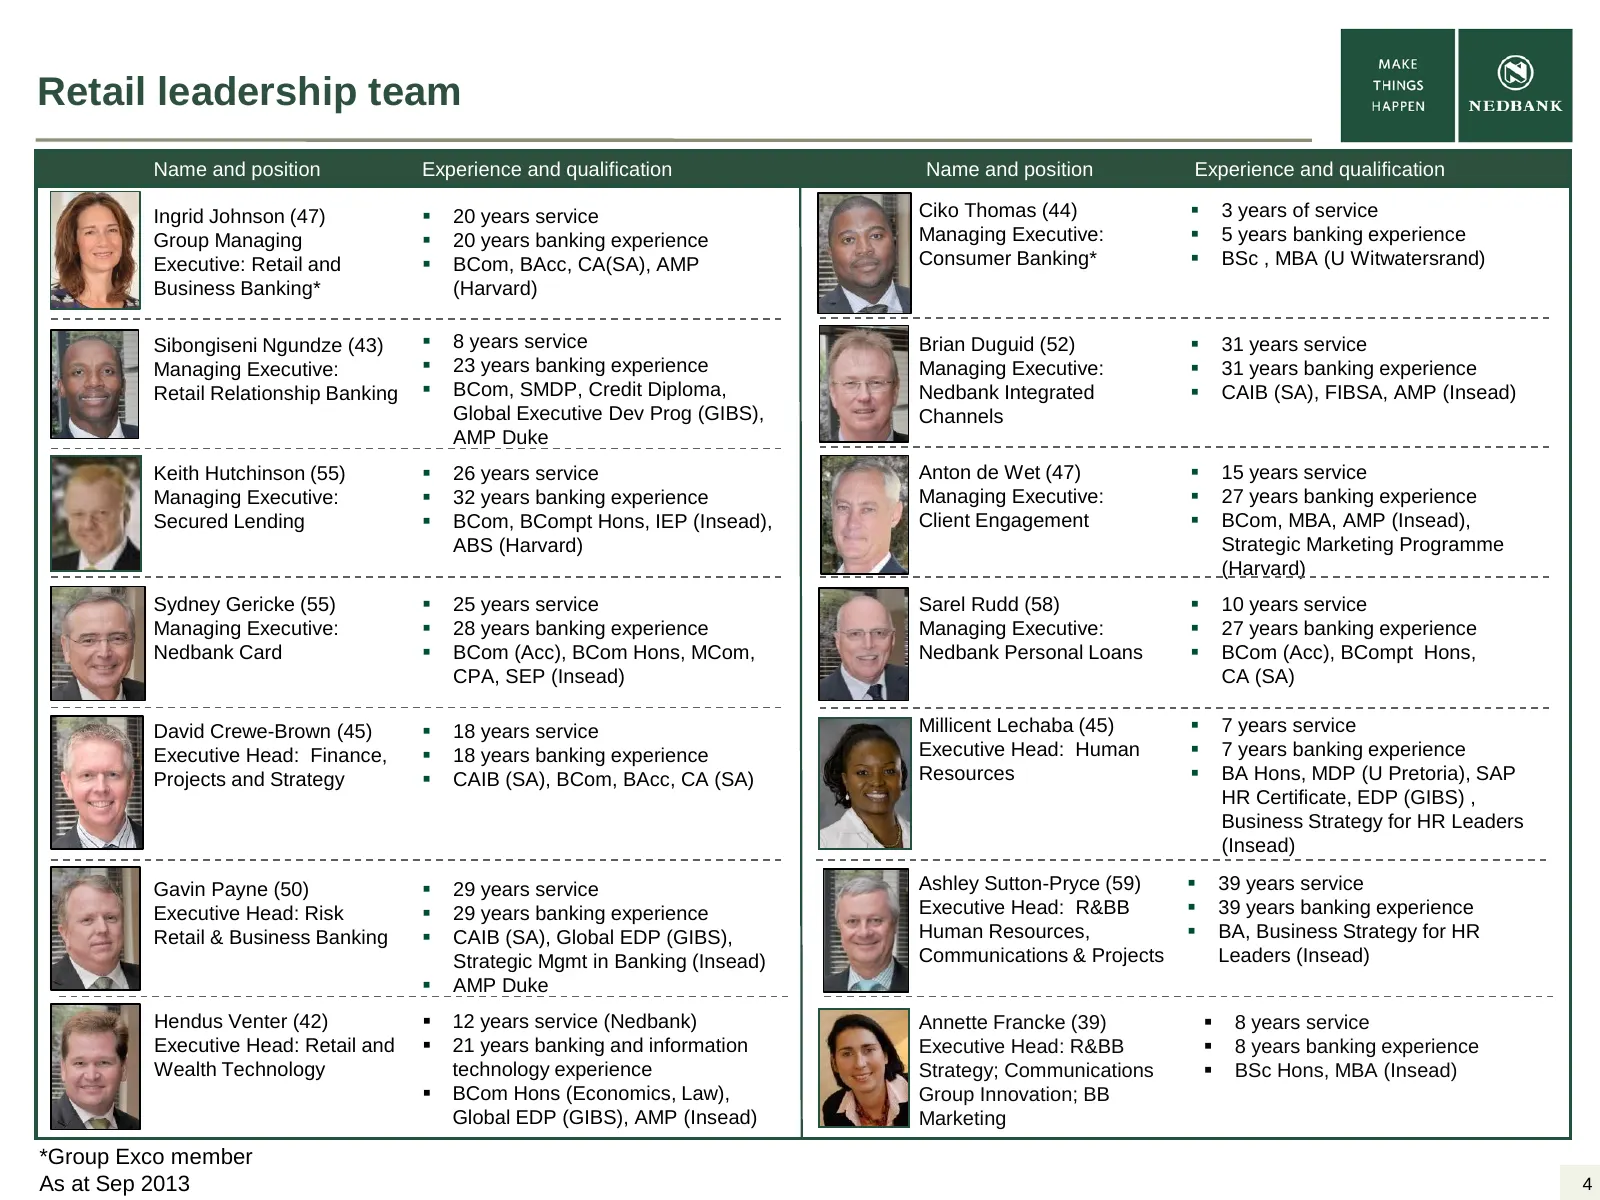
Slide 4: Retail leadership team
Retail leadership team Name and position Experience and qualification Name and position Experience and qualification Ingrid Johnson (47) 20 years service Ciko Thomas (44) 3 years of service Group Managing 20 years banking experience Managing Executive: 5 years banking experience Executive: R
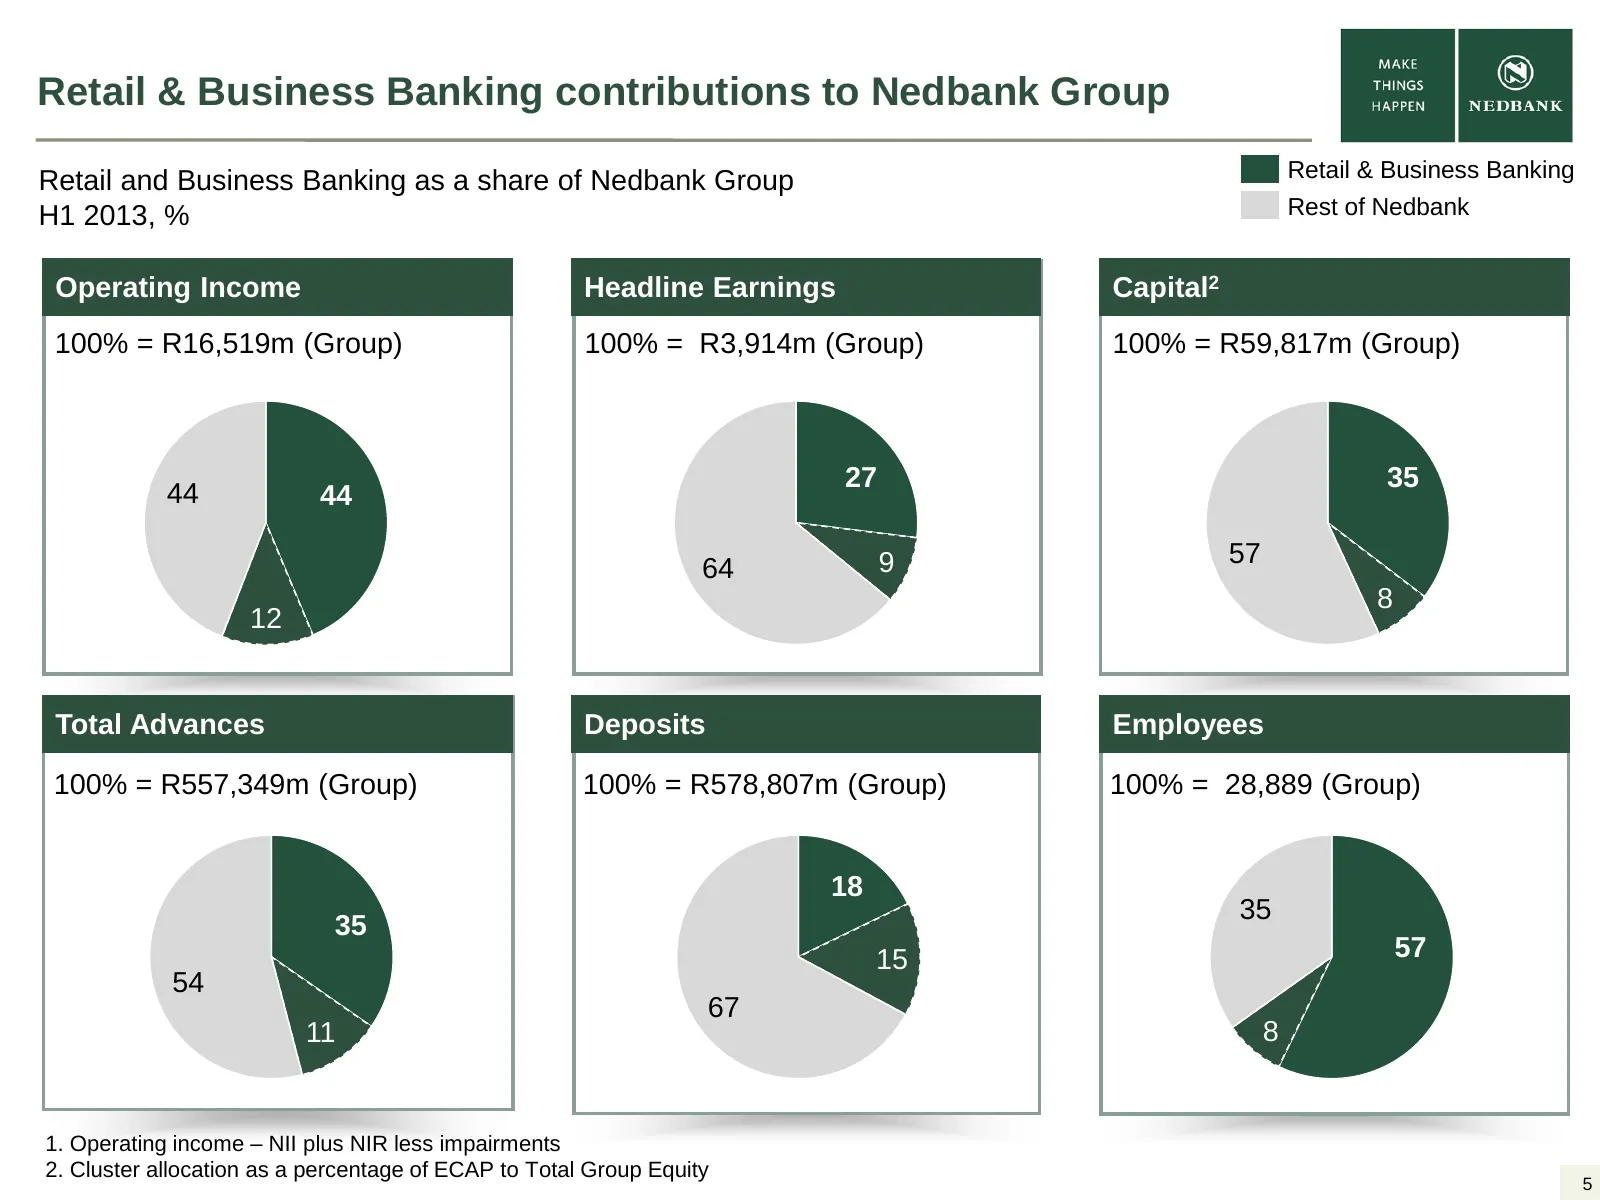
Slide 5: Retail & Business Banking contributions to Nedbank Group
Retail & Business Banking contributions to Nedbank Group Retail and Business Banking as a share of Nedbank Group Retail & Business Banking H1 2013, % Rest of Nedbank Operating Income Headline Earnings Capital2 100% = R16,519m (Group) 100% = R3,914m (Group) 100% = R59,817m (Group) 27 35 44 44 44 64 5
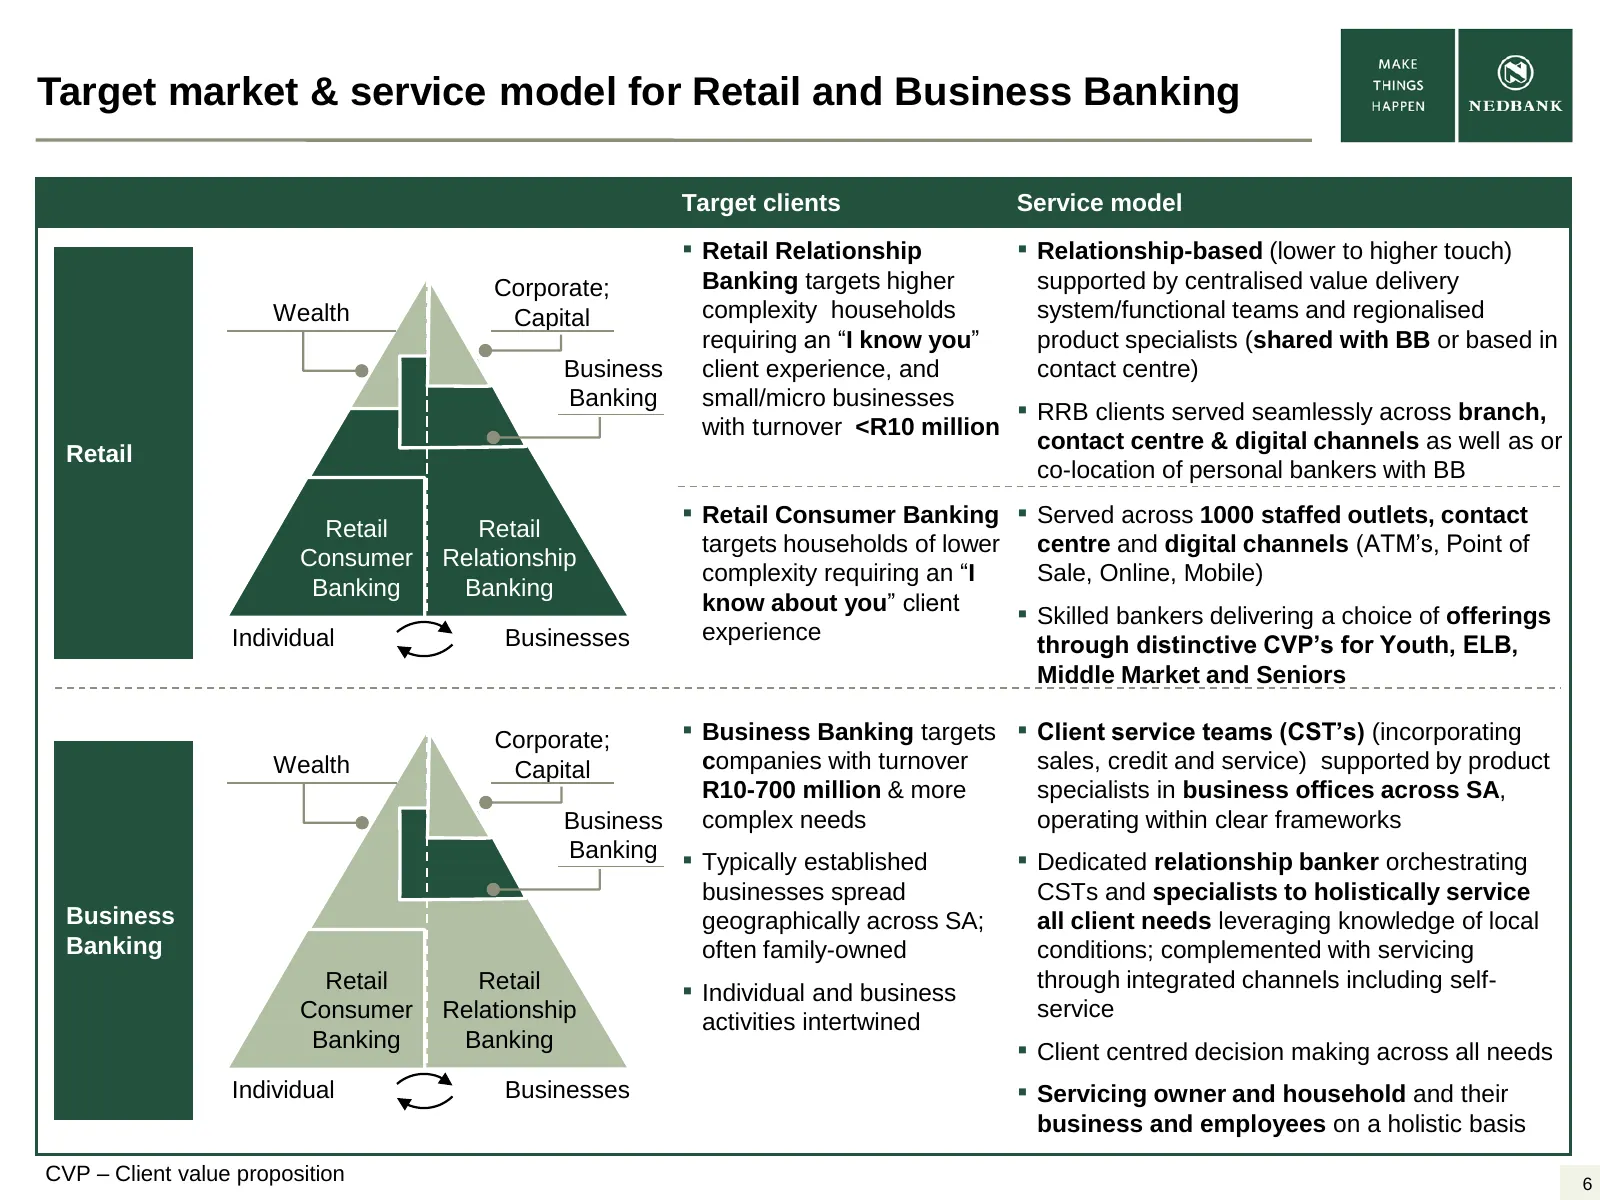
Slide 6: Target market & service model for Retail and Business Banking
Target market & service model for Retail and Business Banking Target clients Service model ▪ Retail Relationship ▪ Relationship-based (lower to higher touch) Corporate; Banking targets higher supported by centralised value delivery Wealth Capital complexity households system/functional teams and reg
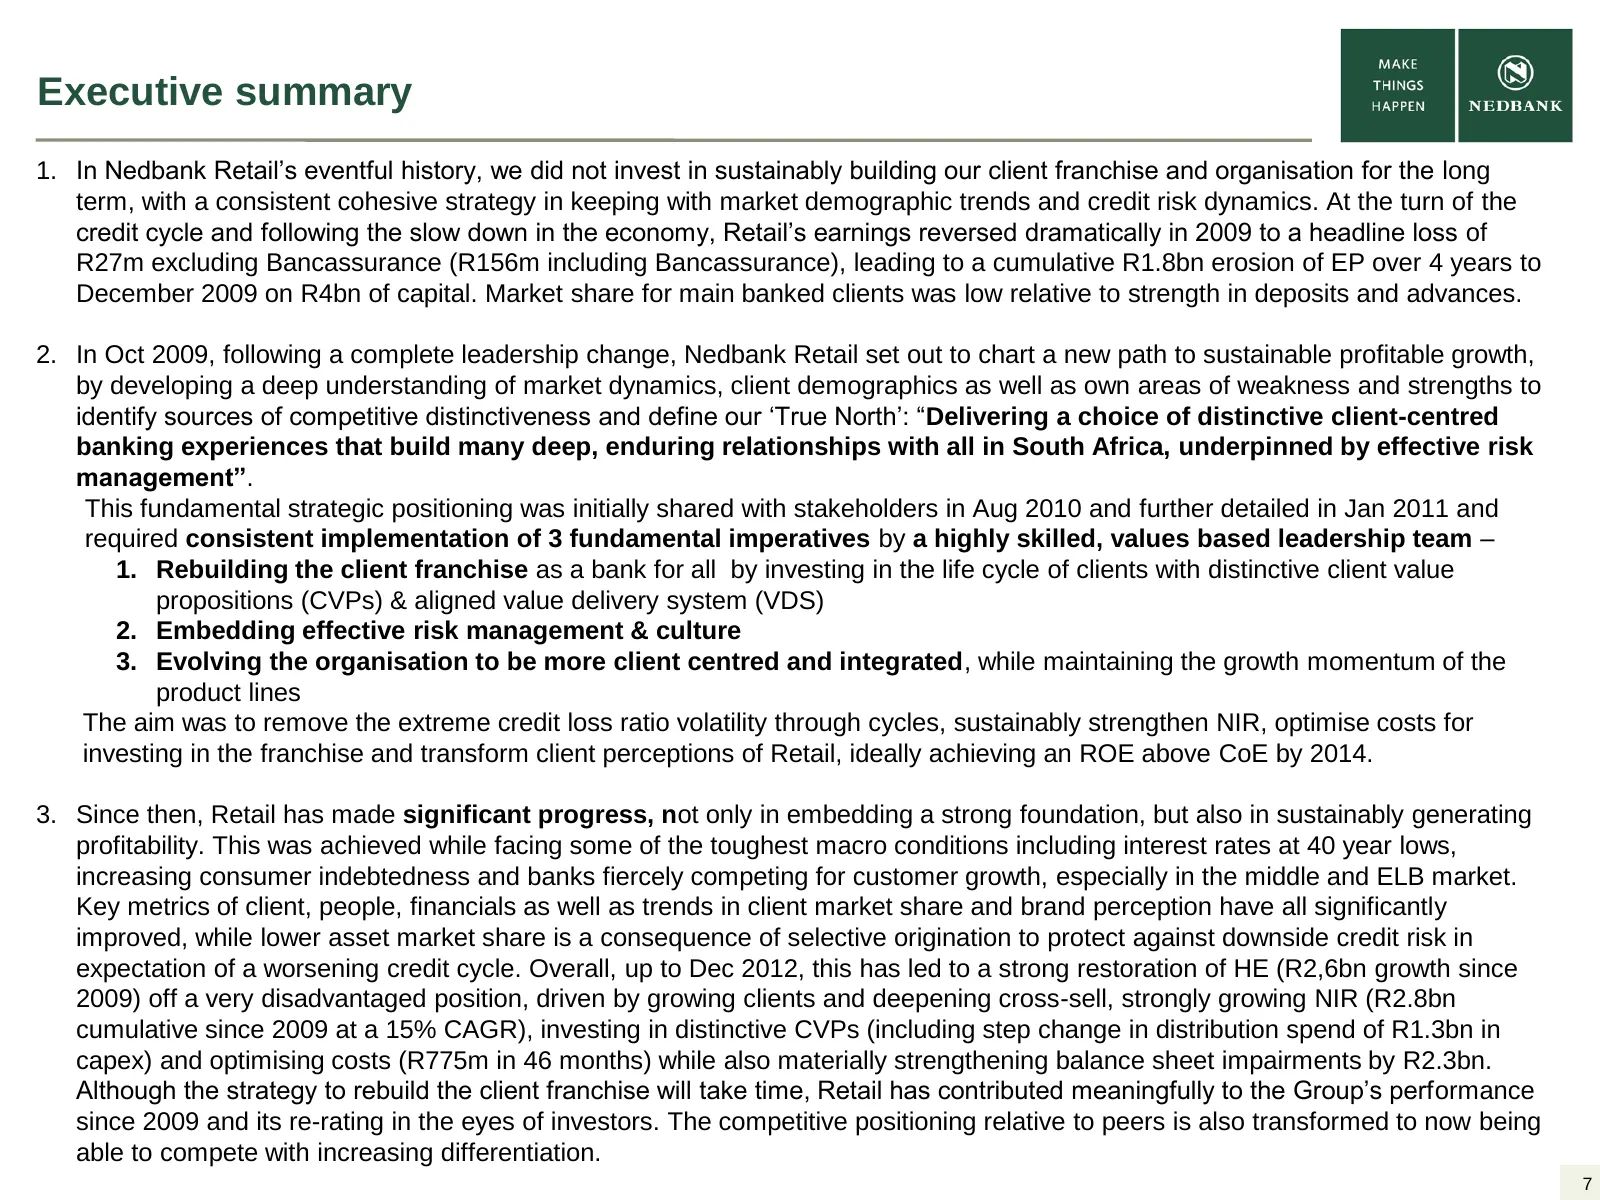
Slide 7: Executive summary
Executive summary 1. In Nedbank Retail’s eventful history, we did not invest in sustainably building our client franchise and organisation for the long term, with a consistent cohesive strategy in keeping with market demographic trends and credit risk dynamics. At the turn of the credit cycle and fo
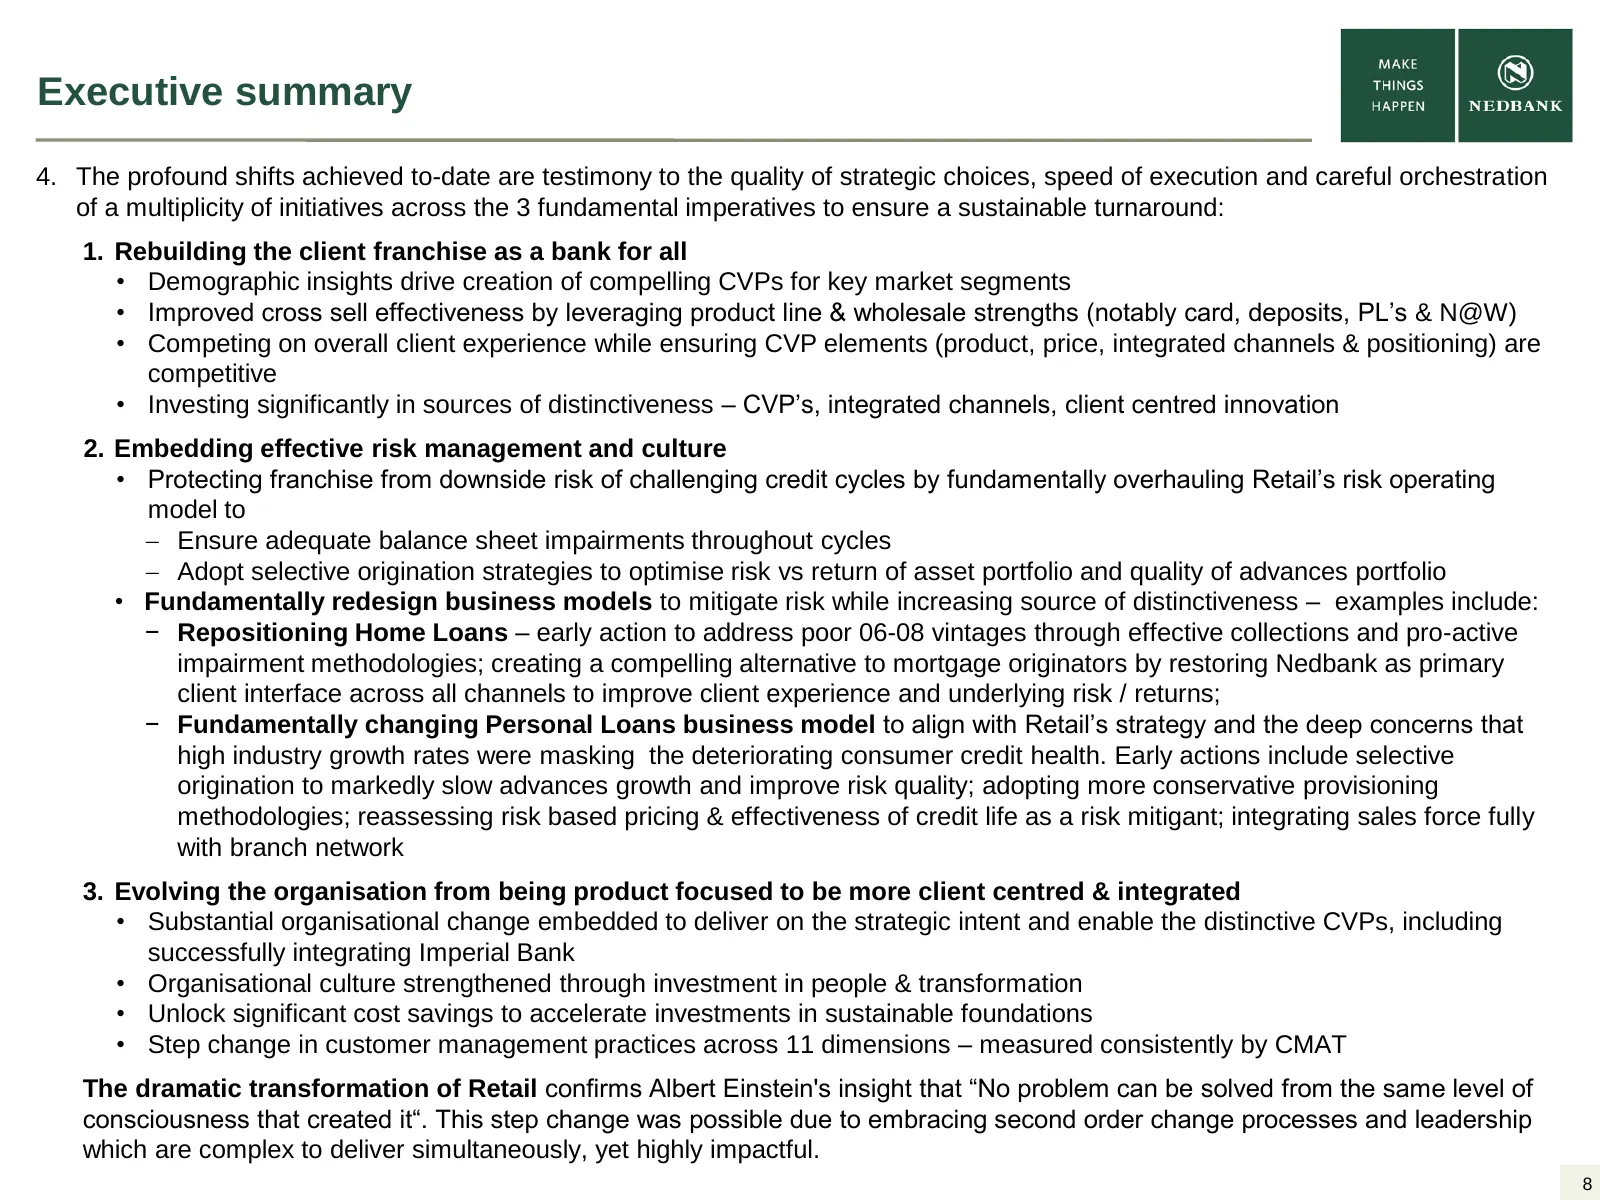
Slide 8: Executive summary
Executive summary 4. The profound shifts achieved to-date are testimony to the quality of strategic choices, speed of execution and careful orchestration of a multiplicity of initiatives across the 3 fundamental imperatives to ensure a sustainable turnaround: 1. Rebuilding the client franchise as a
Slide 9: Executive summary
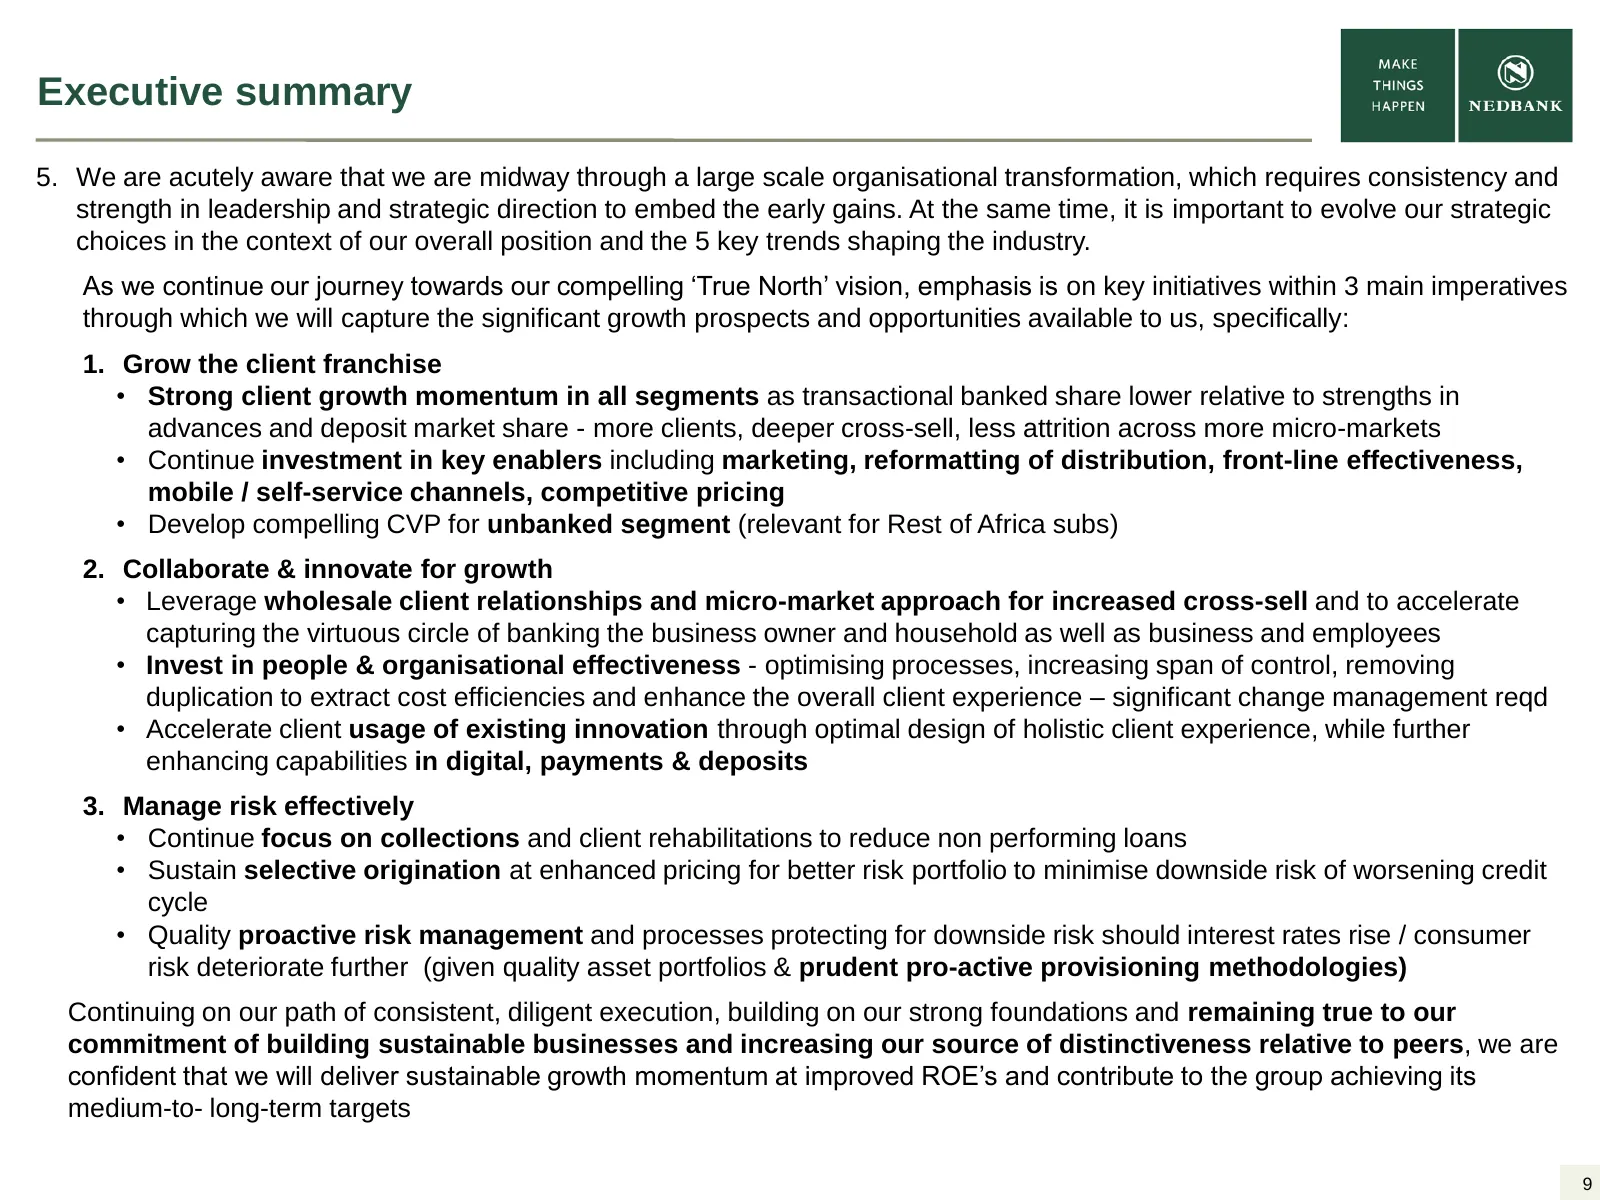
Executive summary 5. We are acutely aware that we are midway through a large scale organisational transformation, which requires consistency and strength in leadership and strategic direction to embed the early gains. At the same time, it is important to evolve our strategic choices in the context o
Slide 10: Repositioning Retail – presentation topics
Repositioning Retail – presentation topics ▪ Executive Summary ▪ What we set out to do in 2010 ▪ Progress to date ▪ How we achieved it ▪ Future trends & prospects 10
Slide 11: Nedbank's eventful history and lack of long-term client franchise investment
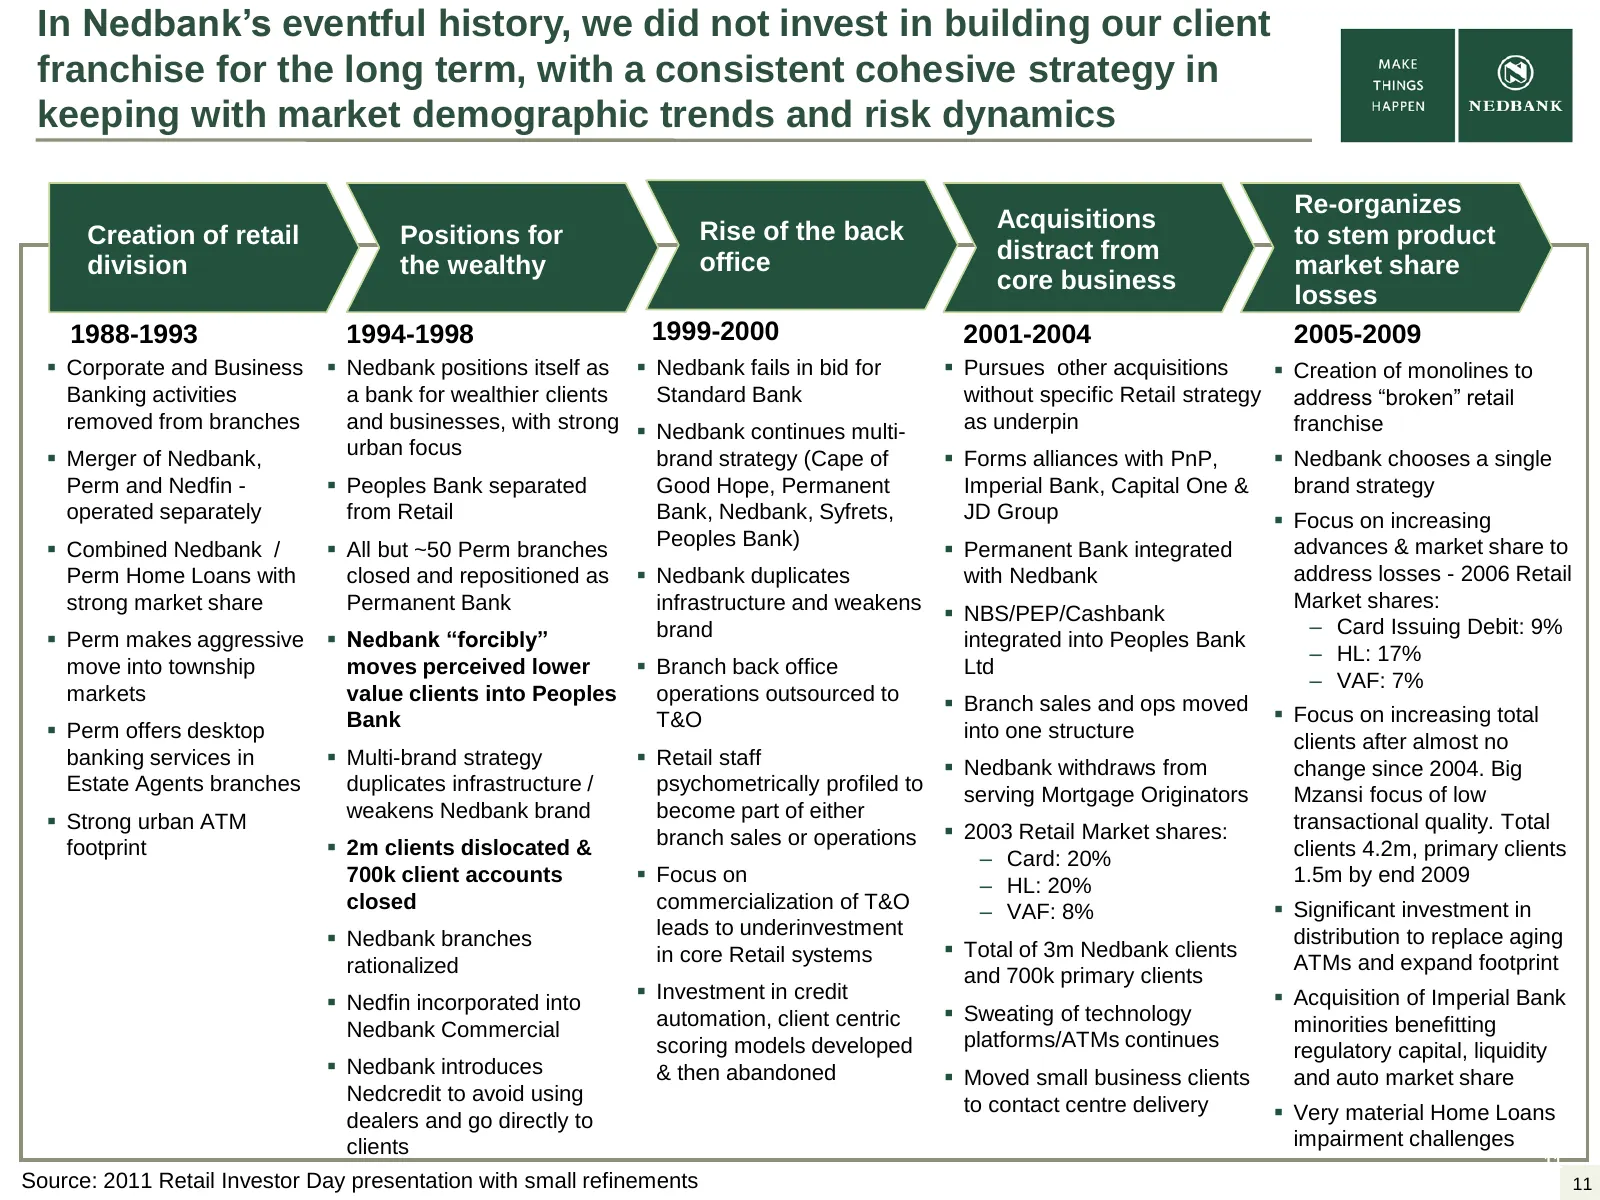
In Nedbank’s eventful history, we did not invest in building our client franchise for the long term, with a consistent cohesive strategy in keeping with market demographic trends and risk dynamics Re-organizes Rise of the back Acquisitions Creation of retail Positions for to stem product office dist
Slide 12: Turn of credit cycle revealed Retail challenges, necessitating strategic review
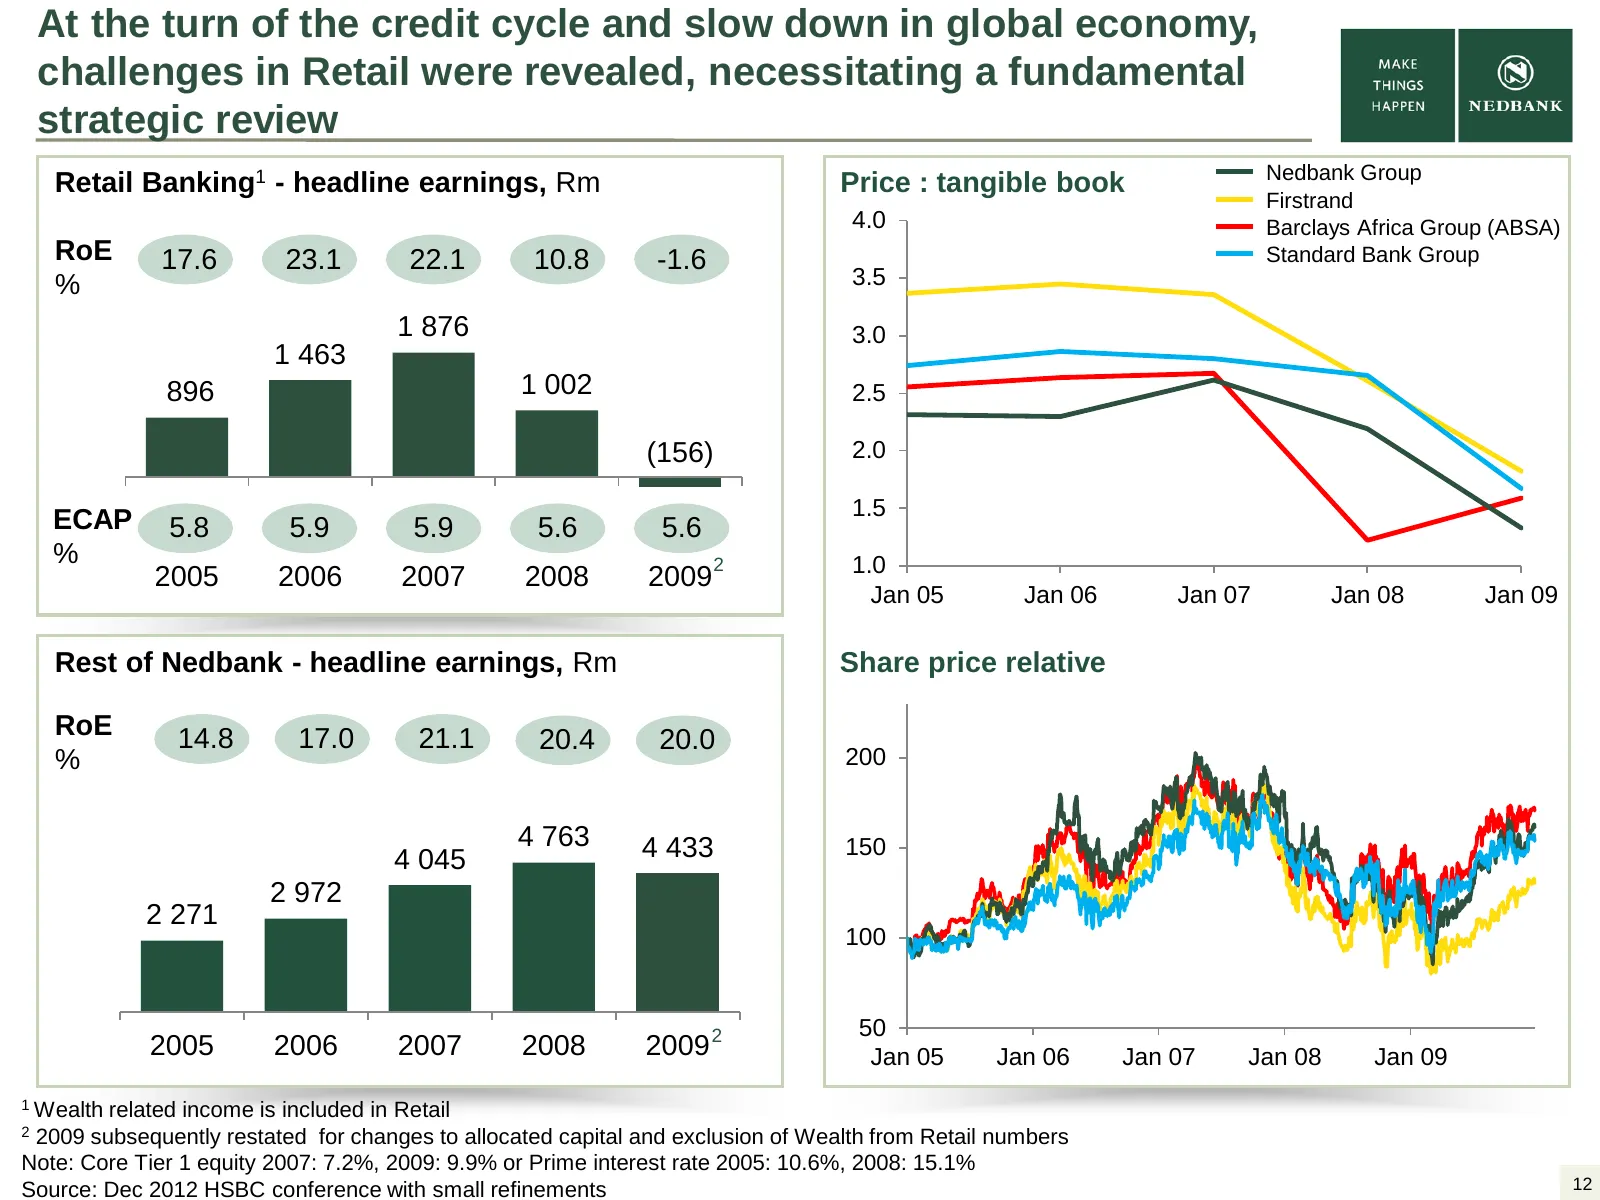
At the turn of the credit cycle and slow down in global economy, challenges in Retail were revealed, necessitating a fundamental strategic review Nedbank Group Retail Banking1 - headline earnings, Rm Price : tangible book Firstrand 4.0 Barclays Africa Group (ABSA) RoE 17.6 23.1 22.1 10.8 -1.6 Standa
Slide 13: In 2009, Retail lagged peers in client numbers
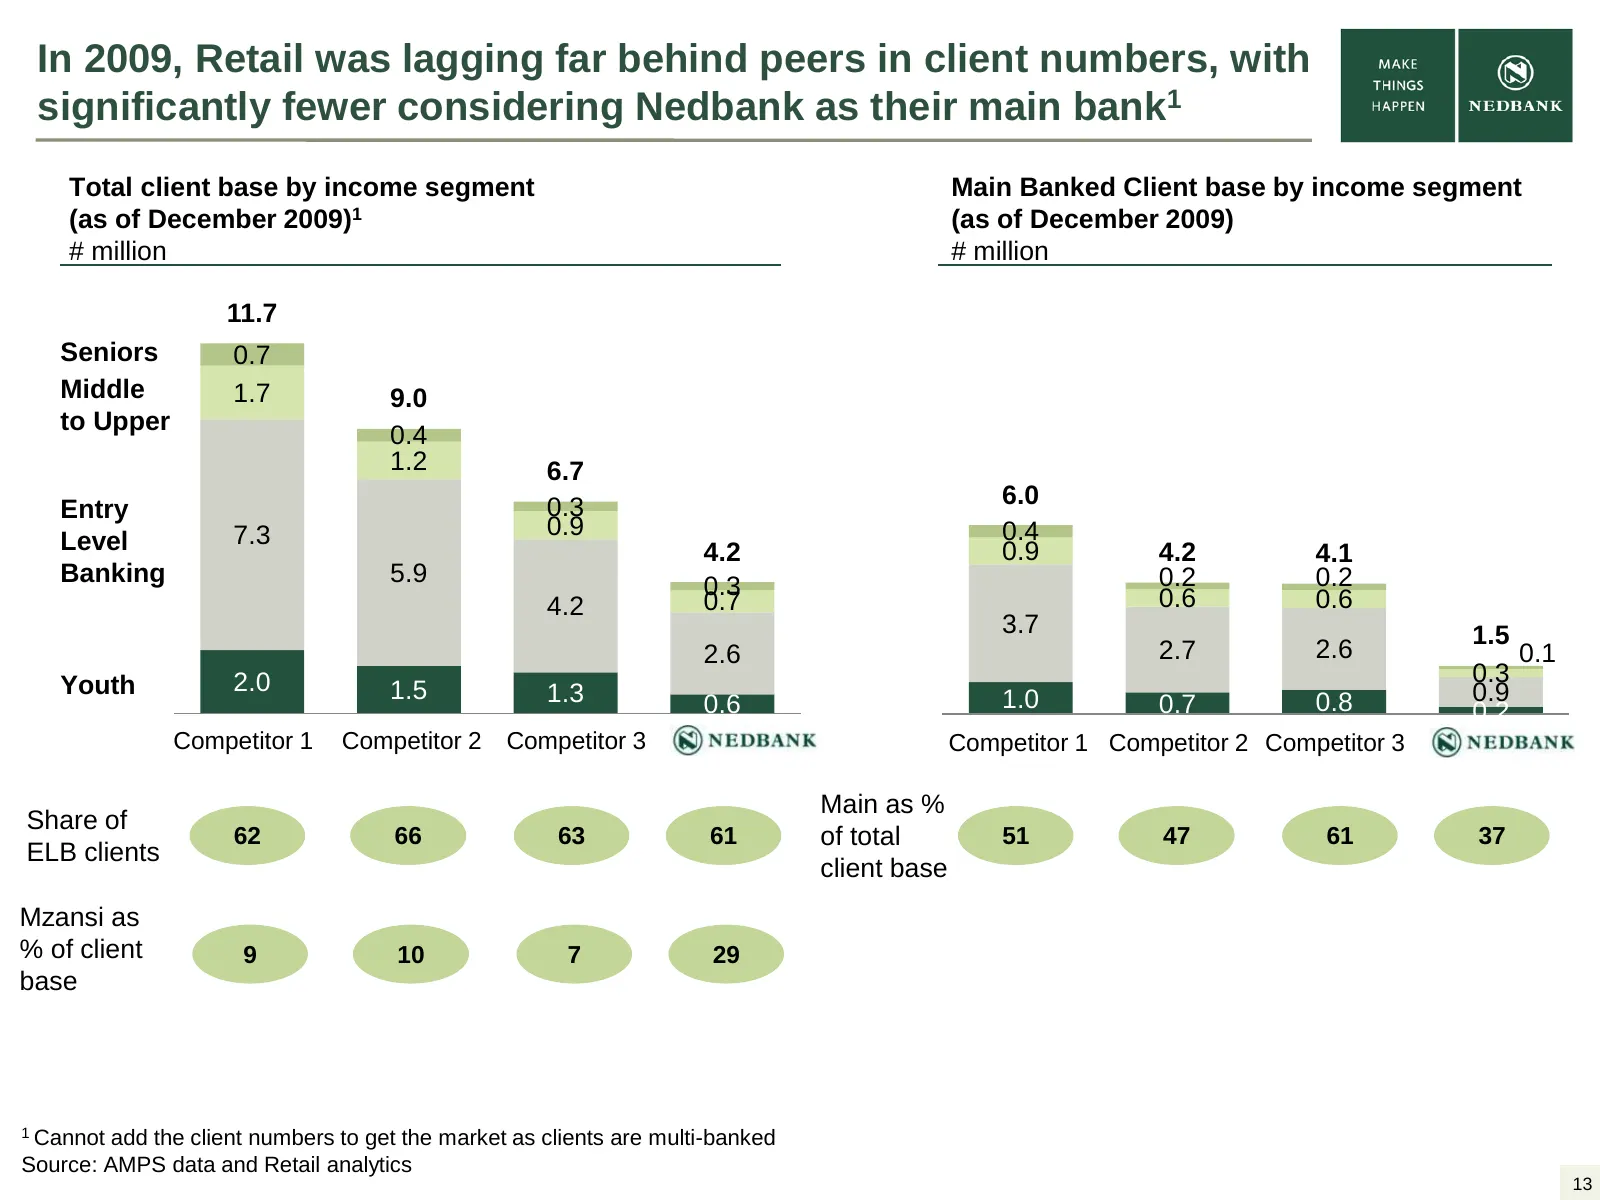
In 2009, Retail was lagging far behind peers in client numbers, with significantly fewer considering Nedbank as their main bank1 Total client base by income segment Main Banked Client base by income segment (as of December 2009)1 (as of December 2009) # million # million 11.7 Seniors 0.7 Middle 1.7
Slide 14: In 2009, Nedbank embarked on a strategic journey to turn around retail
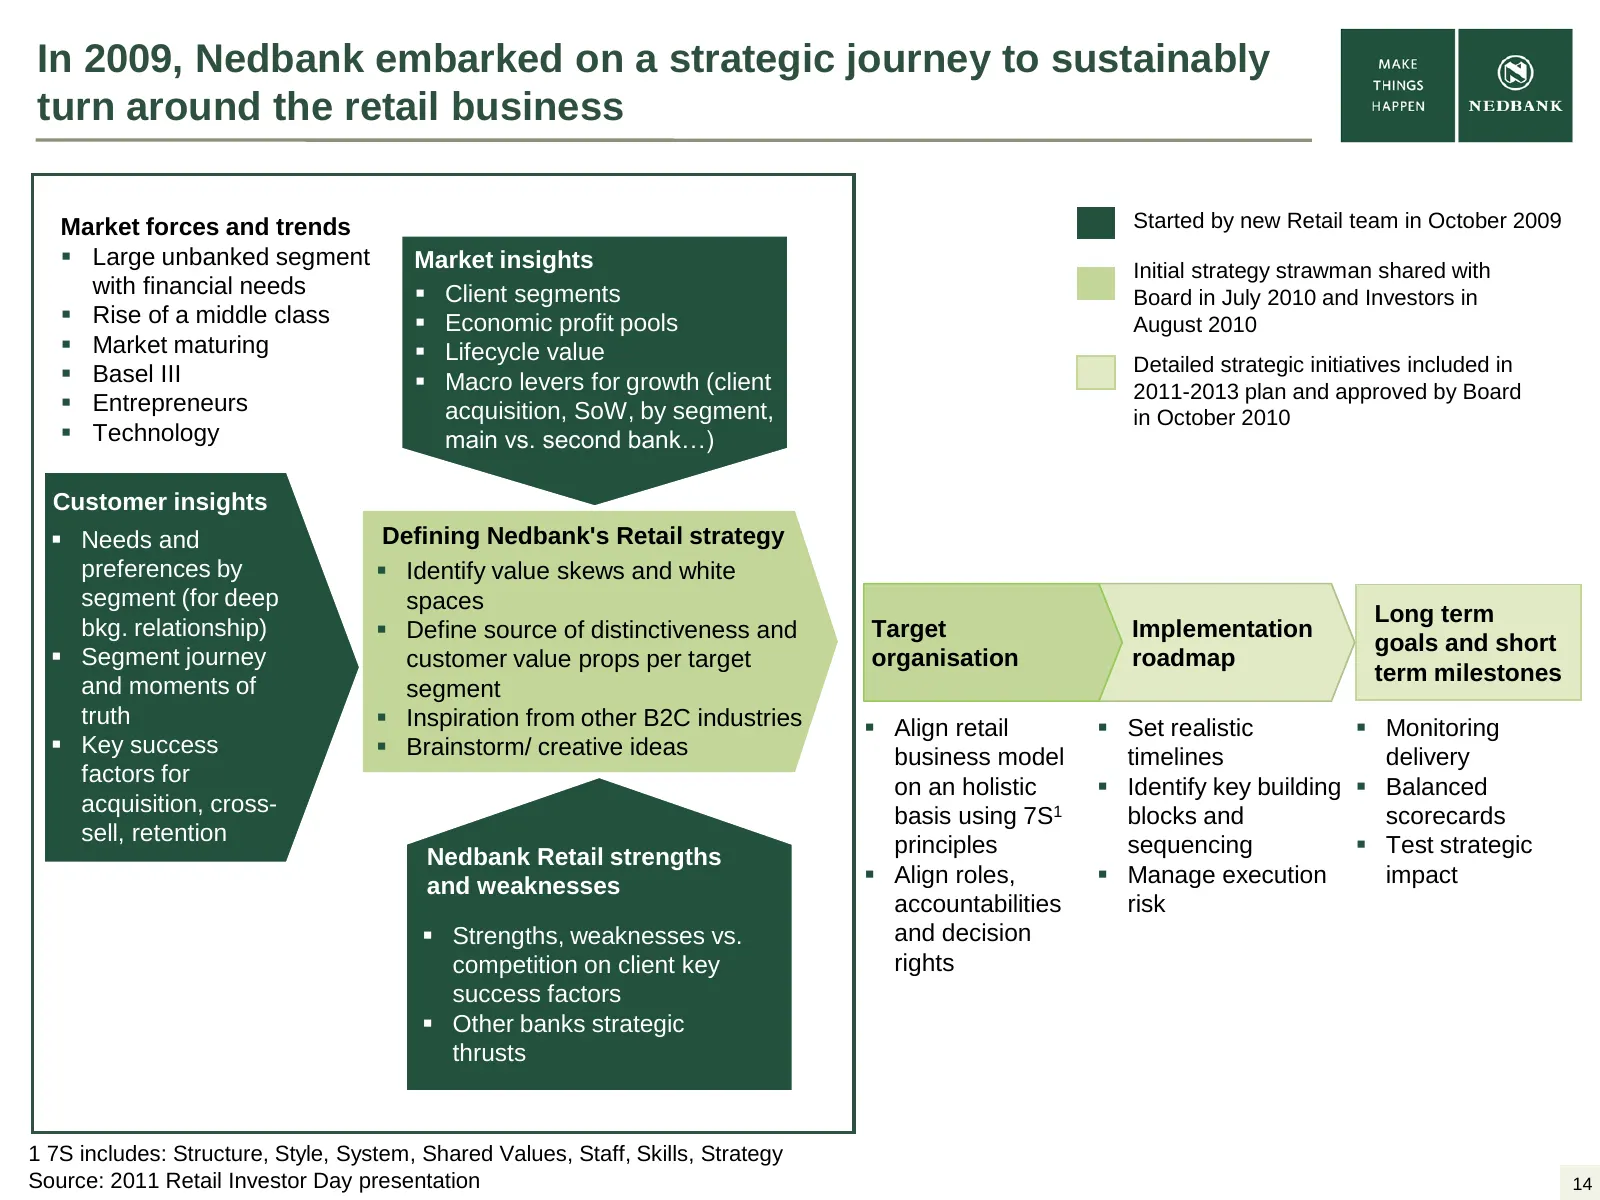
In 2009, Nedbank embarked on a strategic journey to sustainably turn around the retail business Market forces and trends Started by new Retail team in October 2009 Large unbanked segment Market insights Initial strategy strawman shared with with financial needs Client segments Board in July 2010
Slide 15: Three strategic imperatives from external trends and internal context
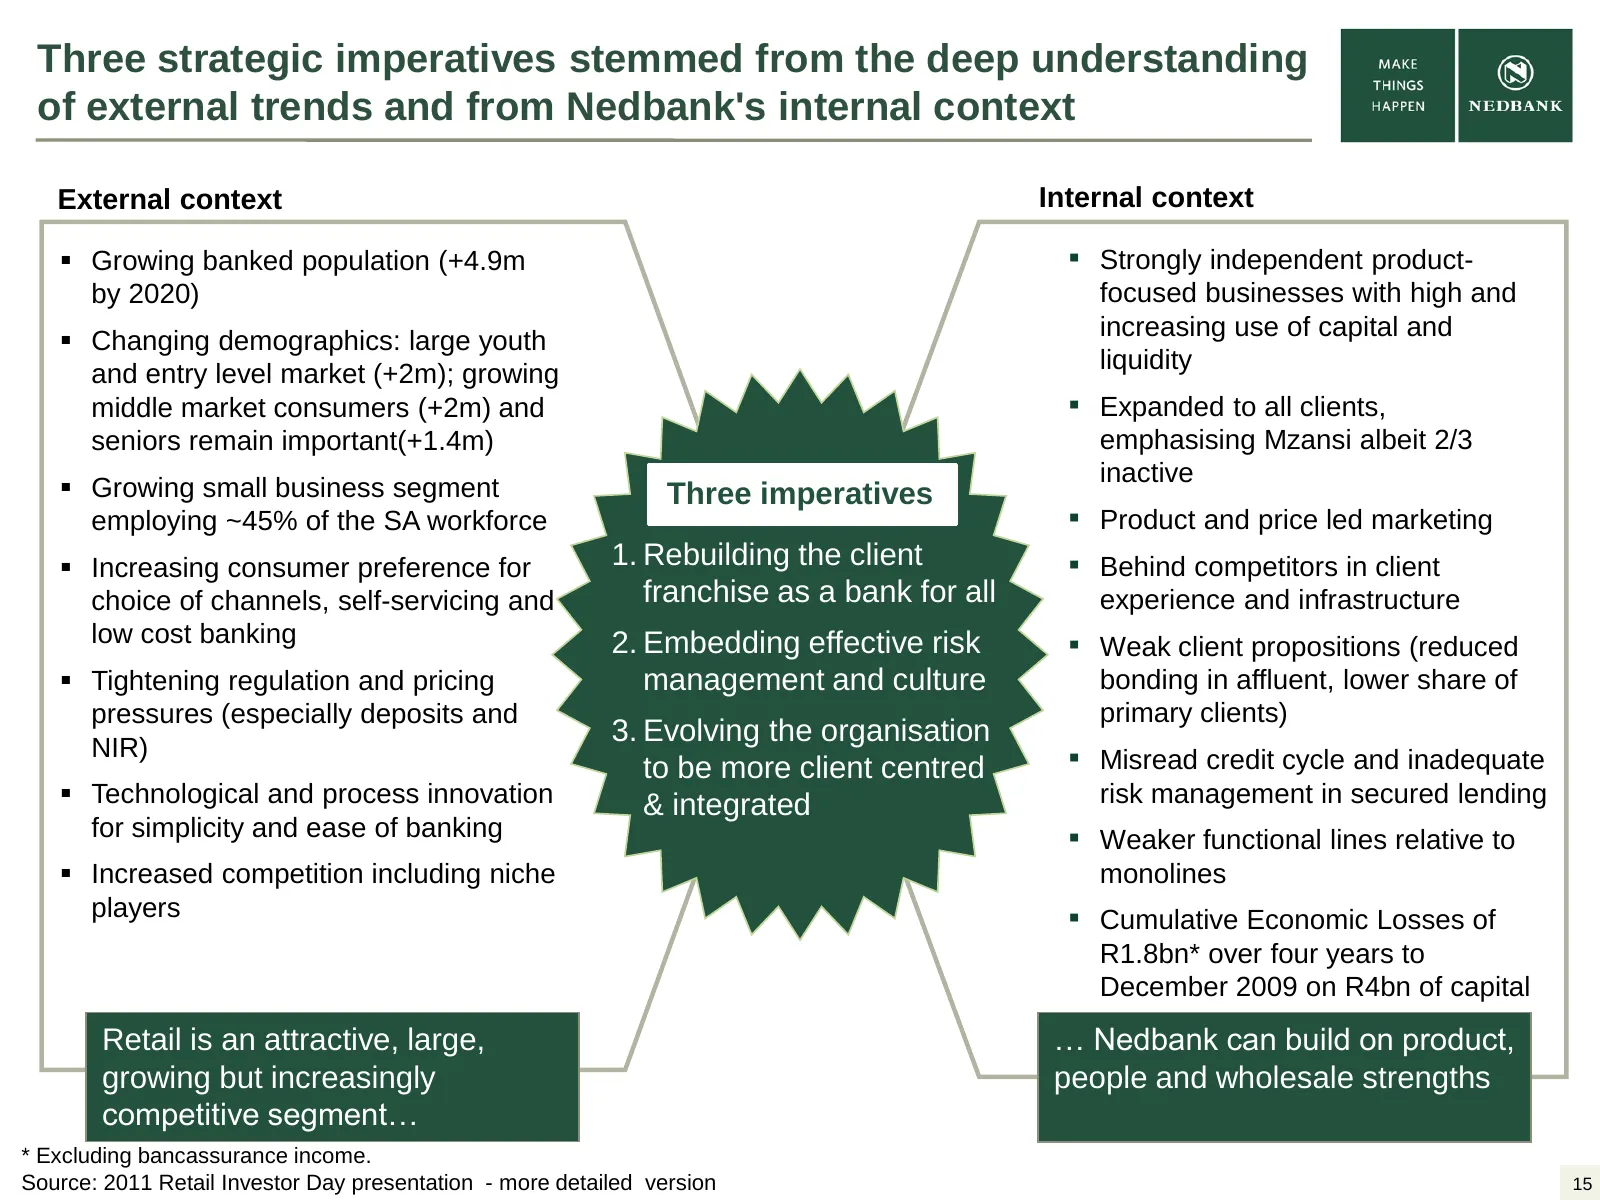
Three strategic imperatives stemmed from the deep understanding of external trends and from Nedbank's internal context External context Internal context Growing banked population (+4.9m ▪ Strongly independent product- by 2020) focused businesses with high and increasing use of capital and Changi
Slide 16: Nedbank Retail will build banking relationships with all in SA
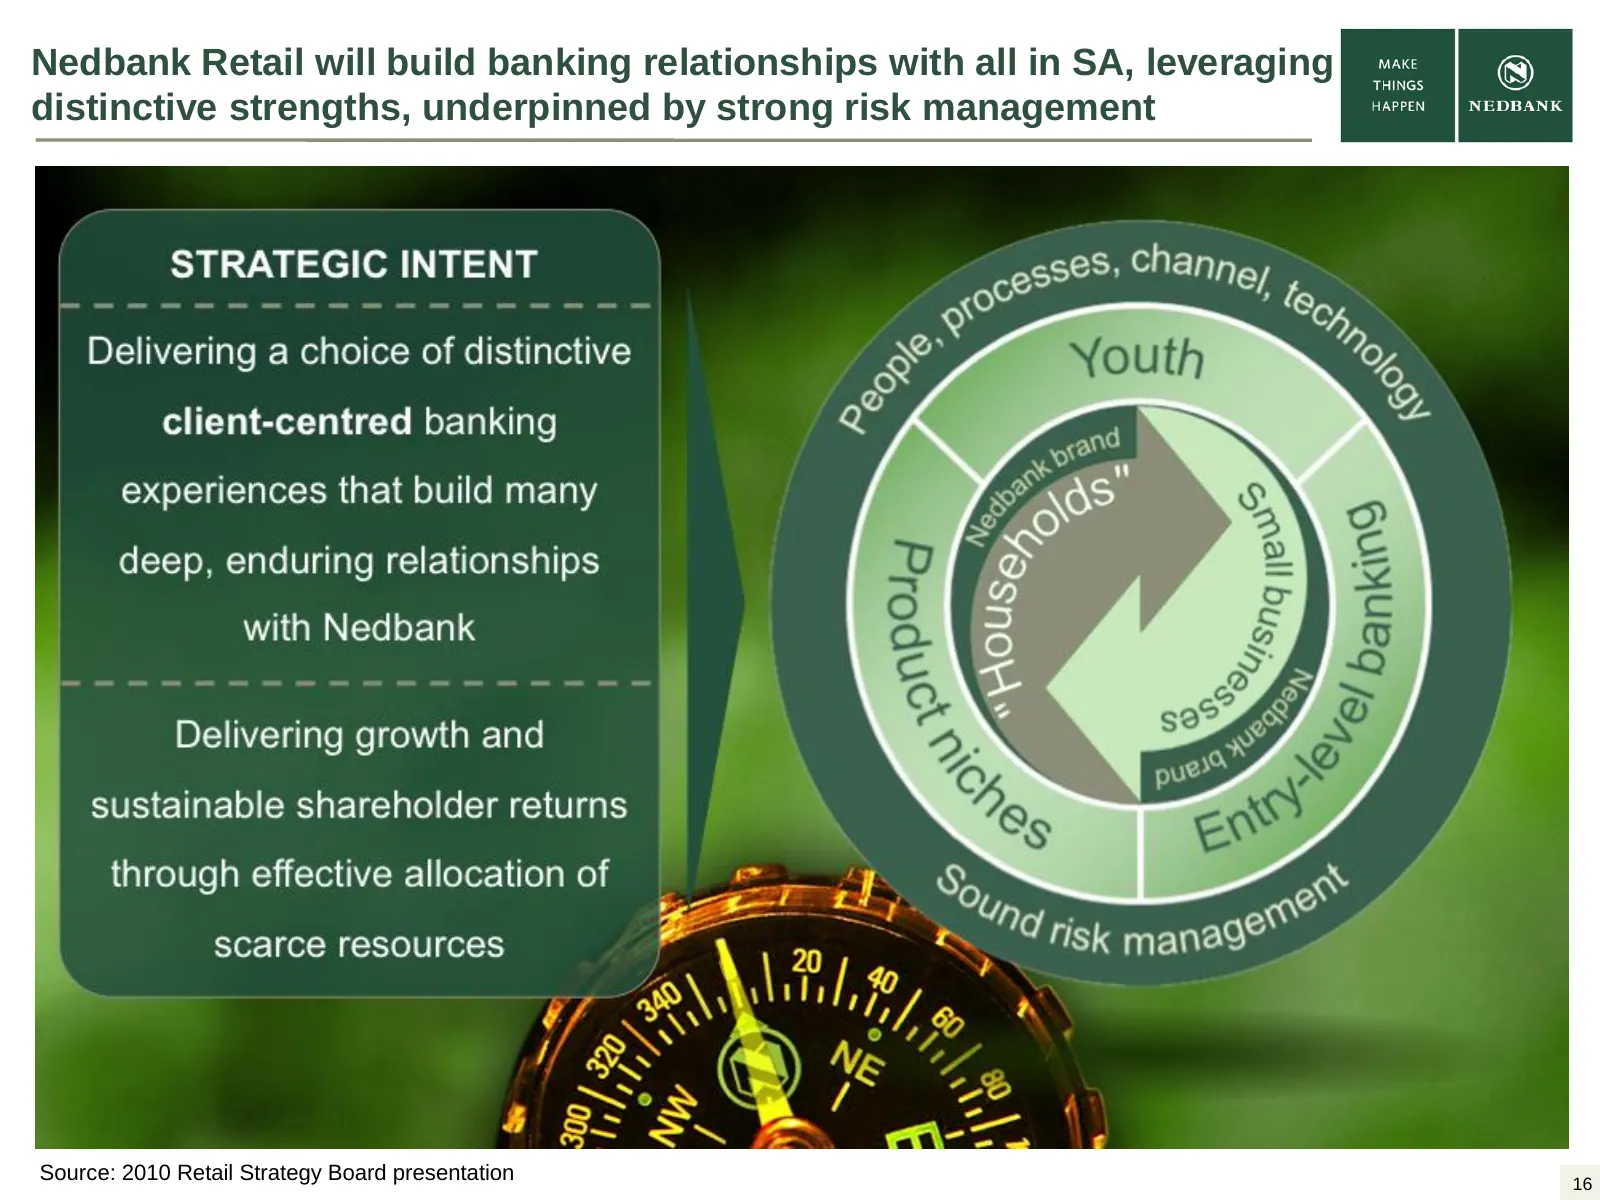
Nedbank Retail will build banking relationships with all in SA, leveraging distinctive strengths, underpinned by strong risk management Source: 2010 Retail Strategy Board presentation 16
Slide 17: Organisational design aligned to client value propositions
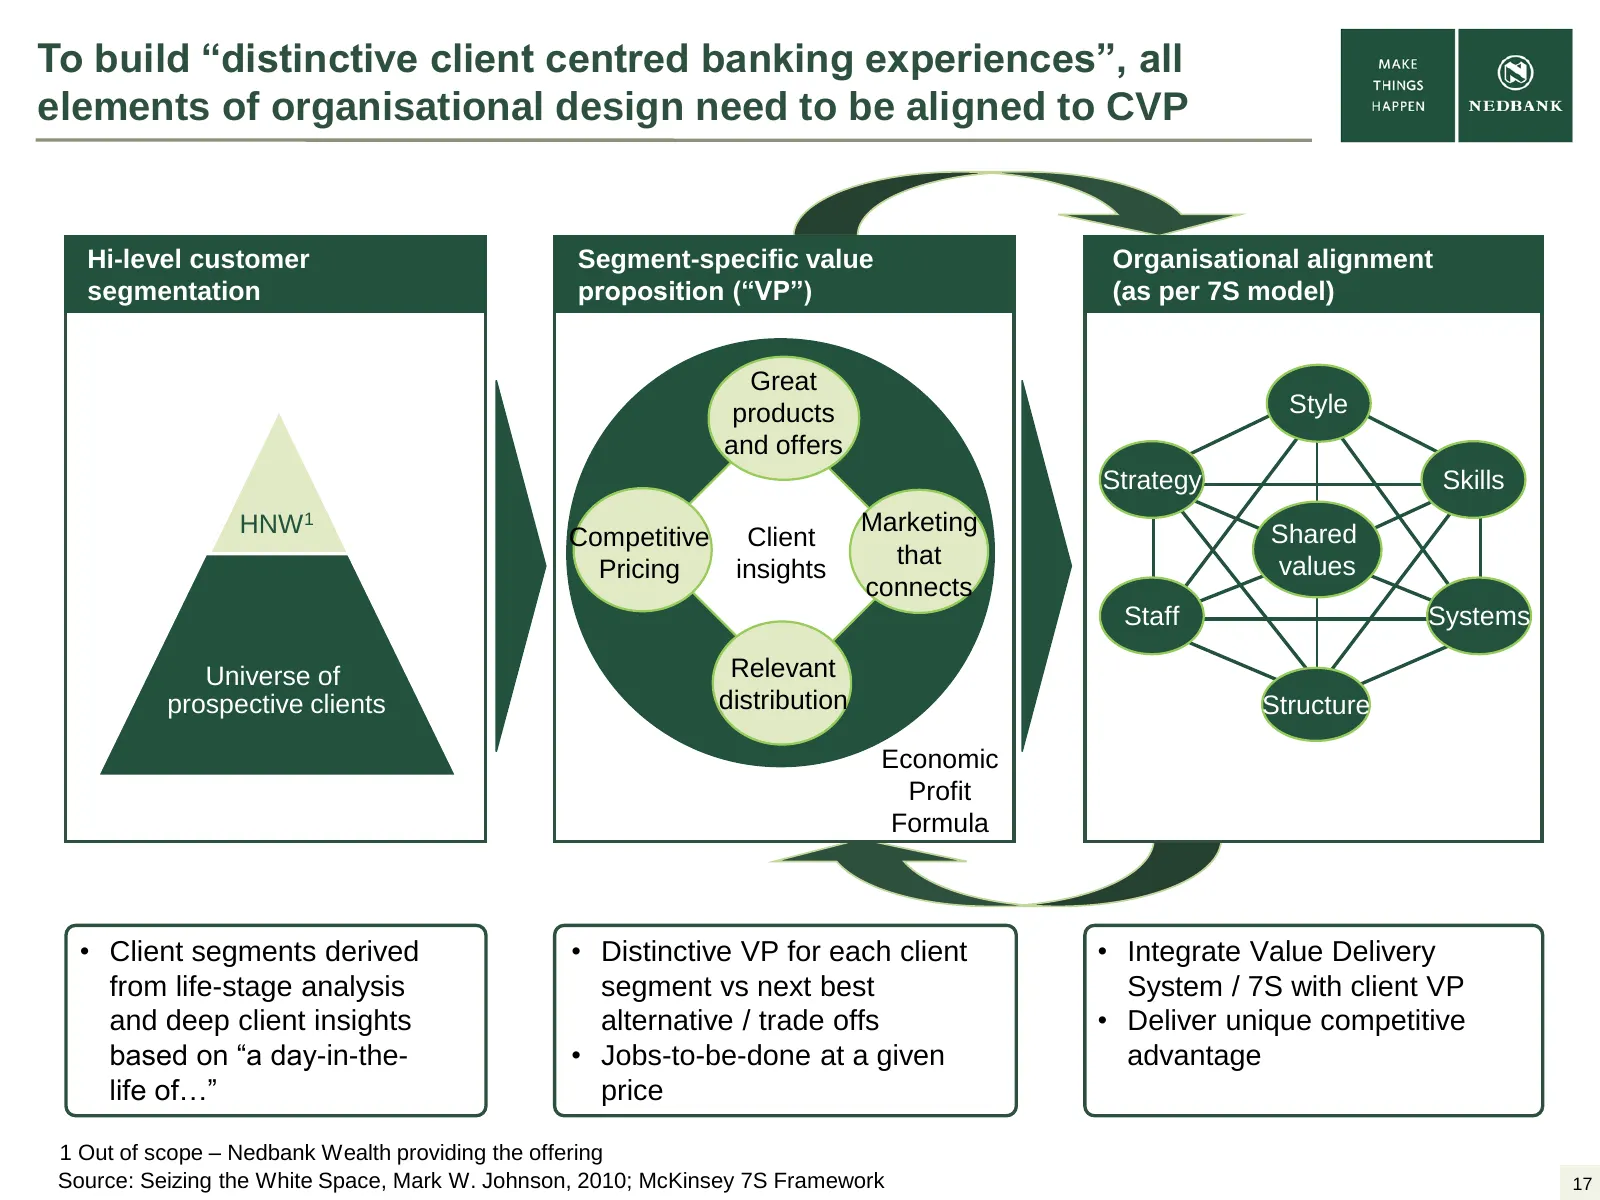
To build “distinctive client centred banking experiences”, all elements of organisational design need to be aligned to CVP Hi-level customer Segment-specific value Organisational alignment segmentation proposition (“VP”) (as per 7S model) Great products Style and offers Strategy Skills HNW 1 Competi
Slide 18: Press release Feb 2011
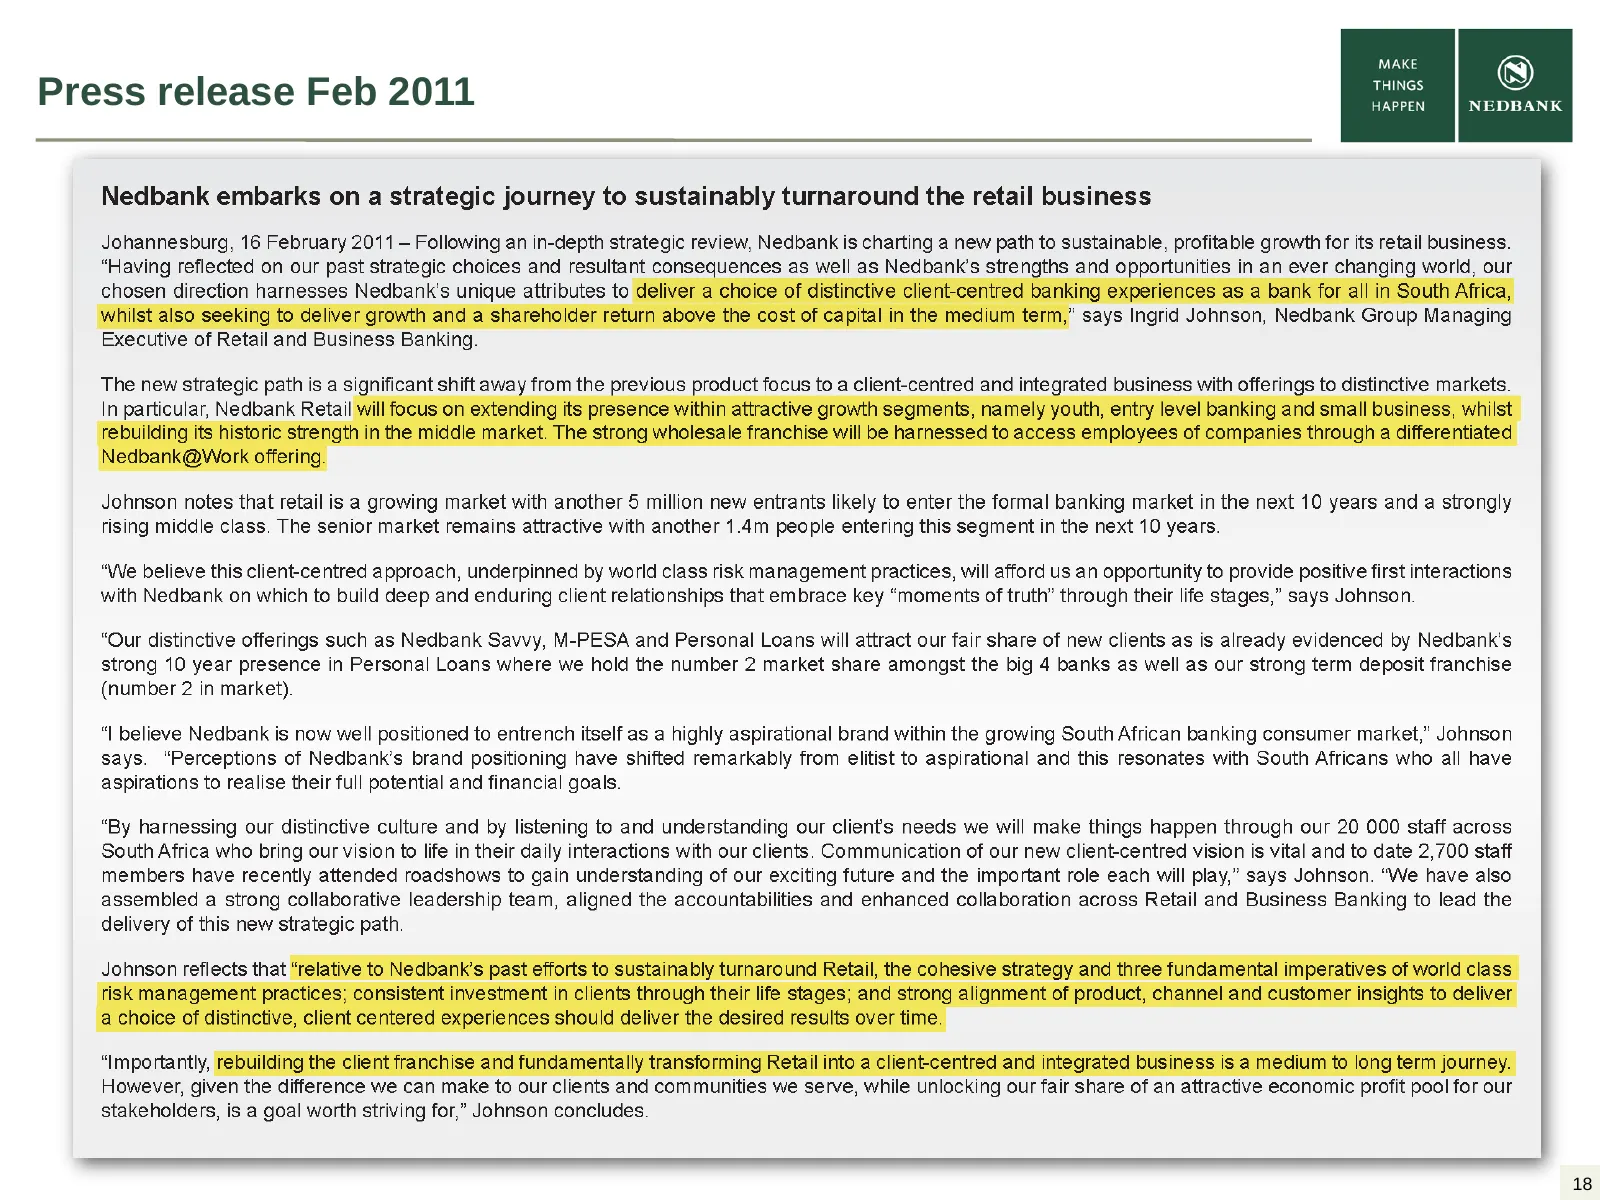
MAKE (©) Press release Feb 2011 woay || armen Nedbank embarks on a strategic journey to sustainably turnaround the retail business Johannesburg, 16 February 2011 — Following an in-depth strategic review, Nedbank is charting a new path to sustainable, profitable growth for its retail business. “Havin
Slide 19: Repositioning Retail – presentation topics
Repositioning Retail – presentation topics ▪ Executive Summary ▪ What we set out to do in 2010 ▪ Progress to date ▪ How we achieved it ▪ Future trends & prospects 19
Slide 20: Strongly repositioning retail while maintaining wholesale strengths
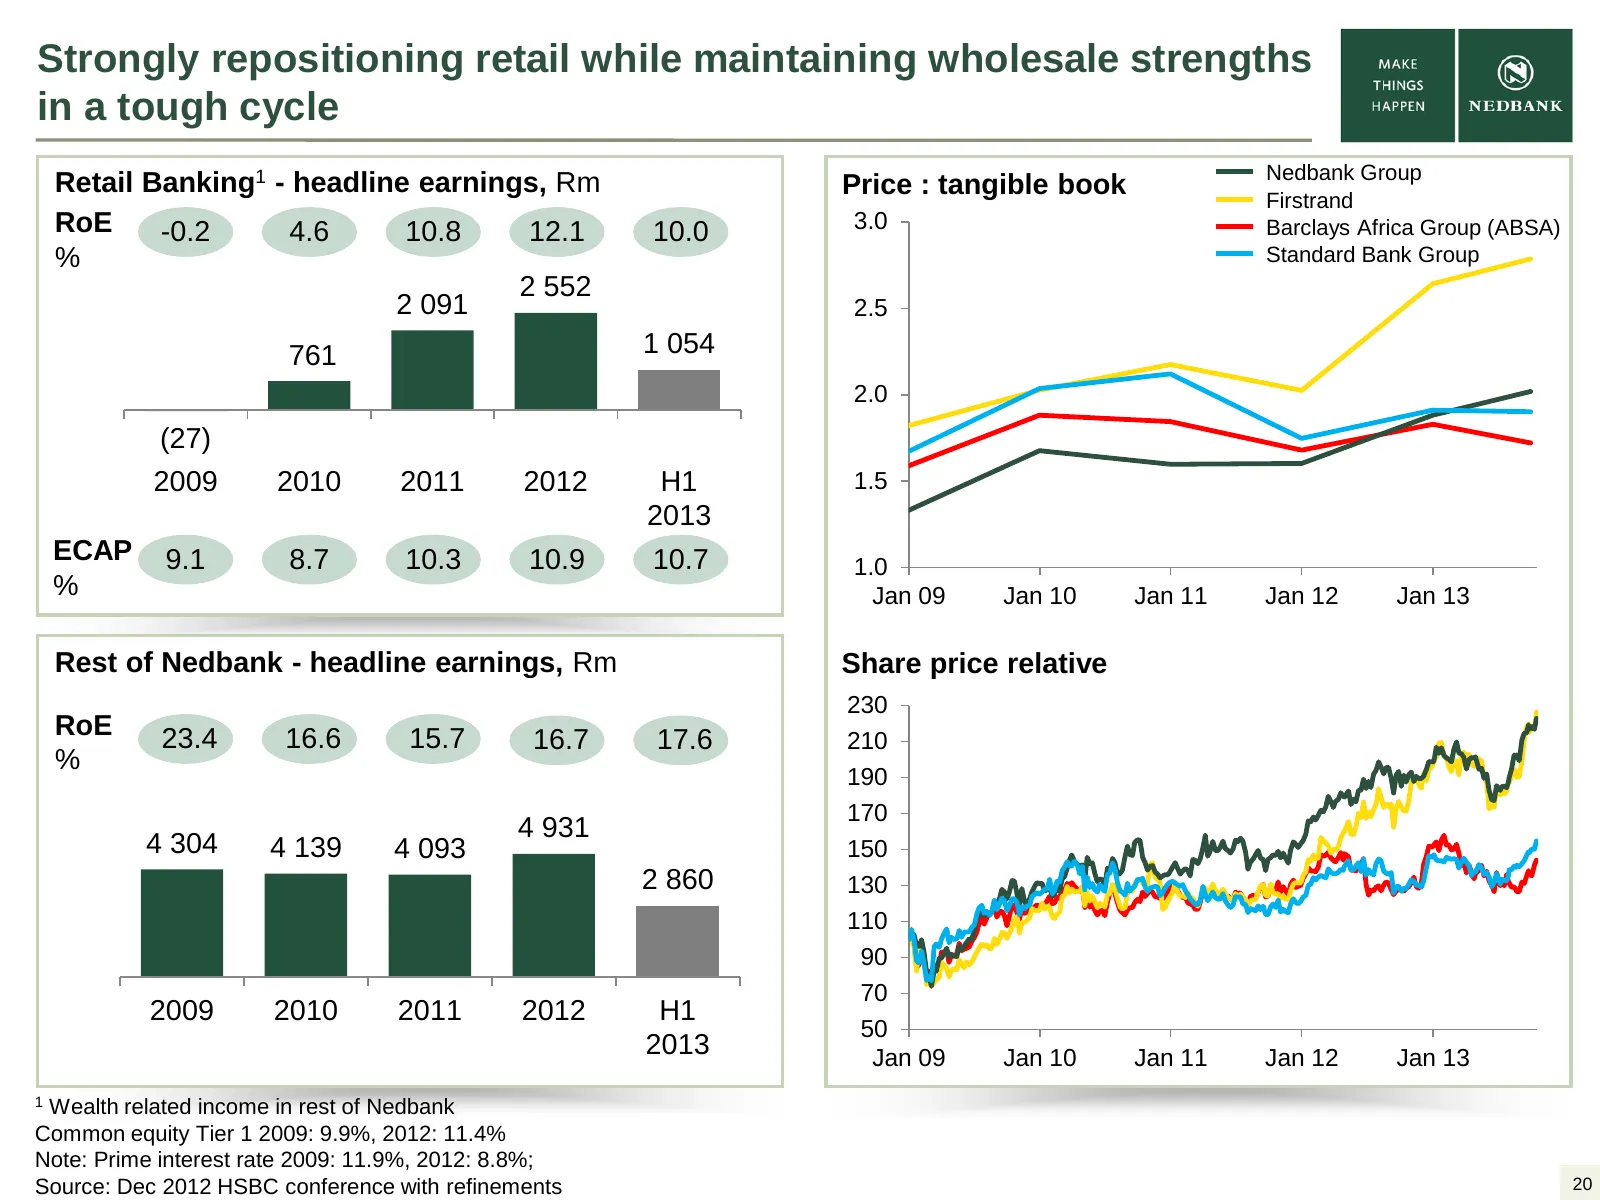
Strongly repositioning retail while maintaining wholesale strengths in a tough cycle Nedbank Group Retail Banking1 - headline earnings, Rm Price : tangible book Firstrand RoE -0.2 4.6 10.8 12.1 10.0 3.0 Barclays Africa Group (ABSA) % Standard Bank Group 2 552 2 091 2.5 761 1 054 2.0 (27) 2009 2010 2
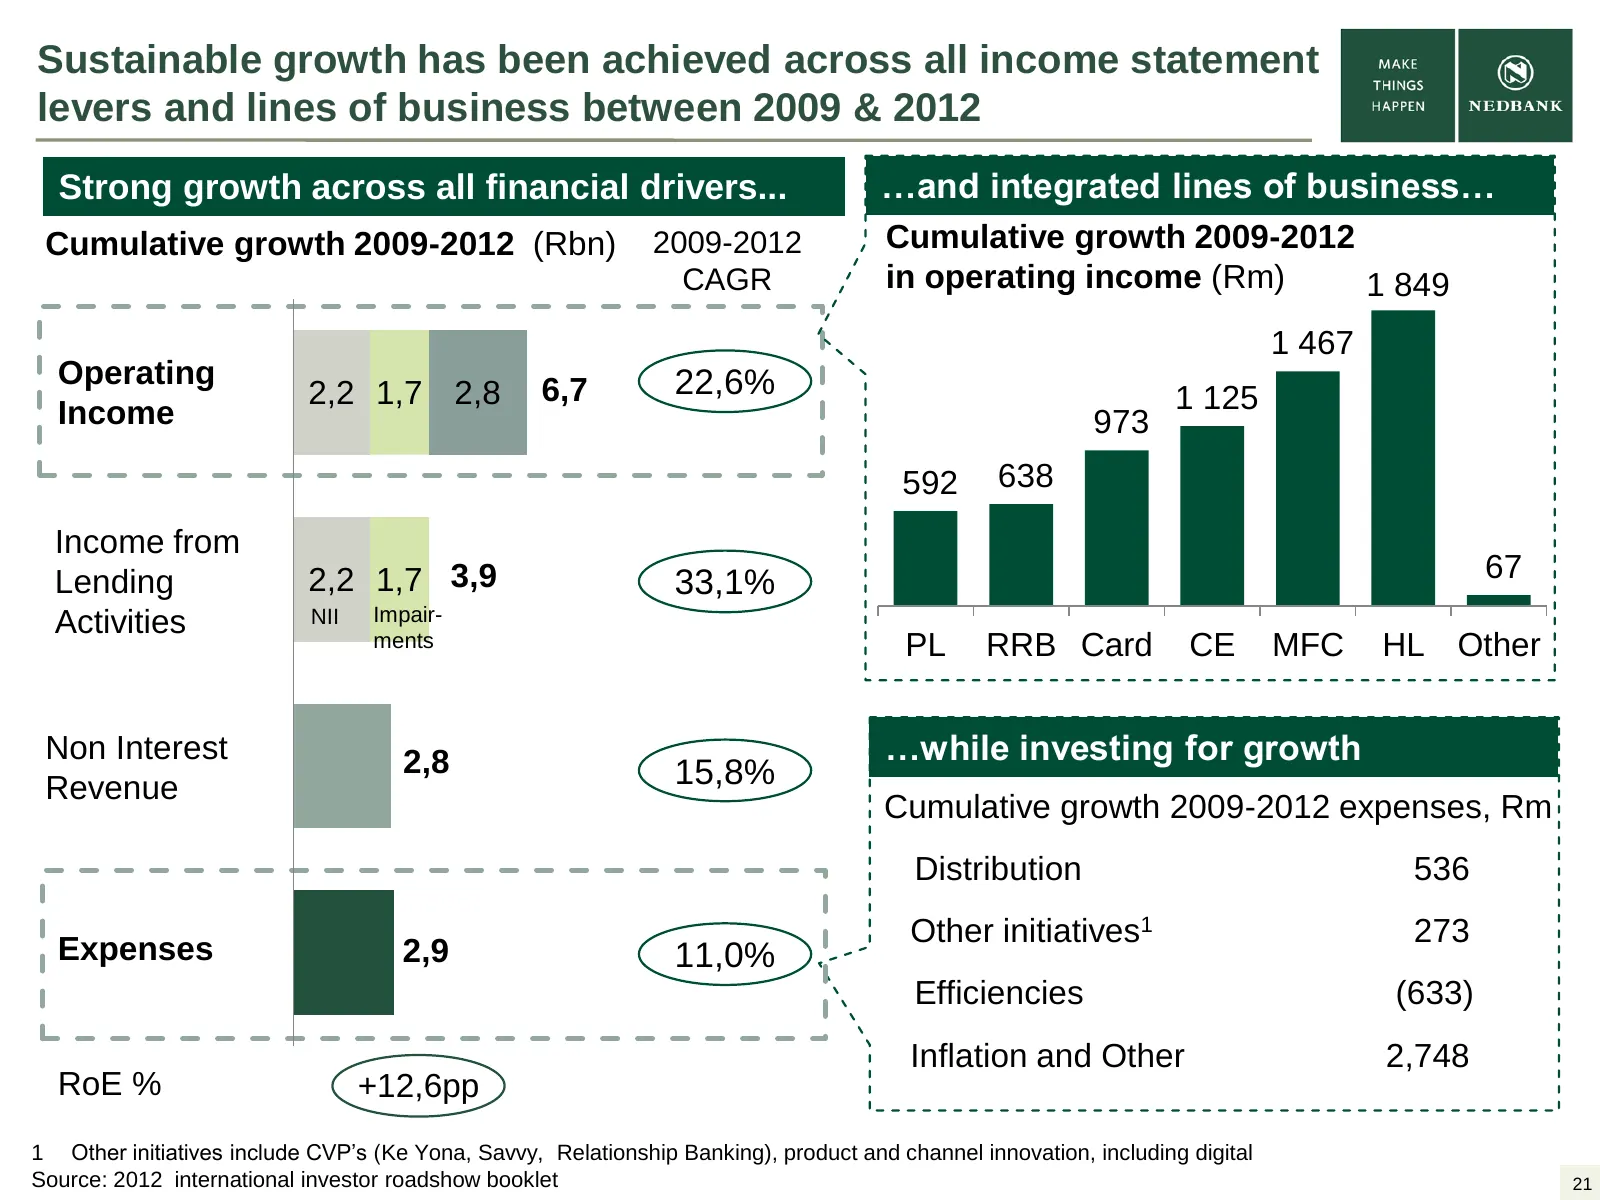
Slide 21: Sustainable growth achieved across income statement levers and lines of business
Sustainable growth has been achieved across all income statement levers and lines of business between 2009 & 2012 Strong growth across all financial drivers... …and integrated lines of business… Cumulative growth 2009-2012 (Rbn) 2009-2012 Cumulative growth 2009-2012 CAGR in operating income (Rm) 1 8
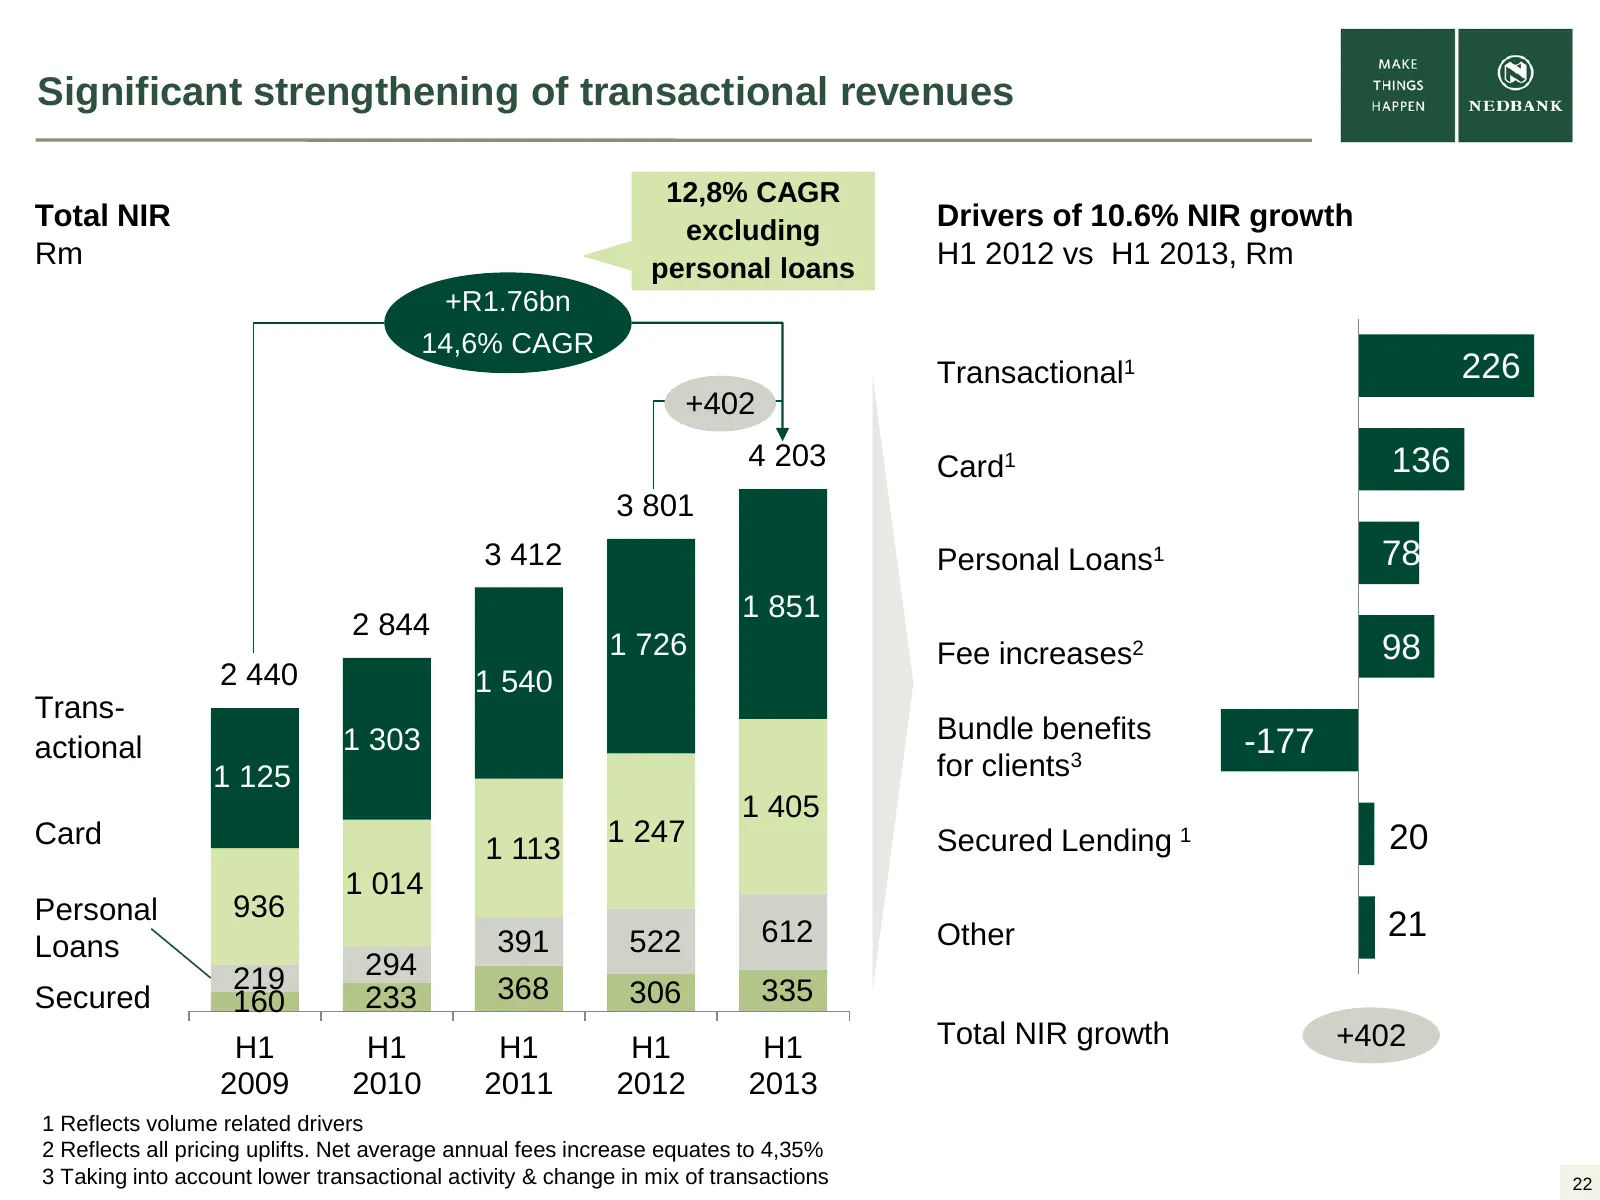
Slide 22: Significant strengthening of transactional revenues
Significant strengthening of transactional revenues 12,8% CAGR Total NIR excluding Drivers of 10.6% NIR growth Rm personal loans H1 2012 vs H1 2013, Rm +R1.76bn 14,6% CAGR Transactional1 226 +402 4 203 Card1 136 3 801 3 412 Personal Loans1 78 1 851 2 844 1 726 Fee increases2 98 2 440 1 540 Trans- 1
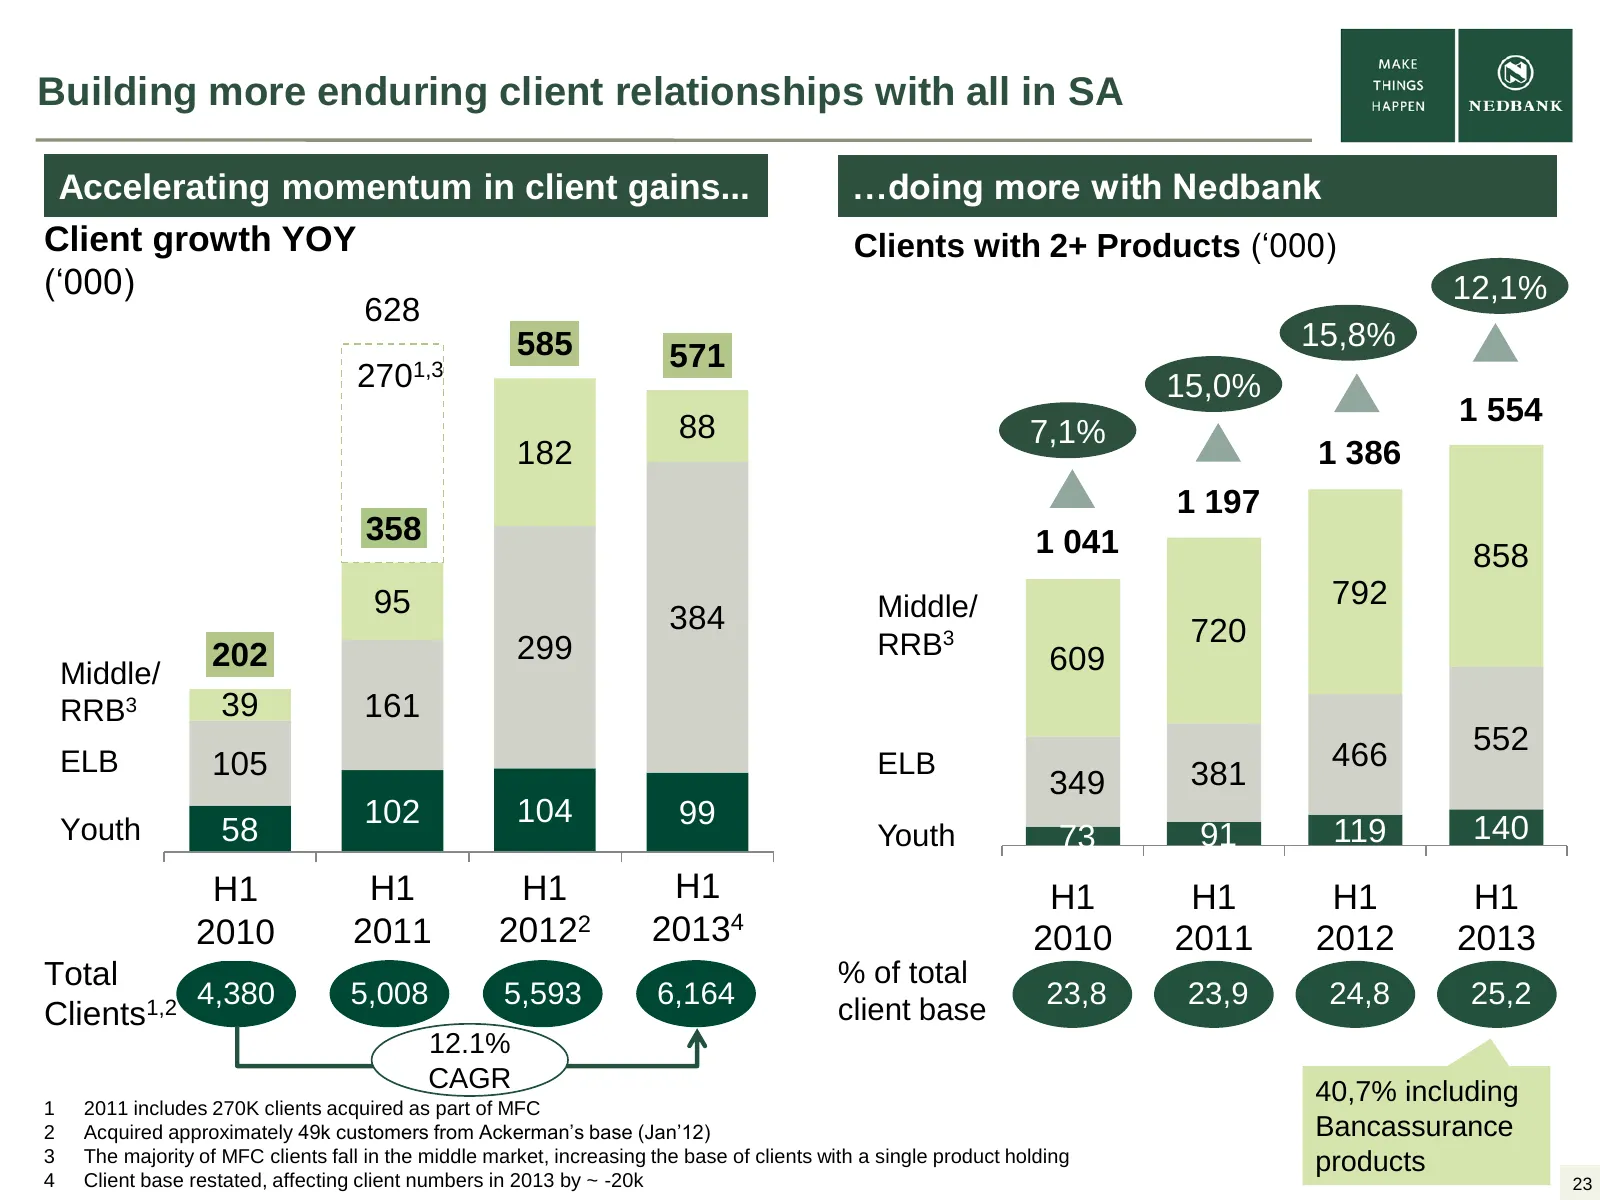
Slide 23: Building more enduring client relationships with all in SA
Building more enduring client relationships with all in SA Accelerating momentum in client gains... …doing more with Nedbank Client growth YOY Clients with 2+ Products (‘000) (‘000) 12,1% 628 585 15,8% 571 2701,3 15,0% 1 554 88 7,1% 182 1 386 1 197 358 1 041 858 95 Middle/ 792 384 720 202 299 RRB3 6
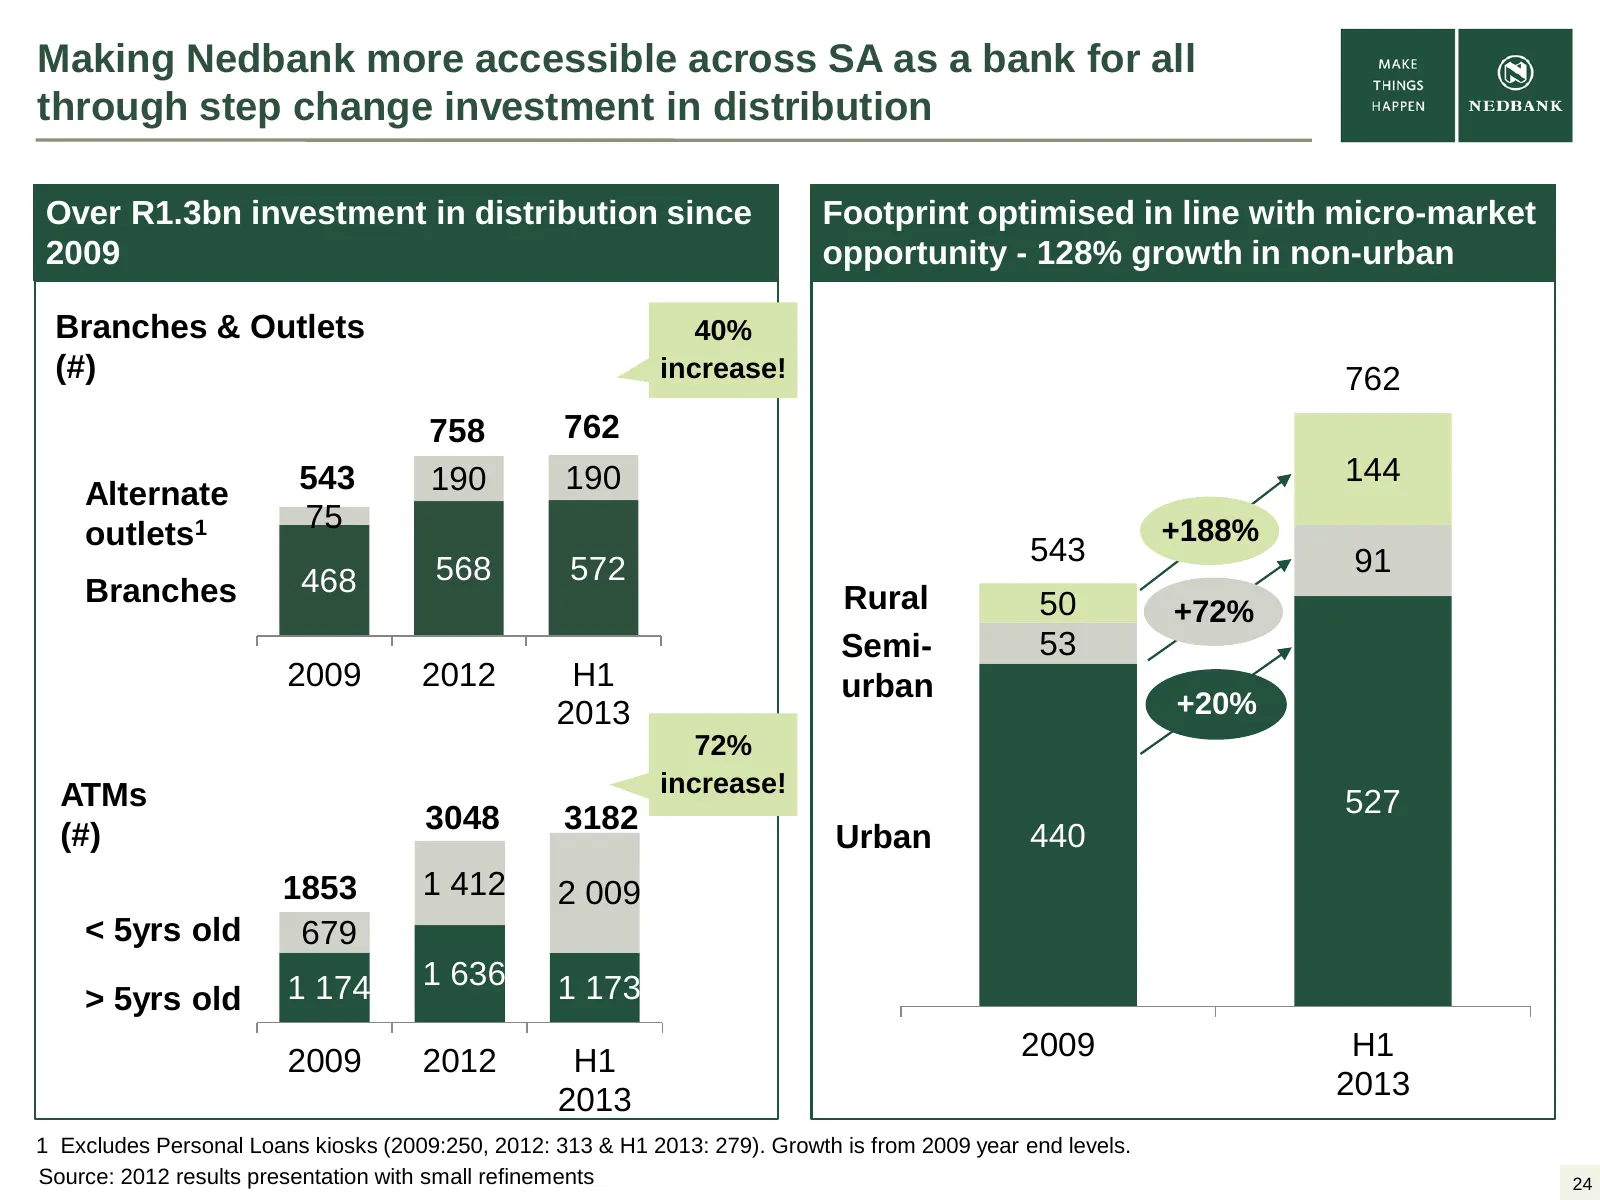
Slide 24: Making Nedbank more accessible through investment in distribution
Making Nedbank more accessible across SA as a bank for all through step change investment in distribution Over R1.3bn investment in distribution since Footprint optimised in line with micro-market 2009 STRATEGIC INTENT STRATEGIC opportunity INTENT - 128% growth in non-urban Branches & Outlets 40% (#
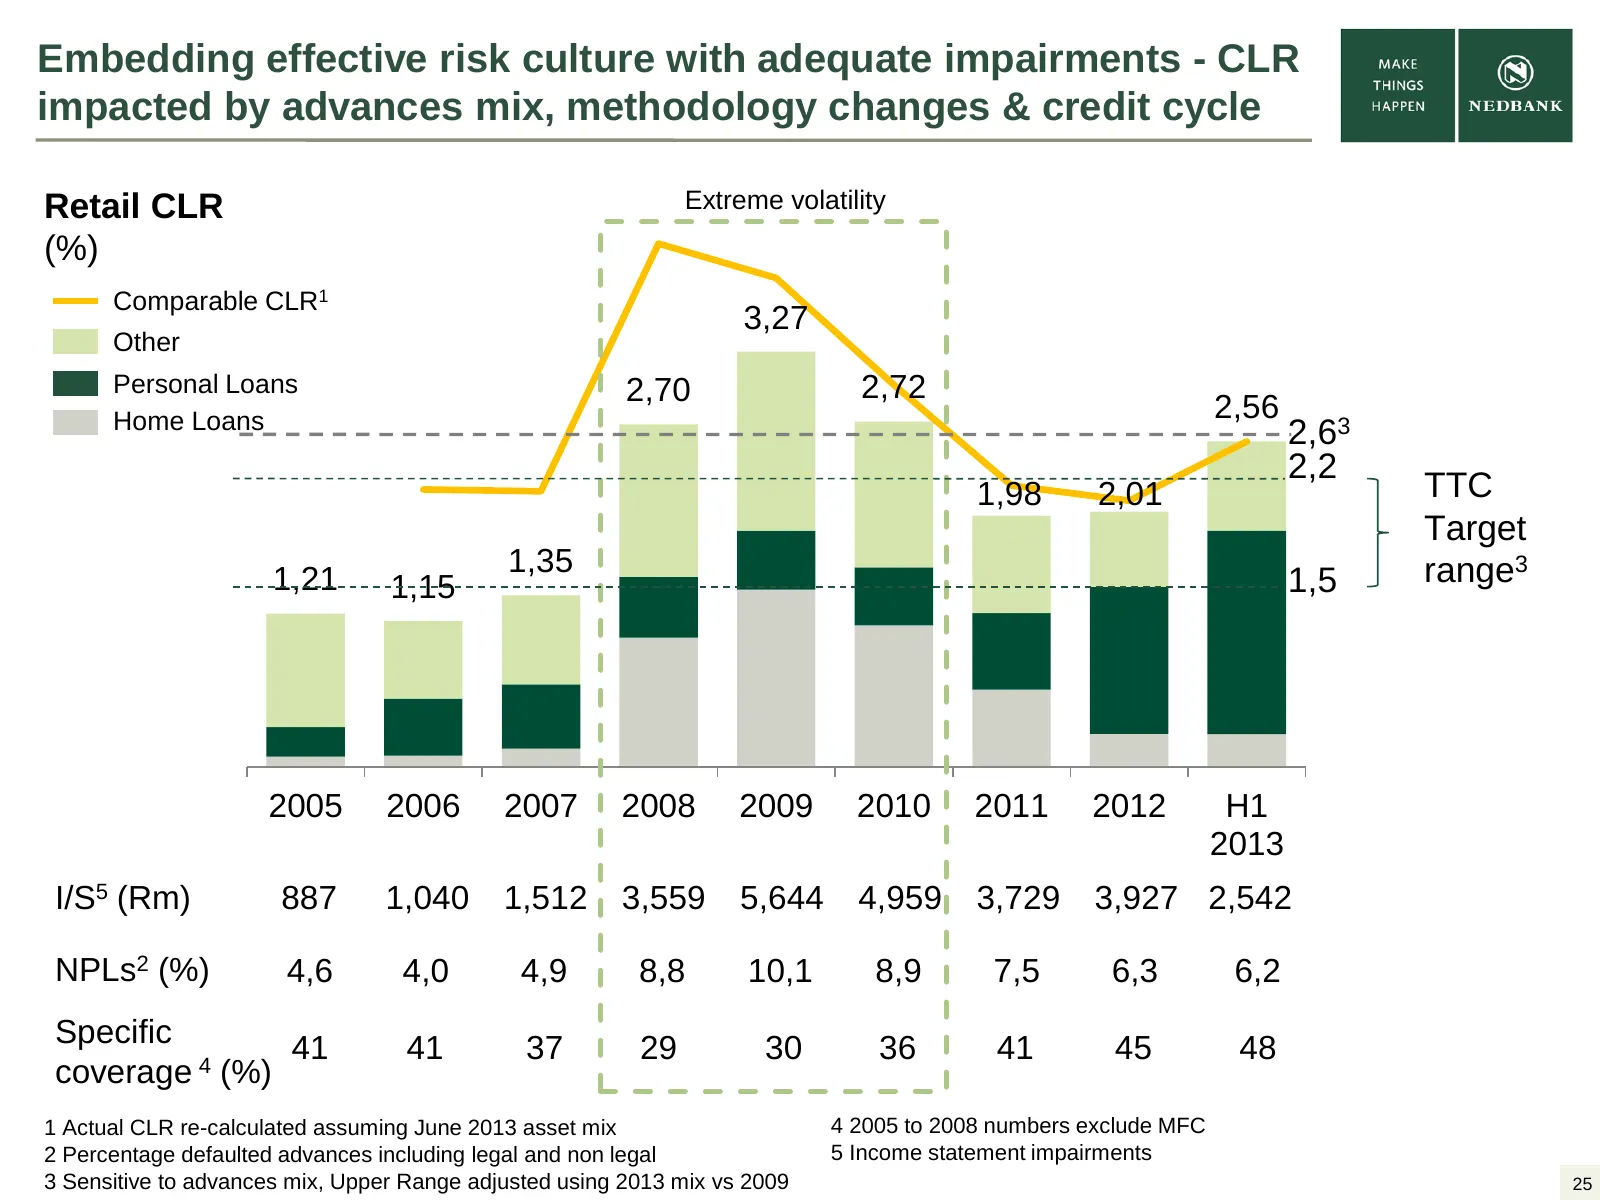
Slide 25: Embedding effective risk culture with adequate impairments
Embedding effective risk culture with adequate impairments - CLR impacted by advances mix, methodology changes & credit cycle Retail CLR Extreme volatility (%) Comparable CLR1 3,27 Other Personal Loans 2,70 2,72 Home Loans 2,56 2,63 2,2 1,98 2,01 TTC Target 1,35 range3 1,21 1,15 1,5 2005 2006 2007 2
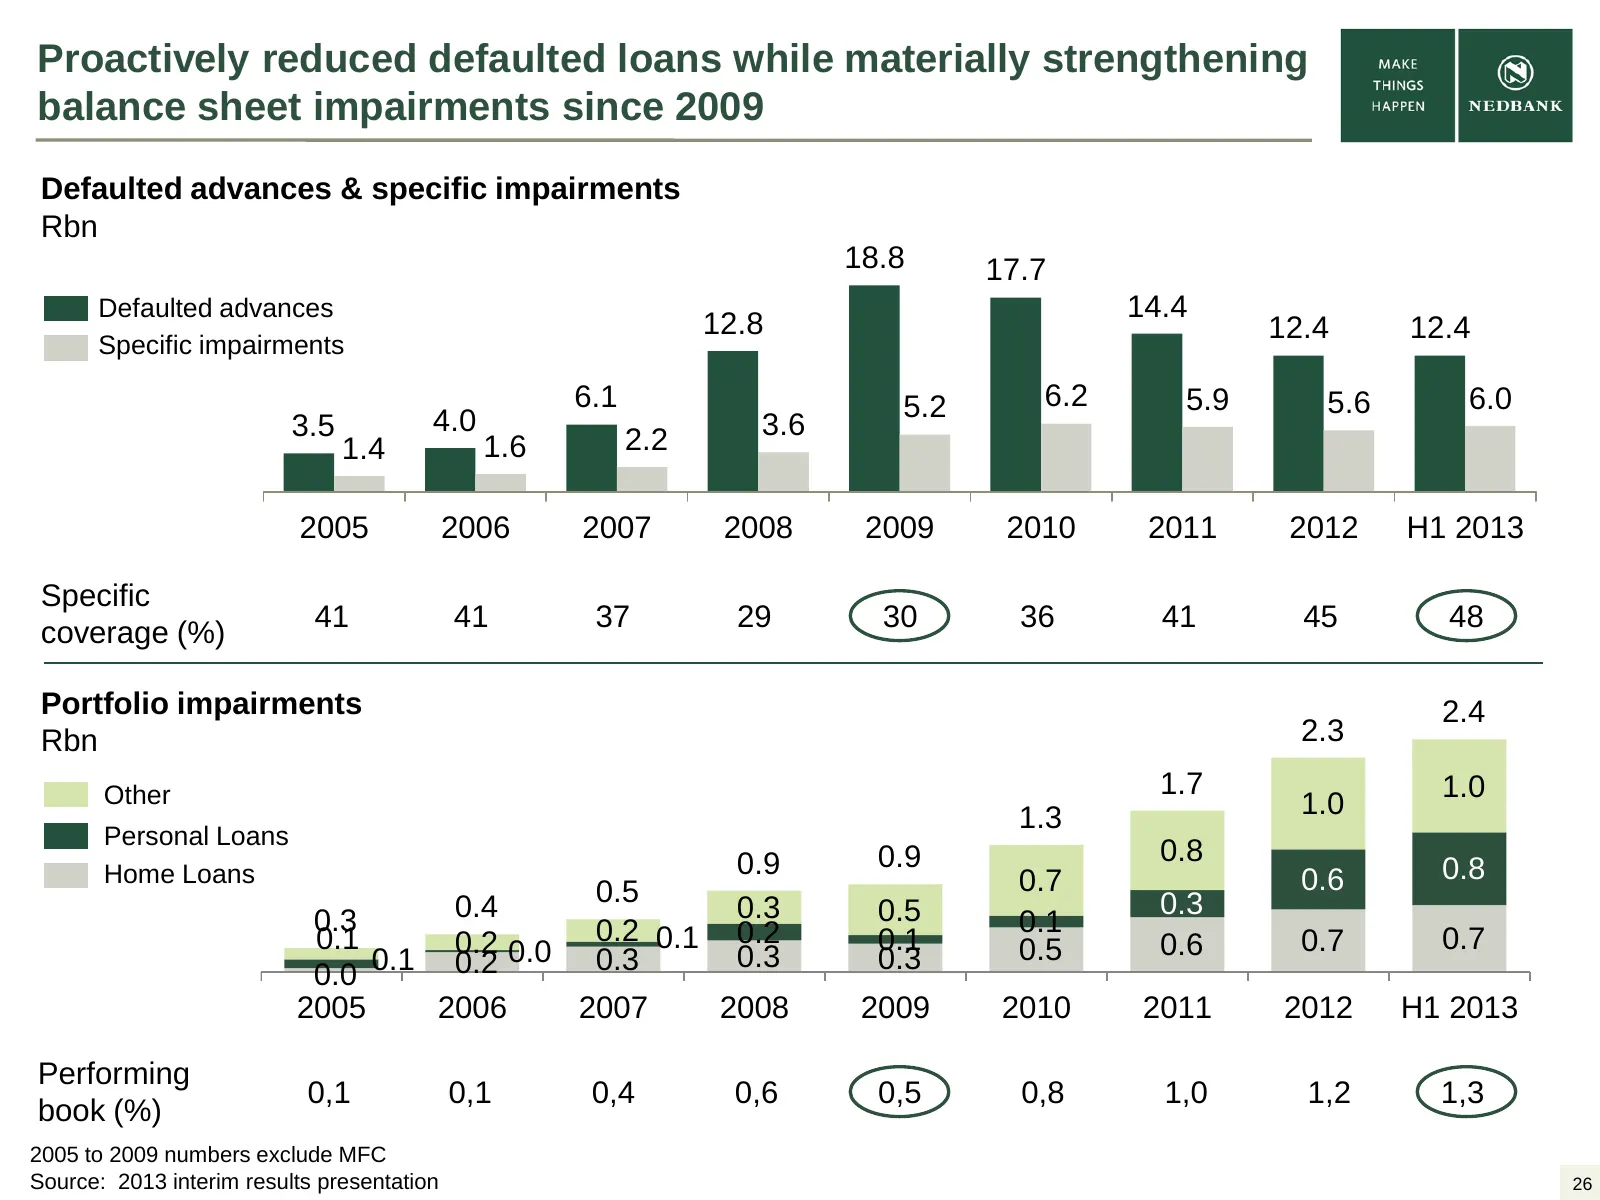
Slide 26: Reduced defaulted loans while strengthening balance sheet impairments
Proactively reduced defaulted loans while materially strengthening balance sheet impairments since 2009 Defaulted advances & specific impairments Rbn 18.8 17.7 Defaulted advances 14.4 12.8 12.4 12.4 Specific impairments 6.1 5.2 6.2 5.9 5.6 6.0 3.5 4.0 3.6 1.4 1.6 2.2 2005 2006 2007 2008 2009 2010 20
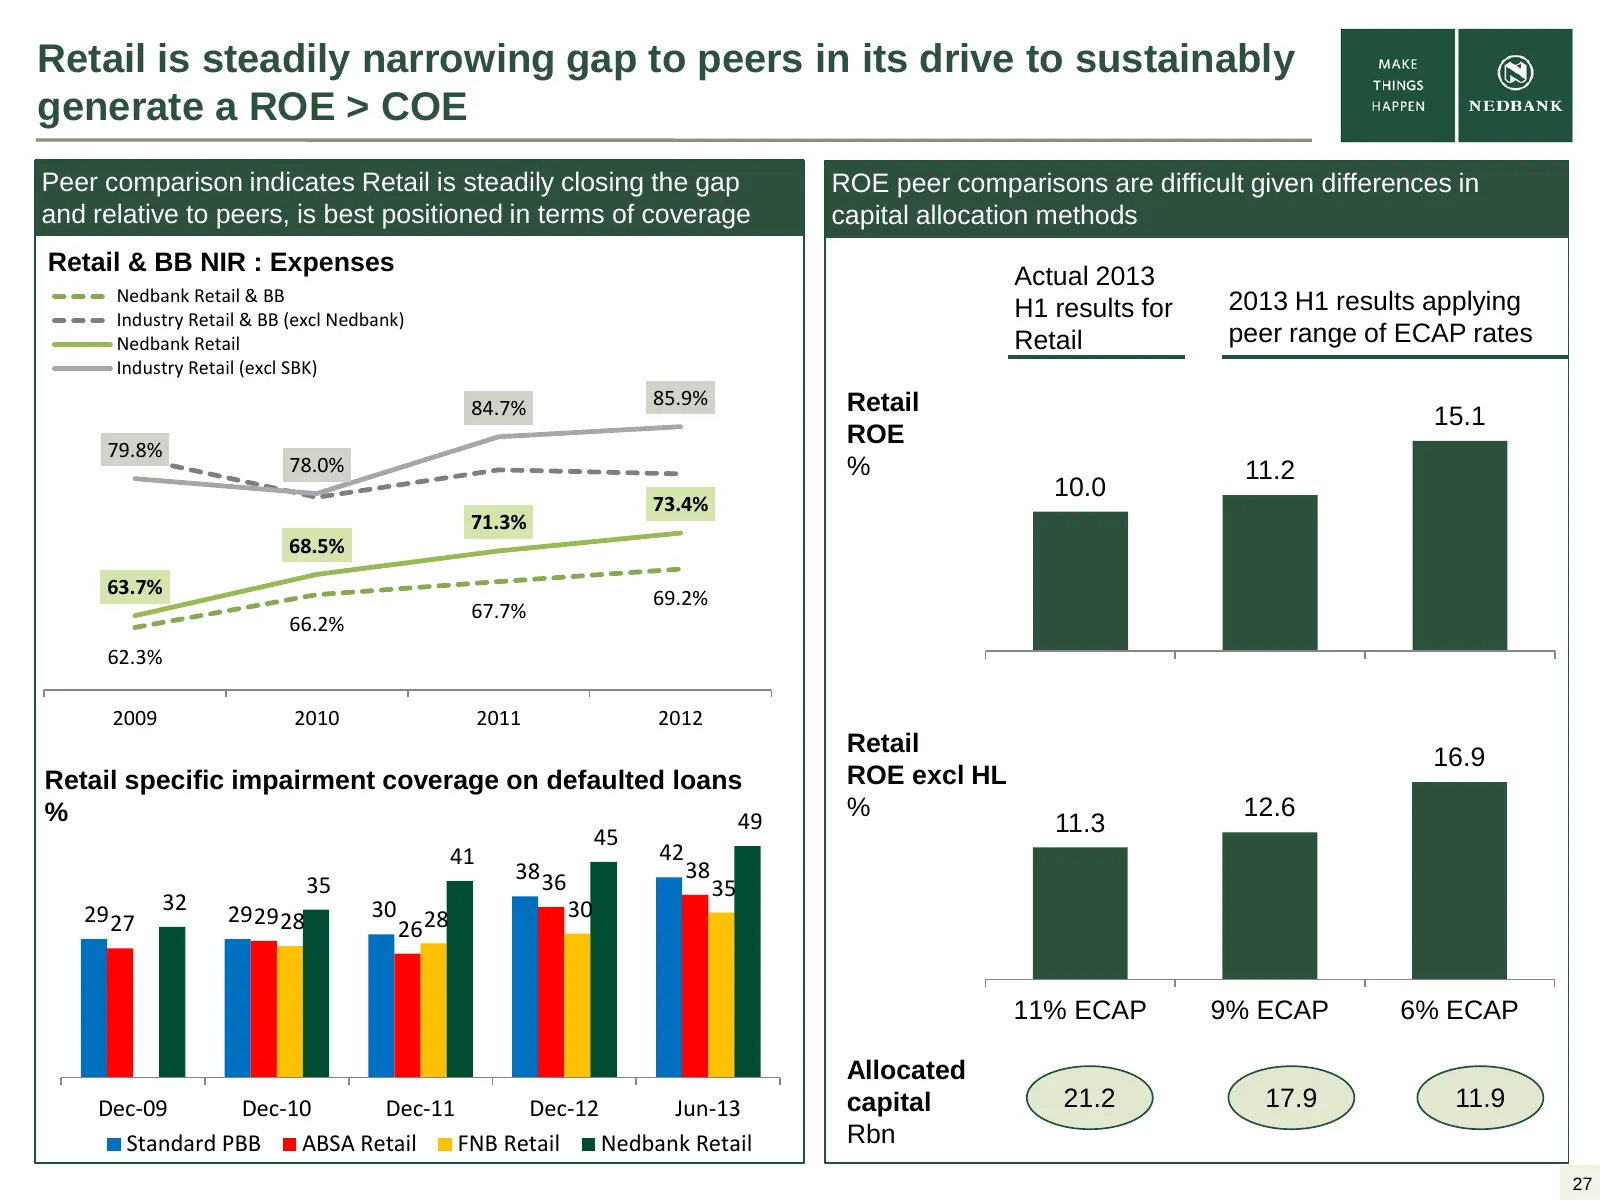
Slide 27: Retail steadily narrowing gap to peers in drive to ROE > COE
Retail is steadily narrowing gap to peers in its drive to sustainably generate a ROE > COE Peer comparison indicates Retail is steadily closing the gap ROE peer comparisons are difficult given differences in and relative to peers, is best positioned in terms of coverage capital allocation methods Re
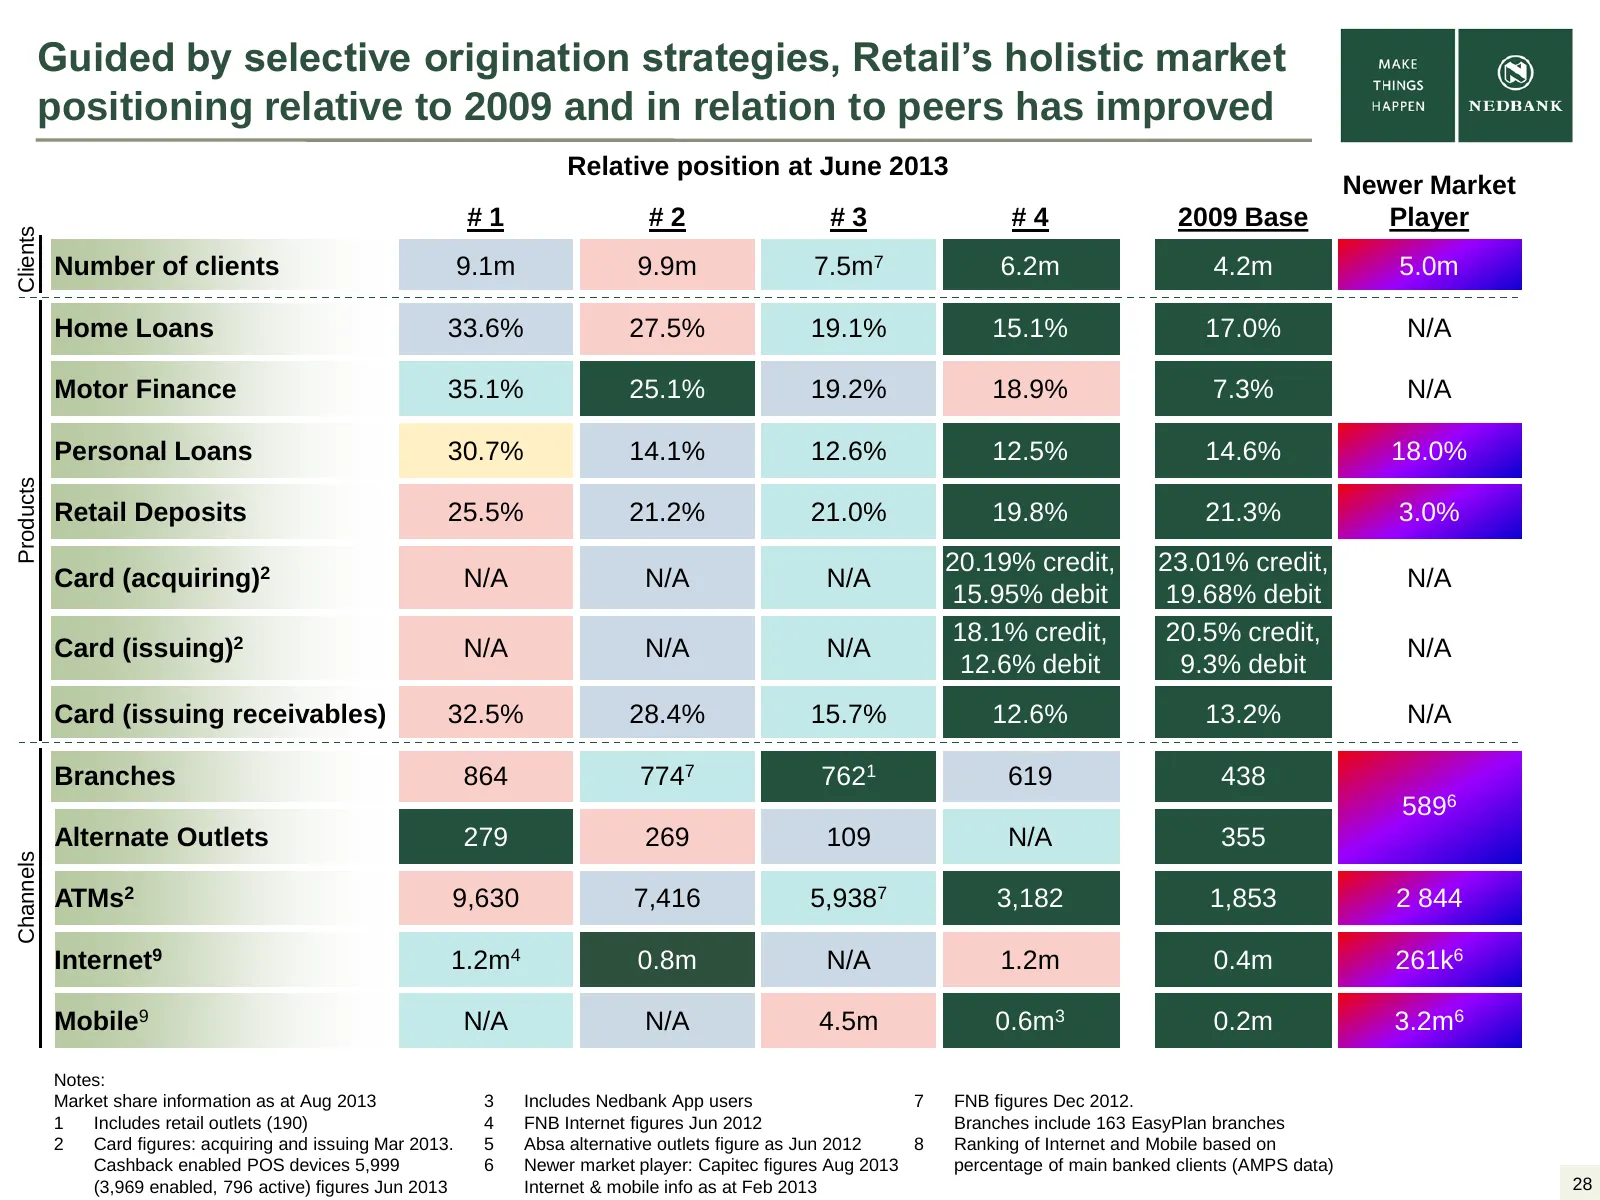
Slide 28: Retail's market positioning relative to 2009 and peers has improved
Guided by selective origination strategies, Retail’s holistic market positioning relative to 2009 and in relation to peers has improved Relative position at June 2013 Newer Market #1 #2 #3 #4 2009 Base Player Clients Number of clients 9.1m 9.9m 7.5m7 6.2m 4.2m 5.0m Home Loans 33.6% 27.5% 19.1% 15.1%
Slide 29: Rebuilding the main banked client franchise takes time
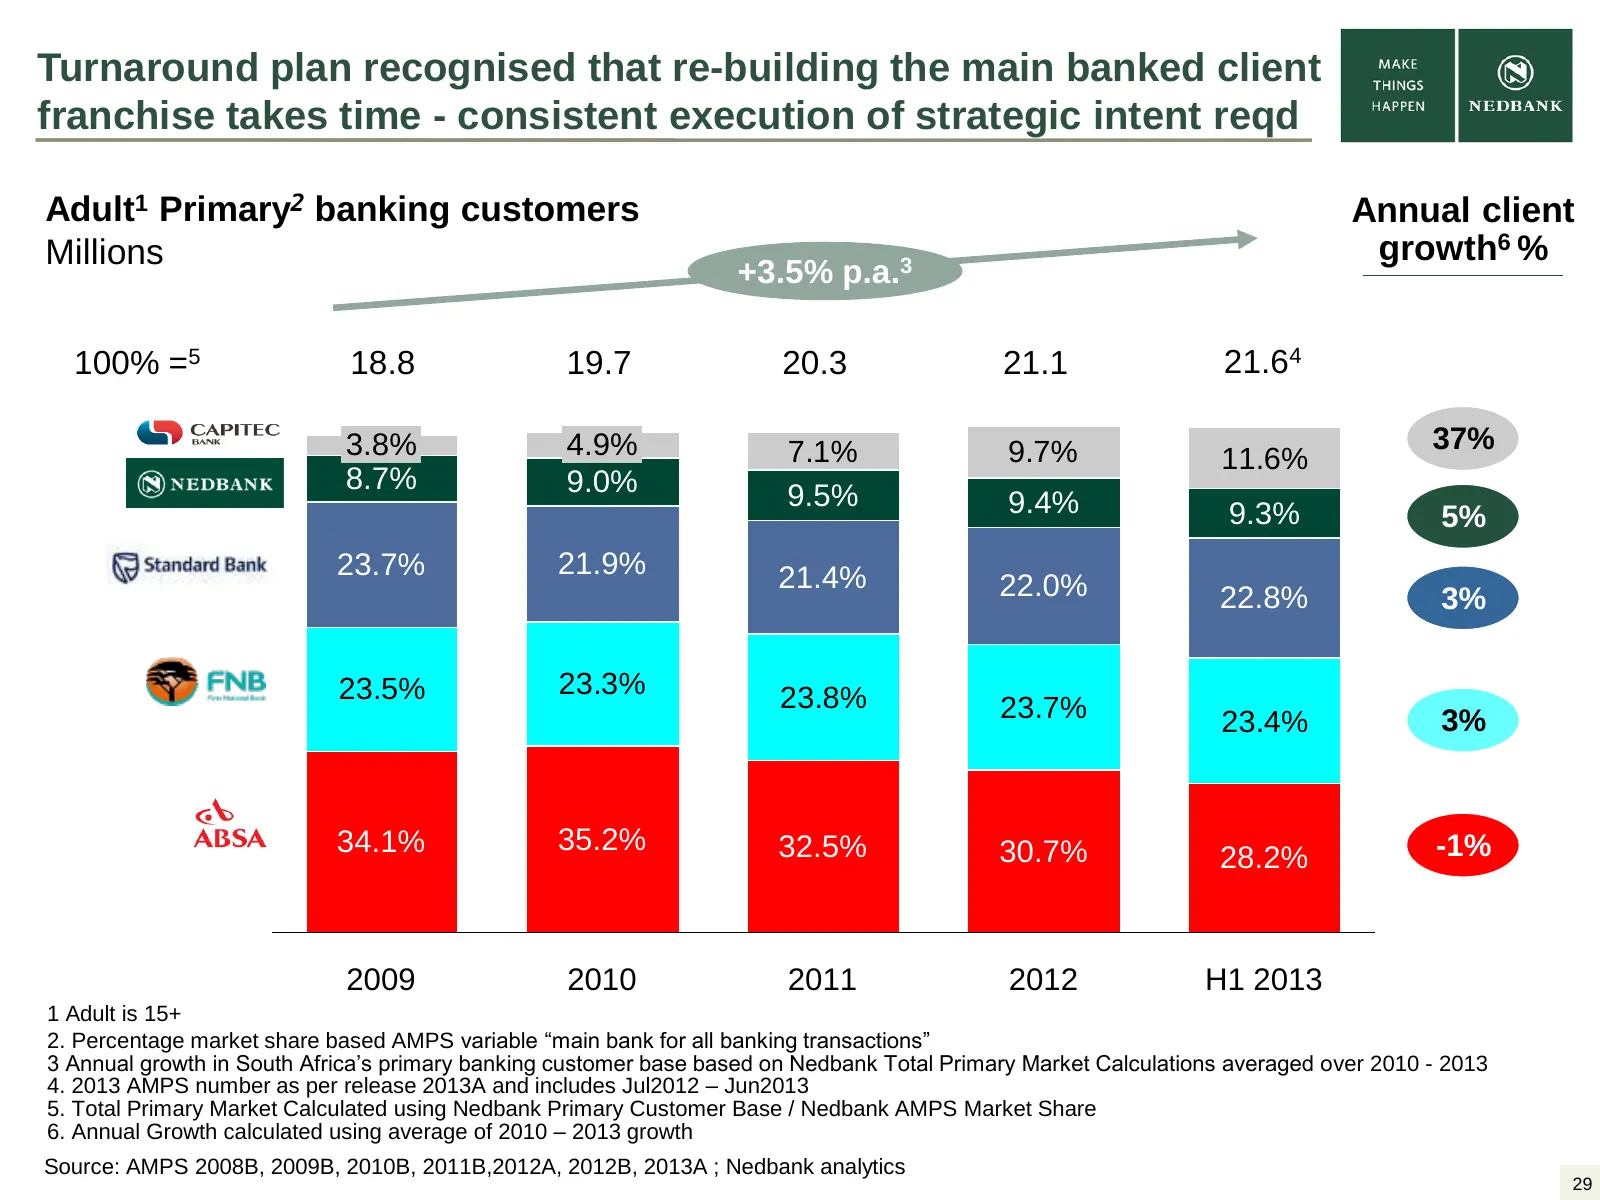
Turnaround plan recognised that re-building the main banked client franchise takes time - consistent execution of strategic intent reqd Adult1 Primary2 banking customers Annual client Millions growth6 % +3.5% p.a.3 100% =5 18.8 19.7 20.3 21.1 21.64 3.8% 4.9% 7.1% 9.7% 37% 11.6% 8.7% 9.0% 9.5% 9.4% 9
Slide 30: Growing total clients in all segments
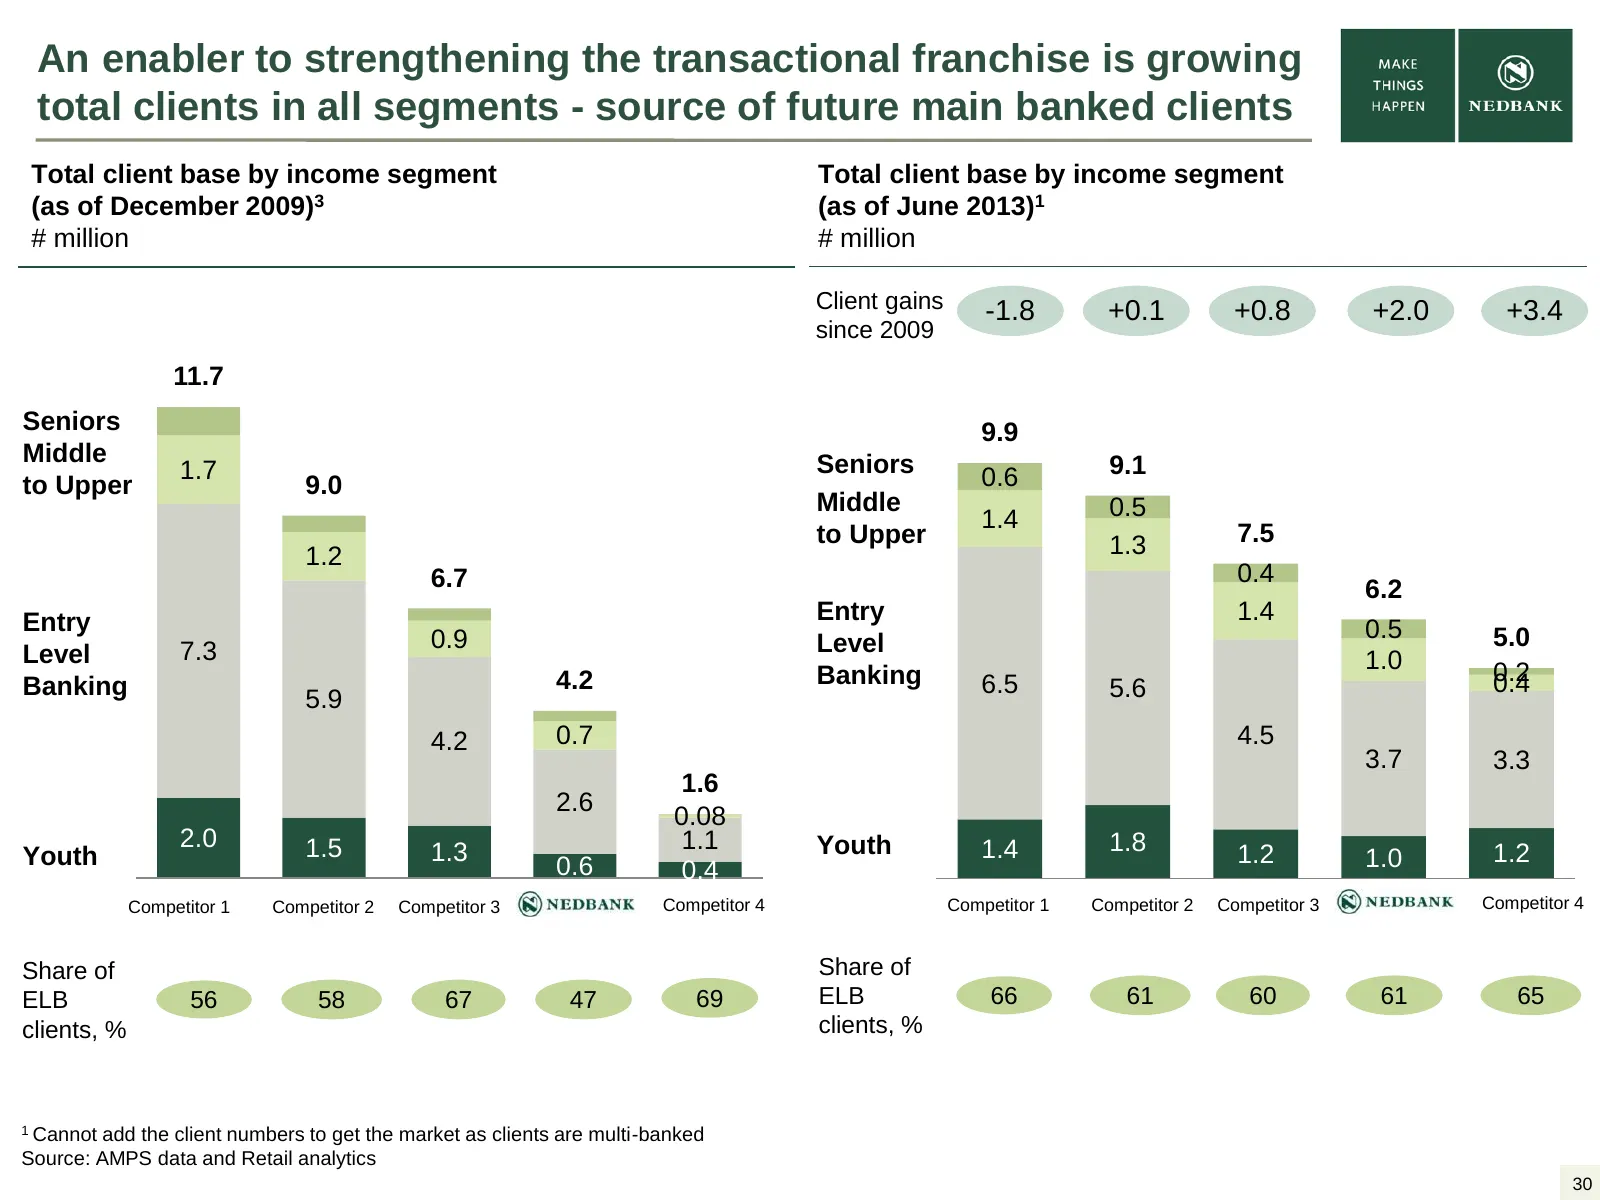
An enabler to strengthening the transactional franchise is growing total clients in all segments - source of future main banked clients Total client base by income segment Total client base by income segment (as of December 2009)3 (as of June 2013)1 # million # million Client gains -1.8 +0.1 +0.8 +2
Slide 31: Nedbank's achievements acknowledged in the market
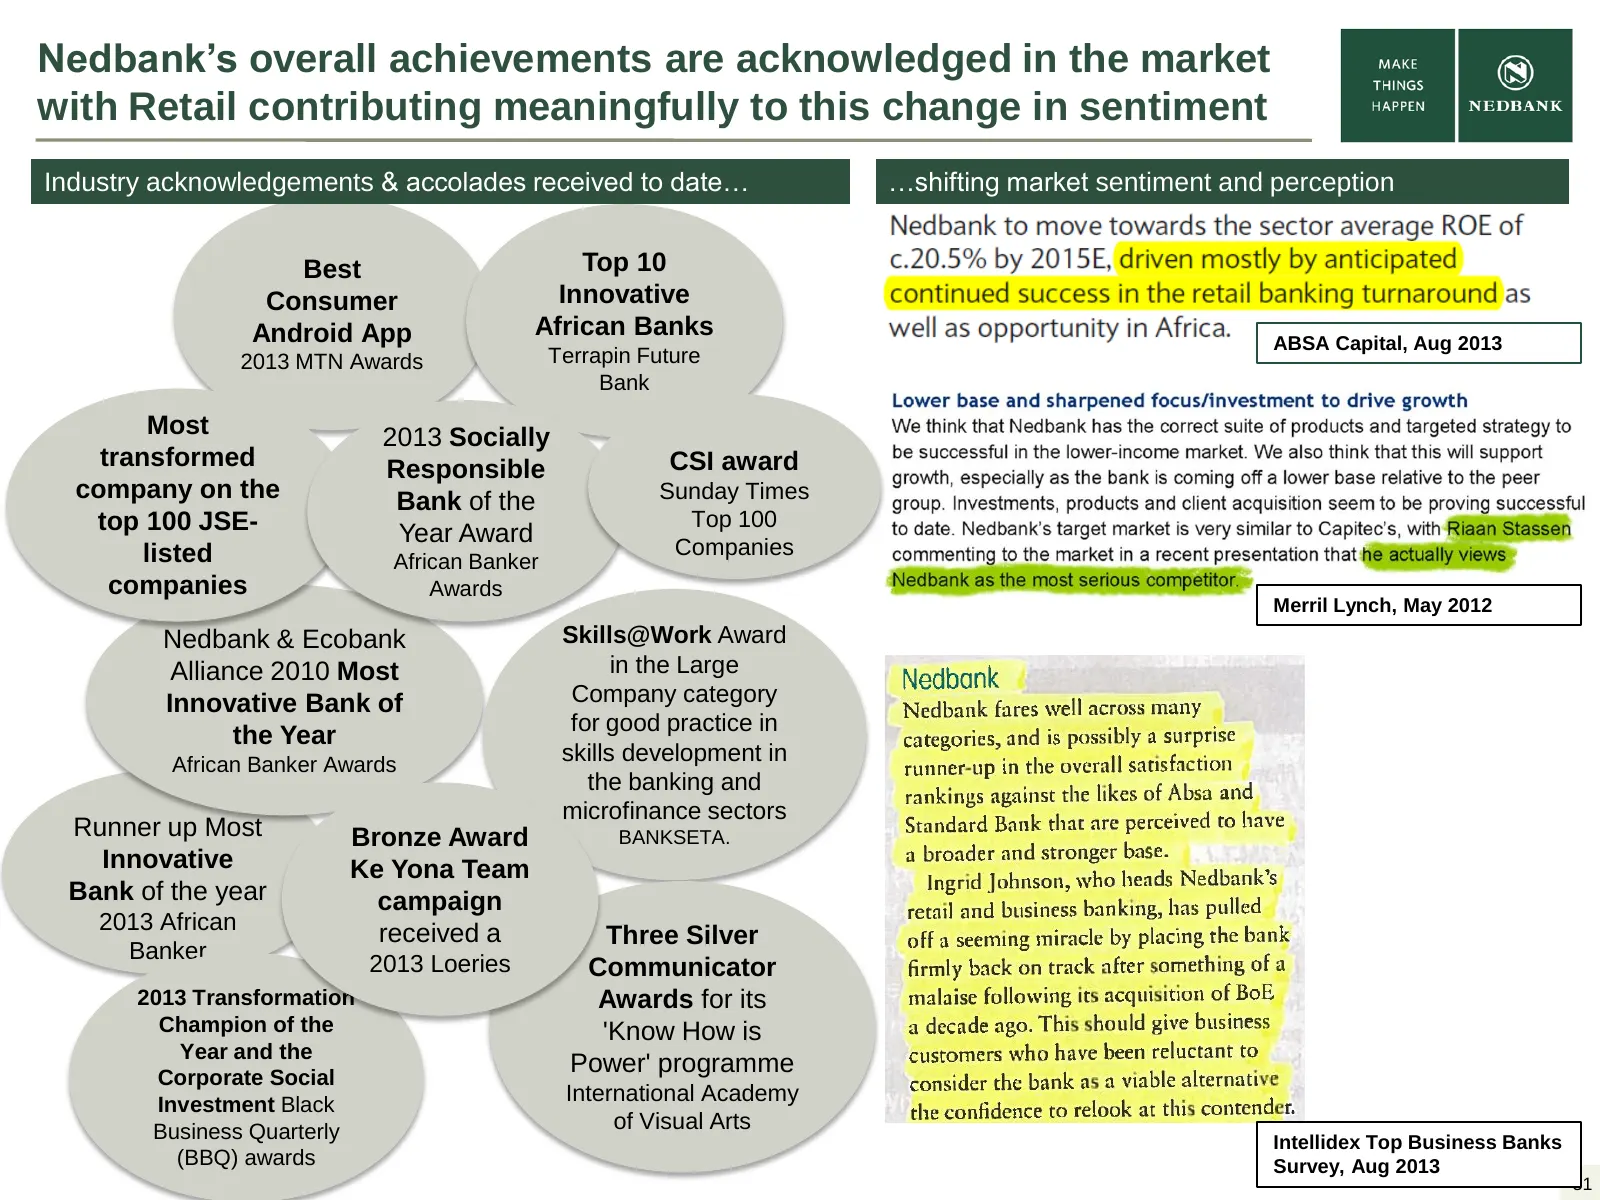
Nedbank’s overall achievements are acknowledged in the market with Retail contributing meaningfully to this change in sentiment Industry acknowledgements & accolades received to date… …shifting market sentiment and perception Best Top 10 Consumer Innovative Android App African Banks ABSA Capital, Au
Slide 32: Repositioning Retail – presentation topics
Repositioning Retail – presentation topics ▪ Executive Summary ▪ What we set out to do in 2010 ▪ Progress to date ▪ How we achieved it ▪ Future trends & prospects 32
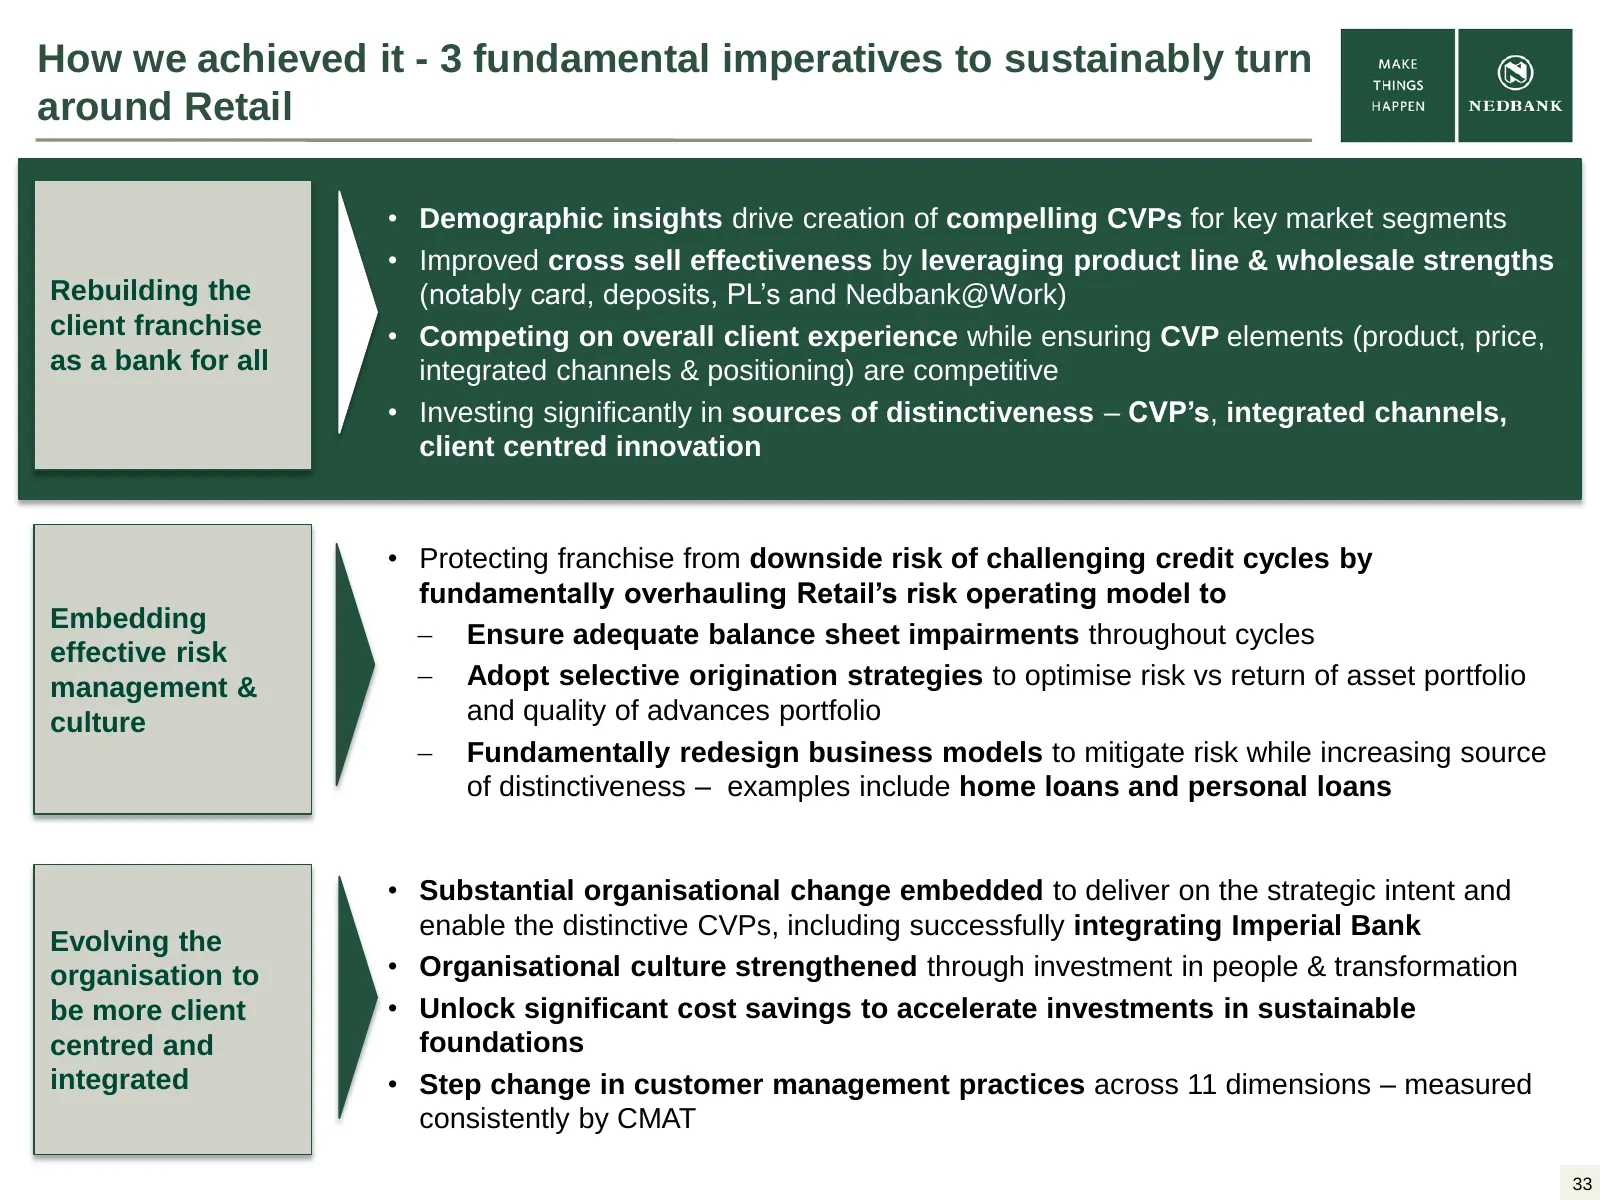
Slide 33: How we achieved it – fundamental imperatives to turn around Retail
How we achieved it - 3 fundamental imperatives to sustainably turn around Retail • Demographic insights drive creation of compelling CVPs for key market segments • Improved cross sell effectiveness by leveraging product line & wholesale strengths Rebuilding the (notably card, deposits, PL’s and Nedb
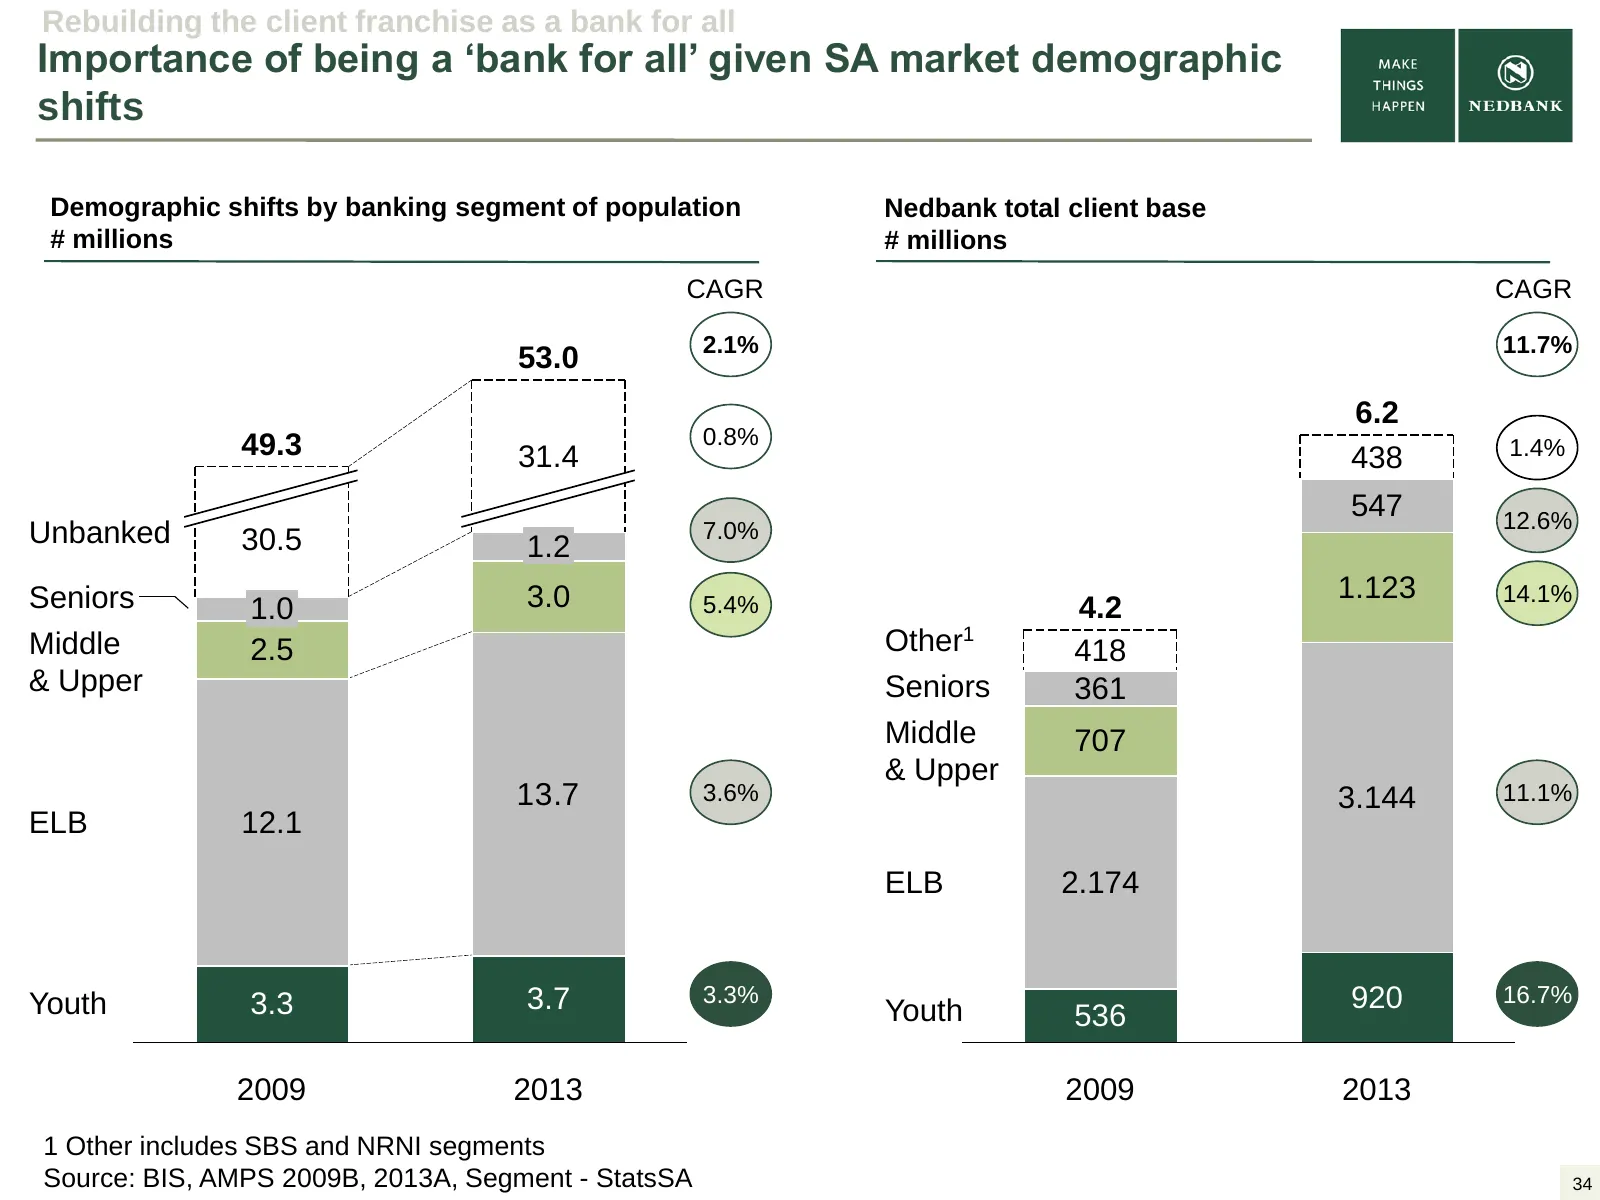
Slide 34: Importance of being a 'bank for all' given demographic shifts
Rebuilding the client franchise as a bank for all Importance of being a ‘bank for all’ given SA market demographic shifts Demographic shifts by banking segment of population Nedbank total client base # millions # millions CAGR CAGR 2.1% 11.7% 53.0 6.2 49.3 0.8% 1.4% 31.4 438 547 12.6% Unbanked 30.5
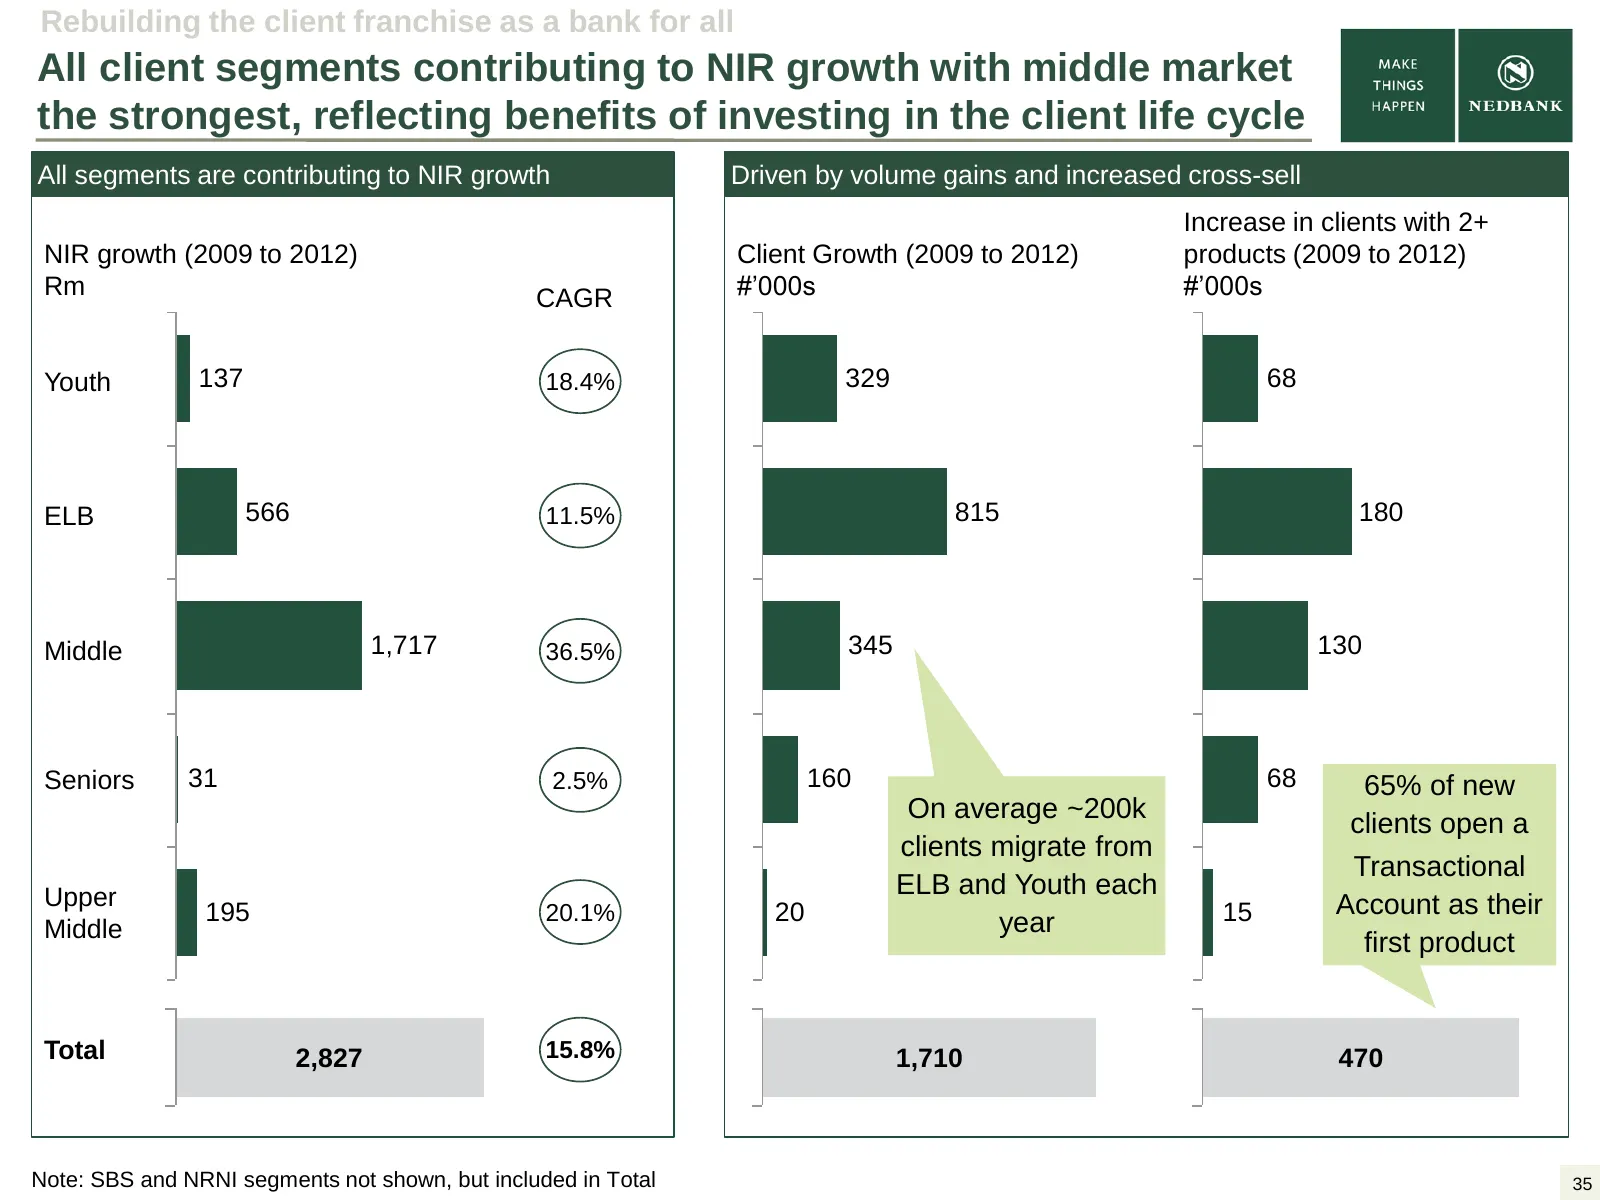
Slide 35: All client segments contributing to NIR growth
Rebuilding the client franchise as a bank for all All client segments contributing to NIR growth with middle market the strongest, reflecting benefits of investing in the client life cycle All segments are contributing to NIR growth Driven by volume gains and increased cross-sell Increase in clients
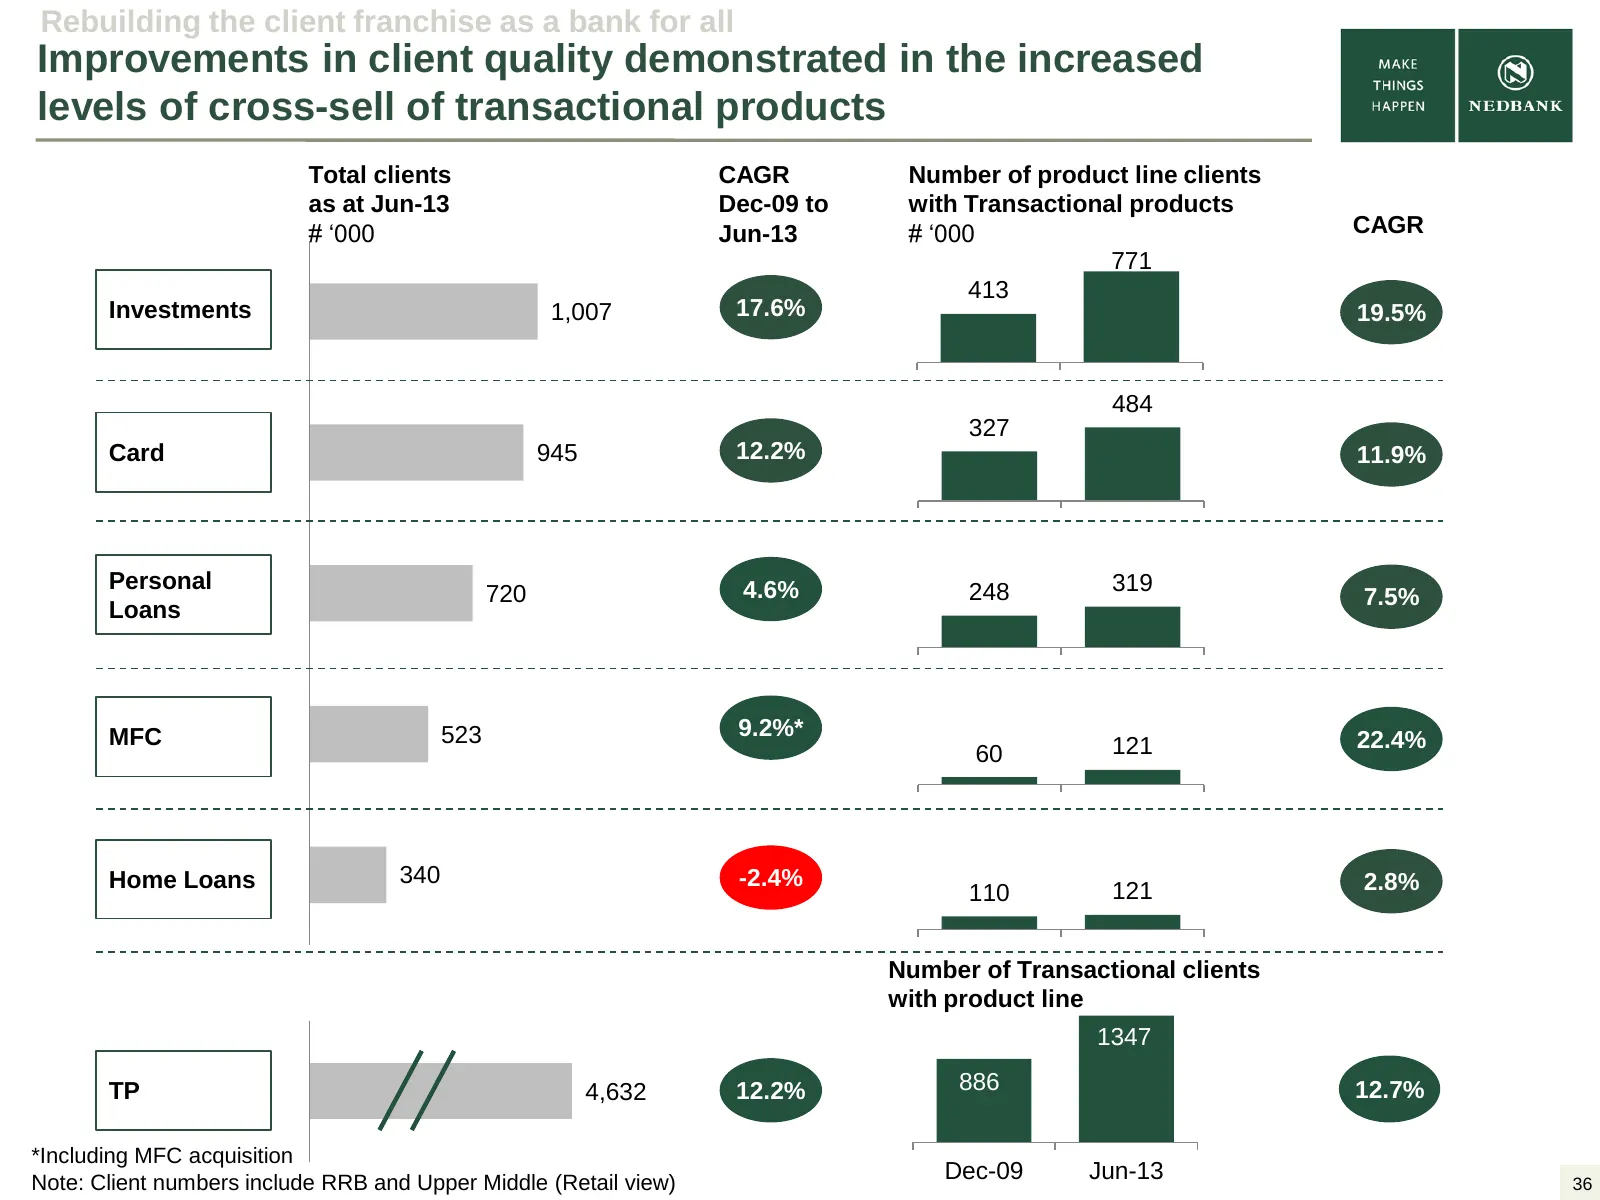
Slide 36: Improved client quality shown in cross-sell of transactional products
Rebuilding the client franchise as a bank for all Improvements in client quality demonstrated in the increased levels of cross-sell of transactional products Total clients CAGR Number of product line clients as at Jun-13 Dec-09 to with Transactional products # ‘000 Jun-13 # ‘000 CAGR 771 413 Investm
Slide 37: Youth: Nedbank4me
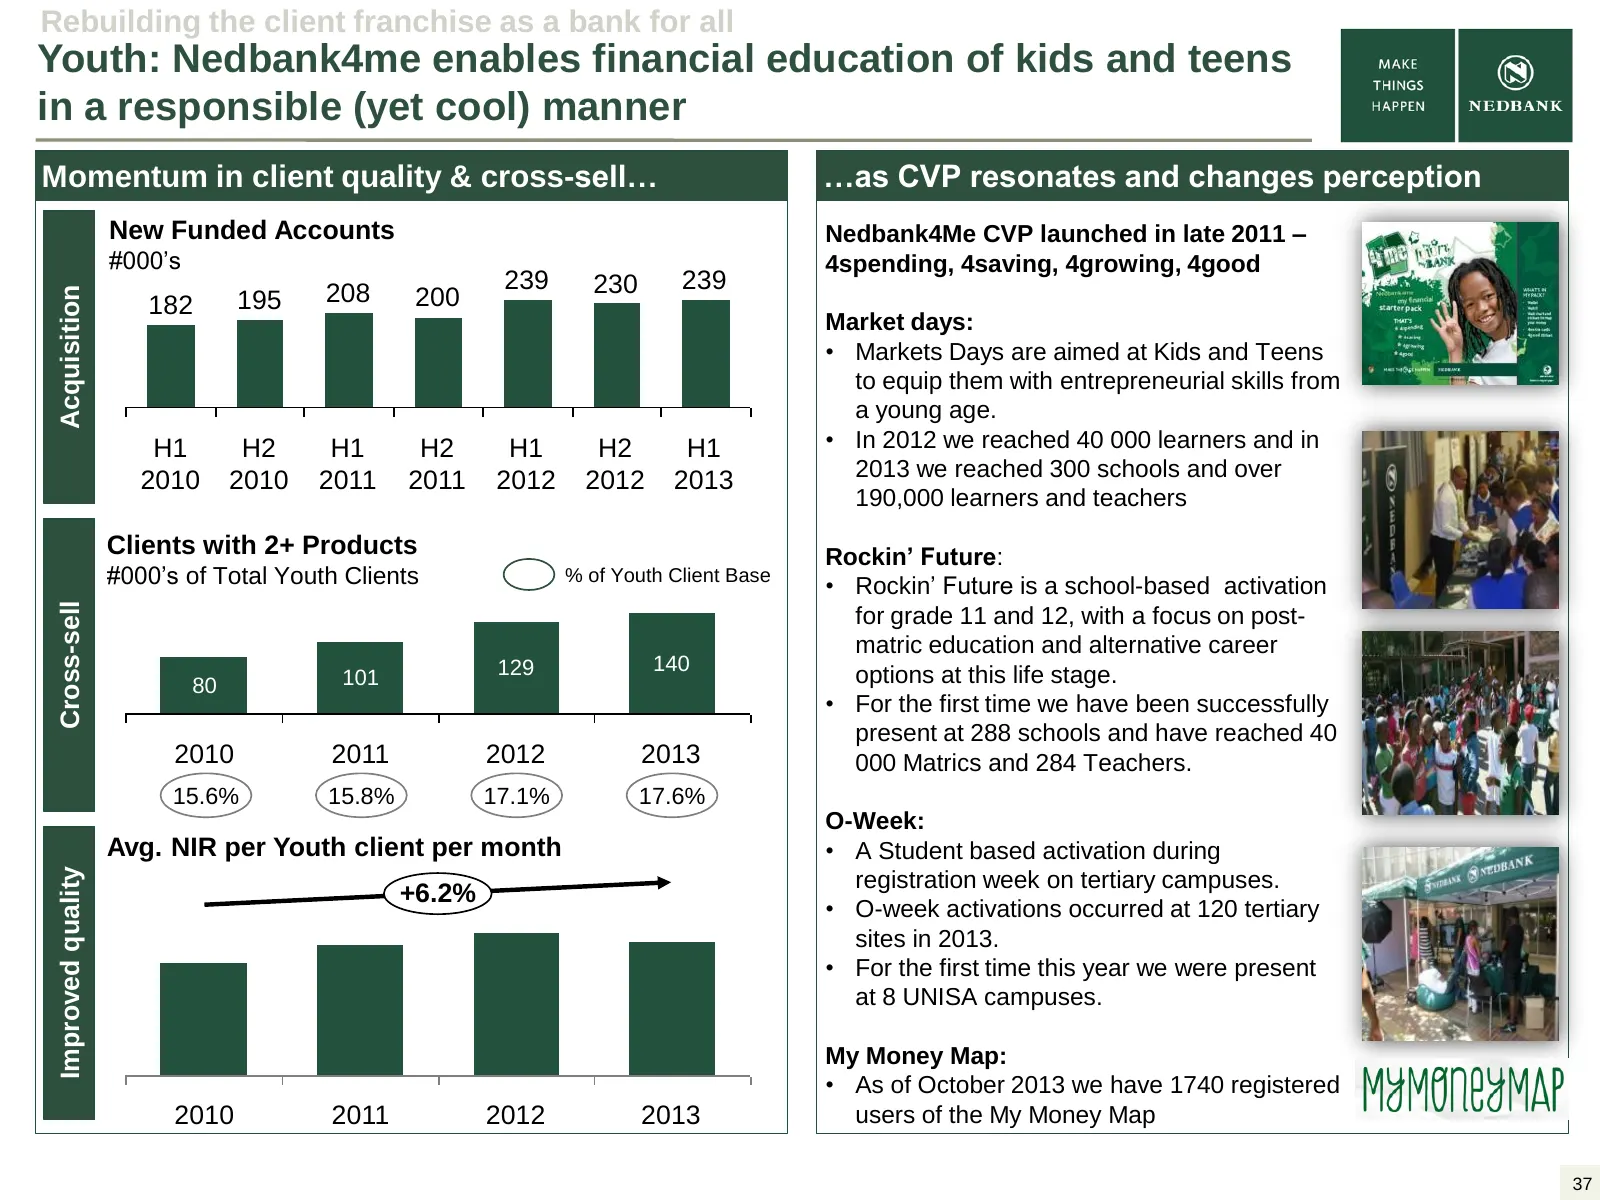
Rebuilding the client franchise as a bank for all Youth: Nedbank4me enables financial education of kids and teens in a responsible (yet cool) manner Momentum in client quality & cross-sell… …as CVP resonates and changes perception New Funded Accounts Nedbank4Me CVP launched in late 2011 – #000’s 4sp
Slide 38: ELB: Nedbank Ke Yona
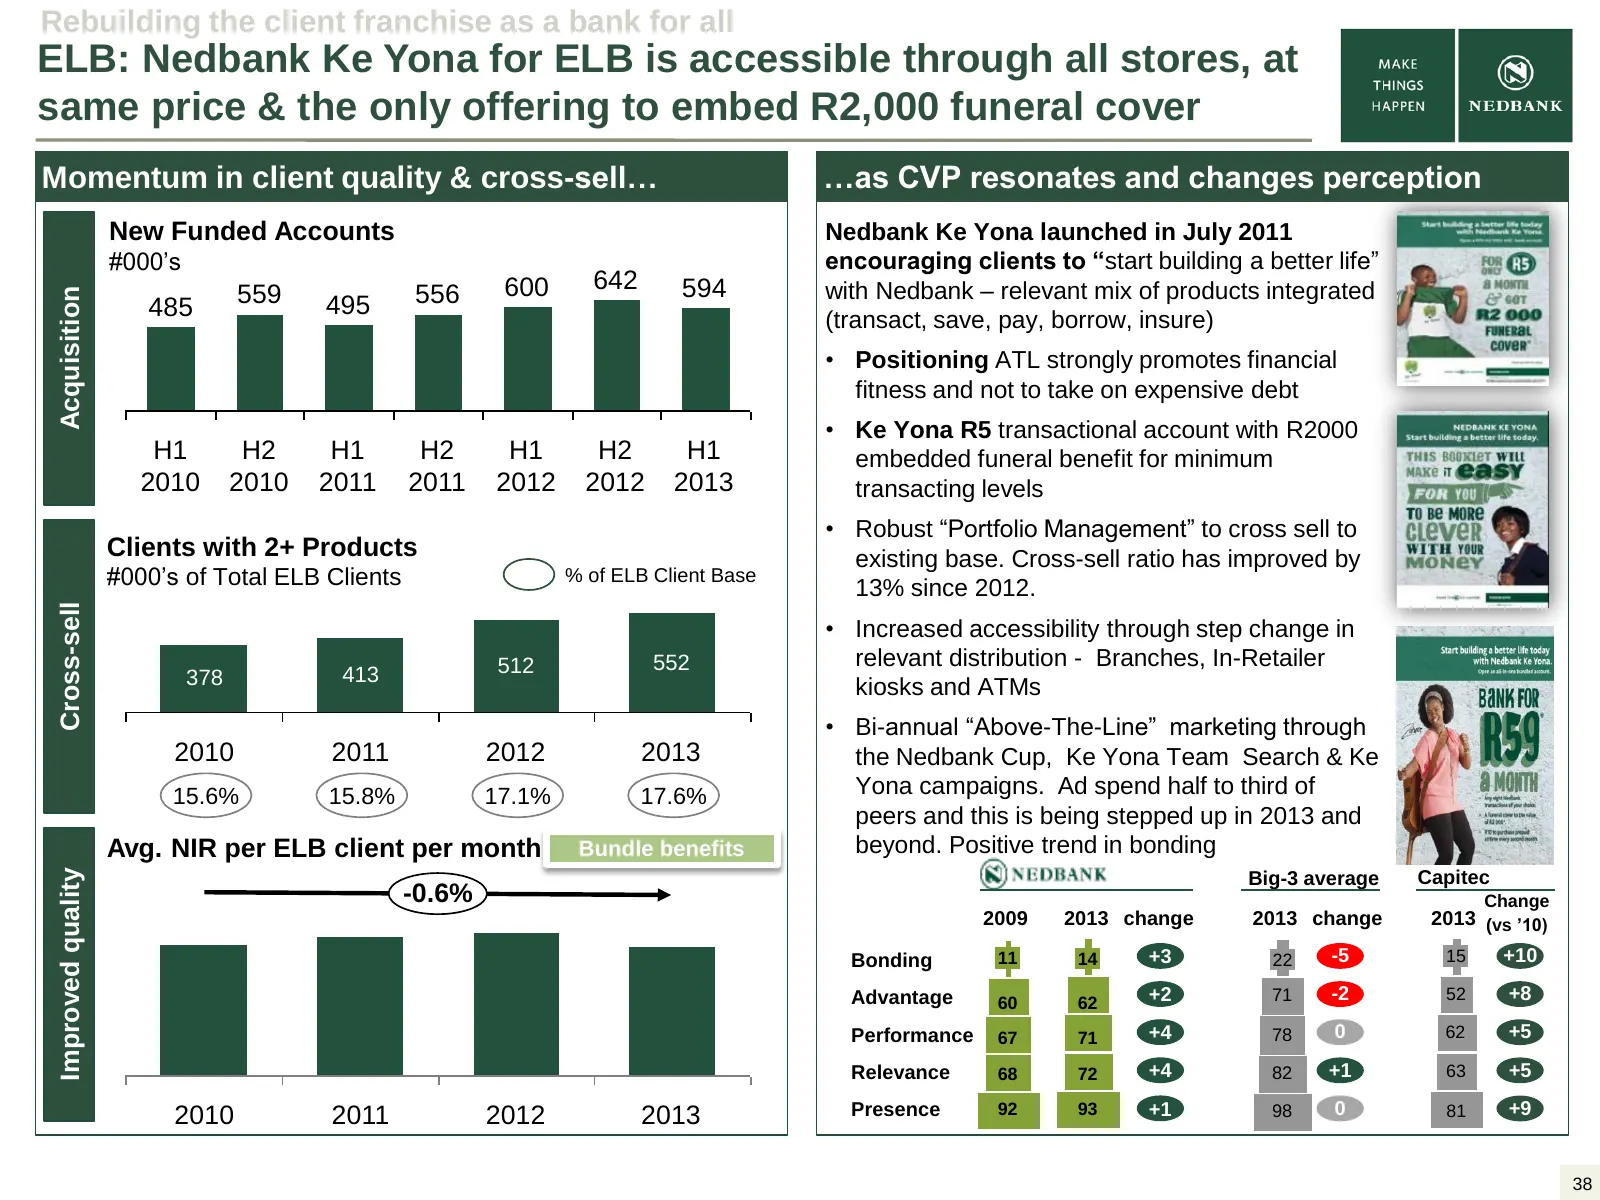
Rebuilding the client franchise as a bank for all ELB: Nedbank Ke Yona for ELB is accessible through all stores, at same price & the only offering to embed R2,000 funeral cover Momentum in client quality & cross-sell… …as CVP resonates and changes perception New Funded Accounts Nedbank Ke Yona launc
Slide 39: Middle: Nedbank Savvy
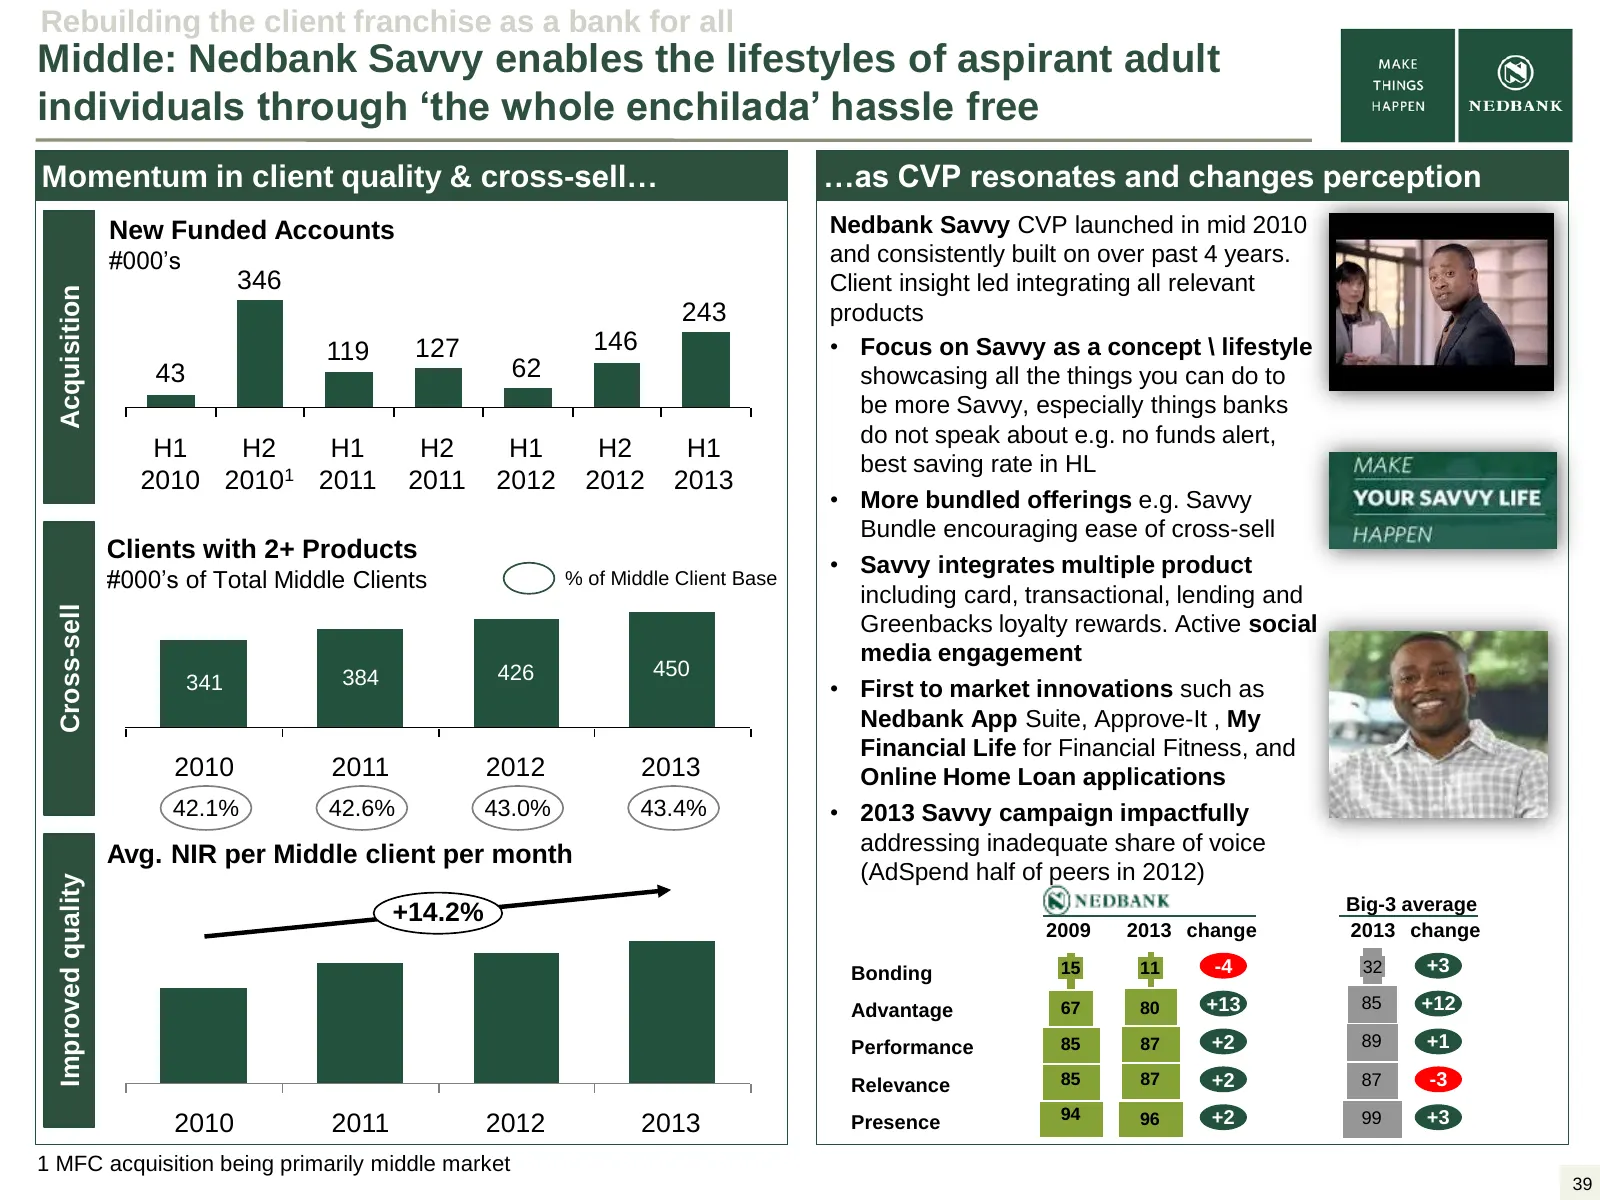
Rebuilding the client franchise as a bank for all Middle: Nedbank Savvy enables the lifestyles of aspirant adult individuals through ‘the whole enchilada’ hassle free Momentum in client quality & cross-sell… …as CVP resonates and changes perception New Funded Accounts Nedbank Savvy CVP launched in m
Slide 40: Building blocks to compete in the middle market
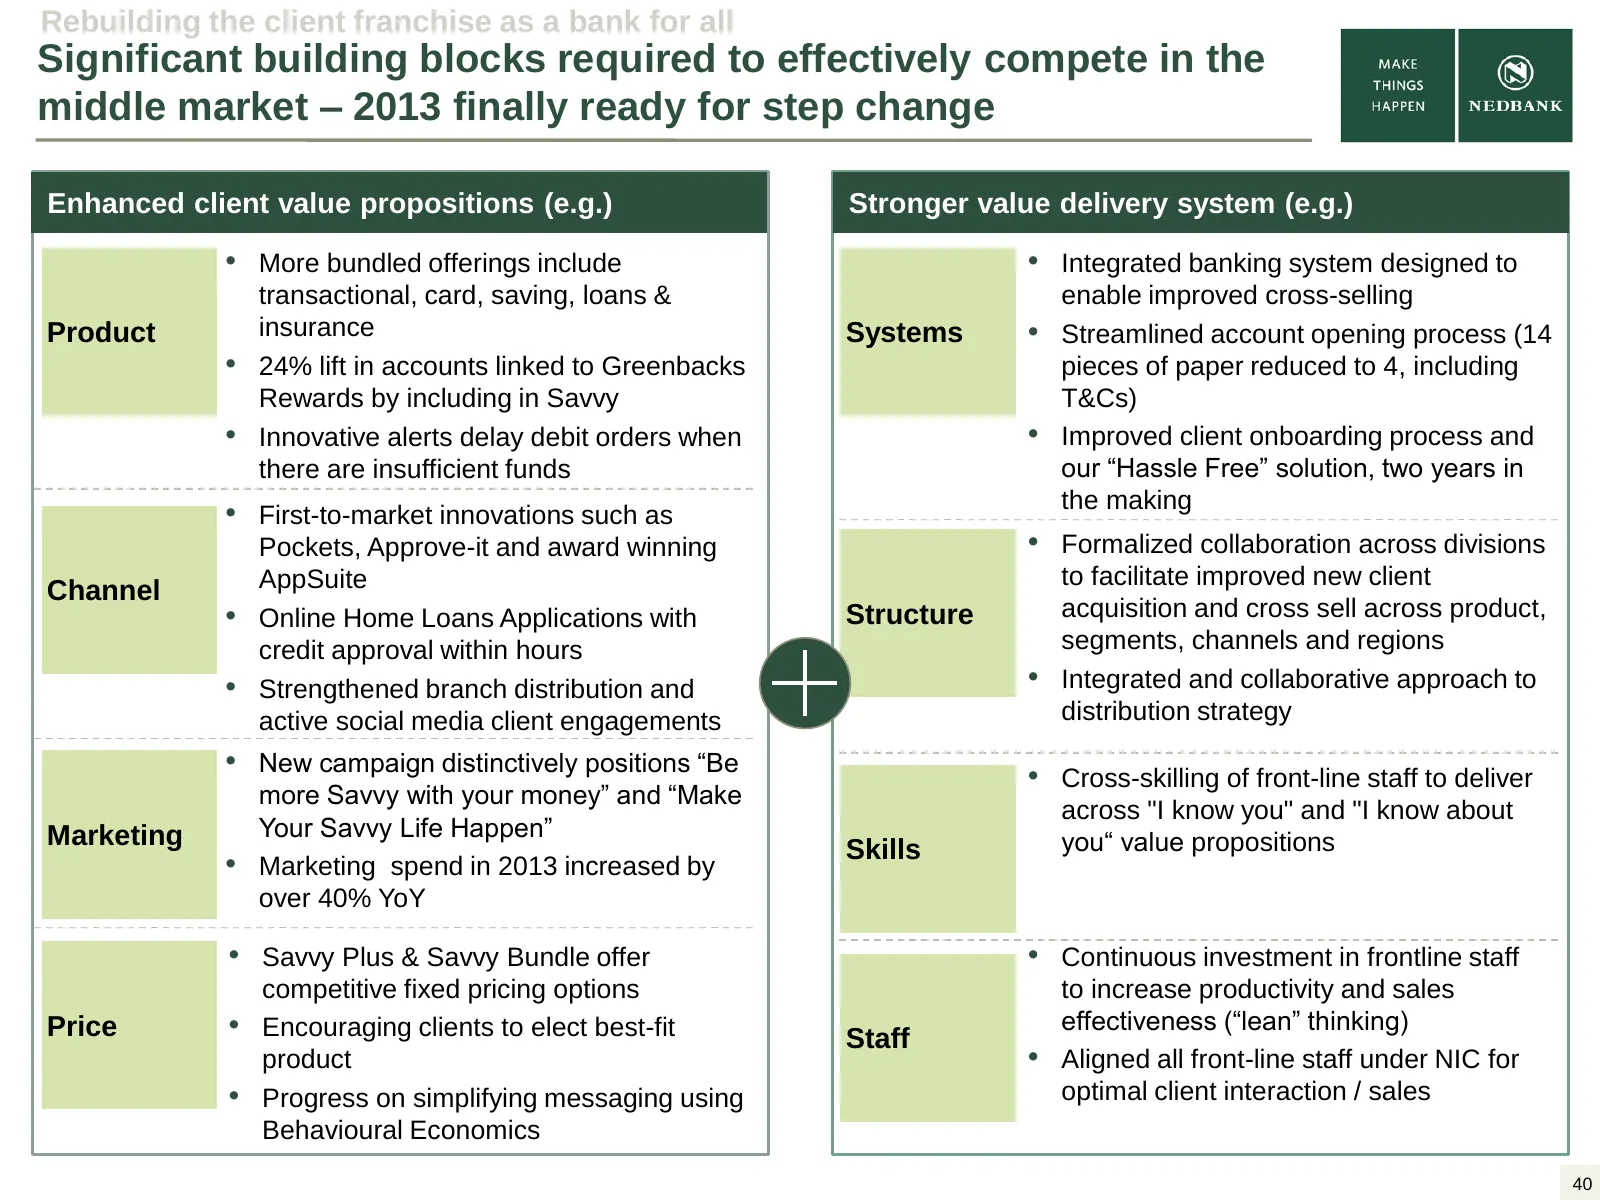
Rebuilding the client franchise as a bank for all Significant building blocks required to effectively compete in the middle market – 2013 finally ready for step change Enhanced client value propositions (e.g.) Stronger value delivery system (e.g.) • More bundled offerings include • Integrated bankin
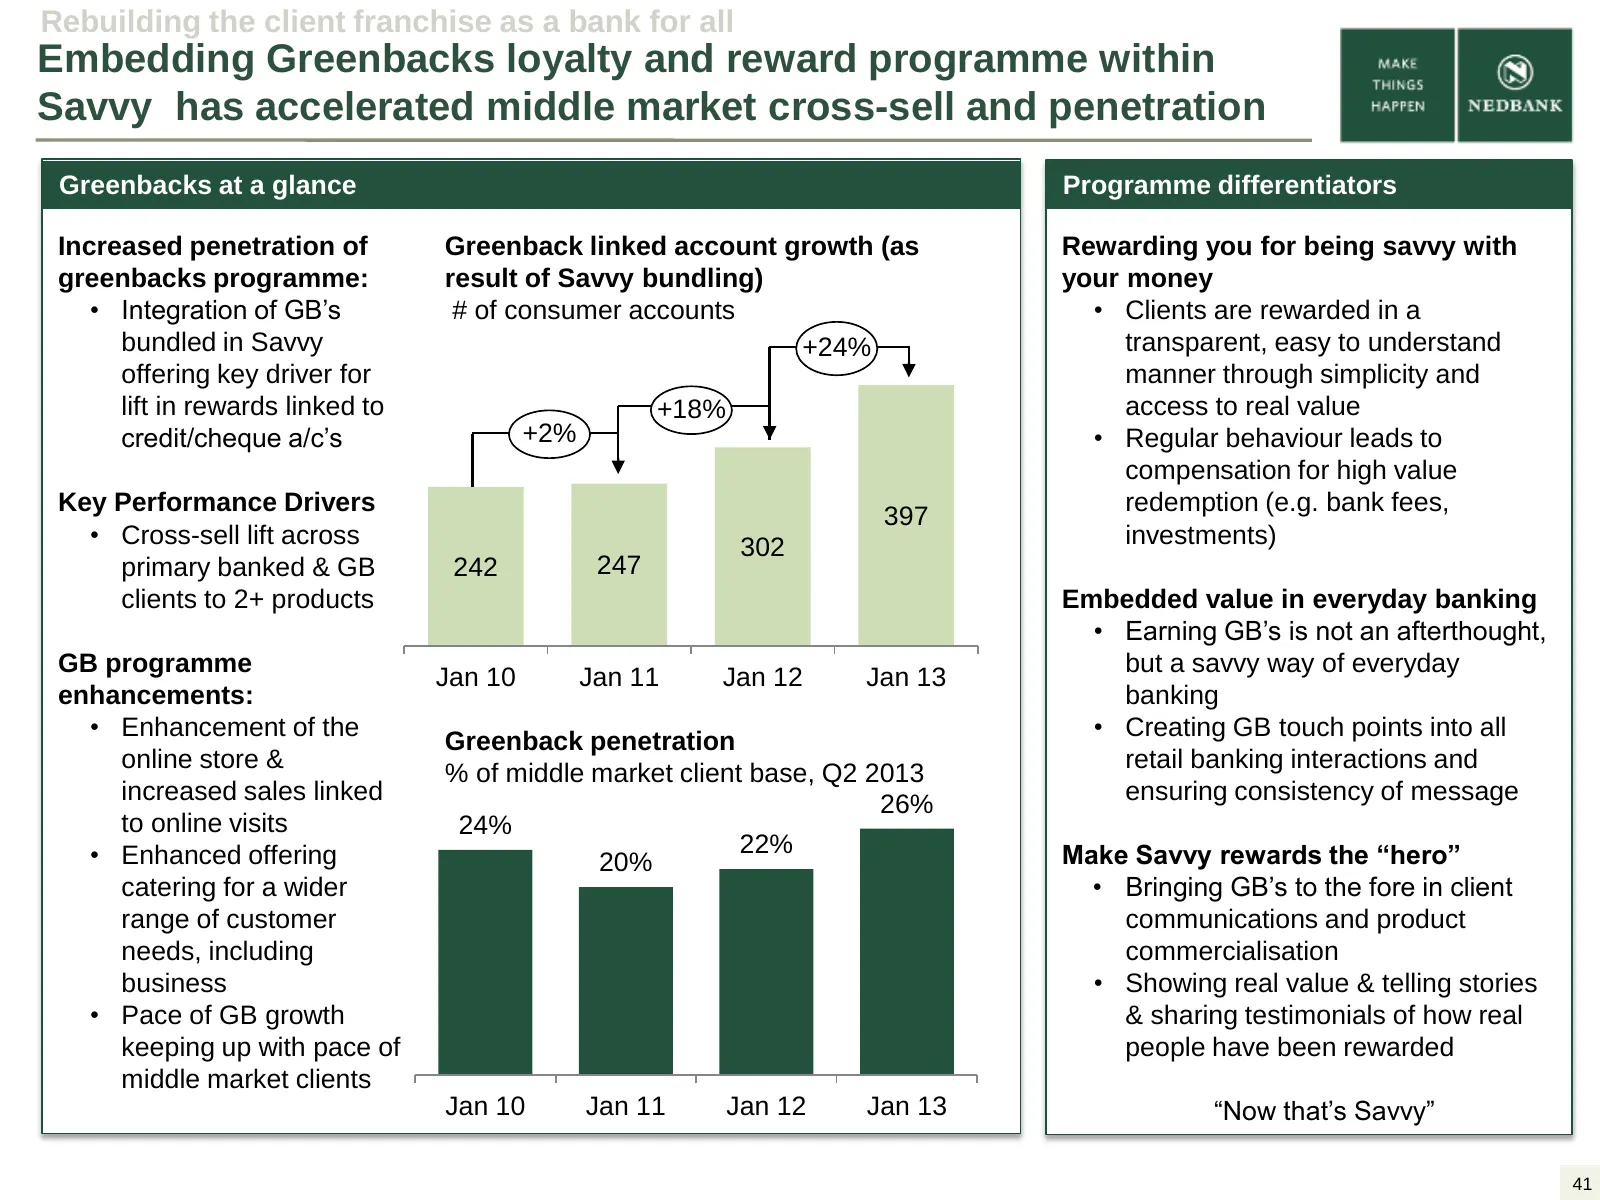
Slide 41: Greenbacks loyalty embedded within Savvy
Rebuilding the client franchise as a bank for all Embedding Greenbacks loyalty and reward programme within Savvy has accelerated middle market cross-sell and penetration Greenbacks at a glance Programme differentiators Increased penetration of Greenback linked account growth (as Rewarding you for be
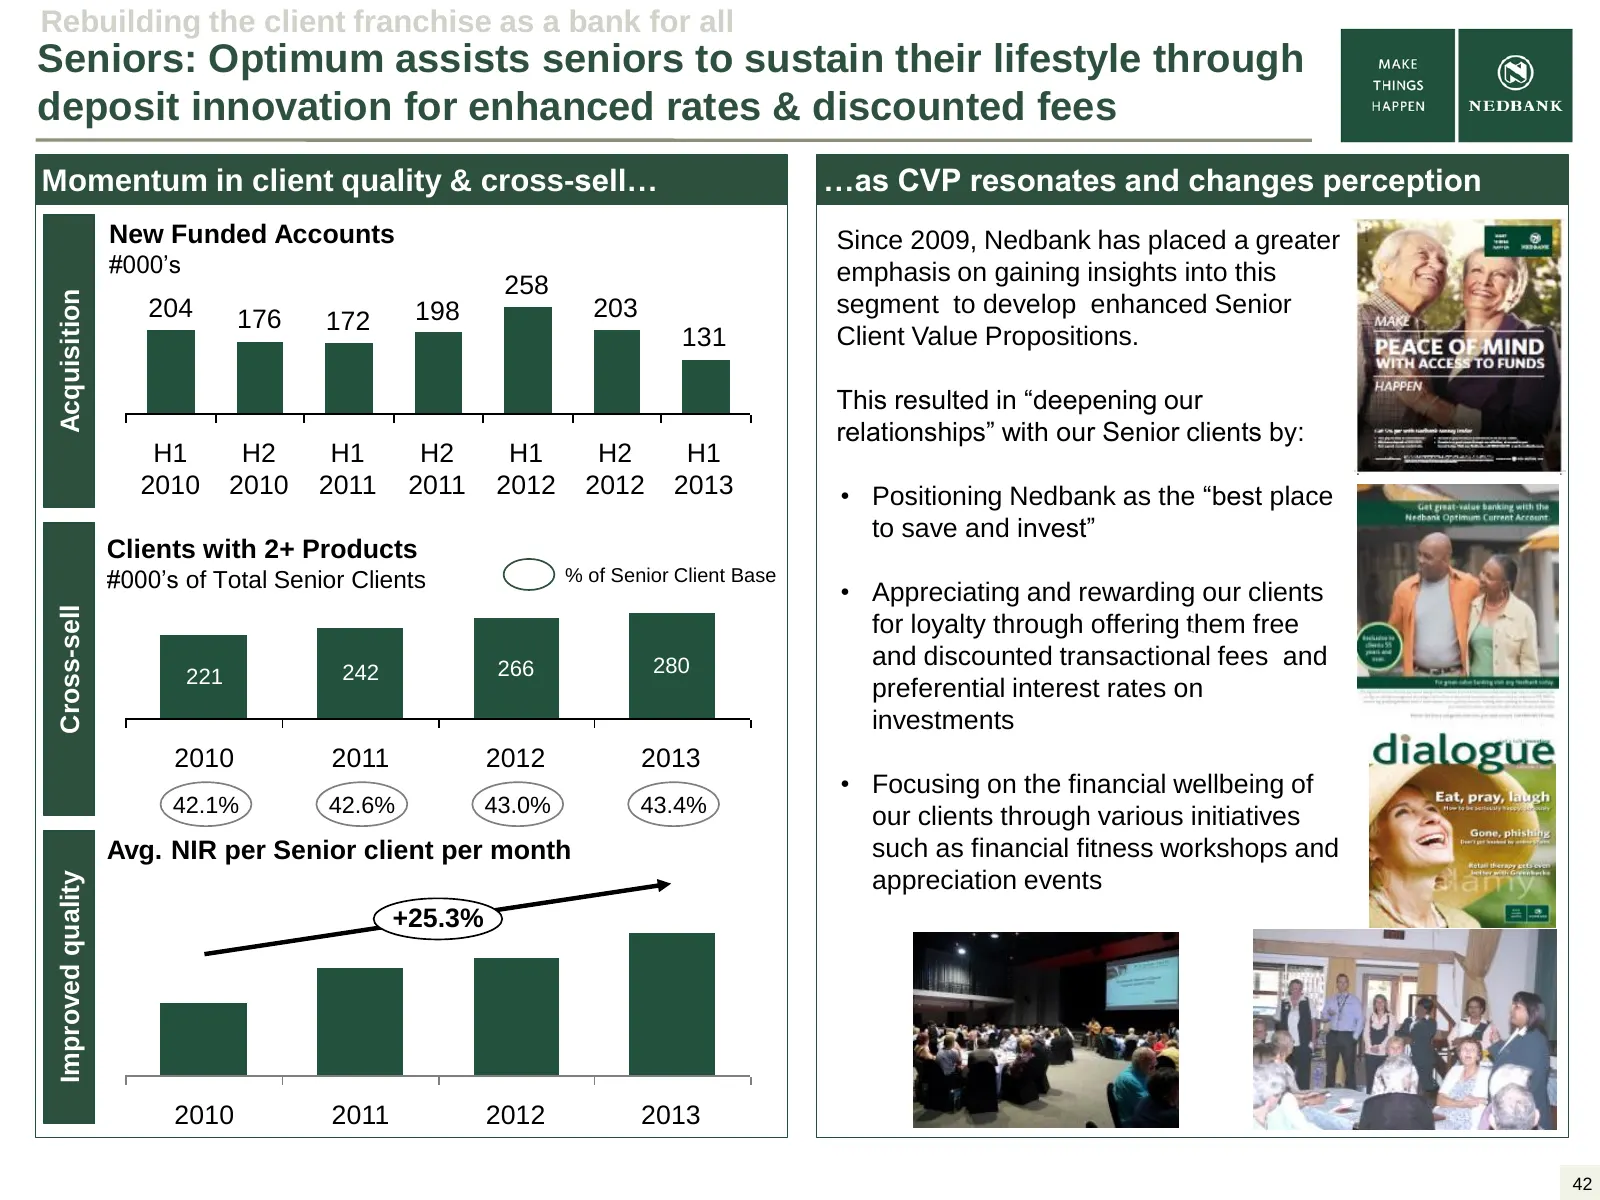
Slide 42: Seniors: Optimum
Rebuilding the client franchise as a bank for all Seniors: Optimum assists seniors to sustain their lifestyle through deposit innovation for enhanced rates & discounted fees Momentum in client quality & cross-sell… …as CVP resonates and changes perception New Funded Accounts Since 2009, Nedbank has
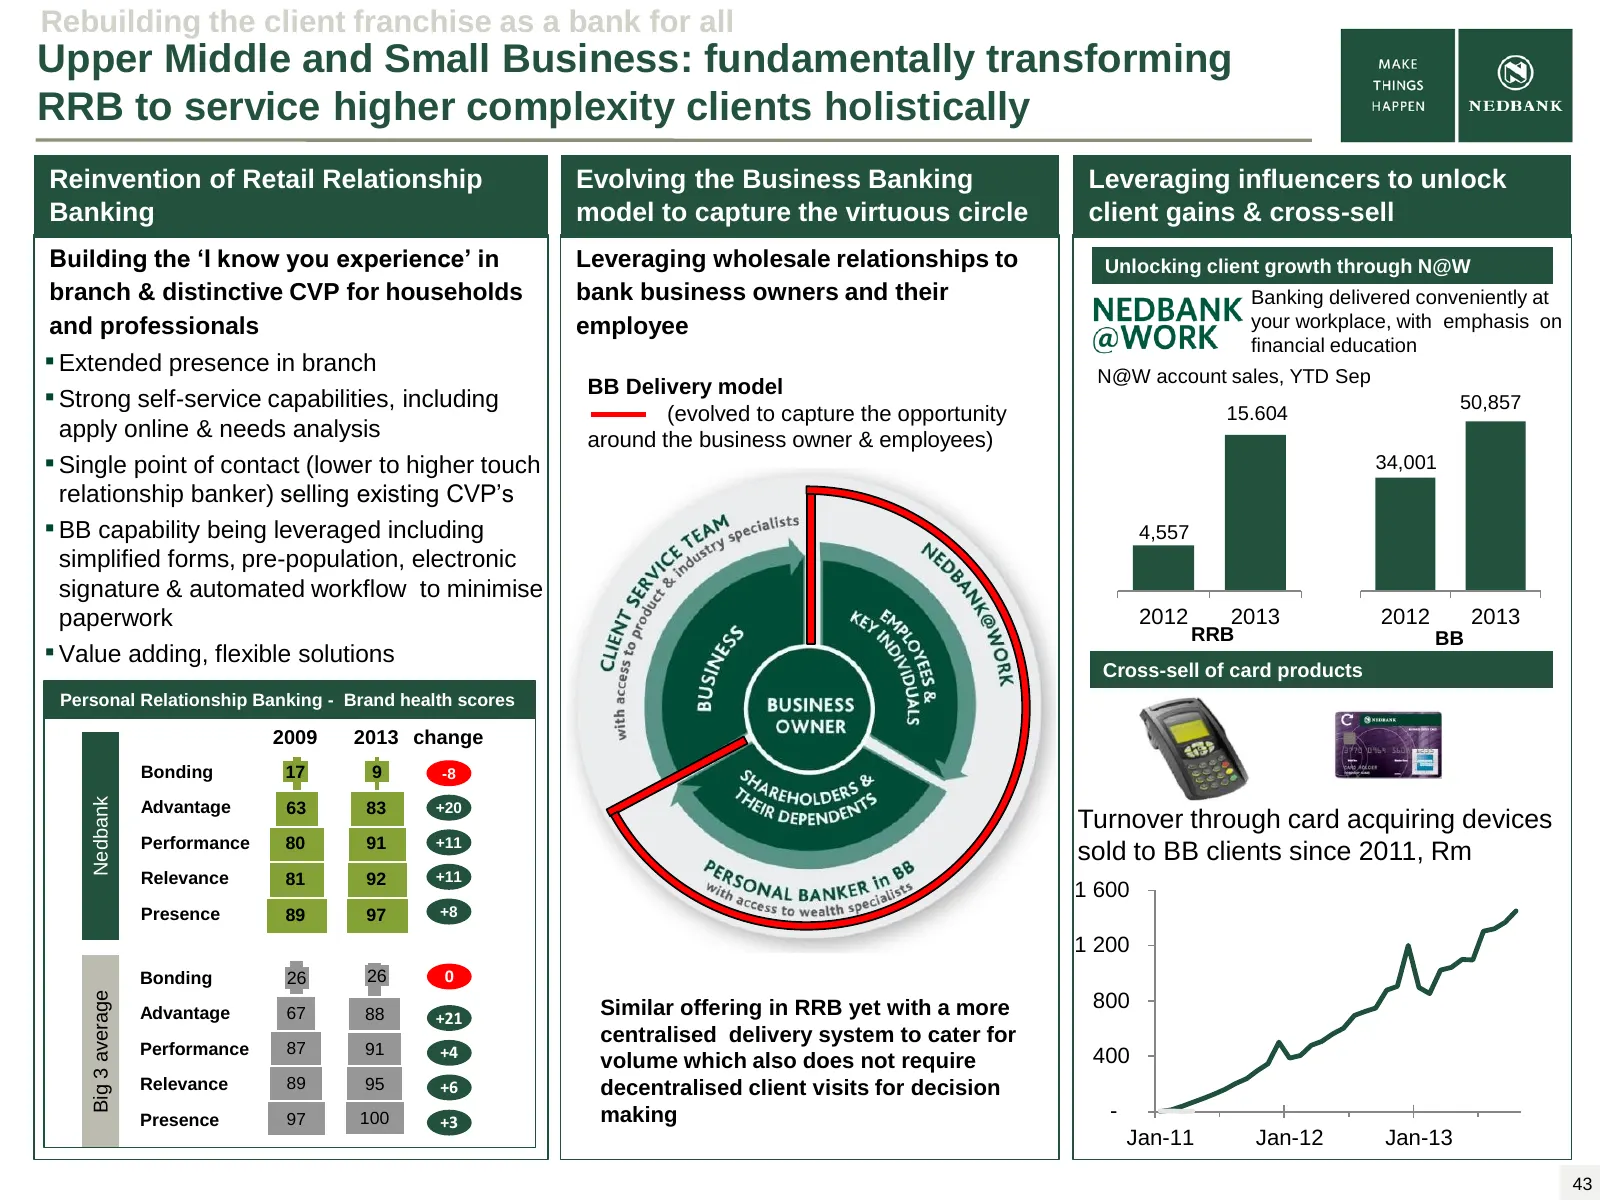
Slide 43: Upper Middle and Small Business: transforming RRB
Rebuilding the client franchise as a bank for all Upper Middle and Small Business: fundamentally transforming RRB to service higher complexity clients holistically Reinvention of Retail Relationship Evolving the Business Banking Leveraging influencers to unlock Banking model to capture the virtuous
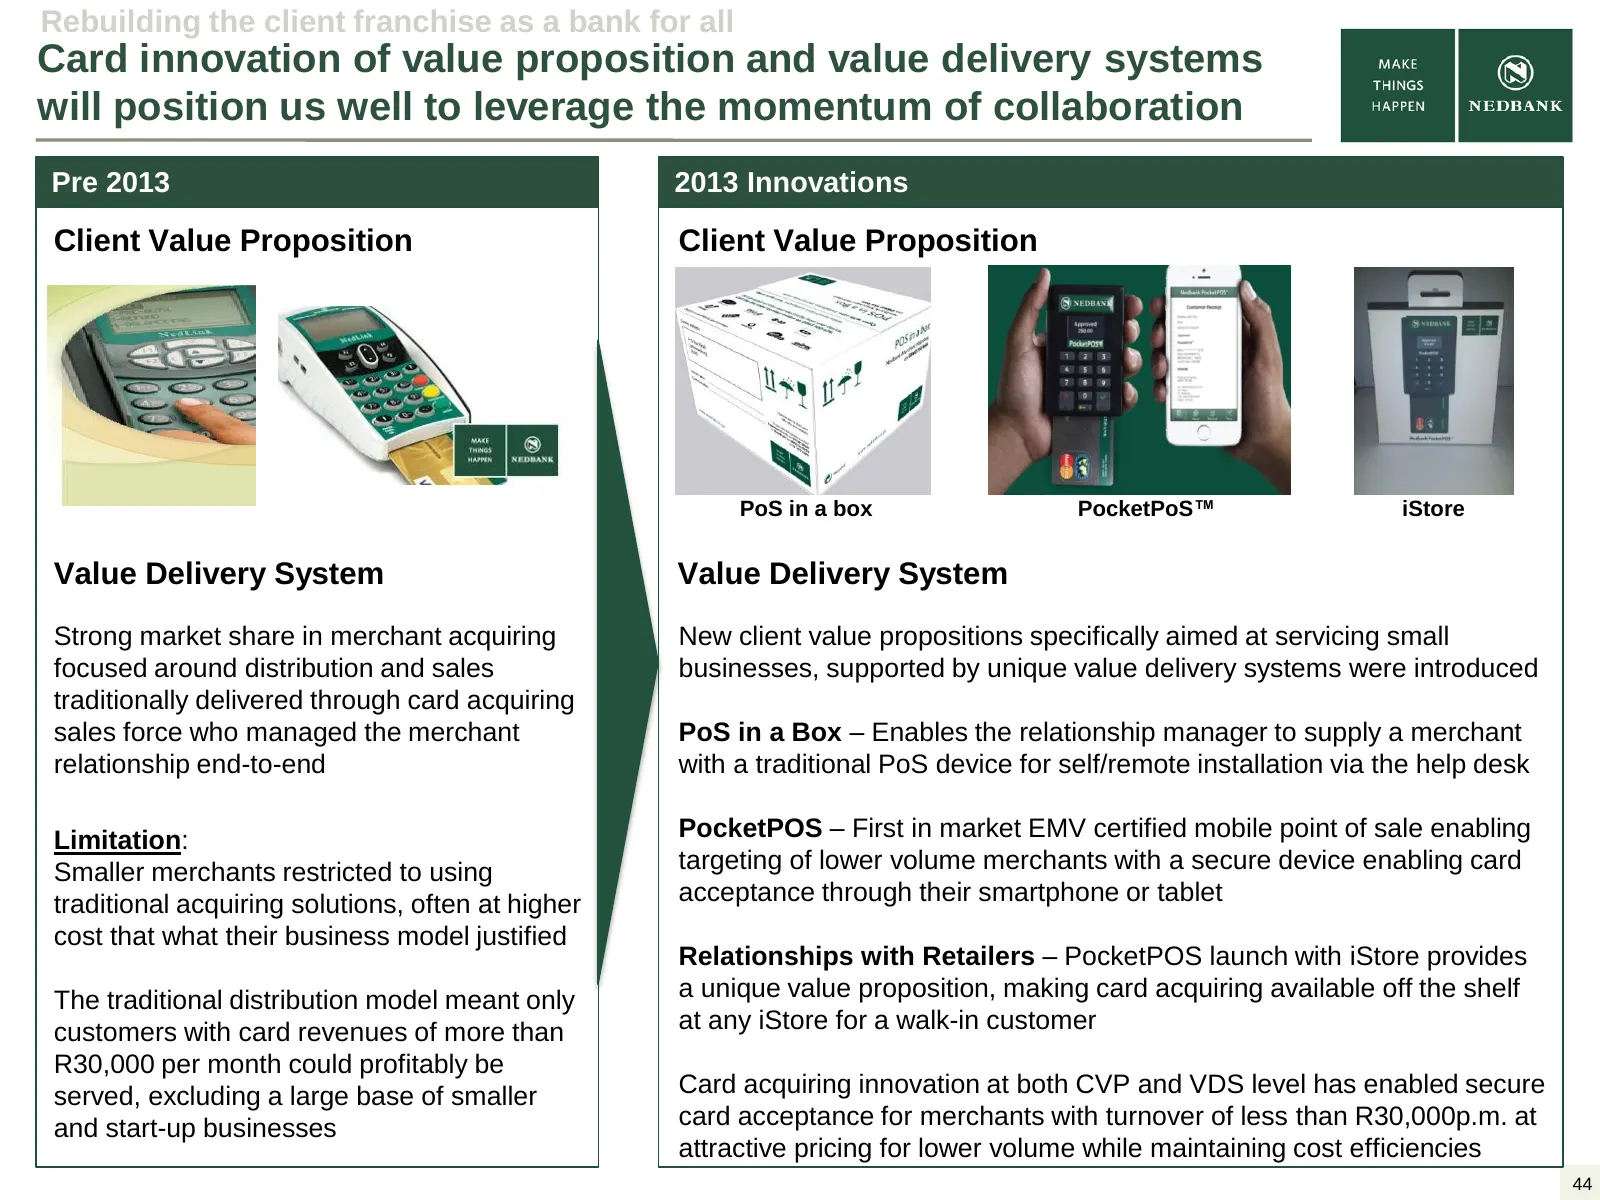
Slide 44: Card innovation of value proposition and value delivery systems
Rebuilding the client franchise as a bank for all Card innovation of value proposition and value delivery systems will position us well to leverage the momentum of collaboration Pre 2013 2013 Innovations Client Value Proposition Client Value Proposition PoS in a box PocketPoS™ iStore Value Delivery
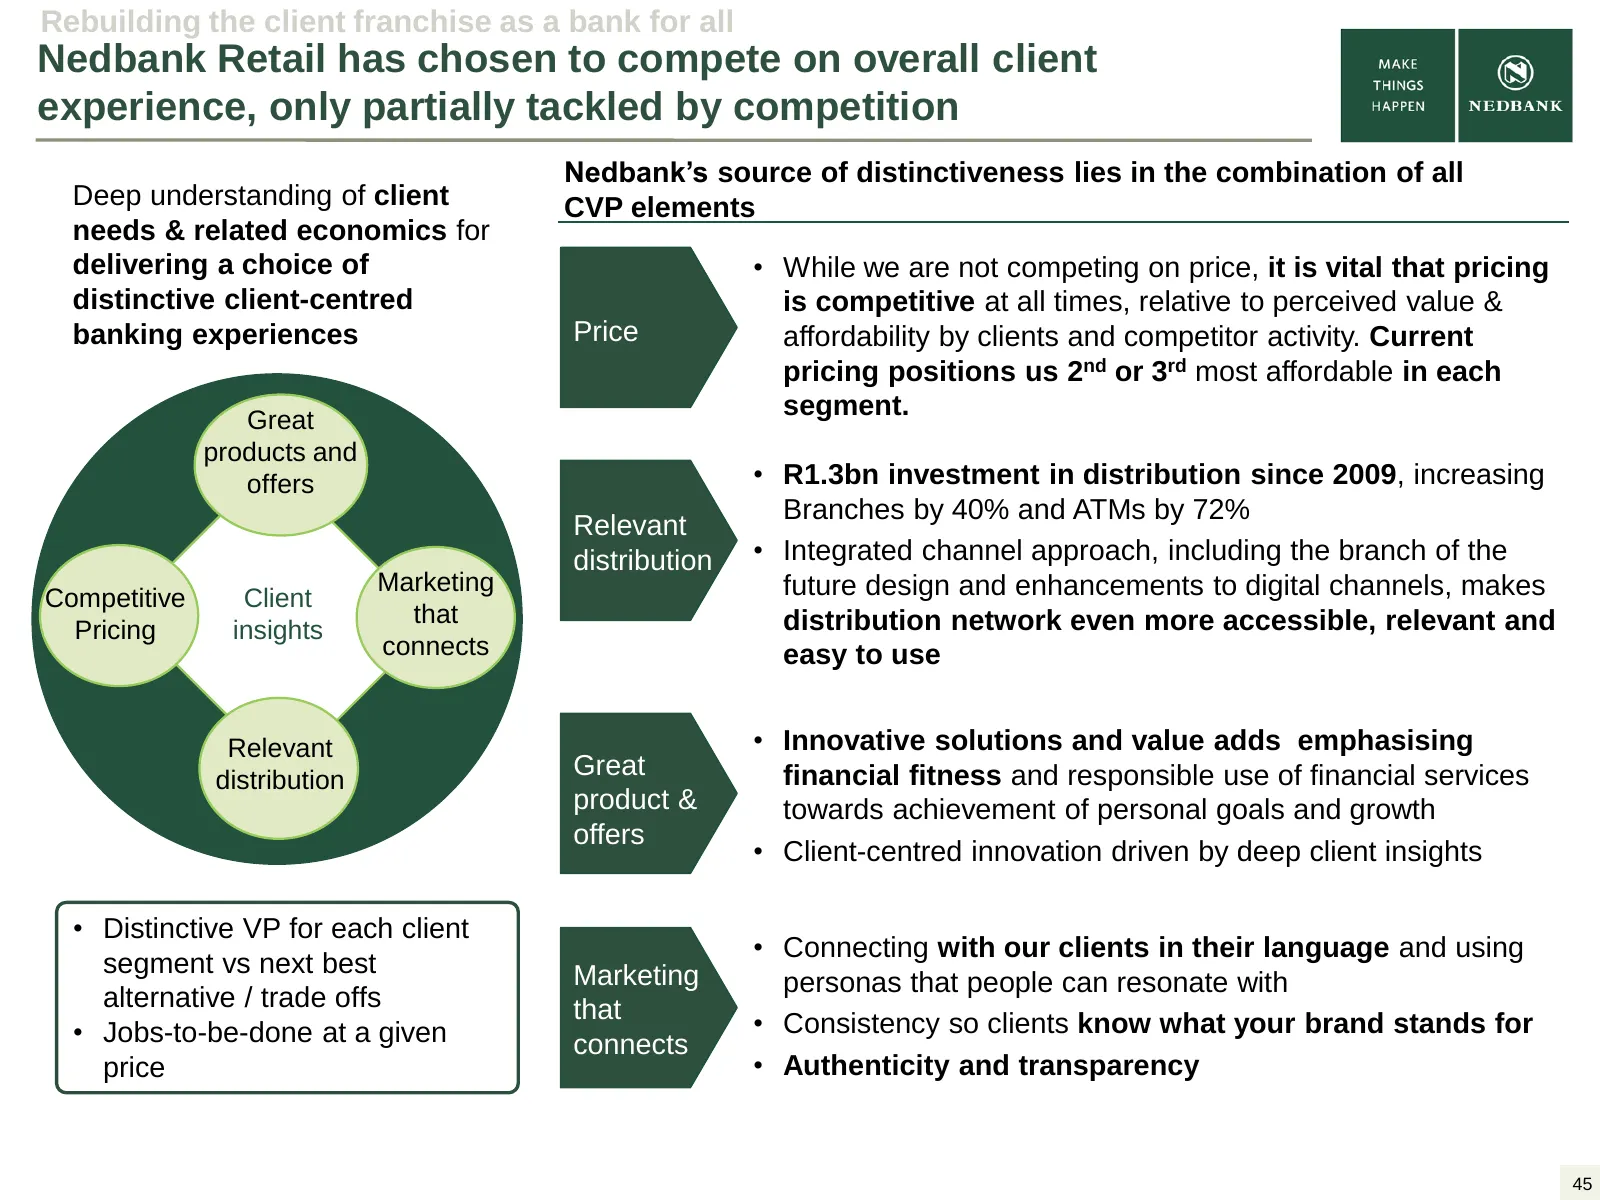
Slide 45: Competing on overall client experience
Rebuilding the client franchise as a bank for all Nedbank Retail has chosen to compete on overall client experience, only partially tackled by competition Nedbank’s source of distinctiveness lies in the combination of all Deep understanding of client CVP elements needs & related economics for delive
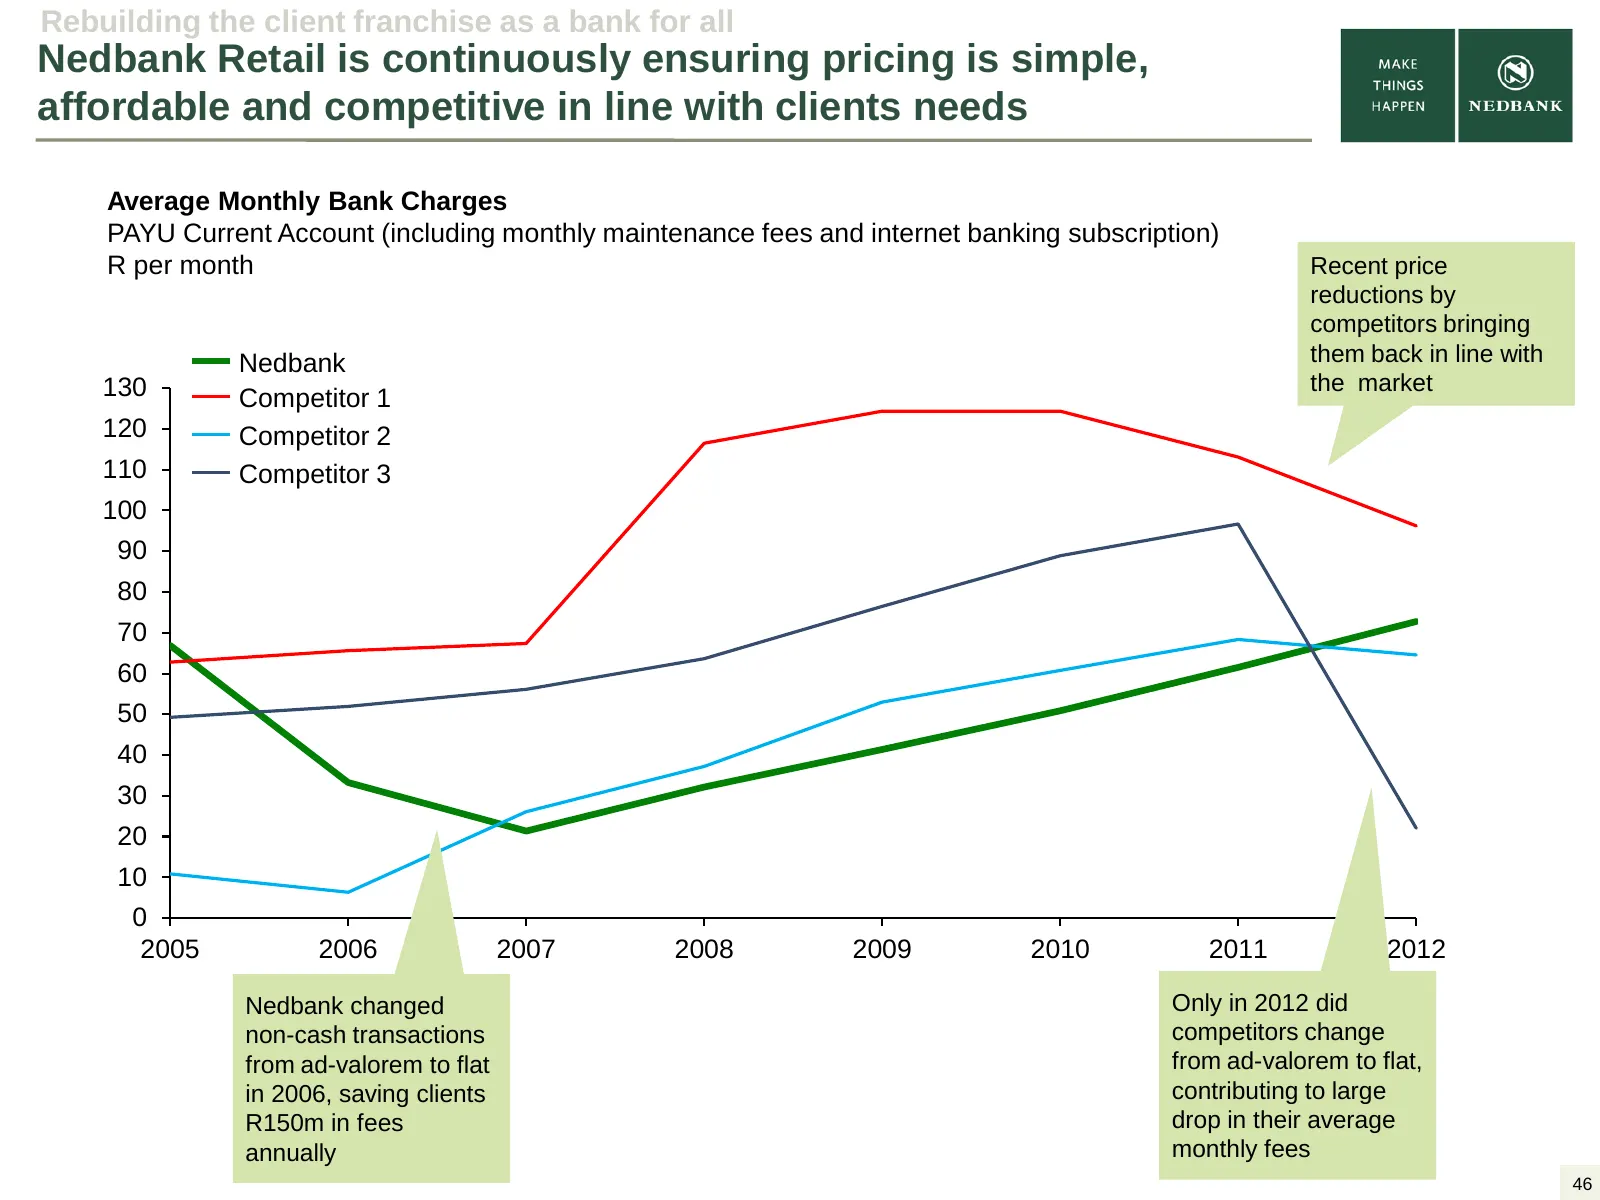
Slide 46: Pricing simple, affordable and competitive
Rebuilding the client franchise as a bank for all Nedbank Retail is continuously ensuring pricing is simple, affordable and competitive in line with clients needs Average Monthly Bank Charges PAYU Current Account (including monthly maintenance fees and internet banking subscription) R per month Rece
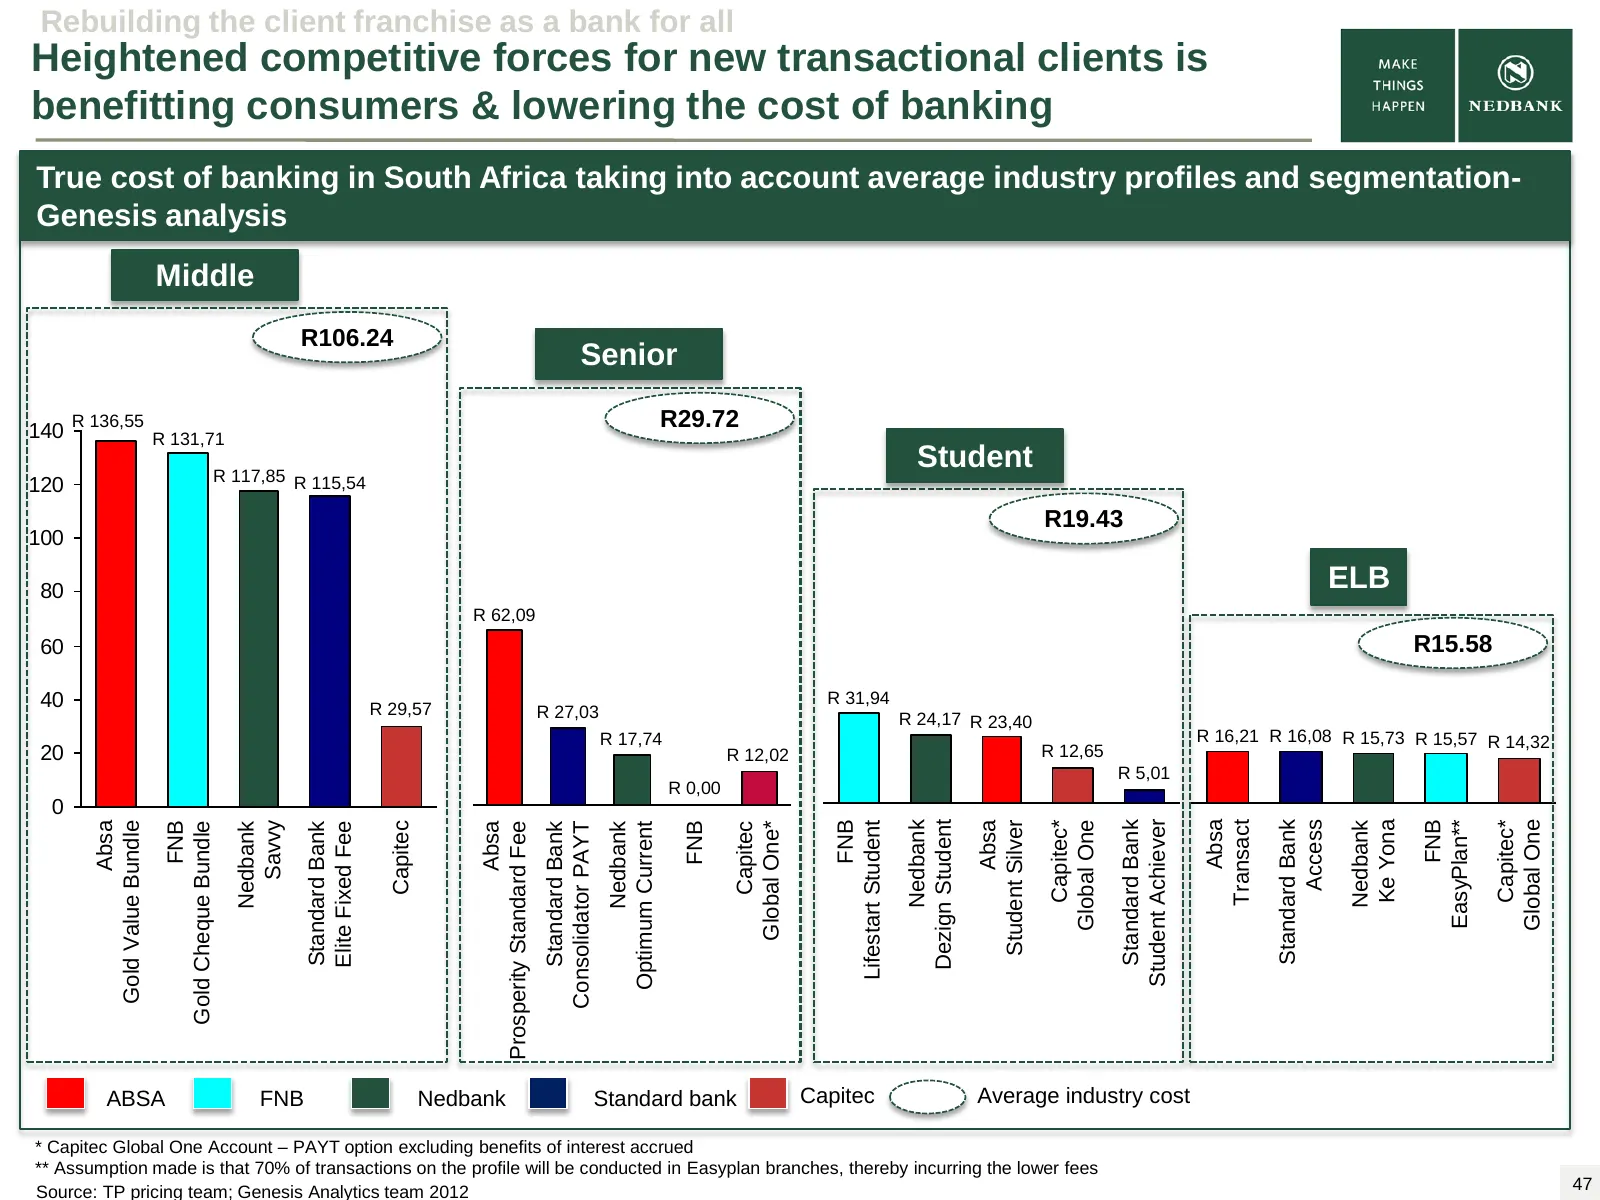
Slide 47: Competitive forces lowering the cost of banking
Rebuilding the client franchise as a bank for all Heightened competitive forces for new transactional clients is benefitting consumers & lowering the cost of banking True cost of banking in South Africa taking into account average industry profiles and segmentation- Genesis analysis Middle R106.24 S
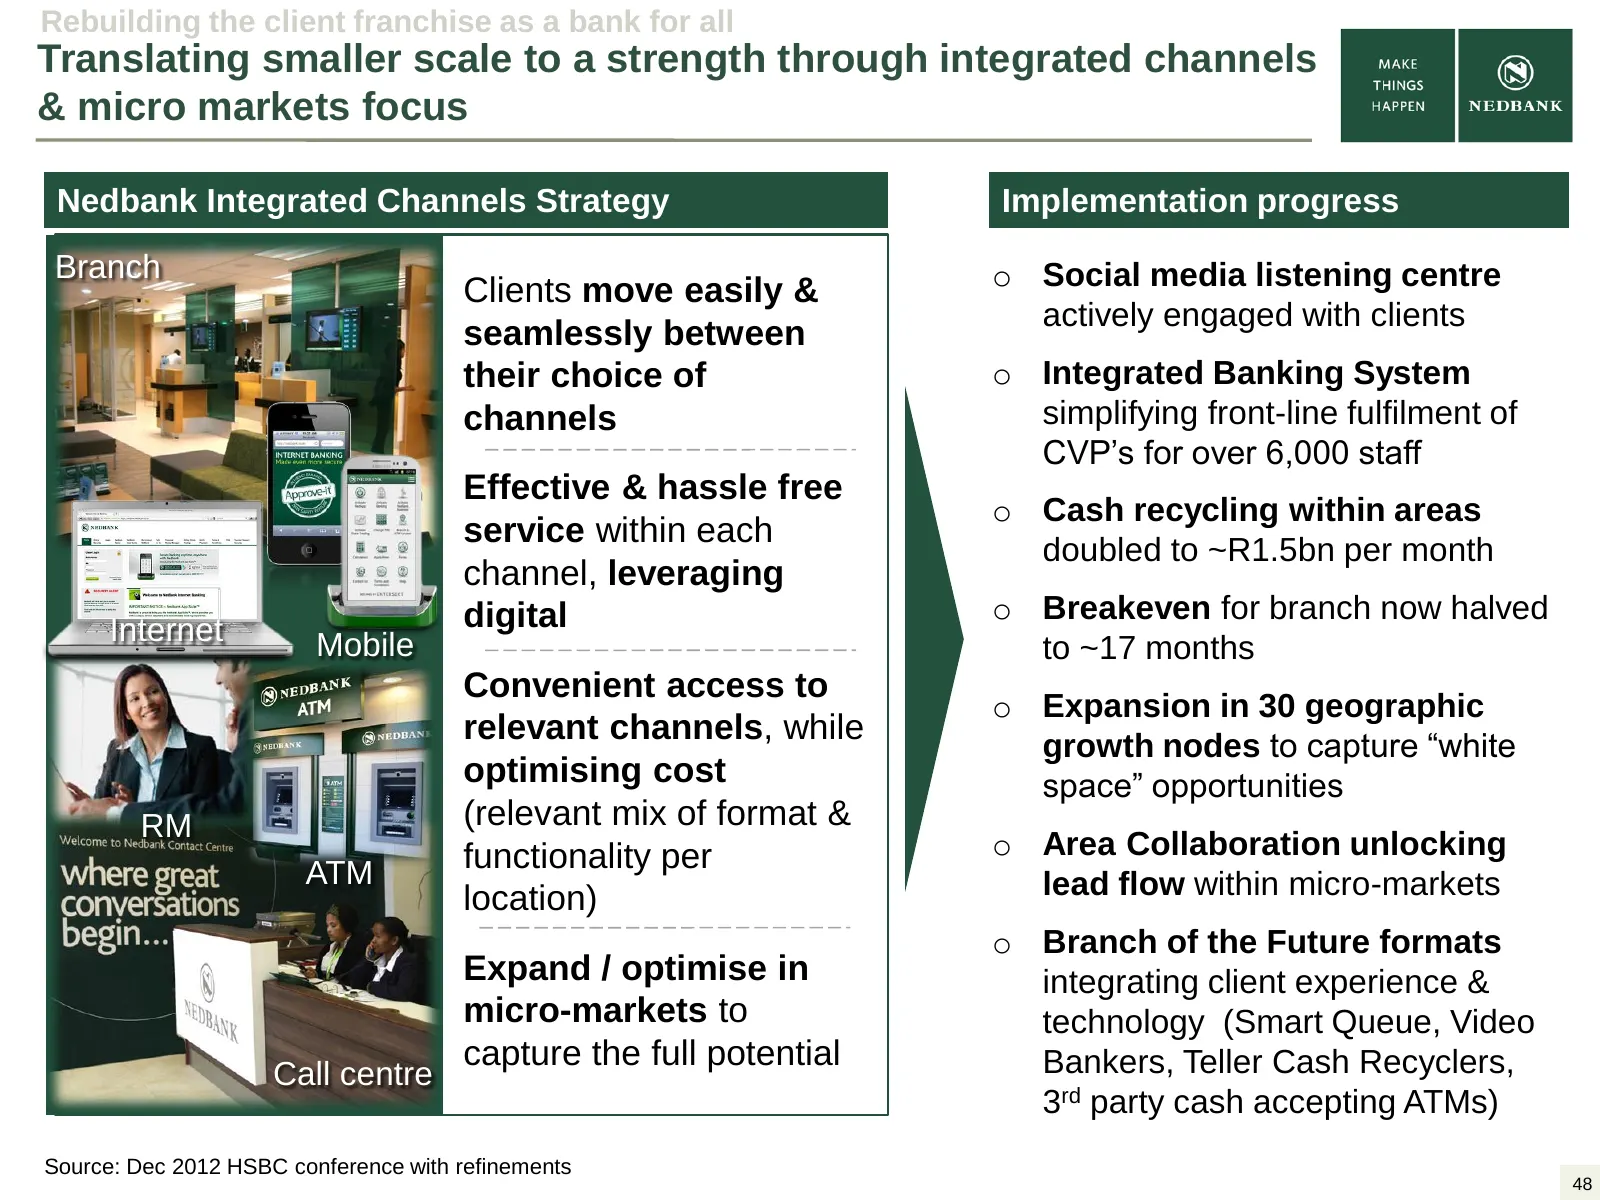
Slide 48: Integrated channels and micro markets focus
Rebuilding the client franchise as a bank for all Translating smaller scale to a strength through integrated channels & micro markets focus Nedbank Integrated Channels Strategy Implementation Implementationprogress progress Branch o Social media listening centre Clients move easily & actively engage
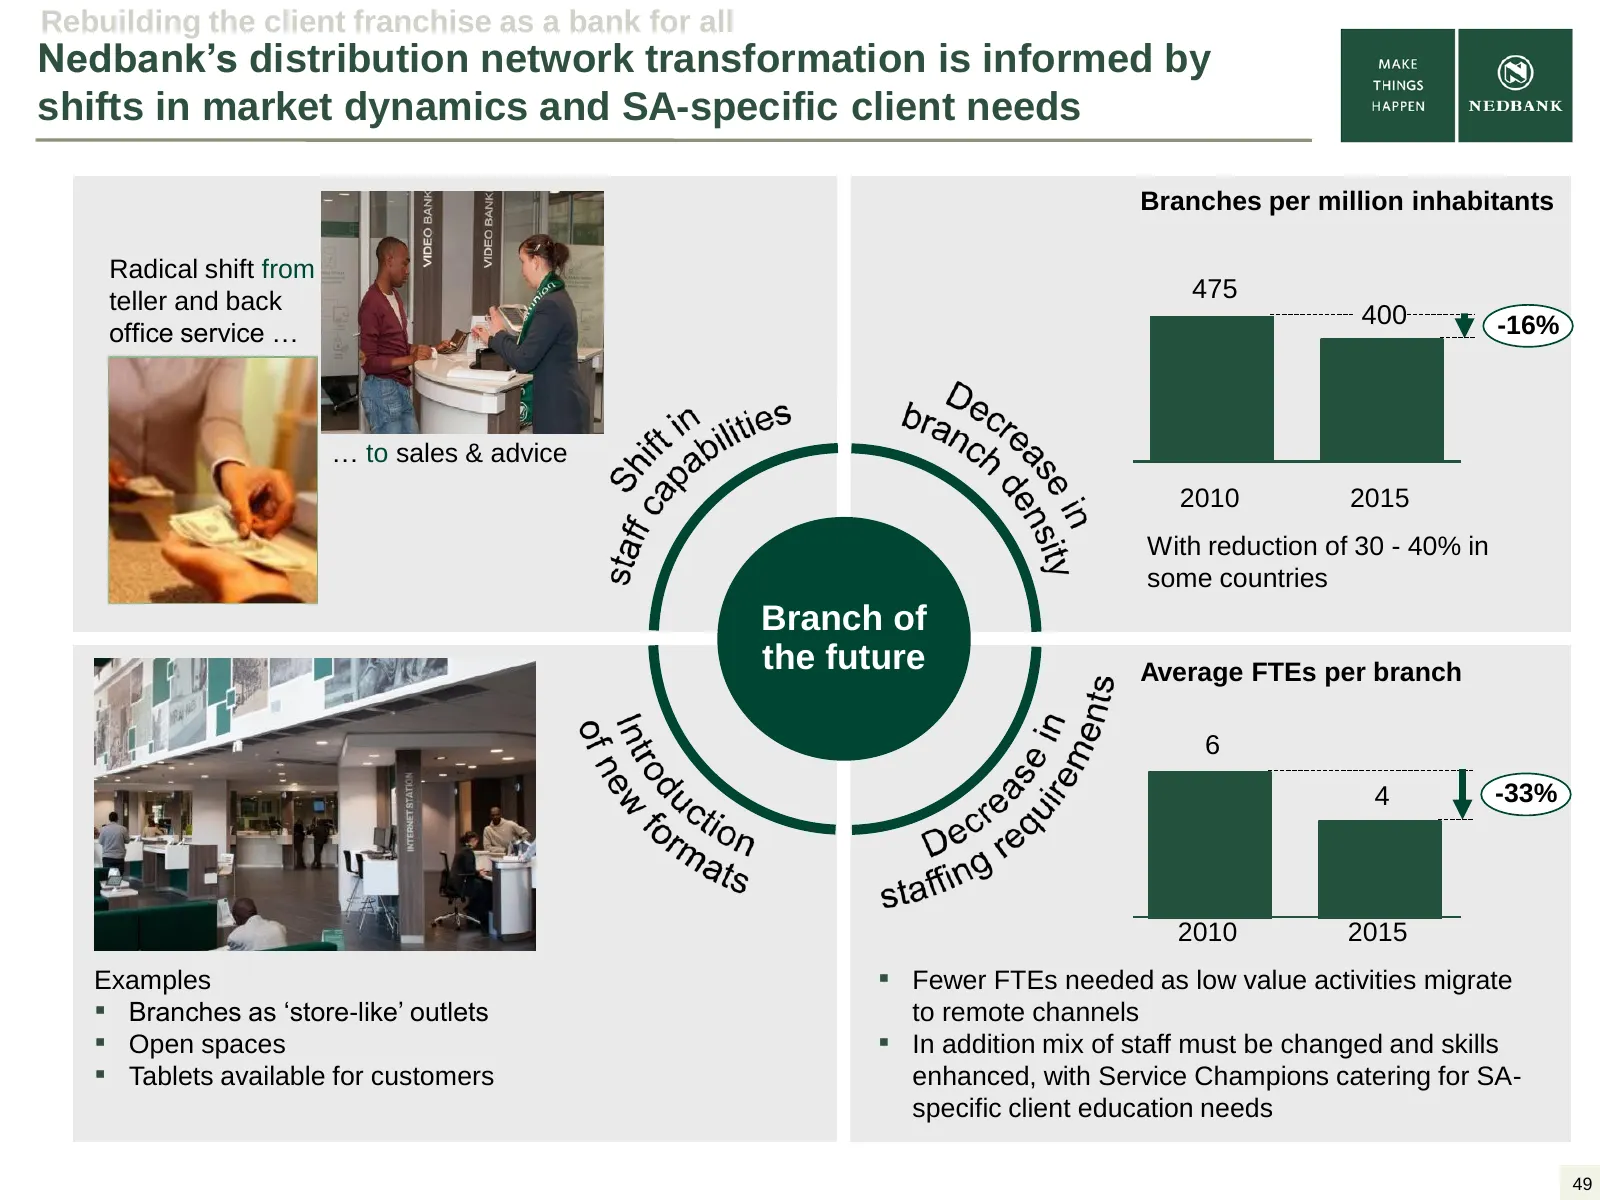
Slide 49: Distribution network transformation and branch of the future
Rebuilding the client franchise as a bank for all Nedbank’s distribution network transformation is informed by shifts in market dynamics and SA-specific client needs Branches per million inhabitants Radical shift from teller and back 475 400 -16% office service … … to sales & advice 2010 2015 With r
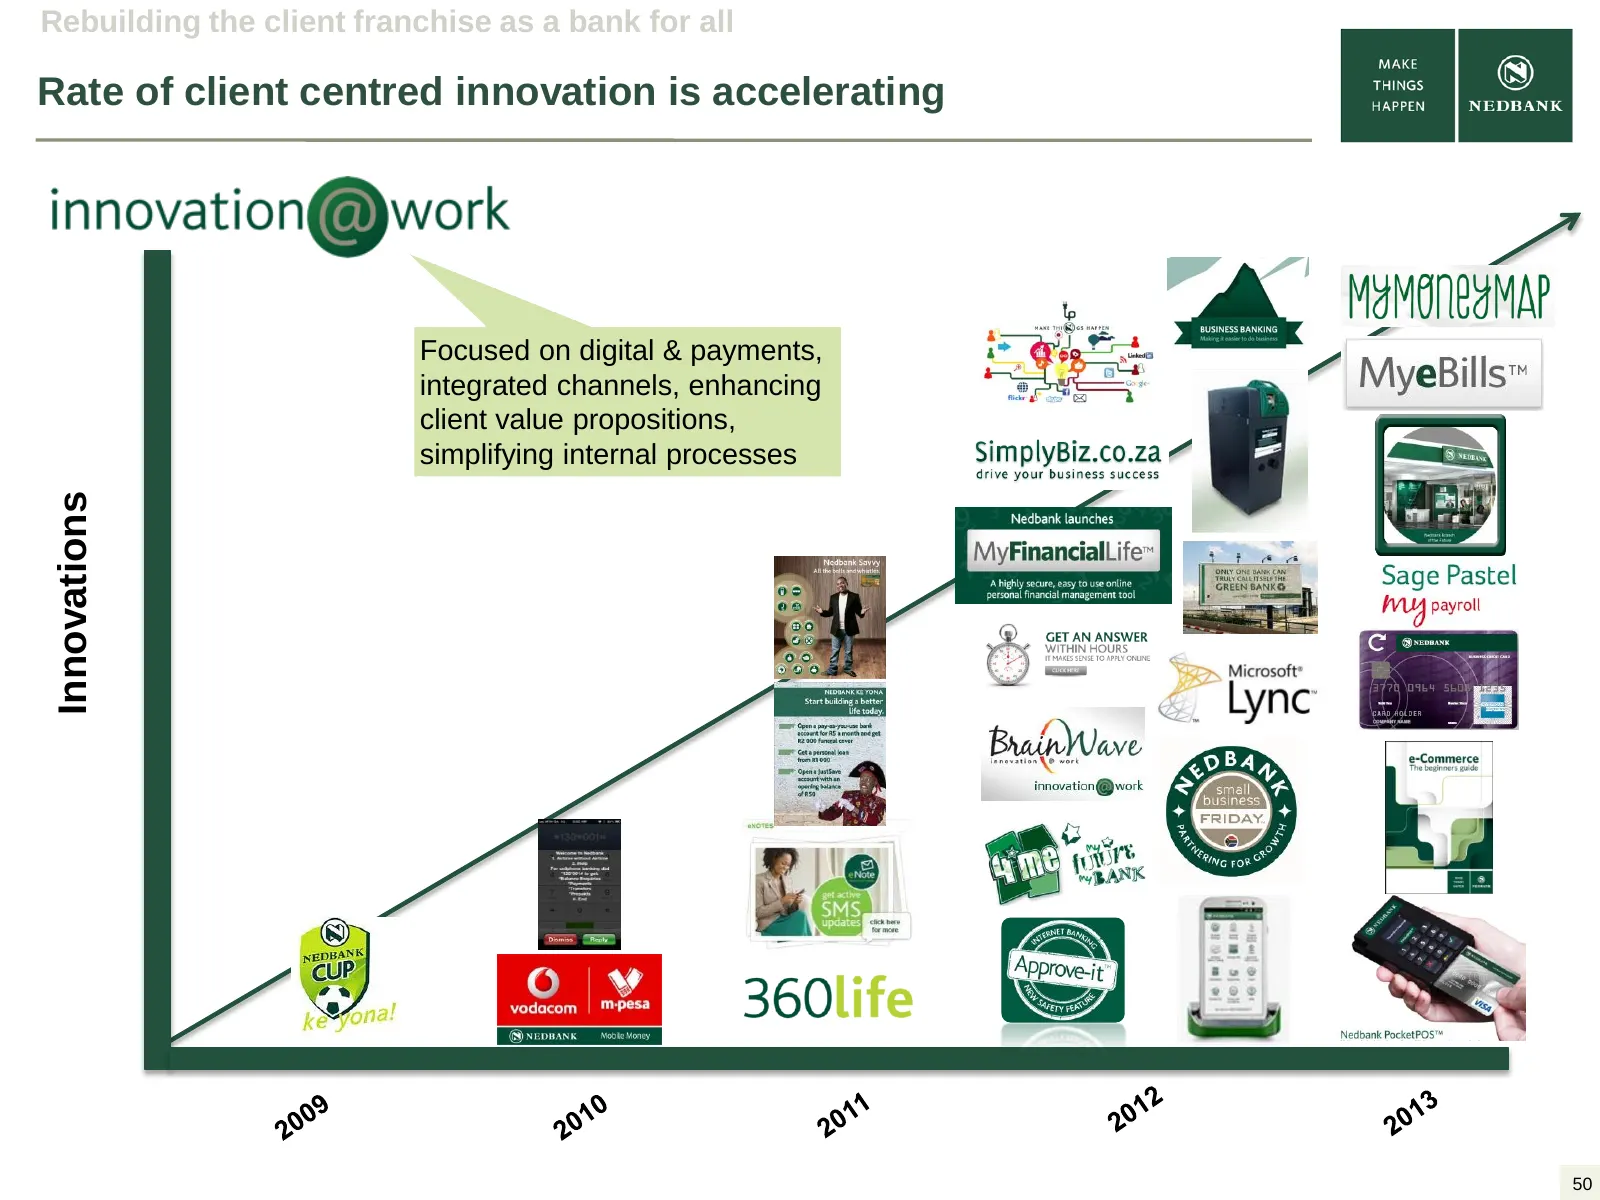
Slide 50: Rate of client centred innovation is accelerating
Rebuilding the client franchise as a bank for all Rate of client centred innovation is accelerating Focused on digital & payments, integrated channels, enhancing client value propositions, simplifying internal processes Innovations 50
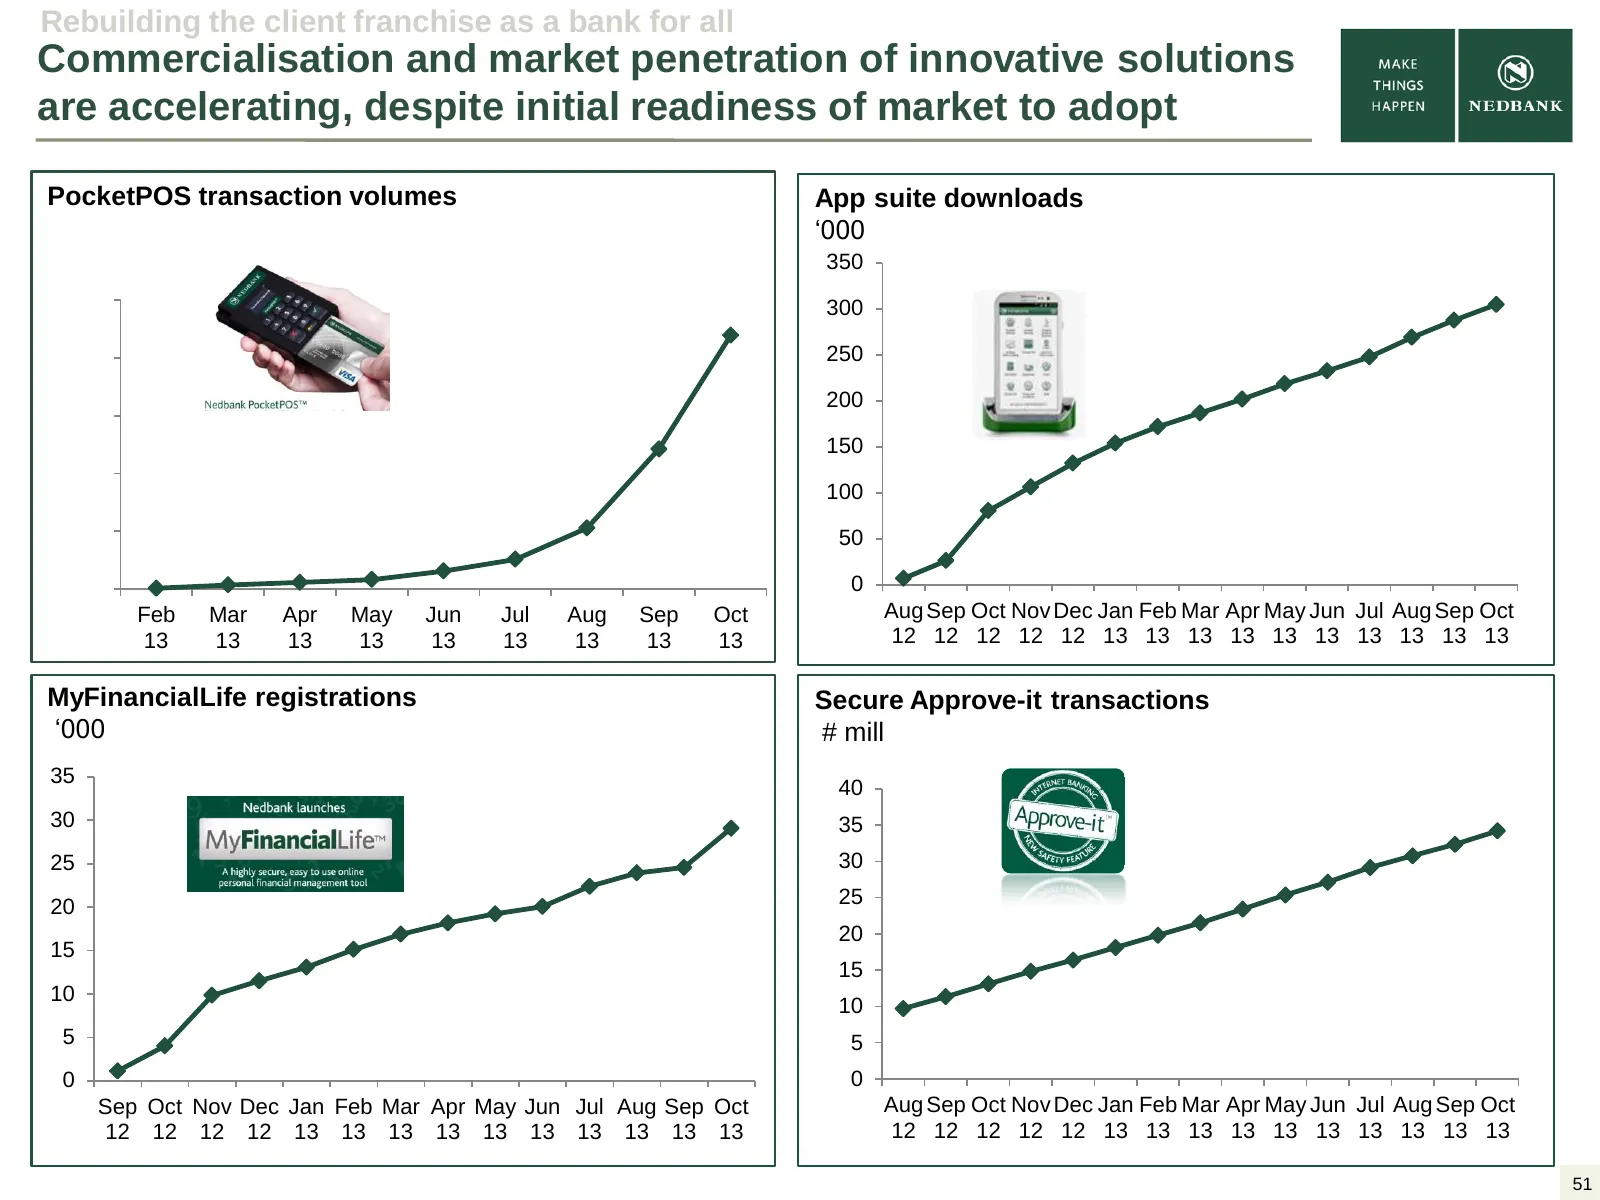
Slide 51: Commercialisation and market penetration of innovative solutions
Rebuilding the client franchise as a bank for all Commercialisation and market penetration of innovative solutions are accelerating, despite initial readiness of market to adopt PocketPOS transaction volumes App suite downloads ‘000 350 300 250 200 150 100 50 0 Feb Mar Apr May Jun Jul Aug Sep Oct Au
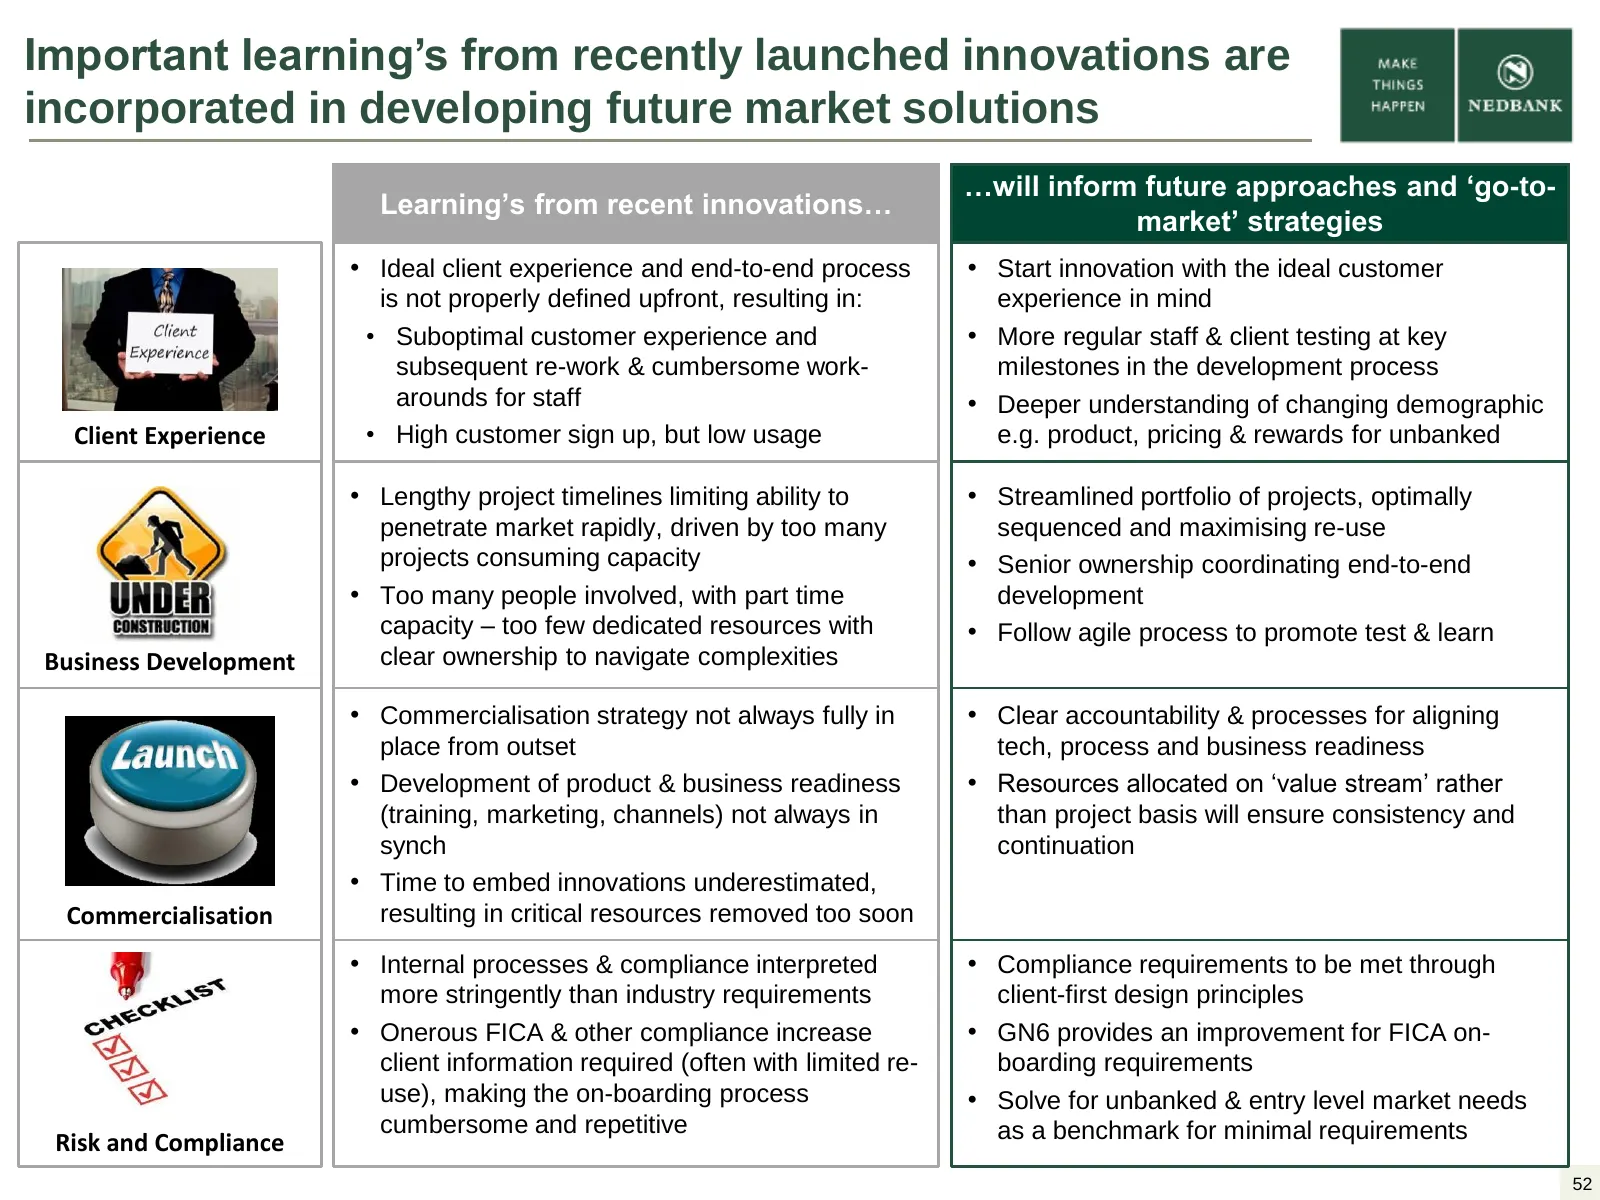
Slide 52: Learnings from recently launched innovations
Important learning’s from recently launched innovations are incorporated in developing future market solutions …will inform future approaches and ‘go-to- Learning’s from recent innovations… market’ strategies • Ideal client experience and end-to-end process • Start innovation with the ideal customer
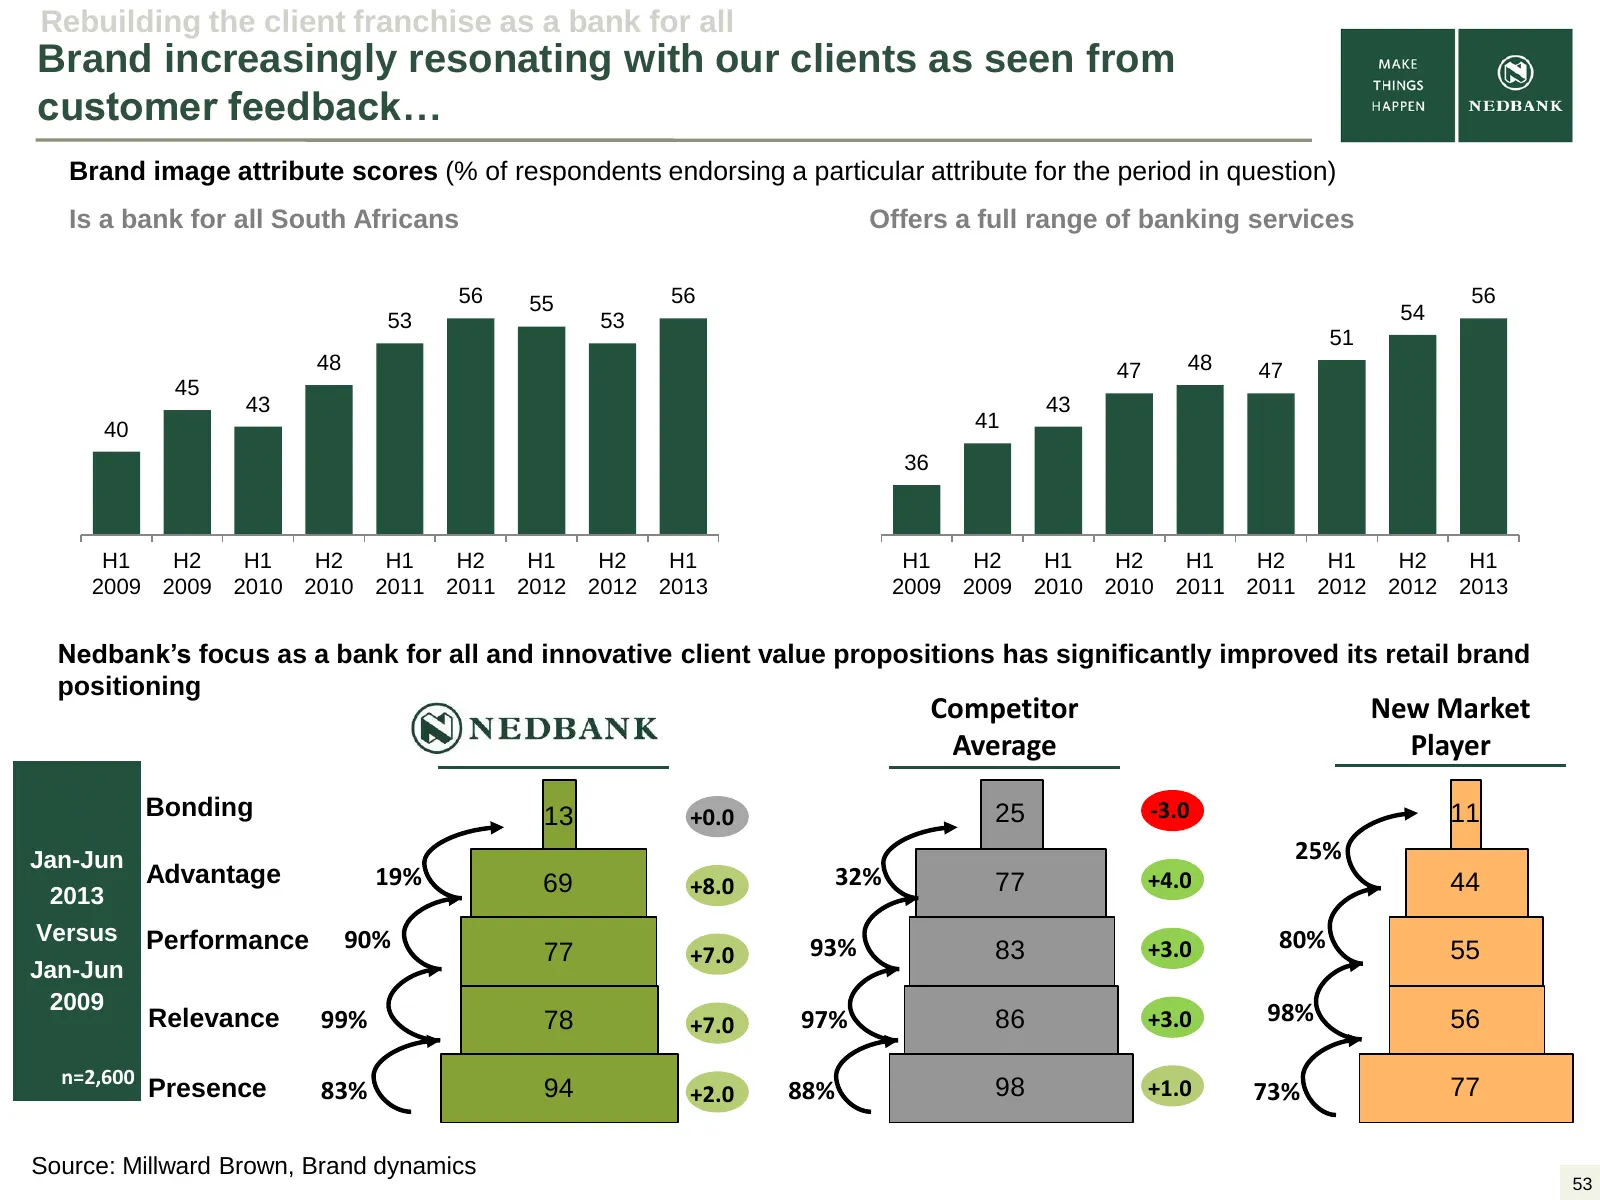
Slide 53: Brand increasingly resonating with clients
Rebuilding the client franchise as a bank for all Brand increasingly resonating with our clients as seen from customer feedback… Brand image attribute scores (% of respondents endorsing a particular attribute for the period in question) Is a bank for all South Africans Offers a full range of banking
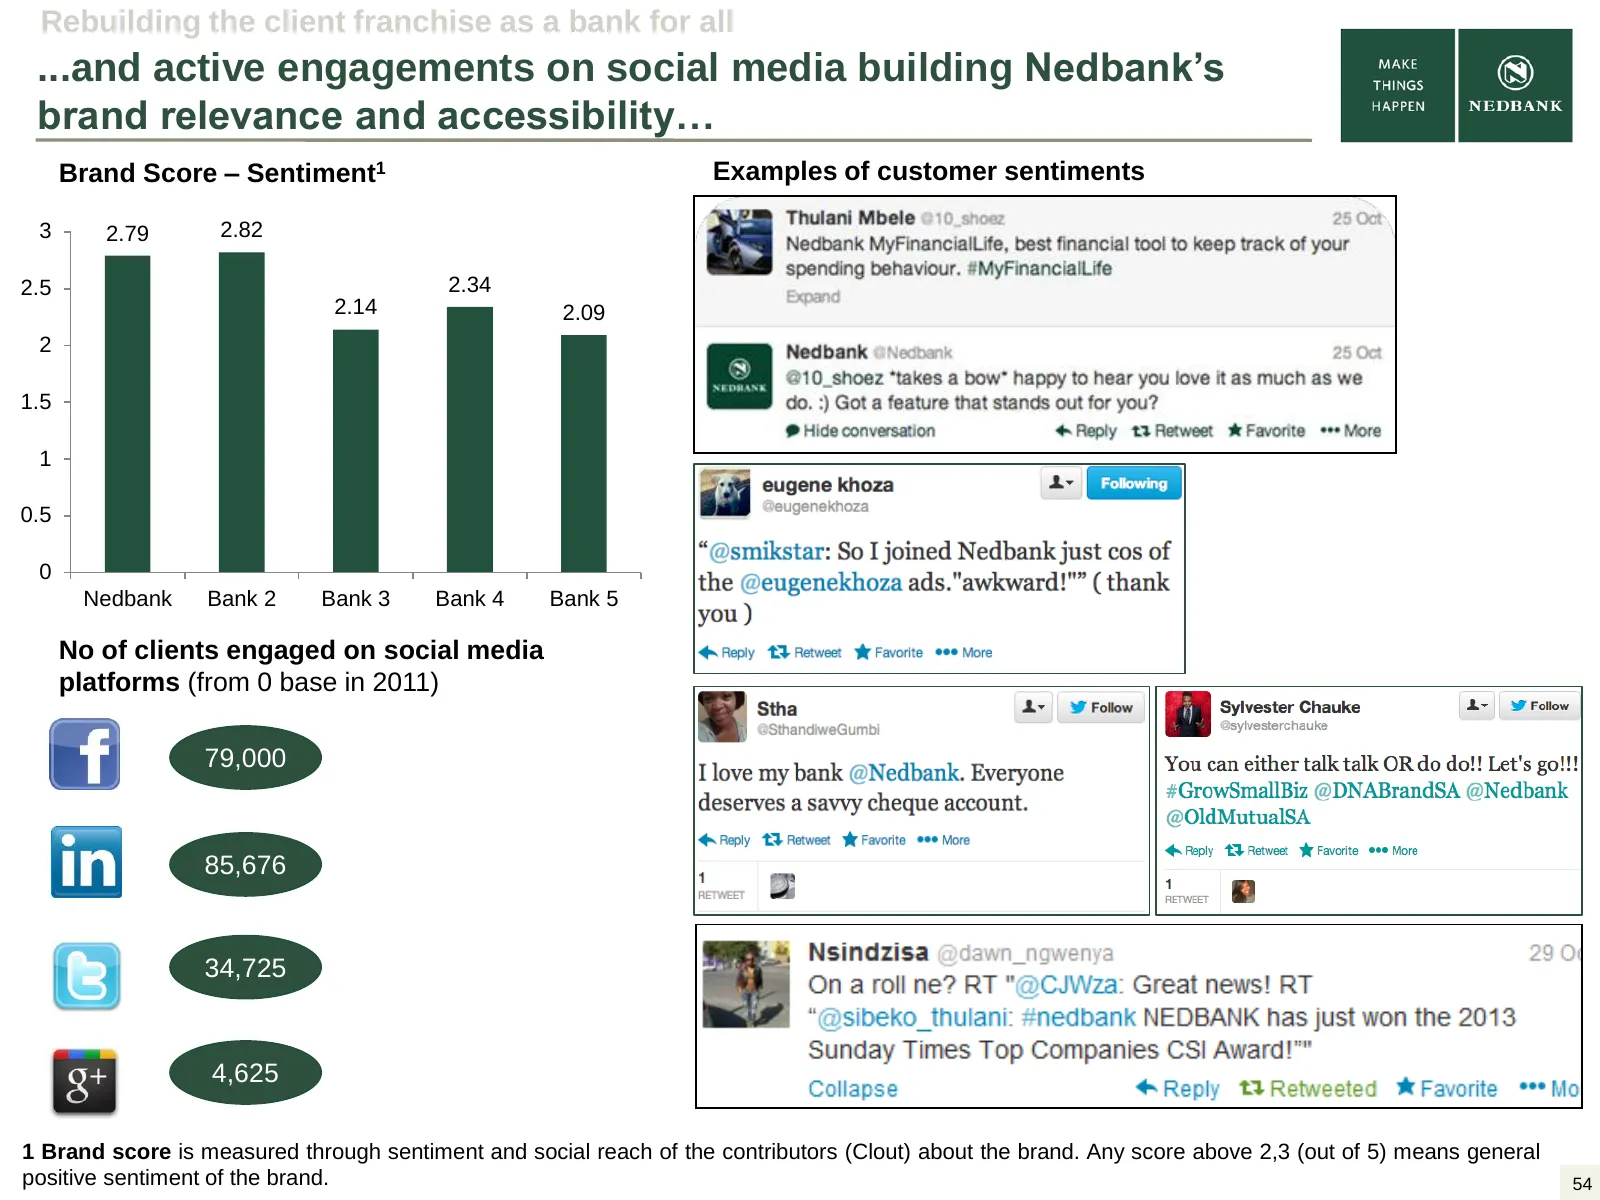
Slide 54: Social media engagement building brand relevance
Rebuilding the client franchise as a bank for all ...and active engagements on social media building Nedbank’s brand relevance and accessibility… Brand Score – Sentiment1 Examples of customer sentiments 3 2.79 2.82 2.5 2.34 2.14 2.09 2 1.5 1 0.5 0 Nedbank Bank 2 Bank 3 Bank 4 Bank 5 No of clients en
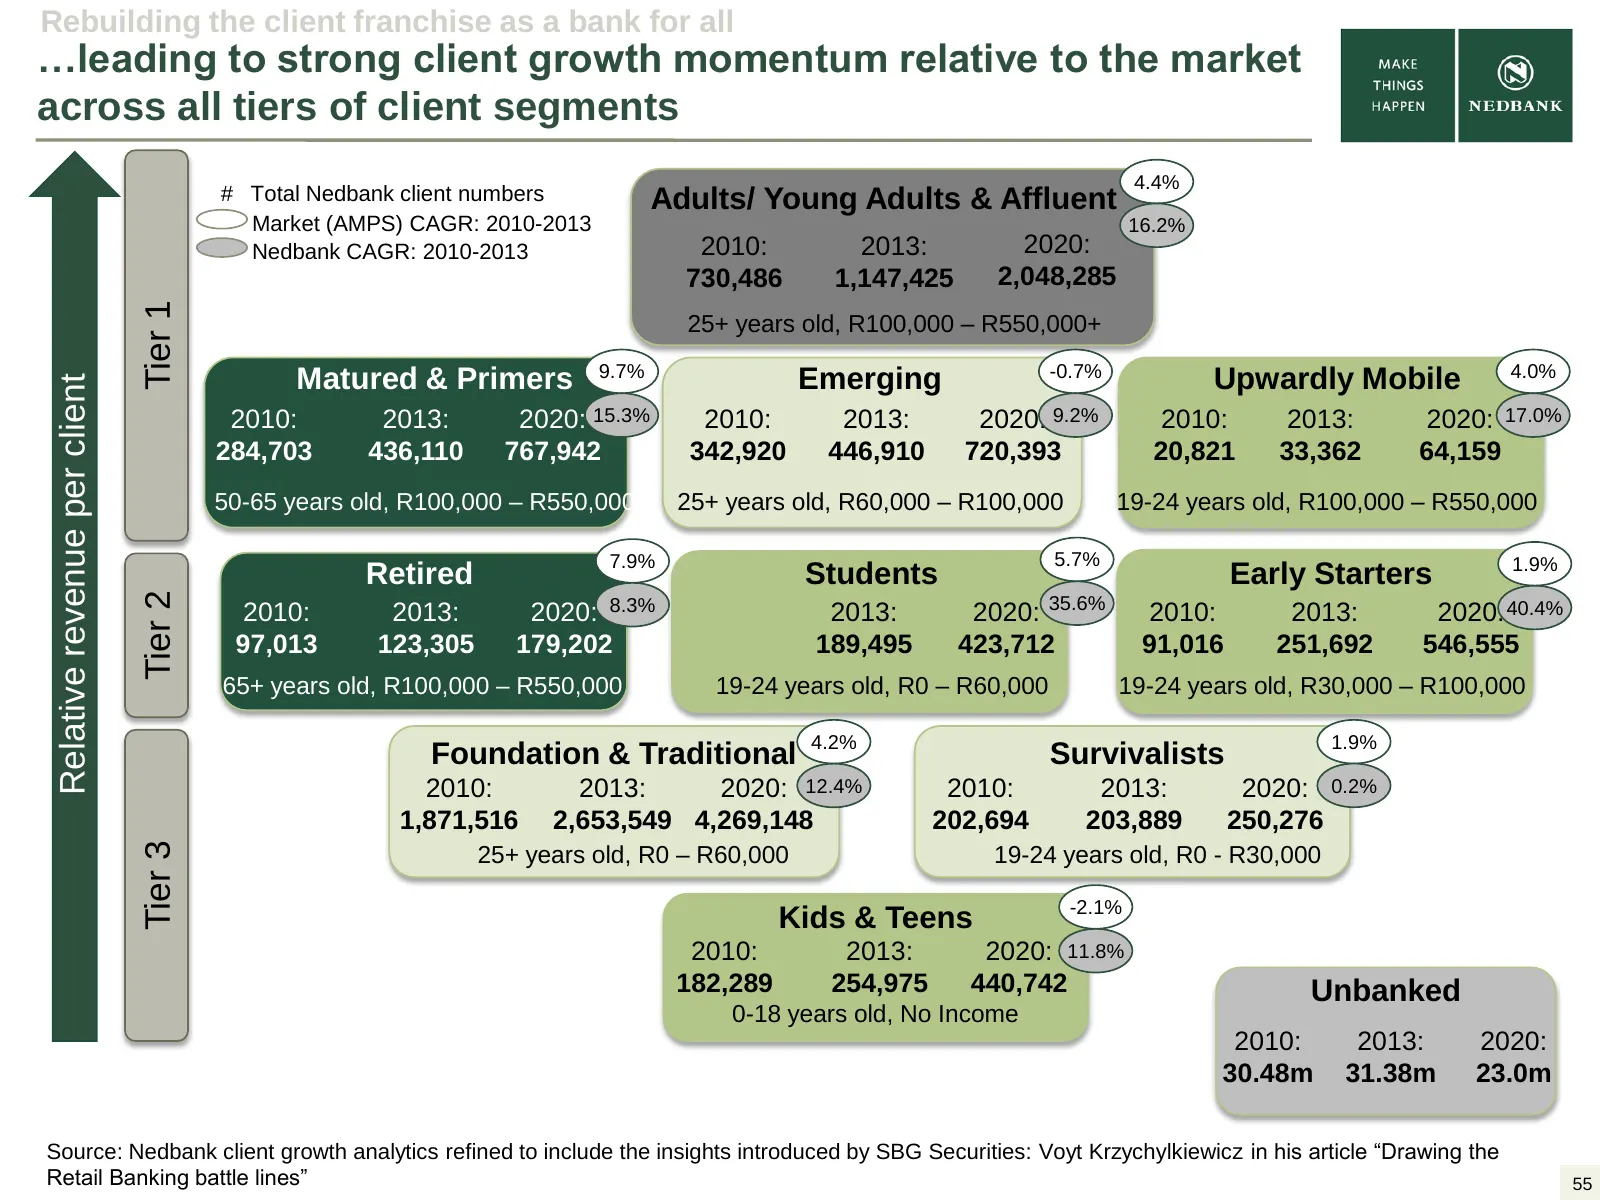
Slide 55: Strong client growth momentum across all client segments
Rebuilding the client franchise as a bank for all …leading to strong client growth momentum relative to the market across all tiers of client segments 4.4% # Total Nedbank client numbers Adults/ Young Adults & Affluent Market (AMPS) CAGR: 2010-2013 16.2% Nedbank CAGR: 2010-2013 2010: 2013: 2020: 730
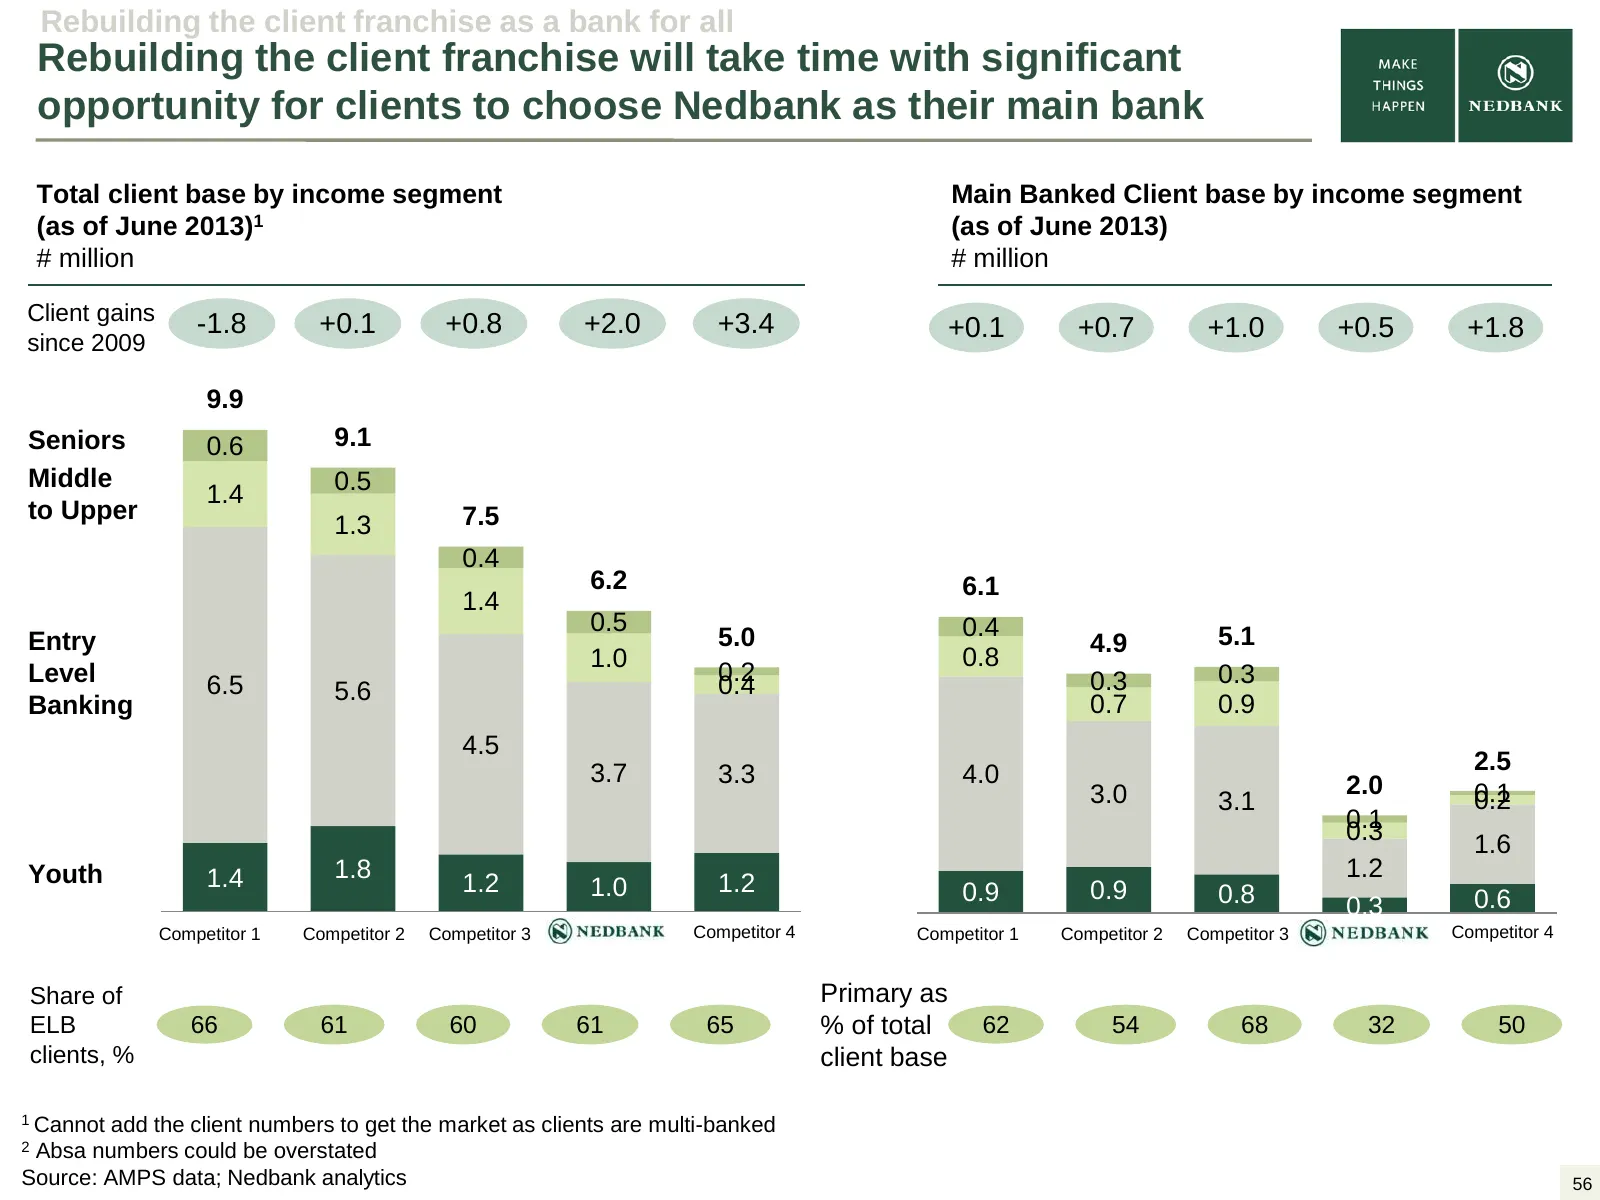
Slide 56: Rebuilding the client franchise will take time
Rebuilding the client franchise as a bank for all Rebuilding the client franchise will take time with significant opportunity for clients to choose Nedbank as their main bank Total client base by income segment Main Banked Client base by income segment (as of June 2013)1 (as of June 2013) # million
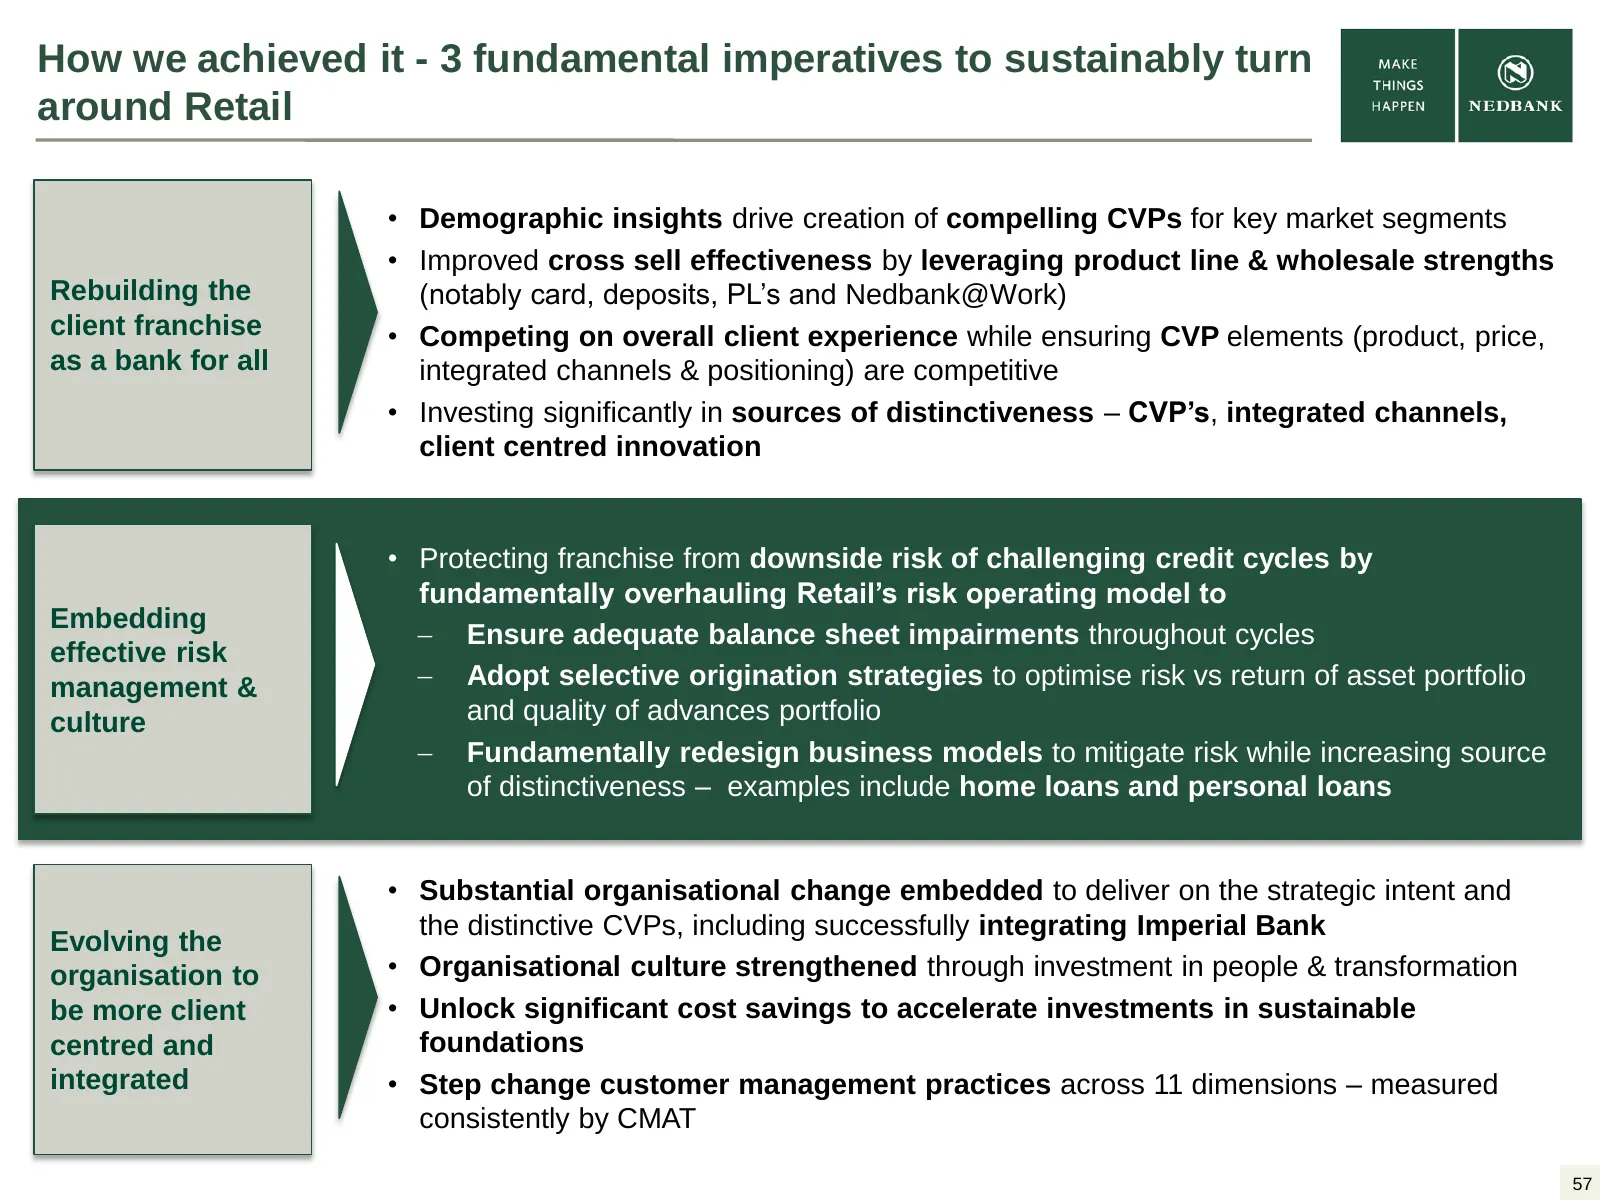
Slide 57: How we achieved it – fundamental imperatives to turn around Retail
How we achieved it - 3 fundamental imperatives to sustainably turn around Retail • Demographic insights drive creation of compelling CVPs for key market segments • Improved cross sell effectiveness by leveraging product line & wholesale strengths Rebuilding the (notably card, deposits, PL’s and Nedb
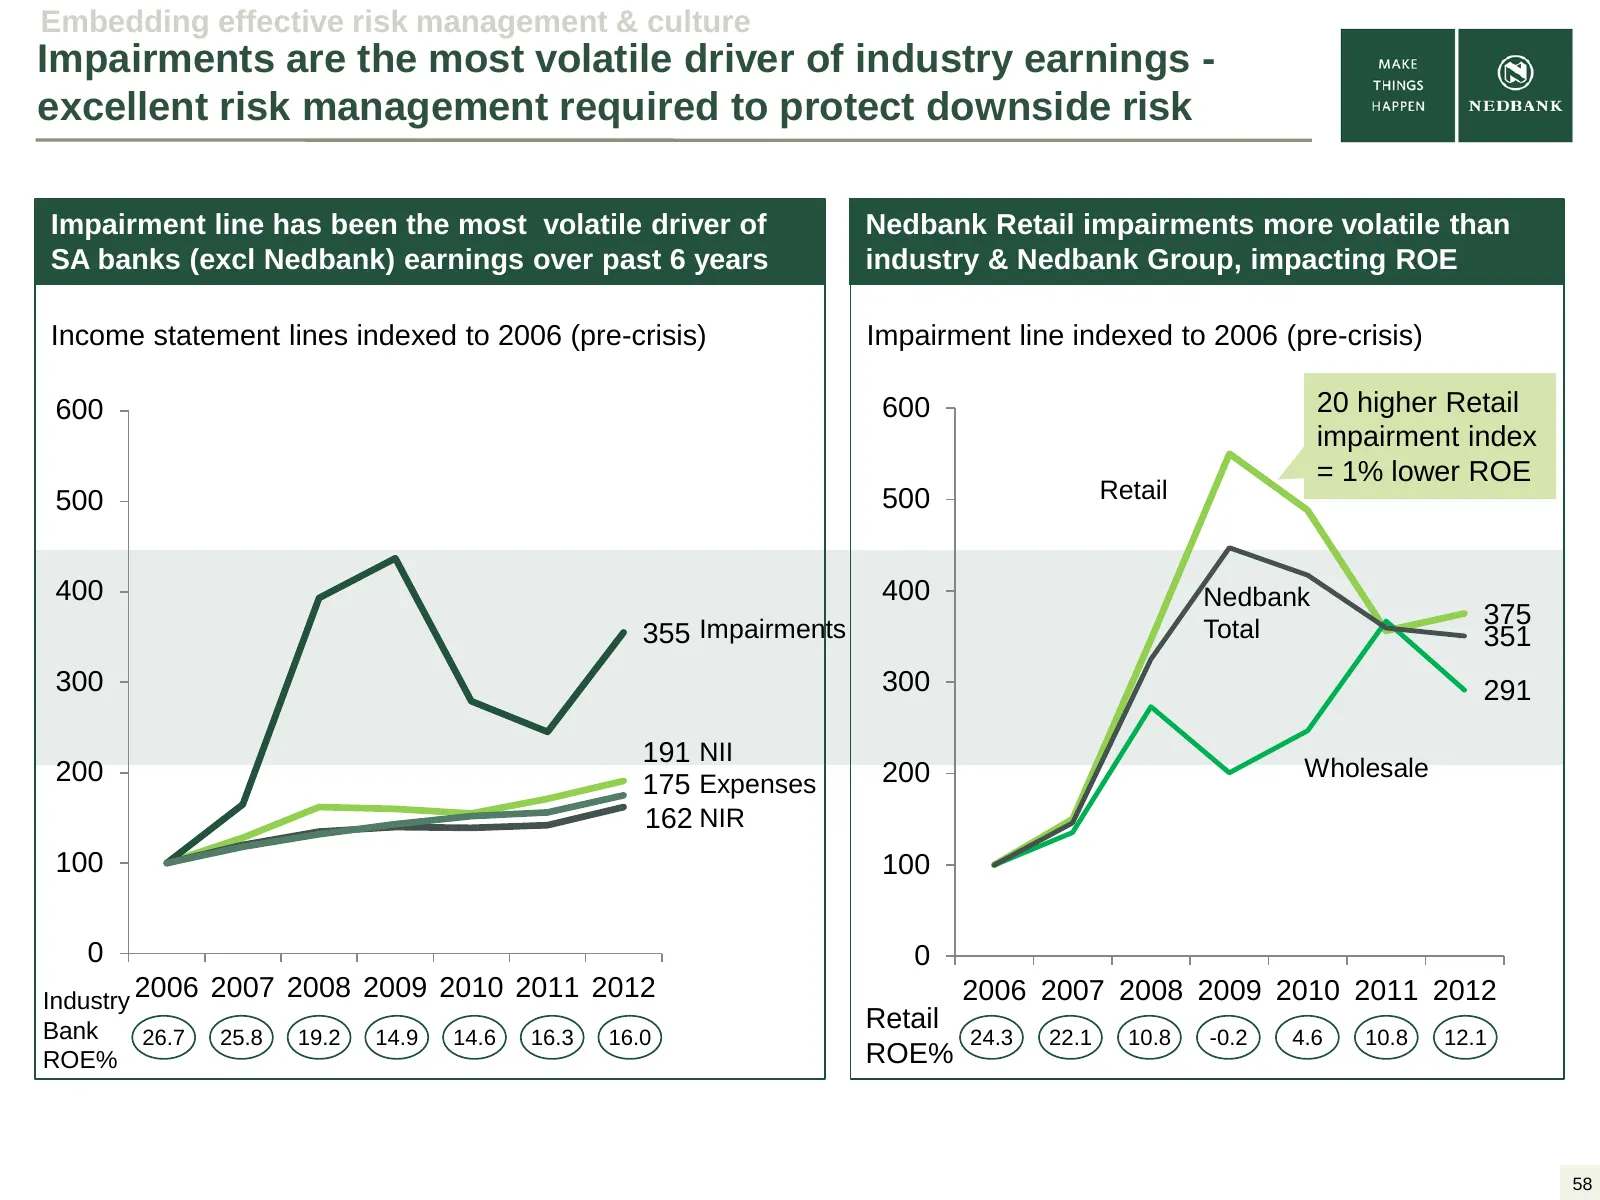
Slide 58: Impairments are the most volatile driver of industry earnings
Embedding effective risk management & culture Impairments are the most volatile driver of industry earnings - excellent risk management required to protect downside risk Impairment line has been the most volatile driver of Nedbank Retail impairments more volatile than SA banks (excl Nedbank) earning
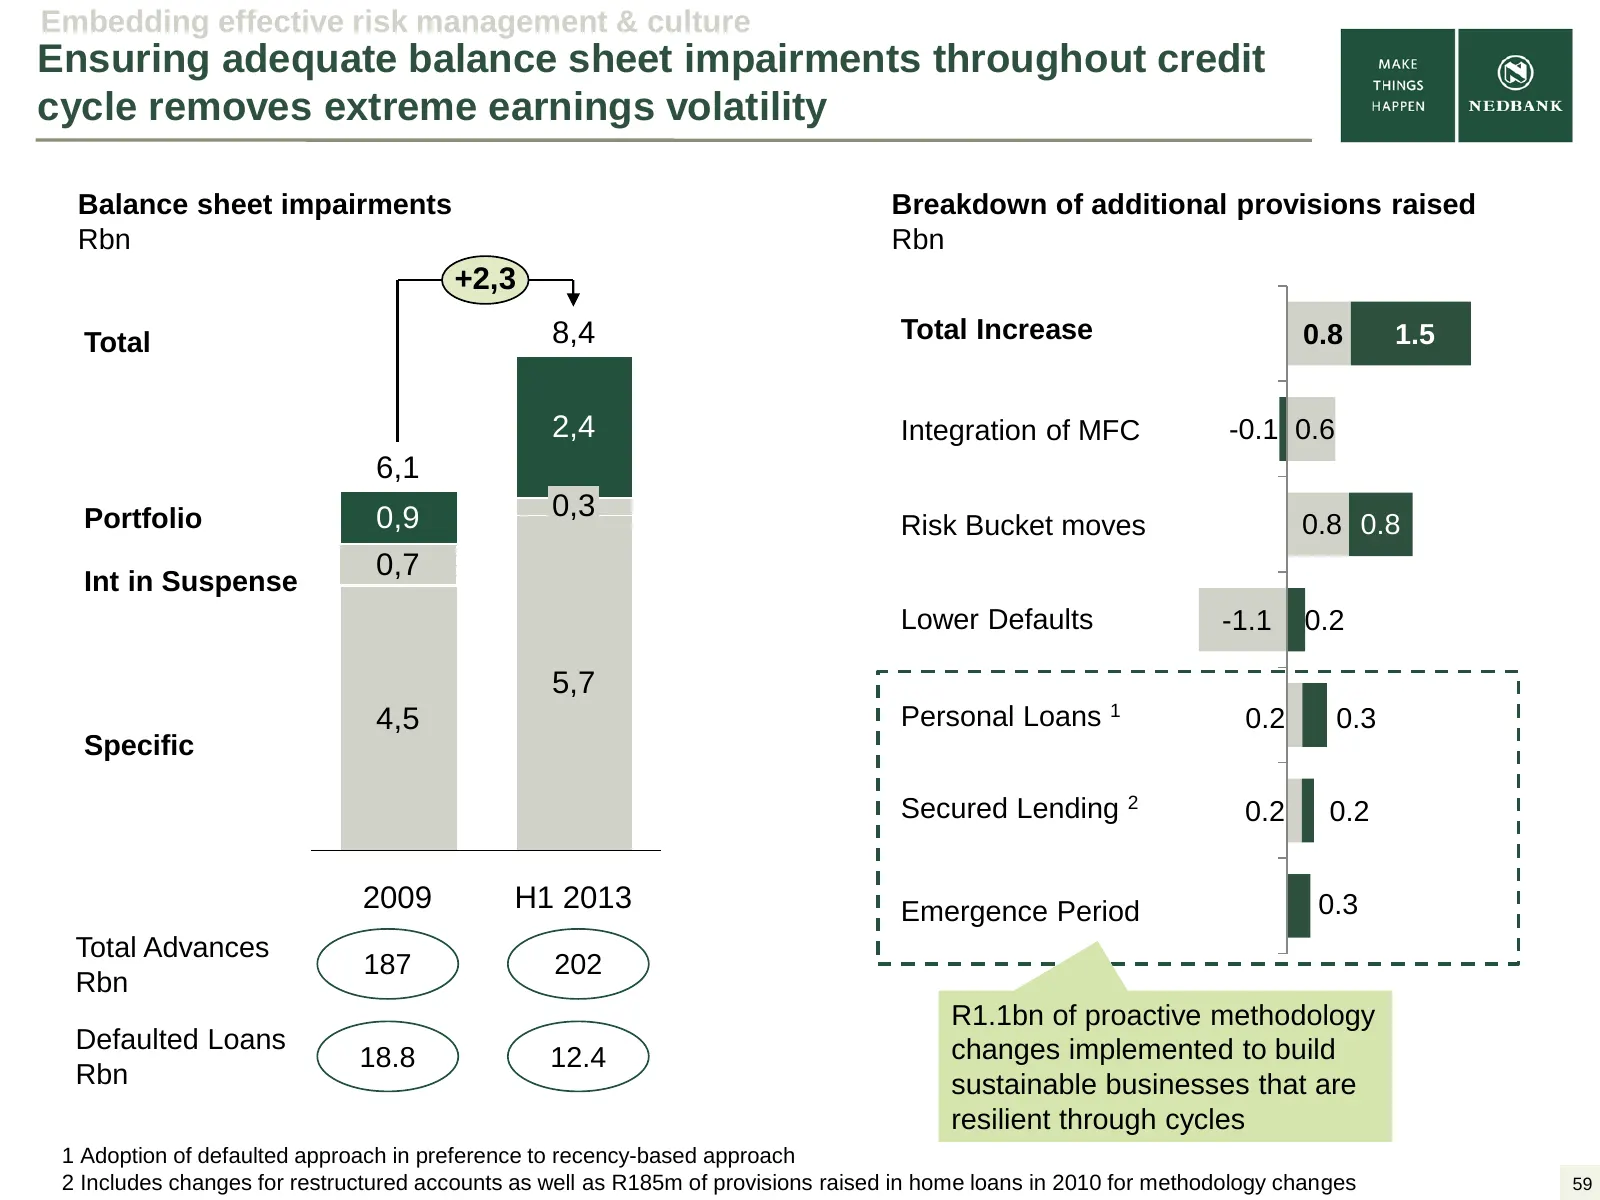
Slide 59: Adequate balance sheet impairments remove earnings volatility
Embedding effective risk management & culture Ensuring adequate balance sheet impairments throughout credit cycle removes extreme earnings volatility Balance sheet impairments Breakdown of additional provisions raised Rbn Rbn +2,3 Total 8,4 Total Increase 0.8 1.5 2,4 Integration of MFC -0.1 0.6 6,1
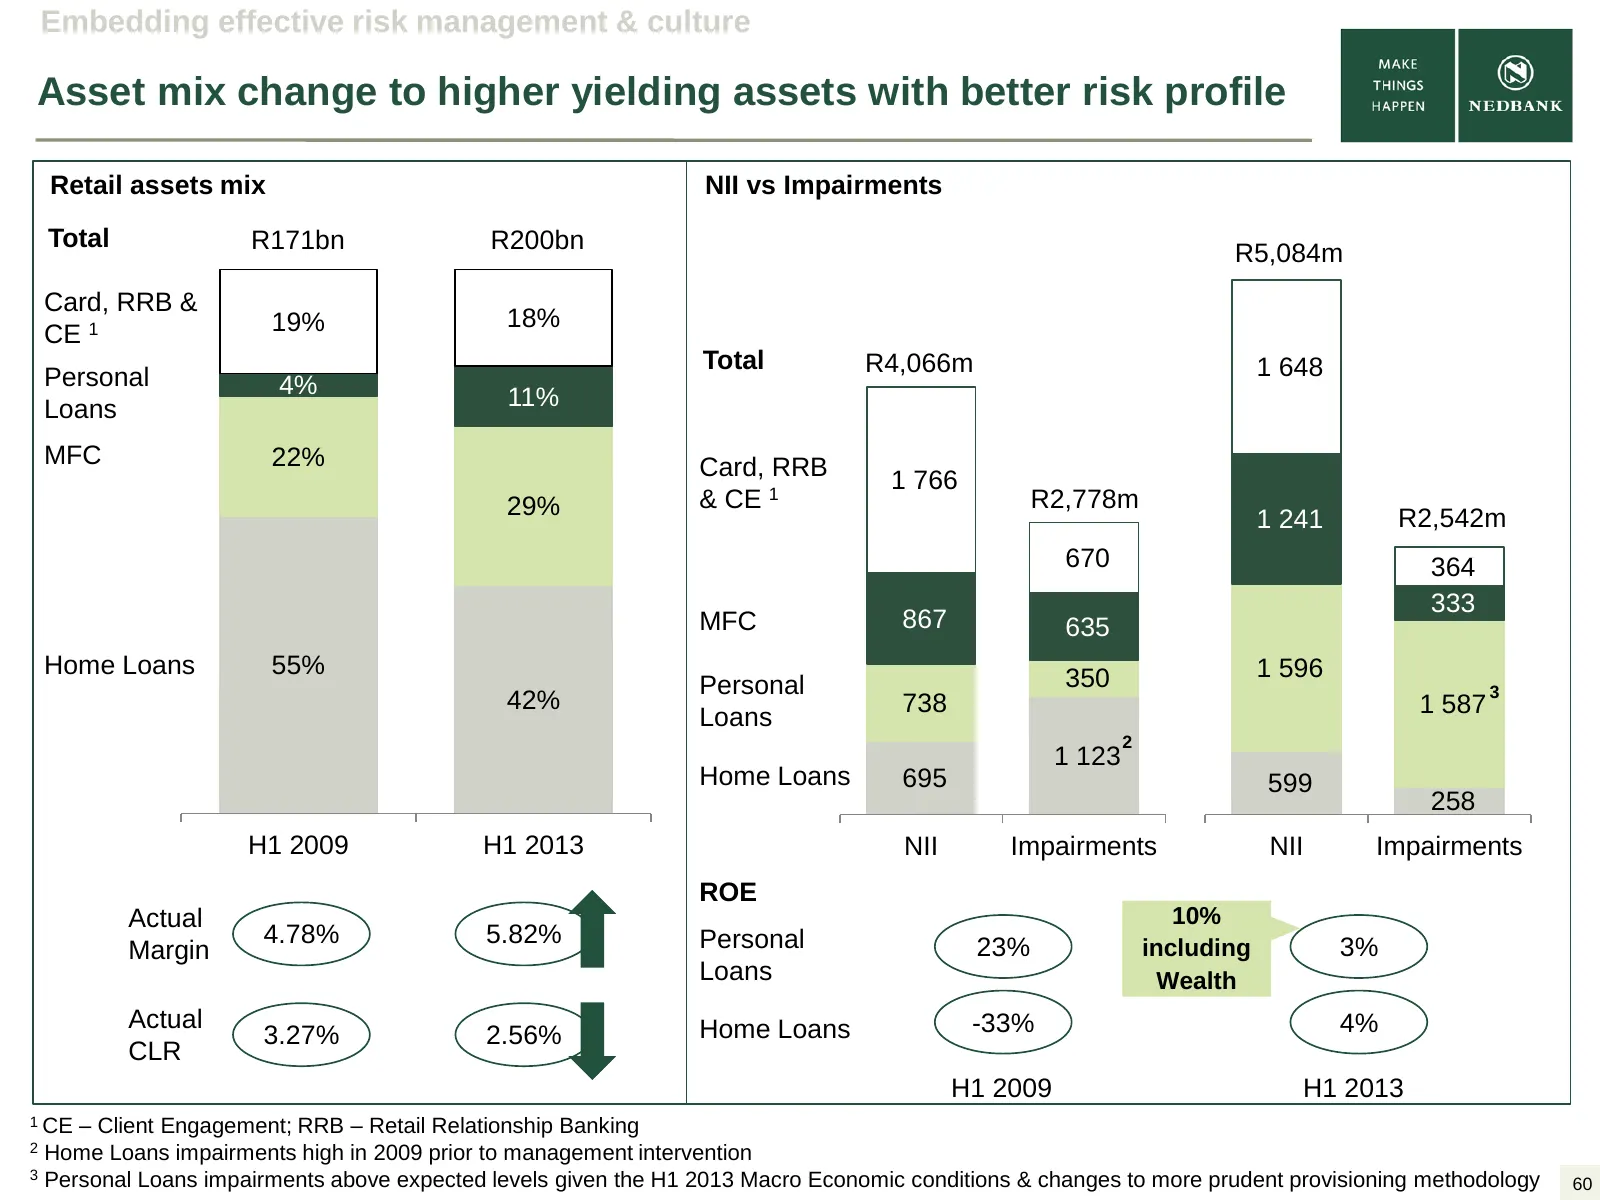
Slide 60: Asset mix change to higher yielding assets
Embedding effective risk management & culture Asset mix change to higher yielding assets with better risk profile Retail assets mix NII vs Impairments Total R171bn R200bn R5,084m Card, RRB & 19% 18% CE 1 Total R4,066m 1 648 Personal 4% Loans 11% MFC 22% Card, RRB 1 766 29% & CE 1 R2,778m 1 241 R2,54
Slide 61: Credit policy and origination changes lower disbursement rates
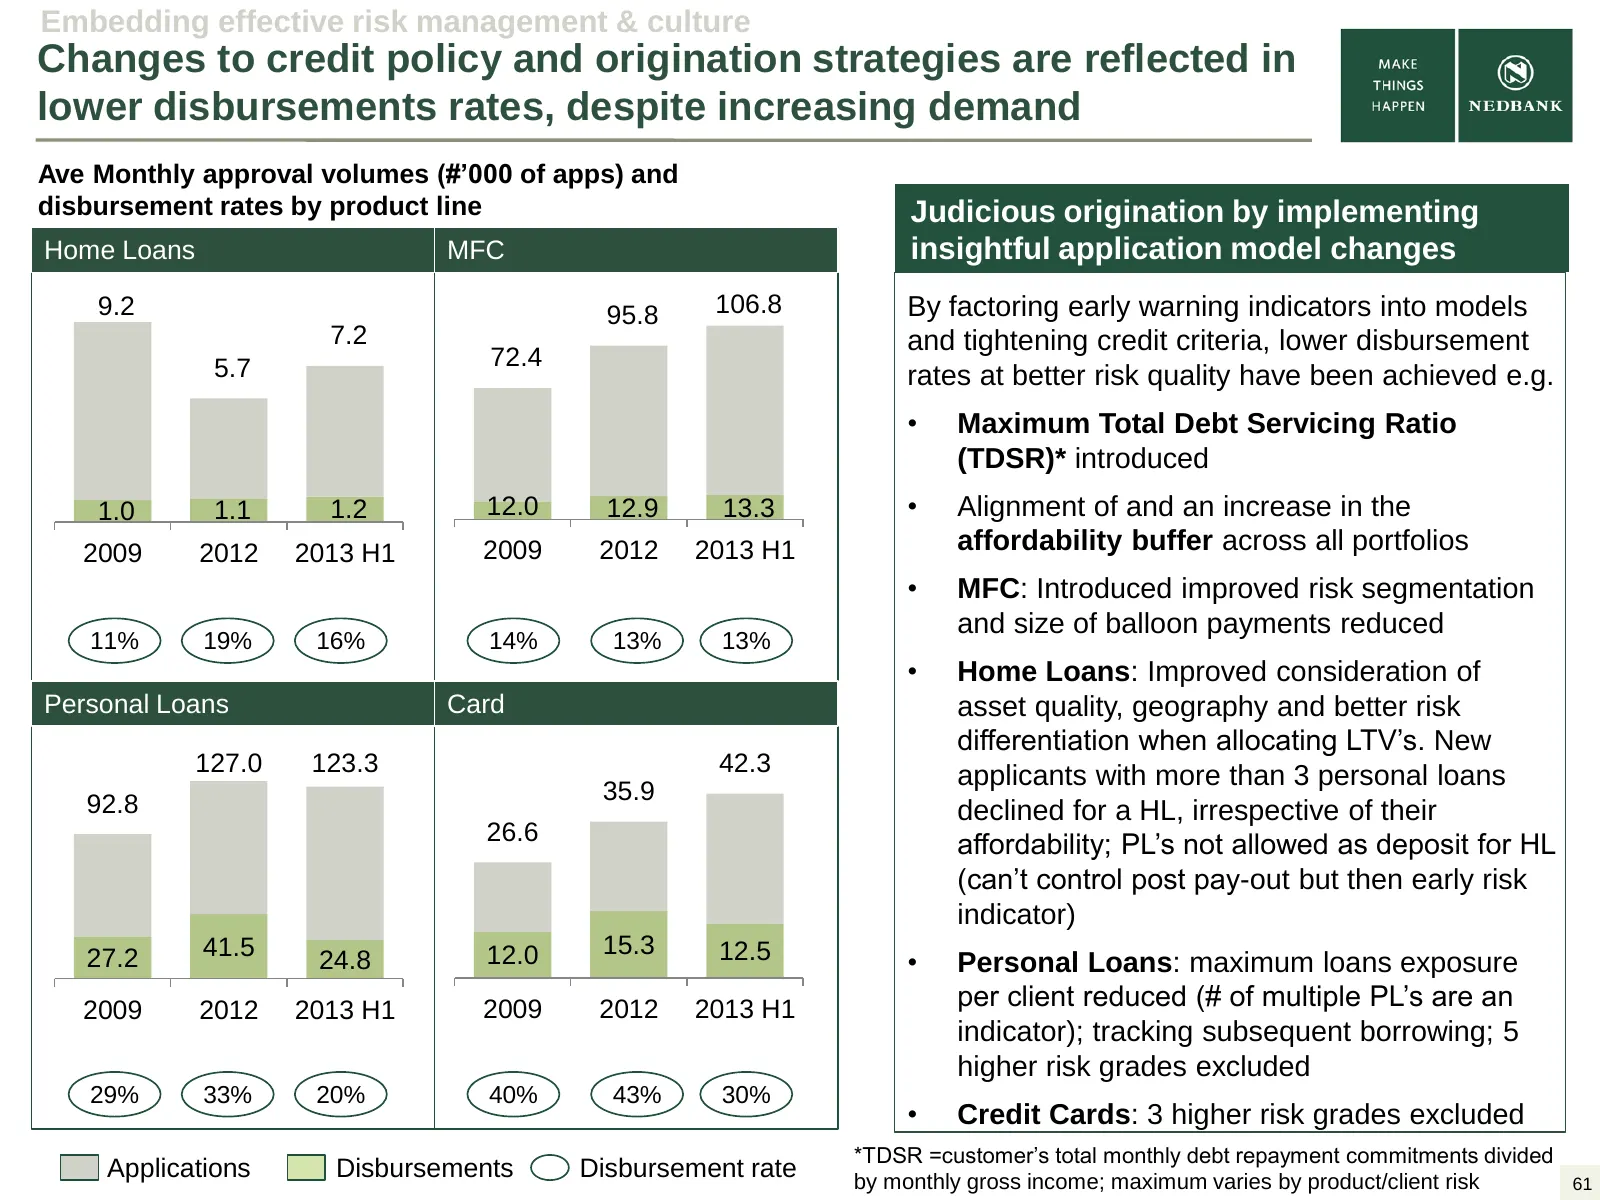
Embedding effective risk management & culture Changes to credit policy and origination strategies are reflected in lower disbursements rates, despite increasing demand Ave Monthly approval volumes (#’000 of apps) and disbursement rates by product line Judicious origination by implementing Home Loans
Slide 62: Redesign of business model for Home Loans and Personal Loans
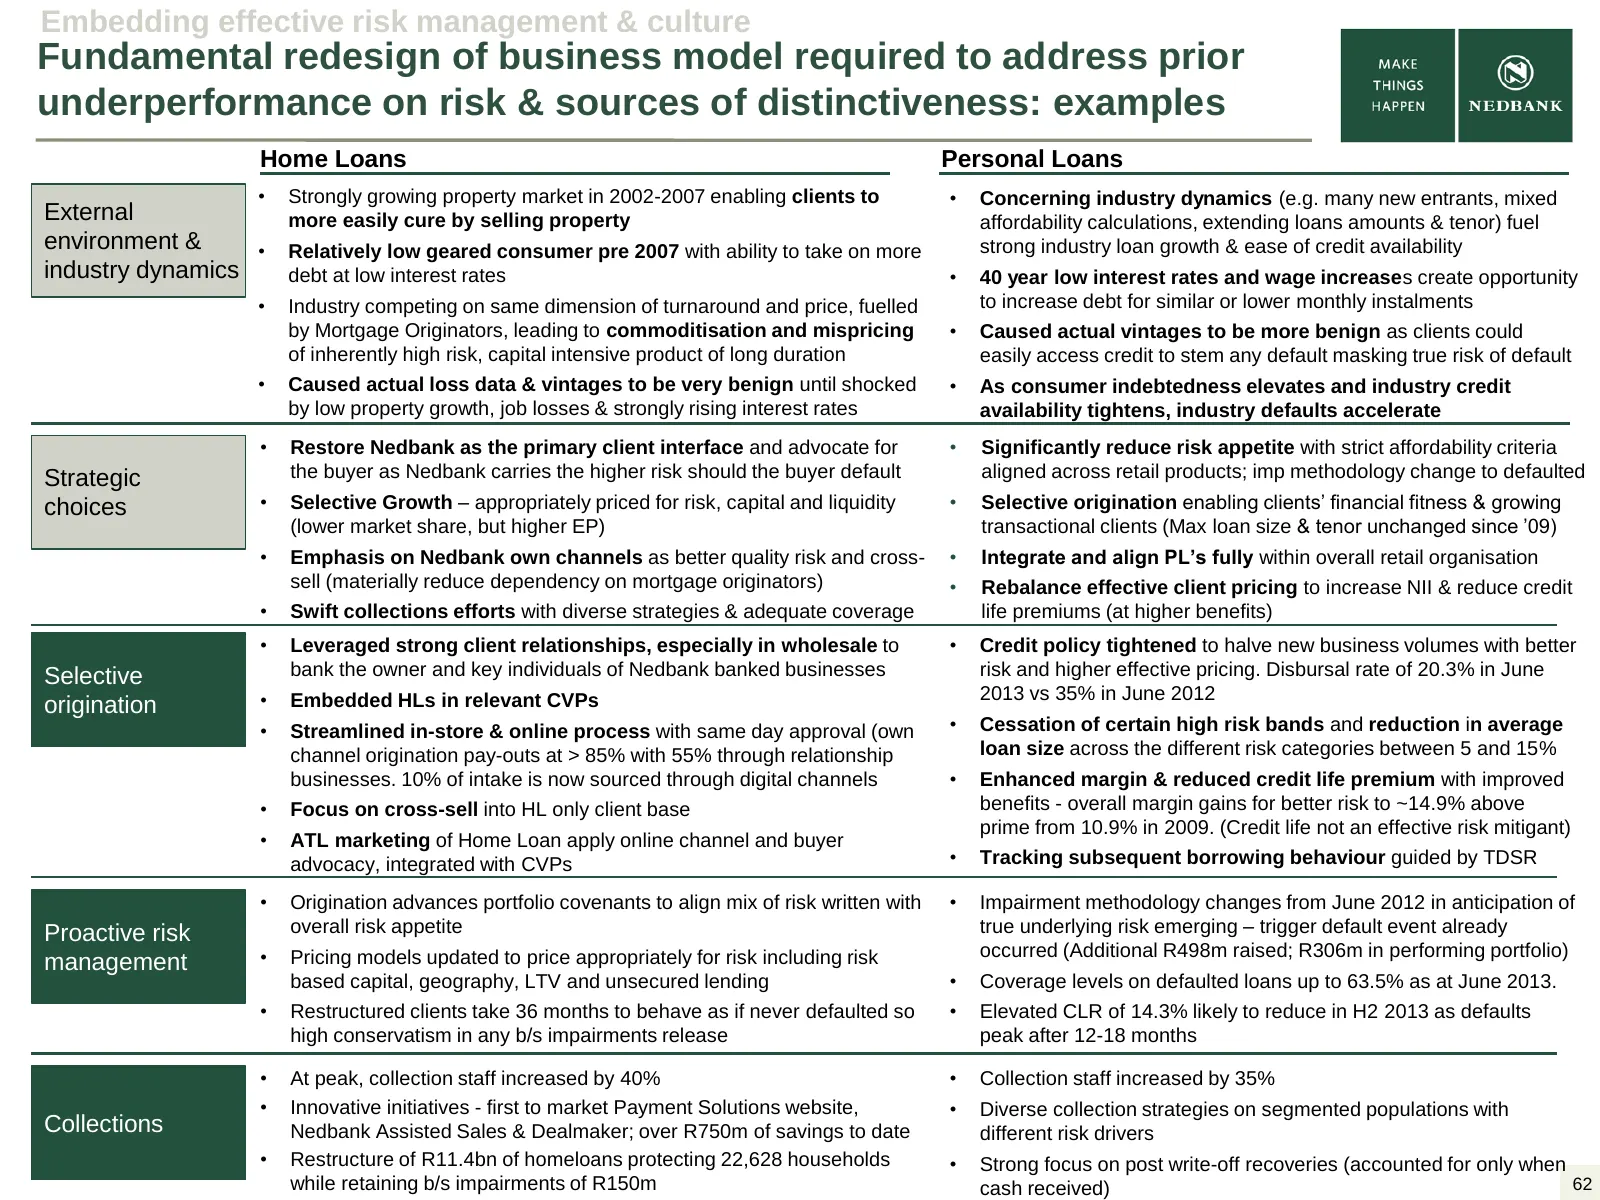
Embedding effective risk management & culture Fundamental redesign of business model required to address prior underperformance on risk & sources of distinctiveness: examples Home Loans Personal Loans • Strongly growing property market in 2002-2007 enabling clients to • Concerning industry dynamics
Slide 63: Improved risk quality of new Home Loan business
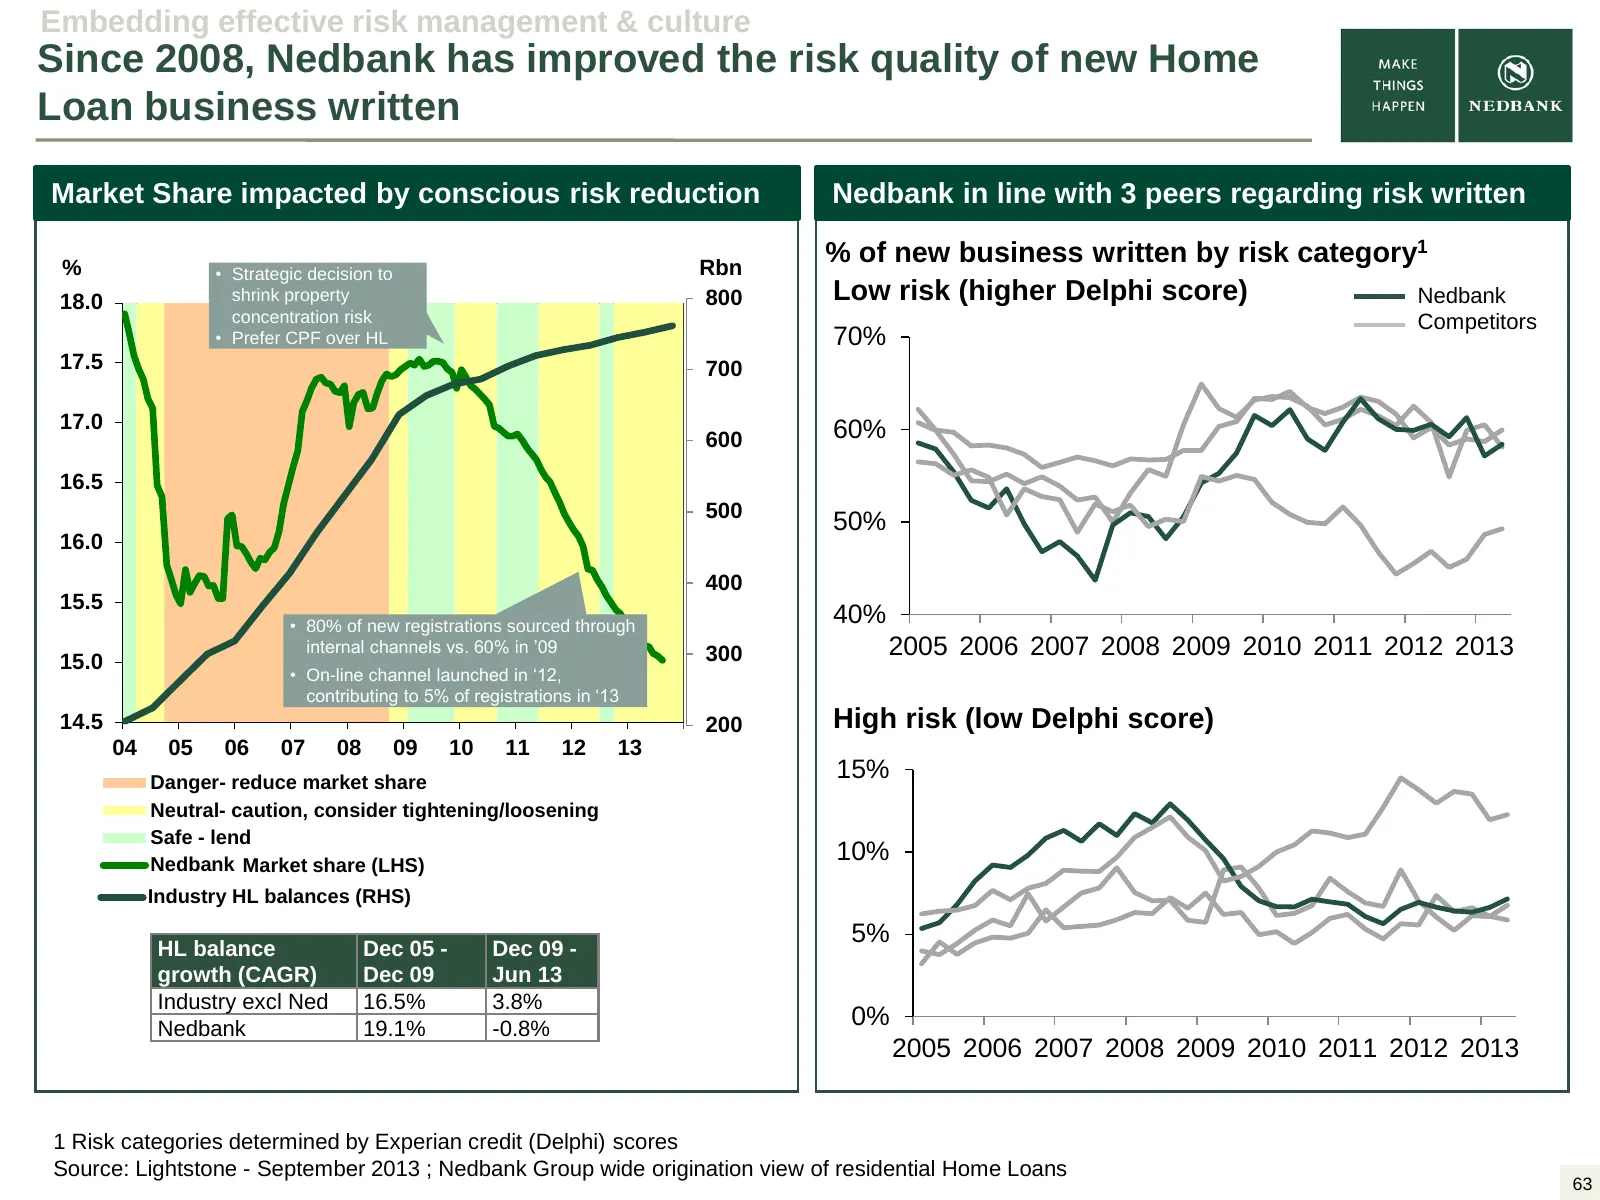
Embedding effective risk management & culture Since 2008, Nedbank has improved the risk quality of new Home Loan business written Market Share impacted by conscious risk reduction Nedbank in line with 3 peers regarding risk written % Rbn % of new business written by risk category1 • Strategic decisi
Slide 64: Poorer risk '06-'08 HL vintages will drain future earnings
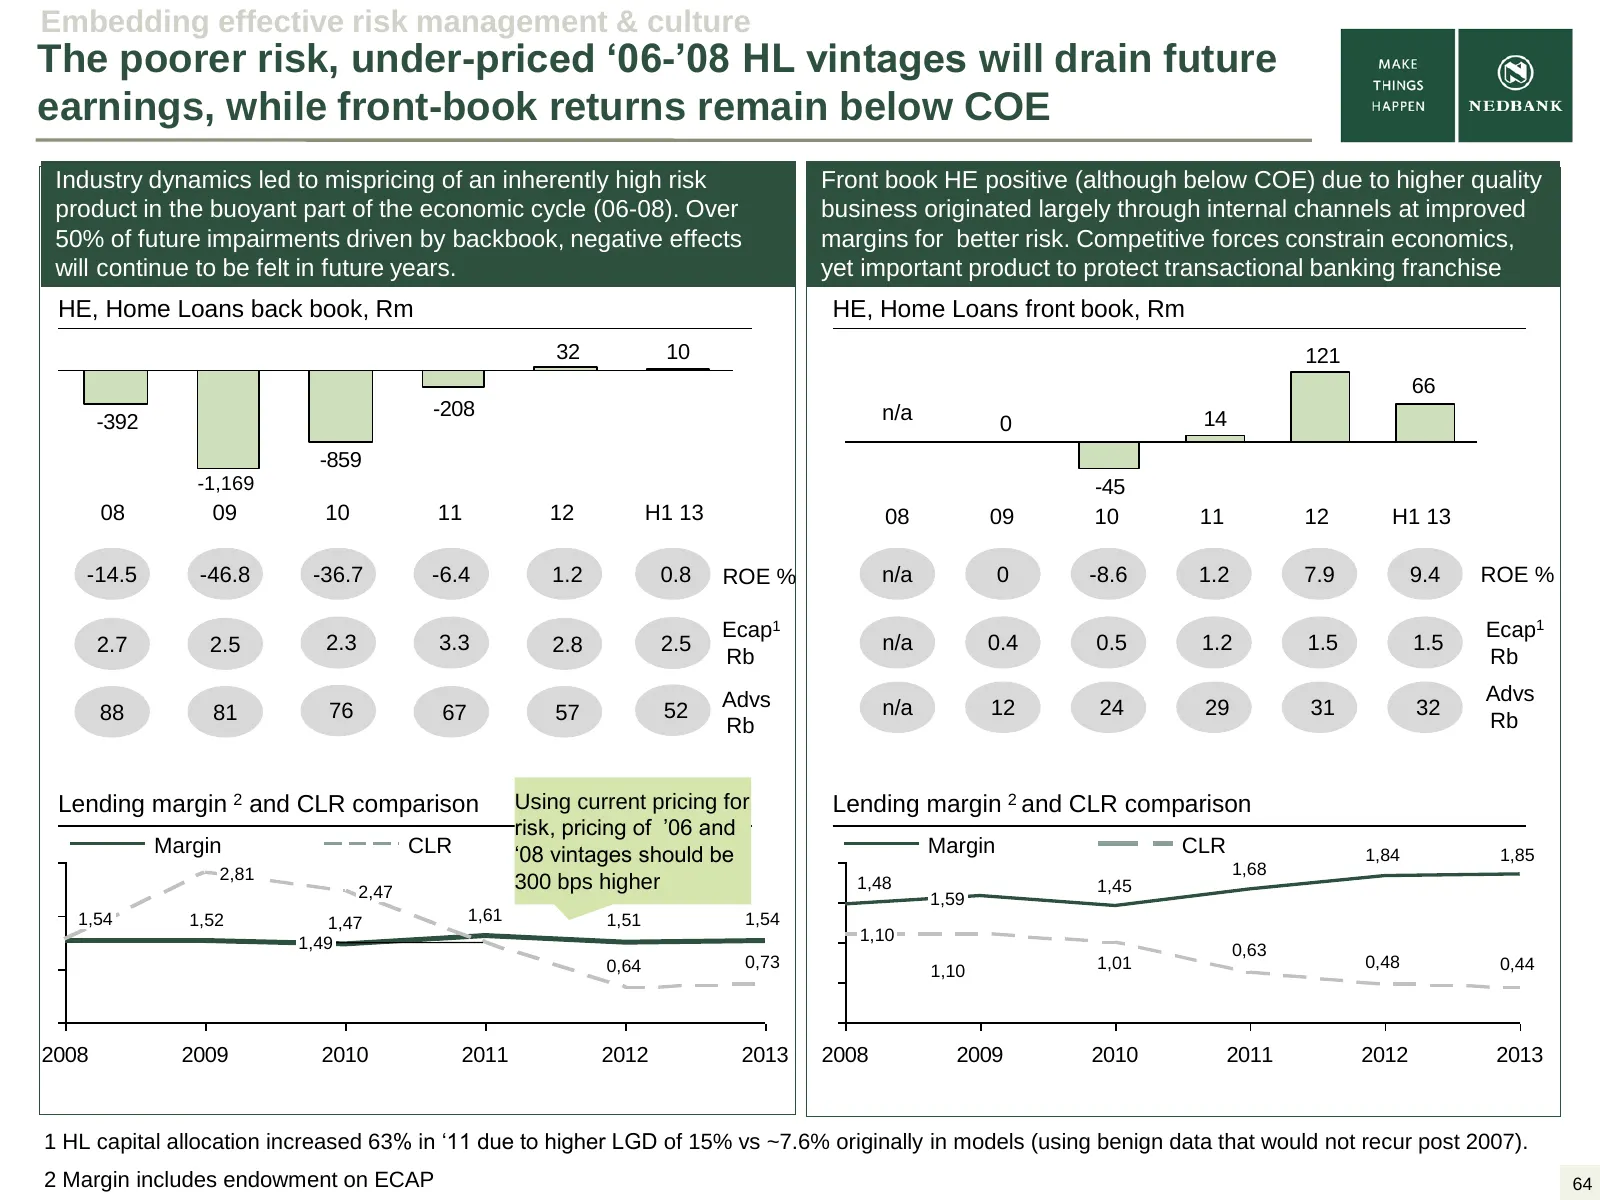
Embedding effective risk management & culture The poorer risk, under-priced ‘06-’08 HL vintages will drain future earnings, while front-book returns remain below COE Industry dynamics led to mispricing of an inherently high risk Front book HE positive (although below COE) due to higher quality produ
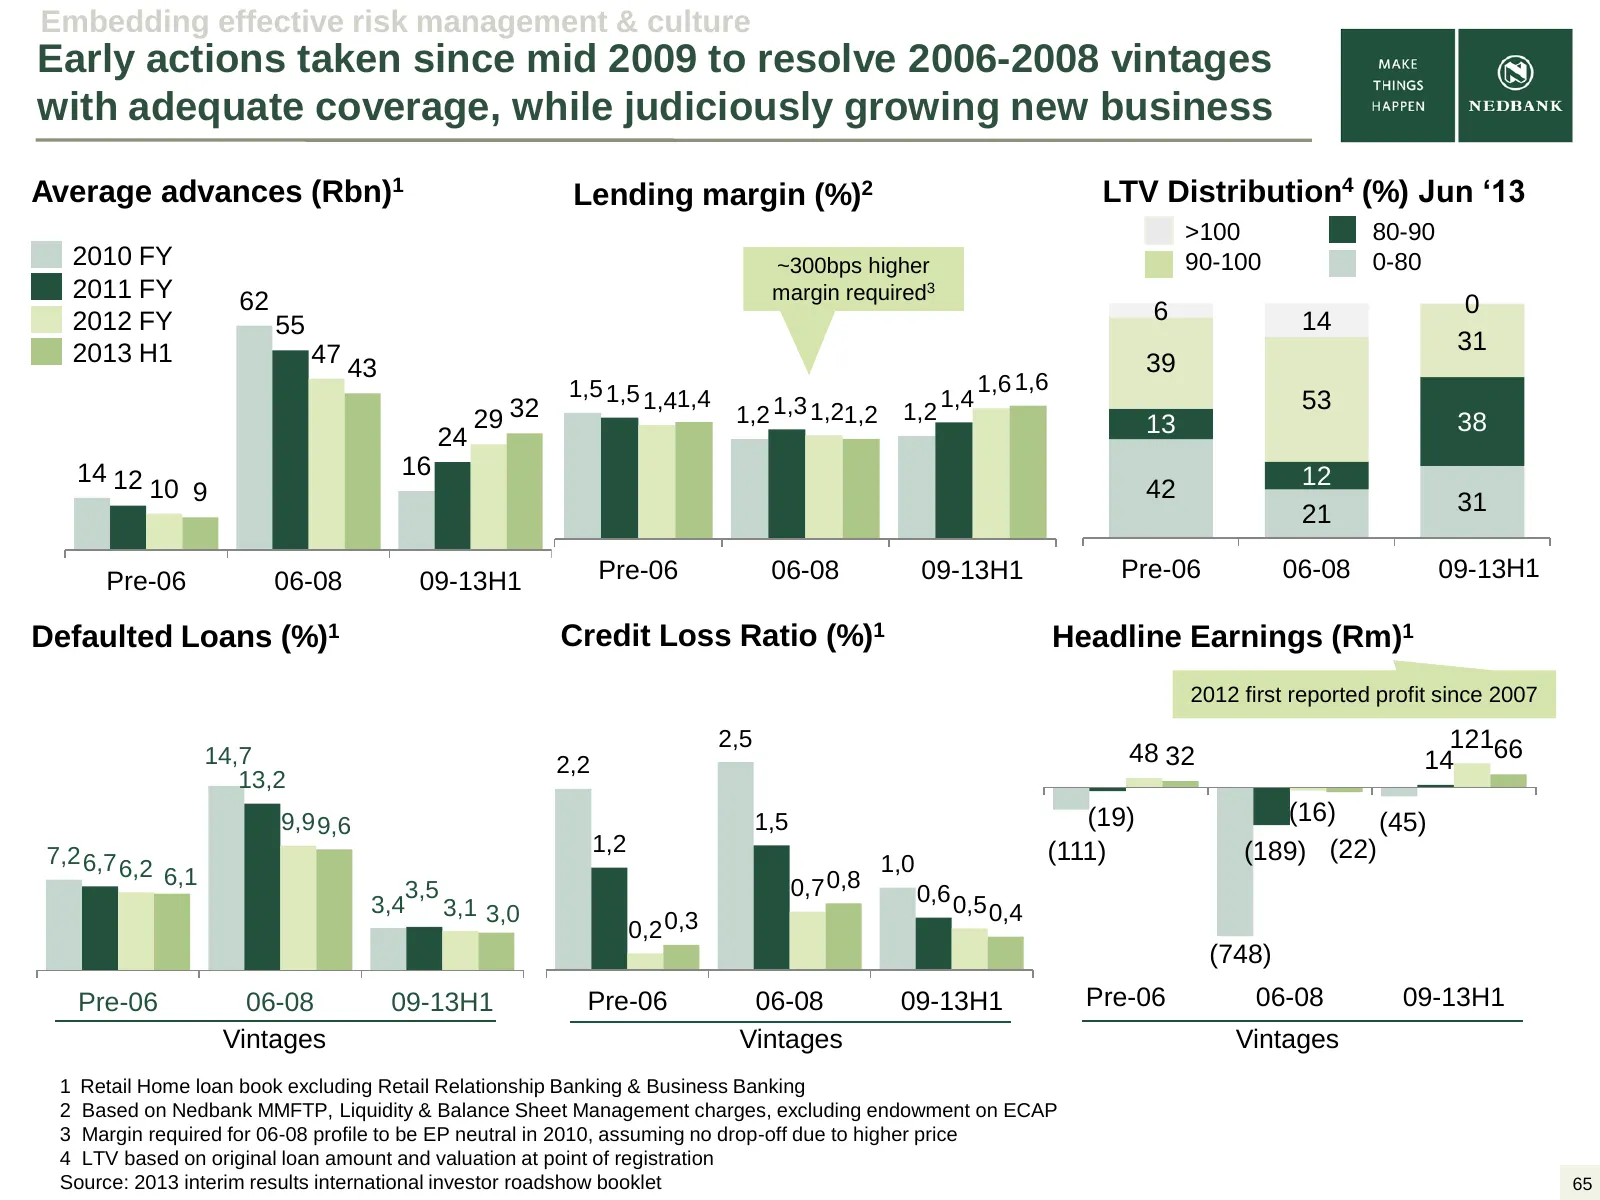
Slide 65: Early actions to resolve 2006-2008 vintages
Embedding effective risk management & culture Early actions taken since mid 2009 to resolve 2006-2008 vintages with adequate coverage, while judiciously growing new business Average advances (Rbn)1 Lending margin (%)2 LTV Distribution4 (%) Jun ‘13 >100 80-90 2010 FY ~300bps higher 90-100 0-80 2011 F
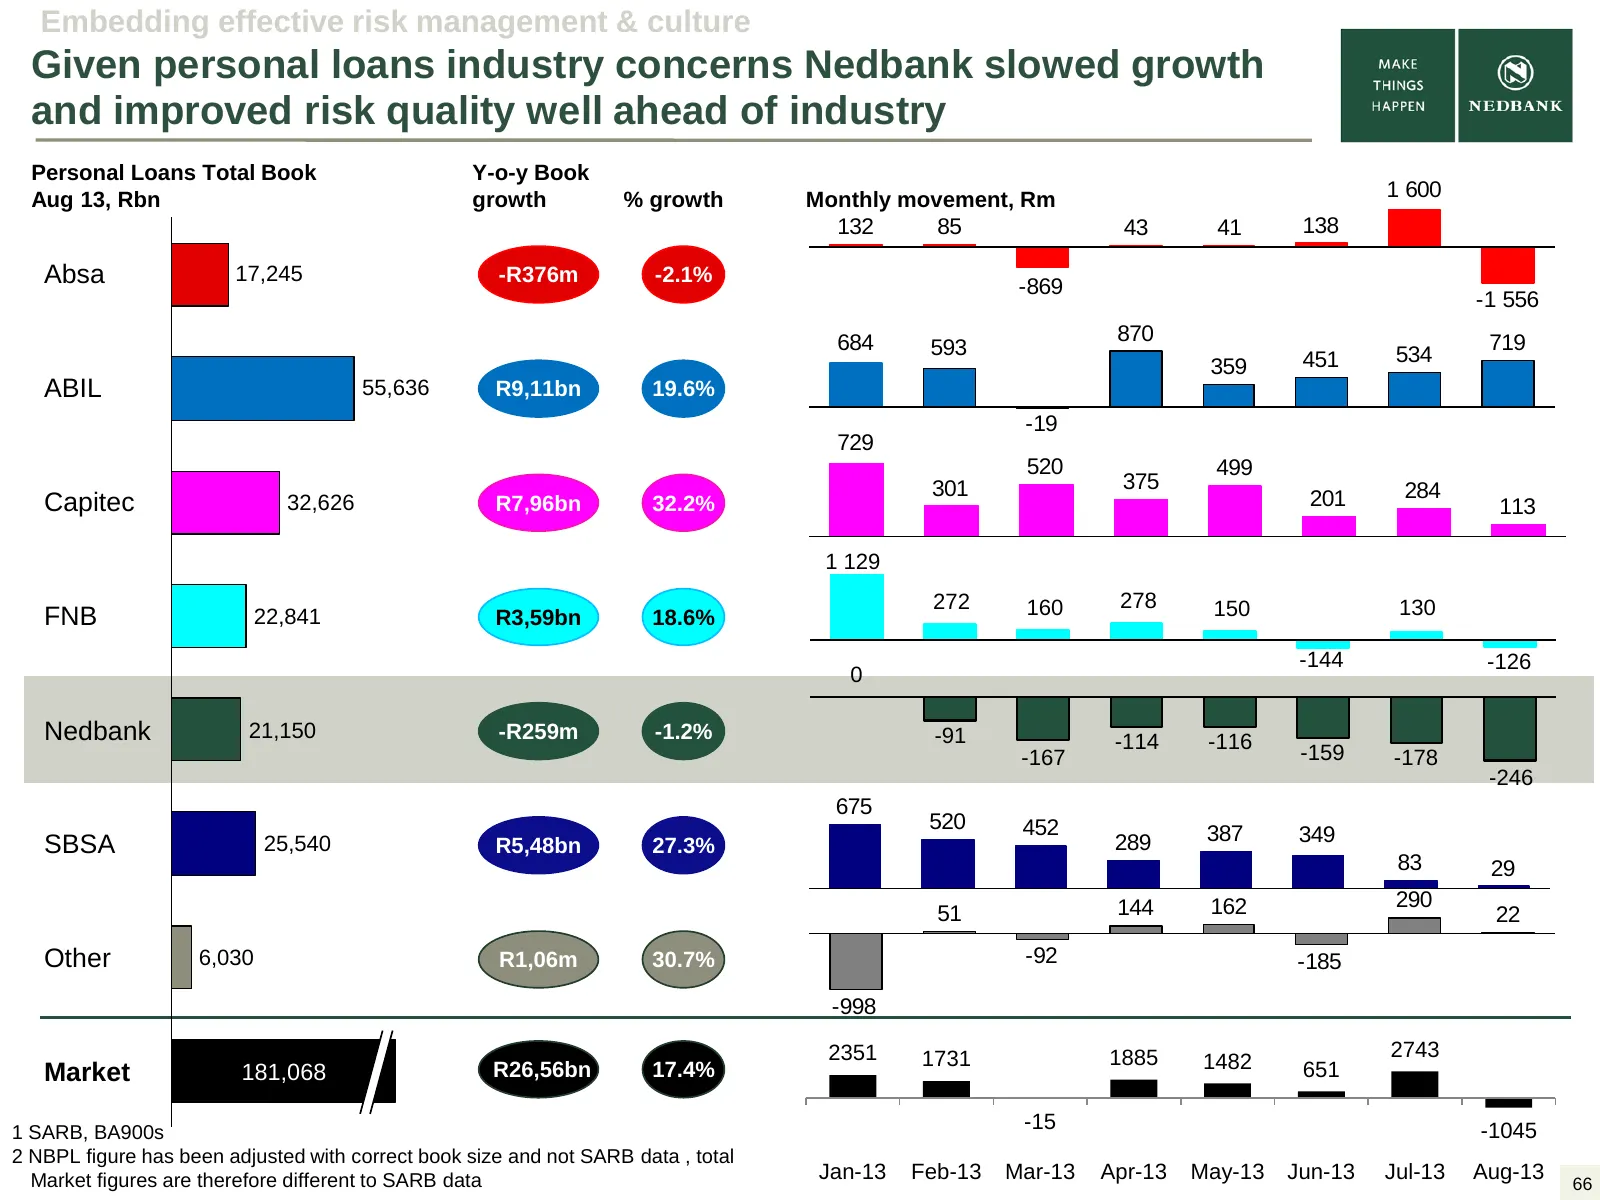
Slide 66: Personal loans: slowed growth and improved risk quality ahead of industry
Embedding effective risk management & culture Given personal loans industry concerns Nedbank slowed growth and improved risk quality well ahead of industry Personal Loans Total Book Y-o-y Book Aug 13, Rbn growth % growth Monthly movement, Rm 1 600 132 85 43 41 138 Absa 17,245 -R376m -2.1% -869 -1 55
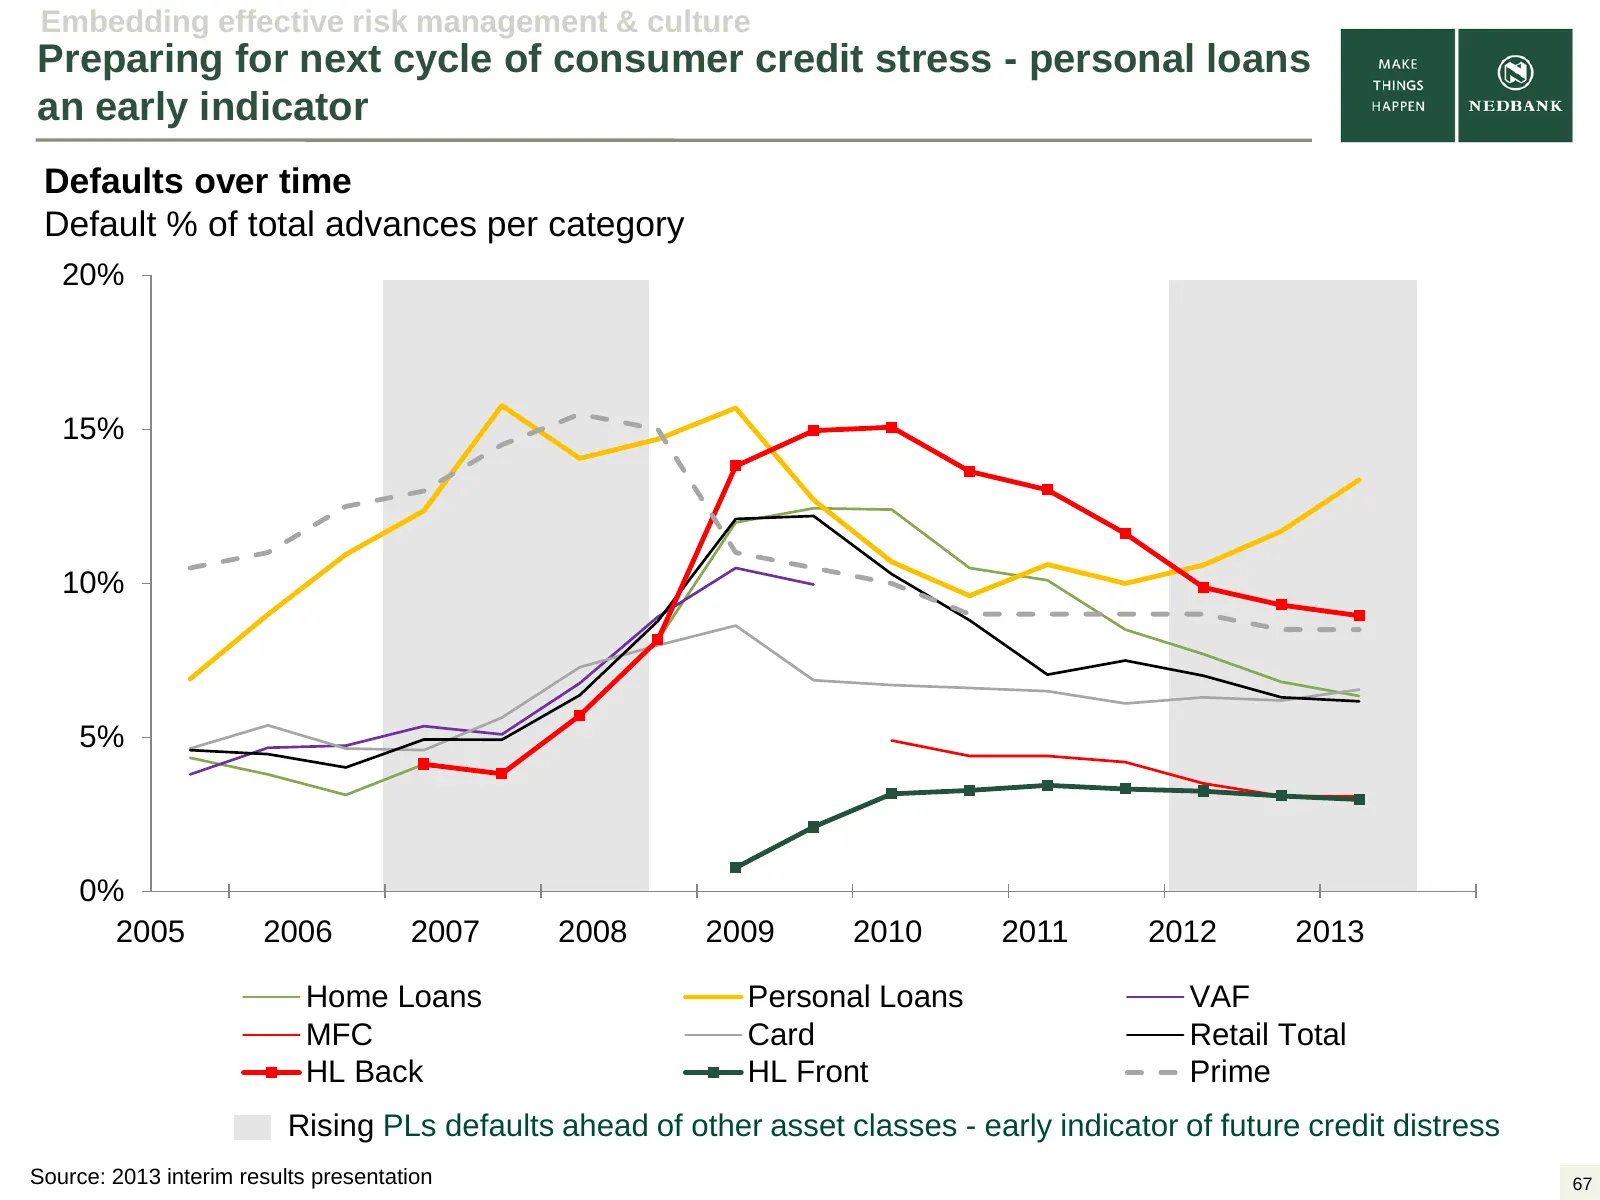
Slide 67: Preparing for next cycle of consumer credit stress
Embedding effective risk management & culture Preparing for next cycle of consumer credit stress - personal loans an early indicator Defaults over time Default % of total advances per category 20% 15% 10% 5% 0% 2005 2006 2007 2008 2009 2010 2011 2012 2013 Home Loans Personal Loans VAF MFC Card Retai
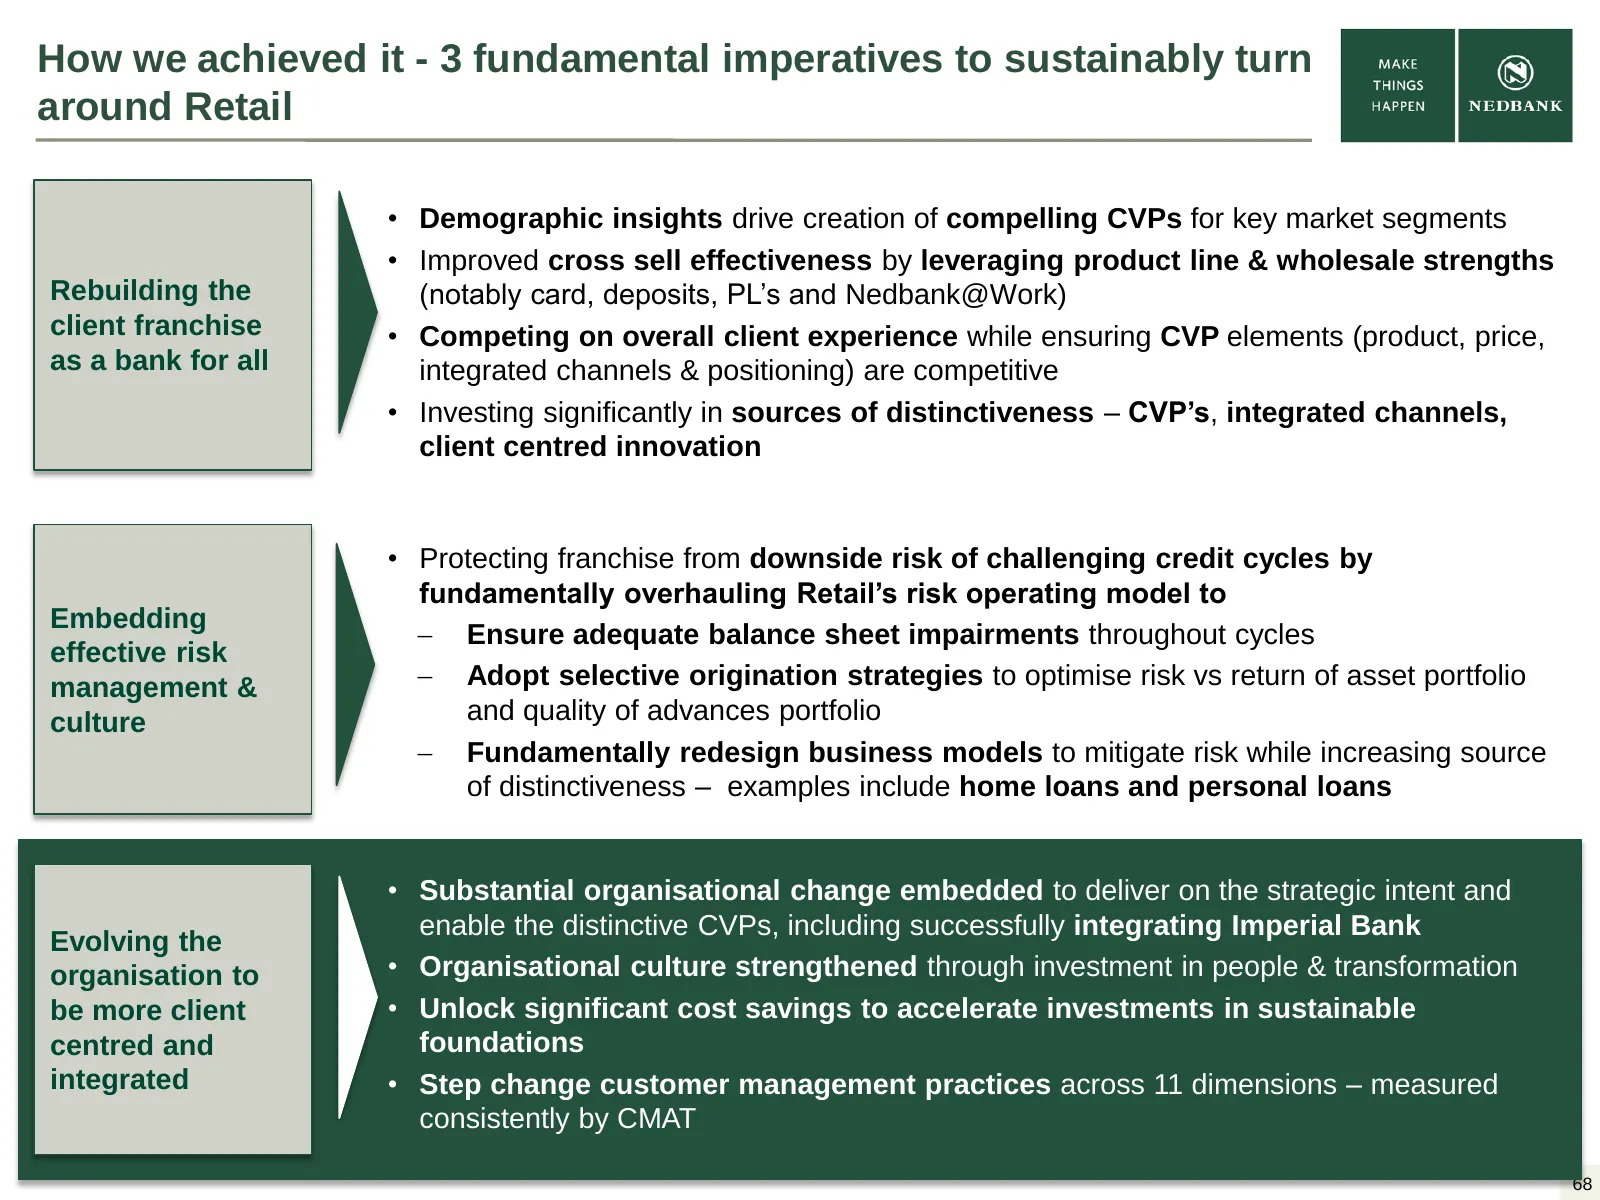
Slide 68: How we achieved it – fundamental imperatives to turn around Retail
How we achieved it - 3 fundamental imperatives to sustainably turn around Retail • Demographic insights drive creation of compelling CVPs for key market segments • Improved cross sell effectiveness by leveraging product line & wholesale strengths Rebuilding the (notably card, deposits, PL’s and Nedb
Slide 69: Orchestrating aligned leaders behind a common vision
Evolving the organisation to be more client centred and integrated Accelerating delivery by orchestrating strongly aligned leaders behind a common vision and clear strategy Key steps in leading substantial organisational change in Retail • Clear, cohesive strategy • Executive leadership changes - 70
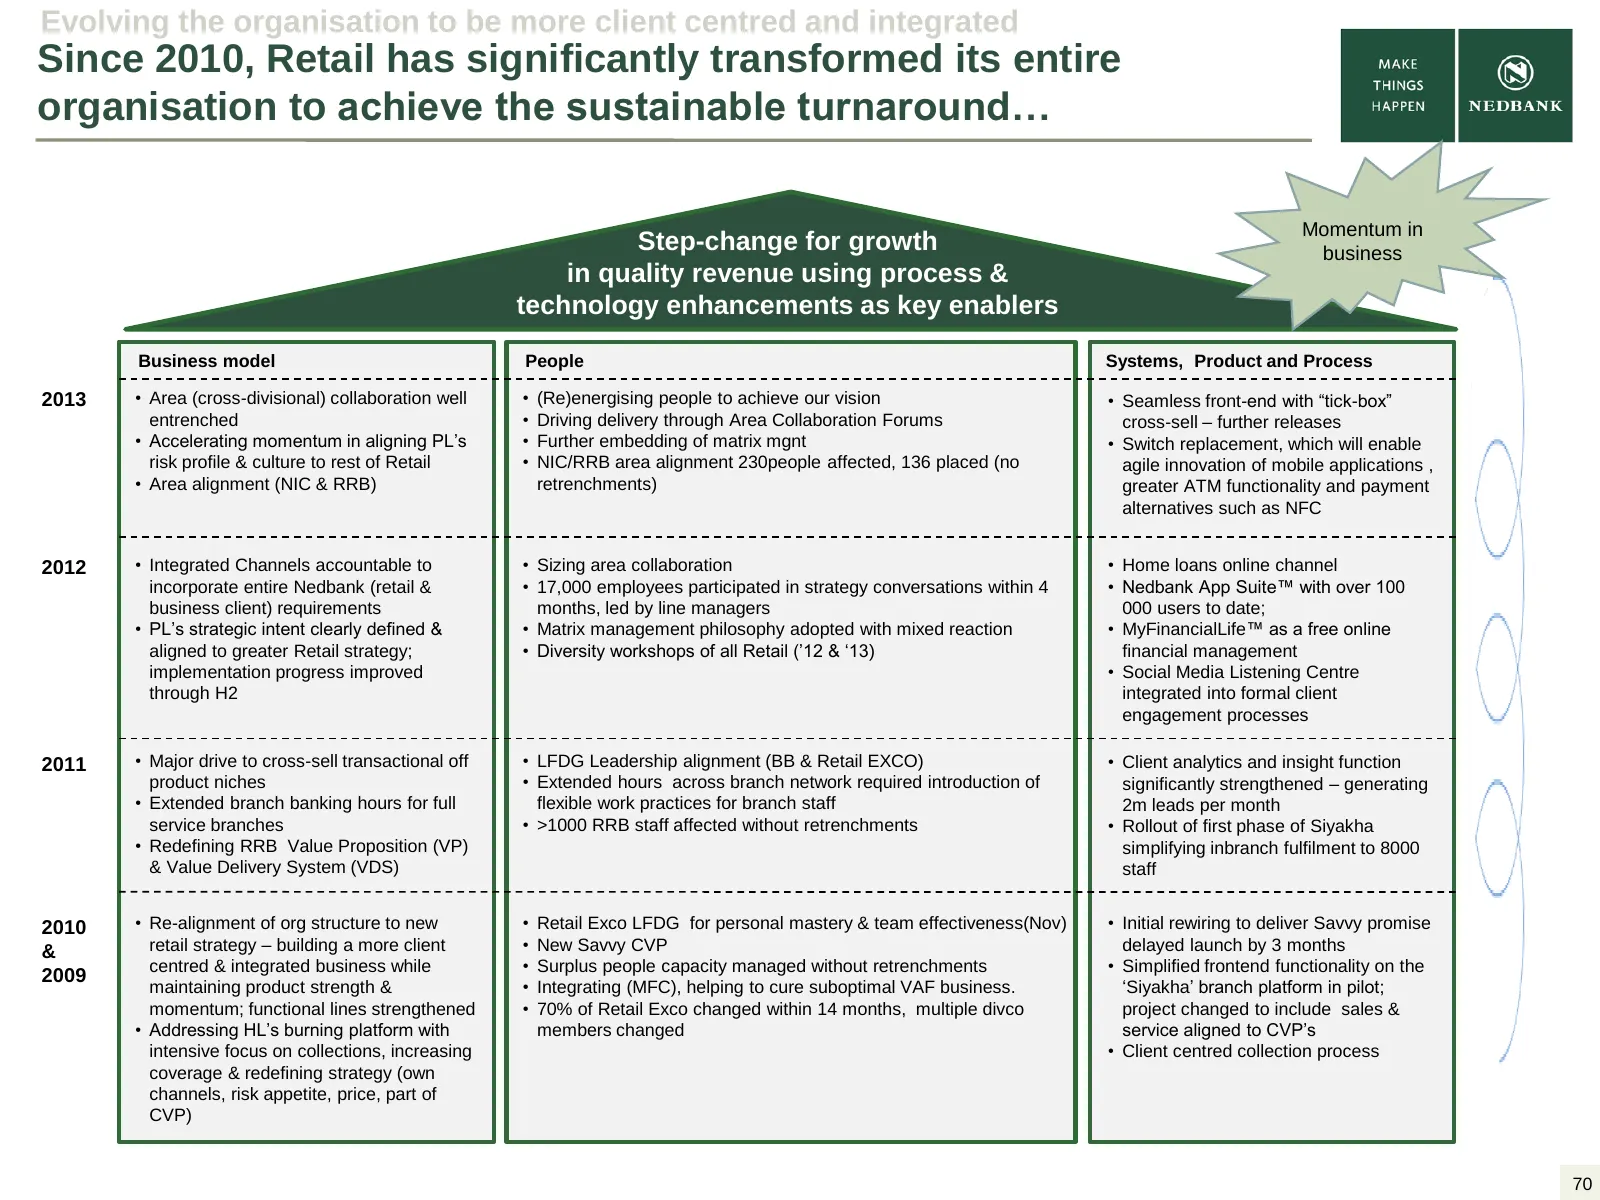
Slide 70: Transforming the organisation to achieve the turnaround
Evolving the organisation to be more client centred and integrated Since 2010, Retail has significantly transformed its entire organisation to achieve the sustainable turnaround… Momentum in Step-change for growth business in quality revenue using process & technology enhancements as key enablers Bu
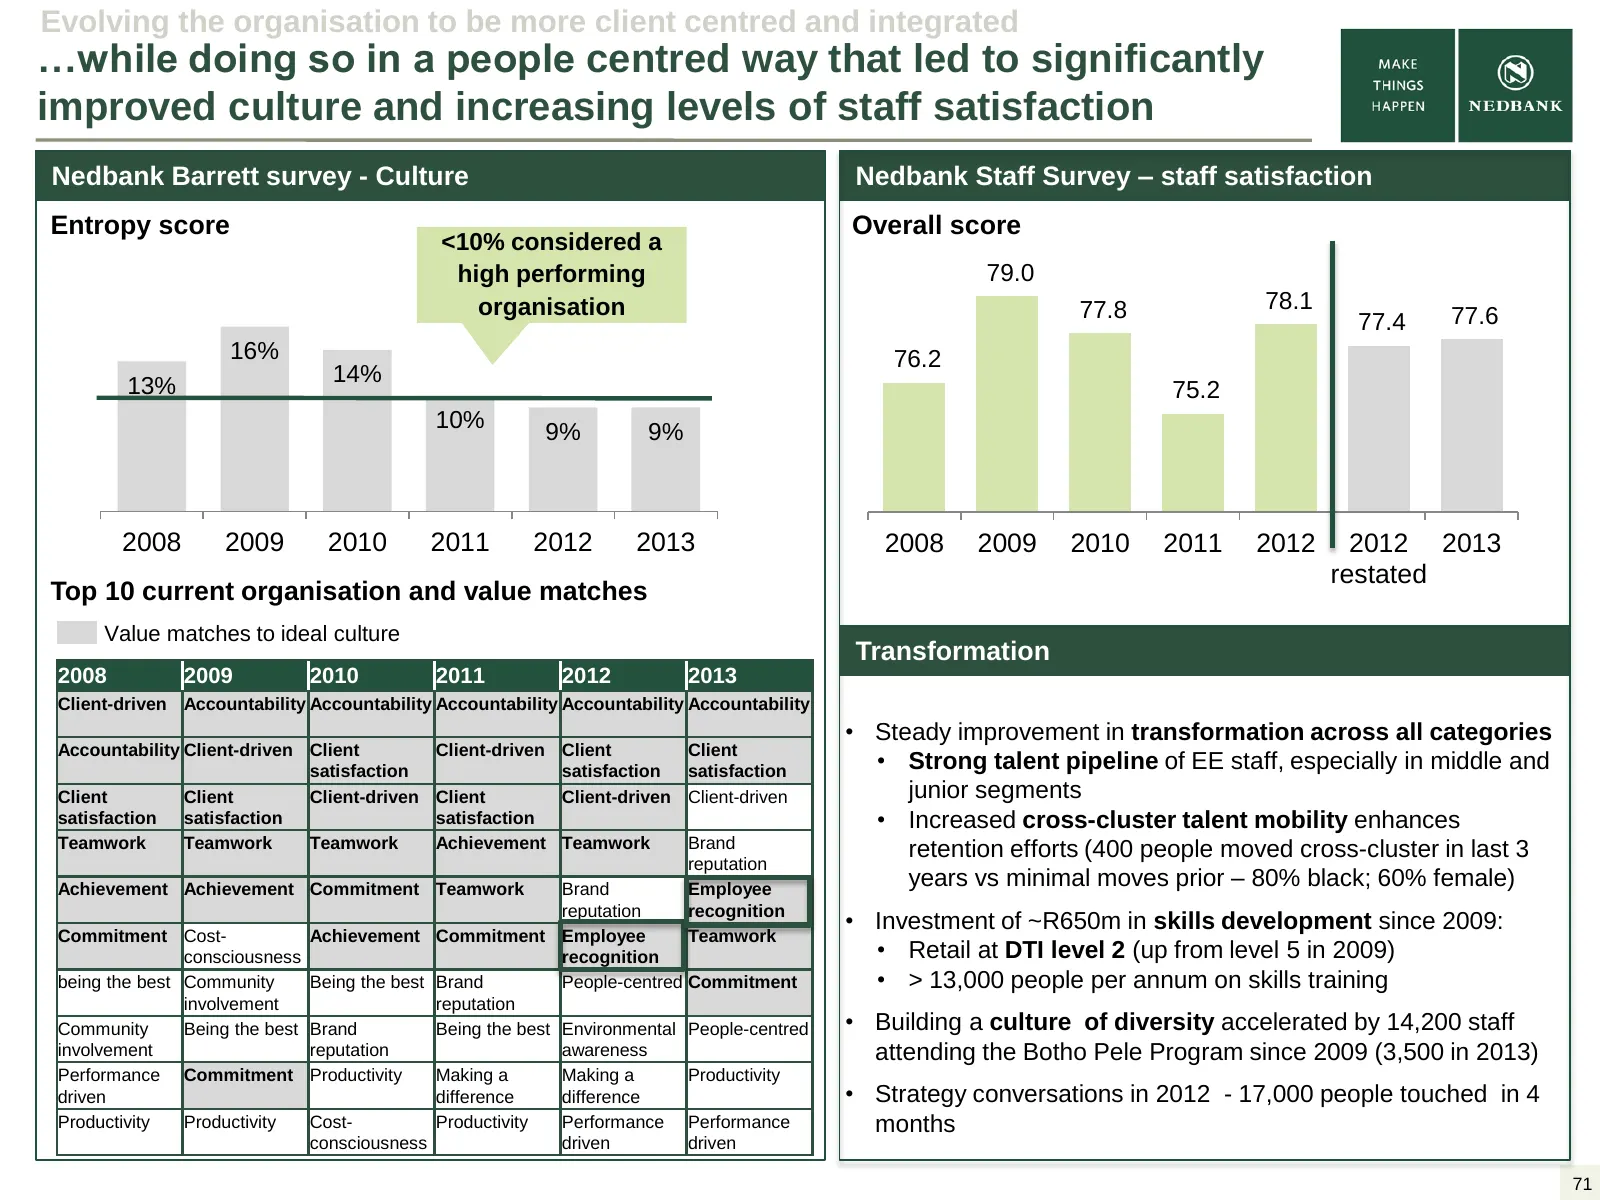
Slide 71: People-centred change improved culture and staff satisfaction
Evolving the organisation to be more client centred and integrated …while doing so in a people centred way that led to significantly improved culture and increasing levels of staff satisfaction Nedbank Barrett survey - Culture Nedbank Staff Survey – staff satisfaction Entropy score Overall score <10
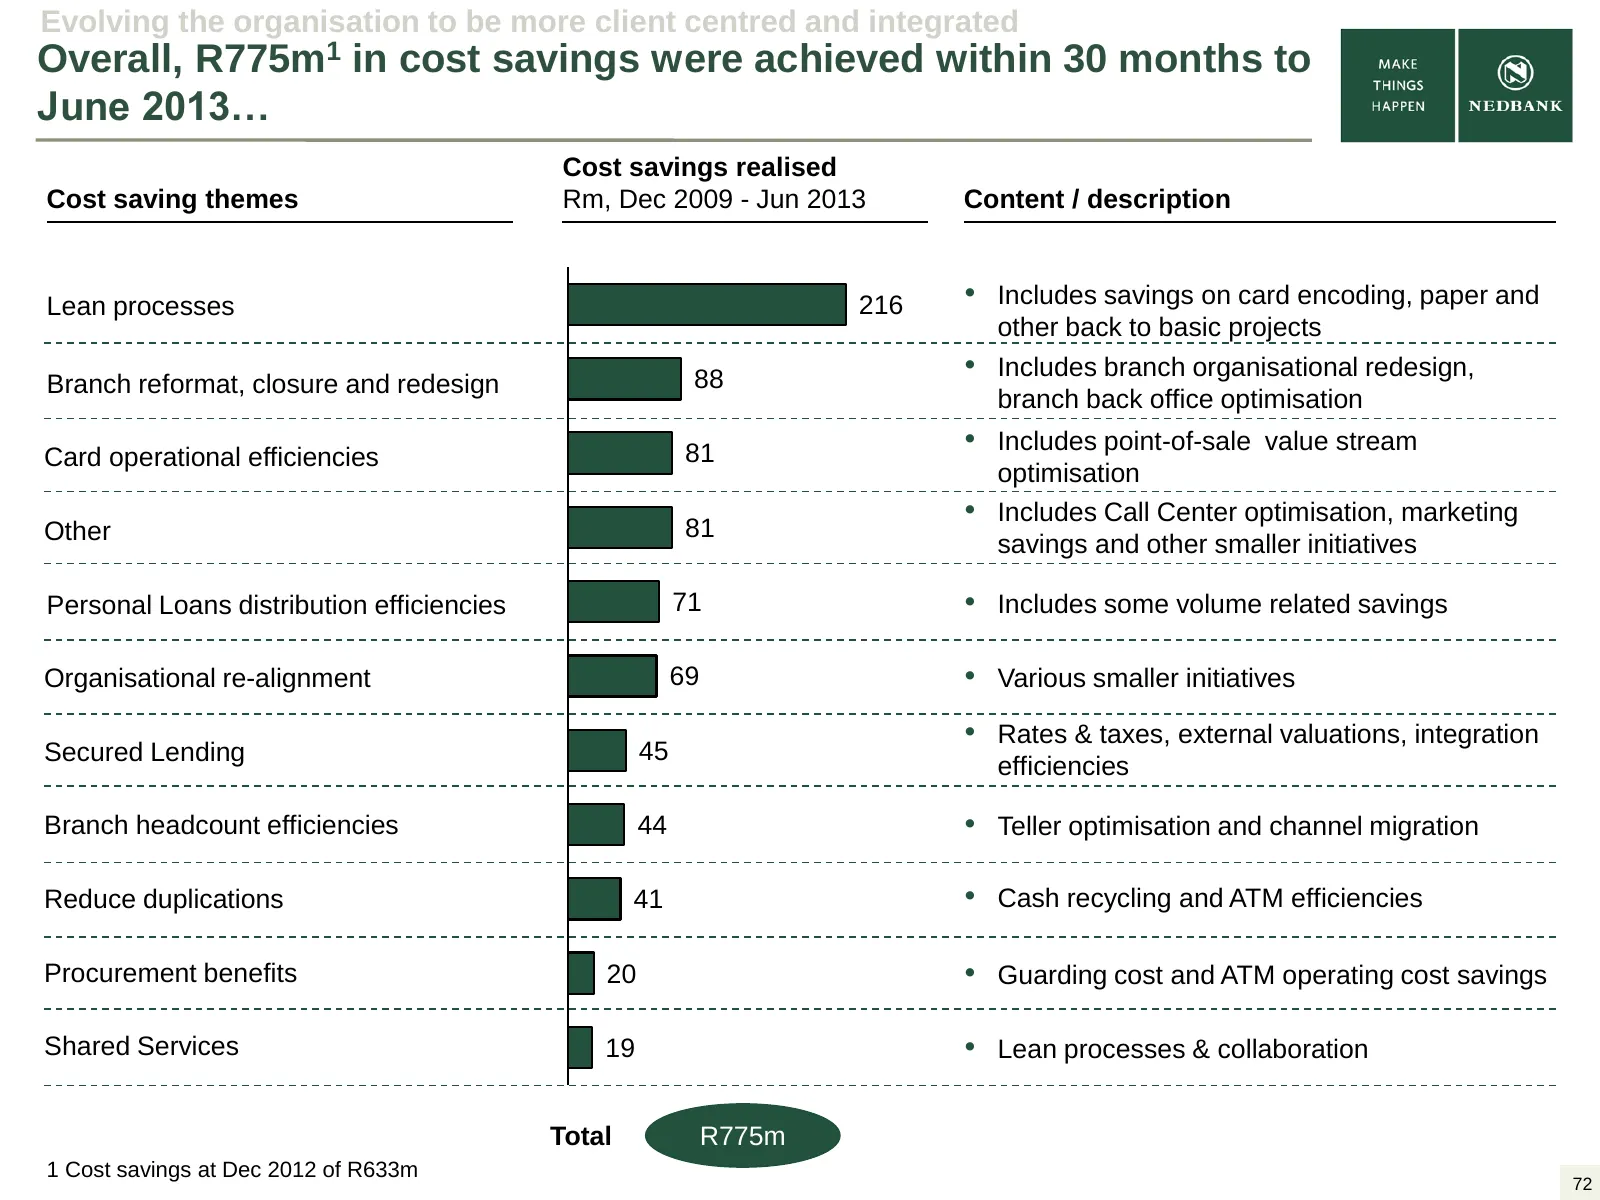
Slide 72: R775m in cost savings achieved within 30 months
Evolving the organisation to be more client centred and integrated Overall, R775m1 in cost savings were achieved within 30 months to June 2013… Cost savings realised Cost saving themes Rm, Dec 2009 - Jun 2013 Content / description Lean processes 216 • Includes savings on card encoding, paper and oth
Slide 73: Investing sustainably in foundations for future growth
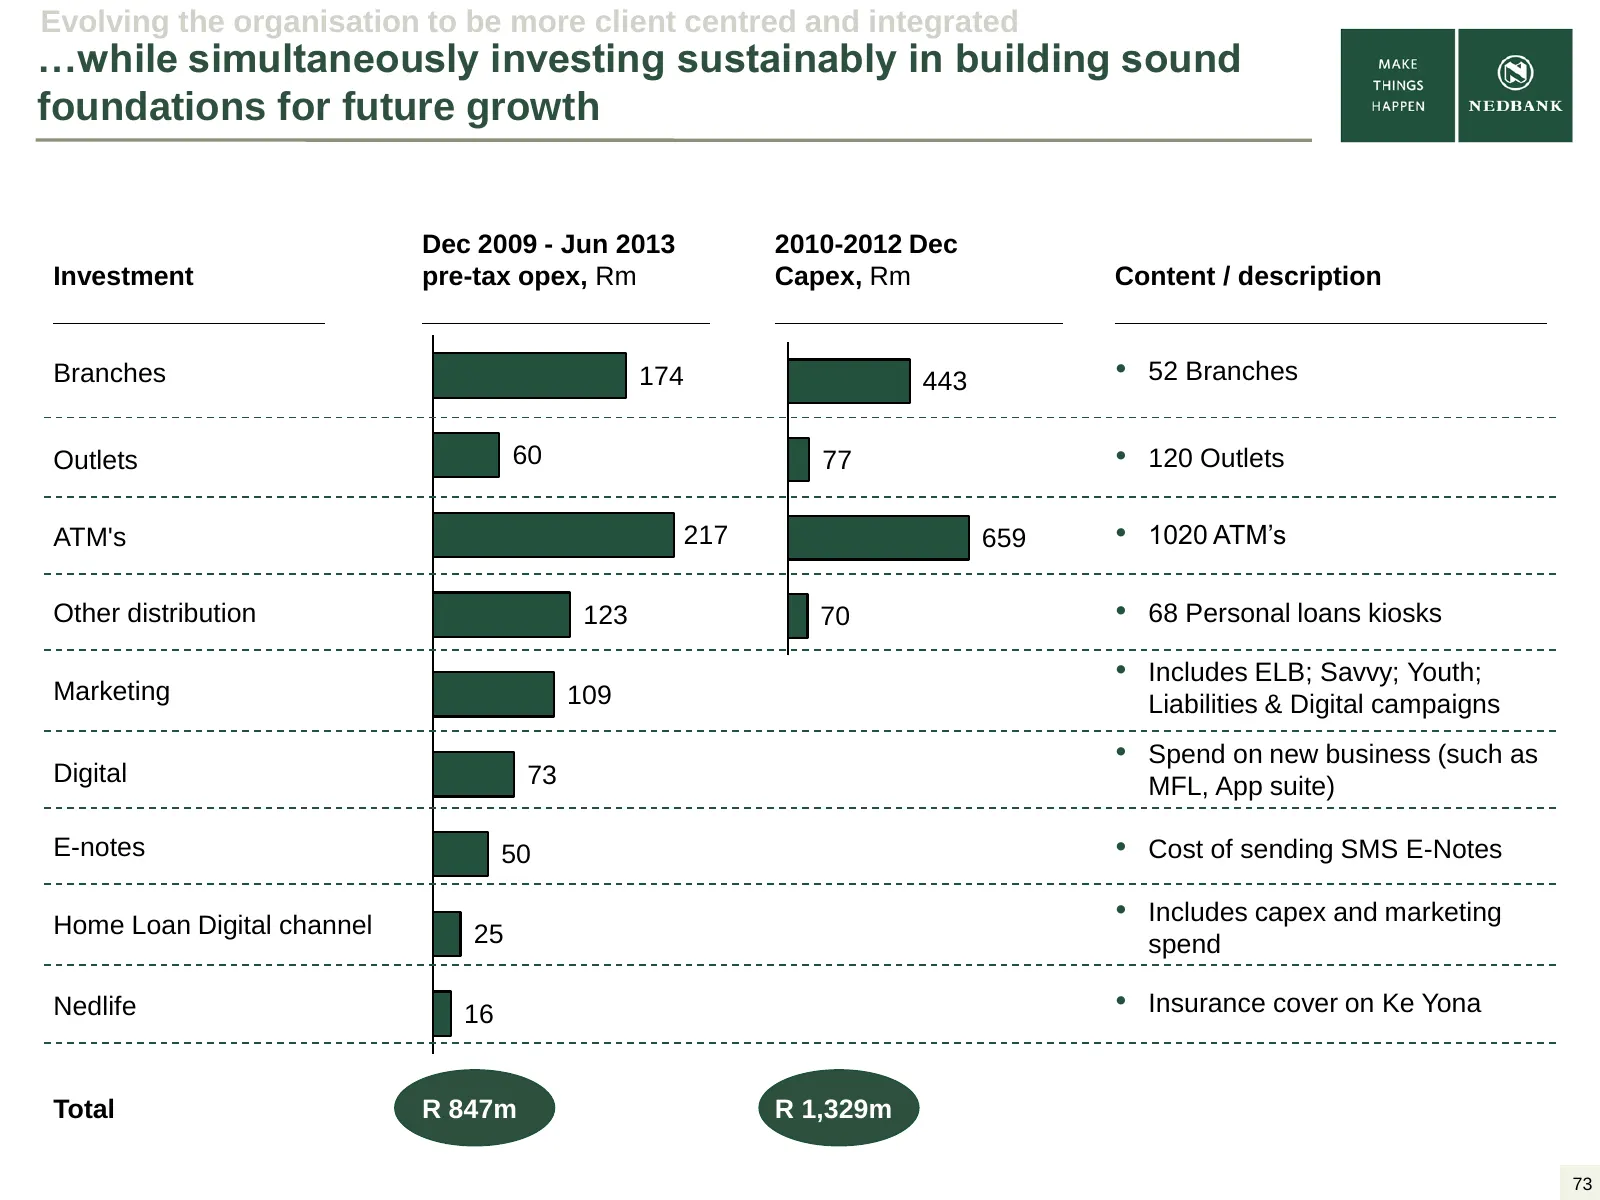
Evolving the organisation to be more client centred and integrated …while simultaneously investing sustainably in building sound foundations for future growth Dec 2009 - Jun 2013 2010-2012 Dec Investment pre-tax opex, Rm Capex, Rm Content / description Branches 174 443 • 52 Branches Outlets 60 77 •
Slide 74: Retail CMAT results reflect significant shifts since 2010
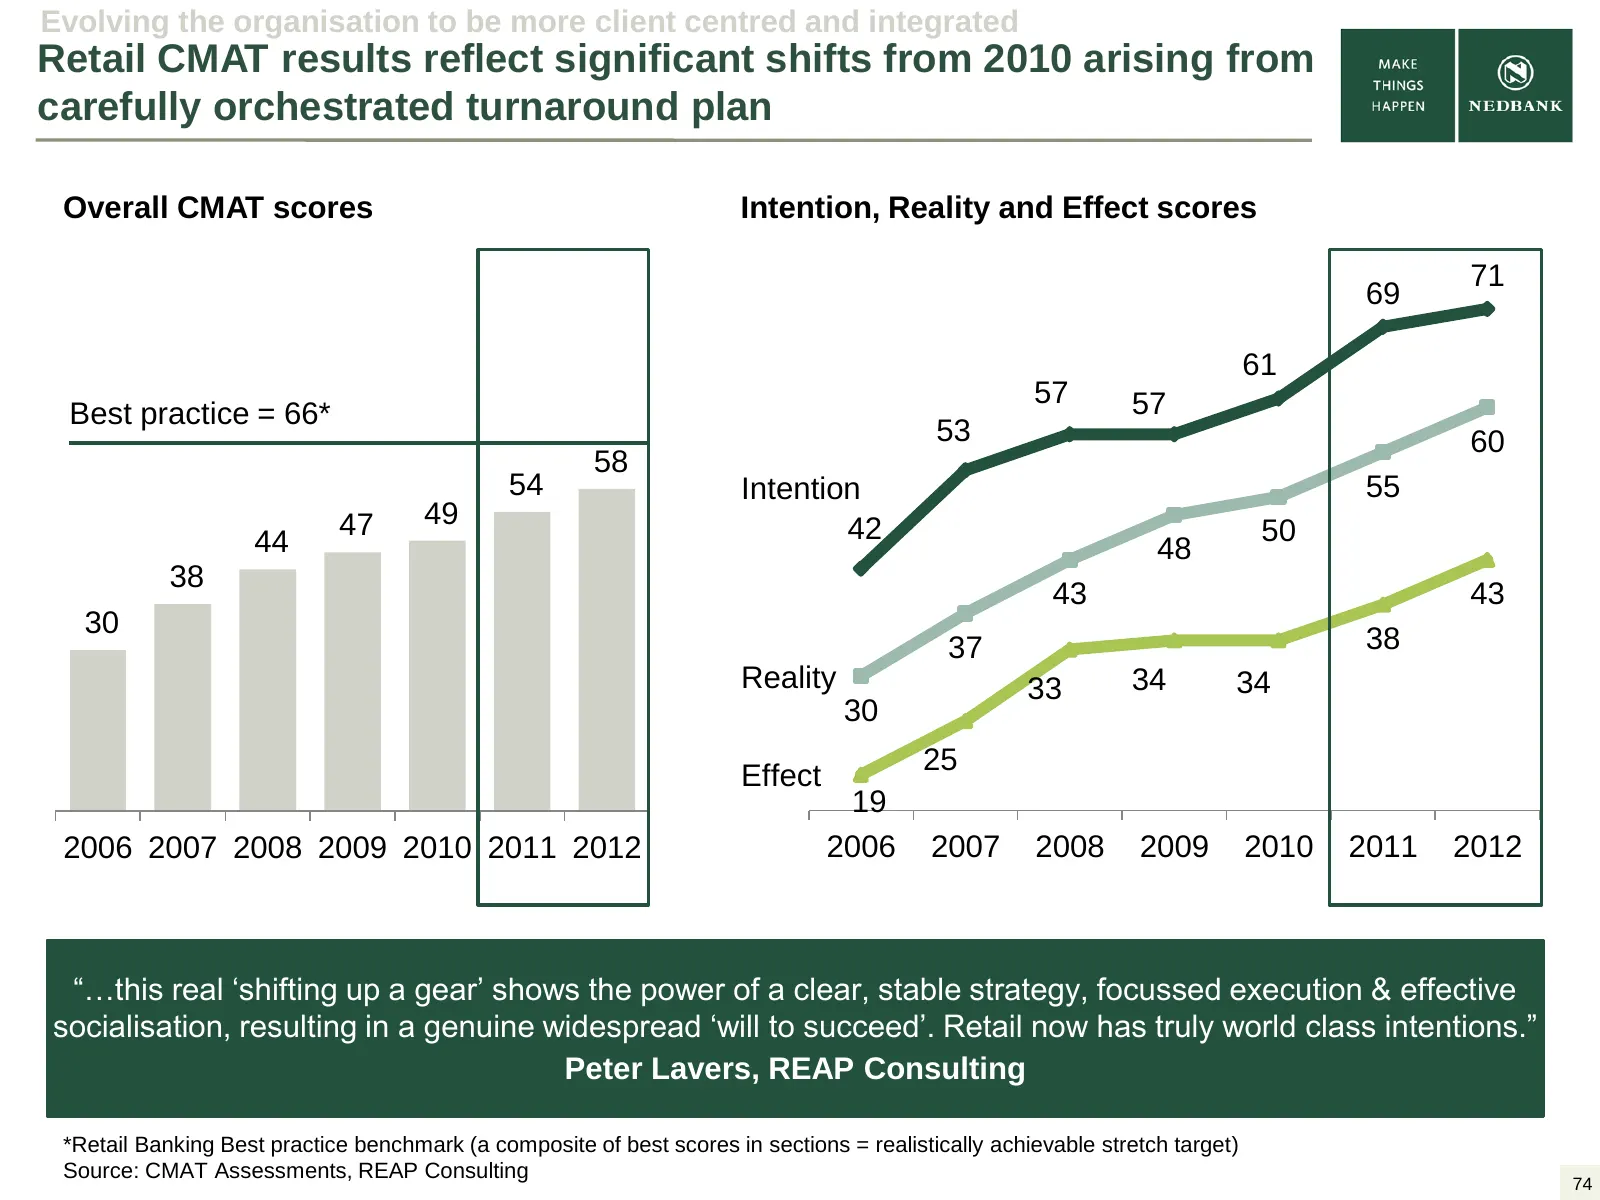
Evolving the organisation to be more client centred and integrated Retail CMAT results reflect significant shifts from 2010 arising from carefully orchestrated turnaround plan Overall CMAT scores Intention, Reality and Effect scores 71 69 61 57 57 Best practice = 66* 53 60 58 54 Intention 55 47 49 4
Slide 75: CMAT scores improved across all 11 categories
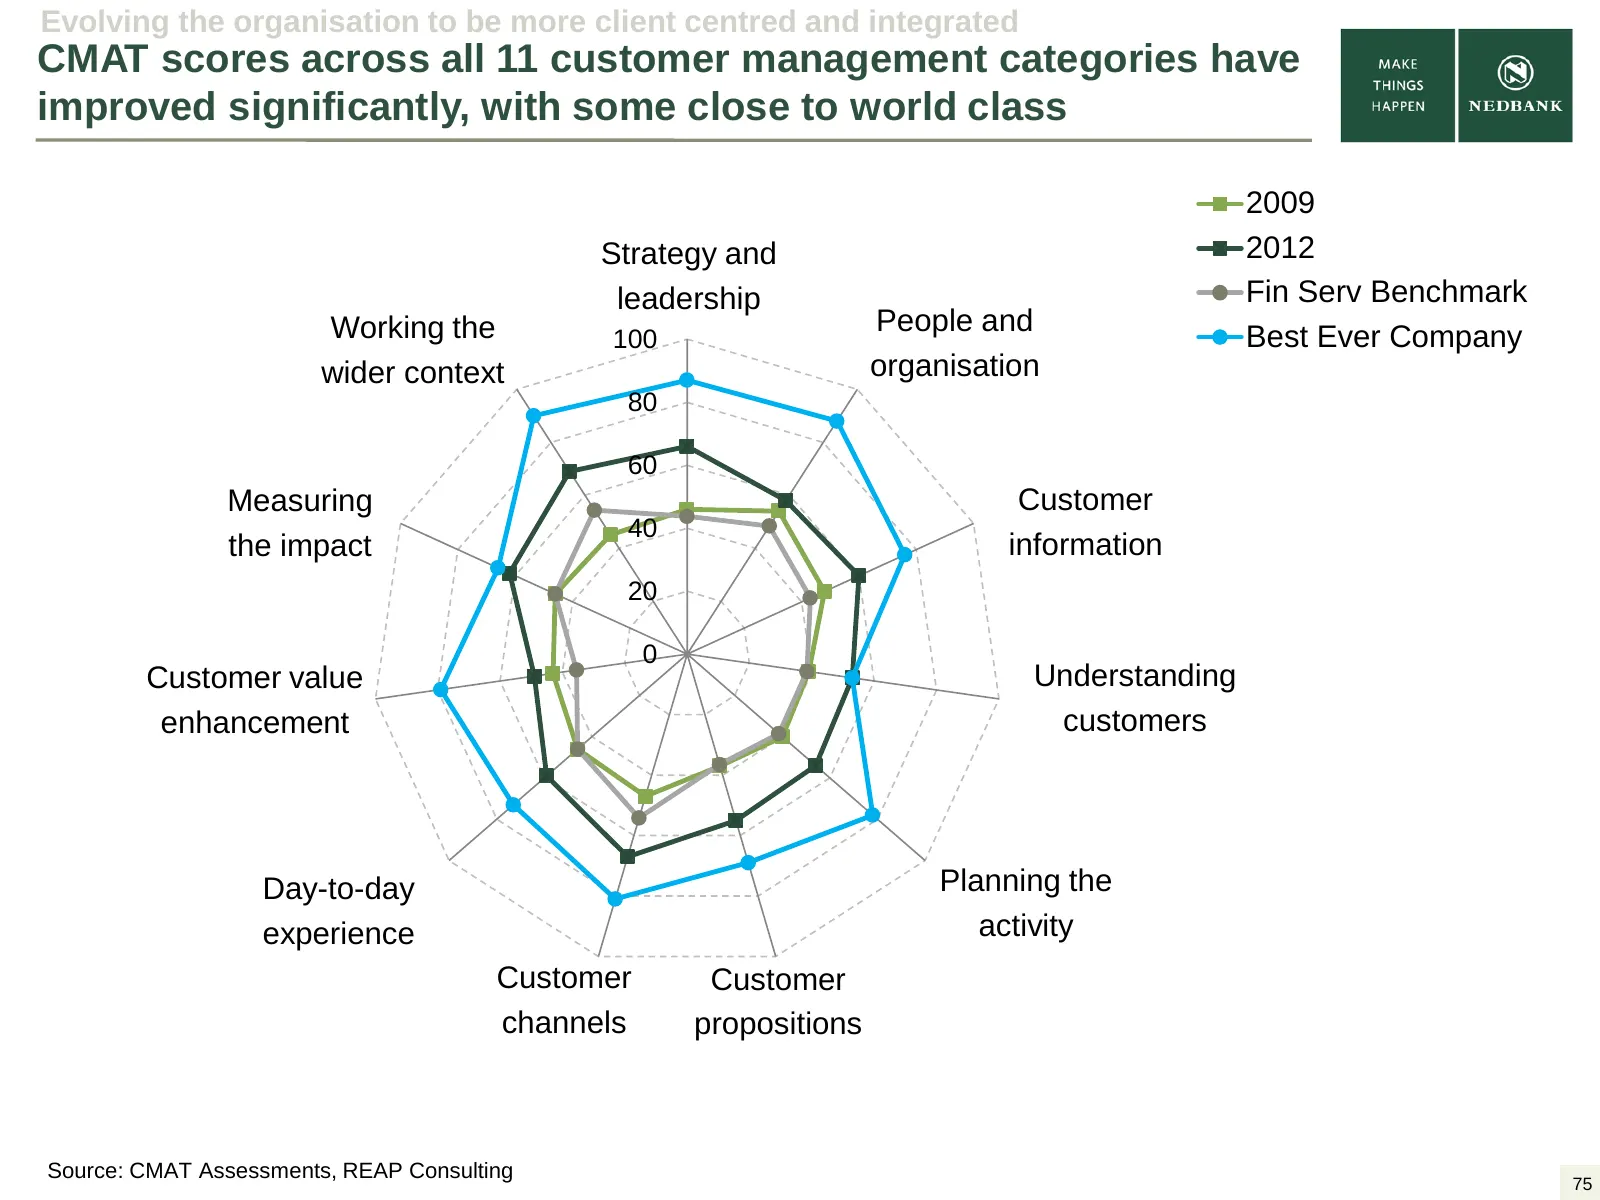
Evolving the organisation to be more client centred and integrated CMAT scores across all 11 customer management categories have improved significantly, with some close to world class 2009 Strategy and 2012 leadership Fin Serv Benchmark Working the People and 100 Best Ever Company wider context orga
Slide 76: Integrating Imperial Bank while maintaining MFC momentum
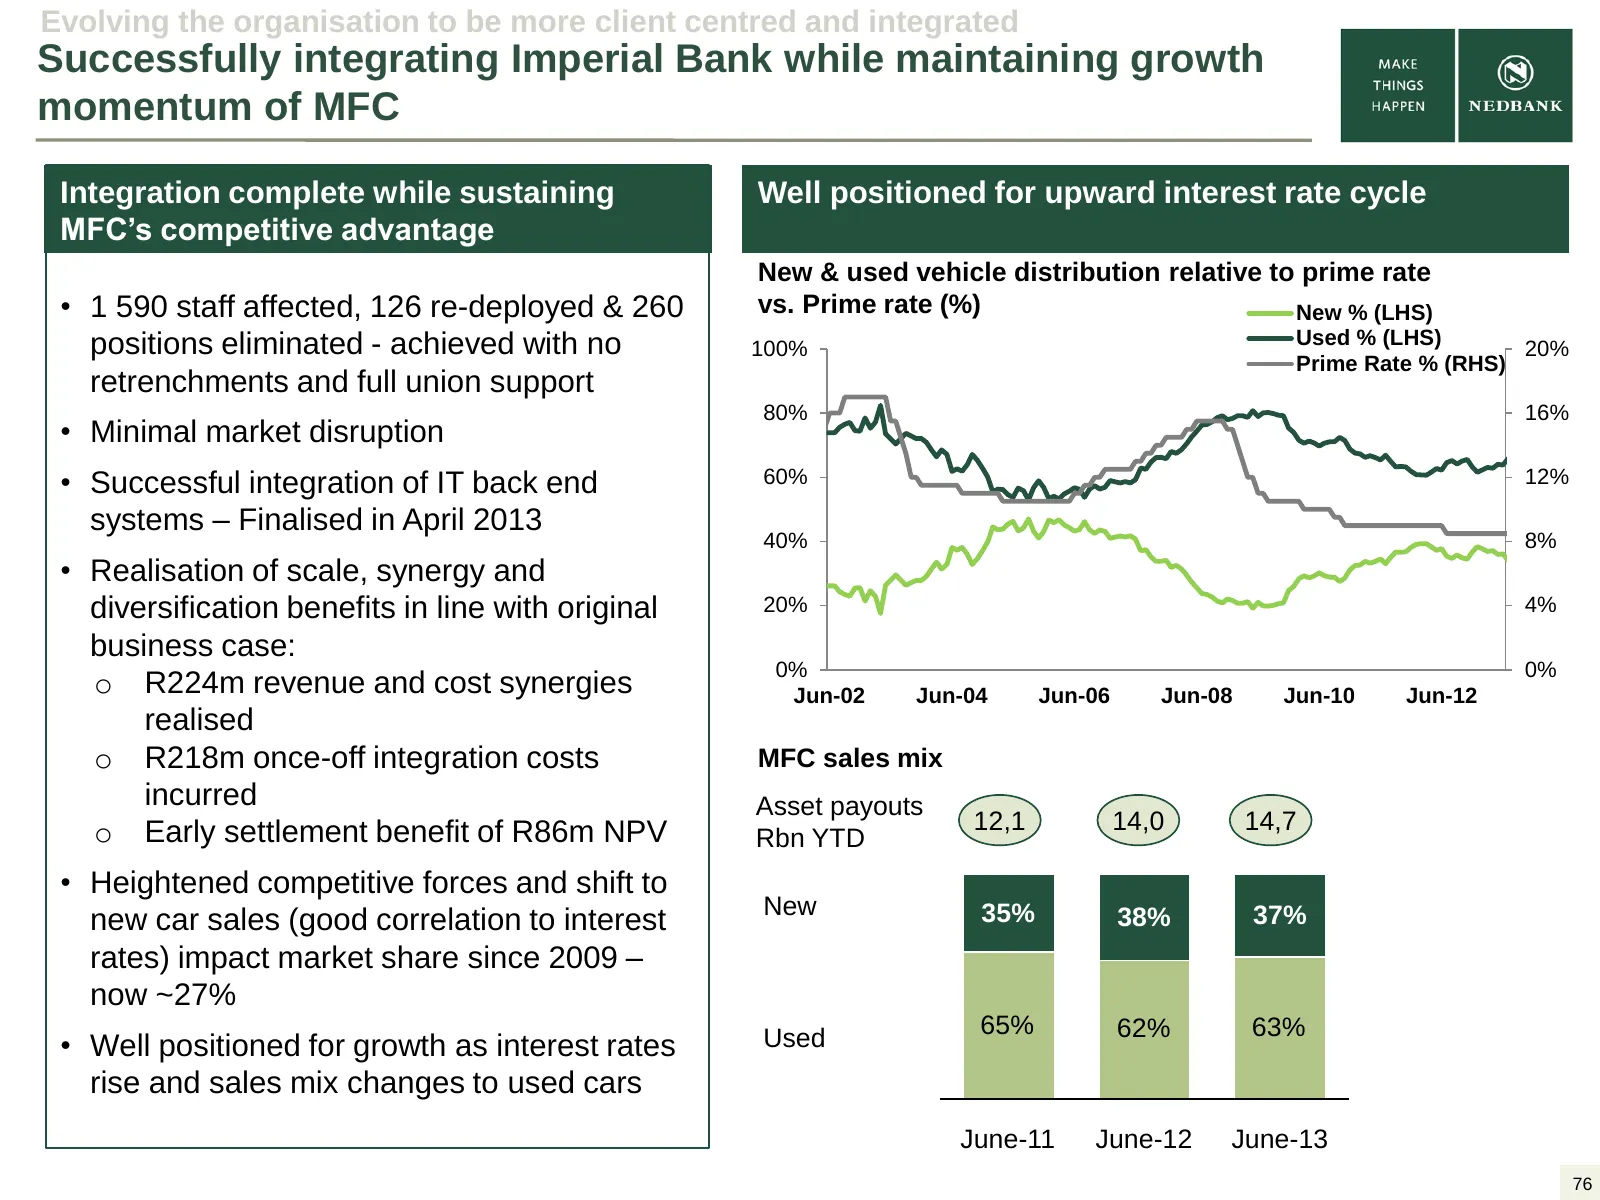
Evolving the organisation to be more client centred and integrated Successfully integrating Imperial Bank while maintaining growth momentum of MFC Integration complete while sustaining Well positioned for upward interest rate cycle MFC’s competitive advantage New & used vehicle distribution relative
Slide 77: Second order change processes and leadership
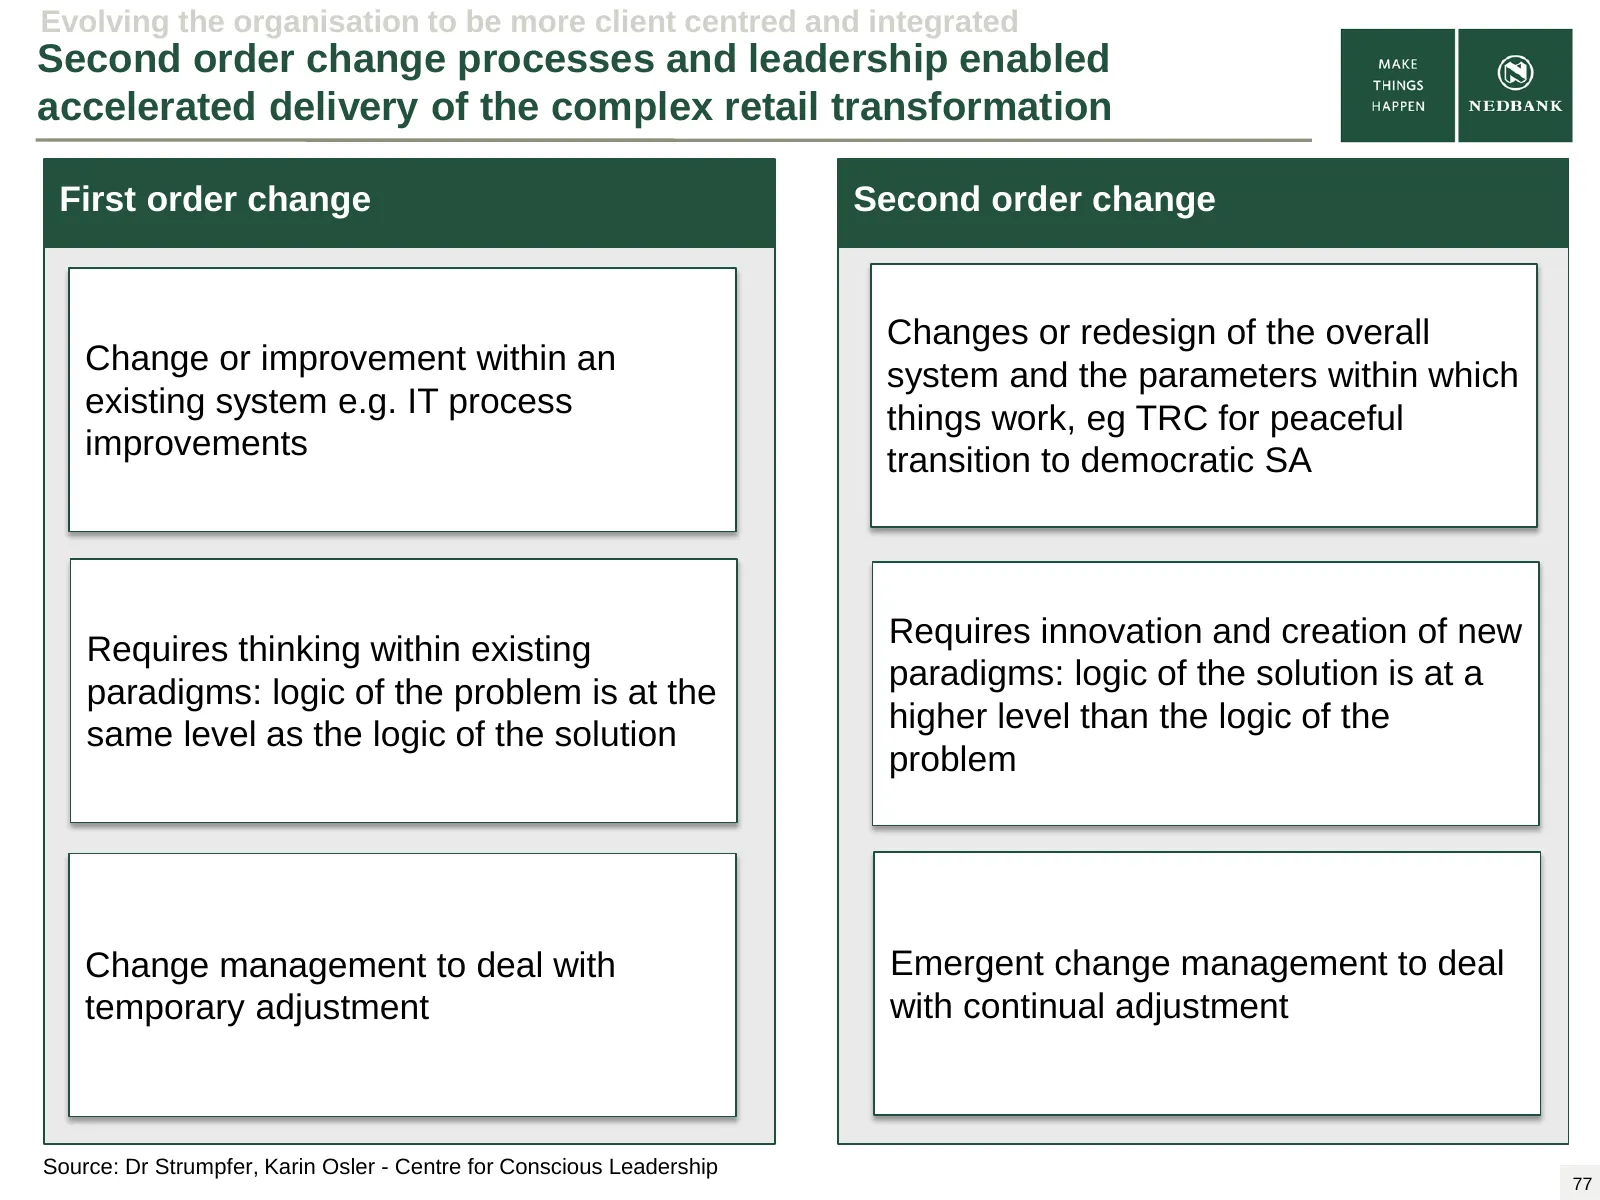
Evolving the organisation to be more client centred and integrated Second order change processes and leadership enabled accelerated delivery of the complex retail transformation First order change Second order change Changes or redesign of the overall Change or improvement within an system and the p
Slide 78: In summary, Retail has made excellent progress
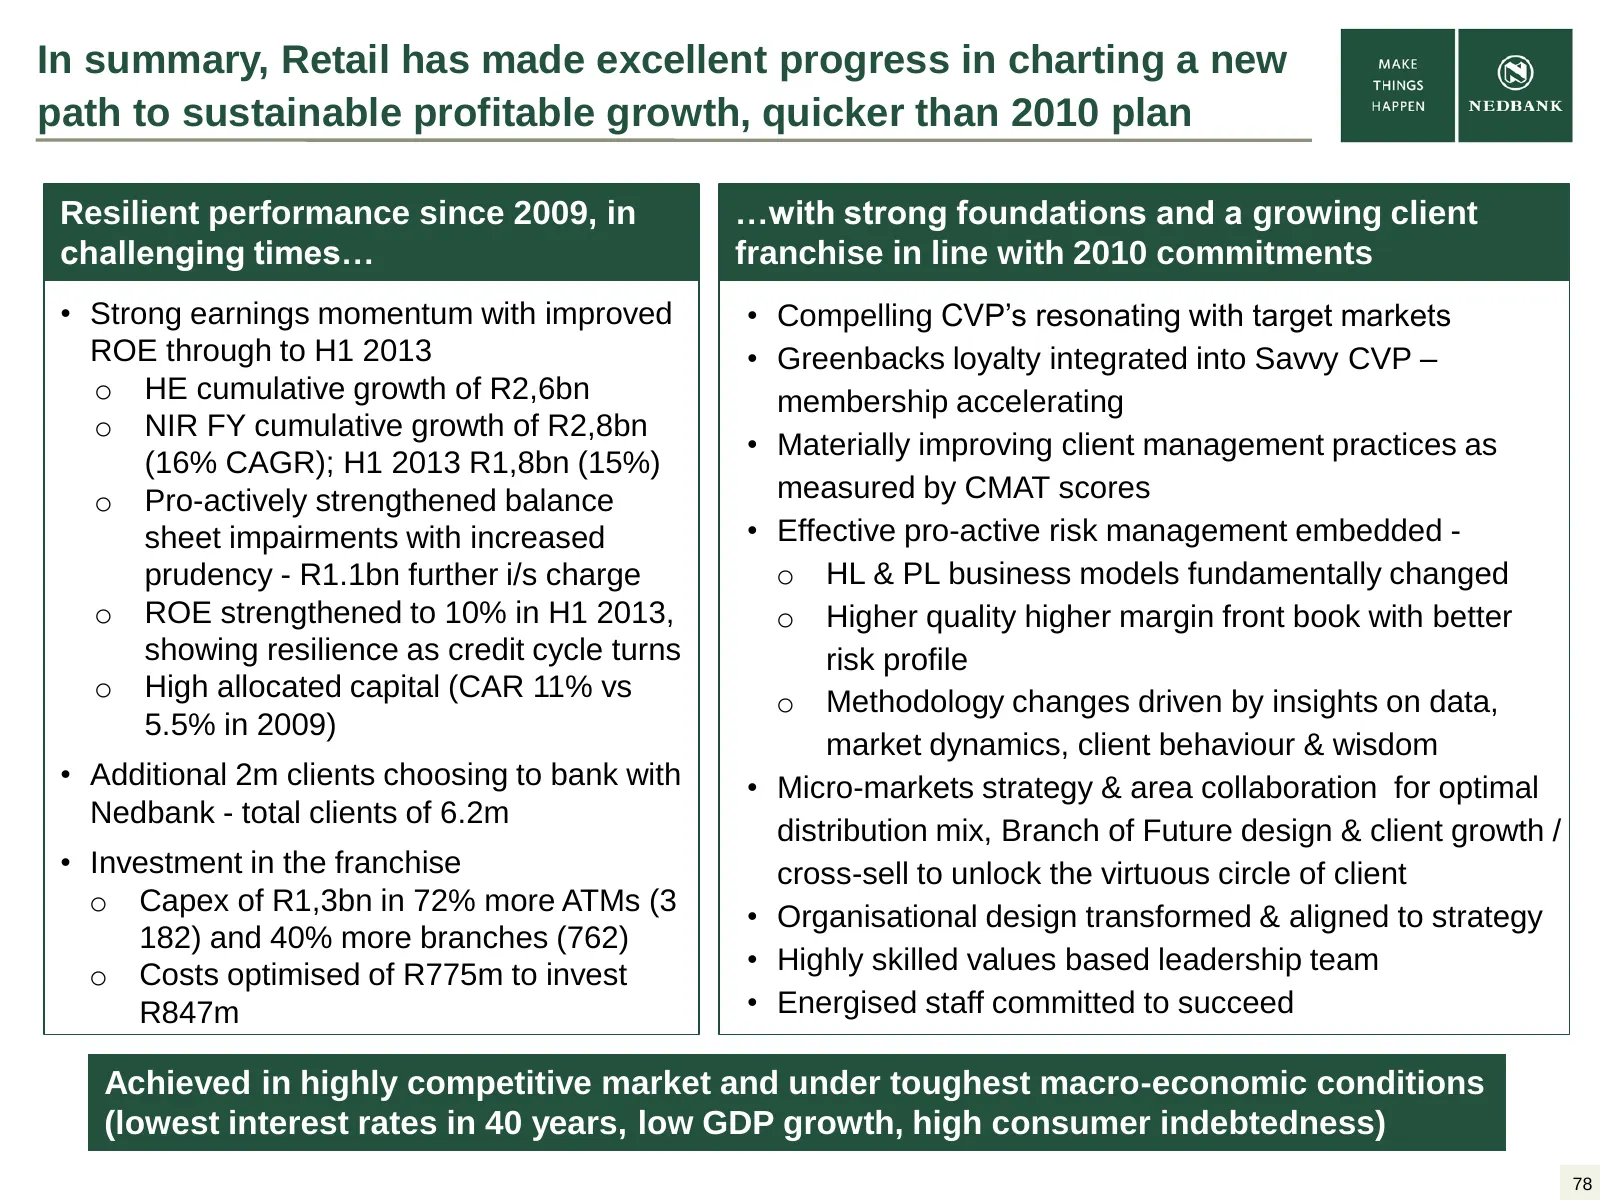
In summary, Retail has made excellent progress in charting a new path to sustainable profitable growth, quicker than 2010 plan Resilient performance since 2009, in …with strong foundations and a growing client challenging times… franchise in line with 2010 commitments • Strong earnings momentum with
Slide 79: Repositioning Retail – presentation topics
Repositioning Retail – presentation topics ▪ Executive Summary ▪ What we set out to do in 2010 ▪ Progress to date ▪ How we achieved it ▪ Future trends & prospects 79
Slide 80: R&BB have a distinctive and differentiated position
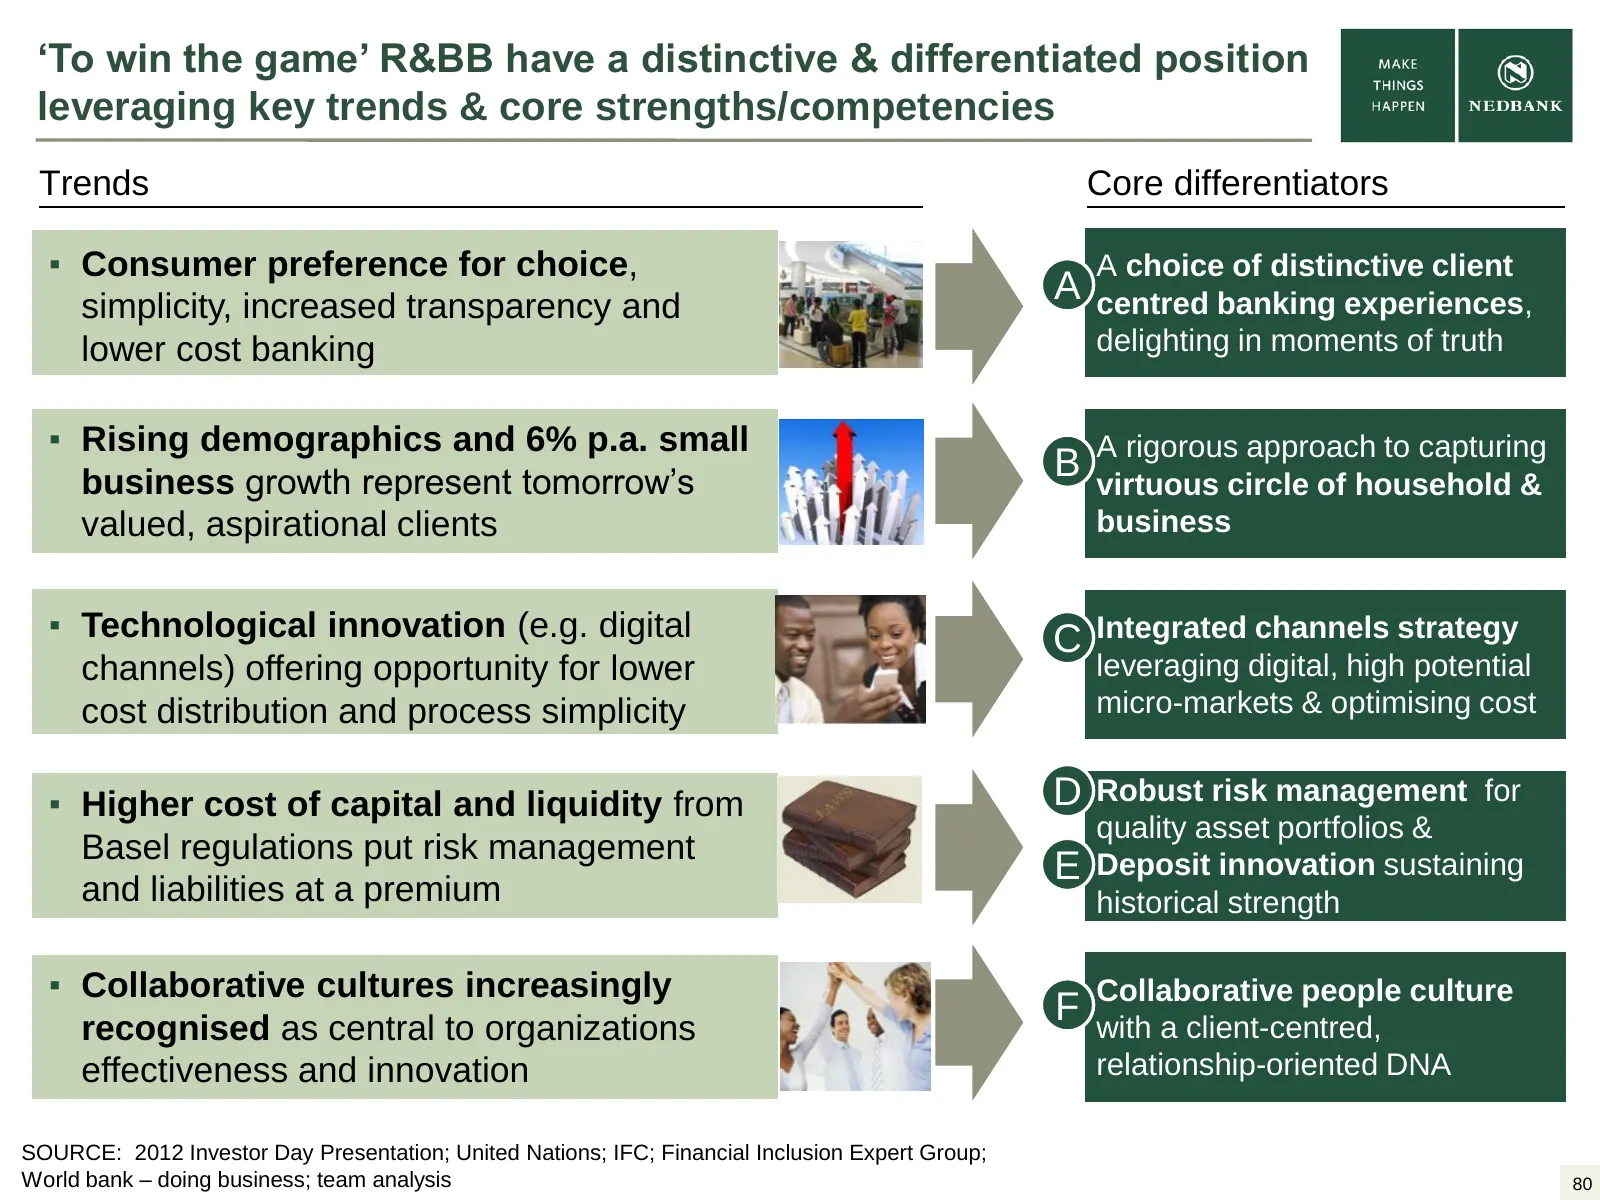
‘To win the game’ R&BB have a distinctive & differentiated position leveraging key trends & core strengths/competencies Trends Core differentiators ▪ Consumer preference for choice, A choice of distinctive client simplicity, increased transparency and A centred banking experiences, lower cost bankin
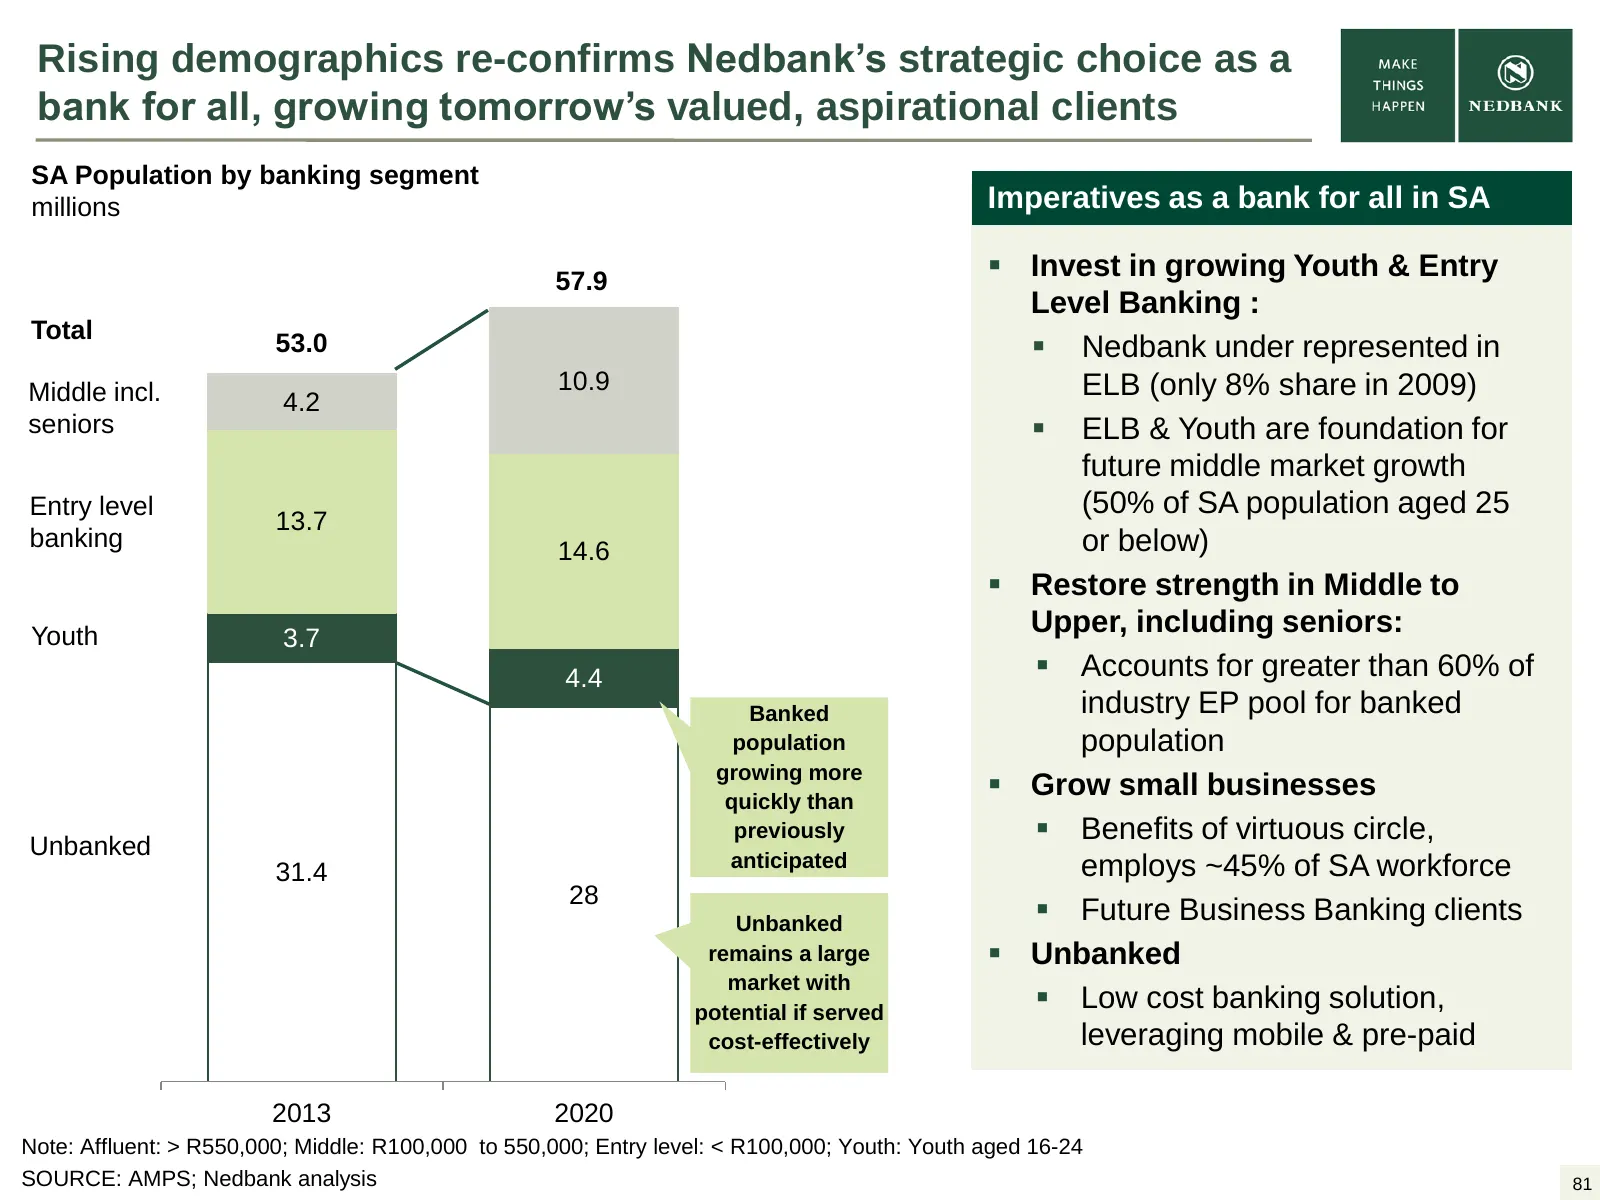
Slide 81: Rising demographics re-confirm strategic choice as a bank for all
Rising demographics re-confirms Nedbank’s strategic choice as a bank for all, growing tomorrow’s valued, aspirational clients SA Population by banking segment millions Imperatives as a bank for all in SA 57.9 Invest in growing Youth & Entry Level Banking : Total 53.0 Nedbank under represented in
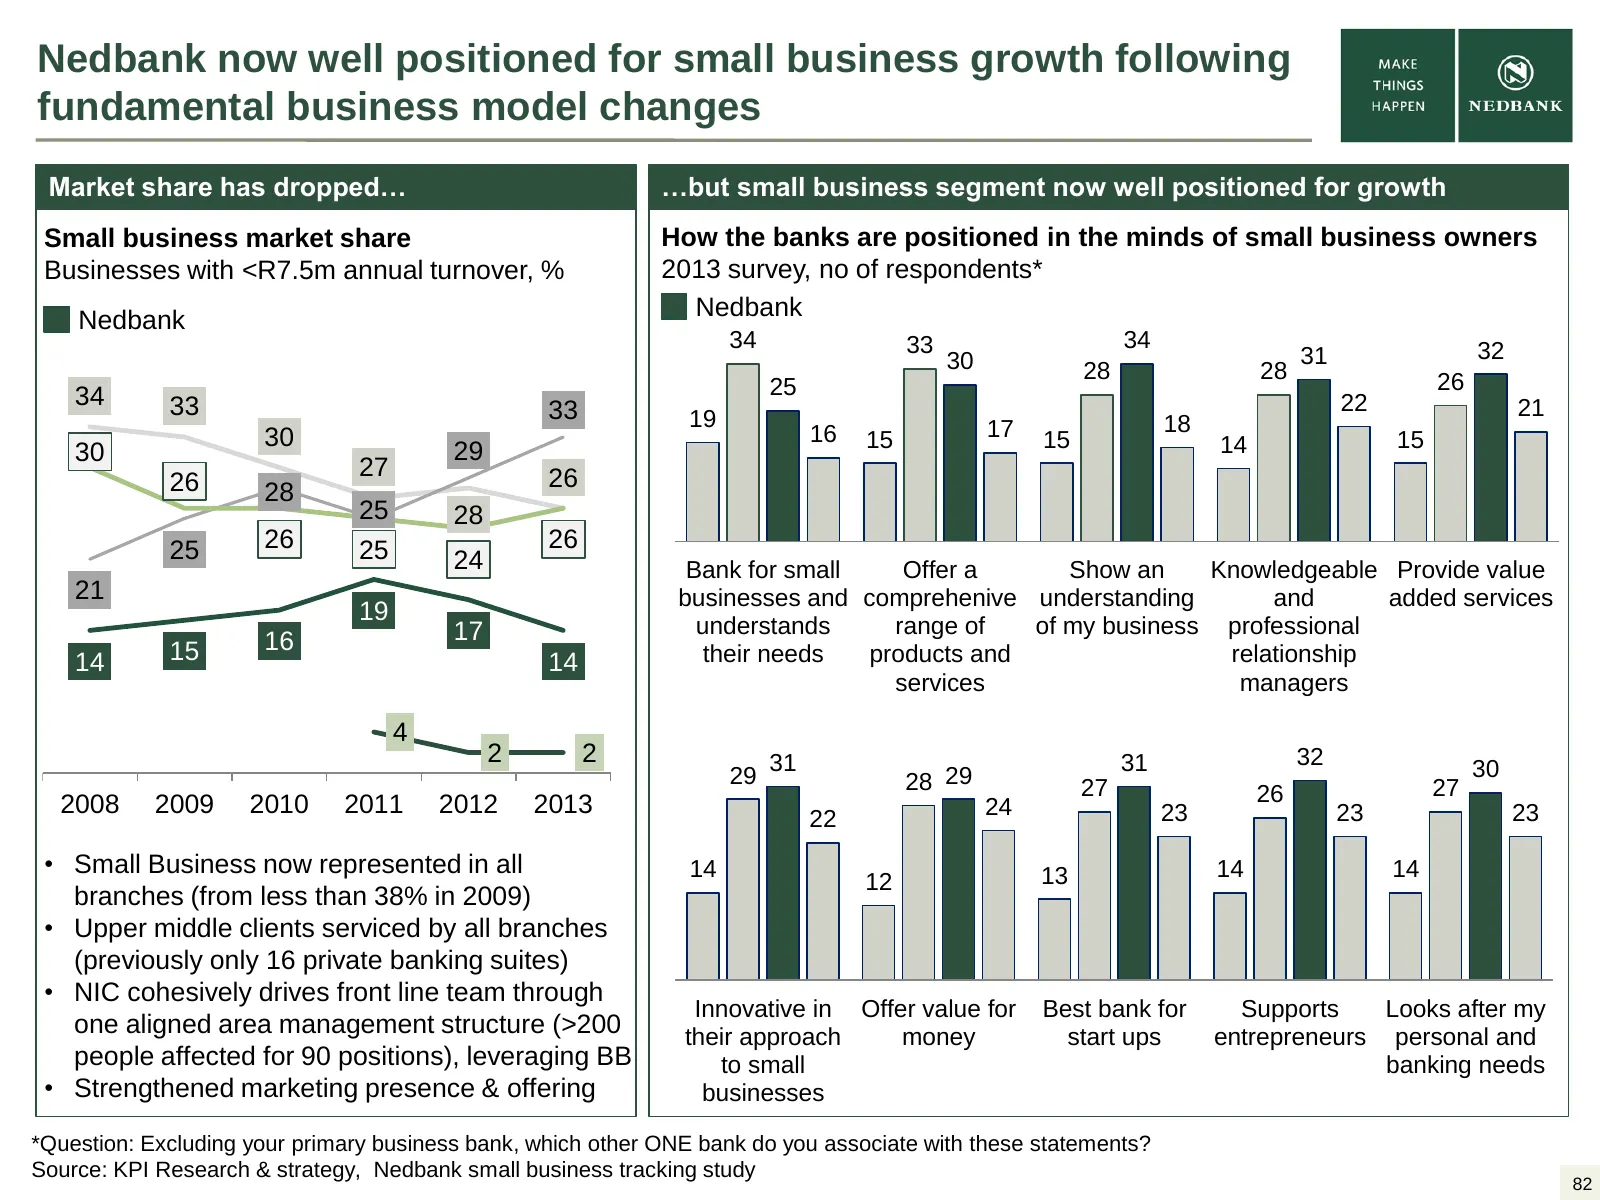
Slide 82: Well positioned for small business growth
Nedbank now well positioned for small business growth following fundamental business model changes Market share has dropped… …but small business segment now well positioned for growth Small business market share How the banks are positioned in the minds of small business owners Businesses with <R7.5
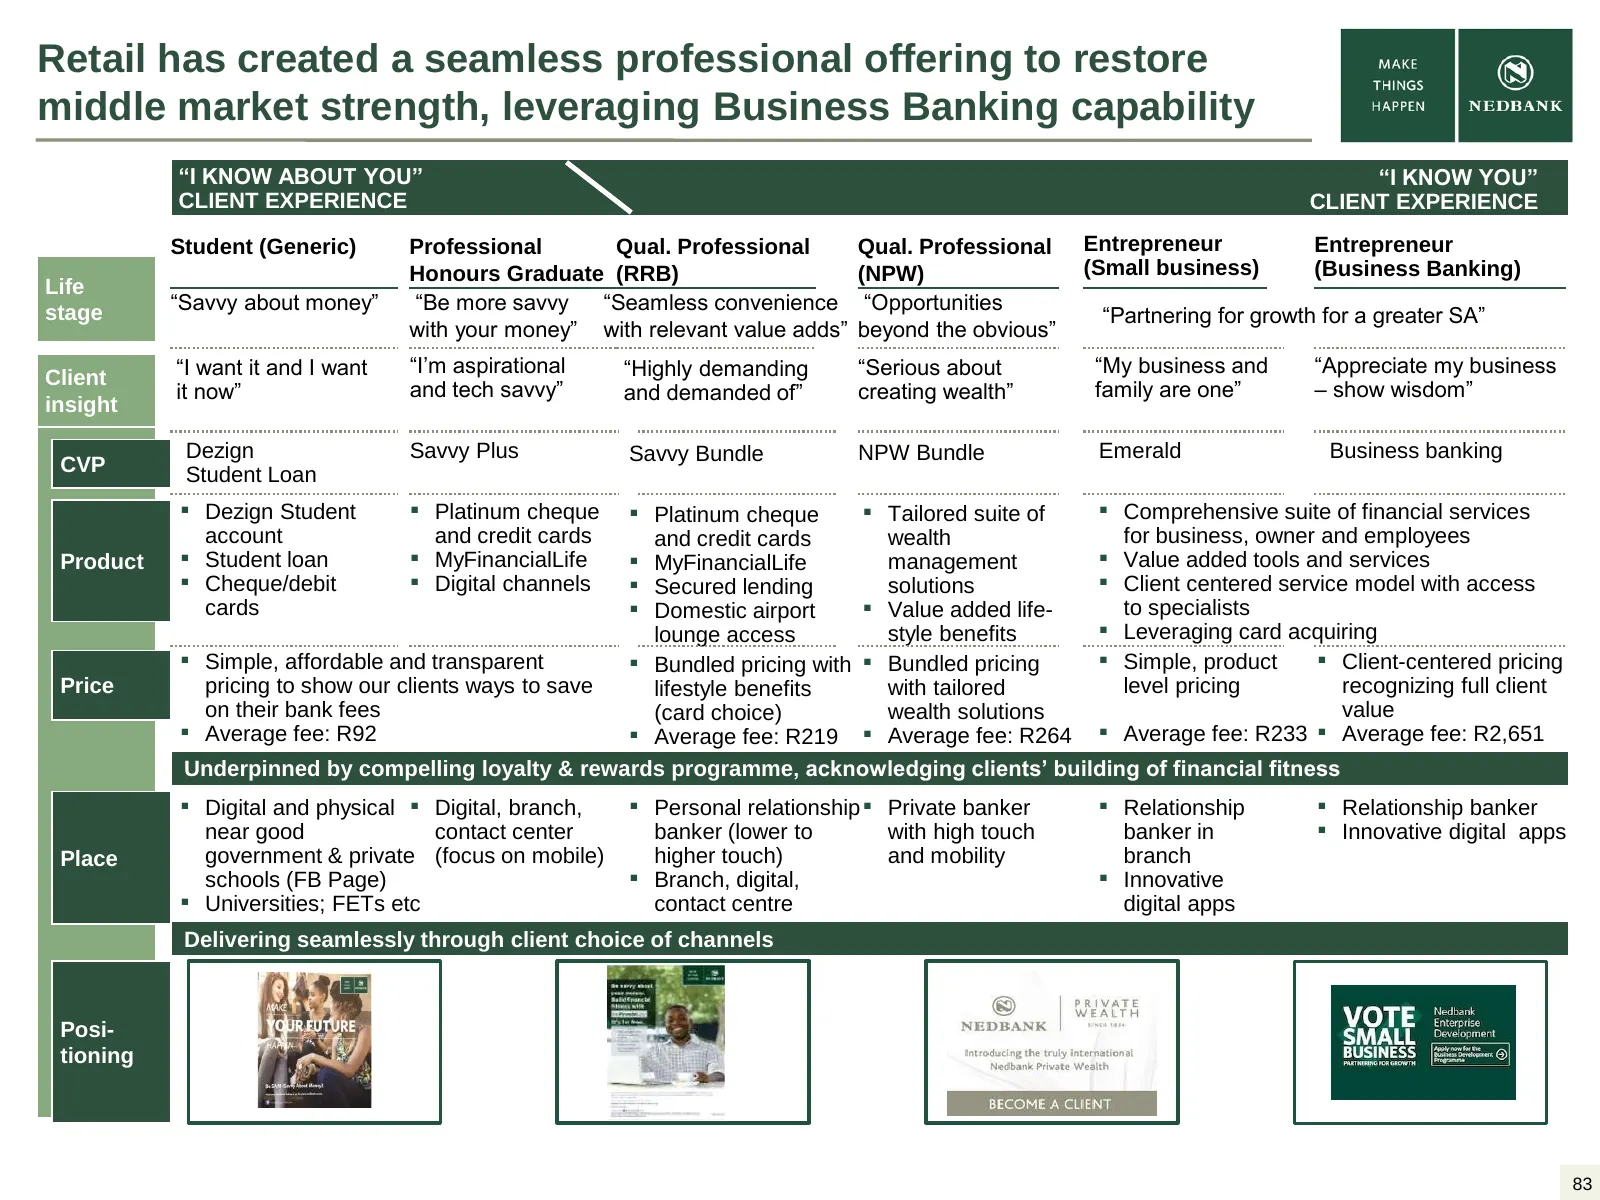
Slide 83: Seamless professional offering to restore middle market strength
Retail has created a seamless professional offering to restore middle market strength, leveraging Business Banking capability “I KNOW ABOUT YOU” “I KNOW YOU” CLIENT EXPERIENCE CLIENT EXPERIENCE Student (Generic) Professional Qual. Professional Qual. Professional Entrepreneur Entrepreneur Honours Gra
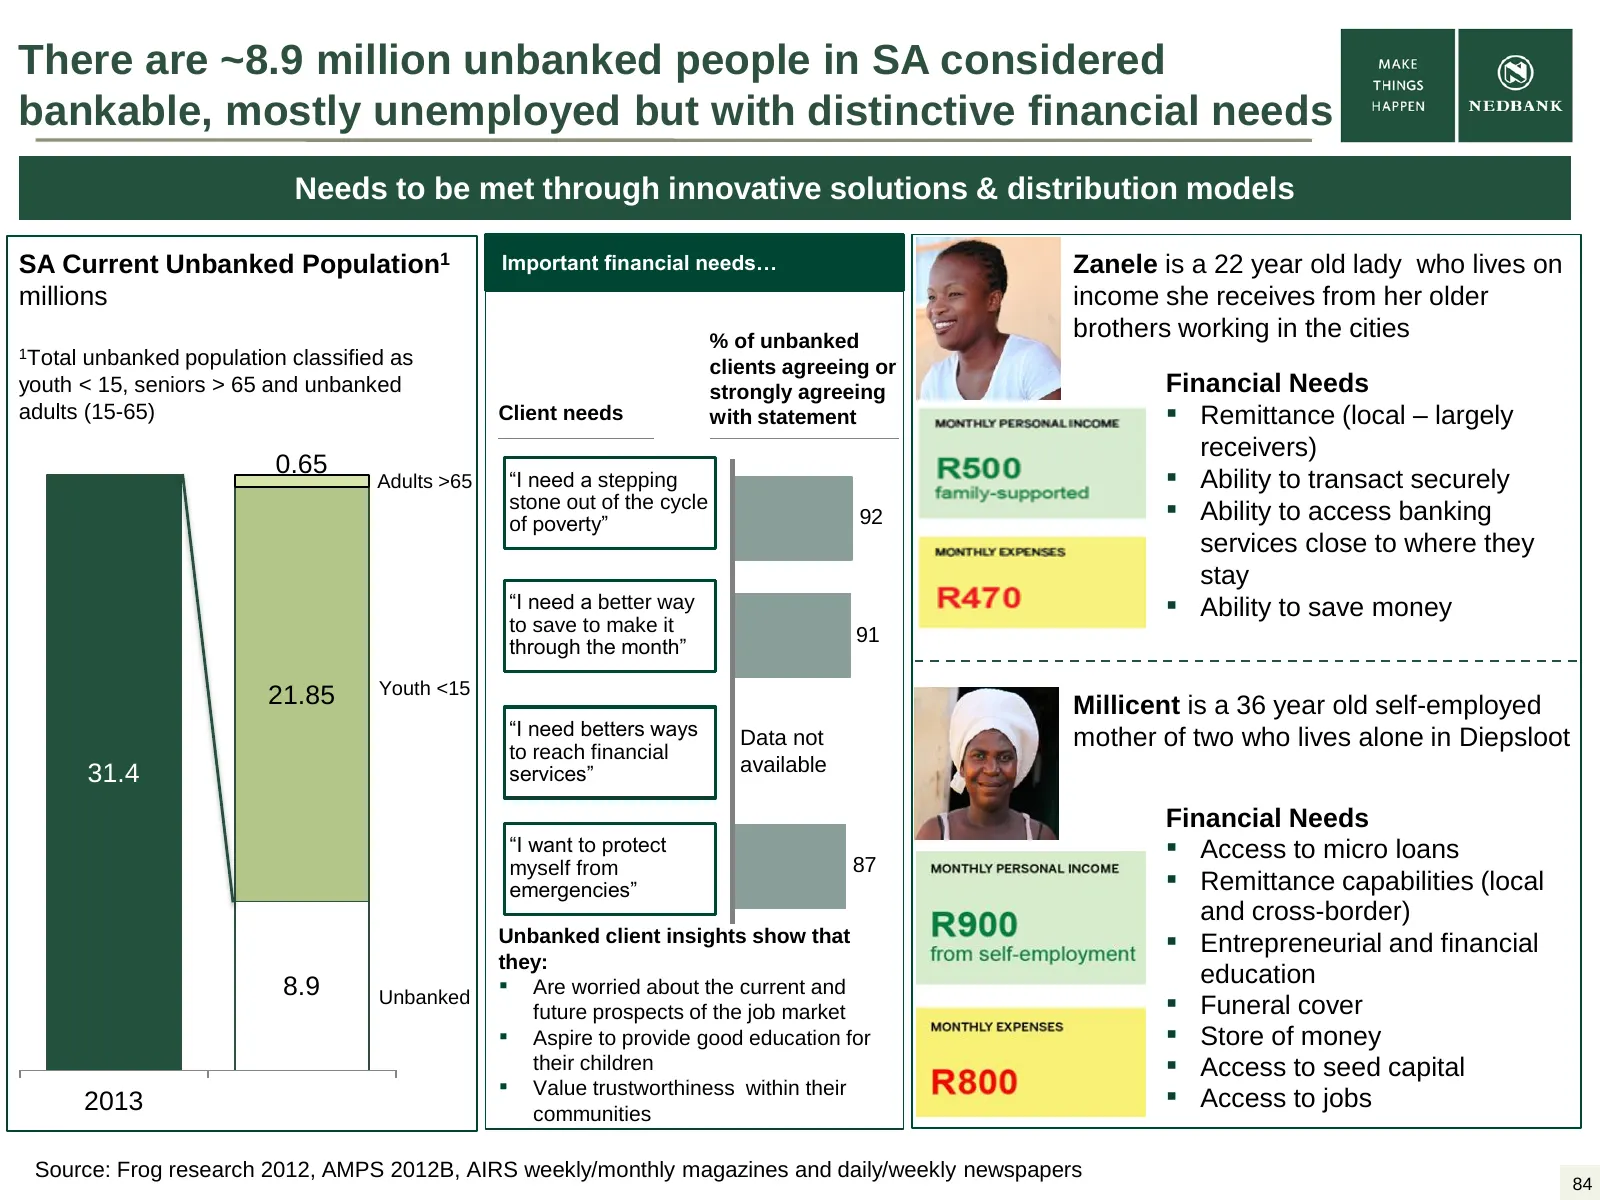
Slide 84: ~8.9 million unbankable people with distinctive financial needs
There are ~8.9 million unbanked people in SA considered bankable, mostly unemployed but with distinctive financial needs Needs to be met through innovative solutions & distribution models SA Current Unbanked Population1 Important financial needs… Zanele is a 22 year old lady who lives on millions in
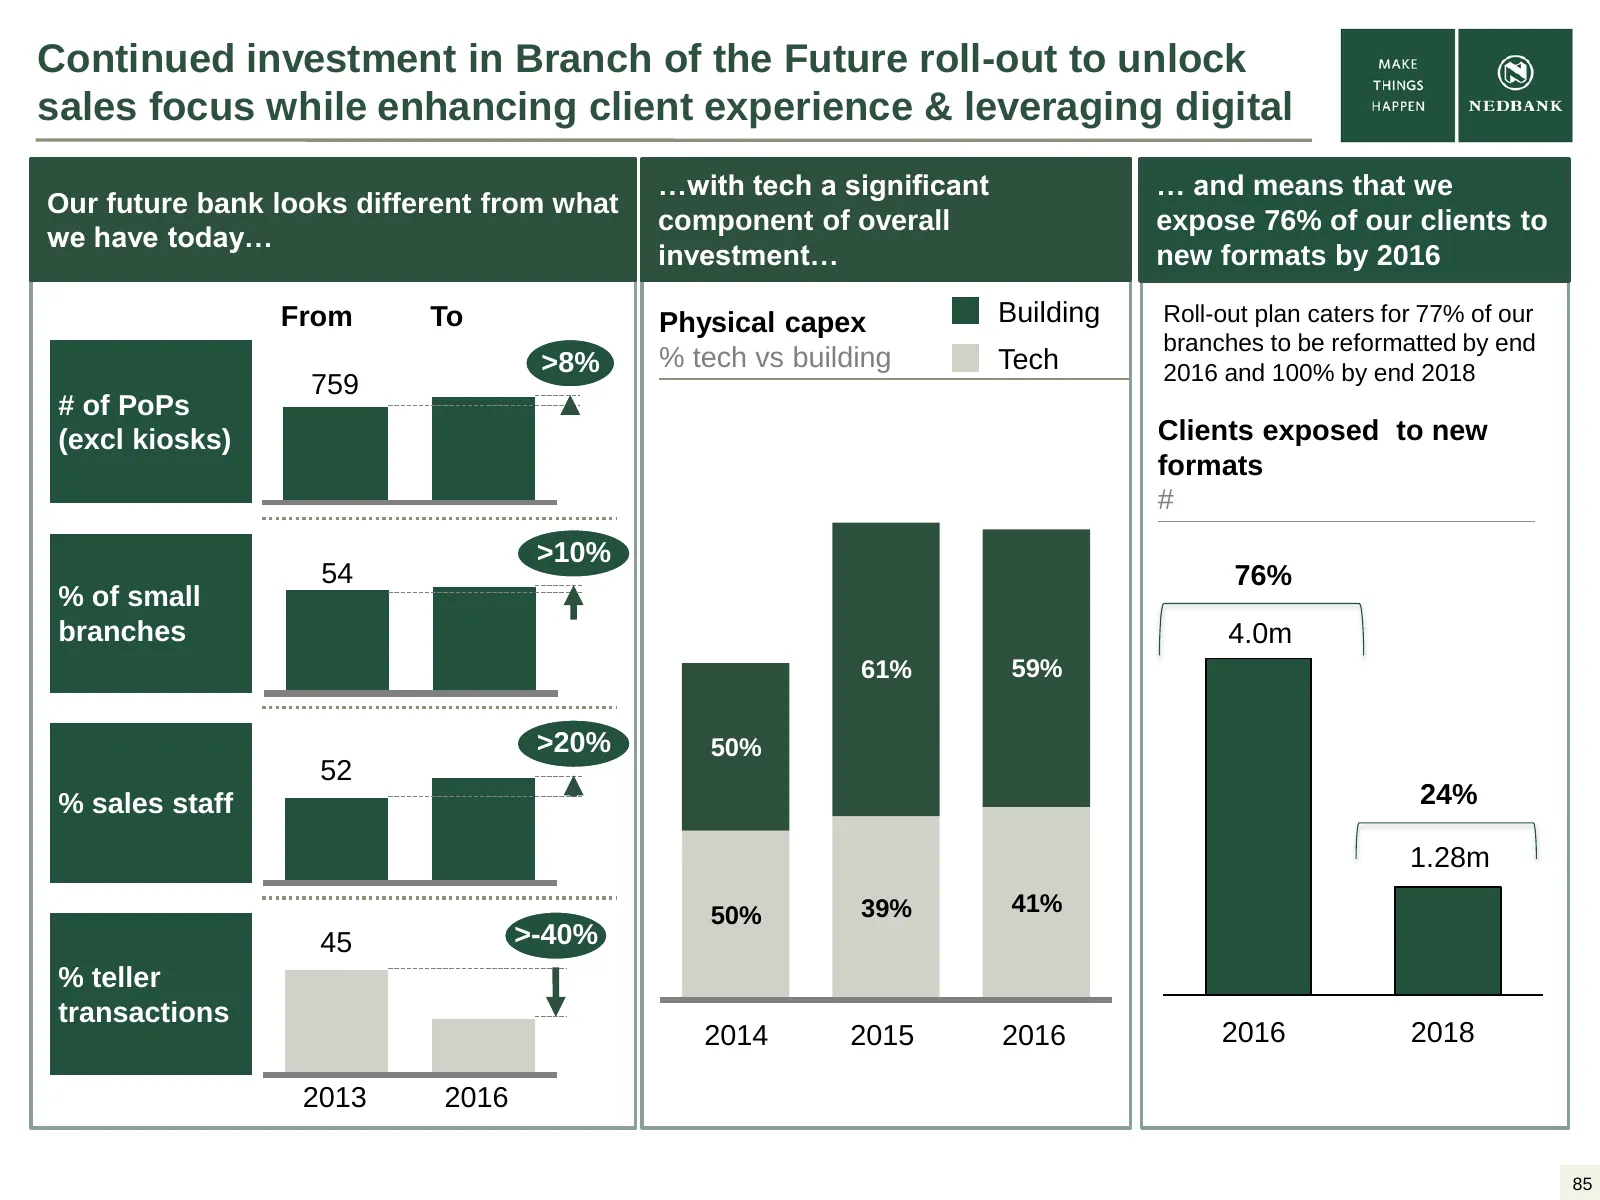
Slide 85: Branch of the Future roll-out
Continued investment in Branch of the Future roll-out to unlock sales focus while enhancing client experience & leveraging digital …with tech a significant … and means that we Our future bank looks different from what component of overall expose 76% of our clients to we have today… investment… new f
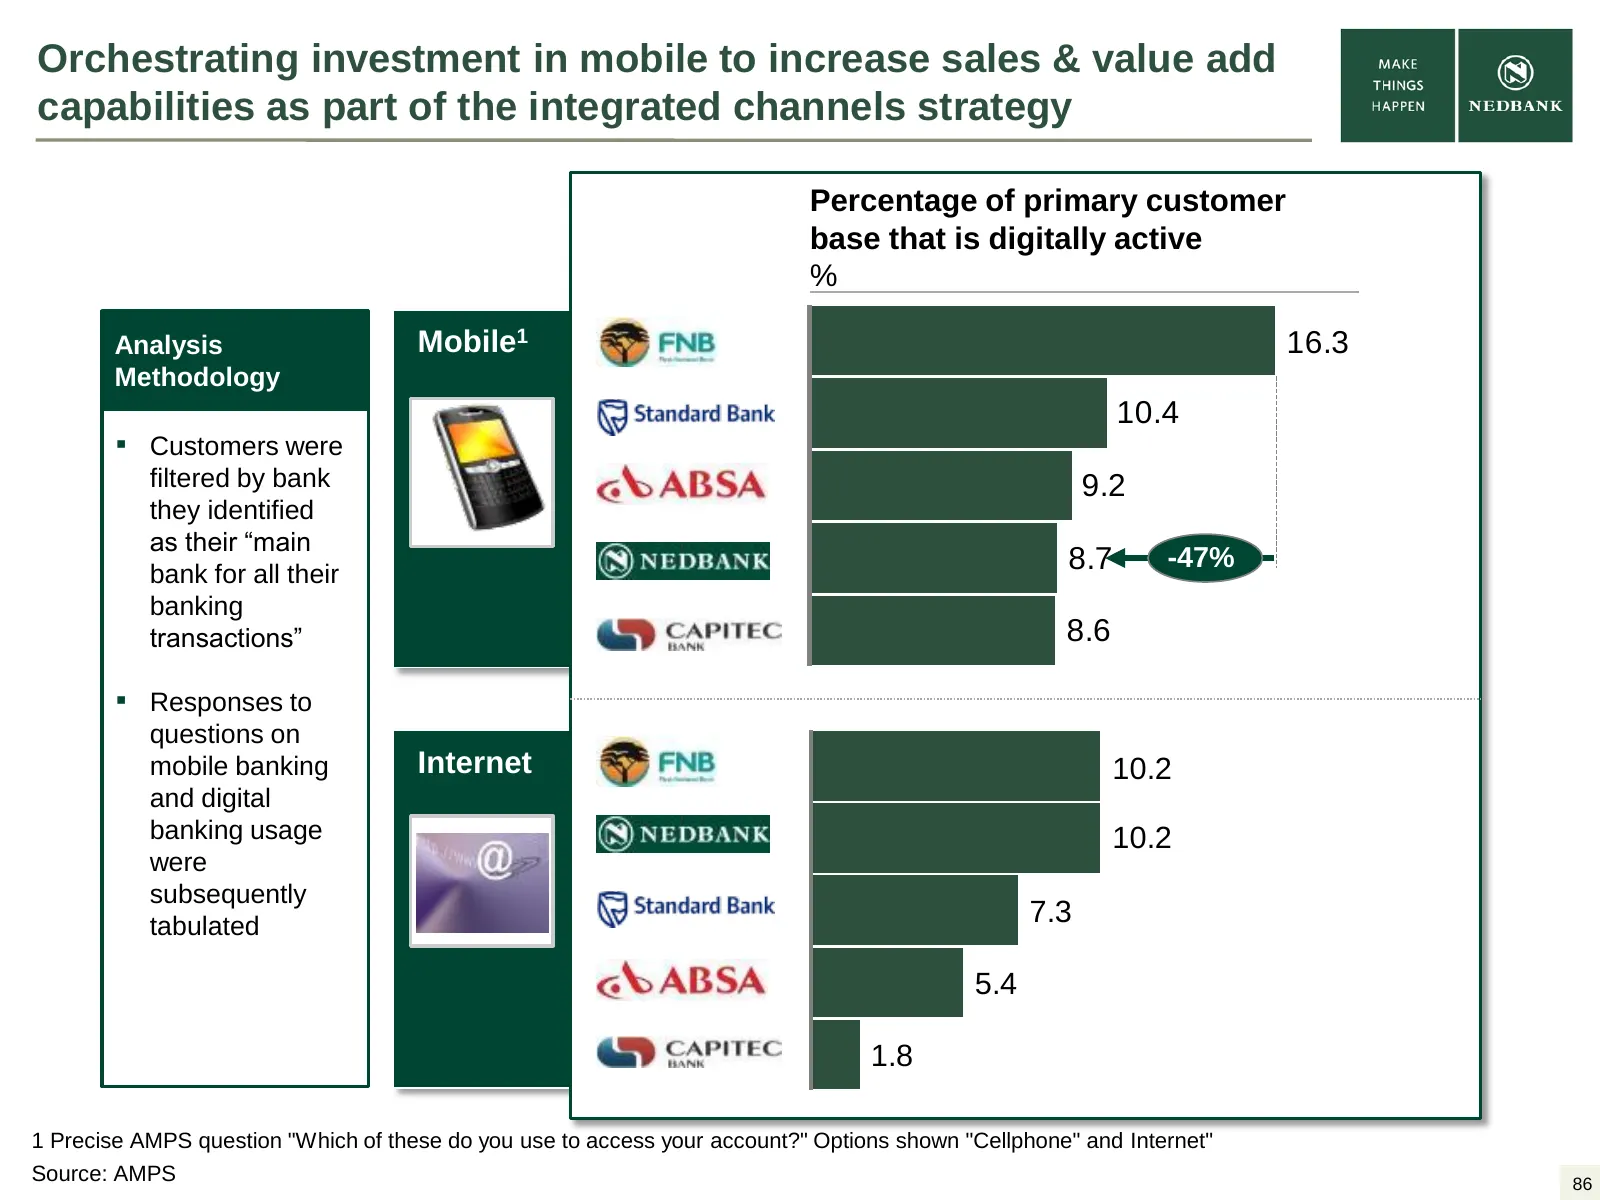
Slide 86: Investment in mobile to increase sales and value add
Orchestrating investment in mobile to increase sales & value add capabilities as part of the integrated channels strategy Percentage of primary customer base that is digitally active % Analysis Mobile1 16.3 Methodology 10.4 ▪ Customers were filtered by bank 9.2 they identified as their “main 8.7 -47
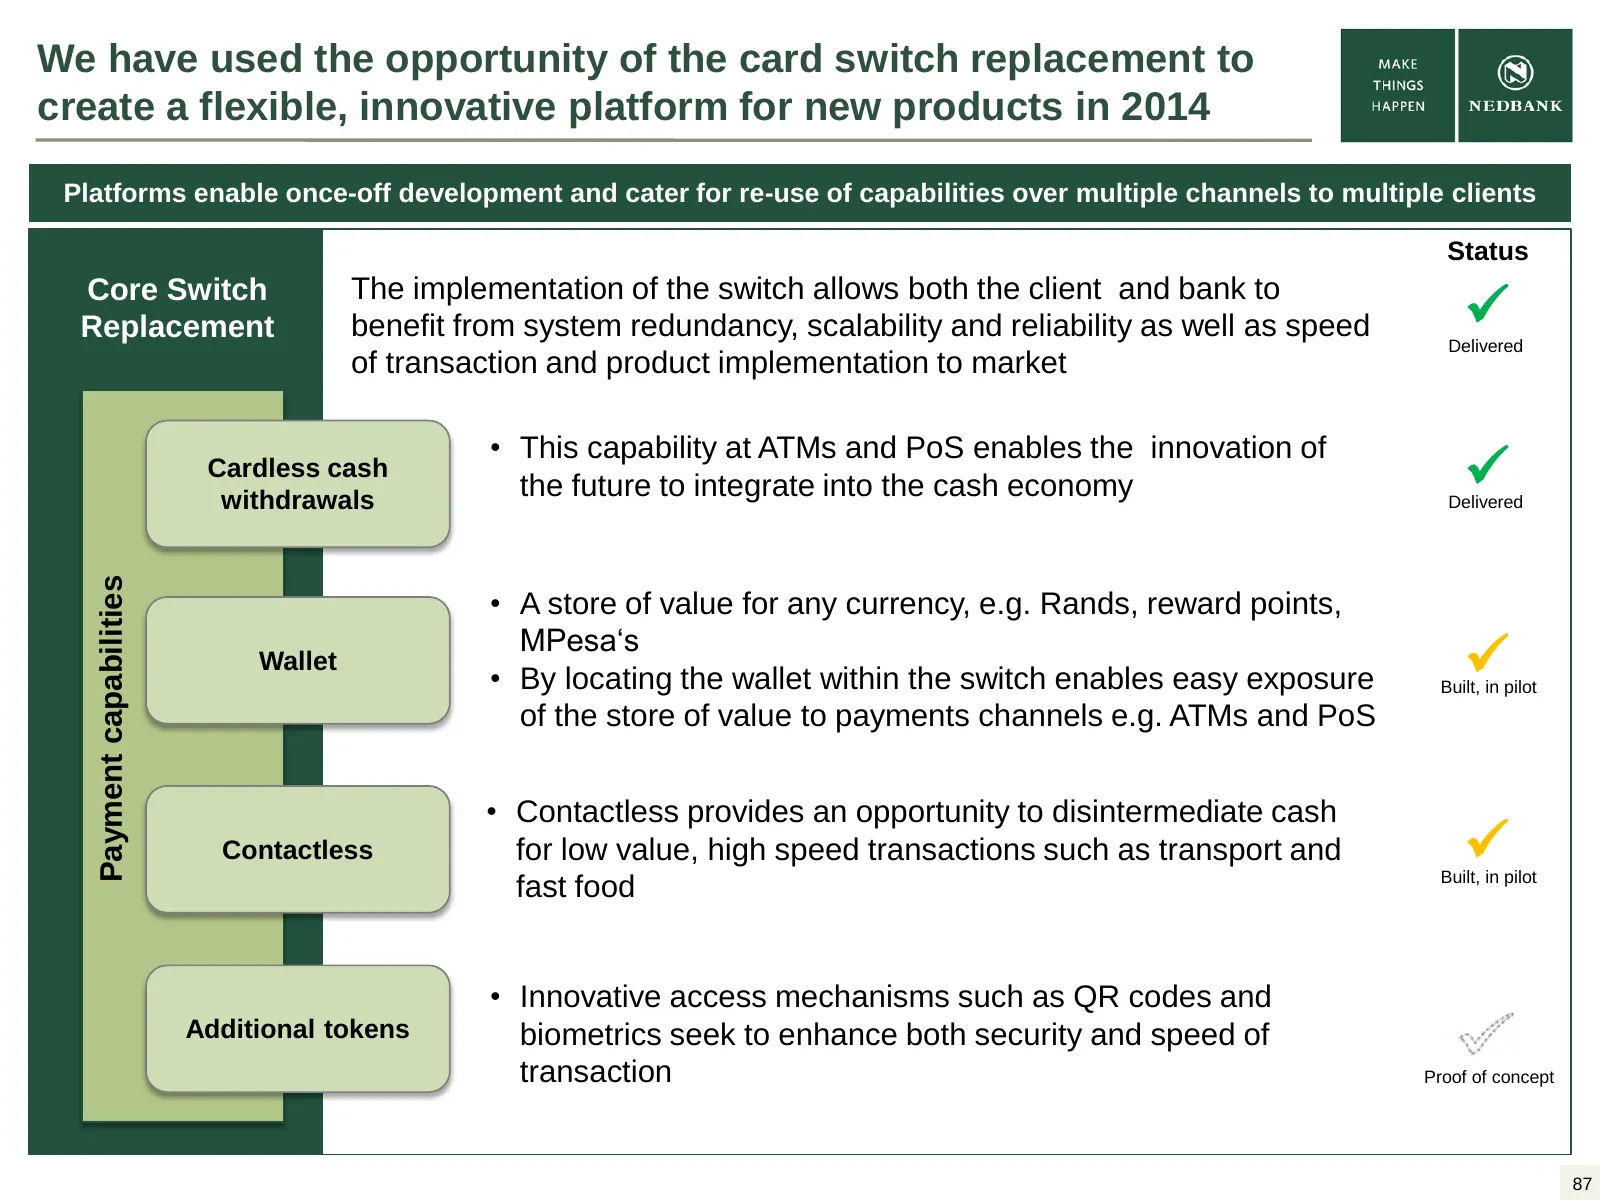
Slide 87: Payment capabilities: card switch replacement platform
We have used the opportunity of the card switch replacement to create a flexible, innovative platform for new products in 2014 Platforms enable once-off development and cater for re-use of capabilities over multiple channels to multiple clients Status Core Switch The implementation of the switch a
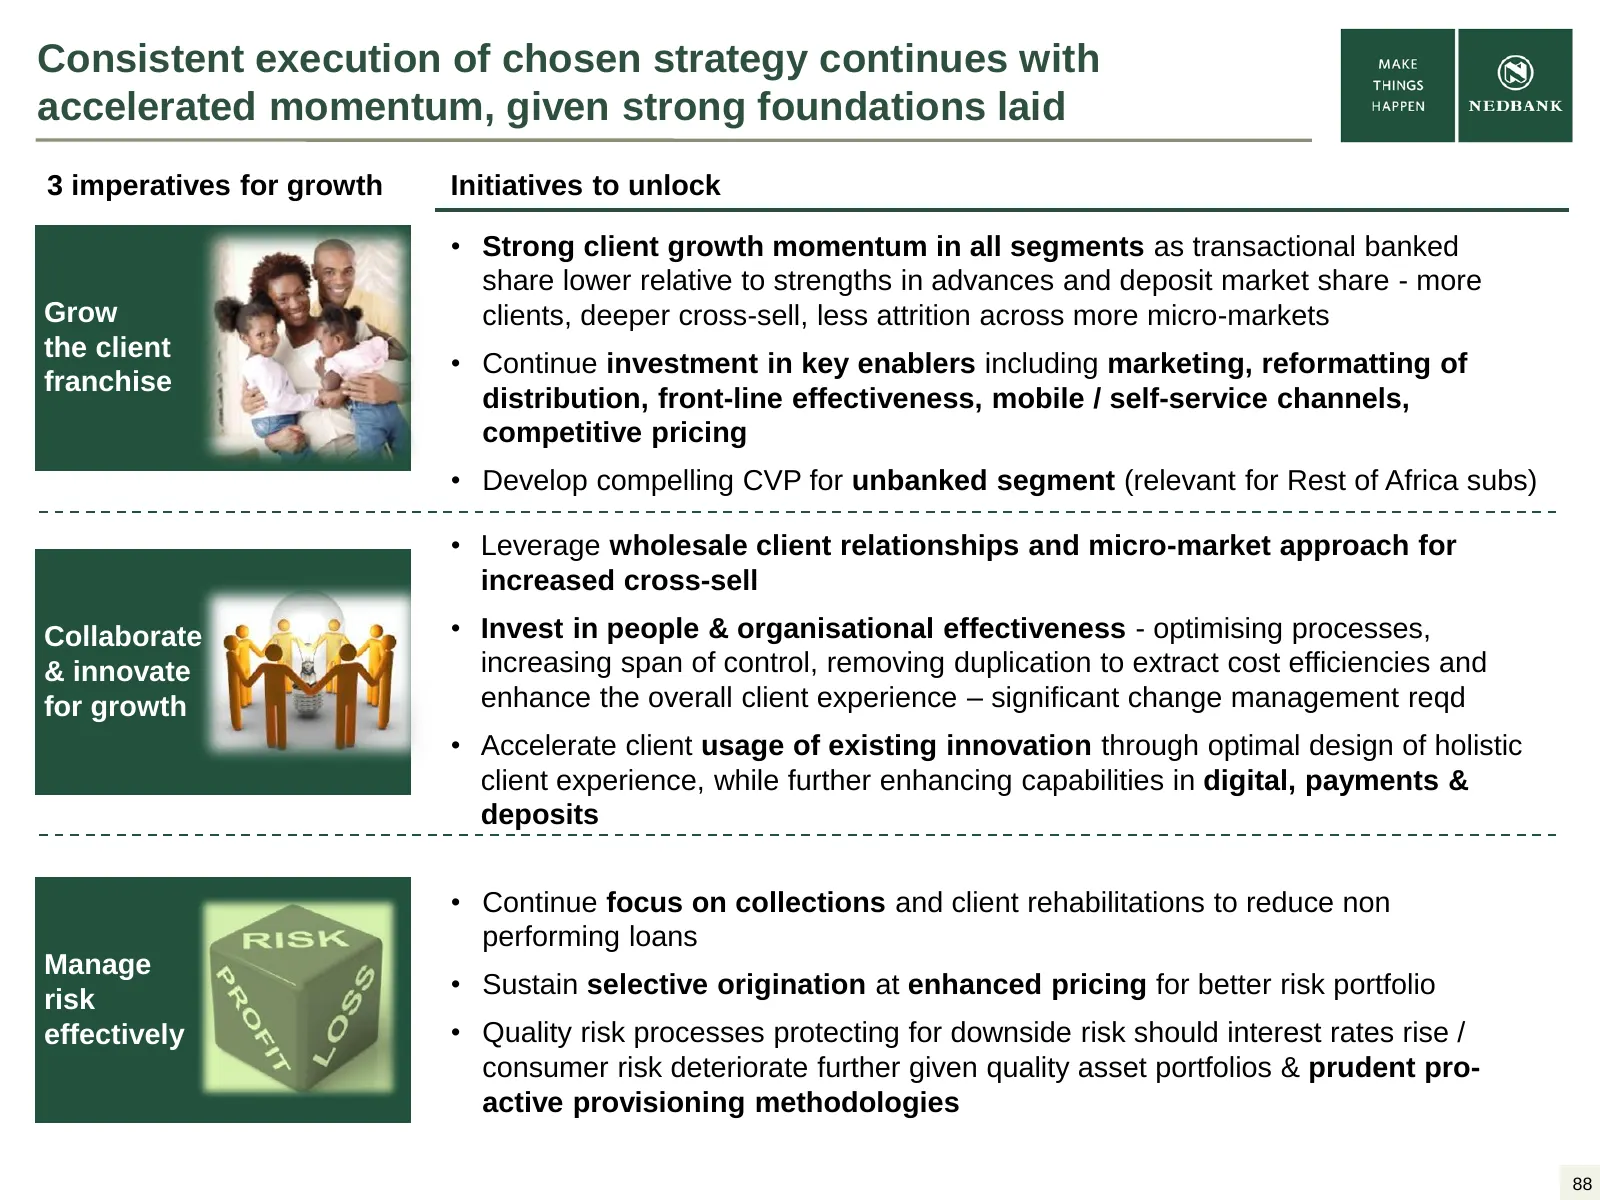
Slide 88: Consistent execution of chosen strategy continues
Consistent execution of chosen strategy continues with accelerated momentum, given strong foundations laid 3 imperatives for growth Initiatives to unlock • Strong client growth momentum in all segments as transactional banked share lower relative to strengths in advances and deposit market share - m
Slide 89: Commitment to build sustainable businesses
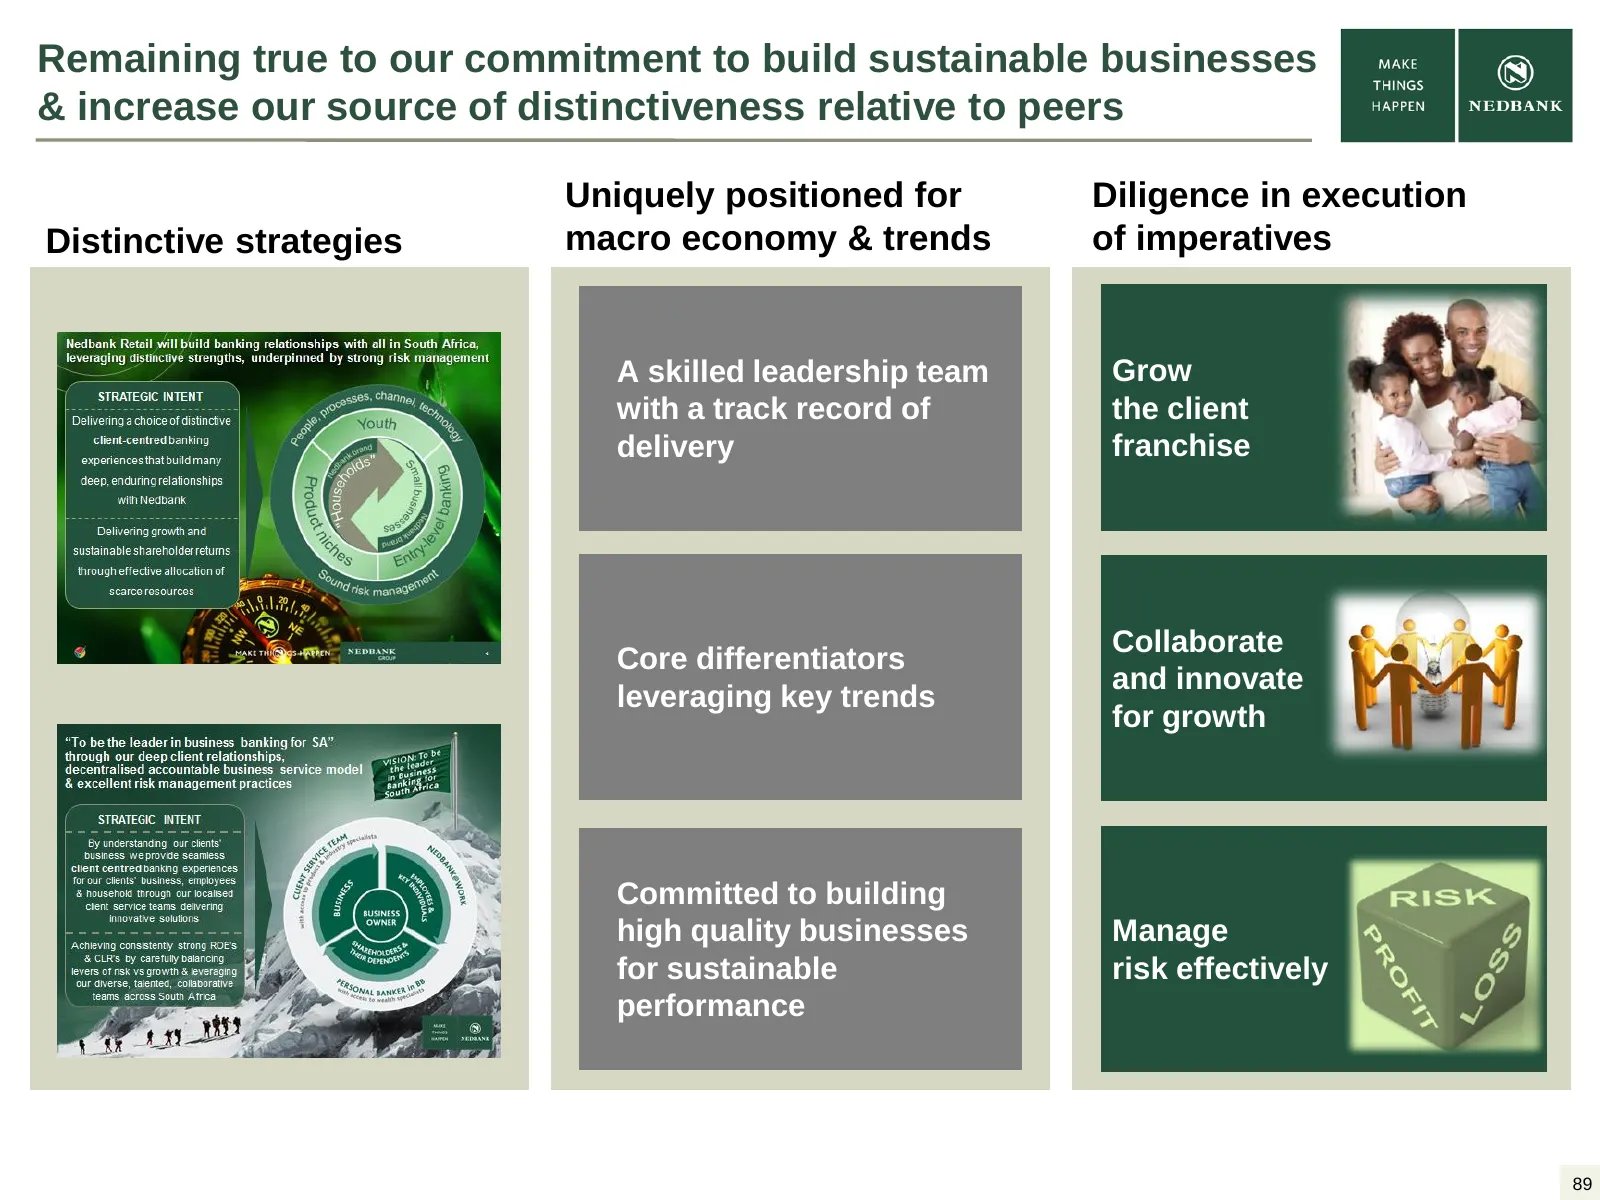
Remaining true to our commitment to build sustainable businesses & increase our source of distinctiveness relative to peers Uniquely positioned for Diligence in execution Distinctive strategies macro economy & trends of imperatives A skilled leadership team Grow with a track record of the client del
Slide 90: Thank you – Question & Answers
Thank you “What lies before us Question & and what lies behind us are small matters Answers compared to what lies within us. And when we bring what is within out into the world, miracles happen.” Henry David Thoreau 90
Slide 91: Contact us
Contact us Nedbank Group Nedbank Investor Relations www.nedbankgroup.co.za Head of Investor Relations Nedbank Group Limited Alfred Visagie Tel: +27 (0) 11a 294 4444 Direct tel: +27 (0) 11 295 6249 Physical address 135 Rivonia Road Cell: +27 (0) 82 855 4692 Sandown Email: AlfredV@nedbank.co.za 2196 S
Source: Internet Archive copy of nedbank.co.za
More decks from Nedbank Group
 FY2025 Earnings Presentation50 slides · February 2026
 FY2024 Earnings Presentation63 slides · March 2025
 27th UBS SA Financial Services Conference 202424 slides · October 2024
 Investor Presentation (October 2024)20 slides · October 2024
 Emerge — Nedbank Investment Conference (2024)22 slides · Sep 10, 2024
 H1 2024 Earnings Presentation85 slides · Aug 6, 2024