Escalera Resources — Double Eagle Petroleum — Collins Stewart Fourth Annual Growth Conference 2008
27 slides from Escalera Resources's conference presentation, Jul 9, 2008
Slide 1: Collins Stewart Fourth Annual Growth Conference
Double Eagle Petroleum Co Collins Stewart Fourth Annual Growth Conference July 9, 2008
Slide 2: Disclaimer
Double Eagle Petroleum Co. DISCLAIMER This presentation may contain projections and other forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934, as amended. Any such projections or statements reflect the Company's current views with respect to future eve
Slide 3: Corporate Profile
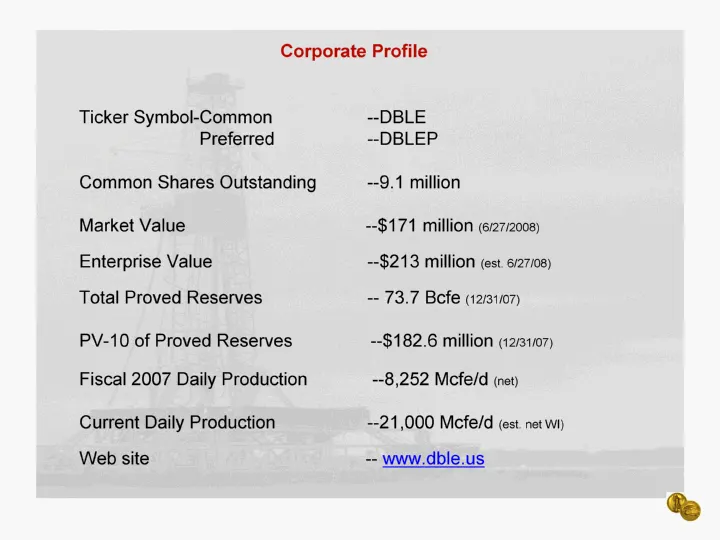
Corporate Profile Ticker Symbol-Common --DBLE Preferred --DBLEP Common Shares Outstanding --9.1 million Market Value --$171 million (6/27/2008) Enterprise Value --$213 million (est. 6/27/08) Total Proved Reserves -- 73.7 Bcfe (12/31/07) PV-10 of Proved Reserves --$182.6 million (12/31/07) Fiscal 200
Slide 4: Developmental Projects
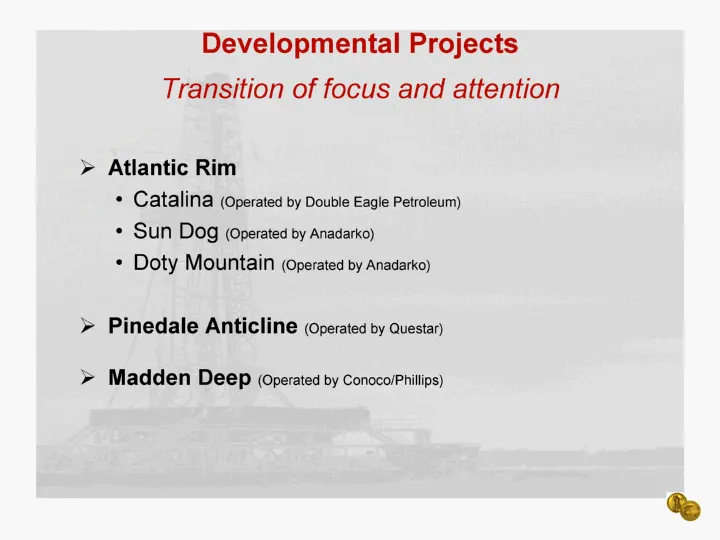
Developmental Projects Transition of focus and attention Atlantic Rim Catalina (Operated by Double Eagle Petroleum) Sun Dog (Operated by Anadarko) Doty Mountain (Operated by Anadarko) Pinedale Anticline (Operated by Questar) Madden Deep (Operated by Conoco/Phillips)
Slide 5: Wyoming Projects Map
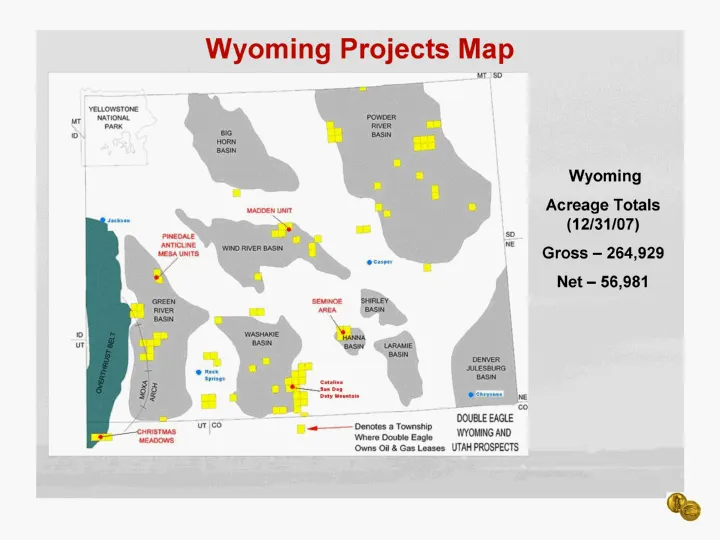
Wyoming Projects Map Wyoming Acreage Totals (12/31/07) Gross - 264,929 Net - 56,981
Slide 6: The Atlantic Rim - Platform for Multi-Year Development
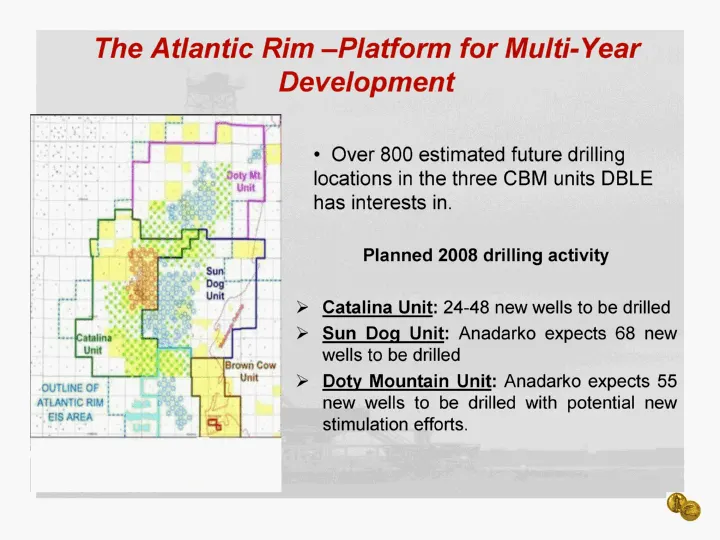
The Atlantic Rim -Platform for Multi-Year Development Planned 2008 drilling activity Catalina Unit: 24-48 new wells to be drilled Sun Dog Unit: Anadarko expects 68 new wells to be drilled Doty Mountain Unit: Anadarko expects 55 new wells to be drilled with potential new stimulation efforts. Over 800
Slide 7: Atlantic Rim Economics
Atlantic Rim Economics Estimated proved reserves of .9 to 1.2 Bcf per well $1.1 million estimated cost per well, including infrastructure Anticipated finding and development costs approximate $1.00/Mcf In the Catalina Unit, DBLE has experienced IP rates: Prior to 2007 drilled wells-IP rates of appro
Slide 8: Pinedale Anticline
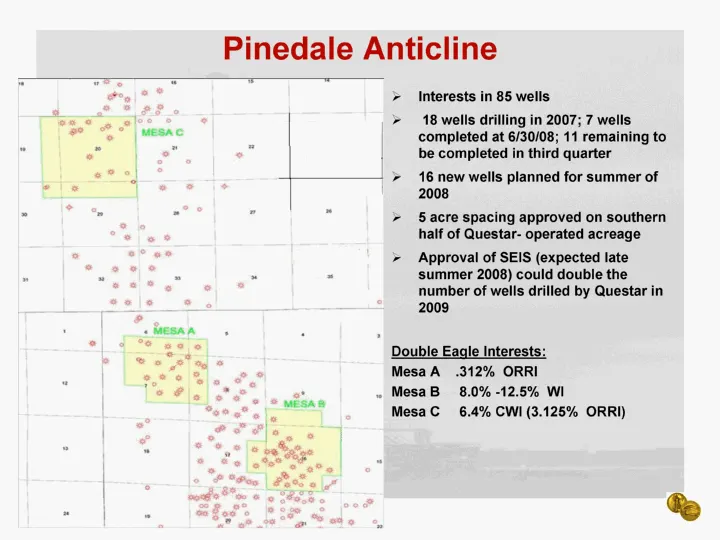
Pinedale Anticline Interests in 85 wells 18 wells drilling in 2007; 7 wells completed at 6/30/08; 11 remaining to be completed in third quarter 16 new wells planned for summer of 2008 5 acre spacing approved on southern half of Questar- operated acreage Approval of SEIS (expected late summer 2008) c
Slide 9: Madden Deep Unit
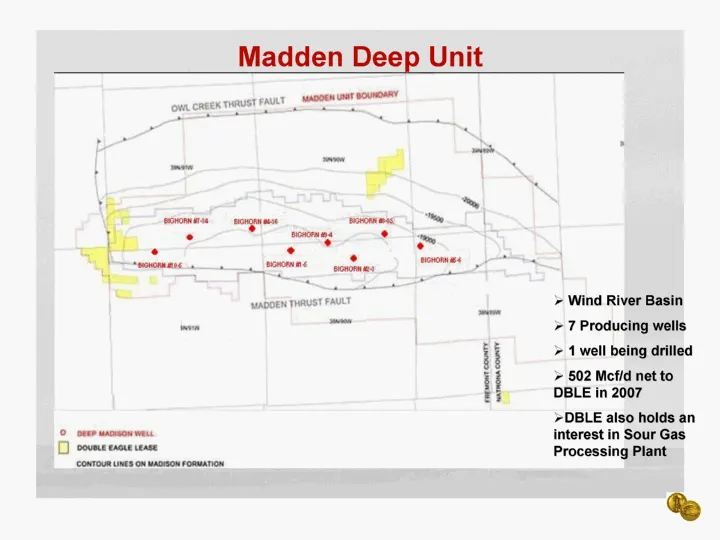
Madden Deep Unit Wind River Basin 7 Producing wells 1 well being drilled 502 Mcf/d net to DBLE in 2007 DBLE also holds an interest in Sour Gas Processing Plant
Slide 10: 2008 Operations Outlook
2008 OPERATIONS OUTLOOK
Slide 11: Catalina Unit Producing Well Count
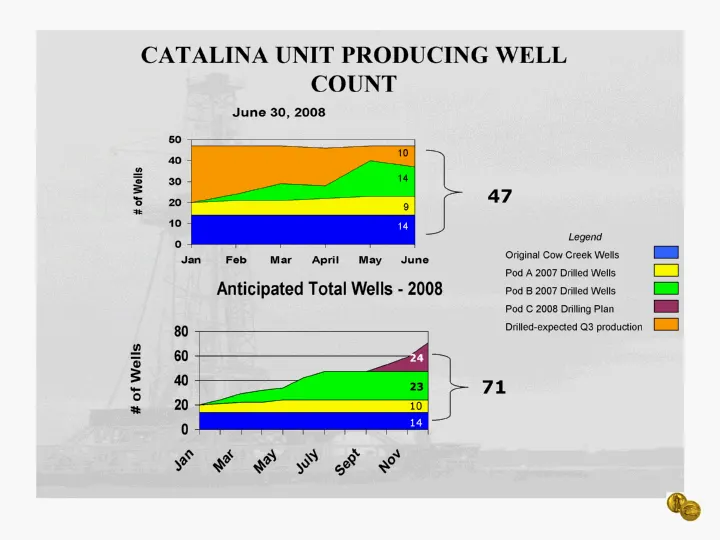
Jan Feb Mar April May June Orig 14 Wells 14 14 14 14 14 14 New Pod A Wells 6 7 7 8 9 9 New Pod B Wells 0 3 8 6 17 14 Drilled and to be brought on 27 23 18 18 7 10 CATALINA UNIT PRODUCING WELL COUNT Jan Feb Mar April May June July August Sept Oct Nov Dec Orig 14 Wells 14 14 14 14 14 14 14 14 14 14 14
Slide 12: Catalina Unit Production
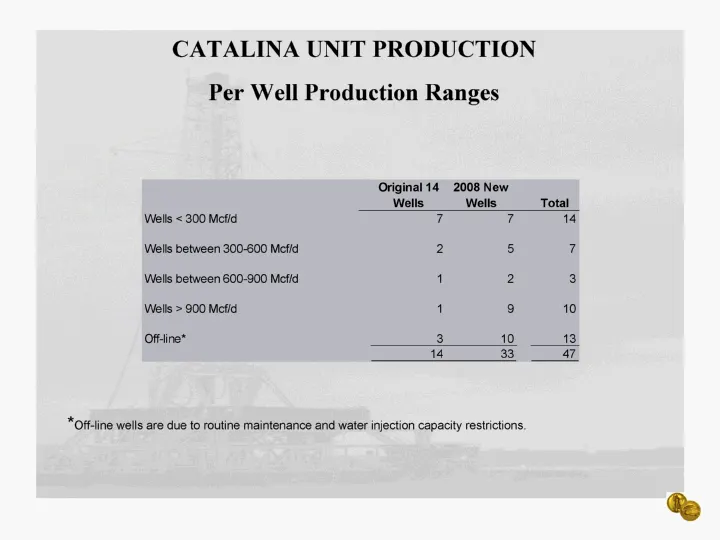
CATALINA UNIT PRODUCTION Per Well Production Ranges *Off-line wells are due to routine maintenance and water injection capacity restrictions.
Slide 13: Catalina Unit Production Gross Monthly Volumes
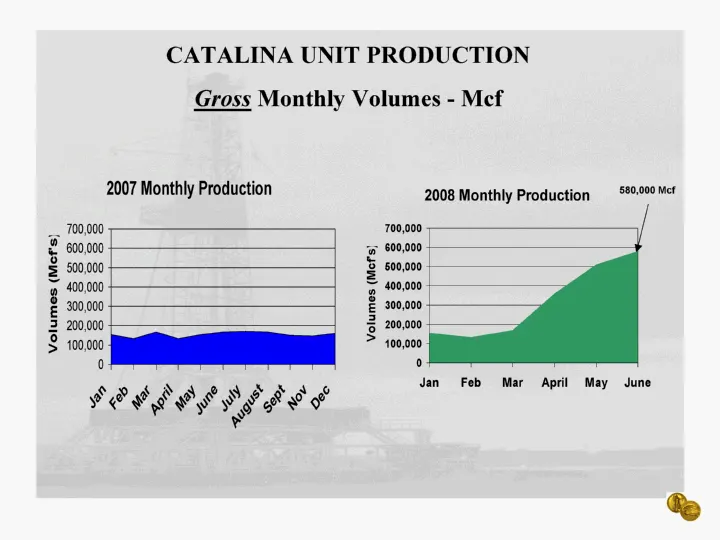
Jan Feb Mar April May June July August Sept October Nov Dec 2007 Orig 14 Well Production 154955 132236 168840 134721 152559 166809 170919 168239 149403 150797.01 146504 160015 Jan Feb Mar April May June 154955 132236 168835 360535 510000 579634 CATALINA UNIT PRODUCTION Gross Monthly Volumes - Mcf 58
Slide 14: Total Company Production
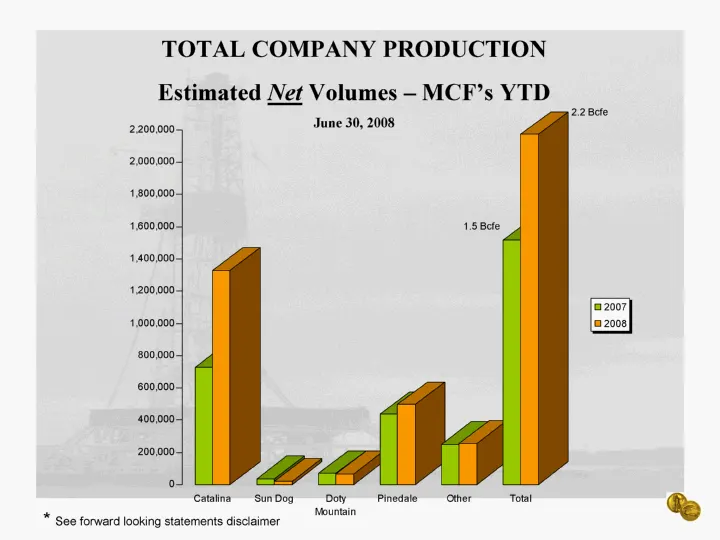
Catalina Sun Dog Doty Mountain Pinedale Other Total 2007 728092 34558 68928 435899 250660 1518139 2008 1329406 20298 66650 497270 257117 2170740 TOTAL COMPANY PRODUCTION Estimated Net Volumes - MCF's YTD June 30, 2008 * See forward looking statements disclaimer 1.5 Bcfe 2.2 Bcfe
Slide 15: Estimated Total Gross Wells By Major Area
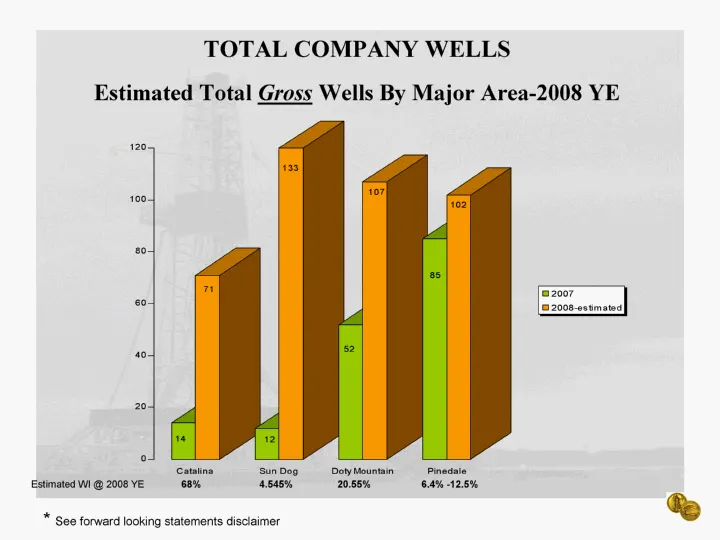
Catalina Sun Dog Doty Mountain Pinedale 2007 14 12 52 85 2008-estimated 71 133 107 102 TOTAL COMPANY WELLS Estimated Total Gross Wells By Major Area-2008 YE * See forward looking statements disclaimer 68% 4.545% 20.55% 6.4% -12.5% Estimated WI @ 2008 YE
Slide 16: Finding Costs ($ per MCFE)
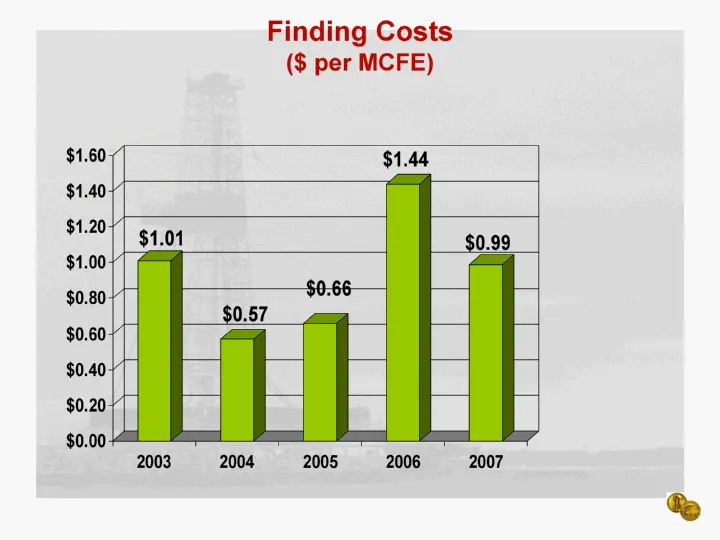
Finding Costs ($ per MCFE) 2003 2004 2005 2006 2007 Total 1.01 0.57 0.66 1.44 0.99
Slide 17: Proved Reserves
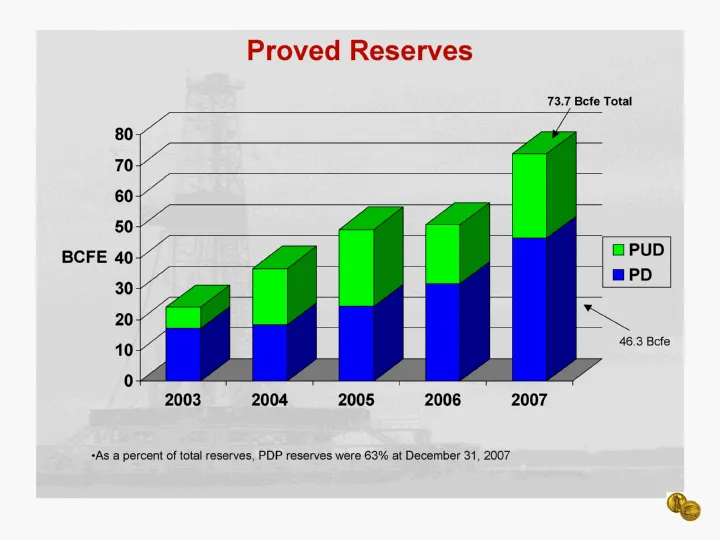
Proved Reserves 2003 2004 2005 2006 2007 PD 17.1 18.2 24.2 31.6 46.3 PUD 6.9 18.4 25 19.1 27.4 As a percent of total reserves, PDP reserves were 63% at December 31, 2007 73.7 Bcfe Total 46.3 Bcfe
Slide 18: Estimated Reserves
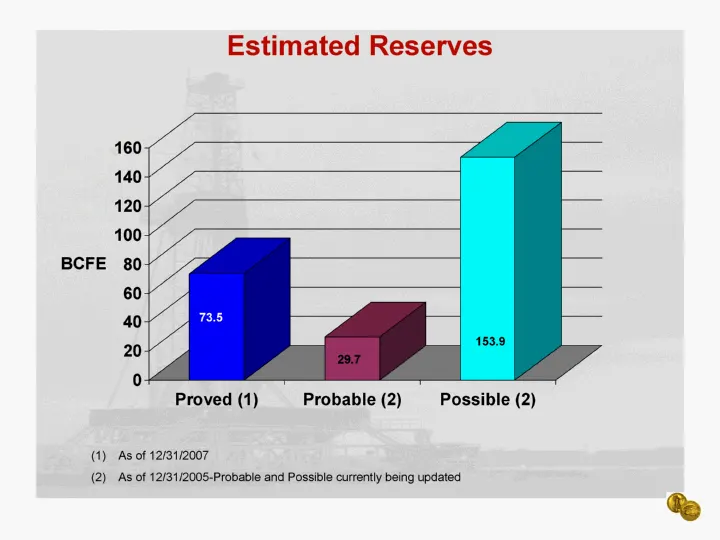
Estimated Reserves Proved (1) Probable (2) Possible (2) P1 73.7 P2 29.7 P3 153.9 As of 12/31/2007 As of 12/31/2005-Probable and Possible currently being updated 73.5 29.7 153.9
Slide 19: Existing Wells and Future Well Potential
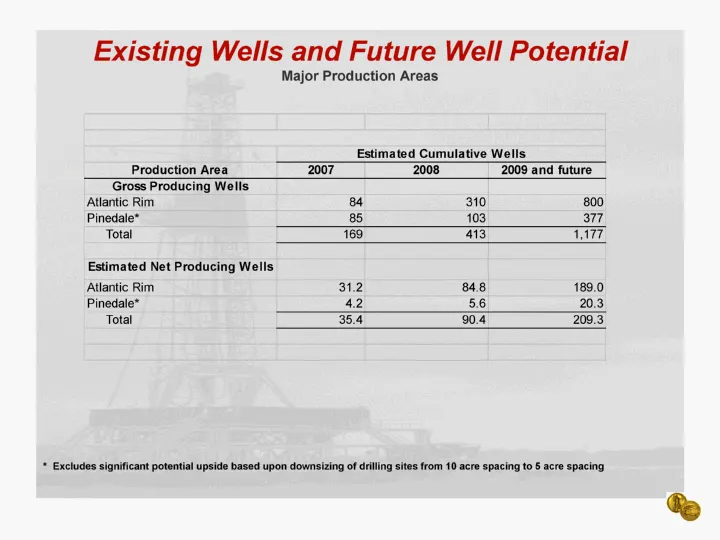
Existing Wells and Future Well Potential Major Production Areas * Excludes significant potential upside based upon downsizing of drilling sites from 10 acre spacing to 5 acre spacing
Slide 20: Capital Spending ($000)
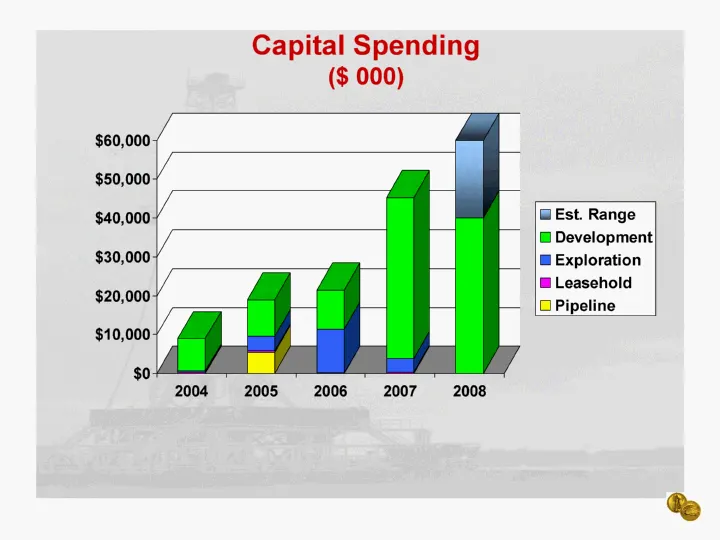
2004 2005 2006 2007 2008 Pipeline 5378 Leasehold 297 407 100 316 0 Exploration 324 3693 11304 3600 0 Development 8366 9494 10046 41337 40000 Est. Range 20000 Capital Spending ($ 000)
Slide 21: Growth Strategies
Focus -- re-align resources to the development of our lower-risk developmental plays in the Atlantic Rim and Pinedale Anticline Execution -build on the knowledge of the 2007 drilling plan to effectively and efficiently execute our future drilling projects Ownership - ownership and control of key inf
Slide 22: Reasons to Invest
Reasons to Invest Strategic Development Growth Atlantic Rim CBM--Multi-year development program with over 250 net wells to DBLE (if fully developed); Pinedale Anticline-accelerated drilling in 2009 upon approval of SEIS expected in late summer of 2008. Additional drilling locations expected due to a
Slide 23: Stock Performance
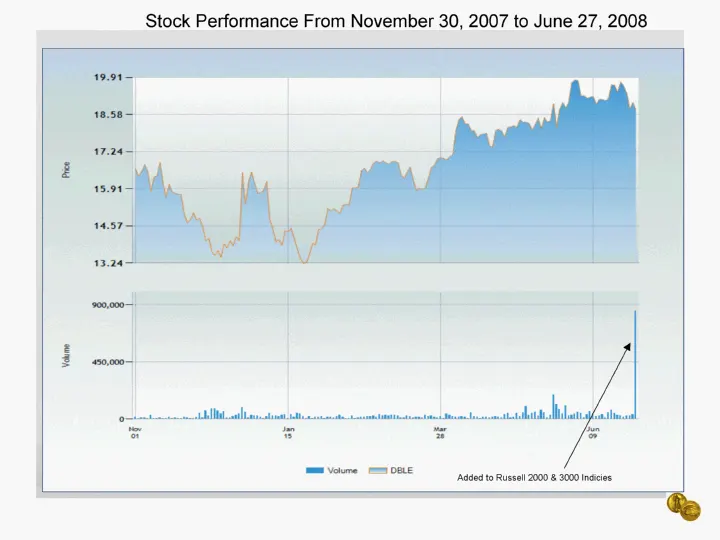
Stock Performance From November 30, 2007 to June 27, 2008 Added to Russell 2000 & 3000 Indicies
Slide 24: Appendix
Appendix Reserve Replacement Status of Prior Exploration Projects Existing Well and Future Well Potential-by project
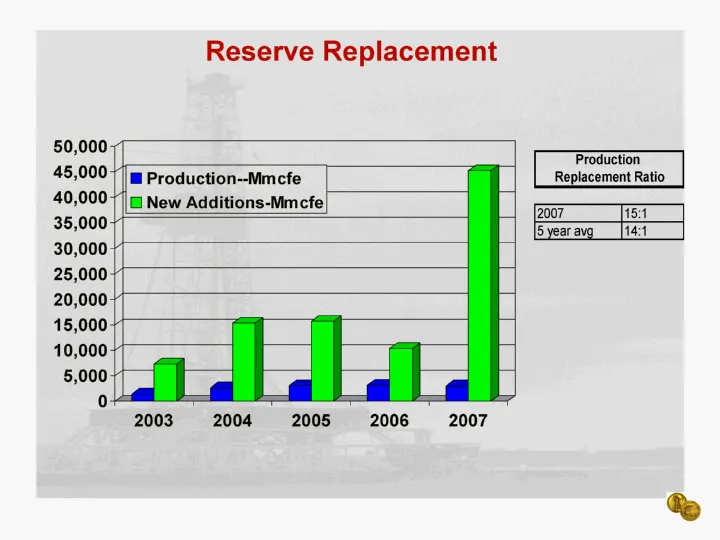
Slide 25: Reserve Replacement
2003 2004 2005 2006 2007 Production--Mmcfe 1425 2661 3069 3217 3012 New Additions-Mmcfe 7353 15311 15700 10395 45200 Reserve Replacement
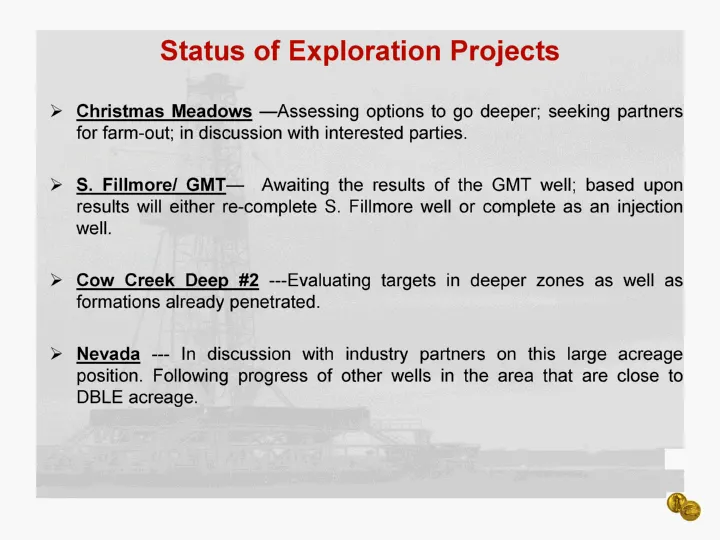
Slide 26: Status of Exploration Projects
Status of Exploration Projects Christmas Meadows -Assessing options to go deeper; seeking partners for farm-out; in discussion with interested parties. S. Fillmore/ GMT- Awaiting the results of the GMT well; based upon results will either re-complete S. Fillmore well or complete as an injection well
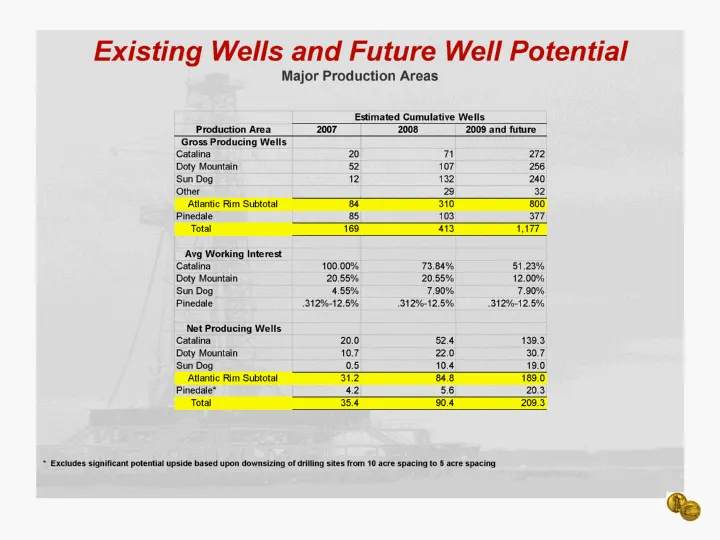
Slide 27: Existing Wells and Future Well Potential
Existing Wells and Future Well Potential Major Production Areas * Excludes significant potential upside based upon downsizing of drilling sites from 10 acre spacing to 5 acre spacing
Source: SEC EDGAR · 8-K filed Jul 9, 2008
More decks from Escalera Resources Company
 EnerCom: The Oil & Gas Conference 201420 slides · Aug 20, 2014
 IPAA OGIS Toronto 201421 slides · Jun 5, 2014
 IPAA Oil & Gas Conference April 201426 slides · Apr 9, 2014
 Double Eagle Petroleum — Euro Pacific Global Investment Conference 201318 slides · Sep 3, 2013
 Double Eagle Petroleum — EnerCom's The Oil & Gas Conference 201318 slides · Aug 14, 2013
 Double Eagle Petroleum — OGIS Conference New York 201316 slides · Apr 15, 2013