South Financial — Shareholder Meeting (May 2009)
37 slides from South Financial's shareholder meeting presentation, May 6, 2009
Slide 1: Annual Meeting of Shareholders
Annual Meeting of Shareholders May 5, 2009
Slide 2: Forward-Looking Statements and Non-GAAP Financial Information
Forward-Looking Statements and Non-GAAP Financial Information The forward-looking statements, as defined in the applicable federal securities laws, being made today are subject to risks and uncertainties. TSFG’s actual results may differ materially from those set forth in such forward-looking statem
Slide 3: Change is needed
Change is needed History of 4 th Quartile Financial Performance Financial performance reputation of the Company is less than stellar
Slide 4: Pre-Cycle ROA vs. Southeast Peers
5-Yr Avg. ROA (2003-2007) Southeast Peer Median TSFG 10-Yr Avg. ROA (1998-2007) 3-Yr Avg. ROA (2005-2007) Pre-Cycle ROA vs. Southeast Peers SOURCE: GAAP ROA per SNL Financial; Southeast peers include BBT, CNB, FCNCA, FHN, RF, SNV, STI, TRMK, UCBI, and WTNY Entered credit cycle with below-peer financ
Slide 5: 2008 Financial Performance
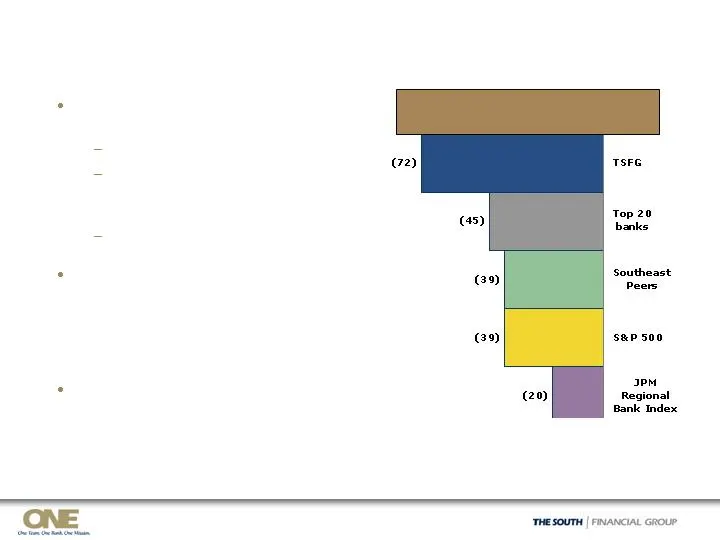
Stock Price Change % Decline in 2008 2008 Financial Performance For non-operating items, see reconciliations of GAAP to non-GAAP measures provided on page 17 of the Quarterly Financial Data Supplement available on TSFG’s web site, www.thesouthgroup.com, in the Investor Relations section. SOURCE: SNL
Slide 6: Challenging Environment
Challenging Environment All financial institutions affected, but TSFG has had higher than peer losses Mix (portfolio and geography) Underwriting Must be prepared – the Credit Contraction/Credit Crunch will deepen and prolong the recession Regulatory environment will become more intense Have the begi
Slide 7: Winners will be rewarded
Winners will be rewarded Fewer Competitors Re-intermediation (for a time) Margin Improvements Core Business continues to be viable In the business of building financial wealth and security The “hope and dream” of every individual
Slide 8: TSFG can be positioned well
TSFG can be positioned well Solidify strong brand and community support in SC and then re-create in Florida and NC Community focused; flexible; “do business” bias Improved controls; adequate now to control/grow the business Simple core operating systems Strategically, enough size (and in the right l
Slide 9: Action Plan to realize the opportunities
Action Plan to realize the opportunities Build/choose leadership that can make the vision come true Preserve and generate capital and liquidity Continue focus on credit management and execution Reduce costs and execute on Revenue and Efficiency Project (Project NOW) Set clear performance targets Bui
Slide 10: The South Financial Group
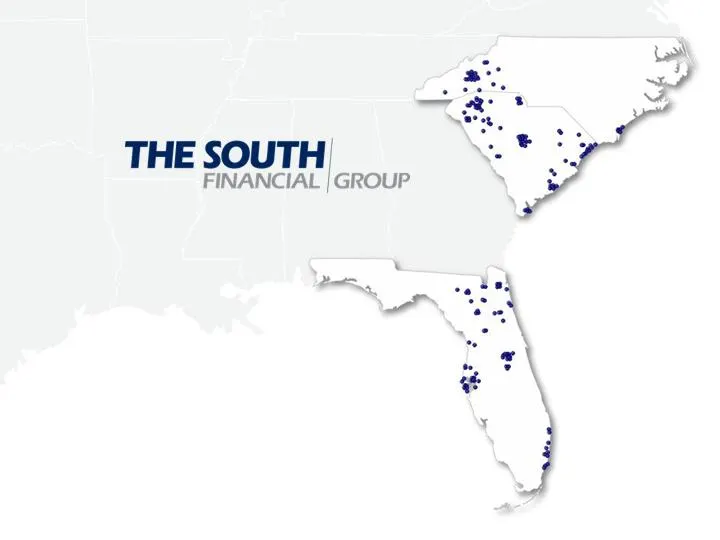
THE SOUTH FINANCIAL | GROUP
Slide 11: Our Executive Management Team
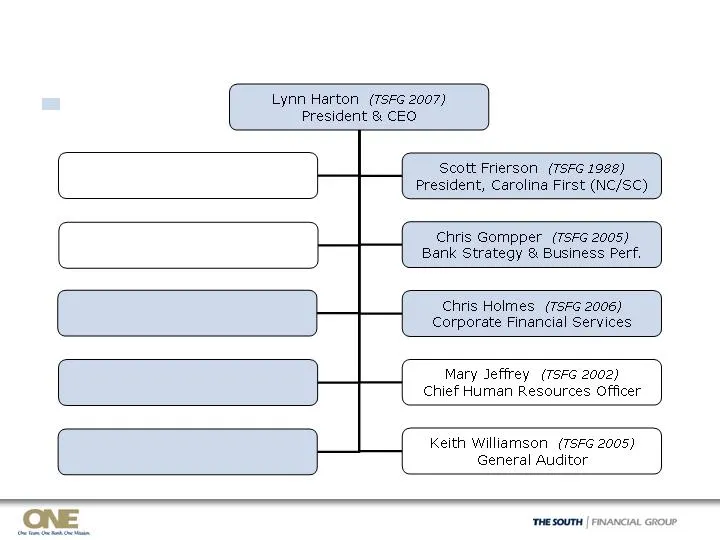
Our Executive Management Team James Gordon (TSFG 2007) Chief Financial Officer Tanya Butts (TSFG 2006) Operations & Technology William Crawford (TSFG 2002) Chief Legal & Risk Officer Ernie Diaz (TSFG 2007) President, Mercantile (FL) Rob Edwards (TSFG 2007) Chief Credit Officer New TSFG role in last
Slide 12: Eliminated line of business silos
Eliminated line of business “silos” All relationship management teams report to and are integrated by Bank Presidents Incentive plans changed to foster cooperation “all win or lose together” Line of Business support (strategies, product development, performance management, etc.) created and consolid
Slide 13: The South Financial Group
THE SOUTH FINANCIAL | GROUP
Slide 14: Capital Base – Proactive Steps Taken
Capital Base – Proactive Steps Taken $347 million preferred from U.S. Treasury’s Capital Purchase Program 12/08: Actively managing balance sheet growth Exited indirect lending in FL and non- relationship dealers in NC/FL Grow core loans Reduced non-core ($230 million in 1Q09) Ongoing: $250 million o
Slide 15: Total Capital Position vs. Southeast Peers
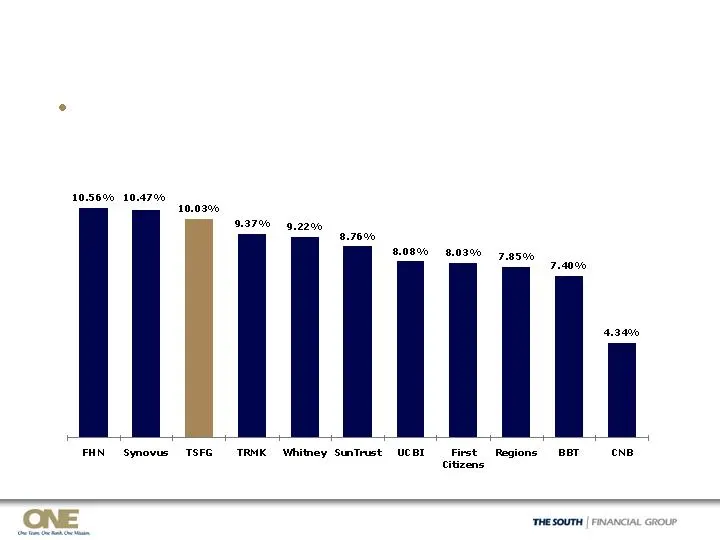
Total Capital Position vs. Southeast Peers Higher is better Tangible Equity as % Tangible Assets As of 3/31/09 SOURCE: SNL Financial; First Citizens as of 12/31/08 since 3/31/09 information is not available
Slide 16: Geographic Diversification and Liquidity
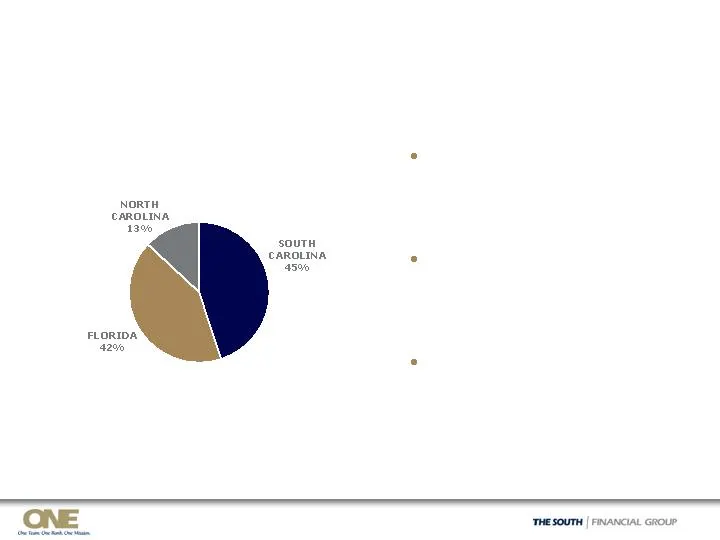
*Customer deposits are total deposits less brokered deposits. Core deposits are total deposits less certificates of deposit. Customer Deposits By State* As of March 31, 2009 Geographic Diversification and Liquidity Liquidity Position: Unused secured borrowing capacity of $3.9 billion at 3/31/09 2.8%
Slide 17: The South Financial Group
THE SOUTH FINANCIAL | GROUP
Slide 18: All about Credit
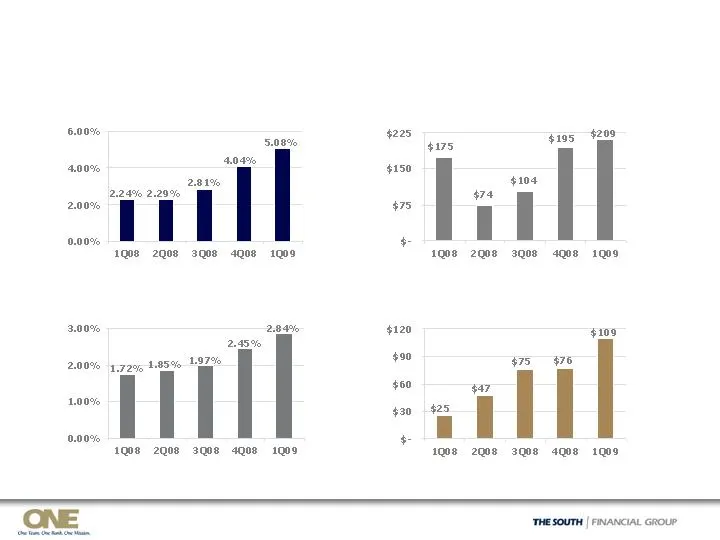
“All about Credit” Gross Nonaccrual Loan Inflows $ in millions Net Charge-Offs $ in millions * Nonperforming assets as a % of loans and foreclosed property Nonperforming Asset Ratio* Allowance for Credit Losses as % of Loans HFI
Slide 19: Credit Actions
Credit Actions Early Identification of real estate credit issues Disclosed rising levels of nonaccruals in 1Q08, ahead of SE Peers Built loan loss reserves to one of highest levels for SE peers Began proactive loan sales in 2Q08 Recognized cumulative NCOs during cycle (1Q08 to 1Q09) of $332 million
Slide 20: Our Credit Team
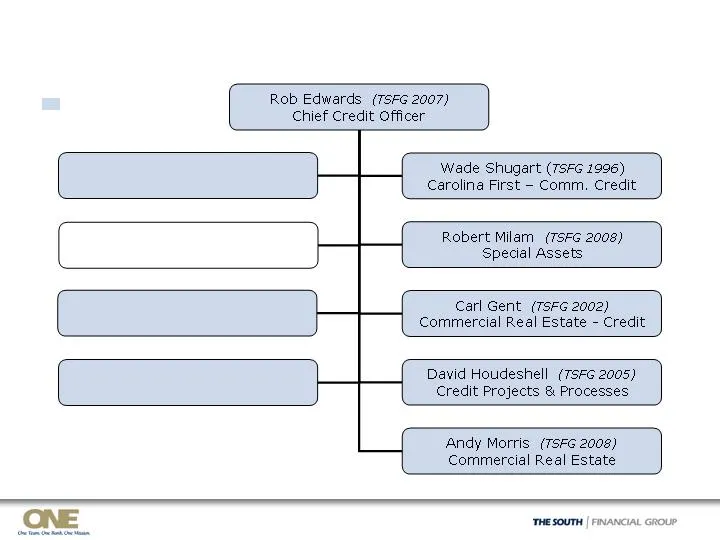
Our Credit Team Jay Richards (TSFG 2008) Mercantile – Comm. Credit Chuck Valerio (TSFG 1999) Retail Credit Mark Mullins (TSFG 2007) Risk Reporting & Analytics Holly Russell (TSFG 2008) Mortgage Credit New TSFG role since mid-2007
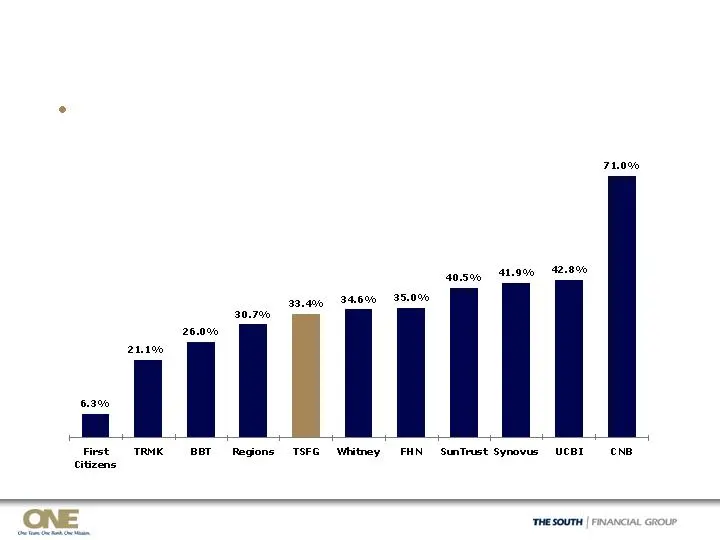
Slide 21: Texas Ratio vs. Southeast Peers
“Texas Ratio” vs. Southeast Peers Lower is better NPAs plus 90+ Days Past Due as % of GAAP Tangible Equity plus Loan Loss Reserve As of 3/31/09 SOURCE: SNL Financial; First Citizens as of 12/31/08 since 3/31/09 information is not available
Slide 22: The South Financial Group
THE SOUTH FINANCIAL | GROUP
Slide 23: Headwinds Immediate Expense Reductions
Headwinds Immediate Expense Reductions Proactive & Realistic Approach to Cycle FDIC insurance; special assessment Loan and foreclosed asset expense Non-operating charges related to Corporate Campus under construction Actions taken: Total Employees down 3% linked-quarter No Executive Management Bonus
Slide 24: Noninterest Expense Control
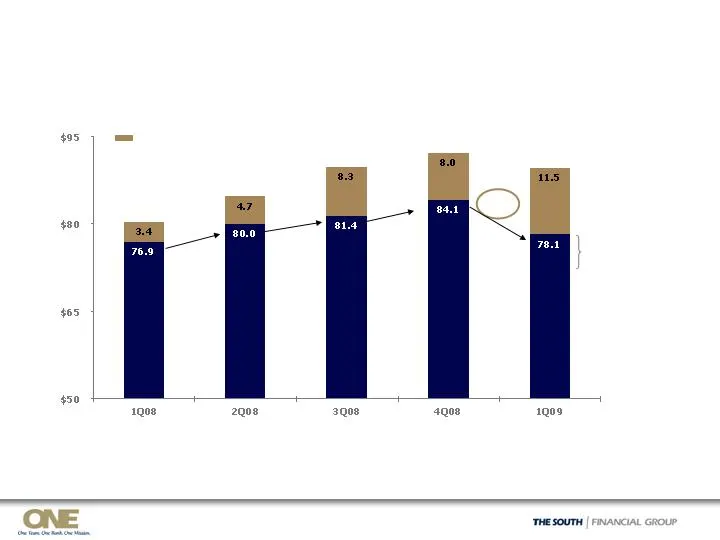
Credit-related costs* and FDIC insurance Noninterest Expense Control * Credit–related costs include loan and foreclosed asset expense, loss on nonperforming loans held for sale, and gain/loss on sale of OREO. For non-operating items, see reconciliations of GAAP to non-GAAP measures provided on page
Slide 25: Project NOW Initial Workstreams (Phase 1)
8 Initial Workstreams (Phase 1) Project NOW Anticipated annual pre-tax operating benefits of $18 to $20 million (revenue improvements of $12 to $13 million and expense savings of $5 to $7 million) Approximately $10 to $11 million on track for realization in second half of 2009 1Q09 noninterest expen
Slide 26: Set Clear Performance Measures
Set Clear Performance Measures
Slide 27: Performance Target Corporate Goals
Performance Target Corporate Goals Performance Measures Achieve Pre-Tax, Pre-Provision Operating Income Budget Reduce 2009 operating noninterest expenses (excl. OREO/LHS write-downs) Deliver Project NOW targets for 2009 Improve efficiency and expense management Maintain NPA% relative to SE peer medi
Slide 28: Vision, Strategy, Communication, Branding
Vision, Strategy, Communication, Branding
Slide 29: Vision/Strategy – Our Mission
Vision/Strategy – Our Mission To be the relationship bank of choice in the markets we serve, distinguished by knowledgeable and trusted professionals working together to make a difference for our customers, shareholders, team members and communities
Slide 30: Vision/Strategy – Our Segments
Vision/Strategy – Our Segments Commercial Banking Local C&I and select real estate and corporate relationships (those with a meaningful opportunity for deposits and noninterest income services) Private Banking Emerging and high net worth persons associated with the businesses we bank (owners and exe
Slide 31: Vision/Strategy – Our Value Proposition
Vision/Strategy – Our Value Proposition We know our customers, and we care about their success We operate with integrity and deliver “plain talk” and personal attention We are big enough to serve our customers, while providing personalized service Decisions are made by local people that our clients
Slide 32: Communication and Market Visits
Communication and Market Visits Clear communication – must be a priority in times of opportunity and rebuilding Improved Internal Communications ONE Messages to all team members Vision/Strategy Workshops TSFG Board tour of Florida markets Market visits Customer Road Shows in 7 Markets since February
Slide 33: Mercantile Bank Carolina First Marketing/Branding Campaign
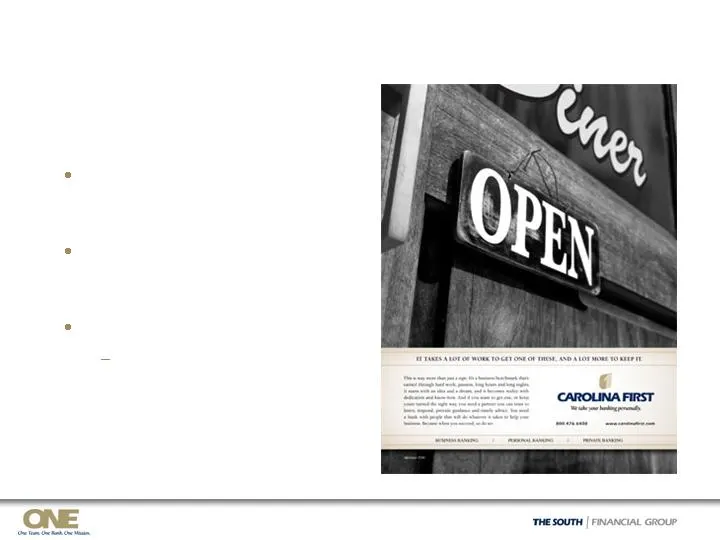
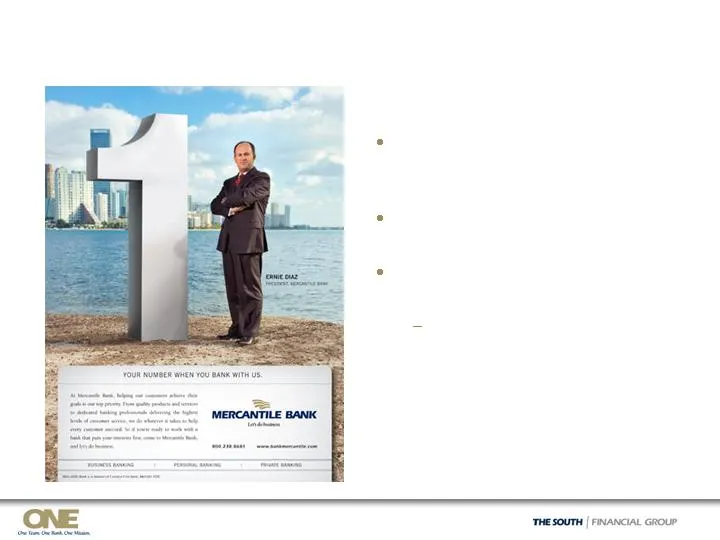
Mercantile Bank Carolina First Marketing/Branding Campaign Our mission – to be the best relationship bank in each of our markets – as the foundation Carolina First and Mercantile Bank start from different positions Tailor marketing/branding accordingly High potential for growth Established history E
Slide 34: Carolina First
Carolina First In keeping with our mission and the methods we use to deliver Builds on existing brand strength and past branding investments Campaign features “icons” Positions us as partner/ trusted advisor “We take your banking personally.”
Slide 35: Mercantile Bank
Mercantile Bank Lack strong brand identity; need more assertive message Simple, straightforward call to action Campaign features “numbers” and “people” Put faces and names on local market leaders, making them recognizable, real, and accessible “Let’s do business.”
Slide 36: Footprint: Long-term Growth Potential
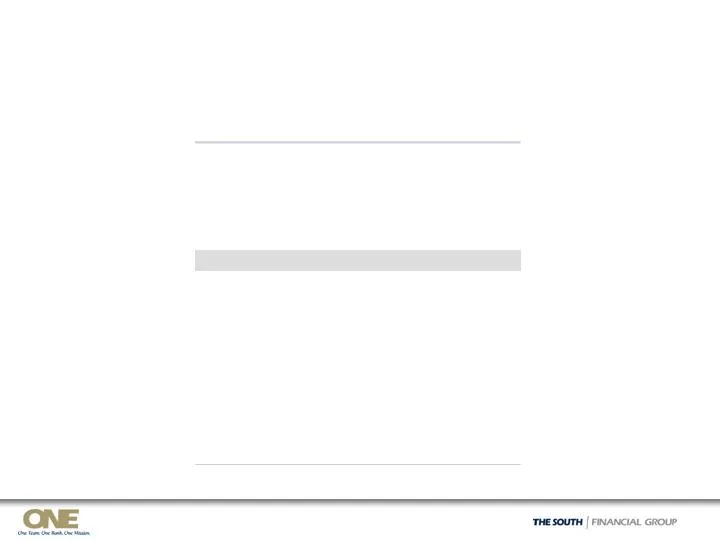
PROJECTED HOUSEHOLD GROWTH (2008-2013) Growth estimates deposit weighted by county as of 6/30/08 SOURCE: SNL Financial Footprint: Long-term Growth Potential Company Name Household Growth (%) United Community Banks 14.2 % Cullen/Frost 11.8 Zions Bancorporation 11.1 SunTrust Banks 10.5 Colonial BancGr
Slide 37: The South Financial Group
THE SOUTH FINANCIAL | GROUP
Source: SEC EDGAR · 8-K filed May 6, 2009
More decks from South Financial Group Inc
 Merger or Acquisition (June 2010)15 slides · Jun 29, 2010
 Debt Investor Presentation (June 2010)84 slides · Jun 18, 2010
 Merger or Acquisition (June 2010)43 slides · Jun 4, 2010
 Merger or Acquisition (May 2010)15 slides · May 17, 2010
 Q1 2010 Earnings Presentation30 slides · Apr 20, 2010
 Q4 2009 Earnings Presentation30 slides · Jan 26, 2010