Perry Ellis International — Investor Day (September 2015)
68 slides from Perry Ellis International's investor day presentation, Sep 11, 2015
Slide 1: Perry Ellis International
Exhibit 99.1 PERRY ELLIS INTERNATIONAL
Slide 2: Safe Harbor Statement
SAFE HARBOR STATEMENT We caution readers that the forward-looking statements (statements which are not historical facts) in this release are made pursuant to the safe harbor provisions of the Private Securities Litigation Reform Act of 1995. Forward-looking statements are based on current expectatio
Slide 3: Agenda Schedule
AGENDA SCHEDULE I. Introduction II. Product Review—A Glimpse into PEI III. Perry Ellis IV. Original Penguin V. PEI Golf VI. Corporate Financial Overview VII. Lunch
Slide 4: Oscar Feldenkreis
Oscar Feldenkreis Vice Chairman of the Board, President and Chief Operating Officer
Slide 5: Key Pillars of Growth and Profitability
KEY PILLARS OF GROWTH AND PROFITABILITY 5 1 2 3 4 Portfolio Retail Expand Direct-to- Operating Optimization Brand International Consumer Efficiencies Enhancement And Licensing Expansion Distribution
Slide 6: Portfolio Optimization
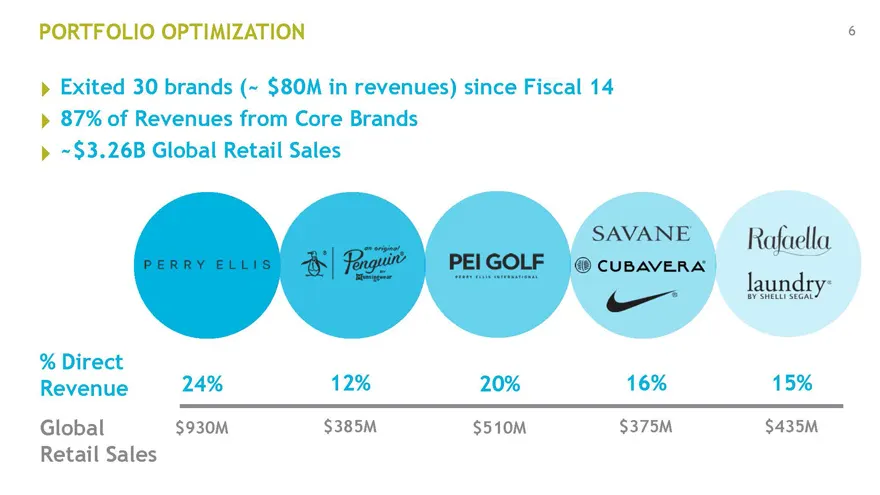
PORTFOLIO OPTIMIZATION 6 Exited 30 brands (~ $80M in revenues) since Fiscal 14 87% of Revenues from Core Brands ~$3.26B Global Retail Sales % Direct Revenue 24% 12% 20% 16% 15% Global $930M $385M $510M $375M $435M Retail Sales
Slide 7: Perry Ellis Brand Overview
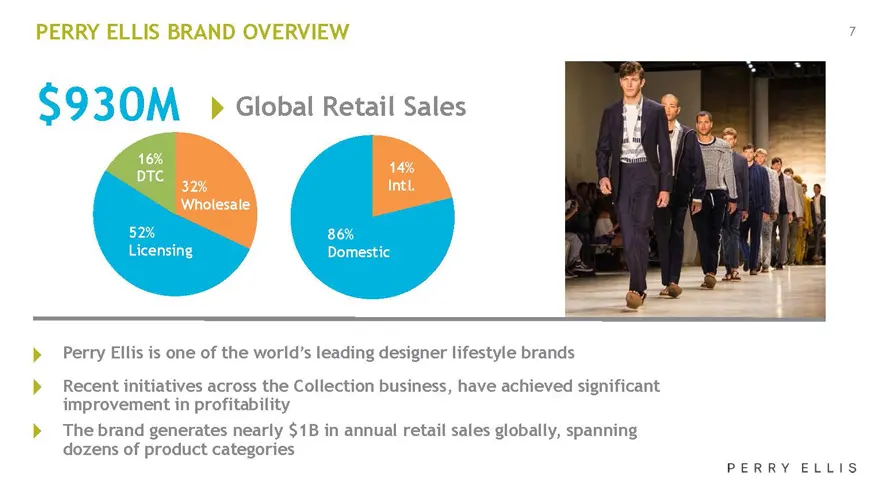
PERRY ELLIS BRAND OVERVIEW 7 $930M Global Retail Sales 16% 14% DTC 32% Intl. Wholesale 52% 86% Licensing Domestic Perry Ellis is one of the world’s leading designer lifestyle brands Recent initiatives across the Collection business, have achieved significant improvement in profitability The brand ge
Slide 8: Original Penguin Brand Overview
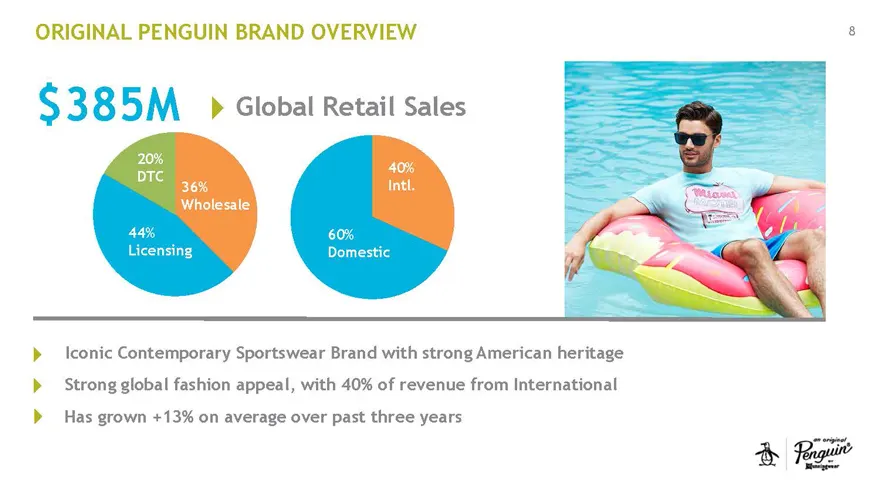
ORIGINAL PENGUIN BRAND OVERVIEW 8 $385M Global Retail Sales 20% 40% DTC 36% Intl. Wholesale 44% 60% Licensing Domestic Iconic Contemporary Sportswear Brand with strong American heritage Strong global fashion appeal, with 40% of revenue from International Has grown +13% on average over past three yea
Slide 9: PEI Golf Division Overview
PEI GOLF DIVISION OVERVIEW 9 $510M Global Retail Sales World-Class portfolio of authentic golf brands, with a good, better, best distribution strategy Production and technological innovation key to future growth
Slide 10: Very Perry Ellis
VERY PERRY ELLIS
Slide 11: Brand Portfolio
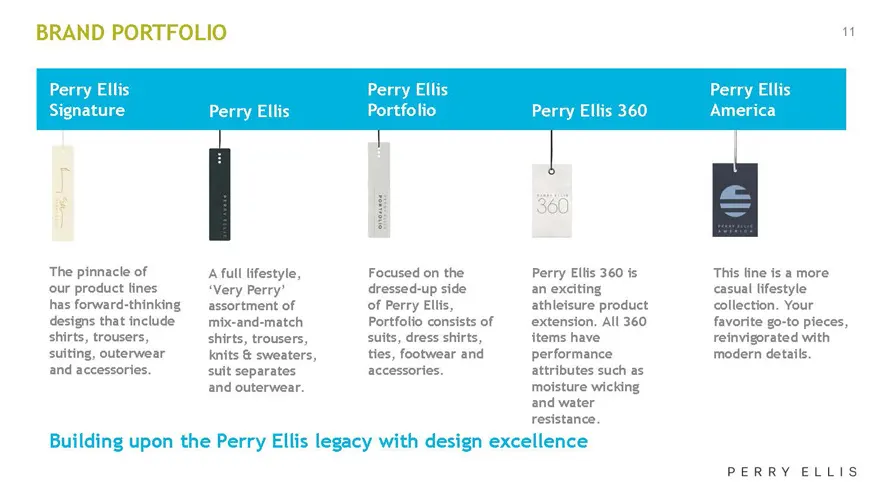
BRAND PORTFOLIO 11 Perry Ellis Perry Ellis Perry Ellis Signature Perry Ellis Portfolio Perry Ellis 360 America The pinnacle of A full lifestyle, Focused on the Perry Ellis 360 is This line is a more our product lines ‘Very Perry’ dressed-up side an exciting casual lifestyle has forward-thinking asso
Slide 12: Wholesale Strategies
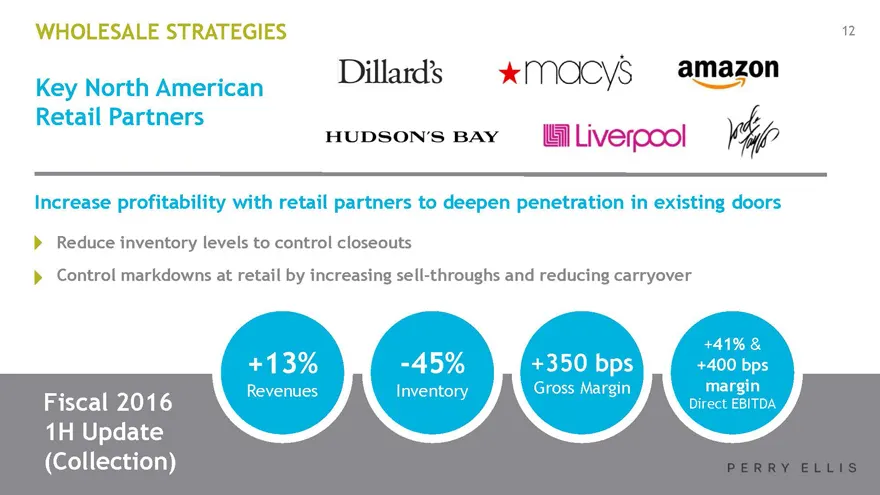
WHOLESALE STRATEGIES 12 Key North American Retail Partners Increase profitability with retail partners to deepen penetration in existing doors Reduce inventory levels to control closeouts Control markdowns at retail by increasing sell-throughs and reducing carryover +41% & +13% -45% +350 bps +400 bp
Slide 13: Wholesale Strategies: E-Commerce
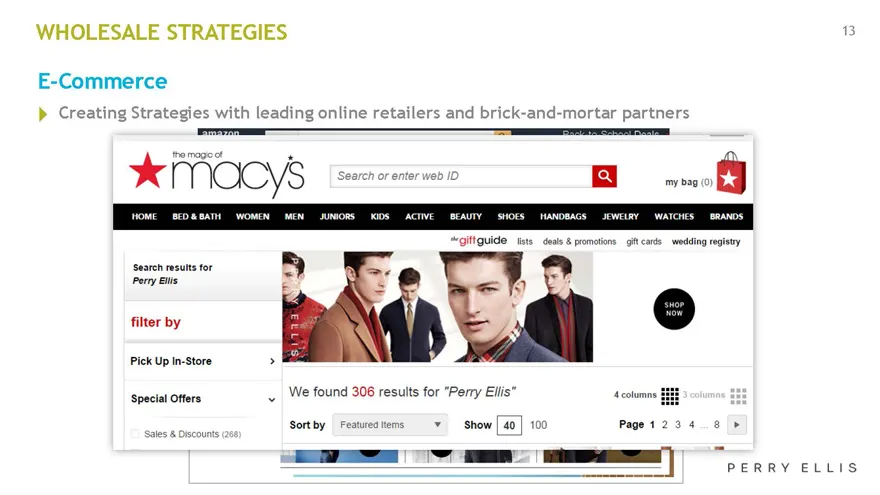
WHOLESALE STRATEGIES 13 E-Commerce Creating Strategies with leading online retailers and brick-and-mortar partners
Slide 14: Wholesale Strategies: Shop-in-Shop Investments
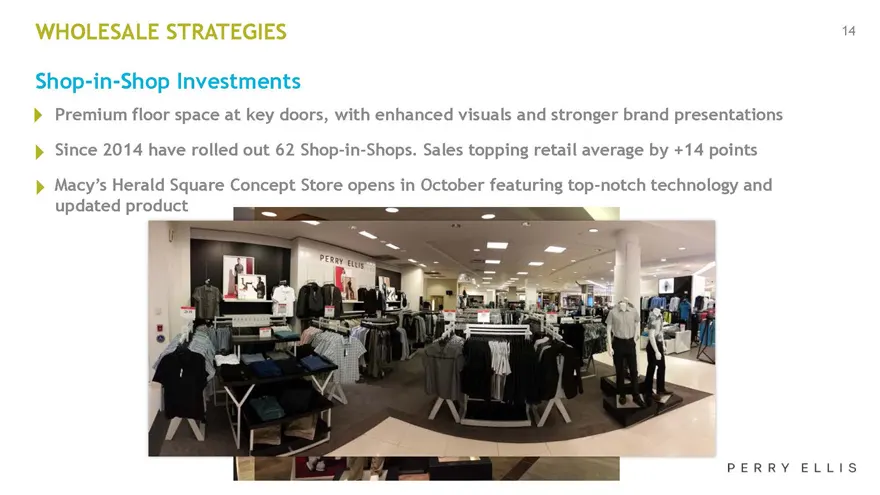
WHOLESALE STRATEGIES 14 Shop-in-Shop Investments Premium floor space at key doors, with enhanced visuals and stronger brand presentations Since 2014 have rolled out 62 Shop-in-Shops. Sales topping retail average by +14 points Macy’s Herald Square Concept Store opens in October featuring top-notch te
Slide 15: Product Strategies
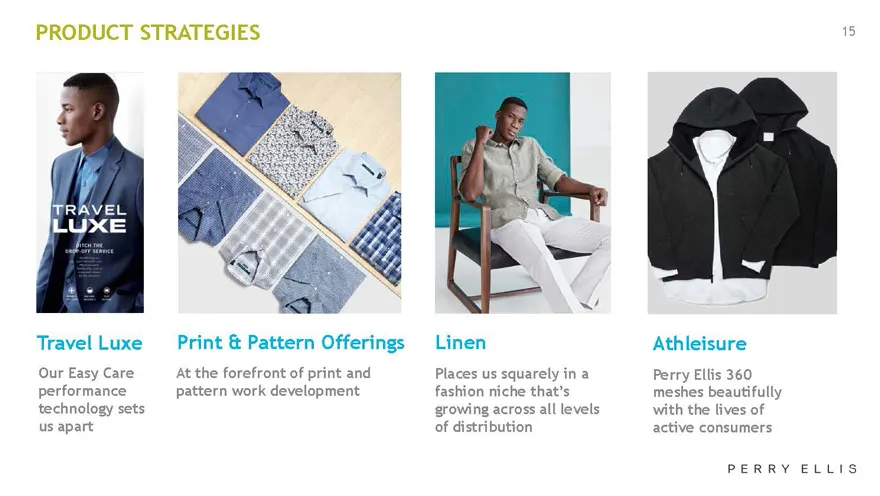
PRODUCT STRATEGIES 15 Travel Luxe Print & Pattern Offerings Linen Athleisure Our Easy Care At the forefront of print and Places us squarely in a Perry Ellis 360 performance pattern work development fashion niche that’s meshes beautifully technology sets growing across all levels with the lives of us
Slide 16: Omnichannel Global Marketing & Communication
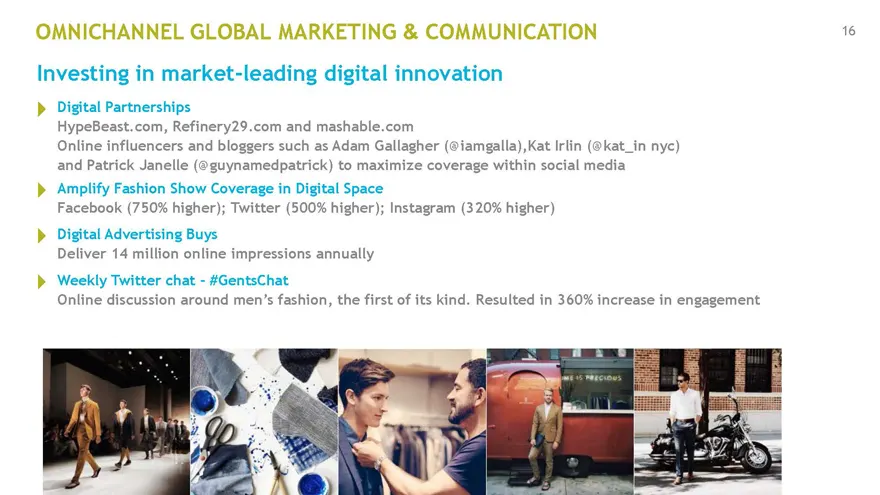
OMNICHANNEL GLOBAL MARKETING & COMMUNICATION 16 Investing in market-leading digital innovation Digital Partnerships HypeBeast.com, Refinery29.com and mashable.com Online influencers and bloggers such as Adam Gallagher (@iamgalla),Kat Irlin (@kat_in nyc) and Patrick Janelle (@guynamedpatrick) to maxi
Slide 17: Omnichannel Global Marketing & Communication
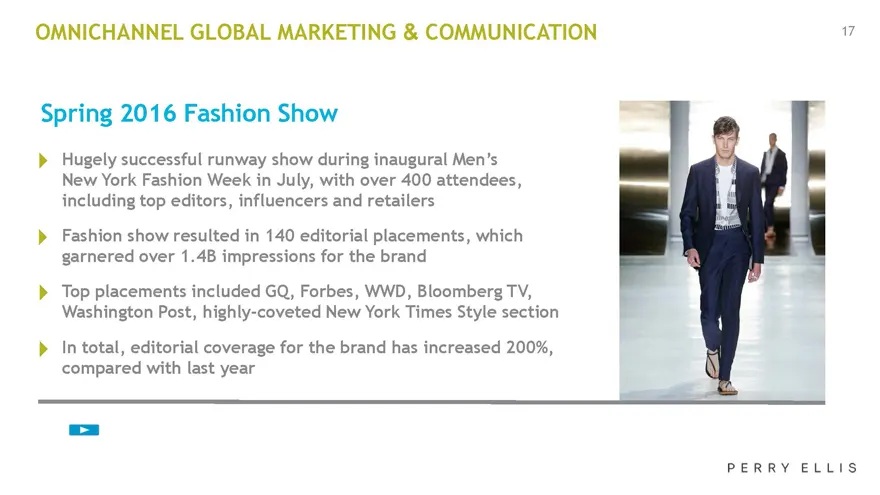
OMNICHANNEL GLOBAL MARKETING & COMMUNICATION 17 Spring 2016 Fashion Show Hugely successful runway show during inaugural Men’s New York Fashion Week in July, with over 400 attendees, including top editors, influencers and retailers Fashion show resulted in 140 editorial placements, which garnered ove
Slide 18: Direct-to-Consumer
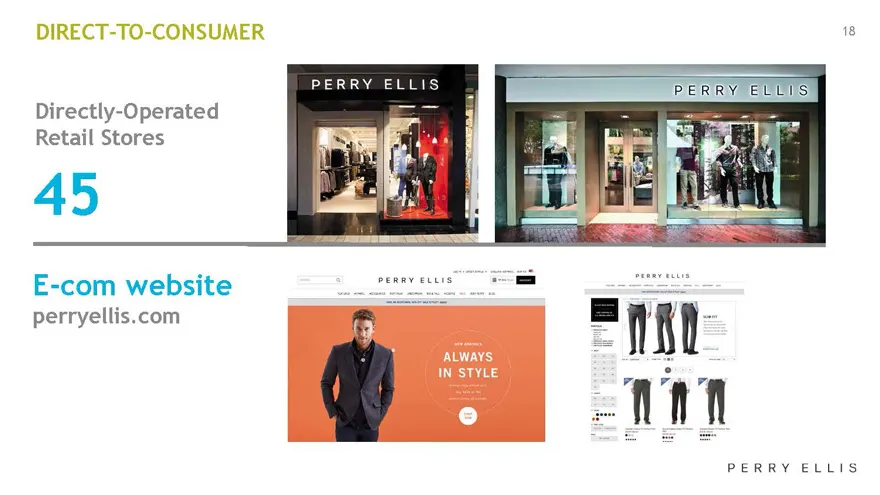
DIRECT-TO-CONSUMER 18 Directly-Operated Retail Stores E-com website perryellis.com
Slide 19: Direct-to-Consumer Strategic Initiatives
DIRECT-TO-CONSUMER 19 Strategic Initiatives Execute localized and climate-right assortment strategies Maximize Omnichannel experience and stores’ fulfillment of online orders Execute improved inventory management, driving faster turns and higher margins Retail excellence via superior systems and cus
Slide 20: Licensing Domestic and International
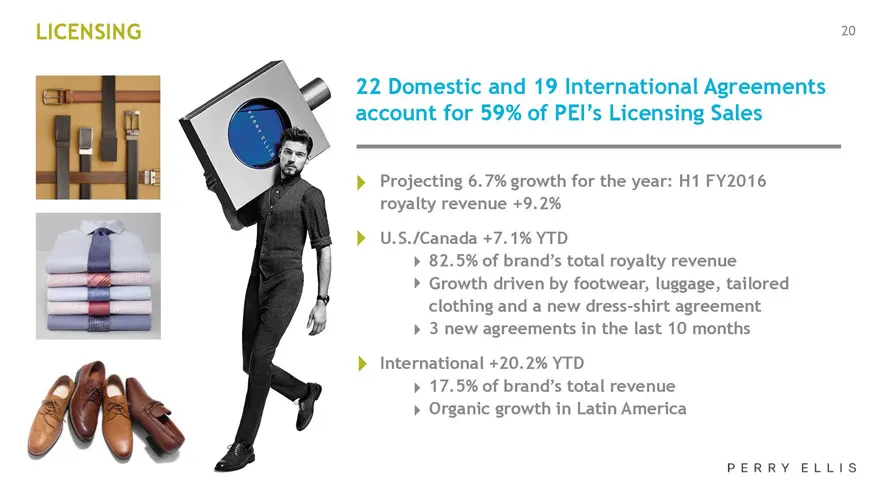
LICENSING 20 22 Domestic and 19 International Agreements account for 59% of PEI’s Licensing Sales Projecting 6.7% growth for the year: H1 FY2016 royalty revenue +9.2% U.S./Canada +7.1% YTD 82.5% of brand’s total royalty revenue Growth driven by footwear, luggage, tailored clothing and a new dress-sh
Slide 21: International Development Growth Opportunities
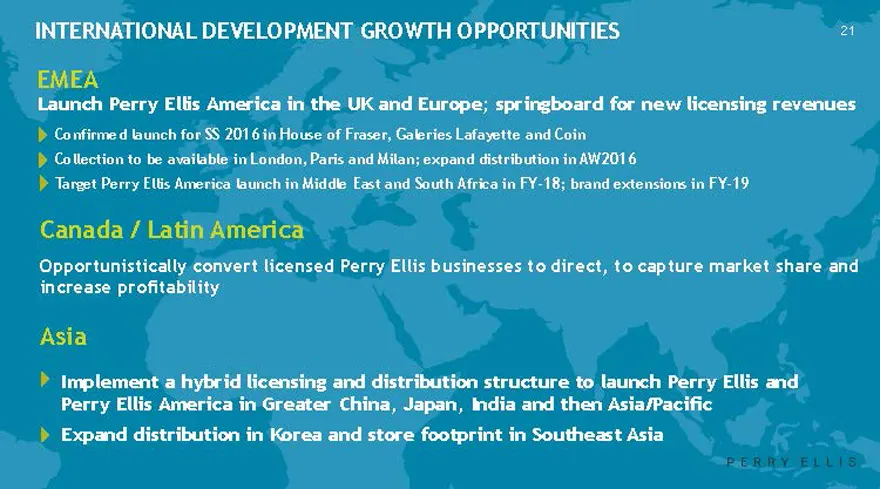
INTERNATIONAL DEVELOPMENT GROWTH OPPORTUNITIES 21 EMEA Launch Perry Ellis America in the UK and Europe; springboard for new licensing revenues Confirmed launch for SS 2016 in House of Fraser, Galeries Lafayette and Coin Collection to be available in London, Paris and Milan; expand distribution in AW
Slide 22
Slide 23: Original Penguin – Brand Portfolio
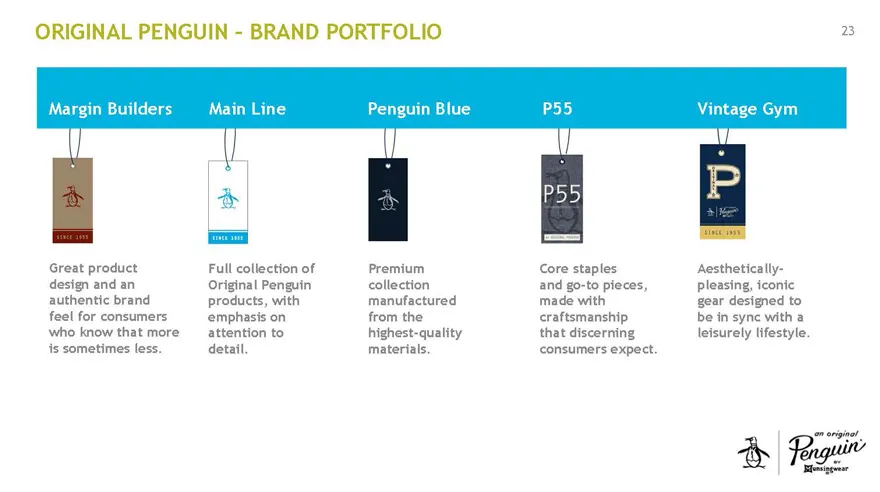
ORIGINAL PENGUIN – BRAND PORTFOLIO 23 Margin Builders Main Line Penguin Blue P55 Vintage Gym Great product Full collection of Premium Core staples Aesthetically- design and an Original Penguin collection and go-to pieces, pleasing, iconic authentic brand products, with manufactured made with gear de
Slide 24: Original Penguin – U.S. Wholesale Strategies
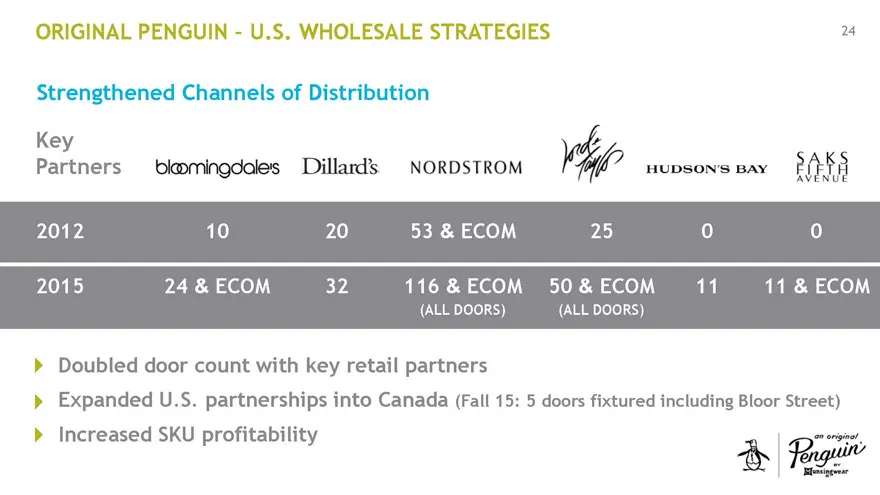
ORIGINAL PENGUIN – U.S. WHOLESALE STRATEGIES 24 Strengthened Channels of Distribution Key Partners 2012 10 20 53 & ECOM 25 0 0 2015 24 & ECOM 32 116 & ECOM 50 & ECOM 11 11 & ECOM (ALL DOORS) (ALL DOORS) Doubled door count with key retail partners Expanded U.S. partnerships into Canada (Fall 15: 5 do
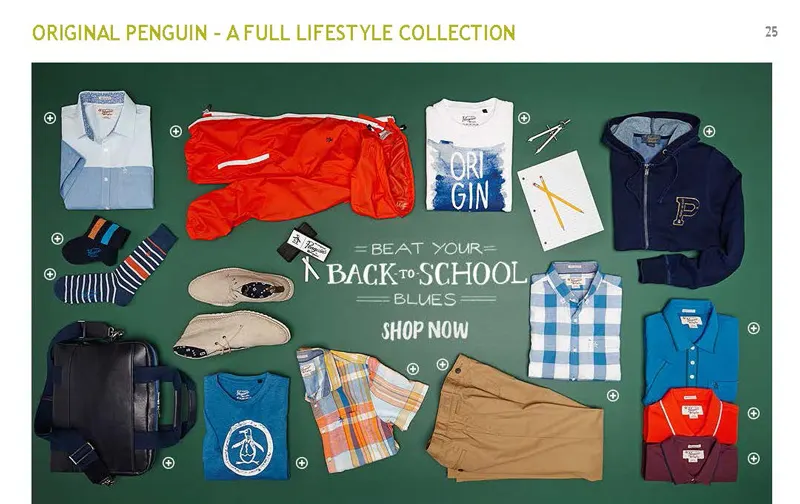
Slide 25: Original Penguin – A Full Lifestyle Collection
ORIGINAL PENGUIN – A FULL LIFESTYLE COLLECTION 25
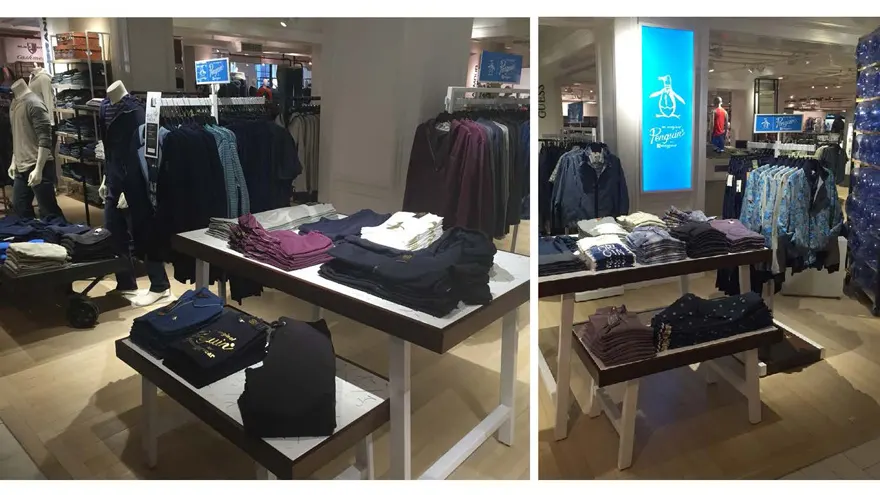
Slide 26
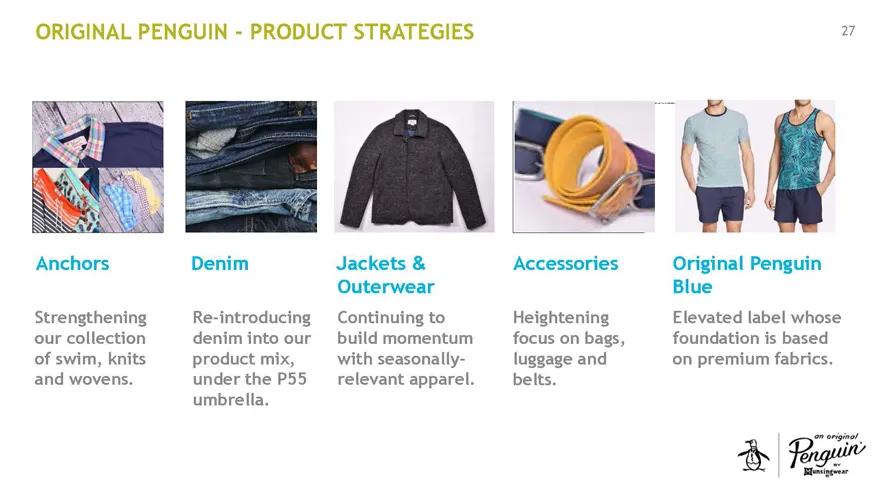
Slide 27: Original Penguin – Product Strategies
ORIGINAL PENGUIN—PRODUCT STRATEGIES 27 appears, you may have to delete the Anchors Denim Jackets & Accessories Original Penguin Outerwear Blue Strengthening Re-introducing Continuing to Heightening Elevated label whose our collection denim into our build momentum focus on bags, foundation is based o
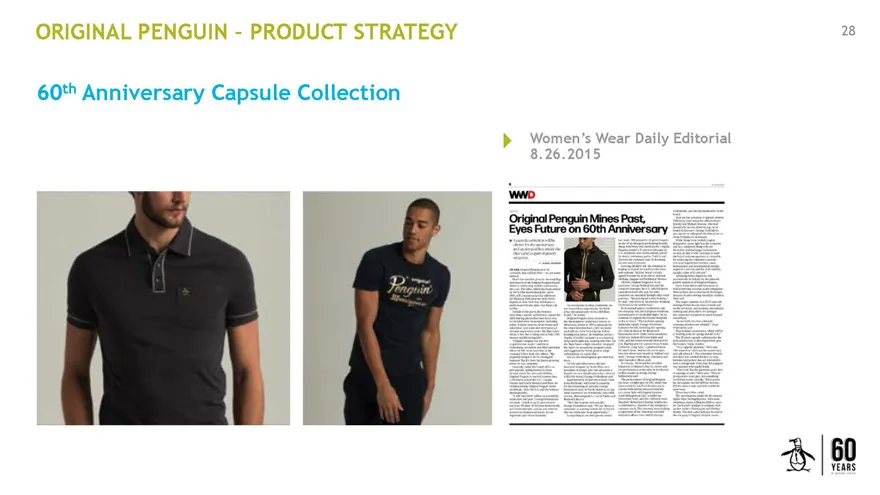
Slide 28: Original Penguin – Product Strategy
ORIGINAL PENGUIN – PRODUCT STRATEGY 28 60th Anniversary Capsule Collection Women’s Wear Daily Editorial 8.26.2015
Slide 29: Original Penguin Global Marketing & Communications Strategy
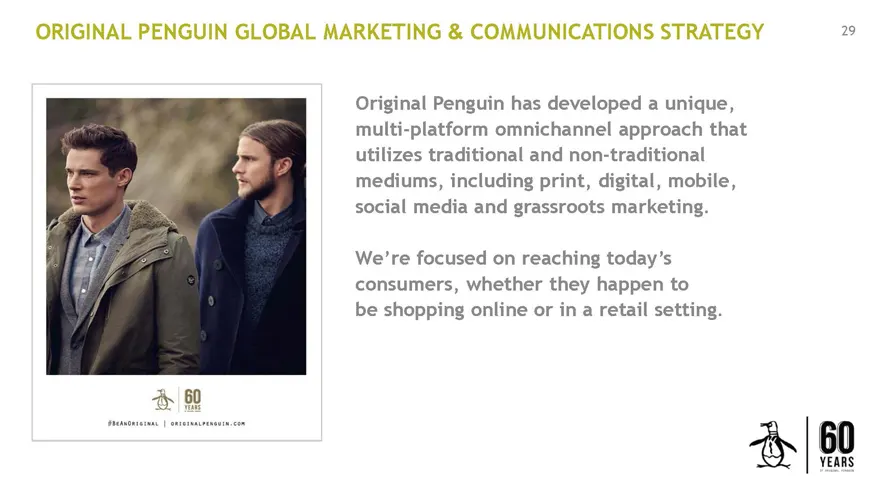
ORIGINAL PENGUIN GLOBAL MARKETING & COMMUNICATIONS STRATEGY 29 Original Penguin has developed a unique, multi-platform omnichannel approach that utilizes traditional and non-traditional mediums, including print, digital, mobile, social media and grassroots marketing. We’re focused on reaching today’
Slide 30: Original Penguin Sensory Marketing Music Strategy
ORIGINAL PENGUIN SENSORY MARKETING MUSIC STRATEGY 30 Partnership with Virgin/EMI Two iconic brands leveraging assets, creating a unique alliance to reach consumers Stunt event will launch campaign, creating buzz and newsworthy PR Video content will include interviews with key artists talking about t
Slide 31
Slide 32: Original Penguin – Direct to Consumer
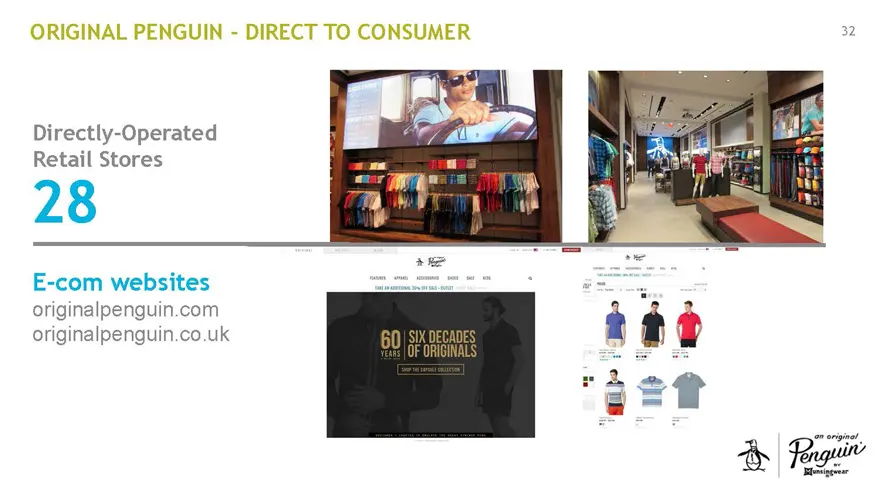
ORIGINAL PENGUIN—DIRECT TO CONSUMER 32 Directly-Operated Retail Stores E-com websites originalpenguin.com originalpenguin.co.uk
Slide 33: Original Penguin – U.S. Direct to Consumer
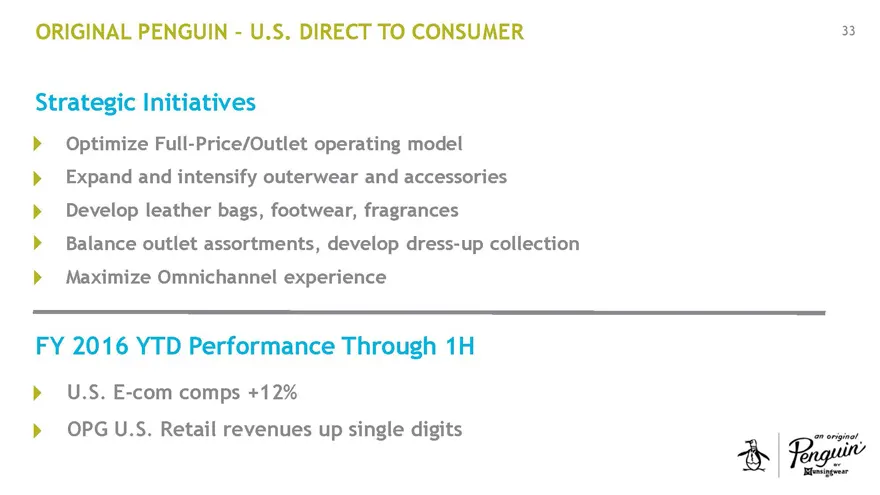
ORIGINAL PENGUIN – U.S. DIRECT TO CONSUMER 33 Strategic Initiatives Optimize Full-Price/Outlet operating model Expand and intensify outerwear and accessories Develop leather bags, footwear, fragrances Balance outlet assortments, develop dress-up collection Maximize Omnichannel experience FY 2016 YTD
Slide 34: Original Penguin – European Wholesale Overview
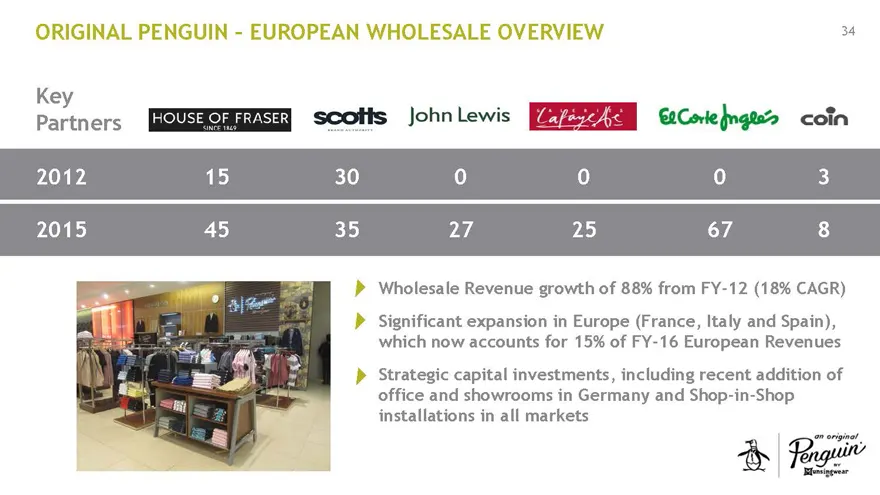
ORIGINAL PENGUIN – EUROPEAN WHOLESALE OVERVIEW 34 Key Partners 2012 15 30 0 0 0 3 2015 45 35 27 25 67 8 Wholesale Revenue growth of 88% from FY-12 (18% CAGR) Significant expansion in Europe (France, Italy and Spain), which now accounts for 15% of FY-16 European Revenues Strategic capital investments
Slide 35: Original Penguin – European Direct-to-Consumer Overview
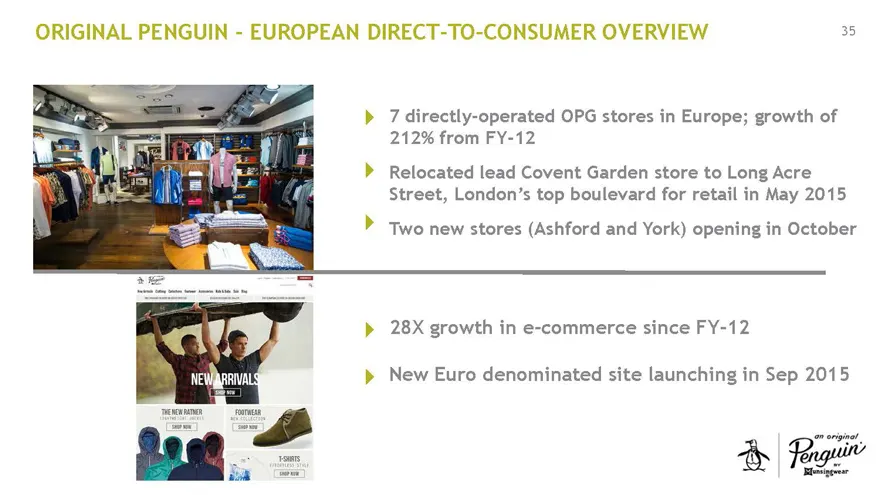
ORIGINAL PENGUIN—EUROPEAN DIRECT-TO-CONSUMER OVERVIEW 35 7 directly-operated OPG stores in Europe; growth of 212% from FY-12 Relocated lead Covent Garden store to Long Acre Street, London’s top boulevard for retail in May 2015 Two new stores (Ashford and York) opening in October 28X growth in e-comm
Slide 36: Original Penguin – Licensing Domestic and International
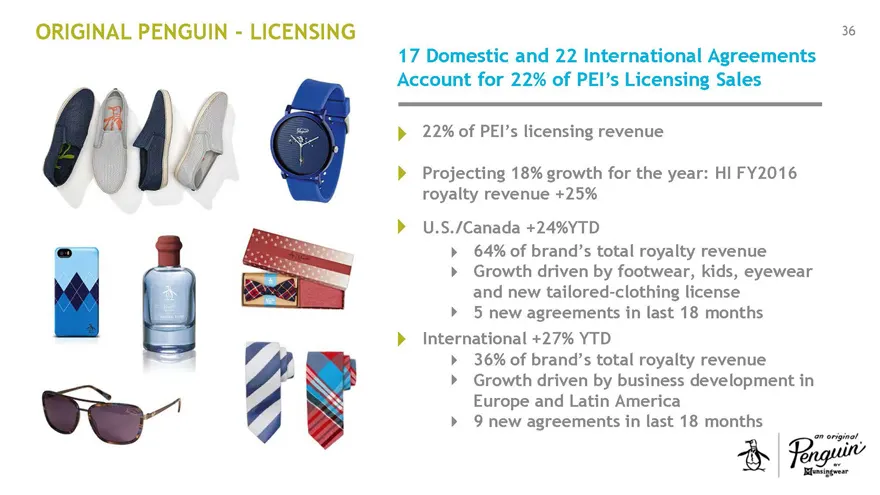
ORIGINAL PENGUIN—LICENSING 36 17 Domestic and 22 International Agreements Account for 22% of PEI’s Licensing Sales 22% of PEI’s licensing revenue Projecting 18% growth for the year: HI FY2016 royalty revenue +25% U.S./Canada +24%YTD 64% of brand’s total royalty revenue Growth driven by footwear, kid
Slide 37: International Development Growth Opportunities
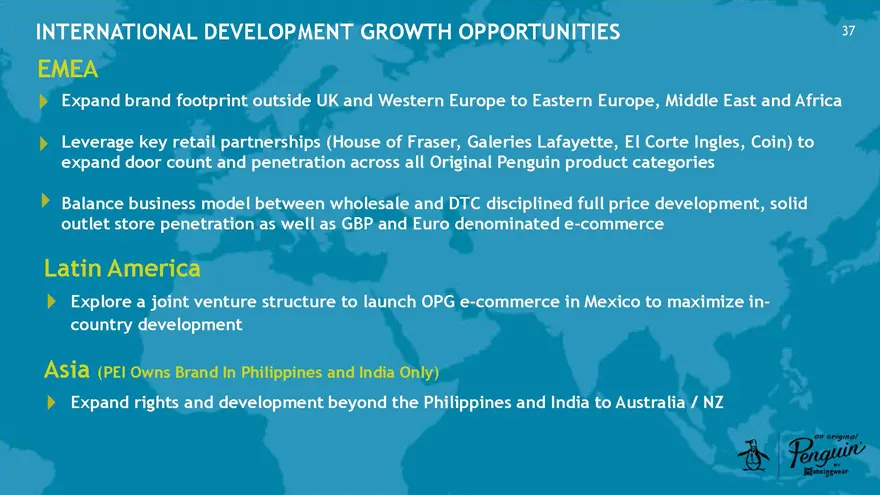
INTERNATIONAL DEVELOPMENT GROWTH OPPORTUNITIES 37 EMEA Expand brand footprint outside UK and Western Europe to Eastern Europe, Middle East and Africa Leverage key retail partnerships (House of Fraser, Galeries Lafayette, El Corte Ingles, Coin) to expand door count and penetration across all Original
Slide 38: PEI Golf
PEI GOLF PERRYCELLIS INTERNATIONAL
Slide 39: PEI Golf – A Tremendous Growth Story
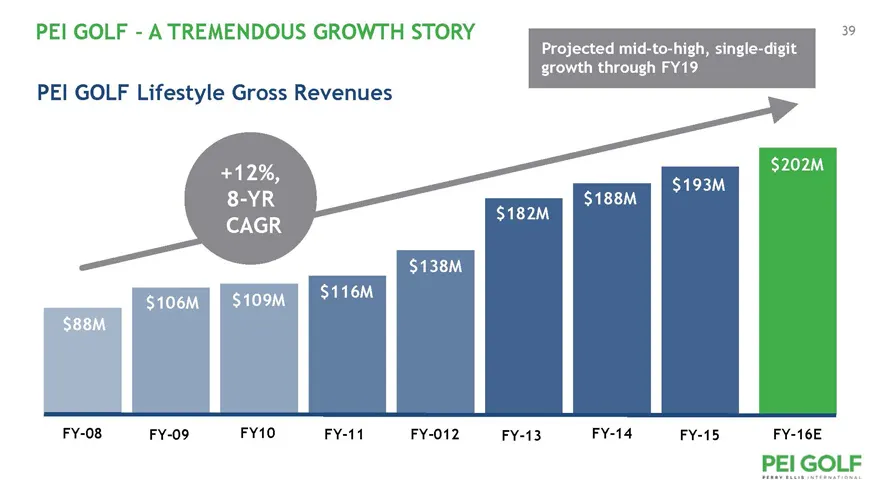
PEI GOLF – A TREMENDOUS GROWTH STORY 39 Projected mid-to-high, single-digit growth through FY19 PEI GOLF Lifestyle Gross Revenues +12%, $202M $193M 8-YR $188M $182M CAGR $138M $109M $116M $106M $88M FY-08 FY-09 FY10 FY-11 FY-012 FY-13 FY-14 FY-15 FY-16E
Slide 40: Global Portfolio of Golf Lifestyle Brands
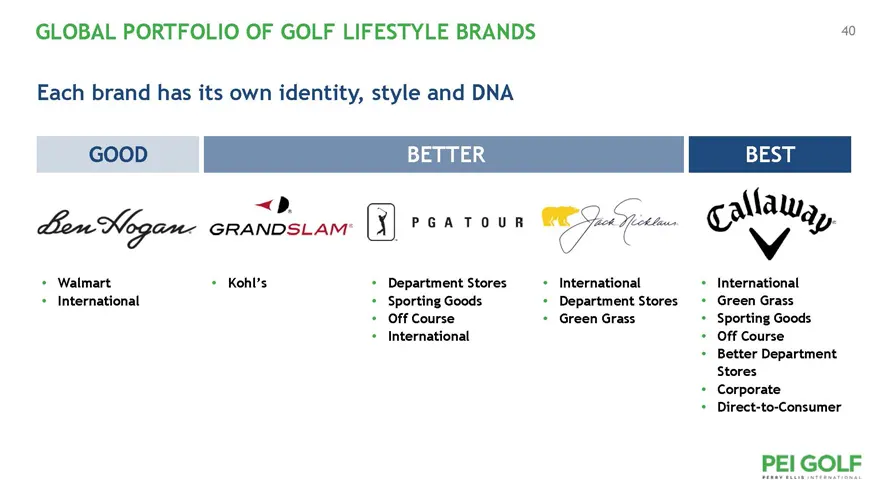
GLOBAL PORTFOLIO OF GOLF LIFESTYLE BRANDS 40 Each brand has its own identity, style and DNA GOOD BETTER BEST Walmart Kohl’s Department Stores International International International Sporting Goods Department Stores Green Grass Off Course Green Grass Sporting Goods International Off Course Better D
Slide 41: Door Growth
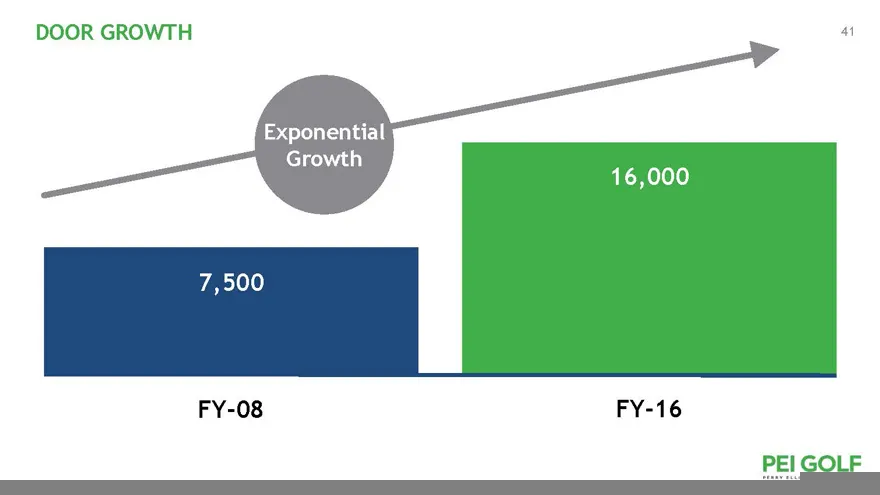
DOOR GROWTH 41 Exponential Growth 16,000 7,500 FY-08 FY-16
Slide 42: Channel Diversification Expansion Within Authentic Golf Landscape
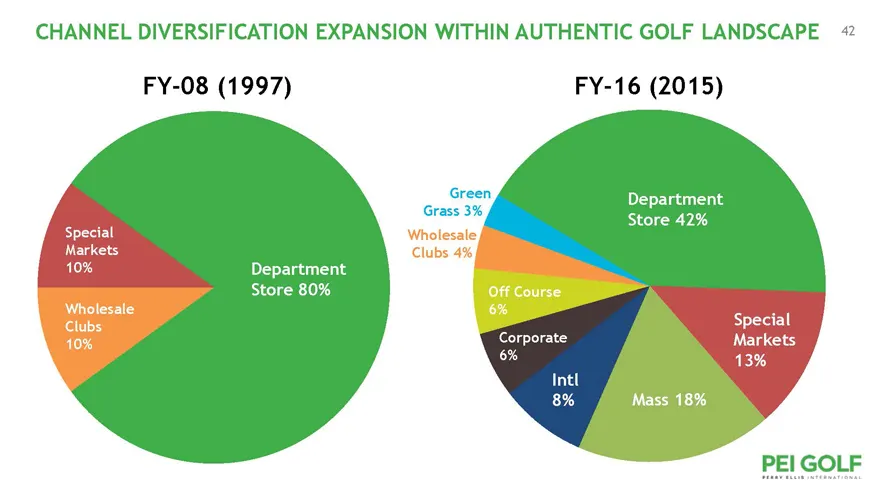
CHANNEL DIVERSIFICATION EXPANSION WITHIN AUTHENTIC GOLF LANDSCAPE 42 FY-08 (1997) FY-16 (2015) eComm XX Green Department Grass 3% Store 42% Special Wholesale Markets Clubs 4% 10% Department Store 80% Off Course Wholesale 6% Clubs Special 10% Corporate Markets 6% 13% Intl 8% Mass 18%
Slide 43: PEI Golf, Leading the Evolution of Golf Lifestyle Apparel
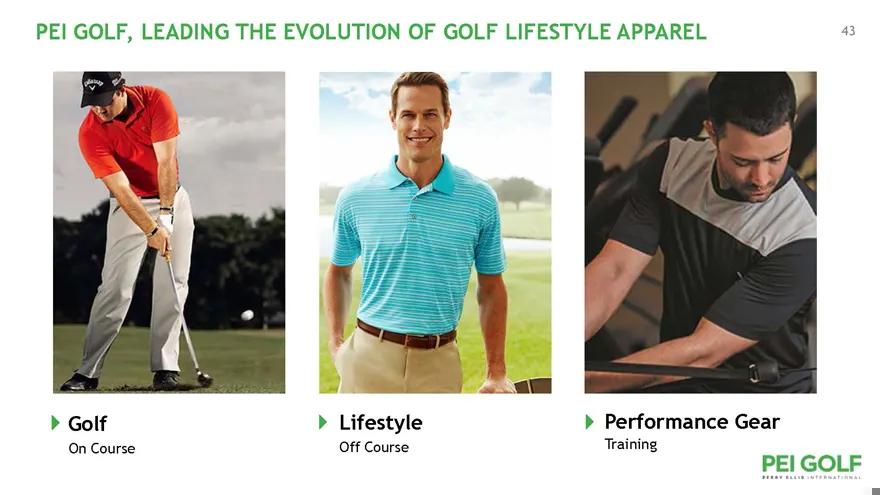
PEI GOLF, LEADING THE EVOLUTION OF GOLF LIFESTYLE APPAREL 43 Golf Lifestyle Performance Gear On Course Off Course Training
Slide 44: Product Technology
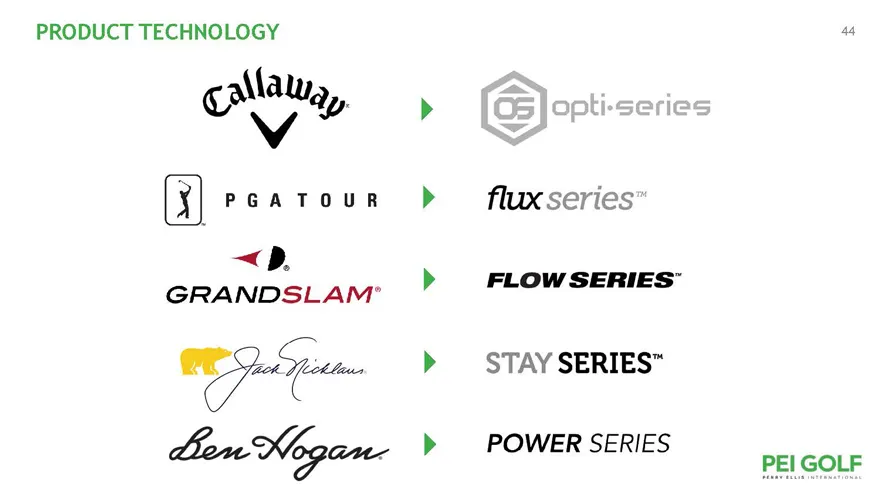
PRODUCT TECHNOLOGY 44 [x] ecatour >» fluxseries ~<D. GRANDSLAM: > FLOWSERIES" re. bast > STAY SERIES™ Lion Mogan > POWER SERIES PEI GOLF
Slide 45: Performance Gear
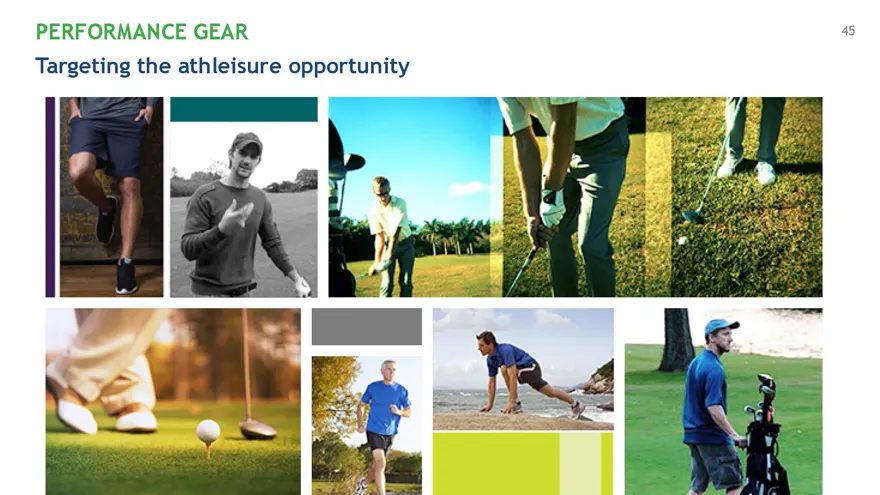
PERFORMANCE GEAR 45 Targeting the athleisure opportunity
Slide 46: Women's Lifestyle: Golf, Active, Leisure (GAL)
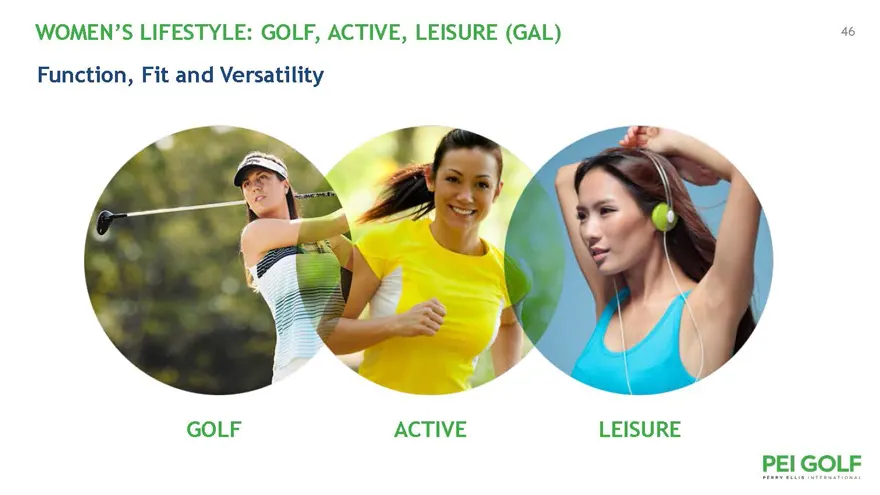
WOMEN’S LIFESTYLE: GOLF, ACTIVE, LEISURE (GAL) 46 Function, Fit and Versatility GOLF ACTIVE LEISURE
Slide 47: Marketing Strategy
MARKETING STRATEGY 47 Key Initiatives TOUR Player Activation with over 30 high-profile players PGA TOUR, Web.com TOUR, Champions TOUR, European TOUR, LPGA TOUR National and Regional media and blogger outreach Editorial coverage garnering 6.5M impressions Social media fan engagement Promotions have g
Slide 48: Tour Player Activation
TOUR PLAYER ACTIVATION PE! GOLF PERRY ELLIS INTERNATIONAL
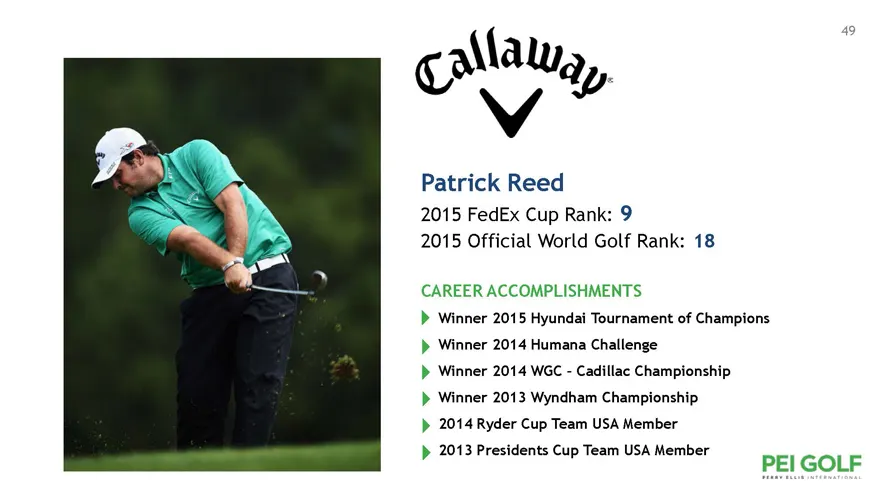
Slide 49: Patrick Reed
Patrick Reed 2015 FedEx Cup Rank: 9 2015 Official World Golf Rank: 18 CAREER ACCOMPLISHMENTS Winner 2015 Hyundai Tournament of Champions Winner 2014 Humana Challenge Winner 2014 WGC – Cadillac Championship Winner 2013 Wyndham Championship 2014 Ryder Cup Team USA Member 2013 Presidents Cup Team USA M
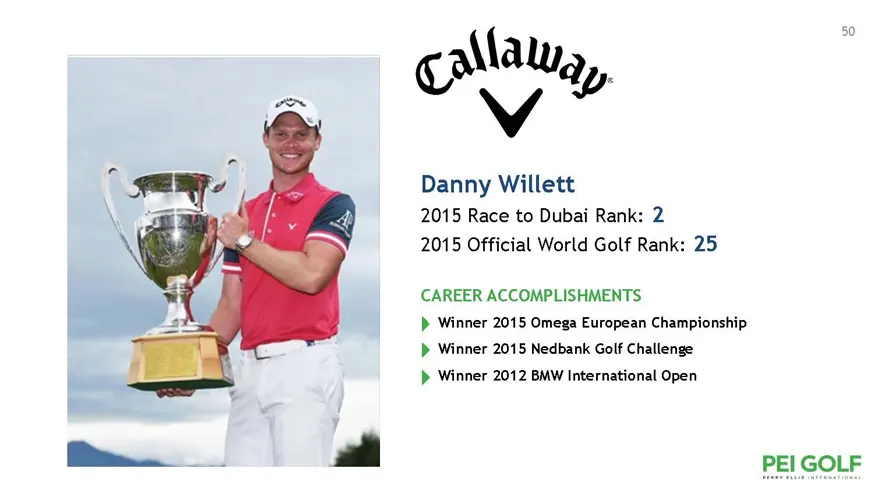
Slide 50: Danny Willett
Danny Willett 2015 Race to Dubai Rank: 2 2015 Official World Golf Rank: 25 CAREER ACCOMPLISHMENTS Winner 2015 Omega European Championship Winner 2015 Nedbank Golf Challenge Winner 2012 BMW International Open
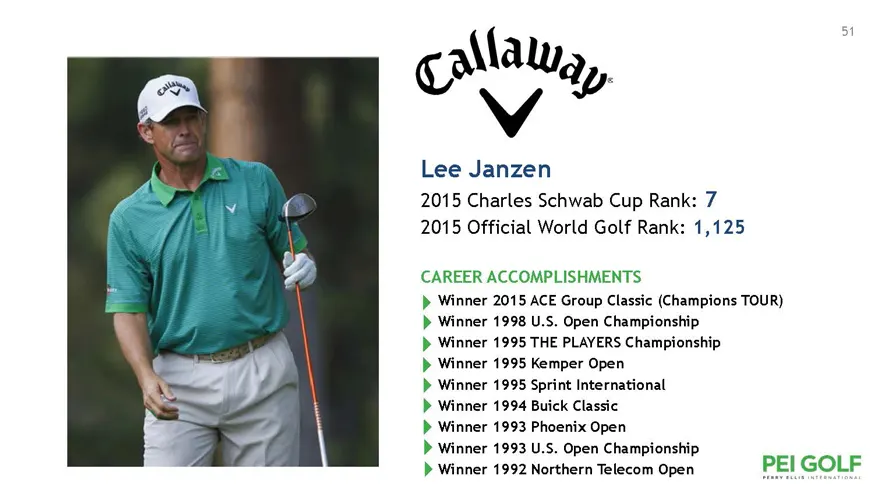
Slide 51: Lee Janzen
Lee Janzen 2015 Charles Schwab Cup Rank: 7 2015 Official World Golf Rank: 1,125 CAREER ACCOMPLISHMENTS Winner 2015 ACE Group Classic (Champions TOUR) Winner 1998 U.S. Open Championship Winner 1995 THE PLAYERS Championship Winner 1995 Kemper Open Winner 1995 Sprint International Winner 1994 Buick Cla
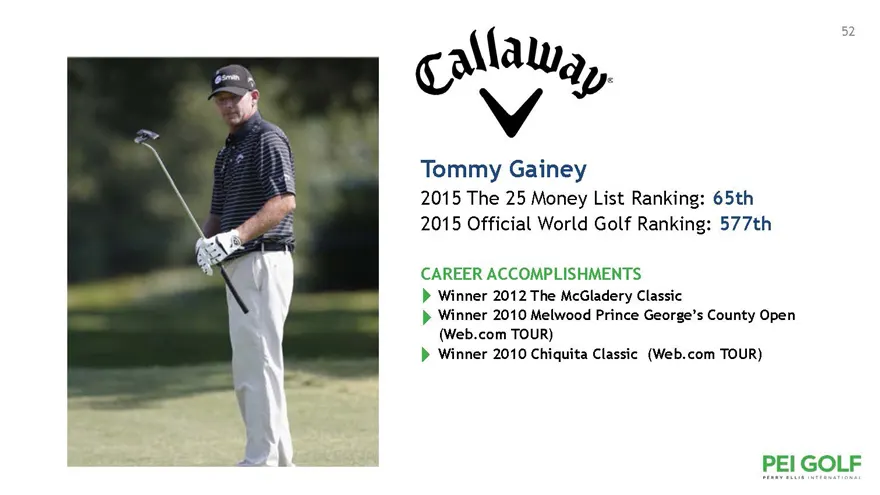
Slide 52: Tommy Gainey
Tommy Gainey 2015 The 25 Money List Ranking: 65th 2015 Official World Golf Ranking: 577th CAREER ACCOMPLISHMENTS Winner 2012 The McGladery Classic Winner 2010 Melwood Prince George’s County Open (Web.com TOUR) Winner 2010 Chiquita Classic (Web.com TOUR)
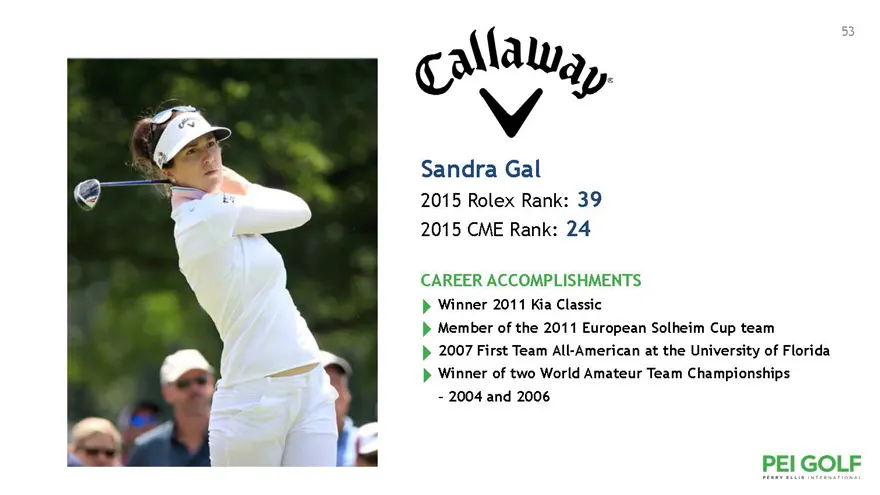
Slide 53: Sandra Gal
Sandra Gal 2015 Rolex Rank: 39 2015 CME Rank: 24 CAREER ACCOMPLISHMENTS Winner 2011 Kia Classic Member of the 2011 European Solheim Cup team 2007 First Team All-American at the University of Florida Winner of two World Amateur Team Championships – 2004 and 2006
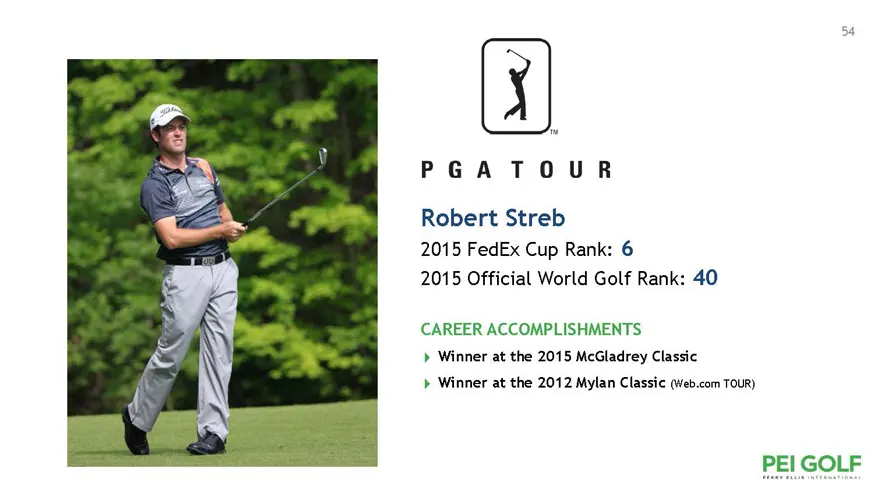
Slide 54: Robert Streb
Robert Streb 2015 FedEx Cup Rank: 6 2015 Official World Golf Rank: 40 CAREER ACCOMPLISHMENTS Winner at the 2015 McGladrey Classic Winner at the 2012 Mylan Classic (Web.com TOUR)
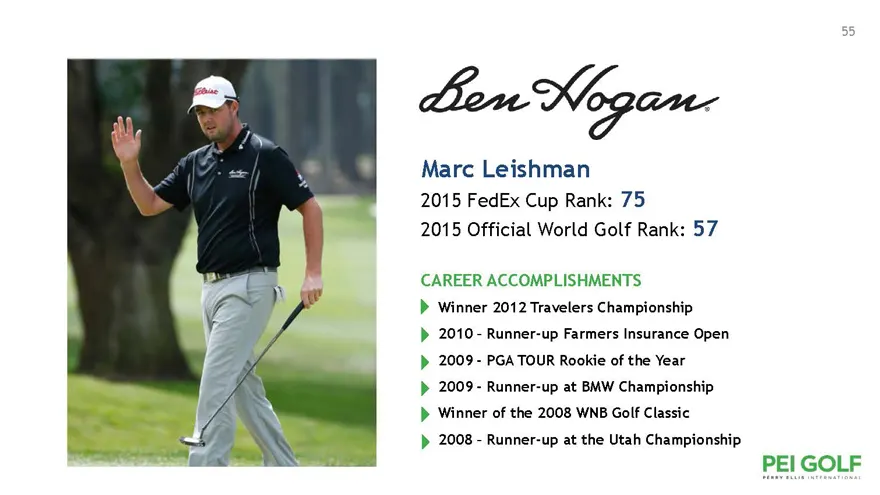
Slide 55: Marc Leishman
Marc Leishman 2015 FedEx Cup Rank: 75 2015 Official World Golf Rank: 57 CAREER ACCOMPLISHMENTS Winner 2012 Travelers Championship 2010 – Runner-up Farmers Insurance Open 2009—PGA TOUR Rookie of the Year 2009—Runner-up at BMW Championship Winner of the 2008 WNB Golf Classic 2008 – Runner-up at the Ut
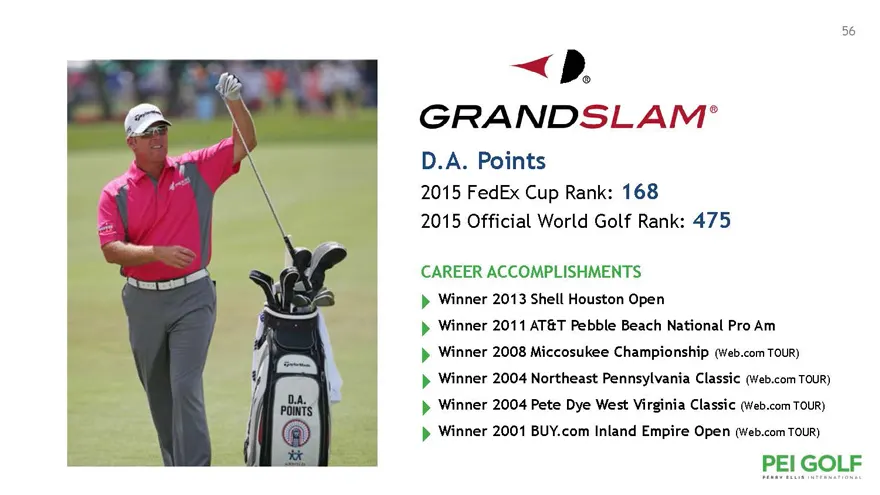
Slide 56: D.A. Points
D.A. Points 2015 FedEx Cup Rank: 168 2015 Official World Golf Rank: 475 CAREER ACCOMPLISHMENTS Winner 2013 Shell Houston Open Winner 2011 AT&T Pebble Beach National Pro Am Winner 2008 Miccosukee Championship (Web.com TOUR) Winner 2004 Northeast Pennsylvania Classic (Web.com TOUR) Winner 2004 Pete Dy
Slide 57: In-Store Visual Experience
IN-STORE VISUAL EXPERIENCE
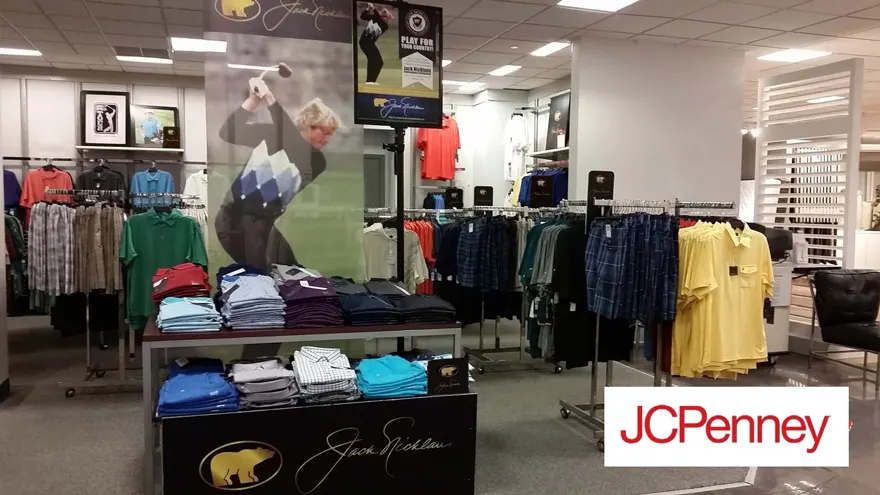
Slide 58: JCPenney
la ee JCPenney |
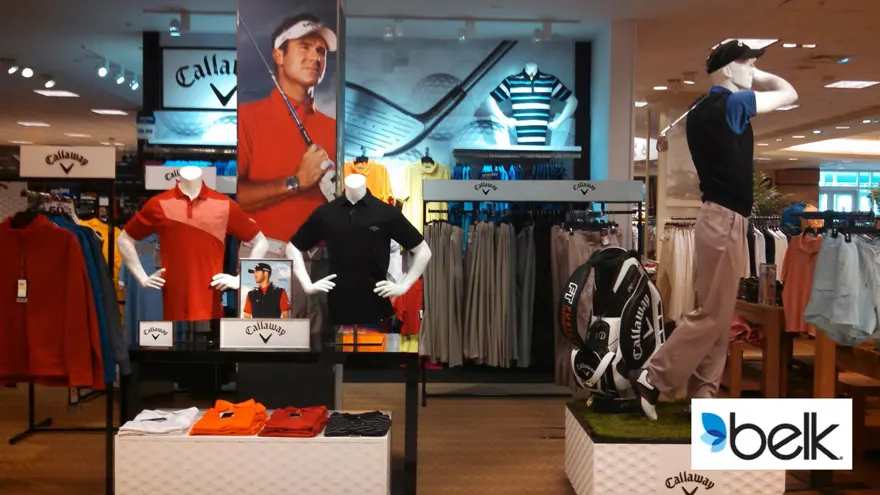
Slide 59
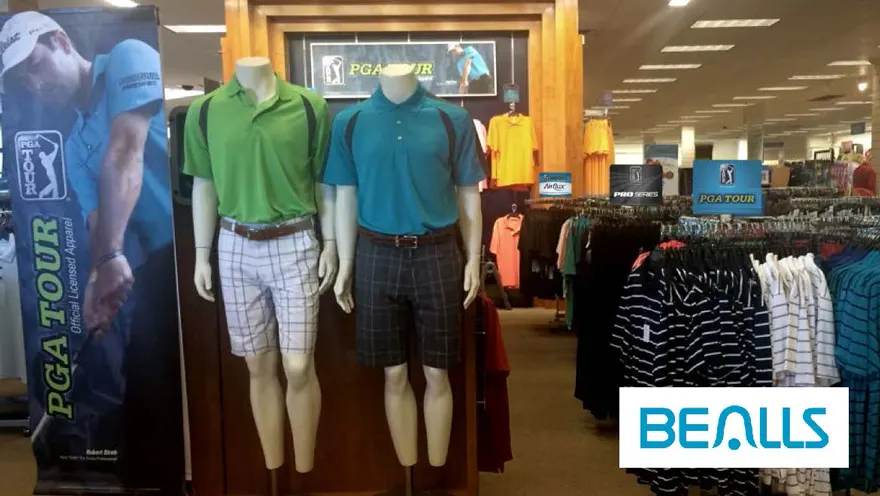
Slide 60
Slide 61
Slide 62: Financial Highlights
FINANCIAL HIGHLIGHTS 62 Anita Britt Chief Financial Officer
Slide 63: Strong 1H Fiscal 2016 Results
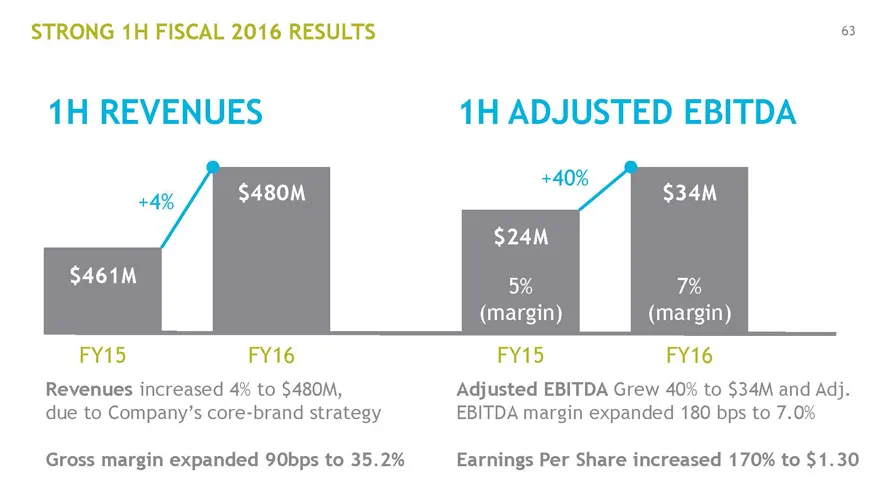
STRONG 1H FISCAL 2016 RESULTS 63 1H REVENUES 1H ADJUSTED EBITDA +40% +4% $480M $34M $24M $461M 5% 7% (margin) (margin) FY15 FY16 FY15 FY16 Revenues increased 4% to $480M, Adjusted EBITDA Grew 40% to $34M and Adj. due to Company’s core-brand strategy EBITDA margin expanded 180 bps to 7.0% Gross margi
Slide 64: Capitalization Summary
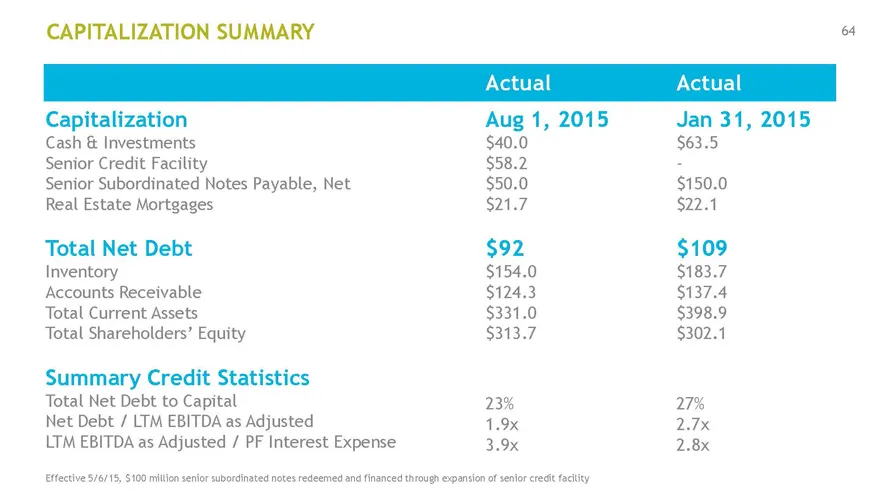
CAPITALIZATION SUMMARY 64 Actual Actual Capitalization Aug 1, 2015 Jan 31, 2015 Cash & Investments $ 40.0 $63.5 Senior Credit Facility $ 58.2 — Senior Subordinated Notes Payable, Net $ 50.0 $150.0 Real Estate Mortgages $ 21.7 $22.1 Total Net Debt $92 $109 Inventory $ 154.0 $183.7 Accounts Receivable
Slide 65: Financial Outlook
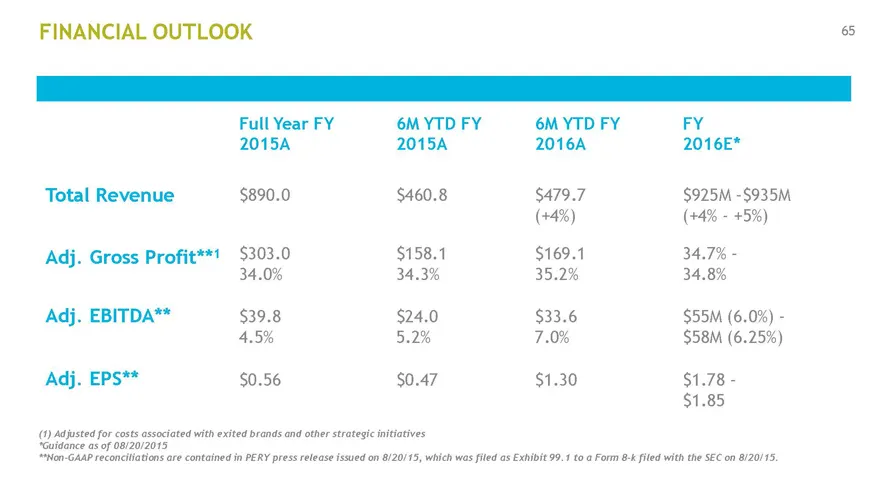
FINANCIAL OUTLOOK 65 Full Year FY 6M YTD FY 6M YTD FY FY 2015A 2015A 2016A 2016E* Total Revenue $890.0 $460.8 $479.7 $925M –$935M (+4%) (+4%—+5%) Adj. Gross Profit**1 $303.0 $158.1 $169.1 34.7% – 34.0% 34.3% 35.2% 34.8% Adj. EBITDA** $39.8 $24.0 $33.6 $55M (6.0%) – 4.5% 5.2% 7.0% $58M (6.25%) Adj. E
Slide 66: Financial Outlook
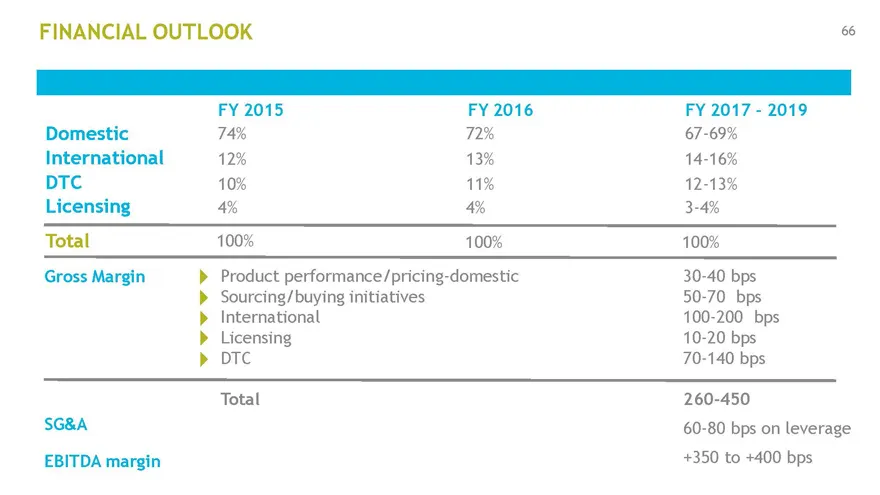
FINANCIAL OUTLOOK 66 FY 2015 FY 2016 FY 2017—2019 Domestic 74% 72% 67-69% International 12% 13% 14-16% DTC 10% 11% 12-13% Licensing 4% 4% 3-4% Total 100% 100% 100% Gross Margin Product performance/pricing-domestic 30-40 bps Sourcing/buying initiatives 50-70 bps International 100-200 bps Licensing 10
Slide 67: Strategic Cost Savings & Operating Efficiencies
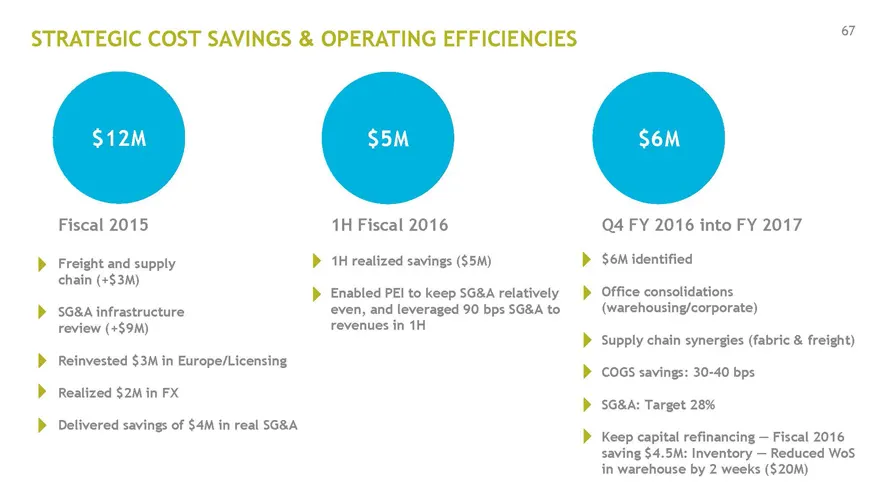
STRATEGIC COST SAVINGS & OPERATING EFFICIENCIES 67 $12M $5M $6M Fiscal 2015 1H Fiscal 2016 Q4 FY 2016 into FY 2017 Freight and supply 1H realized savings ($5M) $6M identified chain (+$3M) Enabled PEI to keep SG&A relatively Office consolidations SG&A infrastructure even, and leveraged 90 bps SG&A to
Slide 68: Performing, Elevating, Reaping, Yielding
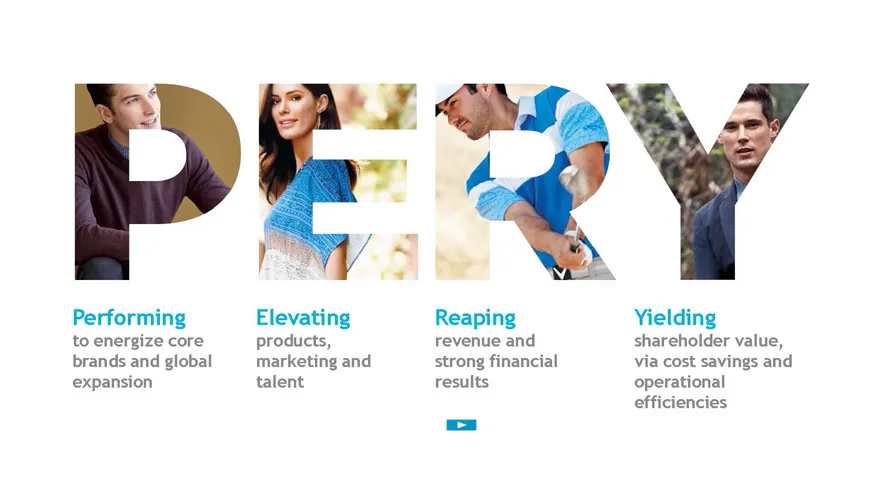
Performing Elevating Reaping Yielding to energize core products, revenue and shareholder value, brands and global marketing and strong financial via cost savings and expansion talent results operational efficiencies
Source: SEC EDGAR · 8-K filed Sep 11, 2015