Legacy Reserves LP — Wachovia Pipeline & MLP Conference 2007
23 slides from Legacy Reserves LP's conference presentation, Dec 6, 2007
Slide 1: Wachovia Pipeline & MLP Conference December 6, 2007
Wachovia Pipeline & MLP Conference December 6, 2007 Legacy Reserves LP
Slide 2: Forward-Looking Statements
Forward-Looking Statements Statements made by representatives of Legacy Reserves LP (the “Partnership”) during the course of this presentation that are not historical facts are forward-looking statements. These statements are based on certain assumptions made by the Partnership based on management’s
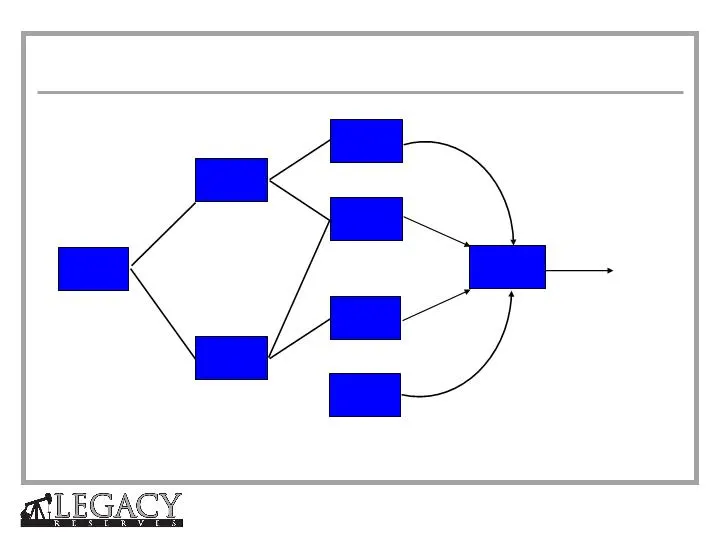
Slide 3: Legacy History
Other Related Entities Brothers Production Company Brothers Moriah Brothers MBN Moriah Legacy Dale Brown & Jack McGraw form company Cary & Dale Brown form Moriah Formation Transaction Through Private Placement 1981 1991 2005 March 2006 January 2007 IPO Kyle McGraw & Cary Brown Assume Management Prue
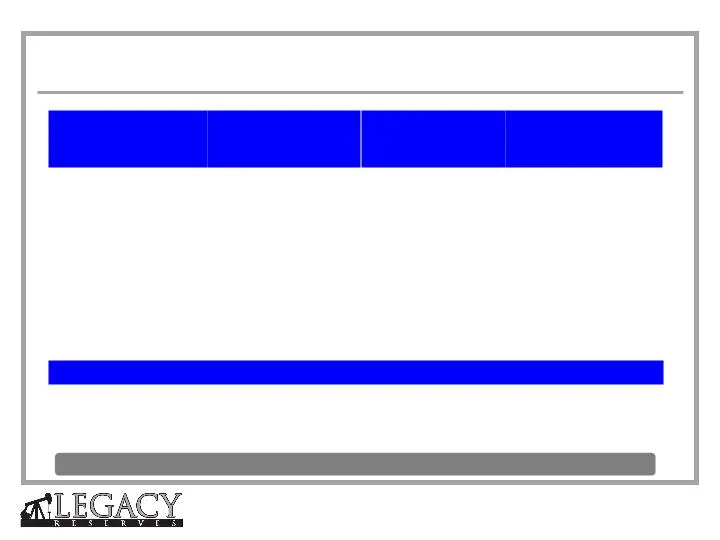
Slide 4: Legacy Management Team
Name Title Years Experience in the Permian Basin Years Experience in the Oil & Gas Industry Independent Board Members Cary D. Brown, CPA Chairman & CEO Steven H. Pruett President & CFO Kyle A. McGraw EVP, Business Development & Land Paul T. Horne VP, Operations William M. Morris, CPA VP, Controller
Slide 5: ig Horn
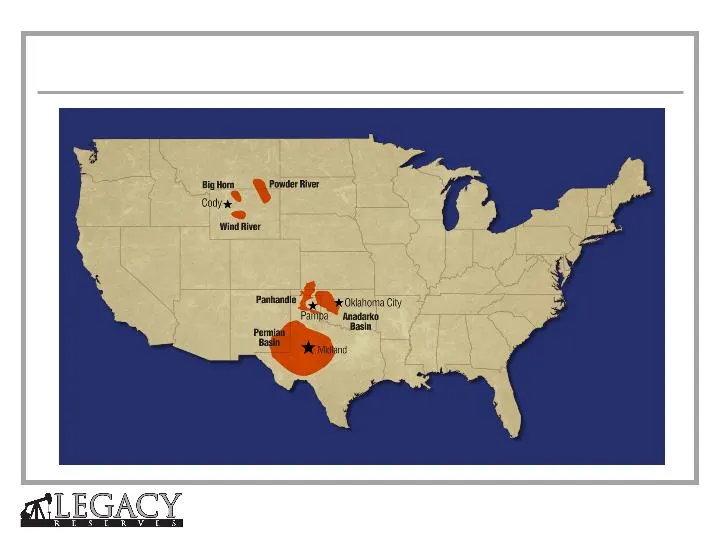
ig Horn Coda Wind River Pannandle FM osanora iy Patna = anadacko es
Slide 6: Legacy Base Asset Overview
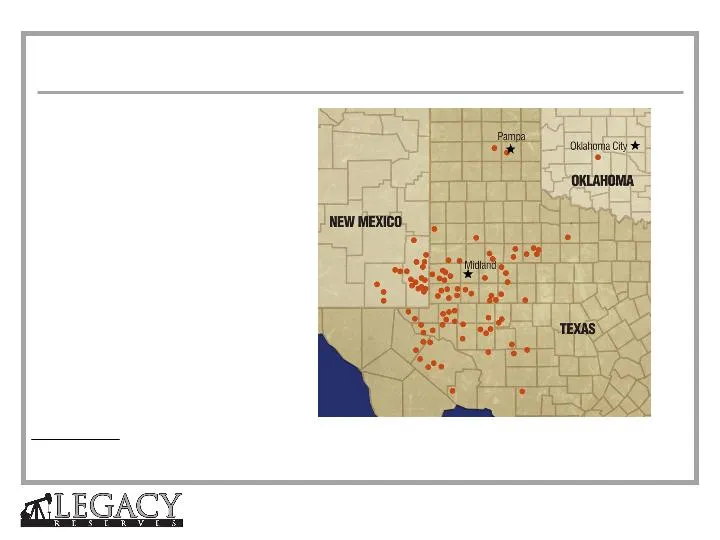
(1) Taken from reserve reports prepared by LaRoche Petroleum Consultants, Ltd. as of 12/31/06 for Legacy Reserves LP plus proved reserves from 2007 acquisitions from internal reserve reports: Binger (4.1 MMBoe), TSF/Ameristate (1.4 MMBoe), Slaughter/Rocker A (1.0 MMBoe), Raven (1.2 MMBoe), TOC (4.0
Slide 7: Stable Platform: Why the Permian Basin?
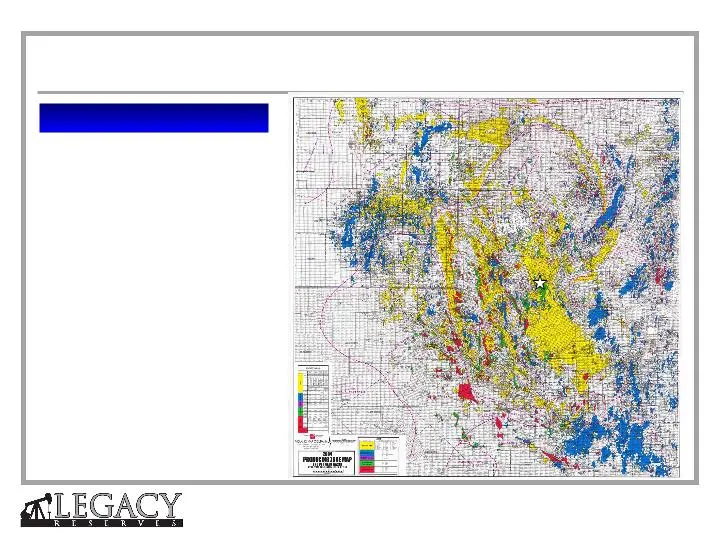
Stable Platform (1) Source: http://www.utpb.edu Map Source: Midland Map Company. Why the Permian Basin? q Over 24 BBbls produced since 1921 q Represents 20% of lower 48 states and 68% of Texas oil production (1) q Multiple producing formations q Established infrastructure and ample take-away capacit
Slide 8: Consolidation Opportunities in the Permian Basin
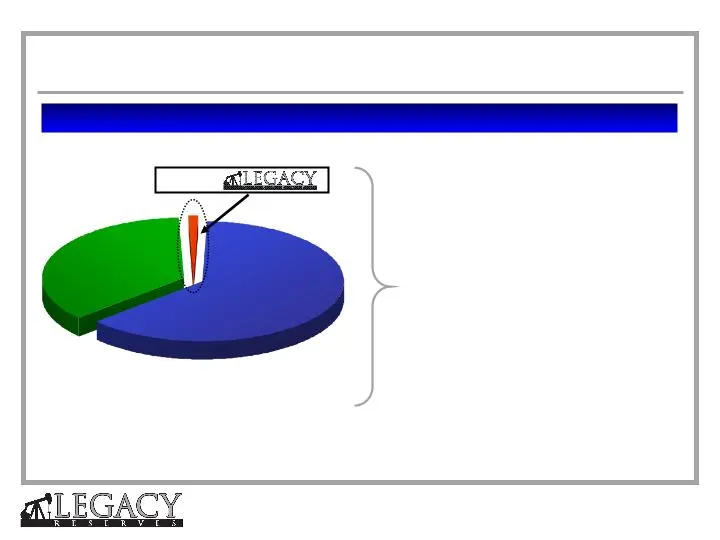
Top 5 Operators 1,700+ Operators Permian Basin Ownership Profile (1) 0.3% (1) Ownership based on production. Permian Basin includes Texas Railroad Commission Districts 7C, 8, 8A and Lea and Eddy County, New Mexico. Permian Basin data as of July 31, 2005; Legacy production data as of September 30, 20
Slide 9: Legacy & Predecessor Acquisition History
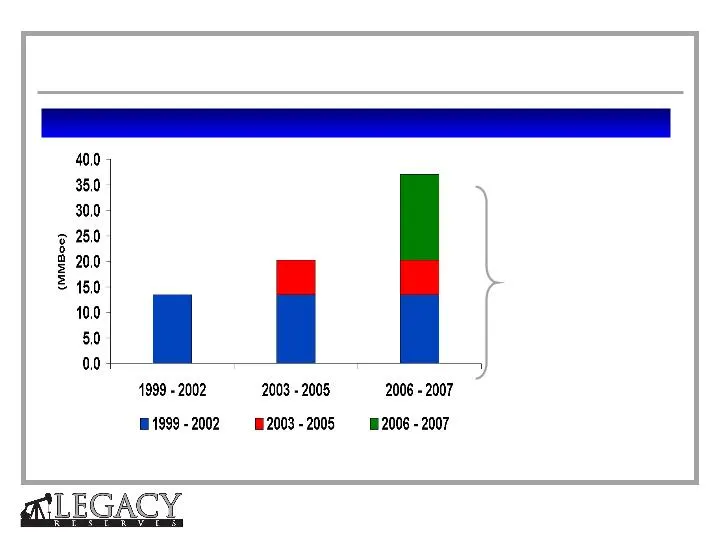
6.8 13.4 6.8 13.4 16.8 Acquired Reserves (1999 - 2007) $339 million of purchases at an average cost of $9.18 per Boe of proved reserves in over 39 deals 13.4 20.2 37.0 Legacy & Predecessor Acquisition History
Slide 10: Legacy 2007 YTD Acquisitions
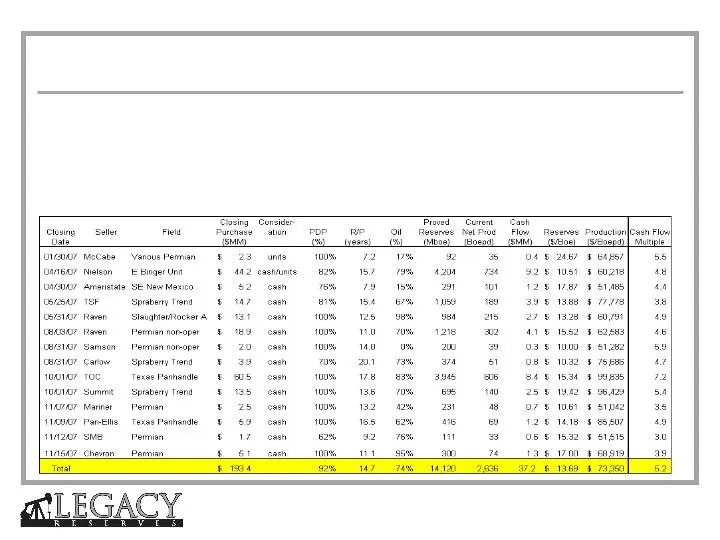
Legacy 2007 YTD Acquisitions q Closed $193 million of acquisitions in 2007 q Fourteen negotiated transactions averaging: – $13.69 per Boe of proved reserves – 92% PDP, R/P ratio of 14.7 years – $73,350 per Boepd – 5.2 times cash flow
Slide 11: Financial Summary
Financial Summary
Slide 12: Financial and Operating Data - Latest Twelve Months
Financial and Operating Data - Latest Twelve Months q Third Quarter earnings continue solid growth trend – 14.4% sequential volume growth over Q2 – Q3 production, revenue, distributable cash flow, and adjusted EBITDA exceeded analyst estimates – Q3 does not include contribution from Panhandle, Summi
Slide 13: Pro Forma Capitalization
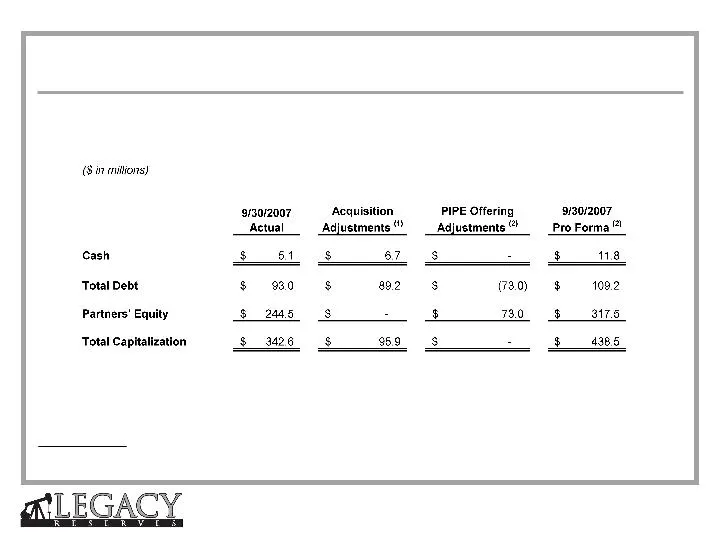
(1) Acquisitions closed subsequent to 9/30/2007, including cash flow adjustment paid to Legacy at deal closing. (2) Pro forma PIPE and November acquisitions. Pro Forma Capitalization
Slide 14: 2007 Exploitation Program
2007 Exploitation Program q $16 million of maintenance and growth capital q 50% of capital directed toward higher IRR, low F&D recompletion, reactivation and restimulation projects q Double digit organic growth over the 12 months ended September 30, 2007 q Program summary (gross production rates): –
Slide 15: Comparable Company Trading Yields
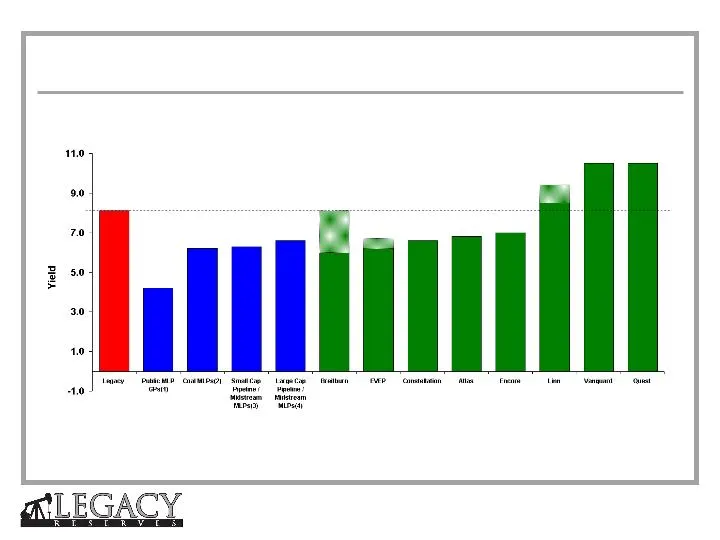
8.1% 4.2% 6.2% 6.3% 6.6% 6.0% 6.6% 6.2% 6.8% 8.5% 7.0% Energy MLP’s as of 11/30/07 As of 11/27/07: (1) Includes General Partners of Alliance, Atlas, Buckeye, Crosstex, Energy Transfer, Enterprise, Hiland, Inergy, Magellan, NuStar, Penn Virginia. (2) Includes Alliance, Natural Resource Partners, Penn
Slide 16: Legacy Unit Returns 2007 YTD
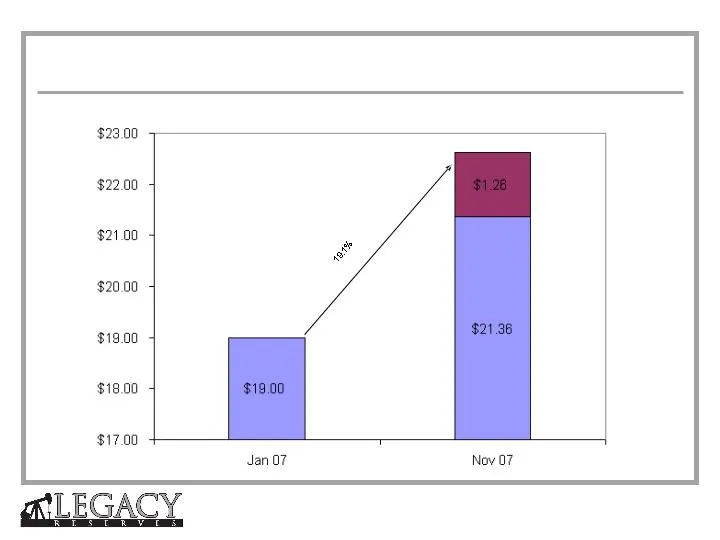
Note: Reflects closing price of 11/30/07 Legacy Unit Returns 2007 YTD
Slide 17: Commodity Price Hedging Summary
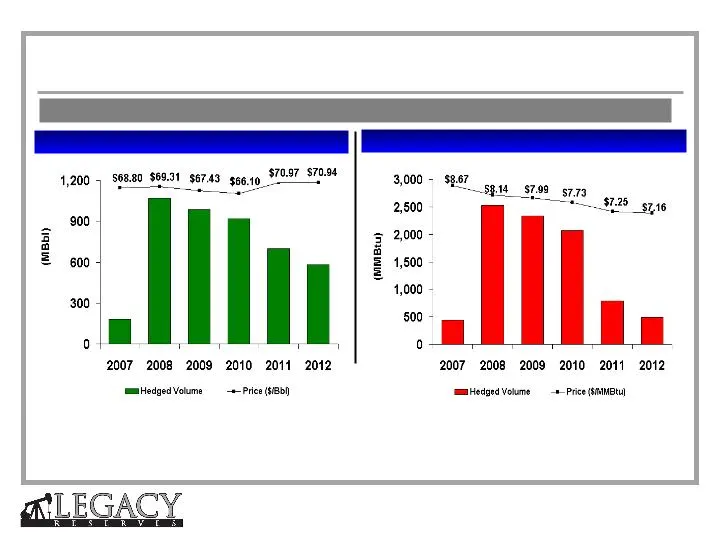
Oil (1) Natural Gas (2) Over 74% of forecasted production hedged for 2007-08 and over 60% hedged through 2010. (1) WTI oil swaps used to hedge NGL production in 2009 (85,200 Bbls), 2010 (84,600 Bbls), 2011 (78,000 Bbls) and 2012 (75,600 Bbls). (2) Includes NYMEX and Waha / ANR-OK swaps, where the la
Slide 18: Commodity Price Hedging Summary
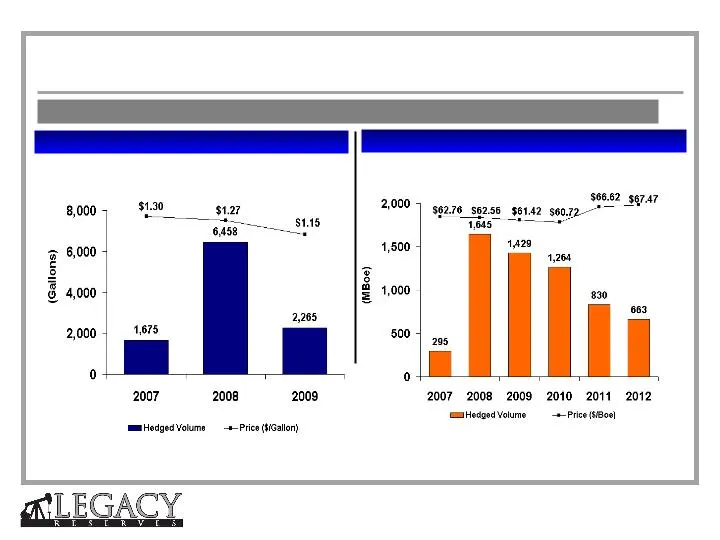
NGL’s BOE’s Over 74% of forecasted production hedged for 2007-08 and over 60% hedged through 2010. * * * 4 th Quarter 2007 volumes Commodity Price Hedging Summary
Slide 19: Legacy Ownership
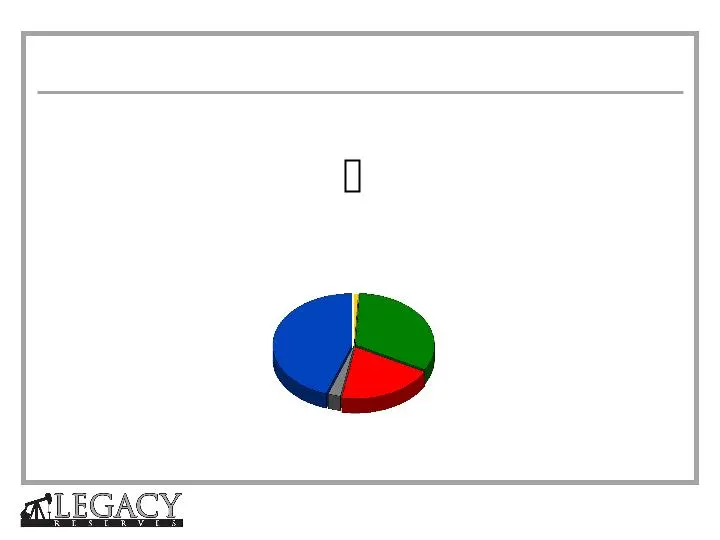
GP Interest <0.1% Public Unitholders 32.4% 144A & PIPE Unitholders 20% Sellers of Assets to Legacy 2.5% Founding Investors, Directors and Management 45% Ticker: LGCY Exchange: NASDAQ Unit Price (11/30/07): $21.36 per unit Quarterly Distribution: $0.43 per unit Yield: 8.05% Market Capitalization: $63
Slide 20: Legacy Summary
Legacy Summary q Only MLP focused on the oil-weighted Permian Basin and Mid-continent regions q Experienced management team with significant equity ownership q Significant organic and external growth opportunities q Long-lived, diversified multi-pay properties q Demonstrated reserve replacement capa
Slide 21: Adjusted EBITDA Reconciliation
Adjusted EBITDA Reconciliation This presentation, the financial tables and other supplemental information, including the reconciliations of certain non-generally accepted accounting principles ("non-GAAP") measures to their nearest comparable generally accepted accounting principles ("GAAP") measure
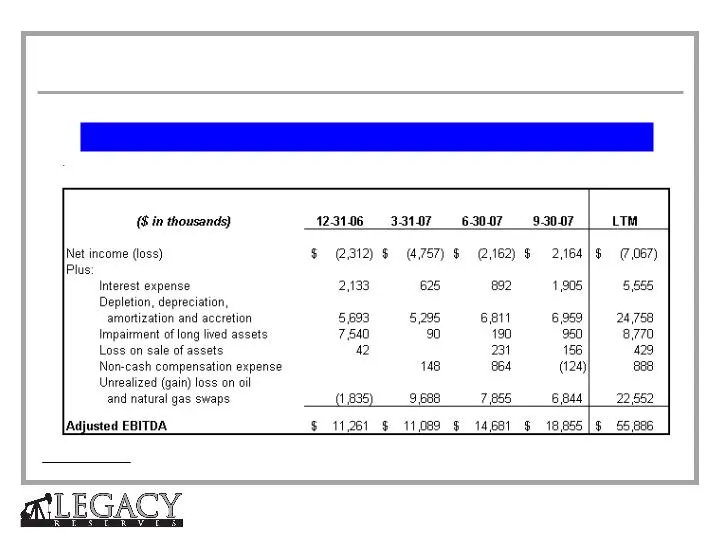
Slide 22: Reconciliation of Net Income to Adjusted EBITDA
Reconciliation of Net Income to Adjusted EBITDA Note: Adjusted EBITDA is a non-GAAP financial measure. Adjusted EBITDA Reconciliation
Slide 23: Legacy Reserves LP
Legacy Reserves LP
Source: SEC EDGAR · 8-K filed Dec 6, 2007
More decks from Legacy Reserves LP
 Investor Presentation (June 2019)9 slides · Jun 14, 2019
 Enercom Oil & Gas Conference 201818 slides · Aug 22, 2018
 Q2 2018 Earnings Presentation19 slides · Aug 2, 2018
 IPAA OGIS New York April 201812 slides · Apr 9, 2018
 Merger or Acquisition (March 2018)9 slides · Mar 26, 2018
 Executive Oil Conference 200919 slides · Apr 14, 2009