BBX Capital Inc · OTC:BBXIA
BBX Capital — BankAtlantic Bancorp — Investor Presentation (July 2004)
53 slides from BBX Capital's investor presentation, Jul 27, 2004
Slide 1: NYSE BBX July 2004
NYSE BBX JULY 2004 July 23, 2004 Prepared:
Slide 2: BankAtlantic Bancorp
BANKATLANTIC BANCORP NYSE:BBX A Florida based financial services holding company Retail and Commercial Banking Investment Banking and Retail Brokerage
Slide 3: BankAtlantic Bancorp key statistics
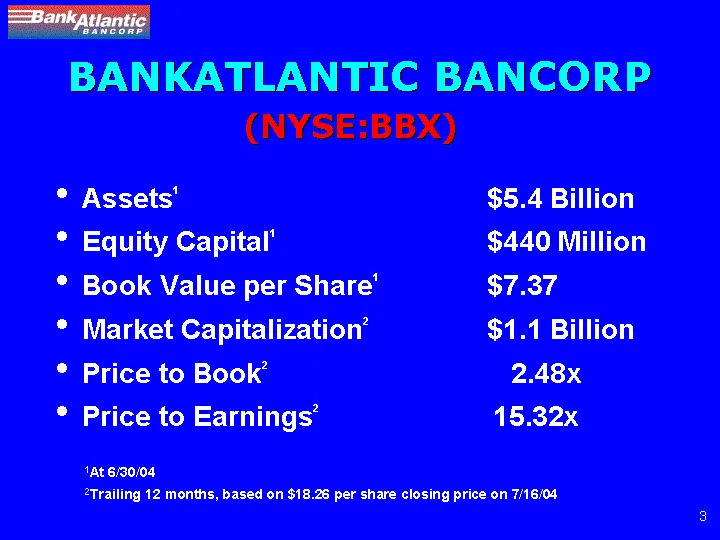
(NYSE:BBX) Assets1 $5.4 Billion Equity Capital1 $440 Million Book Value per Share1 $7.37 Market Capitalization2 $1.1 Billion Price to Book2 2.48x Price to Earnings2 15.32x 1At 6/30/04 2Trailing 12 months, based on $18.26 per share closing price on 7/16/04 BANKATLANTIC BANCORP
Slide 4: Key Financial Highlights
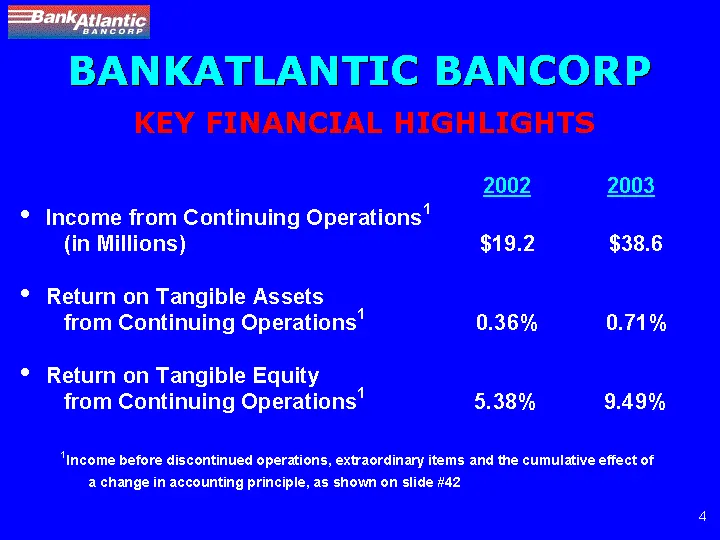
Income from Continuing Operations1 (in Millions) $19.2 $38.6 Return on Tangible Assets from Continuing Operations1 0.36% 0.71% Return on Tangible Equity from Continuing Operations1 5.38% 9.49% 1Income before discontinued operations, extraordinary items and the cumulative effect of a change in accoun
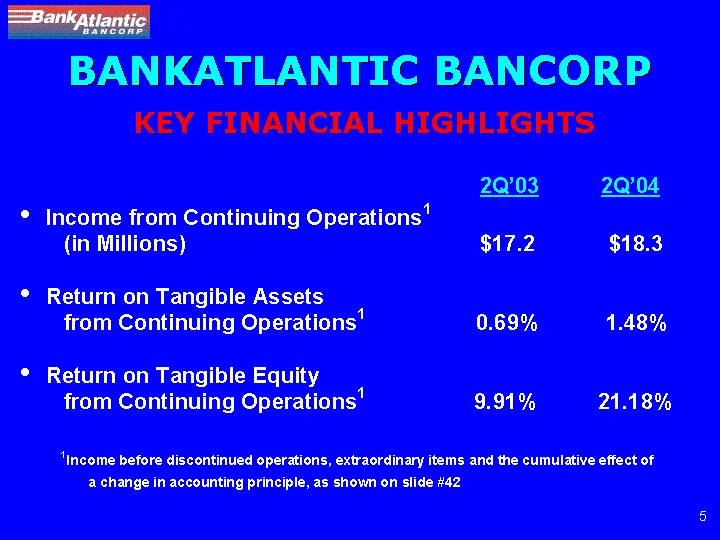
Slide 5: Key Financial Highlights 2Q'04
Income from Continuing Operations1 (in Millions) $17.2 $18.3 Return on Tangible Assets from Continuing Operations1 0.69% 1.48% Return on Tangible Equity from Continuing Operations1 9.91% 21.18% 1Income before discontinued operations, extraordinary items and the cumulative effect of a change in accou
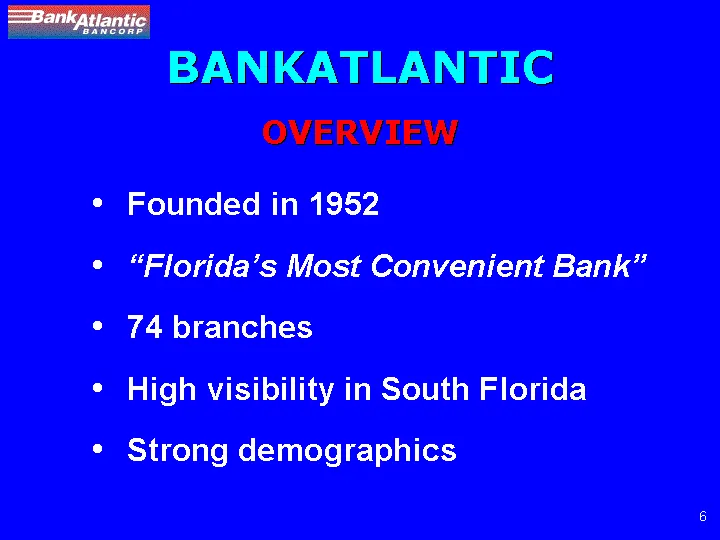
Slide 6: BankAtlantic Overview
BANKATLANTIC Founded in 1952 "Florida's Most Convenient Bank" 74 branches High visibility in South Florida Strong demographics OVERVIEW
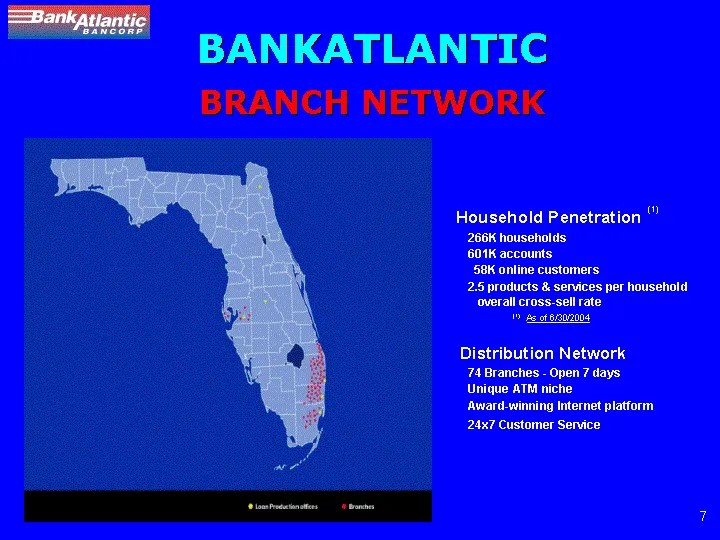
Slide 7: BankAtlantic Branch Network
BANKATLANTIC BRANCH NETWORK Household Penetration (1) 266K households 601K accounts 58K online customers 2.5 products & services per household overall cross-sell rate (1) As of 6/30/2004 Distribution Network 74 Branches - Open 7 days Unique ATM niche Award-winning Internet platform 24x7 Customer Ser
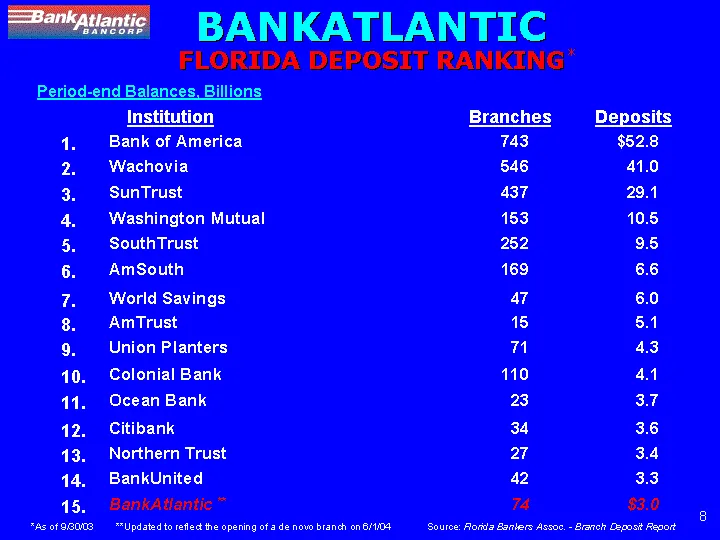
Slide 8: Florida Deposit Ranking
BANKATLANTIC FLORIDA DEPOSIT RANKING* Institution Branches Deposits *As of 9/30/03 **Updated to reflect the opening of a de novo branch on 6/1/04 Source: Florida Bankers Assoc. - Branch Deposit Report 1. Bank of America 743 $52.8 2. Wachovia 546 41.0 3. SunTrust 437 29.1 4. Washington Mutual 153 10.
Slide 9: BankAtlantic Market Share
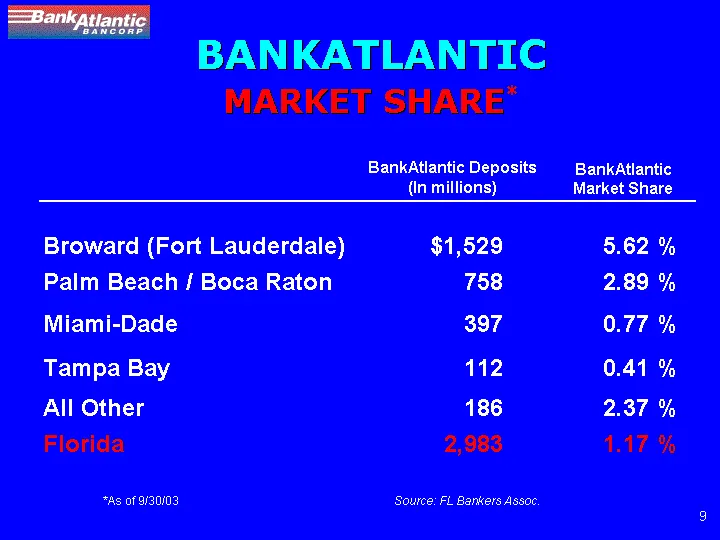
BankAtlantic Deposits (In millions) BankAtlantic Market Share *As of 9/30/03 Source: FL Bankers Assoc. MARKET SHARE* BANKATLANTIC Broward (Fort Lauderdale) $1,529 5.62 % Palm Beach / Boca Raton 758 2.89 % Miami-Dade 397 0.77 % Tampa Bay 112 0.41 % All Other 186 2.37 % Florida 2,983 1.17 %
Slide 10: BankAtlantic Strategy
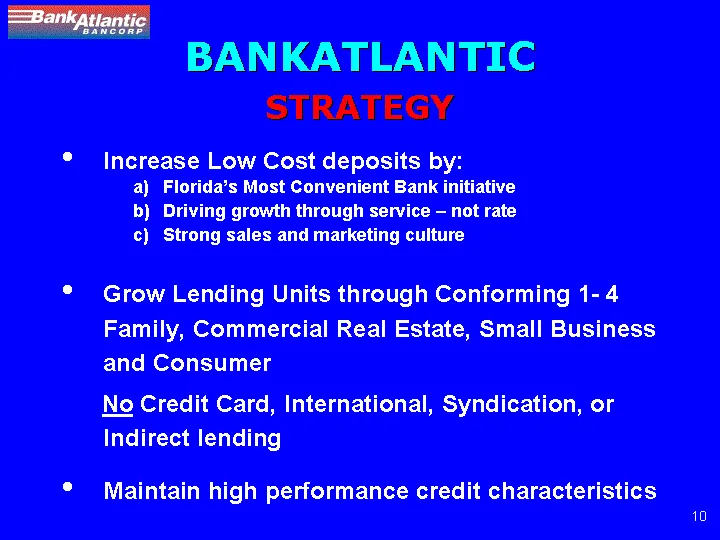
BANKATLANTIC STRATEGY Increase Low Cost deposits by: Florida's Most Convenient Bank initiative Driving growth through service - not rate Strong sales and marketing culture Grow Lending Units through Conforming 1- 4 Family, Commercial Real Estate, Small Business and Consumer No Credit Card, Internati
Slide 11: Florida's Most Convenient Bank
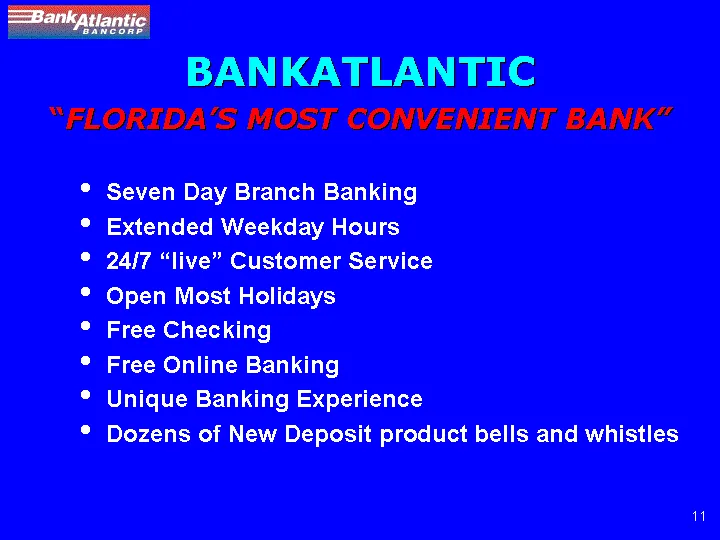
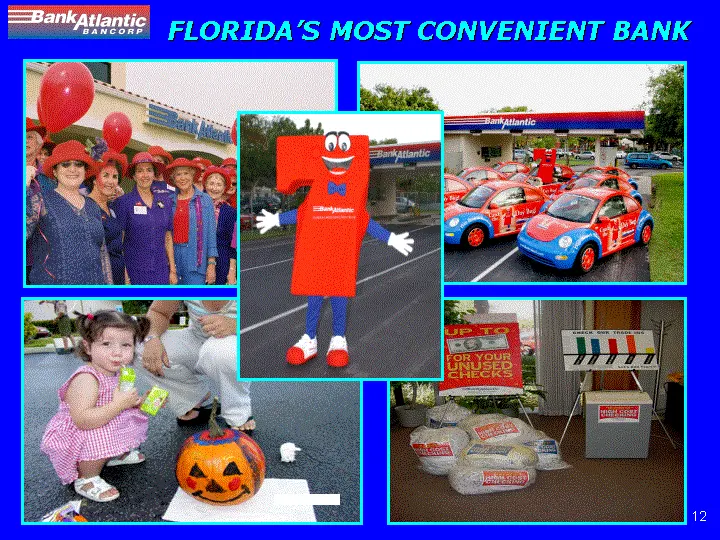
BANKATLANTIC "FLORIDA'S MOST CONVENIENT BANK" Seven Day Branch Banking Extended Weekday Hours 24/7 "live" Customer Service Open Most Holidays Free Checking Free Online Banking Unique Banking Experience Dozens of New Deposit product bells and whistles
Slide 12: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
Slide 13: BankAtlantic New Branch Look
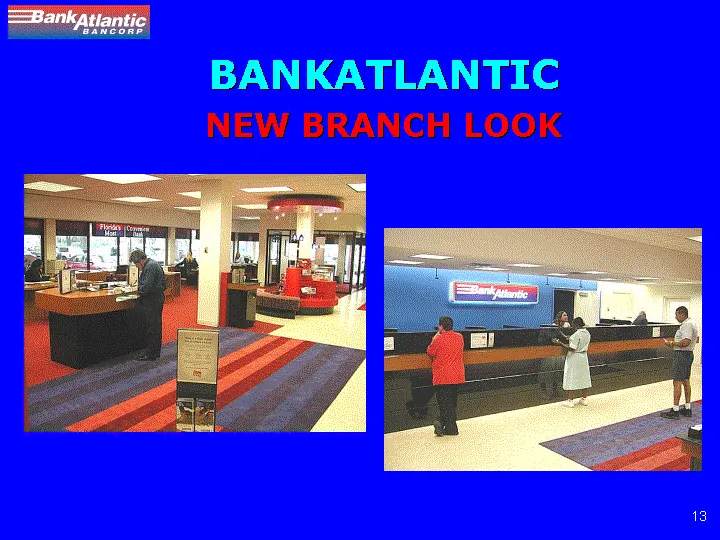
BANKATLANTIC NEW BRANCH LOOK
Slide 14: New Low Cost Accounts
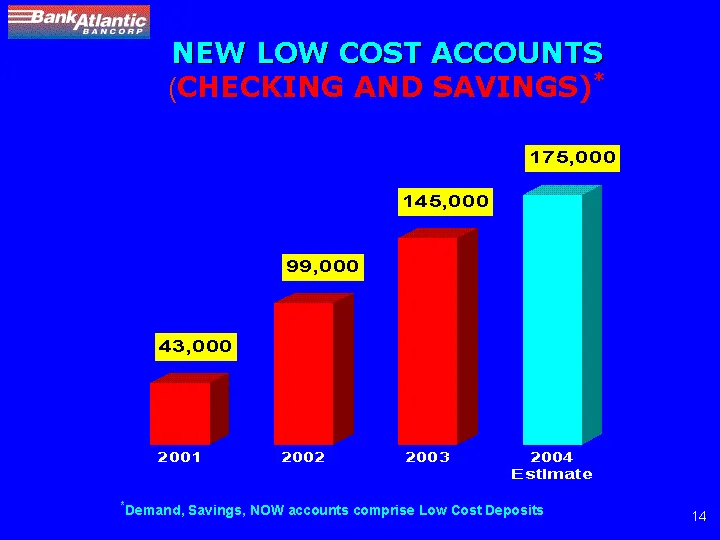
NEW LOW COST ACCOUNTS (CHECKING AND SAVINGS)* 2001 2002 2003 2004 Estimate NEW ACCTS 43000 99000 145000 175000 *Demand, Savings, NOW accounts comprise Low Cost Deposits
Slide 15: Deposit Growth
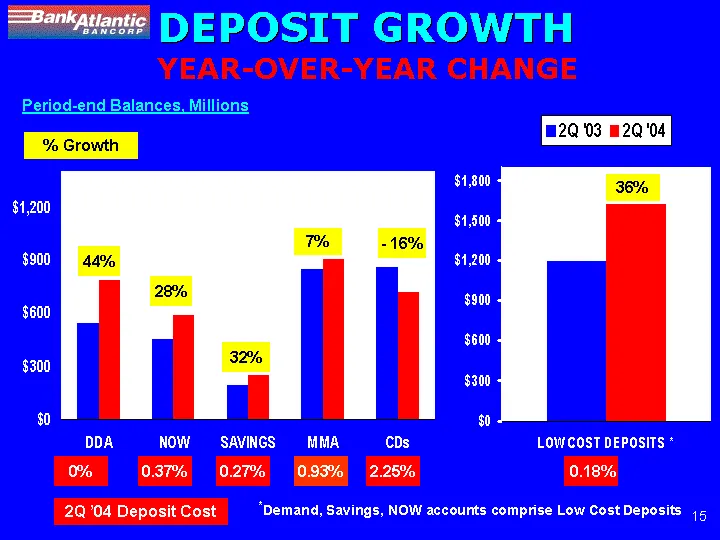
DEPOSIT GROWTH DDA NOW SAVINGS MMA CDs 2Q'03 547 456 191 851 860 2Q'04 788 585 251 907 720 LOW COST DEPOSITS * 2Q '03 1193.9 2Q '04 1623.8 Period-end Balances, Millions 44% 28% 32% - - 16% 0.18% 0% 0.37% 0.27% 2.25% 7% 0.93% 2Q '04 Deposit Cost % Growth 36% *Demand, Savings, NOW accounts comprise Lo
Slide 16: Low Cost Deposit Growth Same Branch
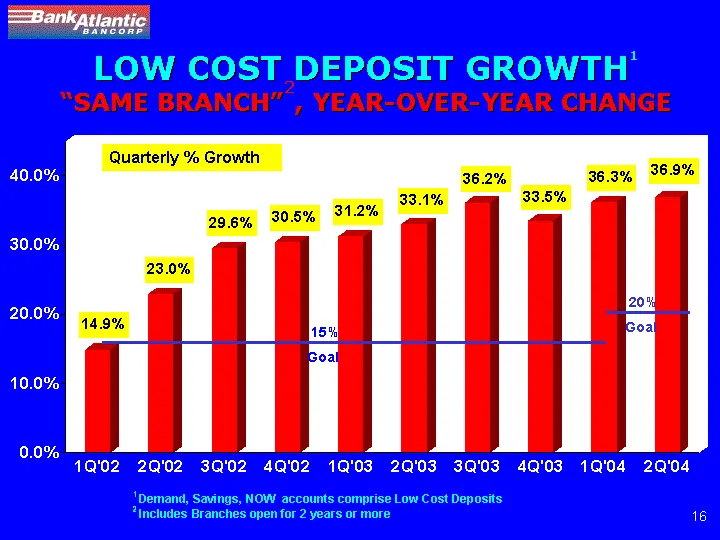
LOW COST DEPOSIT GROWTH1 "SAME BRANCH"2, YEAR-OVER-YEAR CHANGE 1 Demand, Savings, NOW accounts comprise Low Cost Deposits 2 Includes Branches open for 2 years or more 15% Goal 20% '04 Goal 1Q'02 2Q'02 3Q'02 4Q'02 1Q'03 2Q'03 3Q'03 4Q'03 1Q'04 2Q'04 Linked Qtr Growth 0.149 0.23 0.296 0.305 0.312 0.33
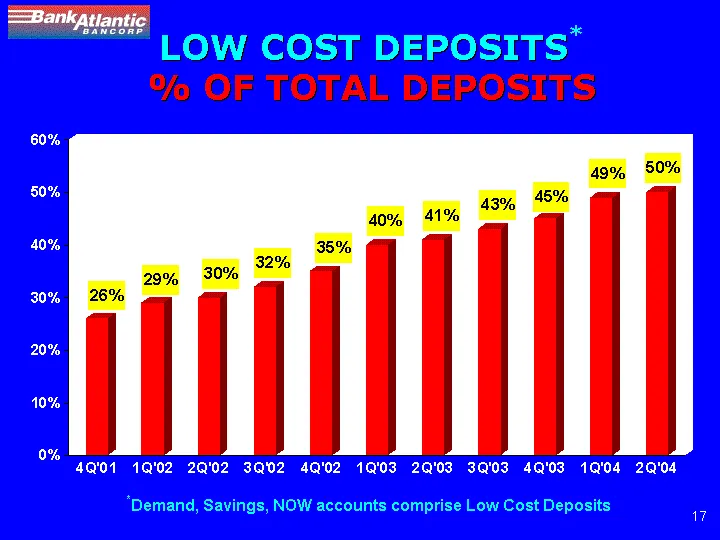
Slide 17: Low Cost Deposits % of Total Deposits
LOW COST DEPOSITS* % OF TOTAL DEPOSITS 4Q'01 1Q'02 2Q'02 3Q'02 4Q'02 1Q'03 2Q'03 3Q'03 4Q'03 1Q'04 2Q'04 Low Cost Deposit % 0.26 0.29 0.3 0.32 0.35 0.4 0.41 0.43 0.45 0.49 0.5 *Demand, Savings, NOW accounts comprise Low Cost Deposits
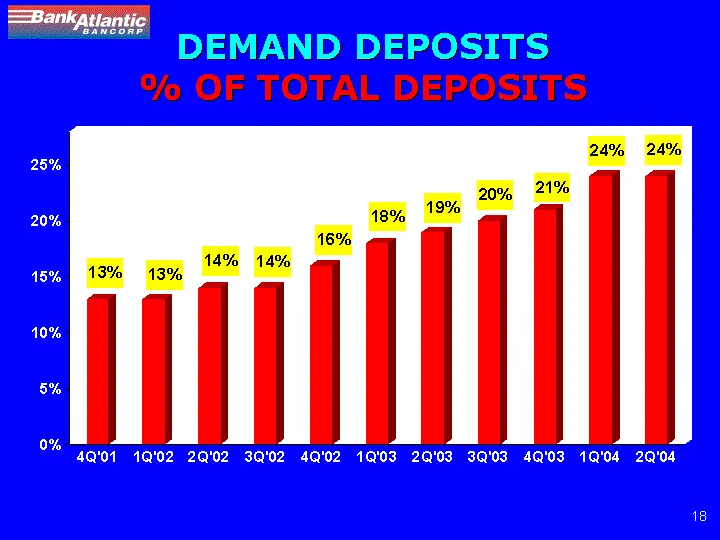
Slide 18: Demand Deposits % of Total Deposits
DEMAND DEPOSITS % OF TOTAL DEPOSITS 4Q'01 1Q'02 2Q'02 3Q'02 4Q'02 1Q'03 2Q'03 3Q'03 4Q'03 1Q'04 2Q'04 DDA % Tl. Deposits 0.13 0.13 0.14 0.14 0.16 0.18 0.19 0.2 0.21 0.24 0.24
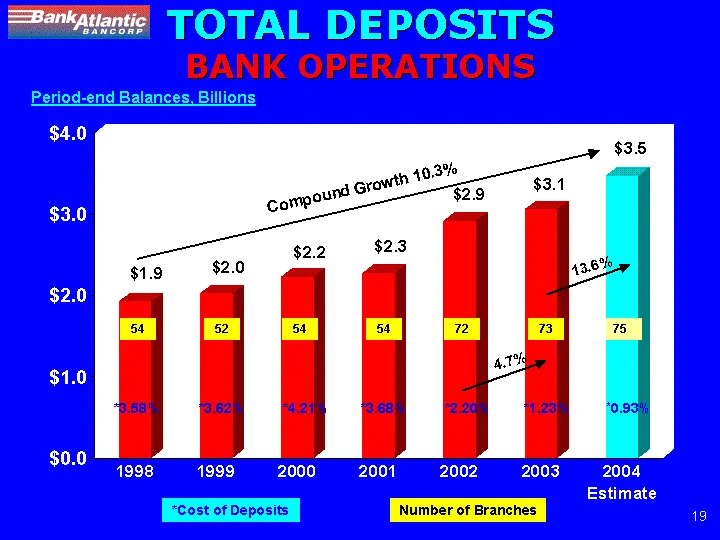
Slide 19: Total Deposits Bank Operations
TOTAL DEPOSITS BANK OPERATIONS 1998 1999 2000 2001 2002 2003 2004 Estimate Total Deposits 1.925772 2.027892 2.234485 2.276567 2.920555 3.058142 3.473226 Compound Growth 10.3% *3.58% *Cost of Deposits *3.62% *4.21% *3.68% *2.20% *1.23% 54 52 54 54 72 73 Number of Branches 4.7% Period-end Balances, Bi
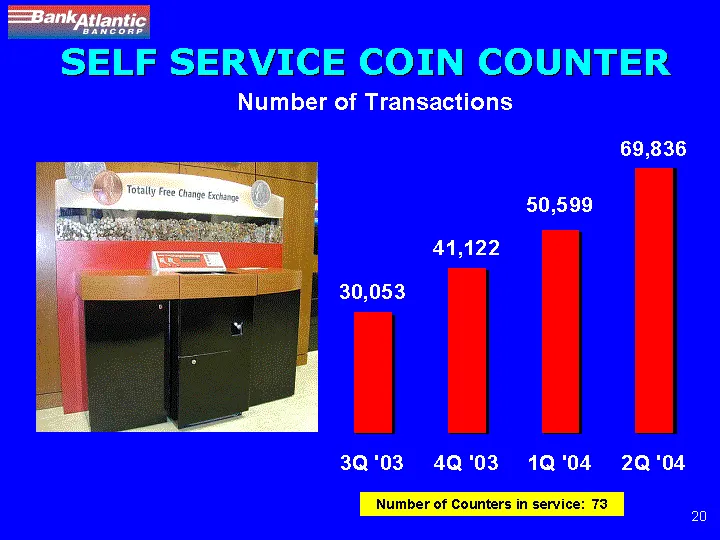
Slide 20: Self Service Coin Counter
SELF SERVICE COIN COUNTER 3Q '03 4Q '03 1Q '04 2Q '04 East 30053 41122 50599 69836 Number of Transactions Number of Counters in service: 73 Number of Counters in service: 73
Slide 21: BankAtlantic.com
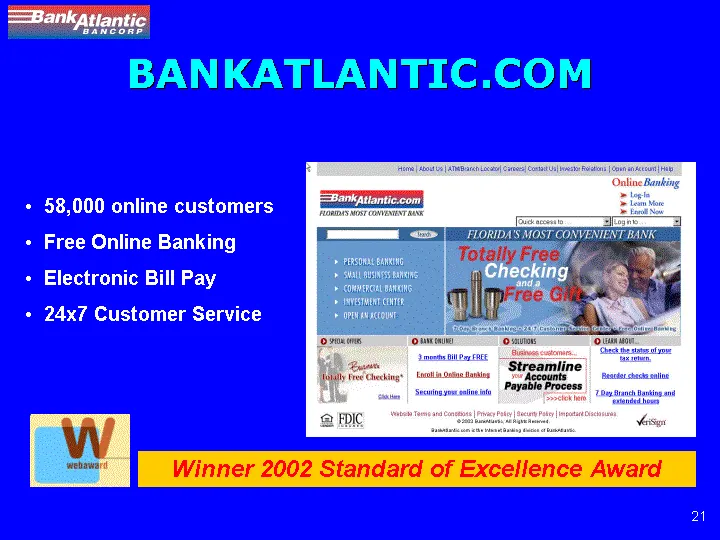
BANKATLANTIC.COM 58,000 online customers Free Online Banking Electronic Bill Pay 24x7 Customer Service Winner 2002 Standard of Excellence Award
Slide 22: Growing Fee Income
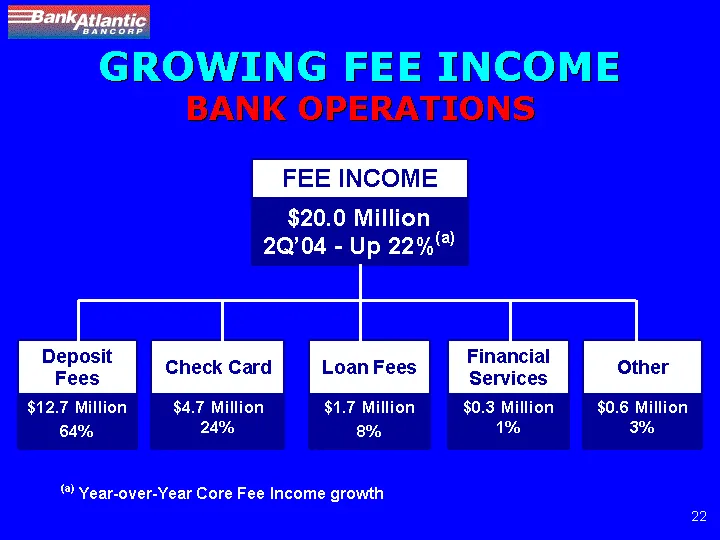
GROWING FEE INCOME BANK OPERATIONS Deposit Fees Check Card Loan Fees Financial Services Other $12.7 Million 64% $4.7 Million 24% $1.7 Million 8% $0.3 Million 1% $0.6 Million 3% FEE INCOME $20.0 Million 2Q'04 - Up 22%(a) (a) Year-over-Year Core Fee Income growth
Slide 23: Fee Income Bank Operations
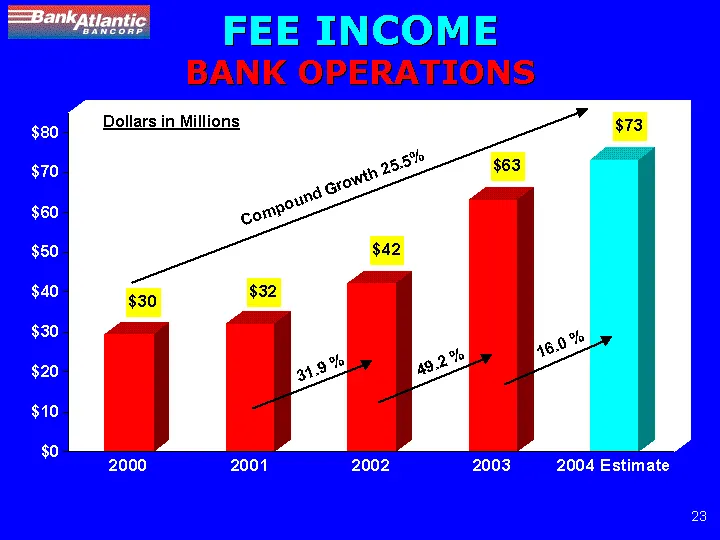
2000 2001 2002 2003 2004 Estimate Fee Income 29.573322 32.077217 42.315973 63.144773 73.247027 Compound Growth 25.5% 16.0 % 49.2 % 31.9 % Dollars in Millions FEE INCOME BANK OPERATIONS
Slide 24: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
Slide 25: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
Slide 26: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
Slide 27: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
Slide 28: Florida's Most Convenient Bank
FLORIDA'S MOST CONVENIENT BANK
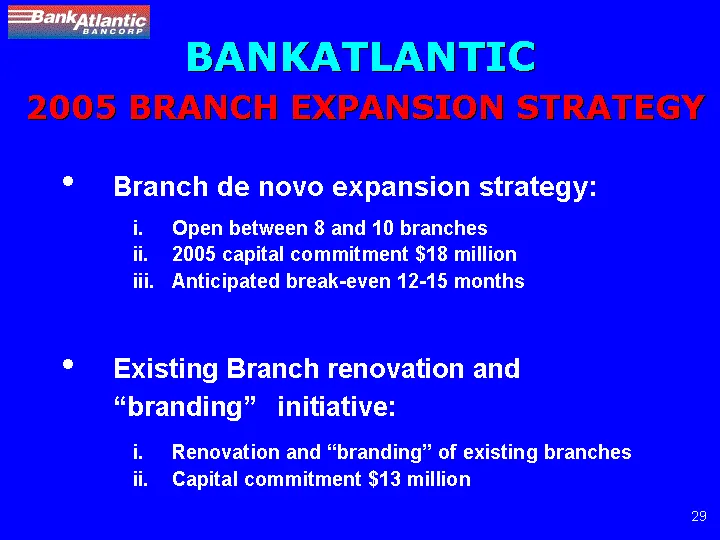
Slide 29: 2005 Branch Expansion Strategy
BANKATLANTIC 2005 BRANCH EXPANSION STRATEGY Branch de novo expansion strategy: Open between 8 and 10 branches 2005 capital commitment $18 million Anticipated break-even 12-15 months Existing Branch renovation and "branding" initiative: Renovation and "branding" of existing branches Capital commitmen
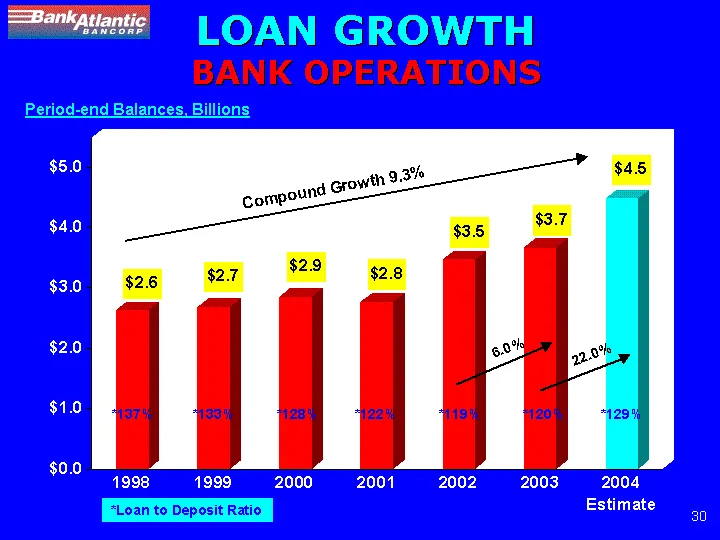
Slide 30: Loan Growth Bank Operations
LOAN GROWTH BANK OPERATIONS 1998 1999 2000 2001 2002 2003 2004 Estimate Total Loans 2.635 2.69 2.854 2.774 3.468 3.676 4.486 Compound Growth 9.3% *137% *Loan to Deposit Ratio *133% *128% *122% *119% *120% 6.0% Period-end Balances, Billions 22.0% *129%
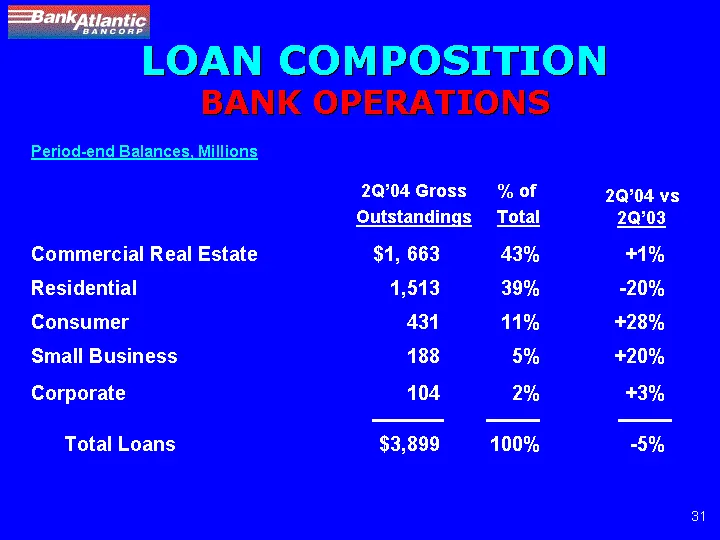
Slide 31: Loan Composition
LOAN COMPOSITION BANK OPERATIONS Commercial Real Estate $1, 663 43% +1% Residential 1,513 39% -20% Consumer 431 11% +28% Small Business 188 5% +20% Corporate 104 2% +3% Total Loans $3,899 100% -5% 2Q'04 Gross Outstandings % of Total 2Q'04 vs 2Q'03 Period-end Balances, Millions
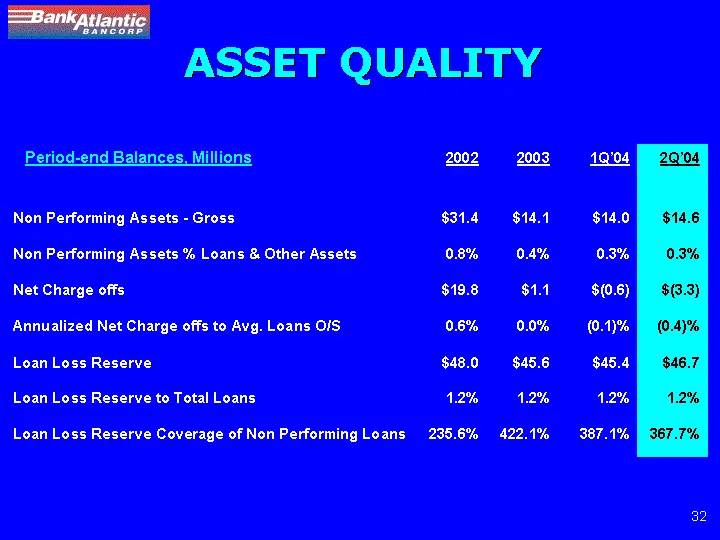
Slide 32: Asset Quality
ASSET QUALITY 2002 2003 1Q'04 2Q'04 Non Performing Assets - Gross $31.4 $14.1 $14.0 $14.6 Non Performing Assets % Loans & Other Assets 0.8% 0.4% 0.3% 0.3% Net Charge offs $19.8 $1.1 $(0.6) $(3.3) Annualized Net Charge offs to Avg. Loans O/S 0.6% 0.0% (0.1)% (0.4)% Loan Loss Reserve $48.0 $45.6 $45.4
Slide 33: Asset/Liability
ASSET/LIABILITY Anticipate continuing upturn in rates in 4Q '04 / 1Q '05 Positioned for rising rates Low Cost Deposits more valuable in rising rate environment Margin reached 3.73% in 2Q '04
Slide 34: Ryan Beck & Co. Overview
RYAN BECK & CO. Full-service investment banking and regional brokerage Founded in 1946 Nationally recognized leader in Financial Institutions investment banking OVERVIEW
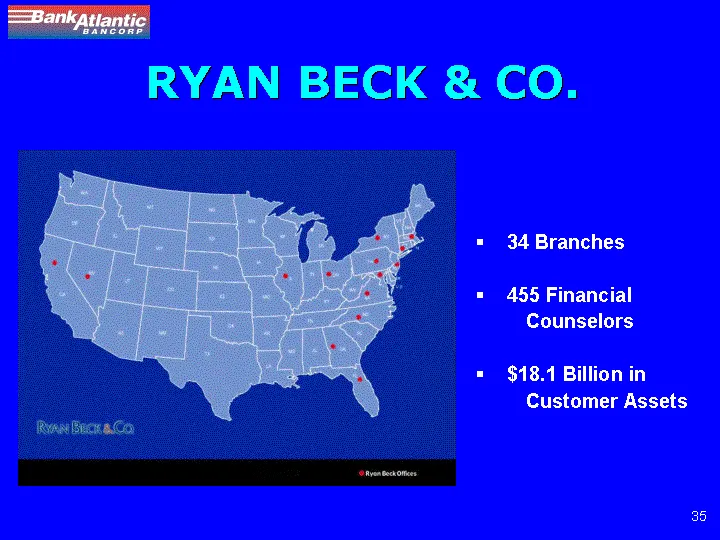
Slide 35: Ryan Beck & Co.
RYAN BECK & CO. 34 Branches 455 Financial Counselors $18.1 Billion in Customer Assets
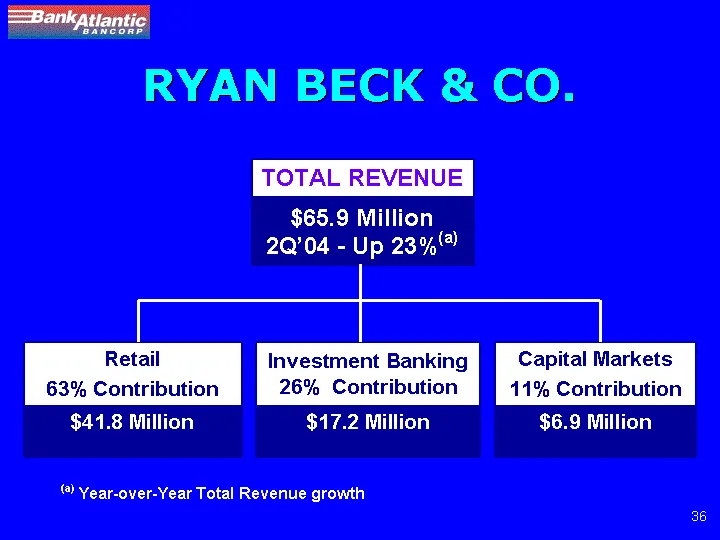
Slide 36: Ryan Beck & Co. Revenue
RYAN BECK & CO. Retail 63% Contribution Investment Banking 26% Contribution Capital Markets 11% Contribution $41.8 Million $17.2 Million $6.9 Million TOTAL REVENUE $65.9 Million 2Q'04 - Up 23%(a) (a) Year-over-Year Total Revenue growth
Slide 37: Financial Results
FINANCIAL RESULTS
Slide 38: Income from Continuing Operations
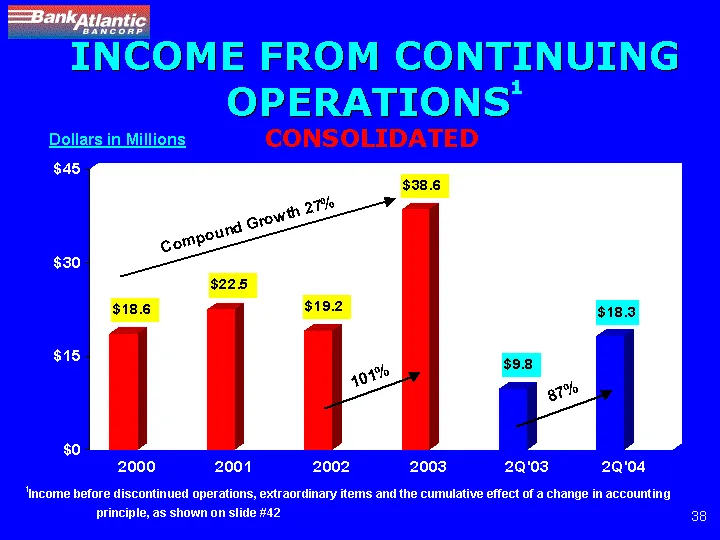
INCOME FROM CONTINUING OPERATIONS1 2000 2001 2002 2003 2Q'03 2Q'04 Income from Continuing Ops 18.644 22.53 19.15 38.597 9.809 18.26 Compound Growth 27% CONSOLIDATED 101% Dollars in Millions 1Income before discontinued operations, extraordinary items and the cumulative effect of a change in accountin
Slide 39: EPS Trend from Continuing Operations
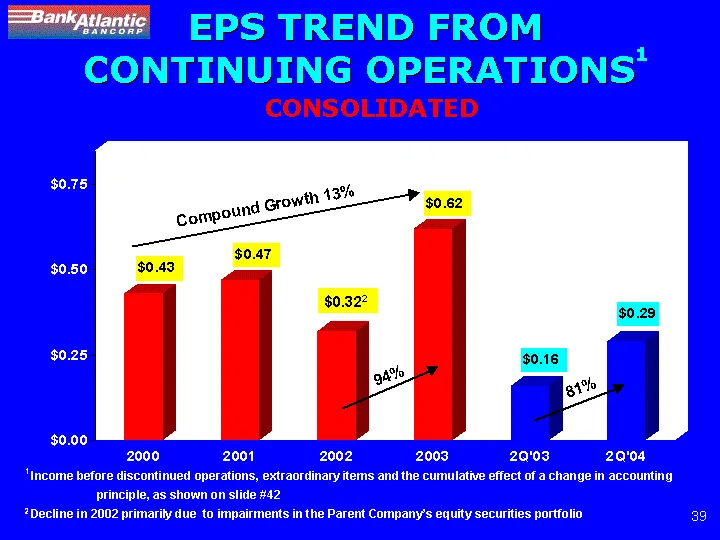
EPS TREND FROM CONTINUING OPERATIONS1 2000 2001 2002 2003 2Q'03 2Q'04 EPS from Continuing Ops 0.43 0.47 0.32 0.62 0.16 0.29 Compound Growth 13% CONSOLIDATED 94% 1 Income before discontinued operations, extraordinary items and the cumulative effect of a change in accounting principle, as shown on sli
Slide 40: Stockholder Value
STOCKHOLDER VALUE
Slide 41: Annual Return
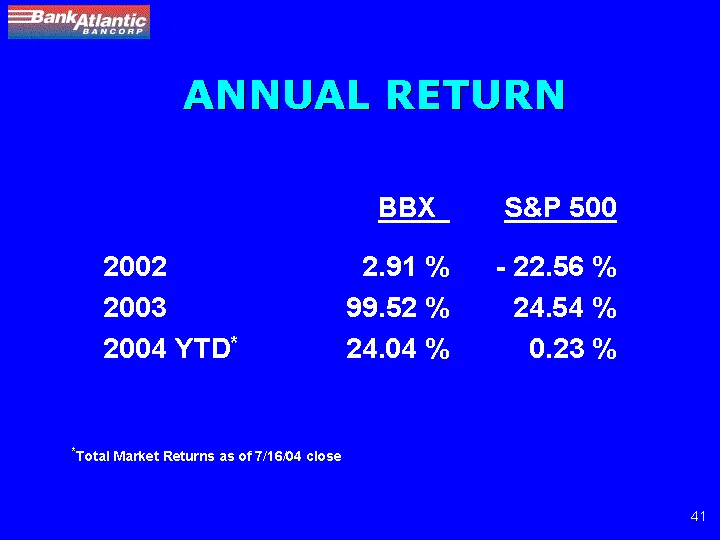
ANNUAL RETURN *Total Market Returns as of 7/16/04 close BBX S&P 500 2002 2.91 % - 22.56 % 2003 99.52 % 24.54 % 2004 YTD* 24.04 % 0.23 %
Slide 42: Consolidated Reconciliation of Net Income and Income from Continuing Operations
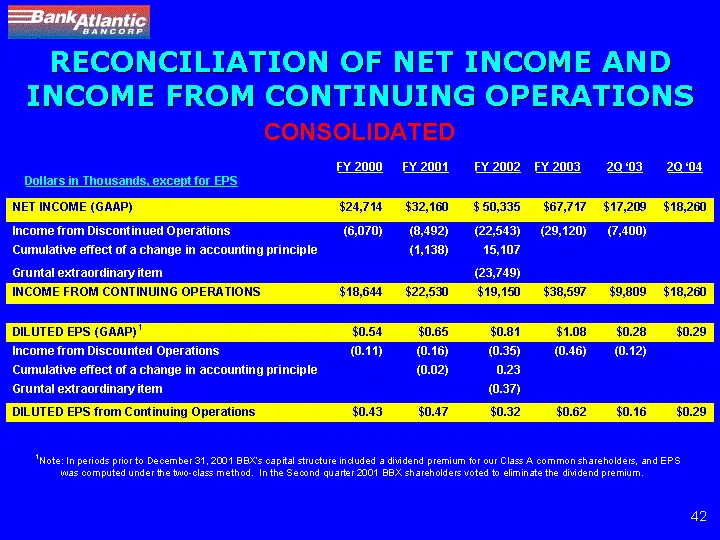
CONSOLIDATED RECONCILIATION OF NET INCOME AND INCOME FROM CONTINUING OPERATIONS Dollars in Thousands, except for EPS NET INCOME (GAAP) $24,714 $32,160 $ 50,335 $67,717 $17,209 $18,260 Income from Discontinued Operations (6,070) (8,492) (22,543) (29,120) (7,400) Cumulative effect of a change in accou
Slide 43: Forward-Looking Information
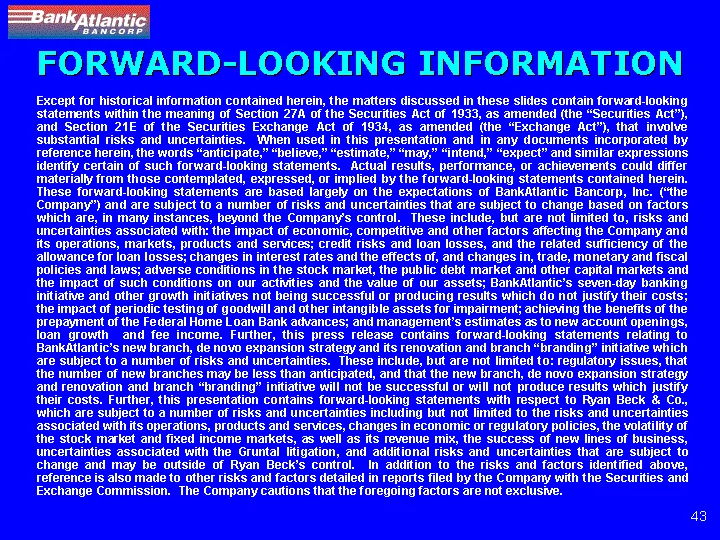
FORWARD-LOOKING INFORMATION Except for historical information contained herein, the matters discussed in these slides contain forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended (the "Securities Act"), and Section 21E of the Securities Exchange Act
Slide 44
Slide 45: Supplemental Data
SUPPLEMENTAL DATA
Slide 46: Earnings, Contribution
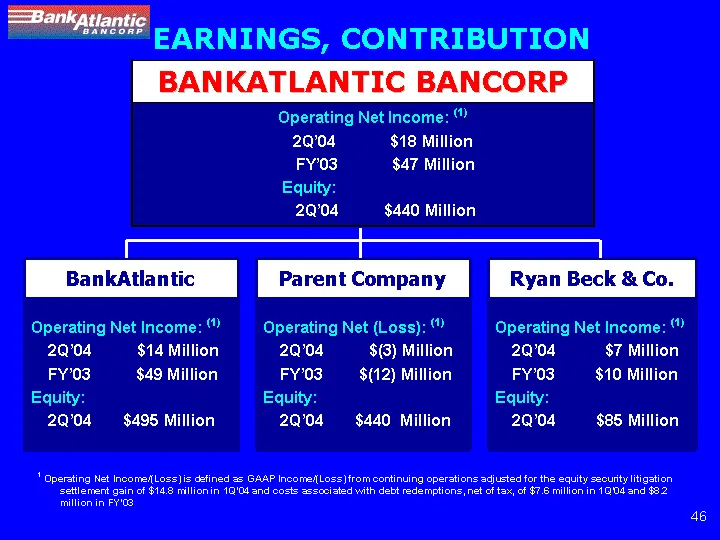
BankAtlantic Parent Company Ryan Beck & Co. Operating Net Income: (1) 2Q'04 $14 Million FY'03 $49 Million Equity: 2Q'04 $495 Million Operating Net (Loss): (1) 2Q'04 $(3) Million FY'03 $(12) Million Equity: 2Q'04 $440 Million Operating Net Income: (1) 2Q'04 $7 Million FY'03 $10 Million Equity: 2Q'04
Slide 47: Net Interest Margin Bank Operations
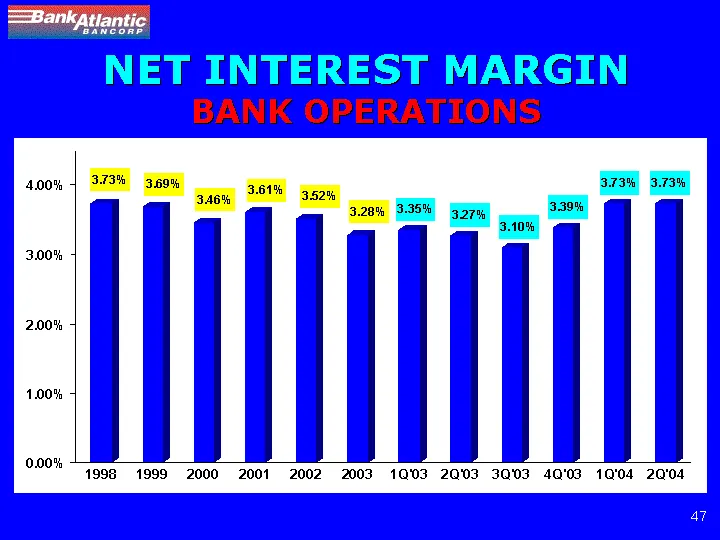
NET INTEREST MARGIN BANK OPERATIONS 1998 1999 2000 2001 2002 2003 1Q'03 2Q'03 3Q'03 4Q'03 1Q'04 2Q'04 NIM 0.0373 0.0369 0.0346 0.0361 0.0352 0.0328 0.0335 0.0327 0.031 0.0339 0.0373 0.0373
Slide 48: Net Interest Margin Funding Mix
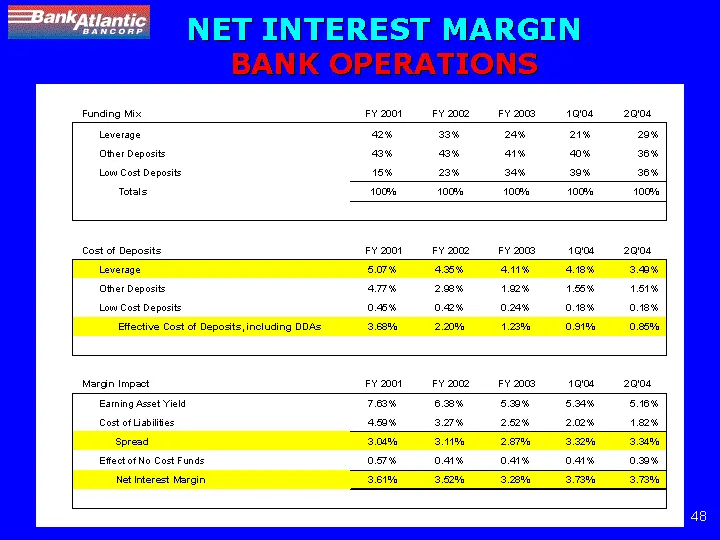
NET INTEREST MARGIN BANK OPERATIONS Funding Mix FY 2001 FY 2002 FY 2003 1Q'04 2Q'04 Leverage 42% 33% 24% 21% 29% Other Deposits 43% 43% 41% 40% 36% Low Cost Deposits 15% 23% 34% 39% 36% Totals 100% 100% 100% 100% 100% Cost of Deposits FY 2001 FY 2002 FY 2003 1Q'04 2Q'04 Leverage 5.07% 4.35% 4.11% 4.
Slide 49: FHLB Advances
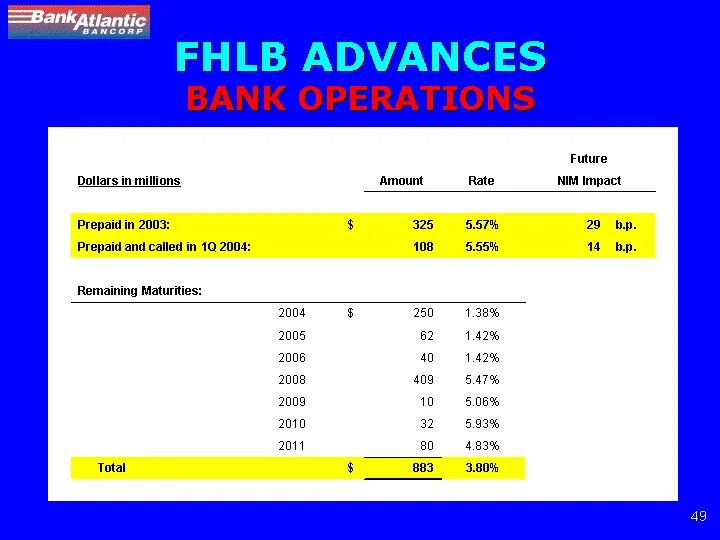
FHLB ADVANCES BANK OPERATIONS Future Future Dollars in millions Amount Rate NIM Impact NIM Impact Prepaid in 2003: $ 325 5.57% 29 b.p. Prepaid and called in 1Q 2004: 108 5.55% 14 b.p. Remaining Maturities: 2004 $ 250 1.38% 2005 62 1.42% 2006 40 1.42% 2008 409 5.47% 2009 10 5.06% 2010 32 5.93% 2011 8
Slide 50: Funding Costs
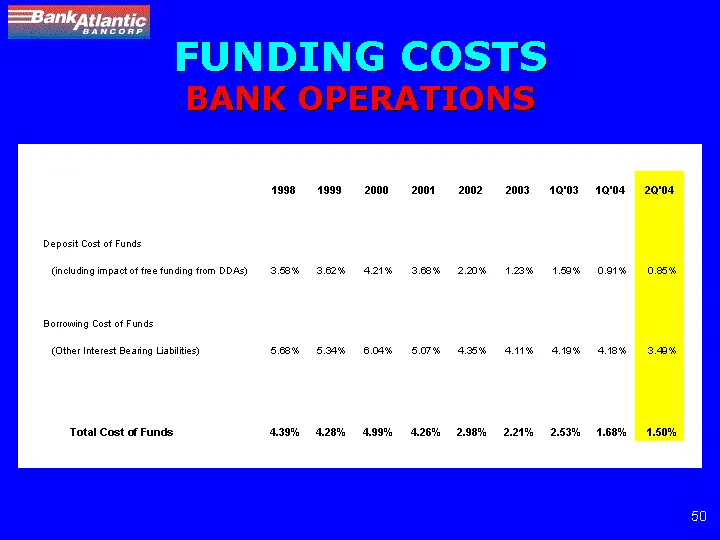
FUNDING COSTS BANK OPERATIONS 1998 1999 2000 2001 2002 2003 1Q'03 1Q'04 2Q'04 Deposit Cost of Funds (including impact of free funding from DDAs) 3.58% 3.62% 4.21% 3.68% 2.20% 1.23% 1.59% 0.91% 0.85% Borrowing Cost of Funds (Other Interest Bearing Liabilities) 5.68% 5.34% 6.04% 5.07% 4.35% 4.11% 4.19
Slide 51: Total Assets
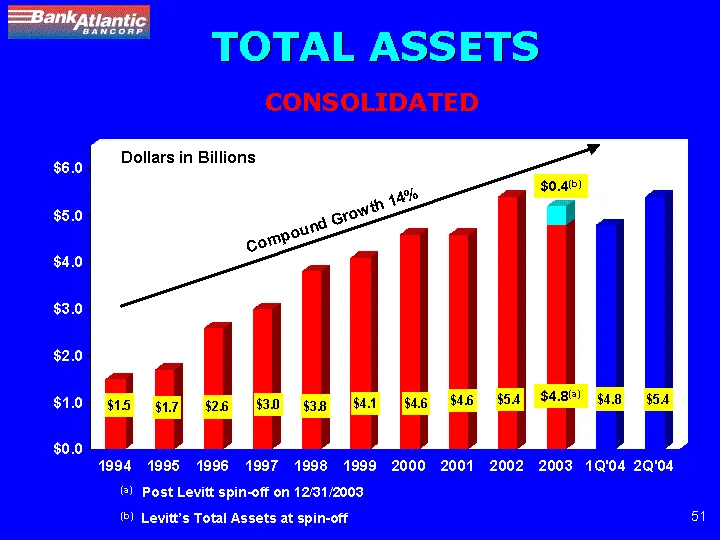
1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 1Q'04 2Q'04 TOTAL ASSETS 1.5 1.7 2.6 3 3.8 4.1 4.6 4.6 5.4 4.8 4.8 5.4 LEVITT 0.4 TOTAL ASSETS Compound Growth 14% Dollars in Billions CONSOLIDATED (a) Post Levitt spin-off on 12/31/2003 (b) Levitt's Total Assets at spin-off $4.8(a) $0.4(b)
Slide 52: Financial Highlights
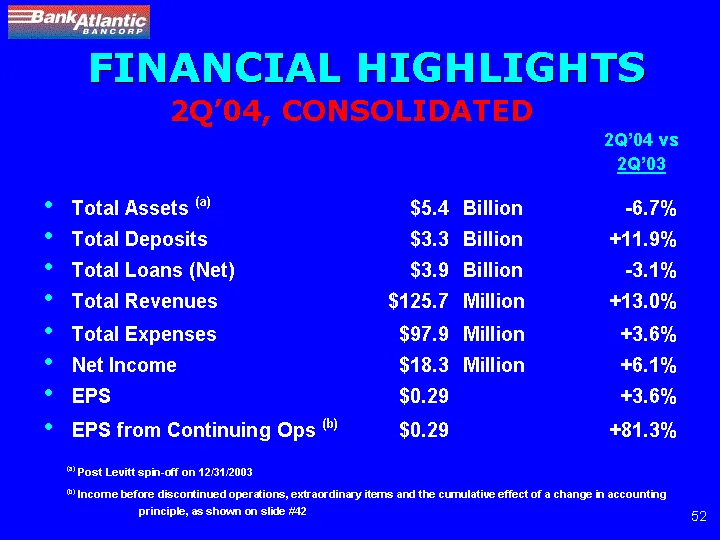
FINANCIAL HIGHLIGHTS Total Assets (a) $5.4 Billion Billion -6.7% Total Deposits $3.3 Billion Billion +11.9% Total Loans (Net) $3.9 Billion Billion -3.1% Total Revenues $125.7 Million Million +13.0% Total Expenses $97.9 Million Million +3.6% Net Income $18.3 Million Million +6.1% EPS $0.29 +3.6% EPS
Slide 53
Source: SEC EDGAR · 8-K filed Jul 27, 2004
More decks from BBX Capital Inc
 Merger or Acquisition (November 2016)60 slides · Nov 21, 2016
 Merger or Acquisition (October 2016)61 slides · Oct 11, 2016
 Merger or Acquisition (July 2016)11 slides · Jul 28, 2016
 Investor Presentation (November 2014)77 slides · Nov 26, 2014
 Merger or Acquisition (November 2014)77 slides · Nov 26, 2014
 Merger or Acquisition (September 2014)74 slides · Sep 19, 2014