Gaztransport & Technigaz SA · EURONEXT:GTT
Gaztransport & Technigaz SA — Q3 2025 Earnings Presentation
40 slides from Gaztransport & Technigaz SA's earnings presentation, November 2025
Slide 1: H1 / Q3 2025 Technology for a Sustainable World
H1 / Q3 2025 TECHNOLOGY FOR A SUSTAINABLE WORLD November 2025
Slide 2: Disclaimer
Disclaimer This presentation does not contain or constitute an offer of securities for sale or an invitation or inducement to invest in securities in France, the United States or any other jurisdiction. It includes only summary information and does not purport to be comprehensive. No representation,
Slide 3: Agenda
Agenda 01 02 03 04 Key Strategy & Financials Outlook & Highlights Activity Conclusion 3
Slide 4: Key Highlights
1 Key Highlights
Slide 5: 9M 2025 Key Figures
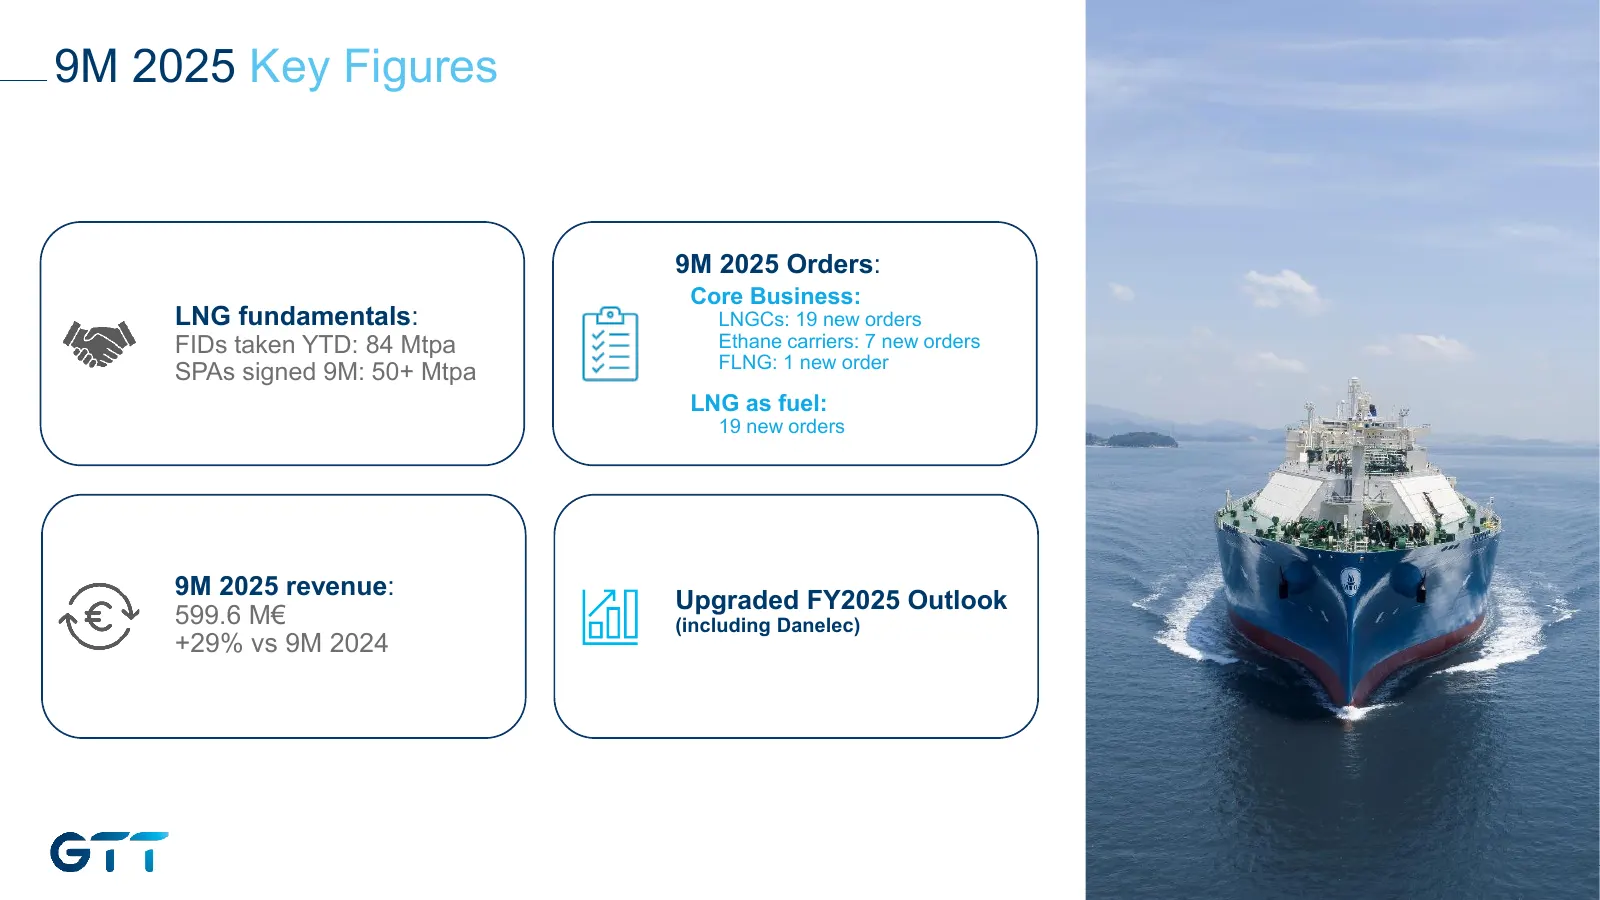
9M 2025 Key Figures 9M 2025 Orders: Core Business: LNG fundamentals: LNGCs: 19 new orders FIDs taken YTD: 84 Mtpa Ethane carriers: 7 new orders FLNG: 1 new order SPAs signed 9M: 50+ Mtpa LNG as fuel: 19 new orders 9M 2025 revenue: Upgraded FY2025 Outlook 599.6 M€ (including Danelec) +29% vs 9M 2024
Slide 6: 9M 2025 Key Highlights
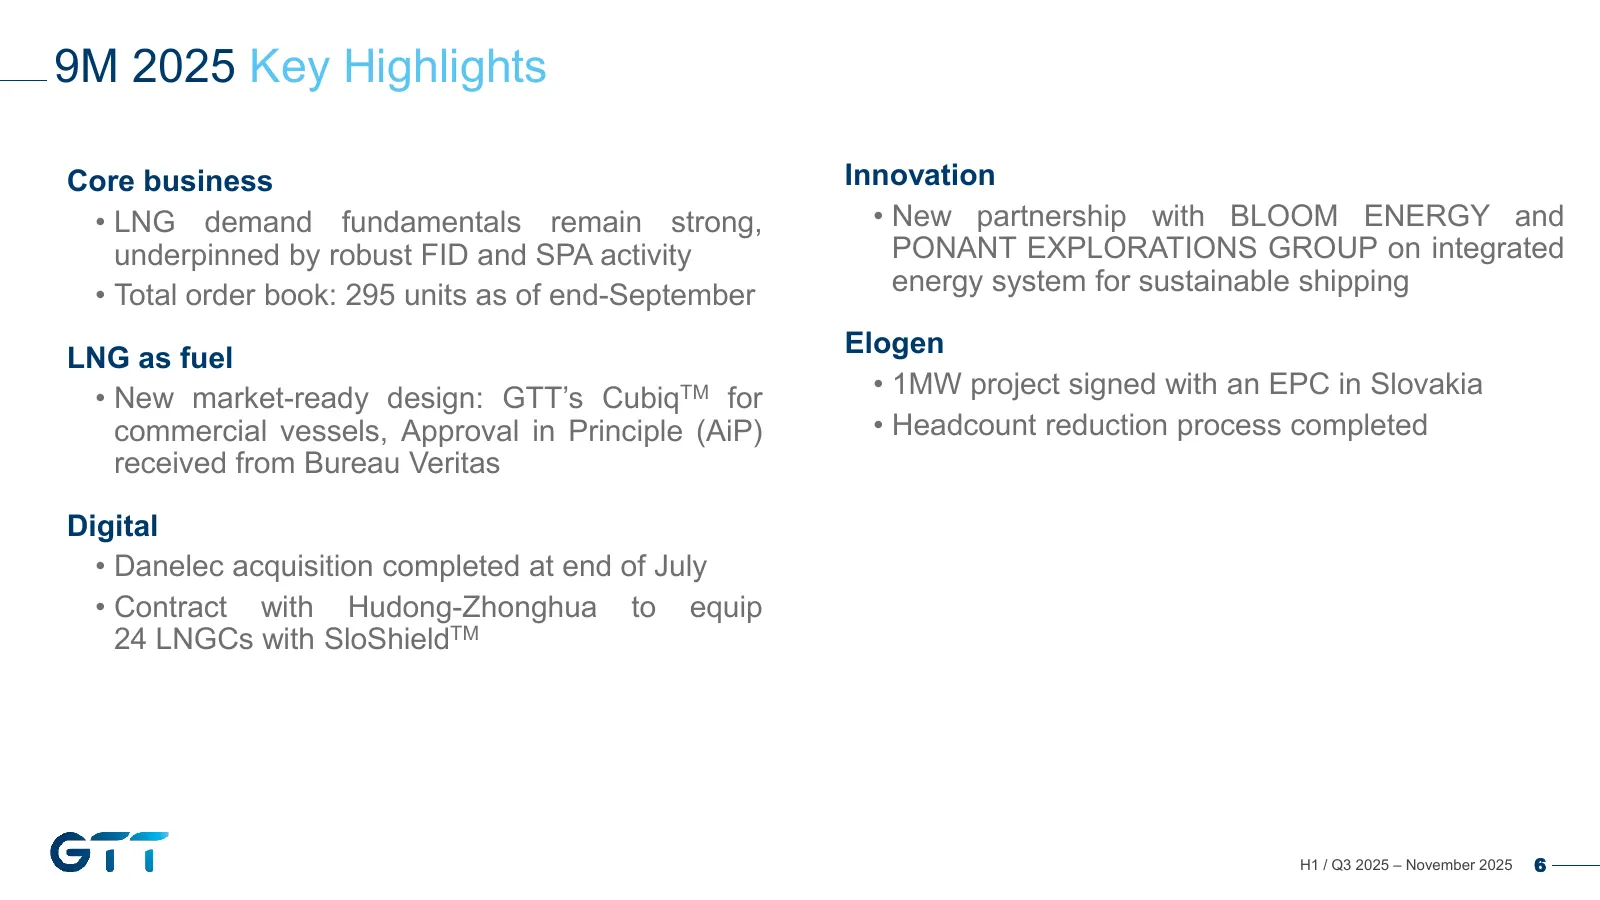
9M 2025 Key Highlights Core business Innovation • LNG demand fundamentals remain strong, • New partnership with BLOOM ENERGY and underpinned by robust FID and SPA activity PONANT EXPLORATIONS GROUP on integrated • Total order book: 295 units as of end-September energy system for sustainable shipping
Slide 7: 9M 2025 orderbook supporting long-term visibility
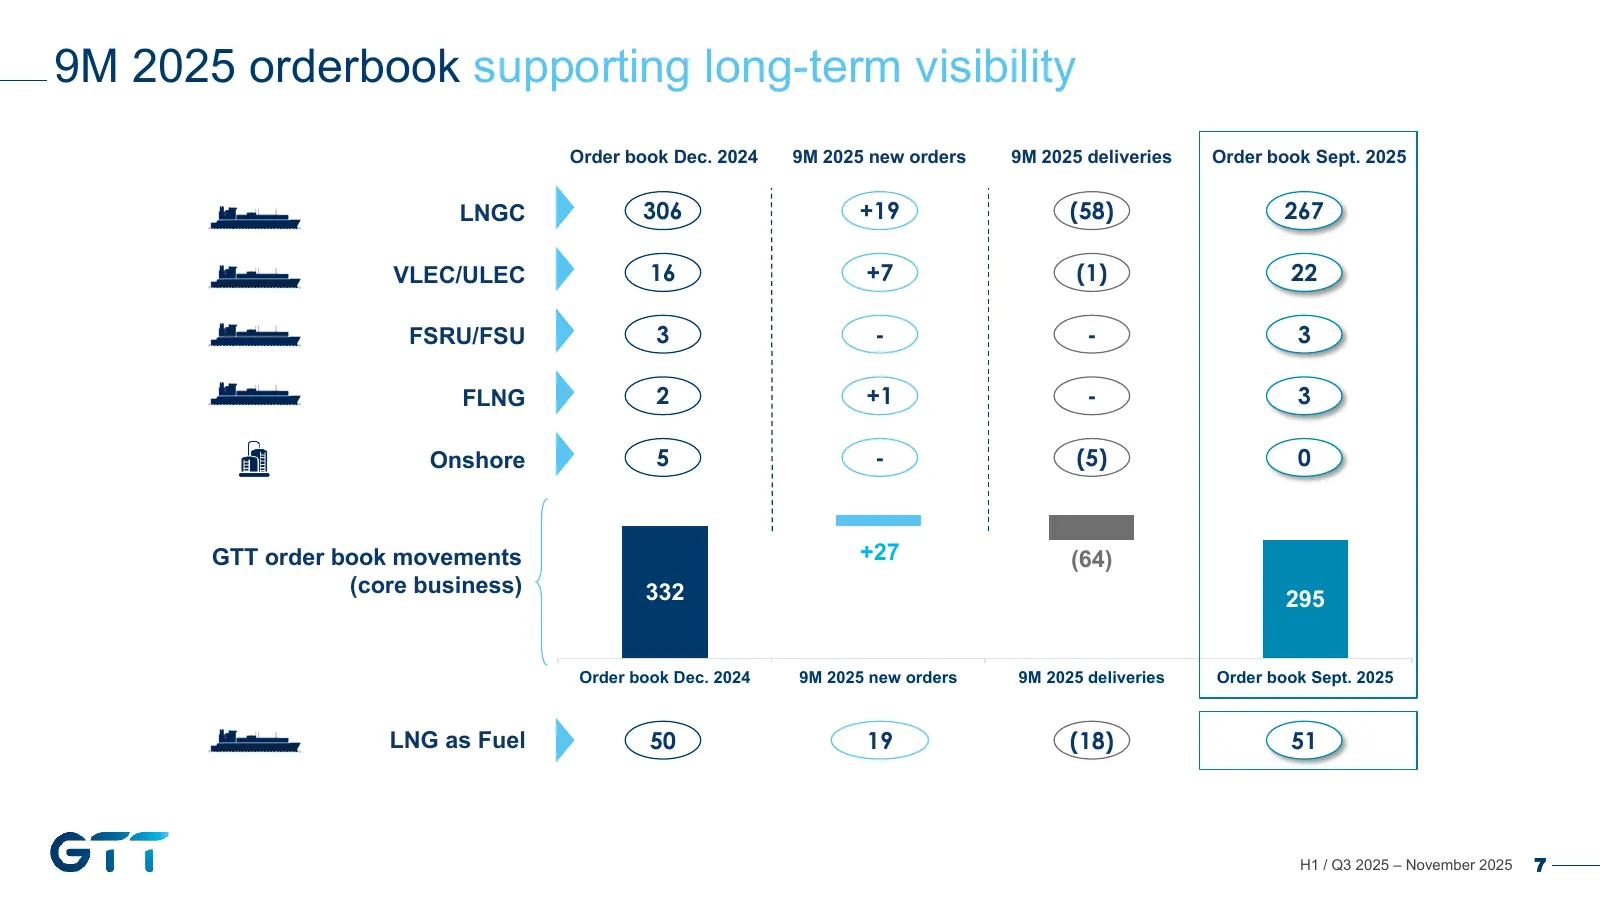
9M 2025 orderbook supporting long-term visibility Order book Dec. 2024 9M 2025 new orders 9M 2025 deliveries Order book Sept. 2025 LNGC 306 +19 (58) 267 VLEC/ULEC 16 +7 (1) 22 FSRU/FSU 3 - - 3 FLNG 2 +1 - 3 Onshore 5 - (5) 0 GTT order book movements +27 (64) (core business) 332 295 Order book Dec. 2
Slide 8: Strategy & Activity: LNG Carriers and Other Core Applications
2 Strategy & Activity LNG CARRIERS AND OTHER CORE APPLICATIONS
Slide 9: Supportive trends for LNG but geopolitical context remains complex
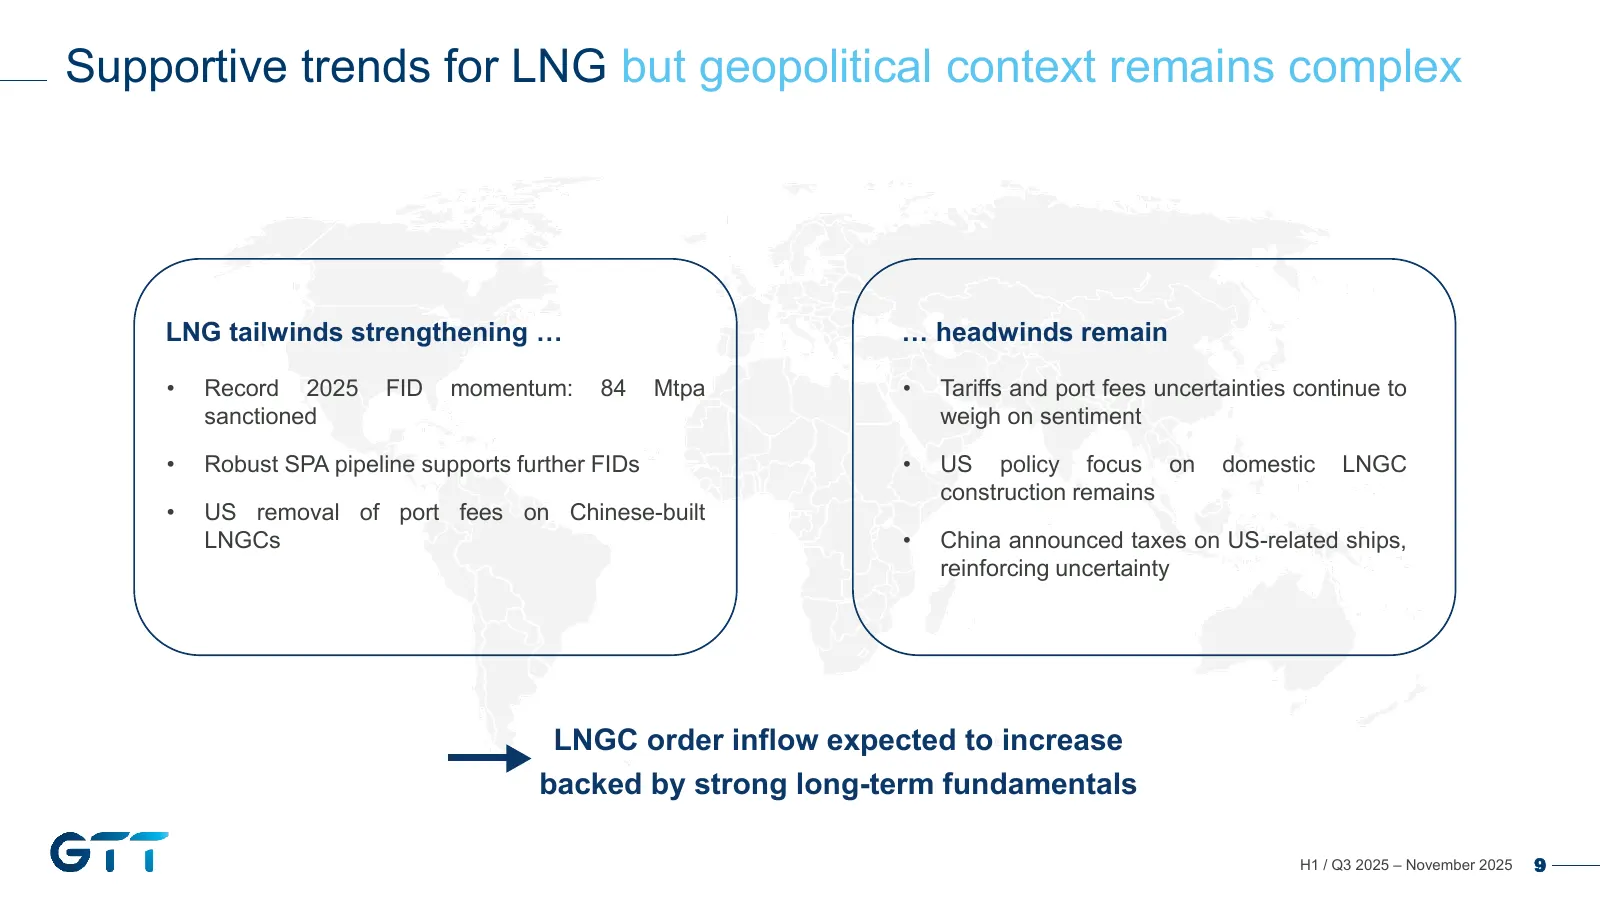
Supportive trends for LNG but geopolitical context remains complex LNG tailwinds strengthening … … headwinds remain • Record 2025 FID momentum: 84 Mtpa • Tariffs and port fees uncertainties continue to sanctioned weigh on sentiment • Robust SPA pipeline supports further FIDs • US policy focus on dom
Slide 10: Liquefaction market: Second consecutive record quarter
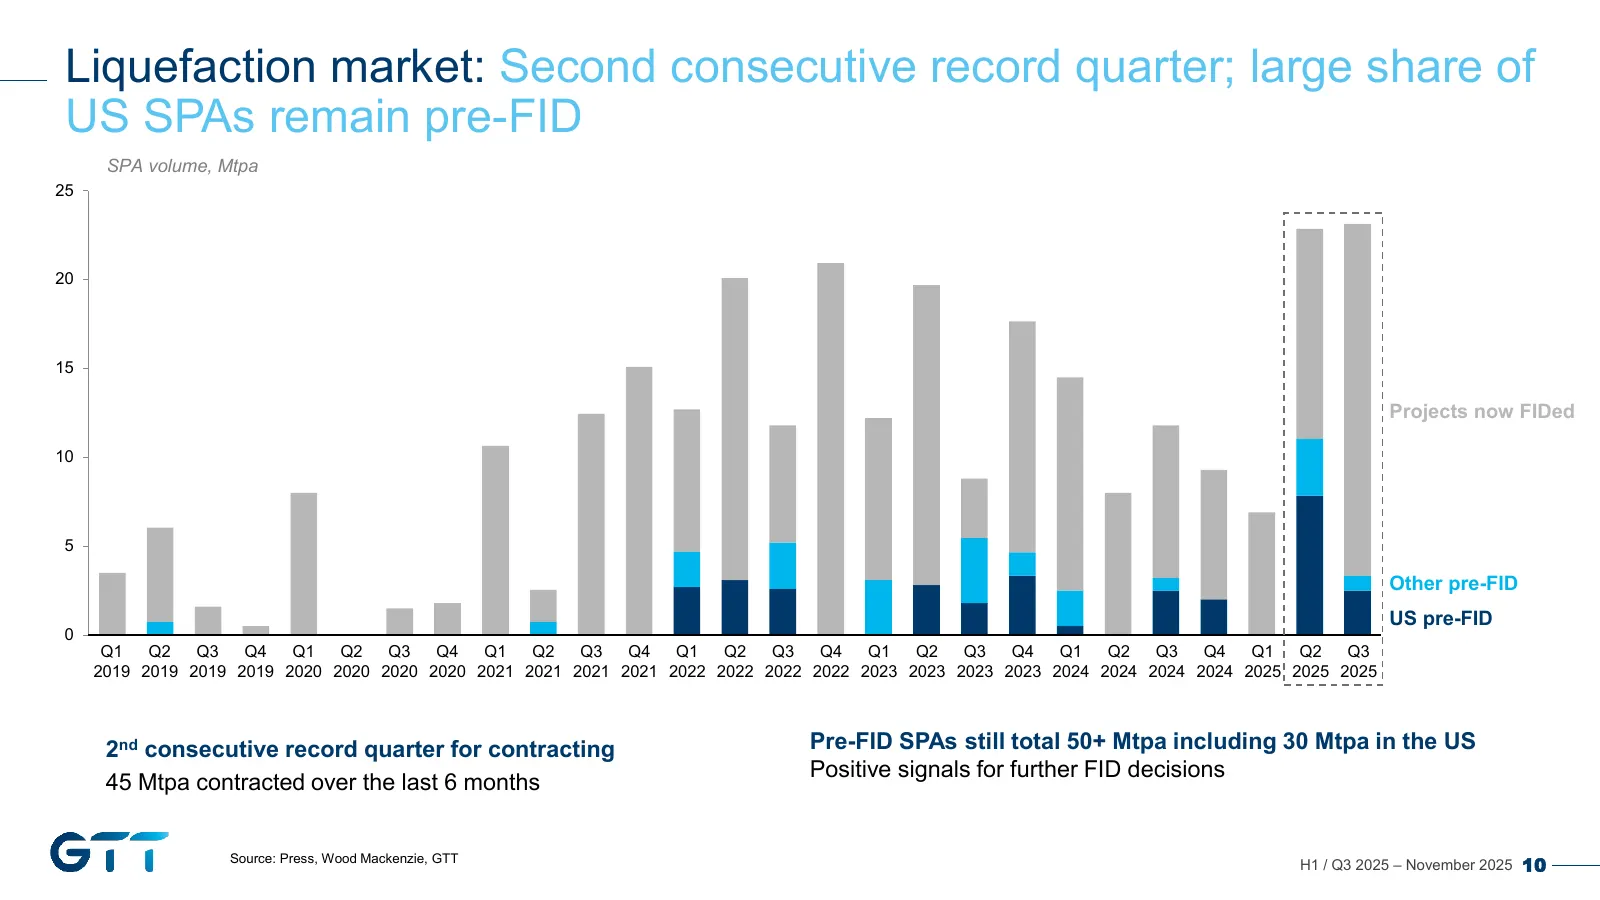
Liquefaction market: Second consecutive record quarter; large share of US SPAs remain pre-FID SPA volume, Mtpa 25 20 15 Projects now FIDed 10 5 Other pre-FID US pre-FID 0 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 Q4 Q1 Q2 Q3 2019 2019 2019 2019 2020 2020 2020 2020 2021 202
Slide 11: All-time record FID activity, led by the US
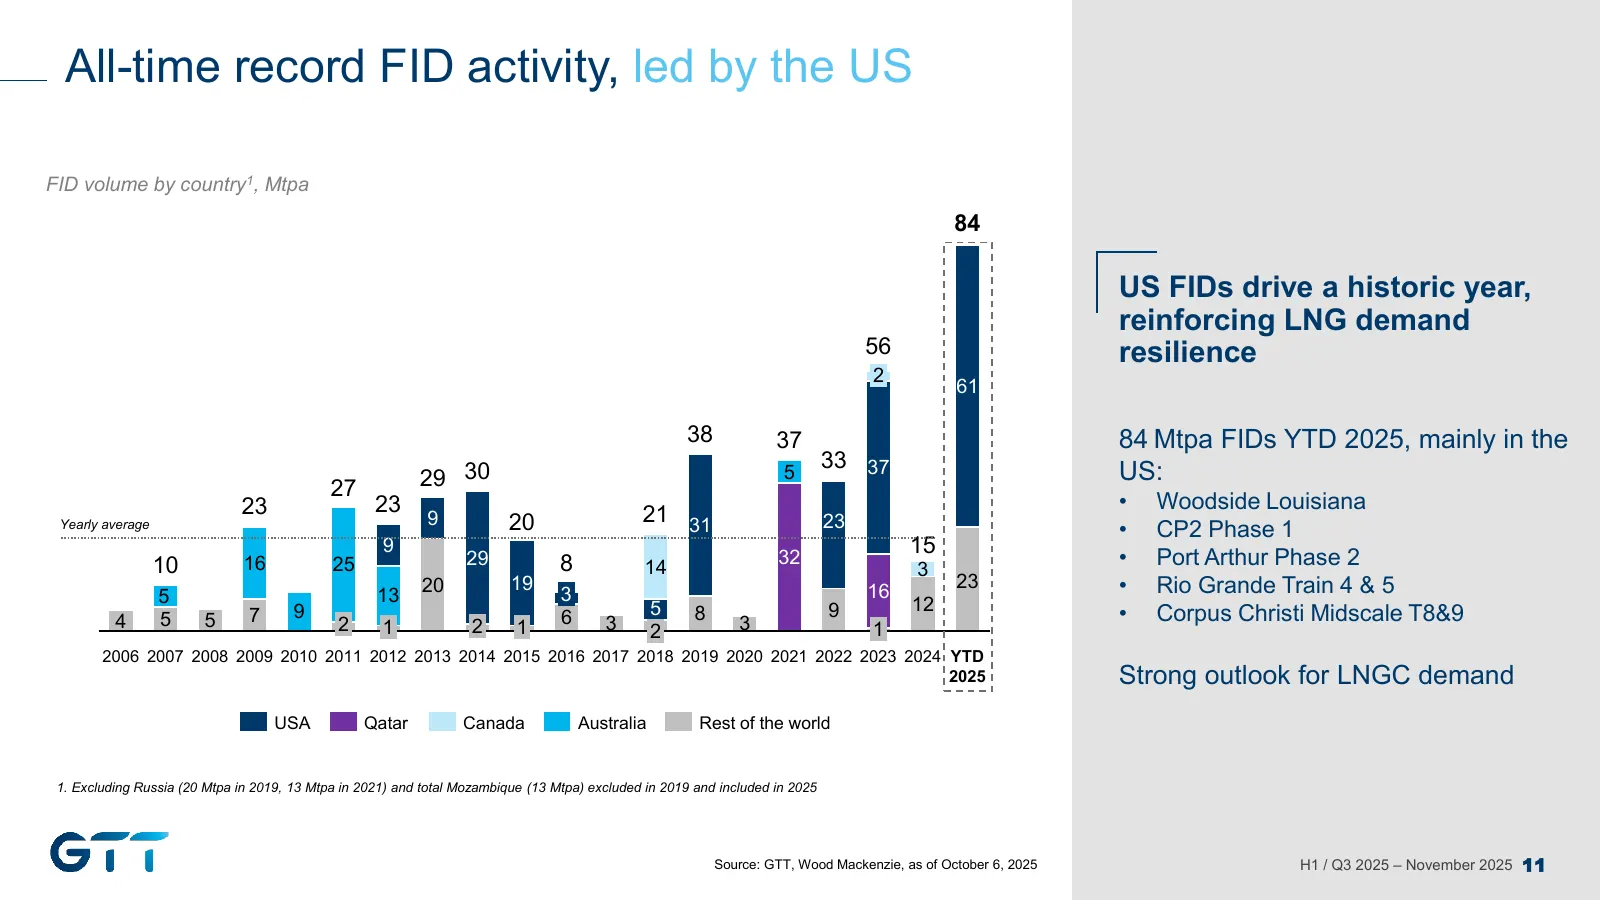
All-time record FID activity, led by the US FID volume by country1, Mtpa 84 US FIDs drive a historic year, reinforcing LNG demand 56 resilience 2 61 38 37 84 Mtpa FIDs YTD 2025, mainly in the 33 37 29 30 5 US: 27 23 23 • Woodside Louisiana 9 20 21 31 23 Yearly average • CP2 Phase 1 9 29 32 15 • Port
Slide 12: FIDs in 2025: record year, more decisions ahead
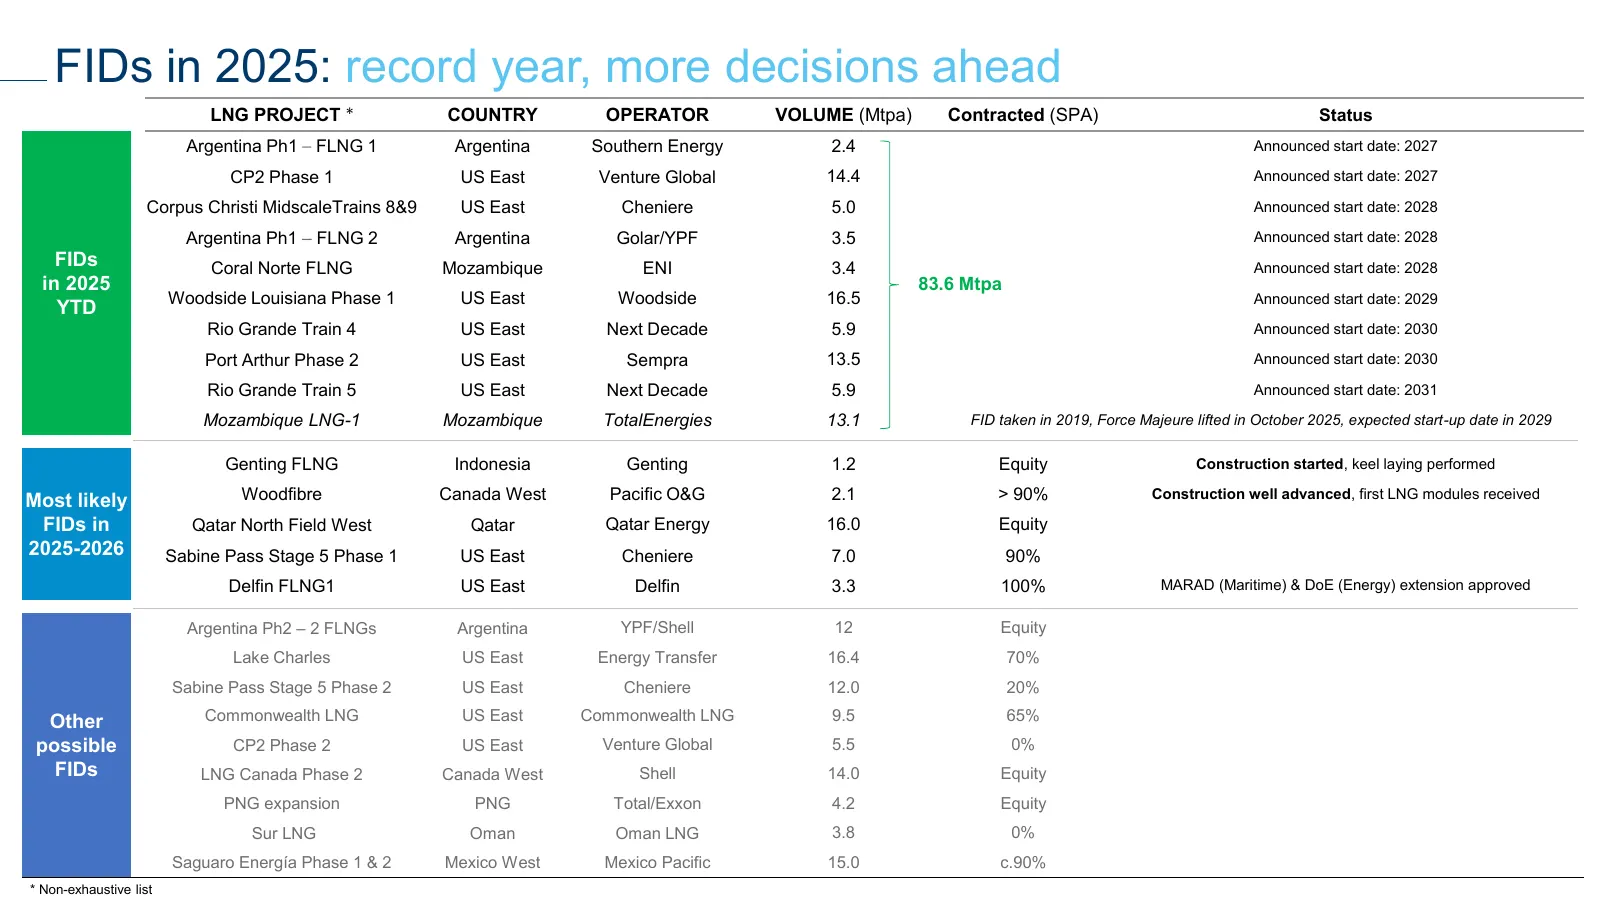
FIDs in 2025: record year, more decisions ahead LNG PROJECT * COUNTRY OPERATOR VOLUME (Mtpa) Contracted (SPA) Status Argentina Ph1 – FLNG 1 Argentina Southern Energy 2.4 Announced start date: 2027 CP2 Phase 1 US East Venture Global 14.4 Announced start date: 2027 Corpus Christi MidscaleTrains 8&9 US
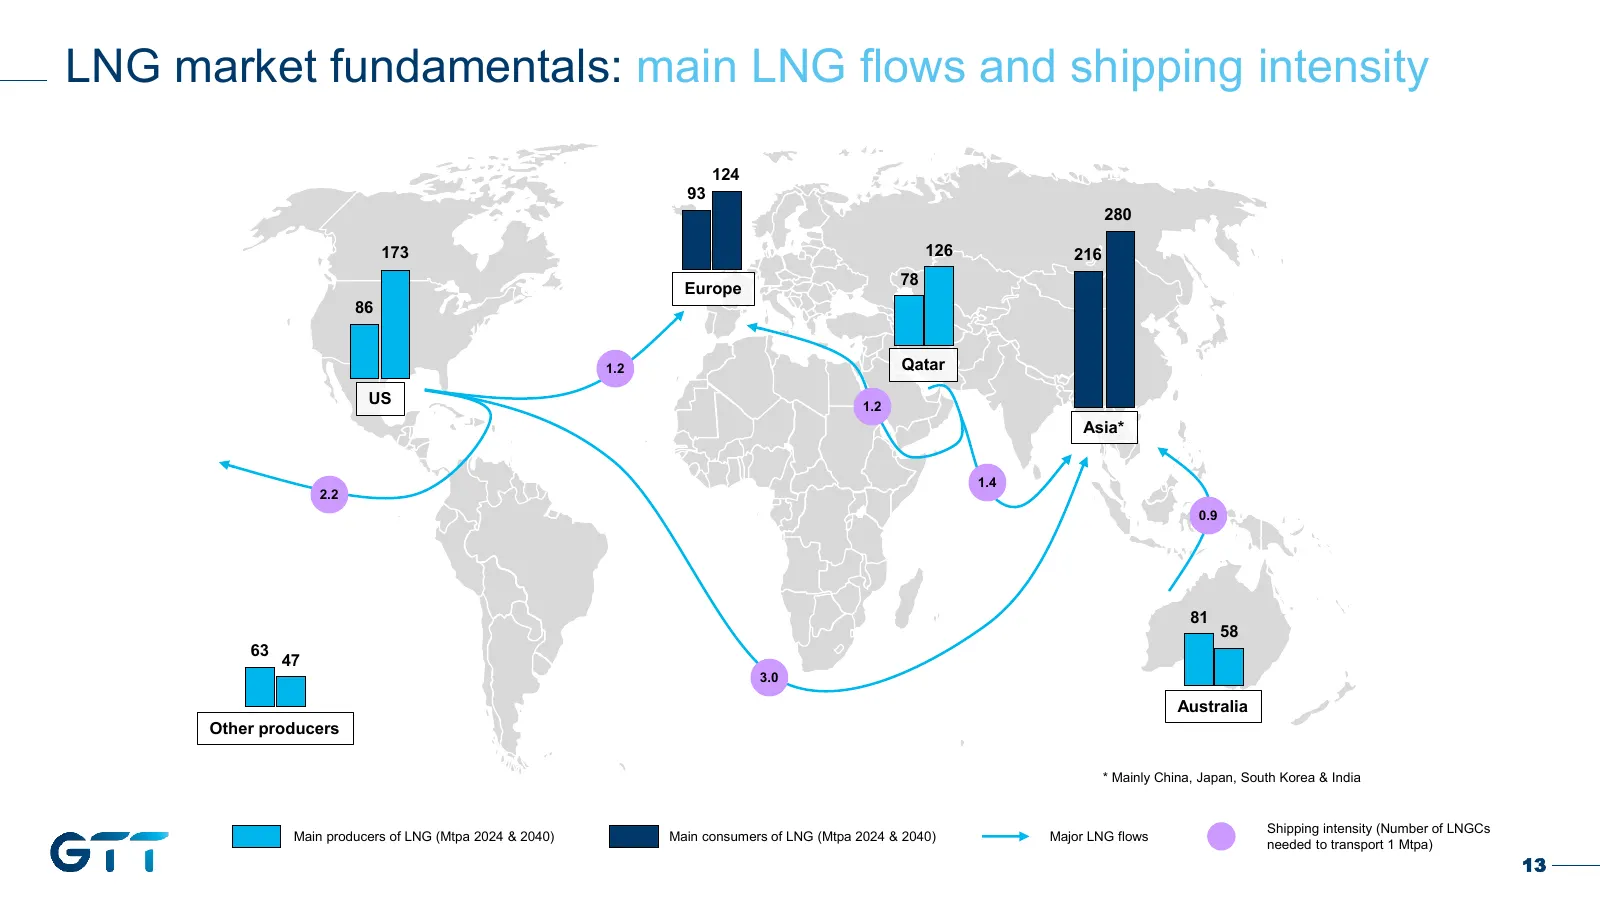
Slide 13: LNG market fundamentals: main LNG flows and shipping intensity
LNG market fundamentals: main LNG flows and shipping intensity 124 93 280 173 126 216 78 Europe 86 1.2 Qatar US 1.2 Asia* 1.4 2.2 0.9 81 58 63 47 3.0 Australia Other producers * Mainly China, Japan, South Korea & India Shipping intensity (Number of LNGCs Main producers of LNG (Mtpa 2024 & 2040) Main
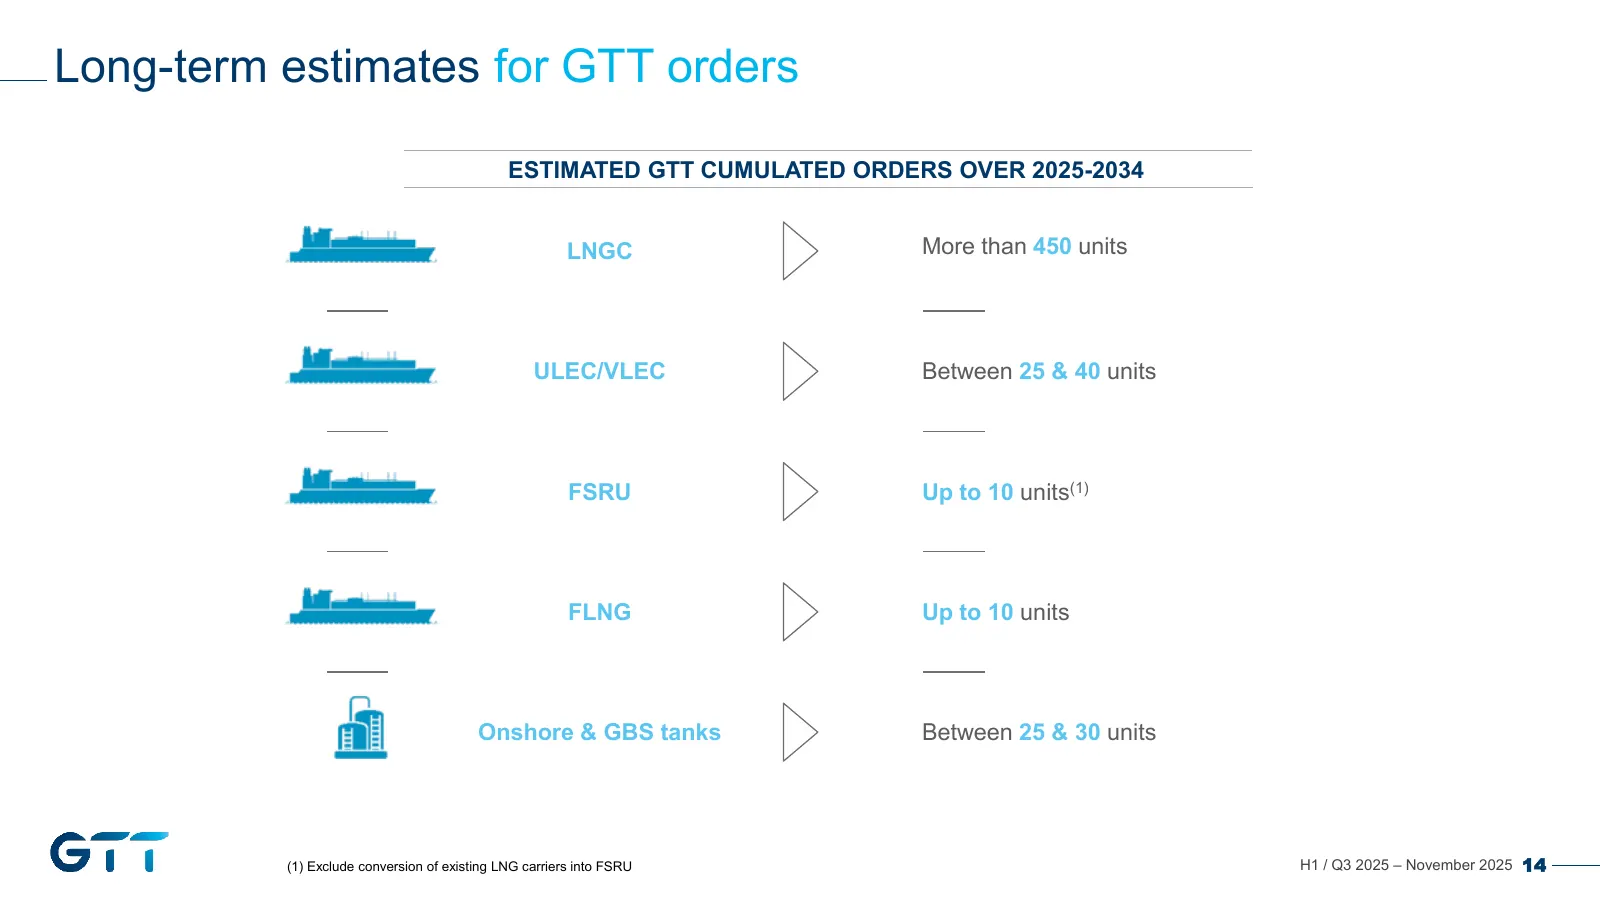
Slide 14: Long-term estimates for GTT orders
Long-term estimates for GTT orders ESTIMATED GTT CUMULATED ORDERS OVER 2025-2034 LNGC More than 450 units ULEC/VLEC Between 25 & 40 units FSRU Up to 10 units(1) FLNG Up to 10 units Onshore & GBS tanks Between 25 & 30 units (1) Exclude conversion of existing LNG carriers into FSRU H1 / Q3 2025 – Nove
Slide 15: Strategy & Activity: Innovation
2 Strategy & Activity INNOVATION
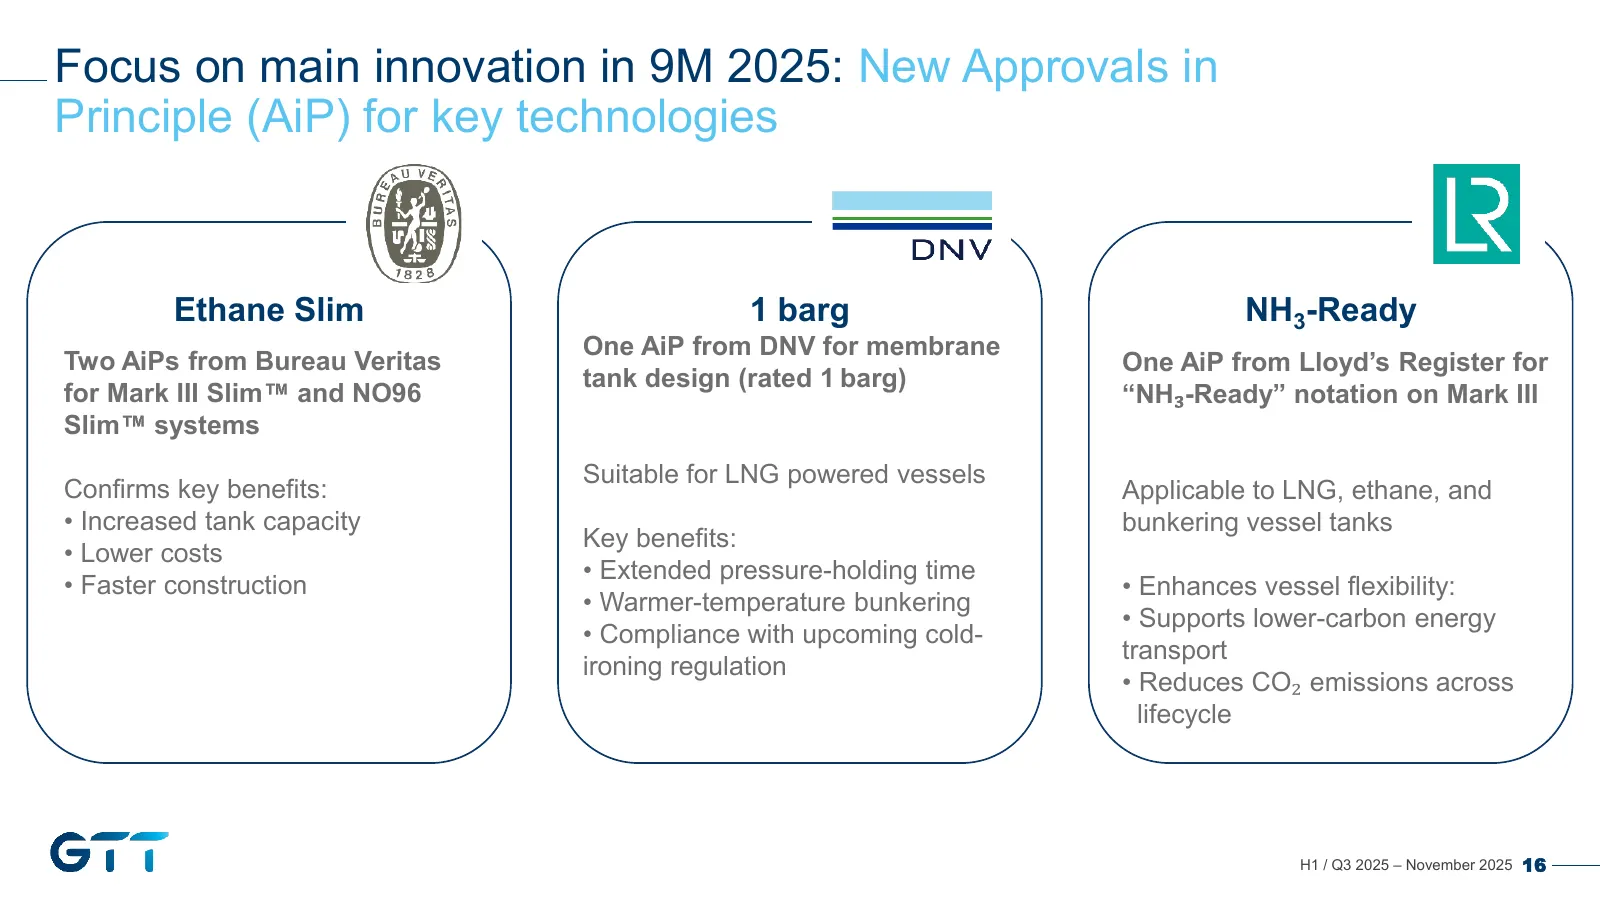
Slide 16: Focus on main innovation in 9M 2025: New Approvals in Principle
Focus on main innovation in 9M 2025: New Approvals in Principle (AiP) for key technologies Ethane Slim 1 barg NH3-Ready One AiP from DNV for membrane Two AiPs from Bureau Veritas One AiP from Lloyd’s Register for tank design (rated 1 barg) for Mark III Slim and NO96 “NH₃-Ready” notation on Mark III
Slide 17: GTT Strategic Ventures: Investing in innovation for a sustainable world
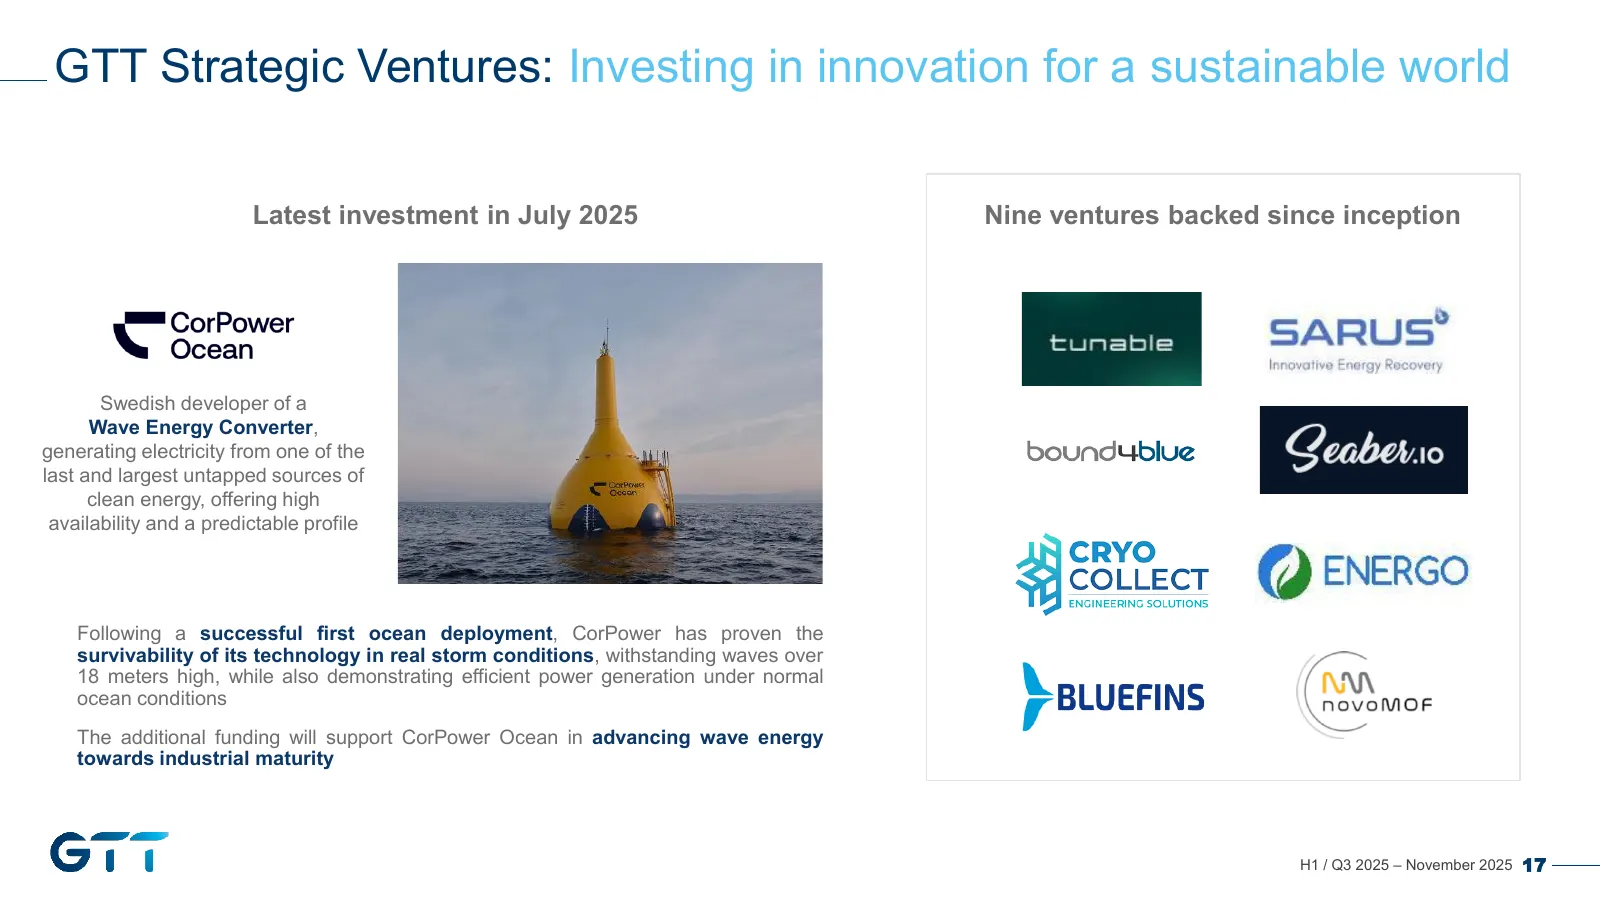
GTT Strategic Ventures: Investing in innovation for a sustainable world Latest investment in July 2025 Nine ventures backed since inception Swedish developer of a Wave Energy Converter, generating electricity from one of the last and largest untapped sources of clean energy, offering high availabili
Slide 18: Strategy & Activity: LNG as Fuel
2 Strategy & Activity LNG AS FUEL
Slide 19: Adoption of LNG as fuel continues to grow
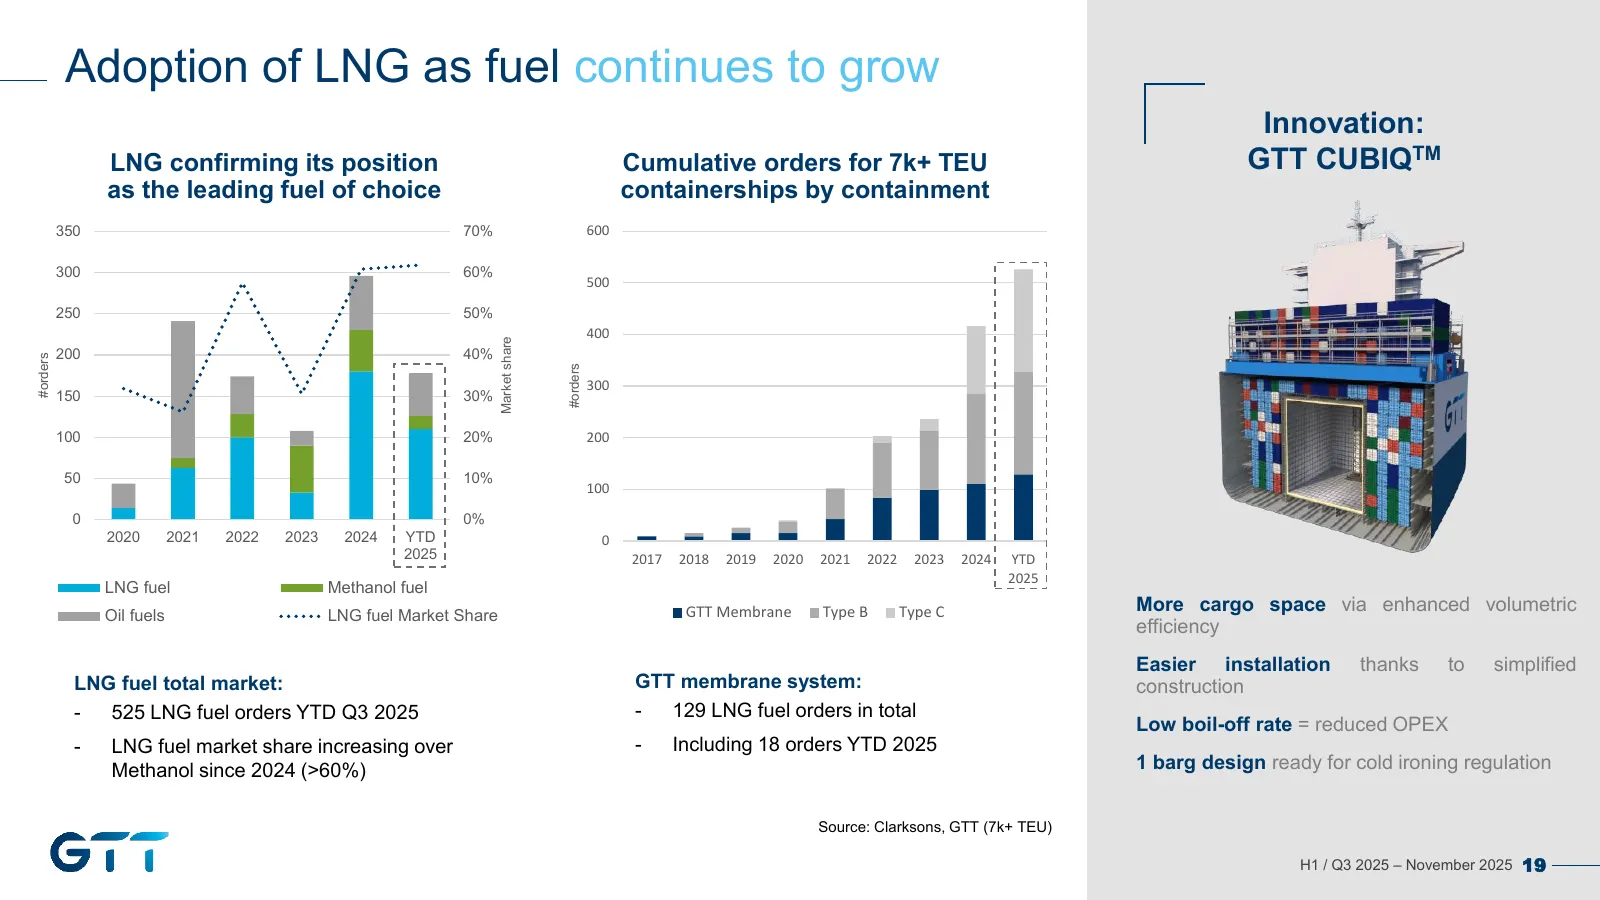
Adoption of LNG as fuel continues to grow Innovation: LNG confirming its position Cumulative orders for 7k+ TEU GTT CUBIQTM as the leading fuel of choice containerships by containment 350 70% 600 300 60% 500 250 50% 400 Market share 200 40% #orders #orders 300 150 30% 100 20% 200 50 10% 100 0 0% 202
Slide 20: Strategy & Activity: Digital Solutions
2 Strategy & Activity DIGITAL SOLUTIONS
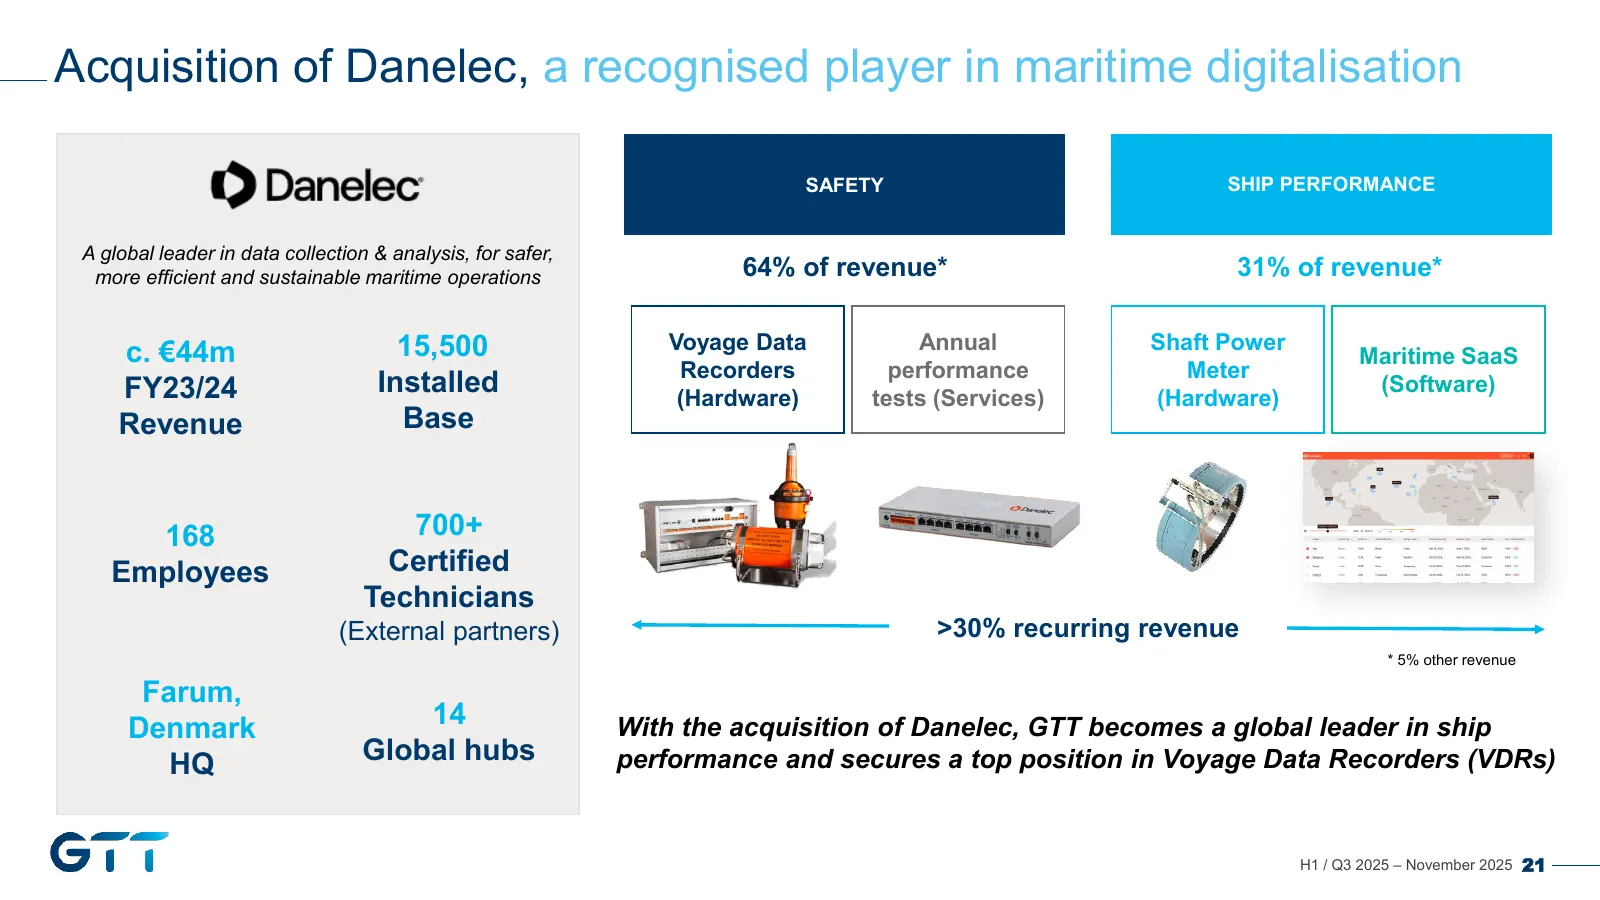
Slide 21: Acquisition of Danelec, a recognised player in maritime digitalisation
Acquisition of Danelec, a recognised player in maritime digitalisation SAFETY SHIP PERFORMANCE A global leader in data collection & analysis, for safer, more efficient and sustainable maritime operations 64% of revenue* 31% of revenue* 15,500 Voyage Data Annual Shaft Power c. €44m Maritime SaaS Reco
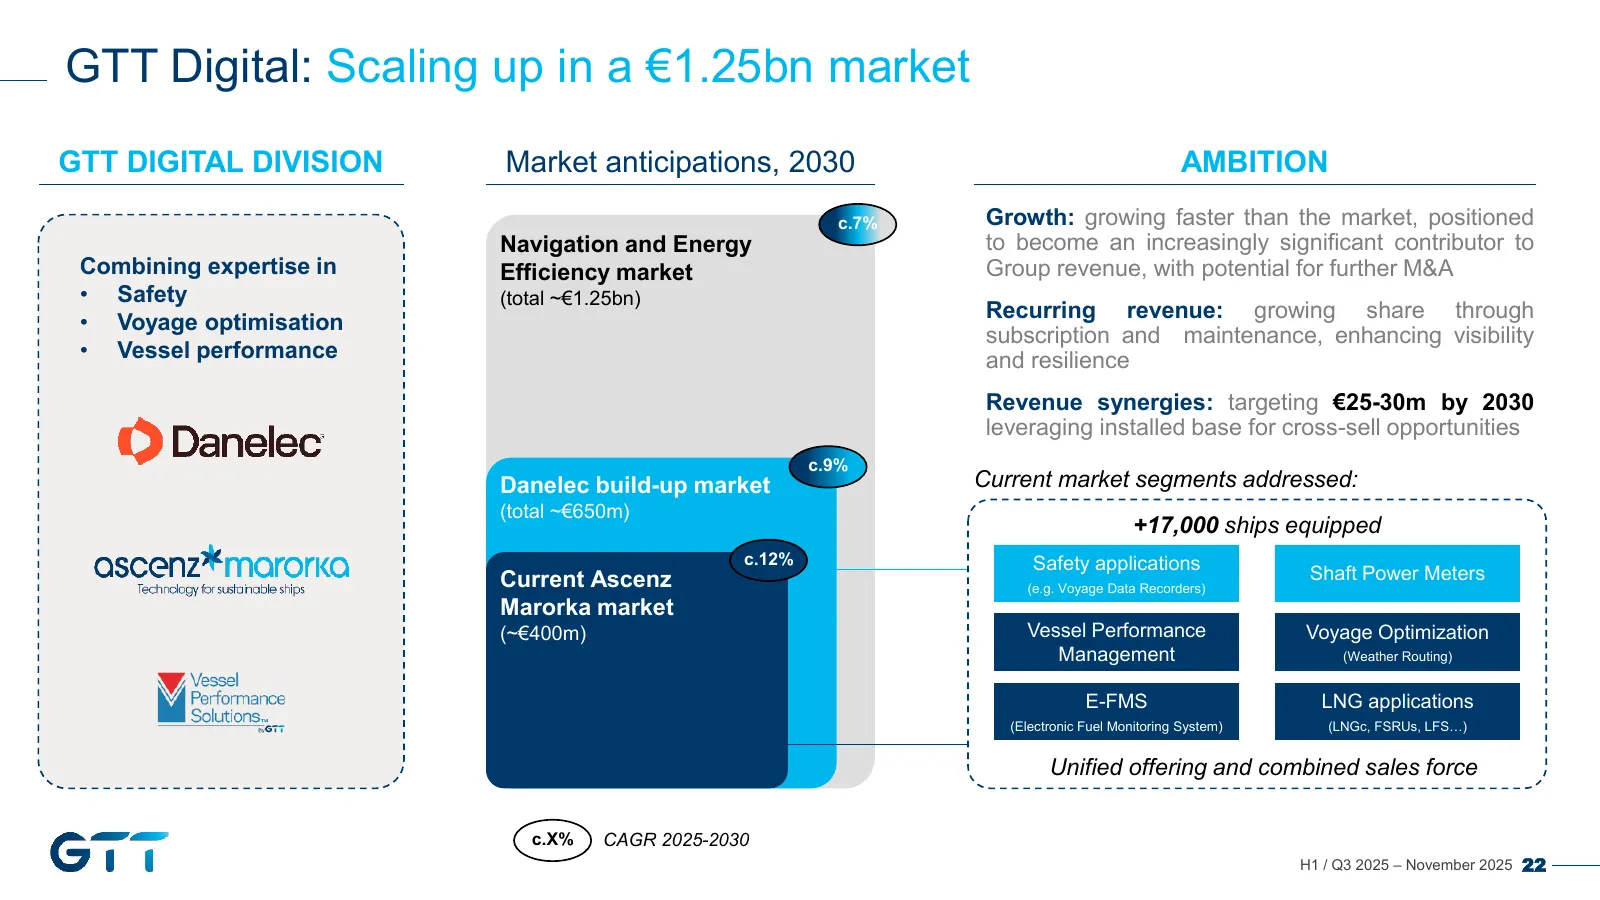
Slide 22: GTT Digital: Scaling up in a €1.25bn market
GTT Digital: Scaling up in a €1.25bn market GTT DIGITAL DIVISION Market anticipations, 2030 AMBITION c.7% Growth: growing faster than the market, positioned Navigation and Energy to become an increasingly significant contributor to Combining expertise in Efficiency market Group revenue, with potenti
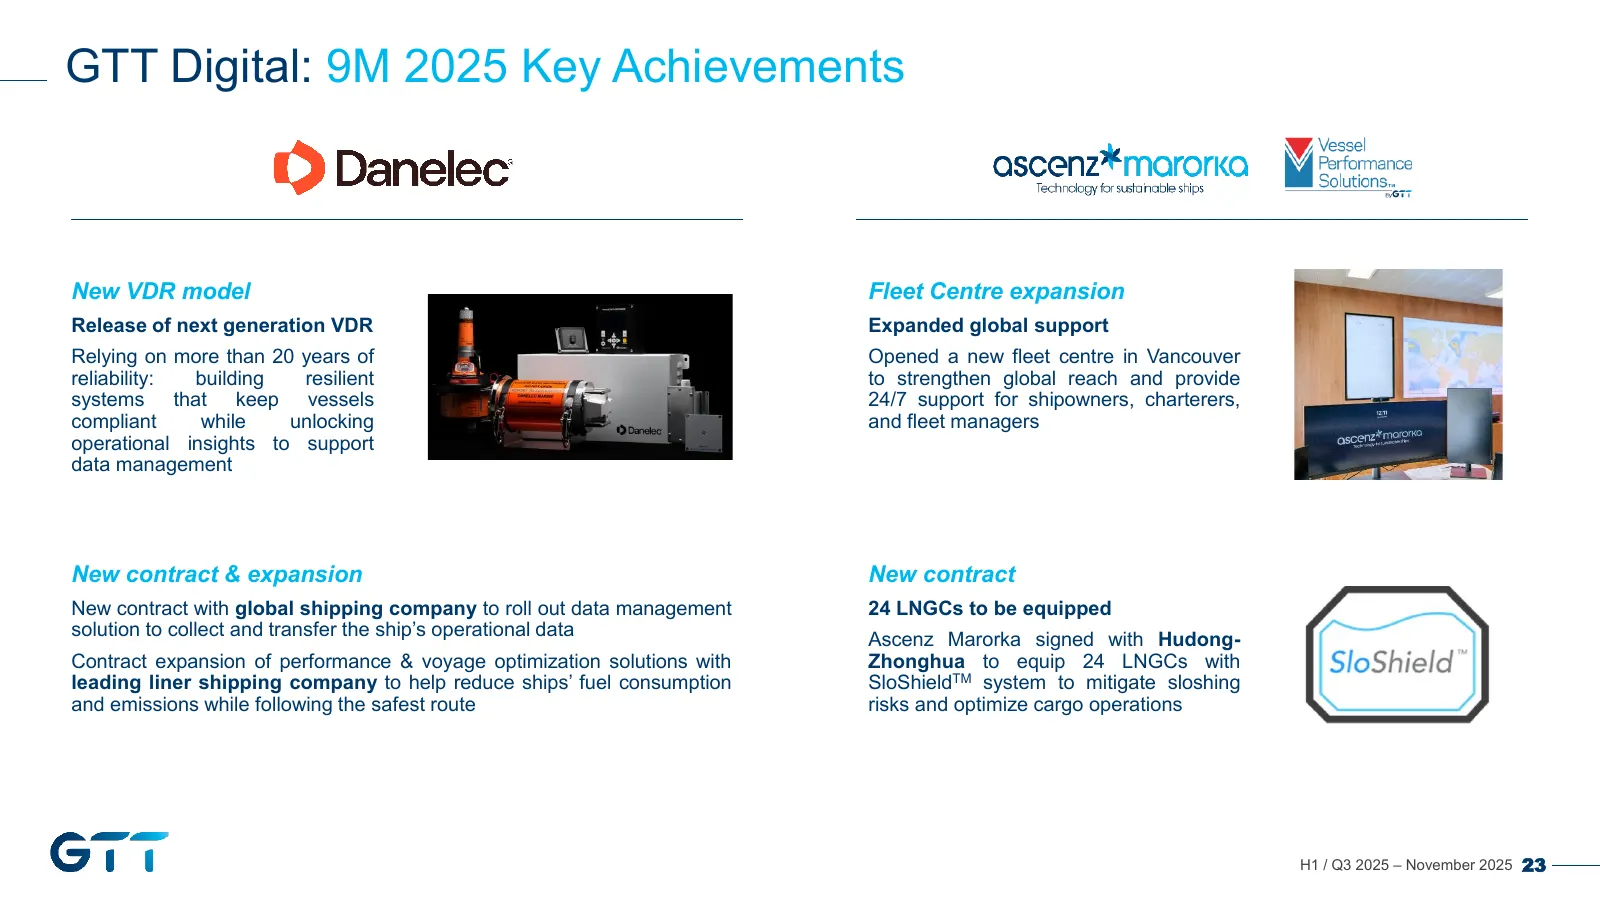
Slide 23: GTT Digital: 9M 2025 Key Achievements
GTT Digital: 9M 2025 Key Achievements New VDR model Fleet Centre expansion Release of next generation VDR Expanded global support Relying on more than 20 years of Opened a new fleet centre in Vancouver reliability: building resilient to strengthen global reach and provide systems that keep vessels 2
Slide 24: Strategy & Activity
fore] > oO) Oo ~y 14) — wy ep) > = 2 > wu — O ee ta
Slide 25: Elogen: Key figures & Strategic review update
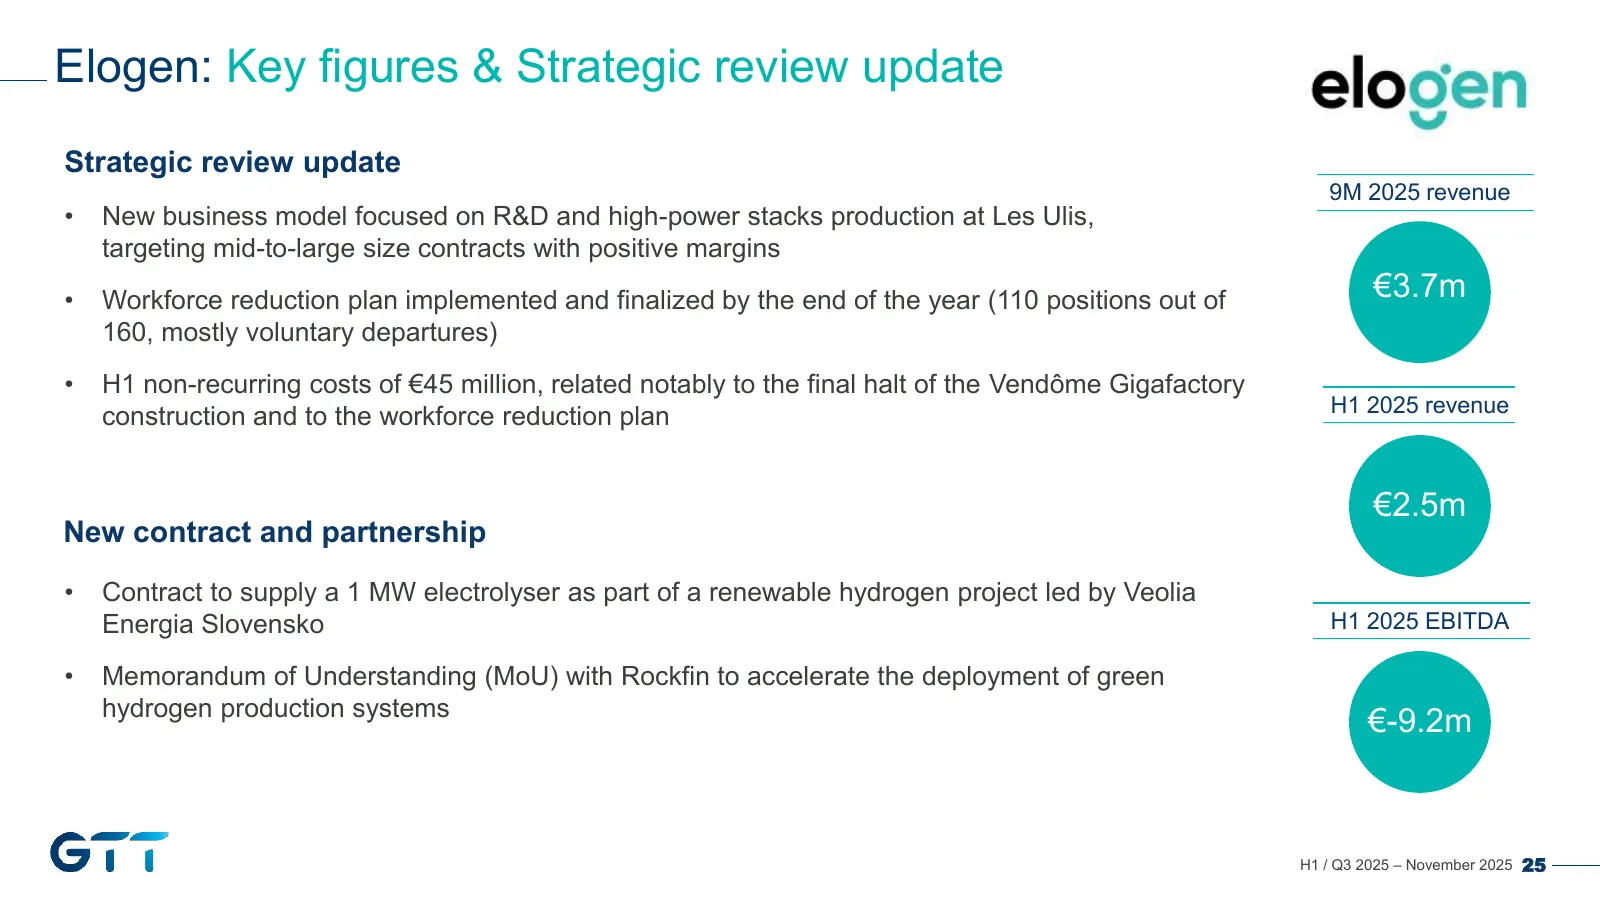
Elogen: Key figures & Strategic review update Strategic review update 9M 2025 revenue • New business model focused on R&D and high-power stacks production at Les Ulis, targeting mid-to-large size contracts with positive margins • Workforce reduction plan implemented and finalized by the end of the y
Slide 26: Financials
3 Financials
Slide 27: H1 2025 core business orderbook: €1.7bn in secured revenue
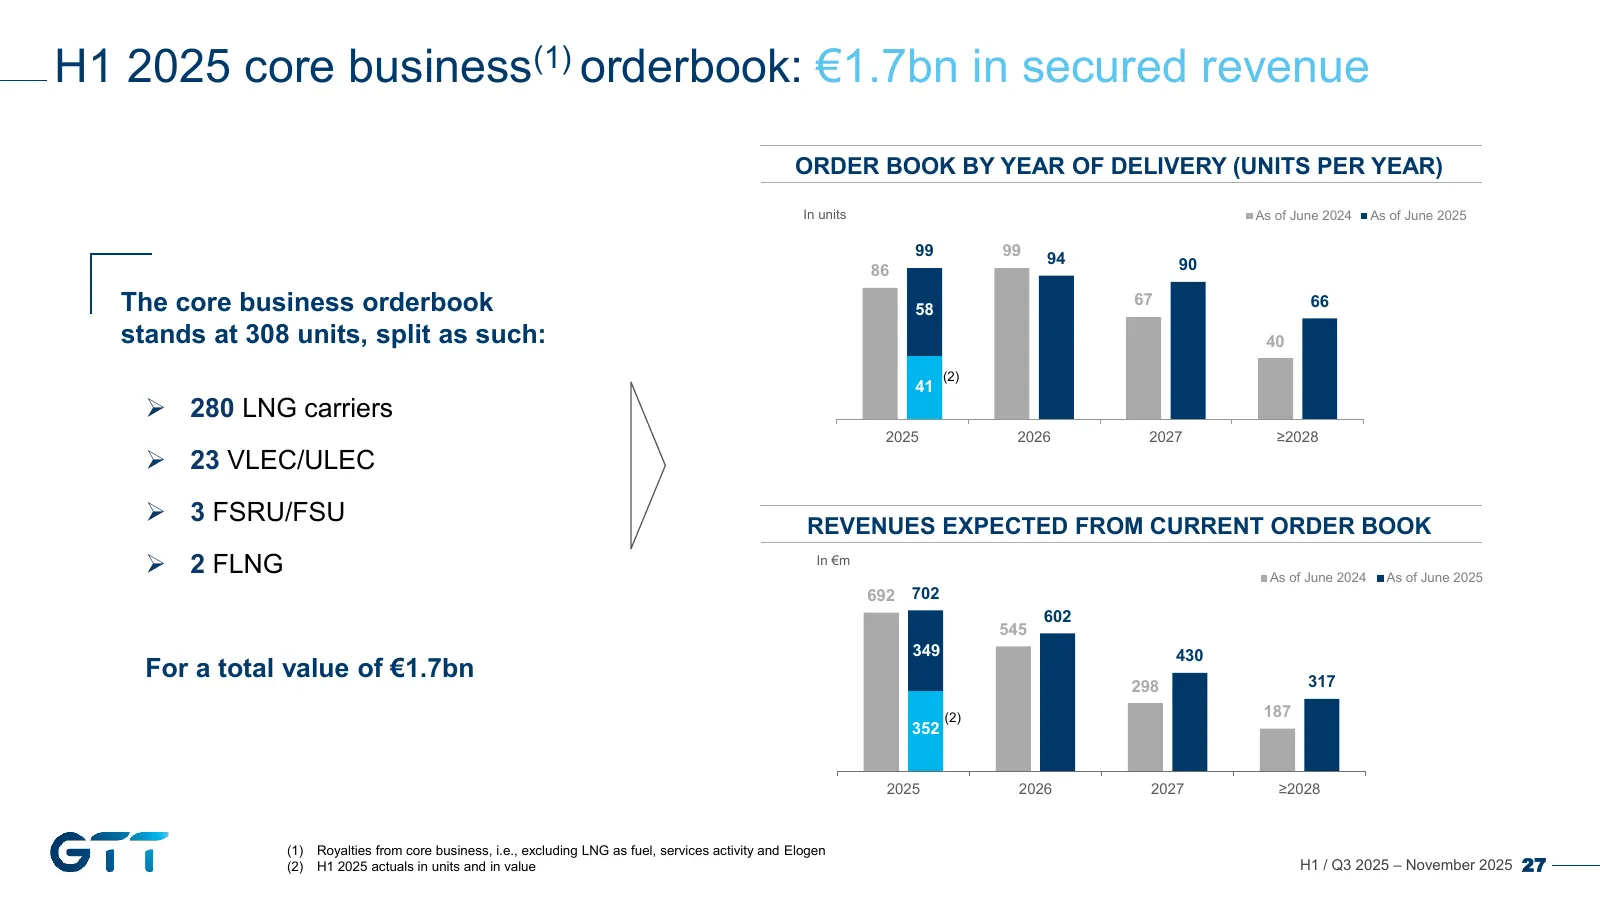
H1 2025 core business(1) orderbook: €1.7bn in secured revenue ORDER BOOK BY YEAR OF DELIVERY (UNITS PER YEAR) In units As of June 2024 As of June 2025 99 99 94 86 90 The core business orderbook 58 67 66 stands at 308 units, split as such: 40 (2) 41 ➢ 280 LNG carriers 2025 2026 2027 ≥2028 ➢ 23 VLEC/U
Slide 28: H1 2025: Consolidated revenue
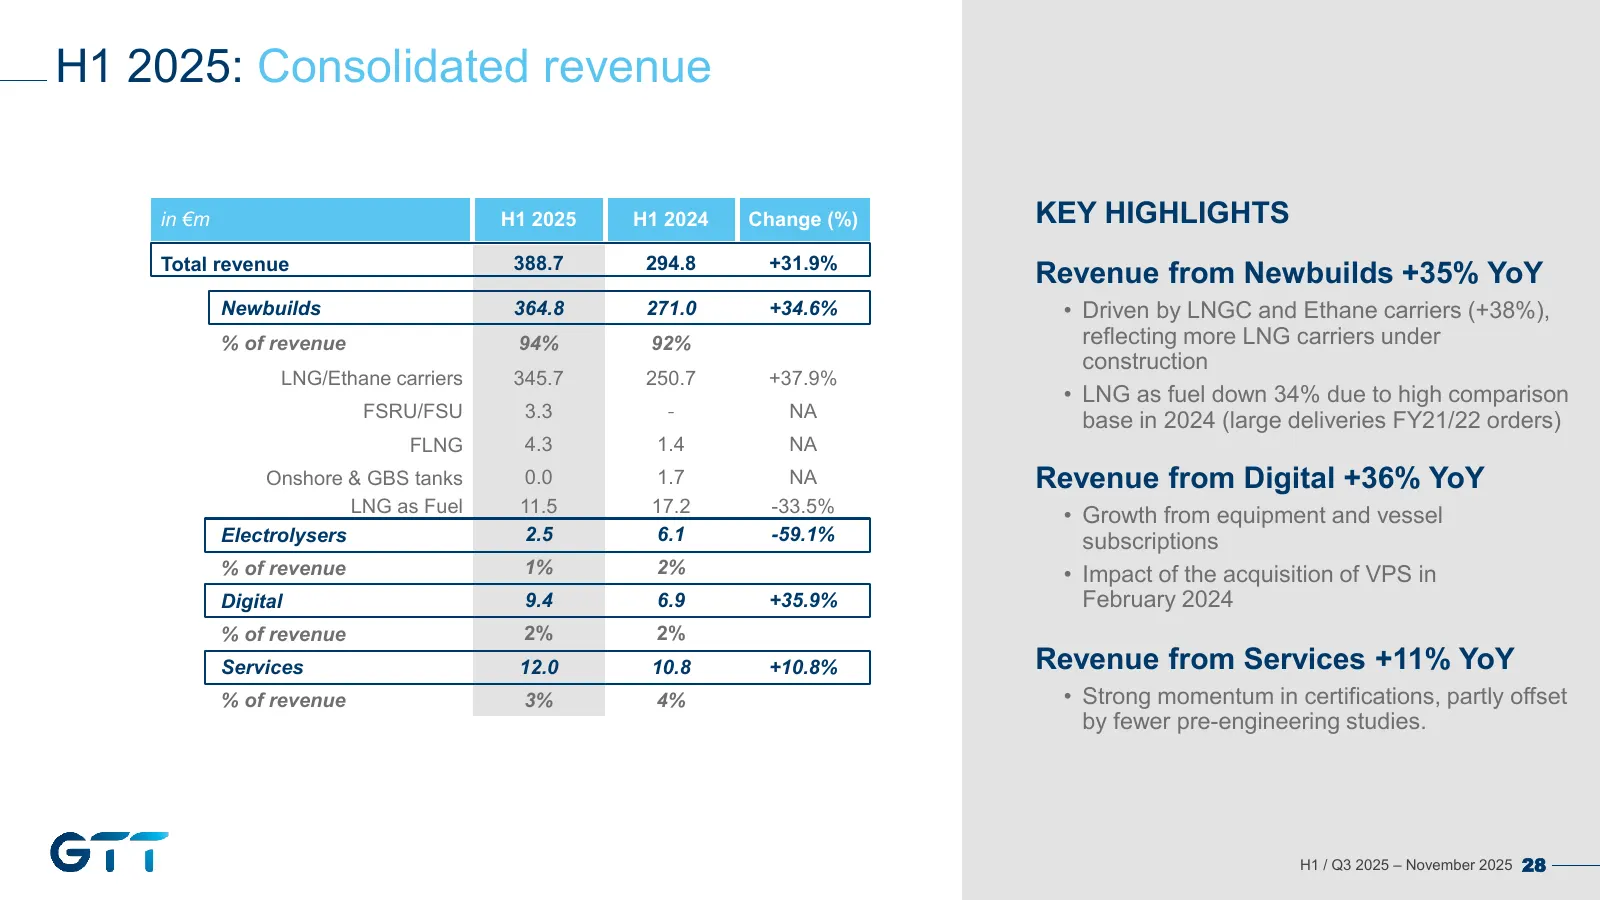
H1 2025: Consolidated revenue in €m H1 2025 H1 2024 Change (%) KEY HIGHLIGHTS Total revenue 388.7 294.8 +31.9% Revenue from Newbuilds +35% YoY Newbuilds 364.8 271.0 +34.6% • Driven by LNGC and Ethane carriers (+38%), % of revenue 94% 92% reflecting more LNG carriers under construction LNG/Ethane car
Slide 29: H1 2025: Financial performance
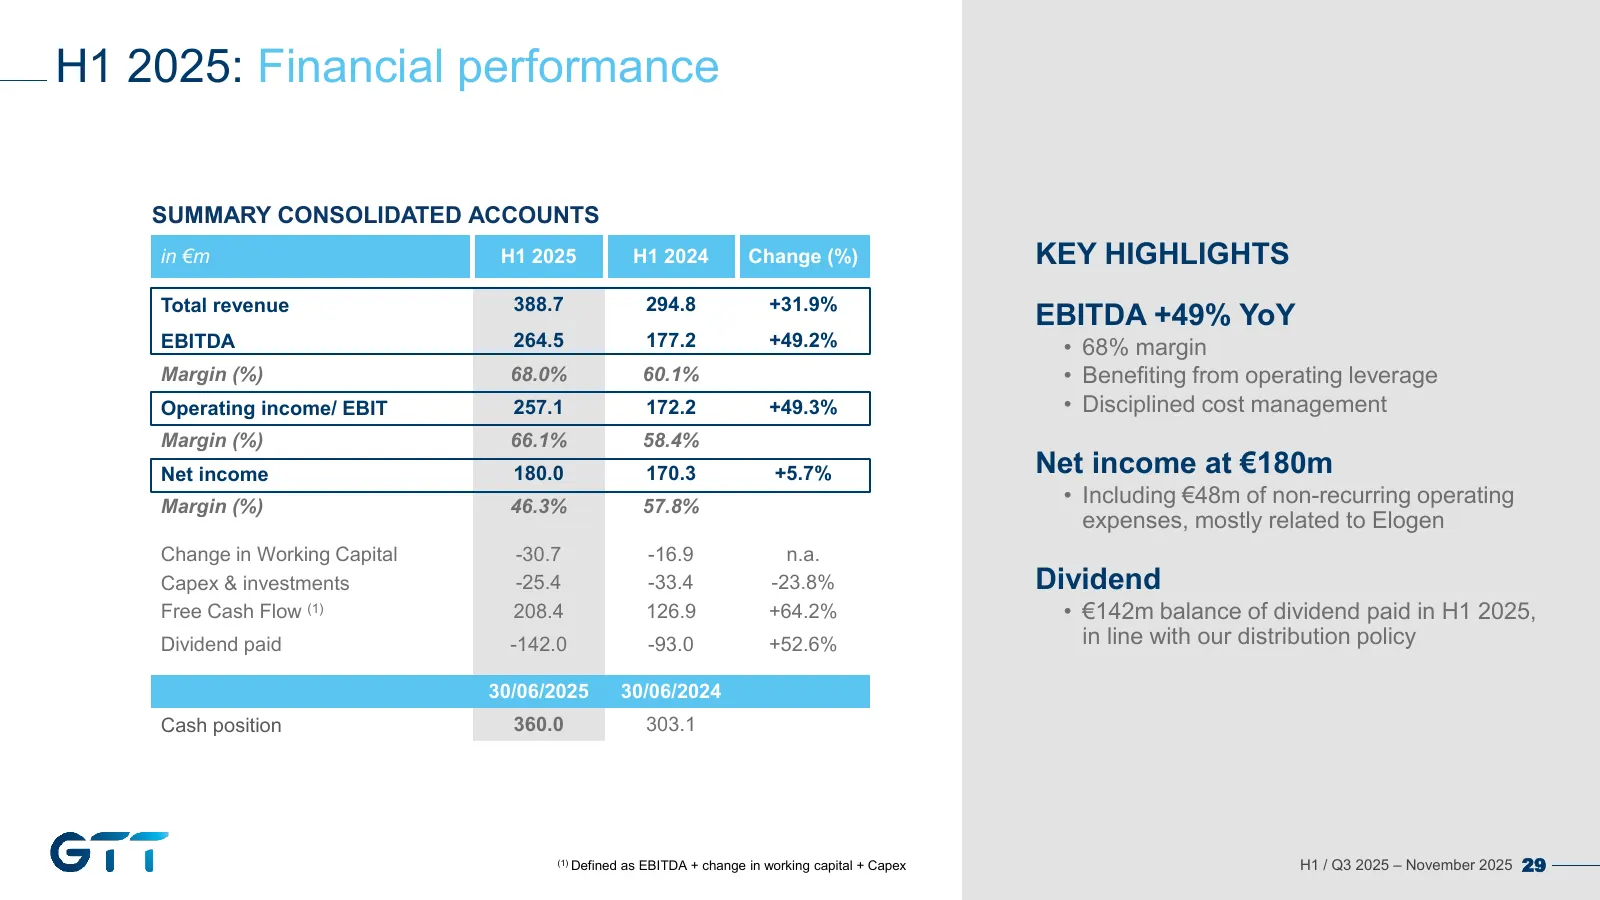
H1 2025: Financial performance SUMMARY CONSOLIDATED ACCOUNTS in €m H1 2025 H1 2024 Change (%) KEY HIGHLIGHTS Total revenue 388.7 294.8 +31.9% EBITDA +49% YoY EBITDA 264.5 177.2 +49.2% • 68% margin Margin (%) 68.0% 60.1% • Benefiting from operating leverage Operating income/ EBIT 257.1 172.2 +49.3% •
Slide 30: 9M 2025: Consolidated Revenue
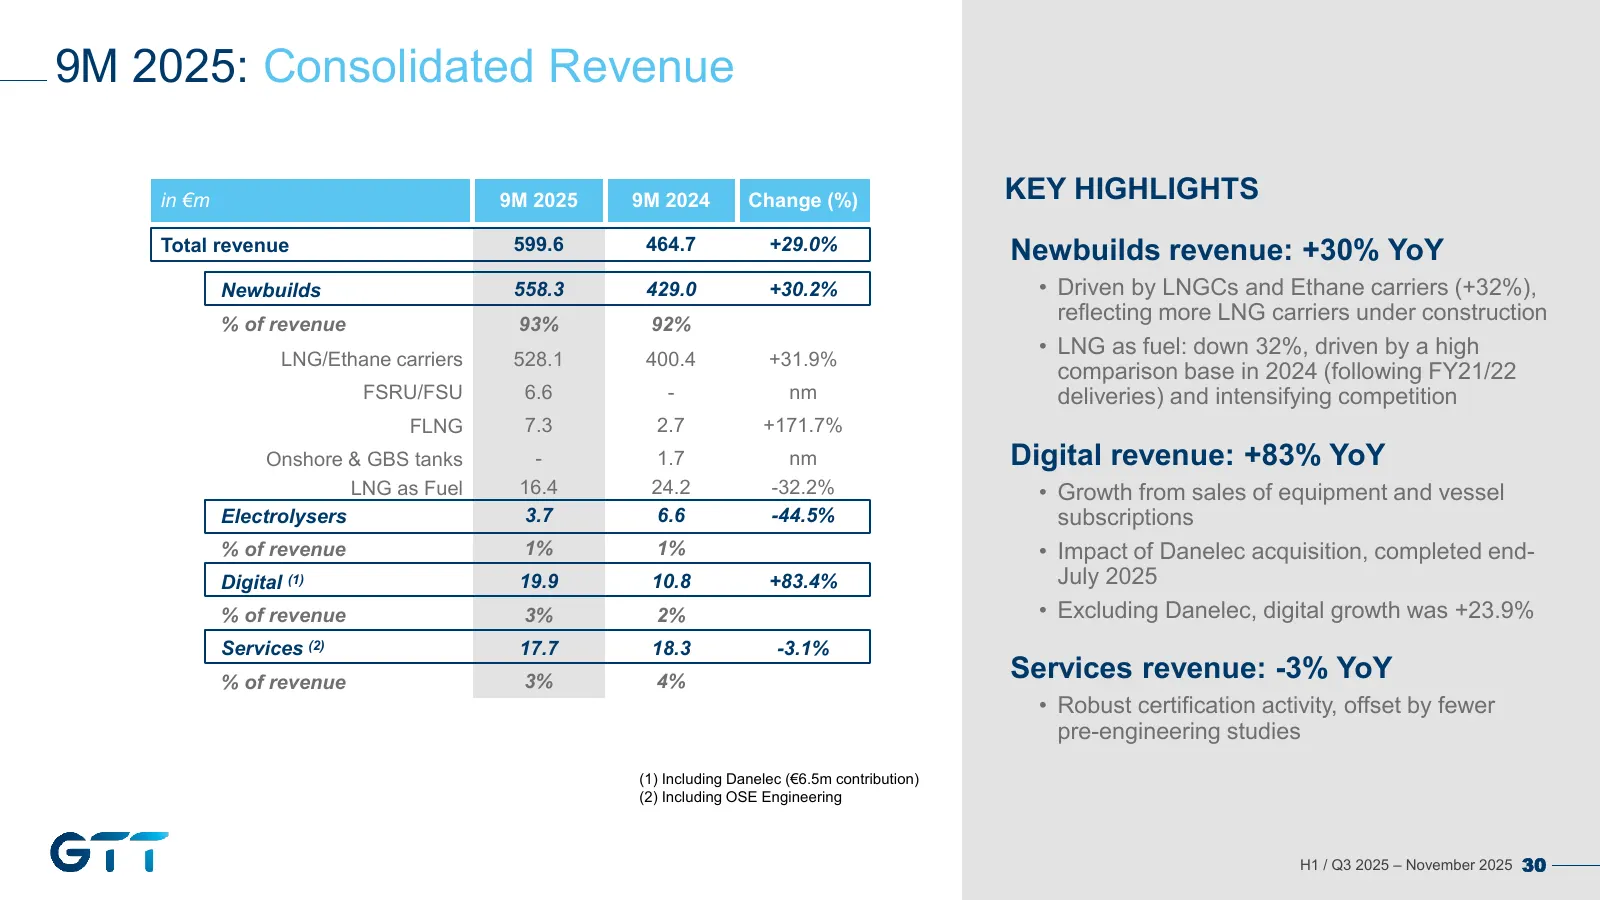
9M 2025: Consolidated Revenue in €m 9M 2025 9M 2024 Change (%) KEY HIGHLIGHTS Total revenue 599.6 464.7 +29.0% Newbuilds revenue: +30% YoY Newbuilds 558.3 429.0 +30.2% • Driven by LNGCs and Ethane carriers (+32%), % of revenue 93% 92% reflecting more LNG carriers under construction • LNG as fuel: do
Slide 31: Outlook & Conclusion
4 Outlook & Conclusion
Slide 32: Upgraded 2025 Outlook including Danelec
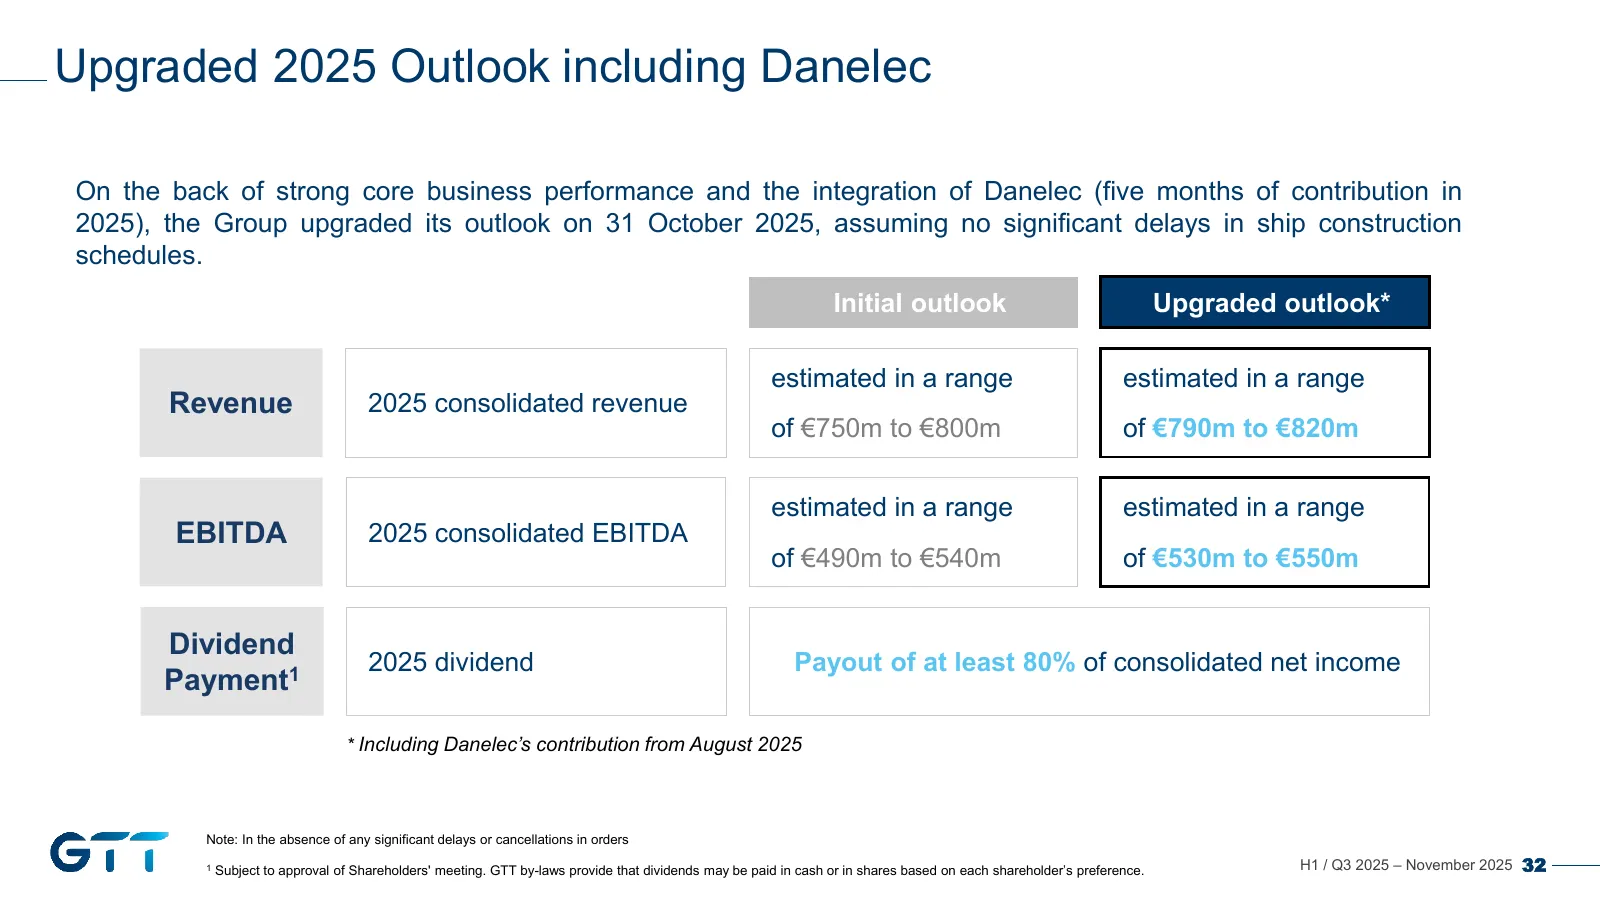
Upgraded 2025 Outlook including Danelec On the back of strong core business performance and the integration of Danelec (five months of contribution in 2025), the Group upgraded its outlook on 31 October 2025, assuming no significant delays in ship construction schedules. Initial outlook Upgraded out
Slide 33: Q&A
Q&A 33
Slide 34: Appendices
Appendices
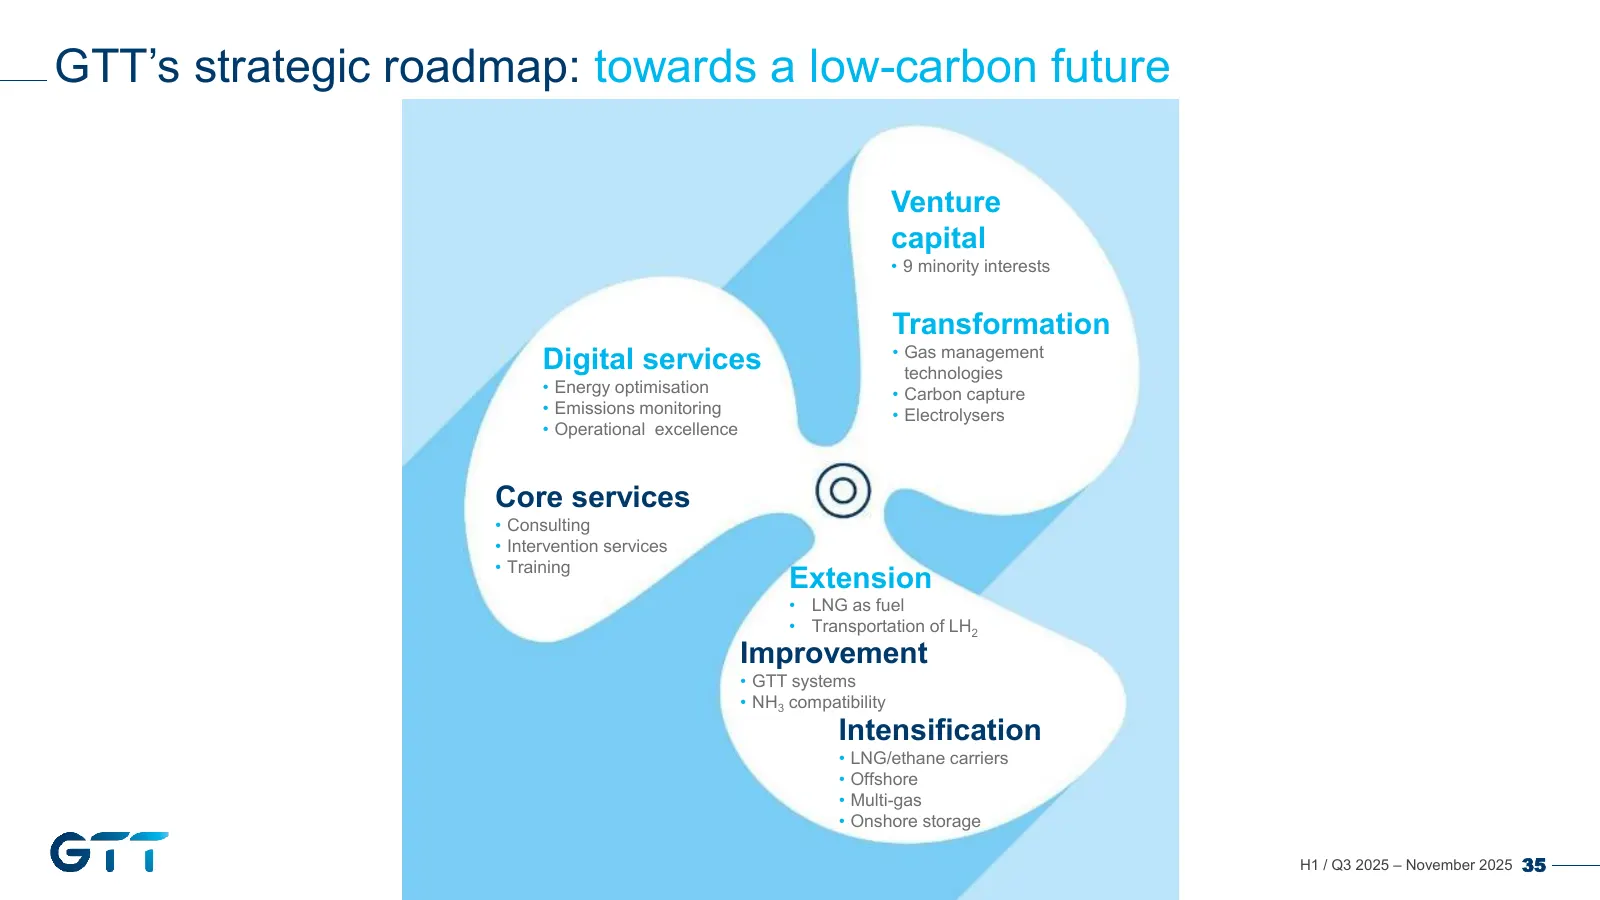
Slide 35: GTT's strategic roadmap: towards a low-carbon future
GTT’s strategic roadmap: towards a low-carbon future Venture capital • 9 minority interests Transformation Digital services • Gas management technologies • Energy optimisation • Carbon capture • Emissions monitoring • Electrolysers • Operational excellence Core services • Consulting • Intervention s
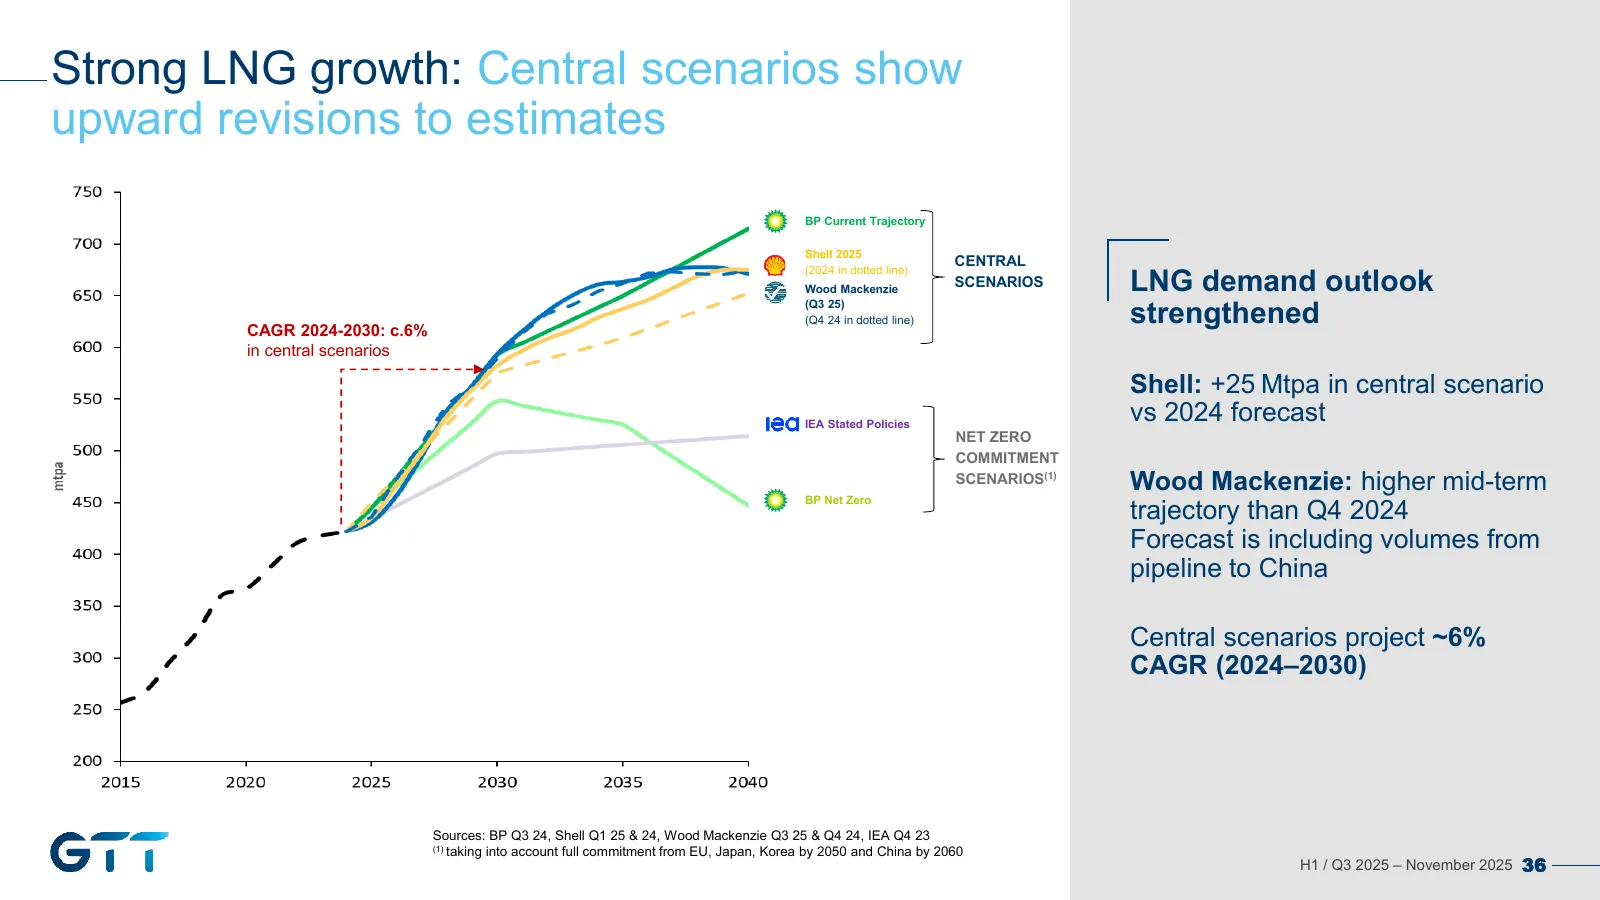
Slide 36: Strong LNG growth: Central scenarios show upward revisions to estimates
Strong LNG growth: Central scenarios show upward revisions to estimates BP Current Trajectory Shell 2025 CENTRAL (2024 in dotted line) Wood Mackenzie SCENARIOS LNG demand outlook CAGR 2024-2030: c.6% (Q3 25) (Q4 24 in dotted line) strengthened in central scenarios Shell: +25 Mtpa in central scenario
Slide 37: LNG supply/demand balance: New liquefaction capacities needed
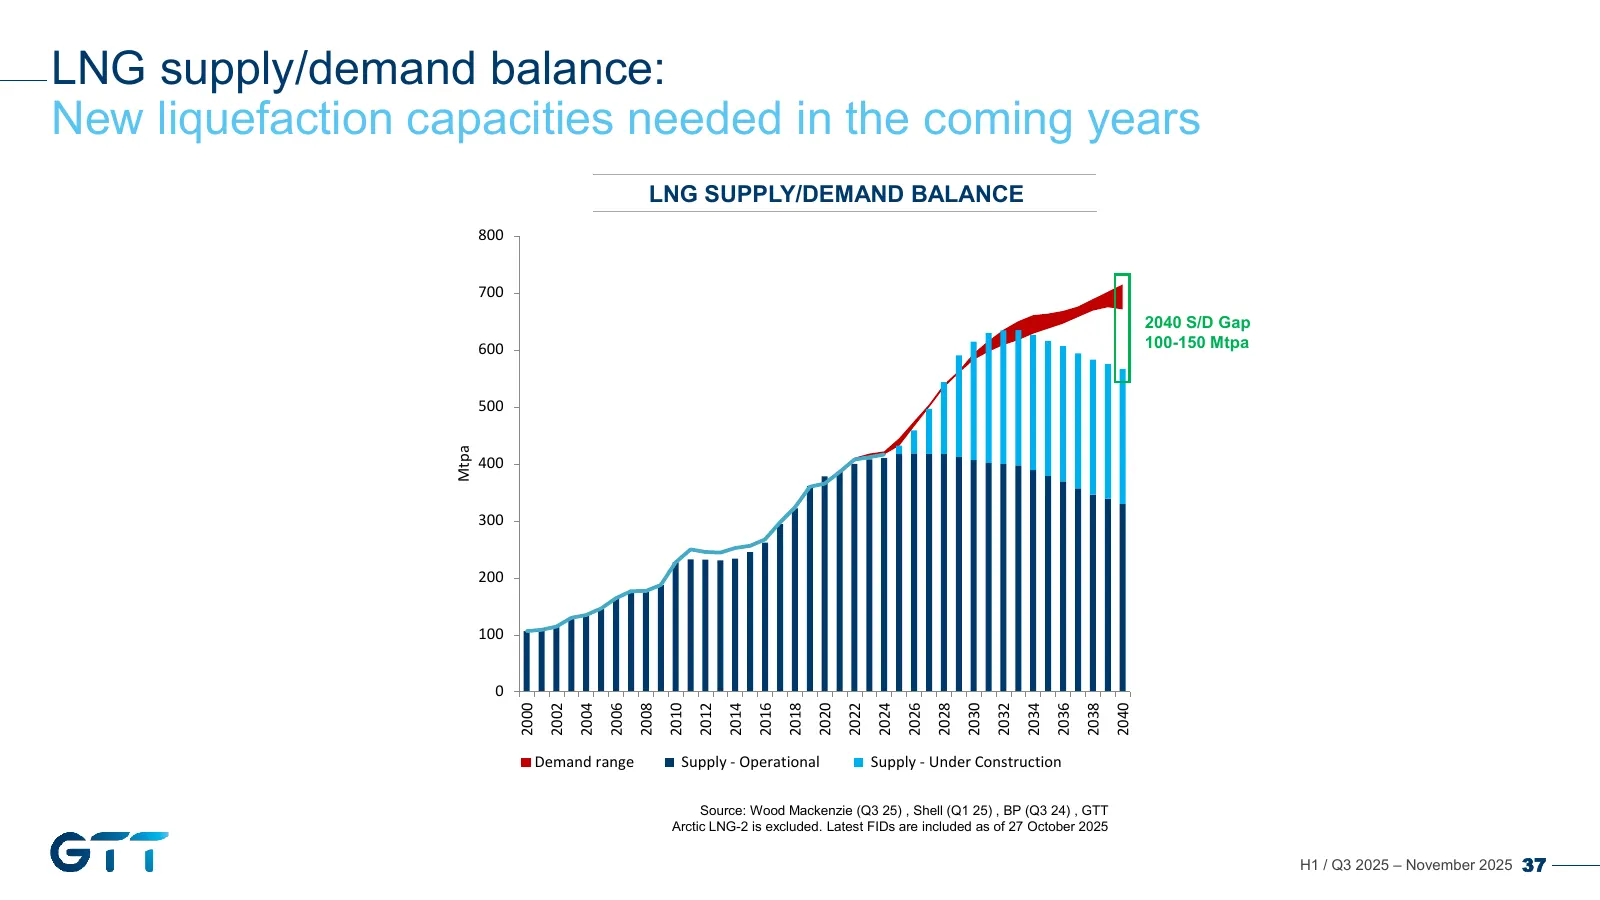
LNG supply/demand balance: New liquefaction capacities needed in the coming years LNG SUPPLY/DEMAND BALANCE 800 700 2040 S/D Gap 600 100-150 Mtpa 500 Mtpa 400 300 200 100 0 2028 2000 2002 2004 2006 2008 2010 2012 2014 2016 2018 2020 2022 2024 2026 2030 2032 2034 2036 2038 2040 Demand range Supply -
Slide 38: An attractive business model supporting high cash generation
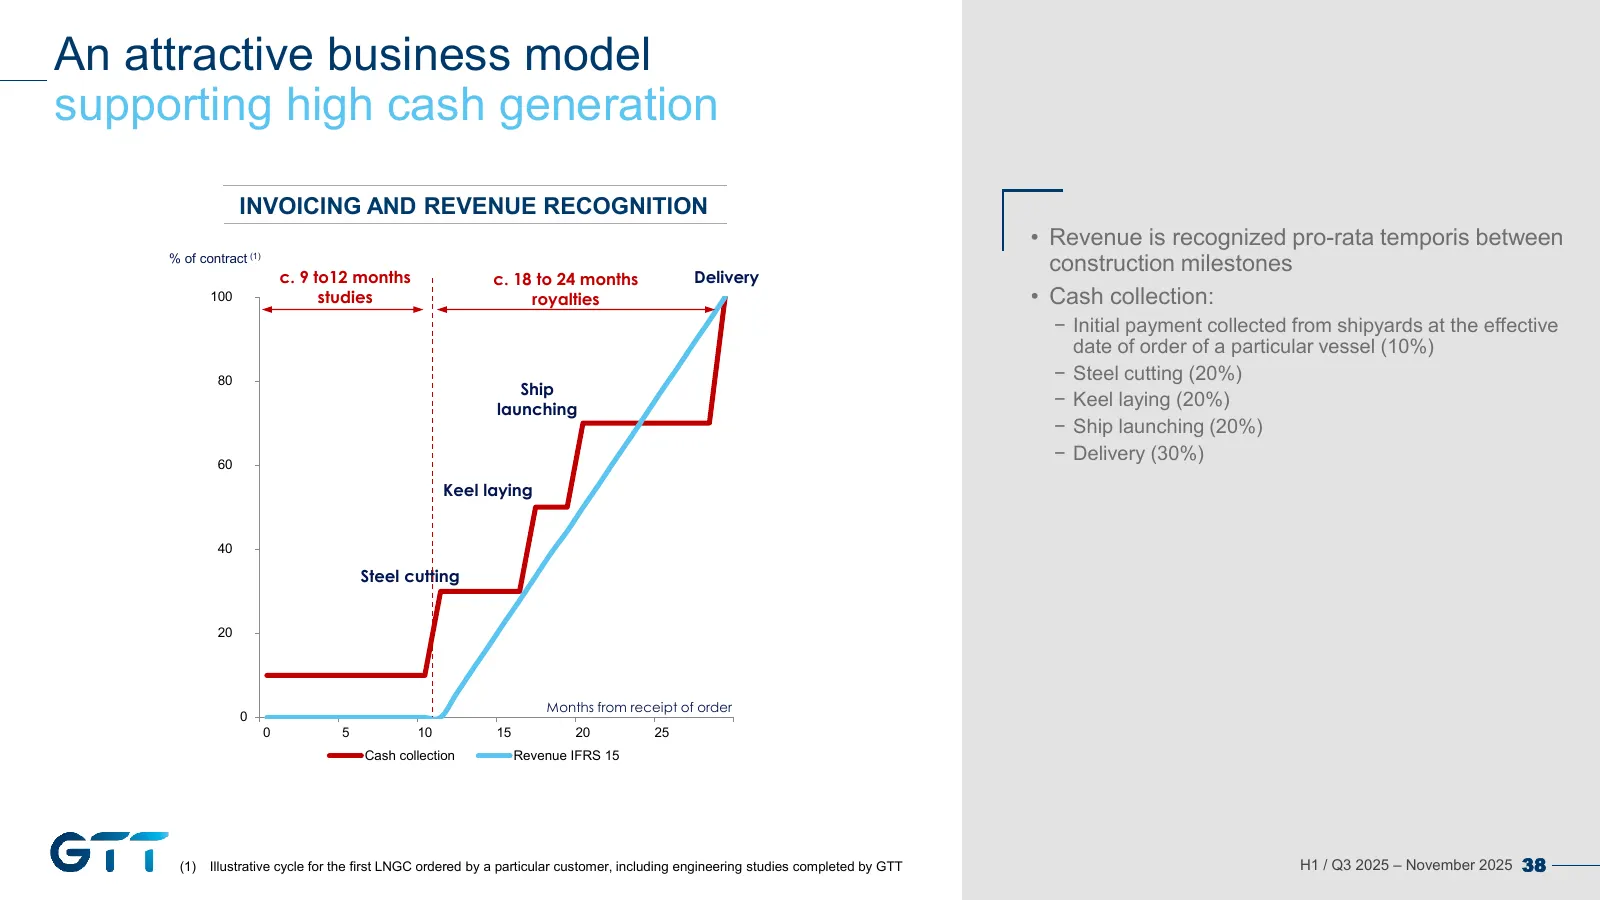
An attractive business model supporting high cash generation INVOICING AND REVENUE RECOGNITION • Revenue is recognized pro-rata temporis between % of contract (1) construction milestones c. 9 to12 months c. 18 to 24 months Delivery 10000 studies royalties • Cash collection: − Initial payment collect
Slide 39: Glossary
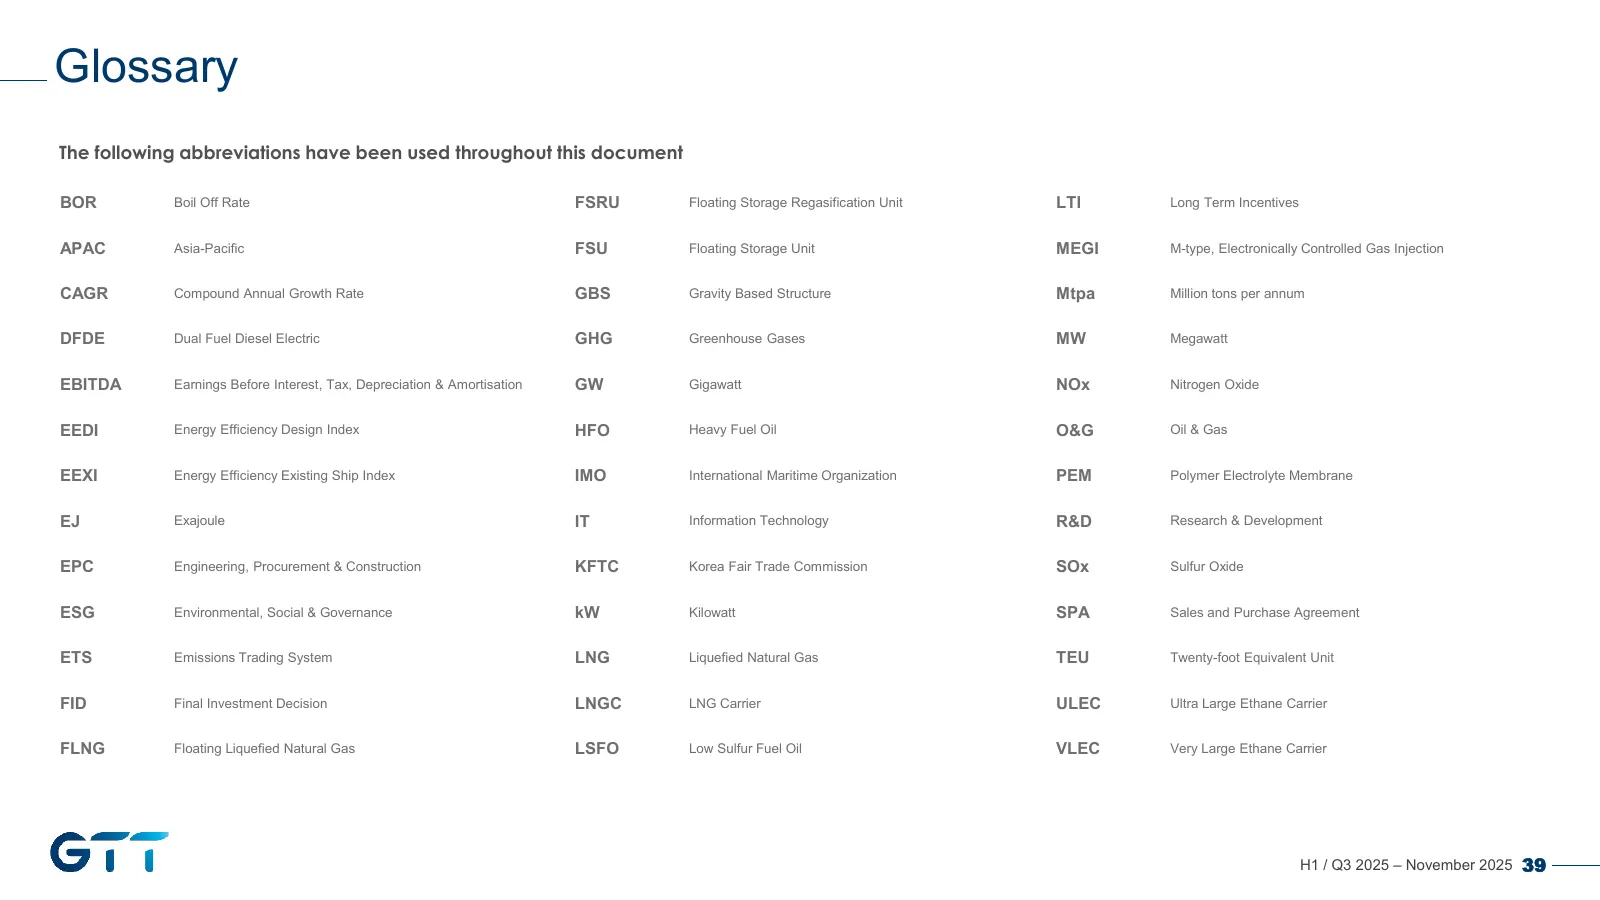
Glossary The following abbreviations have been used throughout this document BOR Boil Off Rate FSRU Floating Storage Regasification Unit LTI Long Term Incentives APAC Asia-Pacific FSU Floating Storage Unit MEGI M-type, Electronically Controlled Gas Injection CAGR Compound Annual Growth Rate GBS Grav
Slide 40: H1 / Q3 2025 Technology for a Sustainable World
H1 / Q3 2025 TECHNOLOGY FOR A SUSTAINABLE WORLD November 2025
Source: company website
More decks from Gaztransport & Technigaz SA
 9M 2026 Earnings Presentation35 slides · Oct 23, 2026
 H1 2026 Earnings Presentation36 slides · Jul 29, 2026
 FY2025 / Q1 2026 Earnings Presentation41 slides · May 2026
 Q1 2026 Earnings Presentation24 slides · Apr 22, 2026
 FY 2025 Earnings Presentation50 slides · Feb 20, 2026
 Q3 2025 Earnings Presentation24 slides · Nov 3, 2025