Kingfisher PLC · LSE:KGF
Kingfisher — FY2013/14 Earnings Presentation
70 slides from Kingfisher's earnings presentation, March 2014
Slide 1: Kingfisher plc Prelim Results
Kingfisher plc Prelim Results Year ended 1 February 2014
Slide 2: Disclaimer
Disclaimer THE FOLLOWING PRESENTATION IS BEING MADE ONLY TO, AND IS ONLY DIRECTED AT, PERSONS TO WHOM SUCH PRESENTATION MAY LAWFULLY BE COMMUNICATED (‘RELEVANT PERSONS’). ANY PERSON WHO IS NOT A RELEVANT PERSON SHOULD NOT ACT OR RELY ON THIS PRESENTATION OR ANY OF ITS CONTENTS. THIS PRESENTATION DOE
Slide 3: Sir Ian Cheshire, Group Chief Executive
Sir Ian Cheshire Group Chief Executive 3
Slide 4: Agenda
Agenda Introduction Sir Ian Cheshire Group Chief Executive Financial review Karen Witts Group Finance Director Creating the Leader Sir Ian Cheshire Group Chief Executive B&Q UK & Ireland update Kevin O’Byrne Chief Executive, B&Q UK & Ireland Questions 4
Slide 5: 2013/14 Summary
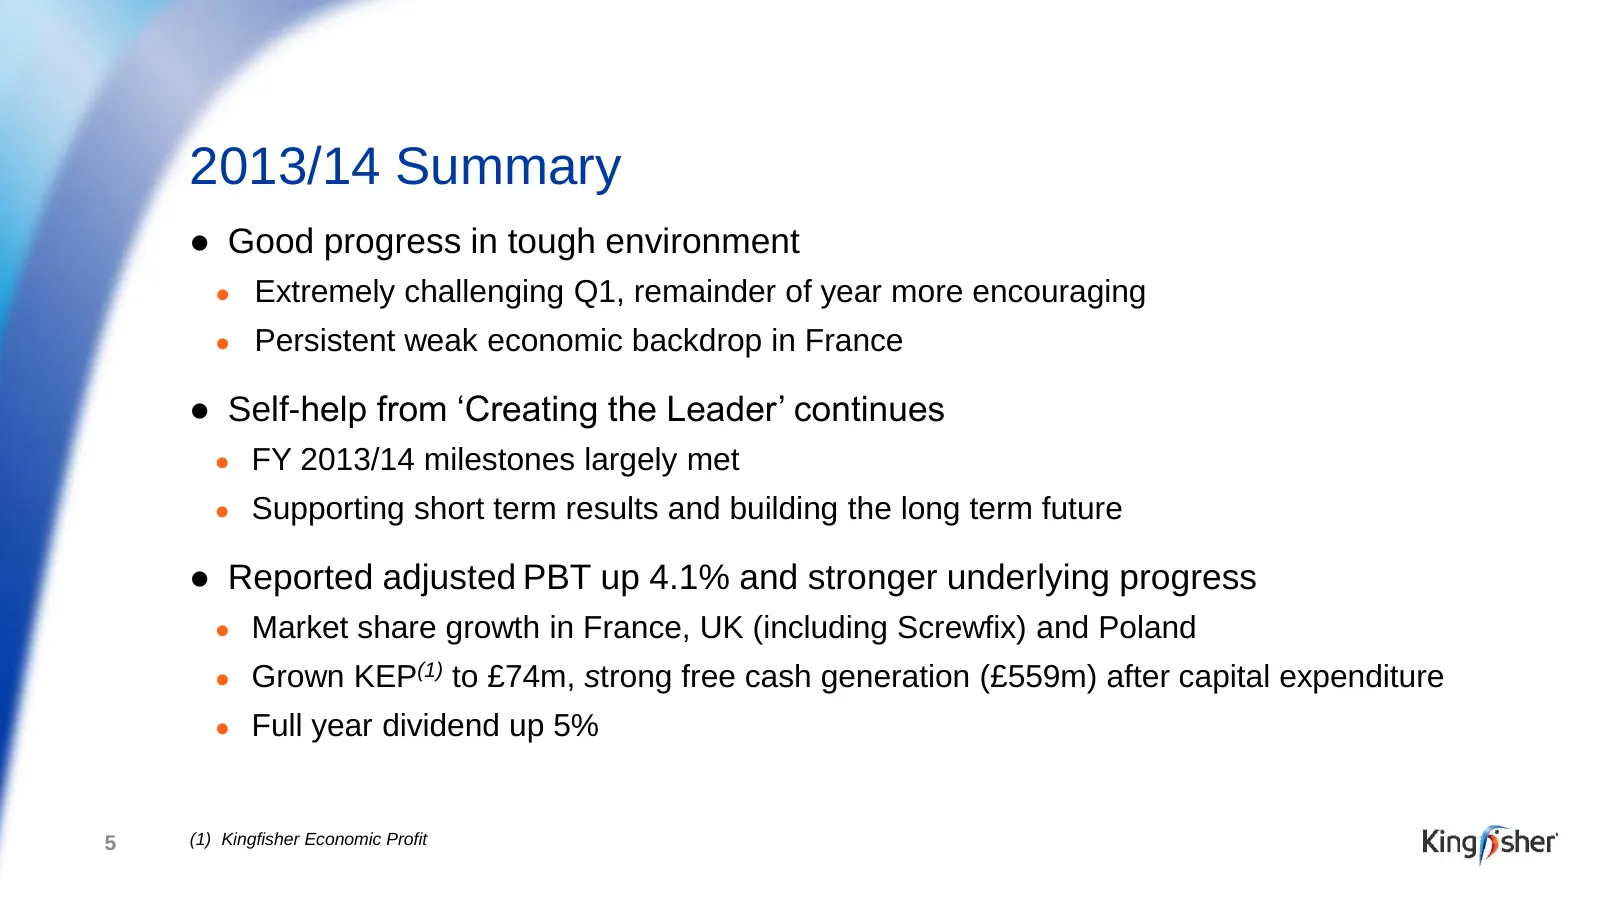
2013/14 Summary ● Good progress in tough environment ● Extremely challenging Q1, remainder of year more encouraging ● Persistent weak economic backdrop in France ● Self-help from ‘Creating the Leader’ continues ● FY 2013/14 milestones largely met ● Supporting short term results and building the long
Slide 6: Priorities for 2014/15
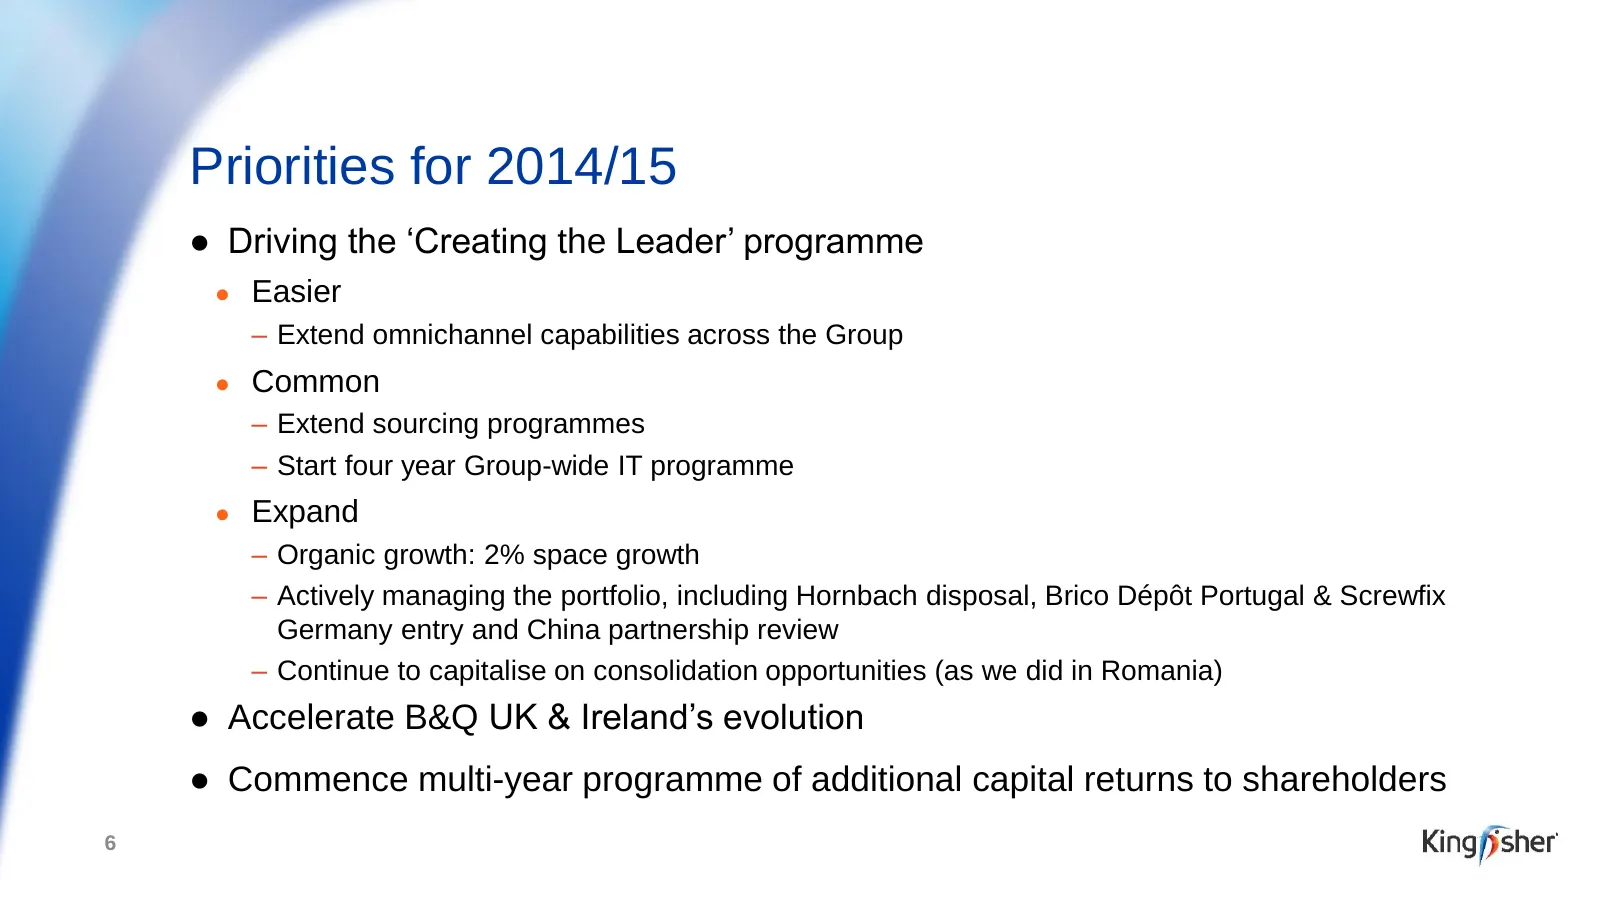
Priorities for 2014/15 ● Driving the ‘Creating the Leader’ programme ● Easier – Extend omnichannel capabilities across the Group ● Common – Extend sourcing programmes – Start four year Group-wide IT programme ● Expand – Organic growth: 2% space growth – Actively managing the portfolio, including Hor
Slide 7: Karen Witts, Group Finance Director
Karen Witts Group Finance Director 7
Slide 8: Financial summary
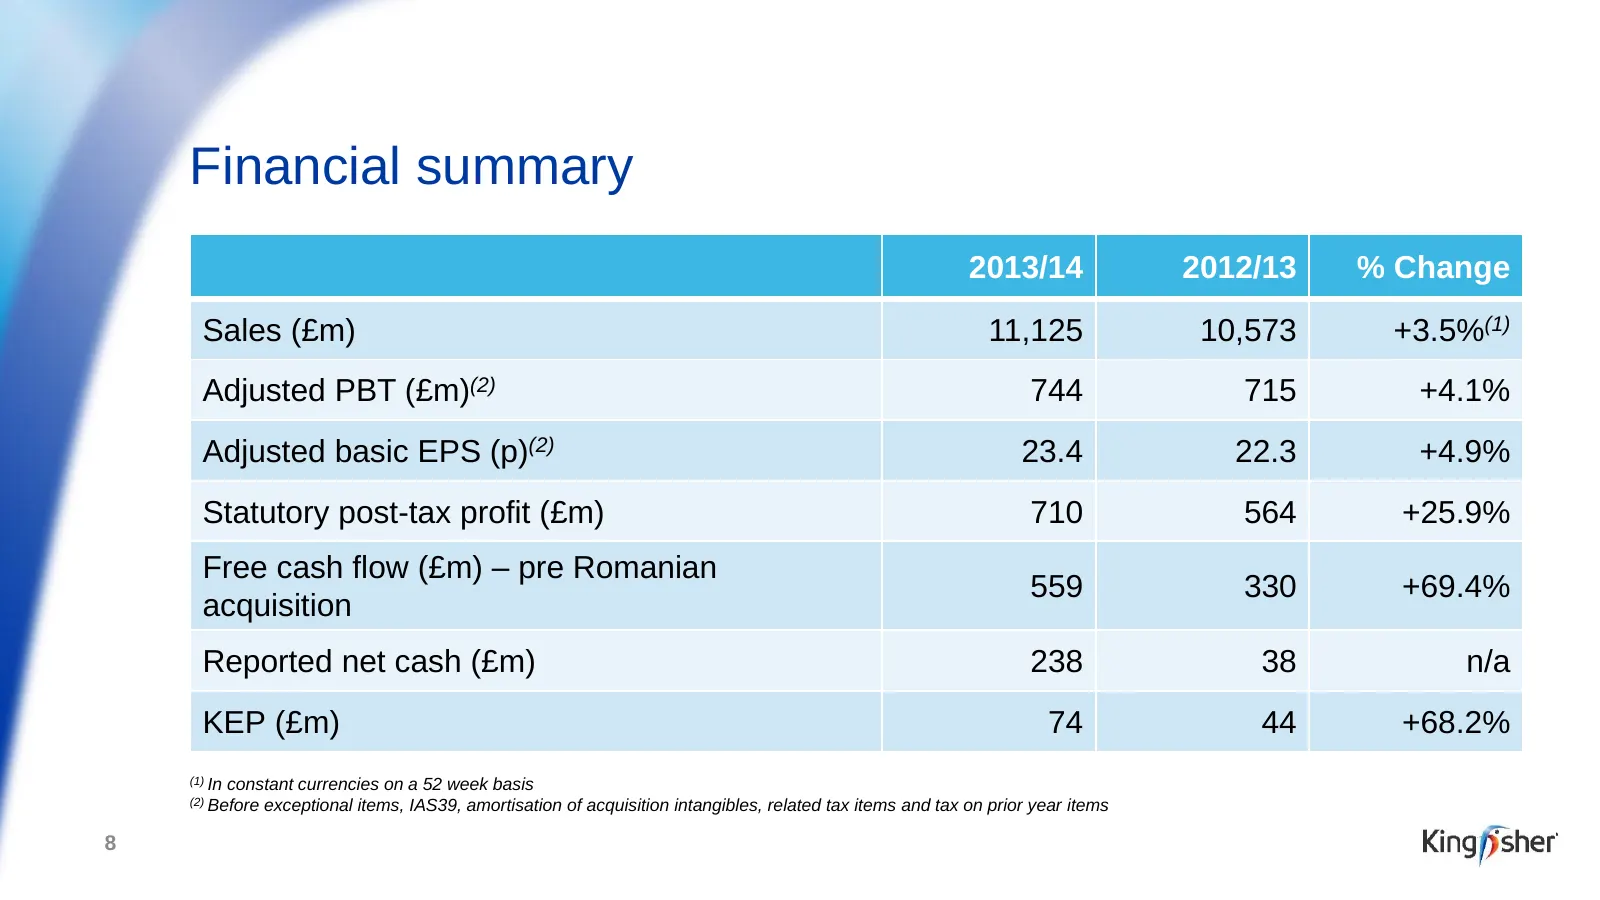
Financial summary 2013/14 2012/13 % Change Sales (£m) 11,125 10,573 +3.5%(1) Adjusted PBT (£m)(2) 744 715 +4.1% Adjusted basic EPS (p)(2) 23.4 22.3 +4.9% Statutory post-tax profit (£m) 710 564 +25.9% Free cash flow (£m) – pre Romanian 559 330 +69.4% acquisition Reported net cash (£m) 238 38 n/a KEP
Slide 9: Key financials continued
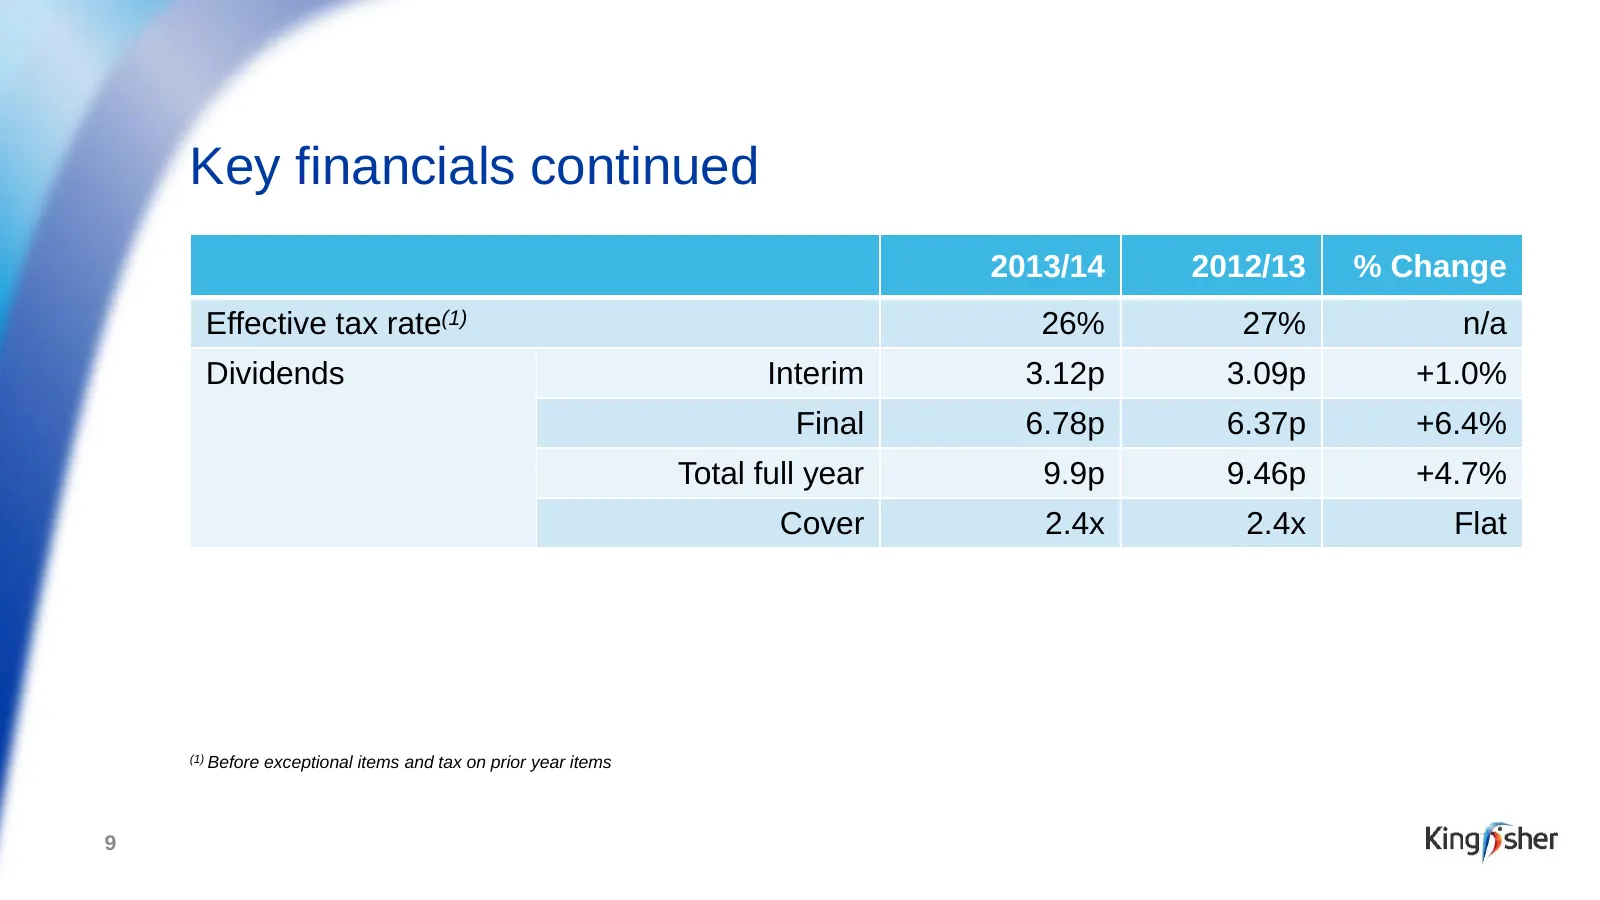
Key financials continued 2013/14 2012/13 % Change Effective tax rate(1) 26% 27% n/a Dividends Interim 3.12p 3.09p +1.0% Final 6.78p 6.37p +6.4% Total full year 9.9p 9.46p +4.7% Cover 2.4x 2.4x Flat (1) Before exceptional items and tax on prior year items 9
Slide 10: Exceptional items
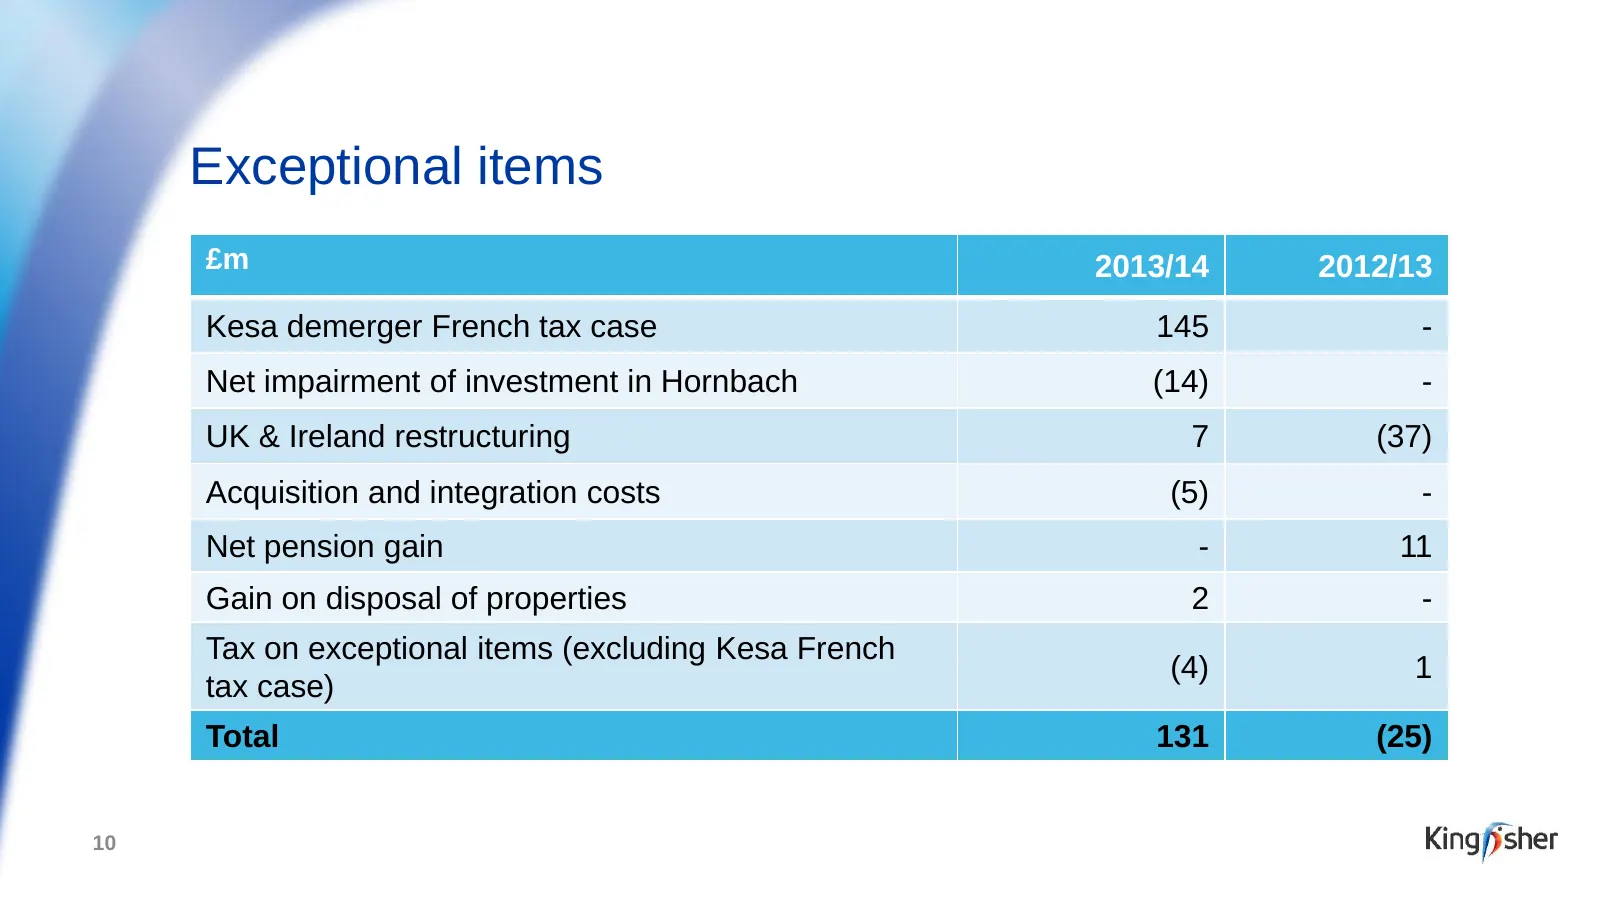
Exceptional items £m 2013/14 2012/13 Kesa demerger French tax case 145 - Net impairment of investment in Hornbach (14) - UK & Ireland restructuring 7 (37) Acquisition and integration costs (5) - Net pension gain - 11 Gain on disposal of properties 2 - Tax on exceptional items (excluding Kesa French
Slide 11: France – performing well in soft markets
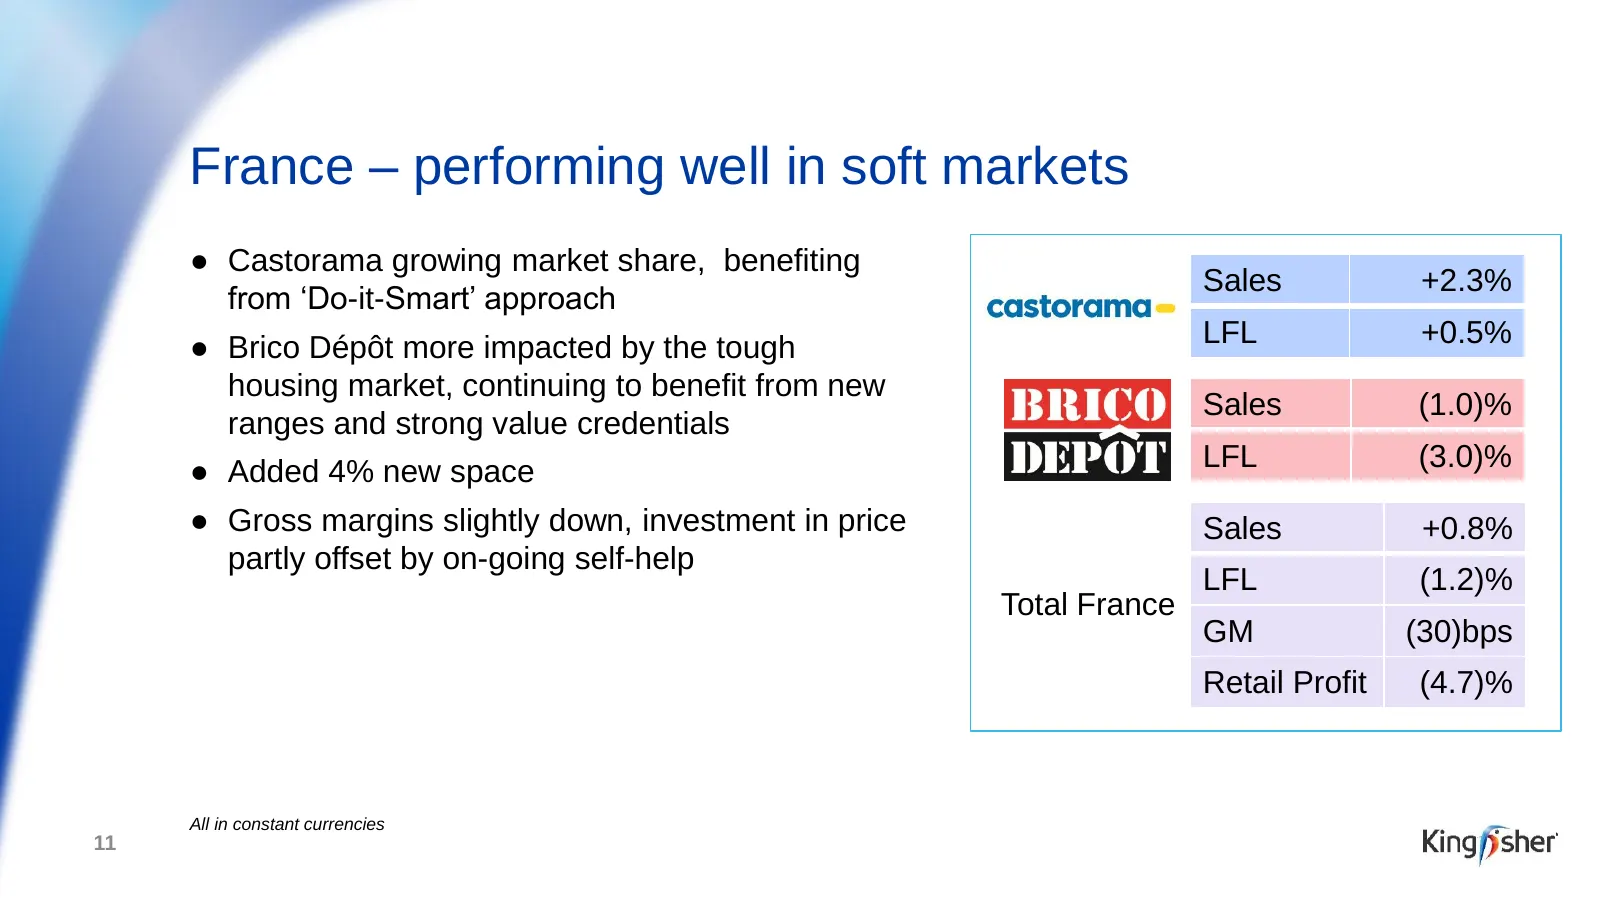
France – performing well in soft markets ● Castorama growing market share, benefiting Sales +2.3% from ‘Do-it-Smart’ approach ● Brico Dépôt more impacted by the tough LFL +0.5% housing market, continuing to benefit from new Sales (1.0)% ranges and strong value credentials LFL (3.0)% ● Added 4% new s
Slide 12: UK & Ireland – profit and sales growth driven by Screwfix
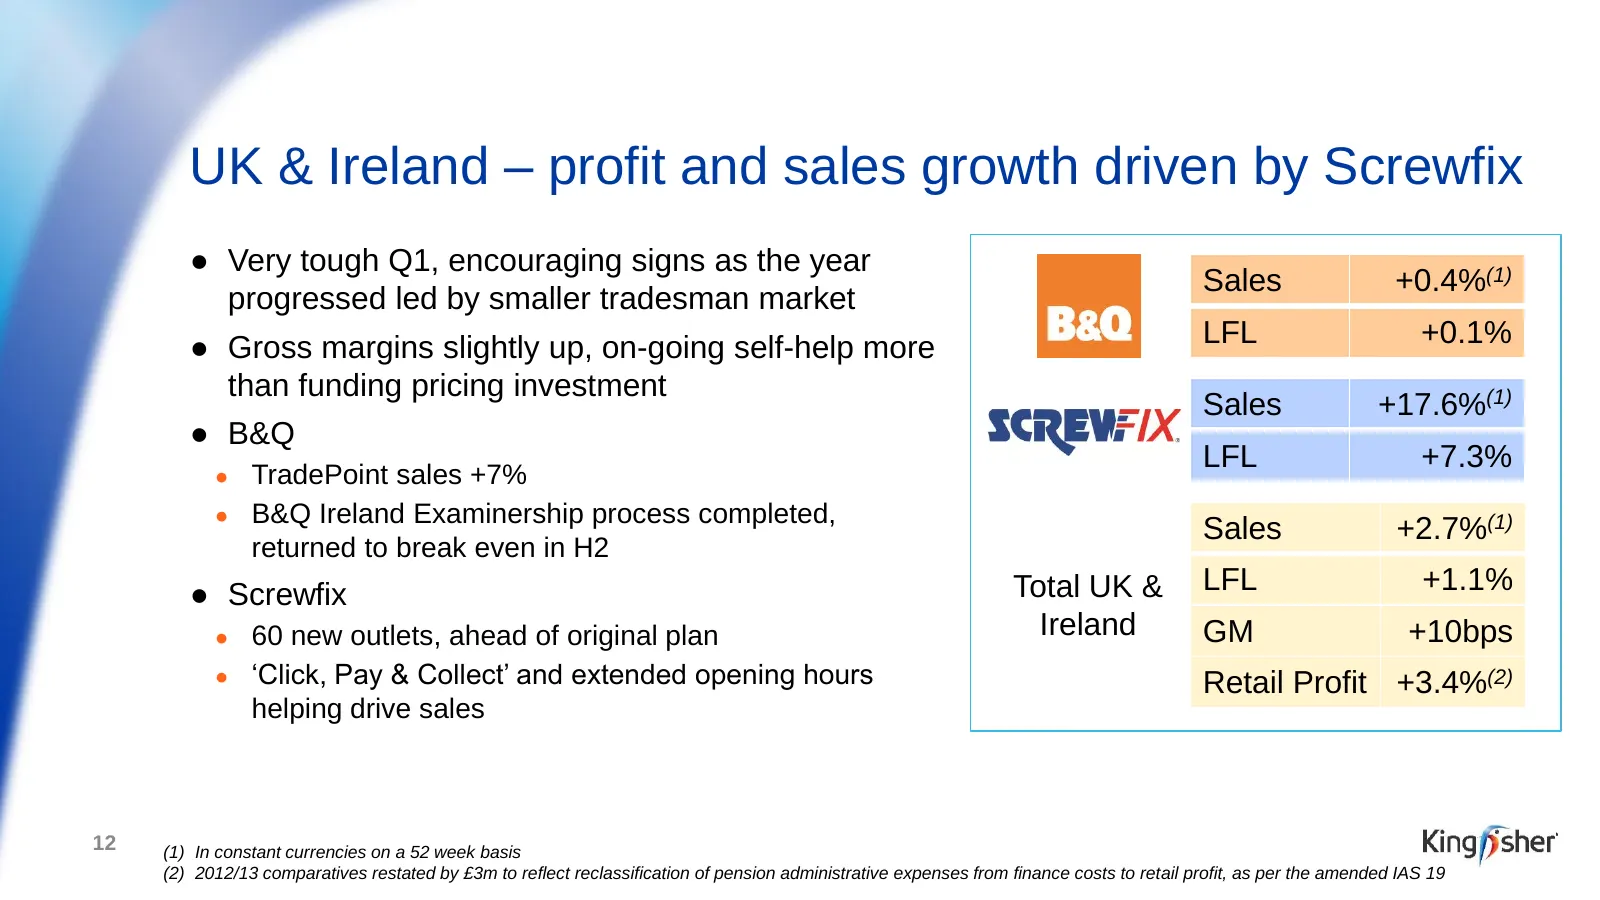
UK & Ireland – profit and sales growth driven by Screwfix ● Very tough Q1, encouraging signs as the year Sales +0.4%(1) progressed led by smaller tradesman market ● Gross margins slightly up, on-going self-help more LFL +0.1% than funding pricing investment Sales +17.6%(1) ● B&Q LFL +7.3% ● TradePoi
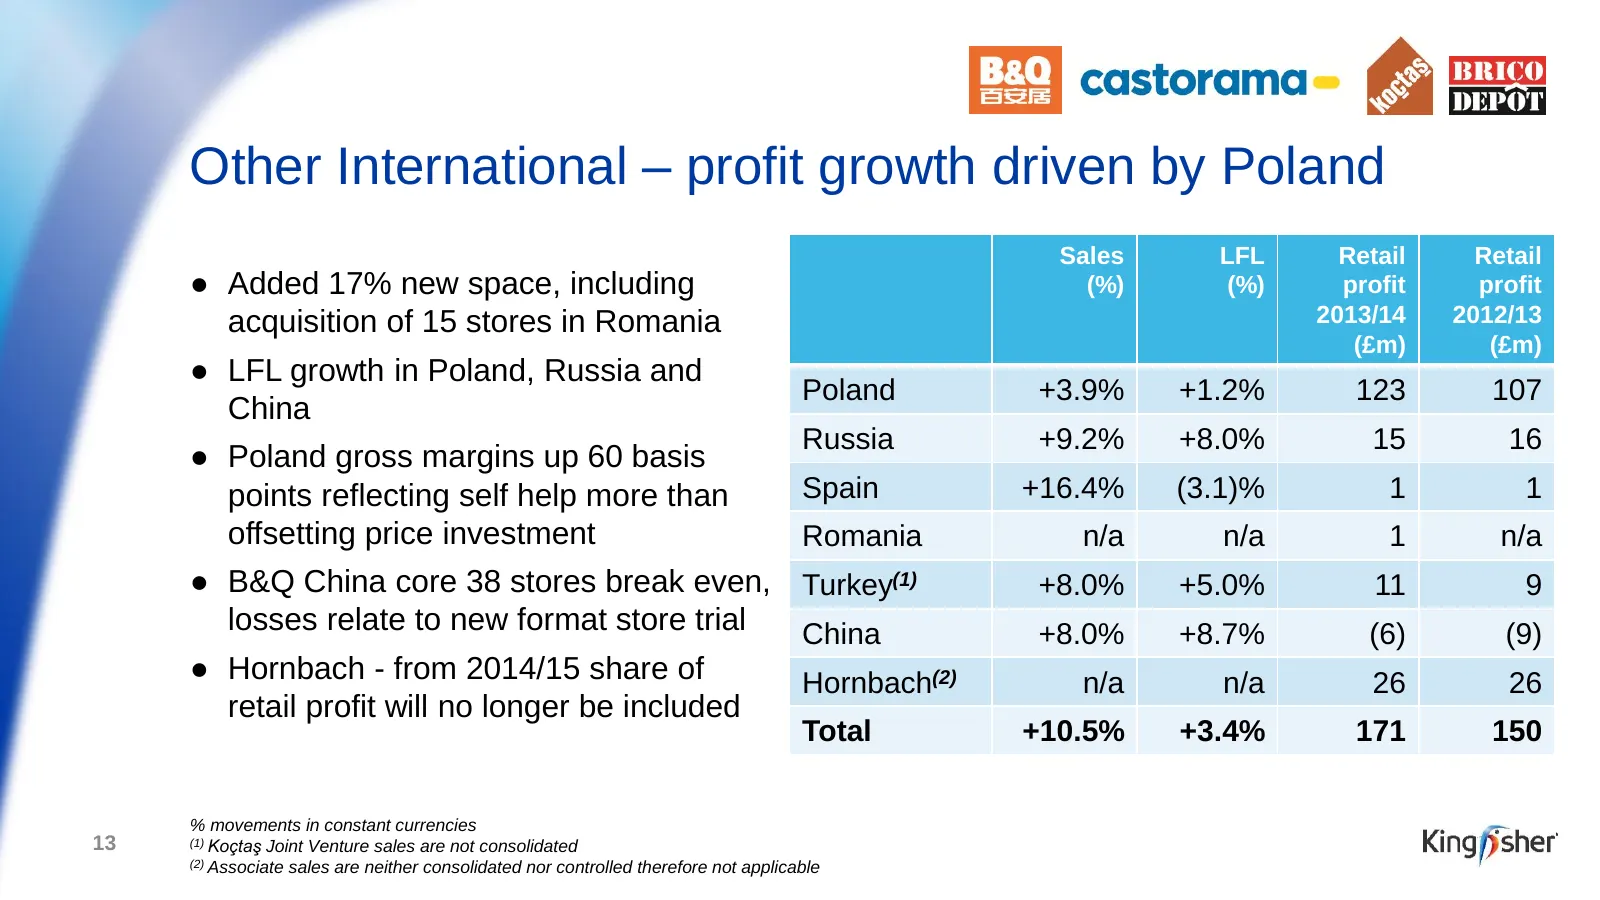
Slide 13: Other International – profit growth driven by Poland
Other International – profit growth driven by Poland Sales LFL Retail Retail ● Added 17% new space, including (%) (%) profit profit acquisition of 15 stores in Romania 2013/14 2012/13 (£m) (£m) ● LFL growth in Poland, Russia and Poland +3.9% +1.2% 123 107 China Russia +9.2% +8.0% 15 16 ● Poland gros
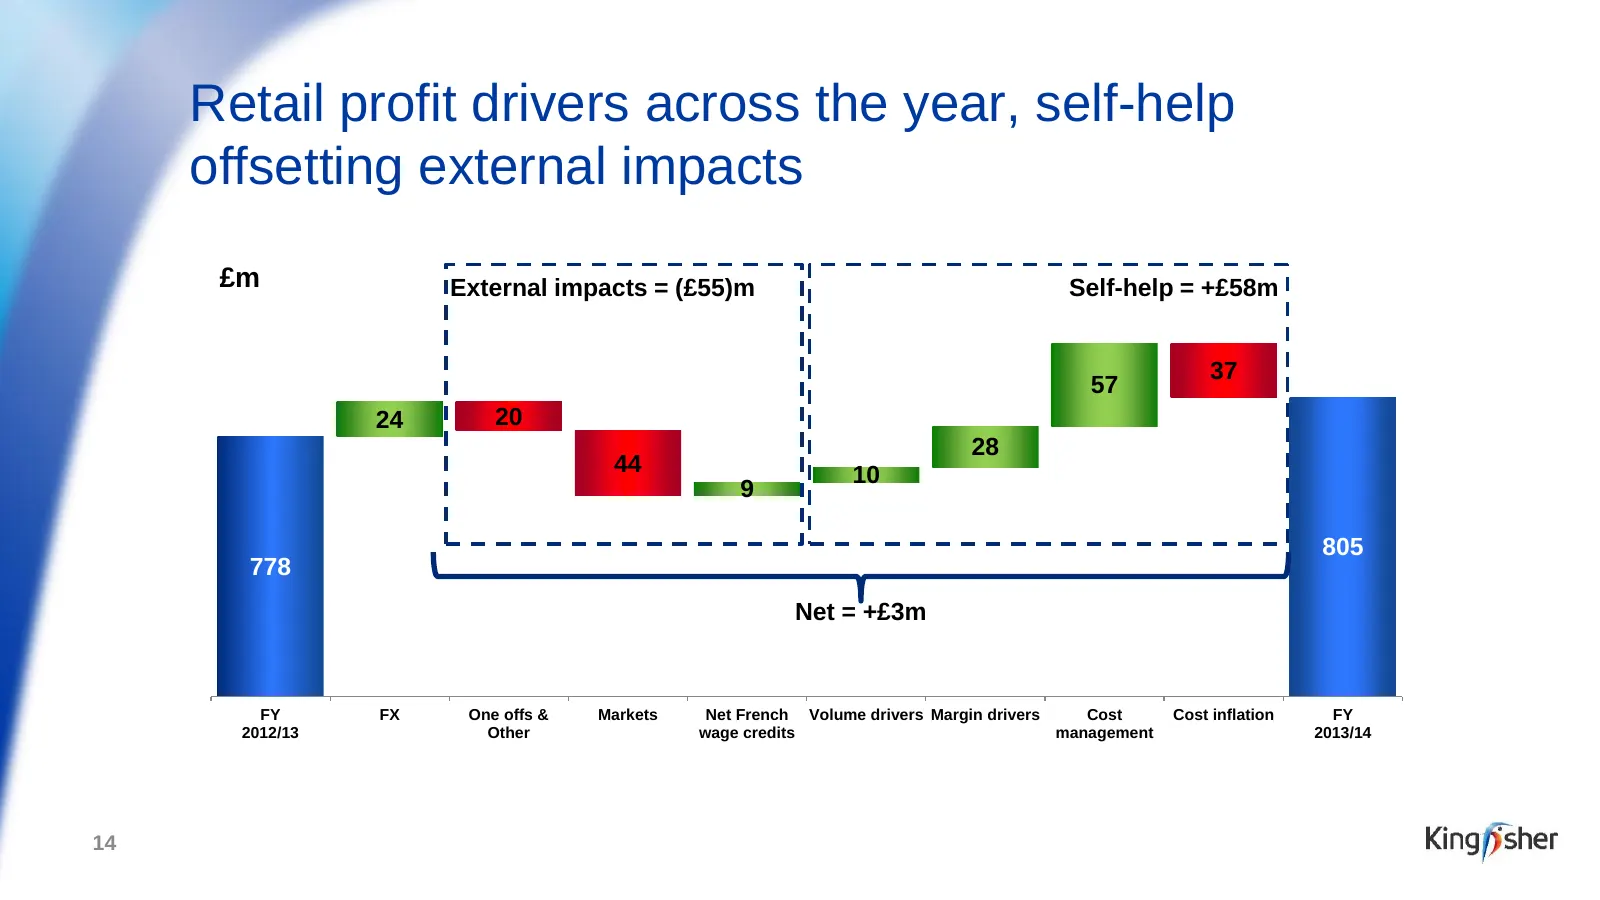
Slide 14: Retail profit drivers across the year
Retail profit drivers across the year, self-help offsetting external impacts £m External impacts = (£55)m Self-help = +£58m 37 57 24 20 28 44 10 9 805 778 Net = +£3m FY FX One offs & Markets Net French Volume drivers Margin drivers Cost Cost inflation FY 2012/13 Other wage credits management 2013/14
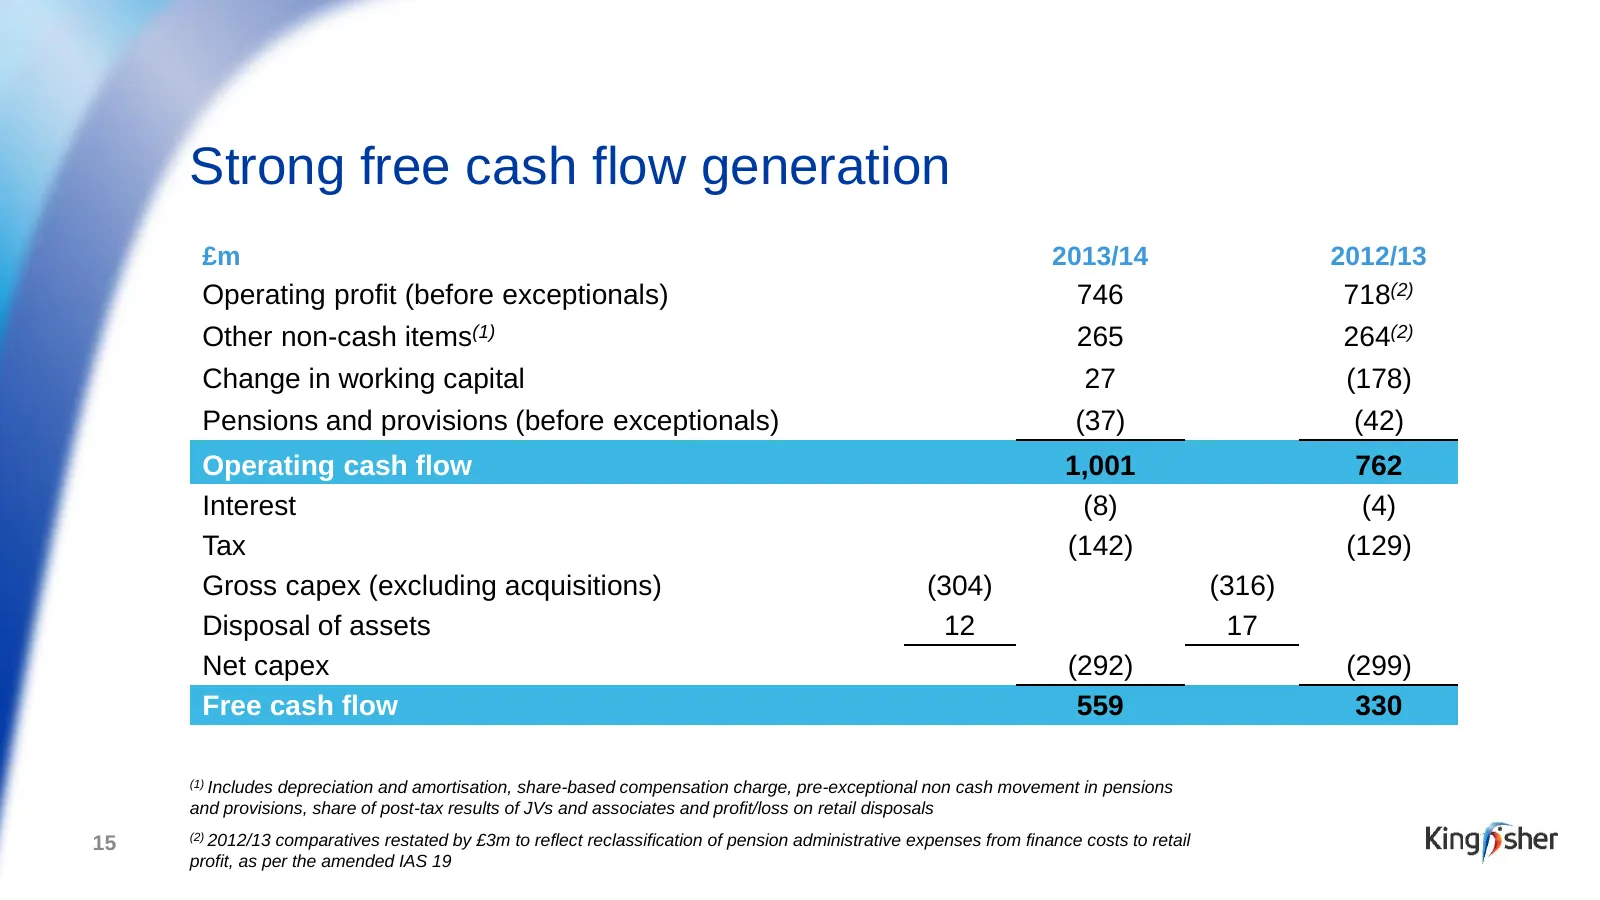
Slide 15: Strong free cash flow generation
Strong free cash flow generation £m 2013/14 2012/13 Operating profit (before exceptionals) 746 718(2) Other non-cash items(1) 265 264(2) Change in working capital 27 (178) Pensions and provisions (before exceptionals) (37) (42) Operating cash flow 1,001 762 Interest (8) (4) Tax (142) (129) Gross cap
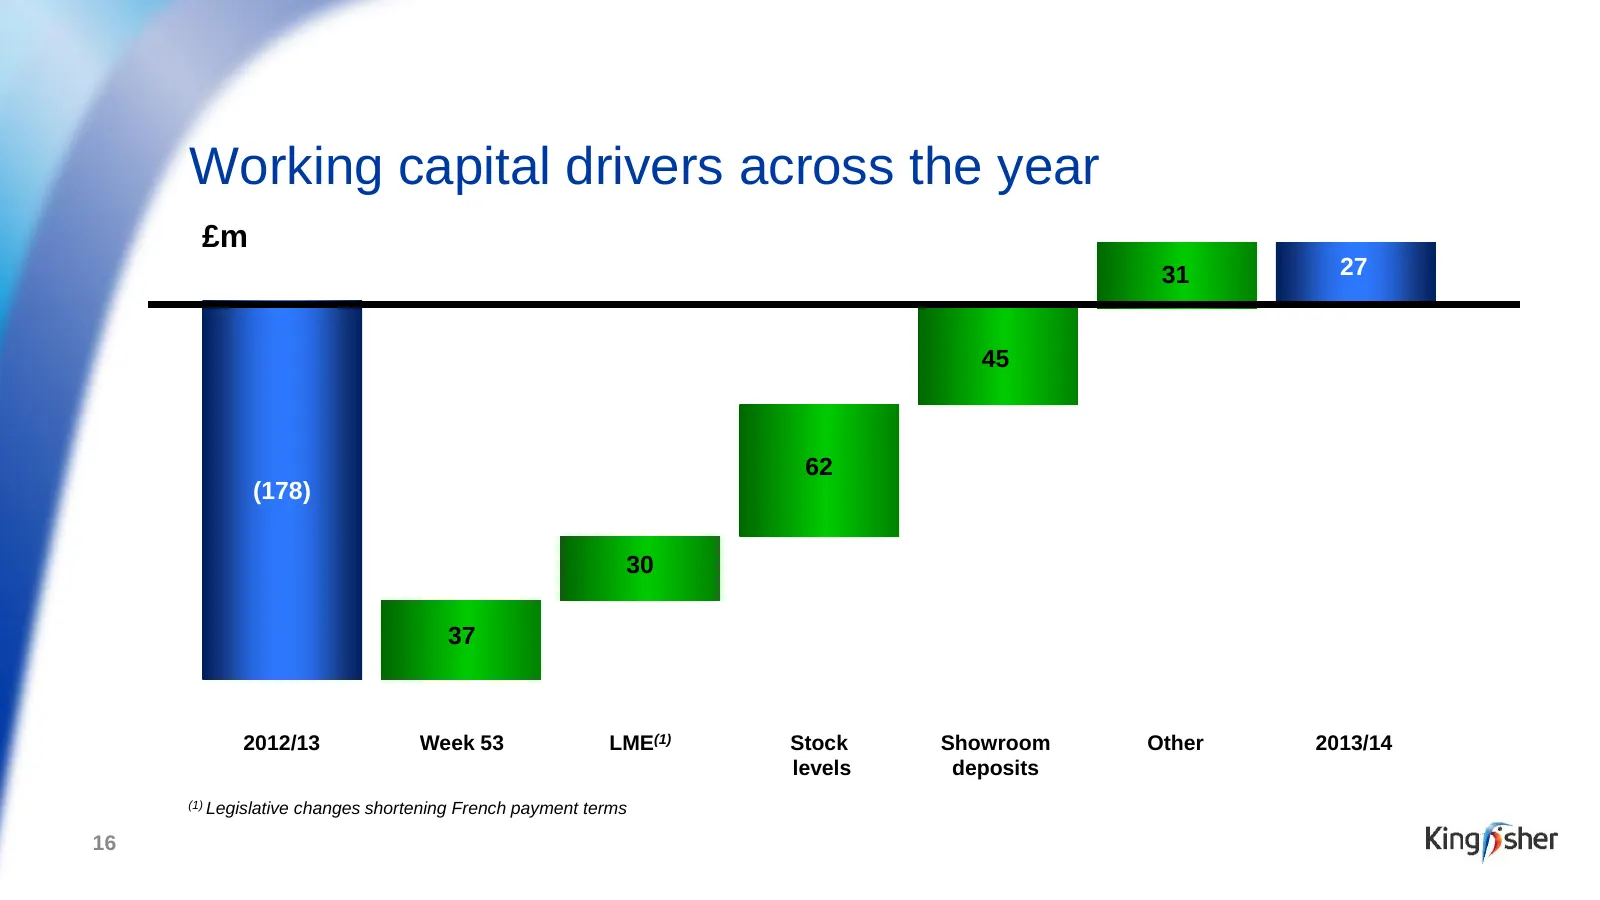
Slide 16: Working capital drivers across the year
Working capital drivers across the year £m 31 27 45 62 (178) 30 37 2012/13 Week 53 LME(1) Stock Showroom Other 2013/14 levels deposits (1) Legislative changes shortening French payment terms 16
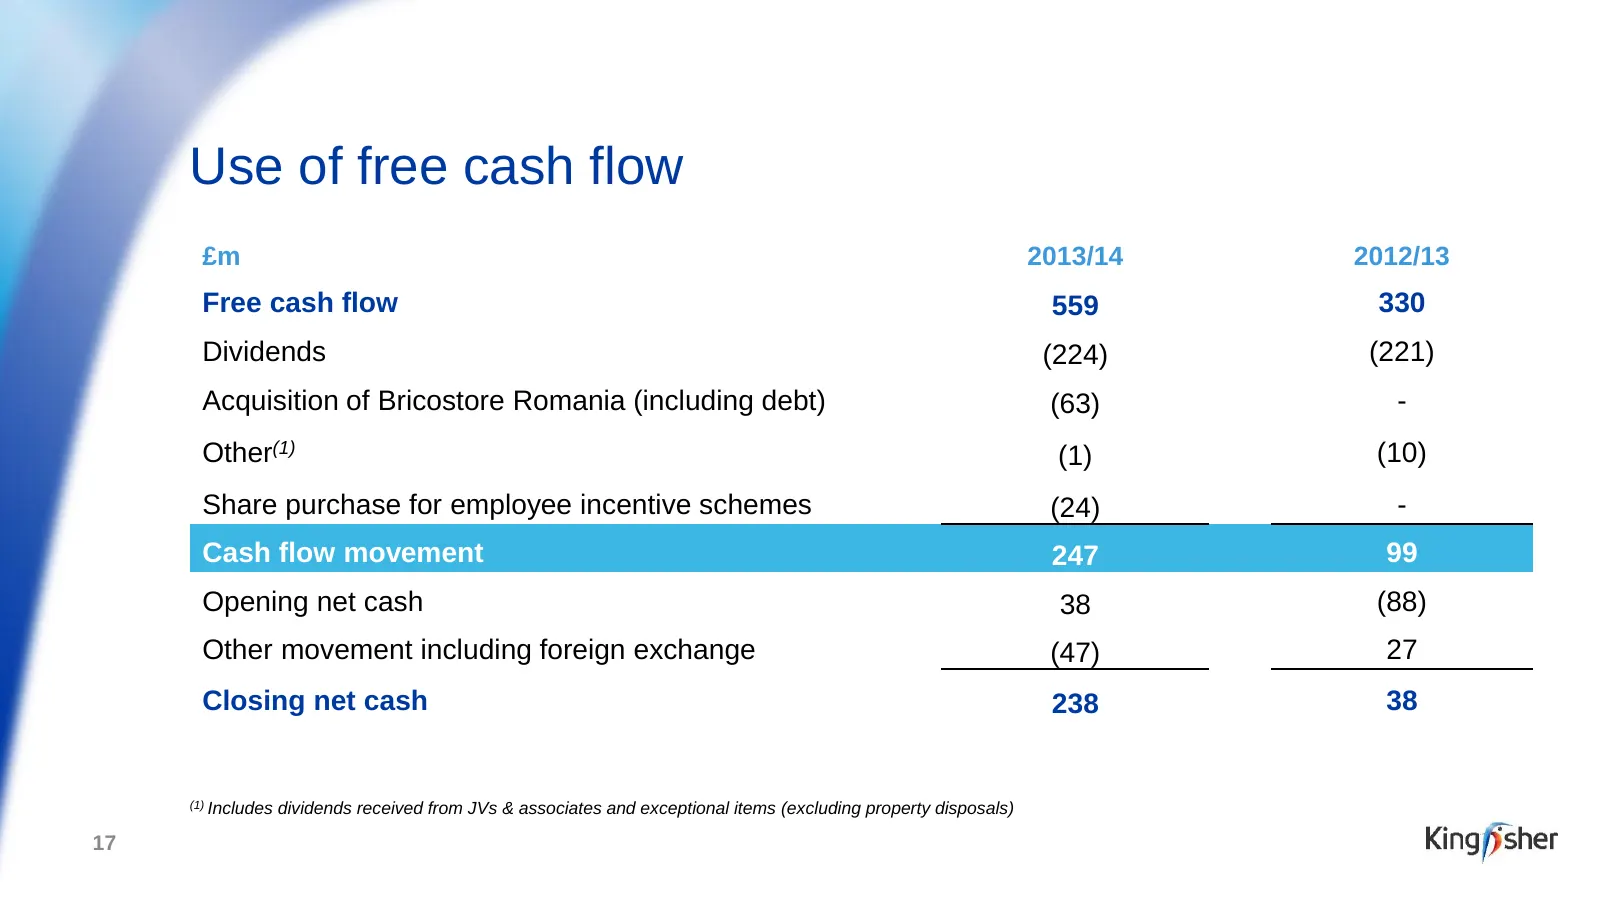
Slide 17: Use of free cash flow
Use of free cash flow £m 2013/14 2012/13 Free cash flow 559 330 Dividends (224) (221) Acquisition of Bricostore Romania (including debt) (63) - Other(1) (1) (10) Share purchase for employee incentive schemes (24) - Cash flow movement 247 99 Opening net cash 38 (88) Other movement including foreign e
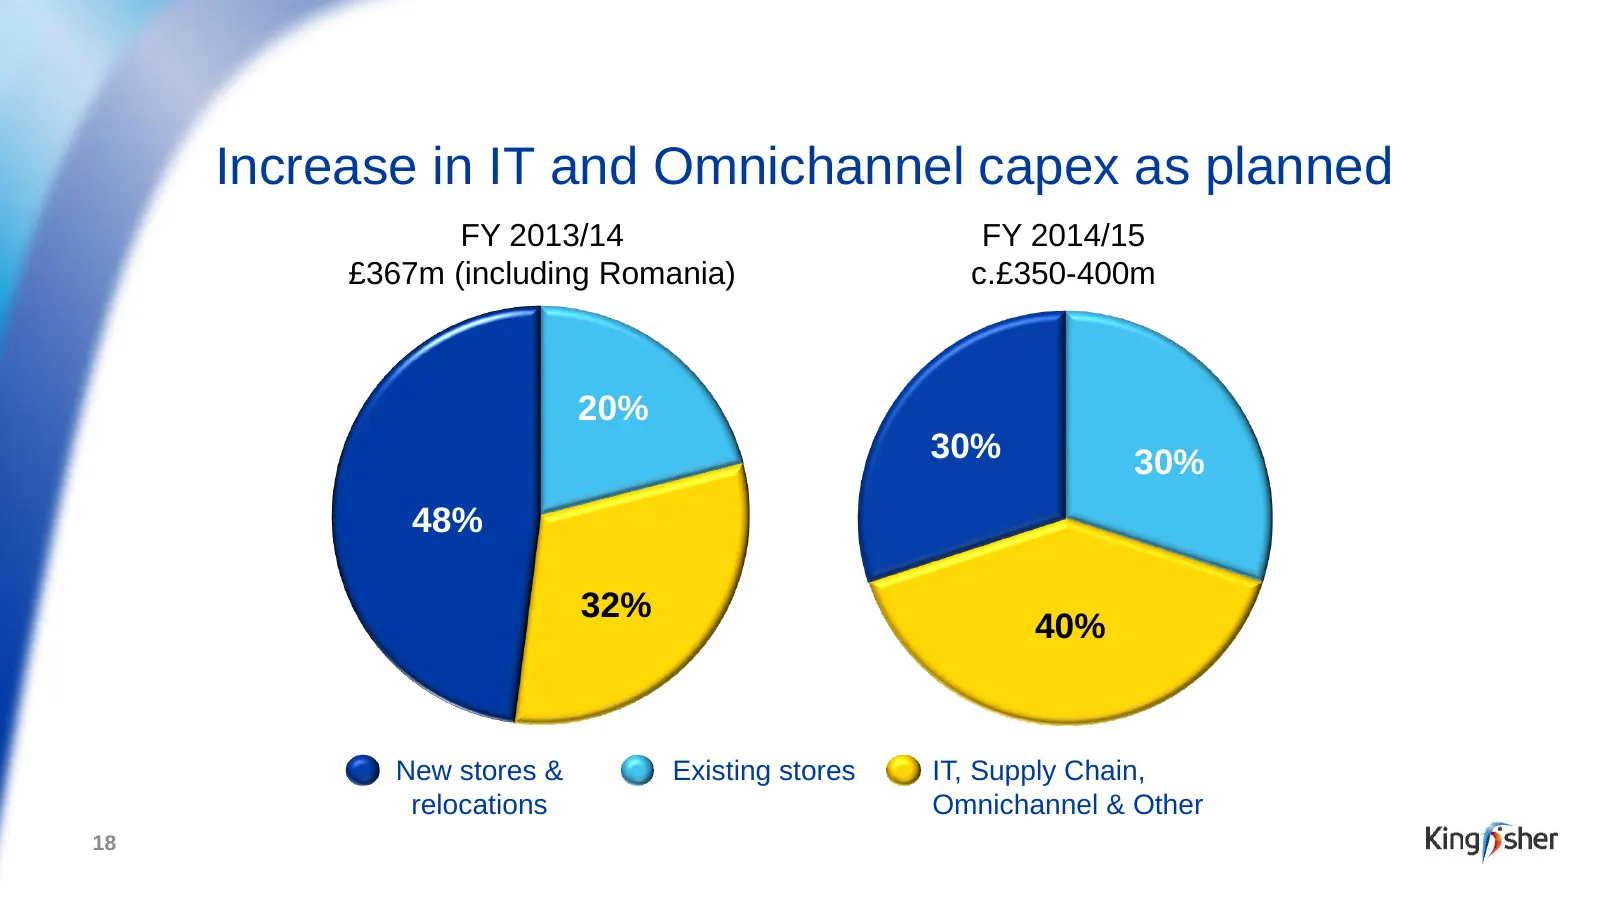
Slide 18: Increase in IT and Omnichannel capex as planned
Increase in IT and Omnichannel capex as planned FY 2013/14 FY 2014/15 £367m (including Romania) c.£350-400m 20% 30% 30% 48% 32% 40% New stores & Existing stores IT, Supply Chain, relocations Omnichannel & Other 18
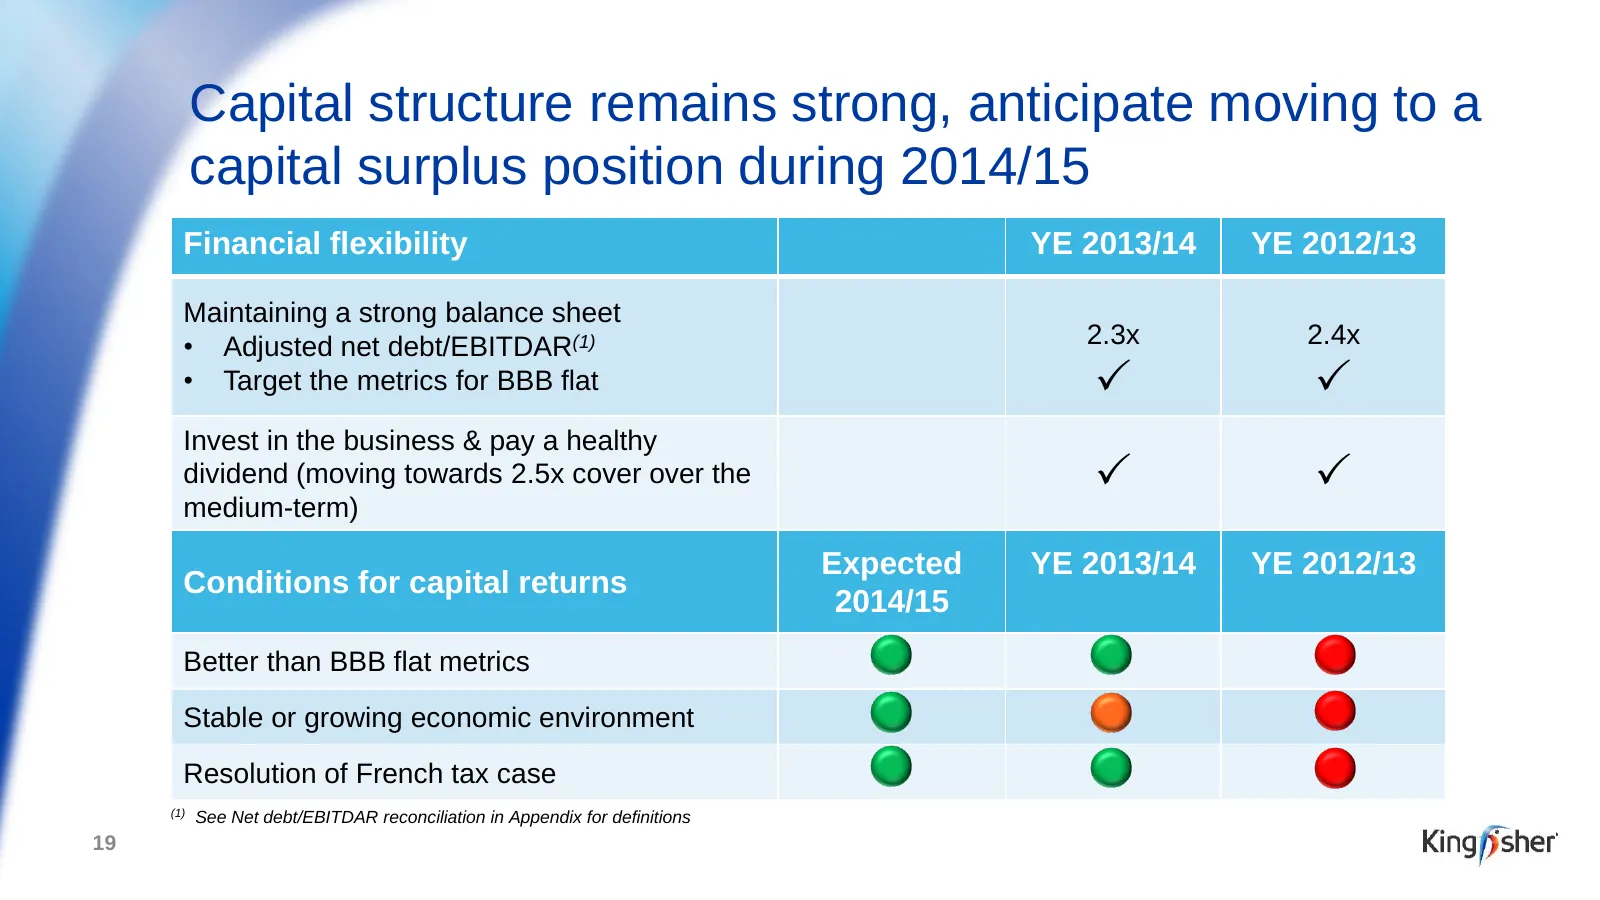
Slide 19: Capital structure remains strong
Capital structure remains strong, anticipate moving to a capital surplus position during 2014/15 Financial flexibility YE 2013/14 YE 2012/13 Maintaining a strong balance sheet • Adjusted net debt/EBITDAR(1) 2.3x 2.4x • Target the metrics for BBB flat P P Invest in the business & pay a healthy divide
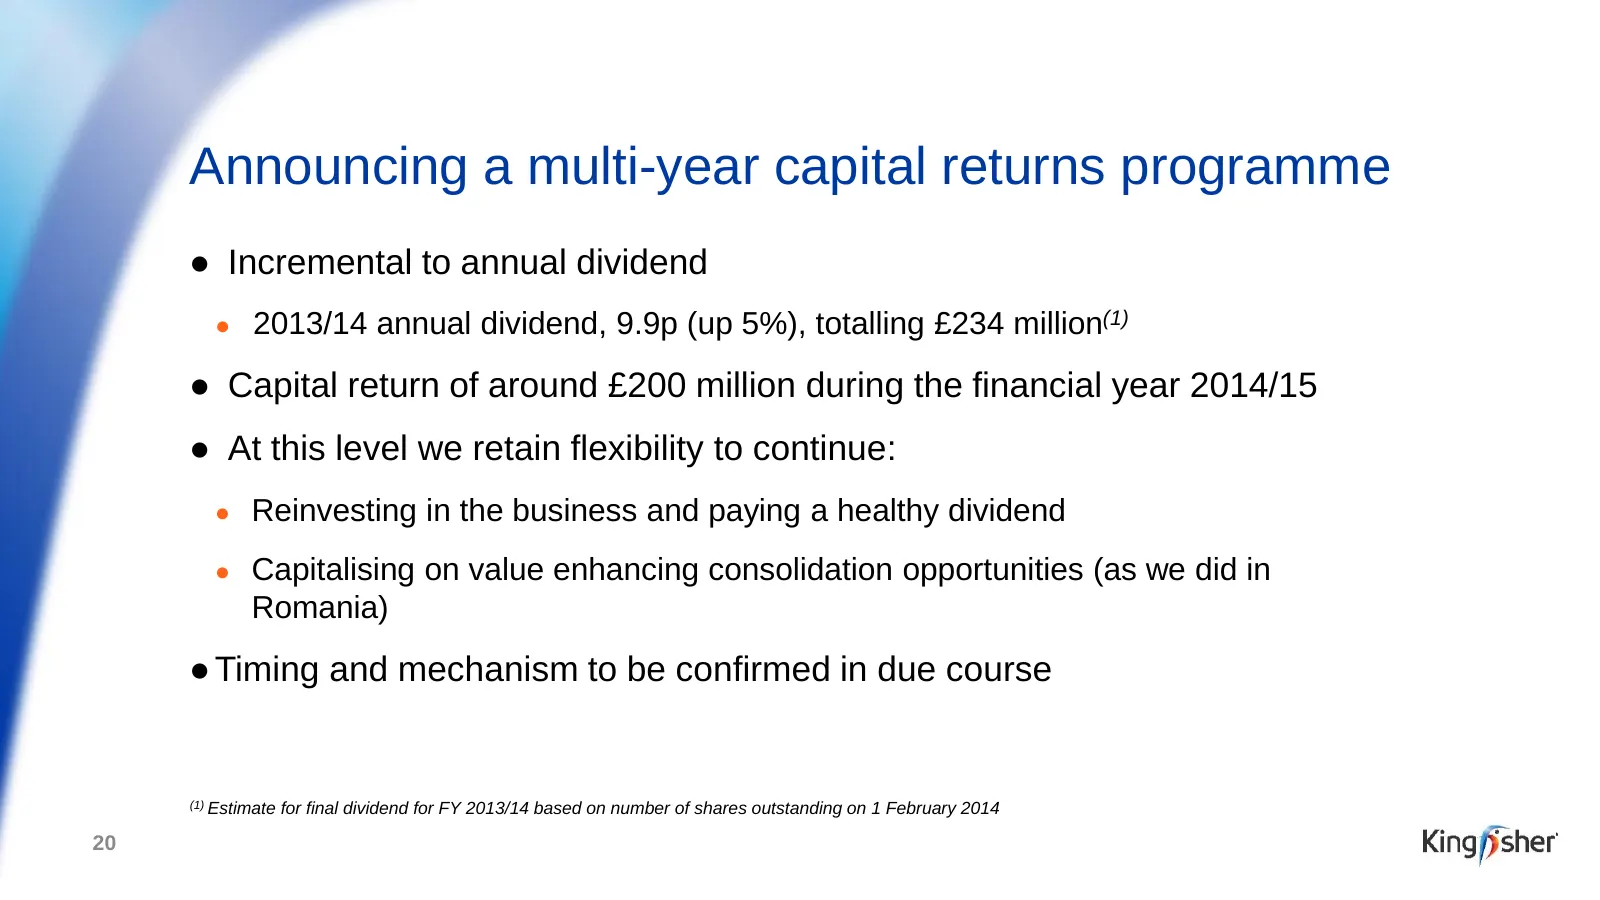
Slide 20: Announcing a multi-year capital returns programme
Announcing a multi-year capital returns programme ● Incremental to annual dividend ● 2013/14 annual dividend, 9.9p (up 5%), totalling £234 million(1) ● Capital return of around £200 million during the financial year 2014/15 ● At this level we retain flexibility to continue: ● Reinvesting in the busi
Slide 21: Sir Ian Cheshire, Group Chief Executive
Sir Ian Cheshire Group Chief Executive 21
Slide 22: 'Creating the Leader'
— ~—z ‘Creating the Leader’ BETTER HOMES, BETTER LIVES
Slide 23: 'Creating the Leader'
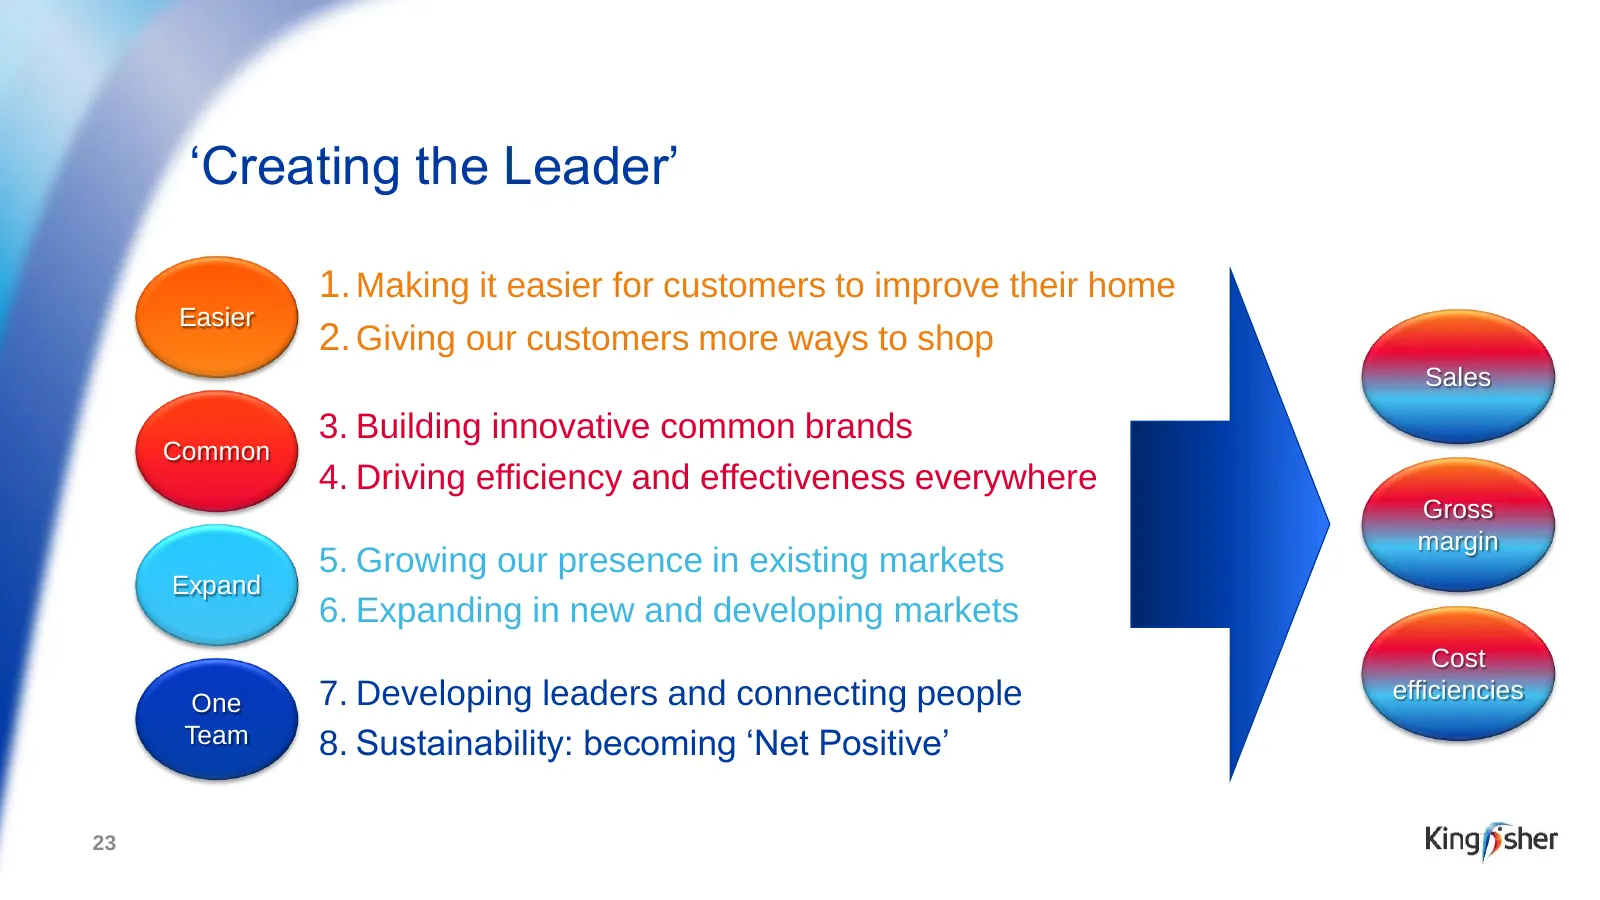
‘Creating the Leader’ 1. Making it easier for customers to improve their home Easier 2. Giving our customers more ways to shop Sales 3. Building innovative common brands Common 4. Driving efficiency and effectiveness everywhere Gross margin 5. Growing our presence in existing markets Expand 6. Expan
Slide 24: Extending omnichannel capabilities across the Group
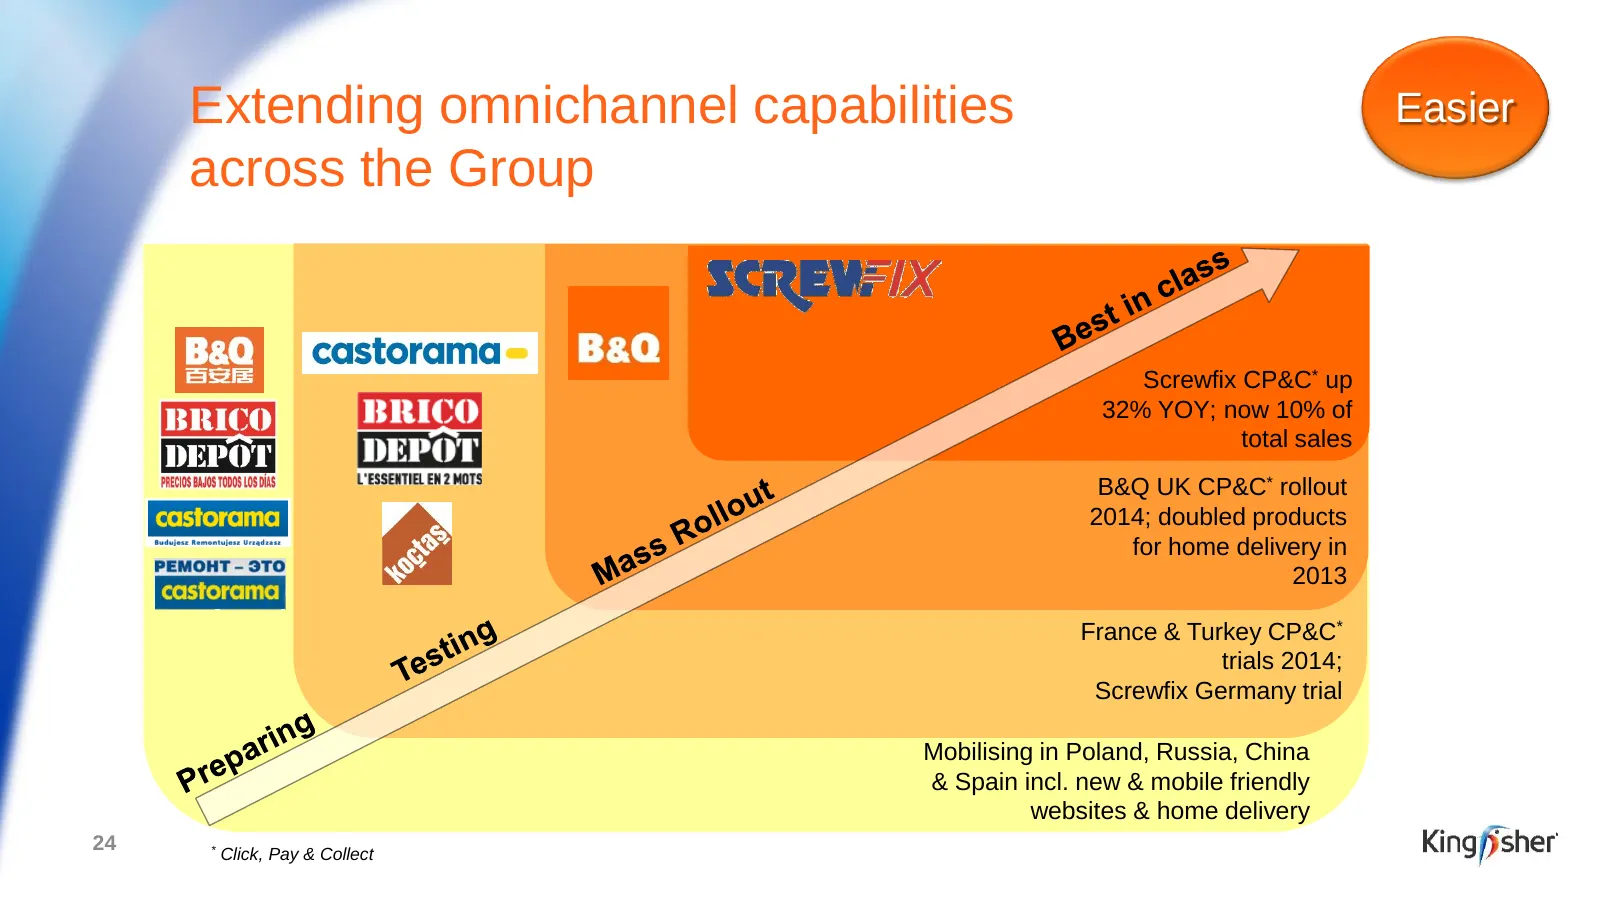
Extending omnichannel capabilities Easier across the Group Screwfix CP&C* up 32% YOY; now 10% of total sales B&Q UK CP&C* rollout 2014; doubled products for home delivery in 2013 France & Turkey CP&C* trials 2014; Screwfix Germany trial Mobilising in Poland, Russia, China & Spain incl. new & mobile
Slide 25: New Castorama France 'Do it Smart Store' format proving a success
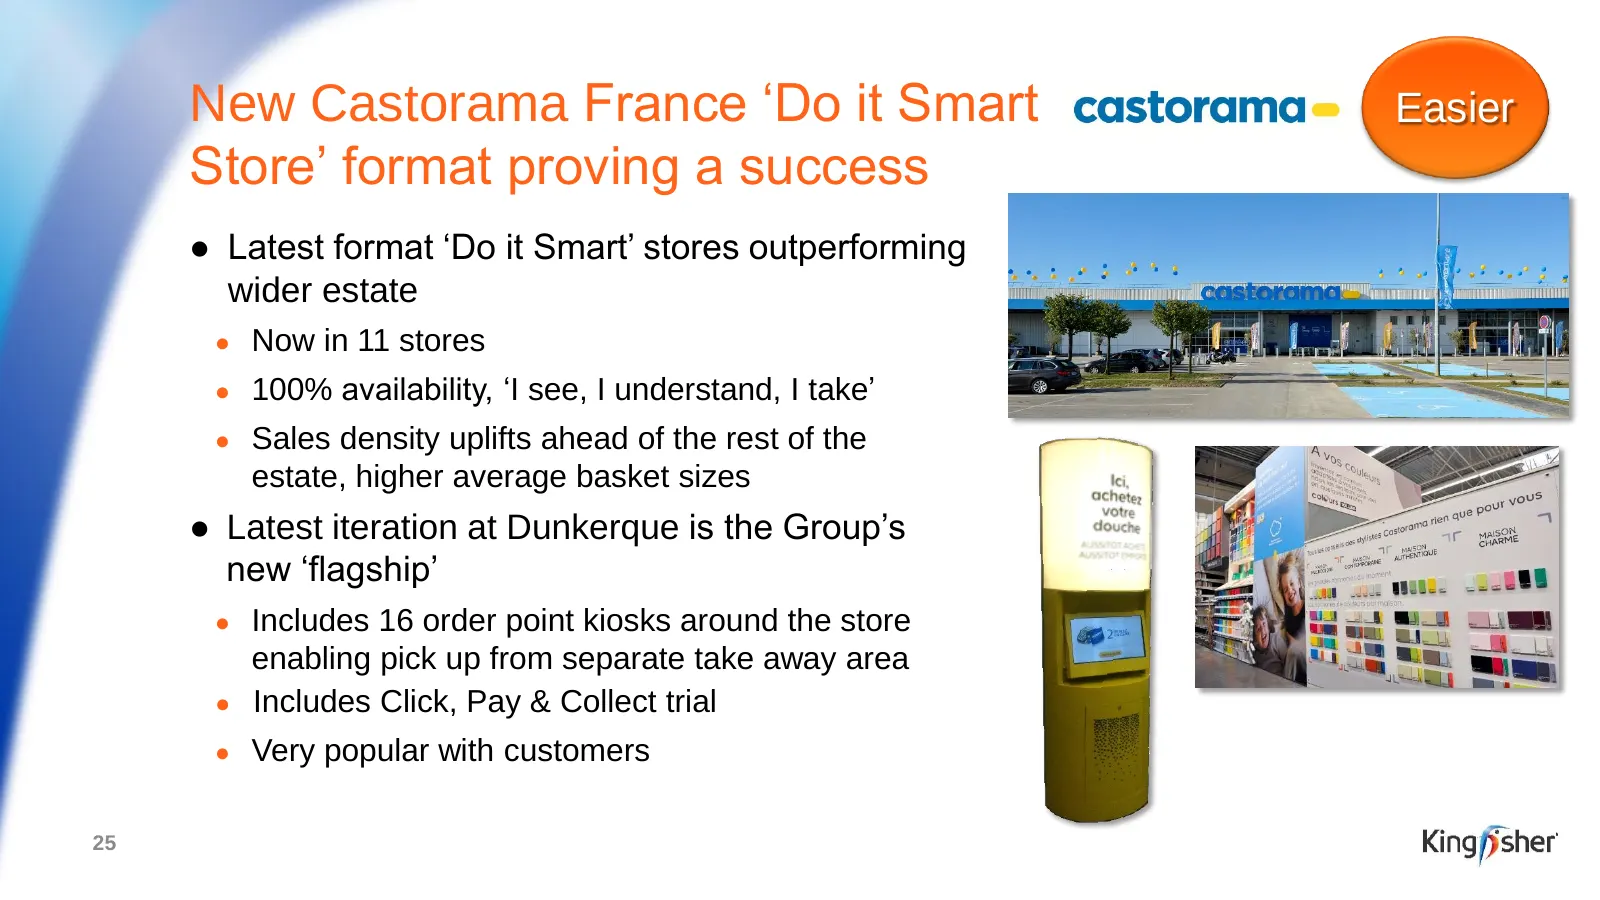
New Castorama France ‘Do it Smart Easier Store’ format proving a success ● Latest format ‘Do it Smart’ stores outperforming wider estate ● Now in 11 stores ● 100% availability, ‘I see, I understand, I take’ ● Sales density uplifts ahead of the rest of the estate, higher average basket sizes ● Latest
Slide 26: Group sourcing programmes progressing
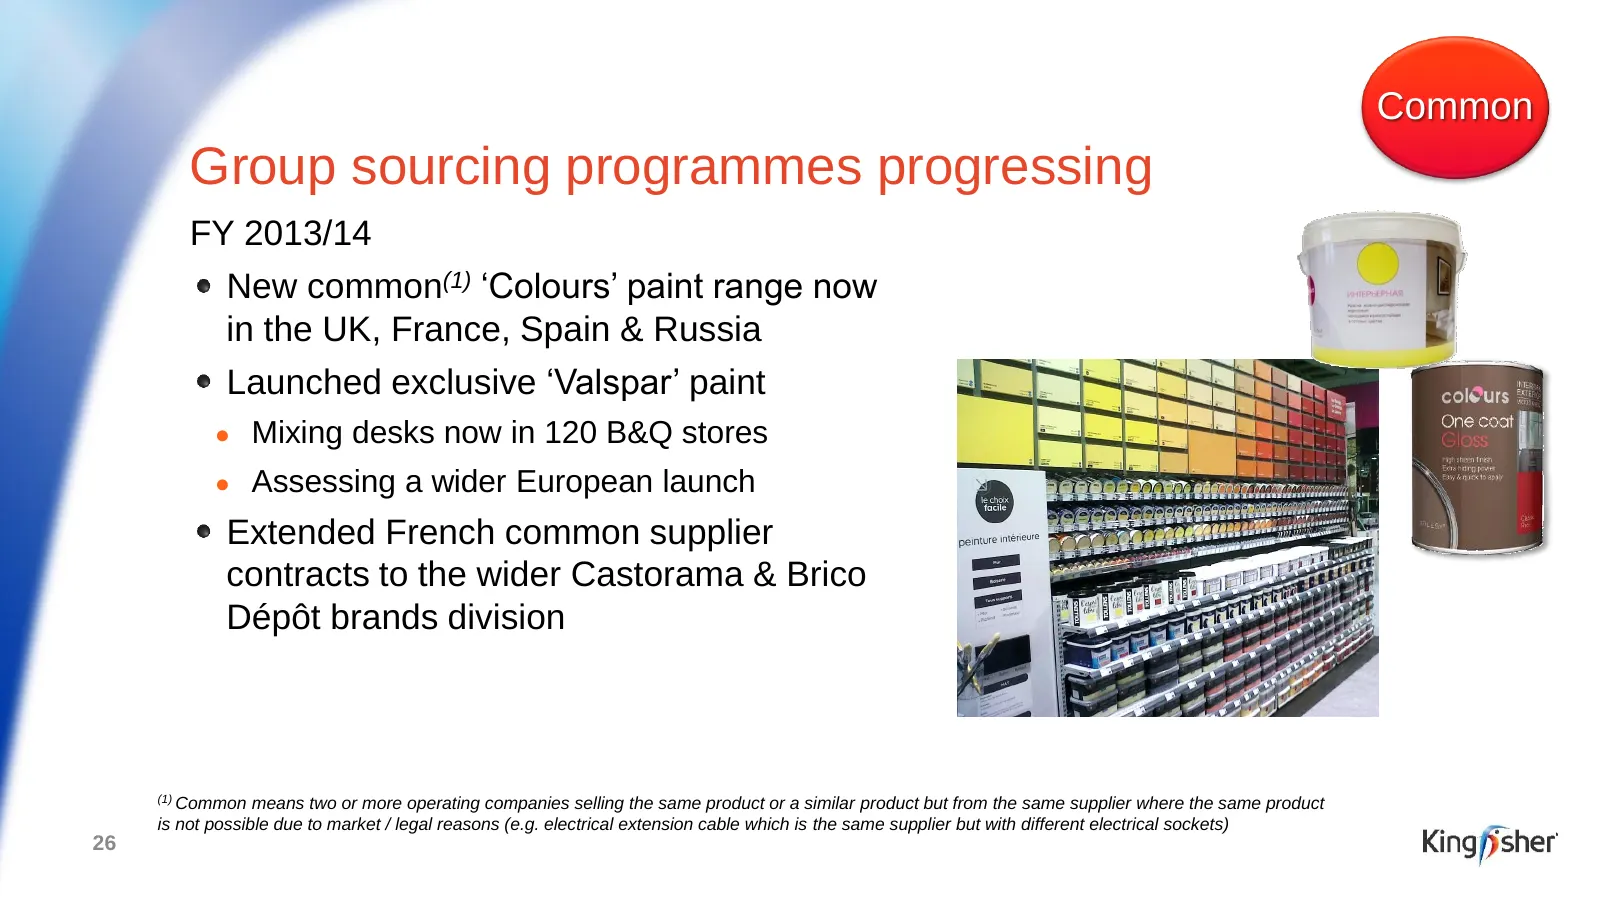
Common Group sourcing programmes progressing FY 2013/14 New common(1) ‘Colours’ paint range now in the UK, France, Spain & Russia Launched exclusive ‘Valspar’ paint ● Mixing desks now in 120 B&Q stores ● Assessing a wider European launch Extended French common supplier contracts to the wider Castora
Slide 27: More to go for, approach evolving
Common More to go for, approach evolving Re-emphasising quality over quantity ● Common(1) now at 9% (8% last year); Direct now at 20%(1) (19% last year) ● Internally KPI is now net cash margin, replacing previous % targets ● Looking at more near sourcing Re-emphasising ‘pull versus push’ ● c.100 peo
Slide 28: Group sourcing programmes – extending into 2014/15
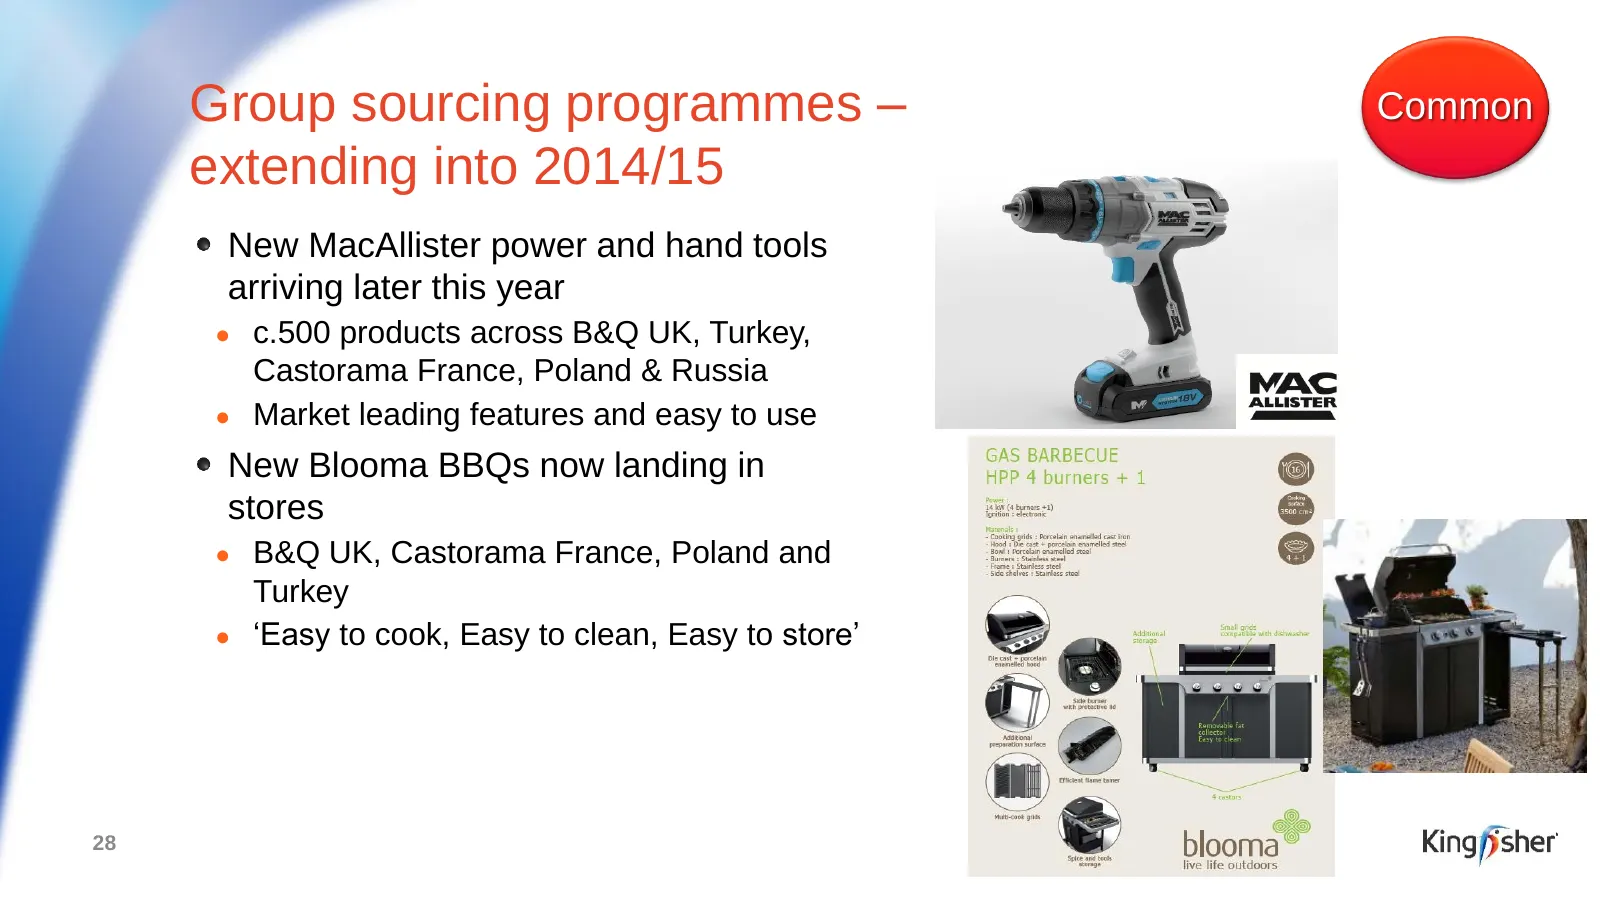
Group sourcing programmes – Common extending into 2014/15 New MacAllister power and hand tools arriving later this year ● c.500 products across B&Q UK, Turkey, Castorama France, Poland & Russia ● Market leading features and easy to use New Blooma BBQs now landing in stores ● B&Q UK, Castorama France
Slide 29: Starting Group-wide IT programme
Common Starting Group-wide IT programme ● Opportunity to step change IT across the Group ● Current infrastructure nearing end of life ● Need to move to web & mobile based solutions ● Flexibility for the future is our key working principle ● Starting a four year change programme led by Steve Willett
Slide 30: Growing the portfolio – organic growth
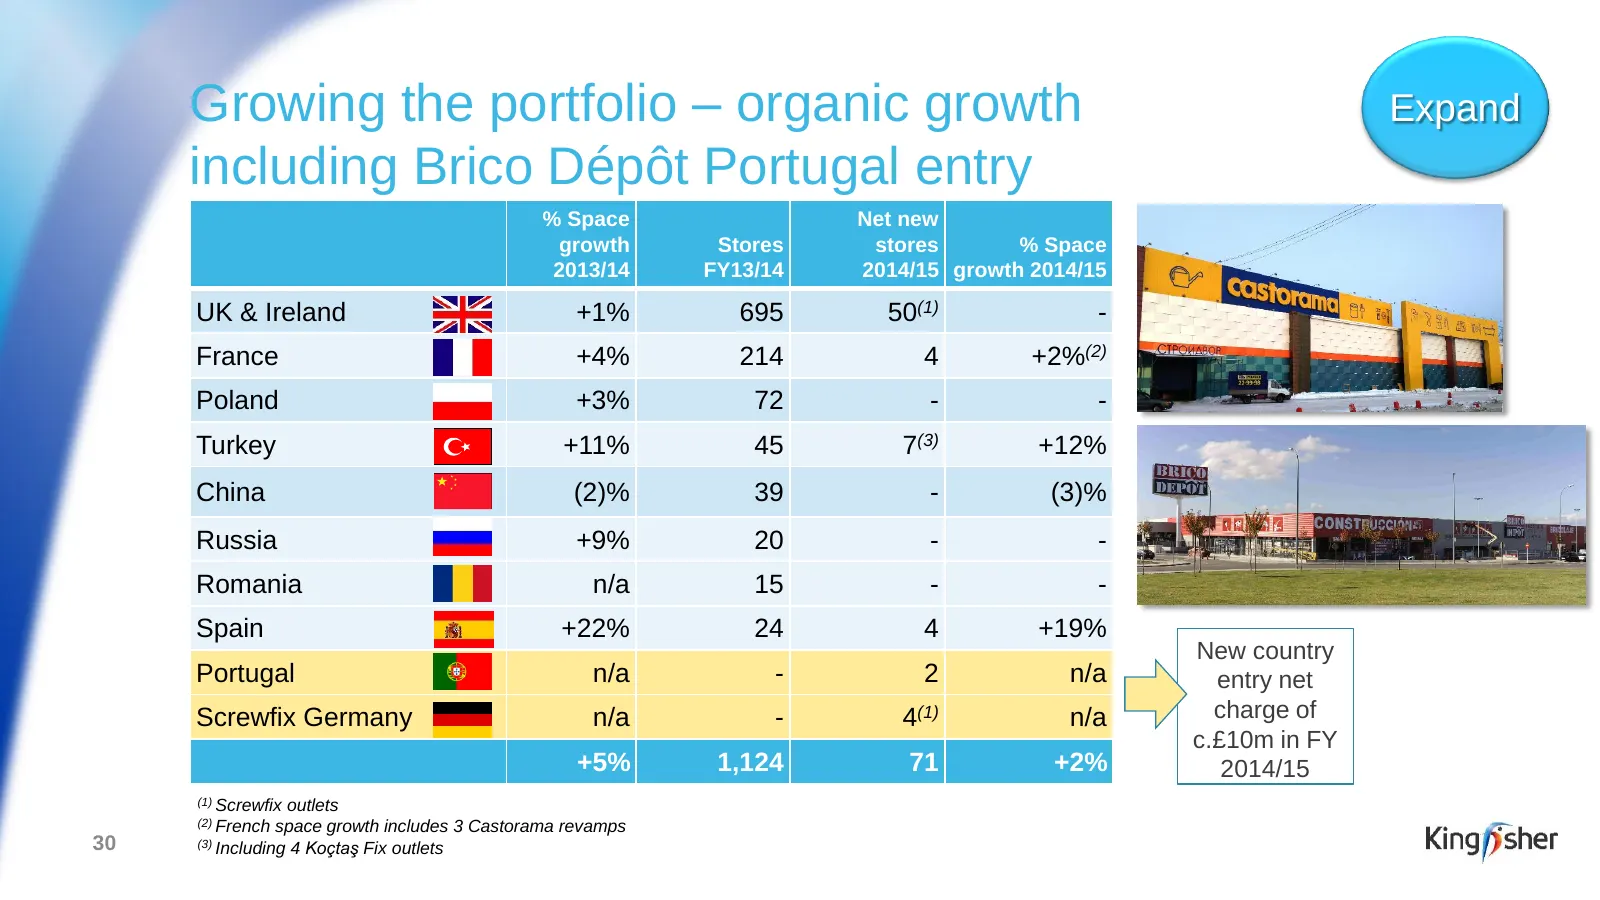
Growing the portfolio – organic growth Expand including Brico Dépôt Portugal entry % Space Net new growth Stores stores % Space 2013/14 FY13/14 2014/15 growth 2014/15 UK & Ireland +1% 695 50(1) - France +4% 214 4 +2%(2) Poland +3% 72 - - Turkey +11% 45 7(3) +12% China (2)% 39 - (3)% Russia +9% 20 -
Slide 31: …and actively managing the portfolio
Expand …and actively managing the portfolio ● Disposal agreed of 21.2% stake in Hornbach ● Agreed on 24 March 2014 ● Proceeds approx. £195m (acquired for £109m) ● Agreed to sell unlisted shares to Hornbach family ● Listed shares sold in an ‘accelerated bookbuilding’ ● Looking for a strategic partner
Slide 32: Right Size Right Place update
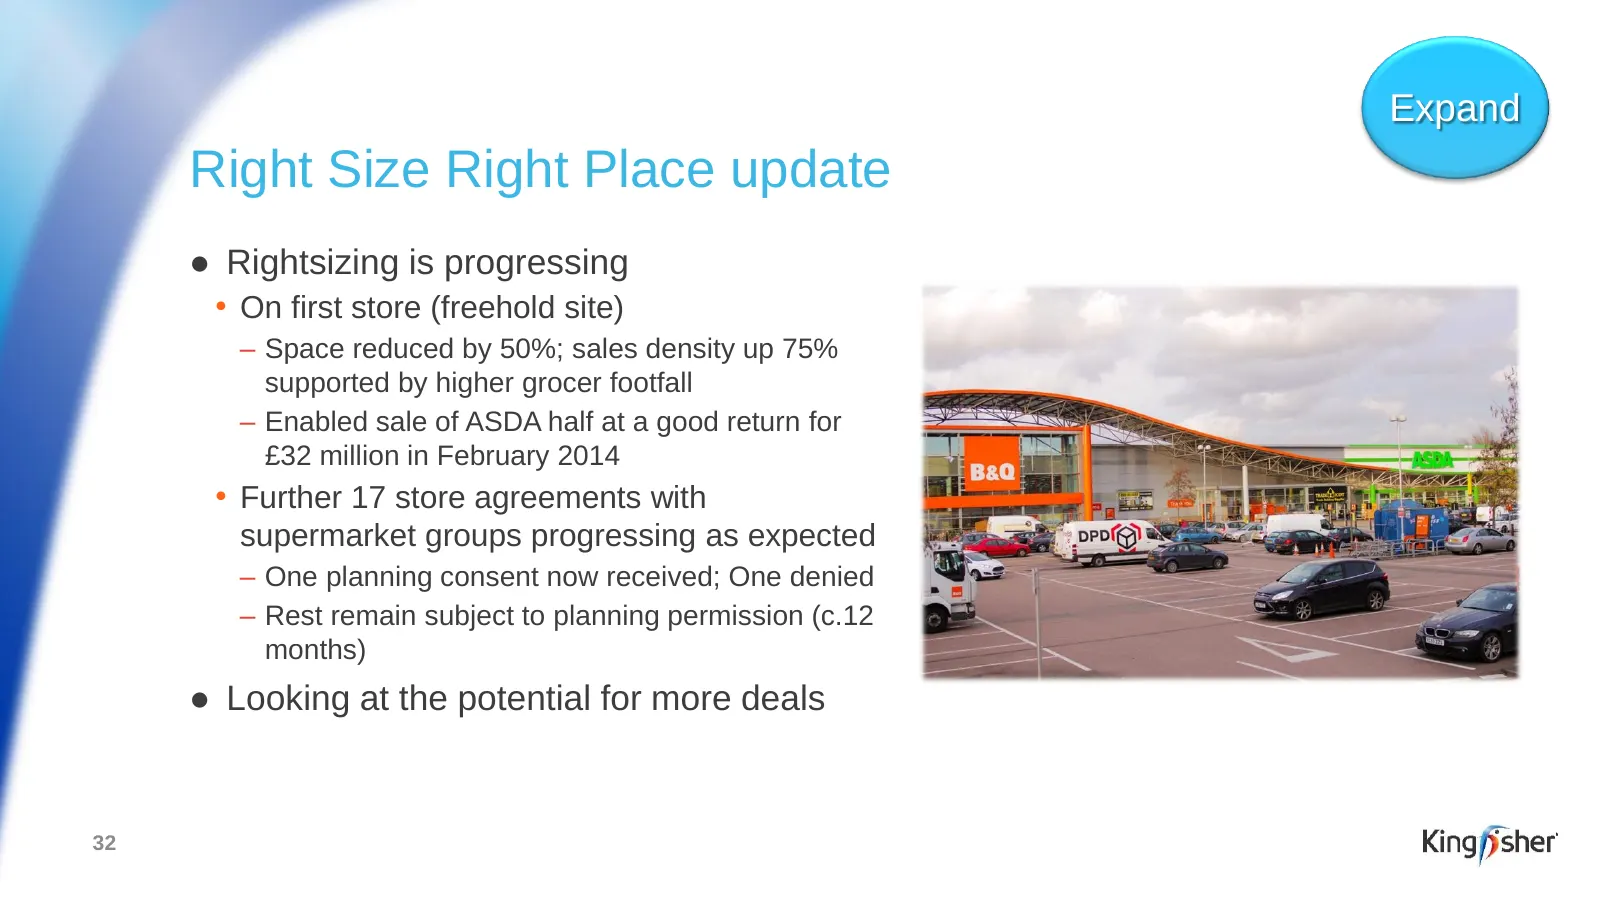
Expand Right Size Right Place update ● Rightsizing is progressing • On first store (freehold site) – Space reduced by 50%; sales density up 75% supported by higher grocer footfall – Enabled sale of ASDA half at a good return for £32 million in February 2014 • Further 17 store agreements with superma
Slide 33: Continuing to capitalise on consolidation opportunities
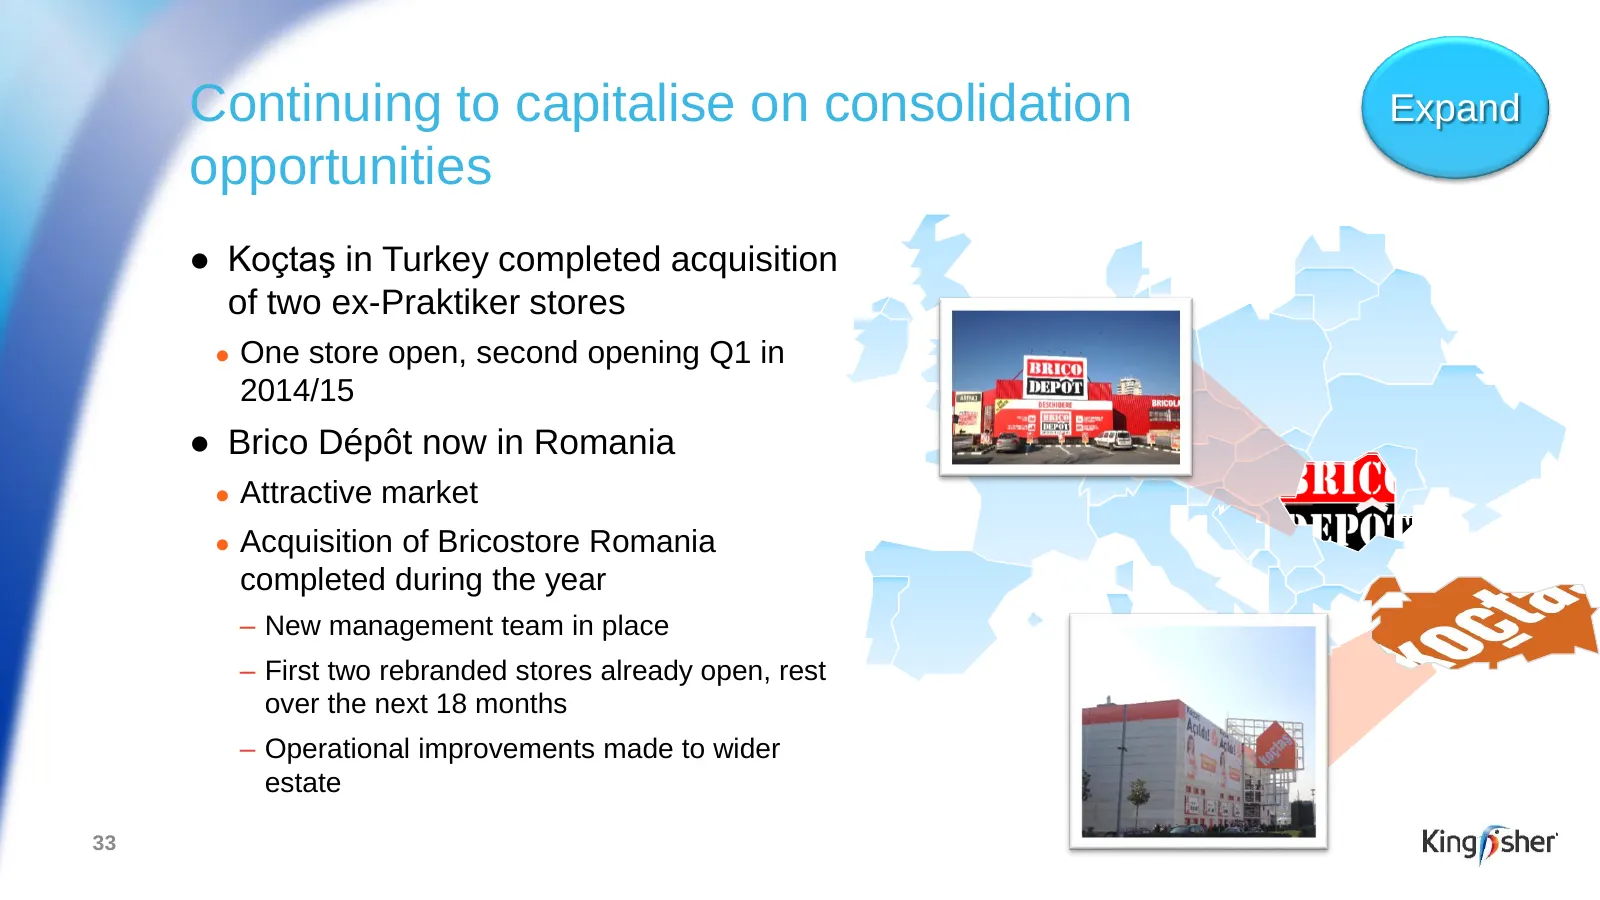
Continuing to capitalise on consolidation Expand opportunities ● Koçtaş in Turkey completed acquisition of two ex-Praktiker stores ● One store open, second opening Q1 in 2014/15 ● Brico Dépôt now in Romania ● Attractive market ● Acquisition of Bricostore Romania completed during the year – New manag
Slide 34: Kevin O'Byrne, Chief Executive, B&Q UK & Ireland
Kevin O’Byrne Chief Executive, B&Q UK & Ireland 34
Slide 35: B&Q is a strong business in an attractive sector of retail
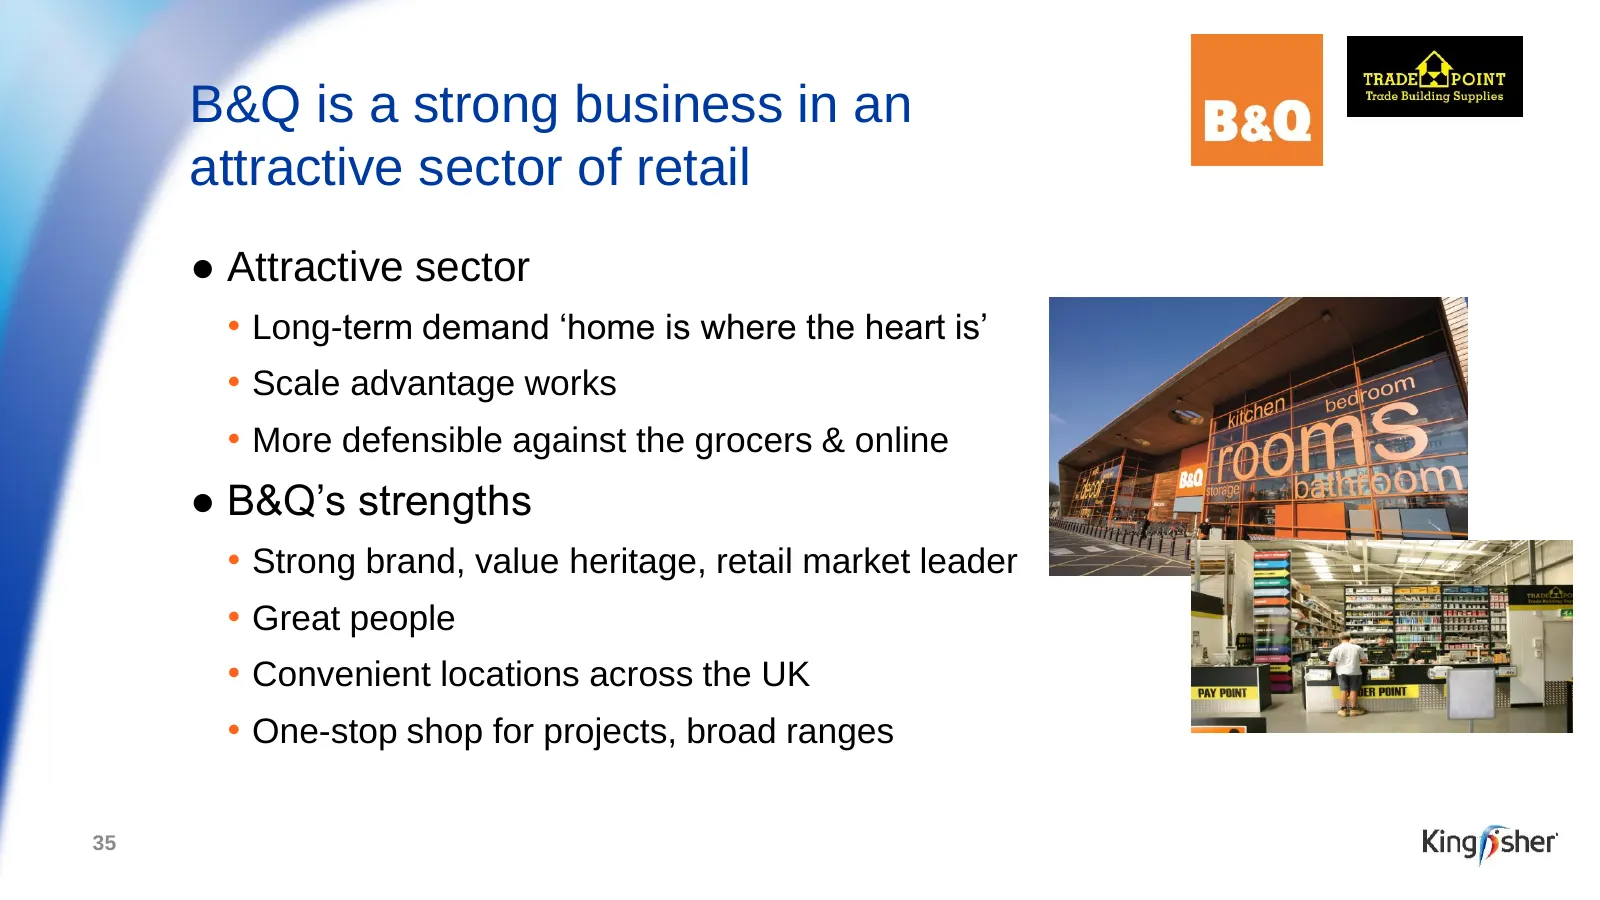
B&Q is a strong business in an attractive sector of retail ● Attractive sector • Long-term demand ‘home is where the heart is’ • Scale advantage works • More defensible against the grocers & online ● B&Q’s strengths • Strong brand, value heritage, retail market leader • Great people • Convenient loc
Slide 36: UK home improvement market has been tough and is evolving rapidly
But the UK home improvement market has been tough and is now evolving rapidly 1. Sharp market decline following a rapid period of growth 2. Pace of change accelerating ● Customer needs and behaviours ● Competitor landscape 36
Slide 37: UK home improvement market has declined since 2007
1. Since the economic & housing downturn started in 2007, the UK HI market has declined by c.12%(1) or c.£6bn(1) Decline by c.£6bn(1) from c.£50bn(1) in 2007 to c.£44bn(1) today due to: ● Fewer housing transactions ● Weak consumer confidence ● Consumer household income squeeze ● Reduction in Home Eq
Slide 38: Kingfisher has been resilient, delivering broadly flat UK & Ireland sales
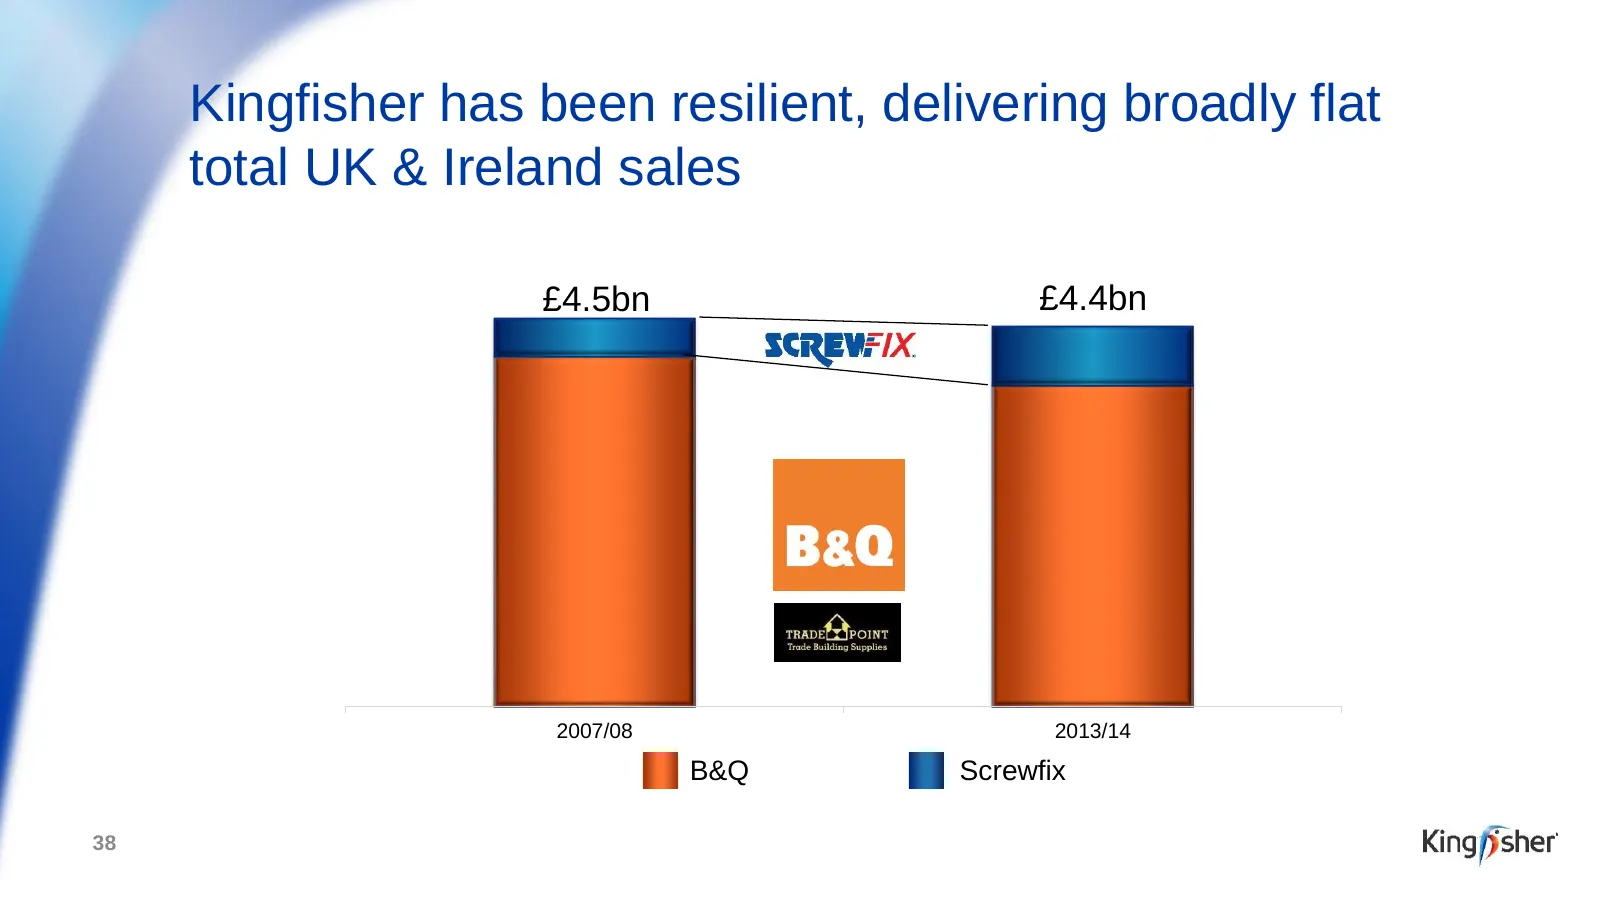
Kingfisher has been resilient, delivering broadly flat total UK & Ireland sales £4.5bn £4.4bn 2007/08 2013/14 B&Q Screwfix 38
Slide 39: Materially rebuilding UK & Ireland retail profit margins
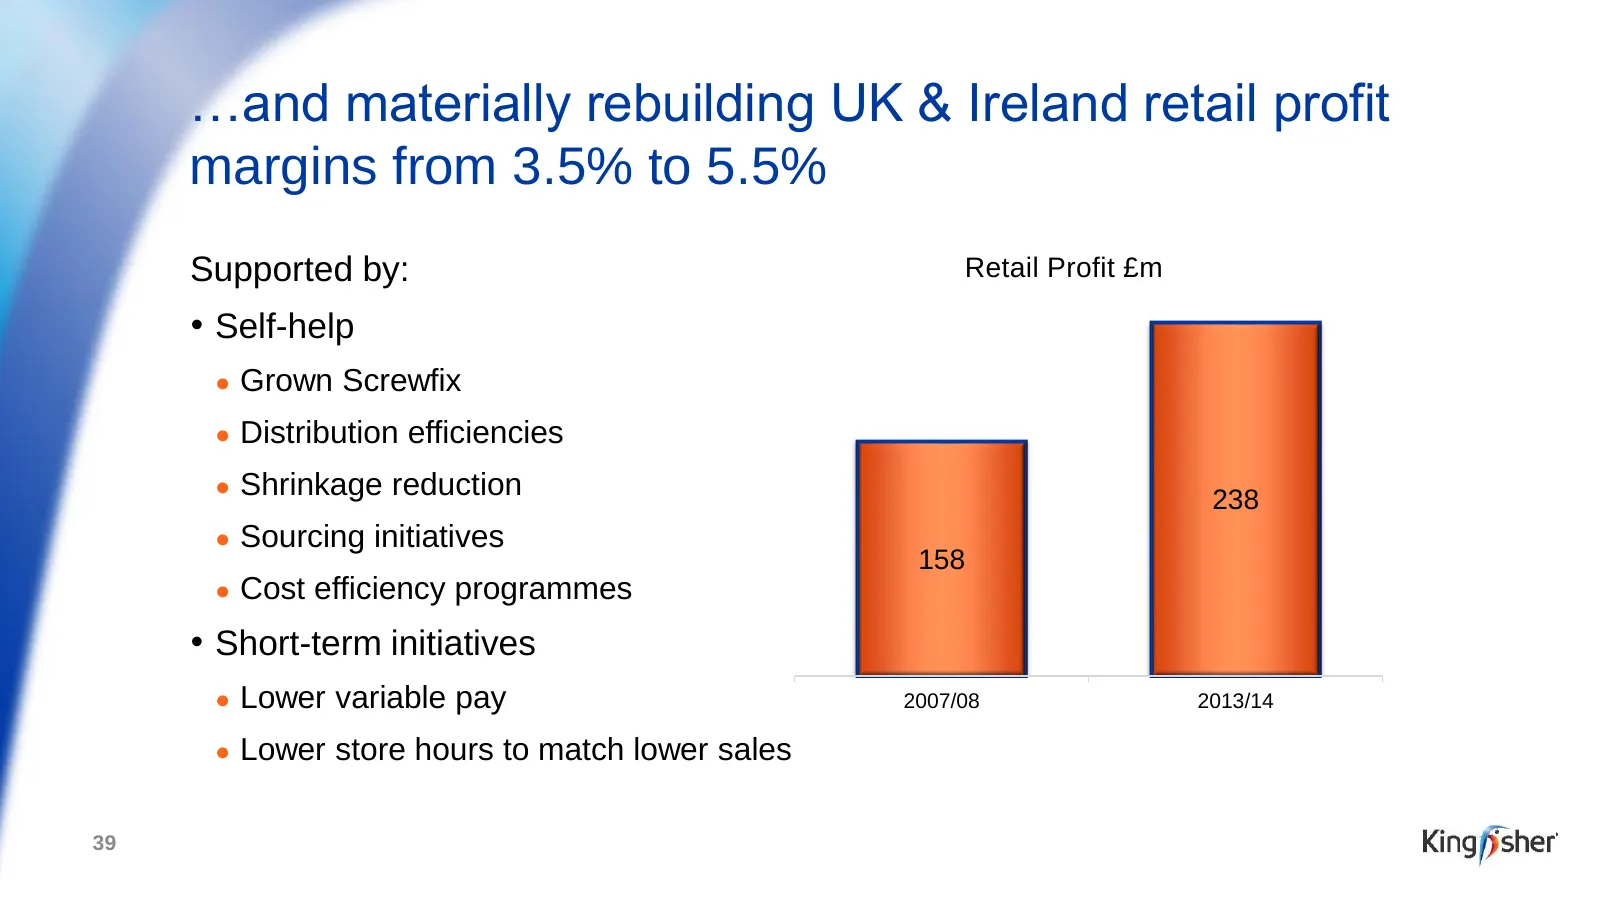
…and materially rebuilding UK & Ireland retail profit margins from 3.5% to 5.5% Supported by: Retail Profit £m • Self-help ● Grown Screwfix ● Distribution efficiencies ● Shrinkage reduction 238 ● Sourcing initiatives 158 ● Cost efficiency programmes • Short-term initiatives ● Lower variable pay 2007
Slide 40: Pace of change is accelerating
2. Pace of change is accelerating – we need to accelerate our response… Competitive landscape Customers’ needs and behaviours Little consolidation, largely long- Rise of convenience term rented More value orientated Previous exits now being offset Online research (66%) by recent store expansion Omni
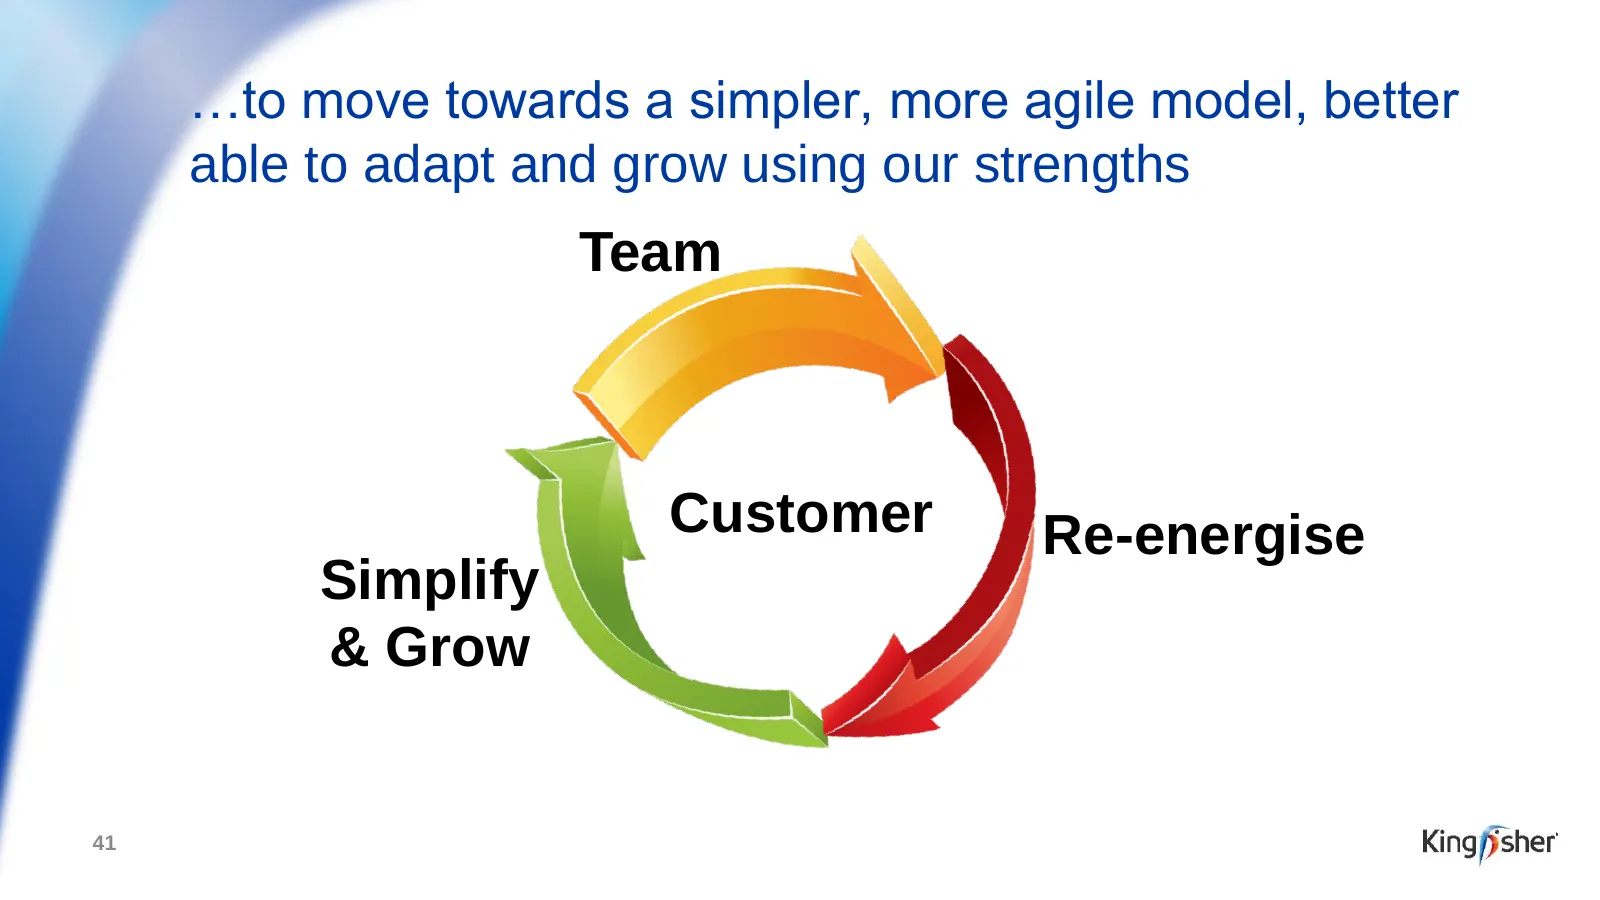
Slide 41: Move towards a simpler, more agile model
…to move towards a simpler, more agile model, better able to adapt and grow using our strengths Team Customer Re-energise Simplify & Grow 41
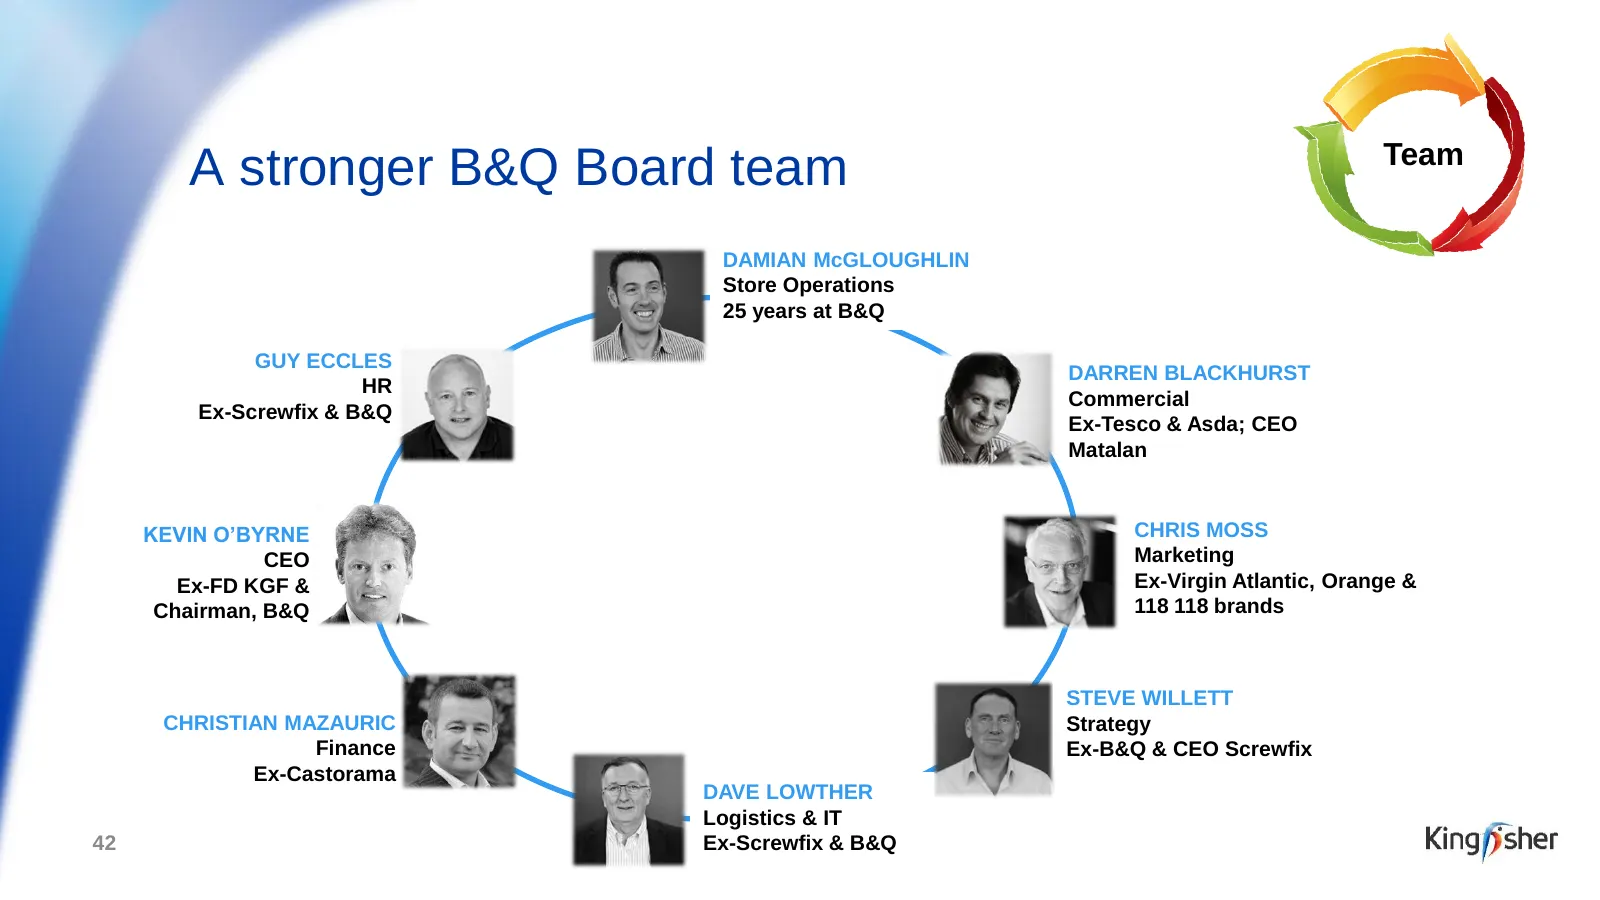
Slide 42: A stronger B&Q Board team
Team A stronger B&Q Board team DAMIAN McGLOUGHLIN Store Operations 25 years at B&Q GUY ECCLES DARREN BLACKHURST HR Commercial Ex-Screwfix & B&Q Ex-Tesco & Asda; CEO Matalan KEVIN O’BYRNE CHRIS MOSS CEO Marketing Ex-FD KGF & Ex-Virgin Atlantic, Orange & Chairman, B&Q 118 118 brands STEVE WILLETT CHRI
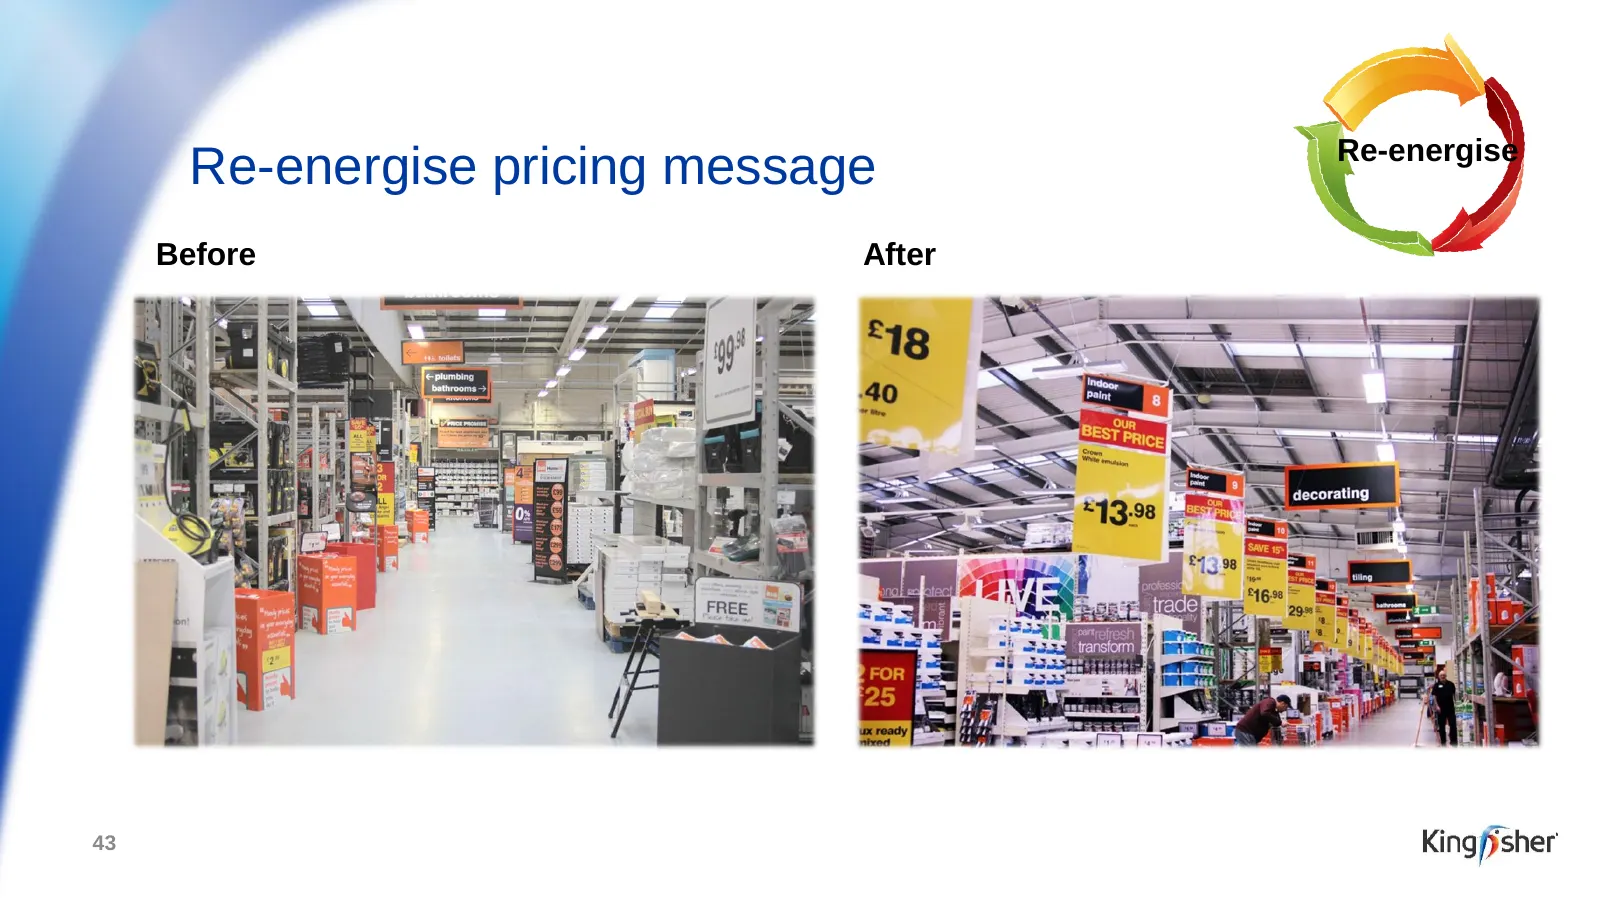
Slide 43: Re-energise pricing message
Re-energise Re-energise pricing message Before After 43
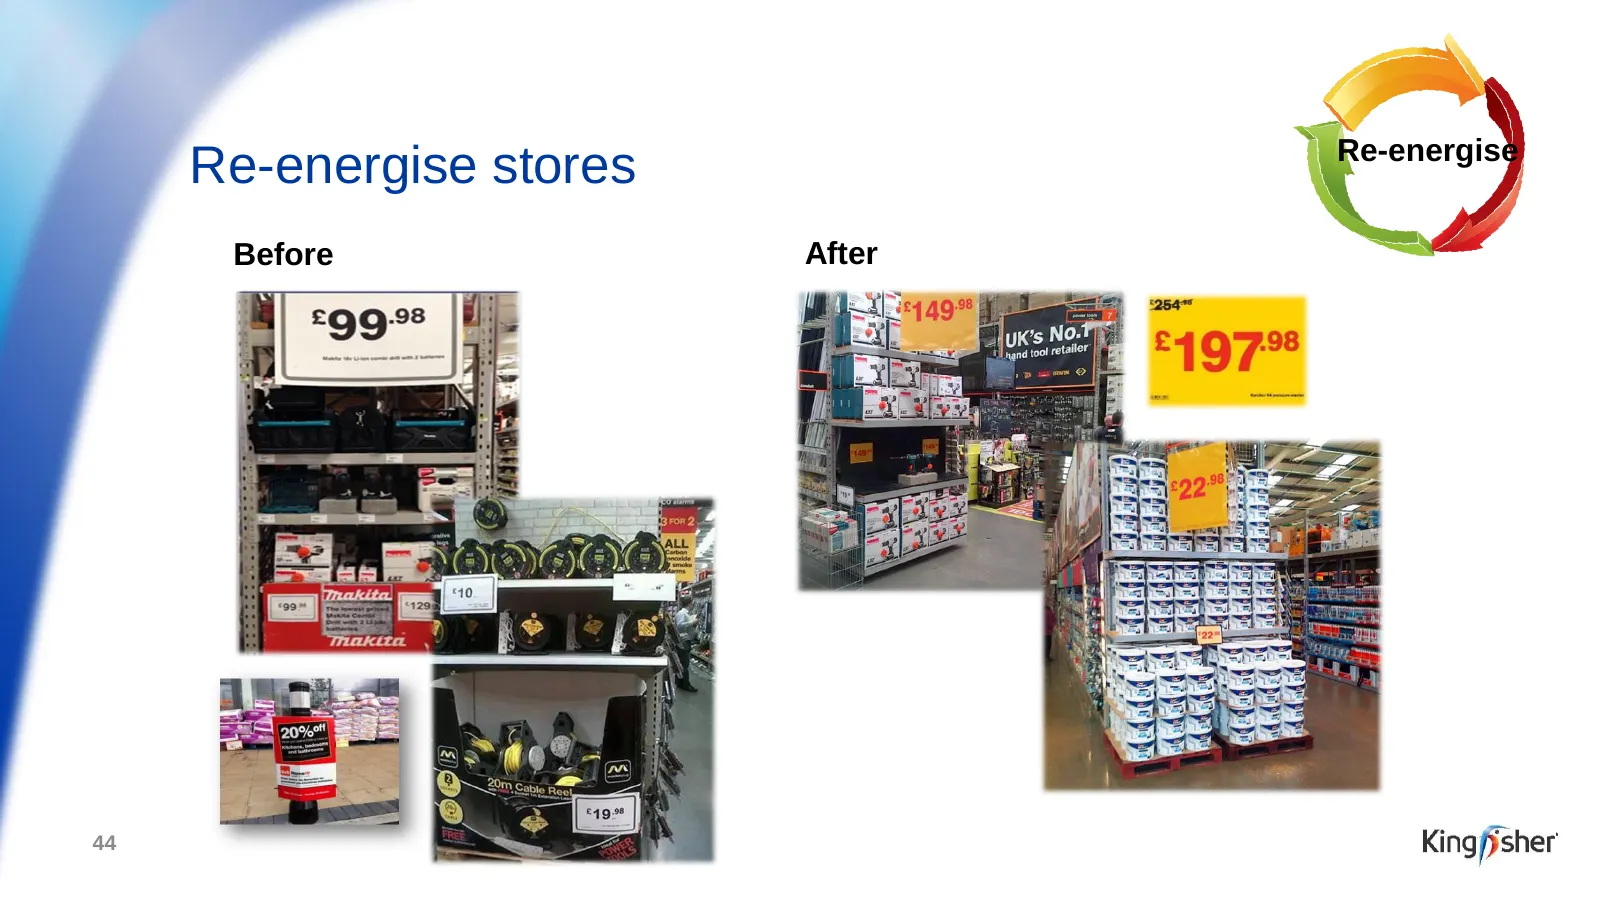
Slide 44: Re-energise stores
Re-energise Re-energise stores Before After 44
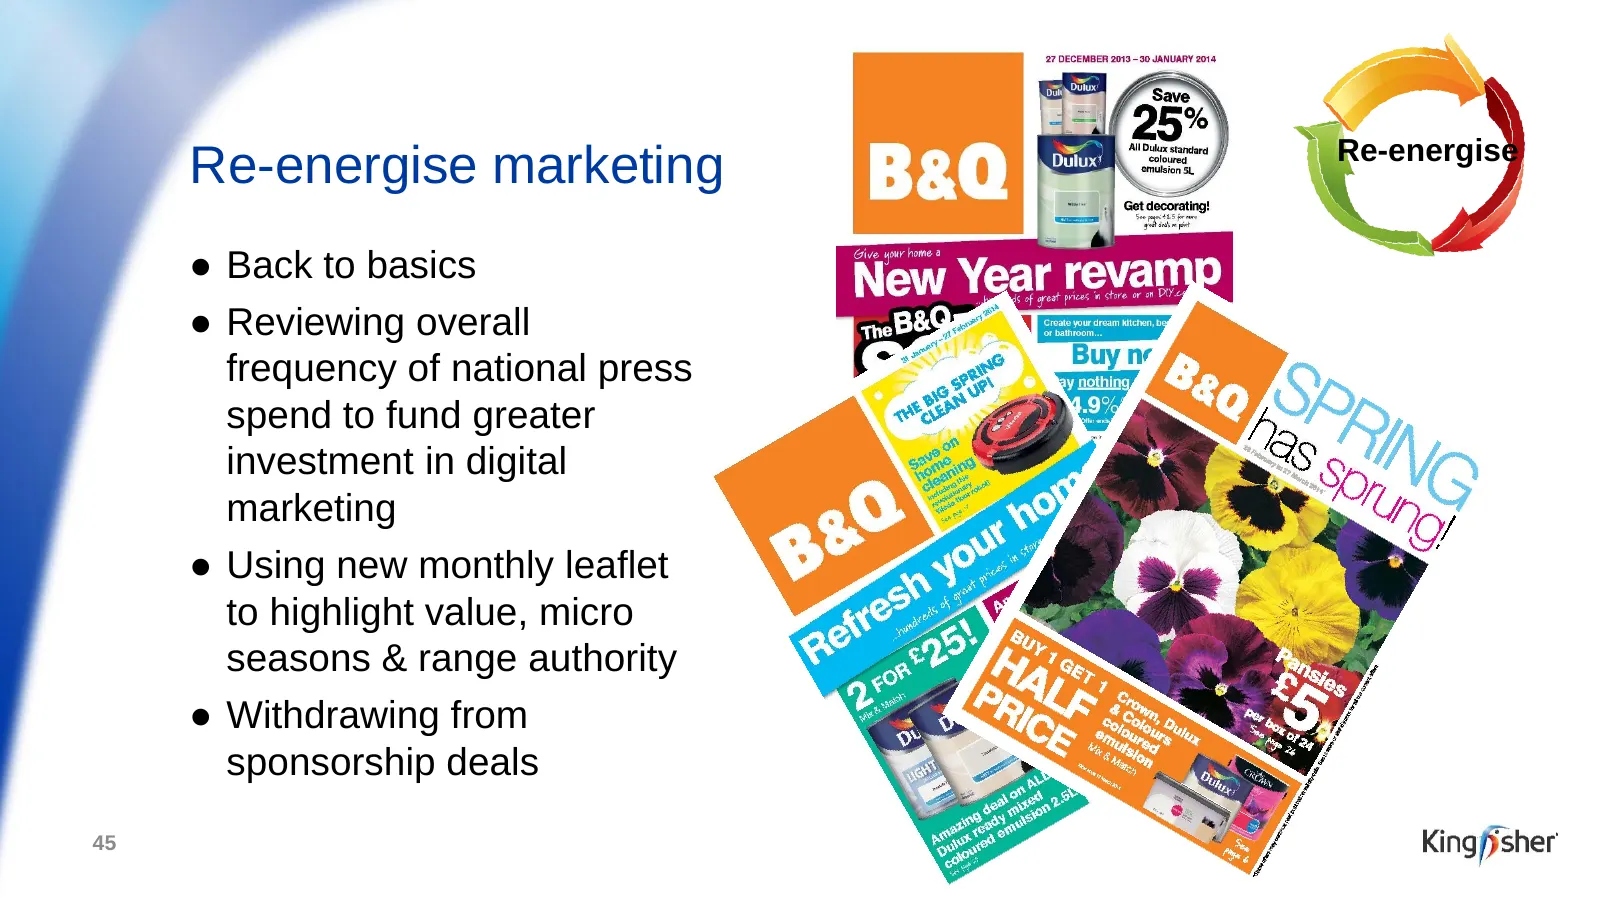
Slide 45: Re-energise marketing
Re-energise Re-energise marketing ● Back to basics ● Reviewing overall frequency of national press spend to fund greater investment in digital marketing ● Using new monthly leaflet to highlight value, micro seasons & range authority ● Withdrawing from sponsorship deals 45
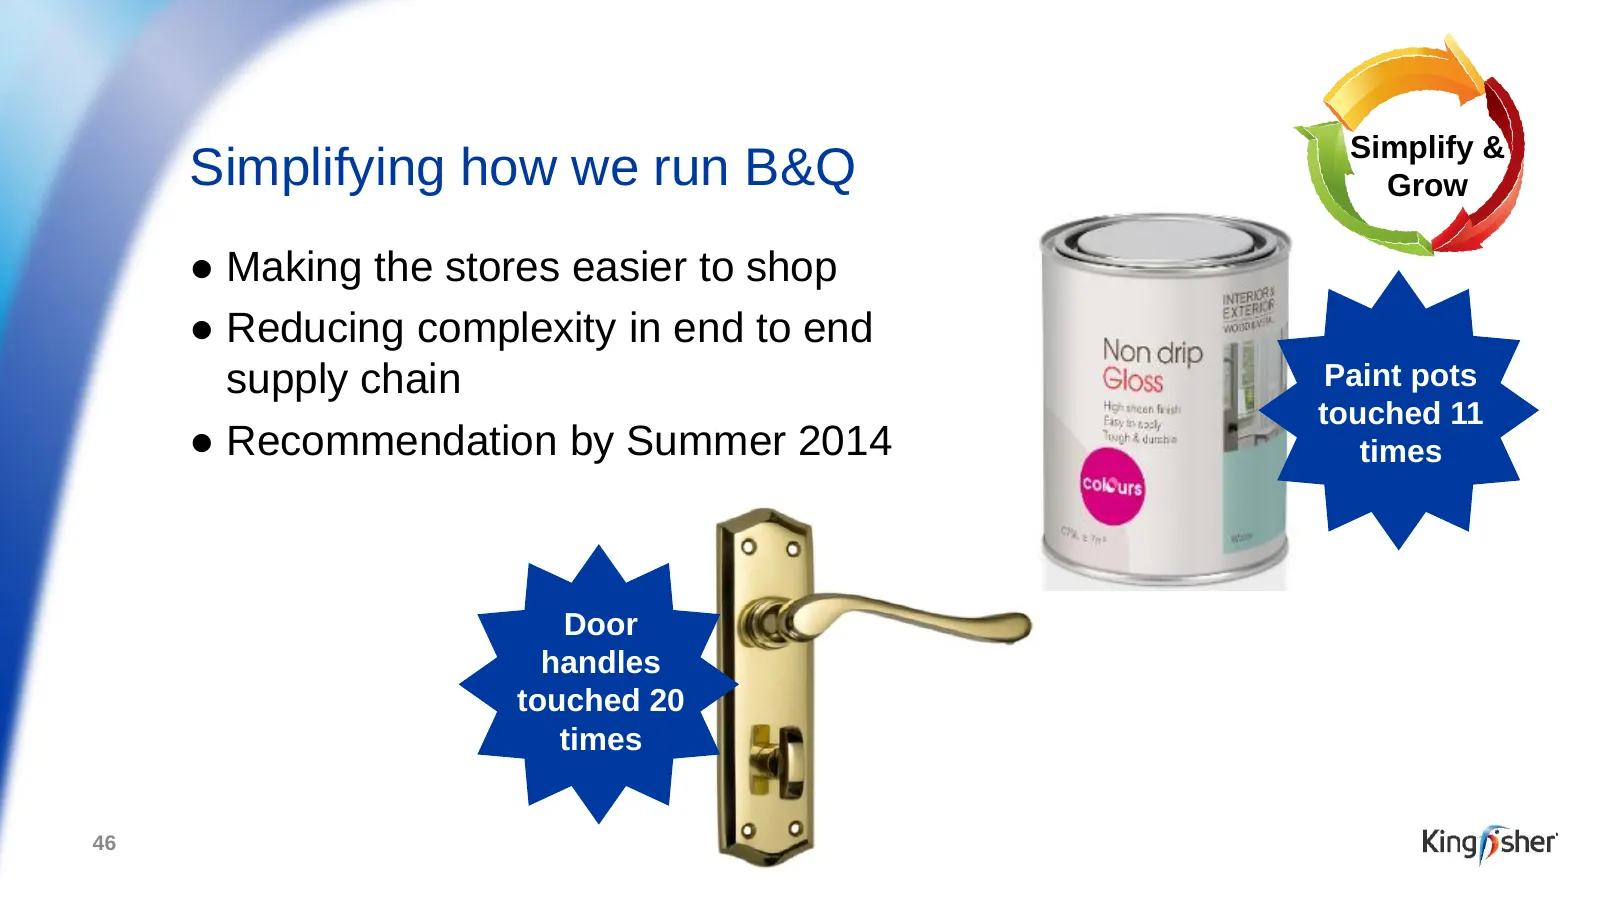
Slide 46: Simplifying how we run B&Q
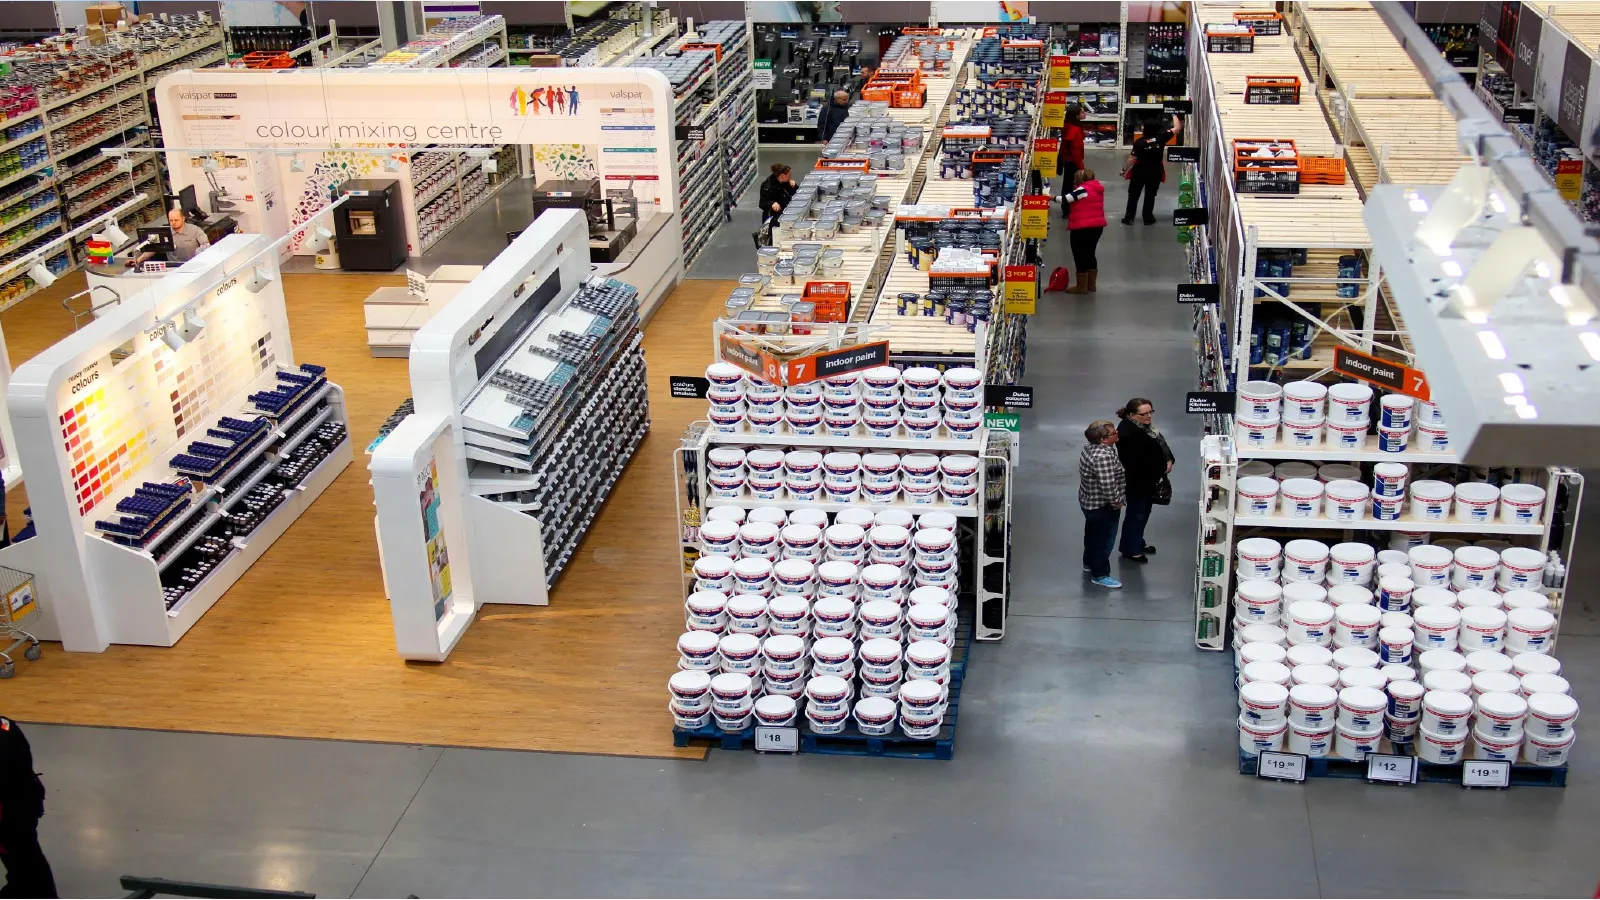
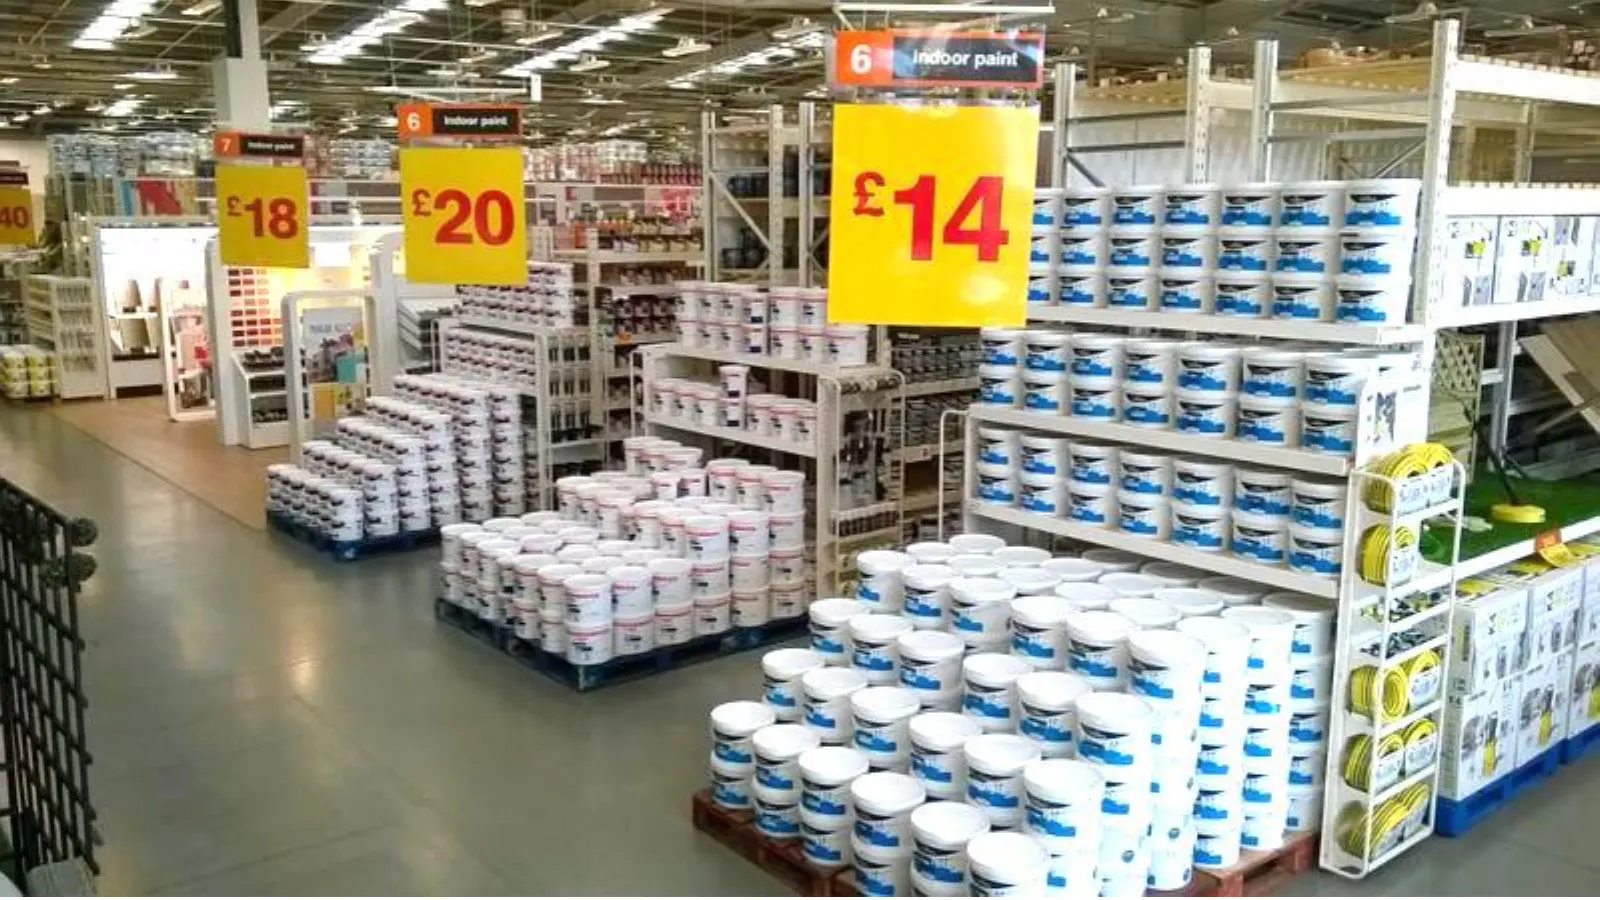
Simplify & Simplifying how we run B&Q Grow ● Making the stores easier to shop ● Reducing complexity in end to end supply chain Paint pots touched 11 ● Recommendation by Summer 2014 times Door handles touched 20 times 46
Slide 47: The offer
Simplify & The offer Grow ● Detailed review of all 19 categories or ‘shops within shops’ focusing on ● Customer needs ● Competition ● Business model ● Milestone to complete review by Summer 2014 ● Will lead by category to one of three outcomes for space in-store: 1. Rearrange 2. Reallocate 3. Revamp
Slide 48: 48
48
Slide 49: 49
49
Slide 50: 50
50
Slide 51: First implementation of Group omnichannel platform launched into B&Q
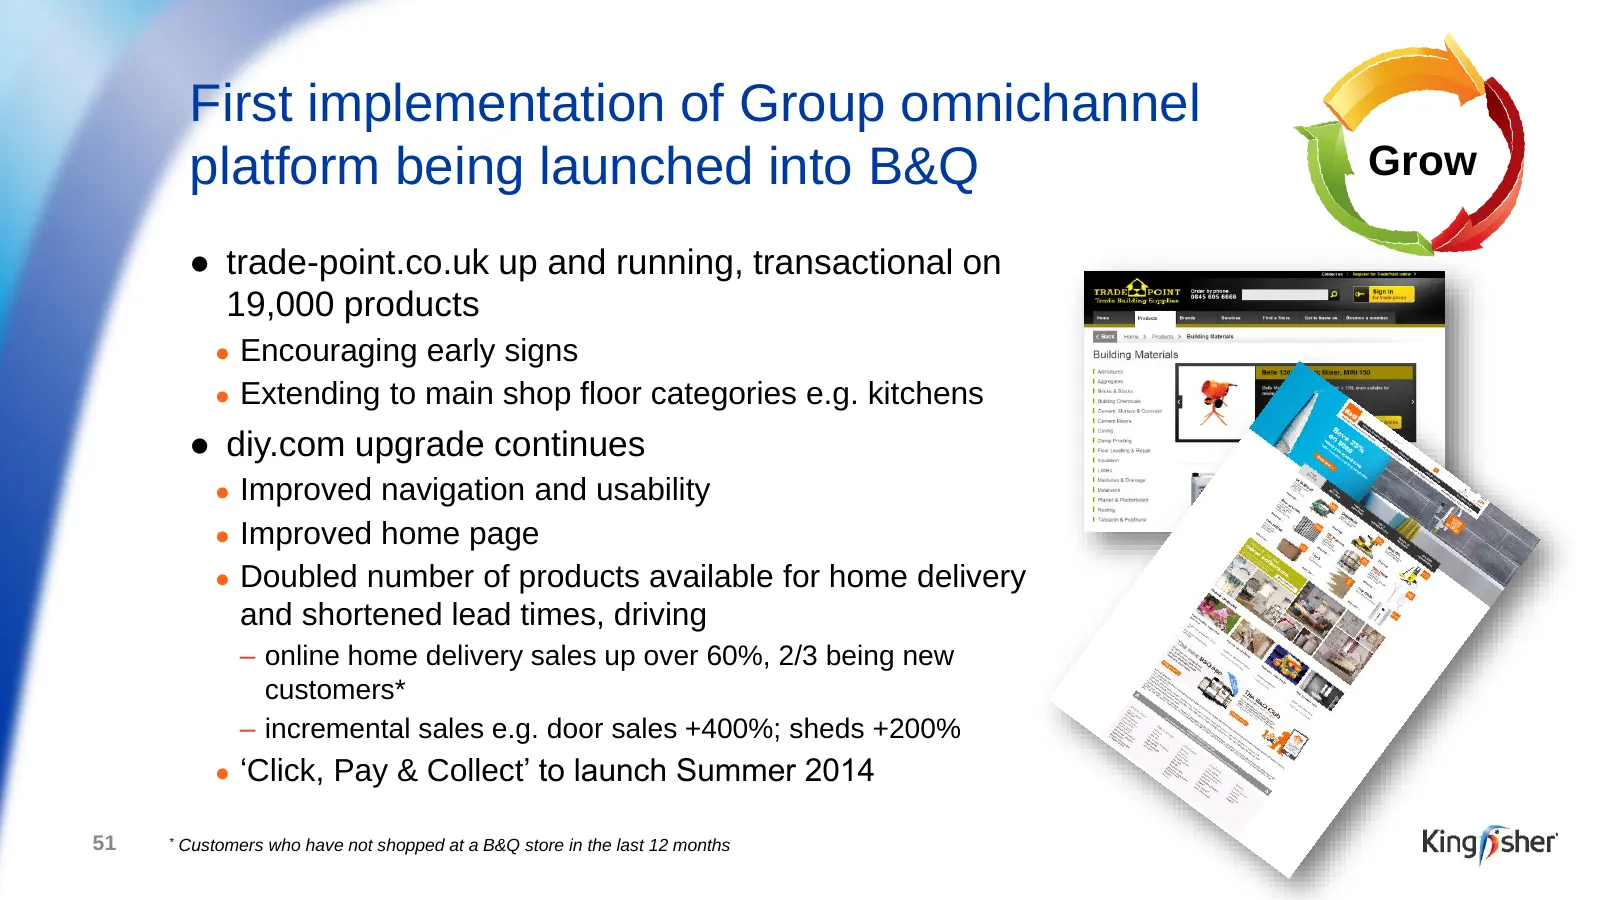
First implementation of Group omnichannel platform being launched into B&Q Grow ● trade-point.co.uk up and running, transactional on 19,000 products ● Encouraging early signs ● Extending to main shop floor categories e.g. kitchens ● diy.com upgrade continues ● Improved navigation and usability ● Imp
Slide 52: Summary
Summary ● B&Q is a strong business ● The market and our customers Team are evolving quickly ● We will evolve to a simpler, more agile model, better able to adapt Re-energise and grow Simplify & ● We have made a good start Grow • Stronger team in place • Things are happening now • Working on the long
Slide 53: Sir Ian Cheshire, Group Chief Executive
Sir Ian Cheshire Group Chief Executive 53
Slide 54: 2013/14 Summary & Outlook
2013/14 Summary & Outlook ● Good progress in tough environment ● Extremely challenging Q1, remainder of the year more encouraging ● Persistent weak economic backdrop in France Self-help from ‘Creating the Leader’ continues to progress well ● Supporting short term results ● Building the long term fut
Slide 55: Cautionary note regarding forward-looking statements
Cautionary note regarding forward-looking statements THIS PRESENTATION CONTAINS FORWARD-LOOKING STATEMENTS, WHICH SHOULD BE CONSIDERED, AMONGST OTHER STATUTORY PROVISIONS, IN LIGHT OF THE SAFE HARBOUR PROVISIONS OF THE UNITED STATES PRIVATE SECURITIES LITIGATION REFORM ACT OF 1995. ALL STATEMENTS OT
Slide 56: Appendices
Appendices 56
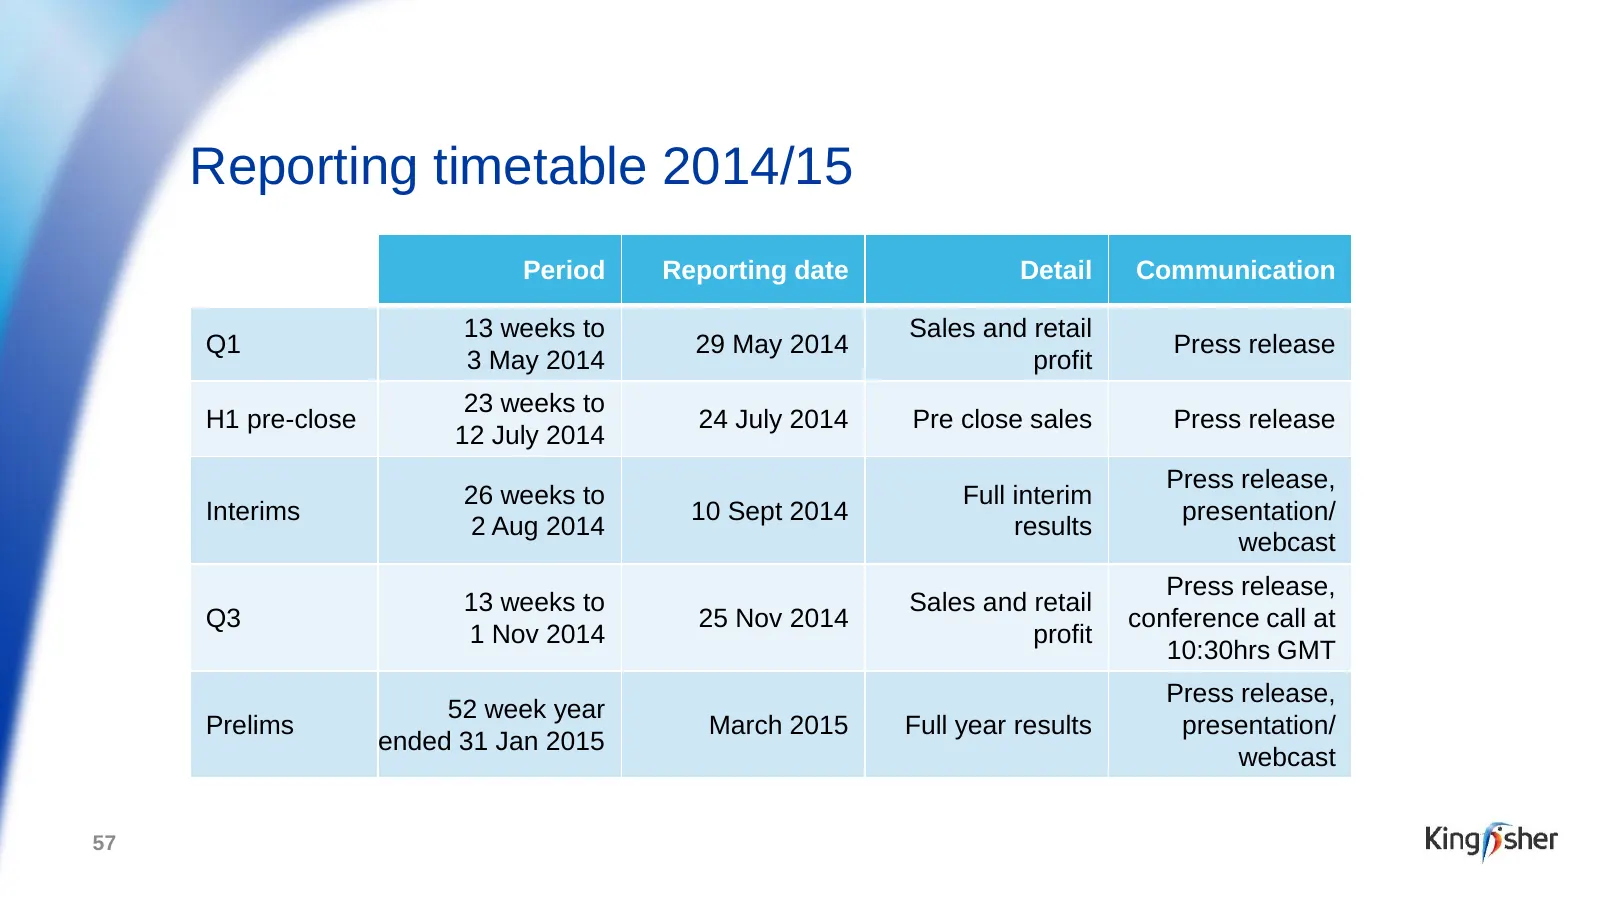
Slide 57: Reporting timetable 2014/15
Reporting timetable 2014/15 Period Reporting date Detail Communication 13 weeks to Sales and retail Q1 29 May 2014 Press release 3 May 2014 profit 23 weeks to H1 pre-close 24 July 2014 Pre close sales Press release 12 July 2014 Press release, 26 weeks to Full interim Interims 10 Sept 2014 presentati
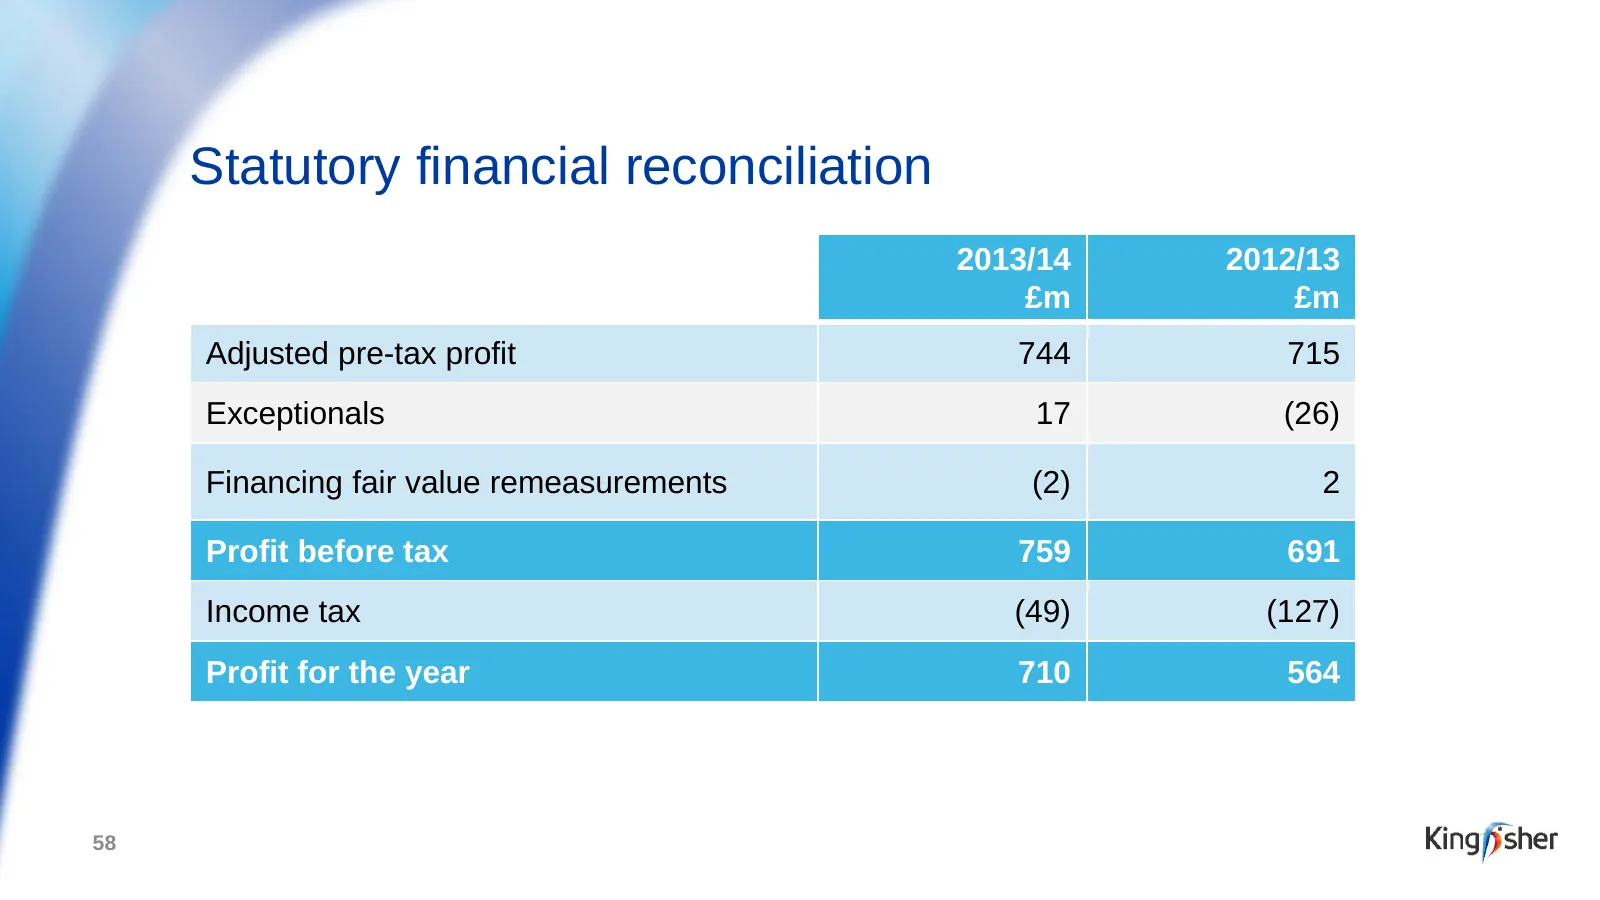
Slide 58: Statutory financial reconciliation
Statutory financial reconciliation 2013/14 2012/13 £m £m Adjusted pre-tax profit 744 715 Exceptionals 17 (26) Financing fair value remeasurements (2) 2 Profit before tax 759 691 Income tax (49) (127) Profit for the year 710 564 58
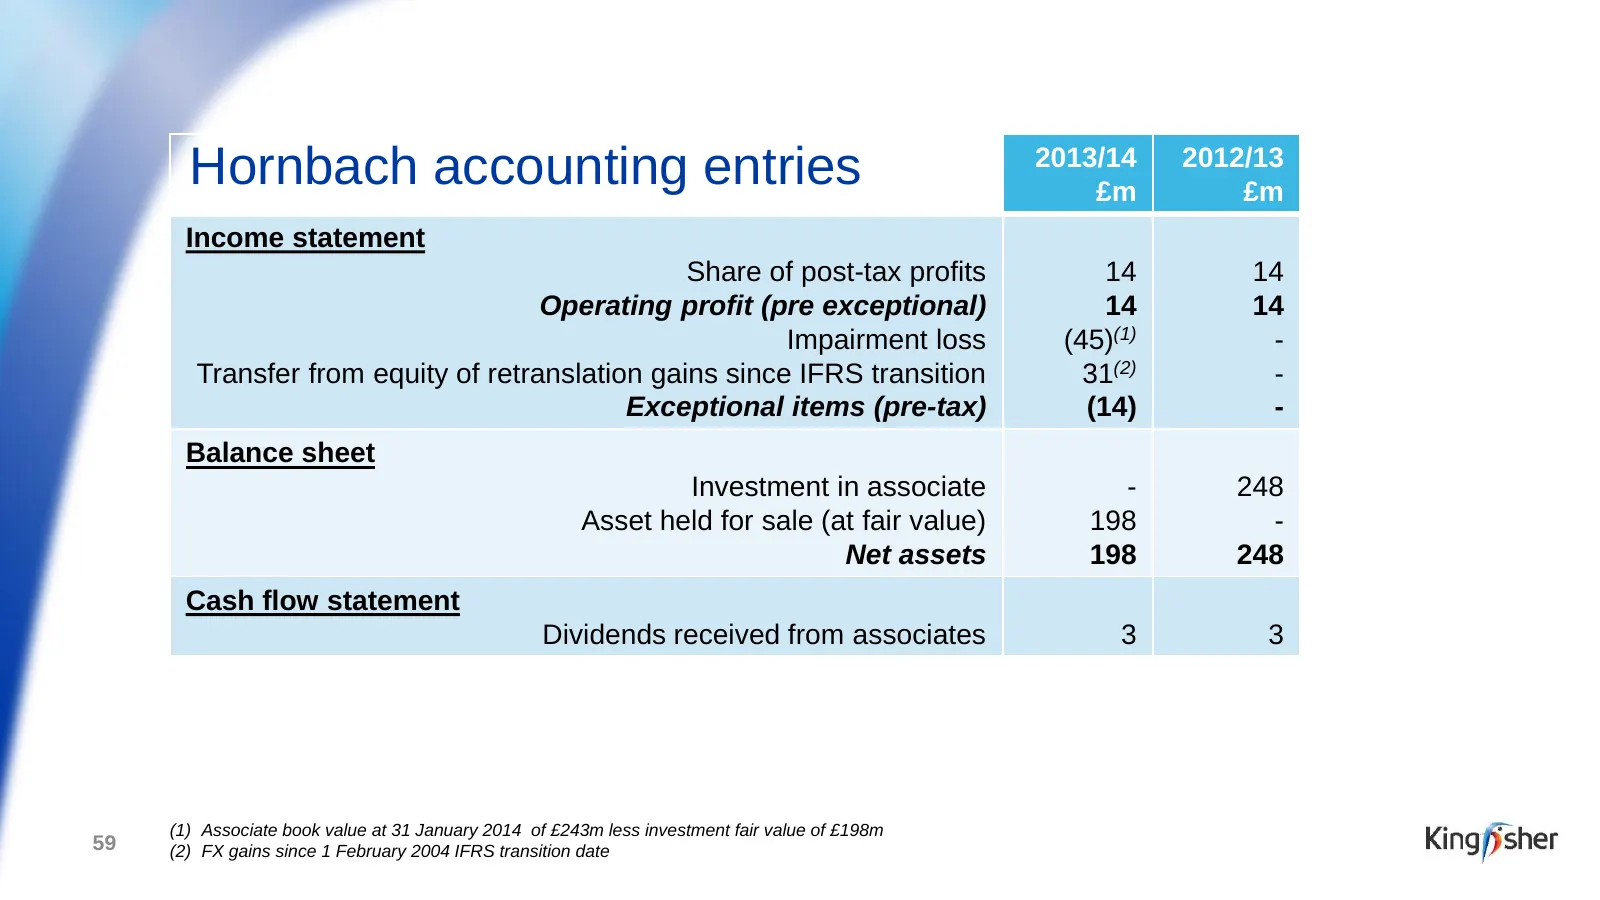
Slide 59: Hornbach accounting entries
Hornbach accounting entries 2013/14 £m 2012/13 £m Income statement Share of post-tax profits 14 14 Operating profit (pre exceptional) 14 14 Impairment loss (45)(1) - Transfer from equity of retranslation gains since IFRS transition 31(2) - Exceptional items (pre-tax) (14) - Balance sheet Investment
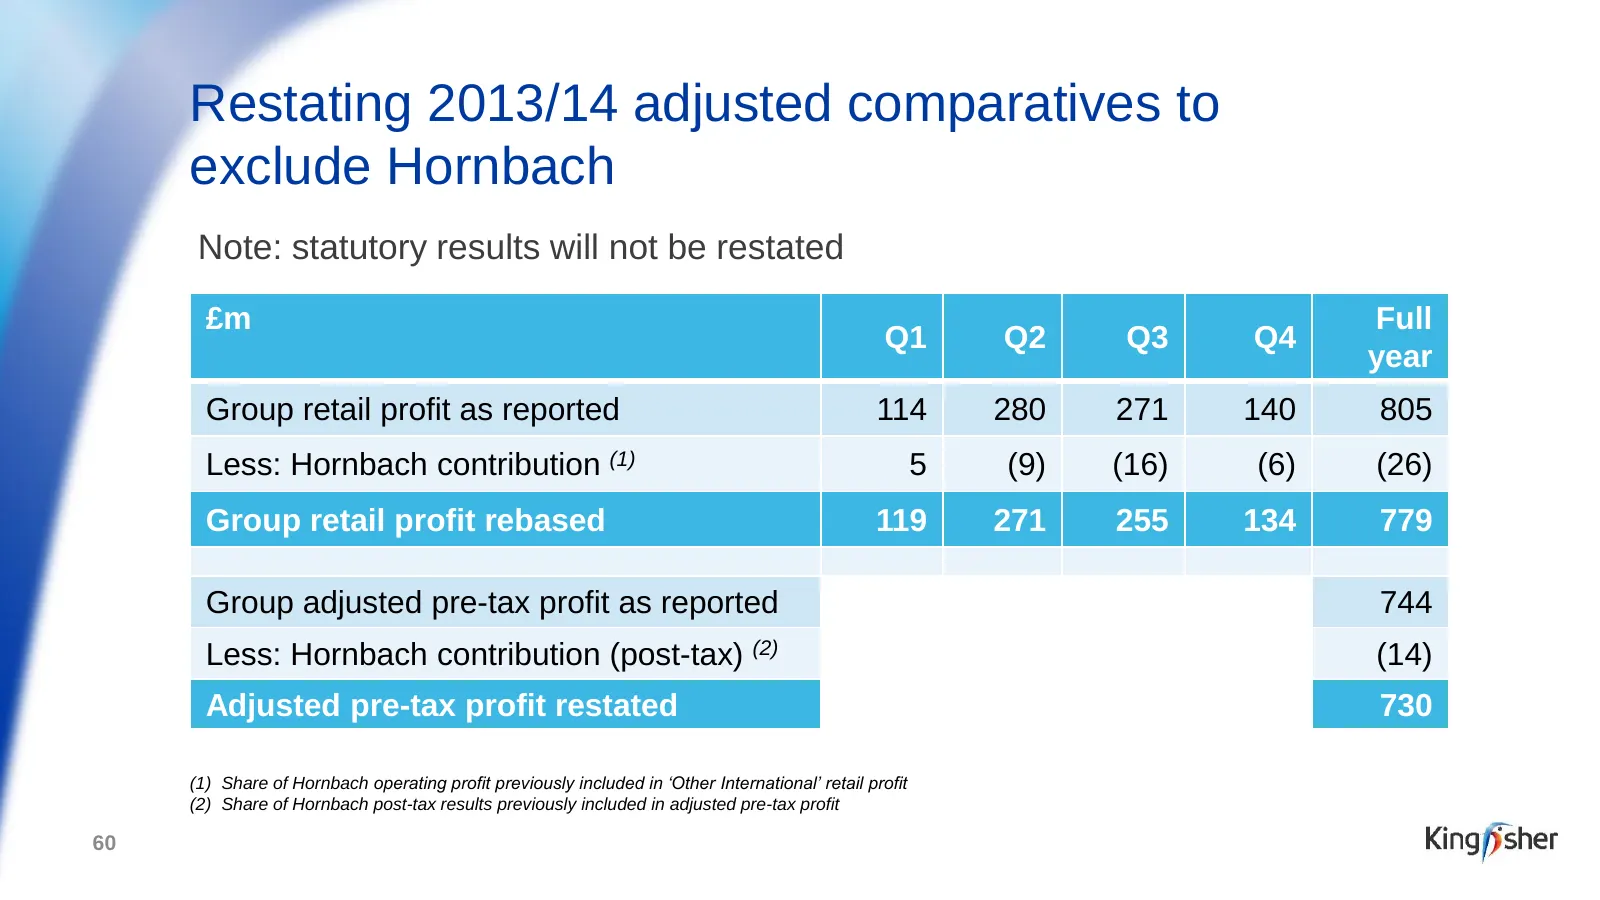
Slide 60: Restating 2013/14 adjusted comparatives to exclude Hornbach
Restating 2013/14 adjusted comparatives to exclude Hornbach Note: statutory results will not be restated £m Full Q1 Q2 Q3 Q4 year Group retail profit as reported 114 280 271 140 805 Less: Hornbach contribution (1) 5 (9) (16) (6) (26) Group retail profit rebased 119 271 255 134 779 Group adjusted pre
Slide 61: Net debt/EBITDAR reconciliation
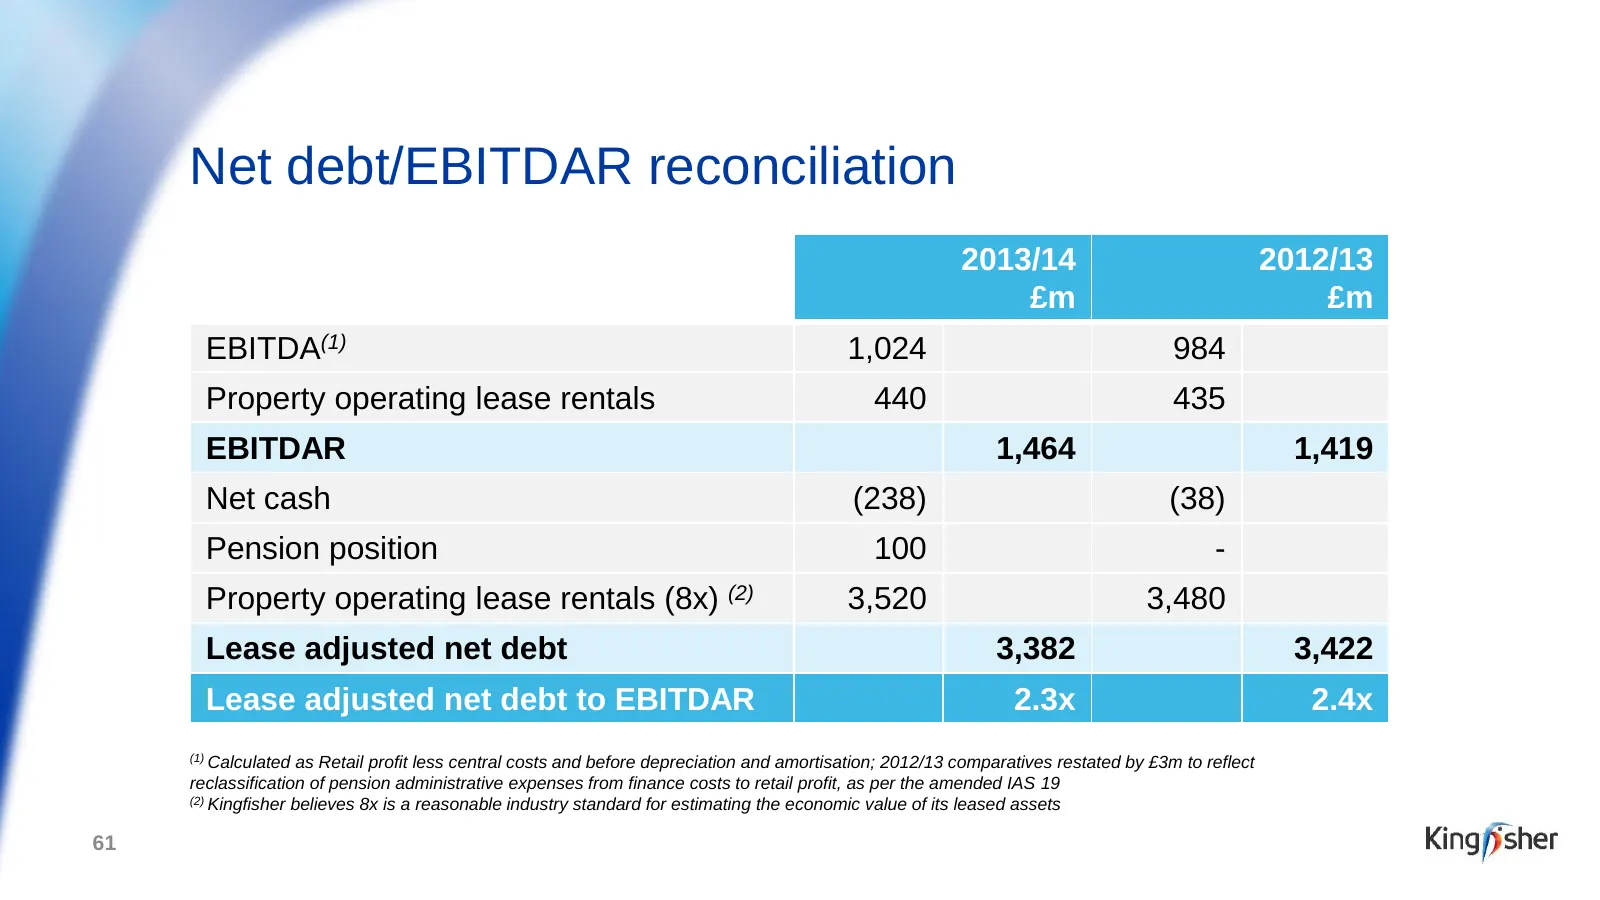
Net debt/EBITDAR reconciliation 2013/14 2012/13 £m £m EBITDA(1) 1,024 984 Property operating lease rentals 440 435 EBITDAR 1,464 1,419 Net cash (238) (38) Pension position 100 - Property operating lease rentals (8x) (2) 3,520 3,480 Lease adjusted net debt 3,382 3,422 Lease adjusted net debt to EBITD
Slide 62: Freehold property
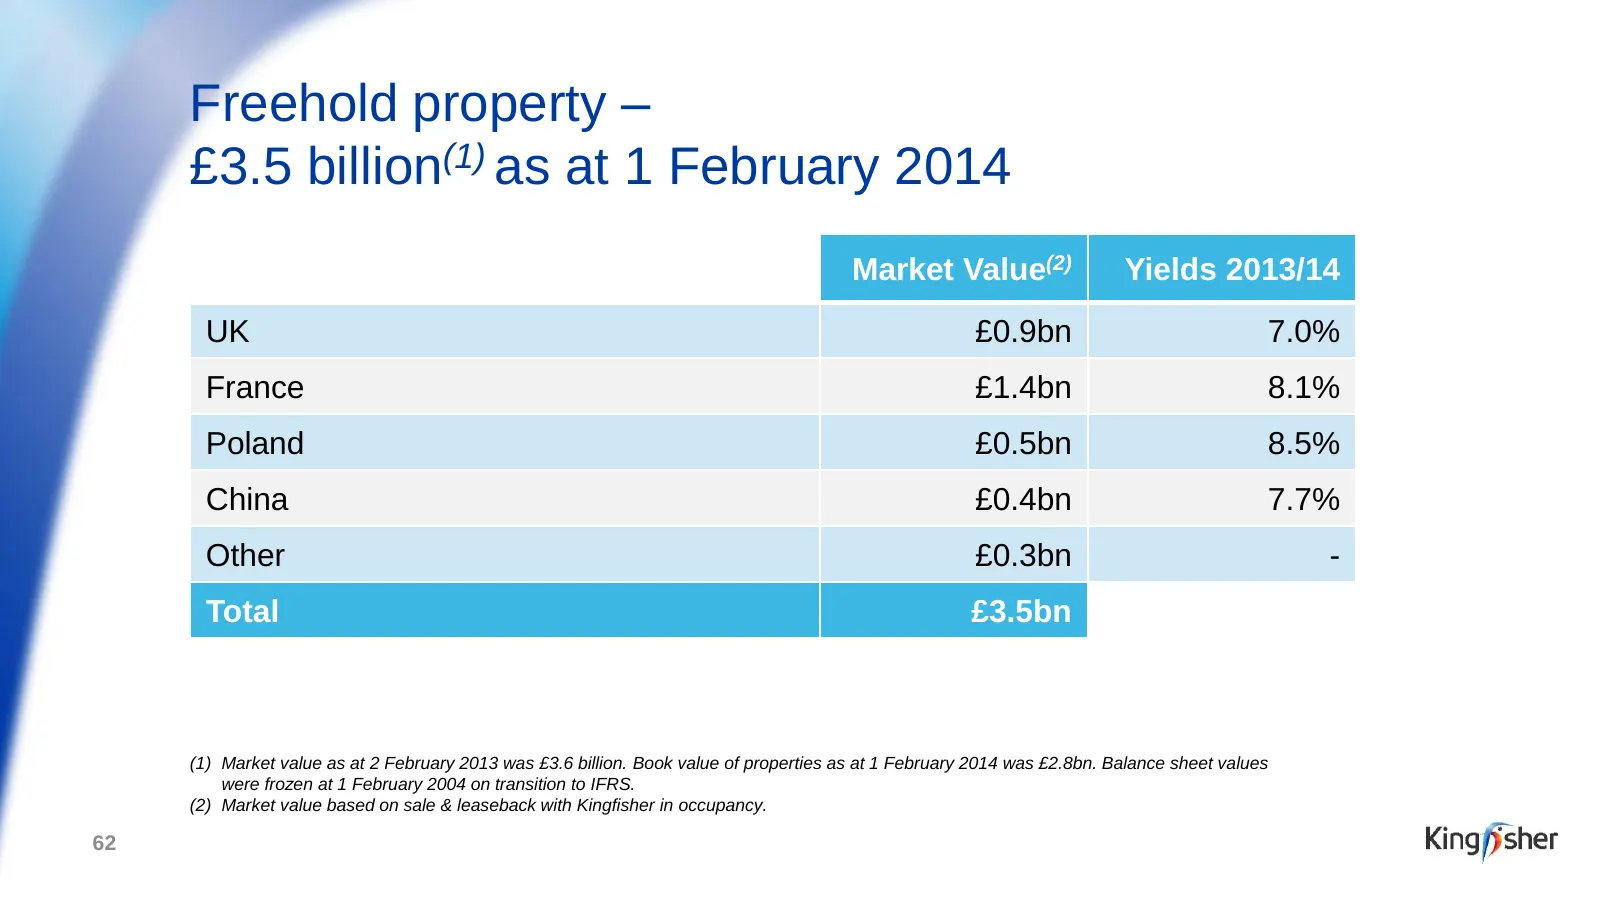
Freehold property – £3.5 billion(1) as at 1 February 2014 Market Value(2) Yields 2013/14 UK £0.9bn 7.0% France £1.4bn 8.1% Poland £0.5bn 8.5% China £0.4bn 7.7% Other £0.3bn - Total £3.5bn (1) Market value as at 2 February 2013 was £3.6 billion. Book value of properties as at 1 February 2014 was £2.8
Slide 63: Sponsored ADR programme
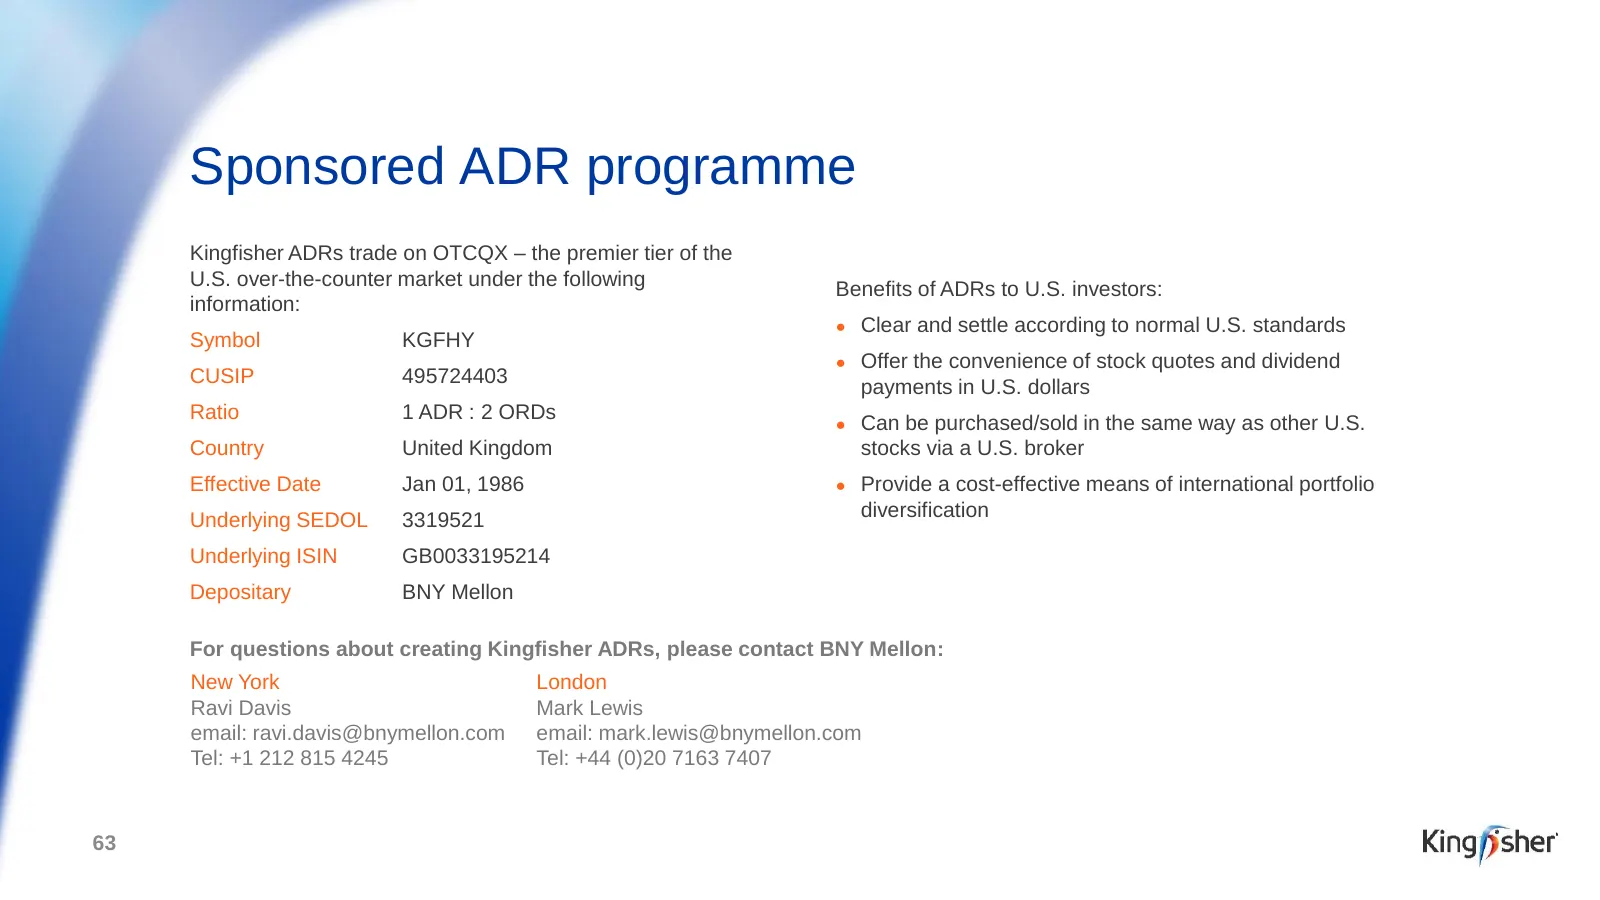
Sponsored ADR programme Kingfisher ADRs trade on OTCQX – the premier tier of the U.S. over-the-counter market under the following Benefits of ADRs to U.S. investors: information: ● Clear and settle according to normal U.S. standards Symbol KGFHY ● Offer the convenience of stock quotes and dividend C
Slide 64: Contacts
Contacts Ian Harding, Group Communications Director 020 7644 1029 Sarah Levy, Director of Investor Relations 020 7644 1032 Nigel Cope, Head of Media Relations 020 7644 1030 Matt Duffy, Investor Relations Manager 020 7644 1082 Clare Feast, Media Relations Manager 020 7644 1286 Brunswick 020 7404 5959
Slide 65: 2013/14 milestones
Easier 2013/14 milestones To do list – Affordability: 1. Launch ‘handy prices’ in B&Q 2. Invested in pricing in Castorama France & Poland 3. Brico Dépôt ‘back to basics’ marketing campaign 4. Extend Brico Dépôt France & Spain programme of ‘arrivages’(1) to Turkey & Poland 5. Launch UK Enterprise Fin
Slide 66: 2013/14 milestones
Easier 2013/14 milestones To do list - Omnichannel: 1. UK omni-channel offer: • Launch upgraded B&Q online offer WIP (www.diy.com), including 20,000 extra products for home delivery (using Screwfix omnichannel infrastructure) • Extend TradePoint website to main shop floor categories e.g. kitchens WI
Slide 67: 2013/14 milestones
EASIER Common 2013/14 milestones To do list – Product: 1. Launch new energy-efficiency ‘iQE’ Group brand 2. Paint (c.9% of Group sales) • Roll out ‘Colours’ Group own-brand paint into Russia & Spain • Roll out new ‘Colours’ emulsion paint range – 2/3 common B&Q UK & Castorama France WIP • Launch exc
Slide 68: 2013/14 milestones
EASIER Common 2013/14 milestones To do list - Efficiency: 1. Upweighted distribution and cross docking capability in Poland, Spain & Turkey 2. SG&A(1) optimisation from media buying programmes across the UK & France 3. Extend Brico Dépôt shelf ready packaging from 20% to 30% 4. Roll out France & Spa
Slide 69: 2013/14 milestones
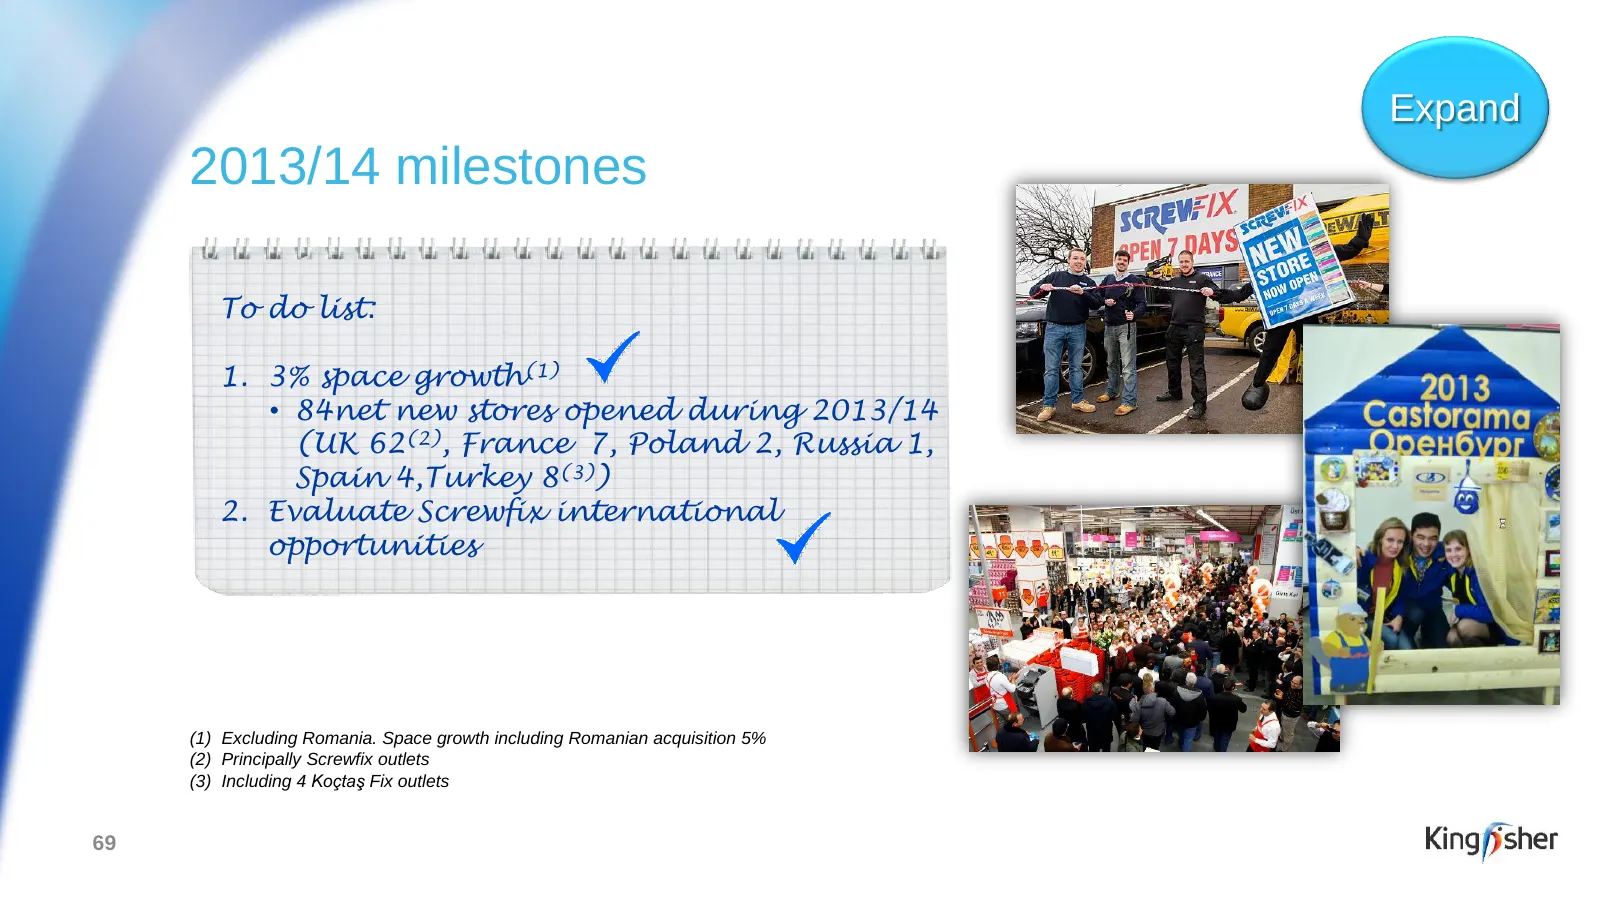
Expand 2013/14 milestones To do list: 1. 3% space growth(1) • 84net new stores opened during 2013/14 (UK 62(2), France 7, Poland 2, Russia 1, Spain 4,Turkey 8(3)) 2. Evaluate Screwfix international opportunities (1) Excluding Romania. Space growth including Romanian acquisition 5% (2) Principally Sc
Slide 70: 2013/14 milestones
One Team 2013/14 milestones To do list: 1. Continue to extend the Kingfisher Academy 2. Net Positive Dashboard to be updated annually 3. Over 1,400 Kingfisher employees shared an estimated gain of £10 million following the maturity of the Sharesave scheme in December 2013 70
Source: Internet Archive copy of kingfisher.com
More decks from Kingfisher PLC
 H1 2026/27 Earnings Presentation33 slides · Sep 22, 2026
 FY2025/26 Earnings Presentation39 slides · Mar 24, 2026
 H1 2025/26 Earnings Presentation38 slides · Sep 23, 2025
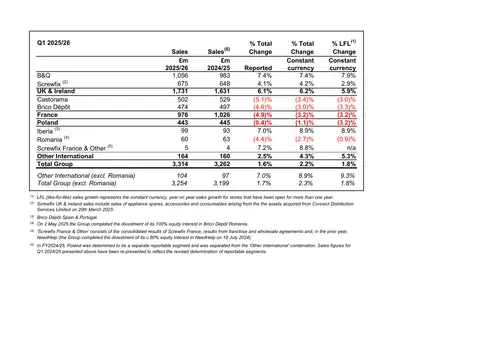 H1 2025/26 Earnings Presentation6 slides · September 2025
 FY2024/25 Earnings Presentation35 slides · Apr 8, 2025
 FY2024/25 Earnings Presentation40 slides · Mar 25, 2025