Mid-Con Energy Partners LP — Merger or Acquisition (January 2021)
19 slides from Mid-Con Energy Partners LP's merger presentation, Jan 15, 2021
Slide 1: January 2021 Presentation
January 2021 PresentationJanuary 2021 Presentation
Slide 2: Cautionary Statements
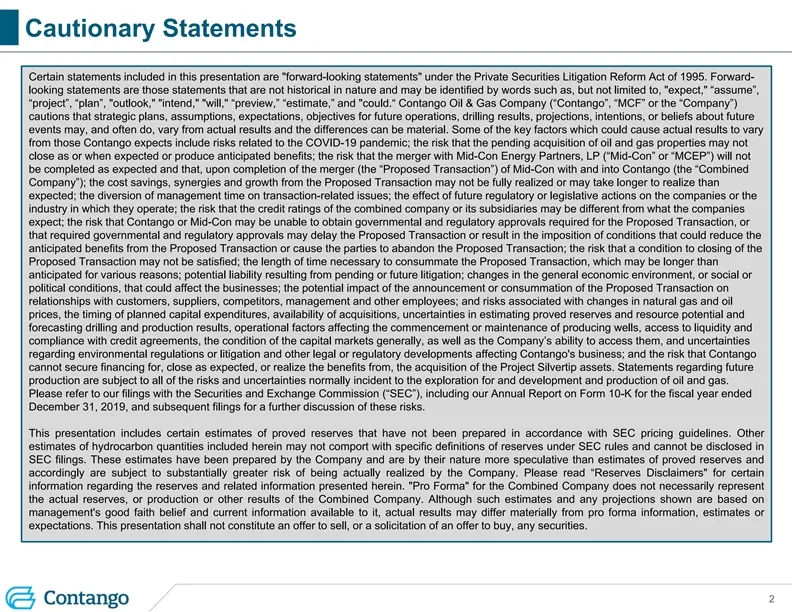
Cautionary Statements Certain statements included in this presentation are forward-looking statements under the Private Securities Litigation Reform Act of 1995. Forward- looking statements are those statements that are not historical in nature and may be identified by words such as, but not limited
Slide 3: Additional Information
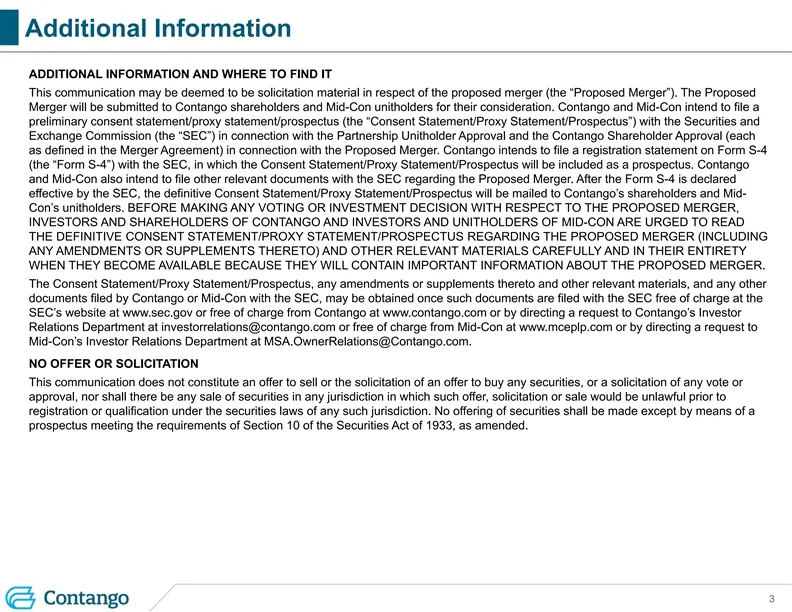
Additional Information ADDITIONAL INFORMATION AND WHERE TO FIND IT This communication may be deemed to be solicitation material in respect of the proposed merger (the “Proposed Merger”). The Proposed Merger will be submitted to Contango shareholders and Mid-Con unitholders for their consideration. C
Slide 4: Contango History and Highlights
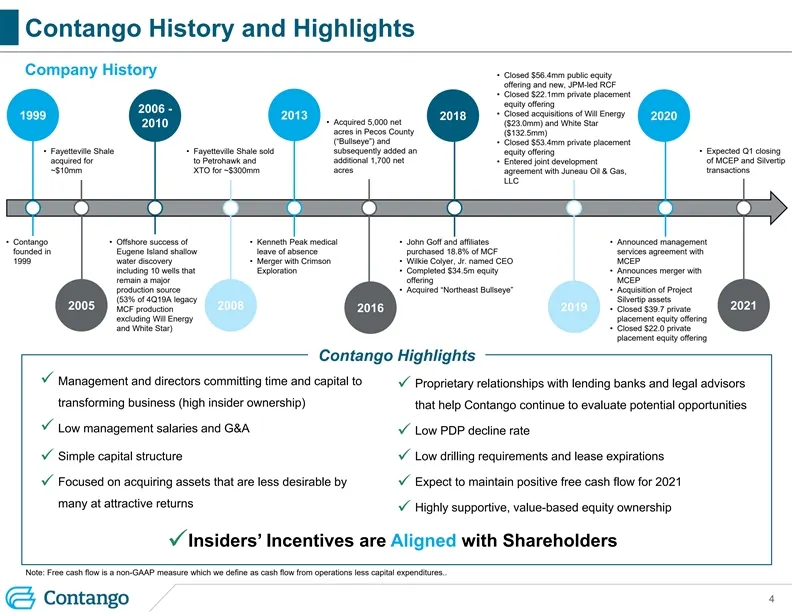
Contango History and Highlights Company History • Closed $56.4mm public equity offering and new, JPM-led RCF • Closed $22.1mm private placement equity offering 2006 - • Closed acquisitions of Will Energy 2013 1999 2018 2020 • Acquired 5,000 net ($23.0mm) and White Star 2010 acres in Pecos County ($1
Slide 5: Incentive Alignment – Equity Ownership
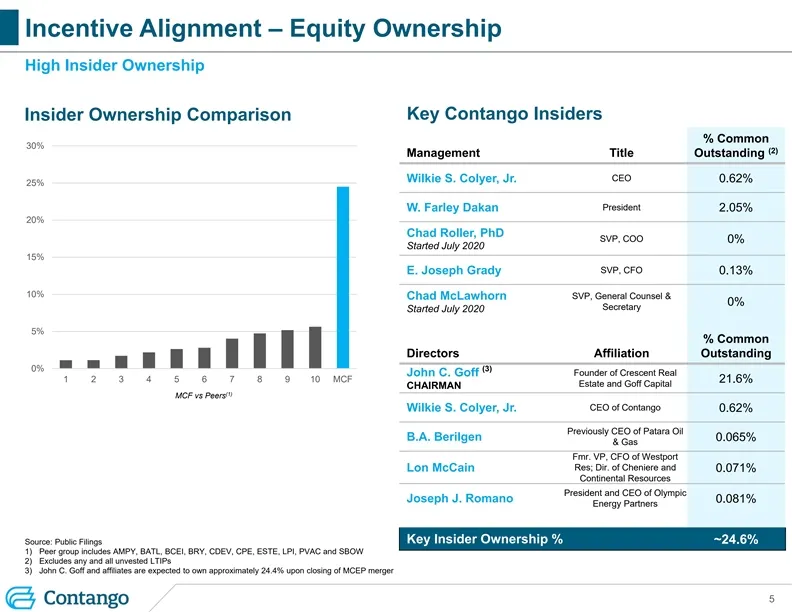
Incentive Alignment – Equity Ownership High Insider Ownership Key Contango Insiders Insider Ownership Comparison % Common 30% (2) Management Title Outstanding CEO Wilkie S. Colyer, Jr. 0.62% 25% President W. Farley Dakan 2.05% 20% Chad Roller, PhD SVP, COO 0% Started July 2020 15% SVP, CFO E. Joseph
Slide 6: Incentive Alignment - Management Compensation
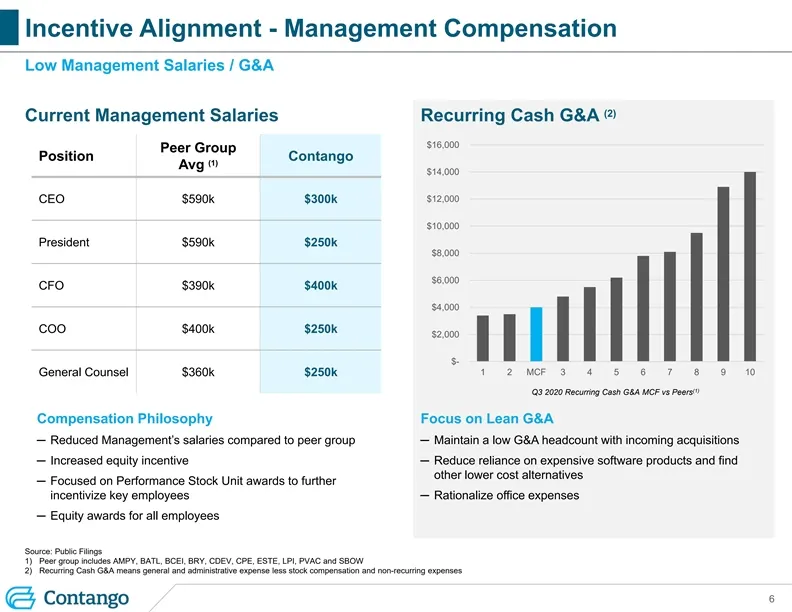
Incentive Alignment - Management Compensation Low Management Salaries / G&A (2) Current Management Salaries Recurring Cash G&A $16,000 Peer Group Position Contango (1) Avg $14,000 $12,000 CEO $590k $300k $10,000 President $590k $250k $8,000 $6,000 CFO $390k $400k $4,000 COO $400k $250k $2,000 $- 12
Slide 7: Simple Capital Structure
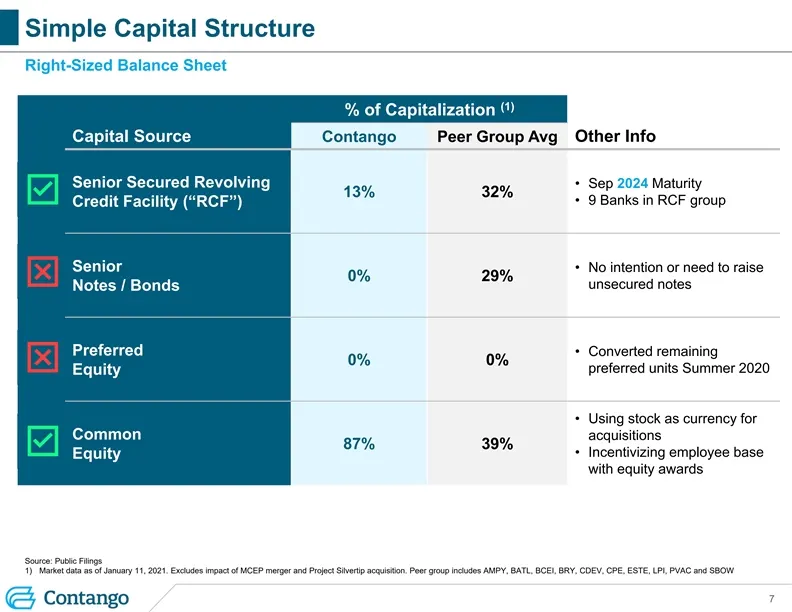
Simple Capital Structure Right-Sized Balance Sheet (1) % of Capitalization Capital Source Contango Peer Group Avg Other Info Senior Secured Revolving •Sep 2024 Maturity 13% 32% • 9 Banks in RCF group Credit Facility (“RCF”) Senior • No intention or need to raise 0% 29% unsecured notes Notes / Bonds
Slide 8: Asset Profile
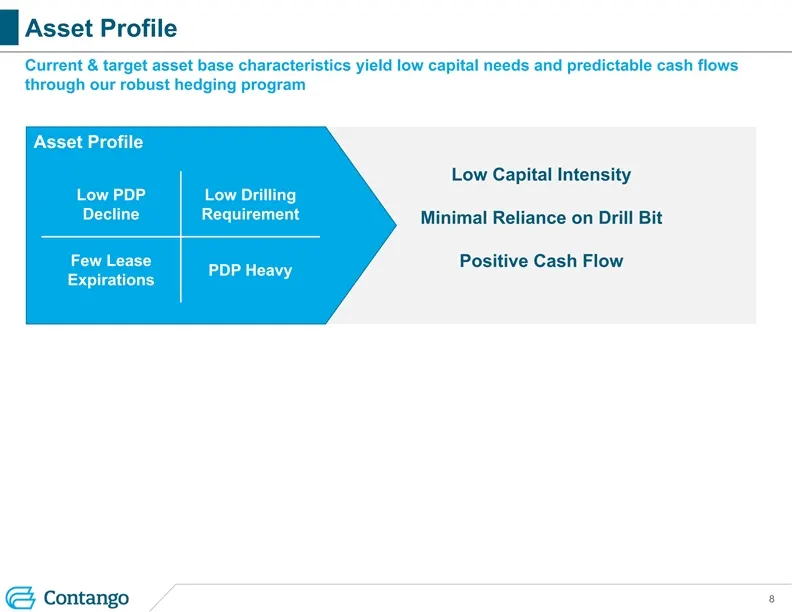
Asset Profile Current & target asset base characteristics yield low capital needs and predictable cash flows through our robust hedging program Asset Profile Low Capital Intensity Low PDP Low Drilling Decline Requirement Minimal Reliance on Drill Bit Few Lease Positive Cash Flow PDP Heavy Expiration
Slide 9: Focus on Growth via Acquisition
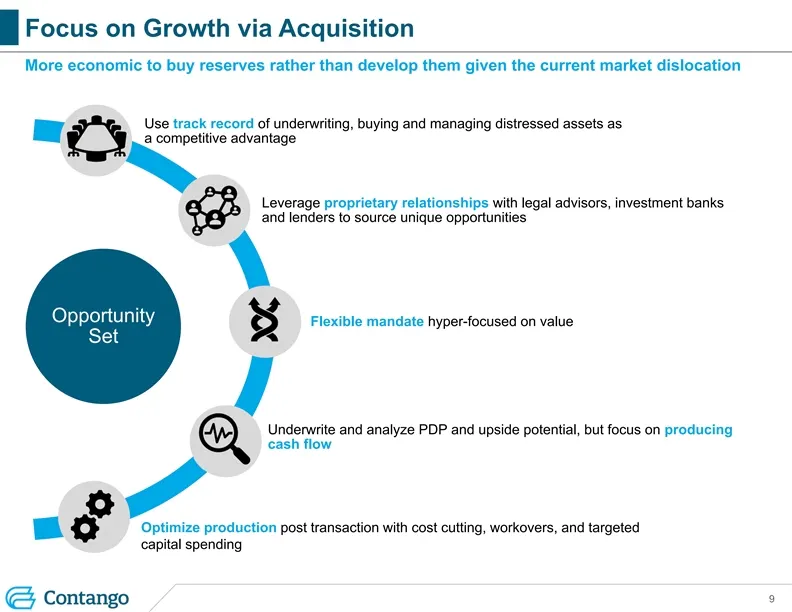
Focus on Growth via Acquisition More economic to buy reserves rather than develop them given the current market dislocation Use track record of underwriting, buying and managing distressed assets as a competitive advantage Leverage proprietary relationships with legal advisors, investment banks and
Slide 10: Executing Our Plan: Central OK YE 2020 Preview
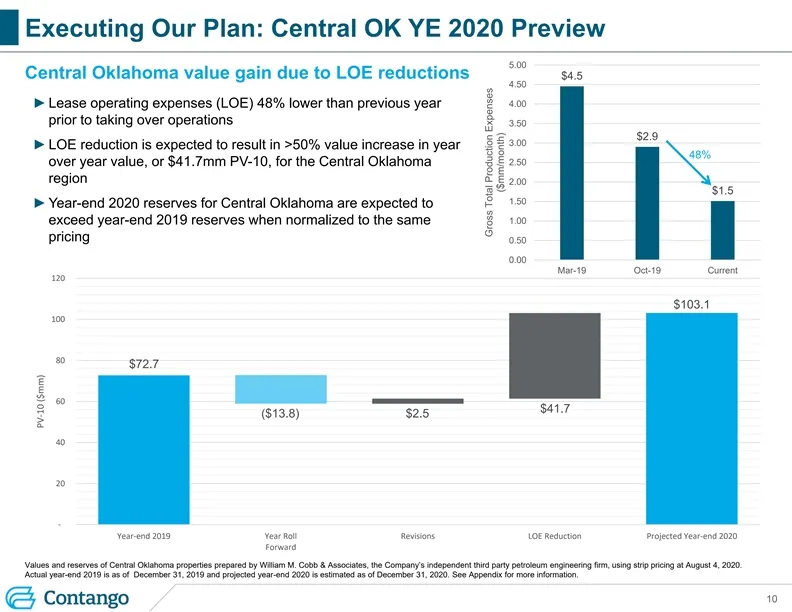
Executing Our Plan: Central OK YE 2020 Preview 5.00 Central Oklahoma value gain due to LOE reductions $4.5 4.50 4.00 ► Lease operating expenses (LOE) 48% lower than previous year prior to taking over operations 3.50 $2.9 3.00 ► LOE reduction is expected to result in >50% value increase in year 48% 2
Slide 11: Summary of Assets and Reserves
Summary of Assets and Reserves January 2021 11 11Summary of Assets and Reserves January 2021 11 11
Slide 12: MCF Current Asset Overview
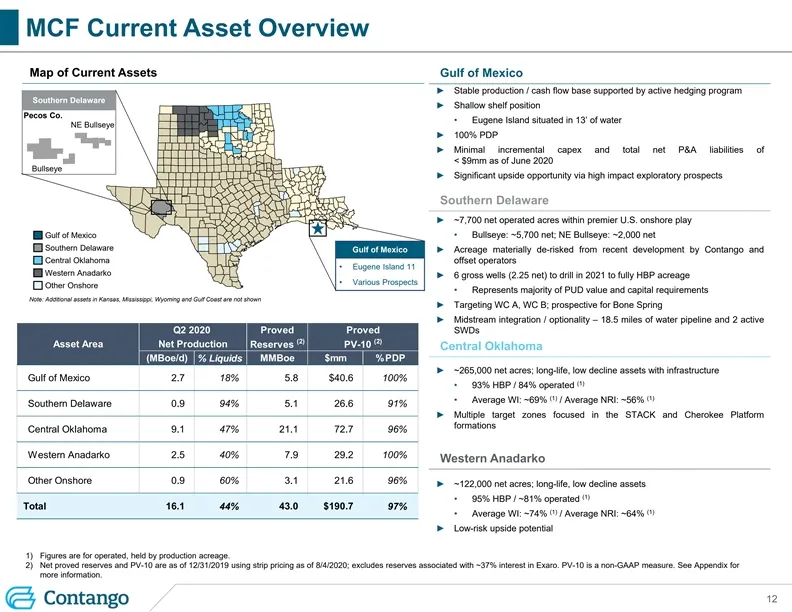
MCF Current Asset Overview Map of Current Assets Gulf of Mexico ► Stable production / cash flow base supported by active hedging program Southern Delaware ► Shallow shelf position Pecos Co. • Eugene Island situated in 13’ of water NE Bullseye ► 100% PDP ► Minimal incremental capex and total net P&A
Slide 13: Mid-Con Energy Partners, LP (MCEP) Asset Overview
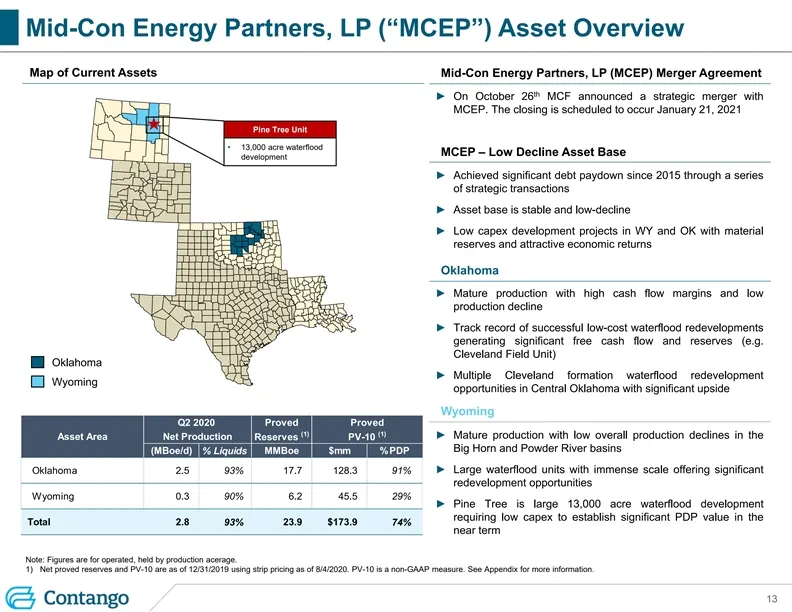
Mid-Con Energy Partners, LP (“MCEP”) Asset Overview Map of Current Assets Mid-Con Energy Partners, LP (MCEP) Merger Agreement th ► On October 26 MCF announced a strategic merger with MCEP. The closing is scheduled to occur January 21, 2021 Pine Tree Unit • 13,000 acre waterflood MCEP – Low Decline A
Slide 14: Project Silvertip Current Asset Overview
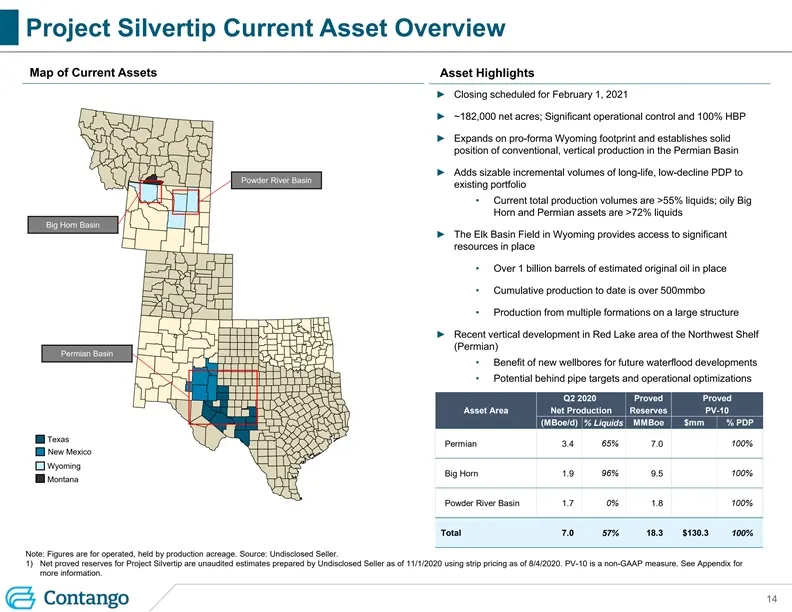
Project Silvertip Current Asset Overview Map of Current Assets Asset Highlights ► Closing scheduled for February 1, 2021 ► ~182,000 net acres; Significant operational control and 100% HBP ► Expands on pro-forma Wyoming footprint and establishes solid position of conventional, vertical production in
Slide 15: Estimated Pro Forma Asset Overview
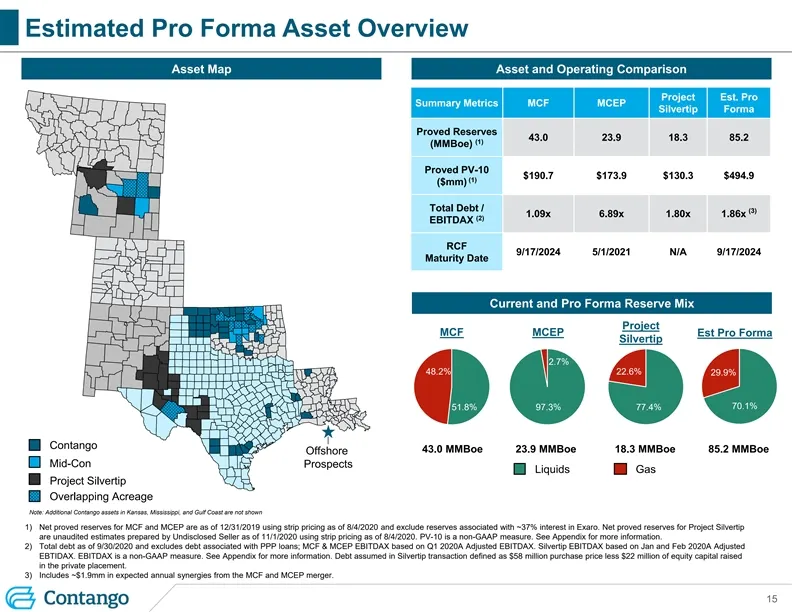
Estimated Pro Forma Asset Overview Asset Map Asset and Operating Comparison Project Est. Pro Summary Metrics MCF MCEP Silvertip Forma Proved Reserves 43.0 23.9 18.3 85.2 (1) (MMBoe) Proved PV-10 $190.7 $173.9 $130.3 $494.9 (1) ($mm) Total Debt / (3) 1.09x 6.89x 1.80x 1.86x (2) EBITDAX RCF 9/17/2024
Slide 16: Estimated Pro Forma 1P Reserves – 8/4/2020 NYMEX Strip Pricing
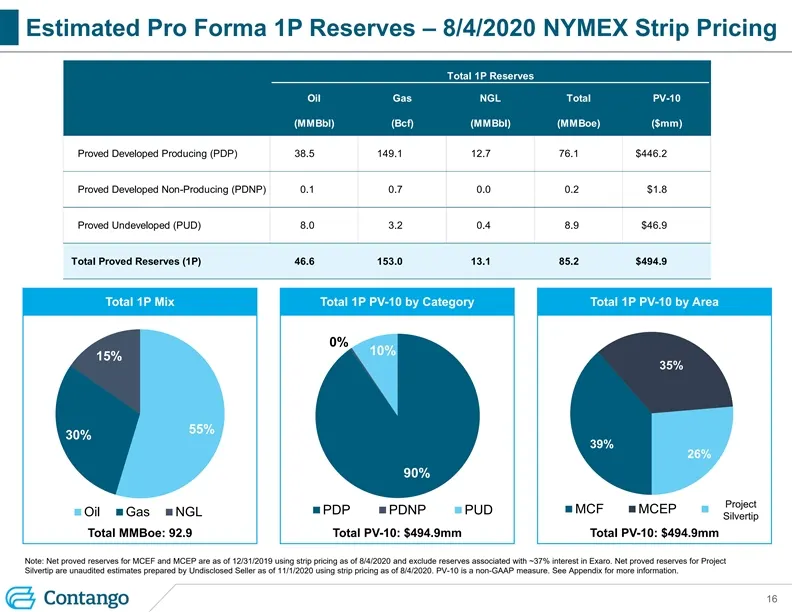
Estimated Pro Forma 1P Reserves – 8/4/2020 NYMEX Strip Pricing Total 1P Reserves Oil Gas NGL Total PV-10 (MMBbl) (Bcf) (MMBbl) (MMBoe) ($mm) Proved Developed Producing (PDP) 38.5 149.1 12.7 76.1 $446.2 Proved Developed Non-Producing (PDNP) 0.1 0.7 0.0 0.2 $1.8 Proved Undeveloped (PUD) 8.0 3.2 0.4 8.
Slide 17: PV-10 Definition
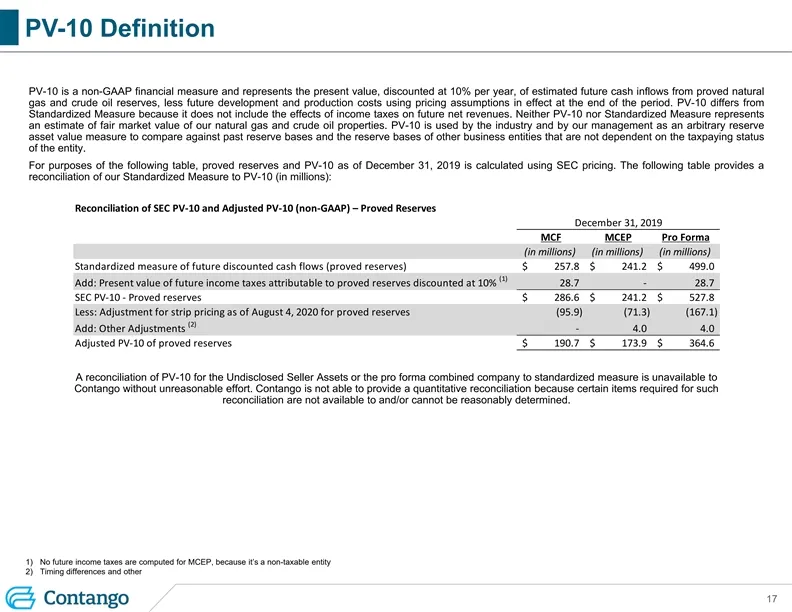
PV-10 Definition PV-10 is a non-GAAP financial measure and represents the present value, discounted at 10% per year, of estimated future cash inflows from proved natural gas and crude oil reserves, less future development and production costs using pricing assumptions in effect at the end of the per
Slide 18: Reserves Disclaimer
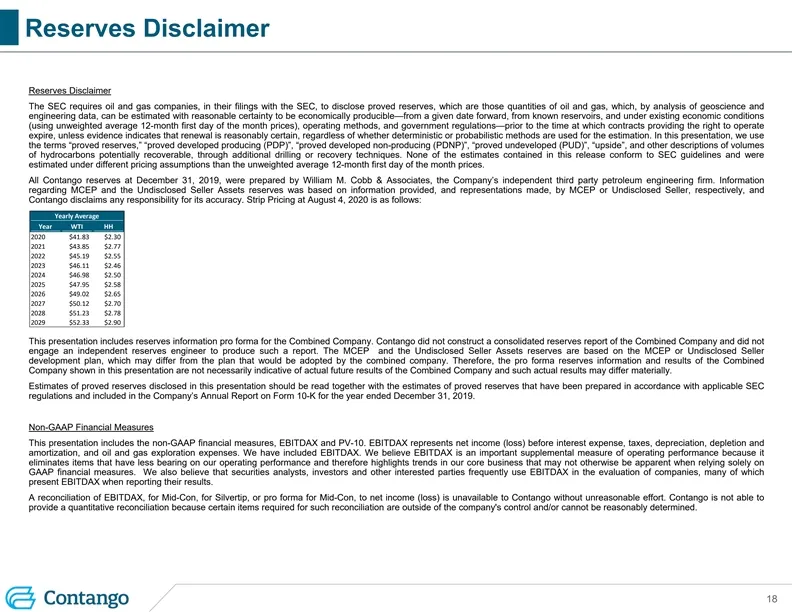
Reserves Disclaimer Reserves Disclaimer The SEC requires oil and gas companies, in their filings with the SEC, to disclose proved reserves, which are those quantities of oil and gas, which, by analysis of geoscience and engineering data, can be estimated with reasonable certainty to be economically
Slide 19: Contango
SG Contango CONTANGO.COM
Source: SEC EDGAR · 425 filed Jan 15, 2021