Scatec ASA · OSL:SCATC
Scatec ASA — Investor Presentation (June 2023)
16 slides from Scatec ASA's investor presentation, June 2023
Slide 1: Investor presentation June 2023
Investor presentation June 2023
Slide 2: Disclaimer
Disclaimer The following presentation is being made only to, and is only directed at, persons to whom such presentation may lawfully be communicated (’relevant persons’). Any person who is not a relevant person should not rely, act or make assessment on the basis of this presentation or anything inc
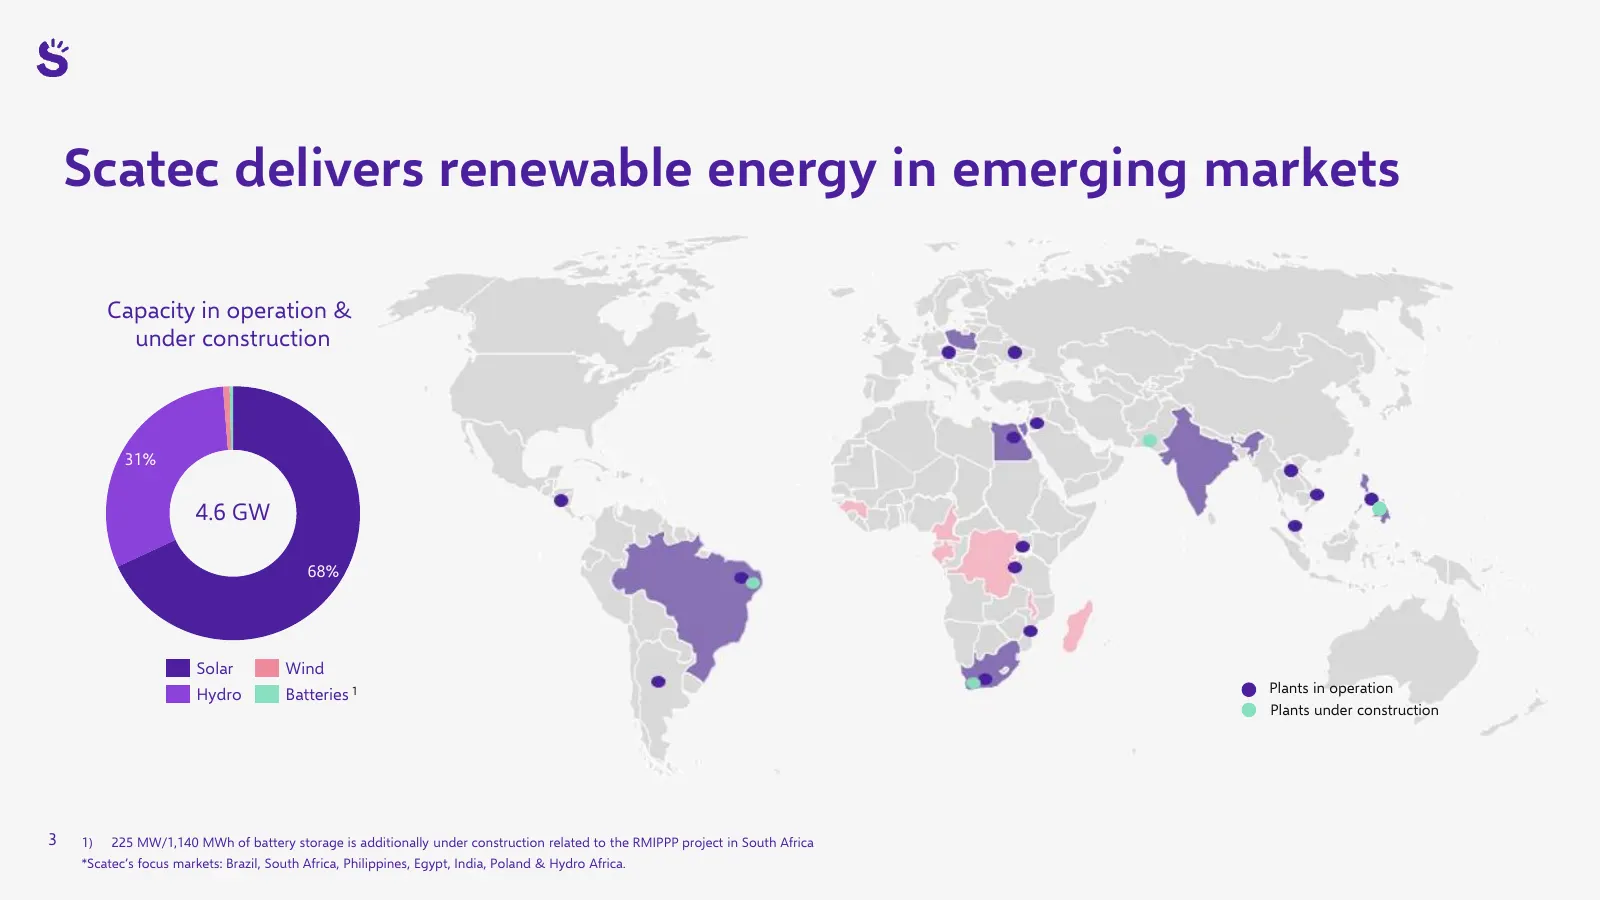
Slide 3: Scatec delivers renewable energy in emerging markets
Scatec delivers renewable energy in emerging markets Capacity in operation & under construction 31% 4.6 GW 68% Solar Wind Hydro Batteries 1 Plants in operation Plants under construction 3 1) 225 MW/1,140 MWh of battery storage is additionally under construction related to the RMIPPP project in South
Slide 4: Our strategy: Develop, build, own and operate renewable energy in emerging markets
Our strategy: Develop, build, own and operate renewable energy in emerging markets Grow Optimise Advance Renewables Portfolio Green Hydrogen 4
Slide 5: Generating strong and predictable cash flow from operating assets
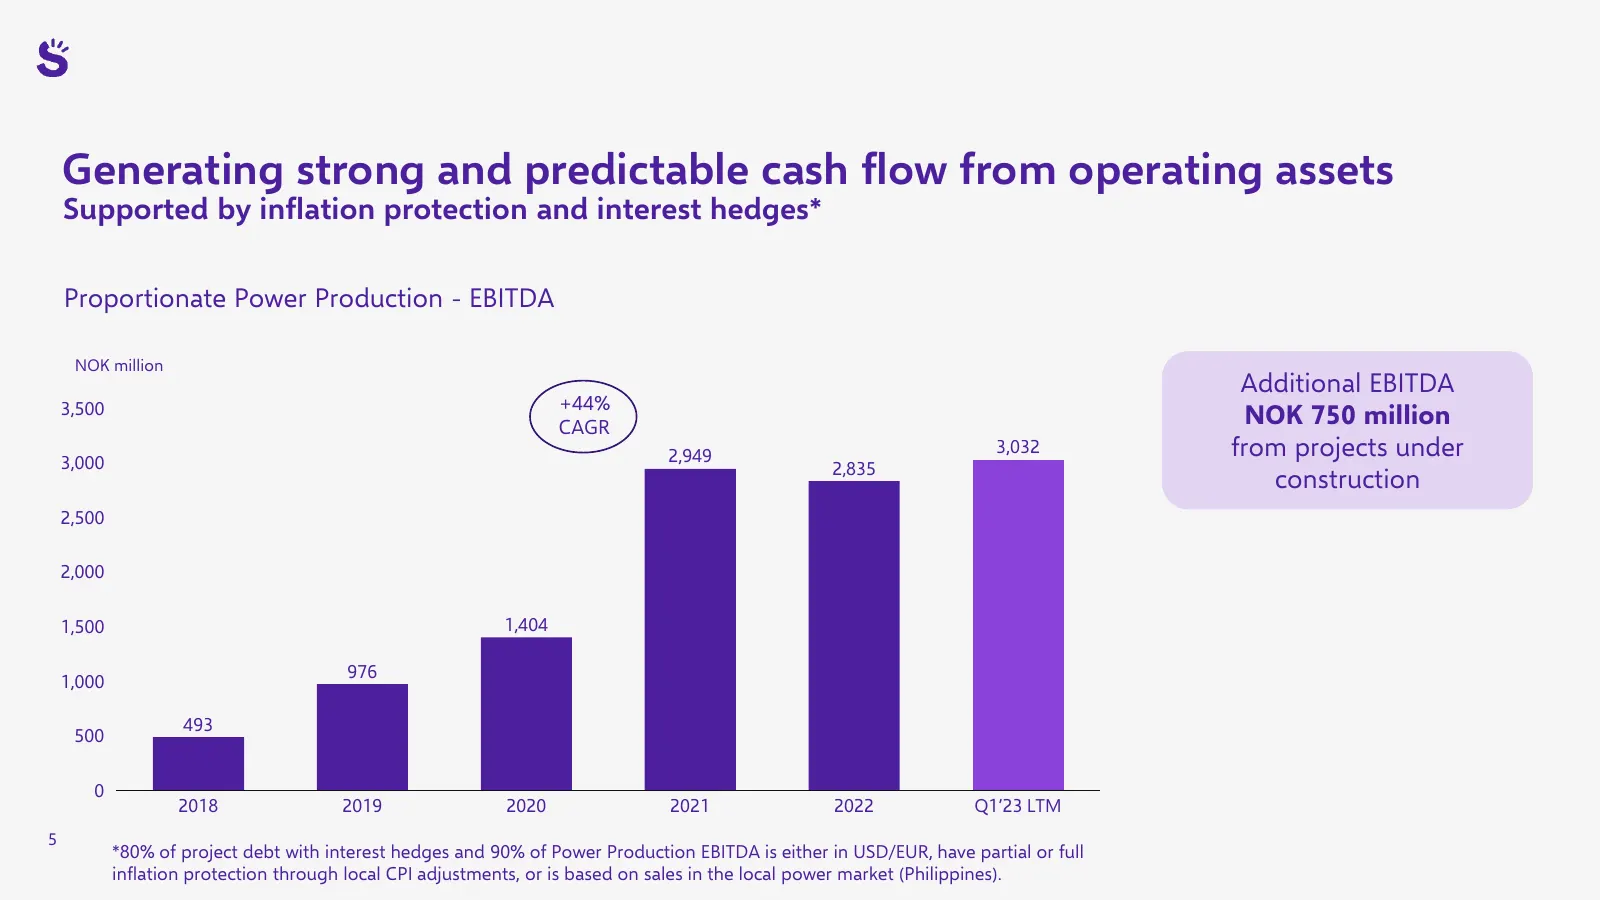
Generating strong and predictable cash flow from operating assets Supported by inflation protection and interest hedges* Proportionate Power Production - EBITDA NOK million Additional EBITDA 3,500 +44% CAGR NOK 750 million 2,949 3,032 from projects under 3,000 2,835 construction 2,500 2,000 1,500 1,
Slide 6: With a large construction programme ensuring short-term growth
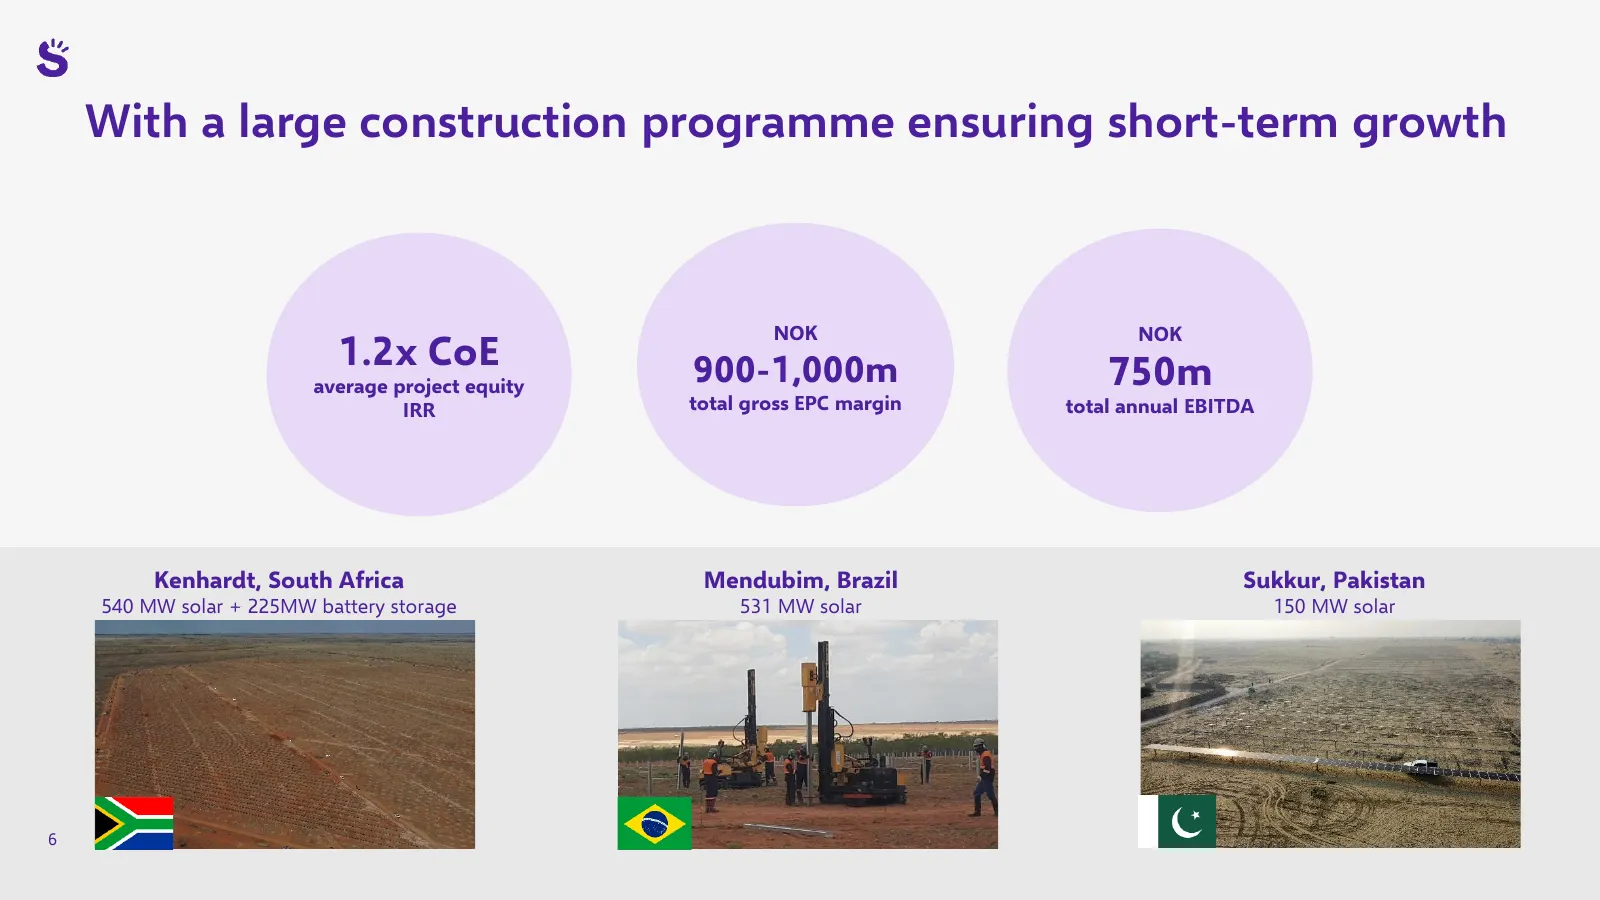
With a large construction programme ensuring short-term growth NOK NOK 1.2x CoE average project equity 900-1,000m 750m IRR total gross EPC margin total annual EBITDA Kenhardt, South Africa Mendubim, Brazil Sukkur, Pakistan 540 MW solar + 225MW battery storage 531 MW solar 150 MW solar 6
Slide 7: Focus on selected markets to enhance value creation, improve predictability and secure competitiveness
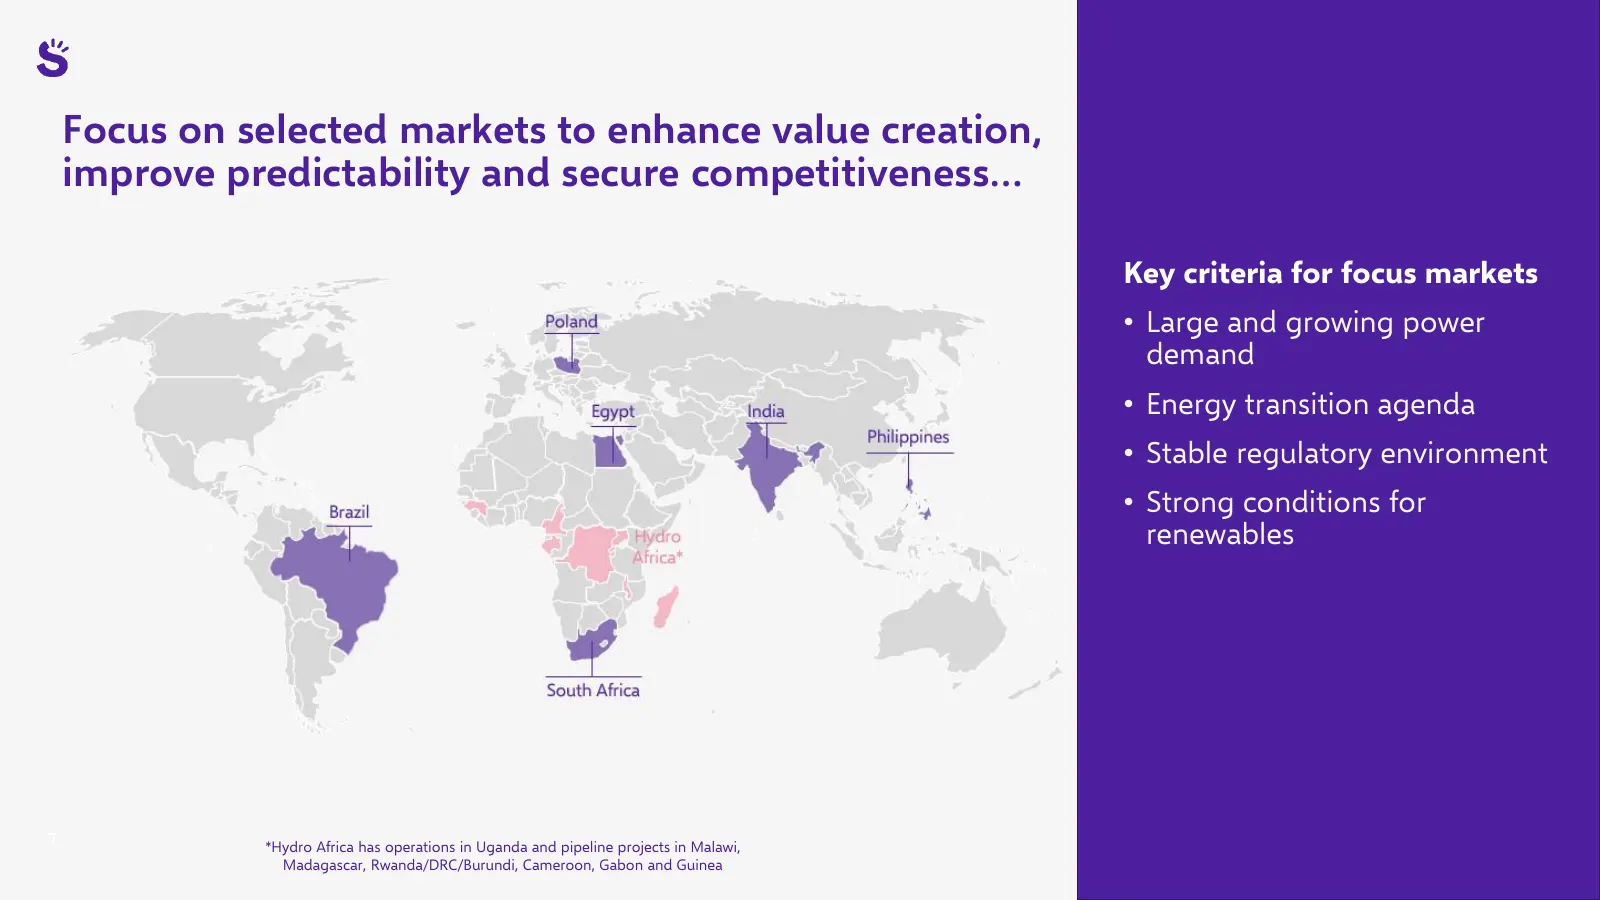
Focus on selected markets to enhance value creation, improve predictability and secure competitiveness… Key criteria for focus markets • Large and growing power demand • Energy transition agenda • Stable regulatory environment • Strong conditions for renewables 7 *Hydro Africa has operations in Ugan
Slide 8: Generating solid returns from the integrated business model
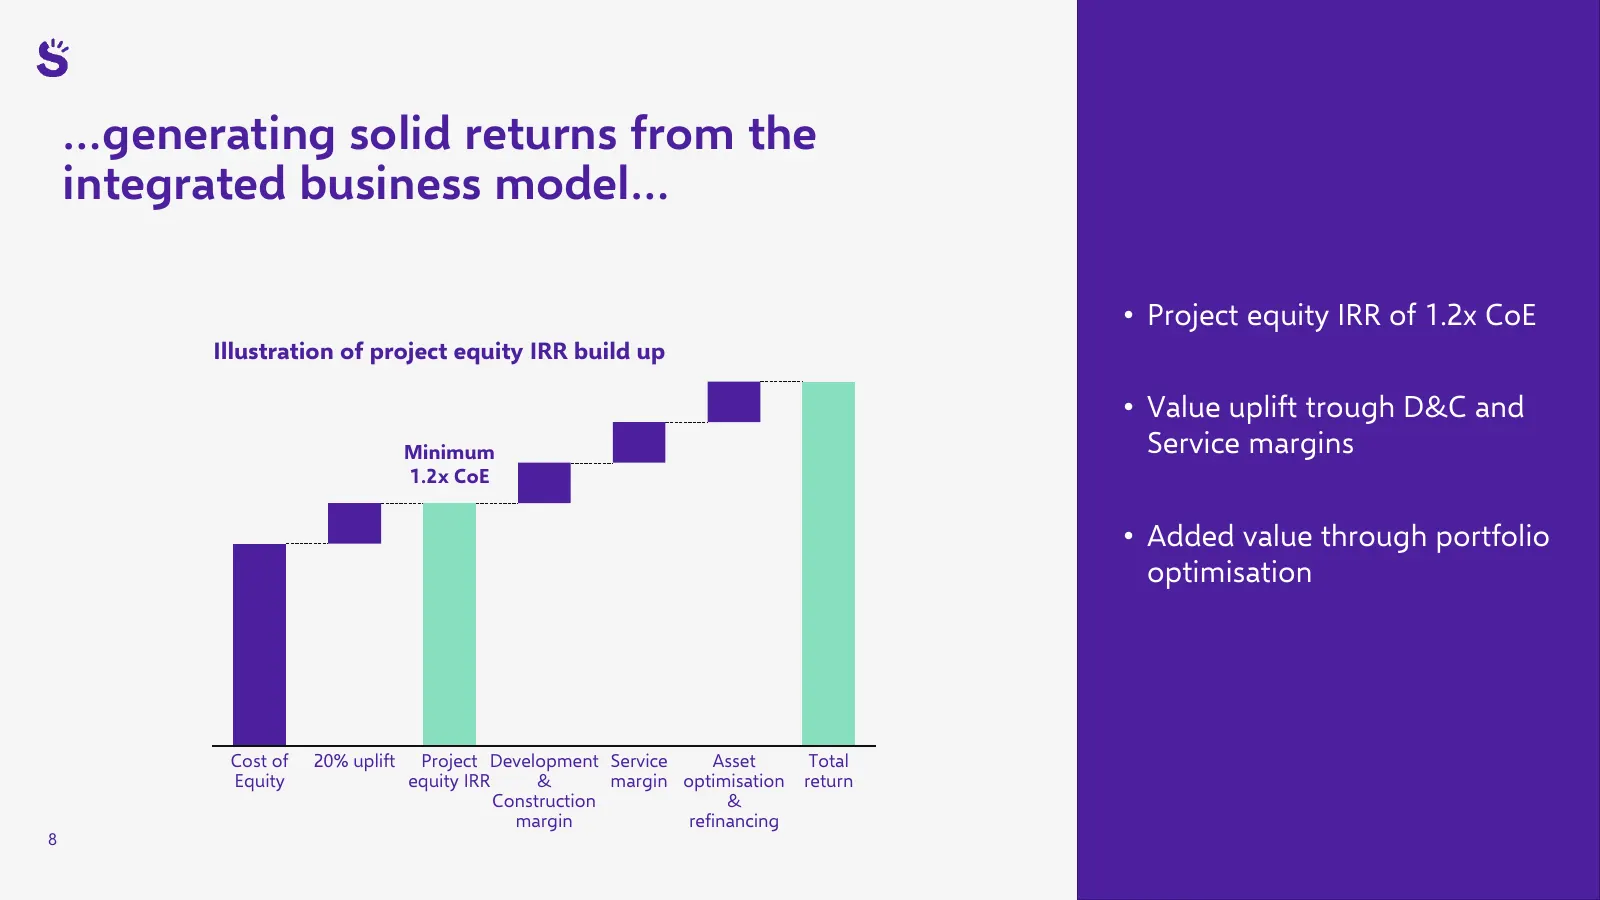
…generating solid returns from the integrated business model… • Project equity IRR of 1.2x CoE Illustration of project equity IRR build up • Value uplift trough D&C and Minimum Service margins 1.2x CoE • Added value through portfolio optimisation Cost of 20% uplift Project Development Service Asset
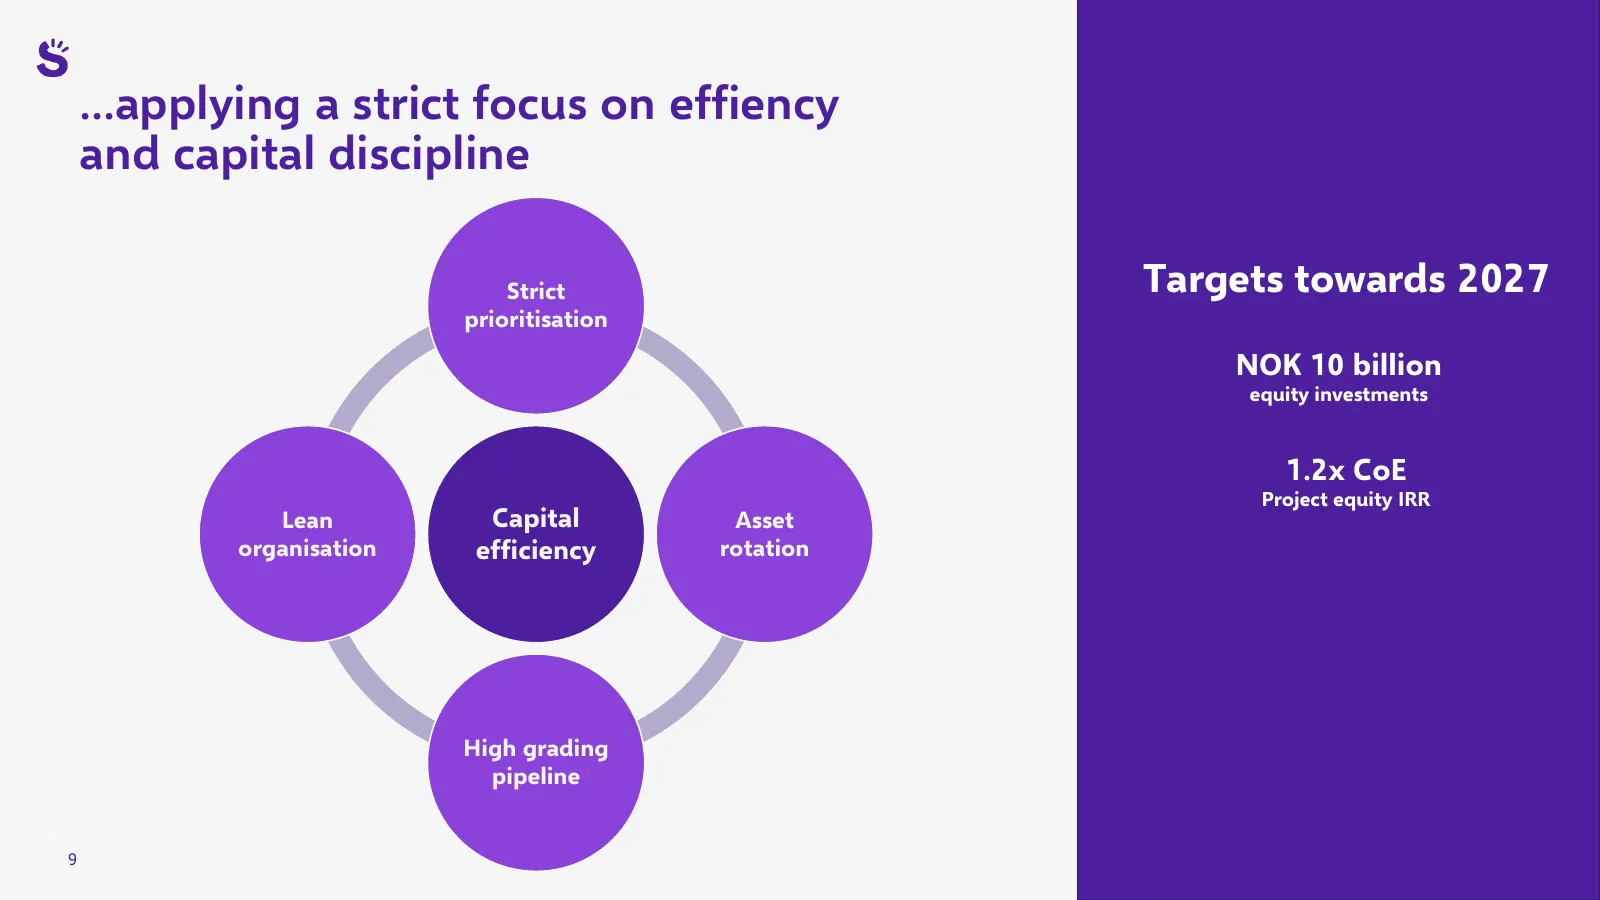
Slide 9: Applying a strict focus on efficiency and capital discipline
...applying a strict focus on effiency and capital discipline Strict Targets towards 2027 prioritisation NOK 10 billion equity investments 1.2x CoE Project equity IRR Lean Capital Asset organisation efficiency rotation High grading pipeline 9 9
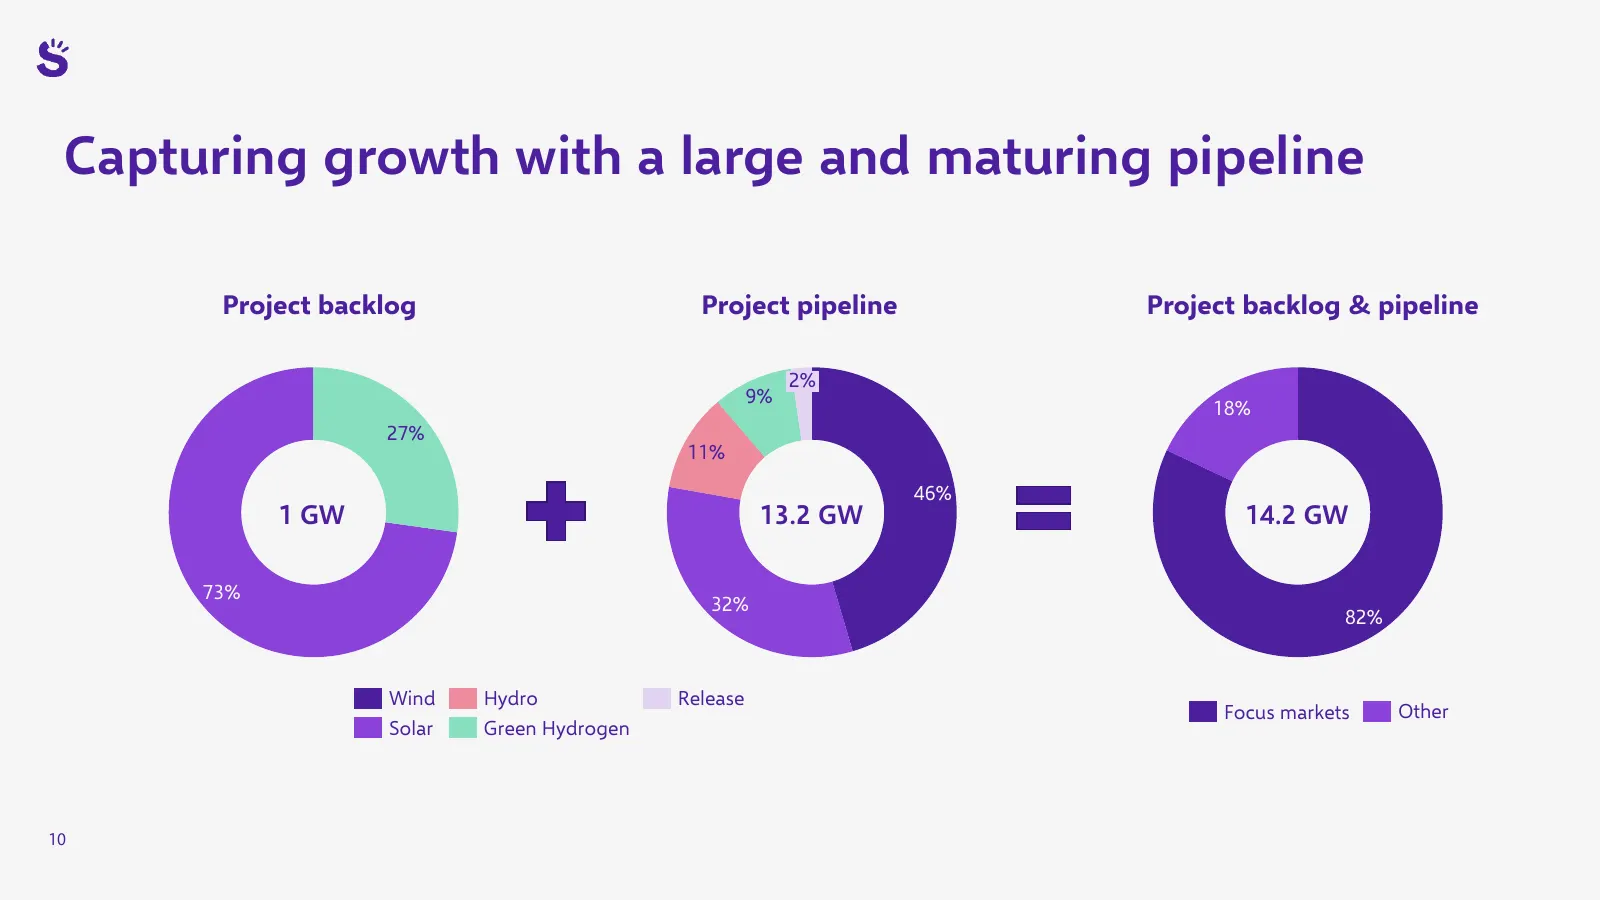
Slide 10: Capturing growth with a large and maturing pipeline
Capturing growth with a large and maturing pipeline Project backlog Project pipeline Project backlog & pipeline 2% 9% 18% 27% 11% 46% 1 GW 13.2 GW 14.2 GW 73% 32% 82% Wind Hydro Release Focus markets Other Solar Green Hydrogen 10
Slide 11: Partnering with Development Banks for project financing and risk mitigation
Partnering with Development Banks for project financing and risk mitigation Multilateral development banks (DFIs) are providing equity and debt to infrastructure projects in emerging markets DFIs are often advising governments on design of renewable programmes to promote private/public partnerships
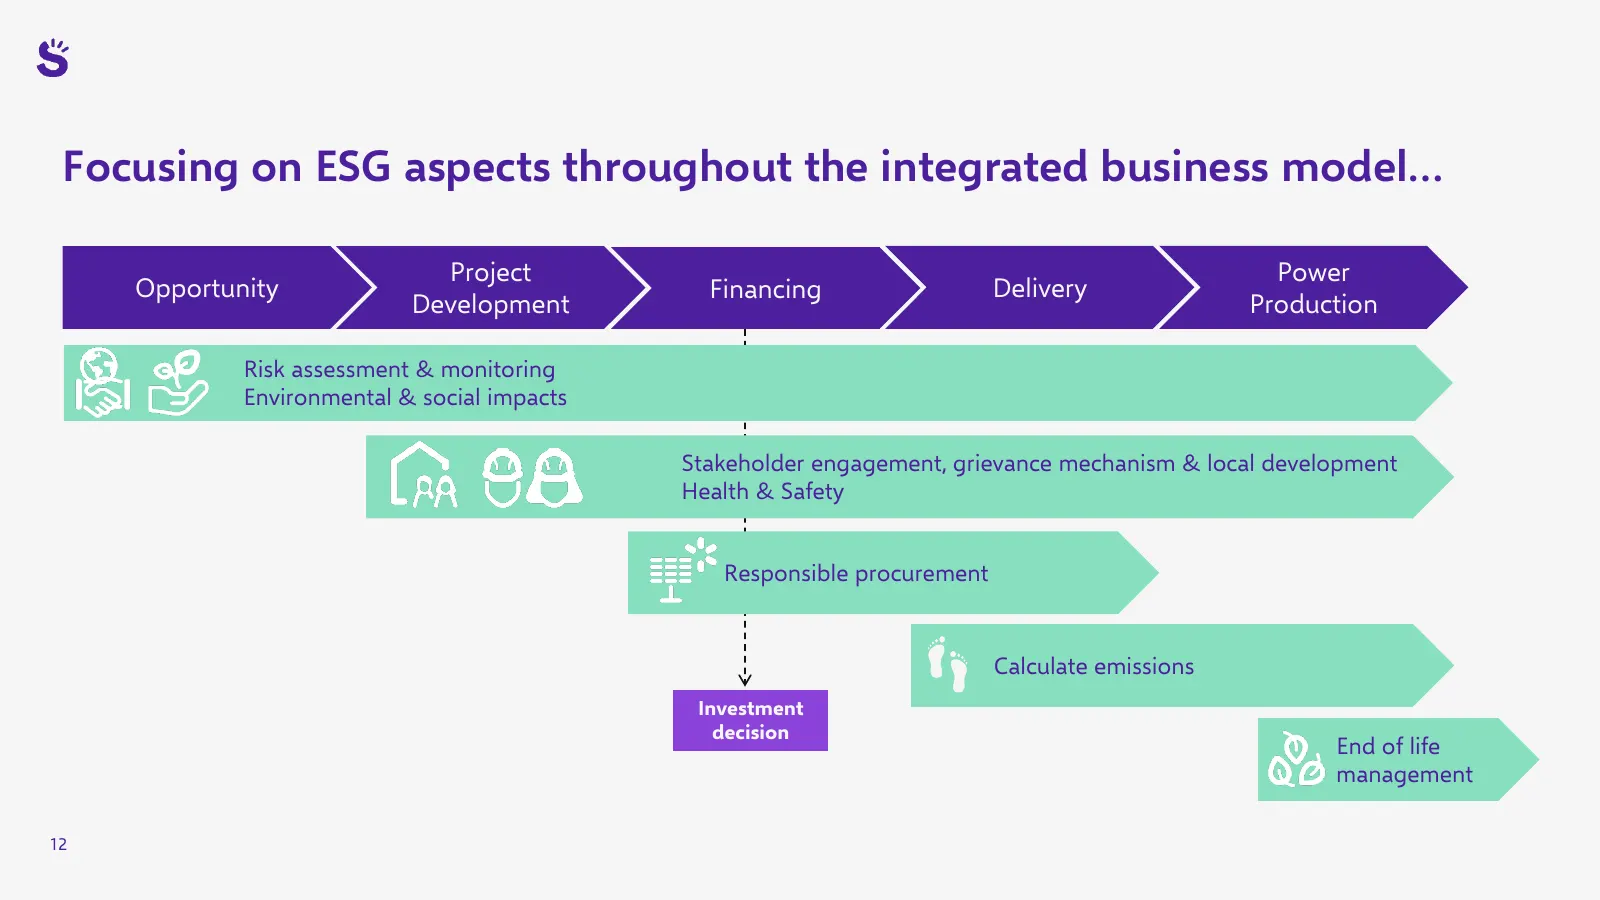
Slide 12: Focusing on ESG aspects throughout the integrated business model
Focusing on ESG aspects throughout the integrated business model… Project Power Opportunity Financing Delivery Development Production Risk assessment & monitoring Environmental & social impacts Stakeholder engagement, grievance mechanism & local development Health & Safety Responsible procurement Ca
Slide 13: Which reduces risks and increases success ratio
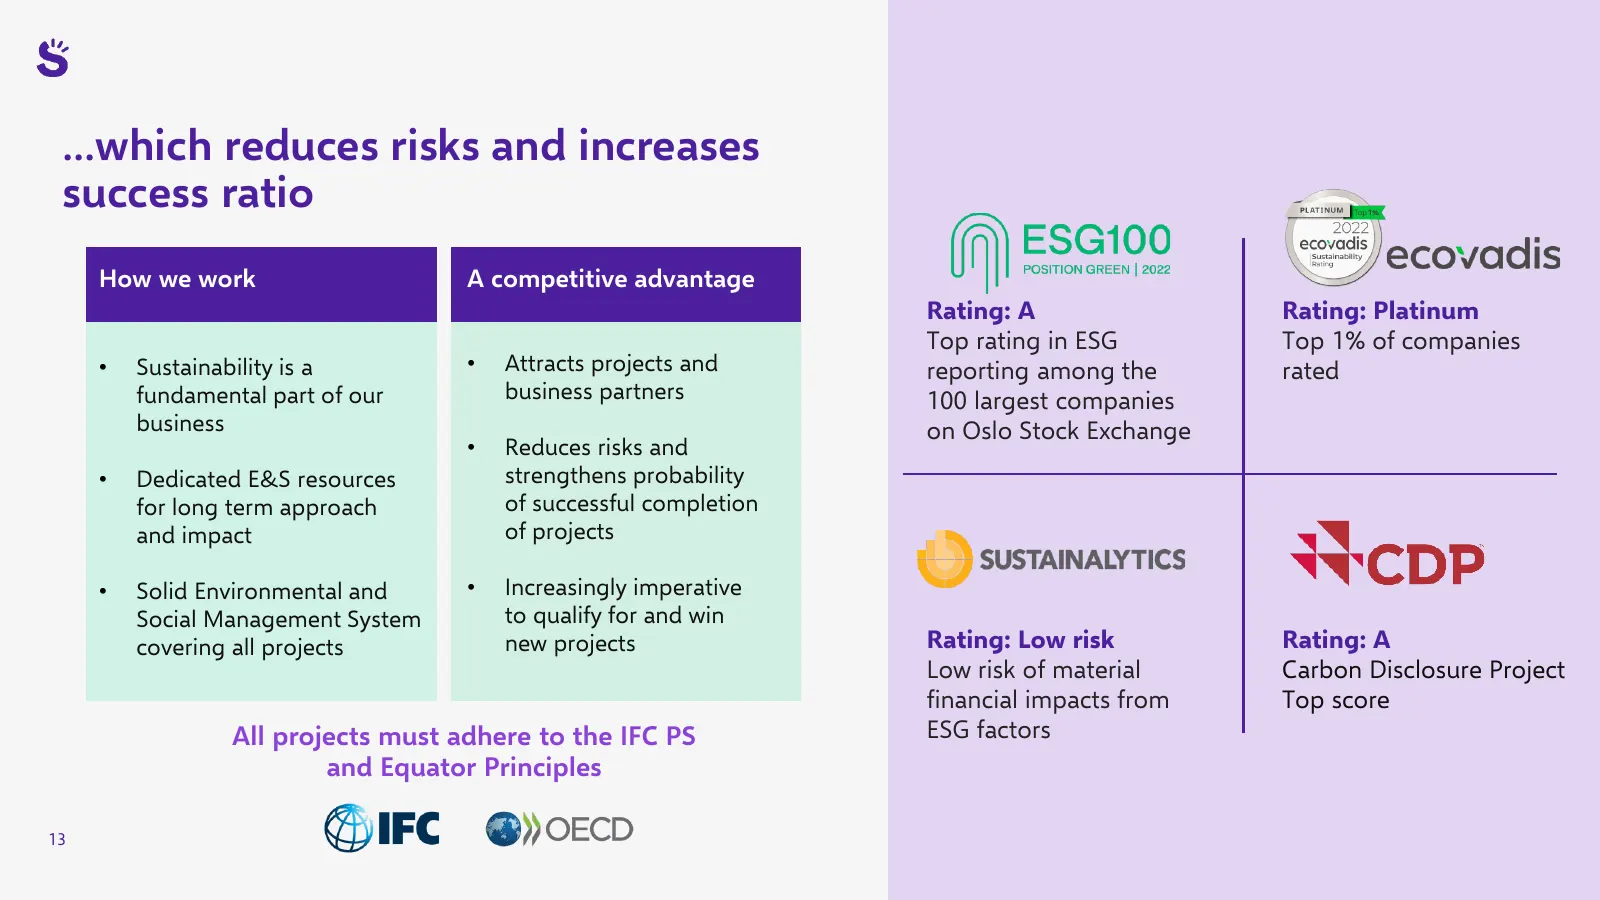
...which reduces risks and increases success ratio How we work A competitive advantage Rating: A Rating: Platinum Top rating in ESG Top 1% of companies • Sustainability is a • Attracts projects and reporting among the rated fundamental part of our business partners 100 largest companies business on
Slide 14: Key takeaways
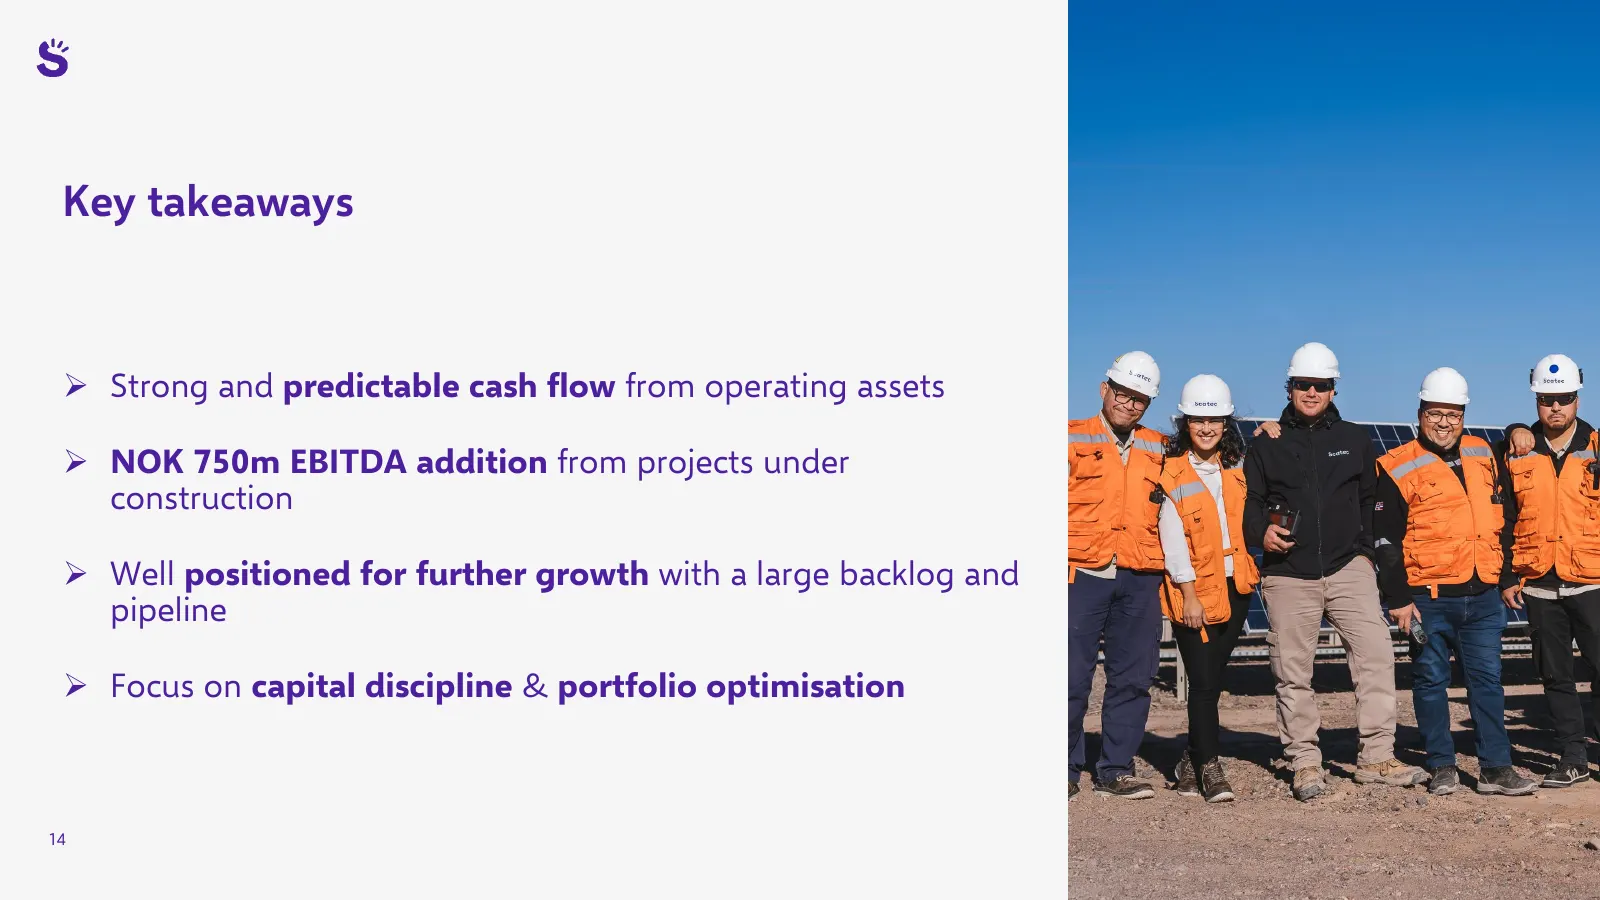
Key takeaways ➢ Strong and predictable cash flow from operating assets ➢ NOK 750m EBITDA addition from projects under construction ➢ Well positioned for further growth with a large backlog and pipeline ➢ Focus on capital discipline & portfolio optimisation 14
Slide 15: Scatec improving our future
Scate improving our future
Slide 16: Our asset portfolio
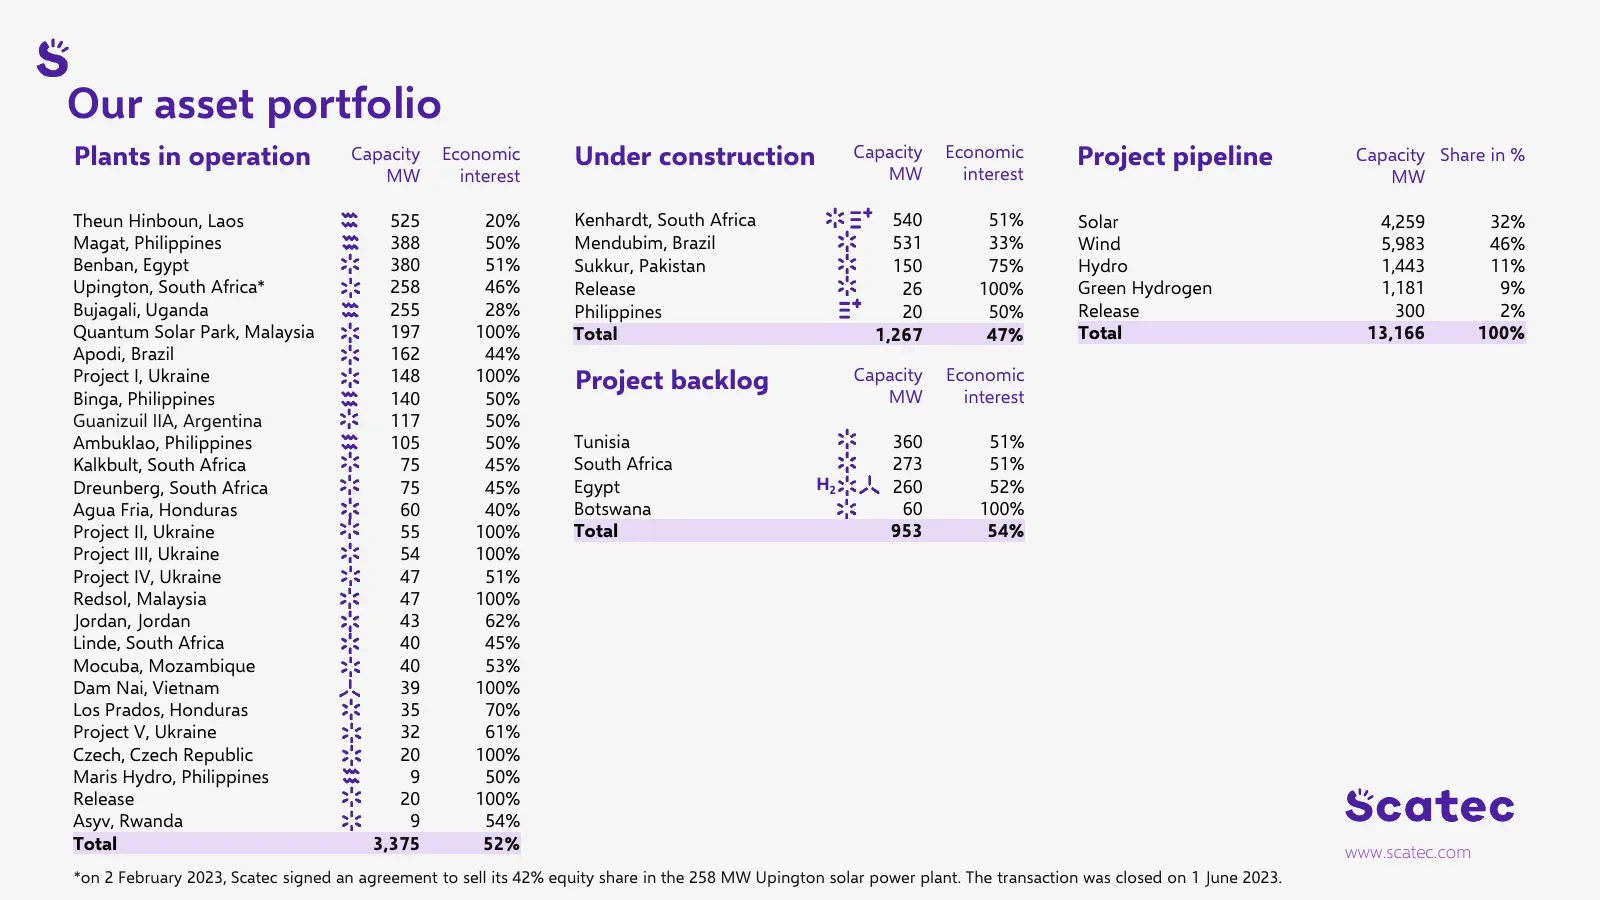
Our asset portfolio Plants in operation Capacity Economic Under construction Capacity Economic Project pipeline Capacity Share in % MW interest MW interest MW Theun Hinboun, Laos 525 20% Kenhardt, South Africa 540 51% Solar 4,259 32% Magat, Philippines 388 50% Mendubim, Brazil 531 33% Wind 5,983 46%
Source: Internet Archive copy of scatec.com
More decks from Scatec ASA
 Q3 2026 Earnings Presentation32 slides · Oct 30, 2026
 Q2 2026 Earnings Presentation23 slides · Aug 21, 2026
 Investor Presentation (August 2026)22 slides · August 2026
 Q1 2026 Earnings Presentation23 slides · May 6, 2026
 Investor Presentation (March 2026)22 slides · March 2026
 Q4 2025 Earnings Presentation24 slides · Jan 30, 2026