Sorrento Therapeutics, Inc. · OTC:SRNE
Sorrento Therapeutics — Investor Presentation (October 2013)
34 slides from Sorrento Therapeutics's investor presentation, October 2013
Slide 1: Sorrento Therapeutics: Next-Generation Cancer Therapeutics
Sorrento Therapeutics Next-Generation Cancer Therapeutics October 2013
Slide 2: Safe Harbor Statement
Safe Harbor Statement OTC QB: SRNE This presentation contains "forward-looking statements" as that term is defined under the Private Securities Litigation Reform Act of 1995 (PSLRA), including statements regarding expectations, beliefs or intentions regarding our business, technologies and products
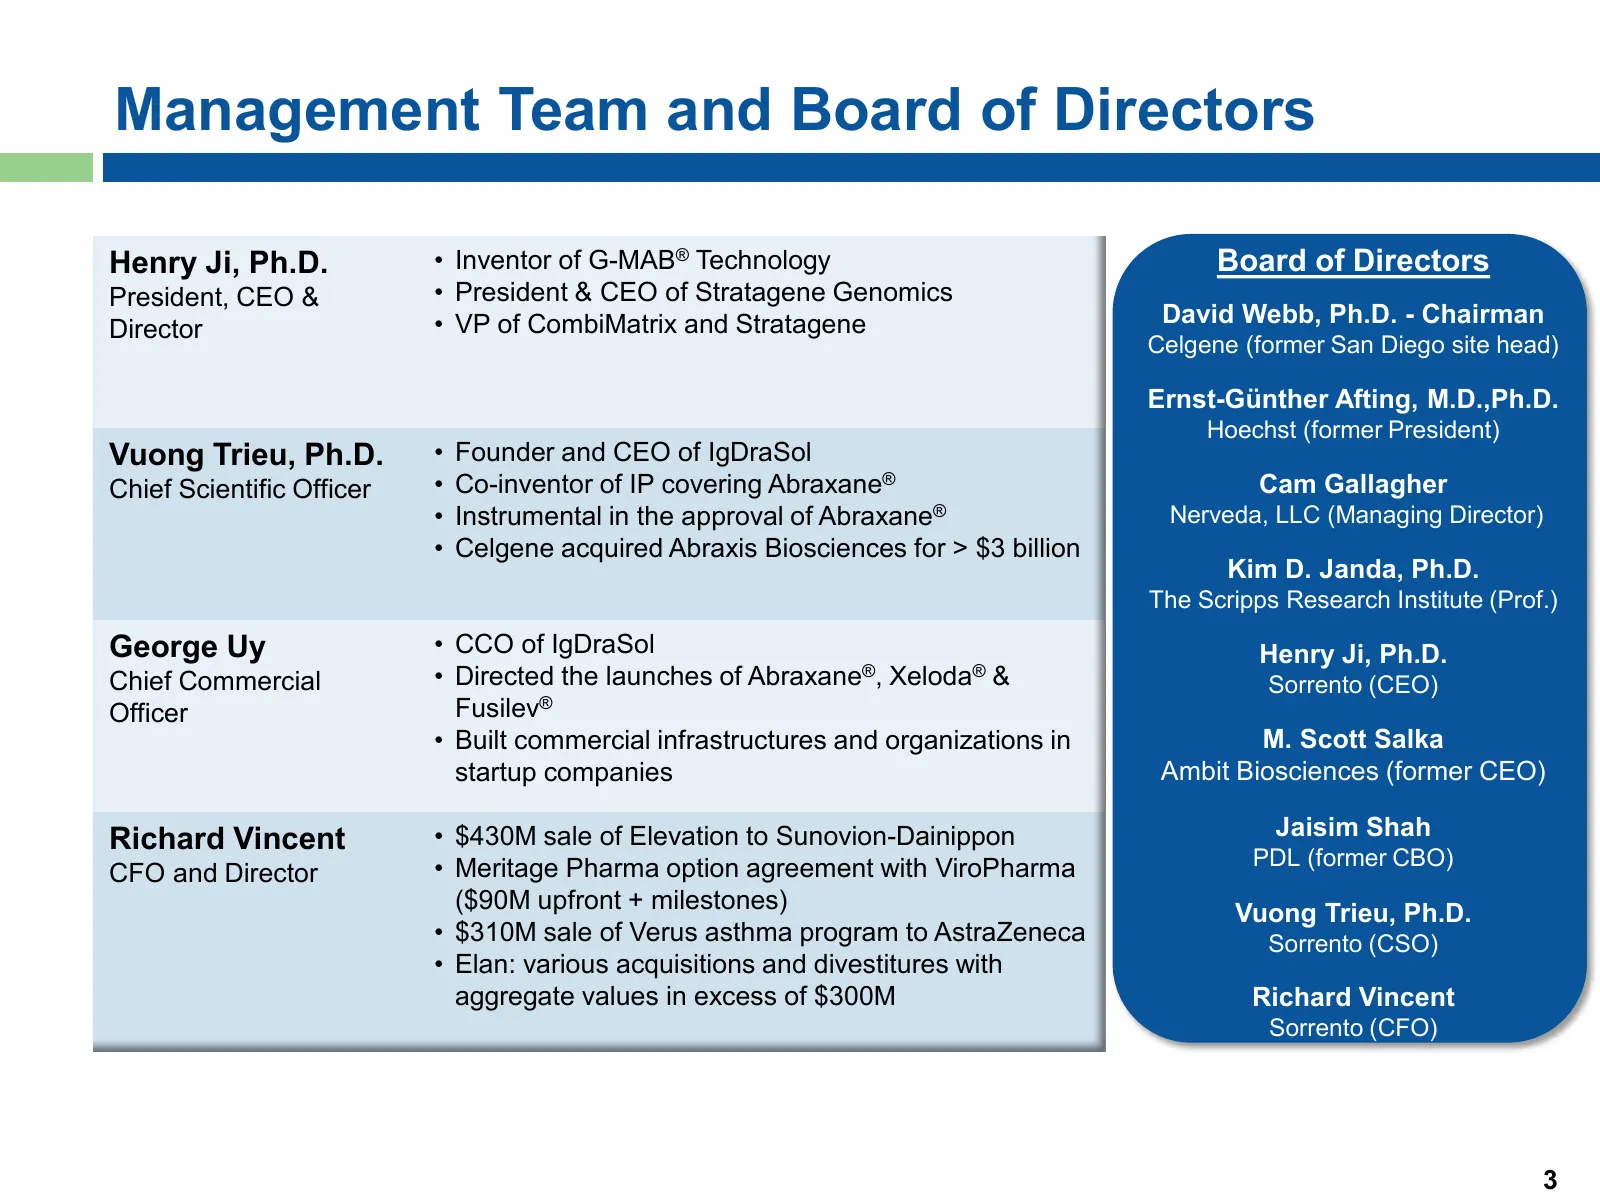
Slide 3: Management Team and Board of Directors
Management Team and Board of Directors Henry Ji, Ph.D. • Inventor of G-MAB® Technology Board of Directors President, CEO & • President & CEO of Stratagene Genomics • VP of CombiMatrix and Stratagene David Webb, Ph.D. - Chairman Director Celgene (former San Diego site head) Ernst-Günther Afting, M.D.
Slide 4: Investment Highlights
Investment Highlights Late Stage Oncology Drug with Exclusive US and EU Rights • Addresses multi-billion dollar paclitaxel market Cynviloq™ • Abbreviated regulatory pathway (“bioequivalence”) for approval • Bioequivalence registration trial in 2014 (study direct costs ~ $5M) • Product launch in 1H 2
Slide 5: Sorrento's Next-Generation Cancer Therapeutics
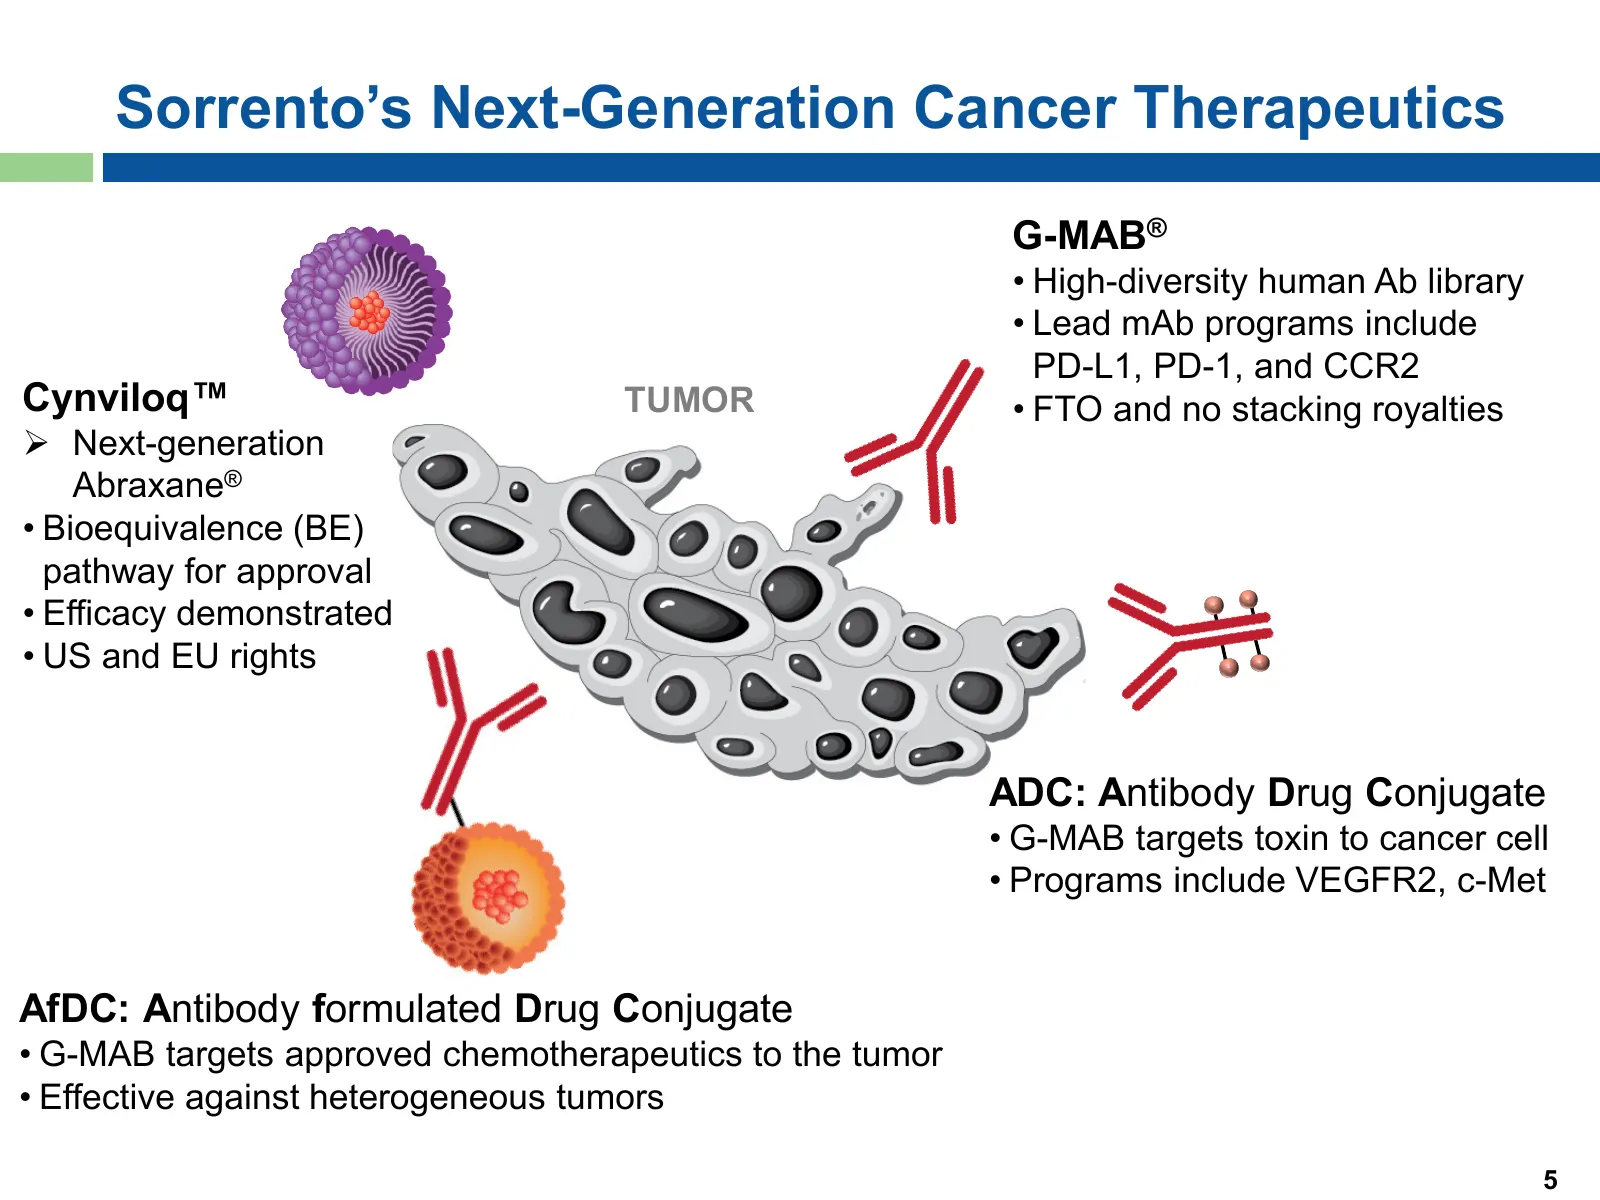
Sorrento’s Next-Generation Cancer Therapeutics G-MAB® • High-diversity human Ab library • Lead mAb programs include PD-L1, PD-1, and CCR2 Cynviloq™ TUMOR • FTO and no stacking royalties Next-generation Abraxane® • Bioequivalence (BE) pathway for approval • Efficacy demonstrated • US and EU rights
Slide 6: Pipeline
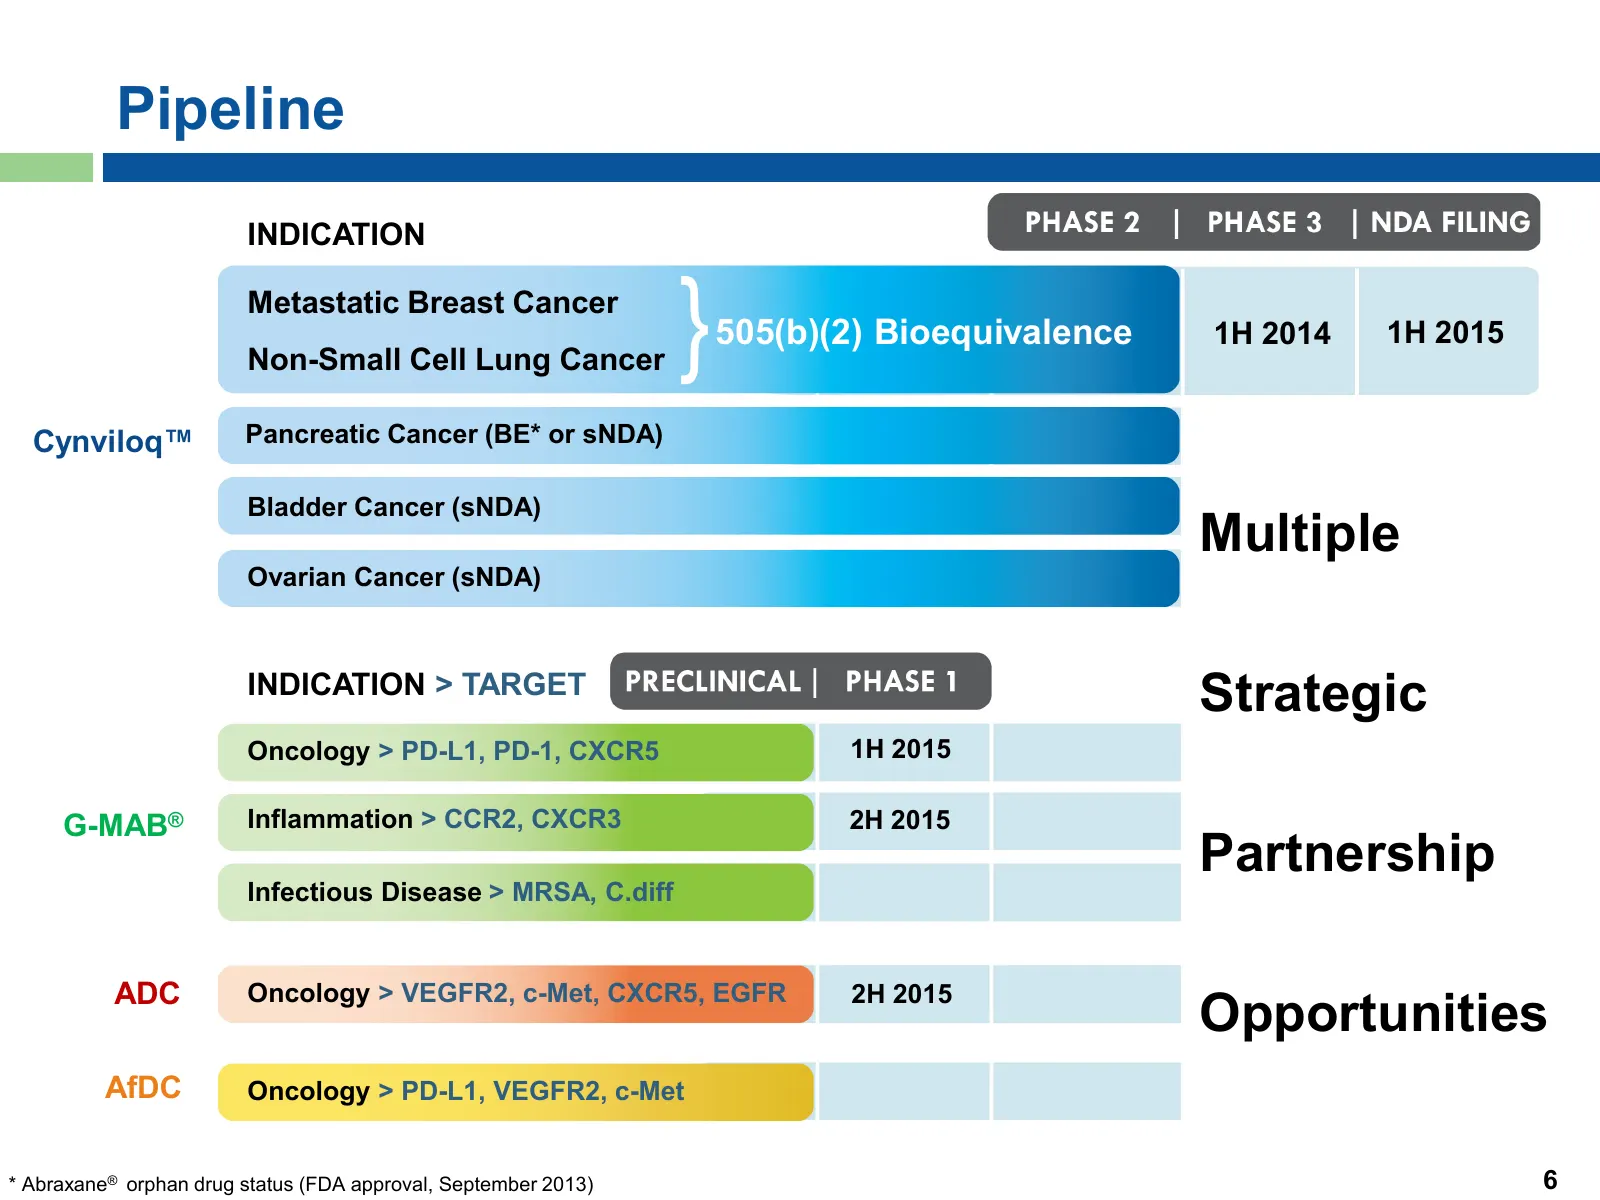
Pipeline INDICATION Metastatic Breast Cancer Non-Small Cell Lung Cancer } 505(b)(2) Bioequivalence 1H 2014 1H 2015 Cynviloq™ Pancreatic Cancer (BE* or sNDA) Bladder Cancer (sNDA) Multiple Ovarian Cancer (sNDA) INDICATION > TARGET Strategic Oncology > PD-L1, PD-1, CXCR5 1H 2015 G-MAB® Inflammation >
Slide 7: Oncology Franchise Cynviloq
Oncology Franchise Cynviloq™ 7
Slide 8: Cynviloq is the 3rd Generation Paclitaxel Therapy
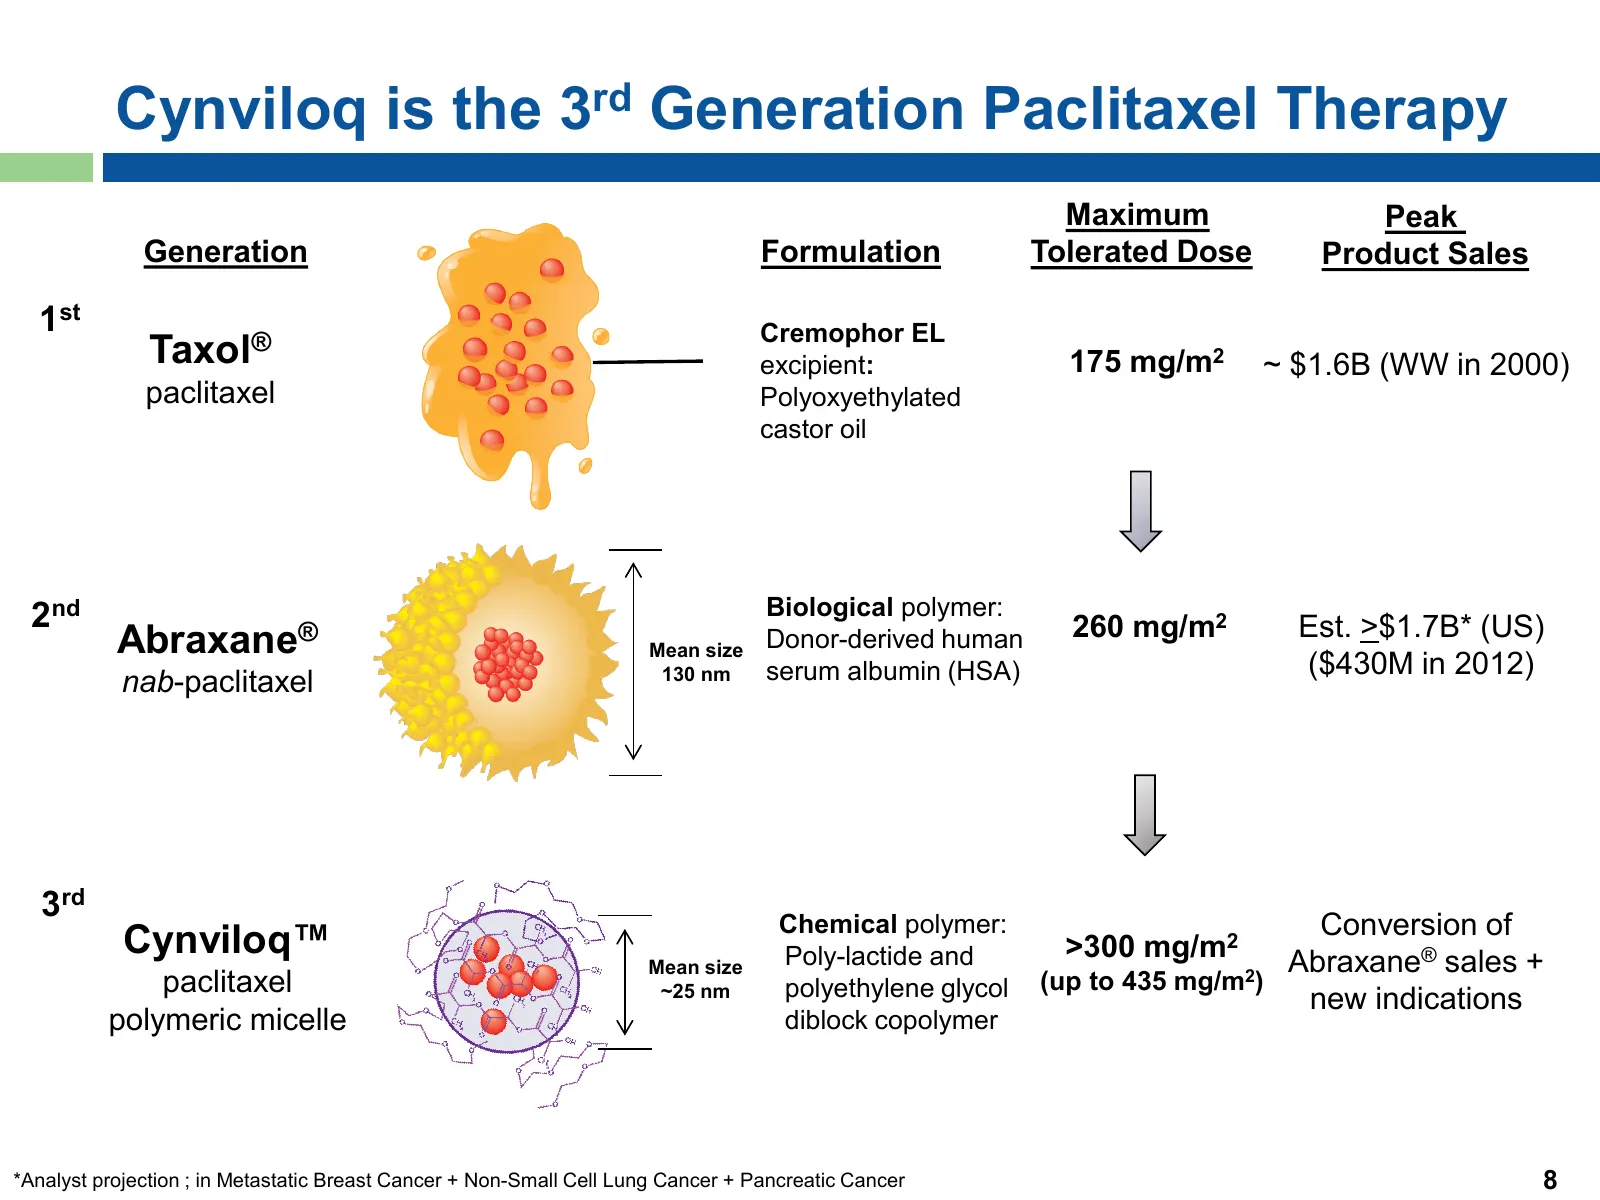
Cynviloq is the 3rd Generation Paclitaxel Therapy Maximum Peak Generation Formulation Tolerated Dose Product Sales 1st Cremophor EL Taxol® excipient: 175 mg/m2 ~ $1.6B (WW in 2000) paclitaxel Polyoxyethylated castor oil 2nd Biological polymer: 260 mg/m2 Est. >$1.7B* (US) Abraxane® Mean size Donor-de
Slide 9: Cynviloq is a High Value Proposition
Cynviloq is a High Value Proposition 1. Exclusive US and EU Rights 2. Cynviloq efficacy demonstrated in Phase 2 and Phase 3 studies 3. FDA concurred a. Available data support pursuing 505(b)(2) regulatory pathway b. Bioequivalence (BE) study sufficient for approval of indications in Abraxane® label
Slide 10: Bioequivalence = Efficient Pathway to Market
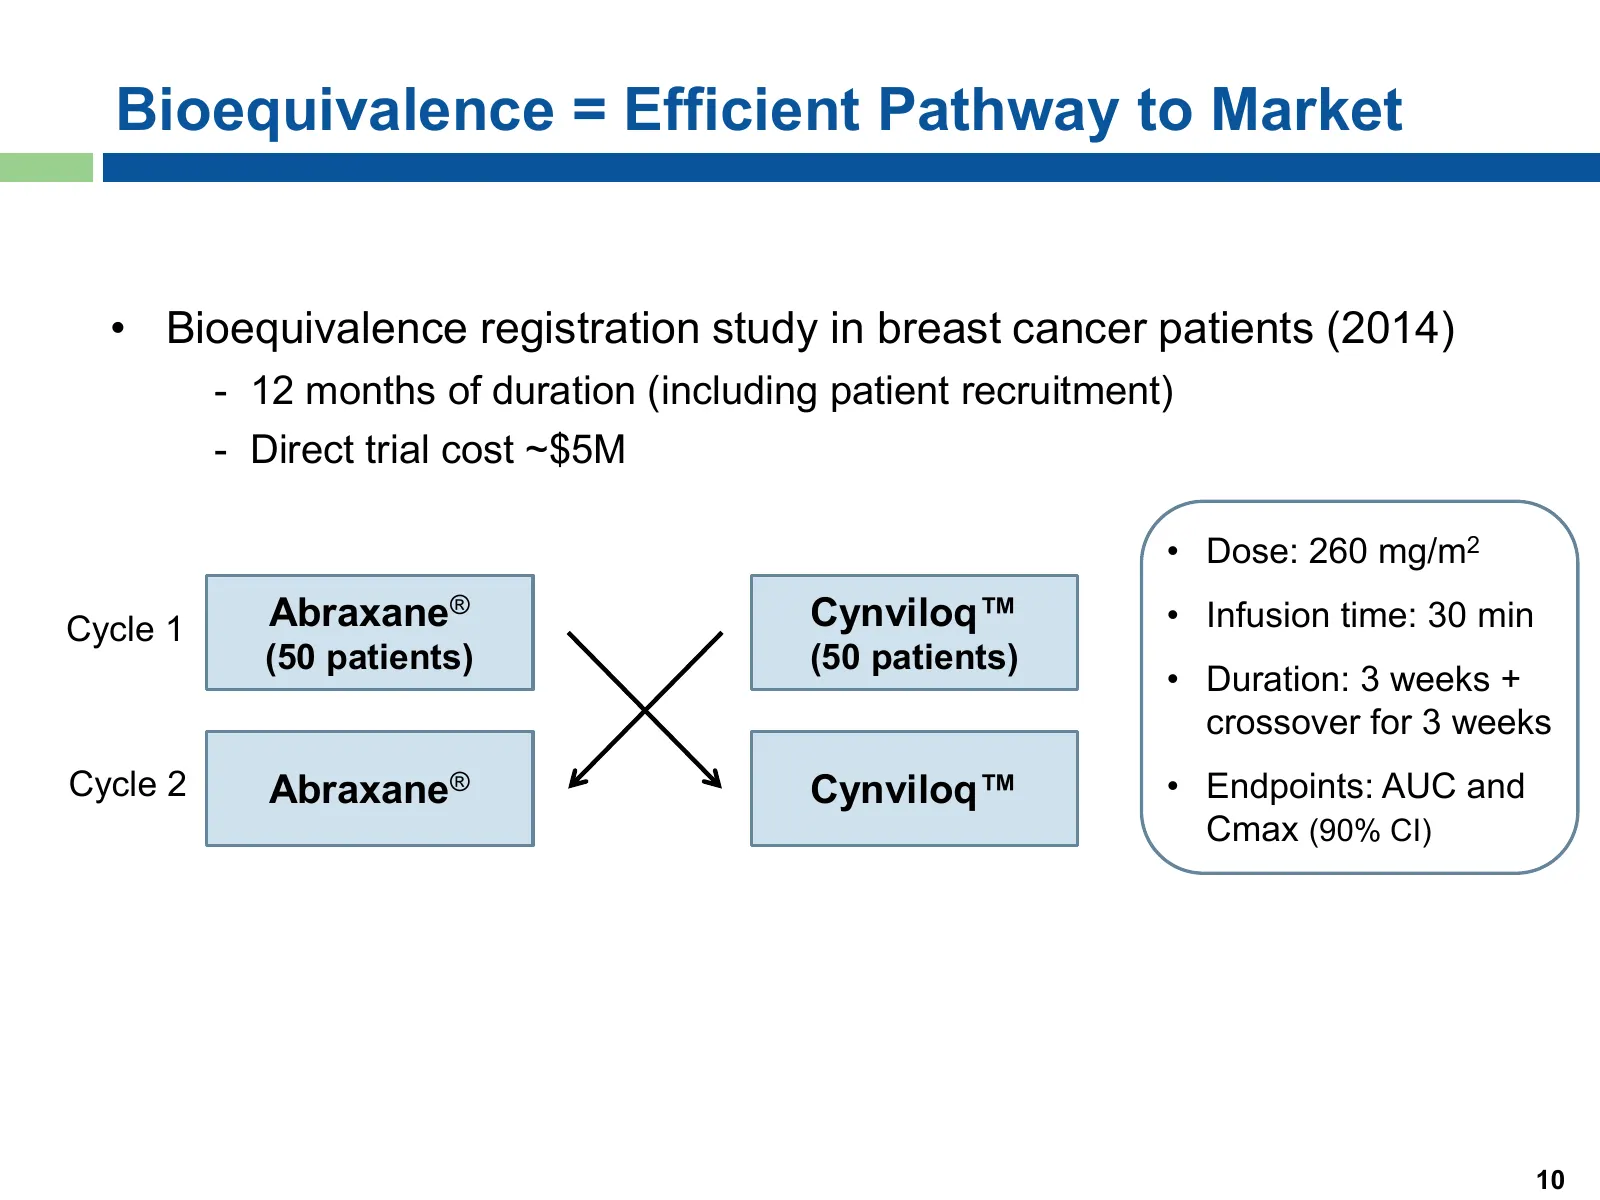
Bioequivalence = Efficient Pathway to Market • Bioequivalence registration study in breast cancer patients (2014) - 12 months of duration (including patient recruitment) - Direct trial cost ~$5M • Dose: 260 mg/m2 Cycle 1 Abraxane® Cynviloq™ • Infusion time: 30 min (50 patients) (50 patients) • Durat
Slide 11: Cynviloq Market Opportunity
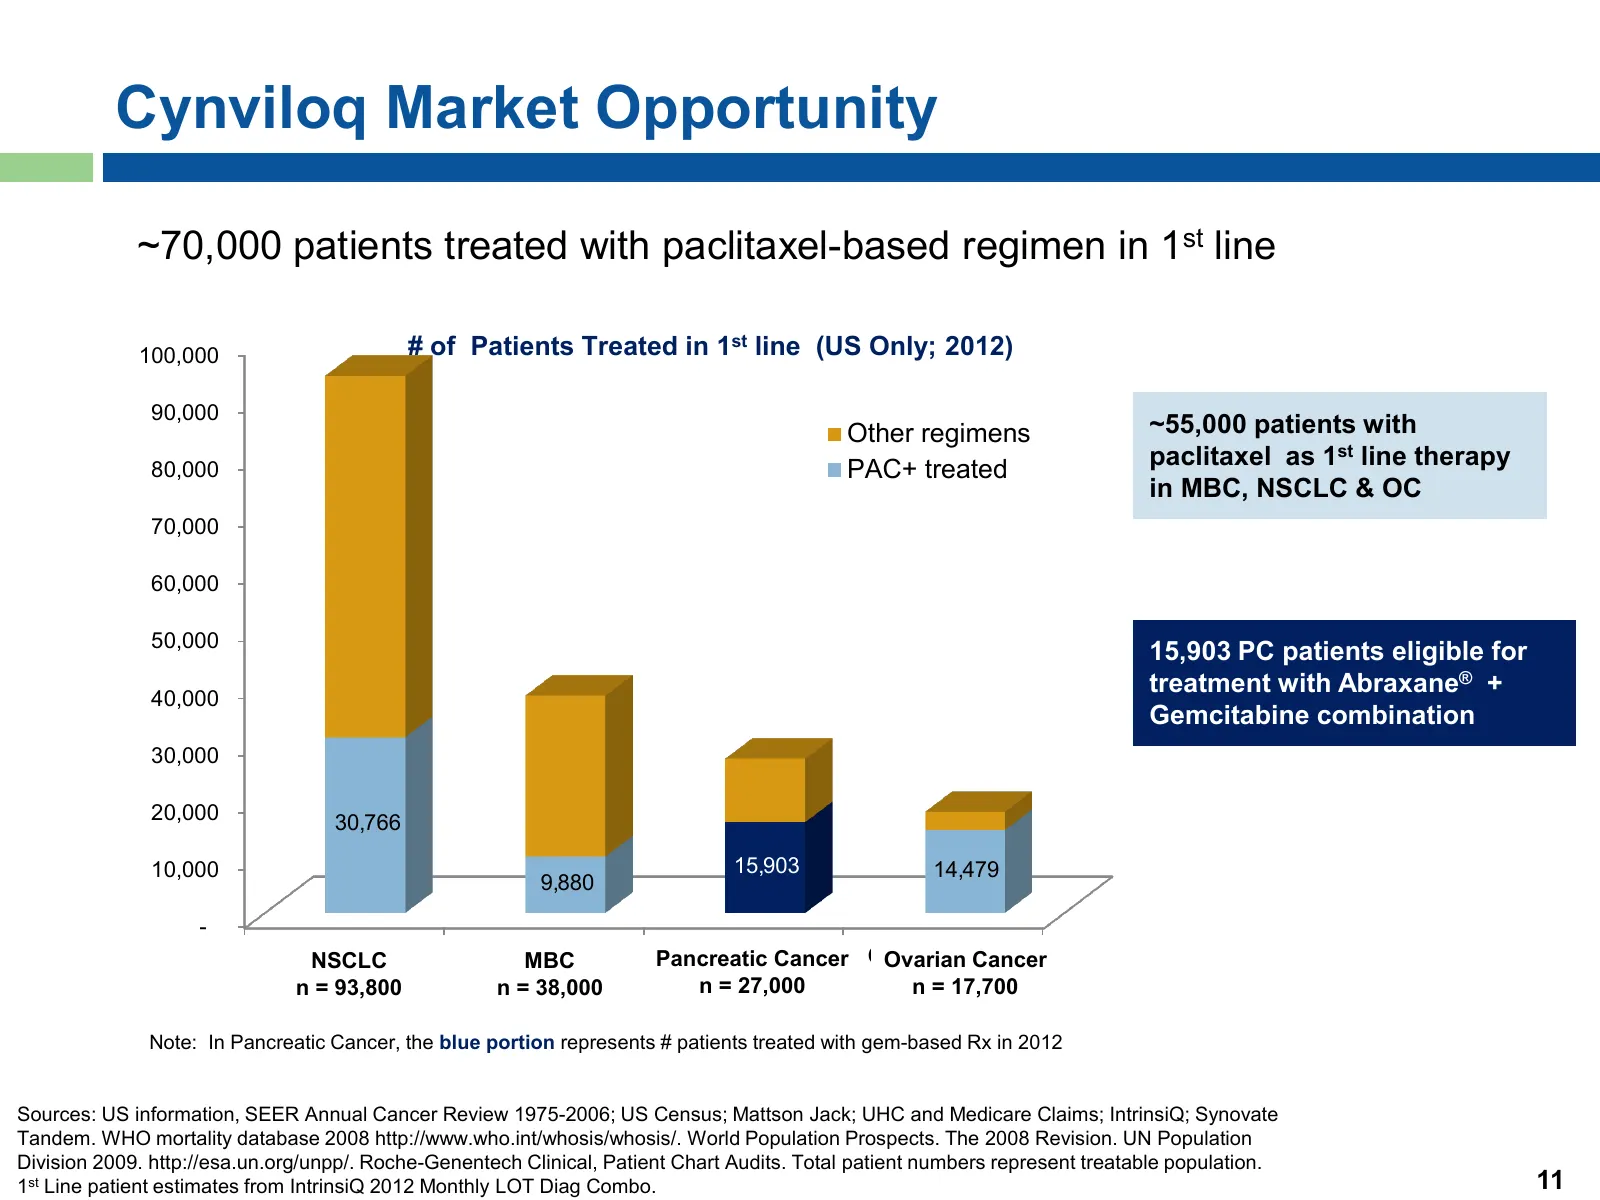
Cynviloq Market Opportunity ~70,000 patients treated with paclitaxel-based regimen in 1st line 100,000 # of Patients Treated in 1st line (US Only; 2012) 90,000 Other regimens ~55,000 patients with 80,000 PAC+ treated paclitaxel as 1st line therapy in MBC, NSCLC & OC 70,000 60,000 50,000 15,903 PC pa
Slide 12: Cynviloq Advantages
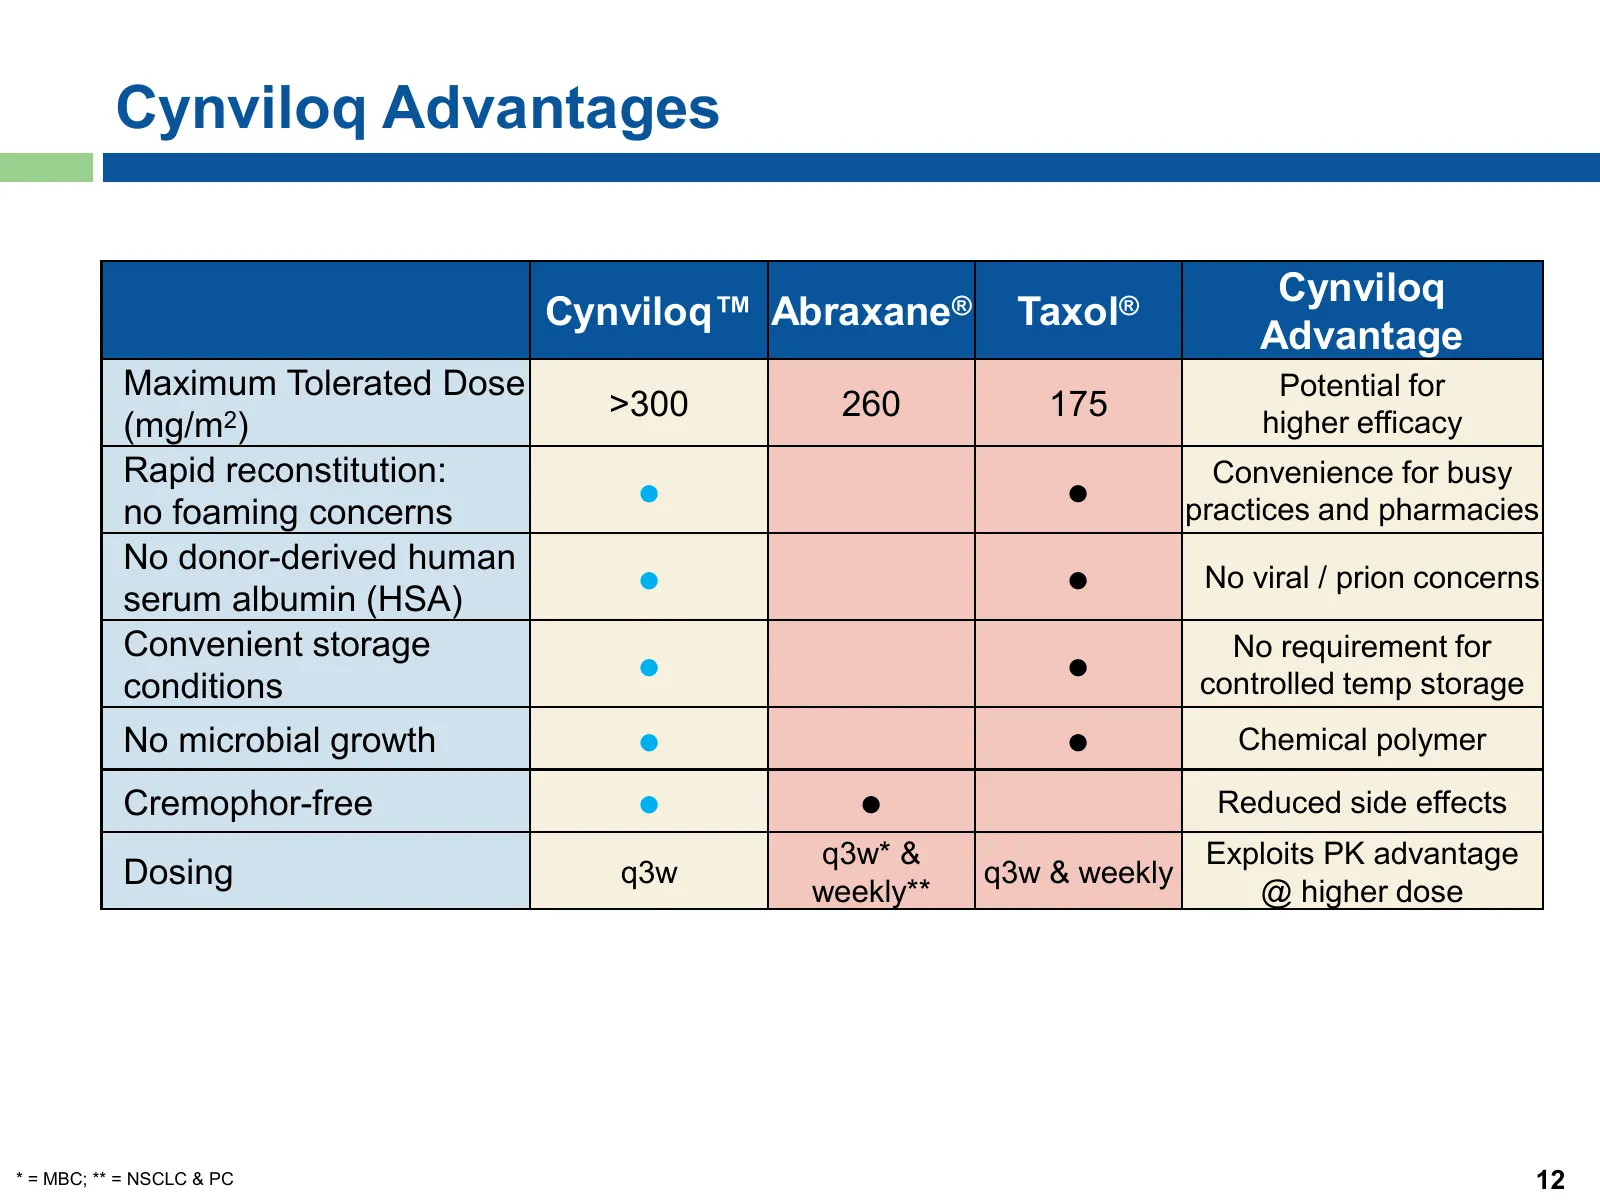
Cynviloq Advantages Cynviloq Cynviloq™ Abraxane® Taxol® Advantage Maximum Tolerated Dose Potential for >300 260 175 (mg/m2) higher efficacy Rapid reconstitution: Convenience for busy no foaming concerns ● ● practices and pharmacies No donor-derived human serum albumin (HSA) ● ● No viral / prion conc
Slide 13: Potential to Expand Label Indications: 2nd Line Bladder Cancer
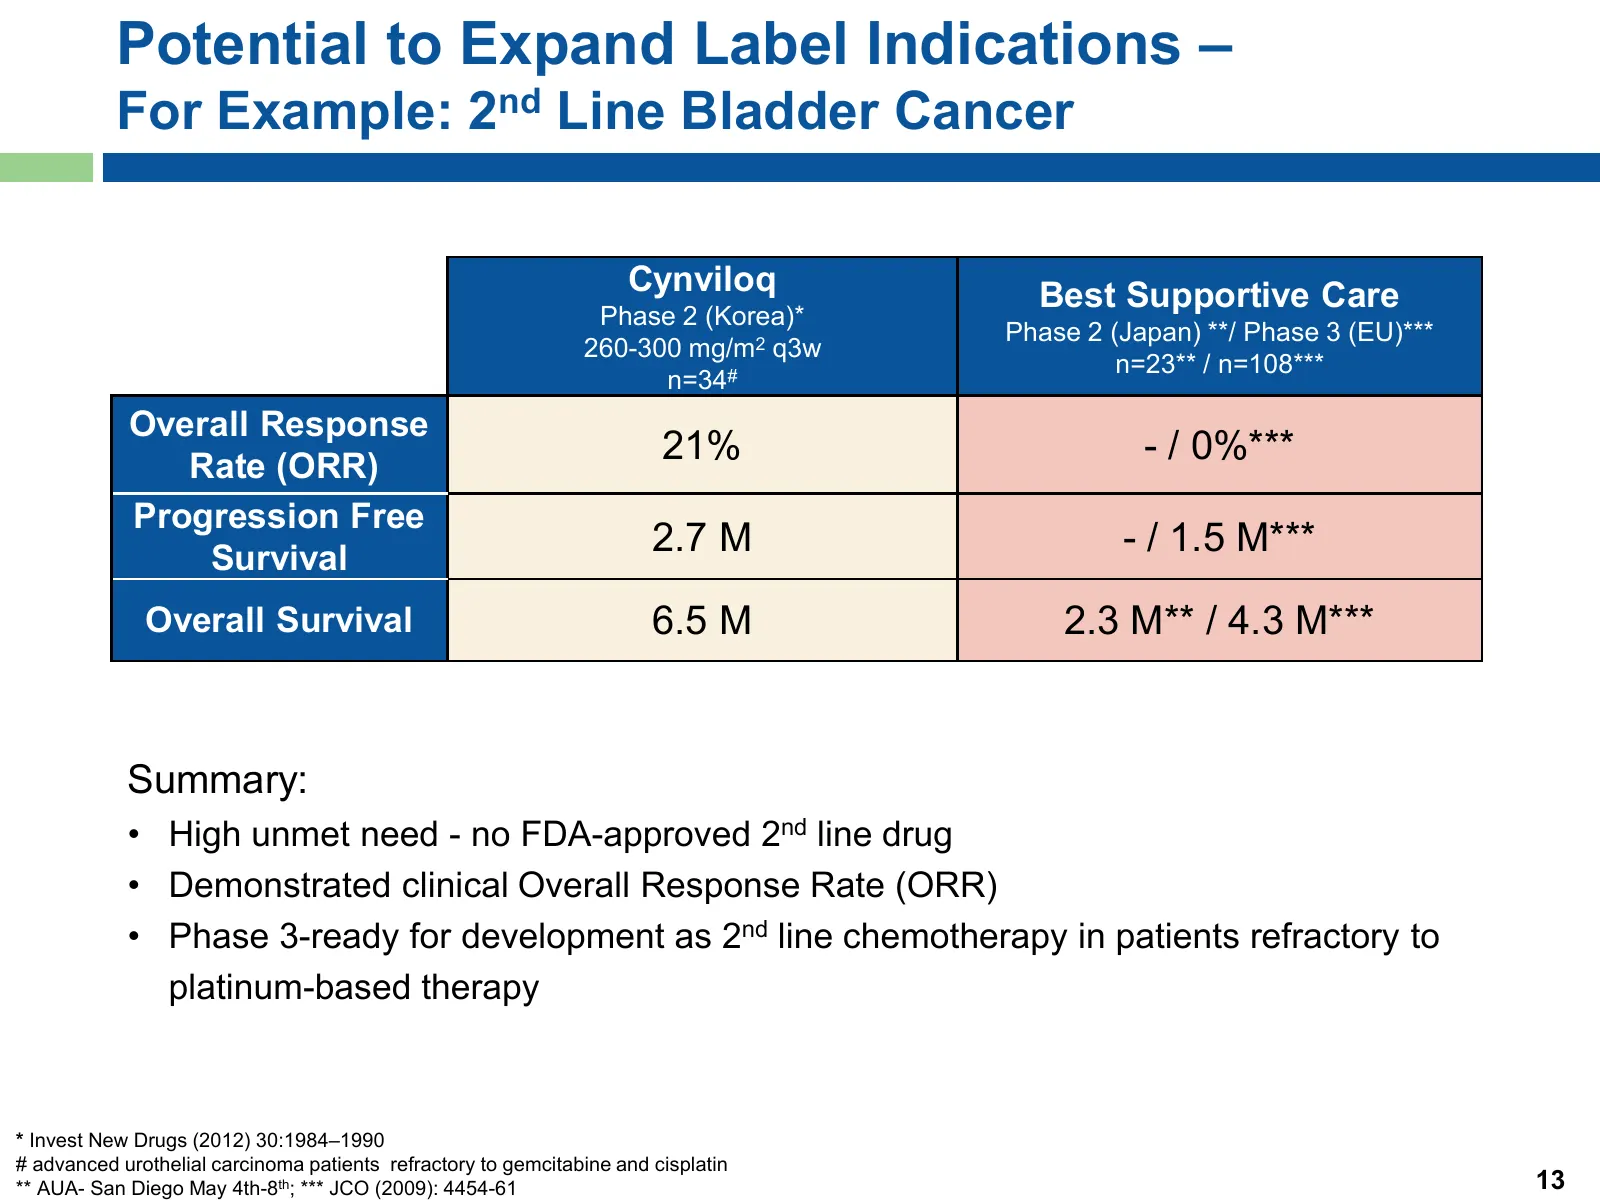
Potential to Expand Label Indications – For Example: 2nd Line Bladder Cancer Cynviloq Best Supportive Care Phase 2 (Korea)* Phase 2 (Japan) **/ Phase 3 (EU)*** 260-300 mg/m2 q3w n=23** / n=108*** n=34# Overall Response Rate (ORR) 21% - / 0%*** Progression Free Survival 2.7 M - / 1.5 M*** Overall Sur
Slide 14: Next Steps for Cynviloq
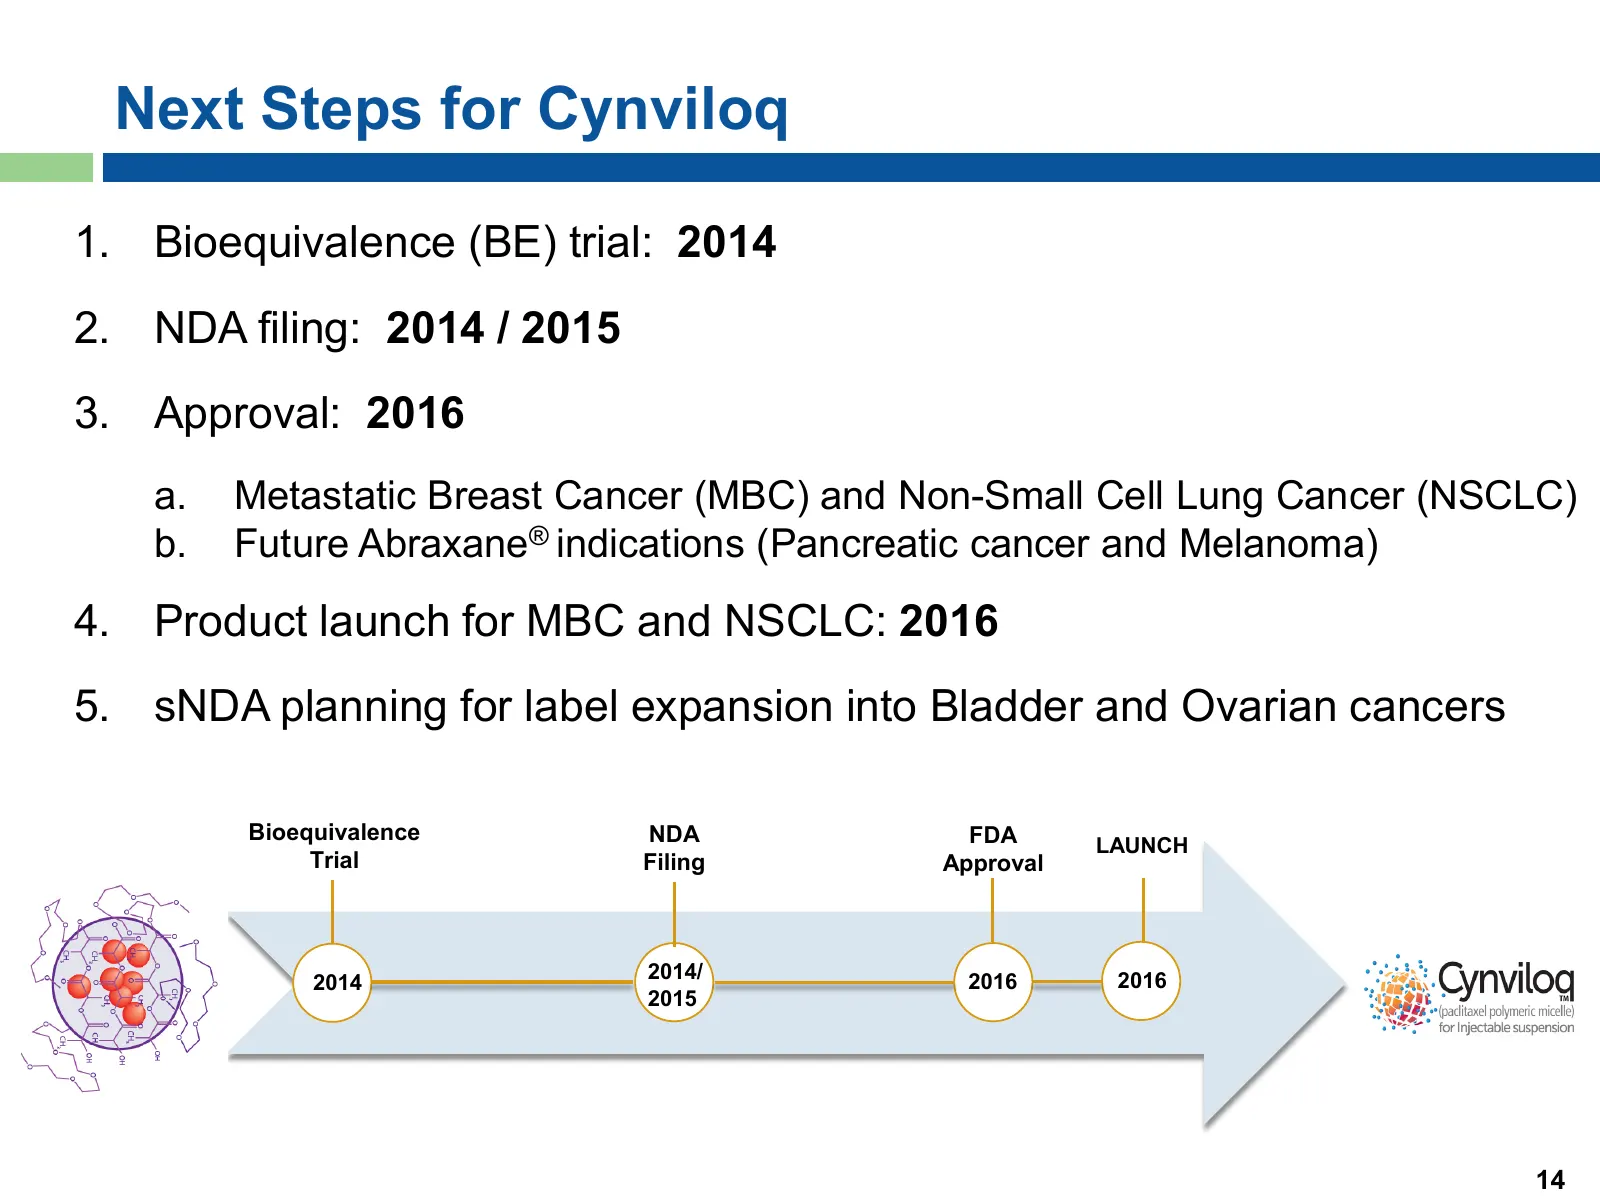
Next Steps for Cynviloq 1. Bioequivalence (BE) trial: 2014 2. NDA filing: 2014 / 2015 3. Approval: 2016 a. Metastatic Breast Cancer (MBC) and Non-Small Cell Lung Cancer (NSCLC) b. Future Abraxane® indications (Pancreatic cancer and Melanoma) 4. Product launch for MBC and NSCLC: 2016 5. sNDA planning
Slide 15: Therapeutic Antibody Engine G-MAB
Therapeutic Antibody Engine G-MAB® 15
Slide 16: G-MAB: Library of Therapeutic Antibodies
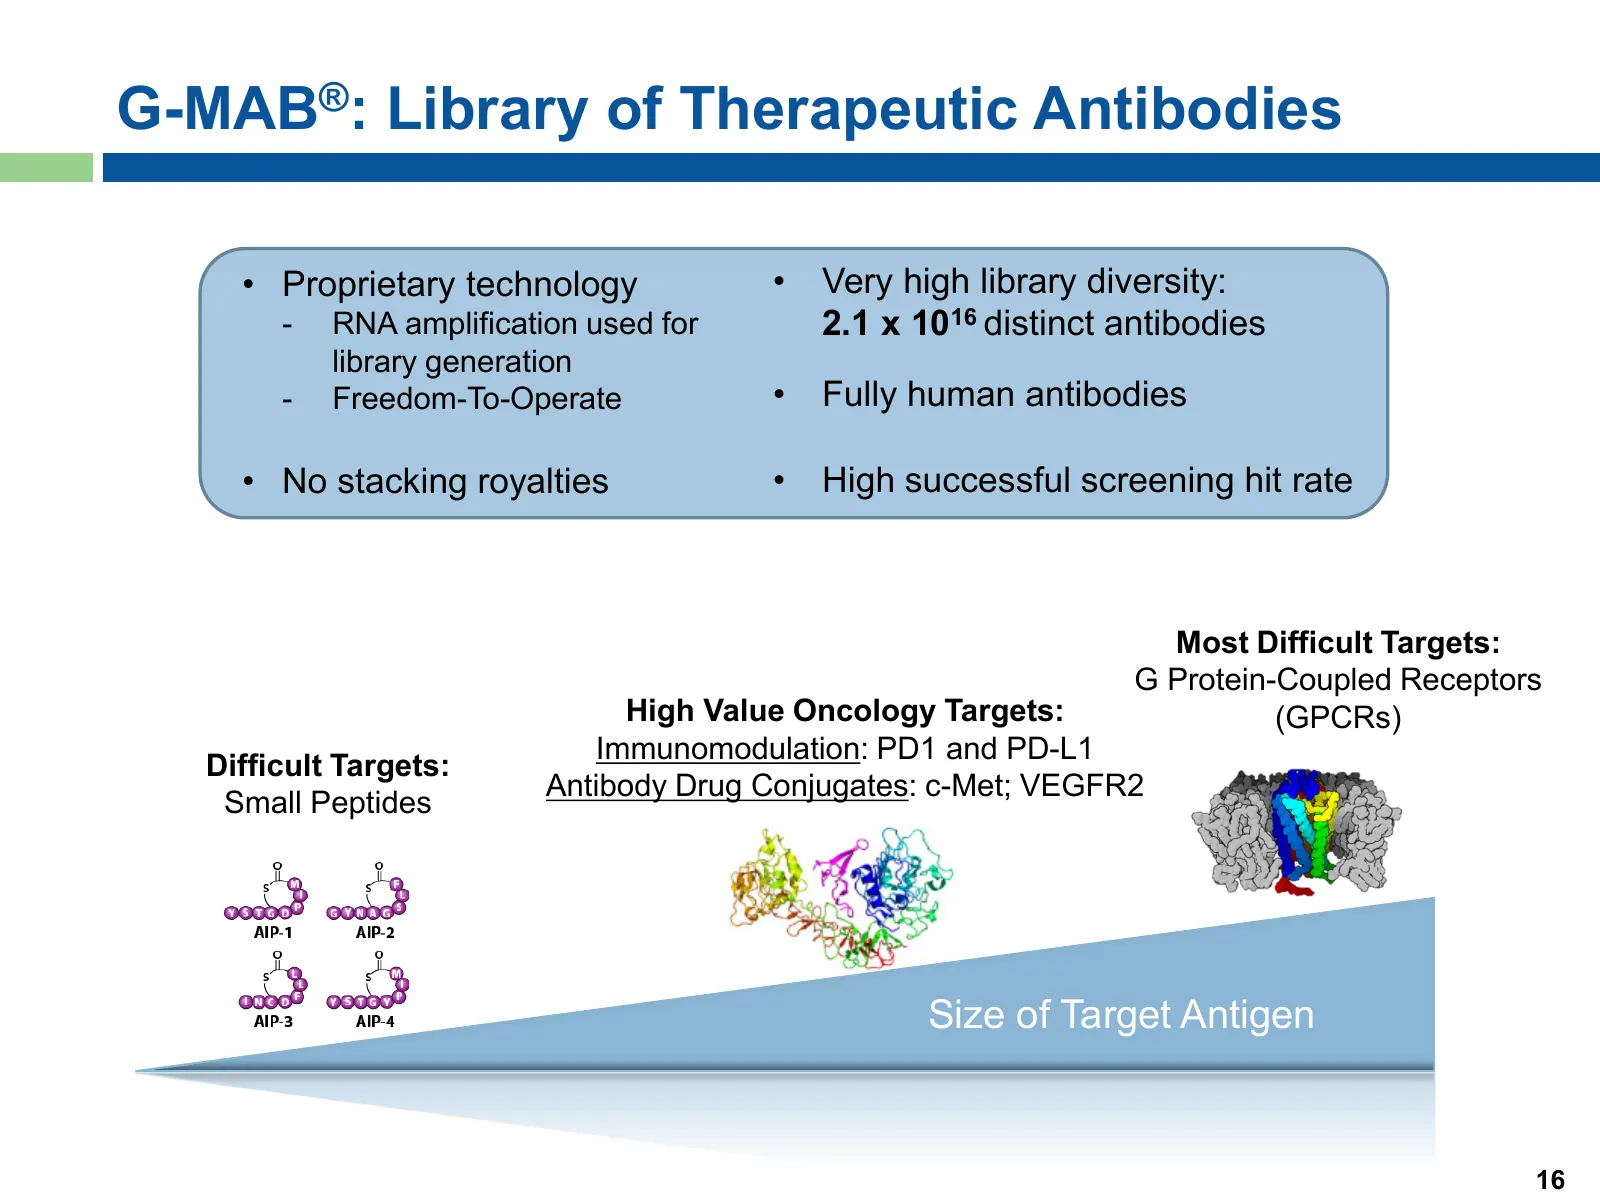
G-MAB®: Library of Therapeutic Antibodies • Proprietary technology • Very high library diversity: - RNA amplification used for 2.1 x 10¹⁶ distinct antibodies library generation - Freedom-To-Operate • Fully human antibodies • No stacking royalties • High successful screening hit rate Most Difficult T
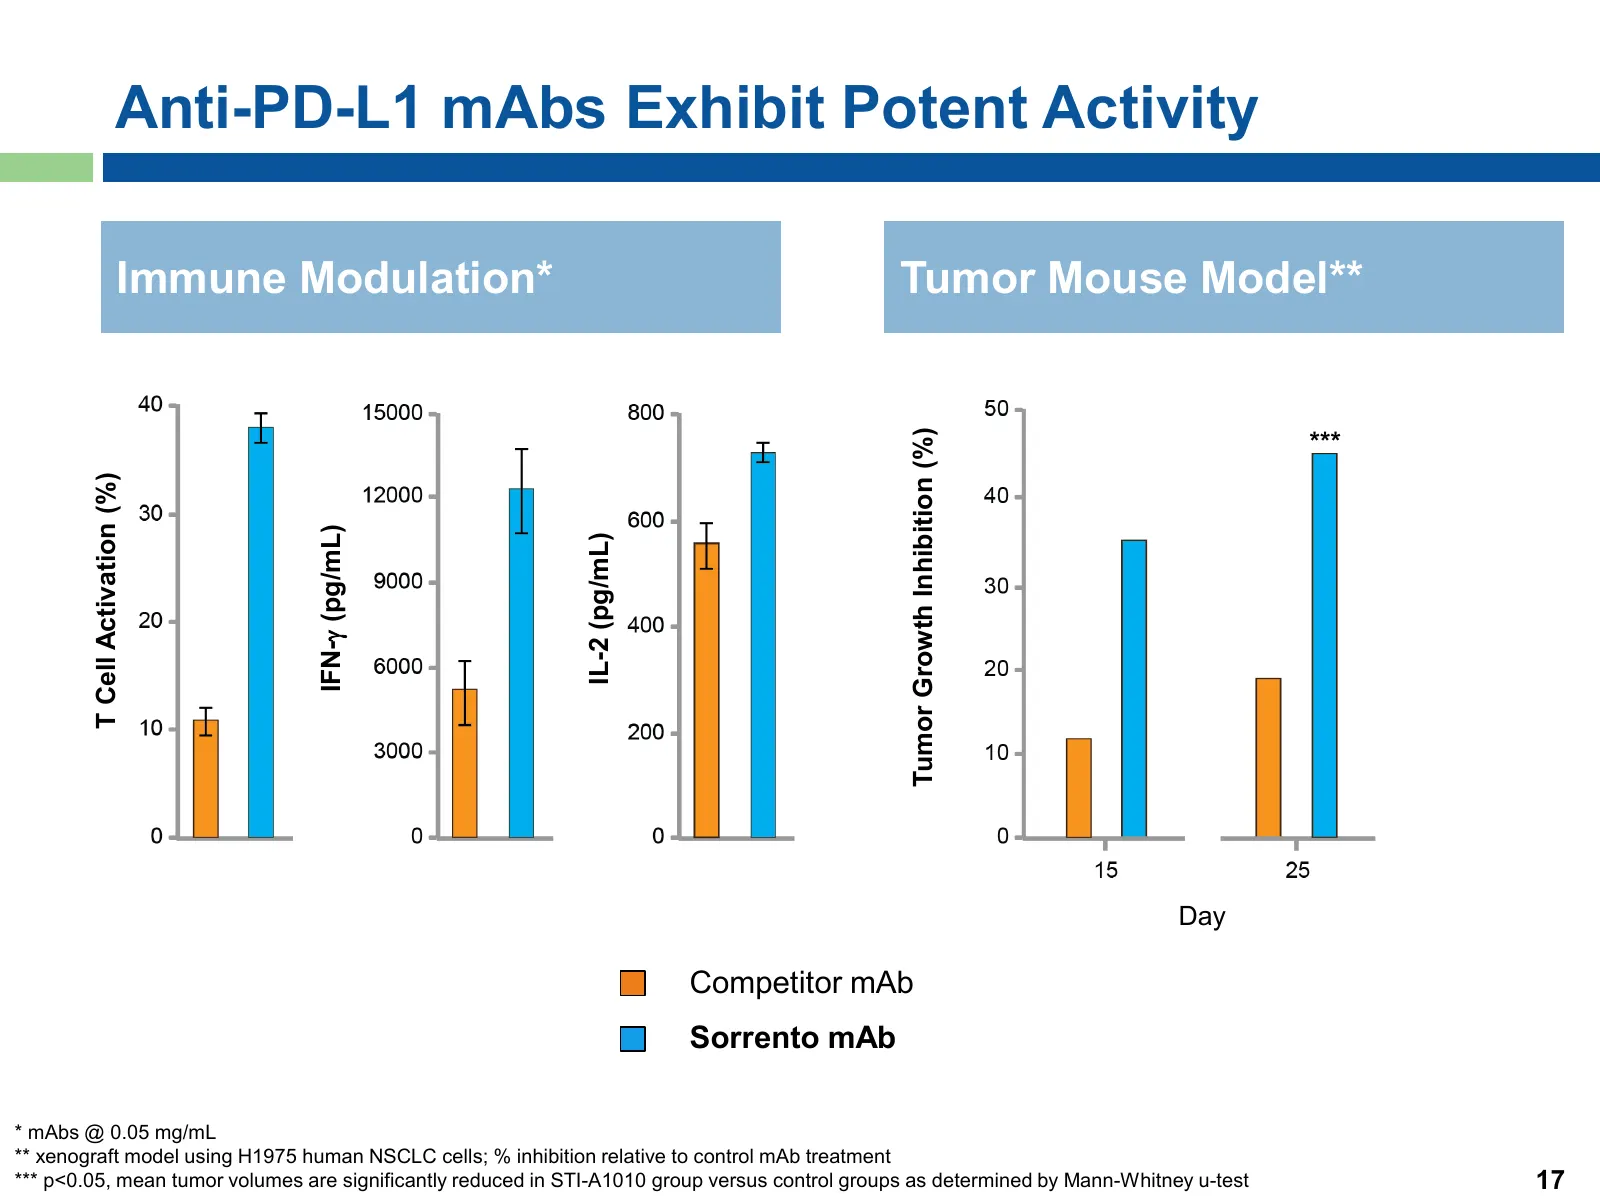
Slide 17: Anti-PD-L1 mAbs Exhibit Potent Activity
Anti-PD-L1 mAbs Exhibit Potent Activity Immune Modulation* Tumor Mouse Model** *** Tumor Growth Inhibition (%) T Cell Activation (%) IFN-γ (pg/mL) IL-2 (pg/mL) Day Competitor mAb Sorrento mAb * mAbs @ 0.05 mg/mL ** xenograft model using H1975 human NSCLC cells; % inhibition relative to control mAb t
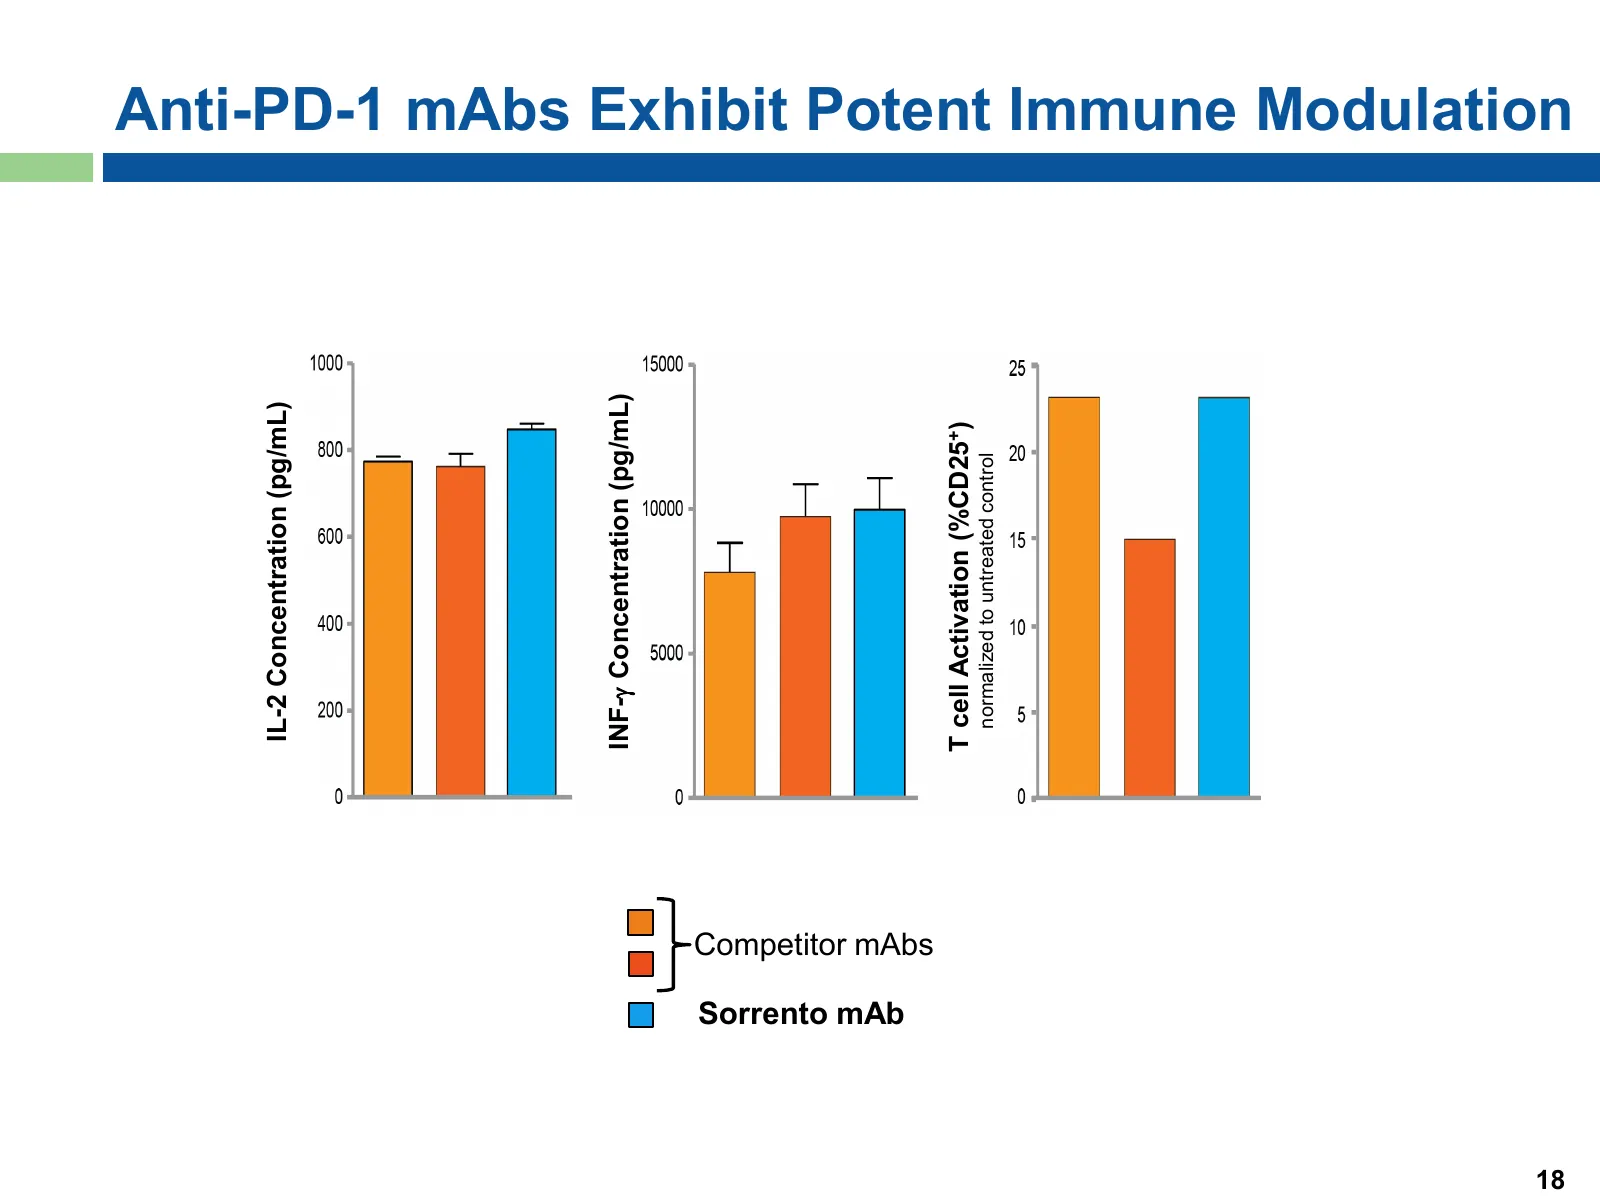
Slide 18: Anti-PD-1 mAbs Exhibit Potent Immune Modulation
IL-2 Concentration (pg/mL) INF-γ Concentration (pg/mL) Sorrento mAb Competitor mAbs T cell Activation (%CD25+) normalized to untreated control 18 Anti-PD-1 mAbs Exhibit Potent Immune Modulation
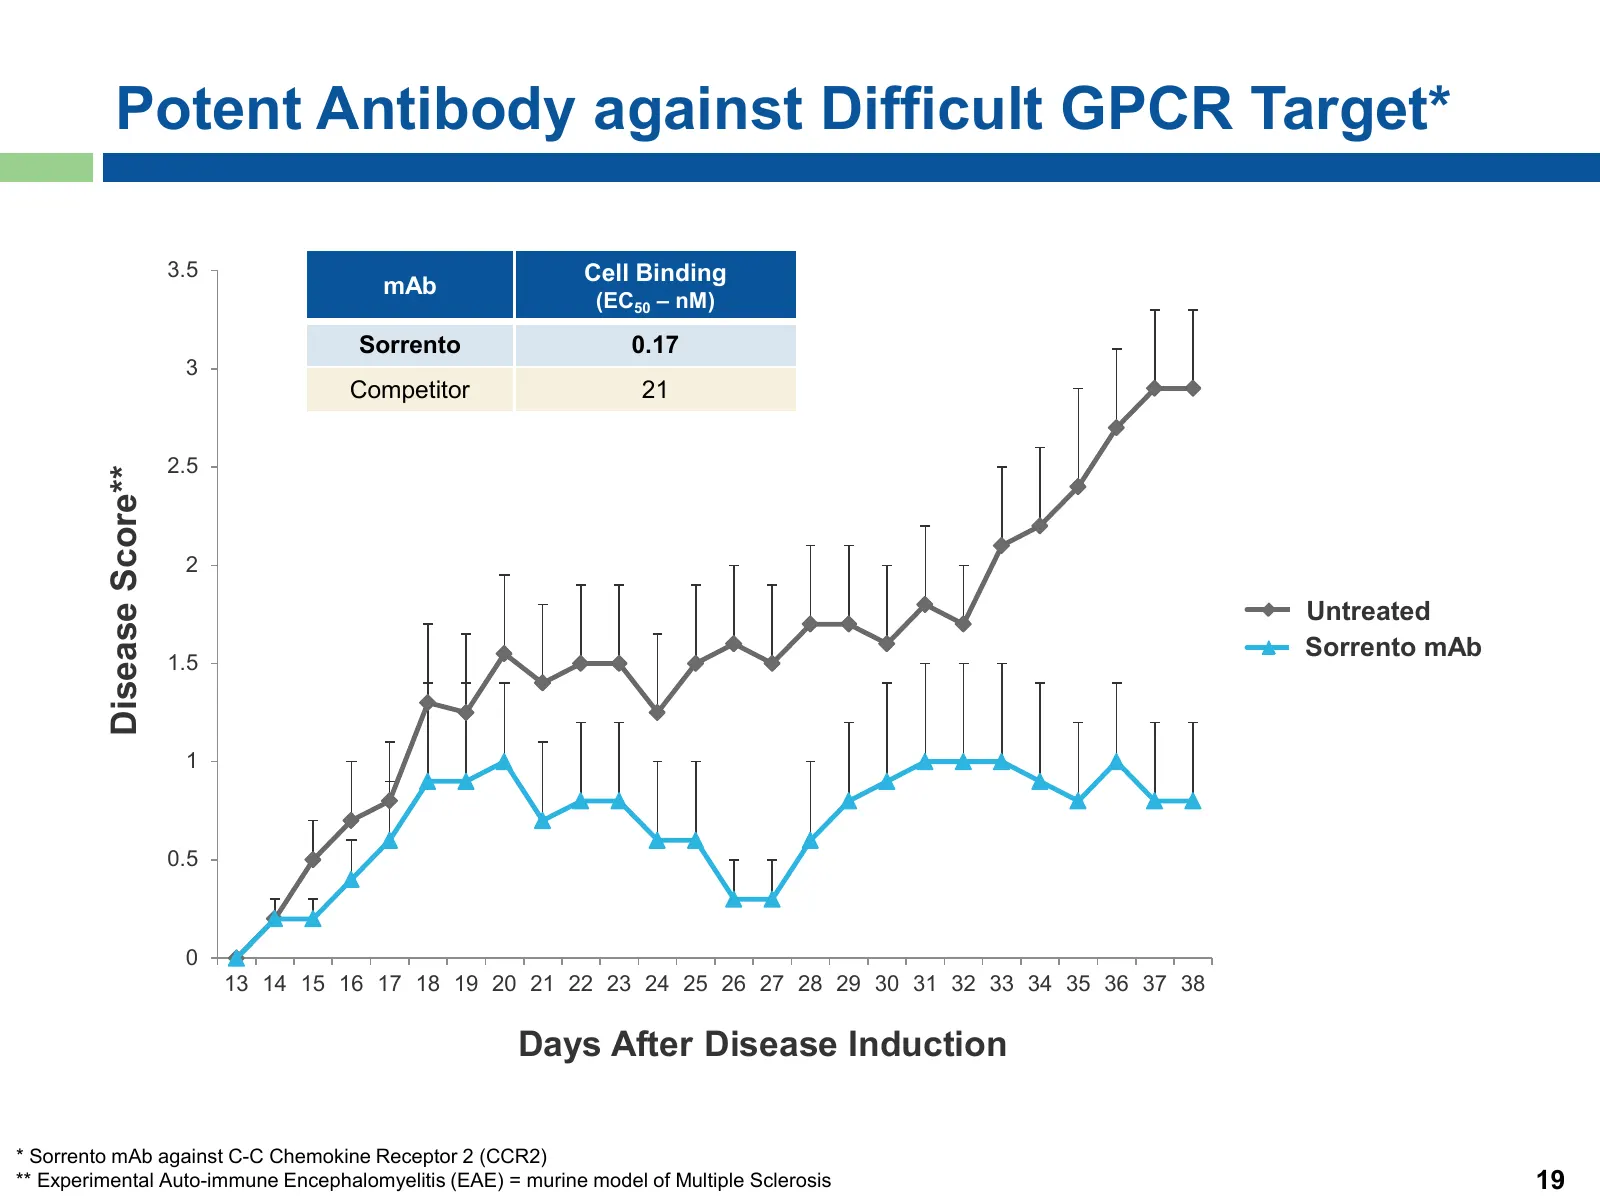
Slide 19: Potent Antibody against Difficult GPCR Target
Potent Antibody against Difficult GPCR Target* 3.5 Cell Binding mAb (EC50 – nM) Sorrento 0.17 3 Competitor 21 2.5 Disease Score** 2 Untreated PBS Sorrento D1 mAb therapeutic 1.5 1 0.5 0 13 14 15 16 17 18 19 20 21 22 23 24 25 26 27 28 29 30 31 32 33 34 35 36 37 38 Days After Disease Induction * Sorre
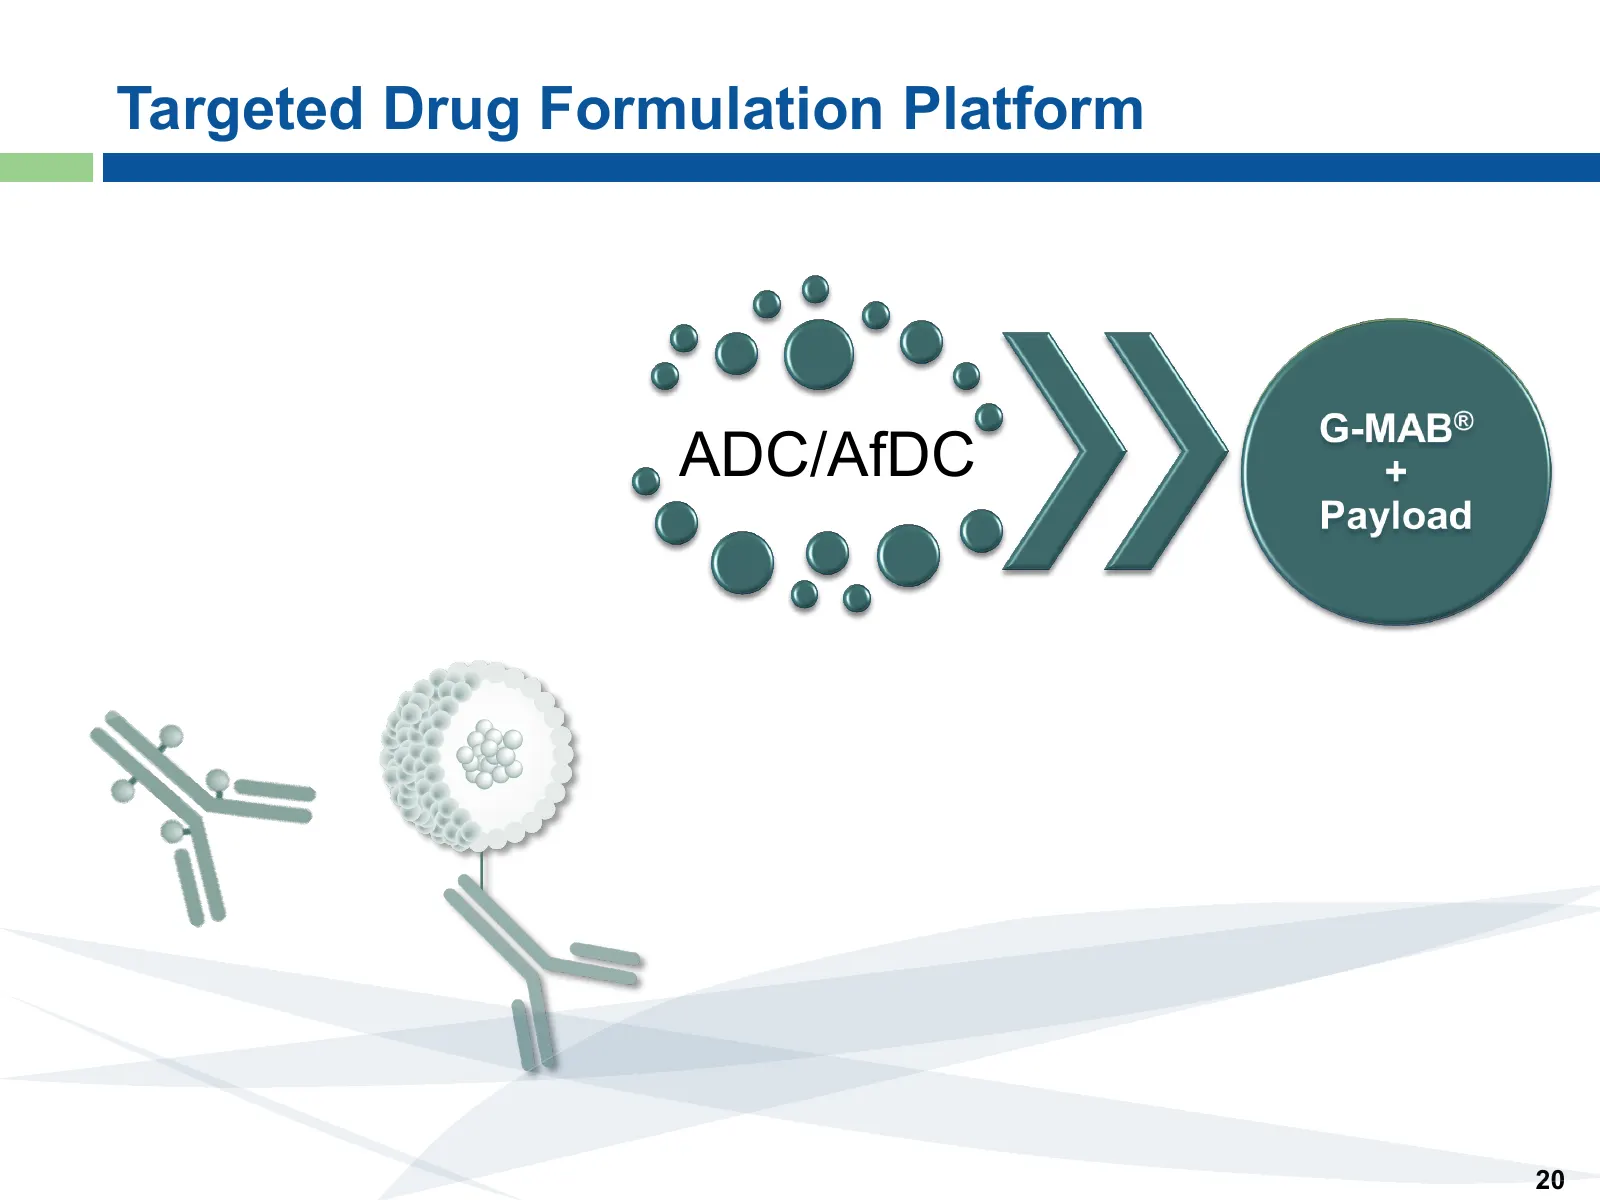
Slide 20: Targeted Drug Formulation Platform ADC/AfDC
Targeted Drug Formulation Platform ADC/AfDC 20
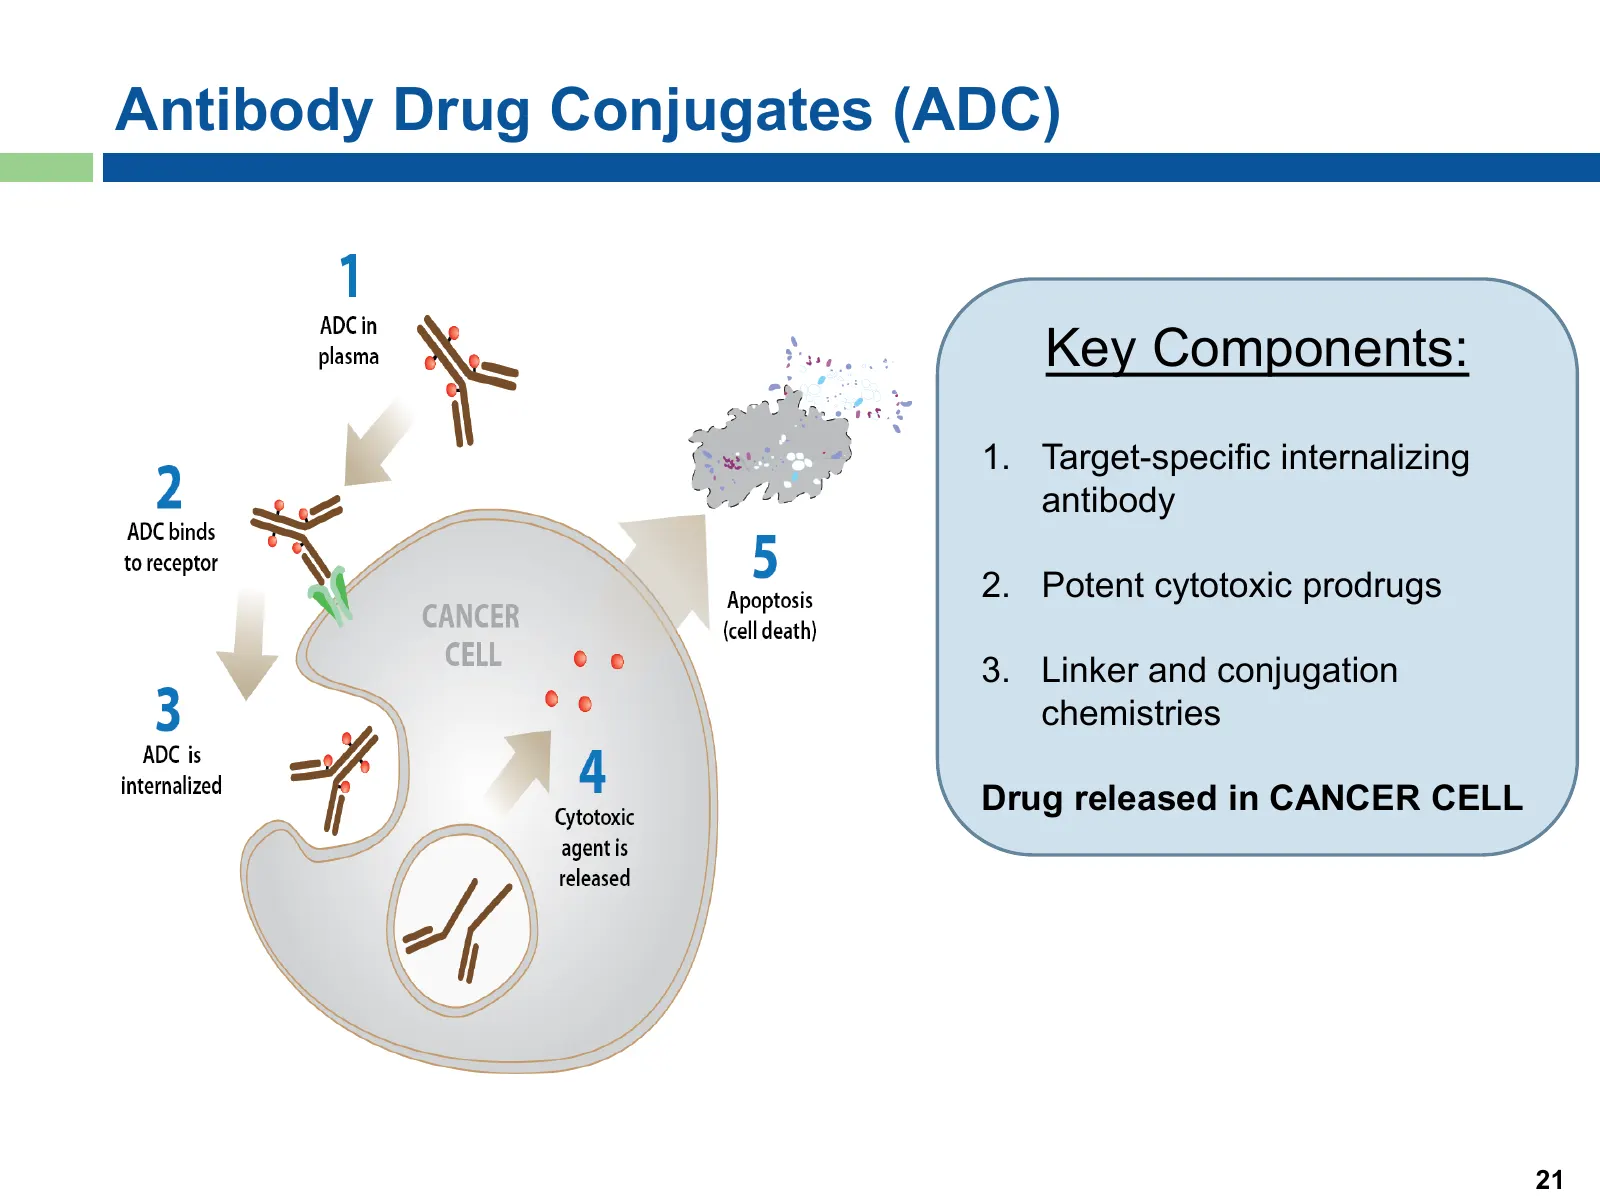
Slide 21: Antibody Drug Conjugates (ADC)
Antibody Drug Conjugates (ADC) Key Components: 1. Target-specific internalizing antibody 2. Potent cytotoxic prodrugs 3. Linker and conjugation chemistries Drug released in CANCER CELL 21
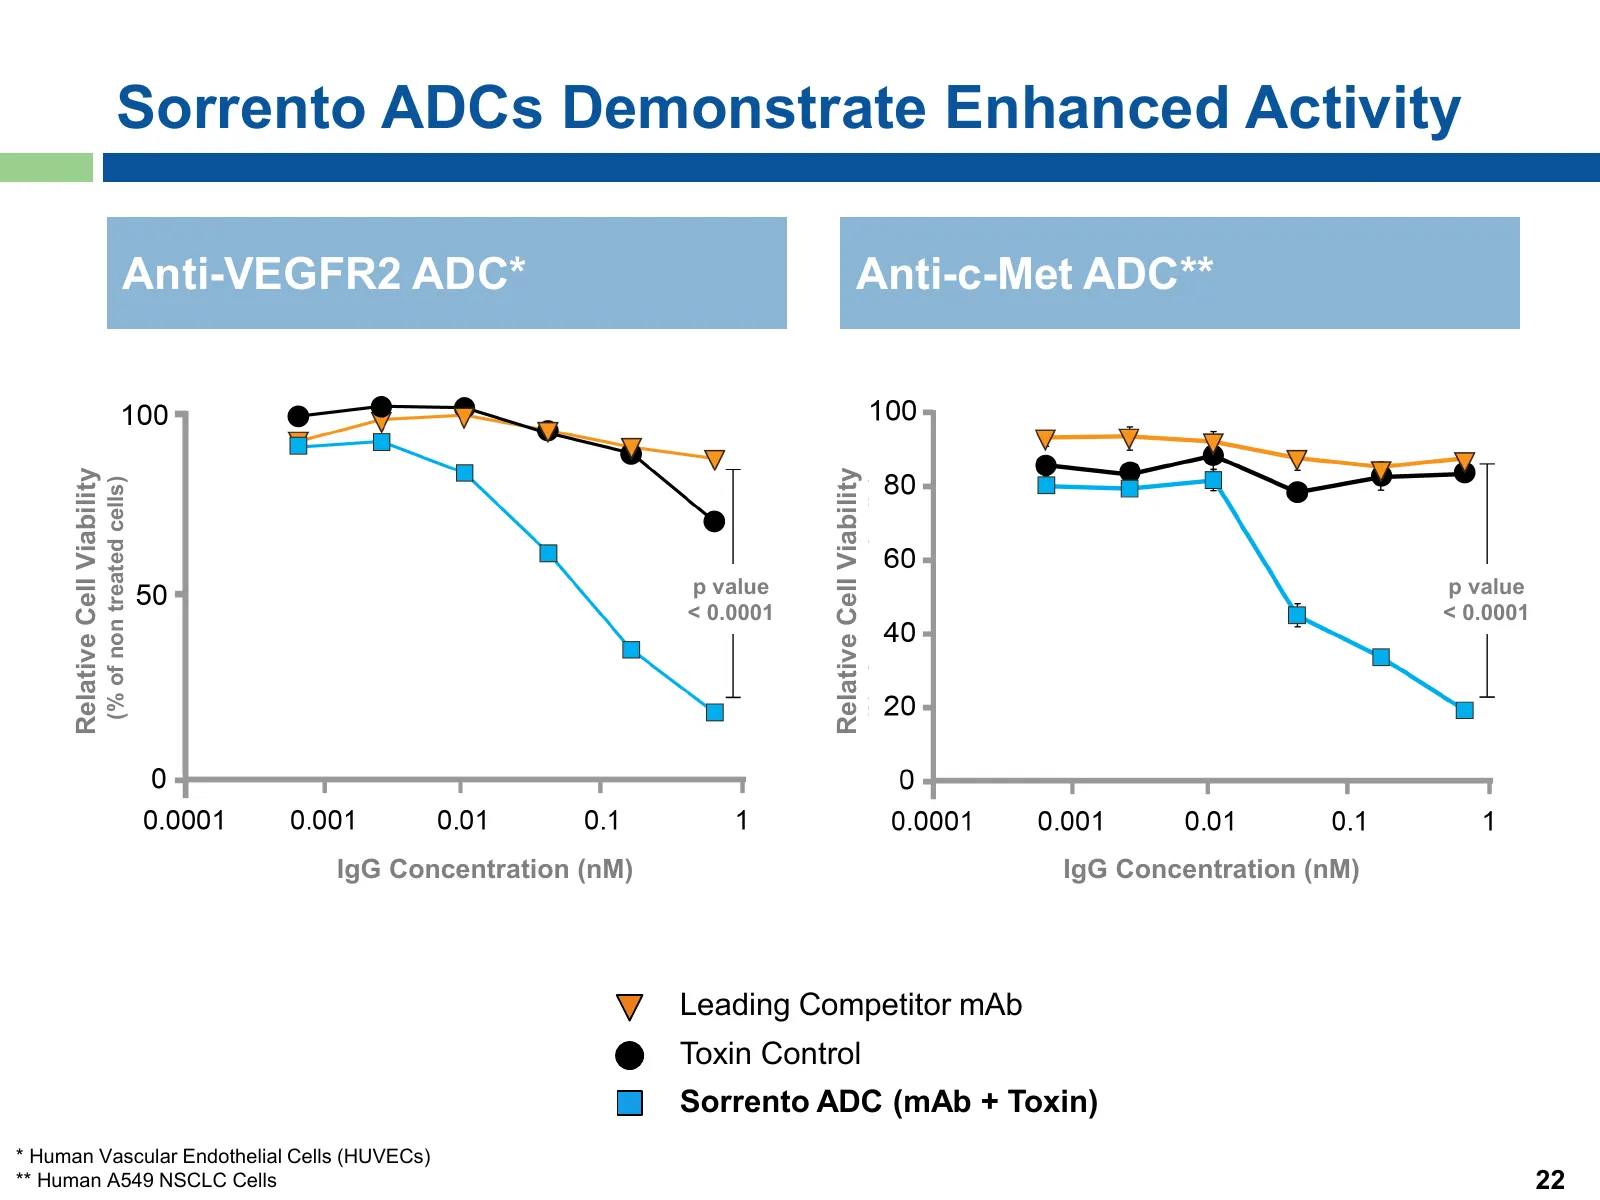
Slide 22: Sorrento ADCs Demonstrate Enhanced Activity
Sorrento ADCs Demonstrate Enhanced Activity Anti-VEGFR2 ADC* Anti-c-Met ADC** Relative Cell Viability Relative Cell Viability (% of non treated cells) (% of non treated cells) p value p value < 0.0001 < 0.0001 IgG Concentration (nM) IgG Concentration (nM) Leading Competitor mAb Toxin Control Sorrent
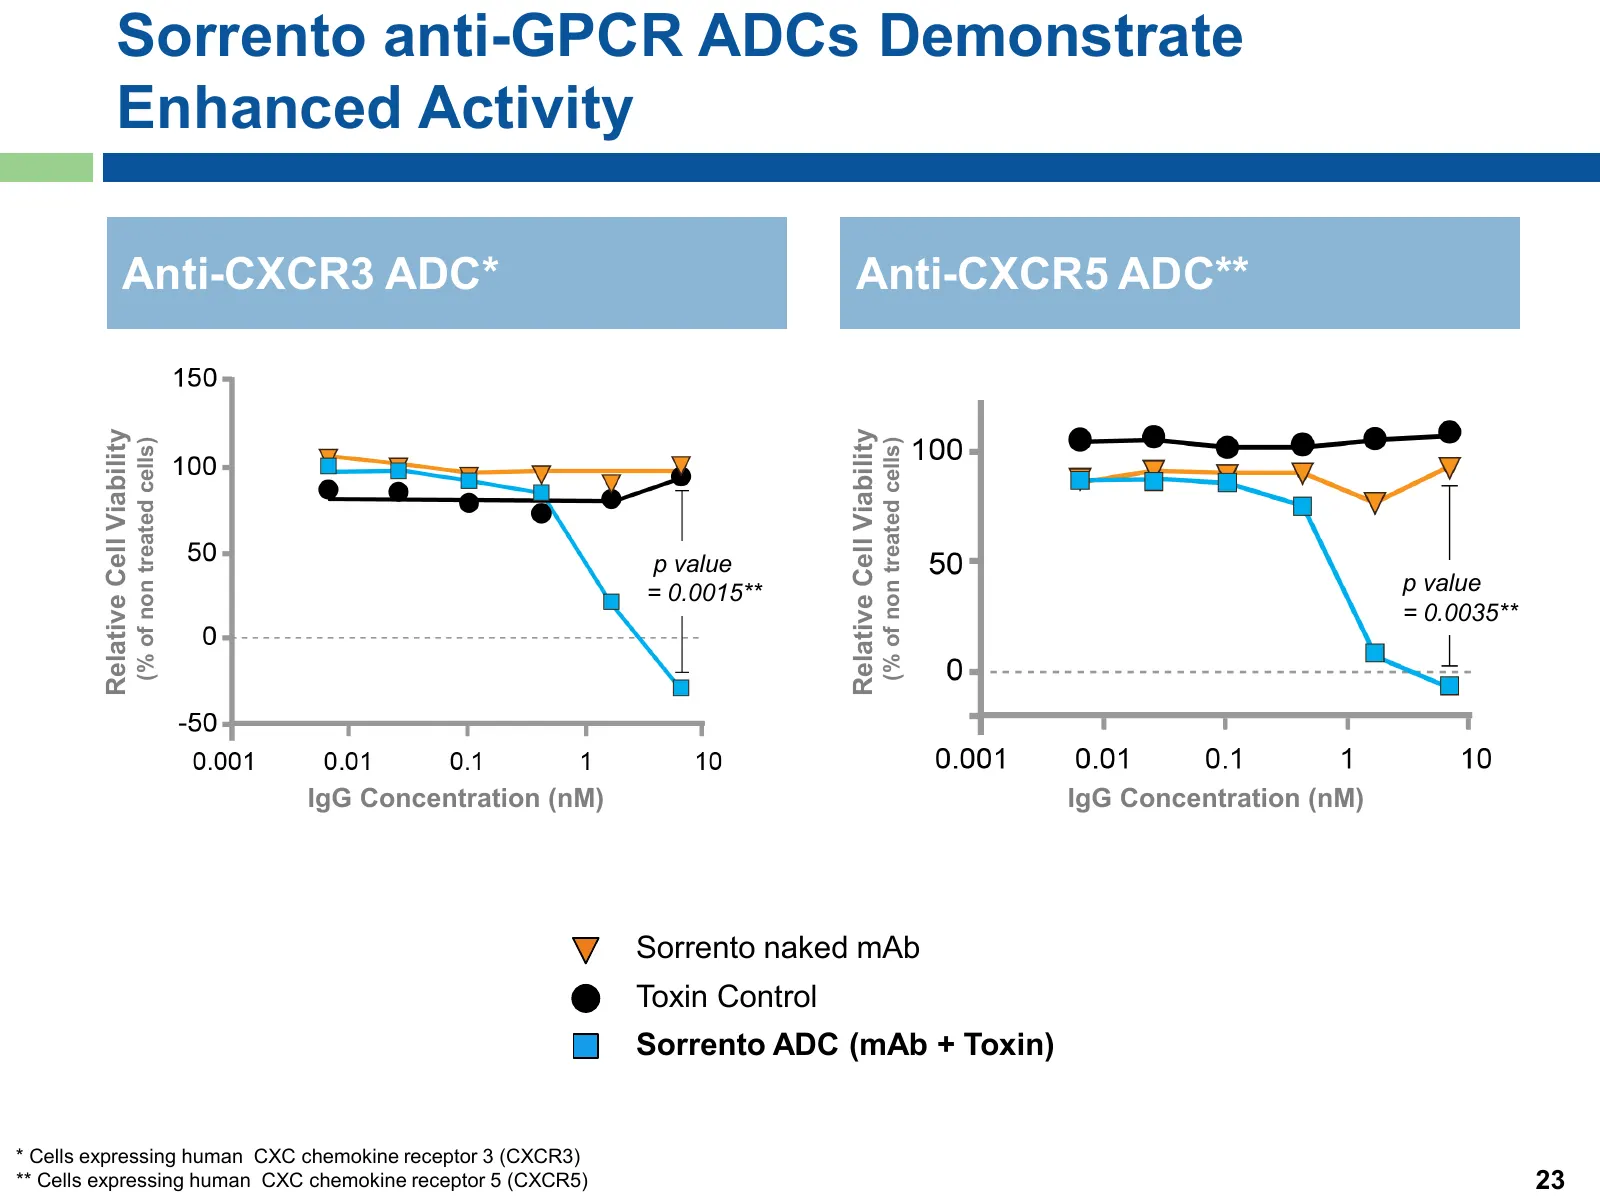
Slide 23: Sorrento anti-GPCR ADCs Demonstrate Enhanced Activity
Sorrento anti-GPCR ADCs Demonstrate Enhanced Activity Anti-CXCR3 ADC* Anti-CXCR5 ADC** Relative Cell Viability Relative Cell Viability (% of non treated cells) (% of non treated cells) p value = 0.0015** p value = 0.0035** IgG Concentration (nM) IgG Concentration (nM) Sorrento naked mAb Toxin Contro
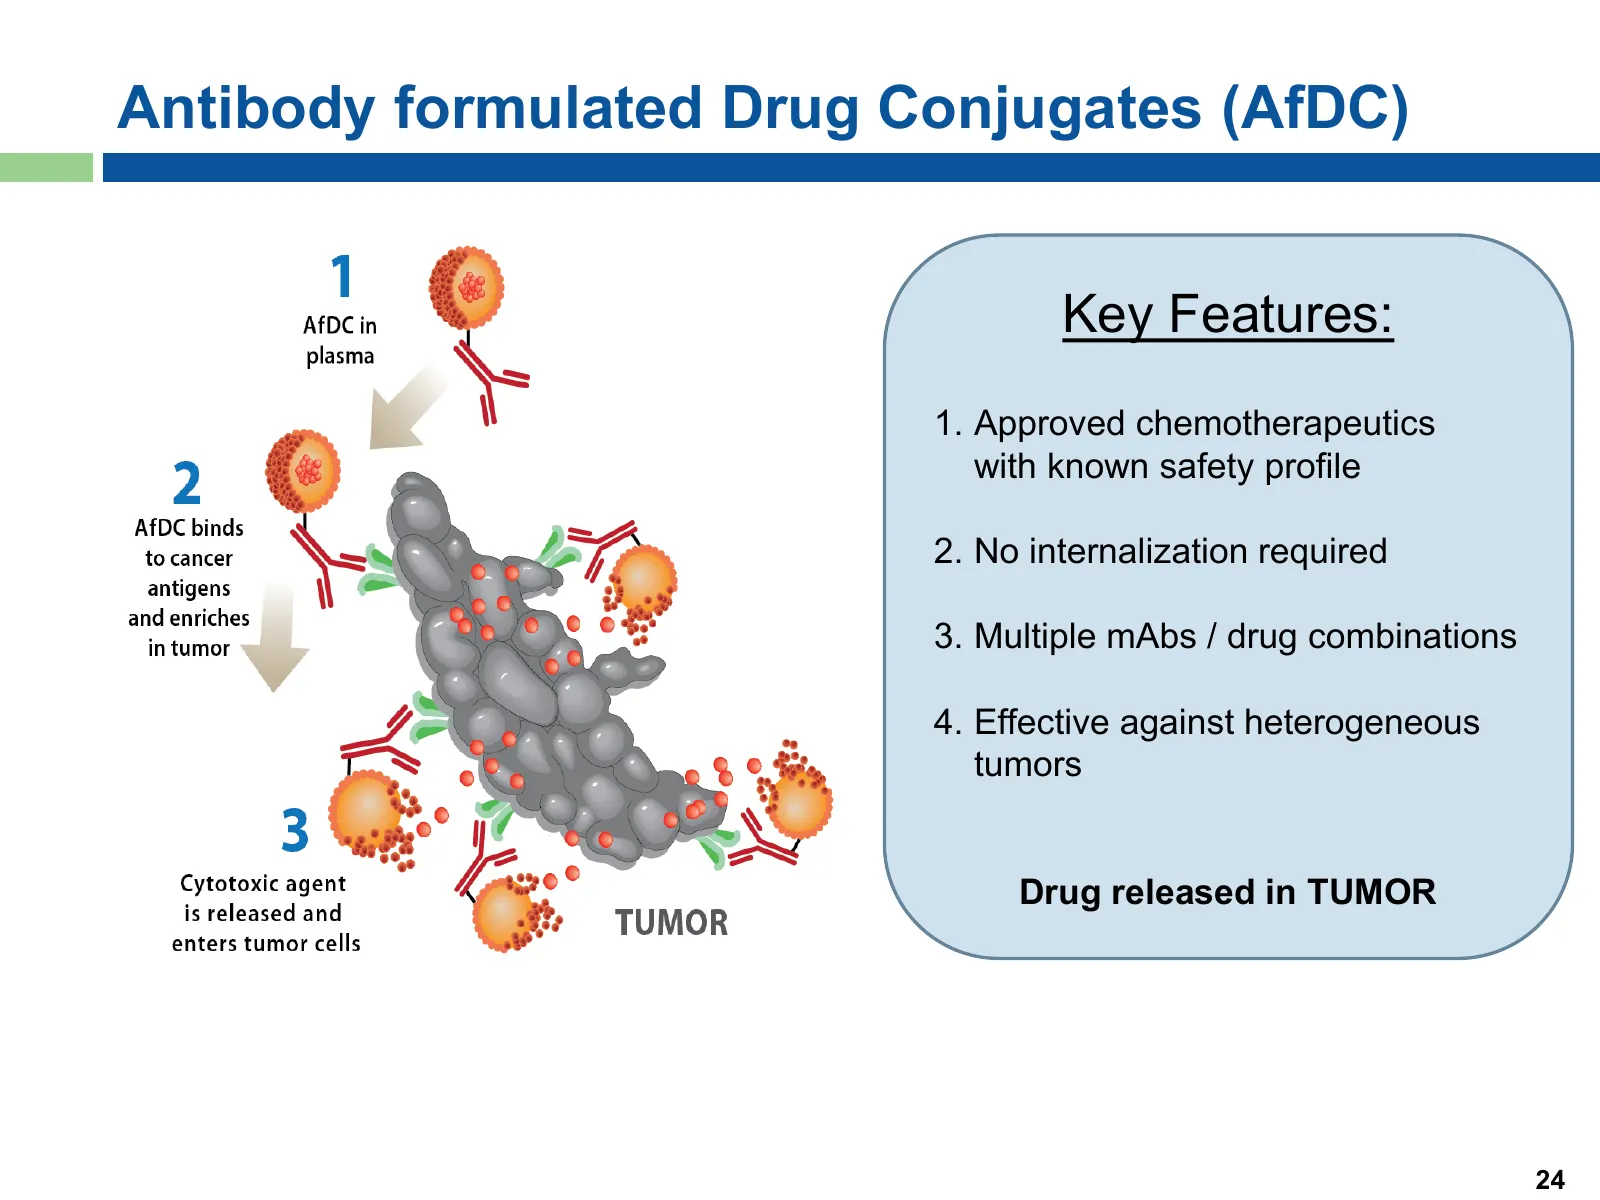
Slide 24: Antibody formulated Drug Conjugates (AfDC)
Current AntibodyParadigm formulated of Cancer Drug Conjugates Therapy (AfDC) Key Features: 1. Approved chemotherapeutics with known safety profile 2. No internalization required 3. Multiple mAbs / drug combinations 4. Effective against heterogeneous tumors Drug released in TUMOR 24
Slide 25: G-MAB, ADC and AfDC Pipeline
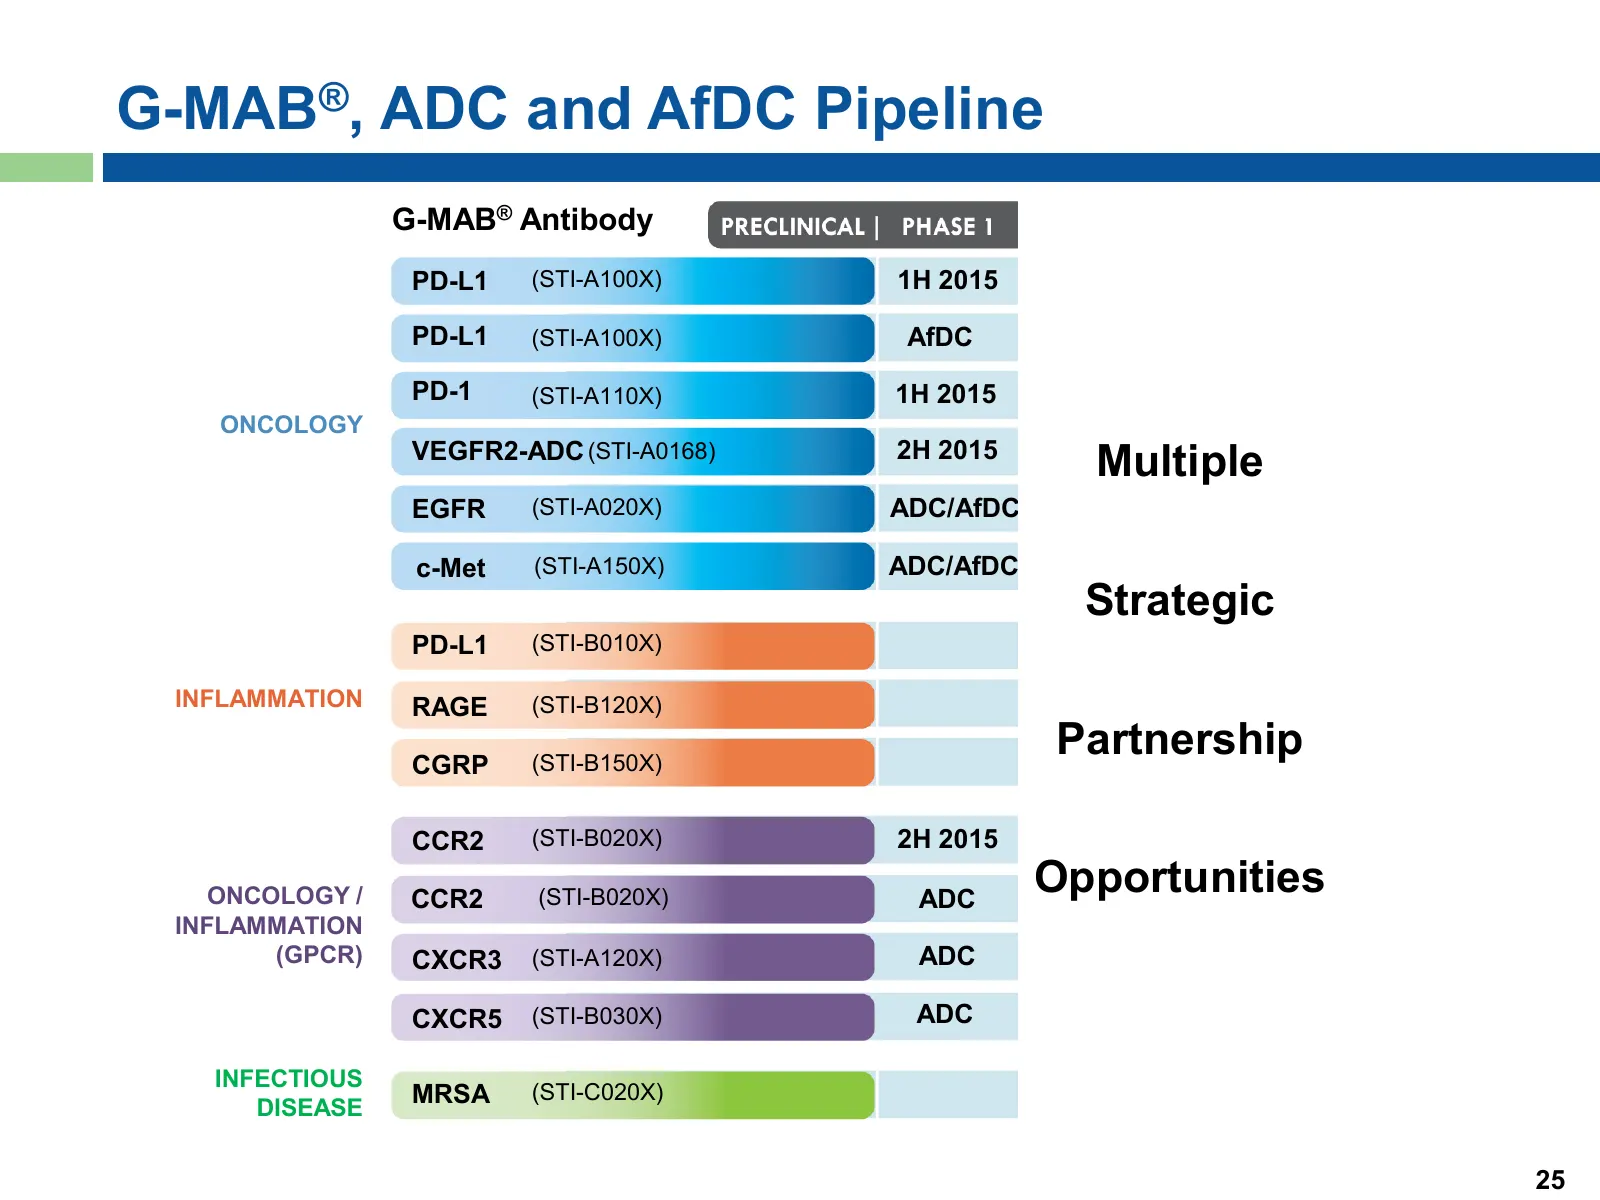
G-MAB®, ADC and AfDC Pipeline G-MAB® Antibody PD-L1 (STI-A100X) 1H 2015 PD-L1 (STI-A100X) AfDC PD-1 (STI-A110X) 1H 2015 ONCOLOGY VEGFR2-ADC (STI-A0168) 2H 2015 Multiple EGFR (STI-A020X) ADC/AfDC c-Met (STI-A150X) ADC/AfDC Strategic PD-L1 (STI-B010X) INFLAMMATION RAGE (STI-B120X) CGRP (STI-B150X) Par
Slide 26: Positioned to Become Oncology Leader
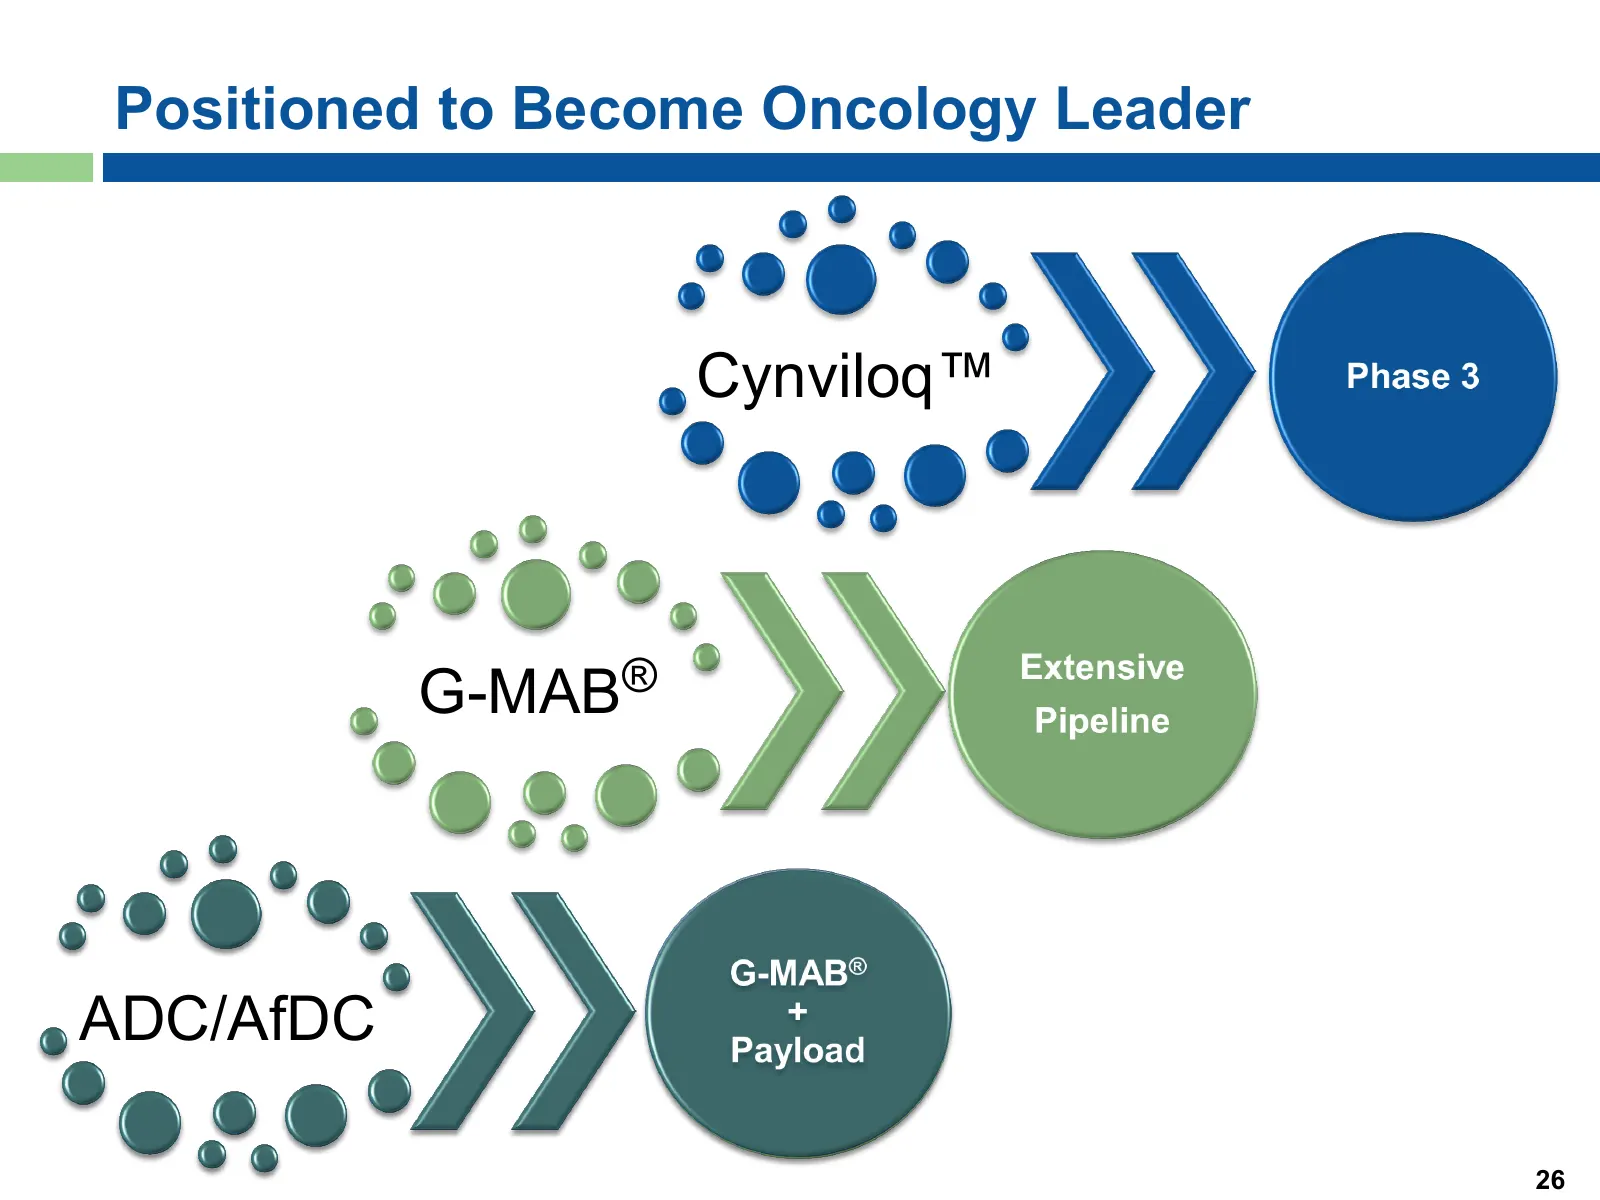
Positioned to Become Oncology Leader Cynviloq™ G-MAB® ADC/AfDC 26
Slide 27: Small Molecule Oncology Drug, Antibody Library and ADC Company Valuations
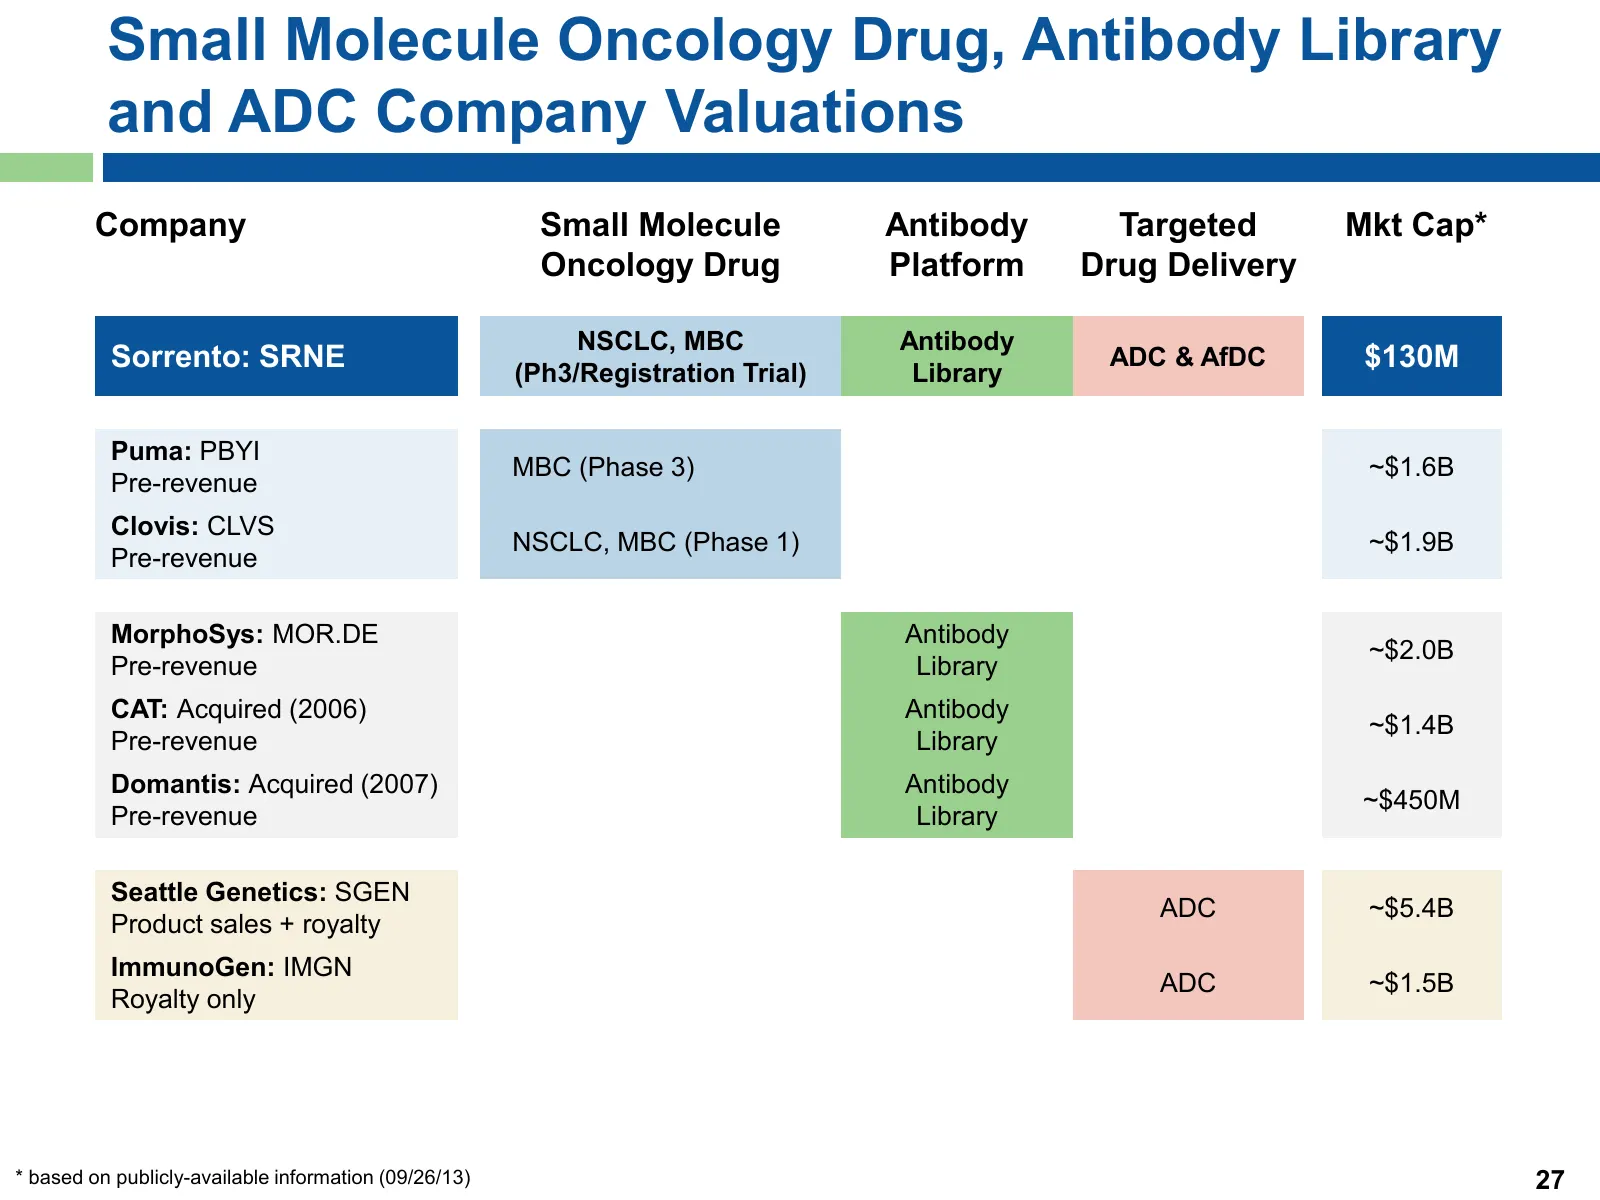
Small Molecule Oncology Drug, Antibody Library and ADC Company Valuations Company Small Molecule Antibody Targeted Mkt Cap* Oncology Drug Platform Drug Delivery NSCLC, MBC Antibody Sorrento: SRNE (Ph3/Registration Trial) Library ADC & AfDC $130M Puma: PBYI MBC (Phase 3) ~$1.6B Pre-revenue Clovis: CL
Slide 28: Investment Highlights
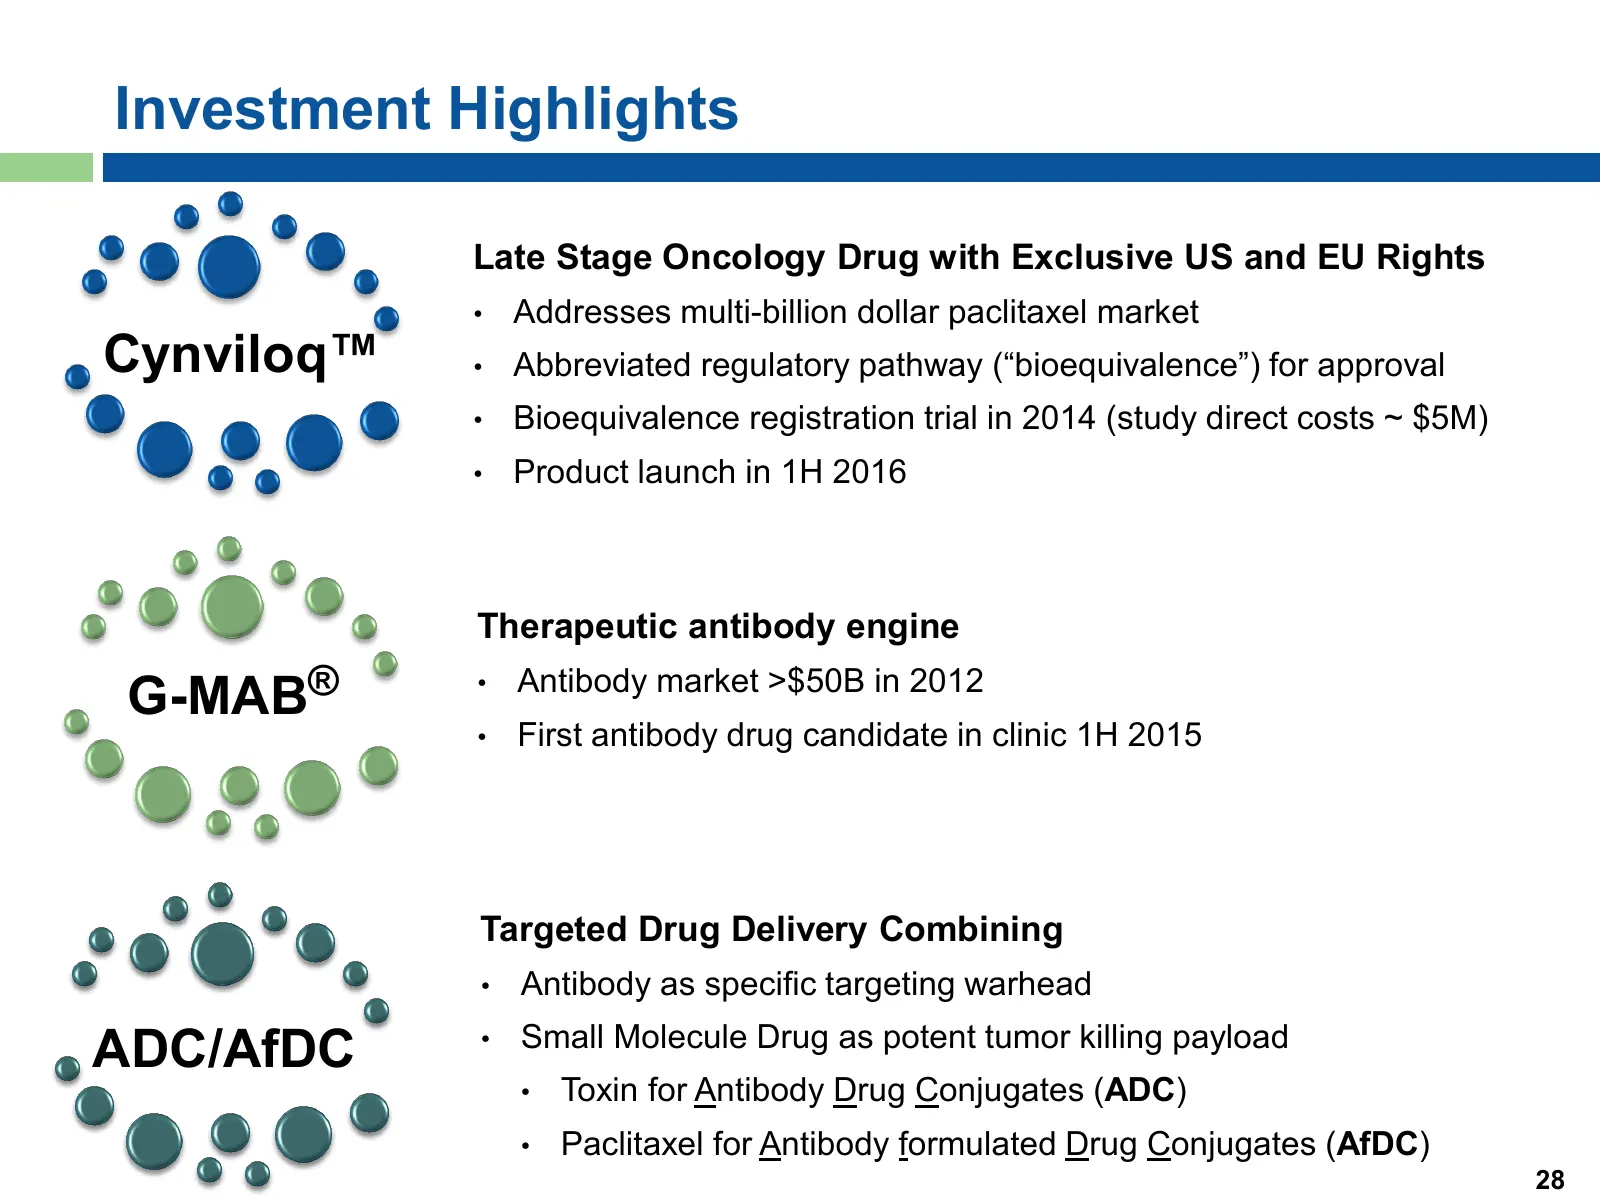
Investment Highlights Late Stage Oncology Drug with Exclusive US and EU Rights • Addresses multi-billion dollar paclitaxel market Cynviloq™ • Abbreviated regulatory pathway (“bioequivalence”) for approval • Bioequivalence registration trial in 2014 (study direct costs ~ $5M) • Product launch in 1H 2
Slide 29: Financials & Capitalization
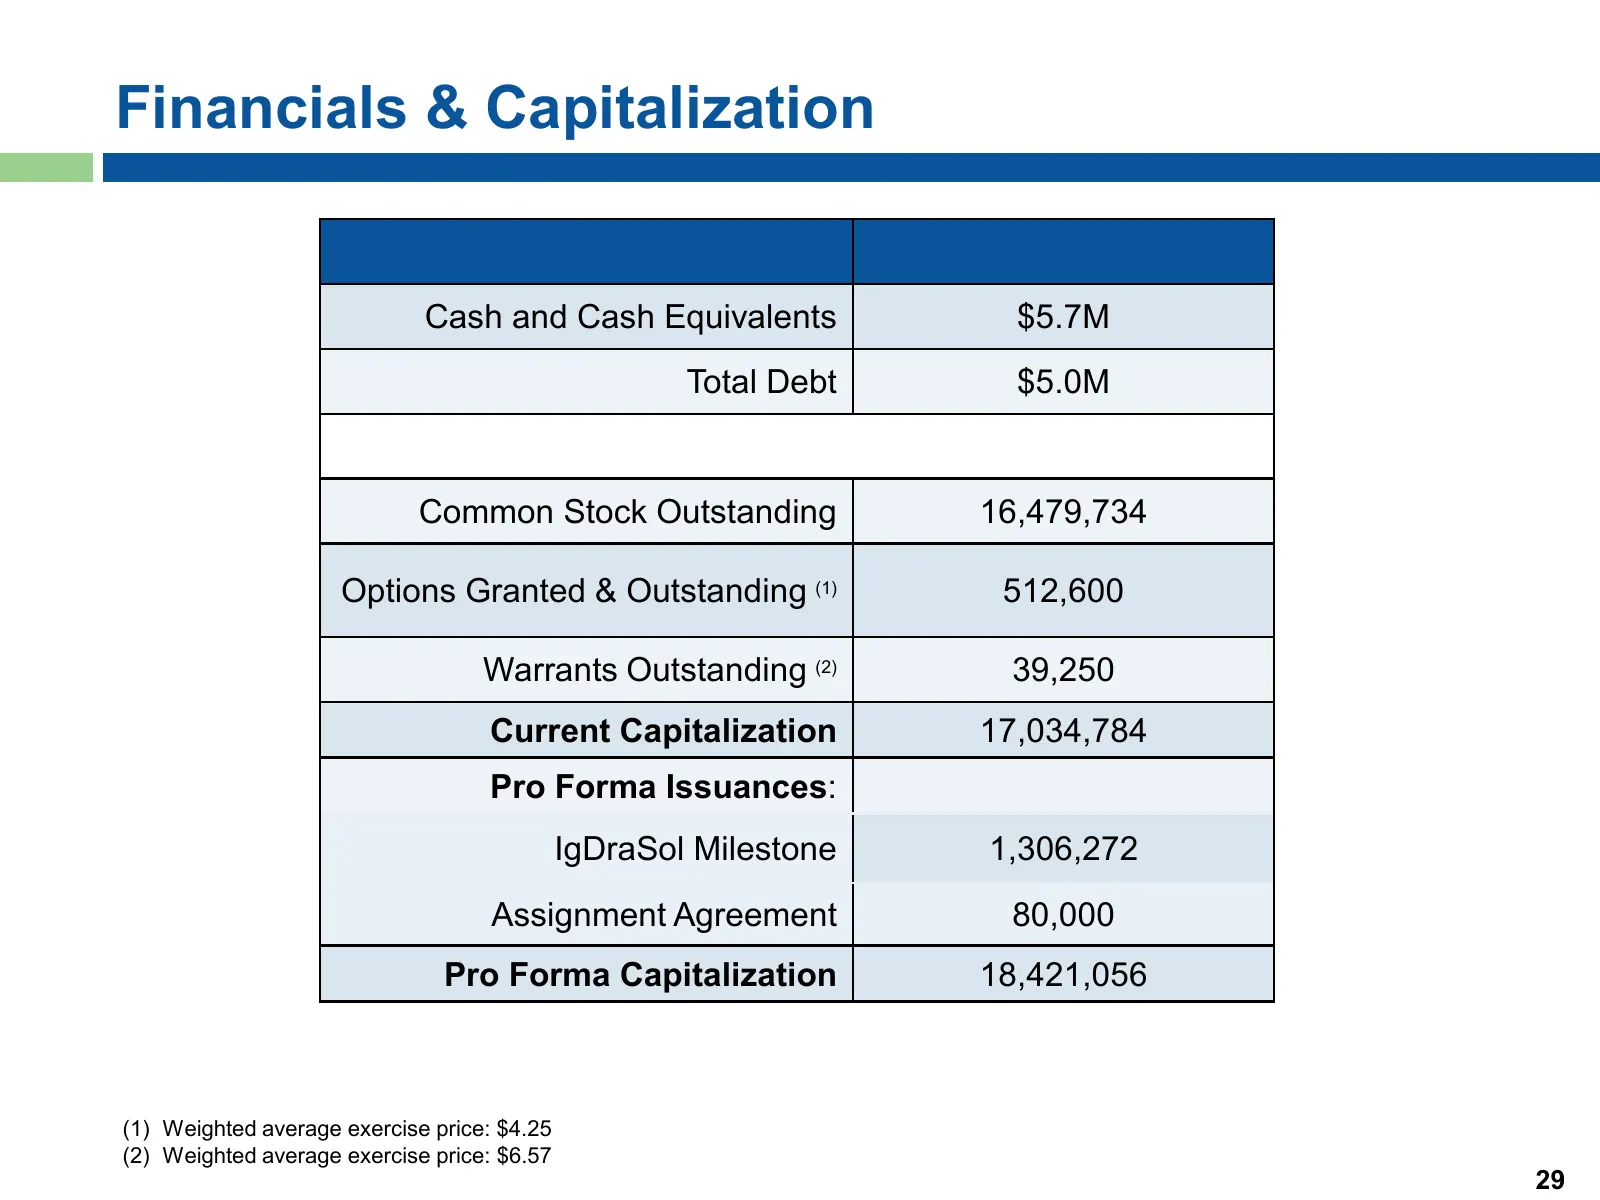
Financials & Capitalization Cash and Cash Equivalents $5.7M Total Debt $5.0M Common Stock Outstanding 16,479,734 Options Granted & Outstanding (1) 512,600 Warrants Outstanding (2) 39,250 Current Capitalization 17,034,784 Pro Forma Issuances: IgDraSol Milestone 1,306,272 Assignment Agreement 80,000 P
Slide 30: Sorrento Therapeutics Contact
Sorrento Therapeutics Next-Generation Cancer Therapeutics Contact: Henry Ji President and CEO hji@sorrentotherapeutics.com (858) 668-6923
Slide 31: Cynviloq: Interim Results from Phase 3 MBC Study
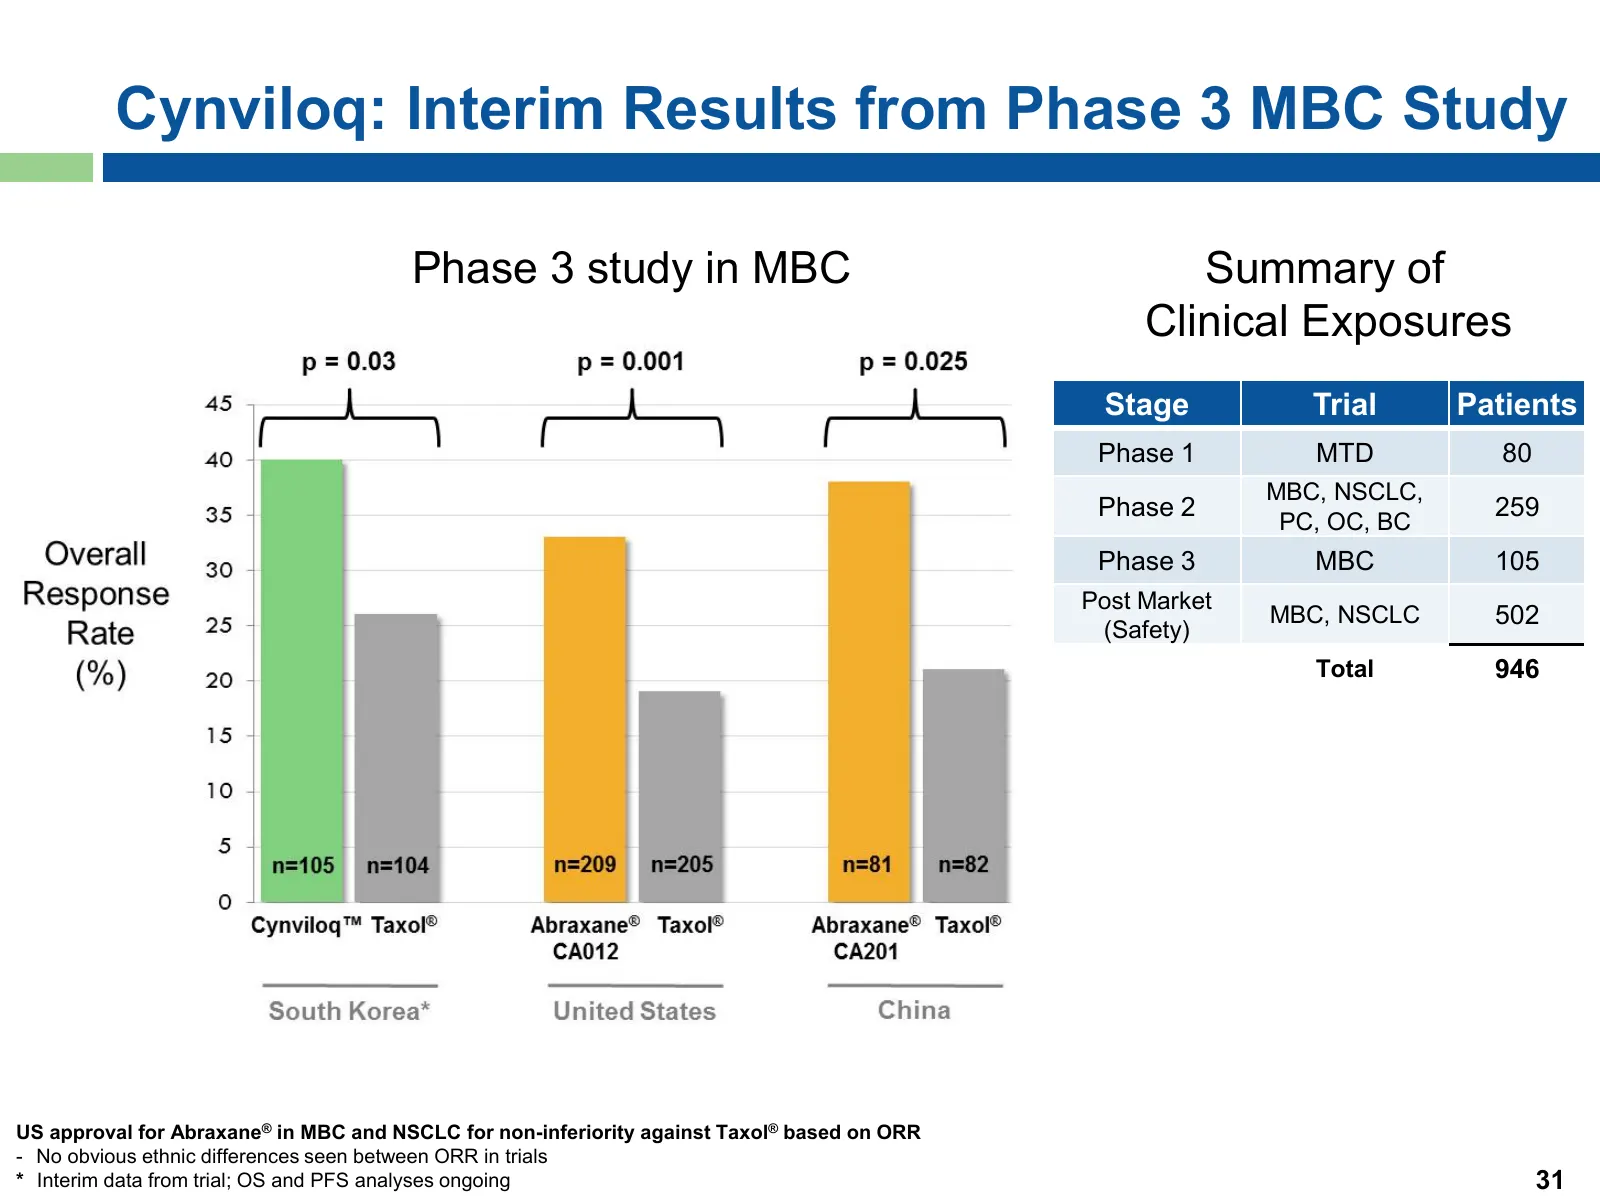
Cynviloq: Interim Results from Phase 3 MBC Study Phase 3 study in MBC Summary of Clinical Exposures Stage Trial Patients Phase 1 MTD 80 MBC, NSCLC, Phase 2 259 PC, OC, BC Phase 3 MBC 105 Post Market MBC, NSCLC 502 (Safety) Total 946 US approval for Abraxane® in MBC and NSCLC for non-inferiority agai
Slide 32: Simulated PK Parameters Supportive of BE
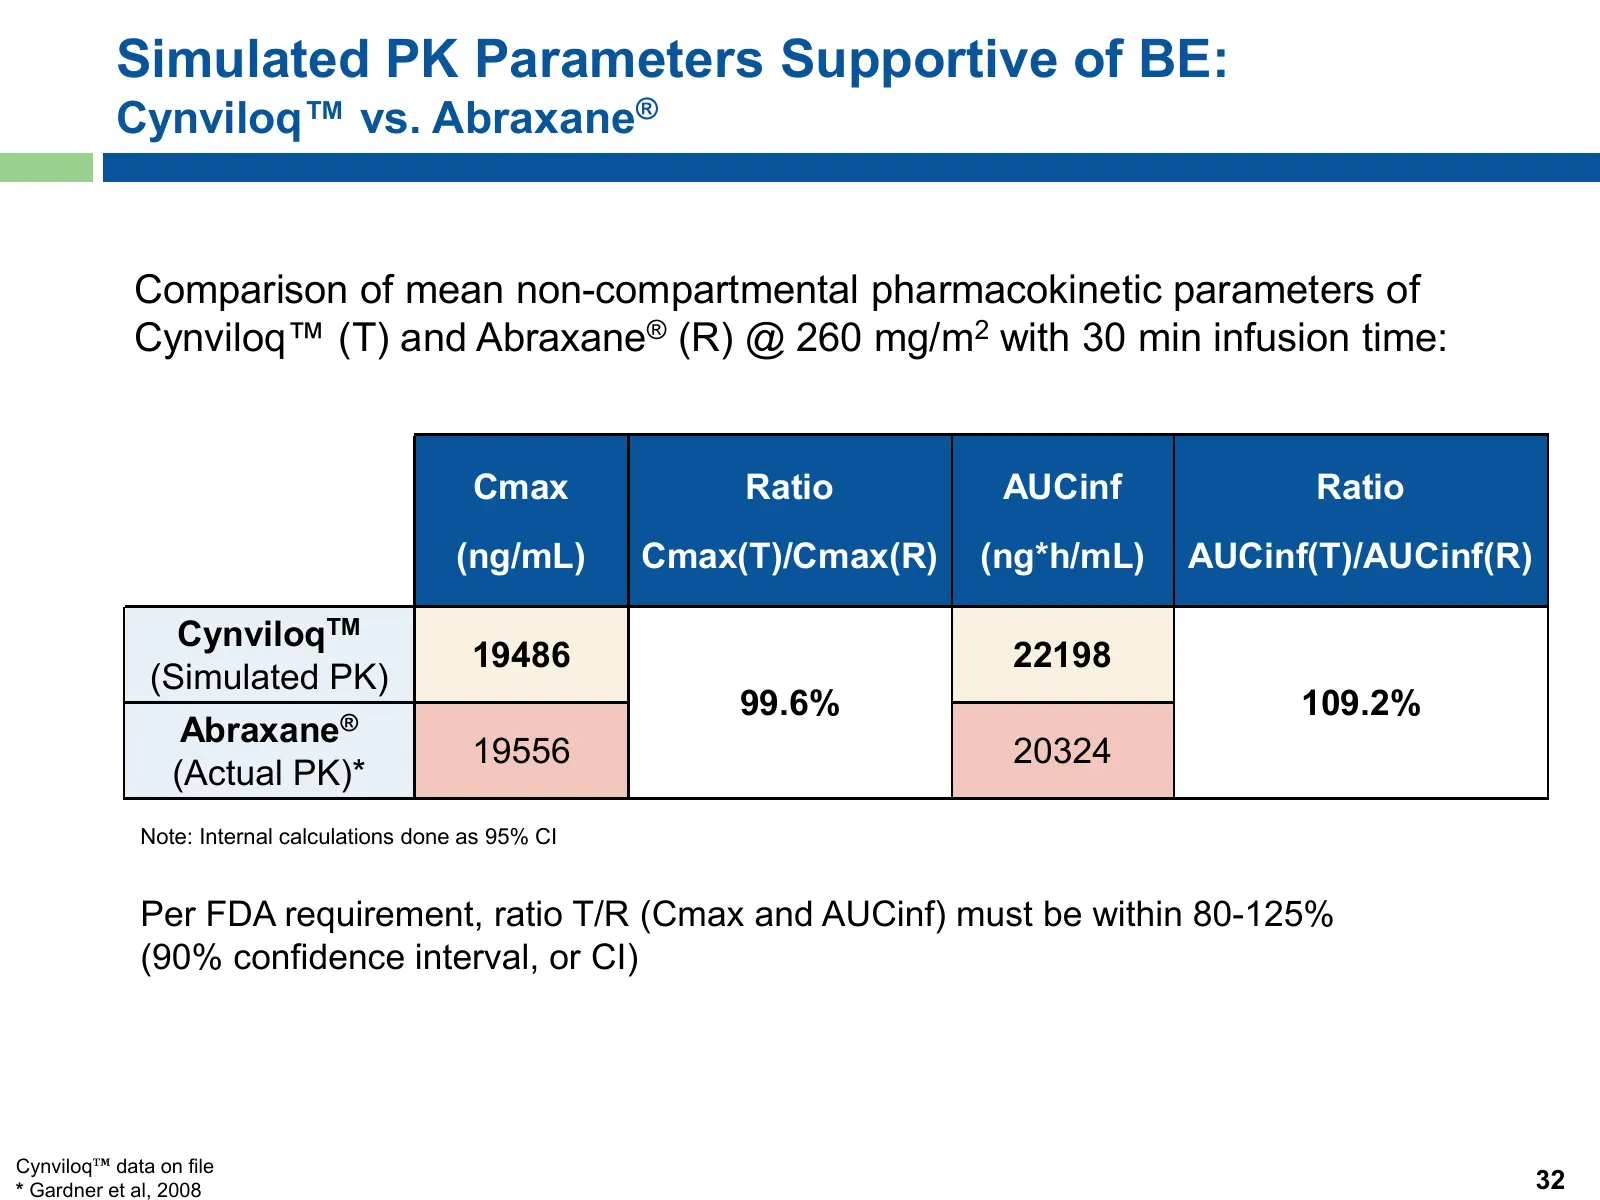
Simulated PK Parameters Supportive of BE: Cynviloq™ vs. Abraxane® Comparison of mean non-compartmental pharmacokinetic parameters of Cynviloq™ (T) and Abraxane® (R) @ 260 mg/m2 with 30 min infusion time: Cmax Ratio AUCinf Ratio (ng/mL) Cmax(T)/Cmax(R) (ng*h/mL) AUCinf(T)/AUCinf(R) CynviloqTM 19486 2
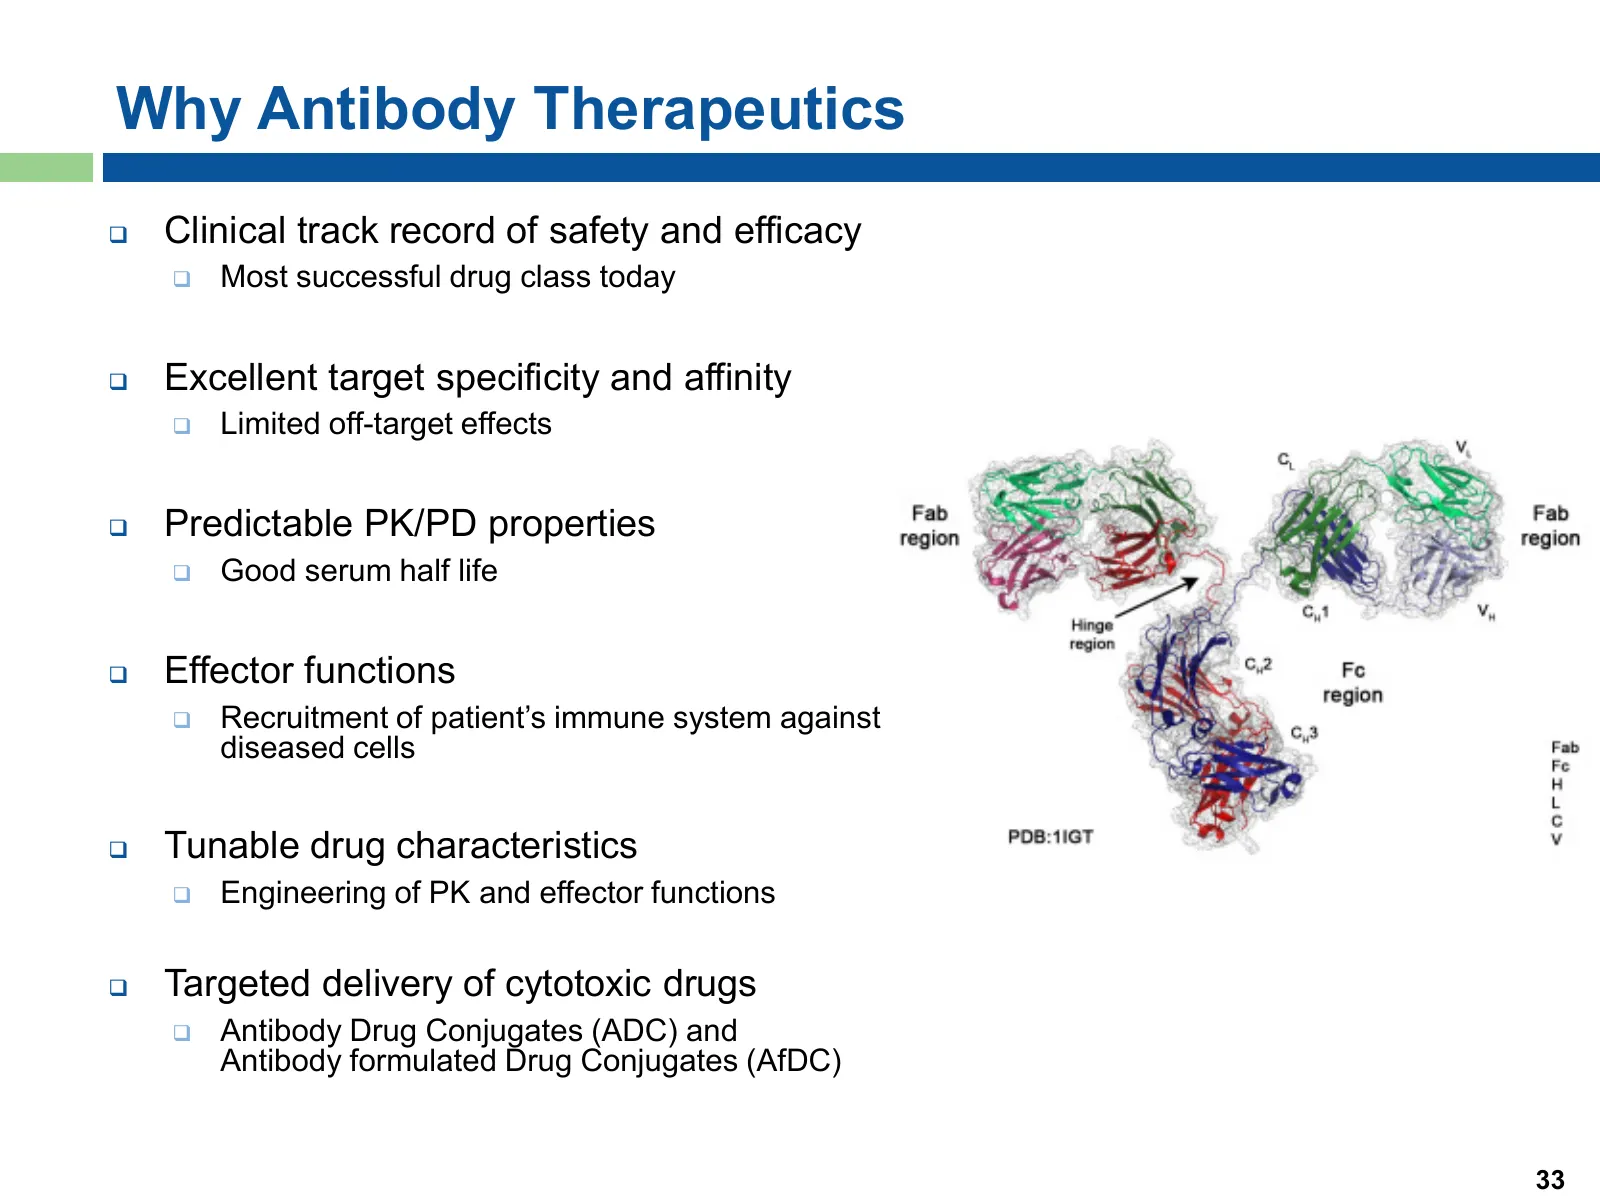
Slide 33: Why Antibody Therapeutics
Why Antibody Therapeutics Clinical track record of safety and efficacy Most successful drug class today Excellent target specificity and affinity Limited off-target effects Predictable PK/PD properties Good serum half life Effector functions Recruitment of patient’s immune system aga
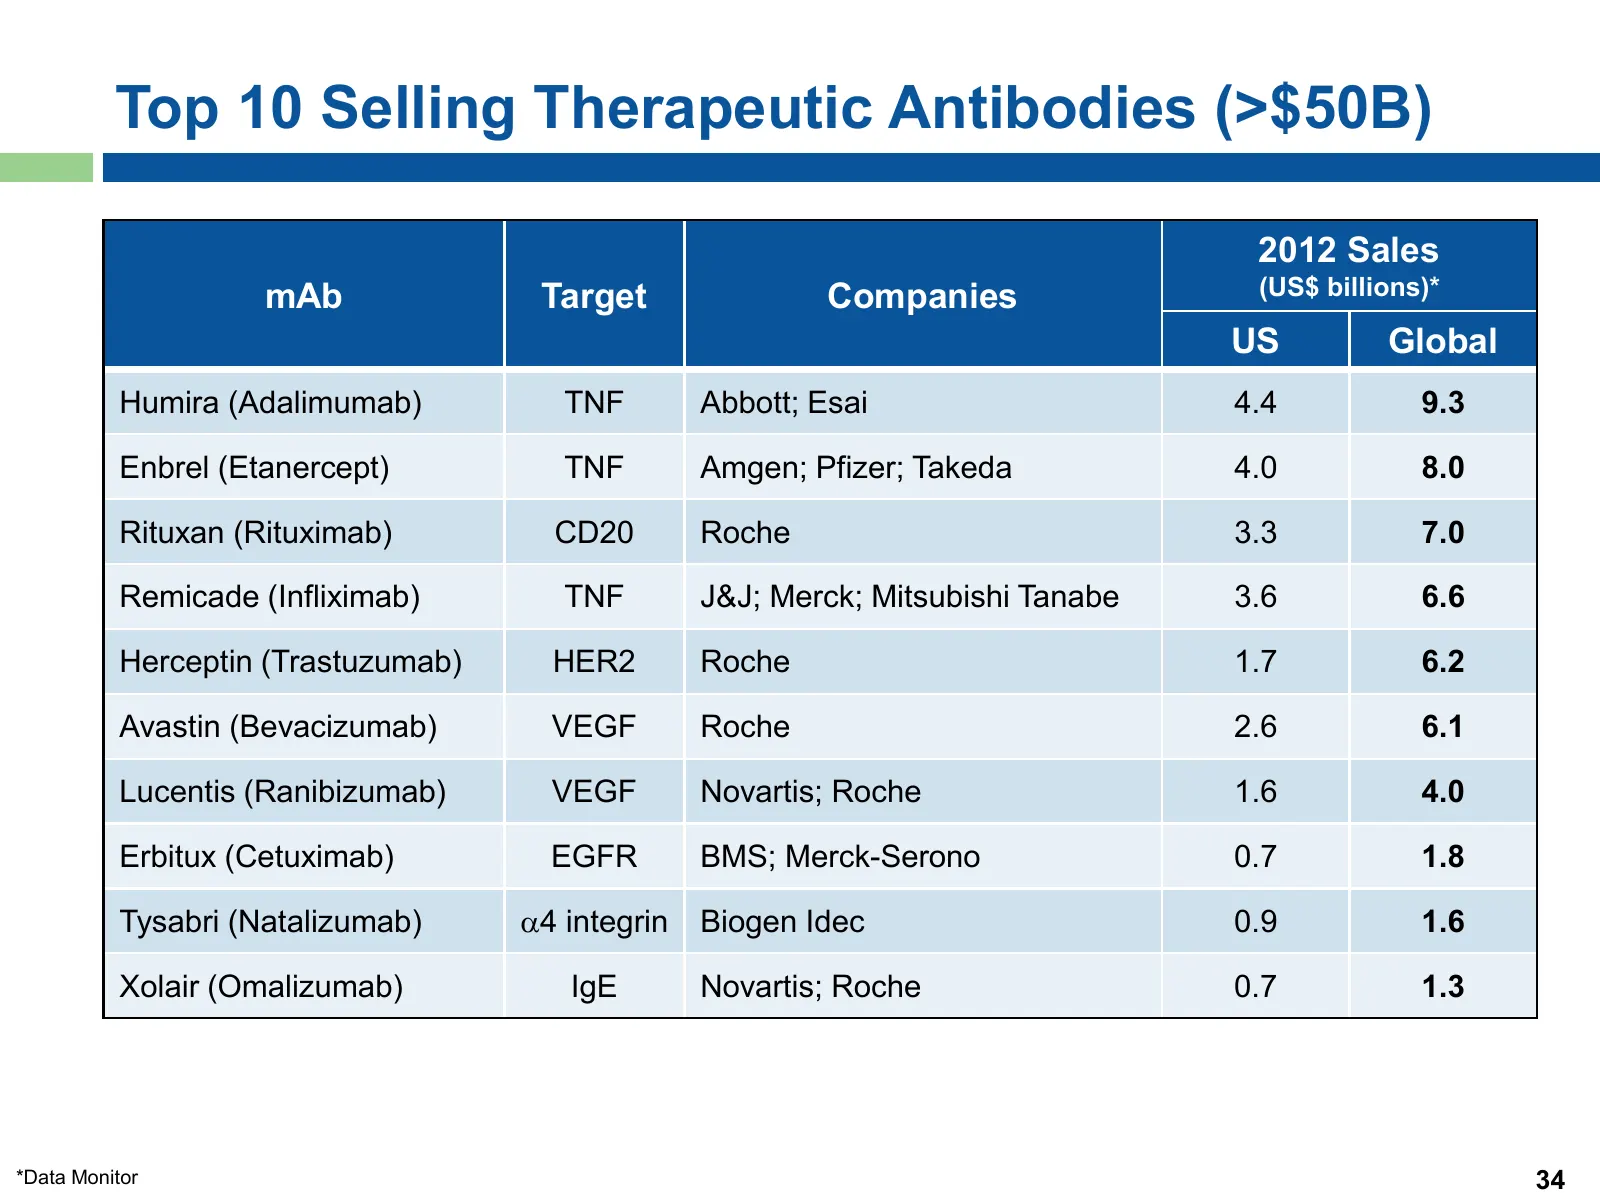
Slide 34: Top Selling Therapeutic Antibodies
Top 10 Selling Therapeutic Antibodies (>$50B) 2012 Sales mAb Target Companies (US$ billions)* US Global Humira (Adalimumab) TNF Abbott; Esai 4.4 9.3 Enbrel (Etanercept) TNF Amgen; Pfizer; Takeda 4.0 8.0 Rituxan (Rituximab) CD20 Roche 3.3 7.0 Remicade (Infliximab) TNF J&J; Merck; Mitsubishi Tanabe 3.
Source: Internet Archive copy of sorrentotherapeutics.com
More decks from Sorrento Therapeutics, Inc.
 Presentation (August 2023)9 slides · Aug 1, 2023
 SPAC Merger (March 2022)21 slides · Mar 18, 2022
 Technical Presentation (January 2022)13 slides · Jan 21, 2022
 SPAC Merger (December 2021)57 slides · Dec 13, 2021
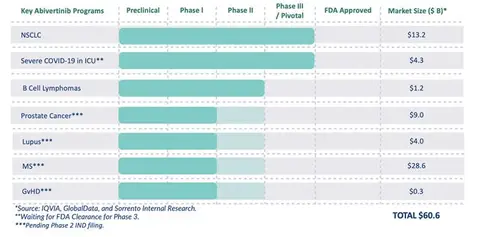 Technical Presentation (November 2021)9 slides · Nov 29, 2021
 Investor Presentation (September 2021)37 slides · Sep 13, 2021