South Jersey Industries — Williams Capital Conference 2014
35 slides from South Jersey Industries's conference presentation, Apr 10, 2014
Slide 1: Williams Capital Conference
Williams Capital Conference Chicago, IL April 10, 2014
Slide 2: Forward-looking statements
Certain statements contained in this presentation may qualify as “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. All statements other than statements of historical fact included in this Report should
Slide 3: Organization of Business Lines
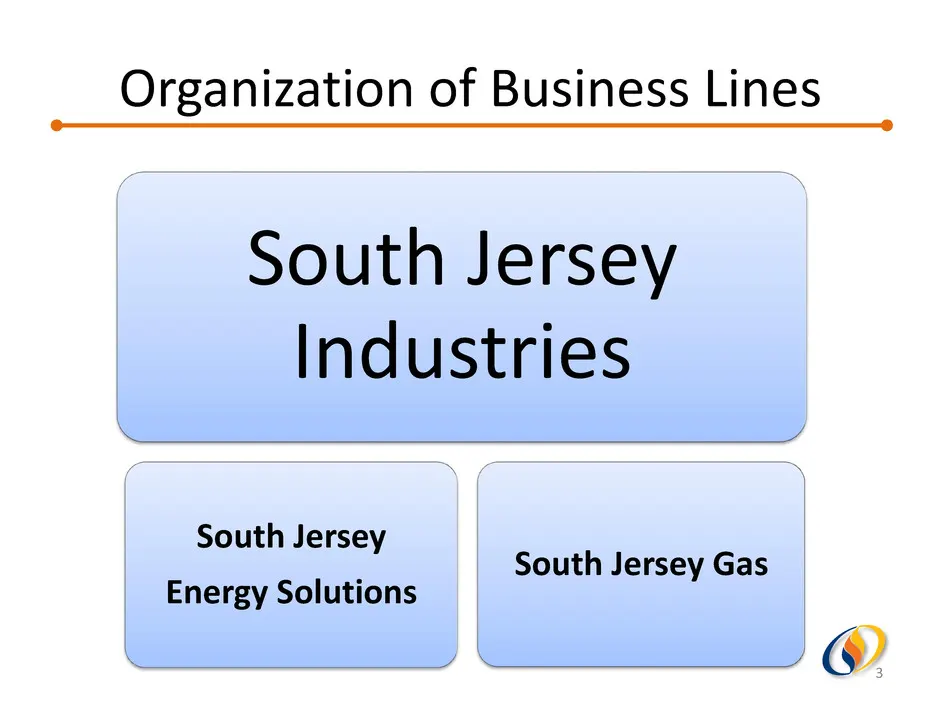
Organization of Business Lines South Jersey Industries South Jersey Energy Solutions South Jersey Gas 3
Slide 4: SJES Regroups
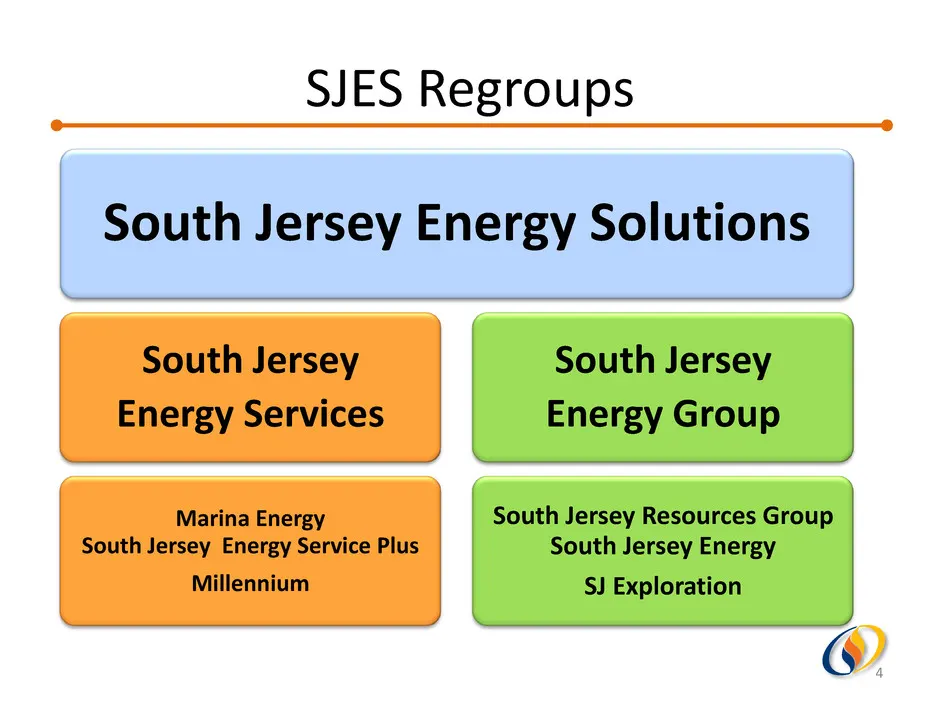
SJES Regroups South Jersey Energy Solutions South Jersey Energy Services Marina Energy South Jersey Energy Service Plus Millennium South Jersey Energy Group South Jersey Resources Group South Jersey Energy SJ Exploration 4
Slide 5: Senior Management Team
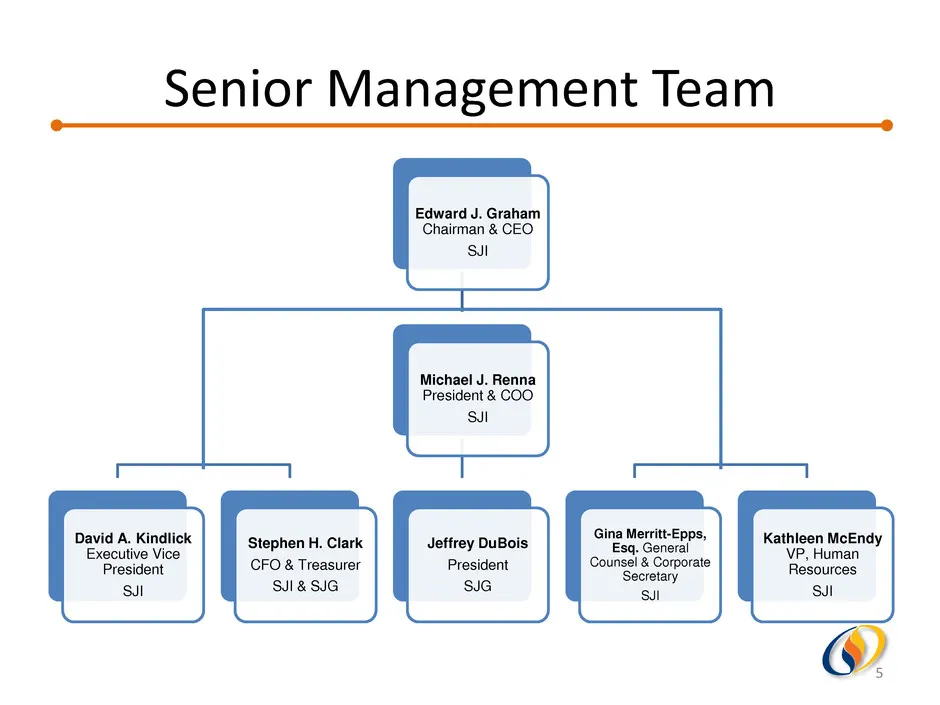
Senior Management Team 5 Edward J. Graham Chairman & CEO SJI David A. Kindlick Executive Vice President SJI Stephen H. Clark CFO & Treasurer SJI & SJG Michael J. Renna President & COO SJI Jeffrey DuBois President SJG Gina Merritt-Epps, Esq. General Counsel & Corporate Secretary SJI Kathleen McEndy V
Slide 6: Long Term Performance - Dividend Growth
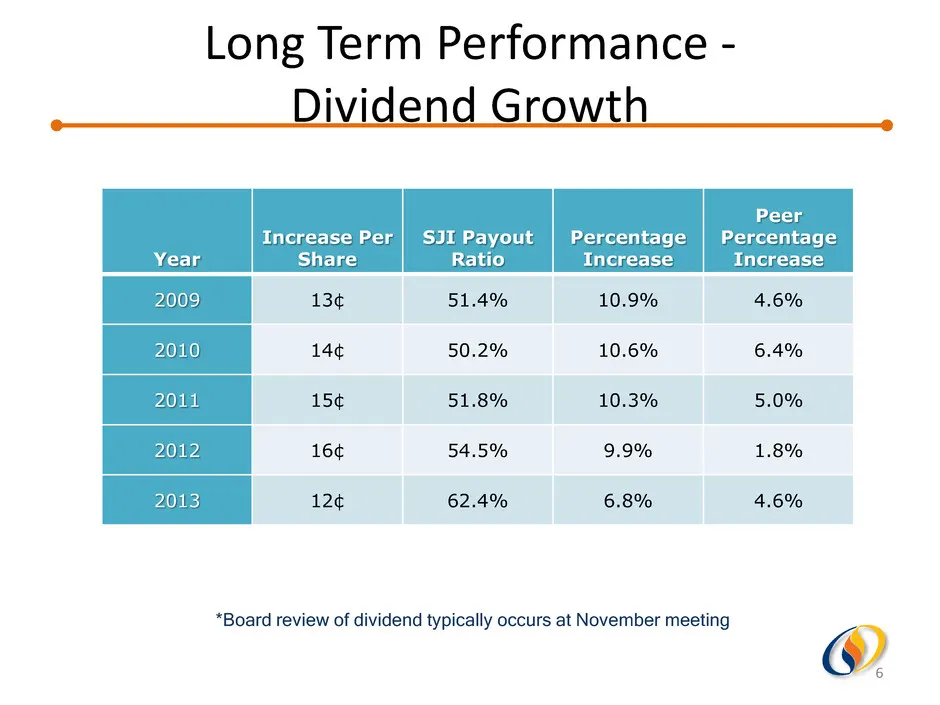
*Board review of dividend typically occurs at November meeting Year Increase Per Share SJI Payout Ratio Percentage Increase Peer Percentage Increase 2009 13¢ 51.4% 10.9% 4.6% 2010 14¢ 50.2% 10.6% 6.4% 2011 15¢ 51.8% 10.3% 5.0% 2012 16¢ 54.5% 9.9% 1.8% 2013 12¢ 62.4% 6.8% 4.6% Long Term Performance -
Slide 7: Total Shareholder Return
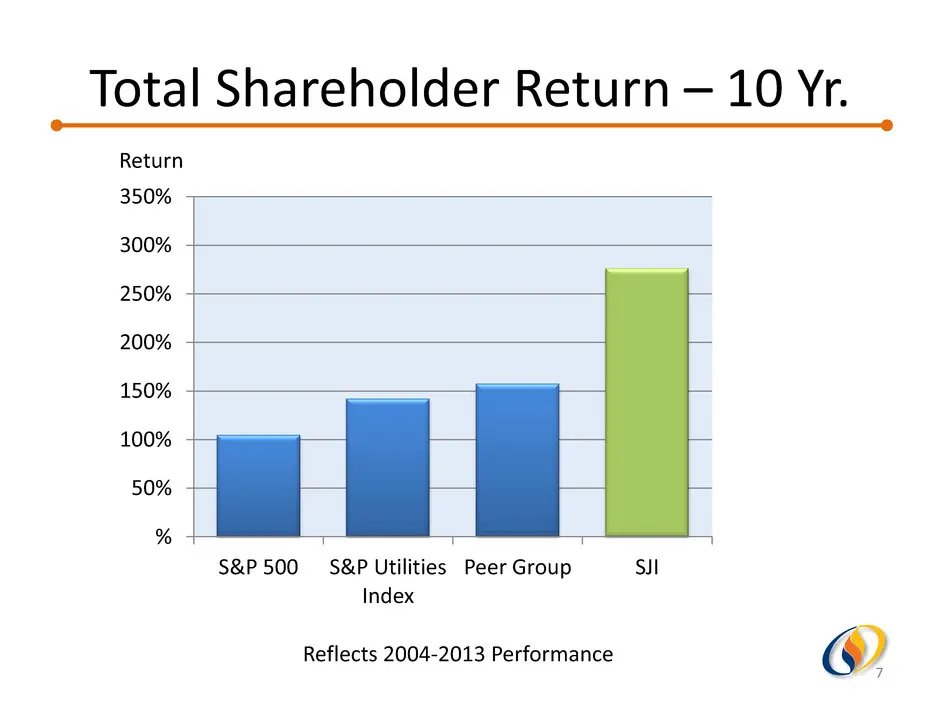
Total Shareholder Return – 10 Yr. % 50% 100% 150% 200% 250% 300% 350% S&P 500 S&P Utilities Index Peer Group SJI Return 7 Reflects 2004-2013 Performance
Slide 8: Near-Term Performance: Economic Earnings
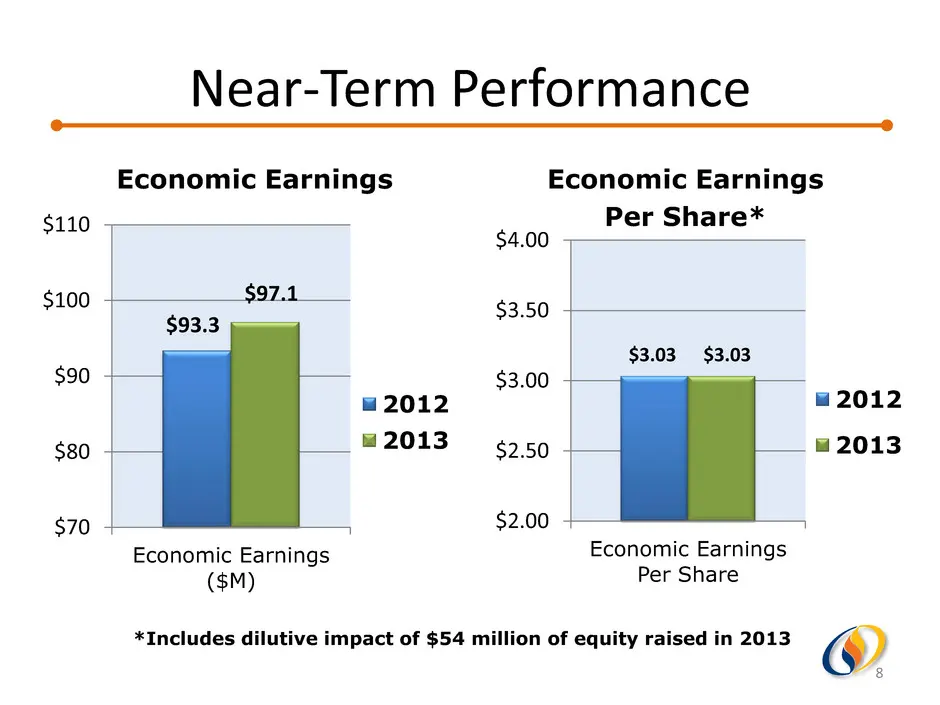
Near-Term Performance 8 Economic Earnings $70 $80 $90 $100 $110 Economic Earnings ($M) 2012 2013 $93.3 $97.1 Economic Earnings Per Share* $2.00 $2.50 $3.00 $3.50 $4.00 Economic Earnings Per Share 2012 2013 $3.03 $3.03 *Includes dilutive impact of $54 million of equity raised in 2013
Slide 9: Near-Term Performance: Economic Earnings Contribution
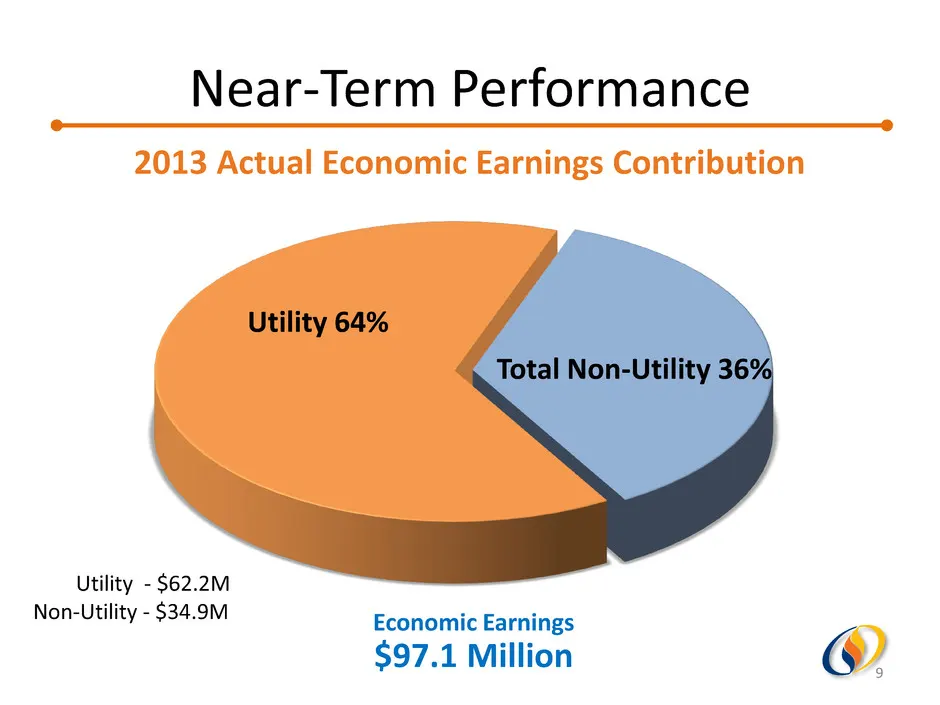
Near-Term Performance 9 Utility 64% Economic Earnings $97.1 Million 2013 Actual Economic Earnings Contribution Total Non-Utility 36% Utility - $62.2M Non-Utility - $34.9M
Slide 10: Near-Term Performance: 2014 Guidance
Near-Term Performance 2014 Guidance 6-12% EPS growth ($3.21 to $3.39) • Utility – Customer growth/Conversion goal – Rate case • Non-utility – Natural gas transmission capacity – Energy project portfolio 10
Slide 11: 2014 Preview: Expected Contributions to Earnings
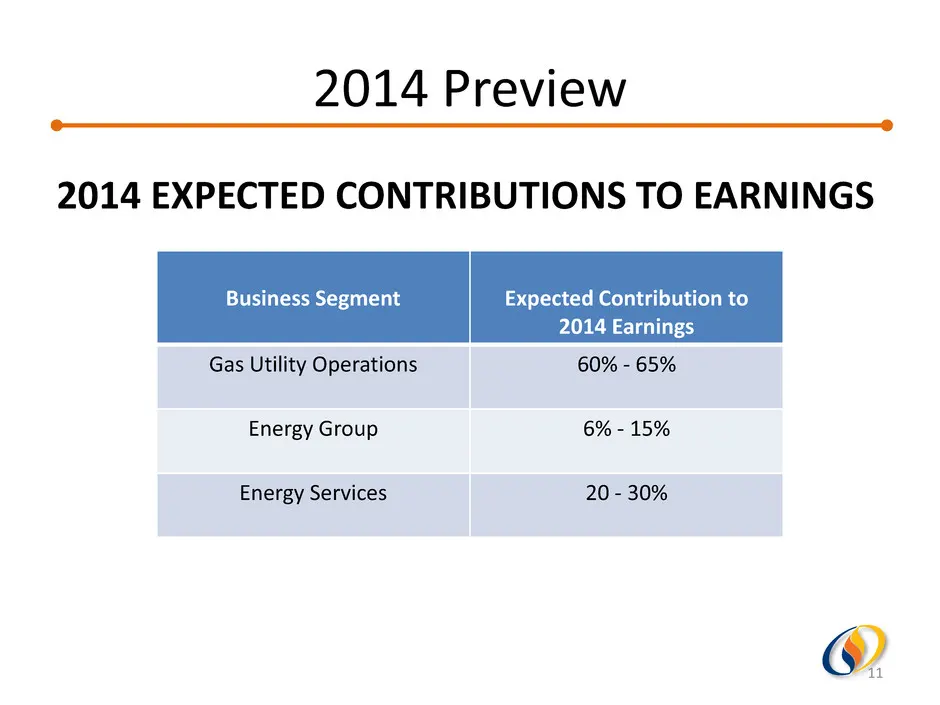
2014 Preview 2014 EXPECTED CONTRIBUTIONS TO EARNINGS 11 Business Segment Expected Contribution to 2014 Earnings Gas Utility Operations 60% - 65% Energy Group 6% - 15% Energy Services 20 - 30%
Slide 12: 2014 Preview: Planned Capital Expenditures
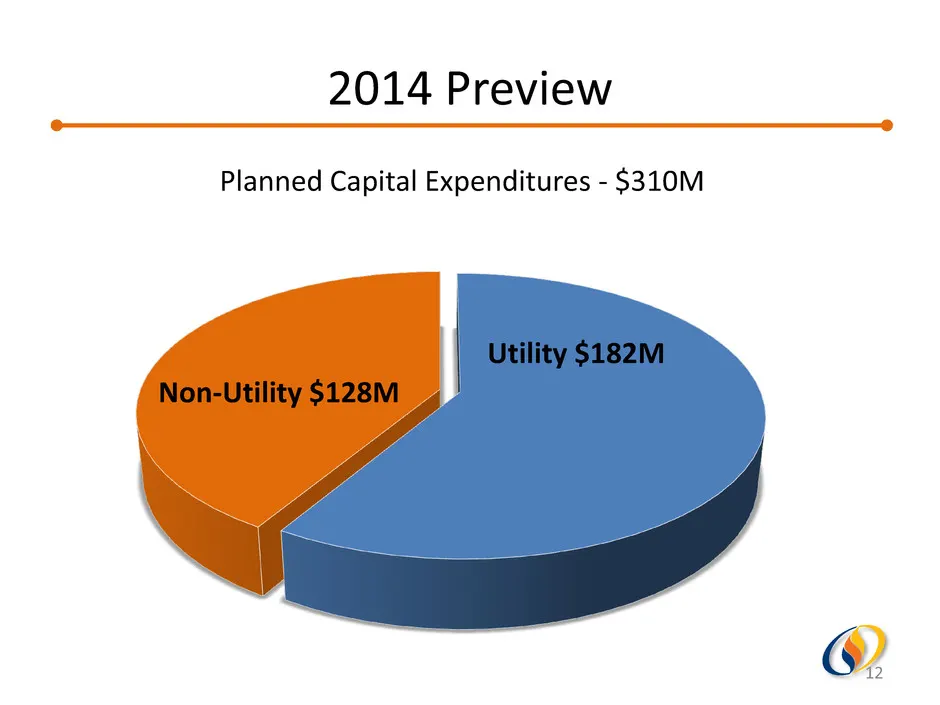
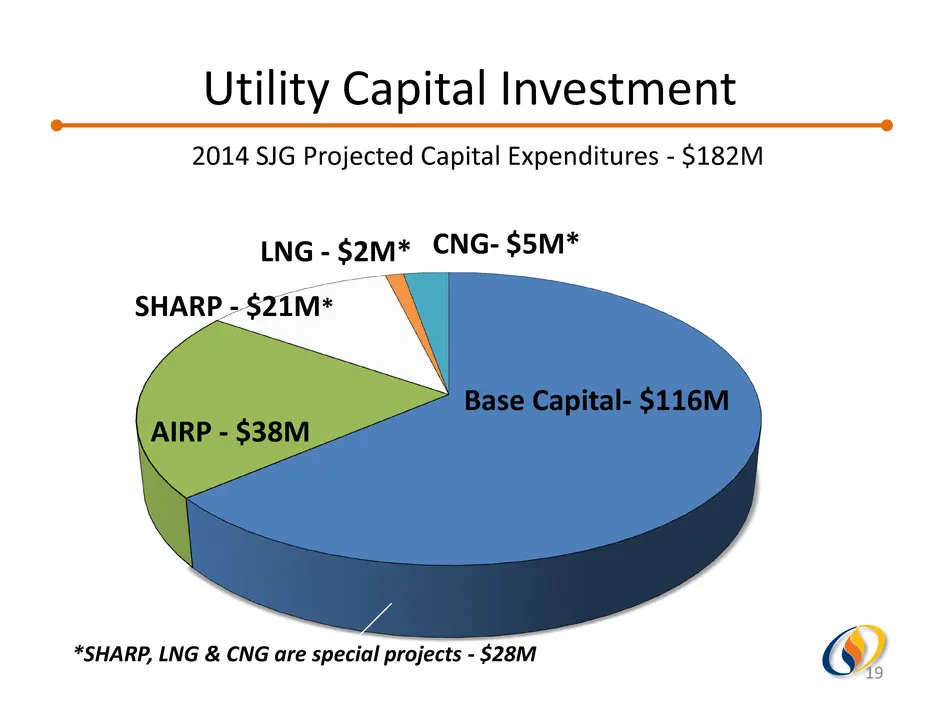
2014 Preview Non-Utility $128M 12 Utility $182M Planned Capital Expenditures - $310M
Slide 13: The Future of SJI
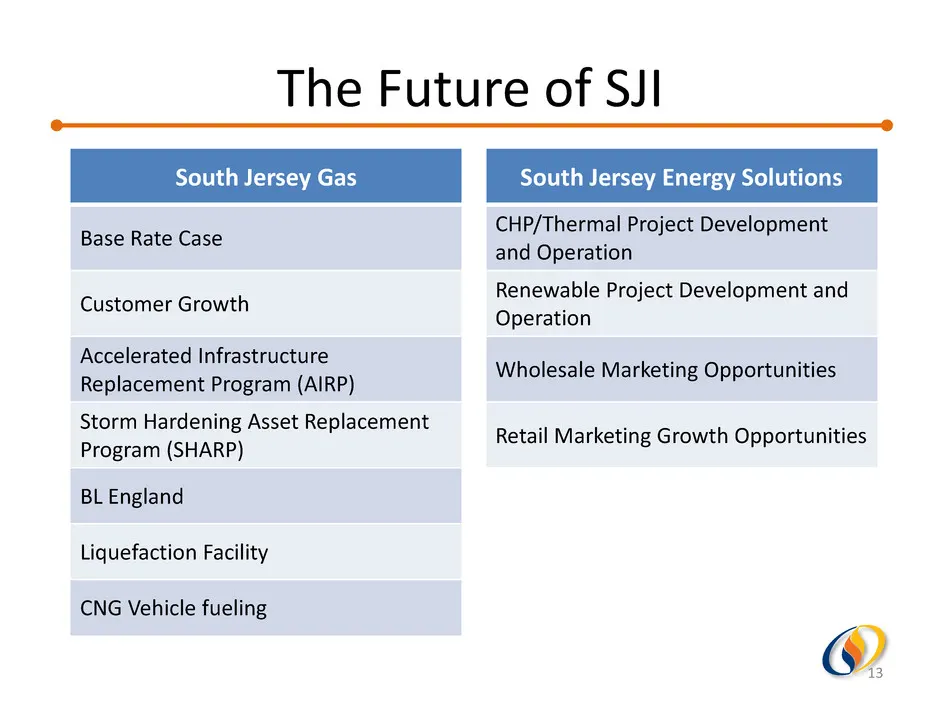
The Future of SJI South Jersey Gas South Jersey Energy Solutions Base Rate Case CHP/Thermal Project Development and Operation Customer Growth Renewable Project Development and Operation Accelerated Infrastructure Replacement Program (AIRP) Wholesale Marketing Opportunities Storm Hardening Asset Repl
Slide 14: South Jersey Gas
@ South Jersey Gas
Slide 15: SJG Service Area
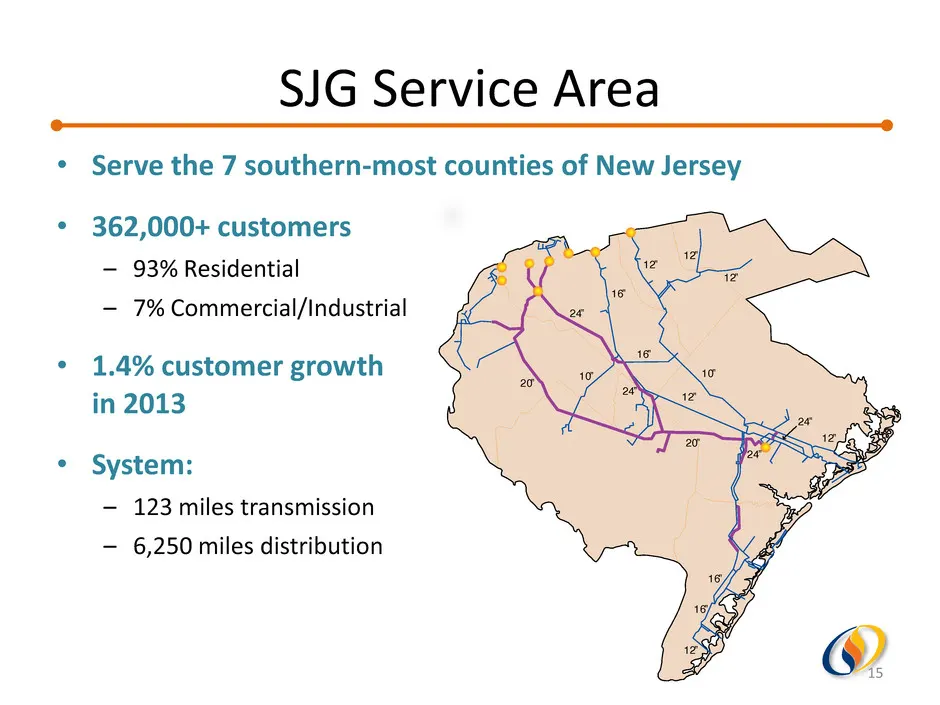
SJG Service Area 15 24” 12” 12” 12” 16” 16” 20” 20” 12” 12” 10” 24” 24” 10” 24” 16” 16” 12” • Serve the 7 southern-most counties of New Jersey • 362,000+ customers – 93% Residential – 7% Commercial/Industrial • 1.4% customer growth in 2013 • System: – 123 miles transmission – 6,250 miles distributio
Slide 16: Utility Growth Drivers
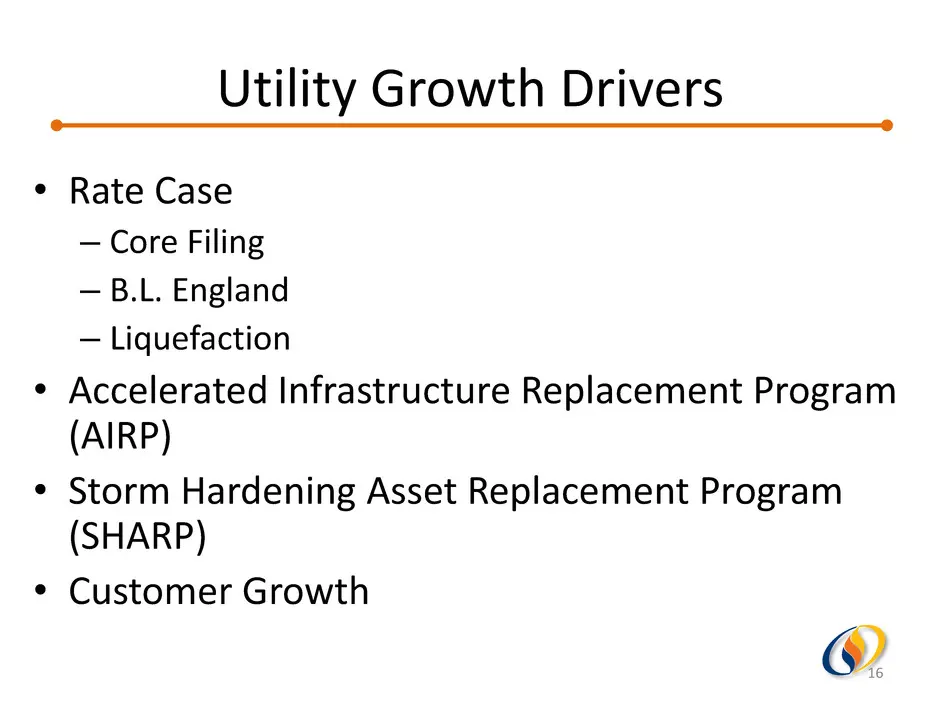
Utility Growth Drivers • Rate Case – Core Filing – B.L. England – Liquefaction • Accelerated Infrastructure Replacement Program (AIRP) • Storm Hardening Asset Replacement Program (SHARP) • Customer Growth 16
Slide 17: Base Rate Case
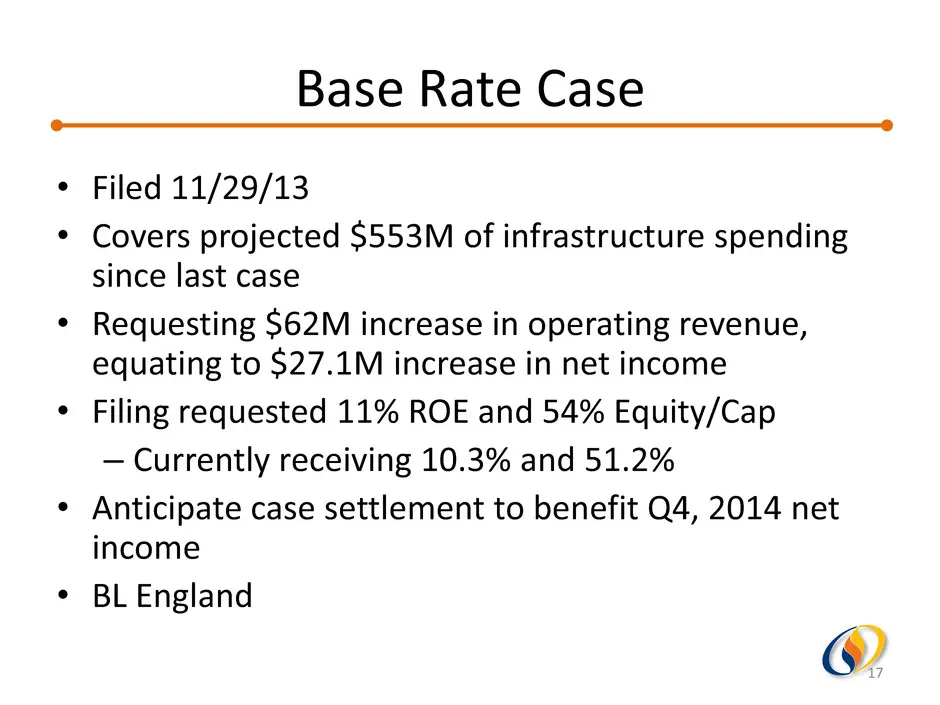
Base Rate Case • Filed 11/29/13 • Covers projected $553M of infrastructure spending since last case • Requesting $62M increase in operating revenue, equating to $27.1M increase in net income • Filing requested 11% ROE and 54% Equity/Cap – Currently receiving 10.3% and 51.2% • Anticipate case settlem
Slide 18: Utility Capital Investment
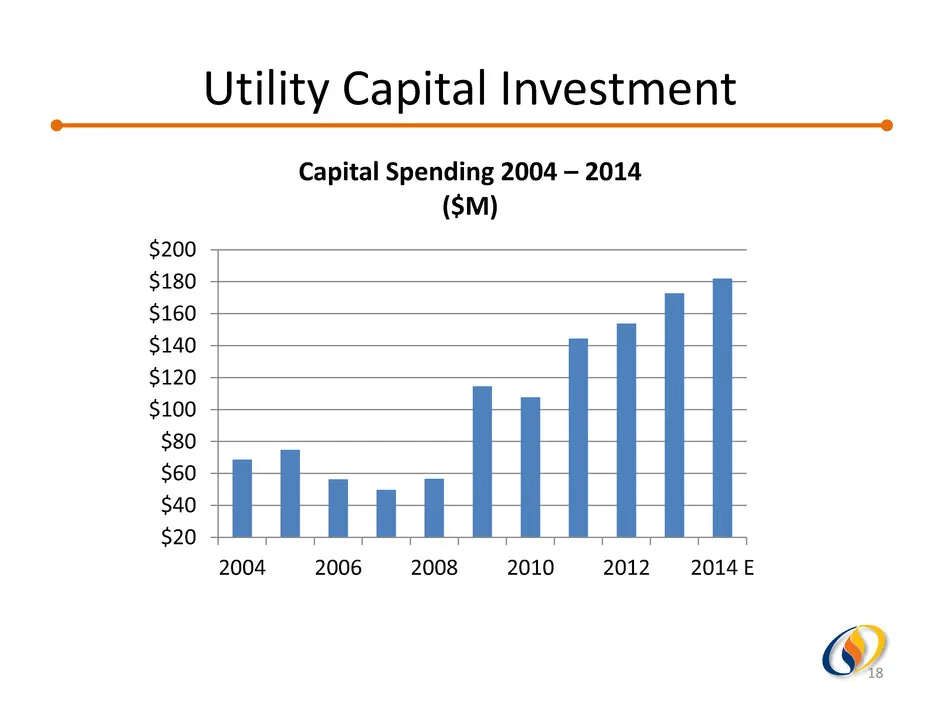
Utility Capital Investment 18 $20 $40 $60 $80 $100 $120 $140 $160 $180 $200 2004 2006 2008 2010 2012 2014 E Capital Spending 2004 – 2014 ($M)
Slide 19: Utility Capital Investment: 2014 Projected Capital Expenditures
Utility Capital Investment AIRP - $38M 19 LNG - $2M* CNG- $5M* Base Capital- $116M *SHARP, LNG & CNG are special projects - $28M SHARP - $21M* 2014 SJG Projected Capital Expenditures - $182M
Slide 20: Utility Regulatory Proposals Valuation Methodology
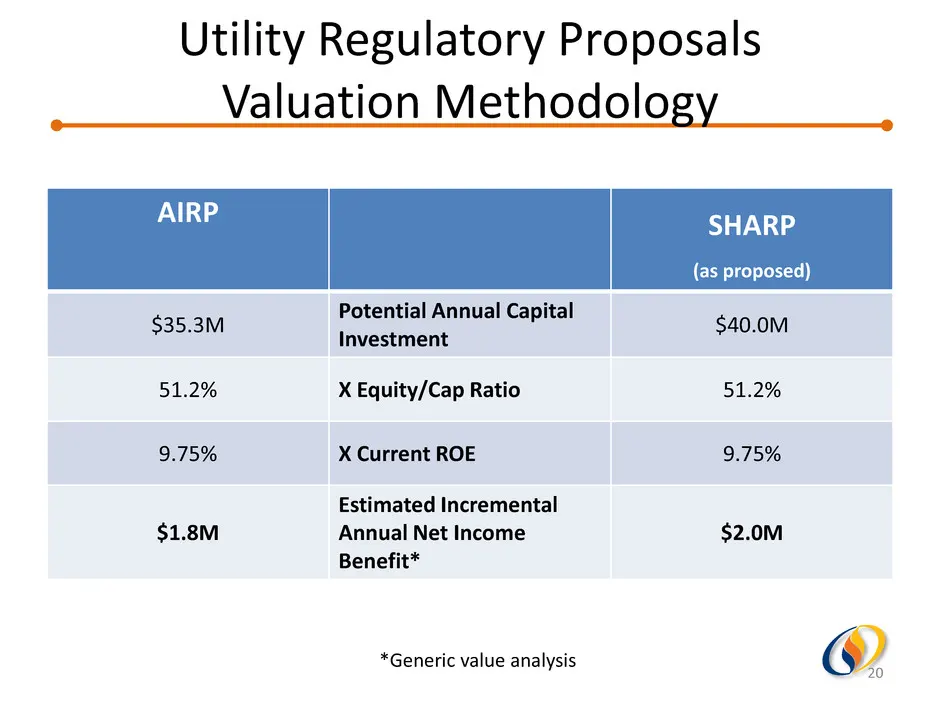
Utility Regulatory Proposals Valuation Methodology AIRP SHARP (as proposed) $35.3M Potential Annual Capital Investment $40.0M 51.2% X Equity/Cap Ratio 51.2% 9.75% X Current ROE 9.75% $1.8M Estimated Incremental Annual Net Income Benefit* $2.0M 20 *Generic value analysis
Slide 21: Utility Customer Growth
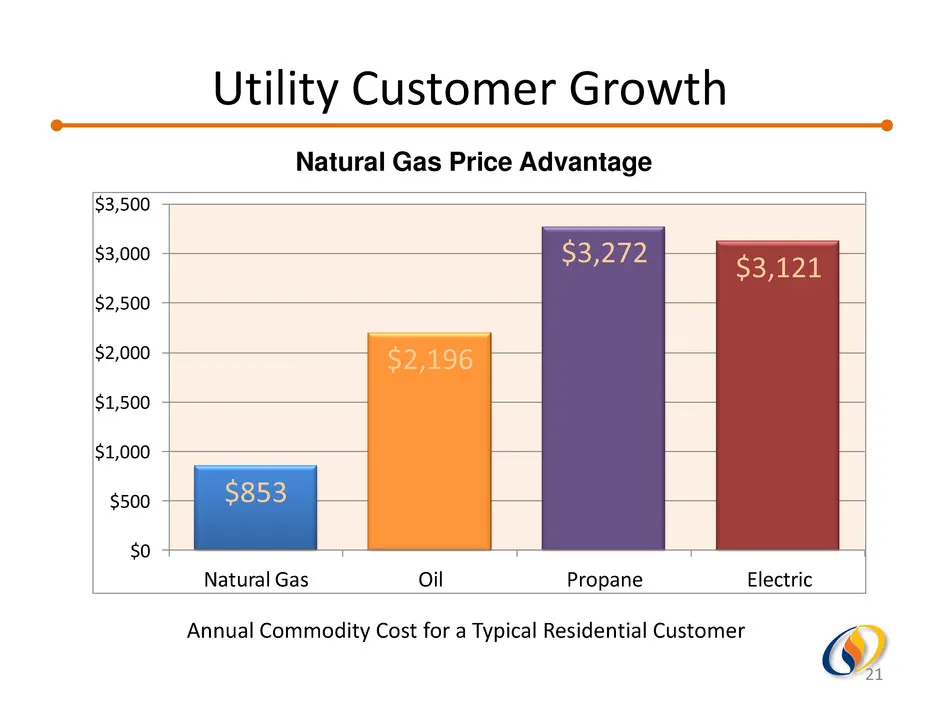
Utility Customer Growth 21 $853 $2,196 $3,272 $3,121 $0 $500 $1,000 $1,500 $2,000 $2,500 $3,000 $3,500 Natural Gas Oil Propane Electric Natural Gas Price Advantage Annual Commodity Cost for a Typical Residential Customer
Slide 22: Compressed Natural Gas
Compressed Natural Gas • Station Construction – CNG pilot station announcement – Two SJG-owned stations operating, two more planned for 2014 – 5 third party owned stations in service area • Current Use – Service area throughput doubled from 2012 to 2013 • Fleet Market – Significant fleet potential a
Slide 23: Utility Growth Summary
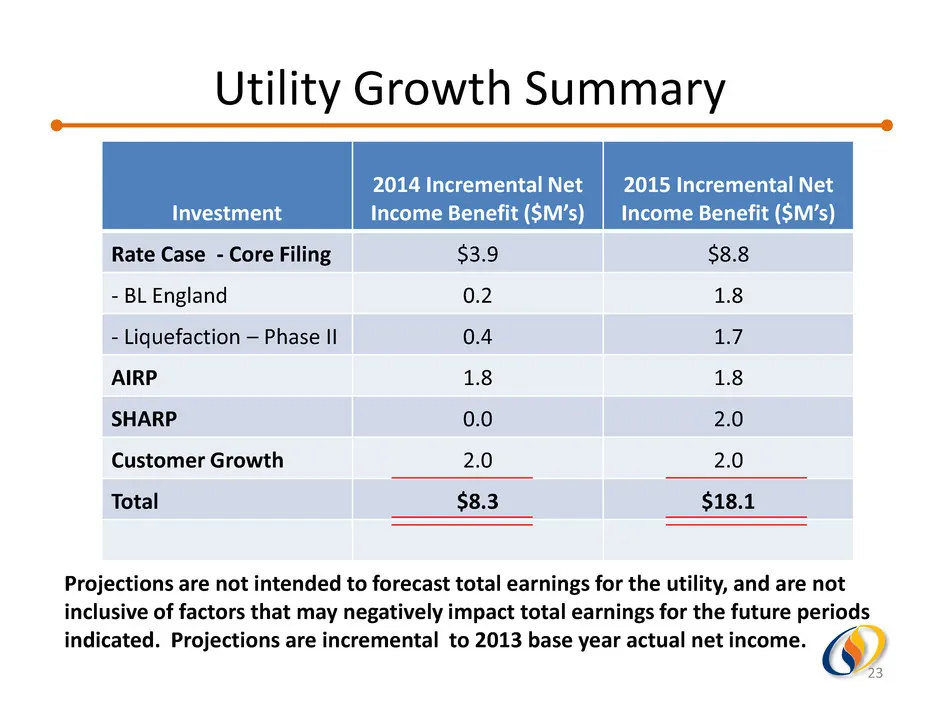
Utility Growth Summary Investment 2014 Incremental Net Income Benefit ($M’s) 2015 Incremental Net Income Benefit ($M’s) Rate Case - Core Filing $3.9 $8.8 - BL England 0.2 1.8 - Liquefaction – Phase II 0.4 1.7 AIRP 1.8 1.8 SHARP 0.0 2.0 Customer Growth 2.0 2.0 Total $8.3 $18.1 23 Projections are not
Slide 24: South Jersey Energy Solutions
@ South Jersey Energy Solutions
Slide 25: Non-Utility Growth Drivers
Non-Utility Growth Drivers South Jersey Energy Services • On-site energy project development • HVAC Service • Meter reading subsidiary South Jersey Energy Group • Marcellus marketing o Wholesale o Retail • Merchant generation fuel supply • Marcellus royalty interests 25
Slide 26: Energy Services: Strategically Targeted Project Development
Energy Services Strategically Targeted Project Development CHP /Thermal • Steady Increasing Income Stream • Opportunities to Develop and/or Acquire • Asset hardening Solar/Renewable • Selective growth • Improving SREC value • ITCs to begin trending downward 26
Slide 27: Energy Services - CHP/Thermal
Energy Services - CHP/Thermal CHP/Thermal Project Analytics • Modeled as: – 20% - 30% equity component – ROE of 15% - 20% – Joint venture ownership with long-time partner – Project financing • Target adding 1-2 new projects per year 27
Slide 28: Energy Services - Solar
Energy Services - Solar Markets • Sharp decline in construction costs • NJ Positive Trends – Slowed build rate – Strengthening SREC market – Selective grid-based development • Increasing Attractiveness of MA market – Proposed extension of solar incentive program through 2024 – Strong / Liquid SREC M
Slide 29: Energy Group – Commodity Marketing
Energy Group – Commodity Marketing Wholesale • Merchant Generation Supply • Valuable transportation capacity • Evolving Markets • Organic Growth Retail • Organic Growth / Cross Selling • Geographic Expansion 29
Slide 30: Merchant Generation Contract Components
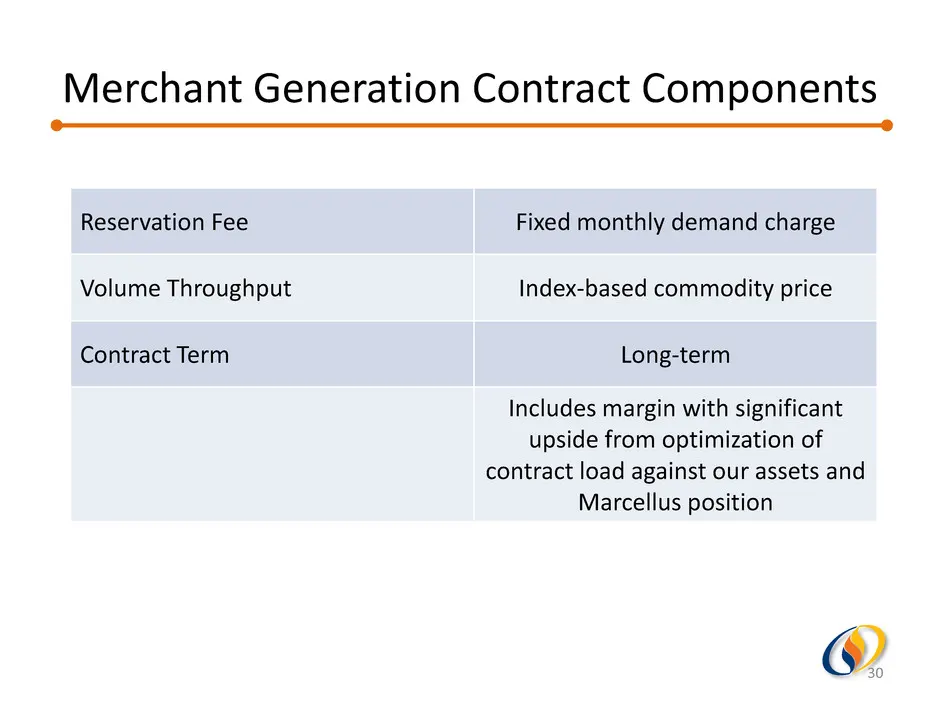
Merchant Generation Contract Components Reservation Fee Fixed monthly demand charge Volume Throughput Index-based commodity price Contract Term Long-term Includes margin with significant upside from optimization of contract load against our assets and Marcellus position 30
Slide 31: Energy Group - Wholesale
Energy Group - Wholesale Business repositioning as fuel manager for merchant electric generating facilities • Actively negotiating multiple fuel management contract opportunities Actions taken to improve profitability • Increased capacity in region • Newly procured capacity • Restructured contracts
Slide 32: Energy Group - Retail
Energy Group - Retail Competitive third party electric/natural gas commodity retailer • Active in 8 states • Focus on organic growth • Geographic expansion 32
Slide 33: South Jersey Industries
@? South Jersey Industries
Slide 34: Liquidity & Capitalization
Liquidity & Capitalization • Target average equity/cap ratio of 50% • $54 million equity capital raised in 2013 through dividend reinvestment & optional cash purchases • Deferred tax assets of $223 million to support further investment • Moody’s Upgrade of SJG 34
Slide 35: Wrap Up: The Future of SJI
Wrap Up The Future of SJI • Utility – Safety & Reliability – B.L. England – CNG – Customer Growth • Non-utility – CHP / Asset hardening – Renewable – Commodity impacts (retail and wholesale) • Capital Investment 35
Source: SEC EDGAR · 8-K filed Apr 10, 2014
More decks from South Jersey Industries Inc
 FY2021 Earnings Presentation29 slides · Feb 24, 2022
 Q3 2021 Earnings Presentation31 slides · Nov 3, 2021
 Q2 2021 Earnings Presentation31 slides · Aug 4, 2021
 Investor Day (May 2021)88 slides · May 6, 2021
 FY2020 Earnings Presentation31 slides · Feb 24, 2021
 Q3 2020 Earnings Presentation37 slides · Nov 4, 2020