Capita plc · LSE:CPI
Capita — FY2016 Earnings Presentation
69 slides from Capita's earnings presentation, Mar 2, 2017
Slide 1: Results for the year ended 31 December 2016
Results for the year ended 31 December 2016 Capita plc 2 March 2017
Slide 2: Agenda
Agenda Introduction Ian Powell, Chairman Capita repositioned Andy Parker, Chief Executive Financial results Nick Greatorex, Group Finance Director Business development Chris Sellers, Group Business Development Director Summary & outlook Andy Parker, Chief Executive 2 | 2016 financialresults
Slide 3: Introduction
Introduction Ian Powell Chairman 3 | 2016 financialresults
Slide 4: Capita repositioned
Capita repositioned Andy Parker Chief Executive 4 | 2016 financialresults
Slide 5: Summary of 2016
Summary of 2016 A challenging year • Flat organic revenue growth and profits down • BPM market subdued, decisions deferred – with lower win rate across our major bids • Some specific businesses and contracts under-performed • Experienced weakness in discretionary services toward year end • Achieved
Slide 6: A challenging year, decisive action taken
A challenging year, decisive action taken New management and organisation structure implemented Comprehensive business review undertaken Performance improvement initiatives commenced Renewed focus on organic growth 6 | 2016 financialresults
Slide 7: New management and organisation structure implemented
A challenging year, decisive action taken New management and organisation structure implemented Repositioned Executive Board: increased transparency and oversight, with renewed focus on consistent operational and customer service excellence Clear and simple structure: 6 divisions, client facing, sho
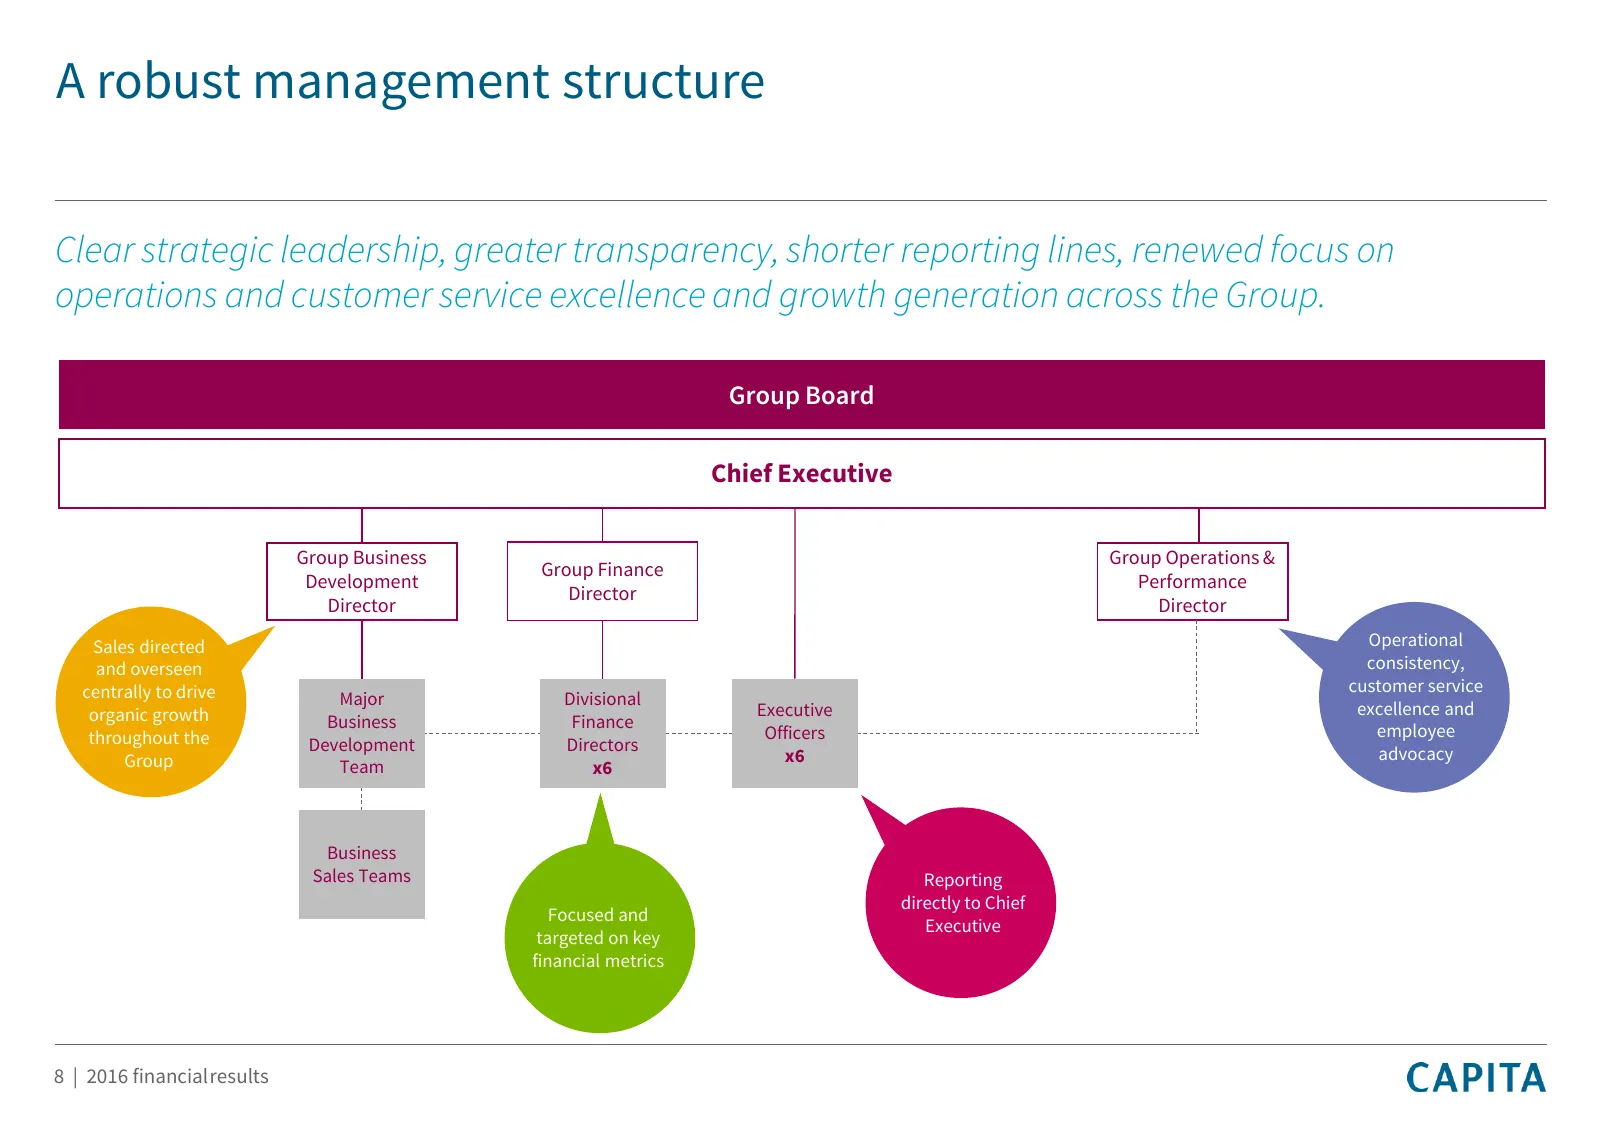
Slide 8: A robust management structure
A robust management structure Clear strategic leadership, greater transparency, shorter reporting lines, renewed focus on operations and customer service excellence and growth generation across the Group. Group Board Chief Executive Group Business Group Operations & Group Finance Development Perform
Slide 9: A simplified, focused business
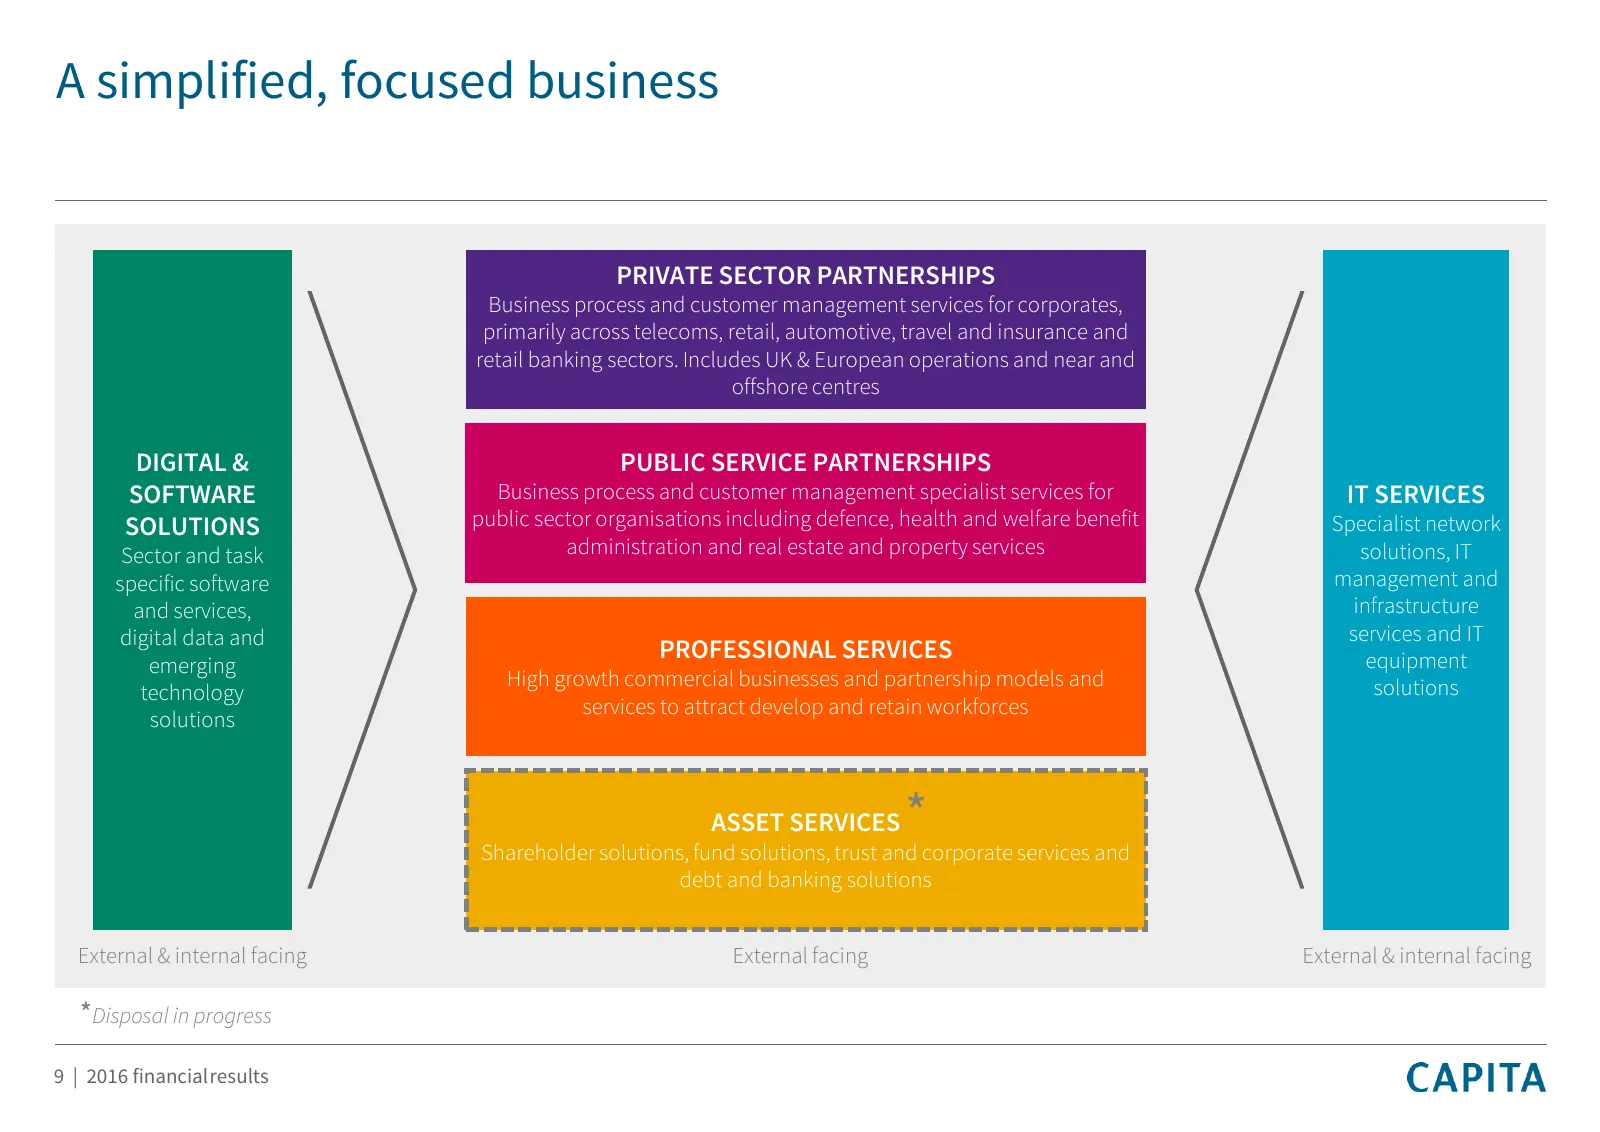
A simplified, focused business PRIVATE SECTOR PARTNERSHIPS Business process and customer management services for corporates, primarily across telecoms, retail, automotive, travel and insurance and retail banking sectors. Includes UK & European operations and near and offshore centres DIGITAL & PUBLI
Slide 10: Comprehensive business review undertaken
A challenging year, decisive action taken Comprehensive business review undertaken Clear focus on core service offering: technology enabled business process management (BPM) and customer management services Strategic disposals: Commenced disposal process - the majority of Capita Asset Services divis
Slide 11: Strategic disposals in progress to re-focus on core BPM
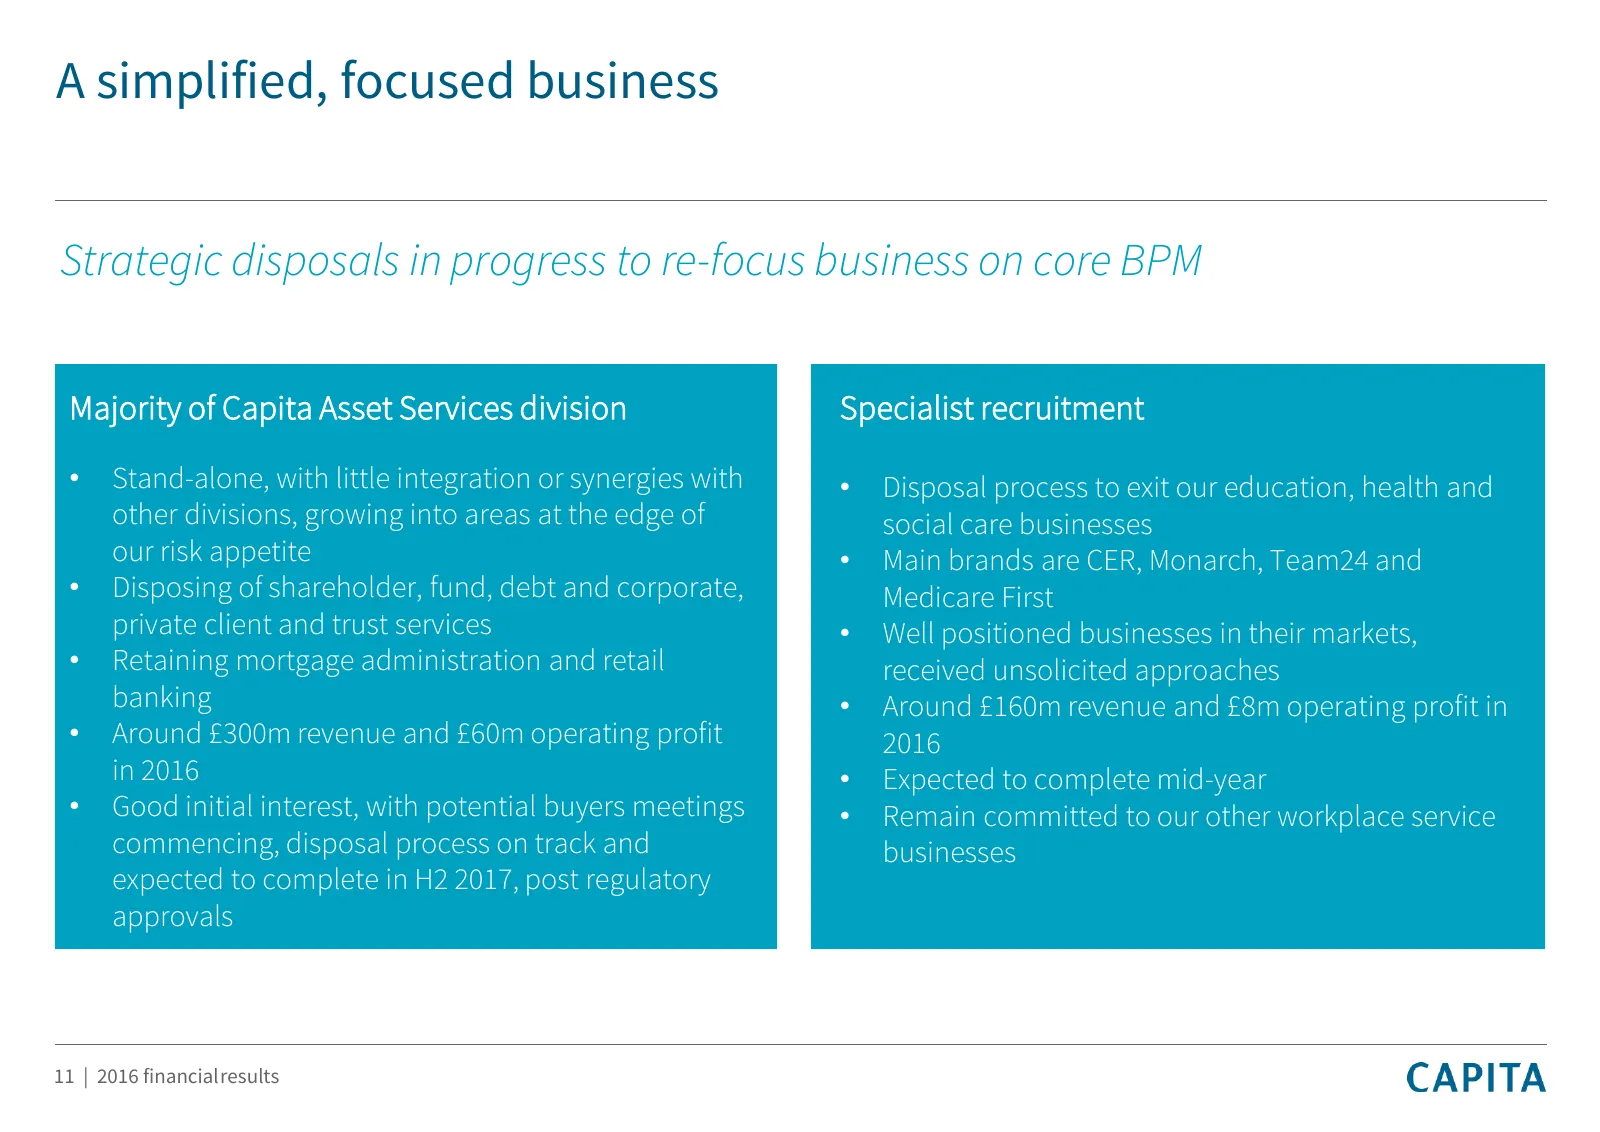
A simplified, focused business Strategic disposals in progress to re-focus business on core BPM Majority of Capita Asset Services division Specialist recruitment • Stand-alone, with little integration or synergies with • Disposal process to exit our education, health and other divisions, growing int
Slide 12: Performance improvement initiatives commenced
A challenging year, decisive action taken Performance improvement initiatives commenced Short and longer term initiatives to address our cost base Cost action: c£60m identified and in progress Addressing IT Services division: new management and turnaround plan 12 | 2016 financialresults
Slide 13: Renewed focus on organic growth
A challenging year, decisive action taken Renewed focus on organic growth Big addressable BPM and customer management markets remain Group Business Development teams re-shaped to evolving needs of clients in their dynamically changing markets Renewed focus on driving divisional growth across trading
Slide 14: A challenging year, decisive action taken
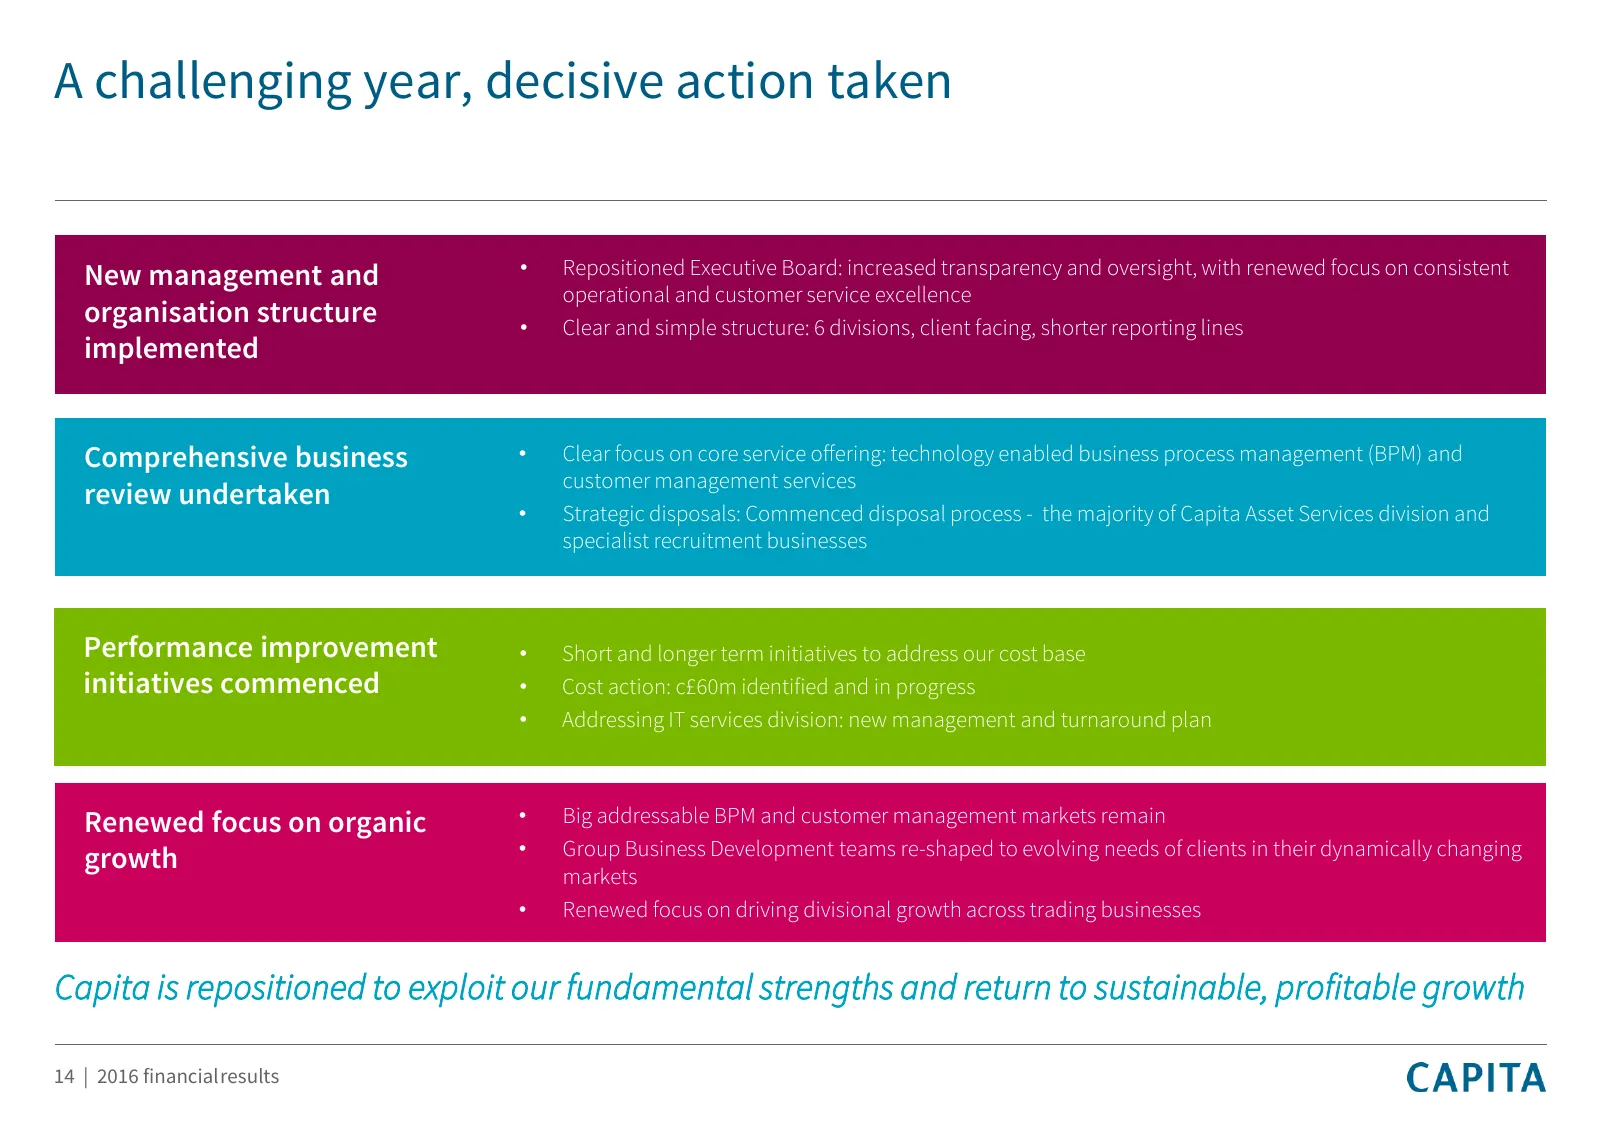
A challenging year, decisive action taken New management and • Repositioned Executive Board: increased transparency and oversight, with renewed focus on consistent operational and customer service excellence organisation structure • Clear and simple structure: 6 divisions, client facing, shorter rep
Slide 15: Financial Results
Financial Results Nick Greatorex Group Finance Director 15 | 2016 financialresults
Slide 16: Underlying income statement
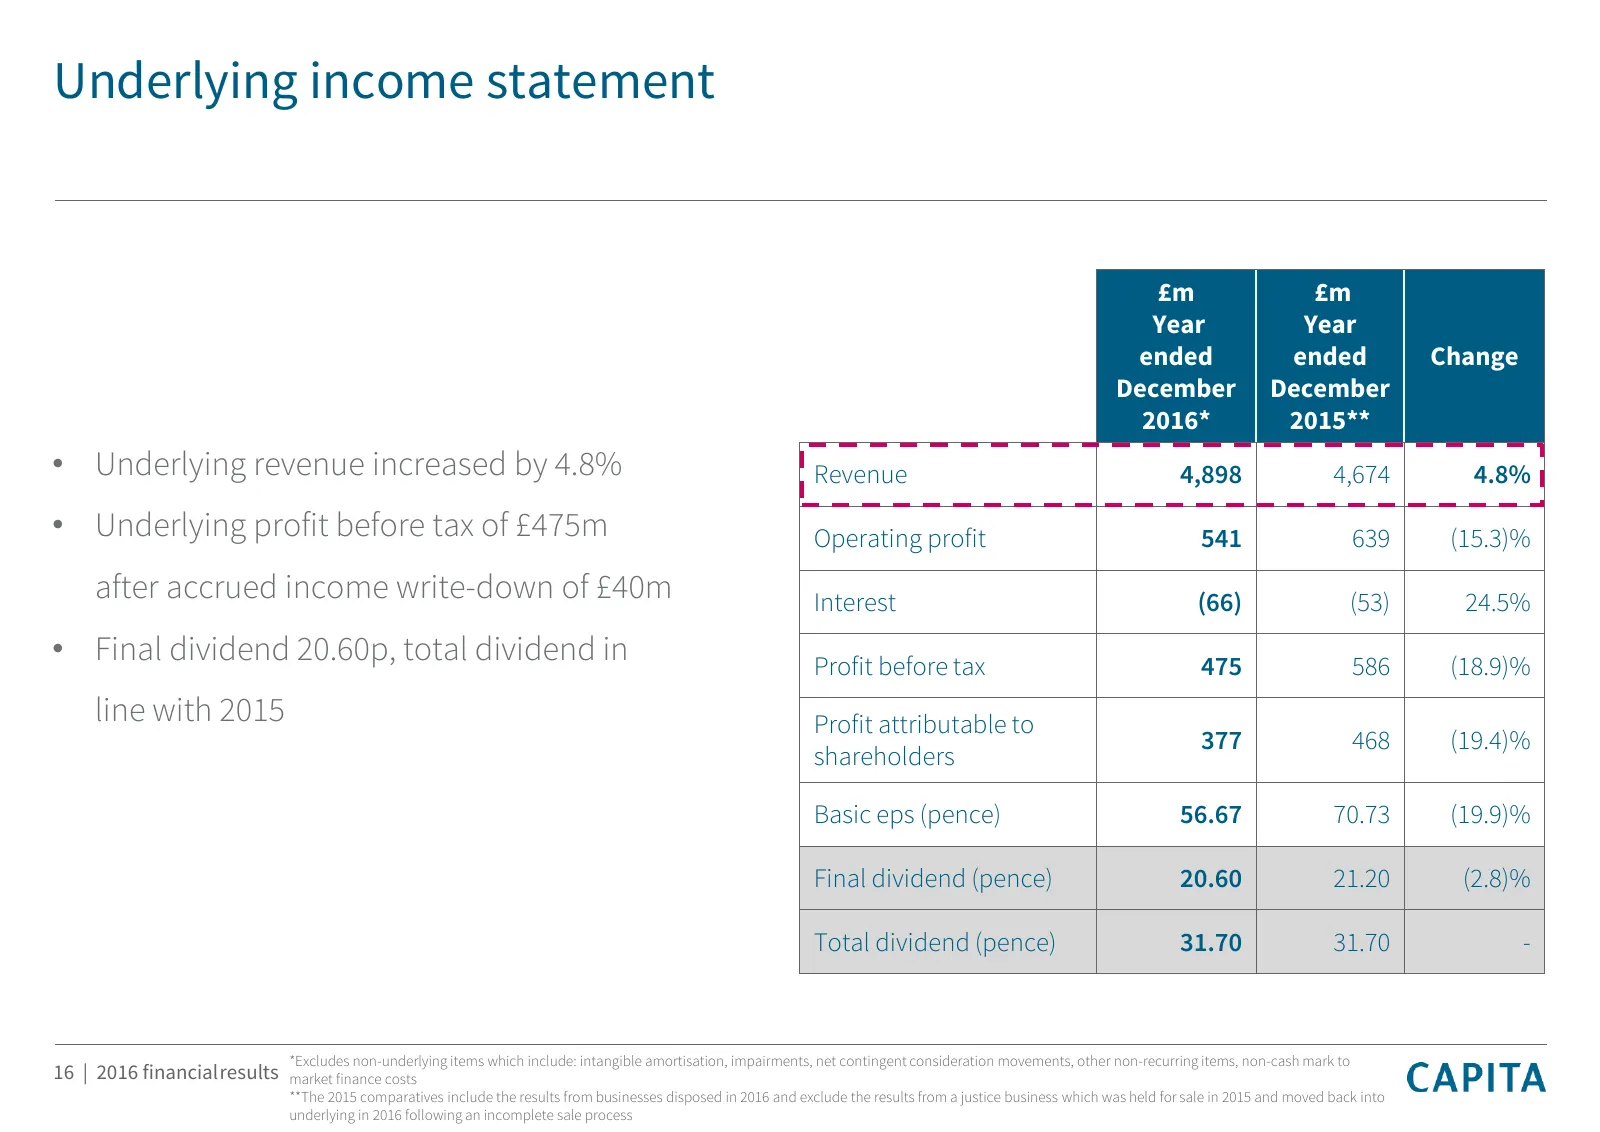
Underlying income statement £m £m Year Year ended ended Change December December 2016* 2015** • Underlying revenue increased by 4.8% Revenue 4,898 4,674 4.8% • Underlying profit before tax of £475m Operating profit 541 639 (15.3)% after accrued income write-down of £40m Interest (66) (53) 24.5% • Fi
Slide 17: Revenue
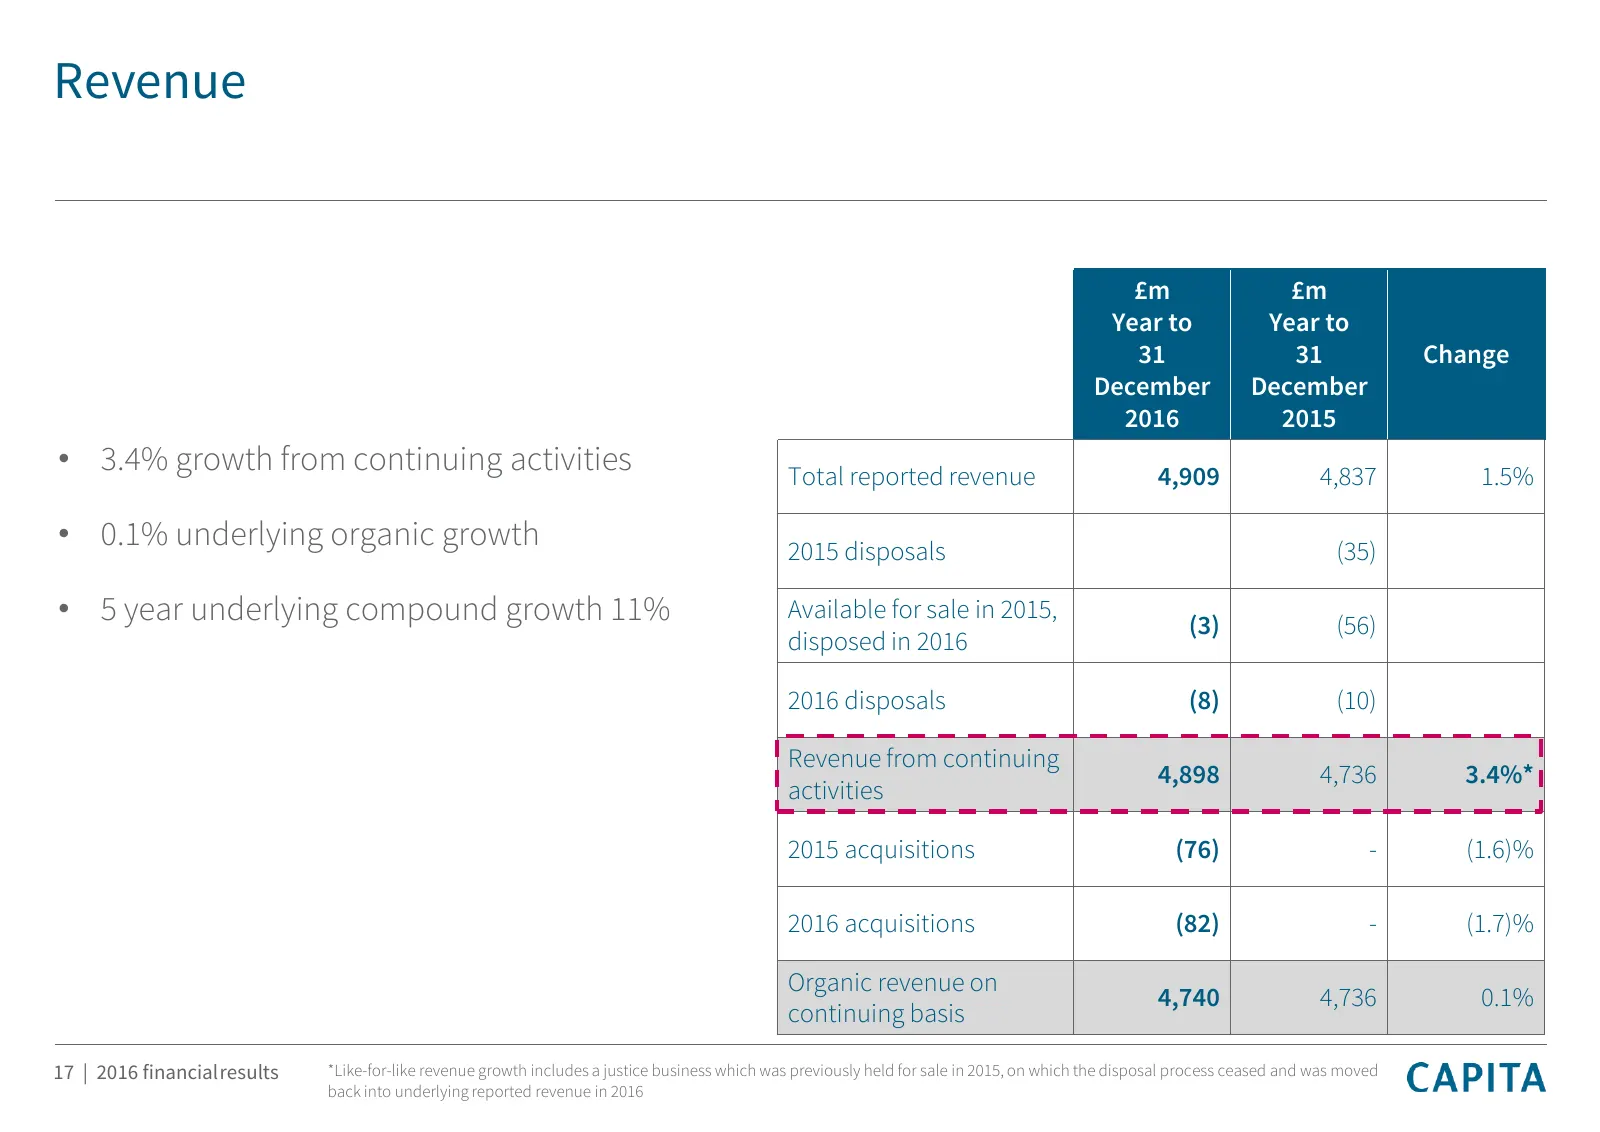
Revenue £m £m Year to Year to 31 31 Change December December 2016 2015 • 3.4% growth from continuing activities Total reported revenue 4,909 4,837 1.5% • 0.1% underlying organic growth 2015 disposals (35) • 5 year underlying compound growth 11% Available for sale in 2015, (3) (56) disposed in 2016 2
Slide 18: Revenue guidance H1 2016 v H2 2016
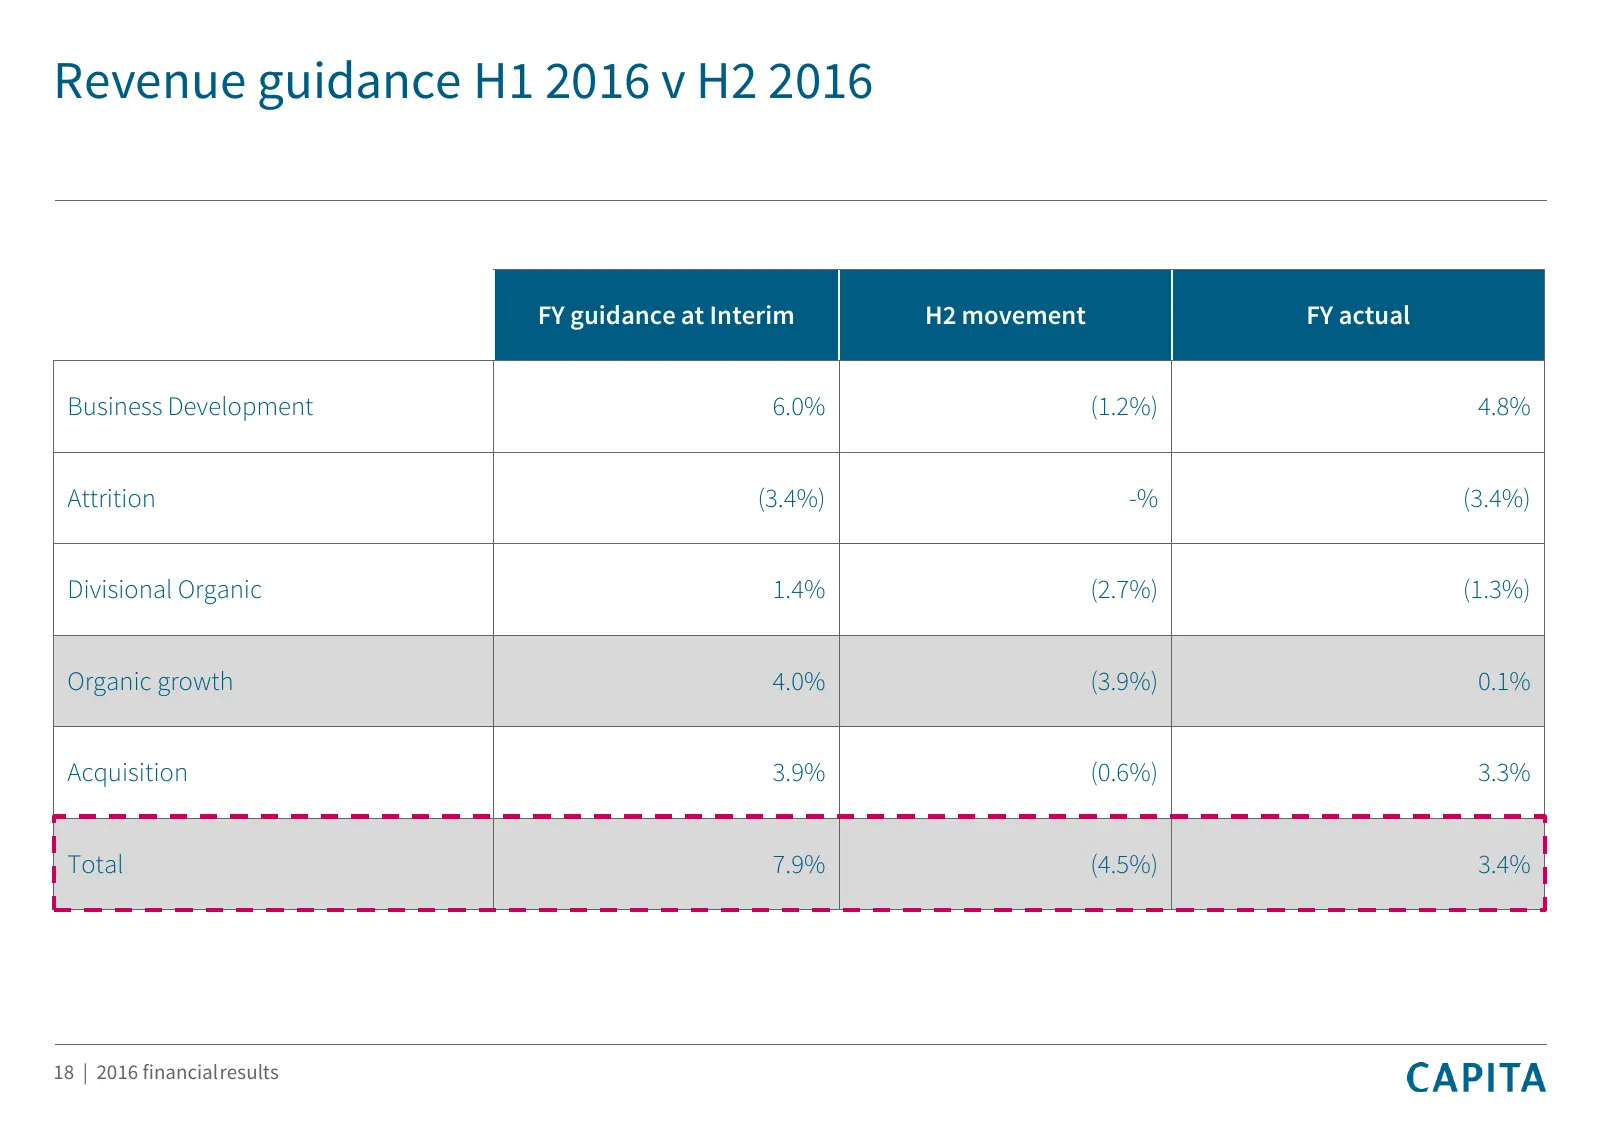
Revenue guidance H1 2016 v H2 2016 FY guidance at Interim H2 movement FY actual Business Development 6.0% (1.2%) 4.8% Attrition (3.4%) -% (3.4%) Divisional Organic 1.4% (2.7%) (1.3%) Organic growth 4.0% (3.9%) 0.1% Acquisition 3.9% (0.6%) 3.3% Total 7.9% (4.5%) 3.4% 18 | 2016 financialresults
Slide 19: Revenue 2015 bridge to 2016
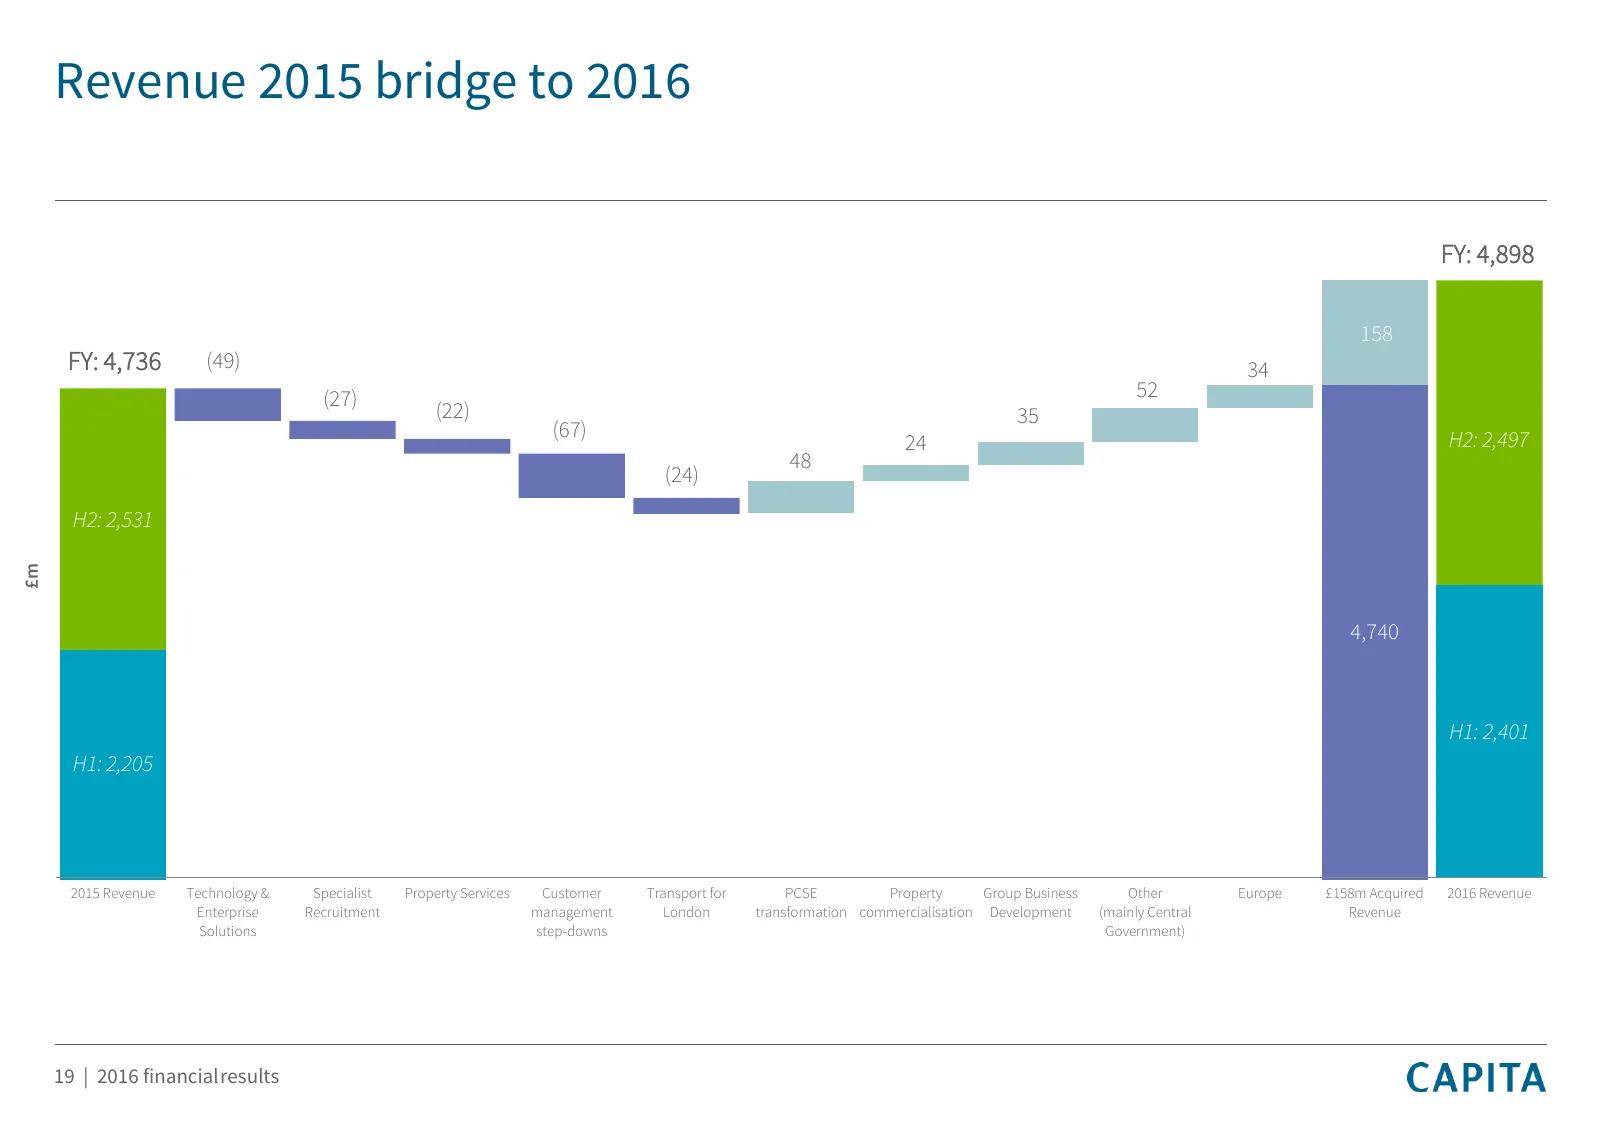
Revenue 2015 bridge to 2016 FY: 4,898 158 FY: 4,736 (49) 34 (27) 52 (22) 35 (67) H2: 2,497 24 48 (24) H2: 2,531 £m 4,740 H1: 2,401 H1: 2,205 2015 Revenue Technology & Specialist Property Services Customer Transport for PCSE Property Group Business Other Europe £158m Acquired 2016 Revenue Enterprise
Slide 20: Operating profit 2015 bridge to 2016
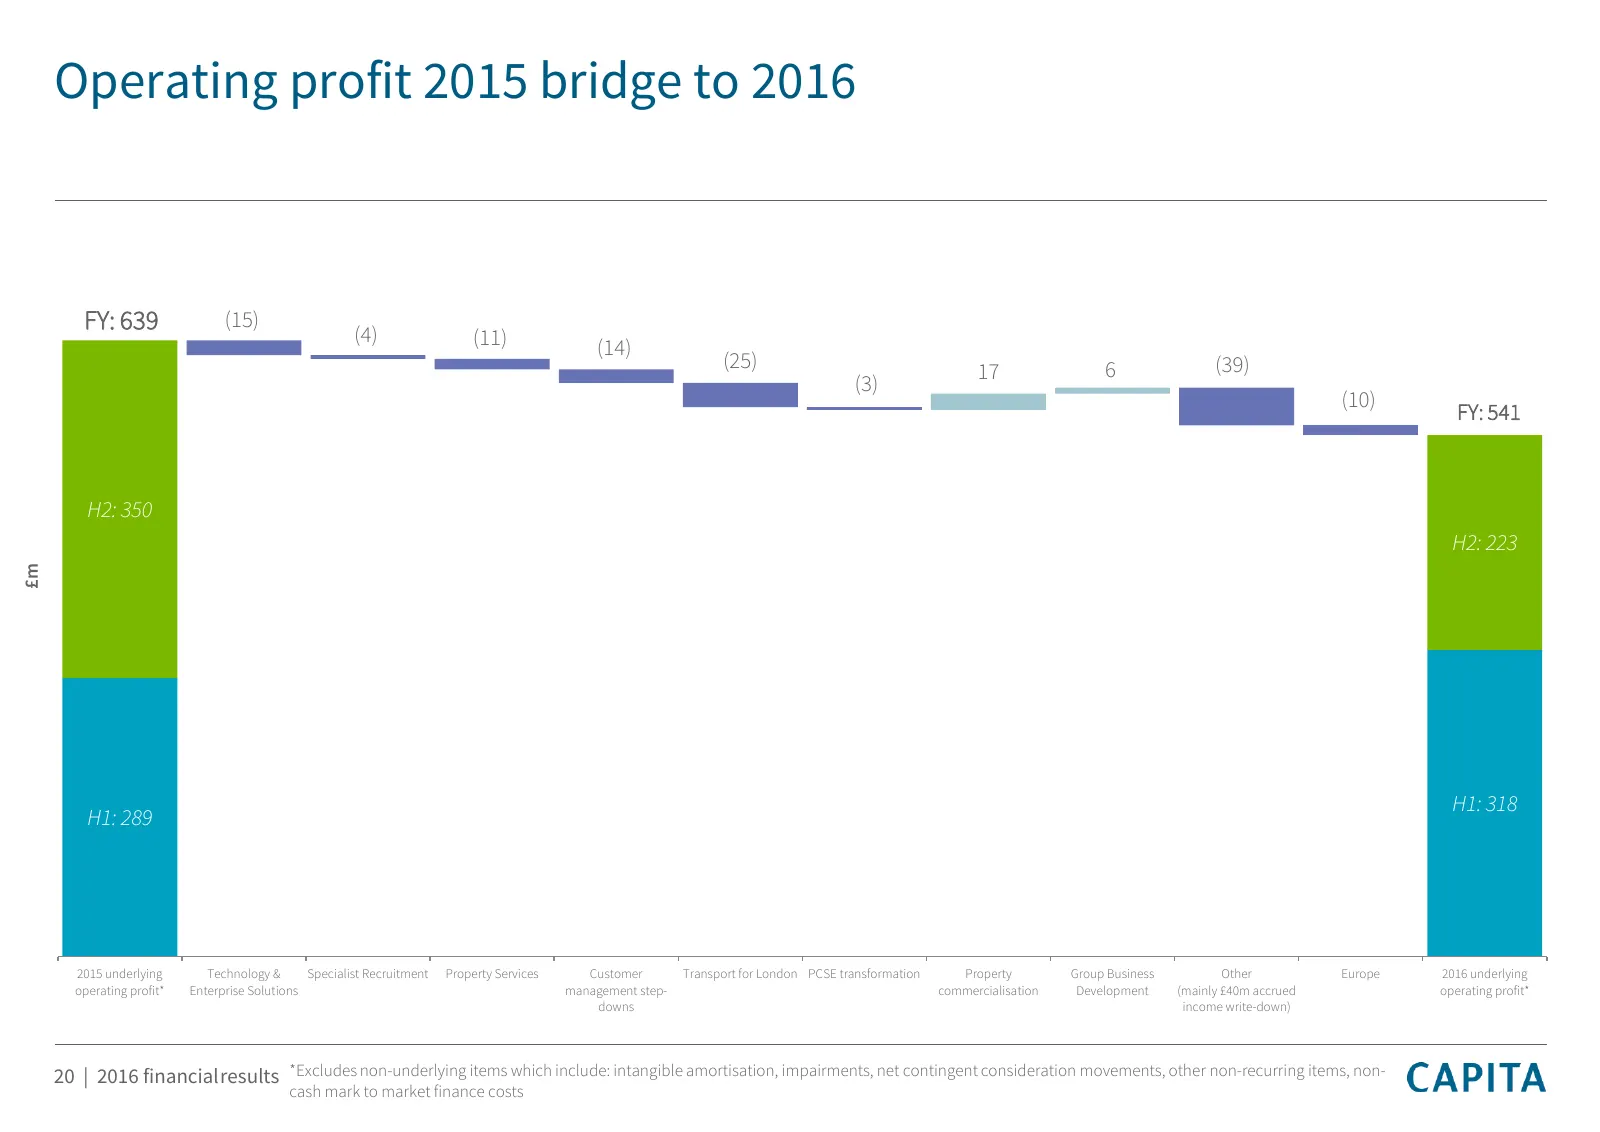
Operating profit 2015 bridge to 2016 FY: 639 (15) (4) (11) (14) (25) 17 6 (39) (3) (10) FY: 541 H2: 350 H2: 223 £m H1: 318 H1: 289 2015 underlying Technology & Specialist Recruitment Property Services Customer Transport for London PCSE transformation Property Group Business Other Europe 2016 underly
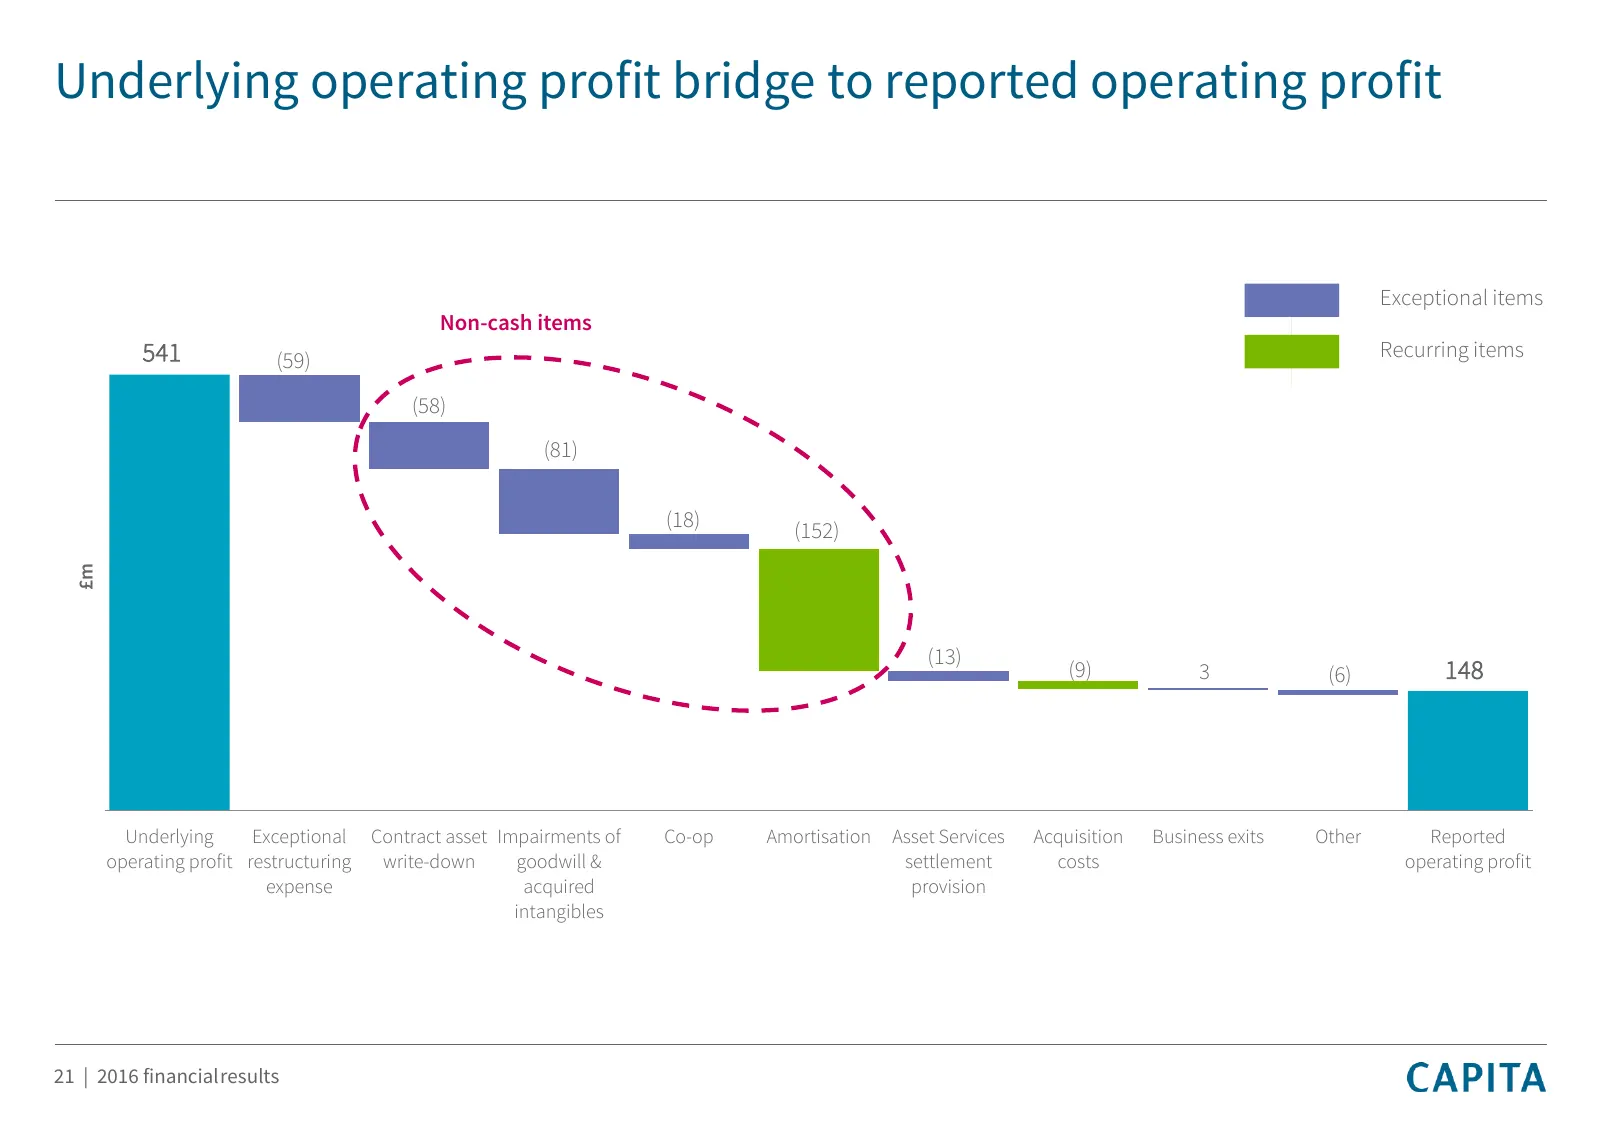
Slide 21: Underlying operating profit bridge to reported operating profit
Underlying operating profit bridge to reported operating profit Exceptional items Non-cash items 541 (59) Recurring items (58) (81) (18) (152) £m (13) (9) 3 (6) 148 Underlying Exceptional Contract asset Impairments of Co-op Amortisation Asset Services Acquisition Business exits Other Reported operat
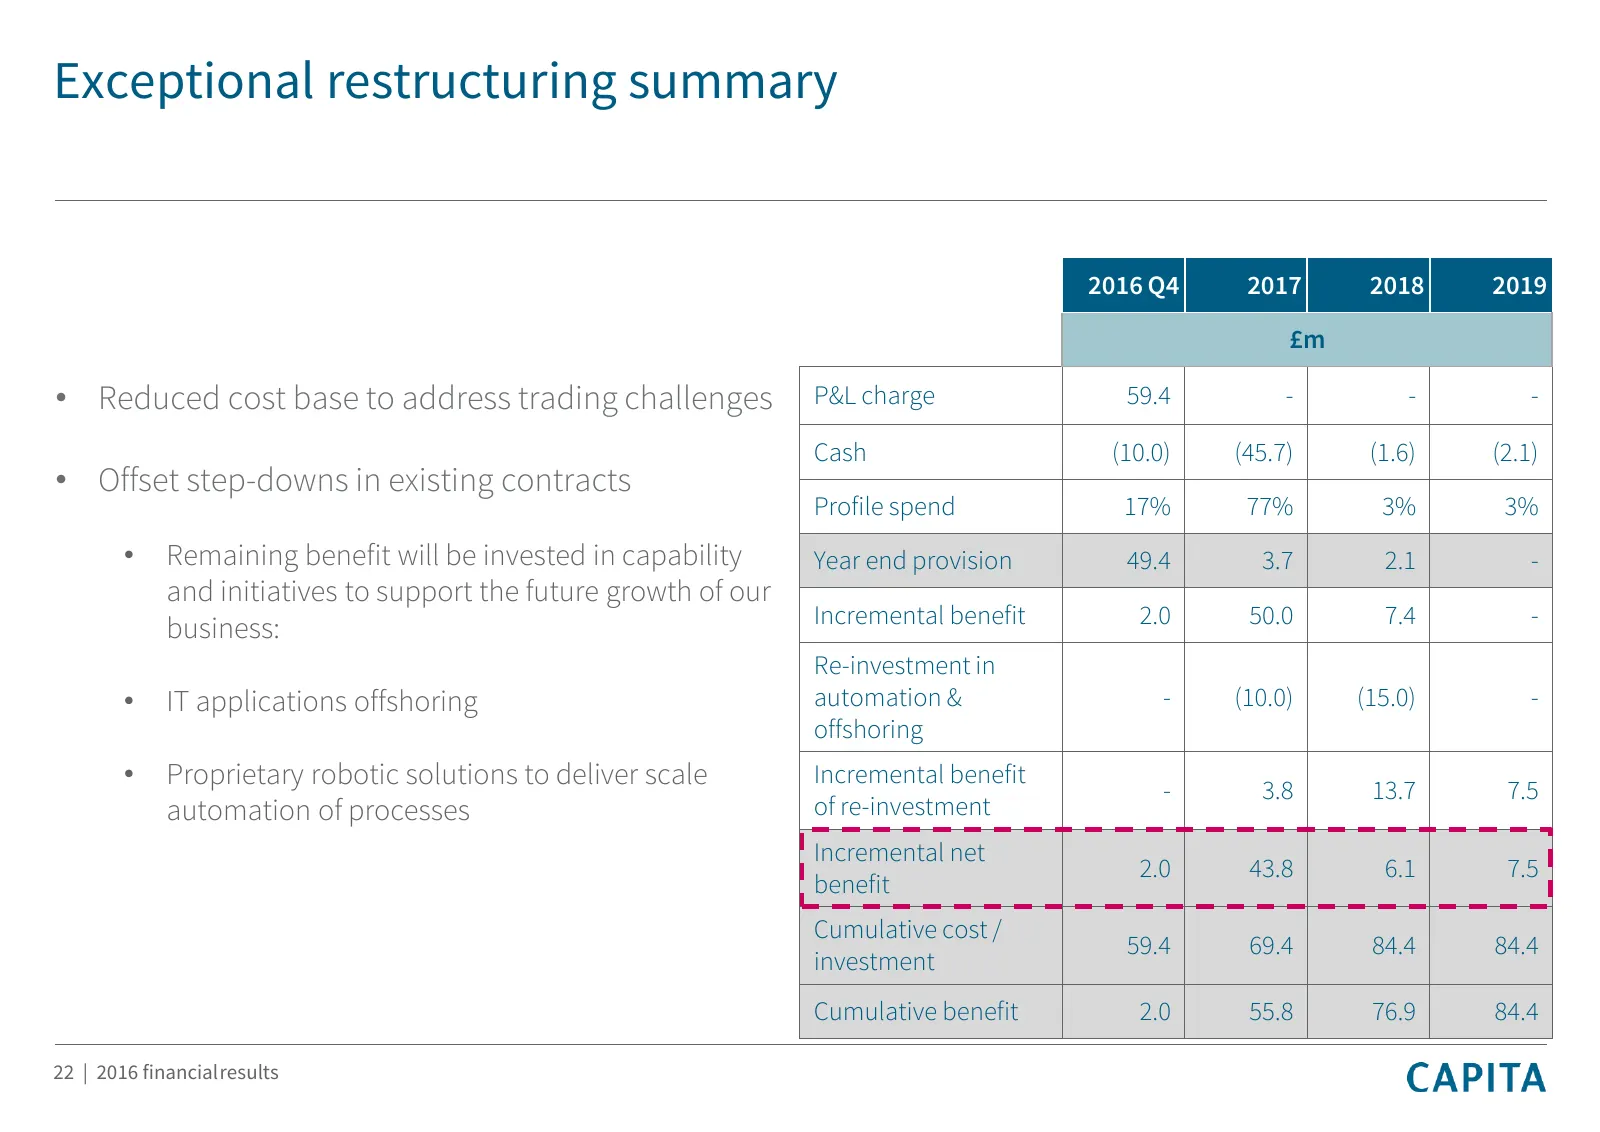
Slide 22: Exceptional restructuring summary
Exceptional restructuring summary 2016 Q4 2017 2018 2019 £m • Reduced cost base to address trading challenges P&L charge 59.4 - - - Cash (10.0) (45.7) (1.6) (2.1) • Offset step-downs in existing contracts Profile spend 17% 77% 3% 3% • Remaining benefit will be invested in capability Year end provisi
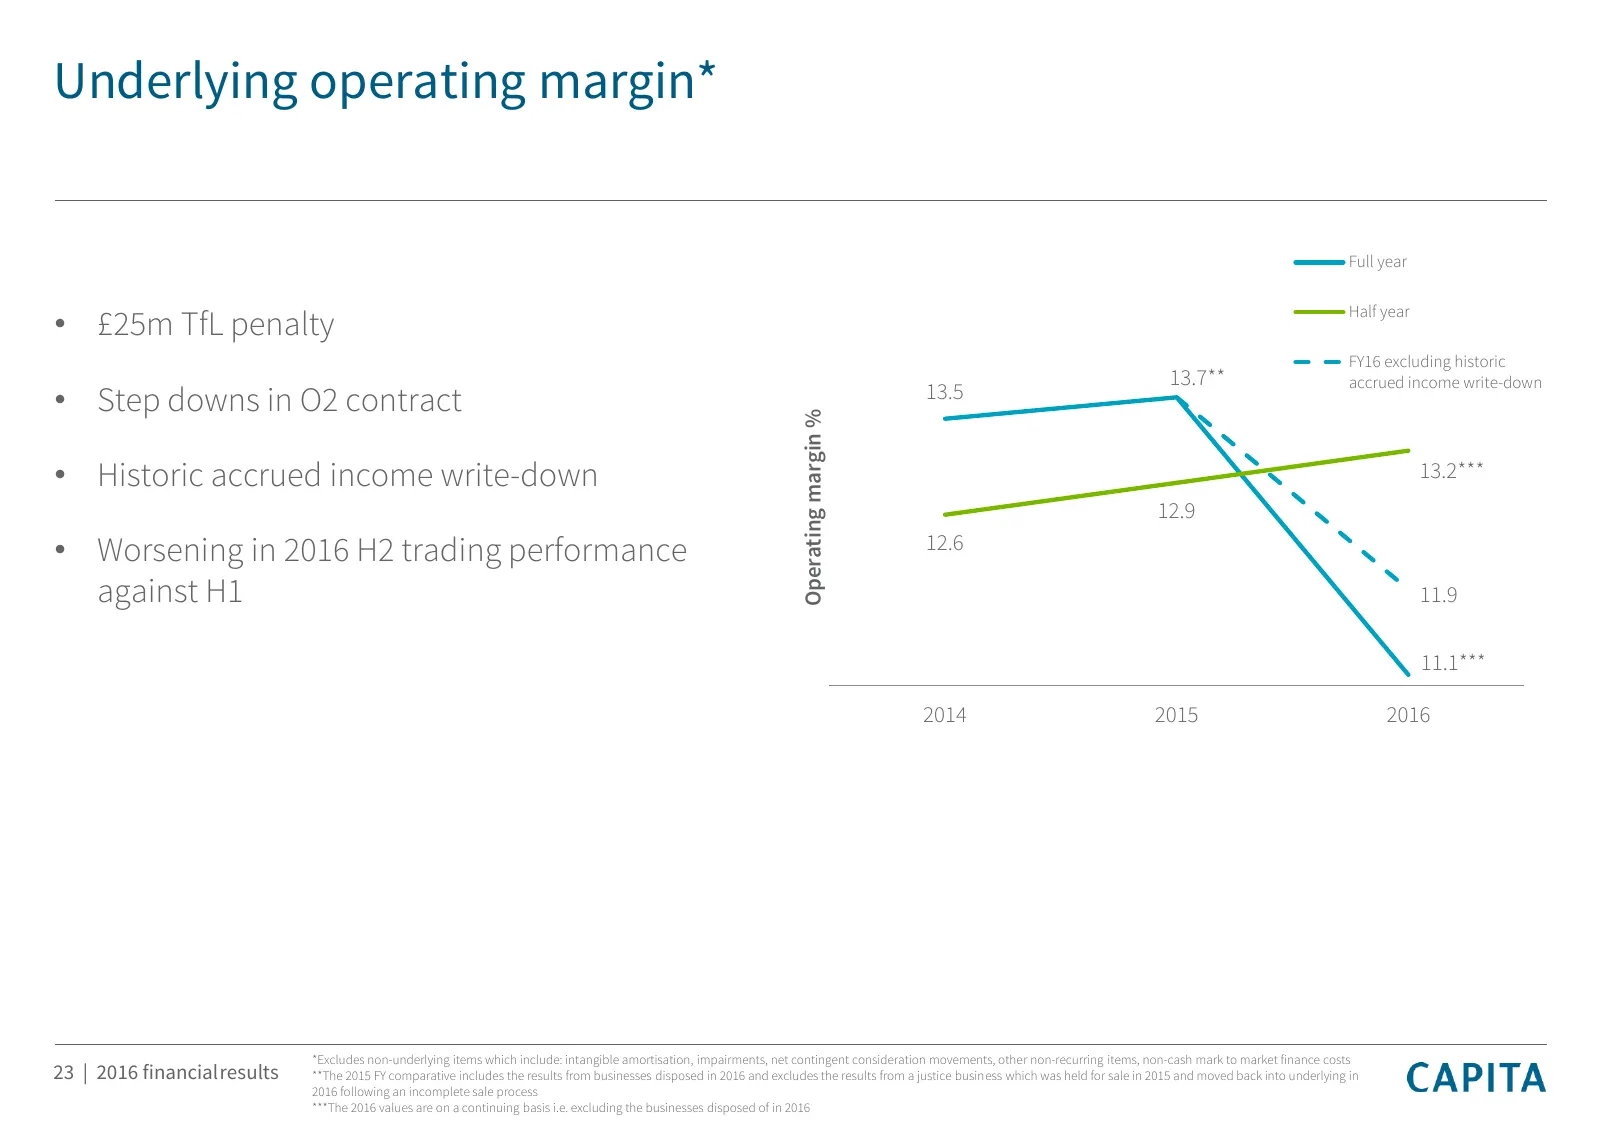
Slide 23: Operating margin %
Underlying operating margin* Full year Half year • £25m TfL penalty FY16 excluding historic 13.7** accrued income write-down 13.5 • Step downs in O2 contract Operating margin % • Historic accrued income write-down 13.2*** 12.9 • Worsening in 2016 H2 trading performance 12.6 against H1 11.9 11.1*** 2
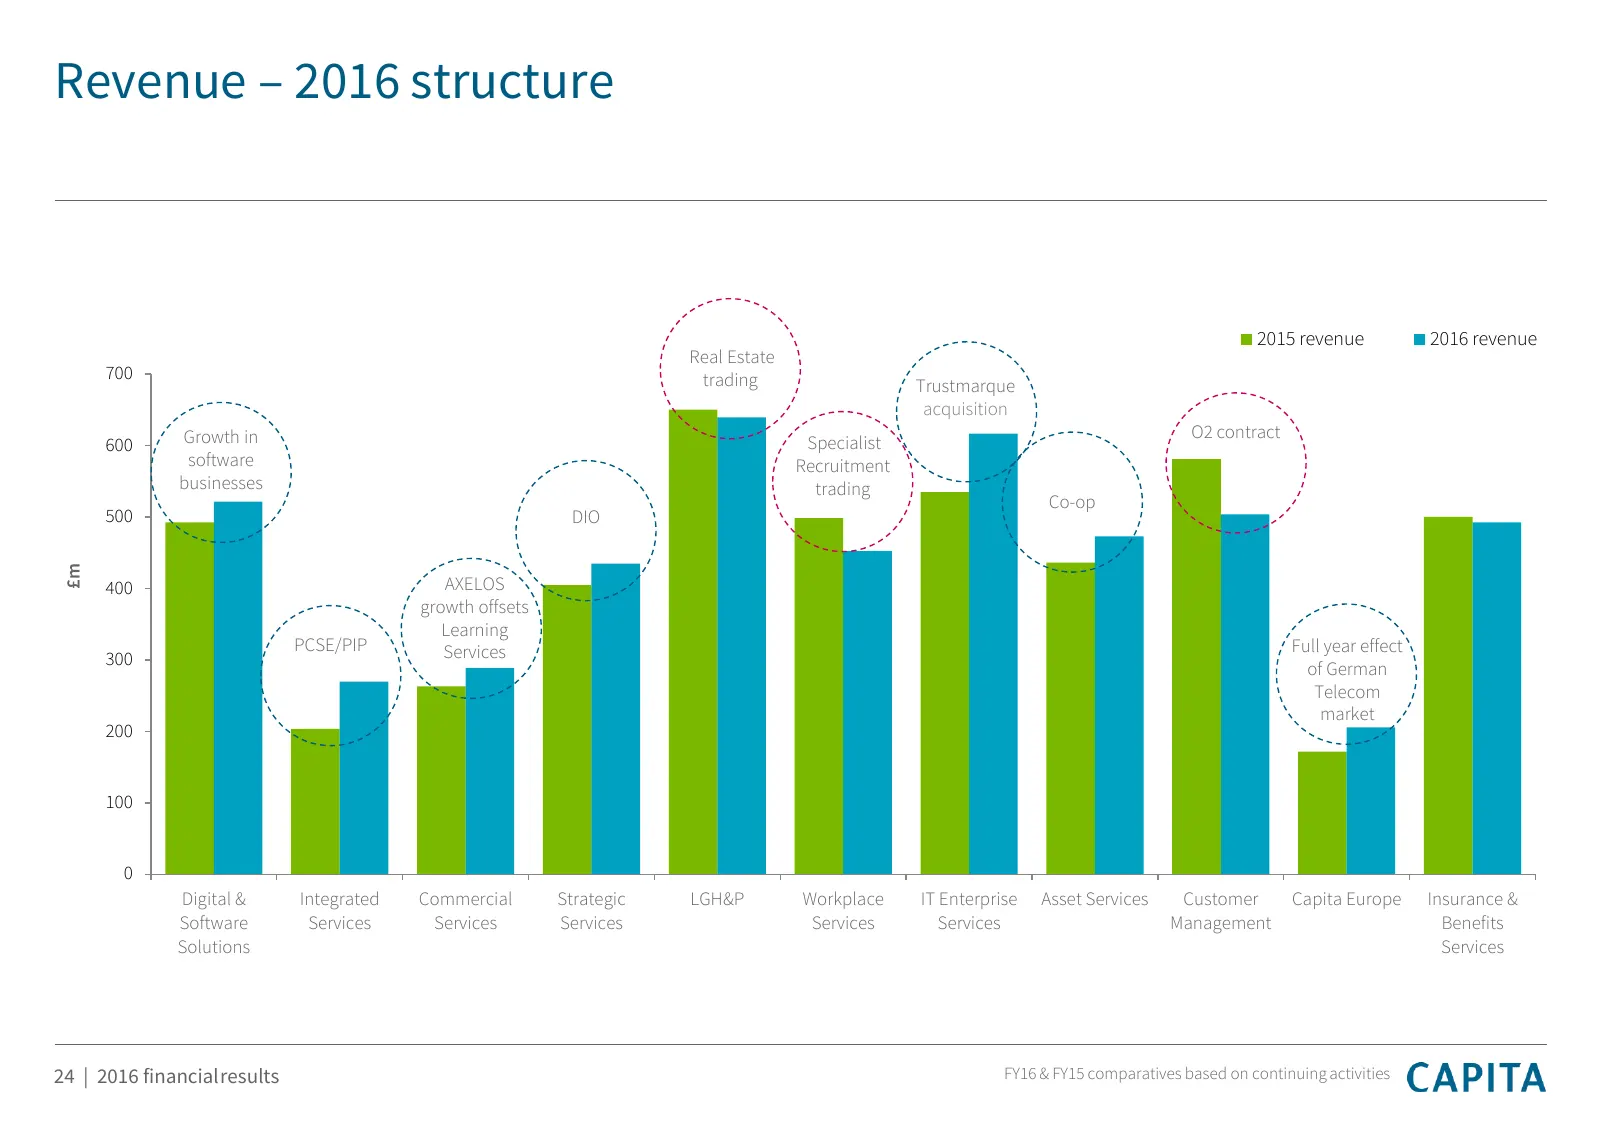
Slide 24: Revenue – 2016 structure
Revenue – 2016 structure 2015 revenue 2016 revenue Real Estate 700 trading Trustmarque acquisition Growth in O2 contract 600 Specialist software Recruitment businesses trading Co-op 500 DIO £m 400 AXELOS growth offsets Learning PCSE/PIP Services Full year effect 300 of German Telecom market 200 100
Slide 25: Underlying operating profit – 2016 structure
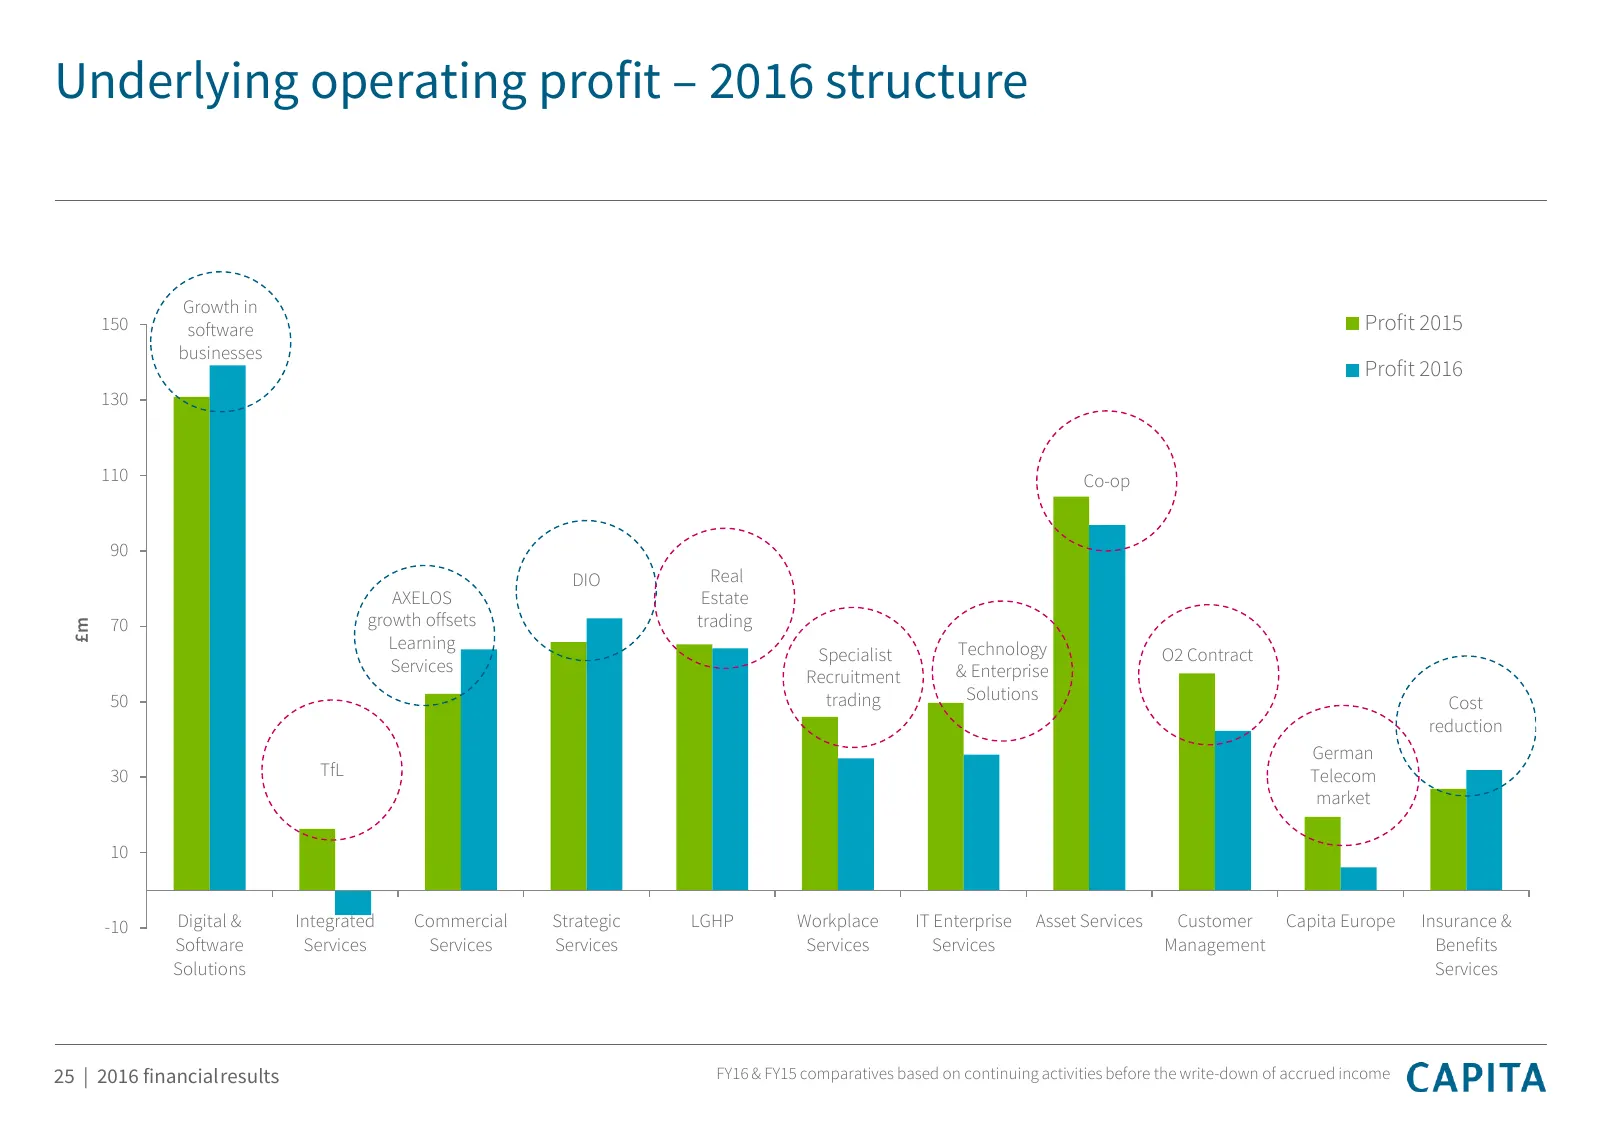
Underlying operating profit – 2016 structure Growth in 150 software Profit 2015 businesses Profit 2016 130 110 Co-op 90 DIO Real AXELOS Estate 70 growth offsets trading £m Learning Technology Specialist O2 Contract Services & Enterprise Recruitment 50 trading Solutions Cost reduction German 30 TfL T
Slide 26: Overall Group revenue split
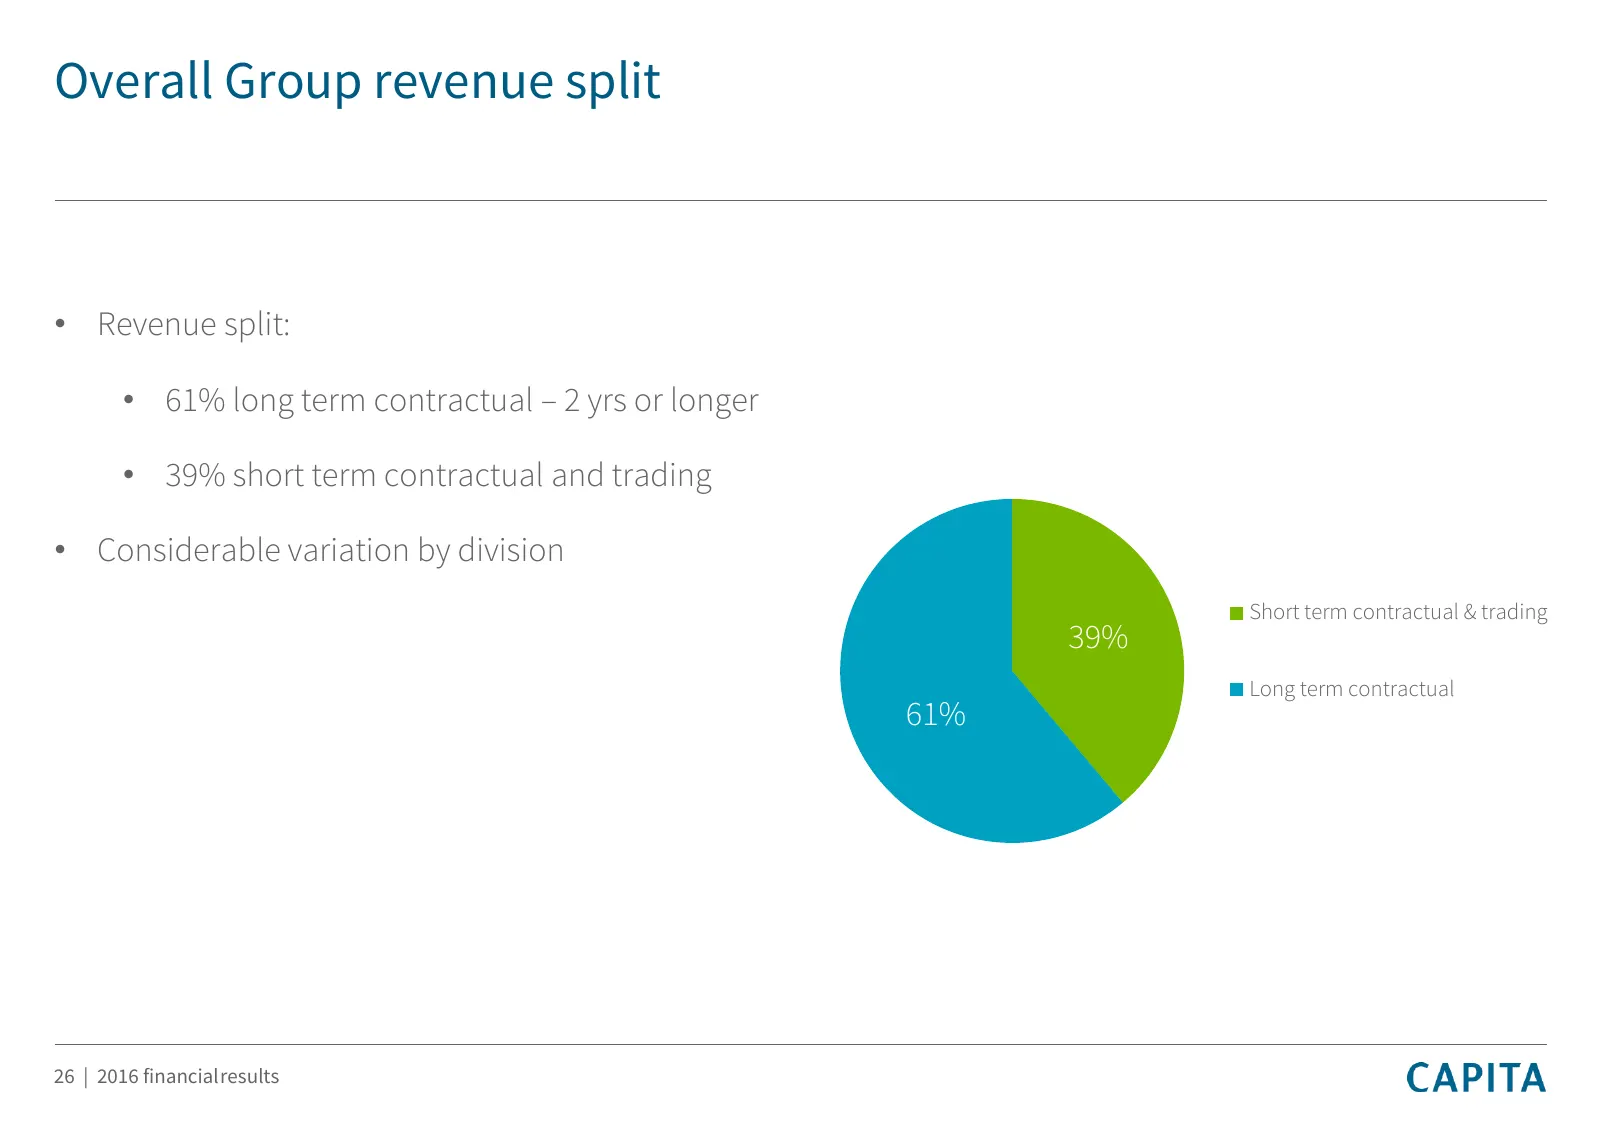
Overall Group revenue split • Revenue split: • 61% long term contractual – 2 yrs or longer • 39% short term contractual and trading • Considerable variation by division Short term contractual & trading 39% Long term contractual 61% 26 | 2016 financialresults
Slide 27: Private Sector Partnerships
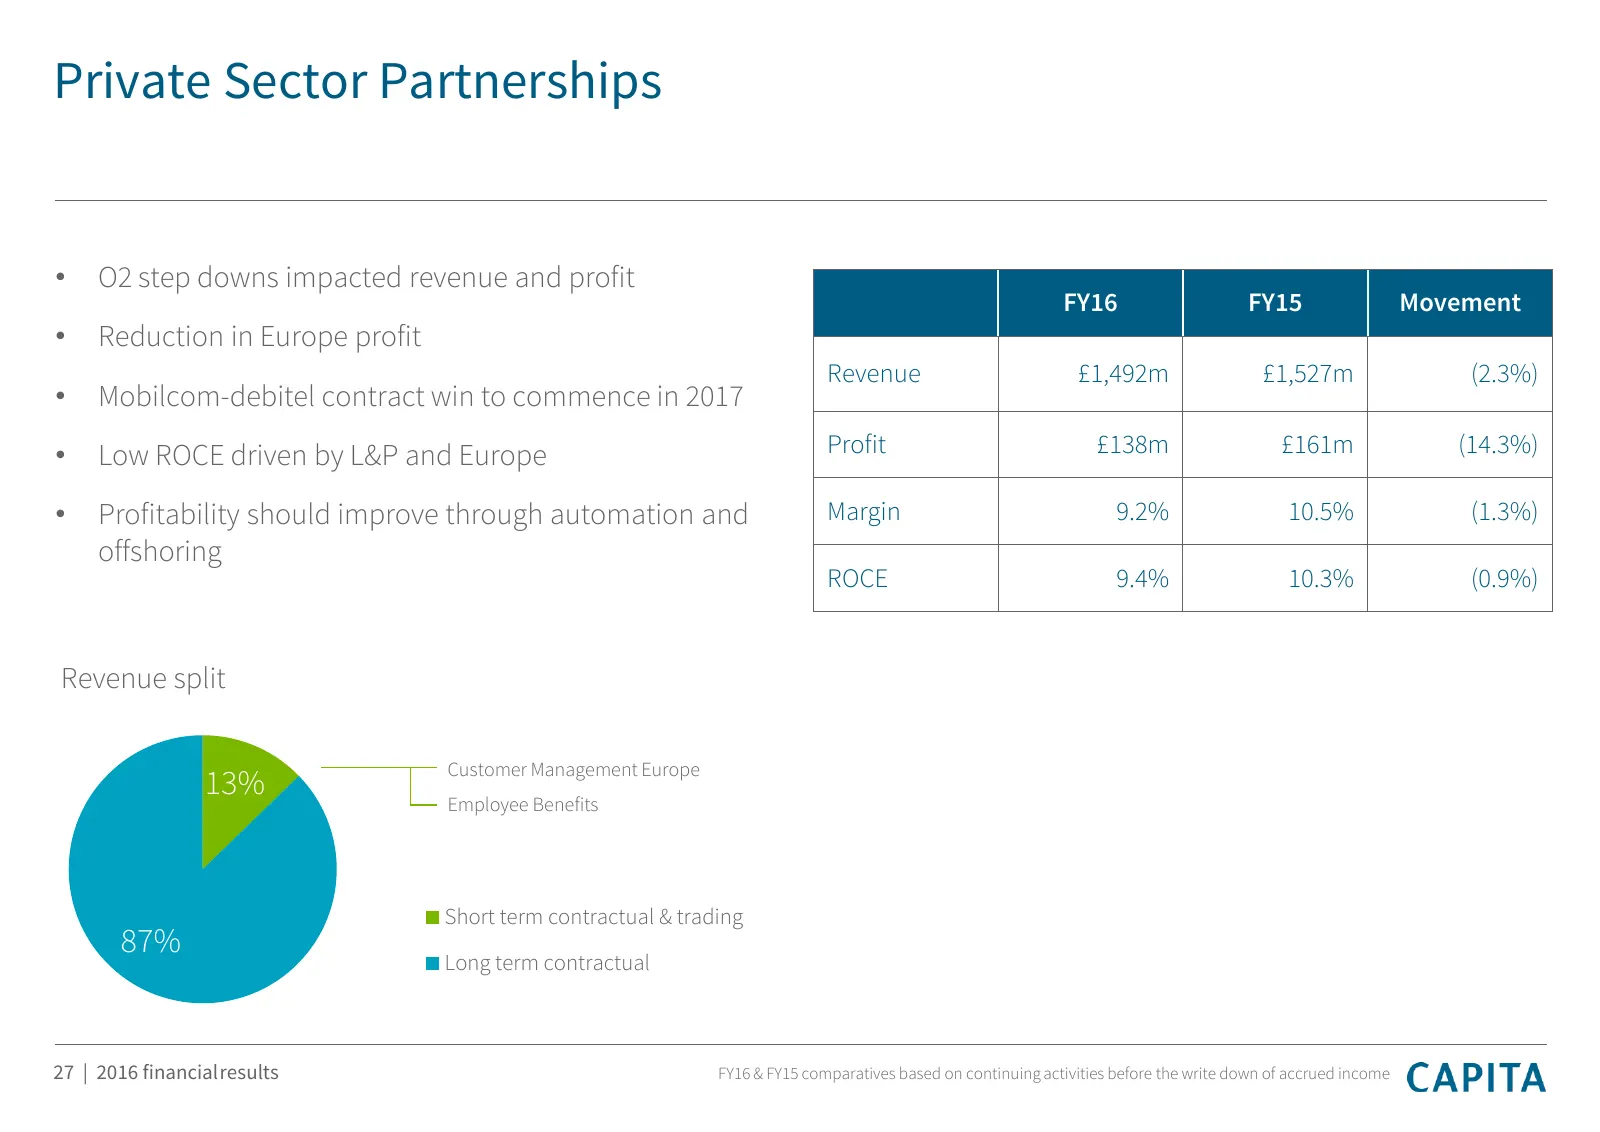
Private Sector Partnerships • O2 step downs impacted revenue and profit FY16 FY15 Movement • Reduction in Europe profit Revenue £1,492m £1,527m (2.3%) • Mobilcom-debitel contract win to commence in 2017 • Low ROCE driven by L&P and Europe Profit £138m £161m (14.3%) • Profitability should improve thr
Slide 28: Public Services Partnerships
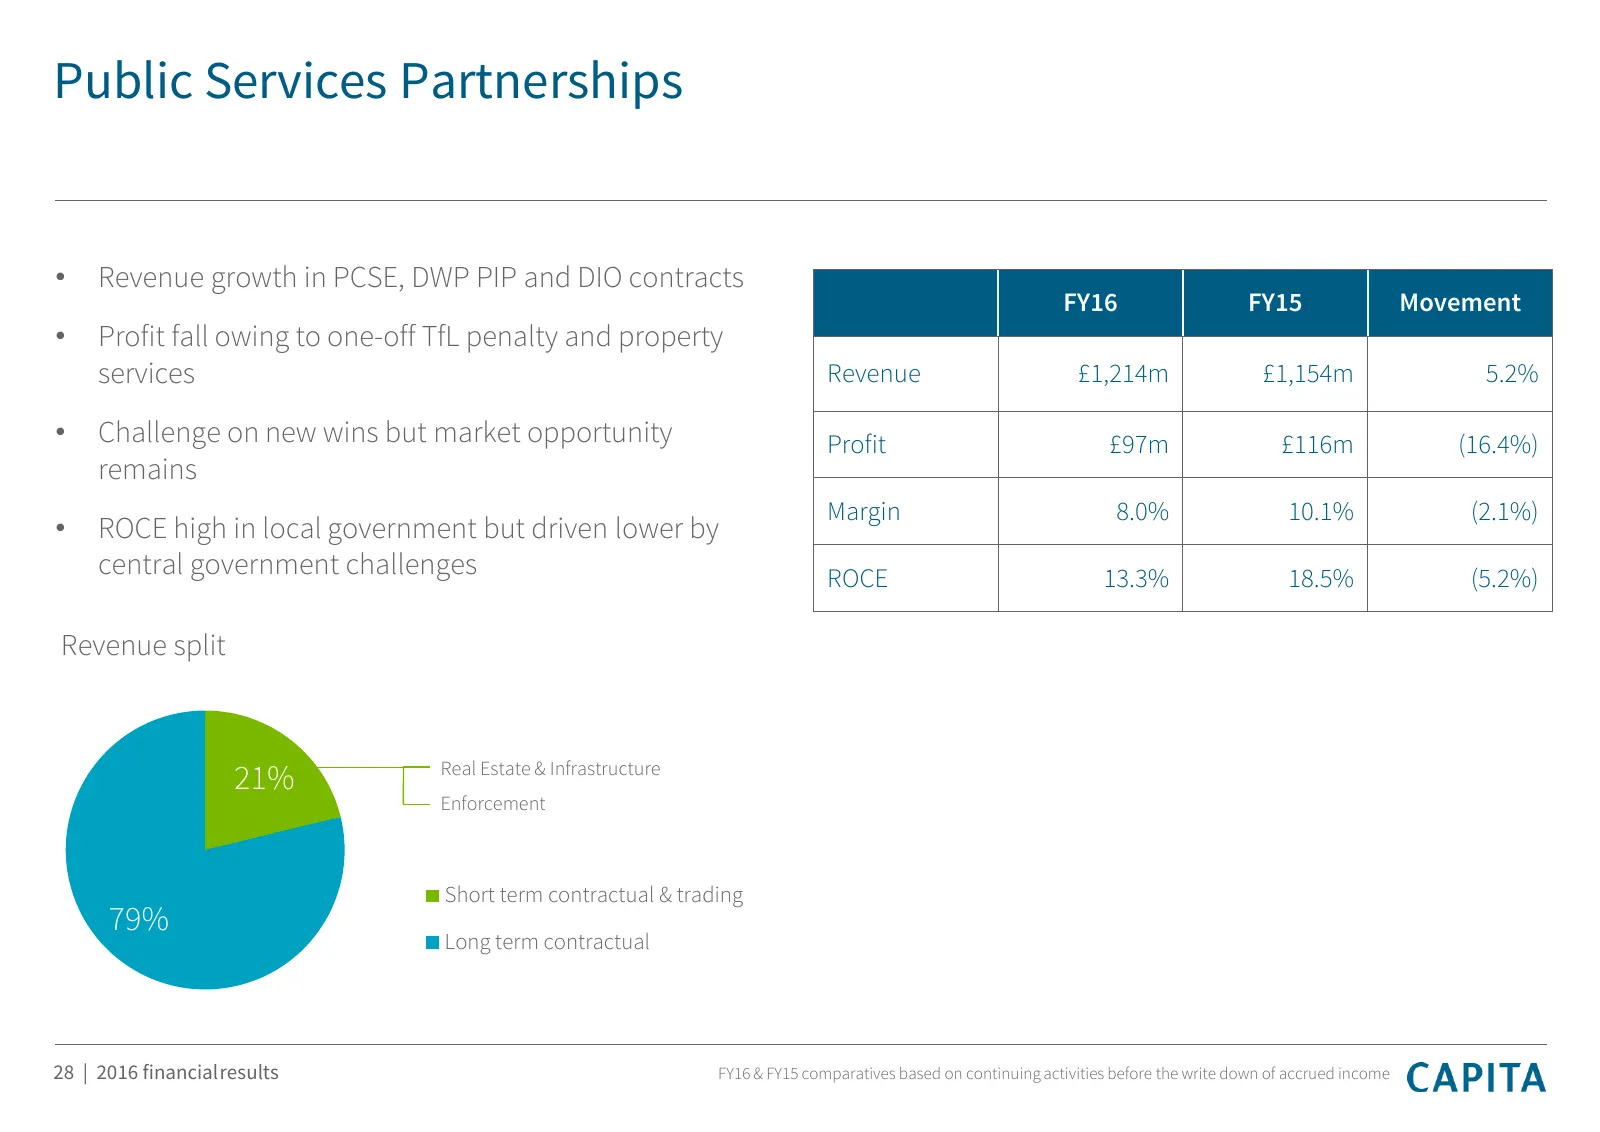
Public Services Partnerships • Revenue growth in PCSE, DWP PIP and DIO contracts FY16 FY15 Movement • Profit fall owing to one-off TfL penalty and property services Revenue £1,214m £1,154m 5.2% • Challenge on new wins but market opportunity Profit £97m £116m (16.4%) remains Margin 8.0% 10.1% (2.1%)
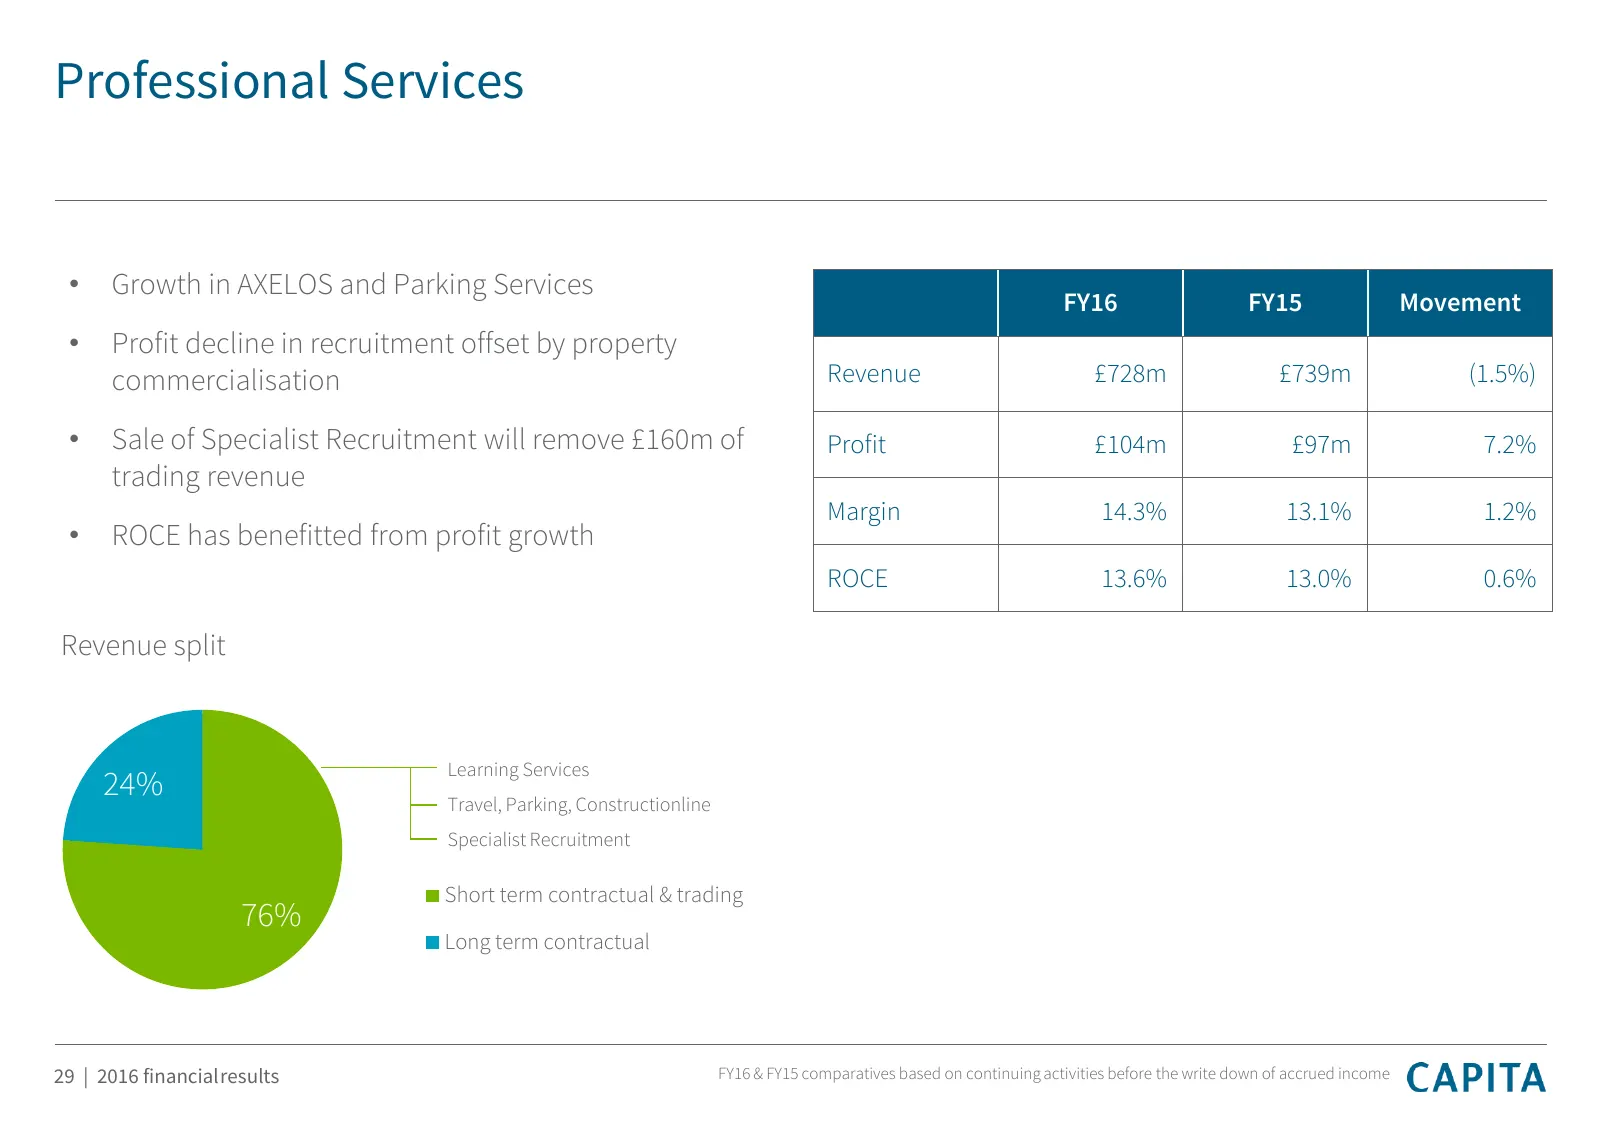
Slide 29: Professional Services
Professional Services • Growth in AXELOS and Parking Services FY16 FY15 Movement • Profit decline in recruitment offset by property commercialisation Revenue £728m £739m (1.5%) • Sale of Specialist Recruitment will remove £160m of Profit £104m £97m 7.2% trading revenue Margin 14.3% 13.1% 1.2% • ROCE
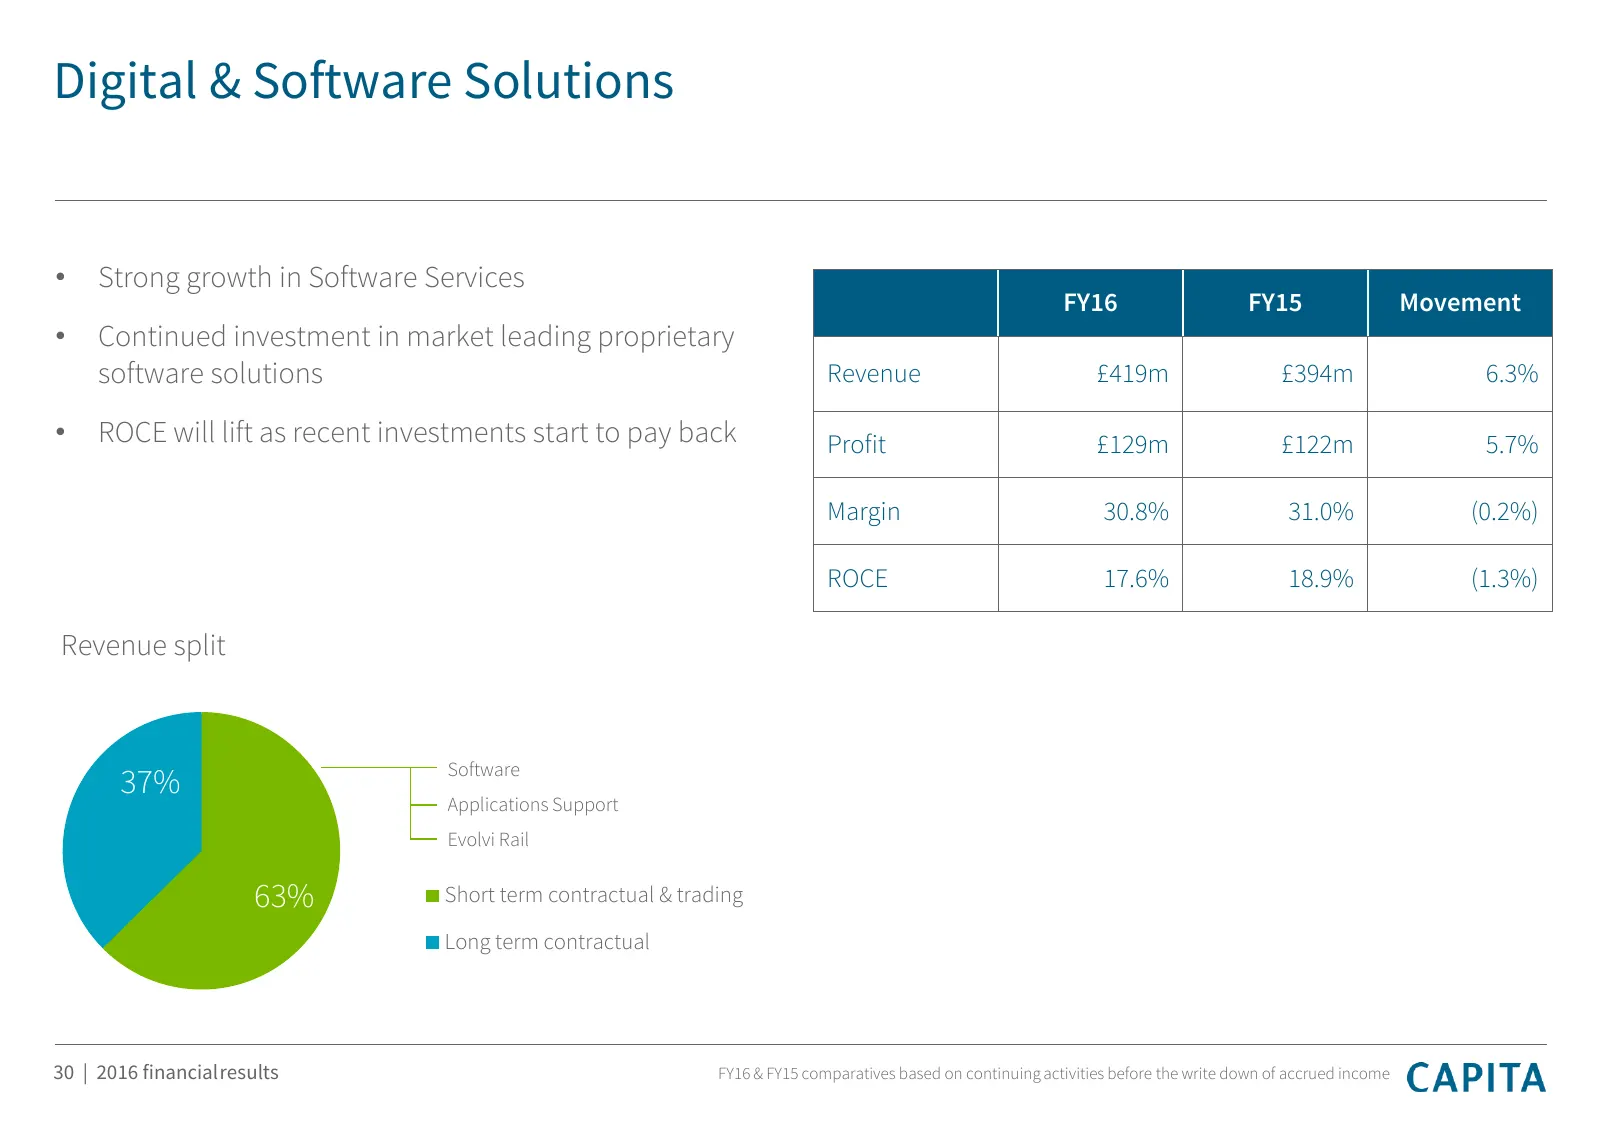
Slide 30: Digital & Software Solutions
Digital & Software Solutions • Strong growth in Software Services FY16 FY15 Movement • Continued investment in market leading proprietary software solutions Revenue £419m £394m 6.3% • ROCE will lift as recent investments start to pay back Profit £129m £122m 5.7% Margin 30.8% 31.0% (0.2%) ROCE 17.6%
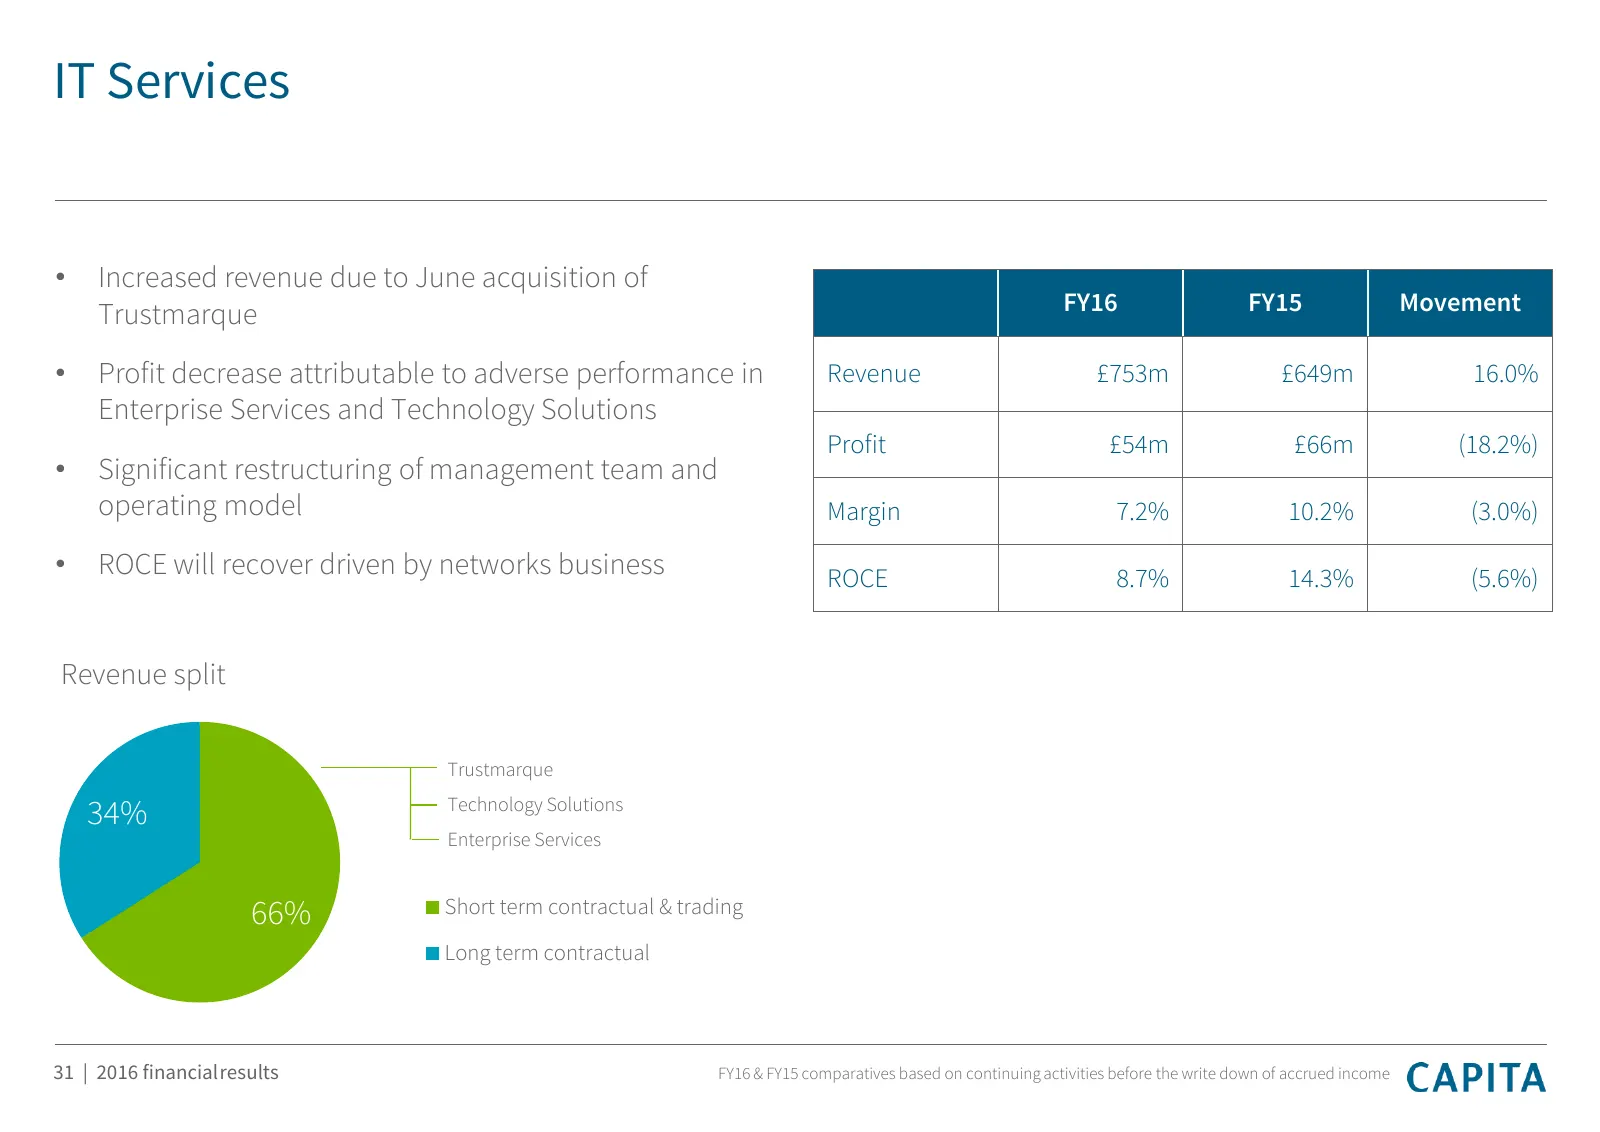
Slide 31: IT Services
IT Services • Increased revenue due to June acquisition of Trustmarque FY16 FY15 Movement • Profit decrease attributable to adverse performance in Revenue £753m £649m 16.0% Enterprise Services and Technology Solutions Profit £54m £66m (18.2%) • Significant restructuring of management team and operat
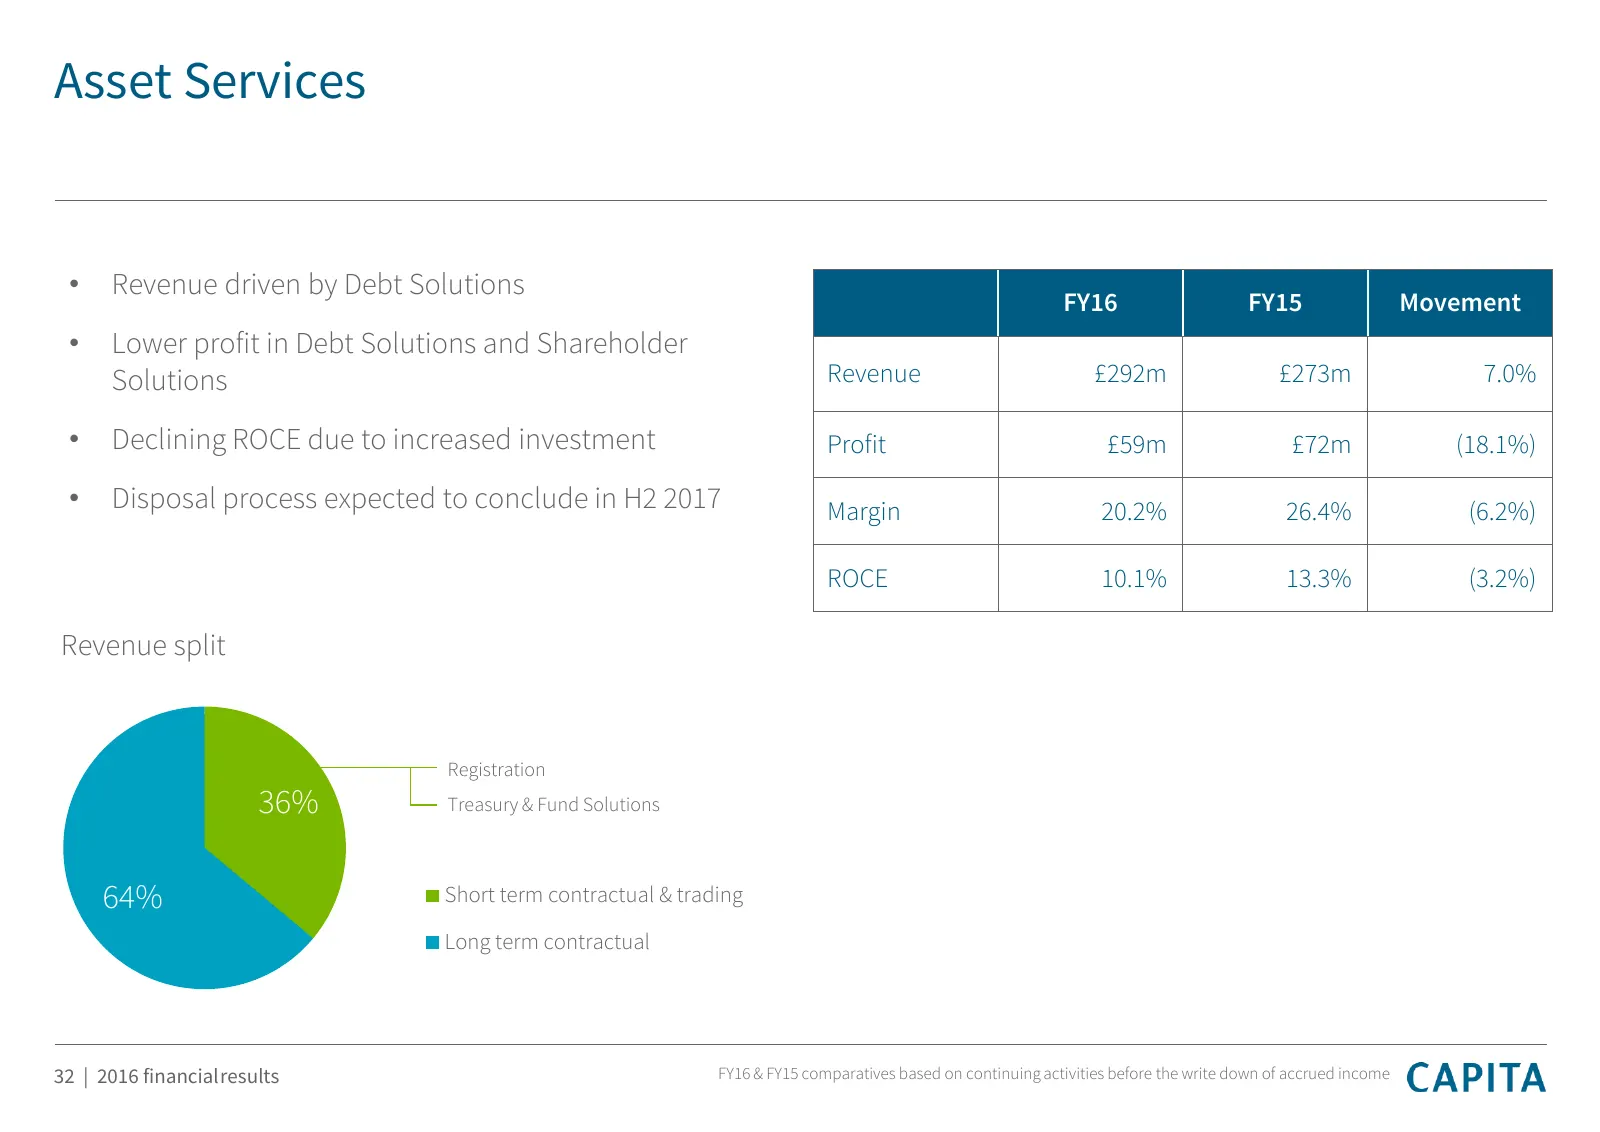
Slide 32: Asset Services
Asset Services • Revenue driven by Debt Solutions FY16 FY15 Movement • Lower profit in Debt Solutions and Shareholder Solutions Revenue £292m £273m 7.0% • Declining ROCE due to increased investment Profit £59m £72m (18.1%) • Disposal process expected to conclude in H2 2017 Margin 20.2% 26.4% (6.2%)
Slide 33: ROCE bridge
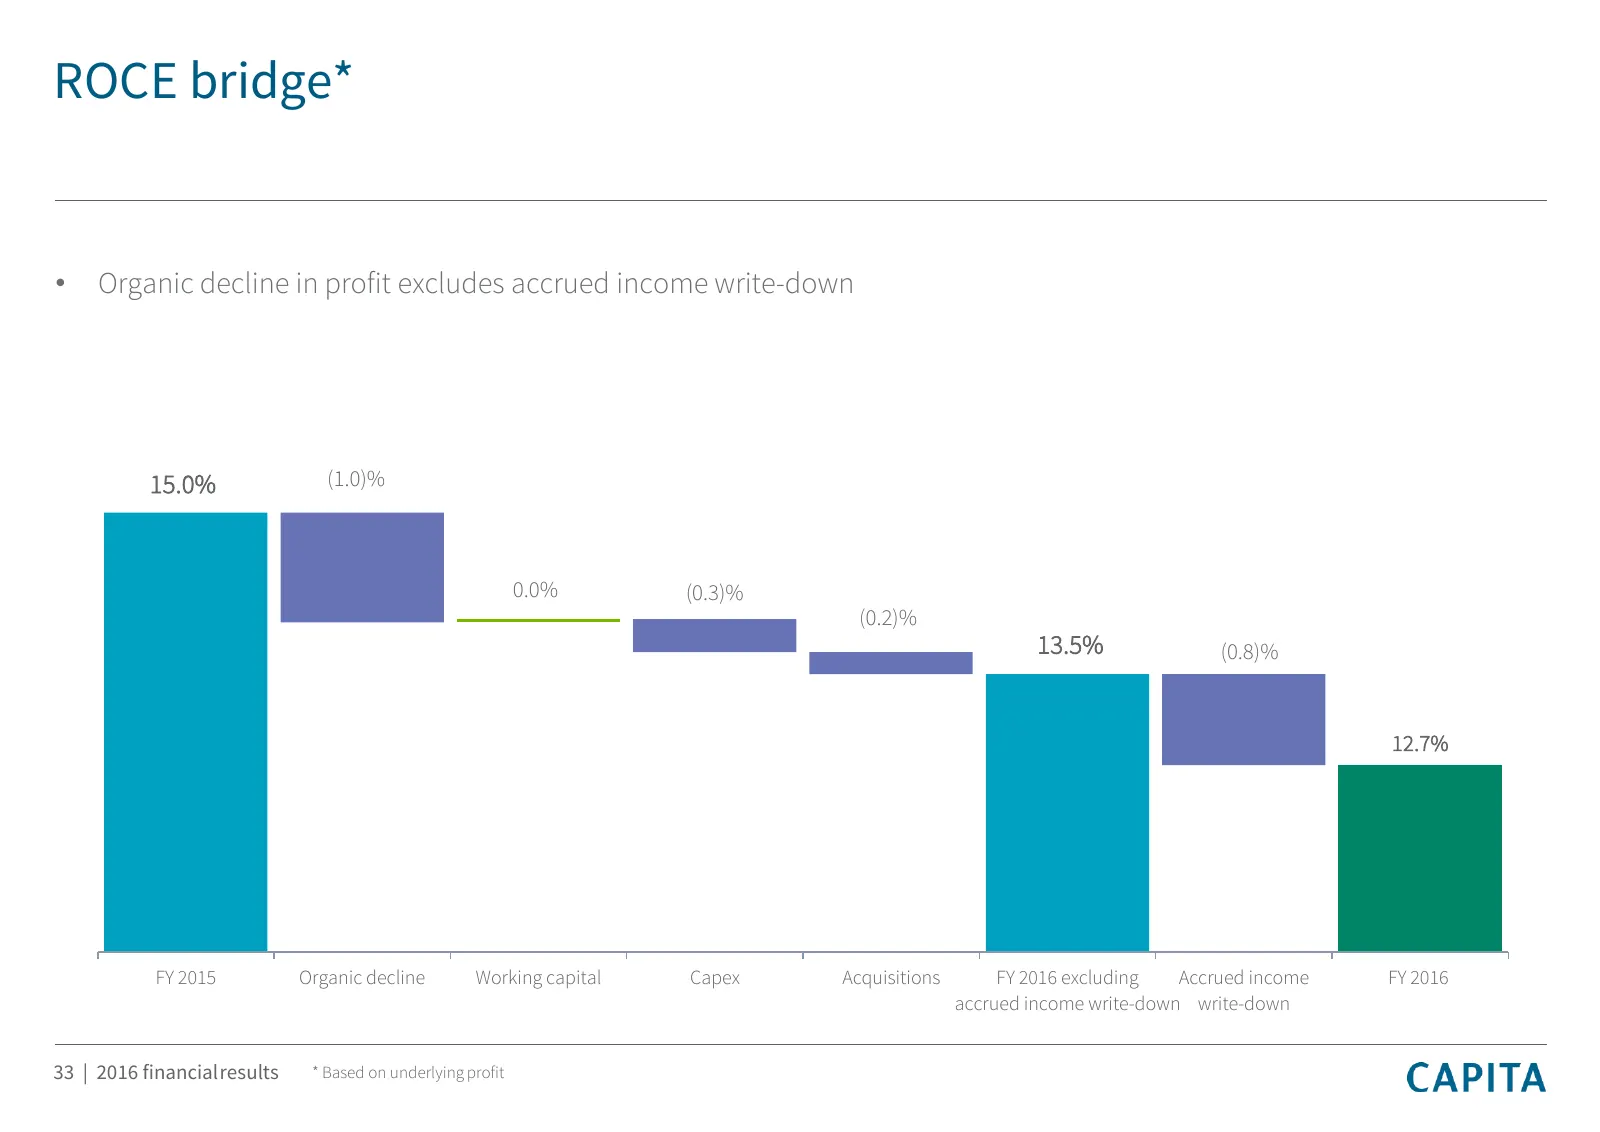
ROCE bridge* • Organic decline in profit excludes accrued income write-down 15.0% (1.0)% 0.0% (0.3)% (0.2)% 13.5% (0.8)% 12.7% FY 2015 Organic decline Working capital Capex Acquisitions FY 2016 excluding Accrued income FY 2016 accrued income write-down write-down 33 | 2016 financialresults * Based o
Slide 34: ROCE on acquisition activity since 2013
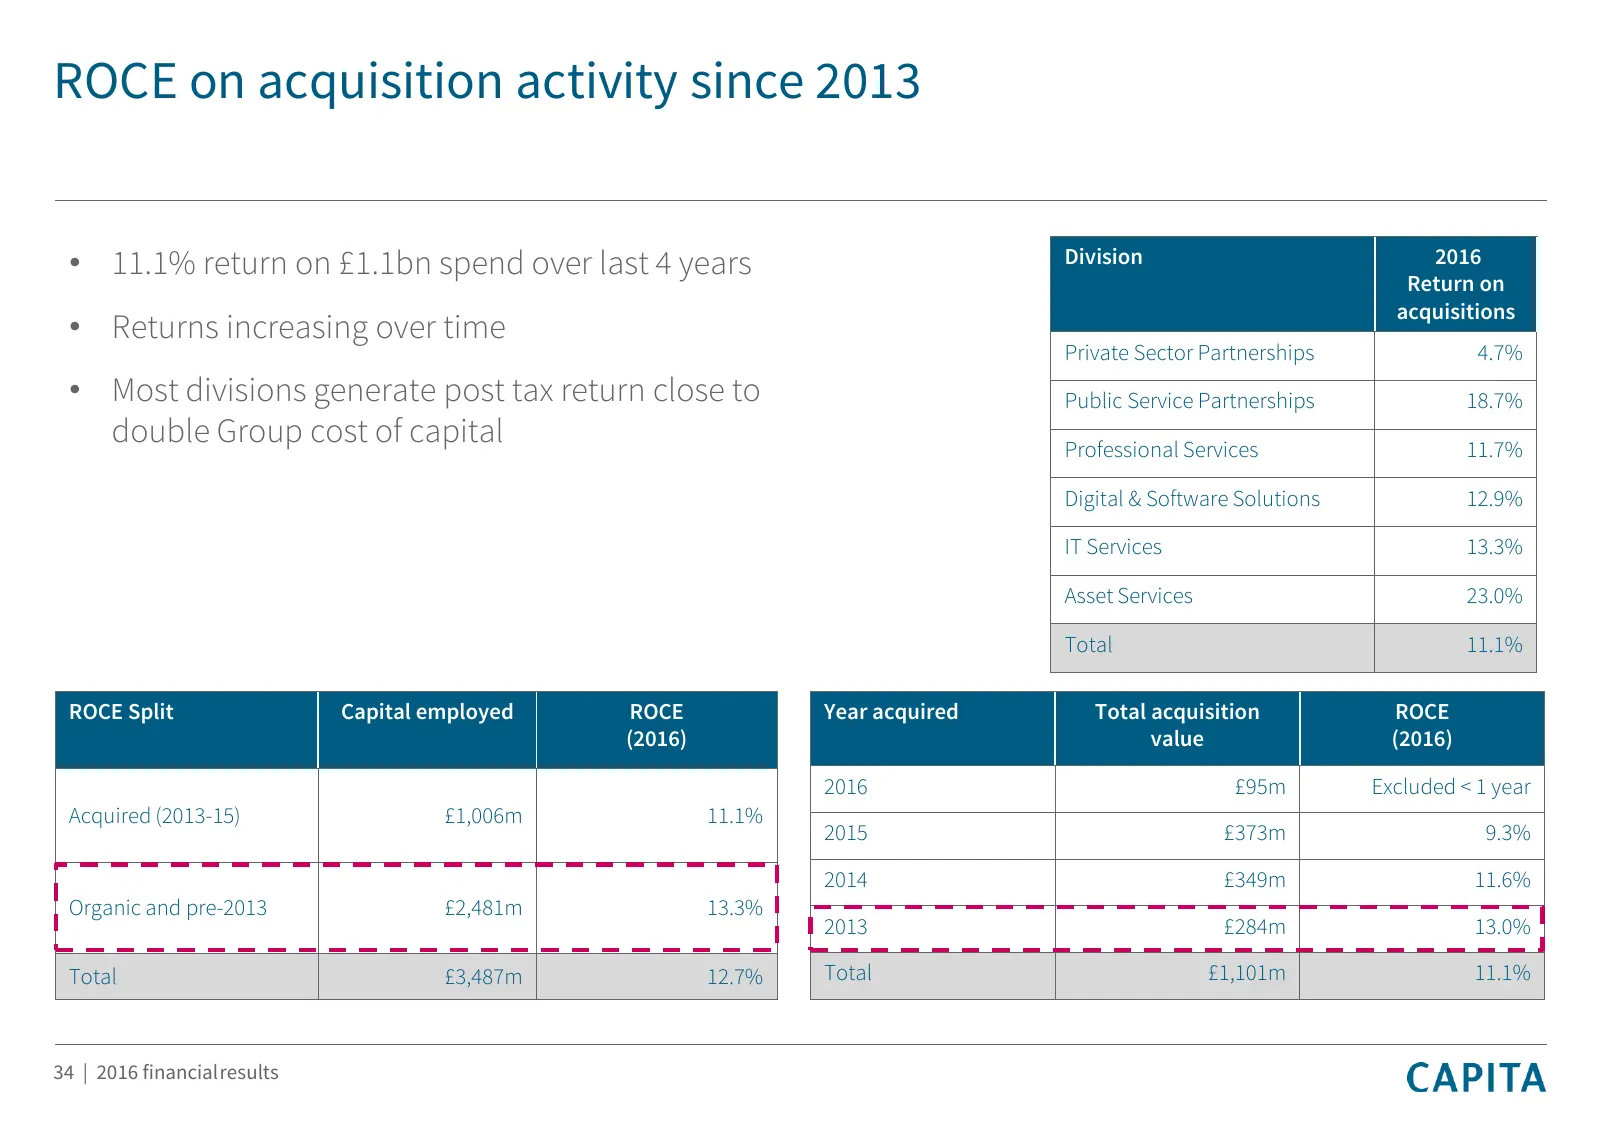
ROCE on acquisition activity since 2013 • 11.1% return on £1.1bn spend over last 4 years Division 2016 Return on acquisitions • Returns increasing over time Private Sector Partnerships 4.7% • Most divisions generate post tax return close to Public Service Partnerships 18.7% double Group cost of capi
Slide 35: Underlying cash flow from operating activities
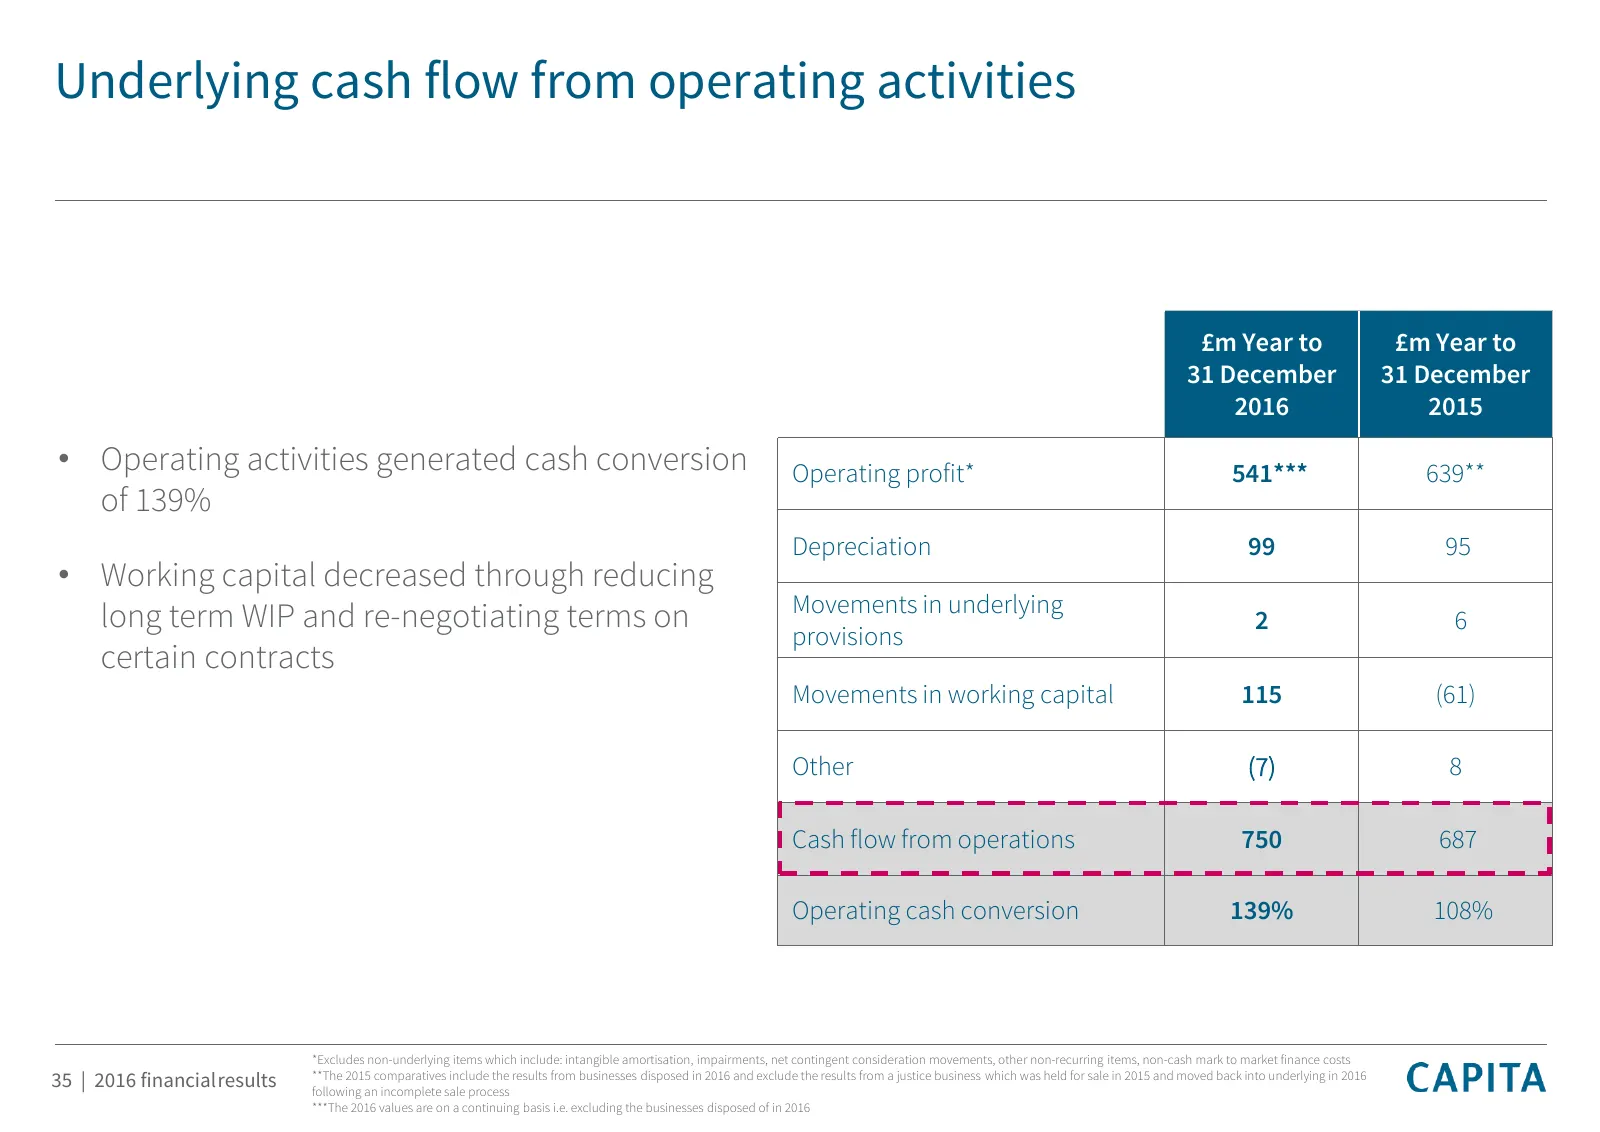
Underlying cash flow from operating activities £m Year to £m Year to 31 December 31 December 2016 2015 • Operating activities generated cash conversion Operating profit* 541*** 639** of 139% Depreciation 99 95 • Working capital decreased through reducing Movements in underlying long term WIP and re-
Slide 36: Underlying cash flow statement
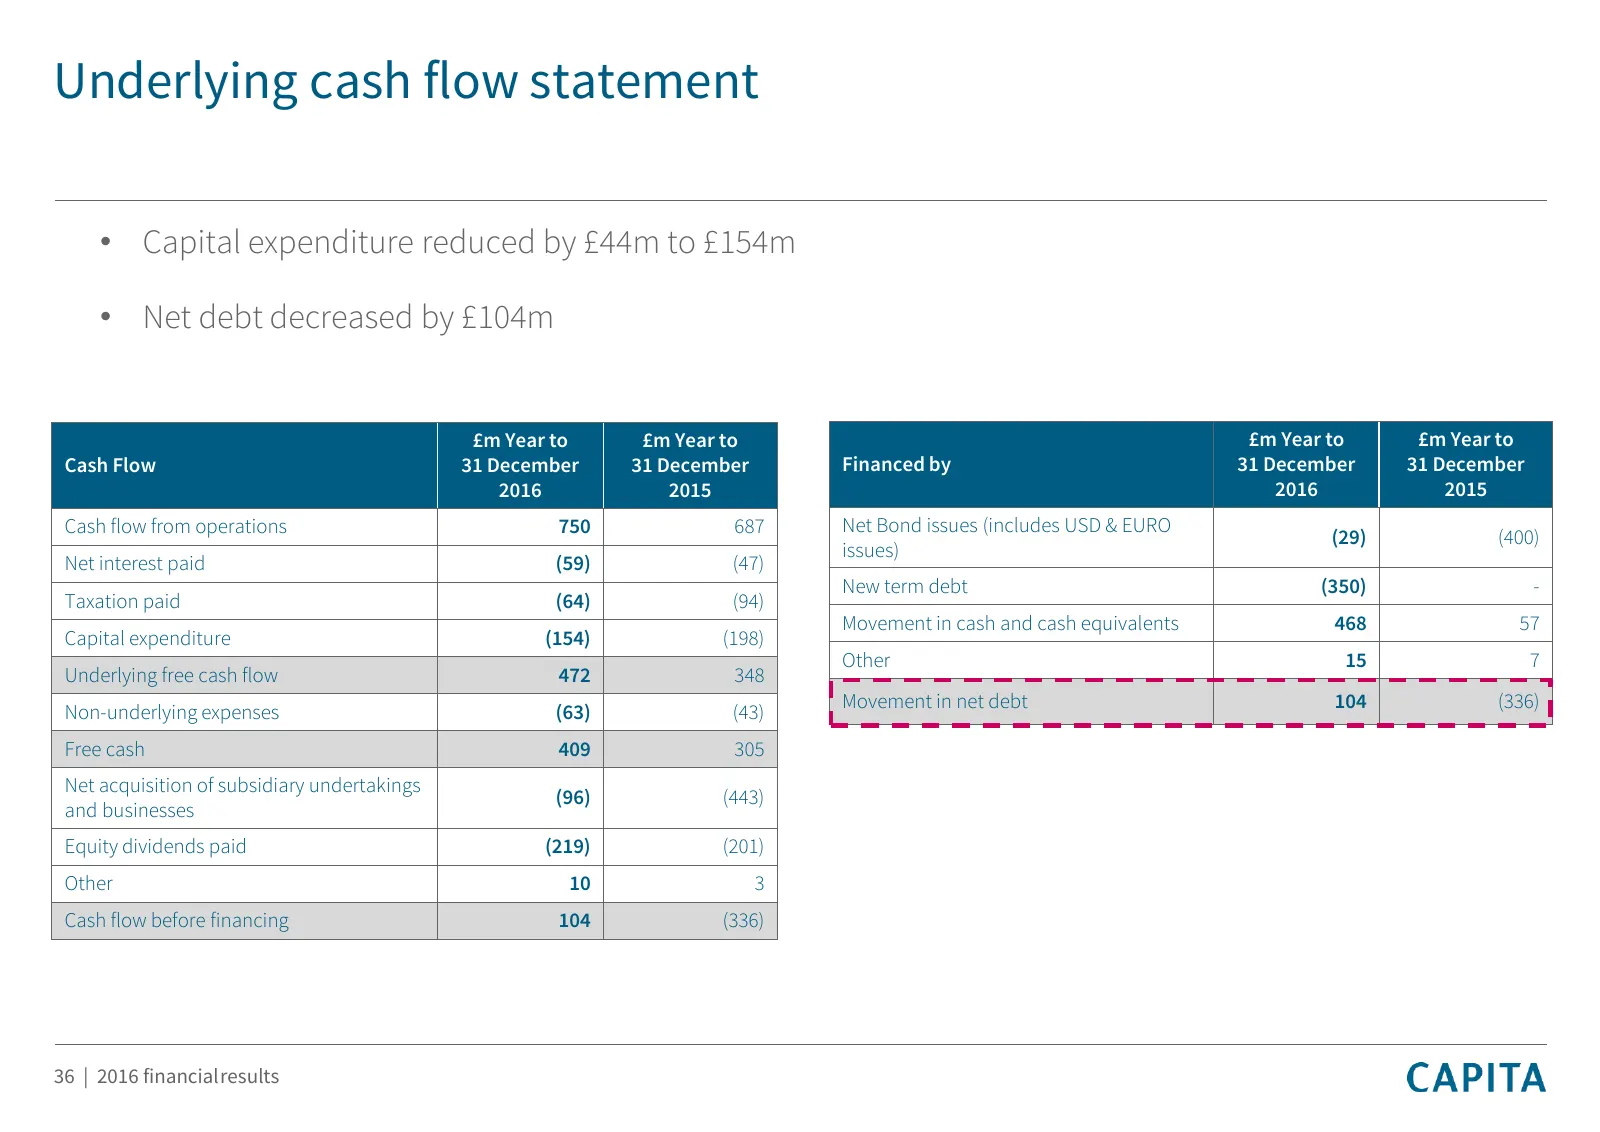
Underlying cash flow statement • Capital expenditure reduced by £44m to £154m • Net debt decreased by £104m £m Year to £m Year to £m Year to £m Year to Cash Flow 31 December 31 December Financed by 31 December 31 December 2016 2015 2016 2015 Cash flow from operations 750 687 Net Bond issues (include
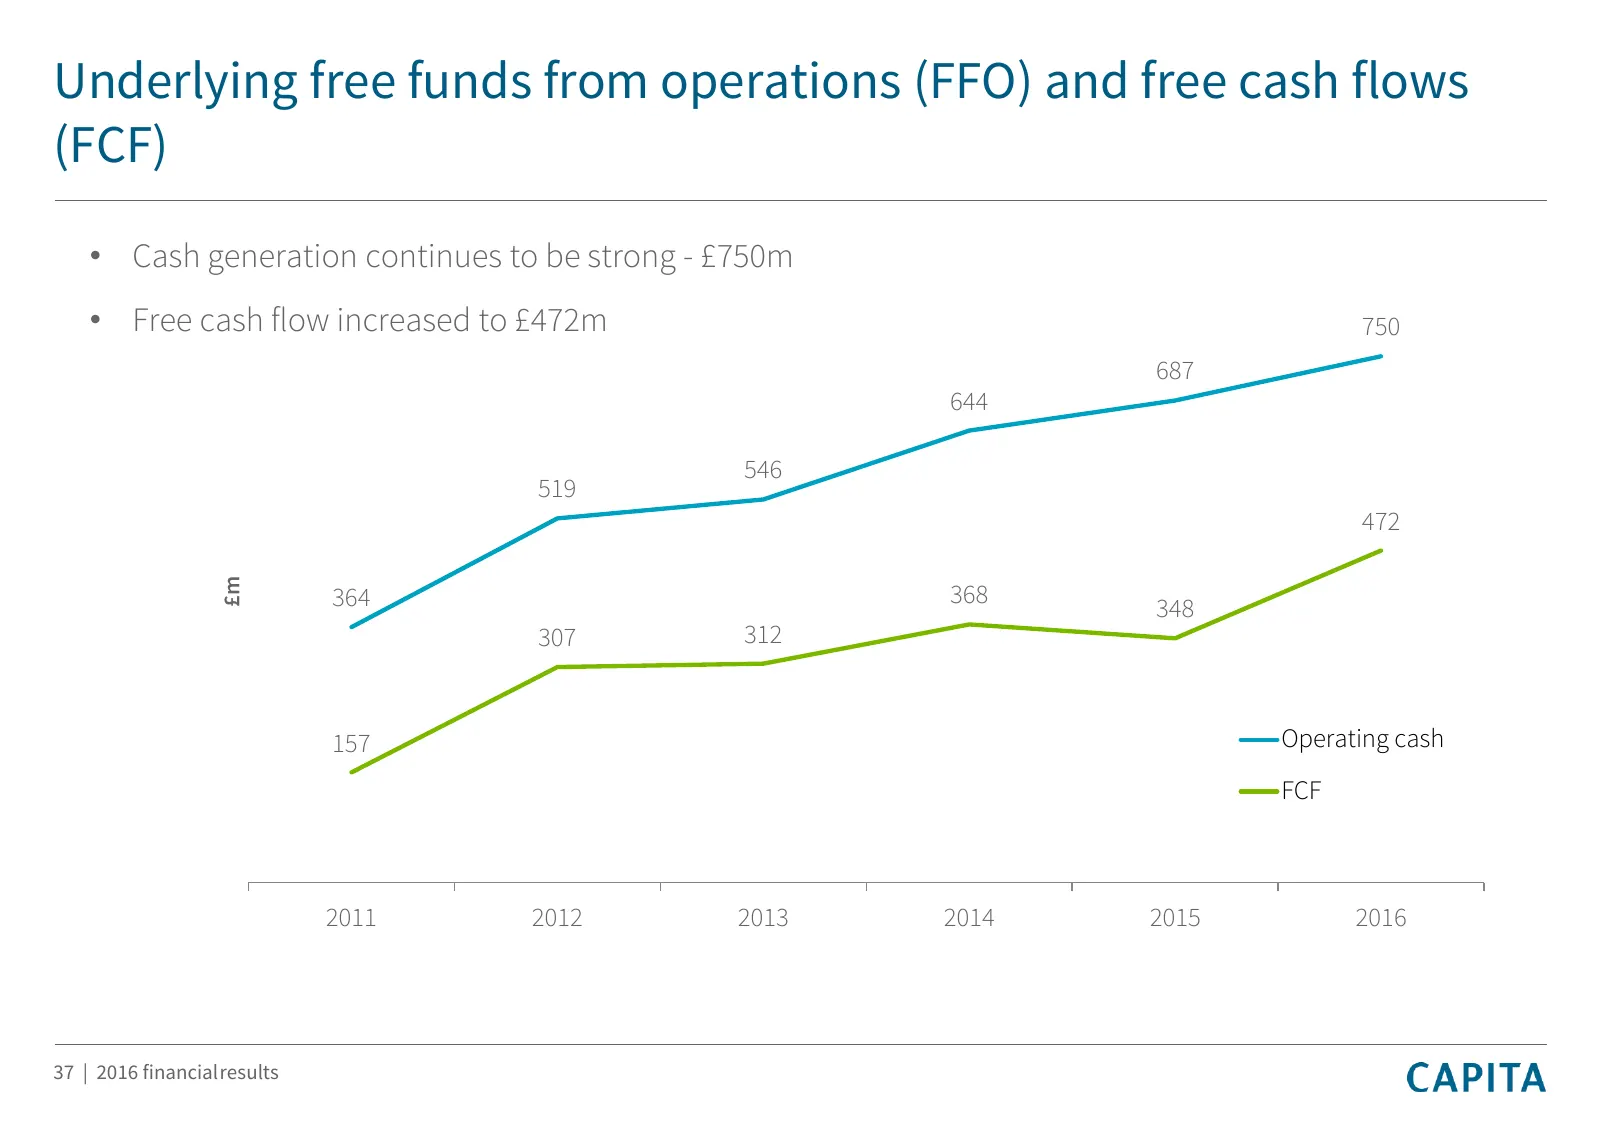
Slide 37: Underlying free funds from operations and free cash flows
Underlying free funds from operations (FFO) and free cash flows (FCF) • Cash generation continues to be strong - £750m • Free cash flow increased to £472m 750 687 644 546 519 472 £m 364 368 348 307 312 157 Operating cash FCF 2011 2012 2013 2014 2015 2016 37 | 2016 financialresults
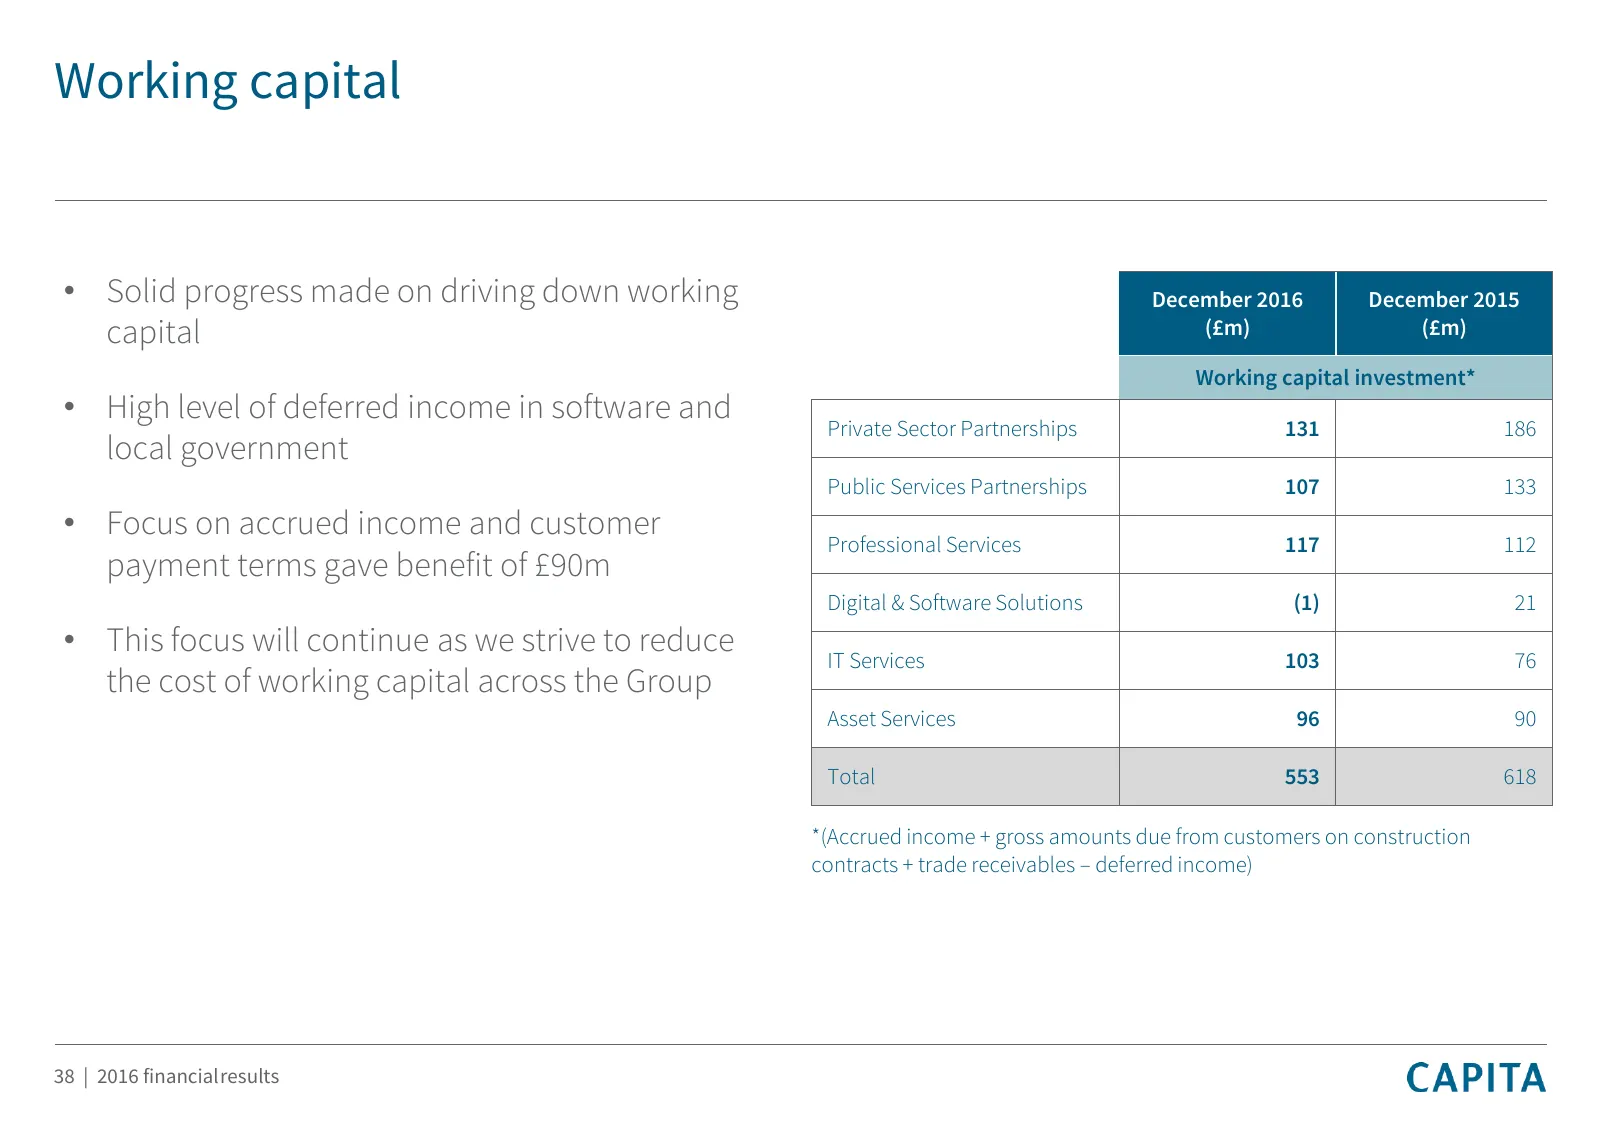
Slide 38: Working capital
Working capital • Solid progress made on driving down working December 2016 December 2015 capital (£m) (£m) Working capital investment* • High level of deferred income in software and Private Sector Partnerships 131 186 local government Public Services Partnerships 107 133 • Focus on accrued income
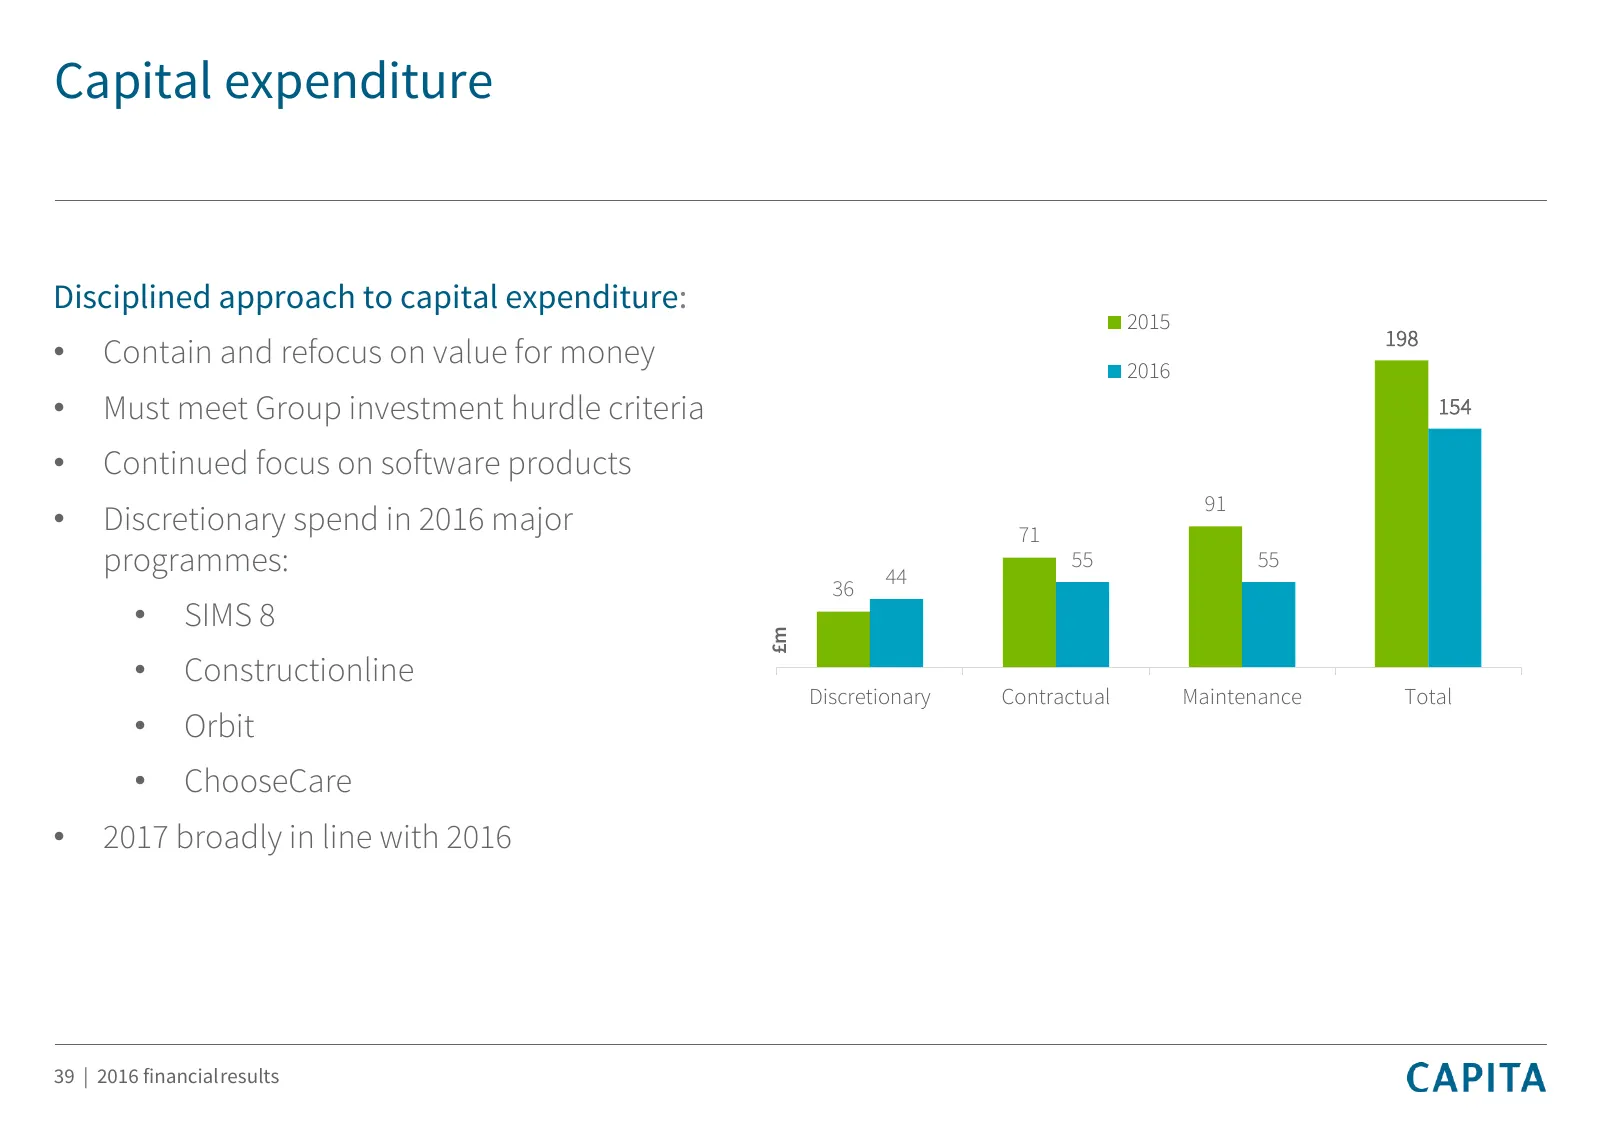
Slide 39: Capital expenditure
Capital expenditure Disciplined approach to capital expenditure: 2015 198 • Contain and refocus on value for money 2016 • Must meet Group investment hurdle criteria 154 • Continued focus on software products 91 • Discretionary spend in 2016 major 71 programmes: 44 55 55 36 • SIMS 8 £m • Construction
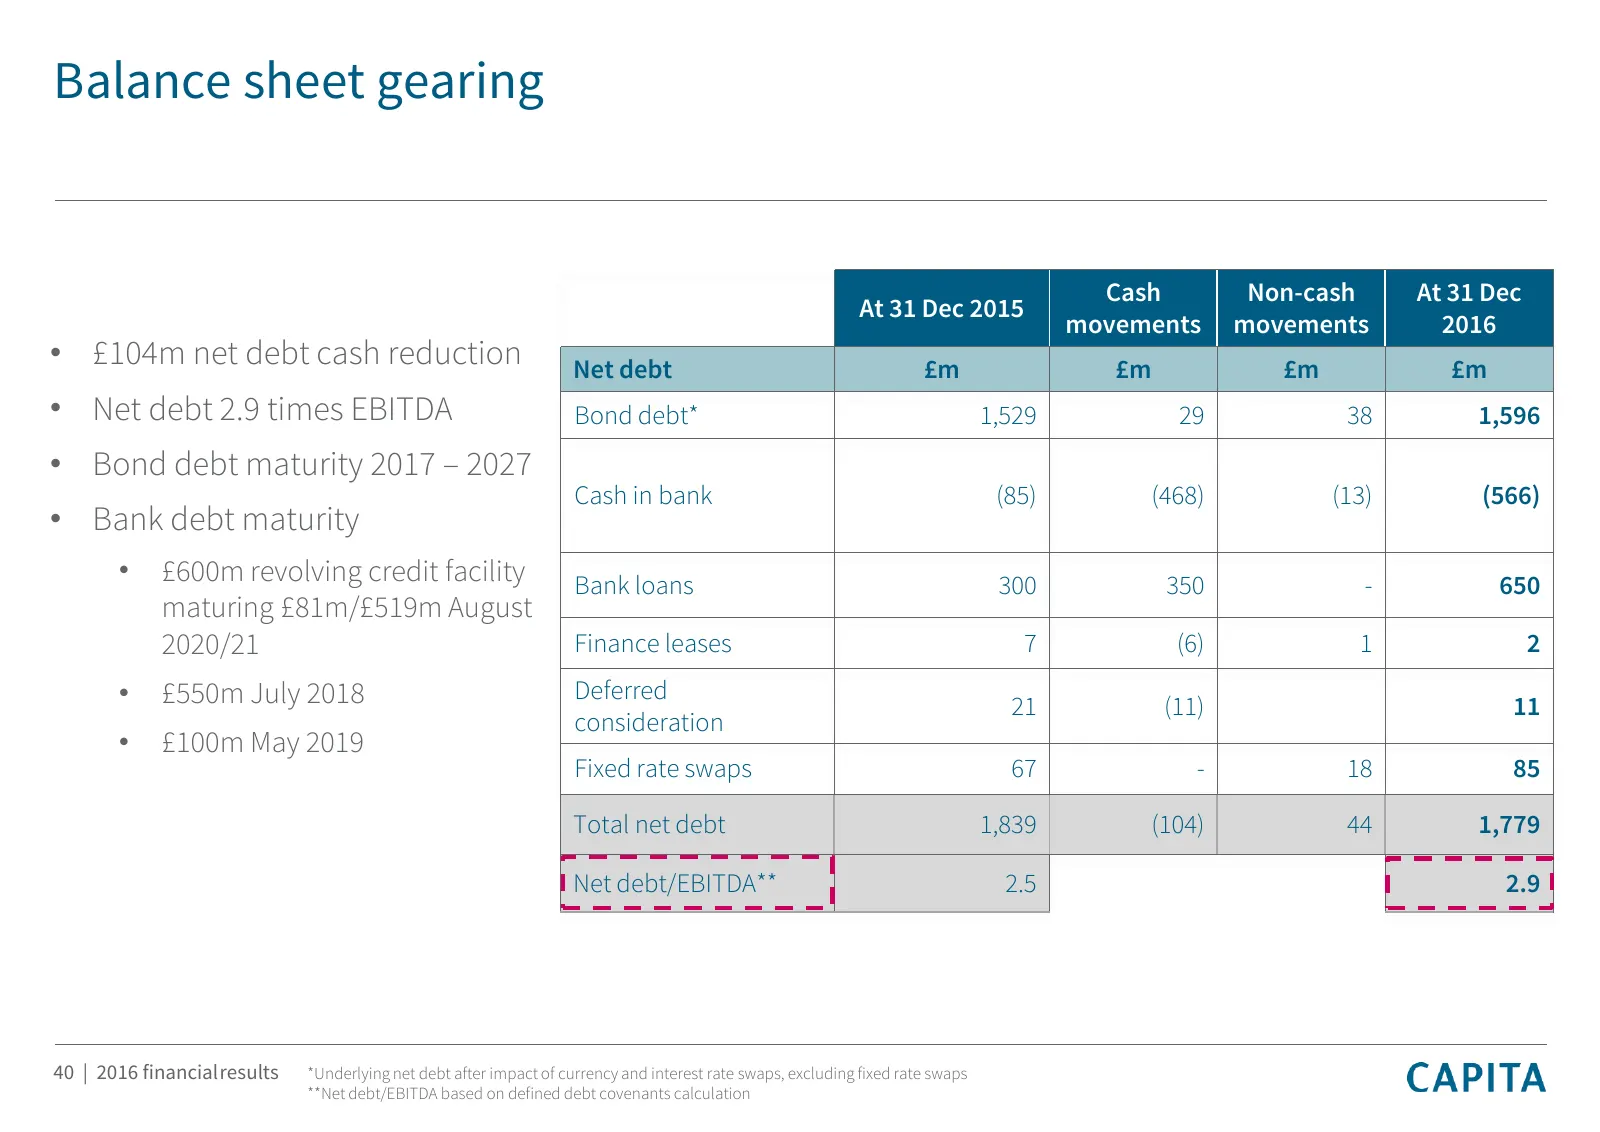
Slide 40: Balance sheet gearing
Balance sheet gearing Cash Non-cash At 31 Dec At 31 Dec 2015 movements movements 2016 • £104m net debt cash reduction Net debt £m £m £m £m • Net debt 2.9 times EBITDA Bond debt* 1,529 29 38 1,596 • Bond debt maturity 2017 – 2027 Cash in bank (85) (468) (13) (566) • Bank debt maturity • £600m revolvi
Slide 41: Interest and debt profile
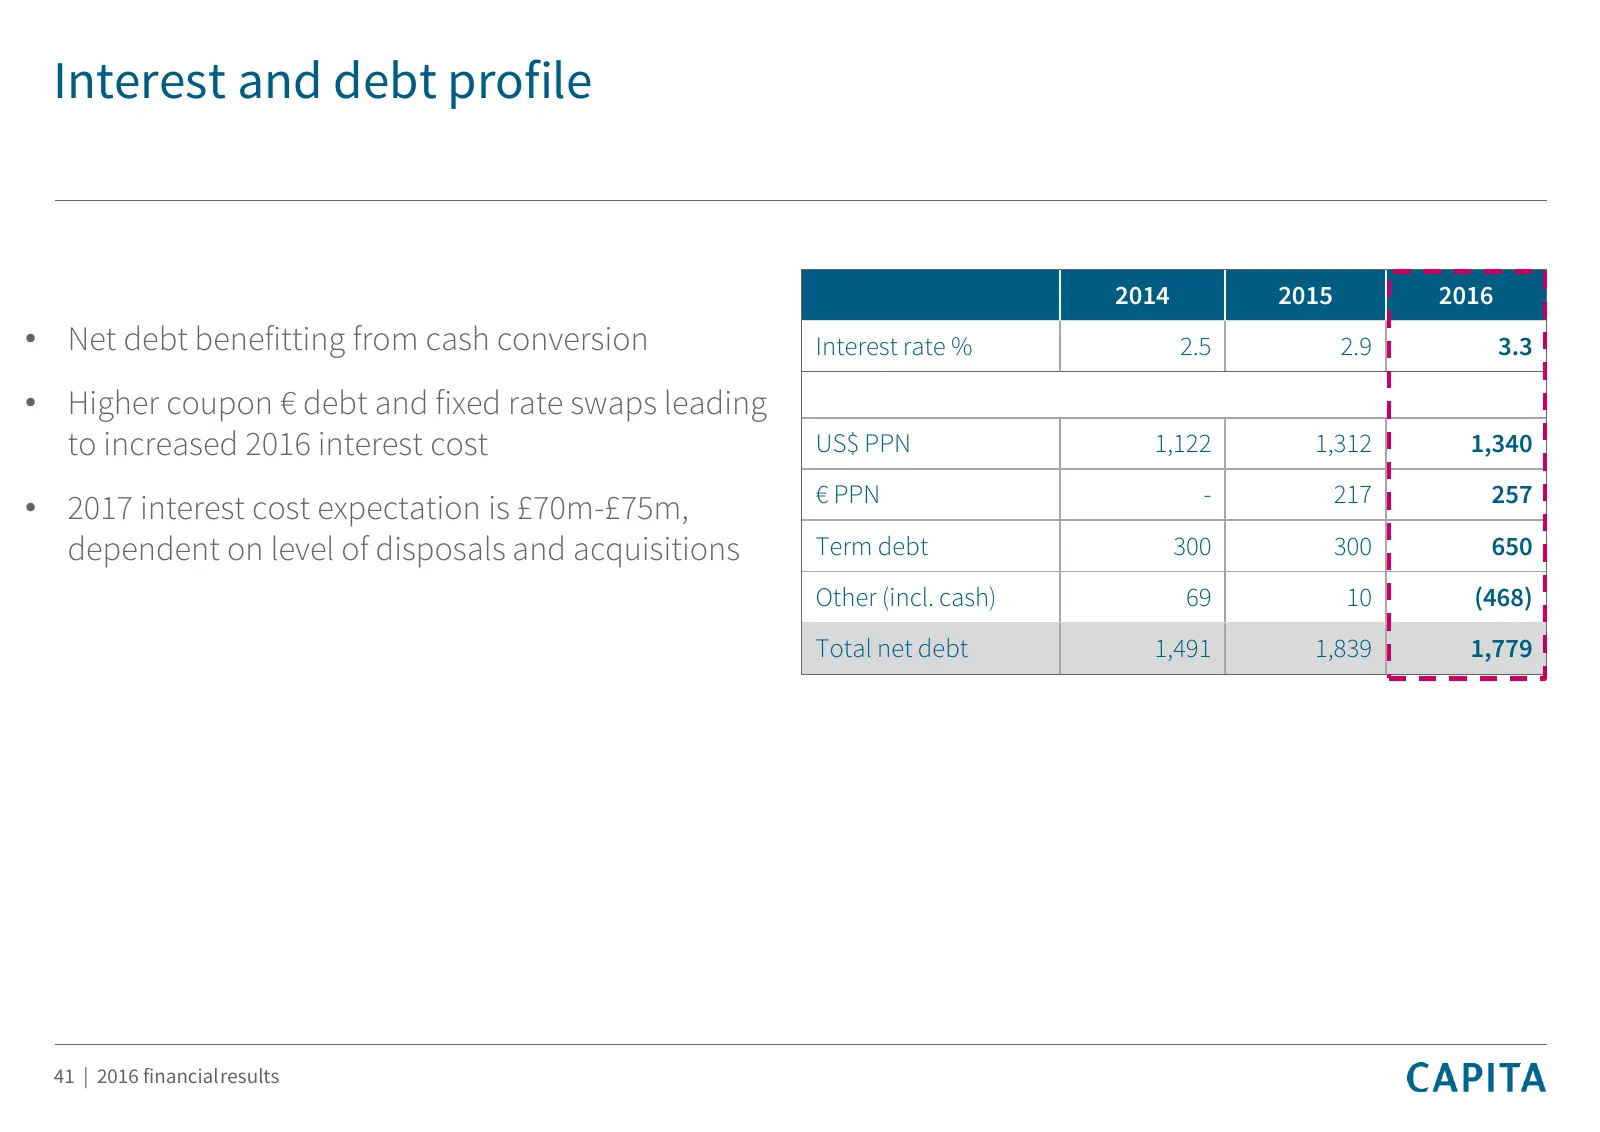
Interest and debt profile 2014 2015 2016 • Net debt benefitting from cash conversion Interest rate % 2.5 2.9 3.3 • Higher coupon € debt and fixed rate swaps leading to increased 2016 interest cost US$ PPN 1,122 1,312 1,340 € PPN - 217 257 • 2017 interest cost expectation is £70m-£75m, dependent on l
Slide 42: Dividend
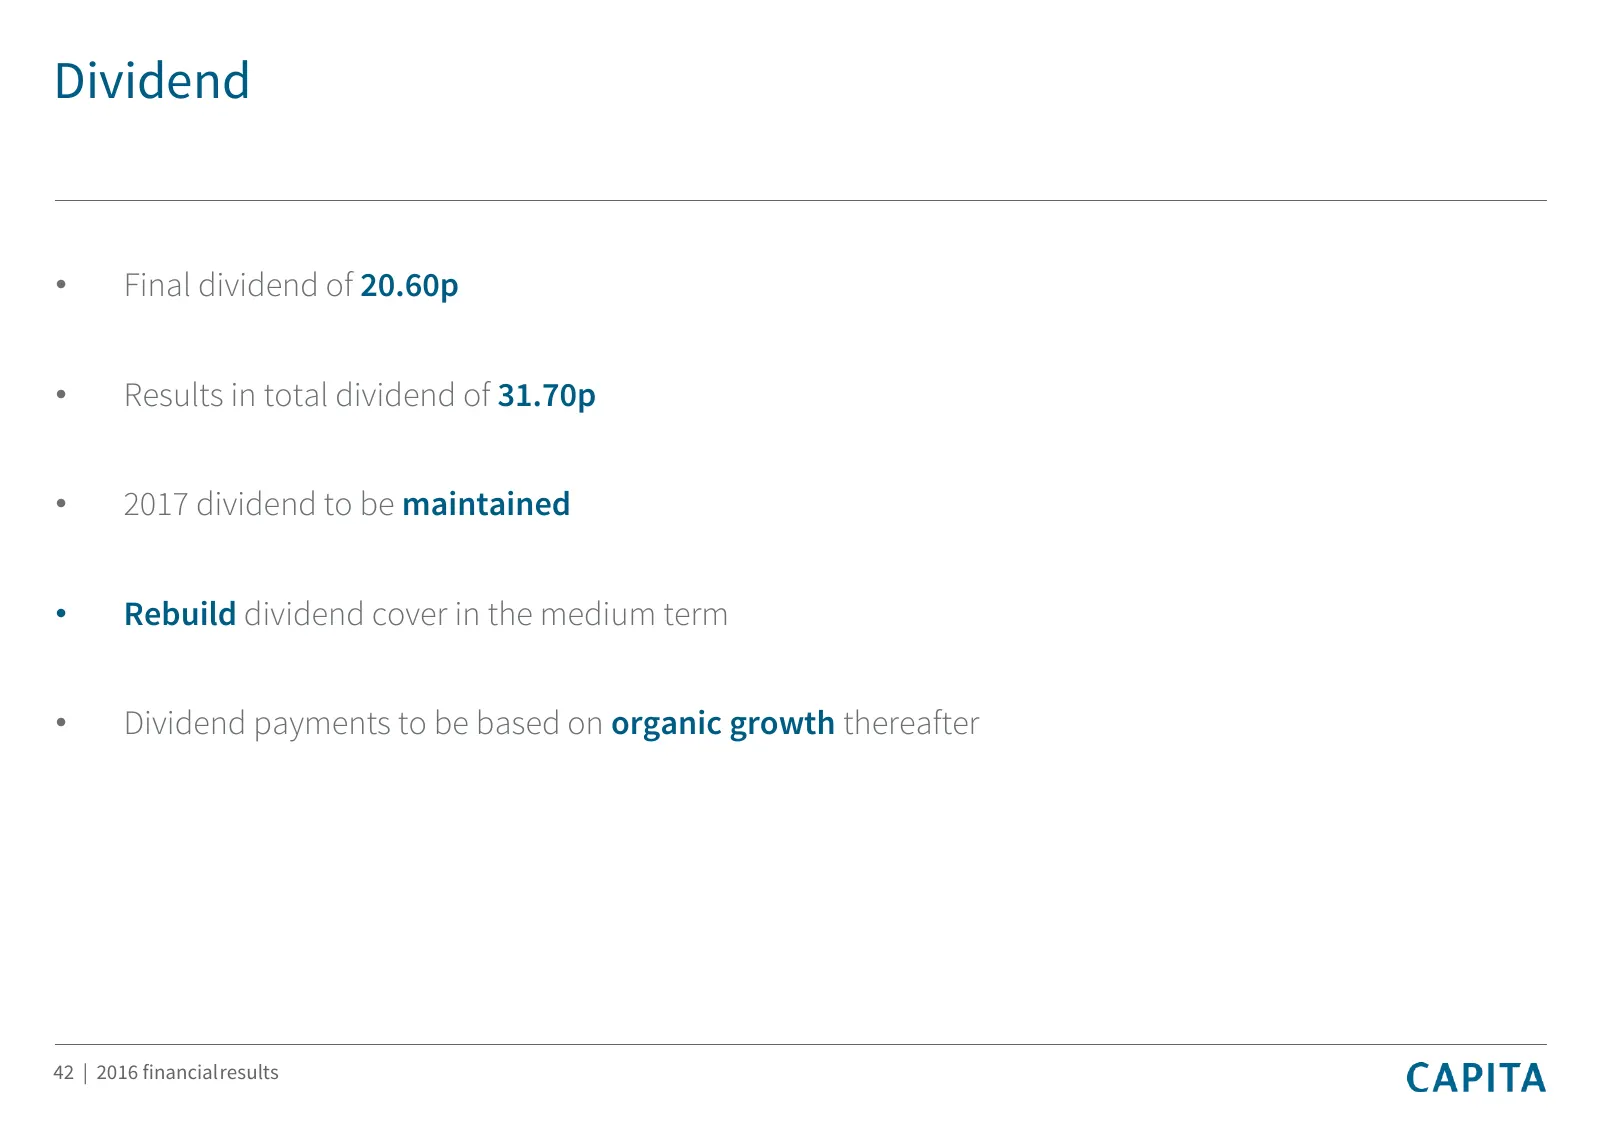
Dividend • Final dividend of 20.60p • Results in total dividend of 31.70p • 2017 dividend to be maintained • Rebuild dividend cover in the medium term • Dividend payments to be based on organic growth thereafter 42 | 2016 financialresults
Slide 43: IFRS 15 - Revenue from contracts with customers
IFRS 15 - Revenue from contracts with customers • Anticipate early adoption of IFRS 15 in 2017, with comparative restatement • Expect most significant impact on those major contracts with multiple components (e.g. transformation, transition and BAU) • Ongoing detailed review of the Group’s contracts
Slide 44: Pension liability
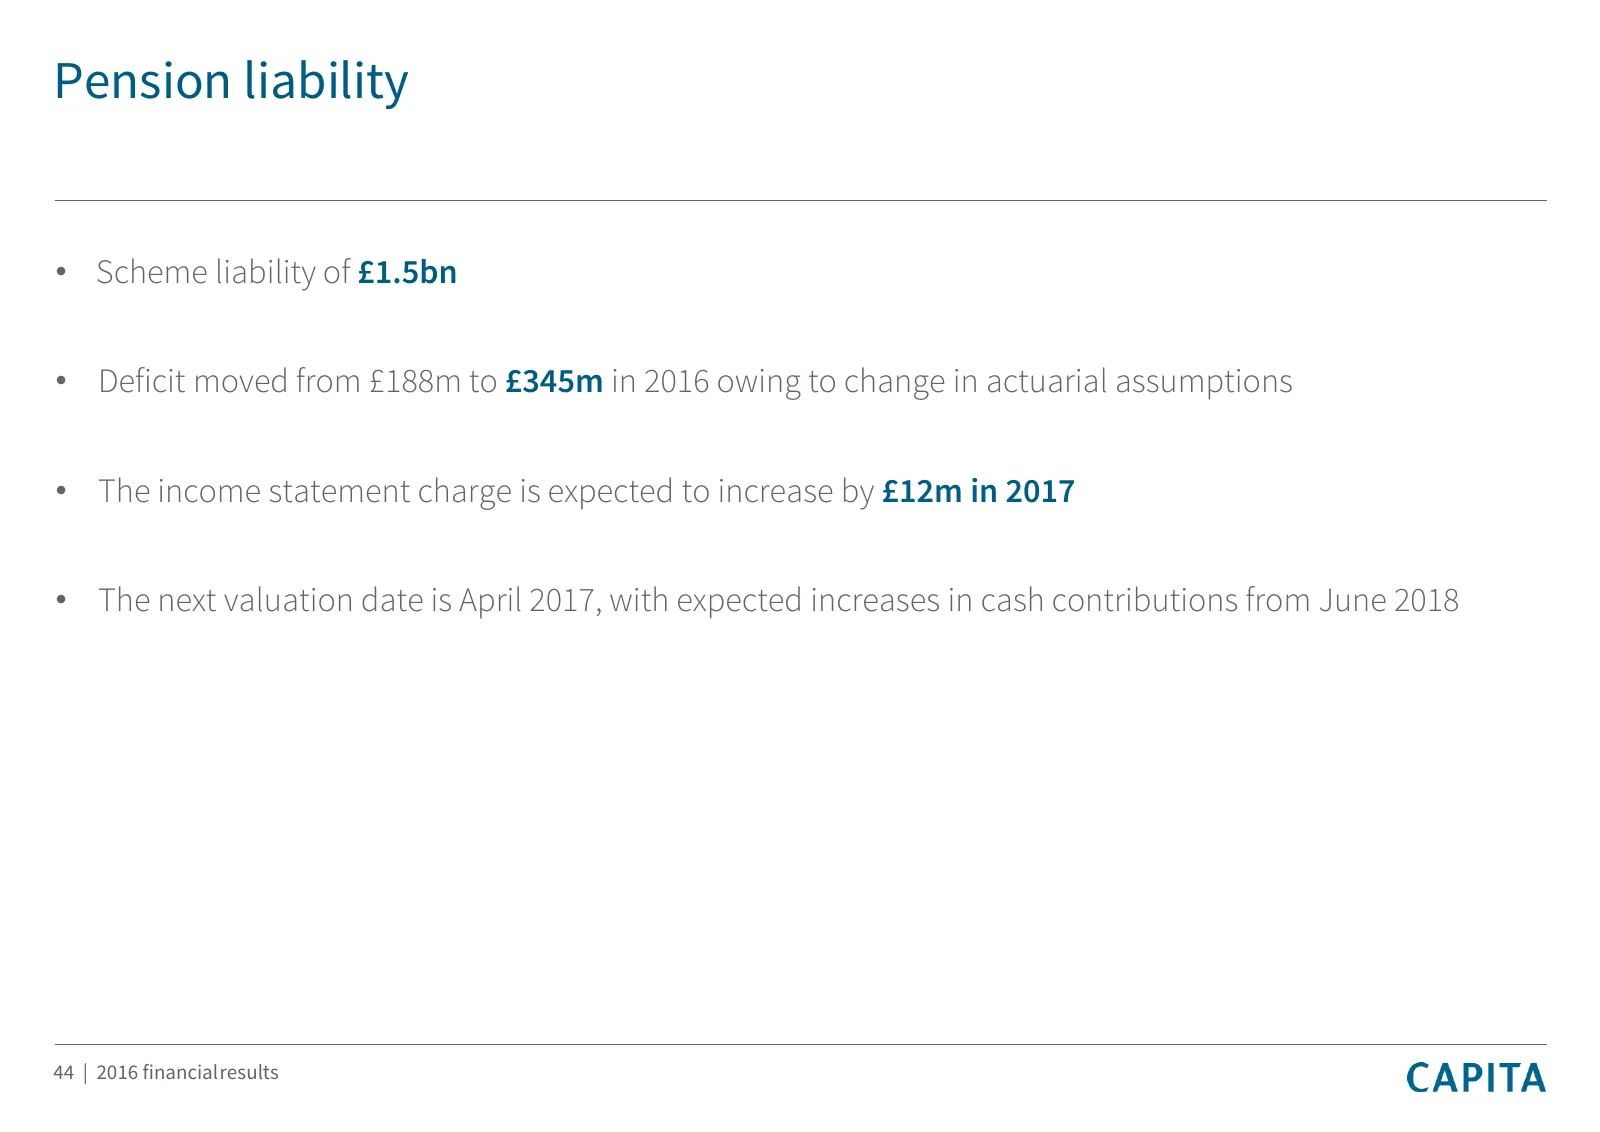
Pension liability • Scheme liability of £1.5bn • Deficit moved from £188m to £345m in 2016 owing to change in actuarial assumptions • The income statement charge is expected to increase by £12m in 2017 • The next valuation date is April 2017, with expected increases in cash contributions from June 2
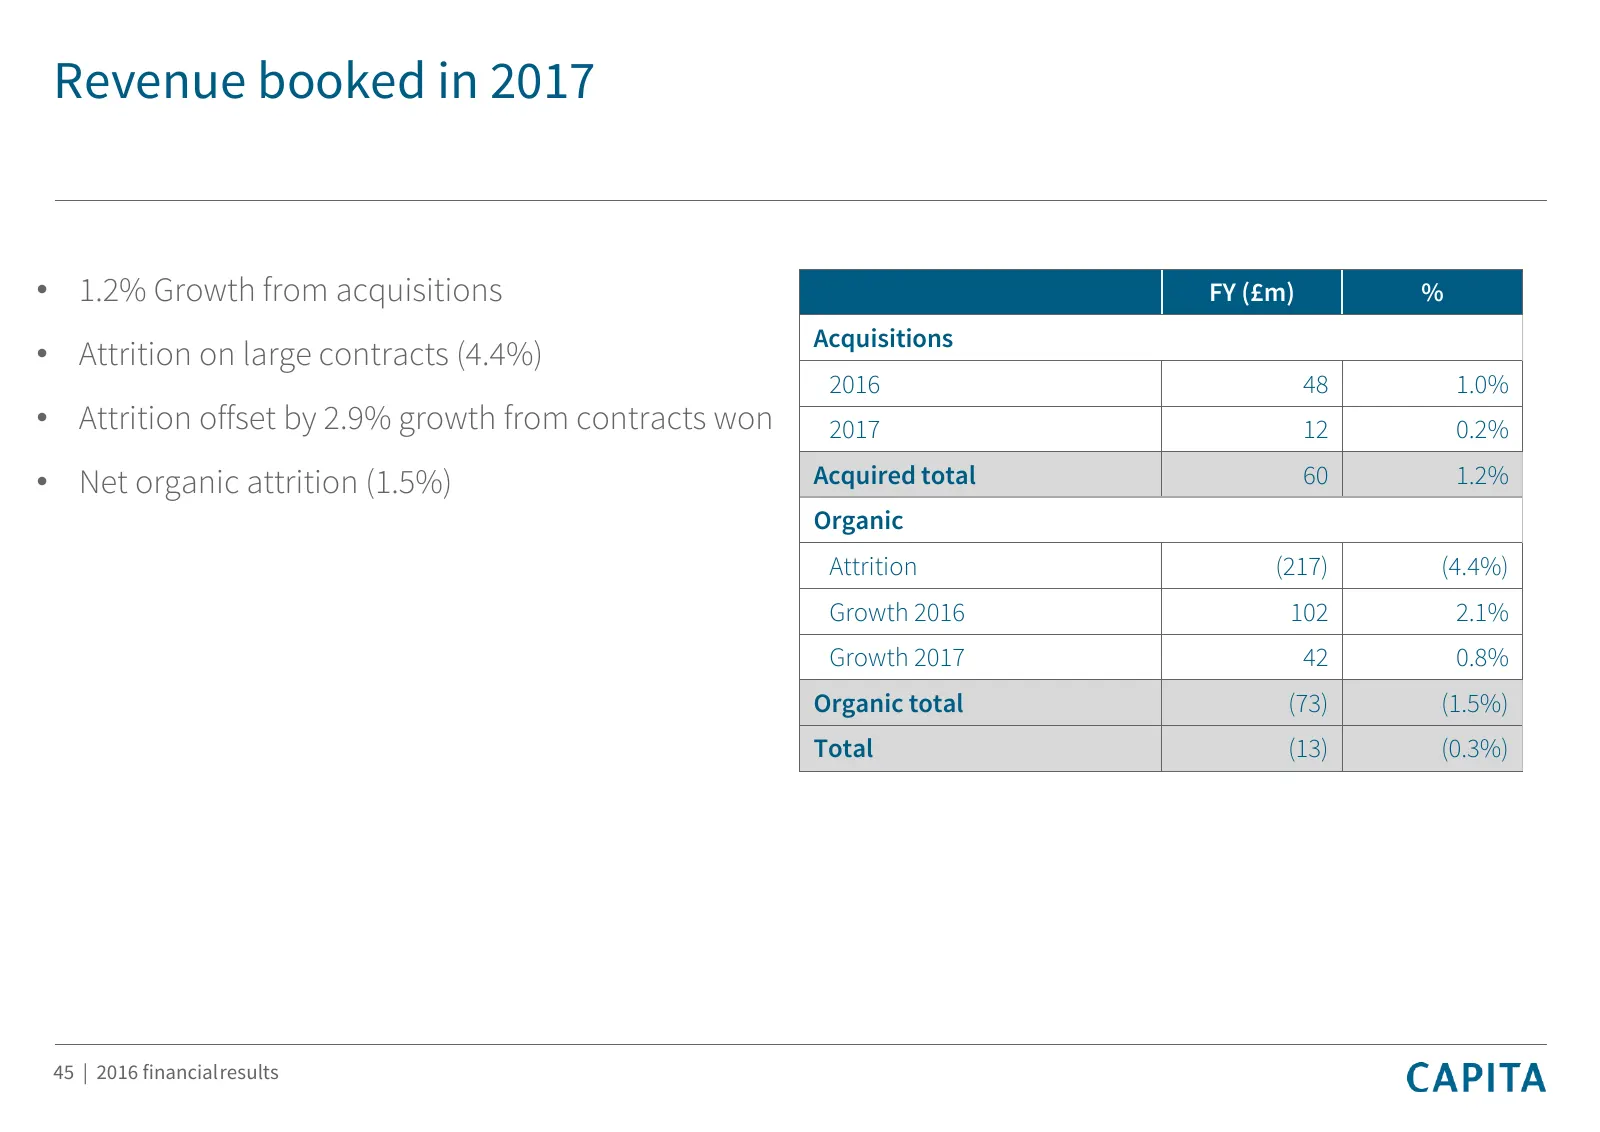
Slide 45: Revenue booked in 2017
Revenue booked in 2017 • 1.2% Growth from acquisitions FY (£m) % Acquisitions • Attrition on large contracts (4.4%) 2016 48 1.0% • Attrition offset by 2.9% growth from contracts won 2017 12 0.2% • Net organic attrition (1.5%) Acquired total 60 1.2% Organic Attrition (217) (4.4%) Growth 2016 102 2.1%
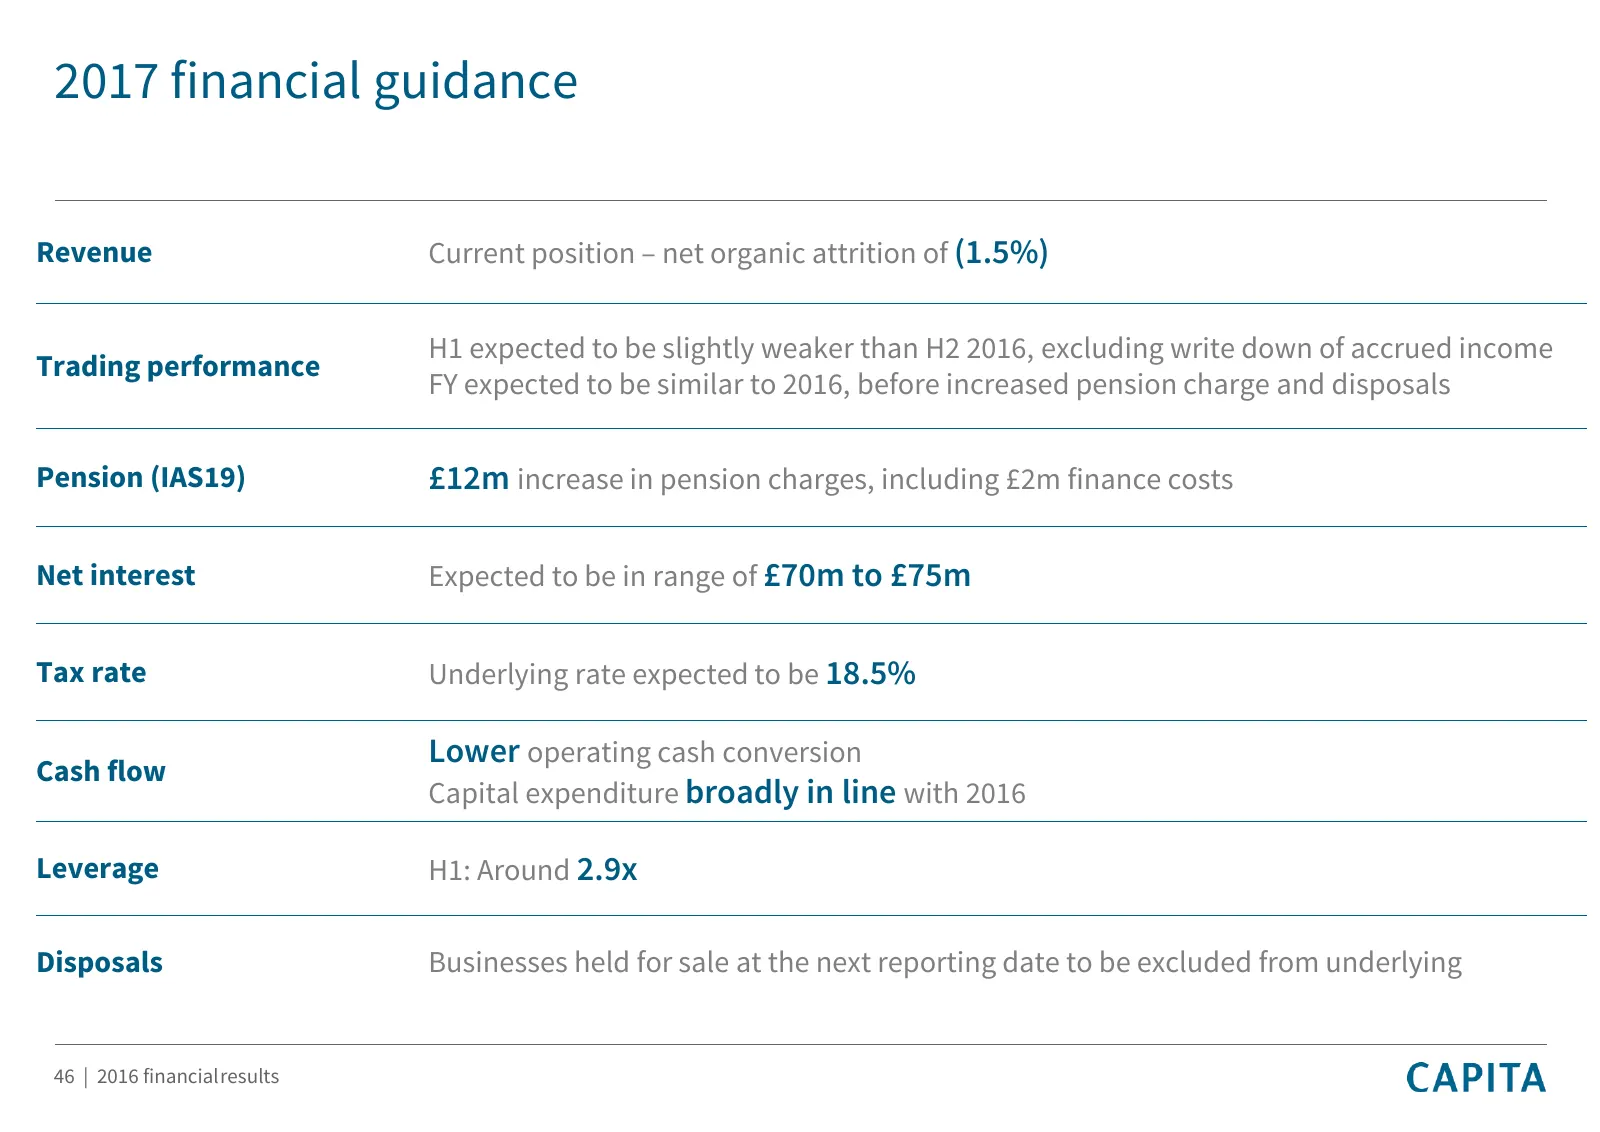
Slide 46: 2017 financial guidance
2017 financial guidance Revenue Current position – net organic attrition of (1.5%) H1 expected to be slightly weaker than H2 2016, excluding write down of accrued income Trading performance FY expected to be similar to 2016, before increased pension charge and disposals Pension (IAS19) £12m increase
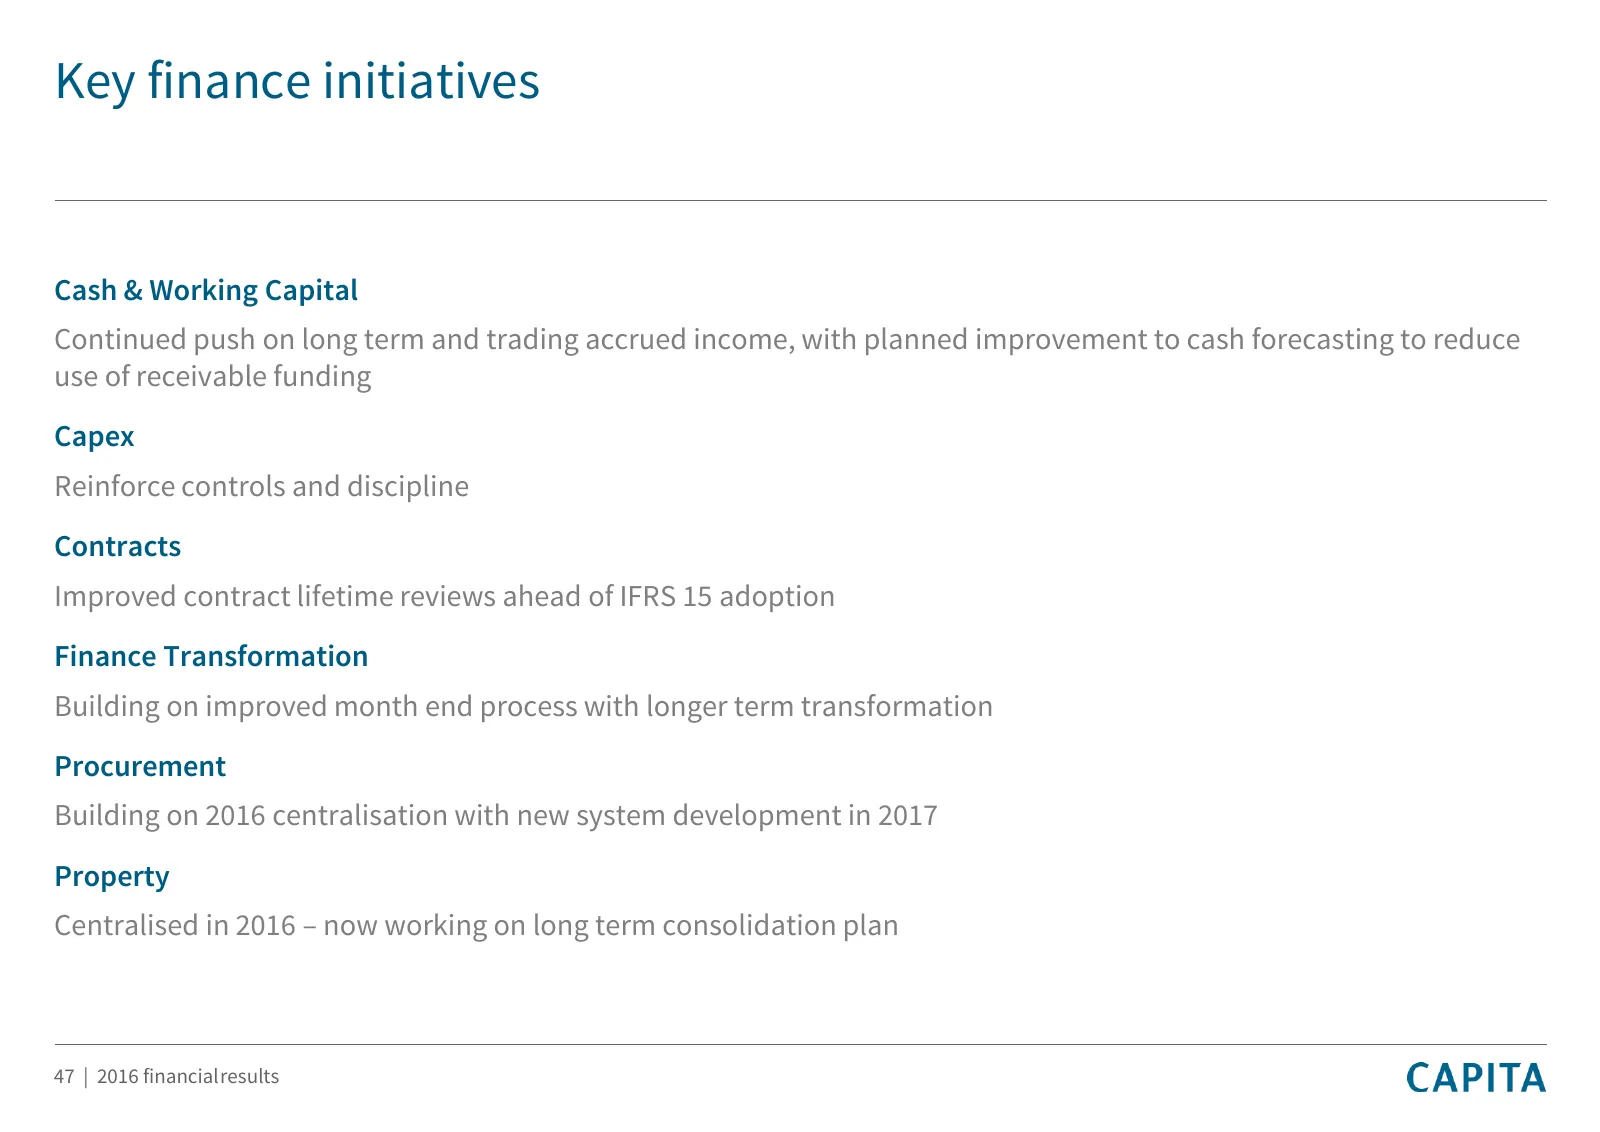
Slide 47: Key finance initiatives
Key finance initiatives Cash & Working Capital Continued push on long term and trading accrued income, with planned improvement to cash forecasting to reduce use of receivable funding Capex Reinforce controls and discipline Contracts Improved contract lifetime reviews ahead of IFRS 15 adoption Finan
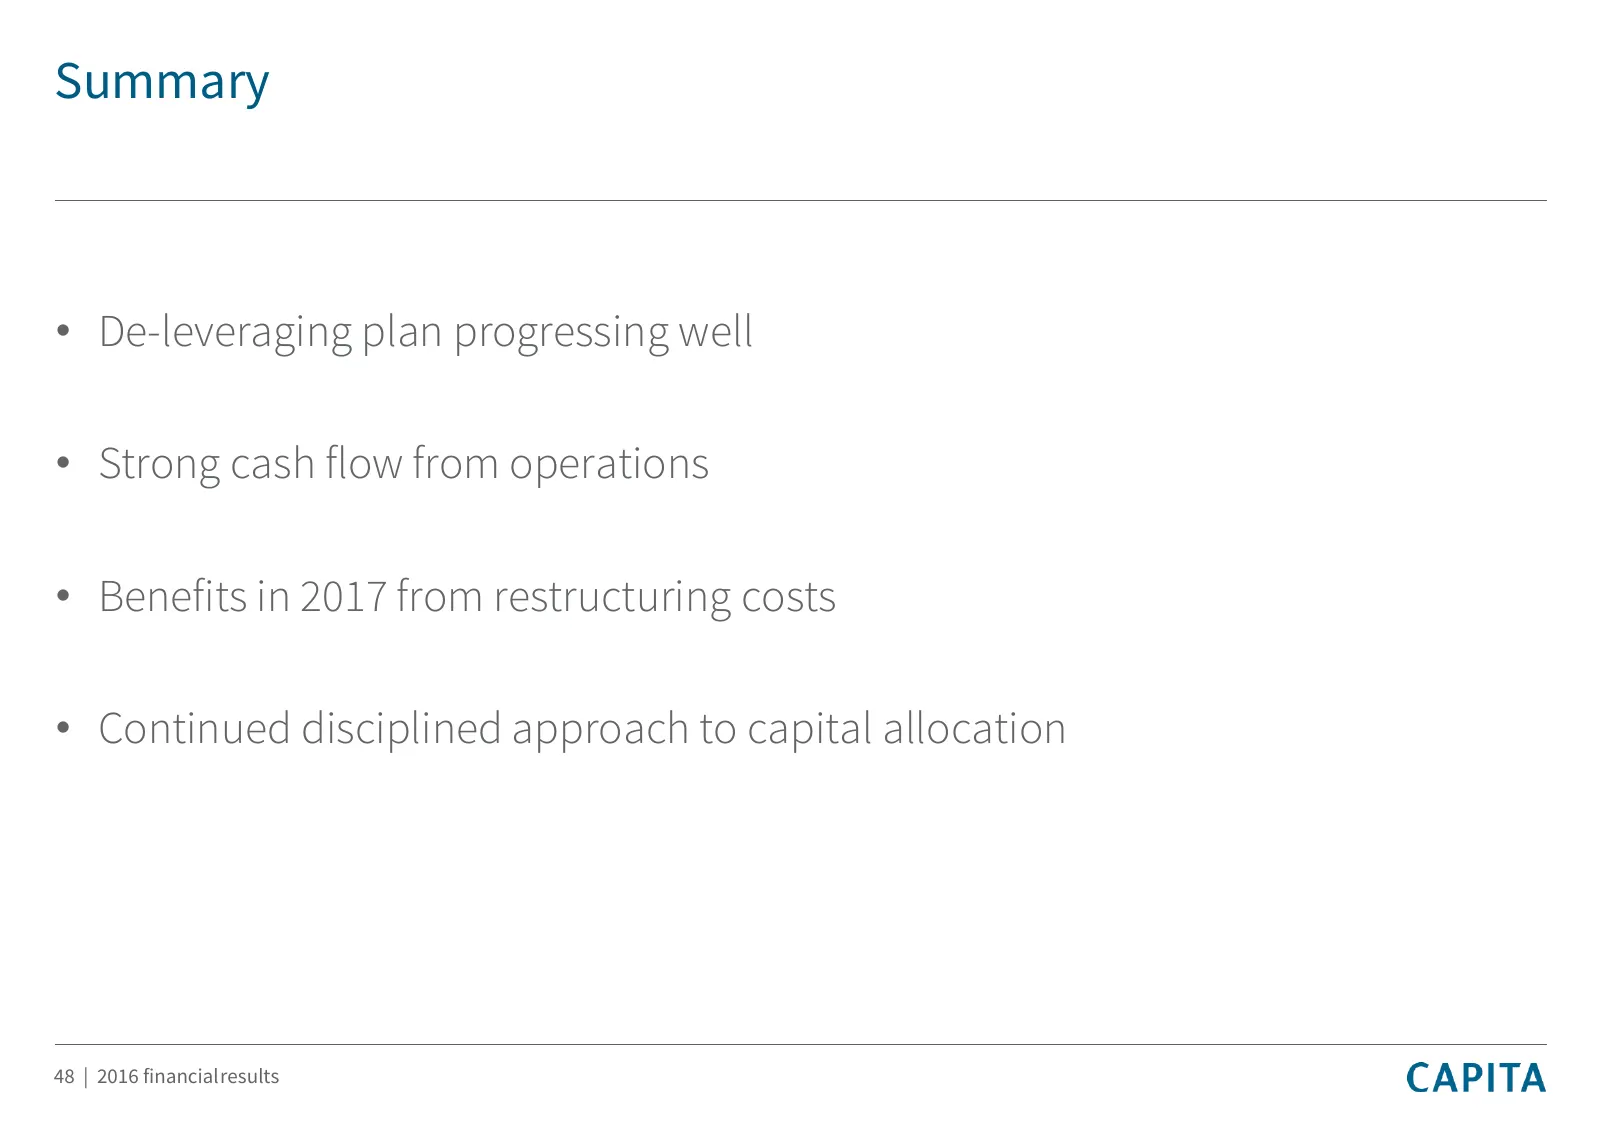
Slide 48: Summary
Summary • De-leveraging plan progressing well • Strong cash flow from operations • Benefits in 2017 from restructuring costs • Continued disciplined approach to capital allocation 48 | 2016 financialresults
Slide 49: Business Development
Business Development Chris Sellers Group Business Development Director 49 | 2016 financialresults
Slide 50: Organic growth generation
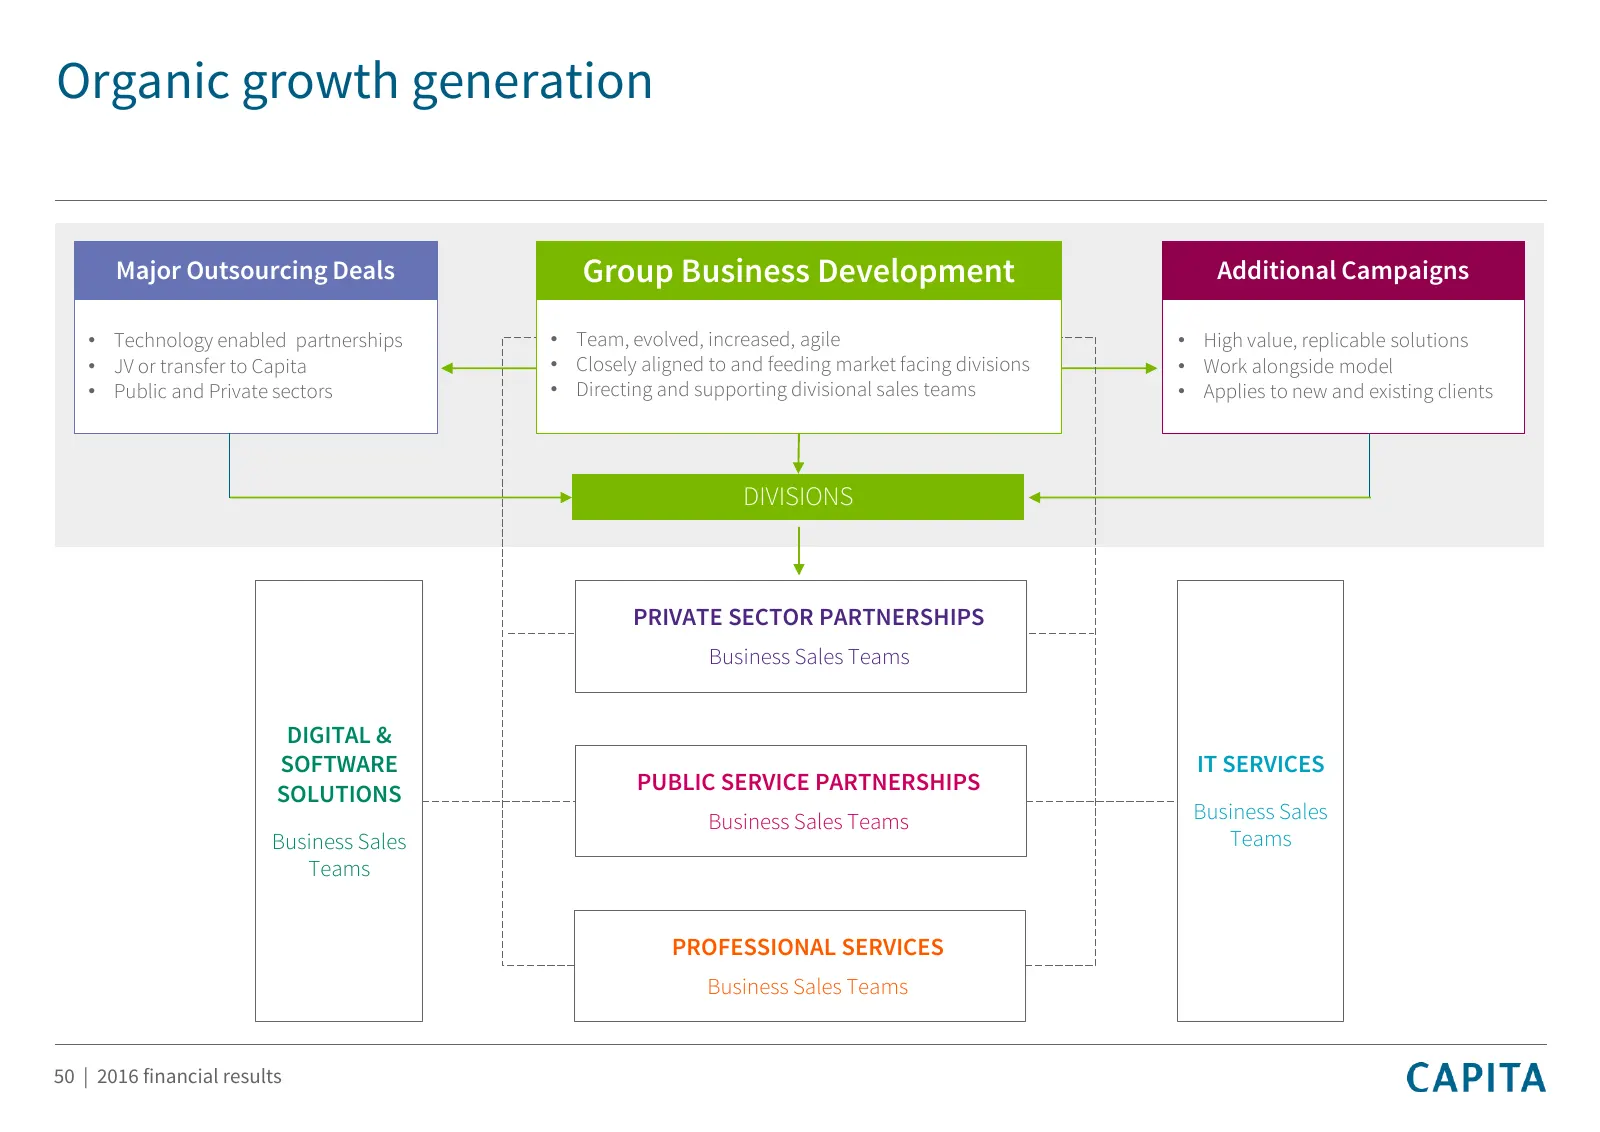
Organic growth generation Major Outsourcing Deals Group Business Development Additional Campaigns • Technology enabled partnerships • Team, evolved, increased, agile • High value, replicable solutions • JV or transfer to Capita • Closely aligned to and feeding market facing divisions • Work alongsid
Slide 51: Organic growth generation: Major Outsourcing Deals
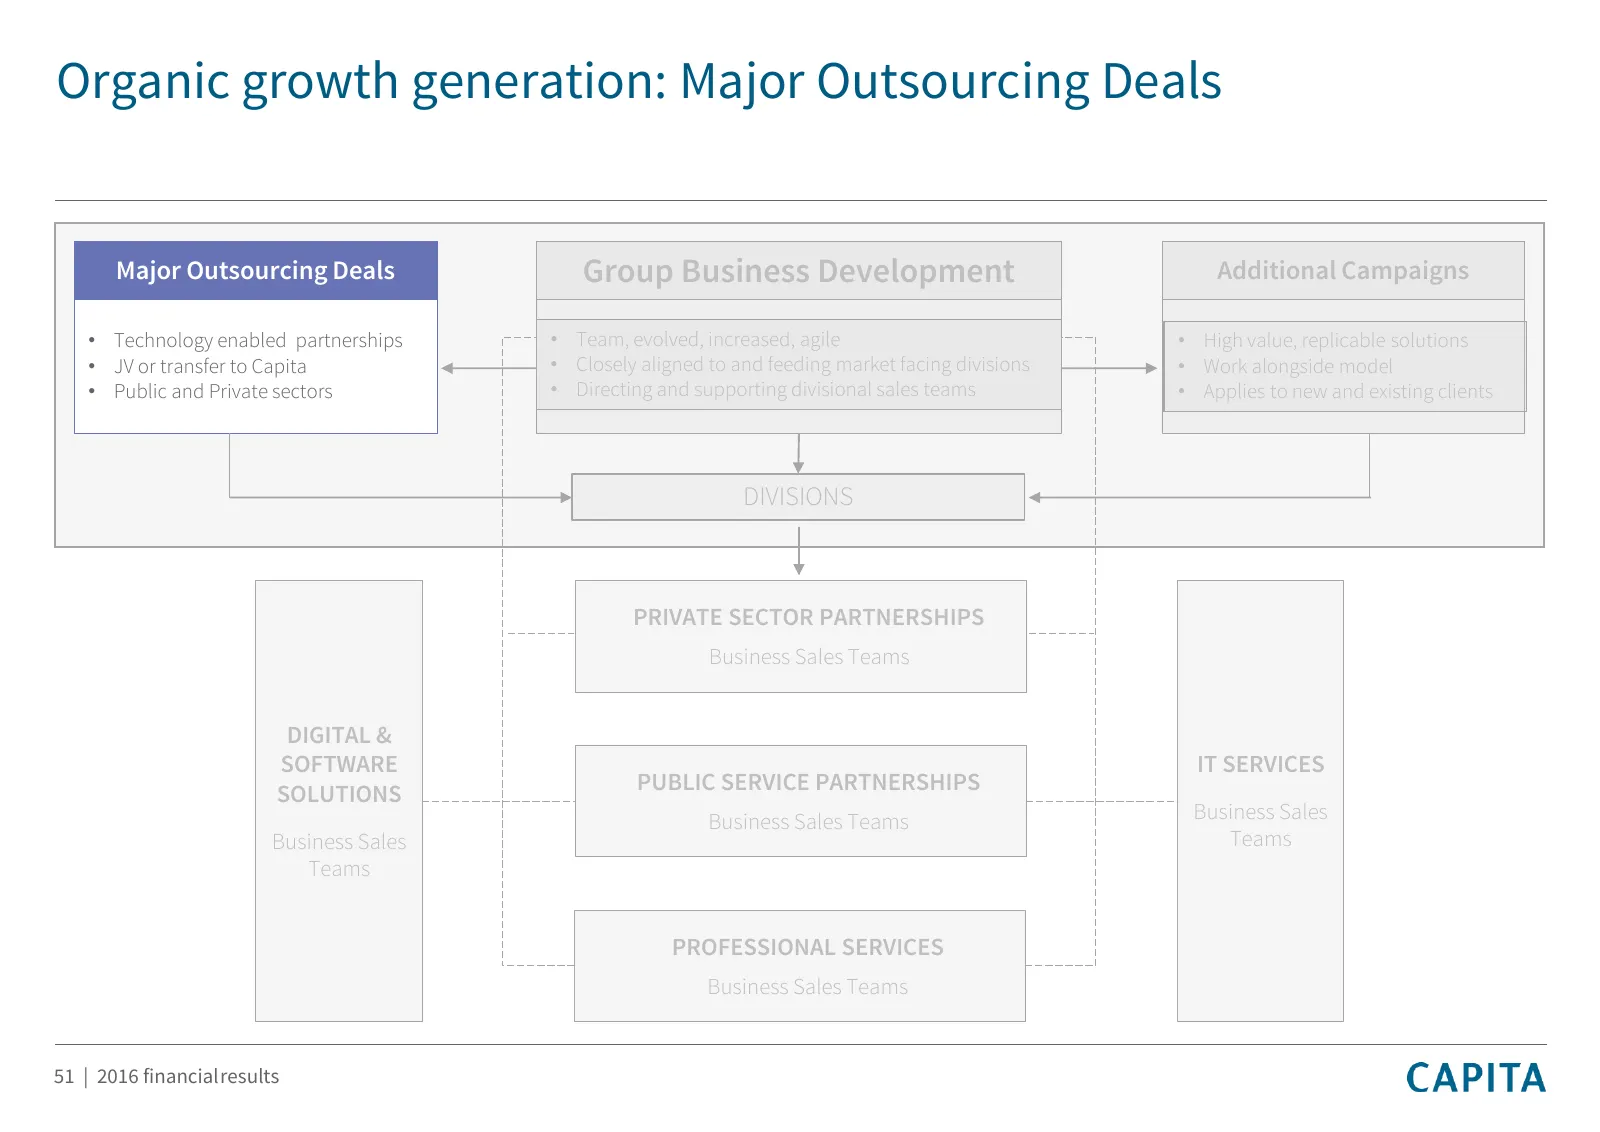
Organic growth generation: Major Outsourcing Deals Major Outsourcing Deals Group Business Development Additional Campaigns • Technology enabled partnerships • Team, evolved, increased, agile • High value, replicable solutions • JV or transfer to Capita • Closely aligned to and feeding market facing
Slide 52: Major Outsourcing Deals continue to drive growth
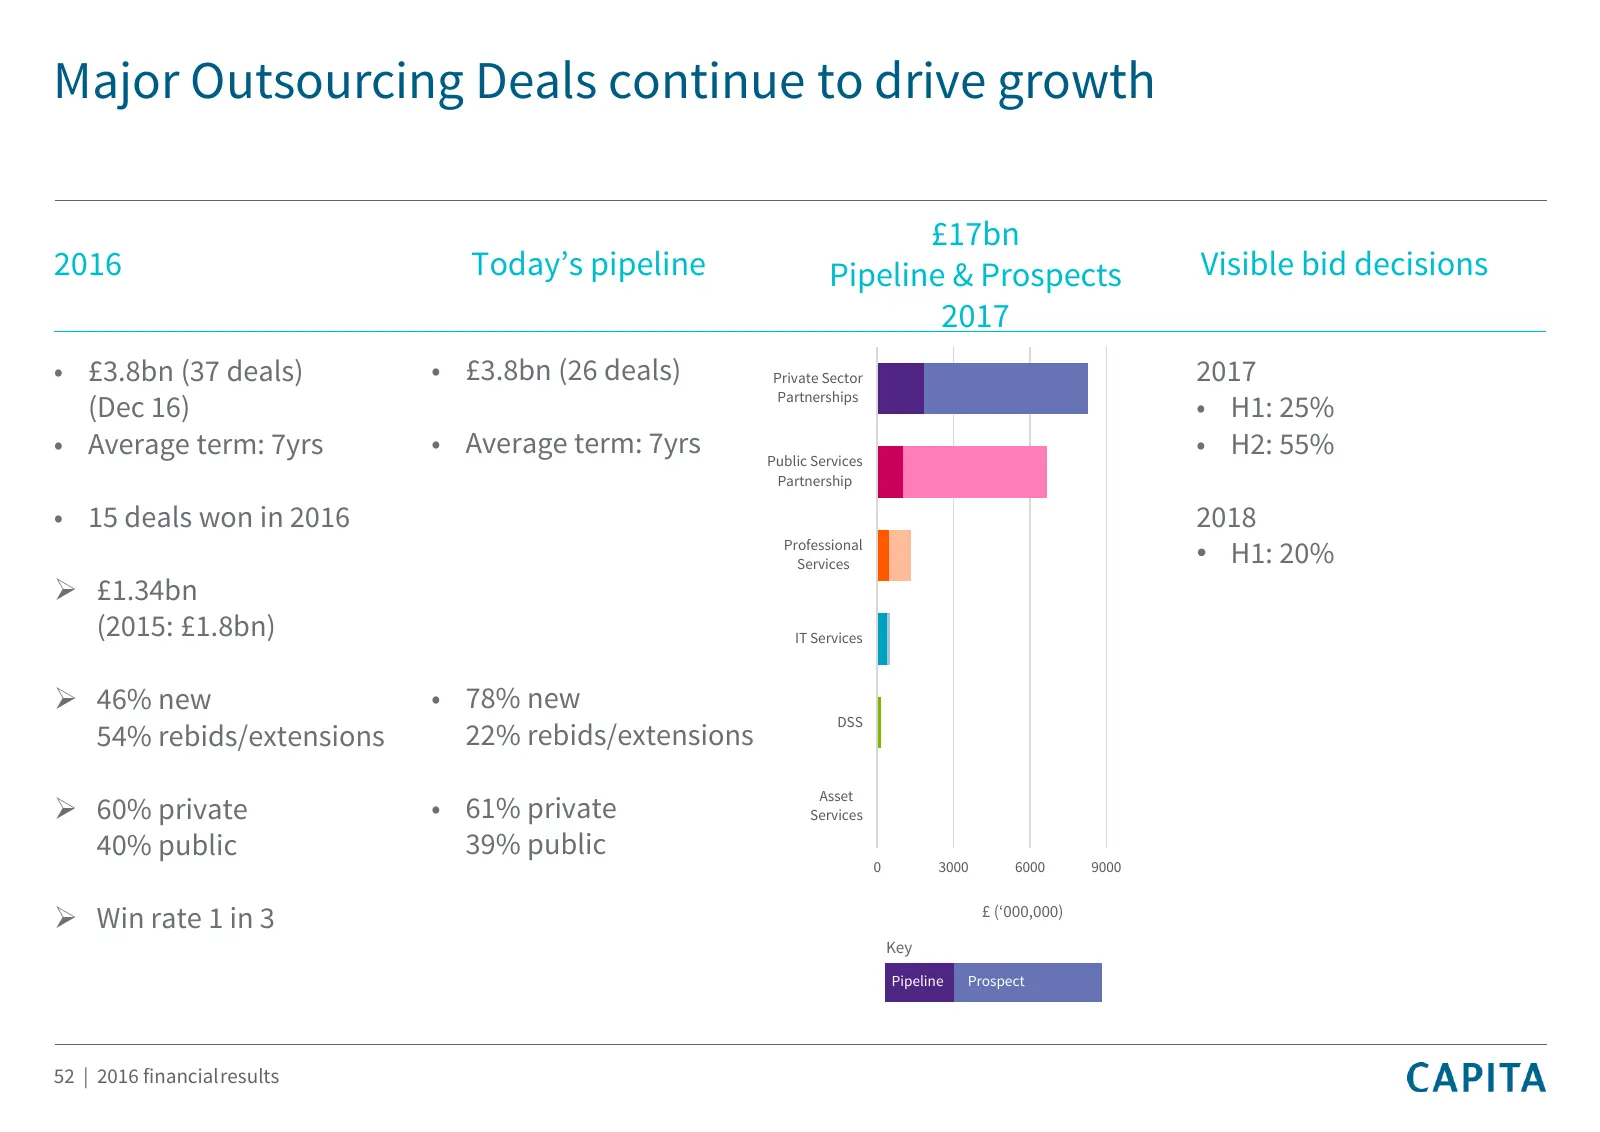
Major Outsourcing Deals continue to drive growth £17bn 2016 Today’s pipeline Pipeline & Prospects Visible bid decisions 2017 • £3.8bn (37 deals) • £3.8bn (26 deals) Private Sector 2017 Partnerships (Dec 16) • H1: 25% • Average term: 7yrs • Average term: 7yrs Public Services • H2: 55% Partnership • 1
Slide 53: Organic growth generation: Additional Campaigns
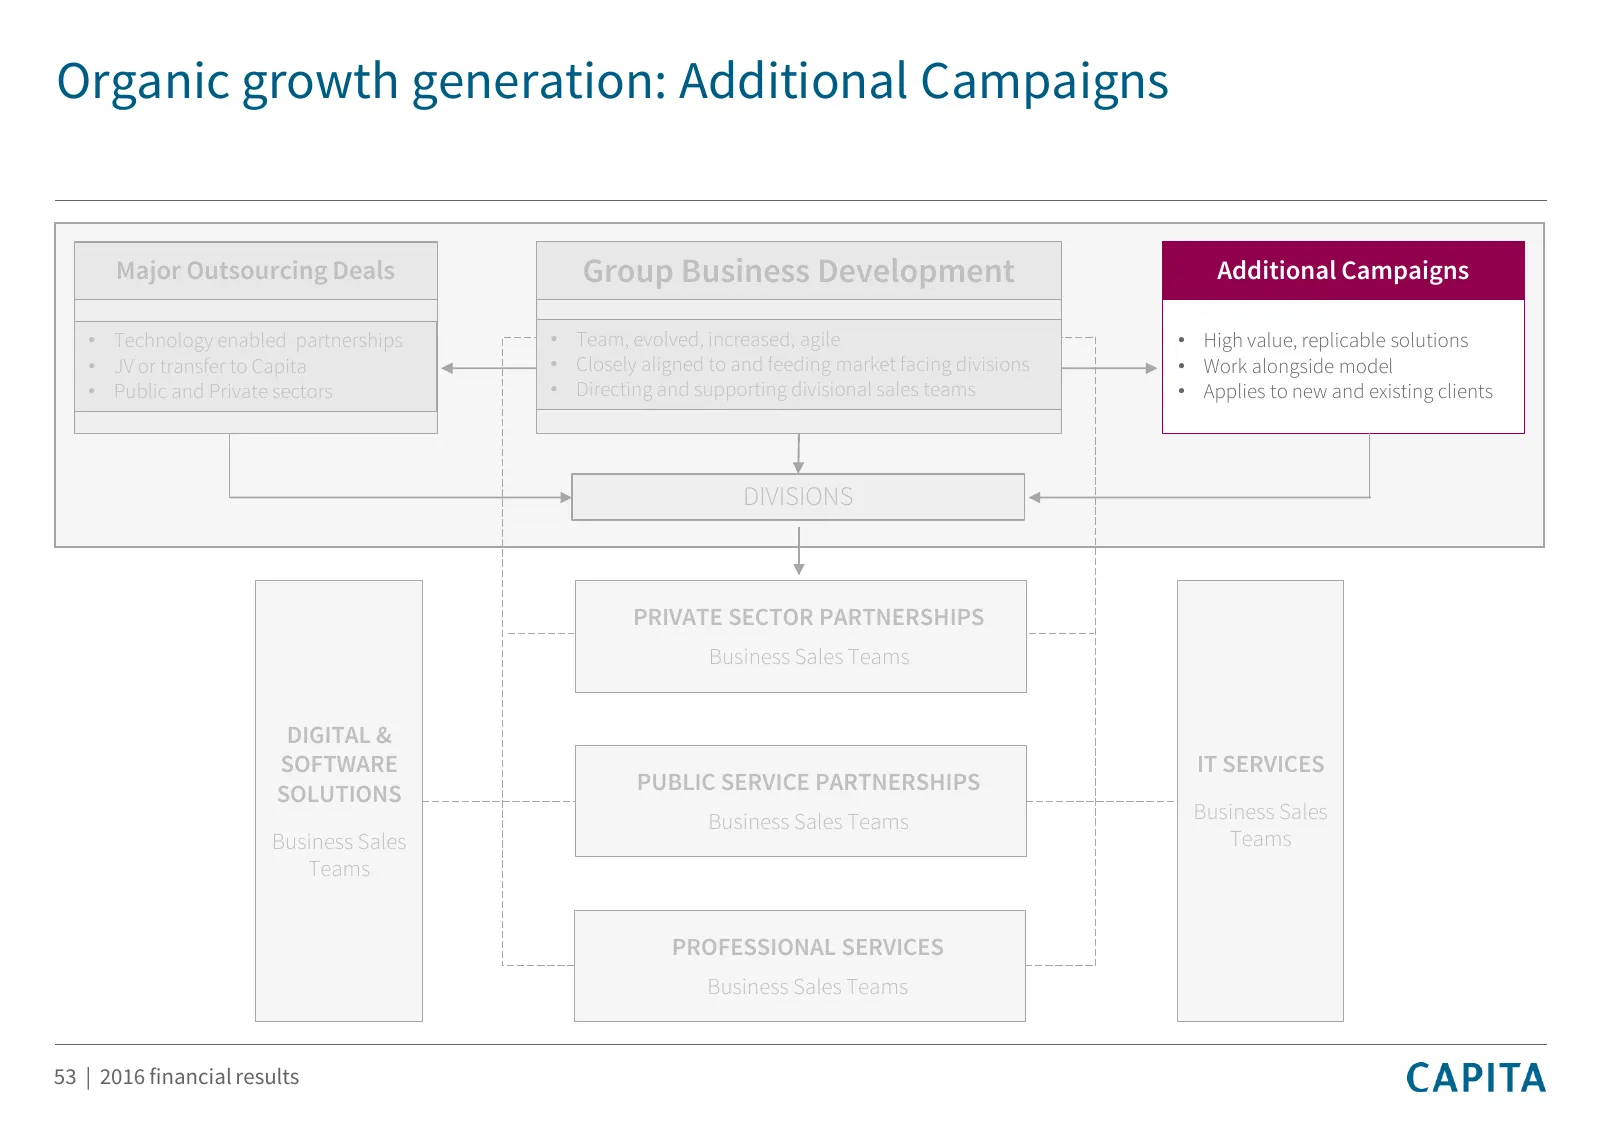
Organic growth generation: Additional Campaigns Major Outsourcing Deals Group Business Development Additional Campaigns • Technology enabled partnerships • Team, evolved, increased, agile • High value, replicable solutions • JV or transfer to Capita • Closely aligned to and feeding market facing div
Slide 54: Additional campaigns: adapting for changing markets
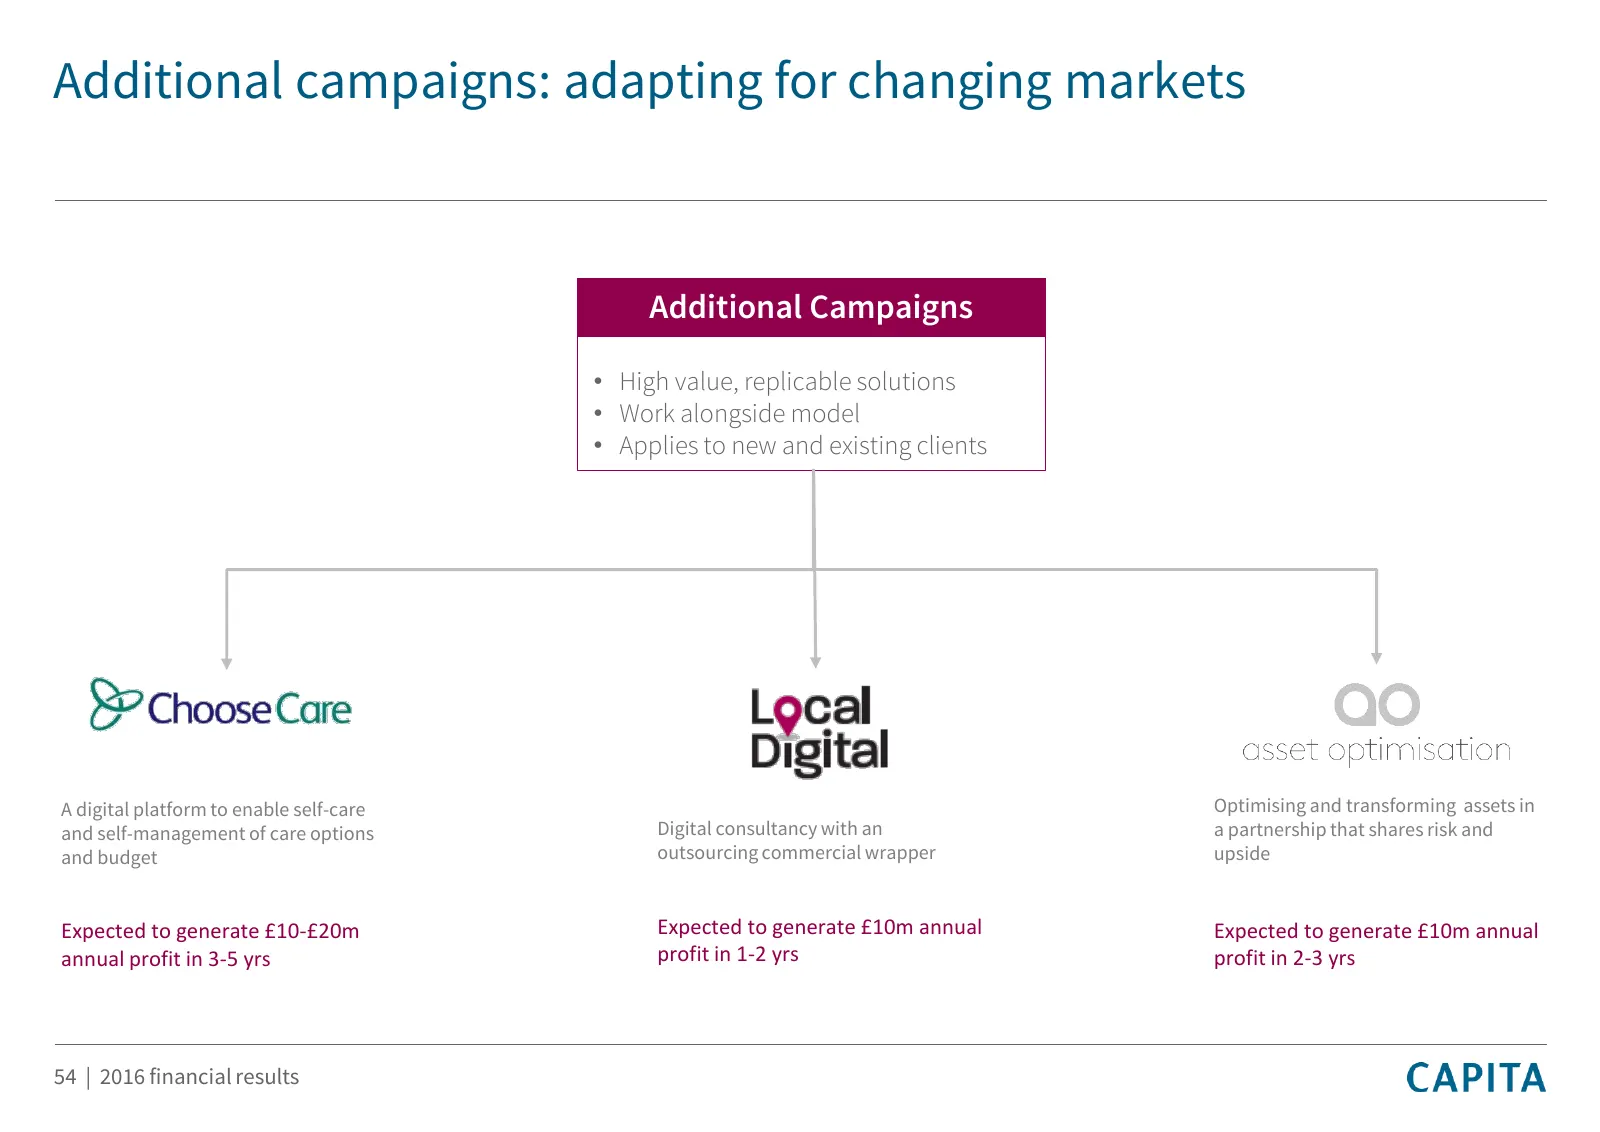
Additional campaigns: adapting for changing markets Additional Campaigns • High value, replicable solutions • Work alongside model • Applies to new and existing clients A digital platform to enable self-care Optimising and transforming assets in and self-management of care options Digital consultanc
Slide 55: Future buying behaviours in sectors
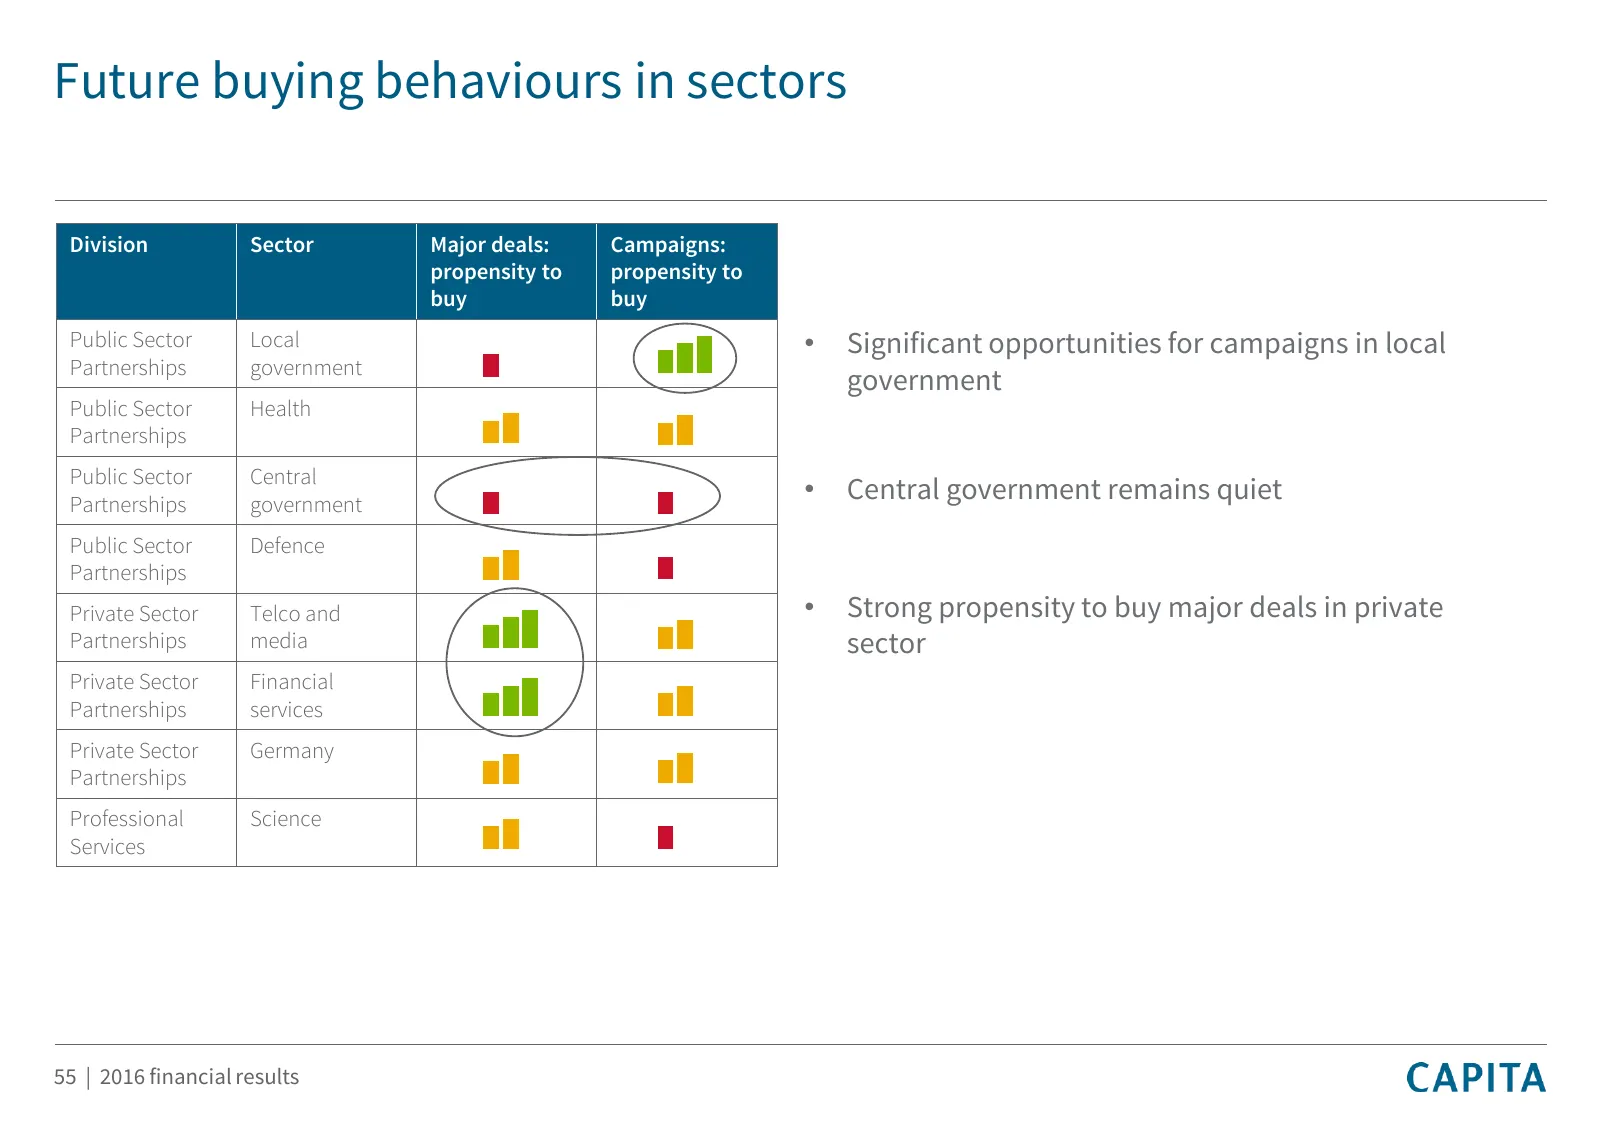
Future buying behaviours in sectors Division Sector Major deals: Campaigns: propensity to propensity to buy buy Public Sector Local • Significant opportunities for campaigns in local Partnerships government government Public Sector Health Partnerships Public Sector Central Partnerships government •
Slide 56: A strong and flexible engine for growth
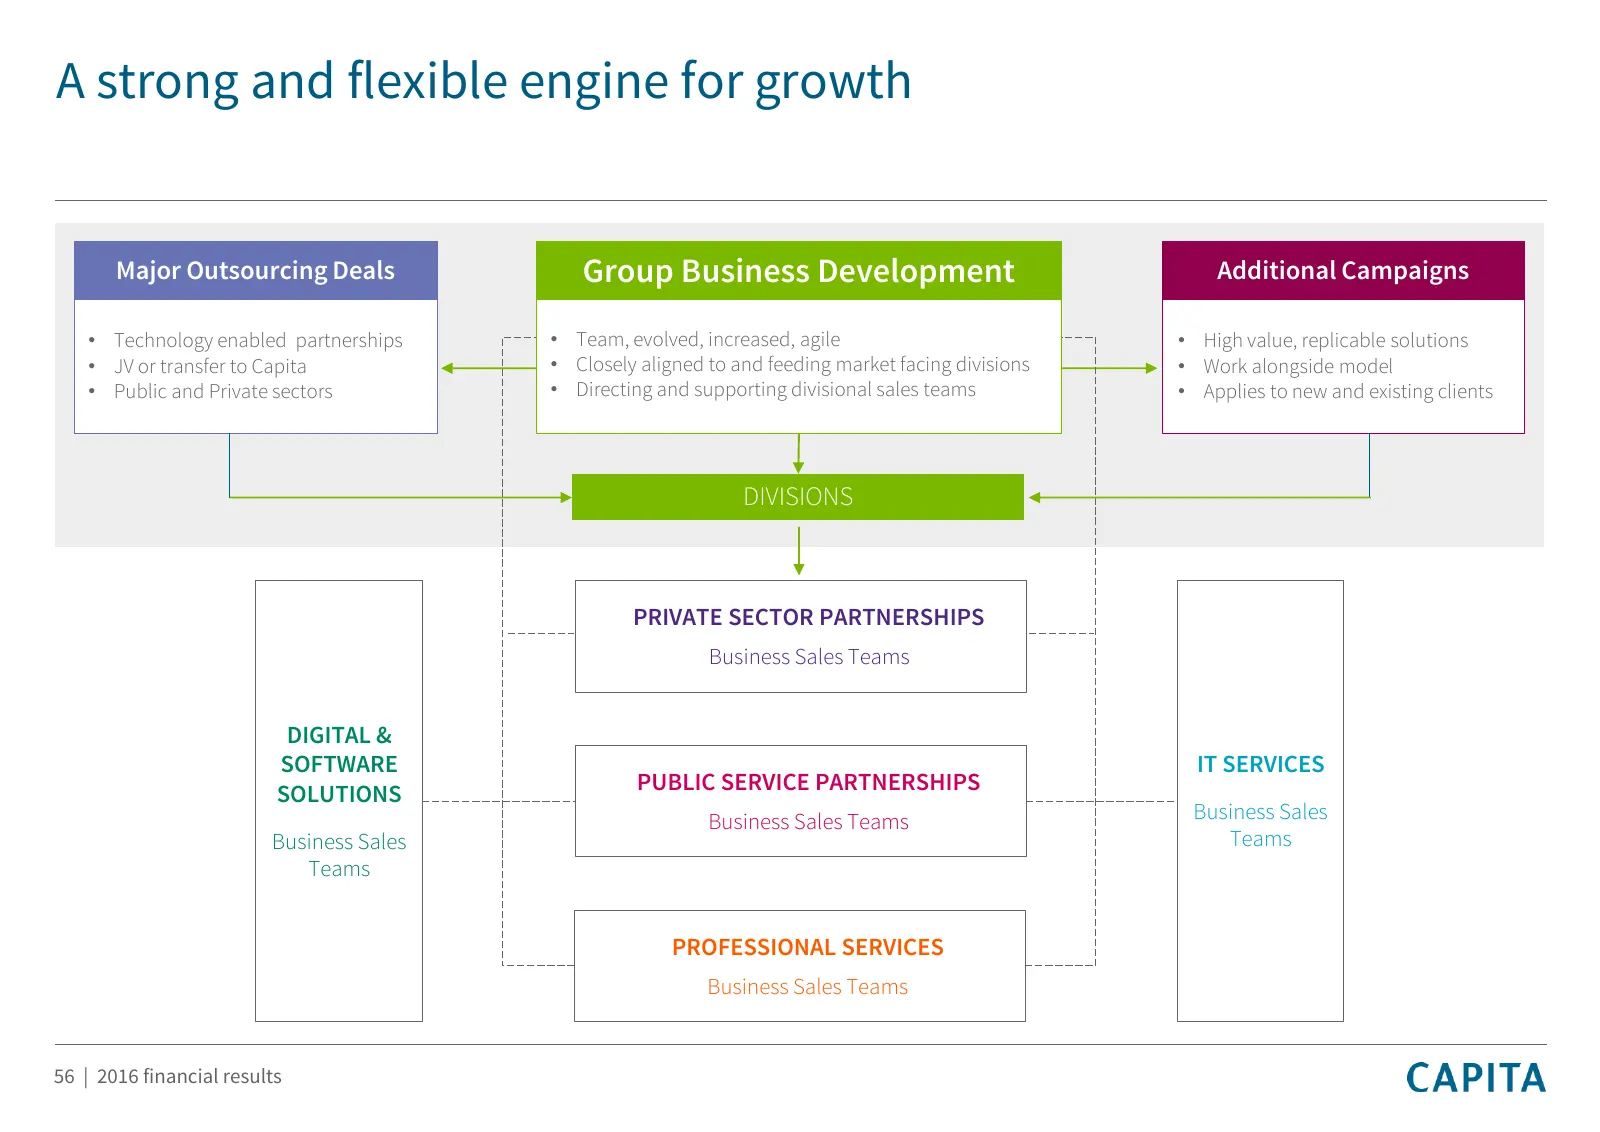
A strong and flexible engine for growth Major Outsourcing Deals Group Business Development Additional Campaigns • Technology enabled partnerships • Team, evolved, increased, agile • High value, replicable solutions • JV or transfer to Capita • Closely aligned to and feeding market facing divisions •
Slide 57: Summary and outlook
Summary and outlook Andy Parker Chief Executive 57 | 2016 financialresults
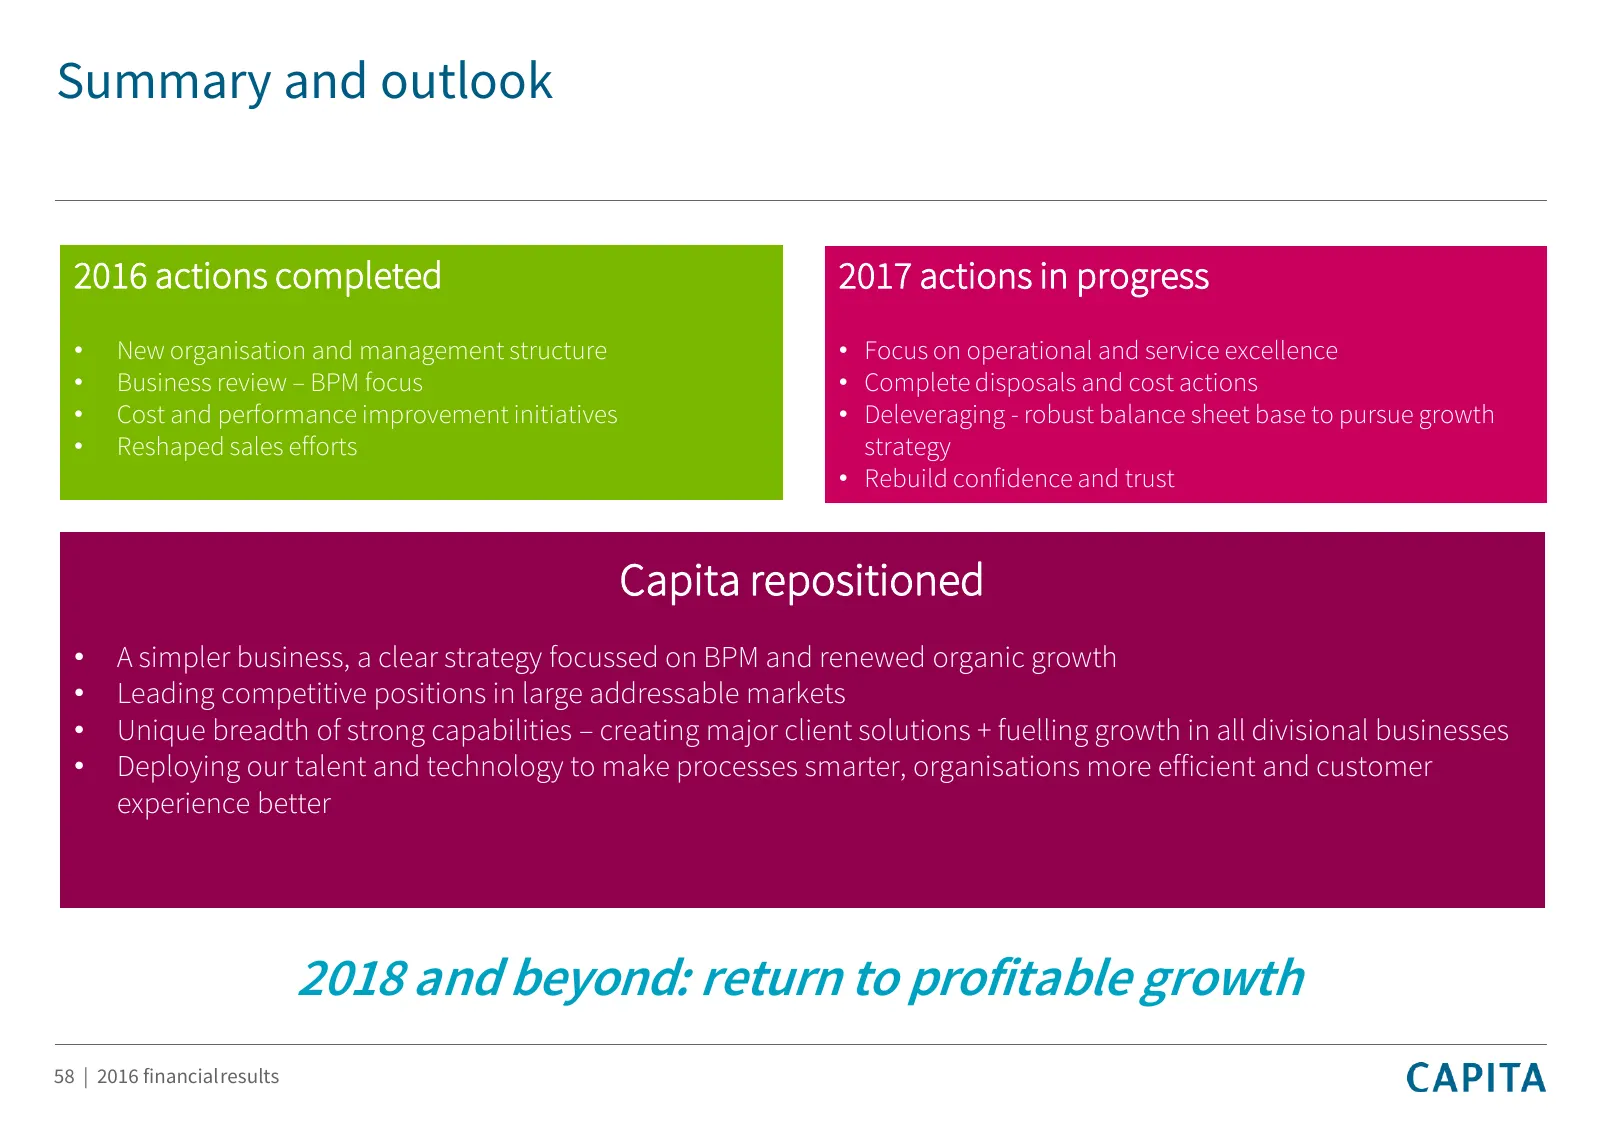
Slide 58: Summary and outlook: 2018 and beyond, return to profitable growth
Summary and outlook 2016 actions completed 2017 actions in progress • New organisation and management structure • Focus on operational and service excellence • Business review – BPM focus • Complete disposals and cost actions • Cost and performance improvement initiatives • Deleveraging - robust bal
Slide 59: 59 | 2016 financialresults
59 | 2016 financialresults CAPITA
Slide 60: Appendices
Appendices 60 | 2016 financialresults
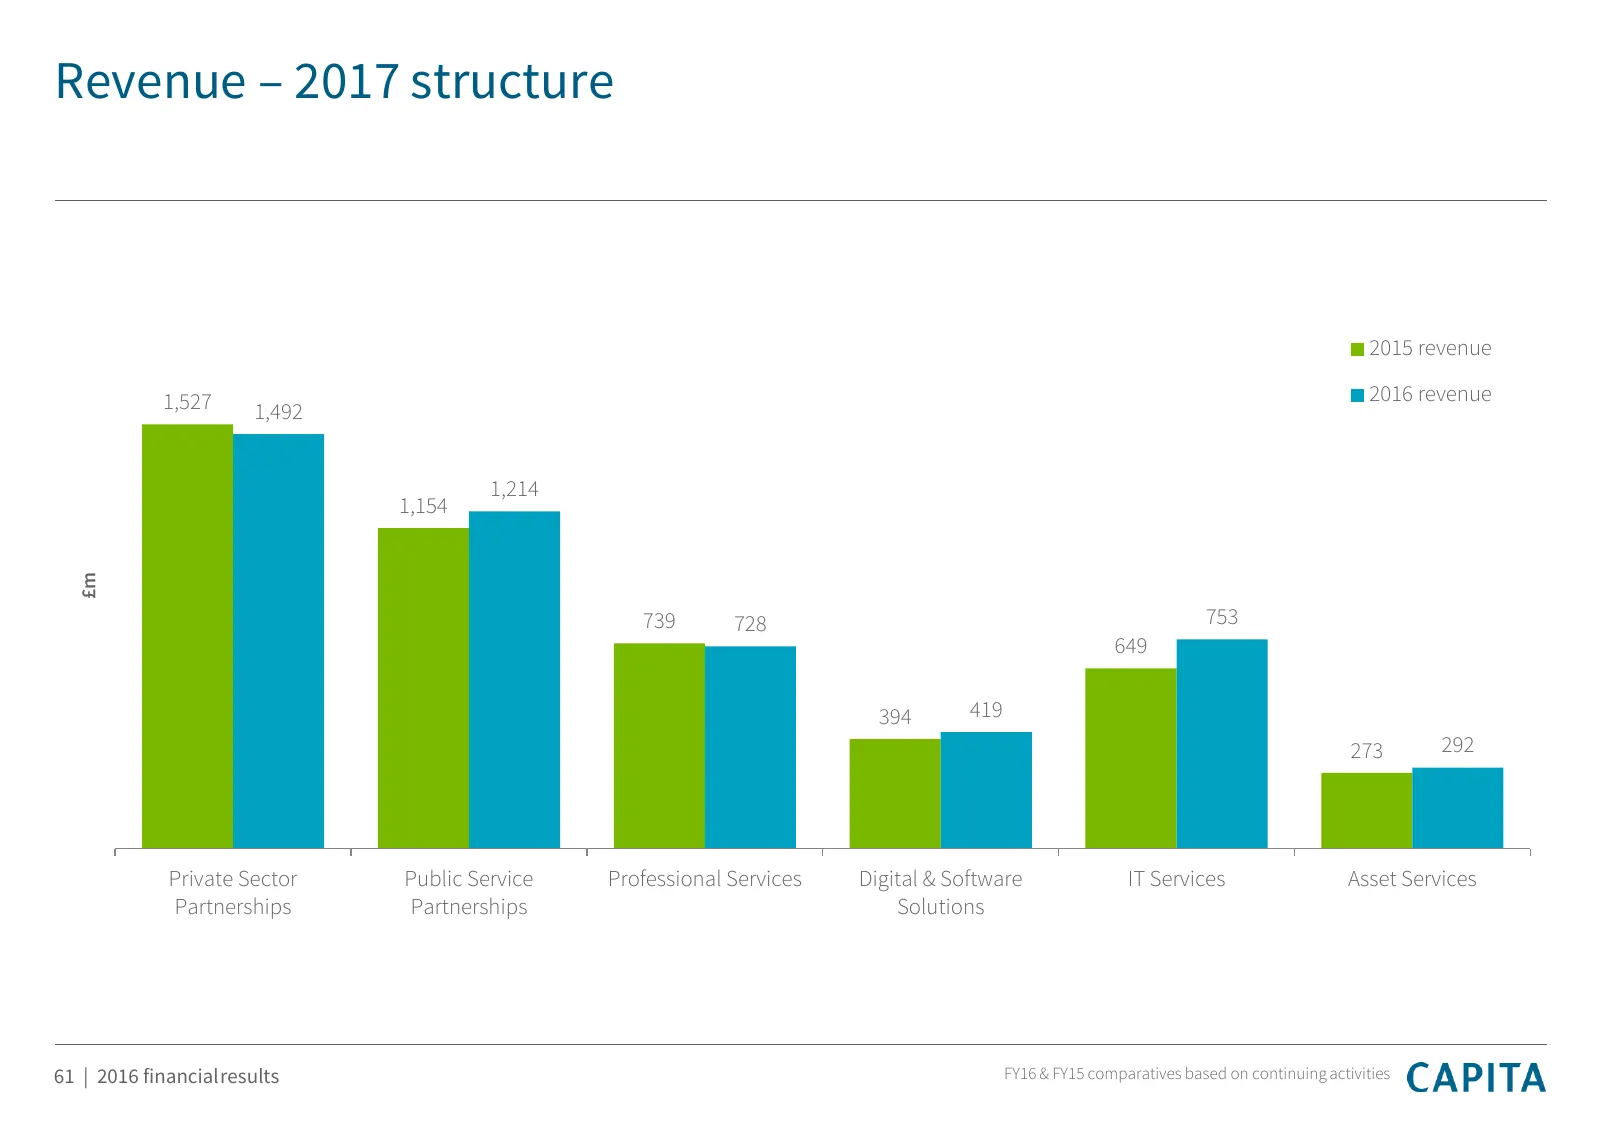
Slide 61: Revenue – 2017 structure
Revenue – 2017 structure 2015 revenue 1,527 2016 revenue 1,492 1,214 1,154 £m 739 728 753 649 394 419 273 292 Private Sector Public Service Professional Services Digital & Software IT Services Asset Services Partnerships Partnerships Solutions 61 | 2016 financialresults FY16 & FY15 comparatives base
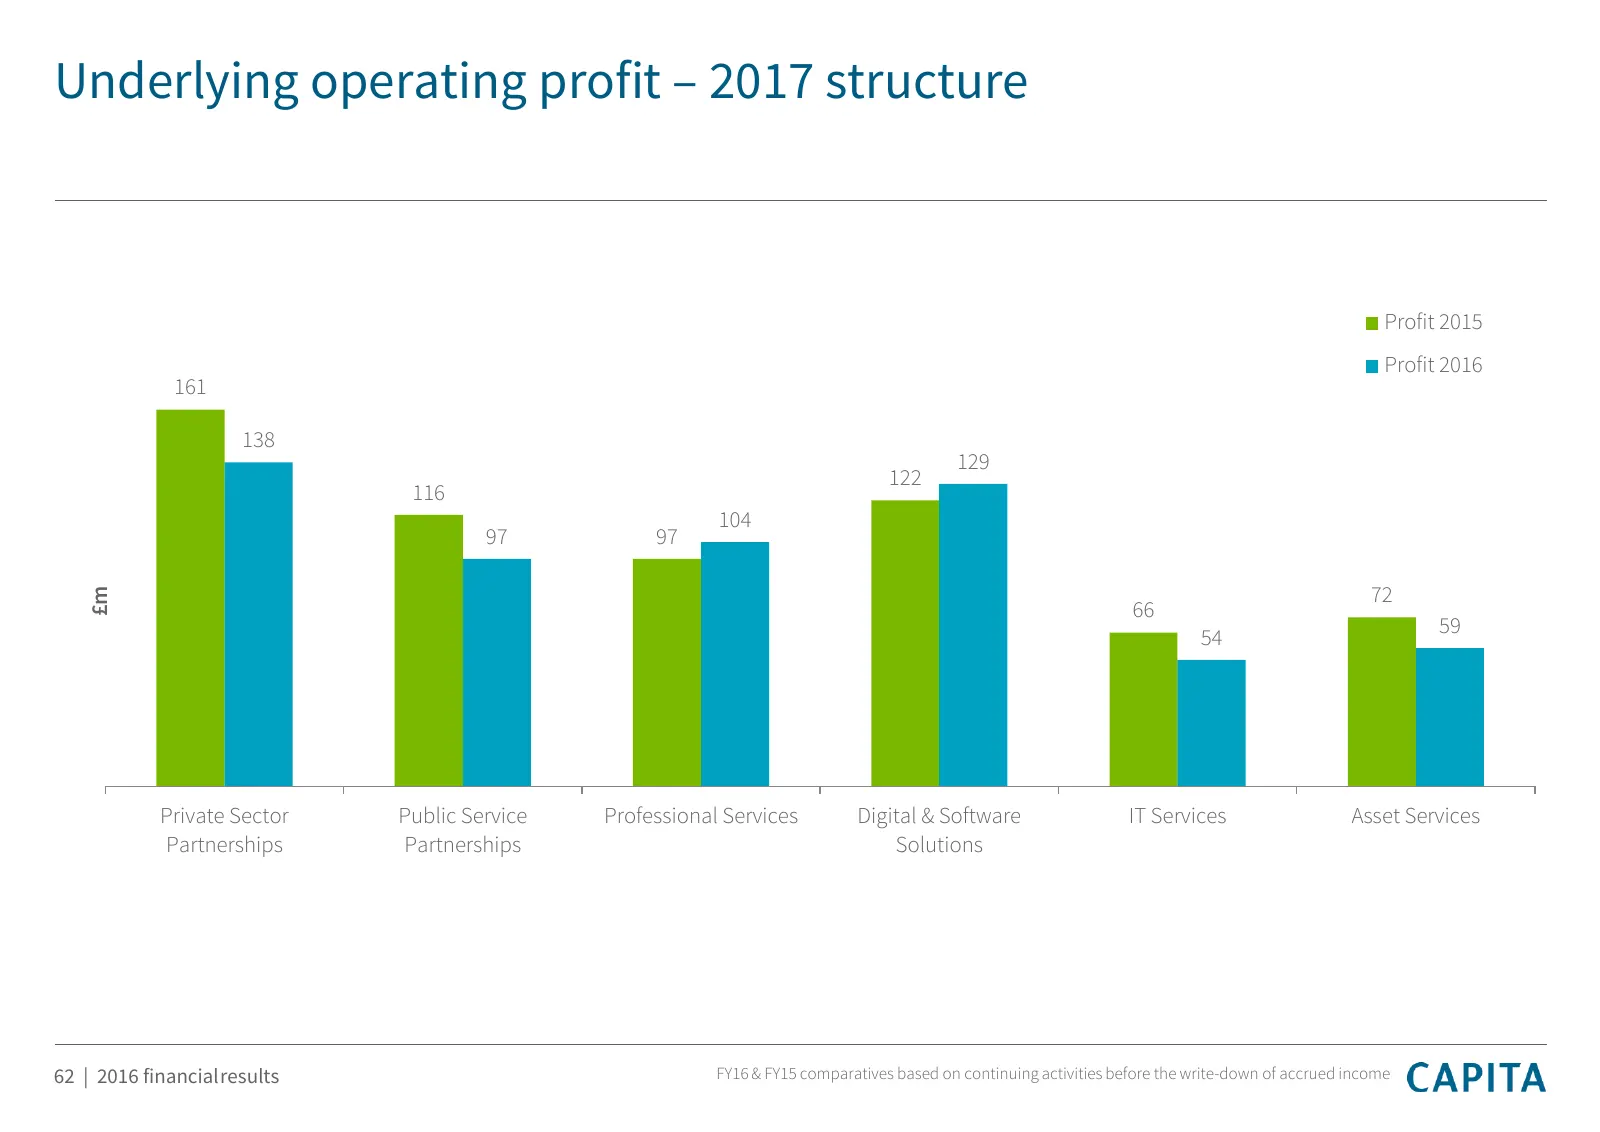
Slide 62: Underlying operating profit – 2017 structure
Underlying operating profit – 2017 structure Profit 2015 Profit 2016 161 138 129 122 116 104 97 97 72 £m 66 59 54 Private Sector Public Service Professional Services Digital & Software IT Services Asset Services Partnerships Partnerships Solutions 62 | 2016 financialresults FY16 & FY15 comparatives
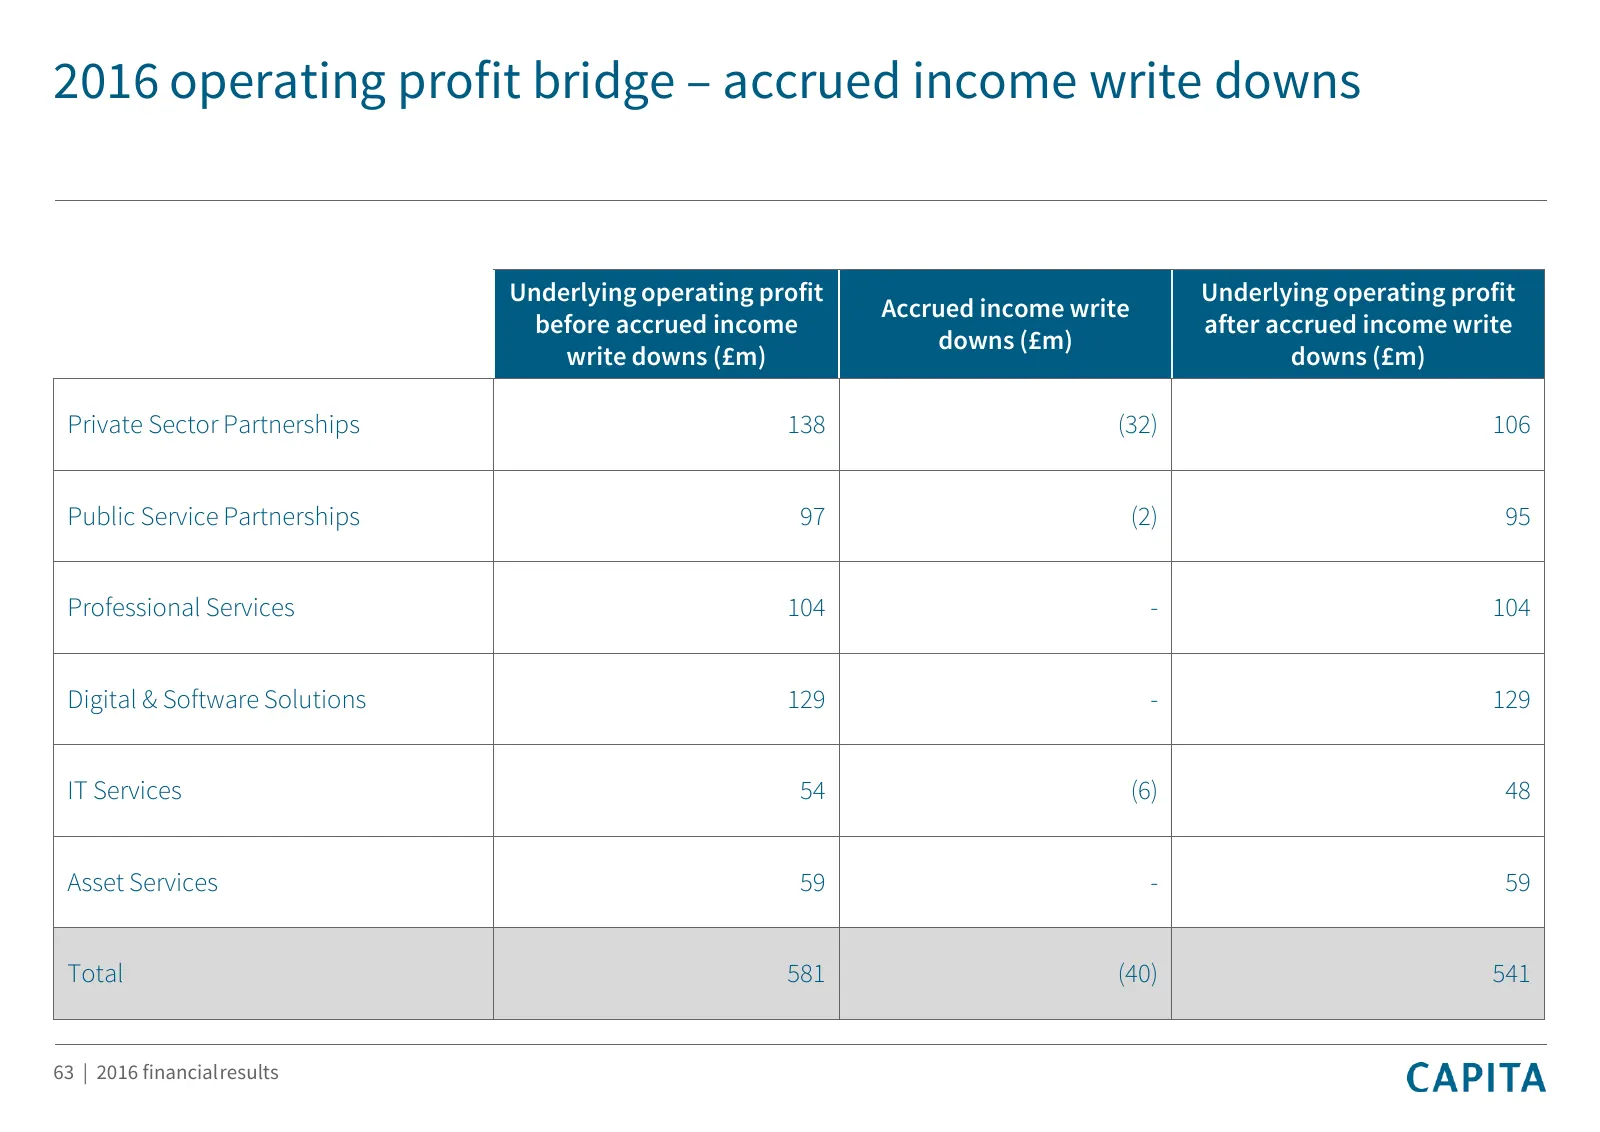
Slide 63: 2016 operating profit bridge – accrued income write downs
2016 operating profit bridge – accrued income write downs Underlying operating profit Underlying operating profit Accrued income write before accrued income after accrued income write downs (£m) write downs (£m) downs (£m) Private Sector Partnerships 138 (32) 106 Public Service Partnerships 97 (2) 9
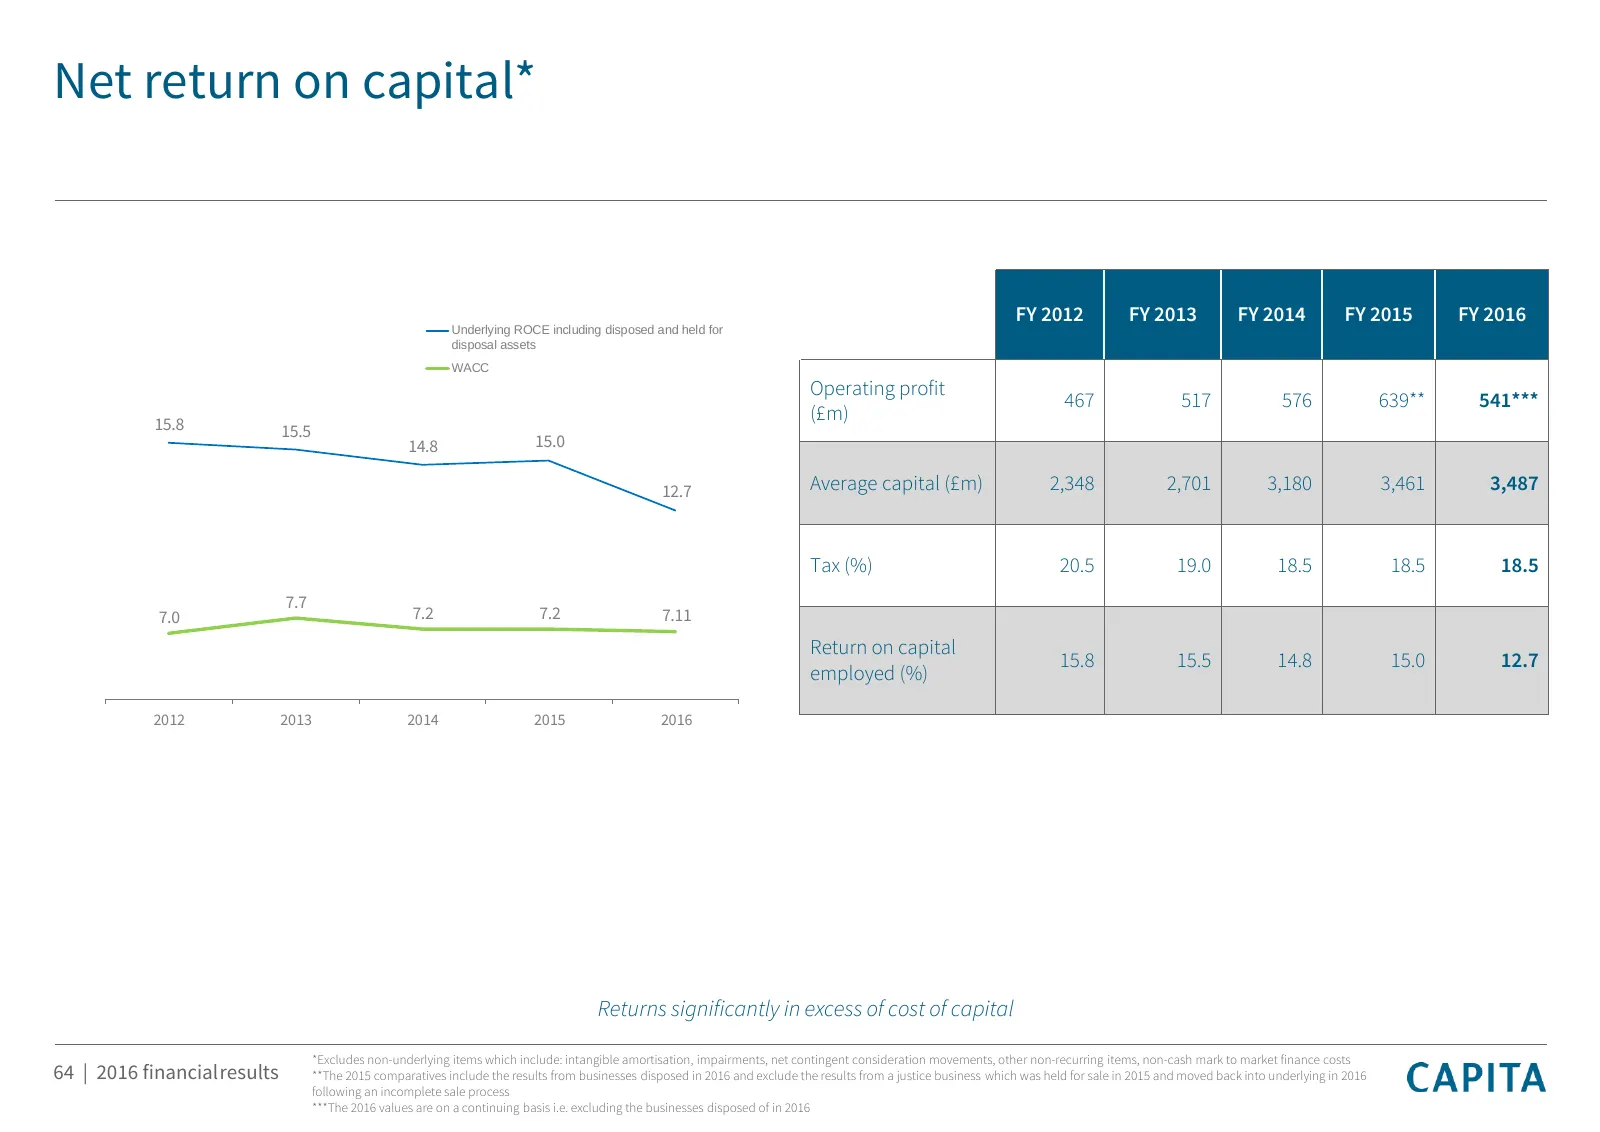
Slide 64: Net return on capital
Net return on capital* FY 2012 FY 2013 FY 2014 FY 2015 FY 2016 Underlying ROCE including disposed and held for disposal assets WACC Operating profit 467 517 576 639** 541*** 15.8 (£m) 15.5 14.8 15.0 12.7 Average capital (£m) 2,348 2,701 3,180 3,461 3,487 Tax (%) 20.5 19.0 18.5 18.5 18.5 7.7 7.0 7.2
Slide 65: Revenue by market
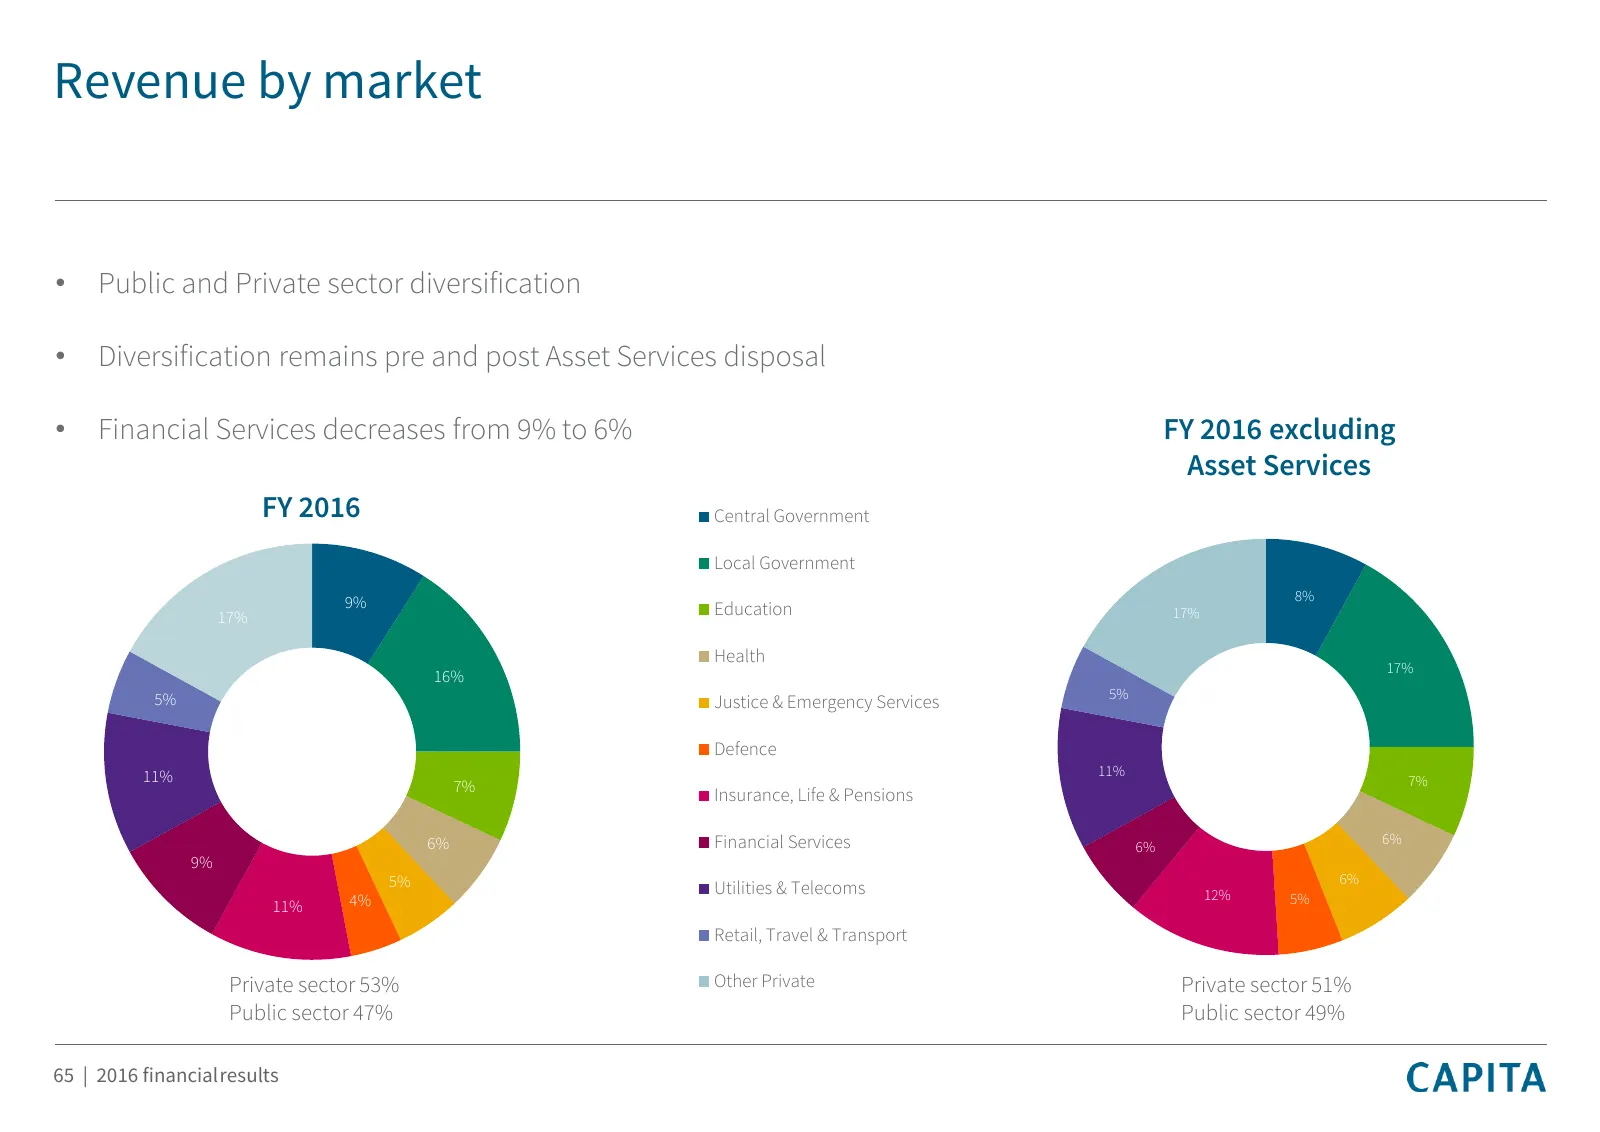
Revenue by market • Public and Private sector diversification • Diversification remains pre and post Asset Services disposal • Financial Services decreases from 9% to 6% FY 2016 excluding Asset Services FY 2016 Central Government Local Government 9% 8% 17% Education 17% Health 17% 16% 5% 5% Justice
Slide 66: 2016 Major contracts
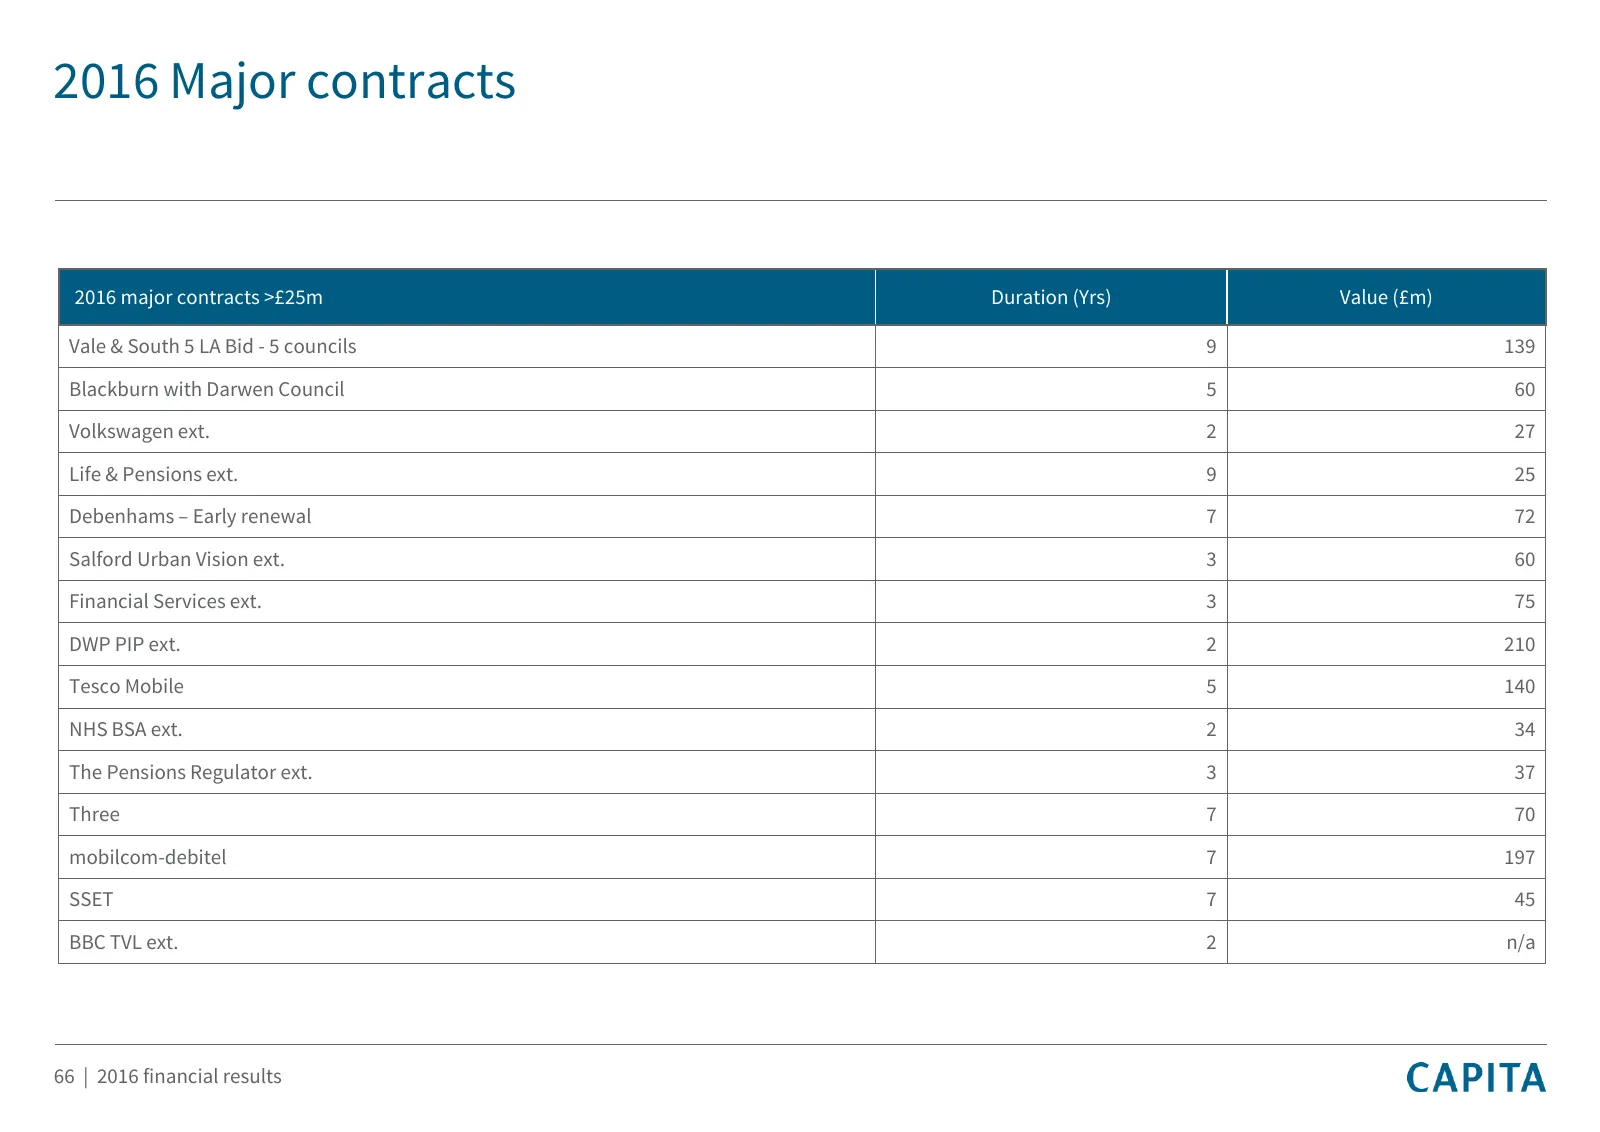
2016 Major contracts 2016 major contracts >£25m Duration (Yrs) Value (£m) Vale & South 5 LA Bid - 5 councils 9 139 Blackburn with Darwen Council 5 60 Volkswagen ext. 2 27 Life & Pensions ext. 9 25 Debenhams – Early renewal 7 72 Salford Urban Vision ext. 3 60 Financial Services ext. 3 75 DWP PIP ext.
Slide 67: mobilcom-debitel strategic partnership
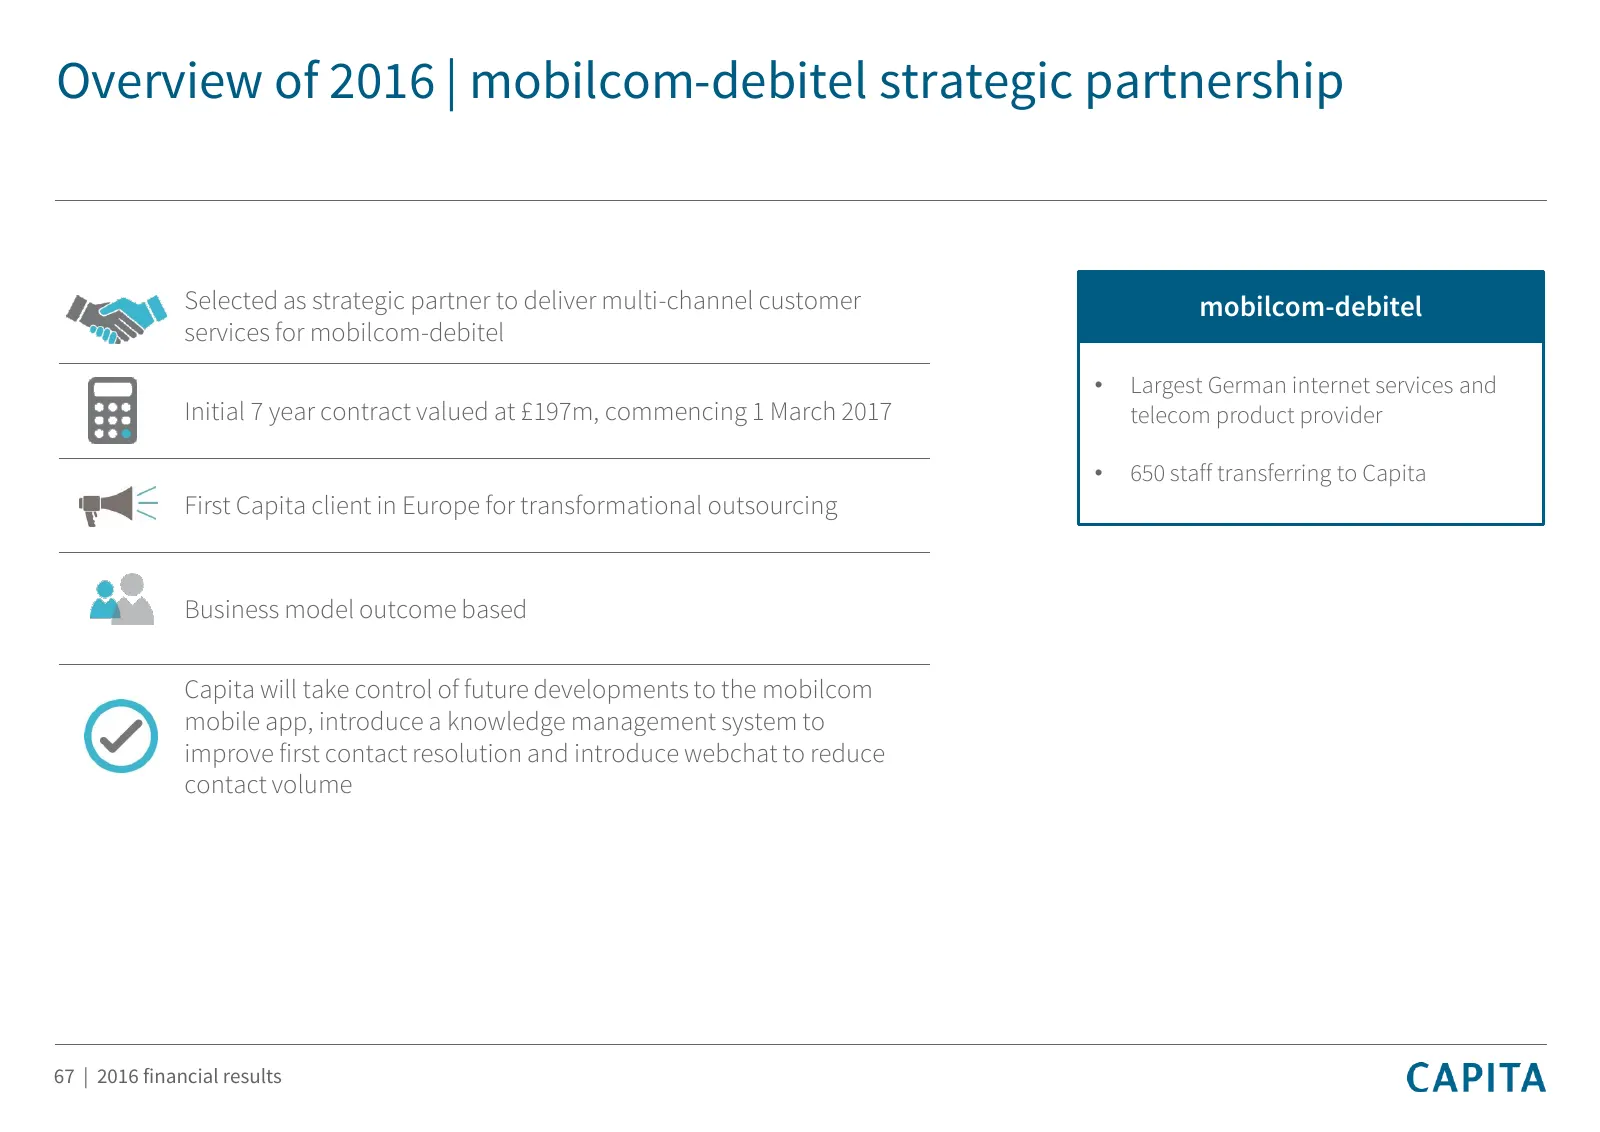
Overview of 2016 | mobilcom-debitel strategic partnership Selected as strategic partner to deliver multi-channel customer mobilcom-debitel services for mobilcom-debitel • Largest German internet services and Initial 7 year contract valued at £197m, commencing 1 March 2017 telecom product provider •
Slide 68: BPM & CM market size
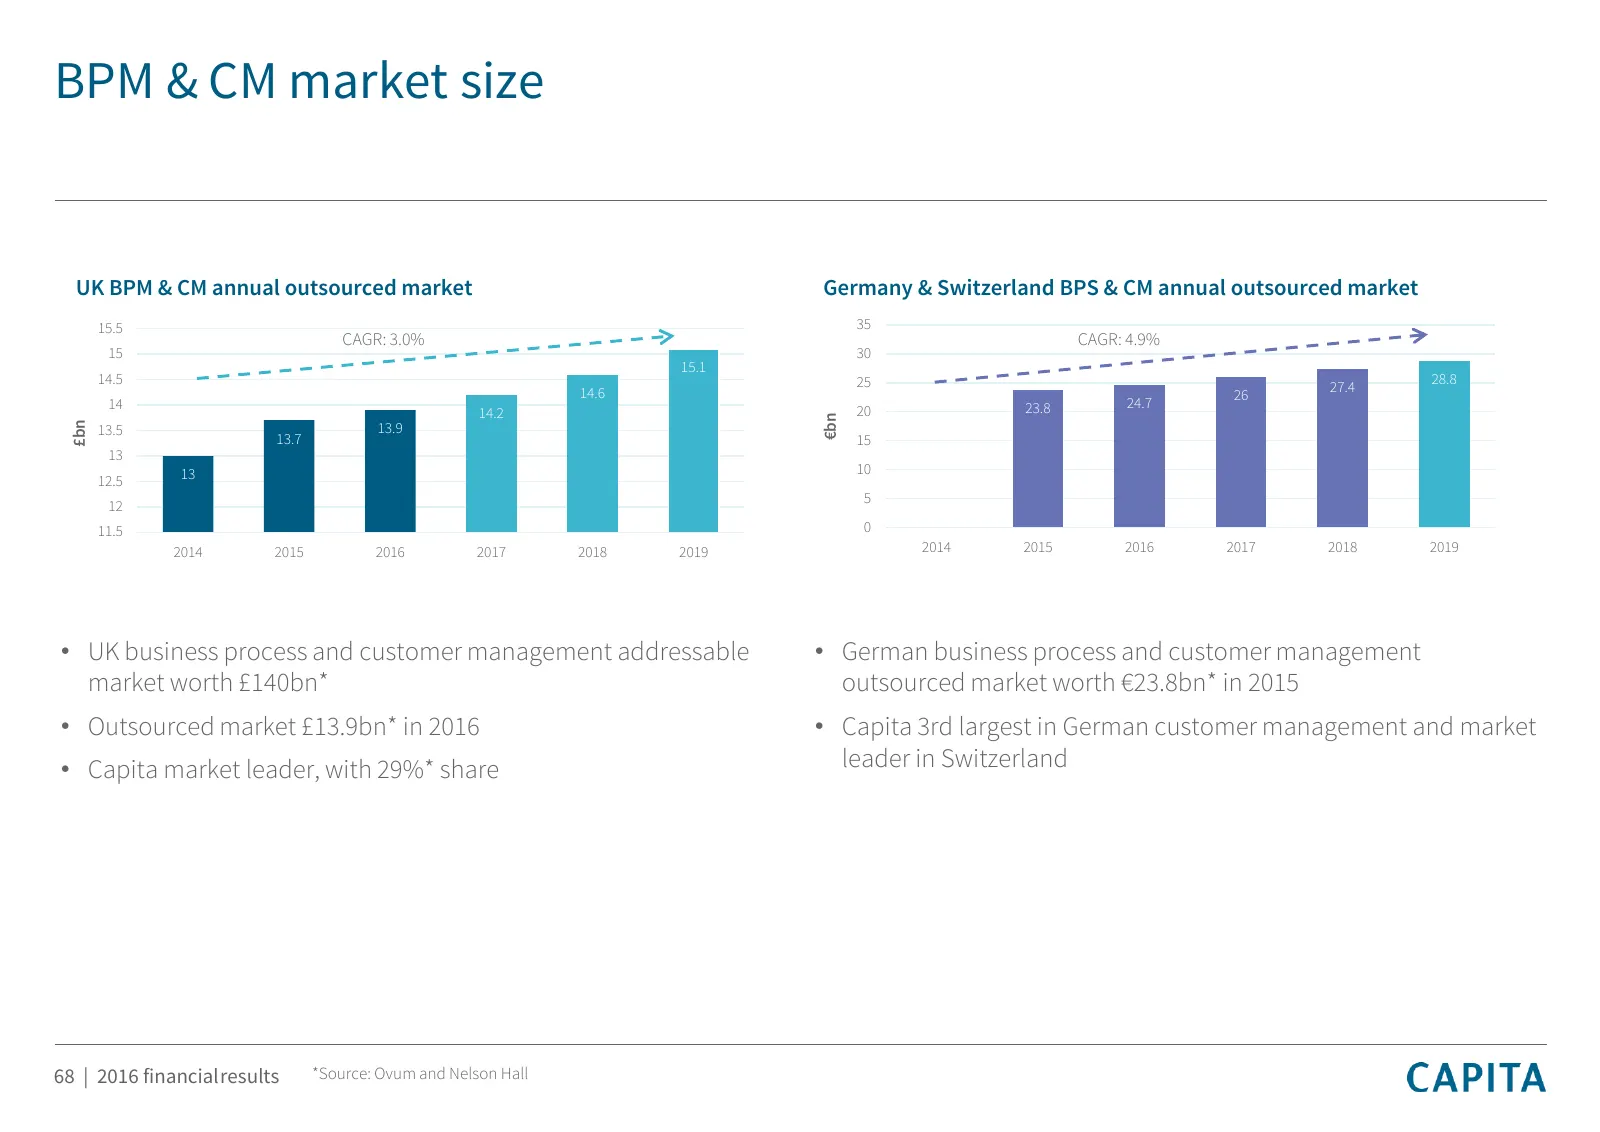
BPM & CM market size UK BPM & CM annual outsourced market Germany & Switzerland BPS & CM annual outsourced market 15.5 35 CAGR: 3.0% CAGR: 4.9% 15 30 15.1 14.5 25 28.8 14.6 27.4 24.7 26 14 20 23.8 14.2 €bn 13.9 £bn 13.5 13.7 15 13 13 10 12.5 5 12 11.5 0 2014 2015 2016 2017 2018 2019 2014 2015 2016 2
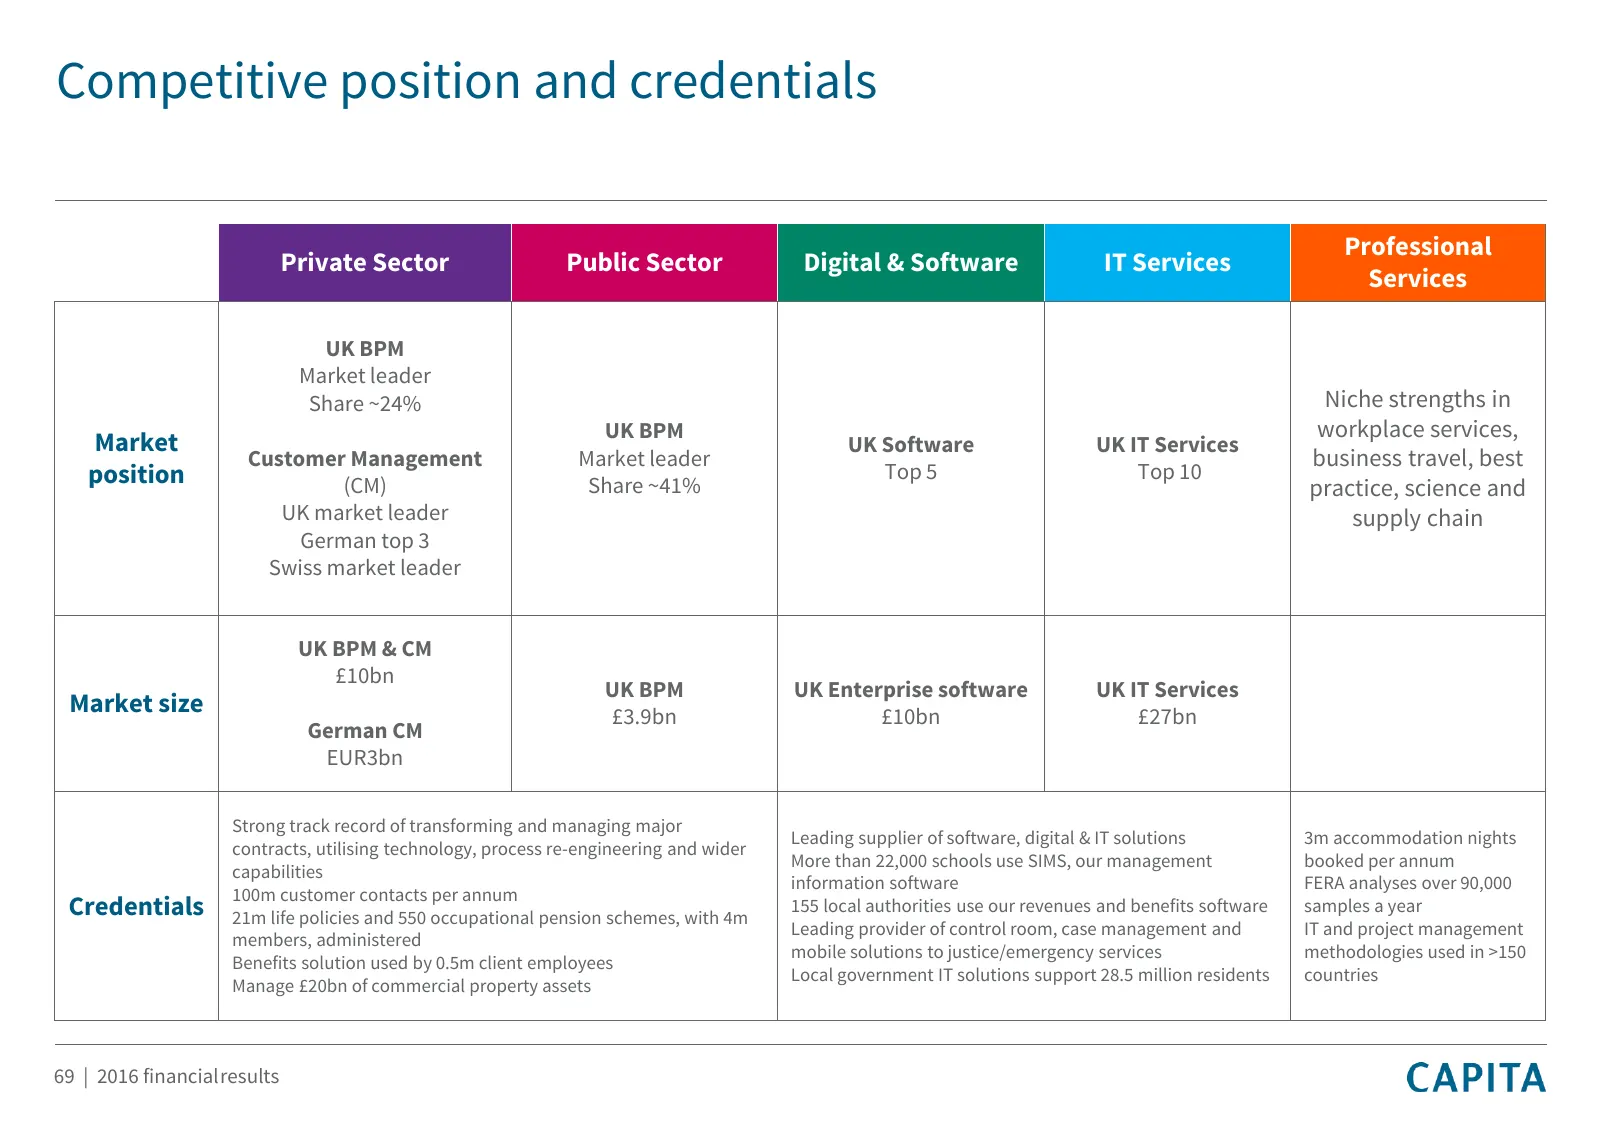
Slide 69: Competitive position and credentials
Competitive position and credentials Professional Private Sector Public Sector Digital & Software IT Services Services UK BPM Market leader Share ~24% Niche strengths in UK BPM workplace services, Market UK Software UK IT Services Customer Management Market leader business travel, best position (CM)
Source: Internet Archive copy of capita.com
More decks from Capita plc
 H1 2026 Earnings Presentation44 slides · Aug 4, 2026
 FY2025 Earnings Presentation46 slides · March 2026
 Merger or Acquisition (March 2026)10 slides · March 2026
 H1 2025 Earnings Presentation51 slides · August 2025
 FY2024 Earnings Presentation44 slides · March 2025
 H1 2024 Earnings Presentation33 slides · Aug 1, 2024