Strategic Hotels and Resorts Inc
Strategic Hotels and Resorts — Investor Presentation (September 2013)
33 slides from Strategic Hotels and Resorts's investor presentation, Sep 30, 2013
Slide 1: Investor Presentation September 2013
Investor Presentation September 2013 Exhibit 99.1
Slide 2: BEE's Unique Value Proposition
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview BEE’s Unique Value Proposition 1
Slide 3: BEE's Unique Value Proposition
o The only pure play high-end lodging REIT o High-end outperforms the industry in a recovery o Industry leading asset management expertise o Assets are in pristine condition o Embedded organic growth through revenue growth and ROI opportunities o Historically low supply growth environment, particula
Slide 4: BEE's Unique Value Proposition
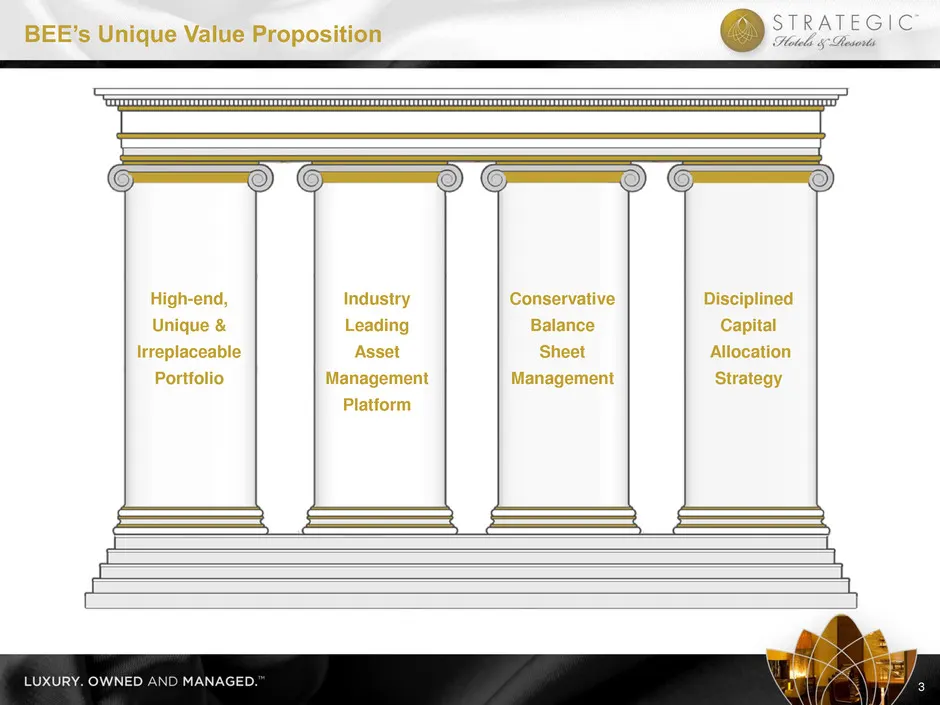
BEE’s Unique Value Proposition 3 High-end, Unique & Irreplaceable Portfolio Industry Leading Asset Management Platform Conservative Balance Sheet Management Disciplined Capital Allocation Strategy
Slide 5: High-end, Unique & Irreplaceable Portfolio
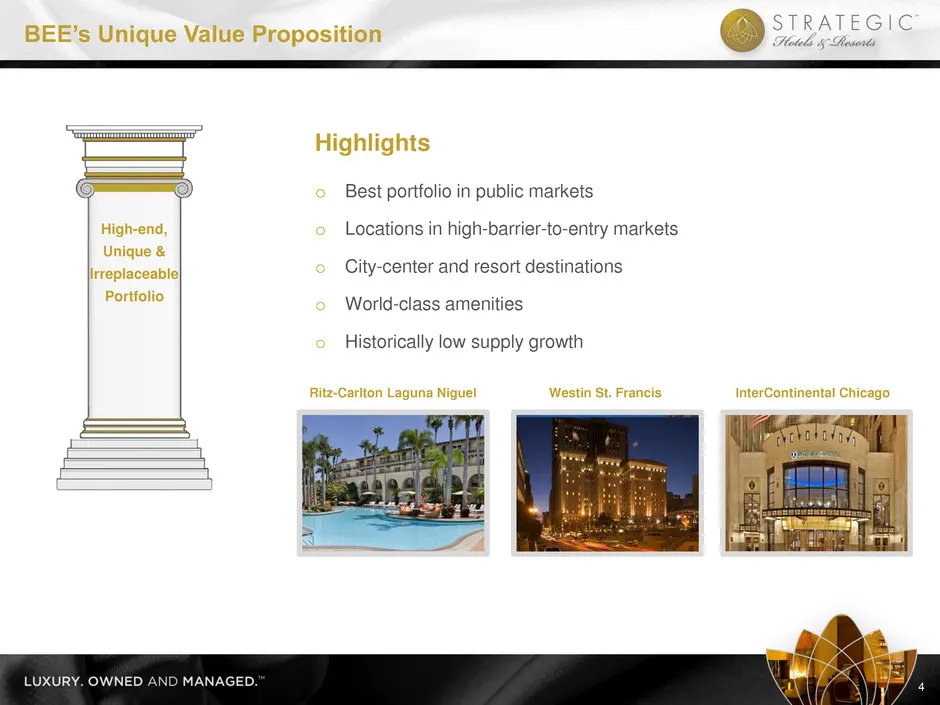
Highlights o Best portfolio in public markets o Locations in high-barrier-to-entry markets o City-center and resort destinations o World-class amenities o Historically low supply growth Westin St. Francis Ritz-Carlton Laguna Niguel InterContinental Chicago BEE’s Unique Value Proposition 4 High-end,
Slide 6: Industry Leading Asset Management Platform
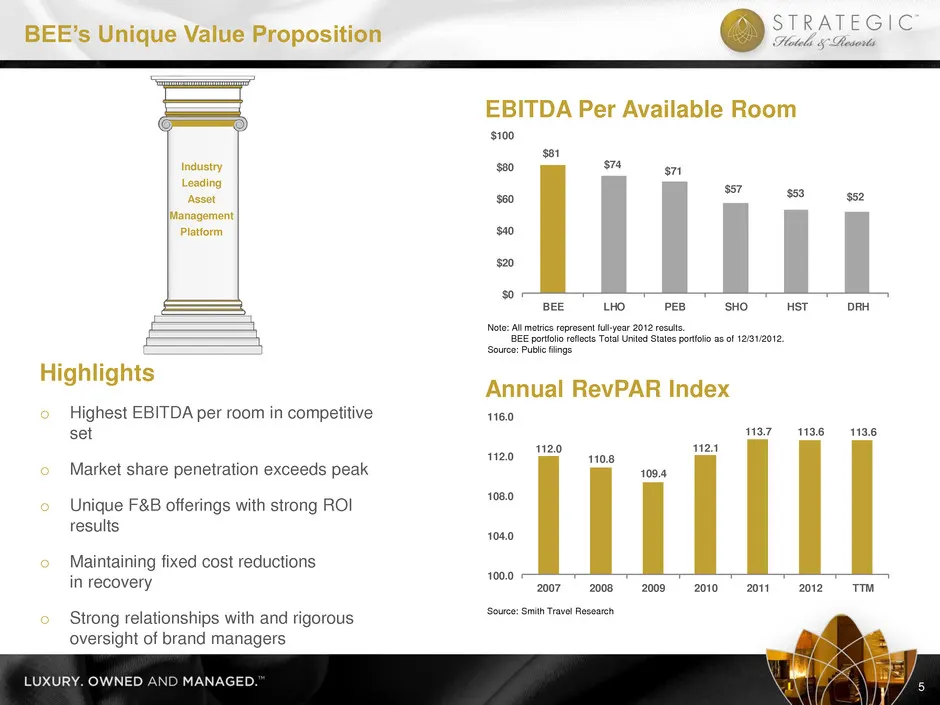
112.0 110.8 109.4 112.1 113.7 113.6 113.6 100.0 104.0 108.0 112.0 116.0 2007 2008 2009 2010 2011 2012 TTM Highlights o Highest EBITDA per room in competitive set o Market share penetration exceeds peak o Unique F&B offerings with strong ROI results o Maintaining fixed cost reductions in recovery o S
Slide 7: Conservative Balance Sheet Management
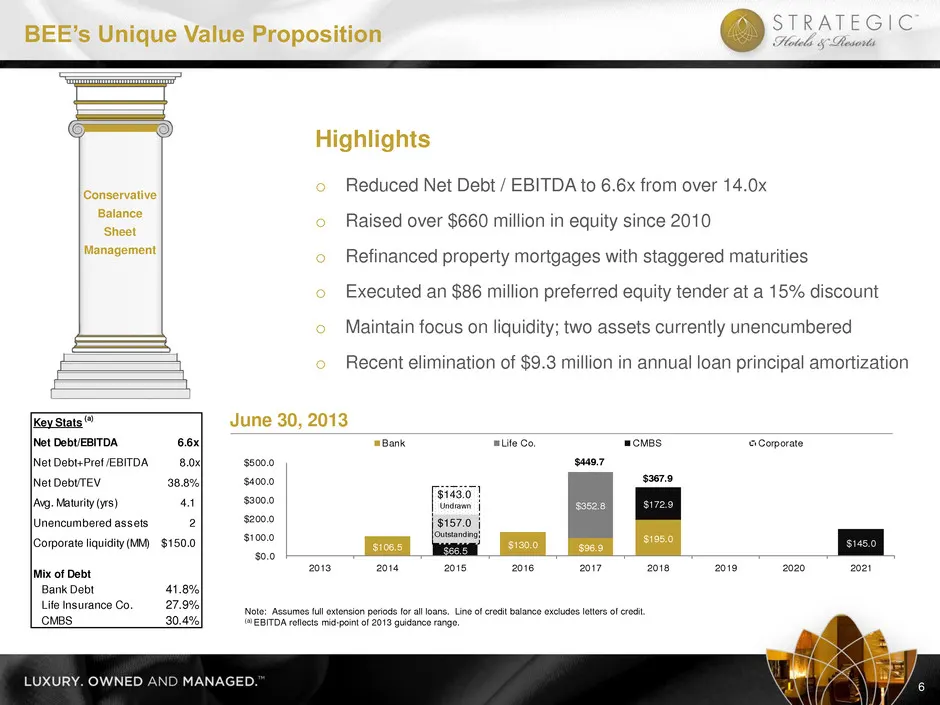
Key Stats (a) Net Debt/EBITDA 6.6x Net Debt+Pref /EBITDA 8.0x Net Debt/TEV 38.8% Avg. Maturity (yrs) 4.1 Unencumbered assets 2 Corporate liquidity (MM) $150.0 Mix of Debt Bank Debt 41.8% Life Insurance Co. 27.9% CMBS 30.4% $106.5 $130.0 $96.9 $195.0 $352.8 $66.5 $172.9 $145.0 $0.0 $100.0 $200.0 $300
Slide 8: Disciplined Capital Allocation Strategy
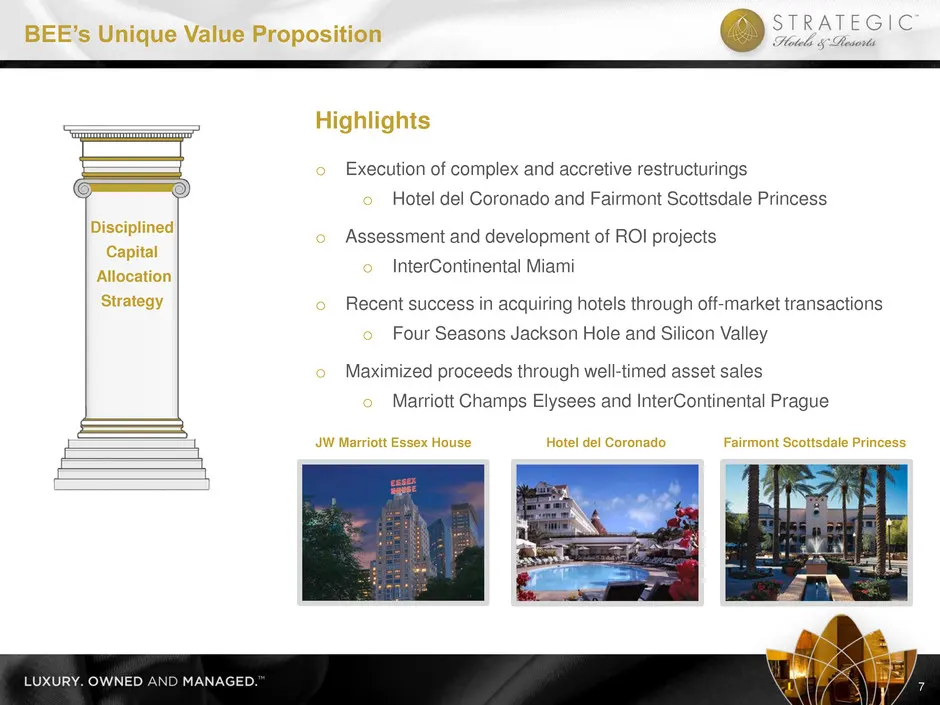
Highlights o Execution of complex and accretive restructurings o Hotel del Coronado and Fairmont Scottsdale Princess o Assessment and development of ROI projects o InterContinental Miami o Recent success in acquiring hotels through off-market transactions o Four Seasons Jackson Hole and Silicon Vall
Slide 9: Company Overview
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Company Overview 8
Slide 10: Top-Tier Market Exposure
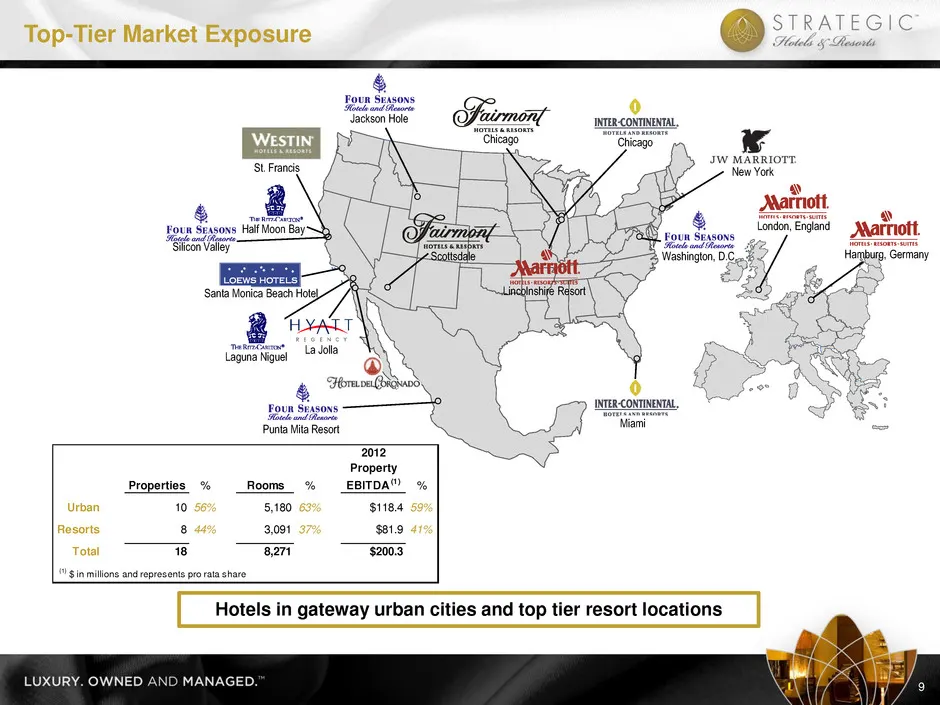
Properties % Rooms % 2012 Property EBITDA (1) % Urban 10 56% 5,180 63% $118.4 59% Resorts 8 44% 3,091 37% $81.9 41% Total 18 8,271 $200.3 (1) $ in millions and represents pro rata share Top-Tier Market Exposure Hotels in gateway urban cities and top tier resort locations Hamburg, Germany Chicago Lin
Slide 11: Portfolio Well-Positioned to Enhance Cash Flow Growth
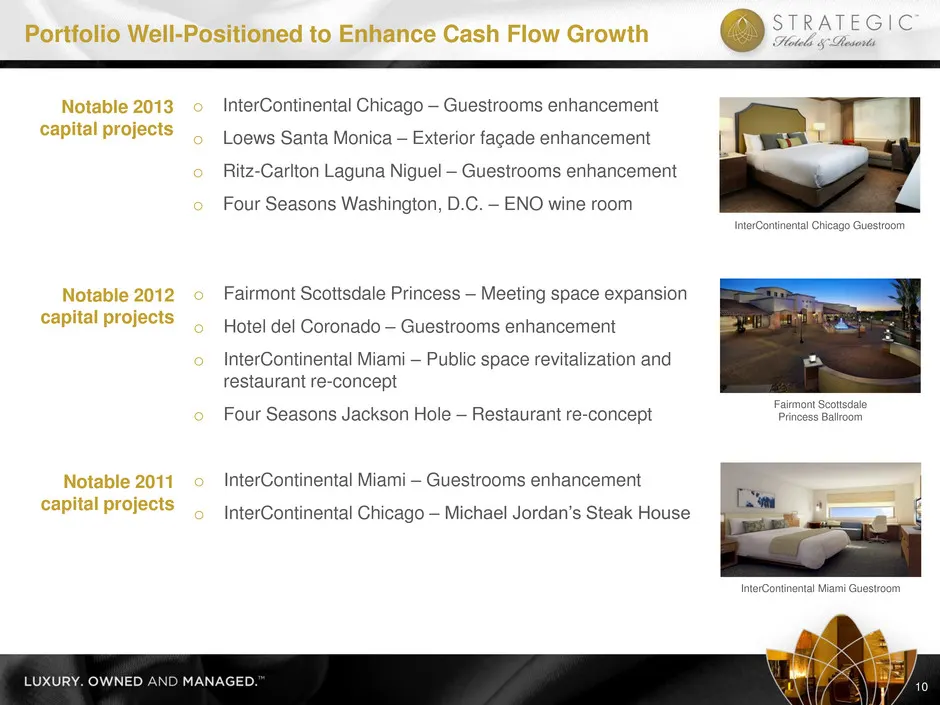
o InterContinental Miami – Guestrooms enhancement o InterContinental Chicago – Michael Jordan’s Steak House o InterContinental Chicago – Guestrooms enhancement o Loews Santa Monica – Exterior façade enhancement o Ritz-Carlton Laguna Niguel – Guestrooms enhancement o Four Seasons Washington, D.C. – E
Slide 12: Fairmont Scottsdale Princess – Palomino Ballroom
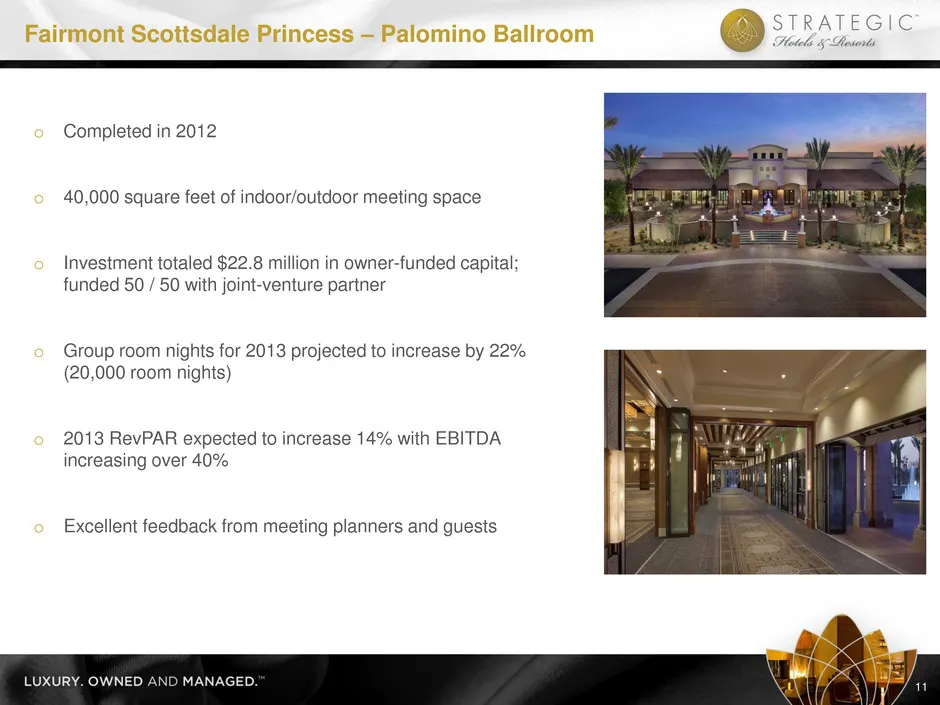
Fairmont Scottsdale Princess – Palomino Ballroom o Completed in 2012 o 40,000 square feet of indoor/outdoor meeting space o Investment totaled $22.8 million in owner-funded capital; funded 50 / 50 with joint-venture partner o Group room nights for 2013 projected to increase by 22% (20,000 room night
Slide 13: InterContinental Miami – Innovative Repositioning
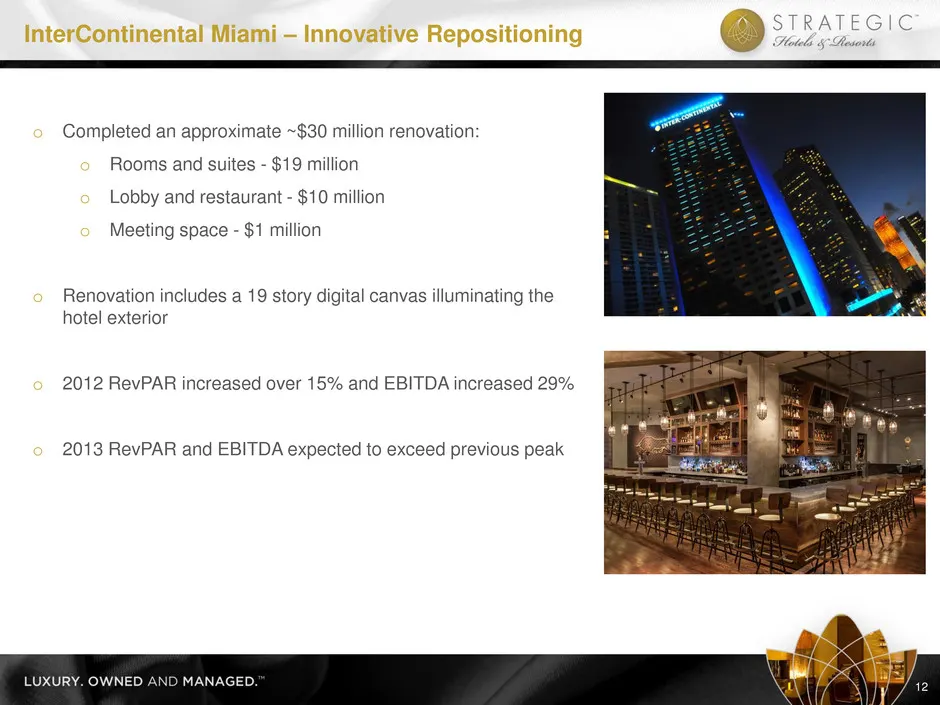
InterContinental Miami – Innovative Repositioning o Completed an approximate ~$30 million renovation: o Rooms and suites - $19 million o Lobby and restaurant - $10 million o Meeting space - $1 million o Renovation includes a 19 story digital canvas illuminating the hotel exterior o 2012 RevPAR incre
Slide 14: Industry Update
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Industry Update 13
Slide 15: Luxury Lodging Supply & Demand Dynamics
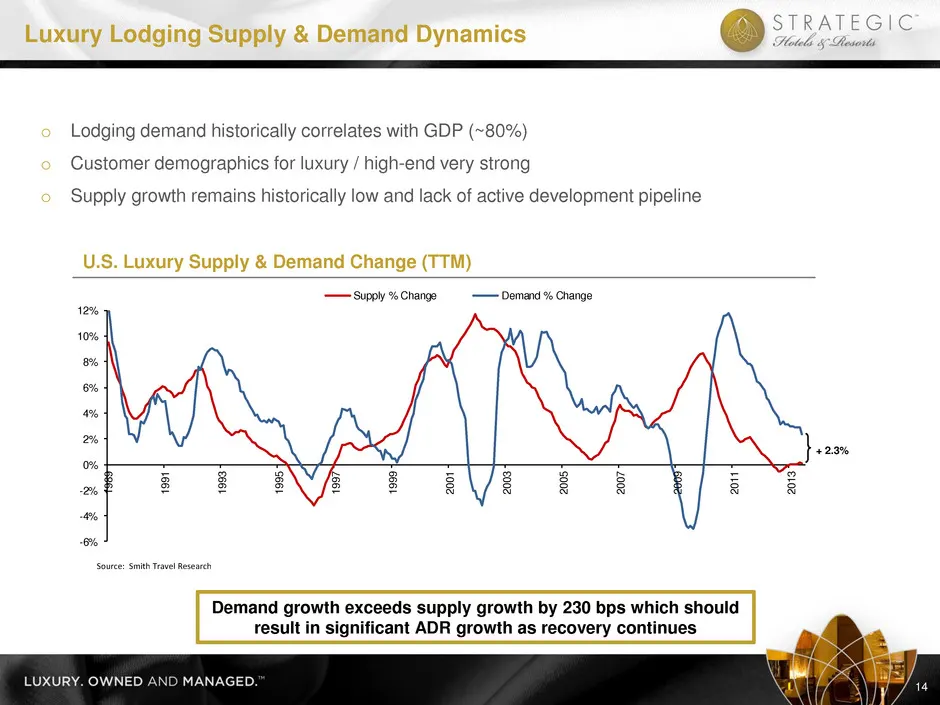
-6% -4% -2% 0% 2% 4% 6% 8% 10% 12% 198 9 199 1 199 3 199 5 199 7 199 9 200 1 200 3 200 5 200 7 200 9 201 1 201 3 Supply % Change Demand % Change o Lodging demand historically correlates with GDP (~80%) o Customer demographics for luxury / high-end very strong o Supply growth remains historically low
Slide 16: Luxury Hotels Outperform in a Recovery
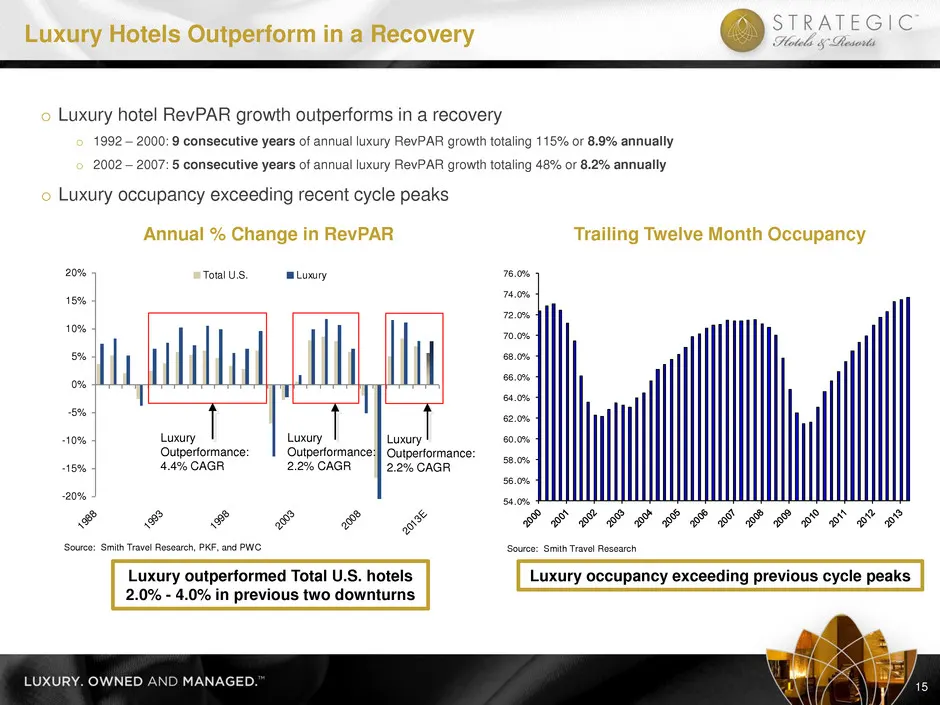
54.0% 56.0% 58.0% 60.0% 62.0% 64.0% 66.0% 68.0% 70.0% 72.0% 74.0% 76.0% 15 Source: Smith Travel Research, PKF, and PWC -20% -15% -10% -5% 0% 5% 10% 15% 20% 19 88 19 93 19 98 20 03 20 08 20 13 E Total U.S. Luxury Source: Smith Travel Research Luxury Outperformance: 4.4% CAGR Luxury Outperformance: 2.
Slide 17: BEE Outperforms Competitors
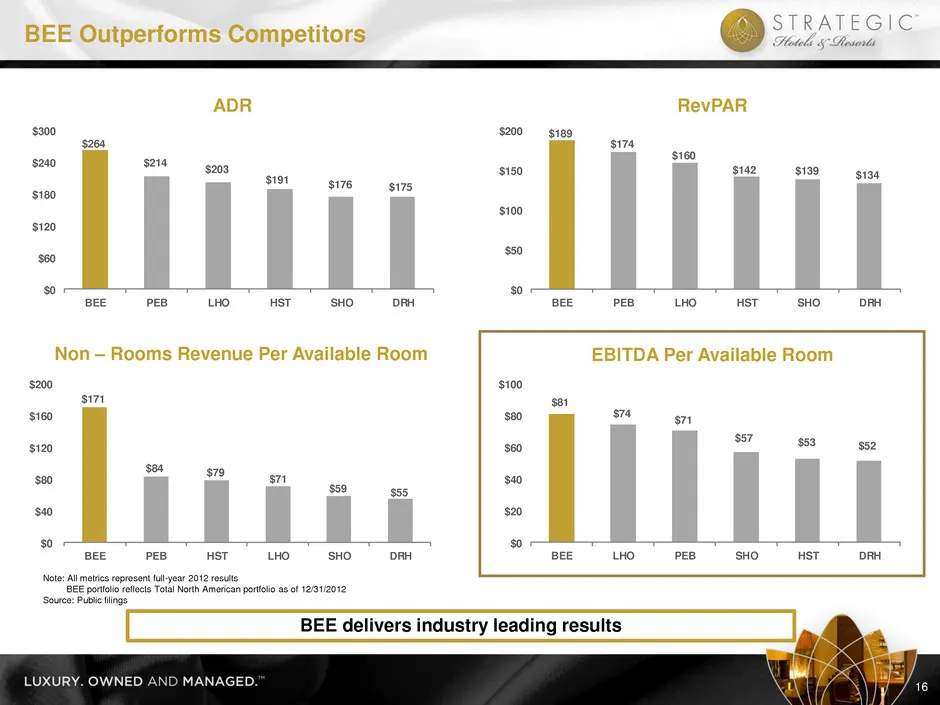
ADR RevPAR EBITDA Per Available Room Non – Rooms Revenue Per Available Room Note: All metrics represent full-year 2012 results BEE portfolio reflects Total North American portfolio as of 12/31/2012 Source: Public filings BEE delivers industry leading results BEE Outperforms Competitors 16 $189 $174
Slide 18: BEE Revenue Mix Compared to Peers
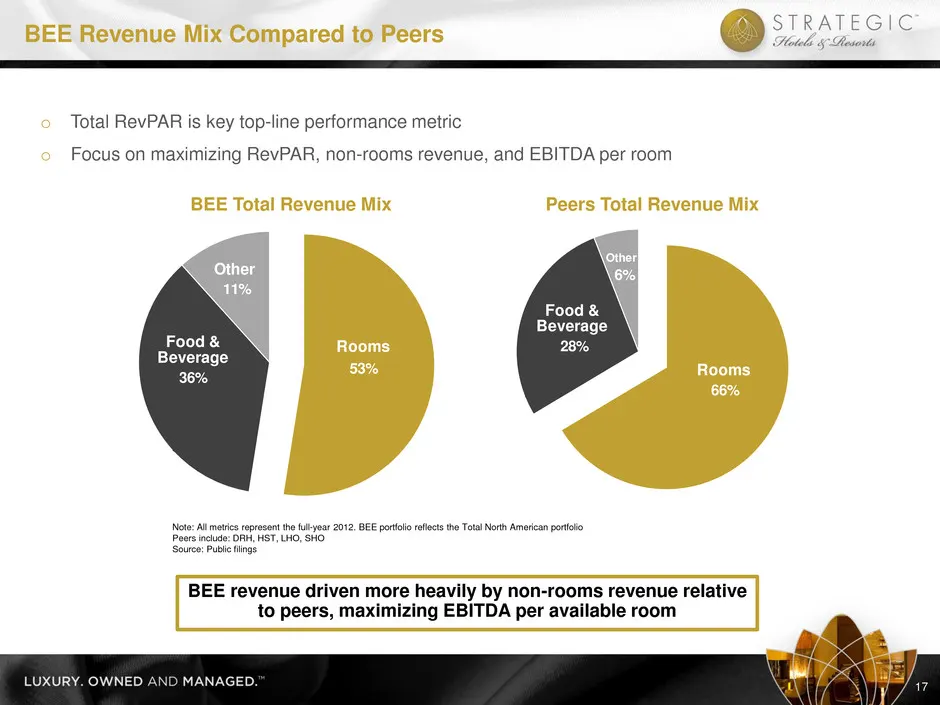
53% 36% 11% Rooms Other Food & Beverage 66% 28% 6% Food & Beverage Other Roomso Total RevPAR is key top-line performance metric o Focus on maximizing RevPAR, non-rooms revenue, and EBITDA per room BEE Total Revenue Mix Peers Total Revenue Mix Note: All metrics represent the full-year 2012. BEE portf
Slide 19: Industry Leading Operating Margins
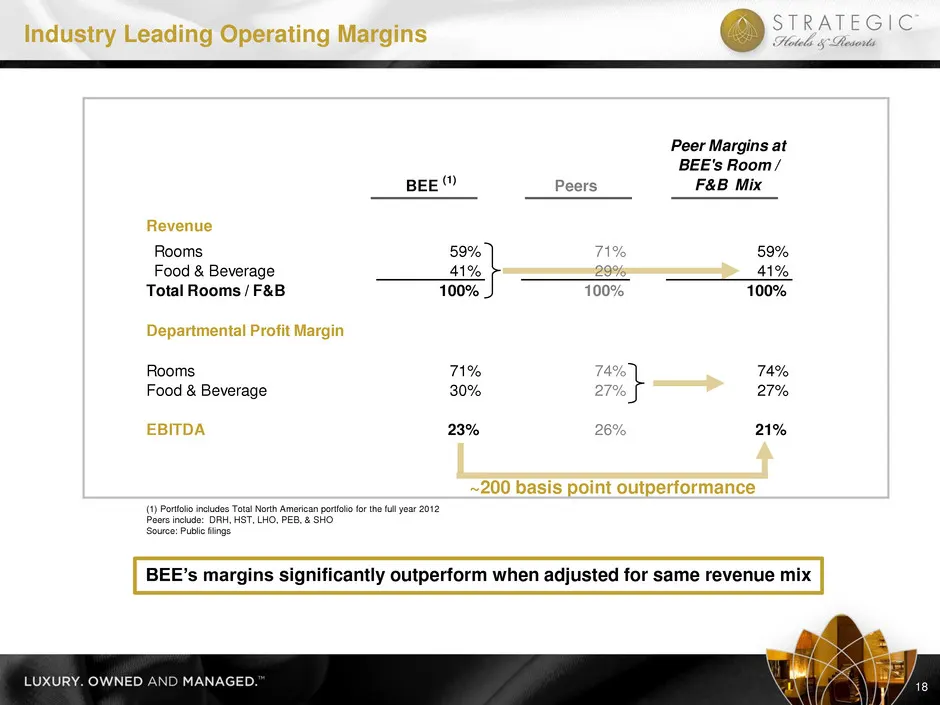
~200 basis point outperformance (1) Portfolio includes Total North American portfolio for the full year 2012 Peers include: DRH, HST, LHO, PEB, & SHO Source: Public filings BEE’s margins significantly outperform when adjusted for same revenue mix Industry Leading Operating Margins 18 BEE (1) Peers P
Slide 20: Operating Trends
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Operating Trends 19
Slide 21: Group Booking Outlook
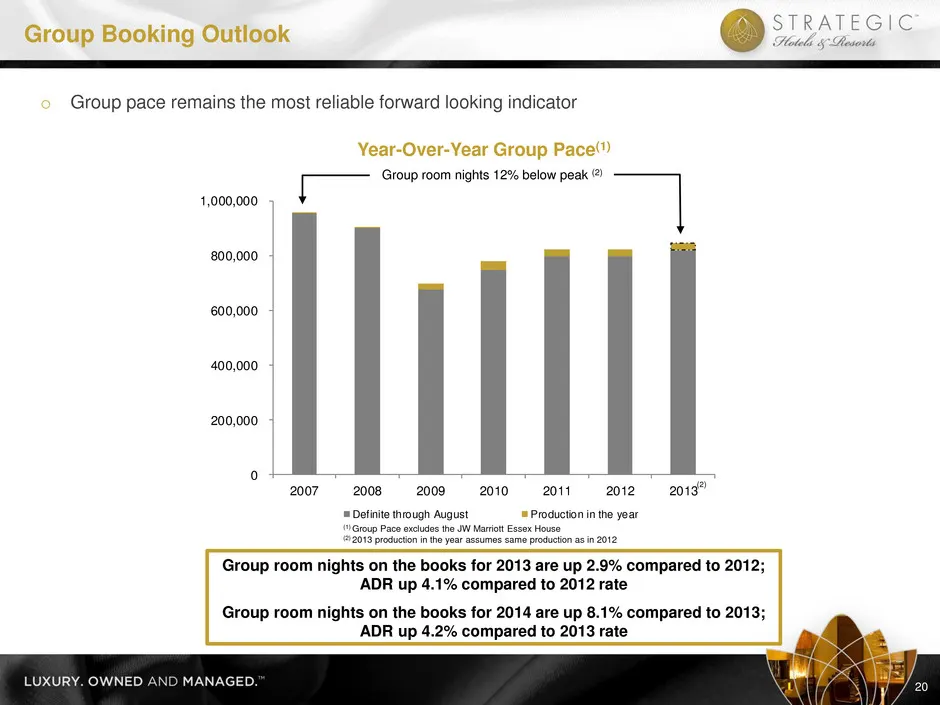
0 200,000 400,000 600,000 800,000 1,000,000 2007 2008 2009 2010 2011 2012 2013 Definite through August Production in the year o Group pace remains the most reliable forward looking indicator Year-Over-Year Group Pace(1) Group room nights 12% below peak (2) (1) Group Pace excludes the JW Marriott Ess
Slide 22: Embedded Portfolio Growth
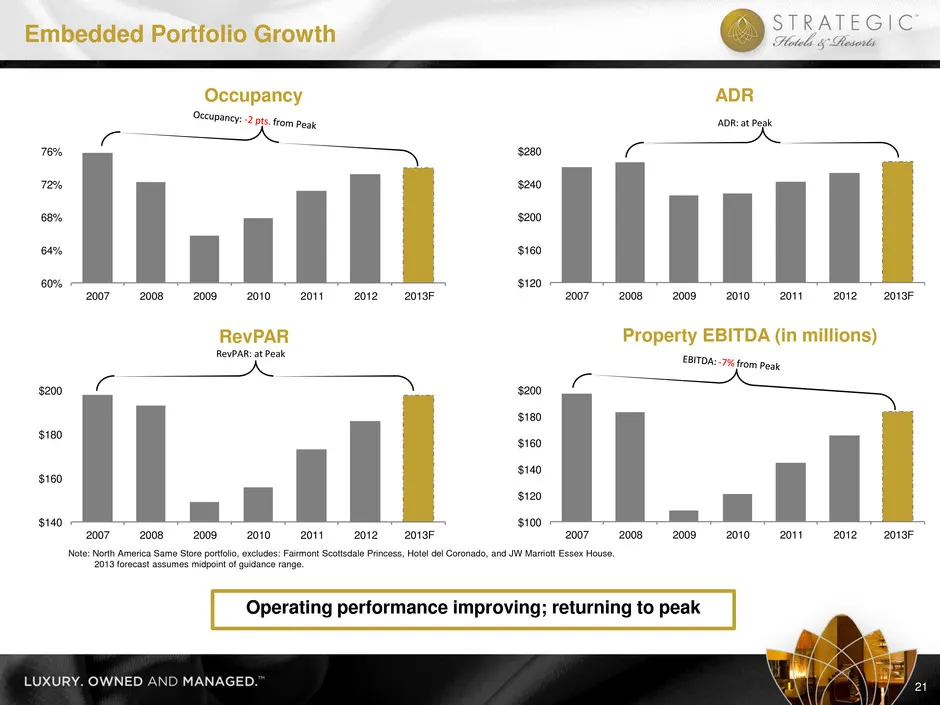
$100 $120 $140 $160 $180 $200 2007 2008 2009 2010 2011 2012 2013F $140 $160 $180 $200 2007 2008 2009 2010 2011 2012 2013F $120 $160 $200 $240 $280 2007 2008 2009 2010 2011 2012 2013F 60% 64% 68% 72% 76% 2007 2008 2009 2010 2011 2012 2013F ADR: at Peak RevPAR: at Peak Occupancy ADR RevPAR Property EB
Slide 23: Financial Overview
I. BEE’s Unique Value Proposition II. Company Overview III. Industry Update IV. Operating Trends V. Financial Overview Financial Overview 22
Slide 24: 2nd Quarter 2013 Results
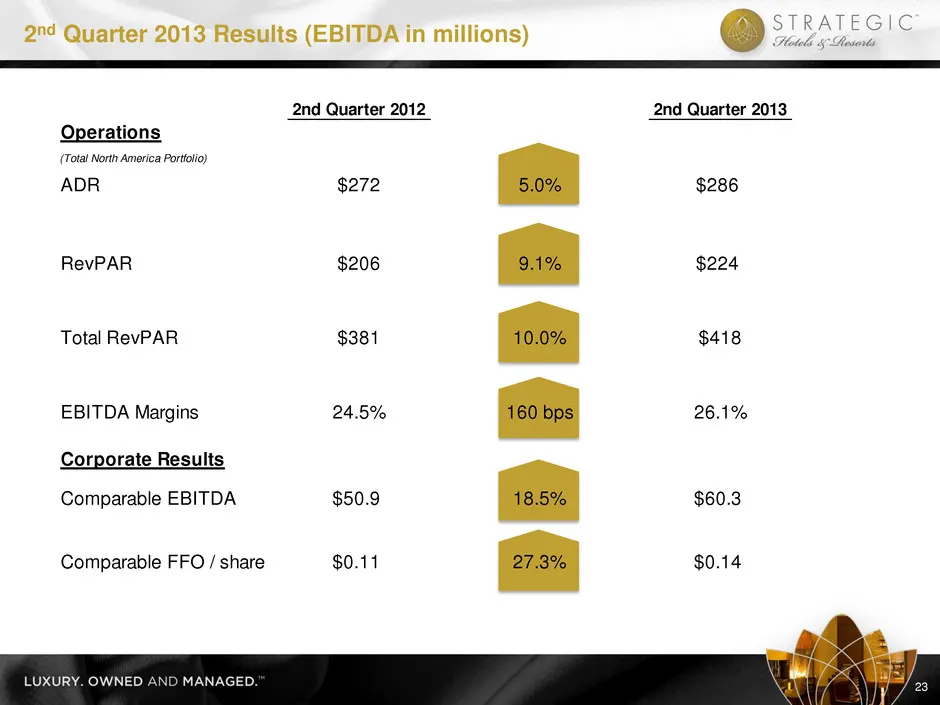
2nd Quarter 2013 Results (EBITDA in millions) 23 2nd Quarter 2012 2nd Quarter 2013 Operations (Total North America Portfolio) ADR $272 5.0% $286 RevPAR $206 9.1% $224 Total RevPAR $381 10.0% $418 EBITDA Margins 24.5% 160 bps 26.1% Corporate Results Comparable EBITDA $50.9 18.5% $60.3 Comparable FFO
Slide 25: YTD 2013 Results
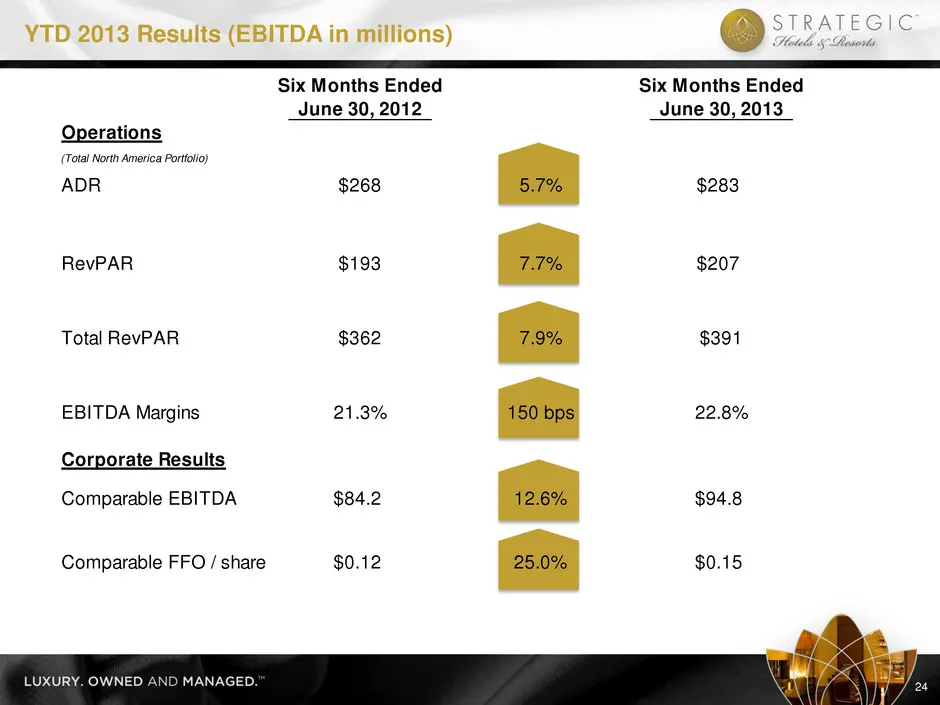
YTD 2013 Results (EBITDA in millions) 24 Six Months Ended Six Months Ended June 30, 2012 June 30, 2013 Operations (Total North America Portfolio) ADR $268 5.7% $283 RevPAR $193 7.7% $207 Total RevPAR $362 7.9% $391 EBITDA Margins 21.3% 150 bps 22.8% Corporate Results Comparable EBITDA $84.2 12.6% $9
Slide 26: 2013 Guidance
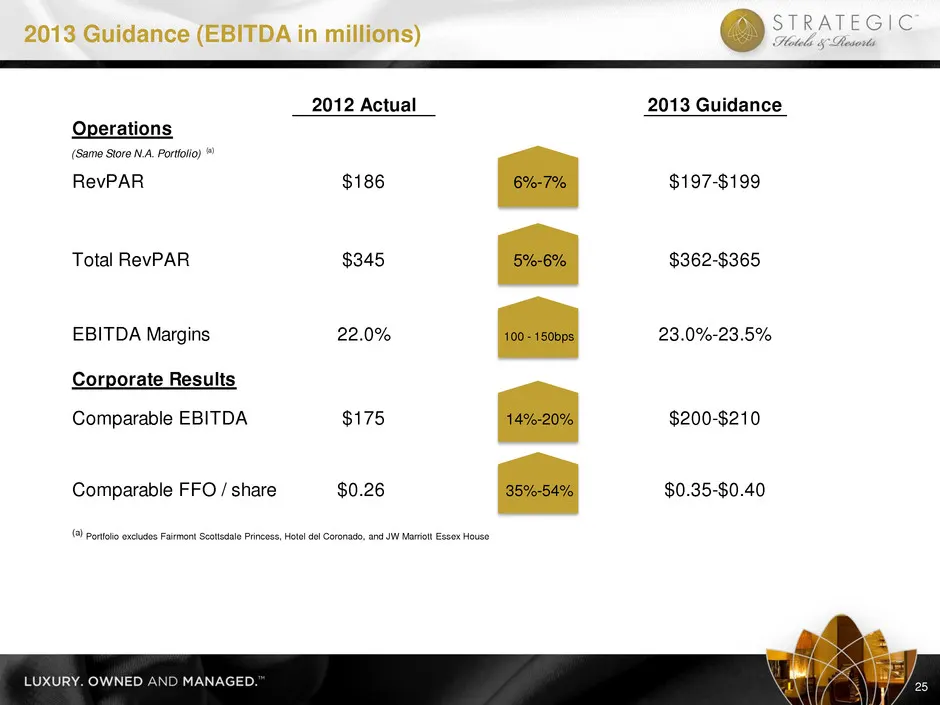
(a) Portfolio excludes Fairmont Scottsdale Princess, Hotel del Coronado, and JW Marriott Essex House 2013 Guidance (EBITDA in millions) 25 2012 Actual 2013 Guidance Operations (Same Store N.A. Portfolio) (a) RevPAR $186 6%-7% $197-$199 Total RevPAR $345 5%-6% $362-$365 EBITDA Margins 22.0% 100 - 150
Slide 27: BEE's Unique Value Proposition
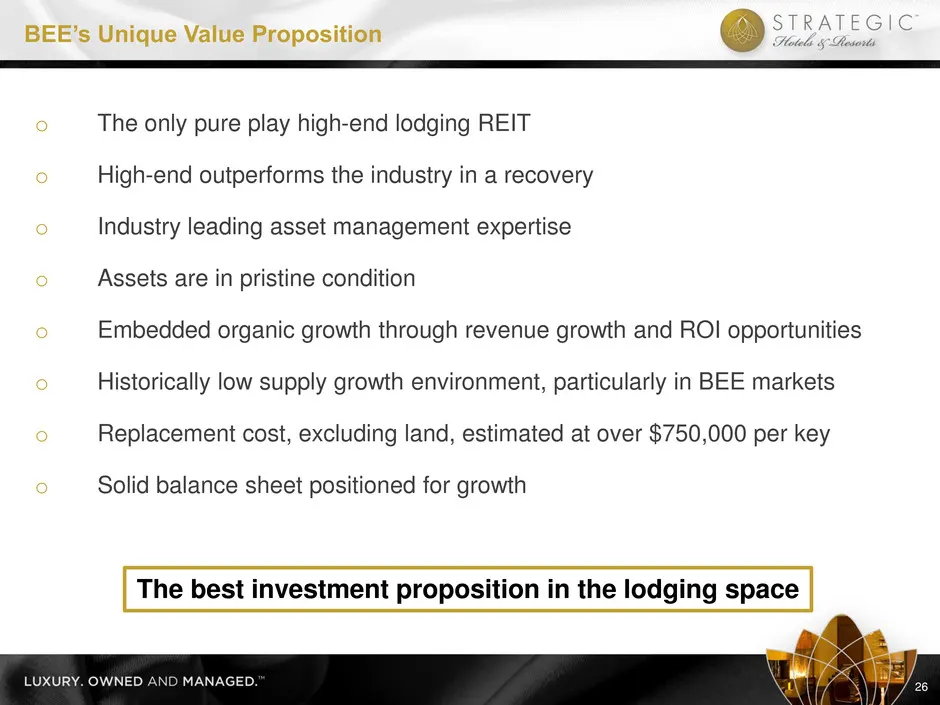
o The only pure play high-end lodging REIT o High-end outperforms the industry in a recovery o Industry leading asset management expertise o Assets are in pristine condition o Embedded organic growth through revenue growth and ROI opportunities o Historically low supply growth environment, particula
Slide 28: Except for historical information, the matters discussed in this presentation are forward-looking statements subject
Except for historical information, the matters discussed in this presentation are forward-looking statements subject to certain risks and uncertainties. Forward-looking statements relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends, and similar exp
Slide 29: Non-GAAP to GAAP Reconciliations
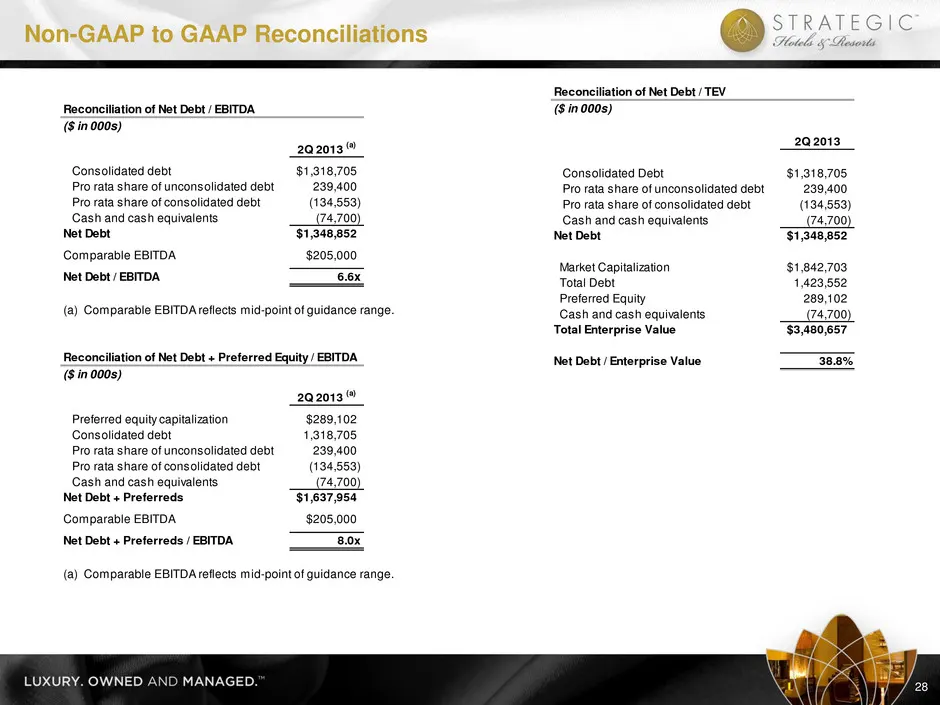
Reconciliation of Net Debt / TEV ($ in 000s) 2Q 2013 Consolidated Debt $1,318,705 Pro rata share of unconsolidated debt 239,400 Pro rata share of consolidated debt (134,553) Cash and cash equivalents (74,700) Net Debt $1,348,852 Market Capitalization $1,842,703 Total Debt 1,423,552 Preferred Equity
Slide 30: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations 29
Slide 31: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations 30
Slide 32: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations 31
Slide 33: Thank You
32 Thank You
Source: SEC EDGAR · 8-K filed Sep 30, 2013
More decks from Strategic Hotels and Resorts Inc
 Investor Presentation (June 2015)43 slides · Jun 1, 2015
 Investor Presentation (February 2015)43 slides · Feb 24, 2015
 Investor Presentation (January 2015)44 slides · Jan 26, 2015
 Investor Presentation (November 2014)50 slides · Nov 5, 2014
 Investor Presentation (October 2014)50 slides · Oct 3, 2014
 Investor Day (September 2014)67 slides · Sep 22, 2014