Metcash Limited · ASX:MTS
Metcash — Investor Day (March 2017)
29 slides from Metcash's investor day presentation, Mar 23, 2017
Slide 1: Investor day – 23 March 2017
Hh 10 ~~ DANAHERS: MITRE 10 Independent - gee Hardware Group Mitre 10 e Home Timber & Hardware « Thrifty-Link *« True Value Hardware Investor day — 23 March 2017 QNCO
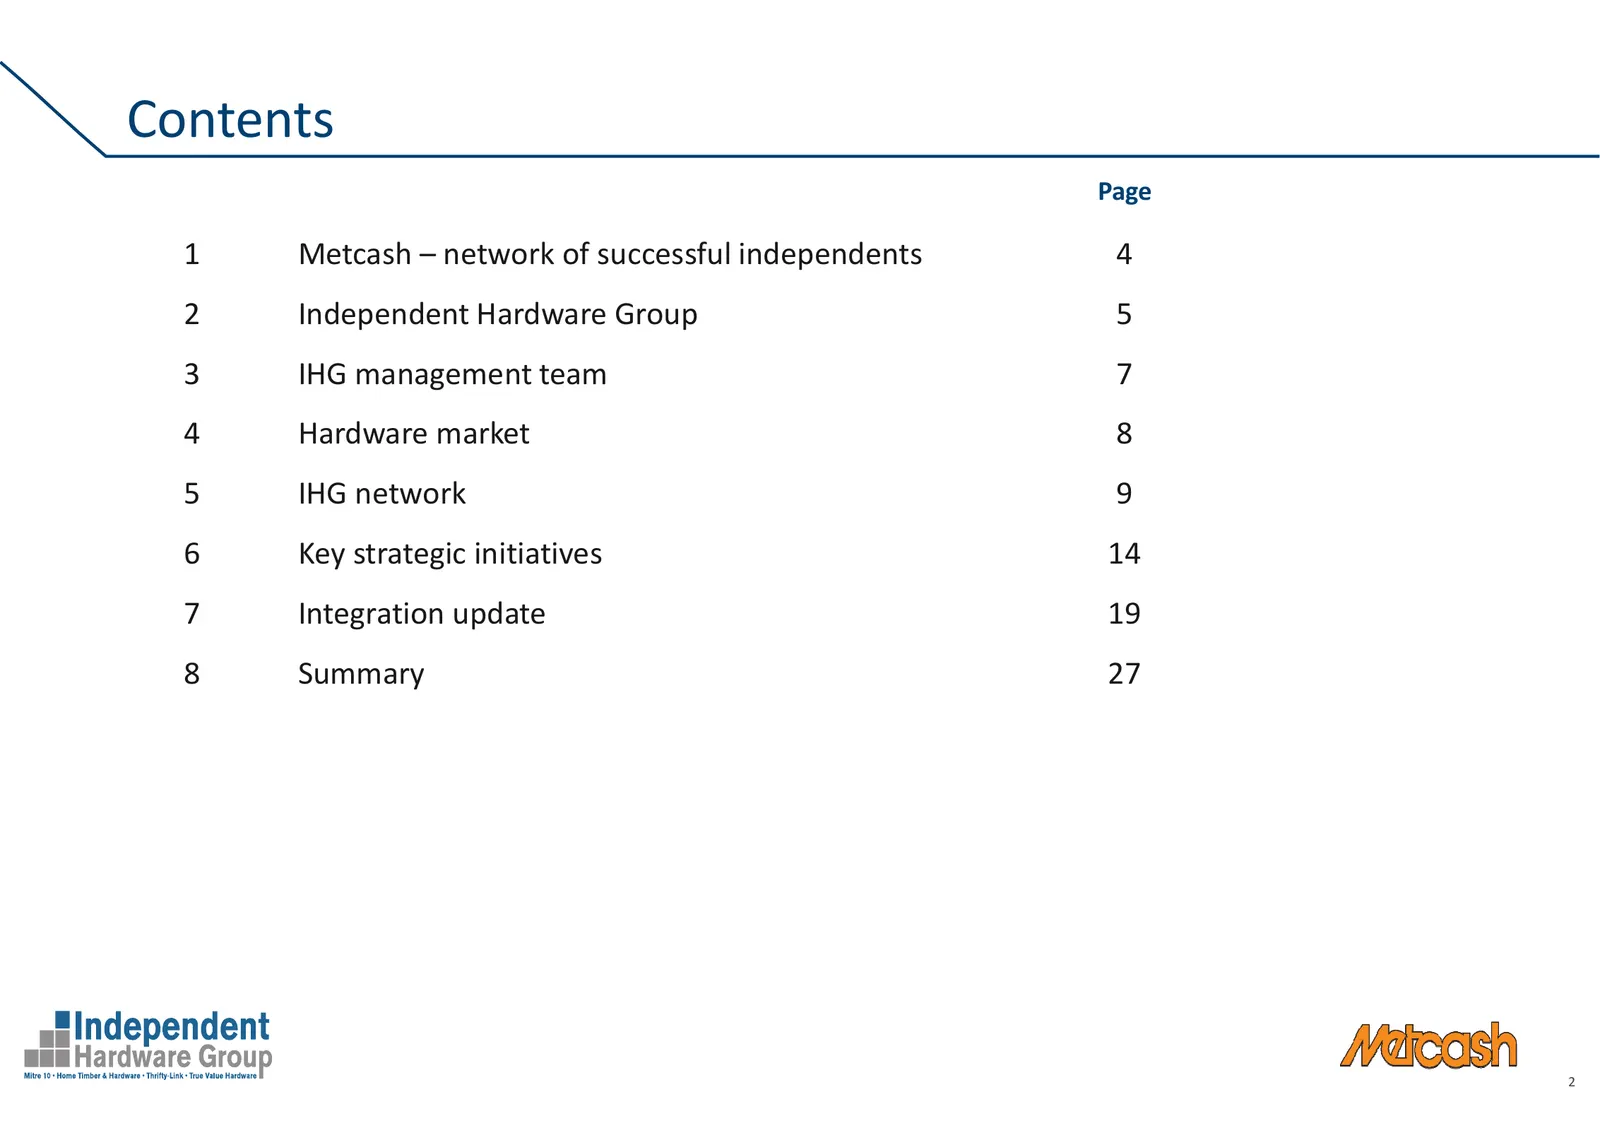
Slide 2: Contents
Contents Page 1 Metcash – network of successful independents 4 2 Independent Hardware Group 5 3 IHG management team 7 4 Hardware market 8 5 IHG network 9 6 Key strategic initiatives 14 7 Integration update 19 8 Summary 27 2
Slide 3: Successful Independents
Successful Independents Ian Morrice Metcash CEO
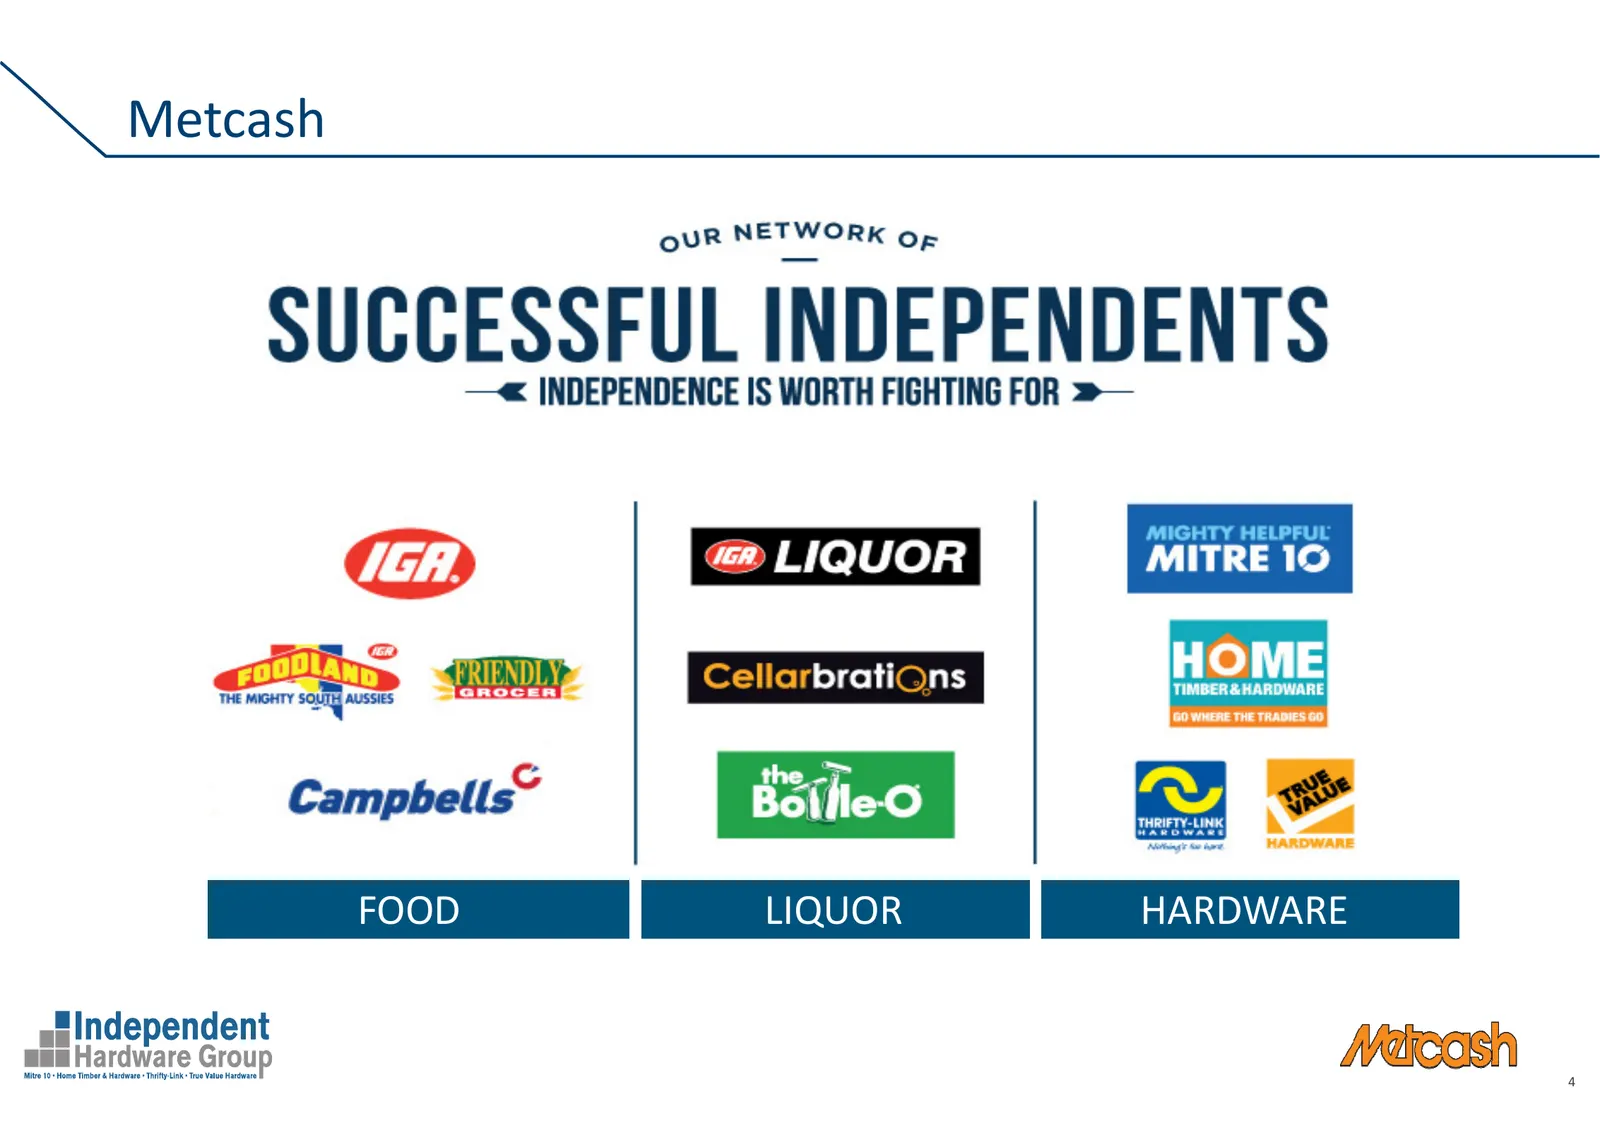
Slide 4: Metcash
Metcash FOOD LIQUOR HARDWARE 4
Slide 5: HTH acquisition – now second largest in Hardware market
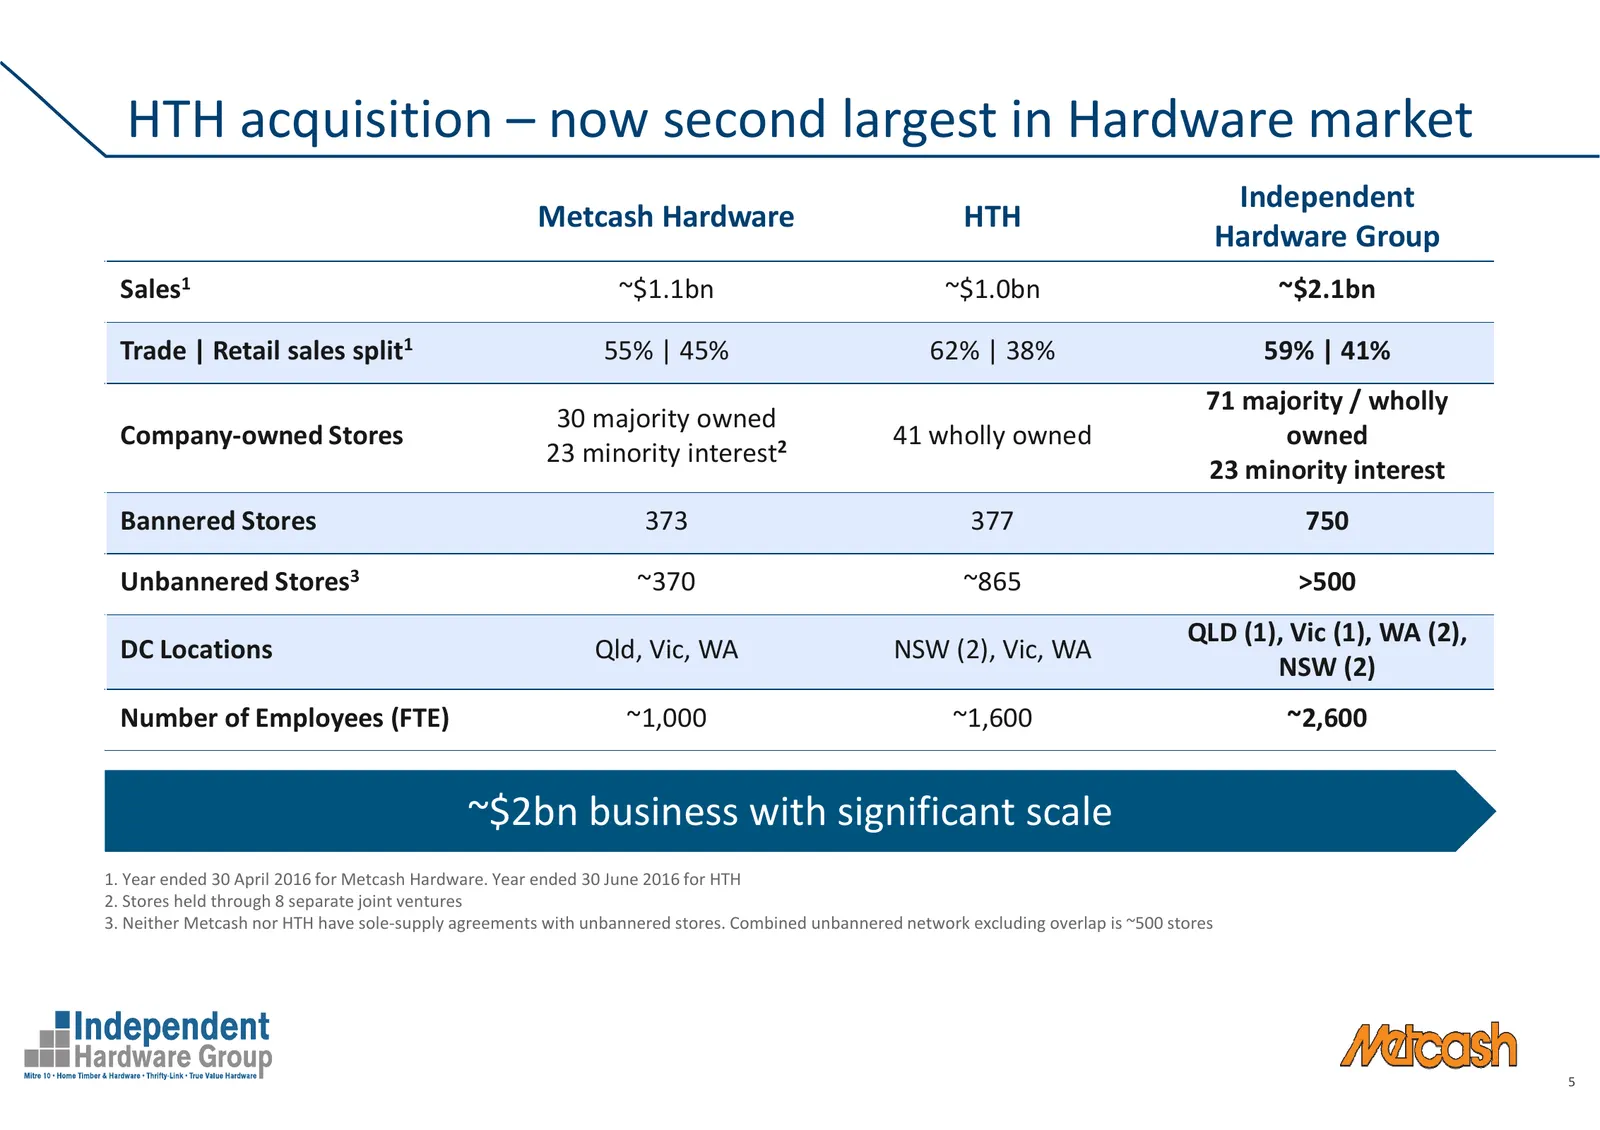
HTH acquisition – now second largest in Hardware market Independent Metcash Hardware HTH Hardware Group Sales1 ~$1.1bn ~$1.0bn ~$2.1bn Trade | Retail sales split1 55% | 45% 62% | 38% 59% | 41% 71 majority / wholly 30 majority owned Company-owned Stores 41 wholly owned owned 23 minority interest2 23
Slide 6: Business Overview
Business Overview Mark Laidlaw CEO, Independent Hardware Group
Slide 7: IHG management team
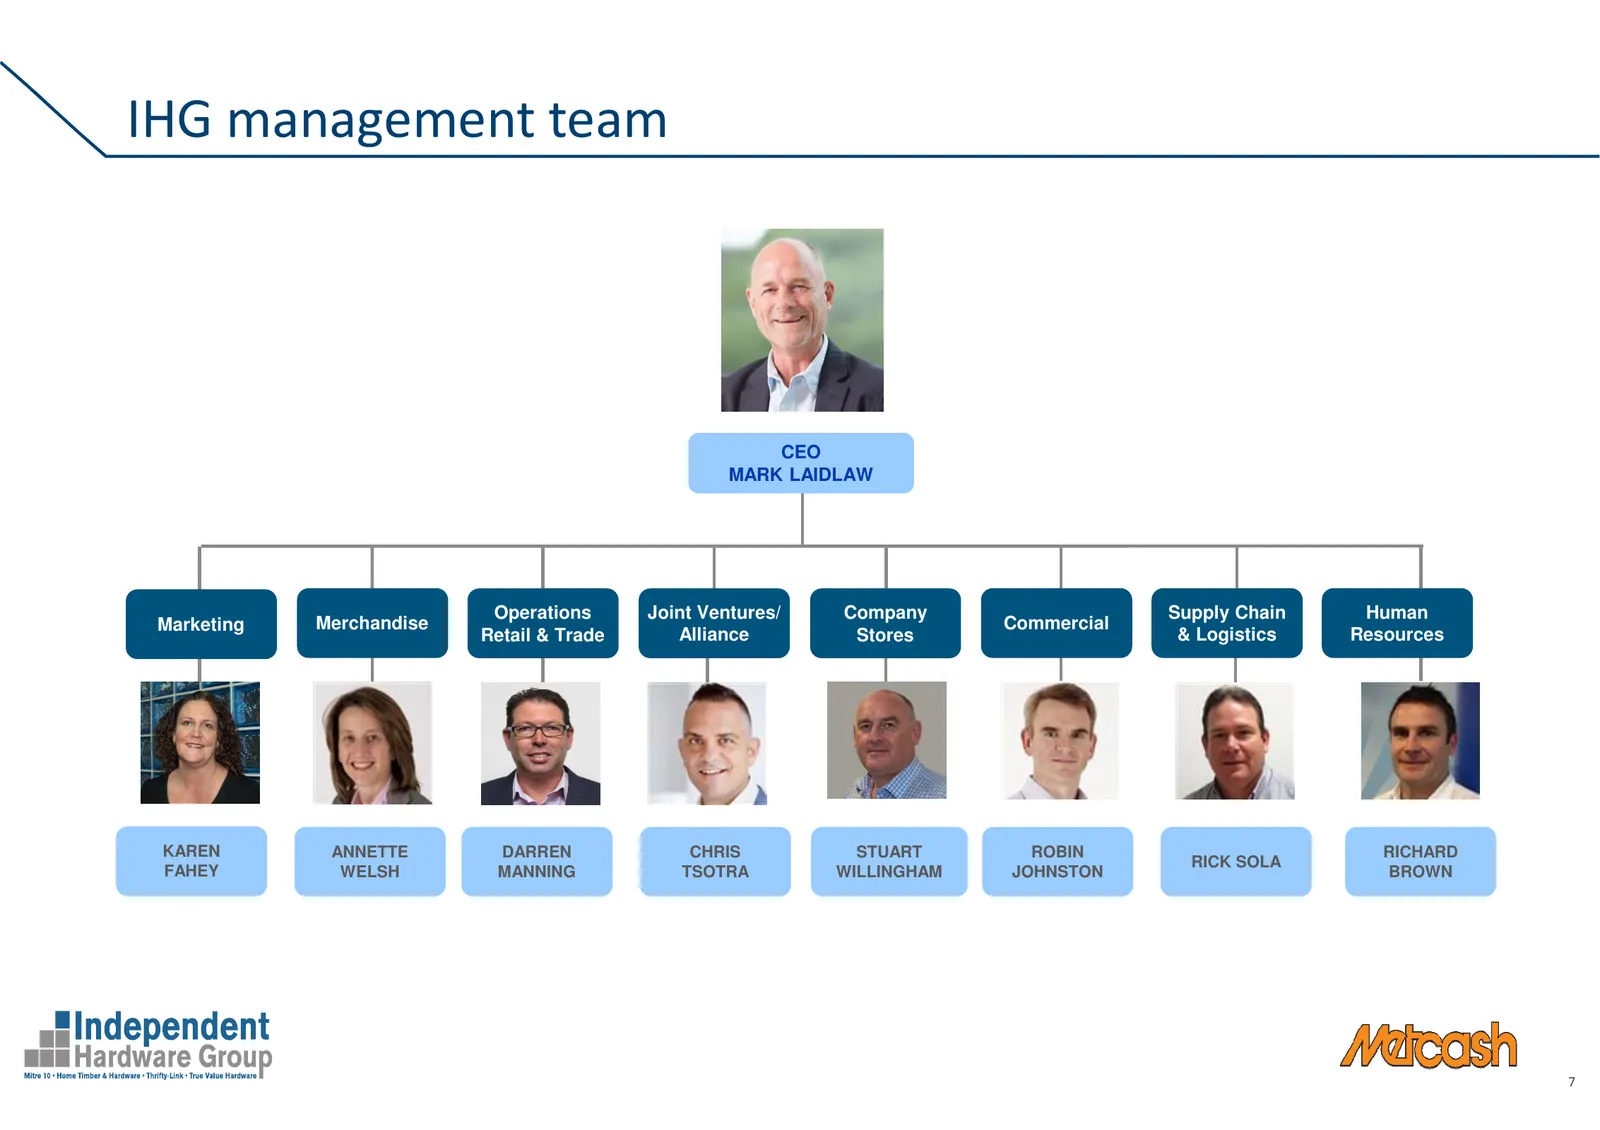
IHG management team CEO MARK LAIDLAW Operations Joint Ventures/ Company Supply Chain Human Marketing Merchandise Commercial Retail & Trade Alliance Stores & Logistics Resources KAREN ANNETTE DARREN CHRIS STUART ROBIN RICHARD RICK SOLA FAHEY WELSH MANNING TSOTRA WILLINGHAM JOHNSTON BROWN 7
Slide 8: IHG – second largest player in Hardware market
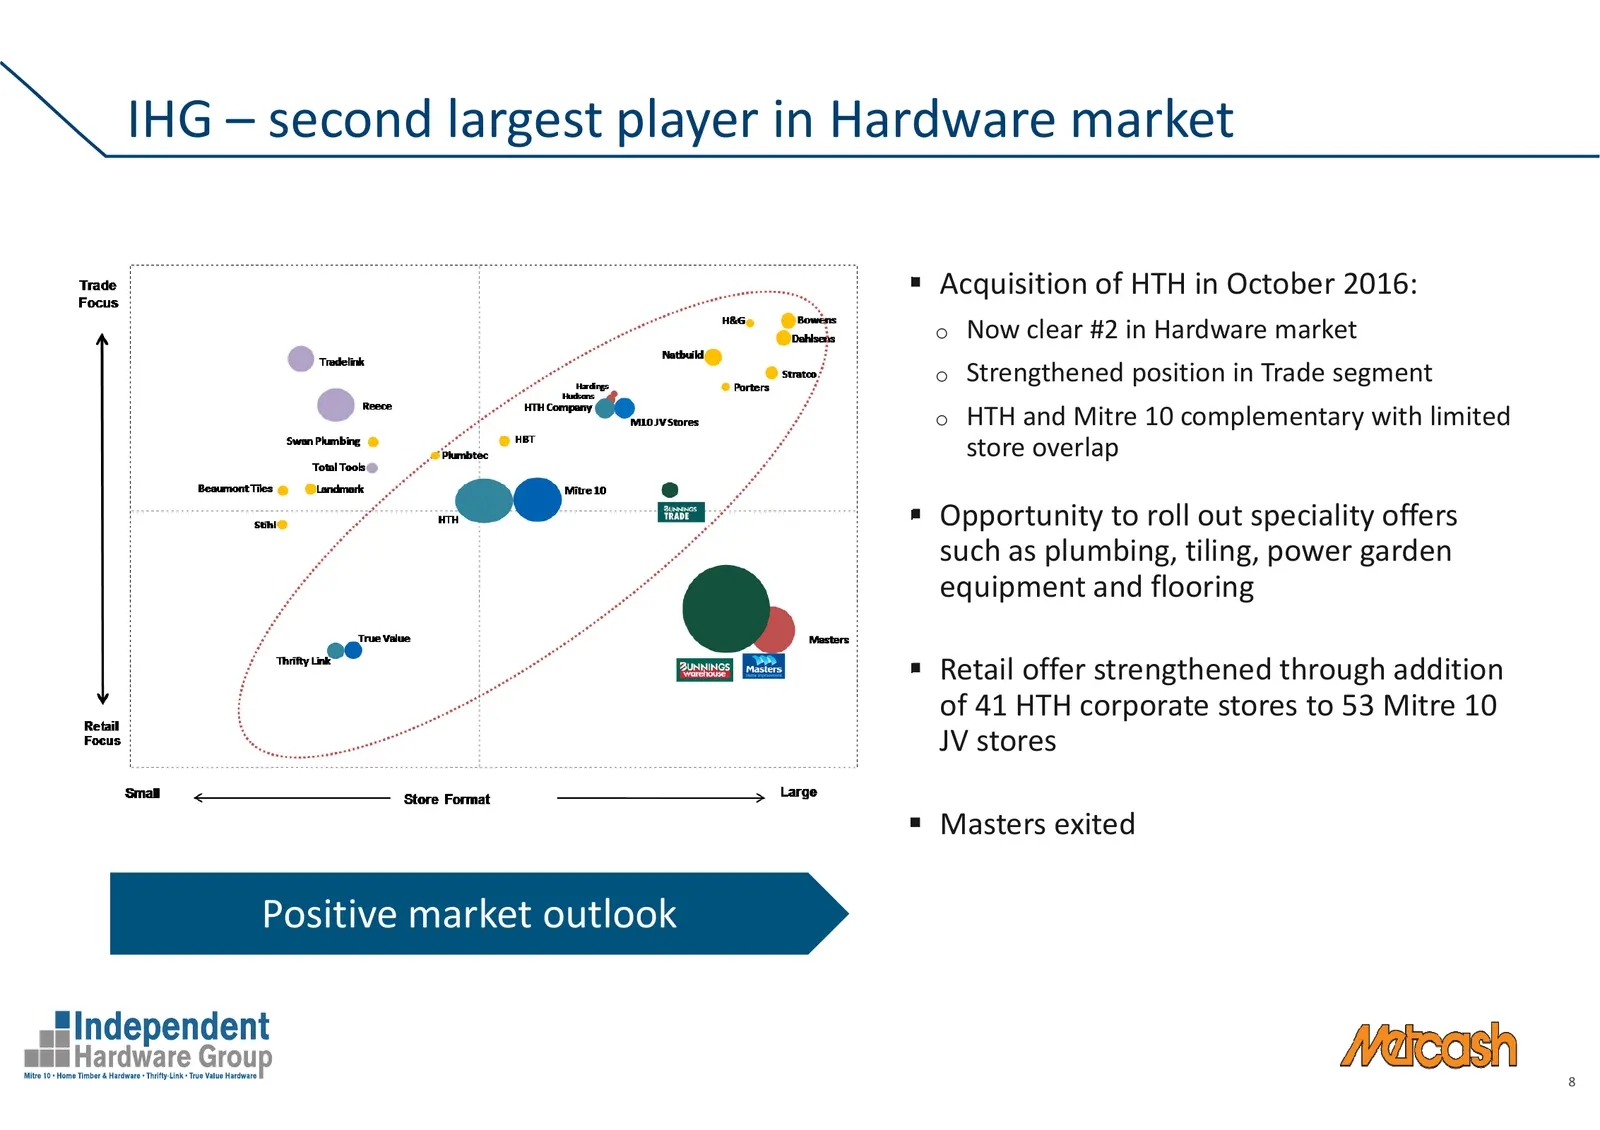
IHG – second largest player in Hardware market Acquisition of HTH in October 2016: o Now clear #2 in Hardware market o Strengthened position in Trade segment o HTH and Mitre 10 complementary with limited store overlap Opportunity to roll out speciality offers such as plumbing, tiling, power garden e
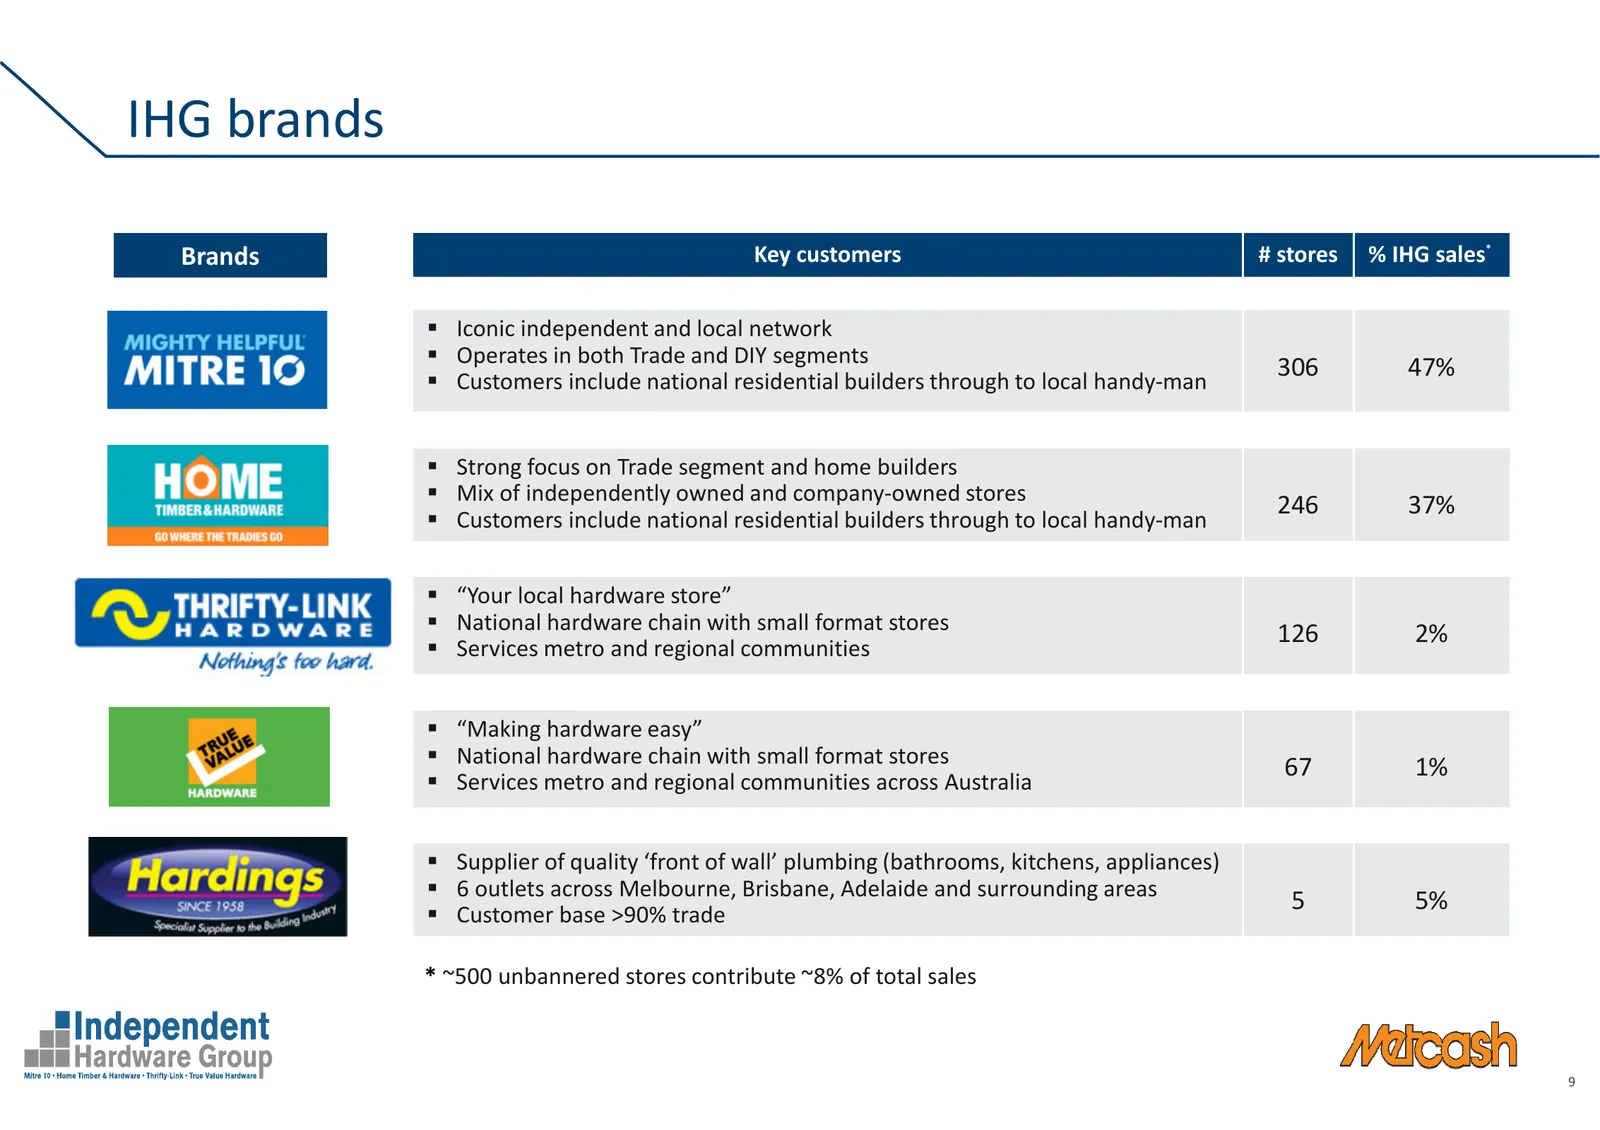
Slide 9: IHG brands
IHG brands Brands Key customers # stores % IHG sales* Iconic independent and local network Operates in both Trade and DIY segments 306 47% Customers include national residential builders through to local handy-man Strong focus on Trade segment and home builders Mix of independently owned and company
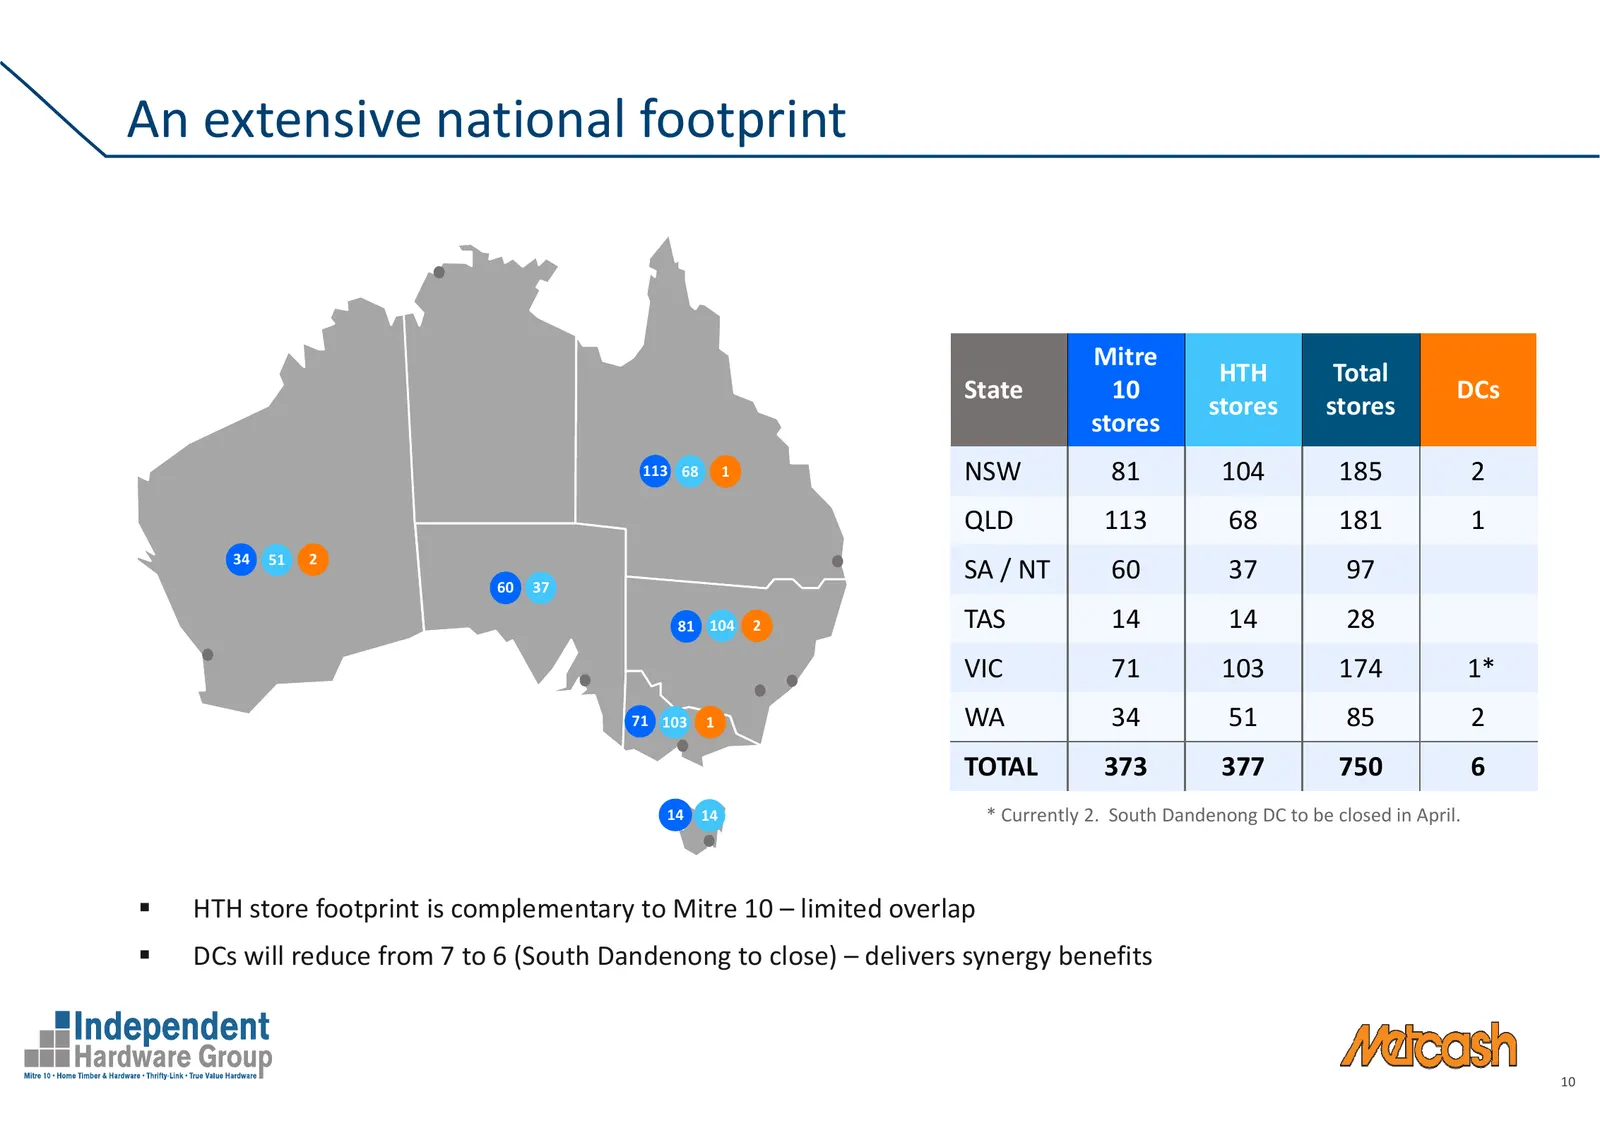
Slide 10: An extensive national footprint
An extensive national footprint Mitre HTH Total State 10 DCs stores stores stores 113 68 1 NSW 81 104 185 2 QLD 113 68 181 1 34 51 2 SA / NT 60 37 97 60 37 81 104 2 TAS 14 14 28 VIC 71 103 174 1* 71 103 1 WA 34 51 85 2 TOTAL 373 377 750 6 14 14 * Currently 2. South Dandenong DC to be closed in April
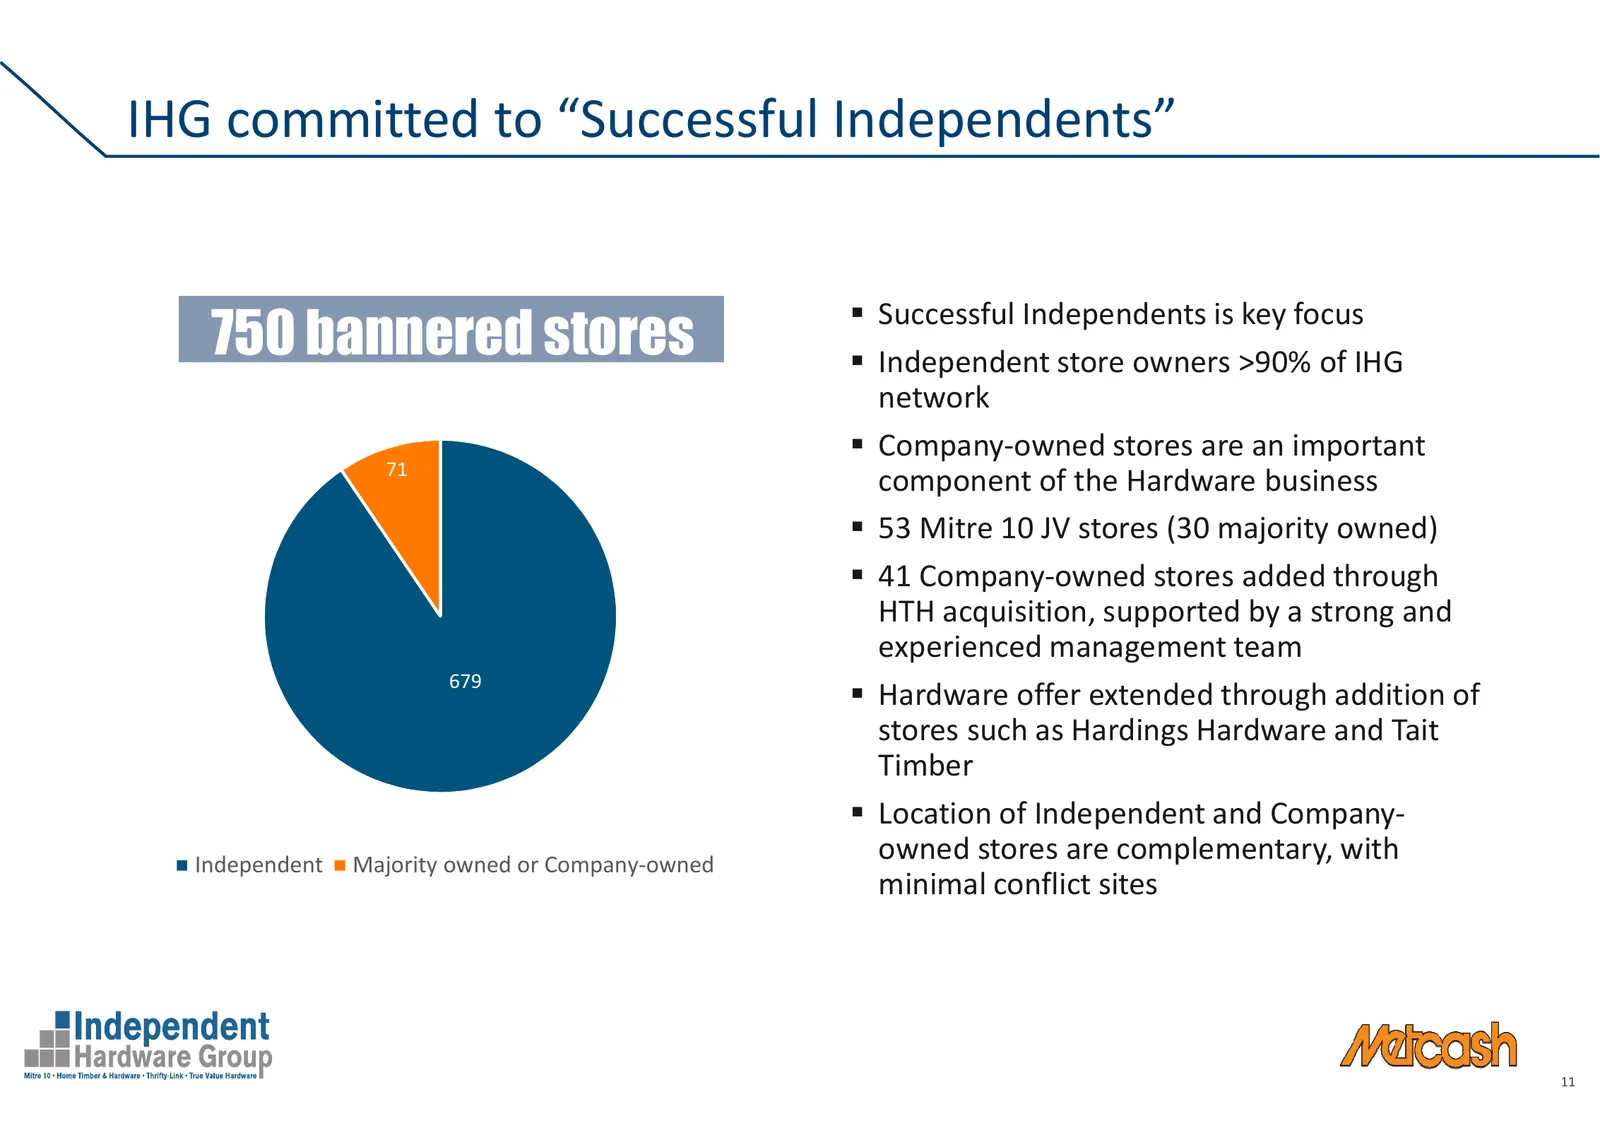
Slide 11: IHG committed to “Successful Independents”
IHG committed to “Successful Independents” Successful Independents is key focus 750 bannered stores Independent store owners >90% of IHG network Company-owned stores are an important 71 component of the Hardware business 53 Mitre 10 JV stores (30 majority owned) 41 Company-owned stores added through
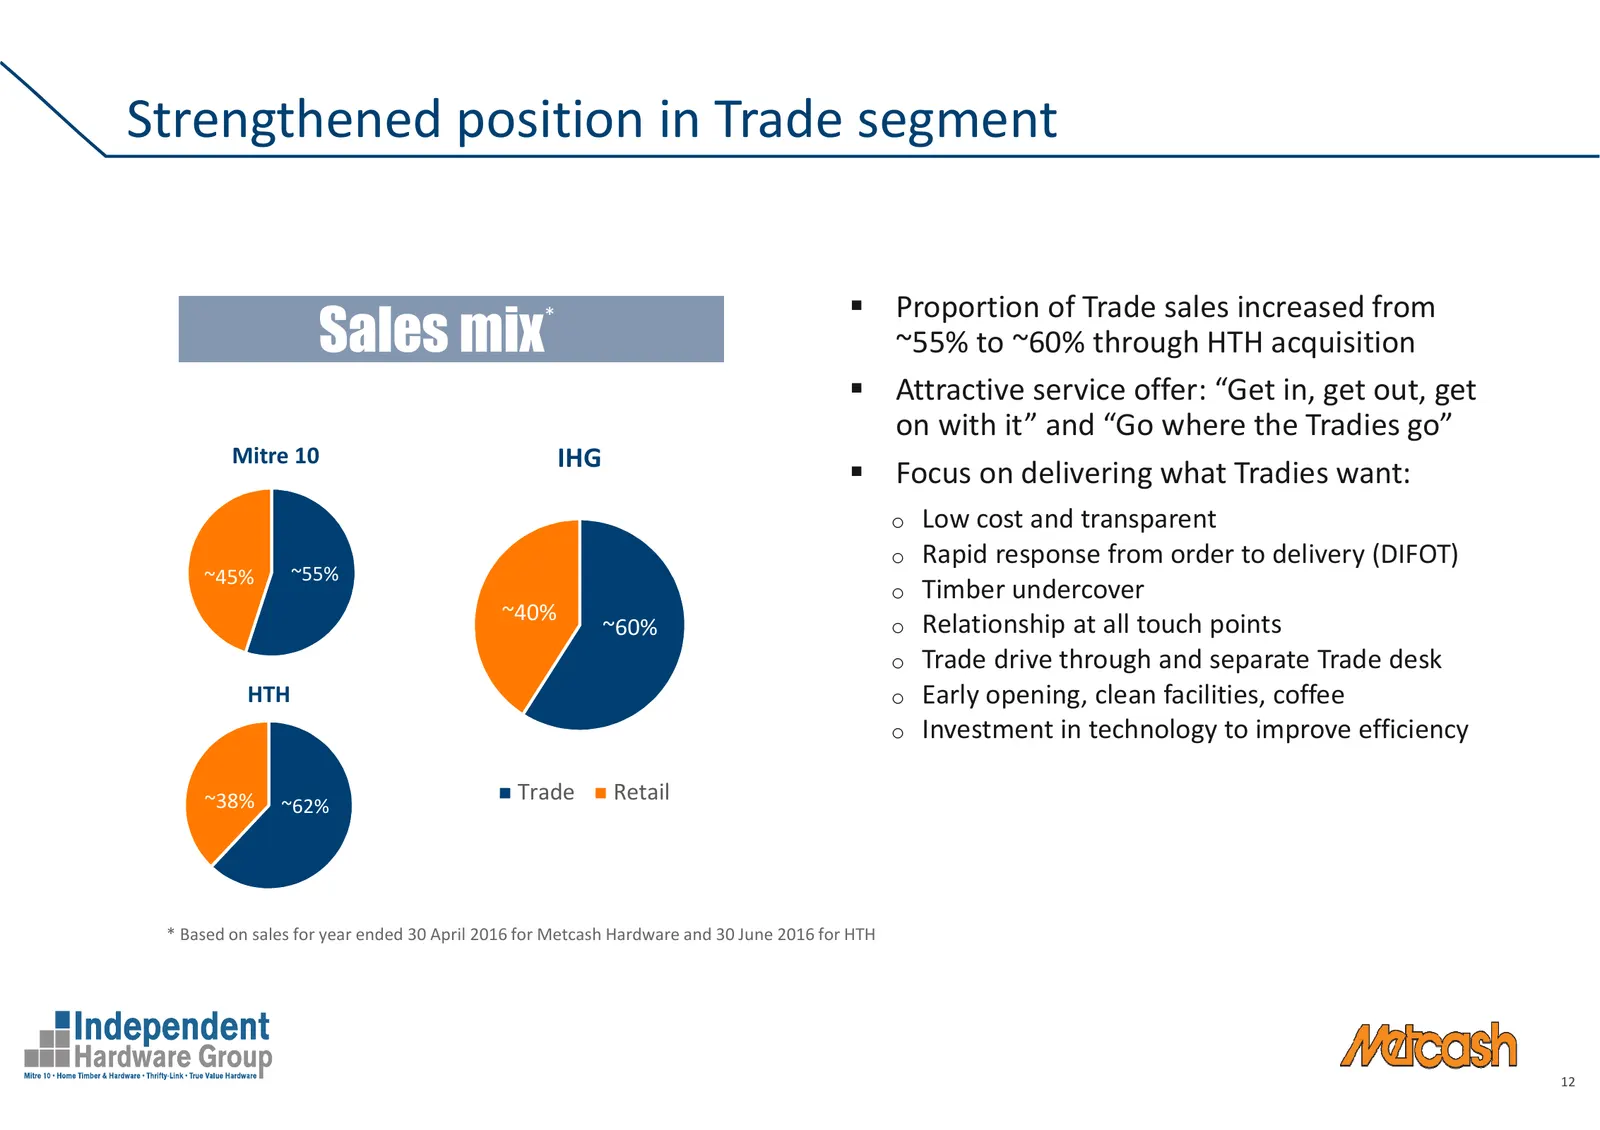
Slide 12: Strengthened position in Trade segment
Strengthened position in Trade segment Proportion of Trade sales increased from Sales mix * ~55% to ~60% through HTH acquisition Attractive service offer: “Get in, get out, get on with it” and “Go where the Tradies go” Mitre 10 IHG Focus on delivering what Tradies want: o Low cost and transparent o
Slide 13: Consumer led strategy
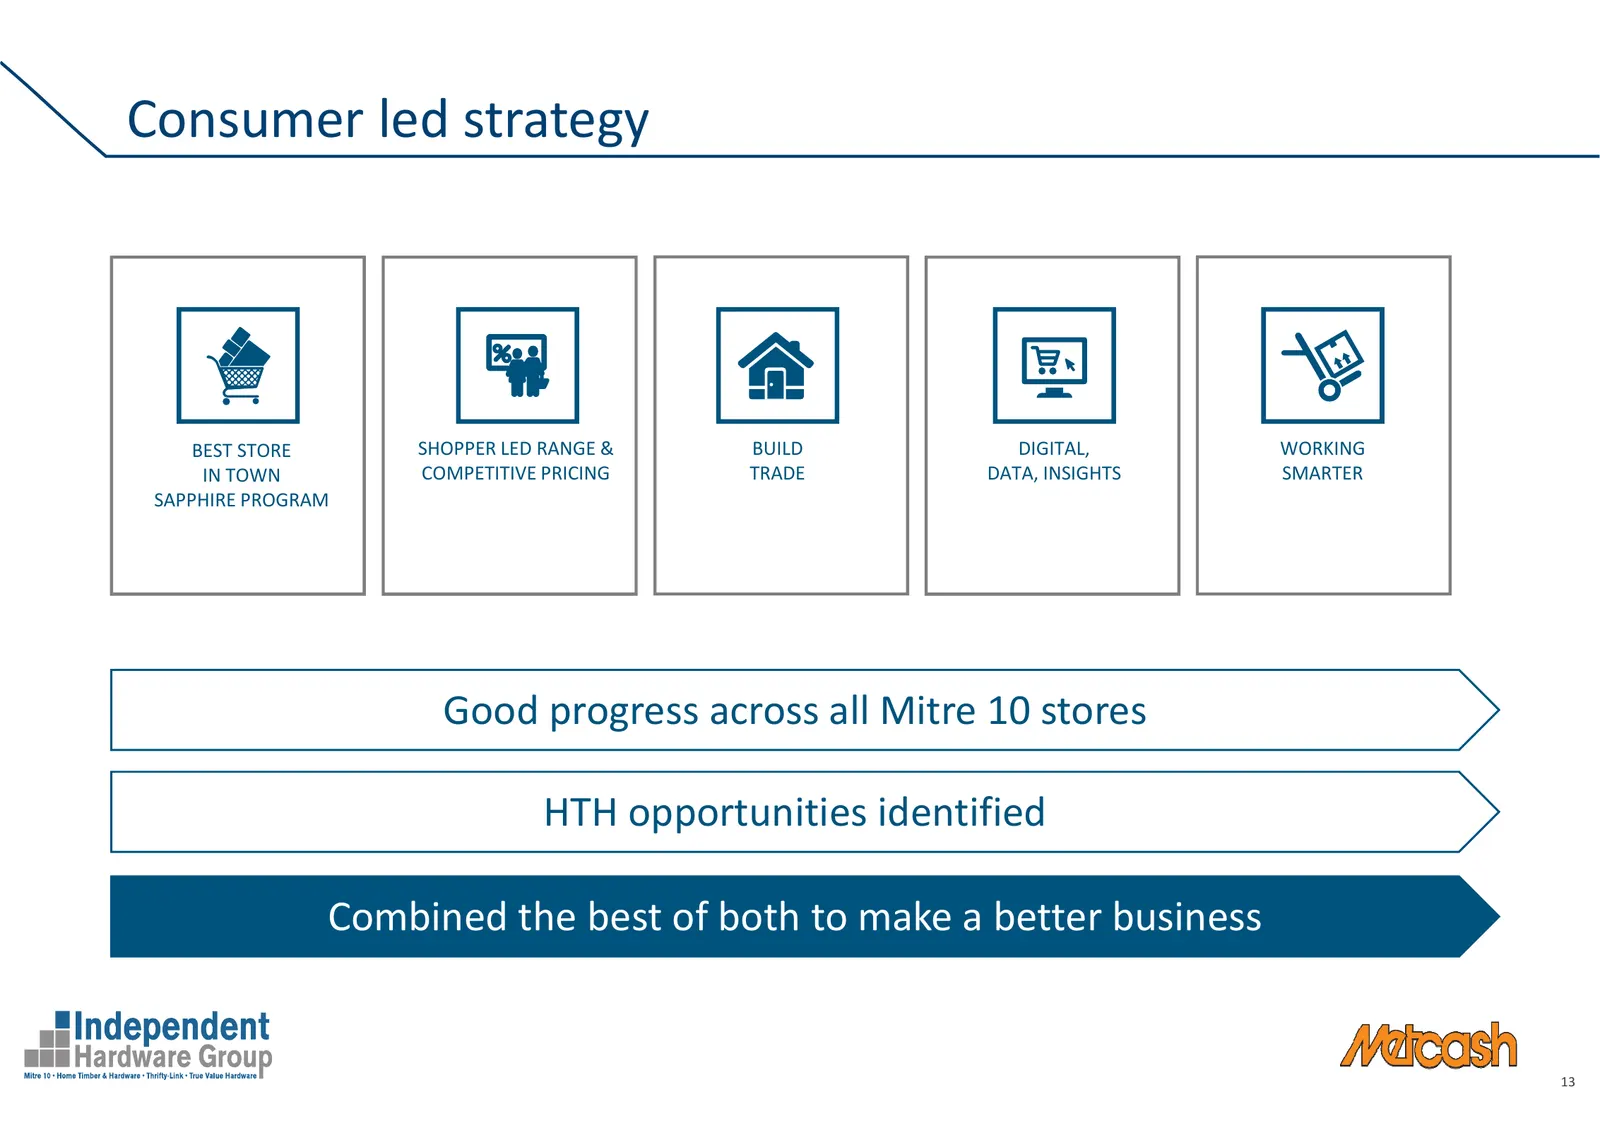
Consumer led strategy BEST STORE SHOPPER LED RANGE & BUILD DIGITAL, WORKING IN TOWN COMPETITIVE PRICING TRADE DATA, INSIGHTS SMARTER SAPPHIRE PROGRAM Good progress across all Mitre 10 stores HTH opportunities identified Combined the best of both to make a better business 13
Slide 14: Key strategic initiatives
Key strategic initiatives Annette Welsh GM – Merchandise
Slide 15: Mitre 10 – “Best Store in Town”
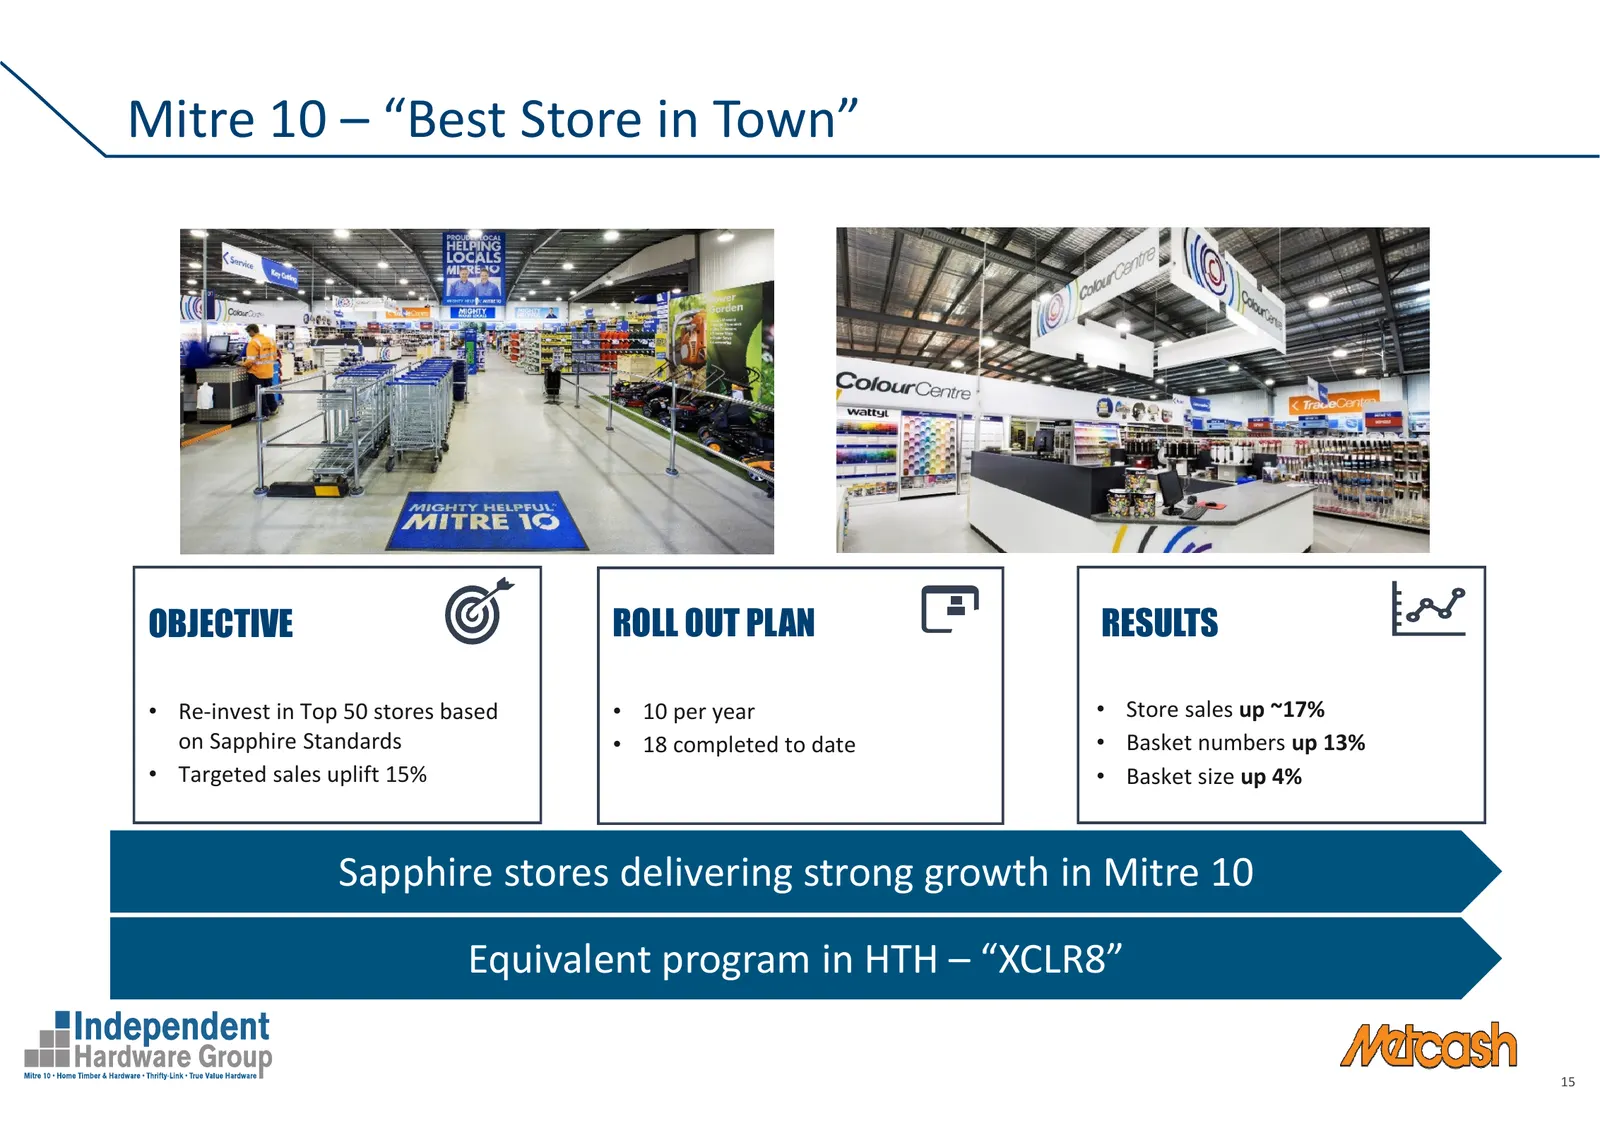
Mitre 10 – “Best Store in Town” OBJECTIVE ROLL OUT PLAN RESULTS • Re-invest in Top 50 stores based • 10 per year • Store sales up ~17% on Sapphire Standards • 18 completed to date • Basket numbers up 13% • Targeted sales uplift 15% • Basket size up 4% Sapphire stores delivering strong growth in Mitr
Slide 16: Mitre 10 – Shopper led range
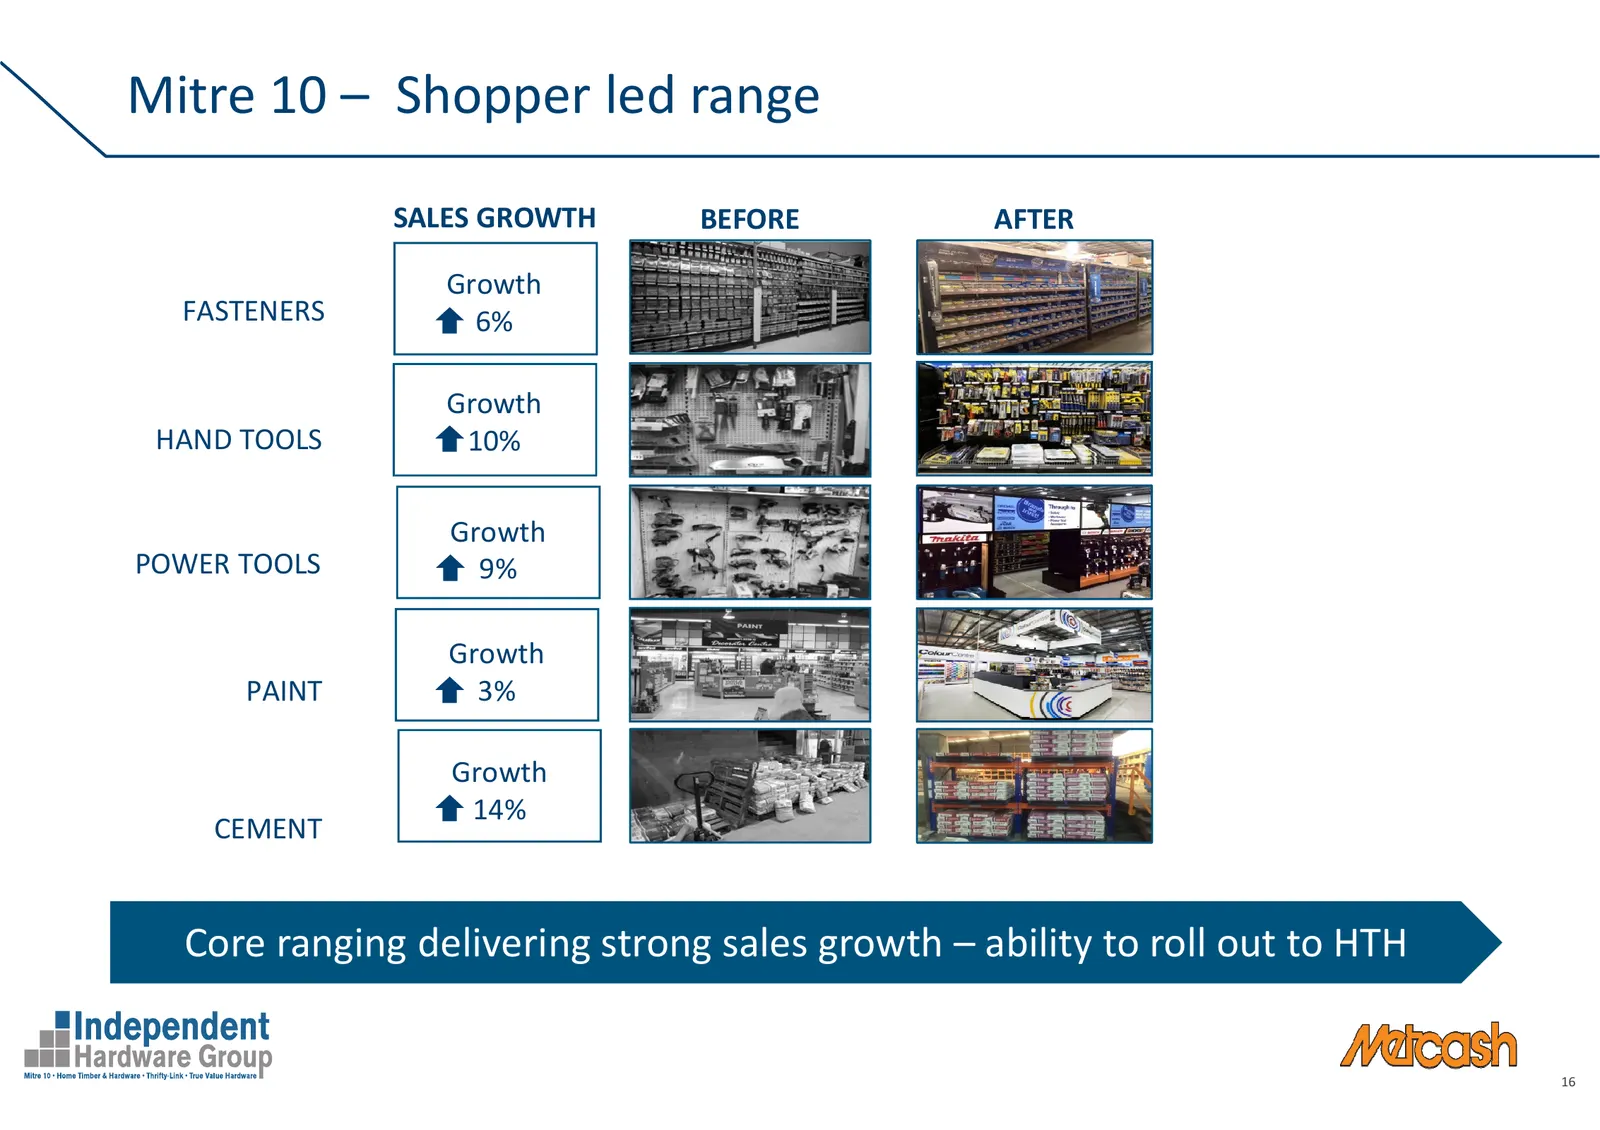
Mitre 10 – Shopper led range SALES GROWTH BEFORE AFTER Growth FASTENERS 6% Growth HAND TOOLS 10% Growth POWER TOOLS 9% Growth PAINT 3% Growth 14% CEMENT Core ranging delivering strong sales growth – ability to roll out to HTH 16
Slide 17: Competitive pricing
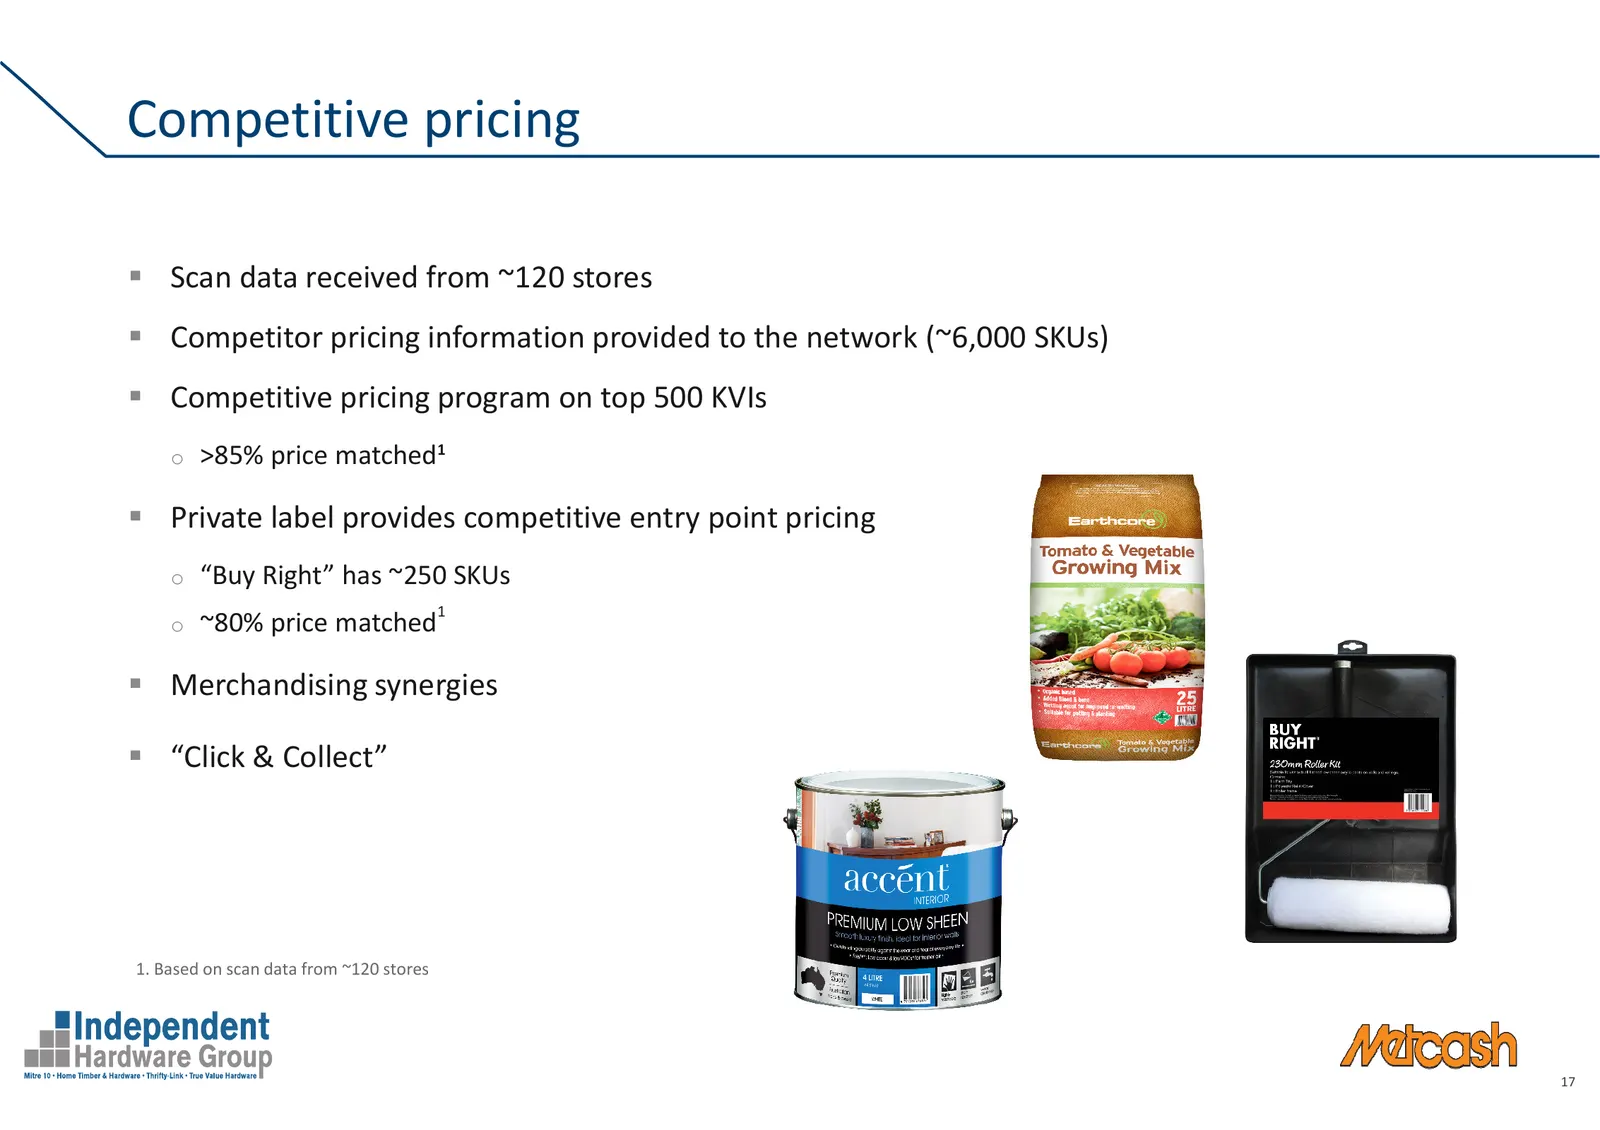
Competitive pricing Scan data received from ~120 stores Competitor pricing information provided to the network (~6,000 SKUs) Competitive pricing program on top 500 KVIs o >85% price matched1 Private label provides competitive entry point pricing o “Buy Right” has ~250 SKUs 1 o ~80% price matched Mer
Slide 18: Digital data and insights
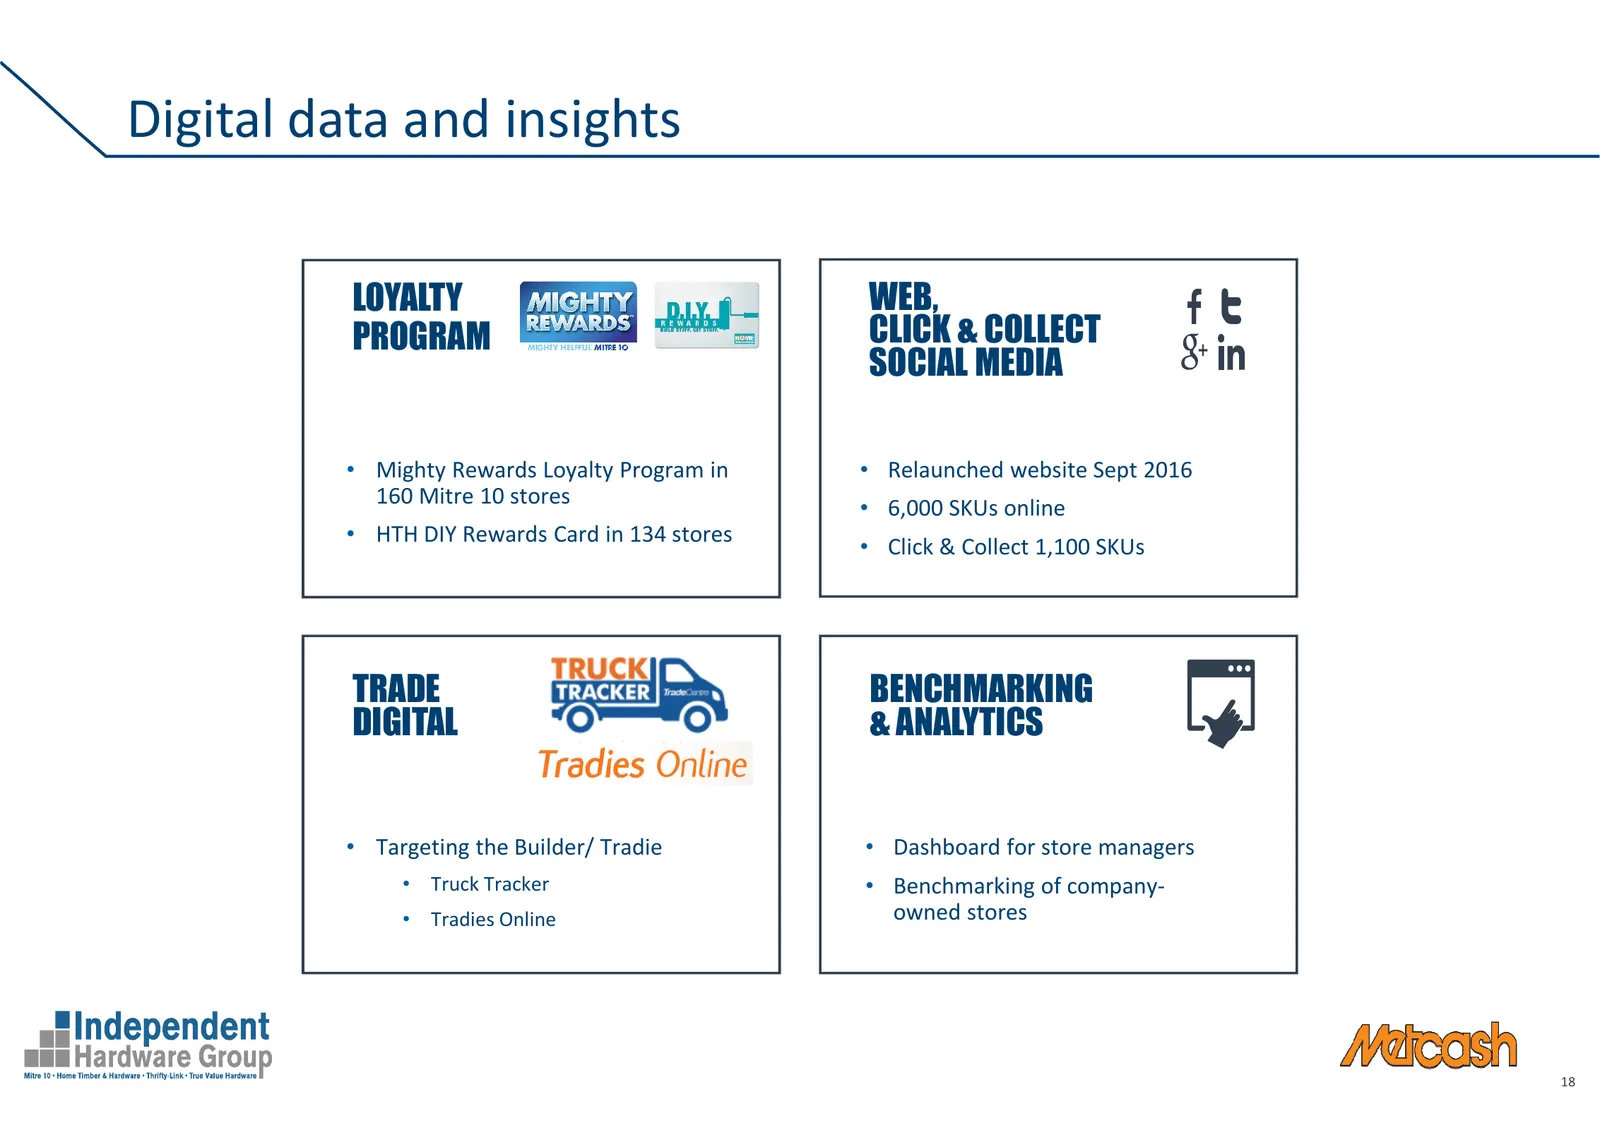
Digital data and insights LOYALTY WEB, PROGRAM CLICK & COLLECT SOCIAL MEDIA • Mighty Rewards Loyalty Program in • Relaunched website Sept 2016 160 Mitre 10 stores • 6,000 SKUs online • HTH DIY Rewards Card in 134 stores • Click & Collect 1,100 SKUs TRADE BENCHMARKING DIGITAL & ANALYTICS • Targeting
Slide 19: Integration update
Integration update Mark Laidlaw CEO, Independent Hardware Group
Slide 20: Integration update
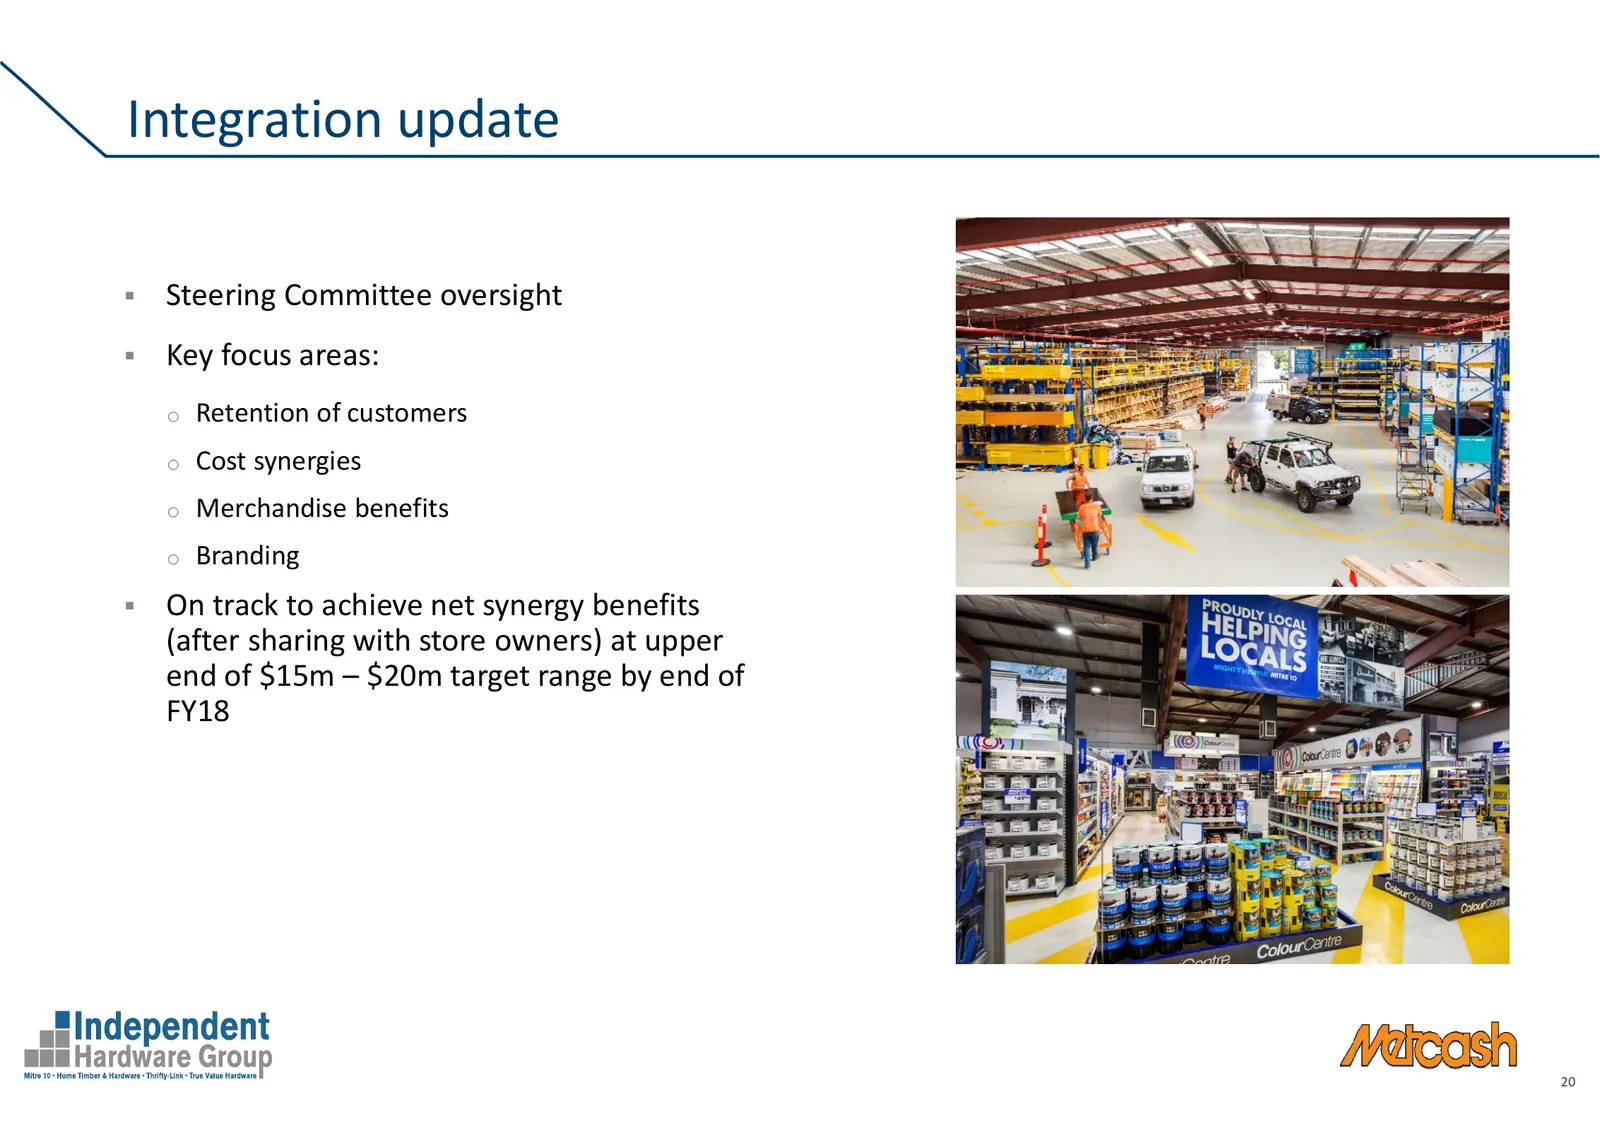
Integration update Steering Committee oversight Key focus areas: o Retention of customers o Cost synergies o Merchandise benefits o Branding On track to achieve net synergy benefits (after sharing with store owners) at upper end of $15m – $20m target range by end of FY18 20
Slide 21: Integration update (cont.)
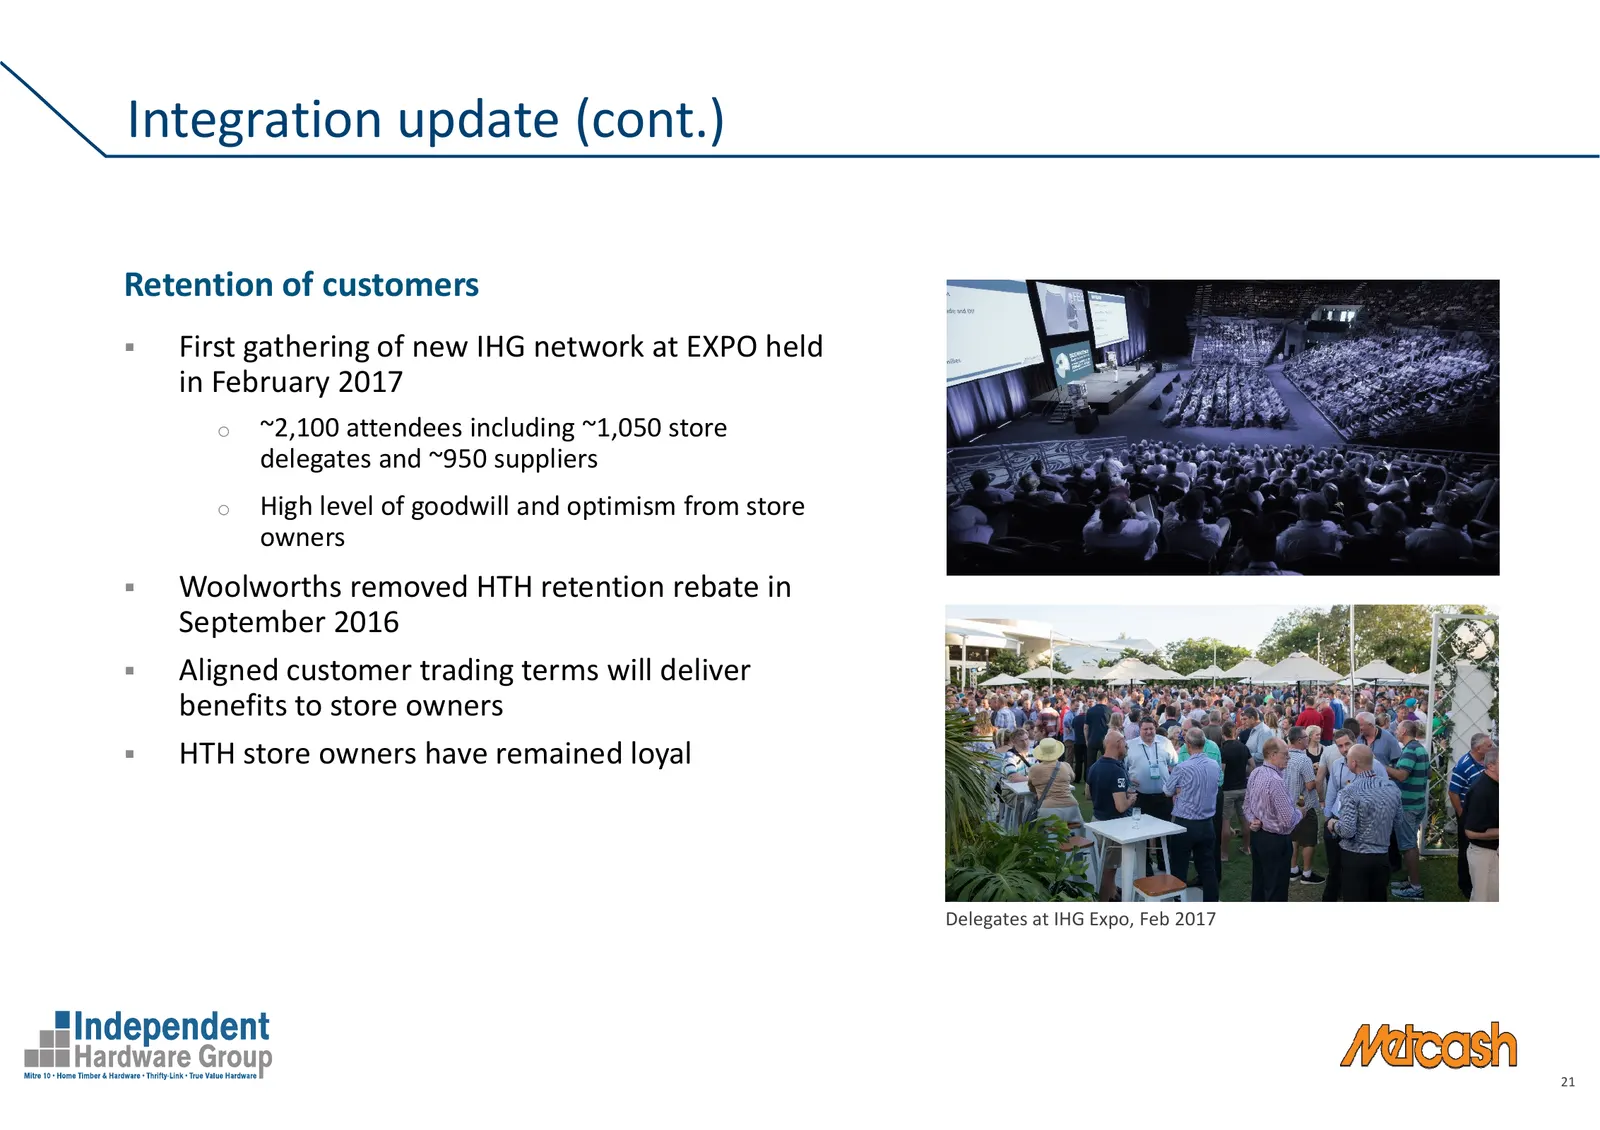
Integration update (cont.) Retention of customers First gathering of new IHG network at EXPO held in February 2017 o ~2,100 attendees including ~1,050 store delegates and ~950 suppliers o High level of goodwill and optimism from store owners Woolworths removed HTH retention rebate in September 2016
Slide 22: Integration update (cont.)
Integration update (cont.) Property rationalisation Two unprofitable stores retained by Woolworths (Launceston, Gungahlin) now closed Rationalisation of DC network – South Dandenong exit planned for April Head Office consolidated at Heatherton, Victoria Management structure New leadership team in pl
Slide 23: Integration update (cont.)
Integration update (cont.) Merchandising synergies Focus on delivering store owners the best products at the most competitive prices Alignment of supplier trading terms Consolidation of core ranges Increased volumes expected to result in more competitive pricing Savings to be shared with store owner
Slide 24: Marketing – Mitre 10
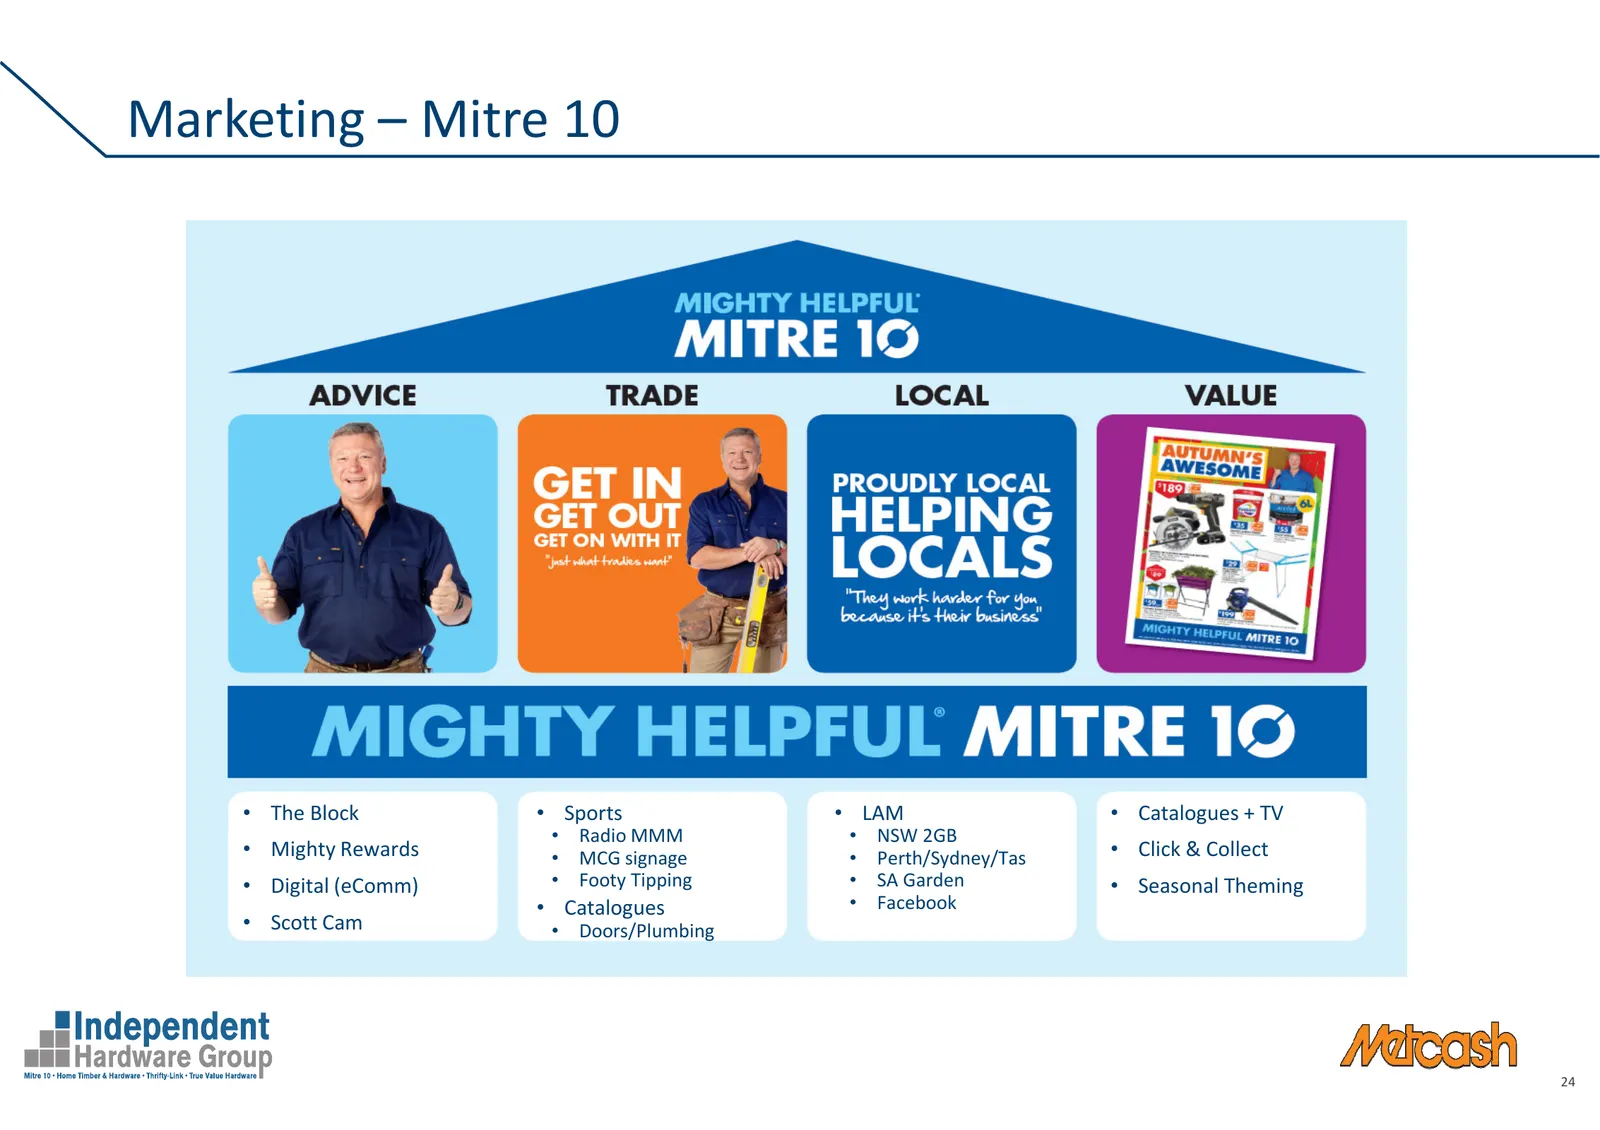
Marketing – Mitre 10 • The Block • Sports • LAM • Catalogues + TV • Radio MMM • NSW 2GB • Mighty Rewards • MCG signage • Perth/Sydney/Tas • Click & Collect • Digital (eComm) • Footy Tipping • SA Garden • Seasonal Theming • Catalogues • Facebook • Scott Cam • Doors/Plumbing 24
Slide 25: Marketing – HTH
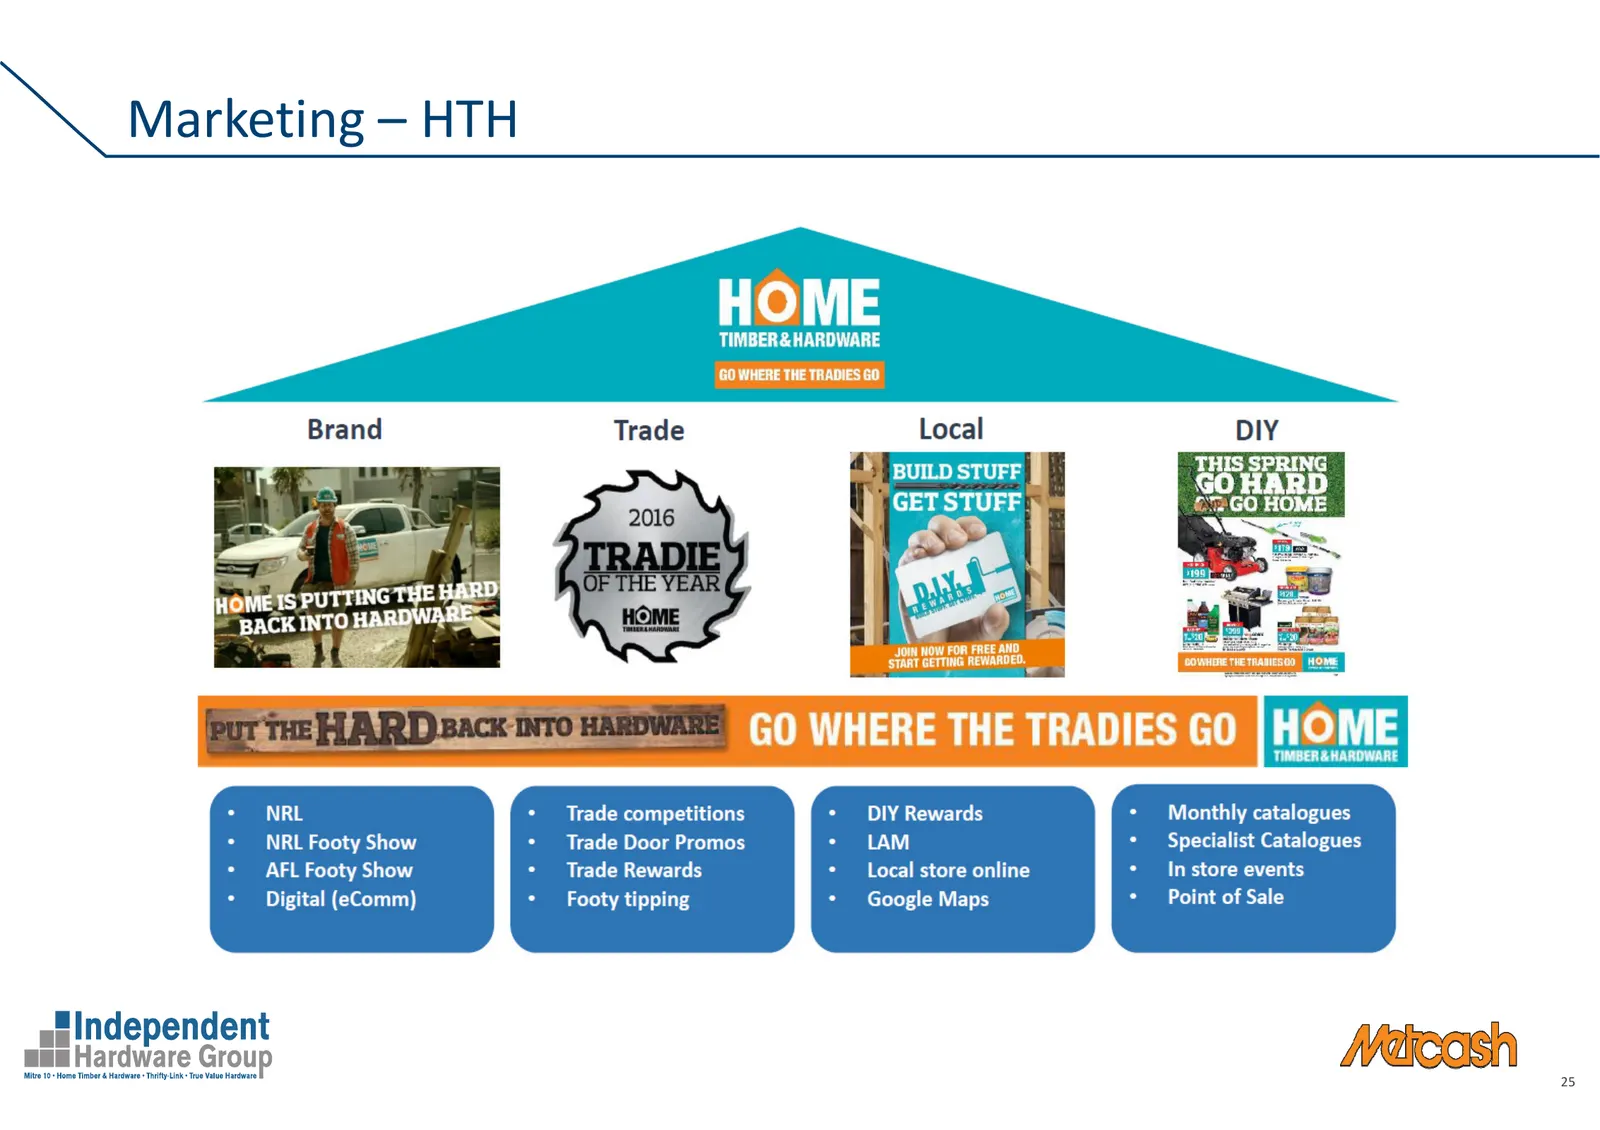
TIMBER & HARDWARE GO WHERE THE TRADIES GO » BUILD STUFF GET STUFF Re IN NOW FOR FREE AND sina GETTING REWARDED. NRL Trade competitions DIY Rewards Monthly catalogues NRL Footy Show Trade Door Promos LAM Specialist Catalogues AFL Footy Show Trade Rewards Local store online In store events Digital (eC
Slide 26: Marketing – Video
gt Independent mam Hardware Group 26
Slide 27: Summary
Summary Mark Laidlaw CEO, Independent Hardware Group
Slide 28: Summary
Summary • IHG is clear number 2 in Hardware market with an extensive national footprint • Strengthened position in Trade segment, which accounts for ~60% of our sales • Strong focus on supporting our independent store owners and growing our brand footprint • Our Sapphire and Core Ranging programs ar
Slide 29: Disclaimer
Disclaimer This presentation contains summary information about Metcash Limited (ABN 32 112 073 480) (Metcash) and its activities current as at the date of this presentation. The information in this presentation is of general background and does not purport to be complete. It should be read in conju
Source: Internet Archive copy of metcash.com
More decks from Metcash Limited
 Shareholder Meeting (September 2026)25 slides · Sep 9, 2026
 FY2026 Earnings Presentation60 slides · Jun 22, 2026
 1H26 Earnings Presentation39 slides · Dec 1, 2025
 FY2025 Earnings Presentation44 slides · Jun 24, 2025
 H1 FY2025 Earnings Presentation39 slides · Dec 2, 2024
 FY2024 Earnings Presentation38 slides · Jun 24, 2024