Healthtronics — Healthtronics Surgical Services — Merger or Acquisition (June 2004)
14 slides from Healthtronics's merger presentation, Jun 16, 2004
Slide 1: Prime Medical and HealthTronics
PRIME MEDICAL EALTHTRON! NASDAQ: PMSI NASDAQ: HTRN
Slide 2: Forward-looking statements
This presentation contains forward-looking statements, including those regarding Prime Medical Services, Inc. (“PMSI”) and HealthTronics Surgical Services, Inc. (“HTRN”), their respective subsidiaries and the services they provide. Investors are cautioned that all such statements involve risks and u
Slide 3: Transaction Overview
TRANSACTION OVERVIEW • Signed Merger Agreement June 11, 2004 • Subject to: Shareholder Approvals from Both Companies Customary Regulatory Approvals • 1:1 stock Exchange Ratio PMSI Shareholders to Receive one HTRN Share for Each PMSI Share • Merged Entity to be called HealthTronics, Inc. • Austin Hea
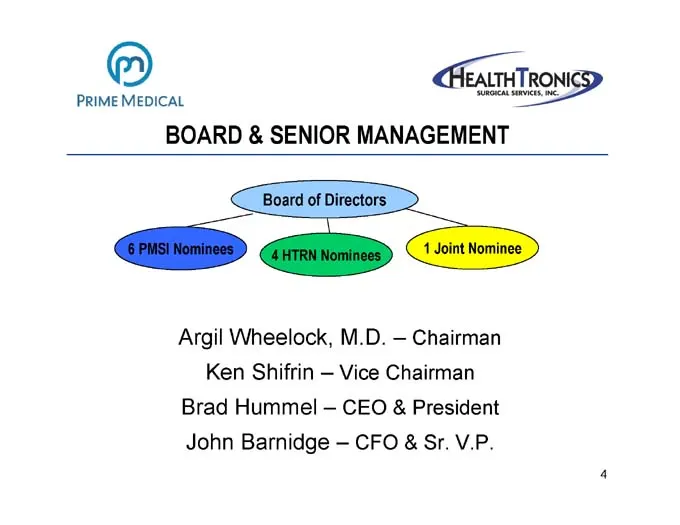
Slide 4: Board & Senior Management
BOARD & SENIOR MANAGEMENT Board of Directors 6 PMSI Nominees 4 HTRN Nominees 1 Joint Nominee Argil Wheelock, M.D. – Chairman Ken Shifrin – Vice Chairman Brad Hummel – CEO & President John Barnidge – CFO & Sr. V.P.
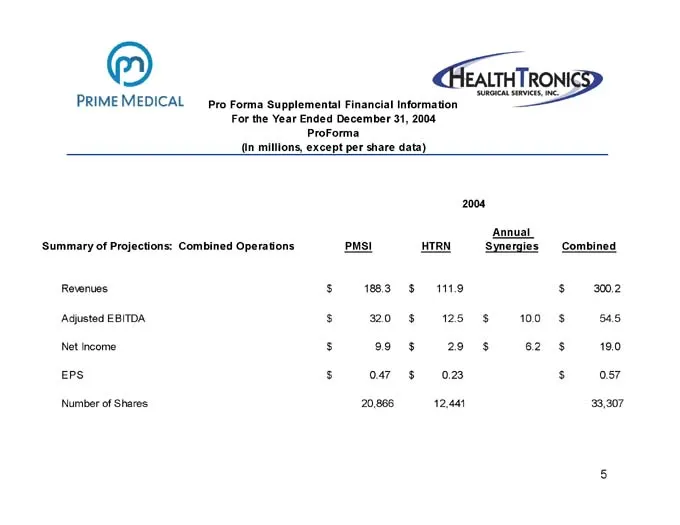
Slide 5: Pro Forma Supplemental Financial Information
Pro Forma Supplemental Financial Information For the Year Ended December 31, 2004 ProForma (In millions, except per share data) Annual Summary of Projections: Combined Operations PMSI HTRN Synergies Combined Revenues $ 188.3 $ 111.9 $ 300.2 Adjusted EBITDA $ 32.0 $ 12.5 $ 10.0 $ 54.5 Net Income $ 9.
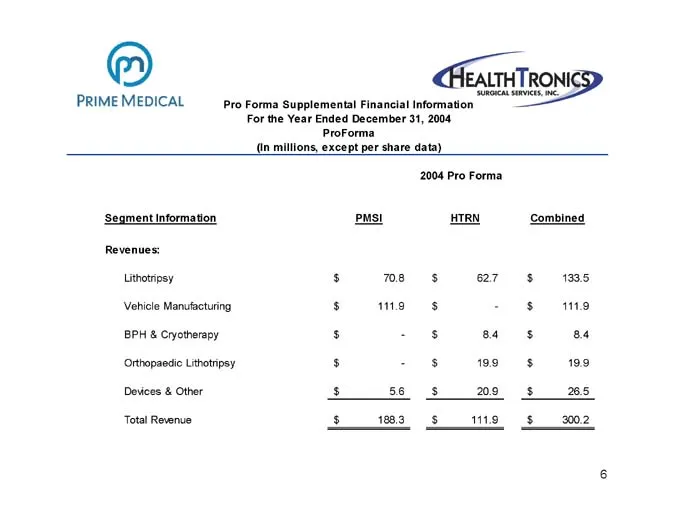
Slide 6: Pro Forma Segment Information
Pro Forma Supplemental Financial Information For the Year Ended December 31, 2004 ProForma (In millions, except per share data) 2004 Pro Forma Segment Information PMSI HTRN Combined Revenues: Lithotripsy $ 70.8 $62.7 $ 133.5 Vehicle Manufacturing $ 111.9 $ - $ 111.9 BPH & Cryotherapy $ - $8.4 $ 8.4
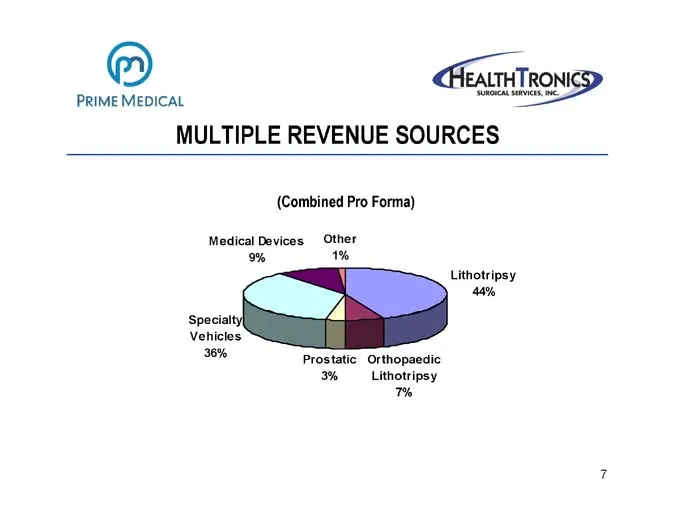
Slide 7: Multiple Revenue Sources
MULTIPLE REVENUE SOURCES (Combined Pro Forma) Medical Devices Other 9% 1% Lithotripsy 44% Specialty Vehicles 36% Prostatic Orthopaedic 3% Lithotripsy 7%
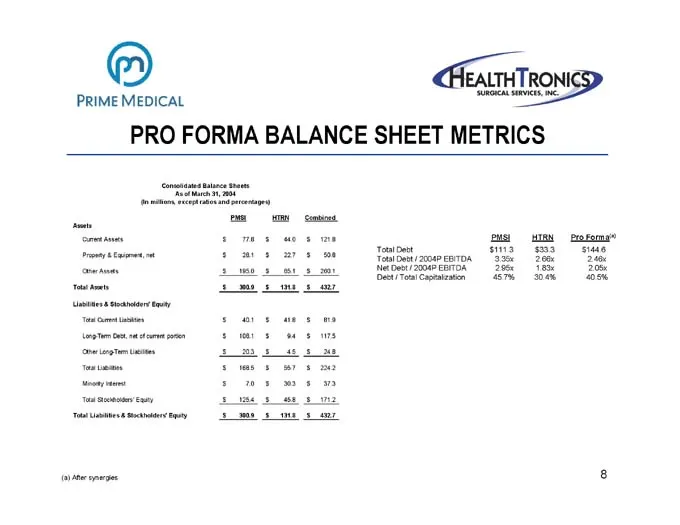
Slide 8: Pro Forma Balance Sheet Metrics
PRO FORMA BALANCE SHEET METRICS Consolidated Balance Sheets As of March 31, 2004 (In millions, except ratios and percentages) PMSI HTRN Combined Assets Current Assets $ 77.8 $ 44.0 $ 121.8 Property & Equipment, net $ 28.1 $ 22.7 $ 50.8 Other Assets $ 195.0 $ 65.1 $ 260.1 Total Assets $ 300.9 $ 131.8
Slide 9: Urology Services
UROLOGY SERVICES • Significant Industry Reach and Breadth Approximately 35% Market Share in Lithotripsy Operations in 47 States More than 3,000 Physician Users 70,000 Lithotripsy Procedures 6,000 Prostate Therapy Procedures • Expanding the Urology Platform Leveraging the Provider Network – TUMT – Cr
Slide 10: Urology Services
UROLOGY SERVICES • Enhanced Vertical Urology Delivery Litho Partnerships Litho Fee for Service Network Lithotripsy Devices – Medstone STS – HMT Diamond Urology Tables Nationwide Service & Maintenance
Slide 11: Urology Services: Market Drivers
UROLOGY SERVICES • Market Drivers Technology – Innovation Leads Patient Demand Delivery System Shift – Procedure Migration to the ASC and Office Demographics – Aging Population and the Informed Patient
Slide 12: Orthopaedic Lithotripsy
ORTHOPAEDIC LITHOTRIPSY • Shock Wave Therapy for Musculoskeletal Injury Plantar Fasciitis (Heel Spur) h Lateral Epicondilitis (Tennis Elbow) • Leading Edge Position Patented Technology (OssaTron™ Device) h FDA Approvals • Key Long-Term Growth Driver 3-4 Million New Cases per Year • Accelerating Payo
Slide 13: Specialty Vehicle Manufacturing
SPECIALTY VEHICLE MANUFACTURING • Leadership Position • Strong Outlook in Homeland Security & Broadcast • Backlog Reveals Strengthening Segment 10% increase from 12/31/03 h 58% rise from 3/31/03 • Plant Consolidation, Fourth Quarter 2004 Expect $2 Million Annual Cost Savings • “Debt-free” Segment
Slide 14: Summary of Merger Benefits
SUMMARY OF MERGER BENEFITS Market Prominence Diverse Revenue Streams Expanded Physician Network Vertical Sales Opportunity Improved Capital Structure Accretive
Source: SEC EDGAR · 425 filed Jun 16, 2004
More decks from Healthtronics Inc
 Investor Presentation (March 2010)22 slides · Mar 23, 2010
 Investor Presentation (September 2009)29 slides · Sep 10, 2009
 Investor Presentation (February 2007)27 slides · Feb 14, 2007
 Investor Presentation (August 2006)11 slides · Aug 16, 2006
 Investor Presentation (January 2006)39 slides · Jan 17, 2006
 Investor Presentation (January 2006)39 slides · Jan 13, 2006