M&G PLC · LSE:MNG
M&G — M&G Wealth — Investor Presentation
55 slides from M&G's investor presentation
Slide 1: Trusts created on death
Trusts created on death The information that follows is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. This is just for UK financial advice professionals.
Slide 2: Important information and disclaimer
This content is based on our understanding of current taxation, legislation and HM Revenue & Customs practice all of which are liable to change without notice. The impact of any taxation (and any tax reliefs) depends on individual circumstances. Where content includes case studies or examples these
Slide 3: Learning Objectives
Learning Objectives By the end of this session, you will be able to: Identify the types of Identify appropriate Describe the income trust that can be tax and CGT treatment investments for a created on a person’s of trustee investments particular trust death
Slide 4: Why are trusts used on death?
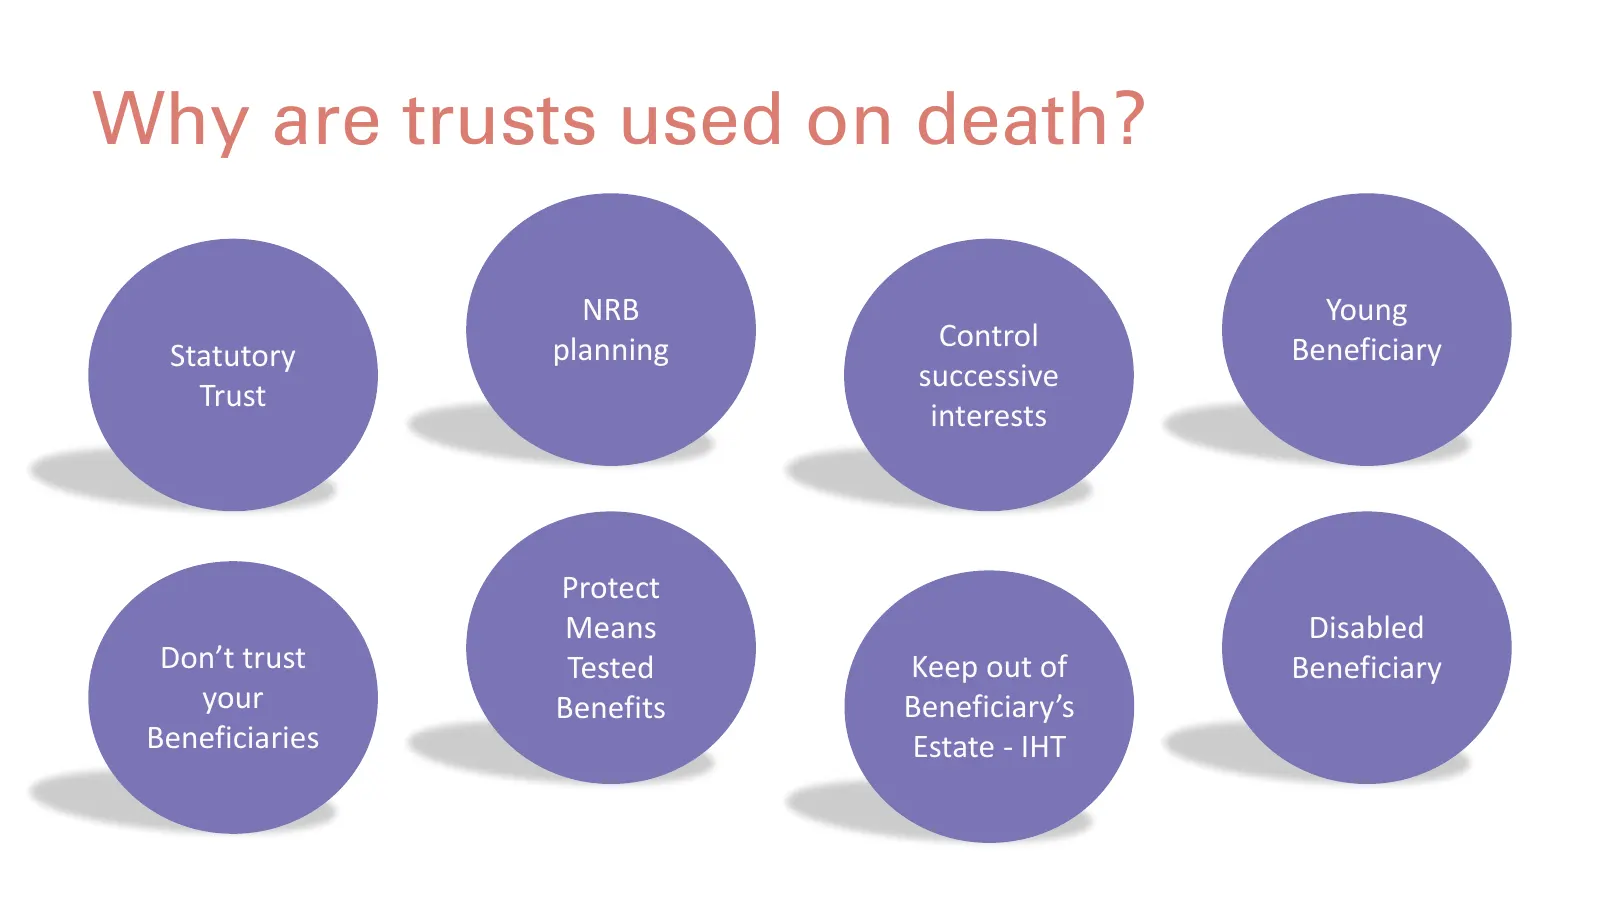
Why are trusts used on death? NRB Young planning Control Beneficiary Statutory successive Trust interests Protect Means Disabled Don’t trust Tested Keep out of Beneficiary your Benefits Beneficiary’s Beneficiaries Estate - IHT
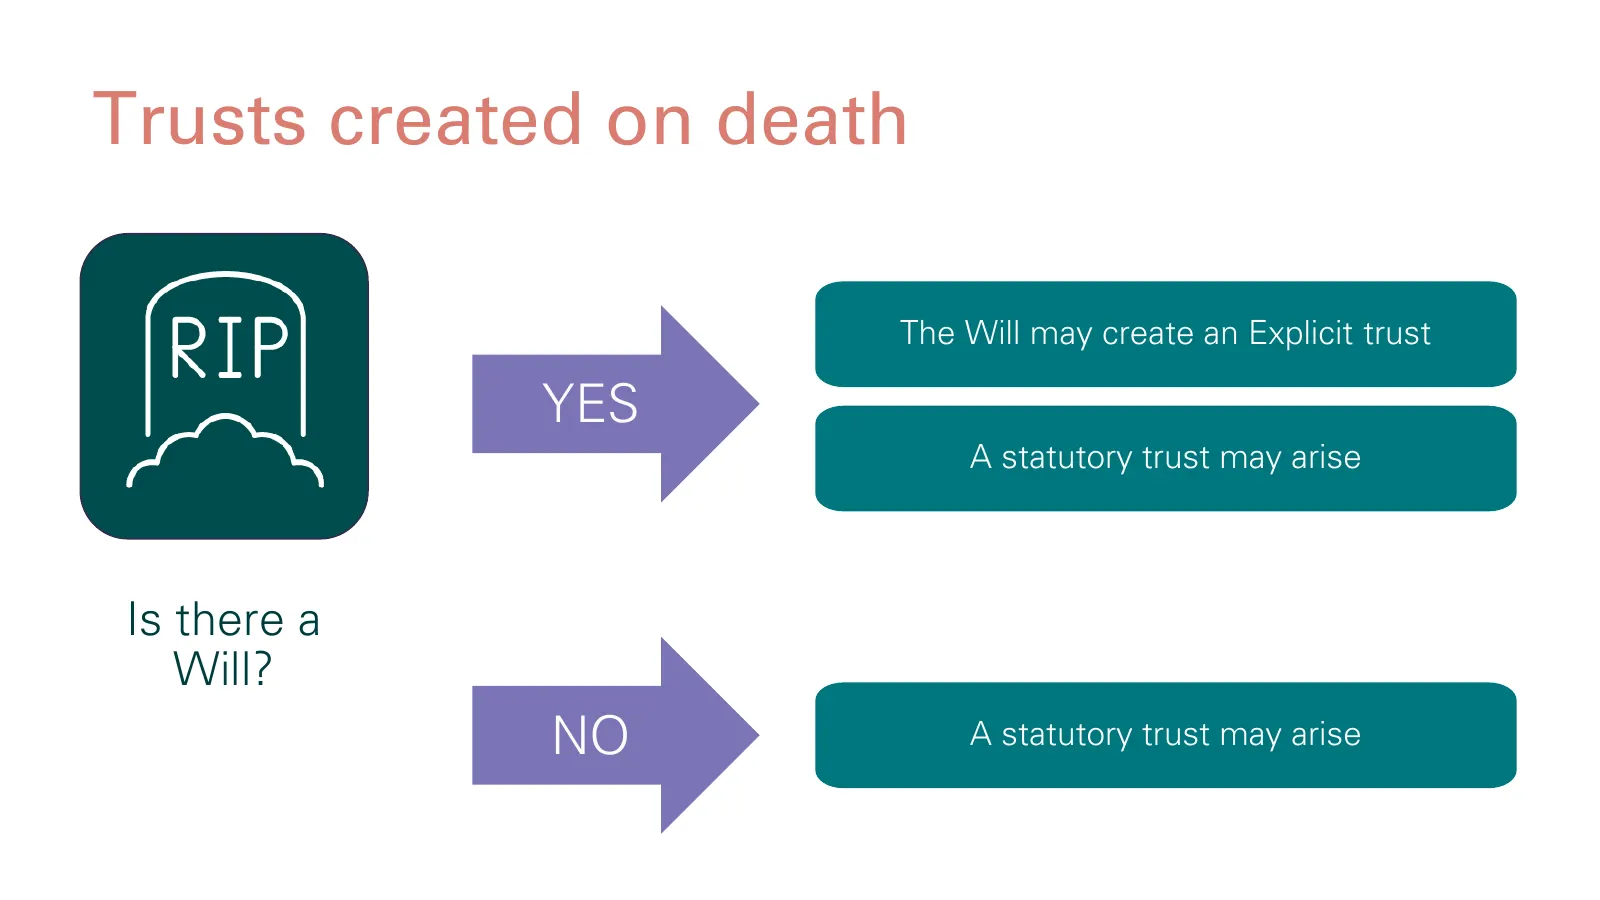
Slide 5: Trusts created on death
Trusts created on death The Will may create an Explicit trust . YES A statutory trust may arise Is there a Will? NO A statutory trust may arise
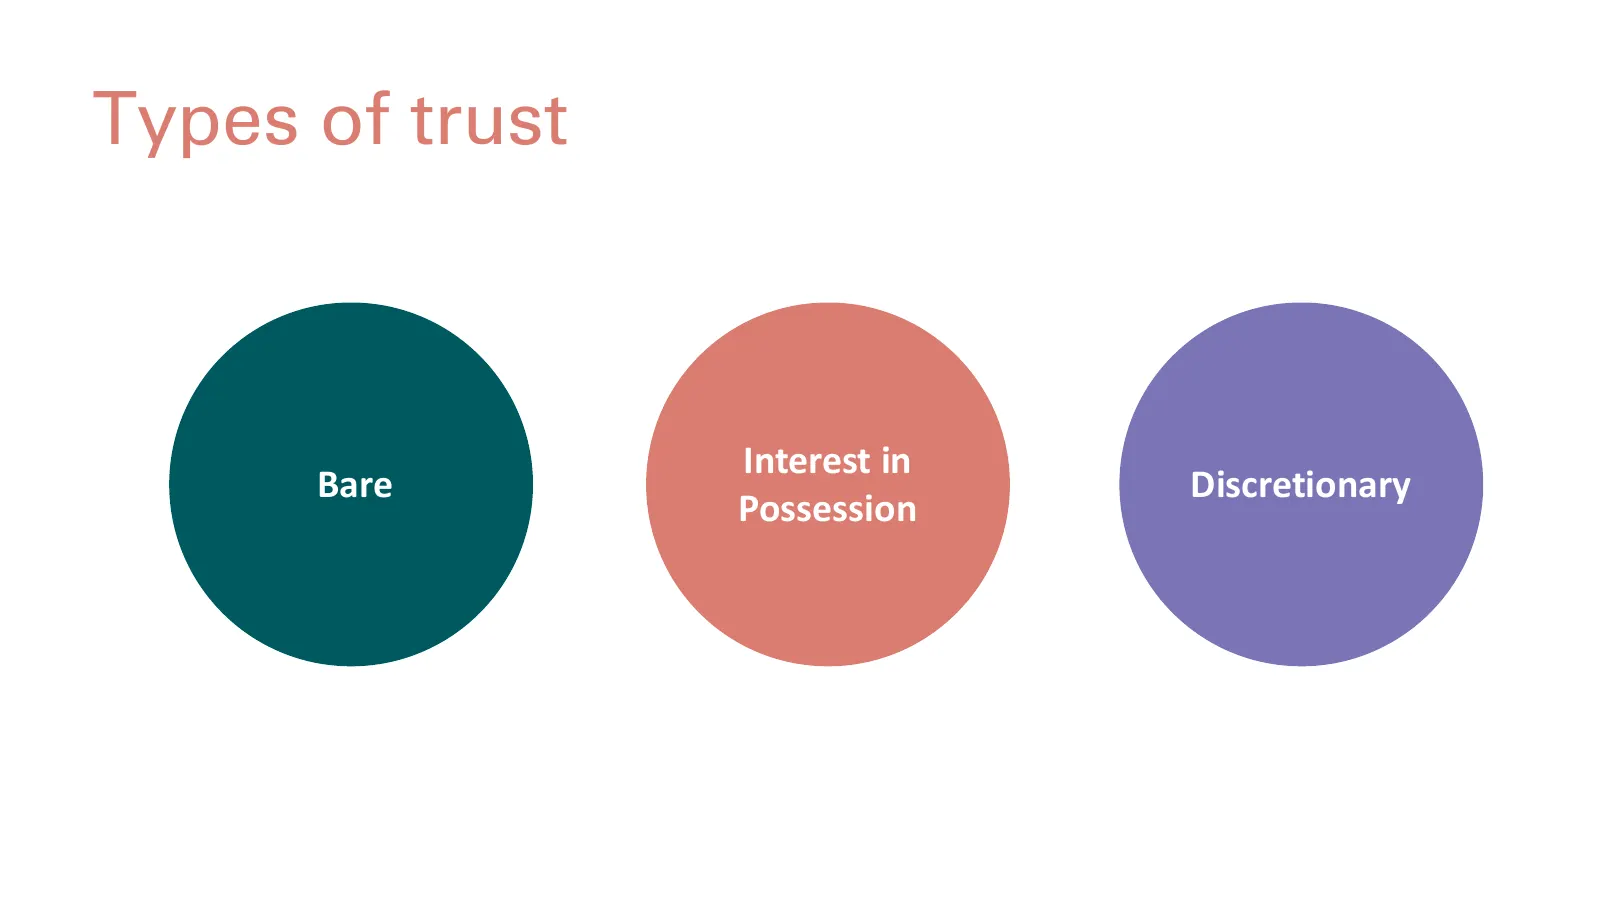
Slide 6: Types of trust
Types of trust Interest in Bare Discretionary Possession
Slide 7: Absolute/Bare Trusts
Absolute/Bare Trusts
Slide 8: Bare/Absolute
Bare/Absolute • Unconditional gift – beneficiary entitled to income and capital • If recipient is over 18 there is no trust and assets Bare are distributed • If recipient is under 18 the trustees hold on bare trust until age 18 (or whatever age stated) • Trust fund in beneficiary’s estate
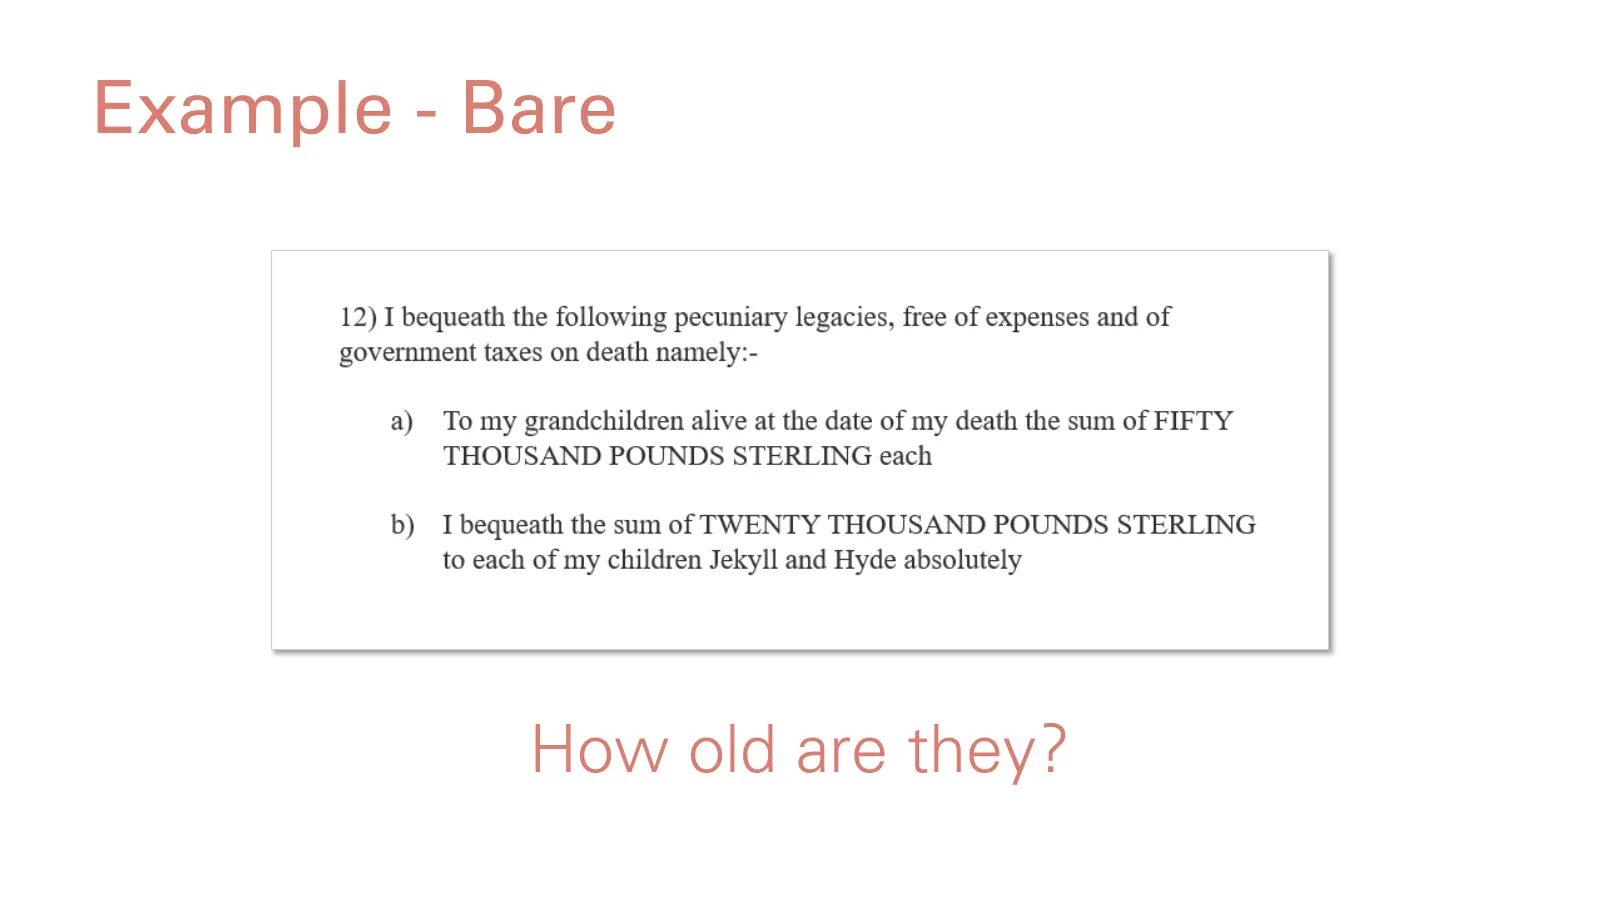
Slide 9: Example - Bare: How old are they?
Example - Bare How old are they?
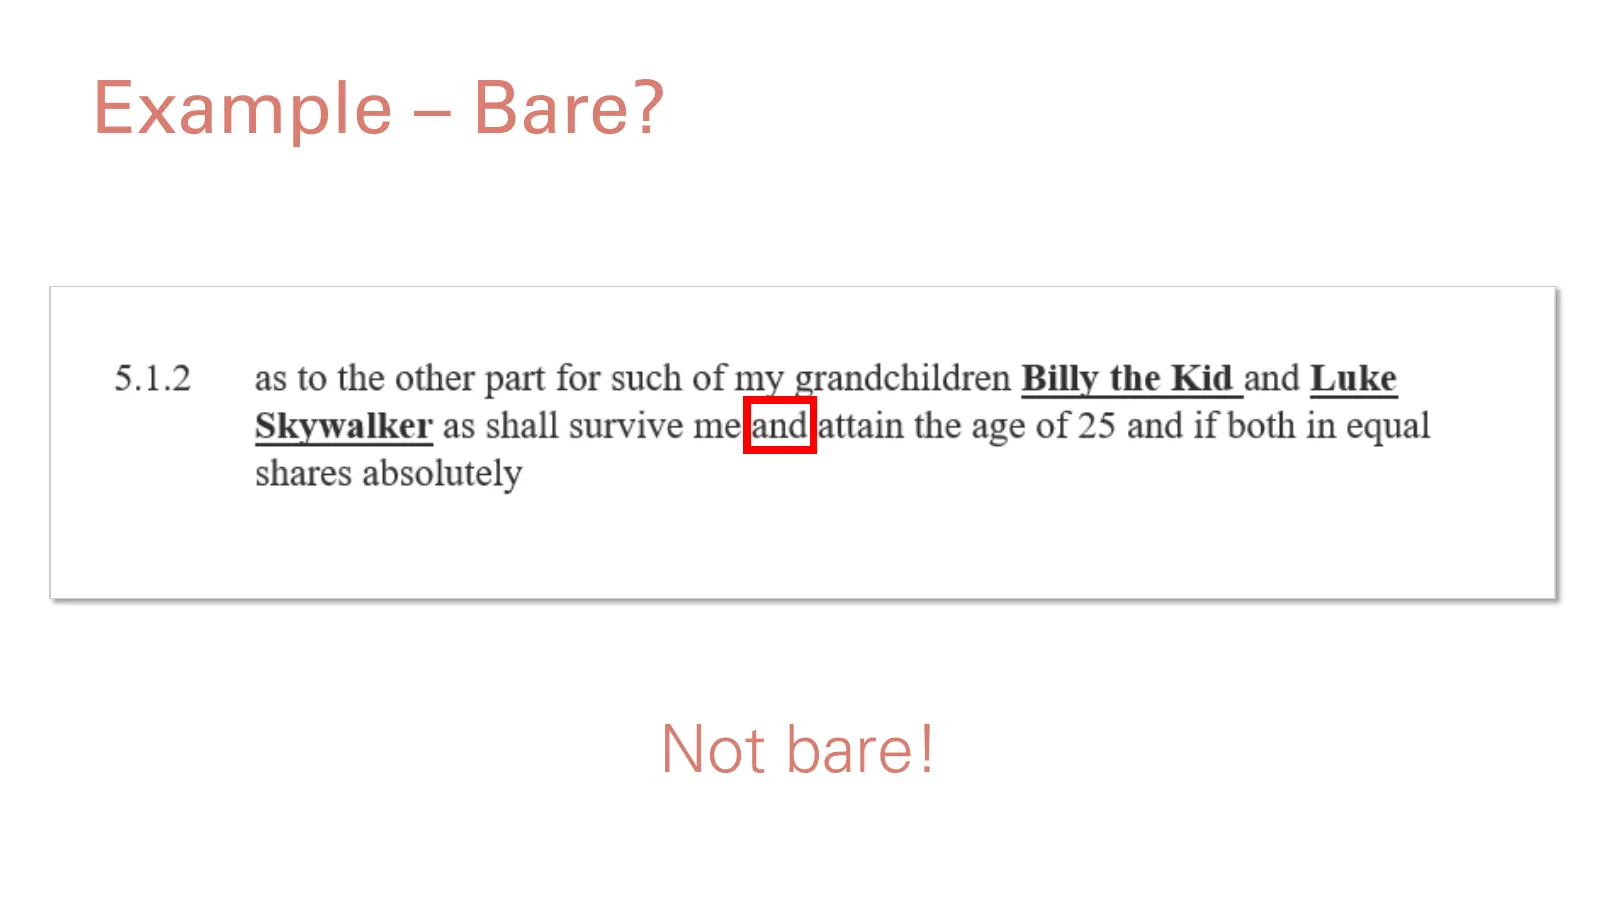
Slide 10: Example – Bare? Not bare!
Example — Bare? 5.1.2 as to the other part for such of my grandchildren Billy the Kid and Luke Skywalker as shall survive mefandfattain the age of 25 and if both in equal shares absolutely Not bare!
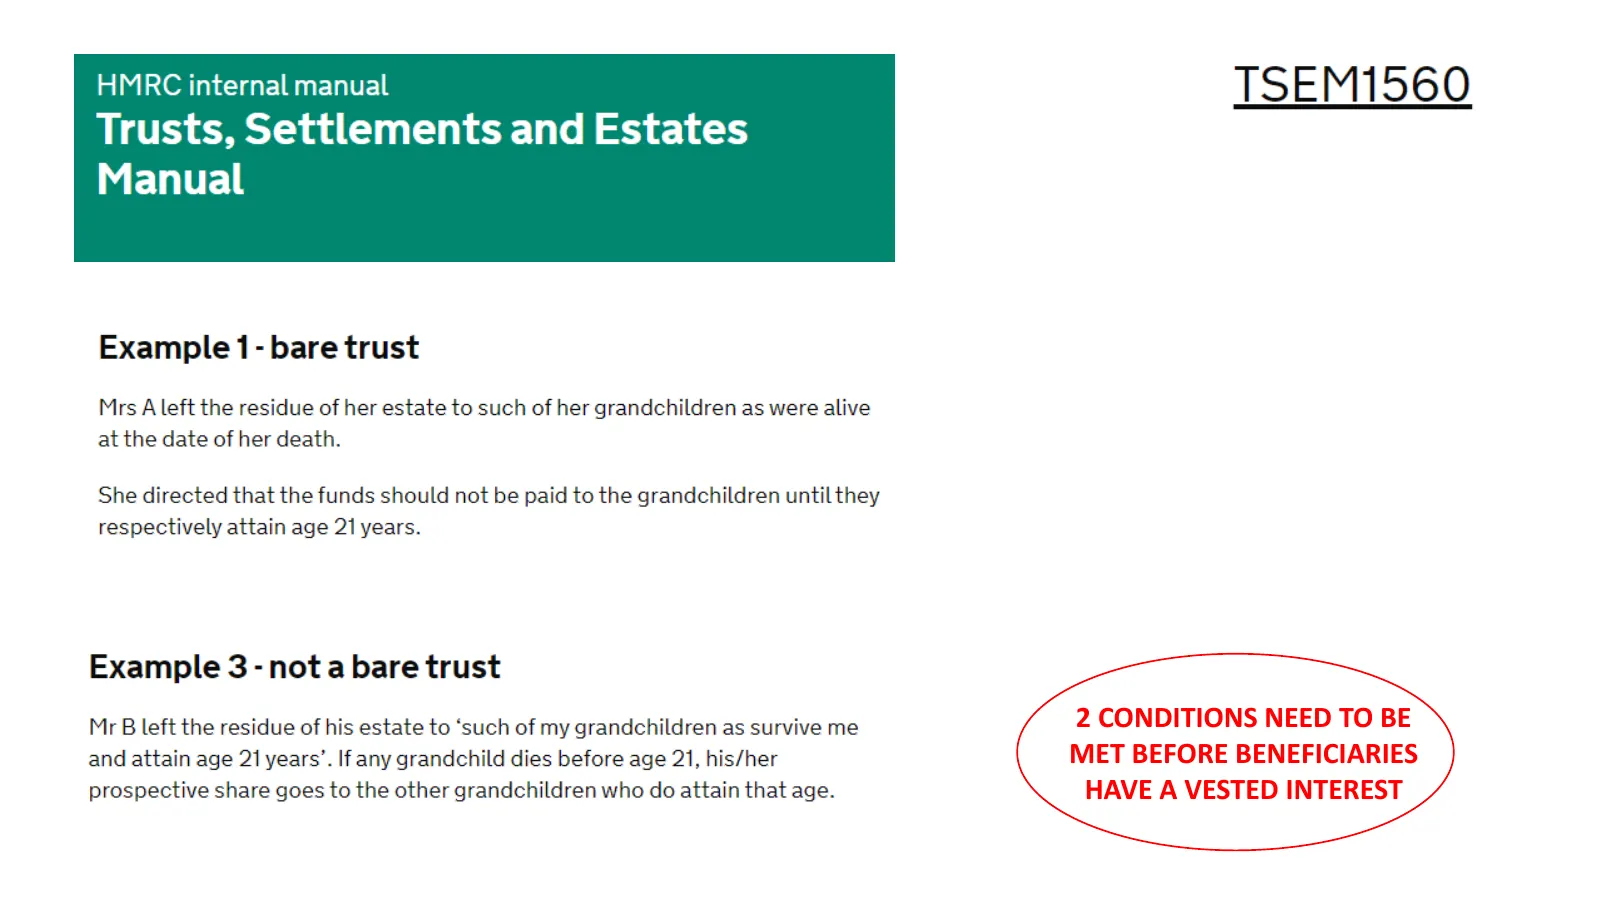
Slide 11: Conditions to be met before beneficiaries have a vested interest
2 CONDITIONS NEED TO BE MET BEFORE BENEFICIARIES HAVE A VESTED INTEREST
Slide 12: Caution! Age contingent gifts
Caution! Age contingent gifts BEREAVED 18-25 MINORS TRUSTS TRUSTS
Slide 13: Discretionary Trusts
Discretionary Trusts
Slide 14: Discretionary
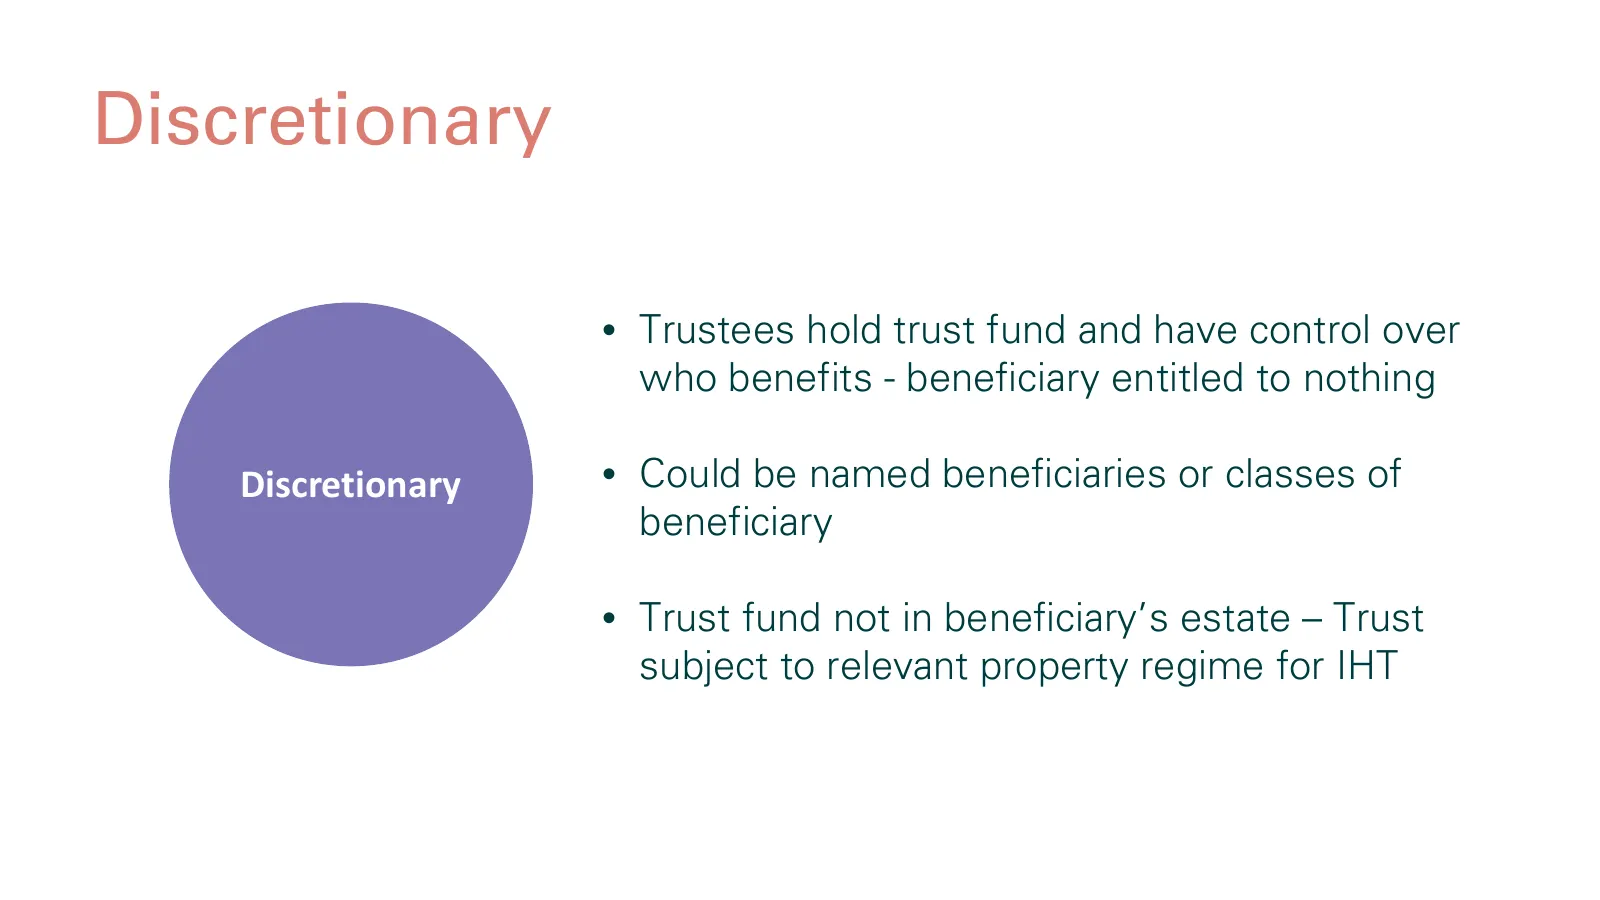
Discretionary • Trustees hold trust fund and have control over who benefits - beneficiary entitled to nothing Discretionary • Could be named beneficiaries or classes of beneficiary • Trust fund not in beneficiary’s estate – Trust subject to relevant property regime for IHT
Slide 15: Example - Discretionary
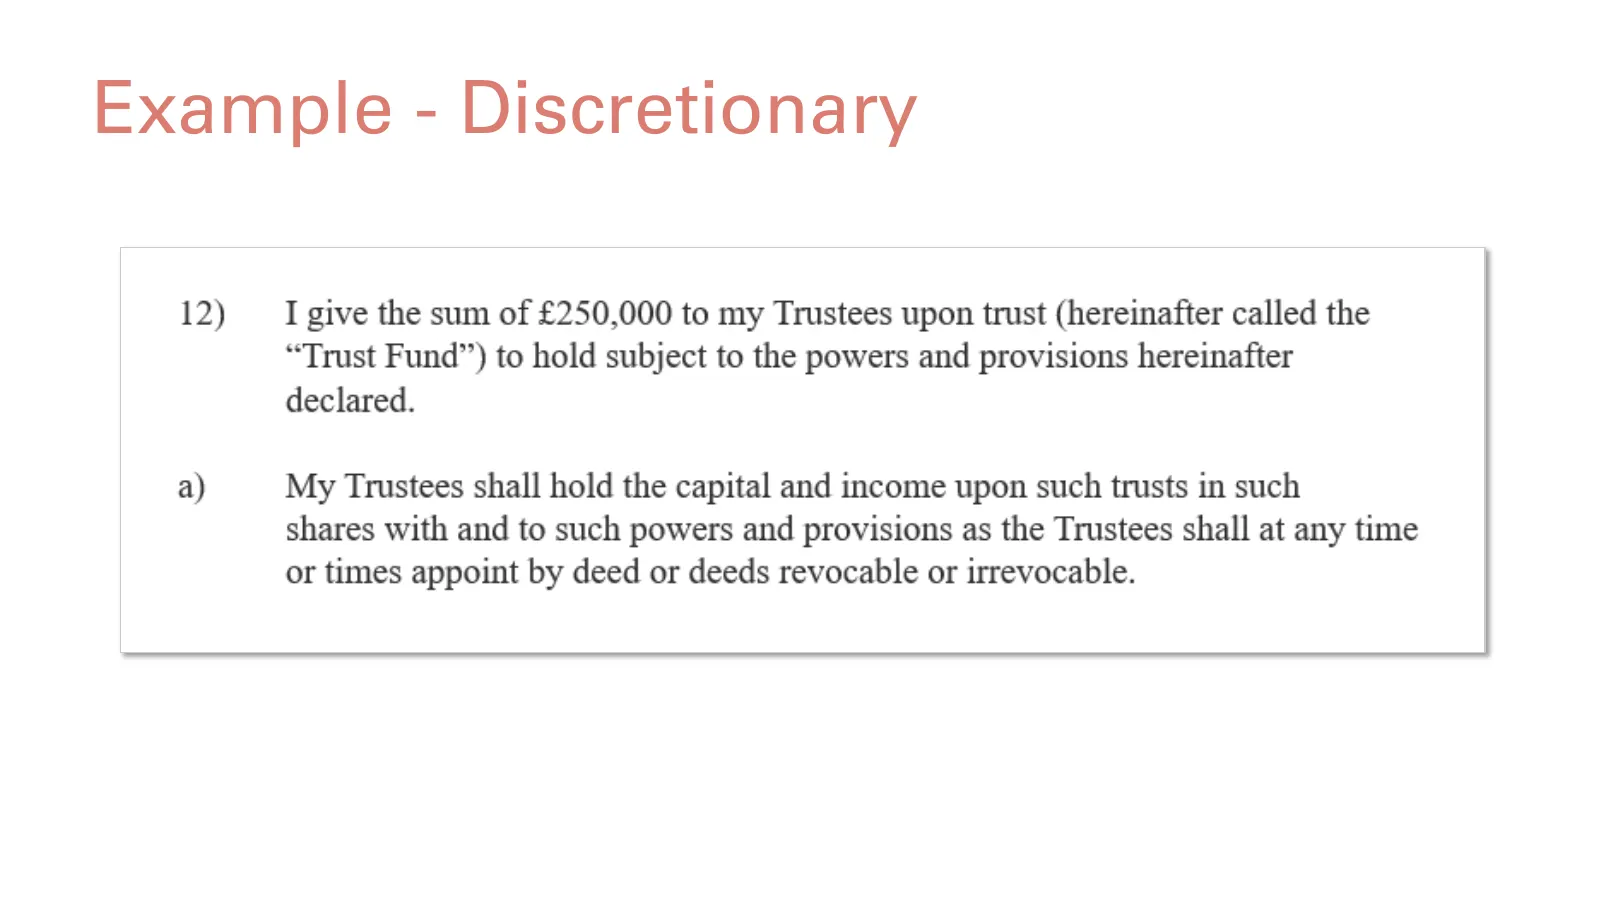
Example - Discretionary 12) I give the sum of £250,000 to my Trustees upon trust (hereinafter called the “Trust Fund’) to hold subject to the powers and provisions hereinafter declared. My Trustees shall hold the capital and income upon such trusts in such shares with and to such powers and provisio
Slide 16: Bereaved Minor's Trusts
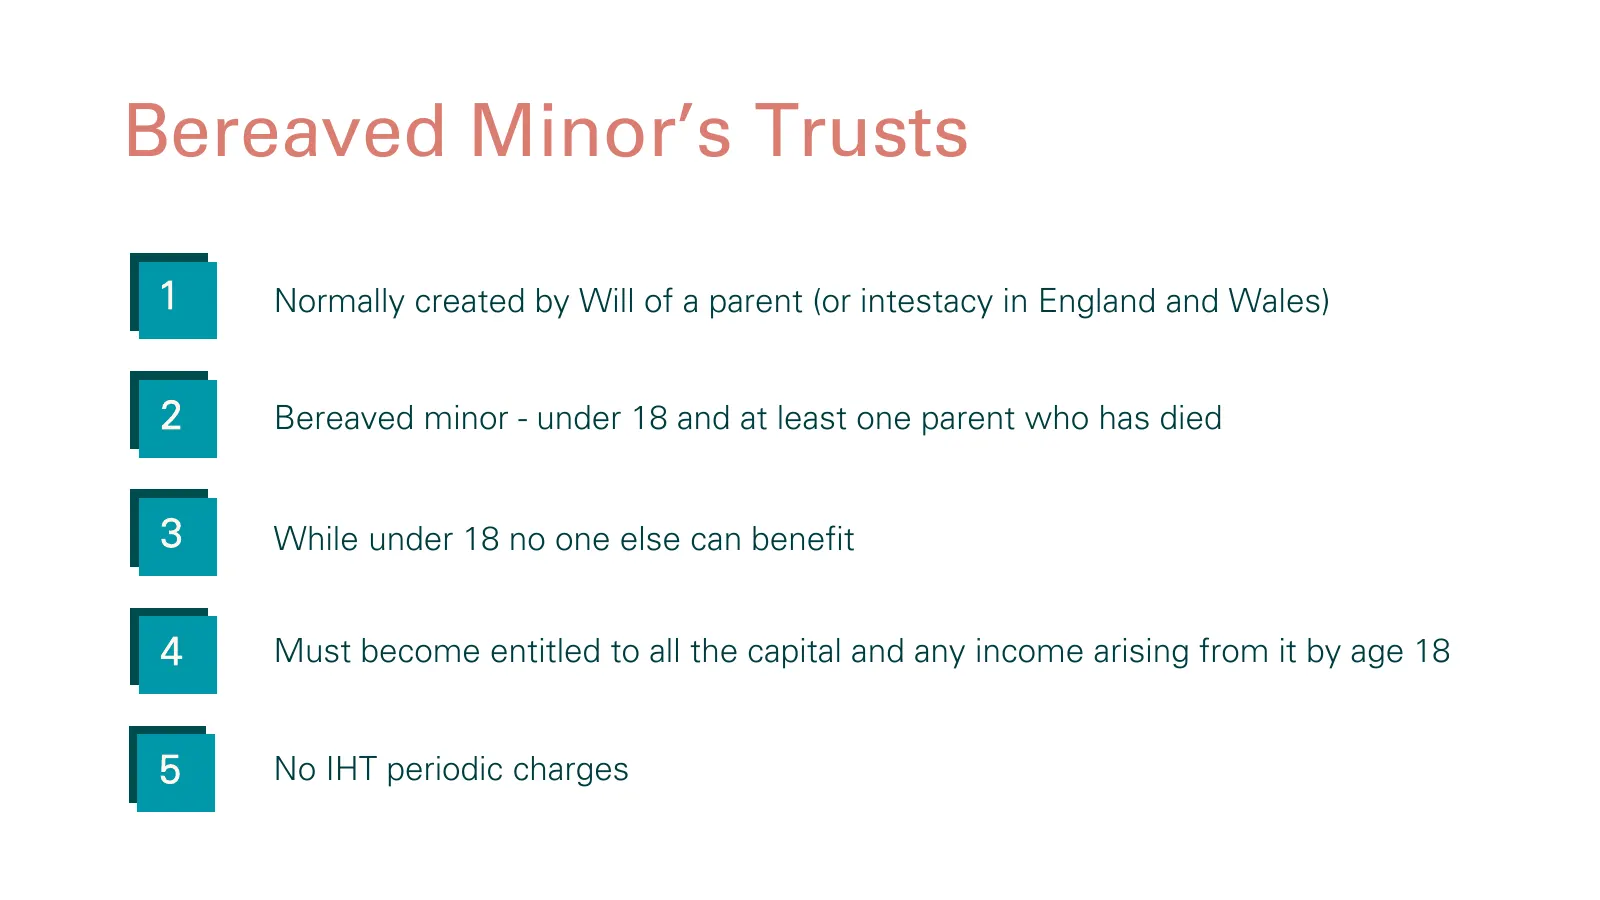
Bereaved Minor’s Trusts 1 Normally created by Will of a parent (or intestacy in England and Wales) 2 Bereaved minor - under 18 and at least one parent who has died Bereaved Minors Trust 3 While under 18 no one else can benefit 4 Must become entitled to all the capital and any income arising from it
Slide 17: 18-25 Trusts
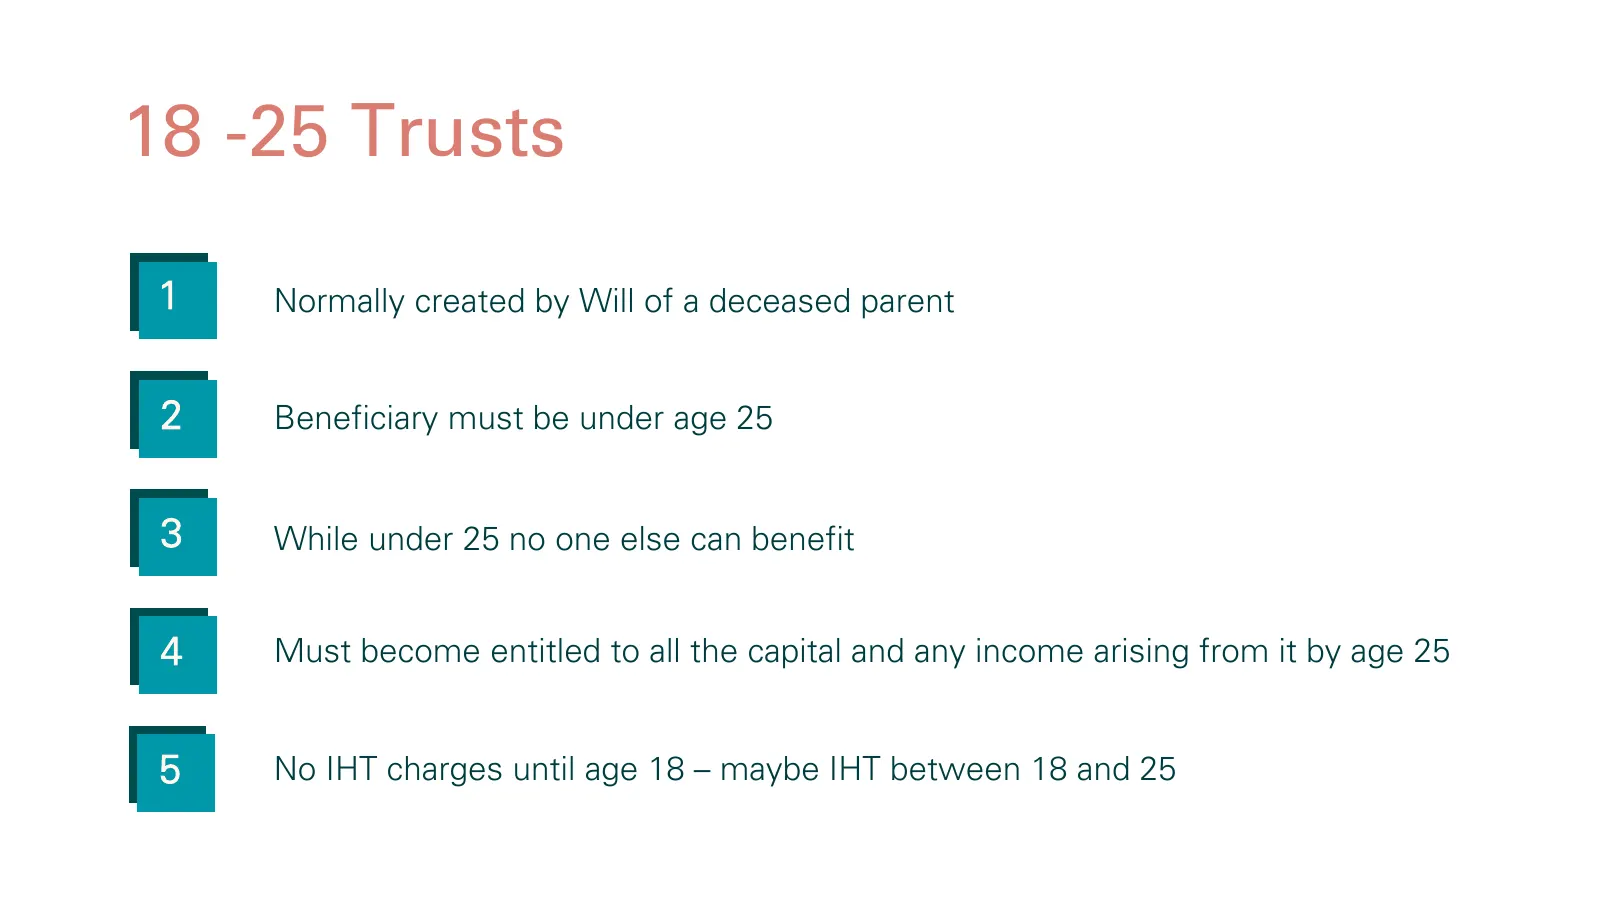
18 -25 Trusts 1 Normally created by Will of a deceased parent 2 Beneficiary must be under age 25 Bereaved Minors Trust 3 While under 25 no one else can benefit 4 Must become entitled to all the capital and any income arising from it by age 25 5 No IHT charges until age 18 – maybe IHT between 18 and
Slide 18: Interest in Possession Trusts
Interest in Possession Trusts
Slide 19: Interest in possession
Interest in possession • Life tenant – entitled to income/enjoyment of trust property e.g. right to live in a house Interest in Possession • Remaindermen – entitled to capital • Trust fund in Life Tenant’s estate
Slide 20: Example – IIP
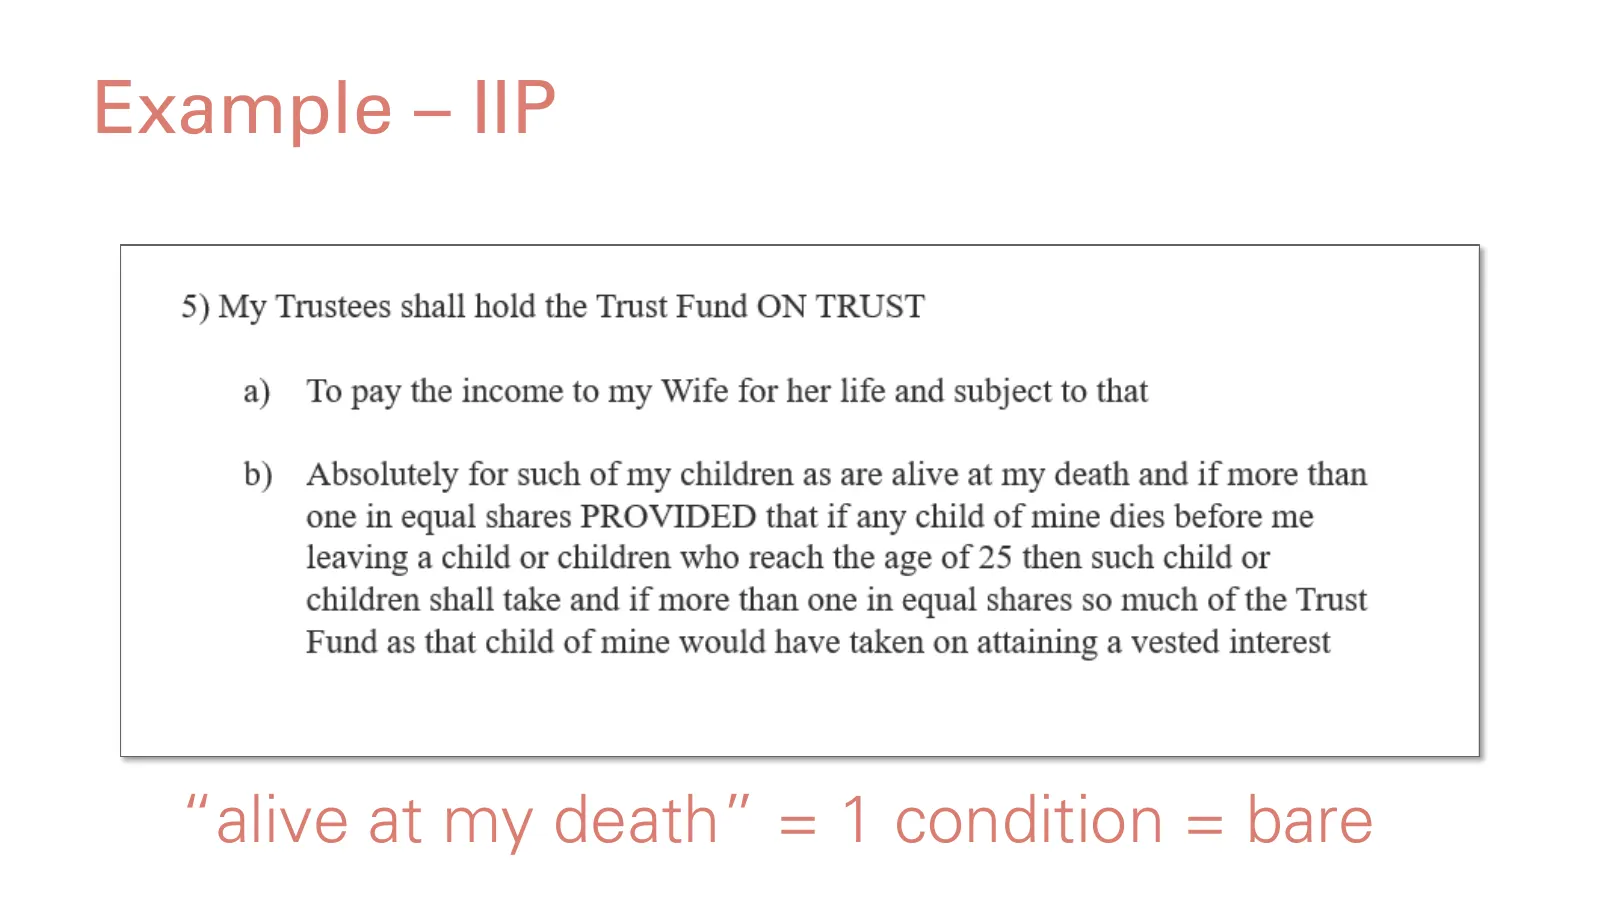
Example – IIP “alive at my death” = 1 condition = bare
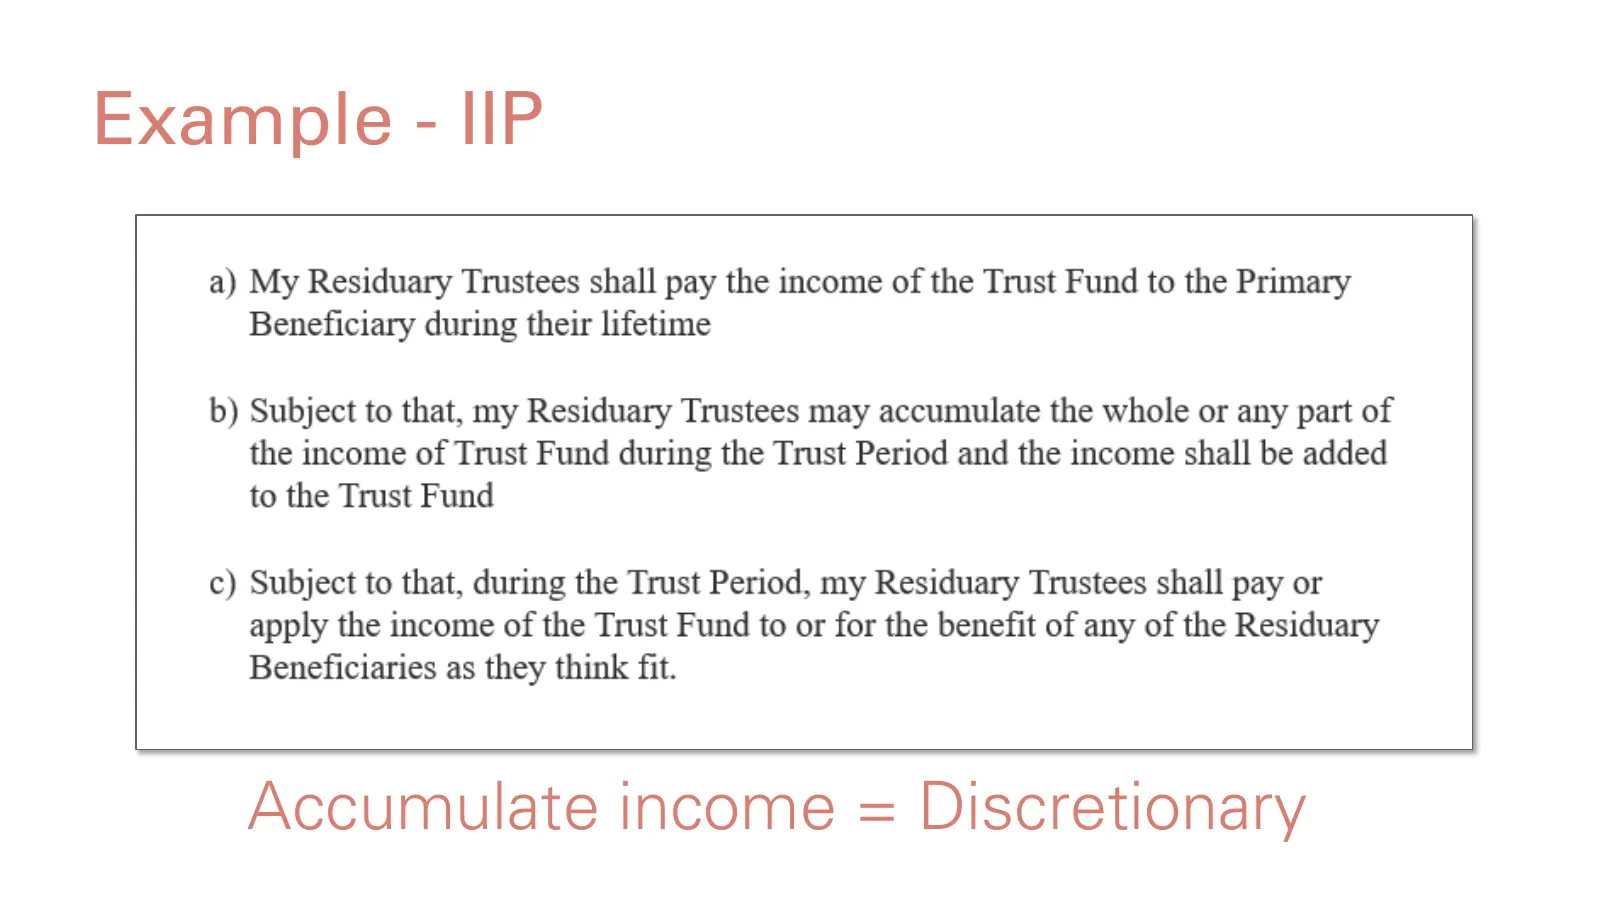
Slide 21: Example - IIP Accumulate income = Discretionary
Example - IIP Accumulate income = Discretionary
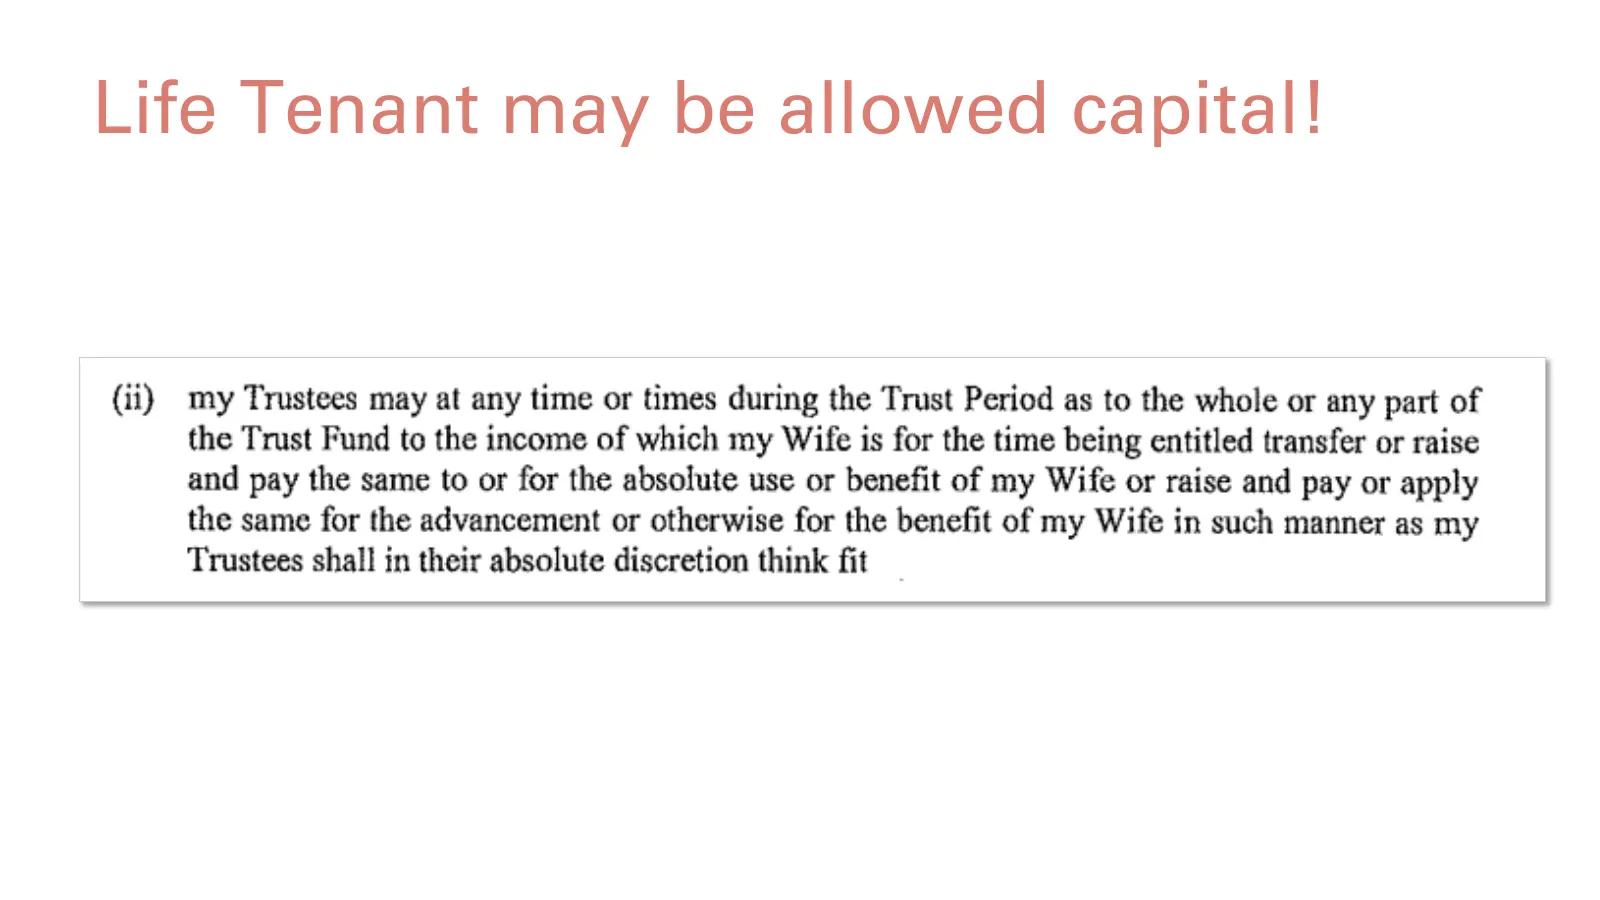
Slide 22: Life Tenant may be allowed capital!
Life Tenant may be allowed capital!
Slide 23: Deeds of Variation
Deeds of Variation
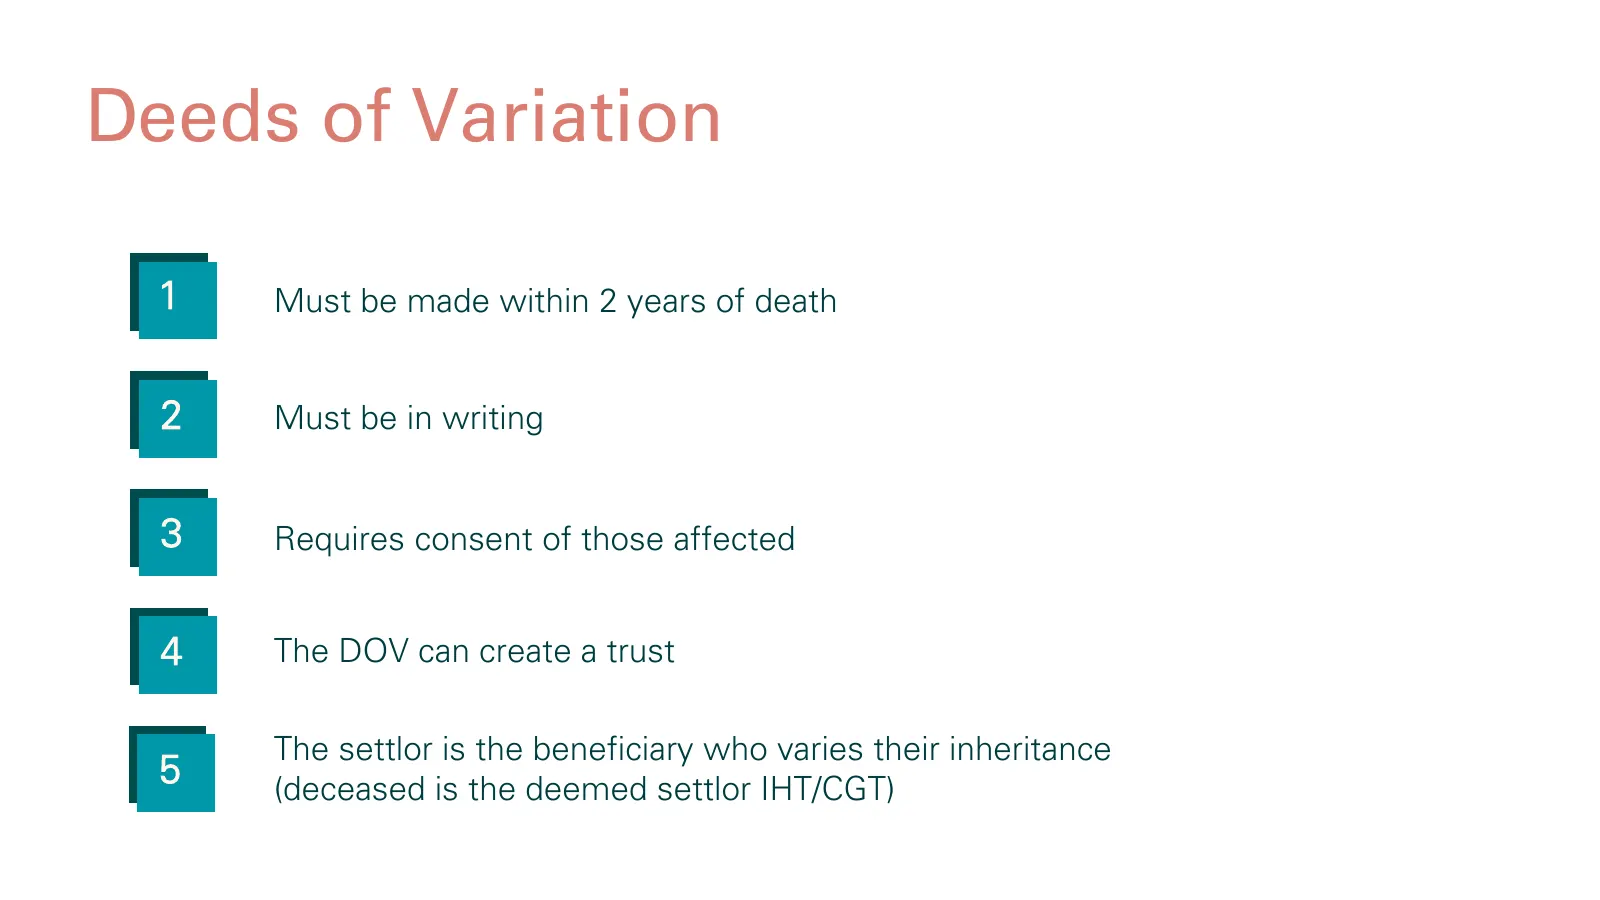
Slide 24: Deeds of Variation
Deeds of Variation 1 Must be made within 2 years of death 2 Must be in writing Bereaved Minors Trust 3 Requires consent of those affected 4 The DOV can create a trust The settlor is the beneficiary who varies their inheritance 5 (deceased is the deemed settlor IHT/CGT)
Slide 25: Trust Registration
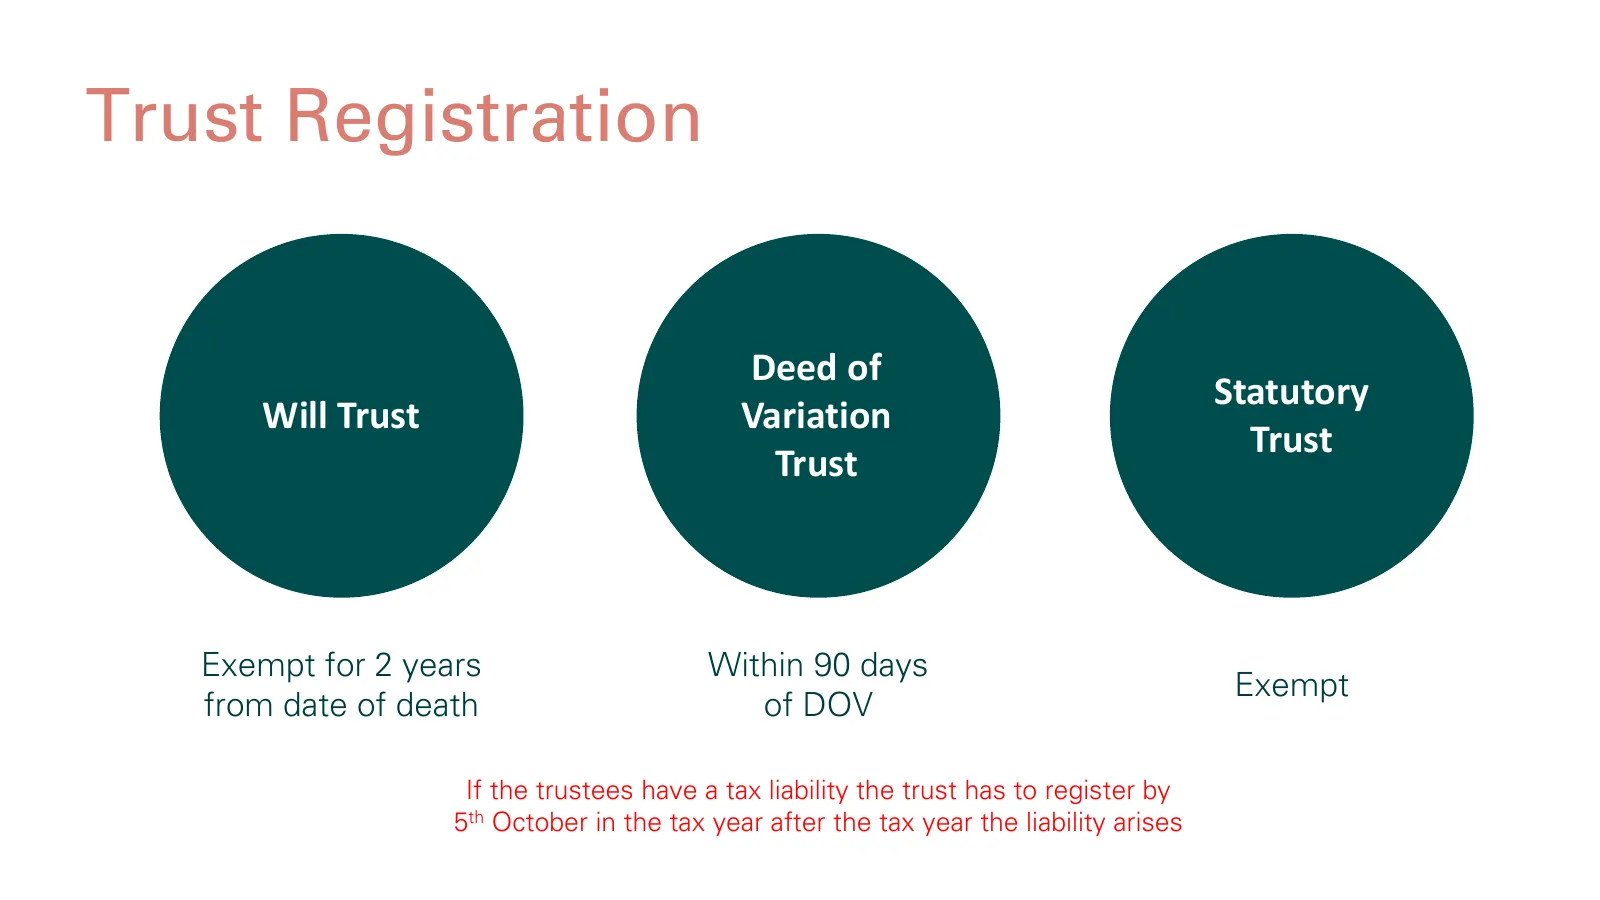
Trust Registration Deed of Statutory Will Trust Variation Trust Trust Exempt for 2 years Within 90 days Exempt from date of death of DOV If the trustees have a tax liability the trust has to register by 5th October in the tax year after the tax year the liability arises
Slide 26: Taxation of Income
Taxation of Tarexe)aal>,
Slide 27: Taxation of income – Interest in possession
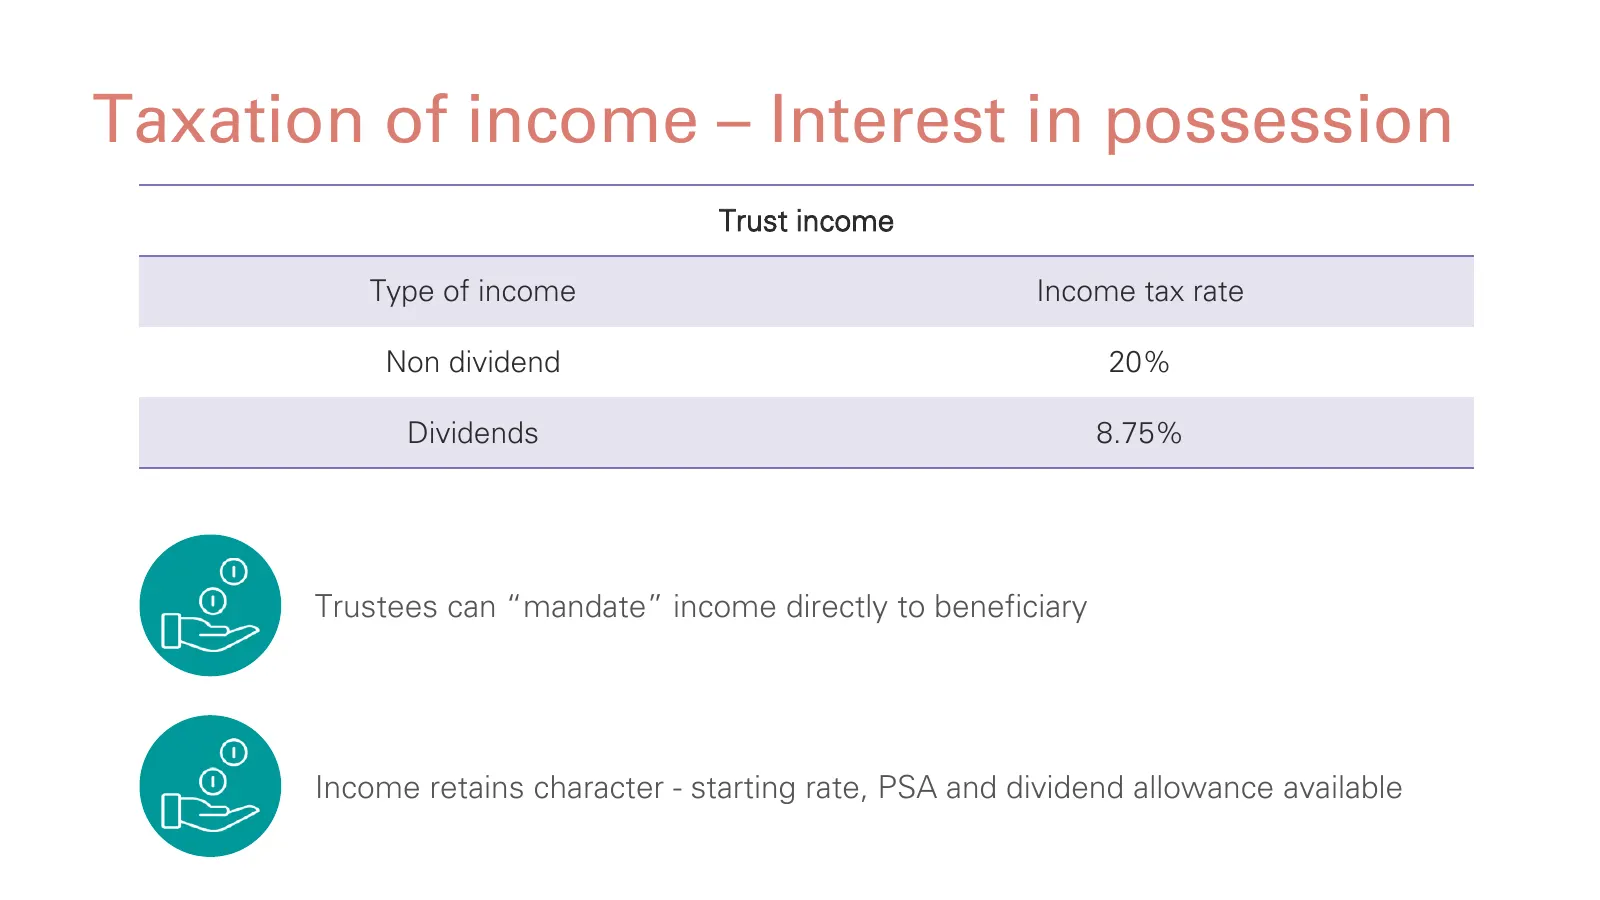
Taxation of income – Interest in possession Trust income Type of income Income tax rate Non dividend 20% Dividends 8.75% Trustees can “mandate” income directly to beneficiary Income retains character - starting rate, PSA and dividend allowance available
Slide 28: Example – taxing IIP interest
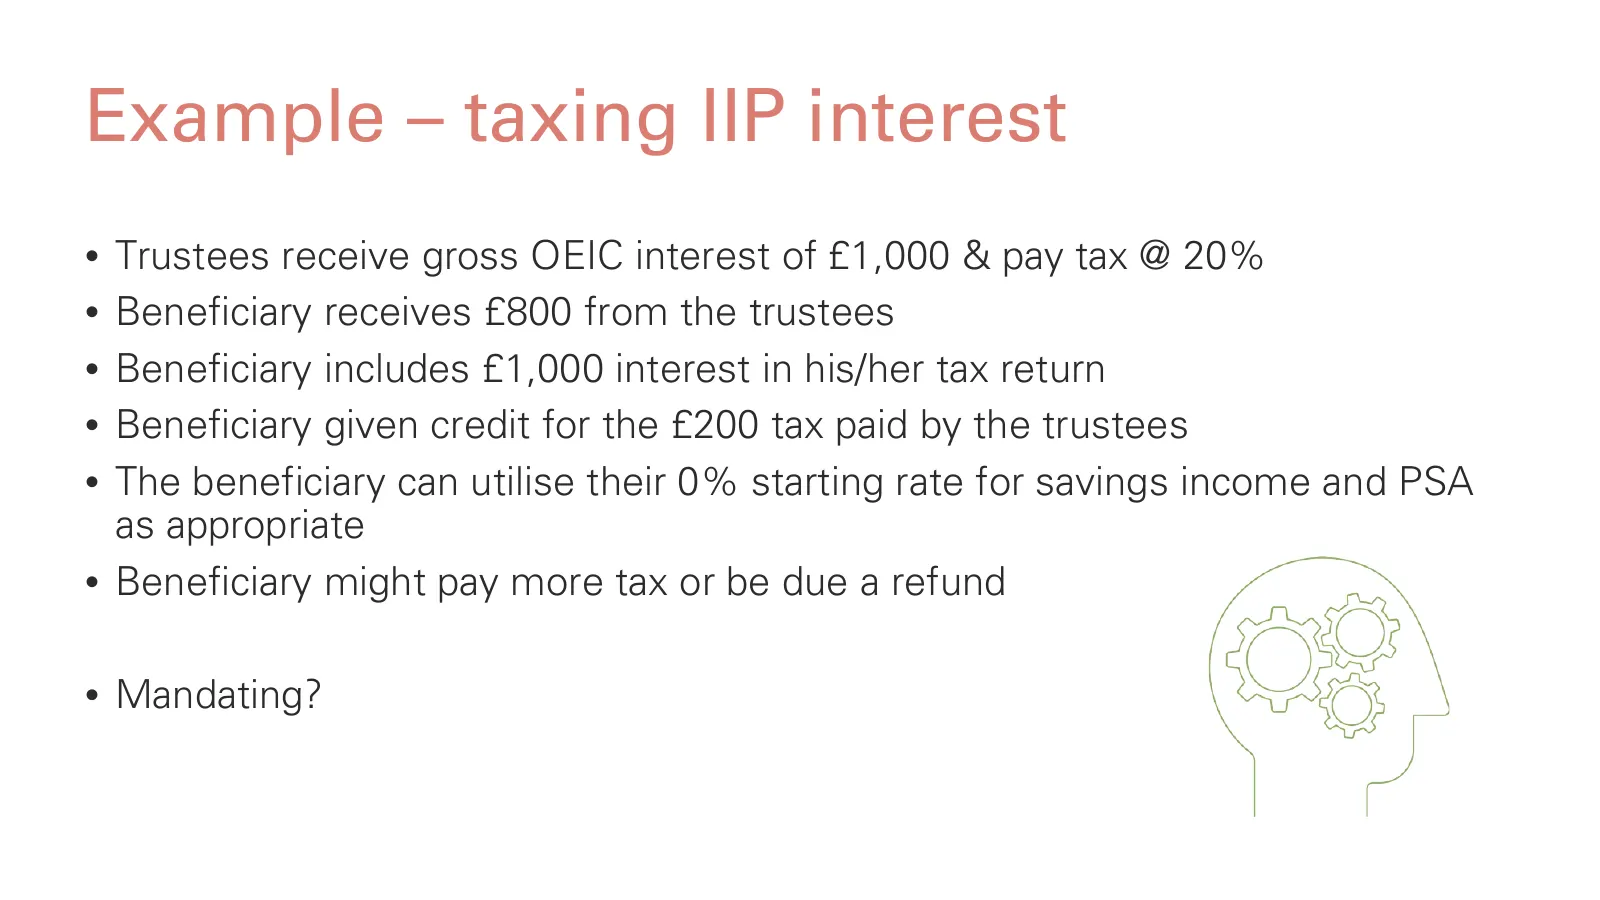
Example – taxing IIP interest • Trustees receive gross OEIC interest of £1,000 & pay tax @ 20% • Beneficiary receives £800 from the trustees • Beneficiary includes £1,000 interest in his/her tax return • Beneficiary given credit for the £200 tax paid by the trustees • The beneficiary can utilise the
Slide 29: Dividend Allowance
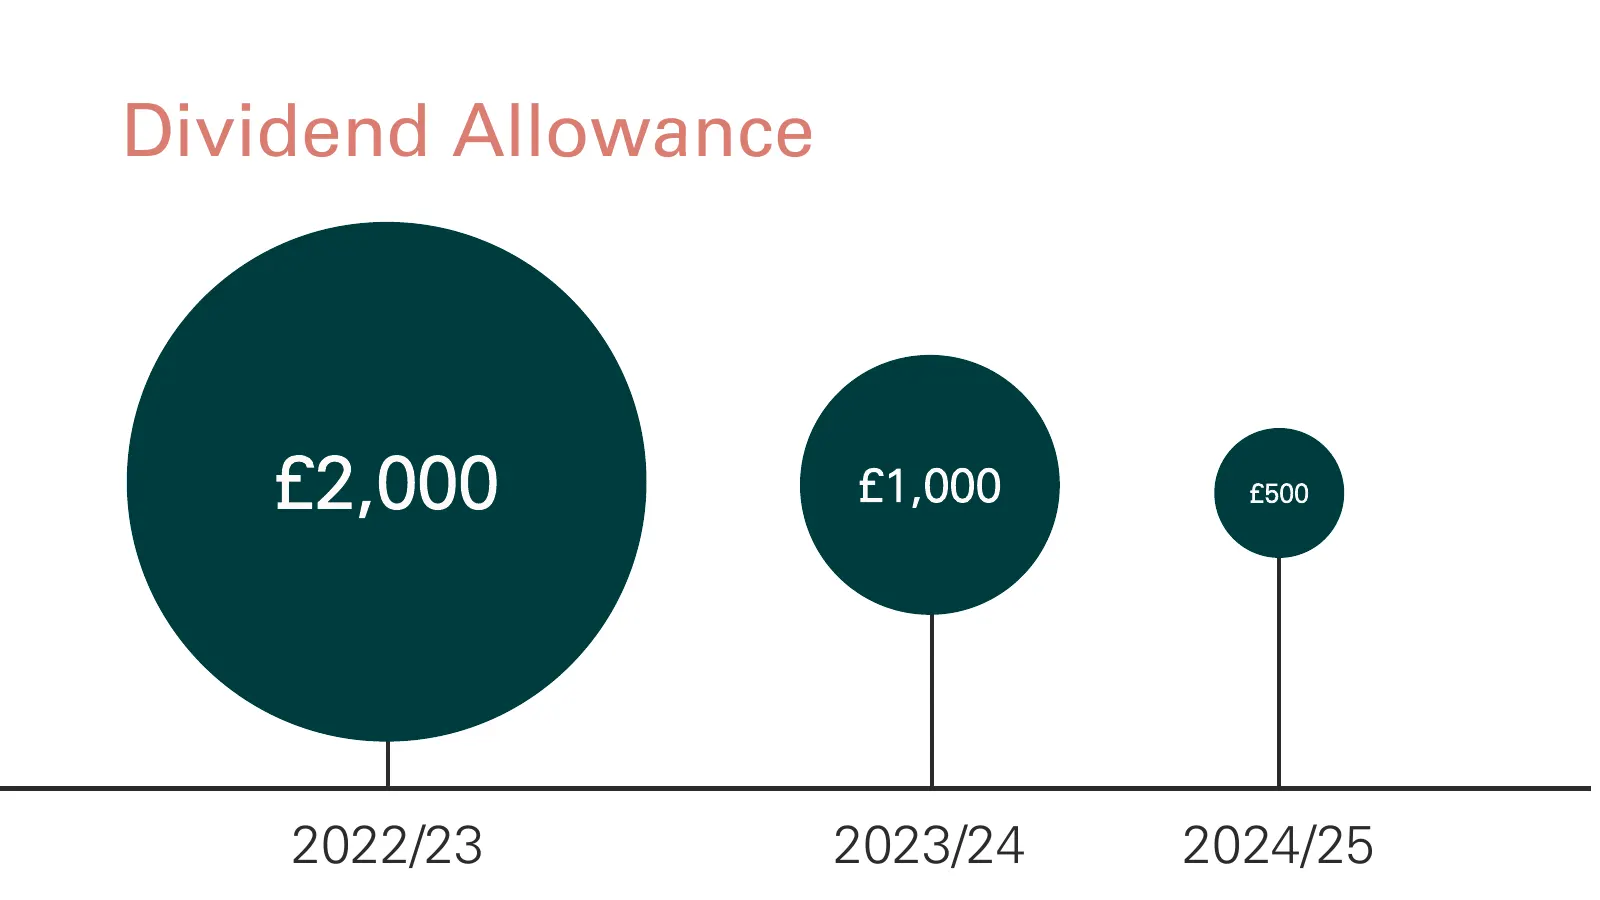
Dividend Allowance £2,000 £1,000 £500 2022/23 2023/24 2024/25
Slide 30: Discretionary Trust Taxation Change
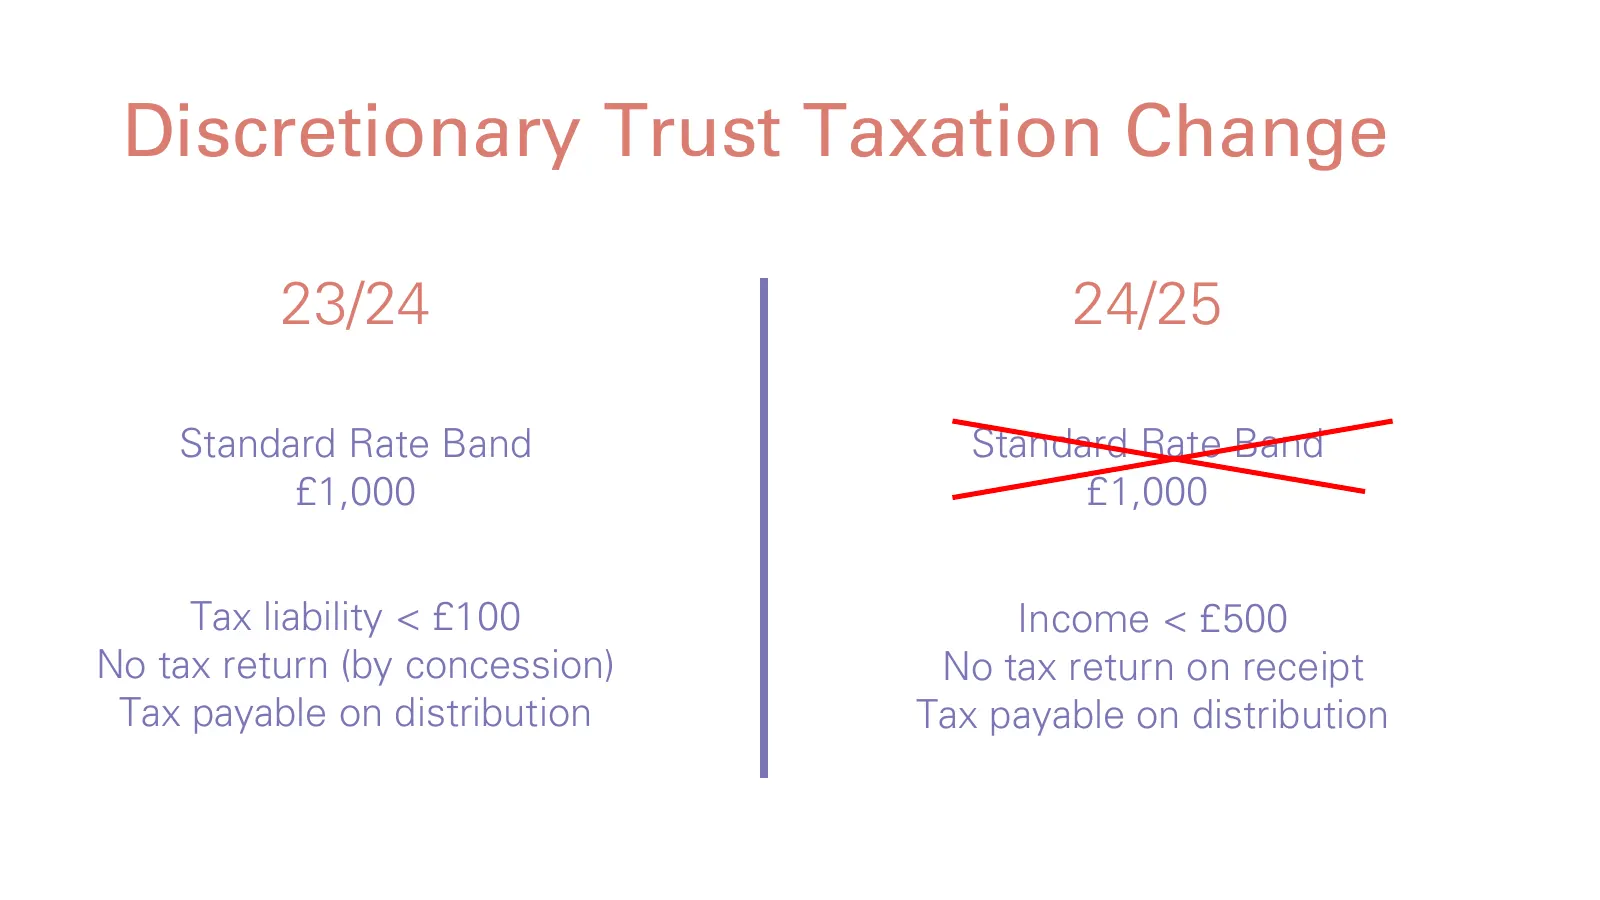
Discretionary Trust Taxation Change 23/24 24/25 Standard Rate Band Standard Rate Band £1,000 £1,000 Tax liability < £100 Income < £500 No tax return (by concession) No tax return on receipt Tax payable on distribution Tax payable on distribution
Slide 31: Taxation of income – Discretionary
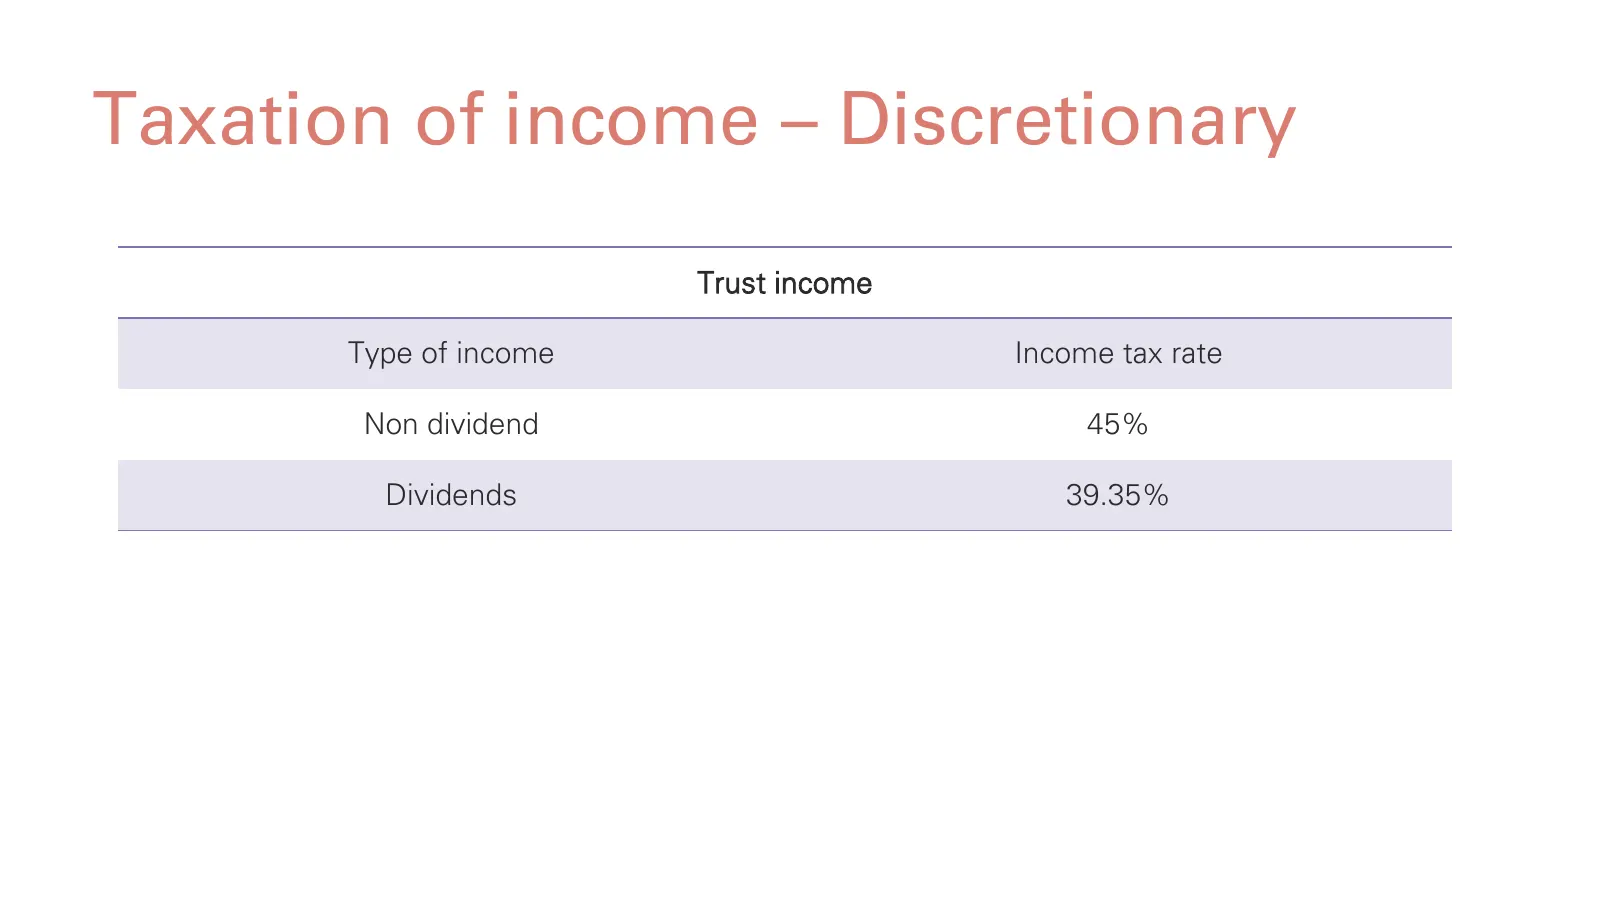
Taxation of income – Discretionary Trust income Type of income Income tax rate Non dividend 45% Dividends 39.35%
Slide 32: Taxation of income – Discretionary example
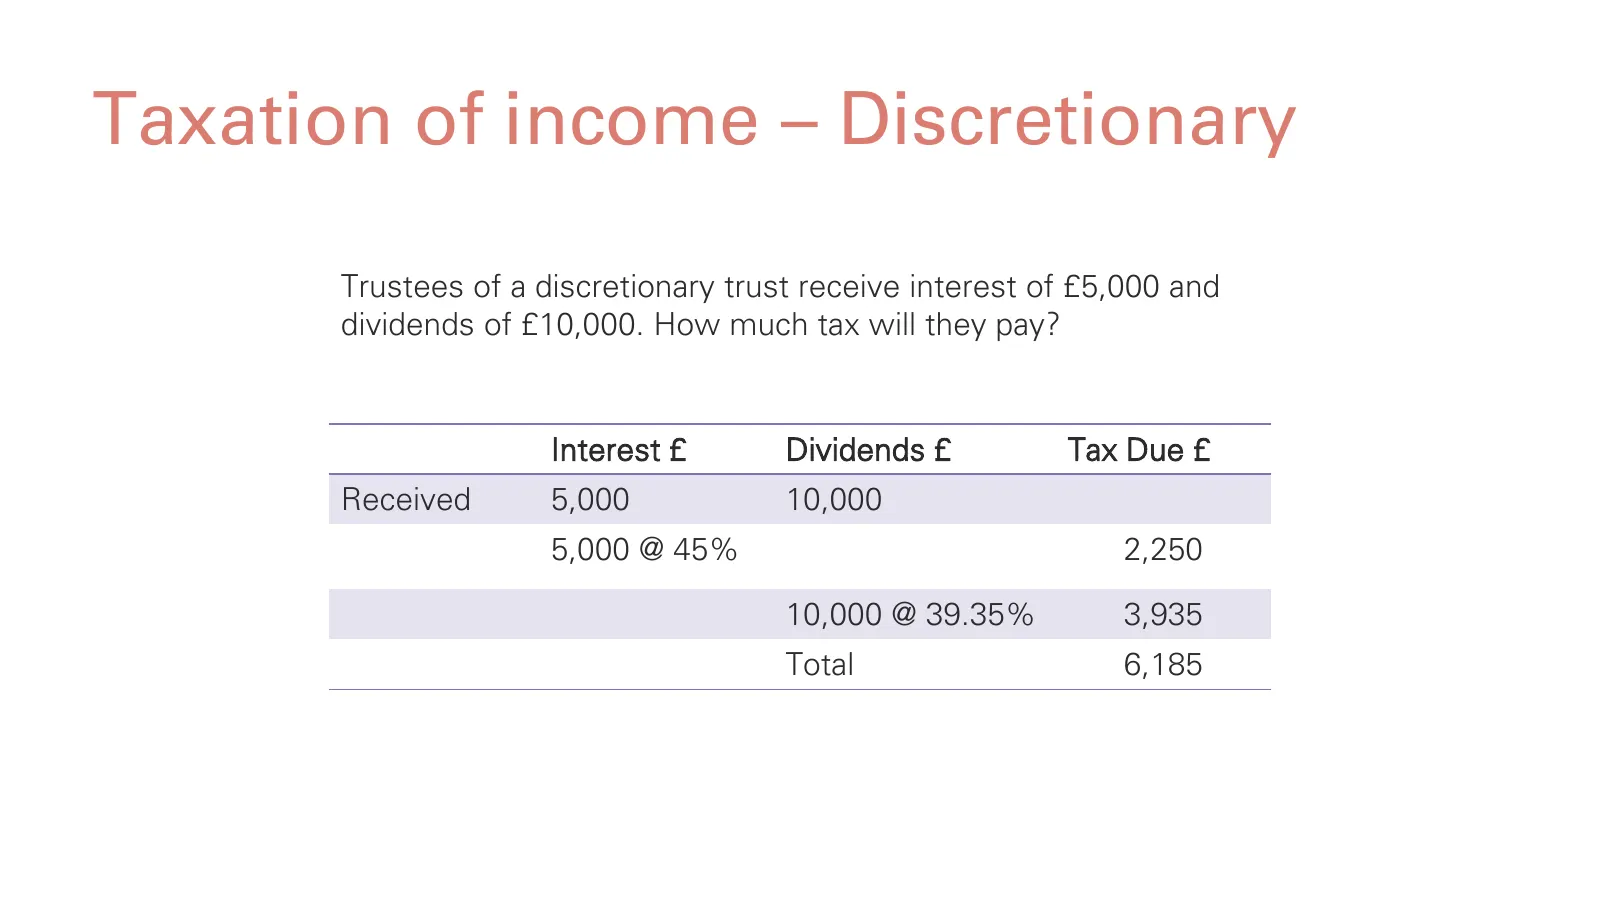
Taxation of income – Discretionary Trustees of a discretionary trust receive interest of £5,000 and dividends of £10,000. How much tax will they pay? Interest £ Dividends £ Tax Due £ Received 5,000 10,000 5,000 @ 45% 2,250 10,000 @ 39.35% 3,935 Total 6,185
Slide 33: Trustees – Tax on distribution
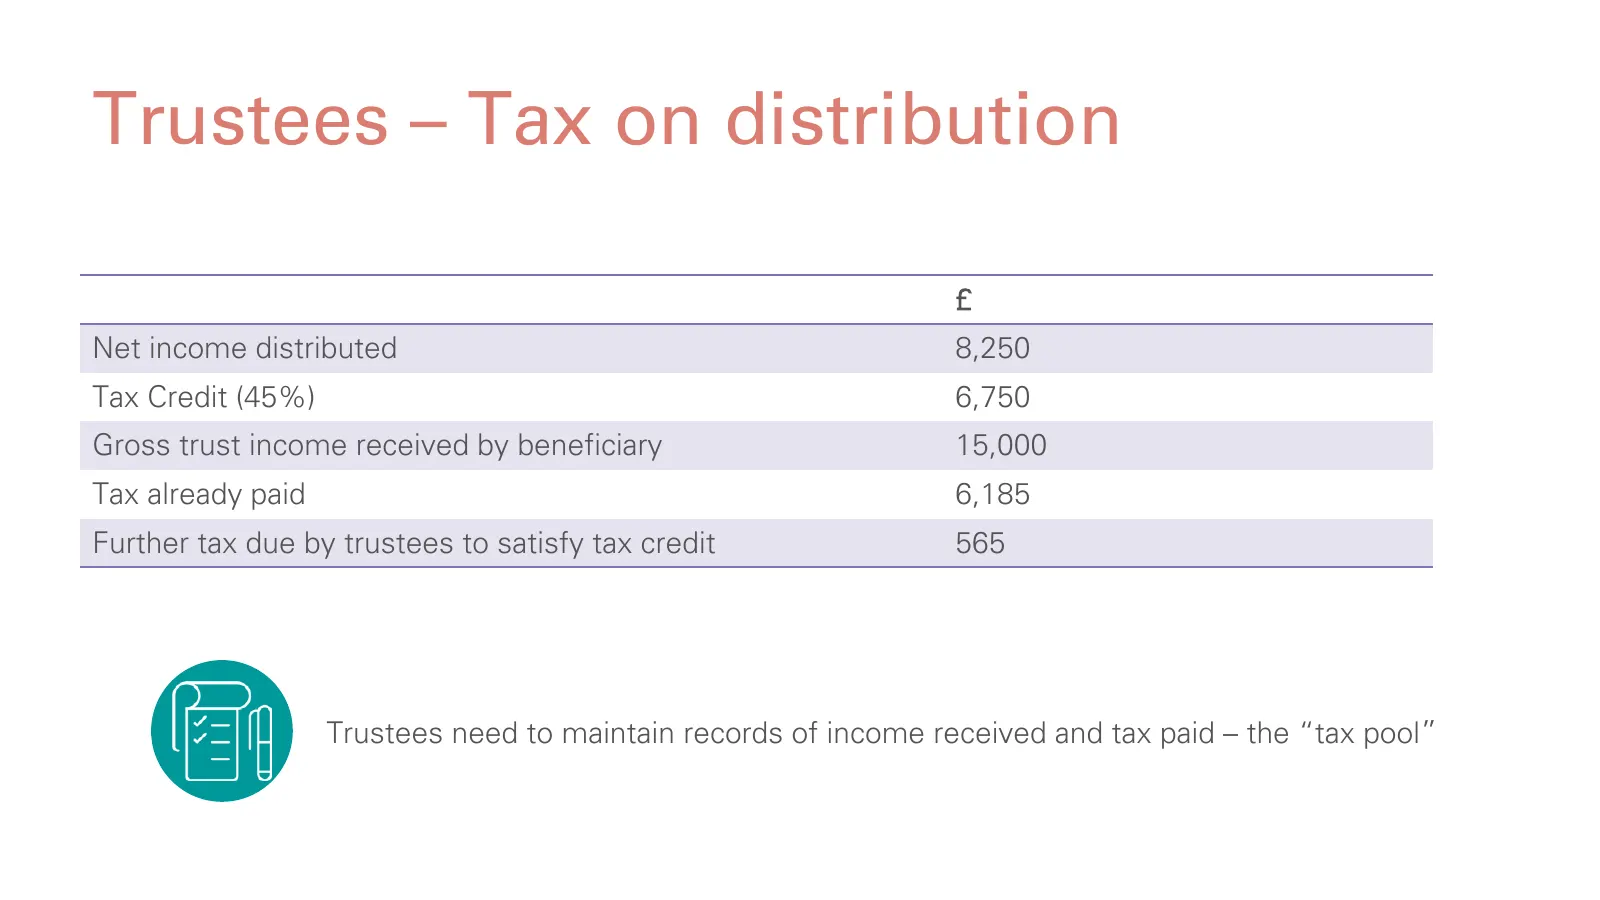
Trustees – Tax on distribution £ Net income distributed 8,250 Tax Credit (45%) 6,750 Gross trust income received by beneficiary 15,000 Tax already paid 6,185 Further tax due by trustees to satisfy tax credit 565 Trustees need to maintain records of income received and tax paid – the “tax pool”
Slide 34: Beneficiary – Tax on receipt
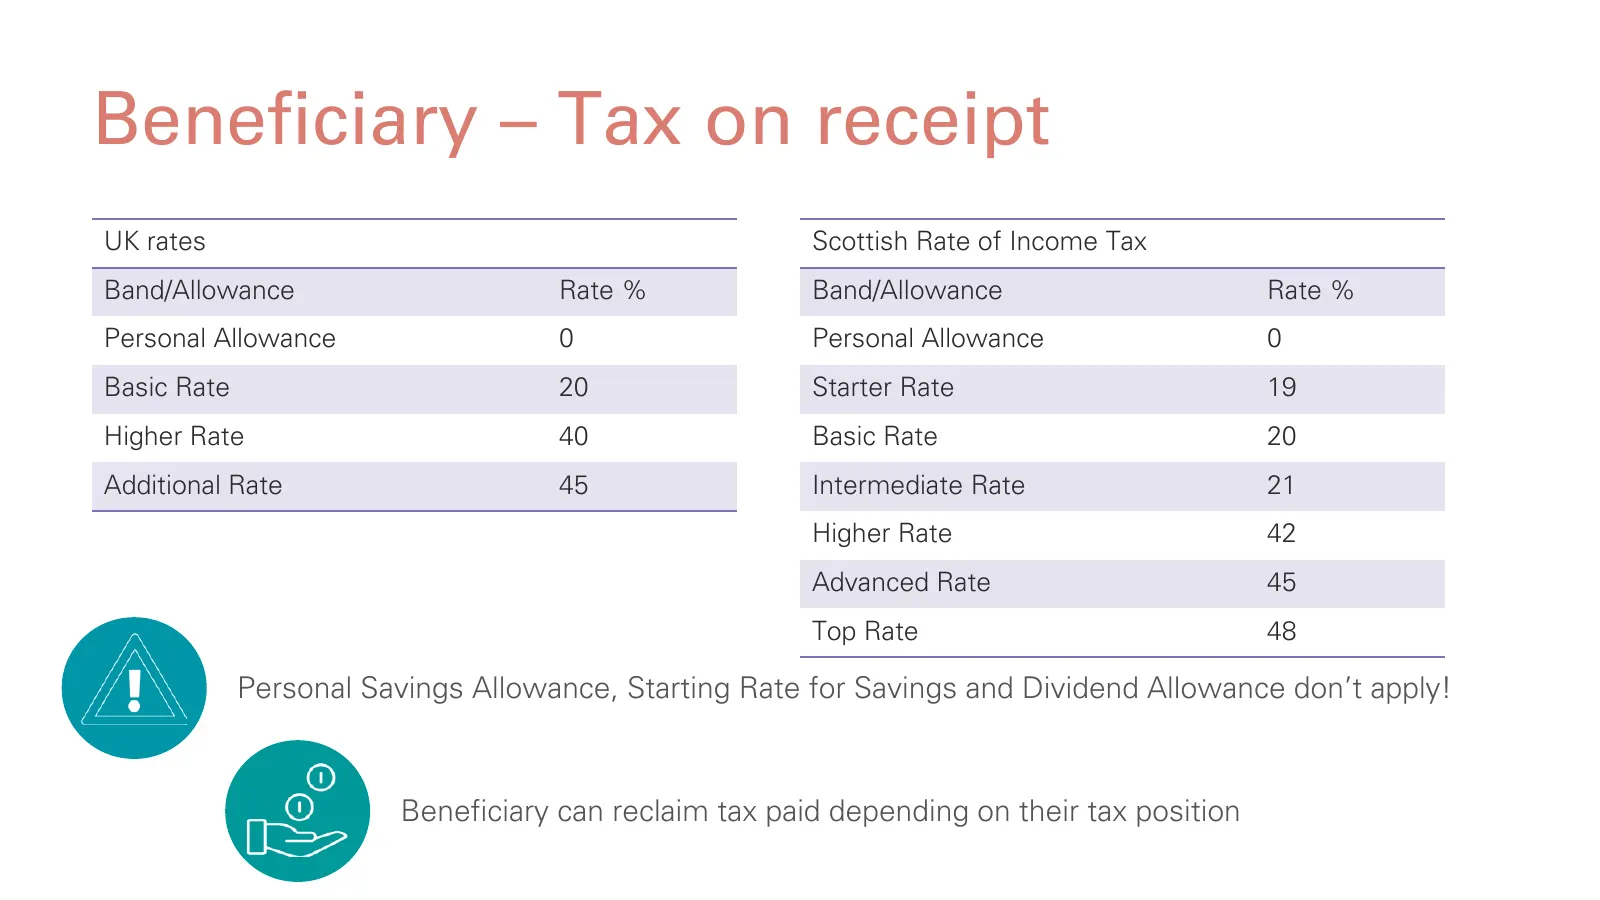
Beneficiary – Tax on receipt UK rates Scottish Rate of Income Tax Band/Allowance Rate % Band/Allowance Rate % Personal Allowance 0 Personal Allowance 0 Basic Rate 20 Starter Rate 19 Higher Rate 40 Basic Rate 20 Additional Rate 45 Intermediate Rate 21 Higher Rate 42 Advanced Rate 45 Top Rate 48 Perso
Slide 35: Taxation of Capital Gains
Taxation of Capital Gains
Slide 36: Capital Gains Tax: Bare, Other
Capital Gains Tax Bare Other
Slide 37: Non Bare trusts & CGT
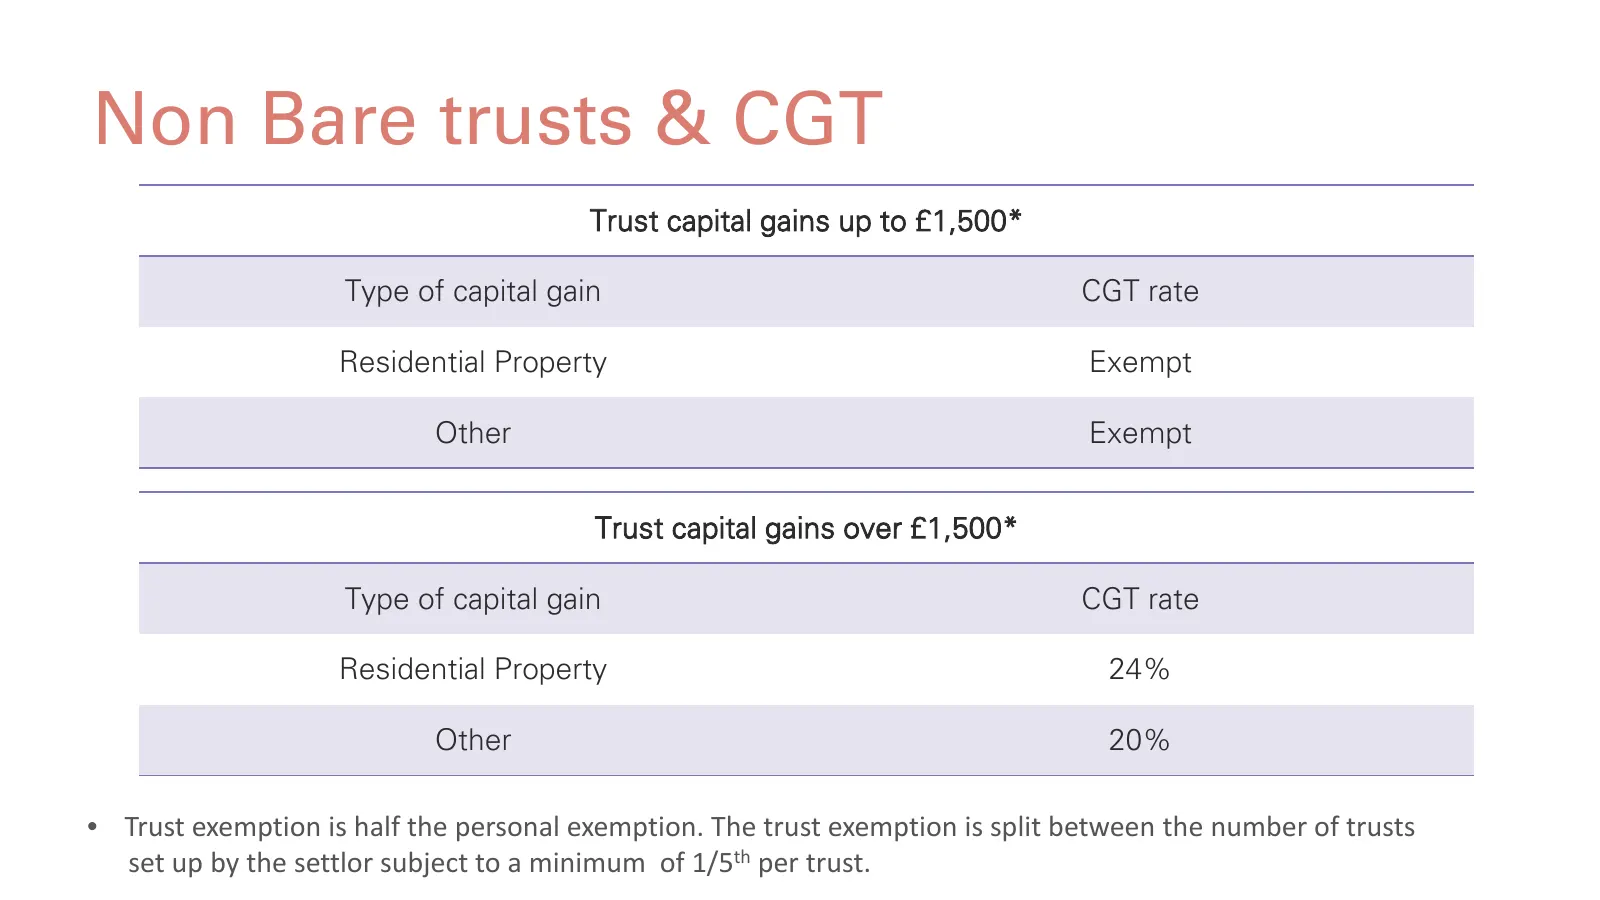
Non Bare trusts & CGT Trust capital gains up to £1,500* Type of capital gain CGT rate Residential Property Exempt Other Exempt Trust capital gains over £1,500* Type of capital gain CGT rate Residential Property 24% Other 20% • Trust exemption is half the personal exemption. The trust exemption is sp
Slide 38: Trustees and CGT
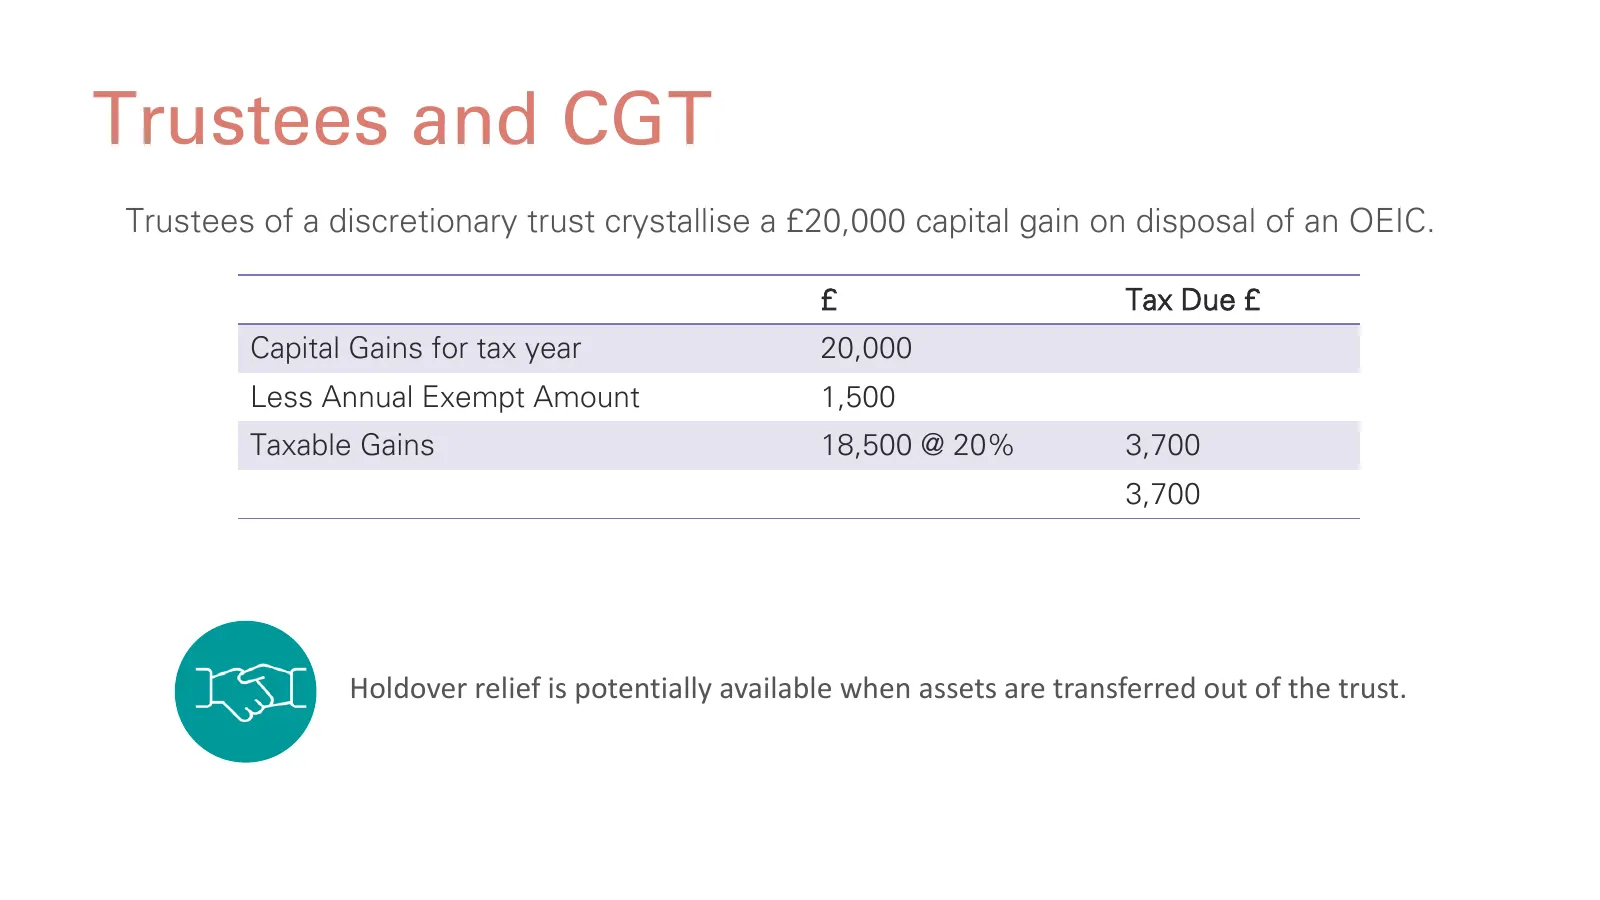
Trustees and CGT Trustees of a discretionary trust crystallise a £20,000 capital gain on disposal of an OEIC. £ Tax Due £ Capital Gains for tax year 20,000 Less Annual Exempt Amount 1,500 Taxable Gains 18,500 @ 20% 3,700 3,700 Holdover relief is potentially available when assets are transferred out
Slide 39: CGT Annual Exempt Amount
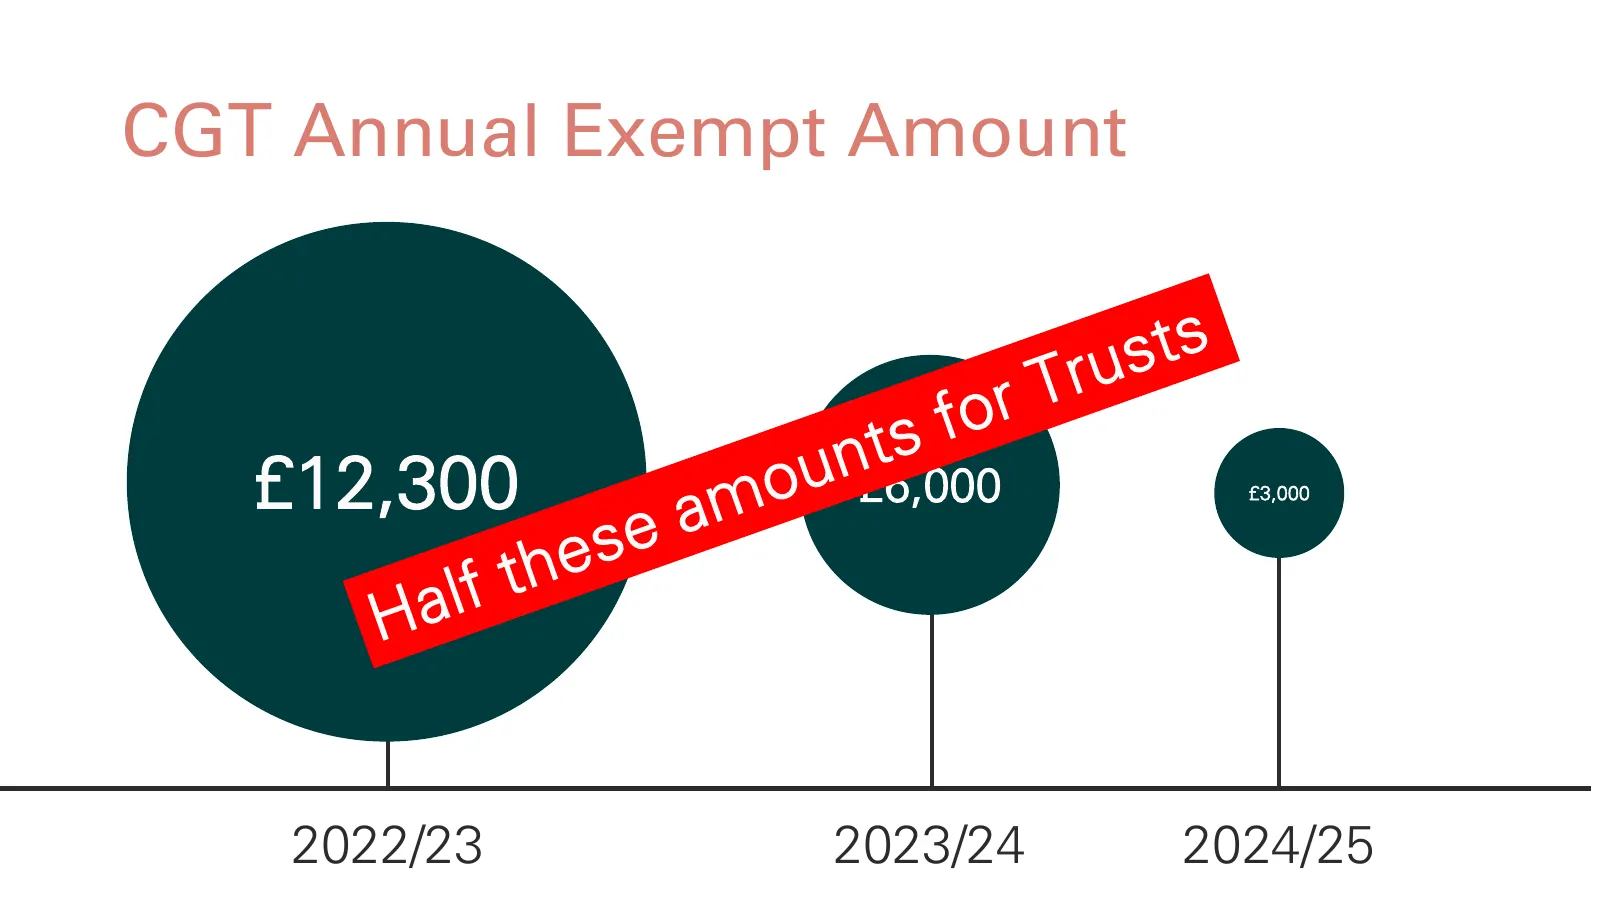
CGT Annual Exempt Amount £12,300 £6,000 £3,000 2022/23 2023/24 2024/25
Slide 40: Taxation of Bond Gains
Taxation of Bond Gains
Slide 41: Chargeable Event Gains: Bare, Other
Chargeable Event Gains Bare Other
Slide 42: Chargeable Event Gains - Who is liable?
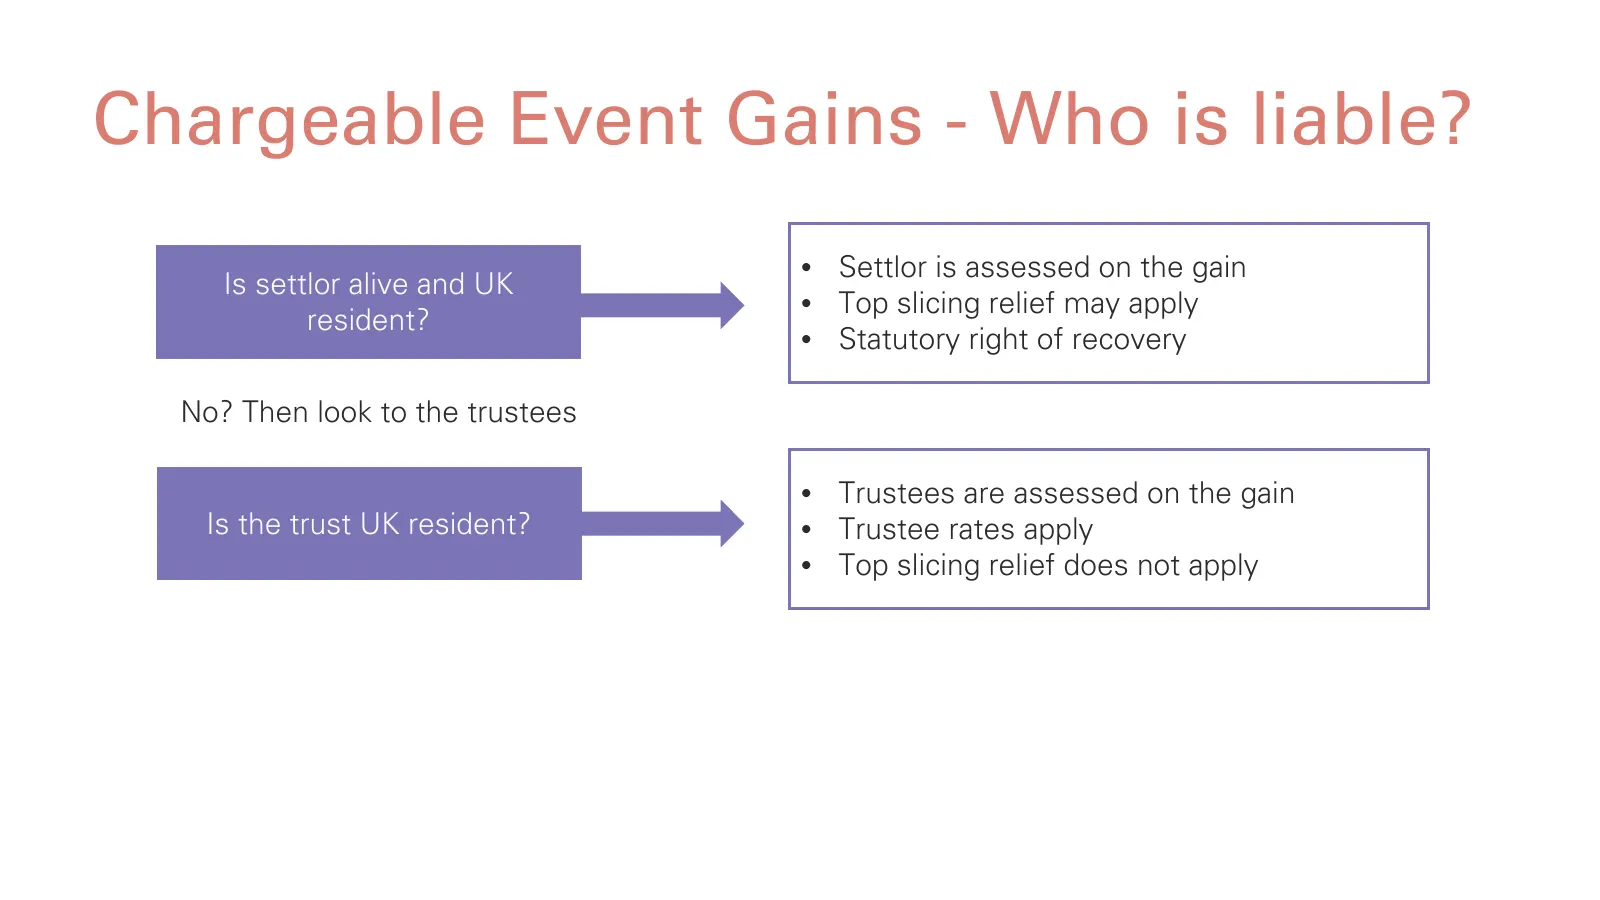
Chargeable Event Gains - Who is liable? • Settlor is assessed on the gain Is settlor alive and UK • Top slicing relief may apply resident? • Statutory right of recovery No? Then look to the trustees • Trustees are assessed on the gain Is the trust UK resident? • Trustee rates apply • Top slicing rel
Slide 43: Is the trust UK resident?
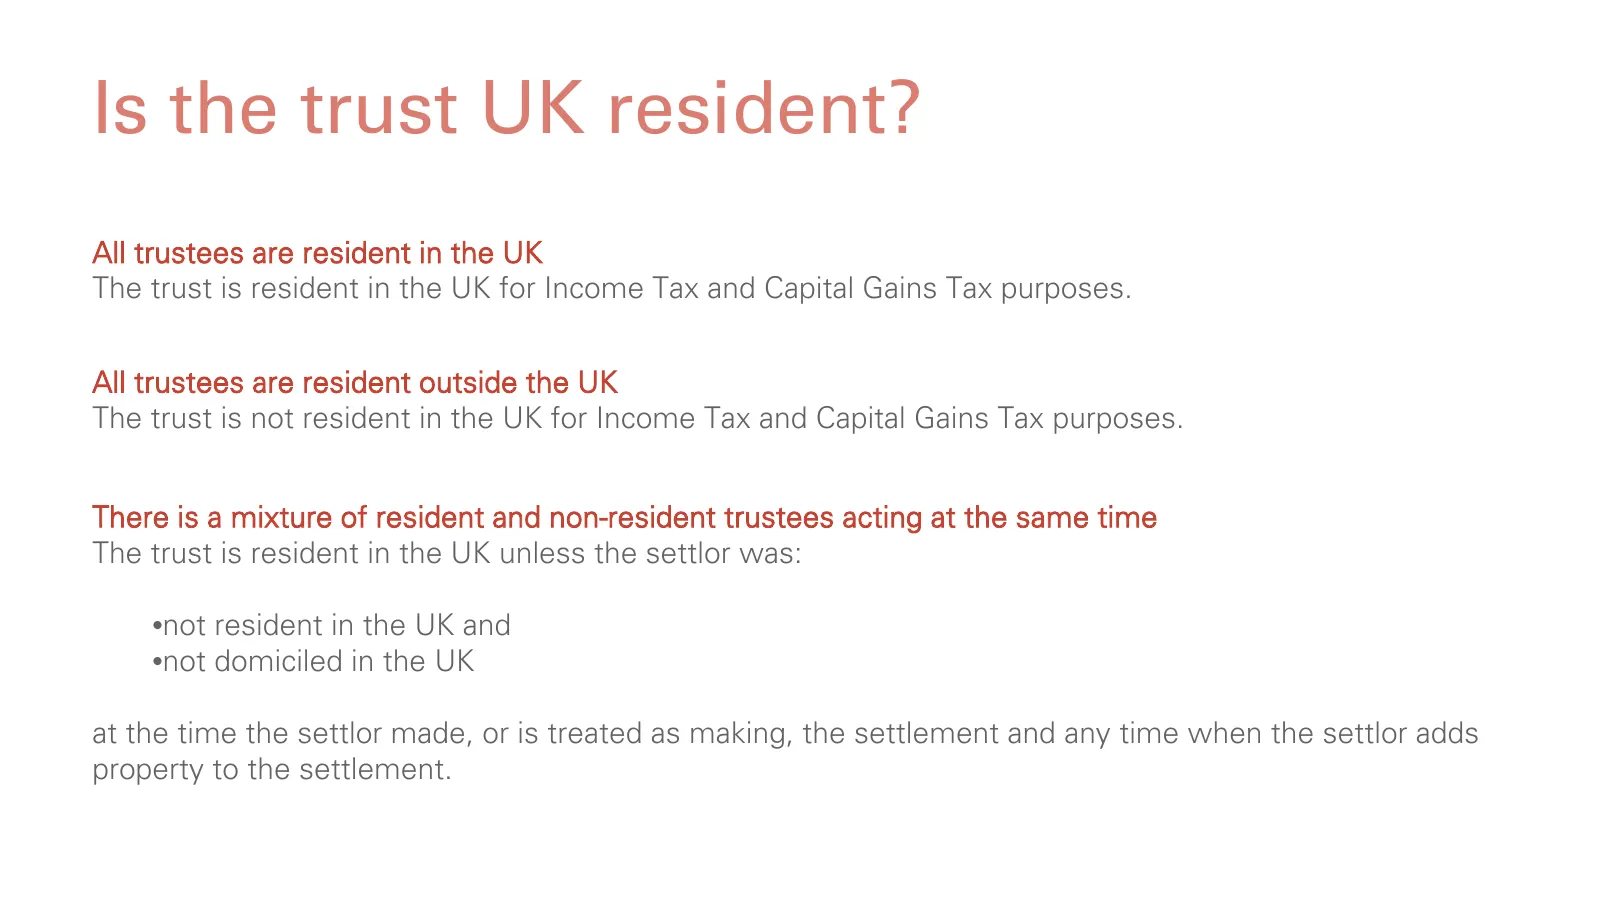
Is the trust UK resident? All trustees are resident in the UK The trust is resident in the UK for Income Tax and Capital Gains Tax purposes. All trustees are resident outside the UK The trust is not resident in the UK for Income Tax and Capital Gains Tax purposes. There is a mixture of resident and
Slide 44: Chargeable Event Gains – Taxed on trustees
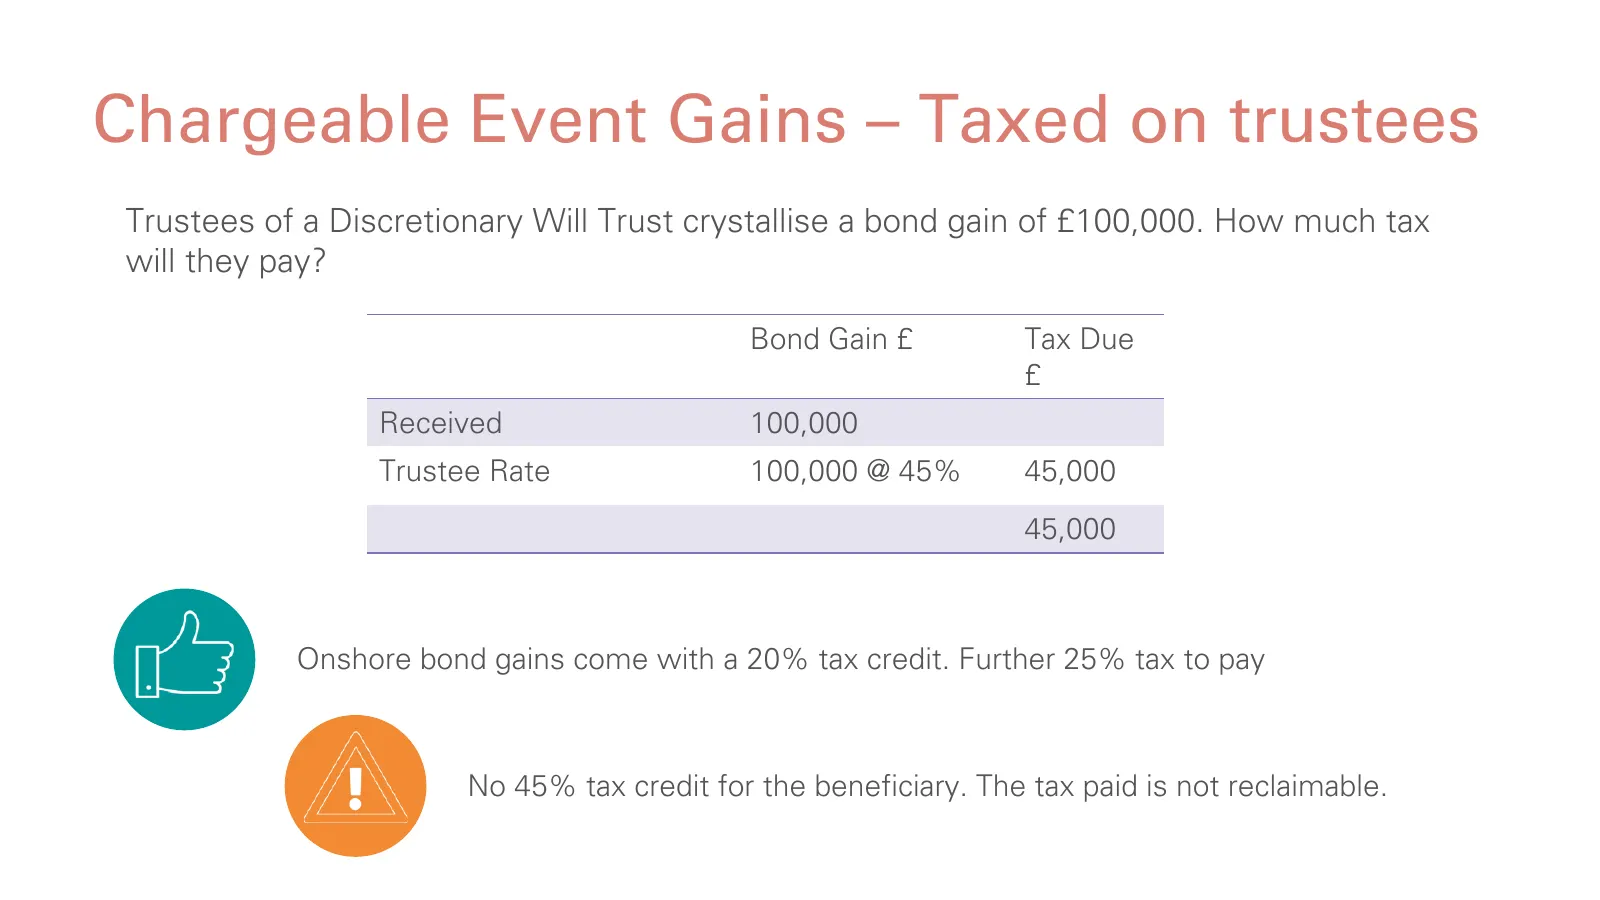
Chargeable Event Gains – Taxed on trustees Trustees of a Discretionary Will Trust crystallise a bond gain of £100,000. How much tax will they pay? Bond Gain £ Tax Due £ Received 100,000 Trustee Rate 100,000 @ 45% 45,000 45,000 Onshore bond gains come with a 20% tax credit. Further 25% tax to pay No
Slide 45: Investment Considerations
Investment Considerations
Slide 46: What can we buy?
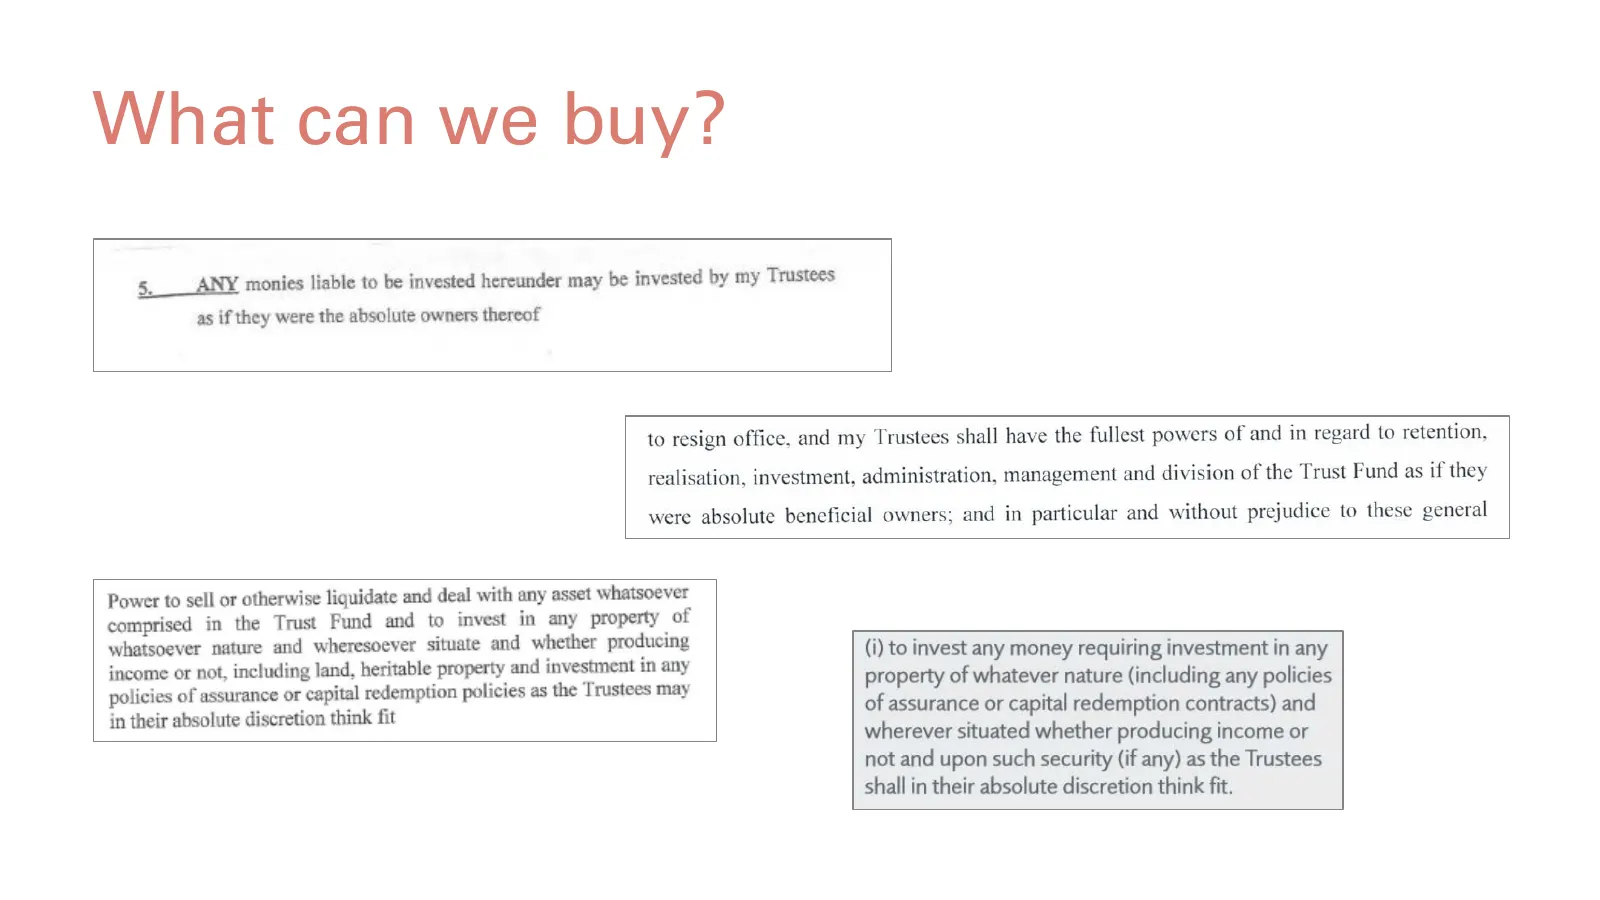
What can we buy? 5,__ ANY monies liable to be invested hereunder may be invested by my Trustees as if they were the absolute owners thereof to resign office, and my Trustees shall have the fullest powers of and in regard to retention, realisation, investment, administration, management and division
Slide 47: What can we buy?
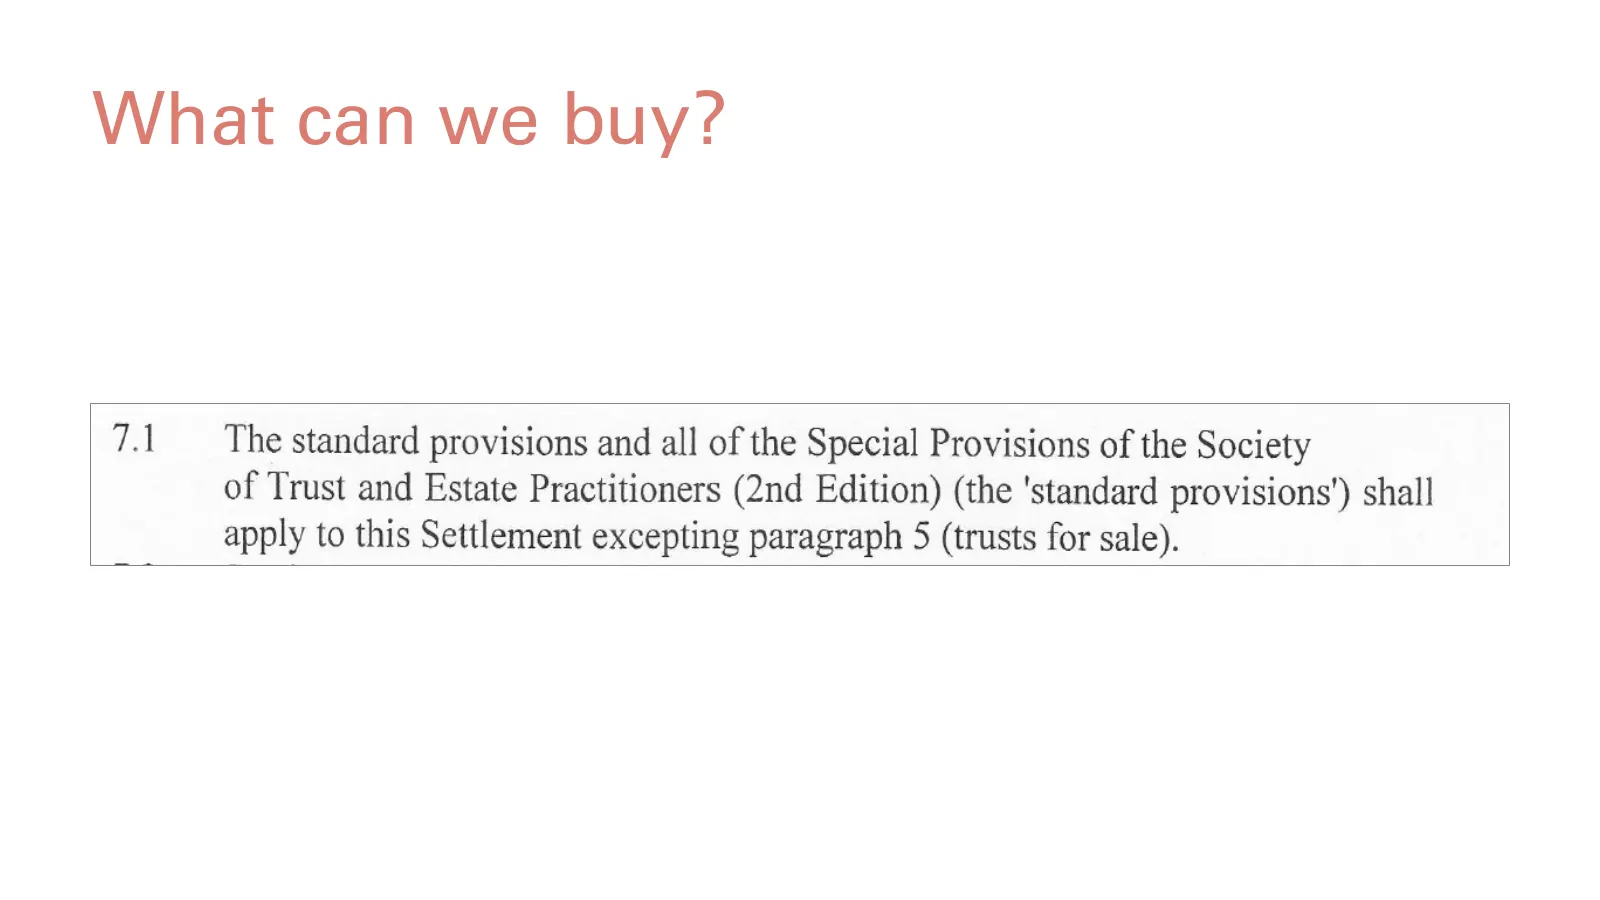
What can we buy? vel The standard provisions and all of the Special Provisions of the Society of Trust and Estate Practitioners (2nd Edition) (the 'standard provisions’) shall apply to this Settlement excepting paragraph 5 (trusts for sale).
Slide 48: Consider tax status of beneficiaries
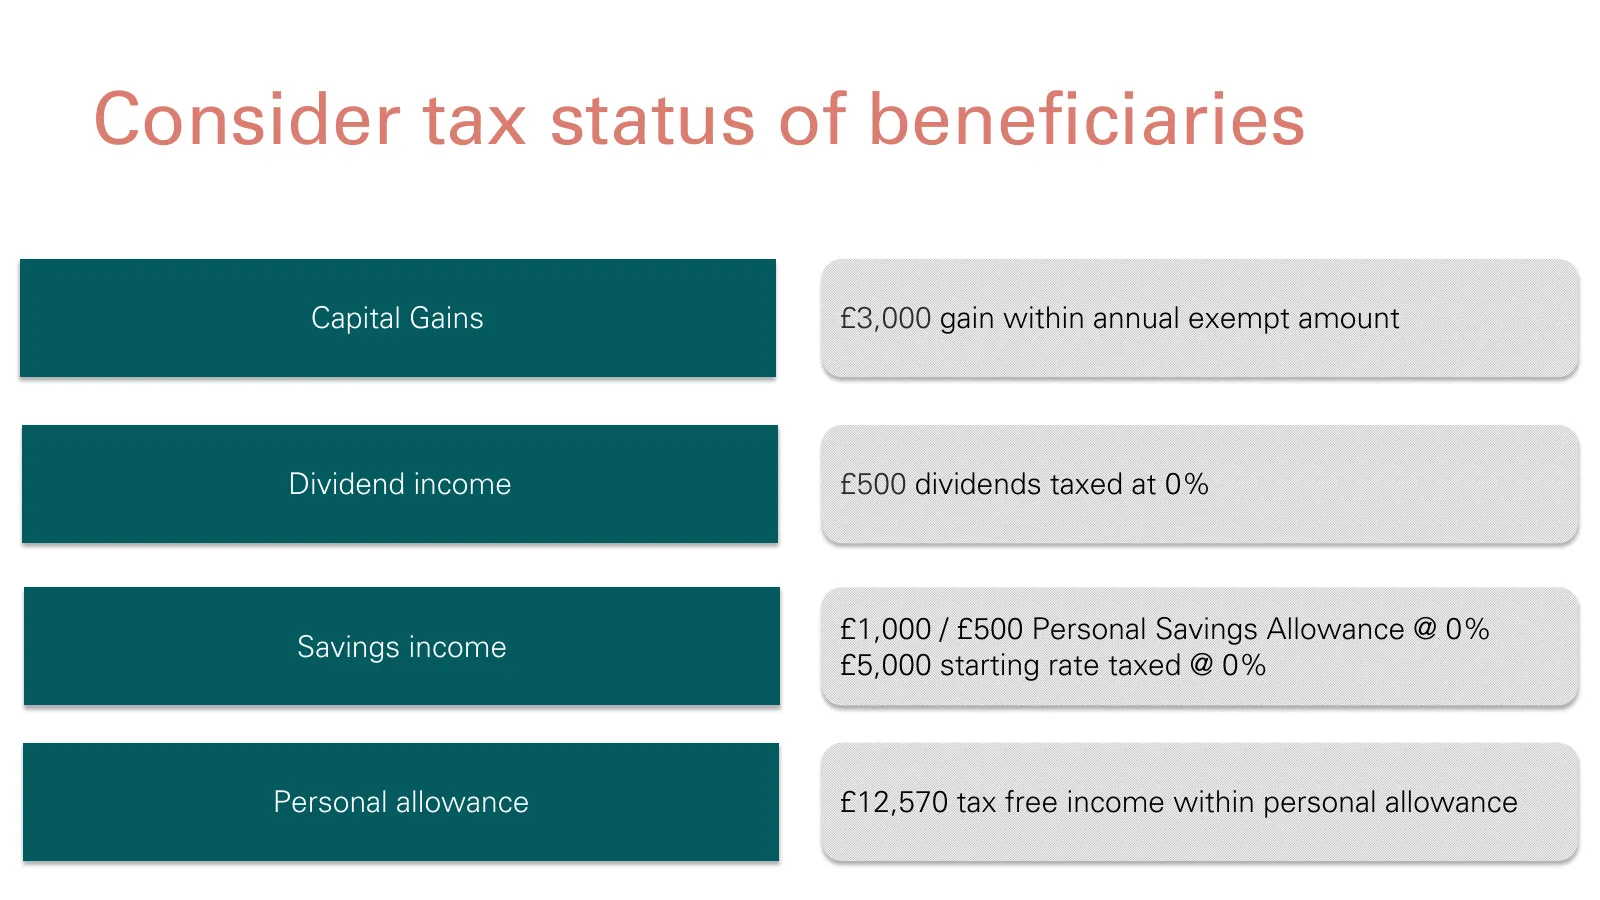
Consider tax status of beneficiaries Capital Gains £3,000 gain within annual exempt amount Dividend income £500 dividends taxed at 0% £1,000 / £500 Personal Savings Allowance @ 0% Savings income £5,000 starting rate taxed @ 0% Personal allowance £12,570 tax free income within personal allowance
Slide 49: Bare - considerations
Bare - considerations Is it definitely bare?? Beneficiary probably 18 OEICs – utilise beneficiary’s allowances Bond – utilise beneficiary’s allowances Bond – offshore likely to be more appropriate
Slide 50: Interest in possession - considerations
Interest in possession - considerations Treat beneficiaries fairly! May need income producing investments OEICs produce income - Bonds don’t How much income is required? Large trust fund - diversify? Power to advance capital?
Slide 51: Discretionary - considerations
Discretionary - considerations Undistributed income expensive Tax returns – trustee and beneficiary Vulnerable beneficiary? (VPE1) £1,500 AEA CGT – 20% Low income/gains – OEIC? Bonds may be appropriate
Slide 52: Learning Objectives
Learning Objectives By the end of this session, you will be able to: Identify the types of Identify appropriate Describe the income trust that can be tax and CGT treatment investments for a created on a person’s of trustee investments particular trust death
Slide 53: Question Time
QUESTION TIME
Slide 54: Thanks for your time
Thanks for your time Get in touch with your usual contact if you need further help.
Slide 55: M&G Wealth legal and regulatory information
M&G Wealth is a trademarked brand of the M&G plc group, which includes 3 business divisions as follows: M&G Wealth Advice, provided by M&G Wealth Advice Limited, registered number: 08022795. Model Portfolio Services, provided by M&G Wealth Investments LLP, registered number: 0C305442. M&G Wealth Pla
Source: company website
More decks from M&G PLC
 Q2 2026 Earnings Presentation54 slides · Sep 2, 2026
 M&G Wealth — M&G MPS Webinar (May 2026)24 slides · May 2026
 FY2025 Earnings Presentation59 slides · Mar 12, 2026
 H1 2025 Earnings Presentation51 slides · Sep 3, 2025
 Investor Presentation (August 2025)58 slides · August 2025
 Merger or Acquisition (May 2025)9 slides · May 30, 2025