Nedbank Group · JSE:NED
Nedbank — Investor Day (May 2013)
41 slides from Nedbank's investor day presentation, May 2013
Slide 1: Nedbank Wealth Investor Day May 2013
Nedbank Wealth Investor Day May 2013 Nedbank Wealth
Slide 2: Make things happen
MAKE THINGS HAPPEN NEDBANK Nedbank Wealth
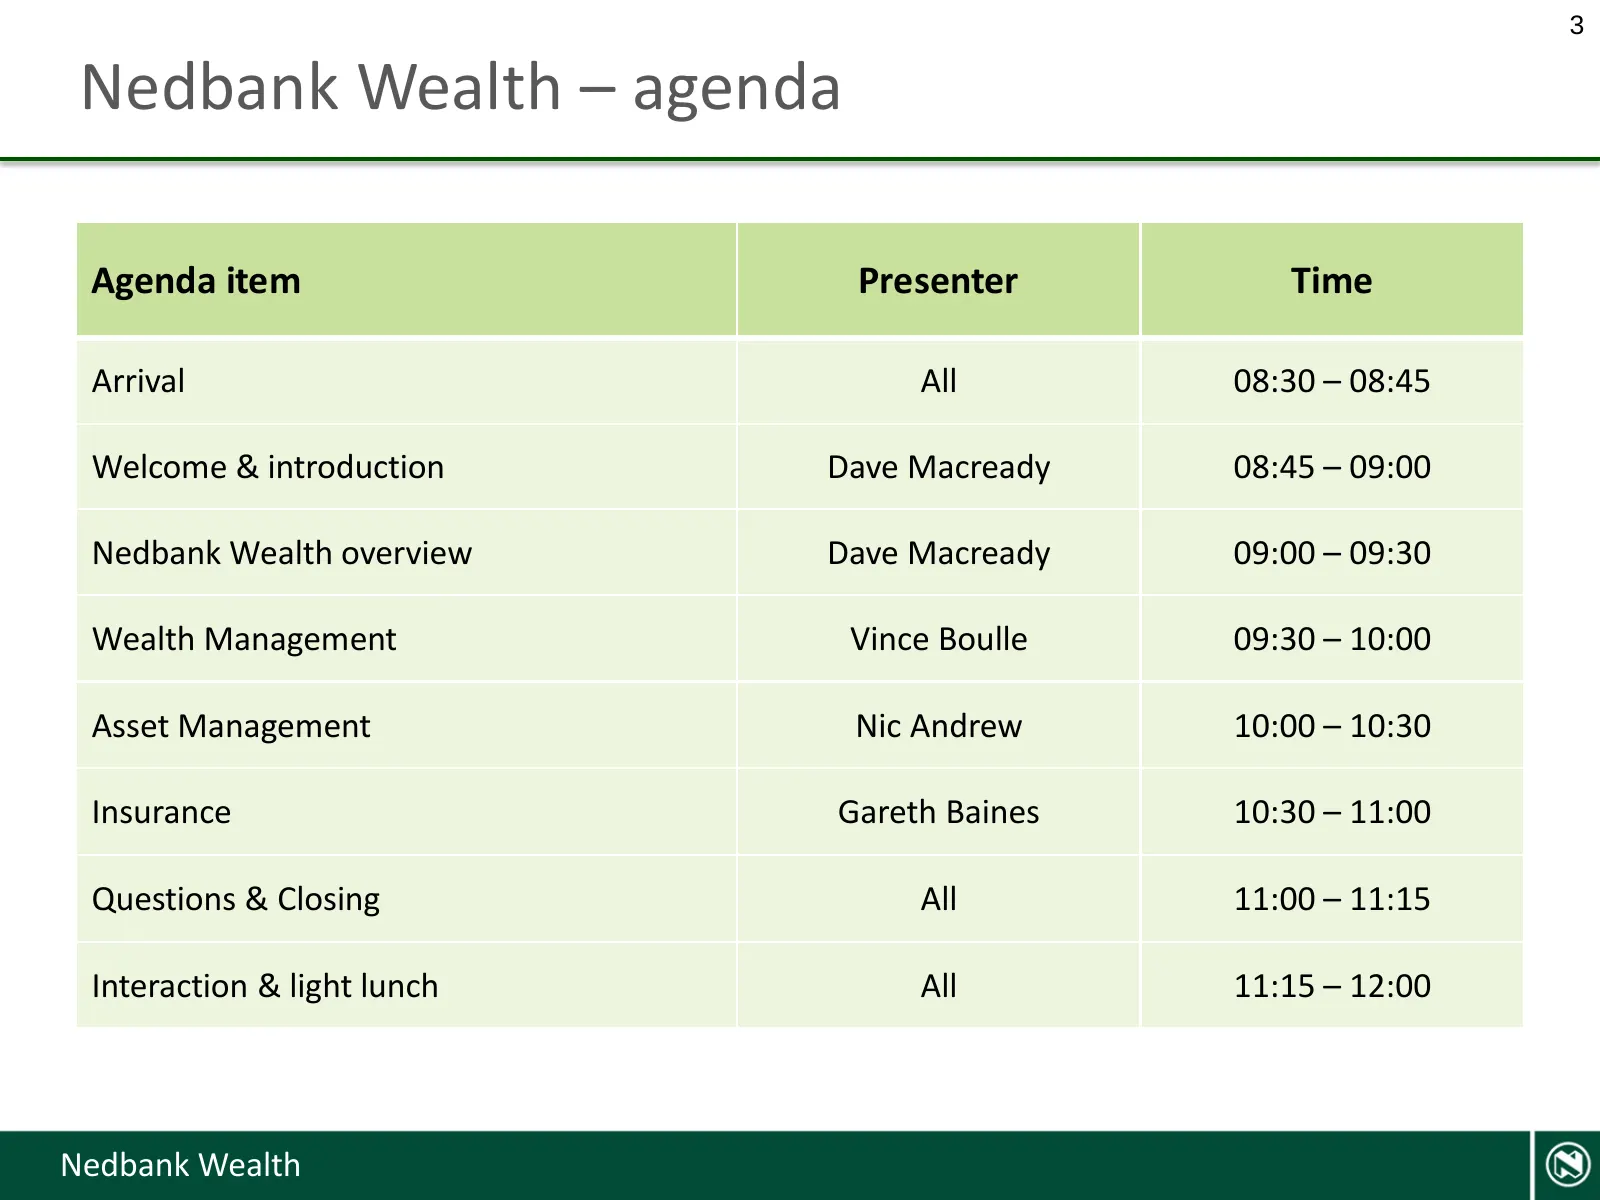
Slide 3: Nedbank Wealth – agenda
3 Nedbank Wealth – agenda Agenda item Presenter Time Arrival All 08:30 – 08:45 Welcome & introduction Dave Macready 08:45 – 09:00 Nedbank Wealth overview Dave Macready 09:00 – 09:30 Wealth Management Vince Boulle 09:30 – 10:00 Asset Management Nic Andrew 10:00 – 10:30 Insurance Gareth Baines 10:30 –
Slide 4: Nedbank Wealth overview
4 Nedbank Wealth overview Nedbank Wealth
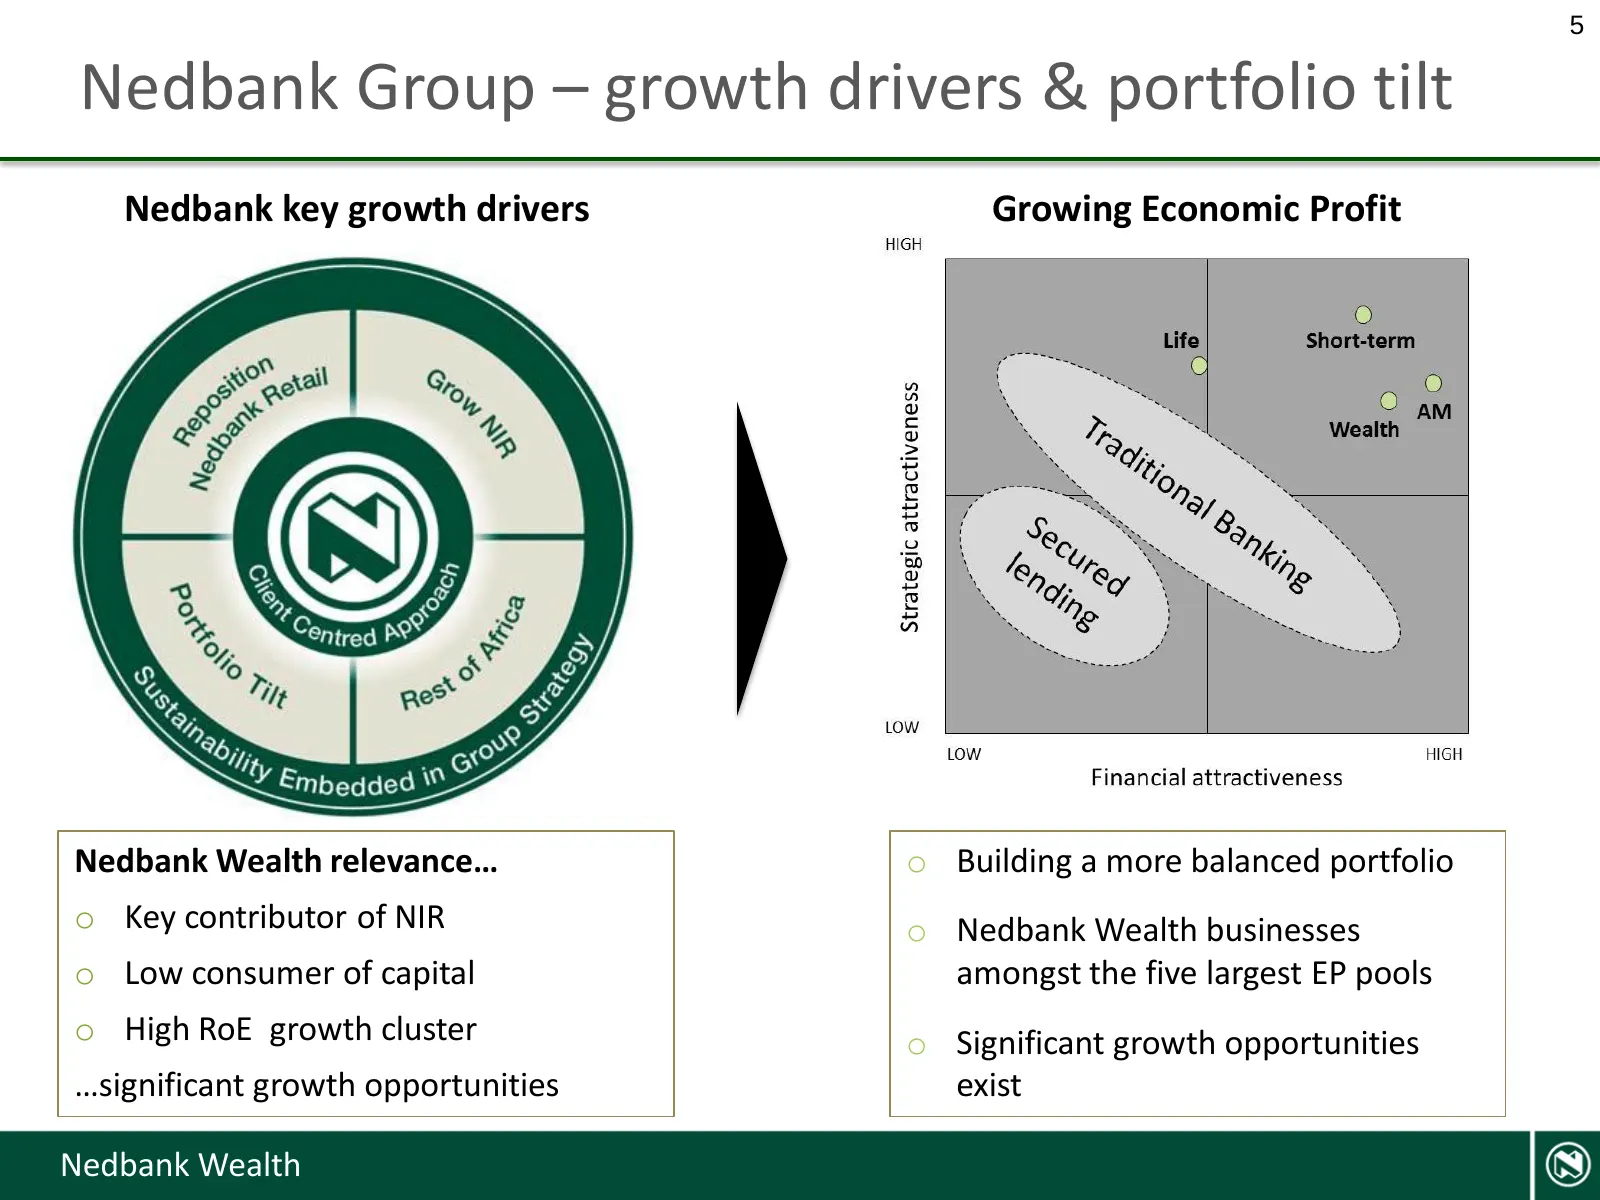
Slide 5: Nedbank Group – growth drivers & portfolio tilt
5 Nedbank Group – growth drivers & portfolio tilt Nedbank key growth drivers Growing Economic Profit Nedbank Wealth relevance… o Building a more balanced portfolio o Key contributor of NIR o Nedbank Wealth businesses o Low consumer of capital amongst the five largest EP pools o High RoE growth clust
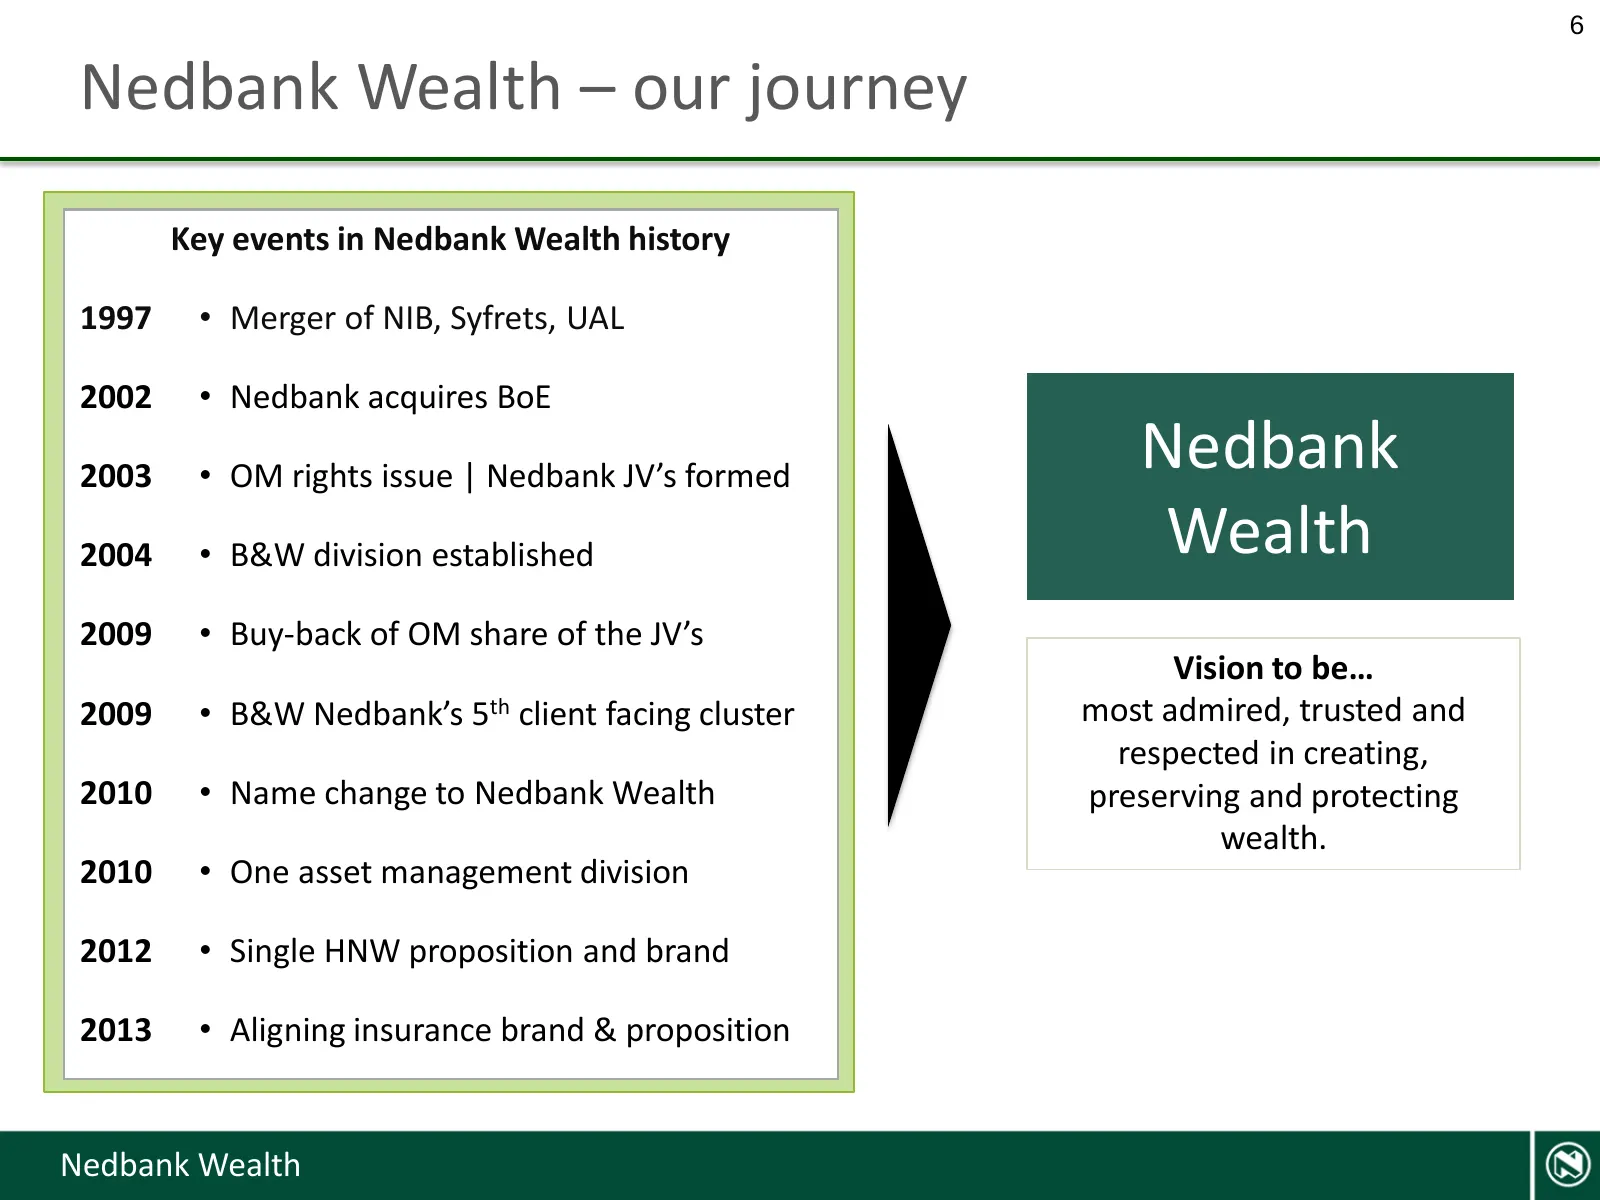
Slide 6: Nedbank Wealth – our journey
6 Nedbank Wealth – our journey Key events in Nedbank Wealth history 1997 • Merger of NIB, Syfrets, UAL 2002 • Nedbank acquires BoE 2003 • OM rights issue | Nedbank JV’s formed Nedbank 2004 • B&W division established Wealth 2009 • Buy-back of OM share of the JV’s Vision to be… 2009 • B&W Nedbank’s 5t
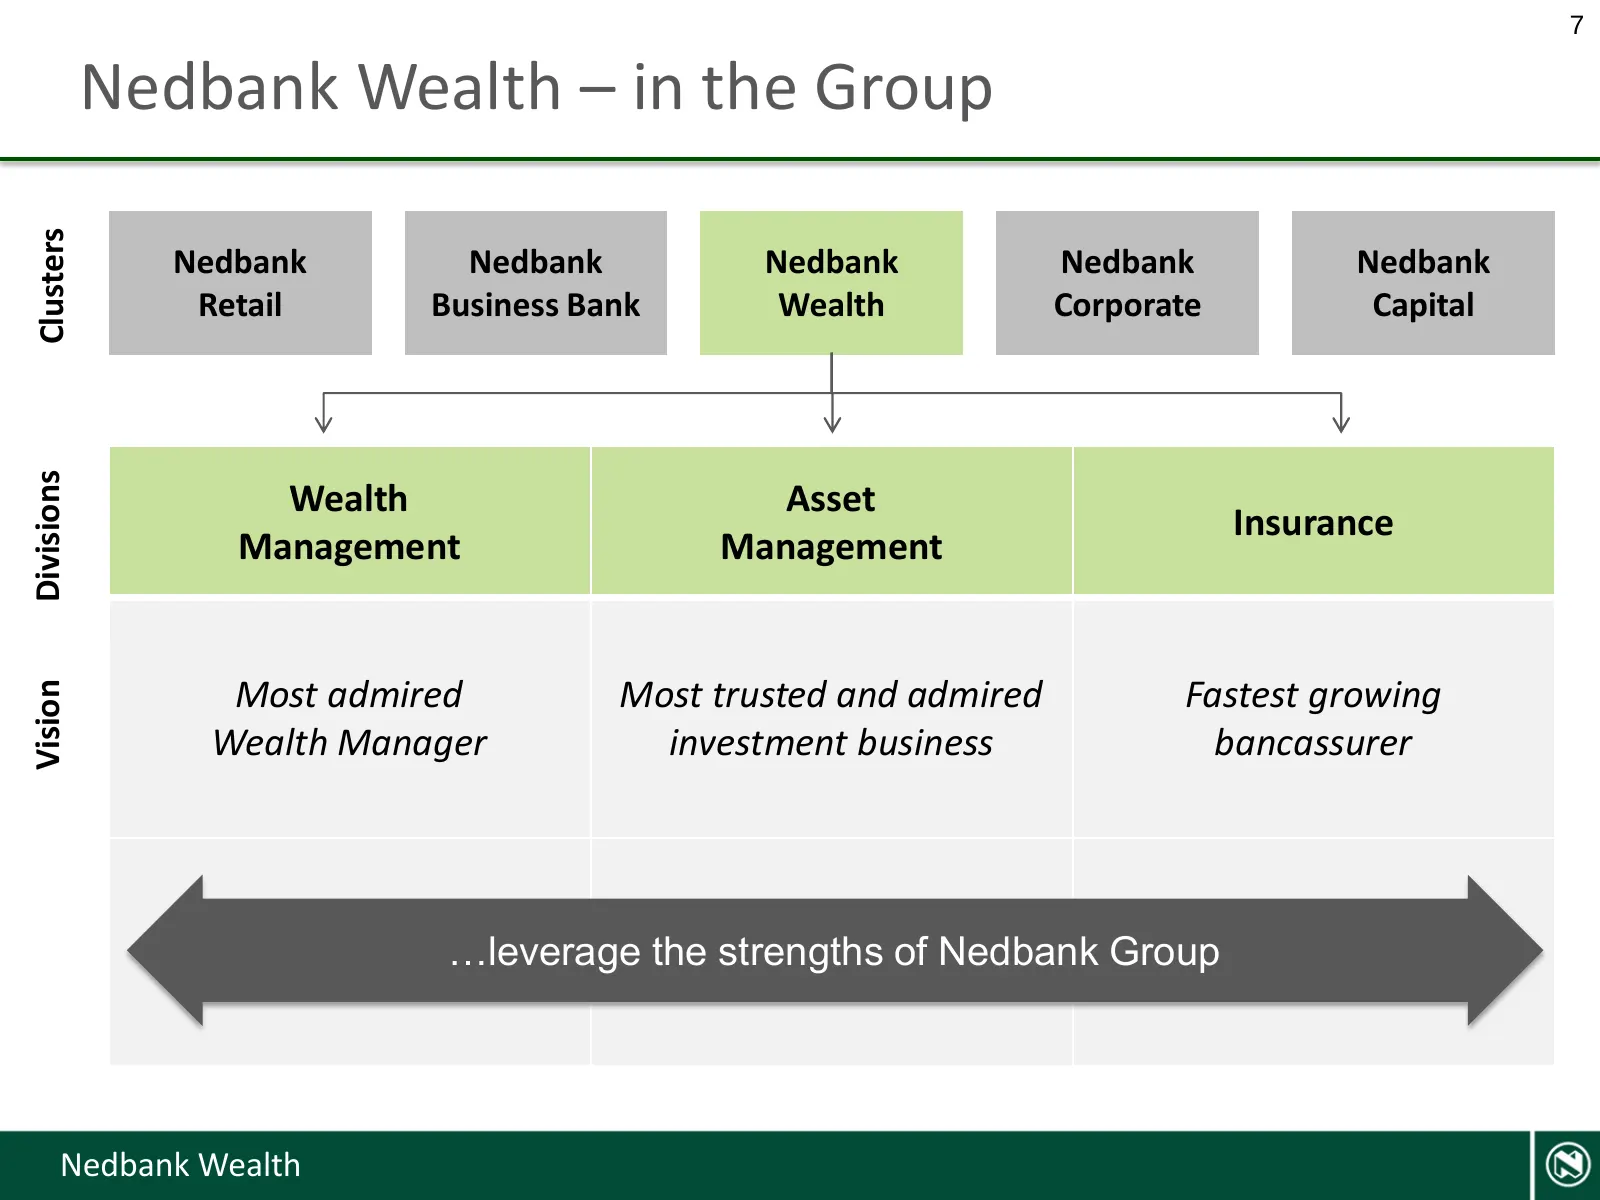
Slide 7: Nedbank Wealth – in the Group
7 Nedbank Wealth – in the Group Clusters Nedbank Nedbank Nedbank Nedbank Nedbank Retail Business Bank Wealth Corporate Capital Divisions Wealth Asset Insurance Management Management Most admired Most trusted and admired Fastest growing Vision Wealth Manager investment business bancassurer …leverage
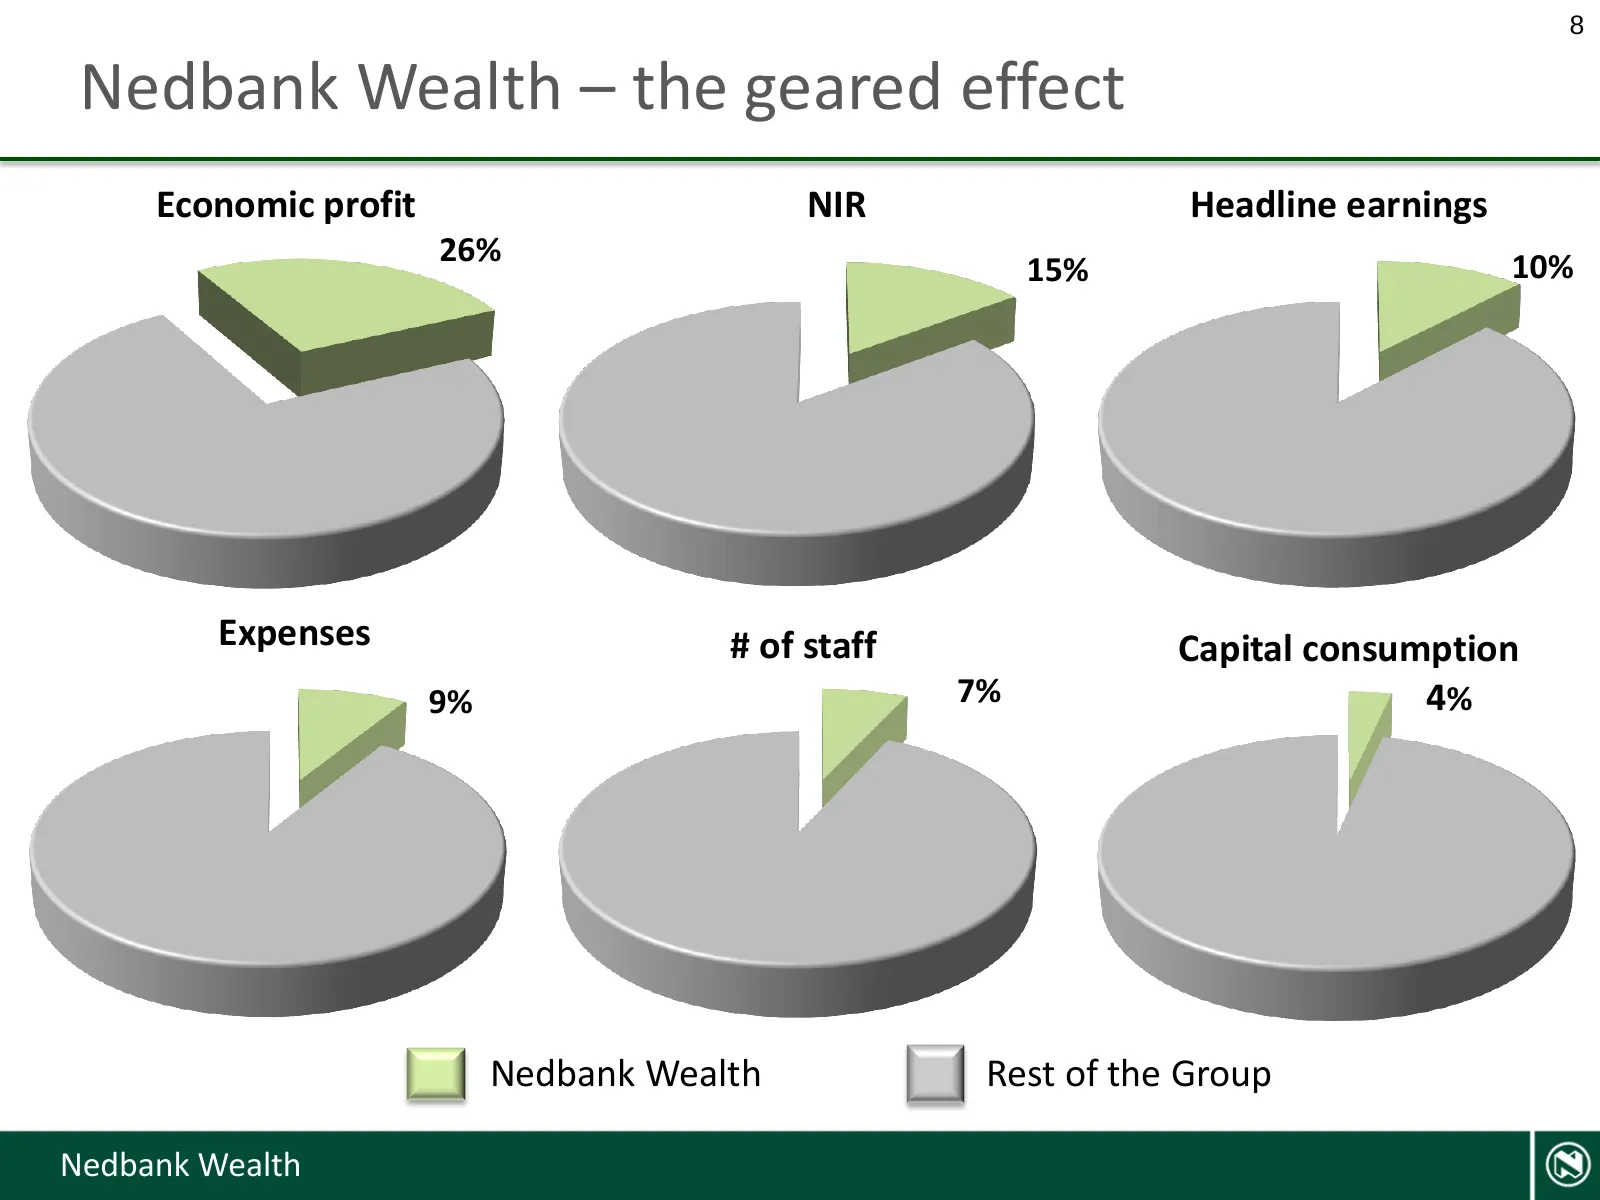
Slide 8: Nedbank Wealth – the geared effect
8 Nedbank Wealth – the geared effect Economic profit NIR Headline earnings 26% 10% 15% Expenses # of staff Capital consumption 9% 7% 4% Nedbank Wealth Rest of the Group Nedbank Wealth
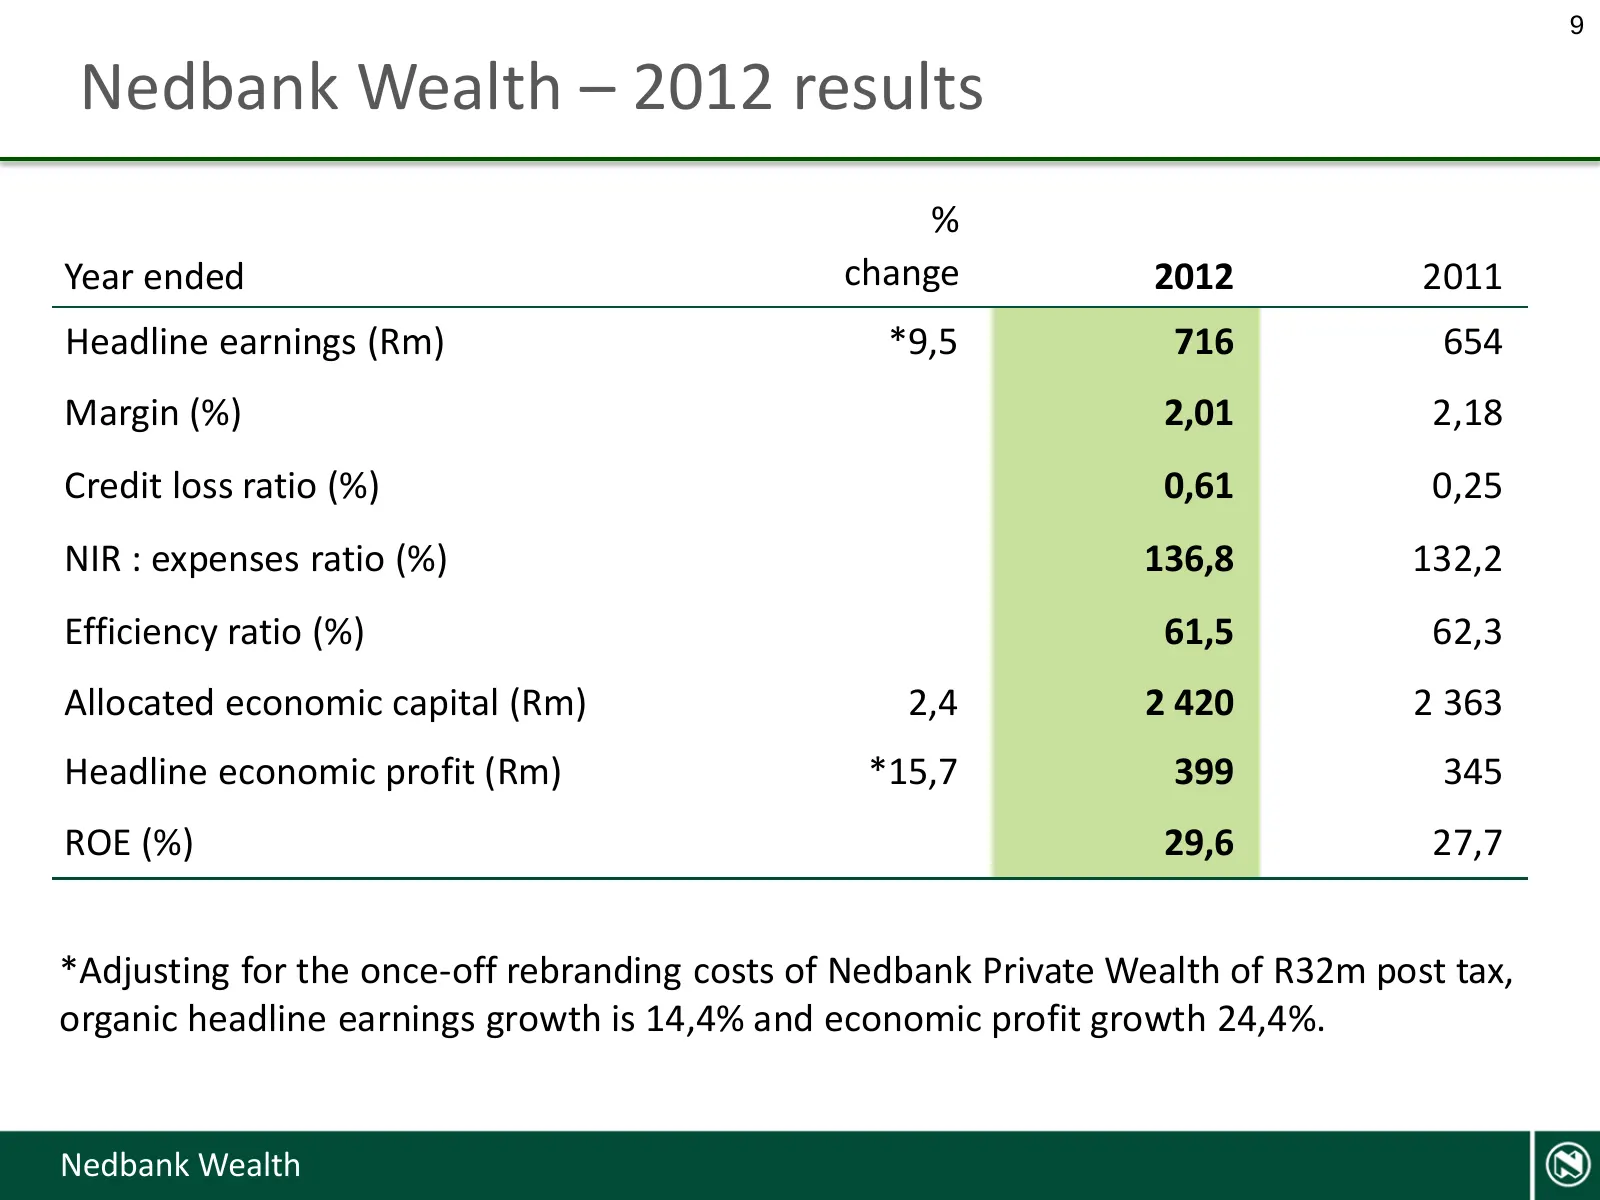
Slide 9: Nedbank Wealth – 2012 results
9 Nedbank Wealth – 2012 results % Year ended change 2012 2011 Headline earnings (Rm) *9,5 716 654 Margin (%) 2,01 2,18 Credit loss ratio (%) 0,61 0,25 NIR : expenses ratio (%) 136,8 132,2 Efficiency ratio (%) 61,5 62,3 Allocated economic capital (Rm) 2,4 2 420 2 363 Headline economic profit (Rm) *15
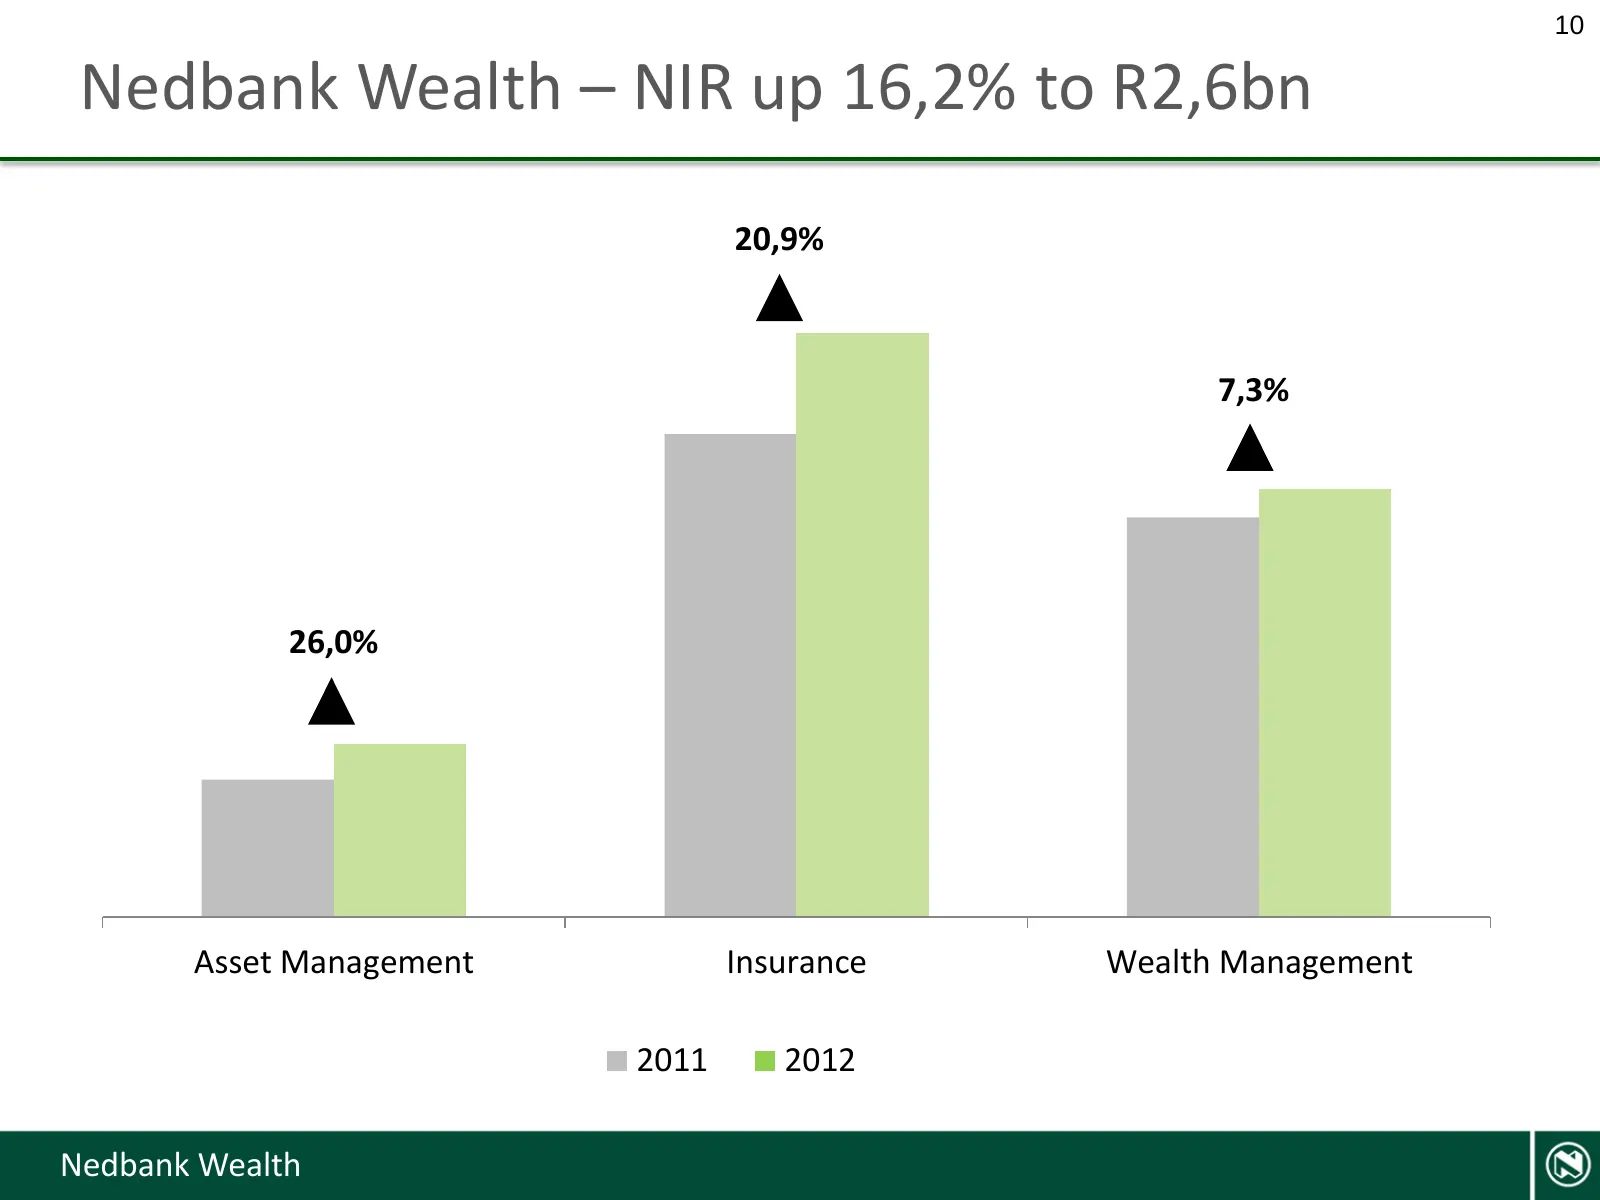
Slide 10: Nedbank Wealth – NIR up 16,2% to R2,6bn
10 Nedbank Wealth – NIR up 16,2% to R2,6bn 20,9% 7,3% 26,0% Asset Management Insurance Wealth Management 2011 2012 Nedbank Wealth
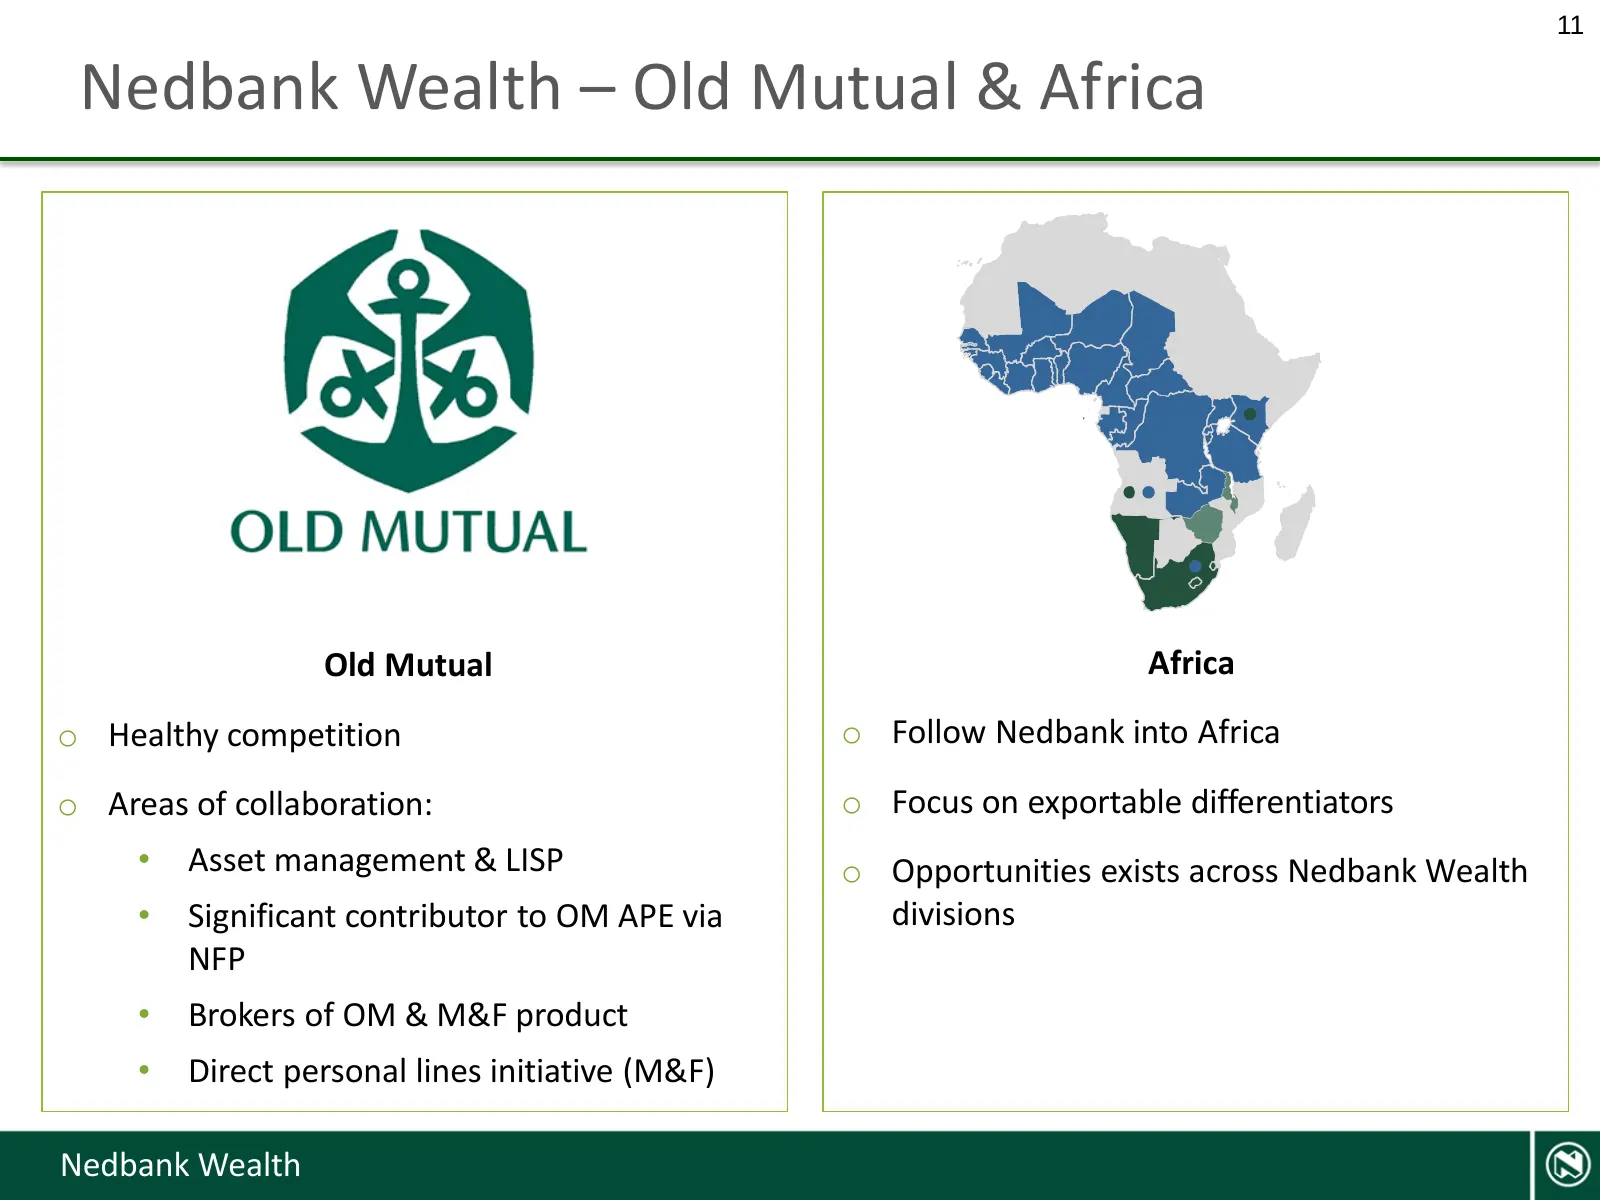
Slide 11: Nedbank Wealth – Old Mutual & Africa
11 Nedbank Wealth – Old Mutual & Africa Old Mutual Africa o Healthy competition o Follow Nedbank into Africa o Areas of collaboration: o Focus on exportable differentiators • Asset management & LISP o Opportunities exists across Nedbank Wealth • Significant contributor to OM APE via divisions NFP •
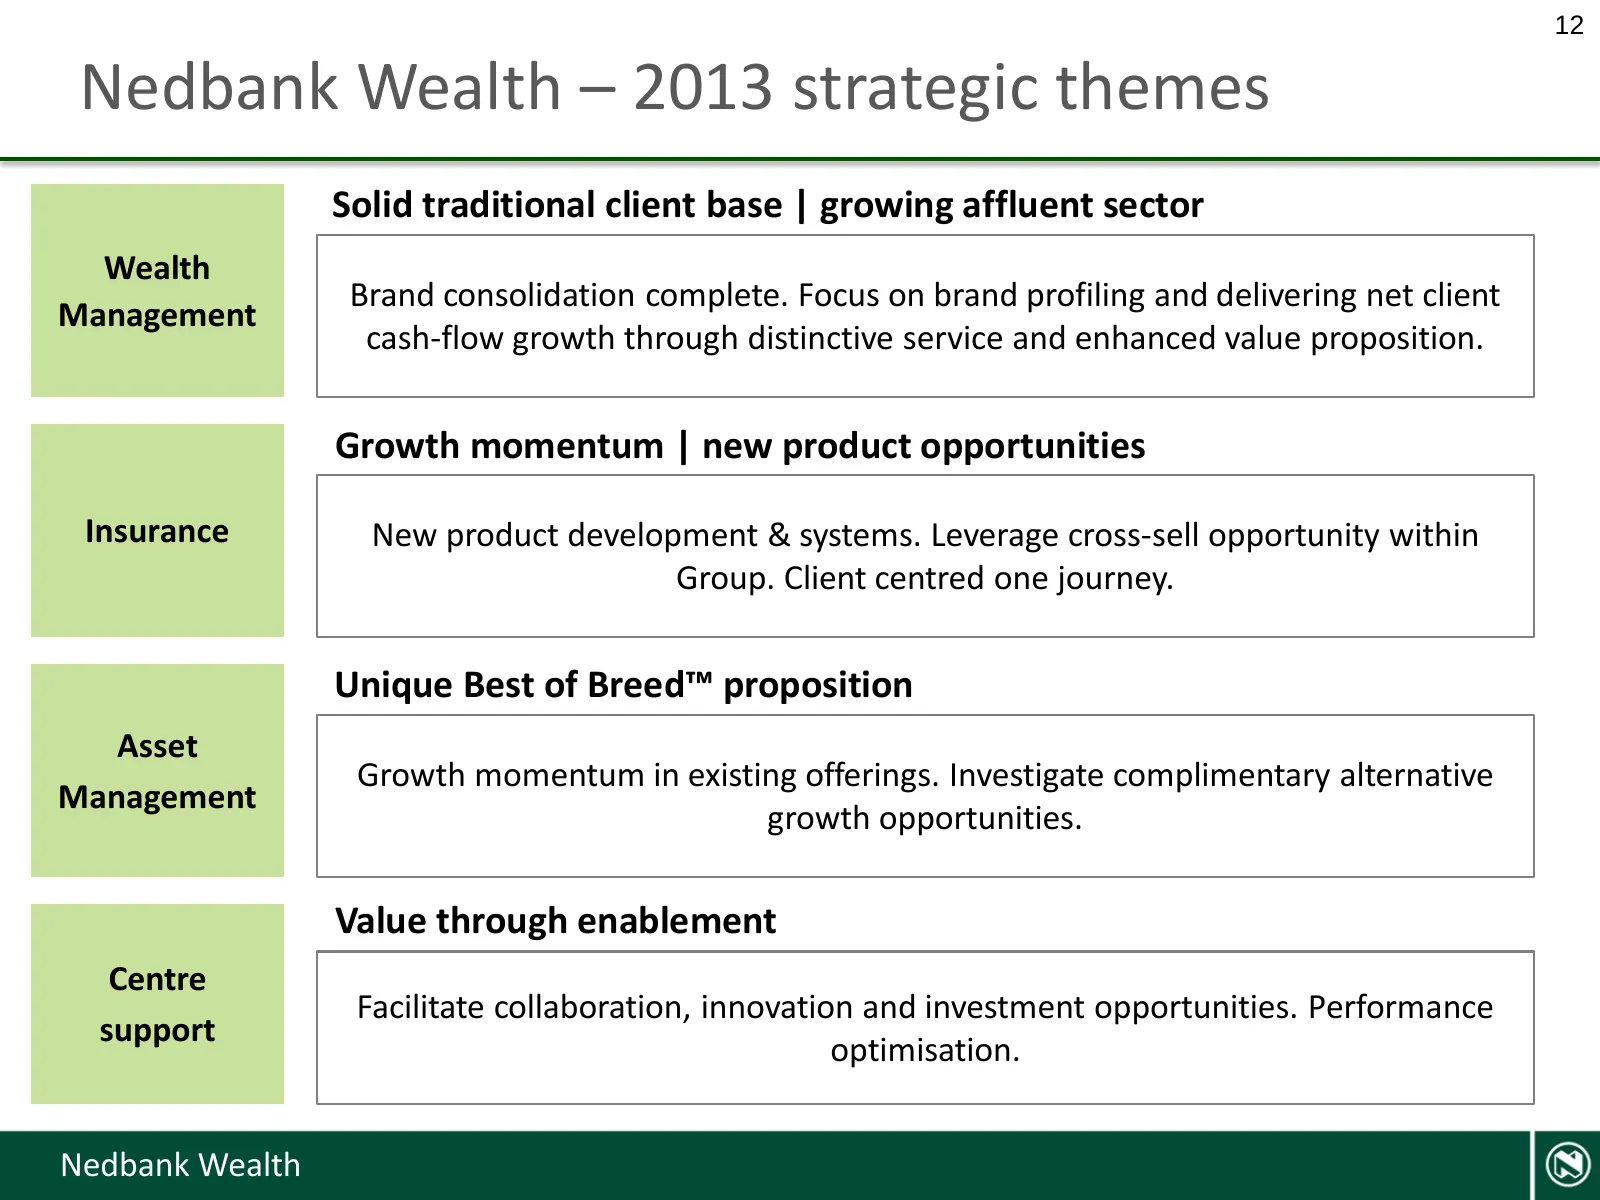
Slide 12: Nedbank Wealth – 2013 strategic themes
12 Nedbank Wealth – 2013 strategic themes Solid traditional client base | growing affluent sector Wealth Brand consolidation complete. Focus on brand profiling and delivering net client Management cash-flow growth through distinctive service and enhanced value proposition. Growth momentum | new prod
Slide 13: Wealth Management
13 Wealth Management Nedbank Wealth
Slide 14: Wealth Management – divisional structure
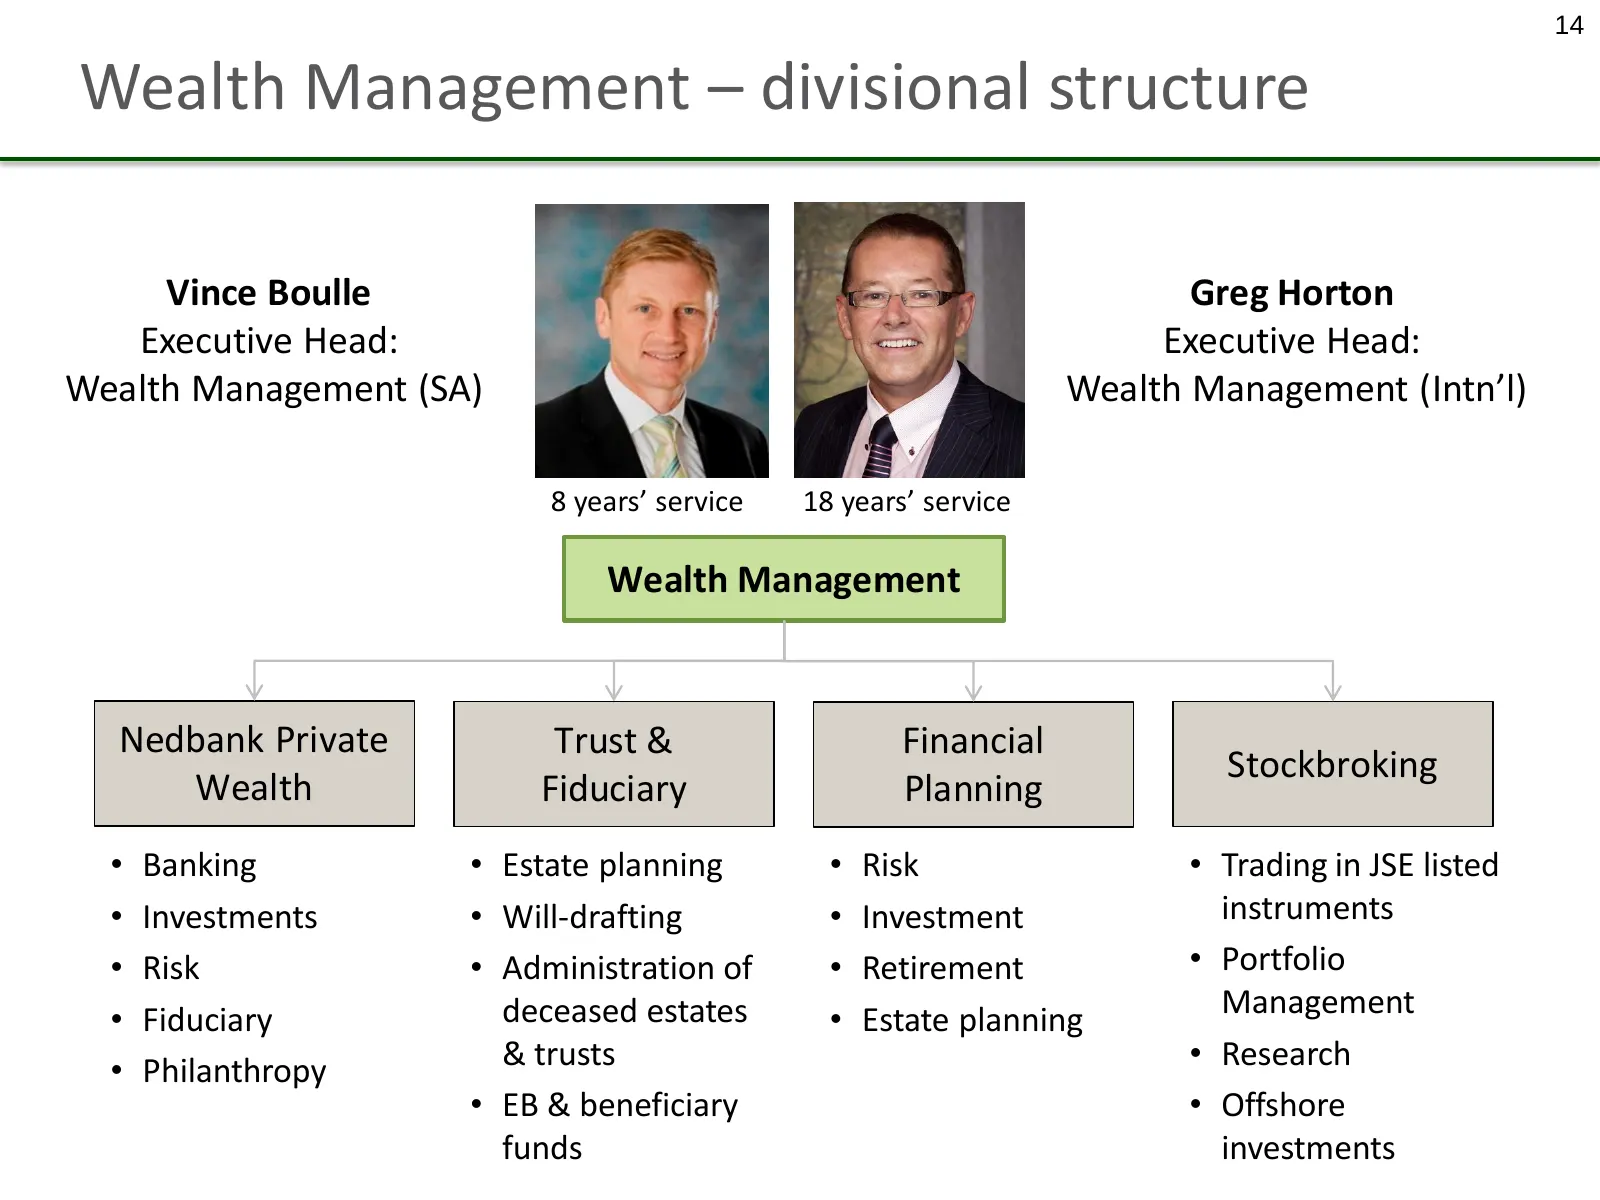
14 Wealth Management – divisional structure Vince Boulle Greg Horton Executive Head: Executive Head: Wealth Management (SA) Wealth Management (Intn’l) 8 years’ service 18 years’ service Wealth Management Nedbank Private Trust & Financial Stockbroking Wealth Fiduciary Planning • Banking • Estate plan
Slide 15: Wealth Management – market positioning
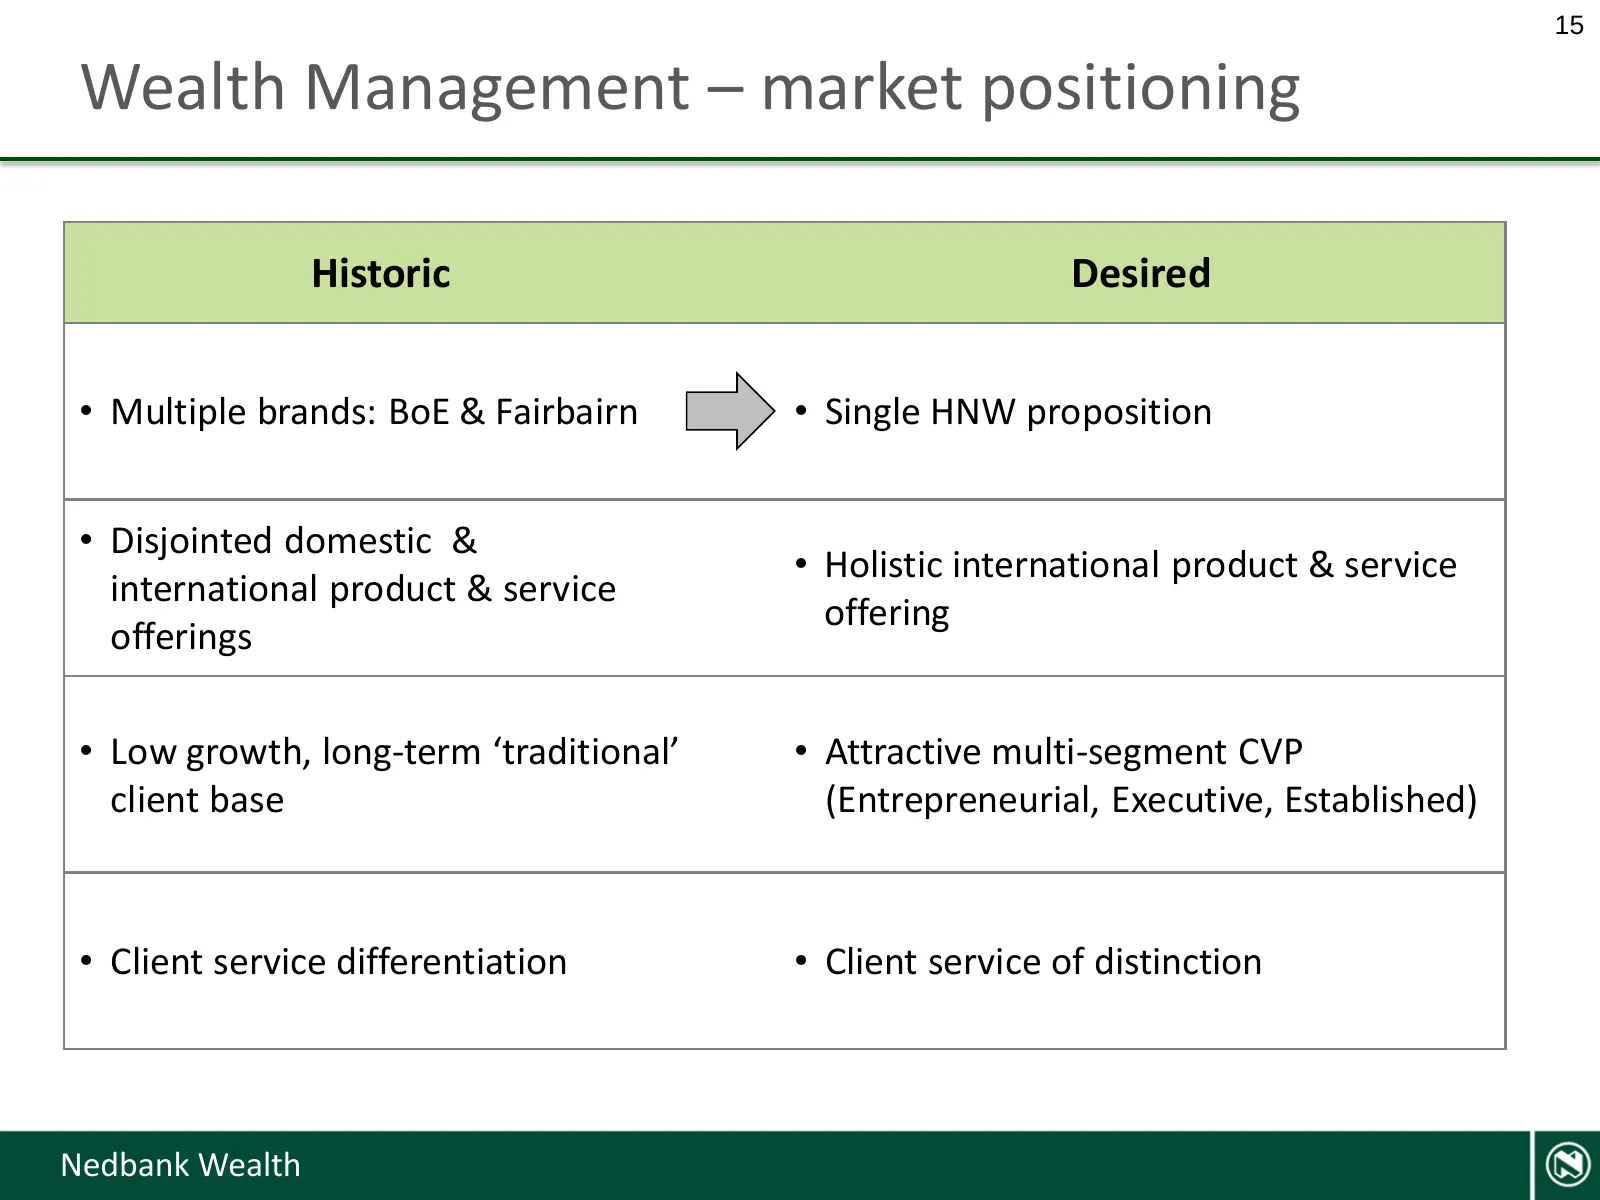
15 Wealth Management – market positioning Historic Desired • Multiple brands: BoE & Fairbairn • Single HNW proposition • Disjointed domestic & • Holistic international product & service international product & service offering offerings • Low growth, long-term ‘traditional’ • Attractive multi-segmen
Slide 16: Wealth Management – developments since 2009
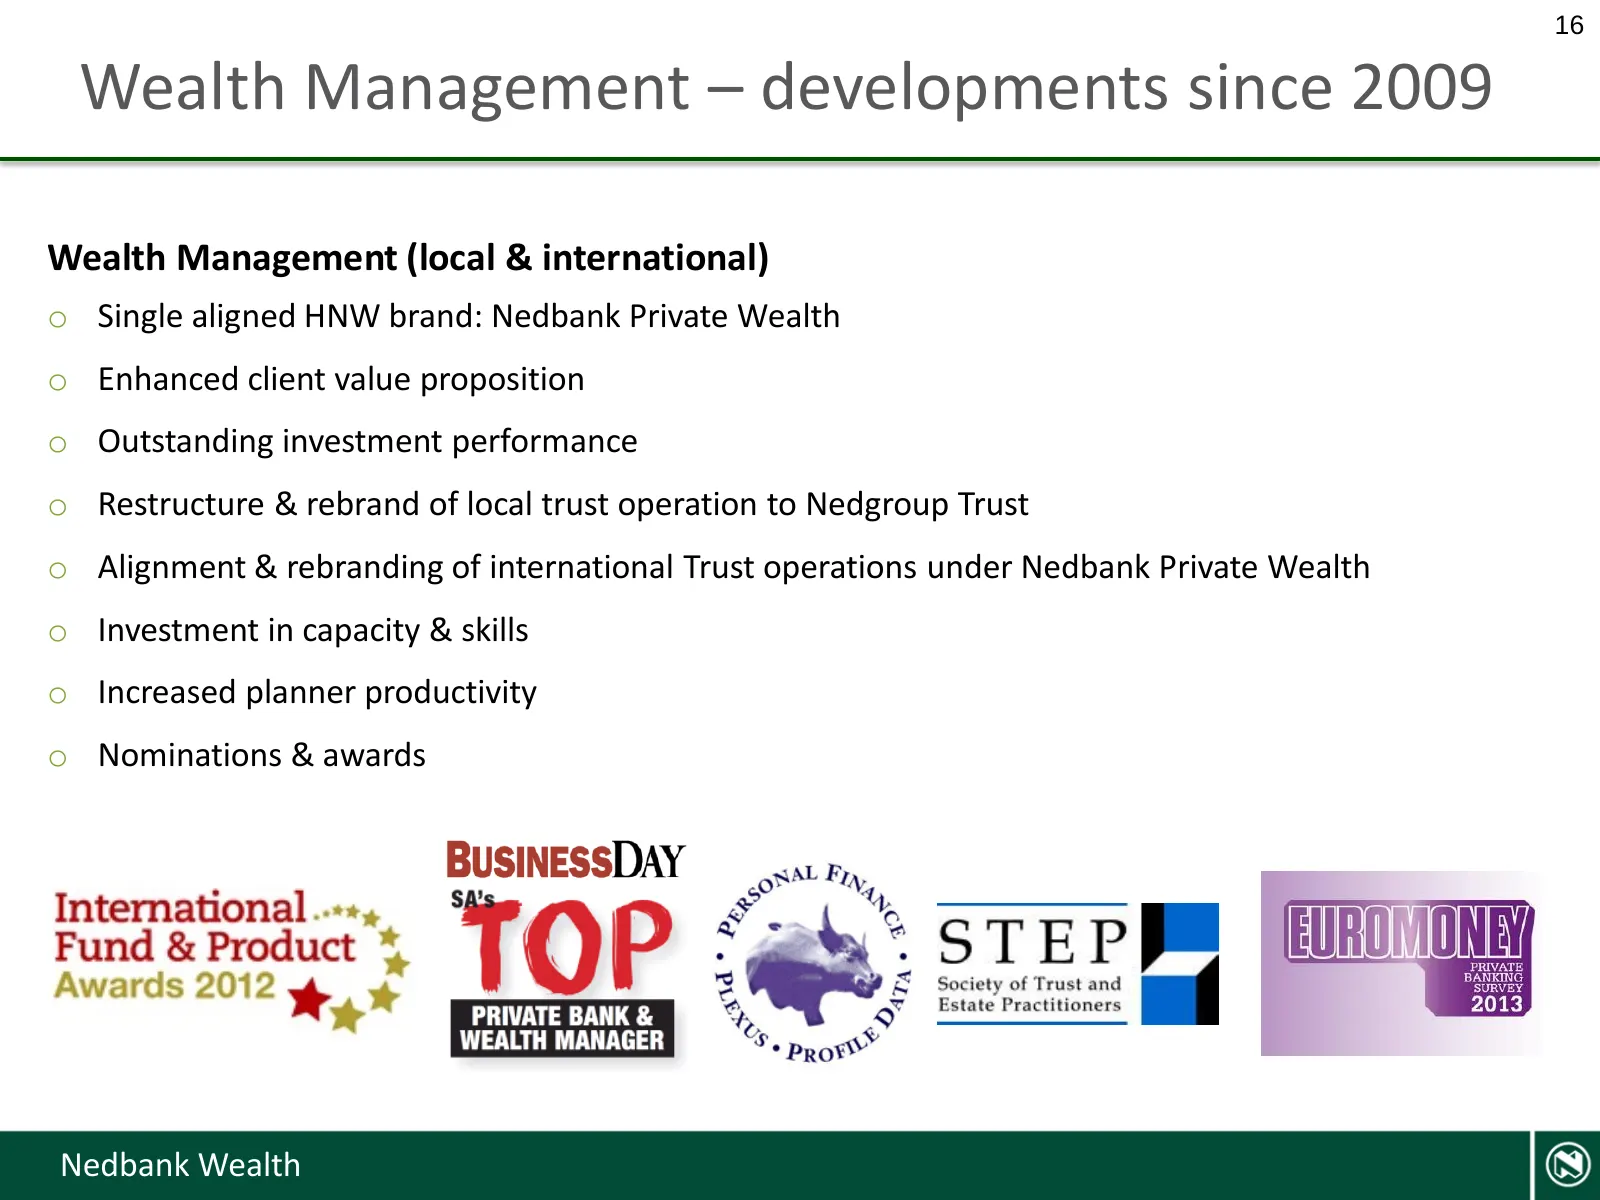
16 Wealth Management – developments since 2009 Wealth Management (local & international) o Single aligned HNW brand: Nedbank Private Wealth o Enhanced client value proposition o Outstanding investment performance o Restructure & rebrand of local trust operation to Nedgroup Trust o Alignment & rebran
Slide 17: Wealth Management – Nedbank Private Wealth
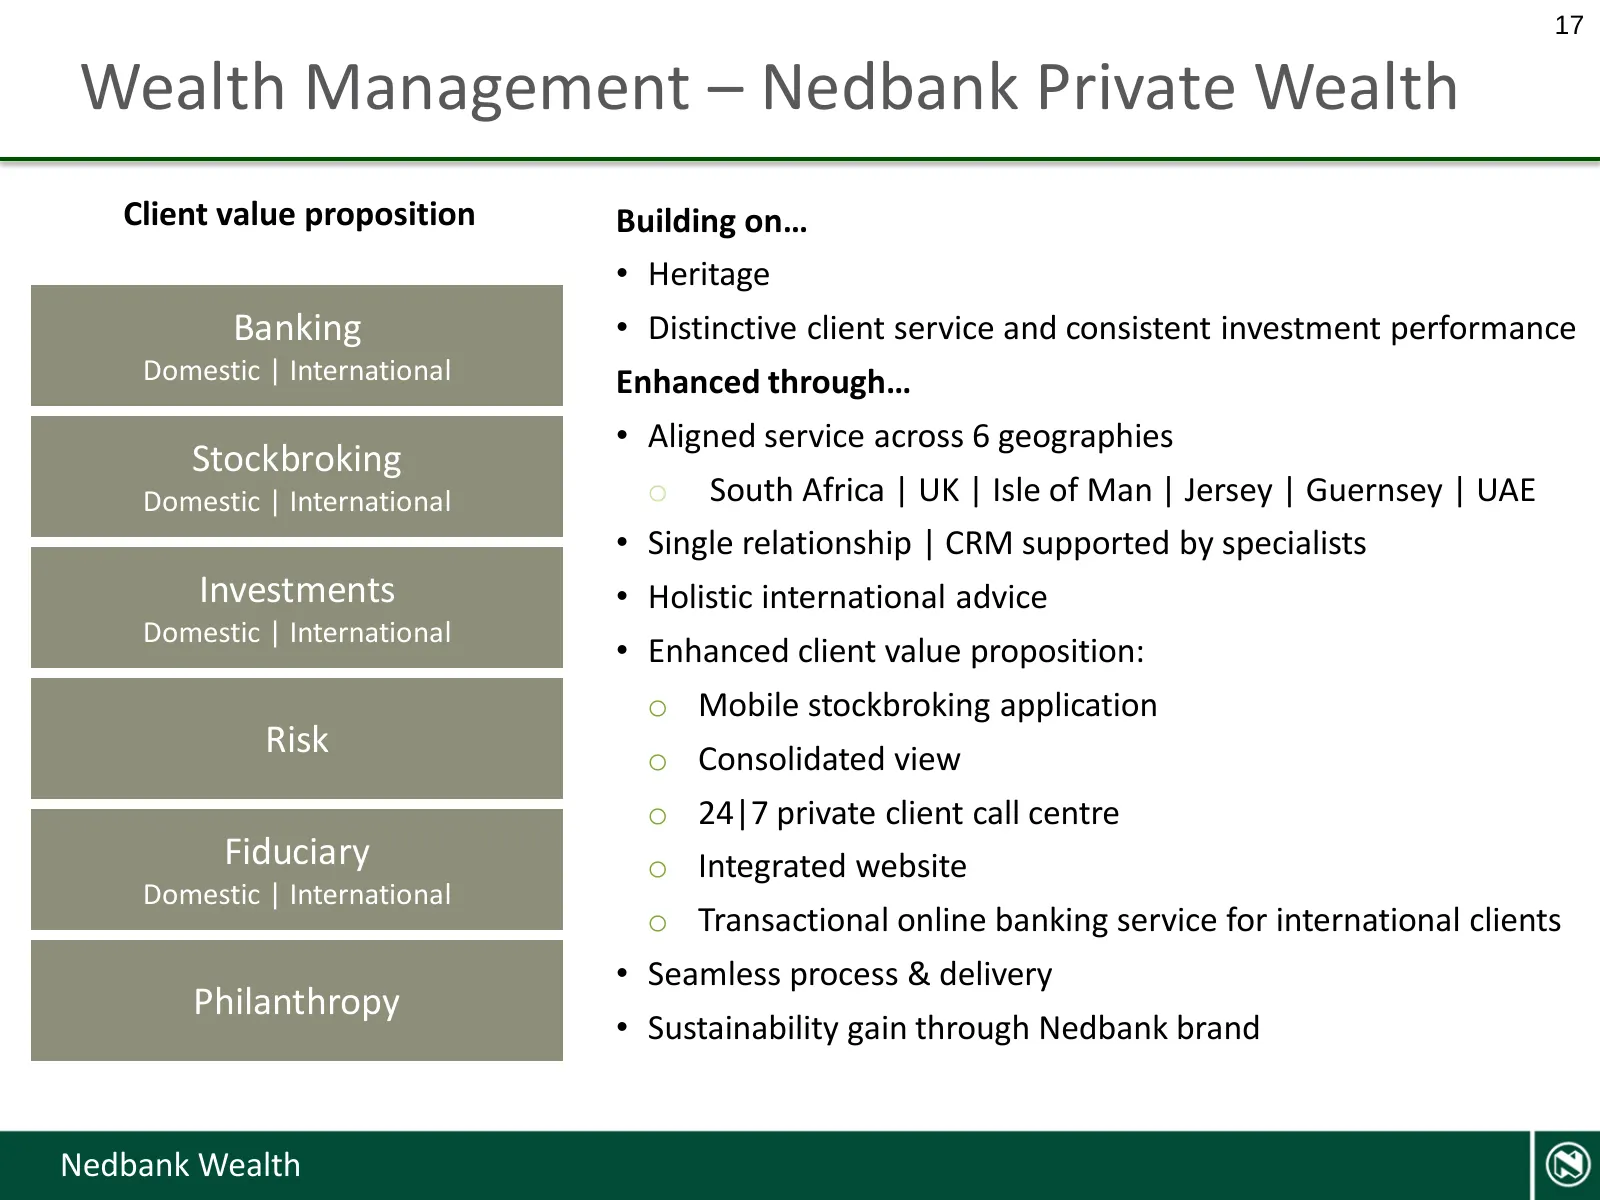
17 Wealth Management – Nedbank Private Wealth Client value proposition Building on… • Heritage Banking • Distinctive client service and consistent investment performance Domestic | International Enhanced through… • Aligned service across 6 geographies Stockbroking Domestic | International o South Af
Slide 18: Wealth Management – fund performance
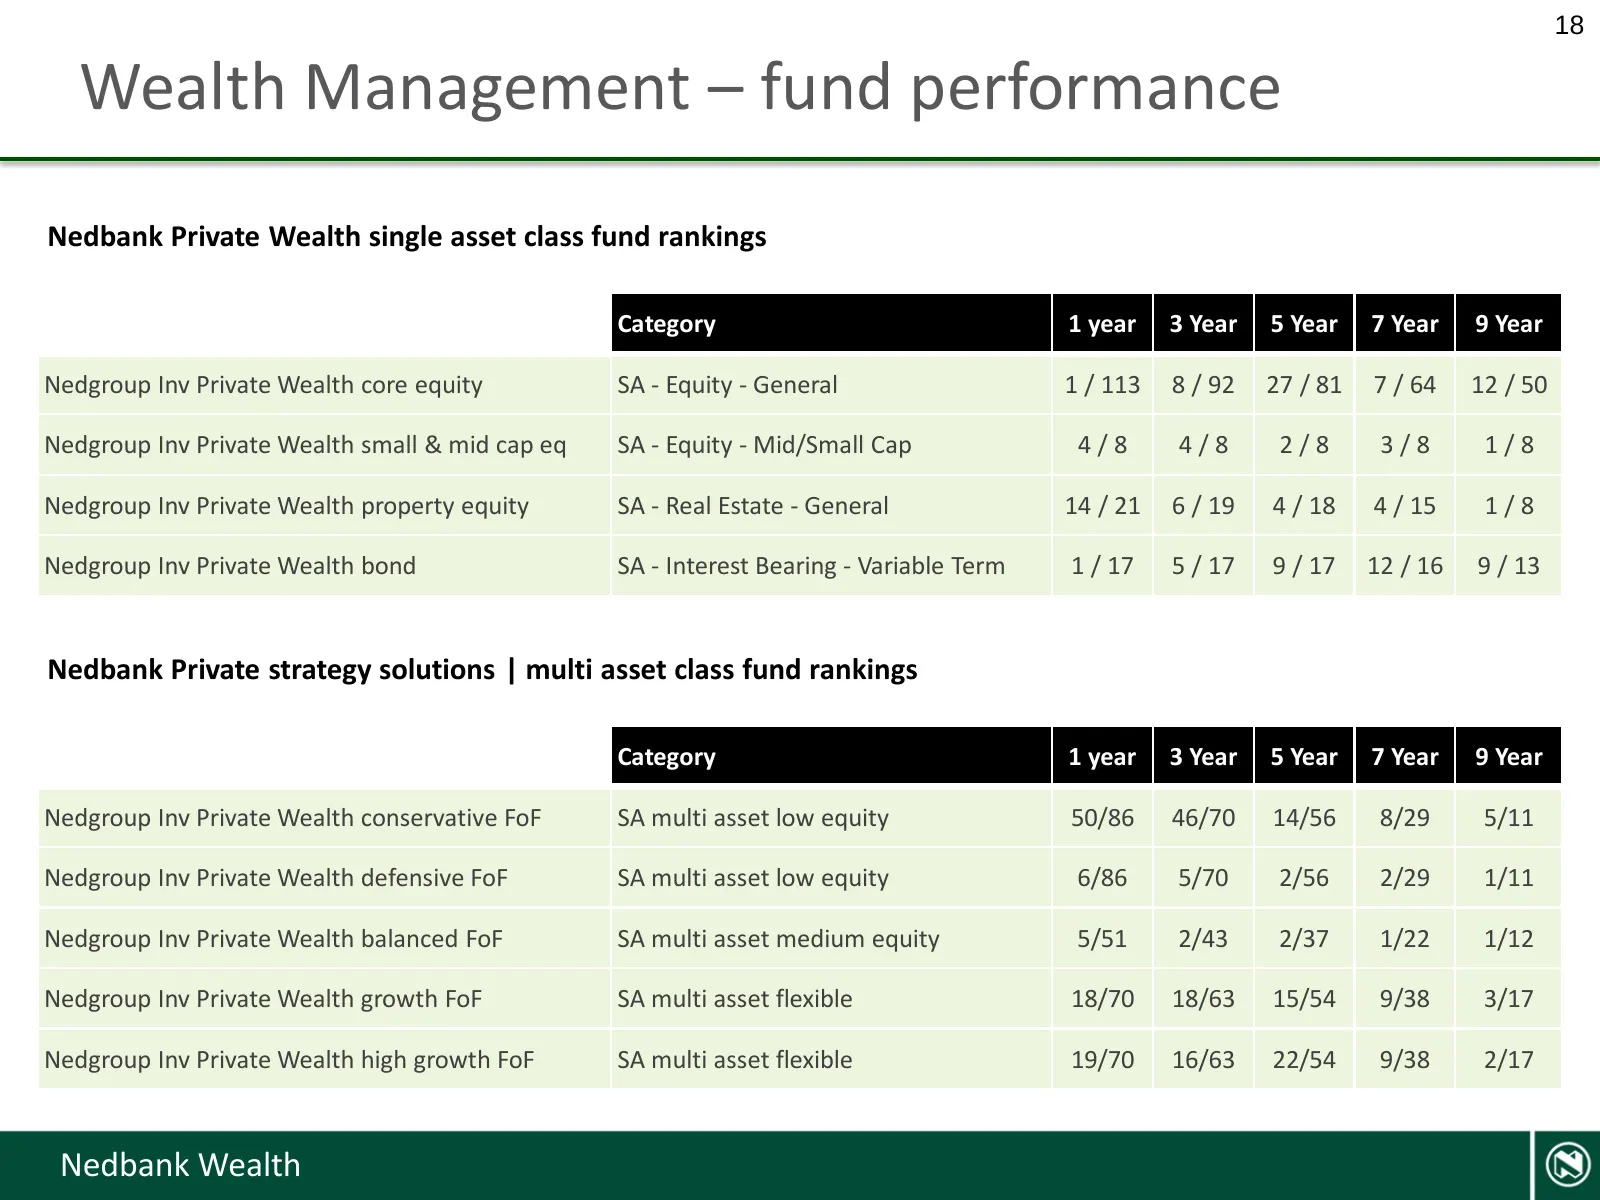
18 Wealth Management – fund performance Nedbank Private Wealth single asset class fund rankings Category 1 year 3 Year 5 Year 7 Year 9 Year Nedgroup Inv Private Wealth core equity SA - Equity - General 1 / 113 8 / 92 27 / 81 7 / 64 12 / 50 Nedgroup Inv Private Wealth small & mid cap eq SA - Equity -
Slide 19: Wealth Management – financial planning
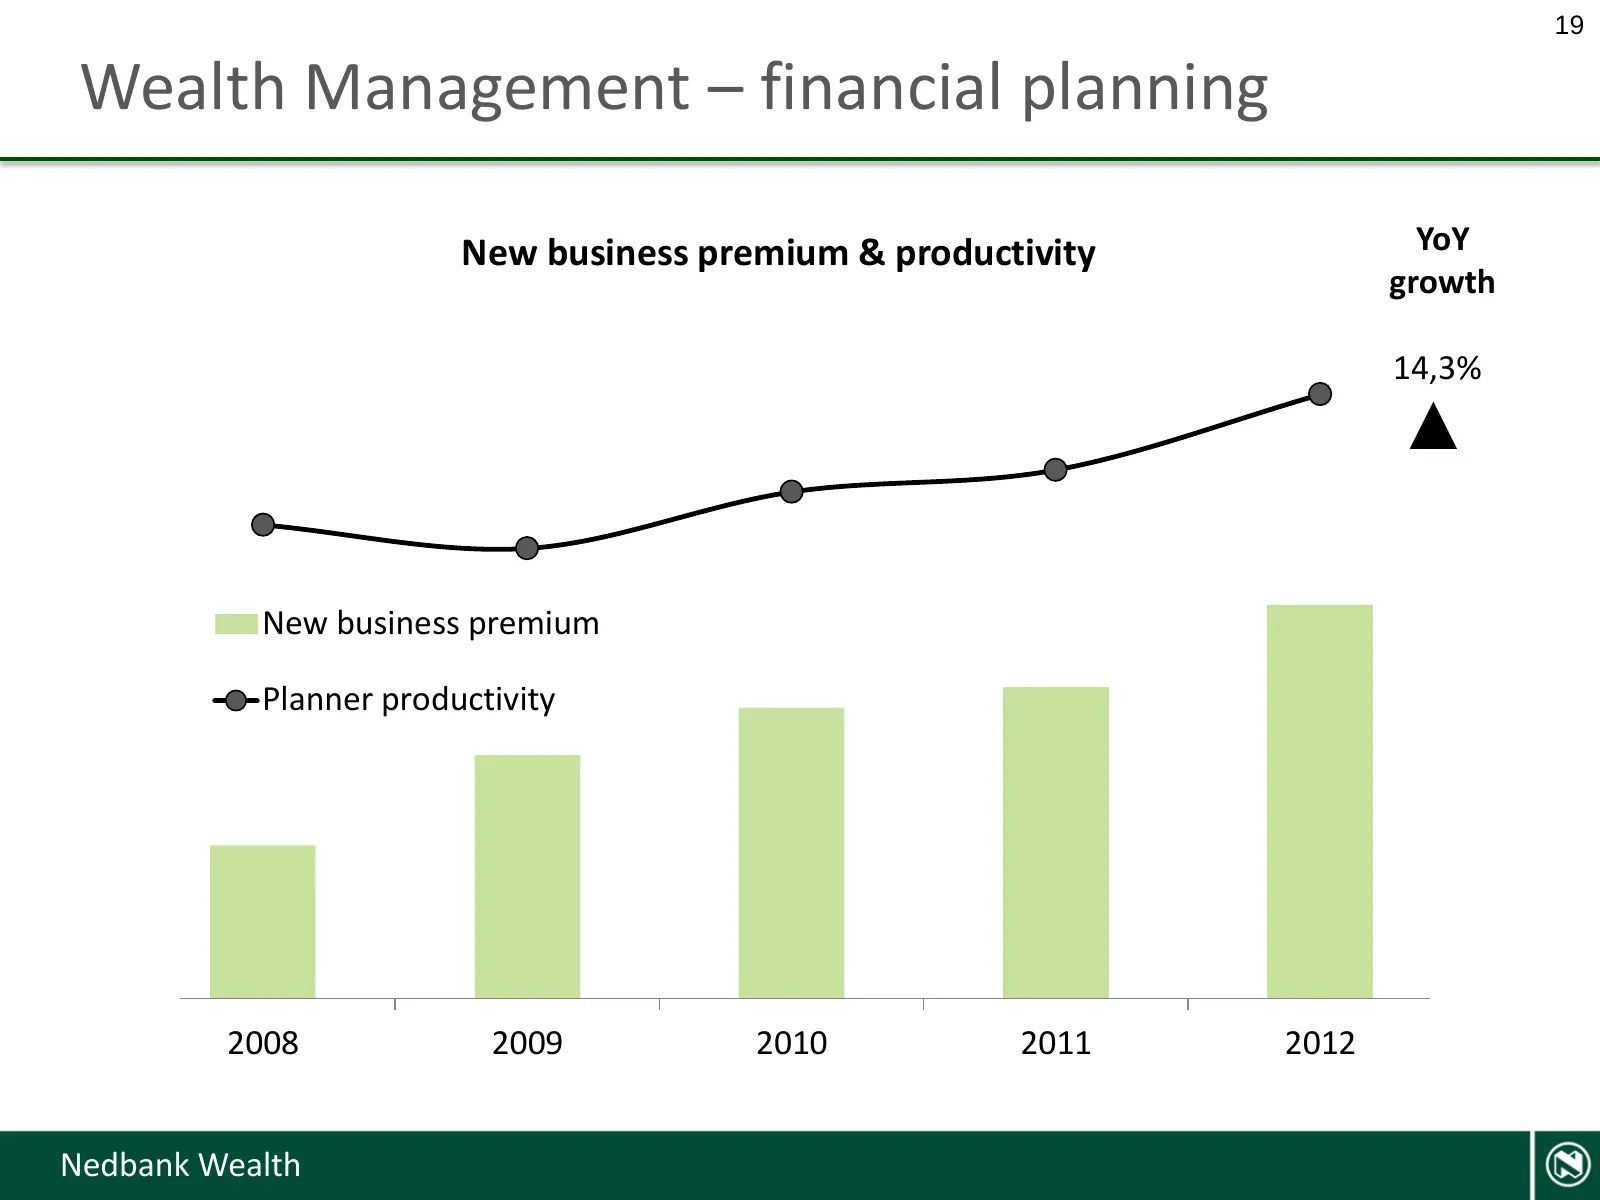
19 Wealth Management – financial planning New business premium & productivity YoY growth 16 70 14,3% 14 60 12 50 10 40 New business premium 8 Planner productivity 30 6 20 4 10 2 - 2008 2009 2010 2011 2012 Nedbank Wealth
Slide 20: Wealth Management – stockbroking
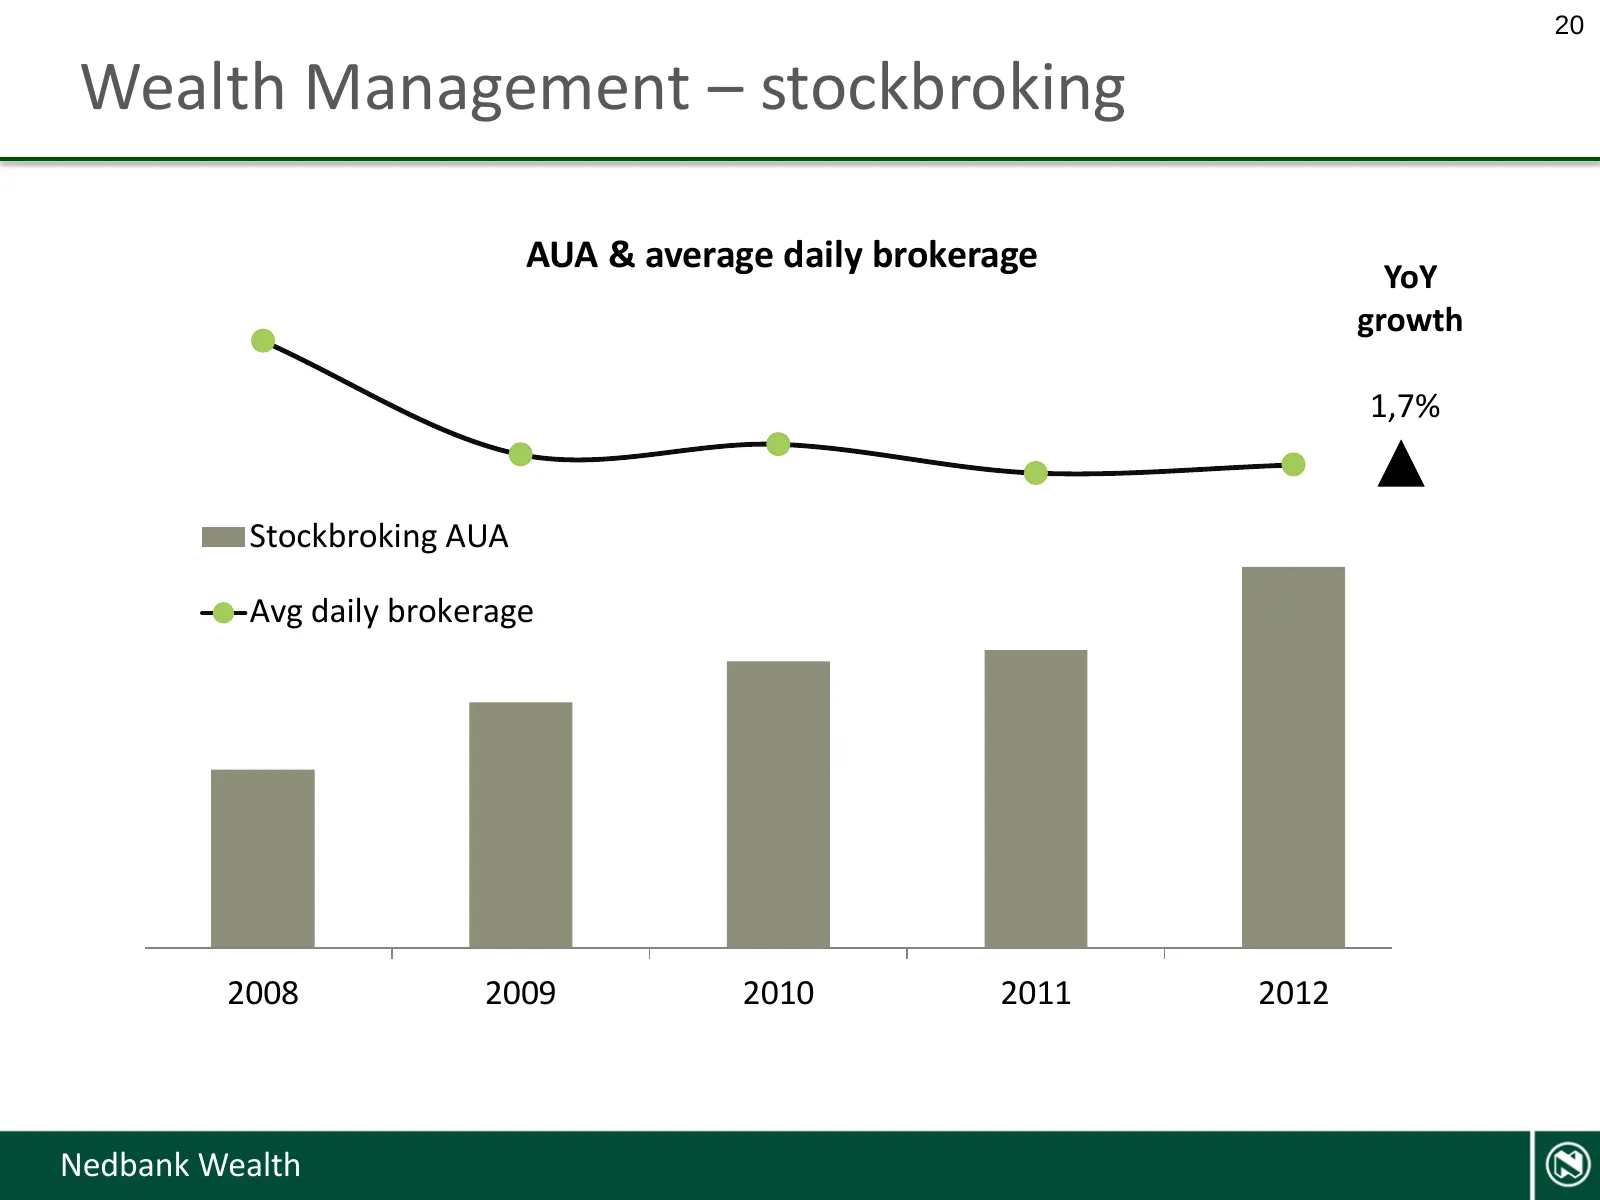
20 Wealth Management – stockbroking AUA & average daily brokerage YoY 100.0 450 growth 90.0 400 1,7% 80.0 350 70.0 300 Stockbroking AUA 60.0 250 Avg daily brokerage 50.0 200 40.0 150 30.0 100 20.0 50 10.0 0 - 2008 2009 2010 2011 2012 Nedbank Wealth
Slide 21: Wealth Management – local fiduciary
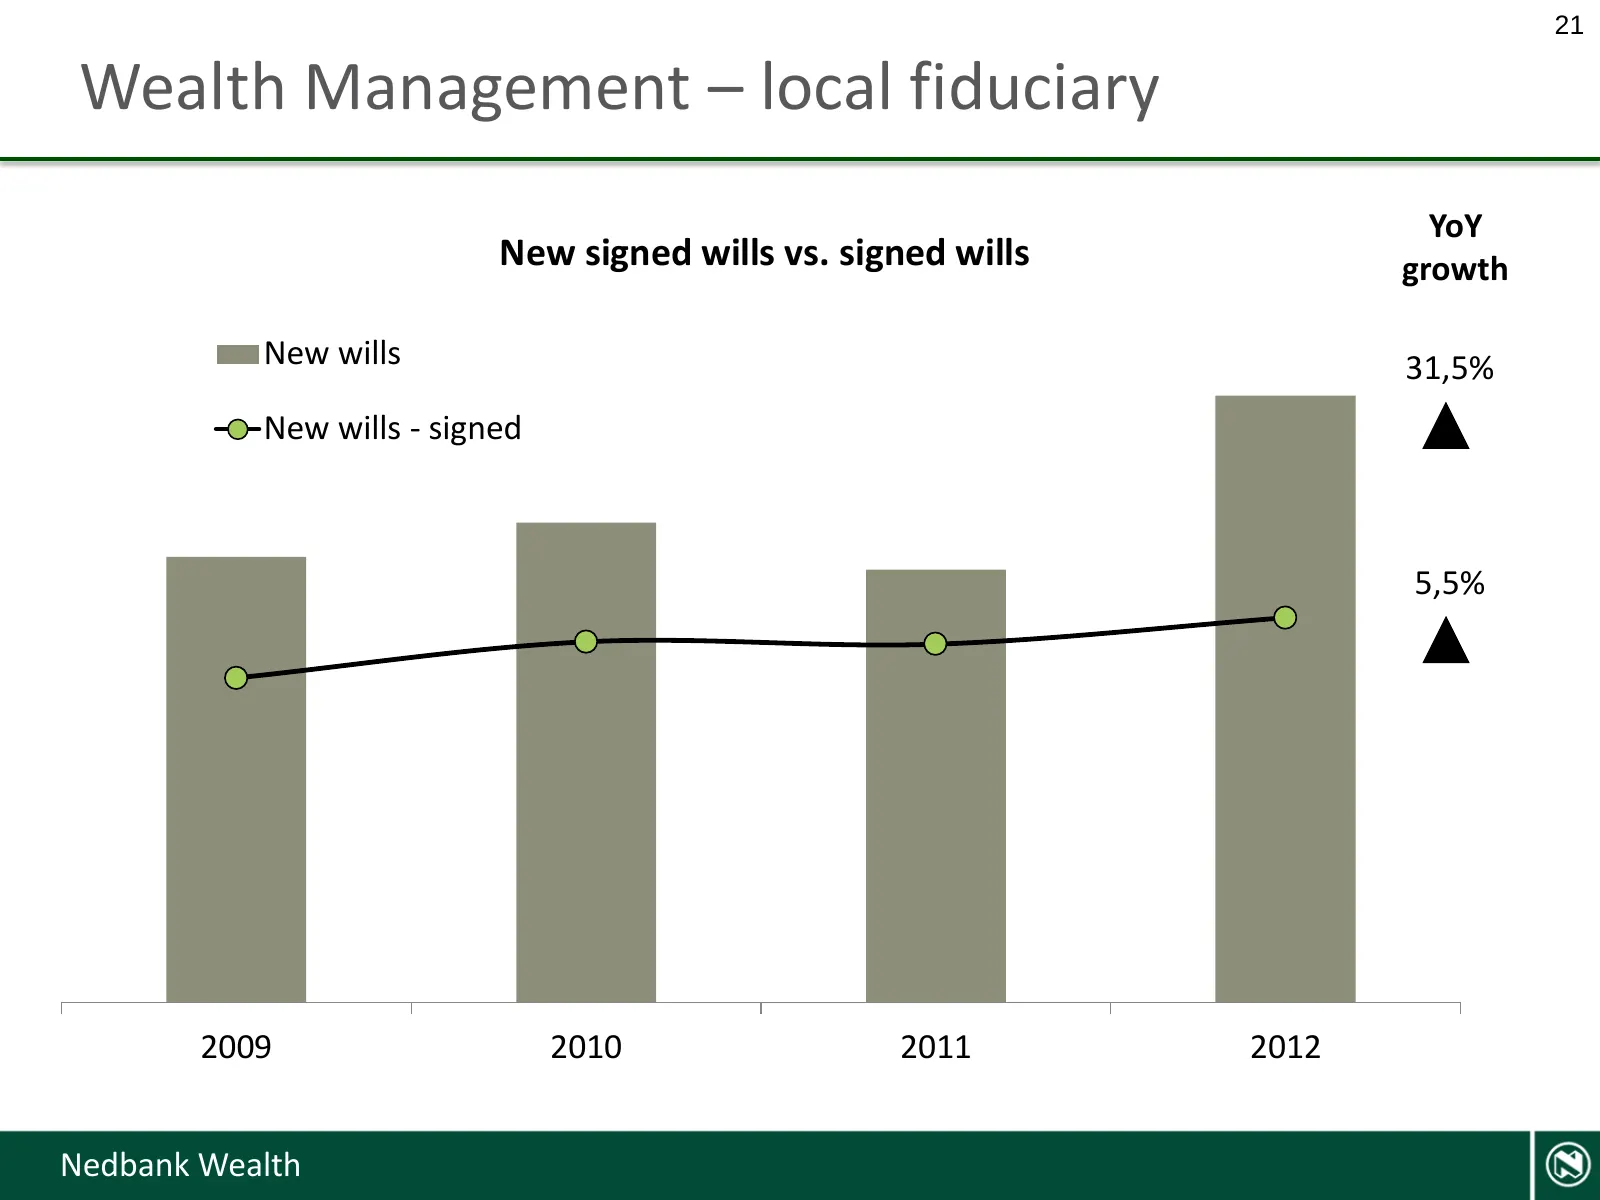
21 Wealth Management – local fiduciary YoY New signed wills vs. signed wills growth New wills 31,5% New wills - signed 5,5% 2009 2010 2011 2012 Nedbank Wealth
Slide 22: Wealth Management – strategy
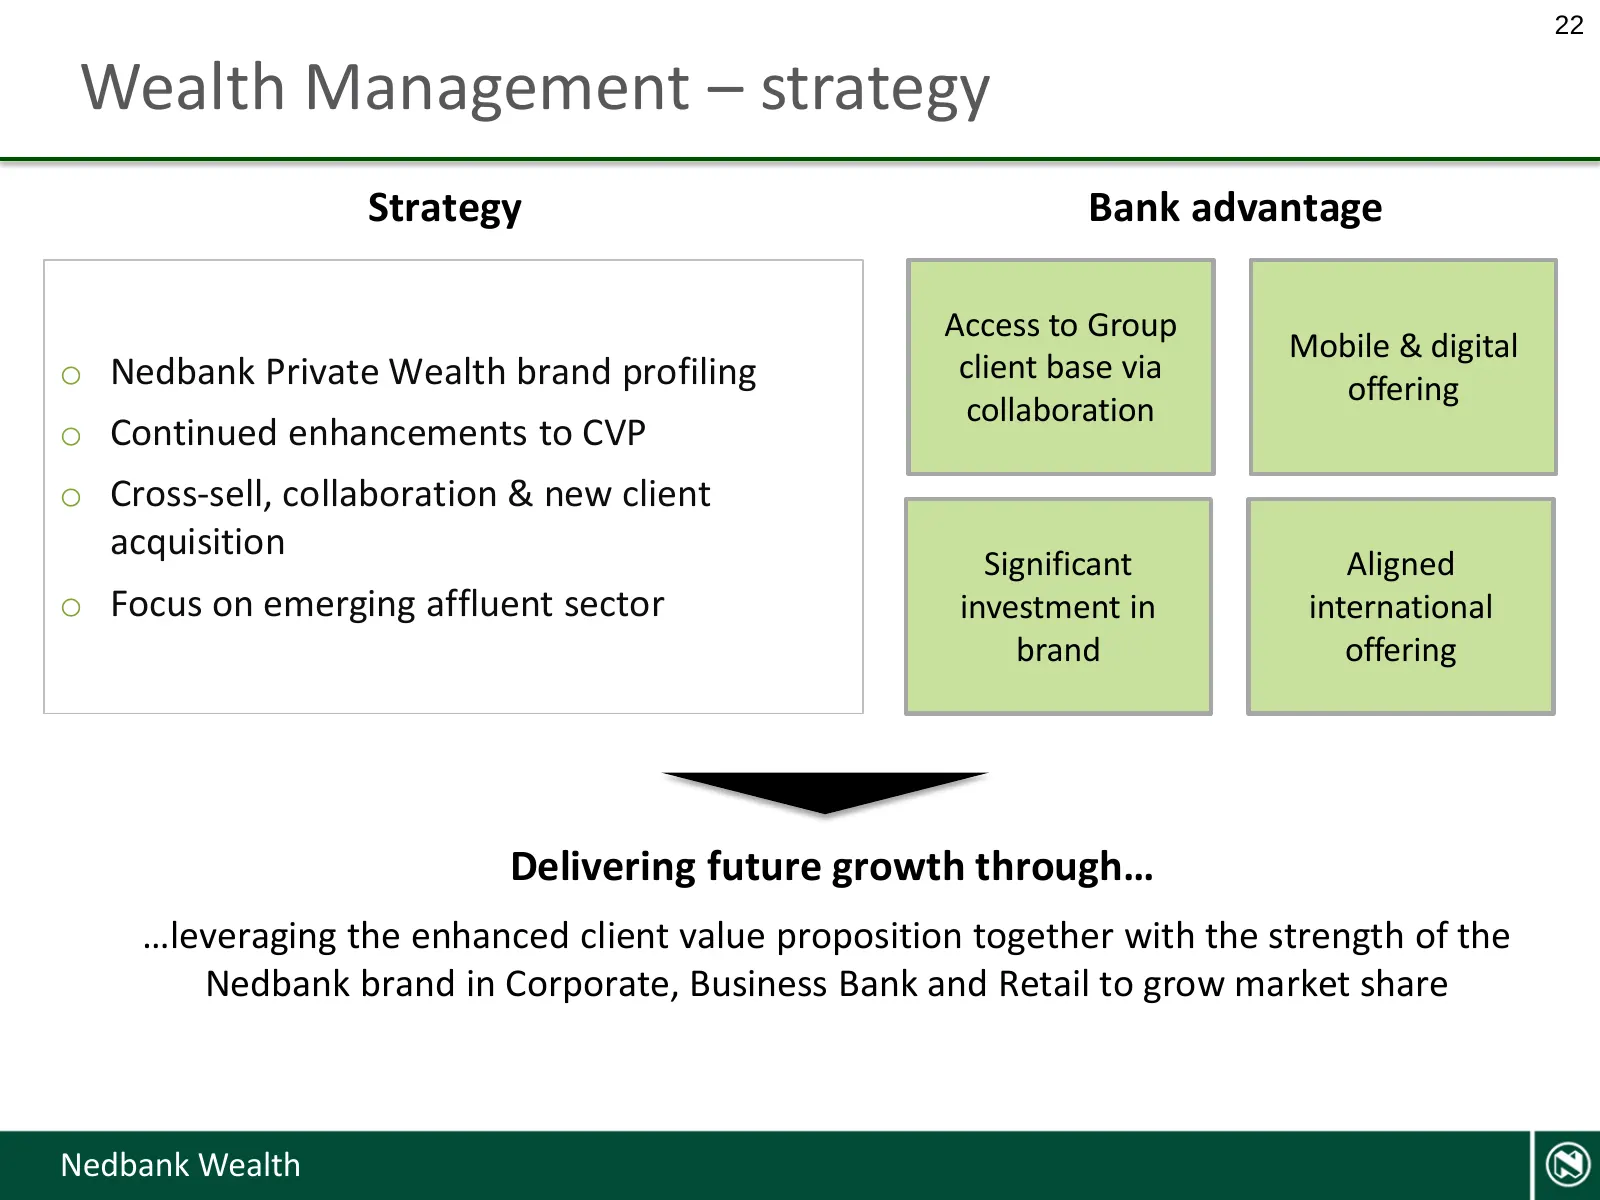
22 Wealth Management – strategy Strategy Bank advantage Access to Group Mobile & digital o Nedbank Private Wealth brand profiling client base via offering collaboration o Continued enhancements to CVP o Cross-sell, collaboration & new client acquisition Significant Aligned o Focus on emerging afflue
Slide 23: Wealth Management – outlook
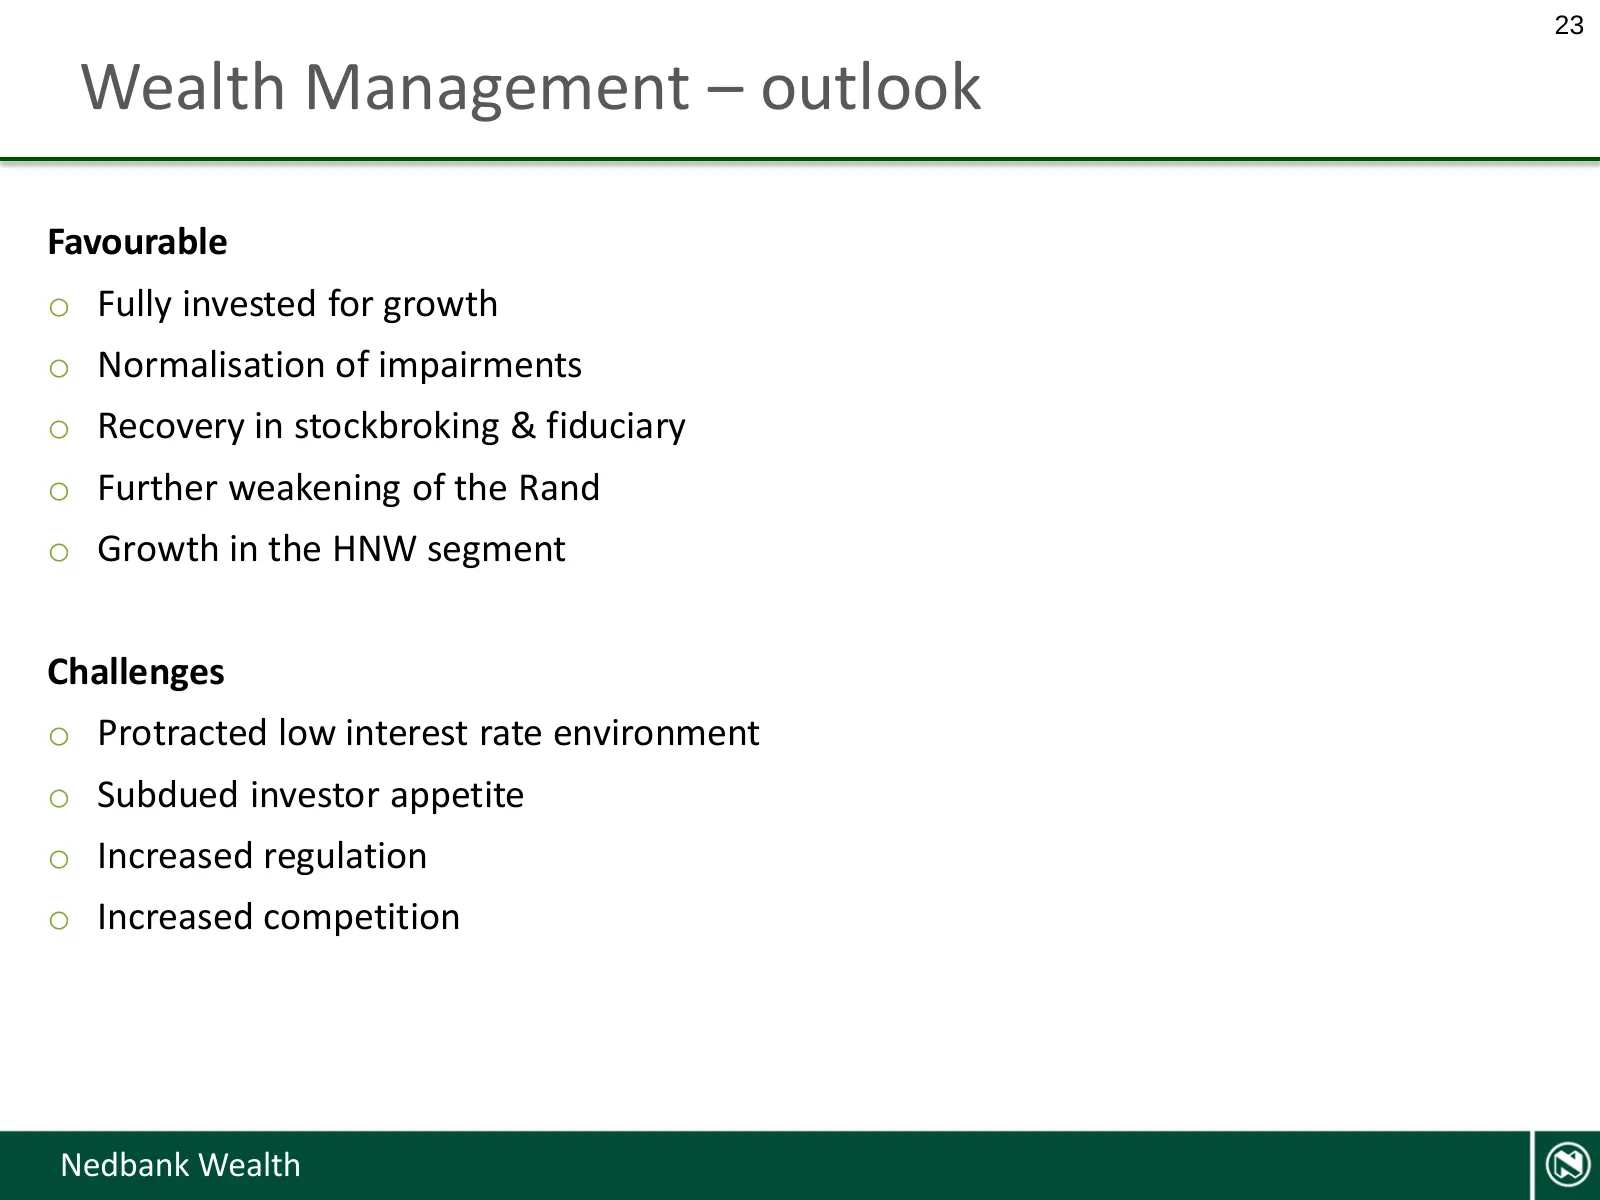
23 Wealth Management – outlook Favourable o Fully invested for growth o Normalisation of impairments o Recovery in stockbroking & fiduciary o Further weakening of the Rand o Growth in the HNW segment Challenges o Protracted low interest rate environment o Subdued investor appetite o Increased regula
Slide 24: Asset Management
24 Asset Management Nedbank Wealth
Slide 25: Asset Management – divisional structure
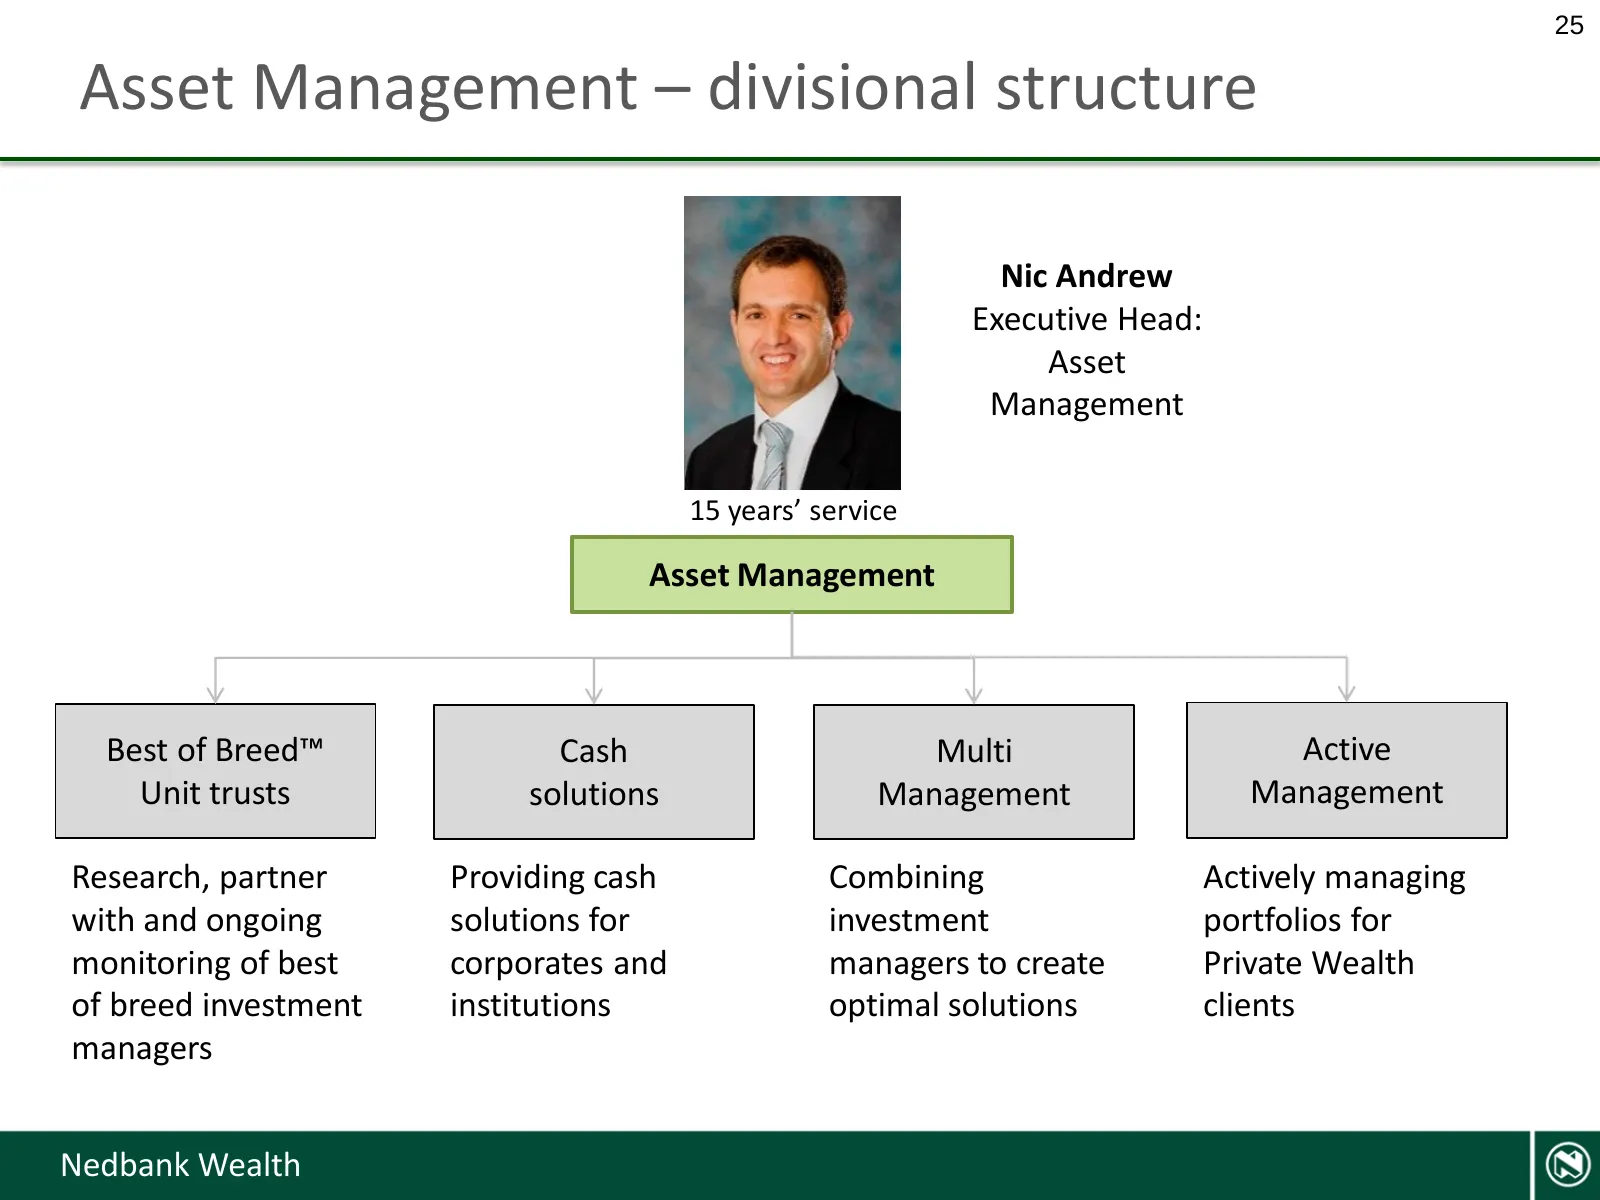
25 Asset Management – divisional structure Nic Andrew Executive Head: Asset Management 15 years’ service Asset Management Best of Breed™ Cash Multi Active Unit trusts solutions Management Management Research, partner Providing cash Combining Actively managing with and ongoing solutions for investmen
Slide 26: Asset Management – market positioning
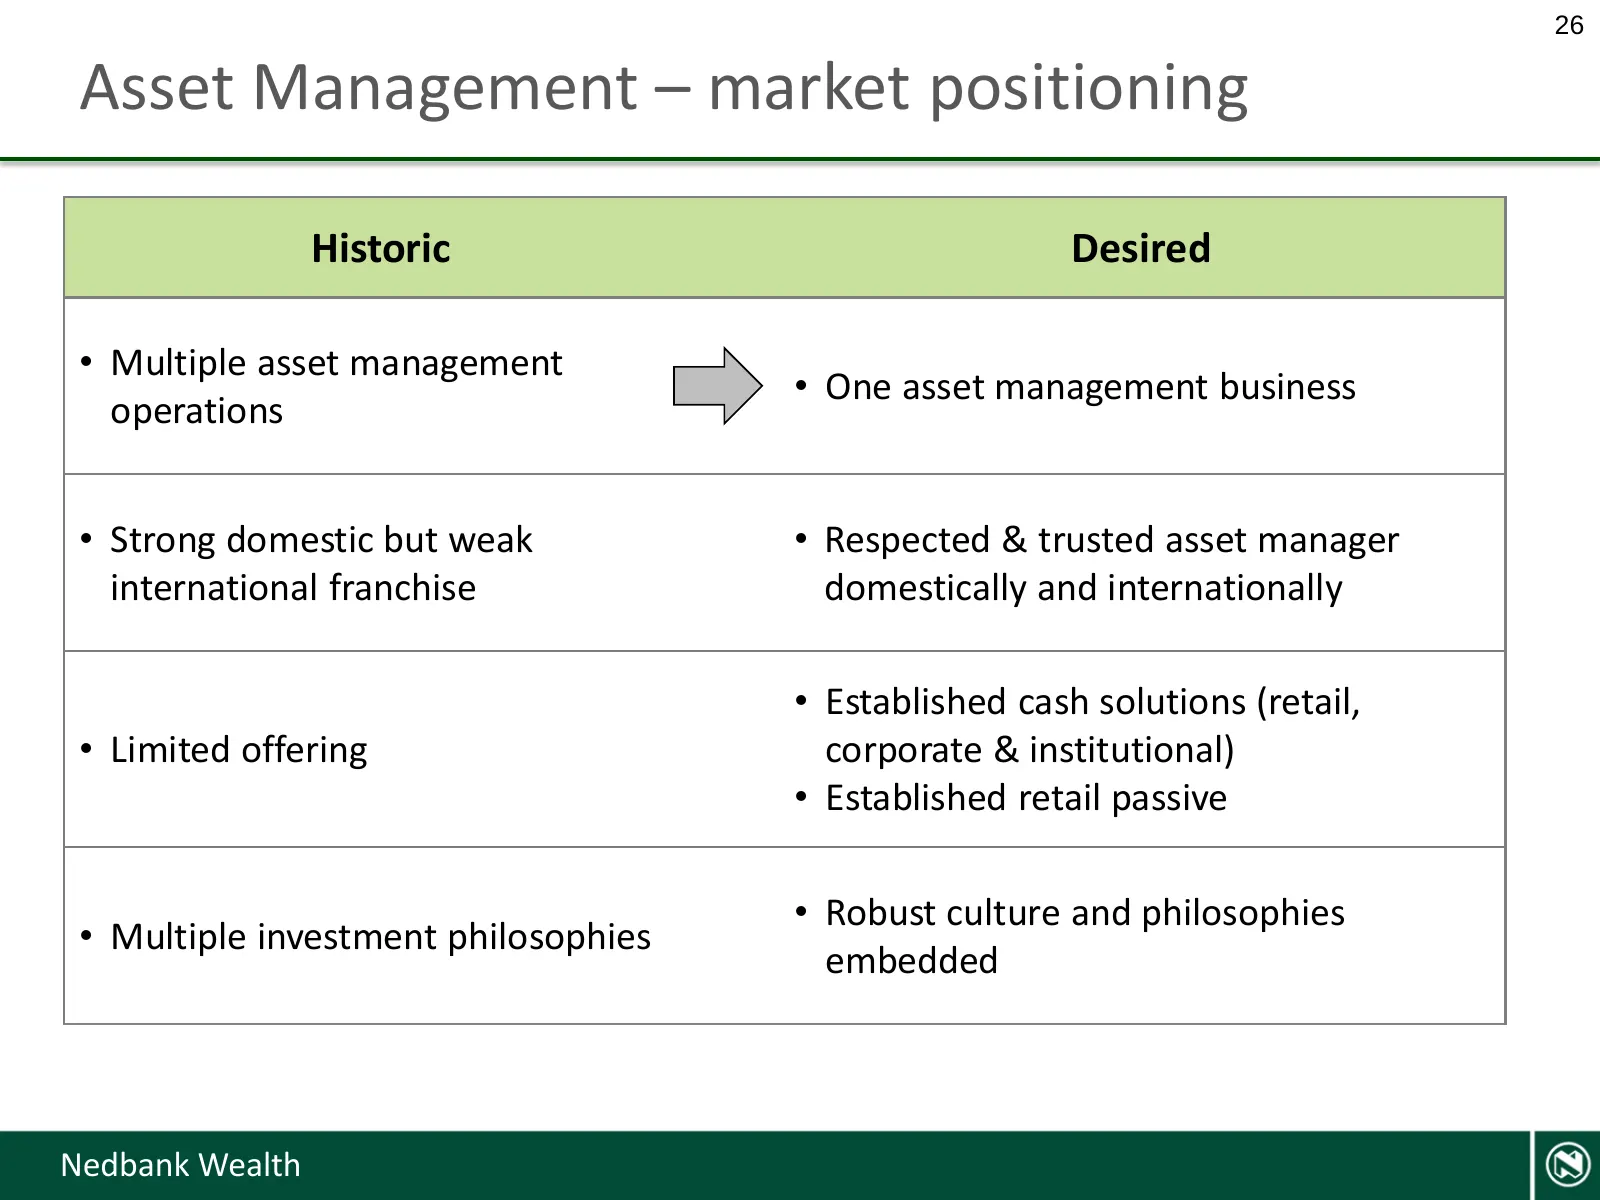
26 Asset Management – market positioning Historic Desired • Multiple asset management • One asset management business operations • Strong domestic but weak • Respected & trusted asset manager international franchise domestically and internationally • Established cash solutions (retail, • Limited off
Slide 27: Asset Management – developments since 2009
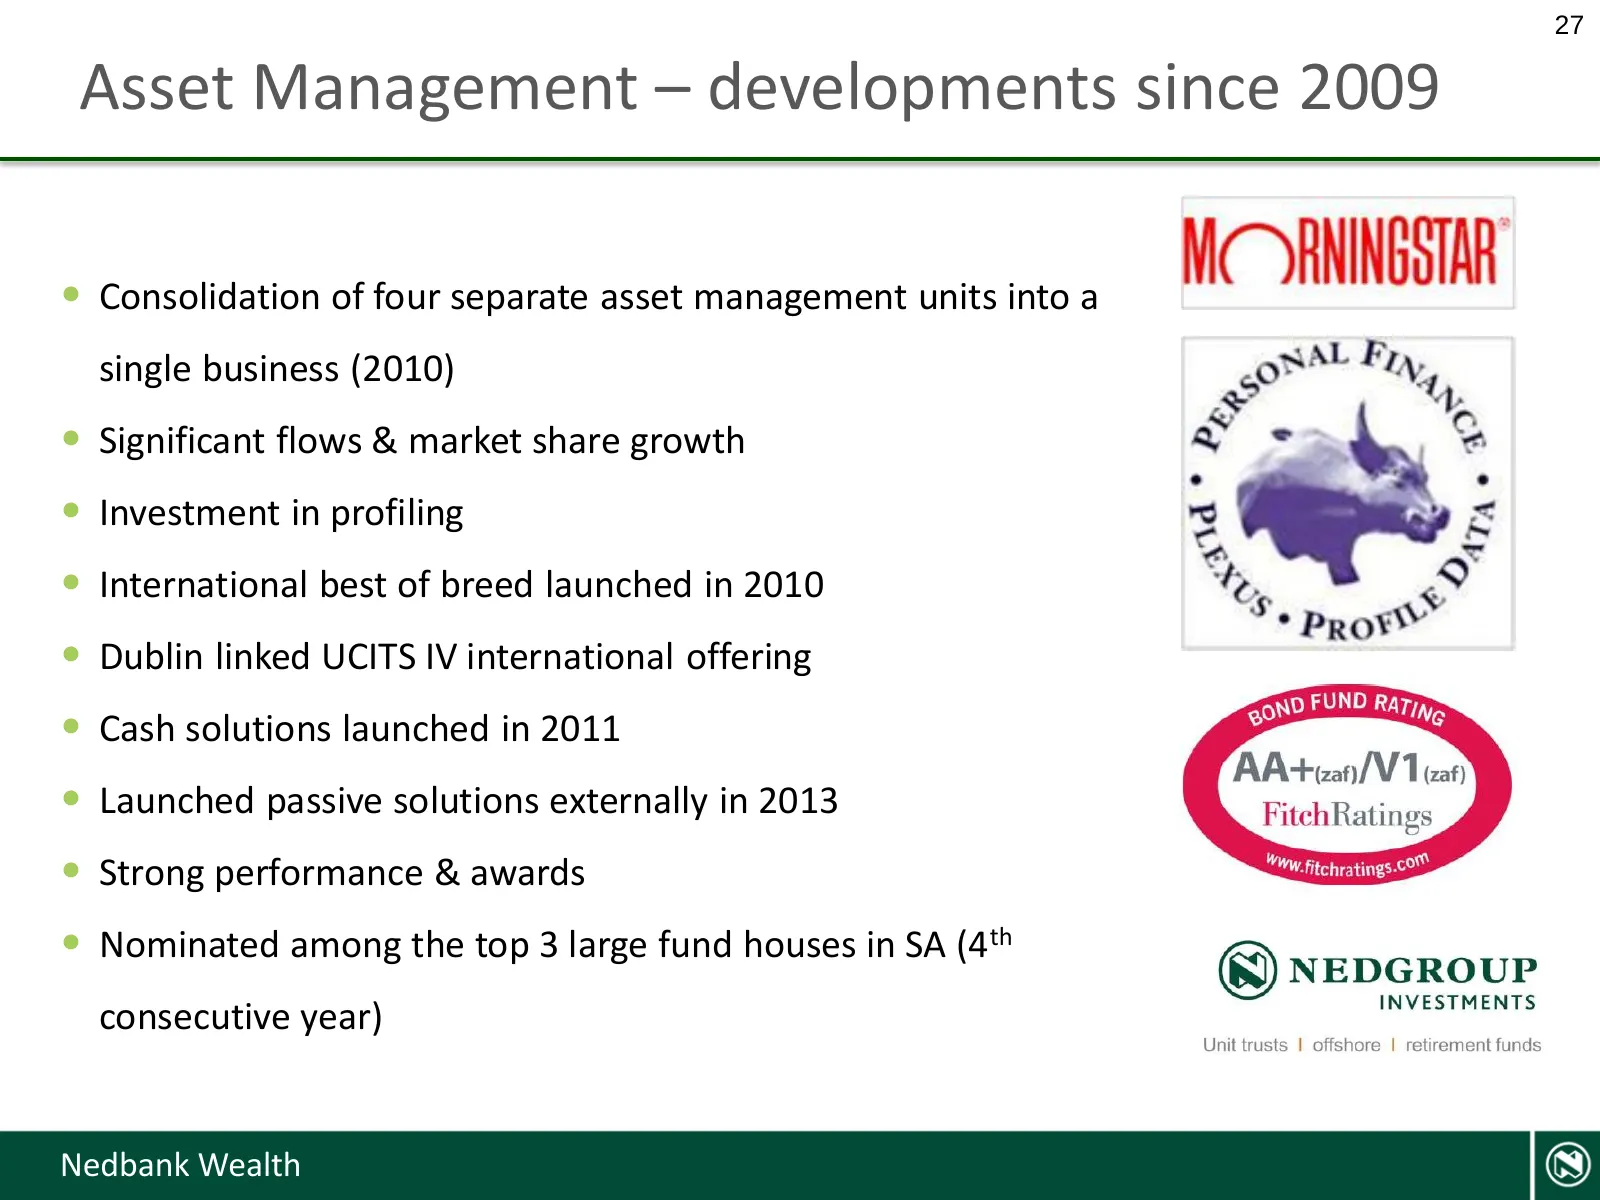
27 Asset Management – developments since 2009 • Consolidation of four separate asset management units into a single business (2010) • Significant flows & market share growth • Investment in profiling • International best of breed launched in 2010 • Dublin linked UCITS IV international offering • Cas
Slide 28: Asset Management – total net flows
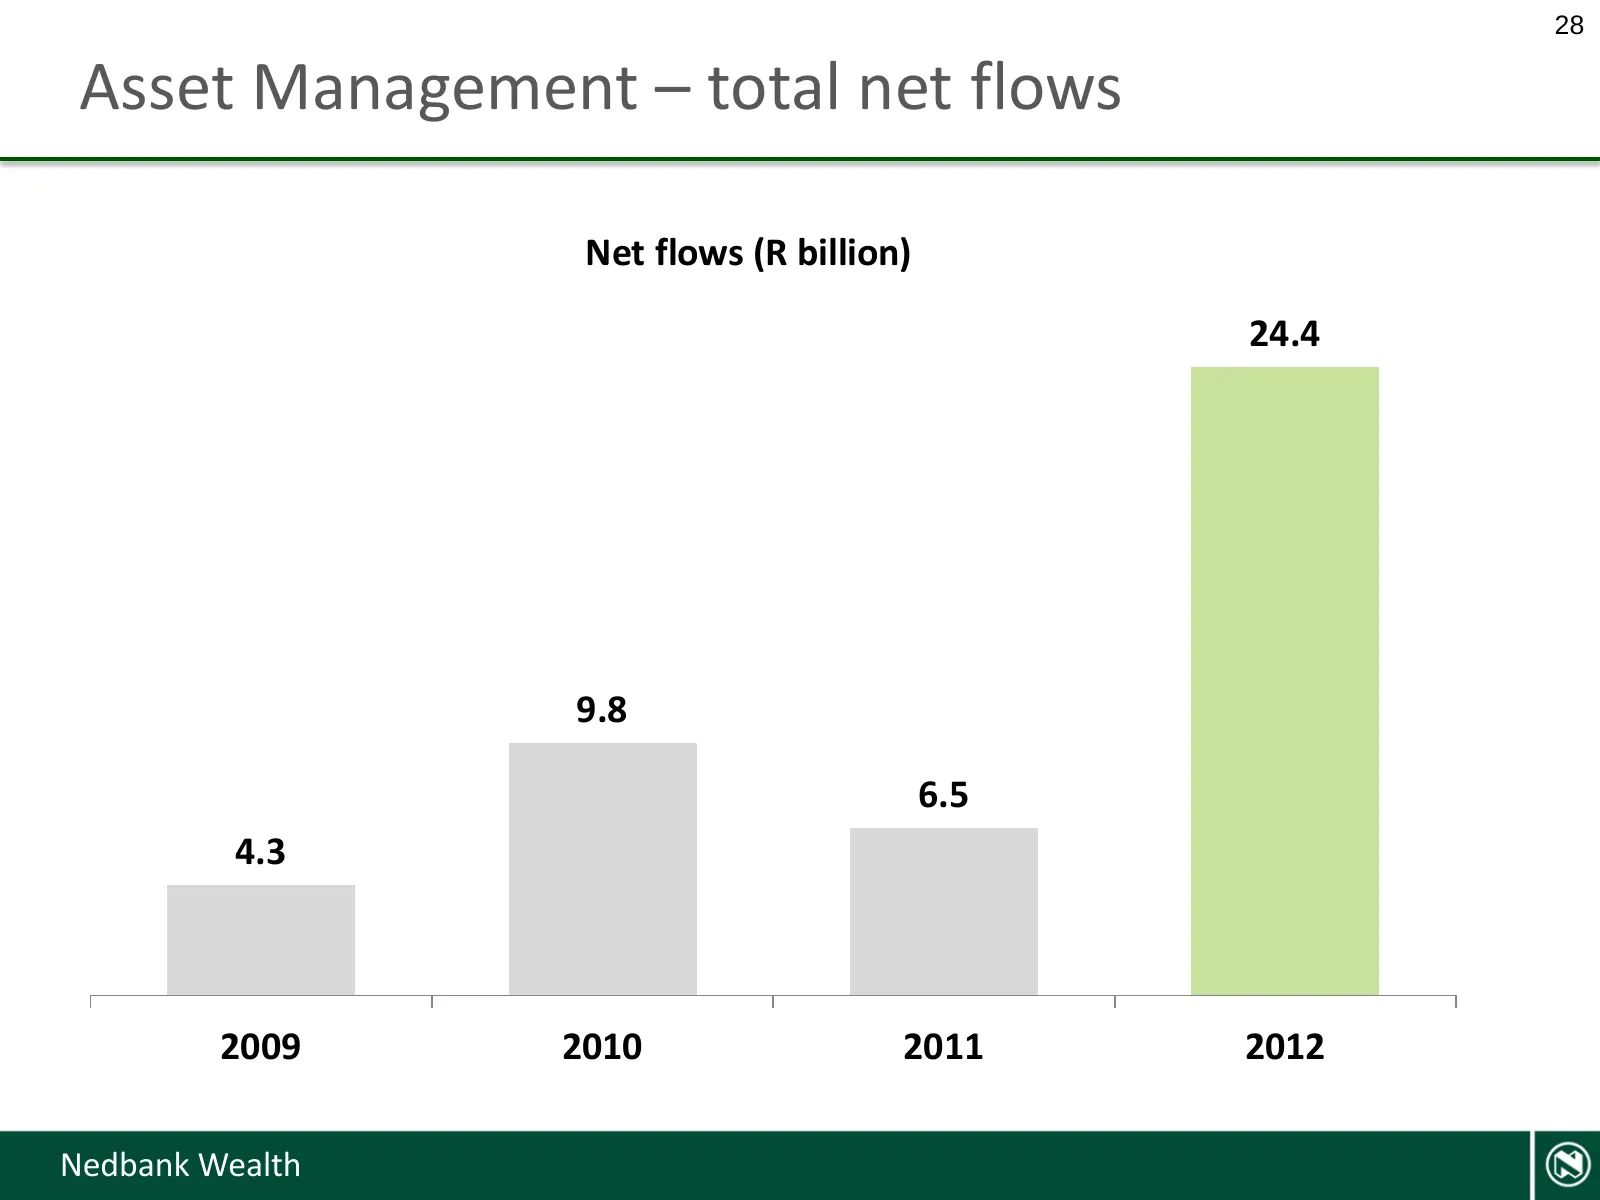
28 Asset Management – total net flows Net flows (R billion) 24.4 9.8 6.5 4.3 2009 2010 2011 2012 Nedbank Wealth
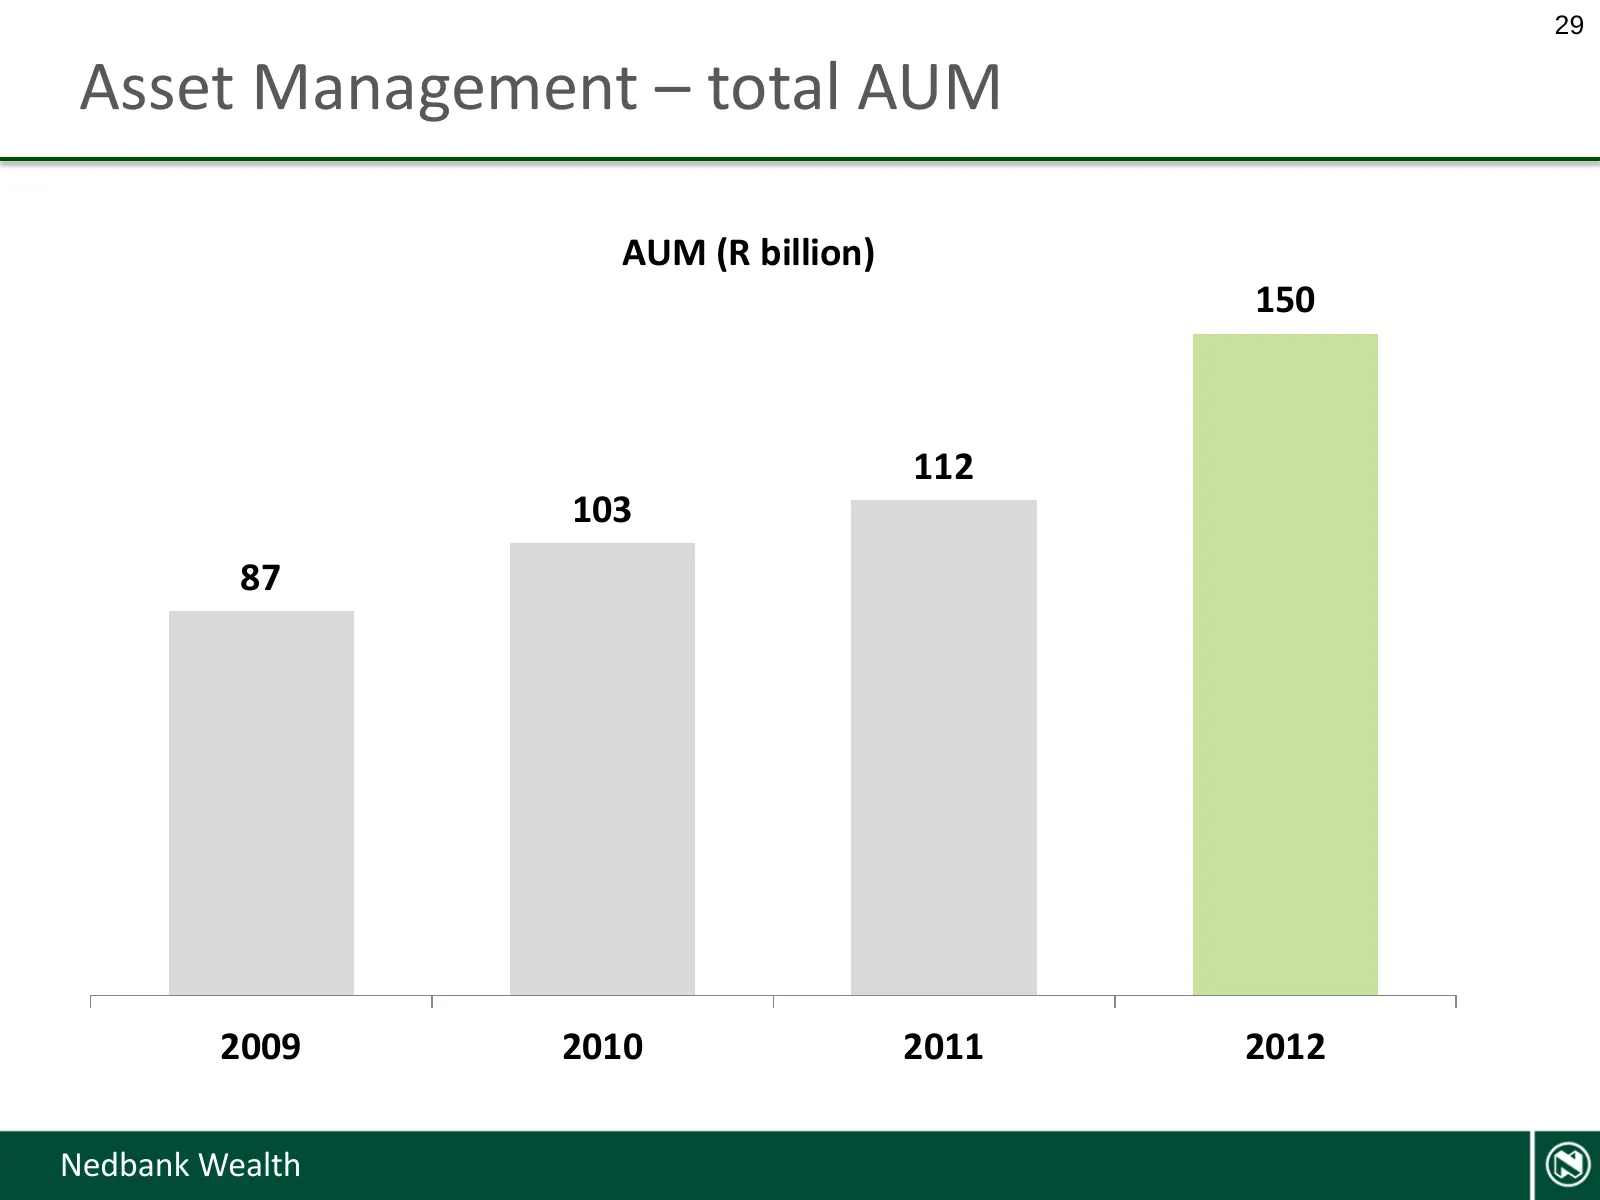
Slide 29: Asset Management – total AUM
29 Asset Management – total AUM AUM (R billion) 150 112 103 87 2009 2010 2011 2012 Nedbank Wealth
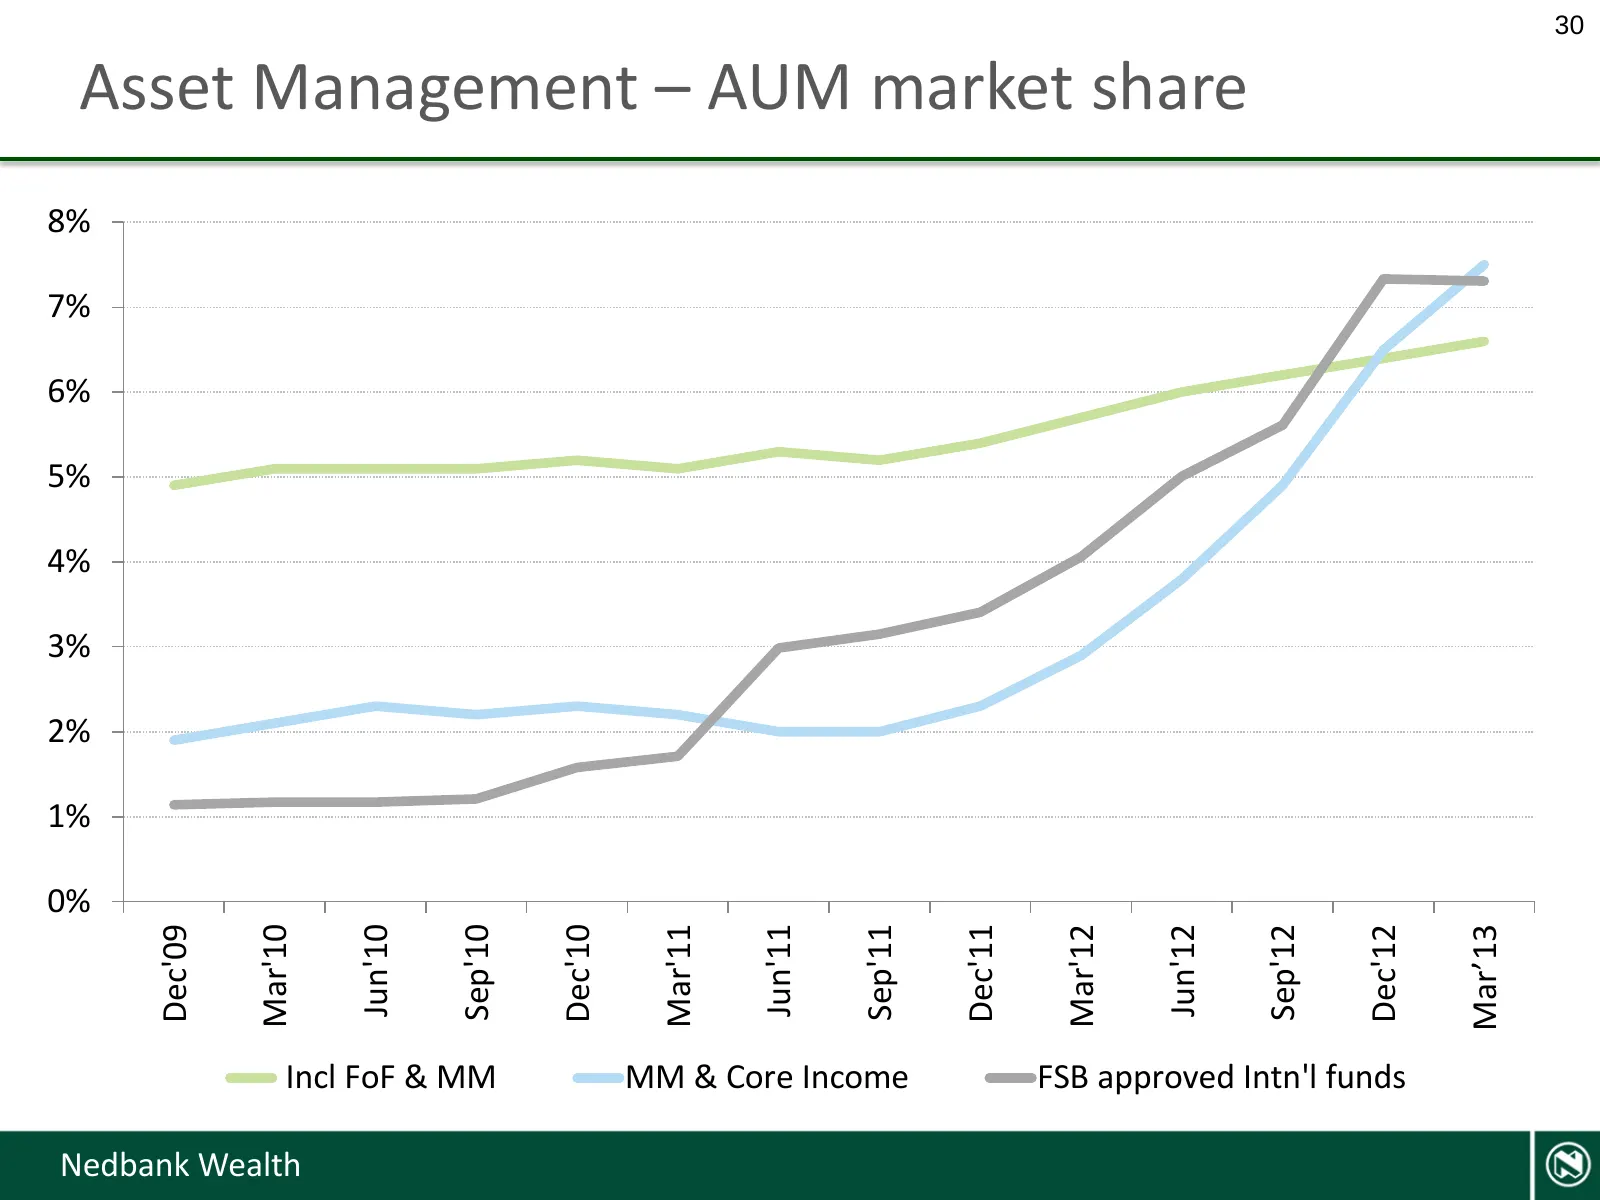
Slide 30: Asset Management – AUM market share
30 Asset Management – AUM market share 8% 7% 6% 5% 4% 3% 2% 1% 0% Jun'10 Jun'12 Mar'10 Mar'11 Jun'11 Mar'12 Dec'10 Dec'11 Dec'12 Dec'09 Mar’13 Sep'10 Sep'11 Sep'12 Incl FoF & MM MM & Core Income FSB approved Intn'l funds Nedbank Wealth
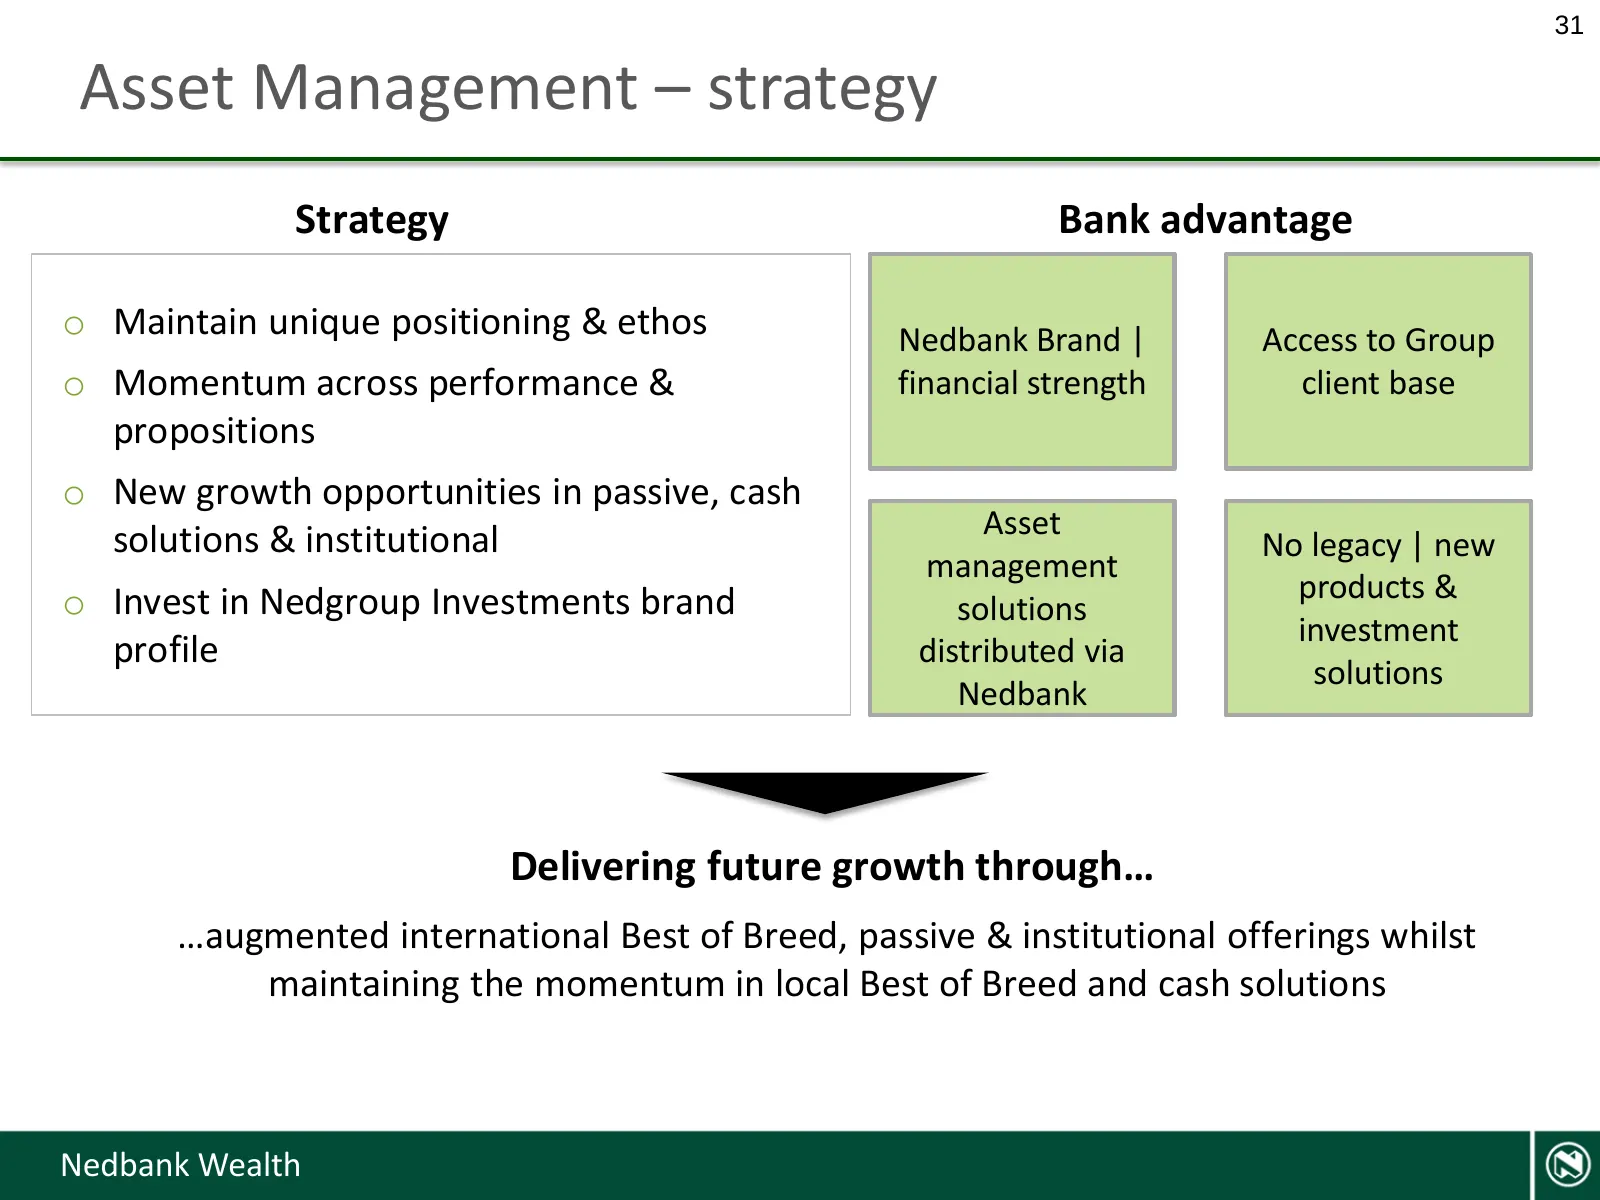
Slide 31: Asset Management – strategy
31 Asset Management – strategy Strategy Bank advantage o Maintain unique positioning & ethos Nedbank Brand | Access to Group o Momentum across performance & financial strength client base propositions o New growth opportunities in passive, cash Asset solutions & institutional No legacy | new managem
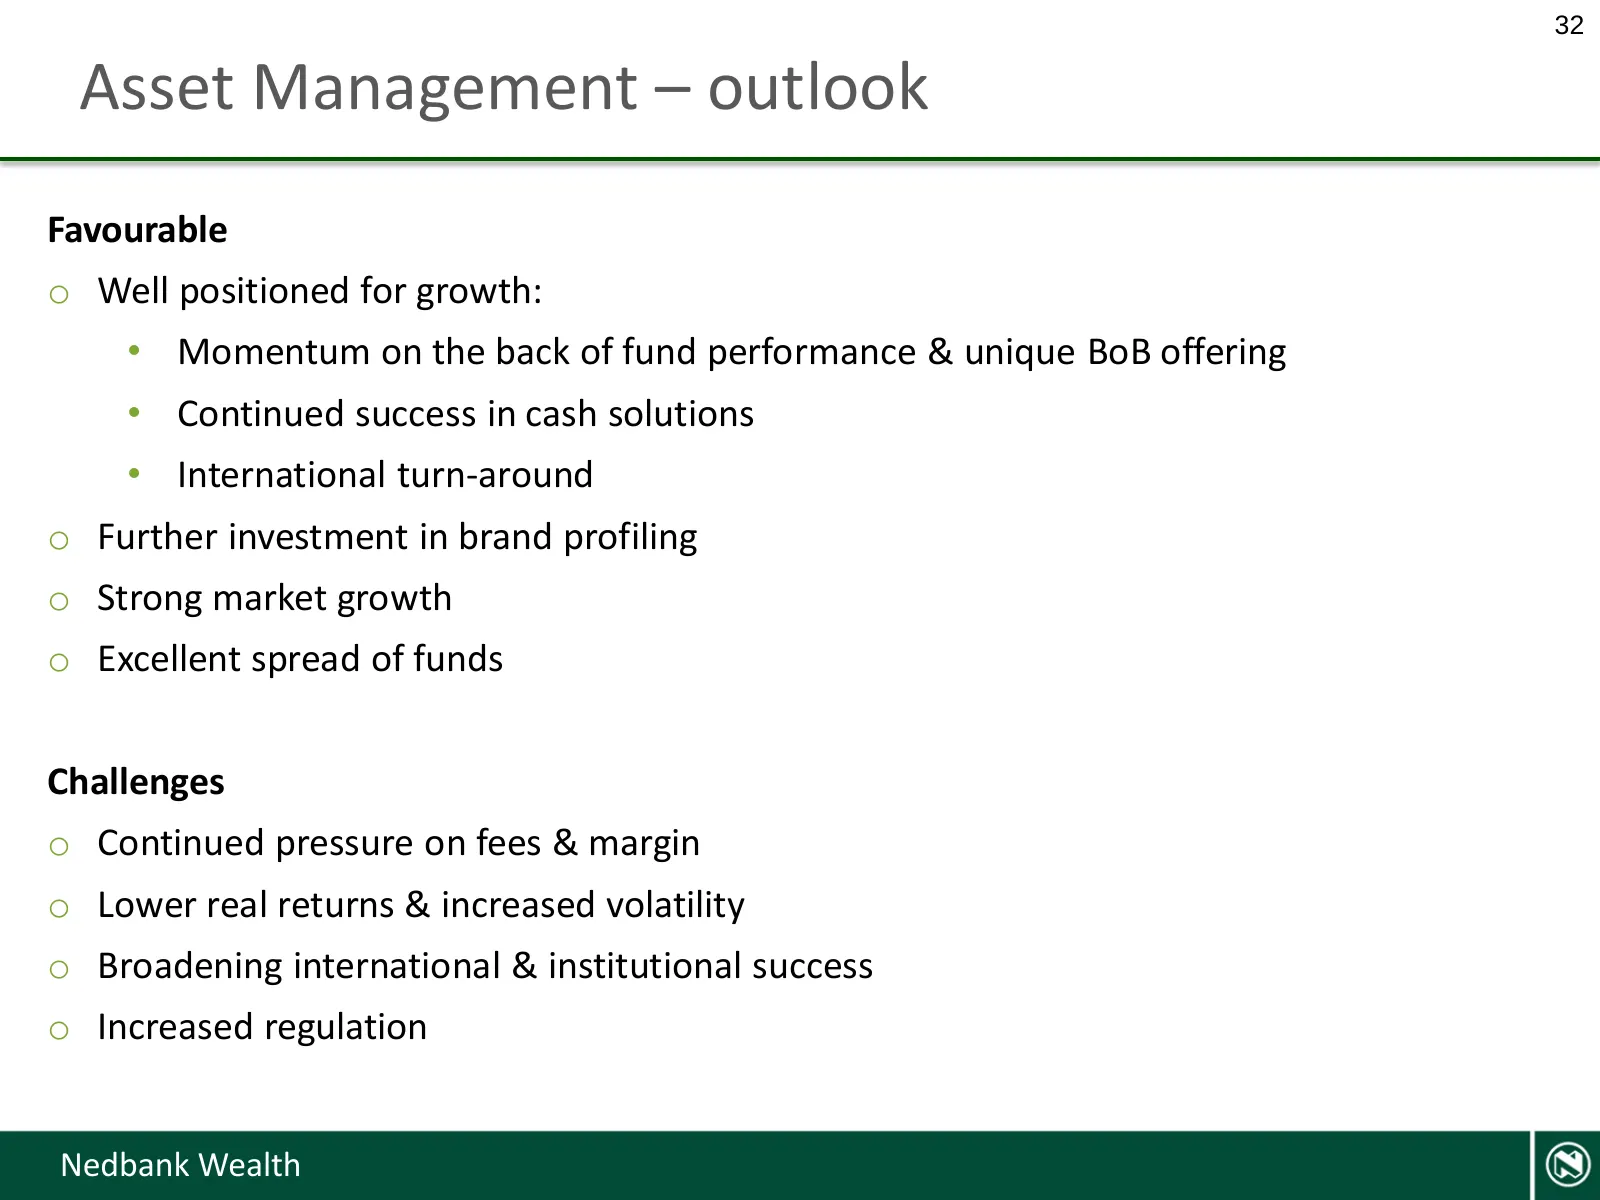
Slide 32: Asset Management – outlook
32 Asset Management – outlook Favourable o Well positioned for growth: • Momentum on the back of fund performance & unique BoB offering • Continued success in cash solutions • International turn-around o Further investment in brand profiling o Strong market growth o Excellent spread of funds Challen
Slide 33: Insurance
33 MAKE THINGS HAPPEN NEDBANK Insurance
Slide 34: Insurance – divisional structure
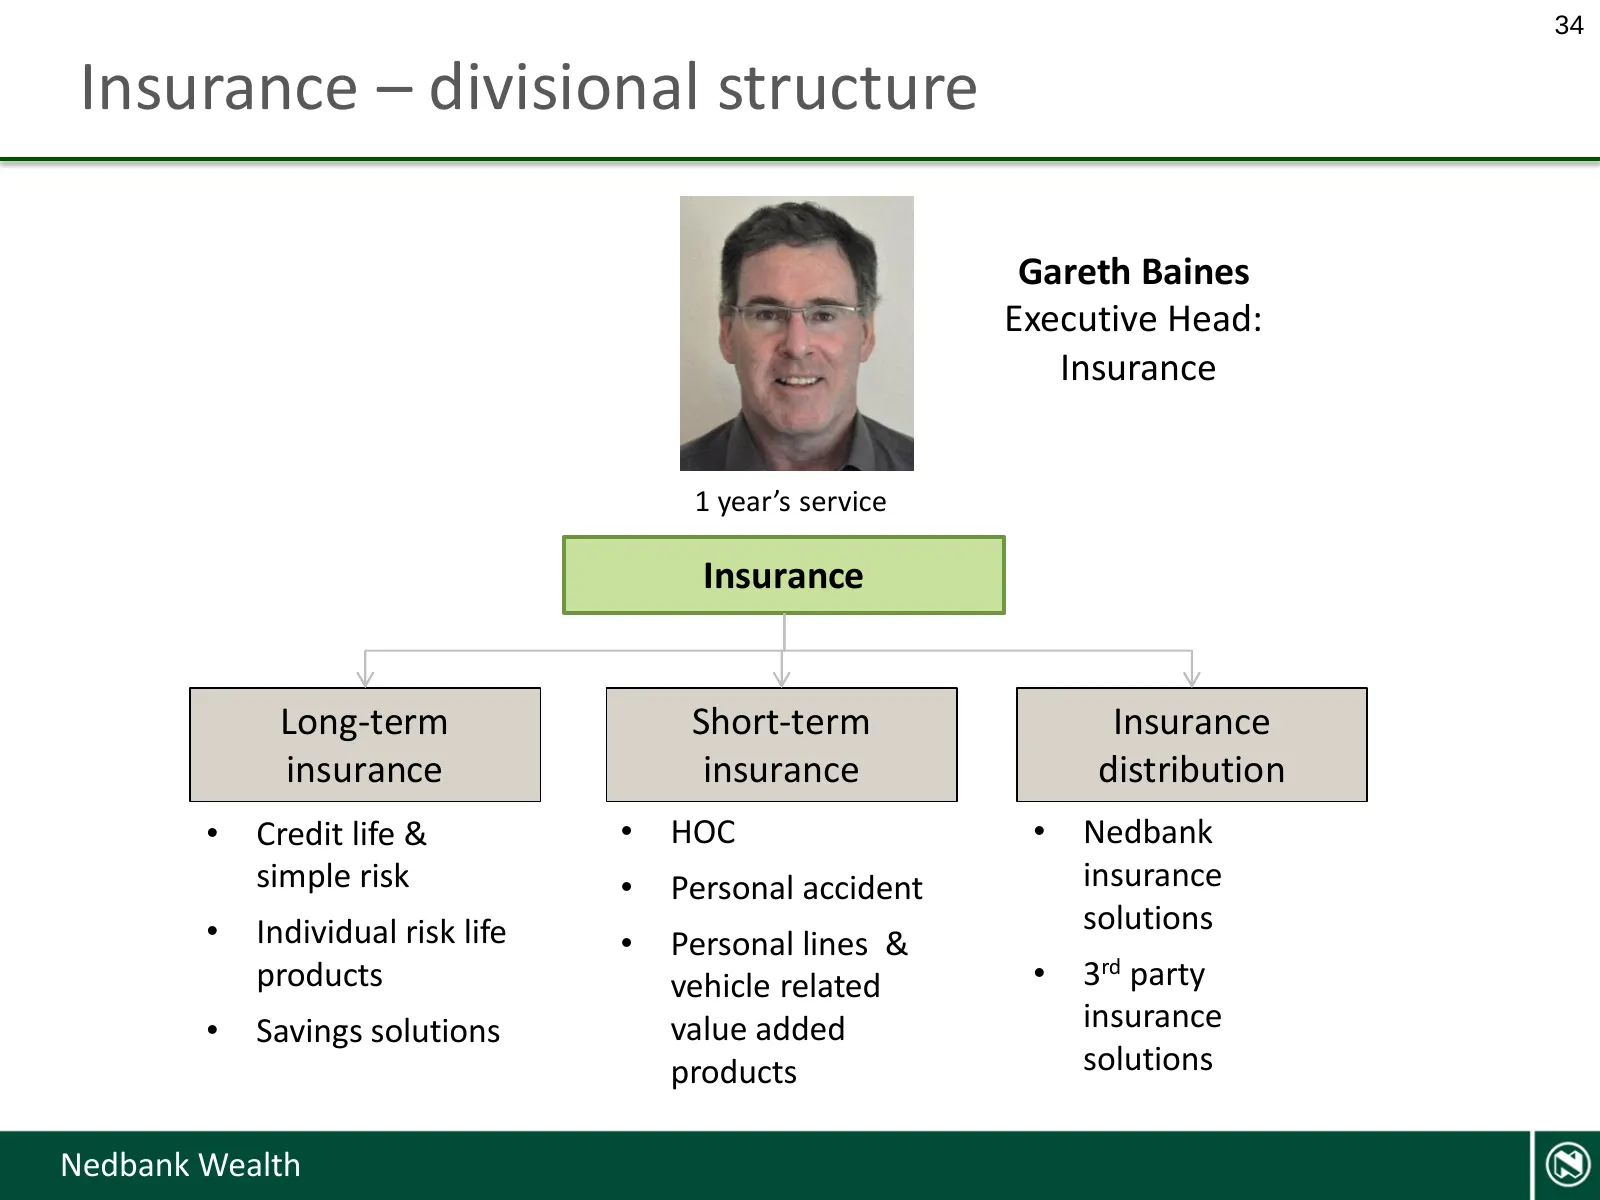
34 Insurance – divisional structure Gareth Baines Executive Head: Insurance 1 year’s service Insurance Long-term Short-term Insurance insurance insurance distribution • Credit life & • HOC • Nedbank simple risk • Personal accident insurance • Individual risk life solutions • Personal lines & product
Slide 35: Insurance – market positioning
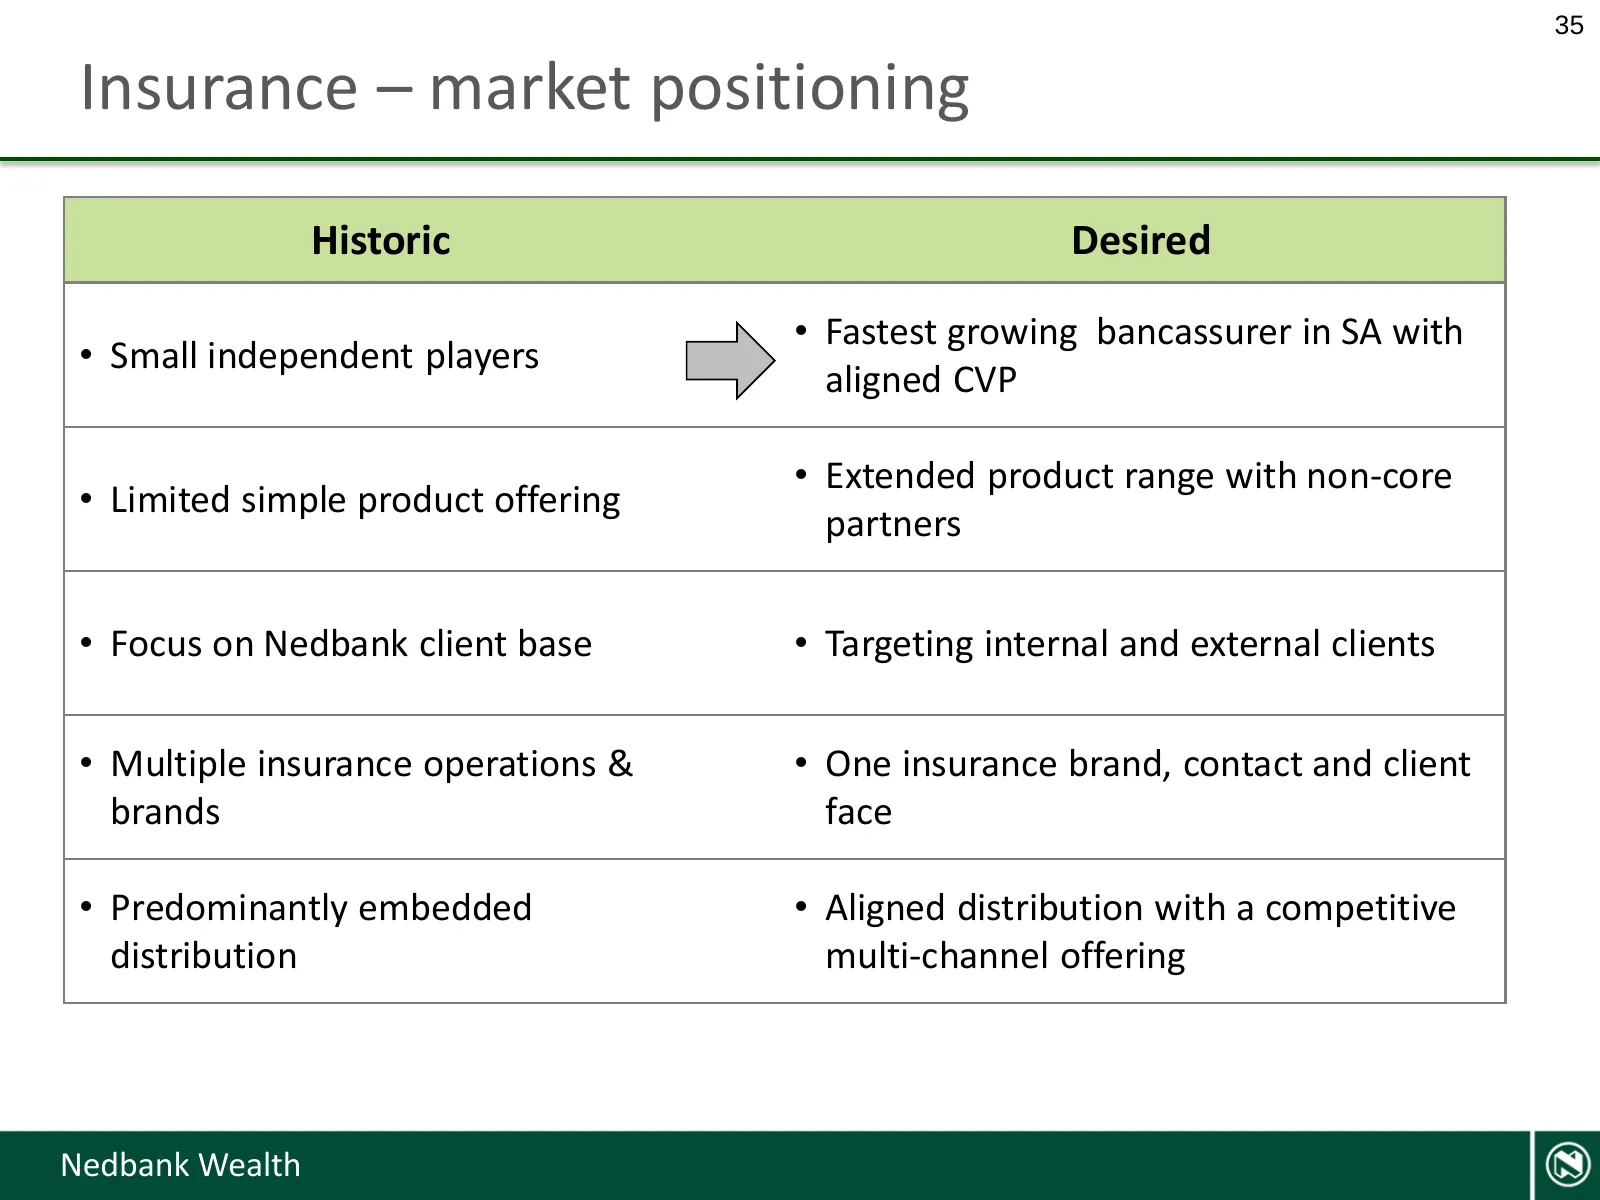
35 Insurance – market positioning Historic Desired • Fastest growing bancassurer in SA with • Small independent players aligned CVP • Extended product range with non-core • Limited simple product offering partners • Focus on Nedbank client base • Targeting internal and external clients • Multiple in
Slide 36: Insurance – new products since 2009
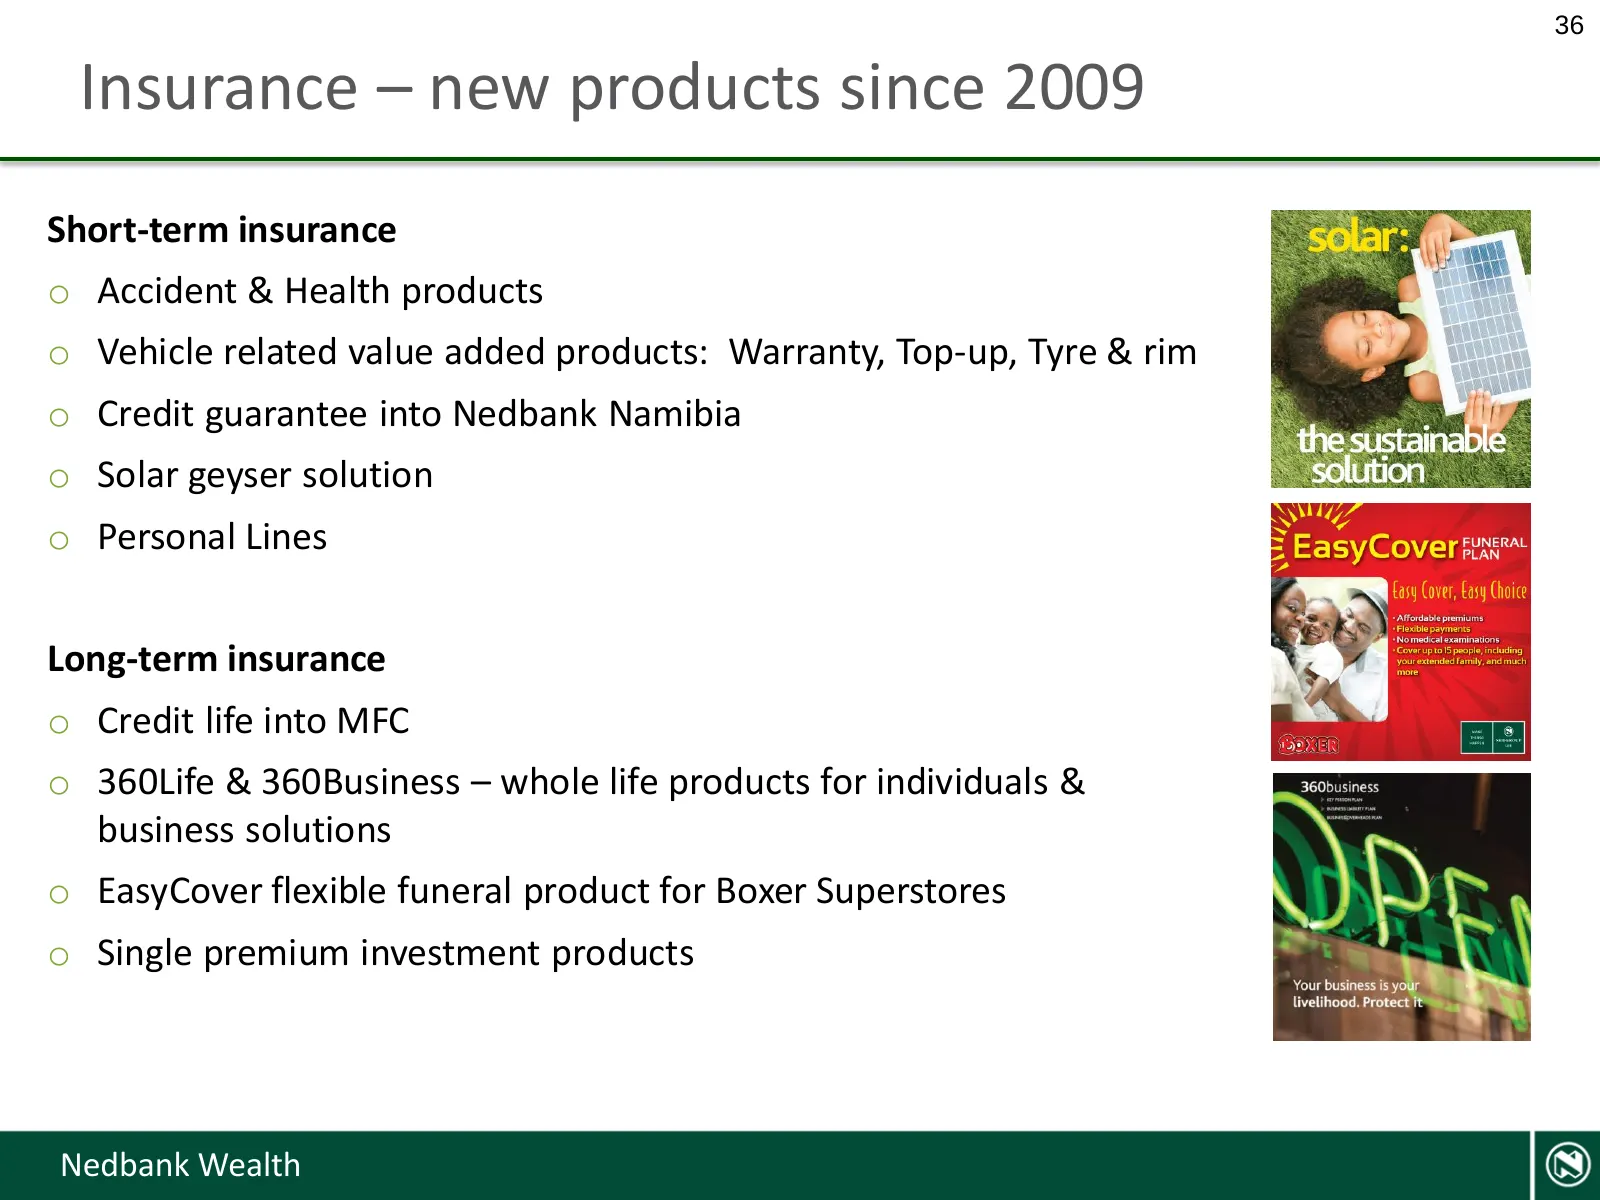
36 Insurance – new products since 2009 Short-term insurance o Accident & Health products o Vehicle related value added products: Warranty, Top-up, Tyre & rim o Credit guarantee into Nedbank Namibia o Solar geyser solution o Personal Lines Long-term insurance o Credit life into MFC o 360Life & 360Bus
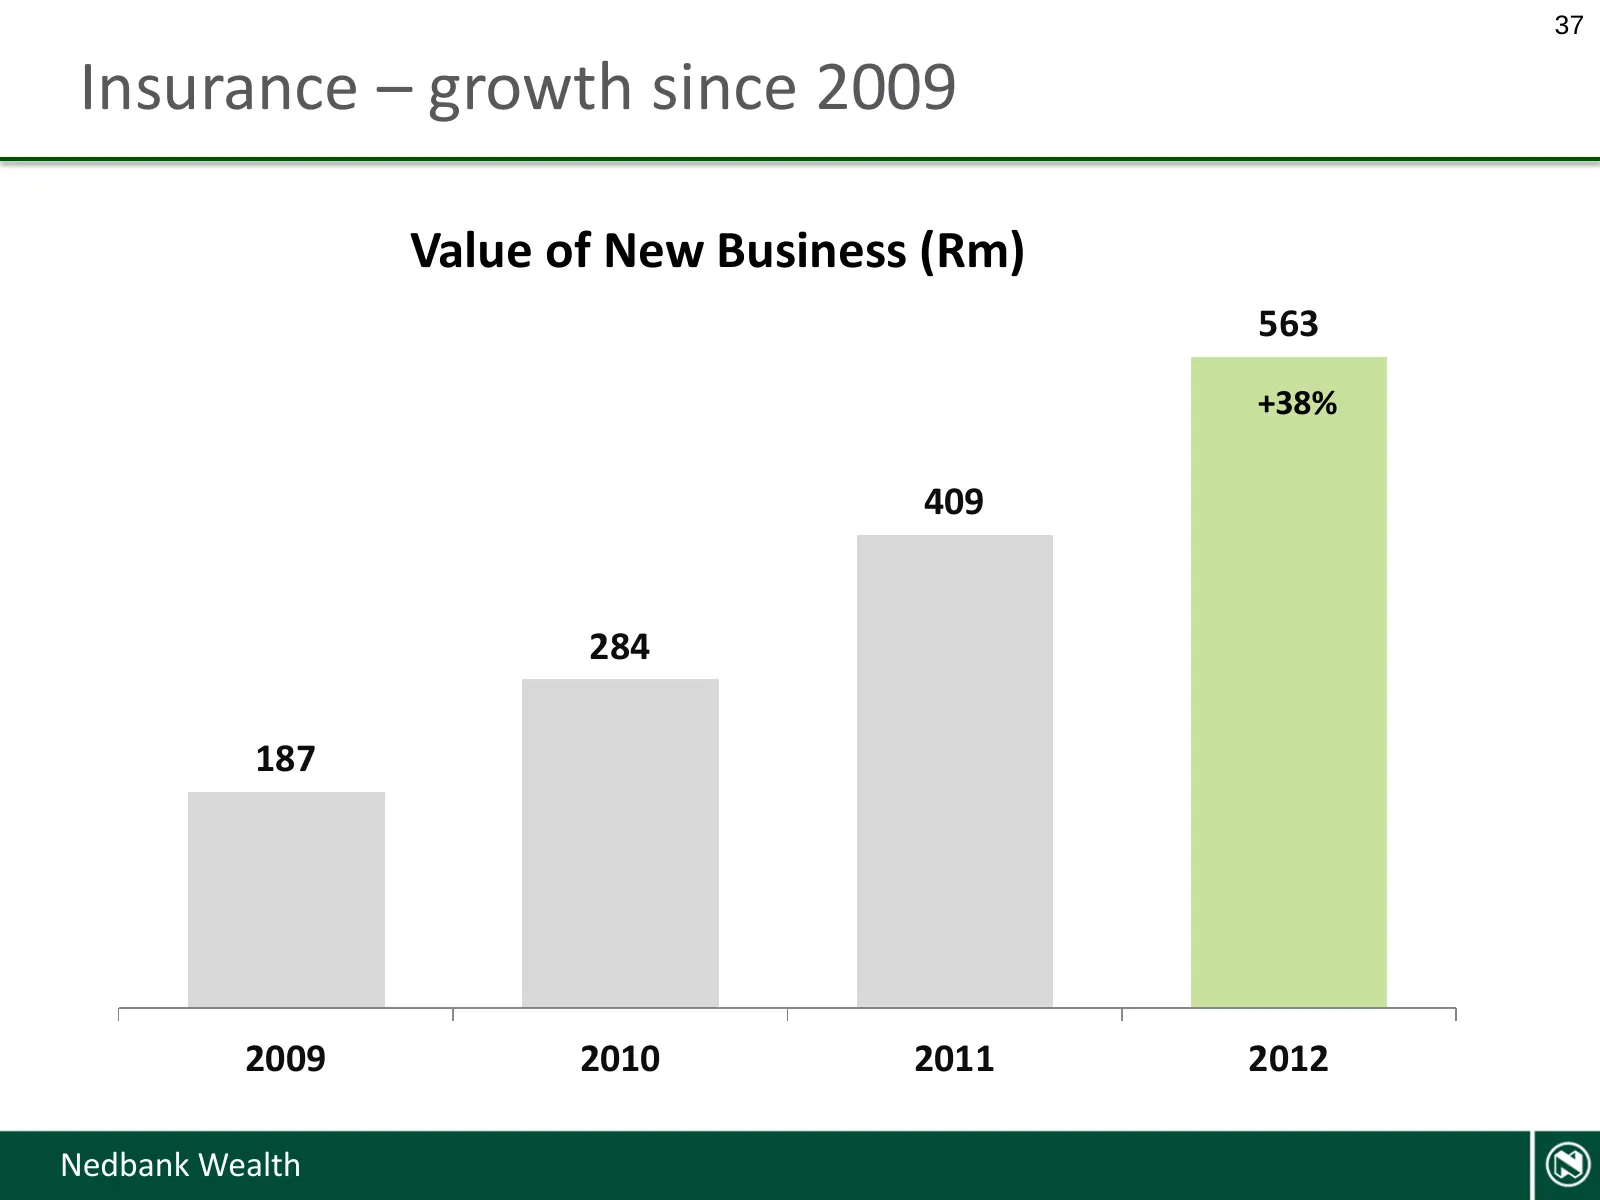
Slide 37: Insurance – growth since 2009
37 Insurance – growth since 2009 Value of New Business (Rm) 563 +38% 409 284 187 2009 2010 2011 2012 Nedbank Wealth
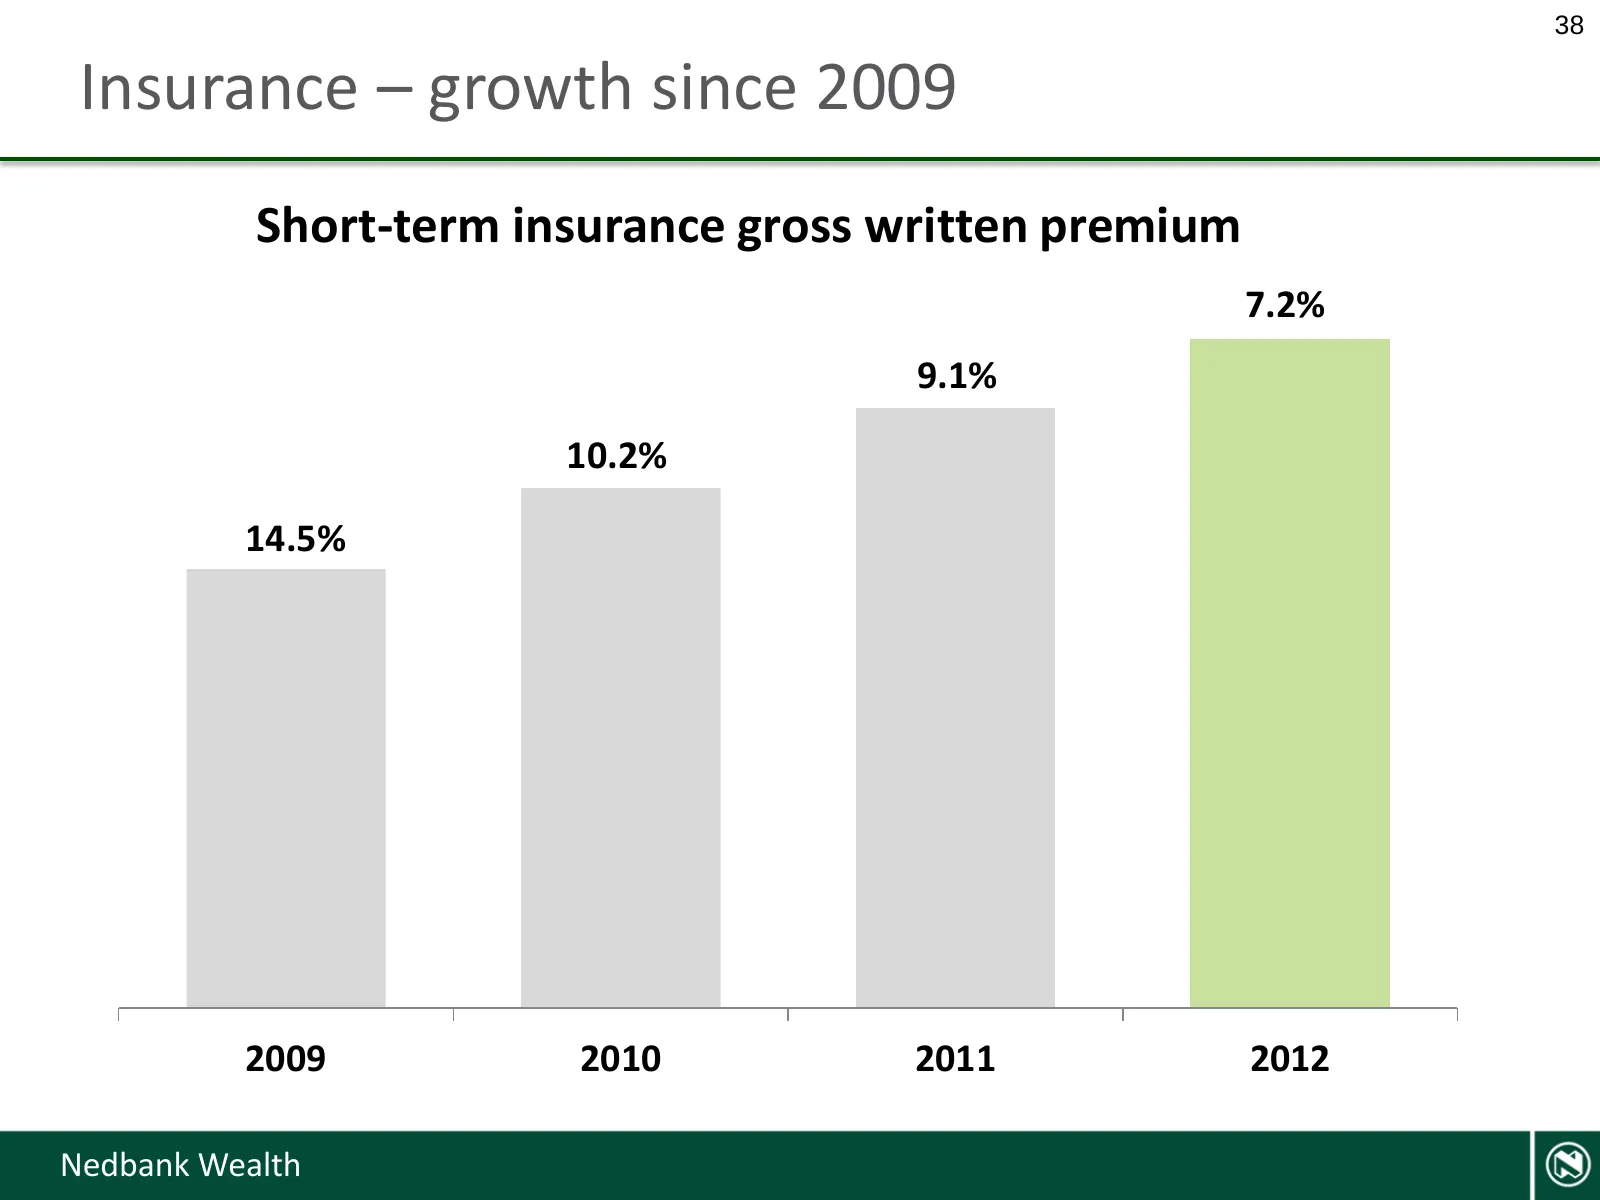
Slide 38: Insurance – growth since 2009
38 Insurance – growth since 2009 Short-term insurance gross written premium 7.2% 9.1% 10.2% 14.5% 2009 2010 2011 2012 Nedbank Wealth
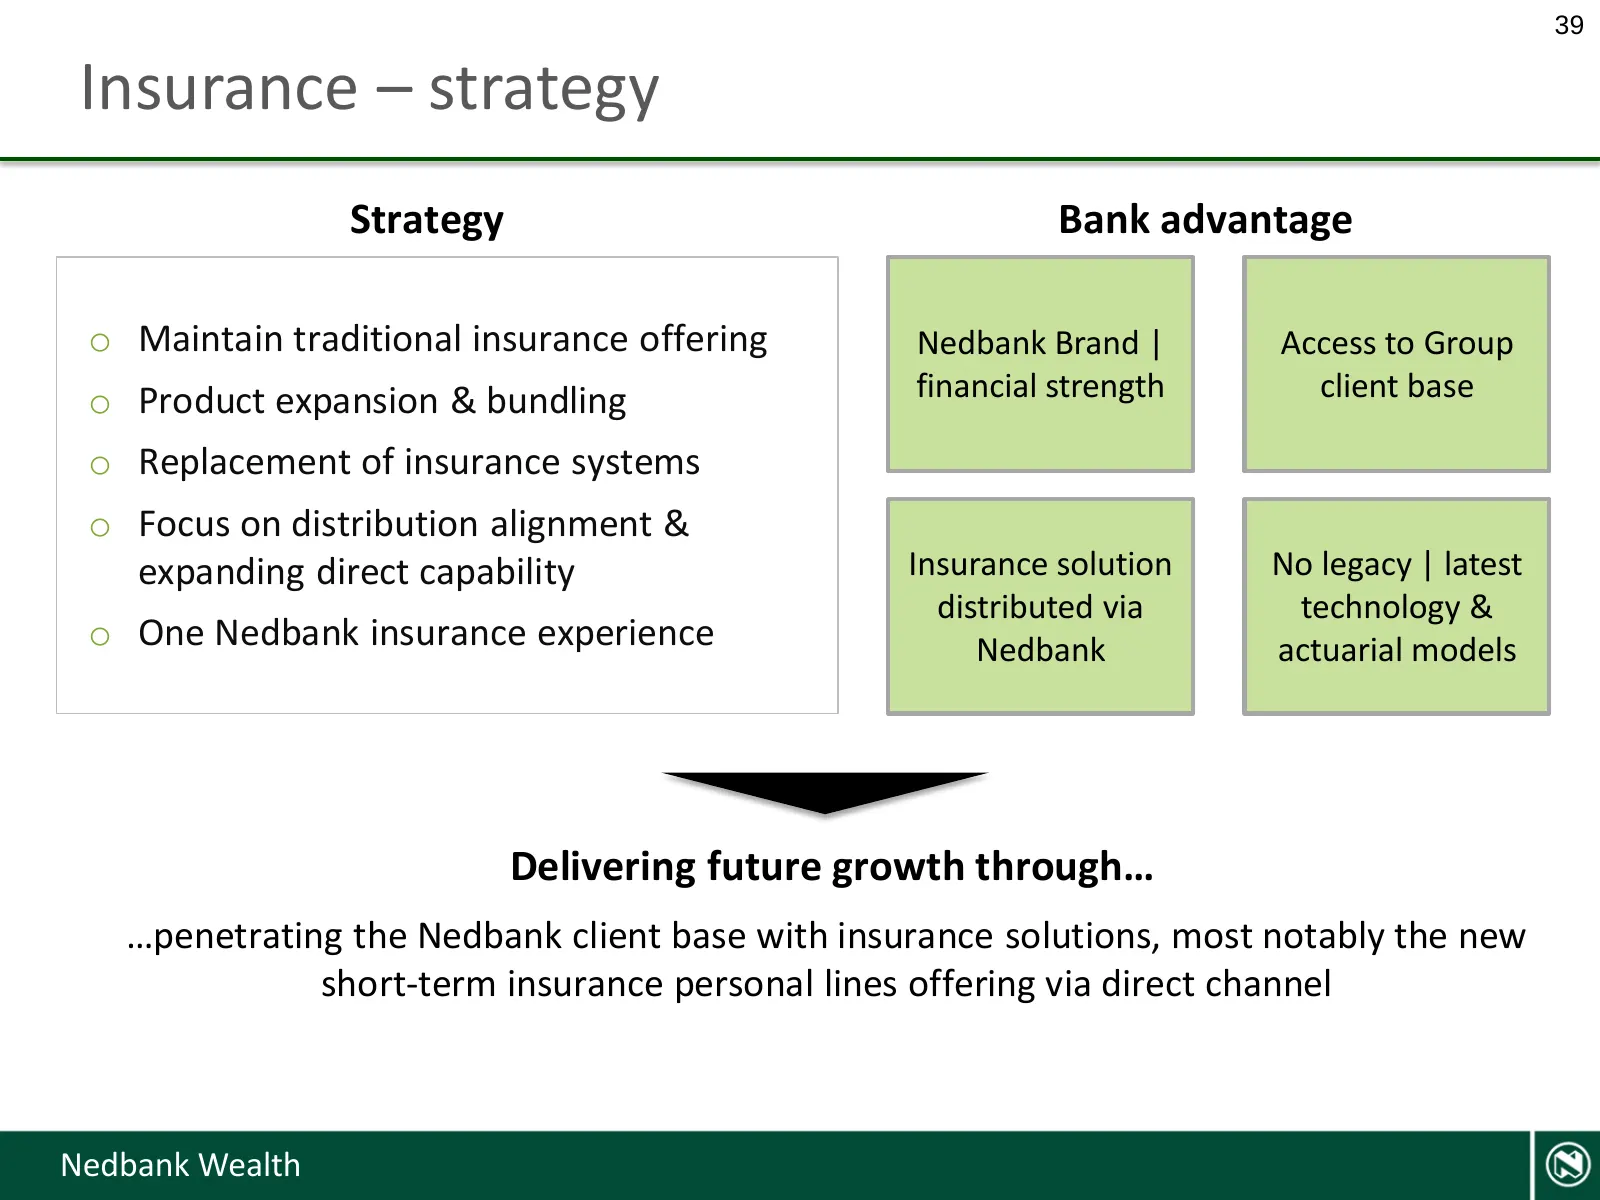
Slide 39: Insurance – strategy
39 Insurance – strategy Strategy Bank advantage o Maintain traditional insurance offering Nedbank Brand | Access to Group o Product expansion & bundling financial strength client base o Replacement of insurance systems o Focus on distribution alignment & expanding direct capability Insurance solutio
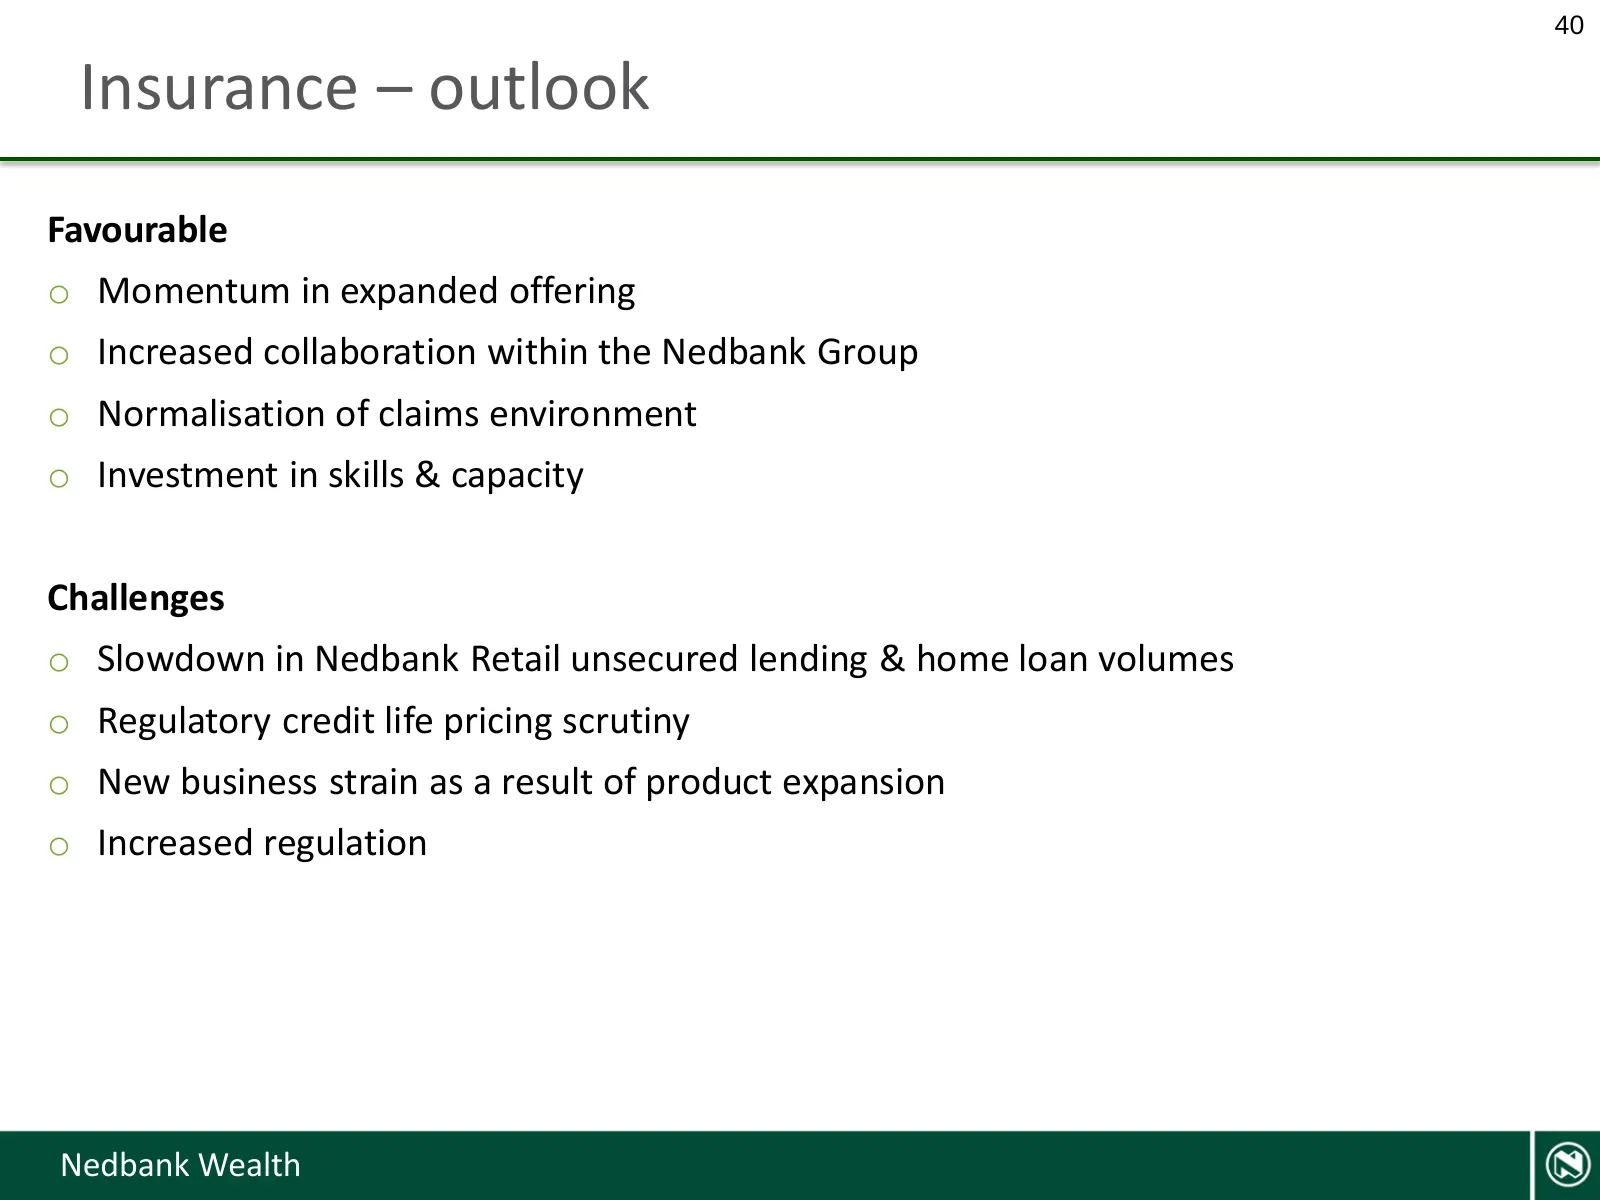
Slide 40: Insurance – outlook
40 Insurance – outlook Favourable o Momentum in expanded offering o Increased collaboration within the Nedbank Group o Normalisation of claims environment o Investment in skills & capacity Challenges o Slowdown in Nedbank Retail unsecured lending & home loan volumes o Regulatory credit life pricing
Slide 41: Questions & Closing
41 Questions & Closing Nedbank Wealth
Source: Internet Archive copy of nedbank.co.za
More decks from Nedbank Group
 FY2025 Earnings Presentation50 slides · February 2026
 FY2024 Earnings Presentation63 slides · March 2025
 27th UBS SA Financial Services Conference 202424 slides · October 2024
 Investor Presentation (October 2024)20 slides · October 2024
 Emerge — Nedbank Investment Conference (2024)22 slides · Sep 10, 2024
 H1 2024 Earnings Presentation85 slides · Aug 6, 2024