Hudson City Bancorp — Investor Presentation (February 2006)
30 slides from Hudson City Bancorp's investor presentation, Feb 21, 2006
Slide 1: Hudson City Bancorp First Quarter 2006
oe Se eee Hupson City BANCORP, | ________ Bank on Better Values” First Quarter 2006
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements include, but are not limited to, statements about (i) the benefits of the merger between Hudson City Bancorp,
Slide 3: Additional Information
Additional Information The proposed transaction will be submitted to Sound Federal's stockholders for their consideration. Sound Federal will file with the SEC a proxy statement and other relevant documents concerning the proposed transaction. Stockholders of Sound Federal are urged to read the prox
Slide 4: Overview & Strategy
oe Se eee Overview & Strategy
Slide 5: Overview
Overview 91 branch locations (not including Sound Federal acquisition): 85 in NJ, 4 in Suffolk County, NY and 2 in Richmond County (Staten Island), NY. "First-step" conversion in July 1999, selling 47% and raising $541 million. Completed "second-step" conversion on June 7, 2005 raising $3.9 billion.
Slide 6: Second-step Conversion
Second-step Conversion June 7th, raised $3.93 billion in "second-step" conversion and stock offering. Sold a total of 392,980,580 shares of common stock in the 7th largest offering (subscription and syndicated offering combined). After related expenses of $125.0 million, net proceeds from the stock
Slide 7: Capital Deployment
Capital Deployment $3.0 billion contributed to Hudson City Savings Bank with balance retained at the holding company Up to $2.8 billion of the total net proceeds invested in short-term government and agency securities Remaining proceeds used primarily for expanded ARM originations and purchases and
Slide 8: Operating Model
Operating Model Simple, consistent operating model Originate and purchase single family mortgage loans A jumbo originator and purchaser Retain all loans originated Outstanding Credit Quality Fund lending and investing activities with retail deposits and borrowings Compete on the basis of effective c
Slide 9: Operating Model (continued)
Operating Model (continued) Mortgage Loans Prime Products Only (Jumbo) No Option Arms or Neg-Am Multiple Distribution Channels Retail - Our Own Agents Retail - Mortgage Brokers and Bankers Wholesale - Geographic Diversity Cross Selling Initiatives and Incentives
Slide 10: Sound Federal Bancorp Acquisition
Sound Federal Bancorp Acquisition 19
Slide 11: Sound Federal Acquisition
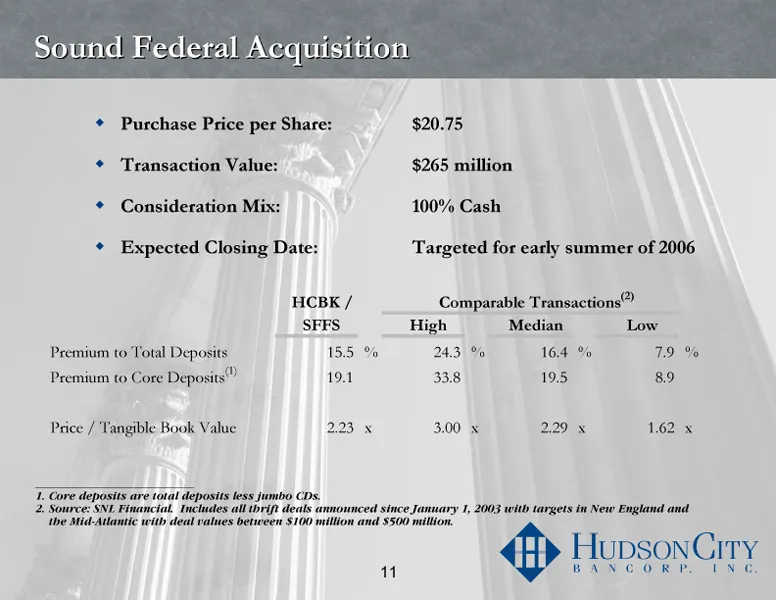
Sound Federal Acquisition Purchase Price per Share: $20.75 Transaction Value: $265 million Consideration Mix: 100% Cash Expected Closing Date: Targeted for early summer of 2006 HCBK / SFFS High Median Low Premium to Total Deposits 15.5 % 24.3 % 16.4 % 7.9 % Premium to Core Deposits (1) 19.1 33.8 19.
Slide 12: Attractive and Complementary Branch Network
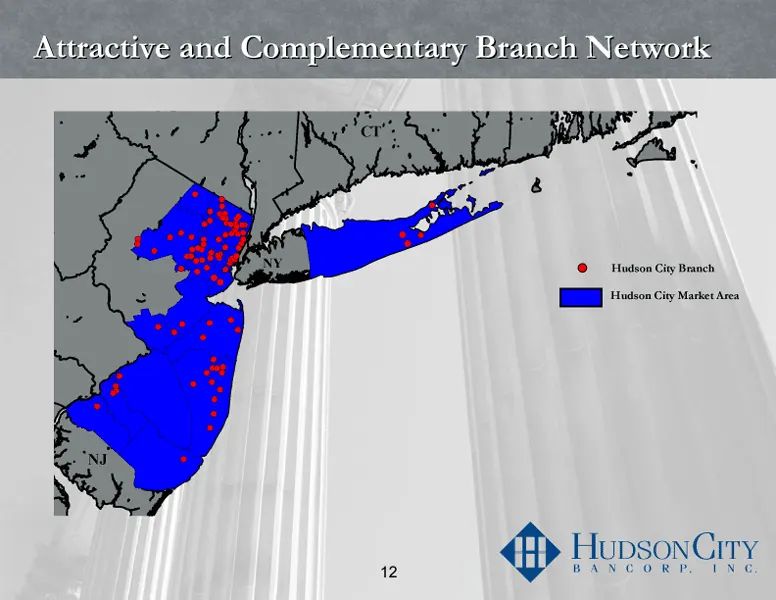
Attractive and Complementary Branch Network Hudson City Market Area Hudson City Branch NY
Slide 13: Attractive and Complementary Branch Network
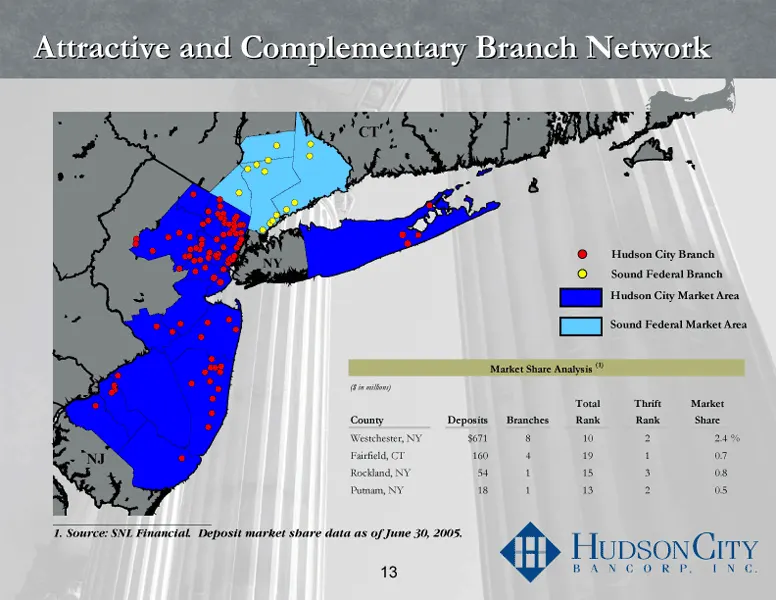
Attractive and Complementary Branch Network ___________________________ Source: SNL Financial. Deposit market share data as of June 30, 2005. Hudson City Market Area Sound Federal Market Area Hudson City Branch Sound Federal Branch NY
Slide 14: Expanding Presence in Desirable Markets
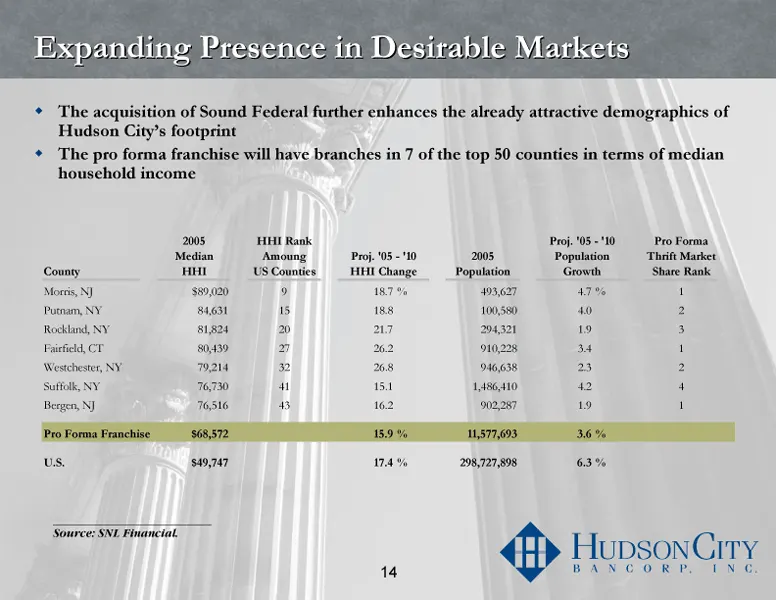
Expanding Presence in Desirable Markets The acquisition of Sound Federal further enhances the already attractive demographics of Hudson City's footprint The pro forma franchise will have branches in 7 of the top 50 counties in terms of median household income ___________________________ Source: SNL
Slide 15: Acquisition Pro Forma Financials
Acquisition Pro Forma Financials 31
Slide 16: Financial Snapshot
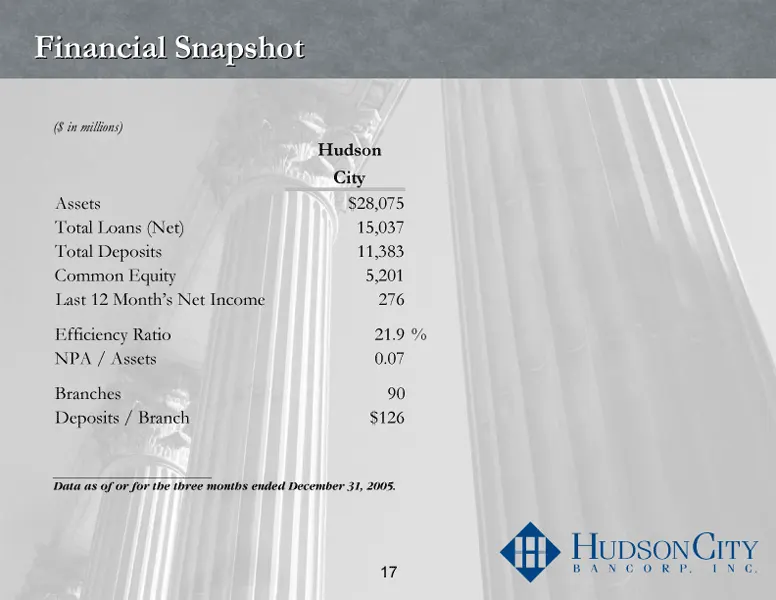
Financial Snapshot ___________________________ Data as of or for the three months ended December 31, 2005. ($ in millions) Hudson City Assets $28,075 Total Loans (Net) 15,037 Total Deposits 11,383 Common Equity 5,201 Last 12 Month's Net Income 276 Efficiency Ratio 21.9 % NPA / Assets 0.07 Branches 9
Slide 17: Pro Forma Financials
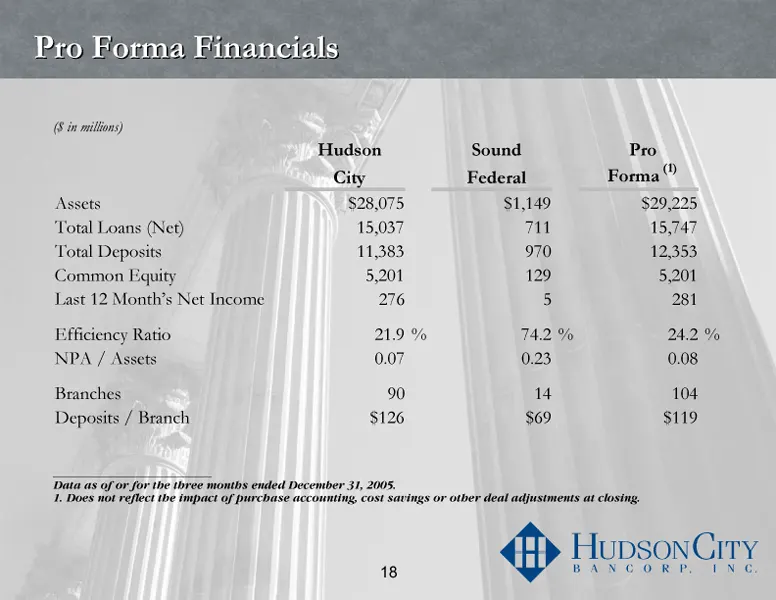
Pro Forma Financials ___________________________ Data as of or for the three months ended December 31, 2005. Does not reflect the impact of purchase accounting, cost savings or other deal adjustments at closing. ($ in millions) Hudson Sound Pro City Federal Forma (1) Assets $28,075 $1,149 $29,225 To
Slide 18: Financial Assumptions
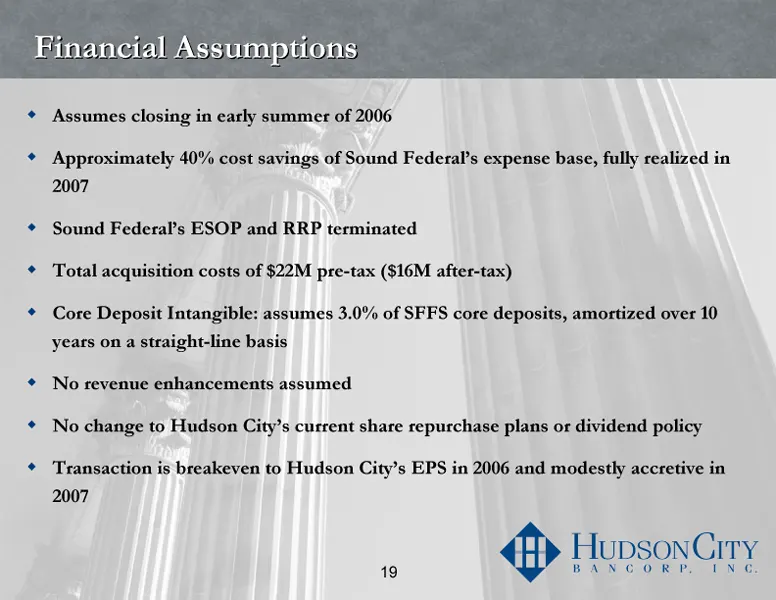
Financial Assumptions Assumes closing in early summer of 2006 Approximately 40% cost savings of Sound Federal's expense base, fully realized in 2007 Sound Federal's ESOP and RRP terminated Total acquisition costs of $22M pre-tax ($16M after-tax) Core Deposit Intangible: assumes 3.0% of SFFS core dep
Slide 19: Hudson City's Financial Review
Hudson City's Financial Review 39
Slide 20: Strong Asset Growth
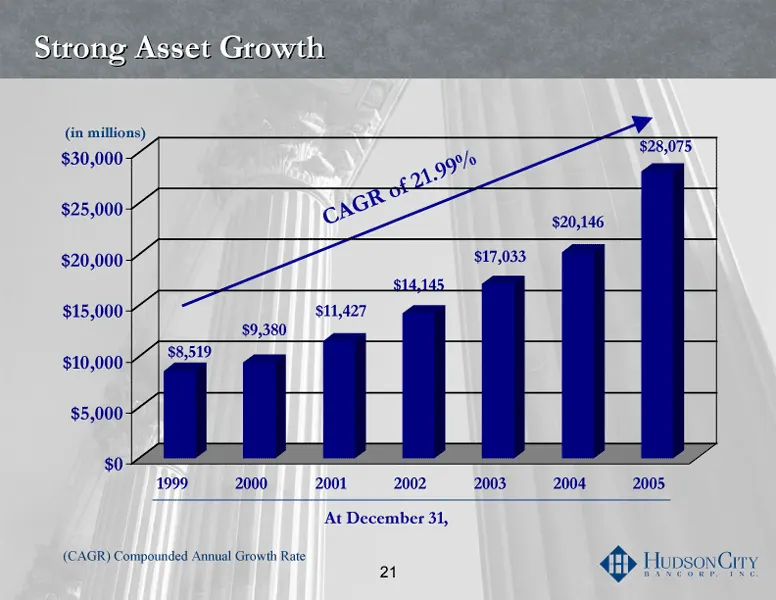
Strong Asset Growth (in millions) CAGR of 21.99% At December 31, (CAGR) Compounded Annual Growth Rate 41
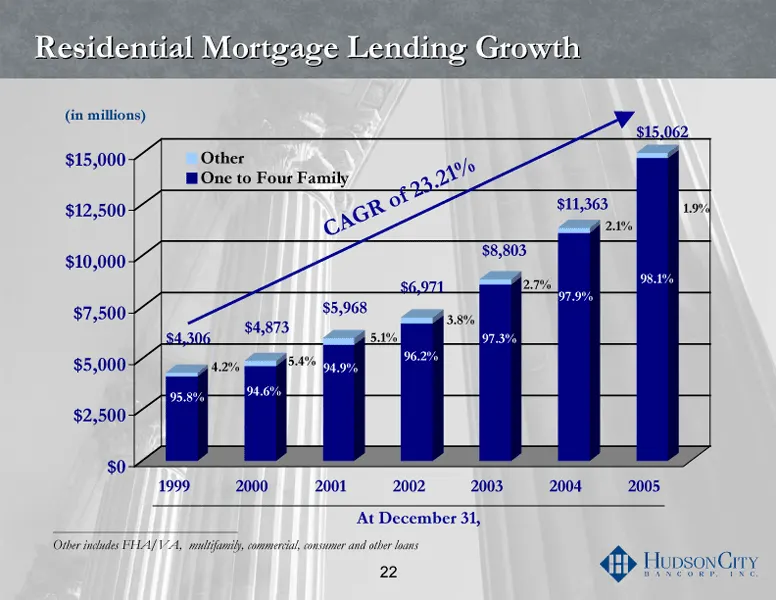
Slide 21: Residential Mortgage Lending Growth
Residential Mortgage Lending Growth CAGR of 23.21% 95.8% 94.6% 94.9% 96.2% 97.3% 97.9% 4.2% 5.4% 5.1% 3.8% 2.7% 2.1% At December 31, (in millions) 98.1% 1.9% ___________________________ Other includes FHA/VA, multifamily, commercial, consumer and other loans 43
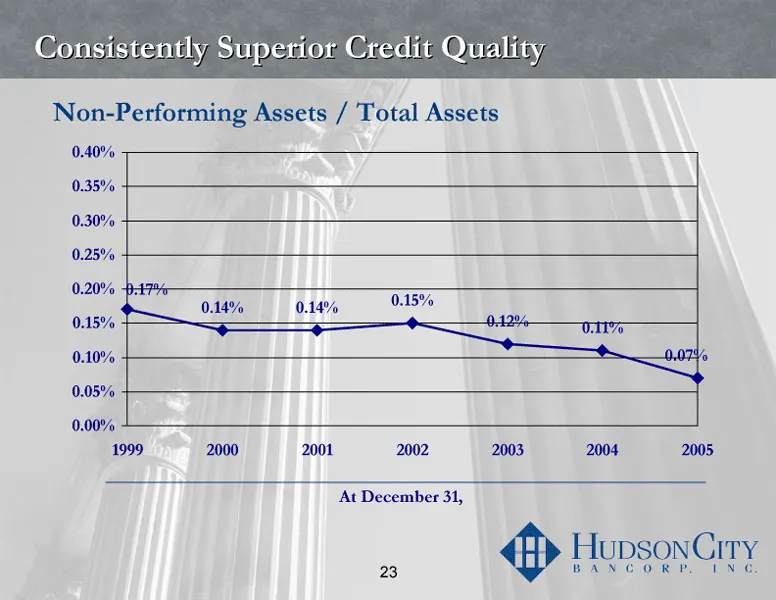
Slide 22: Consistently Superior Credit Quality
Consistently Superior Credit Quality Non-Performing Assets / Total Assets At December 31,
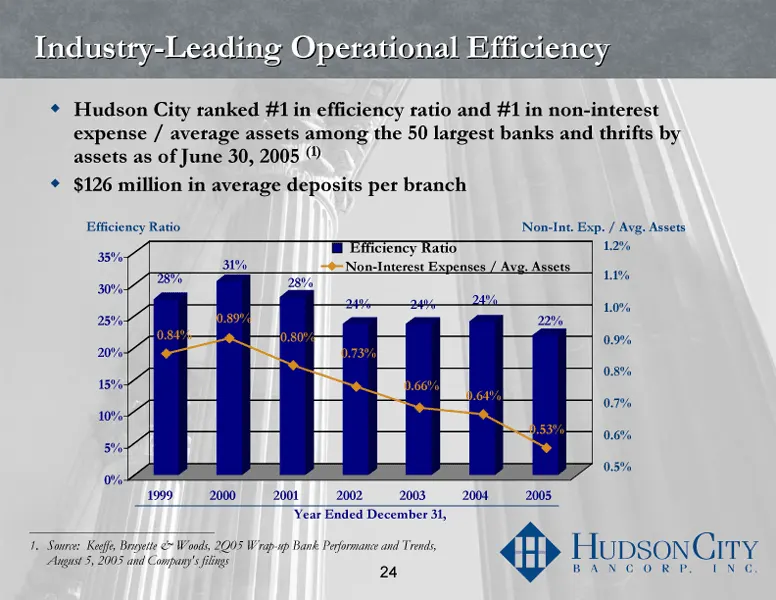
Slide 23: Industry-Leading Operational Efficiency
Industry-Leading Operational Efficiency Hudson City ranked #1 in efficiency ratio and #1 in non-interest expense / average assets among the 50 largest banks and thrifts by assets as of June 30, 2005 (1) $126 million in average deposits per branch ___________________________ Source: Keeffe, Bruyette
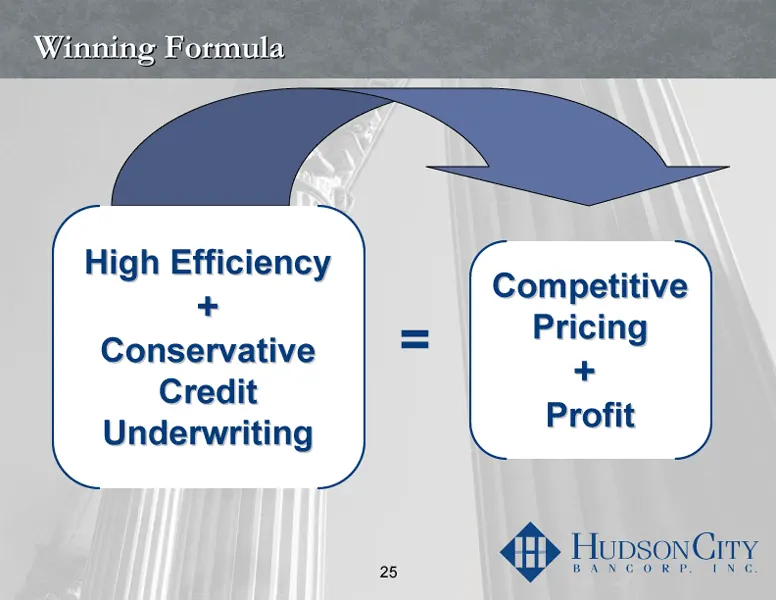
Slide 24: Winning Formula
Winning Formula Competitive Pricing + Profit = High Efficiency + Conservative Credit Underwriting
Slide 25: Earnings and Dividend Growth
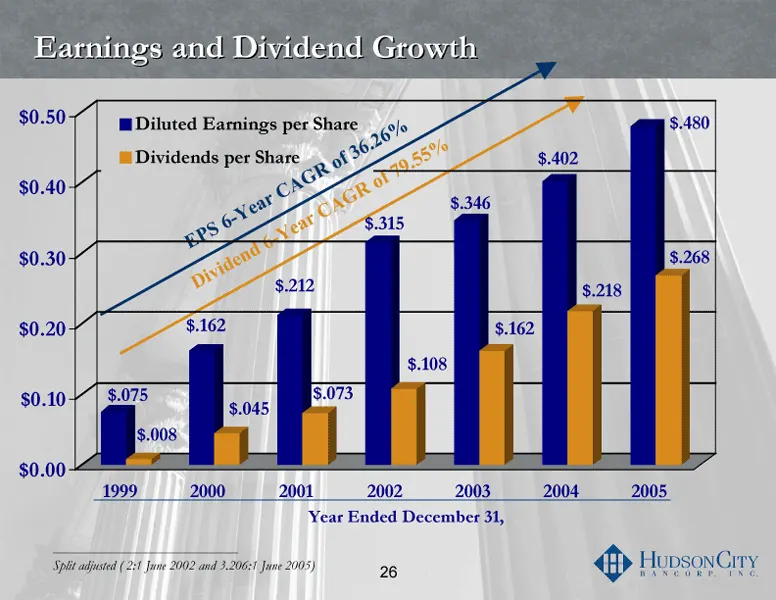
Earnings and Dividend Growth Dividend 6-Year CAGR of 79.55% ___________________________ Split adjusted ( 2:1 June 2002 and 3.206:1 June 2005) Year Ended December 31, EPS 6-Year CAGR of 36.26% 51
Slide 26: Consistent Profitability
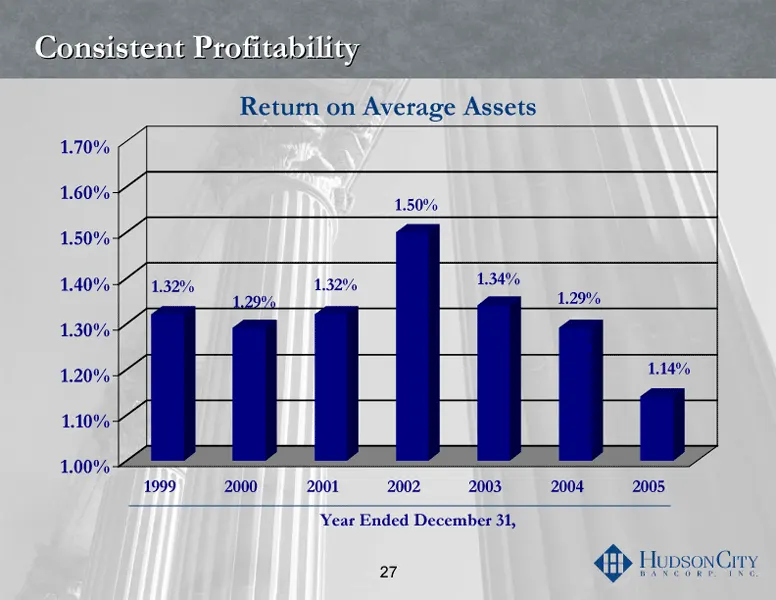
Consistent Profitability Return on Average Assets Year Ended December 31, 53
Slide 27: Superior Stock Price Performance
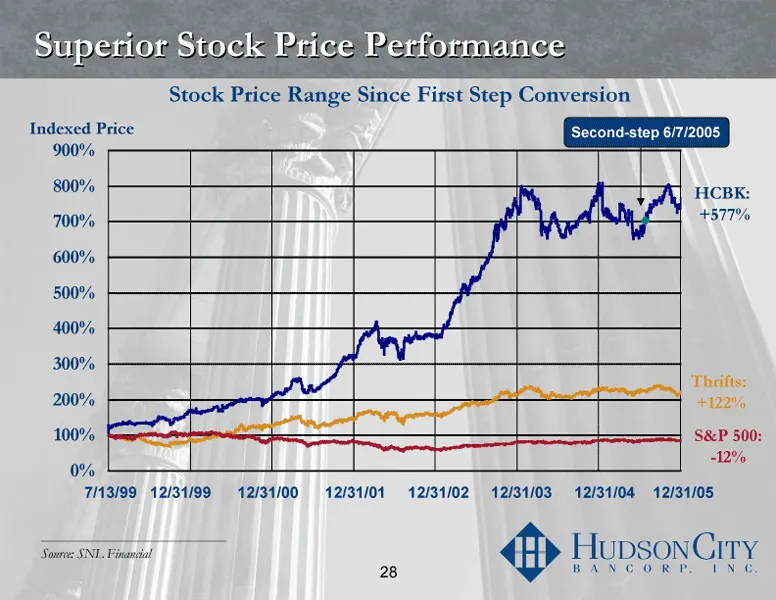
Superior Stock Price Performance ___________________________ Source: SNL Financial Indexed Price Stock Price Range Since First Step Conversion Thrifts: +122% HCBK: +577% S&P 500: - -12% Second-step 6/7/2005 7/13/99 12/31/99 12/31/00 12/31/01 12/31/02 12/31/03 12/31/04 12/31/05
Slide 28: Strategy: Focused Growth
Strategy: Focused Growth Continue strategy of internally-generated growth Increase mortgage originations and purchases Pursue de novo branch expansion in existing and adjacent suburban markets with similar demographics 10 to 15 new branches planned annually Capitalize on merger-related market disrup
Slide 29: Highlights
Highlights A leading franchise in attractive, high-income markets Consistent, straightforward business model Record of strong profitability throughout the economic cycle Capital to Sustain Growth in a Changing Interest Rate Environment ($5.20 billion at December 31, 2005) Best-in-class operating eff
Slide 30: oe Se eee
oe Se eee HupsonCiry NC OR FP, Sat oo
Source: SEC EDGAR · 8-K filed Feb 21, 2006
More decks from Hudson City Bancorp Inc
 Citigroup 2013 US Financial Services Conference30 slides · Mar 6, 2013
 BancAnalysts Association of Boston Conference 201229 slides · Nov 2, 2012
 Barclays Global Financial Services Conference 201234 slides · Sep 10, 2012
 Merger or Acquisition (August 2012)32 slides · Aug 27, 2012
 Shareholder Meeting (April 2012)20 slides · Apr 25, 2012
 Shareholder Meeting (April 2011)38 slides · Apr 19, 2011