Ferrexpo plc · LSE:FXPO
Ferrexpo — H1 2015 Earnings Presentation
23 slides from Ferrexpo's earnings presentation, Aug 5, 2015
Slide 1: 1H 2015 Interim Results Presentation
1 H 2 0 1 5 I N T E R I M R E S U LT S P R E S E N TAT I O N
Slide 2: Disclaimer
DISCLAIMER This document is being supplied to you solely for your information and does not constitute or form any governmental or regulatory body without the prior written consent of the Company. part of any offer or invitation or inducement to sell or issue, or any solicitation of any offer to Cert
Slide 3: Introduction – Michael Abrahams, Chairman
INTRODUCTION MICHAEL ABRAHAMS CBE DL, CHAIRMAN 3
Slide 4: Chris Mawe, CFO
CHRIS MAWE, CFO () FERREXPO ji
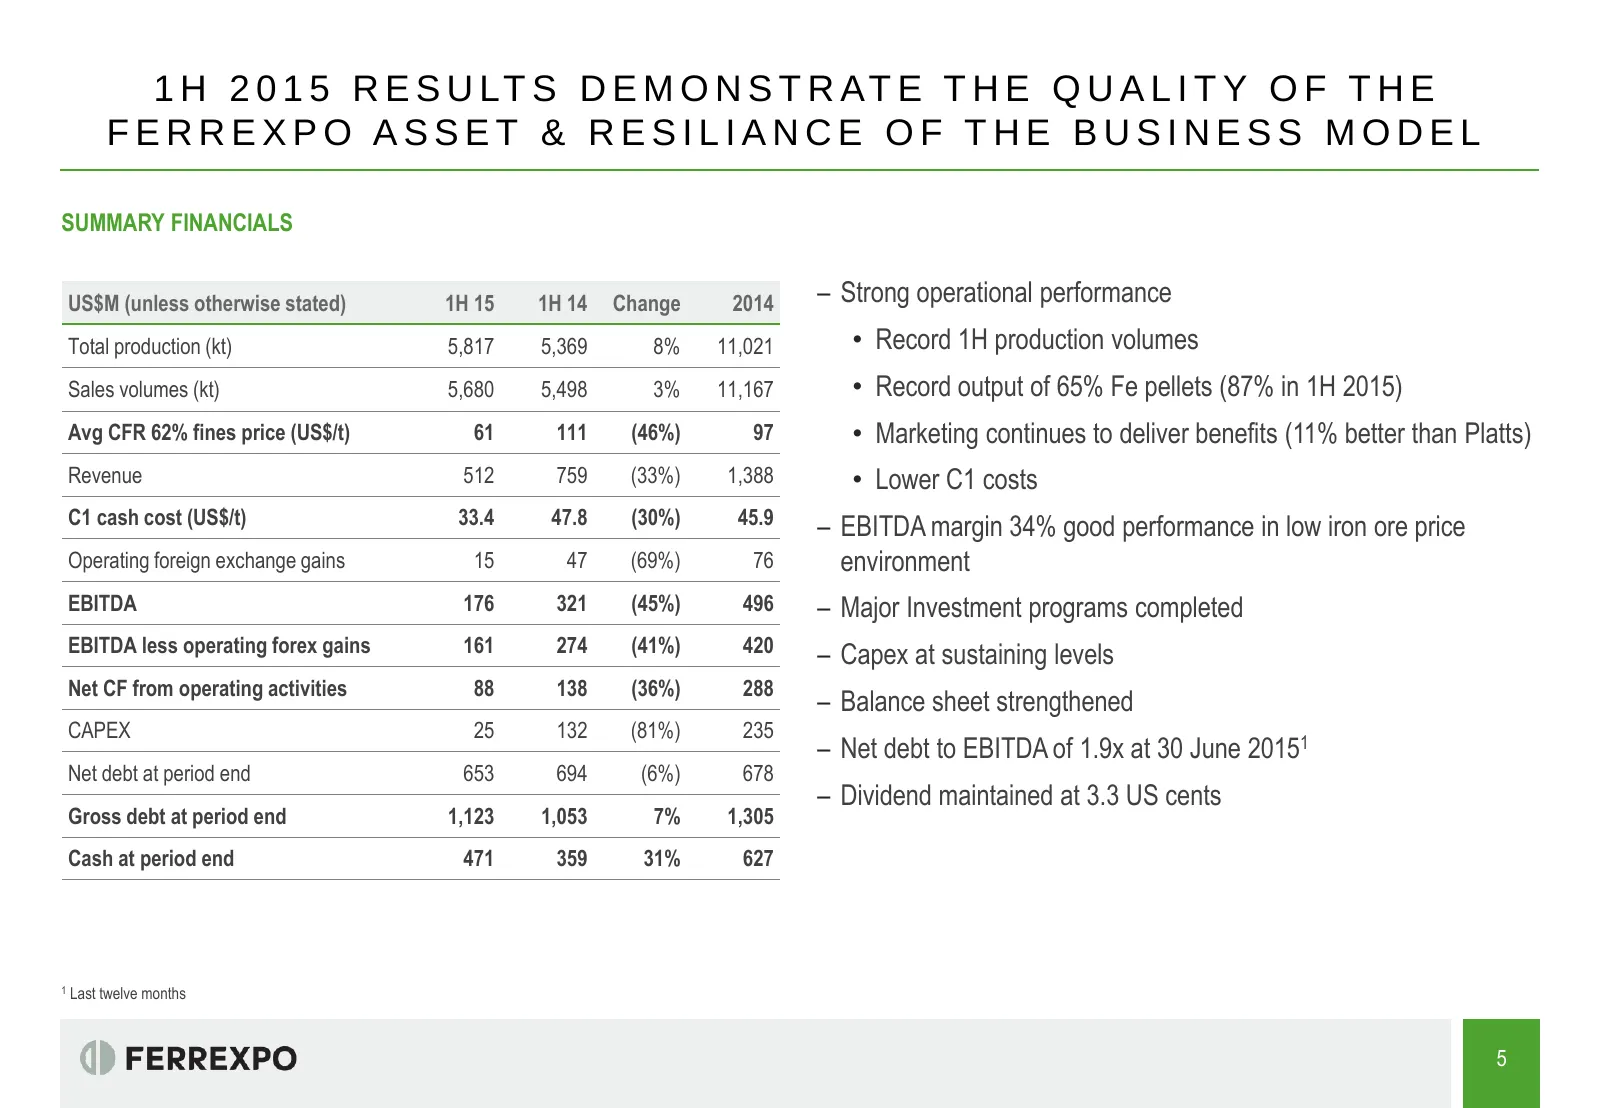
Slide 5: 1H 2015 results demonstrate quality of the asset and resilience of the business model
1 H 2 0 1 5 R E S U LT S D E M O N S T R AT E T H E Q U A L I T Y O F T H E FERREXPO ASSET & RESILIANCE OF THE BUSINESS MODEL SUMMARY FINANCIALS US$M (unless otherwise stated) 1H 15 1H 14 Change 2014 – Strong operational performance Total production (kt) 5,817 5,369 8% 11,021 • Record 1H production
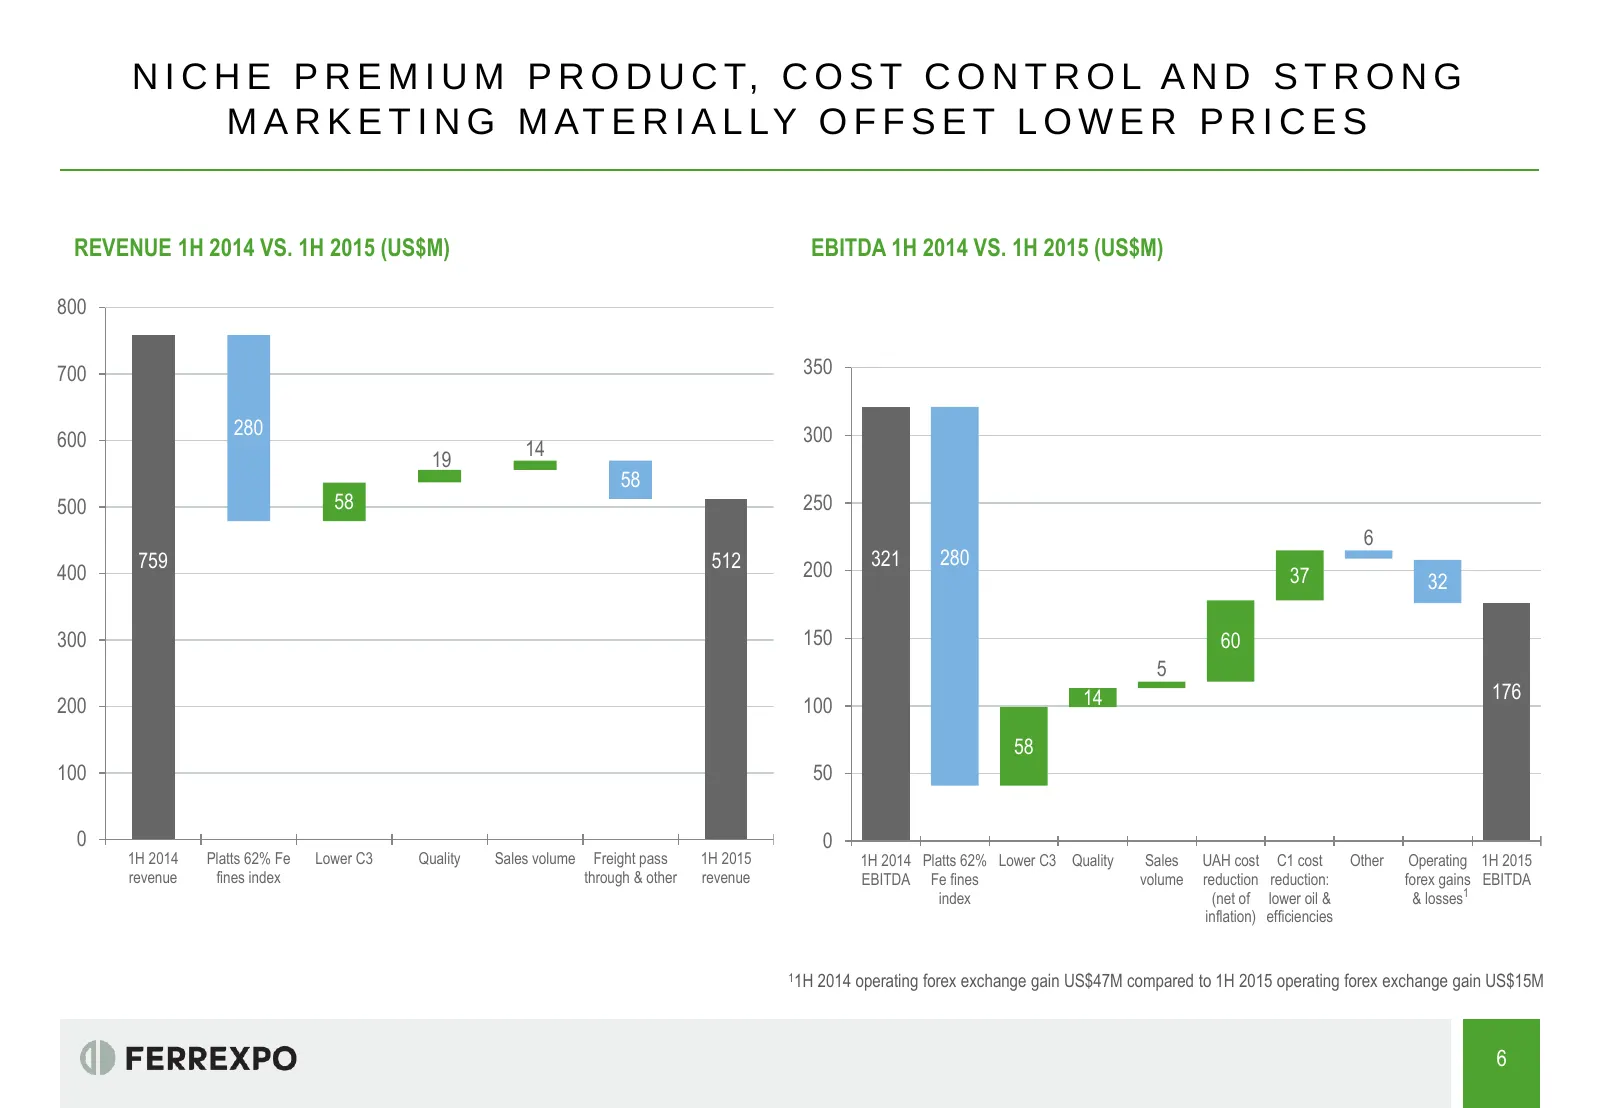
Slide 6: Niche premium product, cost control and strong marketing offset lower prices
N I C H E P R E M I U M P R O D U C T, C O S T C O N T R O L A N D S T R O N G M A R K E T I N G M AT E R I A L LY O F F S E T L O W E R P R I C E S REVENUE 1H 2014 VS. 1H 2015 (US$M) EBITDA 1H 2014 VS. 1H 2015 (US$M) 800 700 350 280 300 600 14 19 58 500 58 250 6 759 512 321 280 400 200 37 32 300 15
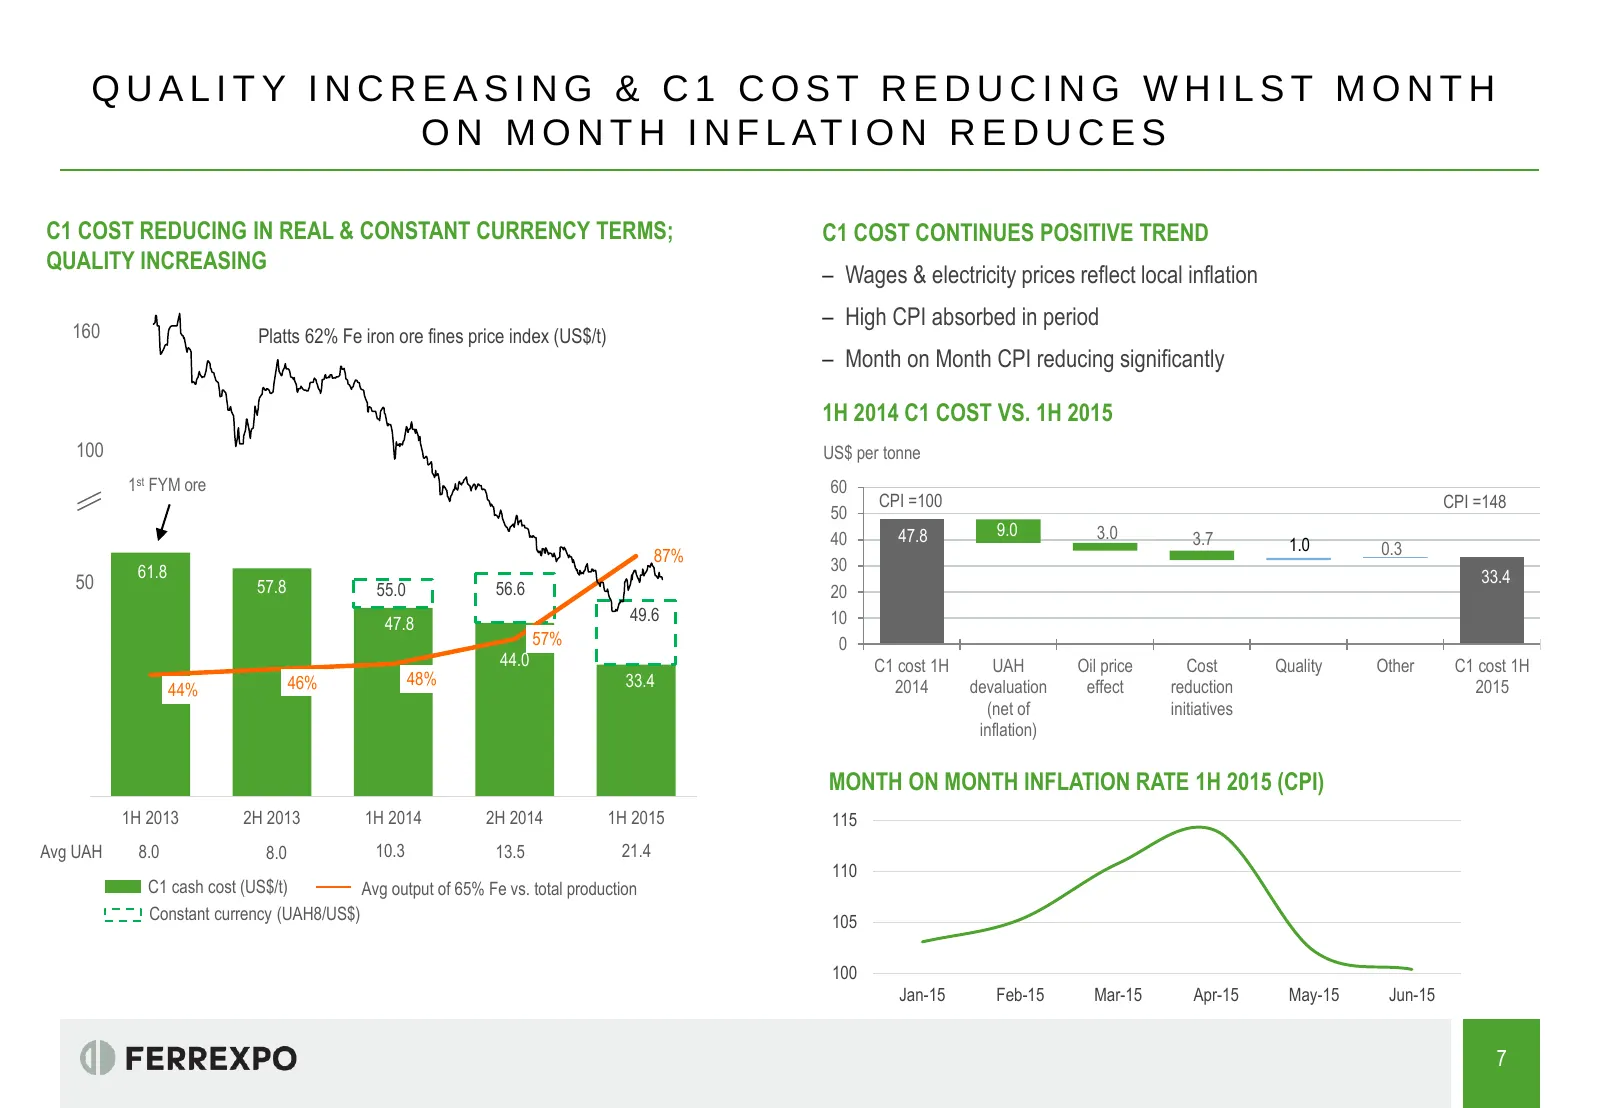
Slide 7: Quality increasing and C1 cost reducing whilst month on month inflation reduces
QUALITY INCREASING & C1 COST REDUCING WHILST MONTH O N M O N T H I N F L AT I O N R E D U C E S C1 COST REDUCING IN REAL & CONSTANT CURRENCY TERMS; C1 COST CONTINUES POSITIVE TREND QUALITY INCREASING – Wages & electricity prices reflect local inflation – High CPI absorbed in period 160 Platts 62% Fe
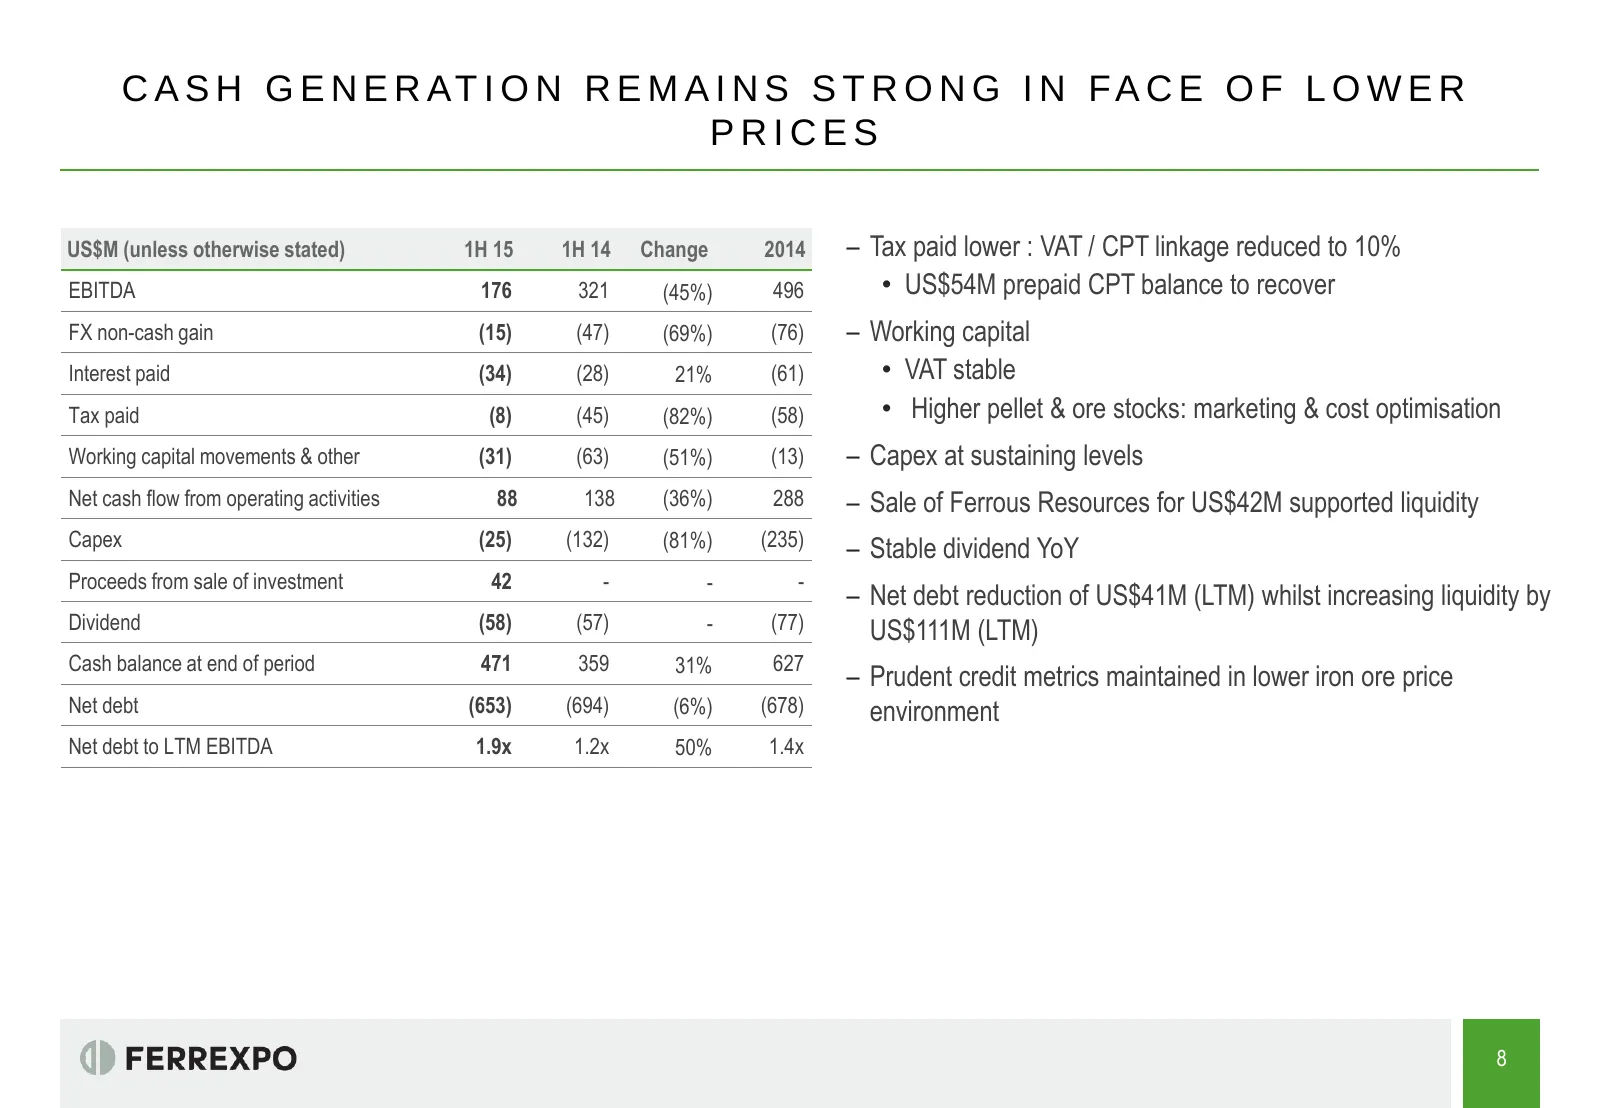
Slide 8: Cash generation remains strong in face of lower prices
C A S H G E N E R AT I O N R E M A I N S S T R O N G I N F A C E O F L O W E R PRICES US$M (unless otherwise stated) 1H 15 1H 14 Change 2014 – Tax paid lower : VAT / CPT linkage reduced to 10% EBITDA 176 321 (45%) 496 • US$54M prepaid CPT balance to recover FX non-cash gain (15) (47) (69%) (76) – Wo
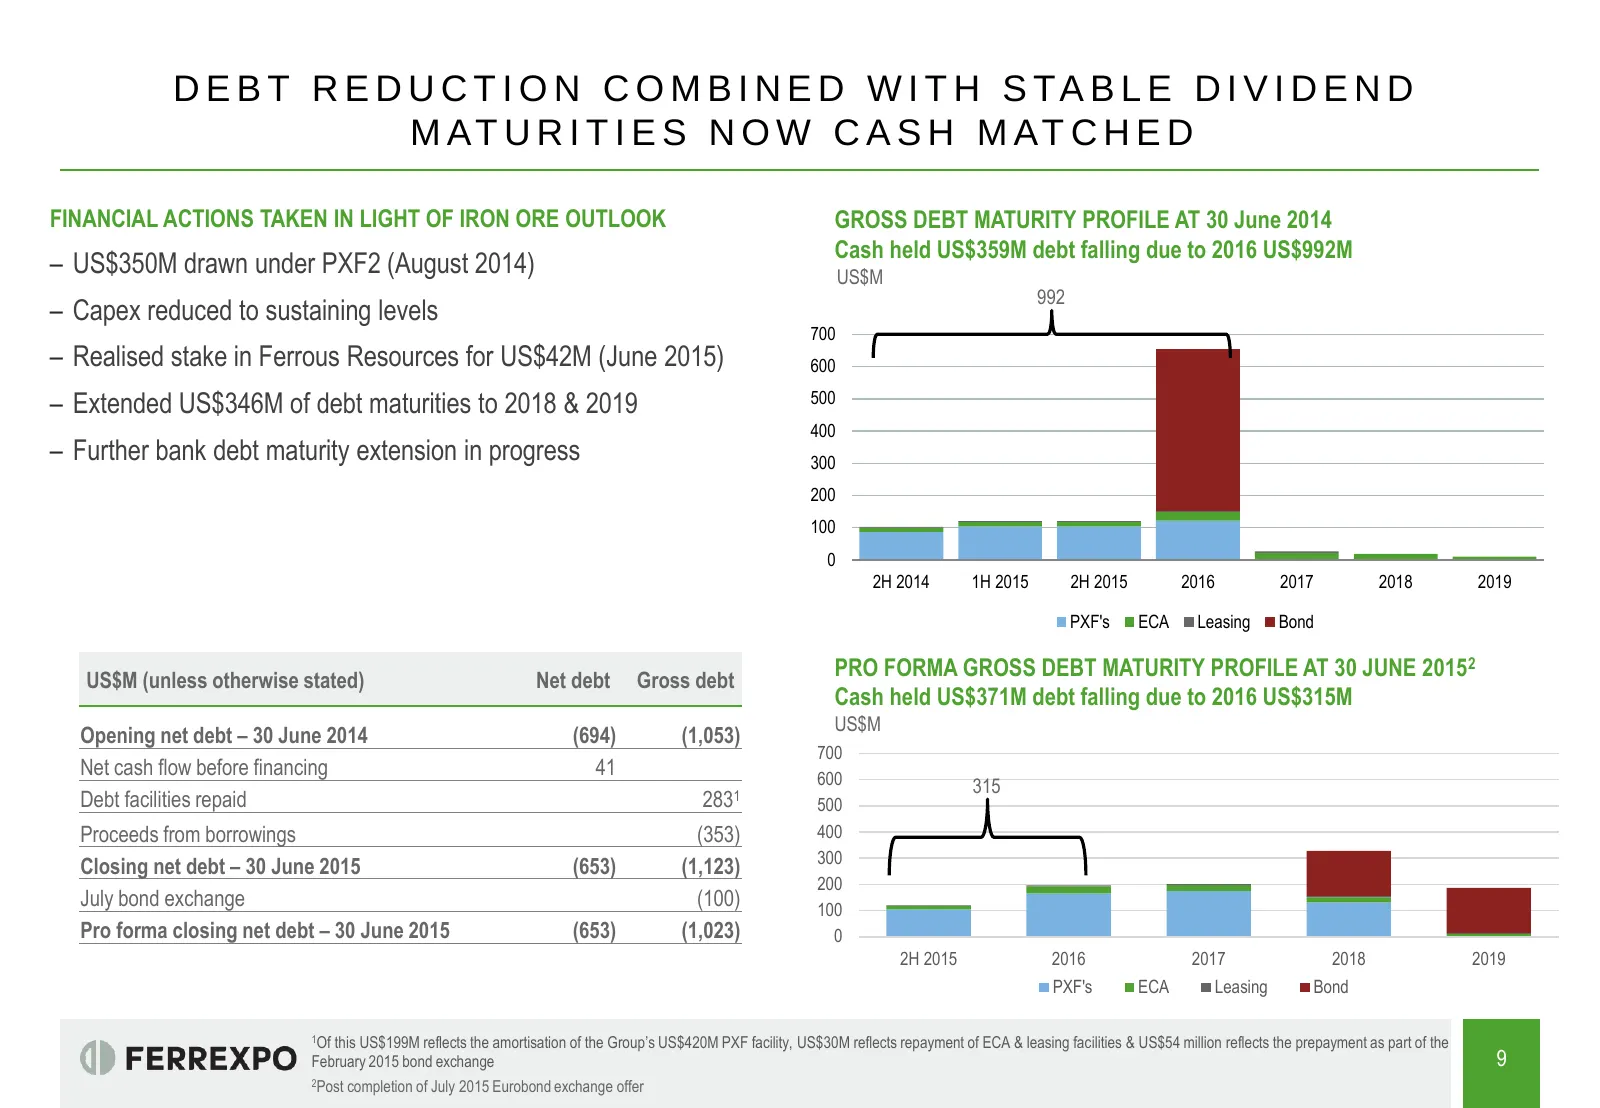
Slide 9: Debt reduction combined with stable dividend; maturities now cash matched
D E B T R E D U C T I O N C O M B I N E D W I T H S TA B L E D I V I D E N D M AT U R I T I E S N O W C A S H M AT C H E D FINANCIAL ACTIONS TAKEN IN LIGHT OF IRON ORE OUTLOOK GROSS DEBT MATURITY PROFILE AT 30 June 2014 Cash held US$359M debt falling due to 2016 US$992M – US$350M drawn under PXF2 (A
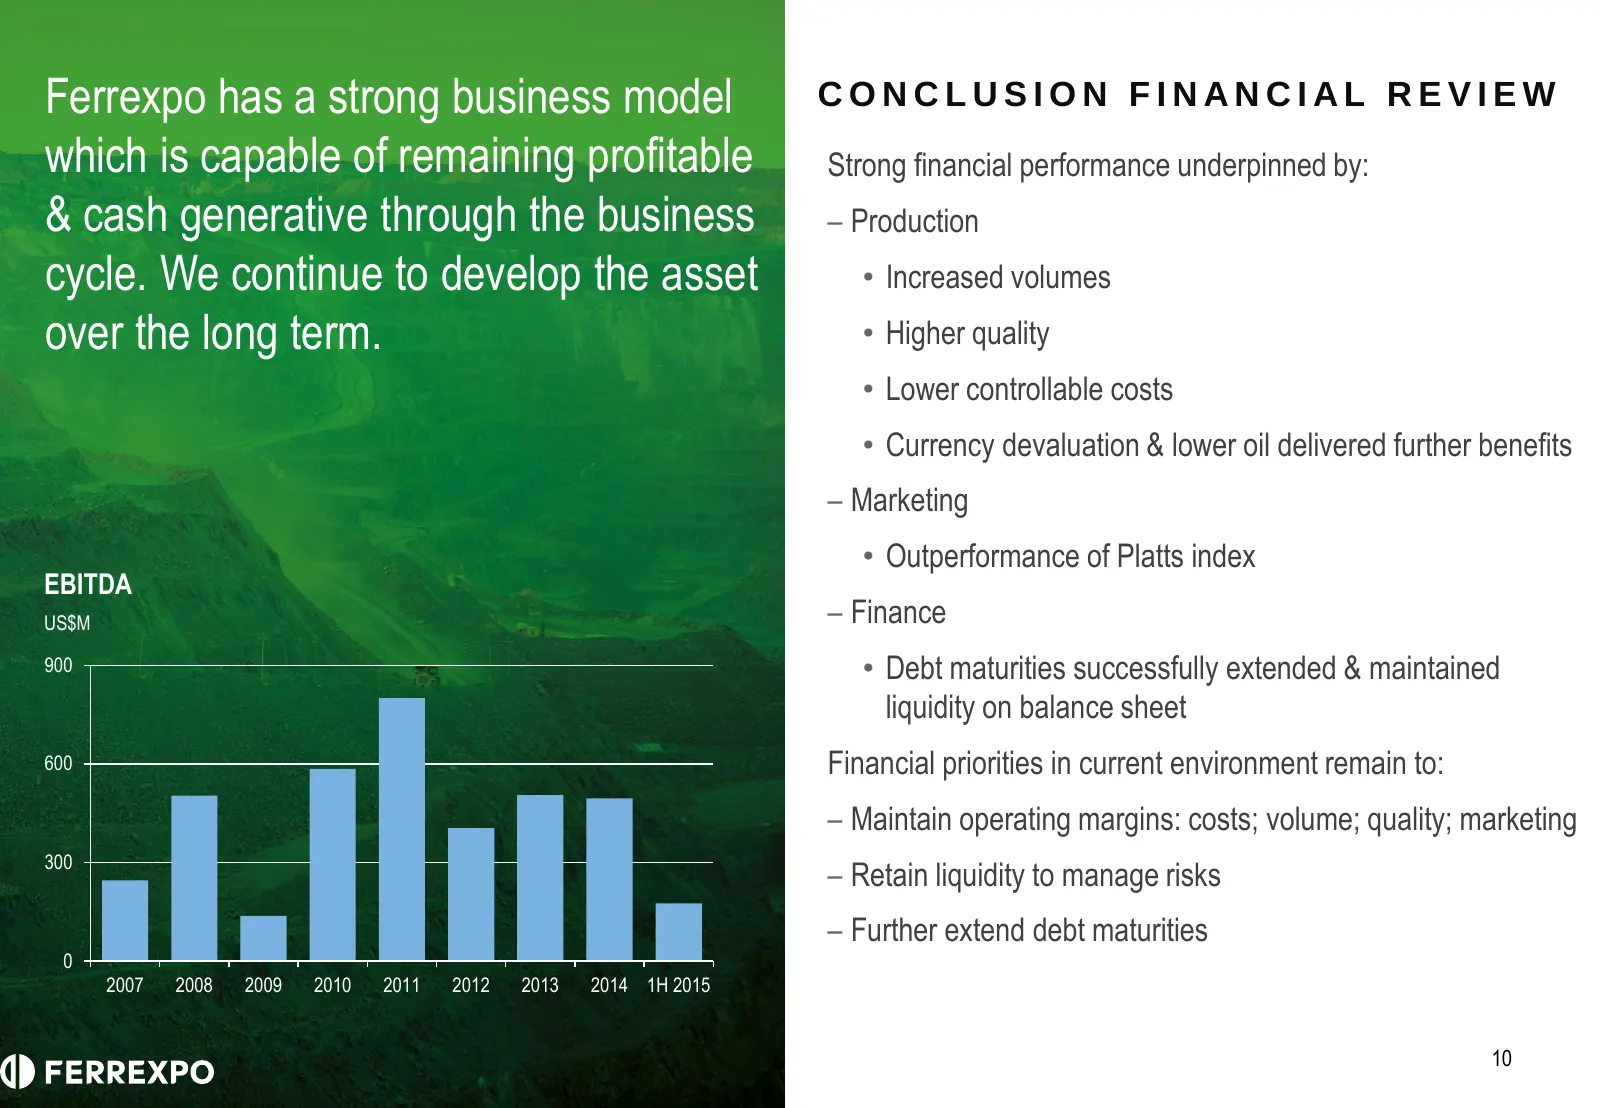
Slide 10: Conclusion financial review
Ferrexpo has a strong business model CONCLUSION FINANCIAL REVIEW which is capable of remaining profitable Strong financial performance underpinned by: & cash generative through the business – Production cycle. We continue to develop the asset • Increased volumes over the long term. • Higher quality
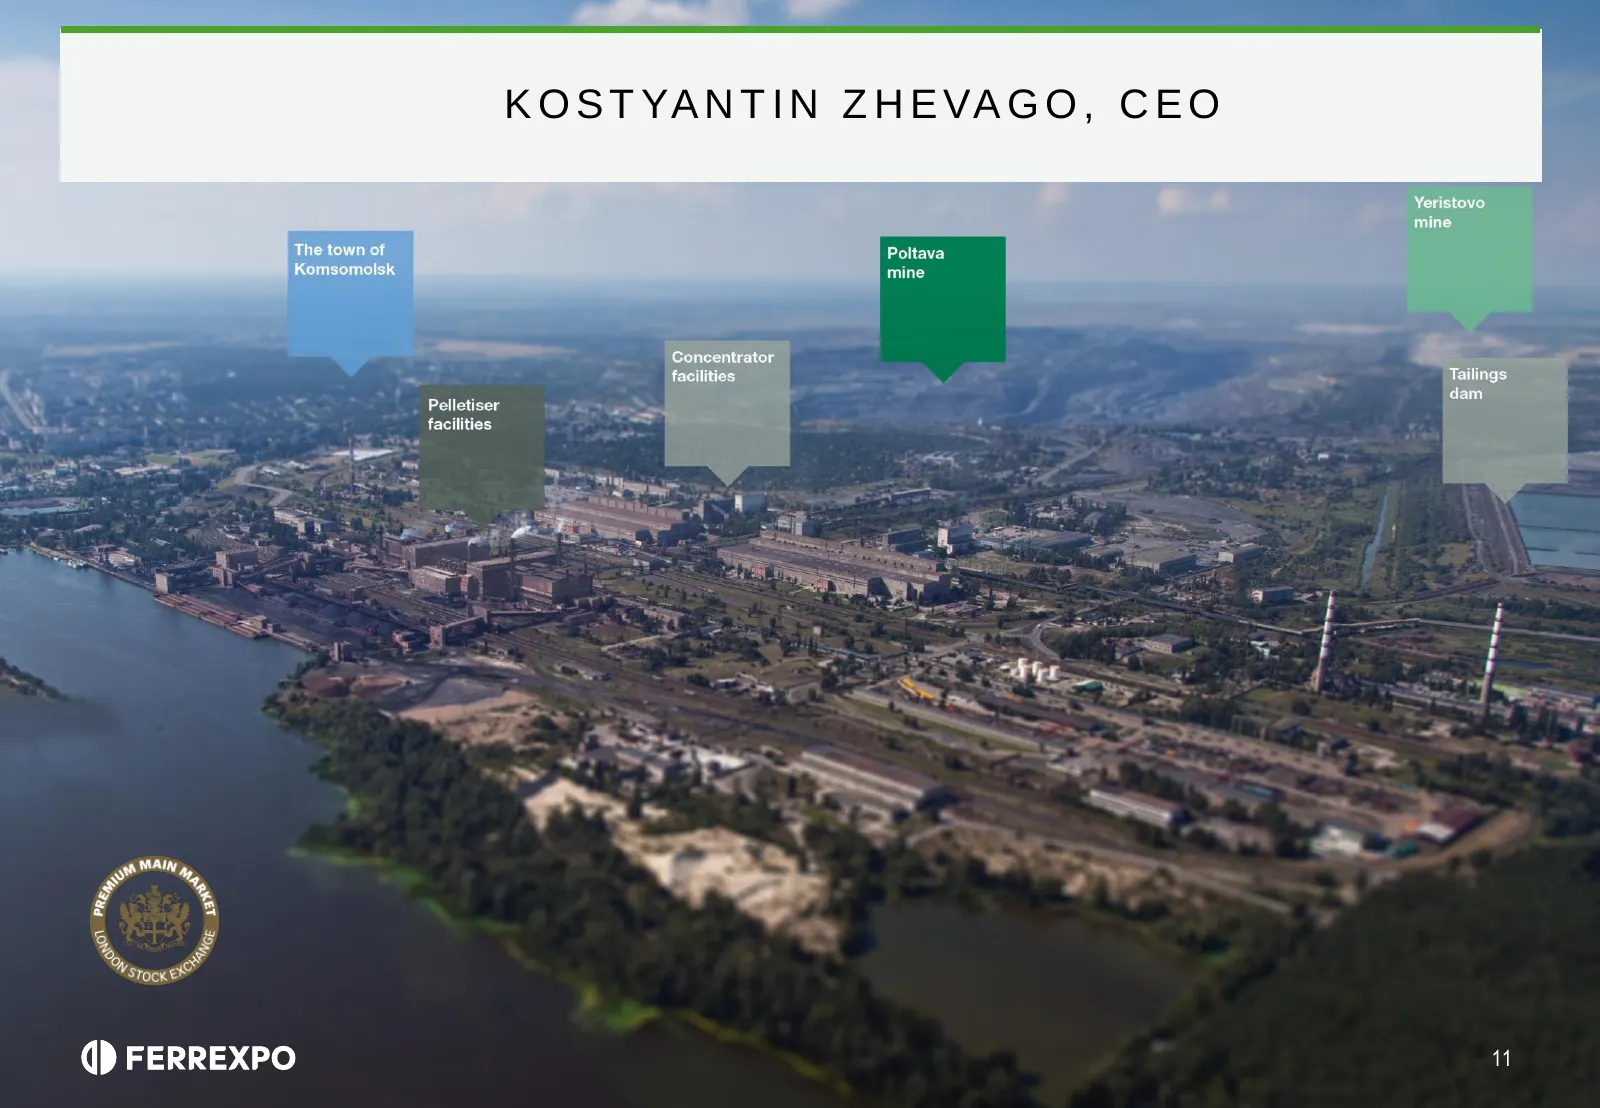
Slide 11: Kostyantynivka Zhevago pelletiser facilities
are a - Pelletiser 7 S | ae facilities () FERREXPO 11
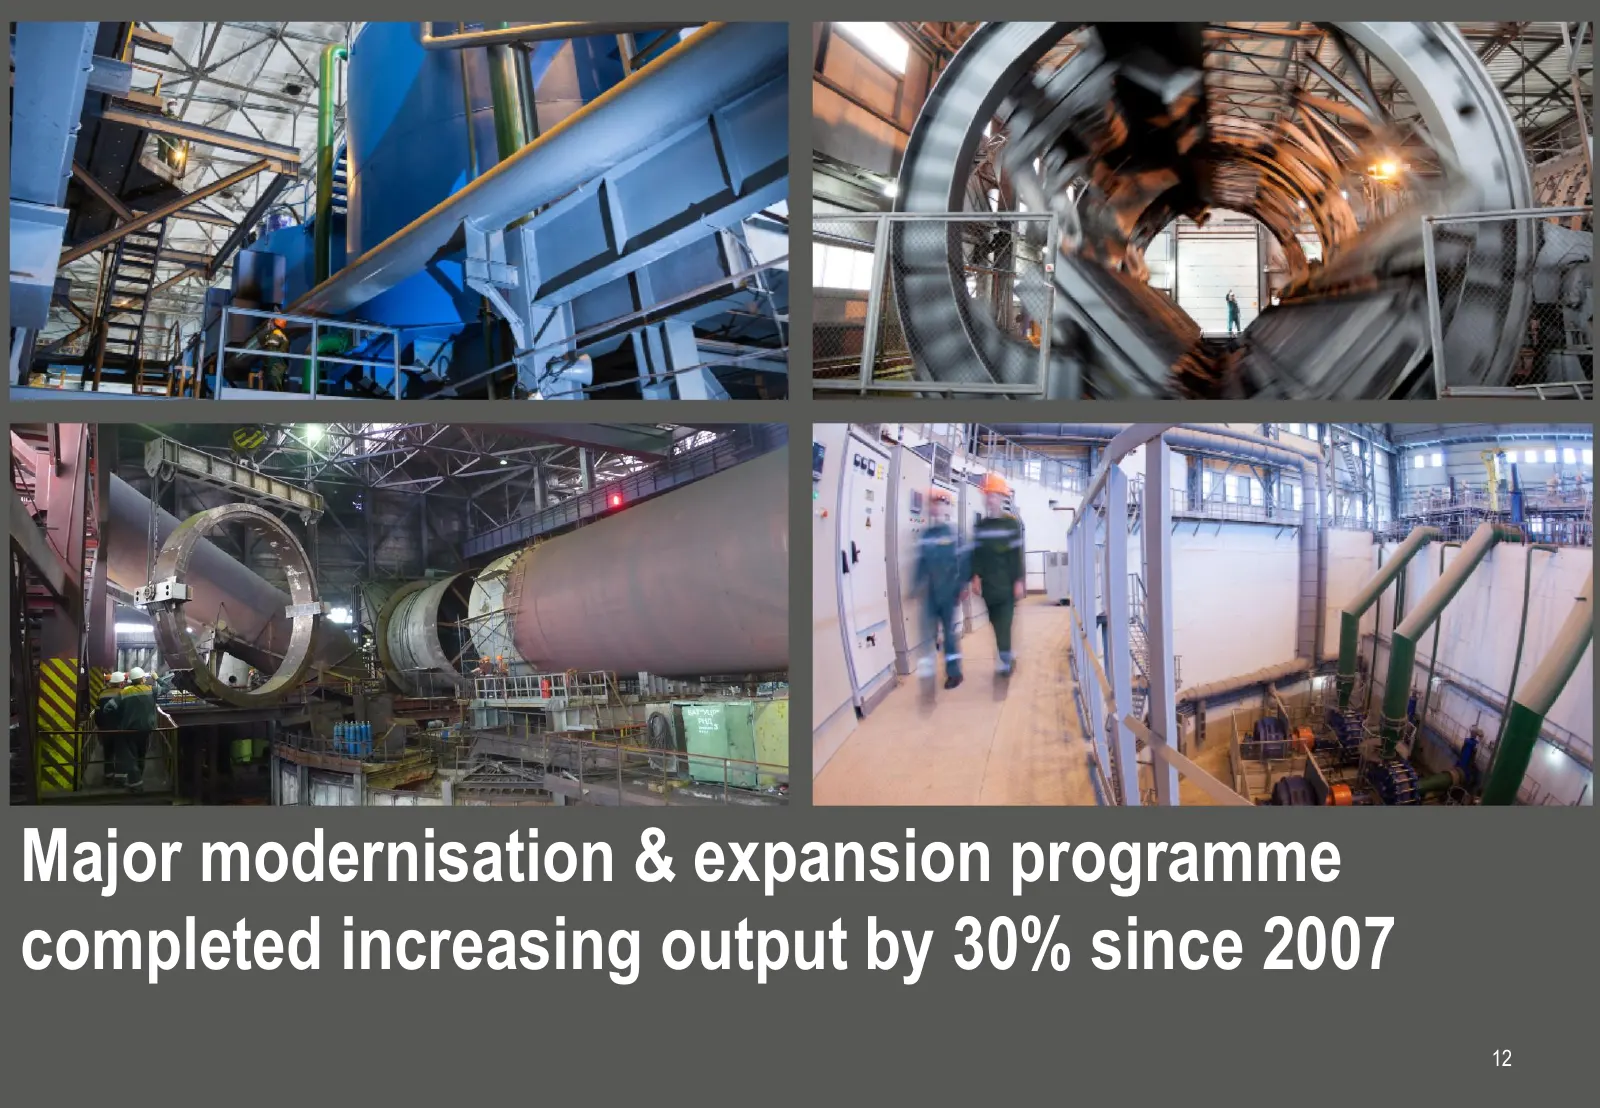
Slide 12: Major modernisation and expansion programme completed
Major modernisation & expansion programme completed increasing output by 30% since 2007 12
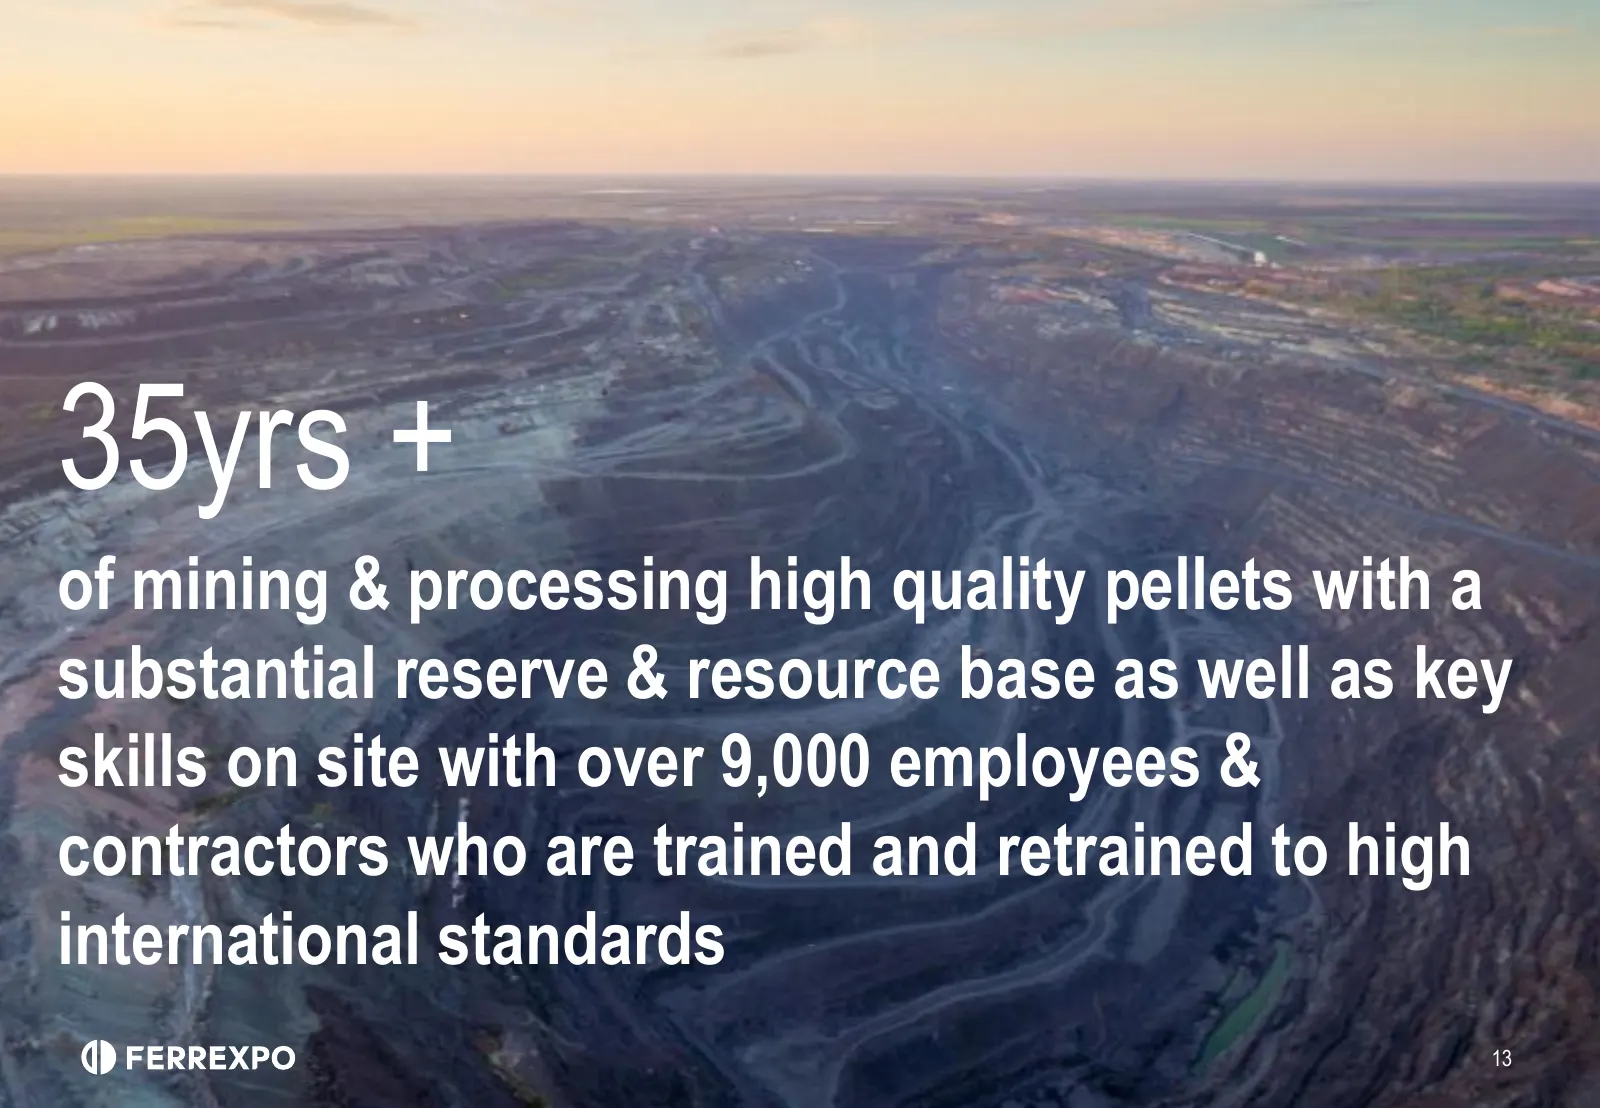
Slide 13: 35 years+ of mining and processing high quality pellets
35yrs + of mining & processing high quality pellets with a substantial reserve & resource base as well as key skills on site with over 9,000 employees & contractors who are trained and retrained to high international standards 13
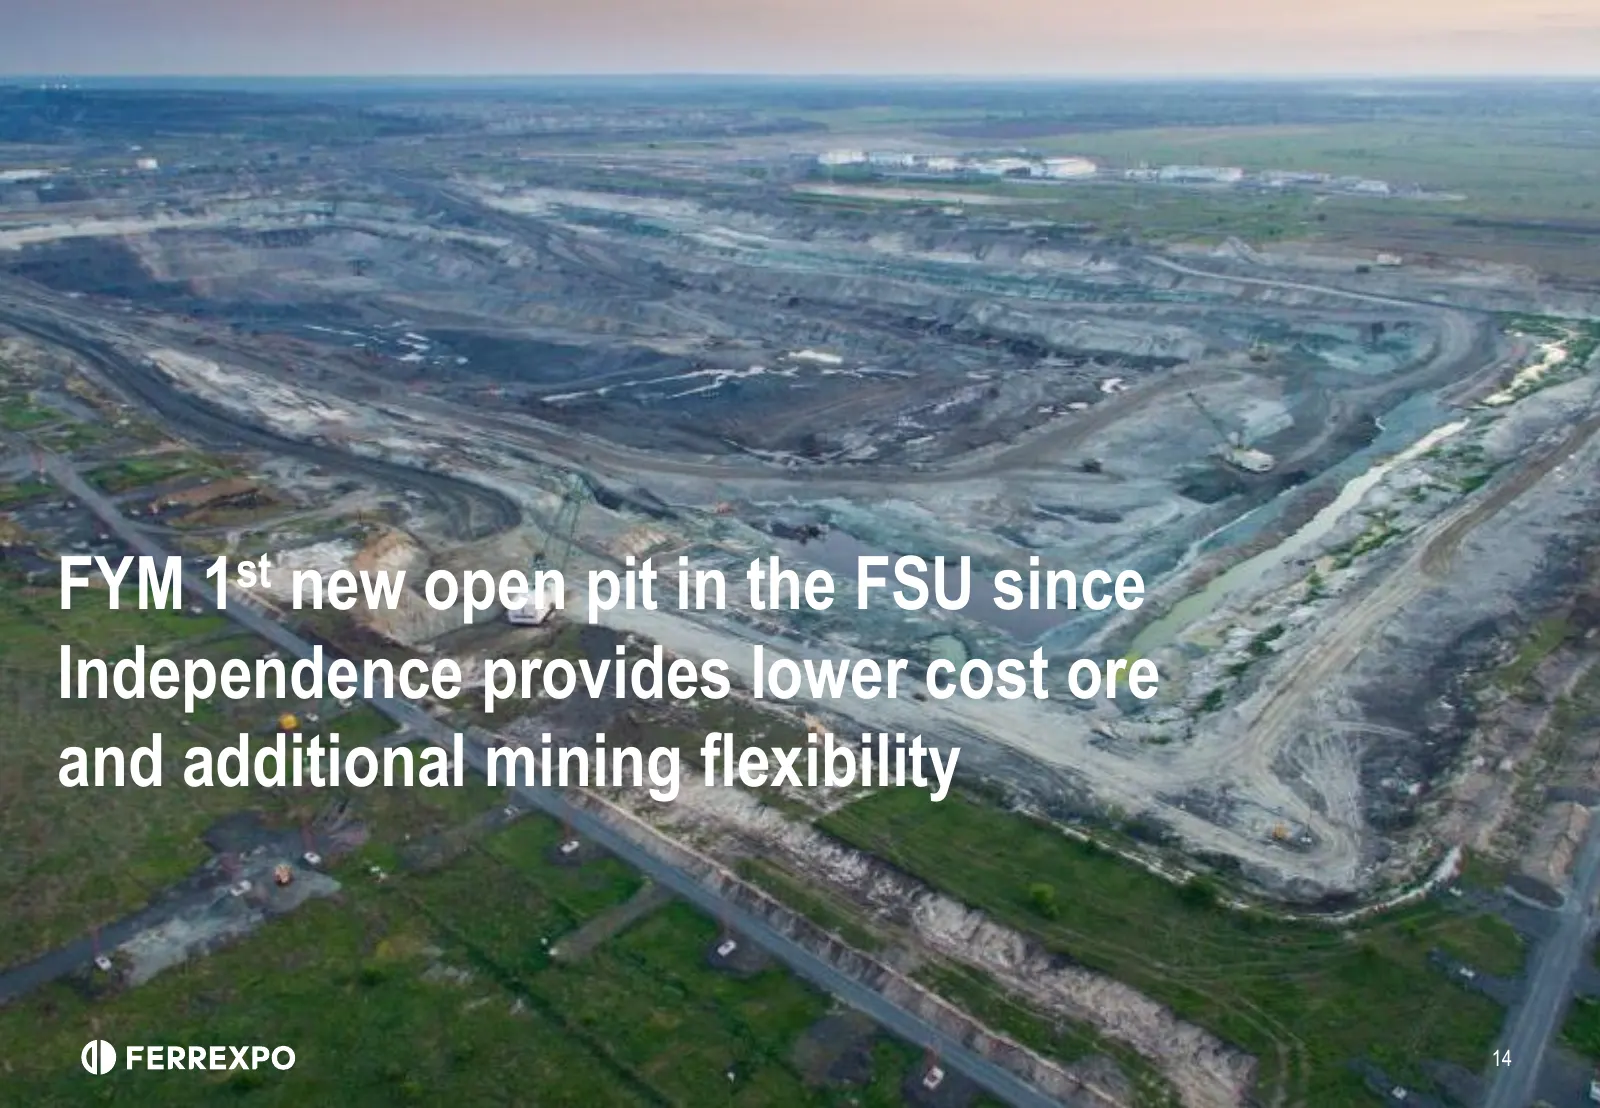
Slide 14: FYM: first new open pit in the FSU since Independence
FYM 1st new open pit in the FSU since Independence provides lower cost ore and additional mining flexibility 14
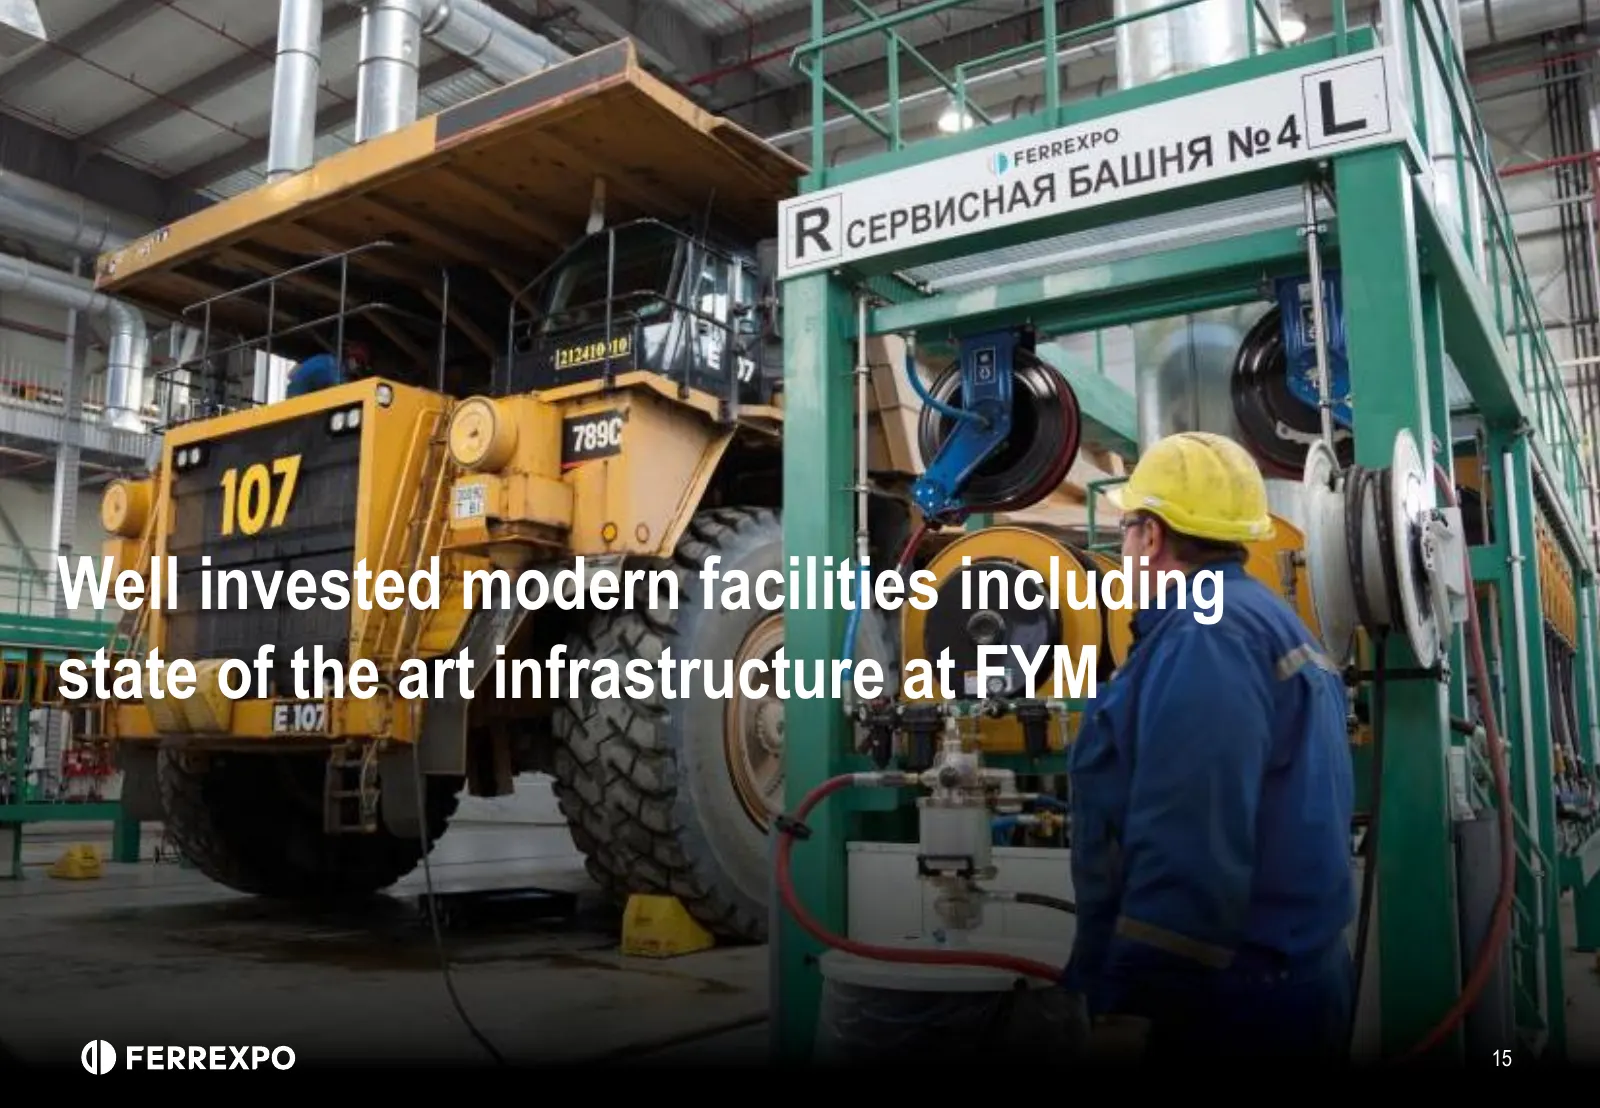
Slide 15: Well invested modern facilities including infrastructure at FYM
Well invested modern facilities including state of the art infrastructure at FYM 15
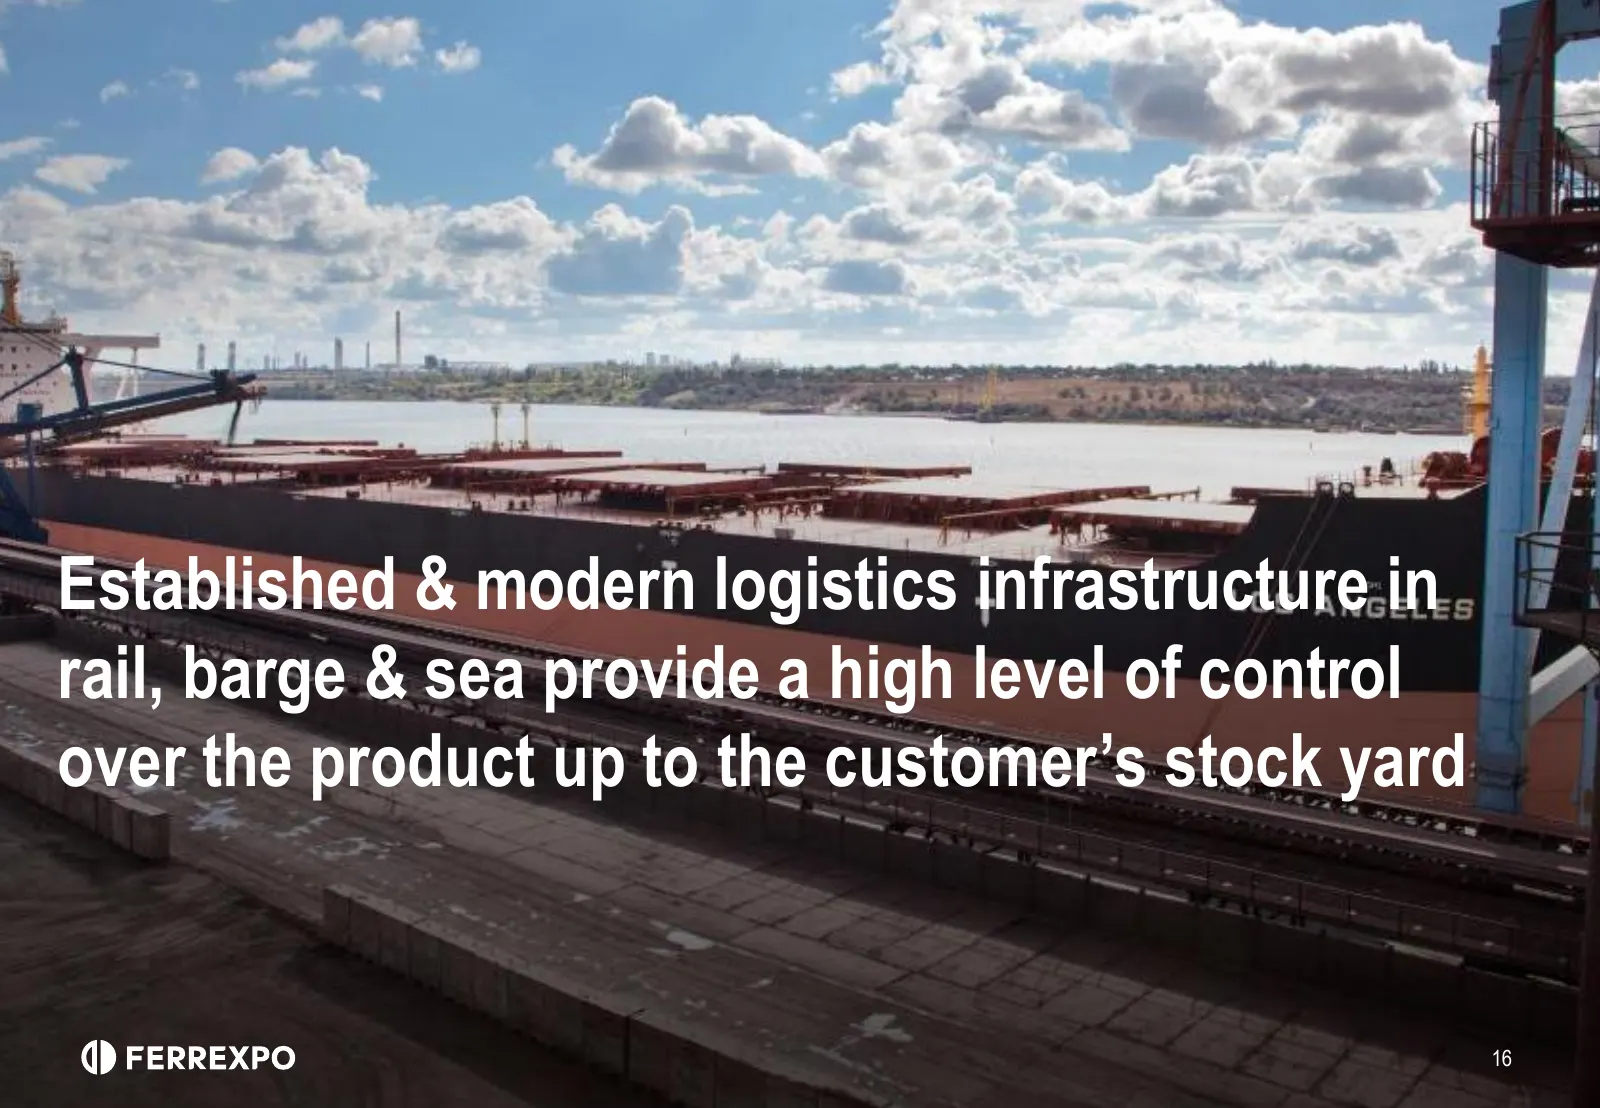
Slide 16: Established modern logistics infrastructure in rail, barge and sea
Established & modern logistics infrastructure in rail, barge & sea provide a high level of control over the product up to the customer’s stock yard 16
Slide 17: Low cost pellet producer
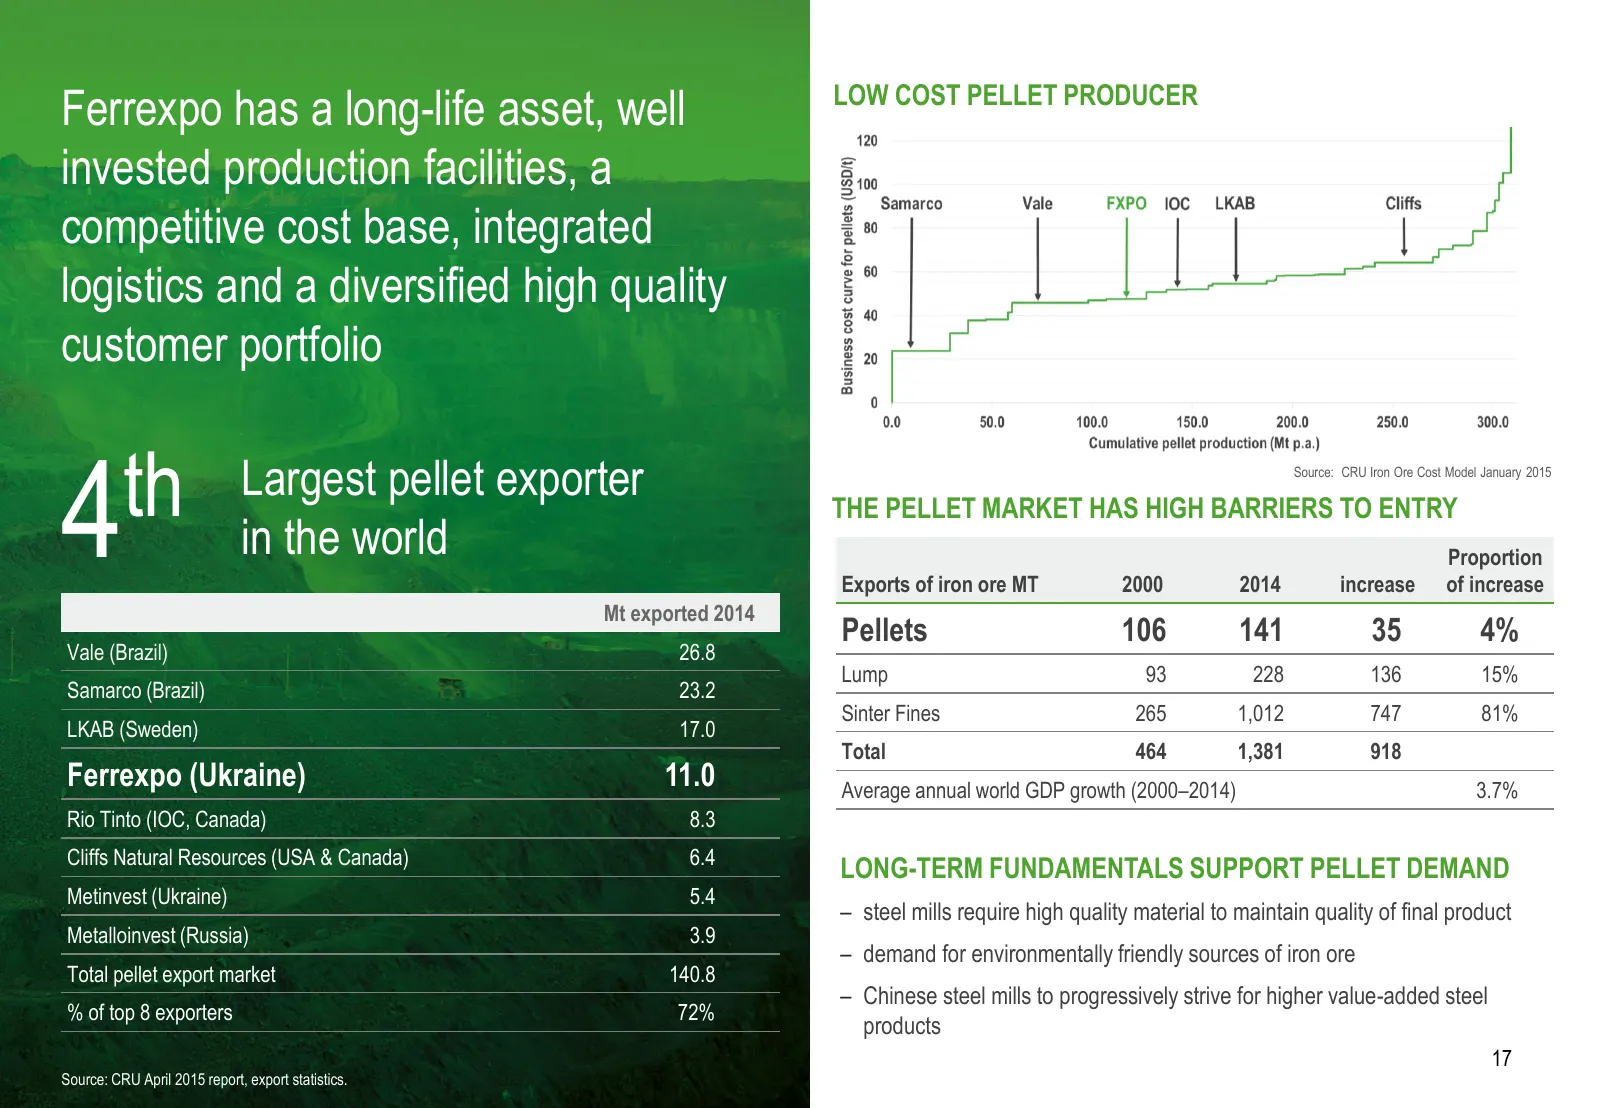
LOW COST PELLET PRODUCER Ferrexpo has a long-life asset, well invested production facilities, a competitive cost base, integrated logistics and a diversified high quality customer portfolio 4 th Largest pellet exporter Source: CRU Iron Ore Cost Model January 2015 THE PELLET MARKET HAS HIGH BARRIERS
Slide 18: Iron ore pellets continue to trade at a price premium
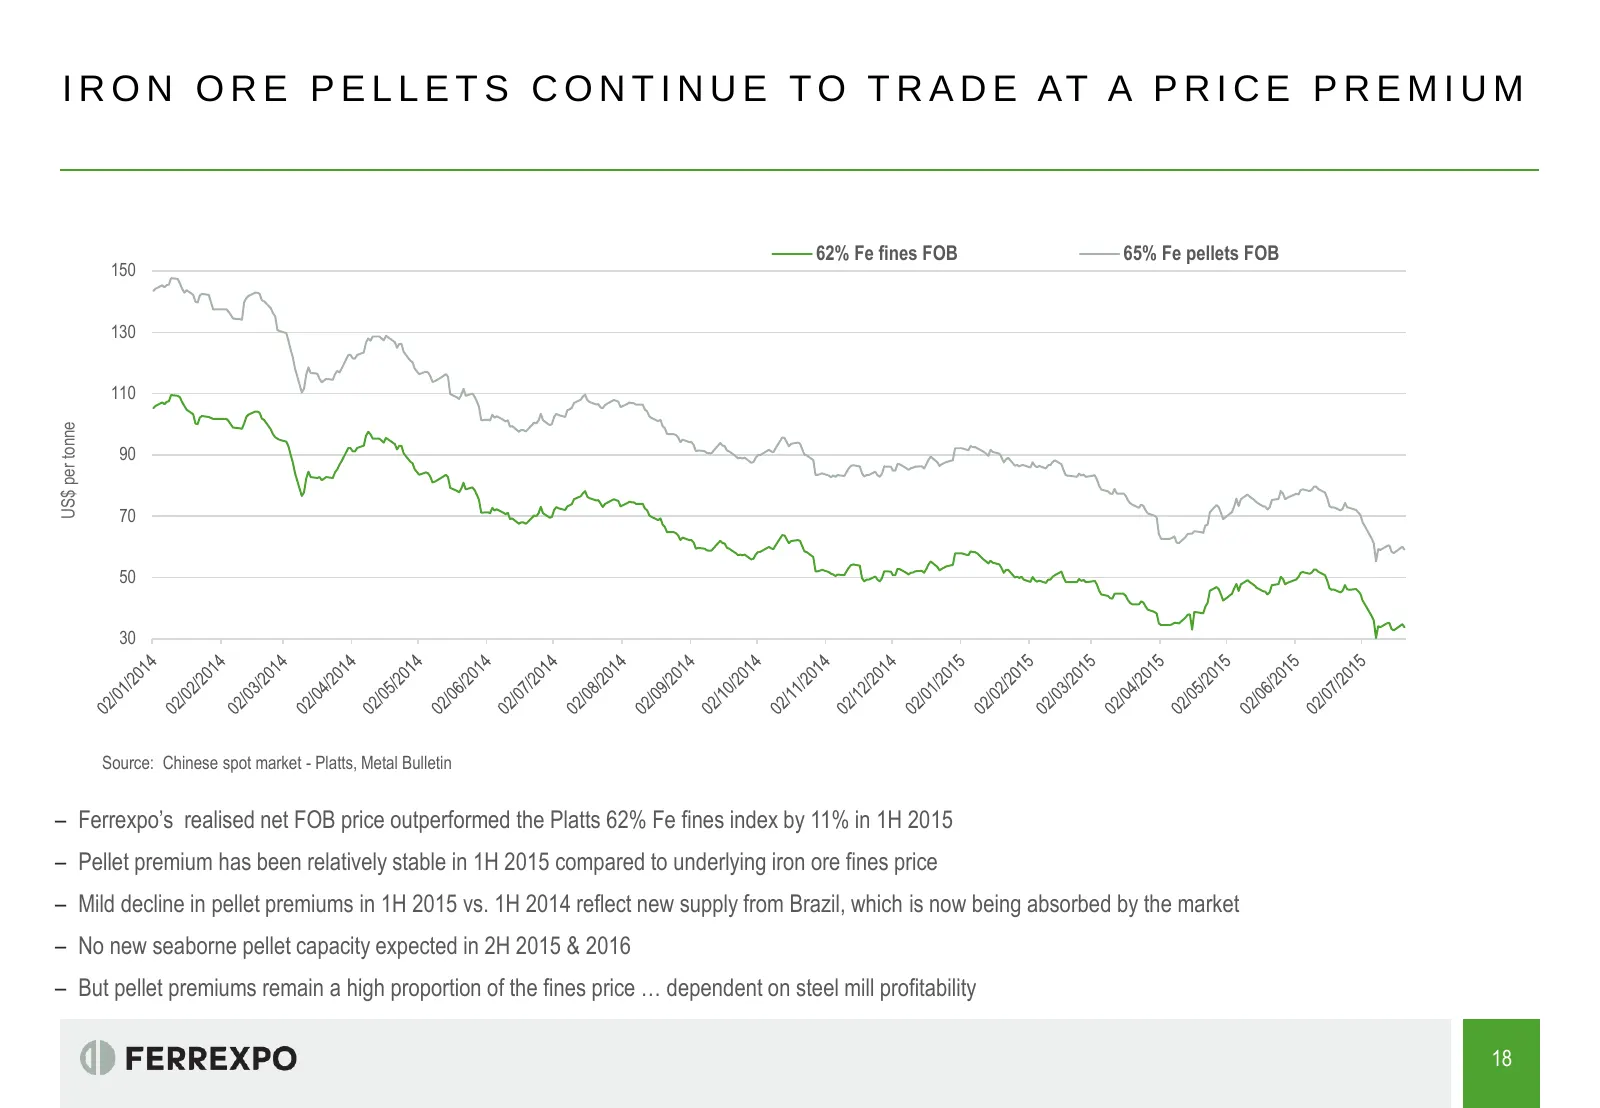
I R O N O R E P E L L E T S C O N T I N U E T O T R A D E AT A P R I C E P R E M I U M 62% Fe fines FOB 65% Fe pellets FOB 150 130 110 US$ per tonne 90 70 50 30 Source: Chinese spot market - Platts, Metal Bulletin – Ferrexpo’s realised net FOB price outperformed the Platts 62% Fe fines index by 11%
Slide 19: Servicing the world's top steel mills
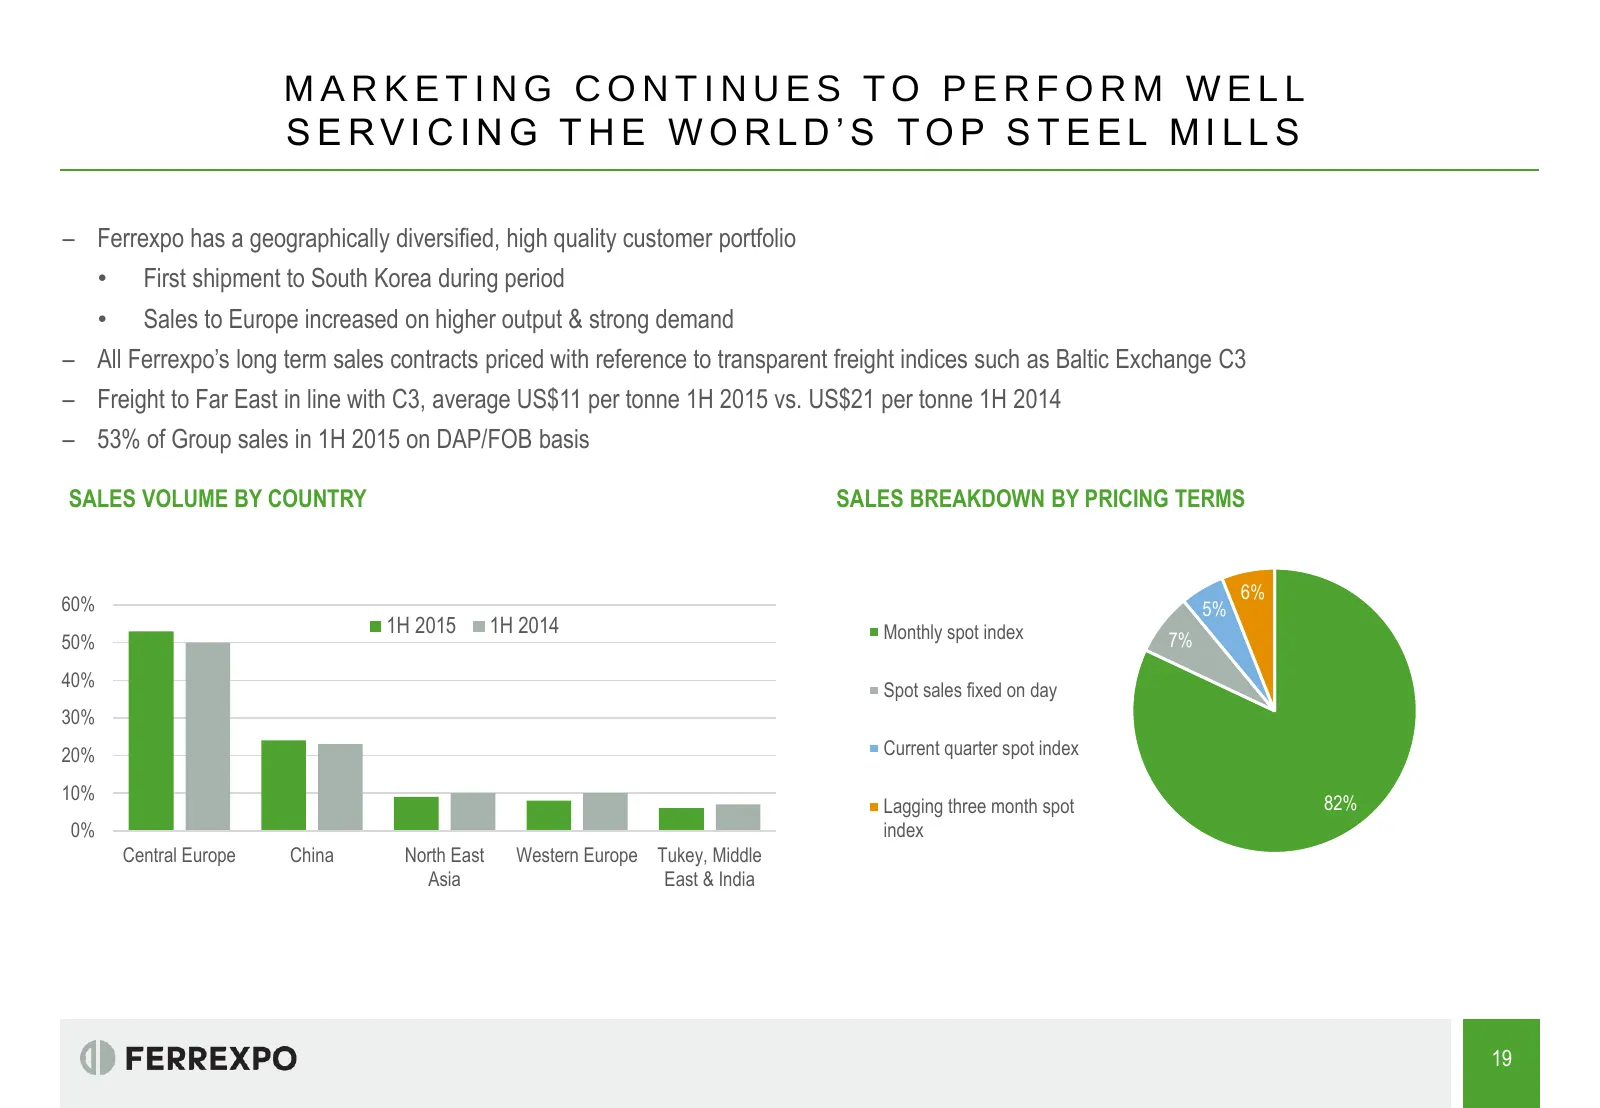
MARKETING CONTINUES TO PERFORM WELL SERVICING THE WORLD’S TOP STEEL MILLS – Ferrexpo has a geographically diversified, high quality customer portfolio • First shipment to South Korea during period • Sales to Europe increased on higher output & strong demand – All Ferrexpo’s long term sales contracts
Slide 20: Ferrexpo delivering consistently higher volume, Fe content and lower costs
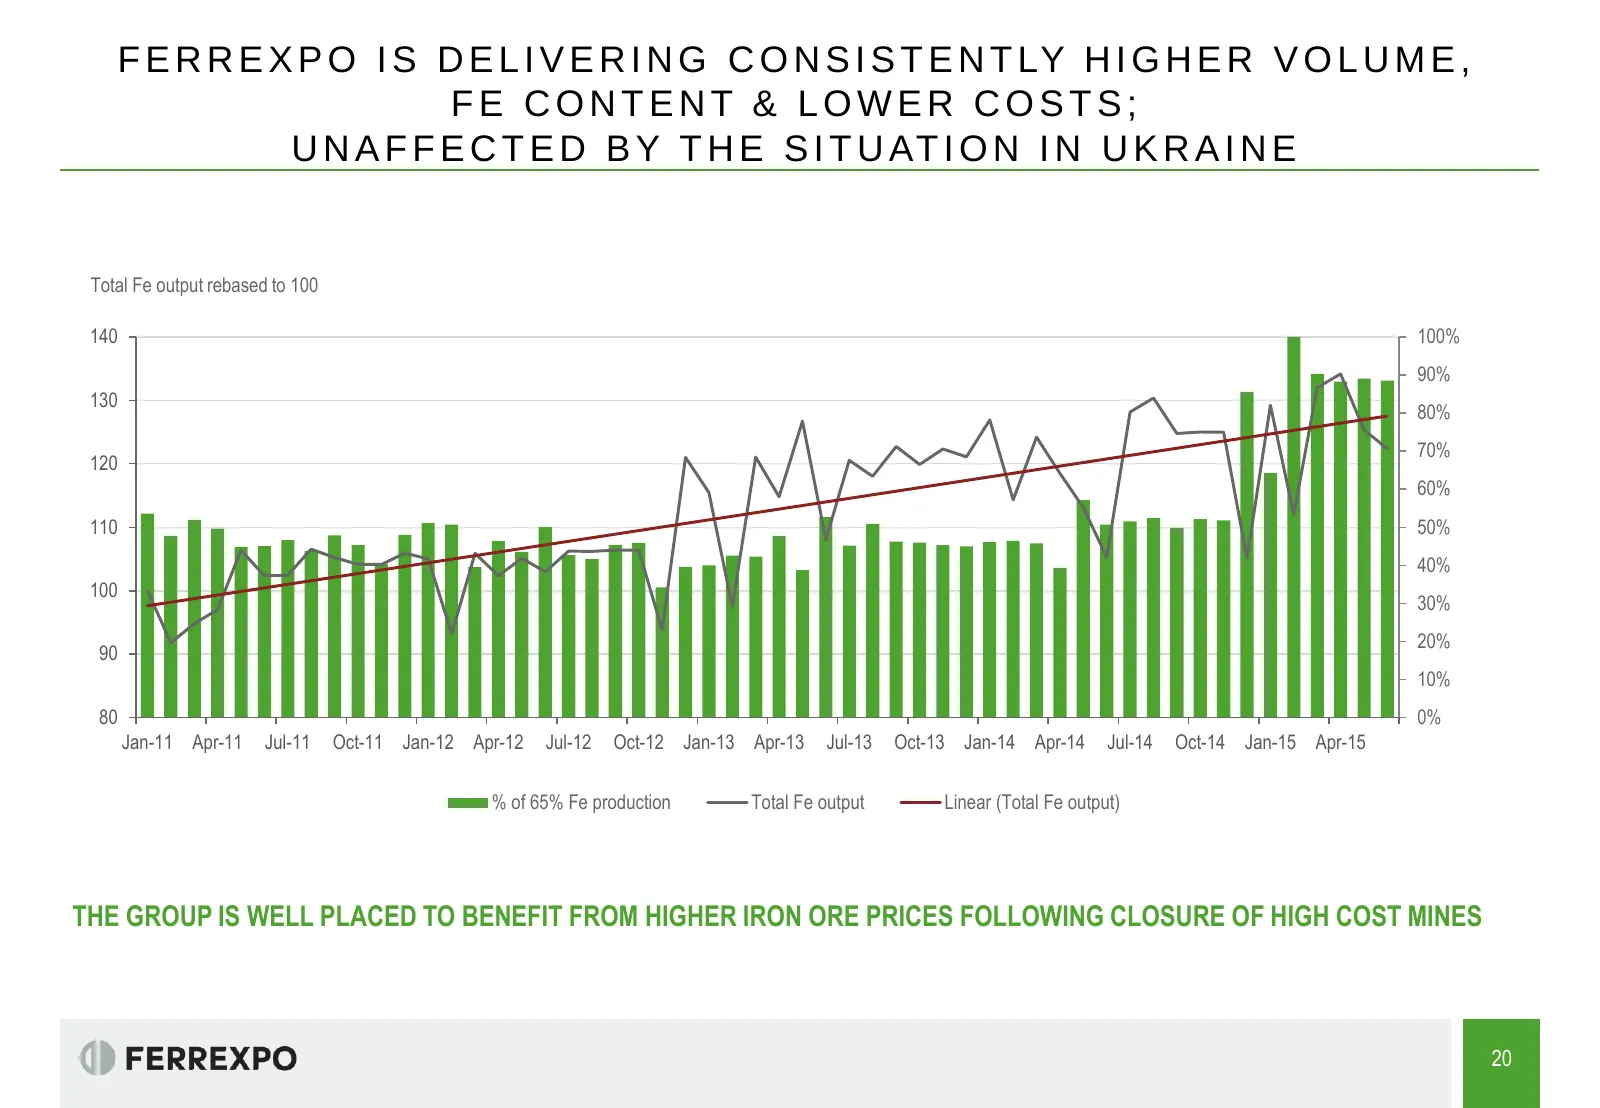
F E R R E X P O I S D E L I V E R I N G C O N S I S T E N T LY H I G H E R V O L U M E , FE CONTENT & LOWER COSTS; U N A F F E C T E D B Y T H E S I T U AT I O N I N U K R A I N E Total Fe output rebased to 100 140 100% 90% 130 80% 70% 120 60% 110 50% 40% 100 30% 20% 90 10% 80 0% Jan-11 Apr-11 Jul-1
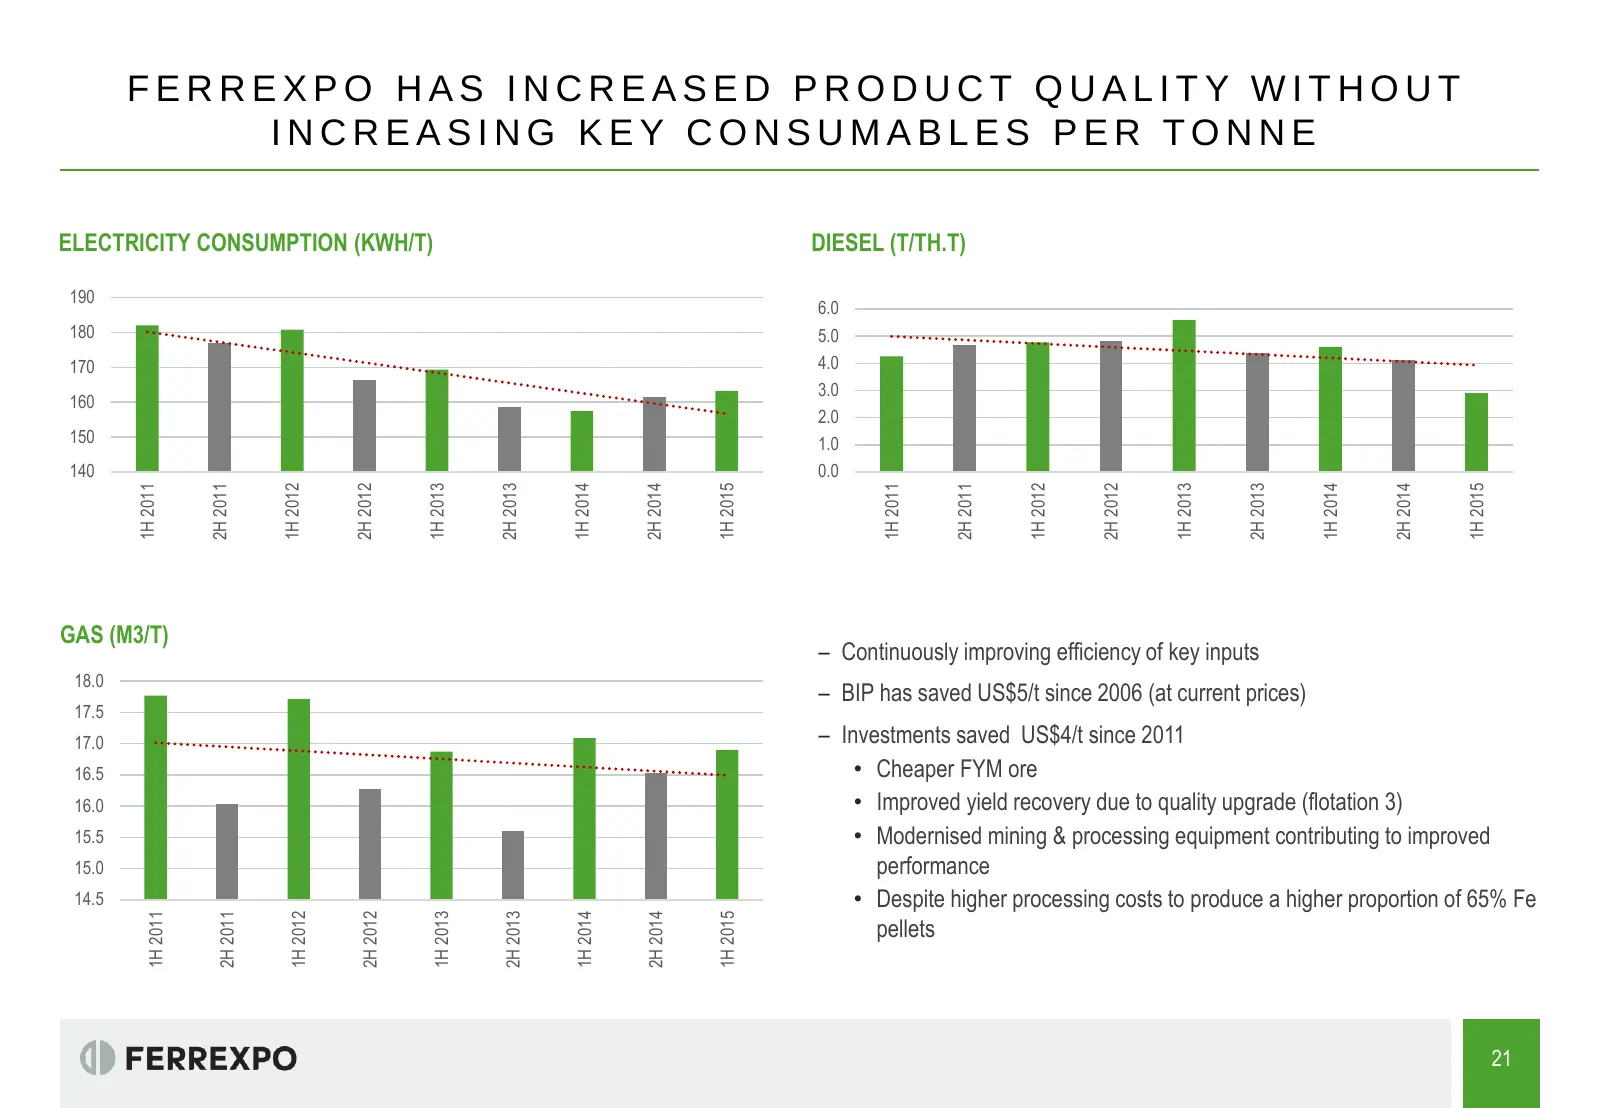
Slide 21: Increased product quality without increasing key consumables per tonne
FERREXPO HAS INCREASED PRODUCT QUALITY WITHOUT INCREASING KEY CONSUMABLES PER TONNE ELECTRICITY CONSUMPTION (KWH/T) DIESEL (T/TH.T) 190 6.0 180 5.0 170 4.0 3.0 160 2.0 150 1.0 140 0.0 1H 2011 2H 2011 1H 2012 2H 2012 1H 2013 2H 2013 1H 2014 2H 2014 1H 2015 1H 2011 2H 2011 1H 2012 2H 2012 1H 2013 2H 2
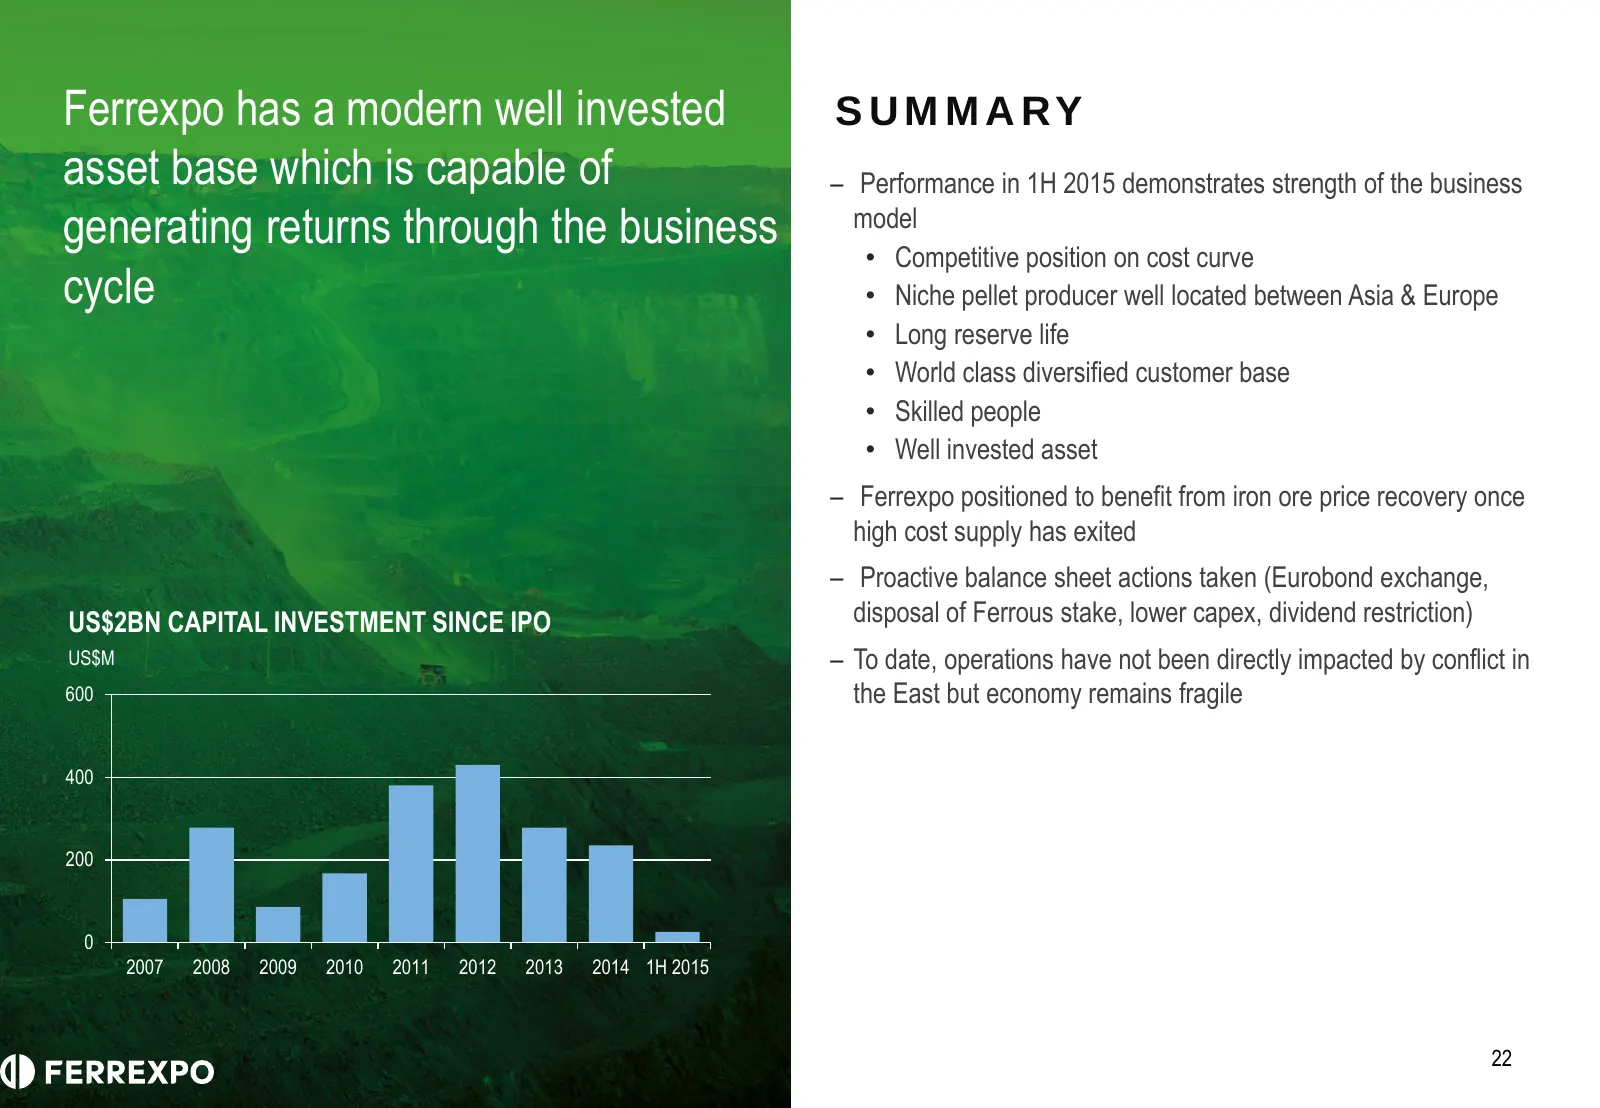
Slide 22: Summary
Ferrexpo has a modern well invested SU MMA RY asset base which is capable of – Performance in 1H 2015 demonstrates strength of the business generating returns through the business model • Competitive position on cost curve cycle • Niche pellet producer well located between Asia & Europe • Long reser
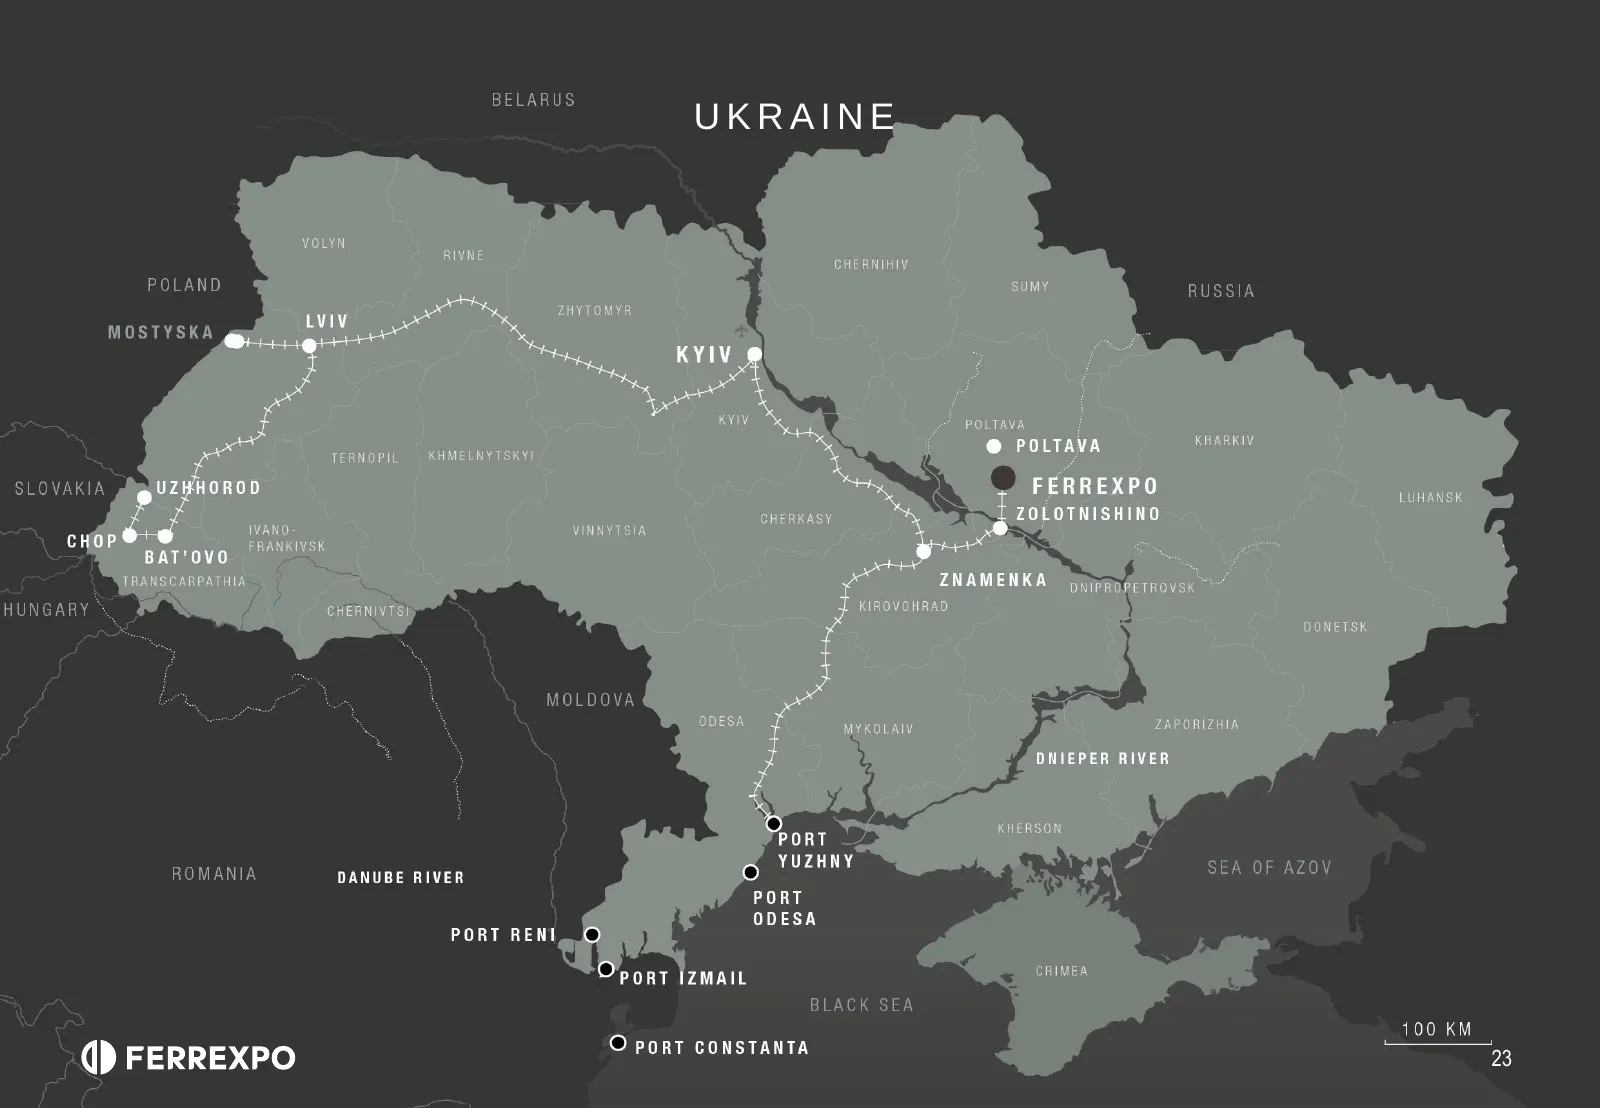
Slide 23: Map of Ukraine and logistics routes
BELARUS UKRAIN POLAND cea MOSTYSKA SLOVAKIA HUNGARY 3. oe a wi Ny \, MOLDOVA PORT YUZHNY EXOT ART DANUBE RIVER Aaa PORT RENI port Izmait BLACK SEA 100 KM ; o FERREXPO O port CONSTANTA }
Source: Internet Archive copy of ferrexpo.com
More decks from Ferrexpo plc
 H1 2025 Earnings Presentation21 slides · Aug 6, 2025
 FY2024 Earnings Presentation24 slides · Mar 19, 2025
 H1 2024 Earnings Presentation21 slides · Sep 1, 2024
 FY2023 Earnings Presentation22 slides · Apr 18, 2024
 H1 2023 Earnings Presentation18 slides · Aug 4, 2023
 Shareholder Meeting (May 2023)8 slides · May 25, 2023