Tribune Media — Investor Day (December 2014)
150 slides from Tribune Media's investor day presentation, Dec 11, 2014
Slide 1: Tribune Media Investor Day Presentation
Tribune Media Investor Day PRESENTATION December 11, 2014I nvestor Day PRESENTATION
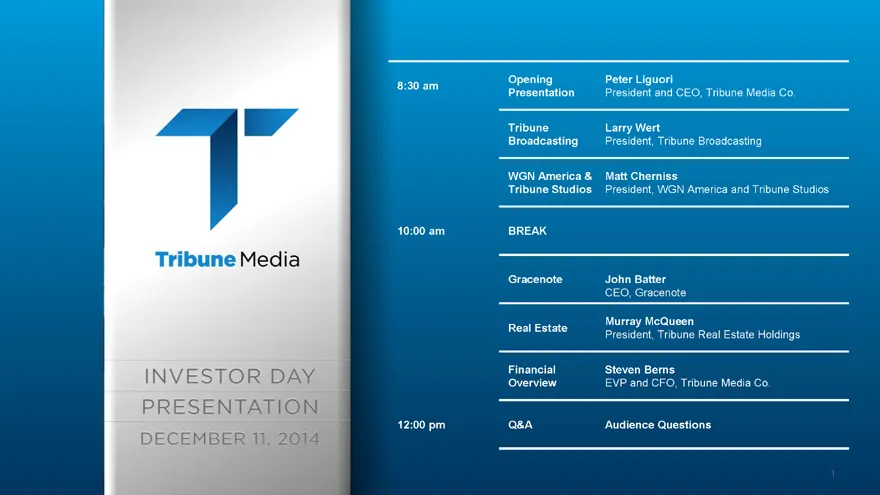
Slide 2: Agenda
MediaInvestor DayPRESENTATIONDecember 11, 2014Opening Peter Liguori 8:30 amPresentation President and CEO, Tribune Media Co.Tribune Larry WertBroadcasting President, Tribune BroadcastingWGN America & Matt ChernissTribune Studios President, WGN America and Tribune Studios10:00 am BREAKGracenote J
Slide 3: Investor Day Presentation
MediaInvestor DayPRESENTATIONDecember 11, 2014Investor DayPRESENTATION
Slide 4: Forward-Looking Disclosures and Disclaimer
o r w a r d L o o k i n g D i s c l o s u r e s D i s c l a i m e rThis presentation includes forward-looking statements within the meaning of the federal securities laws. Forward-looking statements are subject to known and unknown risks and uncertainties, many of which may be beyond our control. Fo
Slide 5: Agenda
MediaInvestor DayPRESENTATIONDecember 11, 2014Opening Peter Liguori 8:30 amPresentation President and CEO, Tribune Media Co.Tribune Larry WertBroadcasting President, Tribune BroadcastingWGN America & Matt ChernissTribune Studios President, WGN America and Tribune Studios10:00 am BREAKGracenote J
Slide 6: Investor Day Presentation
MediaInvestor DayPRESENTATIONDecember 11, 2014Investor DayPRESENTATION
Slide 7: Peter Liguori, President and CEO
MediaInvestor DayPRESENTATIONDecember 11, 2014Peter LiguoriPresident and CEO, Tribune Media Co.
Slide 8: MediaInvestor DayPRESENTATIONDecember 11, 2014
MediaInvestor DayPRESENTATIONDecember 11, 2014
Slide 9: Best-in-Class Leadership Team
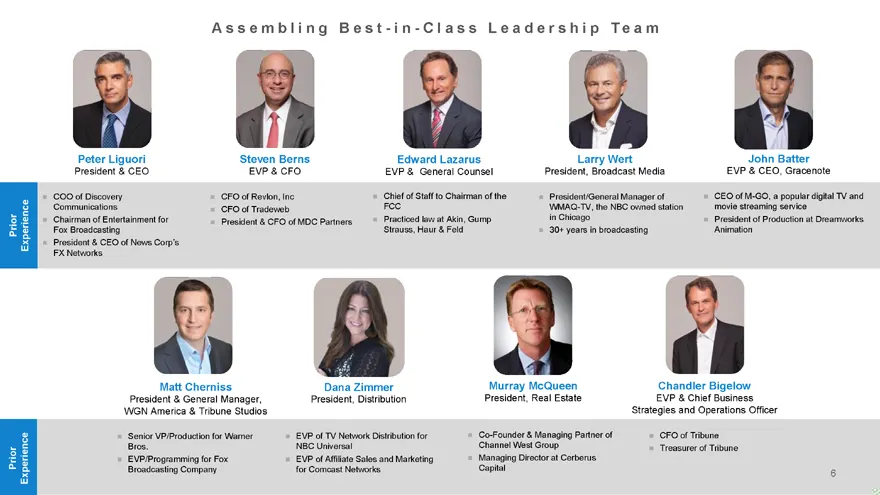
Best—in—Class L e a d e r s h i p T e a mPeter Liguori Steven Berns Edward Lazarus Larry Wert John BatterPresident & CEO EVP & CFO EVP & General Counsel President, Broadcast Media EVP & CEO, GracenoteCOO of Discovery CFO of Revlon, Inc Chief of Staff to Chairman of the President/Gene
Slide 10: A Modern Media Company with Content, Distribution and Data at its Core
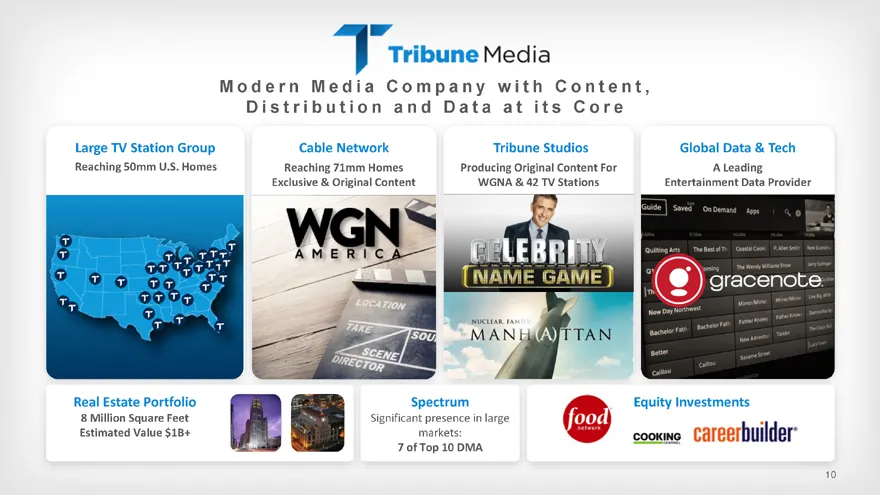
o d e r n M e d i a C o m p a n y w i t h C o n t e n t , D i s t r i b u t i o n a n d D a t a a t i t s C o r eLarge TV Station GroupReaching 50mm U.S. Homes Cable NetworkReaching 71mm Homes Exclusive & Original ContentTribune StudiosProducing Original Content For WGNA & 42 TV StationsGlob
Slide 11: TV Station Group Reaching 50mm U.S. Homes
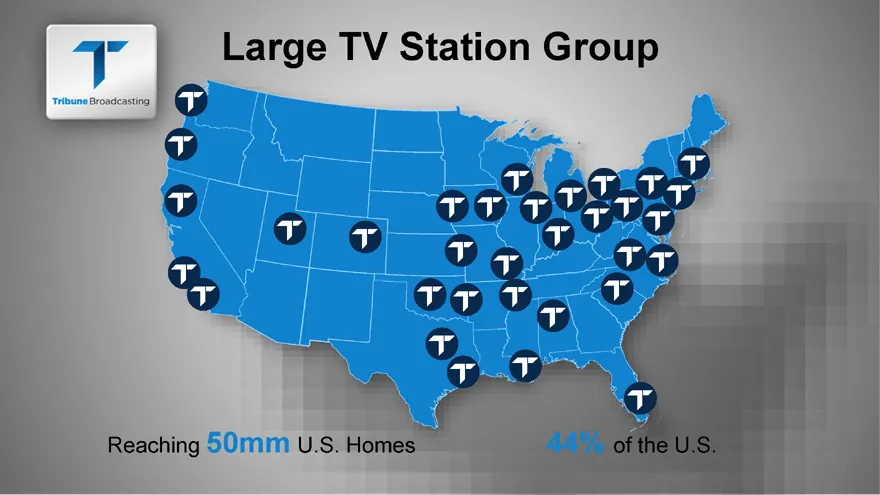
TV Station GroupReaching 50mm U.S. Homes 44% of the U.S.
Slide 12: WGN America Cable Network
AMERICACable NetworkReaching 71mm HomesExclusive & OriginalContent
Slide 13: Tribune Studios
Original Content For WGNA and 42 TV Stations
Slide 14: A Leading Entertainment Data Provider
A Leading Entertainment Date Provider
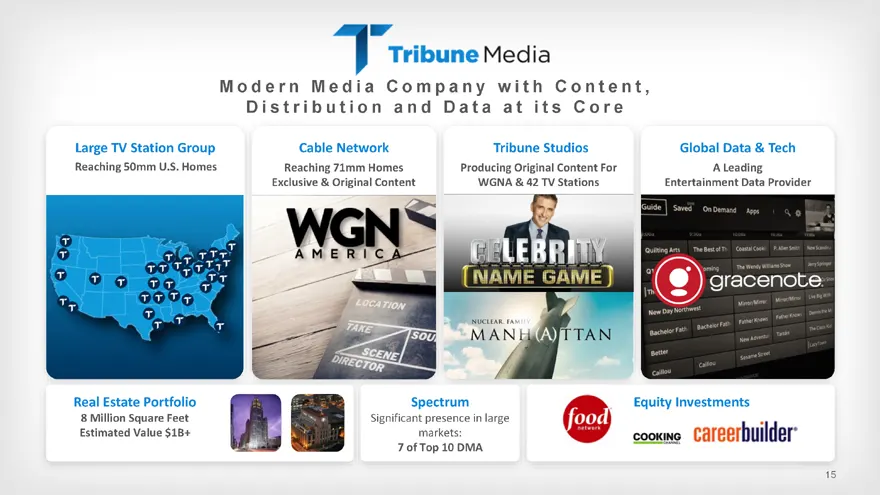
Slide 15: A Modern Media Company with Content, Distribution and Data at its Core
n M e d i a C o m p a n y w i t h C o n t e n t , D i s t r i b u t i o n a n d D a t a a t i t s C o r eLarge TV Station GroupReaching 50mm U.S. HomesCable NetworkReaching 71mm Homes Exclusive & Original ContentTribune StudiosProducing Original Content For WGNA & 42 TV StationsGlobal Data &
Slide 16: Our Strategy: Three Core Principles
by Three Core PrinciplesScaleMattersDiversifyWithin our core competenciesFinancial FocusFor long-term profits and shareholder valueO u r S t r a t e g y
Slide 17: Believe in Broadcasting
Believe in Broadcasting
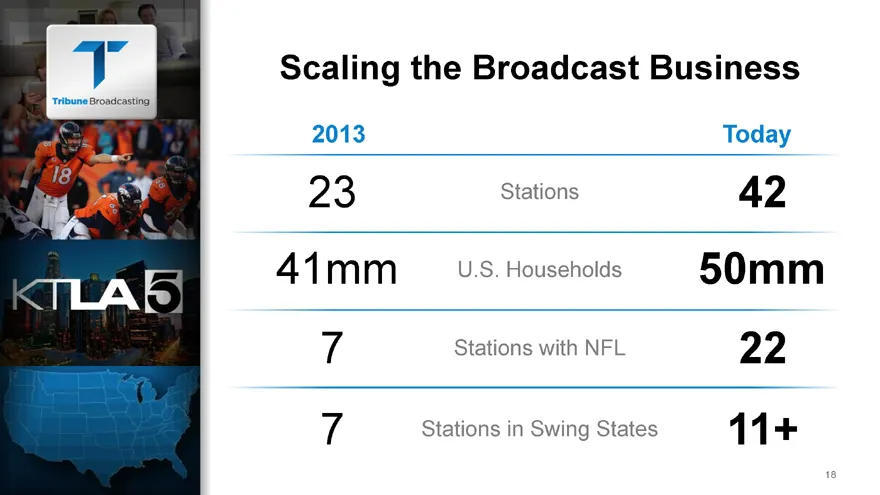
Slide 18: Growth of the Broadcast Business
the Broadcast Business2013 Today23 Stations 4241mm U.S. Households 50mm7 Stations with NFL 227 Stations in Swing States 11+18
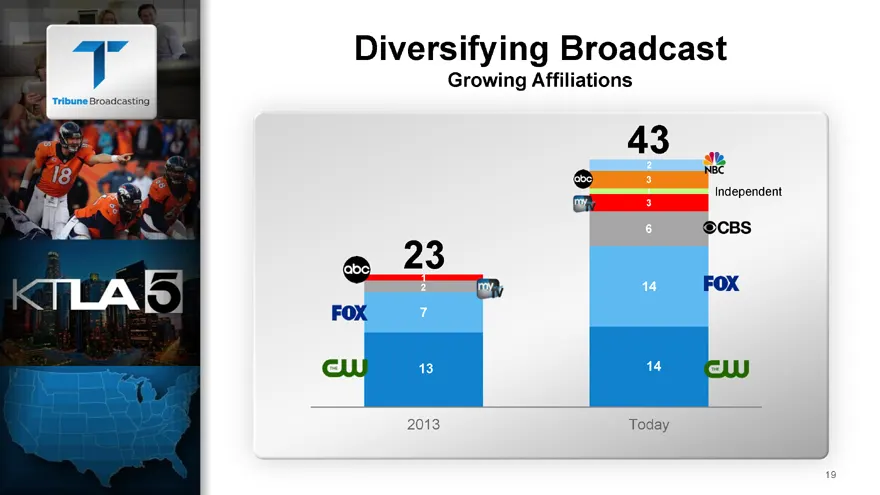
Slide 19: Largest Independent Broadcast Group
Broadcast 432 31 Independent362312 14 713 14 2013 Today
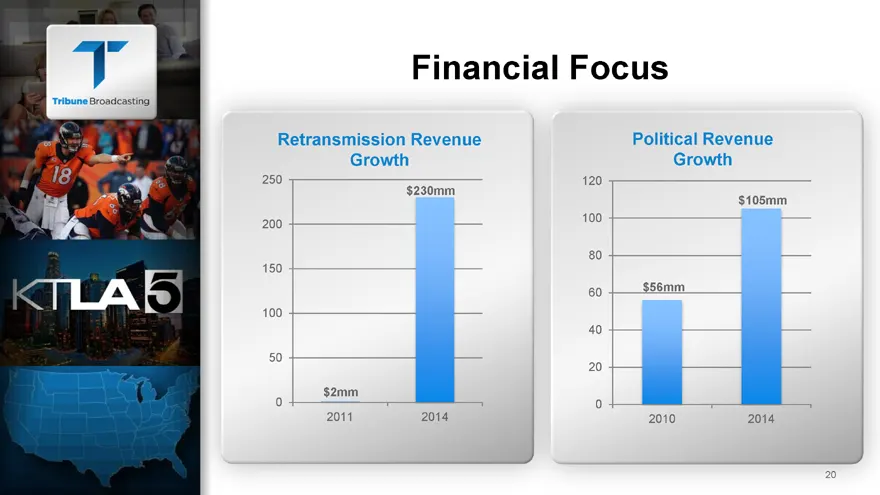
Slide 20: Retransmission and Political Revenue Growth
Revenue Growth250 $230mm200 150 100 50$2mm02011 2014Political Revenue Growth120 $105mm1008060 $56mm402002010 2014
Slide 21: WGN America
AMERICA
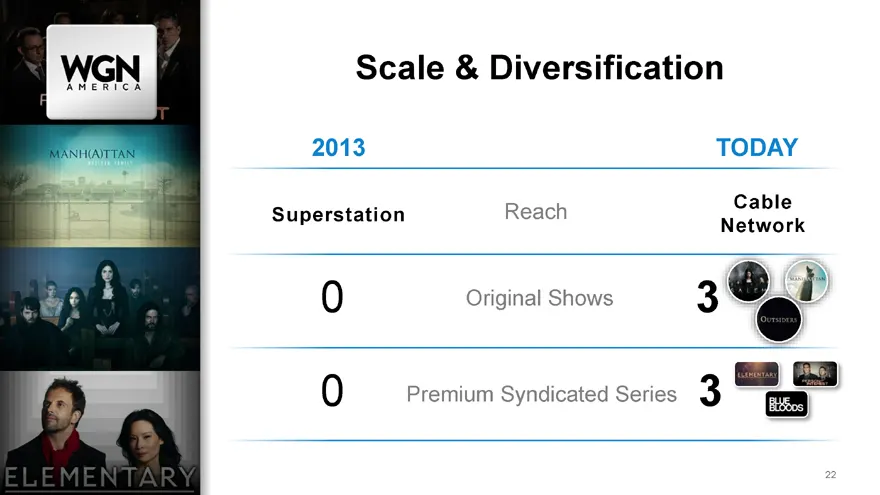
Slide 22: WGN America Scale and Diversification
& Diversification2013 TODAYReach Cable SuperstationNetwork0 Original Shows 30 Premium Syndicated Series 322
Slide 23: Original Programming: Manhattan
| NUCLEAR. FAMILY. MANH(A)TTAN
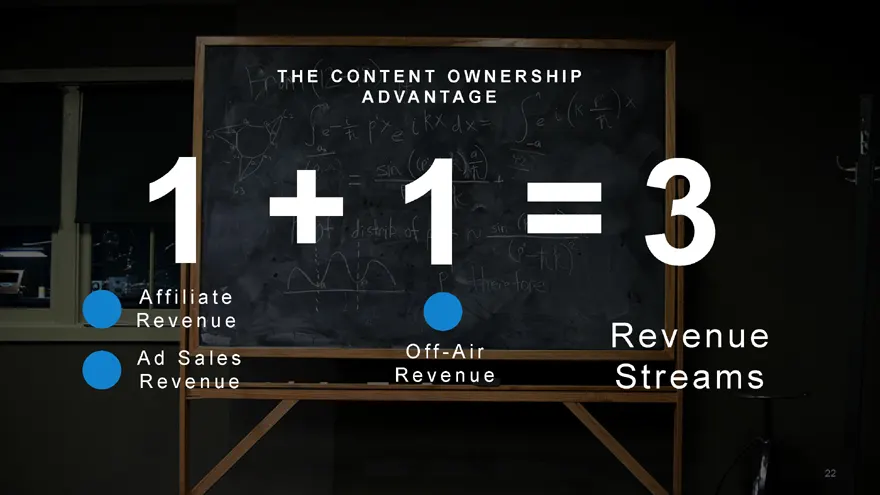
Slide 24: The Content Ownership Advantage
H E C O N T E N T O W N E R S H I P A D V A N T A G E1 + 1 = 3A f f i l i a t e R e v e n u e Revenue A d S a l e s O f f—A i r R e v e n u e R e v e n u e Streams22
Slide 25: Broadcasting Spectrum
Broadcasting Spectrum
Slide 26: Opportunity and Scale: Significant Presence in Large Markets
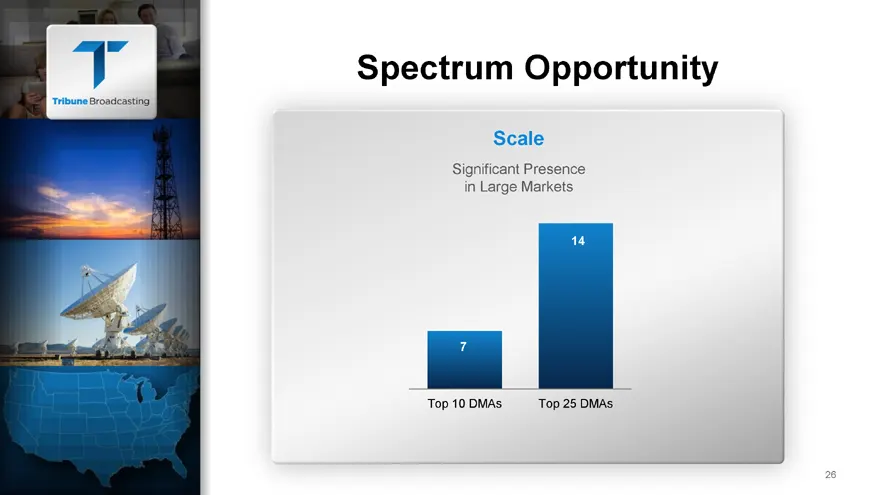
OpportunityScaleSignificant Presence in Large Markets147Top 10 DMAs Top 25 DMAs26
Slide 27
Slide 28: Growth of the Data Business
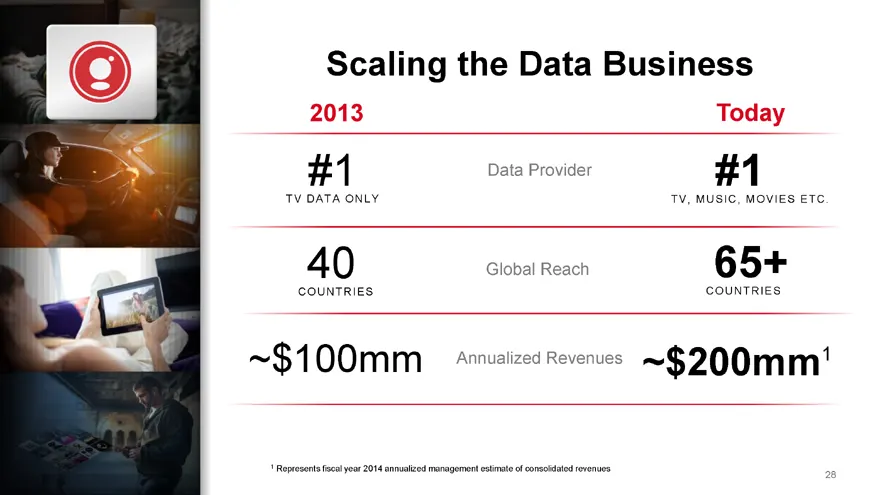
the Data Business2013 Today#1 Data Provider #1T V DA T A O NLY T V , M US I C, M O V I E S E T C.40 Global Reach 65+CO UNT RI E S CO UNT RI E S~$100mm Annualized Revenues ~$200mm11 Represents fiscal year 2014 annualized management estimate of consolidated revenues28
Slide 29: Data Strategy: Diversification Through Organic Growth and Acquisitions
StrategyD i v e r s i f i c a t i o n T h r o u g h O r g a n i c G r o w t h & A c q u i s i t i o n sInternational Growth Increase our international footprint to scale with our global customers.Core Growth Deepen our database to feature additional descriptive information to fuel discovery serv
Slide 30: Real Estate
Real Eastate
Slide 31: Real Estate Strategy: Manage, Maximize and Monetize
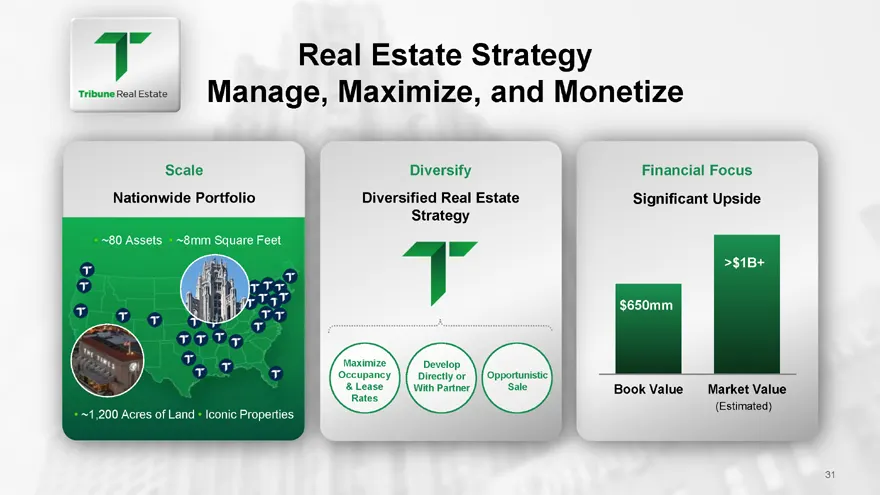
Estate Strategy Manage, Maximize, and MonetizeScaleNationwide Portfolio ~80 Assets ~8mm Square Feet ~1,200 Acres of Land Iconic PropertiDiversifyDiversified Real Estate Strategy Maximize Develop Occupancy Directly or Opportunistic & Lease With Partner Sale RatesFinancial Focus Significant Upside
Slide 32: Investment Strategy
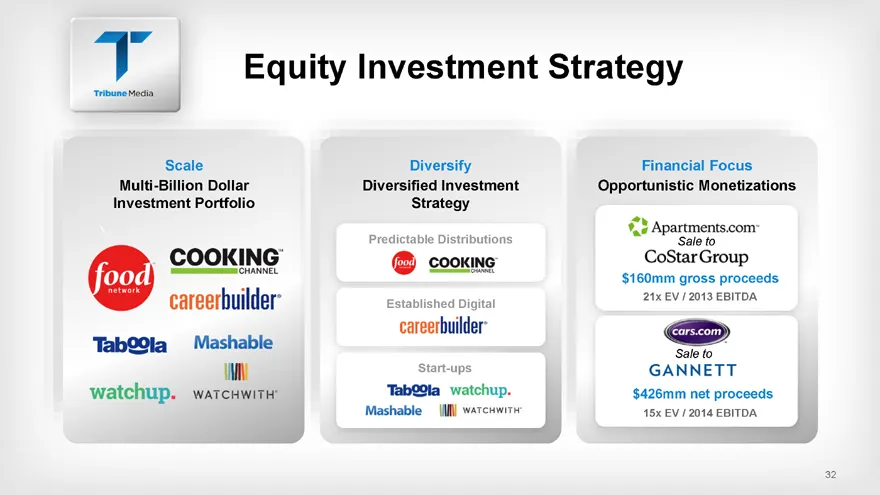
Investment StrategyScaleMulti-Billion Dollar Investment PortfolioDiversifyDiversified Investment StrategyFinancial Focus Opportunistic MonetizationsSale to$160mm gross proceeds21x EV / 2013 EBITDASale to$426mm net proceeds15x EV / 2014 EBITDA32
Slide 33: Investment Highlights
n v e s t m e n t H i g h l i g h t so We have scale, a critical component to success o Significant assets in TV, the most powerful media platform today o Diversified portfolio of revenue beyond traditional broadcast TVo Exclusive and distinctive content, which drives long-term and lucrative relatio
Slide 34: WGN America
MediaInvestor DayPRESENTATIONDecember 11, 2014WGN America
Slide 35: WGN America
Media Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 36: Larry Wert, President, Broadcast Media
Broadcasting Investor Day PRESENTATION December 11, 2014Larry WertPresident, Broadcast MediaTribune Broadcasting2
Slide 37: Best-in-Class Leadership Team
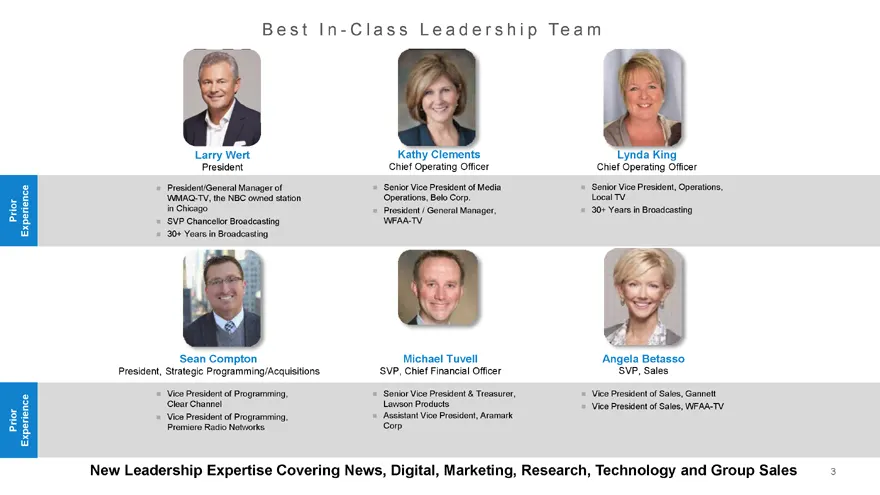
e s t I n—C l a s s L e a d e r s h i p Te a mLarry WertPresidentPresident/General Manager of WMAQ-TV, the NBC owned station in Chicago SVP Chancellor Broadcasting 30+ Years in BroadcastingChief Operating OfficerSenior Vice President of Media Operations, Belo Corp.President / General Manager, WFAA-T
Slide 38: Our Core Beliefs
Media Our Core BeliefsWe Believe in We Control Our We Believe in Local Broadcasting Destiny4
Slide 39: Key Differentiators
e y D i f f e r e n t i a t o r sAmerica s largest local independent broadcast groupSignificant upside in retransmission, political and digital revenue Develop and own content
Slide 40: TV Remains the Most Influential Force in U.S. Media
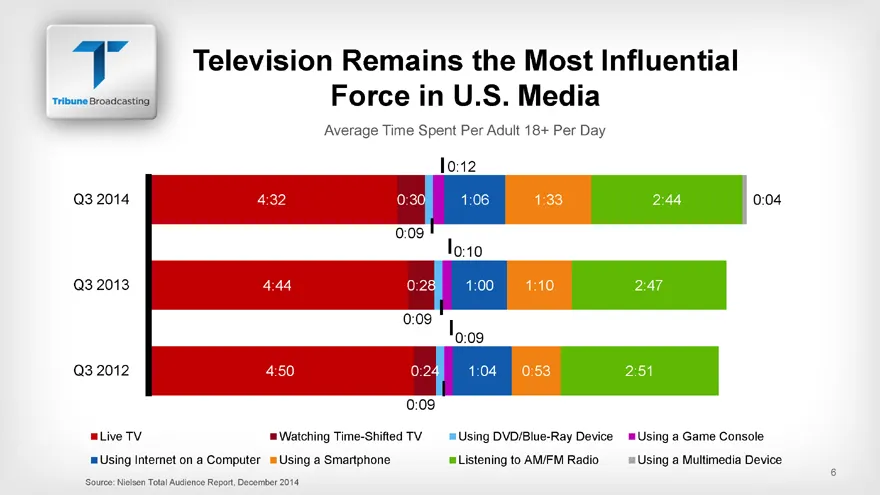
Remains the Most Influential Force in U.S. MediaAverage Time Spent Per Adult 18+ Per Day0:12Q3 2014 4:32 0:30 1:06 1:33 2:44 0:040:090:10Q3 2013 4:44 0:28 1:00 1:10 2:470:090:09Q3 2012 4:50 0:24 1:04 0:53 2:510:09Live TV Watching Time-Shifted TV Using DVD/Blue-Ray Device Using a Game Console Using I
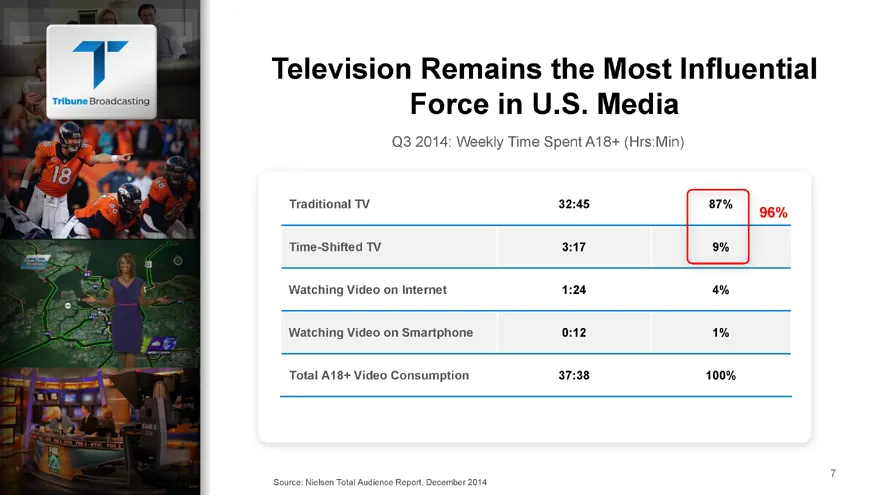
Slide 41: TV Remains the Most Influential Force in U.S. Media
Remains the Most Influential Force in U.S. MediaQ3 2014: Weekly Time Spent A18+ (Hrs:Min) 87% 9%Traditional TV 32:4596%Time-Shifted TV 3:17Watching Video on Internet 1:24 4% Watching Video on Smartphone 0:12 1% Total A18+ Video Consumption 37:38 100%7Source: Nielsen Total Audience Report, December 2
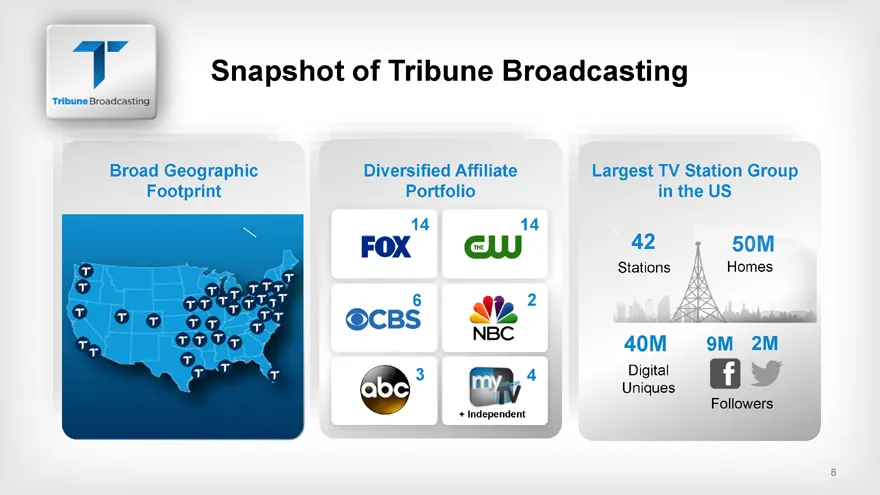
Slide 42: Overview of Tribune Broadcasting
of Tribune BroadcastingBroad Geographic FootprintDiversified Affiliate Portfolio14 146 23 4+ IndependentLargest TV Station Group in the USStations40M 9M 2MDigital UniquesFollowers8
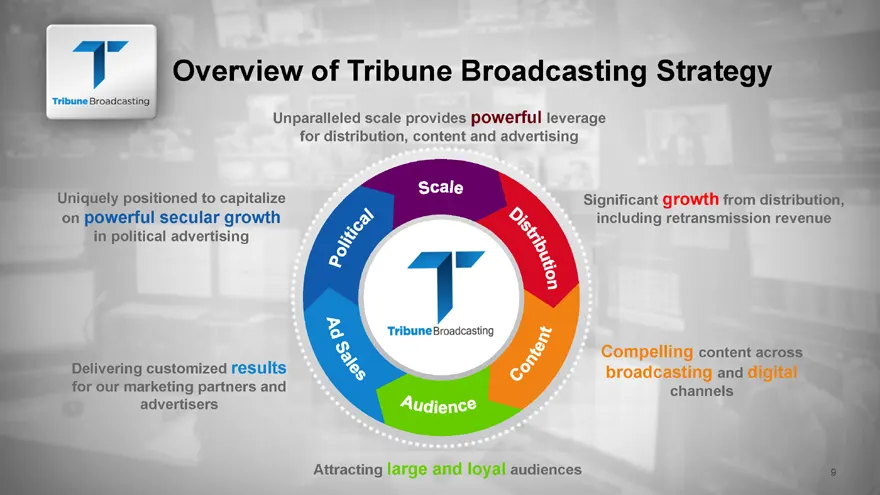
Slide 43: Overview of Tribune Broadcasting Strategy
of Tribune Broadcasting StrategyUnparalleled scale provides powerful leverage for distribution, content and advertisingUniquely positioned to capitalize Significant growth from distribution, on powerful secular growth including retransmission revenue in political advertisingCompelling content across
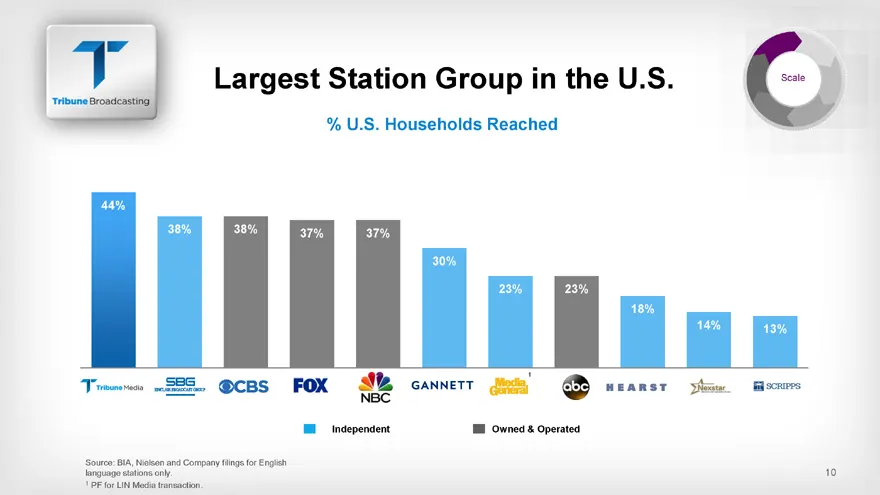
Slide 44: Largest Station Group in the U.S.
Station Group in the U.S.% U.S. Households Reached44%38% 38% 37% 37%30%23% 23%18%14% 13%1Independent Owned & OperatedSource: BIA, Nielsen and Company filings for English language stations only. 101 PF for LIN Media transaction.
Slide 45: Reach, Local Connection and Scale
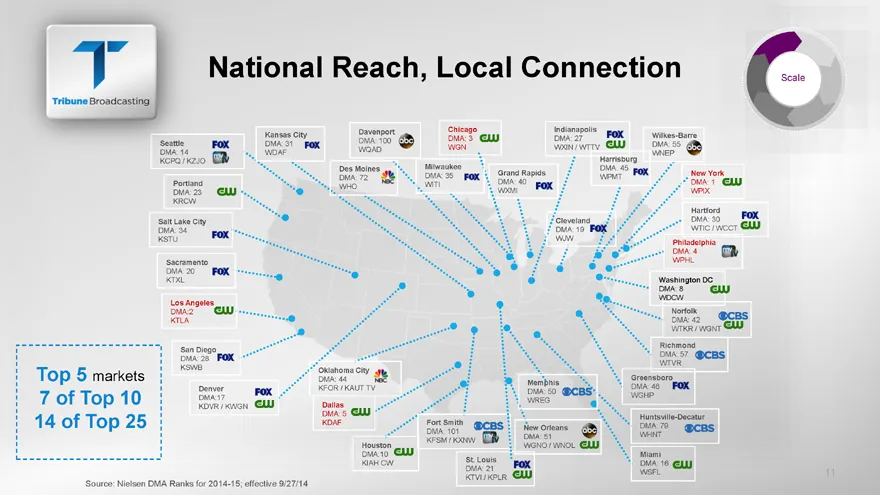
Reach, Local Connection ScaleDavenport Chicago Indianapolis Kansas CityDMA: 100 DMA: 3 DMA: 27 DMA: 31 WQAD WGN WXIN / WTTVWDAF Harrisburg ZJO Milwaukee Des Moines DMA: 45 DMA: 35 Grand RapidsDMA: 72 WPMT Portland WITI DMA: 40 WHODMA: 23 WXMI KRCWSalt Lake City ClevelandDMA: 34 DMA: 19 WTIC / WCCT K
Slide 46: Stations #1 or #2 in Markets
is#1 or #2In 22 Markets12
Slide 47: Overview of Distribution Strategy
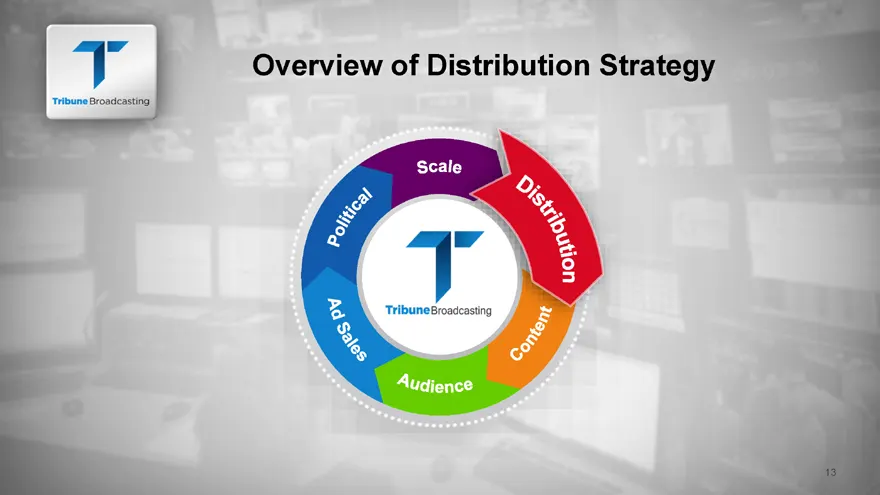
Overview of Distribution Strategy Audience
Slide 48: Significant Retransmission Revenue Growth
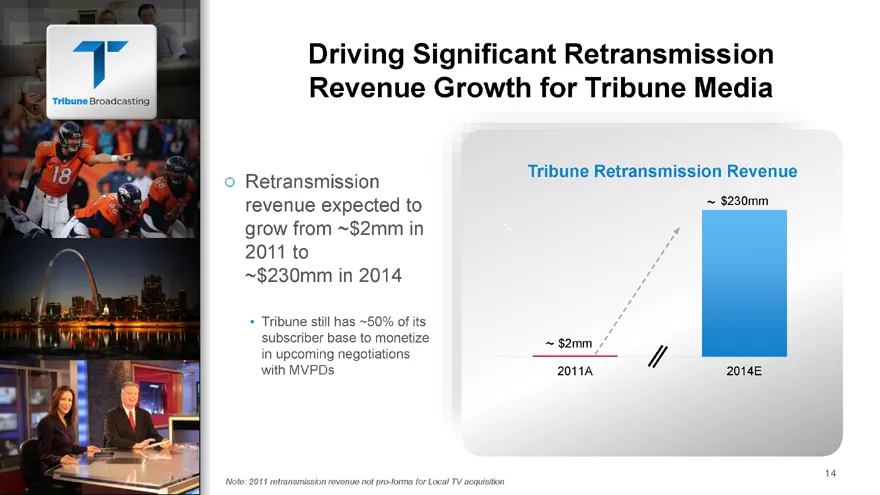
Significant Retransmission Revenue Growth for Tribune MediaTribune Retransmission Revenue Retransmission revenue expected to ~ $230mm grow from ~$2mm in 2011 to ~$230mm in 2014 Tribune still has ~50% of its subscriber base to monetize ~ $2mm in upcoming negotiations with MVPDs 2011A 2014ENote: 2011
Slide 49: Diversified Revenue Composition
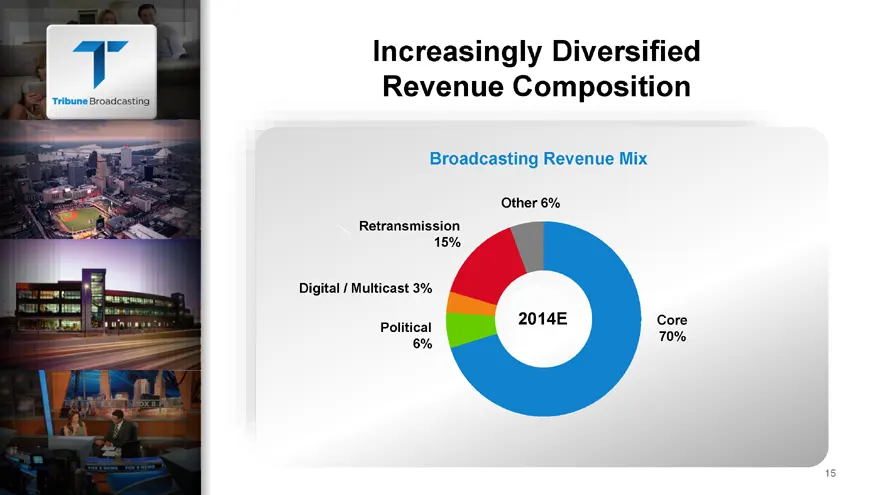
Diversified Revenue CompositionBroadcasting Revenue MixOther 6% Retransmission 15%Digital / Multicast 3%2014E Core Political 70% 6%15
Slide 50: Stations Drive Balanced Relationship with Networks
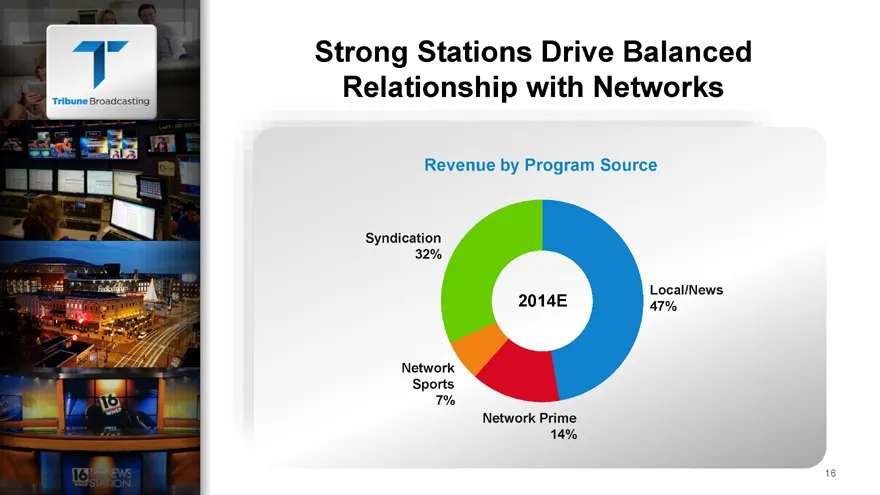
Stations Drive Balanced Relationship with NetworksRevenue by Program SourceSyndication 32%Local/News2014E 47%Network Sports 7%Network Prime 14%16
Slide 51: Model Varies by Network
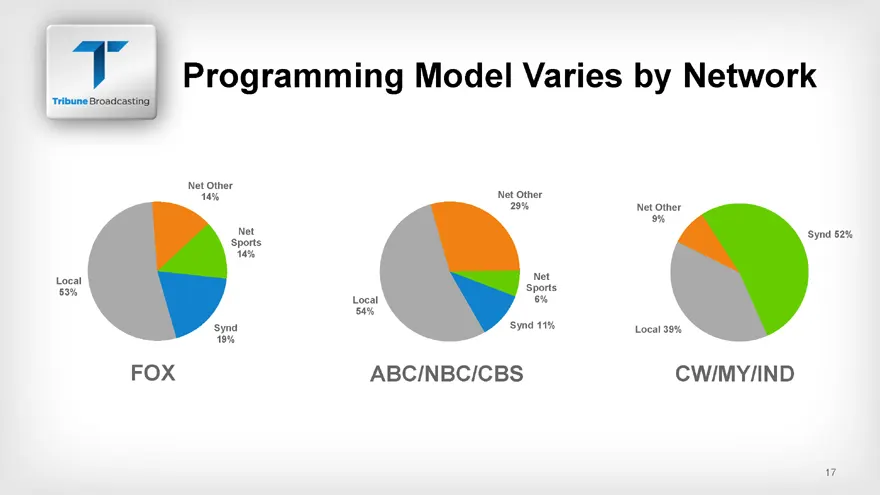
Model Varies by NetworkNet Other14% Net Other29% Net Other 9%Net Synd 52% Sports 14%Net Local Sports 53% Local 6% 54%Synd Synd 11% Local 39% 19%FOX ABC/NBC/CBS CW/MY/IND17
Slide 52: Overview of Content Strategy
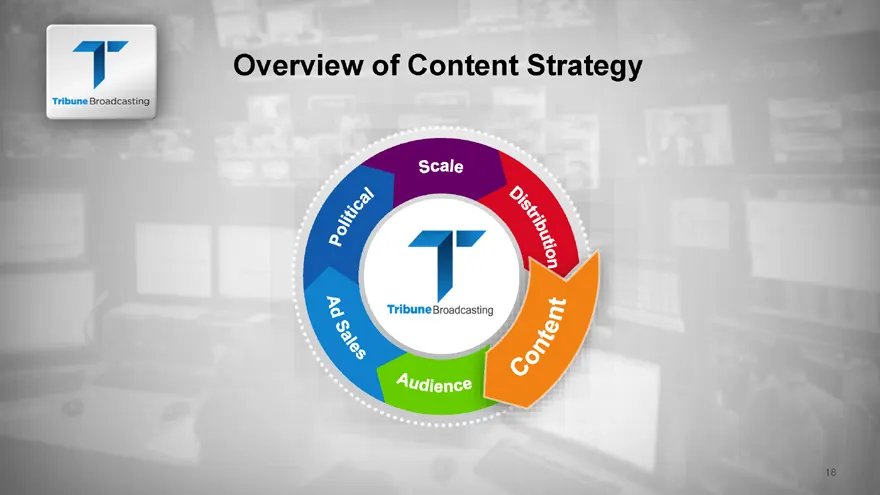
Overview of Content Strategy
Slide 53: Content Strategy
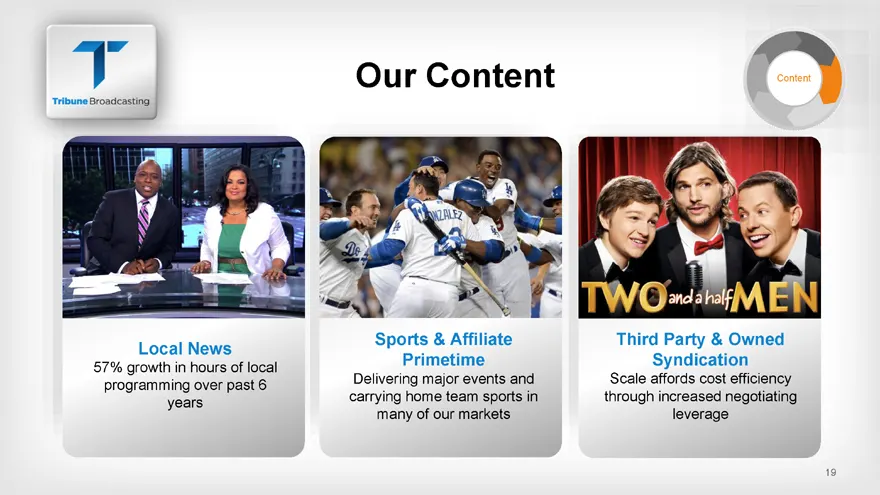
ContentLocal News57% growth in hours of local programming over past 6 yearsSports & Affiliate Primetime Delivering major events and carrying home team sports in many of our marketsThird Party & Owned Syndication Scale affords cost efficiency through increased negotiating leverage19
Slide 54: Broadcasting Content Ownership
Broadcasting Content Ownership
Slide 55: Expansion in News
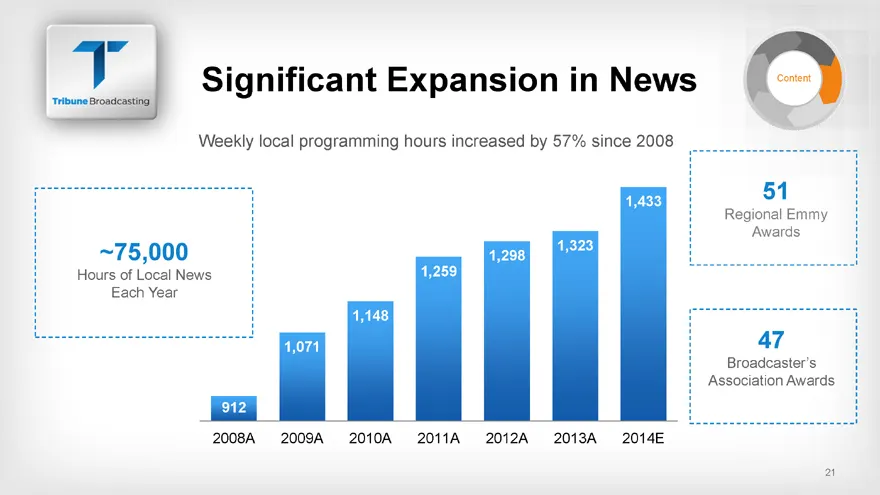
Expansion in NewsWeekly local programming hours increased by 57% since 20 ~75,000Hours of Local News Each Year51 Regional Emmy Awards 47Broadcaster sAssociation Awards1,4331,323 1,298 1,259 1,148 1,071 912 2008A 2009A 2010A 2011A 2012A 2013A 2014E 21
Slide 56: News Commands Greater Viewership than Cable: KTLA
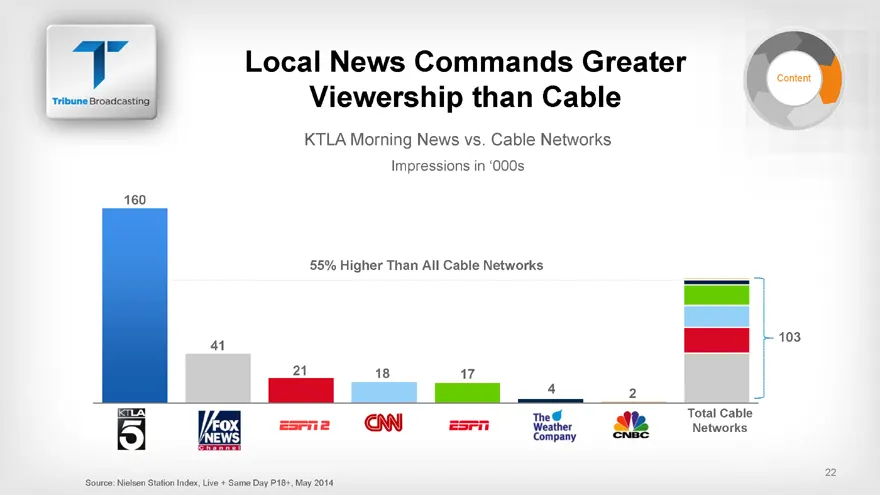
News Commands Greater Viewership than CableKTLA Morning News vs. Cable NetworksImpressions in 000s16055% Higher Than All Cable Networks 103 41 21 18 17 4 2 Total Cable Networks22Source: Nielsen Station Index, Live + Same Day P18+, May 2014
Slide 57: News Commands Greater Viewership than Cable: WGN
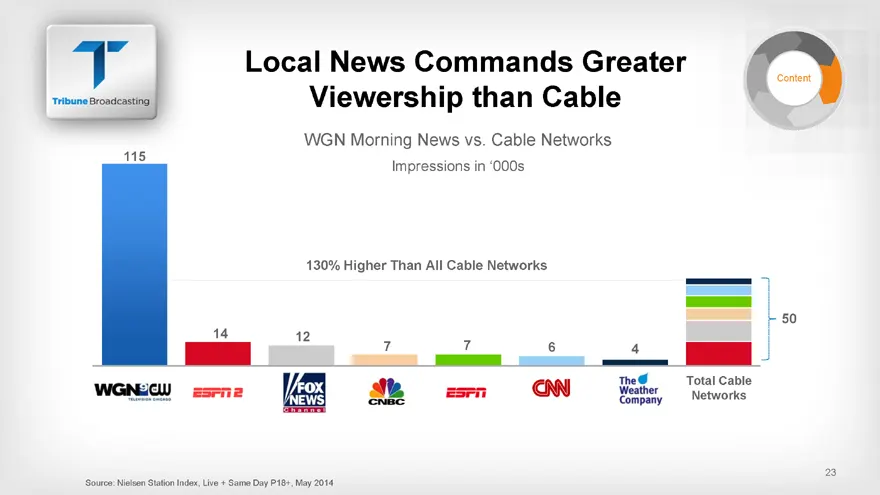
News Commands Greater Viewership than CableWGN Morning News vs. Cable NetworksImpressions in 000s130% Higher Than All Cable Networks 5014 12 7 7 6 4 Total Cable Networks23Source: Nielsen Station Index, Live + Same Day P18+, May 2014
Slide 58: News Commands Greater Viewership than Cable: WJW
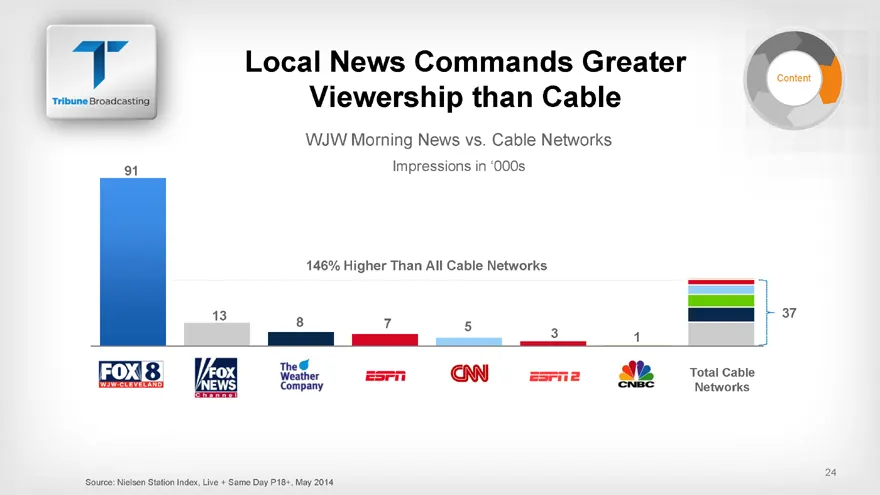
News Commands Greater Viewership than CableWJW Morning News vs. Cable NetworksImpressions in 000s91 146% Higher Than All Cable Networks 13 378 7 5 3 1 Total Cable Networks
Slide 59: Digital Strategy
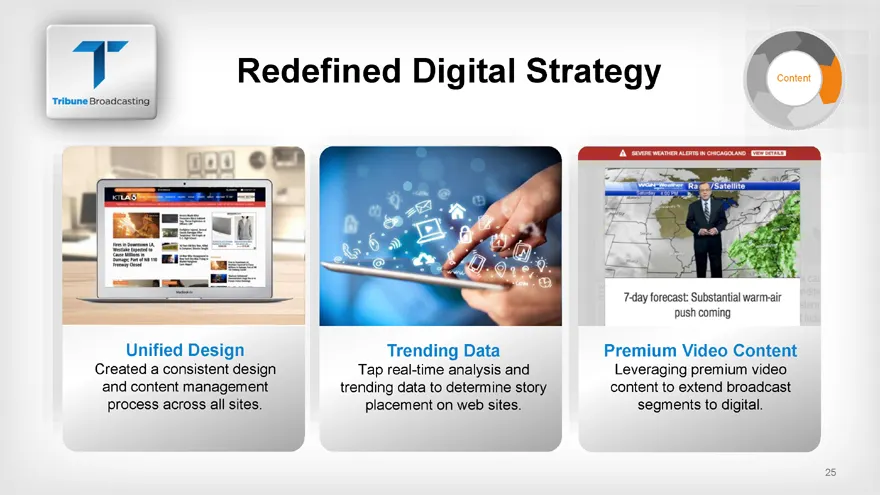
Digital StrategyUnified DesignCreated a consistent design and content management process across all sites.Trending DataTap real-time analysis and trending data to determine story placement on web sites.Premium Video Content Leveraging premium video content to extend broadcast segments to digital.25
Slide 60: Strong Momentum in Digital and Mobile Traffic
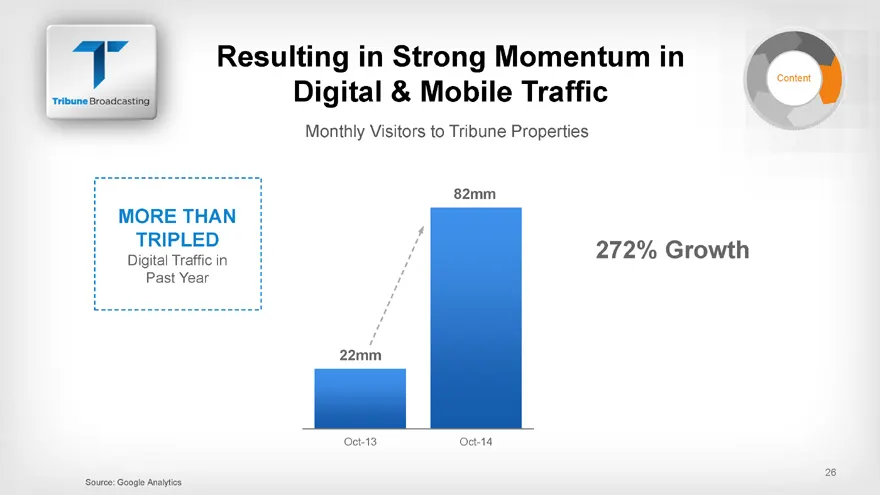
in Strong Momentum Digital & Mobile TrafficMonthly Visitors to Tribune Properties 82mmMORE THAN TRIPLED 272% GrowthDigital Traffic in Past Year22mmOct-13 Oct-1426Source: Google Analytics
Slide 61: Our Audience
Our Audience
Slide 62: News Rules in Time of Crisis: Moore Tornado
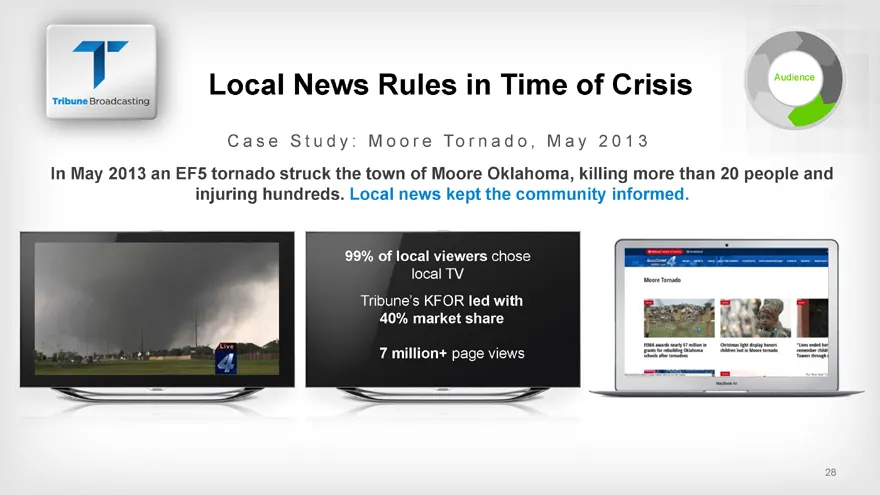
News Rules in Time of AudienceC a s e S t u d y : M o o r e To r n a d o , M a y 2 0 1 3In May 2013 an EF5 tornado struck the town of Moore Oklahoma, killing injuring hundreds. Local news kept the community 99% of local viewers chose local TVTribune s KFOR led with 40% market share7 million+ page vi
Slide 63: Reaching the Major Sports Audience
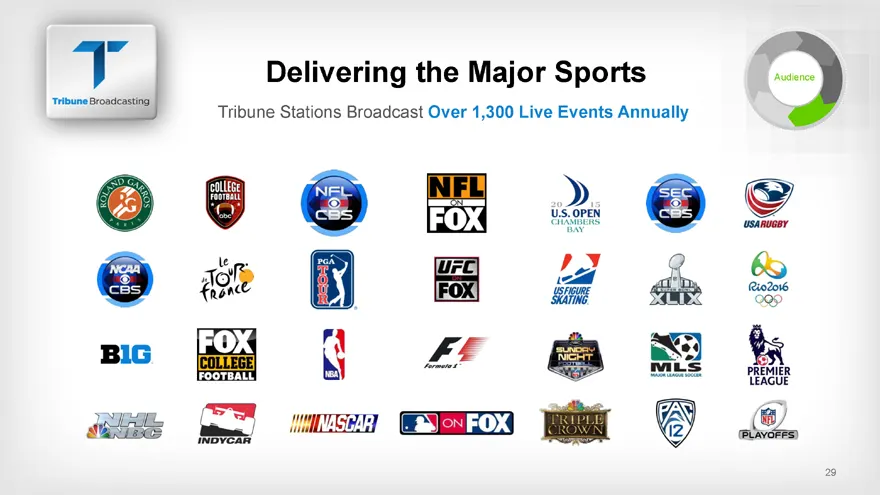
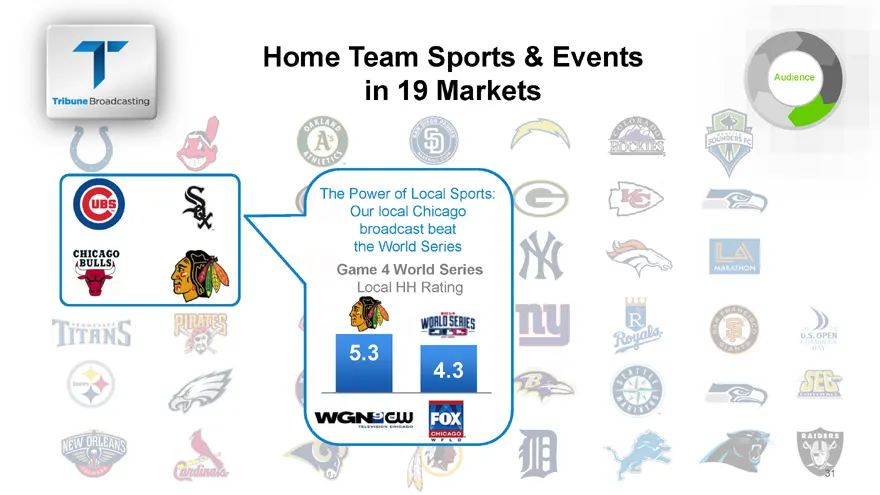
the Major Sports AudienceTribune Stations Broadcast Over 1,300 Live Events Ann29
Slide 64: Reaching the Major Sports Audience
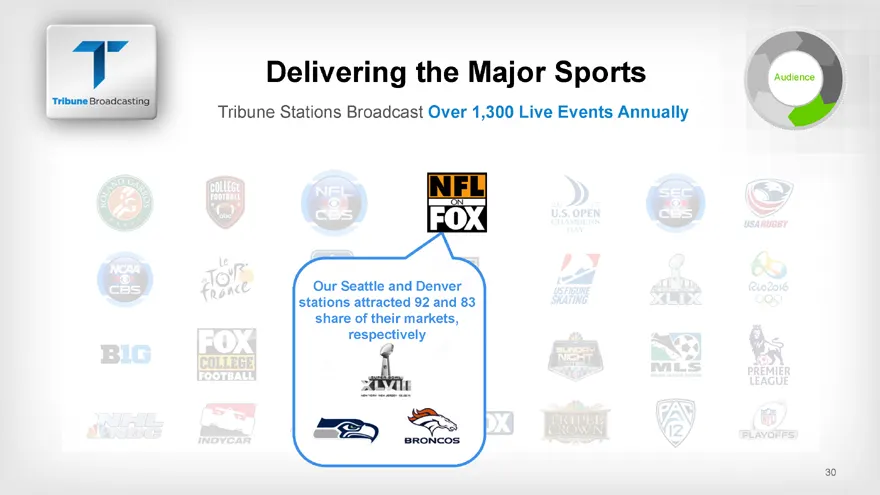
the Major Sports AudienceTribune Stations Broadcast Over 1,300 Live Events AnnOur Seattle and Denver stations attracted 92 and 83 share of their markets, respectively30
Slide 65: The Power of Local Sports
Team Sports & Events in 19 Markets AudienceThe Power of Local Sports: Our local Chicago broadcast beat the World SeriesGame 4 World SeriesLocal HH Rating5.34.331
Slide 66: Overview of Ad Sales Strategy
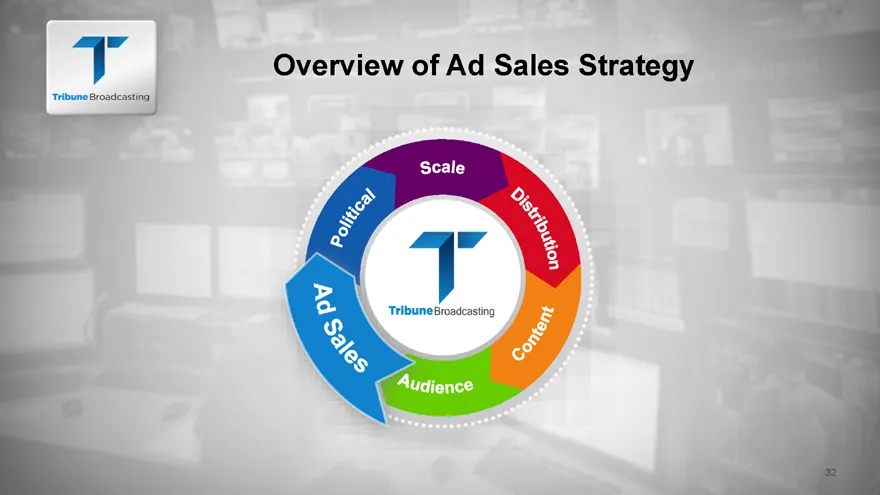
Overview of Ad Sales Strategy “THbune Broadcasting
Slide 67: Customer-Centric Ad Sales
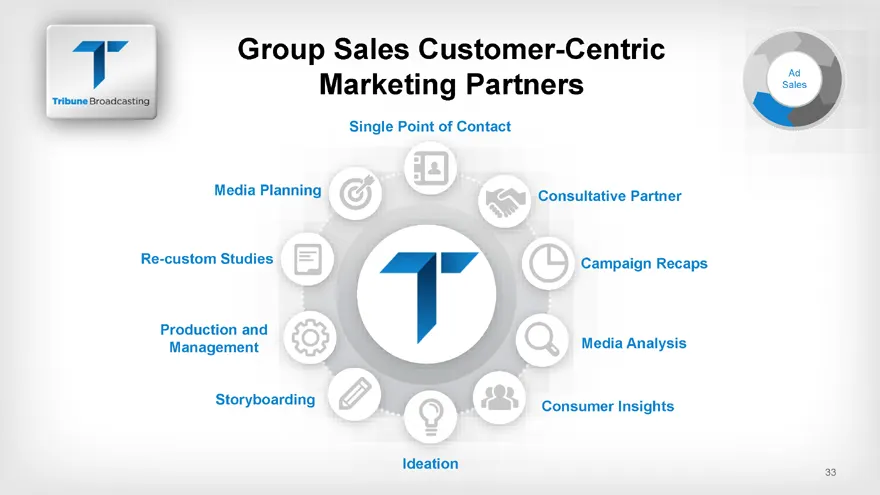
Sales Customer-CentricAdMarketing Partners SalesSingle Point of ContactMedia Planning Consultative Re-custom Studies Campaign RecapsProduction and Management Media AnalysisStoryboardingConsumer InsightsIdeation33
Slide 68: Solutions that Drive Ad Sales
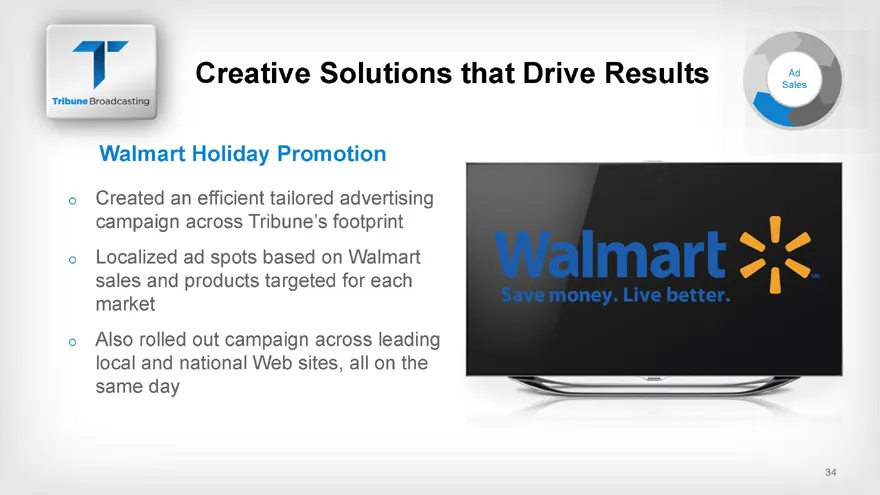
Solutions that Drive AdSalesWalmart Holiday Promotion Created an efficient tailored advertising campaign across Tribune s footprintLocalized ad spots based on Walmart sales and products targeted for each market Also rolled out campaign across leading local and national Web sites, all on the same day
Slide 69: Overview of Political Strategy
Overview of Political Strategy Audience
Slide 70: Secular Growth in Political Advertising
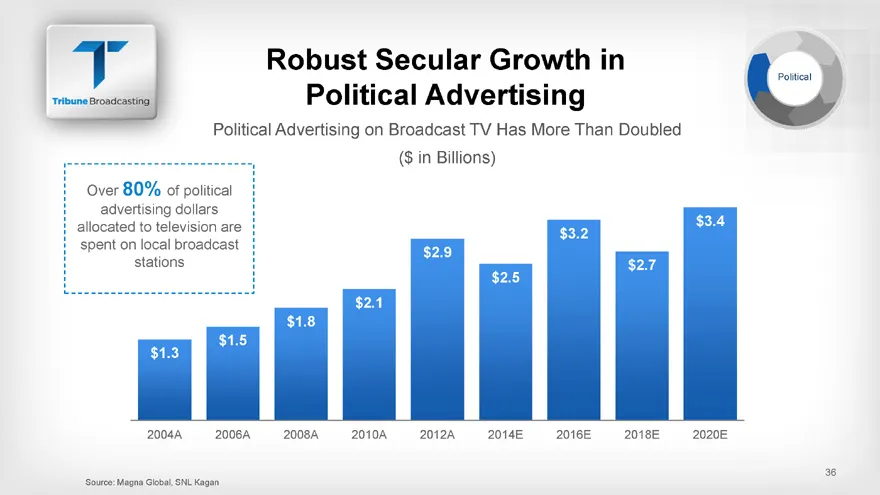
Secular Growth in PoliticalPolitical AdvertisingPolitical Advertising on Broadcast TV Has More Than Double($ in Billions)Over 80% of political advertising dollars allocated to television are $3.2 spent on local broadcast $2.9 stations $2.7 $2.5 $2.1 $1.8 $1.3 $1.5 2004A 2006A 2008A 2010A 2012A 2014E
Slide 71: Positioned for Battle in Political Advertising
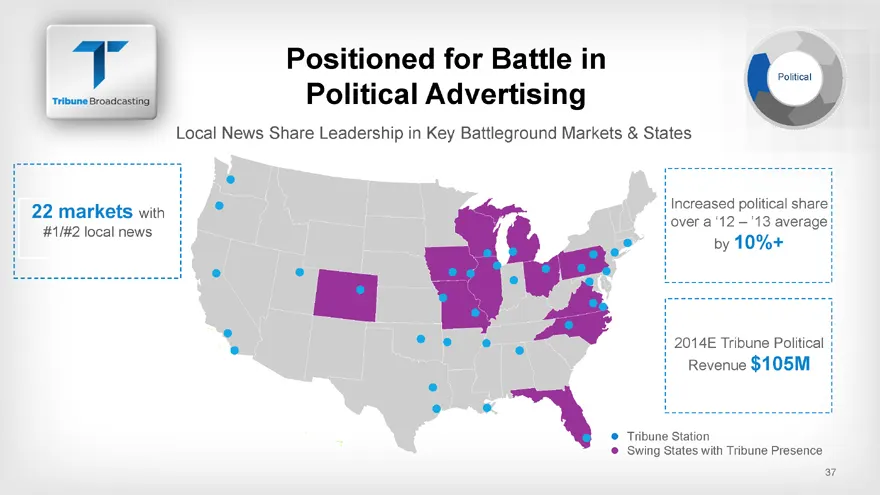
for Battle in PoliticalPolitical Advertisingcal News Share Leadership in Key Battleground Markets & 22 markets with #1/#2 local newsby 10% 10%+2014E Tribune Political Revenue $105MTribune StationSwing States with Tribune Presence37
Slide 72: Overview of Tribune Broadcasting Strategy
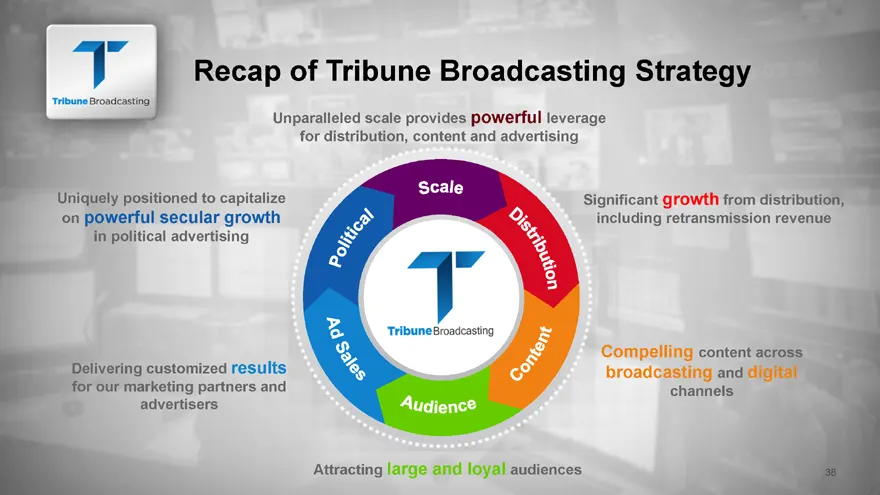
of Tribune Broadcasting StrategyUnparalleled scale provides powerful leverage for distribution, content and advertisingUniquely positioned to capitalize Significant growth from distribution, on powerful secular growth including retransmission revenue in political advertisingCompelling content across
Slide 73: WGN America
Media Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 74: WGN America
Media Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 75: Matt Cherniss, WGN America and Tribune Studios
Studios Investor Day PRESENTATION December 11, 2014 WGN AMERICA Matt Cherniss President WGN America and T ribune Studios WGN America and Tribune Studios2
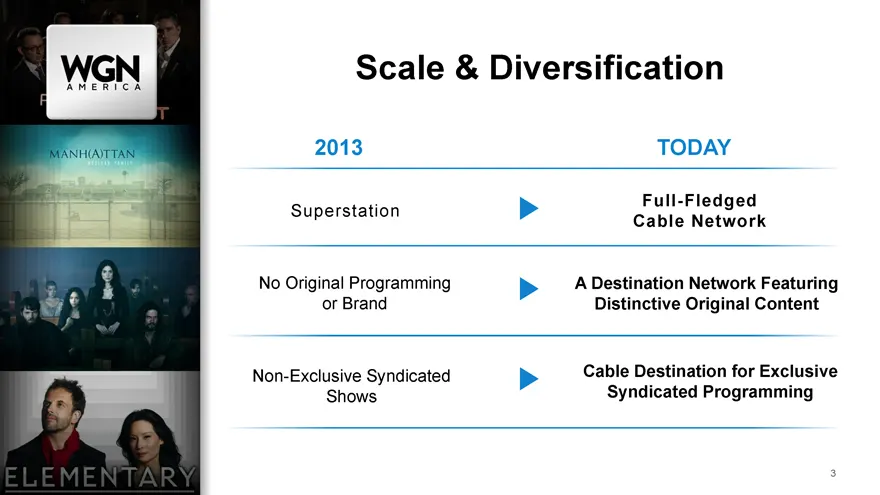
Slide 76: WGN America Scale and Diversification
Scale & Diversification2013 TODAY ull-Fledged Superstation Cable Net work No Original Programming A Destination Network Featuring or Brand Distinctive Original Content Non-Exclusive Syndicated Cable Destination for Exclusive Shows Syndicated Programming3
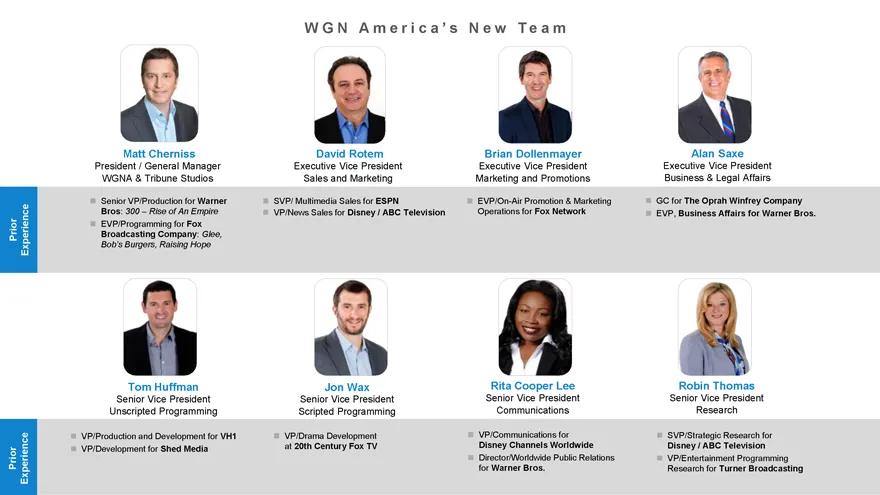
Slide 77: WGN America's New Team
G N A m e r i c a s N e w T e a m Matt Cherniss President / General Manager WGNA & Tribune Studios Senior VP/Production for Warner Bros: 300 Rise of An Empire EVP/Programming for Fox Broadcasting Company: Glee, Bob s Burgers, Raising Hope David Rotem Brian Dollen mayer Alan Saxe Executive Vice P
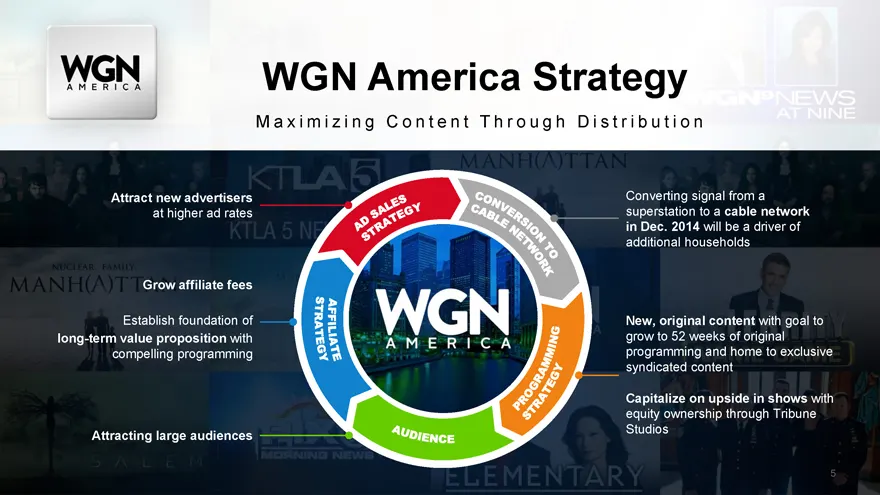
Slide 78: WGN America Strategy
America Strategy M a x i m i z i n g C o n t e n t T h r o u g h D i s t r i b u t i o n Attract new advertisers Converting signal from a at higher ad rates superstation to a cable network in Dec. 2014 will be a driver of additional house holds Grow affiliate fees Establish foundation of New, origin
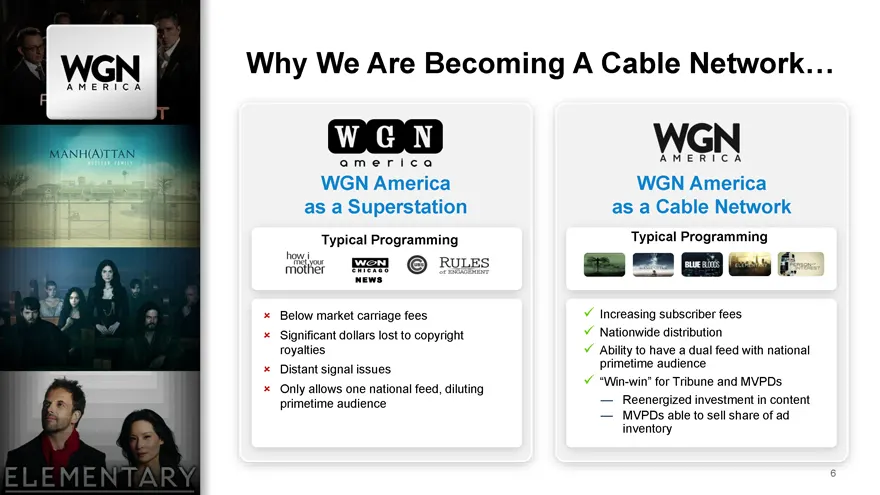
Slide 79: Why We Are Becoming a Cable Network
Why We Are Becoming A Cable Network WGN America WGN America as a Superstation as a Cable Network Typical Programming Typical Programming NEWS Below market carriage fees Increasing subscriber fees Significant dollars lost to copyright Nationwide distribution royalties Ability to have a dual feed with
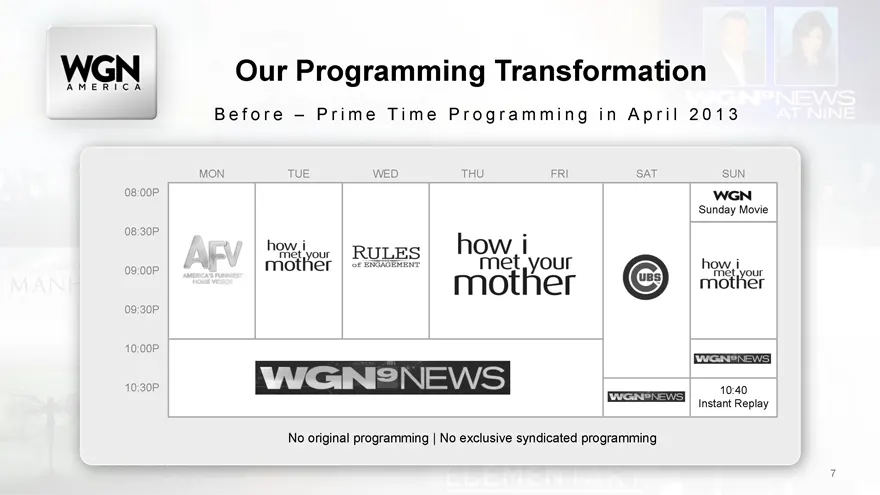
Slide 80: Programming Transformation: Before
Programming Trans formationB e f o r e P r i m e T i m e P r o g r a m m i n g i n A p r i l 2 0 1 3MON TUE WED THU FRI SAT SUN 08:00PSunday Movie08:30P09:00P 09:30P 10:00P10:30P 10:40 Instant ReplayNo original programming | No exclusive syndicated programming7
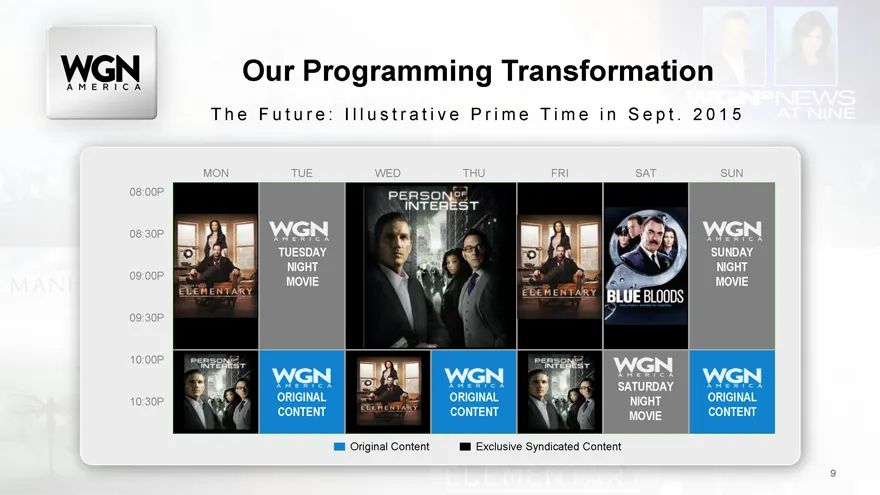
Slide 81: Programming Transformation: The Future
Programming TransformationT h e F u t u r e : I l l u s t r a t i v e P r i m e T i m e i n S e p t . 2 0 1 5MON TUE WED THU FRI SAT SUN 08:00P08:30PTUESDAY SUNDAY NIGHT NIGHT 09:00P MOVIE MOVIE09:30P10:00PSATURDAY10:30P ORIGINAL ORIGINAL NIGHT ORIGINAL CONTENT CONTENT MOVIE CONTENTOriginal Content
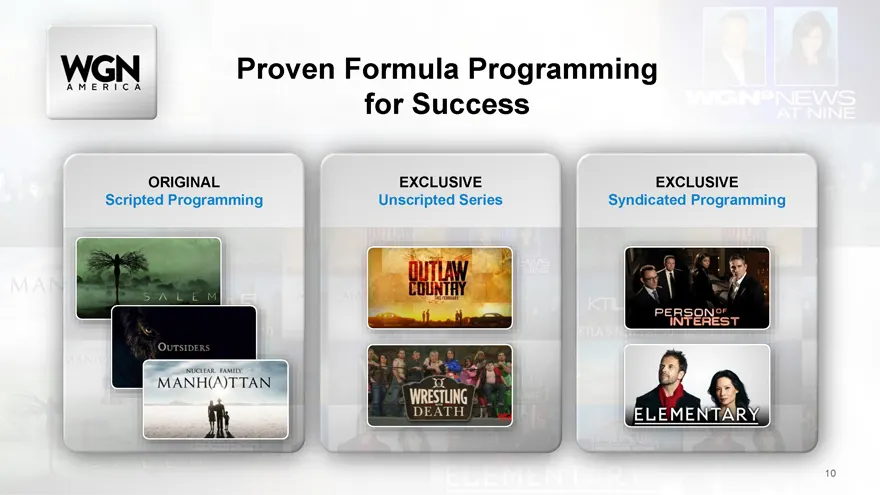
Slide 82: Formula for Programming Success
Formula Programming for SuccessORIGINAL EXCLUSIVE EXCLUSIVE Scripted Programming Unscripted Series Syndicated Programming10
Slide 83: How We Measure Success
How We Measure Success
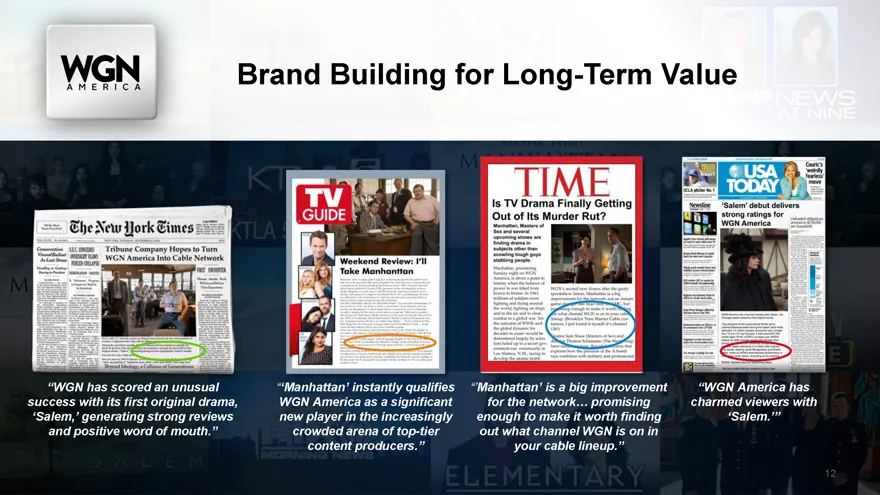
Slide 84: Building for Long-Term Value
Building for Long-Term Value WGN has scored an unusual Manhattan instantly qualifies Manhattan is a big improvement WGN America has success with its first original drama, WGN America as a significant for the network promising charmed viewers with Salem, generating strong reviews new player in the in
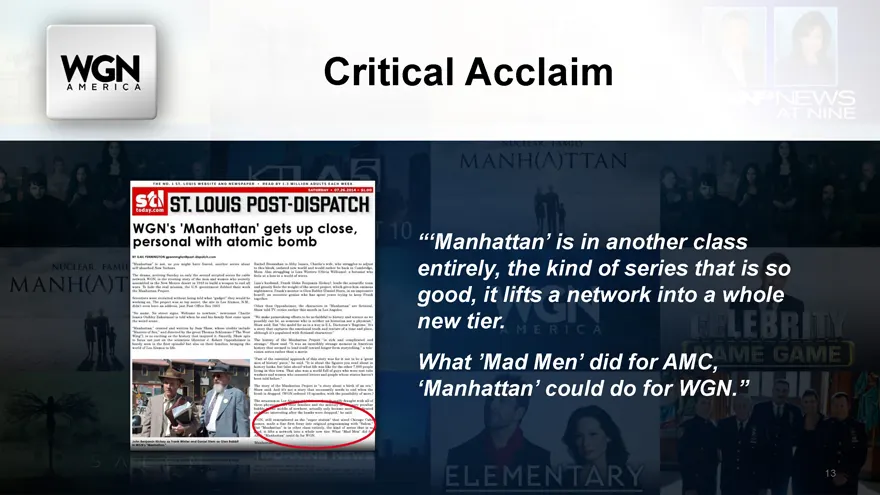
Slide 85: Critical Acclaim
Acclaim Manhattan is in another class entirely, the kind of series that is so good, it lifts a network into a whole new tier. What Mad Men did for AMC, Manhattan could do for WGN. 13
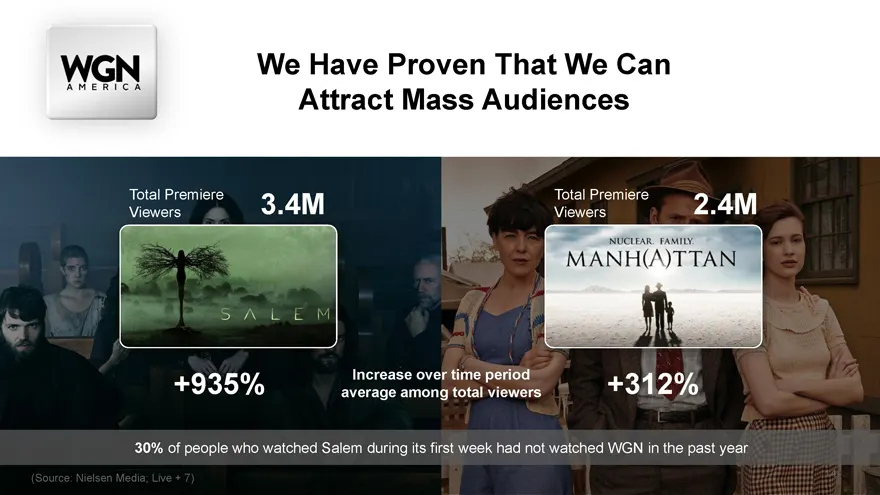
Slide 86: We Have Proven That We Can Attract Mass Audiences
Have Proven That We Can Attract Mass AudiencesTotal Premiere 3.4M Total Premiere 2.4M Viewers Viewers+935% Increase over time period +312% average among total viewers 30% of people who watched Salem during its first week had not watched WGN in the past year(Source: Nielsen Media; Live + 7) 14
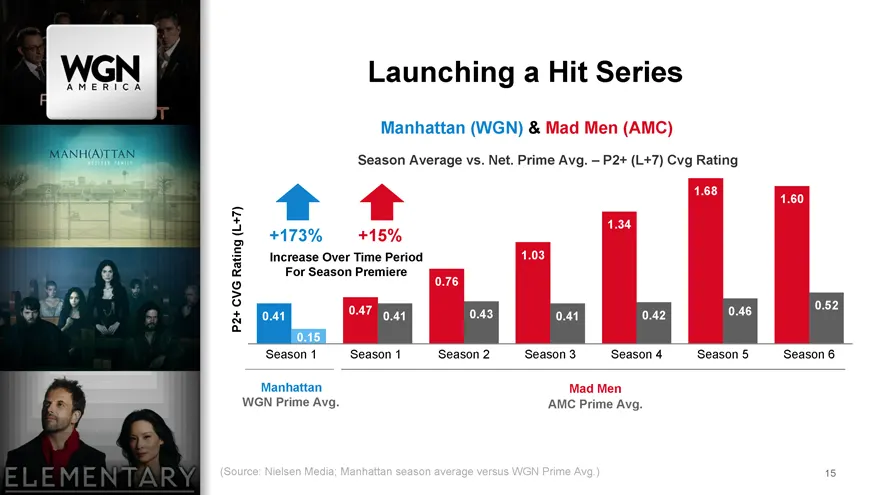
Slide 87: Building a Hit Series: Manhattan and Mad Men
a Hit SeriesManhattan (WGN) & Mad Men (AMC)Season Average vs. Net. Prime Avg. P2+ (L+7) Cvg Rating1.68 1.60 (L+7) 1.34 +173% +15%Increase Over Time Period 1.03 Rating For Season Premiere CVG 0.76 0.47 0.52 0.41 0.41 0.43 0.41 0.42 0.46 P2+0.15 Season 1 Season 1 Season 2 Season 3 Season 4 Season
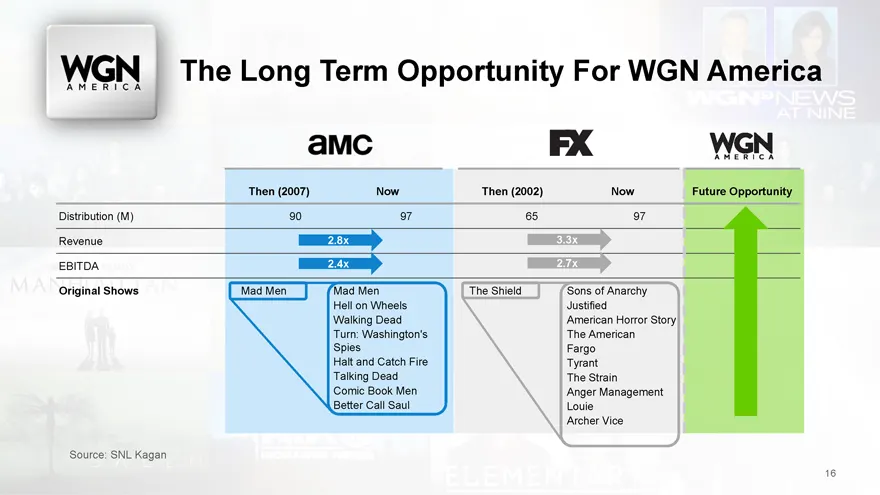
Slide 88: Long Term Opportunity for WGN America
Long Term Opportunity For WGN AmericaThen (2007) Now Then (2002) Now Future OpportunityDistribution (M) 90 97 65 97Revenue 2.8x 3.3x EBITDA 2.4x 2.7xOriginal Shows Mad Men Mad Men The Shield Sons of Anarchy Hell on Wheels Justified Walking Dead American Horror Story Turn: Washington’s The American S
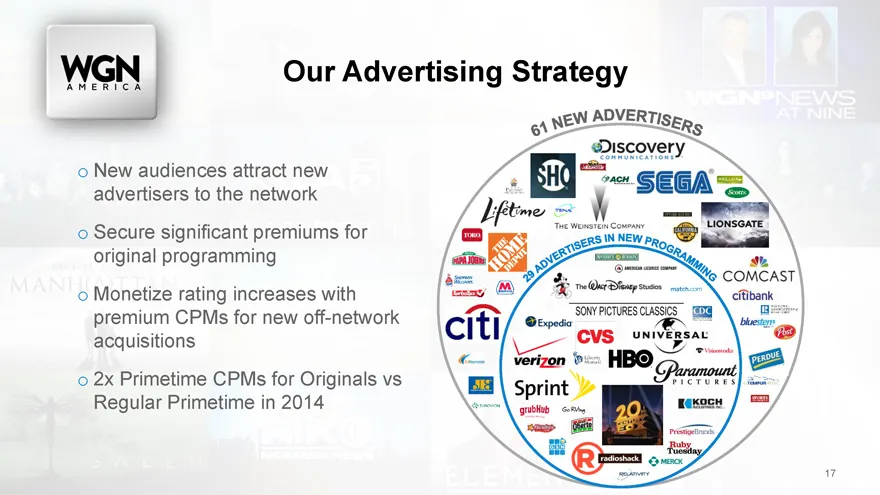
Slide 89: Advertising Strategy
Advertising Strategyo New audiences attract new advertisers to the network o Secure significant premiums for original programming o Monetize rating increases with premium CPMs for new off-network acquisitions o 2x Primetime CPMs for Originals vs Regular Primetime in 201417
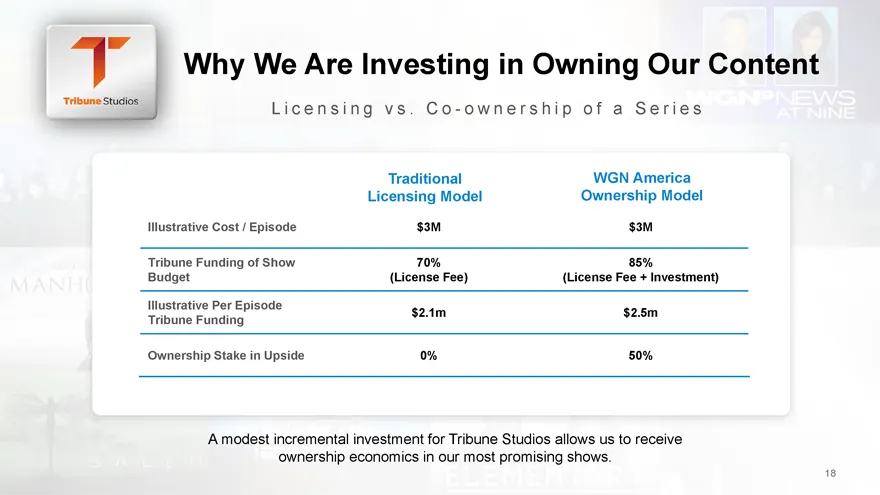
Slide 90: We Are Investing in Owning Our Content
We Are Investing in Owning Our ContentLicensin g v s . C o—o w n e r s h i p o f a S e r i e sTraditional WGN America Licensing Model Ownership ModelIllustrative Cost / Episode $3M $3MTribune Funding of Show 70% 85%Budget (License Fee) (License Fee + Investment)Illustrative Per Episode $2.1m $2.5m T
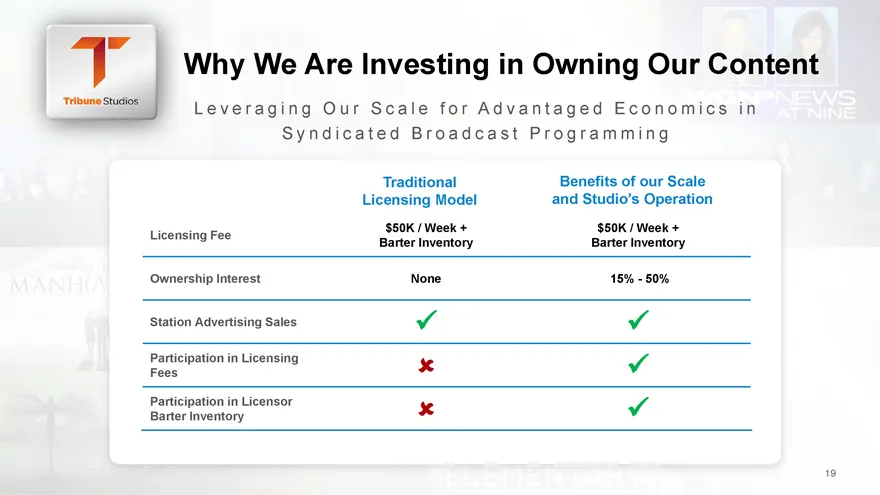
Slide 91: Leveraging Our Scale for Advantaged Economics
We Are Investing in Owning Our ContentL e v e r a g i n g O u r S c a l e f o r A d v a n t a g e d E c o n o m i c s i n S y n d i c a t e d B r o a d c a s t P r o g r a m m i n gTraditional Benefits of our Scale Licensing Model and Studio s Operation $50K / Week + $50K / Week + Licensing Fee Bart
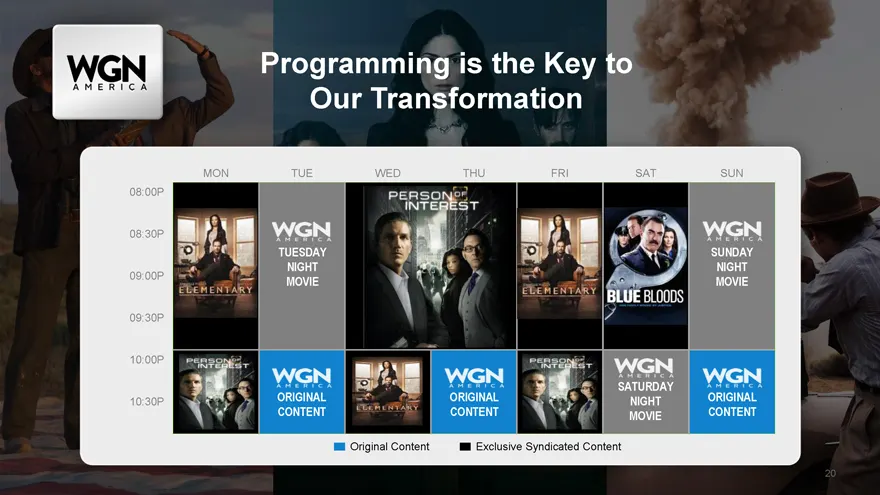
Slide 92: Original Content Is the Key to Our Transformation
is the Key to Our TransformationMON TUE WED THU FRI SAT SUN 08:00P08:30PTUESDAY SUNDAY NIGHT NIGHT 09:00P MOVIE MOVIE09:30P10:00PSATURDAY10:30P ORIGINAL ORIGINAL NIGHT ORIGINAL CONTENT CONTENT MOVIE CONTENTOriginal Content Exclusive Syndicated Content20
Slide 93: WGN America
Media Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 94: Gracenote
Media grace note Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 95: John Batter, CEO, Gracenote
note Investor Day PRESENTATION December 11, 2014 John BatterEVP, Tribune Media Co. and CEO, GracenoteGracenote
Slide 96: Gracenote Company Overview
is Gracenote C O M P A N Y O V E R V I E WA leading entertainment data and technology companyWe power the world s top music services, consumer electronics, automakers, cable and satellite providers
Slide 97: What Is Metadata and Why Should You Care
is Metadata And why should you care 12
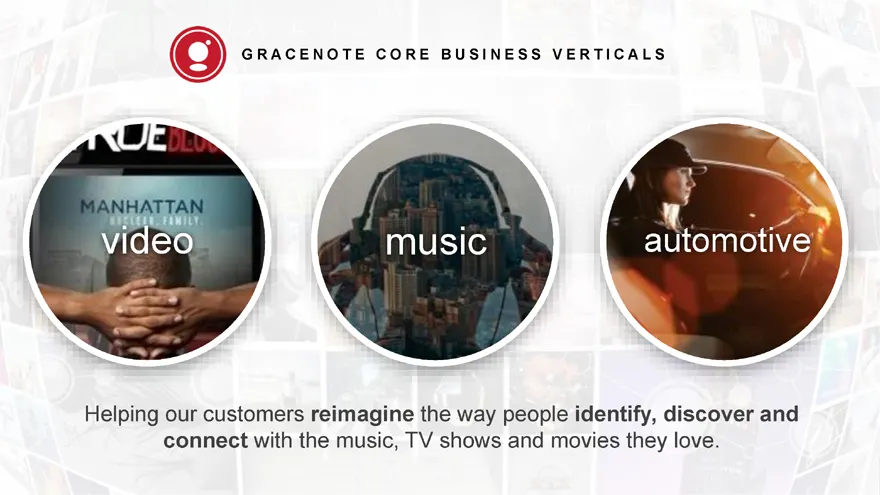
Slide 98: Gracenote Core Business Verticals
R A C E N O T E C O R E B U S I N E S S V E R T I C A L Svideo music automotiveHelping our customers reimagine the way people identify, discover and connect with the music, TV shows and movies they love.
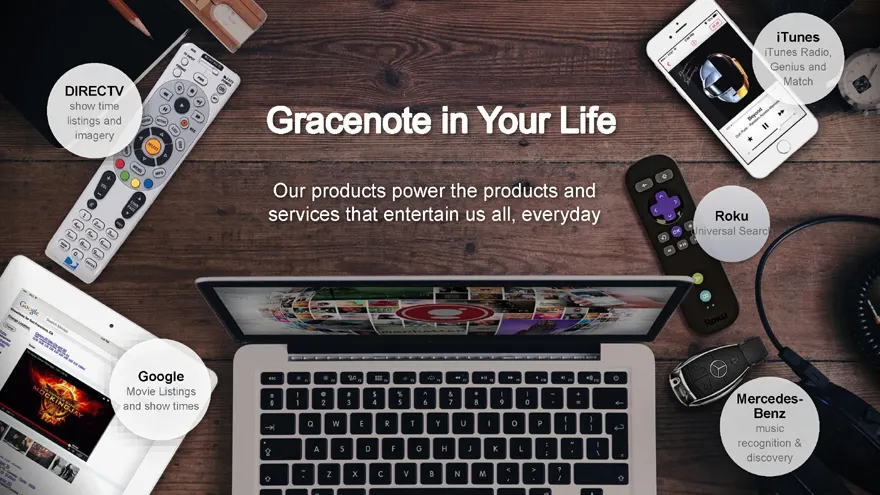
Slide 99: Our Products Power Everyday Entertainment
iTunes Radio, Genius and MatchDIRECTV show time listings and imageryOur products power the products and services that entertain us all, everyday RokuUniversal SearchGoogleMovie Listings Mercedes-and show timesBenz music recognition & discovery
Slide 100: 70% of Typical New Yorkers Used Gracenote This Week
e e s t i m a t e t h a t :70%O f t y p i c a l N e w Yo r k e r s h a v e u s e d G r a c e n o t e t h i s w e e k .
Slide 101: Gracenote Global Platform
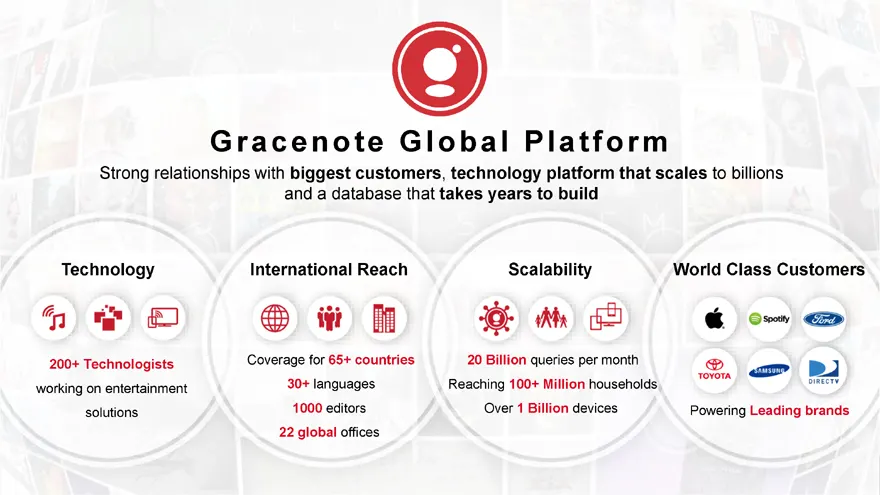
r a c e n o t e G l o b a l P l a t f o r mStrong relationships with biggest customers, technology platform that scales to billions and a database that takes years to buildTechnology International Reach Scalability World Class Customers200+ Technologists Coverage for 65+ countries 20 Billion queries
Slide 102: Video Customers
Video CustomersOur Video Customers Represent top cable and satellite providers, Internet companies and OTT platforms worldwide
Slide 103: FOX wn FOX HD
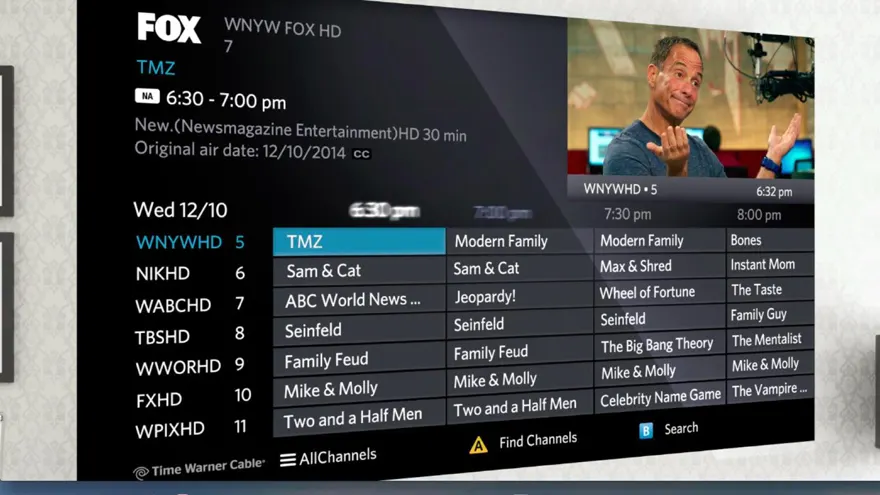
FOX wn FOX HD Tz © 6:30 - 7:00 pm New.(Newsma wsmagazine Entertai Original air date: 2/10/2014 Wed 12/10 _— a WxywHo 5 [Zinn = 730 pm a ‘Modern Family Moder Family a NIKHD 6 — Sam&Cat Sam & Cat ‘Max & Shred Instant Mom WABCHD 7 ABCWorldNews.. Jeopardy! Wheel of Fortune The Taste TBSHD 8 _ Seinfeld S
Slide 104: search The Hunger Games (2012)
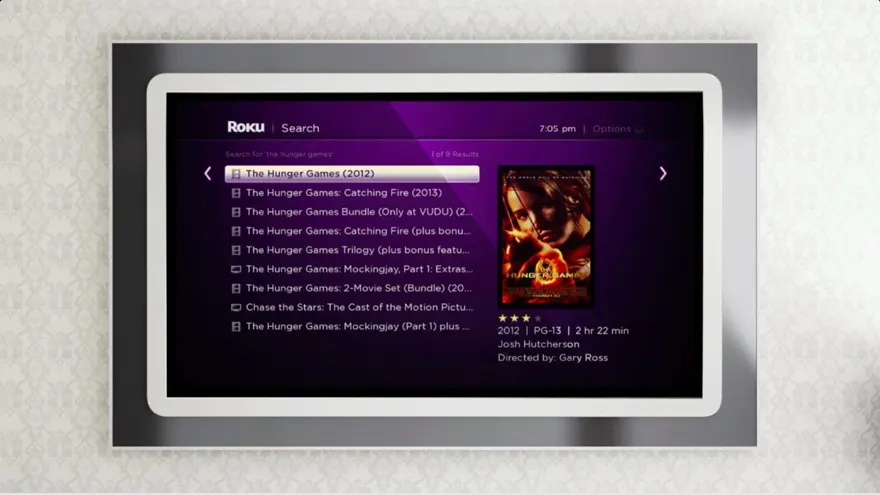
search The Hunger Games (2012)
Slide 105: Music Customers
Music CustomersOur Music Customers Represent the biggest names in streaming,
Slide 106: Sleep Till Brooklyn Beastle Boys Licensed to III No Sleep Till
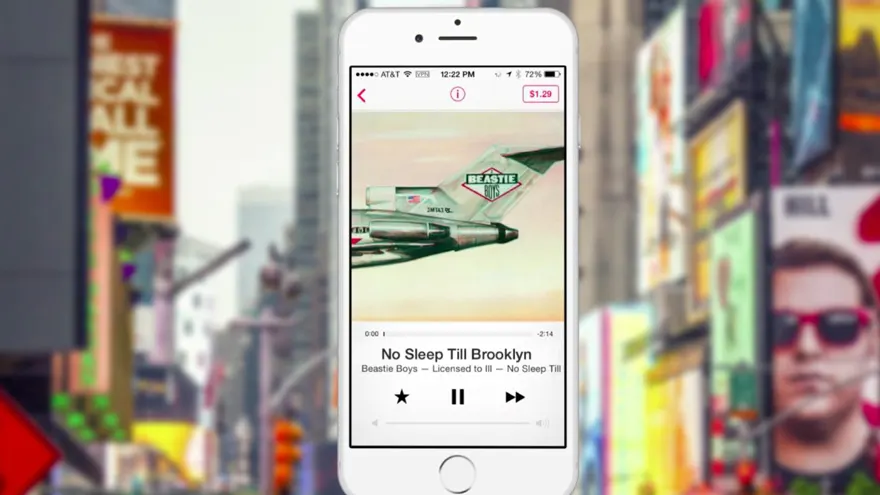
Sleep Till Brooklyn Beastle Boys Licensed to III No Sleep Till
Slide 107: Auto Customers
Auto CustomersGracenote works with every major automotive manufacturer
Slide 108
Slide 109: Predictable Business Model
Predictable Business Model1 2 3Licensing Data & Long Term Strong Customer Technology Contracts RetentionWe license our data and Contracts run between 2-6 Major customers span technologies to a diverse years, providing a more than a decade, with customer base from Auto and predictable form of 90%
Slide 110: Opportunities
OpportunitiesDeepen our database to feature Increase our international Expand our data & technology additional descriptive information footprint to scale with our global expertise to cover additional to fuel discovery services. customers. forms of entertainment.17
Slide 111: Acquisition: Expansion of Core Business
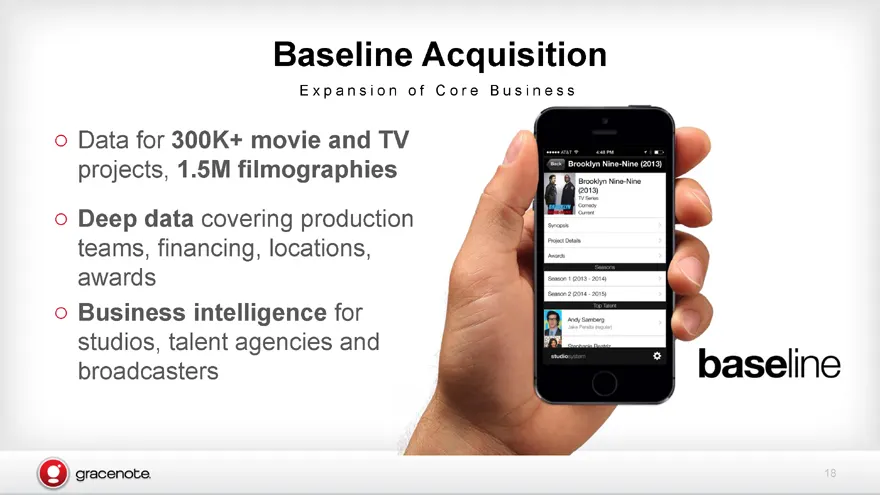
AcquisitionE x p a n s i o n o f C o r e B u s i n e s s Data for 300K+ movie and projects, 1.5M filmographie Deep data covering production teams, financing, locations, awards Business intelligence for studios, talent agencies and broadcasters Base line18
Slide 112: Opportunities: Expansion of Our Core Business
OpportunitiesE X P A N S I O N O F O U R C O R E B U S I N E S SConnected Car Next Gen Guides Live Music PersonalizationHelping automakers Building next Tapping into the largest Creating data-powered unify the music generation guides for revenue source for music discovery and experience across all c
Slide 113: Opportunities: International Growth
OpportunitiesI N T E R N A T I O N A L G R O W T H S U P P O R T I N G C U S T O M E R E X P A N S I O NGrow our own sales, Acquire the market leader editorial and tech teams to in a specific region to gain support key strategic an immediate foothold regions 20
Slide 114: Opportunities: Horizontal Expansion Beyond Music and Video
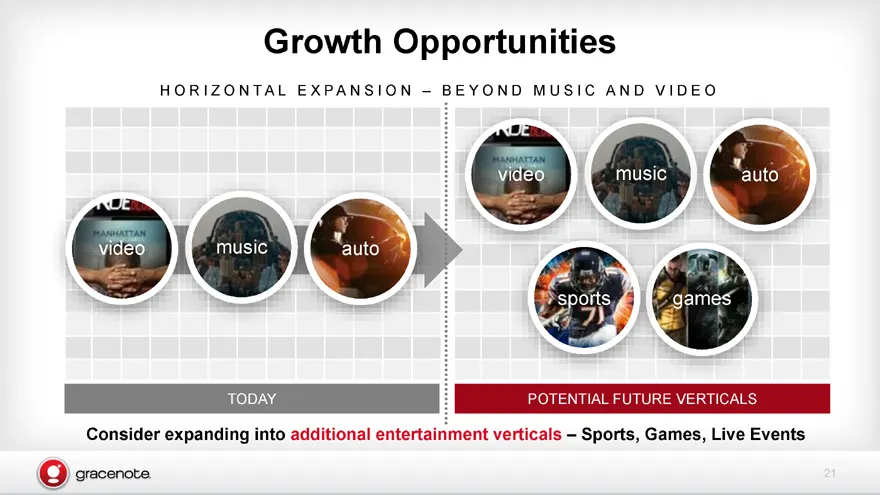
OpportunitiesH O R I Z O N T A L E X P A N S I O N B E Y O N D M U S I C A N D V I D E Ovideo music autovideo music autosports gamesTODAY POTENTIAL FUTURE VERTICALSConsider expanding into additional entertainment verticals Sports, Games, Live Events21
Slide 115: Uniquely Positioned for the Future
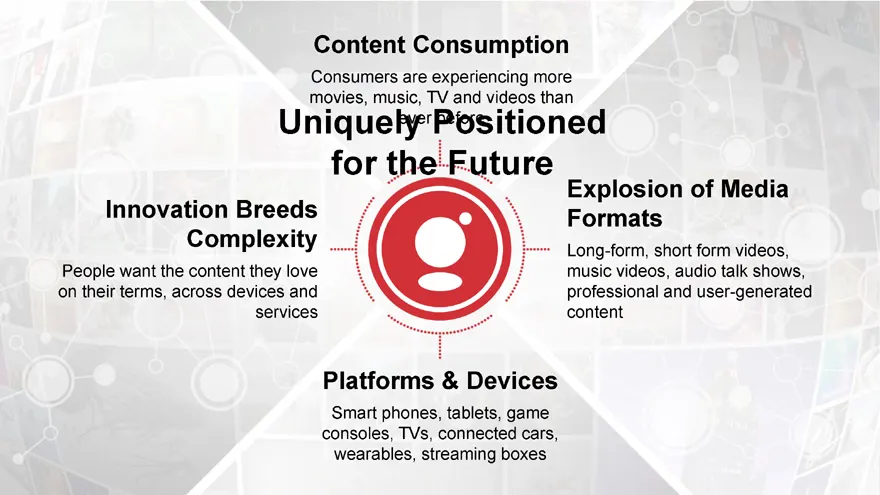
ConsumptionConsumers are experiencing more movies, music, TV and videos than Uniquely ever Positioned before for the FutureExplosion of Media Innovation Breeds Formats ComplexityLong-form, short form videos, People want the content they love music videos, audio talk shows, on their terms, across dev
Slide 116: Gracenote
Media grace note Investor Day PRESENTATION December 11, 2014 WGN AMERICA
Slide 117: Tribune Real Estate, Murray McQueen
Tribune Real Estate Investor Day PRESENTATION December 11, 2014 Murray McQueen President, Tribune Real Estate Holdings Real Estate
Slide 118: Investment Highlights
I n v e s t m e n t H i g h l i g h t s o Maximizing the value of Tribune’s real estate portfolio o ~8mm sq. feet generating ~$50M annually of rental revenues o Maximizing cash flow and pursuing development opportunities o Deliberate monetization strategy
Slide 119: Real Estate Management Team
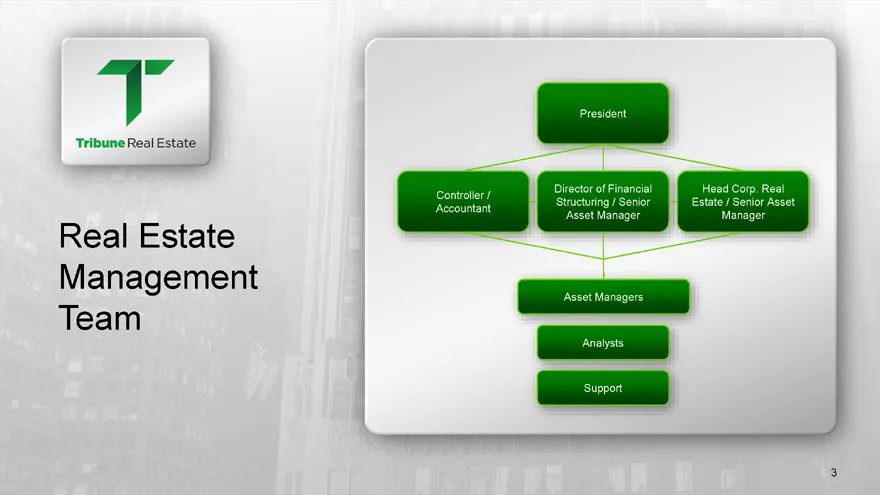
President Director of Financial Head Corp. Real Controller / Structuring / Senior Estate / Senior Asset Accountant Asset Manager Manager Real Estate Management Asset Managers Team Analysts Support
Slide 120: Overview of Tribune's Real Estate Portfolio
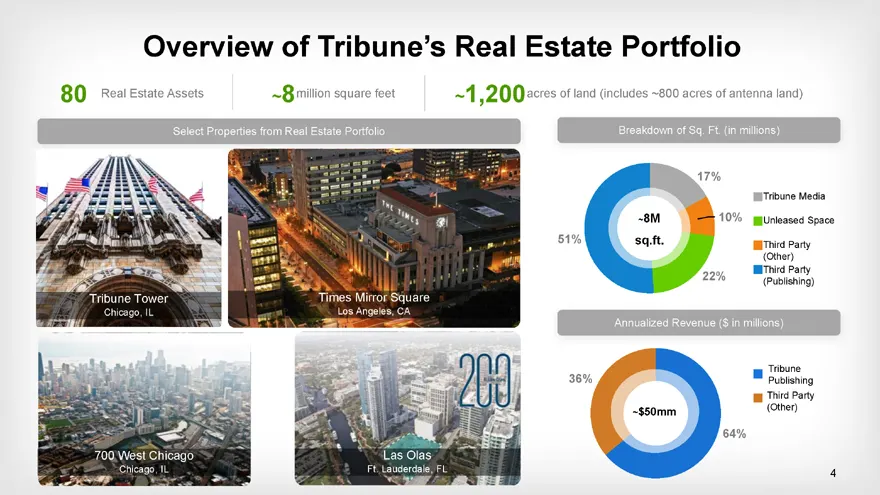
Overview of Tribune’s Real Estate Portfolio 80 Real Estate Assets ~8million square feet ~1,200acres of land (includes ~800 acres of antenna land) Select Properties from Real Estate Portfolio Breakdown of Sq. Ft. (in millions) 17% Tribune Media ~8M 10% Unleased Space 51% sq.ft. Third Party (Other) Th
Slide 121: Operating and Investment Strategy
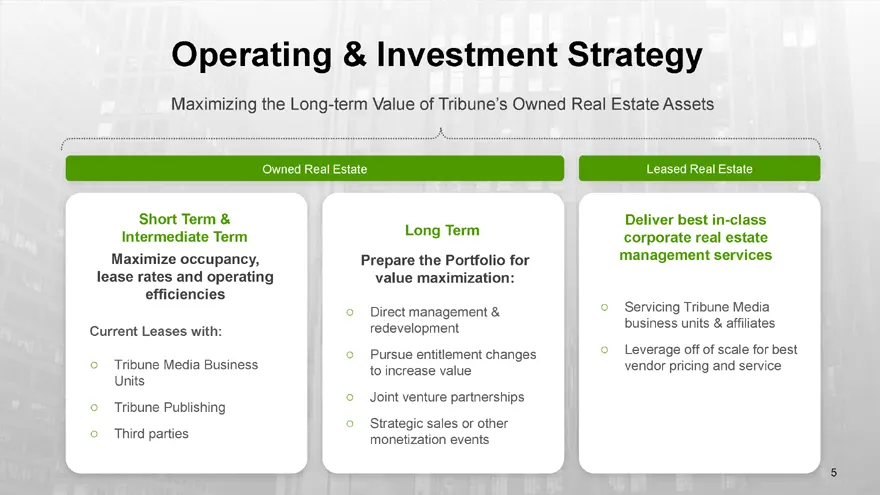
Operating & Investment Strategy Maximizing the Long-term Value of Tribune’s Owned Real Estate Assets Owned Real Estate Leased Real Estate Short Term & Deliver best in-class Long Term Intermediate Term corporate real estate Maximize occupancy, Prepare the Portfolio for management services lease rates
Slide 122: Tribune Real Estate Holdings: Geographically Diverse
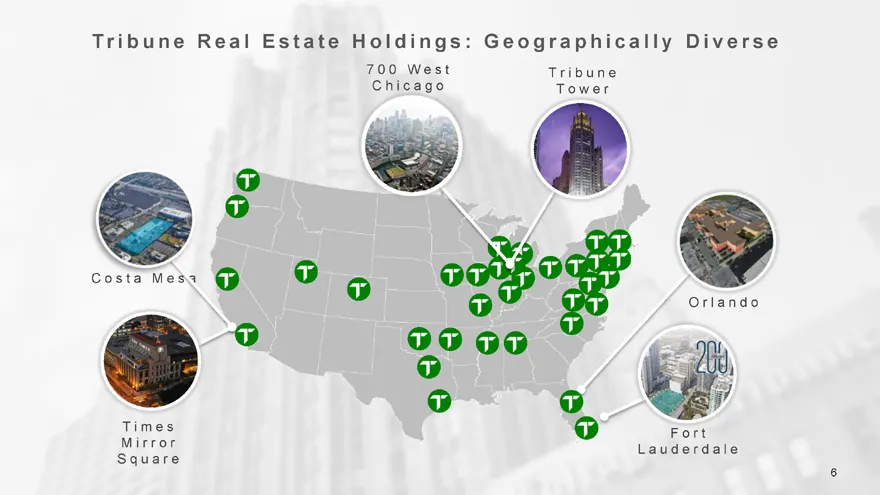
T r i b u n e R e a l E s t a t e H o l d i n g s : G e o g r a p h i c a l l y D i v e r s e 0 0 W e s t T r i b u n e C h i c a g o T o w e r l a n d o T i m e s F o r t M i r r o r L a u d e r d a l e S q u a r e
Slide 123: Joint Venture Redevelopment Model
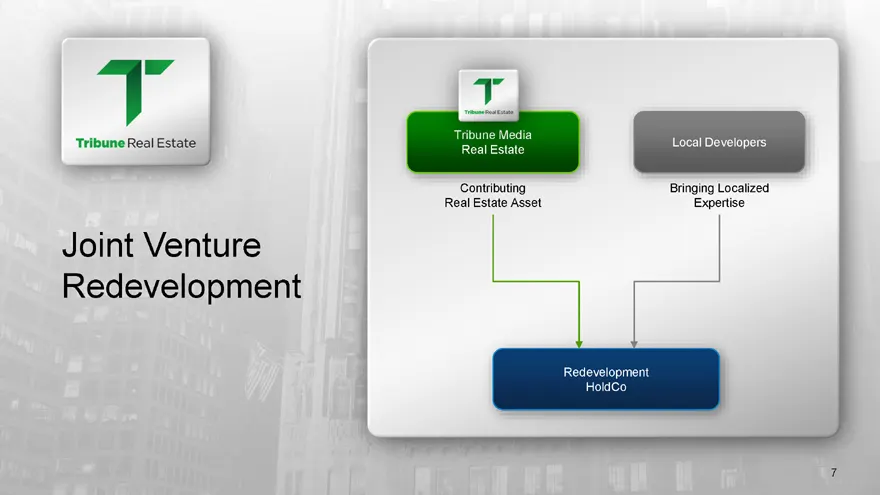
Local Developers Contributing Bringing Localized Real Estate Asset Expertise Joint Venture Redevelopment Redevelopment HoldCo
Slide 124: Redevelopment Case Study
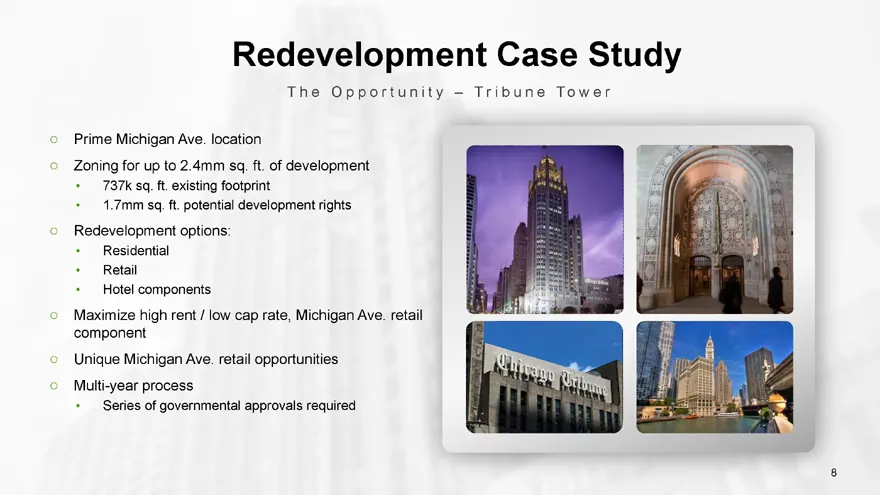
Redevelopment Case Study T h e O p p o r t u Prime Michigan Ave. location Zoning for up to 2.4mm sq. ft. of development 737k sq. ft. existing footprint 1.7mm sq. ft. potential development rights Redevelopment options: Residential Retail Hotel components Maximize high rent / low cap rate, Michigan Av
Slide 125: Redevelopment Case Study: Tribune Tower
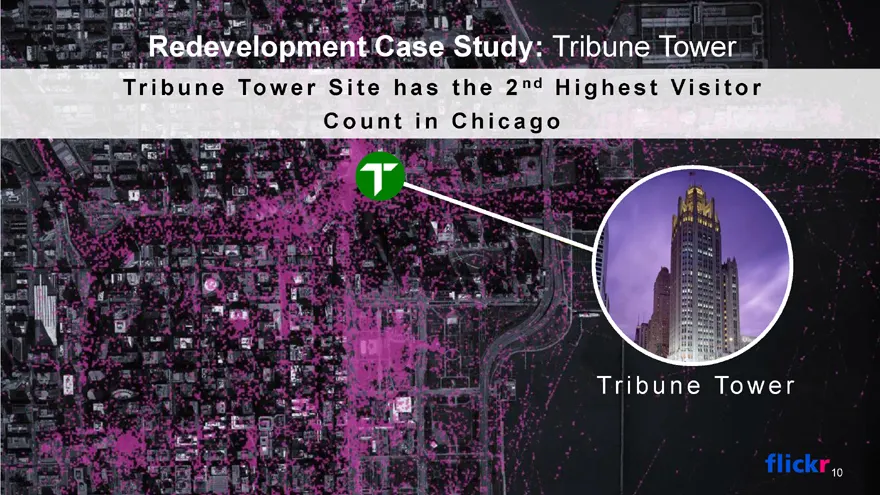
Redevelopment Case Study: Tribune Tower Tr i b u n e To w e r S i t e h a s t h e 2 nd H i g h e s t V i s i t o r C o u n t i n C h i c a g o ribune Tower Tr i b u n e To w e r
Slide 126: Tribune Tower Retail
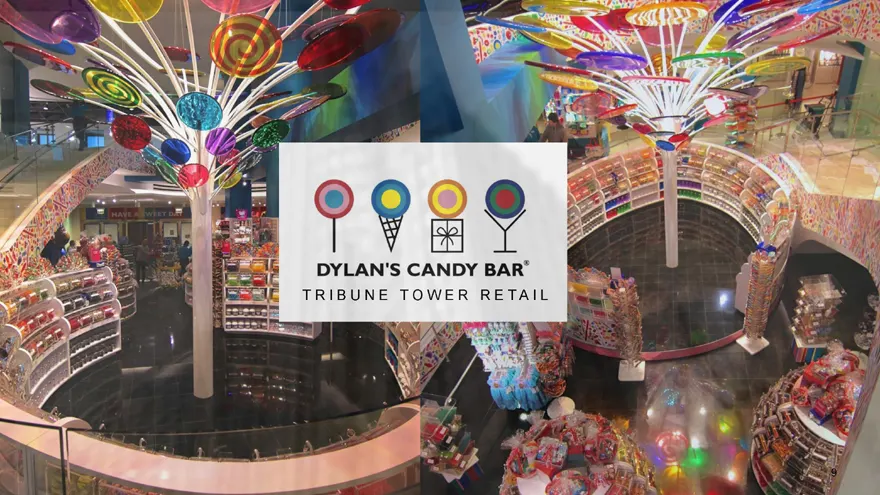
Dylan’s Candy Bar Tribune Tower Retail
Slide 127: Potential Redevelopment on Tribune Tower Site
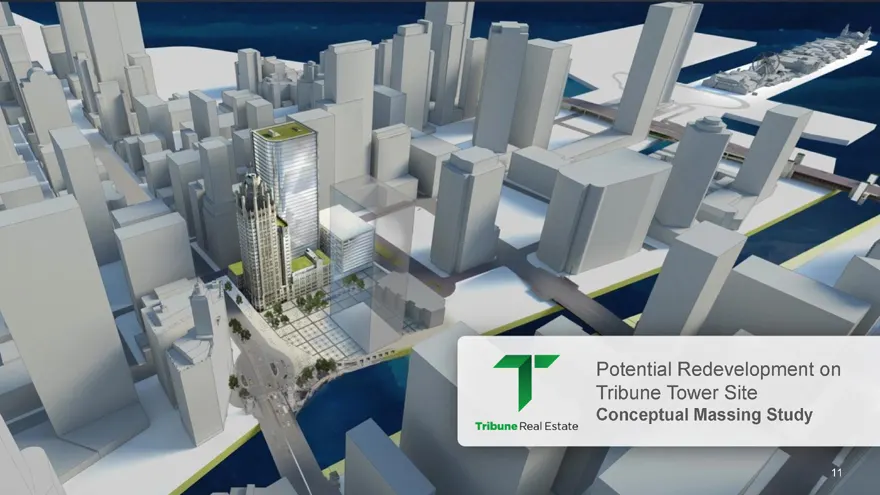
Potential Redevelopment on Tribune Tower Site Conceptual Massing Study
Slide 128: Redevelopment Case Study: Times Mirror Square
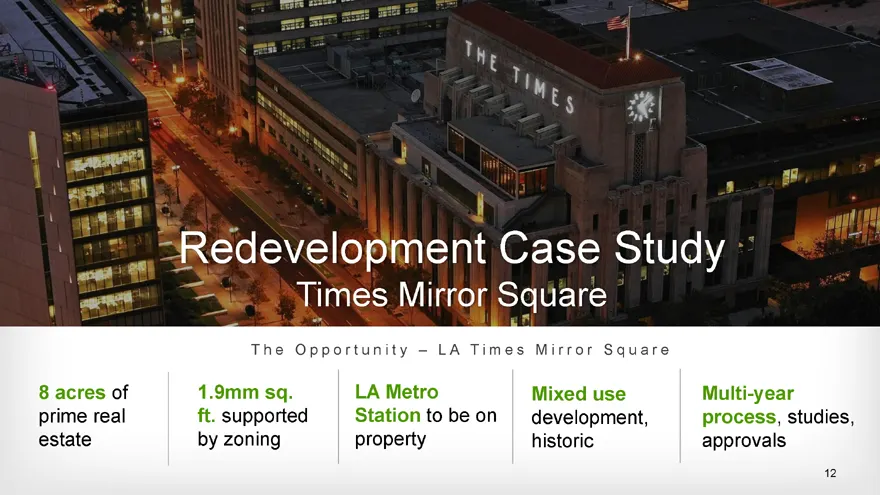
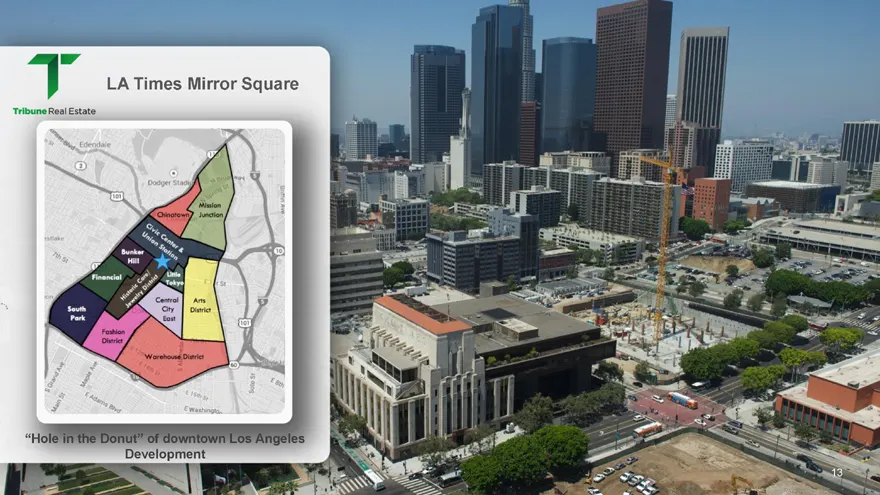
Redevelopment Case Study Times Mirror Square T h e O p p o r t u n i t y – L A T i m e s M i r r o r S q u a r e 8 acres of 1.9mm sq. LA Metro Mixed use Multi-year prime real ft. supported Station to be on development, process, studies, estate by zoning property historic approvals
Slide 129: LA Times Mirror Square
LA Times Mirror Square “Hole in the Donut” of downtown Los Angeles Development
Slide 130: Real Estate Summary
R e a l E s t a t e S u m m a r y Portfolio of mission critical, single purpose facilities Attractive locations that capitalize on the renaissance of urban centers Capitalize on previously undermanaged real estate holdings and underutilized locations Strategy to maximize value creation by forming st
Slide 131
Slide 132: Steven Berns, Tribune Media
Media Investor Day presentation December 11, 2014 Steven BernsO, ribune Media Tribune Media
Slide 133: Financial Overview Topics
Enhanced understanding of our financials Update on our key strategic and financial initiatives in 2014 Review of each of our businesses Key highlights in our investment portfolio Update on our balance sheet and free cash flow generation2
Slide 134: Our Investment Highlights
u r I n v e s t m e n t H i g h l i g h t sStrong foundation for growth Revenue diversification opportunities Strong cash flow generationOpportunity to benefit from operating efficiencies
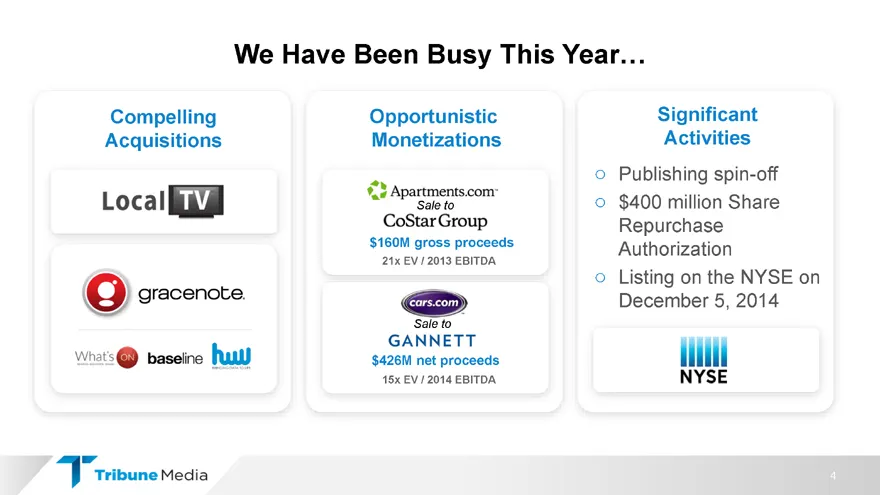
Slide 135: We Have Been Busy This Year
Have Been Busy This YearCompelling Opportunistic Significant Acquisitions Monetizations Activities Publishing spin-off Sale to $400 million Share Repurchase $160M gross proceeds Authorization21x EV / 2013 EBITDA Listing on the NYSE on December 5, 2014Sale to$426M net proceeds15x EV / 2014 EBITDA4
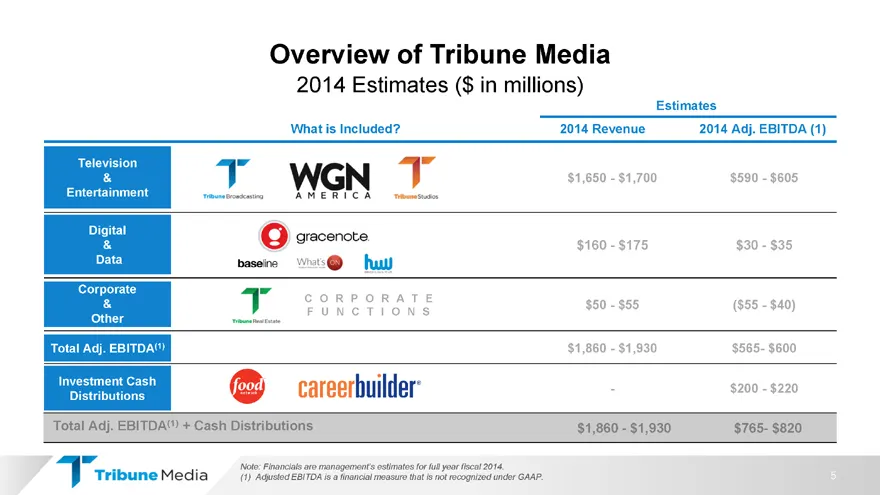
Slide 136: Overview of Tribune Media 2014 Estimates
of Tribune Media2014 Estimates ($ in millions)Estimates What is Included 2014 Revenue 2014 Adj. EBITDA (1)Television& $1,650—$1,700 $590—$605EntertainmentDigital& $160—$175 $30—$35DataCorporateC O R P O R A T E & $50—$55 ($55—$40)F U N C T I O N SOtherTotal Adj. EBITDA(1) $1,860—$1,930 $
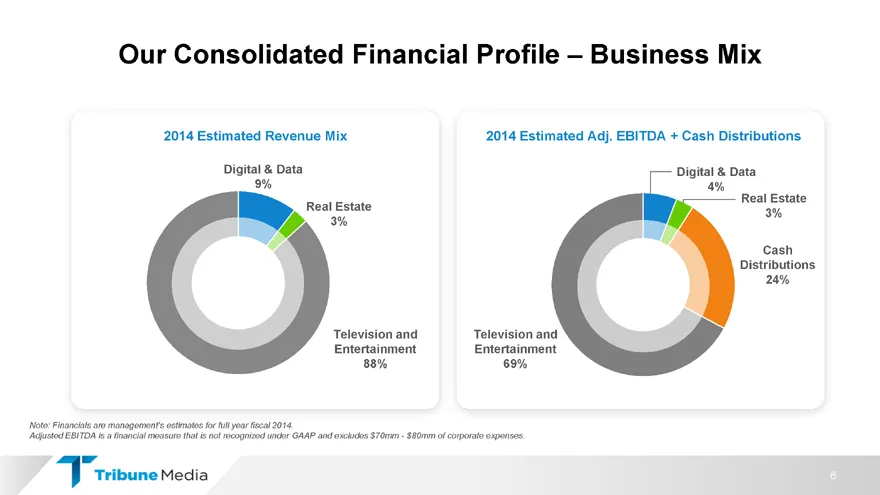
Slide 137: Consolidated Financial Profile
Consolidated Financial Profile Business Mix2014 Estimated Revenue Mix 2014 Estimated Adj. EBITDA + Cash DistributionsDigital & Data Digital & Data 9% 4% Real EstateReal Estate3% 3%Cash Distributions 24%Television and Television and Entertainment Entertainment 88% 69%Note: Financials are mana
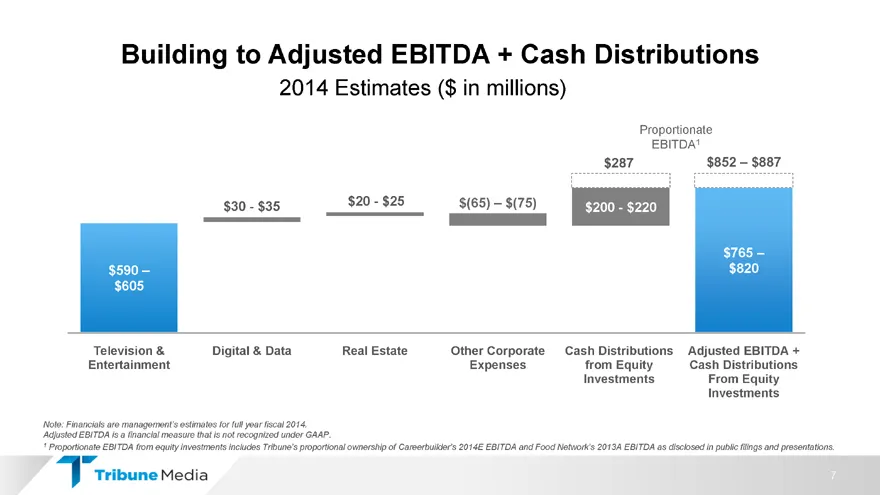
Slide 138: Bridge to Adjusted EBITDA plus Cash Distributions
to Adjusted EBITDA + Cash Distributions2014 Estimates ($ in millions)Proportionate EBITDA1 $287 $852 $887$30—$35 $20—$25 $(65) $(75) $200—$220$765 $590 $820 598 630 578 578 $605Television & Digital & Data Real Estate Other Corporate Cash Distributions Adjusted EBITDA + Entertainment Expenses
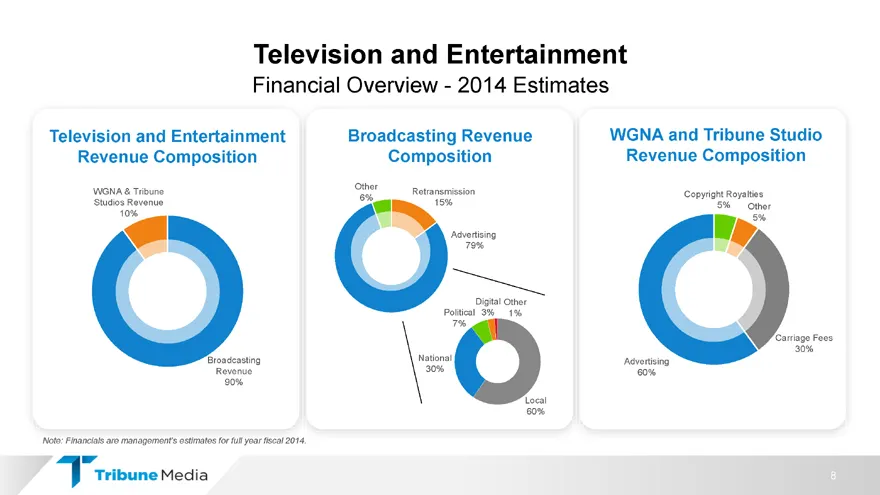
Slide 139: Television and Entertainment Financial Overview
and EntertainmentFinancial Overview—2014 EstimatesTelevision and Entertainment Broadcasting Revenue WGNA and Tribune Studio Revenue Composition Composition Revenue CompositionOtherWGNA & Tribune Retransmission Copyright Royalties 6% Studios Revenue 15% 5% Other 10% 5% Advertising 79%Digital Othe
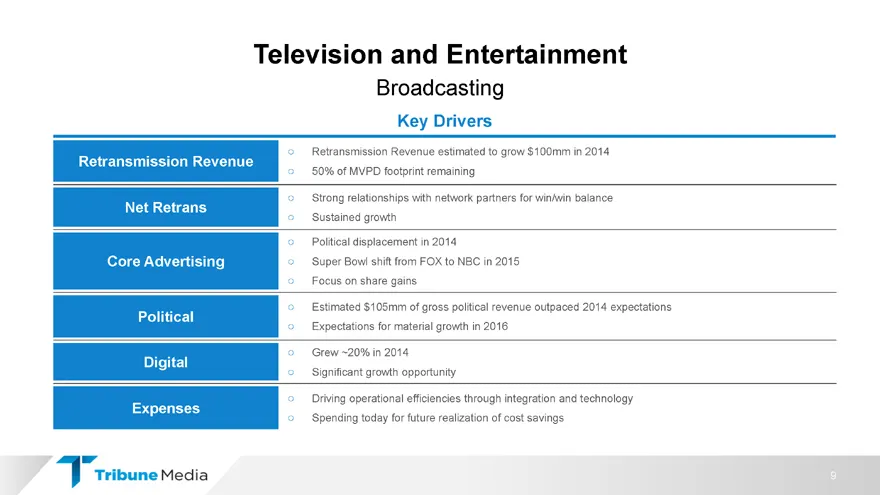
Slide 140: Television and Entertainment: Broadcasting Key Drivers
and EntertainmentBroadcastingKey Drivers Retransmission Revenue estimated to grow $100mm in 2014 Retransmission Revenue 50% of MVPD footprint remaining Strong relationships with network partners for win/win balanceNet Retrans Sustained growth Political displacement in 2014Core Advertising Super Bowl
Slide 141: Television and Entertainment: WGN America and Tribune Studios
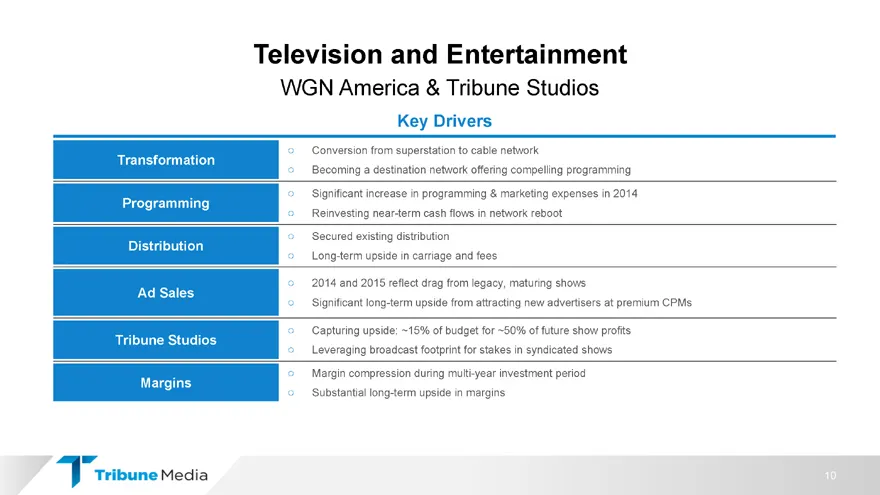
and EntertainmentWGN America & Tribune StudiosKey Drivers Conversion from superstation to cable networkTransformation Becoming a destination network offering compelling programming Significant increase in programming & marketing expenses in 2014 Programming Reinvesting near-term cash flows i
Slide 142: Digital and Data Financial Overview
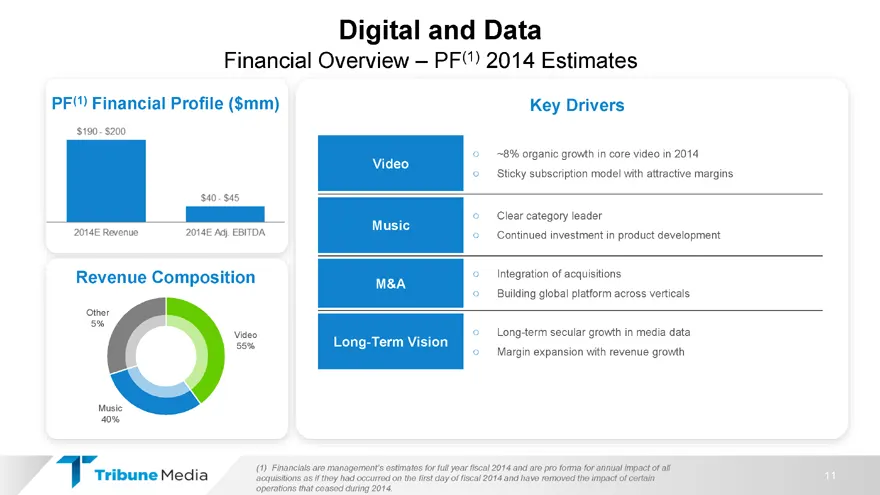
and DataFinancial Overview PF(1) 2014 EstimatesPF(1) Financial Profile ($mm) Key Drivers ~8% organic growth in core video in 2014Video Sticky subscription model with attractive margins Clear category leaderMusic Continued investment in product developmentRevenue Composition Integration of acquisitio
Slide 143: Real Estate Financial Overview
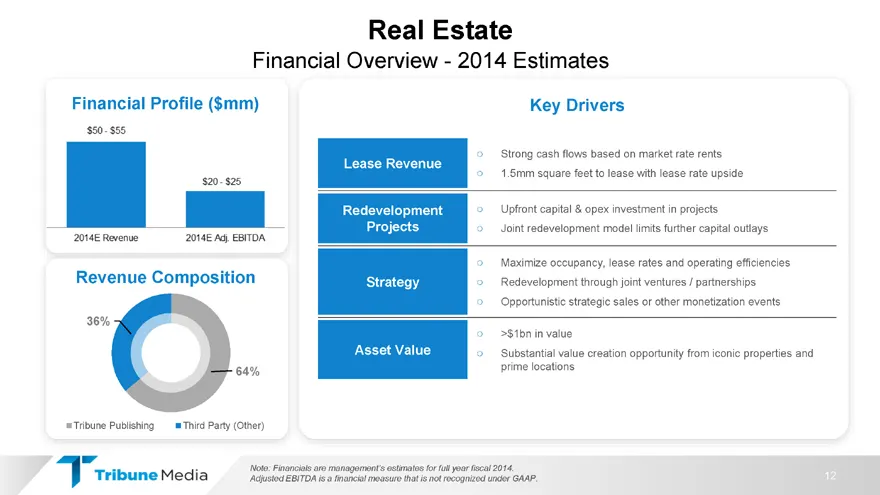
EstateFinancial Overview—2014 EstimatesFinancial Profile ($mm) Key Drivers Strong cash flows based on market rate rentsLease Revenue 1.5mm square feet to lease with lease rate upsideRedevelopment Upfront capital & opex investment in projectsProjects Joint redevelopment model limits further capit
Slide 144: Overview of Our Investment Portfolio
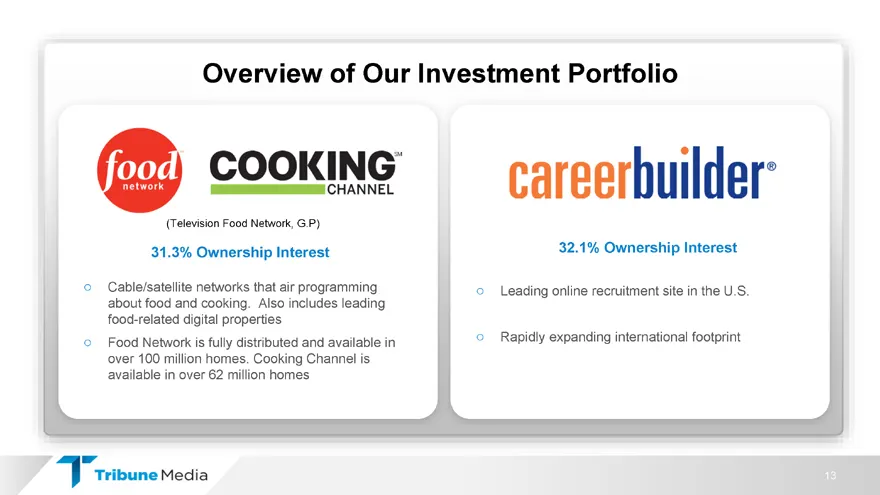
of Our Investment Portfolio(Television Food Network, G.P)31.3% Ownership Interest 32.1% Ownership Interest Cable/satellite networks that air programming Leading online recruitment site in the U.S. about food and cooking. Also includes leading food-related digital properties Food Network is fully dis
Slide 145: Partnership Investments
Partnership InvestmentsContent Recommendation Digital News Platform Video News Platform Hyperlocal Content Provider ServiceRecruitment & Staffing Advanced TV Programming News Aggregation Website Start-Up Incubator Software SoftwareWe continue to opportunistically invest in new, cutting-edge tech
Slide 146: Free Cash Flow Generation
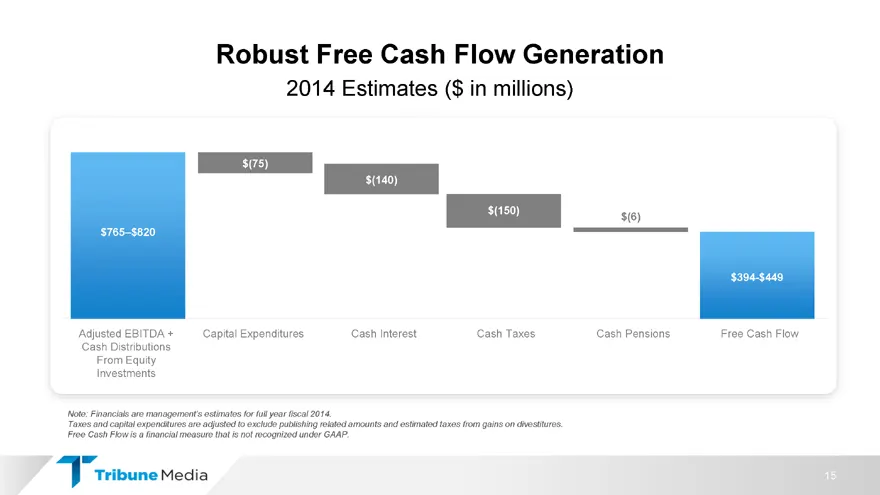
Free Cash Flow Generation2014 Estimates ($ in millions)$(75) $(140)$(150) $(6) $765 $820$394-$449Adjusted EBITDA + Capital Expenditures Cash Interest Cash Taxes Cash Pensions Free Cash Flow Cash Distributions From Equity InvestmentsNote: Financials are management s estimates for full year fiscal 201
Slide 147: Balance Sheet and Credit Profile
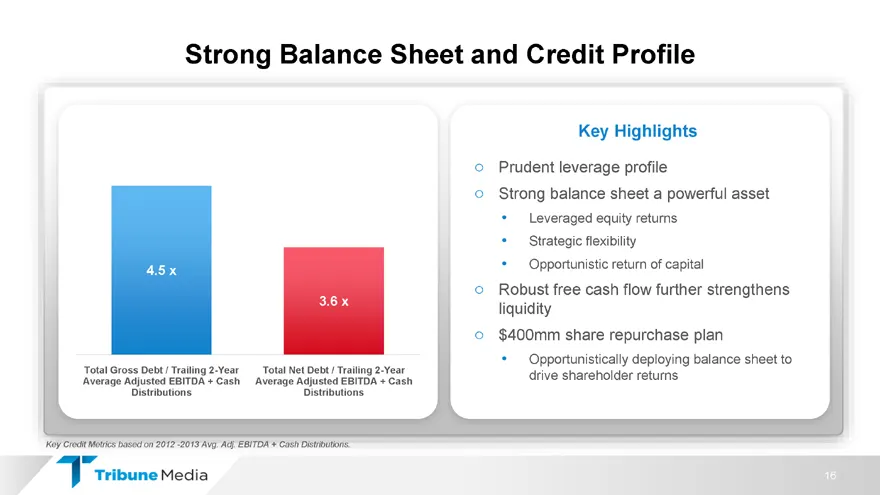
Balance Sheet and Credit Profile Key Highlights Prudent leverage profile Strong balance sheet a powerful asset Leveraged equity returns Strategic flexibility Opportunistic return of capital4.5 x Robust free cash flow further strengthens 3.6 xliquidity $400mm share repurchase plan Opportunistically d
Slide 148: Our Investment Highlights
u r I n v e s t m e n t H i g h l i g h t sStrong foundation for growth Revenue diversification opportunities Strong cash flow generationOpportunity to benefit from operating efficiencies
Slide 149: Appendix
Media Investor Day presentation December 11, 2014 Appendix
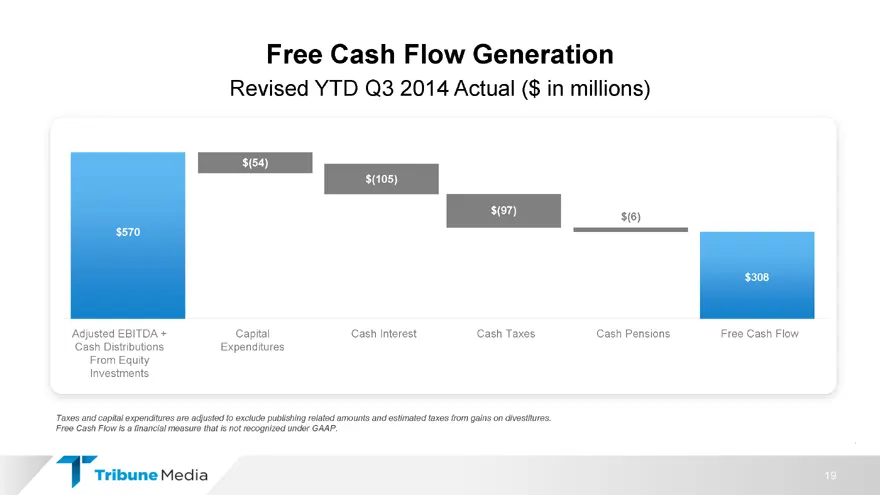
Slide 150: Cash Flow Generation: Revised YTD Q3 2014 Actual
Cash Flow GenerationRevised YTD Q3 2014 Actual ($ in millions)$(54) $(105)$(97) $(6) $570$308Adjusted EBITDA + Capital Cash Interest Cash Taxes Cash Pensions Free Cash Flow Cash Distributions Expenditures From Equity InvestmentsTaxes and capital expenditures are adjusted to exclude publishing relate
Source: SEC EDGAR · 8-K filed Dec 11, 2014
More decks from Tribune Media Company
 Merger or Acquisition (May 2017)11 slides · May 8, 2017
 FY2016 Earnings Presentation20 slides · Mar 1, 2017
 Q3 2016 Earnings Presentation23 slides · Nov 9, 2016
 Q2 2016 Earnings Presentation24 slides · Aug 9, 2016
 Q1 2016 Earnings Presentation22 slides · May 10, 2016
 FY2015 Earnings Presentation27 slides · Feb 29, 2016