Centrica plc · LSE:CNA
Centrica — H1 2019 Earnings Presentation
80 slides from Centrica's earnings presentation, Jul 30, 2019
Slide 1: Interim Results and Strategic Update
centrica Centrica ple Interim Results and Strategic Update for the period ended 30 June 2019
Slide 2: Disclaimer
centrica Disclaimer This presentation does not constitute an invitation to underwrite, subscribe for, or otherwise acquire or dispose of any Centrica shares or other securities. This presentation contains certain forward-looking statements with respect to the financial condition, results, operations
Slide 3: Iain Conn, Group Chief Executive
centrica lain Conn Group Chief Executive
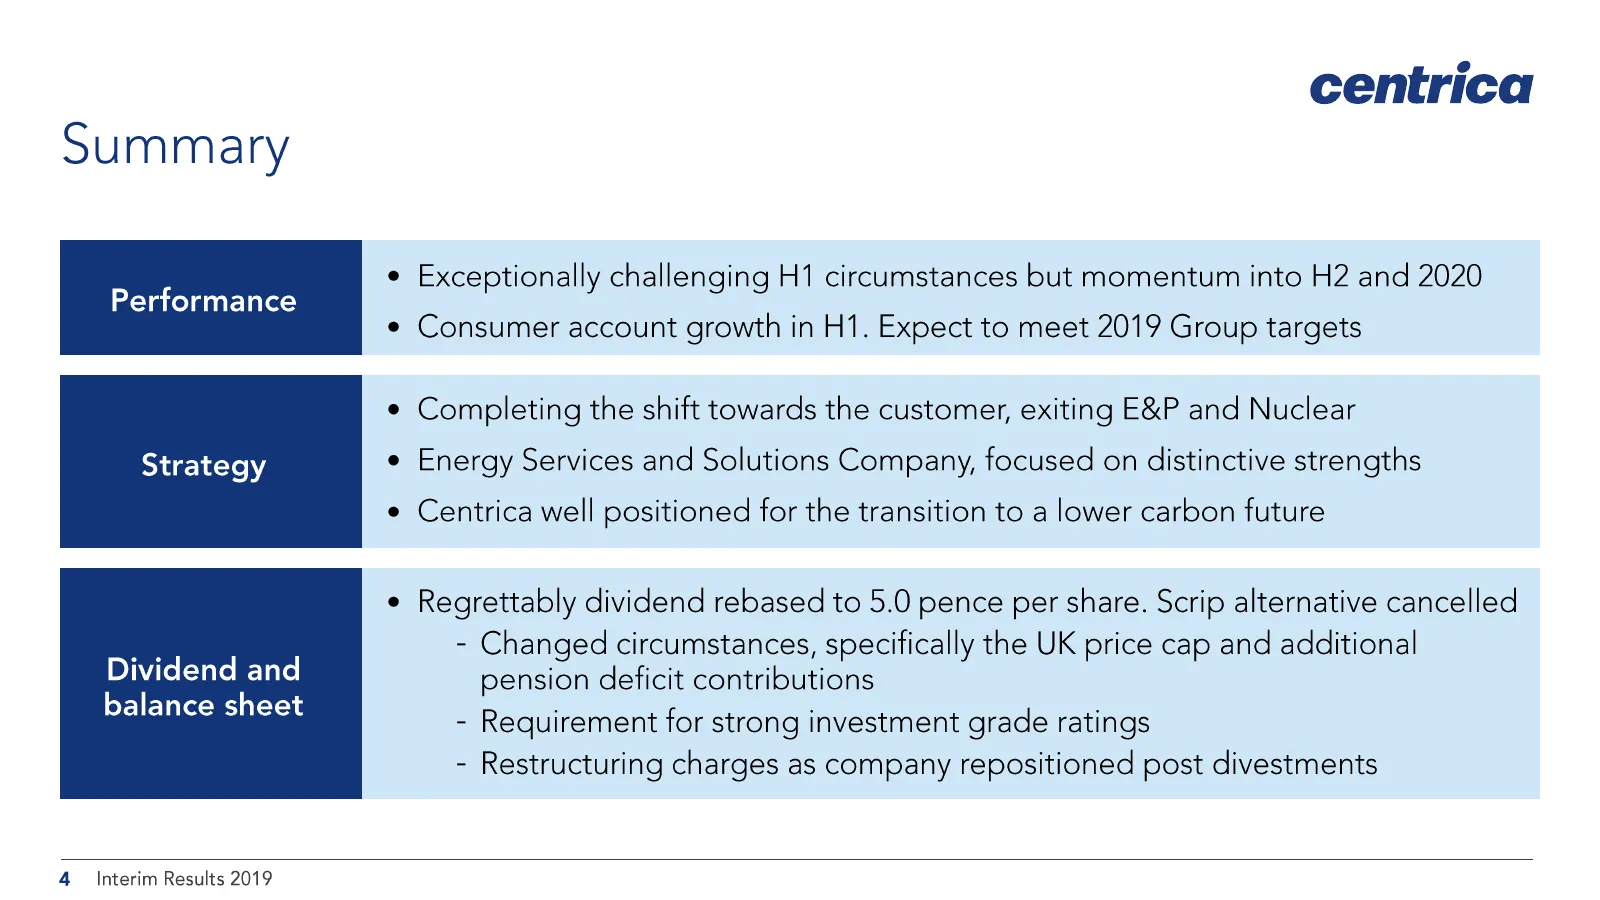
Slide 4: Summary
centrica Summary Exceptionally challenging H1 circumstances but momentum into H2 and 2020 Performance . ¢ Consumer account growth in H1. Expect to meet 2019 Group targets ¢ Completing the shift towards the customer, exiting E&P and Nuclear Energy Services and Solutions Company, focused on distinctiv
Slide 5: What to expect
centrica What to expect Focus on distinctive strengths in Energy Services and Solutions: - Energy supply and its optimisation - Services and solutions centred around energy ¢ Growing importance of Home Energy Management and Electric Vehicle Integration — exclusive Ford deal announced today ¢ Reposit
Slide 6: Exceptionally challenging H1 2019
Exceptionally challenging H1 2019 UK energy default tariff cap including Q1 one-off impact Very low UK natural gas prices Nuclear inspection outages at Hunterston B and Dungeness B - Very warm weather in UK and North America Weak adjusted earnings: - Adjusted operating profit of £399m, down 49% - Ad
Slide 7: Growth in consumer accounts in H1 2019
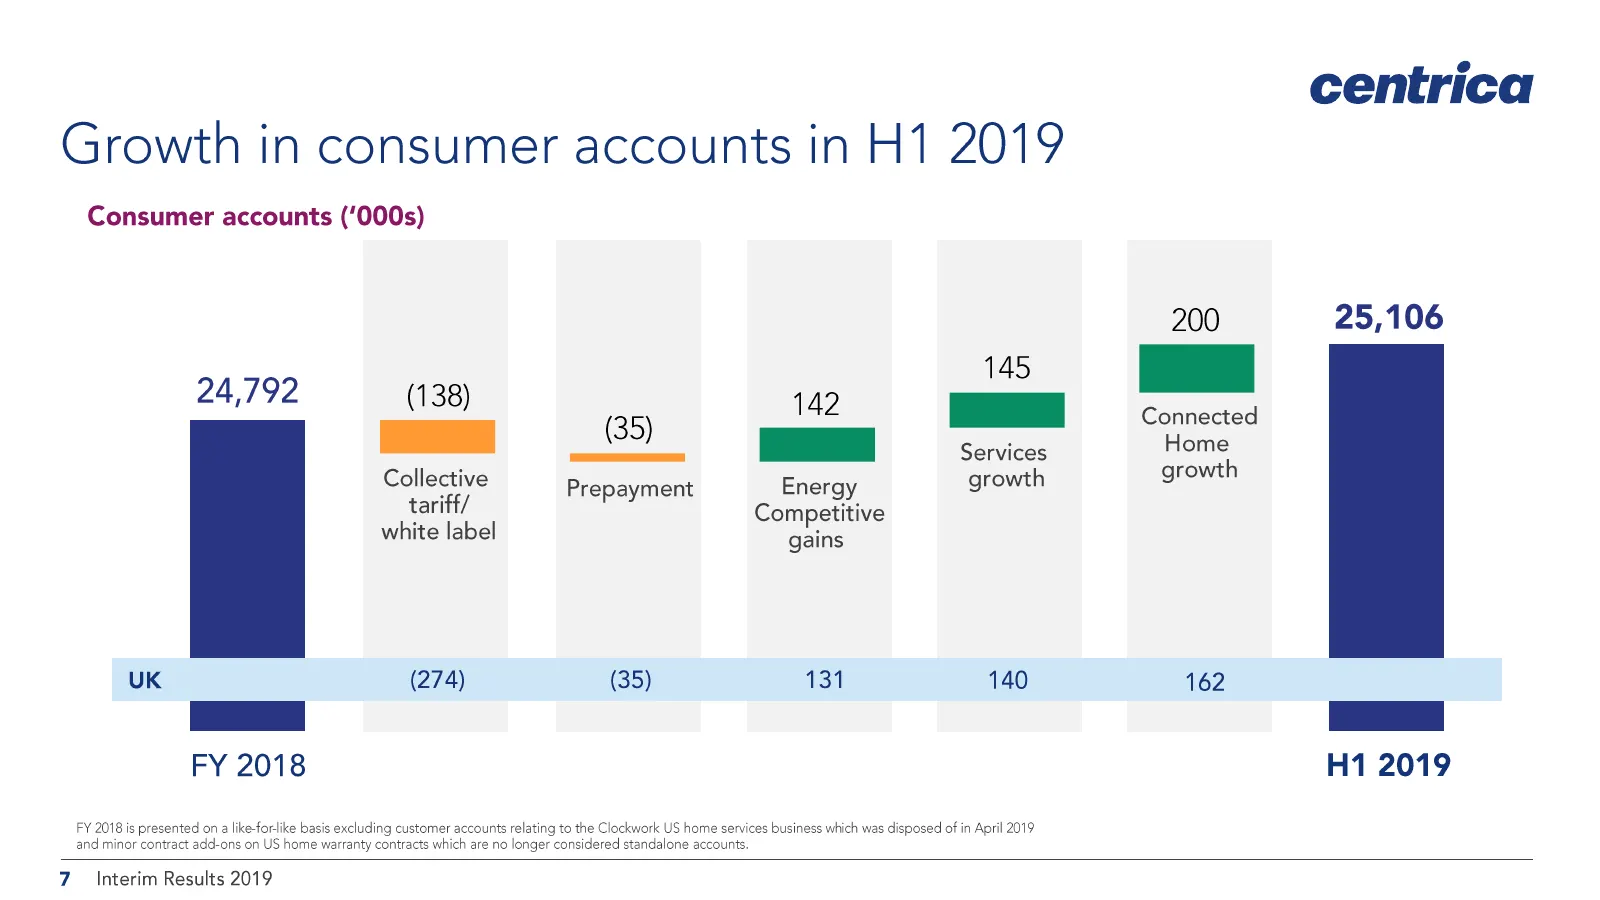
Growth in consumer accounts in H1 2019 Consumer accounts (‘000s) Collective tariff/ white label UK (274) Pe FY 2018 (35) Prepayment (35) 142 a Energy Competitive gains 131 145 a Services growth 140 FY 2018s presented on a like-forlike basis excluding customer accounts relating to the Clockwork US ho
Slide 8: UK Home energy customer accounts
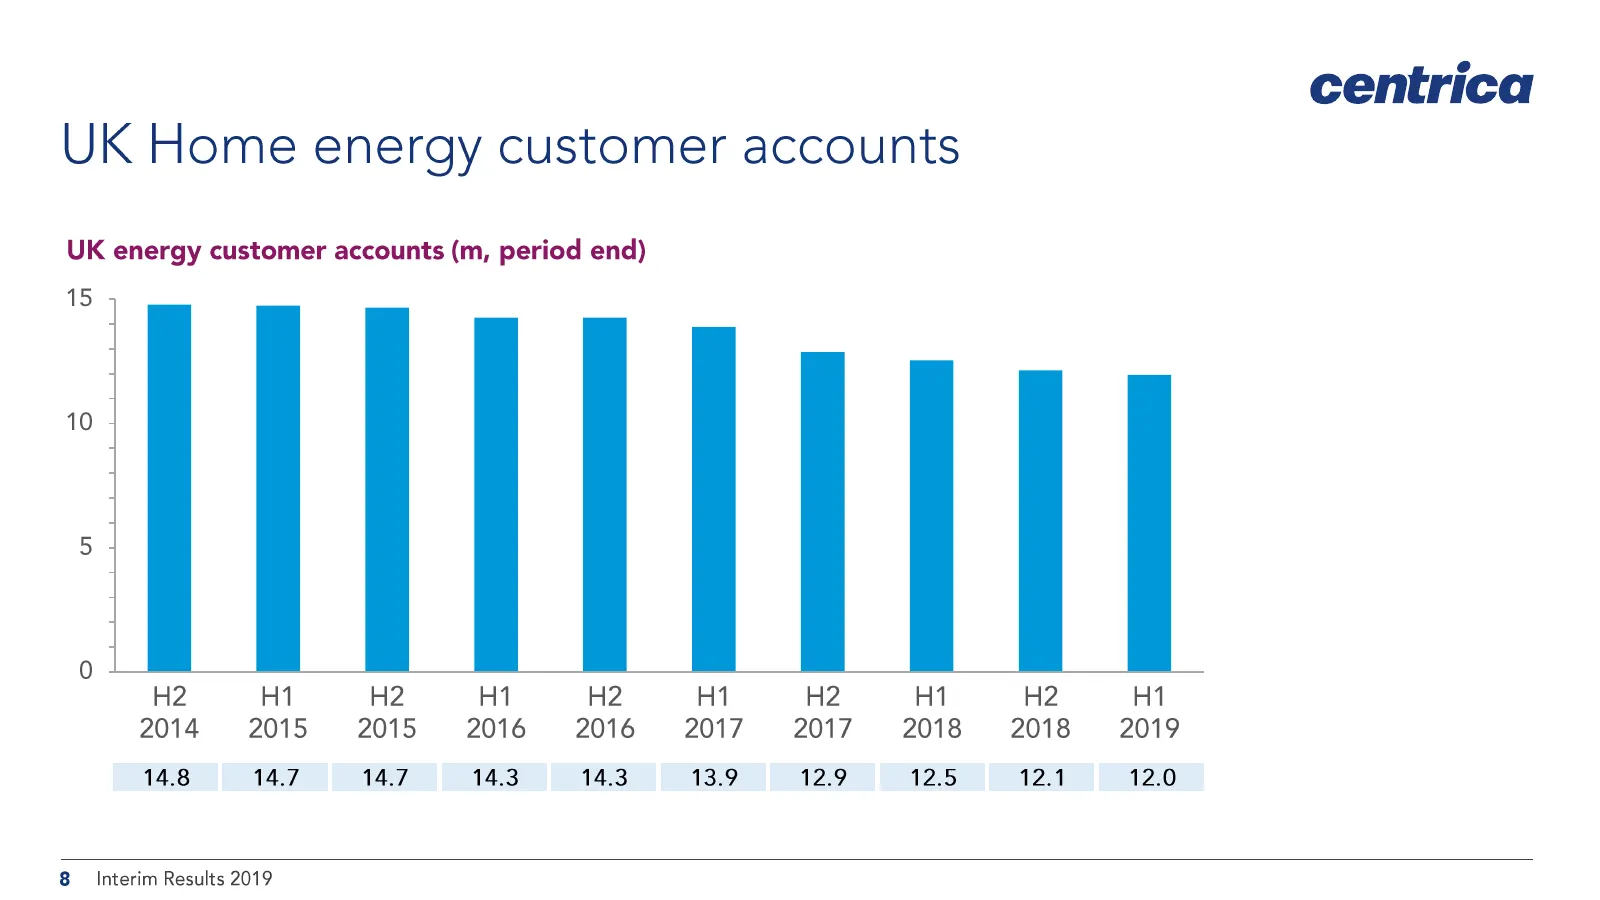
centrica UK Home energy customer accounts UK energy customer accounts (m, period end) 15 10 5 0 H2 H1 H2 H1 H2 H1 H2 H1 H2 H1 2014 «2015. 2015, 2016) 2016S 2017-2017 2018 = 2018 =. 2019 14.8 14.7 14.7 14.3 14.3 13.9 12.9 12.5 12.1 12.0 8 Interim Results 2019
Slide 9: UK energy market under price caps
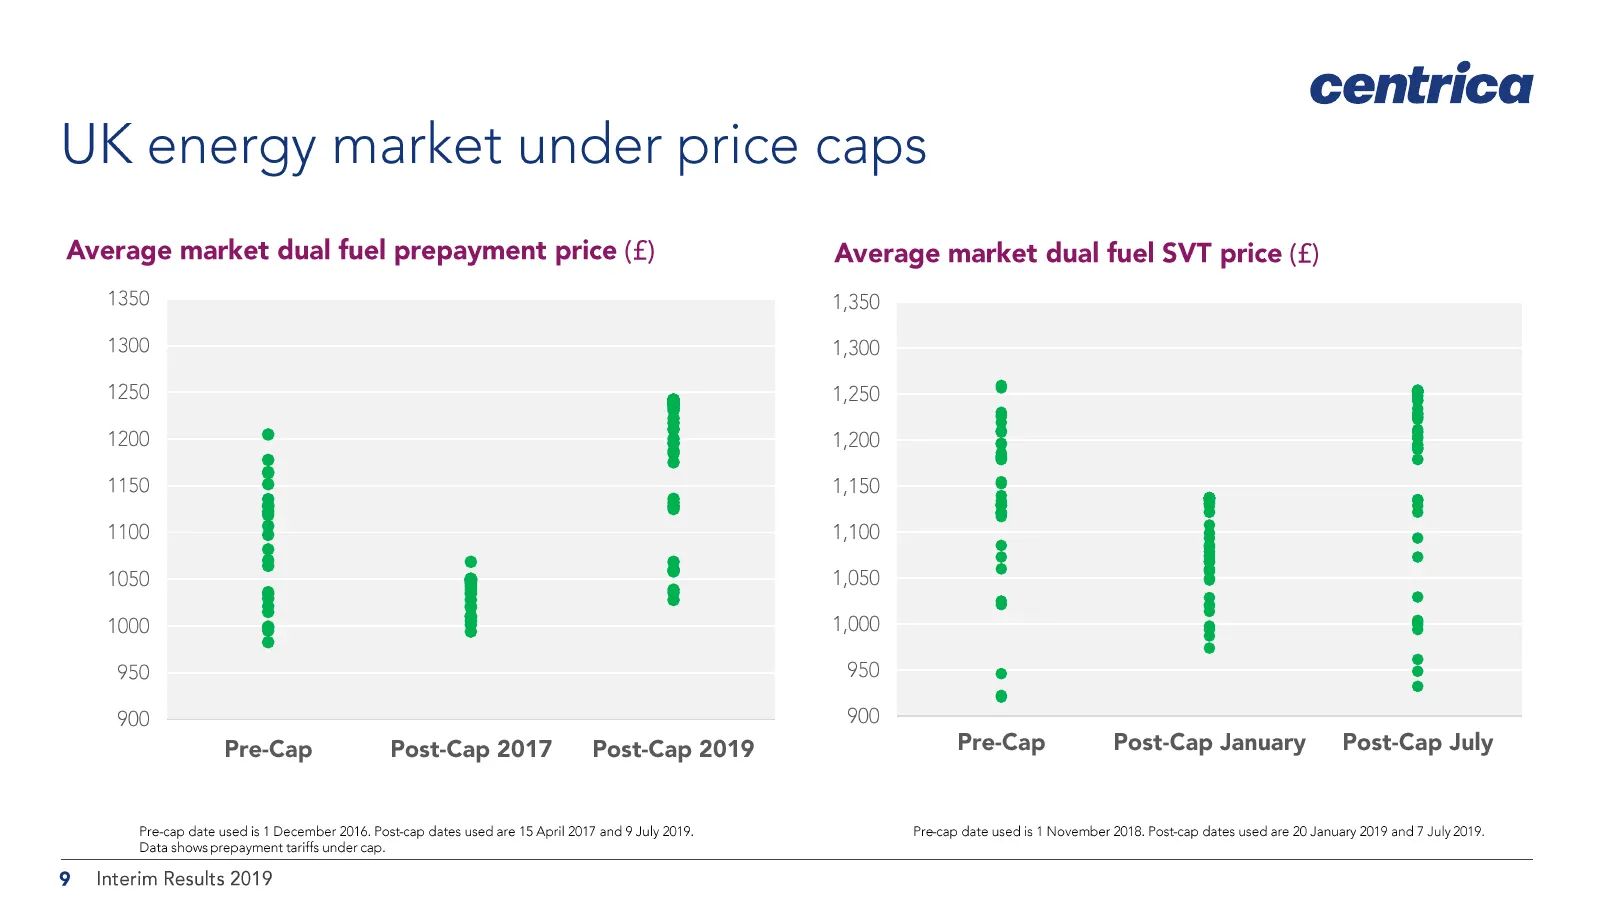
centrica UK energy market under price caps Average market dual fuel prepayment price (£) Average market dual fuel SVT price (£) 1350 1,350 1300 1,300 1250 1,250 ° 1200 e | 1,200 H 1150 3 1,150 H 6 8 8 1100 1,100 e $ ° 8 3 ° 1050 1,050 8 8 . § ° 1000 8 1,000 8 8 950 950 ° Hy e e 900 900 Pre-Cap Post-
Slide 10: Earnings momentum in H2 2019 and into 2020
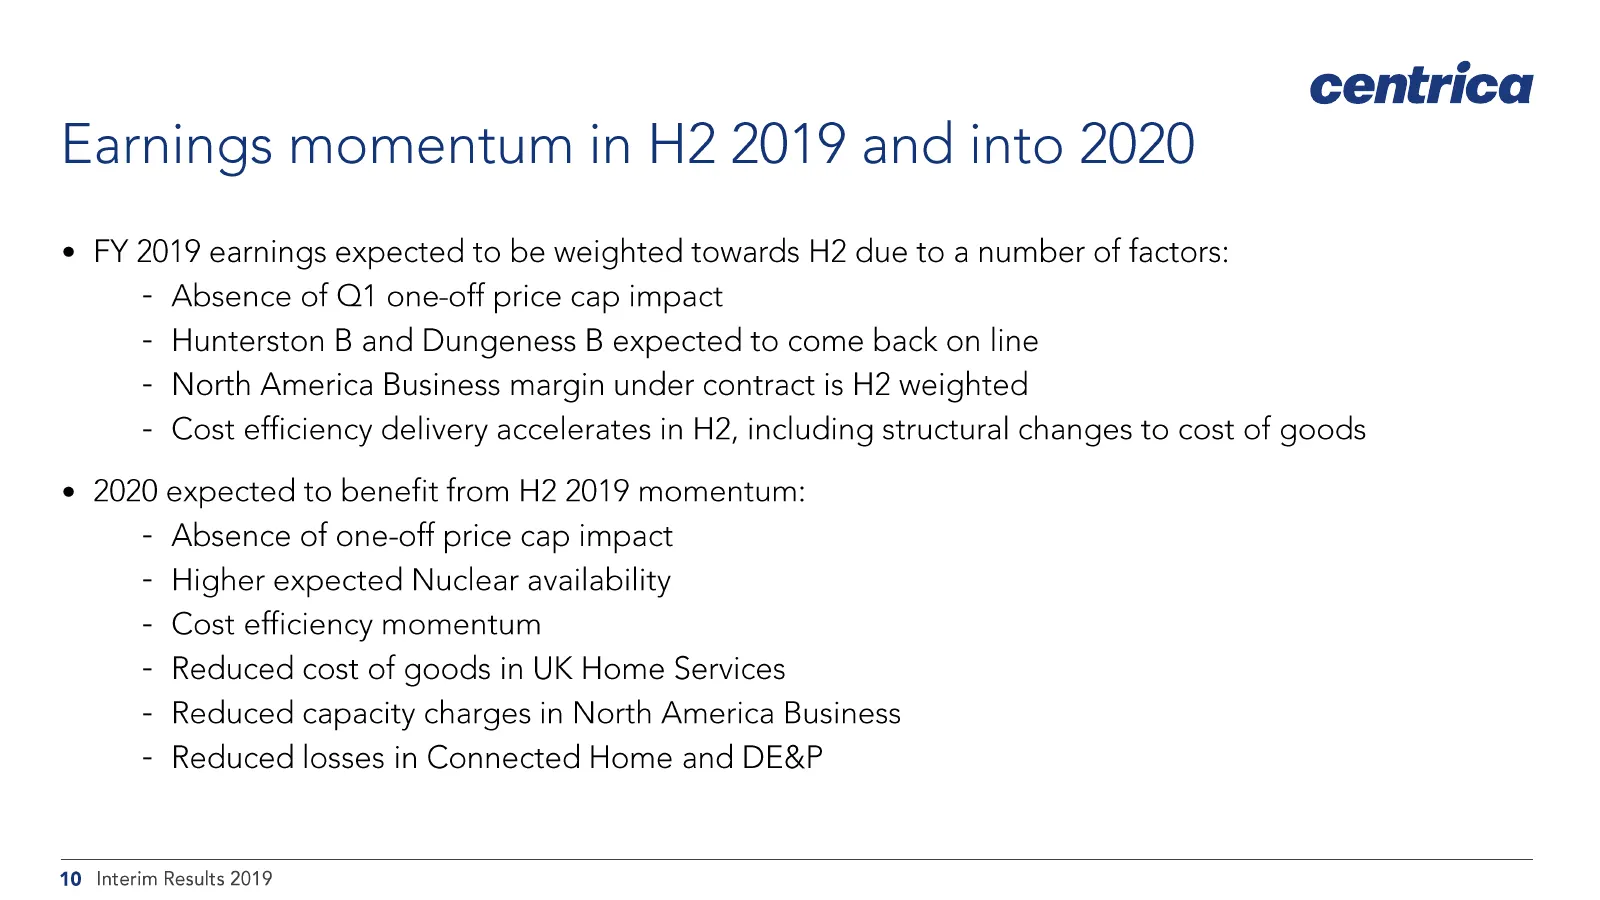
centrica Earnings momentum in H2 2019 and into 2020 ¢ FY 2019 earnings expected to be weighted towards H2 due to a number of factors: - Absence of Q1 one-off price cap impact - Hunterston B and Dungeness B expected to come back on line - North America Business margin under contract is H2 weighted -
Slide 11: Portfolio update
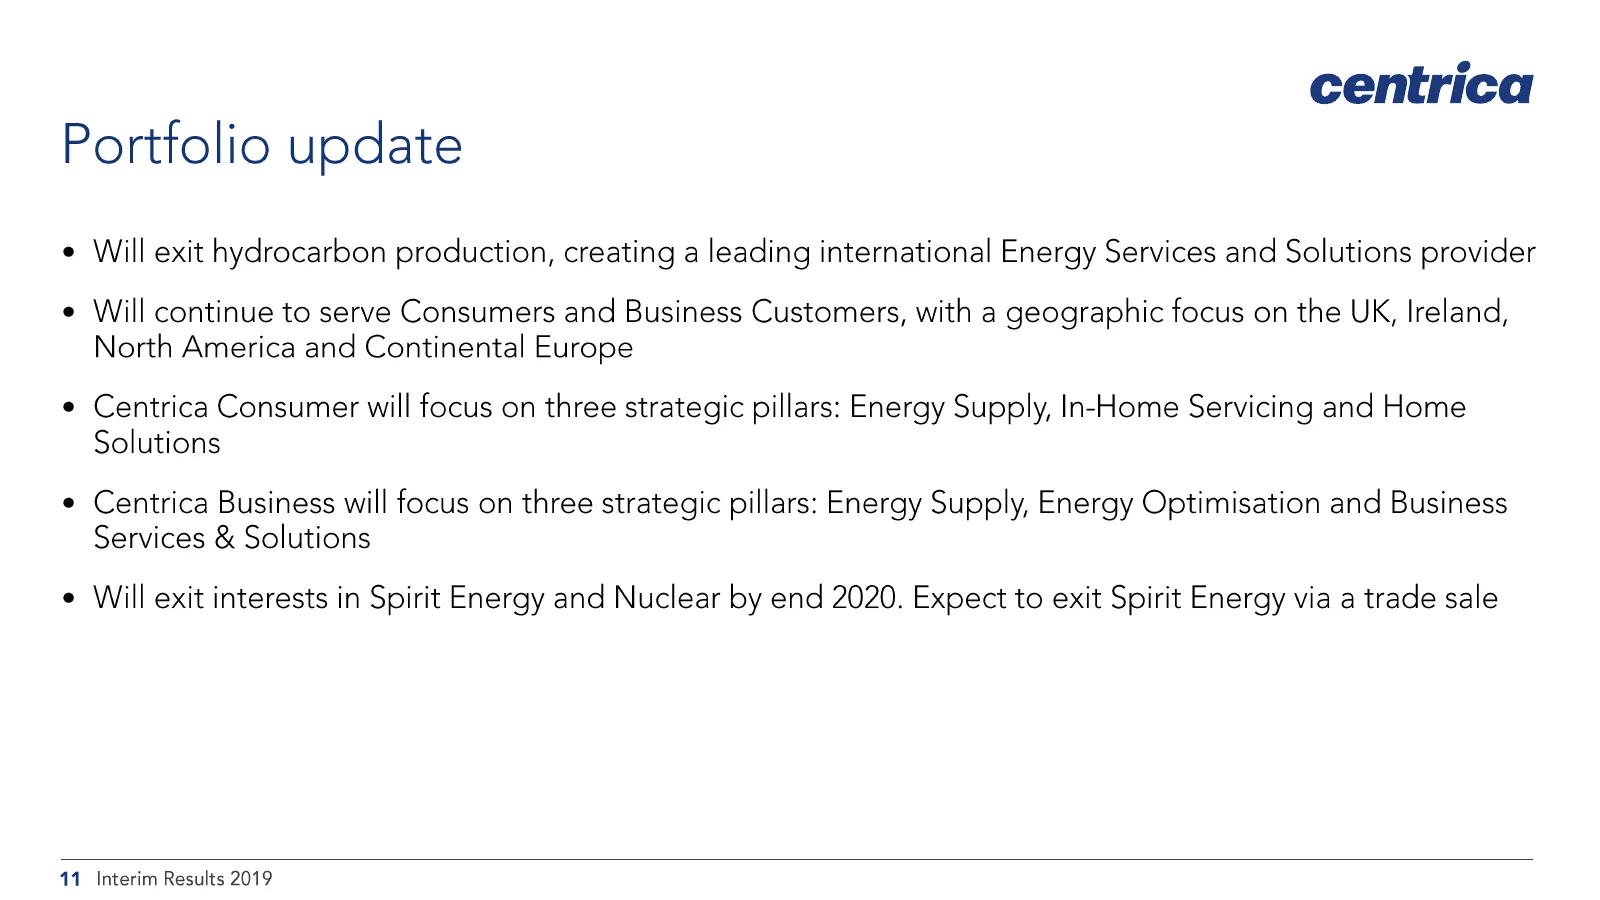
centrica Portfolio update ¢ Will exit hydrocarbon production, creating a leading international Energy Services and Solutions provider ¢ Will continue to serve Consumers and Business Customers, with a geographic focus on the UK, Ireland, North America and Continental Europe ¢ Centrica Consumer will f
Slide 12: Business unit decisions
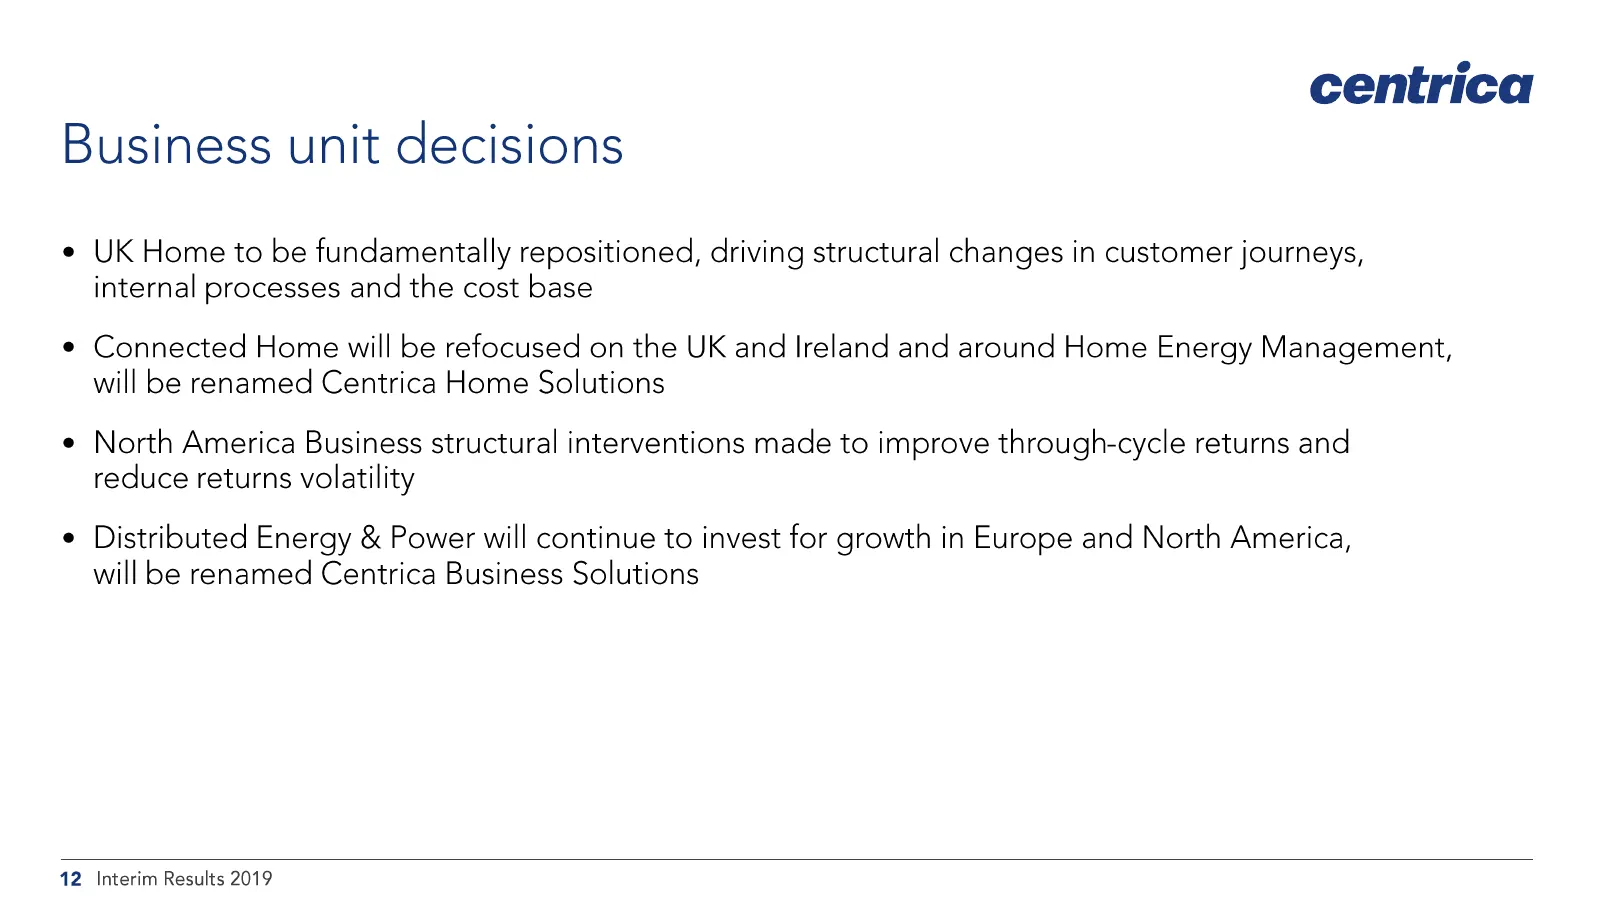
centrica Business unit decisions ¢ UK Home to be fundamentally repositioned, driving structural changes in customer journeys, internal processes and the cost base ¢ Connected Home will be refocused on the UK and Ireland and around Home Energy Management, will be renamed Centrica Home Solutions ¢ Nor
Slide 13: Improving competitiveness
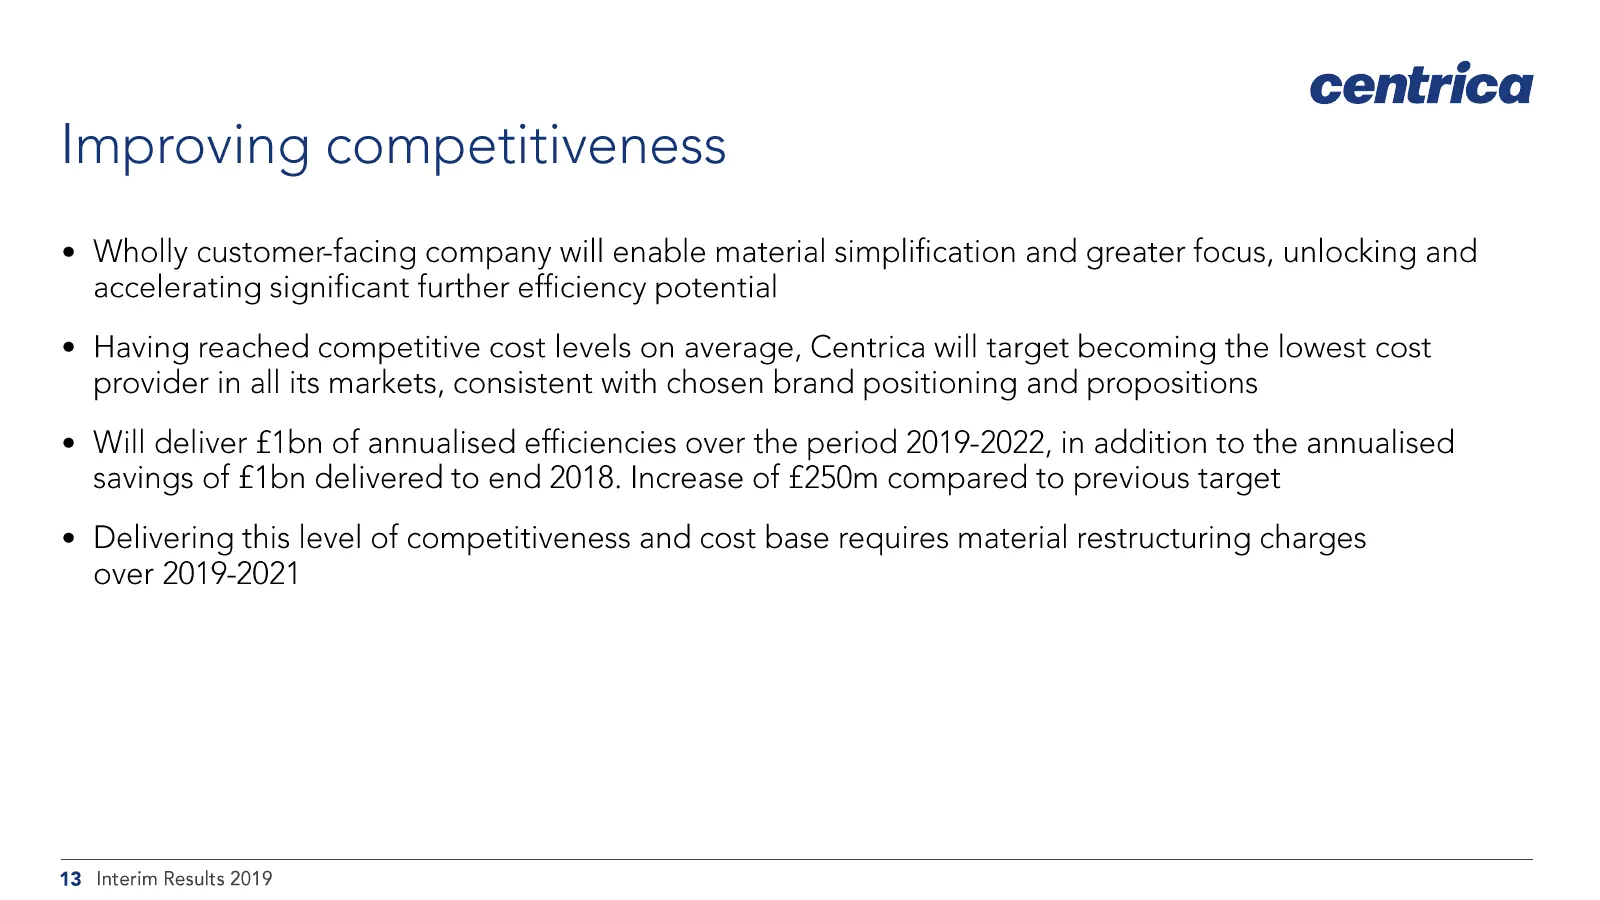
centrica Improving competitiveness ¢ Wholly customer-facing company will enable material simplification and greater focus, unlocking and accelerating significant further efficiency potential ¢ Having reached competitive cost levels on average, Centrica will target becoming the lowest cost provider i
Slide 14: Dividend and capital structure
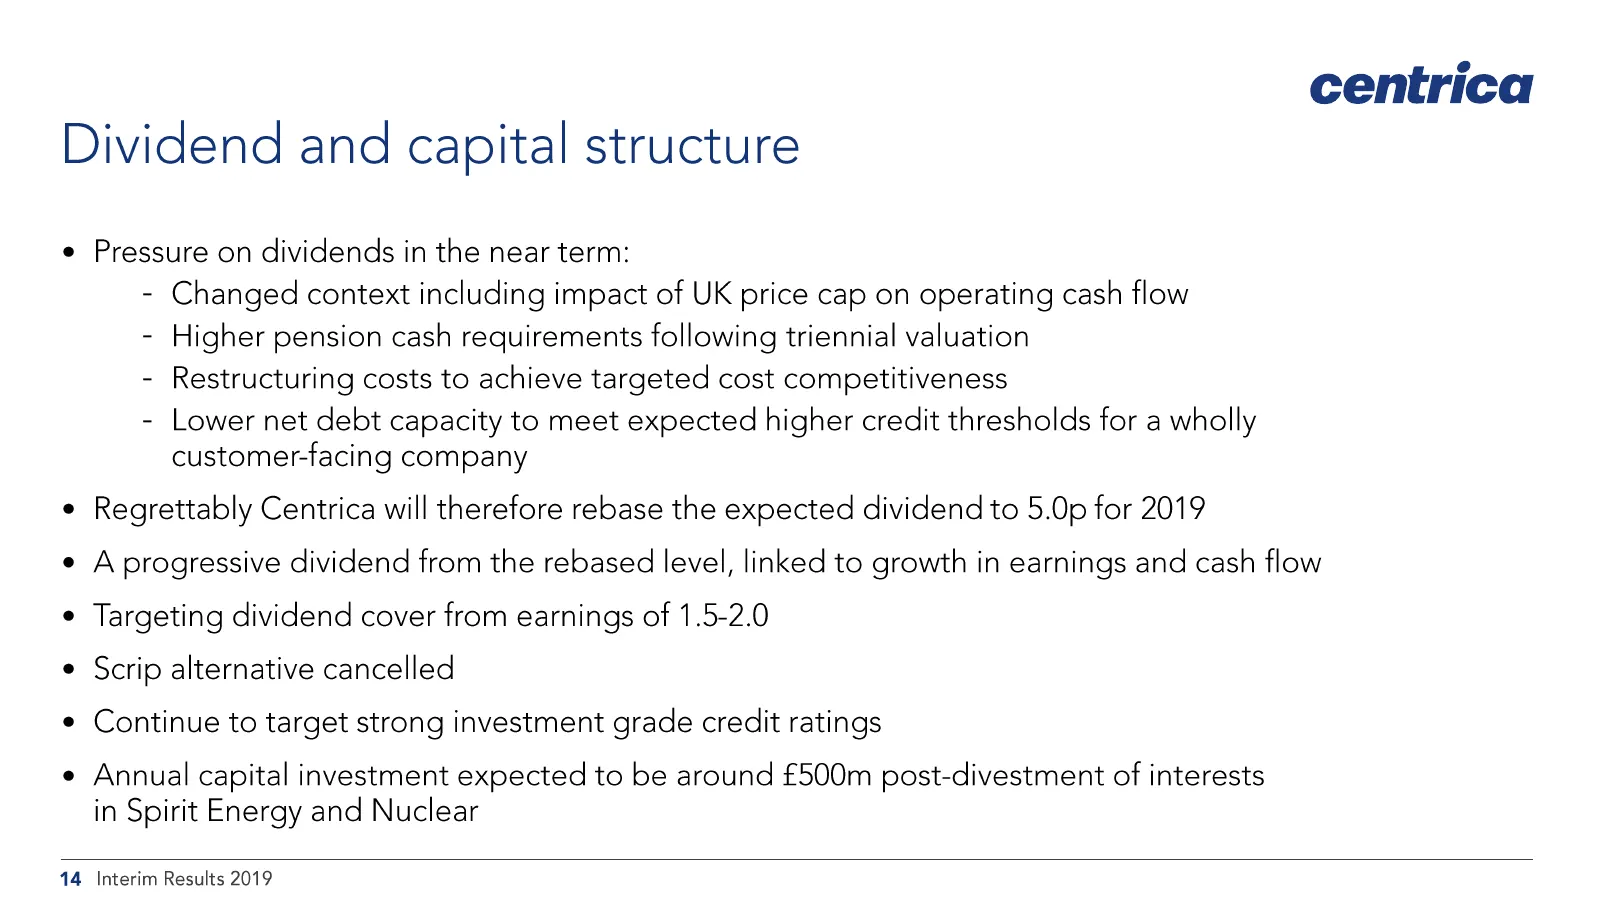
centrica Dividend and capital structure ¢ Pressure on dividends in the near term: - Changed context including impact of UK price cap on operating cash flow - Higher pension cash requirements following triennial valuation - Restructuring costs to achieve targeted cost competitiveness - Lower net debt
Slide 15: Chris O'Shea, Group Chief Financial Officer
centrica Chris O’Shea Group Chief Financial Officer
Slide 16: First half financial result
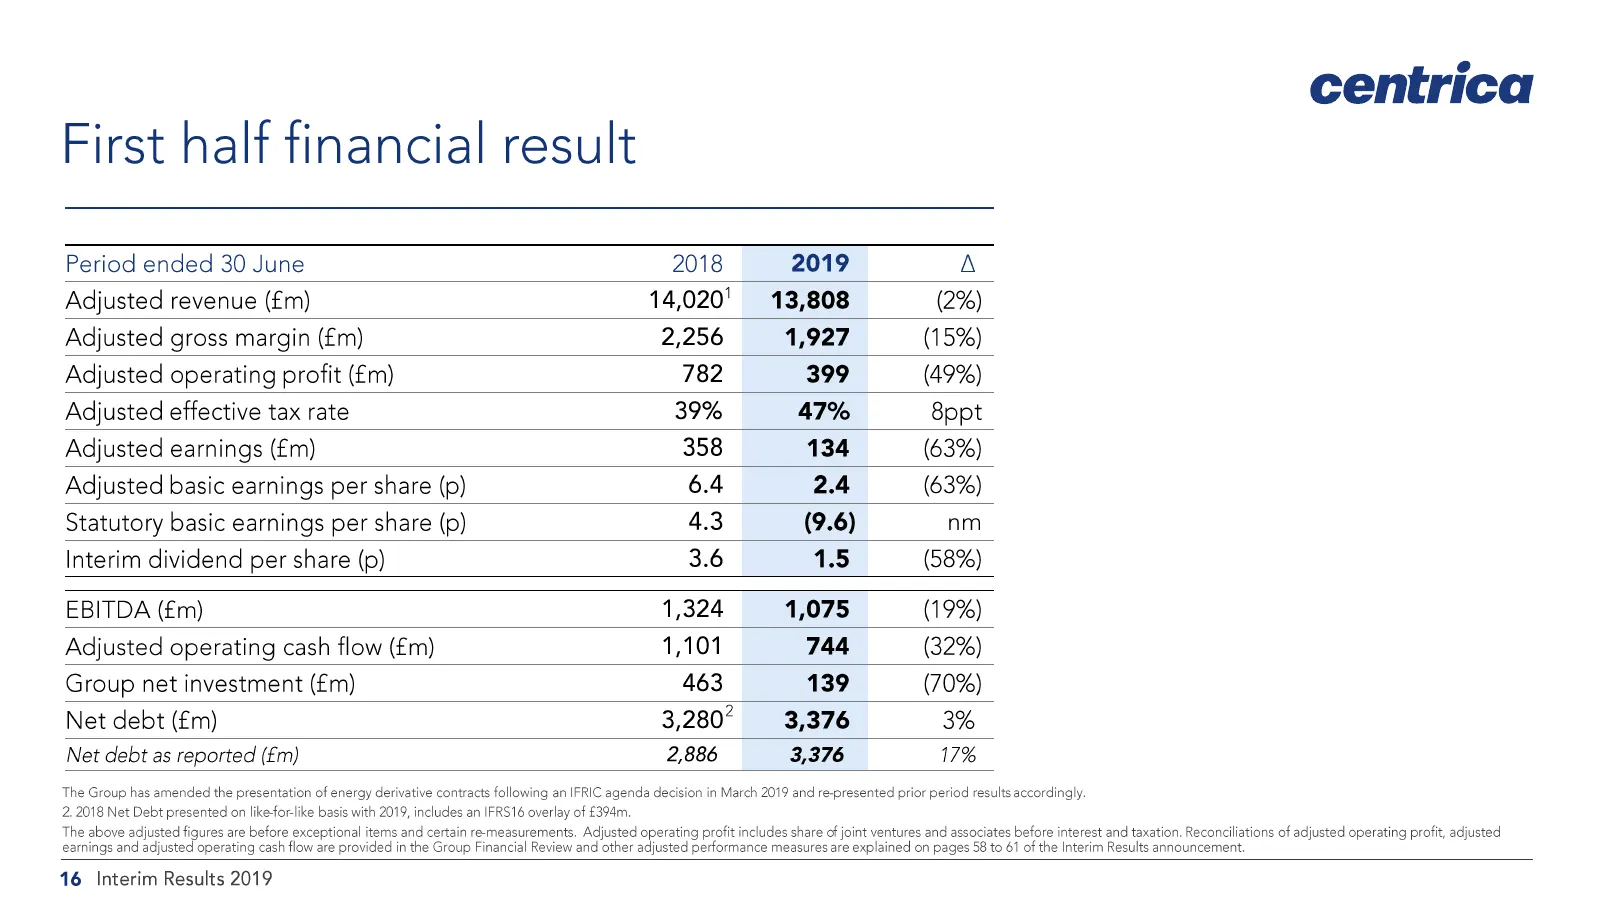
First half financial result Period ended 30 June 2018 2019 A Adjusted revenue (£m) 14,020' 13,808 (2%) Adjusted gross margin (£m) 2,256 1,927 (15%) Adjusted operating profit (£m) 782 399 (49%) Adjusted effective tax rate 39% 47% 8ppt Adjusted earnings (£m) 358 134 (63%) Adjusted basic earnings per s
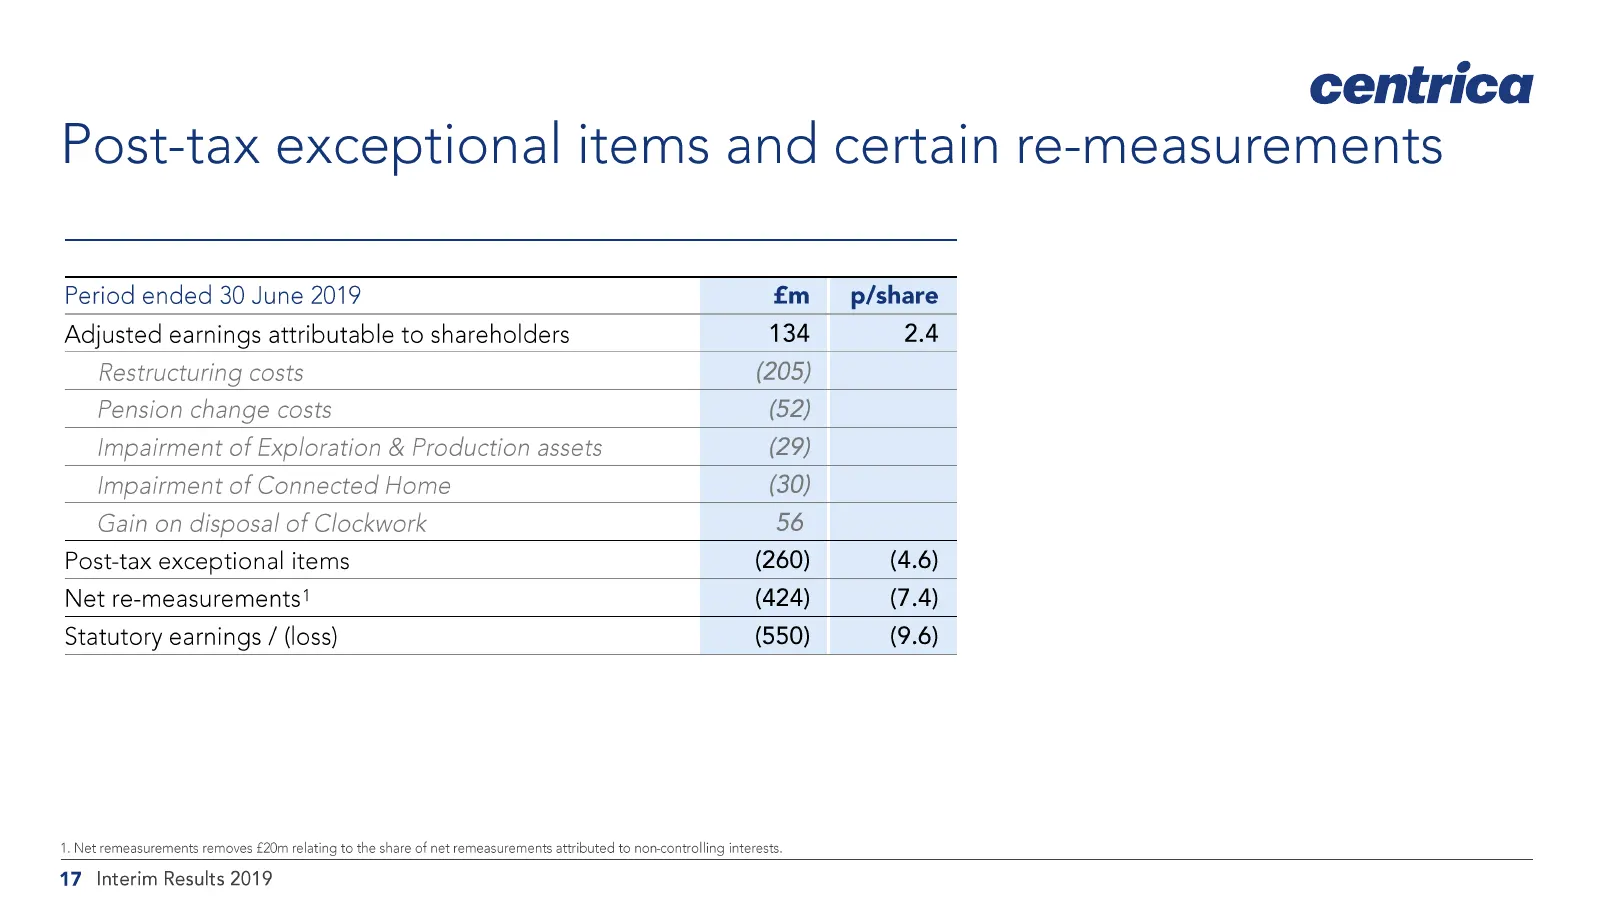
Slide 17: Post-tax exceptional items and certain re-measurements
centrica Post-tax exceptional items and certain re-measurements Period ended 30 June 2019 £m __p/share Adjusted earnings attributable to shareholders 134 2.4 Restructuring costs (205) Pension change costs (52) Impairment of Exploration & Production assets (29) Impairment of Connected Home (30) Gain
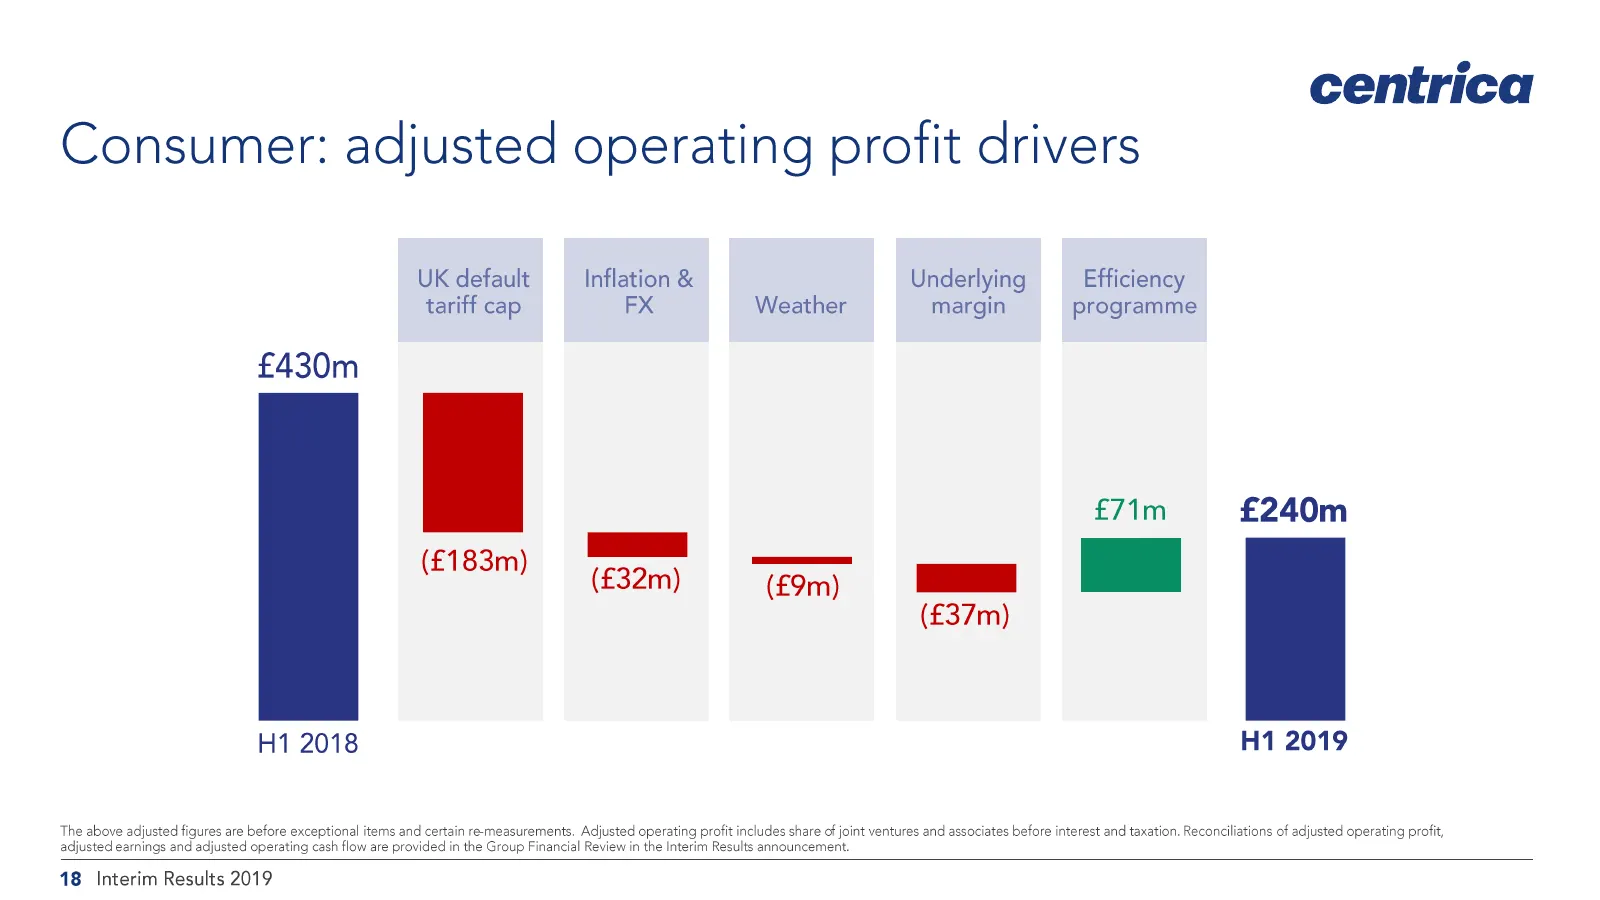
Slide 18: Consumer: adjusted operating profit drivers
centrica Consumer: adjusted operating profit drivers UK default Inflation & Underlying Efficiency tariff cap FX Weather margin programme £430m (£183m) (oon) (£9m) iz | H1 2018 H1 2019 The above adjusted figures are before exceptional items and certain re measurements. Adjusted operating profit inclu
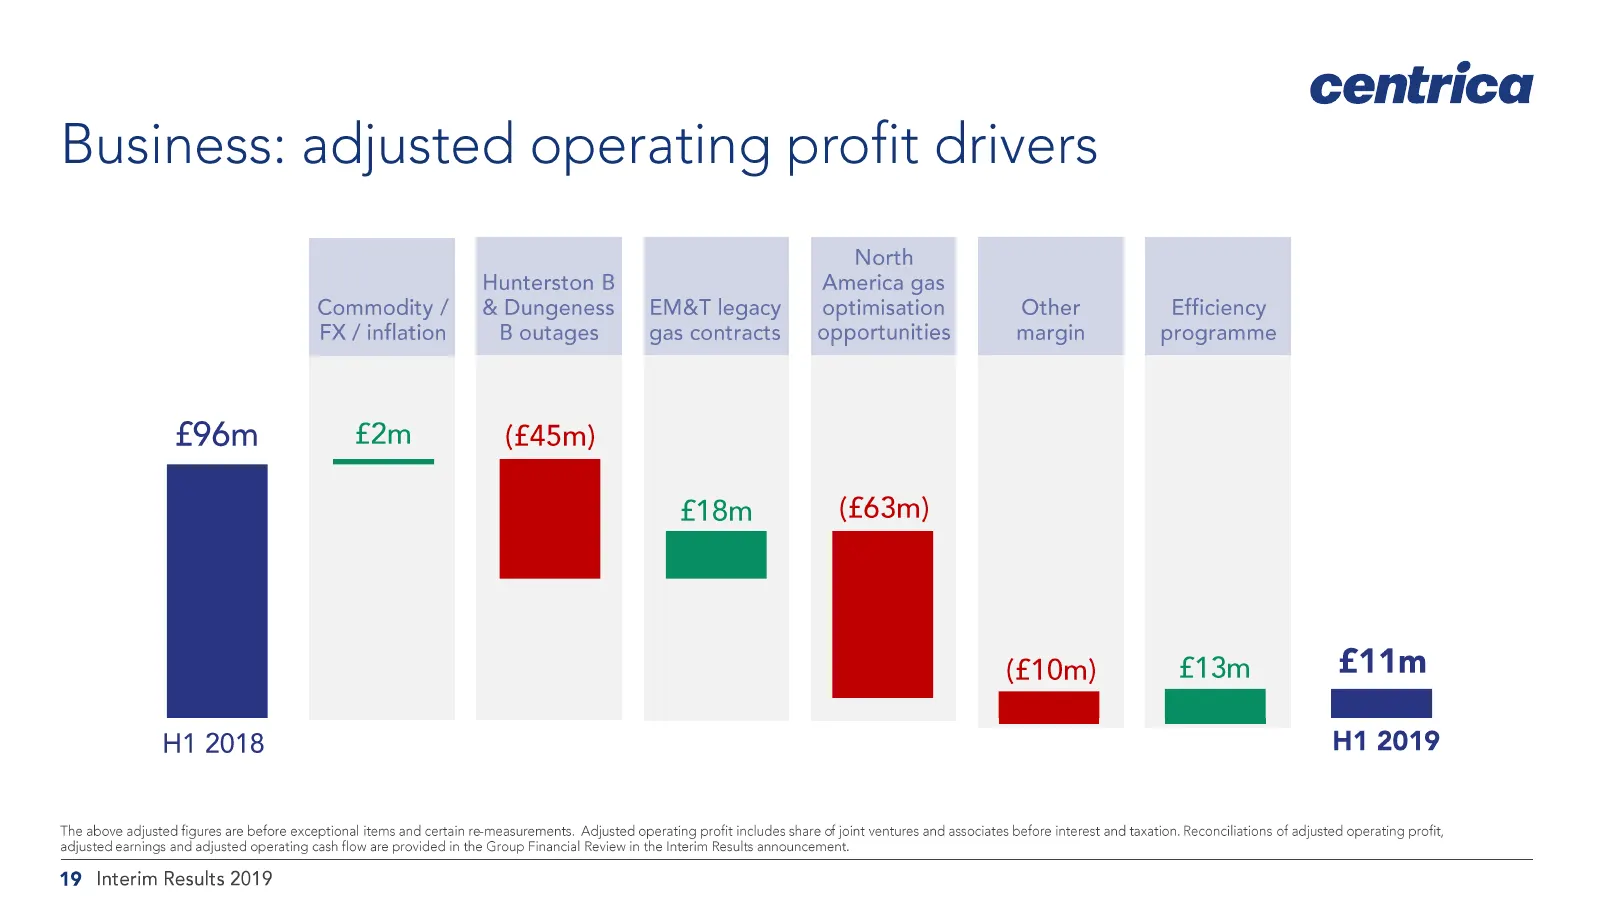
Slide 19: Business: adjusted operating profit drivers
Business: adjusted operating profit drivers North Hunterston B America gas Commodity/ &Dungeness EM&T legacy optimisation Other FX / inflation B outages gas contracts opportunities margin £96m £2m (£45m) a £18m (£63m) H1 2018 centrica Efficiency programme £13m £11m H1 2019 The above adjusted figures
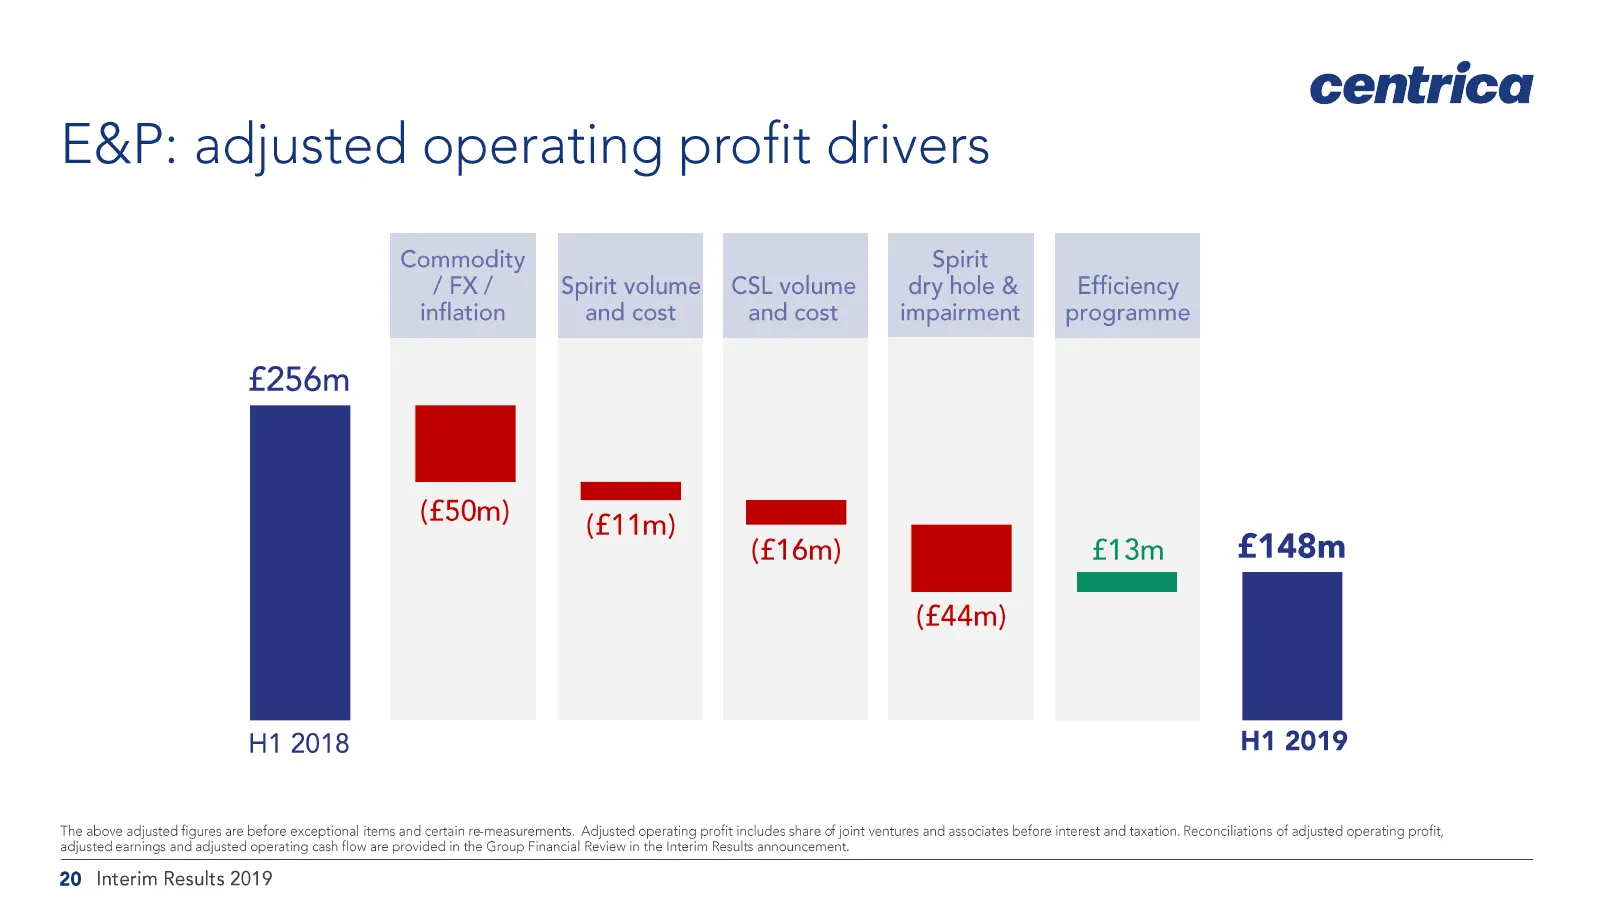
Slide 20: E&P: adjusted operating profit drivers
E&P: adjusted operating profit drivers Commodity Spirit /FX/ Spirit volume CSL volume dry hole & Efficiency inflation and cost and cost impairment programme (£16m) | | £13m ; H1 2018 centrica £148m H1 2019 The above adjusted figures are before exceptional items and certain re-measurements. Adjusted
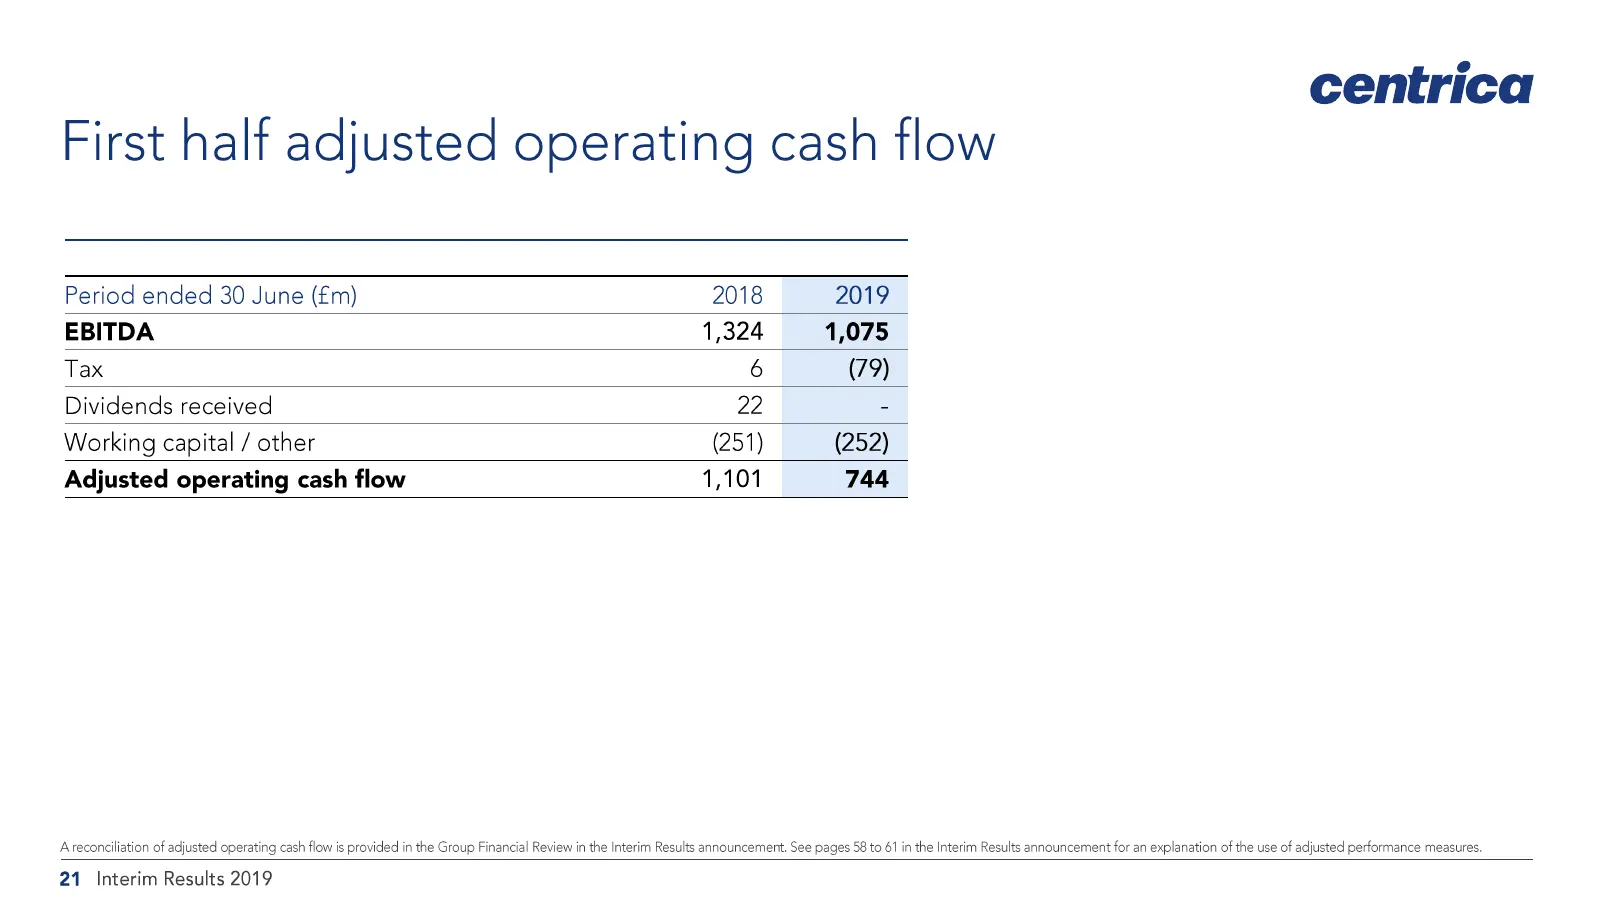
Slide 21: First half adjusted operating cash flow
centrica First half adjusted operating cash flow Period ended 30 June (£m) 2018 2019 EBITDA 1,324 1,075 Tax 6 (79) Dividends received 22 - Working capital / other (251) (252) Adjusted operating cash flow 1,101 744 Areconeiliation of adjusted operating cash flow is provided in the Group Financial Rev
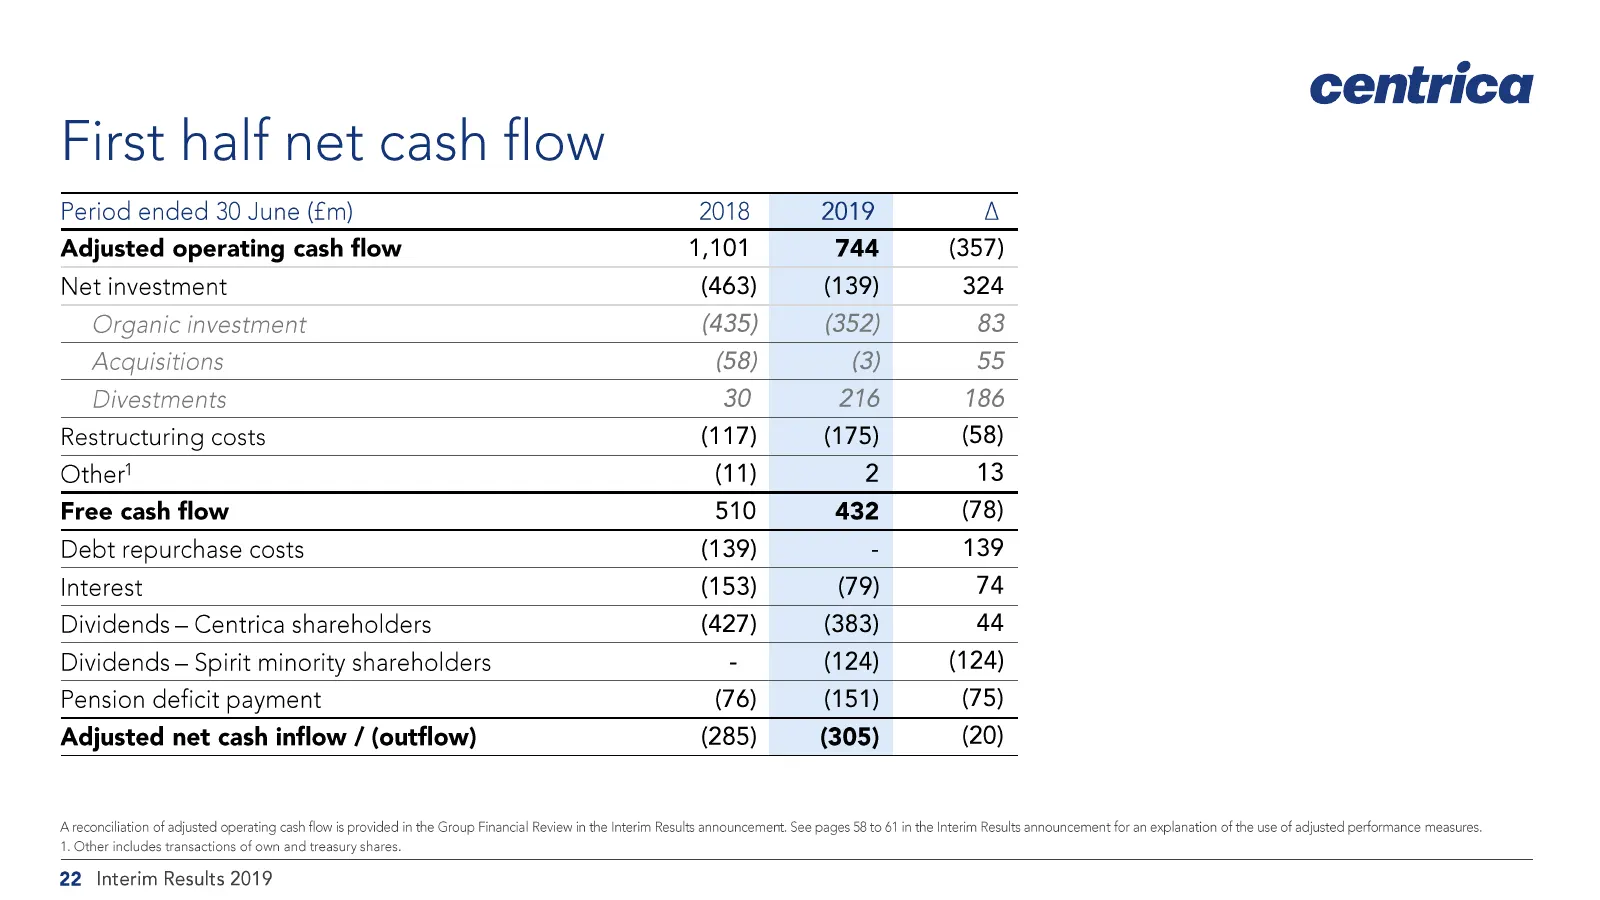
Slide 22: First half net cash flow
First half net cash flow Period ended 30 June (£m) 2018 2019 A Adjusted operating cash flow 1,101 744 (357) Net investment (463) (139) 324 Organic investment (435) (352) 83 Acquisitions (58) (3) 55 Divestments 30 216 186 Restructuring costs (117) (175) (58) Other! (11) 2 13 Free cash flow 510 432 (7
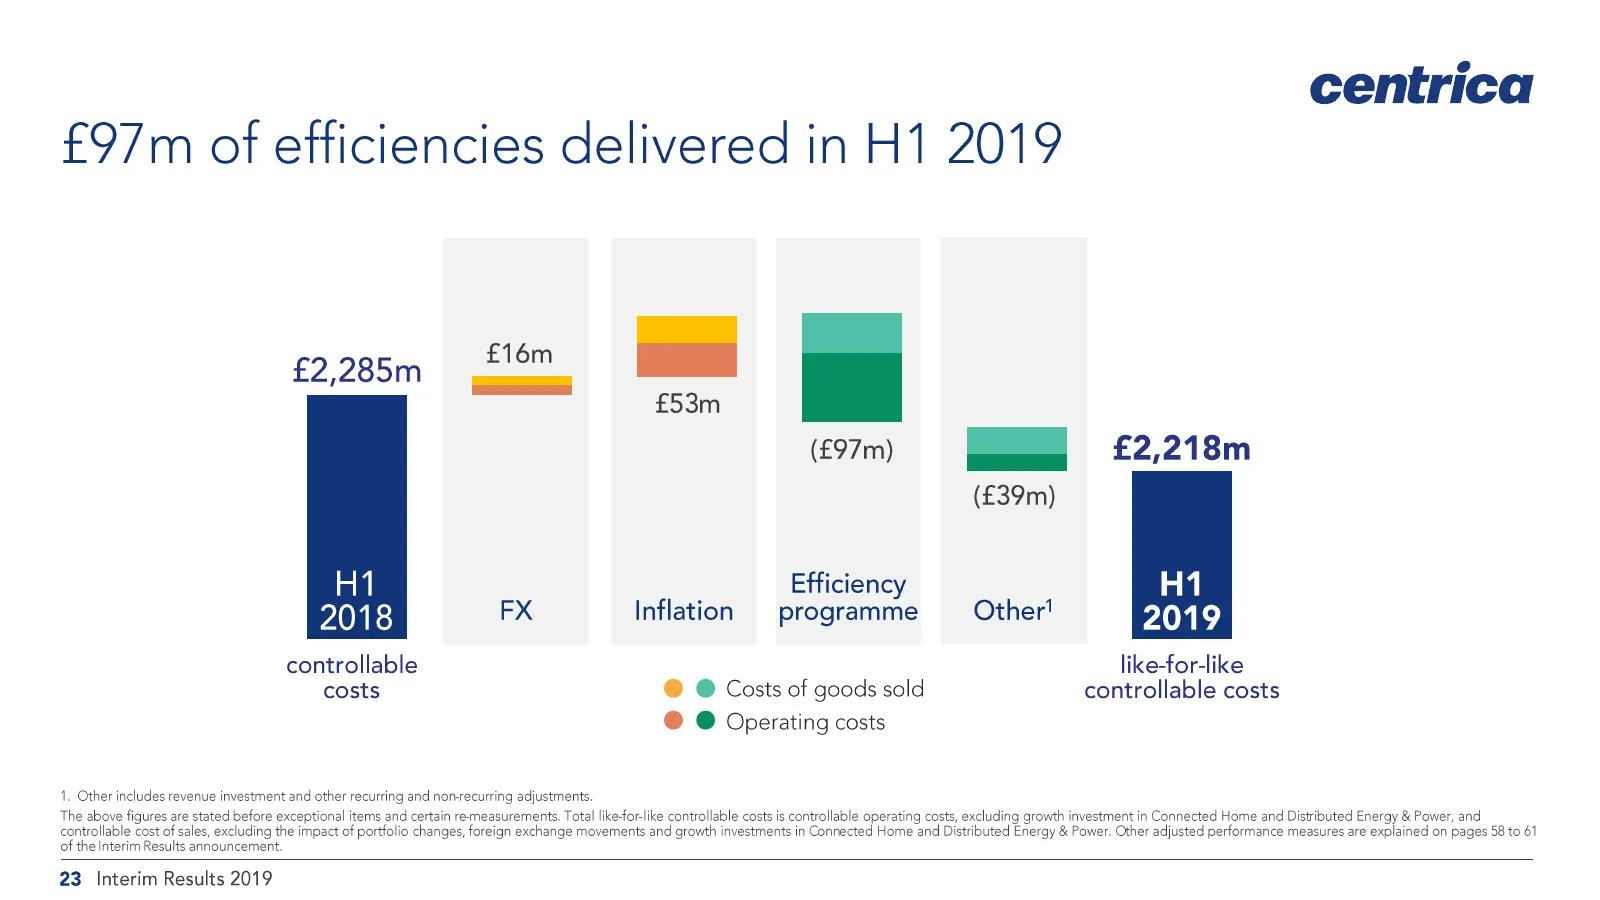
Slide 23: £97m of efficiencies delivered in H1 2019
centrica £97m of efficiencies delivered in H1 2019 £2,285m _f16m a £53m (e97m) = SCs«é£2,218m (£39m) H1 Efficiency 2018 FX Inflation programme — Other! like-for-like © © Costs of goods sold controllable costs @ @ Operating costs controllable costs 1. Other includes revenue investment and other recur
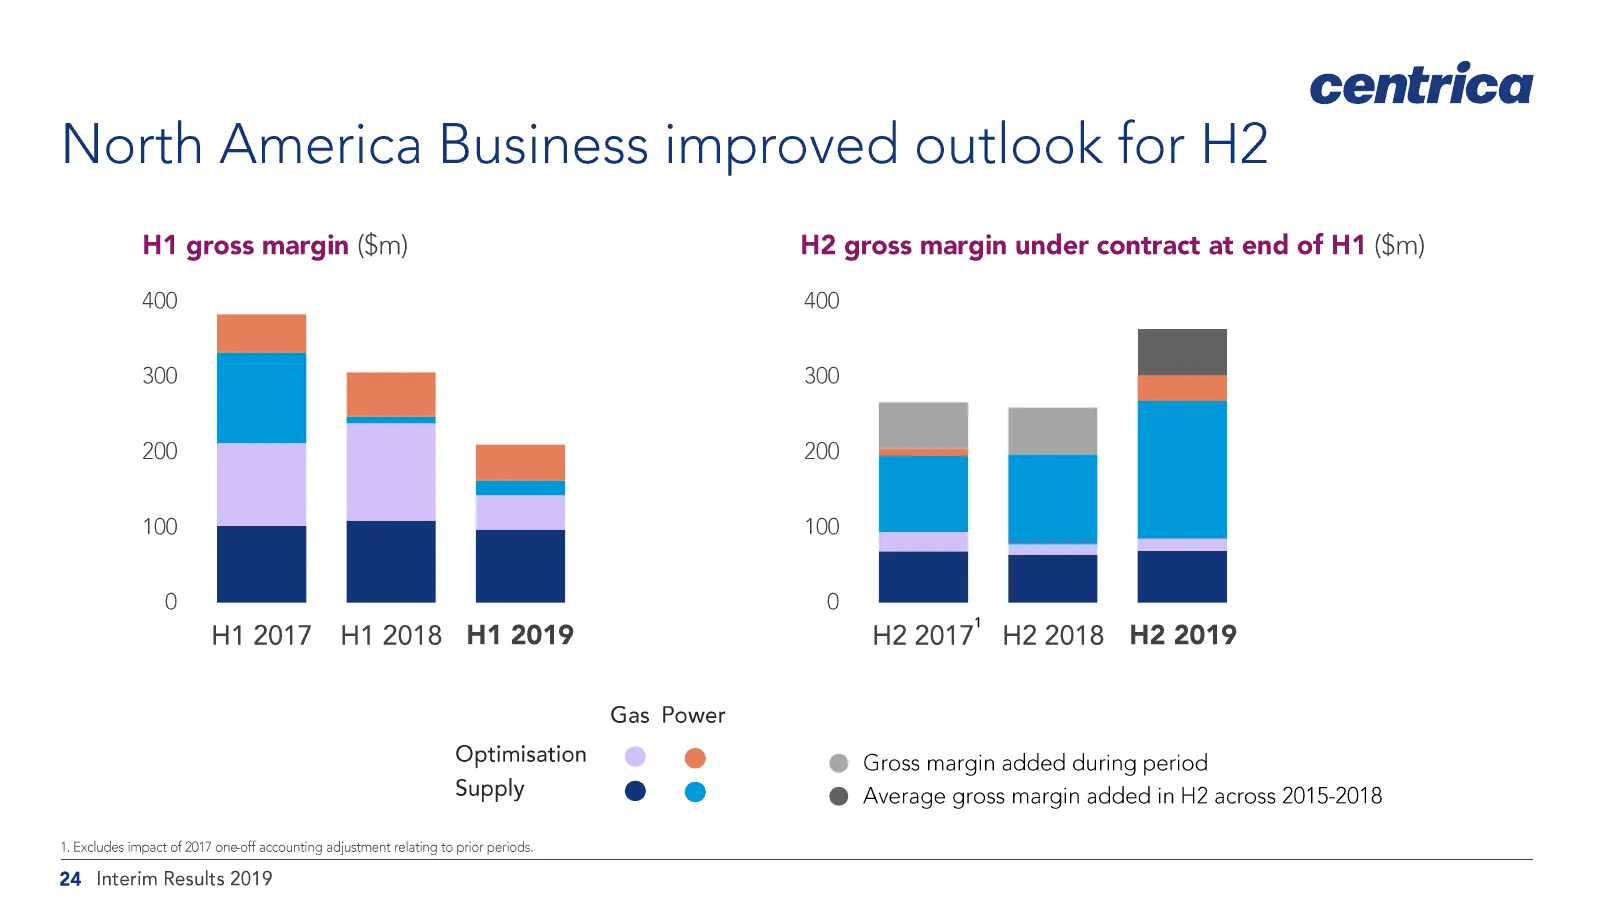
Slide 24: North America Business improved outlook for H2
centrica North America Business improved outlook for H2 H1 gross margin ($m) H2 gross margin under contract at end of H1 ($m) 400 400 300 7 a 300 HEH 0 H1 2017 H12018 H1 2019 H2 2017' H2 2018 H2 2019 Gas Power Optimisation e@ @ Gross margin added during period Supply e@.°e @ Average gross margin add
Slide 25: Expect to meet 2019 Group targets
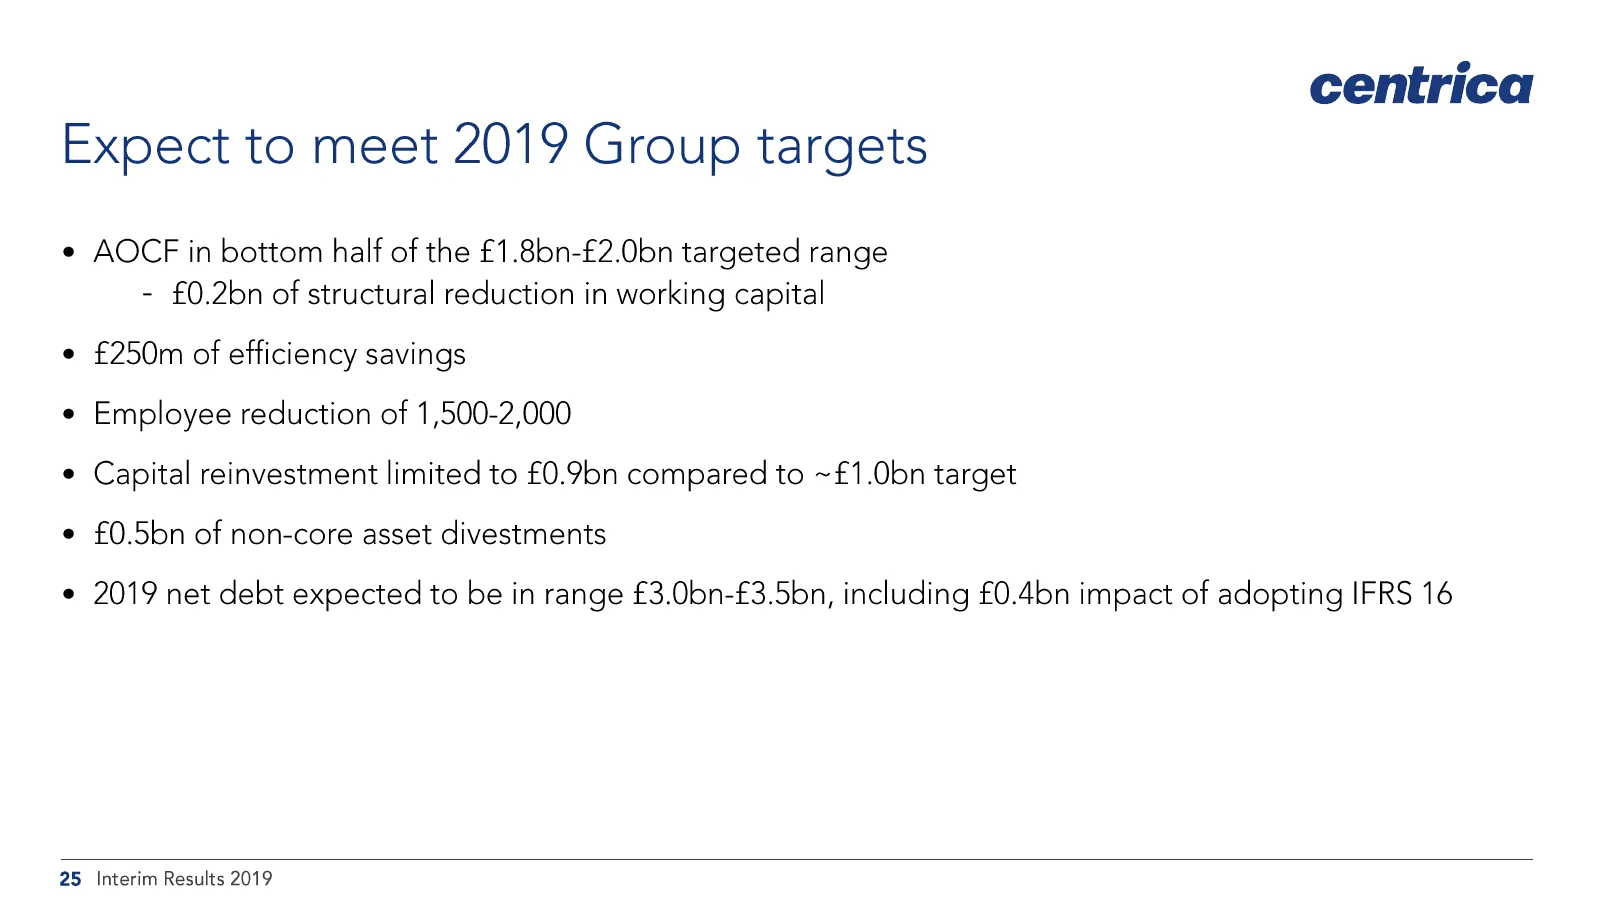
centrica Expect to meet 2019 Group targets AOCF in bottom half of the £1.8bn-£2.0bn targeted range - £0.2bn of structural reduction in working capital £250m of efficiency savings Employee reduction of 1,500-2,000 Capital reinvestment limited to £0.9bn compared to ~£1.0bn target £0.5bn of non-core as
Slide 26: Strong balance sheet to support risk management
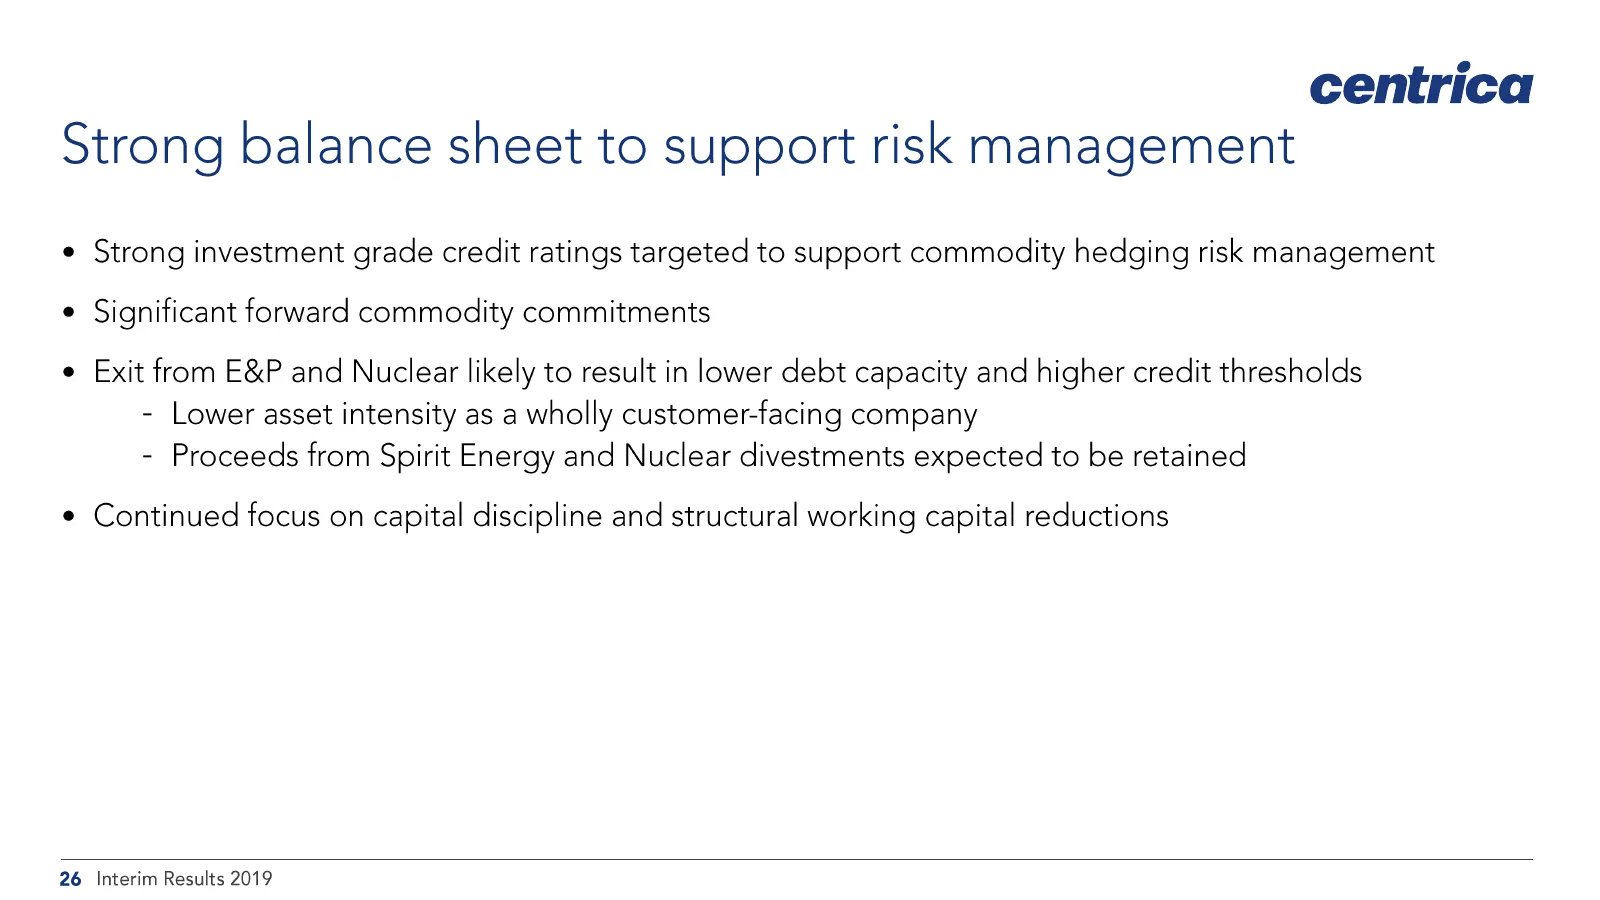
centrica Strong balance sheet to support risk management Strong investment grade credit ratings targeted to support commodity hedging risk management Significant forward commodity commitments Exit from E&P and Nuclear likely to result in lower debt capacity and higher credit thresholds - Lower asset
Slide 27: Debt maturity profile
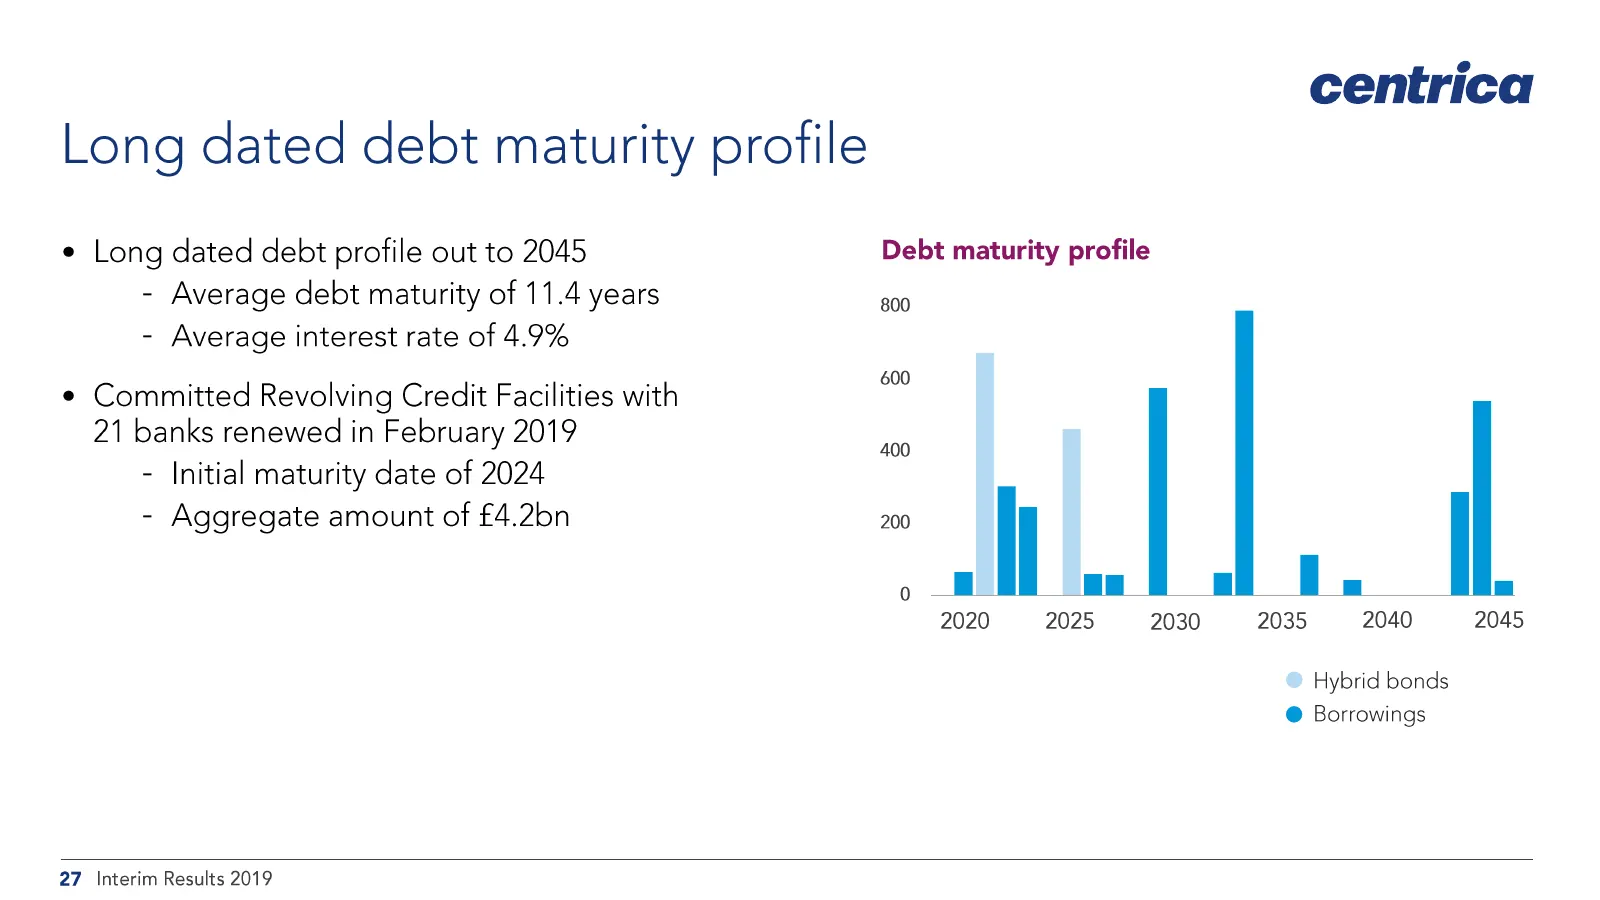
- - - - 2019 2020 2021 2022 2023 2024 2025 2026 2027 2028 2029 2030 2031 2032 2033 2034 2035 2036 2037 2038 2039 2040 2041 2042 2043 2044 2045
Slide 28: Opportunity to reduce structural working capital
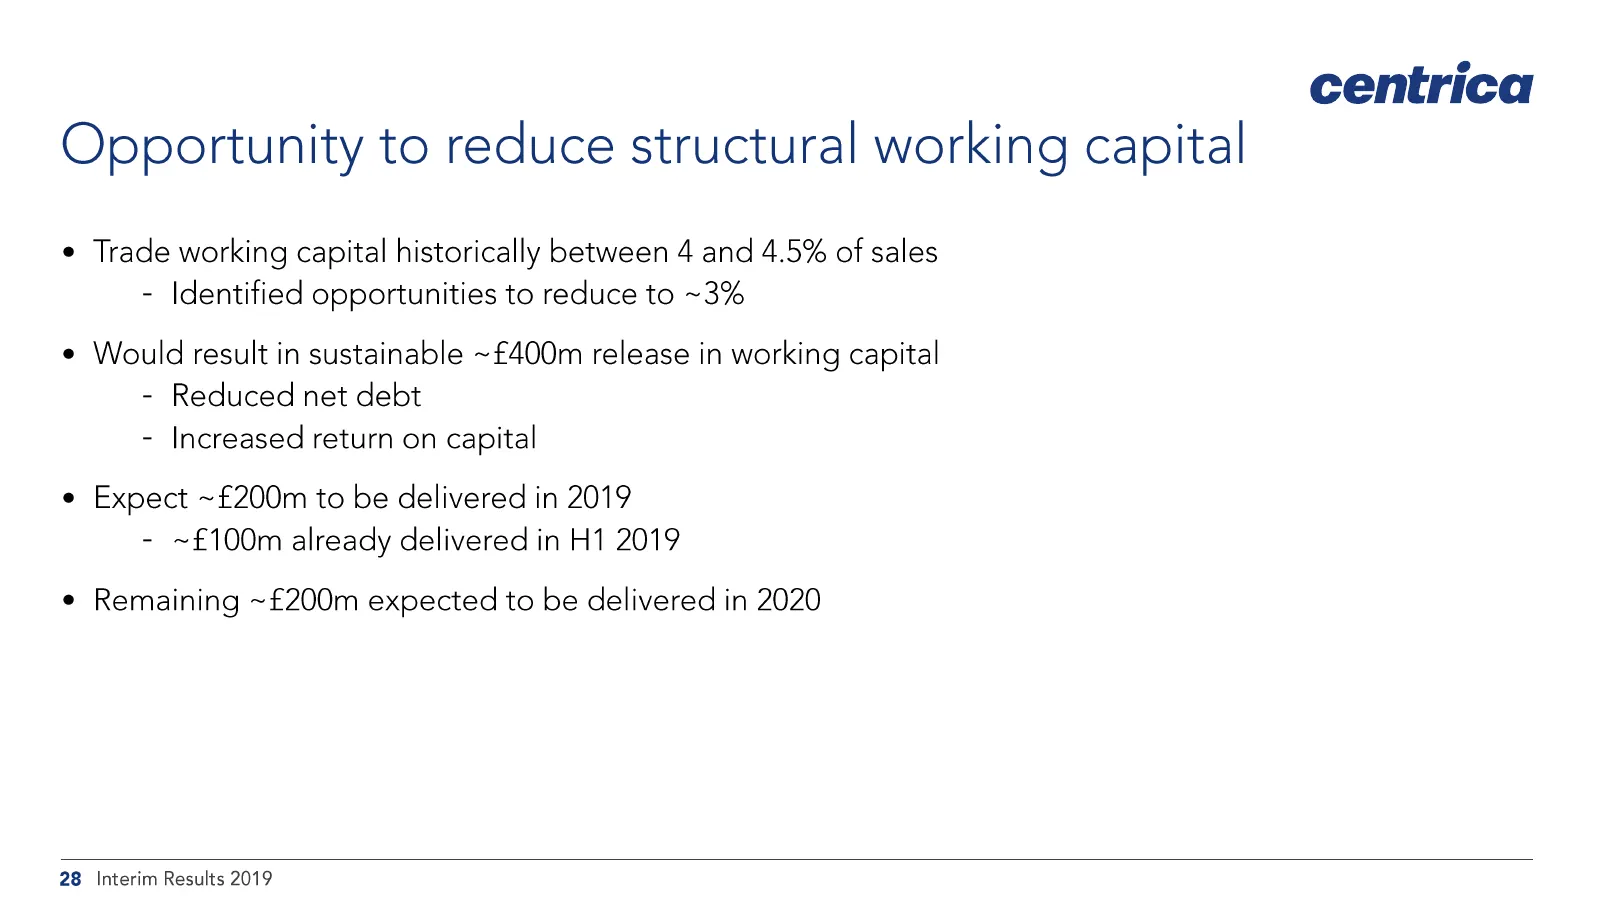
centrica Opportunity to reduce structural working capital Trade working capital historically between 4 and 4.5% of sales - Identified opportunities to reduce to ~3% Would result in sustainable ~£400m release in working capital - Reduced net debt - Increased return on capital Expect ~£200m to be deli
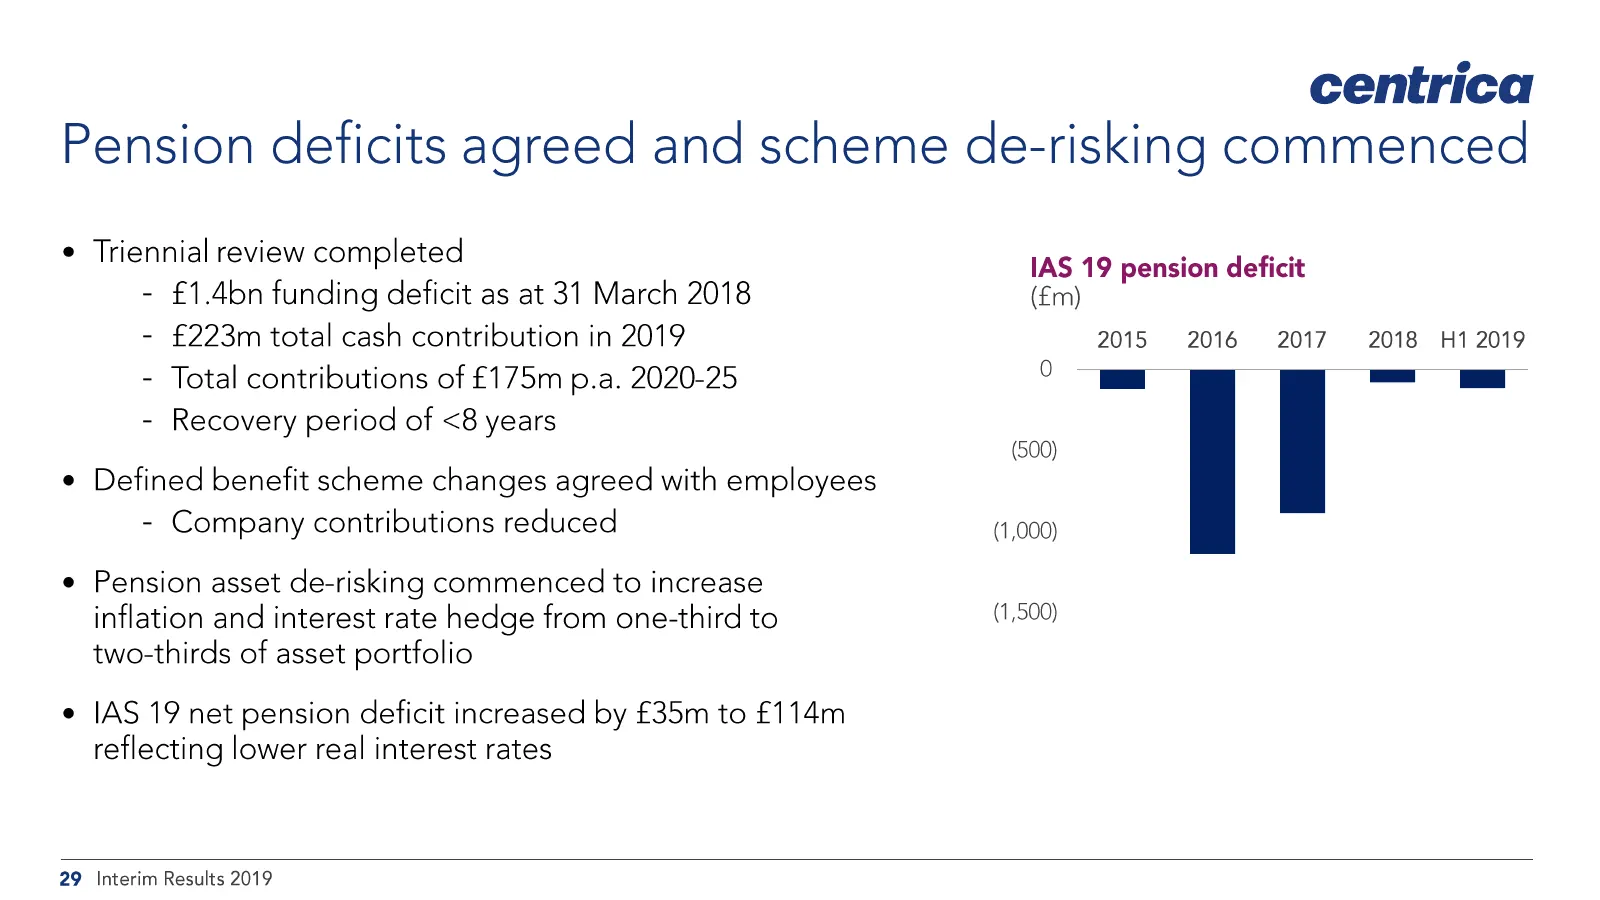
Slide 29: Pension deficits agreed and scheme de-risking commenced
centrica Pension deficits agreed and scheme de-risking commenced ¢ Triennial review completed IAS 19 pension deficit - £1.4bn funding deficit as at 31 March 2018 (£m) - £223m total cash contribution in 2019 2015 2016 2017 2018 H1 2019 - Total contributions of £175m p.a. 2020-25 | = = - Recovery peri
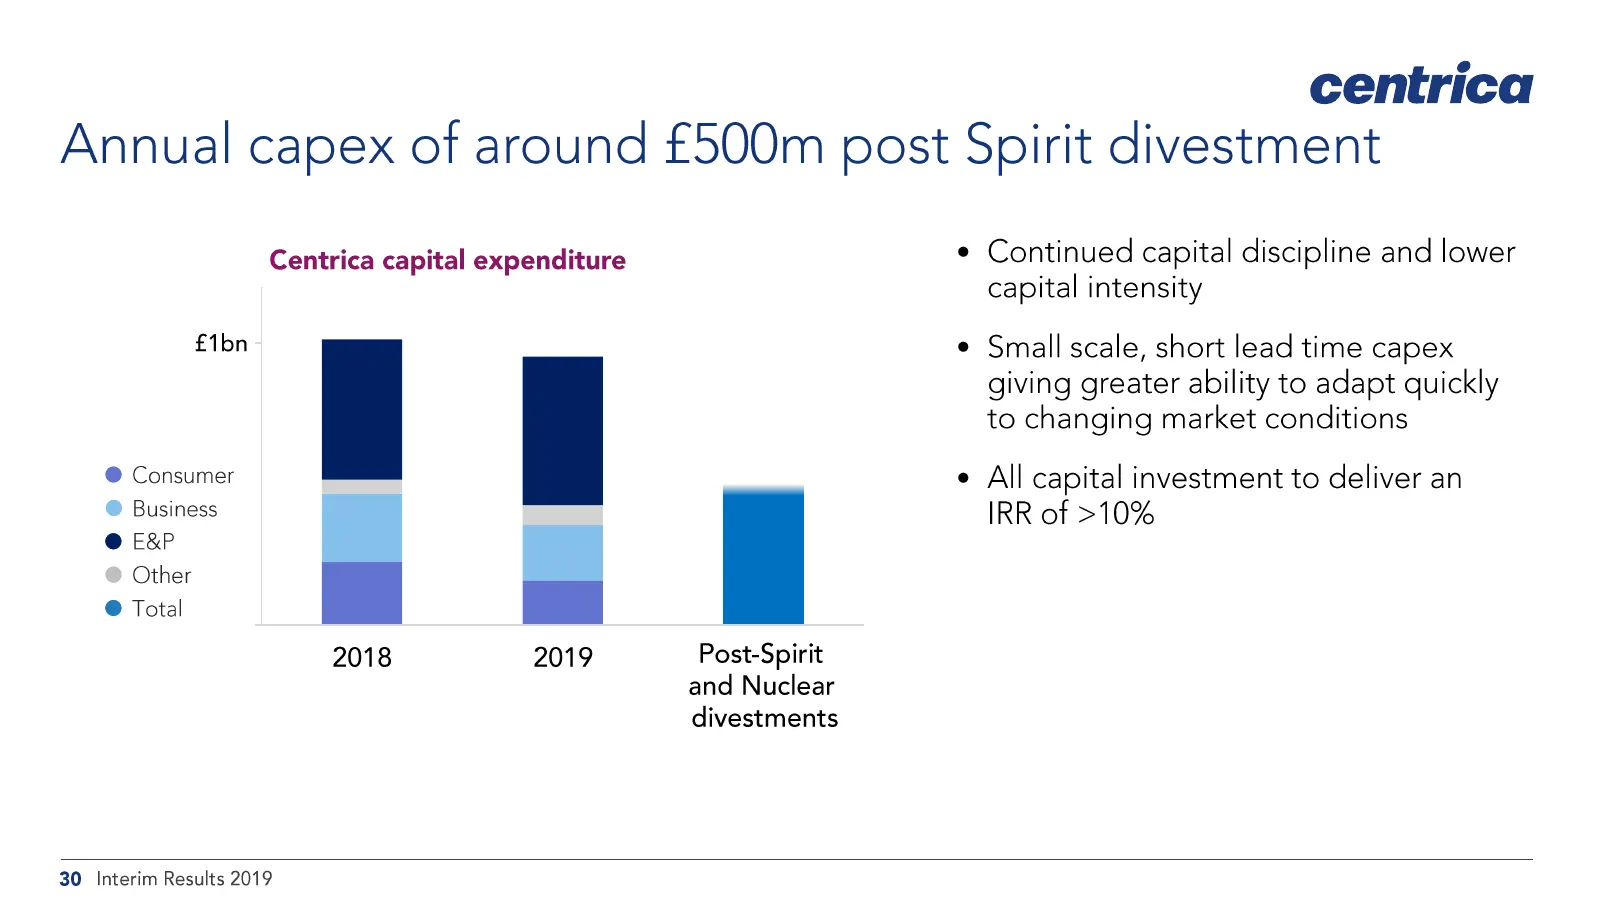
Slide 30: Annual capex of around £500m post Spirit divestment
centrica Annual capex of around £500m post Spirit divestment ¢ Continued capital discipline and lower Centrica capital expenditure are } capital intensity fbn ¢ Small scale, short lead time capex giving greater ability to adapt quickly to changing market conditions © Consumer ¢ All capital investmen
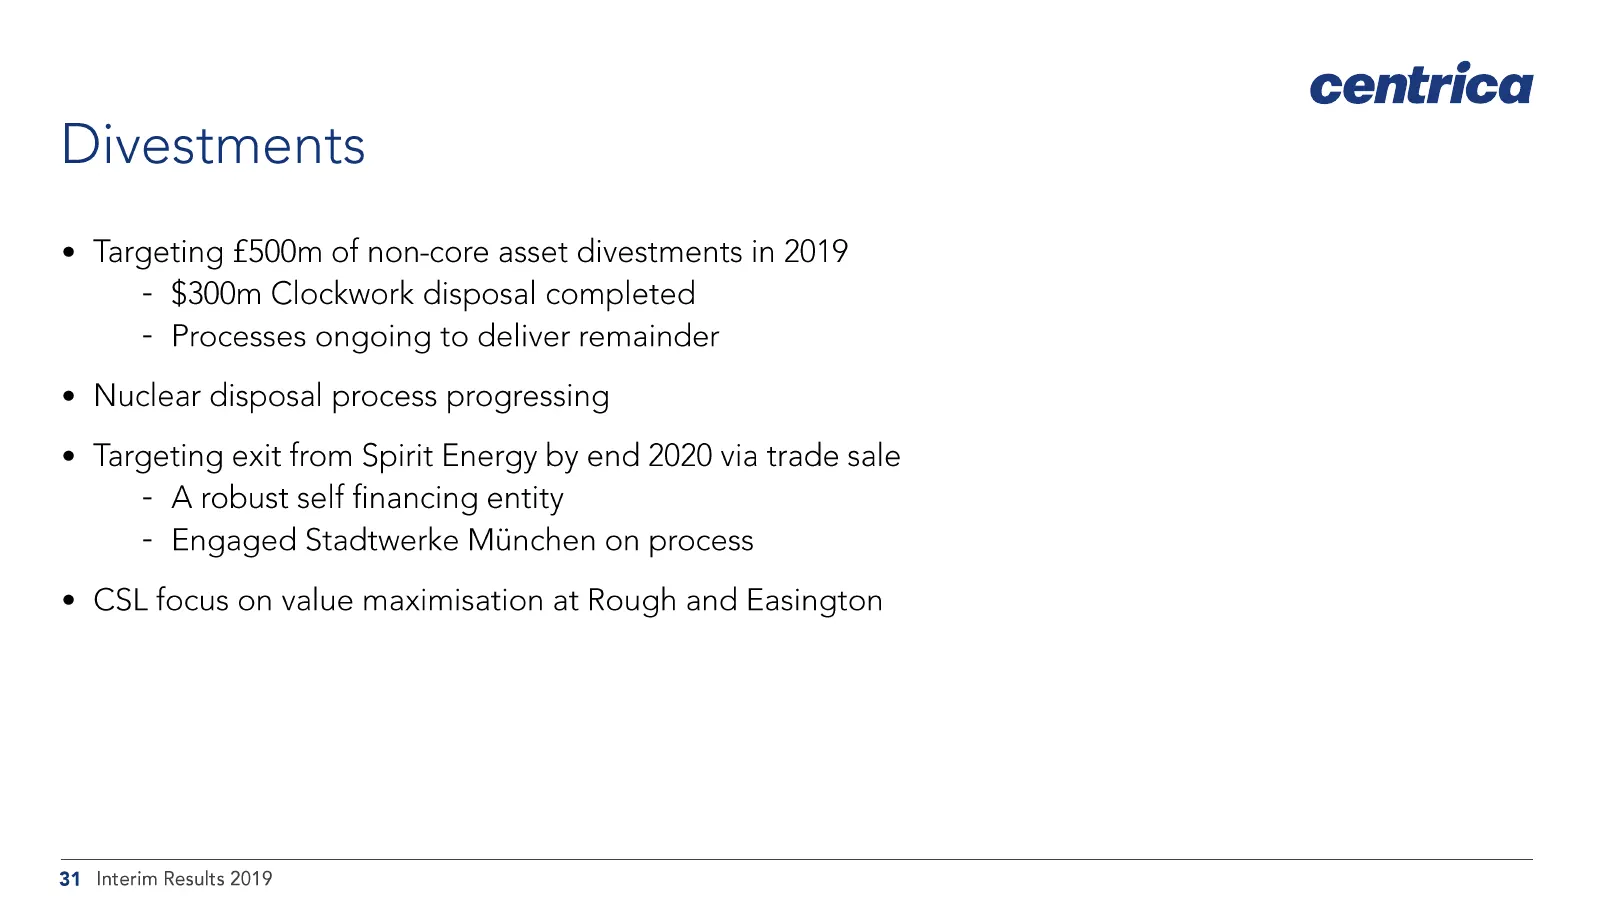
Slide 31: Divestments
centrica Divestments Targeting £500m of non-core asset divestments in 2019 - $300m Clockwork disposal completed - Processes ongoing to deliver remainder Nuclear disposal process progressing Targeting exit from Spirit Energy by end 2020 via trade sale - Arobust self financing entity - Engaged Stadtwe
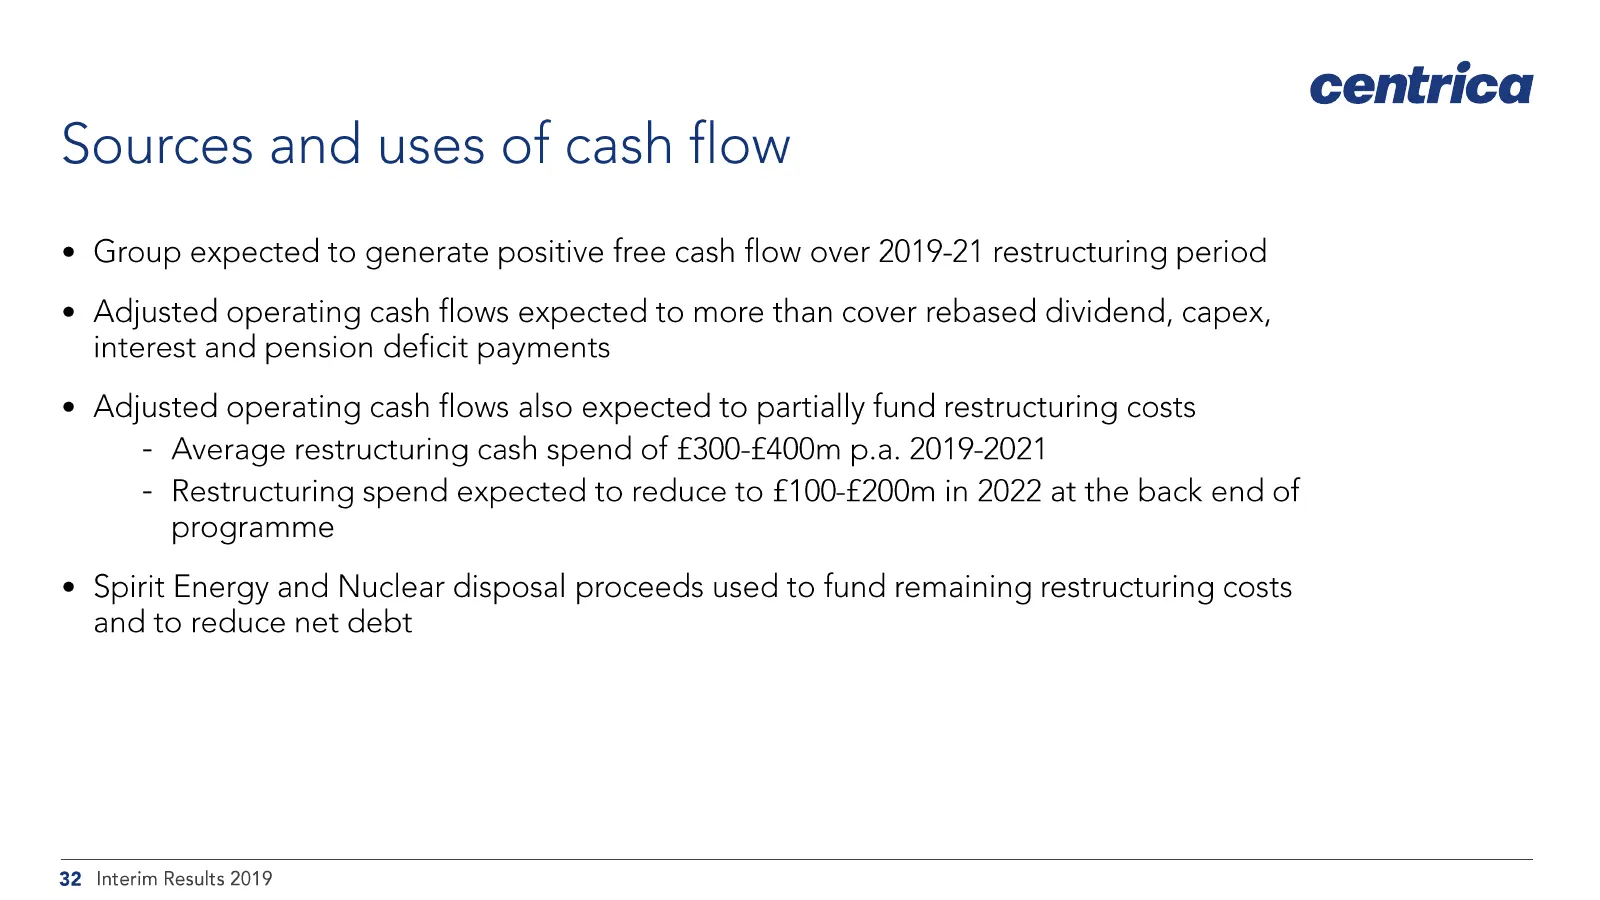
Slide 32: Sources and uses of cash flow
centrica Sources and uses of cash flow ¢ Group expected to generate positive free cash flow over 2019-21 restructuring period ¢ Adjusted operating cash flows expected to more than cover rebased dividend, capex, interest and pension deficit payments ¢ Adjusted operating cash flows also expected to pa
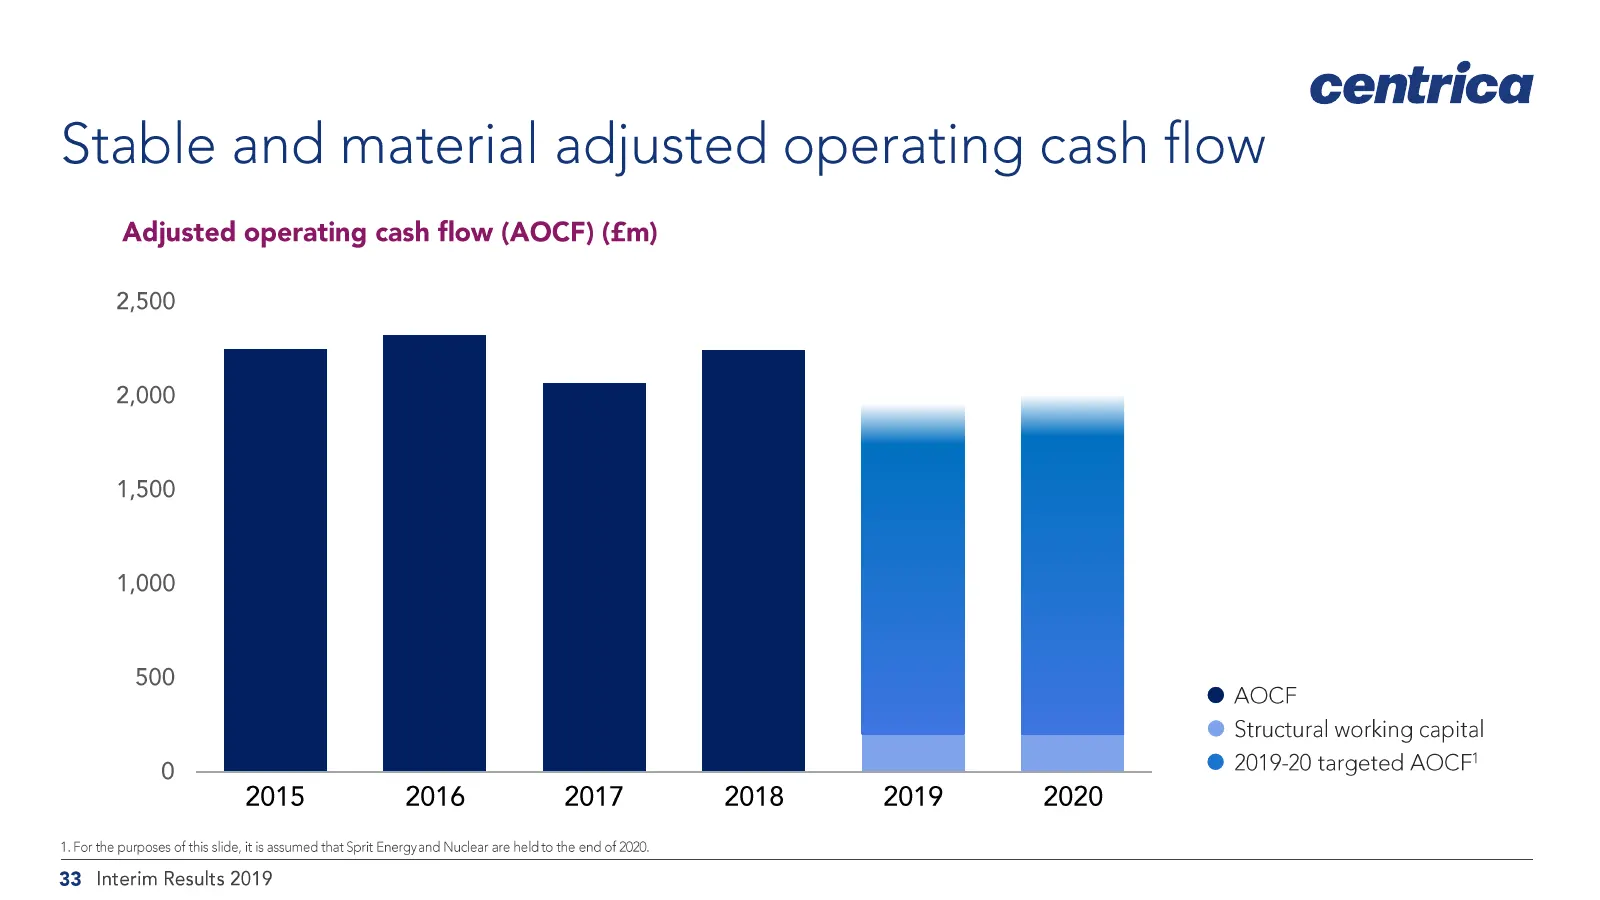
Slide 33: Stable and material adjusted operating cash flow
centrica Stable and material adjusted operating cash flow Adjusted operating cash flow (AOCF) (£m) 2,500 2,000 1,500 1,000 500 @ AOCF © Structural working capital 0 @ 2019-20 targeted AOCF' 2015 2016 2017 2018 2019 2020 1. For the purposes of this slide, itis assumed that Sprit Energyand Nuclear are
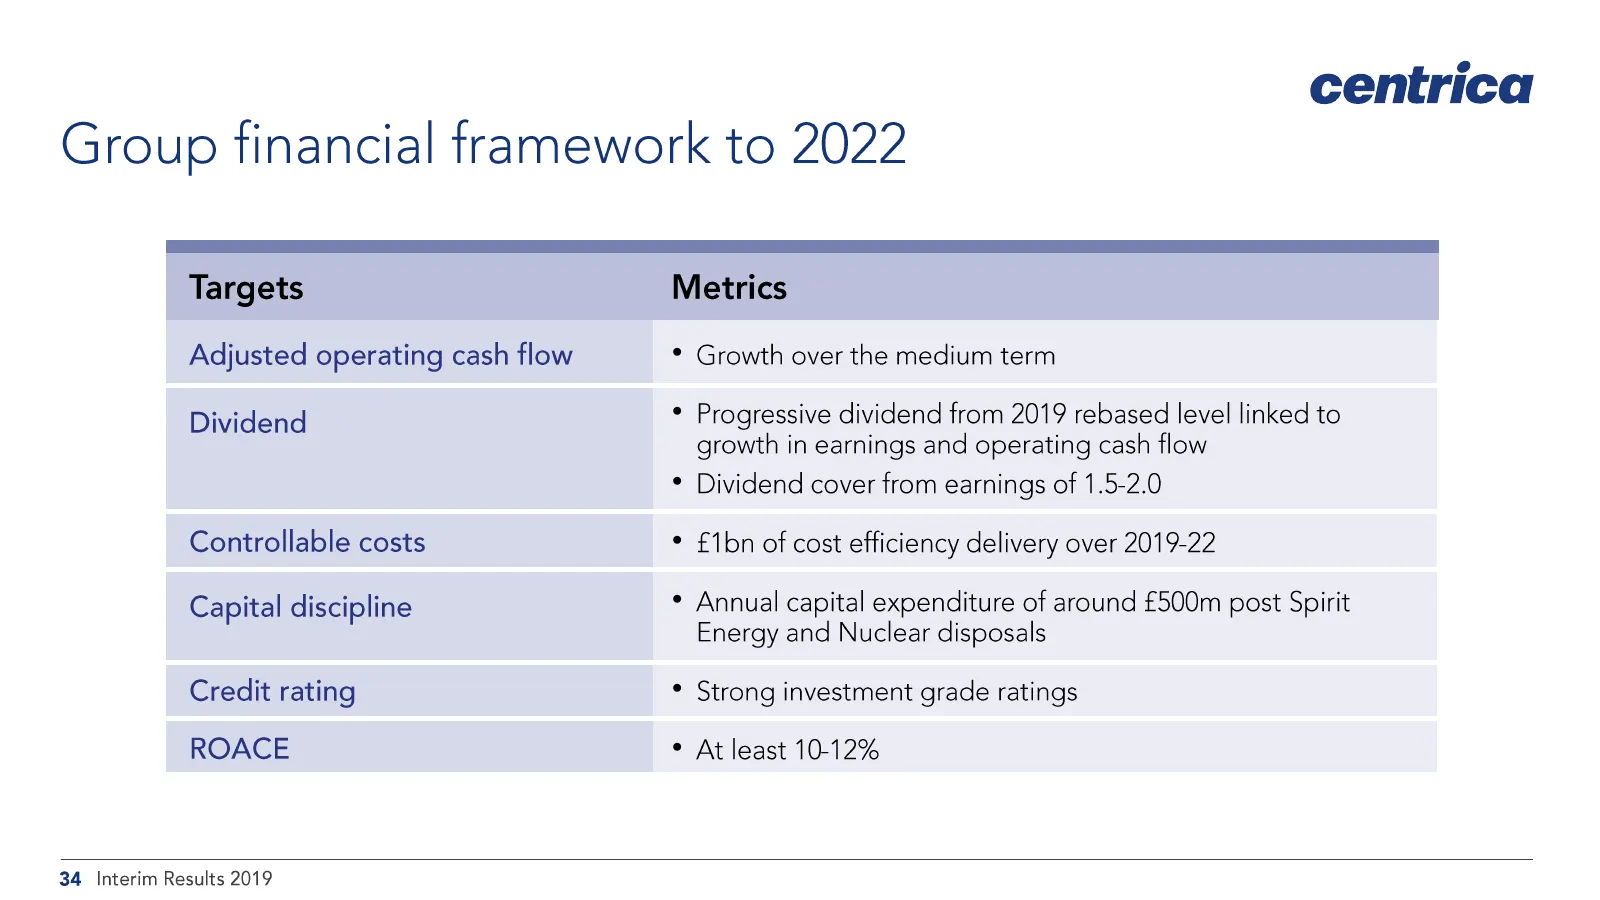
Slide 34: Group financial framework to 2022
centrica Group financial framework to 2022 Targets Adjusted operating cash flow Dividend Controllable costs Capital discipline Credit rating ROACE Metrics * Growth over the medium term * Progressive dividend from 2019 rebased level linked to growth in earnings and operating cash flow * Dividend cove
Slide 35: Iain Conn, Group Chief Executive
centrica lain Conn Group Chief Executive
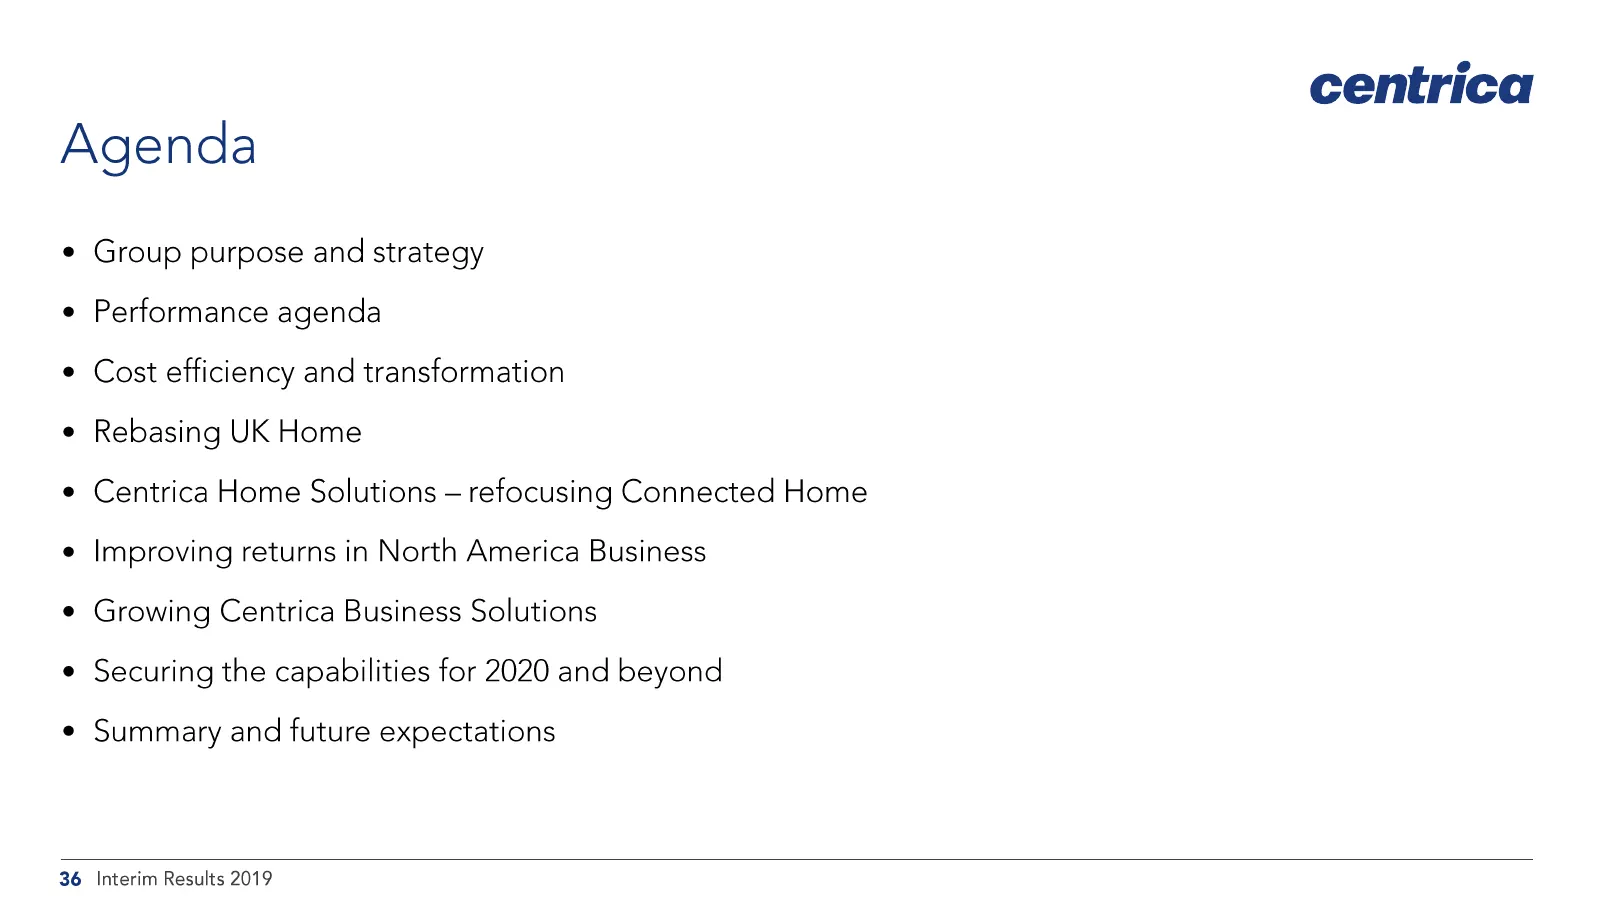
Slide 36: Agenda
centrica Agenda ¢ Group purpose and strategy ¢ Performance agenda * Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 37: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 38: Centrica's purpose and strategy
centrica Centrica’s purpose and strategy Satisfying the changing needs of our customers, enabling the transition to a lower carbon future - “Helping you run your world in ever more sustainable ways” A "21st Century Energy Services and Solutions company” Delivering long-term shareholder value through
Slide 39: The changing energy landscape and Centrica's role
centrica The changing energy landscape and Centrica’s role ¢ The trends we identified in 2015 continue to play out - Decentralisation of the energy system as distributed technology supports decarbonisation - Choice, power and influence moving to the customer - Digitalisation accelerating proposition
Slide 40: Enabling the energy transition to a low carbon future
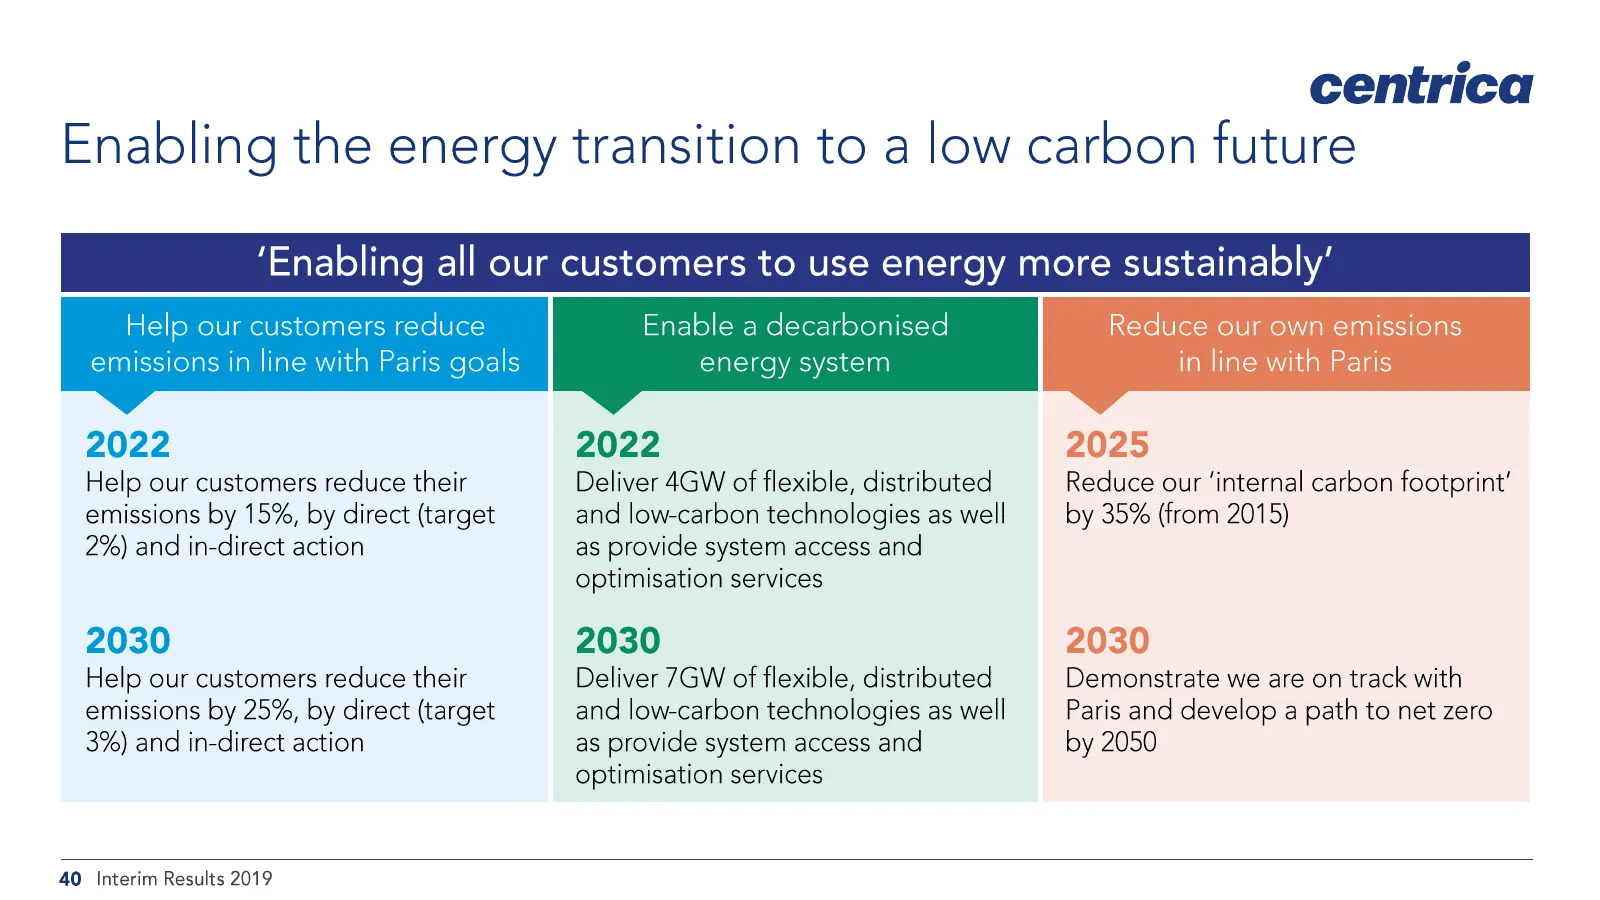
centrica Enabling the energy transition to a low carbon future ‘Enabling all o Help our customers reduce emissions in line with Paris goals tomers to use en Enable a decarbonised energy system ore sustai Reduce our own emissions in line with Paris 2022 Help our customers reduce their emissions by 15
Slide 41: What we will focus on for our customers
centrica What we will focus on for our customers Satisfying their changing needs, including the transition to a lower carbon future ¢ Provide them more than just energy supply - it is one of the services we provide ¢ Provide services and solutions which customers value and are willing to pay for, se
Slide 42: Centrica team priorities
centrica Centrica team priorities Customer obsession Operational excellence Cash flow growth Most competitive provider Empowered colleagues 42 Interim Results 2019
Slide 43: Centrica Consumer strategic pillars and capabilities
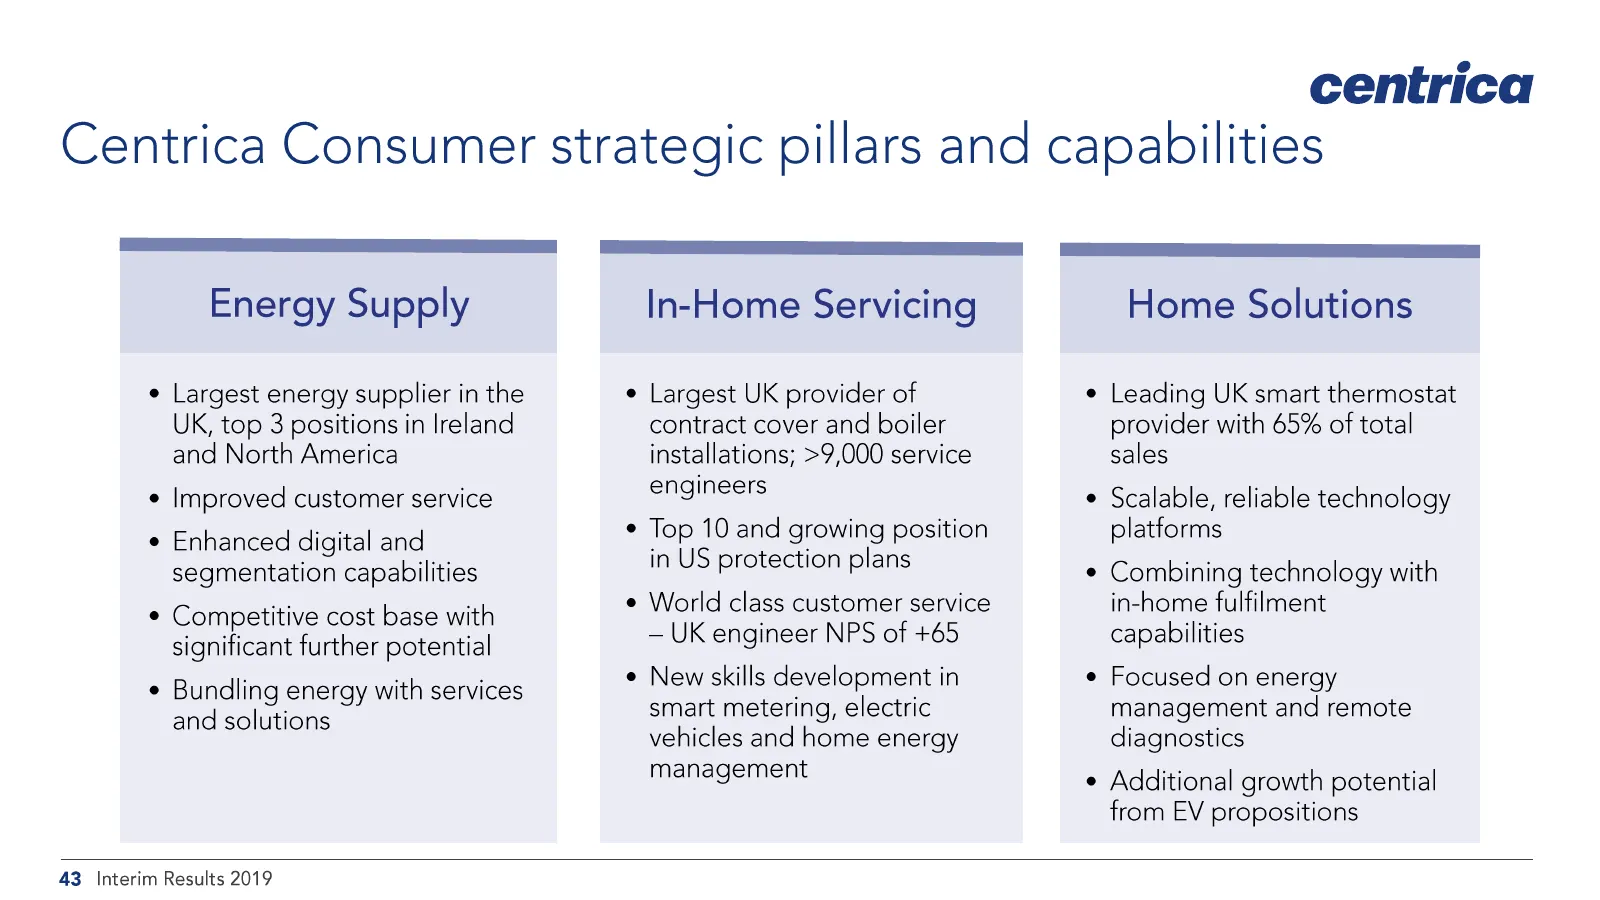
centrica Centrica Consumer strategic pillars and capabilities Energy Supply Largest energy supplier in the UK, top 3 positions in Ireland and North America Improved customer service Enhanced digital and segmentation capabilities Competitive cost base with significant further potential Bundling energ
Slide 44: Centrica Business strategic pillars and capabilities
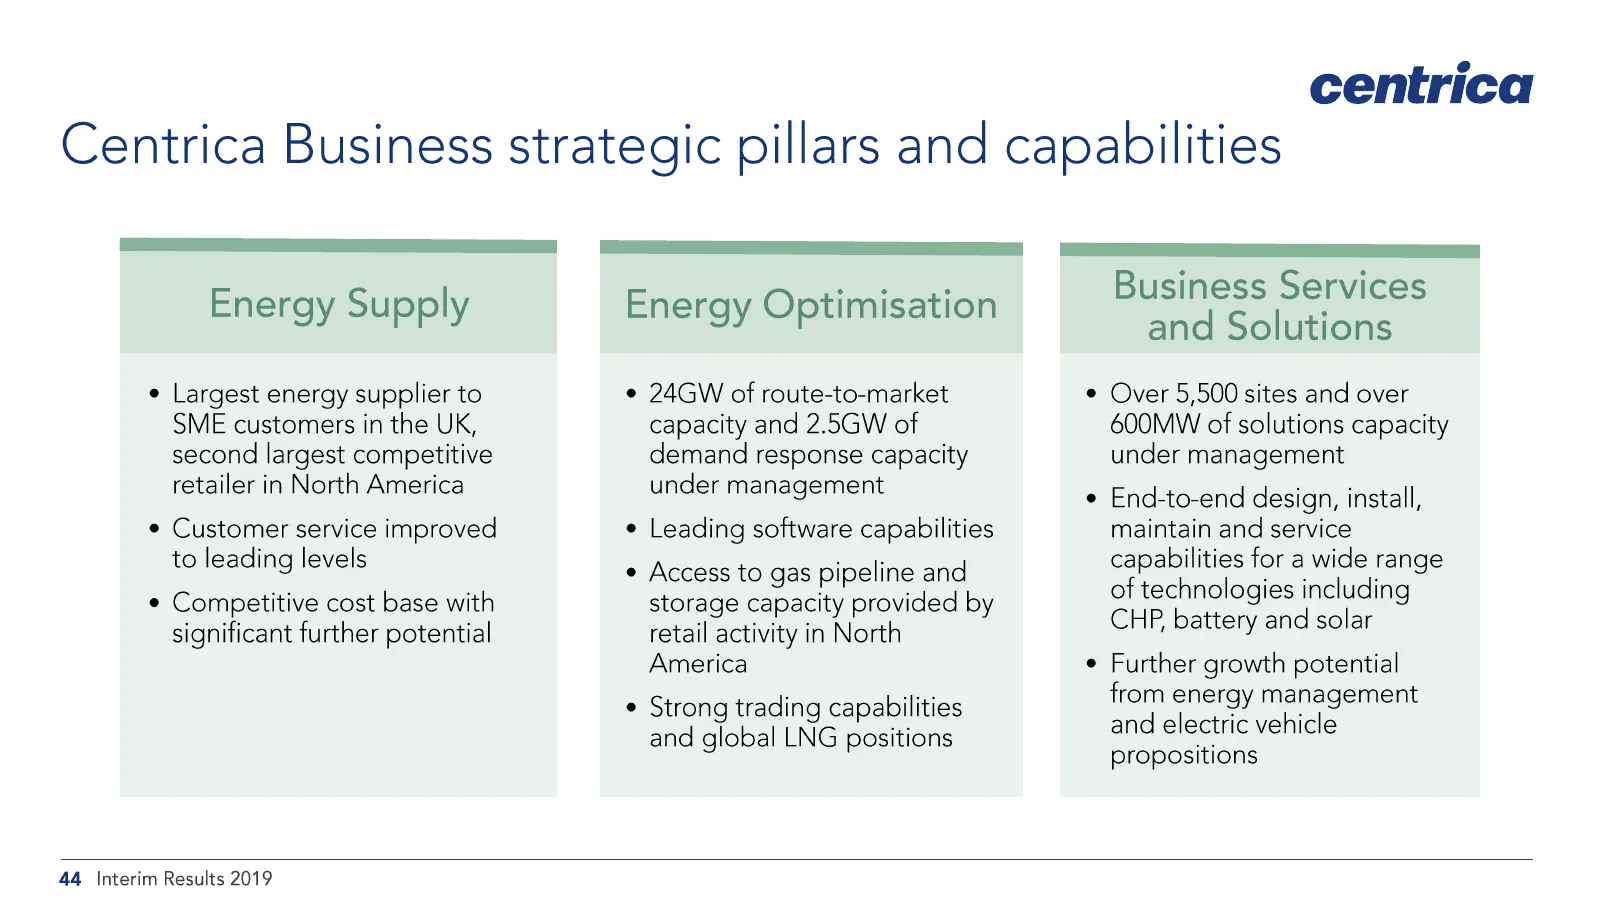
centrica Centrica Business strategic pillars and capabilities Energy Supply ¢ Largest energy supplier to SME customers in the UK, second largest competitive retailer in North America ¢ Customer service improved to leading levels ¢ Competitive cost base with significant further potential Energy Optim
Slide 45: Agenda
centrica Agenda ¢ Group purpose and strategy ¢ Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 46: 2018-20 performance agenda
centrica 2018-20 performance agenda ¢ Demonstrating customer-led gross margin growth Driving cost efficiency towards being ‘most efficient price-setter’ ¢ Improving organisational effectiveness Securing the capabilities we need for 2020 and beyond Maintaining capital discipline and balance sheet str
Slide 47: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 48: A further £1bn of cost efficiencies by 2022
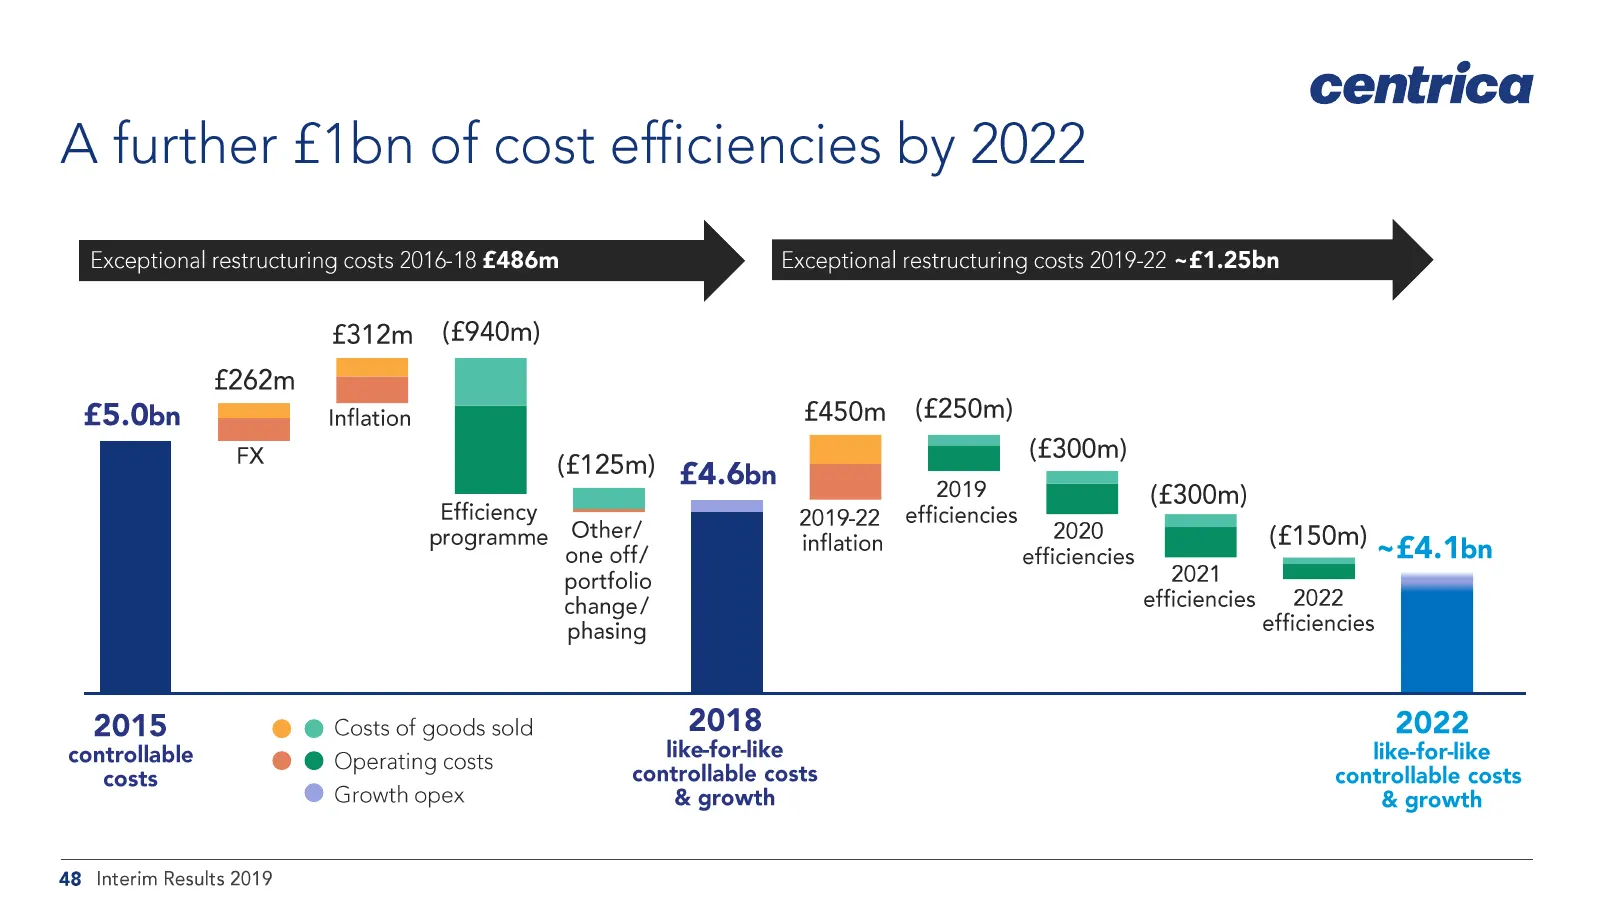
centrica A further £1bn of cost efficiencies by 2022 Exceptional restructuring costs 2016-18 £486m Exceptional restructuring costs 2019-22 ~£1.25bn £312m (£940m) £262m £5.0bn P| Inflation £450m FX (£125m) £4.6b = (£300m) ° n — | 2019 EE (300m) Efficiency Other/ 2019-22 efficiencies 2020 = (£150m) on
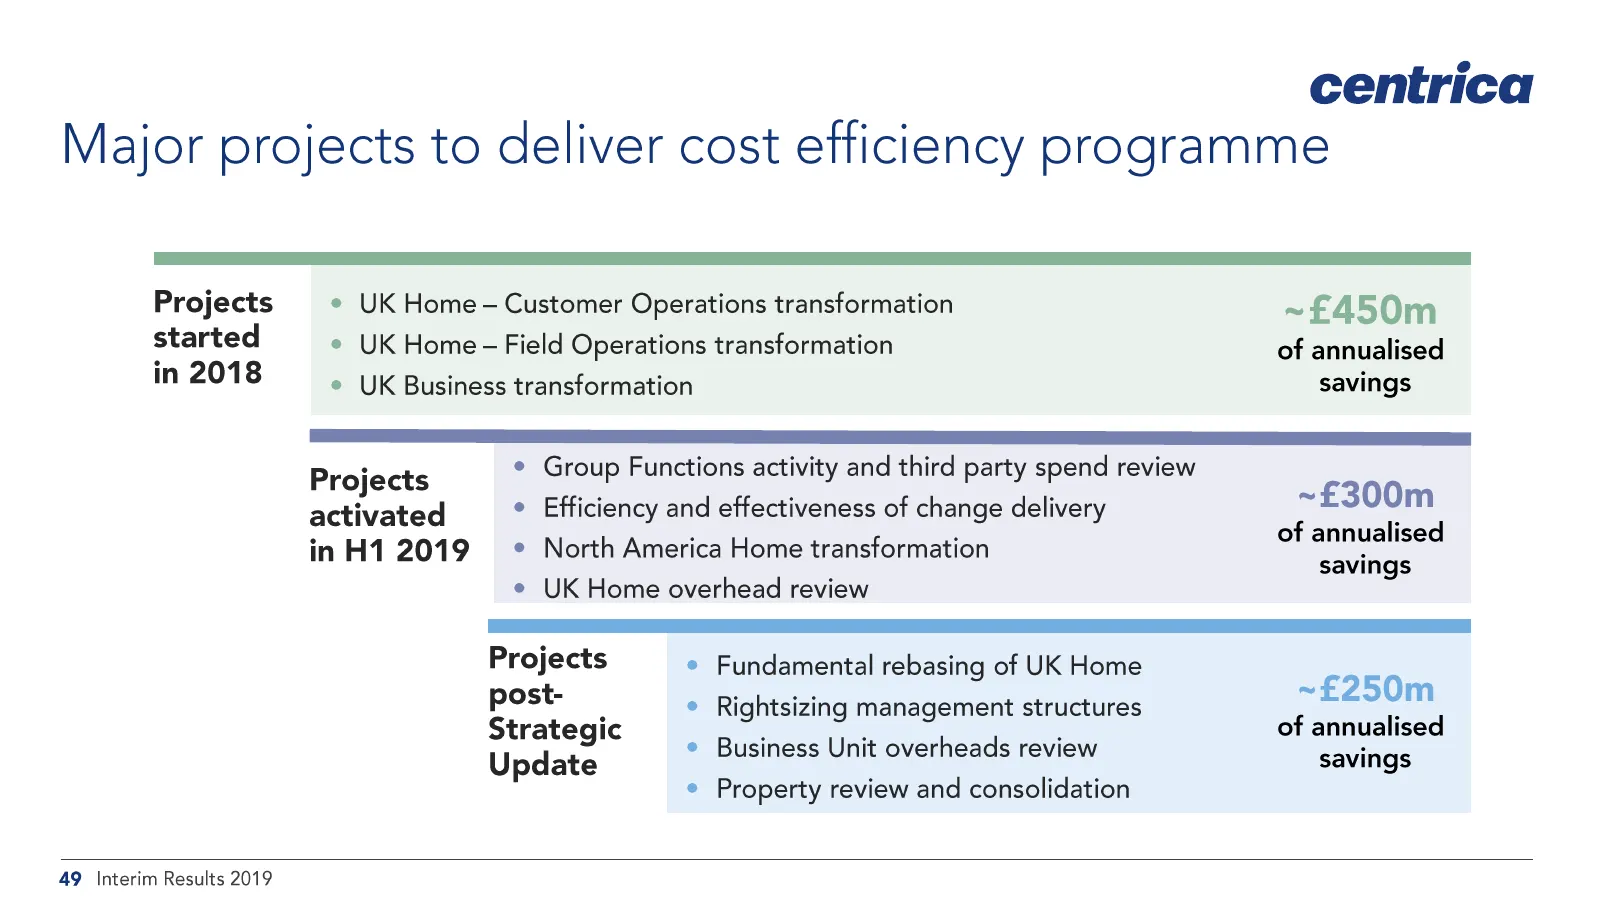
Slide 49: Major projects to deliver cost efficiency programme
centrica Major projects to deliver cost efficiency programme Projects e UK Home - Customer Operations transformation ~£450m started e UK Home - Field Operations transformation of annualised in 2018 e UK Business transformation savings Projects e Group Functions activity and third party spend review
Slide 50: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation e Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
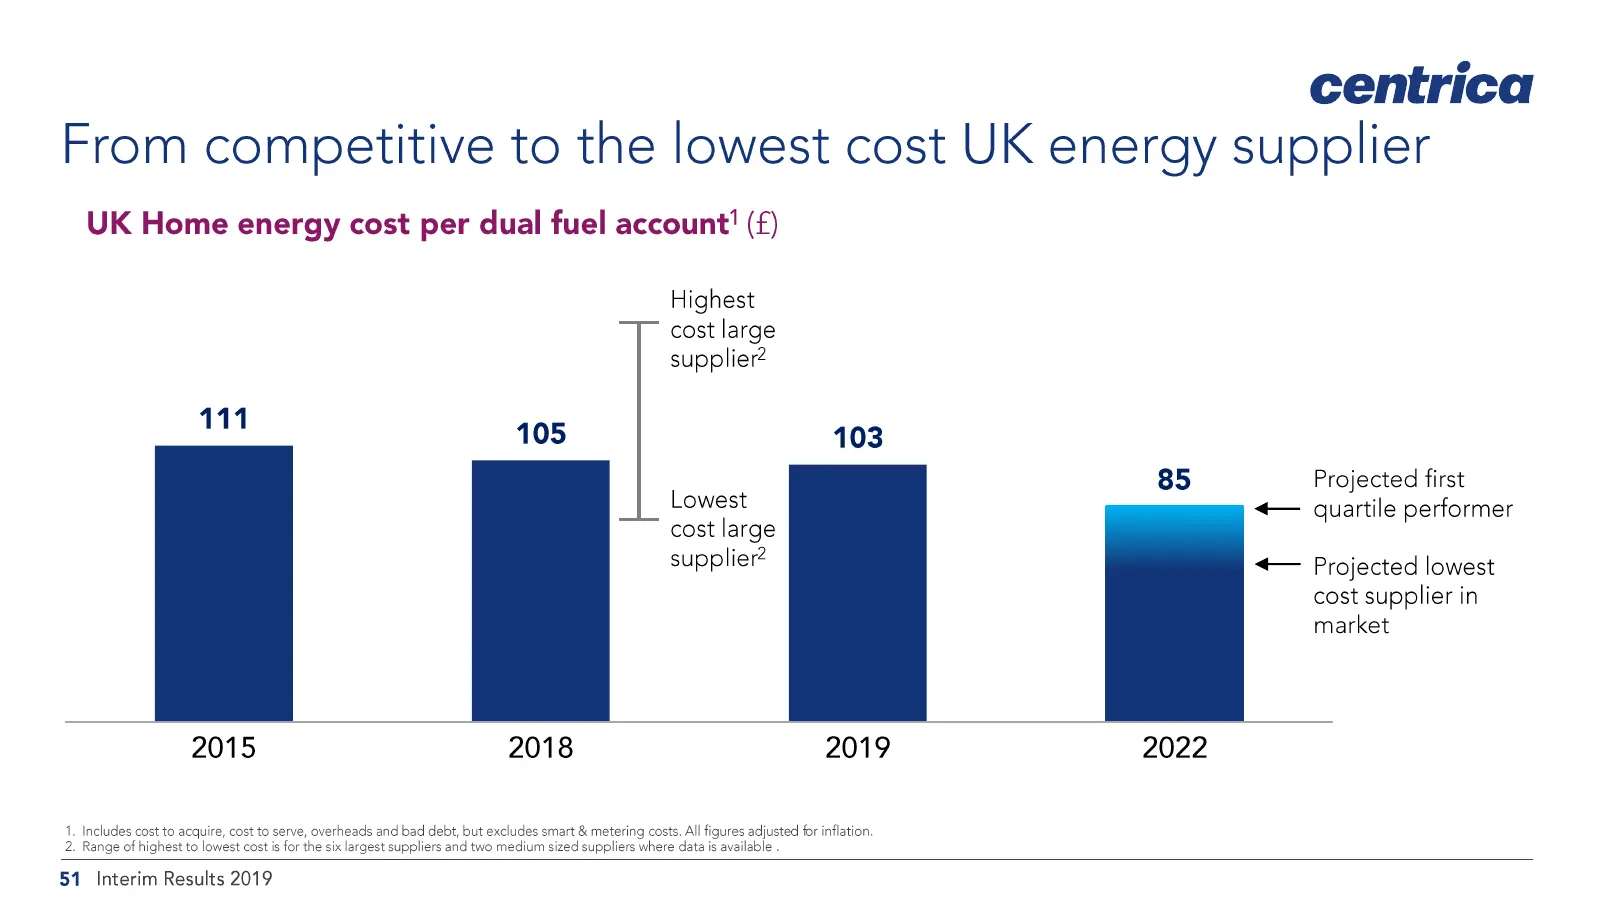
Slide 51: From competitive to the lowest cost UK energy supplier
centrica From competitive to the lowest cost UK energy supplier UK Home energy cost per dual fuel account" (f) Highest —T cost large supplier? 111 105 103 85 Projected first _|_ Lowest <— quartile performer cost large supplier? +— Projected lowest cost supplier in market 2015 2018 2019 2022 1. Inclu
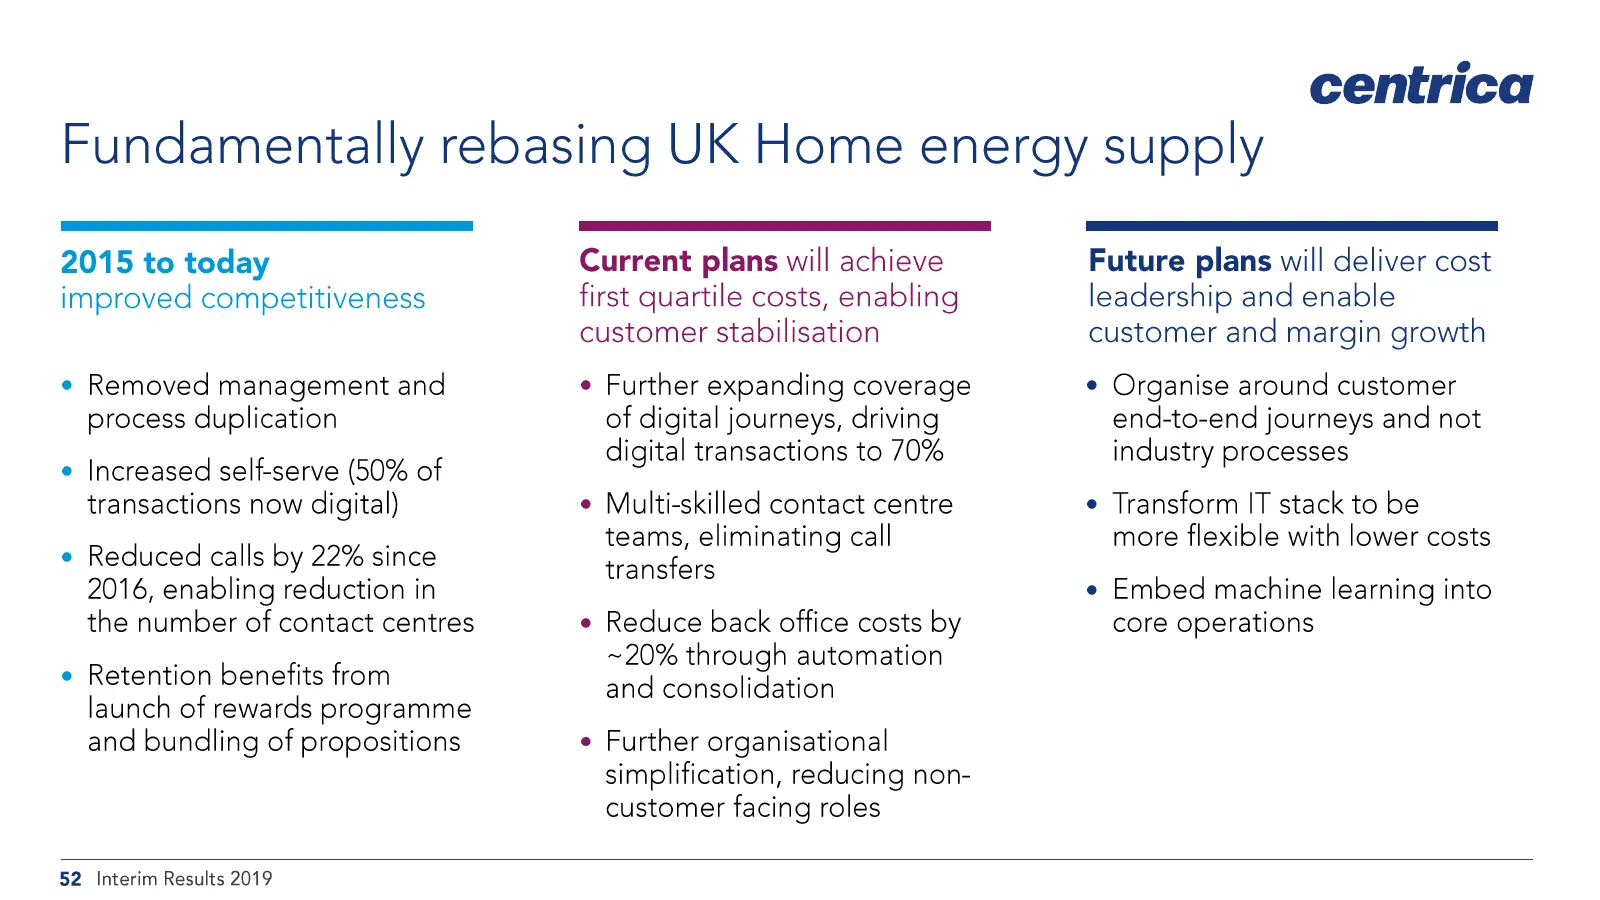
Slide 52: Fundamentally rebasing UK Home energy supply
centrica Fundamentally rebasing UK Home energy supply 2015 to today improved competitiveness e Removed management and process duplication e Increased self-serve (50% of transactions now digital) e Reduced calls by 22% since 2016, enabling reduction in the number of contact centres e Retention benefi
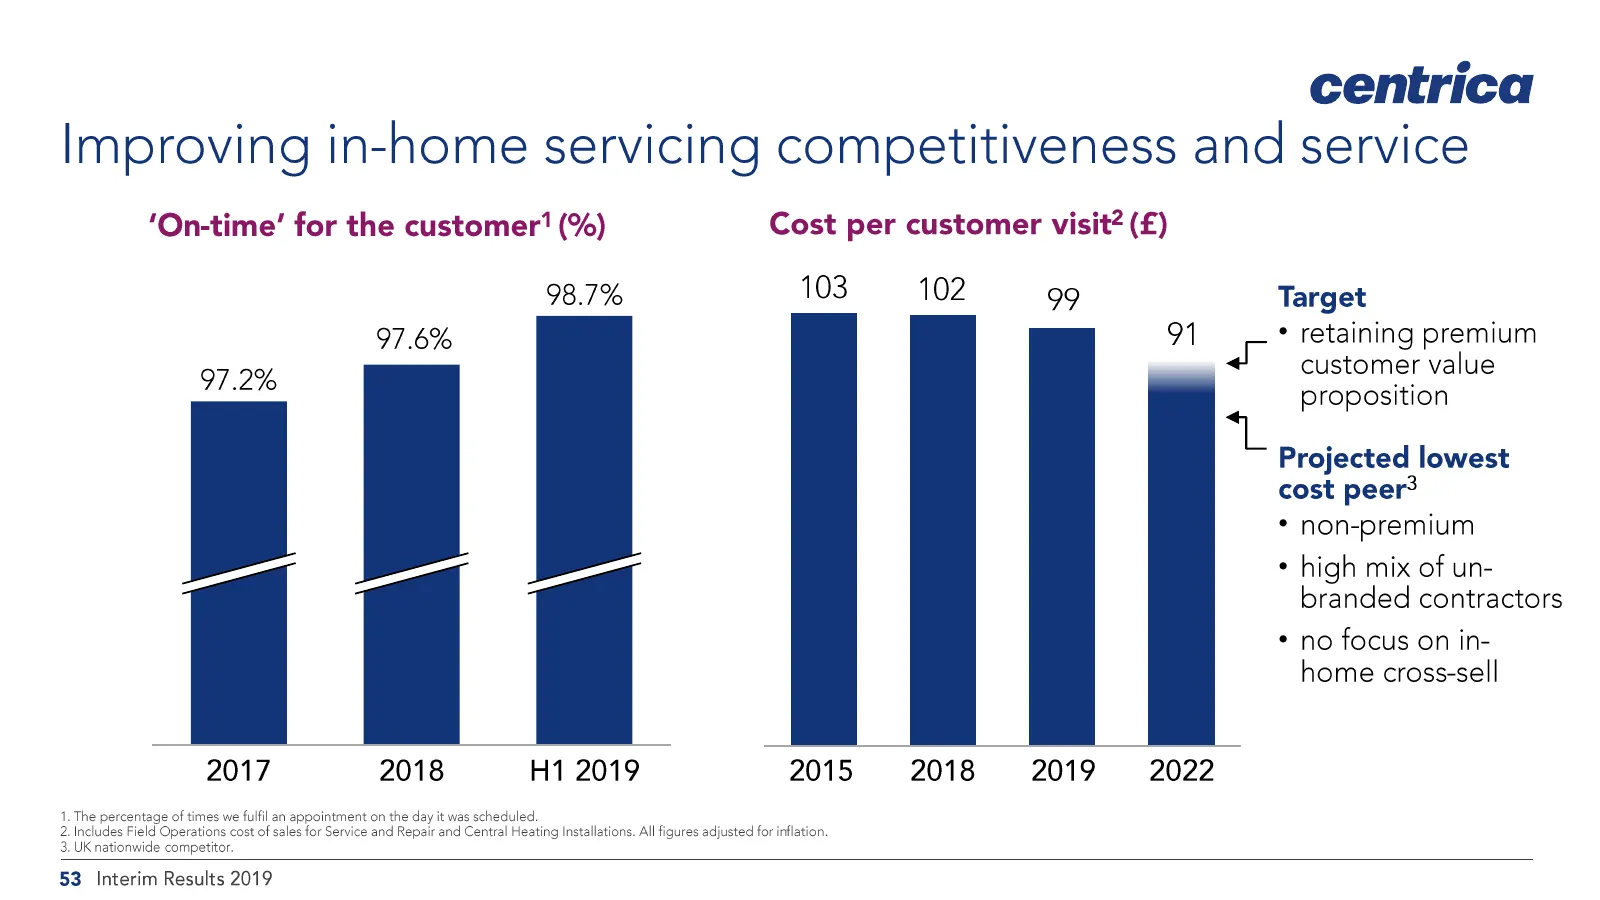
Slide 53: Improving in-home servicing competitiveness and service
centrica Improving in-home servicing competitiveness and service ‘On-time’ for the customer’ (%) Cost per customer visit? (£) 98.7% 103 102 99 Target 97.6% 91 * retaining premium < customer value 97.2% proposition Projected lowest cost peer? * non-premium * high mix of un- branded contractors * no f
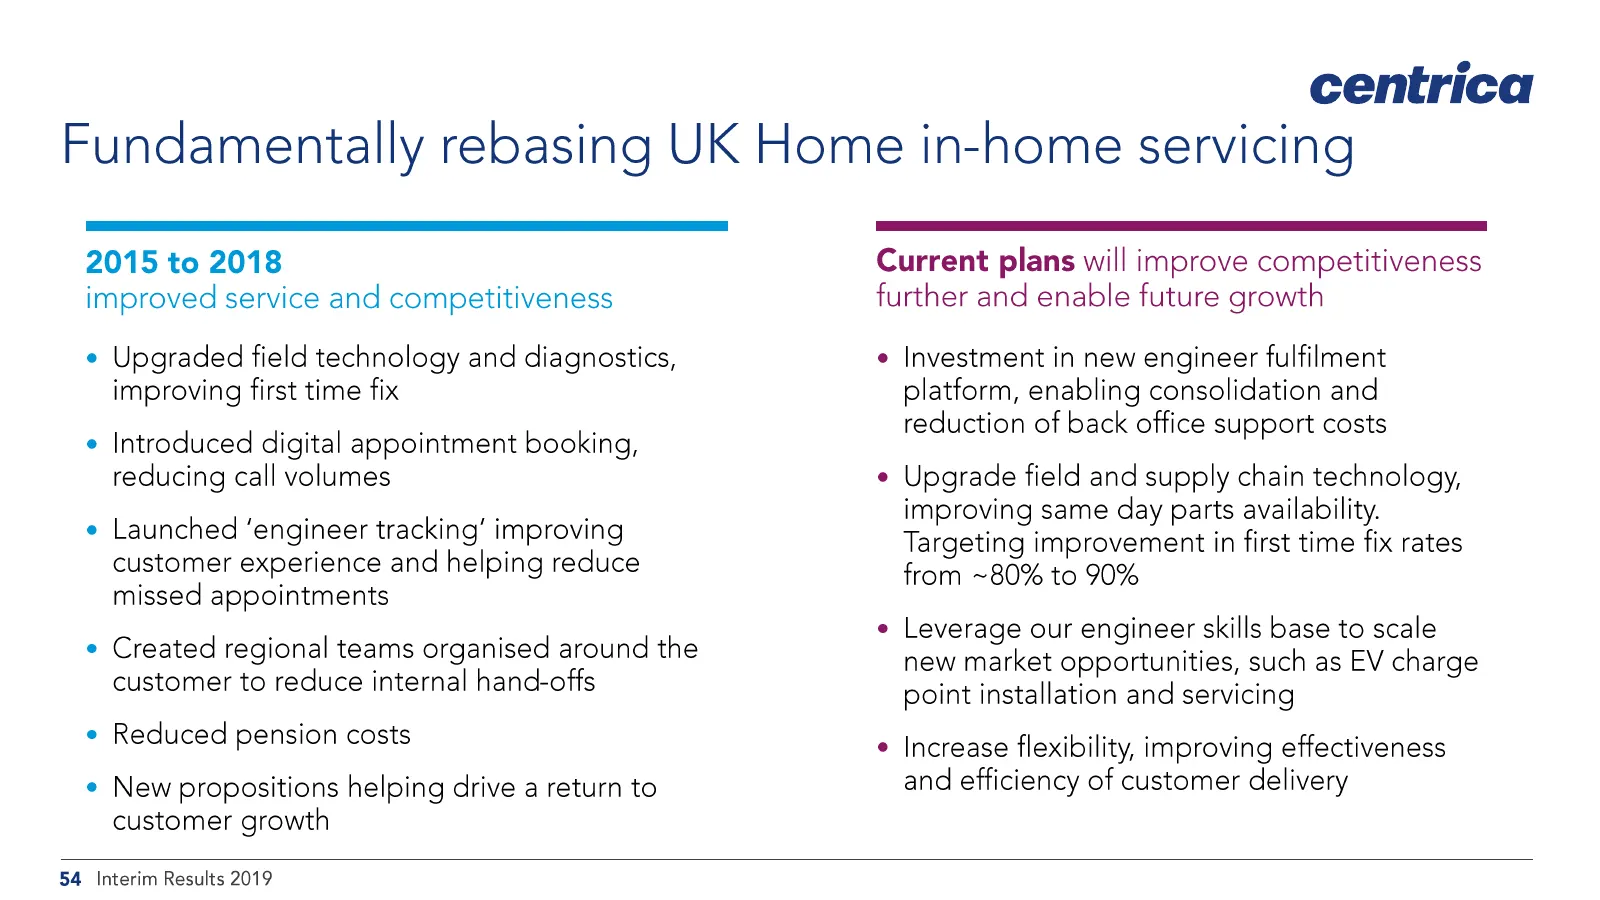
Slide 54: Fundamentally rebasing UK Home in-home servicing
centrica Fundamentally rebasing UK Home in-home servicing 2015 to 2018 improved service and competitiveness e Upgraded field technology and diagnostics, improving first time fix Introduced digital appointment booking, reducing call volumes e Launched ‘engineer tracking’ improving customer experience
Slide 55: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
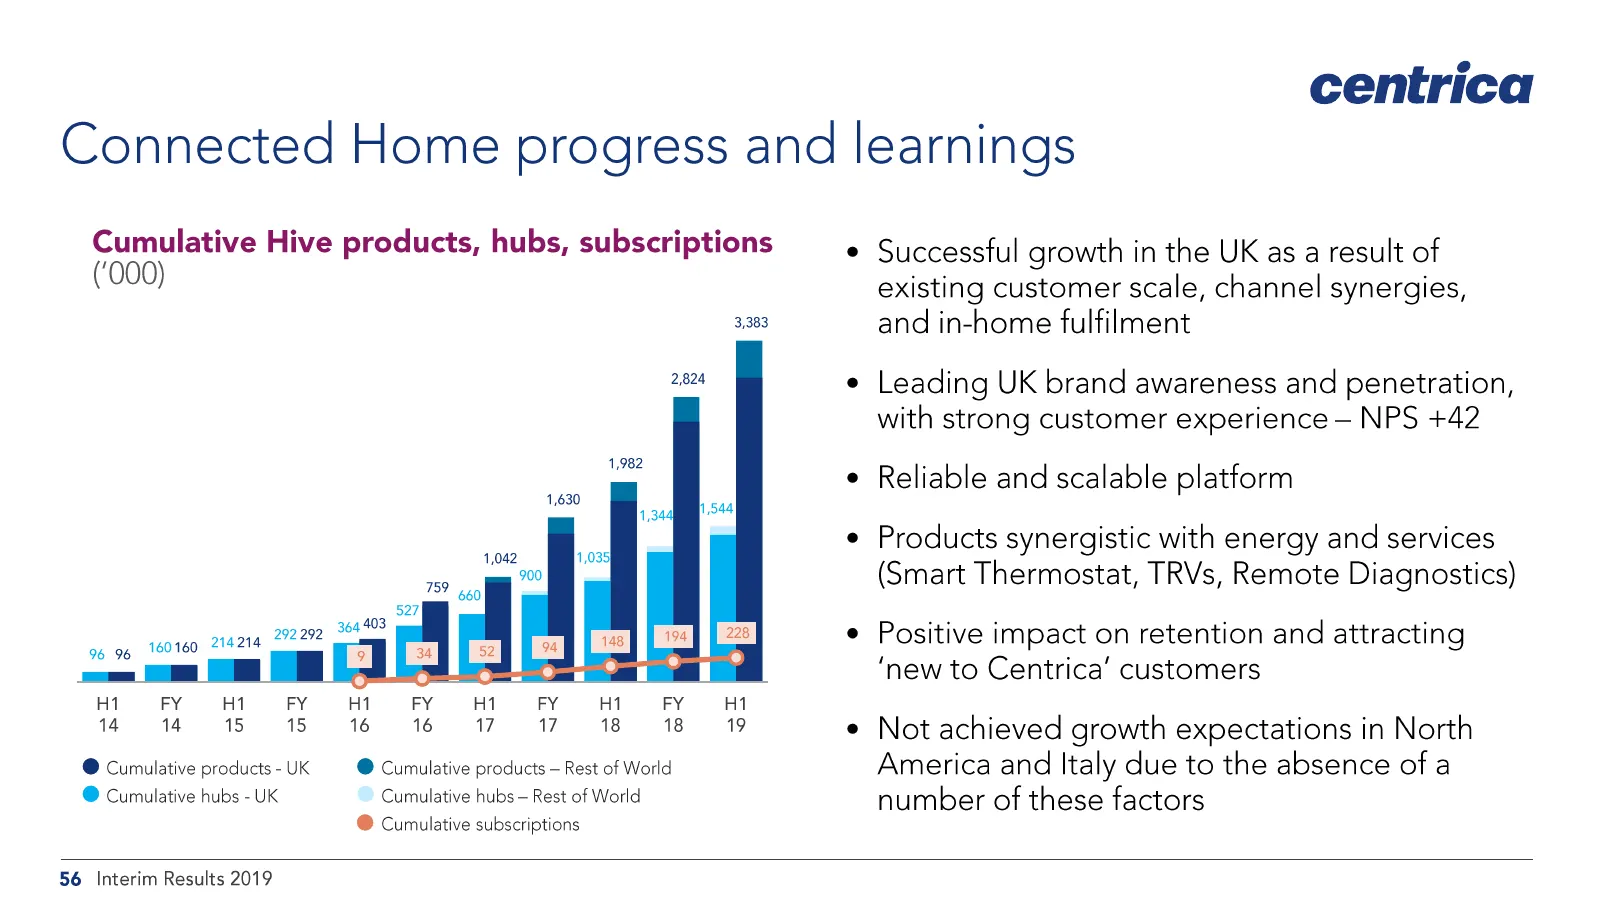
Slide 56: Connected Home progress and learnings
centrica Connected Home progress and learnings Cumulative Hive products, hubs, subscriptions (‘000) 3,383 214214 96 96 160160 H1 FY H1 FY H1 14 14 15 15 16 16 17 17 18 18 19 @ Cumulative products - UK @ Cumulative products — Rest of World @ Cumulative hubs - UK Cumulative hubs — Rest of World @ Cumu
Slide 57: Refocusing Home Solutions
centrica Refocusing Home Solutions ¢ Connected Home activity refocused on the UK and Ireland where Centrica is advantaged and renamed Centrica Home Solutions ¢ Leverage distinctive field force asset for new propositions ¢ Propositions centred around Home Energy Management and Remote Diagnostics and
Slide 58: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 59: Business energy supply in North America
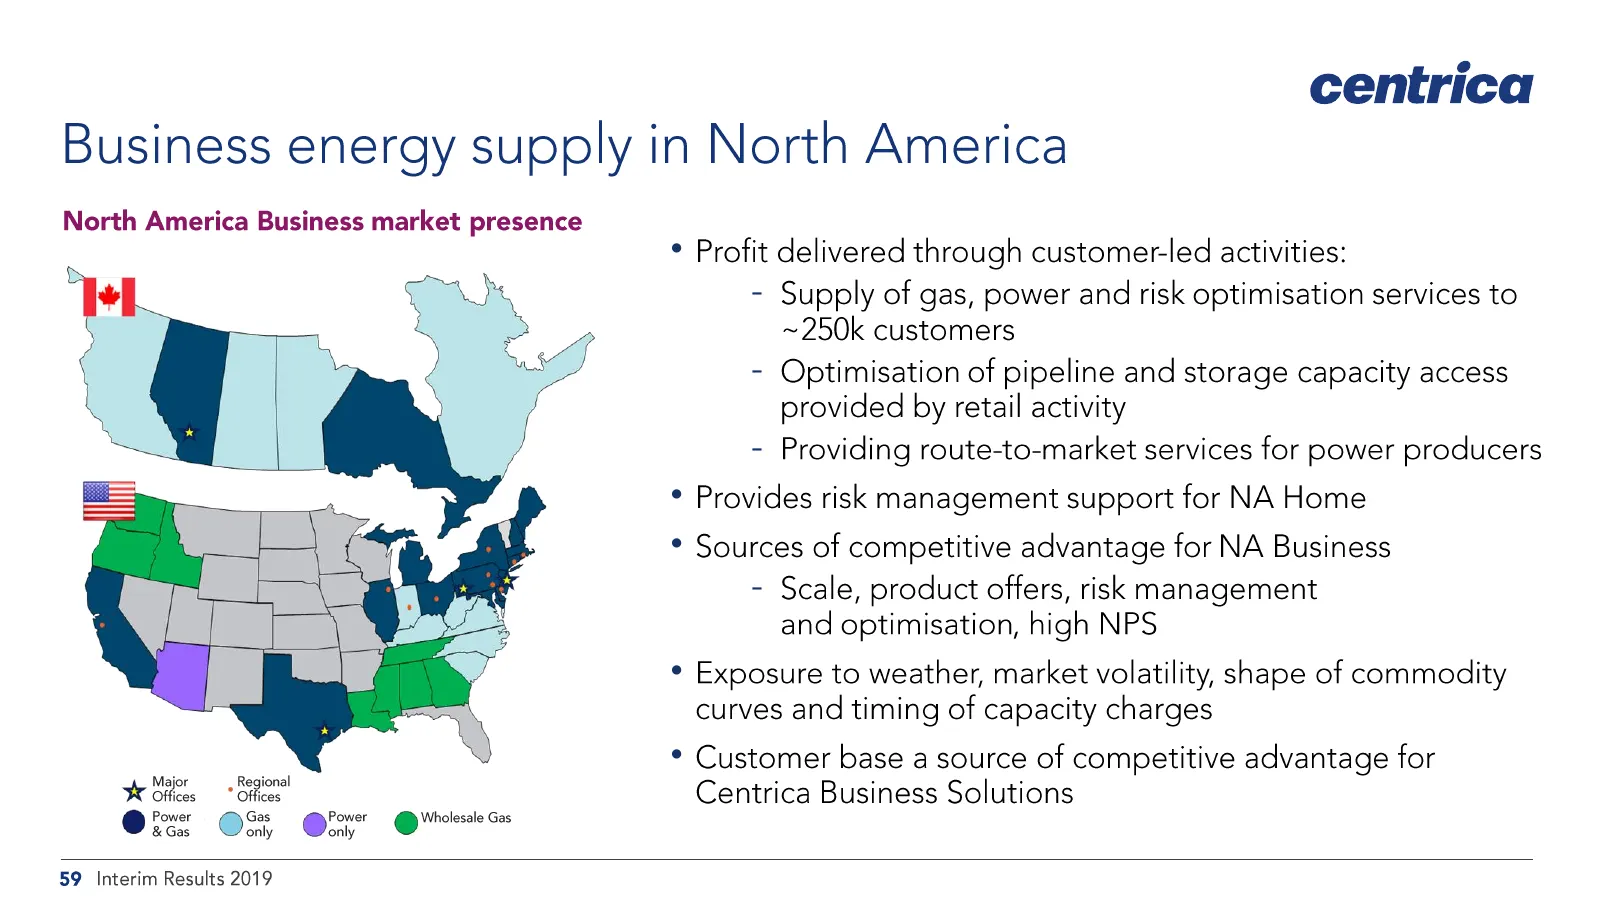
centrica Business energy supply in North America North America Business market presence * Profit delivered through customer-led activities: LN - Supply of gas, power and risk optimisation services to 4 ry . ~250k customers is } — - Optimisation of pipeline and storage capacity access / provided by r
Slide 60: North America Business performance
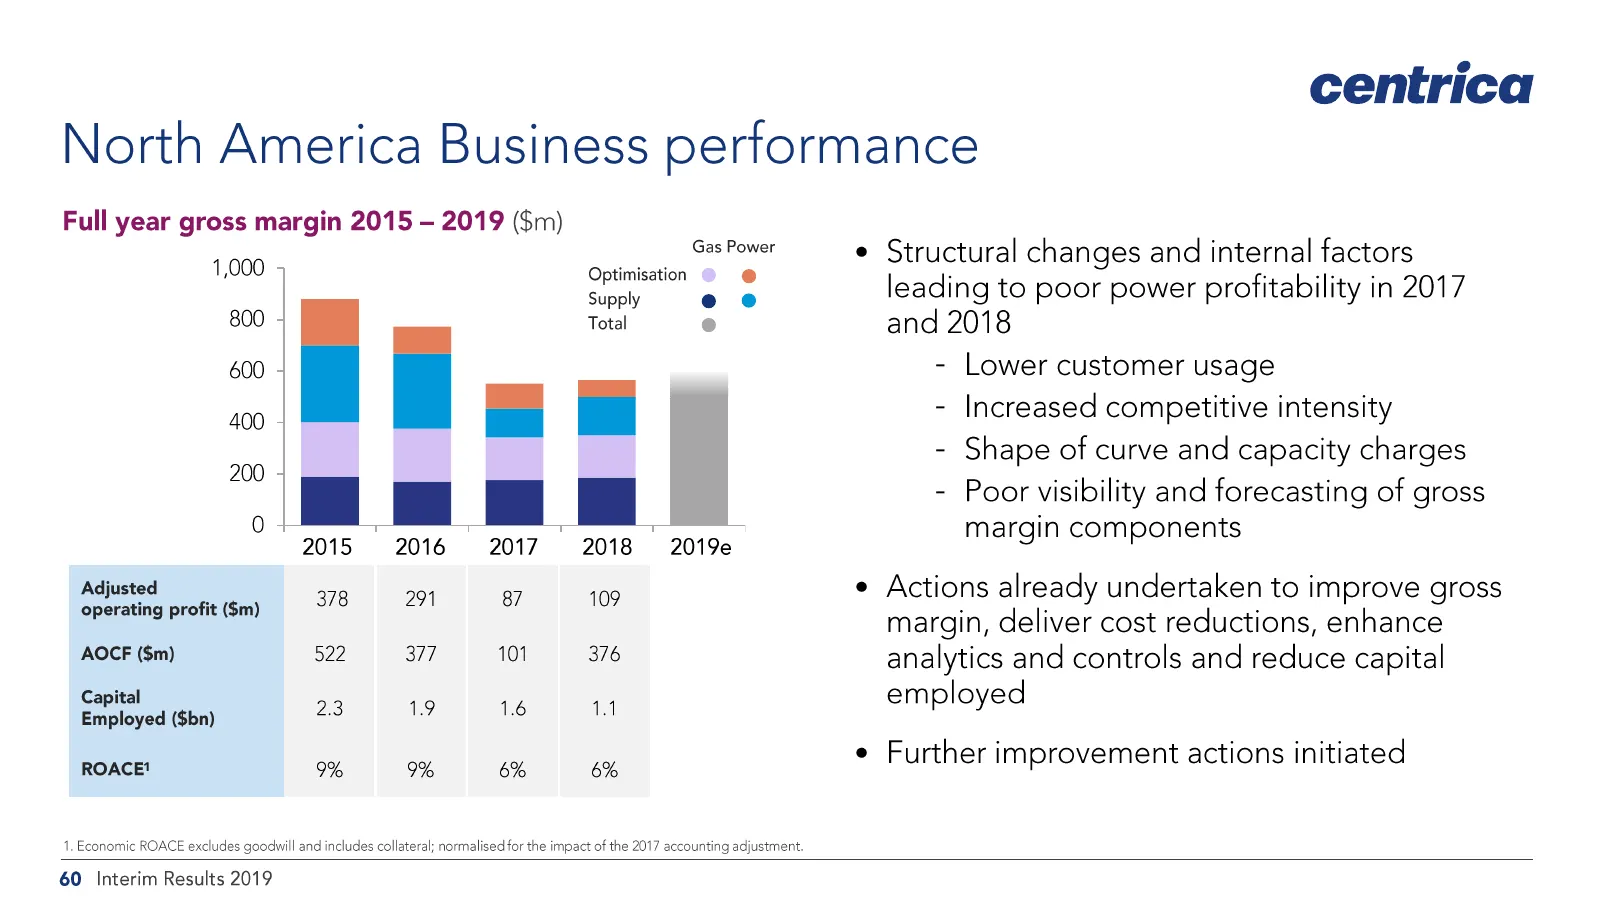
centrica North America Business performance Full year gross margin 2015 - 2019 ($m) 1,000 Gas Power ¢ Structural changes and internal factors ‘ owe 8 leading to poor power profitability in 2017 800 Total ° and 2018 600 - Lower customer usage - Increased competitive intensity Shape of curve and capac
Slide 61: Actions underway to improve returns in NAB
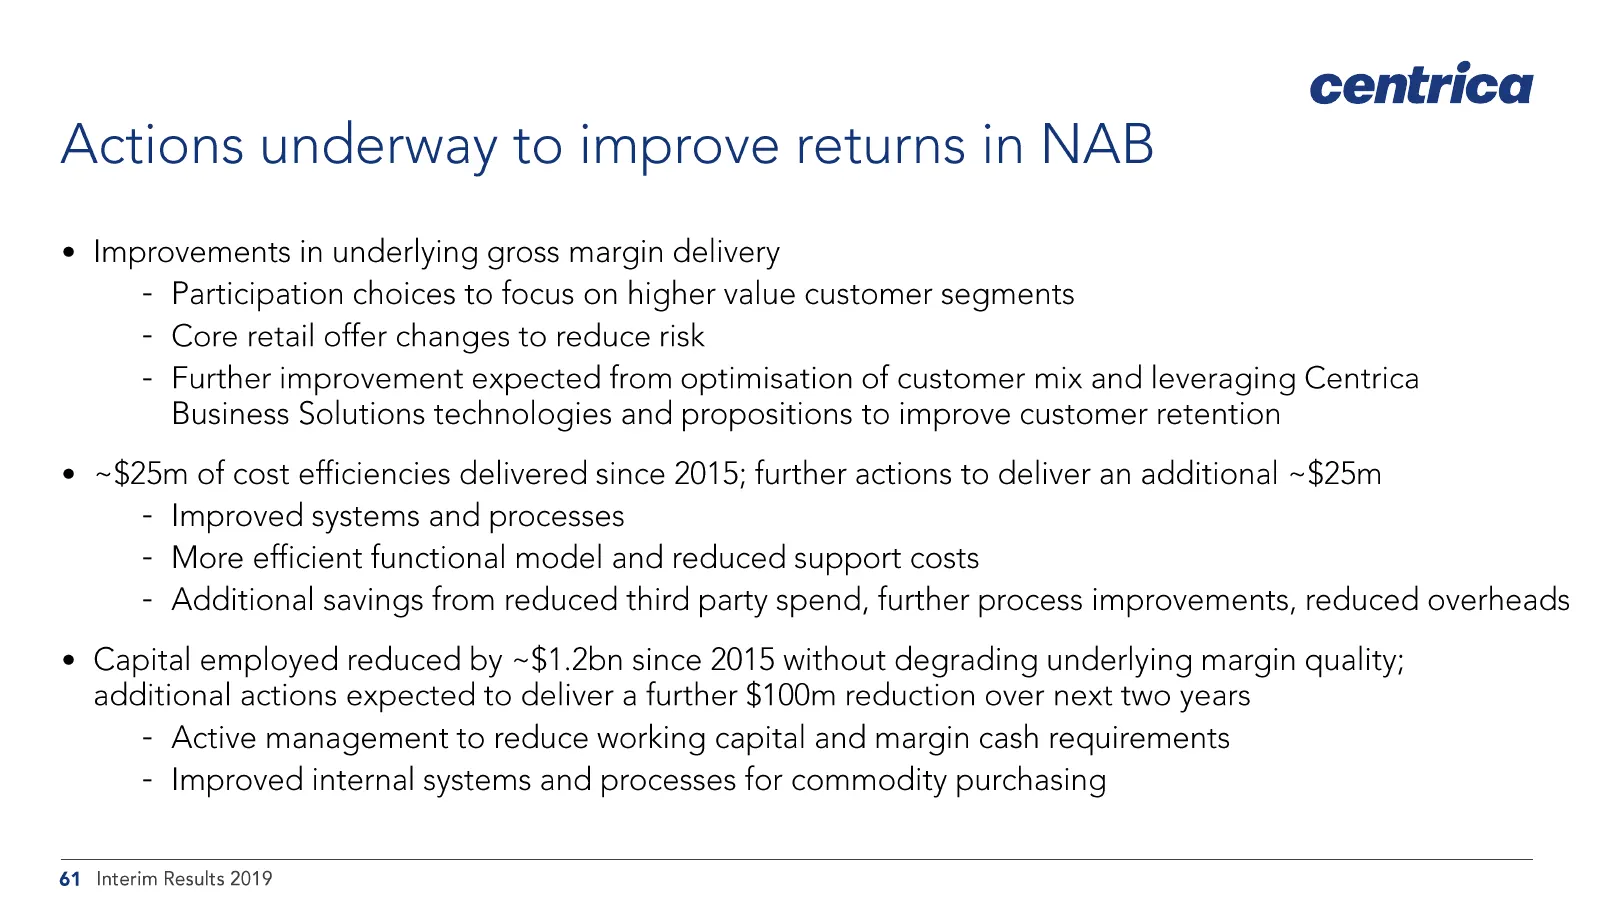
centrica Actions underway to improve returns in NAB Improvements in underlying gross margin delivery - Participation choices to focus on higher value customer segments - Core retail offer changes to reduce risk - Further improvement expected from optimisation of customer mix and leveraging Centrica
Slide 62: North America Business outlook
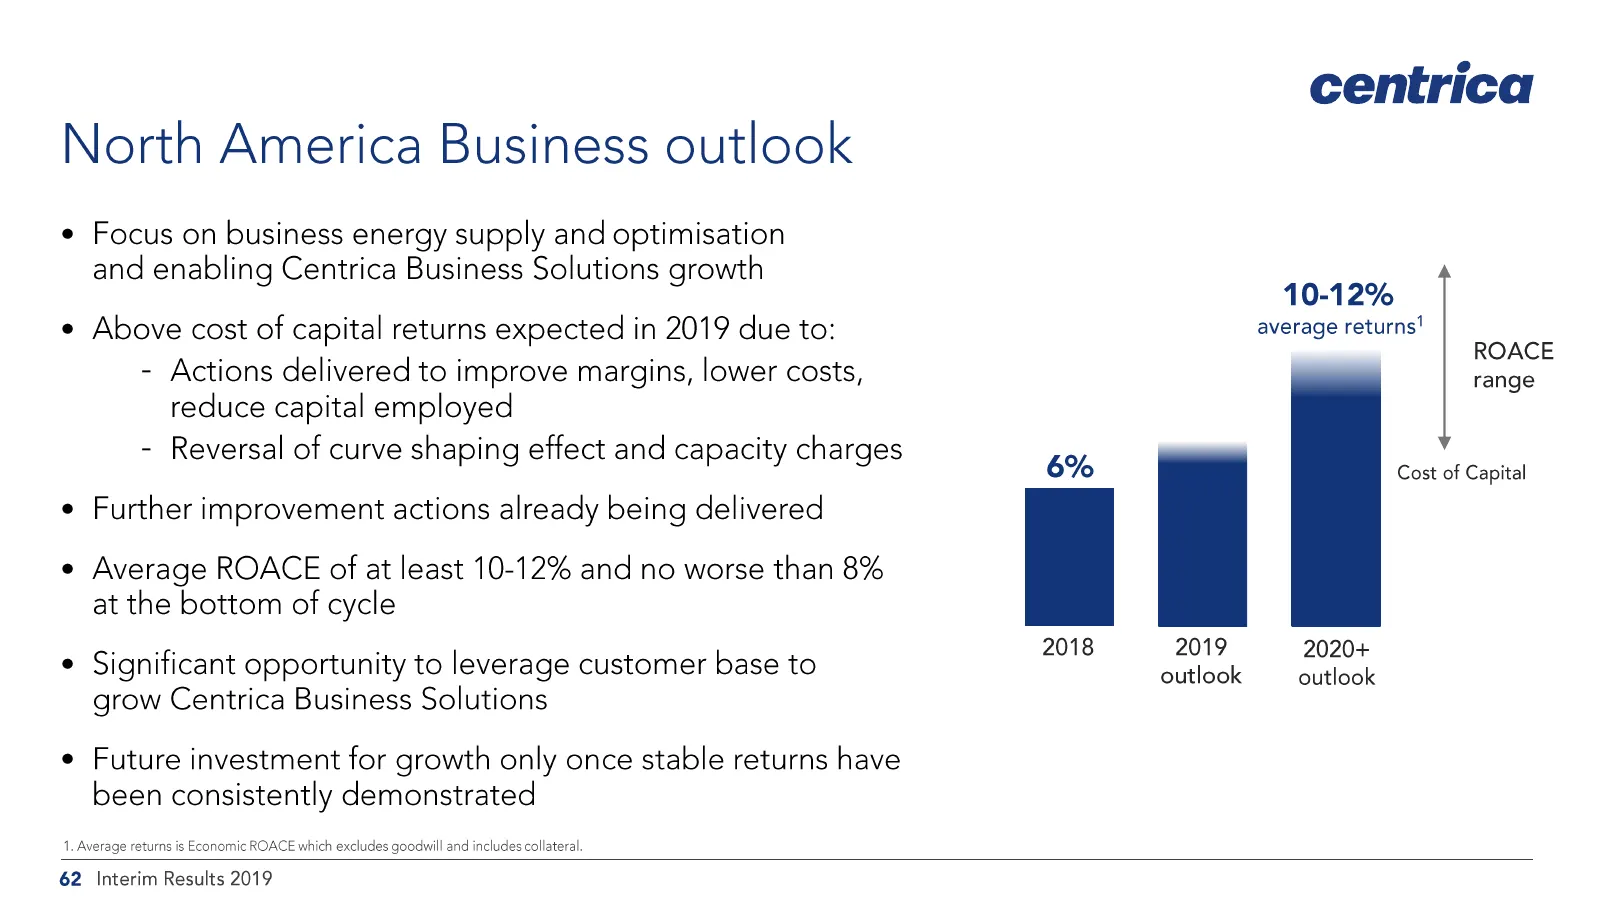
North America Business outlook ¢ Focus on business energy supply and optimisation and enabling Centrica Business Solutions growth ¢ Above cost of capital returns expected in 2019 due to: - Actions delivered to improve margins, lower costs, reduce capital employed - Reversal of curve shaping effect a
Slide 63: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 64: Centrica Business Solutions progress
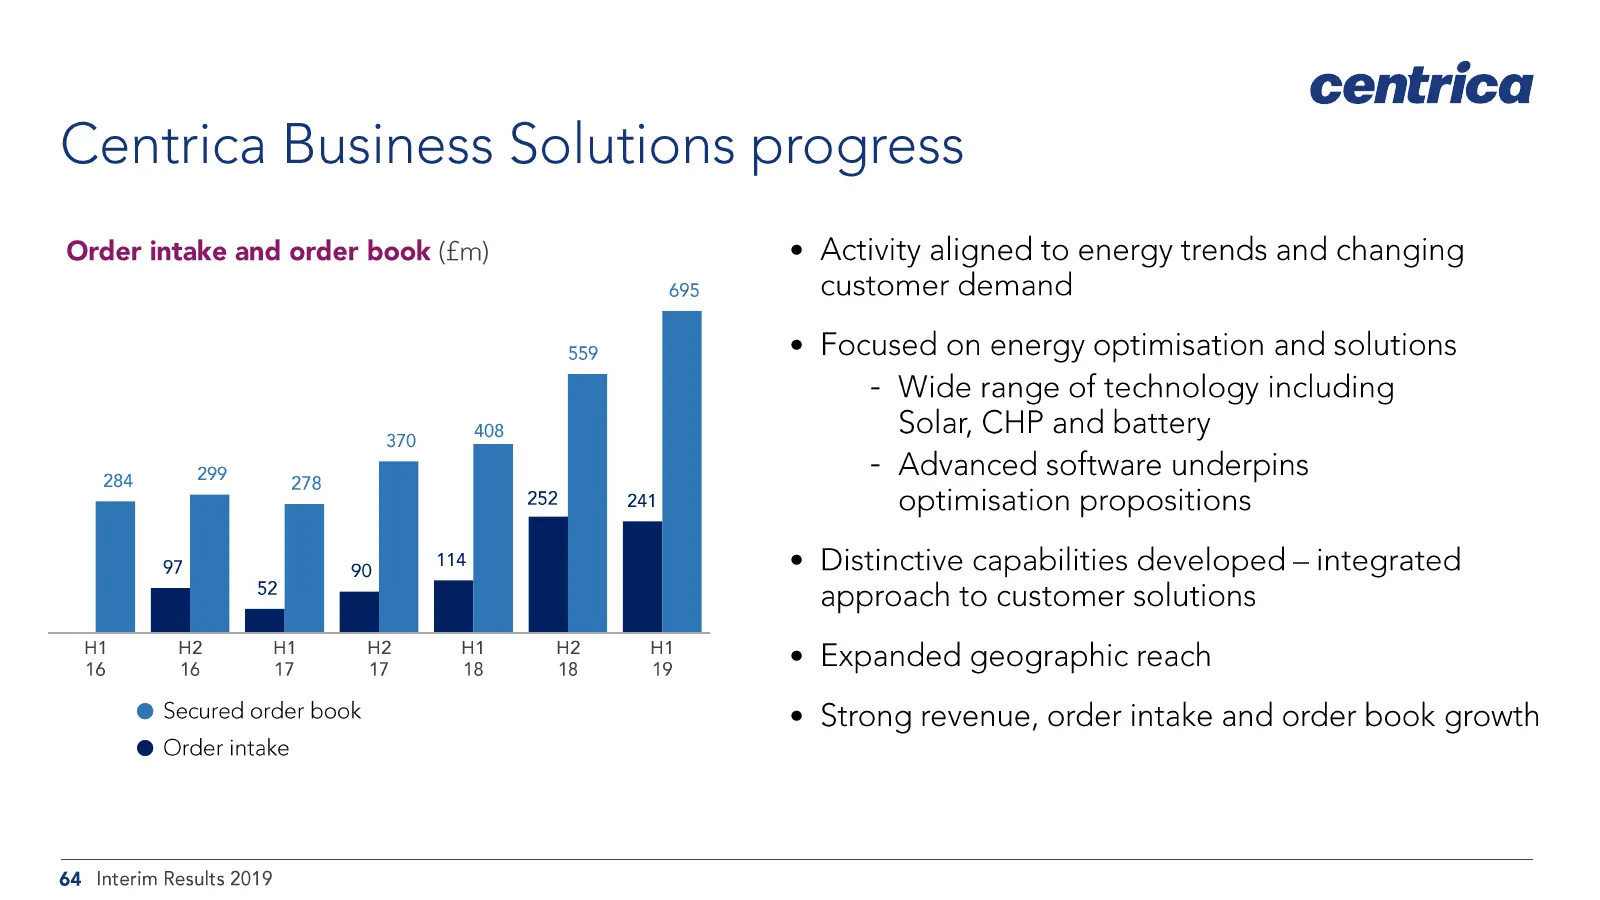
centrica Centrica Business Solutions progress Order intake and order book (£m) H2 H1 H2 16 16 17 17 @ Secured order book @ Order intake 18 18 19 Activity aligned to energy trends and changing customer demand Focused on energy optimisation and solutions - Wide range of technology including Solar, CHP
Slide 65: Growing Centrica Business Solutions
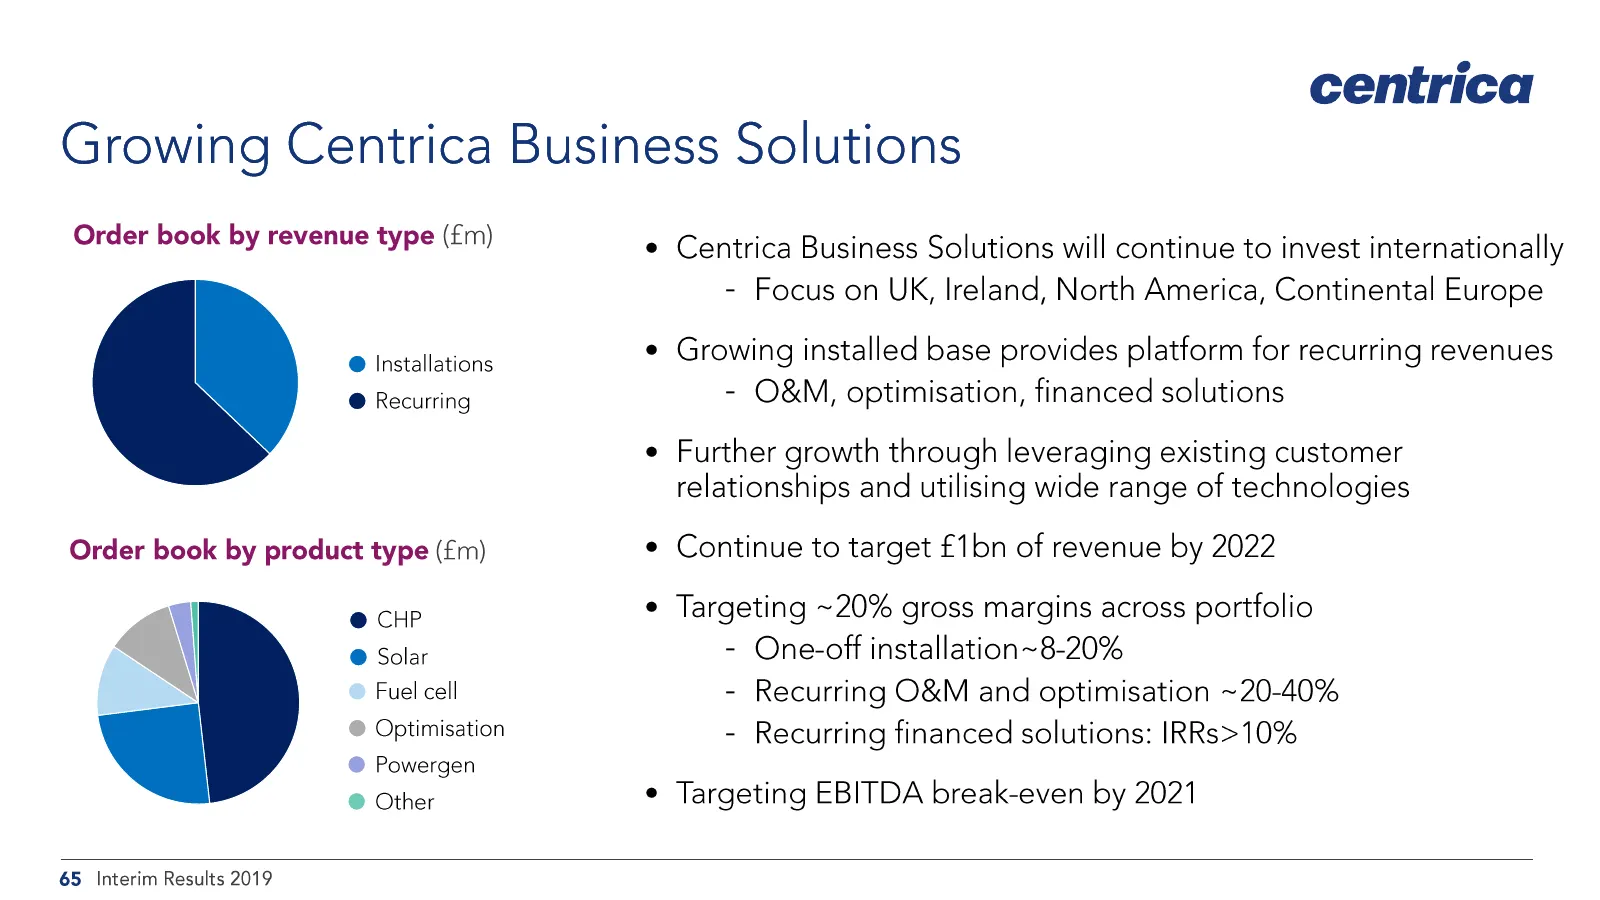
centrica Growing Centrica Business Solutions Order book by revenue type (fm) Centrica Business Solutions will continue to invest internationally - Focus on UK, Ireland, North America, Continental Europe ¢ Growing installed base provides platform for recurring revenues - O&M, optimisation, financed s
Slide 66: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
Slide 67: HEM EV
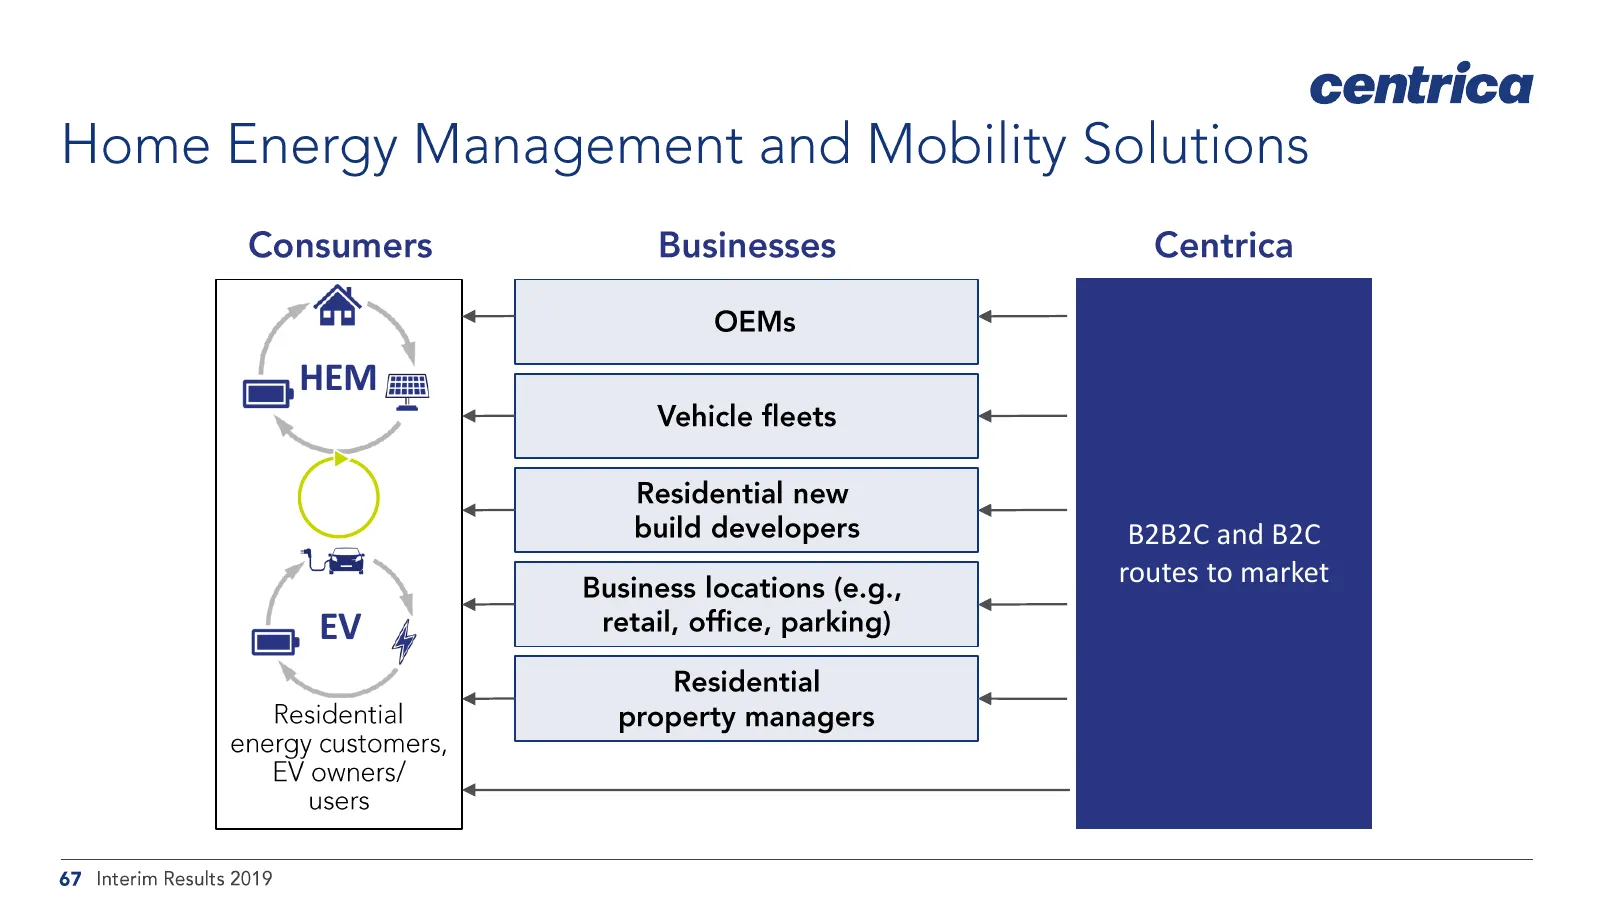
HEM B2B2C and B2C routes to market EV
Slide 68: Exclusive partnership with Ford in the UK and Ireland
centrica Exclusive partnership with Ford in the UK and Ireland centrica
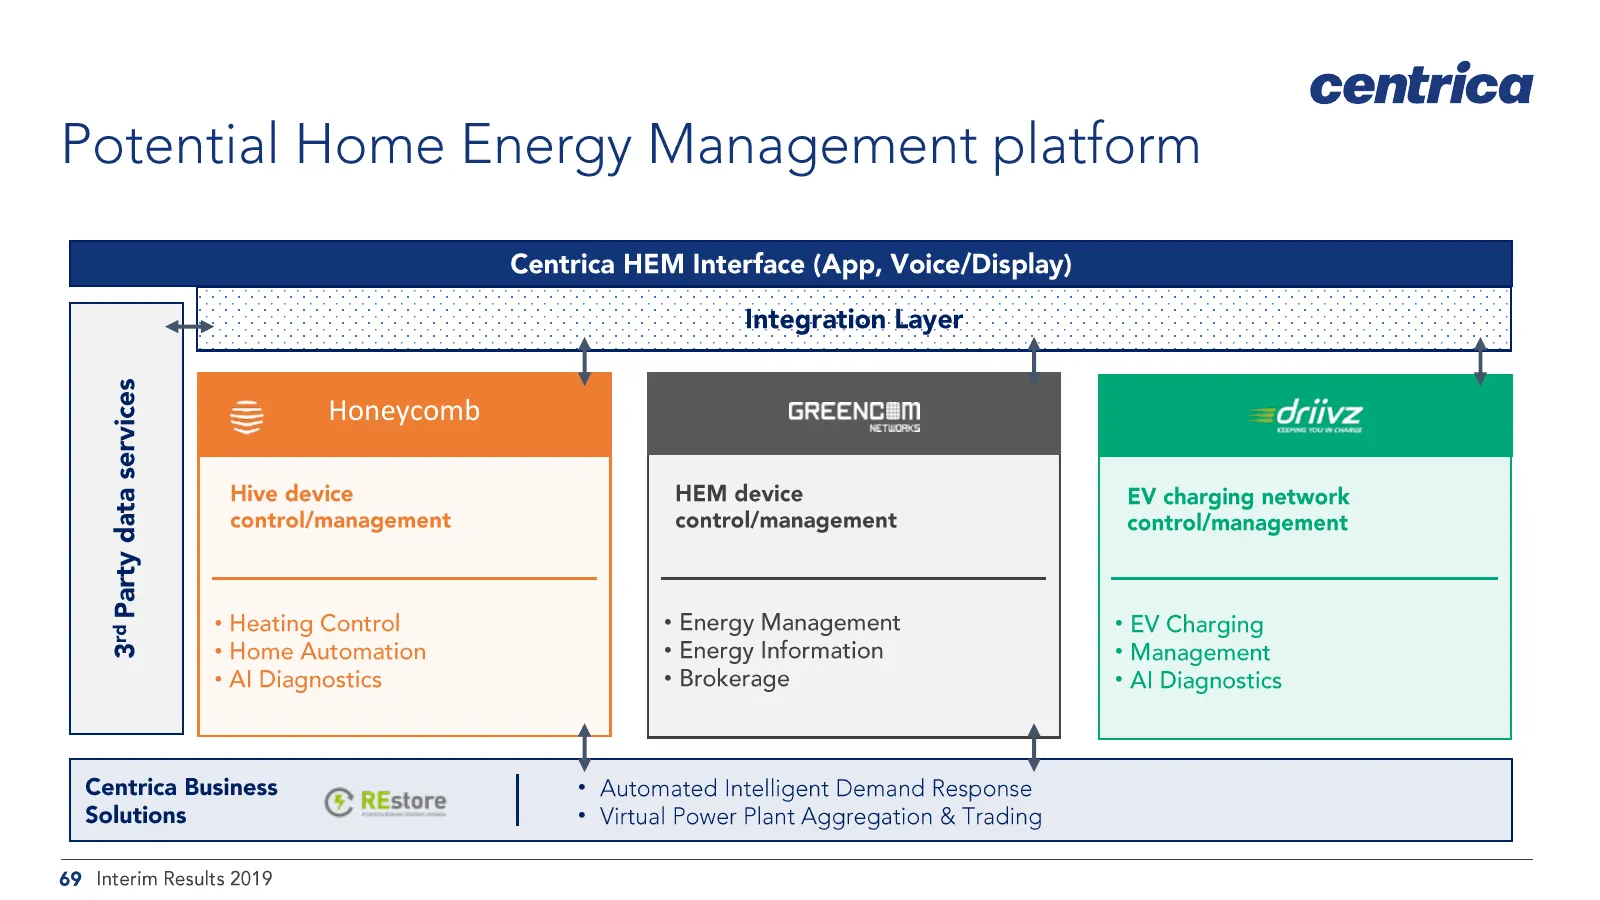
Slide 69: Honeycomb: Potential Home Energy Management platform
centrica Potential Home Energy Management platform Centrica HEM Interface (App, Voice/Display) 3 u = Honeycomb GREENCEM = = NETWORKS a sg Hive device HEM device EV charging network 8 control/management control/management control/management 5 3 + Heating Control + Energy Management * EV Charging o +
Slide 70: Agenda
centrica Agenda ¢ Group purpose and strategy e Performance agenda ¢ Cost efficiency and transformation ¢ Rebasing UK Home ¢ Centrica Home Solutions — refocusing Connected Home ¢ Improving returns in North America Business ¢ Growing Centrica Business Solutions ¢ Securing the capabilities for 2020 and
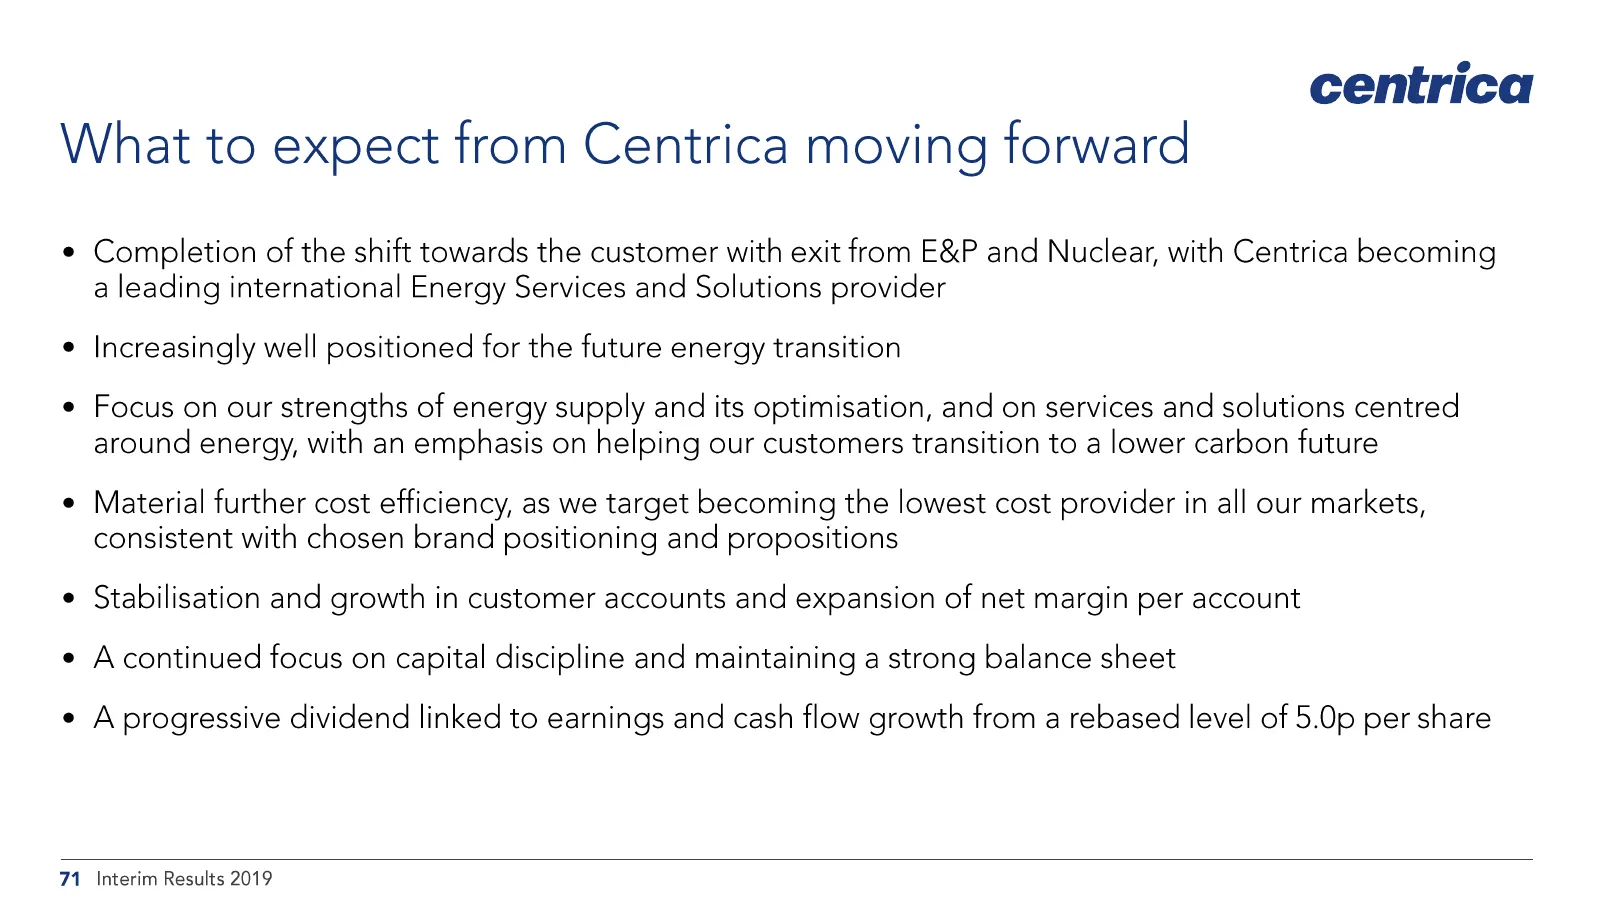
Slide 71: What to expect from Centrica moving forward
centrica What to expect from Centrica moving forward ¢ Completion of the shift towards the customer with exit from E&P and Nuclear, with Centrica becoming a leading international Energy Services and Solutions provider ¢ Increasingly well positioned for the future energy transition ¢ Focus on our str
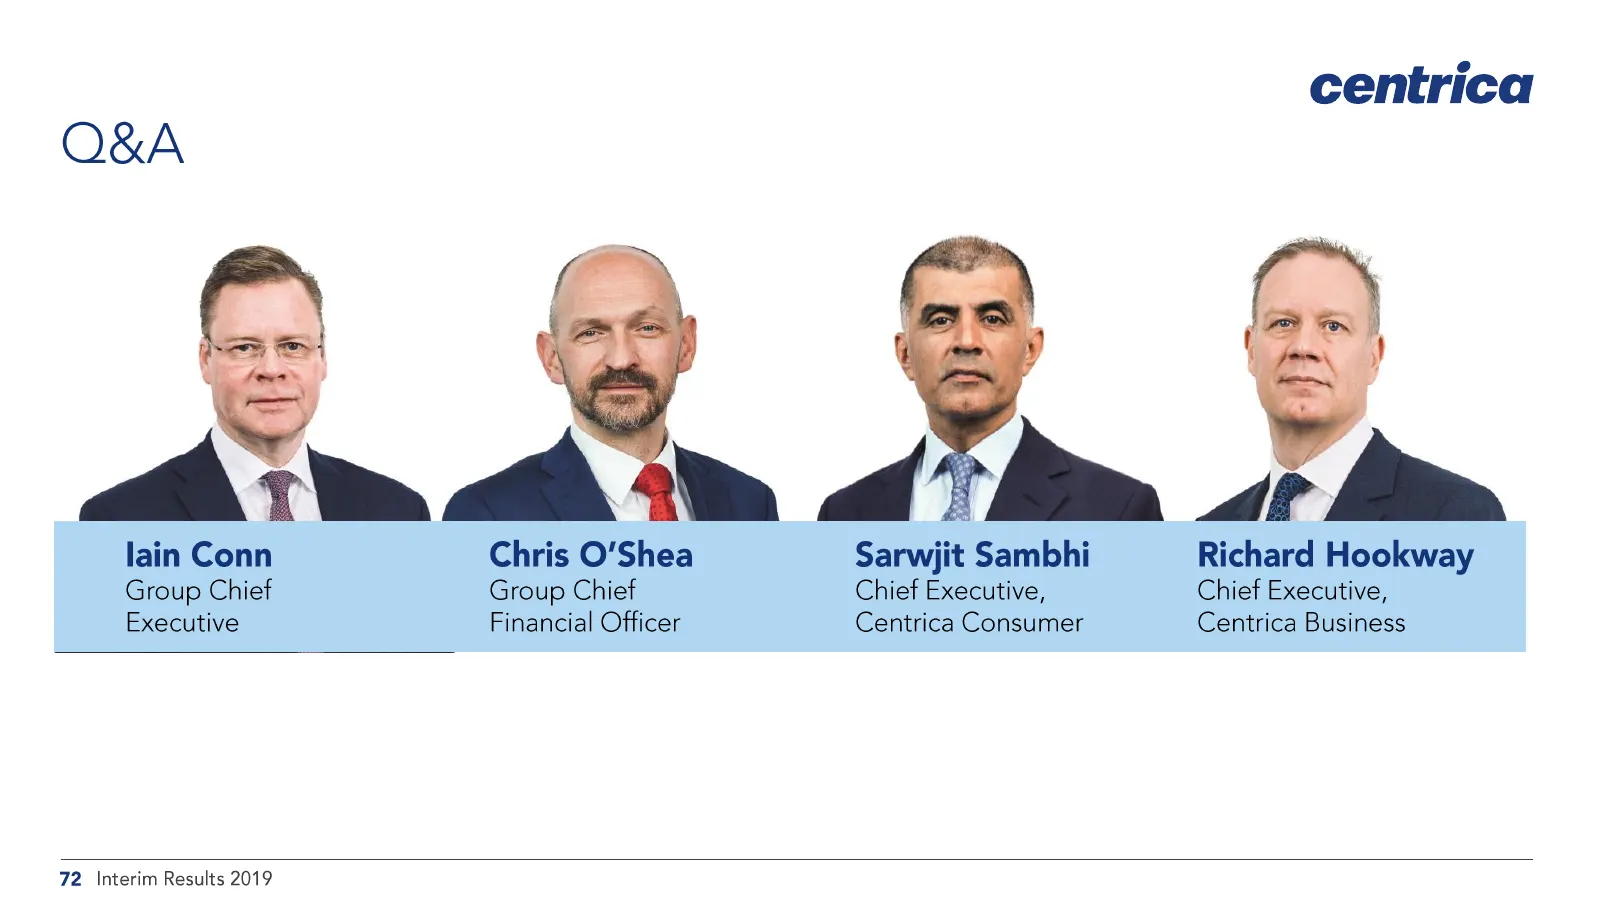
Slide 72: Q&A
centrica Q&A 72. Interim Results 2019
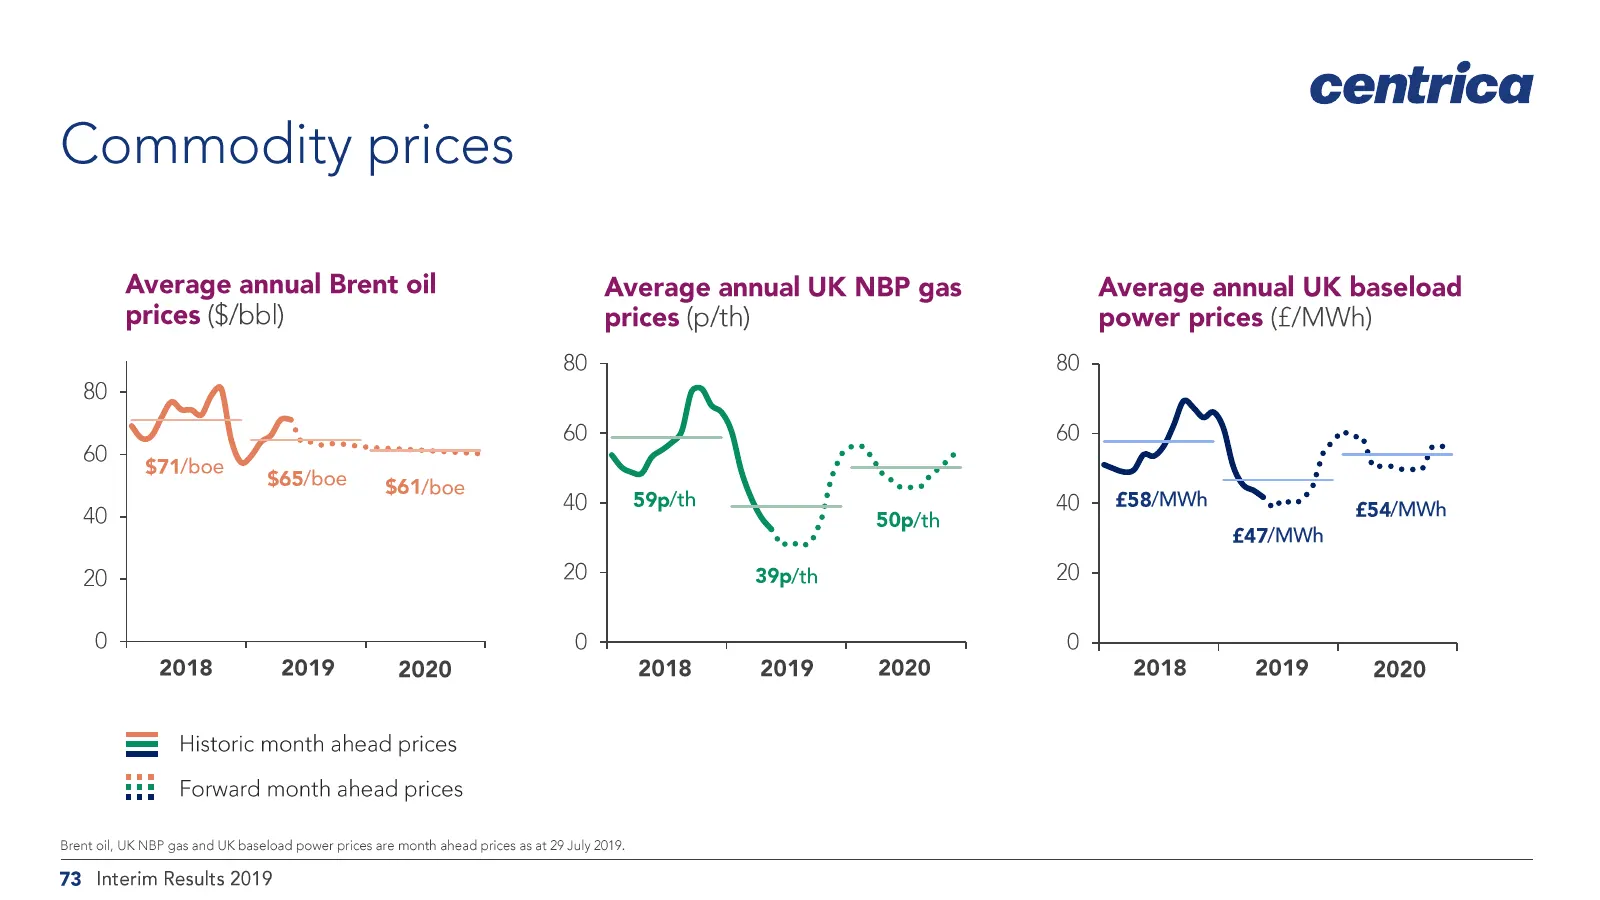
Slide 73: Commodity prices
Commodity prices Average annual Brent oil Average annual UK NBP gas centrica Average annual UK baseload prices ($/bbl) prices (p/th) power prices (£/MWh) 80 80 80 a 60 60 $71/boe : oe $65/boe $6 41/boe oe £58/MWh : 40 40 50p/th 40 “et £54/MWh teeet £47/MWh 20 20 39p/th 20 of + r 1 o4 04 : 1 1 2018 2
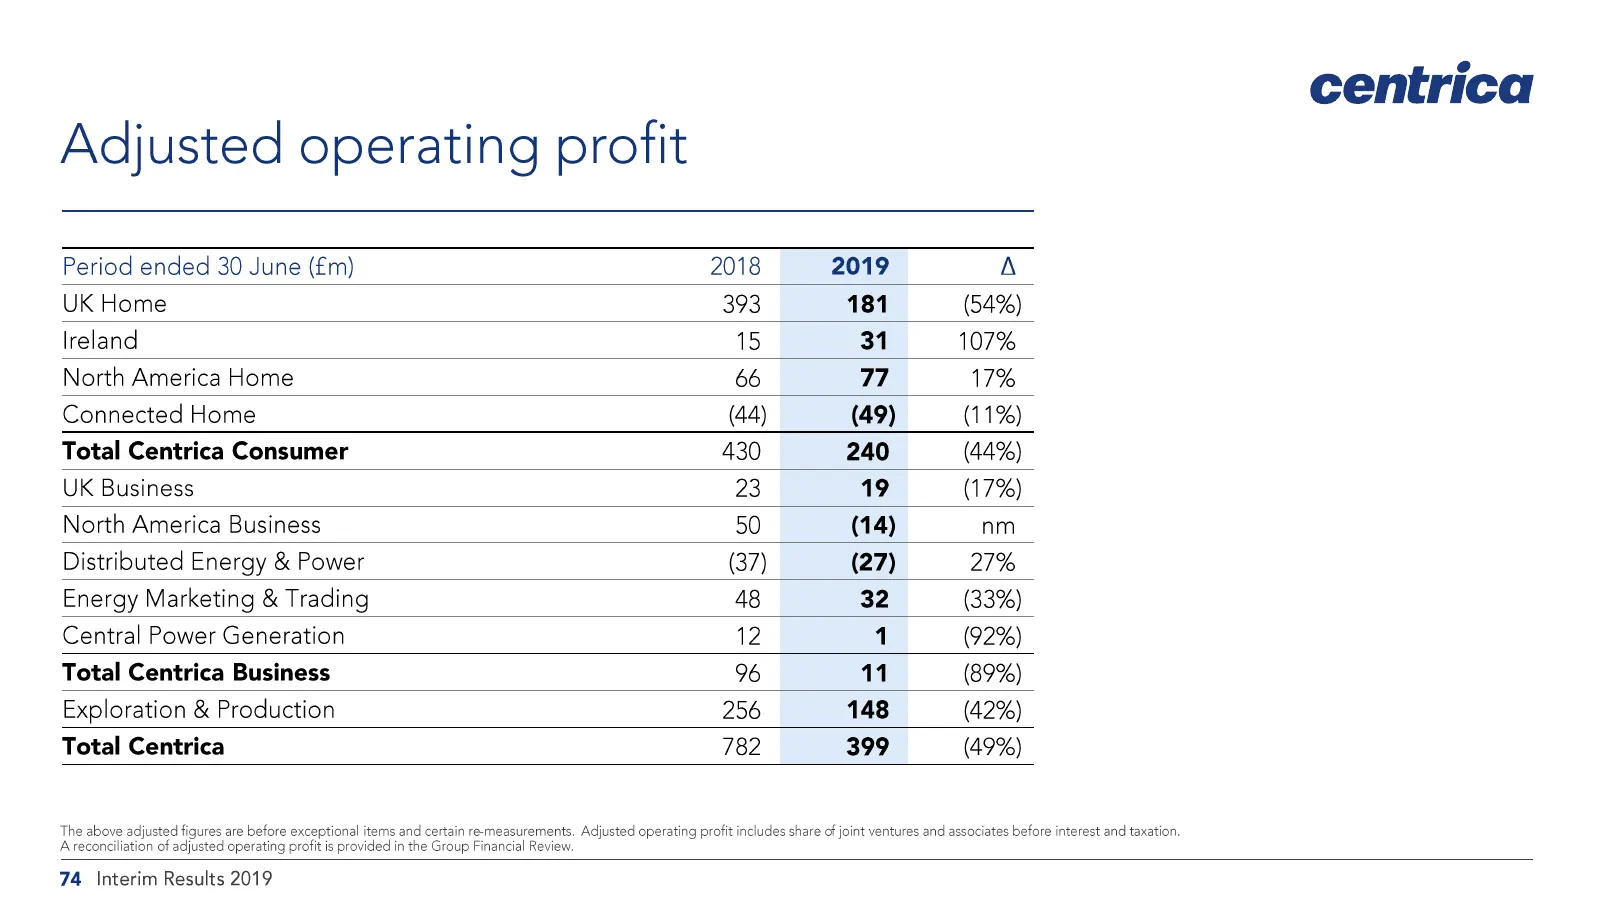
Slide 74: Adjusted operating profit
centrica Adjusted operating profit Period ended 30 June (£m) 2018 2019 A UK Home 393 181 (54%) Ireland 15 31 107% North America Home 66 77 17% Connected Home (44) (49) (11%) Total Centrica Consumer 430 240 (44%) UK Business 23 19 (17%) North America Business 50 (14) nm Distributed Energy & Power (37
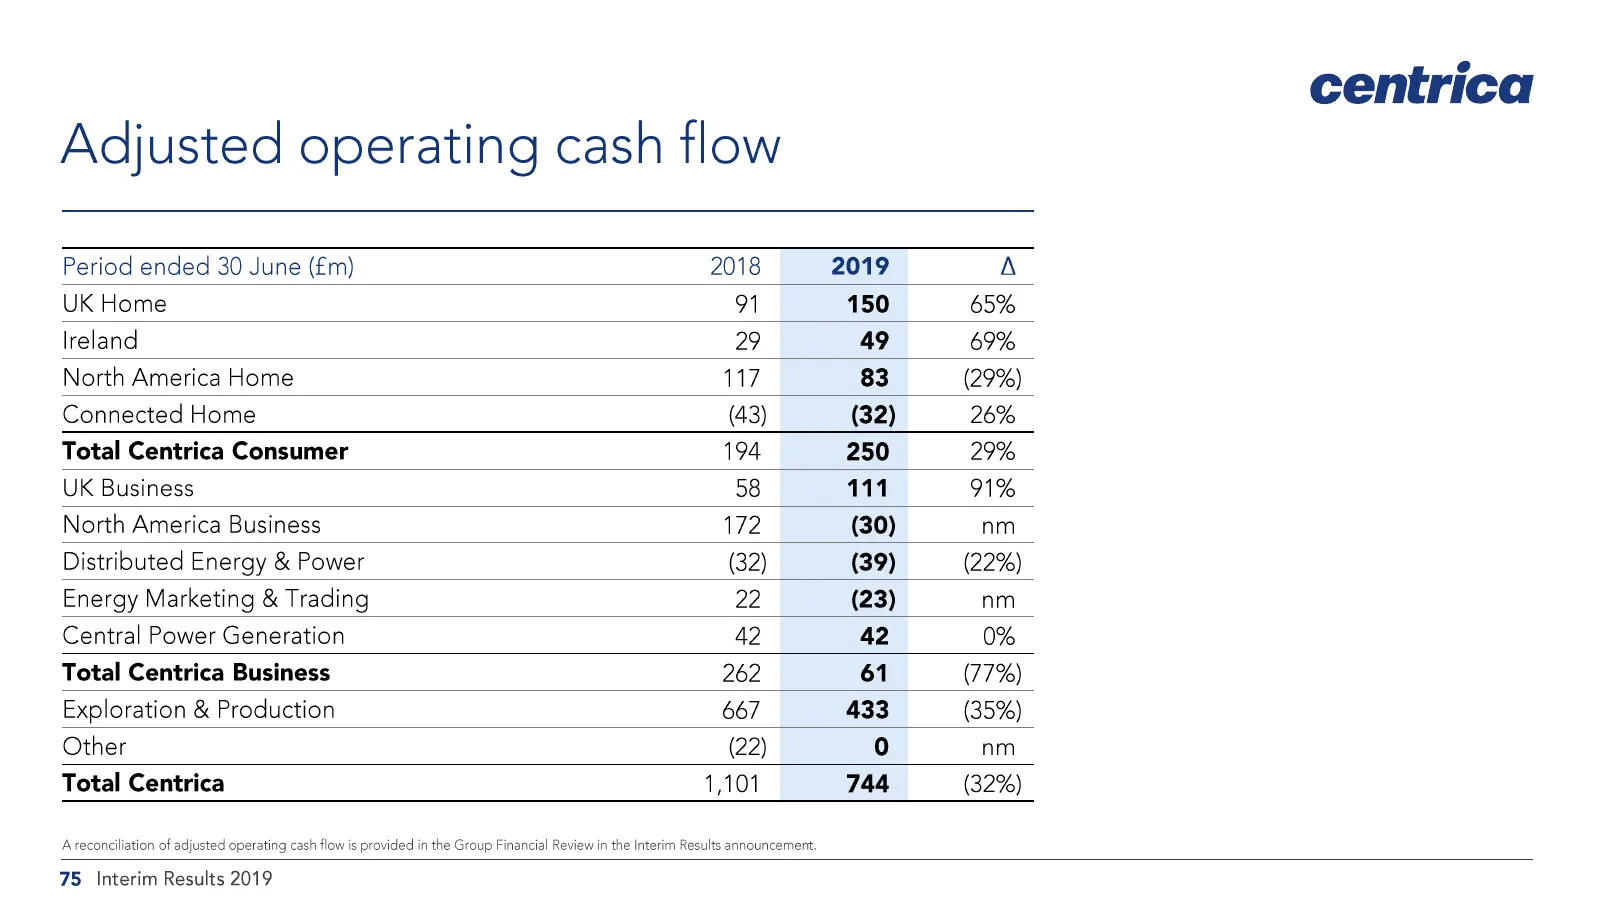
Slide 75: Adjusted operating cash flow
Adjusted operating cash flow Period ended 30 June (£m) 2018 2019 A UK Home 91 150 65% Ireland 29 49 69% North America Home 117 83 (29%) Connected Home (43) (32) 26% Total Centrica Consumer 194 250 29% UK Business 58 111 91% North America Business 172 (30) nm Distributed Energy & Power (32) (39) (22%
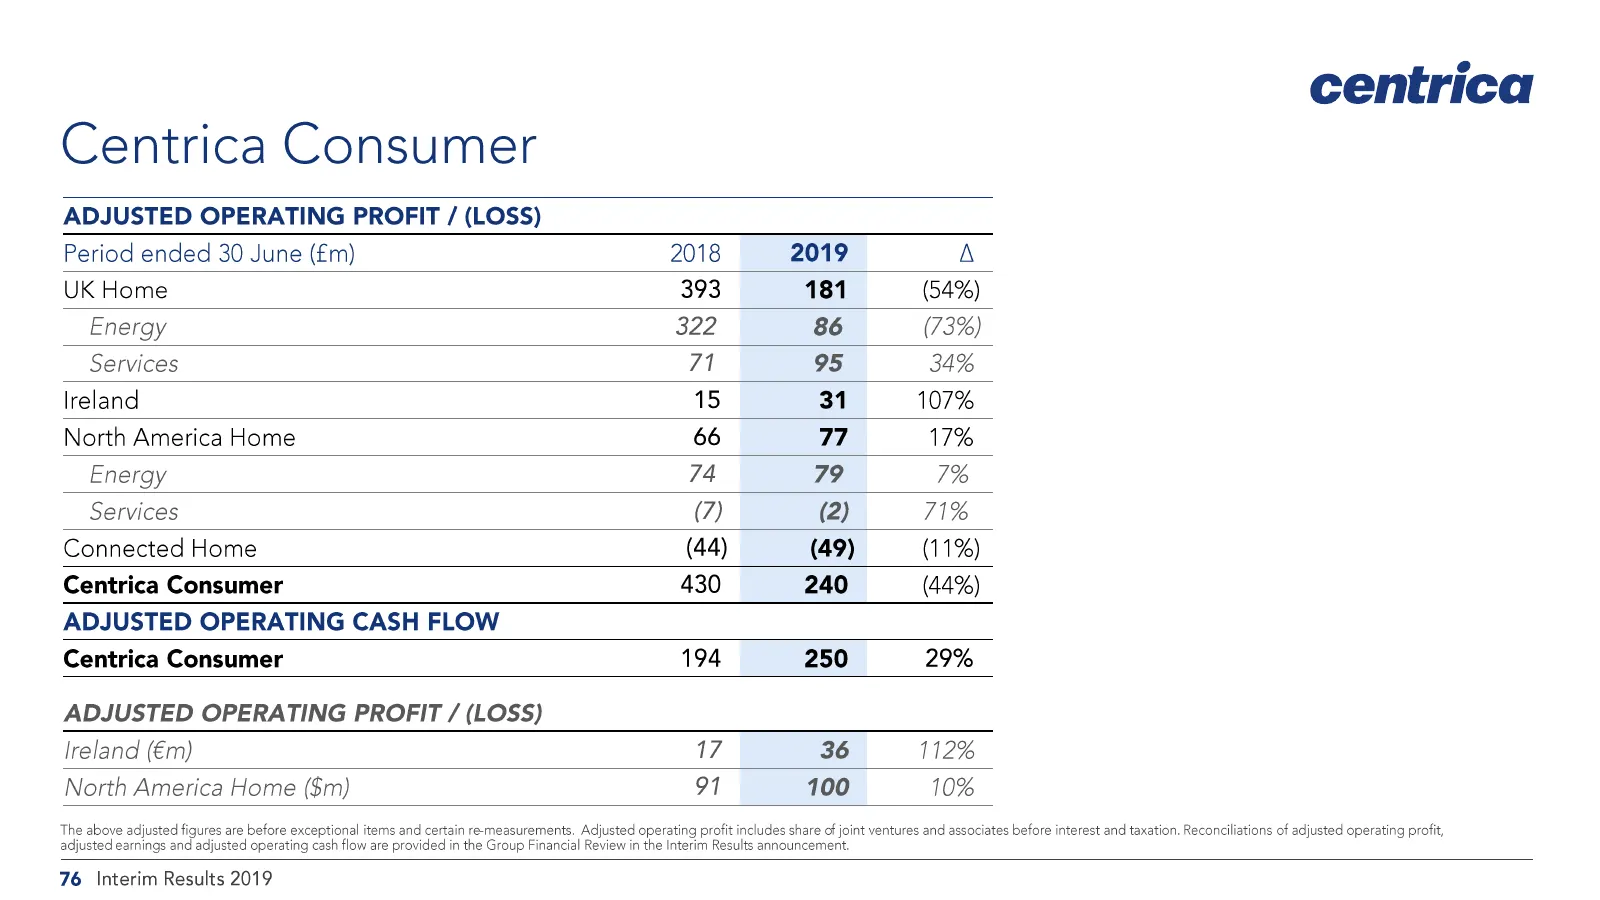
Slide 76: Centrica Consumer
Centrica Consumer ADJUSTED OPERATING PROFIT / (LOSS) Period ended 30 June (£m) 2018 2019 A UK Home 393 181 (54%) Energy 322 86 (73%) Services 71 95 34% Ireland 15 31 107% North America Home 66 77 17% Energy 74 79 7% Services (7) (2) 71% Connected Home (44) (49) (11%) Centrica Consumer 430 240 (44%)
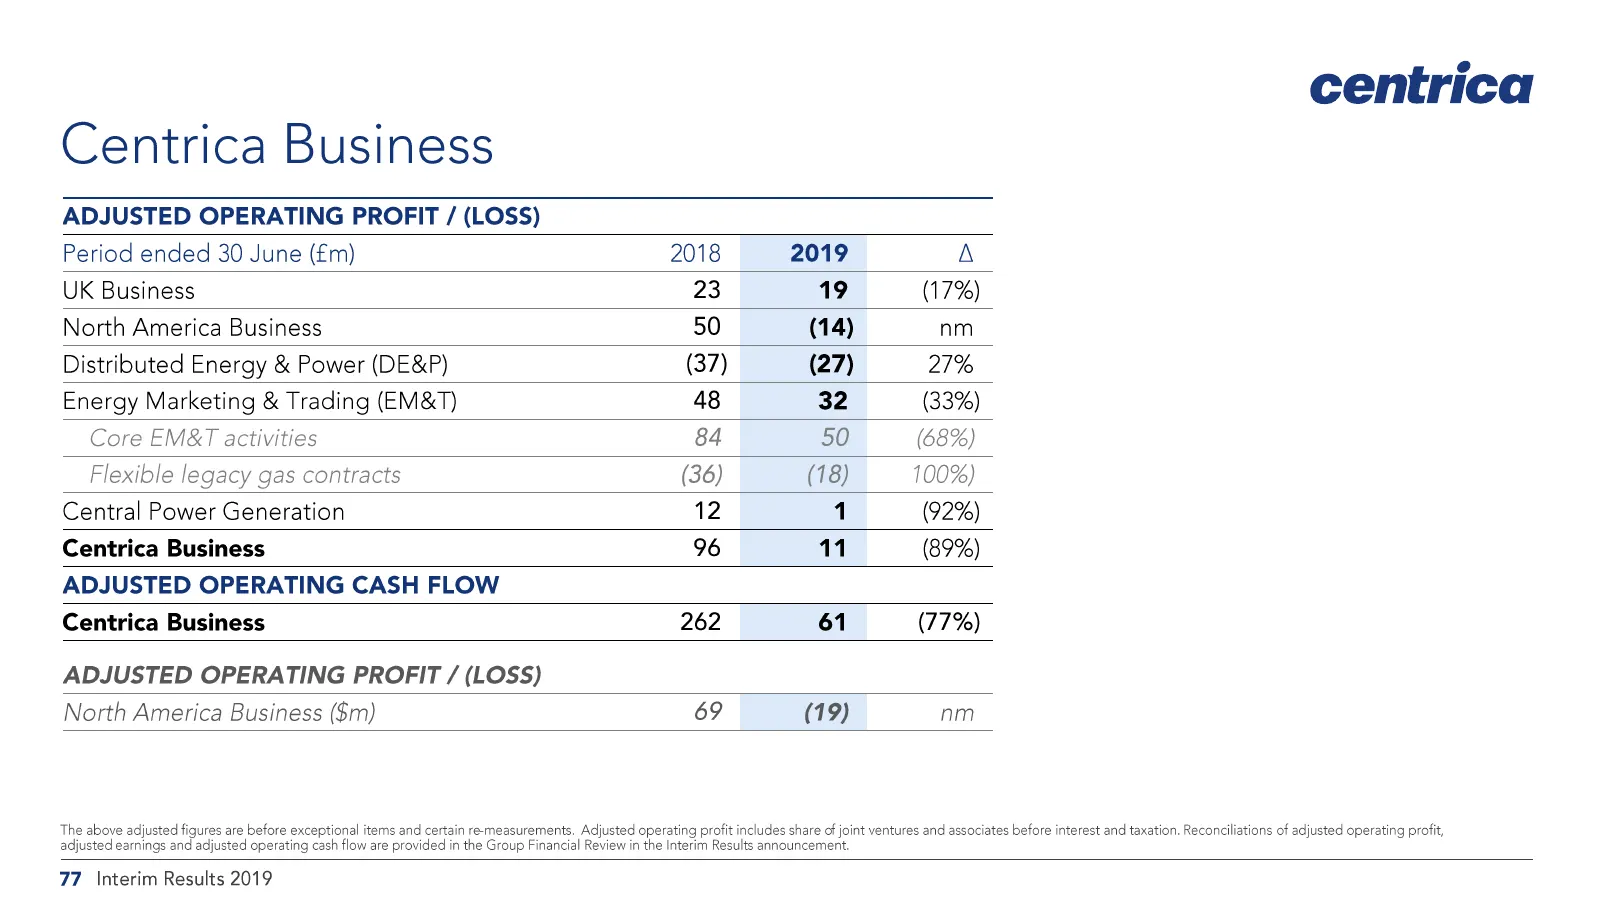
Slide 77: Centrica Business
Centrica Business ADJUSTED OPERATING PROFIT / (LOSS) Period ended 30 June (£m) 2018 2019 A UK Business 23 19 (17%) North America Business 50 (14) nm Distributed Energy & Power (DE&P) (37) (27) 27% Energy Marketing & Trading (EM&T) 48 32 (33%) Core EM&T activities 84 50 (68%) Flexible legacy gas cont
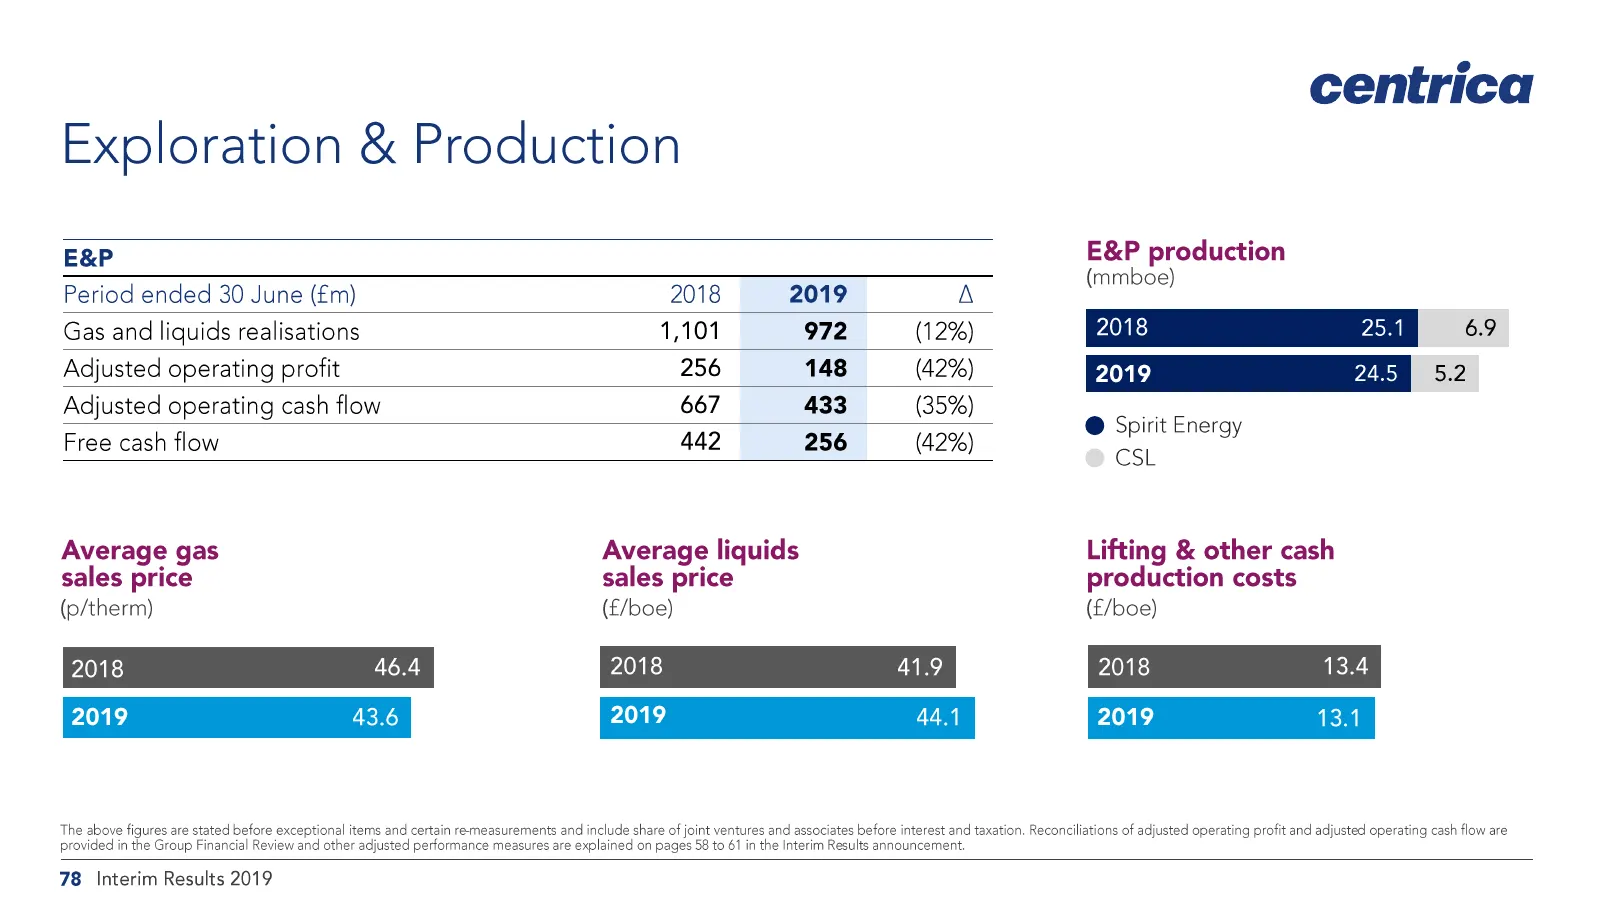
Slide 78: Exploration & Production
centrica Exploration & Production E&P E&P production 7 (mmboe) Period ended 30 June (£m) 2018 2019 A Gas and liquids realisations 1,101 972 (12%) 6.9 Adjusted operating profit 256 148 (42%) 5.2 Adjusted operating cash flow 667 433 (35%) . @ Spirit Energy Free cash flow 442 256 (42%) CSL Average gas
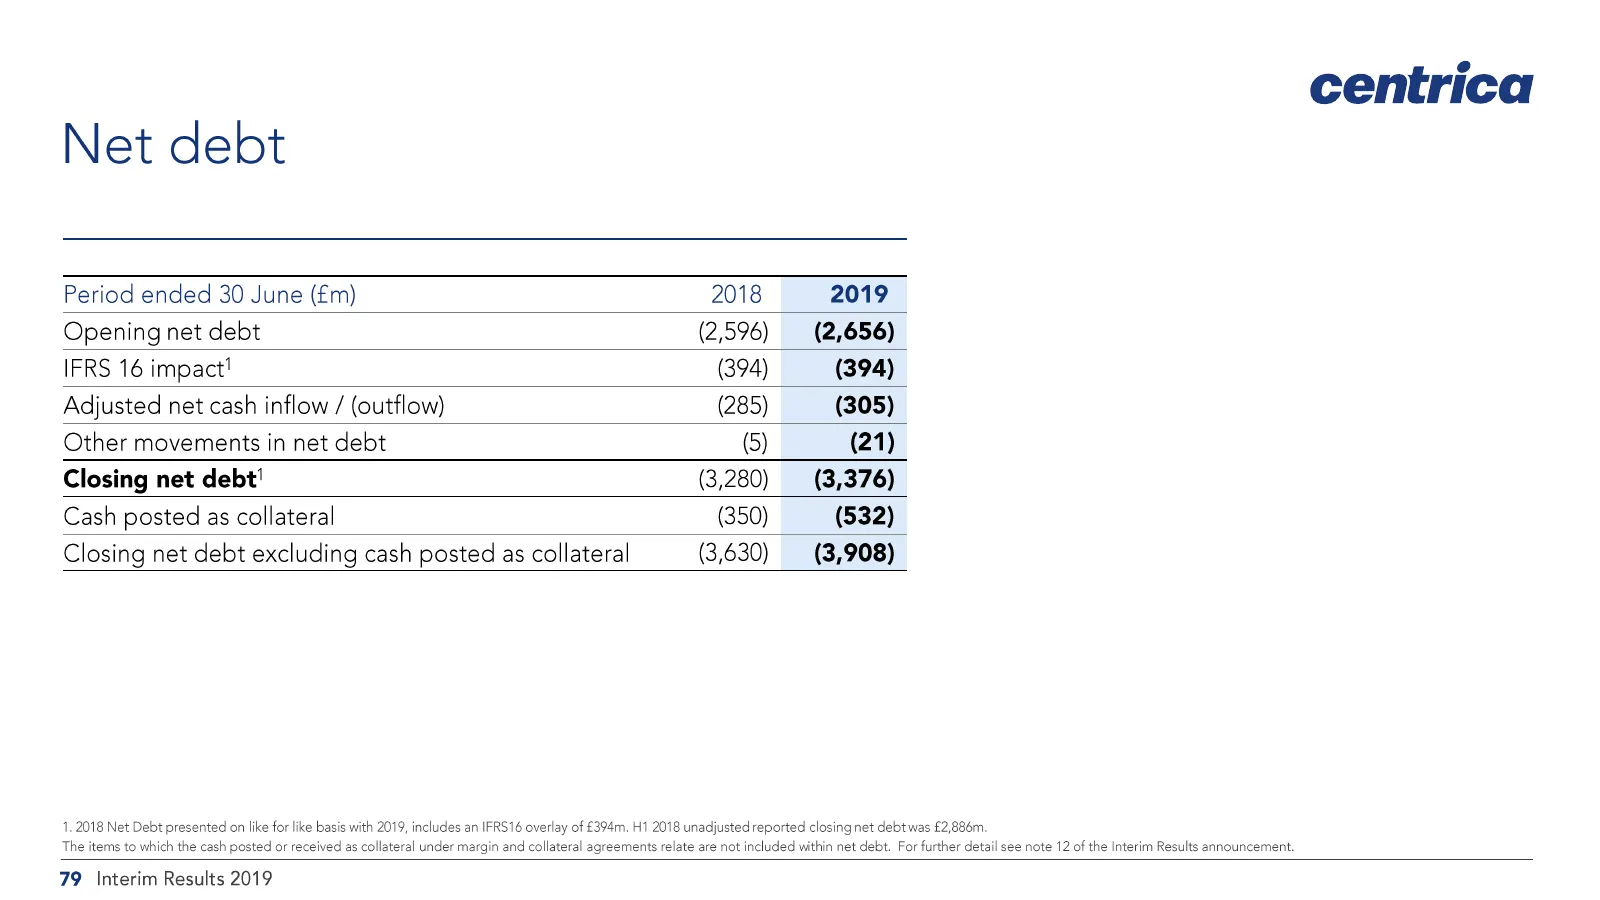
Slide 79: Net debt
Net debt Period ended 30 June (£m) 2018 2019 Opening net debt (2,596) (2,656) IFRS 16 impact! (394) (394) Adjusted net cash inflow / (outflow) (285) (305) Other movements in net debt (5) (21) Closing net debt! (3,280) (3,376) Cash posted as collateral (350) (532) Closing net debt excluding cash post
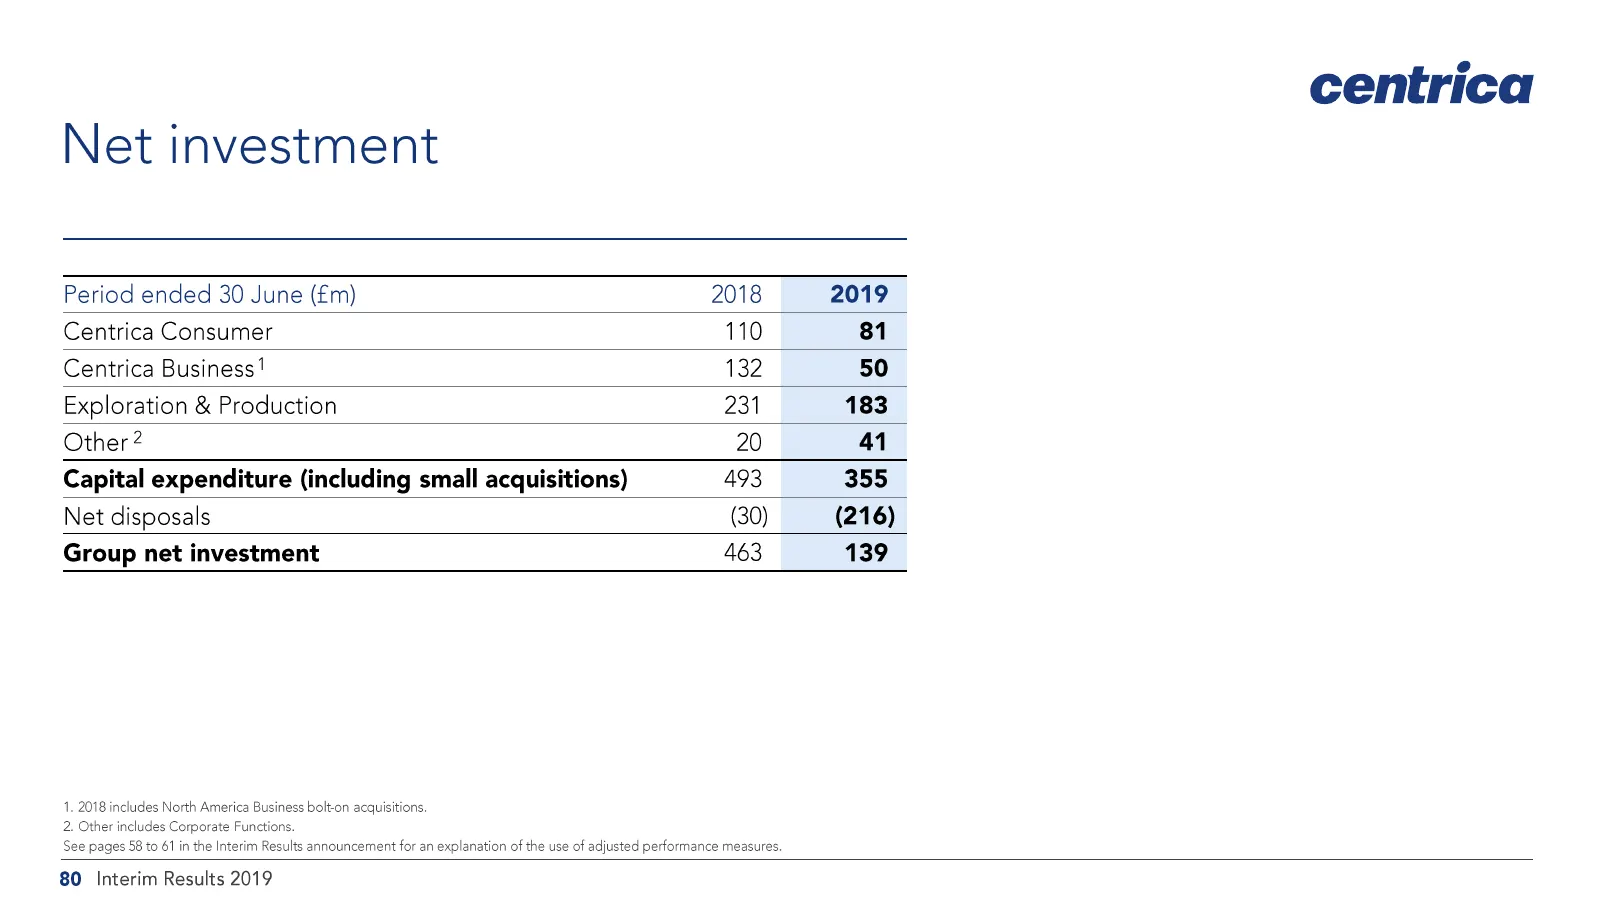
Slide 80: Net investment
Net investment Period ended 30 June (£m) 2018 2019 Centrica Consumer 110 81 Centrica Business! 132 50 Exploration & Production 231 183 Other? 20 41 Capital expenditure (including small acquisitions) 493 355 Net disposals (30) (216) Group net investment 463 139 1. 2018 includes North America Business
Source: Internet Archive copy of centrica.com
More decks from Centrica plc
 H1 2026 Earnings Presentation31 slides · Jul 23, 2026
 Q2 2026 Earnings Presentation30 slides · Jul 23, 2026
 FY2025 Earnings Presentation39 slides · Feb 19, 2026
 Fact Sheet (2026)2 slides · 2026
 H1 2025 Earnings Presentation32 slides · Jul 24, 2025
 Investor Presentation (July 2025)24 slides · Jul 22, 2025