Apartment Investment and Management Company · NYSE:AIV
Apartment Investment and Management — Proxy Contest (October 2020)
29 slides from Apartment Investment and Management's proxy contest presentation, Oct 20, 2020
Slide 1: Aimco — 26 Years Is Long Enough
AIMCO — 26 YEARS IS LONG ENOUGH LANDand VOTE GOLD FOR SPECIAL MEETING EME DIINGS en www.AimHighAlV.com
Slide 2: Calling for a Special Meeting of AIV Shareholders
CALLING FOR A SPECIAL MEETING OF AIV SHAREHOLDERS TABLE OF CONTENTS 1. Why Are We Here? — Vote for Special Meeting 2. A Strong Case for Change LéBJ>
Slide 3: 1. Why Are We Here? — Vote for Special Meeting
1. WHY ARE WE HERE? — VOTE FOR SPECIAL MEETING
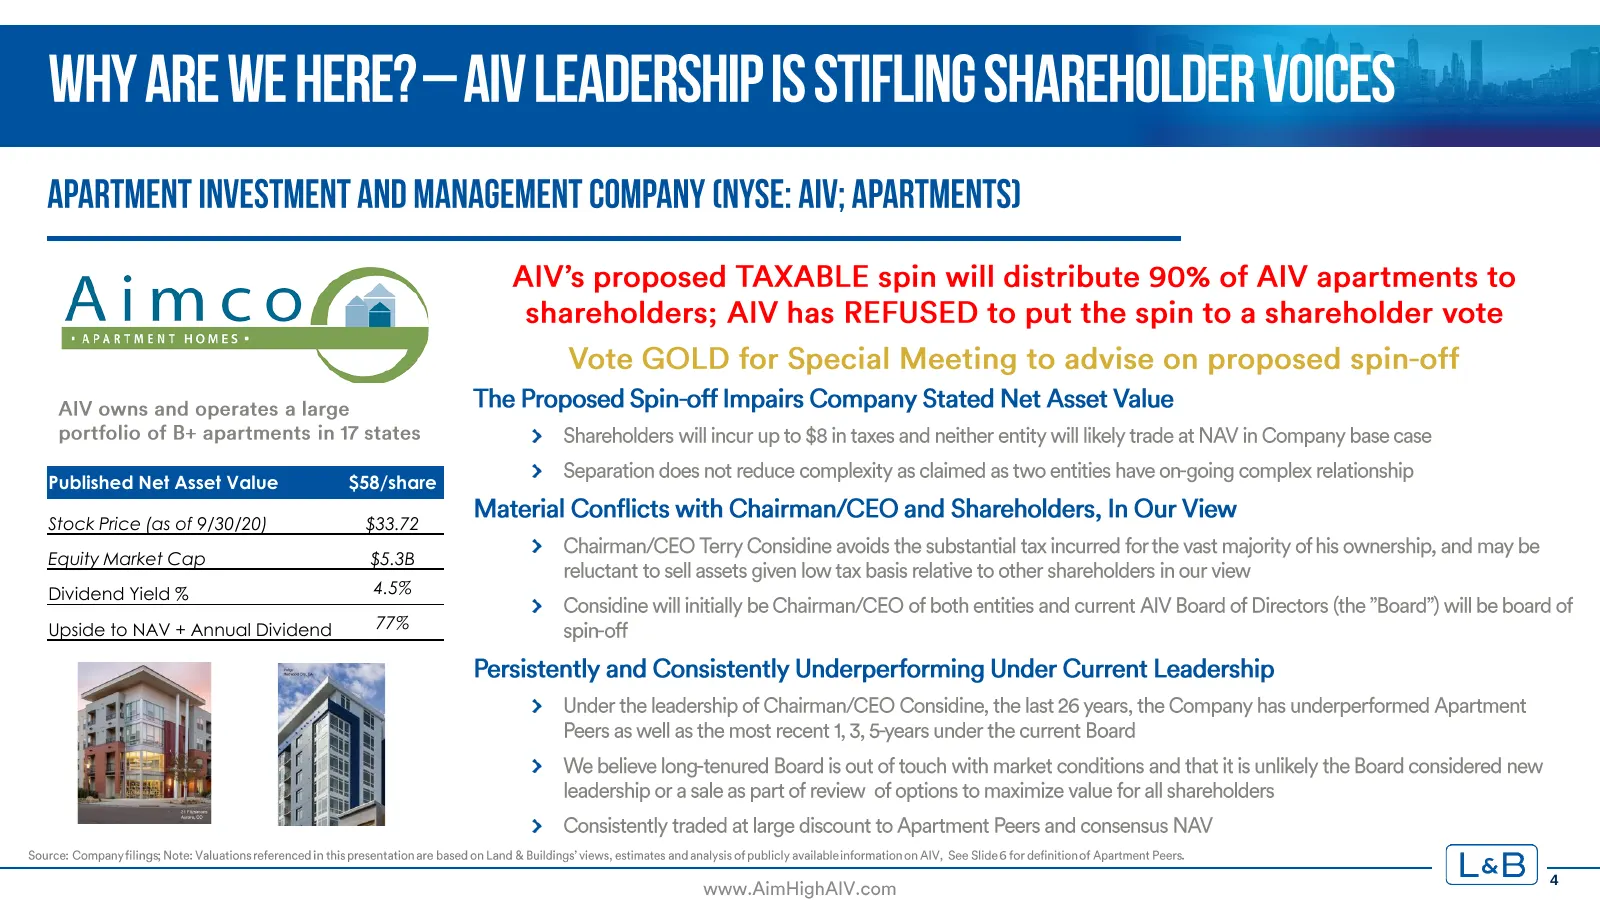
Slide 4: Published Net Asset Value $58/share
Published Net Asset Value $58/share Stock Price (as of 9/30/20) $33.72 Equity Market Cap $5.3B Dividend Yield % 4.5% Upside to NAV + Annual Dividend 77% 4
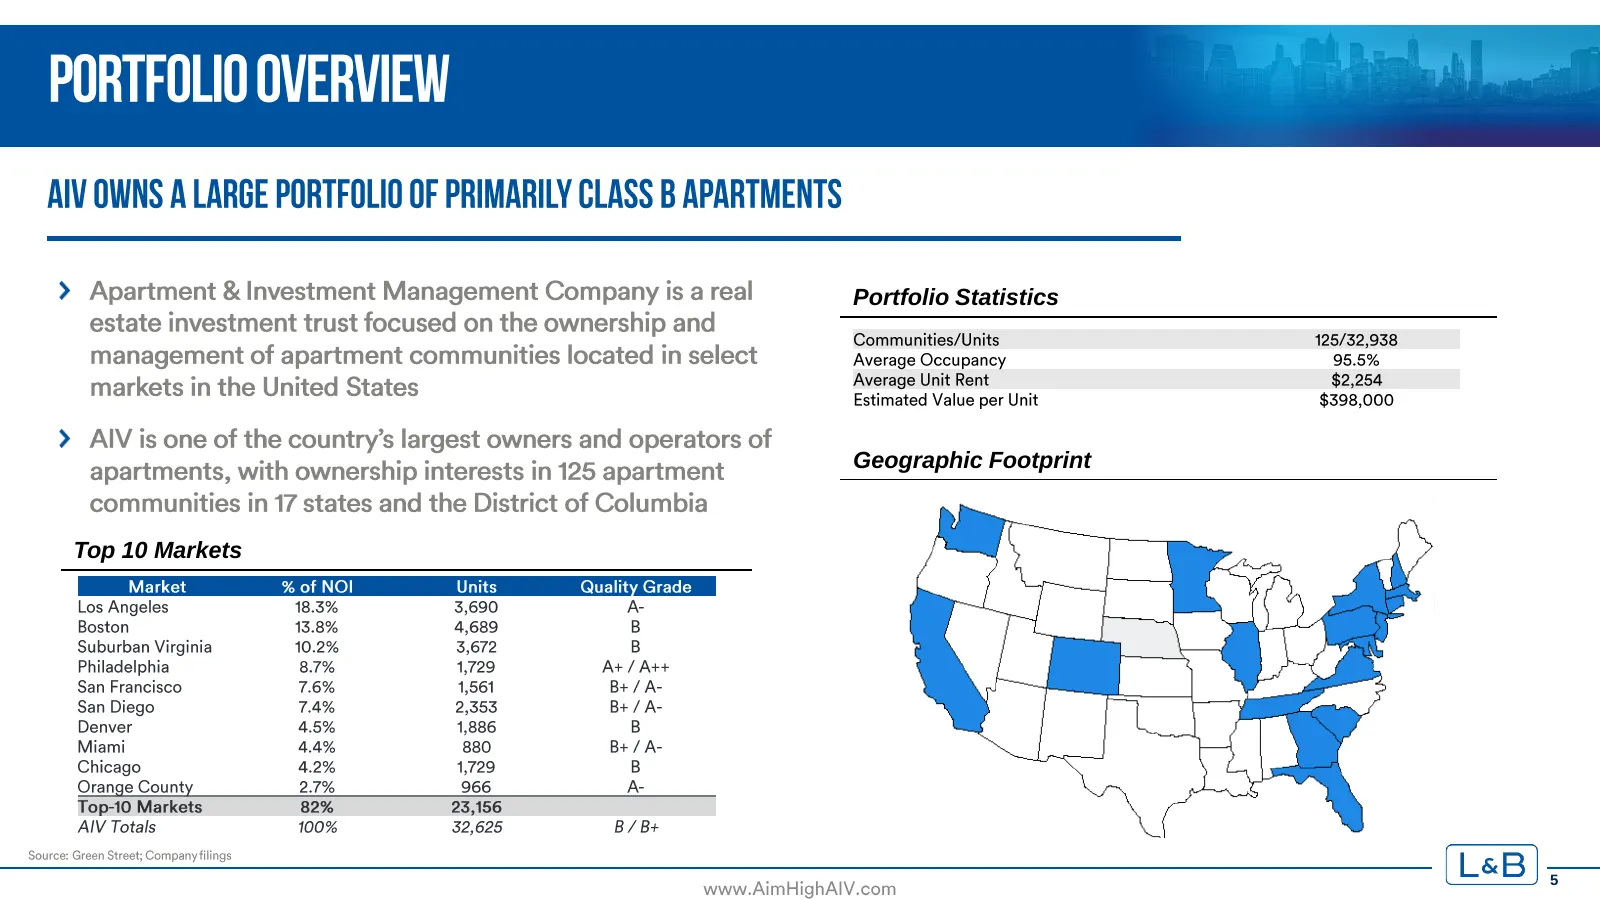
Slide 5: Portfolio Statistics, Geographic Footprint, Top Markets
Portfolio Statistics Geographic Footprint Top 10 Markets 5
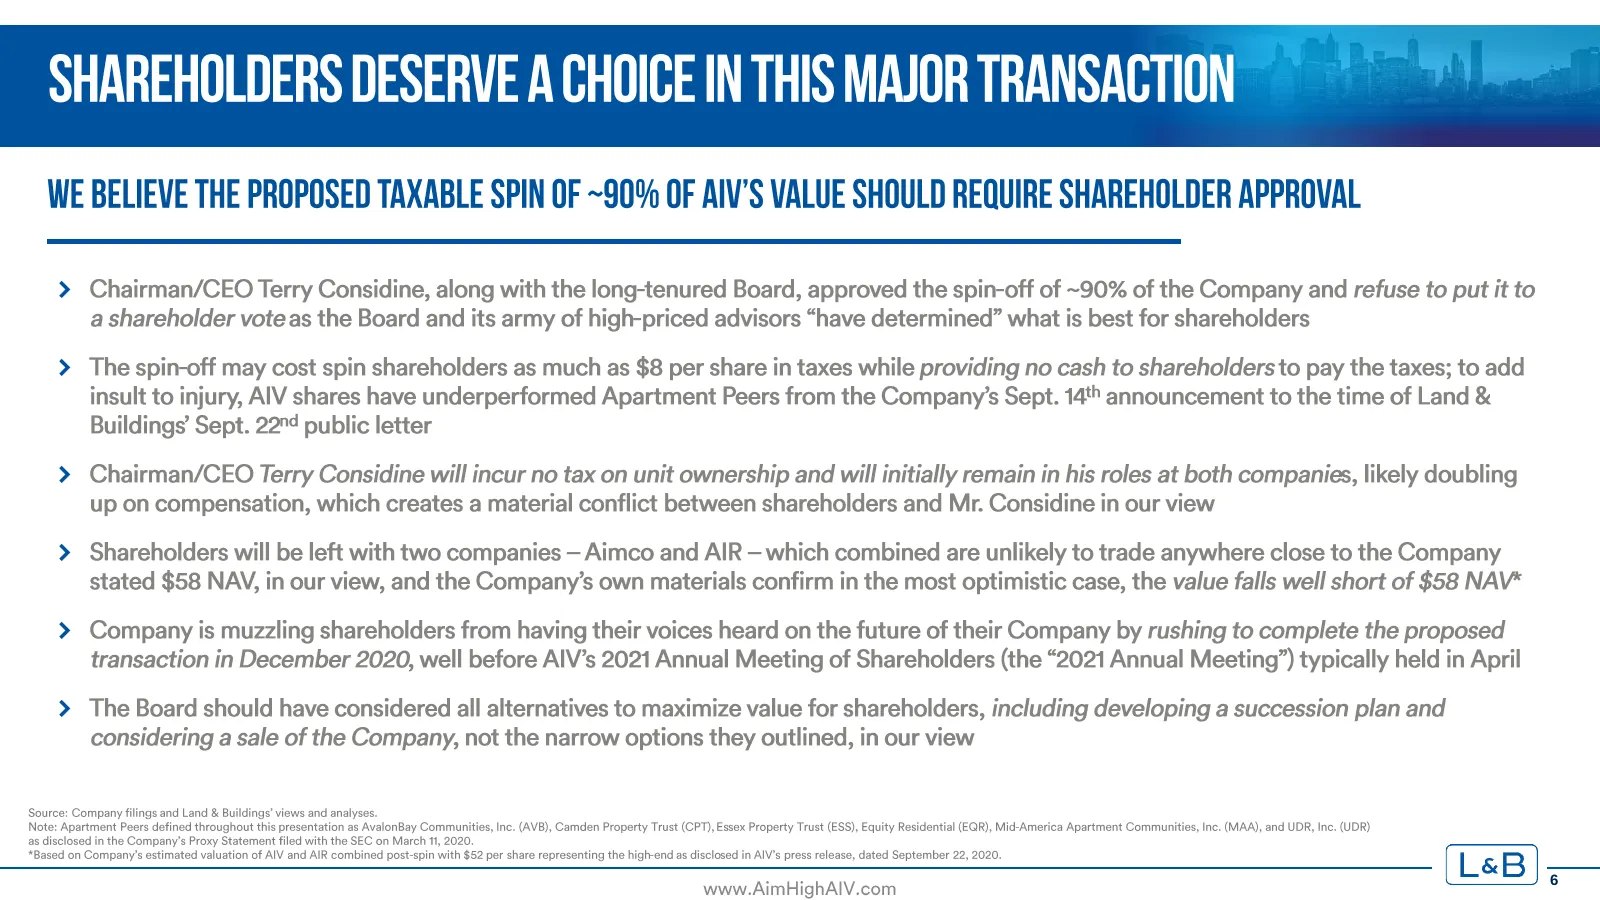
Slide 6: Shareholders Deserve a Choice in This Major Transaction
SHAREHOLDERS DESERVE A CHOICE IN THIS MAJOR TRANSACTION WE BELIEVE THE PROPOSED TAXABLE SPIN OF ~90% OF AIV'S VALUE SHOULD REQUIRE SHAREHOLDER APPROVAL > Chairman/CEO Terry Considine, along with the long-tenured Board, approved the spin-off of ~90% of the Company and refuse to put it to a shareholde
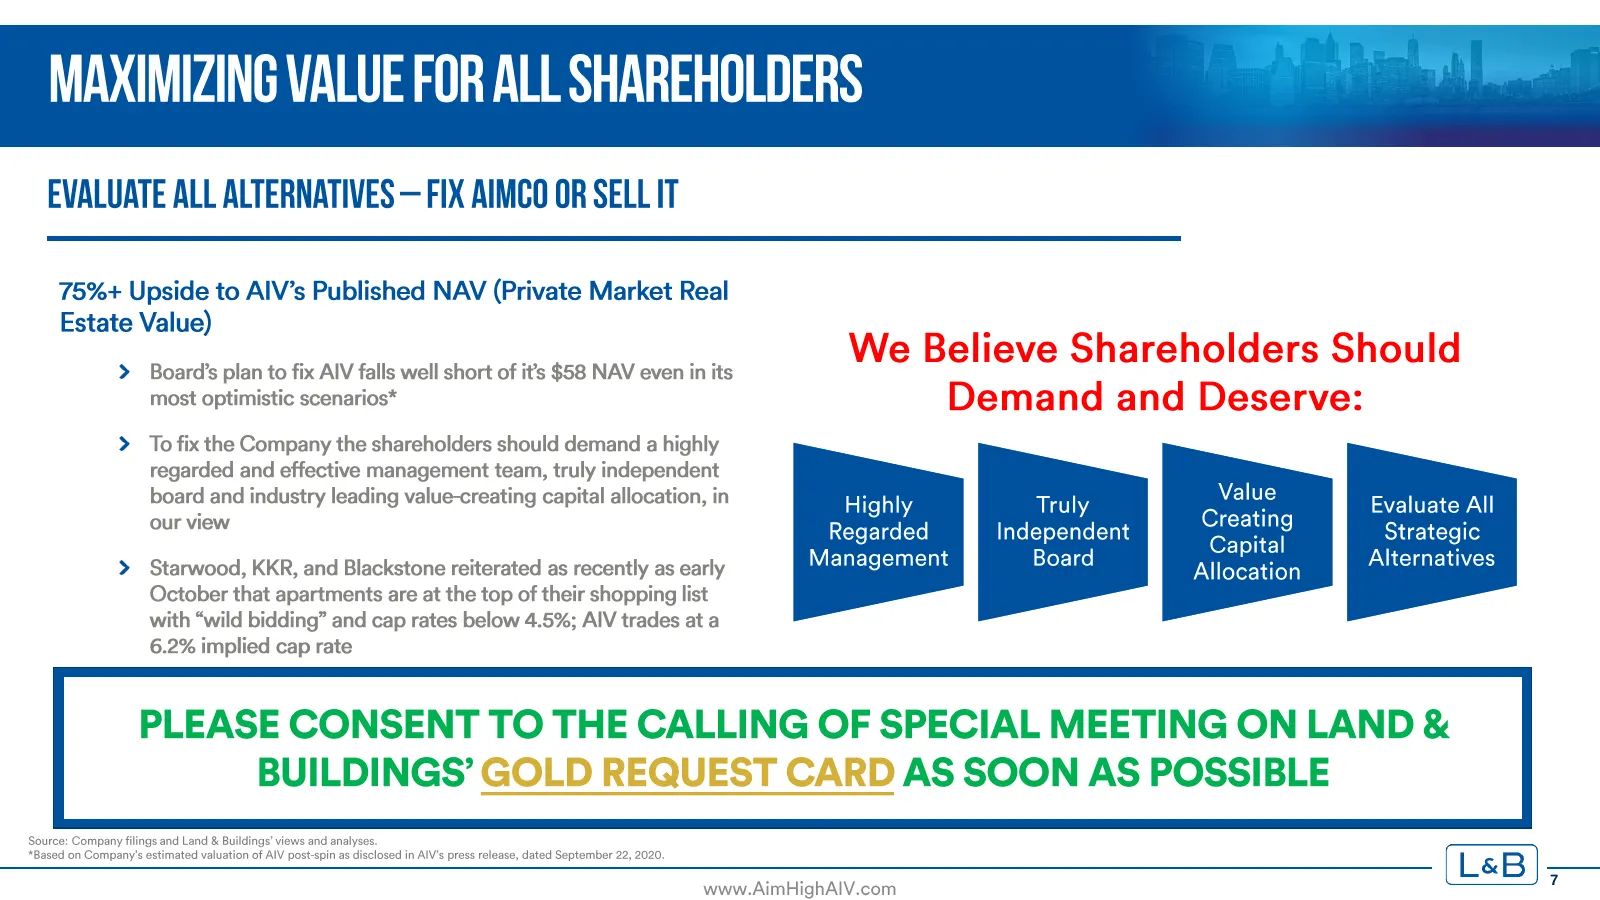
Slide 7: Maximizing Value for All Shareholders
MAXIMIZING VALUE FOR ALL SHAREHOLDERS EVALUATE ALL ALTERNATIVES — FIX AIMCO OR SELL IT 75%+ Upside to AIV’s Published NAV (Private Market Real Estate Value) . . “es - We Believe Shareholders Should > Board’s plan to fix AlV falls well short of it’s $58 NAV even in its most optimistic scenarios* Dema
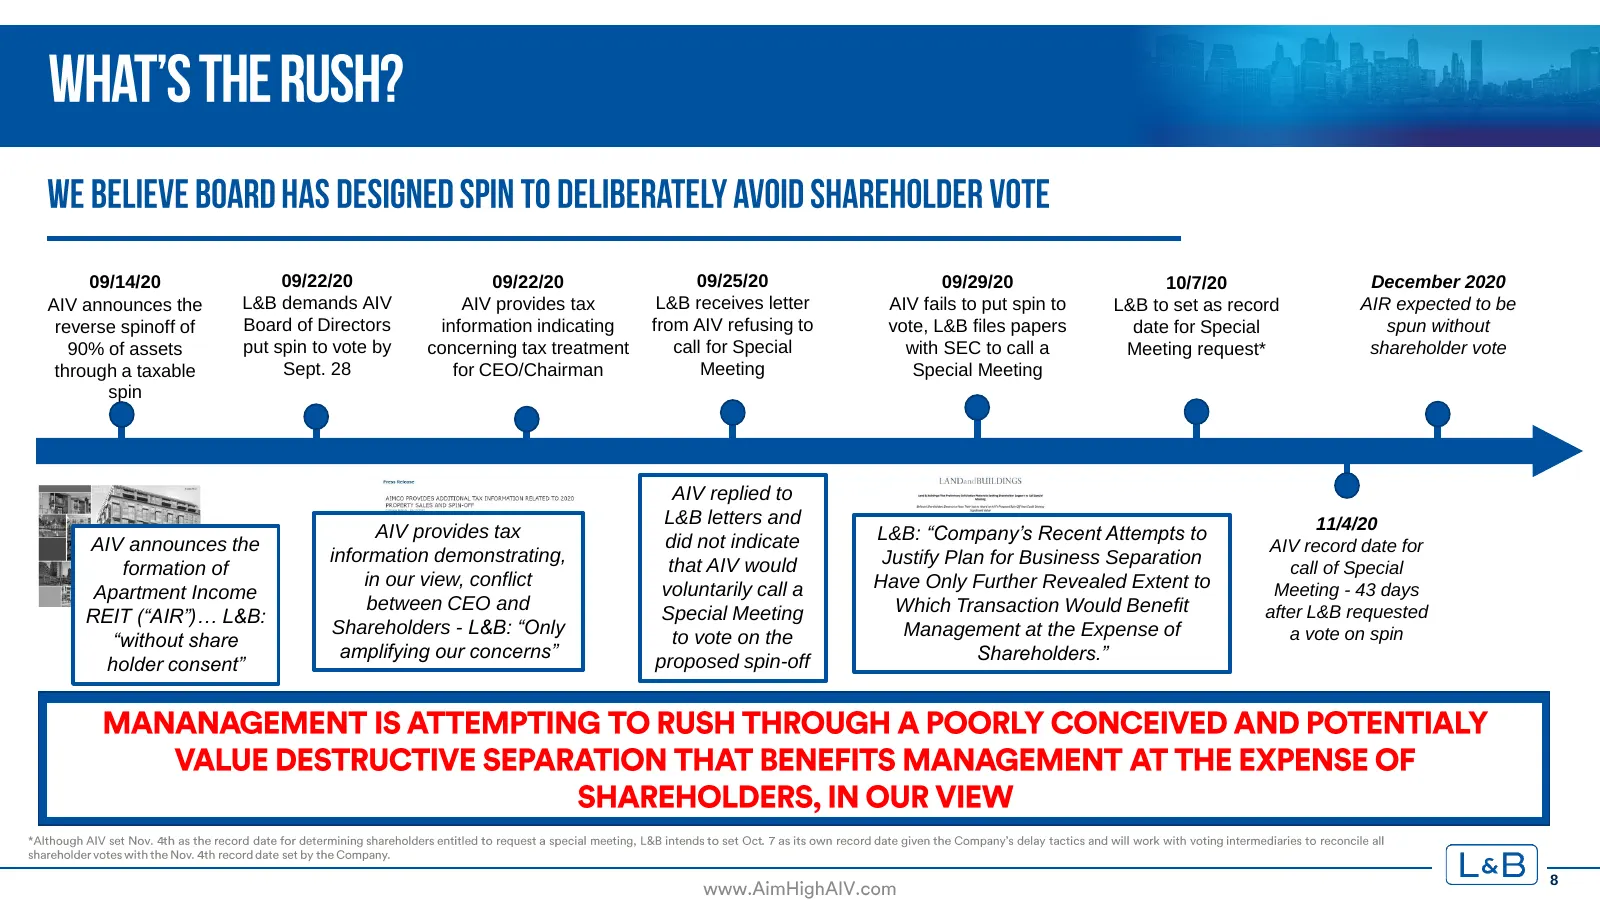
Slide 8: Timeline of spin-off and special meeting request
09/14/20 09/22/20 09/22/20 09/25/20 09/29/20 10/7/20 December 2020 AIV announces the L&B demands AIV AIV provides tax L&B receives letter AIV fails to put spin to L&B to set as record AIR expected to be reverse spinoff of Board of Directors information indicating from AIV refusing to vote, L&B files
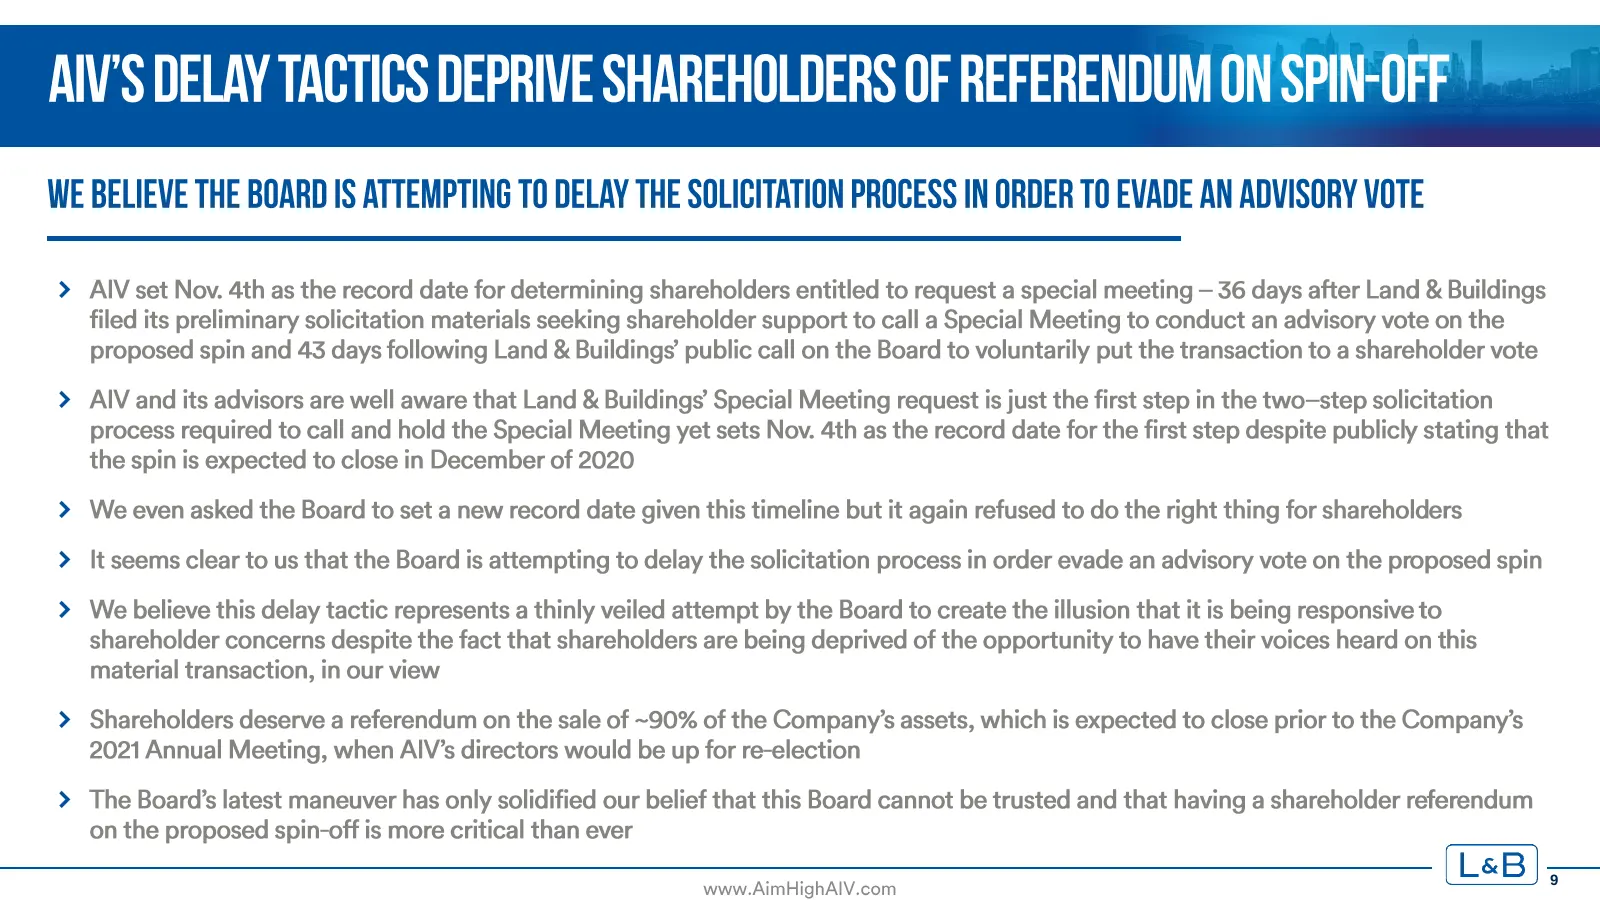
Slide 9: AIV's Delay Tactics Deprive Shareholders of Referendum on Spin-Off
AIN’S DELAY TACTICS DEPRIVE SHAREHOLDERS OF REFERENDUM ON SPIN-OFF WE BELIEVE THE BOARD IS ATTEMPTING TO DELAY THE SOLICITATION PROCESS IN ORDER TO EVADE AN ADVISORY VOTE > AlV set Nov. 4th as the record date for determining shareholders entitled to request a special meeting — 36 days after Land & B
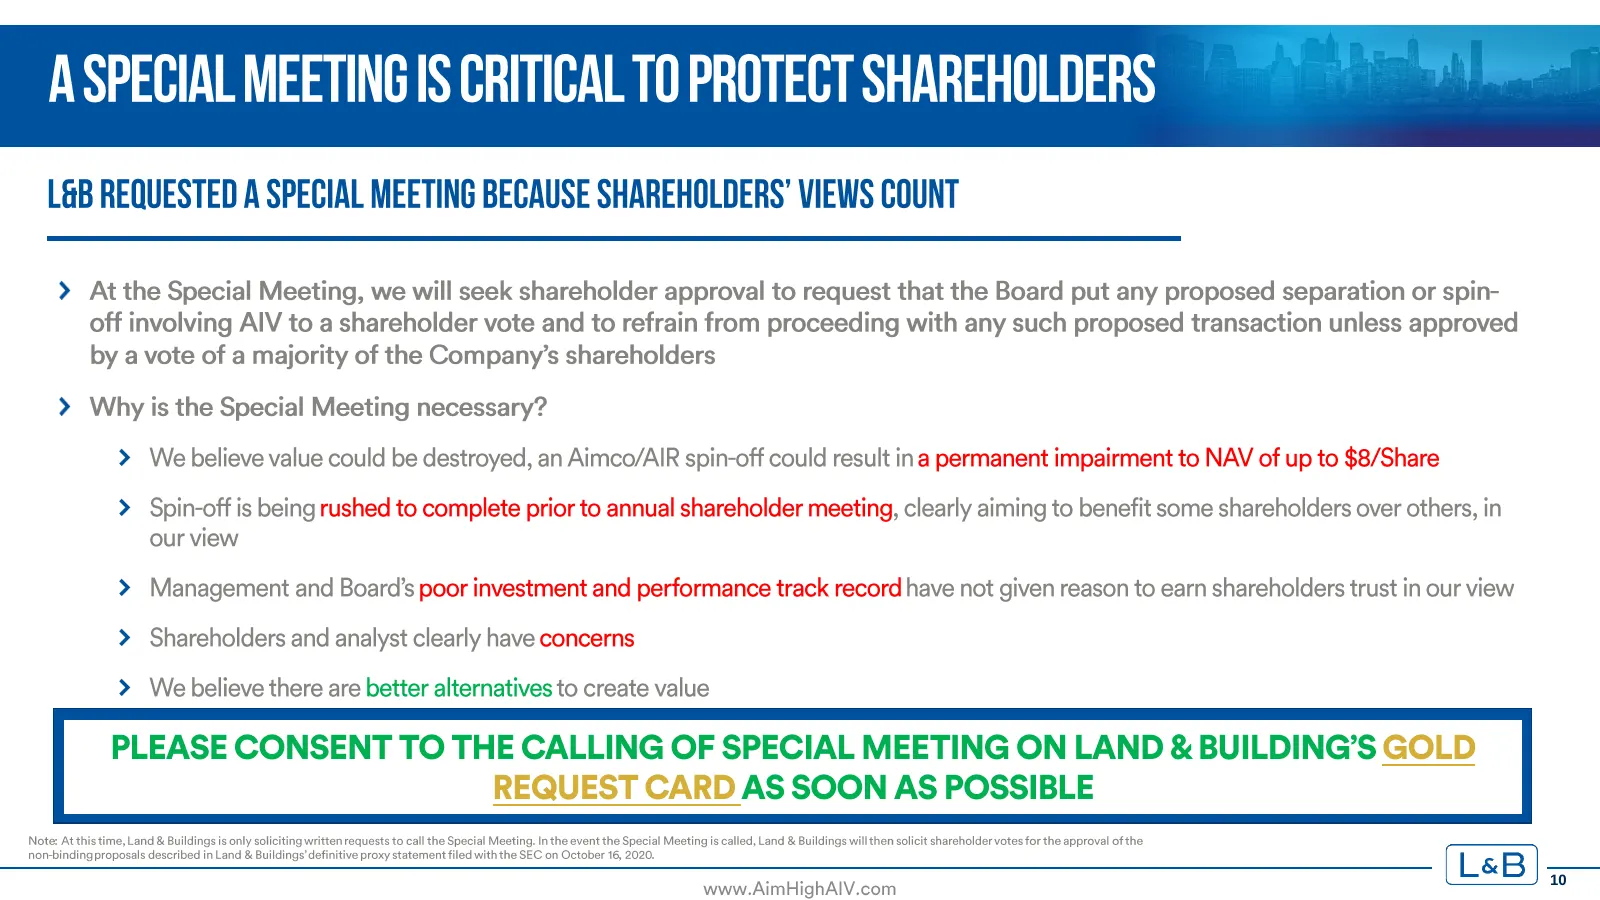
Slide 10: A Special Meeting Is Critical to Protect Shareholders
A SPECIAL MEETING IS CRITICAL TO PROTECT SHAREHOLDERS L&B REQUESTED A SPECIAL MEETING BECAUSE SHAREHOLDERS’ VIEWS COUNT > At the Special Meeting, we will seek shareholder approval to request that the Board put any proposed separation or spin- off involving AlV to a shareholder vote and to refrain fr
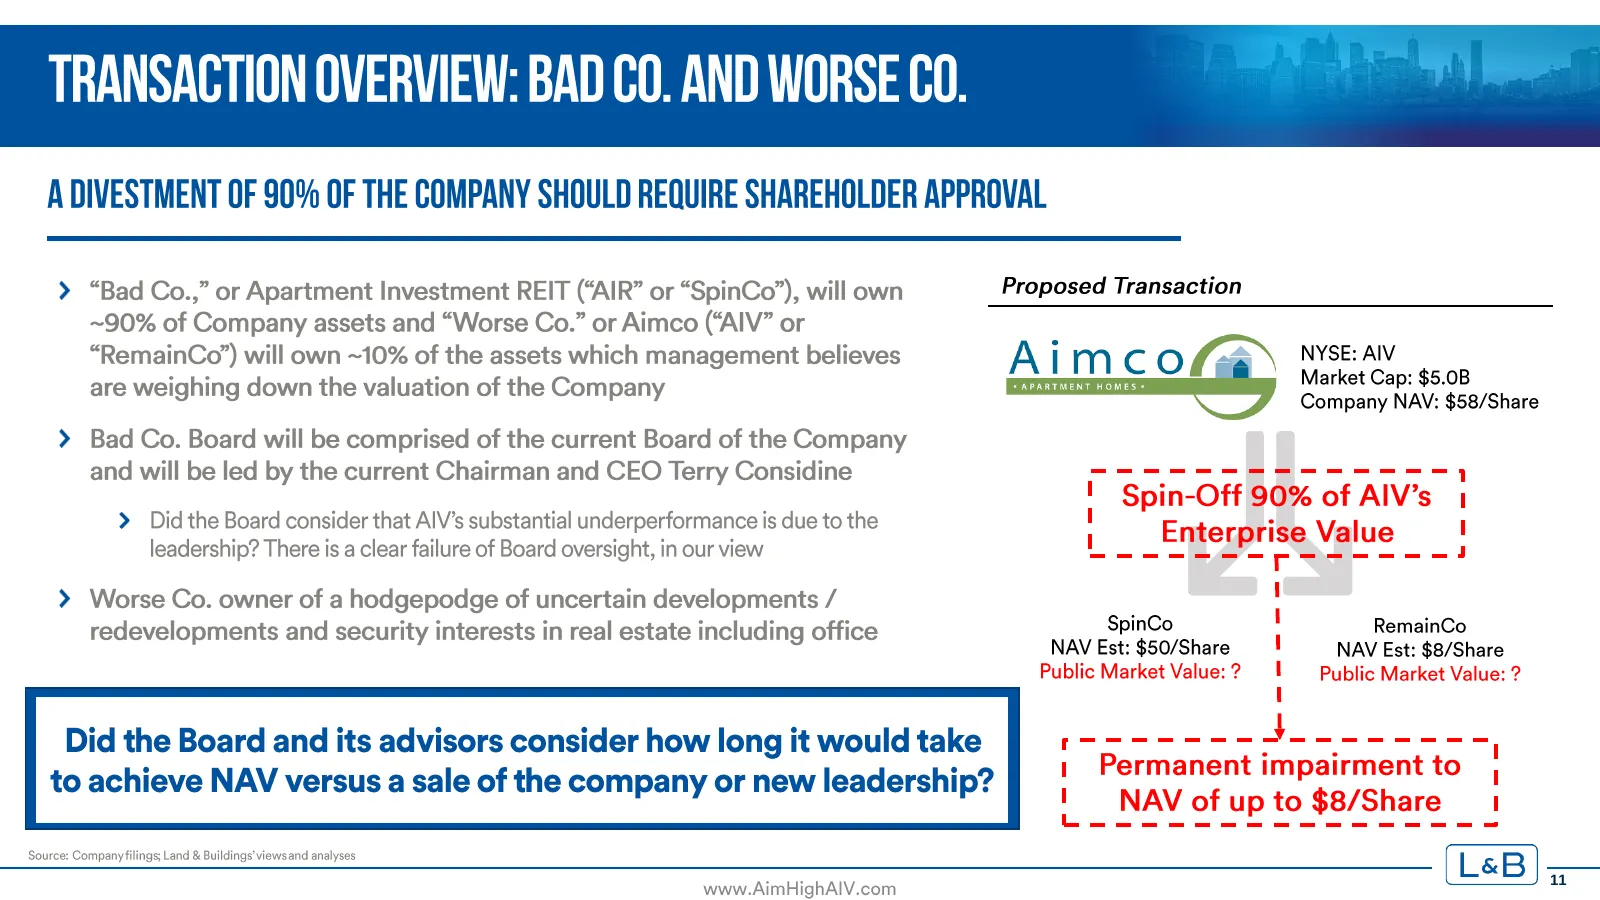
Slide 11: Transaction Overview: Bad Co. and Worse Co.
TRANSACTION OVERVIEW: BAD CO. AND WORSE CO. A DIVESTMENT OF 90% OF THE COMPANY SHOULD REQUIRE SHAREHOLDER APPROVAL > “Bad Co.,” or Apartment Investment REIT (“AIR” or “SpinCo”), will own Proposed Transaction ~90% of Company assets and “Worse Co.” or Aimco (“AlV” or “RemainCo”) will own ~10% of the a
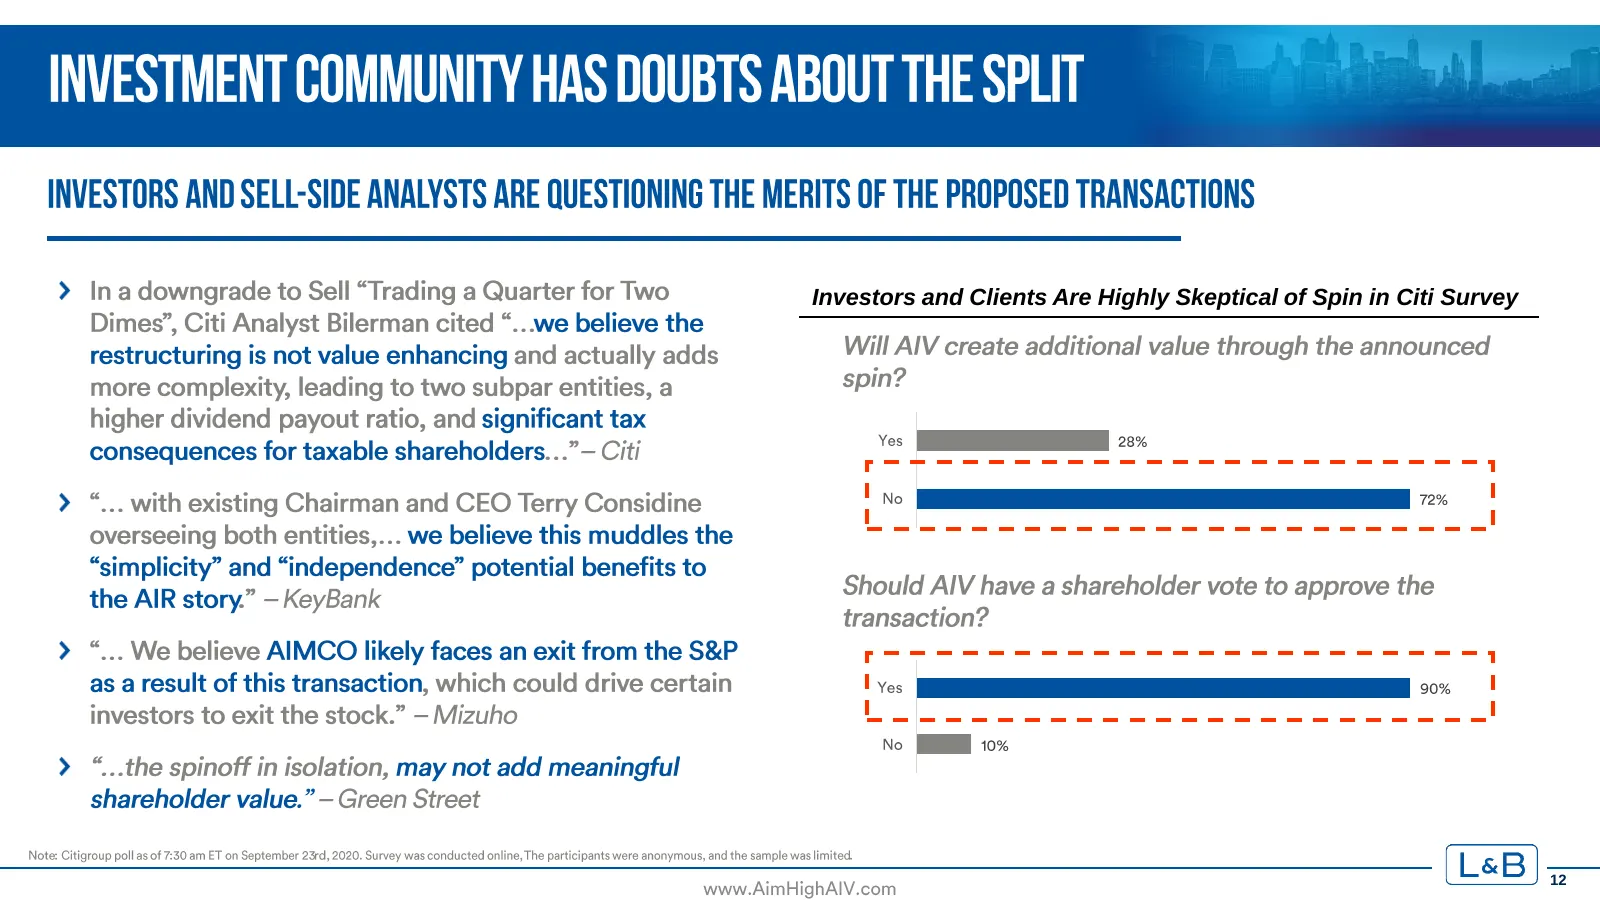
Slide 12: Investors and Clients Are Highly Skeptical of Spin in Citi Survey
Investors and Clients Are Highly Skeptical of Spin in Citi Survey 12
Slide 13: AIV Board Hides Behind State Law to Avoid Shareholder Vote
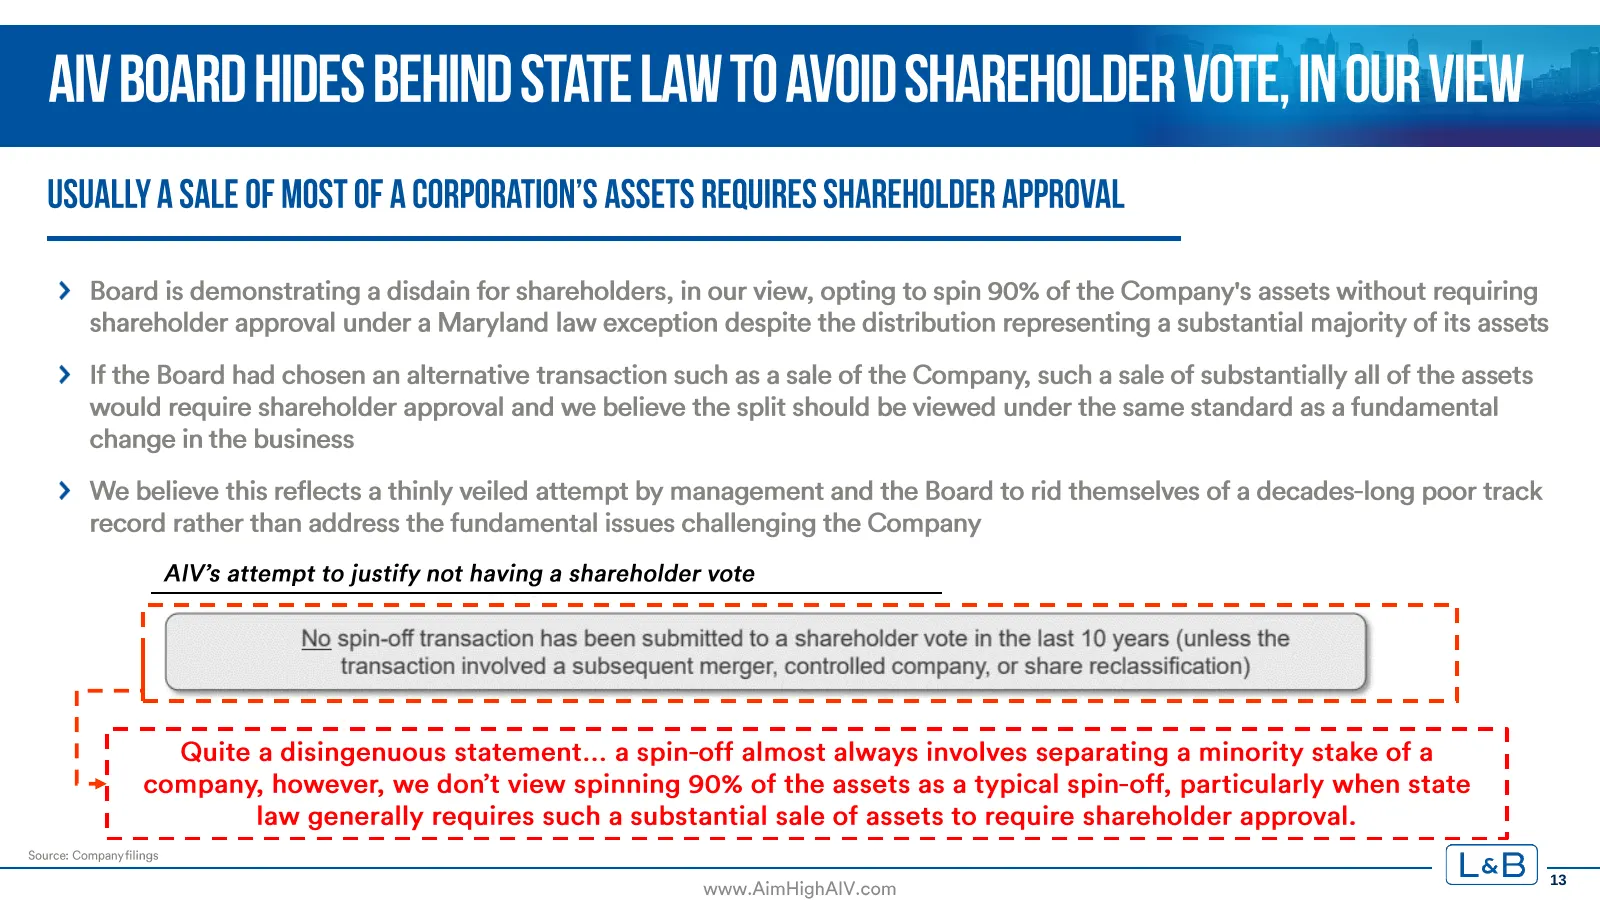
AlV BOARD HIDES BEHIND STATE LAW T0 AVOID SHAREHOLDER VOTE, IN OUR VIEW USUALLY A SALE OF MOST OF A CORPORATION'S ASSETS REQUIRES SHAREHOLDER APPROVAL > Board is demonstrating a disdain for shareholders, in our view, opting to spin 90% of the Company's assets without requiring shareholder approval u
Slide 14: AIV Does Not Want to Hear From Their Shareholders
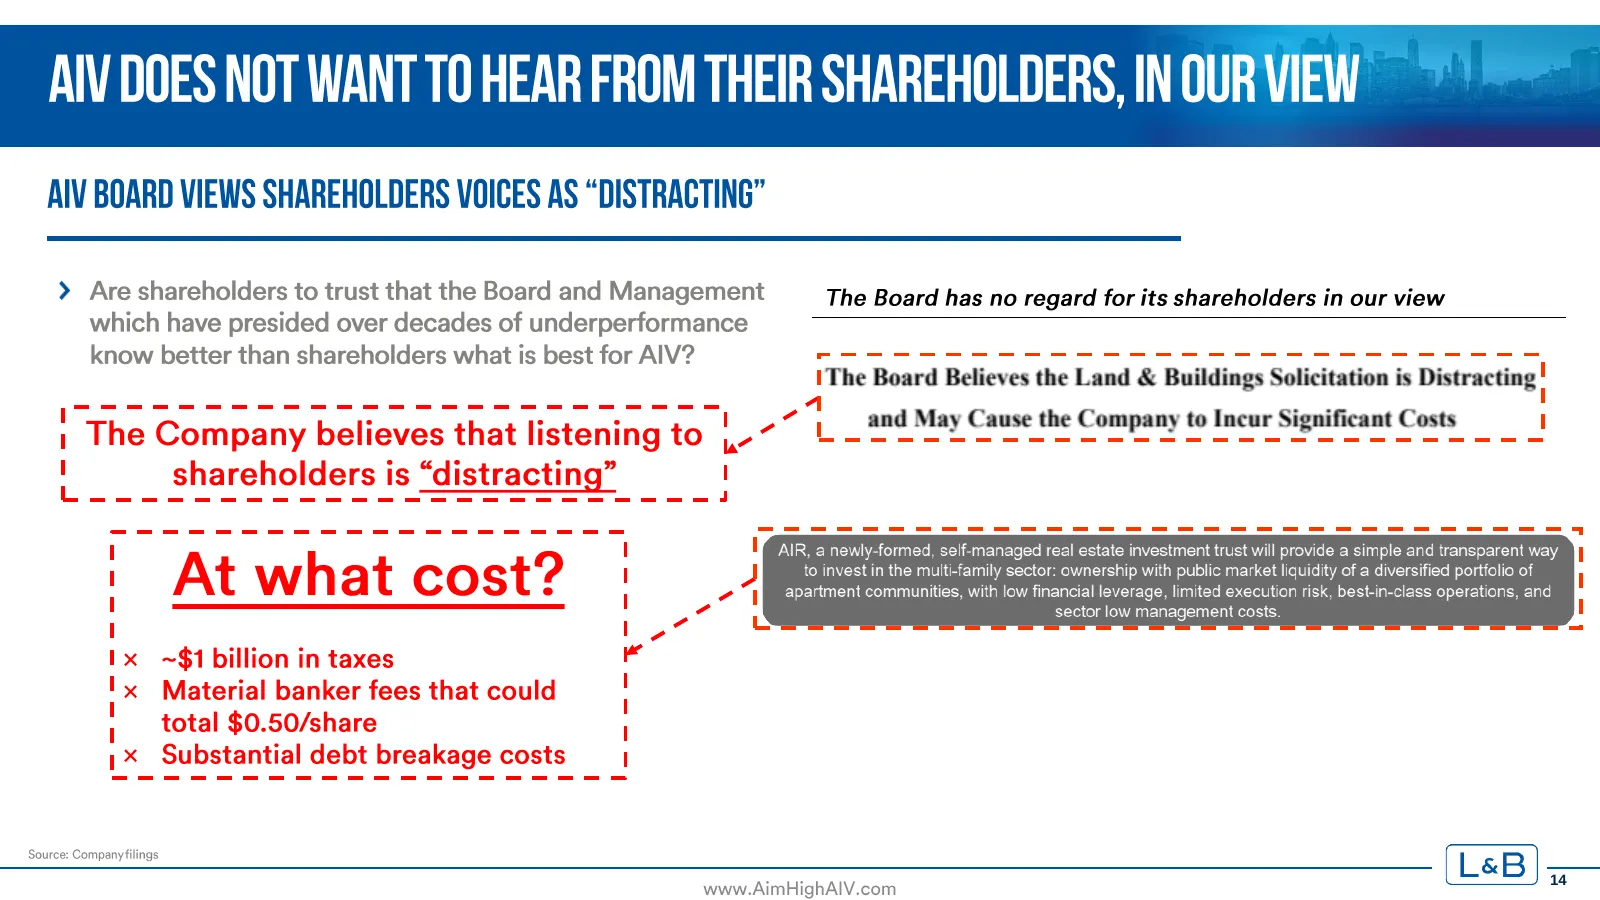
AI DOES NOT WANT TO HEAR FROM THEIR SHAREHOLDERS, IN OUR VIEW AIV BOARD VIEWS SHAREHOLDERS VOICES AS “DISTRACTING” > Are shareholders to trust that the Board and Management The Board has no regard for its shareholders in our view which have presided over decades of underperformance know better than
Slide 15: Board's Own Analysis Makes Clear Value Would Be Impaired
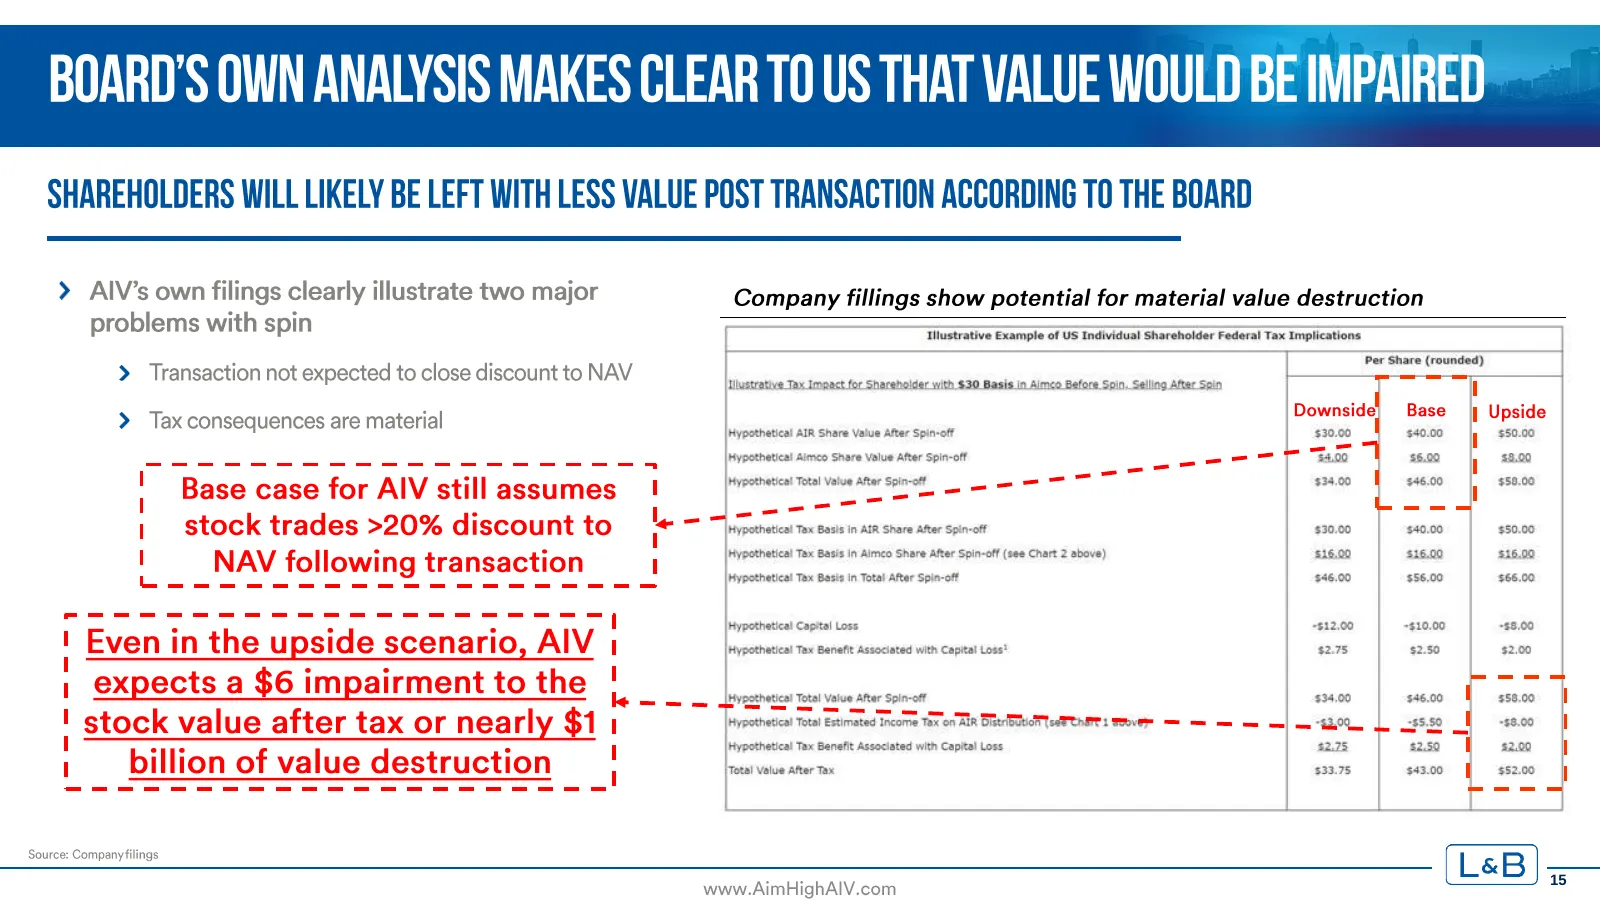
BOARD'S OWN ANALYSIS MAKES CLEAR TO US THAT VALUE WOULD BE IMPAIRED SHAREHOLDERS WILL LIKELY BE LEFT WITH LESS VALUE POST TRANSACTION ACCORDING TO THE BOARD > AlV’s own filings clearly illustrate two major Company fillings show potential for material value destruction problems with spin Tistrative G
Slide 16: 2. A Strong Case for Change
2. ASTRONG CASE FOR CHANGE
Slide 17: Persistent Discount, Operational Underperformance, Over-Tenured Board
C) Persistent Discount to NAV C} Operational Underperformance ( ) Over-Tenured Board www.AimHighAlV.com
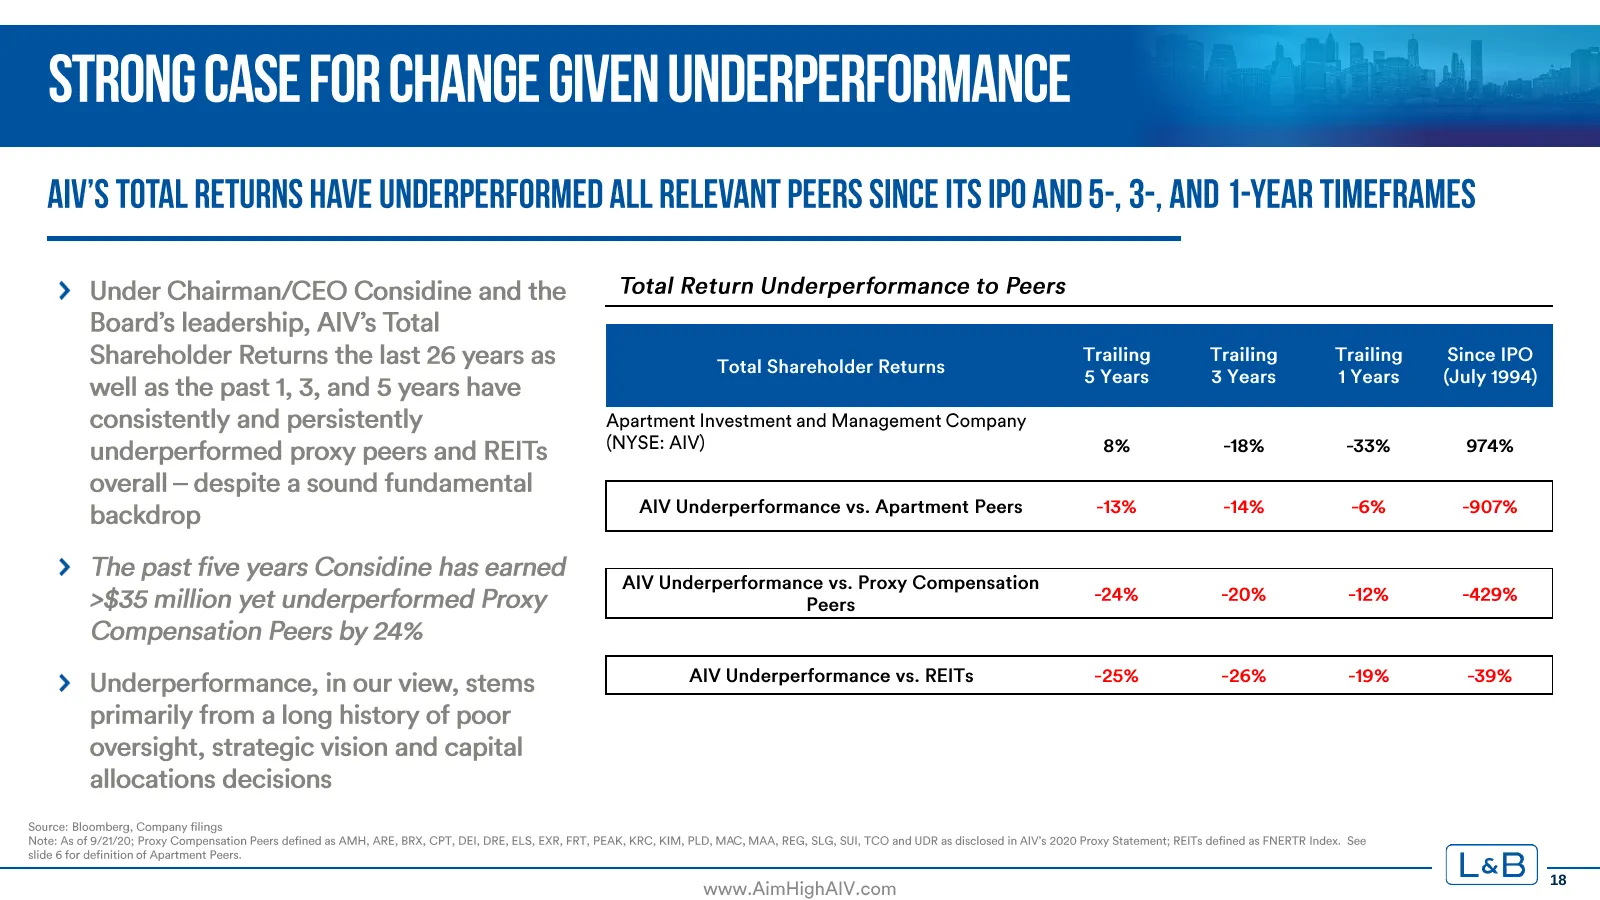
Slide 18: Strong Case for Change Given Underperformance
STRONG CASE FOR CHANGE GIVEN UNDERPERFORMANCE AIV’S TOTAL RETURNS HAVE UNDERPERFORMED ALL RELEVANT PEERS SINCE ITS IPO AND 5-, 3-, AND 1-YEAR TIMEFRAMES > Under Chairman/CEO Considine and the Total Return Underperformance to Peers Board’s leadership, AlV’s Total Shareholder Returns the last 26 years
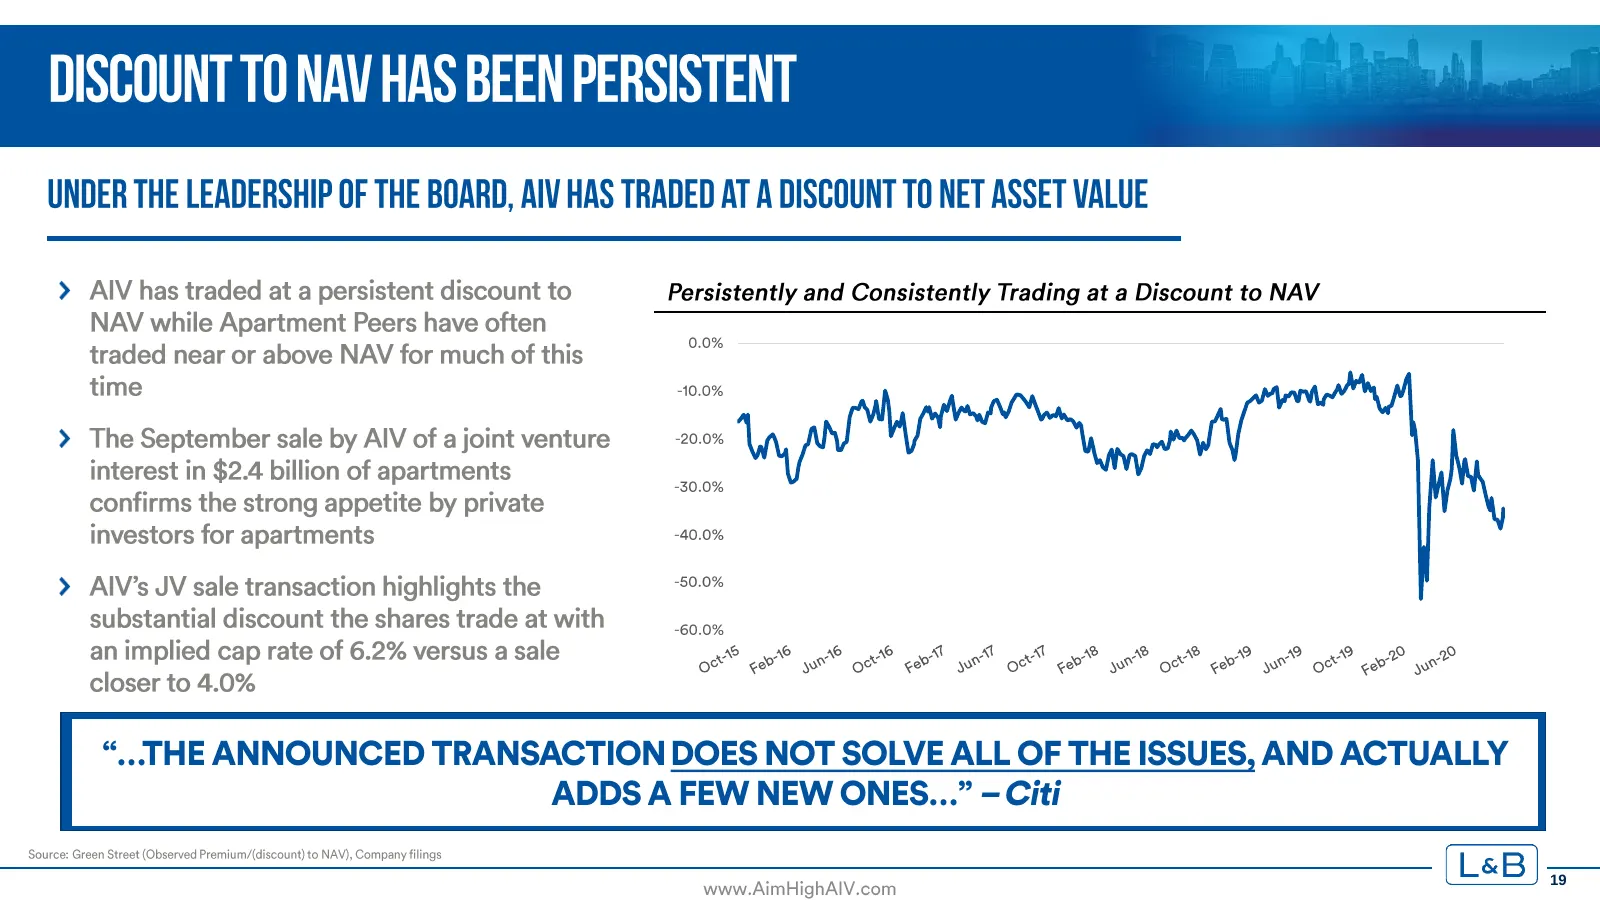
Slide 19: Discount to NAV Has Been Persistent
DISCOUNT T0 NAV HAS BEEN PERSISTENT UNDER THE LEADERSHIP OF THE BOARD, AlV HAS TRADED AT A DISCOUNT TO NET ASSET VALUE > AIV has traded at a persistent discount to Persistently and Consistently Trading at a Discount to NAV NAV while Apartment Peers have often traded near or above NAV for much of thi
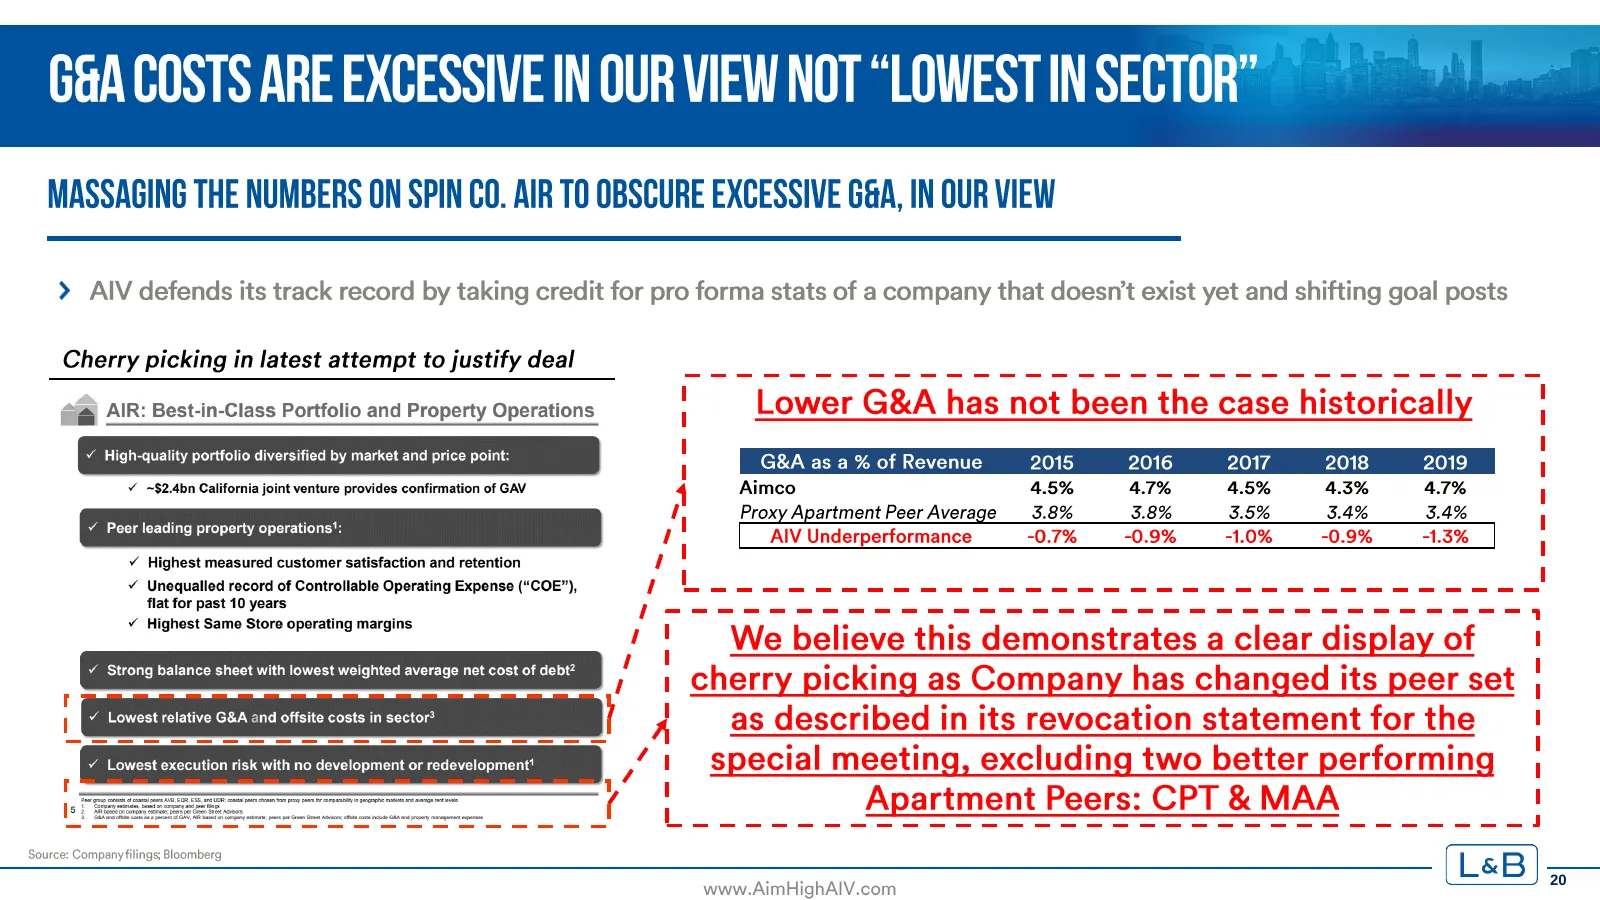
Slide 20: G&A Costs Are Excessive, Not Lowest in Sector
G&A COSTS ARE EXCESSIVE IN OUR VIEW NOT “LOWEST IN SECTOR” MASSAGING THE NUMBERS ON SPIN CO. AIR TO OBSCURE EXCESSIVE G&A, IN OUR VIEW > AIV defends its track record by taking credit for pro forma stats of a company that doesn’t exist yet and shifting goal posts Cherry picking in latest attempt to j
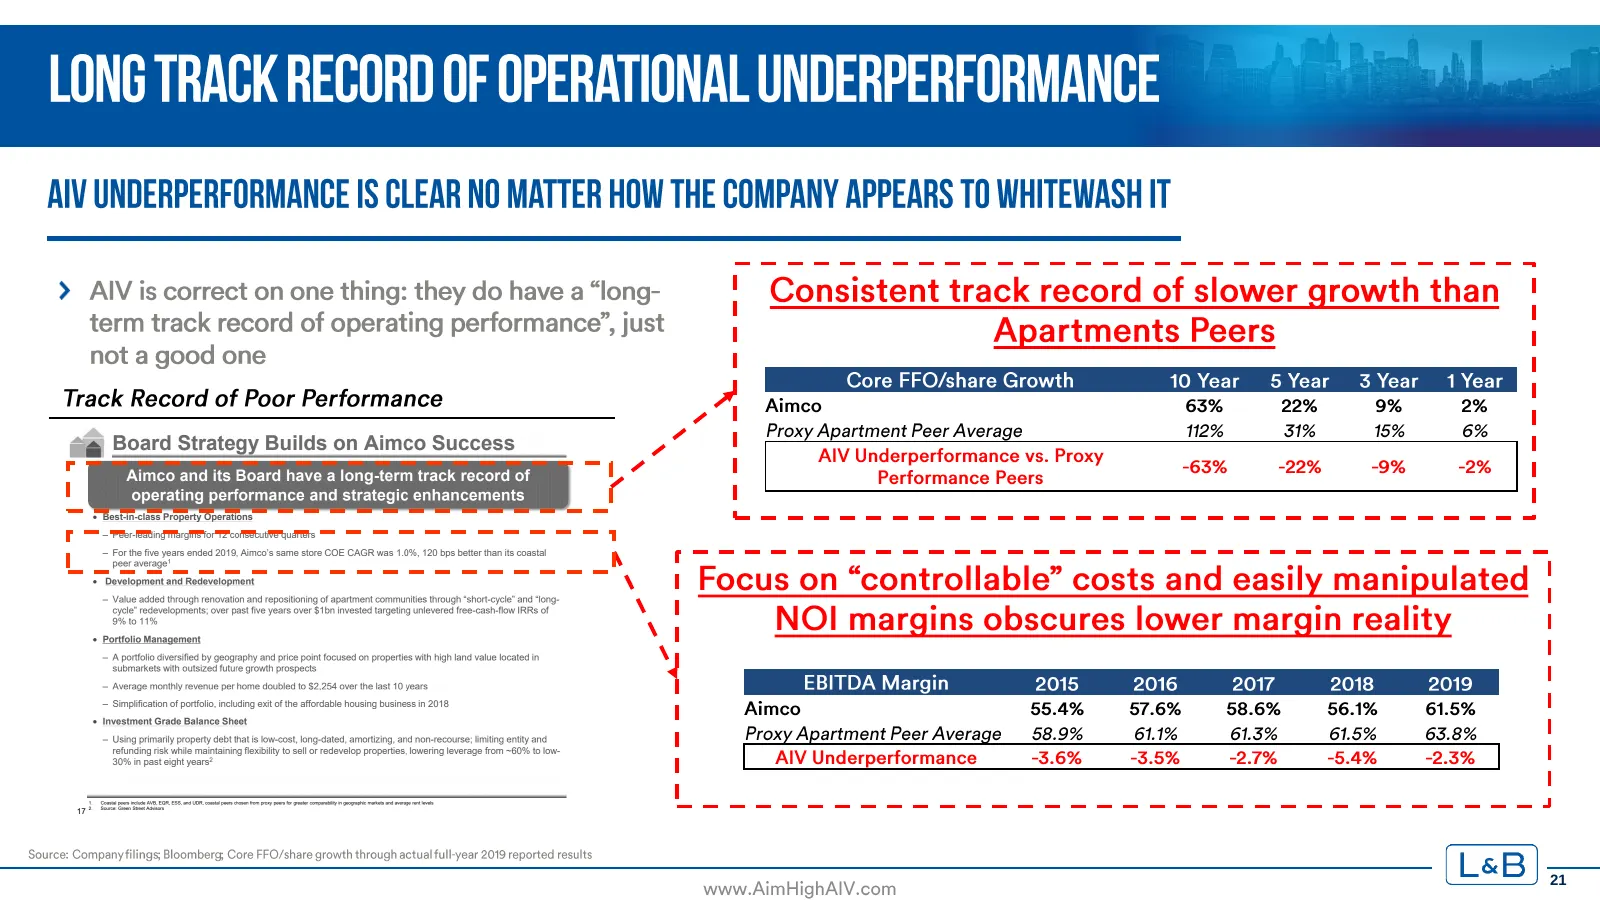
Slide 21: Long Track Record of Operational Underperformance
LONG TRACK RECORD OF OPERATIONAL UNDERPERFORMANCE AIV UNDERPERFORMANCE IS CLEAR NO MATTER HOW THE COMPANY APPEARS TO WHITEWASH IT Consistent track record of slower growth than I I ! I I Apartments Peers I I A | Core FFO/share Growth 10 Year_SYear_3Year_1Year J I I I I ! I I I > AIV is correct on one
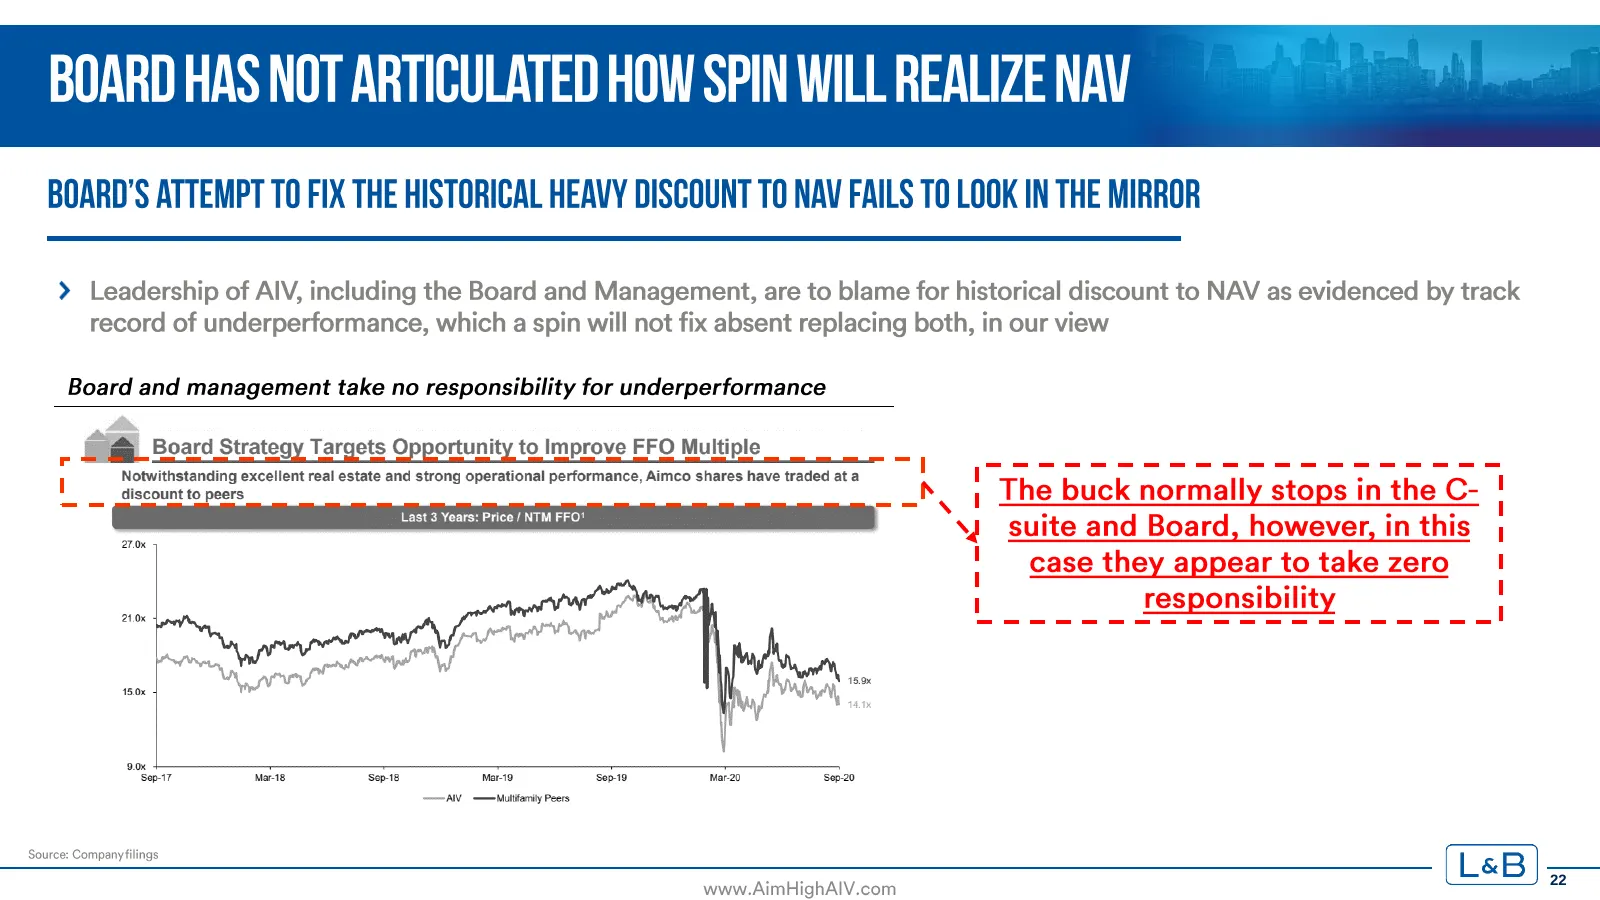
Slide 22: Board Has Not Articulated How Spin Will Realize NAV
BOARD HAS NOT ARTICULATED HOW SPIN WILL REALIZE NAV BOARD'S ATTEMPT TO FIX THE HISTORICAL HEAVY DISCOUNT TO NAV FAILS TO LOOK IN THE MIRROR > Leadership of AIV, including the Board and Management, are to blame for historical discount to NAV as evidenced by track record of underperformance, which a s
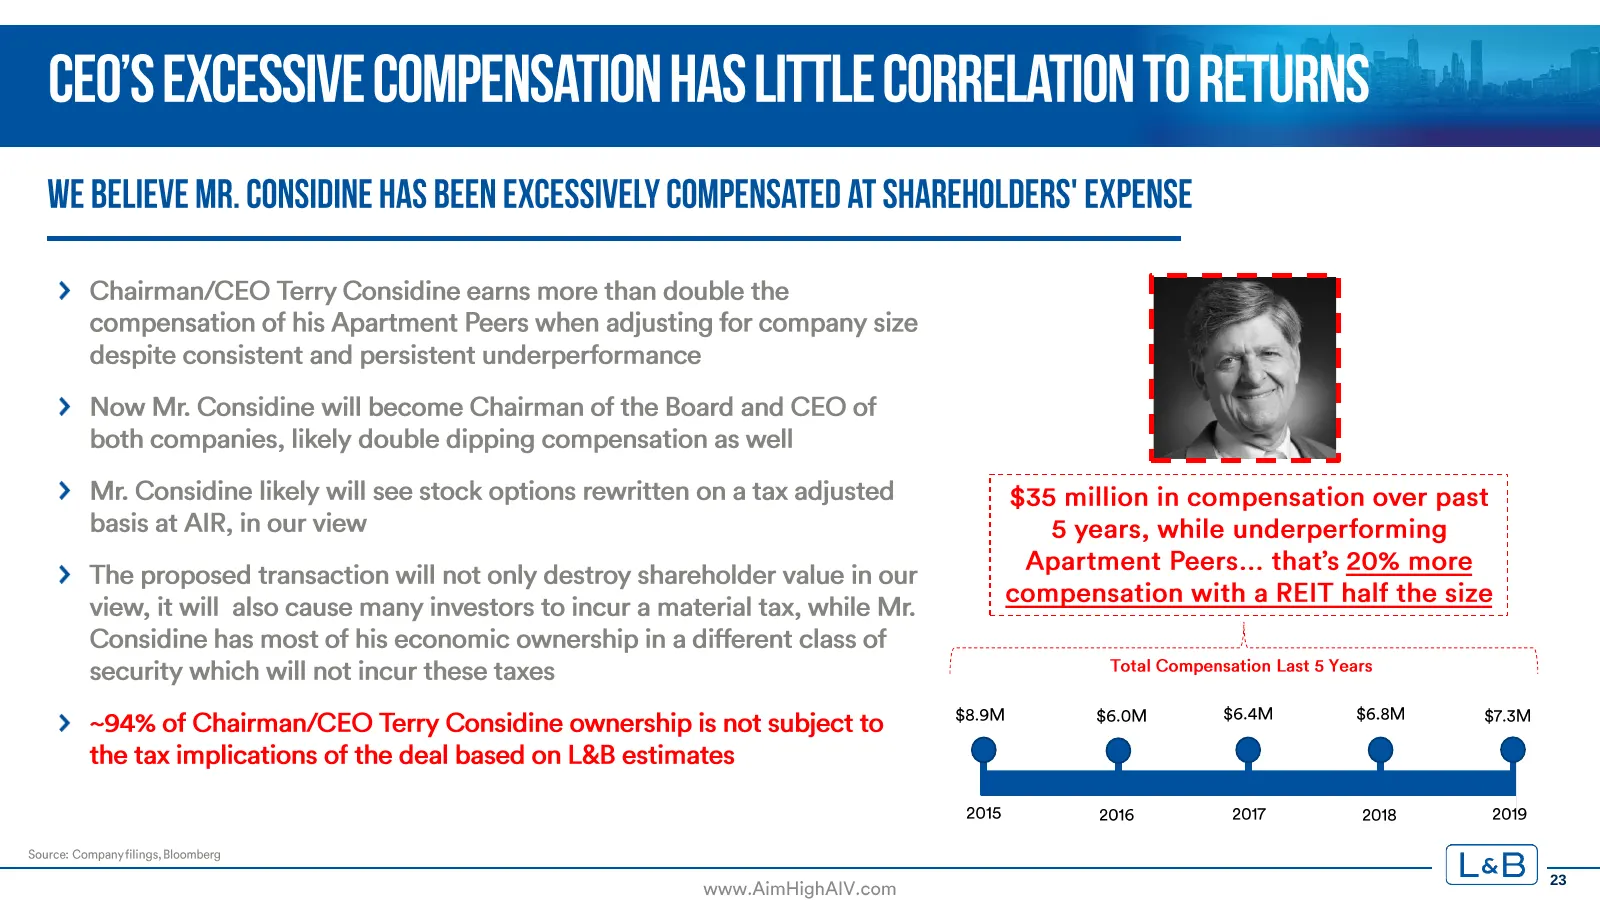
Slide 23: CEO's Excessive Compensation Has Little Correlation to Returns
CEO'S EXCESSIVE COMPENSATION HAS LITTLE CORRELATION TO RETURNS WE BELIEVE MR. CONSIDINE HAS BEEN EXCESSIVELY COMPENSATED AT SHAREHOLDERS’ EXPENSE > Chairman/CEO Terry Considine earns more than double the compensation of his Apartment Peers when adjusting for company size despite consistent and persi
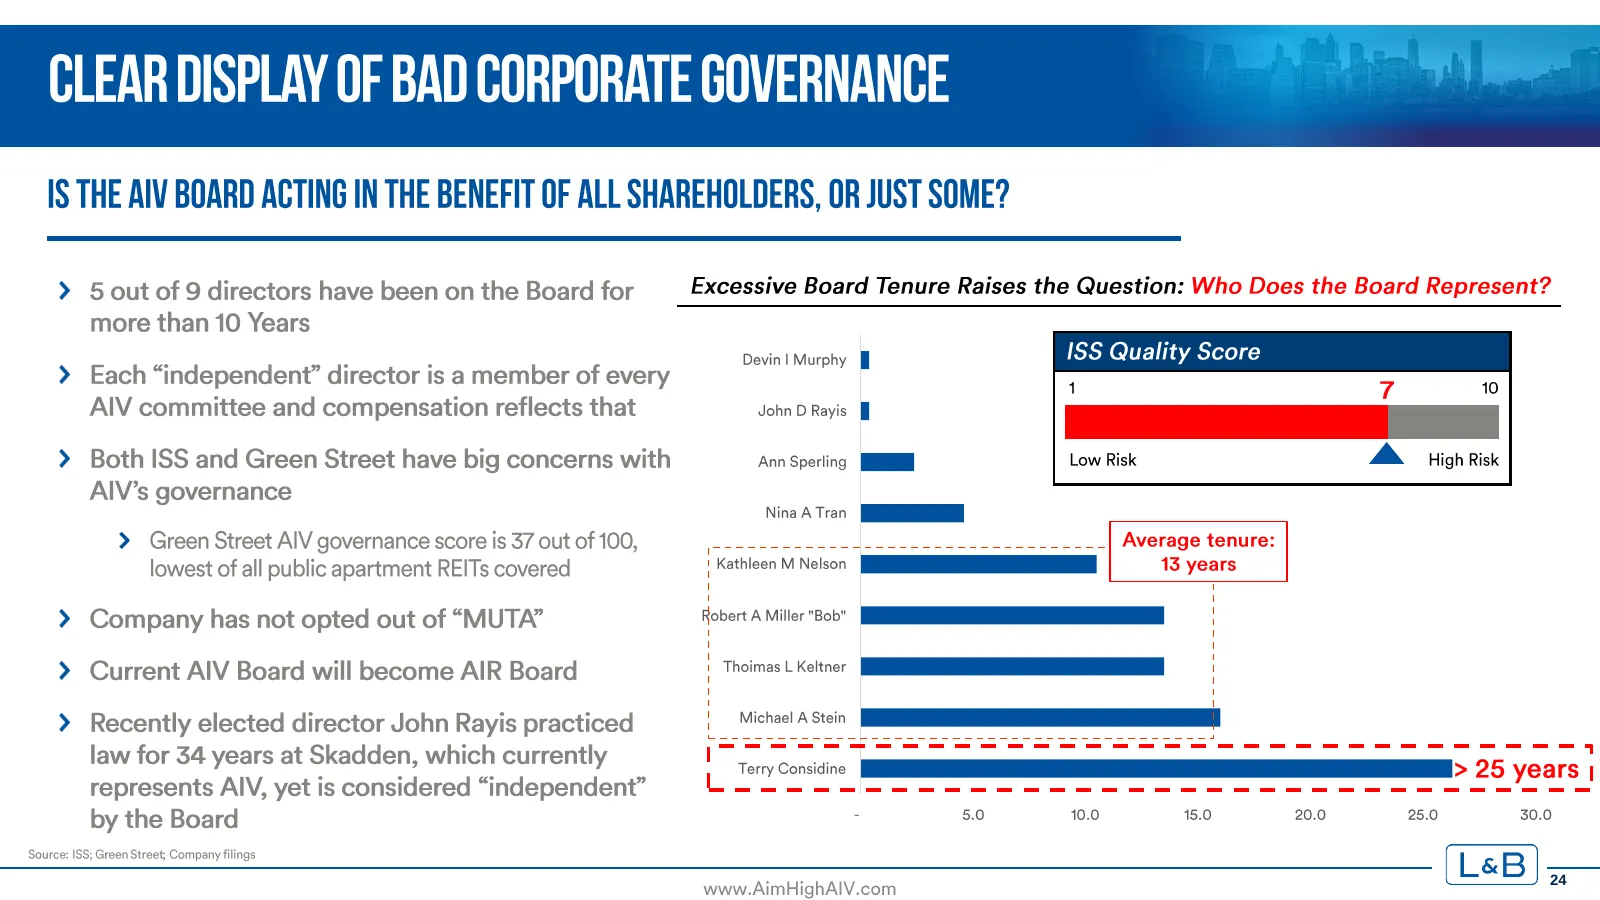
Slide 24: Clear Display of Bad Corporate Governance
CLEAR DISPLAY OF BAD CORPORATE GOVERNANCE IS THE AIV BOARD ACTING IN THE BENEFIT OF ALL SHAREHOLDERS, OR JUST SOME? > 5 out of 9 directors have been on the Board for Excessive Board Tenure Raises the Question: Who Does the Board Represent? more than 10 Years . ISS Quality Score 2 2 . De | Murphy > E
Slide 25: There Is a Clear Pattern of Value Destruction
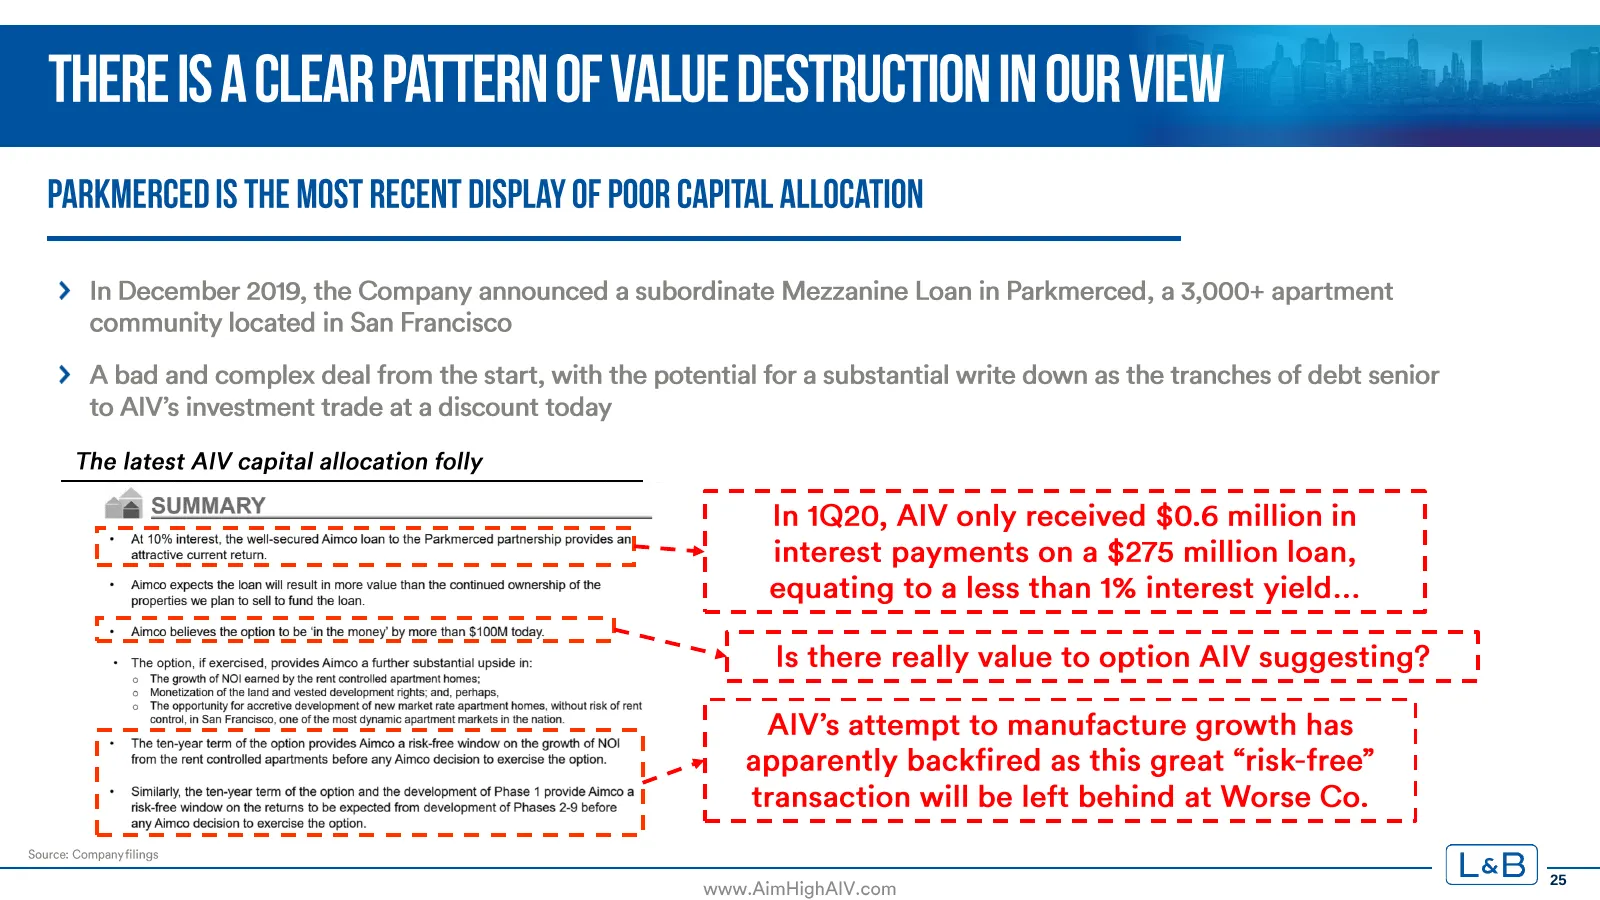
THERE IS A CLEAR PATTERN OF VALUE DESTRUCTION IN OUR VIEW PARKMERCED IS THE MOST RECENT DISPLAY OF POOR CAPITAL ALLOCATION > In December 2019, the Company announced a subordinate Mezzanine Loan in Parkmerced, a 3,000+ apartment community located in San Francisco > Abad and complex deal from the star
Slide 26: The Pattern of Value Destruction Continues
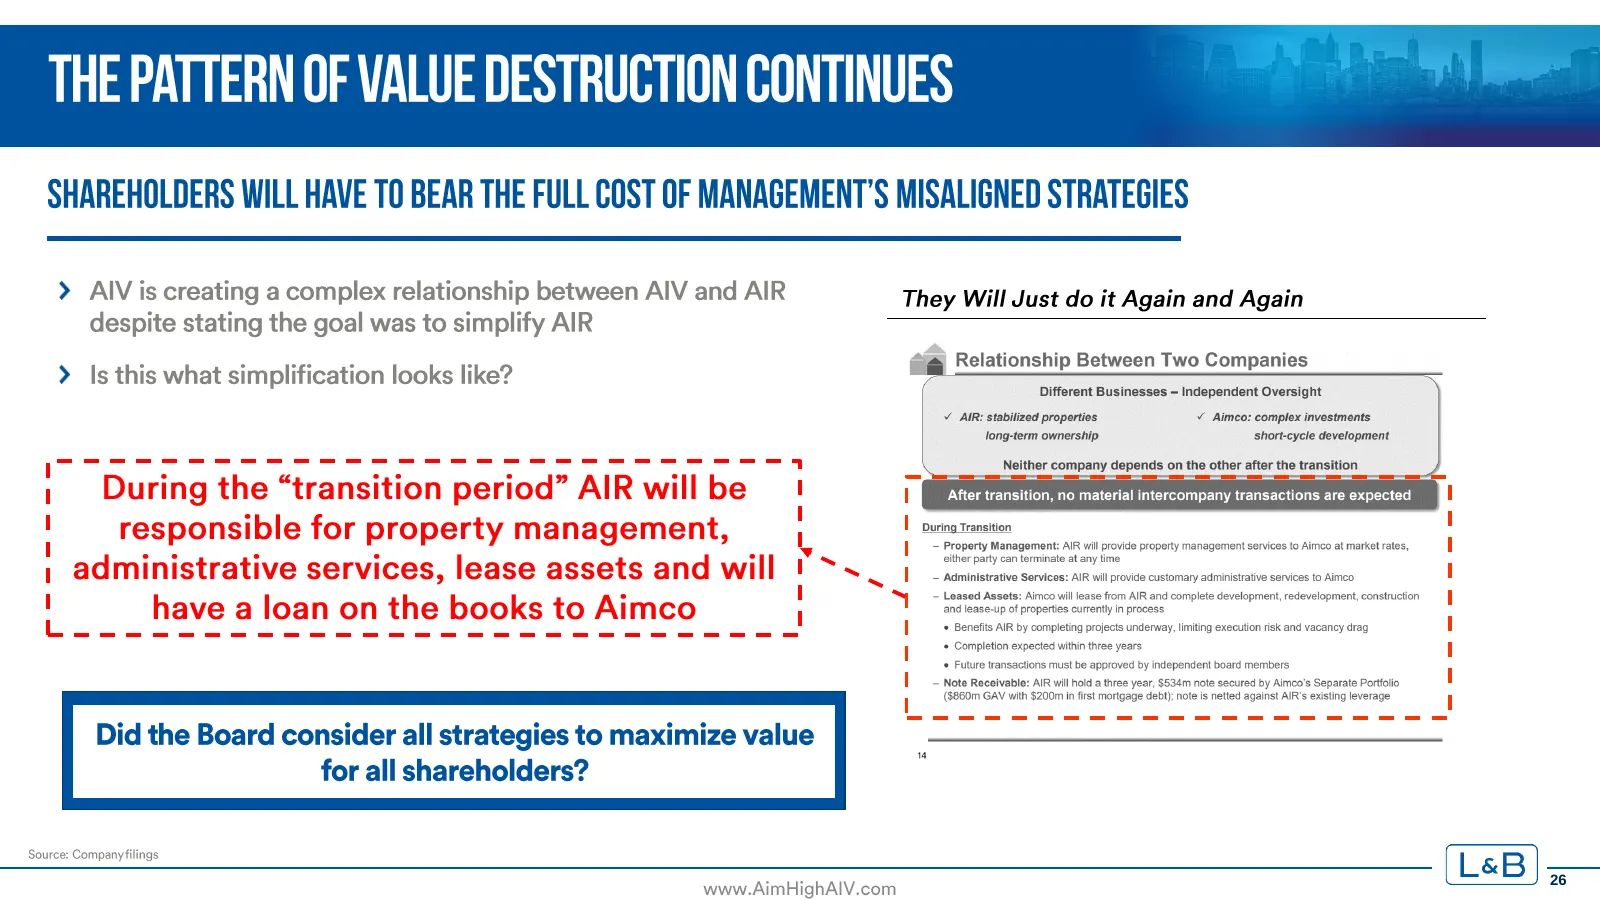
THE PATTERN OF VALUE DESTRUCTION CONTINUES SHAREHOLDERS WILL HAVE TO BEAR THE FULL COST OF MANAGEMENT'S MISALIGNED STRATEGIES > AlV is creating a complex relationship between AIV and AIR despite stating the goal was to simplify AIR > Is this what simplification looks like? They Will Just do it Again
Slide 27: Shareholders Deserve to Have Their Voices Heard on the Spin
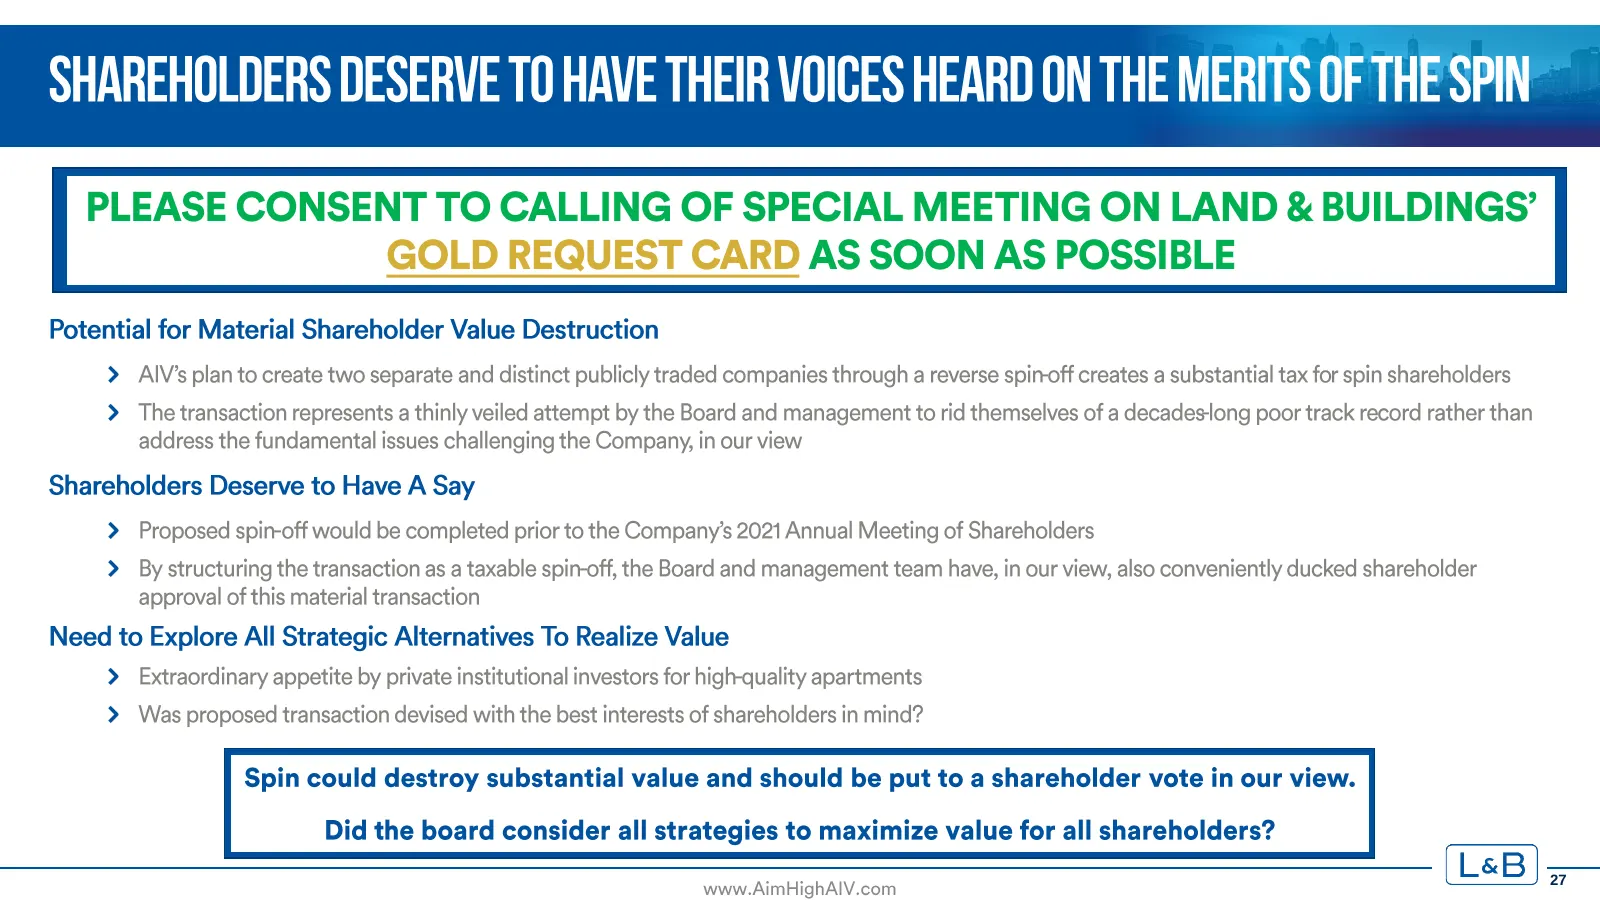
SHAREHOLDERS DESERVE TO HAVE THEIR VOICES HEARD ON THE MERITS OF THE SPIN PLEASE CONSENT TO CALLING OF SPECIAL MEETING ON LAND & BUILDINGS’ GOLD REQUEST CARD AS SOON AS POSSIBLE Potential for Material Shareholder Value Destruction > AIV’s plan to create two separate and distinct publicly traded comp
Slide 28: Legal Disclosure
LEGAL DISCLOSURE The materials in this presentation (the “Materials”) are for informational purposes only and may not be relied on by any person for any purpose and are not, and should not be construed as, investment, financial, legal, tax or other advice. The Materials represent the opinions of Lan
Slide 29: Legal Disclosure — Additional Information
LEGAL DISC ADDITIONAL INFORMATION Land & Buildings has made a definitive filing with the SEC of a solicitation statement and an accompanying GOLD request card to be used to solicit requests for the calling of a special meeting of shareholders of the Company to conduct an advisory vote on the propose
Source: SEC EDGAR · DFAN14A filed Oct 20, 2020
More decks from Apartment Investment and Management Company
 REITWorld Investor Conference 202426 slides · Nov 18, 2024
 Zelman Housing Summit 202426 slides · Sep 11, 2024
 Nareit REITweek 202426 slides · Jun 3, 2024
 Investor Presentation (February 2024)26 slides · Feb 29, 2024
 Nareit REITworld Conference 202331 slides · Nov 13, 2023
 Investor Presentation (September 2023)39 slides · Sep 13, 2023