Protection One — Imperial Capital's Global Opportunities Conference 2008
32 slides from Protection One's conference presentation, Nov 18, 2008
Slide 1: Imperial Capital's Global Opportunities Conference
Imperial Capital’s Global Opportunities Conference November 18, 2008 New York, NY Richard Ginsburg, CEO Darius G. Nevin, CFO
Slide 2: Forward-looking Statements
Forward-looking Statements Certain statements in this presentation may contain forward-looking statements regarding Protection One, Inc. that are intended to qualify for the safe harbor from liability established by the Private Securities Litigation Reform Act of 1995. Statements that are not histor
Slide 3: Company Snapshot
Company Snapshot 2nd largest pure play security monitoring company in US (1) Sectors: Retail and Wholesale 2008 Revenue: $371mm (2) 2008 EBITDA: $108 (2) 9-30-08 RMR: $26.9mm 3,100 employees in 75 locations Excellent liquidity (3) No near term debt maturities (4) (1) Based on the 2008 SDM 100, May 2
Slide 4: Protection One Executive Leadership
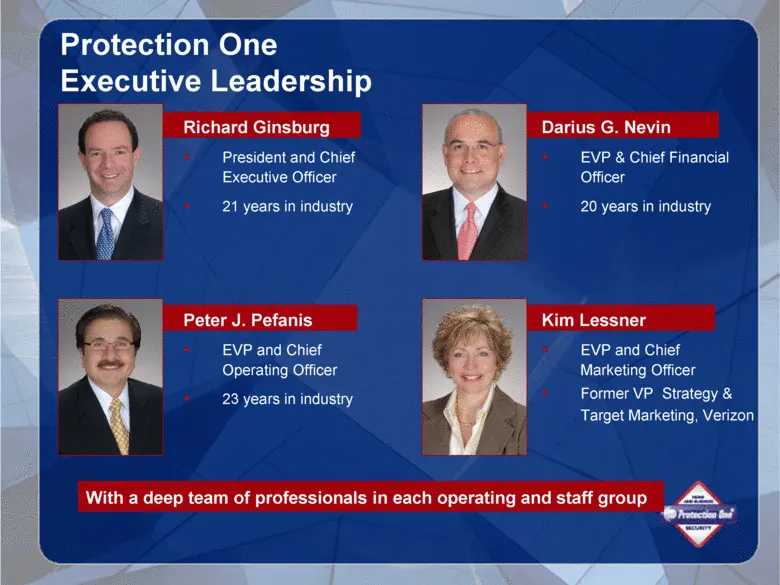
Protection One Executive Leadership Richard Ginsburg President and Chief Executive Officer 21 years in industry Darius G. Nevin EVP & Chief Financial Officer 20 years in industry Peter J. Pefanis EVP and Chief Operating Officer 23 years in industry With a deep team of professionals in each operating
Slide 5: Core Product & Service Offerings
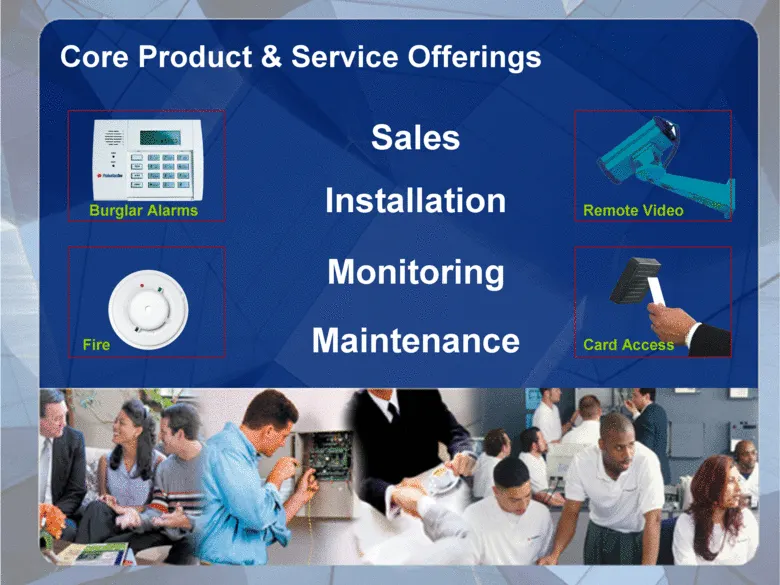
Core Product & Service Offerings Installation Sales Maintenance Monitoring Burglar Alarms Card Access Remote Video Fire
Slide 6: Retail Operations
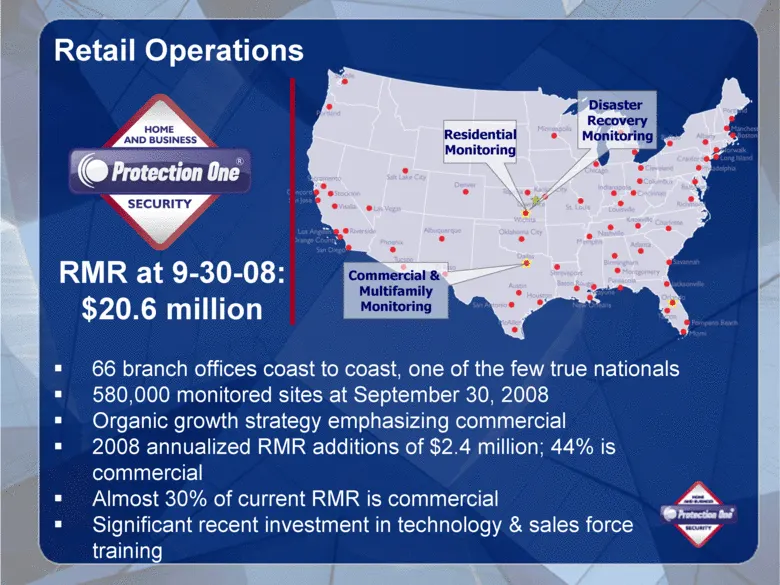
Retail Operations 66 branch offices coast to coast, one of the few true nationals 580,000 monitored sites at September 30, 2008 Organic growth strategy emphasizing commercial 2008 annualized RMR additions of $2.4 million; 44% is commercial Almost 30% of current RMR is commercial Significant recent i
Slide 7: Predictable Revenues
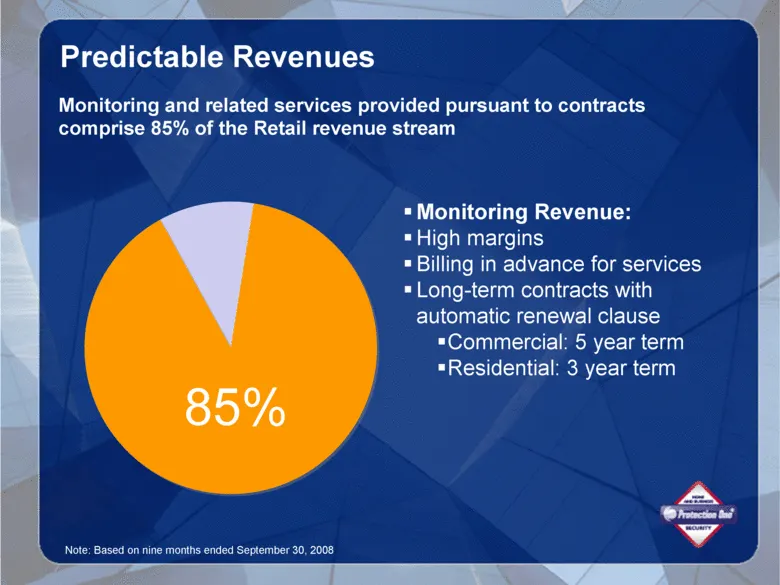
Note: Based on nine months ended September 30, 2008 Predictable Revenues Monitoring and related services provided pursuant to contracts comprise 85% of the Retail revenue stream Monitoring Revenue: High margins Billing in advance for services Long-term contracts with automatic renewal clause Commerc
Slide 8: Retail Revenues Growing
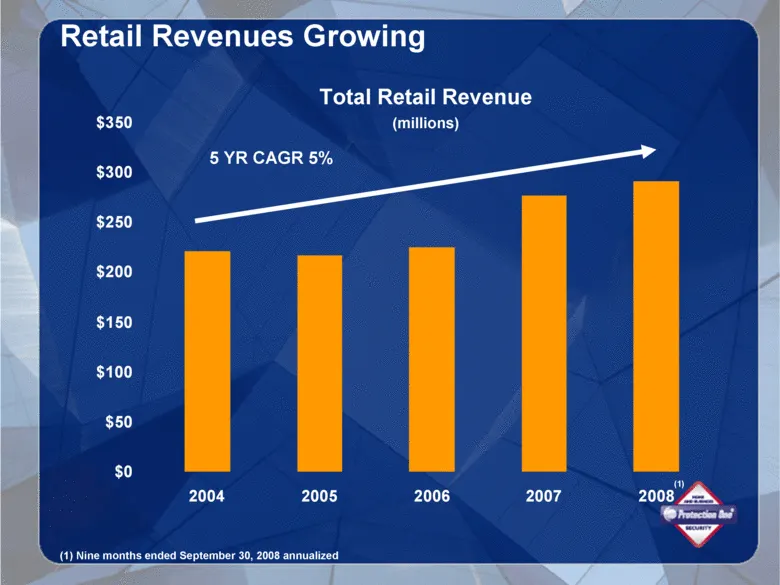
Retail Revenues Growing $0 $50 $100 $150 $200 $250 $300 $350 2004 2005 2006 2007 2008 Total Retail Revenue (millions) (1) (1) Nine months ended September 30, 2008 annualized 5 YR CAGR 5%
Slide 9: Significant Market Opportunity
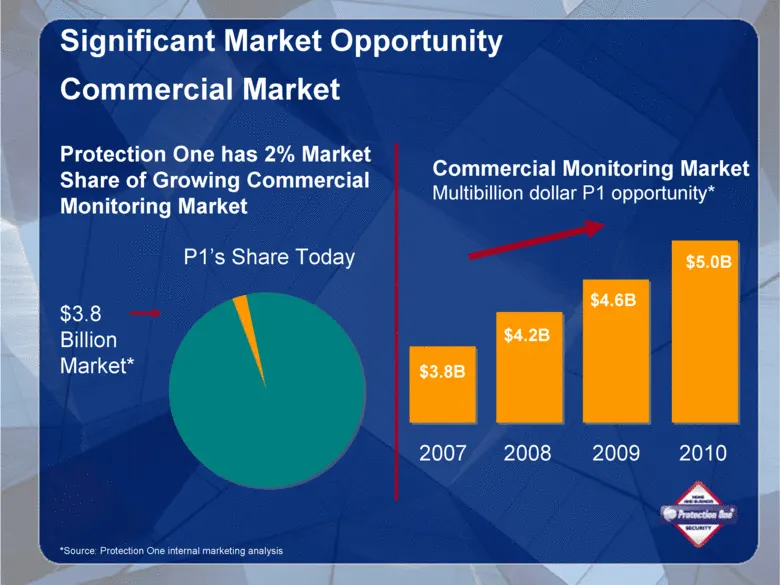
Significant Market Opportunity Commercial Market Protection One has 2% Market Share of Growing Commercial Monitoring Market $3.8 Billion Market* P1’s Share Today 2007 2008 2009 2010 $3.8B $4.2B $4.6B $5.0B *Source: Protection One internal marketing analysis Commercial Monitoring Market Multibillion
Slide 10: Commercial Growth Progress
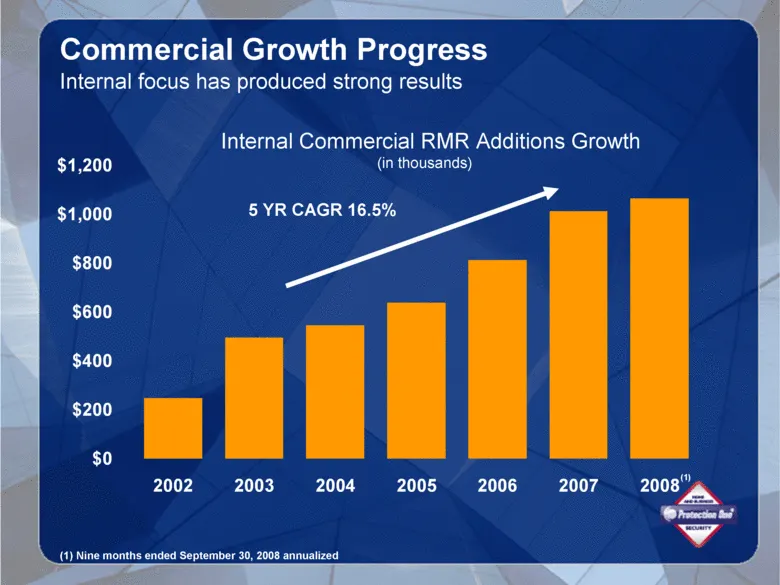
$0 $200 $400 $600 $800 $1,000 $1,200 2002 2003 2004 2005 2006 2007 2008 Internal Commercial RMR Additions Growth (in thousands) Internal focus has produced strong results (1) Commercial Growth Progress (1) Nine months ended September 30, 2008 annualized 5 YR CAGR 16.5%
Slide 11: Wholesale Operations
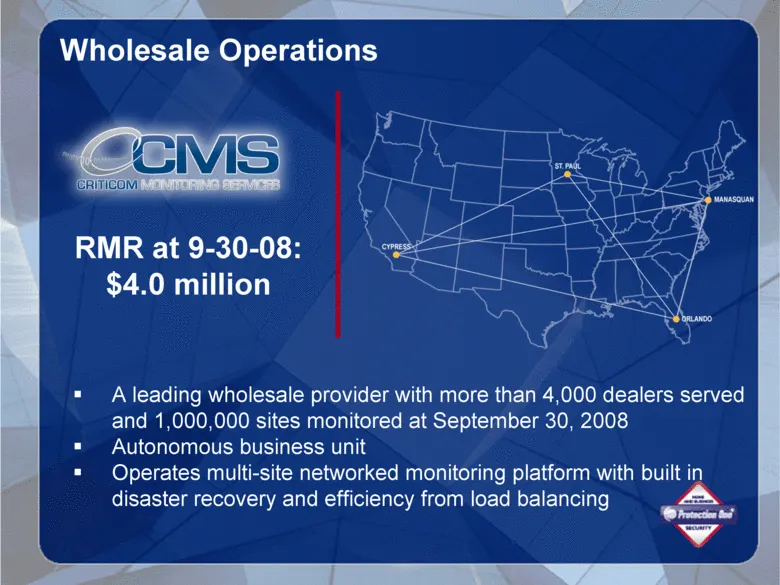
Wholesale Operations A leading wholesale provider with more than 4,000 dealers served and 1,000,000 sites monitored at September 30, 2008 Autonomous business unit Operates multi-site networked monitoring platform with built in disaster recovery and efficiency from load balancing RMR at 9-30-08: $4.0
Slide 12: Competitive Landscape
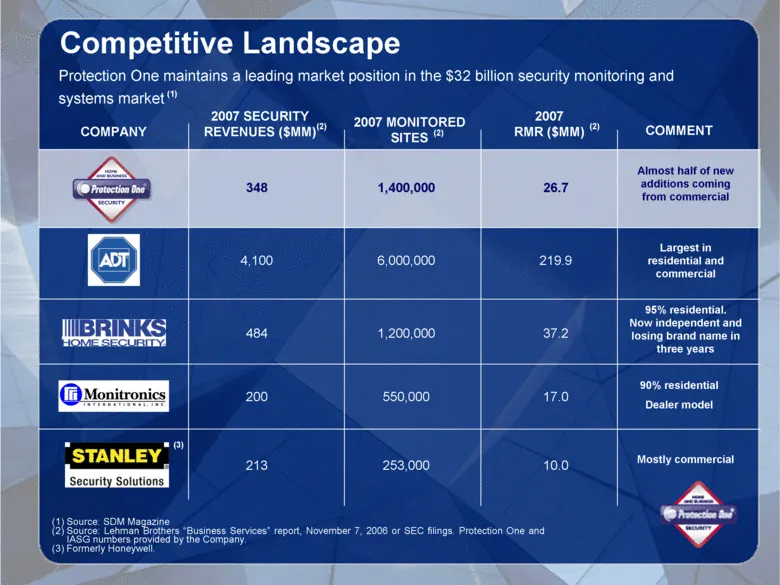
Competitive Landscape Protection One maintains a leading market position in the $32 billion security monitoring and systems market (1) Source: SDM Magazine (2) Source: Lehman Brothers “Business Services” report, November 7, 2006 or SEC filings. Protection One and IASG numbers provided by the Company
Slide 13: Industry opportunities in challenging economic times
Industry opportunities in challenging economic times . . . however
Slide 14: Industry growth during recent recessions
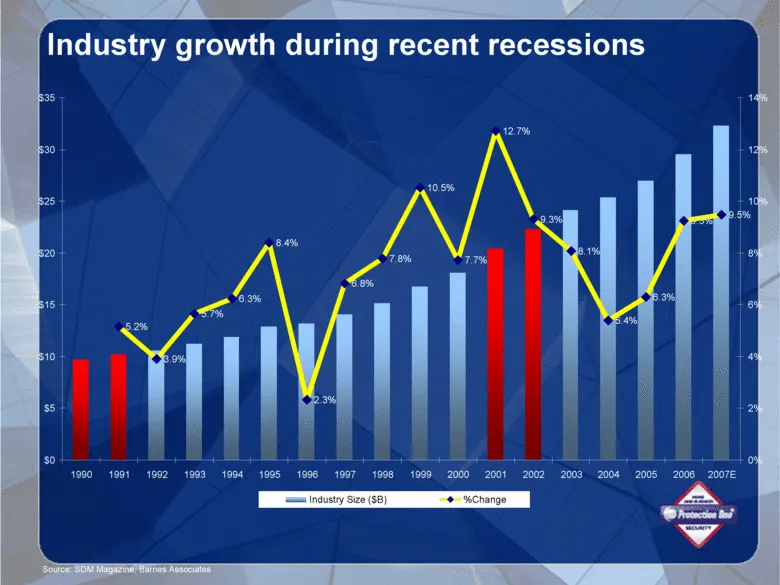
Source: SDM Magazine, Barnes Associates Industry growth during recent recessions 5.2% 3.9% 5.7% 6.3% 8.4% 2.3% 6.8% 7.8% 10.5% 7.7% 12.7% 9.3% 8.1% 5.4% 6.3% 9.3% 9.5% $0 $5 $10 $15 $20 $25 $30 $35 1990 1991 1992 1993 1994 1995 1996 1997 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007E 0% 2% 4% 6%
Slide 15: Impact on crime and police budgets
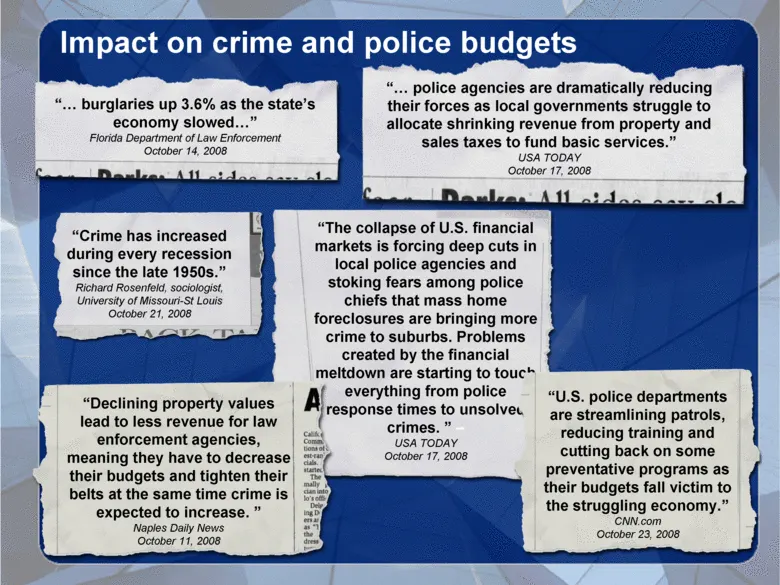
Impact on crime and police budgets “ burglaries up 3.6% as the state’s economy slowed” Florida Department of Law Enforcement October 14, 2008 “Crime has increased during every recession since the late 1950s.” Richard Rosenfeld, sociologist, University of Missouri-St Louis October 21, 2008 “The colla
Slide 16: Sample situations that can drive security solutions: Residential
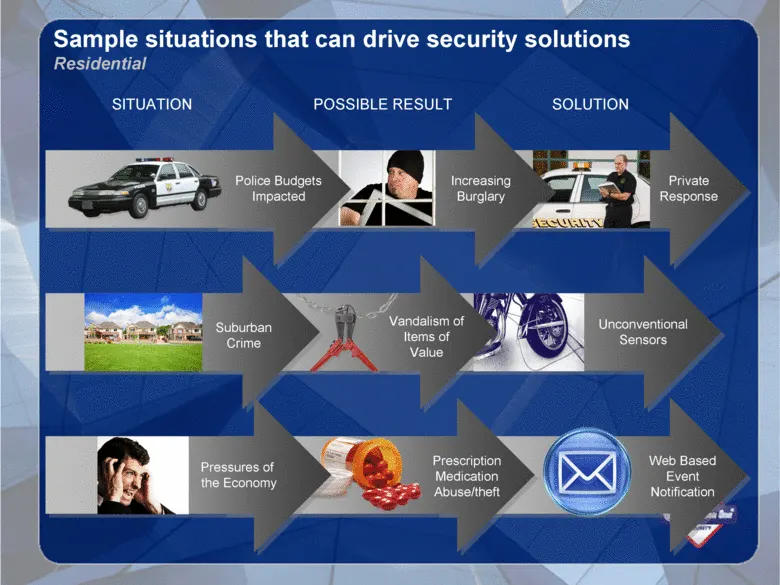
Sample situations that can drive security solutions Residential Private Response Police Budgets Impacted Increasing Burglary Unconventional Sensors Vandalism of Items of Value Suburban Crime Web Based Event Notification Prescription Medication Abuse/theft Pressures of the Economy SOLUTION POSSIBLE R
Slide 17: Sample situations that can drive security solutions: Commercial
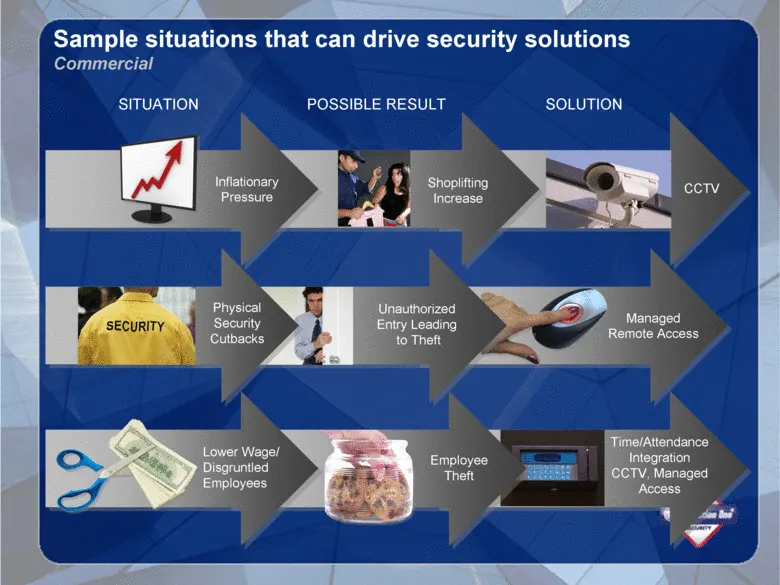
Sample situations that can drive security solutions Commercial Managed Remote Access CCTV Shoplifting Increase Unauthorized Entry Leading to Theft Physical Security Cutbacks Time/Attendance Integration CCTV, Managed Access SOLUTION POSSIBLE RESULT SITUATION Inflationary Pressure Employee Theft Lower
Slide 18: Value Add Differentiator: e-Secure
Value Add Differentiator: e-Secure Web-based control Online remote video viewing Text and e-mail notifications User-friendly remote access Event images sent via e-mail Works with any business phone and/or communication platform Enhances basic system monitoring Affordable Protection One was first nat
Slide 19: ‘@ Protection One
‘@ Protection One . ~— ee HOME SS AND BUSINESS “__
Slide 20: Capitalization
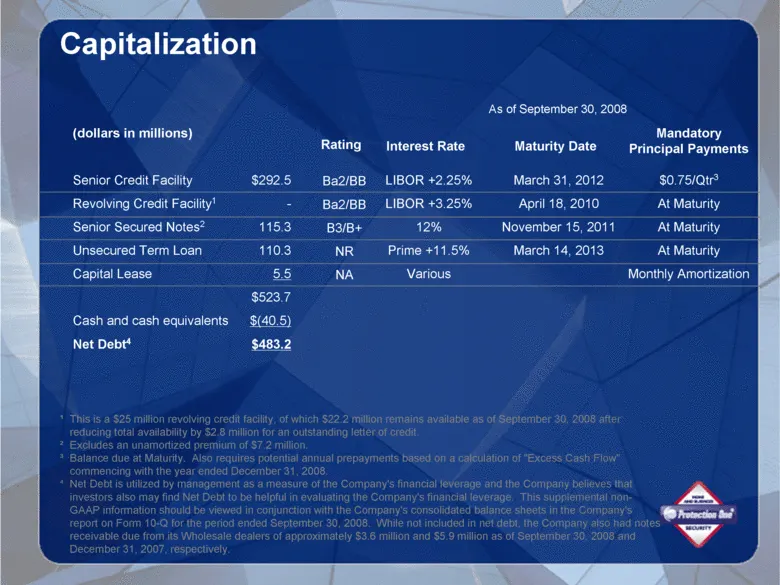
Capitalization (dollars in millions) Maturity Date Mandatory Principal Payments Senior Credit Facility Revolving Credit Facility1 Senior Secured Notes2 Unsecured Term Loan Capital Lease Cash and cash equivalents Net Debt4 March 31, 2012 April 18, 2010 November 15, 2011 March 14, 2013 As of September
Slide 21: Key Leverage Ratios and Sensitivities
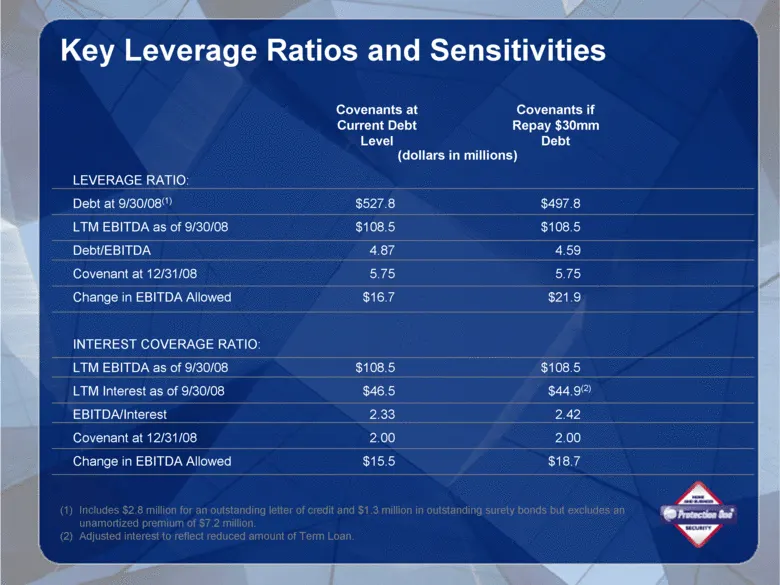
Key Leverage Ratios and Sensitivities (dollars in millions) LEVERAGE RATIO: Debt at 9/30/08(1) LTM EBITDA as of 9/30/08 Debt/EBITDA Covenant at 12/31/08 Change in EBITDA Allowed INTEREST COVERAGE RATIO: LTM EBITDA as of 9/30/08 LTM Interest as of 9/30/08 EBITDA/Interest Covenant at 12/31/08 Change i
Slide 22: Good Asset Coverage Given Industry M&A
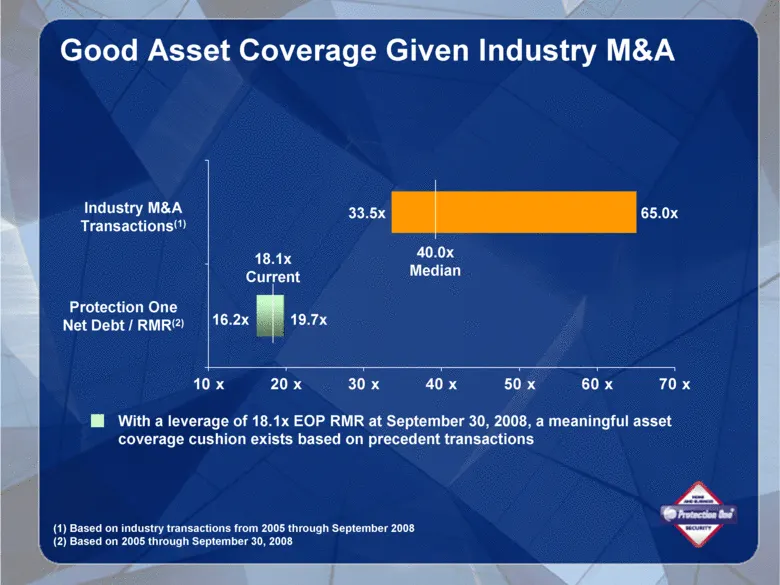
10x 20x 30x 40x 50x 60x 70x Industry M&A Transactions(1) Protection One Net Debt / RMR(2) 40.0x Median 18.1x Current 33.5x 65.0x 19.7x 16.2x With a leverage of 18.1x EOP RMR at September 30, 2008, a meaningful asset coverage cushion exists based on precedent transactions (1) Based on industry transa
Slide 23: Key Retail Performance Metrics
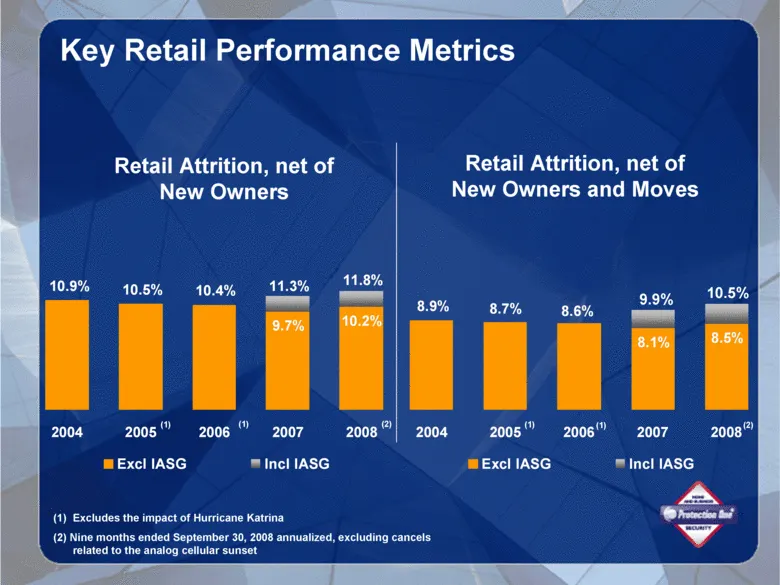
Key Retail Performance Metrics 8.1% 8.9% 8.7% 8.6% 8.5% 2004 2005 2006 2007 2008 Excl IASG Incl IASG Retail Attrition, net of New Owners 10.2% 10.4% 10.5% 10.9% 9.7% 11.8% 11.3% 2004 2005 2006 2007 2008 Excl IASG Incl IASG (1) (1) (2) (2) (1) (1) 9.9% 10.5% (1) Excludes the impact of Hurricane Katri
Slide 24: Key Retail Performance Metrics
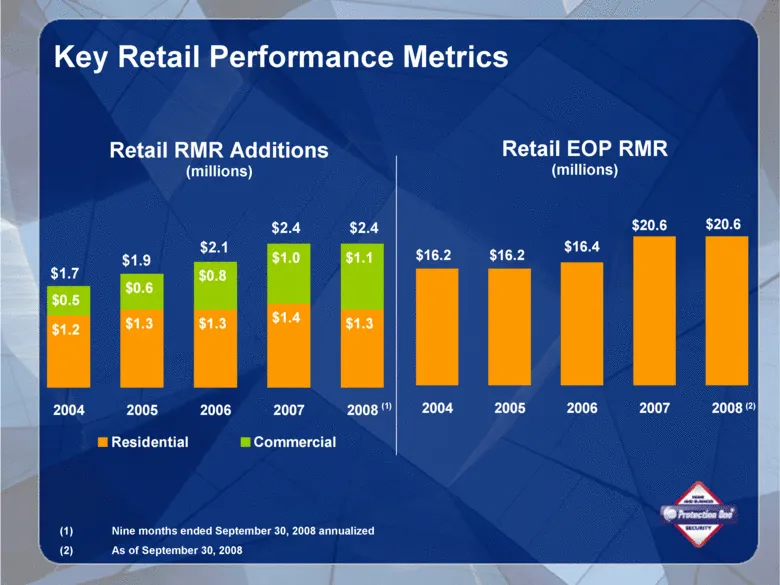
Key Retail Performance Metrics $20.6 $20.6 $16.4 $16.2 $16.2 2004 2005 2006 2007 2008 Retail EOP RMR (millions) Retail RMR Additions (millions) $1.2 $1.3 $1.3 $1.4 $1.3 $0.5 $0.6 $0.8 $1.0 $1.1 2004 2005 2006 2007 2008 Residential Commercial $1.7 $1.9 $2.1 $2.4 $2.4 (1) (2) (1) Nine months ended Sep
Slide 25: Retail Cash Payback
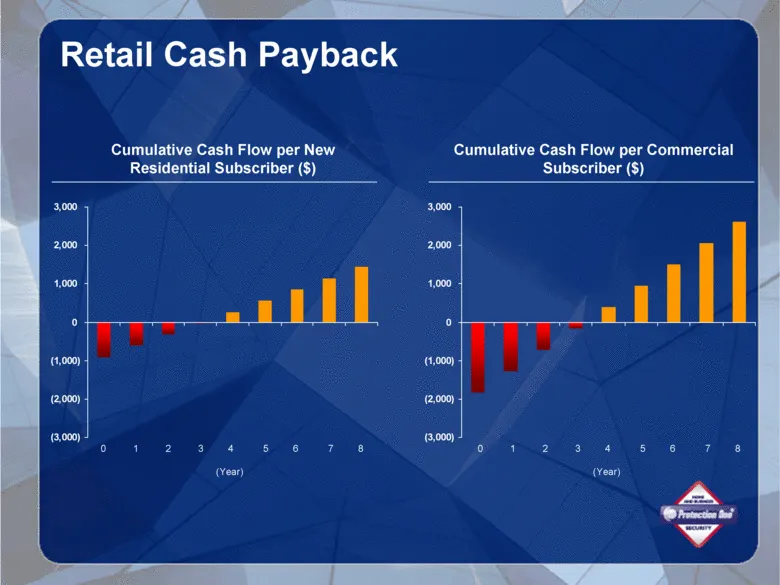
Retail Cash Payback (3,000) (2,000) (1,000) 0 1,000 2,000 3,000 (3,000) (2,000) (1,000) 0 1,000 2,000 3,000 Cumulative Cash Flow per New Residential Subscriber ($) Cumulative Cash Flow per Commercial Subscriber ($) 0 1 2 3 4 5 6 7 8 0 1 2 3 4 5 6 7 8 (Year) (Year)
Slide 26: SS SN
SS SN AND S BUSINESS me @ Protection One LISTED
Slide 27: Investment Highlights
Investment Highlights One of the largest companies in North America serving the residential, commercial and wholesale market Residential business is a strong cash generator based on ARPU growth, lower attrition, and improved operating productivity Wholesale business provides cash, growth, and acquis
Slide 28: Investment Highlights (cont.)
Investment Highlights (cont.) Capital structure provides runway to execute operating plans Only national provider focused on web-based service (e-Secure) in order to add to the customer value experience Since 2003, have built a top 5 position in the growing commercial market Experienced public compa
Slide 29: HOME
HOME AND BUSINESS @ Protection One
Slide 30: —s SS
—s 2 SS AND Y BUSINESS = @ Protection One | LISTED
Slide 31: Adjusted EBITDA Reconciliation
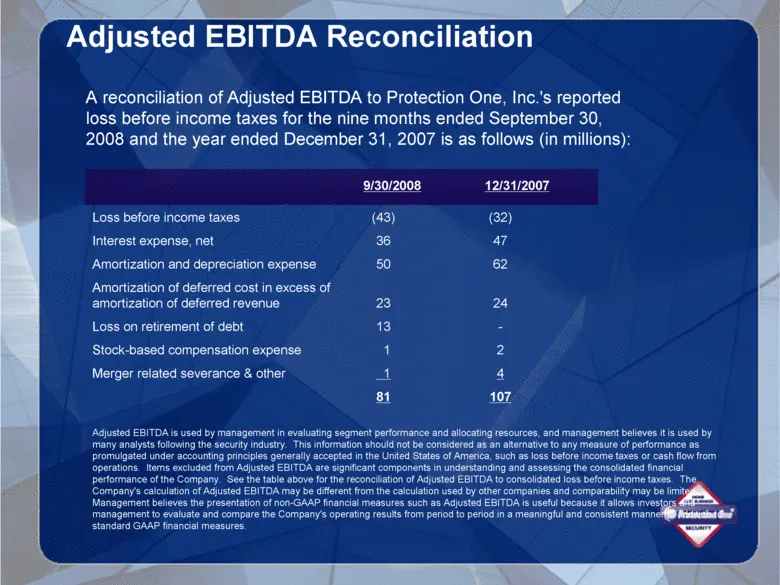
Adjusted EBITDA Reconciliation A reconciliation of Adjusted EBITDA to Protection One, Inc.'s reported loss before income taxes for the nine months ended September 30, 2008 and the year ended December 31, 2007 is as follows (in millions): 9/30/2008 12/31/2007 Loss before income taxes Interest expense
Slide 32: RMR Reconciliation
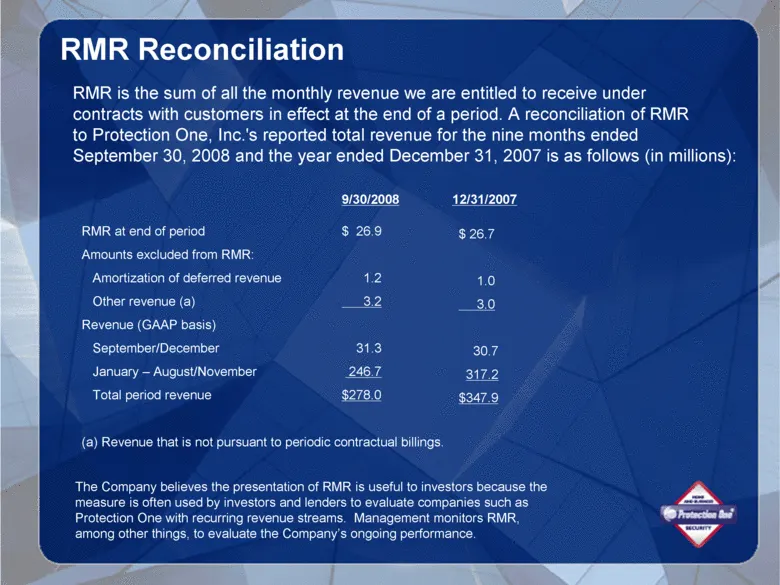
RMR Reconciliation RMR is the sum of all the monthly revenue we are entitled to receive under contracts with customers in effect at the end of a period. A reconciliation of RMR to Protection One, Inc.'s reported total revenue for the nine months ended September 30, 2008 and the year ended December 3
Source: SEC EDGAR · 8-K filed Nov 18, 2008