Companhia Siderurgica Nacional · BMFBOVESPA:CSNA3
Companhia Siderurgica Nacional — Wheeling Pittsburgh — Merger or Acquisition (August 2006)
19 slides from Companhia Siderurgica Nacional's merger presentation, Aug 3, 2006
Slide 1: The Transformation of Wheeling-Pittsburgh
The Transformation of Wheeling-Pittsburgh August 2006
Slide 2: Forward-looking statements
The information contained in this presentation, other than historical information, consists of forward-looking statements within the meaning of Section 27A of the Securities Act and Section 21E of the Securities Exchange Act. In particular, statements containing estimates or projections of future op
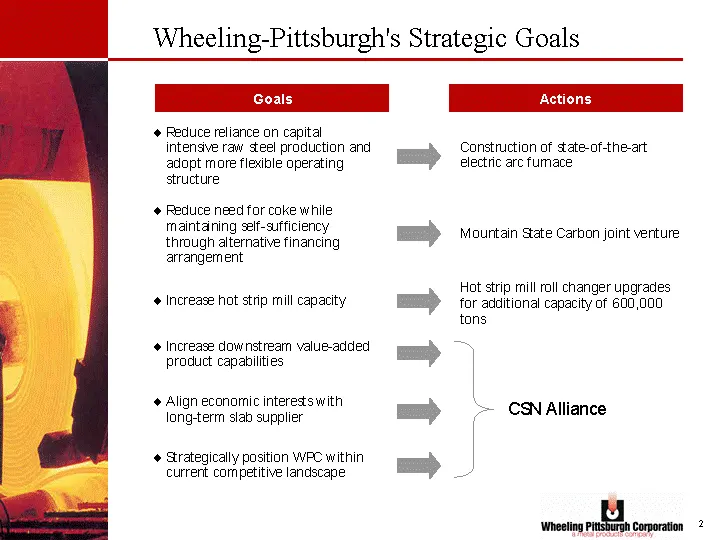
Slide 3: Wheeling-Pittsburgh's Strategic Goals
Wheeling-Pittsburgh's Strategic Goals Actions Goals
Slide 4: Strong Strategic Rationale
Strong Strategic Rationale Upgrade of hot strip mill and increased capacity to 4.0mm tons energy efficient new furnace will drive a competitive cost structure through gas savings additional throughput of 600,000 tons reduces costs per ton significant operating efficiencies and improved productivity
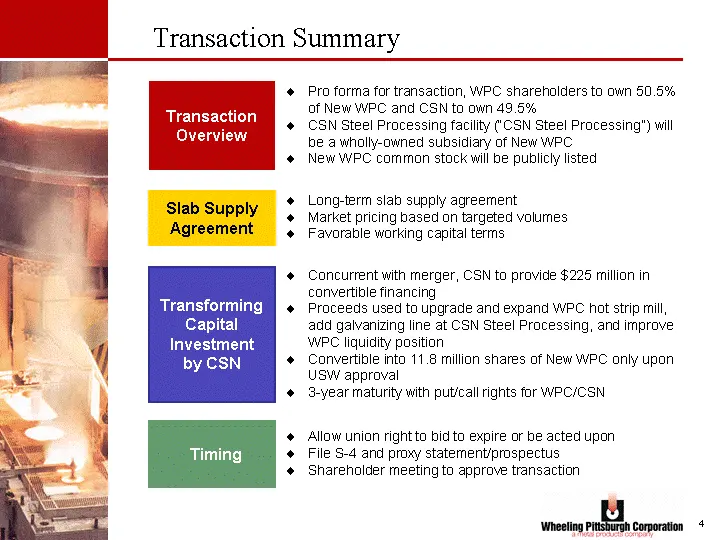
Slide 5: Transaction Summary
Transaction Summary Transaction Overview Transforming Capital Investment by CSN Timing Slab Supply Agreement Pro forma for transaction, WPC shareholders to own 50.5% of New WPC and CSN to own 49.5% CSN Steel Processing facility ("CSN Steel Processing") will be a wholly-owned subsidiary of New WPC Ne
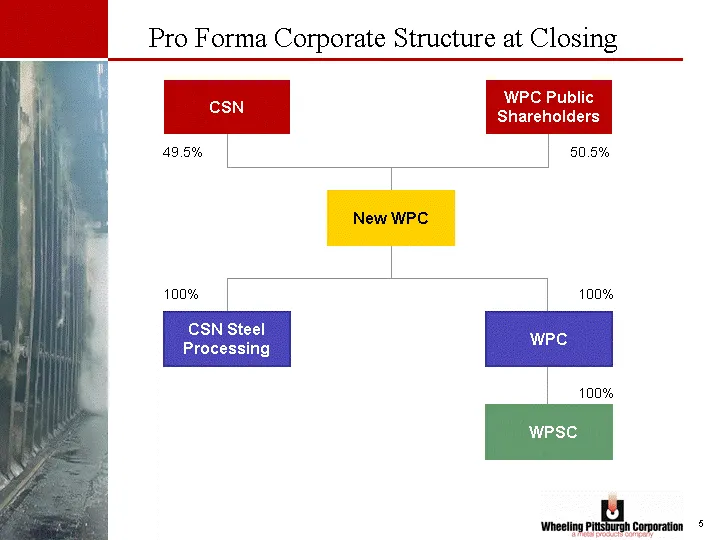
Slide 6: Pro Forma Corporate Structure at Closing
Pro Forma Corporate Structure at Closing CSN WPC Public Shareholders New WPC CSN Steel Processing WPC WPSC 100% 100% 100% 49.5% 50.5%
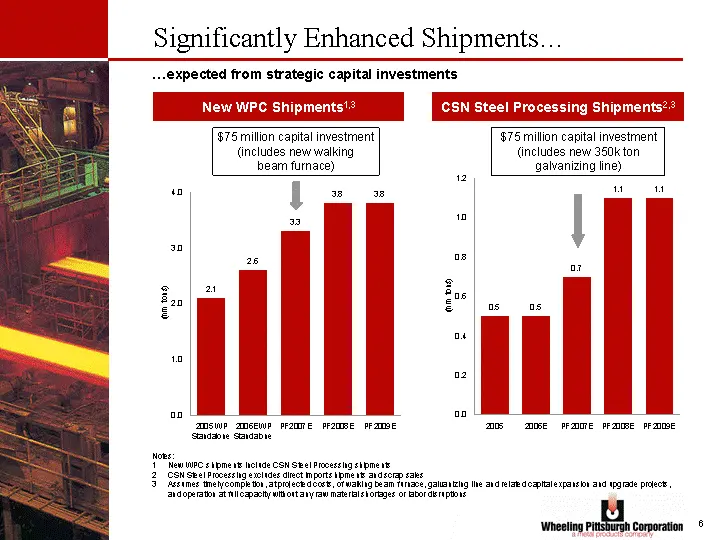
Slide 7: Significantly Enhanced Shipments
Significantly Enhanced Shipments... ....expected from strategic capital investments New WPC Shipments1,3 CSN Steel Processing Shipments2,3 $75 million capital investment (includes new walking beam furnace) $75 million capital investment (includes new 350k ton galvanizing line) Notes: 1 New WPC shipm
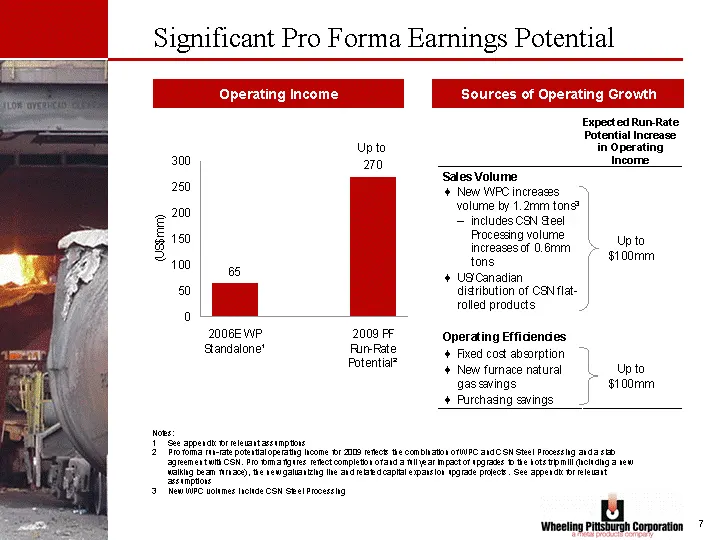
Slide 8: Significant Pro Forma Earnings Potential
Significant Pro Forma Earnings Potential Operating Income Sources of Operating Growth Up to Notes: 1 See appendix for relevant assumptions 2 Pro forma run-rate potential operating income for 2009 reflects the combination of WPC and CSN Steel Processing and a slab agreement with CSN. Pro forma figure
Slide 9: Extensive and Rigorous Internal Process
Extensive and Rigorous Internal Process In exploratory talks with broad range of parties regarding strategic alternatives in most recent 18 months and signed confidentiality agreements with several parties Proposals received from Esmark and CSN CSN proposal and business plan jointly developed with W
Slide 10: CSN Alliance Provides Superior Value
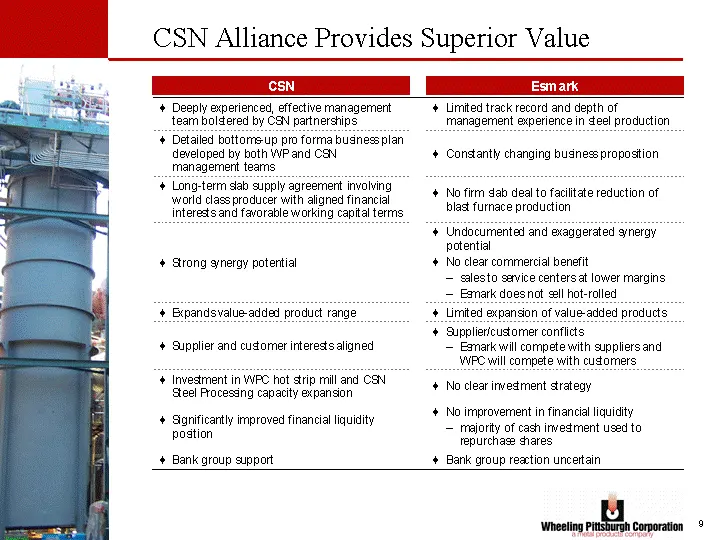
CSN Alliance Provides Superior Value
Slide 11: Superior Pro Forma Financial and Liquidity Position
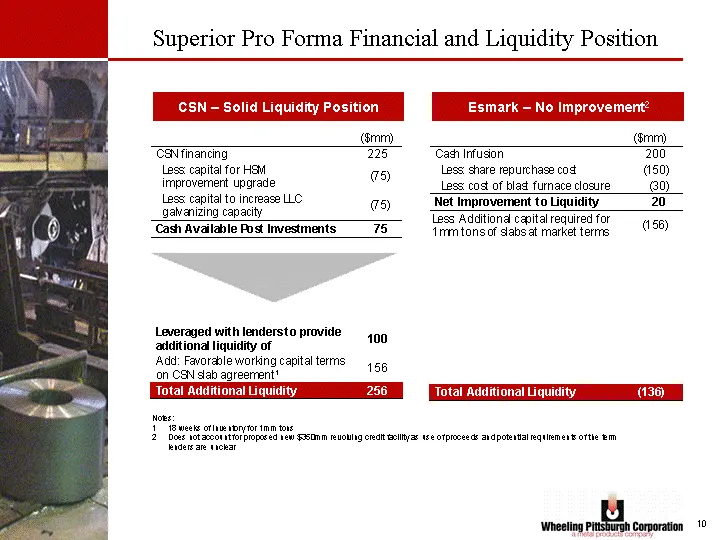
CSN - Solid Liquidity Position Esmark - No Improvement2 Notes: 1 18 weeks of inventory for 1mm tons 2 Does not account for proposed new $350mm revolving credit facility as use of proceeds and potential requirements of the term lenders are unclear Superior Pro Forma Financial and Liquidity Position
Slide 12: Contributes 900,000 tons of capacity for value-added products
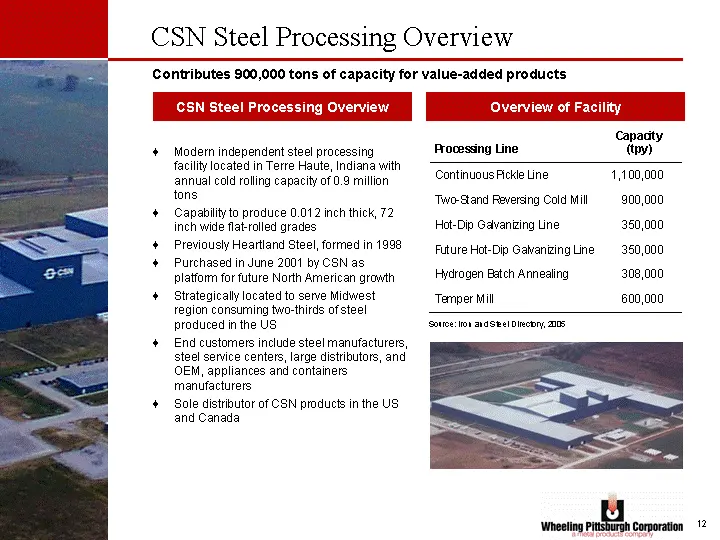
Contributes 900,000 tons of capacity for value-added products CSN Steel Processing Overview CSN Steel Processing Overview Overview of Facility Modern independent steel processing facility located in Terre Haute, Indiana with annual cold rolling capacity of 0.9 million tons Capability to produce 0.01
Slide 13: Broader Value-Added Product Offering
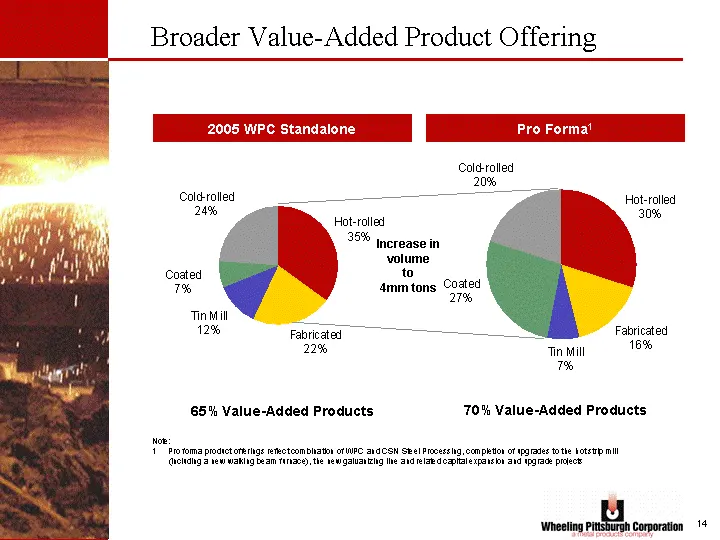
Broader Value-Added Product Offering 65% Value-Added Products 70% Value-Added Products 2005 WPC Standalone Pro Forma1 Increase in volume to 4mm tons Note: 1 Pro forma product offerings reflect combination of WPC and CSN Steel Processing, completion of upgrades to the hot strip mill (including a new
Slide 14: Favorable Long-Term Slab Supply Agreement
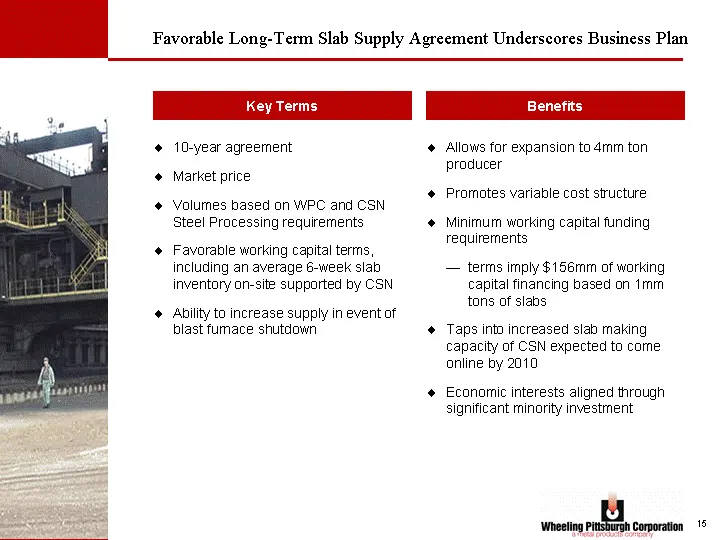
10-year agreement Market price Volumes based on WPC and CSN Steel Processing requirements Favorable working capital terms, including an average 6-week slab inventory on-site supported by CSN Ability to increase supply in event of blast furnace shutdown Key Terms Benefits Allows for expansion to 4mm
Slide 15: Governance Provisions and Shareholder Rights
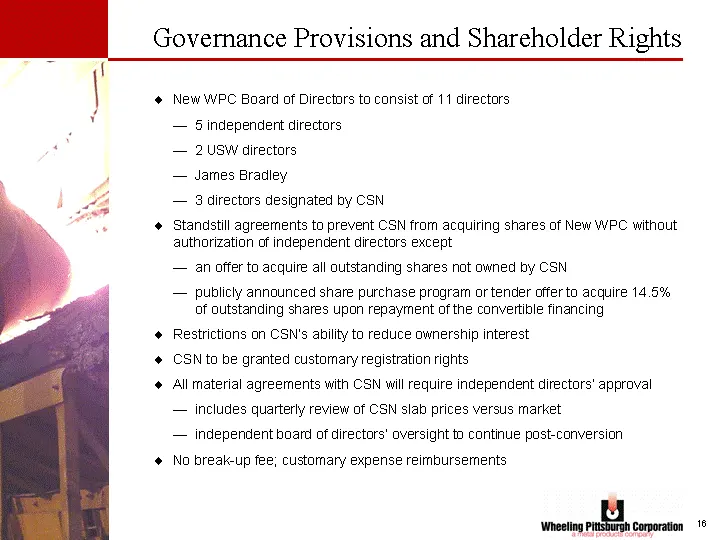
Governance Provisions and Shareholder Rights New WPC Board of Directors to consist of 11 directors 5 independent directors 2 USW directors James Bradley 3 directors designated by CSN Standstill agreements to prevent CSN from acquiring shares of New WPC without authorization of independent directors
Slide 16: CSN Is The Right Next Step for WPC
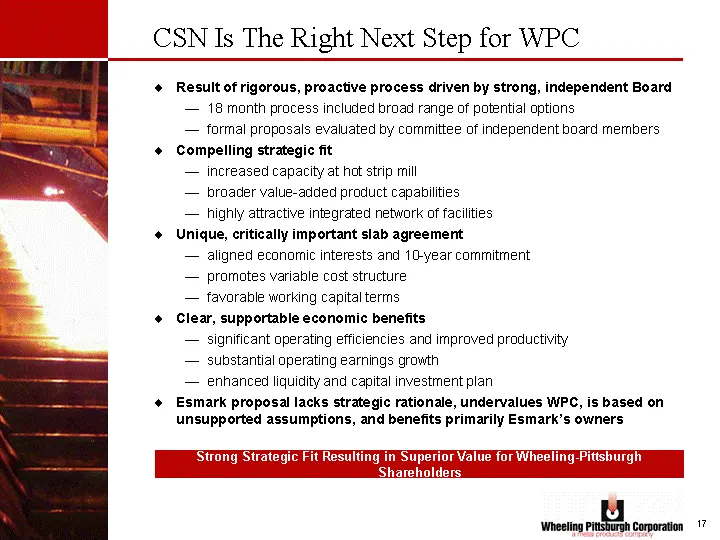
CSN Is The Right Next Step for WPC Result of rigorous, proactive process driven by strong, independent Board 18 month process included broad range of potential options formal proposals evaluated by committee of independent board members Compelling strategic fit increased capacity at hot strip mill b
Slide 17: Appendix
Appendix
Slide 18: Assumptions For Run-Rate Operating Earnings Potential
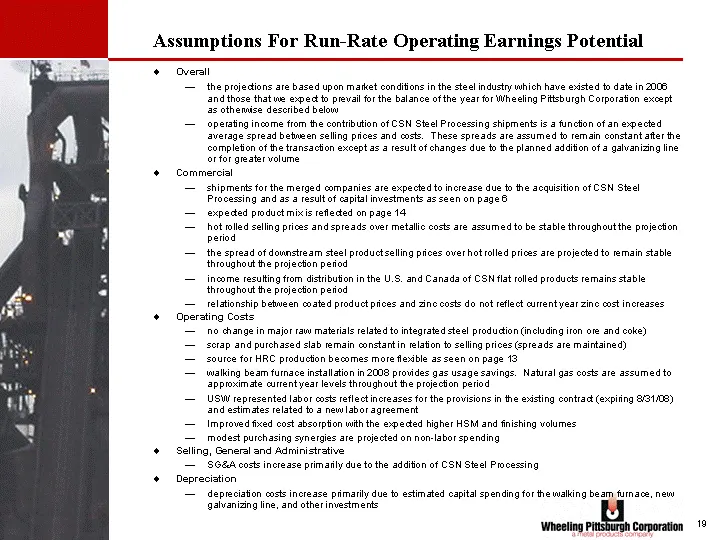
Assumptions For Run-Rate Operating Earnings Potential Overall the projections are based upon market conditions in the steel industry which have existed to date in 2006 and those that we expect to prevail for the balance of the year for Wheeling Pittsburgh Corporation except as otherwise described be
Slide 19: ‘Wheeling Pit
‘Wheeling Pit Metal pr
Source: SEC EDGAR · 8-K filed Aug 3, 2006
More decks from Companhia Siderurgica Nacional
 Q3 2026 Earnings Presentation25 slides · Nov 13, 2026
 National Steel — Q3 2026 Earnings Presentation29 slides · Nov 13, 2026
 Q2 2026 Earnings Presentation27 slides · Aug 13, 2026
 National Steel — Q1 2026 Earnings Presentation29 slides · May 14, 2026
 Q1 2026 Earnings Presentation24 slides · May 14, 2026
 National Steel — Q4 2025 Earnings Presentation31 slides · Mar 12, 2026