Flutter Entertainment plc · NYSE:FLUT
Flutter Entertainment — Paddy Power — H1 2015 Earnings Presentation
25 slides from Flutter Entertainment's earnings presentation, 2015
Slide 1: 2015 Interim Results
2015 INTERIM R
Slide 2: 2
2
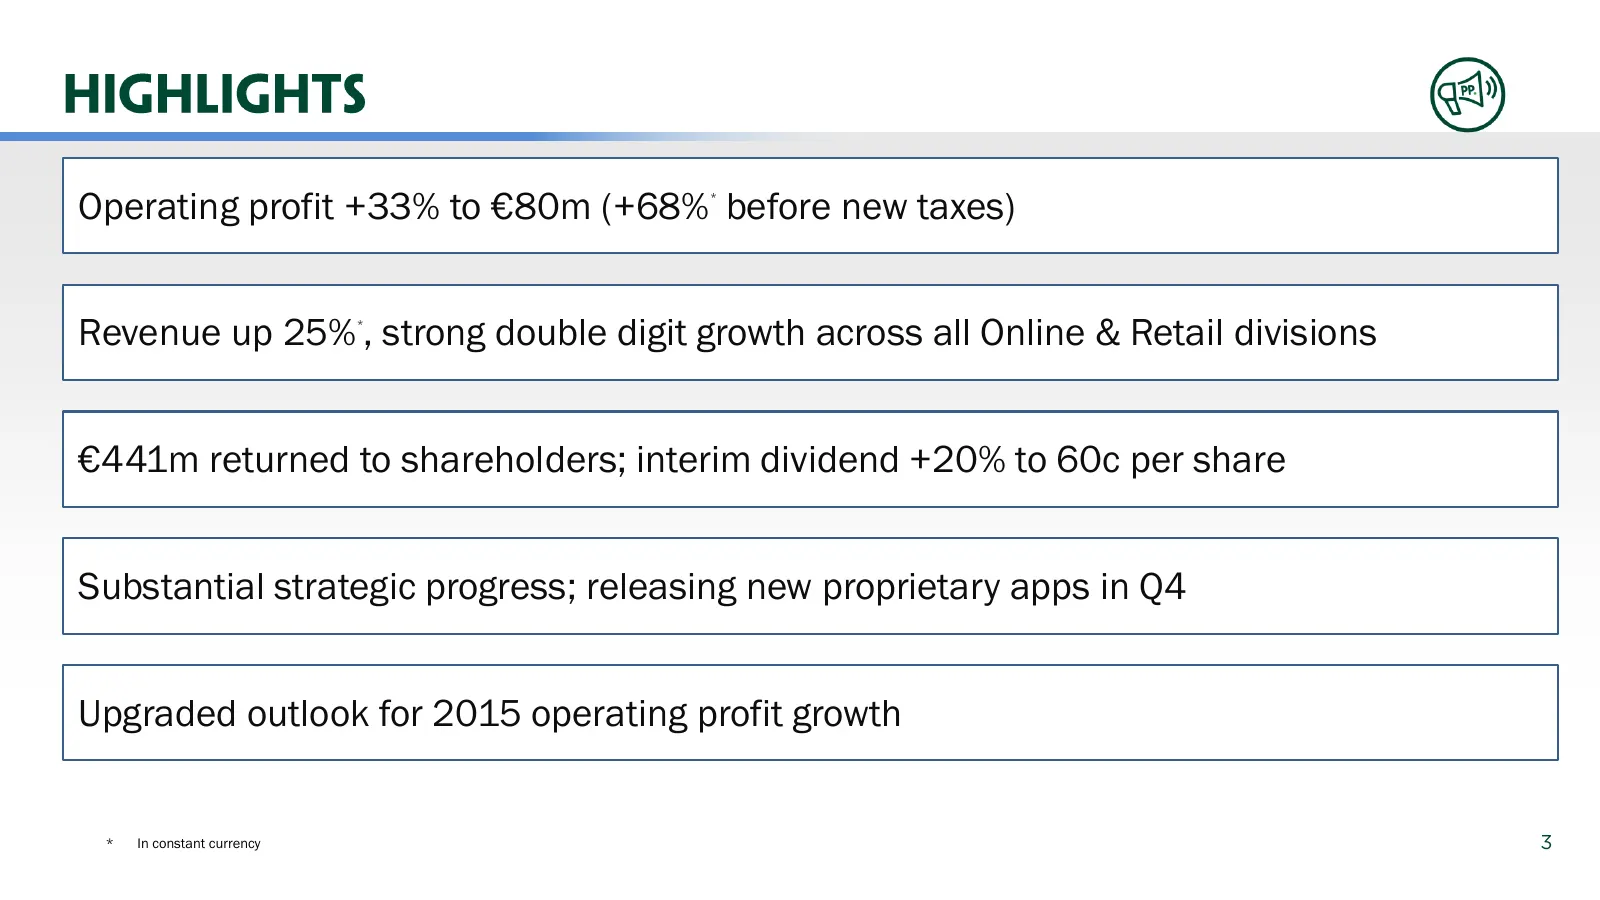
Slide 3: Operating profit +33% to €80m
Operating profit +33% to €80m (+68% before new taxes) * Revenue up 25% , strong double digit growth across all Online & Retail divisions * €441m returned to shareholders; interim dividend +20% to 60c per share Substantial strategic progress; releasing new proprietary apps in Q4 Upgraded outlook for
Slide 4: 4
4
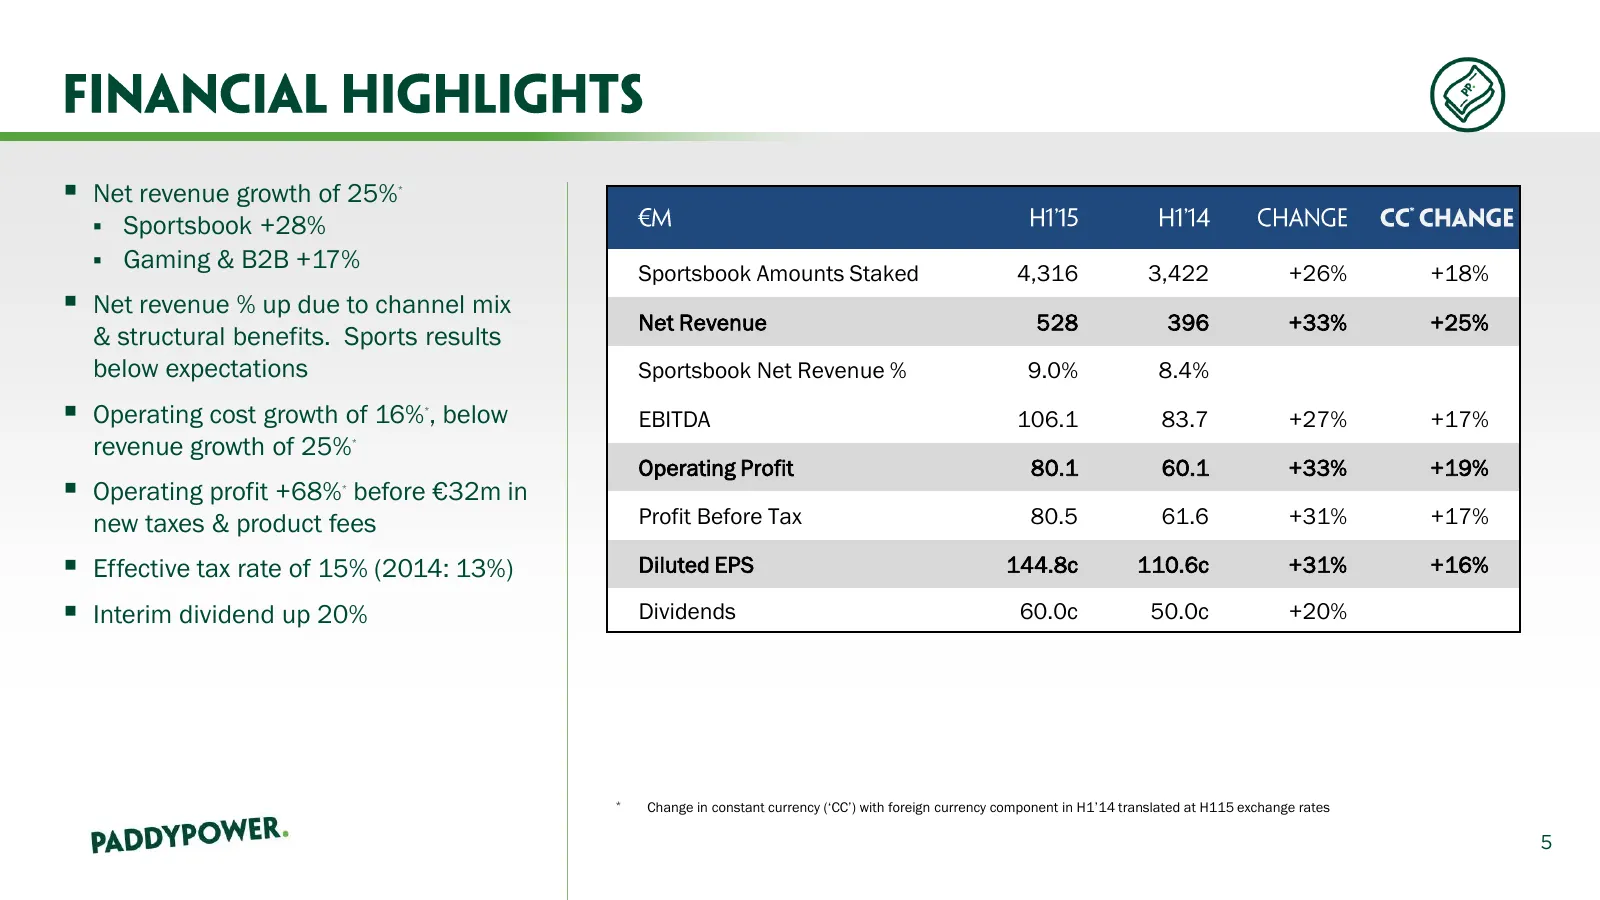
Slide 5: Net revenue growth of 25%
Net revenue growth of 25% * Sportsbook +28% Gaming & B2B +17% Sportsbook Amounts Staked 4,316 3,422 +26% +18% Net revenue % up due to channel mix Net Revenue 528 396 +33% +25% & structural benefits. Sports results below expectations Sportsbook Net Revenue % 9.0% 8.4% Operating cost growth
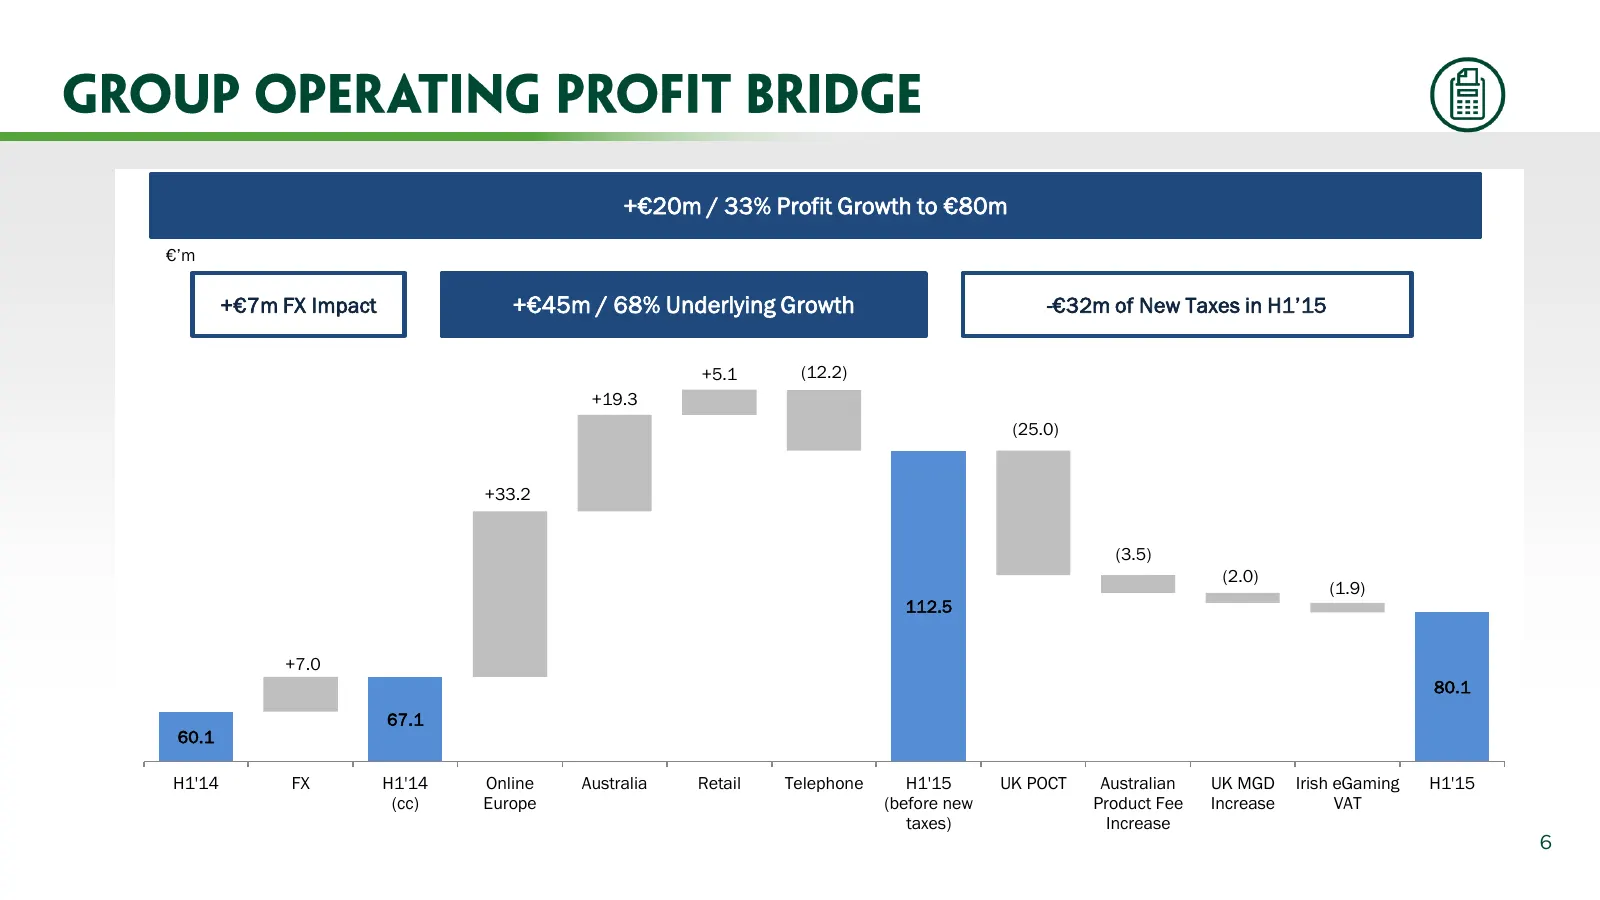
Slide 6: Profit growth to €80m
+€20m / 33% Profit Growth to €80m €’m +€7m FX Impact +€45m / 68% Underlying Growth -€32m of New Taxes in H1’15 +5.1 (12.2) +19.3 (25.0) +33.2 (3.5) (2.0) (1.9) 112.5 +7.0 80.1 67.1 60.1 H1'14 FX H1'14 Online Australia Retail Telephone H1'15 UK POCT Australian UK MGD Irish eGaming H1'15 (cc) Europe (
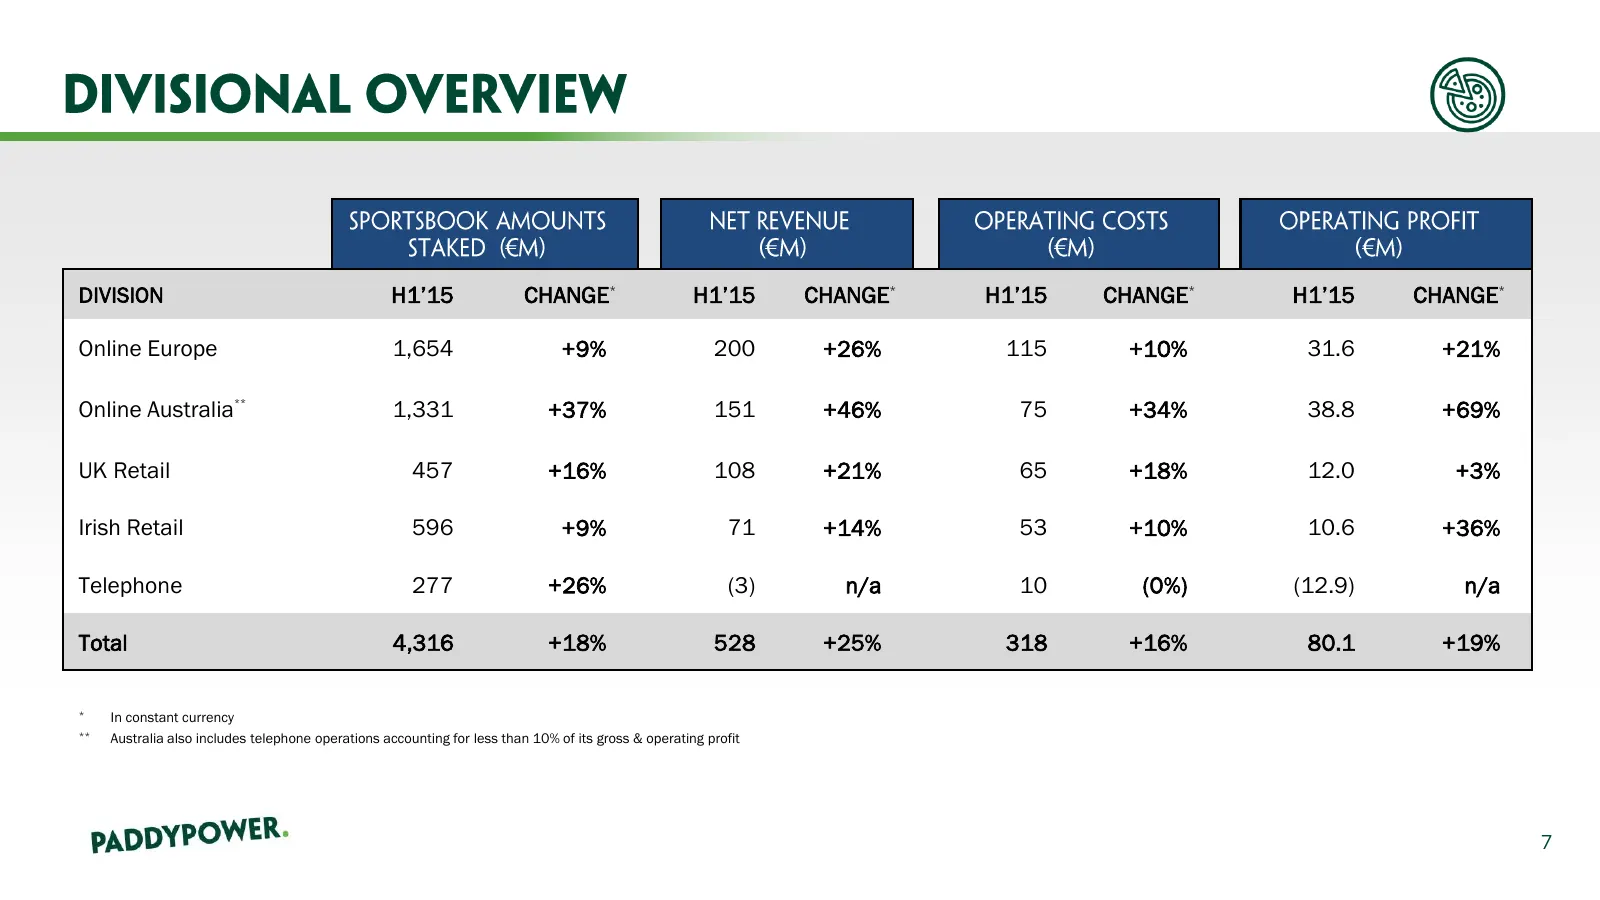
Slide 7: Divisional results H1'15
DIVISION H1’15 CHANGE* H1’15 CHANGE* H1’15 CHANGE* H1’15 CHANGE* Online Europe 1,654 +9% 200 +26% 115 +10% 31.6 +21% Online Australia** 1,331 +37% 151 +46% 75 +34% 38.8 +69% UK Retail 457 +16% 108 +21% 65 +18% 12.0 +3% Irish Retail 596 +9% 71 +14% 53 +10% 10.6 +36% Telephone 277 +26% (3) n/a 10 (0%)
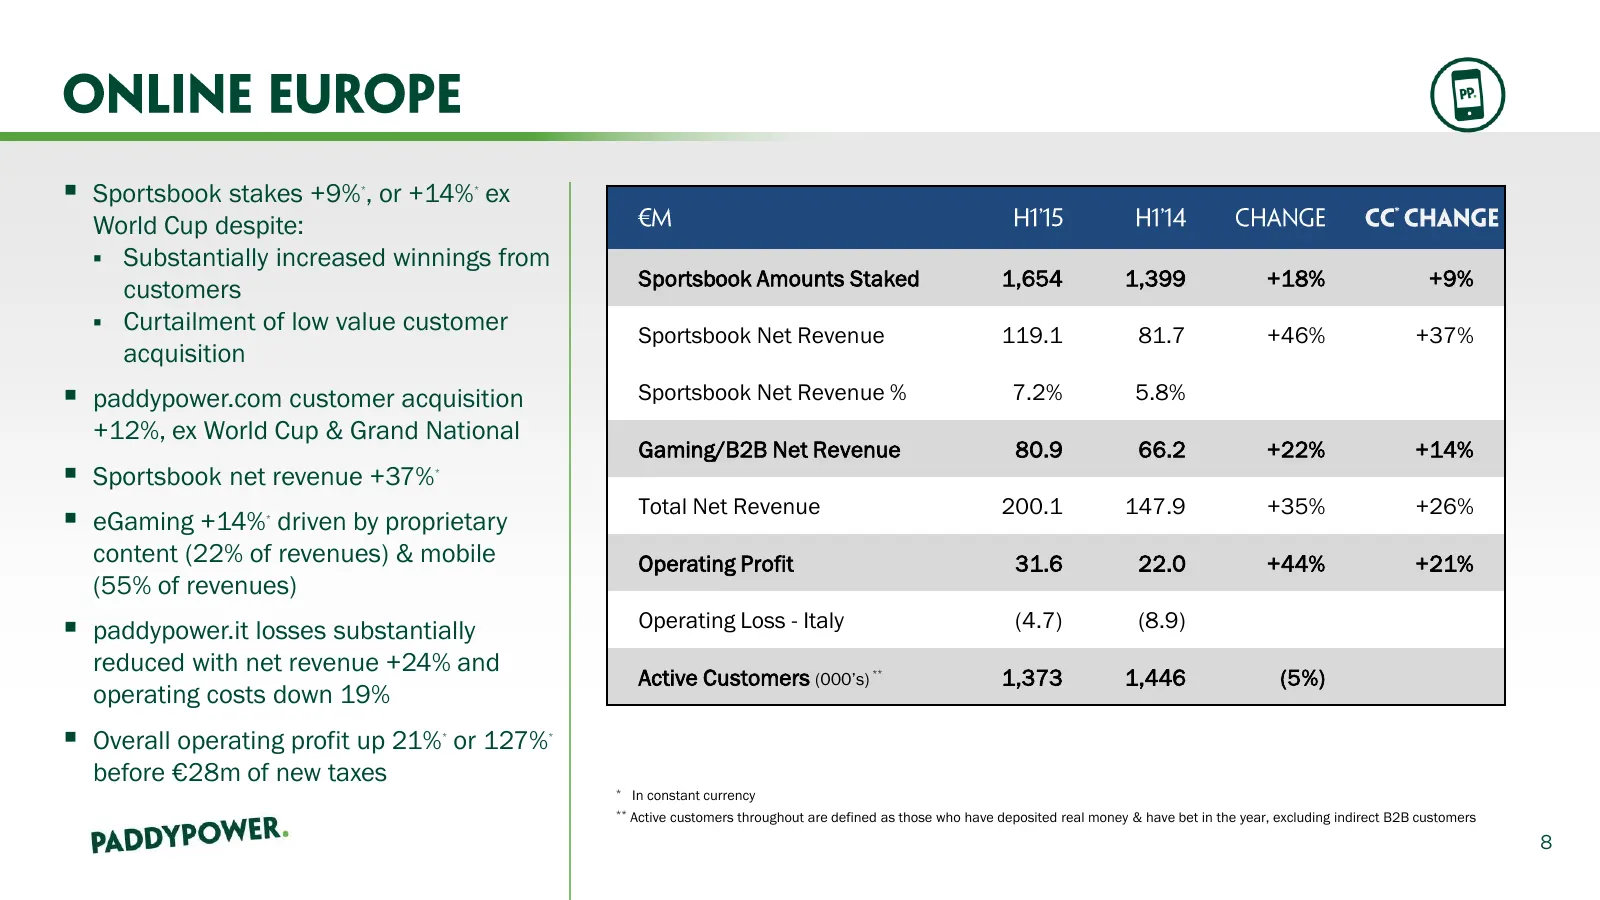
Slide 8: Online Europe
Sportsbook stakes +9% , or +14% ex * * World Cup despite: Substantially increased winnings from Sportsbook Amounts Staked 1,654 1,399 +18% +9% customers Curtailment of low value customer Sportsbook Net Revenue 119.1 81.7 +46% +37% acquisition paddypower.com customer acquisition Sportsbook Ne
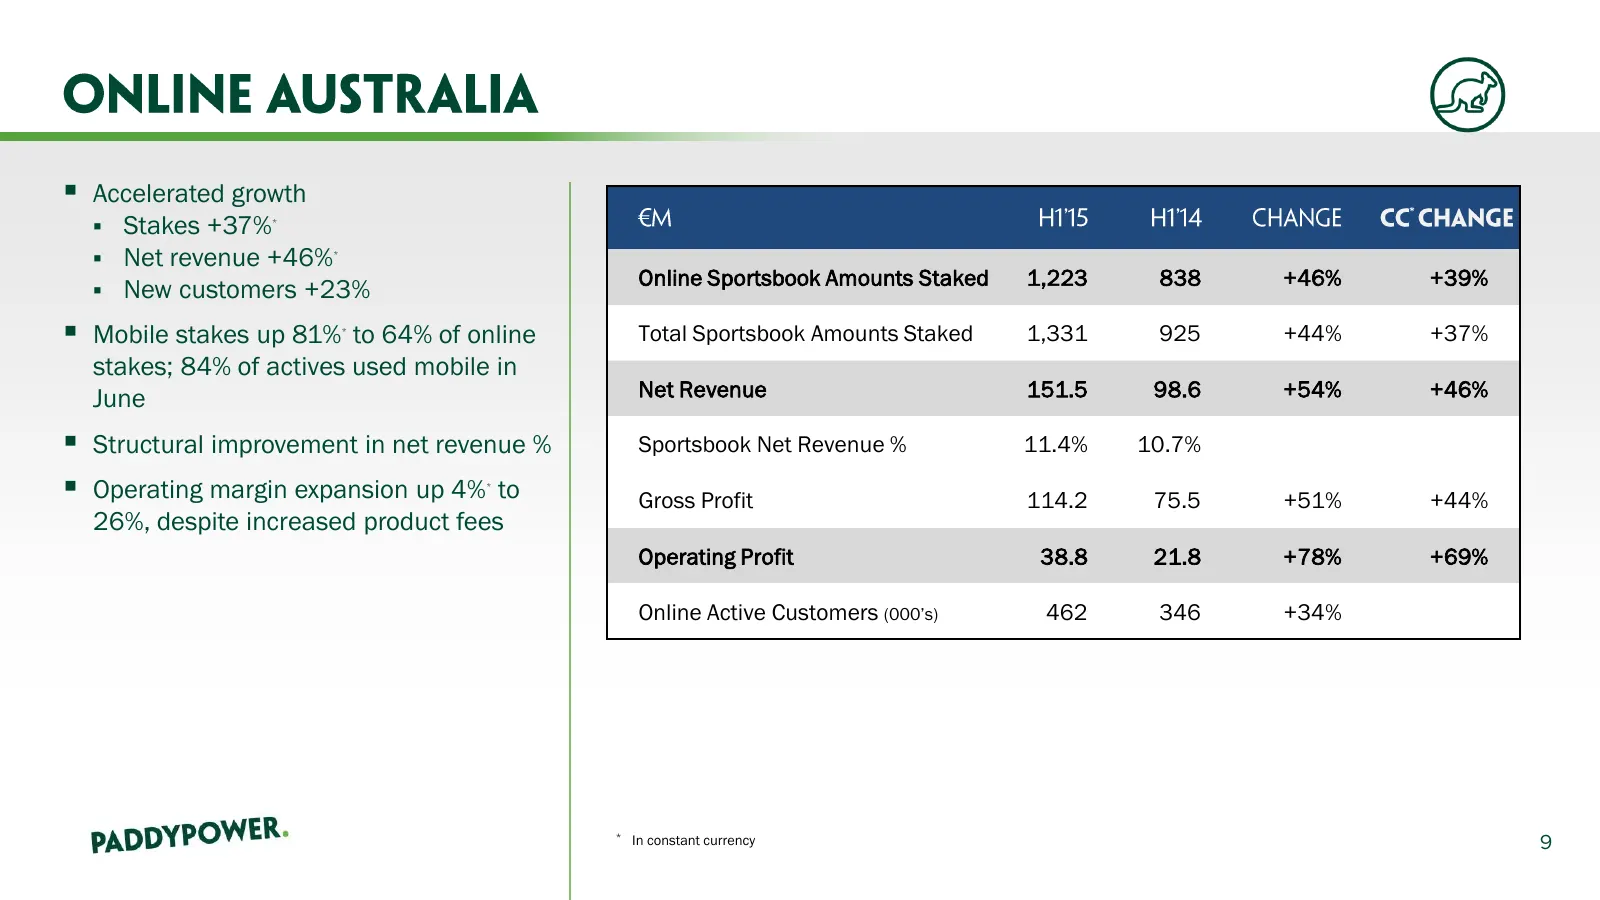
Slide 9: Online Australia
Accelerated growth Stakes +37%* Net revenue +46% * Online Sportsbook Amounts Staked 1,223 838 +46% +39% New customers +23% Mobile stakes up 81% to 64% of online * Total Sportsbook Amounts Staked 1,331 925 +44% +37% stakes; 84% of actives used mobile in June Net Revenue 151.5 98.6 +54% +46%
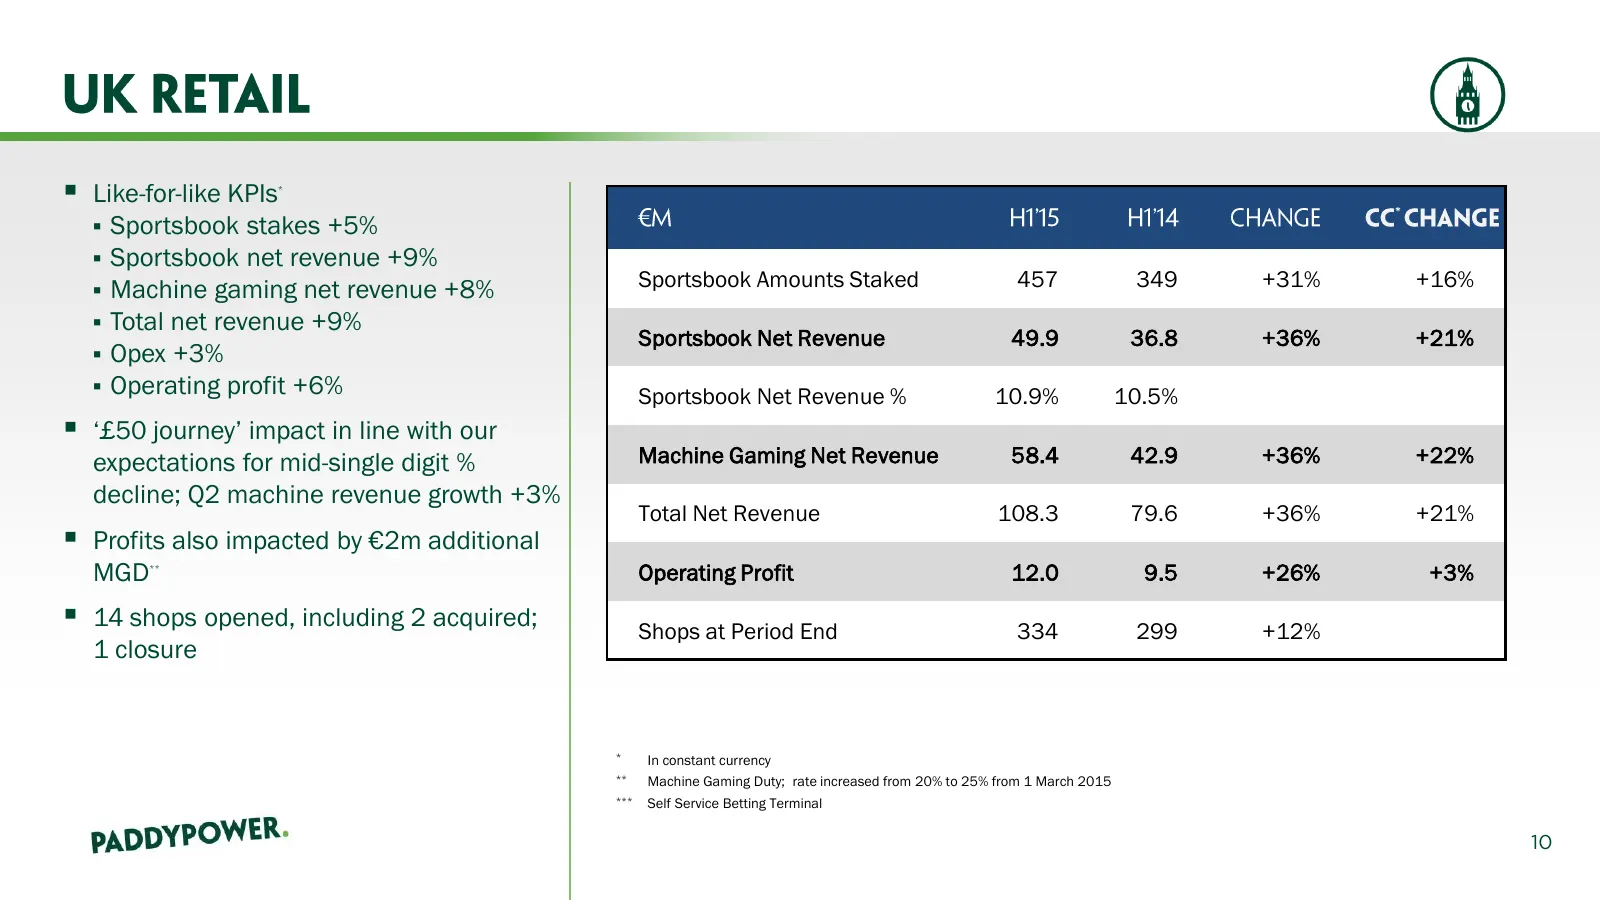
Slide 10: UK Retail
Like-for-like KPIs * Sportsbook stakes +5% Sportsbook net revenue +9% Machine gaming net revenue +8% Sportsbook Amounts Staked 457 349 +31% +16% Total net revenue +9% Sportsbook Net Revenue 49.9 36.8 +36% +21% Opex +3% Operating profit +6% Sportsbook Net Revenue % 10.9% 10.5% ‘£50 jo
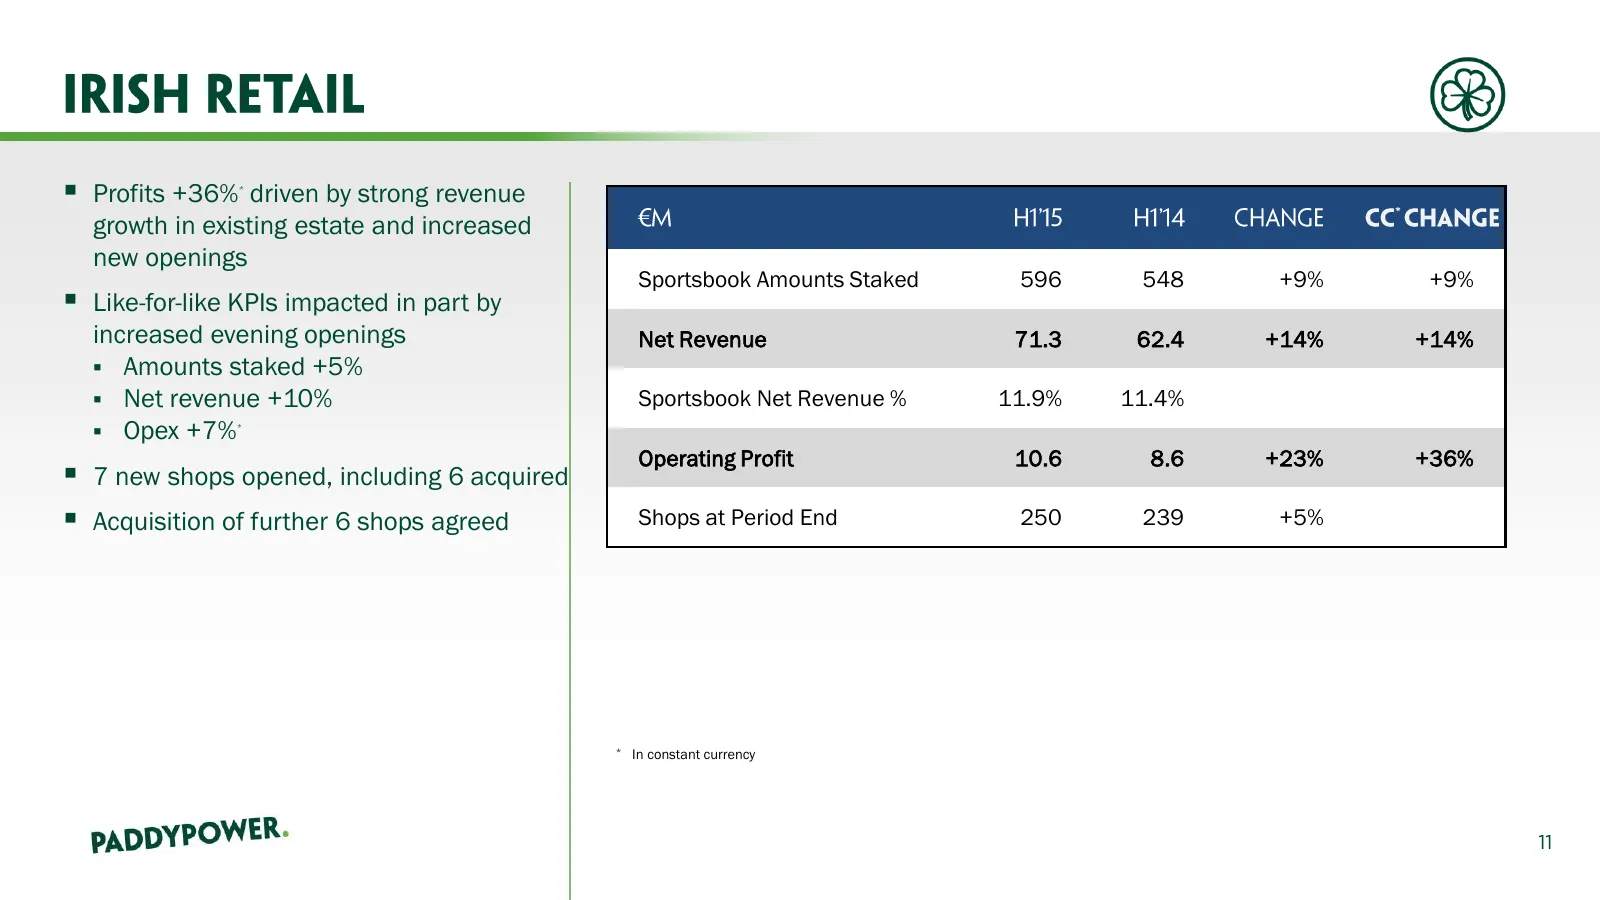
Slide 11: Irish Retail
Profits +36% driven by strong revenue * growth in existing estate and increased new openings Sportsbook Amounts Staked 596 548 +9% +9% Like-for-like KPIs impacted in part by increased evening openings Net Revenue 71.3 62.4 +14% +14% Amounts staked +5% Net revenue +10% Sportsbook Net Revenue
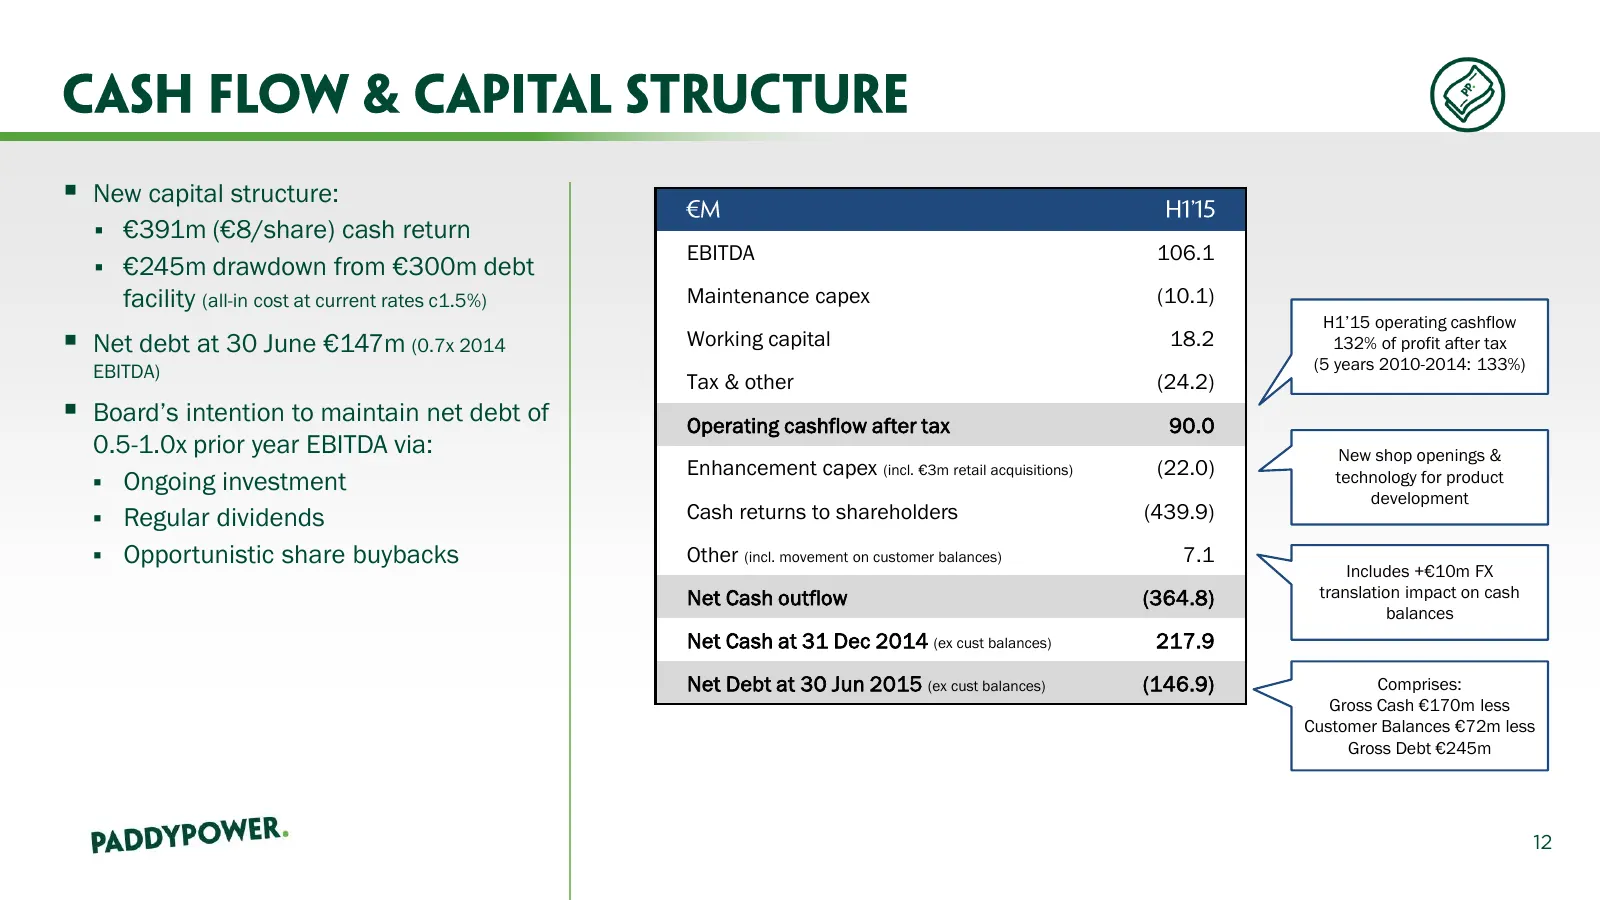
Slide 12: New capital structure and cash flow
New capital structure: €391m (€8/share) cash return EBITDA 106.1 €245m drawdown from €300m debt facility (all-in cost at current rates c1.5%) Maintenance capex (10.1) H1’15 operating cashflow Net debt at 30 June €147m (0.7x 2014 Working capital 18.2 132% of profit after tax EBITDA) (5 years
Slide 13: Strategy & Outlook
si a : as ia a _ STRATEGY & OUTLOOK QuickBooks
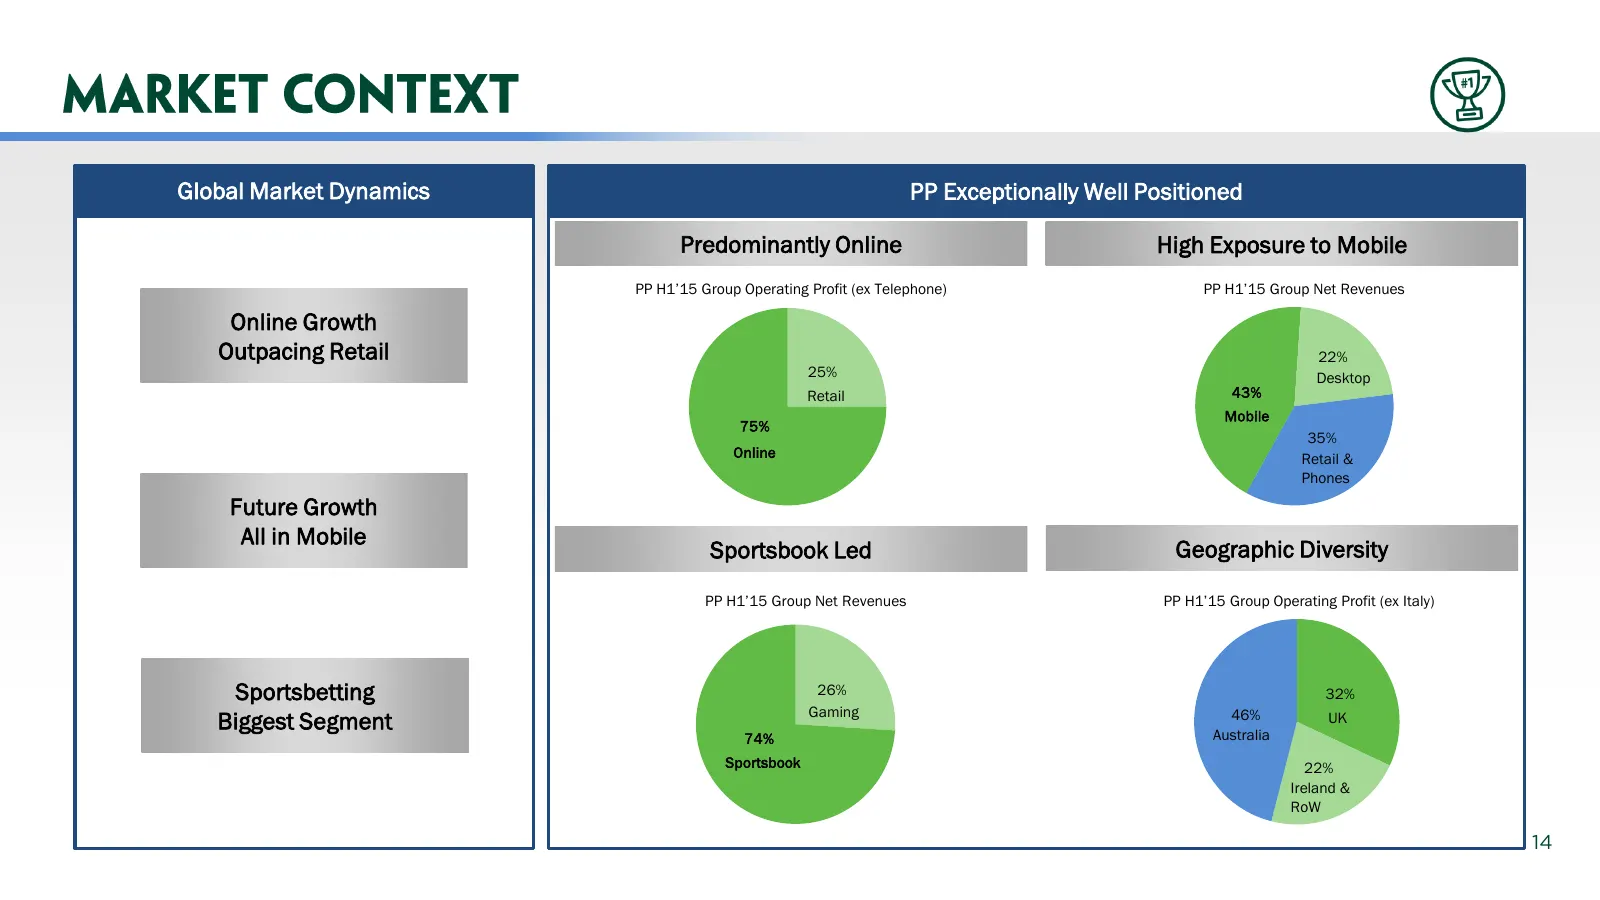
Slide 14: Global Market Dynamics
Global Market Dynamics PP Exceptionally Well Positioned Predominantly Online High Exposure to Mobile PP H1’15 Group Operating Profit (ex Telephone) PP H1’15 Group Net Revenues Online Growth Outpacing Retail 22% 25% Desktop Retail 43% Mobile 75% 35% Online Retail & Phones Future Growth All in Mobile
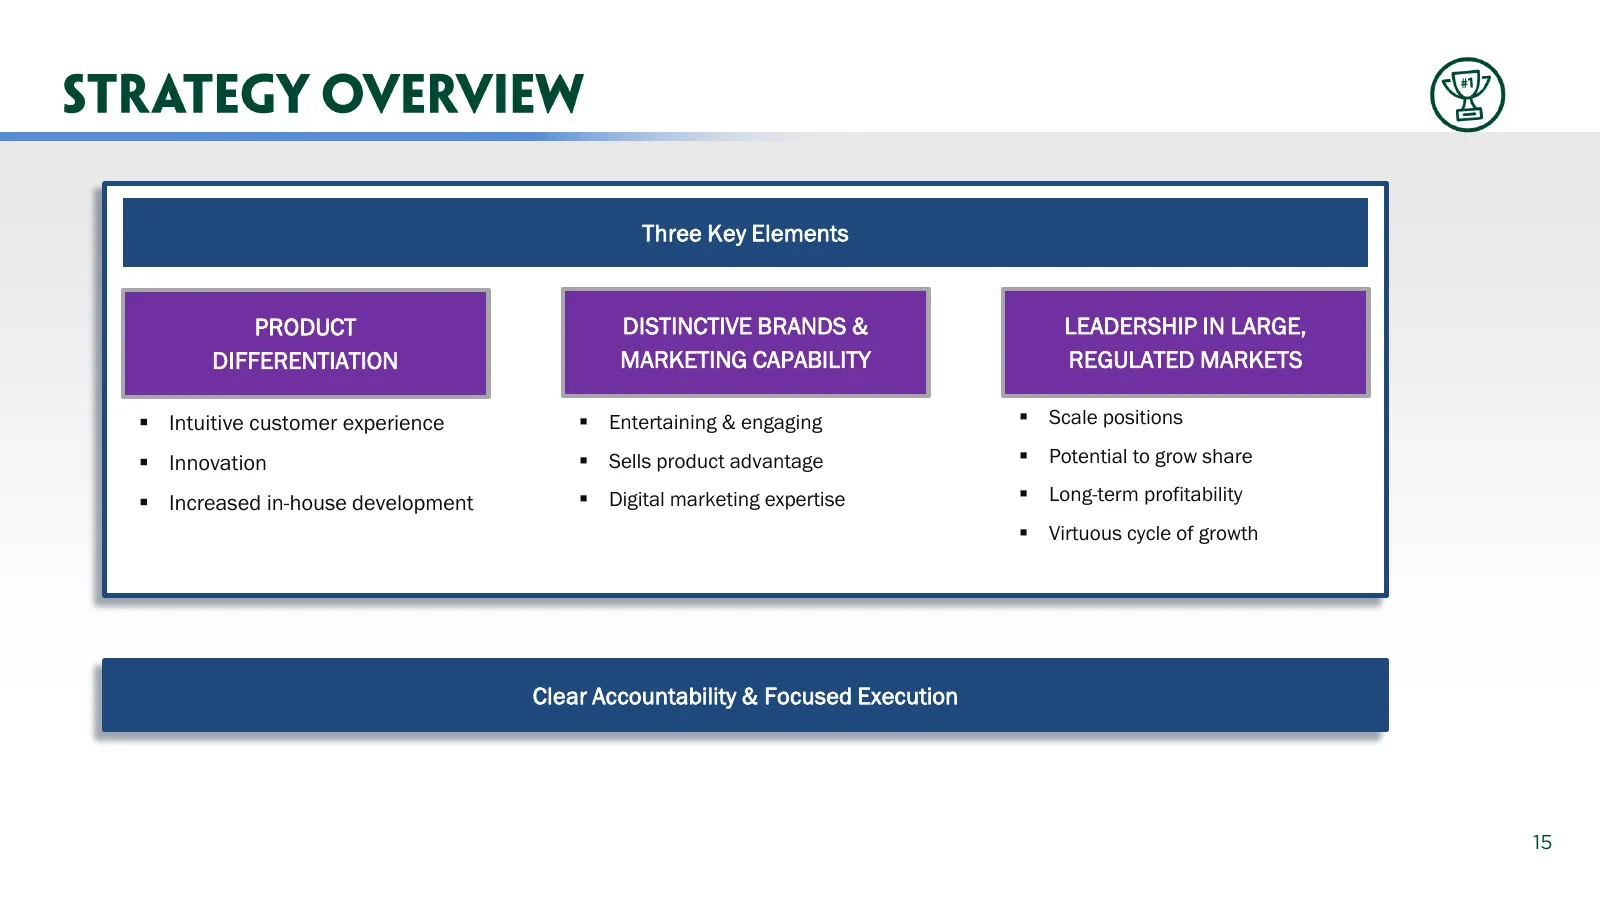
Slide 15: Three Key Elements
Three Key Elements PRODUCT DISTINCTIVE BRANDS & LEADERSHIP IN LARGE, DIFFERENTIATION MARKETING CAPABILITY REGULATED MARKETS Intuitive customer experience Entertaining & engaging Scale positions Innovation Sells product advantage Potential to grow share Increased in-house development
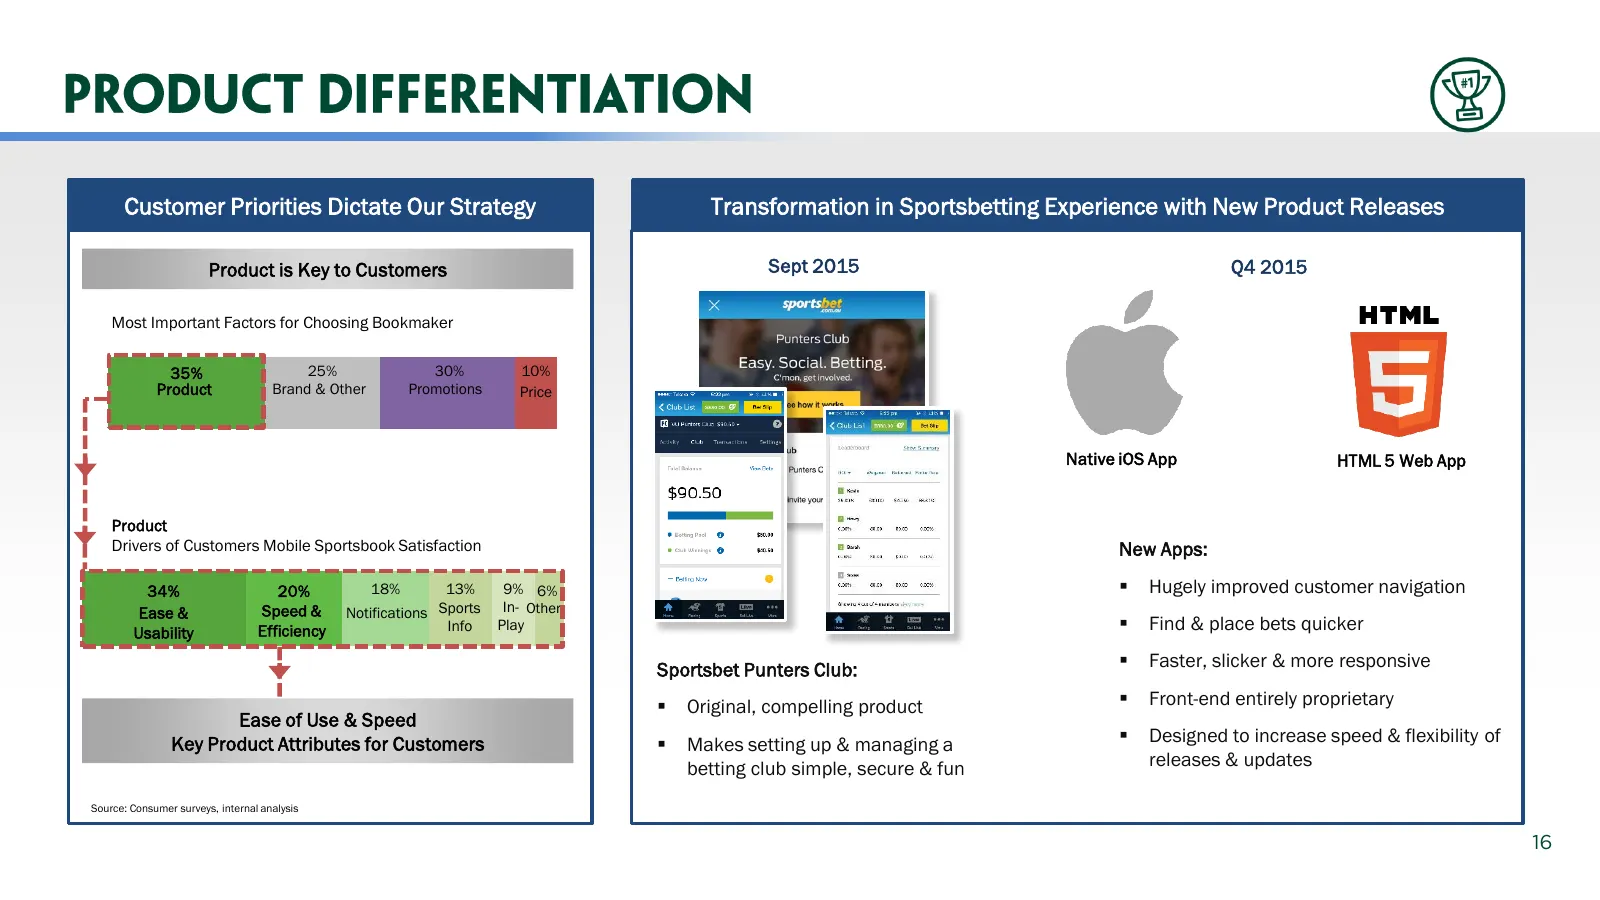
Slide 16: Customer Priorities Dictate Our Strategy
Customer Priorities Dictate Our Strategy Transformation in Sportsbetting Experience with New Product Releases Product is Key to Customers Sept 2015 Q4 2015 Most Important Factors for Choosing Bookmaker 35% 25% 30% 10% Product Brand & Other Promotions Price Native iOS App HTML 5 Web App Product Drive
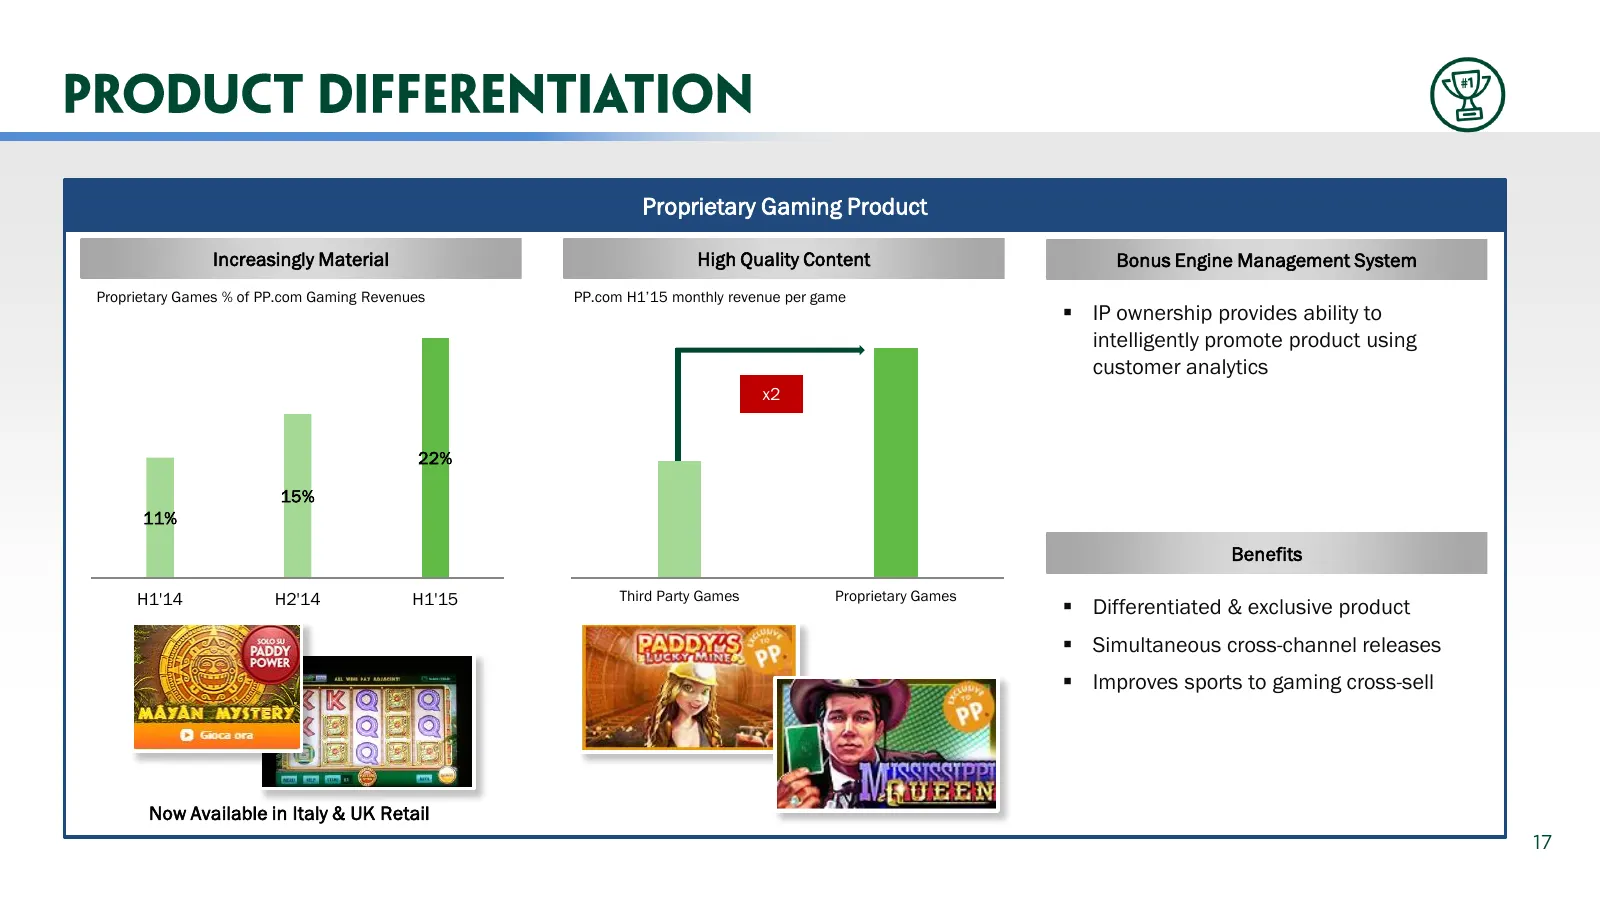
Slide 17: Proprietary Gaming Product
Proprietary Gaming Product recent launchesIncreasingly Material High Quality Content Bonus Engine Management System Proprietary Games % of PP.com Gaming Revenues PP.com H1’15 monthly revenue per game IP ownership provides ability to intelligently promote product using customer analytics x2 22% 15%
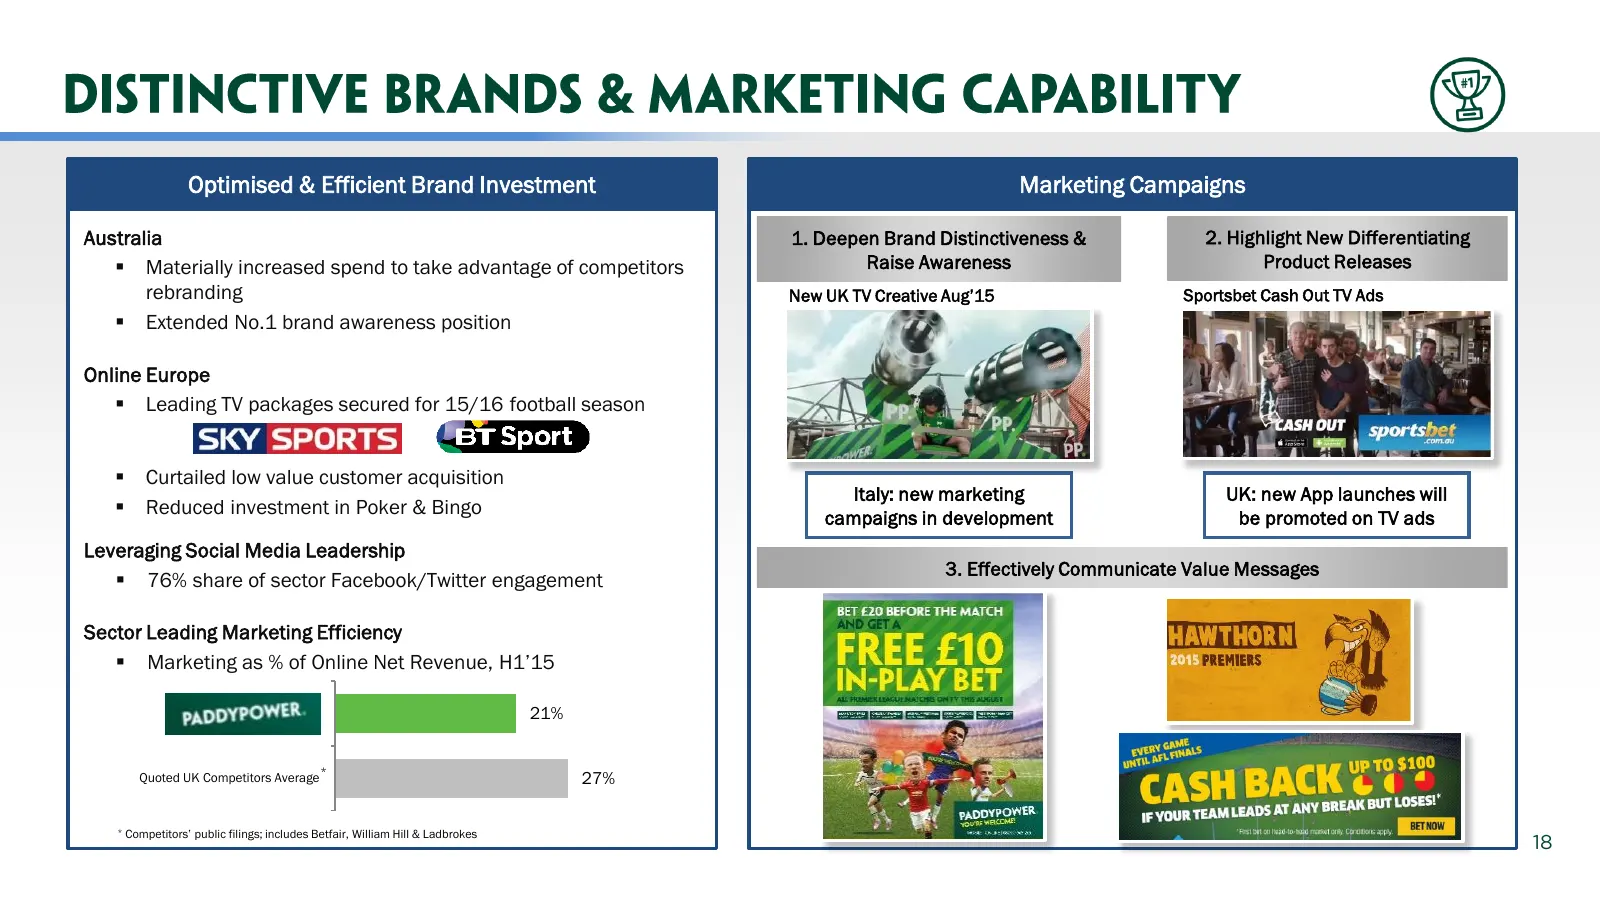
Slide 18: Optimised & Efficient Brand Investment
Optimised & Efficient Brand Investment Marketing Campaigns Australia 1. Deepen Brand Distinctiveness & 2. Highlight New Differentiating Materially increased spend to take advantage of competitors Raise Awareness Product Releases rebranding New UK TV Creative Aug’15 Sportsbet Cash Out TV Ads Exte
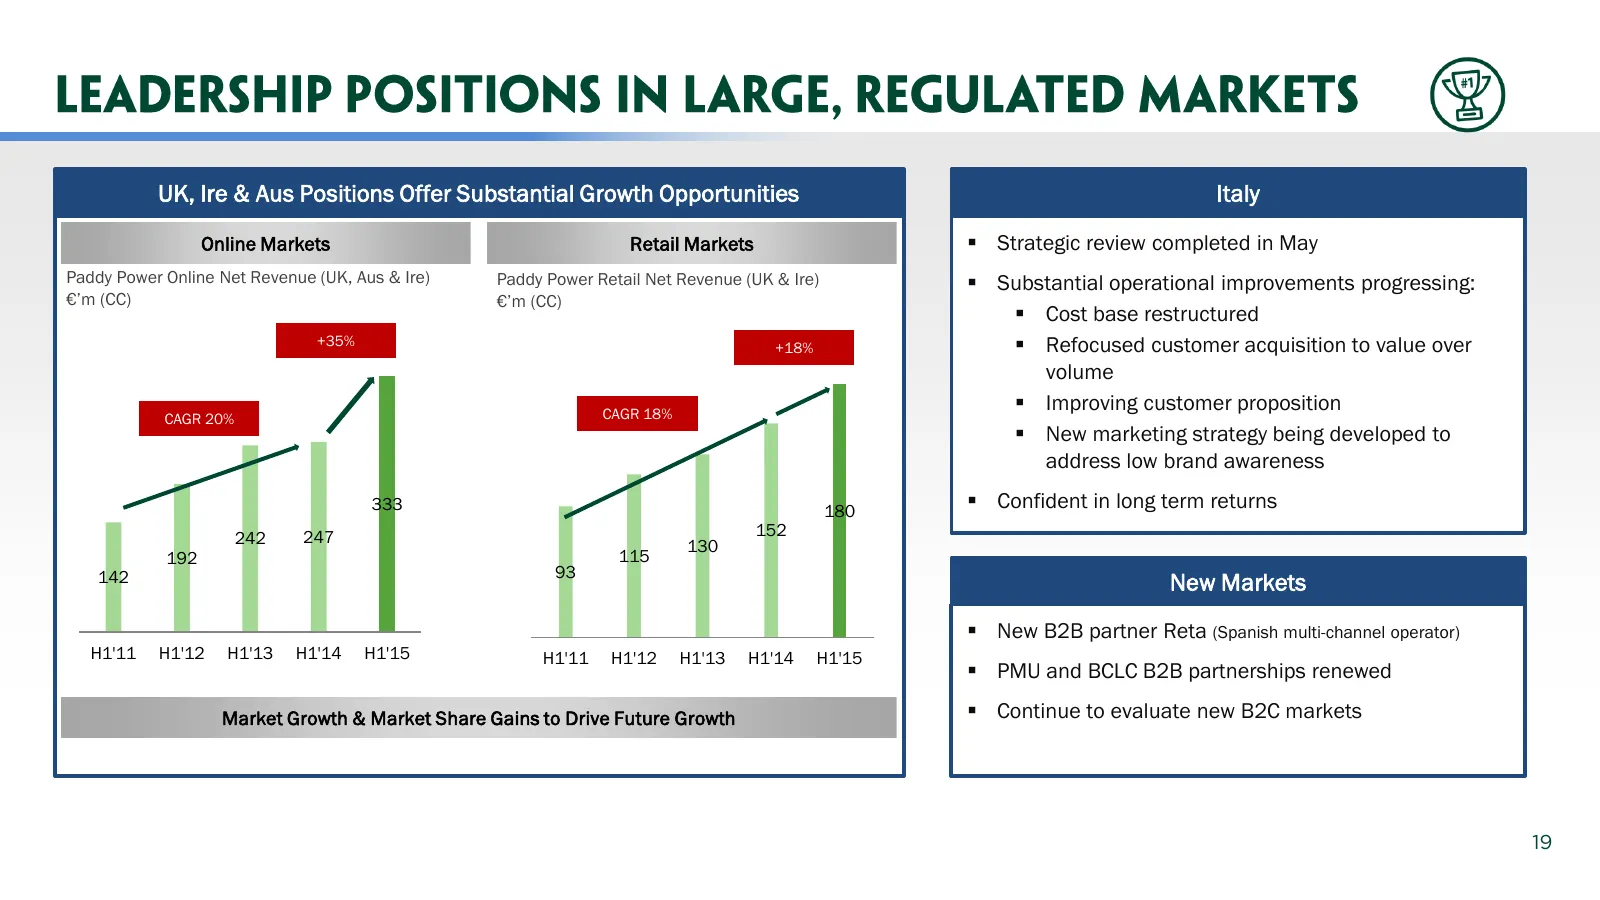
Slide 19: UK, Ireland & Australia Growth Opportunities
UK, Ire & Aus Positions Offer Substantial Growth Opportunities Italy Online Markets Retail Markets Strategic review completed in May Paddy Power Online Net Revenue (UK, Aus & Ire) Paddy Power Retail Net Revenue (UK & Ire) Substantial operational improvements progressing: €’m (CC) €’m (CC) Cost
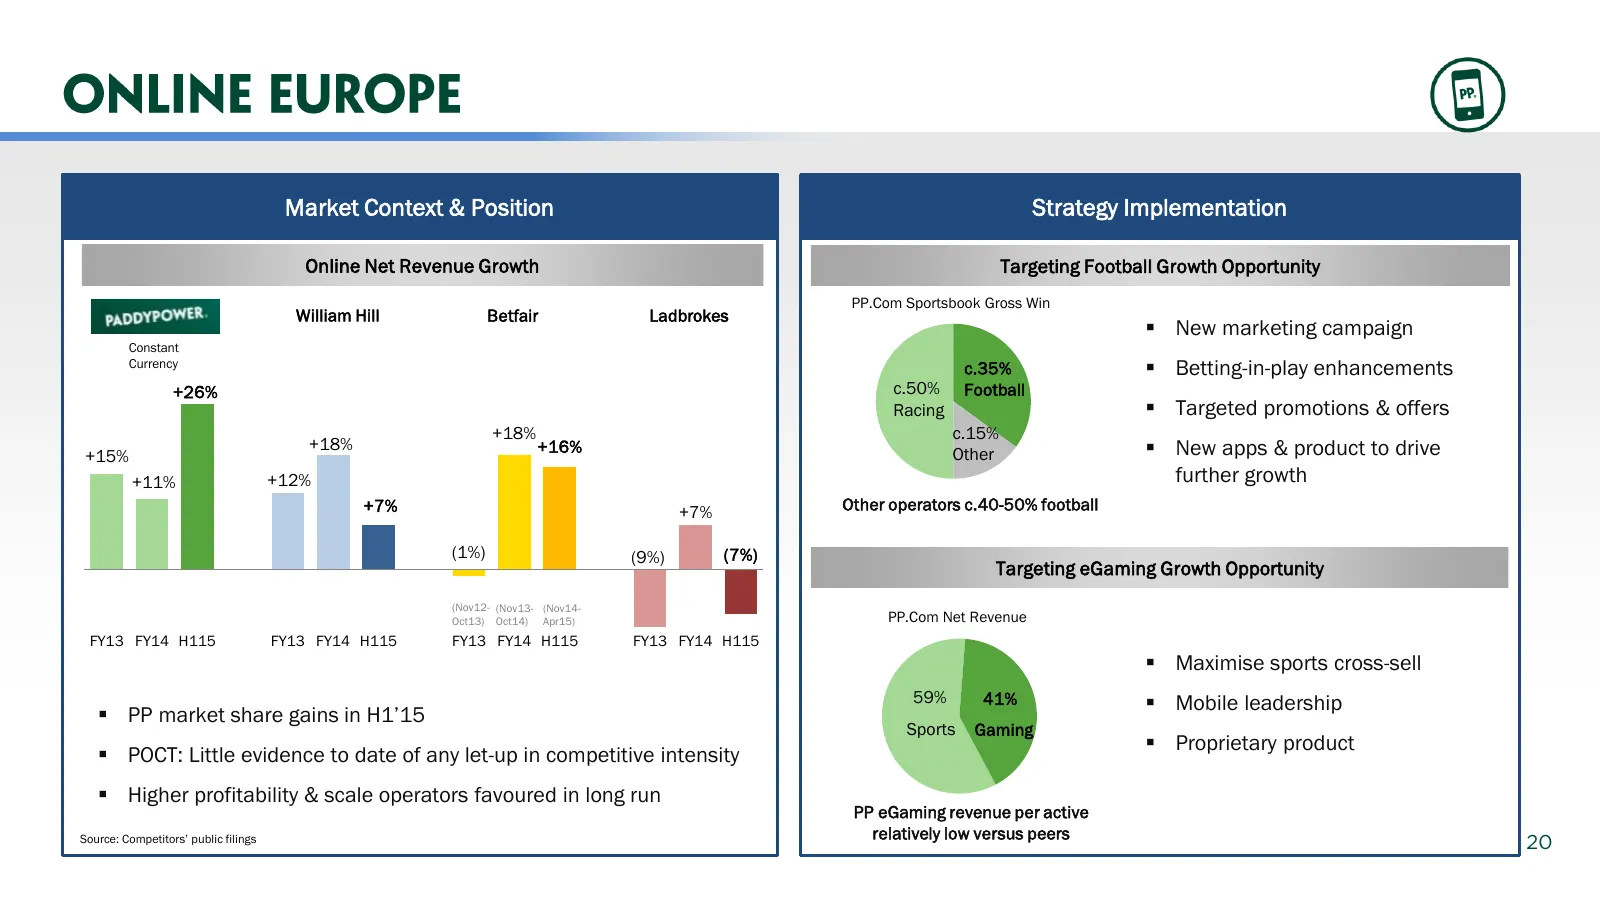
Slide 20: Online market context and strategy implementation
Market Context & Position Strategy Implementation Online Net Revenue Growth Targeting Football Growth Opportunity PP.Com Sportsbook Gross Win William Hill Betfair Ladbrokes New marketing campaign Constant Currency c.35% Betting-in-play enhancements +26% c.50% Football Racing Targeted promotion
Slide 21: Australia market context and strategy implementation
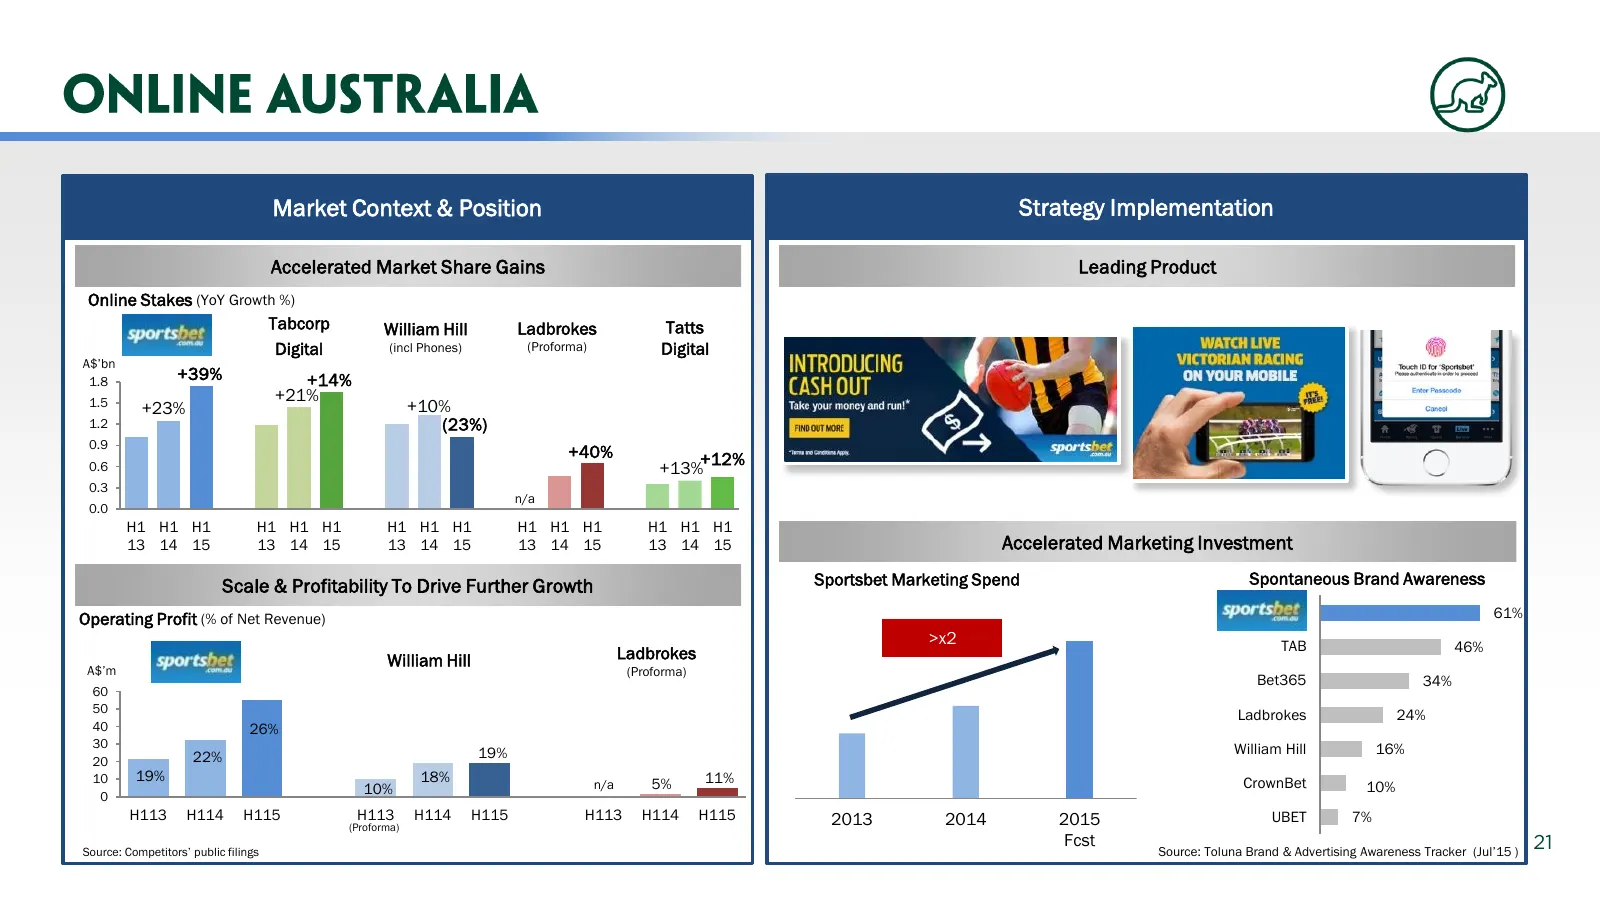
Market Context & Position Strategy Implementation Accelerated Market Share Gains Leading Product Online Stakes (YoY Growth %) Tabcorp William Hill Ladbrokes Tatts Digital (incl Phones) (Proforma) Digital A$’bn 1.8 +39% +14% 1.5 +21% +23% +10% 1.2 (23%) 0.9 +40% +12% ds 0.6 +13% 0.3 n/a 0.0 H1 H1 H1
Slide 22: UK Retail market context and strategy implementation
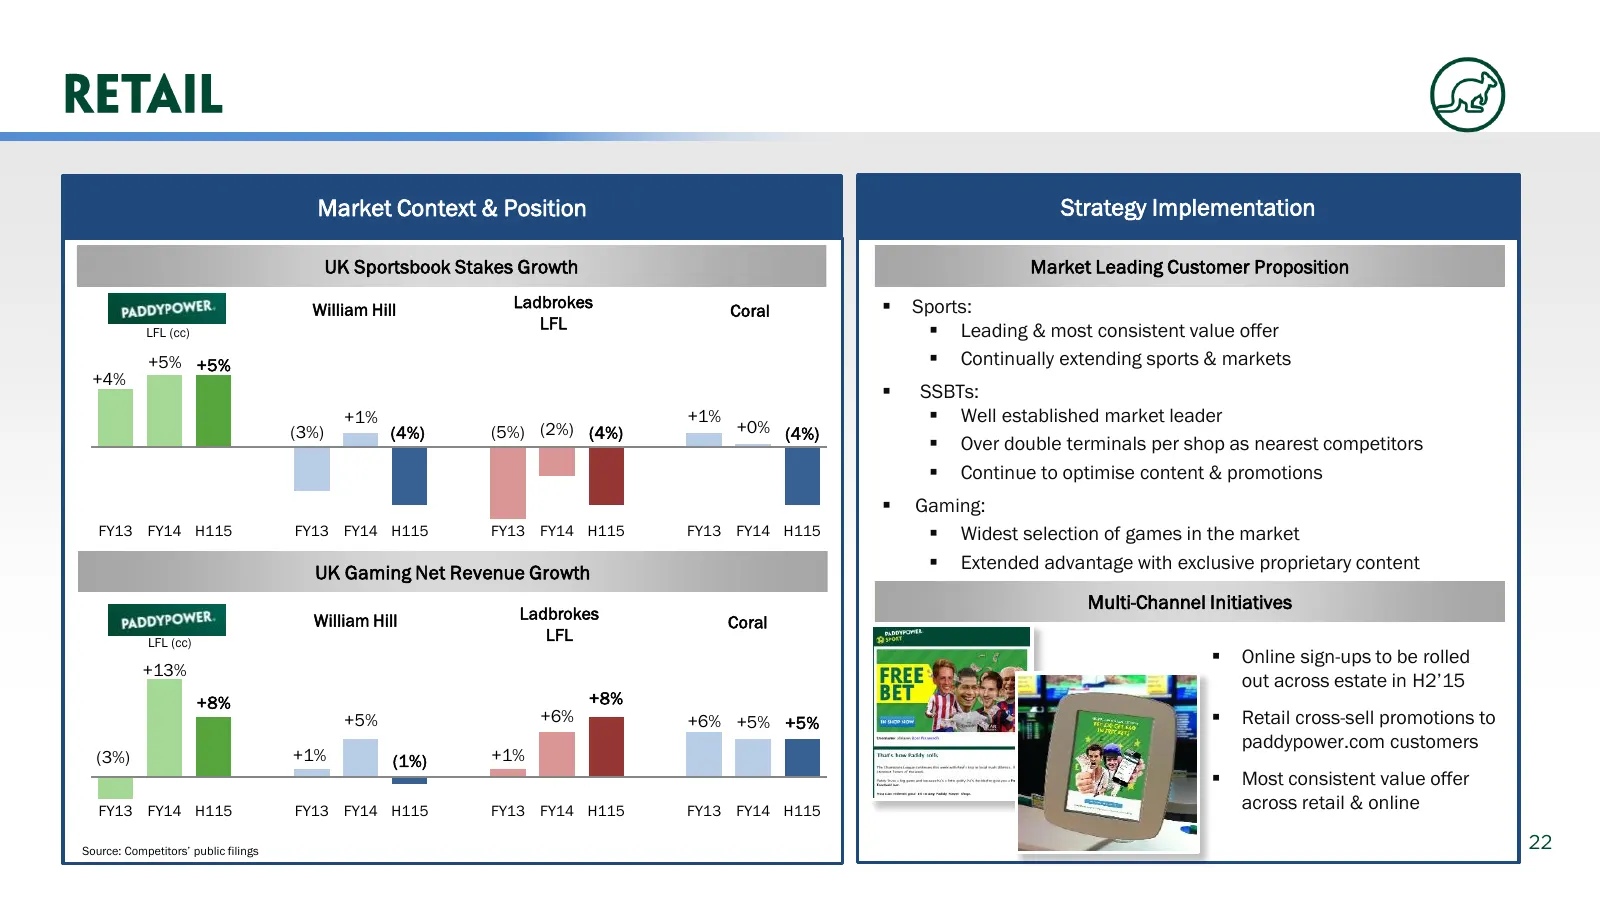
Market Context & Position Strategy Implementation UK Sportsbook Stakes Growth Market Leading Customer Proposition William Hill Ladbrokes Coral Sports: LFL (cc) LFL Leading & most consistent value offer +5% +5% Continually extending sports & markets +4% SSBTs: +1% +1% Well established marke
Slide 23: Current Trading & Outlook
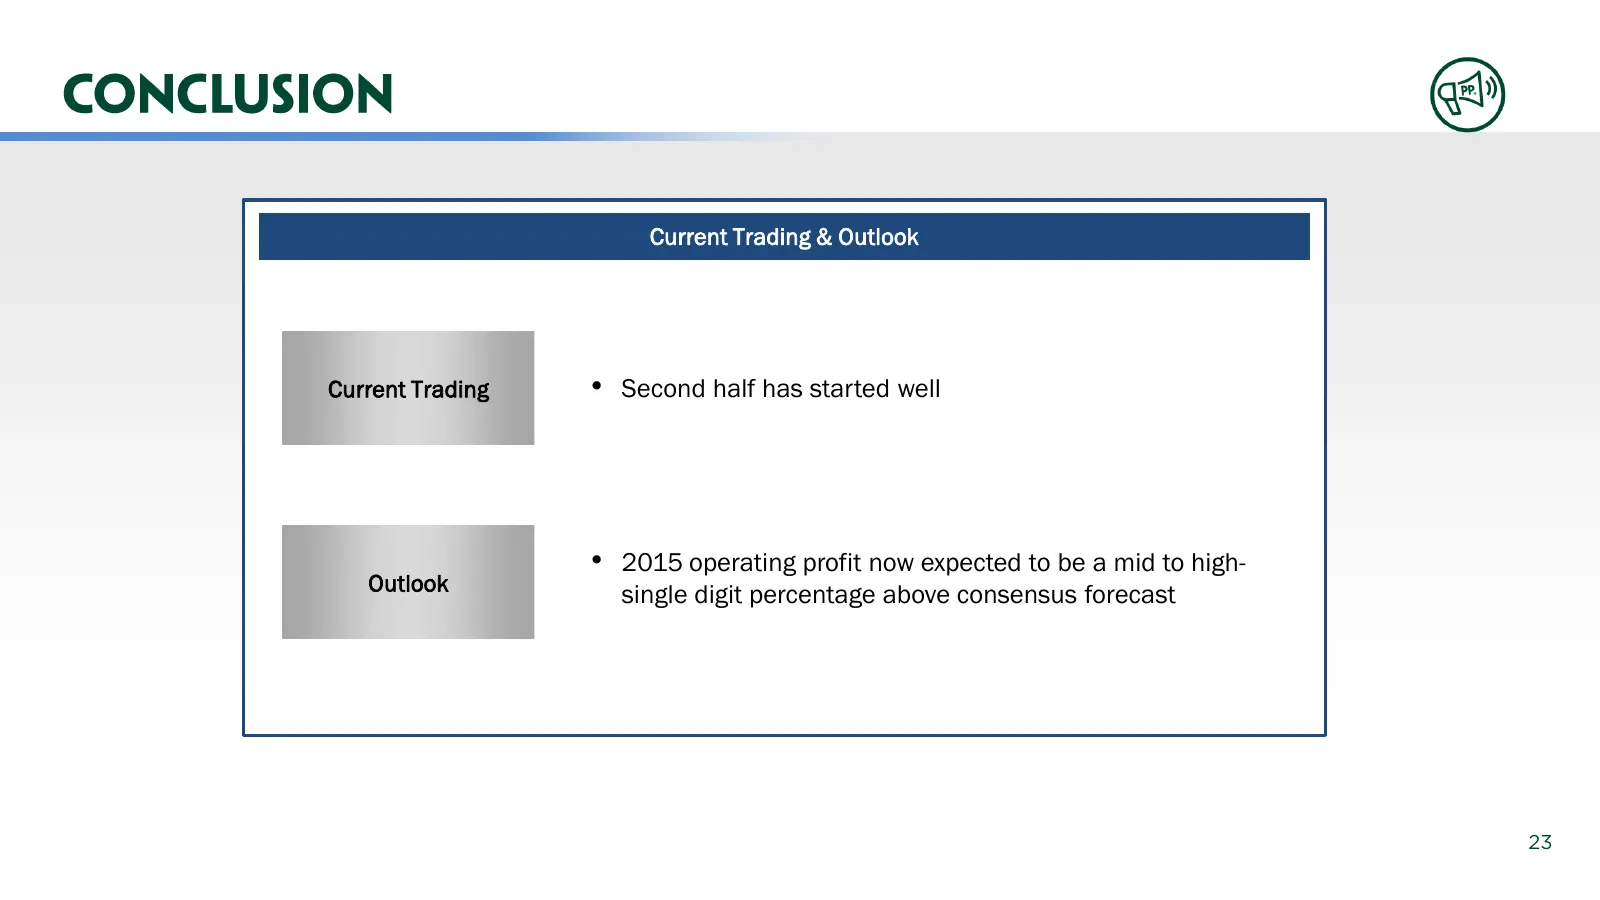
Current Trading & Outlook Current Trading • Second half has started well • 2015 operating profit now expected to be a mid to high- Outlook single digit percentage above consensus forecast 23
Slide 24: Possible Merger of Paddy Power & Betfair
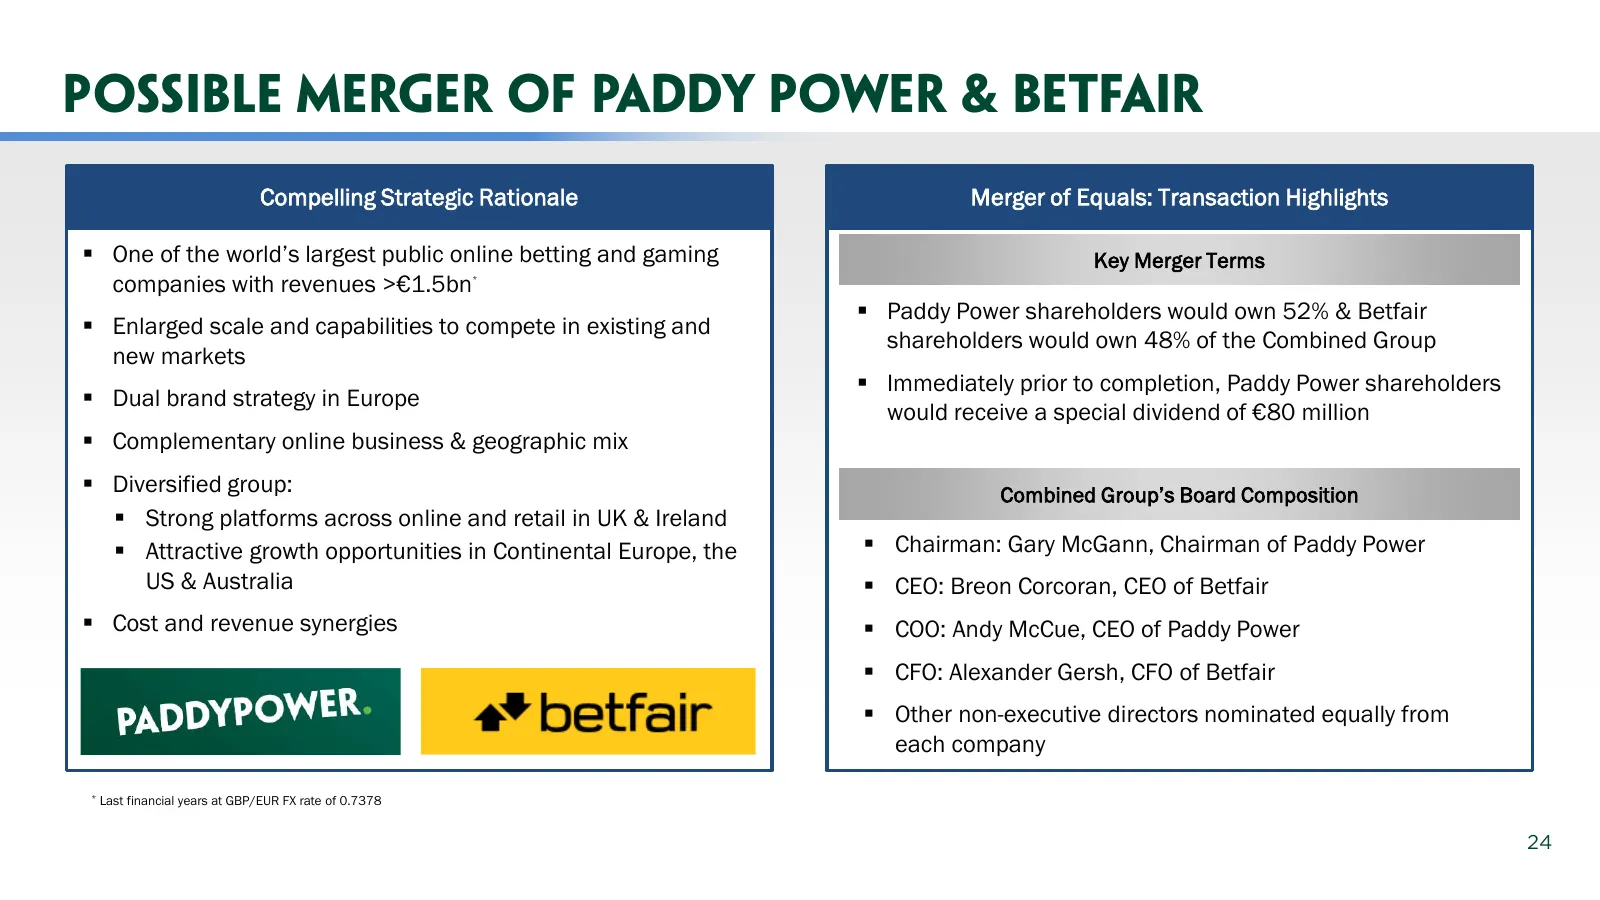
Possible Merger of Paddy Power & Betfair Compelling Strategic Rationale Merger of Equals: Transaction Highlights One of the world’s largest public online betting and gaming Key Merger Terms companies with revenues >€1.5bn * Paddy Power shareholders would own 52% & Betfair Enlarged scale and ca
Slide 25: Disclaimer
Disclaimer The directors of Paddy Power accept responsibility for the information contained in this presentation. To the best of the knowledge and belief of the directors of Paddy Power (who have taken all reasonable care to ensure that such is the case) the information contained in this presentat
Source: Internet Archive copy of flutter.com
More decks from Flutter Entertainment plc
 Q3 2026 Earnings Presentation15 slides · Nov 4, 2026
 Q2 2026 Earnings Presentation14 slides · Aug 5, 2026
 Investor Day (September 2024)152 slides · Sep 25, 2024
 Q2 2024 Earnings Presentation20 slides · Aug 13, 2024
 Q1 2024 Earnings Presentation20 slides · May 14, 2024
 FY2023 Earnings Presentation36 slides · Mar 26, 2024