Markwest Energy Partners LP — Merger or Acquisition (July 2015)
24 slides from Markwest Energy Partners LP's merger presentation, Jul 20, 2015
Slide 1: MPLX and MarkWest Strategic Combination
Exhibit 99.2 MPLX and MarkWest Strategic Combination As Revised July 20, 2015
Slide 2: Forward-Looking Statements
Forward-Looking Statements This presentation contains forward-looking statements within the meaning of federal securities laws regarding MPLX LP (“MPLX”), Marathon Petroleum Corporation (“MPC”), and MarkWest Energy Partners, L.P. (“MWE”). These forward-looking statements relate to, among other thing
Slide 3: Additional Information
Additional Information Non-GAAP Financial Measures Adjusted EBITDA and Net Operating Margin are non-GAAP financial measures provided in this presentation. Reconciliation to the nearest GAAP financial measure is included in the Appendix to this presentation. Adjusted EBITDA is not defined by GAAP and
Slide 4: Summary of Supplemental Information
Summary of Supplemental Information Slide 5, 10, 20: Updates distribution growth targets for 2018 and 2019 – Combined partnership expects compound annual distribution growth rate of 25% through 2017 and approximately 20% annual distribution growth in years 2018 and 2019 Slide 12-15: Additional infor
Slide 5: Powerful Strategic Combination
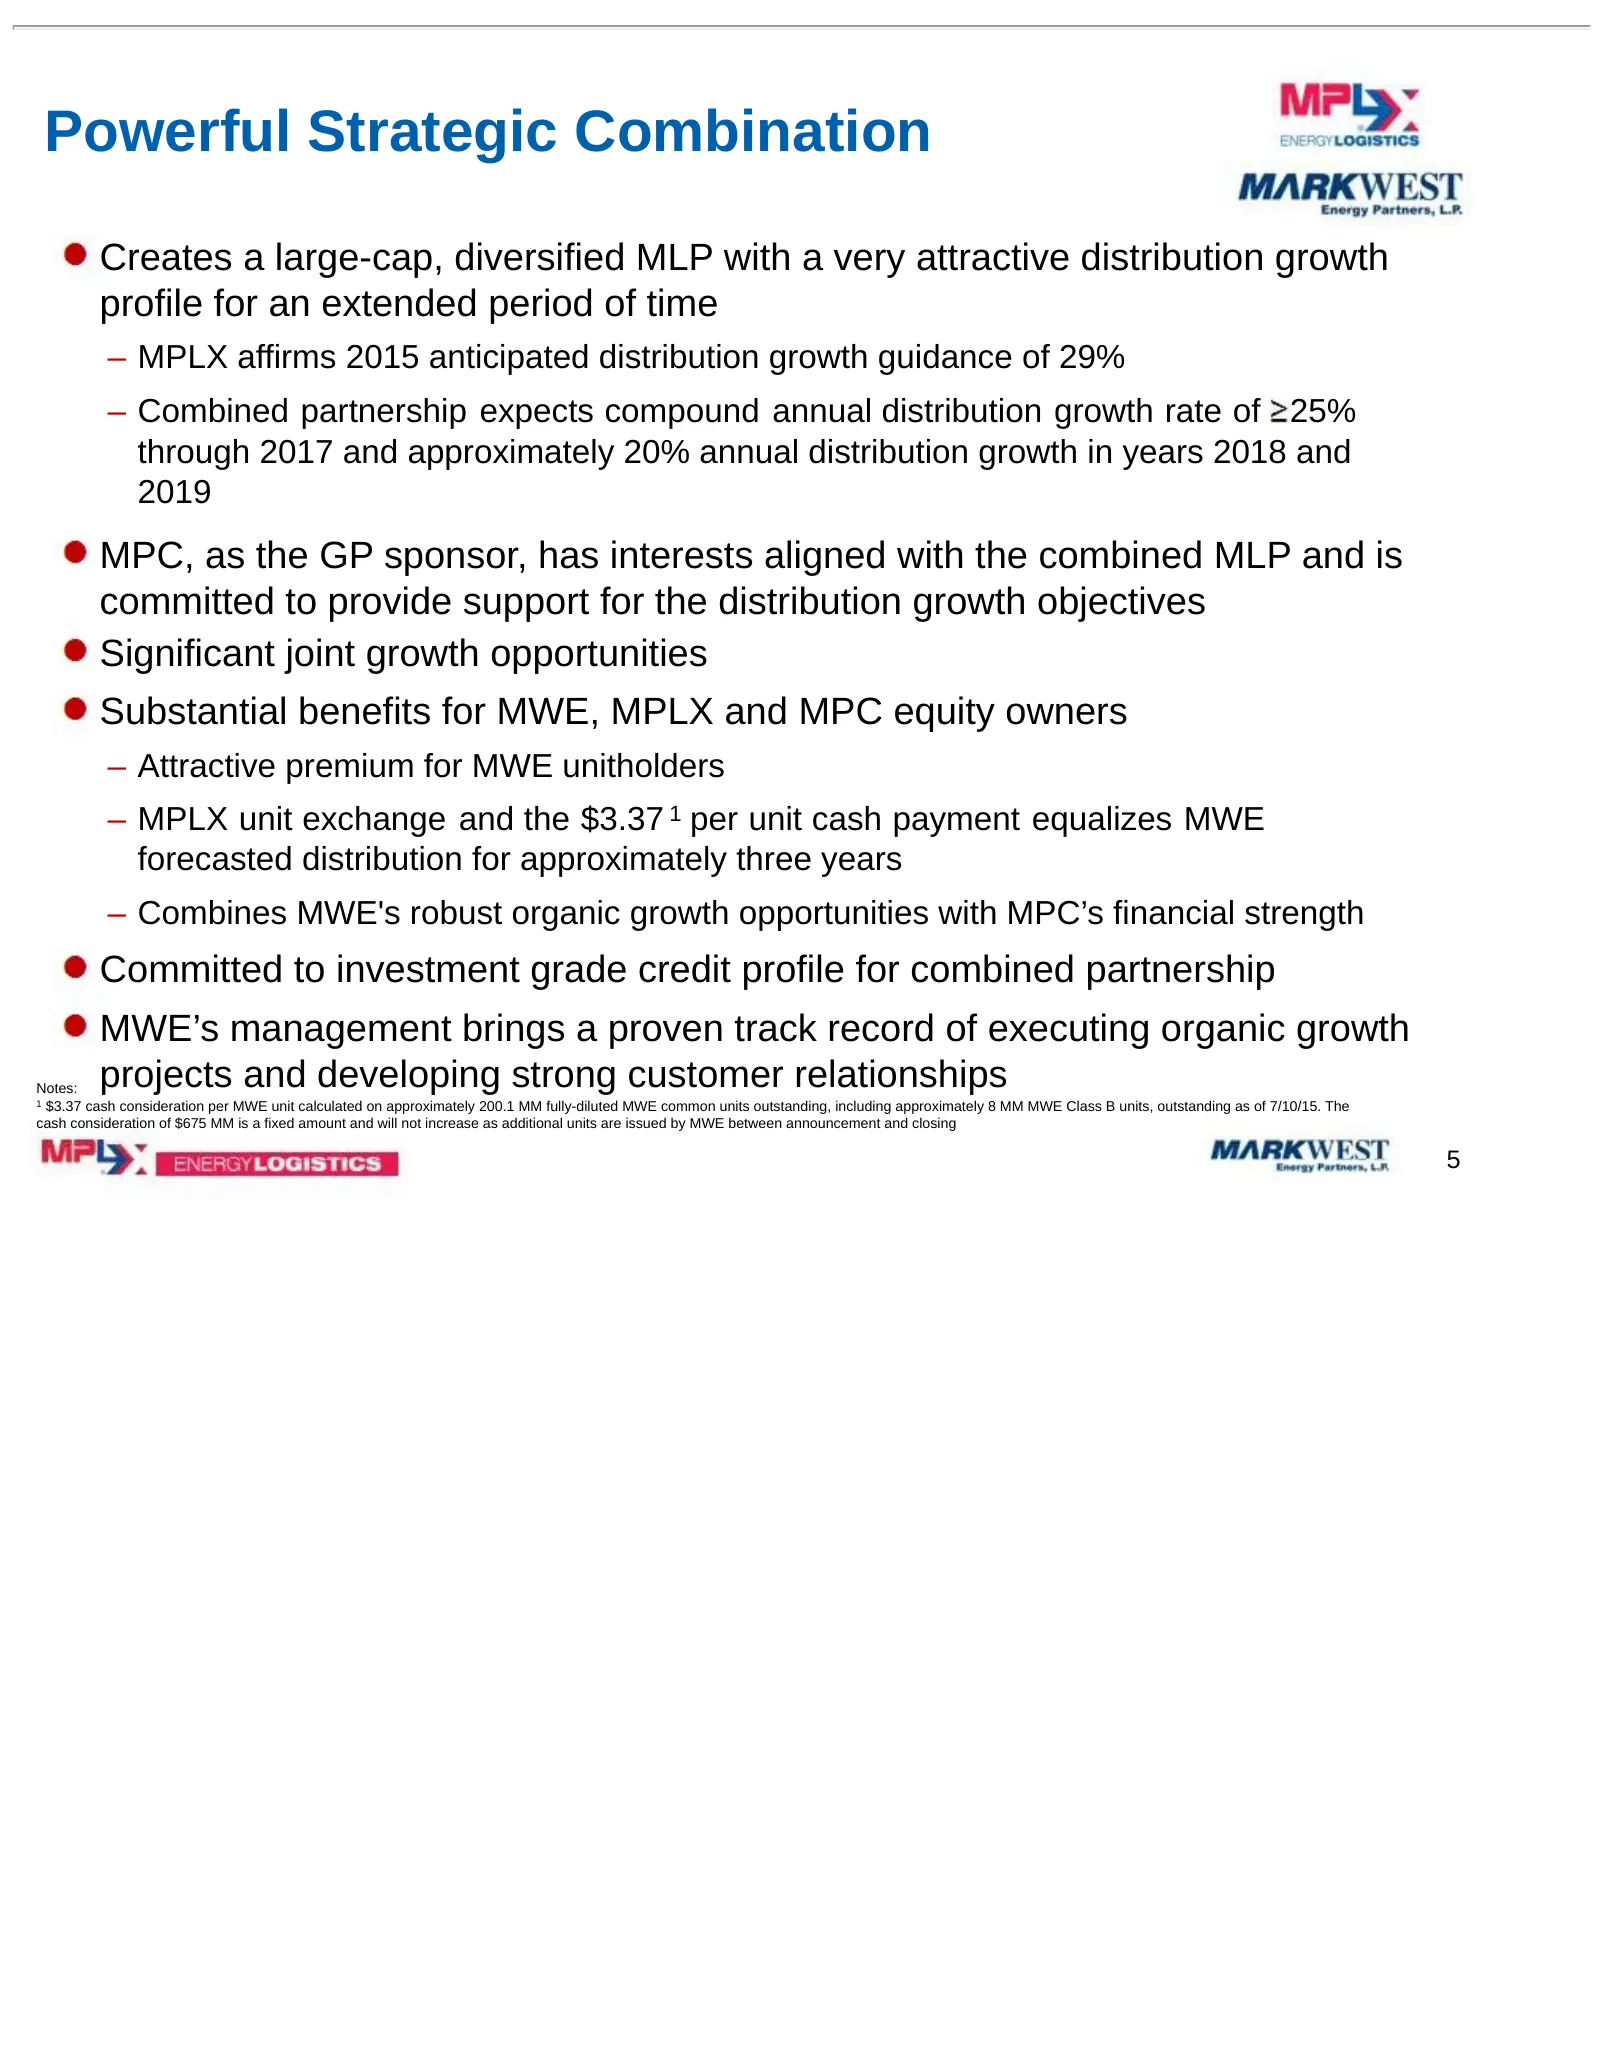
Powerful Strategic Combination Creates a large-cap, diversified MLP with a very attractive distribution growth profile for an extended period of time – MPLX affirms 2015 anticipated distribution growth guidance of 29% – Combined partnership expects compound annual distribution growth rate of 25% thr
Slide 6: Transaction Structure and Terms
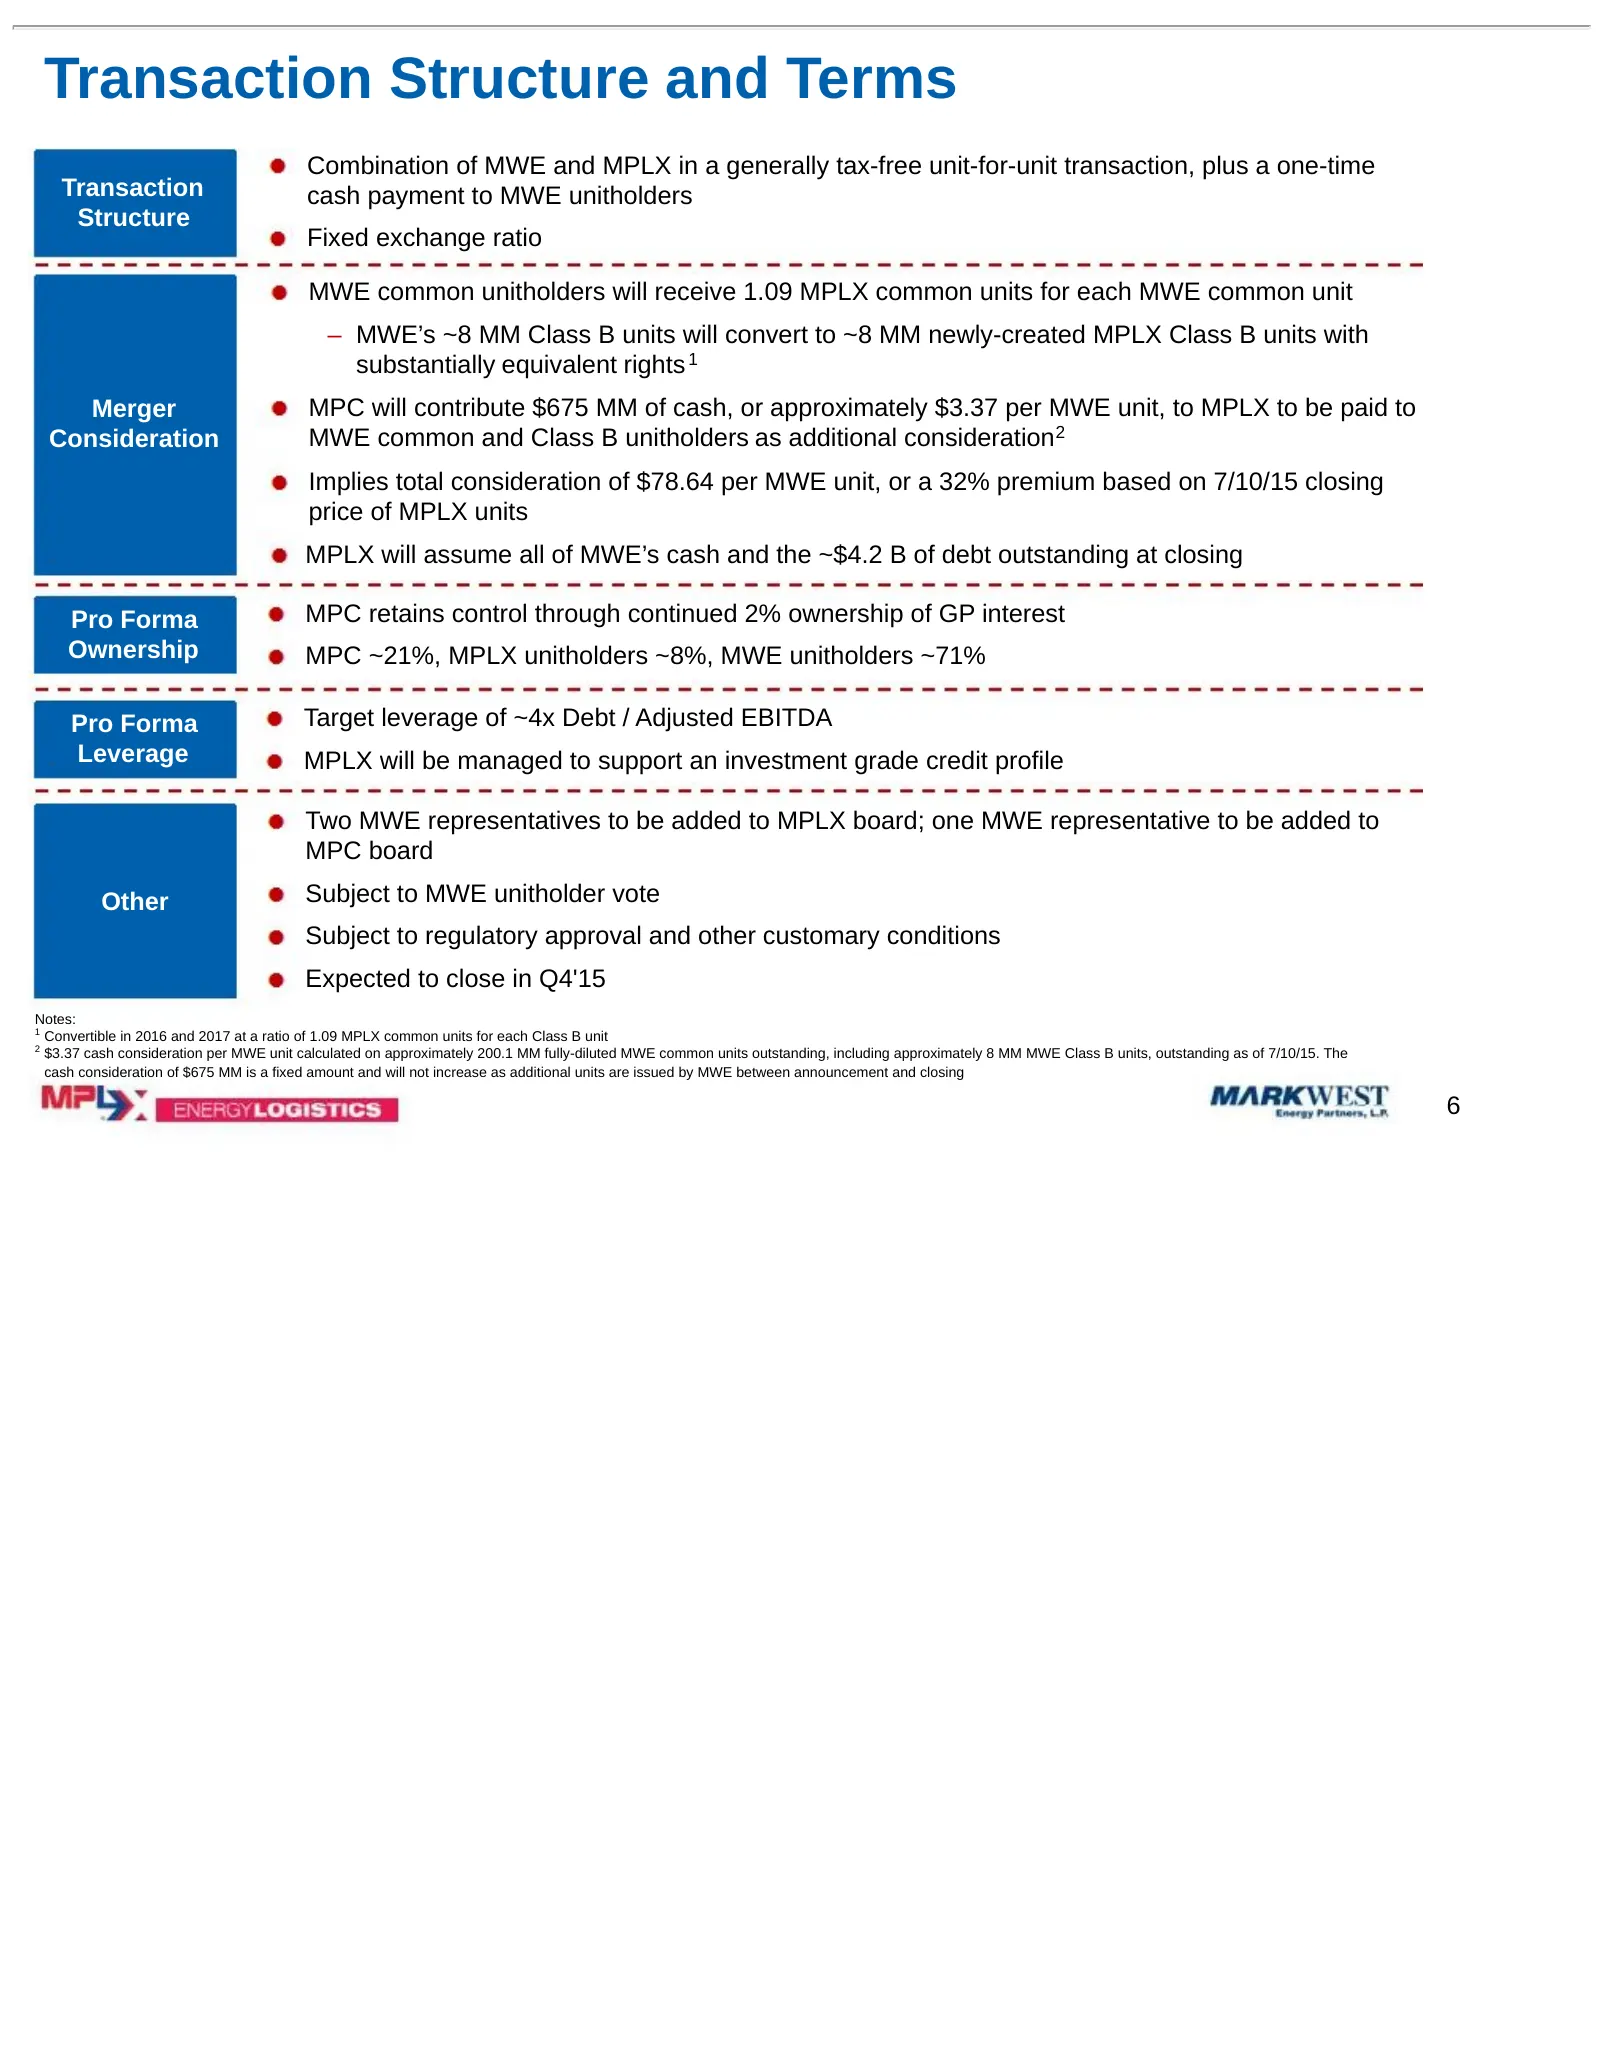
Transaction Structure and Terms Combination of MWE and MPLX in a generally tax-free unit-for-unit transaction, plus a one-time Transaction cash payment to MWE unitholders Structure Fixed exchange ratio MWE common unitholders will receive 1.09 MPLX common units for each MWE common unit – MWE’s ~8 MM
Slide 7: Pro Forma Organizational Structure
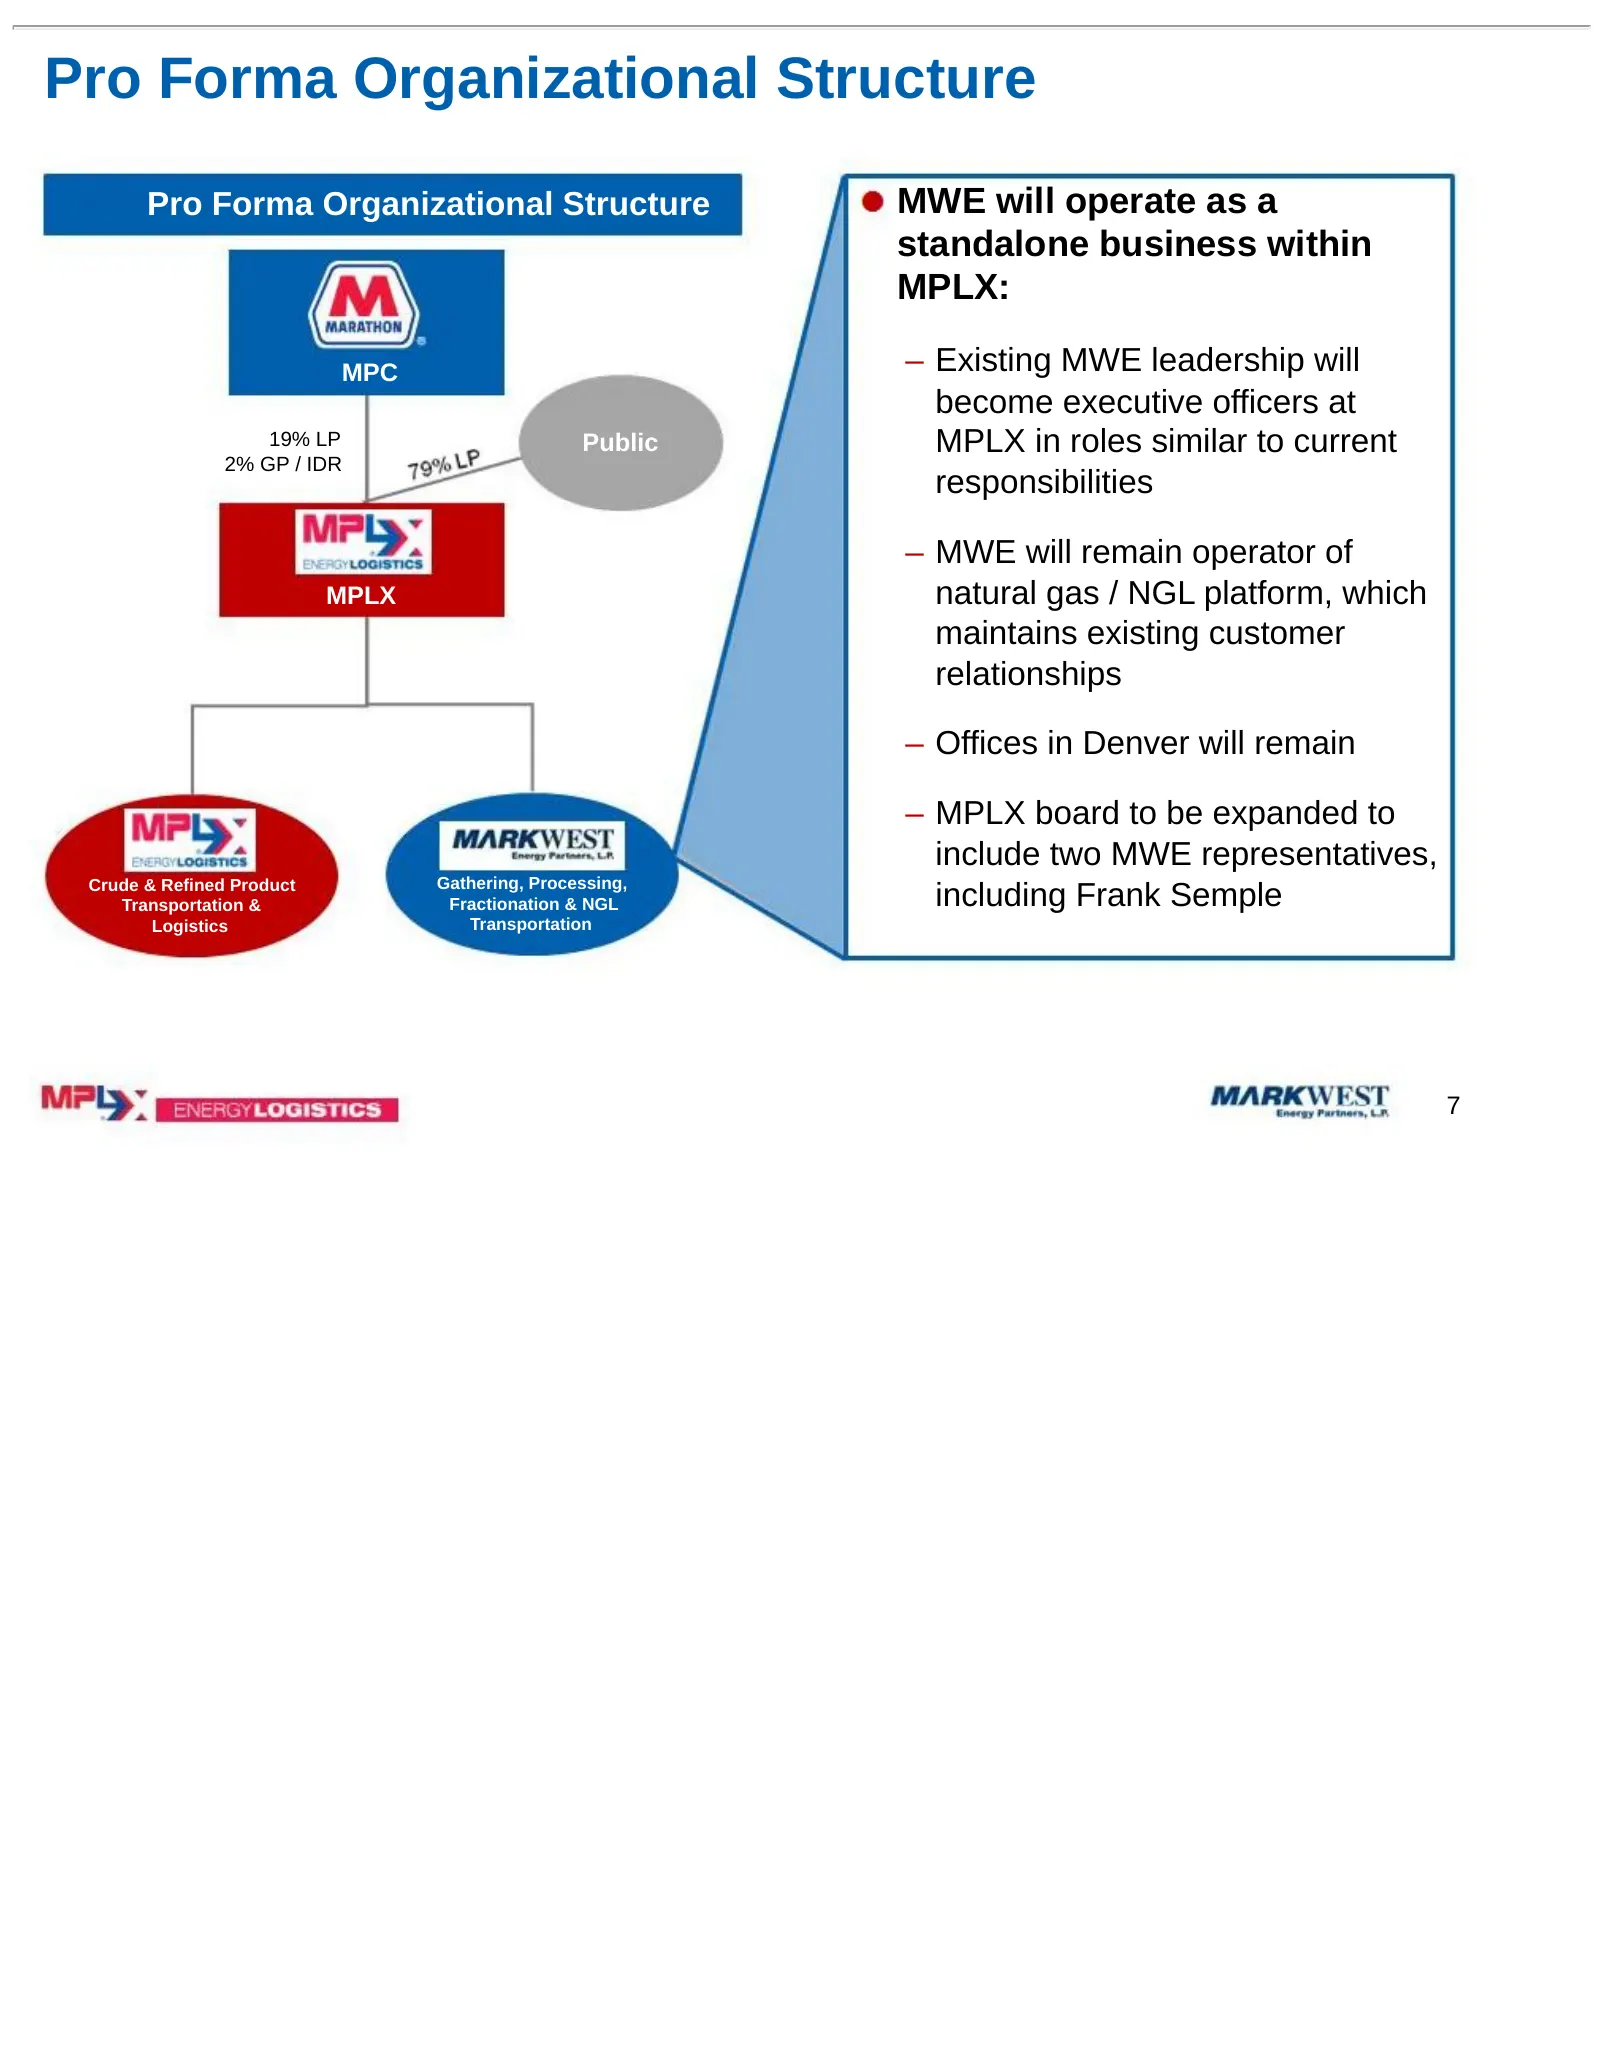
Pro Forma Organizational Structure Pro Forma Organizational Structure MWE will operate as a standalone business within MPLX: MPC – Existing MWE leadership will become executive officers at 19% LP Public MPLX in roles similar to current 2% GP / IDR responsibilities – MWE will remain operator of MPLX
Slide 8: MWE Has the Premier Position in Marcellus / Utica
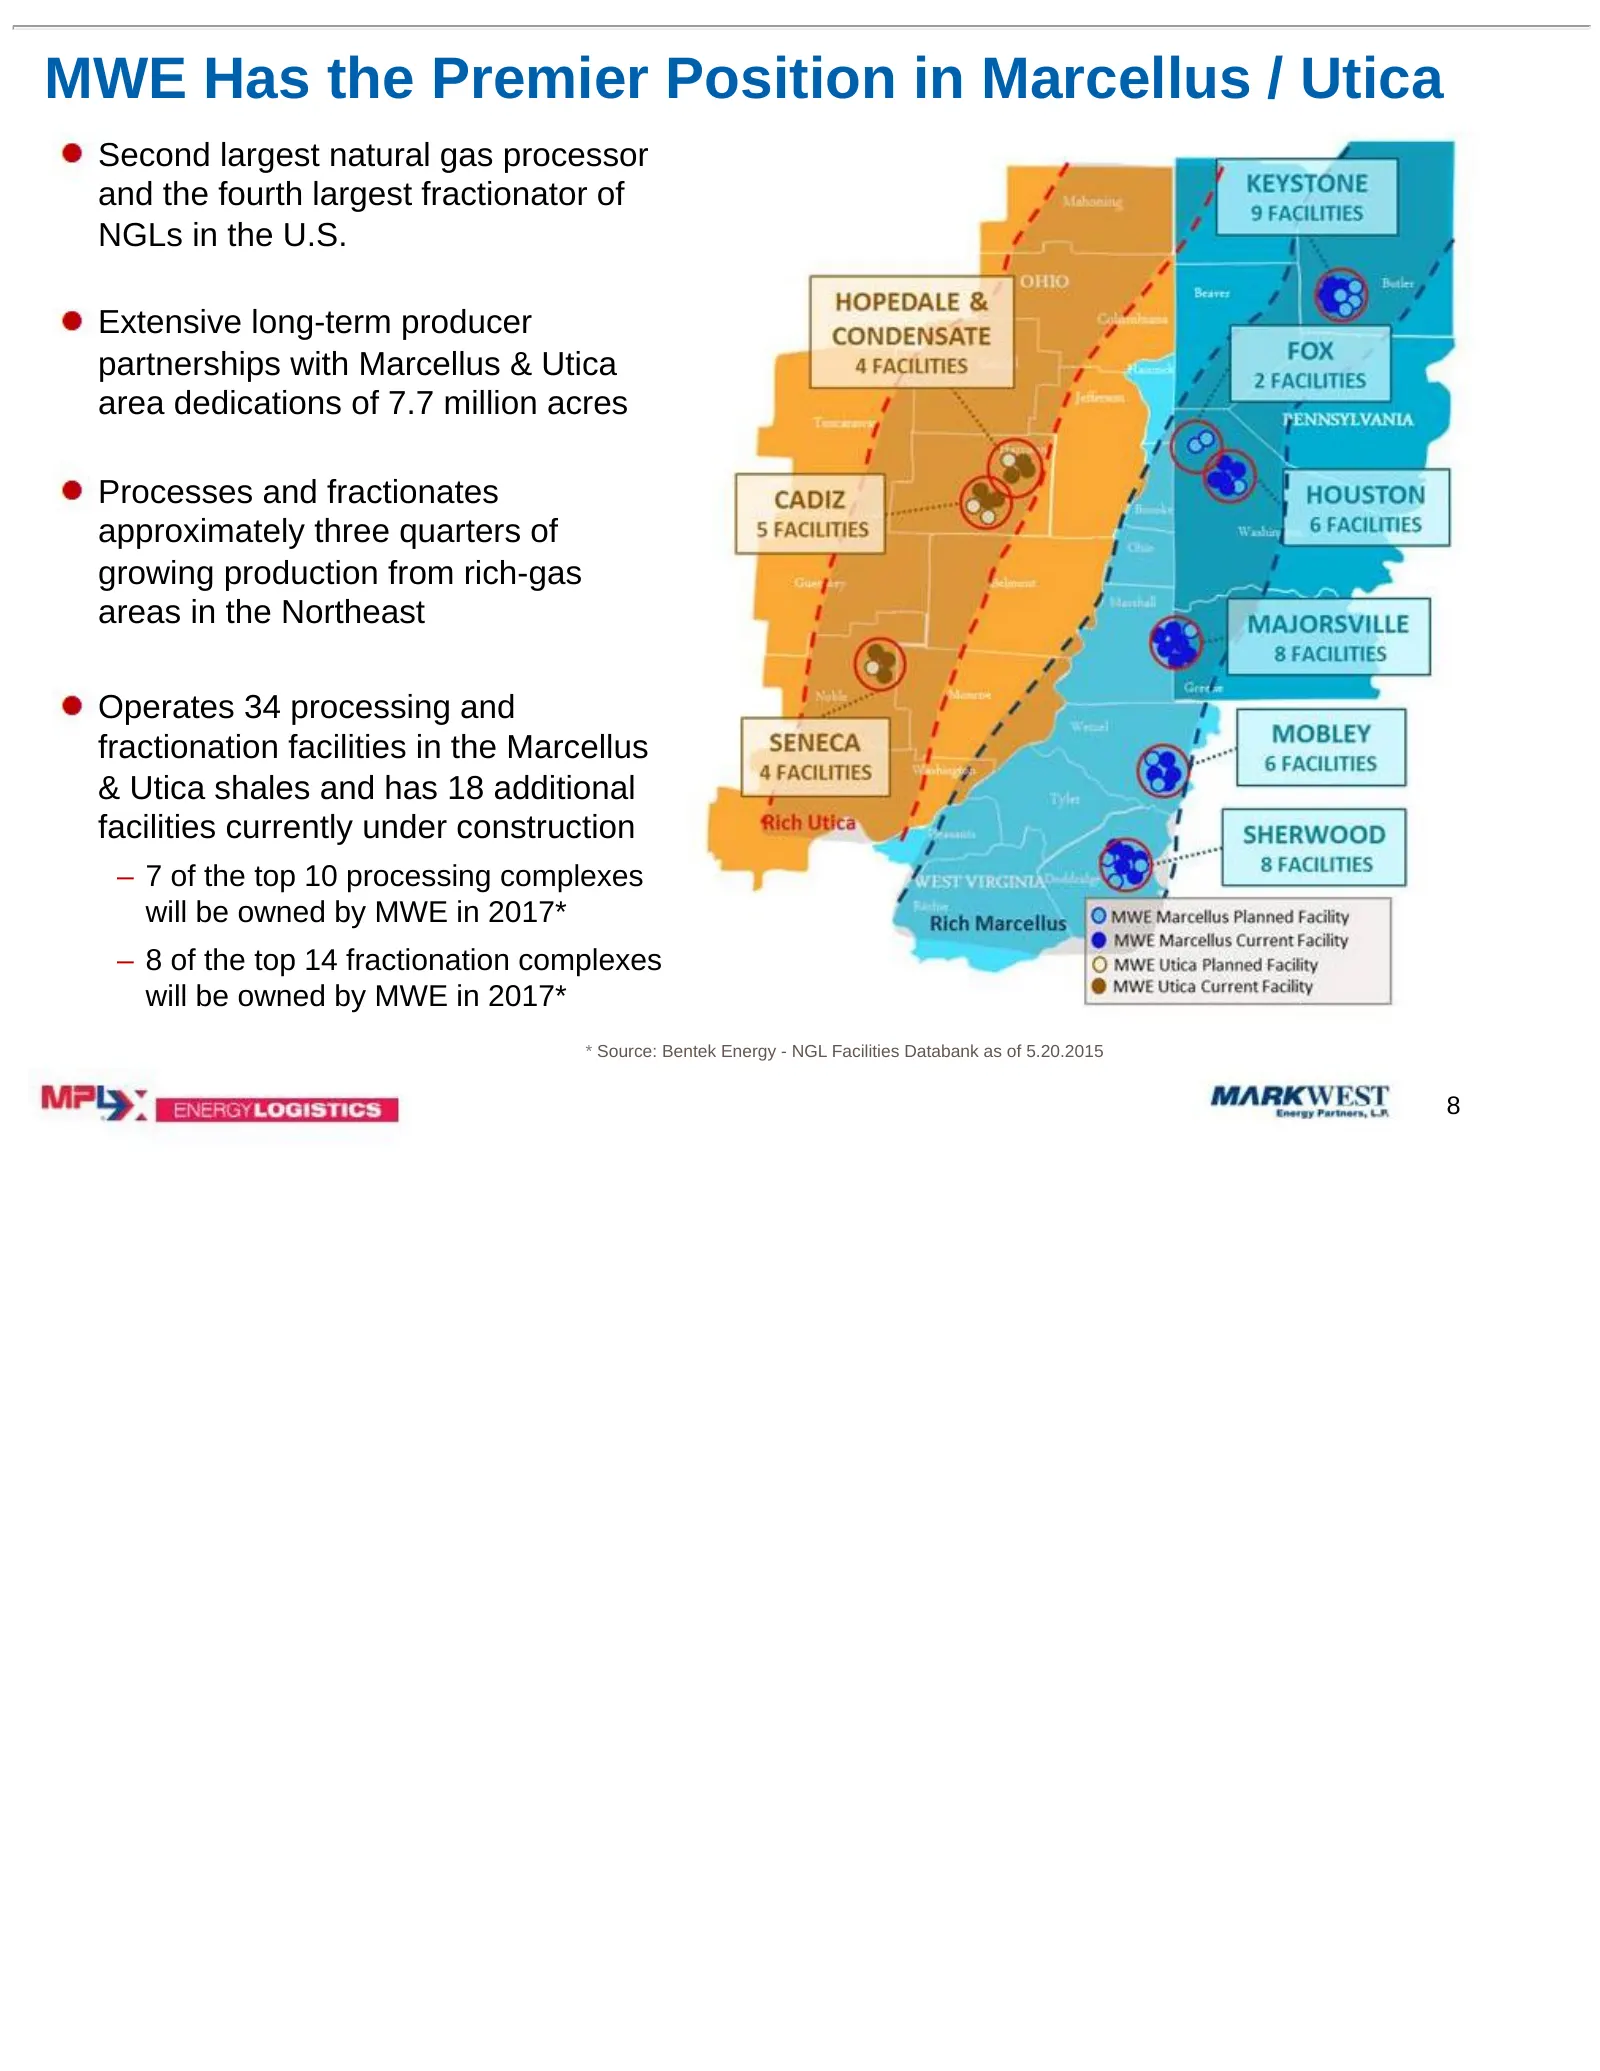
MWE Has the Premier Position in Marcellus / Utica Second largest natural gas processor and the fourth largest fractionator of NGLs in the U.S. Extensive long-term producer partnerships with Marcellus & Utica area dedications of 7.7 million acres Processes and fractionates approximately three quarter
Slide 9: Growth Driven by Customer Satisfaction
Growth Driven by Customer Satisfaction MarkWest has received the #1 rating for total customer satisfaction in every EnergyPoint Research survey since its inception in 2006 9
Slide 10: Pro forma MPLX – Best-in-Class Large Cap MLP
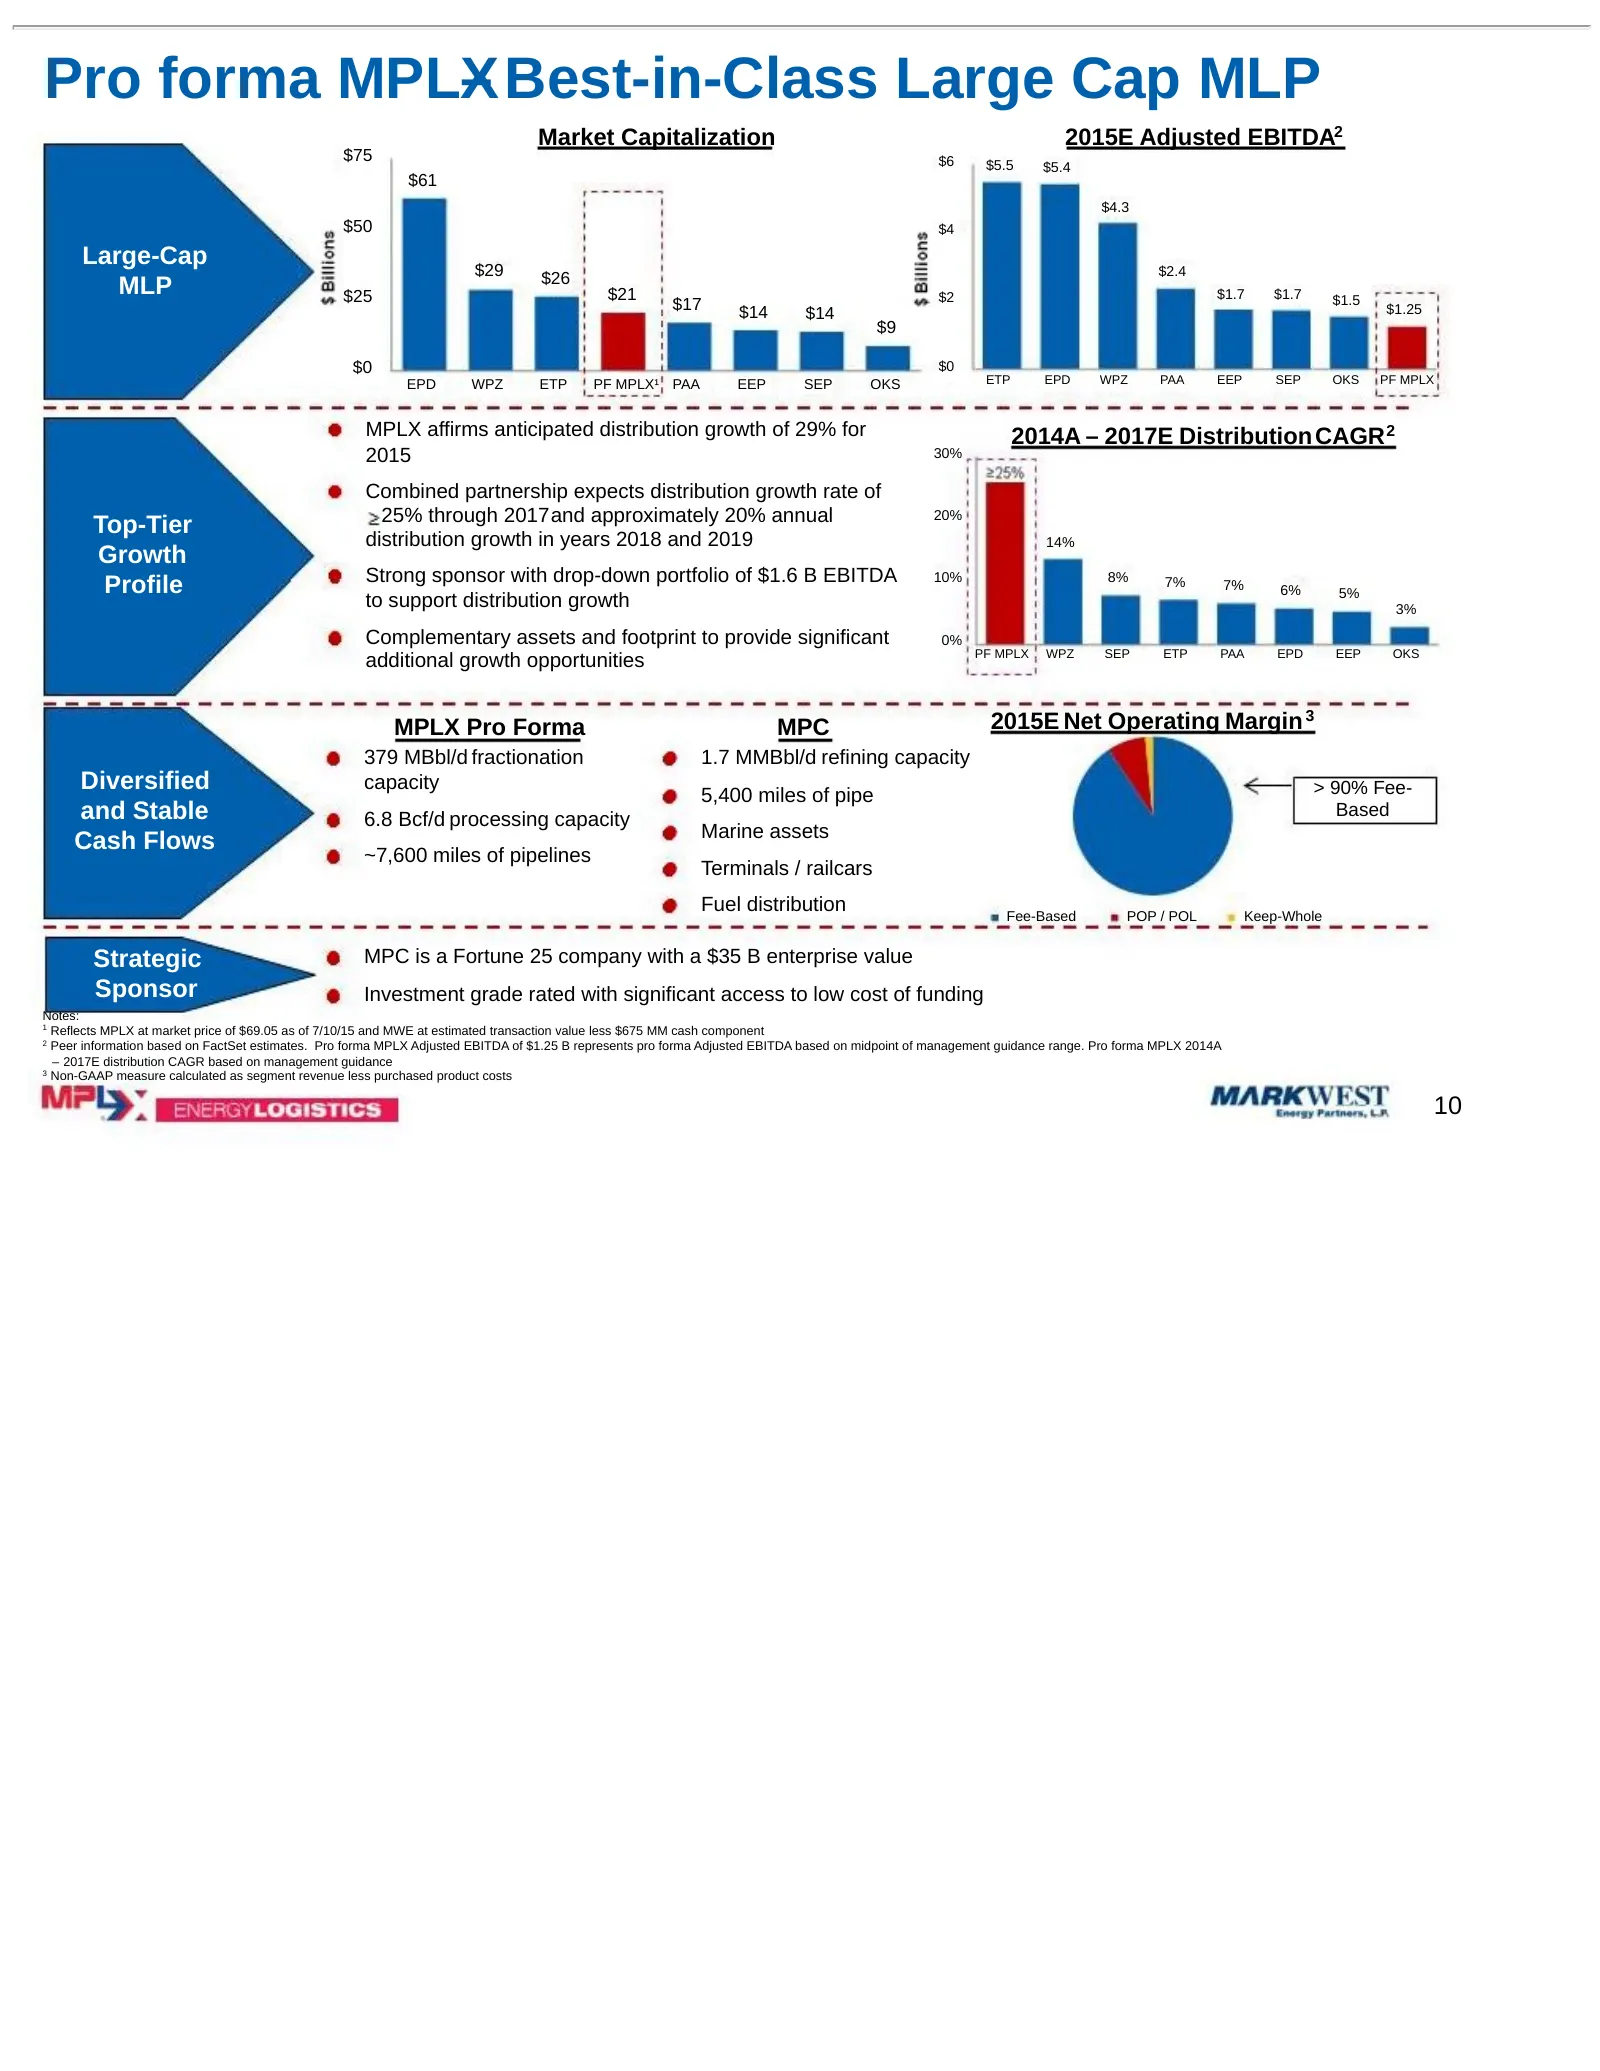
Pro forma MPLX – Best-in-Class Large Cap MLP Market Capitalization 2015E Adjusted EBITDA2 $75 $6 $5.5 $5.4 $61 $4.3 $50 $4 Large-Cap $29 $2.4 $26 MLP $25 $21 $2 $1.7 $1.7 $1.5 $17 $14 $1.25 $14 $9 $0 $0 EPD WPZ ETP PF MPLX¹ PAA EEP SEP OKS ETP EPD WPZ PAA EEP SEP OKS PF MPLX MPLX affirms anticipated
Slide 11: Strategic Geographic Footprint
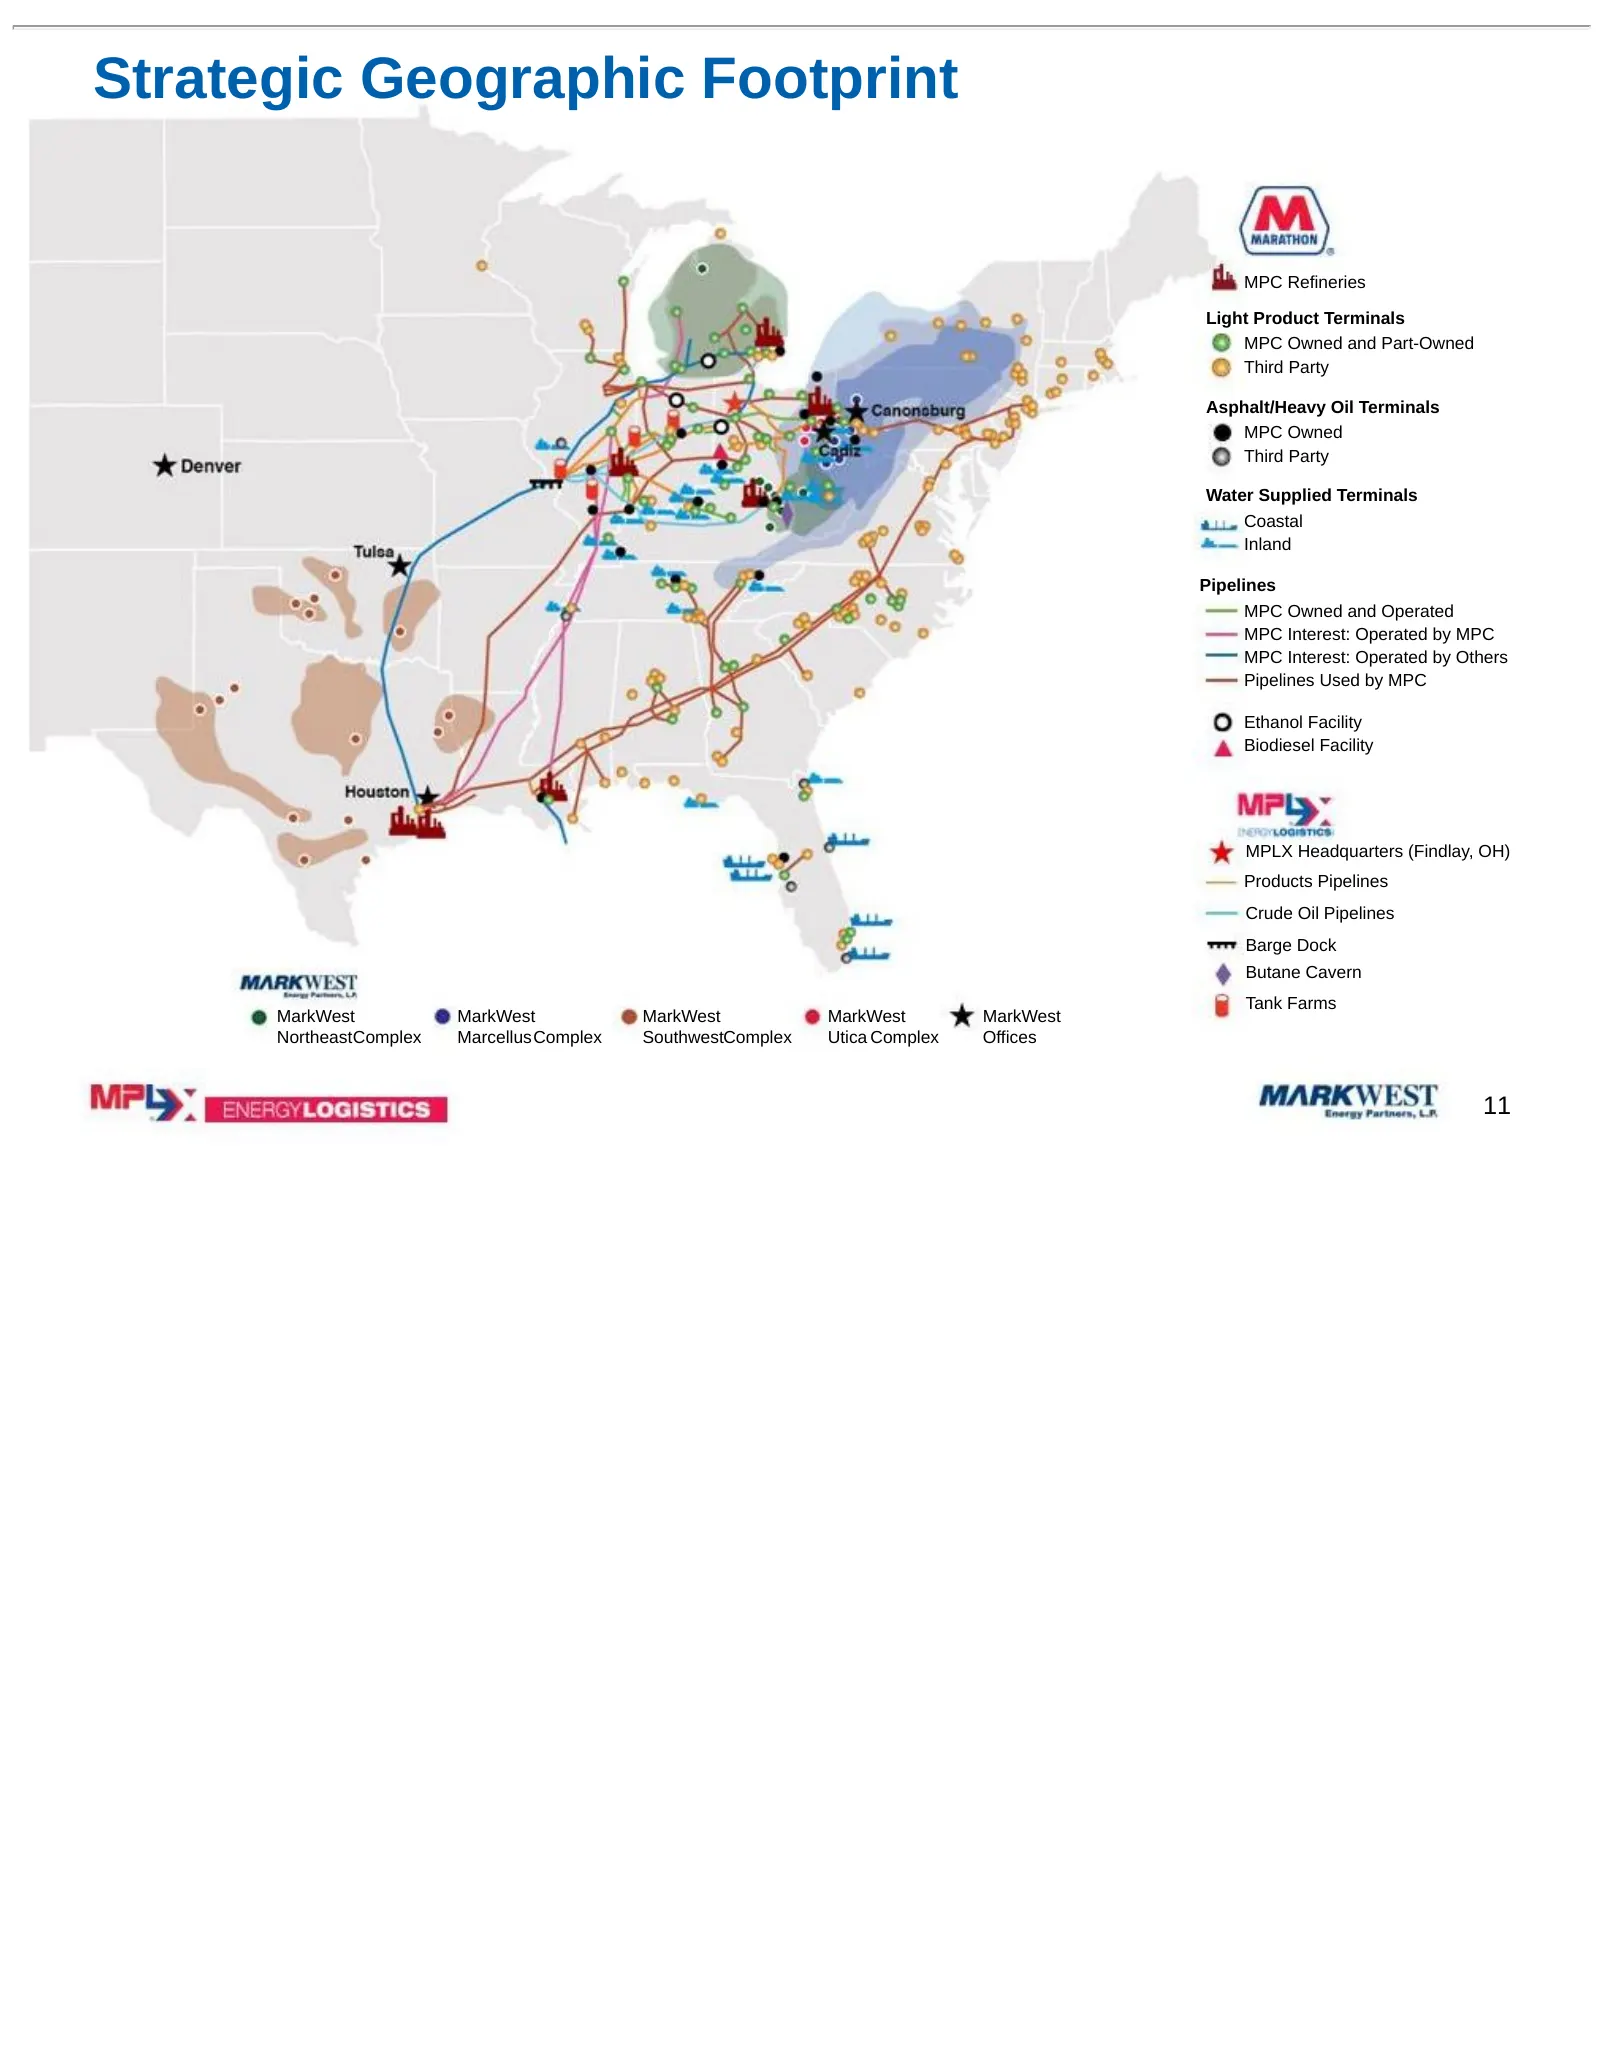
Strategic Geographic Footprint MPC Refineries Light Product Terminals MPC Owned and Part-Owned Third Party Asphalt/Heavy Oil Terminals MPC Owned Third Party Water Supplied Terminals Coastal Inland Pipelines MPC Owned and Operated MPC Interest: Operated by MPC MPC Interest: Operated by Others Pipelin
Slide 12: Significant Joint Growth Opportunities
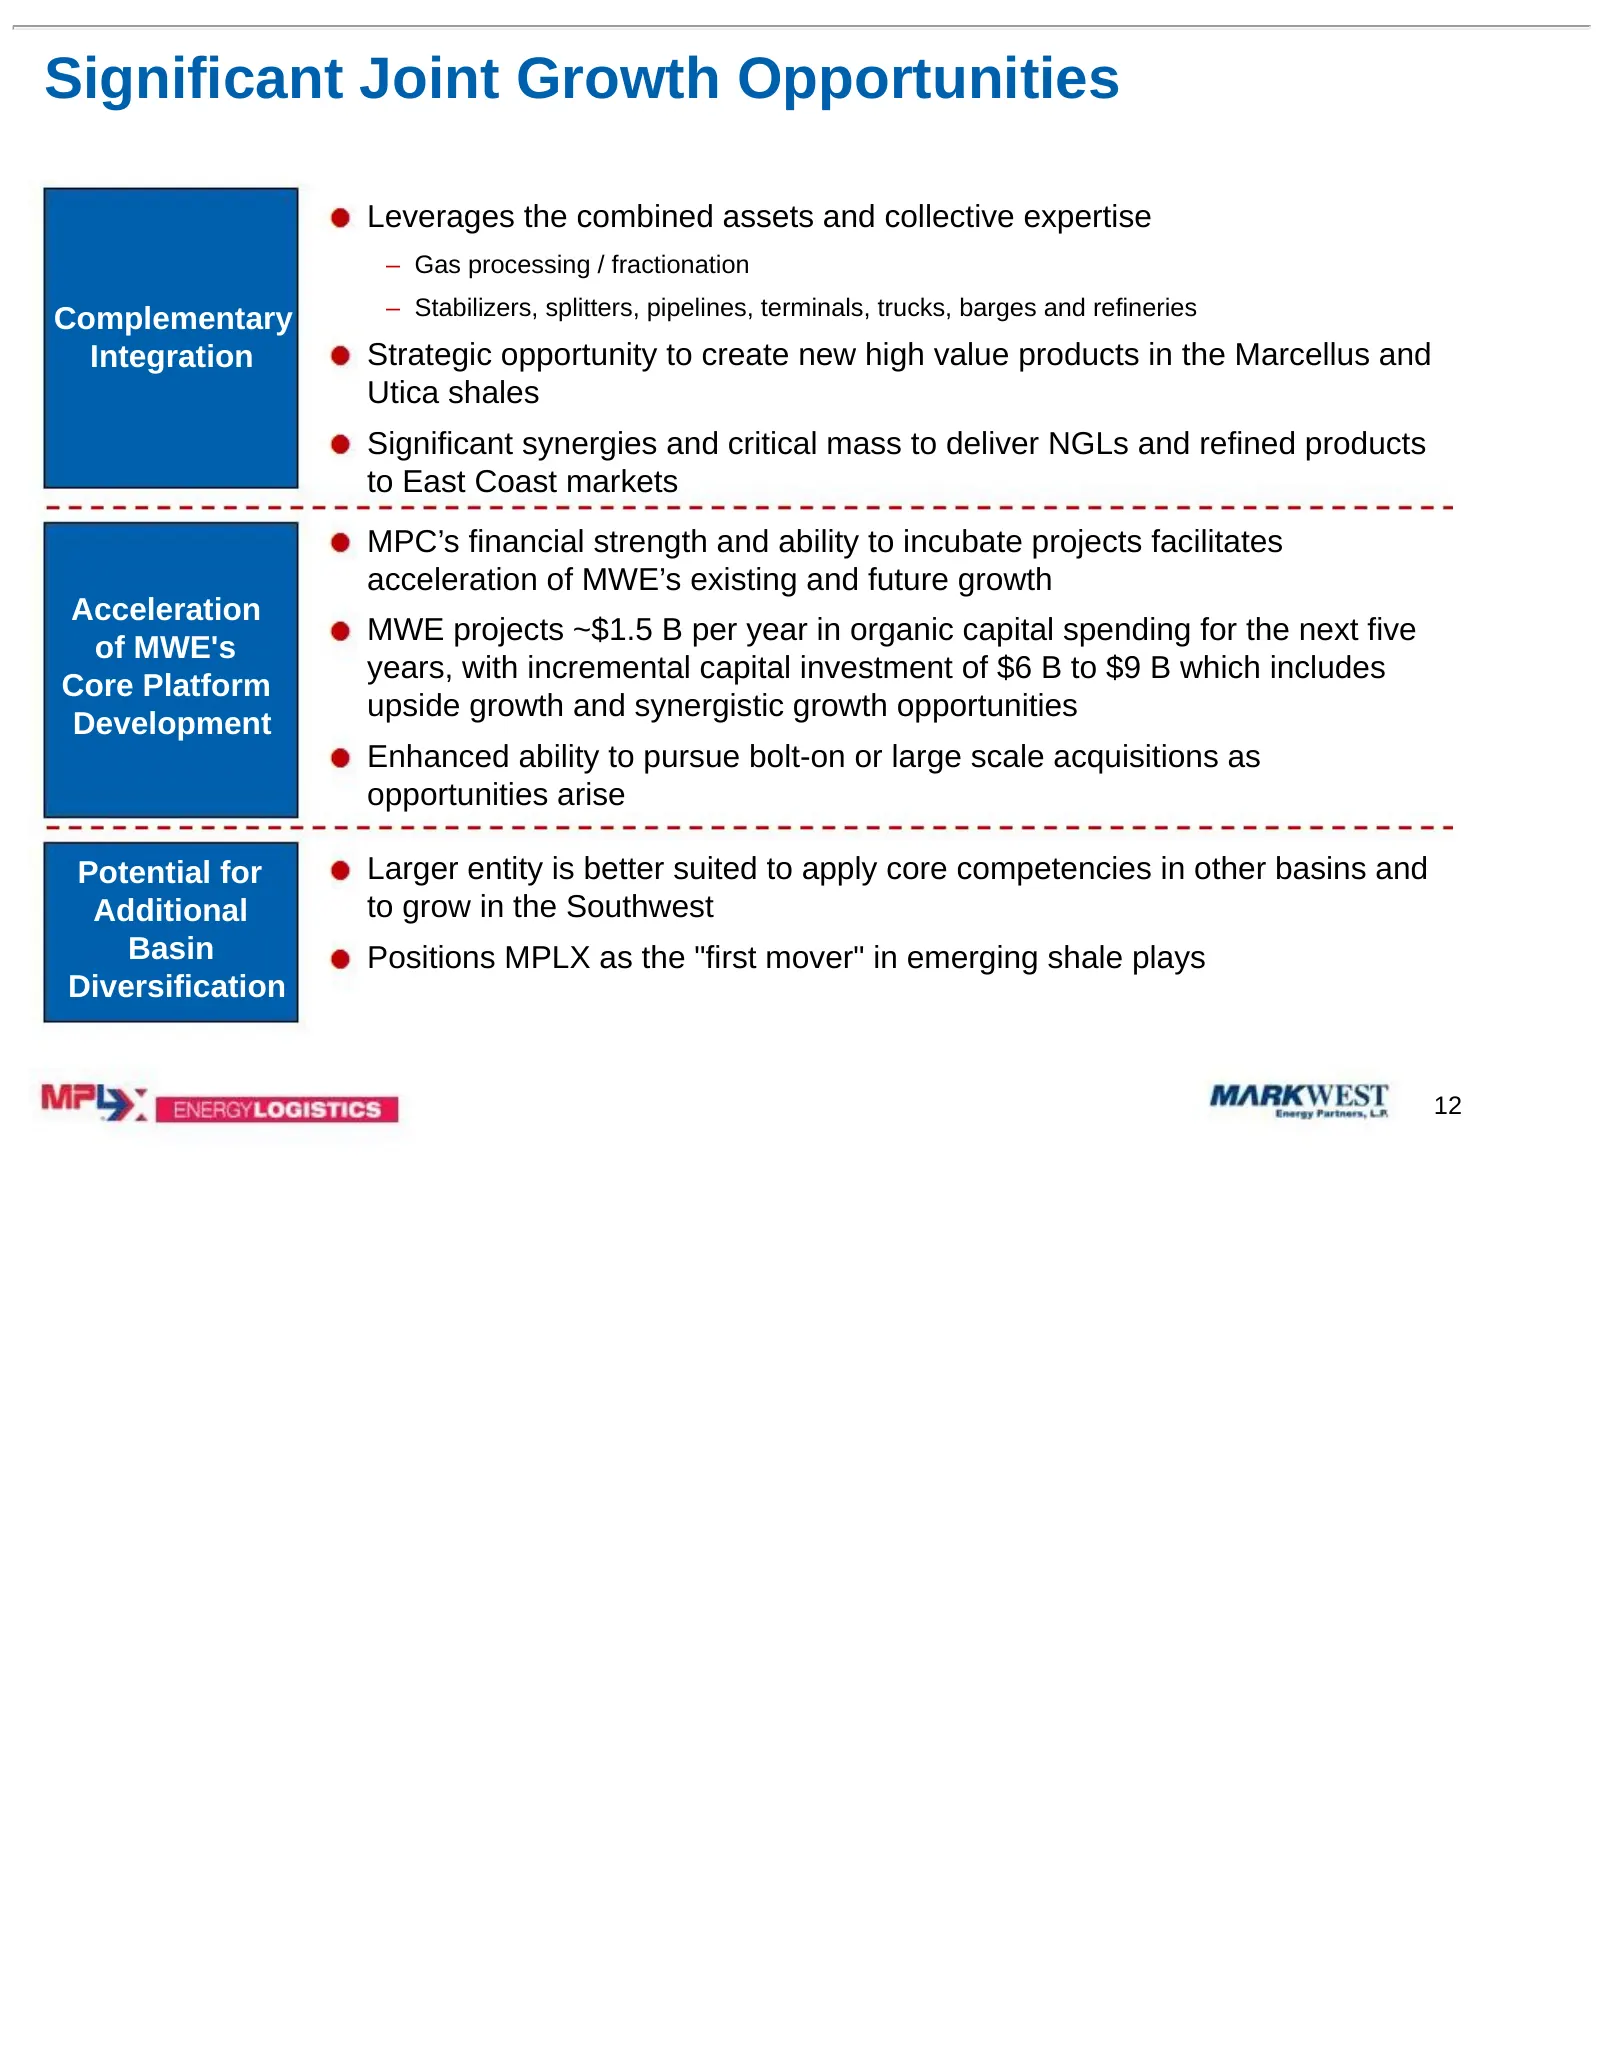
Significant Joint Growth Opportunities Leverages the combined assets and collective expertise – Gas processing / fractionation – Stabilizers, splitters, pipelines, terminals, trucks, barges and refineries Complementary Integration Strategic opportunity to create new high value products in the Marcel
Slide 13: MarkWest’s Premier Position Drives ~$1.5 B of Annual Investment Opportunity
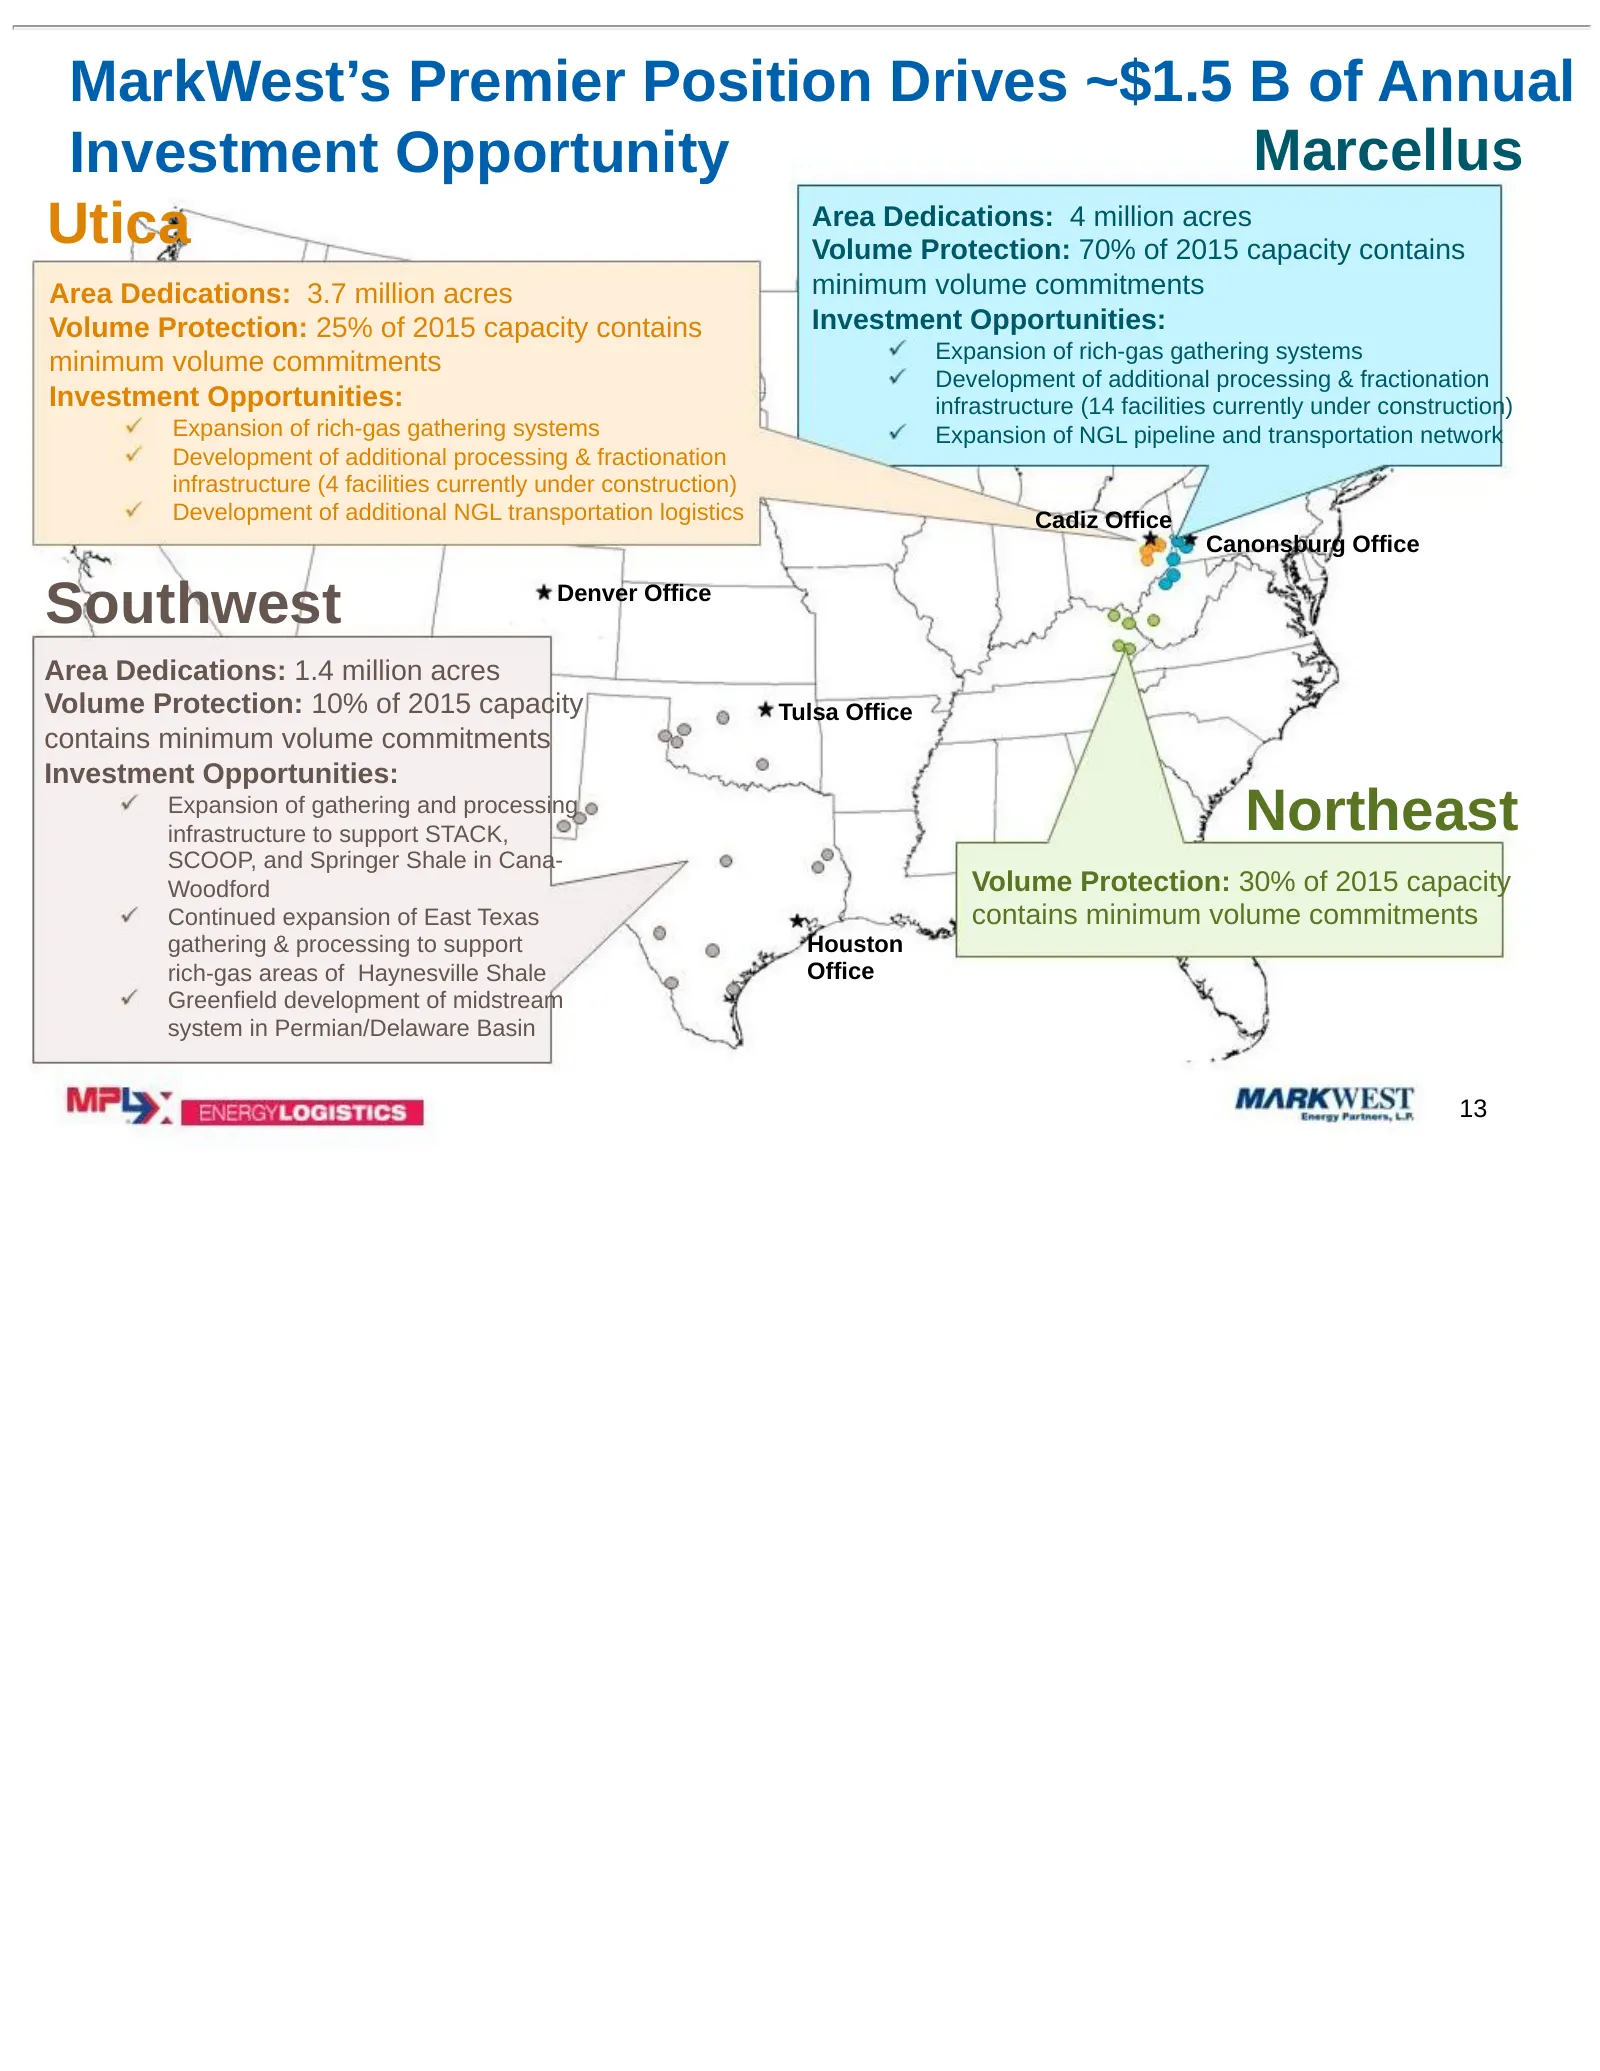
MarkWest’s Premier Position Drives ~$1.5 B of Annual Investment Opportunity Marcellus Utica Area Dedications: 4 million acres Volume Protection: 70% of 2015 capacity contains Area Dedications: 3.7 million acres minimum volume commitments Volume Protection: 25% of 2015 capacity contains Investment Op
Slide 14: MarkWest’s Premier Position Drives Incremental Upside Growth Opportunities
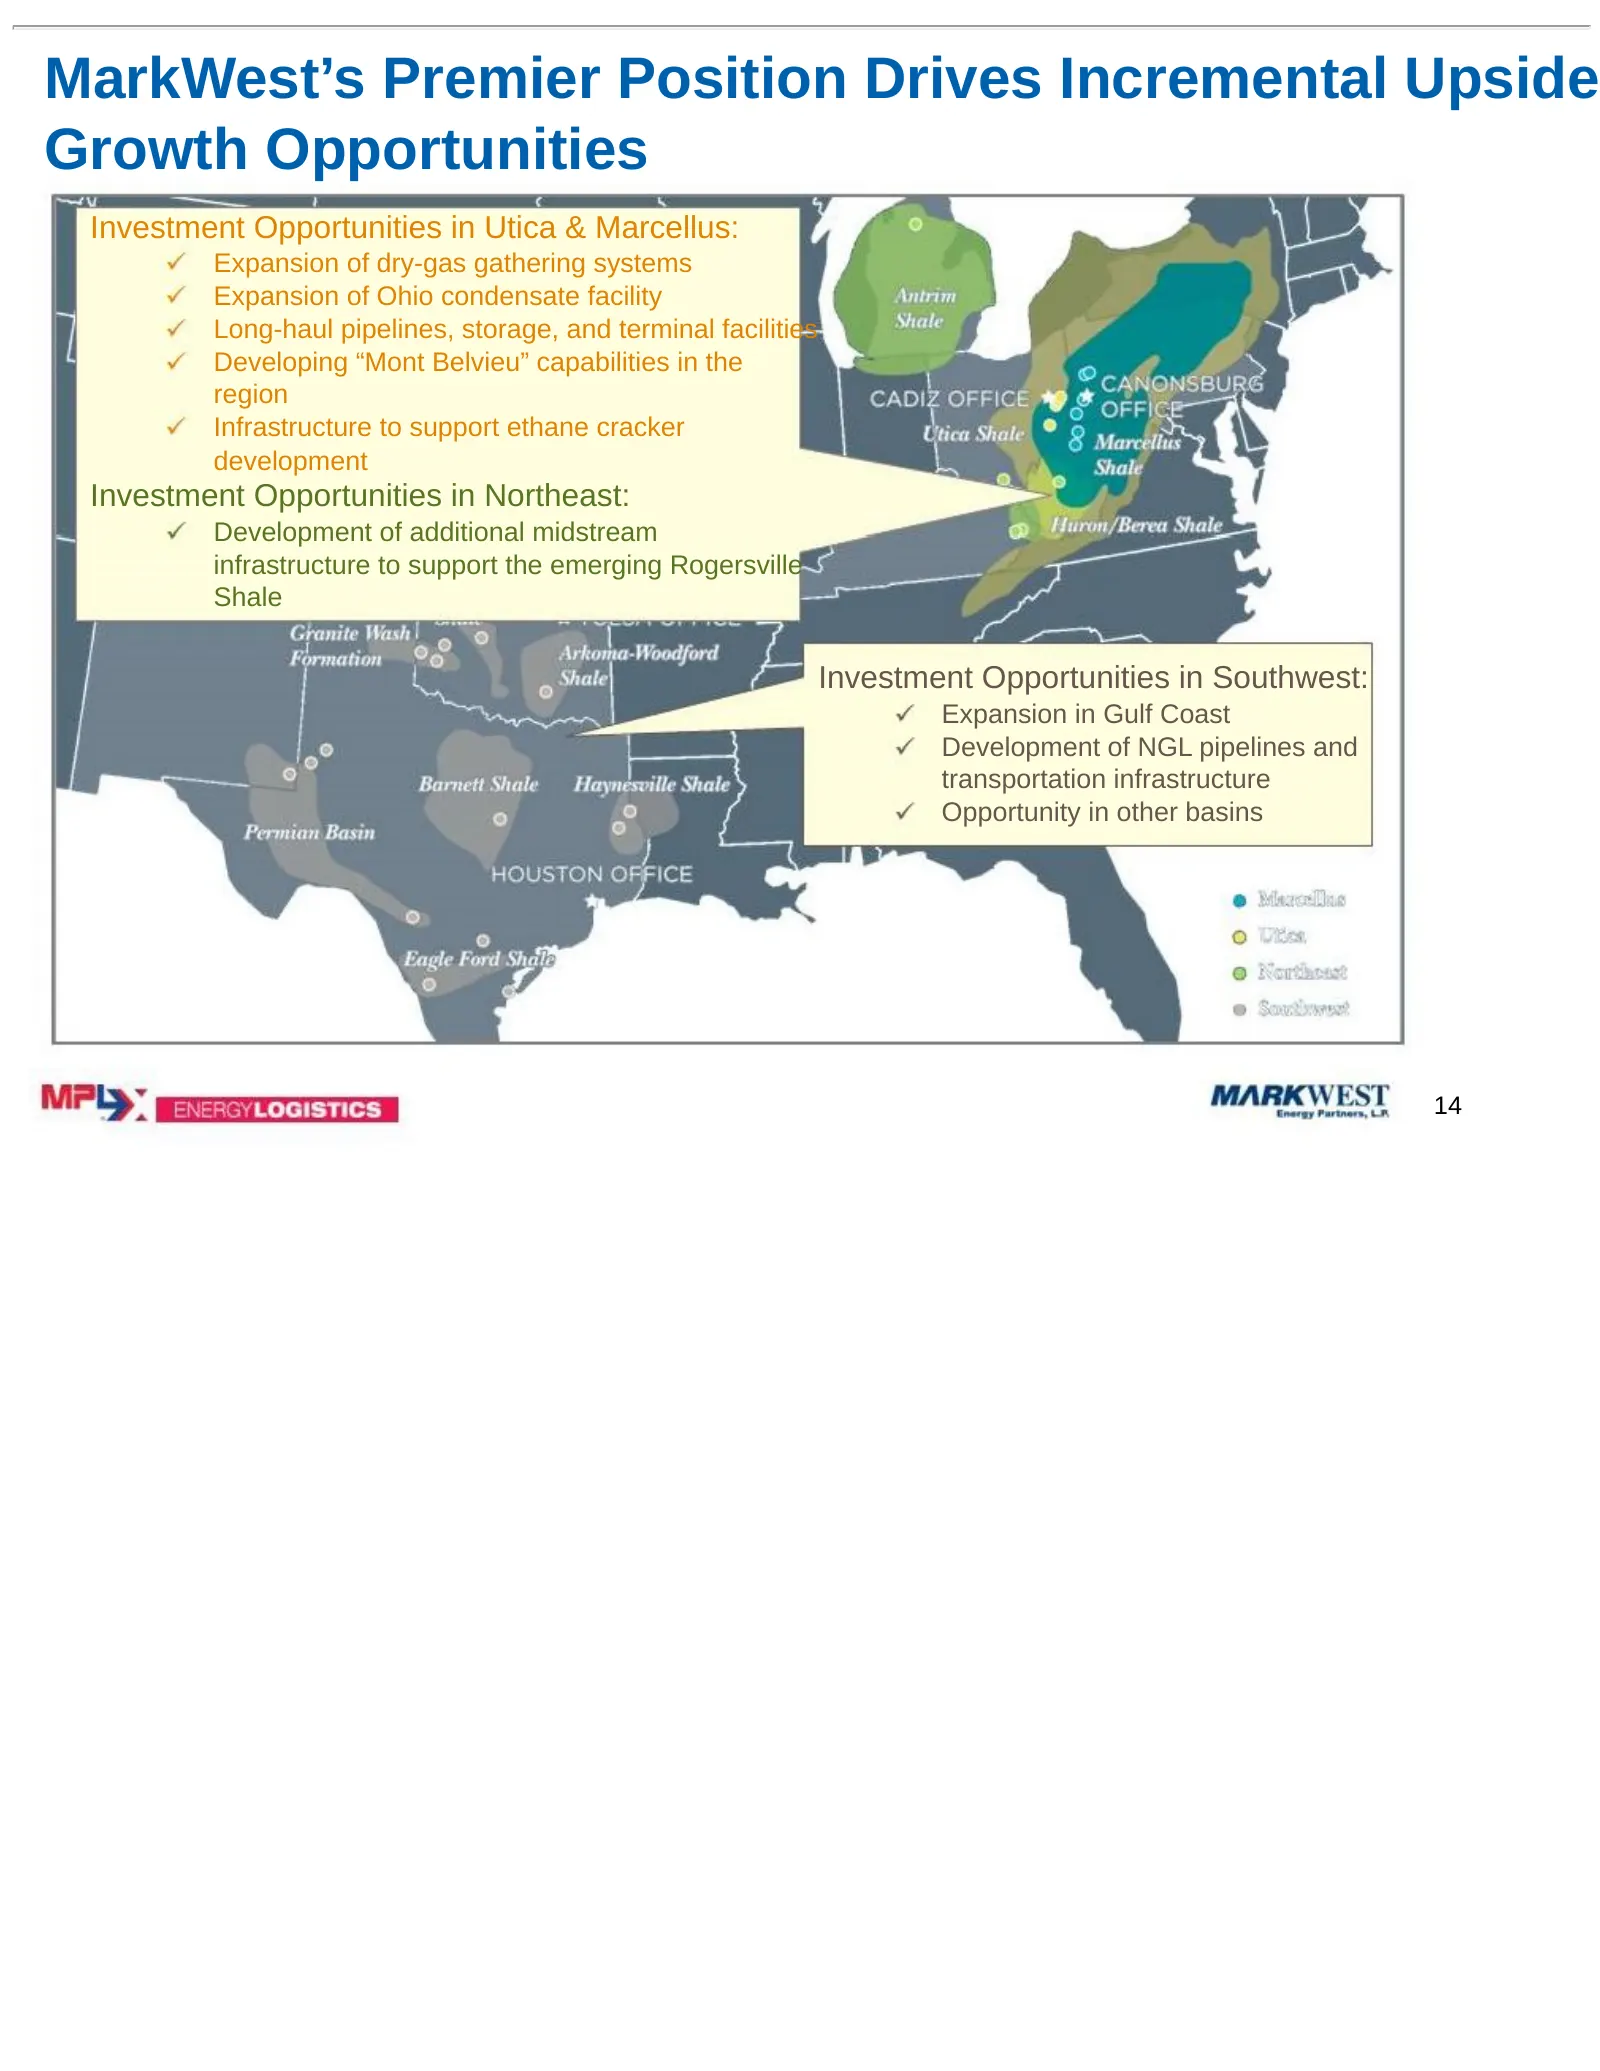
MarkWest’s Premier Position Drives Incremental Upside Growth Opportunities Investment Opportunities in Utica & Marcellus: Expansion of dry-gas gathering systems Expansion of Ohio condensate facility Long-haul pipelines, storage, and terminal facilities Developing “Mont Belvieu” capabilities in the r
Slide 15: Significant Synergistic Opportunities
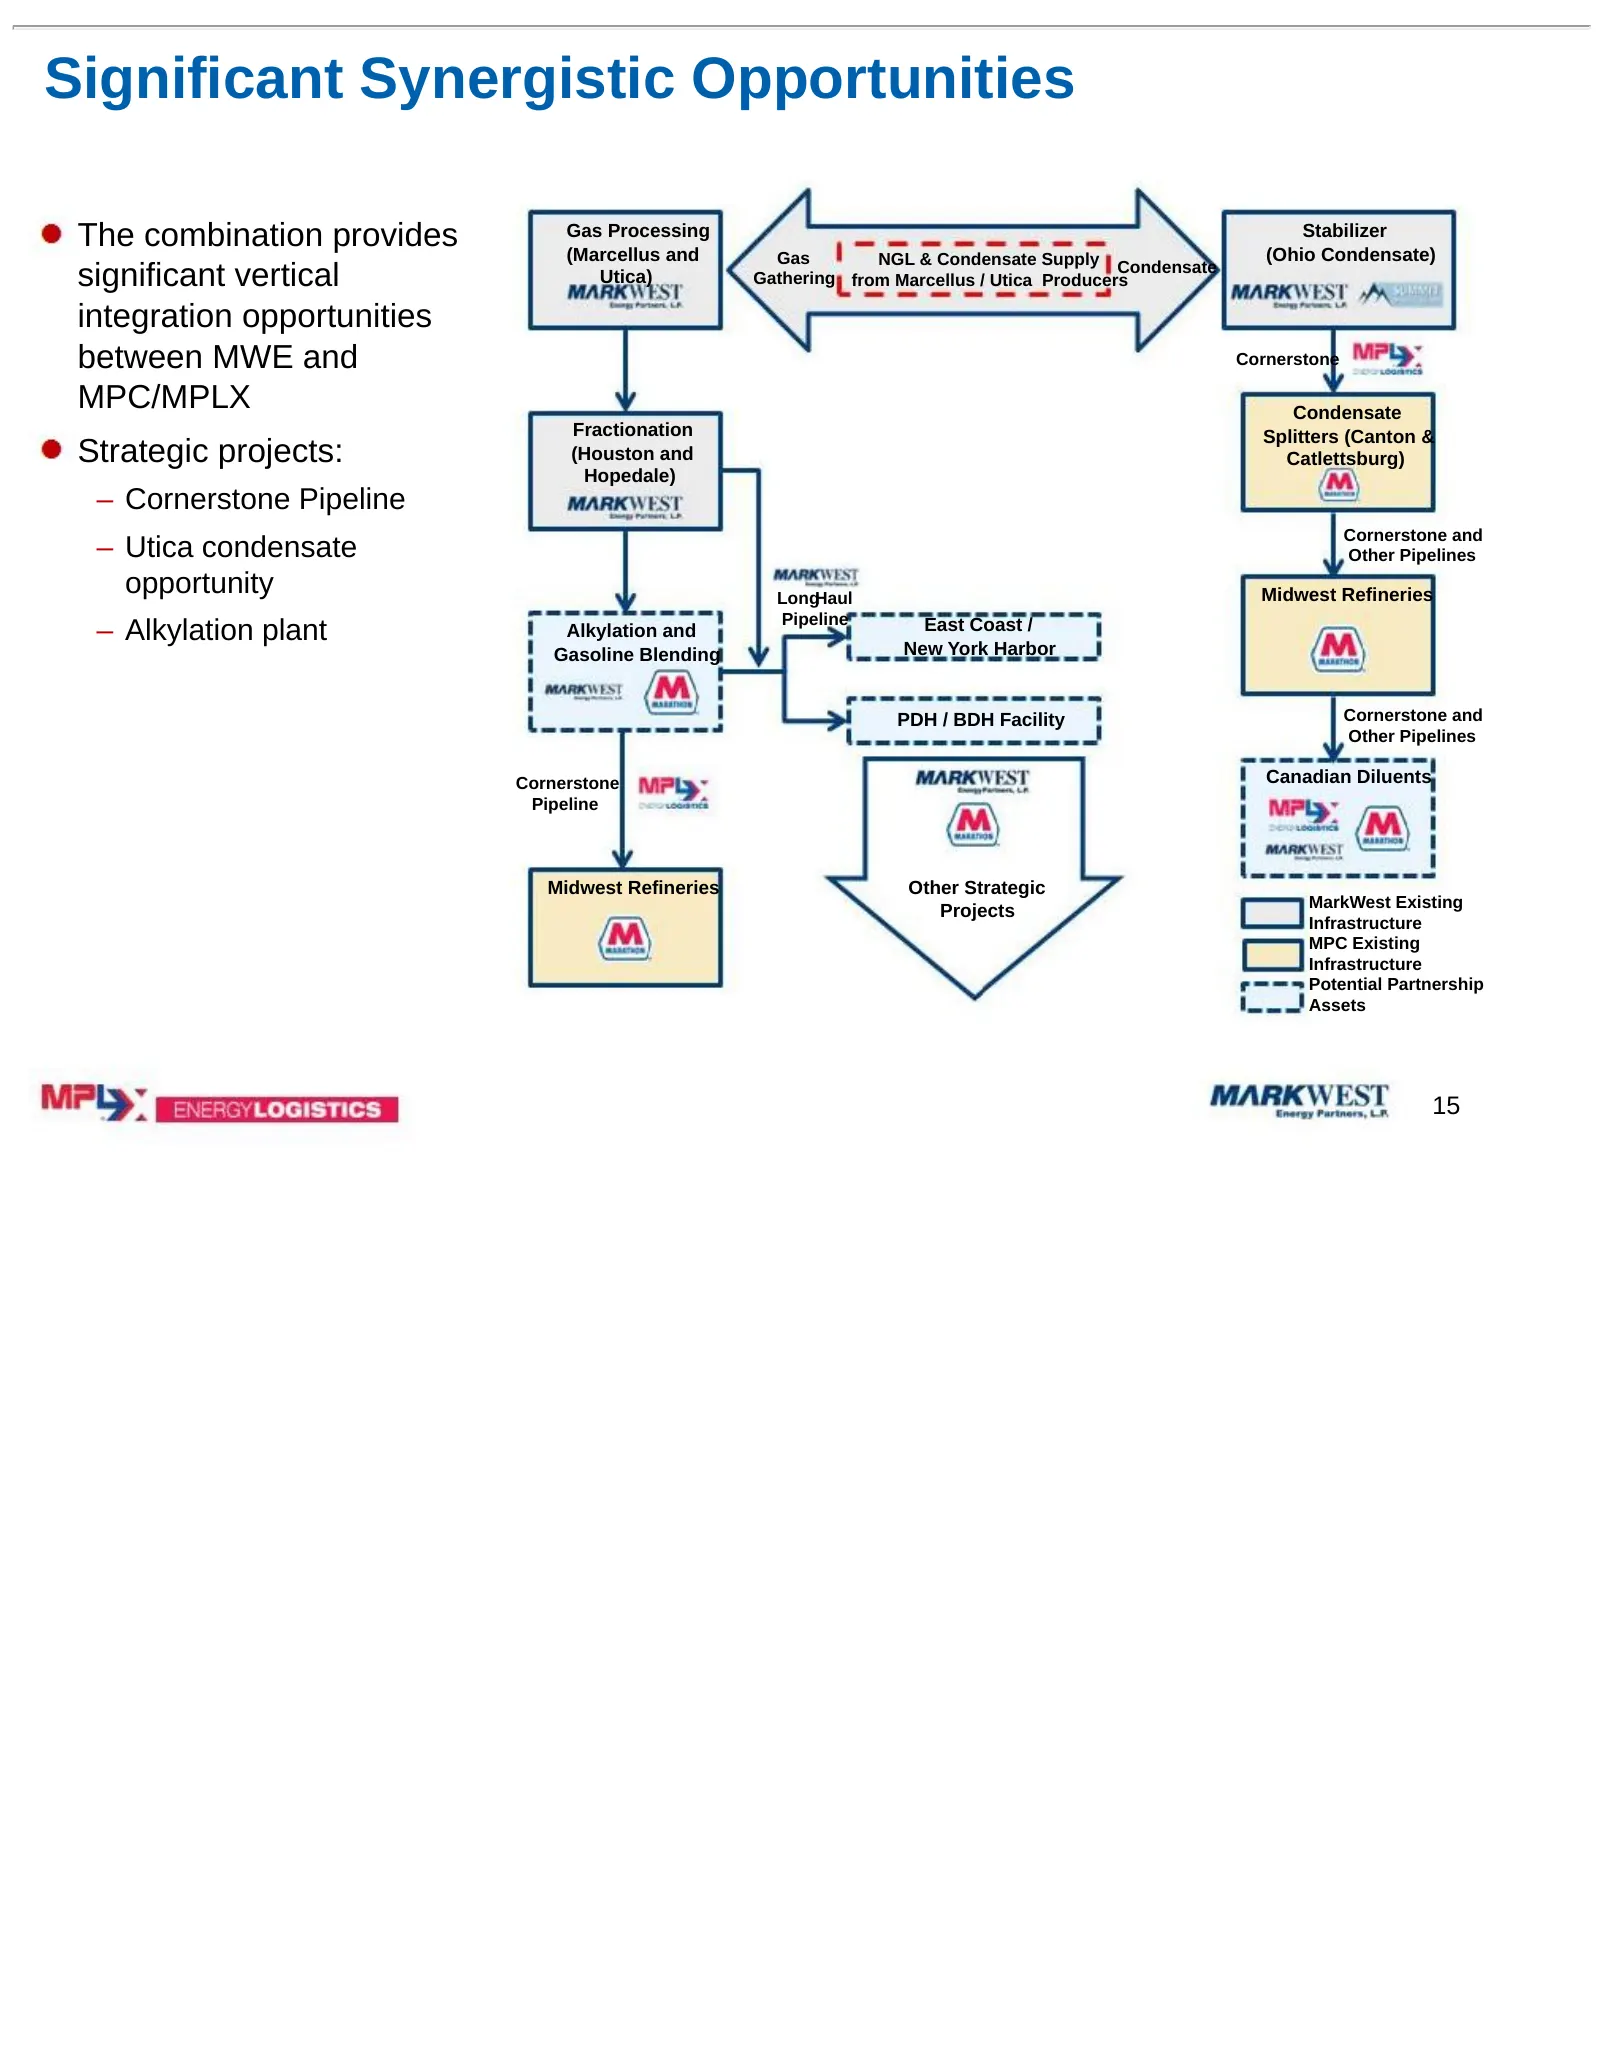
Significant Synergistic Opportunities The combination provides Gas Processing (Marcellus and Stabilizer (Ohio Condensate) Gas NGL & Condensate Supply Condensate significant vertical Utica) Gathering from Marcellus / Utica Producers integration opportunities between MWE and Cornerstone MPC/MPLX Conde
Slide 16: Access to Robust Inventory of Drop-downs
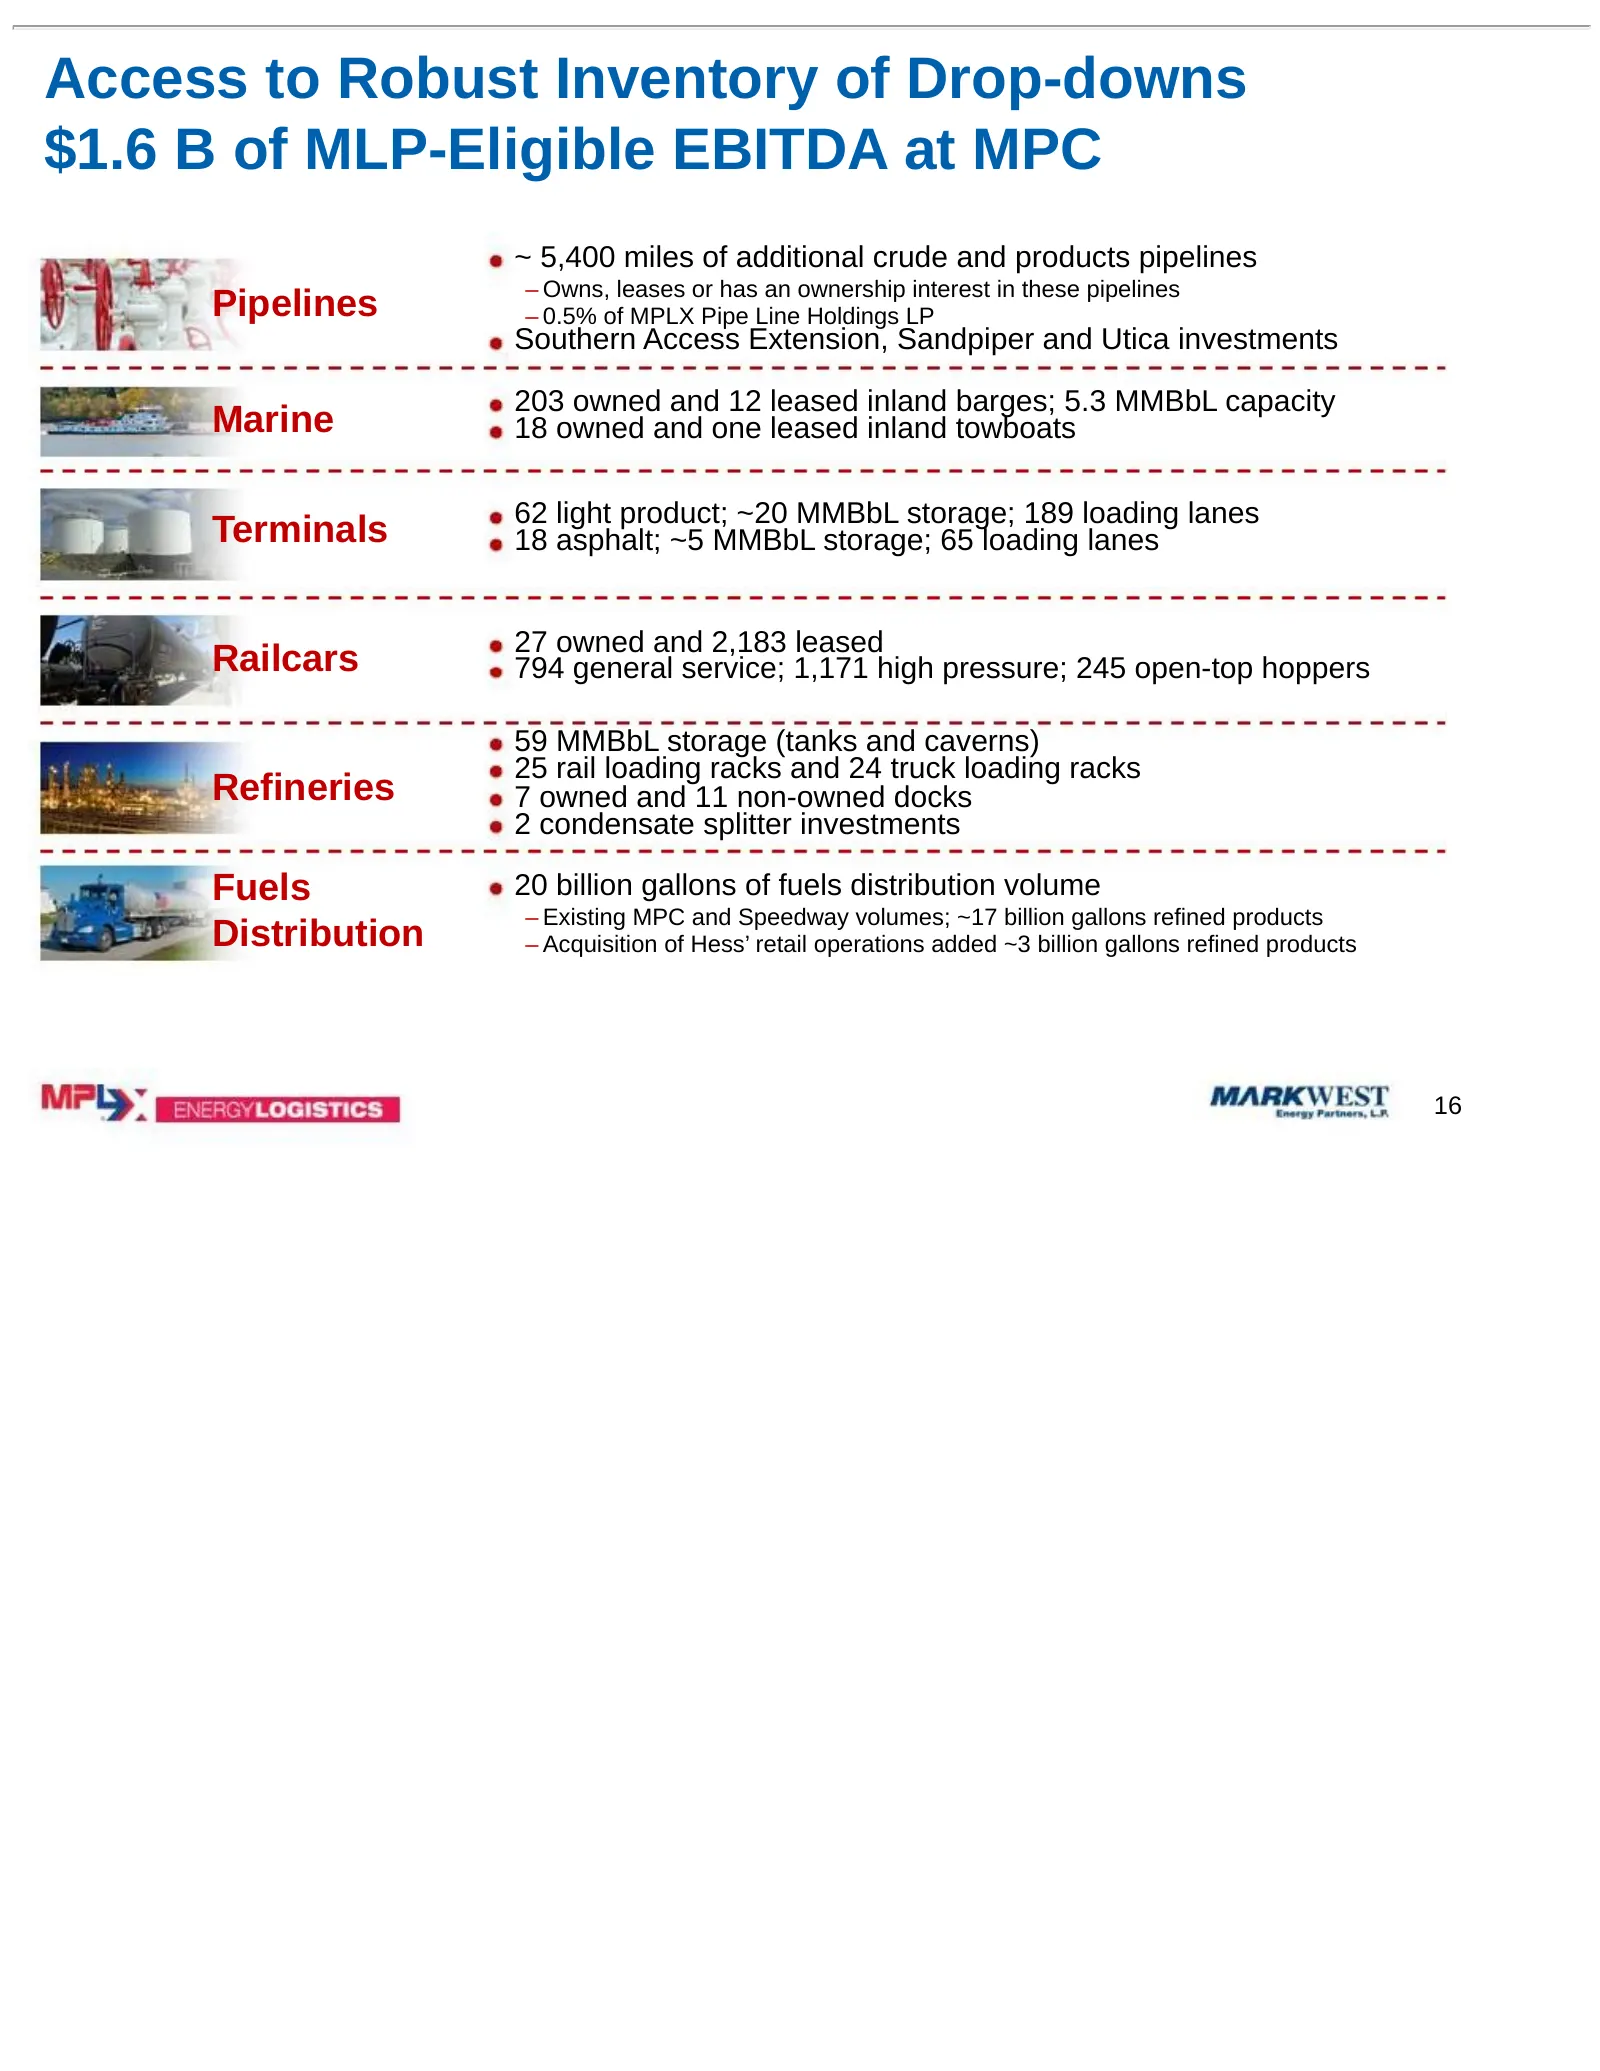
Access to Robust Inventory of Drop-downs $1.6 B of MLP-Eligible EBITDA at MPC ~ 5,400 miles of additional crude and products pipelines – Owns, leases or has an ownership interest in these pipelines Pipelines – 0.5% of MPLX Pipe Line Holdings LP Southern Access Extension, Sandpiper and Utica investme
Slide 17: Combination Benefits All Equity Owners
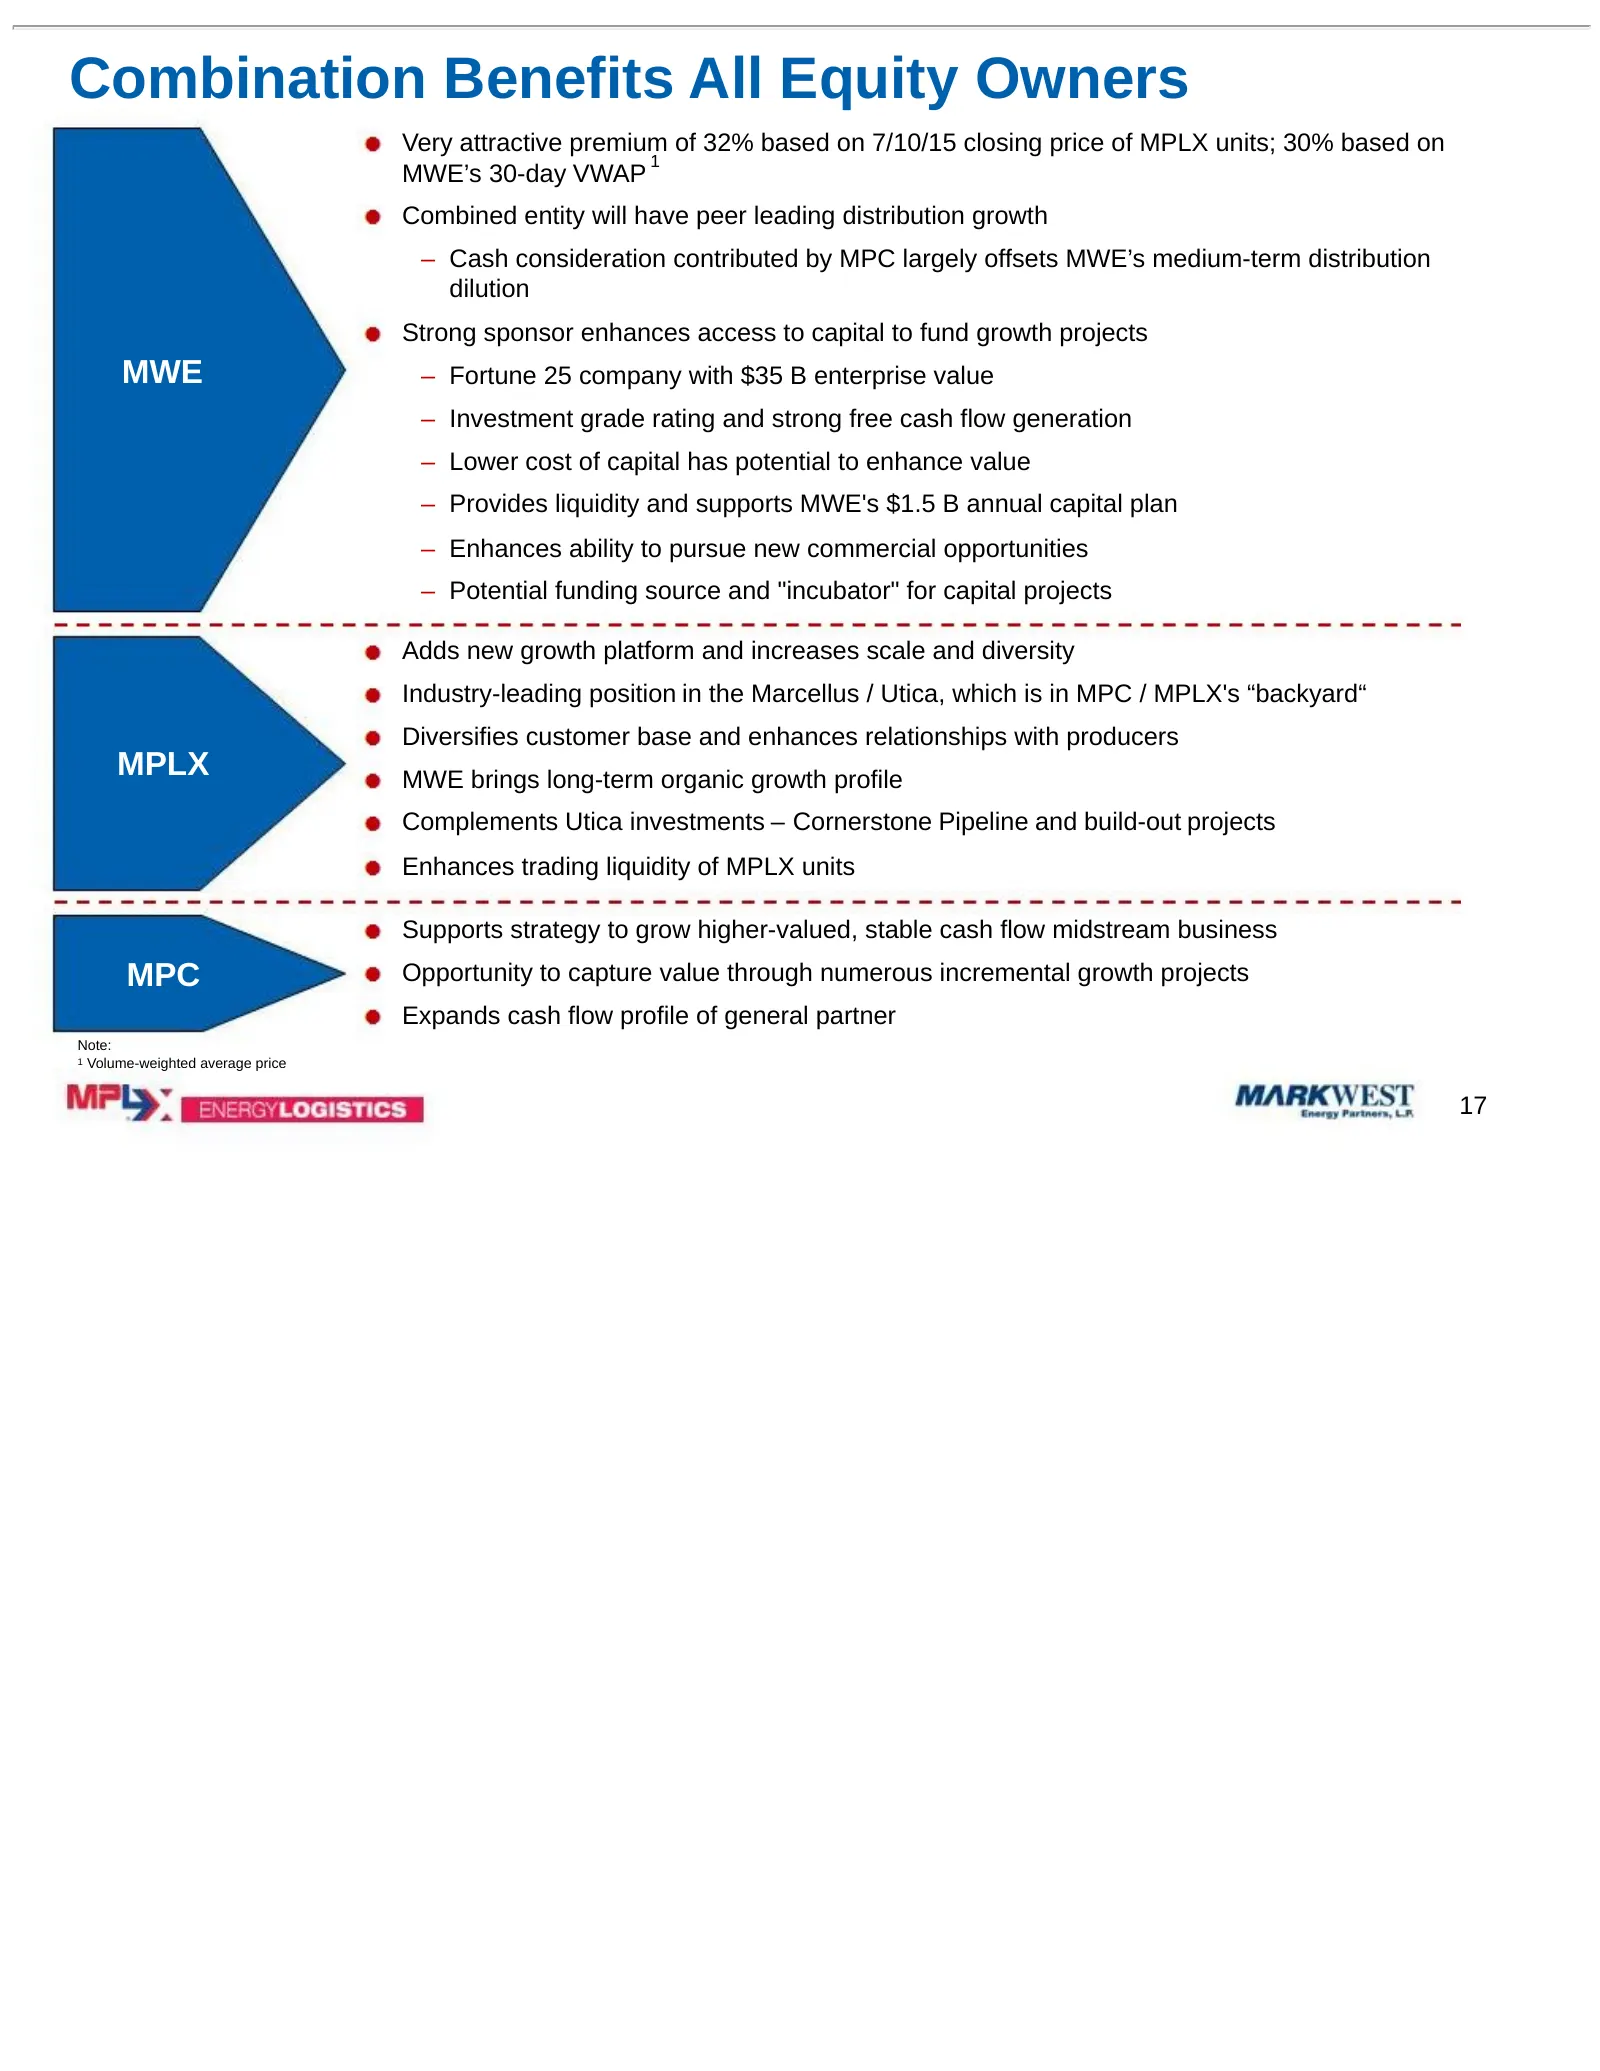
Combination Benefits All Equity Owners Very attractive premium of 32% based on 7/10/15 closing price of MPLX units; 30% based on 1 MWE’s 30-day VWAP Combined entity will have peer leading distribution growth – Cash consideration contributed by MPC largely offsets MWE’s medium-term distribution dilut
Slide 18: Q&A
Q&A - MARKWEST i MPLp: WEST
Slide 19: Appendix
Appendix 4 MARKWEST 49 la OM ENencyLoaistics | ait 4
Slide 20: Strategic Highlights
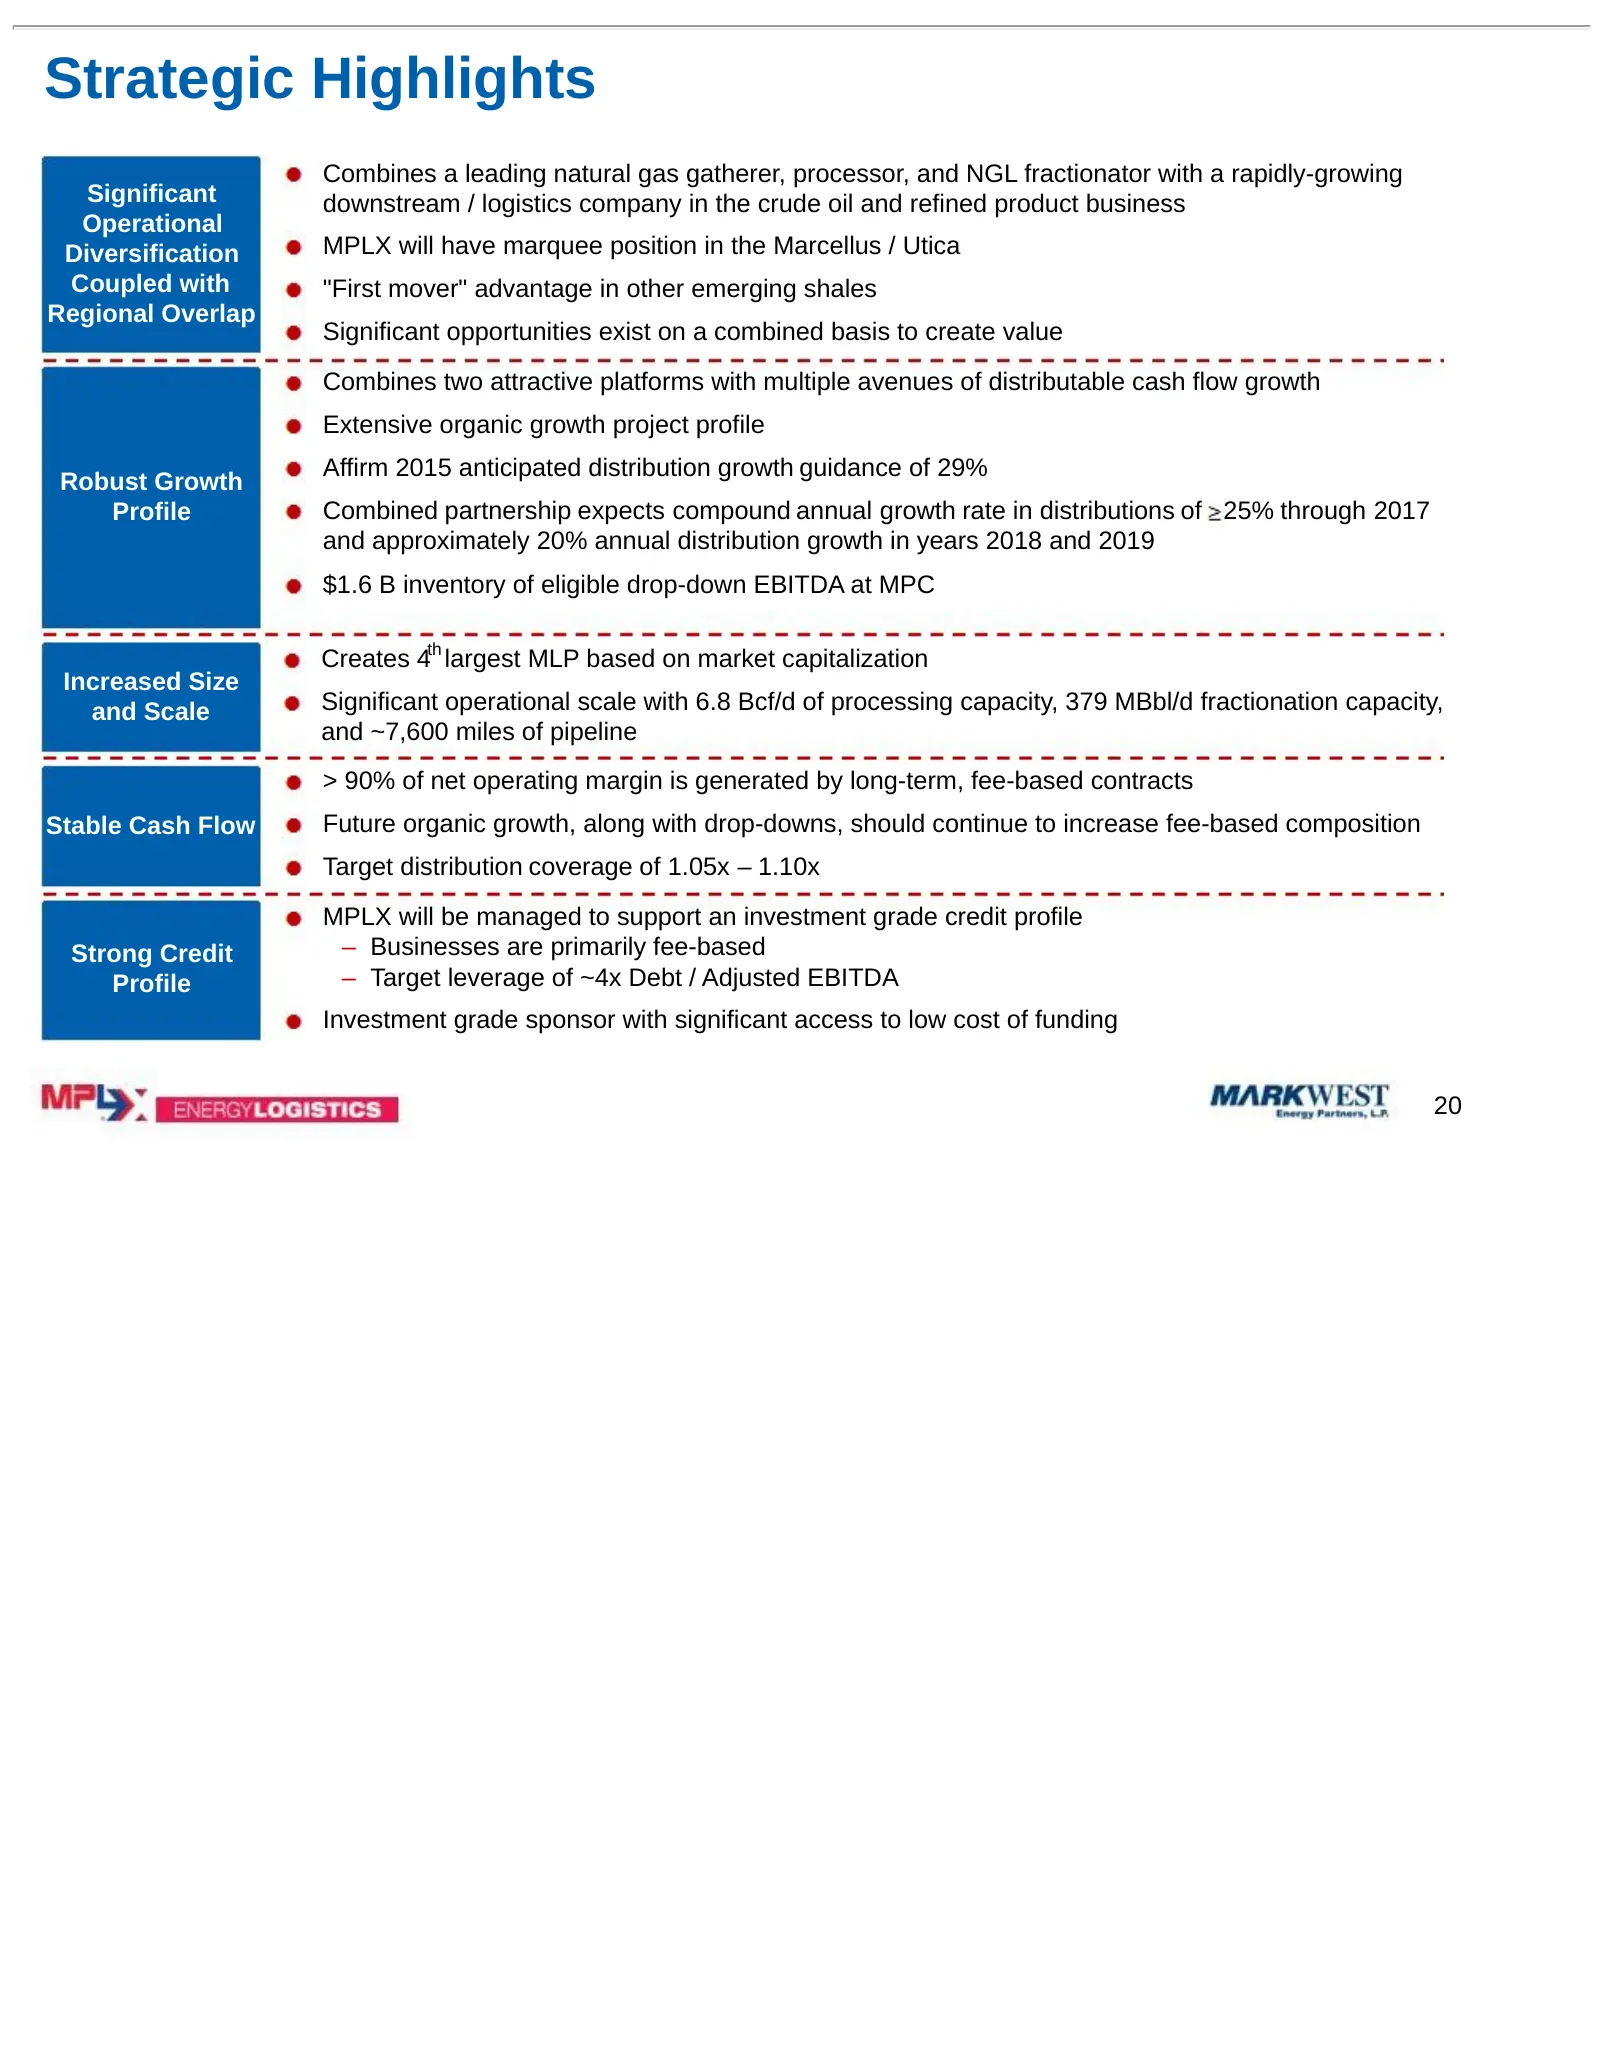
Strategic Highlights Combines a leading natural gas gatherer, processor, and NGL fractionator with a rapidly-growing Significant downstream / logistics company in the crude oil and refined product business Operational Diversification MPLX will have marquee position in the Marcellus / Utica Coupled w
Slide 21: Proven Track Record of Delivering Results
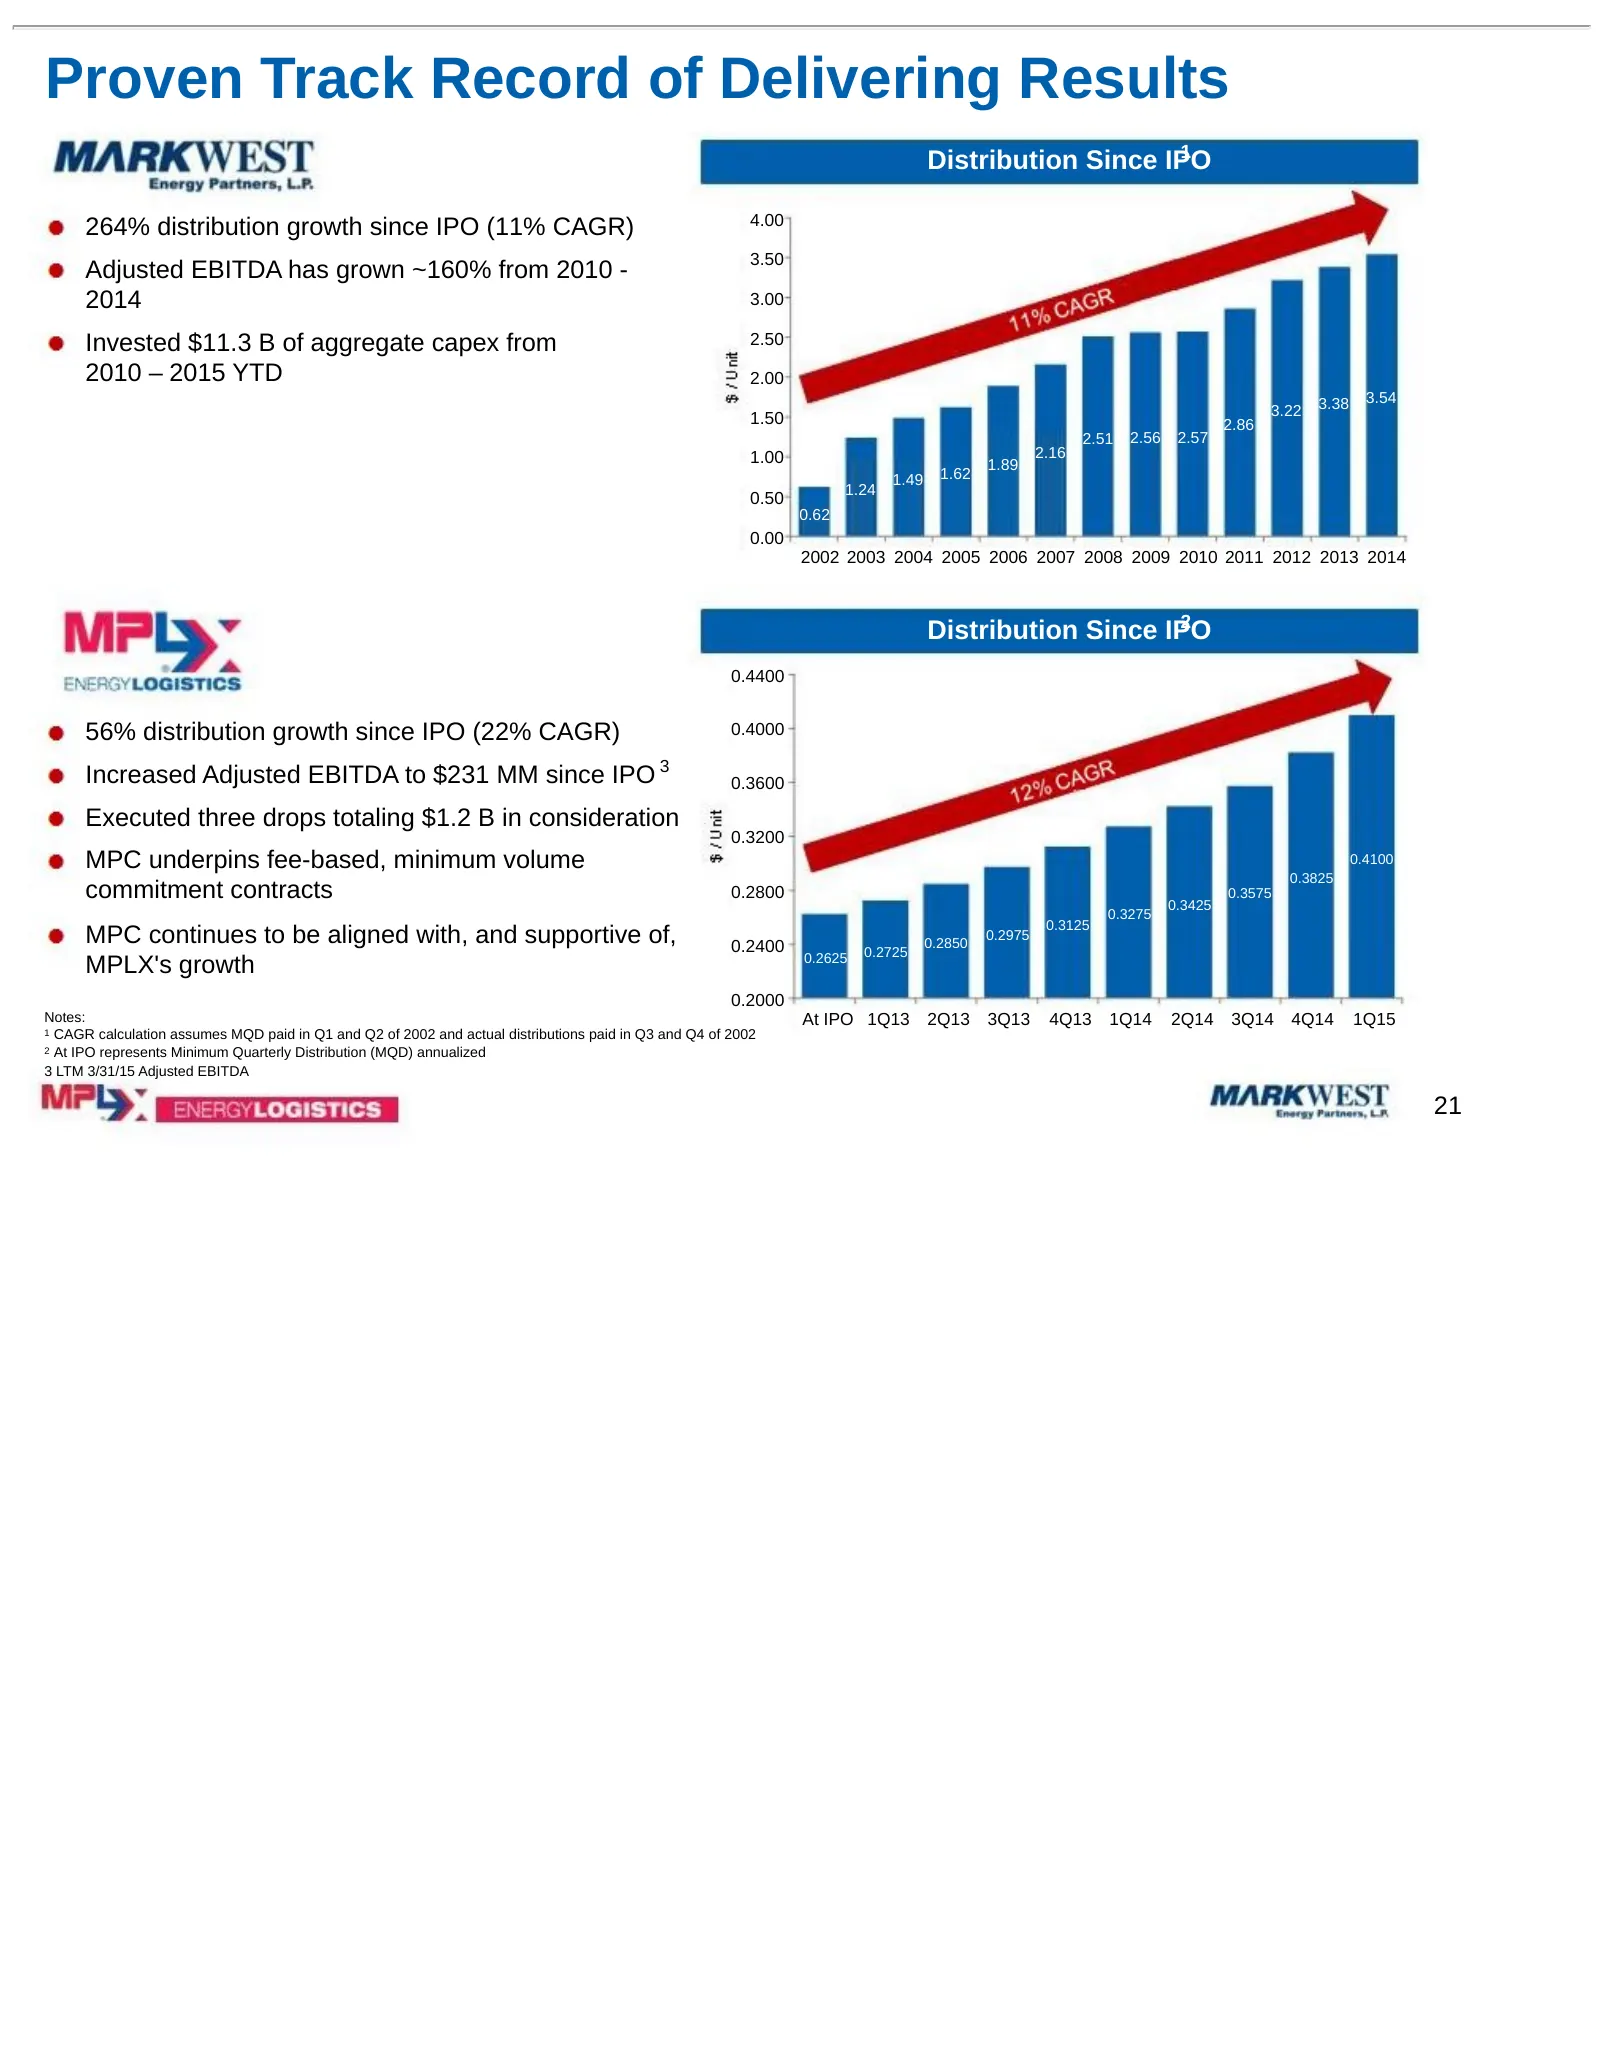
Proven Track Record of Delivering Results 1 Distribution Since IPO 4.00 264% distribution growth since IPO (11% CAGR) 3.50 Adjusted EBITDA has grown ~160% from 2010 - 2014 3.00 Invested $11.3 B of aggregate capex from 2.50 2010 – 2015 YTD 2.00 3.38 3.54 3.22 1.50 2.86 2.51 2.56 2.57 1.00 2.16 1.89 1
Slide 22: Increased Size, Diversity and Stability
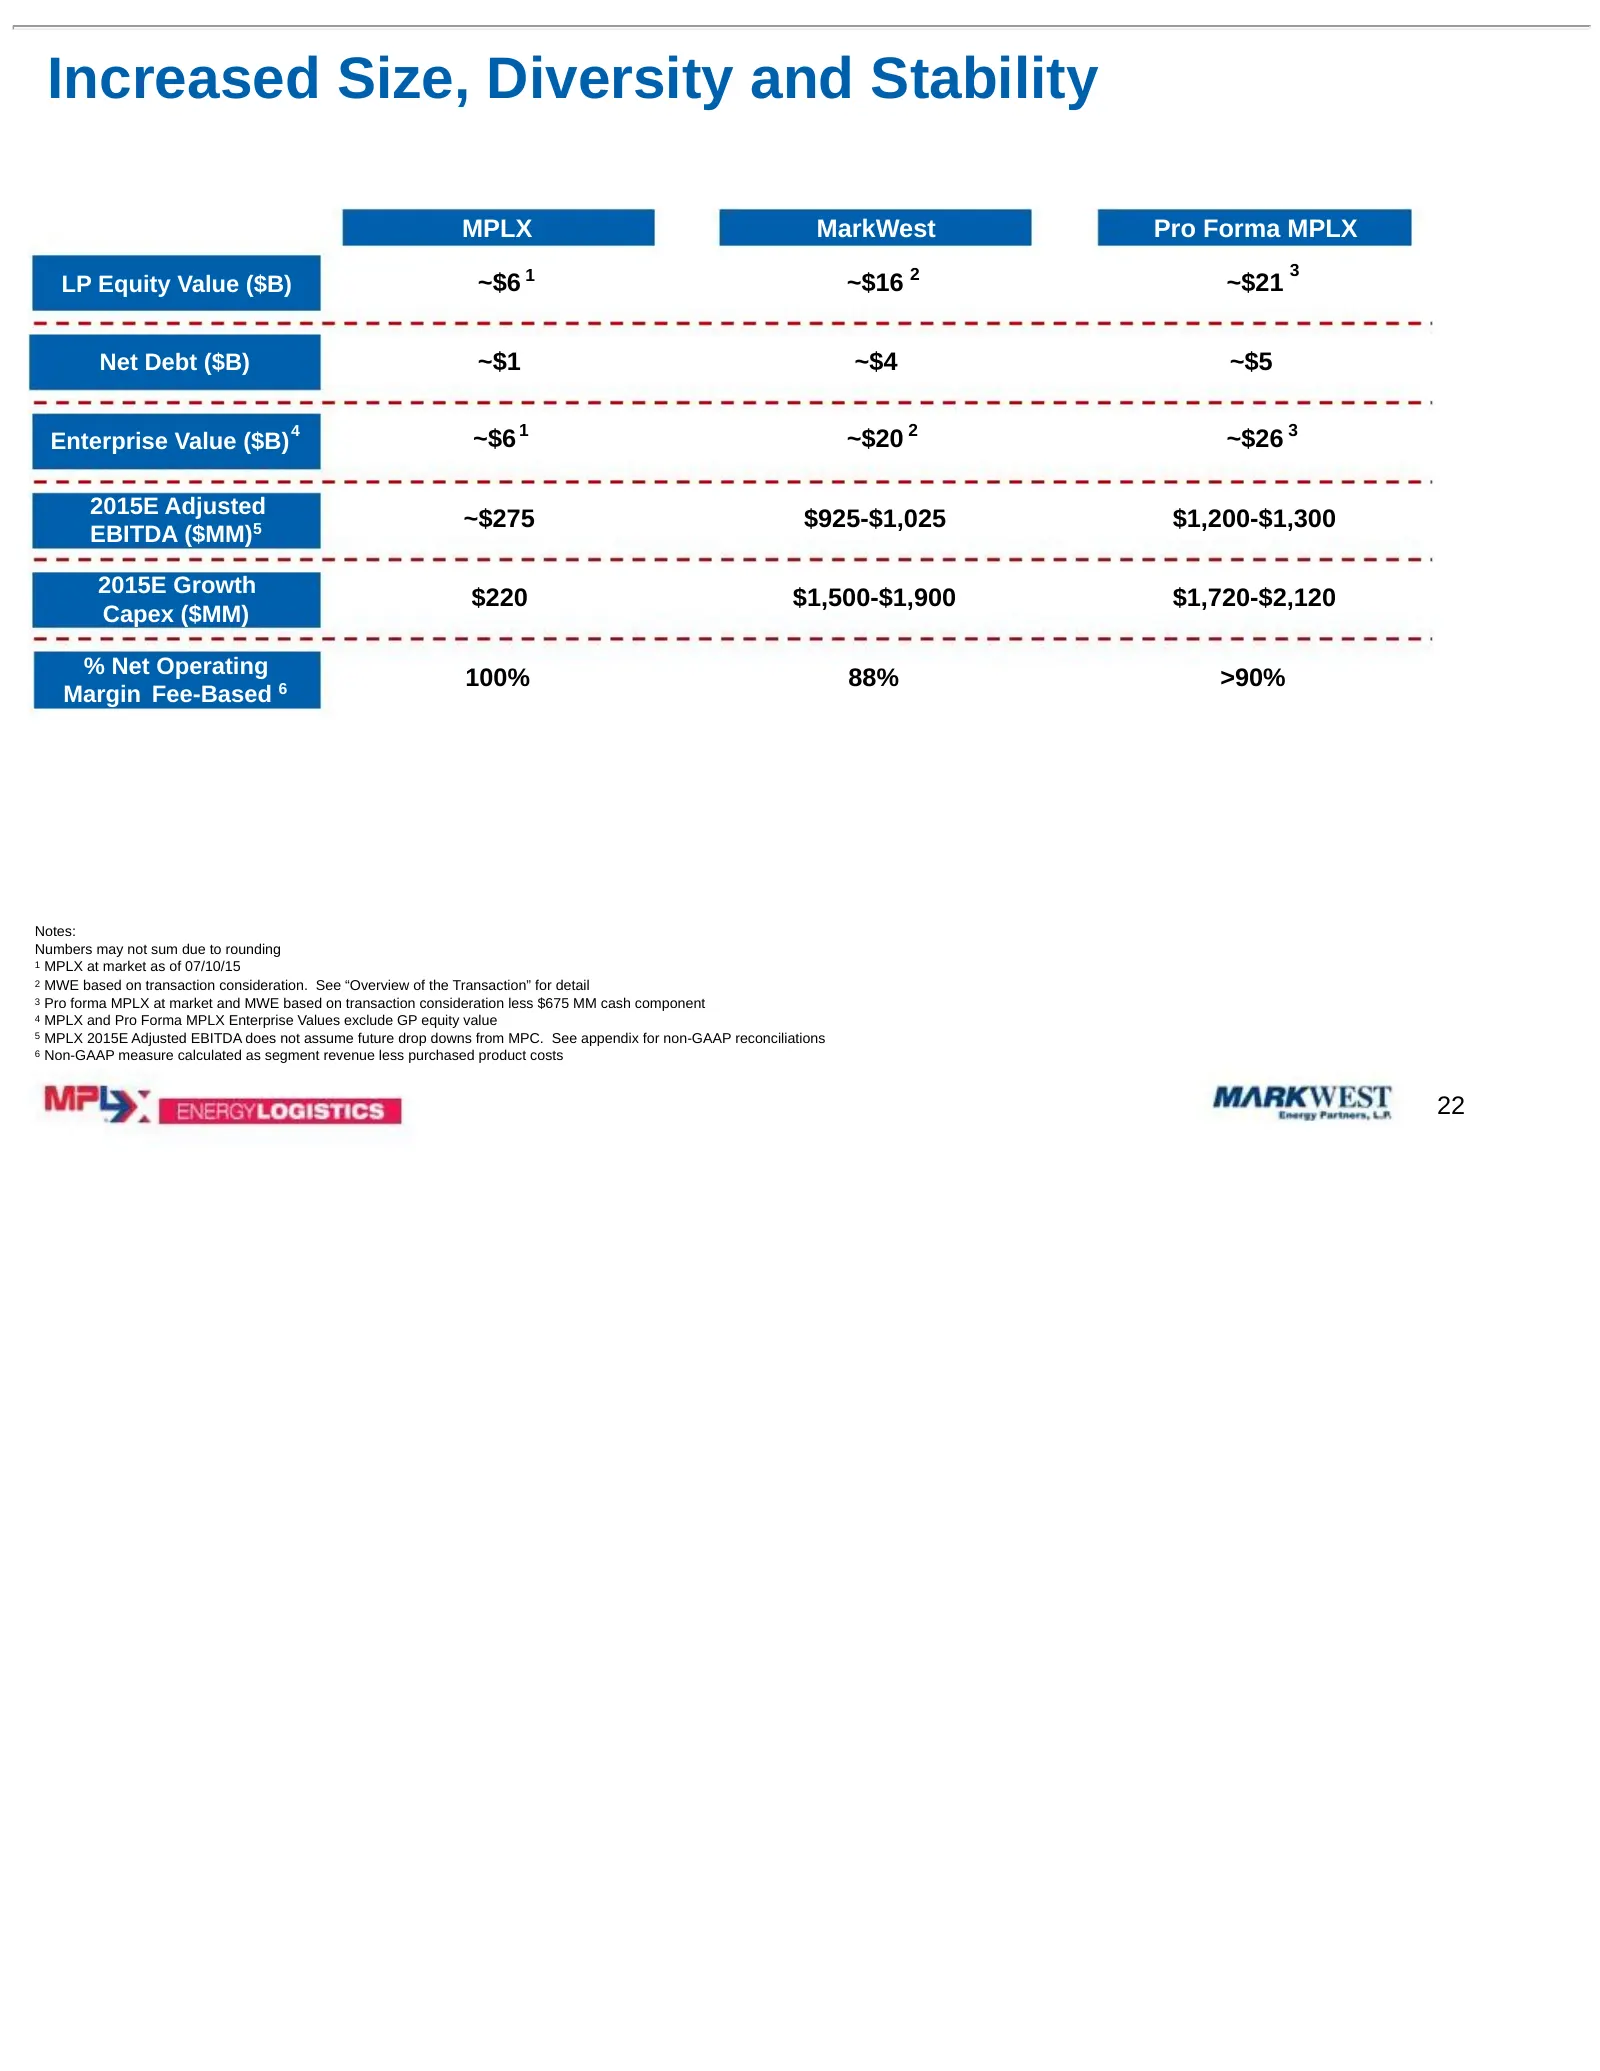
Increased Size, Diversity and Stability MWE Pro Forma MPLX MPLX MarkWest Pro Forma MPLX 3 LP Equity Value ($B) ~$6 1 ~$16 2 ~$21 Net Debt ($B) ~$1 ~$4 ~$5 Enterprise Value ($B) 4 ~$6 1 ~$20 2 ~$26 3 2015E Adjusted ~$275 $925-$1,025 $1,200-$1,300 EBITDA ($MM)5 2015E Growth $220 $1,500-$1,900 $1,720-$
Slide 23: Overview of the Transaction
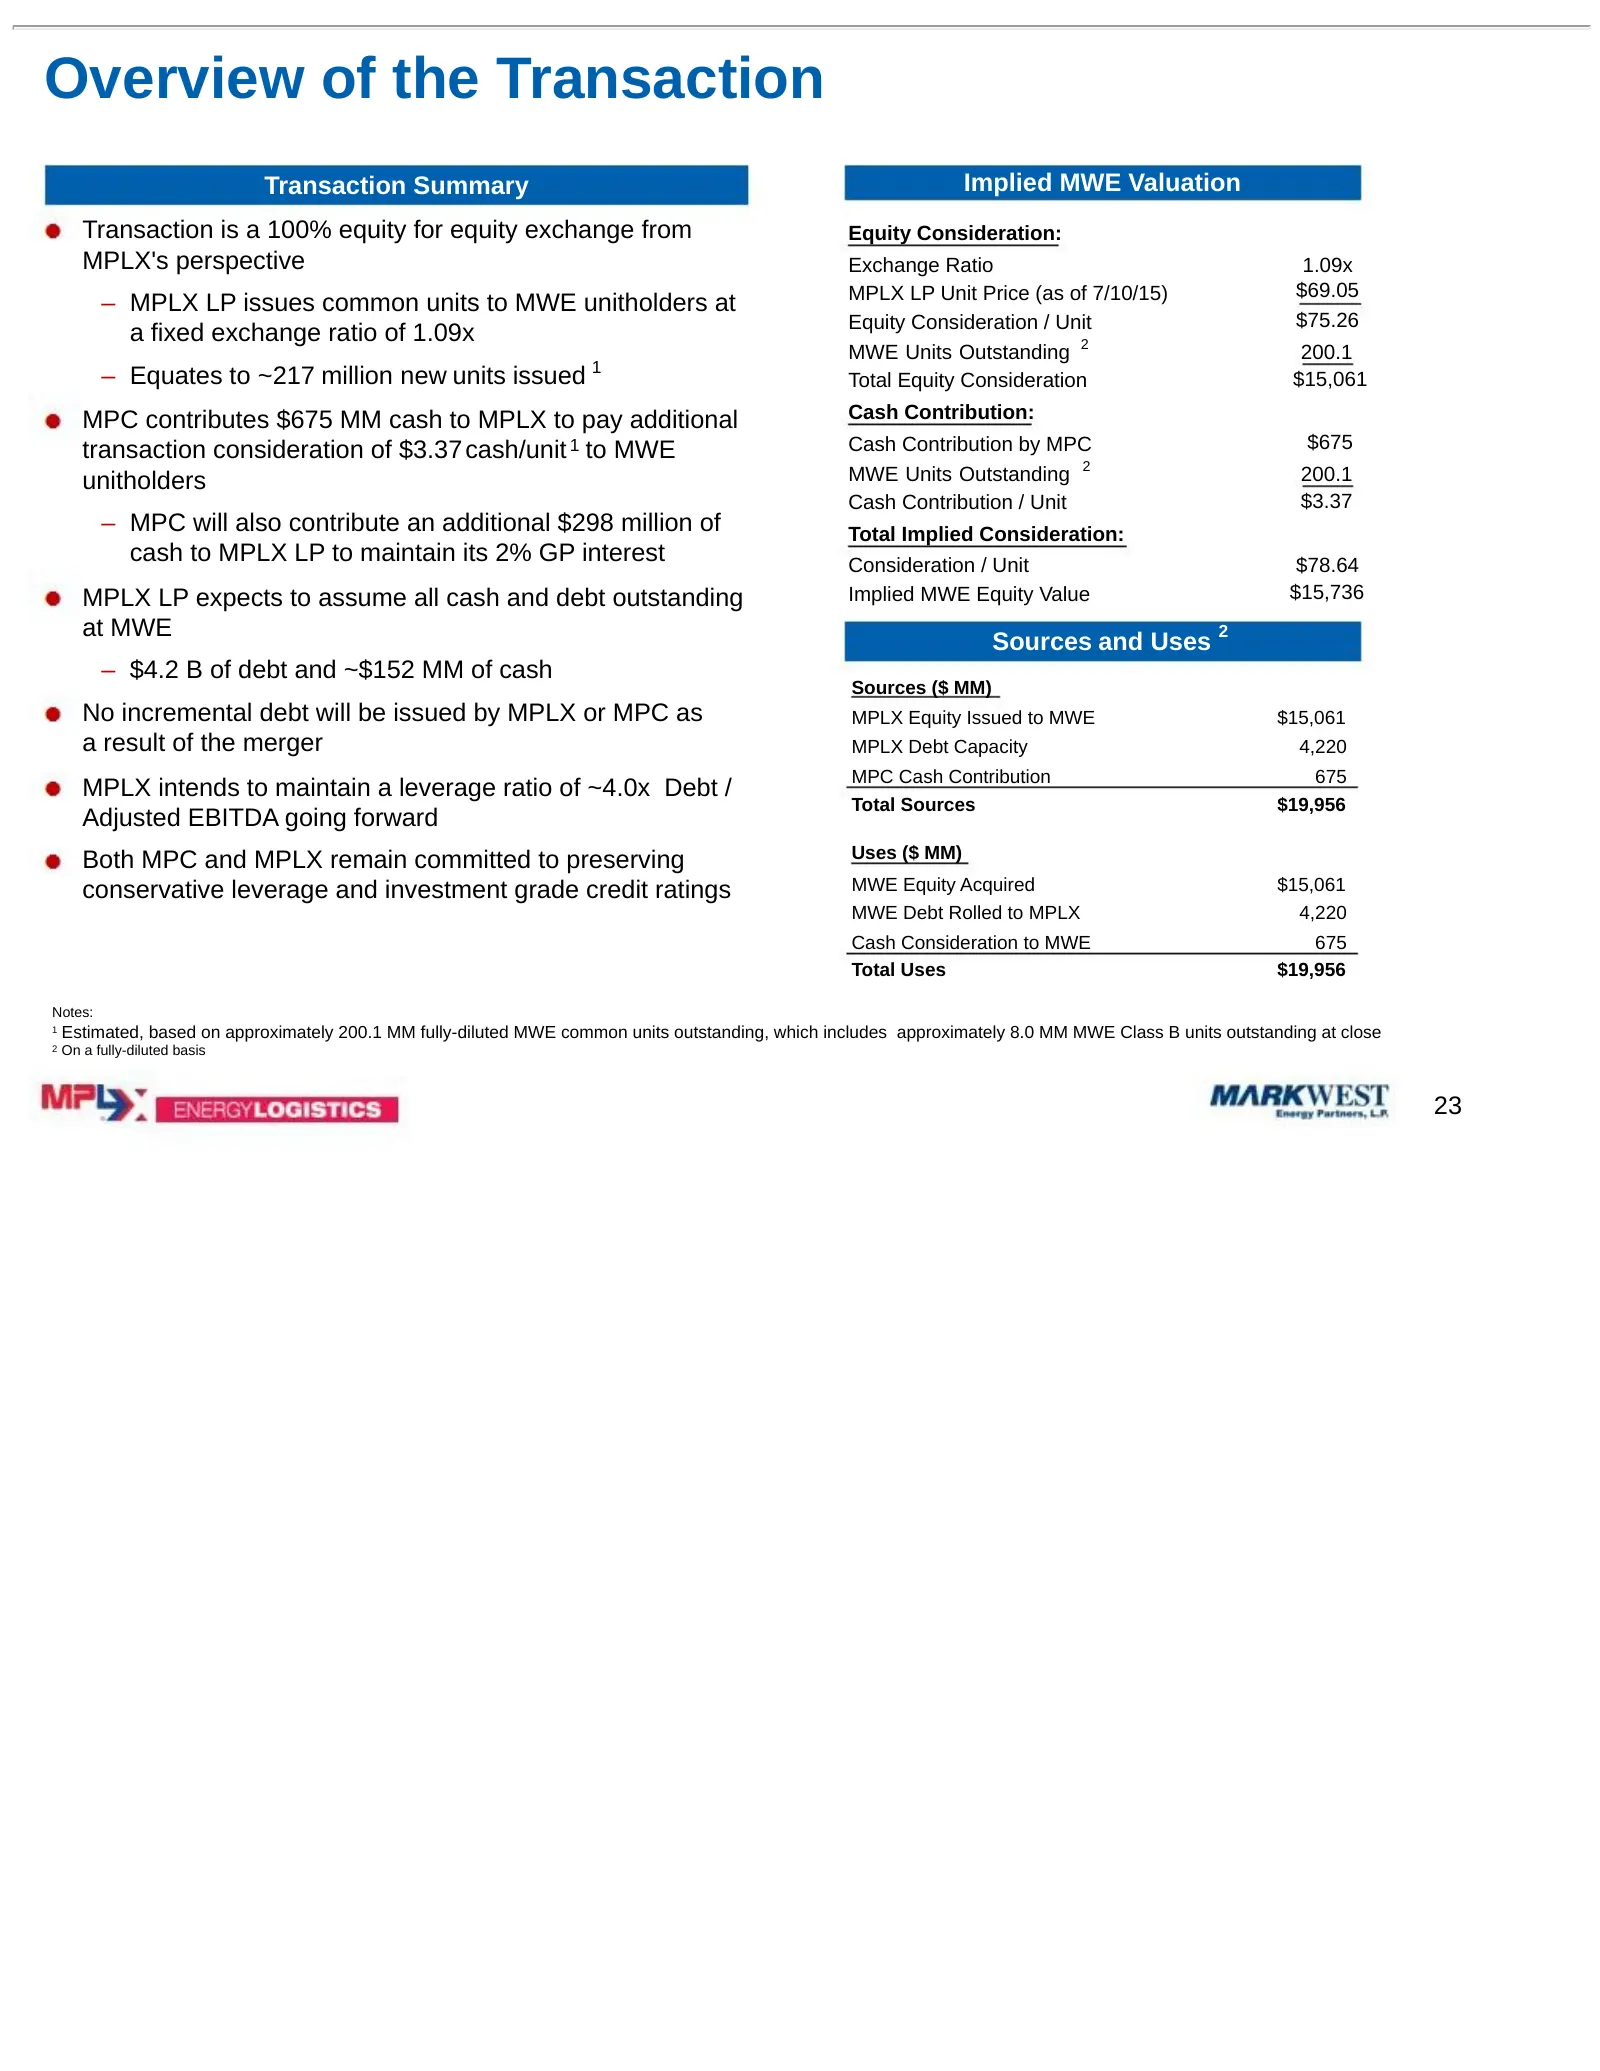
Overview of the Transaction Transaction Summary Implied MWE Valuation Transaction is a 100% equity for equity exchange from Equity Consideration: MPLX's perspective Exchange Ratio 1.09x MPLX LP Unit Price (as of 7/10/15) $69.05 – MPLX LP issues common units to MWE unitholders at Equity Consideration
Slide 24: Adjusted EBITDA Reconciliations from Net Income
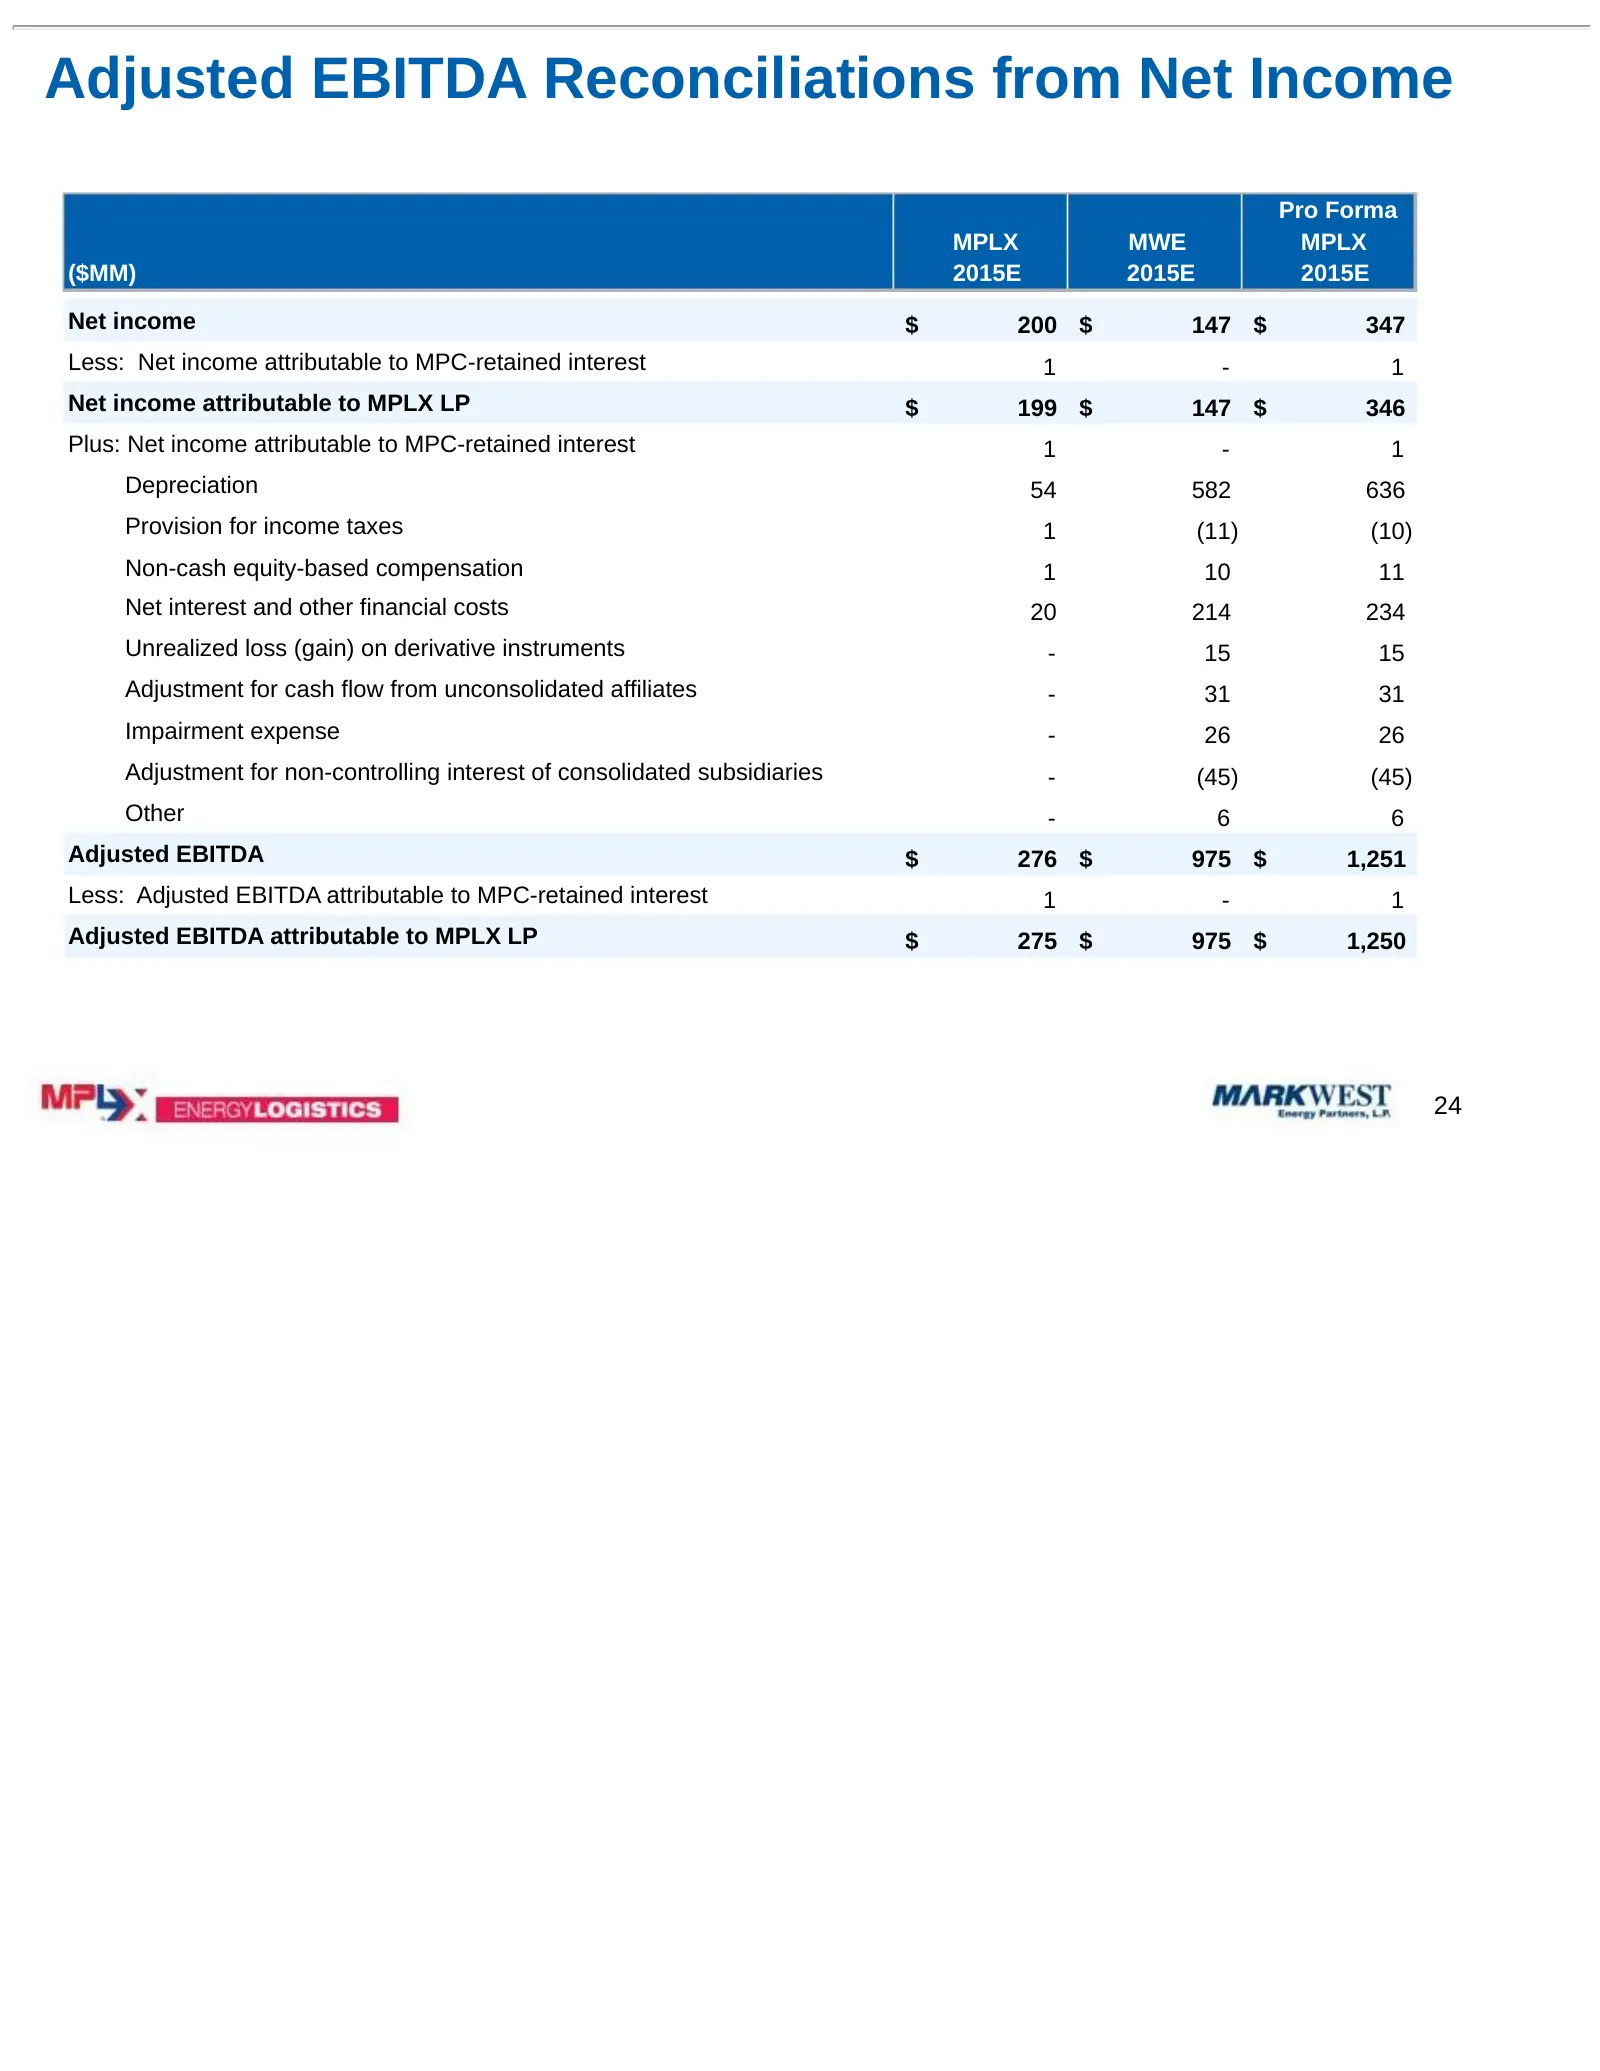
Adjusted EBITDA Reconciliations from Net Income Pro Forma MPLX MWE MPLX ($MM) 2015E 2015E 2015E Net income $ 200 $ 147 $ 347 Less: Net income attributable to MPC-retained interest 1 - 1 Net income attributable to MPLX LP $ 199 $ 147 $ 346 Plus: Net income attributable to MPC-retained interest 1 - 1
Source: SEC EDGAR · 425 filed Jul 20, 2015
More decks from Markwest Energy Partners LP
 Fact Sheet (July 2017)1 slide · July 2017
 Fact Sheet (July 2017)1 slide · July 2017
 Fact Sheet (July 2017)1 slide · July 2017
 Markwest Energy Partners L P — Investor Day (December 2015)116 slides · Dec 3, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 13, 2015
 Merger or Acquisition (November 2015)17 slides · Nov 12, 2015