Tropicana Entertainment — Debt Investor Presentation (November 2013)
49 slides from Tropicana Entertainment's debt investor presentation, Nov 18, 2013
Slide 1: Presentation to Lenders Public Version November 18, 2013
Presentation to Lenders Public Version November 18, 2013
Slide 2: Disclaimers
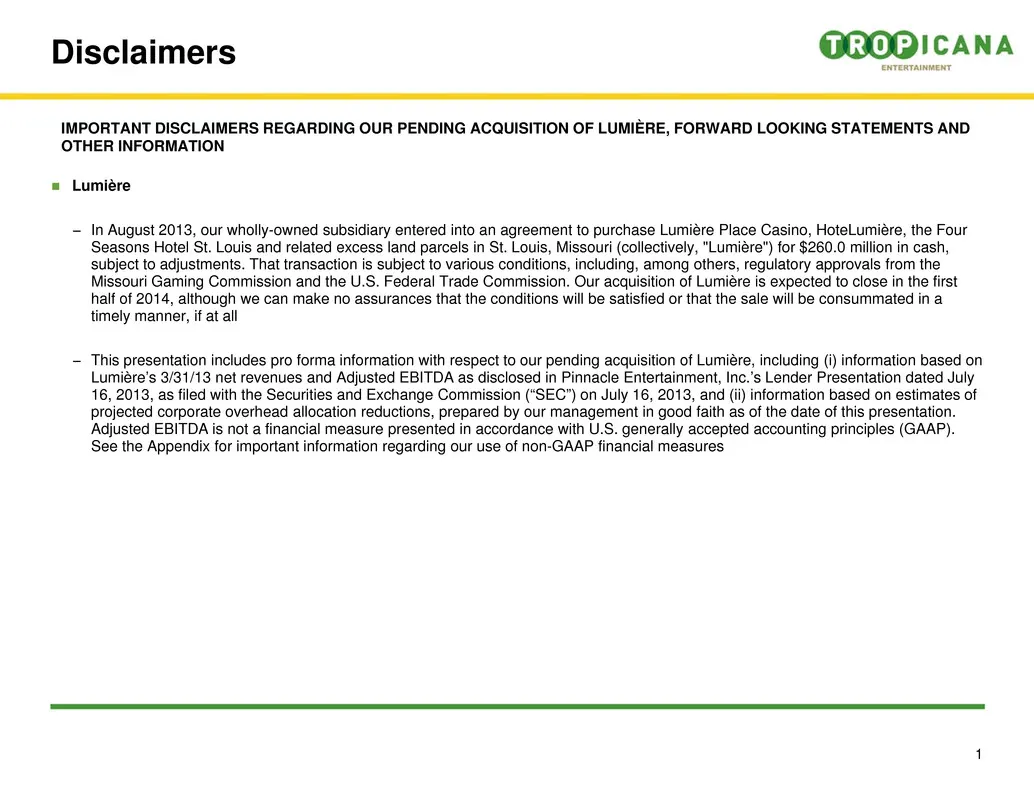
1 Disclaimers Lumière − In August 2013, our wholly-owned subsidiary entered into an agreement to purchase Lumière Place Casino, HoteLumière, the Four Seasons Hotel St. Louis and related excess land parcels in St. Louis, Missouri (collectively, "Lumière") for $260.0 million in cash, subject to adju
Slide 3: Disclaimers (cont'd)
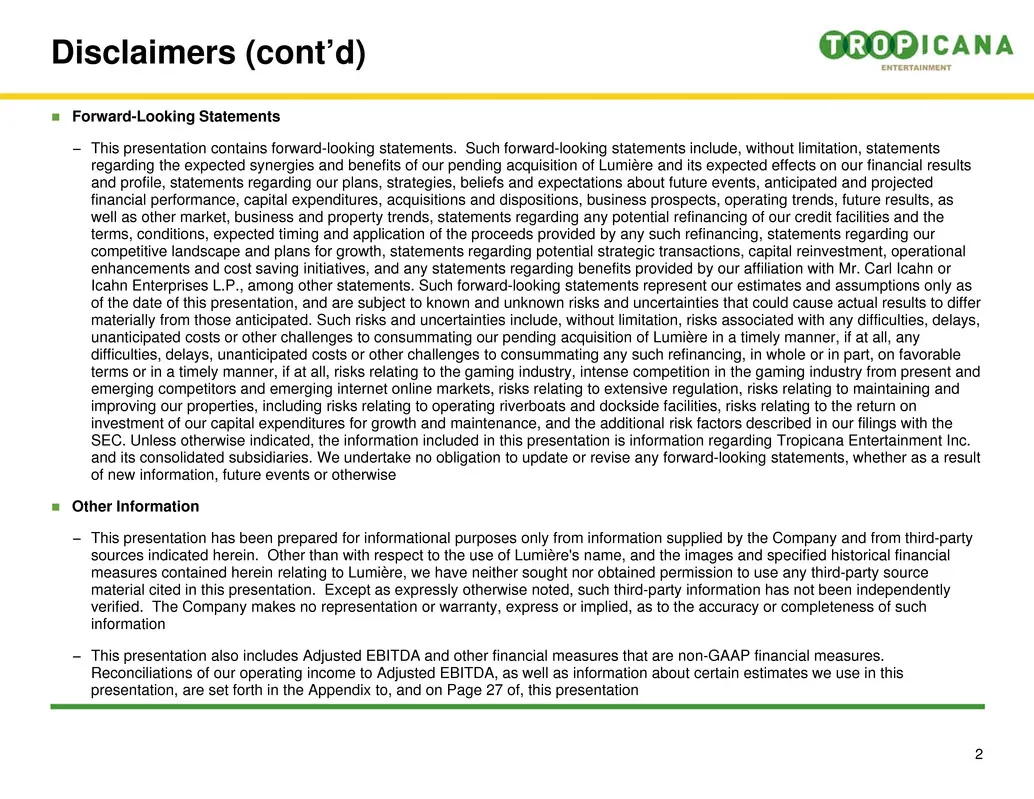
2 Disclaimers (cont’d) Forward-Looking Statements − This presentation contains forward-looking statements. Such forward-looking statements include, without limitation, statements regarding the expected synergies and benefits of our pending acquisition of Lumière and its expected effects on our fin
Slide 4: Agenda
Lumière Place Acquisition Historical Financial Performance Transaction Overview 3 Agenda Credit Suisse Tropicana Entertainment Inc. Tony Rodio President and Chief Executive Officer Lance Millage Chief Financial Officer Key Credit Highlights Company Overview Syndication Overview Credit Suisse
Slide 5: Transaction Overview
Transaction Overview
Slide 6: Transaction Summary
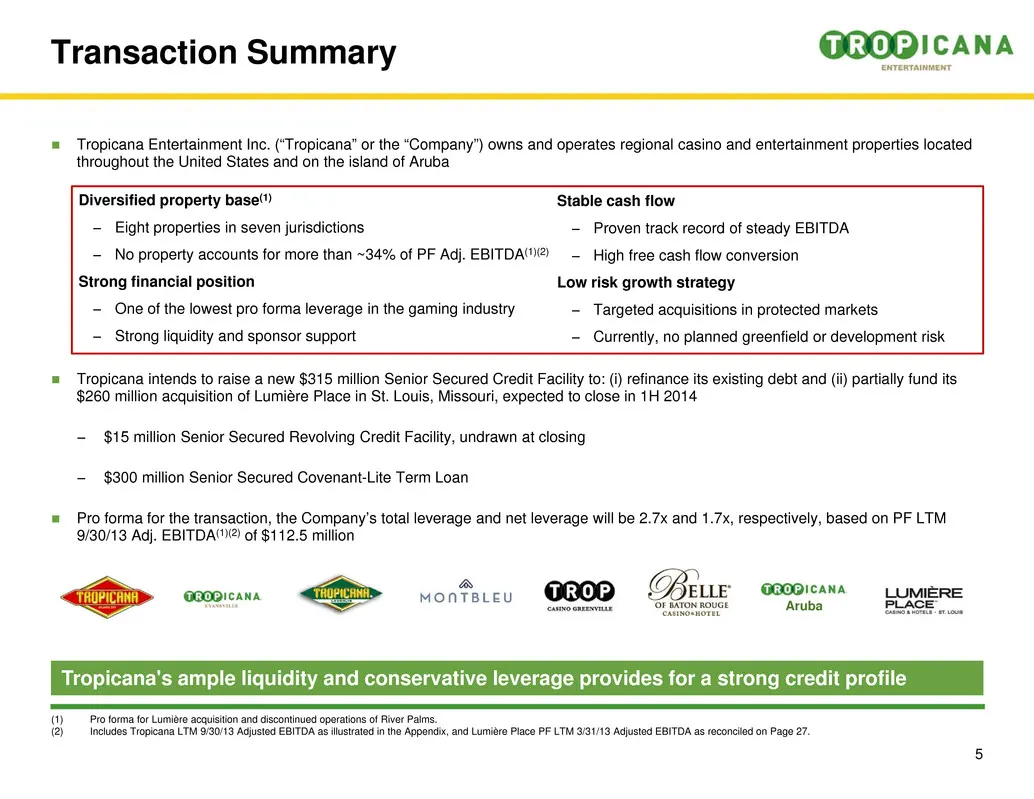
5 Transaction Summary Tropicana intends to raise a new $315 million Senior Secured Credit Facility to: (i) refinance its existing debt and (ii) partially fund its $260 million acquisition of Lumière Place in St. Louis, Missouri, expected to close in 1H 2014 − $15 million Senior Secured Revolving C
Slide 7: Sources & Uses and Pro Forma Capitalization
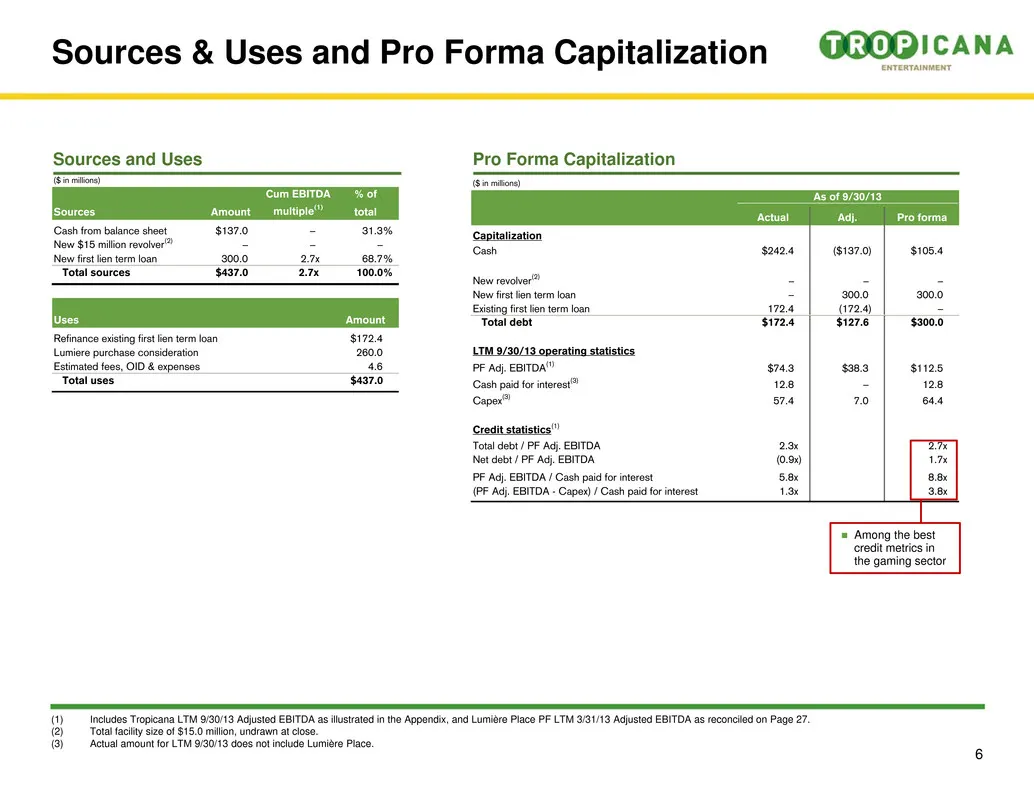
6 Sources & Uses and Pro Forma Capitalization ($ in millions) Cum EBITDA % of Sources Amount multiple(1) total Cash from balance sheet $137.0 – 31.3% New $15 million revolver(2) – – – New first lien term loan 300.0 2.7x 68.7% Total sources $437.0 2.7x 100.0% Uses Amount Refinance existing first lien
Slide 8: Corporate Structure
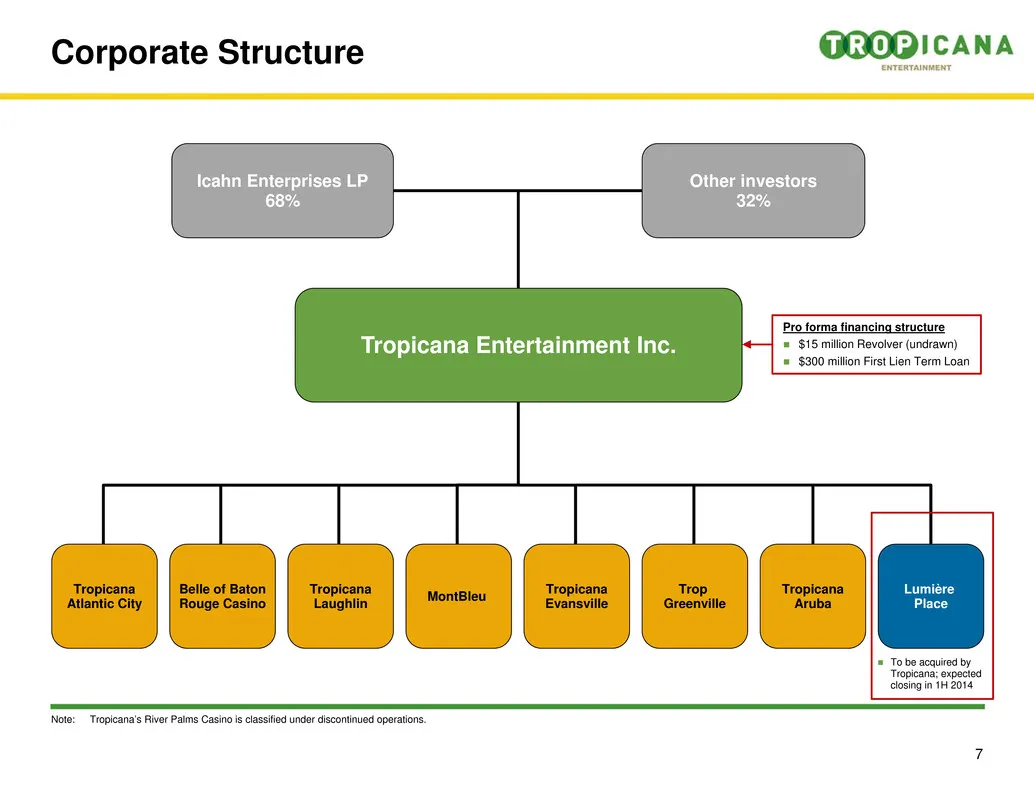
7 Corporate Structure Icahn Enterprises LP 68% Other investors 32% Note: Tropicana’s River Palms Casino is classified under discontinued operations. Pro forma financing structure $15 million Revolver (undrawn) $300 million First Lien Term Loan Tropicana Entertainment Inc. Tropicana Atlantic City
Slide 9: Key Credit Highlights
Key Credit Highlights
Slide 10: Key Credit Highlights
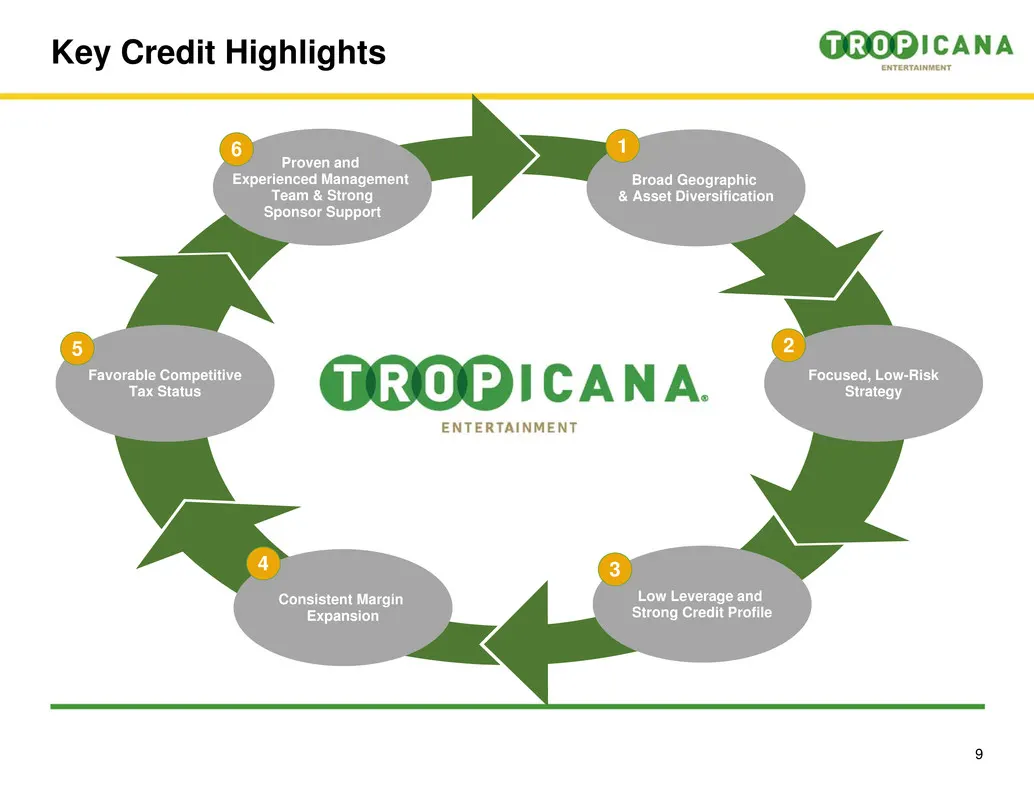
9 Key Credit Highlights Proven and Experienced Management Team & Strong Sponsor Support Broad Geographic & Asset Diversification Favorable Competitive Tax Status Focused, Low-Risk Strategy Consistent Margin Expansion Low Leverage and Strong Credit Profile 1 2 3 6 4 5
Slide 11: Broad Geographic & Asset Diversification
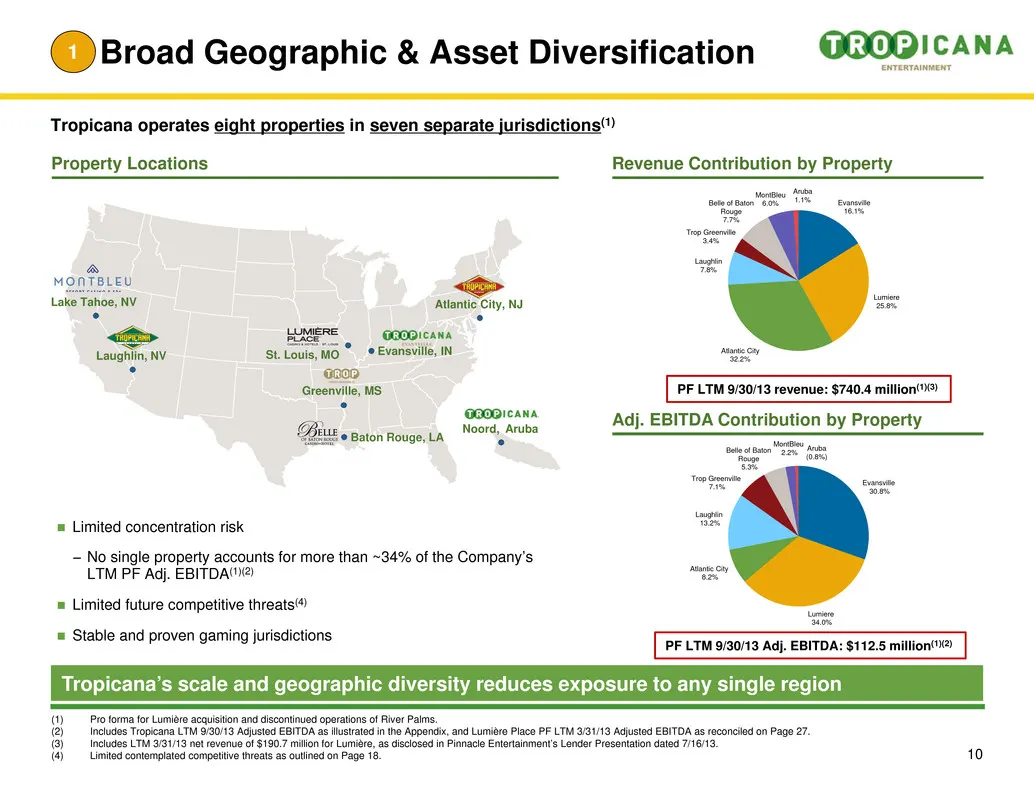
Broad Geographic & Asset Diversification Tropicana operates eight properties in seven separate jurisdictions(1) 10 Tropicana’s scale and geographic diversity reduces exposure to any single region Property Locations Limited concentration risk − No single property accounts for more than ~34% of the
Slide 12: Focused, Low Risk Strategy
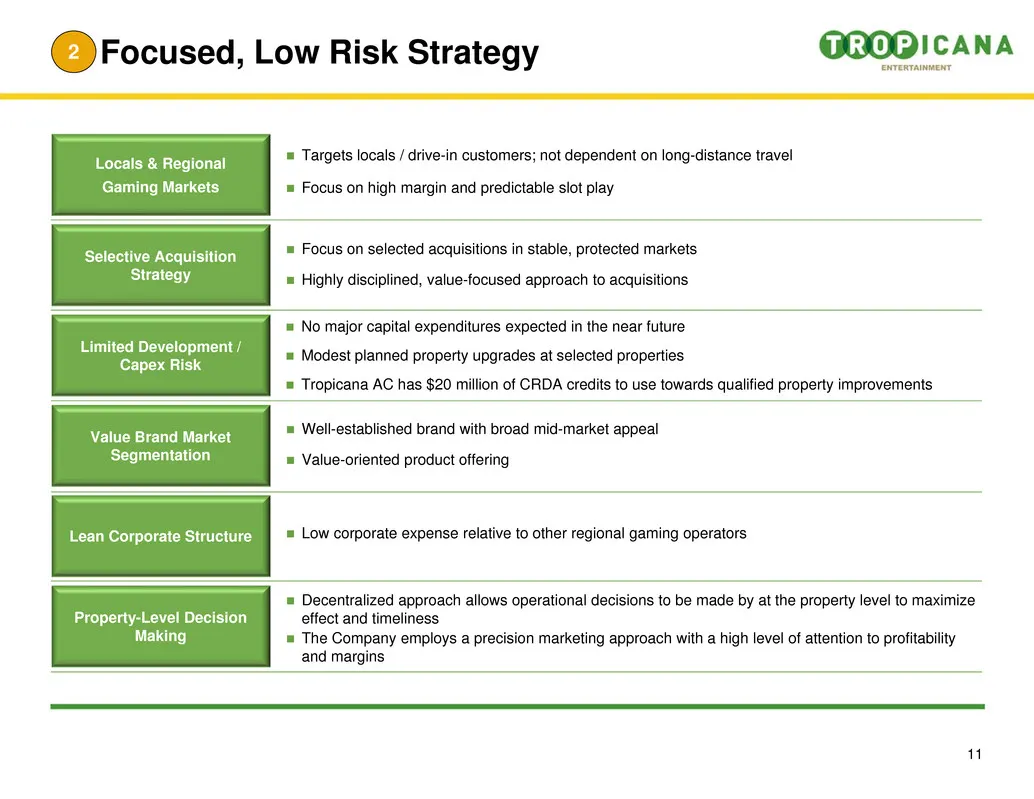
11 Focused, Low Risk Strategy2 Locals & Regional Gaming Markets Limited Development / Capex Risk Selective Acquisition Strategy Value Brand Market Segmentation Lean Corporate Structure Property-Level Decision Making Targets locals / drive-in customers; not dependent on long-distance travel Focus
Slide 13: Low Leverage and Strong Credit Profile
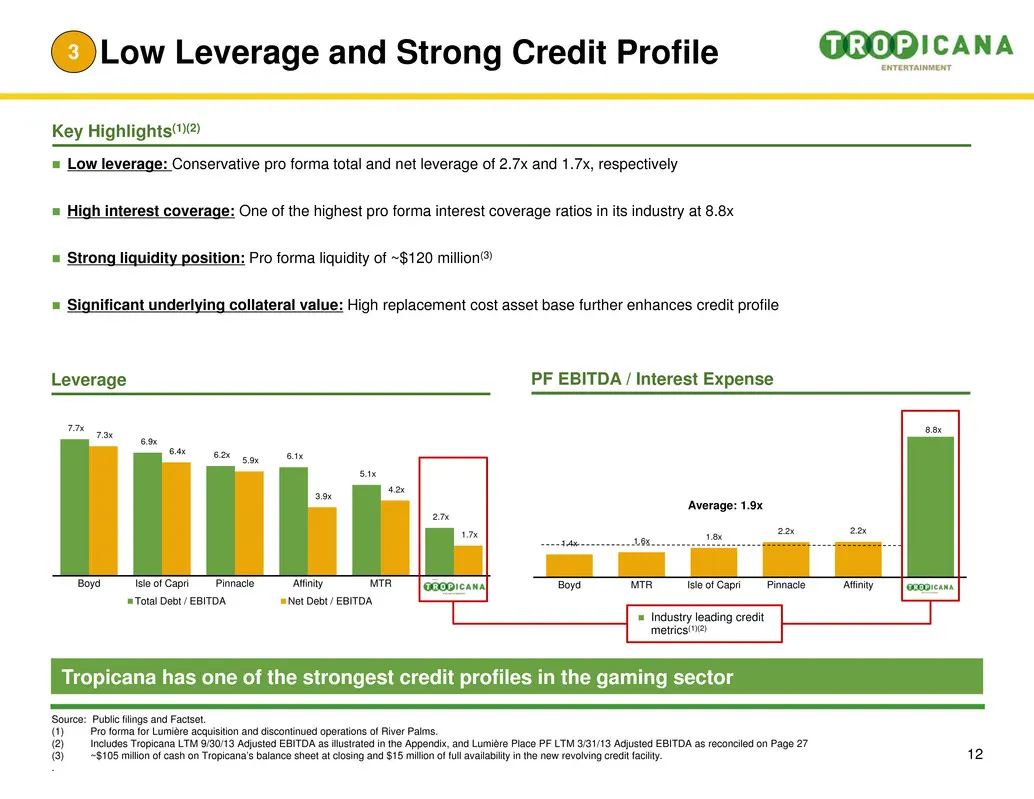
1.4x 1.6x 1.8x 2.2x 2.2x 8.8x Boyd MTR Isle of Capri Pinnacle Affinity Low Leverage and Strong Credit Profile 12 Tropicana has one of the strongest credit profiles in the gaming sector Key Highlights(1)(2) Leverage PF EBITDA / Interest Expense Source: Public filings and Factset. (1) Pro forma for Lu
Slide 14: Consistent Margin Expansion
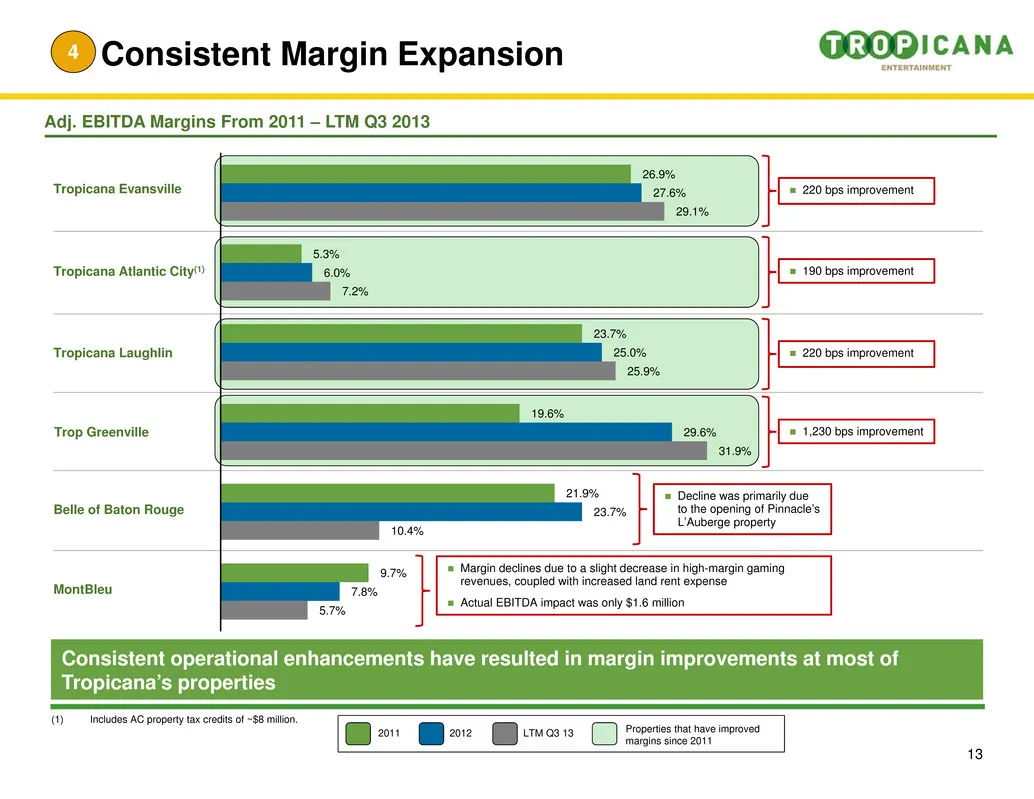
13 Trop Greenville Belle of Baton Rouge Tropicana Evansville Tropicana Laughlin MontBleu 4 Adj. EBITDA Margins From 2011 – LTM Q3 2013 Tropicana Atlantic City(1) (1) Includes AC property tax credits of ~$8 million. Properties that have improved margins since 2011 2011 2012 LTM Q3 13 26.9% 5.3% 23.7%
Slide 15: Favorable Competitive Tax Status
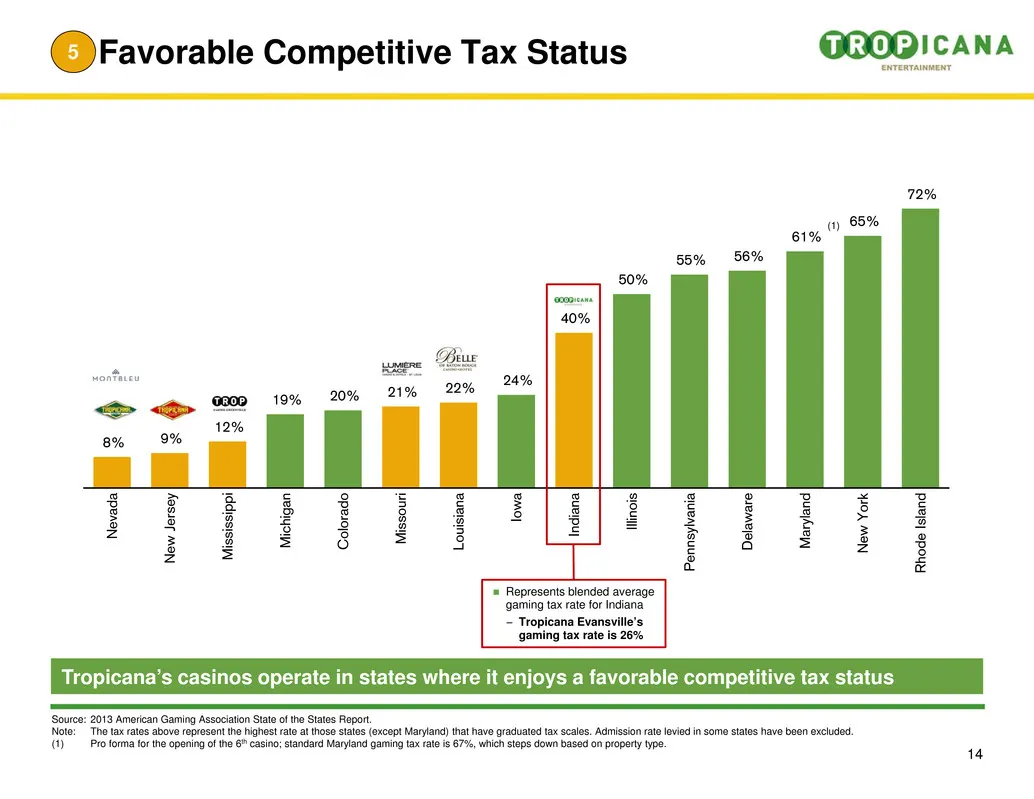
14 Tropicana’s casinos operate in states where it enjoys a favorable competitive tax status 8% 9% 12% 19% 20% 21% 22% 24% 40% 50% 55% 56% 61% 65% 72% N e v a d a N e w J e r s e y M i s s i s s i p p i M i c h i g a n C o l o r a d o M i s s o u r i L o u i s i a n a I o w a I n d i a n a I l l i n
Slide 16: Proven & Experienced Management Team
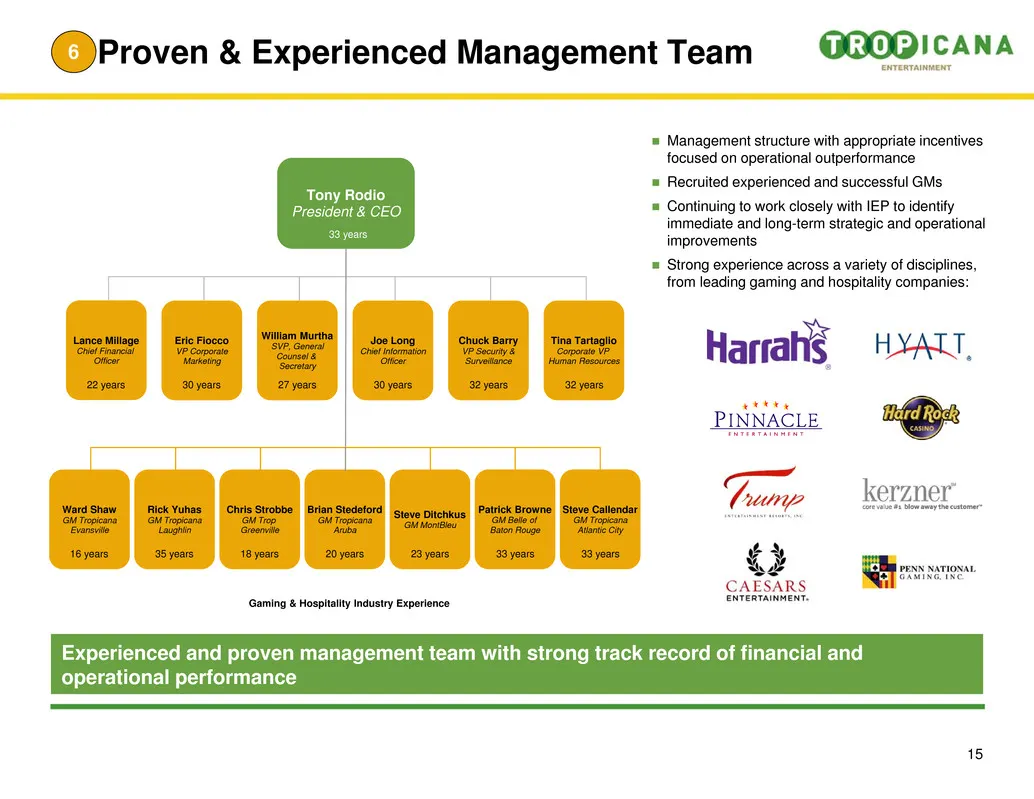
Management structure with appropriate incentives focused on operational outperformance Recruited experienced and successful GMs Continuing to work closely with IEP to identify immediate and long-term strategic and operational improvements Strong experience across a variety of disciplines, fr
Slide 17: Icahn Enterprises: Strong Sponsor Support
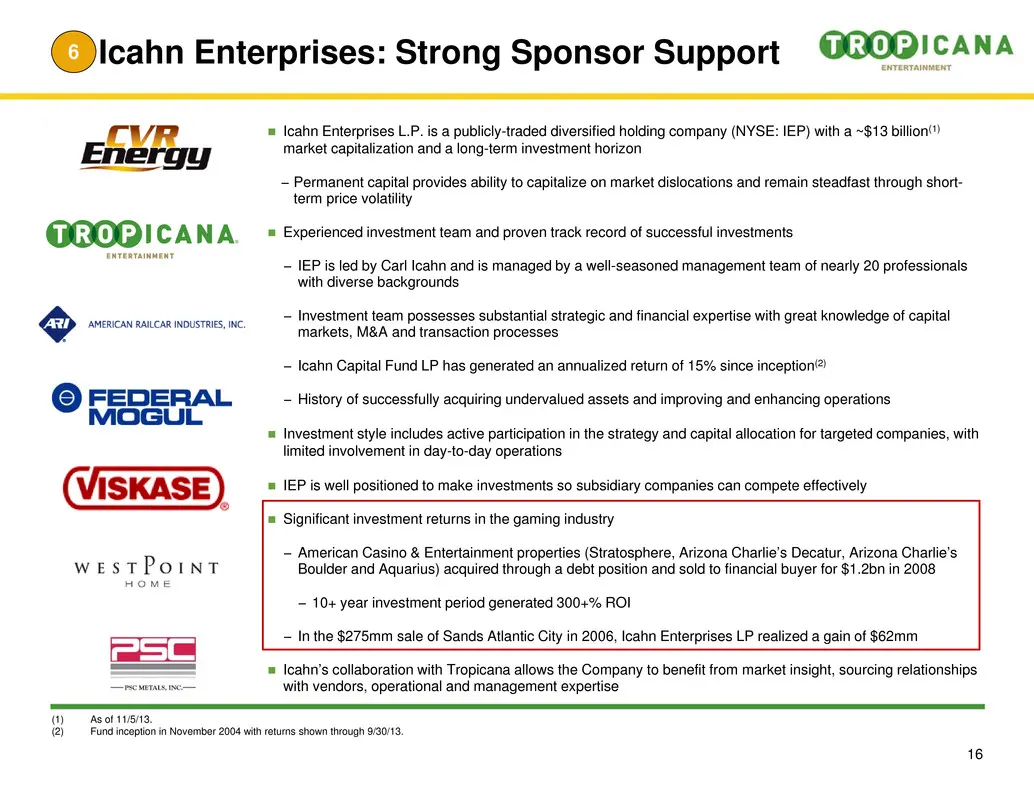
Icahn Enterprises: Strong Sponsor Support 16 6 Icahn Enterprises L.P. is a publicly-traded diversified holding company (NYSE: IEP) with a ~$13 billion(1) market capitalization and a long-term investment horizon − Permanent capital provides ability to capitalize on market dislocations and remain st
Slide 18: Company Overview
Company Overview
Slide 19: Property Overview
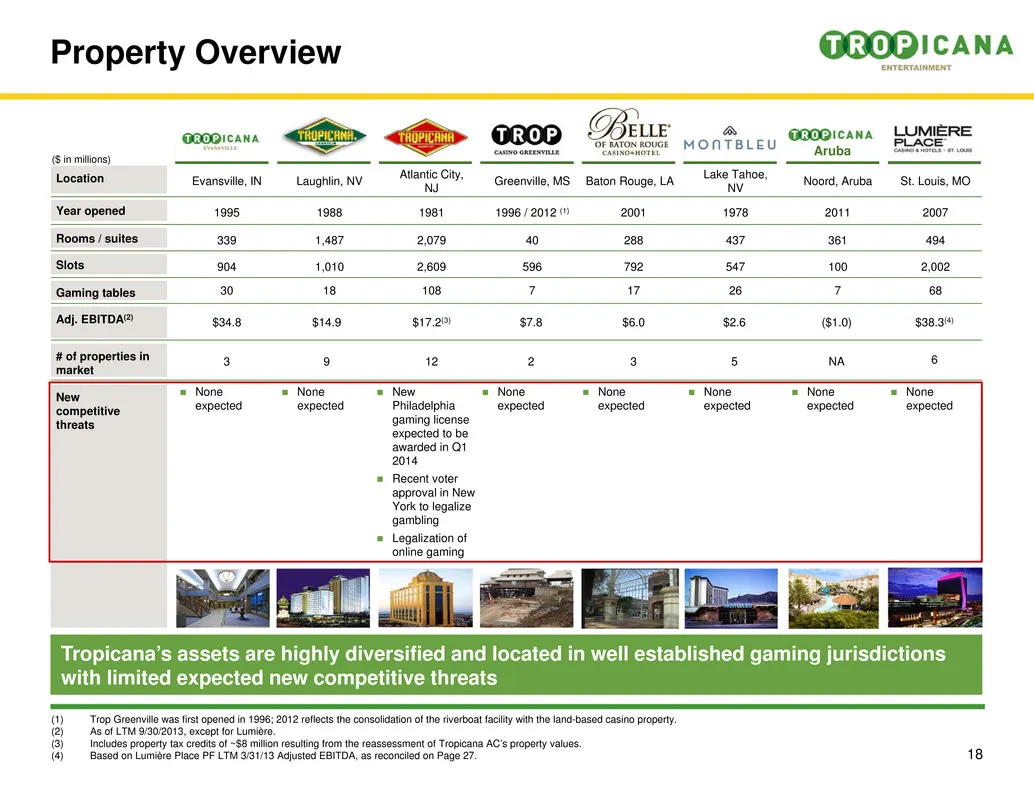
St. Louis, MO 2007 494 2,002 68 $38.3(4) None expected Laughlin, NV 1988 1,487 1,010 18 $14.9 None expected Atlantic City, NJ 1981 2,079 2,609 108 $17.2(3) New Philadelphia gaming license expected to be awarded in Q1 2014 Recent voter approval in New York to legalize gambling Legalization
Slide 20: Tropicana Evansville
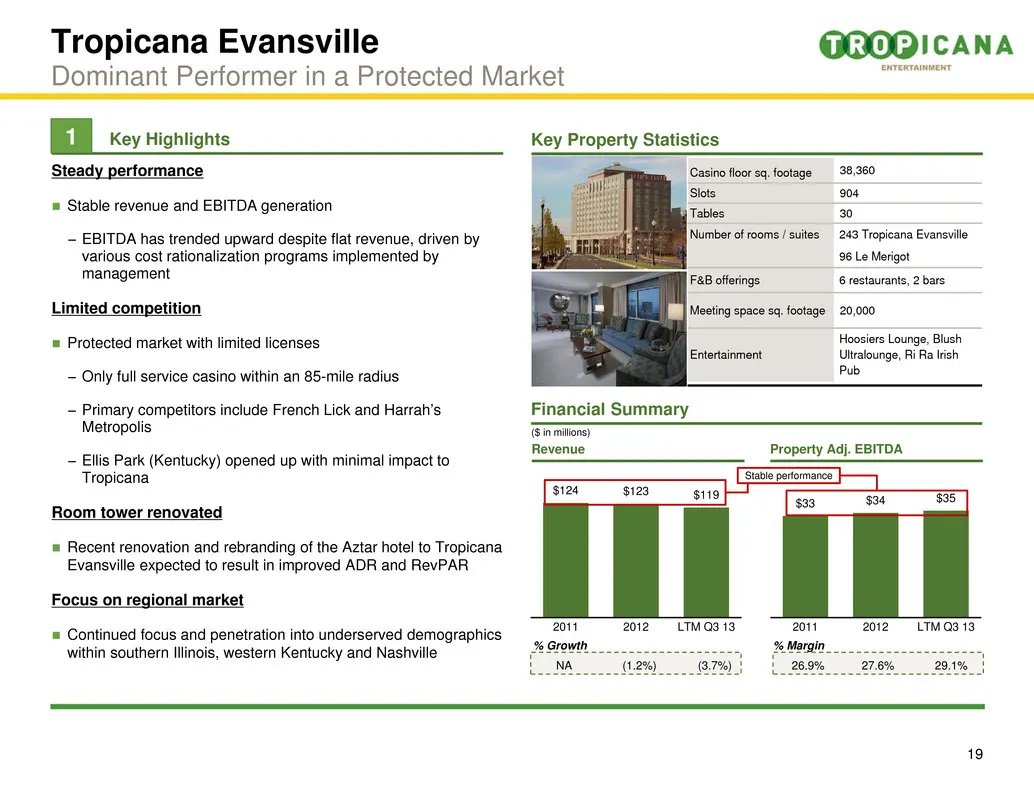
19 Steady performance Stable revenue and EBITDA generation − EBITDA has trended upward despite flat revenue, driven by various cost rationalization programs implemented by management Limited competition Protected market with limited licenses − Only full service casino within an 85-mile radius −
Slide 21: Tropicana Laughlin
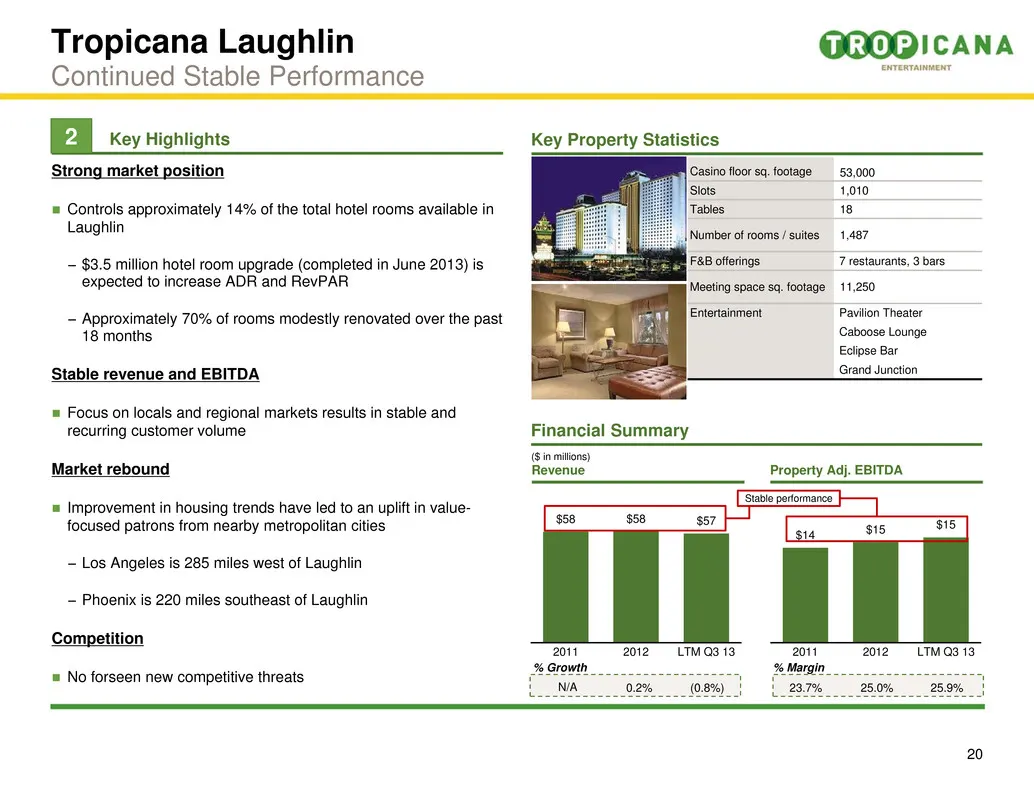
Key Highlights 20 Strong market position Controls approximately 14% of the total hotel rooms available in Laughlin − $3.5 million hotel room upgrade (completed in June 2013) is expected to increase ADR and RevPAR − Approximately 70% of rooms modestly renovated over the past 18 months Stable revenu
Slide 22: Tropicana Atlantic City
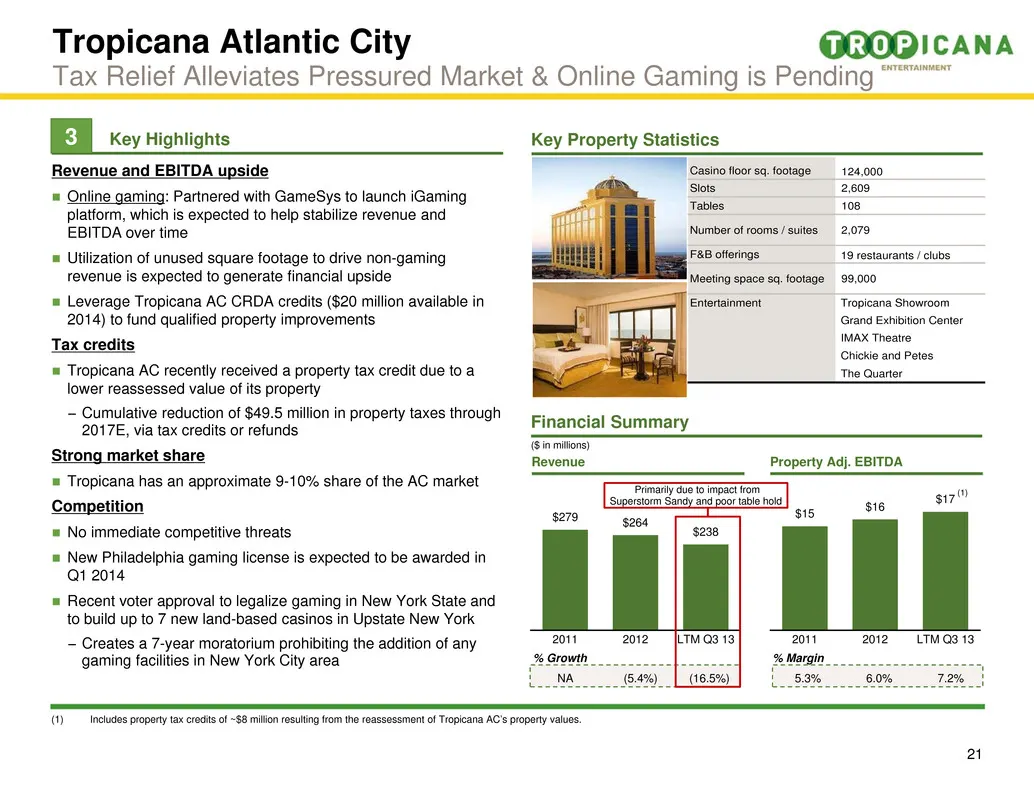
Key Highlights 21 Revenue and EBITDA upside Online gaming: Partnered with GameSys to launch iGaming platform, which is expected to help stabilize revenue and EBITDA over time Utilization of unused square footage to drive non-gaming revenue is expected to generate financial upside Leverage Trop
Slide 23: Trop Greenville
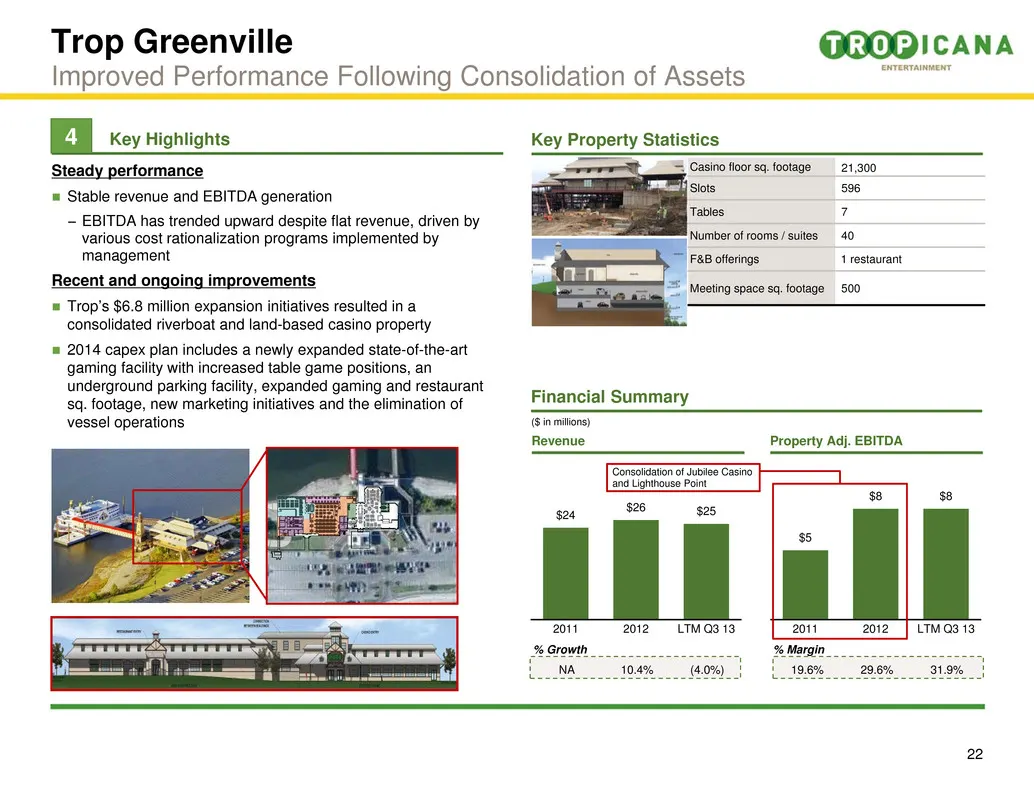
Key Highlights 22 Steady performance Stable revenue and EBITDA generation − EBITDA has trended upward despite flat revenue, driven by various cost rationalization programs implemented by management Recent and ongoing improvements Trop’s $6.8 million expansion initiatives resulted in a consolidat
Slide 24: Belle of Baton Rouge
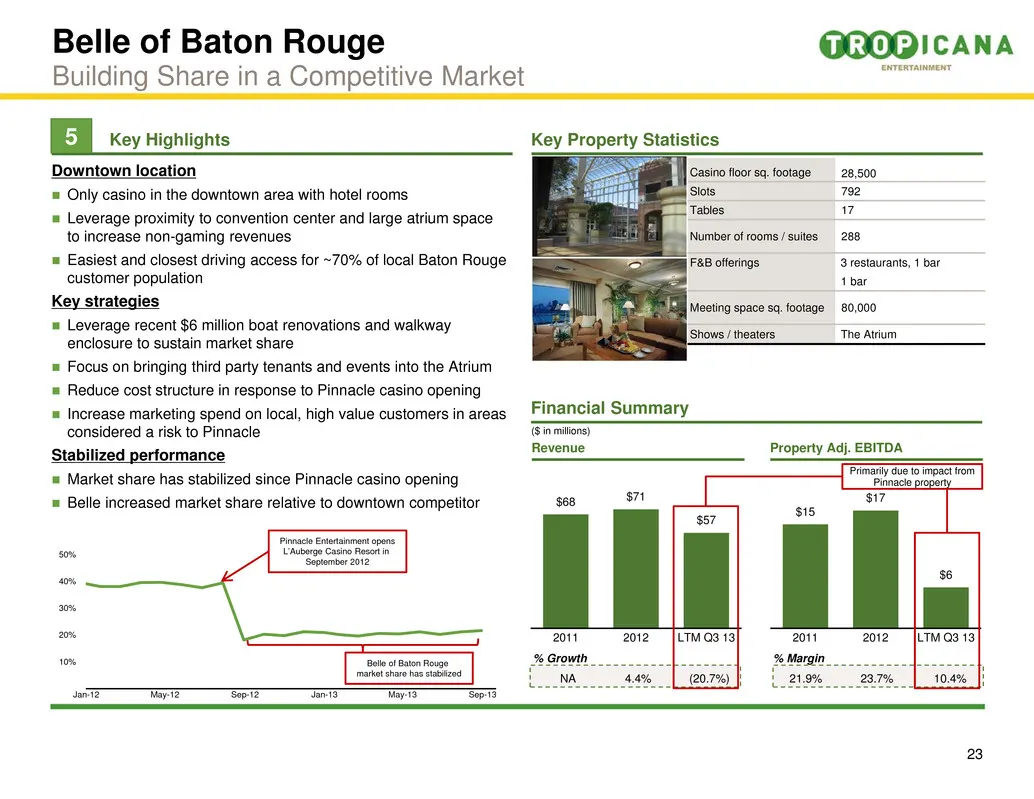
Casino floor sq. footage 28,500 Slots 792 Tables 17 Number of rooms / suites 288 F&B offerings 3 restaurants, 1 bar 1 bar Meeting space sq. footage 80,000 Shows / theaters The Atrium 23 Downtown location Only casino in the downtown area with hotel rooms Leverage proximity to convention center an
Slide 25: MontBleu
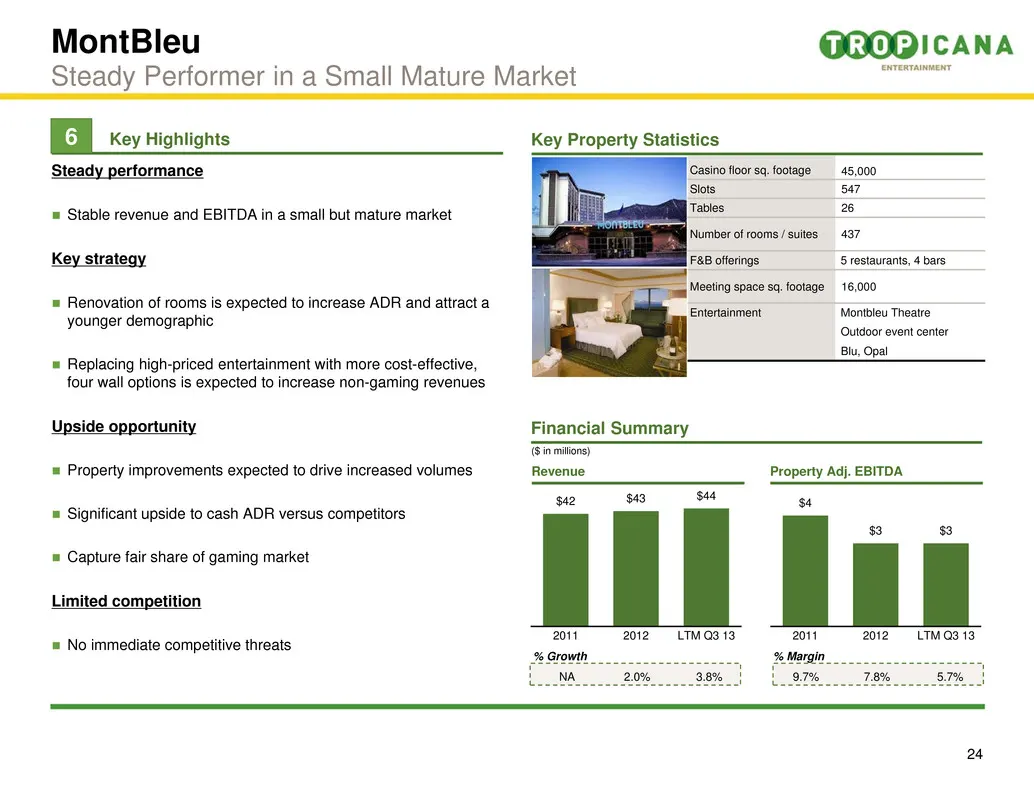
Key Highlights Casino floor sq. footage 45,000 Slots 547 Tables 26 Number of rooms / suites 437 F&B offerings 5 restaurants, 4 bars Meeting space sq. footage 16,000 Entertainment Montbleu Theatre Outdoor event center Blu, Opal 24 Steady performance Stable revenue and EBITDA in a small but mature m
Slide 26: Tropicana Aruba
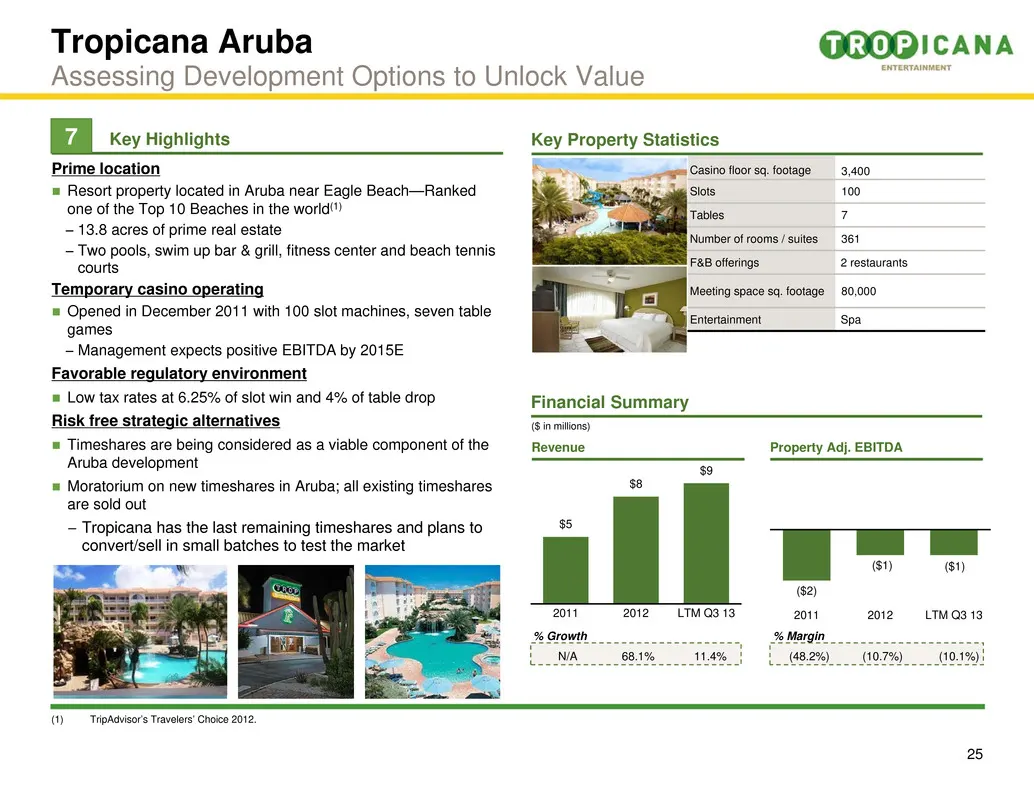
Key Highlights Casino floor sq. footage 3,400 Slots 100 Tables 7 Number of rooms / suites 361 F&B offerings 2 restaurants Meeting space sq. footage 80,000 Entertainment Spa 25 Prime location Resort property located in Aruba near Eagle Beach—Ranked one of the Top 10 Beaches in the world(1) − 13.8 a
Slide 27: Lumière Place Acquisition
Lumière Place Acquisition
Slide 28: Lumière Place Key Highlights
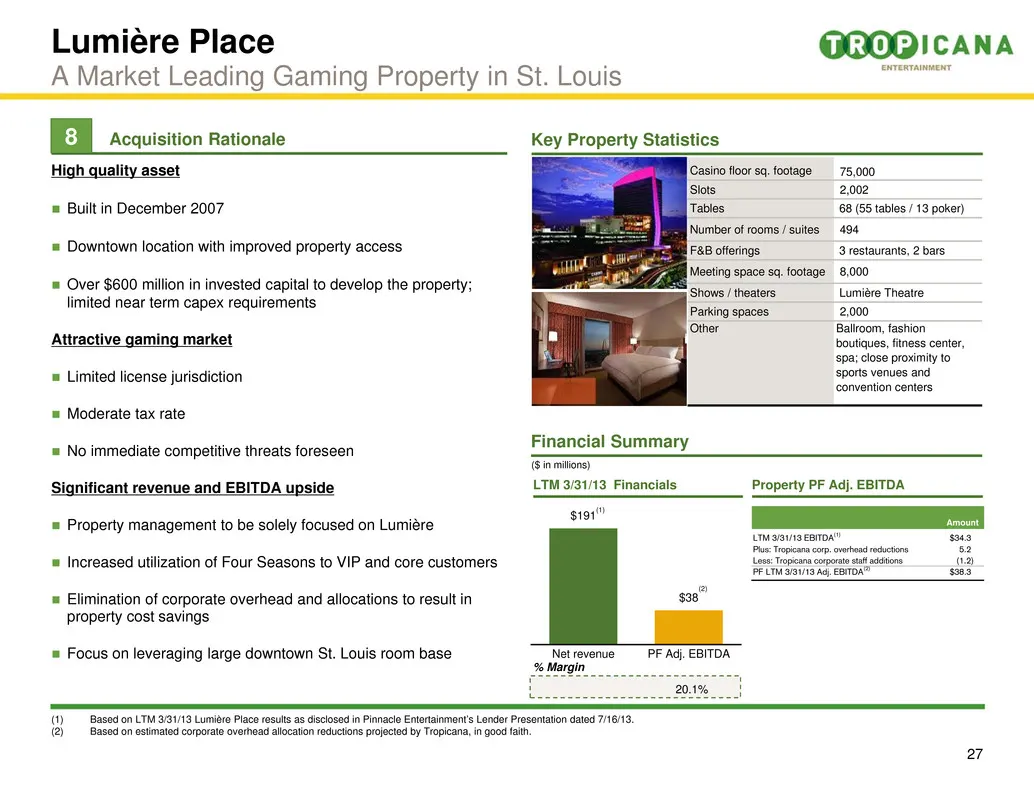
Casino floor sq. footage 75,000 Slots 2,002 Tables 68 (55 tables / 13 poker) Number of rooms / suites 494 F&B offerings 3 restaurants, 2 bars Meeting space sq. footage 8,000 Shows / theaters Lumière Theatre Parking spaces 2,000 Other Ballroom, fashion boutiques, fitness center, spa; close proximity
Slide 29: Lumière Place Property Highlights
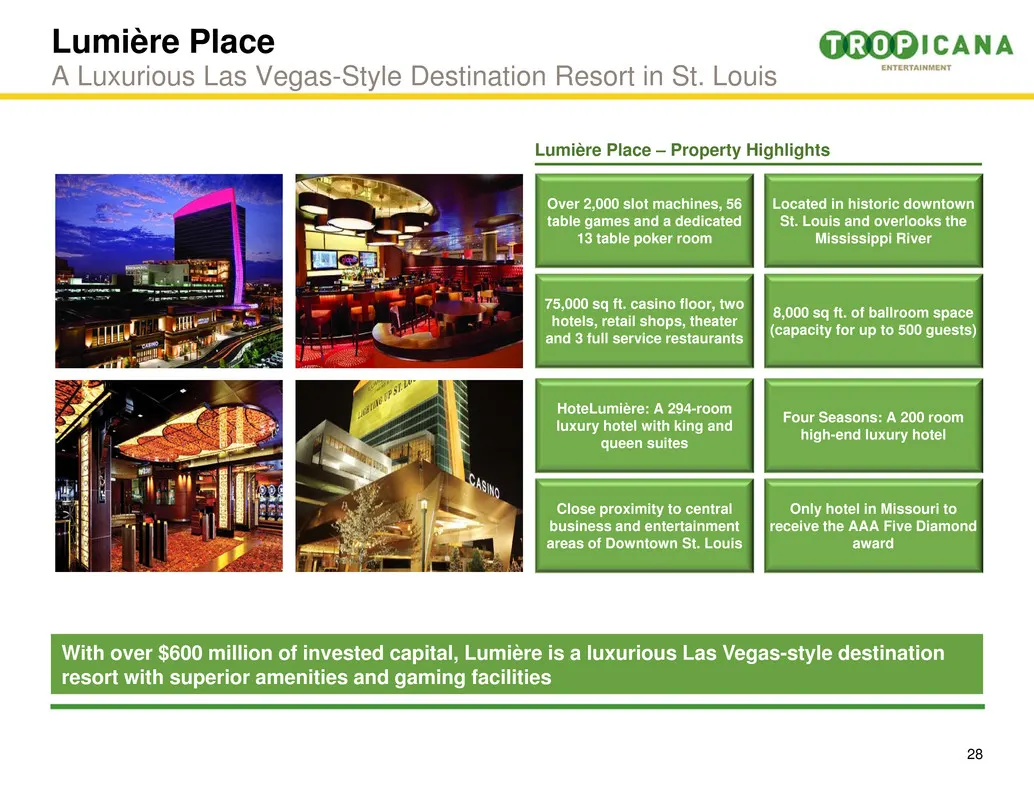
28 With over $600 million of invested capital, Lumière is a luxurious Las Vegas-style destination resort with superior amenities and gaming facilities Lumière Place – Property Highlights Over 2,000 slot machines, 56 table games and a dedicated 13 table poker room Located in historic downtown St. Lou
Slide 30: Superior Downtown Location & Improved Accessibility
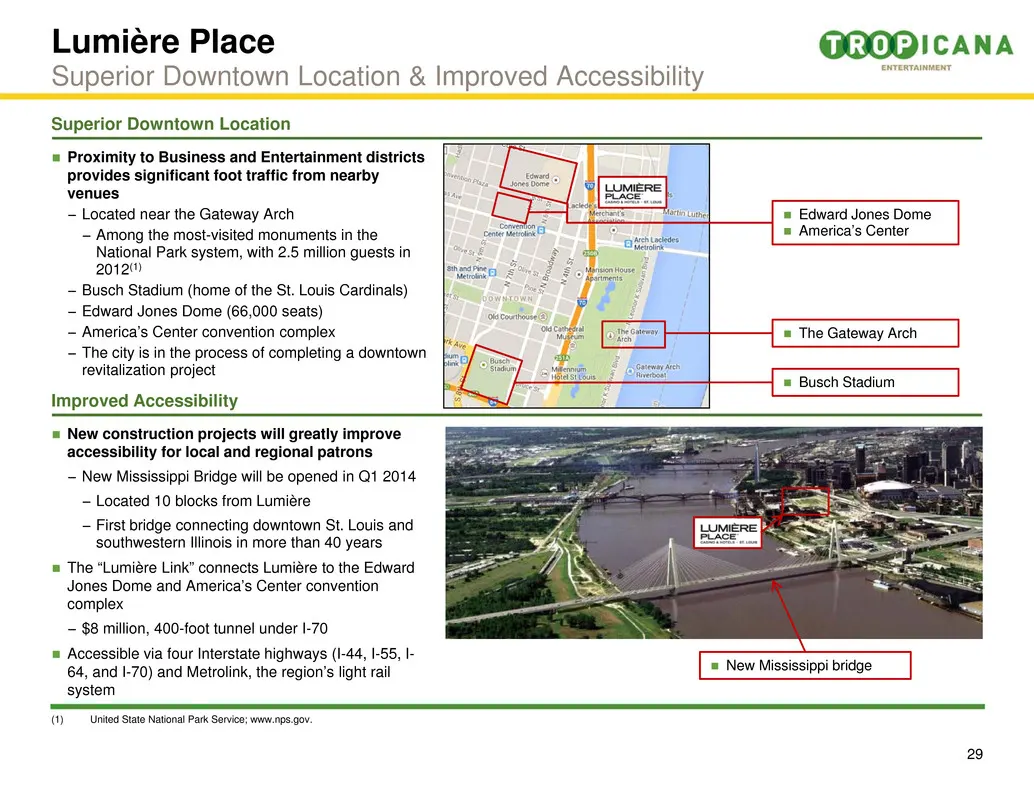
Edward Jones Dome America’s Center 29 Superior Downtown Location Proximity to Business and Entertainment districts provides significant foot traffic from nearby venues − Located near the Gateway Arch − Among the most-visited monuments in the National Park system, with 2.5 million guests in 201
Slide 31: Historical Financial Performance
Historical Financial Performance
Slide 32: Summary Historical Financials
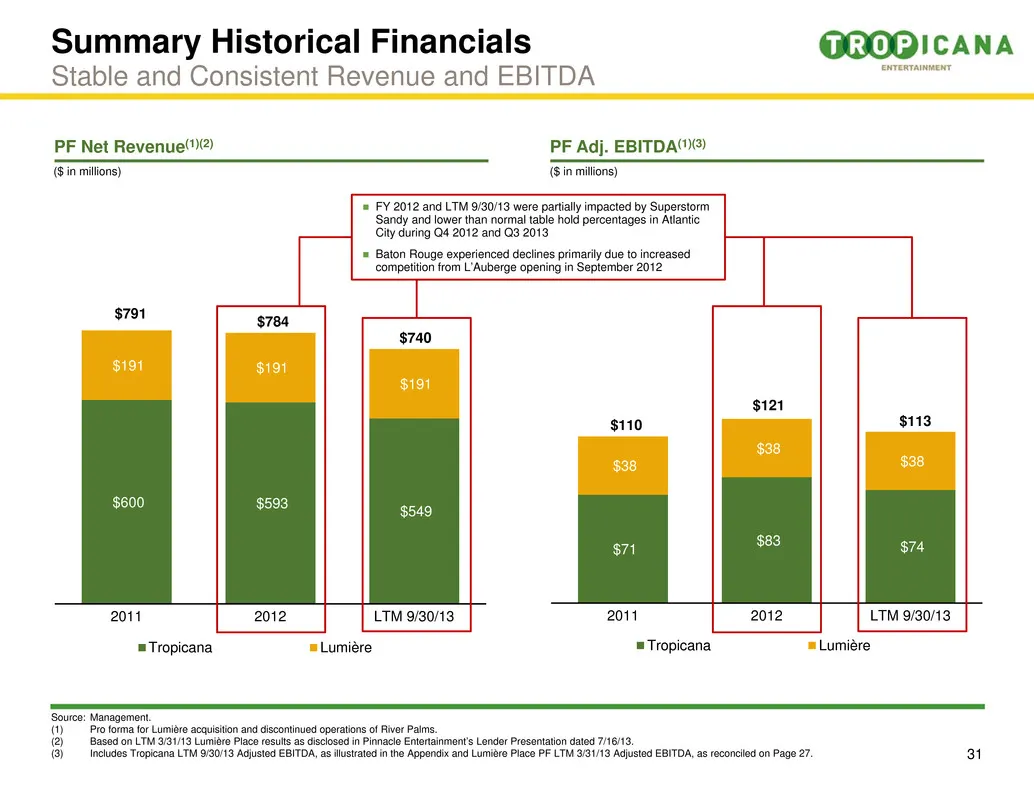
31 Source: Management. (1) Pro forma for Lumière acquisition and discontinued operations of River Palms. (2) Based on LTM 3/31/13 Lumière Place results as disclosed in Pinnacle Entertainment’s Lender Presentation dated 7/16/13. (3) Includes Tropicana LTM 9/30/13 Adjusted EBITDA, as illustrated in th
Slide 33: Historical Financials by Property
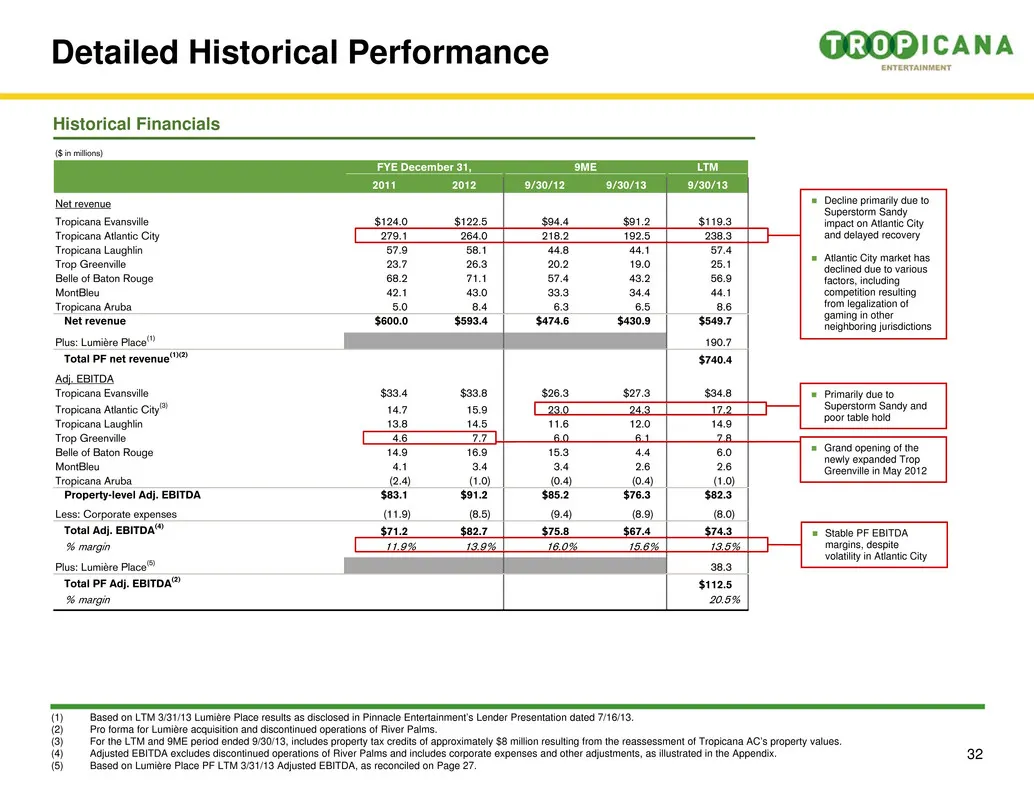
($ in millions) FYE December 31, 9ME LTM 2011 2012 9/30/12 9/30/13 9/30/13 Net revenue Tropicana Evansville $124.0 $122.5 $94.4 $91.2 $119.3 Tropicana Atlantic City 279.1 264.0 218.2 192.5 238.3 Tropicana Laughlin 57.9 58.1 44.8 44.1 57.4 Trop Greenville 23.7 26.3 20.2 19.0 25.1 Belle of Baton Rouge
Slide 34: Syndication Overview
Surexrannent Syndication Overview
Slide 35: Summary of Proposed Terms
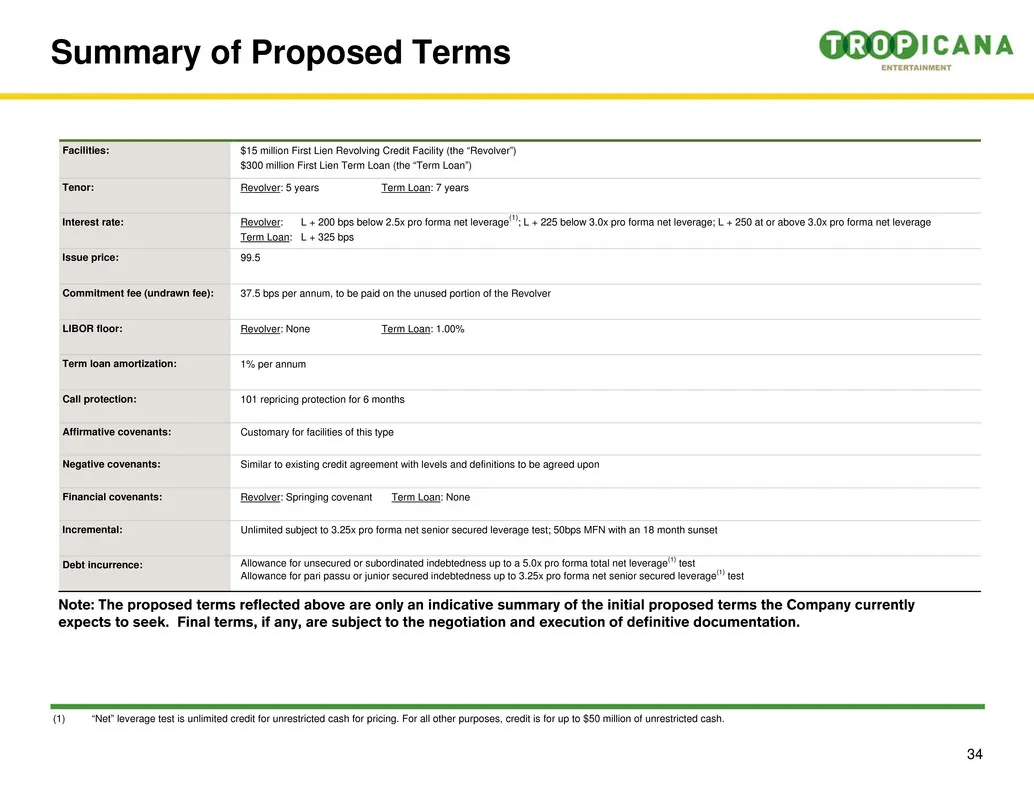
34 Summary of Proposed Terms Facilities: $15 million First Lien Revolving Credit Facility (the “Revolver”) $300 million First Lien Term Loan (the “Term Loan”) Tenor: Revolver: 5 years Term Loan: 7 years Interest rate: Revolver: L + 200 bps below 2.5x pro forma net leverage(1); L + 225 below 3.0x pro
Slide 36: Q&A
Q&A
Slide 37: Appendix: Market Overview
ENTERTAINWENT Appendix Market Overview
Slide 38: Market Overview – Evansville, Indiana
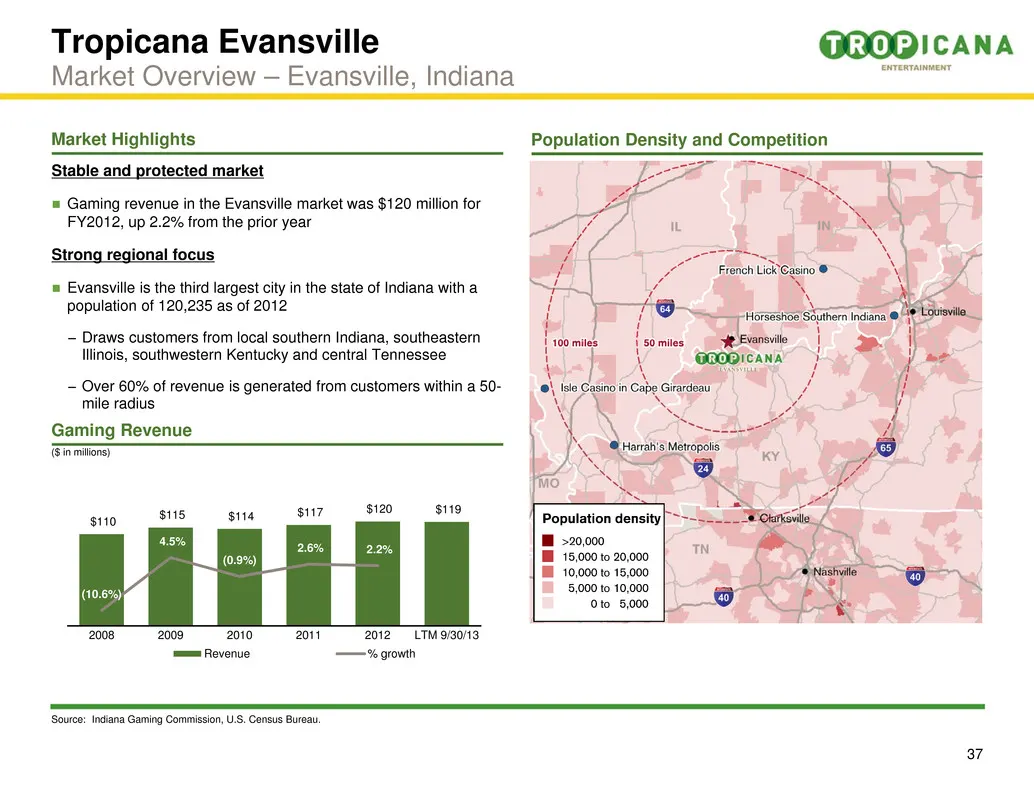
37 Market Highlights Population Density and Competition Stable and protected market Gaming revenue in the Evansville market was $120 million for FY2012, up 2.2% from the prior year Strong regional focus Evansville is the third largest city in the state of Indiana with a population of 120,235 as
Slide 39: Market Overview – Laughlin, Nevada
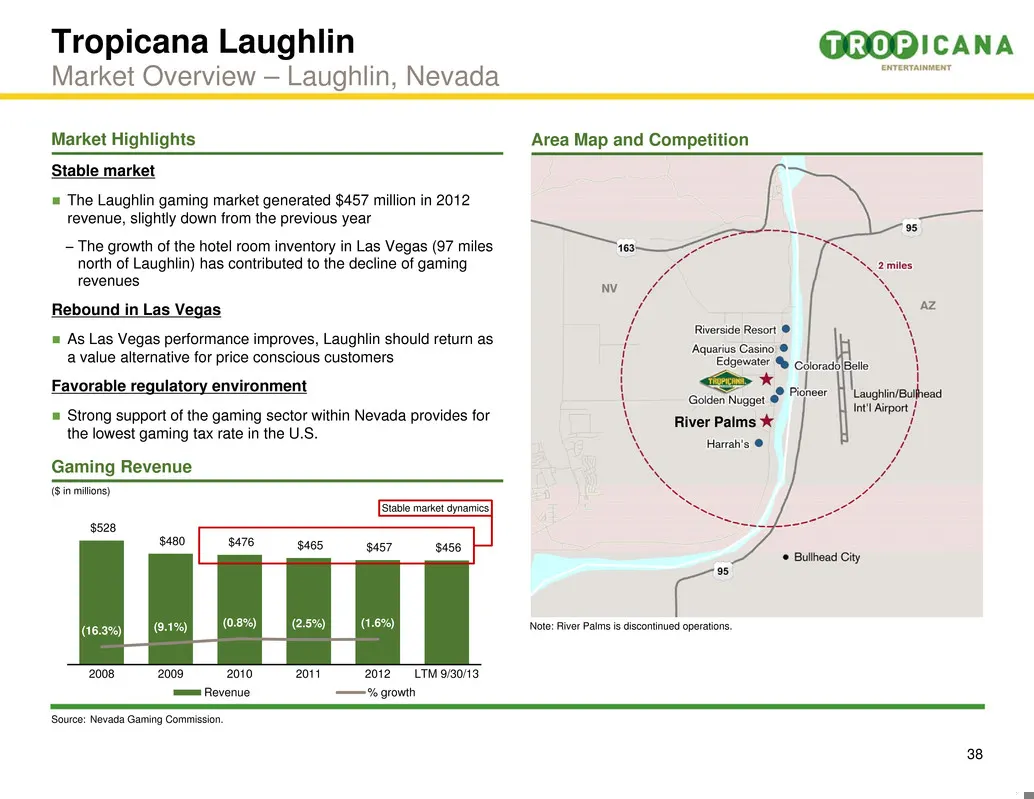
38 Market Highlights Area Map and Competition Source: Nevada Gaming Commission. Stable market The Laughlin gaming market generated $457 million in 2012 revenue, slightly down from the previous year − The growth of the hotel room inventory in Las Vegas (97 miles north of Laughlin) has contributed t
Slide 40: Market Overview – Atlantic City, New Jersey
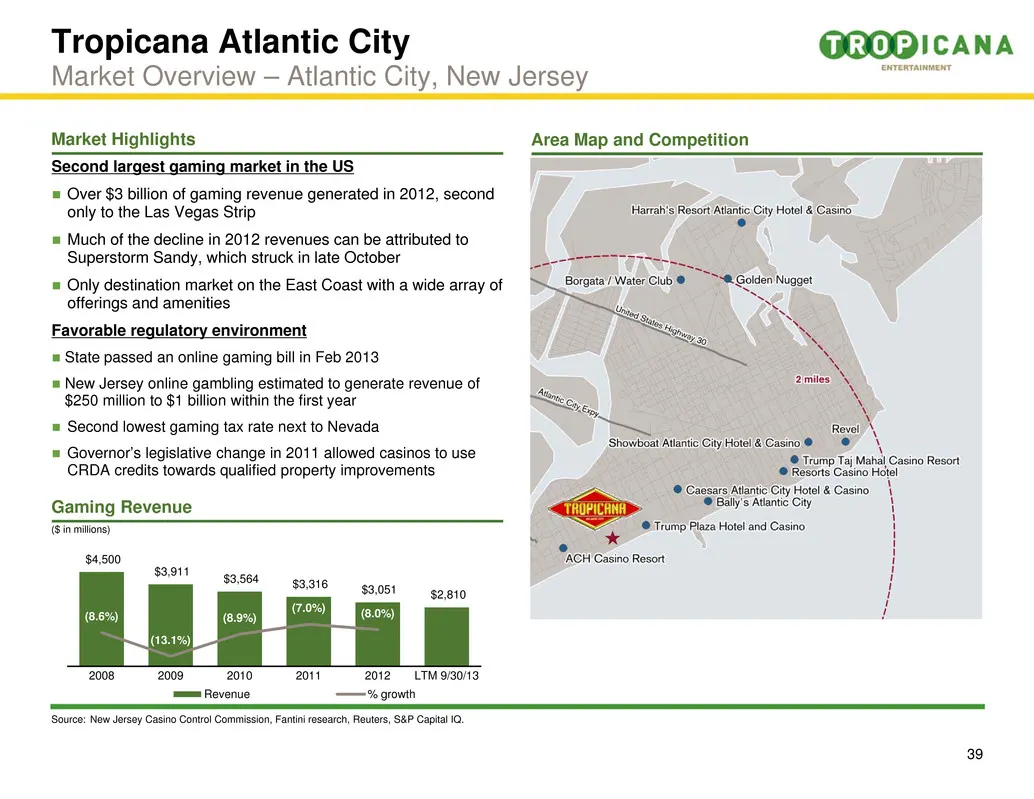
39 Market Highlights Area Map and Competition Source: New Jersey Casino Control Commission, Fantini research, Reuters, S&P Capital IQ. Second largest gaming market in the US Over $3 billion of gaming revenue generated in 2012, second only to the Las Vegas Strip Much of the decline in 2012 revenu
Slide 41: Market Overview – Greenville, Mississippi
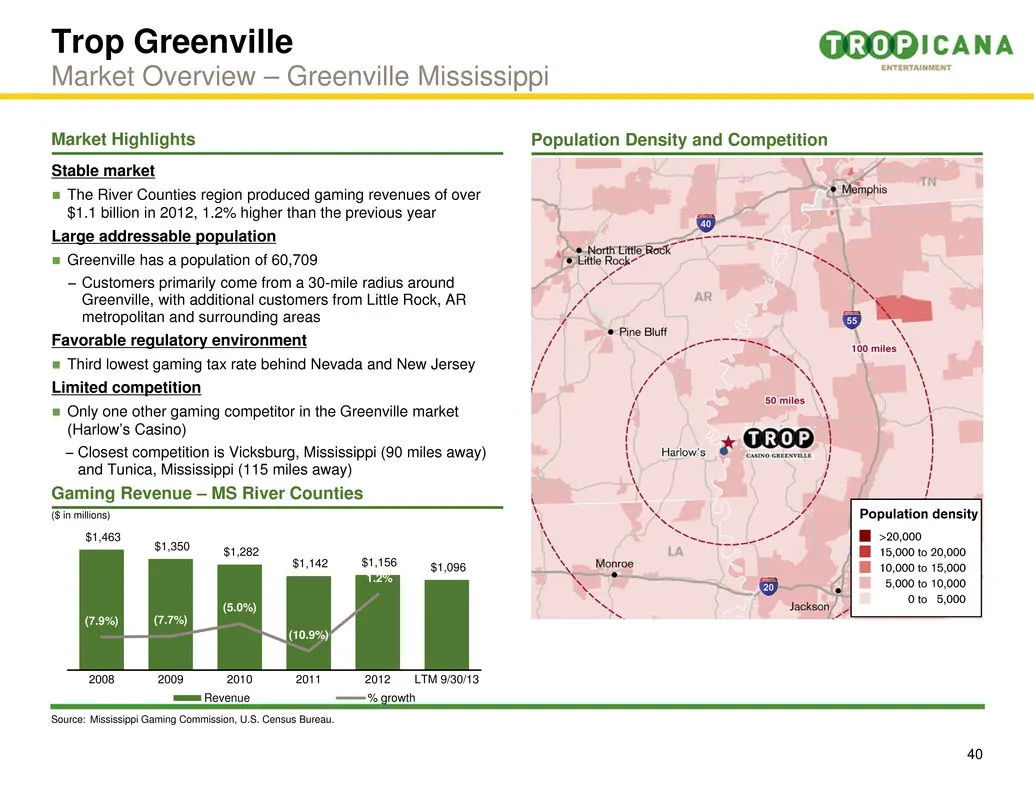
40 Market Highlights Population Density and Competition Stable market The River Counties region produced gaming revenues of over $1.1 billion in 2012, 1.2% higher than the previous year Large addressable population Greenville has a population of 60,709 − Customers primarily come from a 30-mile r
Slide 42: Market Overview – Baton Rouge, Louisiana
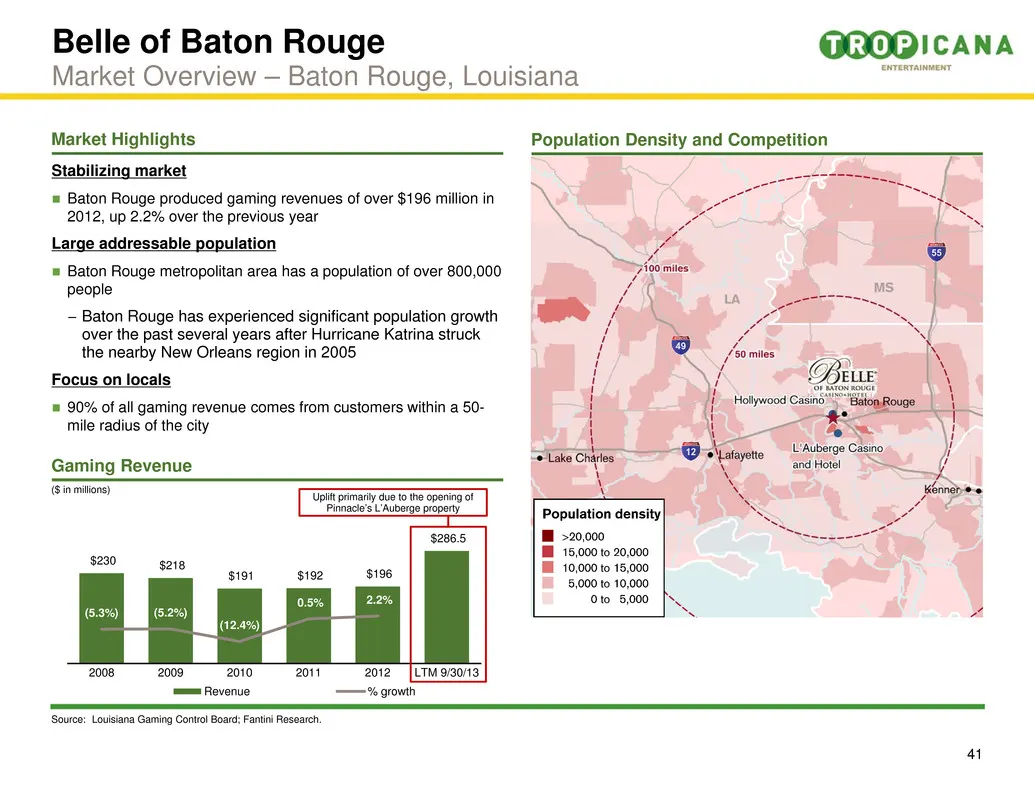
41 Market Highlights Population Density and Competition Source: Louisiana Gaming Control Board; Fantini Research. Stabilizing market Baton Rouge produced gaming revenues of over $196 million in 2012, up 2.2% over the previous year Large addressable population Baton Rouge metropolitan area has a
Slide 43: Market Overview – Lake Tahoe, Nevada
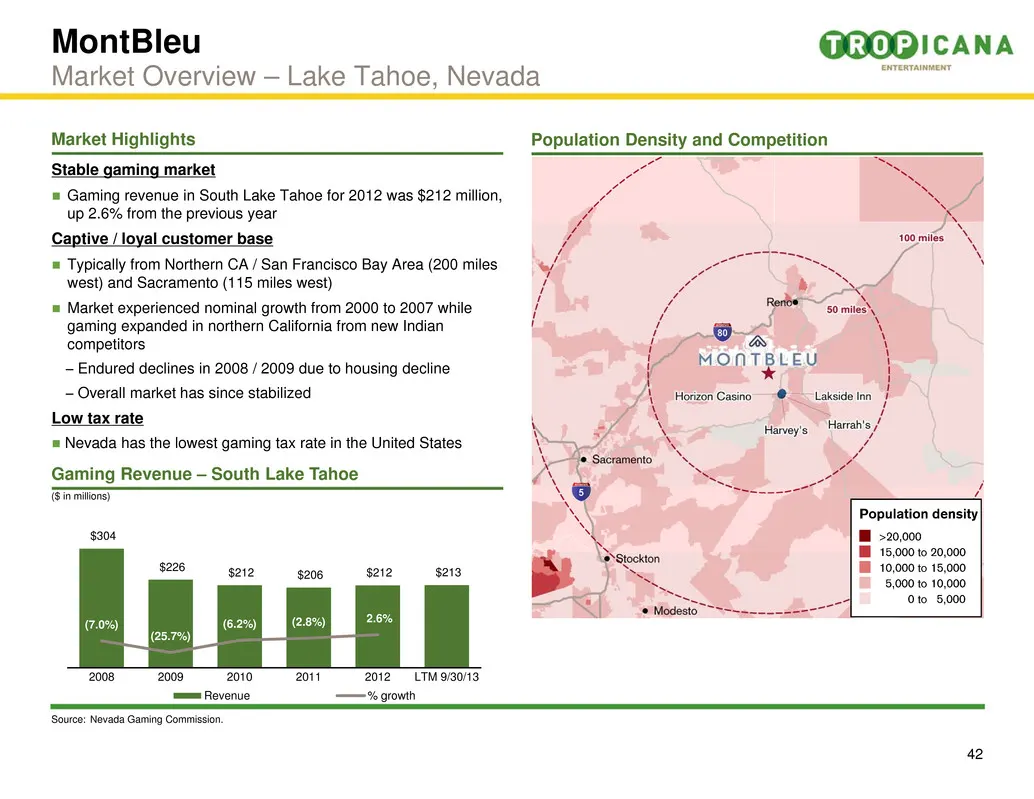
42 Market Highlights Population Density and Competition Stable gaming market Gaming revenue in South Lake Tahoe for 2012 was $212 million, up 2.6% from the previous year Captive / loyal customer base Typically from Northern CA / San Francisco Bay Area (200 miles west) and Sacramento (115 miles w
Slide 44: Market Overview – St. Louis, Missouri
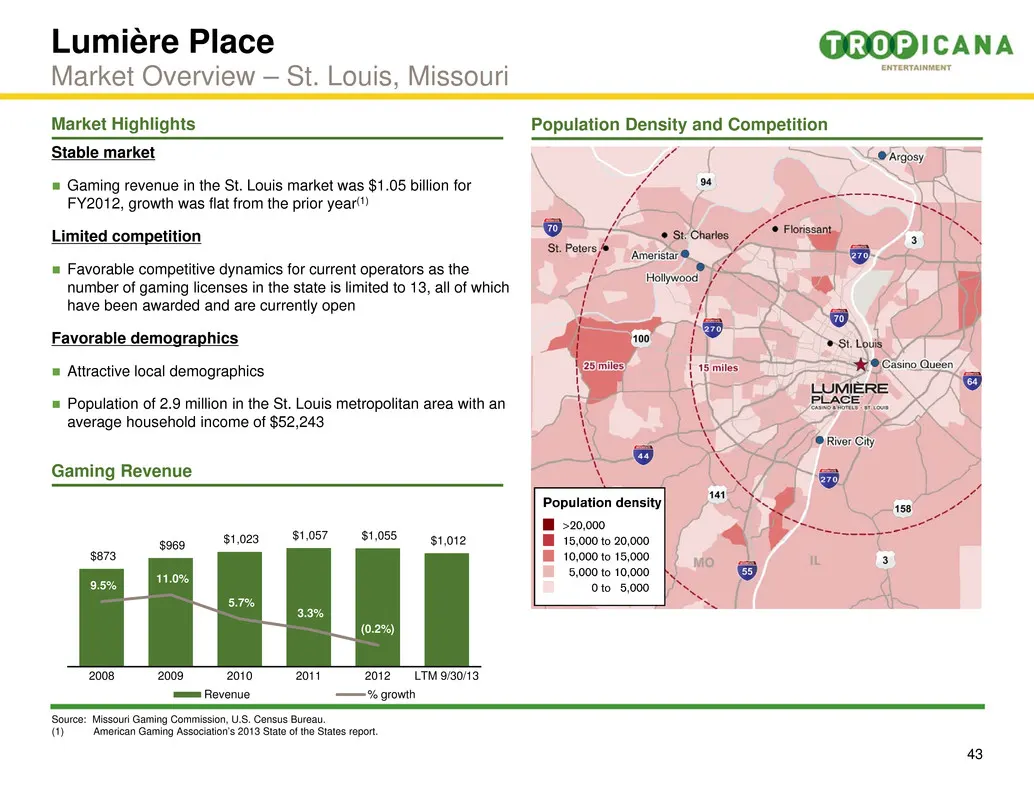
43 Market Highlights Population Density and Competition Source: Missouri Gaming Commission, U.S. Census Bureau. (1) American Gaming Association’s 2013 State of the States report. Stable market Gaming revenue in the St. Louis market was $1.05 billion for FY2012, growth was flat from the prior year(
Slide 45: Appendix Non-GAAP Reconciliation
Appendix Non-GAAP Reconciliation
Slide 46: Non-GAAP Reconciliation LTM 9/30/13 and FY2012
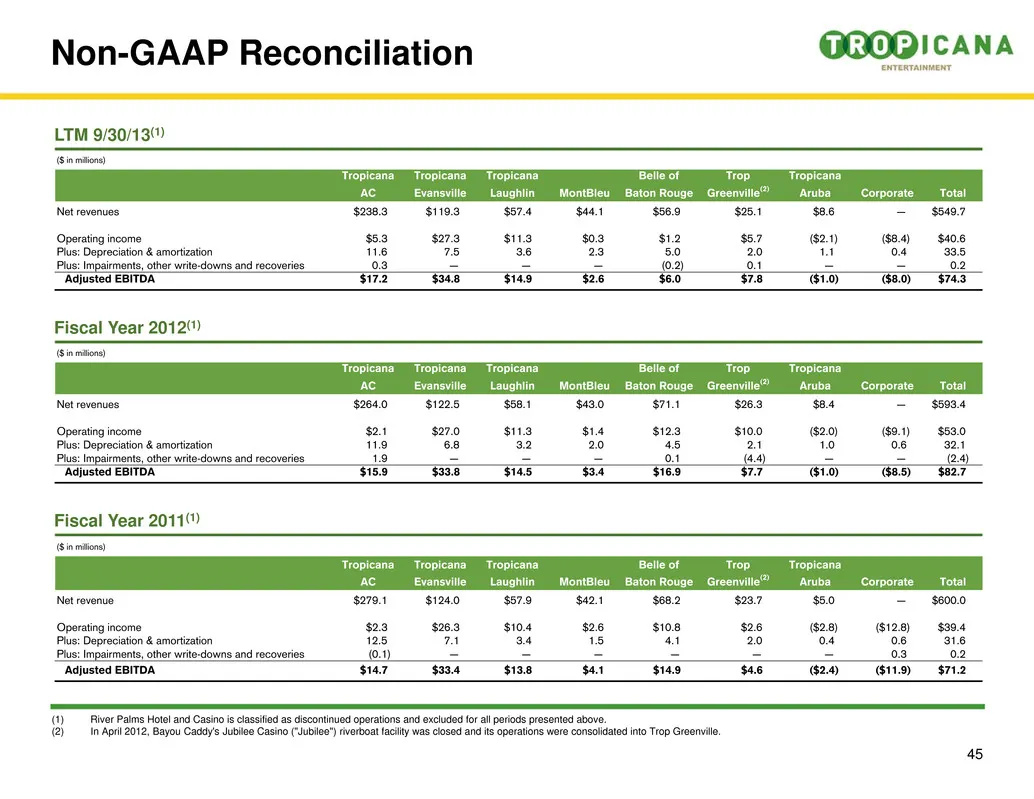
45 LTM 9/30/13(1) Non-GAAP Reconciliation ($ in millions) Tropicana Tropicana Tropicana Belle of Trop Tropicana AC Evansville Laughlin MontBleu Baton Rouge Greenville(2) Aruba Corporate Total Net revenues $238.3 $119.3 $57.4 $44.1 $56.9 $25.1 $8.6 — $549.7 Operating income $5.3 $27.3 $11.3 $0.3 $1.2
Slide 47: Non-GAAP Reconciliation Nine Months Ended 9/30/13
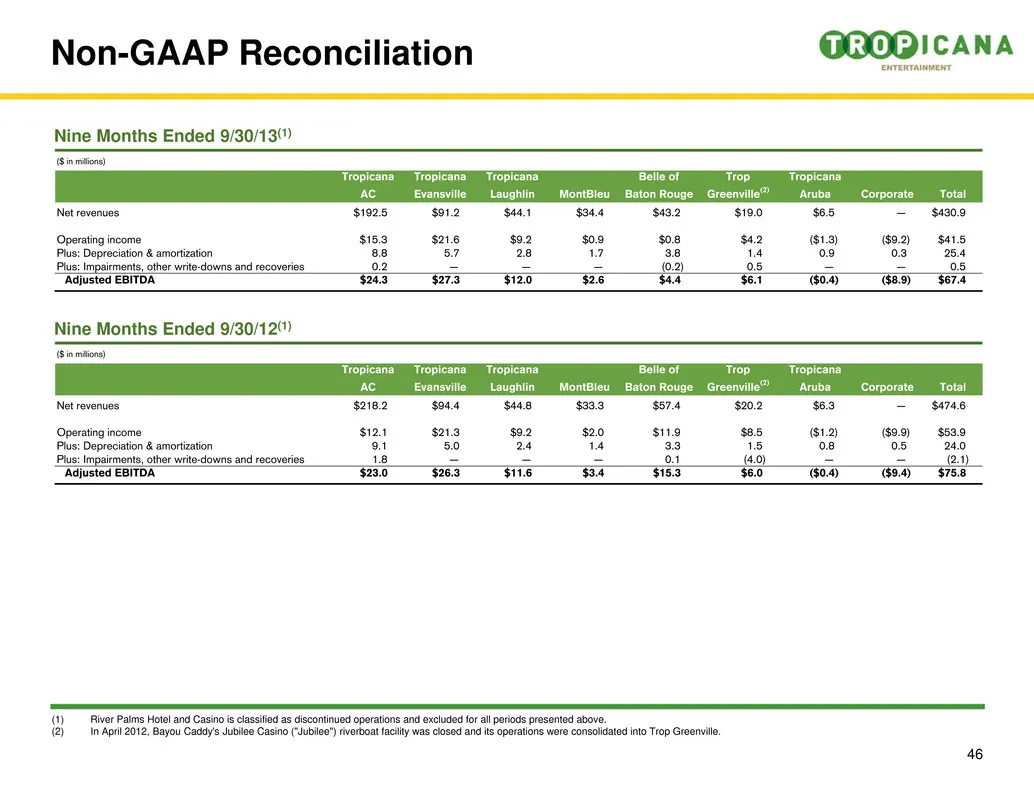
46 Nine Months Ended 9/30/13(1) Non-GAAP Reconciliation ($ in millions) Tropicana Tropicana Tropicana Belle of Trop Tropicana AC Evansville Laughlin MontBleu Baton Rouge Greenville(2) Aruba Corporate Total Net revenues $192.5 $91.2 $44.1 $34.4 $43.2 $19.0 $6.5 — $430.9 Operating income $15.3 $21.6 $
Slide 48: Disclaimer: Non-GAAP Financial Measures
47 Disclaimer Non-GAAP Financial Measures − Adjusted EBITDA is not a financial measure presented in accordance with U.S. generally accepted accounting principles (GAAP). Accordingly, when analyzing the Company’s operating performance, Adjusted EBITDA should not be considered in isolation, and shou
Slide 49: GDODICANA.
GDODICANA. ENTERTAINMENT
Source: SEC EDGAR · 8-K filed Nov 18, 2013