Pharmacopeia — Pharmacopeia Drug Discovery — Pacific Growth Equities Life Sciences Growth Conference 2005
31 slides from Pharmacopeia's conference presentation, Jun 3, 2005
Slide 1: Pharmacopeia – Pacific Growth Equities Life Sciences Growth Conference
») Pharmacopeia Pharmacopeia Pacific Growth Equities Life Sciences Growth Conference San Francisco, California June 6-86, 2005
Slide 2: Forward-Looking Statements
Forwar oking Statemen When used anywhere in this presentation the words "expects," "believes," "anticipates," ‘estimates" and similar expressions are intended to identity forward-looking statements. Forward-looking statements herein may include statements addressing future financial and operating re
Slide 3: Pharmacopeia Drug Discovery company description
Pharmacopeia ) p Pharmacopeia Drug Discovery, Inc. is a biopharmaceutical company, focused on the creation of new small molecule therapeutics to address significant unmet medical needs
Slide 4: PCOP Investment Drivers
Pharmacopeia O PCOP Investment Drivers + Comprehensive, integrated drug discovery capabilities + Proven track record of development success — 10 therapeutic candidates with 6 pharma collaborators + Future ‘annuity’ from broad partnered portfolio * Growing portfolio of small molecule drug candidates
Slide 5: Business Strategy
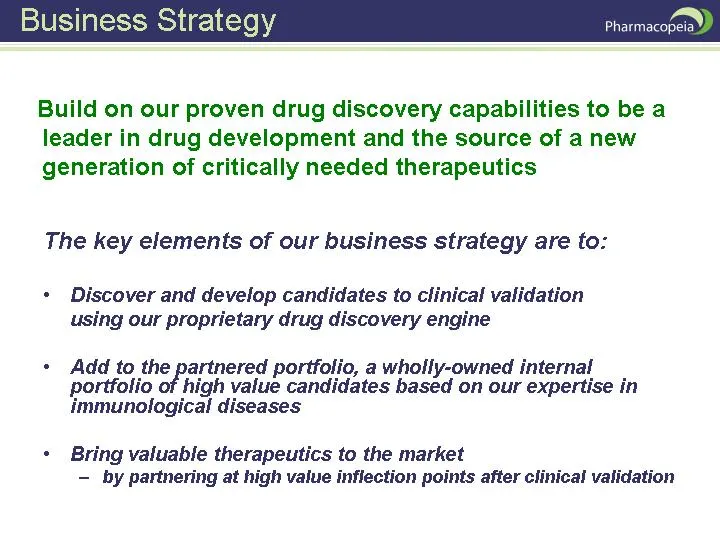
Business Strategy Build on our proven drug discovery capabilities to be a leader in drug development and the source of a new generation of critically needed therapeutics The key elements of our business strategy are to: + Discover and develop candidates to clinical validation using our proprietary d
Slide 6: Validated Discovery Platform
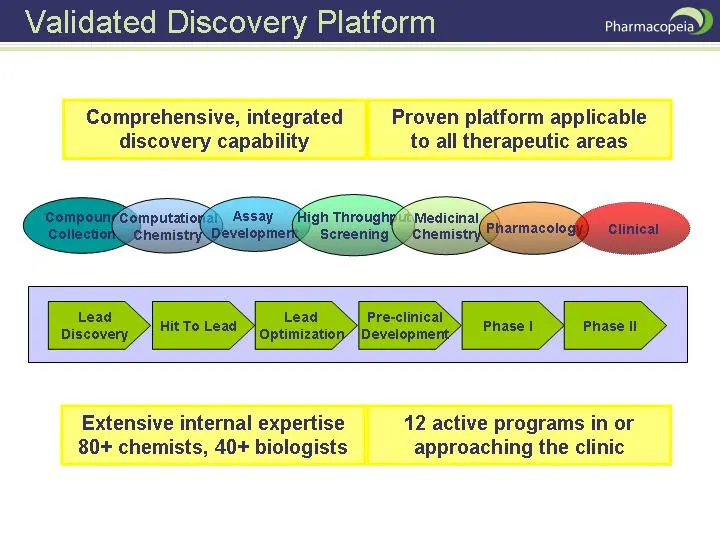
Validated Discovery Platform Comprehensive, integrated Proven platform applicable discovery capability to all therapeutic areas Extensive internal expertise 12 active programs in or 80+ chemists, 40+ biologists approaching the clinic
Slide 7: Successful Discovery Business
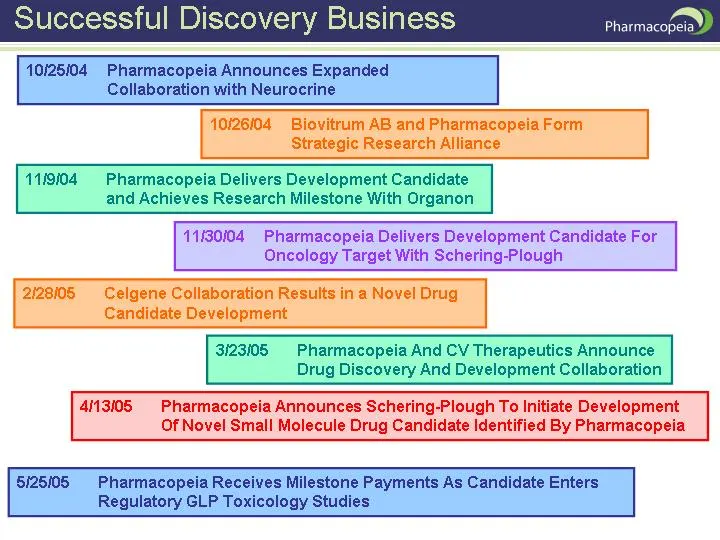
ccessful Discovery Business 10/25/04 Pharmacopeia Announces Expanded Collaboration with Neurocrine 10/26/04 Biovitrum AB and Pharmacopeia Form Strategic Research Alliance 1119104 Pharmacopeia Delivers Development Candidate and Achieves Research Milestone With Organon 11130104 Pharmacopeia Delivers D
Slide 8: Business Evolution
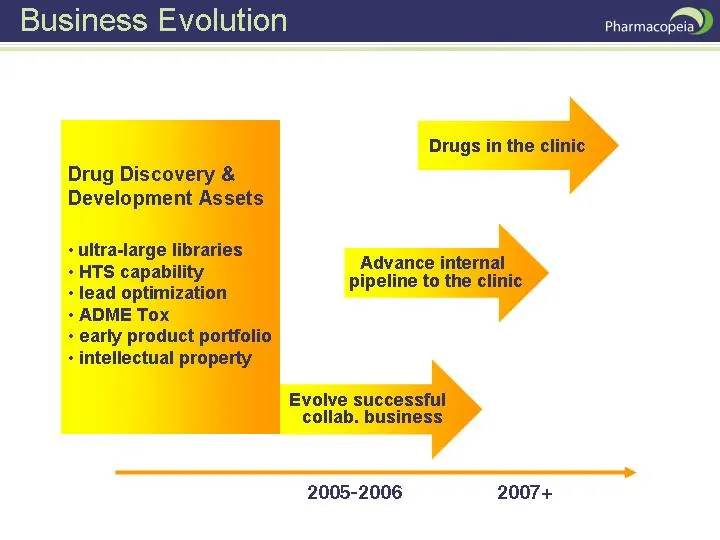
Business Evolutio Drugs in the clinic Drug Discovery & Development Assets — -ultra-t libraries: aa Advance internal pipeline to the clinic ~ + lead optimization + ADME Tox + early product portfolio + intellectual property — Evolve successful collab. business 2005-2006 2007+
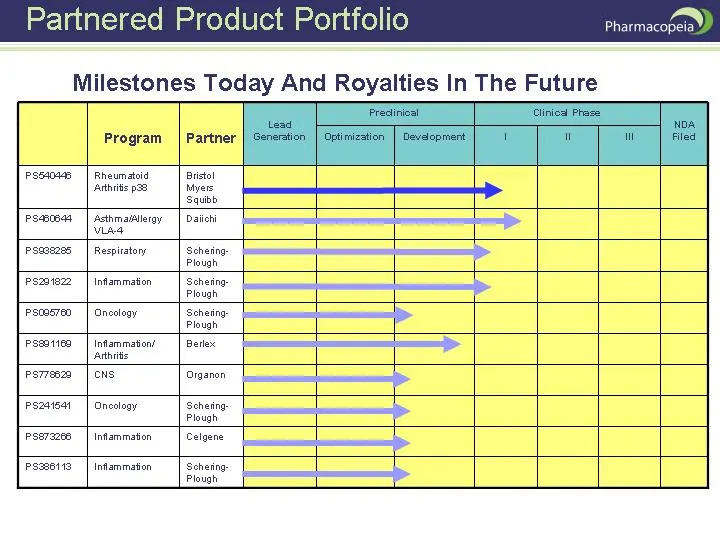
Slide 9: Milestones Today And Royalties In The Future
Milestones Today And Royalties In The Future Program | Partner Pscamas | Rheumatoid | Bristol FEES | Bigillos Toots T Paneres | Sroscay Svea me aw —— aati Psvzeeze | ens a a Peziieat | Oncoleay ae a Plough Pee7a286 | Intammaton | Celgene b PSH6118 | Infammaton | Scheing el —$———<— >
Slide 10: Implementation of strategy
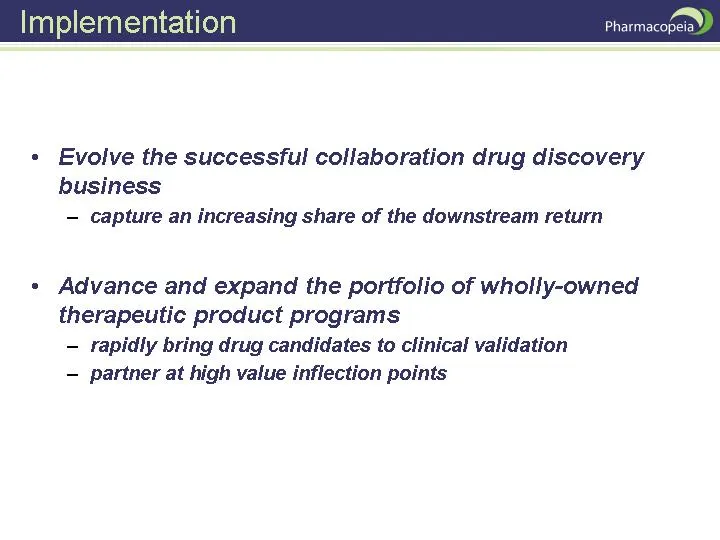
Implemen « Evolve the successful collaboration drug discovery business — capture an increasing share of the downstream return « Advance and expand the portfolio of wholly-owned therapeutic product programs — rapidly bring drug candidates to clinical validation — partner at high value inflection poin
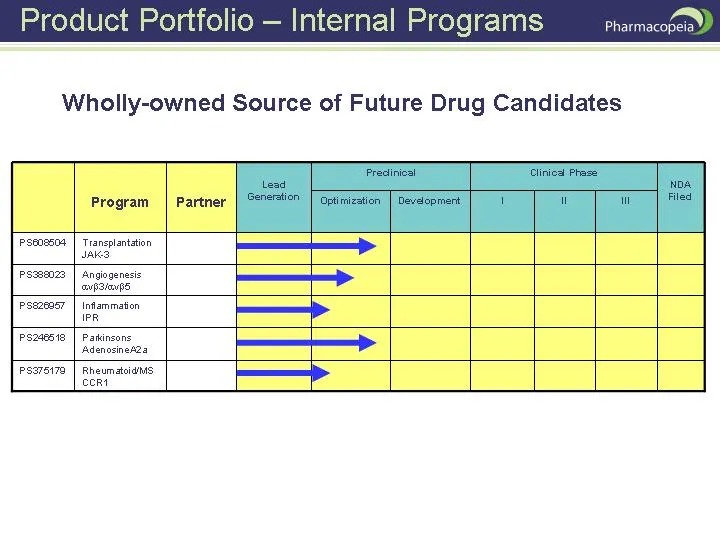
Slide 11: Wholly-owned Source of Future Drug Candidates
Wholly-owned Source of Future Drug Candidates ct Portfolio — Internal Programs Program Partner PSenEE04 Transplantation JAK Pewee ‘Angiogenesis coh 3h Paazeaer | intammaton — > PR Pa2ateie | Pakinzone Adenosinee2a Paarei7a | Rheumatoians cor
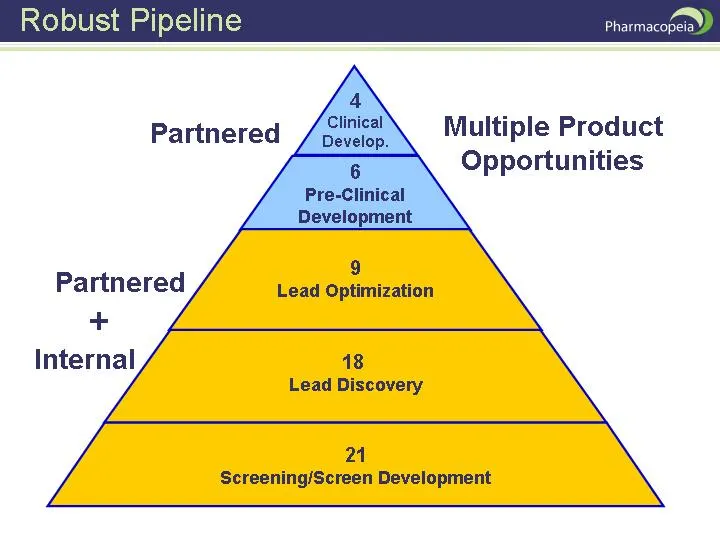
Slide 12: Robust Pipeline
Robust Pipeline Pharr Multiple Product Partnered ; Opportunities 9 Partnered Lead Optimization Internal 48 Lead Discovery 241 Screening/Screen Development
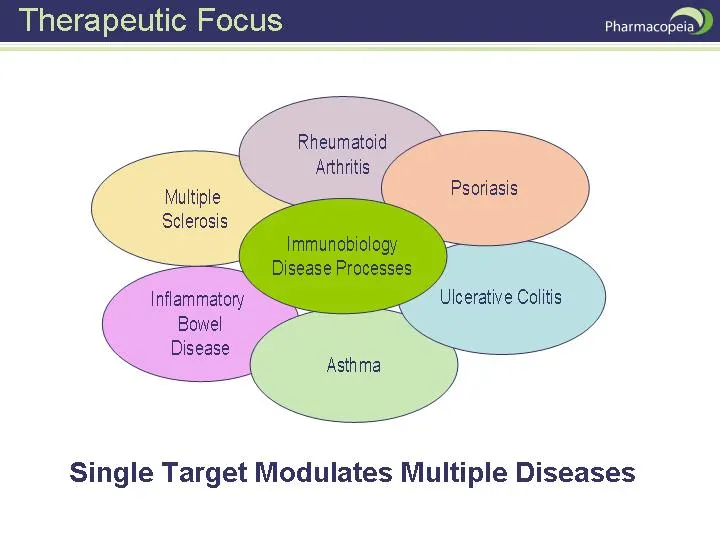
Slide 13: Therapeutic Focus
Therapeutic Focus eh Rheumatoid Arthritis“ Psoriasis Sclerosis 4 Ulcerative Colitis Inflammatory Bowel Disease Single Target Modulates Multiple Diseases
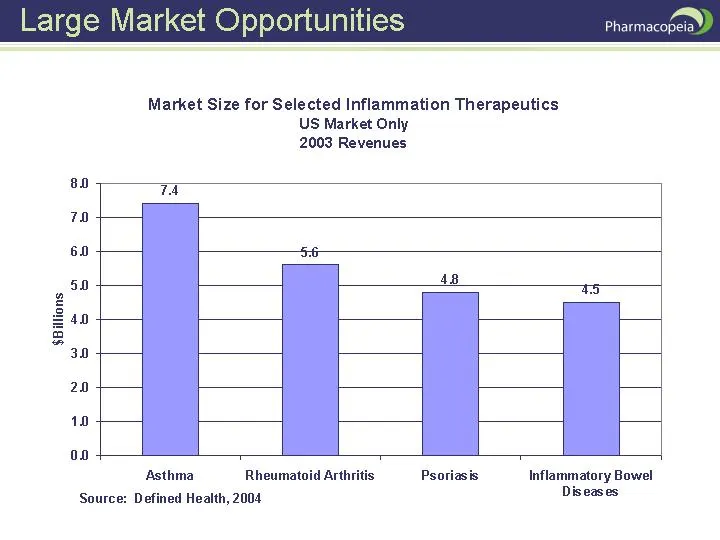
Slide 14: Market Opportunities
e Market Opportuniti ao 70 60 50 40 B 30 20 10 oo Source: Defined Health, 2004 Market Size for Selected Inflammation Therapeutics US Market Only 2003 Revenues 74 | | I | Asthma Rheumatoid Arthritis Psoriasis Inflammatory Bowel Diseases
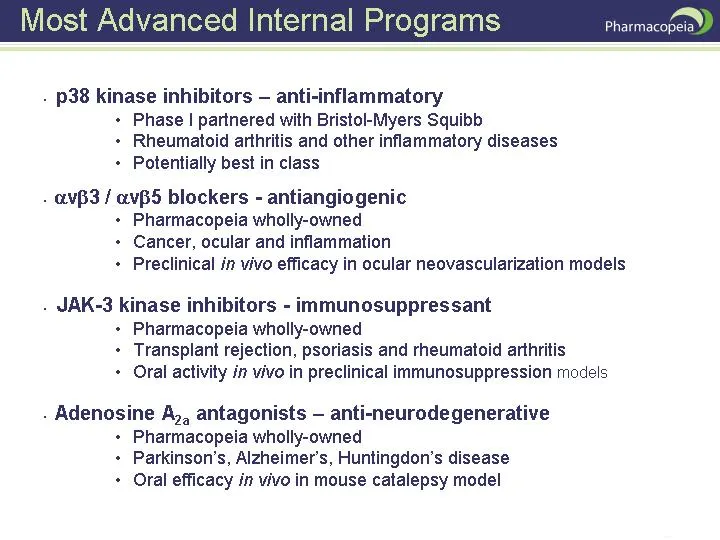
Slide 15: Advanced Internal Programs
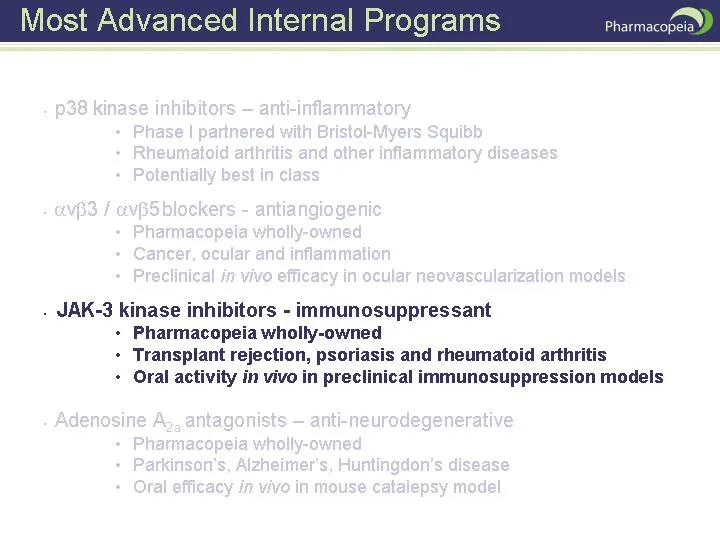
vanced Internal Programs . p38 kinase inhibitors — anti-inflammatory + Phase | partnered with Bristol-Myers Squibb + Rheumatoid arthritis and other inflammatory diseases + Potentially best in class - avB3 / avB5 blockers - antiangiogenic + Pharmacopeia wholly-owned + Cancer, ocular and inflammation
Slide 16: Most Advanced Internal Programs: p38 kinase inhibitors
Most Advanced In - p38 kinase inhibitors — anti-inflammatory + Phase | partnered with Bristol-Myers Squibb + Rheumatoid arthritis and other inflammatory diseases + Potentially best in class
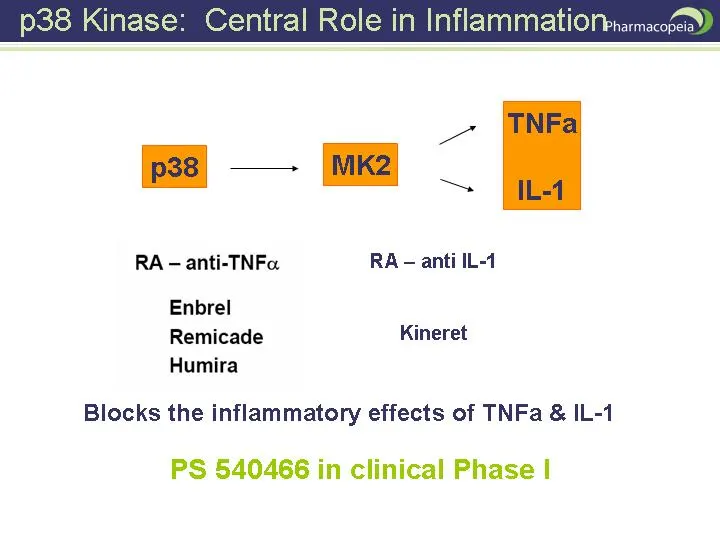
Slide 17: RA – anti-TNFa, anti-IL-1
RA — anti-TNFo RA - anti IL-1 Enbrel Remicade Kineret Humira Blocks the inflammatory effects of TNFa & IL-1 PS 540466 in clinical Phase |
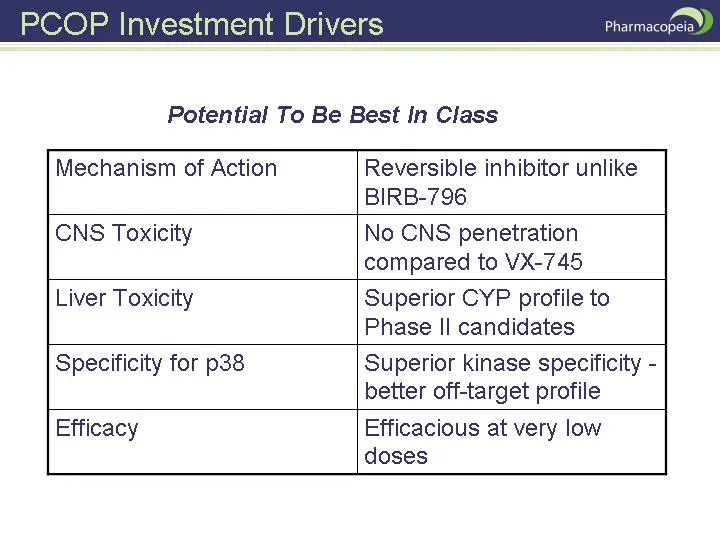
Slide 18: PCOP Investment: Potential To Be Best In Class
PCOP Investme Potential To Be Best In Class Mechanism of Action Reversible inhibitor unlike BIRB-796 CNS Toxicity No CNS penetration compared to VX-745 Liver Toxicity Superior CYP profile to Phase II candidates Specificity for p38 Superior kinase specificity - better off-target profile Efficacy Effi
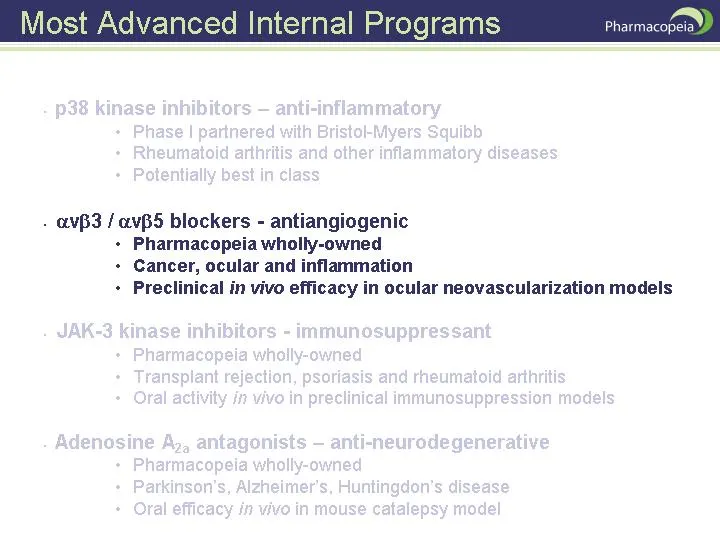
Slide 19: avB3 / avB5 blockers - antiangiogenic
- avp3 / avB5 blockers - antiangiogenic + Pharmacopeia wholly-owned + Cancer, ocular and inflammation + Preclinical in vivo efficacy in ocular neovascularization models
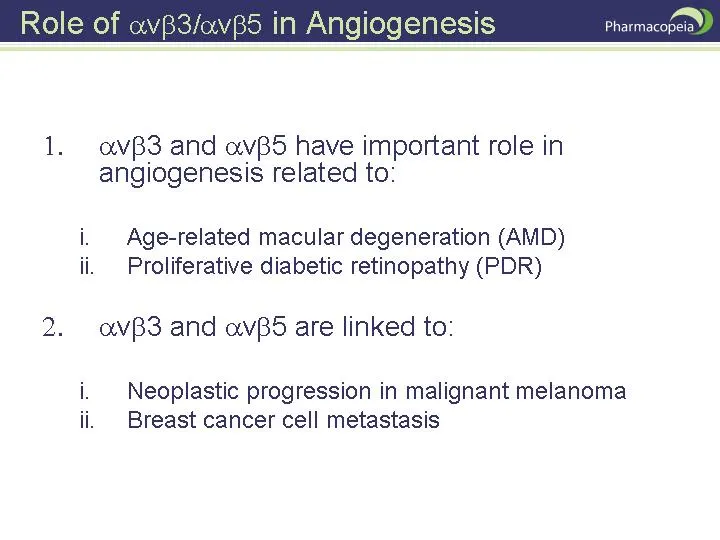
Slide 20: Role of avB3/avB5 in Angiogenesis
Role of avB3/avps in Angiogen 1. avB3 and avB5 have important role in angiogenesis related to: i. Age-related macular degeneration (AMD) ii. Proliferative diabetic retinopathy (PDR) 2. avB3 and avB5 are linked to: i. Neoplastic progression in malignant melanoma ii, Breast cancer cell metastasis
Slide 21: PS388023 In Vivo Antiangiogenic Activity
PS388023 In Vivo Antiangiogenic « PS388023 active fn vivo upon i.p. administration « Equally efficacious to Irinotecan in bFGF-induced corneal neovascularization in the rat « Superior efficacy to cCRGD peptide in a hypoxia- induced rat model of retinal neovascularization
Slide 22: Most Advanced Internal Programs: JAK-3 kinase inhibitors
Most Advanced Int . JAK-3 kinase inhibitors - immunosuppressant + Pharmacopeia wholly-owned + Transplant rejection, psoriasis and rheumatoid arthritis + Oral activity in vivo in preclinical immunosuppression models
Slide 23: Immunosuppressive Agents
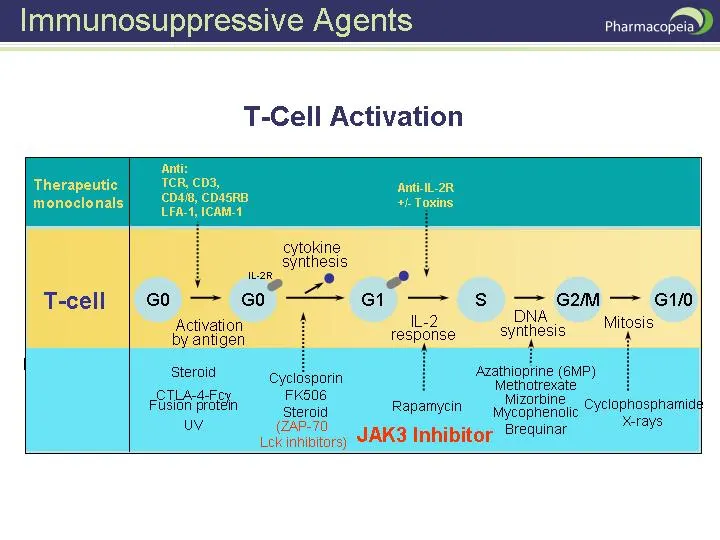
Immunosuppressive Agents T-Cell Activation cytokine synthesis i “ye 2 T-cell | GO — co G1 s 62M G10 DNA Activation L2 Mitosis by antigen response —_symitiesis ry Steroid 5 Azathioprine (6MP) ene) Methotrexate oa oy Serald Rapamycin 4hlzarelne Sa eee (ZAP-70, . ct Lokinhiotors) YAK3 Inhibitor Presuna
Slide 24: Orally Active JAK-3 Inhibitors
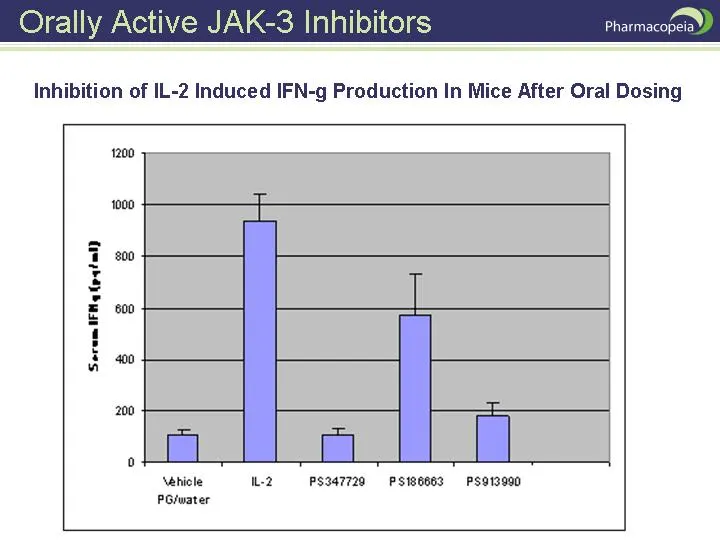
Orally Active JAK-3 Inhibitors Pharmacopeia Inhibition of IL-2 Induced IFN-g Production In Mice After Oral Dosing SoremIFNq(pqinl) 200 a 2 Ps347720 Psis666s Pso1s990
Slide 25: JAK-3 competitive landscape: clinical and preclinical
¢ Clinical - Pfizer — PIl for psoriasis — Transplant ¢ Preclinical — Pharmacopeia — Cytopia — Novartis — Aventis — J&J
Slide 26: Most Advanced Internal Programs: Adenosine A2a antagonists
Most Advanced Int . Adenosine A,, antagonists — anti-neurodegenerative + Pharmacopeia wholly-owned + Parkinson’s, Alzheimer’s, Huntingdon’s disease + Oral efficacy in vivo in mouse catalepsy model
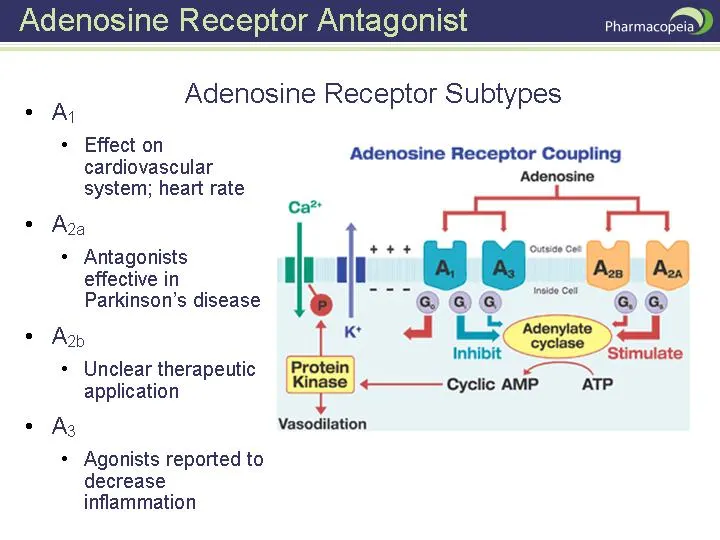
Slide 27: Adenosine Receptor Subtypes
Adenosine Receptor Subtypes - A * Effect on i Adenosine Receptor Coupling cardiovascular ‘Adenosine system; heart rate ca a eS ° Ara + Antagonists Outsce Cot effective in lai Parkinson’s disease hy Le @ Leet Ker + Unclear therapeutic application < Cyclic ave ATP © As Vasodilation + Agonists reported
Slide 28: Adenosine A2a Receptor Neurodegenerative Disease Indications
Adenosine A,, Rece Neurodegenerative Disease Indications « Ao, receptor antagonists potentiate the anti-parkinsonian response to levodopa in patients, with less dyskinesia * Ao, receptors may play a more global role in neuronal injury and degeneration * Ao, antagonists demonstrate a protective role
Slide 29: A2a Program Status
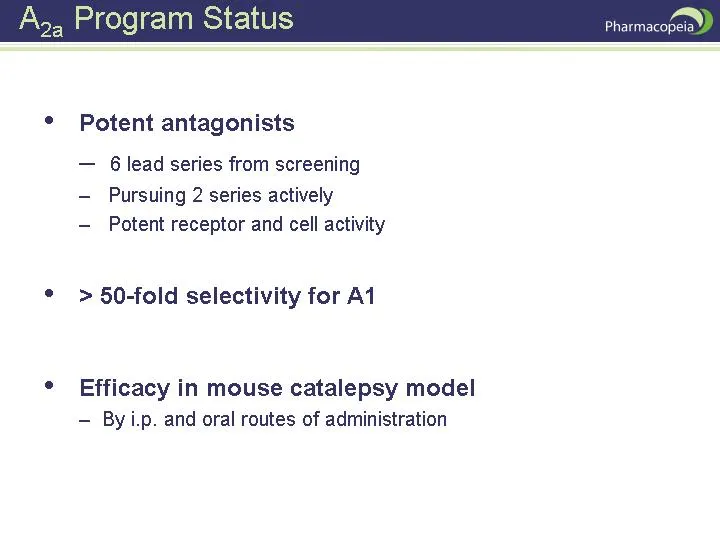
A,, Program Sta ¢ Potent antagonists — 6 lead series from screening — Pursuing 2 series actively — Potent receptor and cell activity ° > 50-fold selectivity for A1 ° Efficacy in mouse catalepsy model — Byi.p. and oral routes of administration
Slide 30: Q1 2005 Financial Data
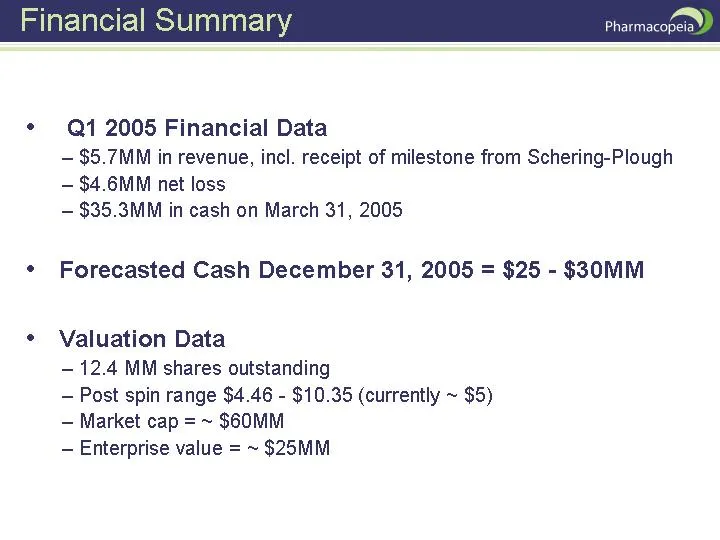
Q1 2005 Financial Data — $5.7MM in revenue, incl. receipt of milestone from Schering-Plough — $4.6MM net loss — $35.3MM in cash on March 31, 2005 Forecasted Cash December 31, 2005 = $25 - $30MM Valuation Data - 12.4 MM shares outstanding — Post spin range $4.46 - $10.35 (currently ~ $5) — Market cap
Slide 31: Searchable text section of graphics
Searchable text section of graphics shown above [ LOG O] [LOGO] Pacific Growth Equities Life Sciences Growth Conference San Francisco, California June 6-8 th , 2005 For ward-Looking Statements When used anywhere in this presentation the words “expects,” “believes,” “anticipates,” “estimates” and sim
Source: SEC EDGAR · 8-K filed Jun 3, 2005
More decks from Pharmacopeia Inc
 Pharmacopeia — Merger or Acquisition (November 2008)34 slides · Nov 3, 2008
 The Oppenheimer 19th Annual Healthcare Conference (November 2008)33 slides · Nov 3, 2008
 Ligand Pharmaceuticals — Merger or Acquisition (September 2008)18 slides · Sep 24, 2008
 BMO Capital Markets 7th Annual Focus on Healthcare Conference 200822 slides · Aug 5, 2008
 Investor Presentation (May 2008)36 slides · May 19, 2008
 Investor Presentation (May 2008)11 slides · May 16, 2008