Quadient SA · EURONEXT:QDT
Quadient SA — Neopost — Investor Day (January 2019)
120 slides from Quadient SA's investor day presentation, Jan 23, 2019
Slide 1: Capital Markets Day
CAPITAL MARKETS DAY 23 January 2019
Slide 2: Limitation of Liability
LIMITATION OF LIABILITY Forward-looking statement (Safe Harbour) This presentation contains forward-looking statements (made pursuant to the safe harbour provisions of the Private Securities Litigation Reform Act of 1995), which, by their nature, involve a degree of risk and uncertainty. Forward-loo
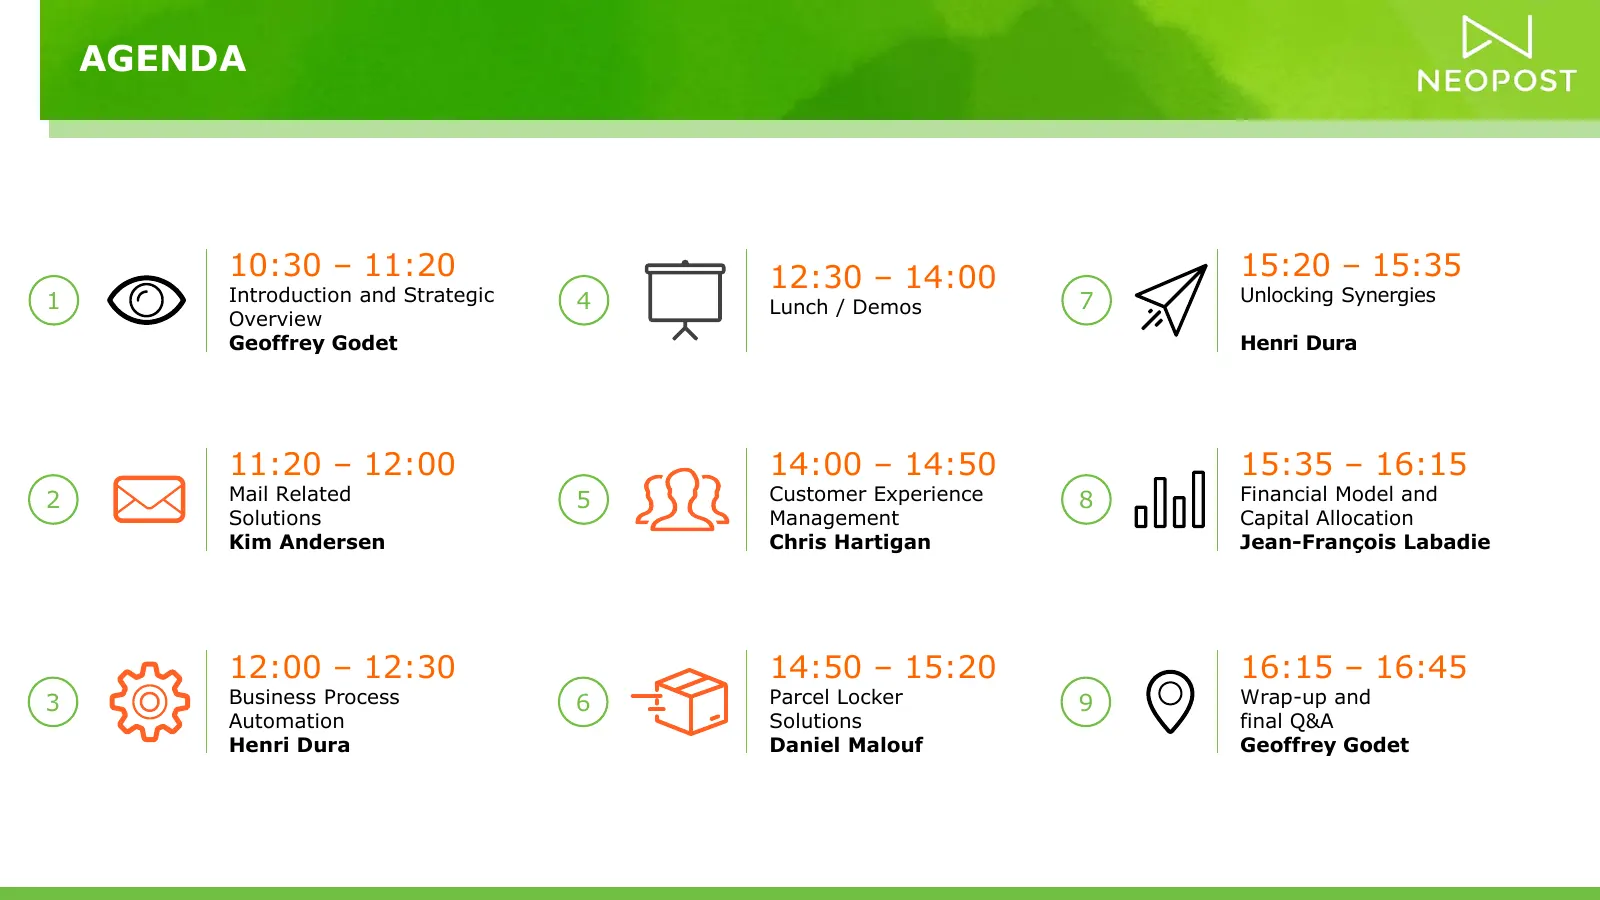
Slide 3: Agenda
AGENDA 10:30 – 11:20 12:30 – 14:00 15:20 – 15:35 1 Introduction and Strategic 4 7 Unlocking Synergies Lunch / Demos Overview Geoffrey Godet Henri Dura 11:20 – 12:00 14:00 – 14:50 15:35 – 16:15 2 Mail Related 5 Customer Experience 8 Financial Model and Solutions Management Capital Allocation Kim Ande
Slide 4: Back to Growth: Introduction and Strategic Overview
Back to Growth Introduction and Strategic Overview • Geoffrey Godet • Chief Executive Officer
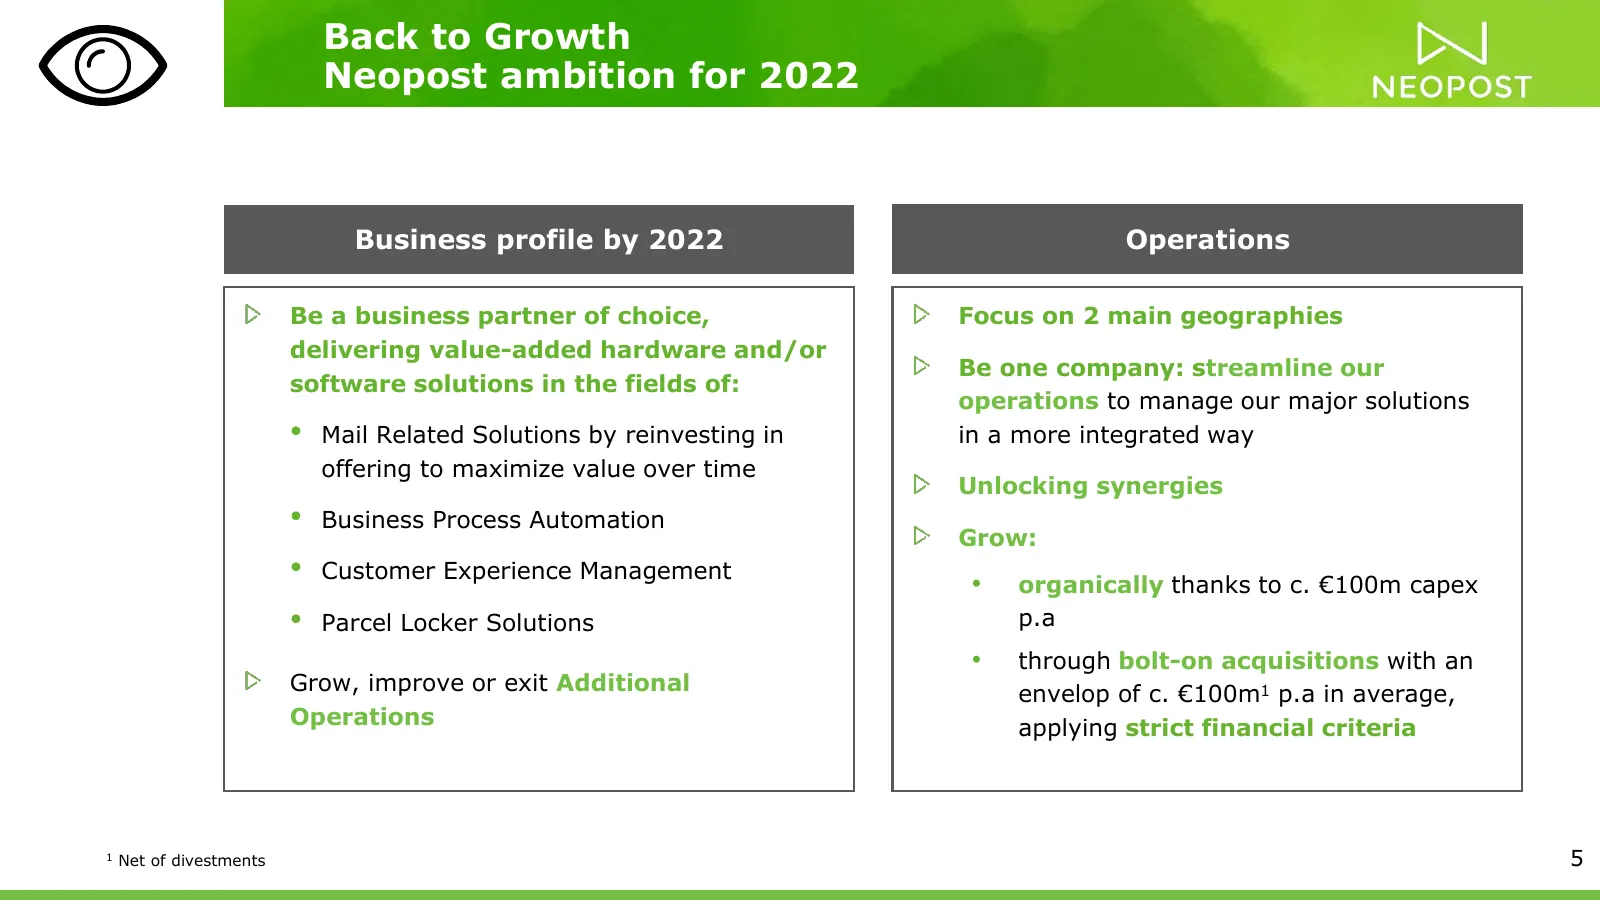
Slide 5: Neopost ambition for 2022
Back to Growth Neopost ambition for 2022 Business profile by 2022 Operations Be a business partner of choice, Focus on 2 main geographies delivering value-added hardware and/or Be one company: streamline our software solutions in the fields of: operations to manage our major solutions • Mail Related
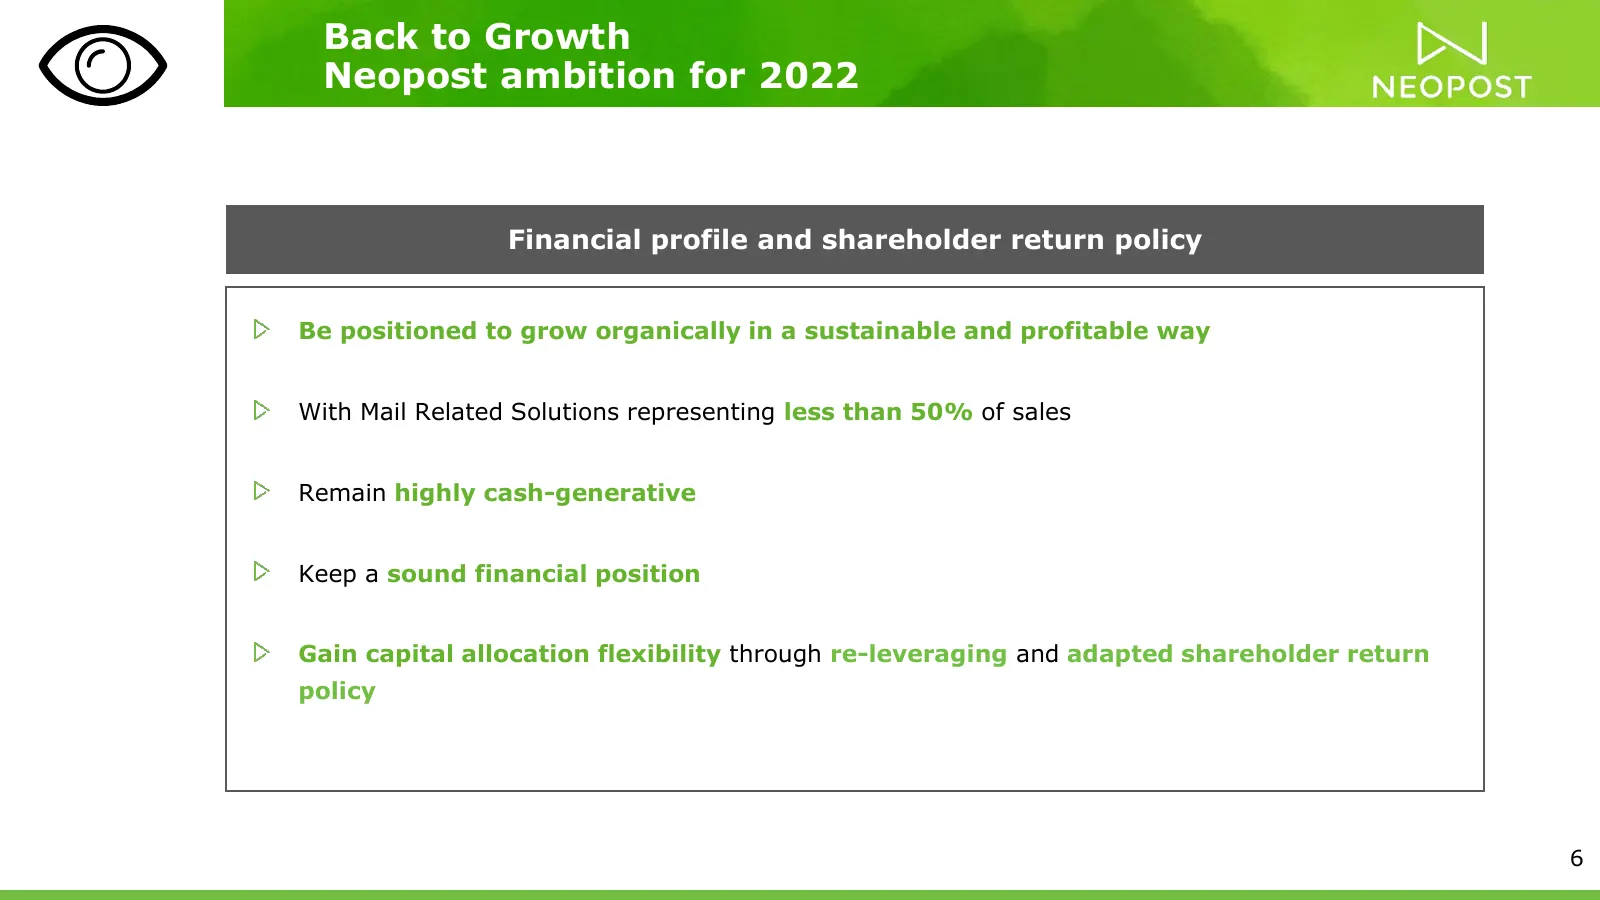
Slide 6: Neopost ambition for 2022: financial profile and shareholder return
Back to Growth Neopost ambition for 2022 Financial profile and shareholder return policy Be positioned to grow organically in a sustainable and profitable way With Mail Related Solutions representing less than 50% of sales Remain highly cash-generative Keep a sound financial position Gain capital al
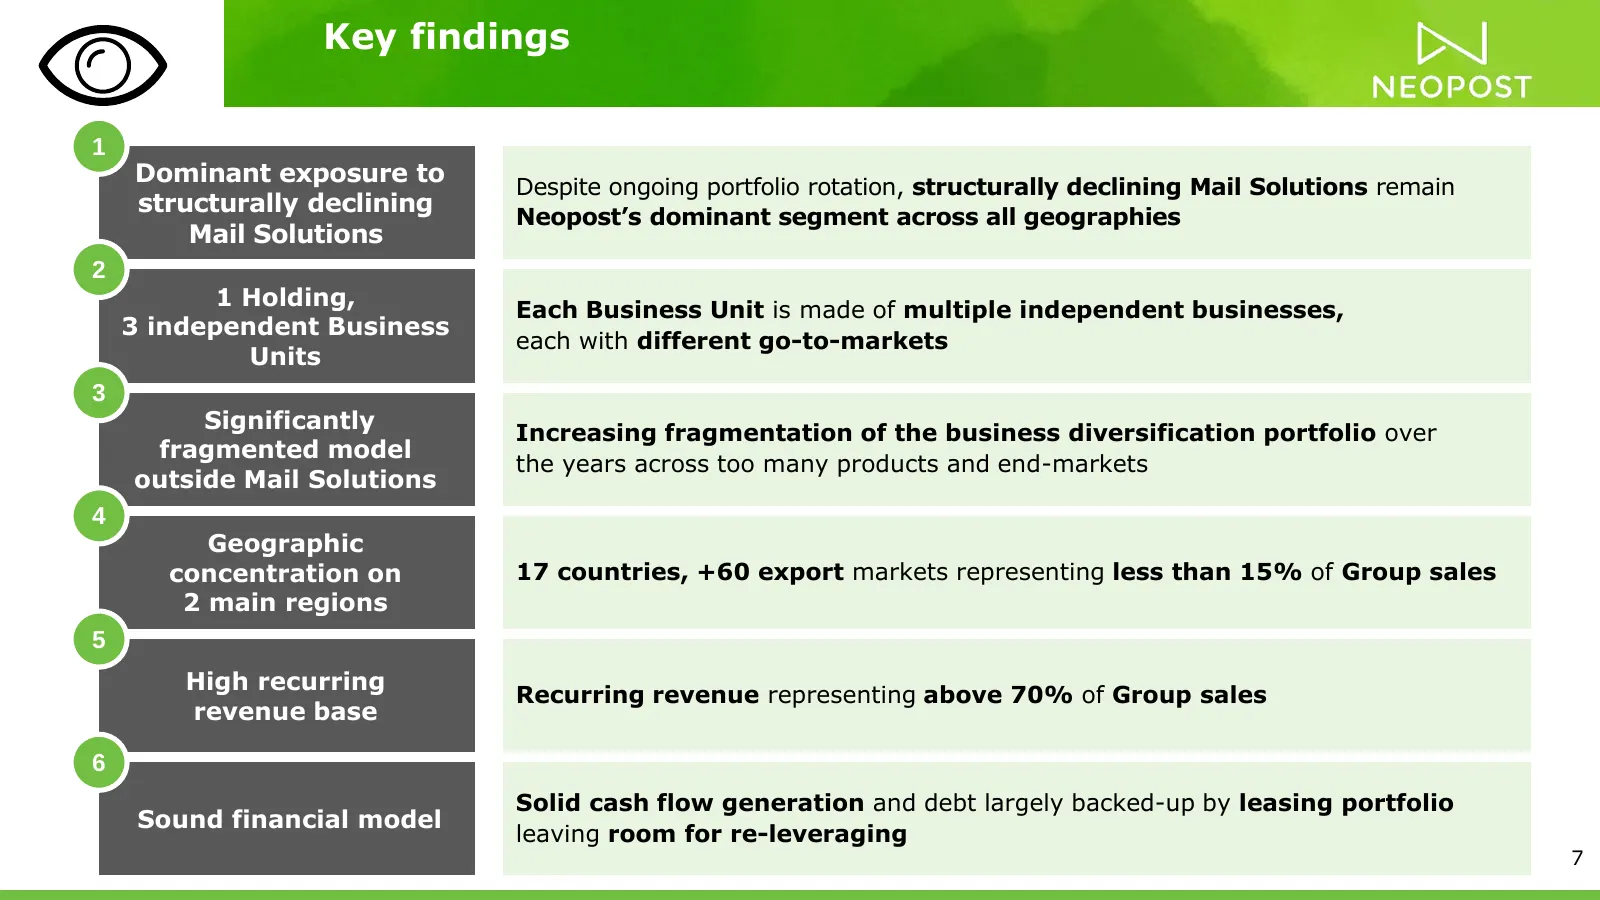
Slide 7: Key findings
Key findings 1 Dominant exposure to Despite ongoing portfolio rotation, structurally declining Mail Solutions remain structurally declining Neopost’s dominant segment across all geographies Mail Solutions 2 1 Holding, Each Business Unit is made of multiple independent businesses, 3 independent Busin
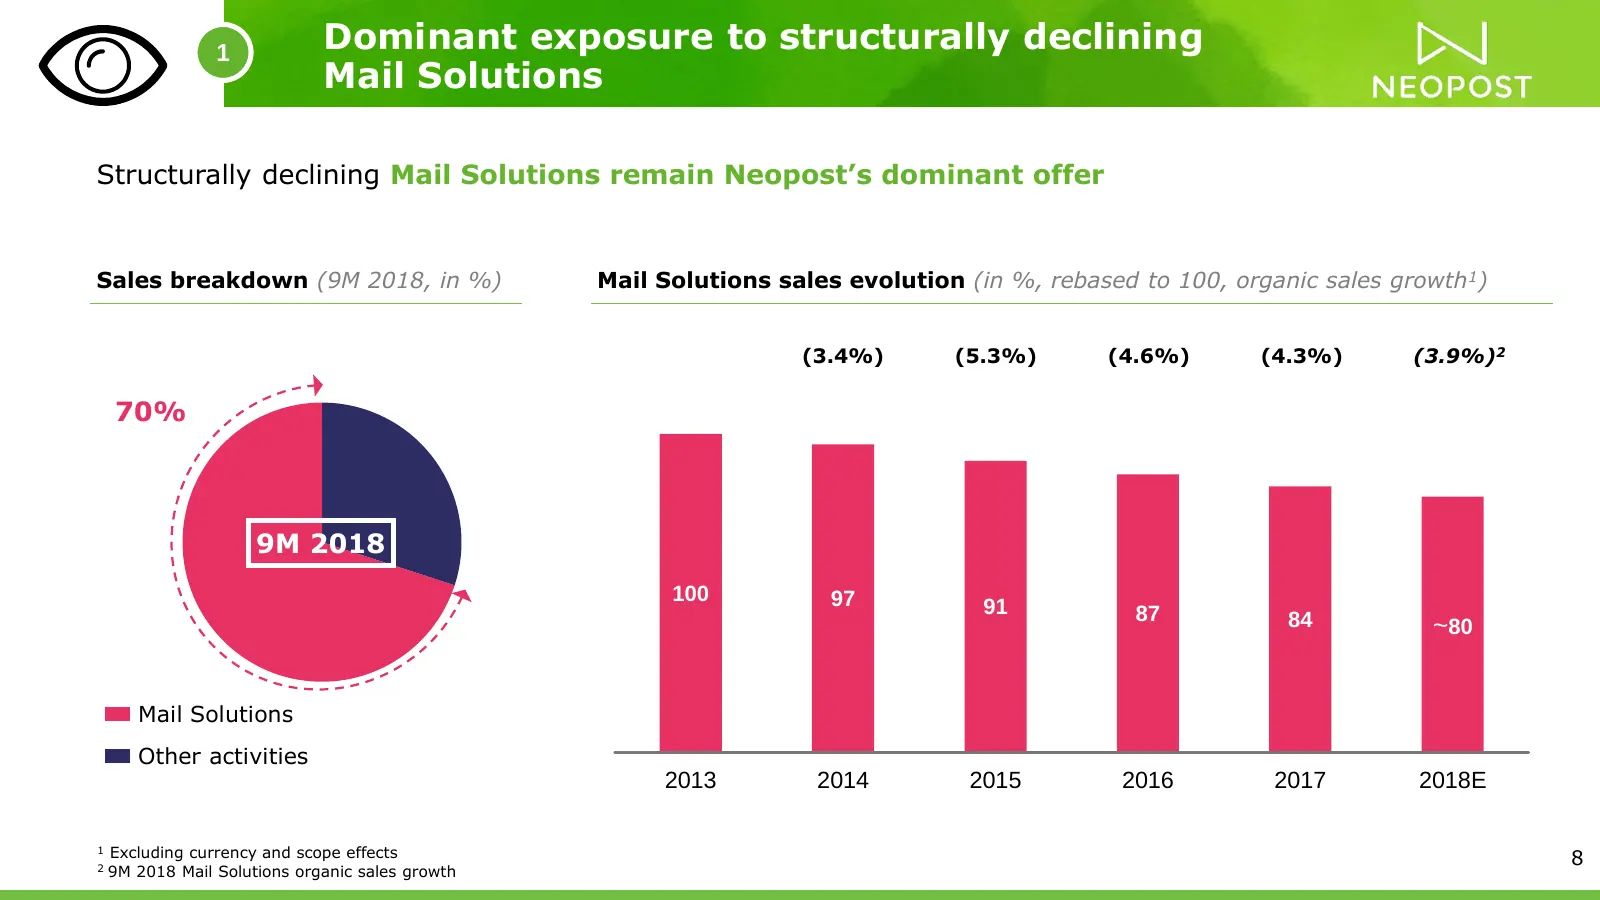
Slide 8: Dominant exposure to structurally declining Mail Solutions
1 Dominant exposure to structurally declining Mail Solutions Structurally declining Mail Solutions remain Neopost’s dominant offer Sales breakdown (9M 2018, in %) Mail Solutions sales evolution (in %, rebased to 100, organic sales growth1) (3.4%) (5.3%) (4.6%) (4.3%) (3.9%)2 70% 9M 2018 100 97 91 87
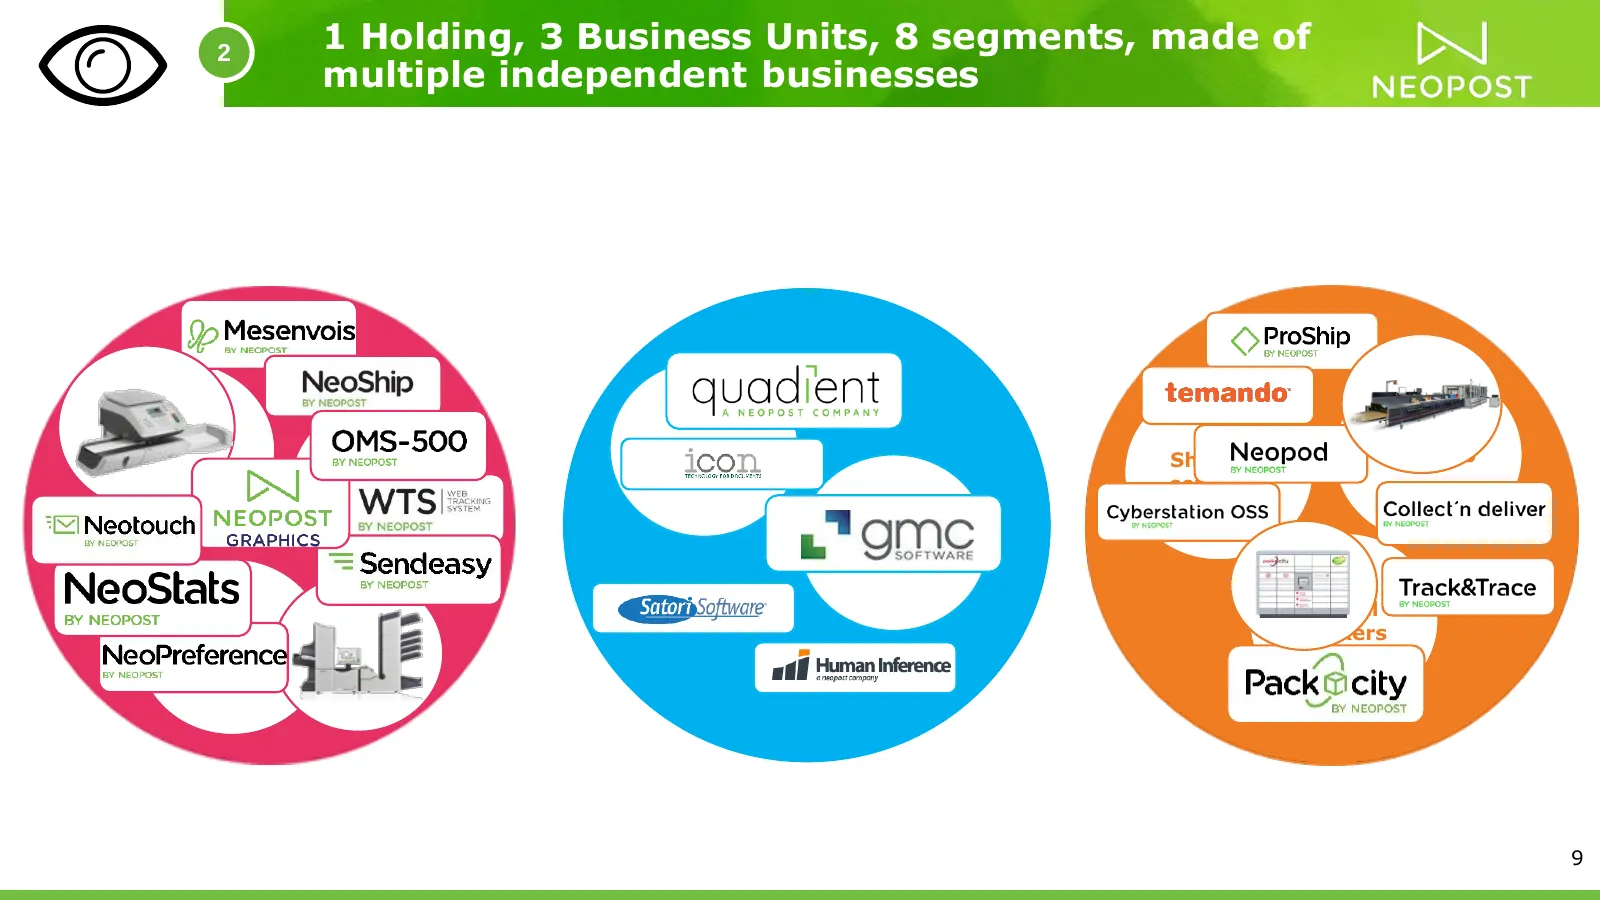
Slide 9: Holding, Business Units, segments, multiple independent businesses
2 1 Holding, 3 Business Units, 8 segments, made of multiple independent businesses ENTERPRISE Digital comm & DIGITAL CCM SOLUTIONS CVP-500 Shipping shipping Mail software Solutions Data Quality Parcel Lockers Graphics 9
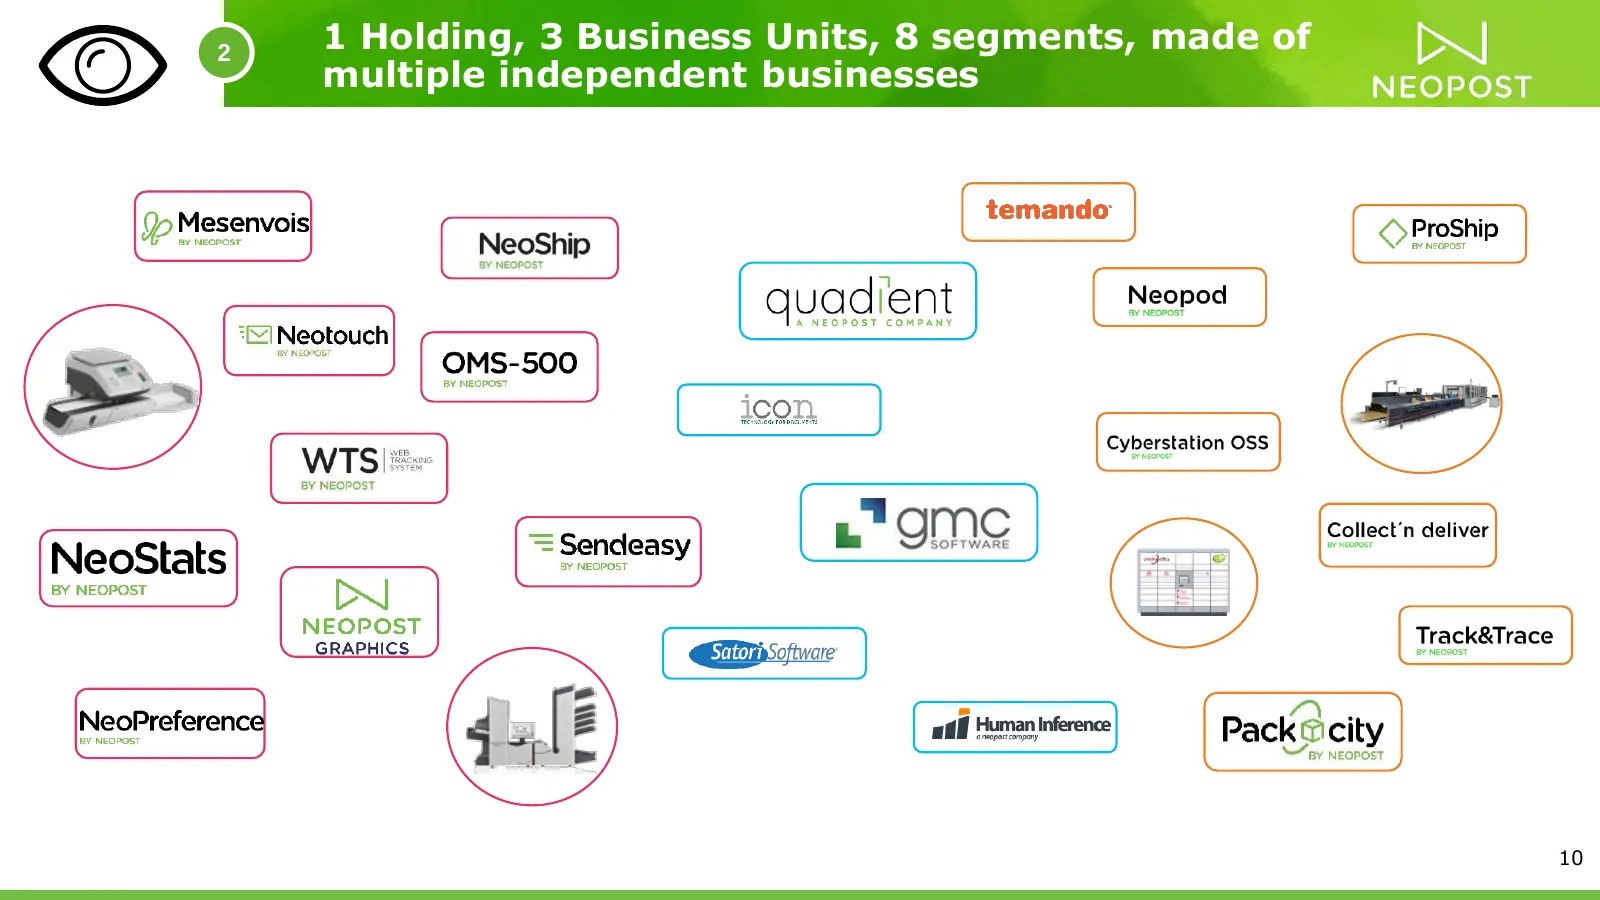
Slide 10: Holding, Business Units, segments, multiple independent businesses
2 1 Holding, 3 Business Units, 8 segments, made of multiple independent businesses 10
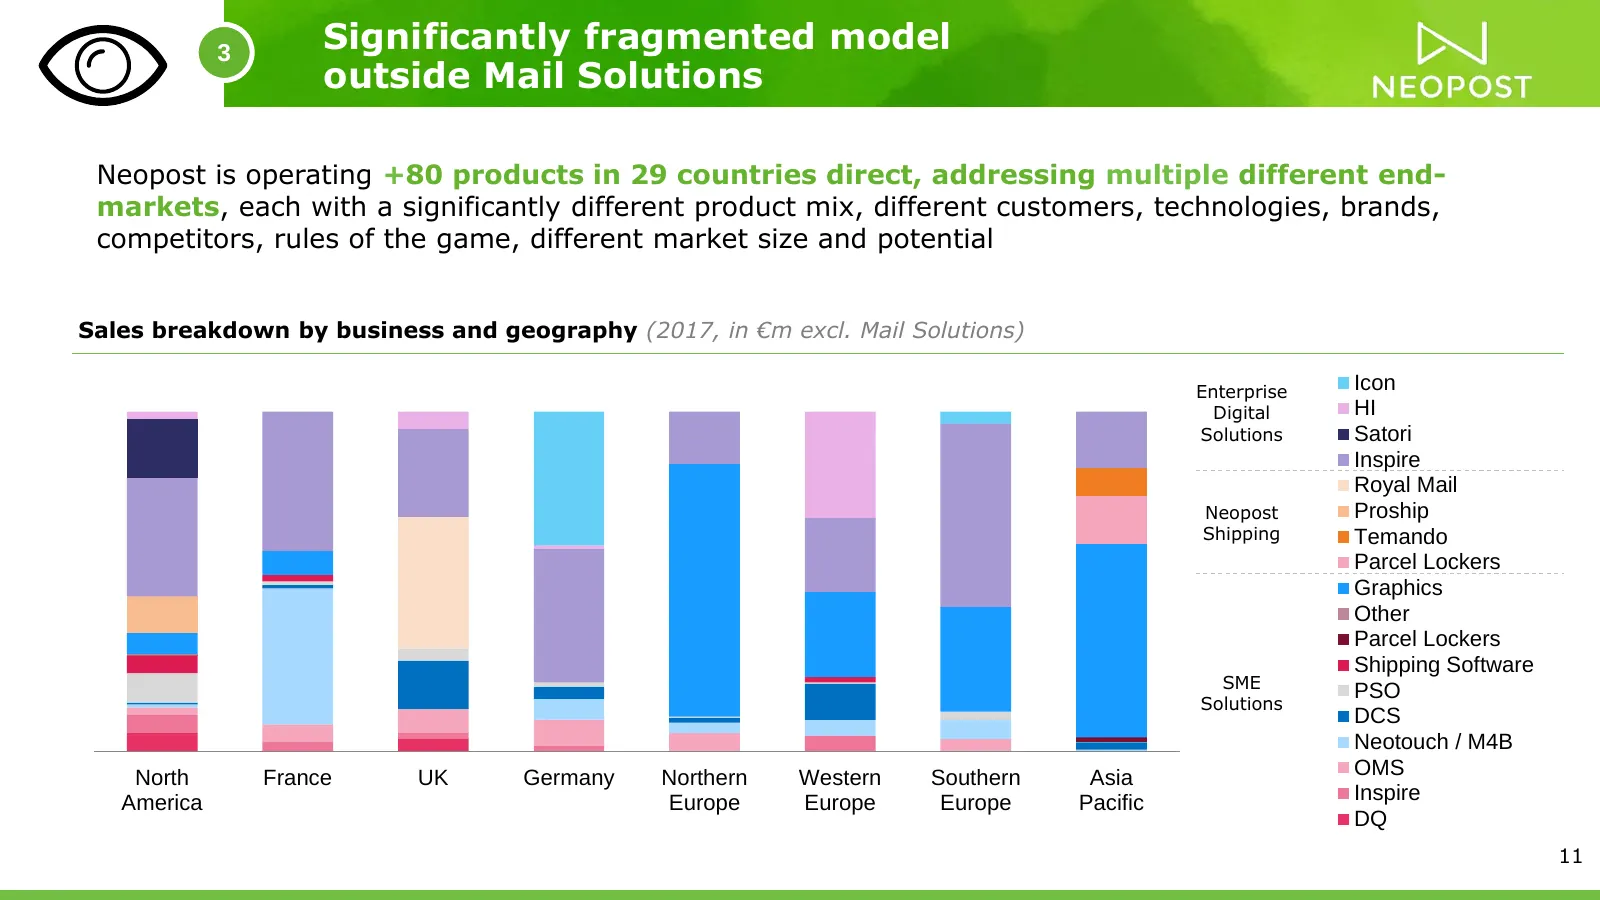
Slide 11: Significantly fragmented model outside Mail Solutions
3 Significantly fragmented model outside Mail Solutions Neopost is operating +80 products in 29 countries direct, addressing multiple different end- markets, each with a significantly different product mix, different customers, technologies, brands, competitors, rules of the game, different market s
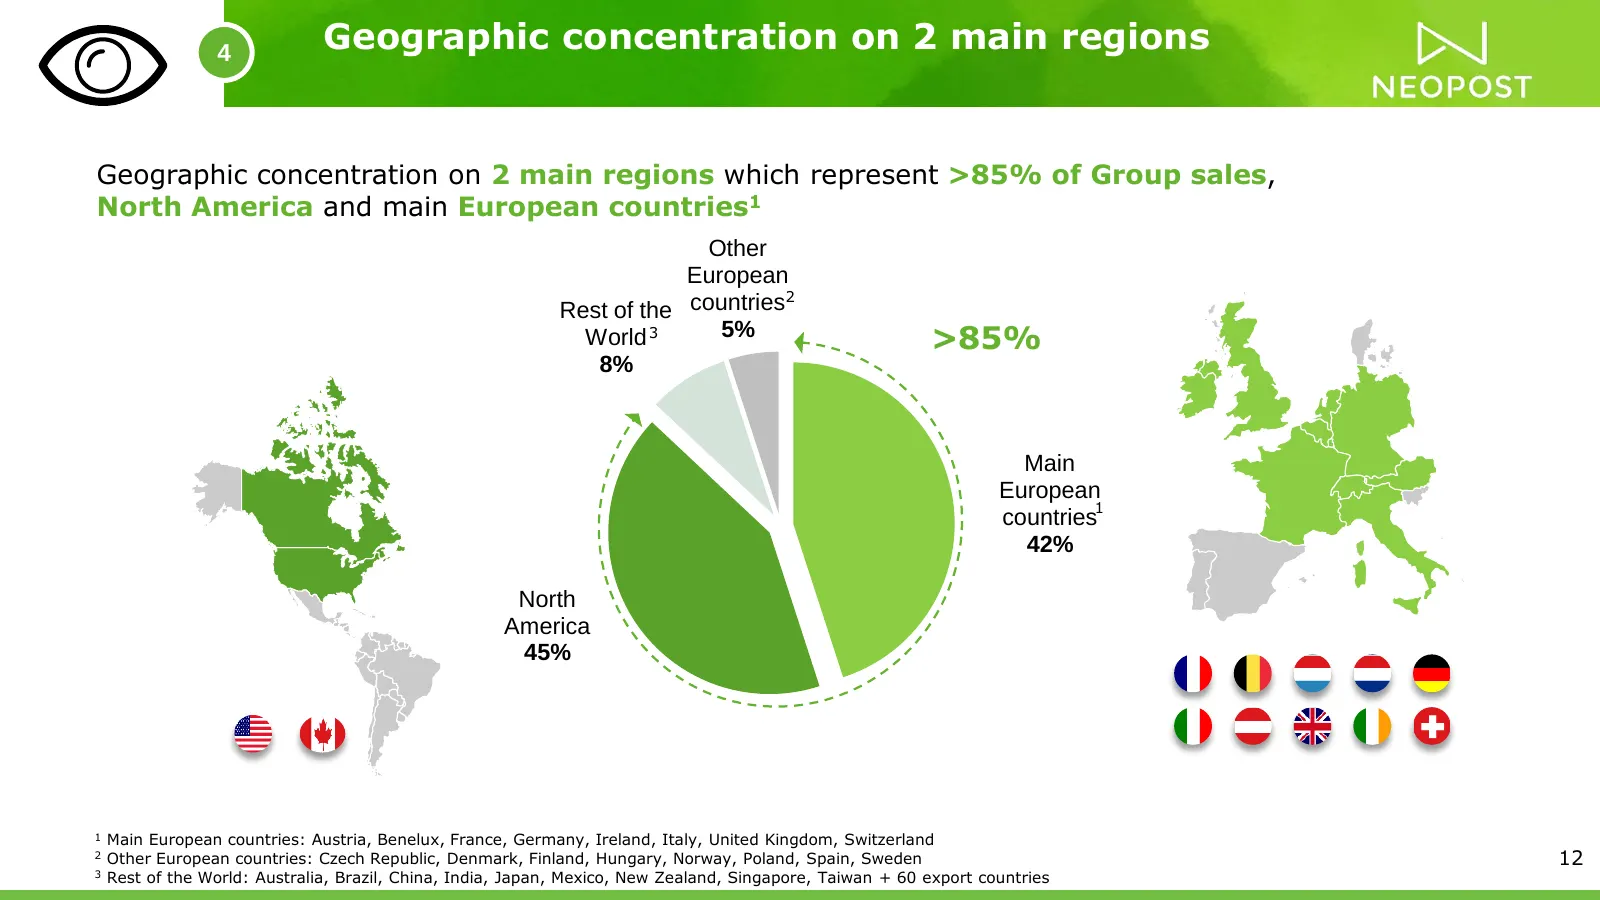
Slide 12: Geographic concentration on 2 main regions
4 Geographic concentration on 2 main regions Geographic concentration on 2 main regions which represent >85% of Group sales, North America and main European countries1 Other European 2 Rest of the countries World 3 5% >85% 8% Main European countries1 42% North America 45% 1 Main European countries:
Slide 13: High recurring revenue base
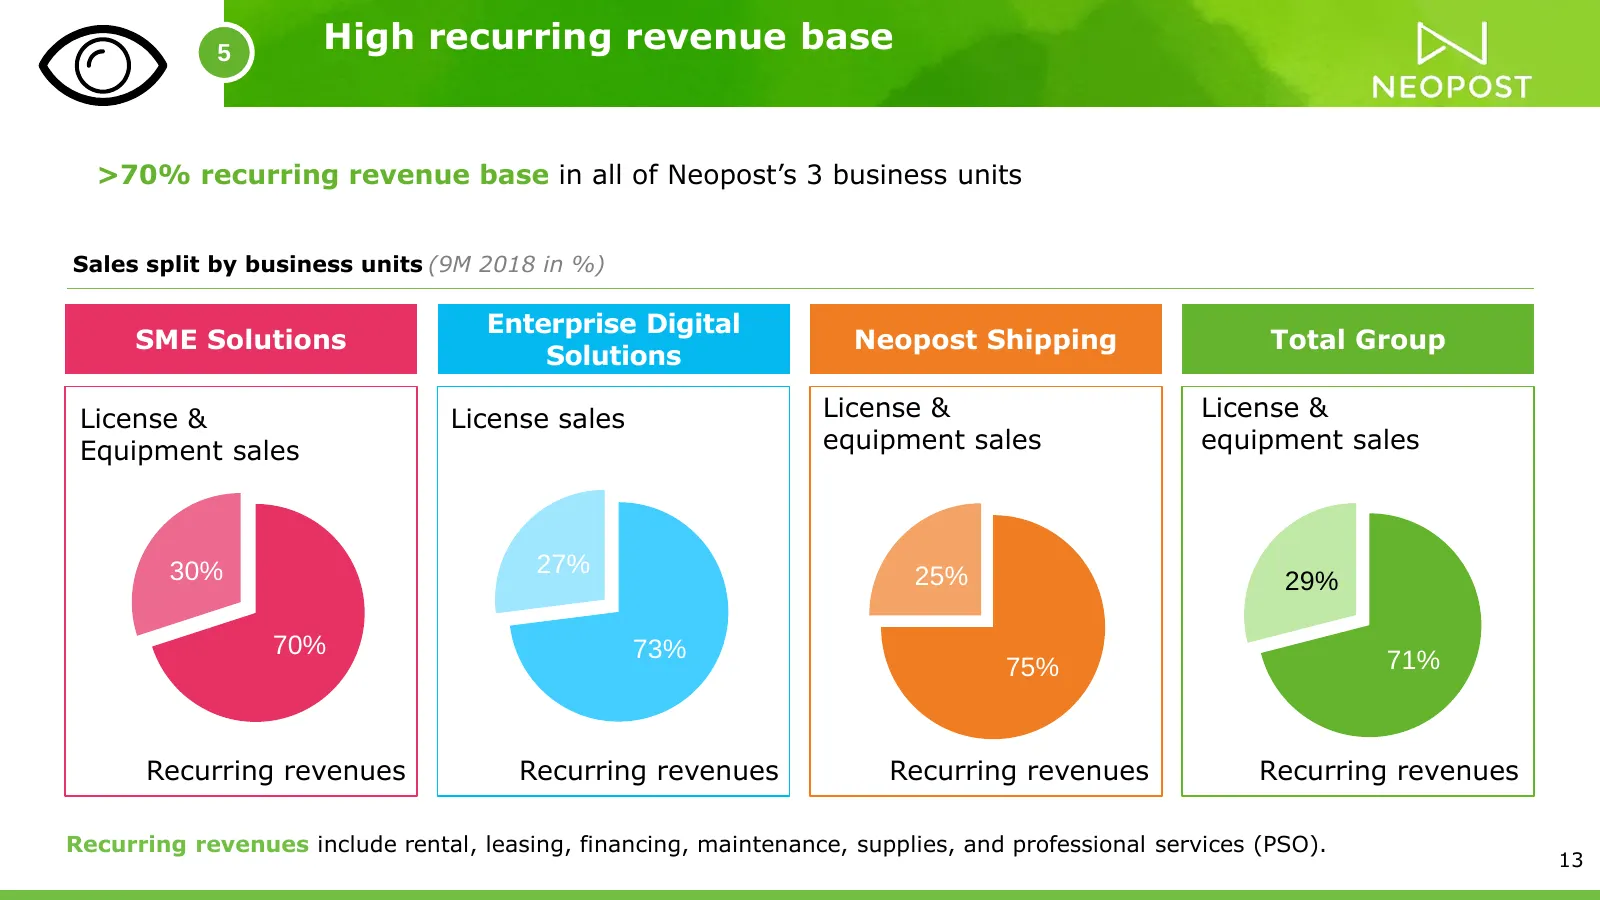
5 High recurring revenue base >70% recurring revenue base in all of Neopost’s 3 business units Sales split by business units (9M 2018 in %) Enterprise Digital SME Solutions Neopost Shipping Total Group Solutions License & License sales License & License & Equipment sales equipment sales equipment sa
Slide 14: Sound financial model with solid cash flow generation and low leverage
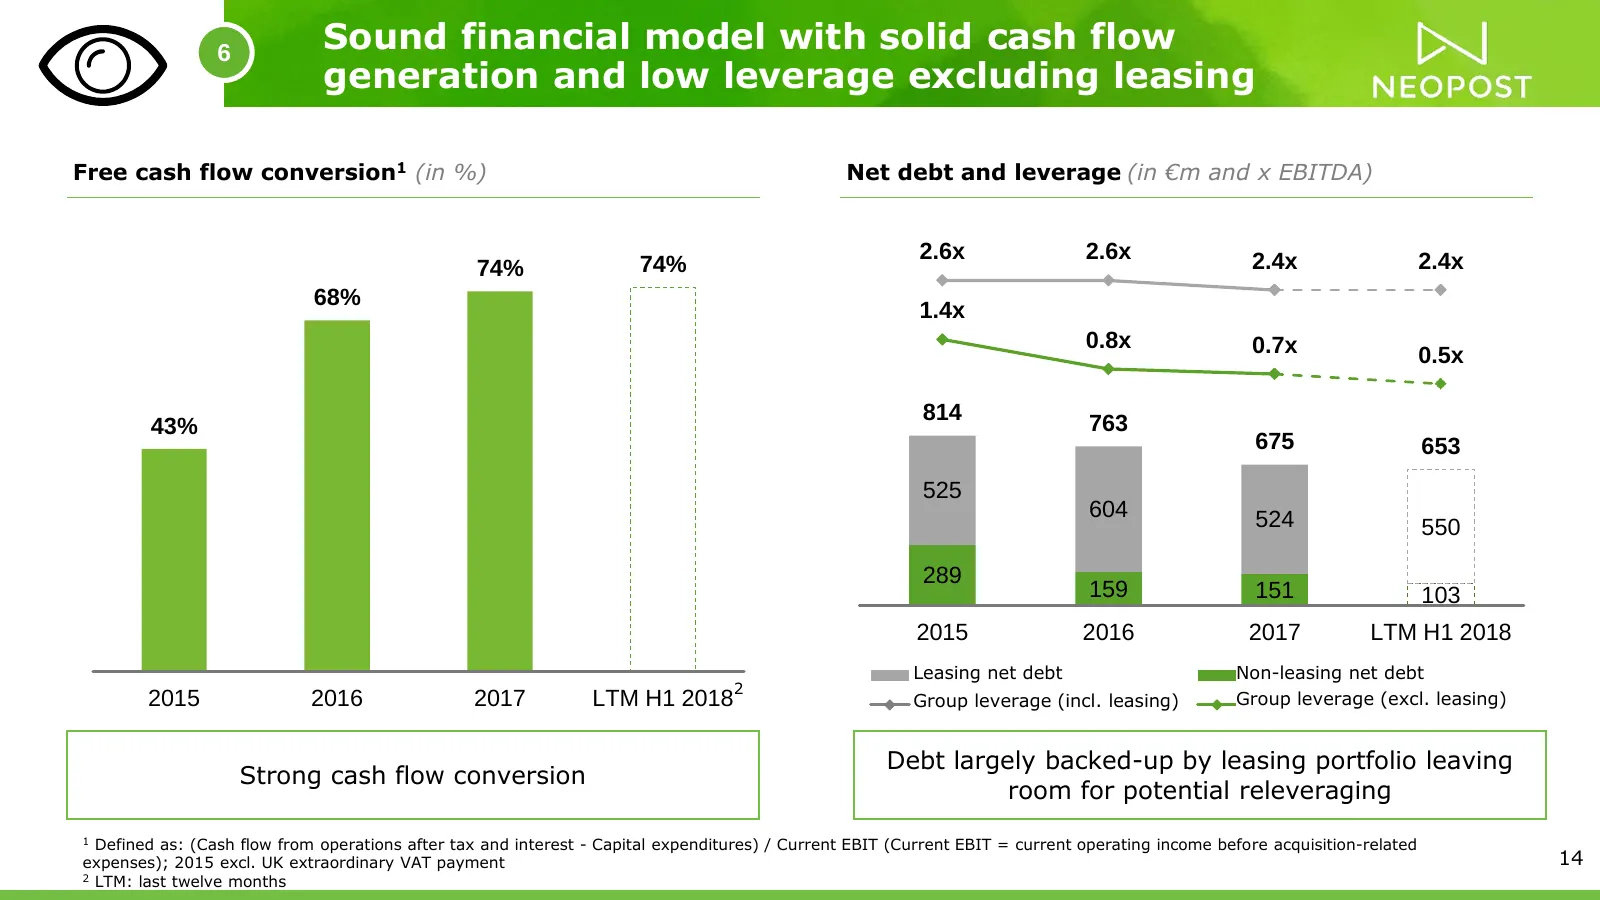
3.0x 6 Sound financial model with solid 2.2xcash 2.4x 2.2xflow 2.1x 2.4x 2.4x 2.6x 2.6x 2.4x 525 generation and low leverage 1.5x excluding leasing 565 590 448 1.0x 1.1x 1.2x 1.4x 604 426 500 0.8x 0.9x 0.9x 0.8x 0.7x 540 0.5x 524 0.3x 550 Free cash flow conversion1 (in %) Net debt and leverage (in €
Slide 15: Key convictions
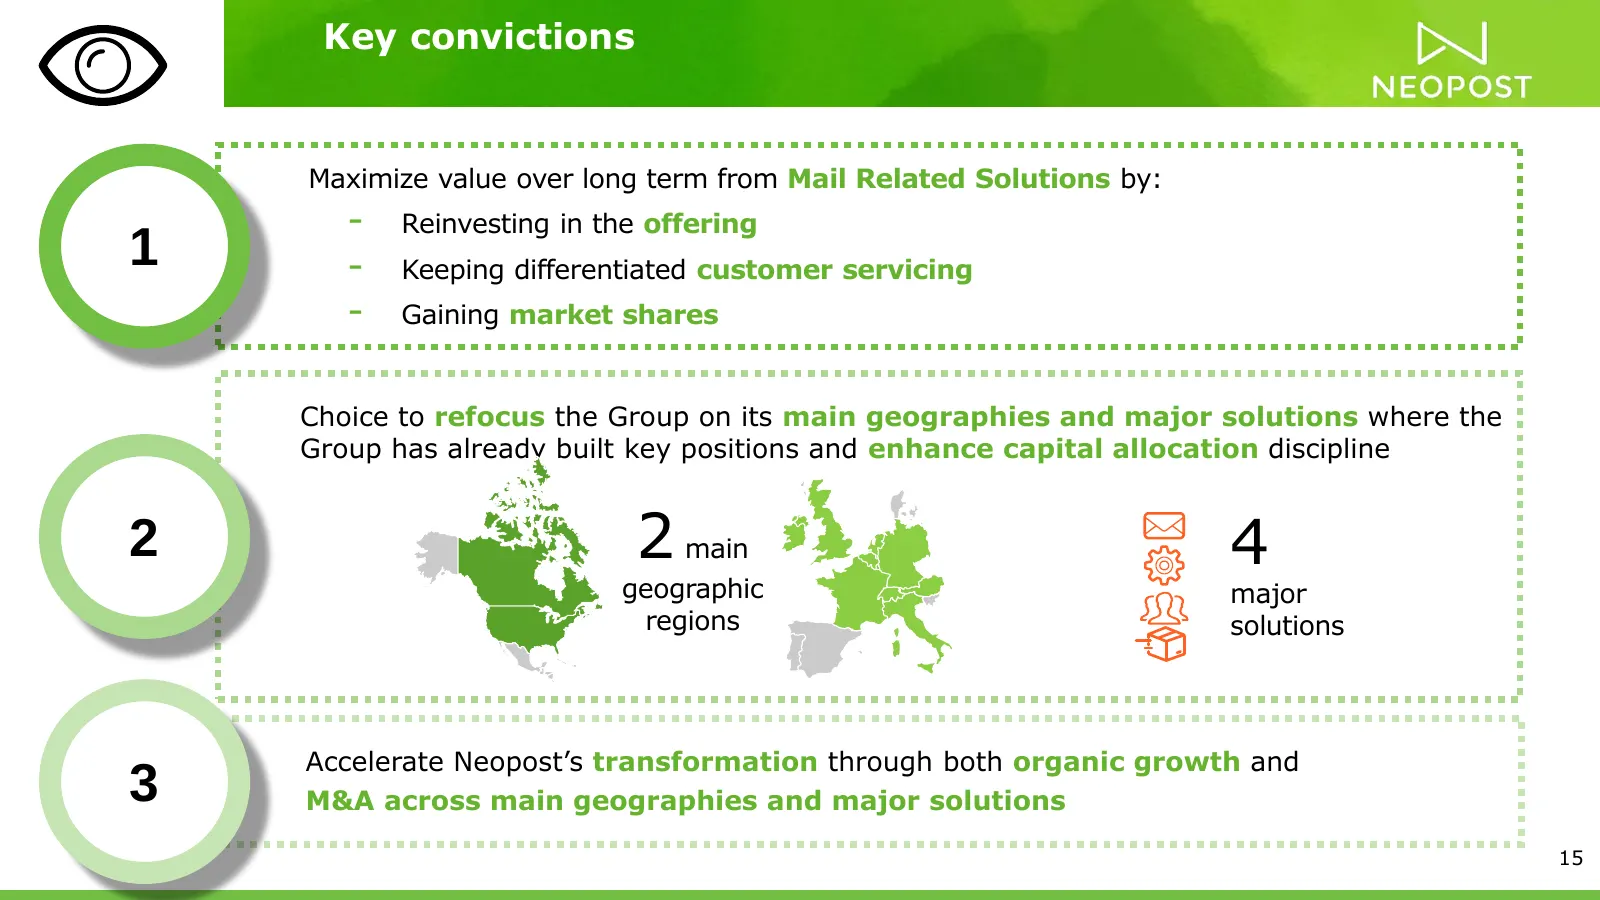
Key convictions Maximize value over long term from Mail Related Solutions by: - Reinvesting in the offering 1 - Keeping differentiated customer servicing - Gaining market shares Choice to refocus the Group on its main geographies and major solutions where the Group has already built key positions an
Slide 16: Maximize value over long term from Mail Related Solutions
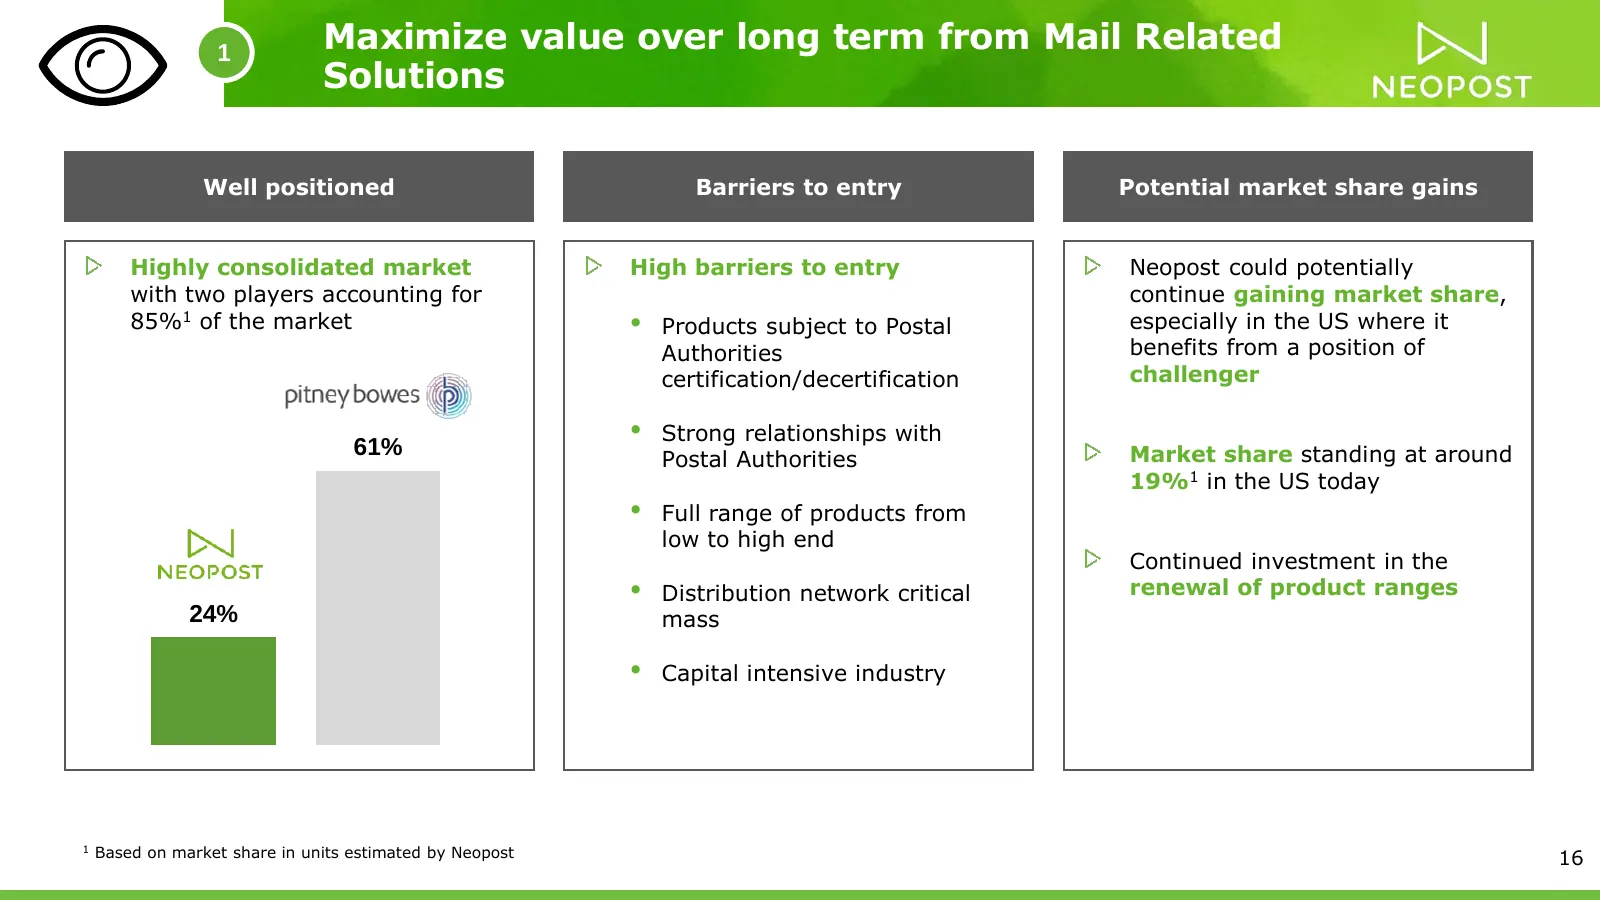
1 Maximize value over long term from Mail Related Solutions Well positioned Barriers to entry Potential market share gains Highly consolidated market High barriers to entry Neopost could potentially with two players accounting for continue gaining market share, 85%1 of the market • Products subject
Slide 17: Choice to refocus on 4 major solutions
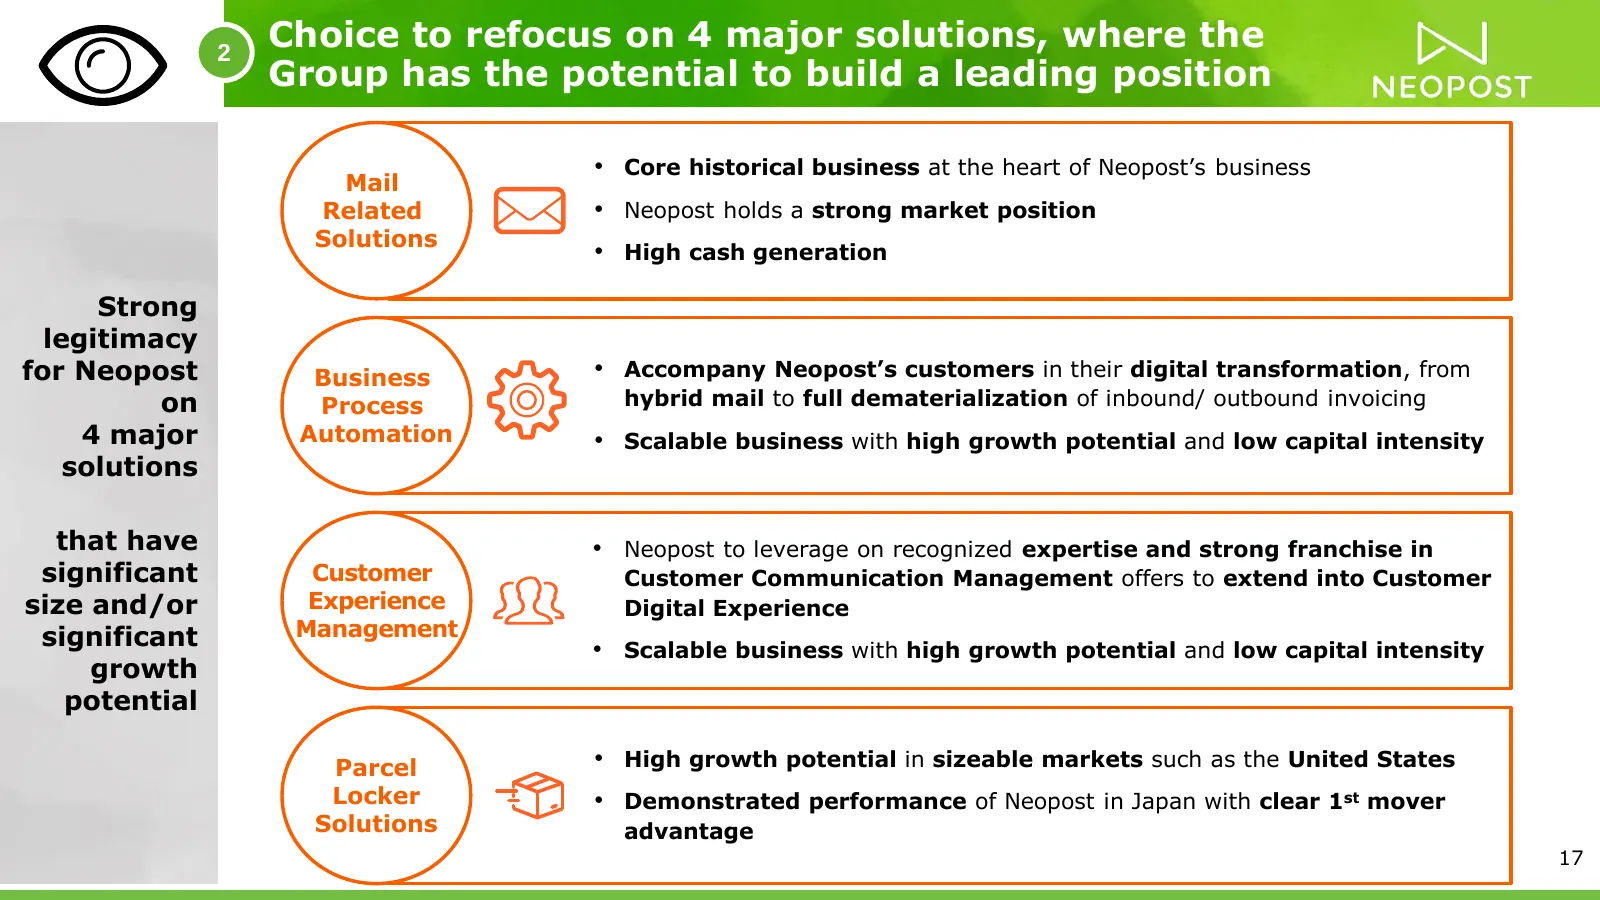
2 Choice to refocus on 4 major solutions, where the Group has the potential to build a leading position • Core historical business at the heart of Neopost’s business Mail Related • Neopost holds a strong market position Solutions • High cash generation Strong legitimacy for Neopost Business • Accomp
Slide 18: Accelerate transformation through organic growth and M&A in Major Operations
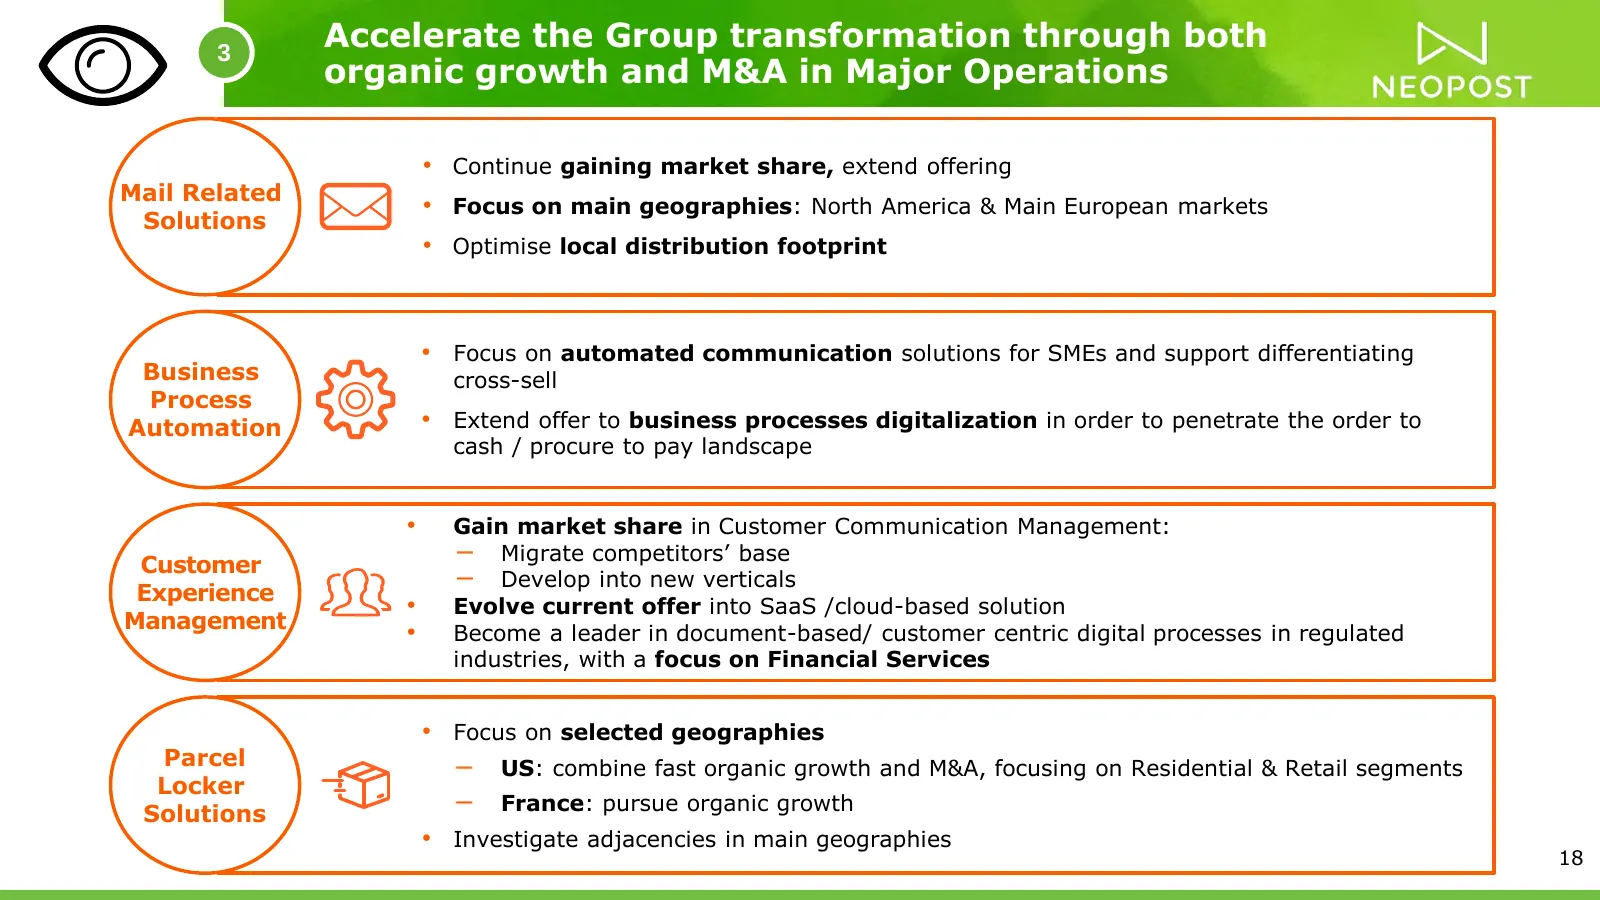
3 Accelerate the Group transformation through both organic growth and M&A in Major Operations • Continue gaining market share, extend offering Mail Related • Focus on main geographies: North America & Main European markets Solutions • Optimise local distribution footprint • Focus on automated commun
Slide 19: Implications on Group organization and reporting
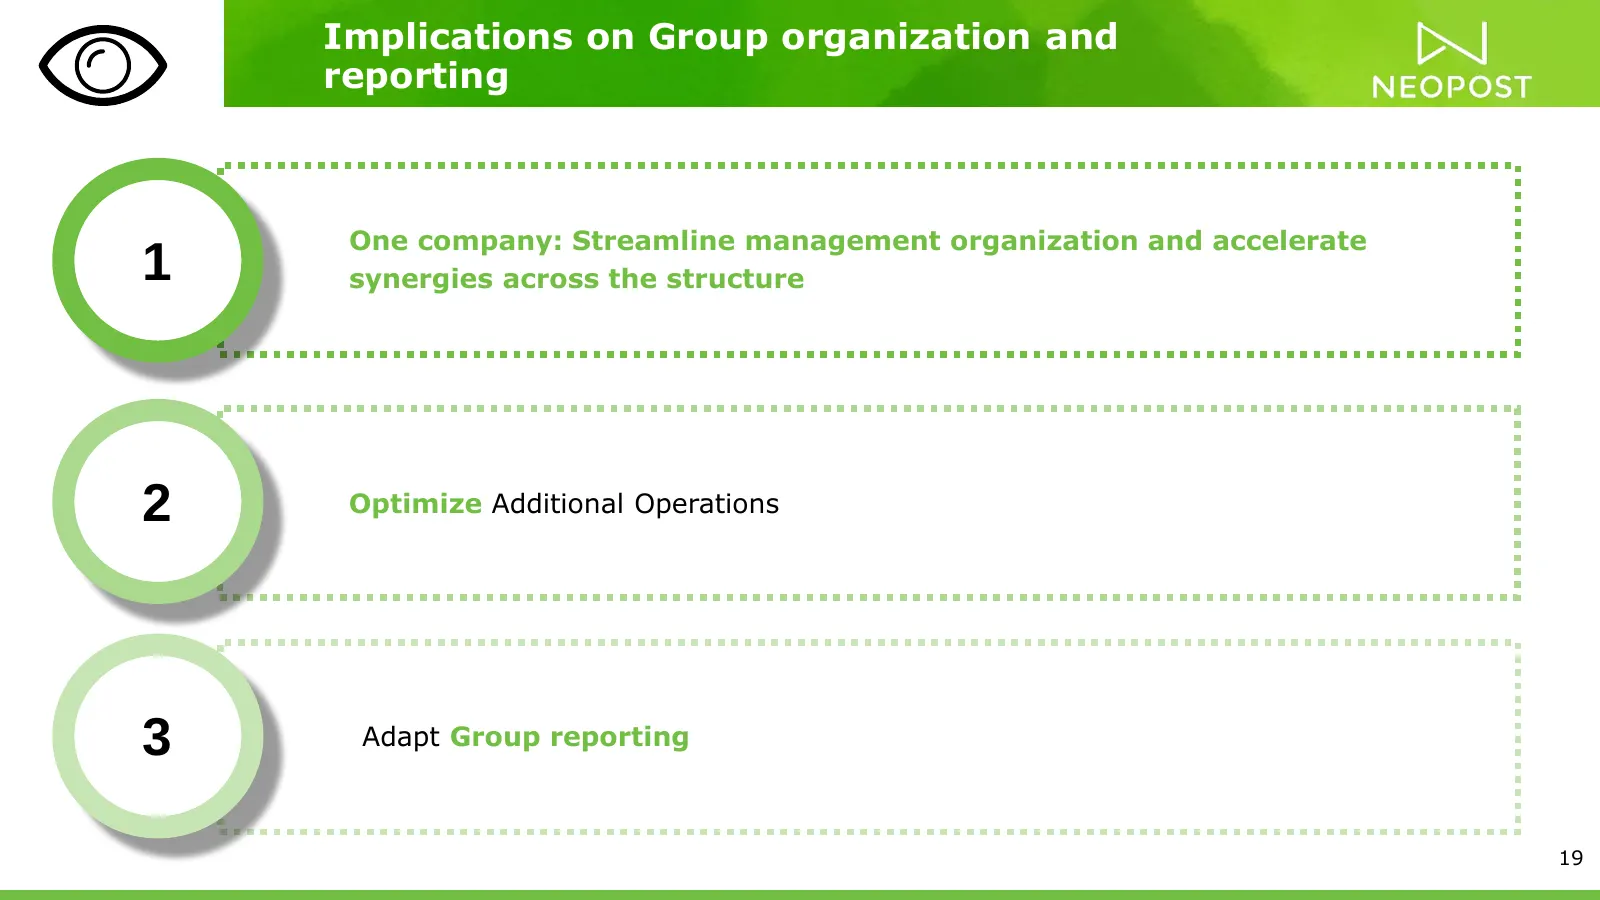
Implications on Group organization and reporting One company: Streamline management organization and accelerate 1 synergies across the structure 2 Optimize Additional Operations 3 Adapt Group reporting 19
Slide 20: One company: streamline management organization
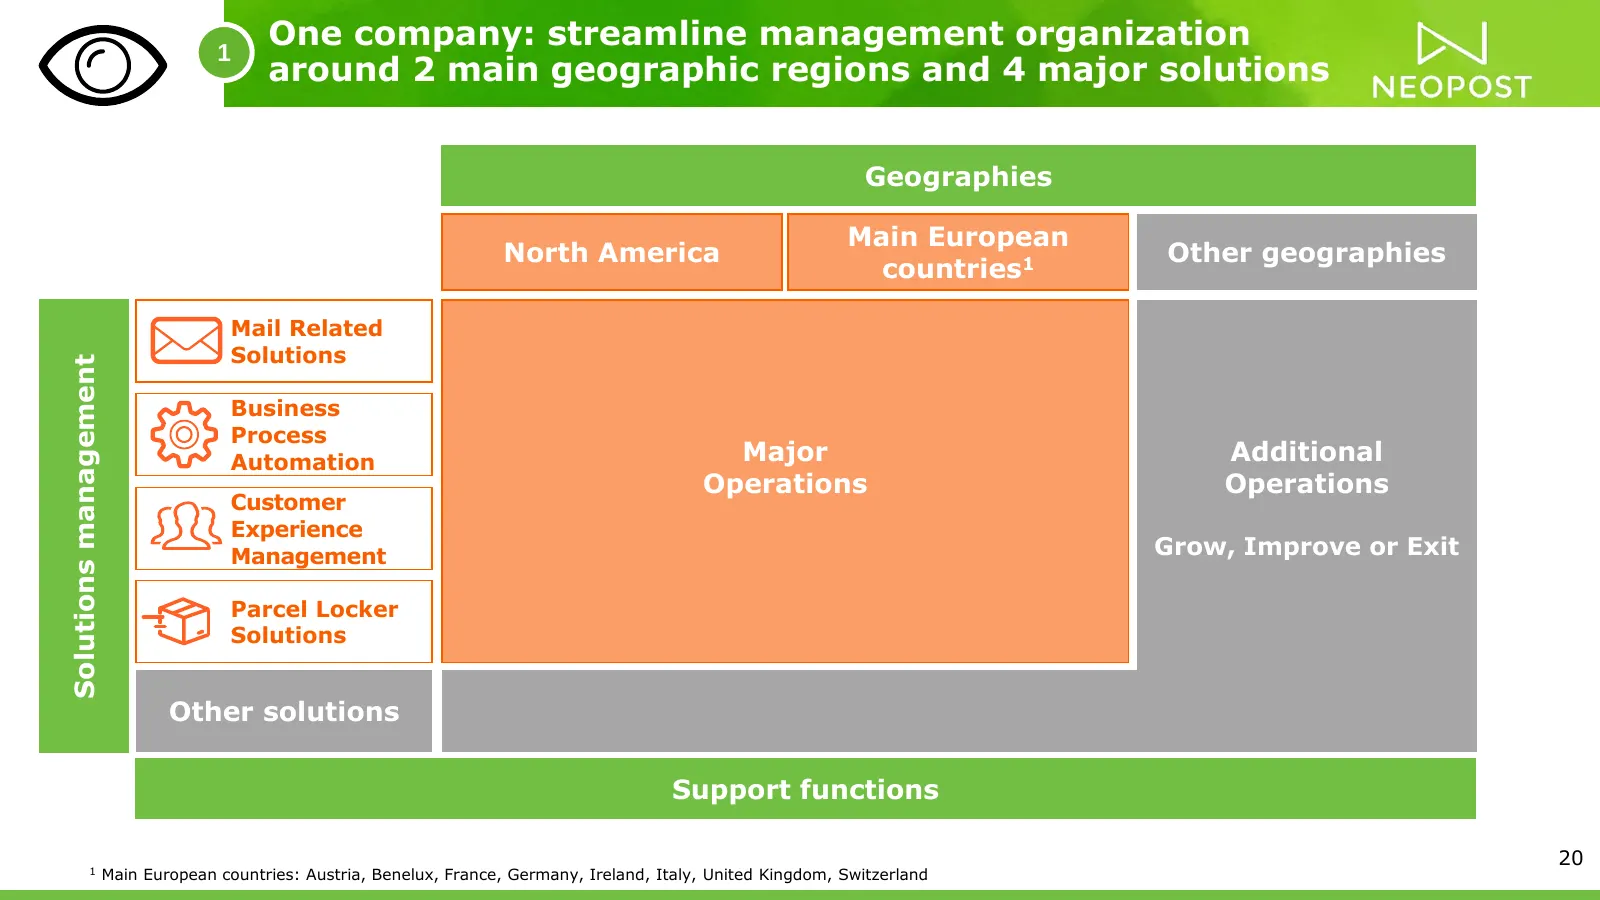
1 One company: streamline management organization around 2 main geographic regions and 4 major solutions Geographies Main European North America Other geographies countries1 Mail Related Solutions Solutions management Business Process Automation Major Additional Operations Operations Customer Experi
Slide 21: Optimize Additional Operations
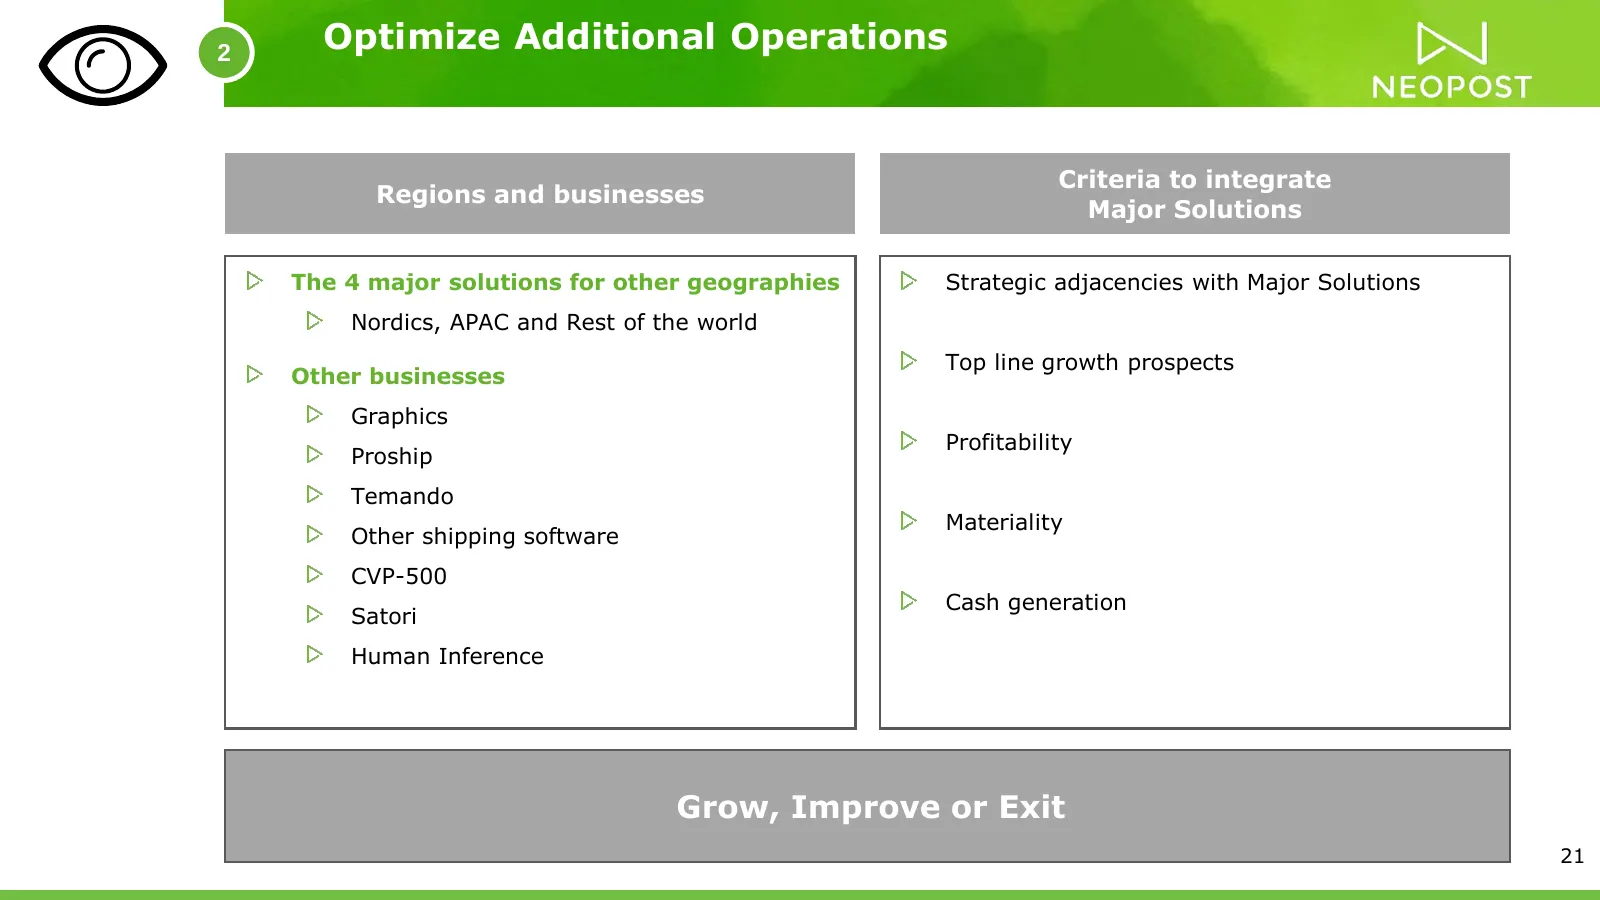
2 Optimize Additional Operations Criteria to integrate Regions and businesses Major Solutions The 4 major solutions for other geographies Strategic adjacencies with Major Solutions Nordics, APAC and Rest of the world Top line growth prospects Other businesses Graphics Profitability Proship Temando M
Slide 22: Adapt Group reporting to isolate Major Operations
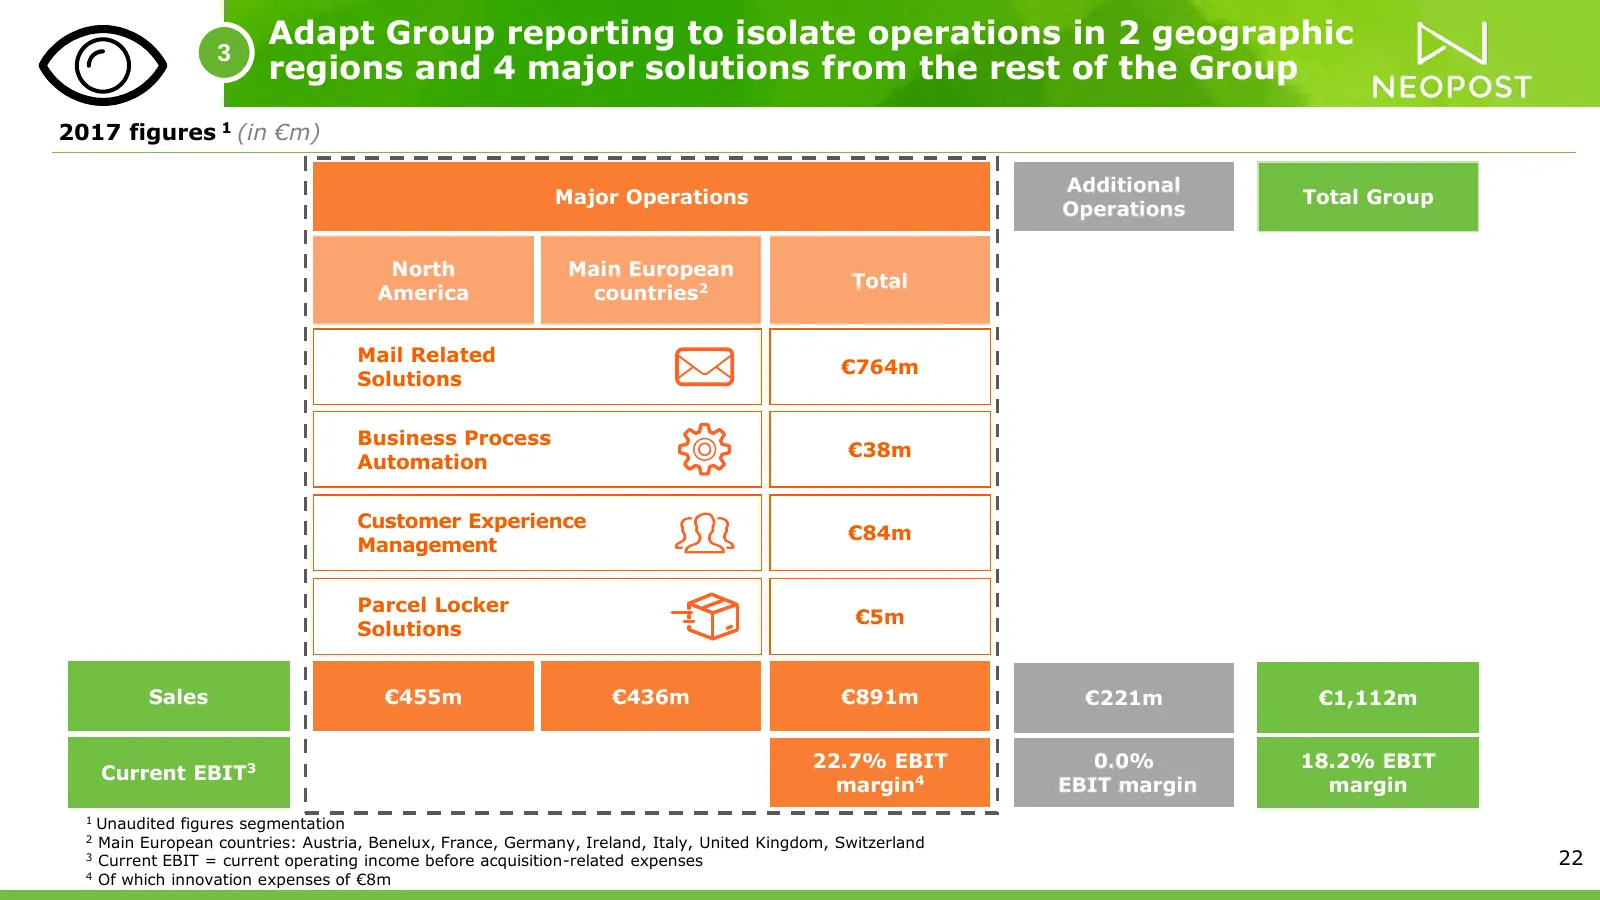
Adapt Group reporting to isolate operations in 2 geographic 3 regions and 4 major solutions from the rest of the Group 2017 figures 1 (in €m) Additional Major Operations Total Group Operations North Main European Total America countries2 Mail Related €764m Solutions Business Process €38m Automation
Slide 23: Implications on management team and new corporate governance
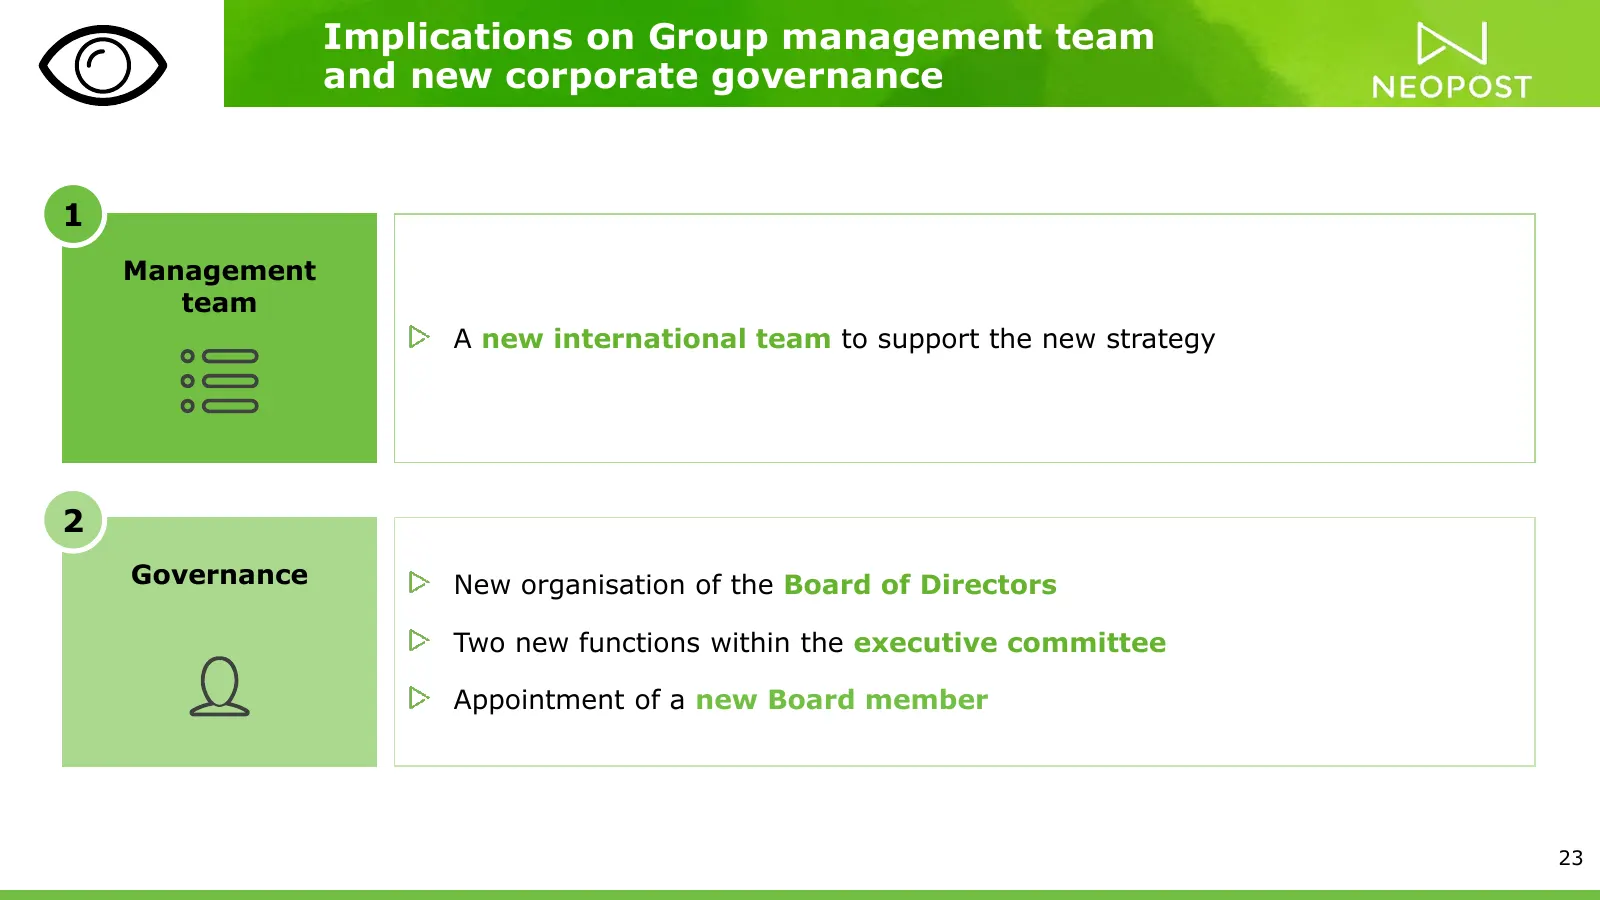
Implications on Group management team and new corporate governance 1 Management team A new international team to support the new strategy 2 Governance New organisation of the Board of Directors Two new functions within the executive committee Appointment of a new Board member 23
Slide 24: A new international team to support the new strategy (1/2)
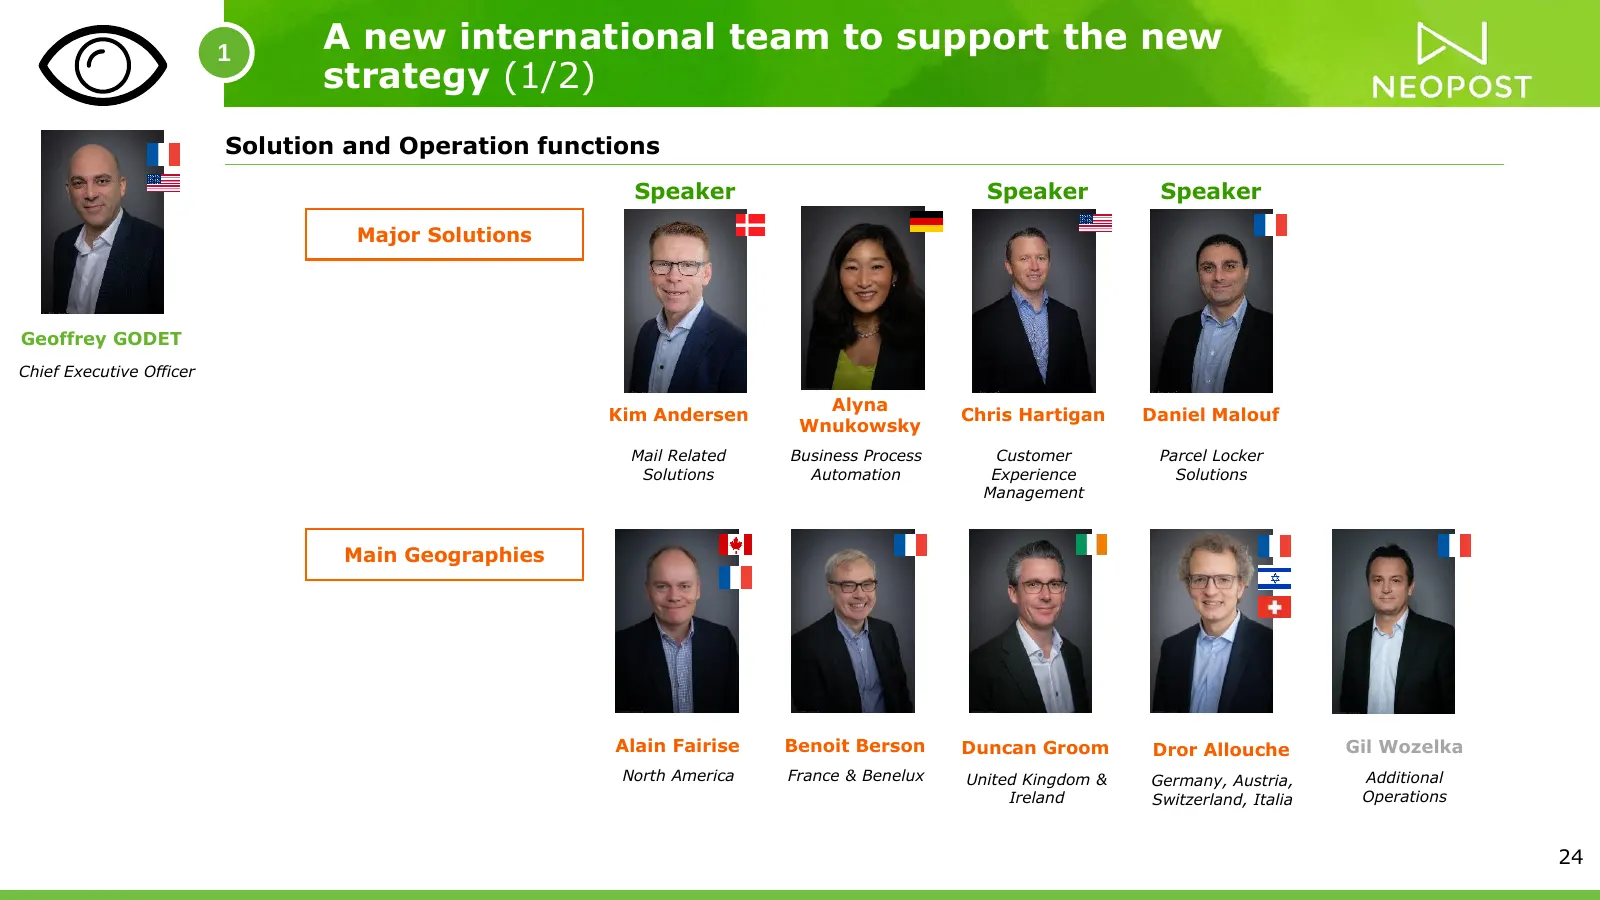
1 A new international team to support the new strategy (1/2) Solution and Operation functions Speaker Speaker Speaker Major Solutions Geoffrey GODET Chief Executive Officer Alyna Kim Andersen Chris Hartigan Daniel Malouf Wnukowsky Mail Related Business Process Customer Parcel Locker Solutions Automa
Slide 25: A new international team to support the new strategy (2/2)
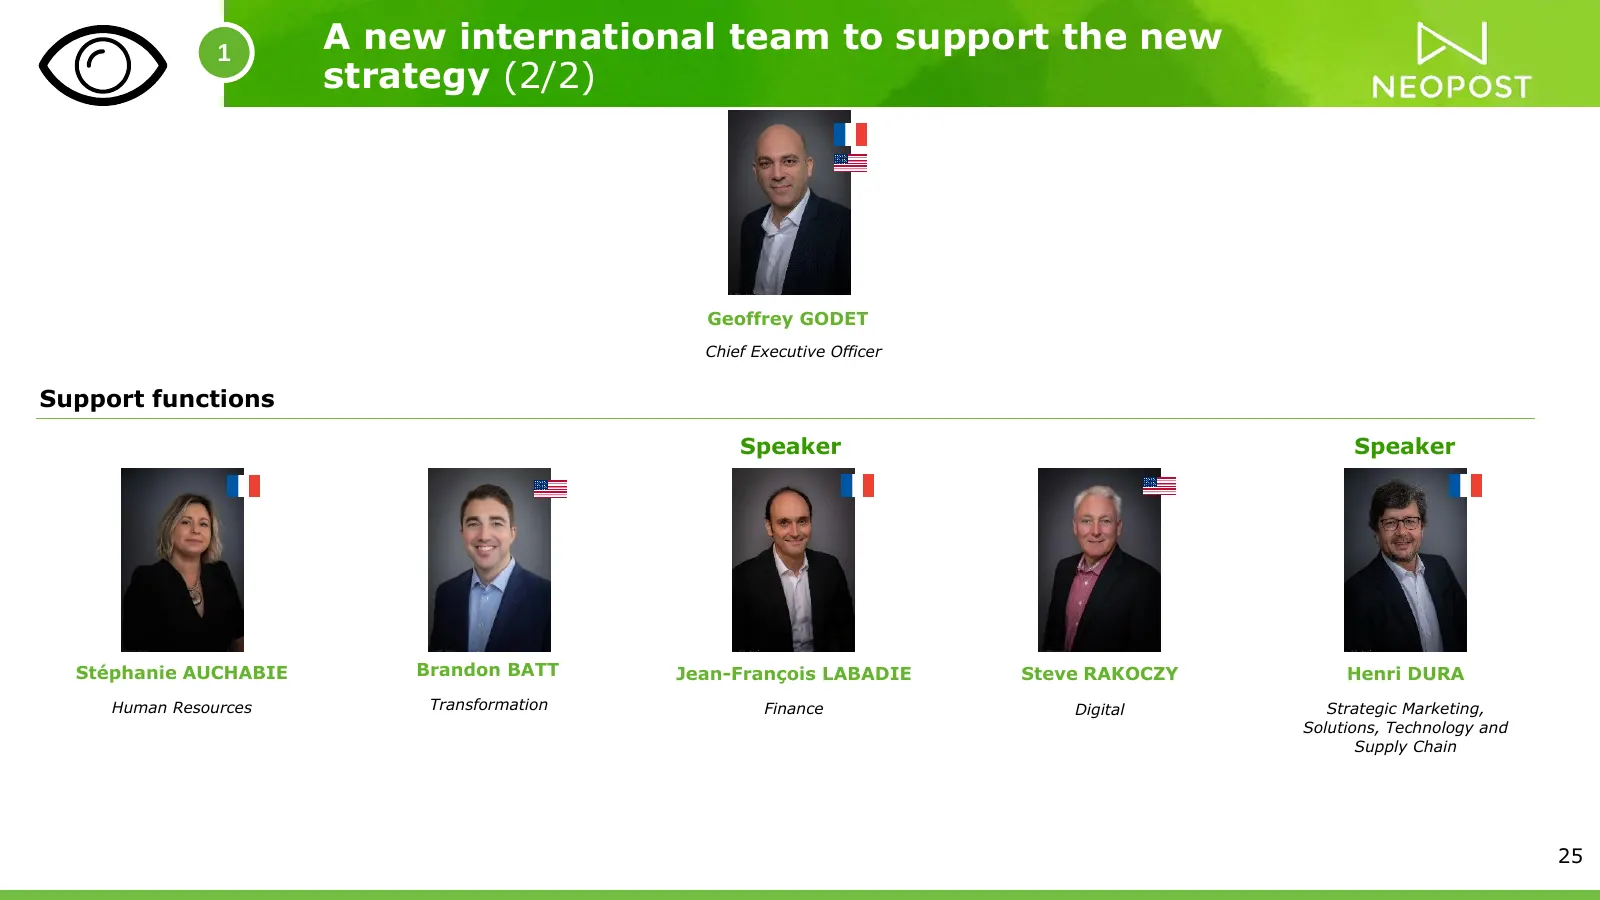
1 A new international team to support the new strategy (2/2) Geoffrey GODET Chief Executive Officer Support functions Speaker Speaker Stéphanie AUCHABIE Brandon BATT Jean-François LABADIE Steve RAKOCZY Henri DURA Human Resources Transformation Finance Digital Strategic Marketing, Solutions, Technolo
Slide 26: Change in corporate governance
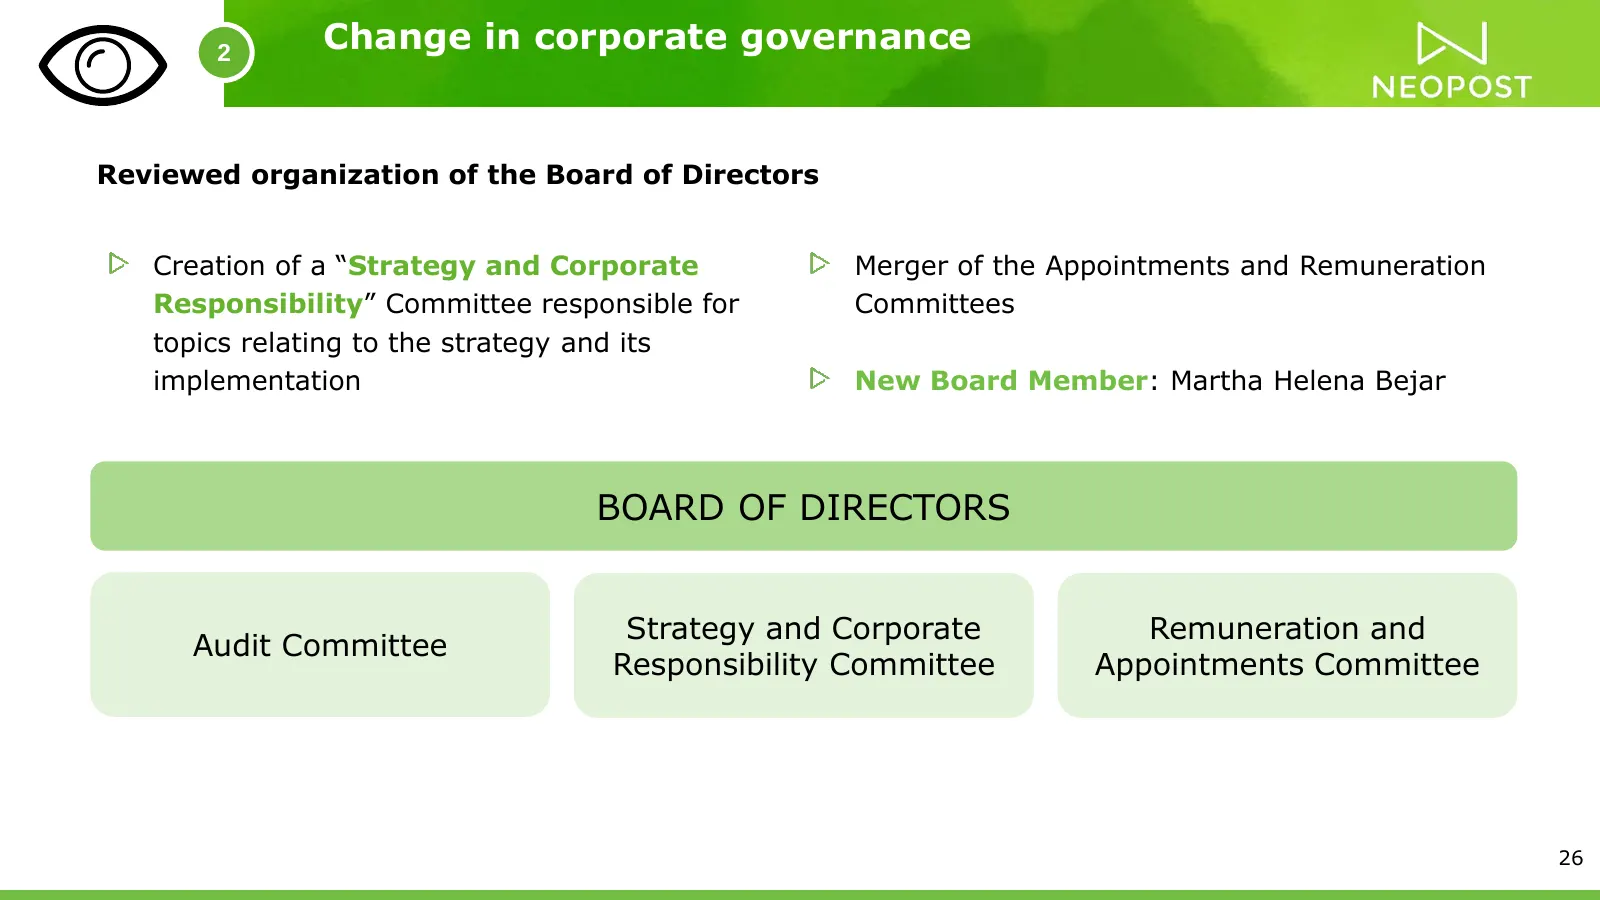
2 Change in corporate governance Reviewed organization of the Board of Directors Creation of a “Strategy and Corporate Merger of the Appointments and Remuneration Responsibility” Committee responsible for Committees topics relating to the strategy and its implementation New Board Member: Martha Hele
Slide 27: Medium term financial targets
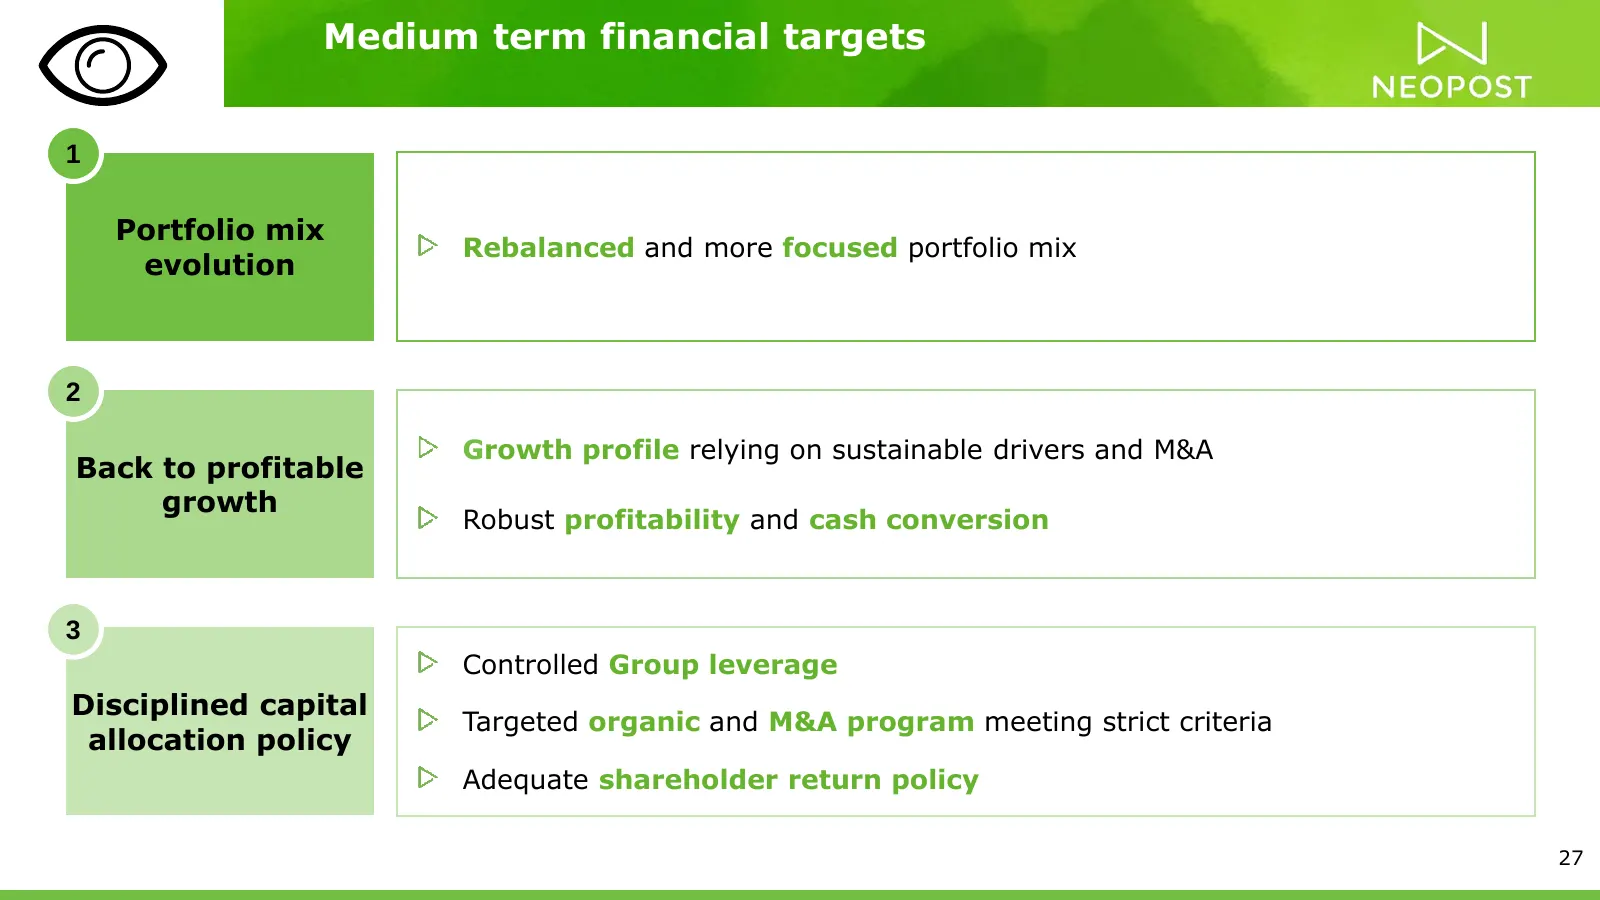
Medium term financial targets 1 Portfolio mix Rebalanced and more focused portfolio mix evolution 2 Growth profile relying on sustainable drivers and M&A Back to profitable growth Robust profitability and cash conversion 3 Controlled Group leverage Disciplined capital Targeted organic and M&A progra
Slide 28: Rebalanced and focused portfolio mix by 2022
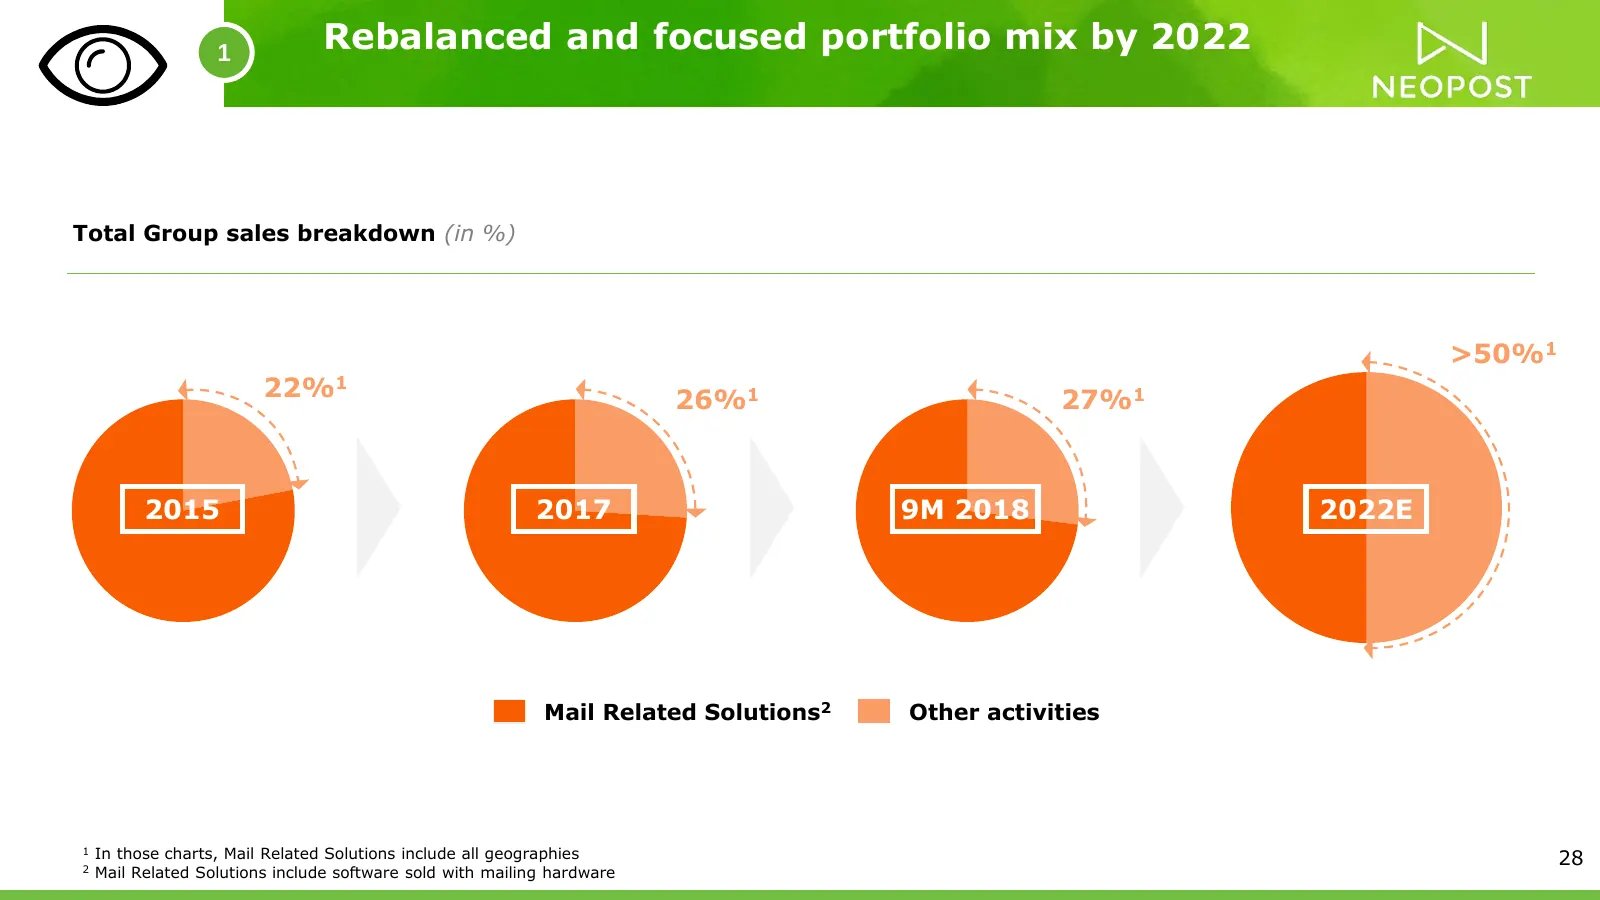
1 Rebalanced and focused portfolio mix by 2022 Total Group sales breakdown (in %) >50%1 22%1 26%1 27%1 2015 2017 9M 2018 2022E Mail Related Solutions2 Other activities 1 In those charts, Mail Related Solutions include all geographies 2 Mail Related Solutions include software sold with mailing hardwa
Slide 29: Back to profitable growth over 2019–2022
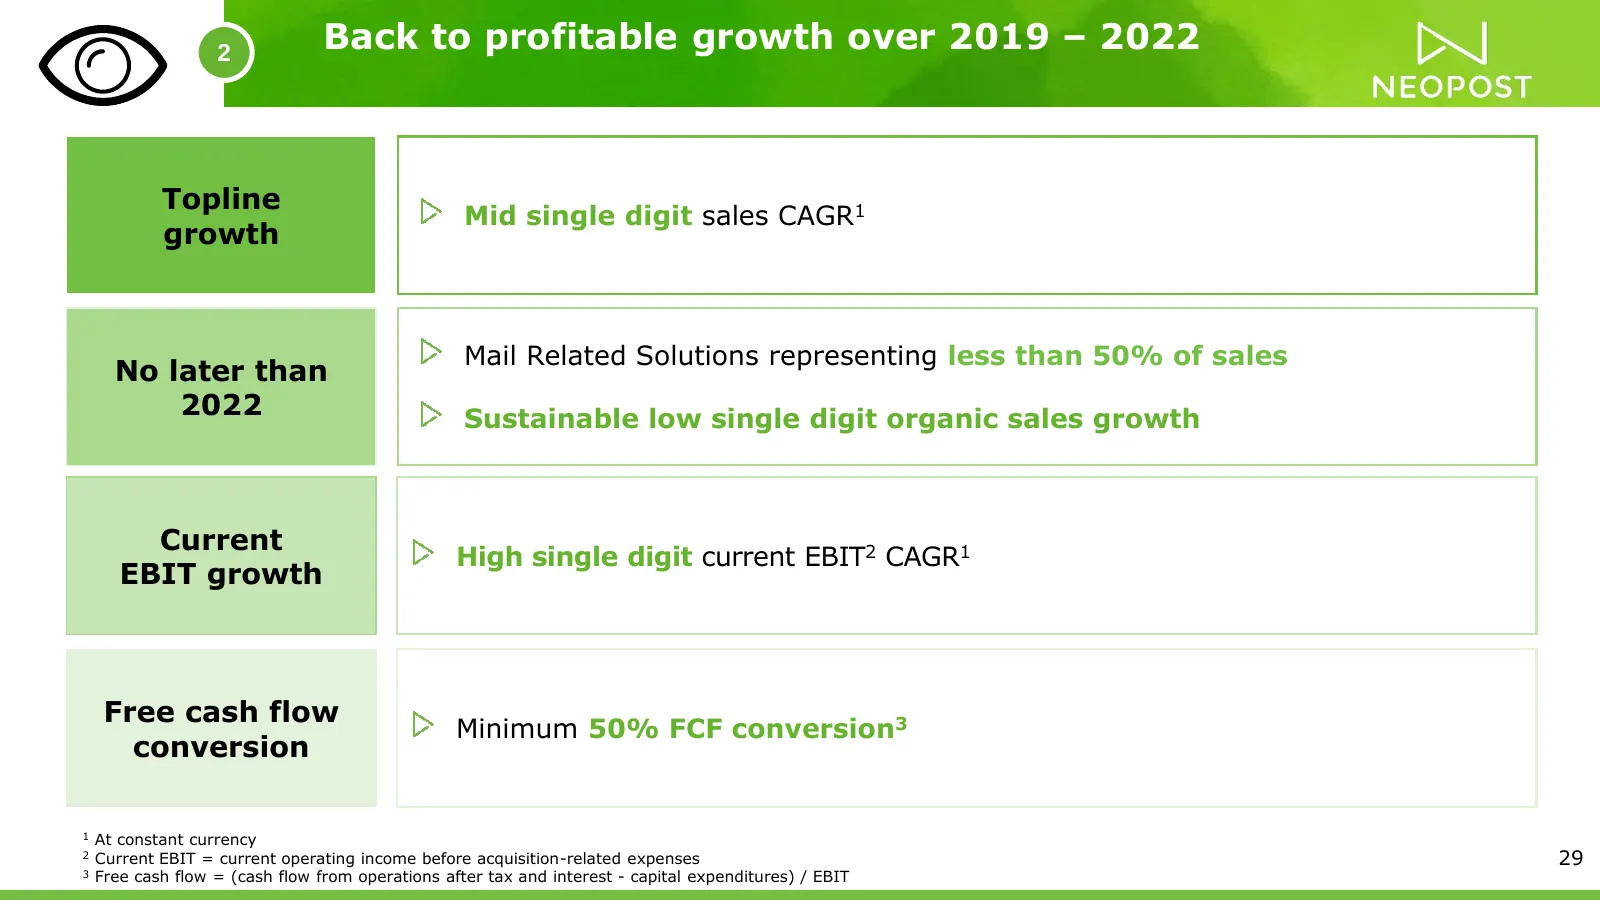
2 Back to profitable growth over 2019 – 2022 Topline Mid single digit sales CAGR1 growth Mail Related Solutions representing less than 50% of sales No later than 2022 Sustainable low single digit organic sales growth Current High single digit current EBIT2 CAGR1 EBIT growth Free cash flow Minimum 50
Slide 30: Disciplined capital allocation policy over 2019–2022
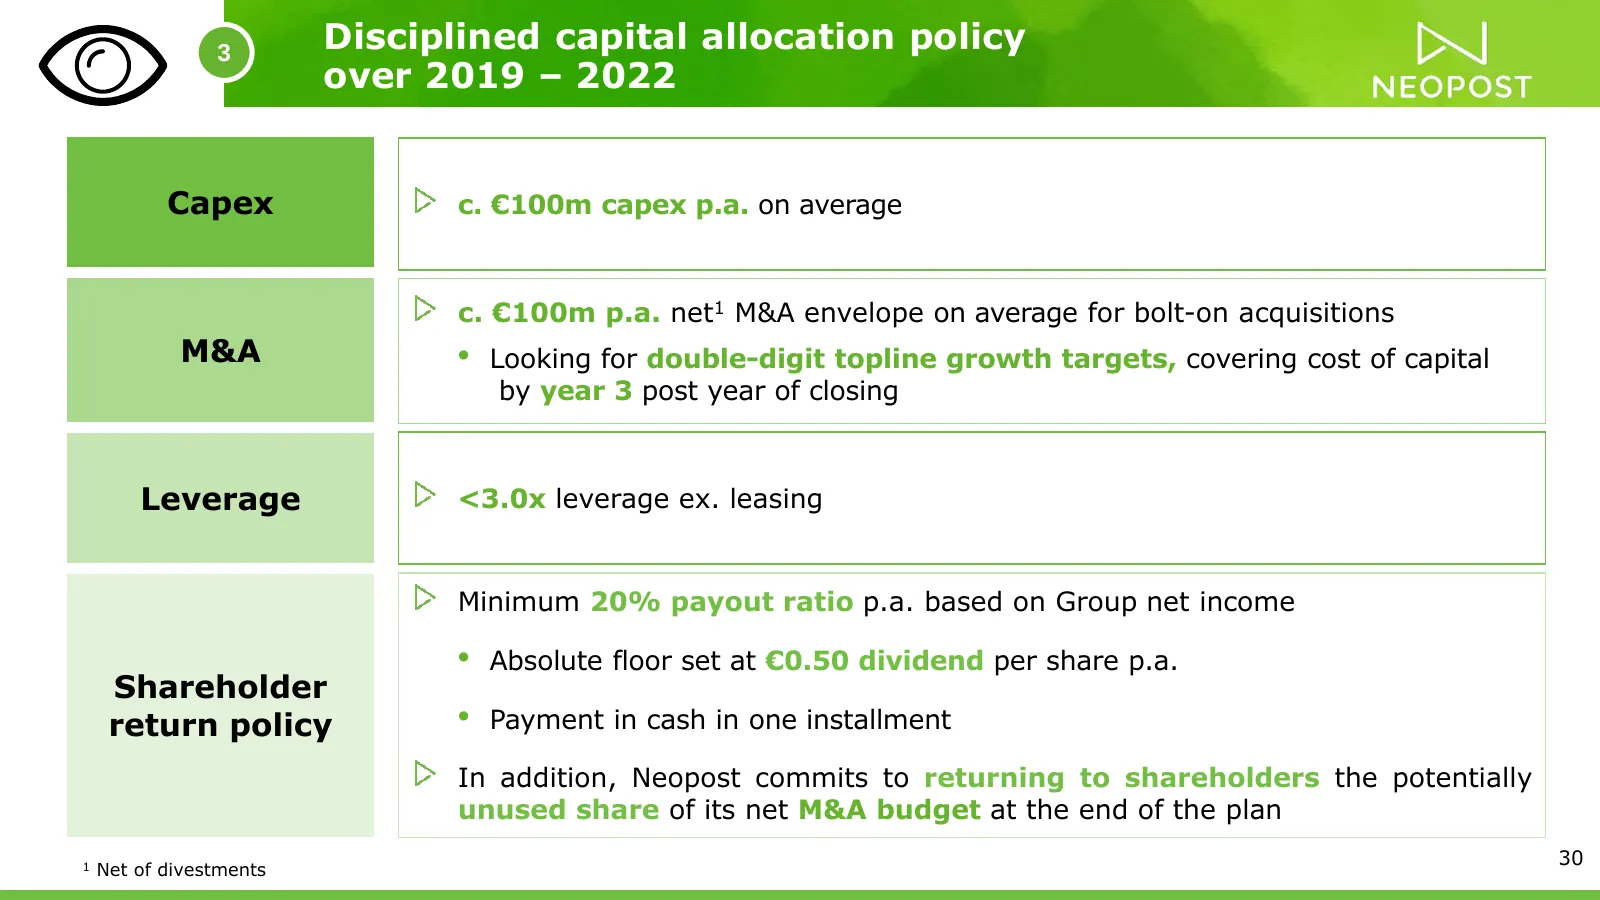
3 Disciplined capital allocation policy over 2019 – 2022 Capex c. €100m capex p.a. on average c. €100m p.a. net1 M&A envelope on average for bolt-on acquisitions M&A • Looking for double-digit topline growth targets, covering cost of capital by year 3 post year of closing Leverage <3.0x leverage ex.
Slide 31: Back to Growth
Pies — — # } ACK TO GROWTH
Slide 32: Mail Related Solutions
Mail Related Solutions • Kim Andersen
Slide 33: Letter mail remains a very large market
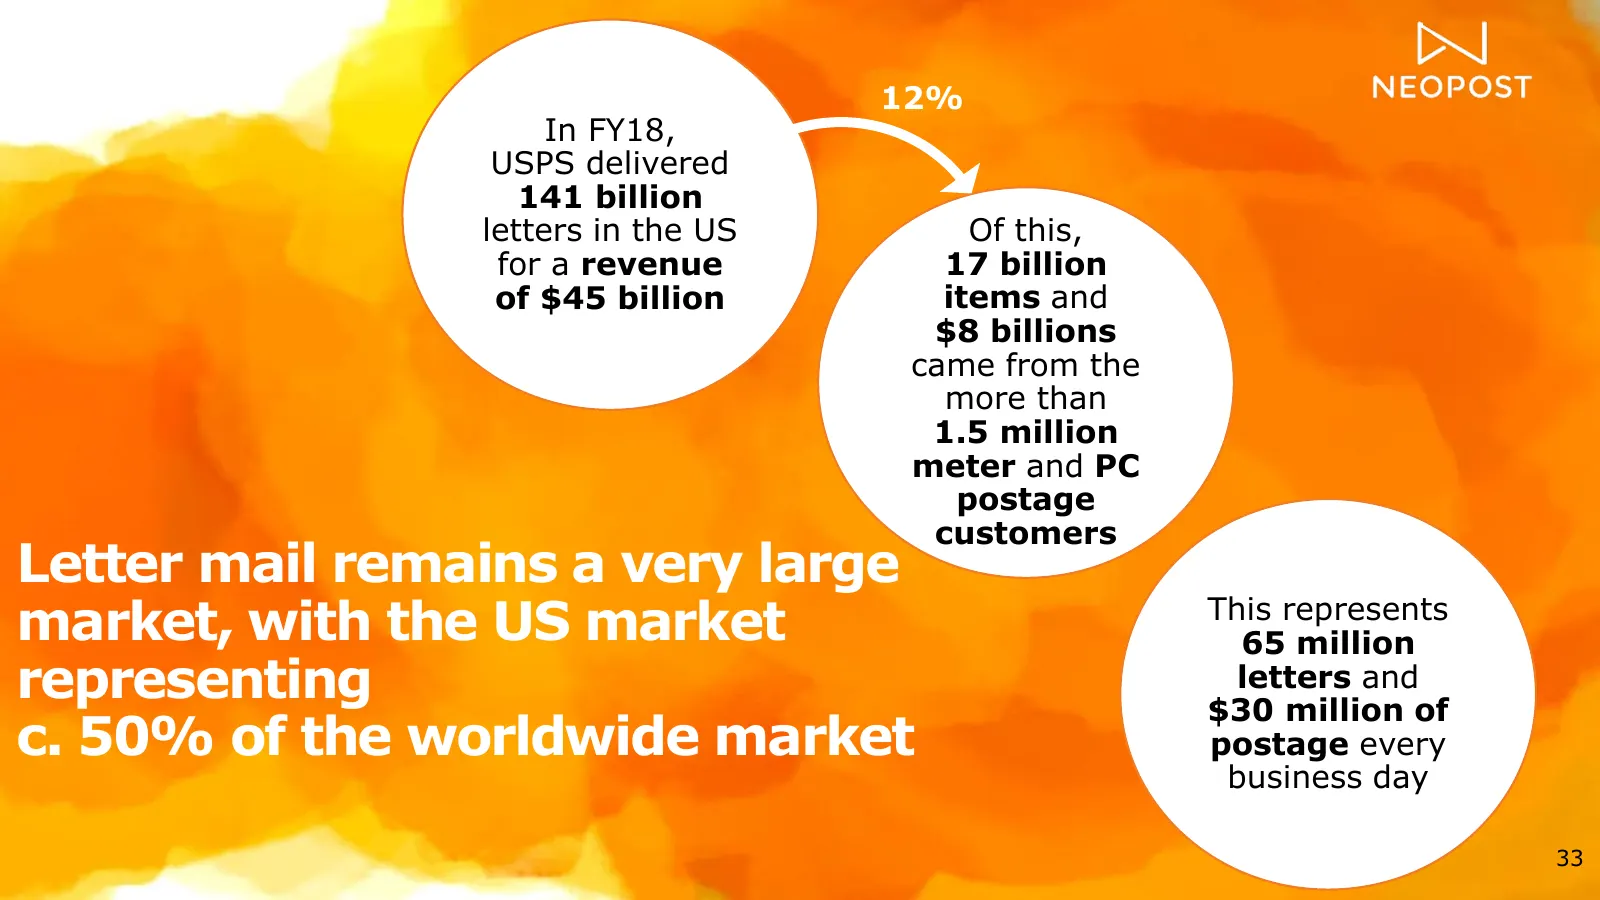
12% In FY18, USPS delivered 141 billion letters in the US Of this, for a revenue 17 billion of $45 billion items and $8 billions came from the more than 1.5 million meter and PC postage customers Letter mail remains a very large market, with the US market This represents 65 million representing lett
Slide 34: The market will remain large for years to come
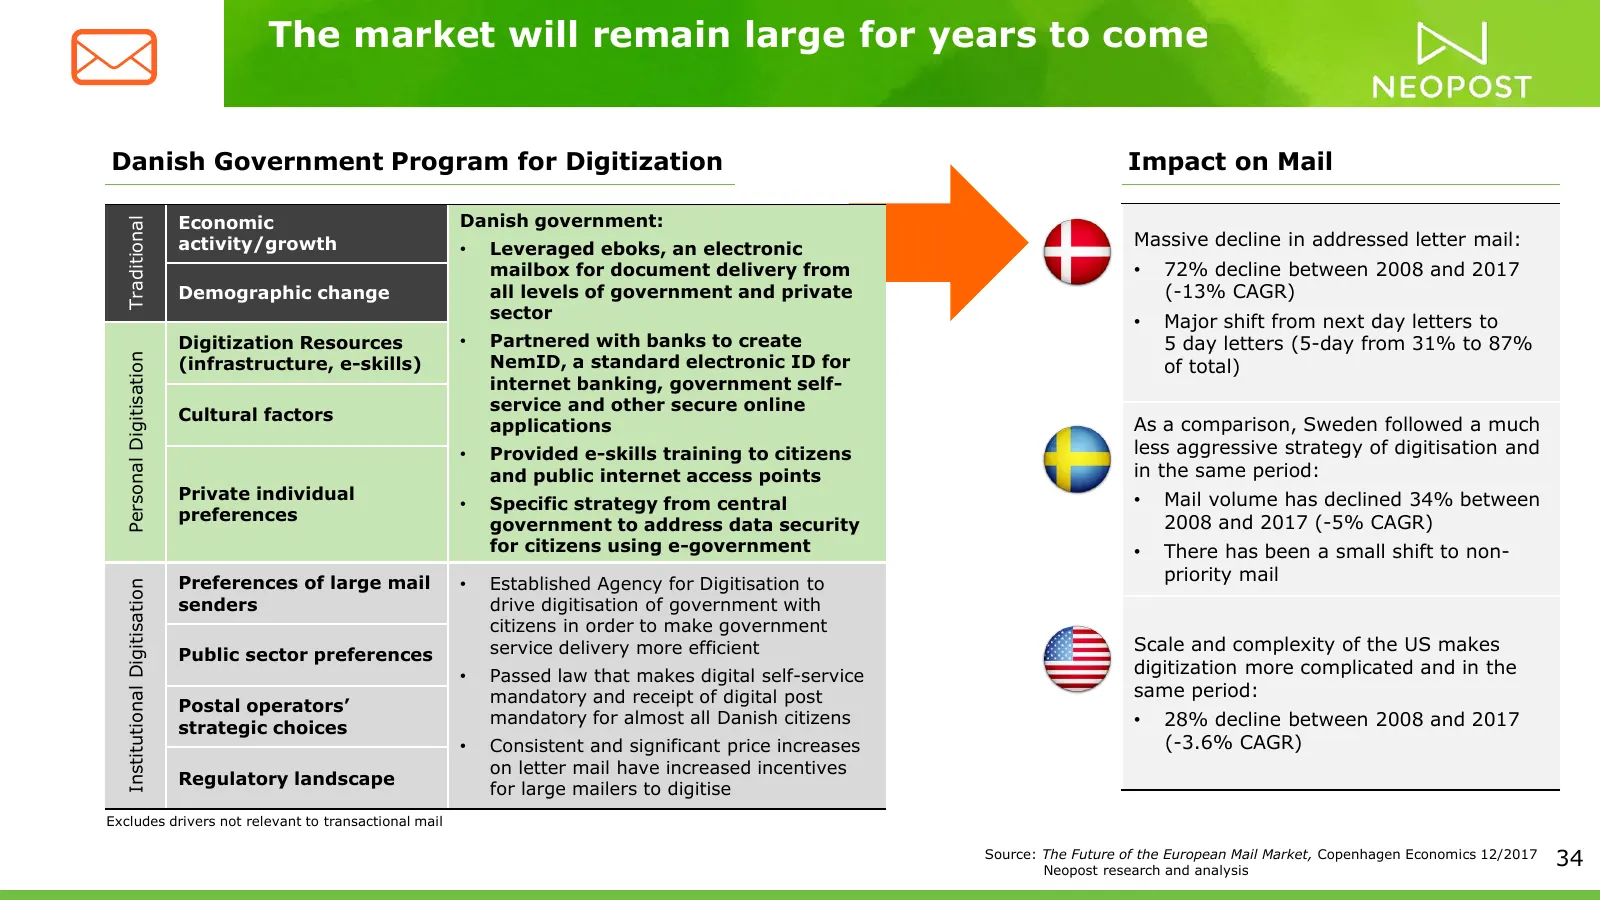
The market will remain large for years to come Danish Government Program for Digitization Impact on Mail Economic Danish government: Traditional activity/growth • Leveraged eboks, an electronic Massive decline in addressed letter mail: mailbox for document delivery from • 72% decline between 2008 an
Slide 35: Our positioning: what do we bring to customers?
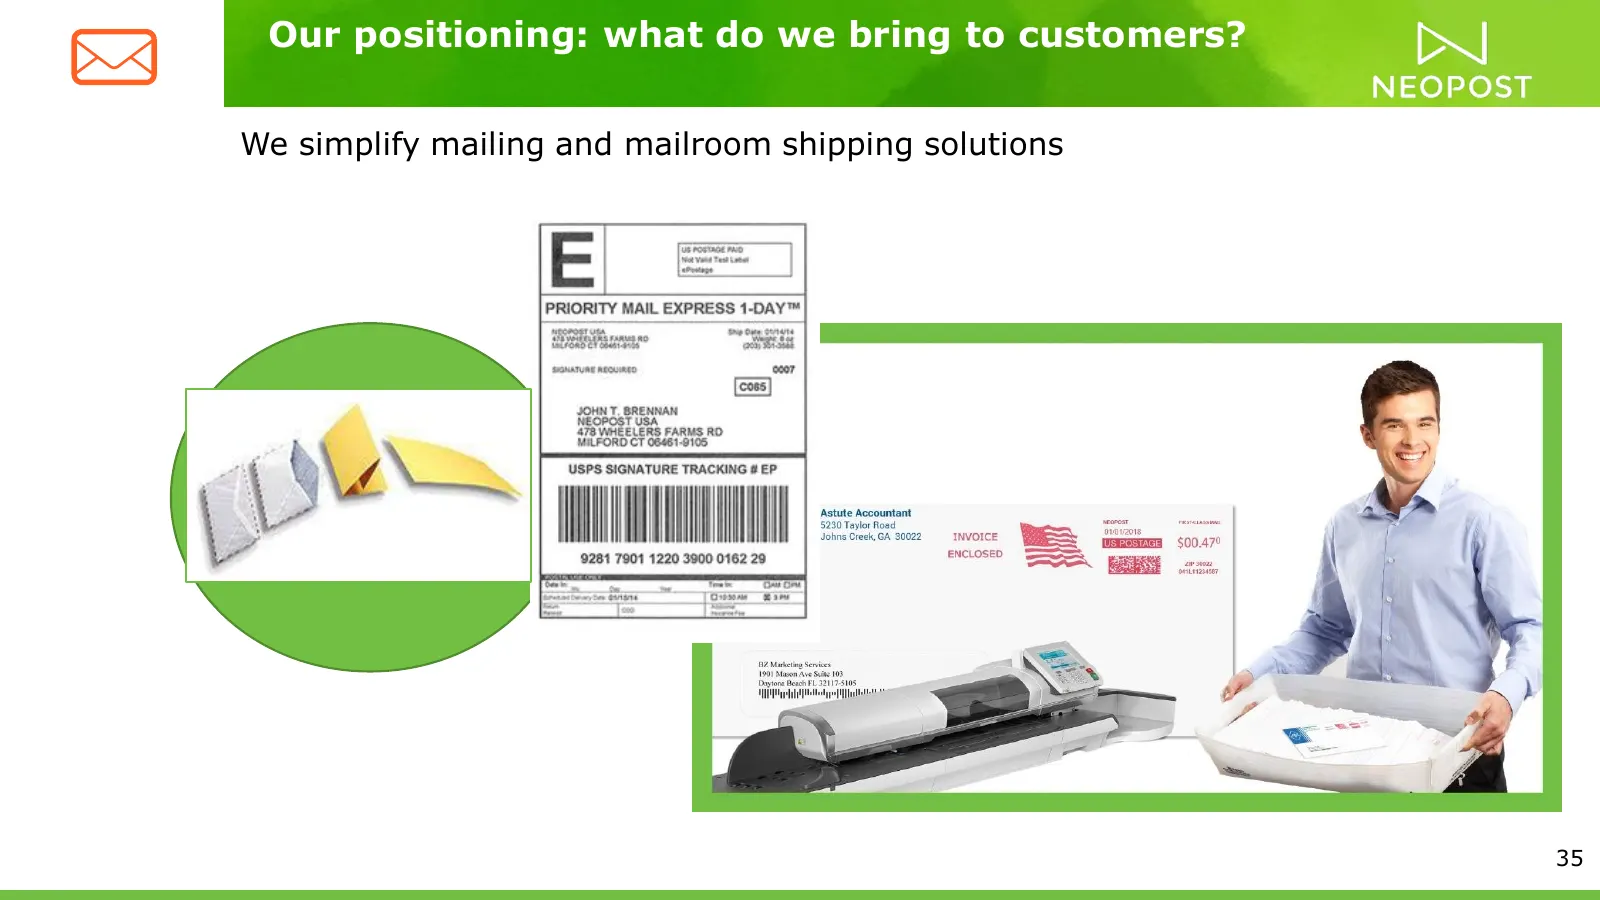
Our positioning: what do we bring to customers? We simplify mailing and mailroom shipping solutions Add picture of DH 35
Slide 36: We serve different kinds of customers
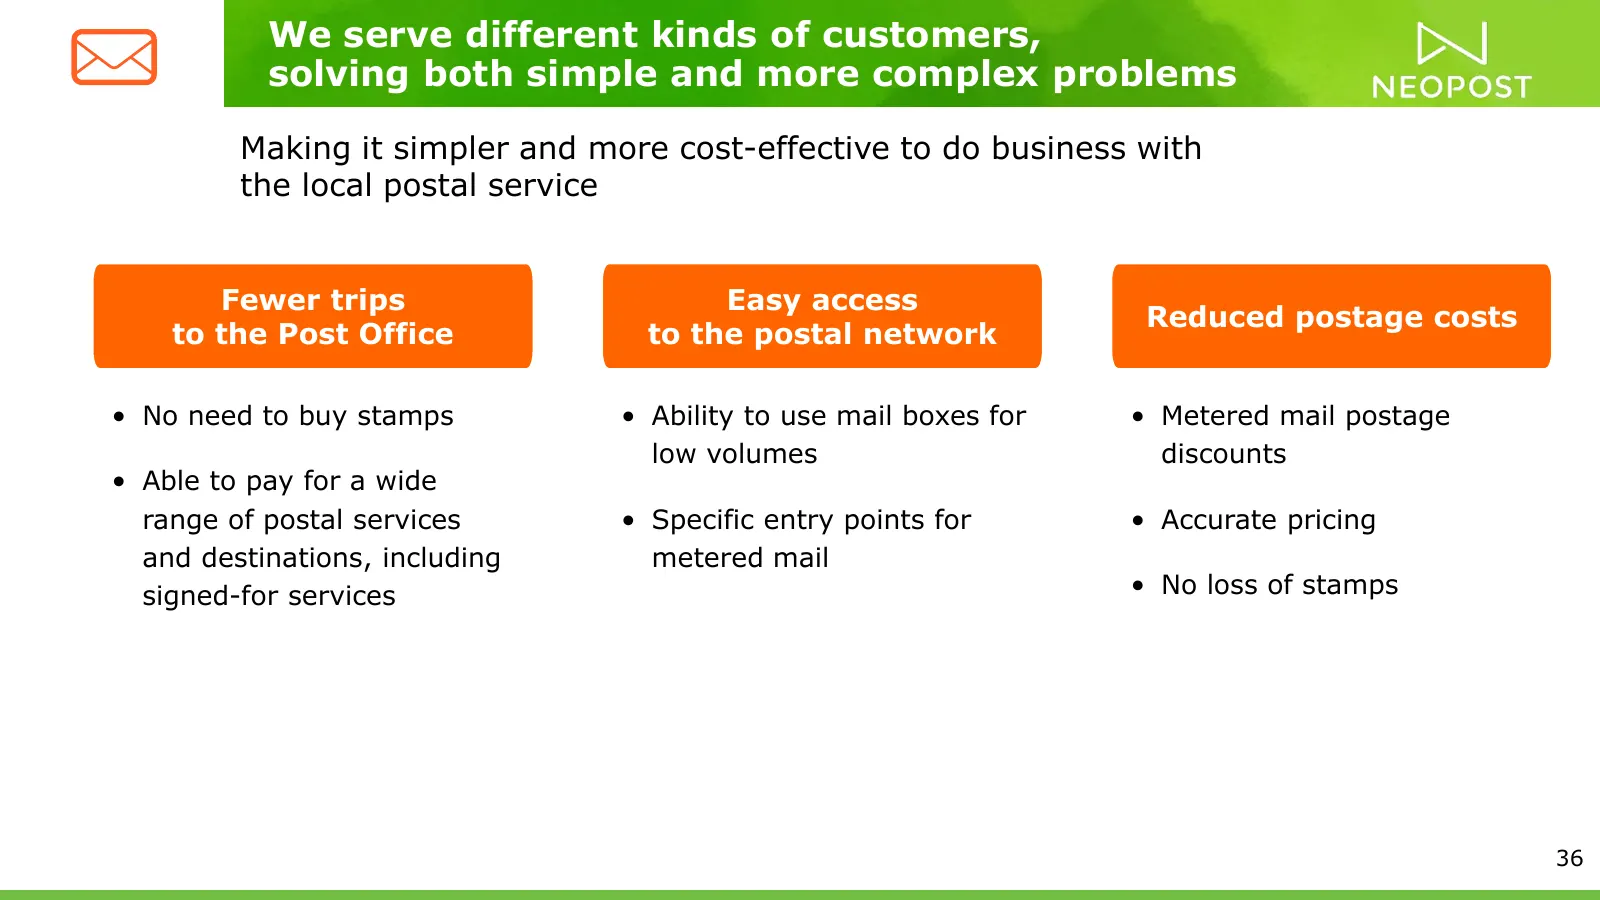
We serve different kinds of customers, solving both simple and more complex problems Making it simpler and more cost-effective to do business with the local postal service Fewer trips Easy access Reduced postage costs to the Post Office to the postal network • No need to buy stamps • Ability to use
Slide 37: We serve different kinds of customers
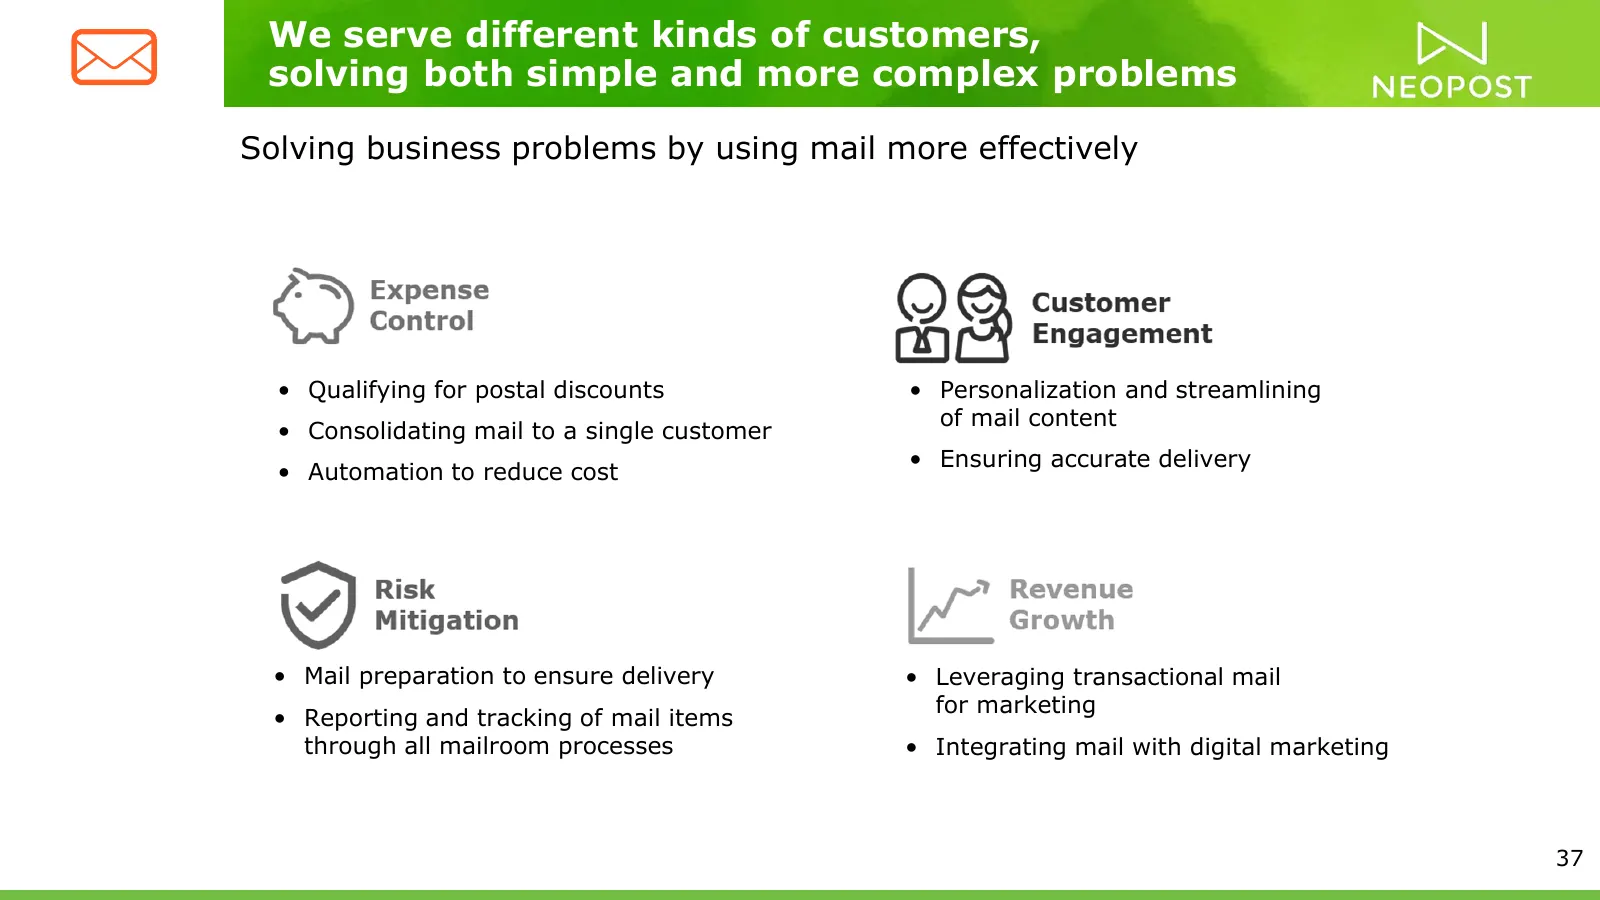
We serve different kinds of customers, solving both simple and more complex problems Solving business problems by using mail more effectively • Qualifying for postal discounts • Personalization and streamlining of mail content • Consolidating mail to a single customer • Ensuring accurate delivery •
Slide 38: Mail Related Solutions: What solution do we bring?
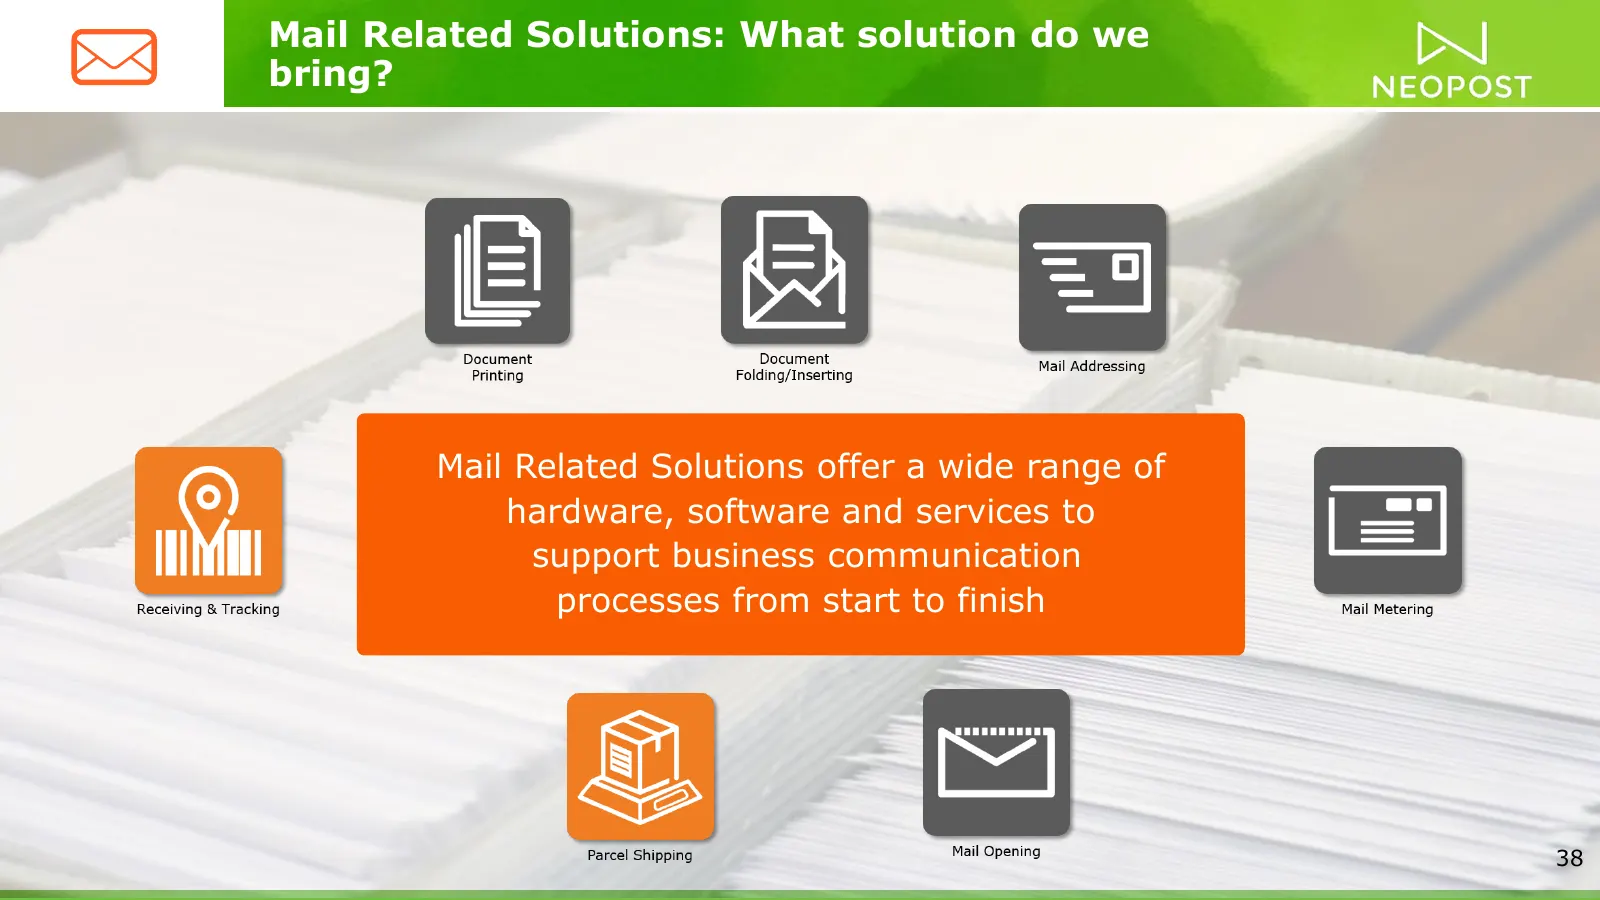
Mail Related Solutions: What solution do we bring? Mail Related Solutions offer a wide range of hardware, software and services to support business communication processes from start to finish 38
Slide 39: Widest range of mailing equipment in the market
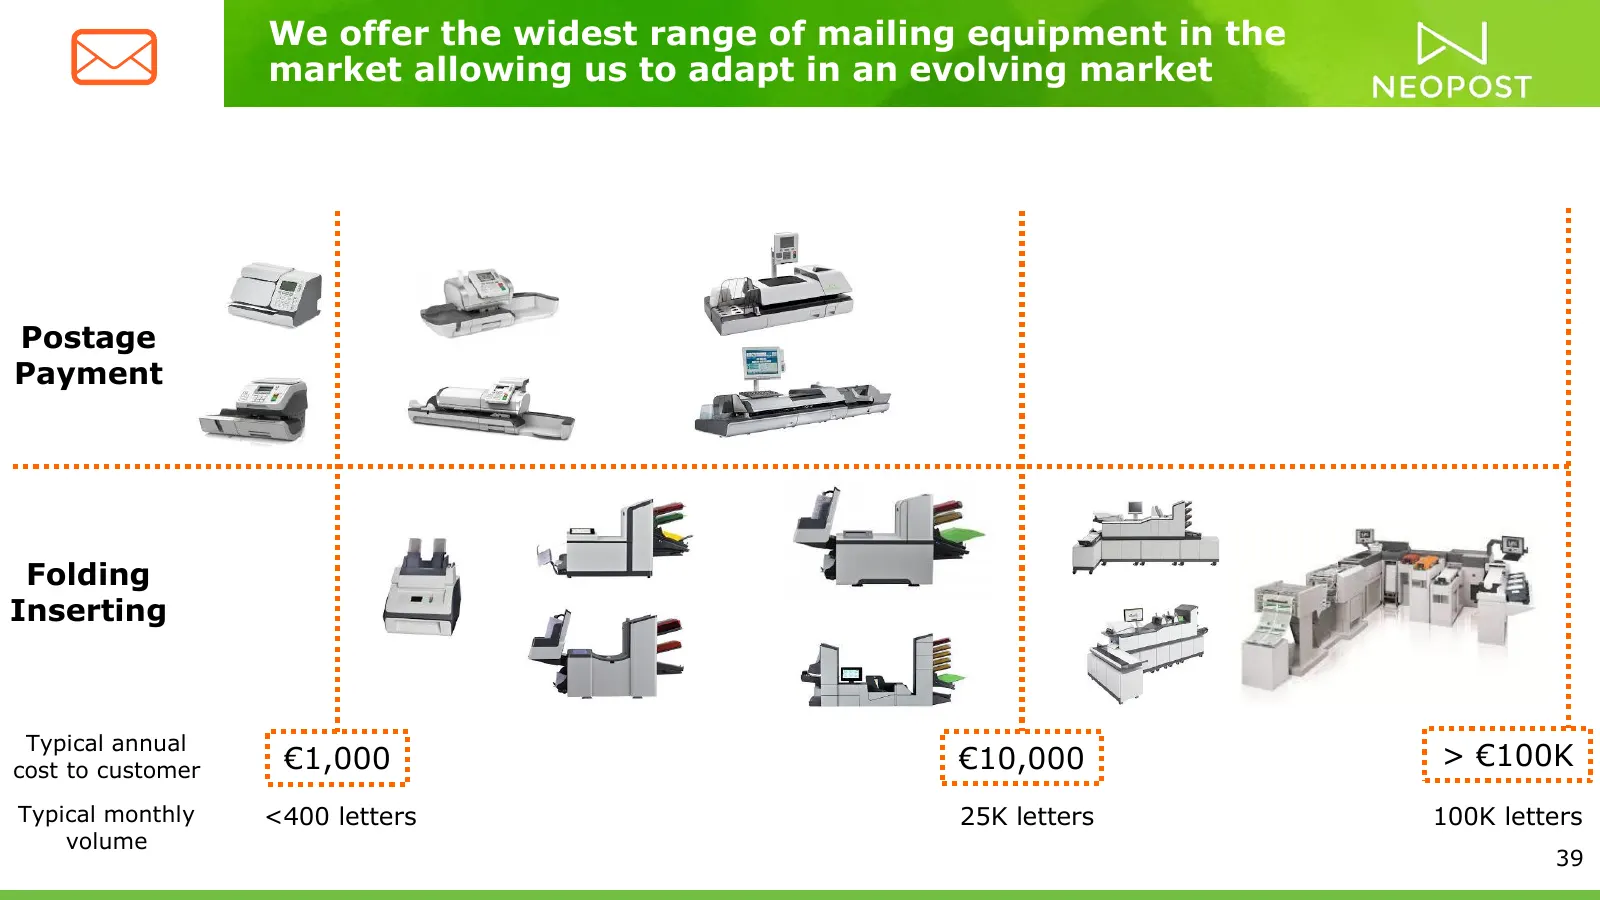
We offer the widest range of mailing equipment in the market allowing us to adapt in an evolving market Postage Payment Folding Inserting Typical annual cost to customer €1,000 €10,000 > €100K Typical monthly <400 letters 25K letters 100K letters volume 39
Slide 40: A Continuous Product Renewal
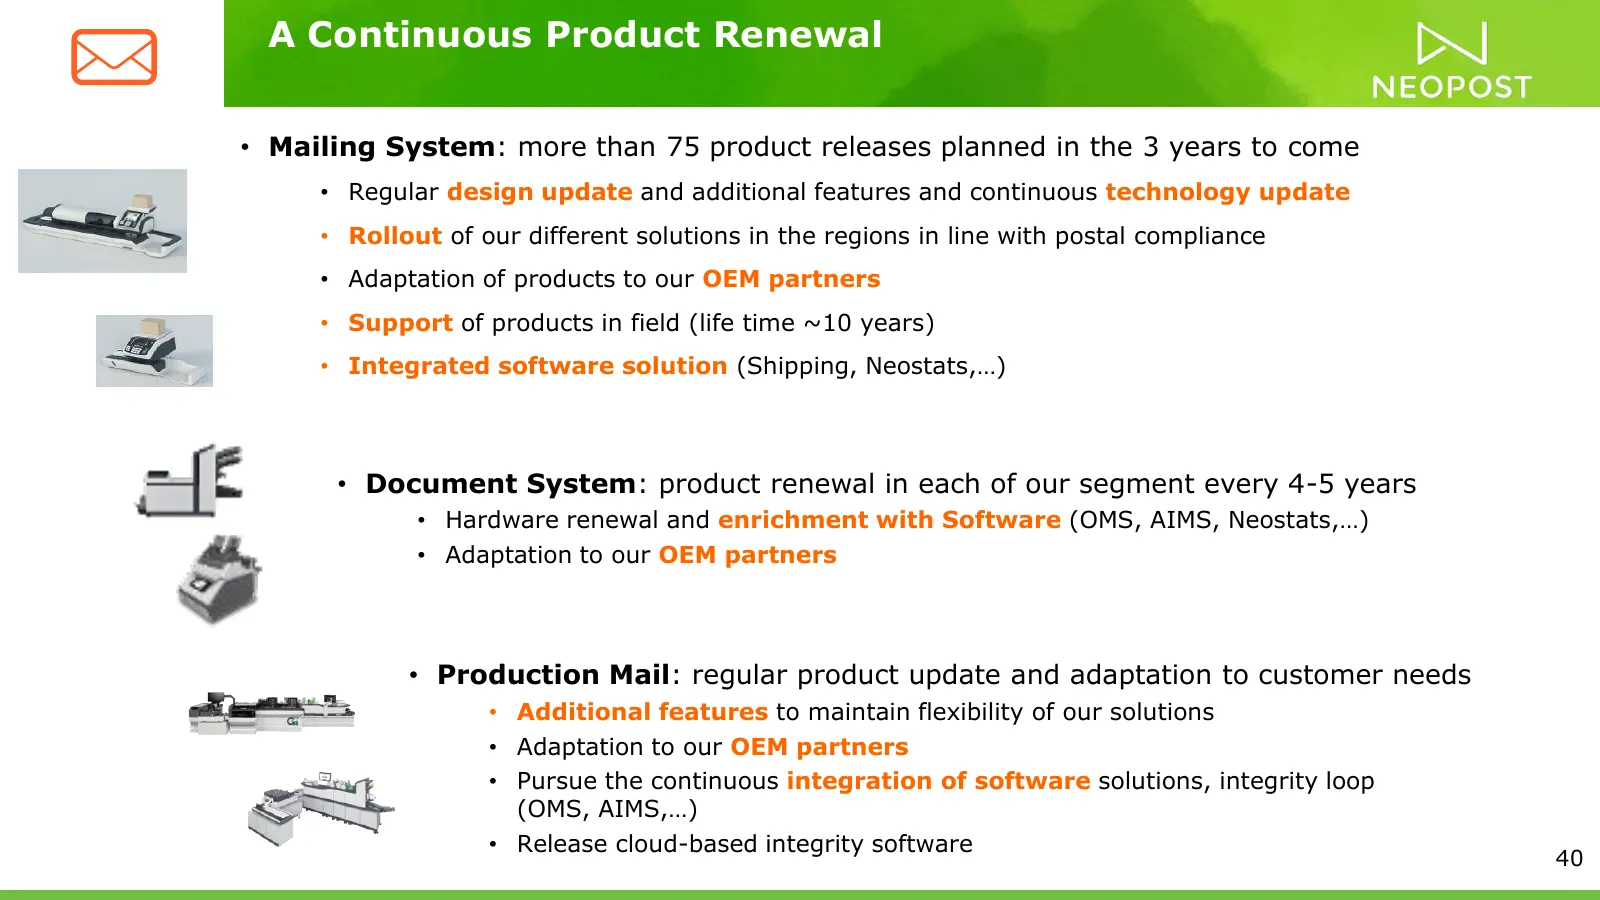
A Continuous Product Renewal • Mailing System: more than 75 product releases planned in the 3 years to come • Regular design update and additional features and continuous technology update • Rollout of our different solutions in the regions in line with postal compliance • Adaptation of products to
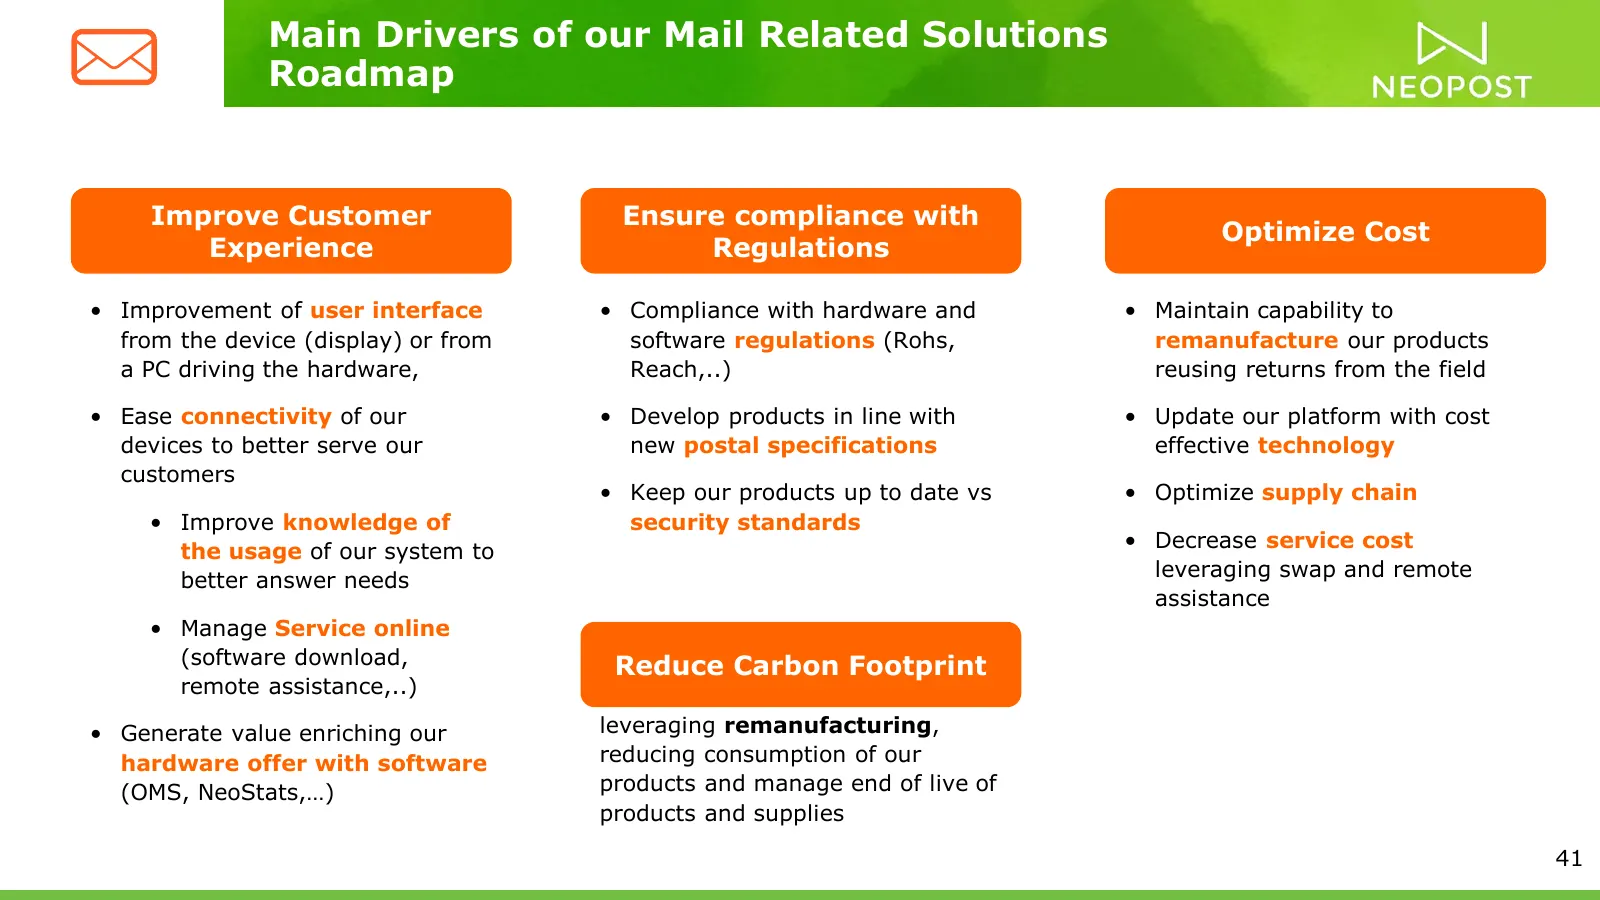
Slide 41: Main Drivers of our Mail Related Solutions Roadmap
Main Drivers of our Mail Related Solutions Roadmap Improve Customer Ensure compliance with Optimize Cost Experience Regulations • Improvement of user interface • Compliance with hardware and • Maintain capability to from the device (display) or from software regulations (Rohs, remanufacture our prod
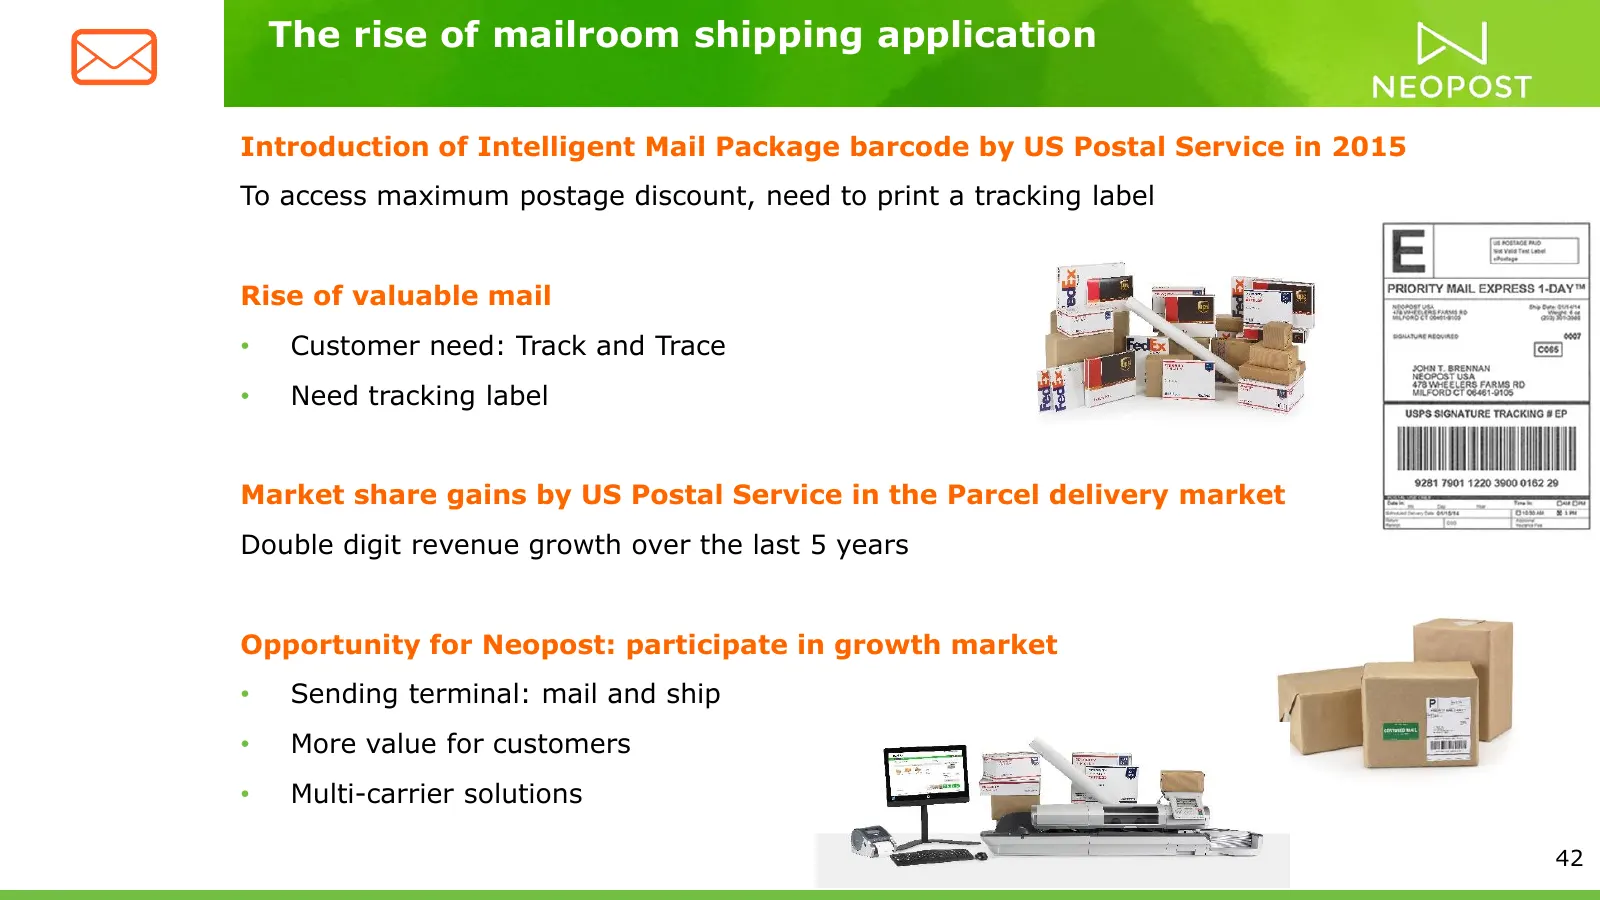
Slide 42: The rise of mailroom shipping application
The rise of mailroom shipping application Introduction of Intelligent Mail Package barcode by US Postal Service in 2015 To access maximum postage discount, need to print a tracking label Rise of valuable mail • Customer need: Track and Trace • Need tracking label Market share gains by US Postal Serv
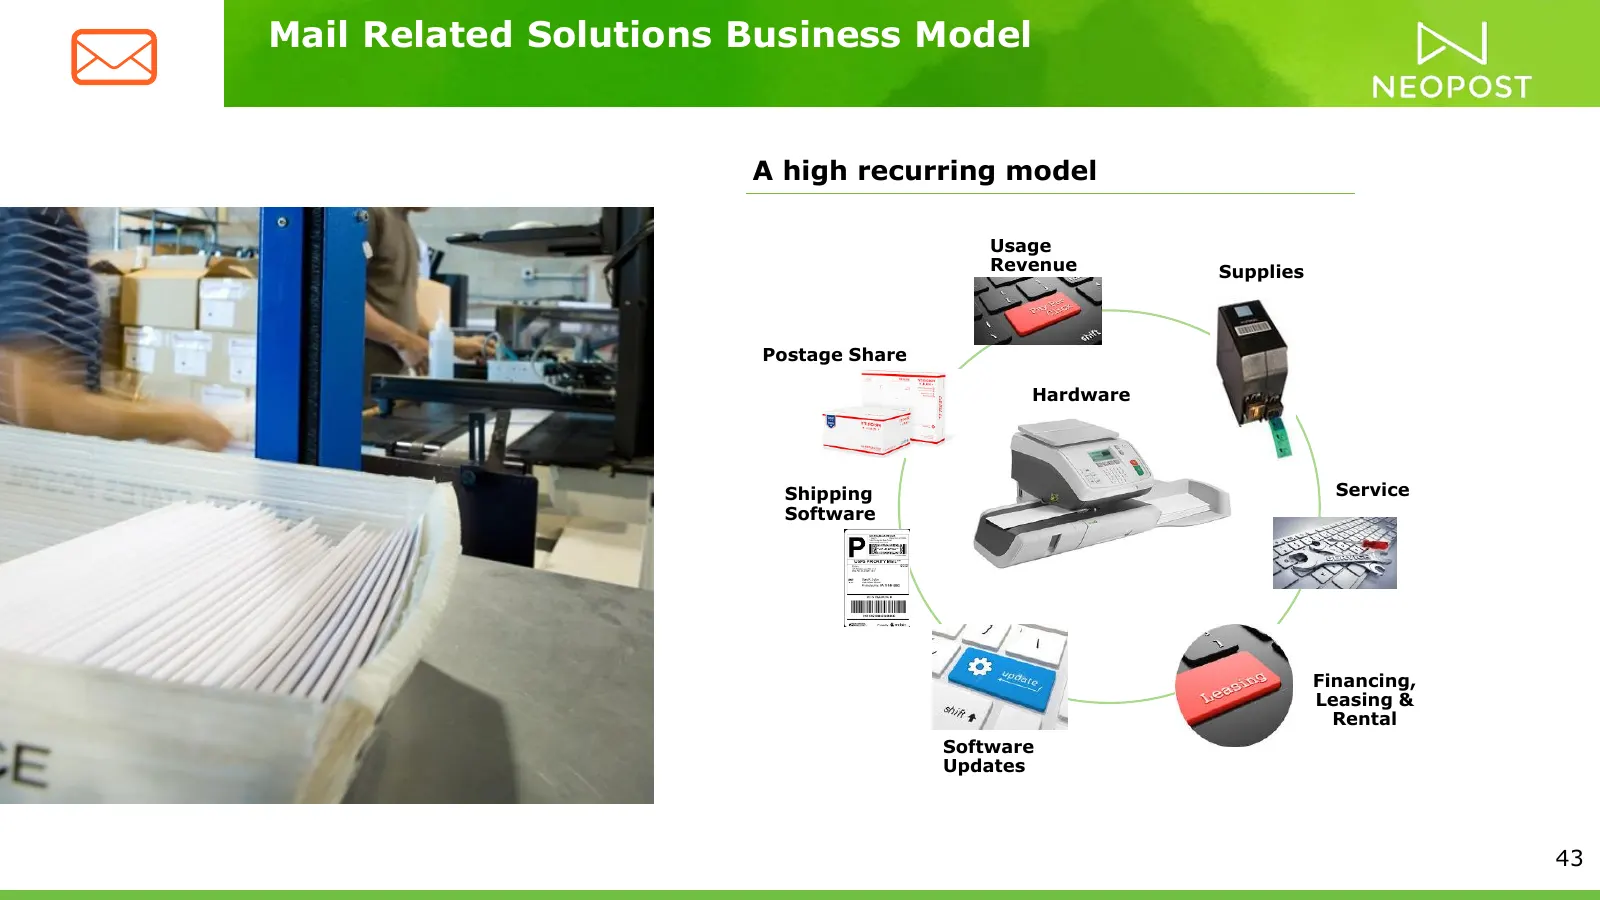
Slide 43: Mail Related Solutions Business Model
Mail Related Solutions Business Model A high recurring model Usage Revenue Supplies Postage Share Hardware Shipping Service Software Financing, Leasing & Rental Software Updates 43
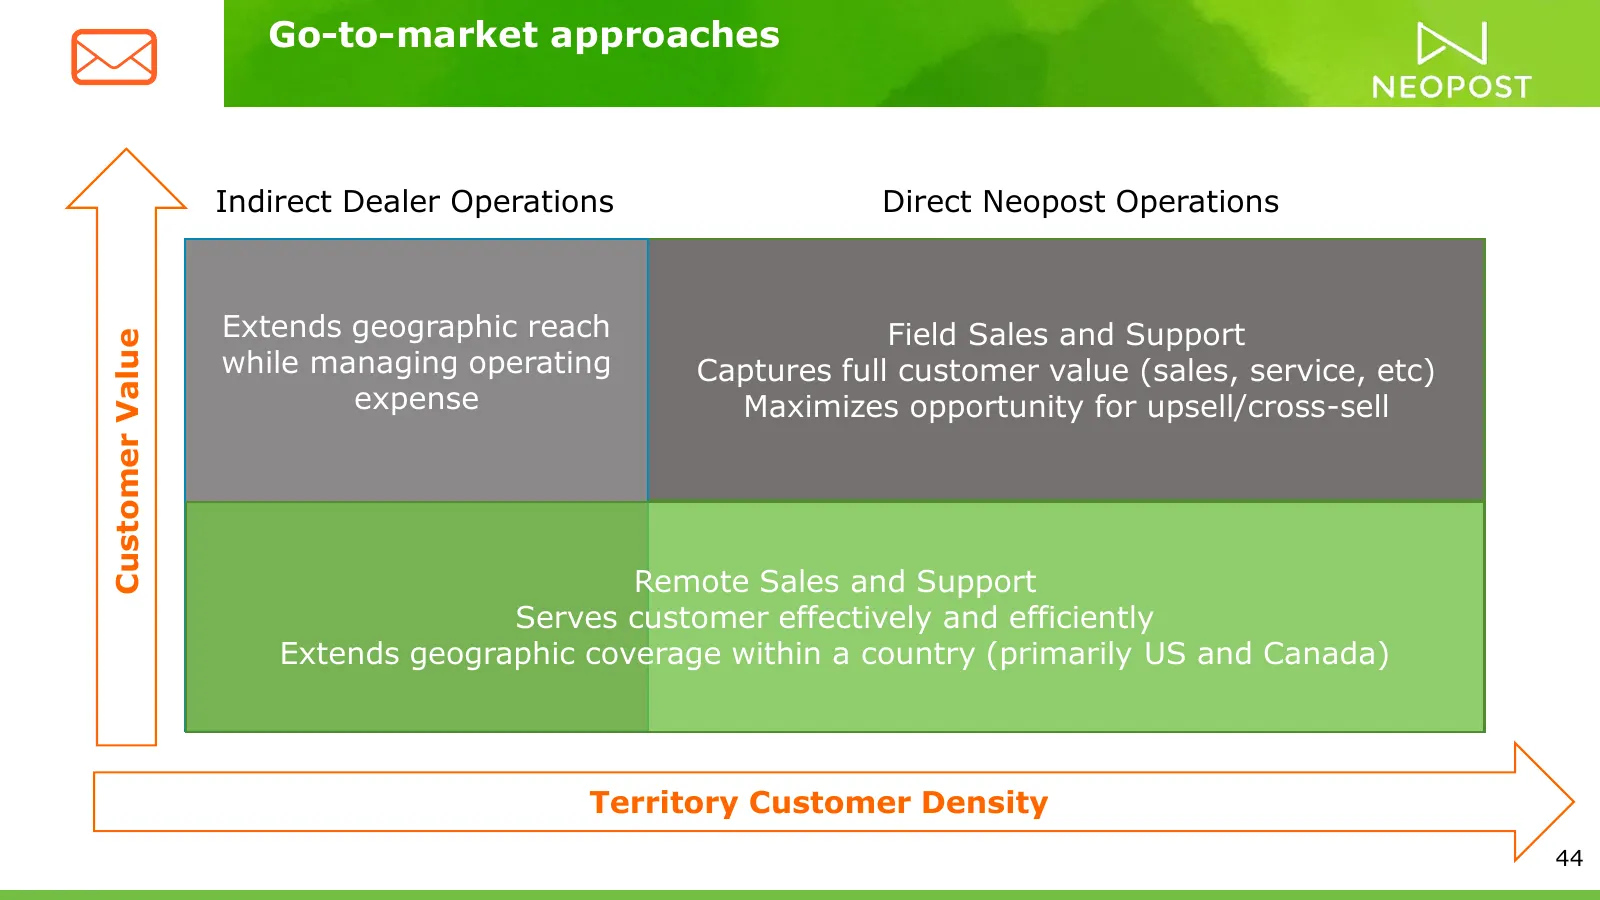
Slide 44: Go-to-market approaches
Go-to-market approaches Indirect Dealer Operations Direct Neopost Operations Extends geographic reach Field Sales and Support Customer Value while managing operating Captures full customer value (sales, service, etc) expense Maximizes opportunity for upsell/cross-sell Remote Sales and Support Serves
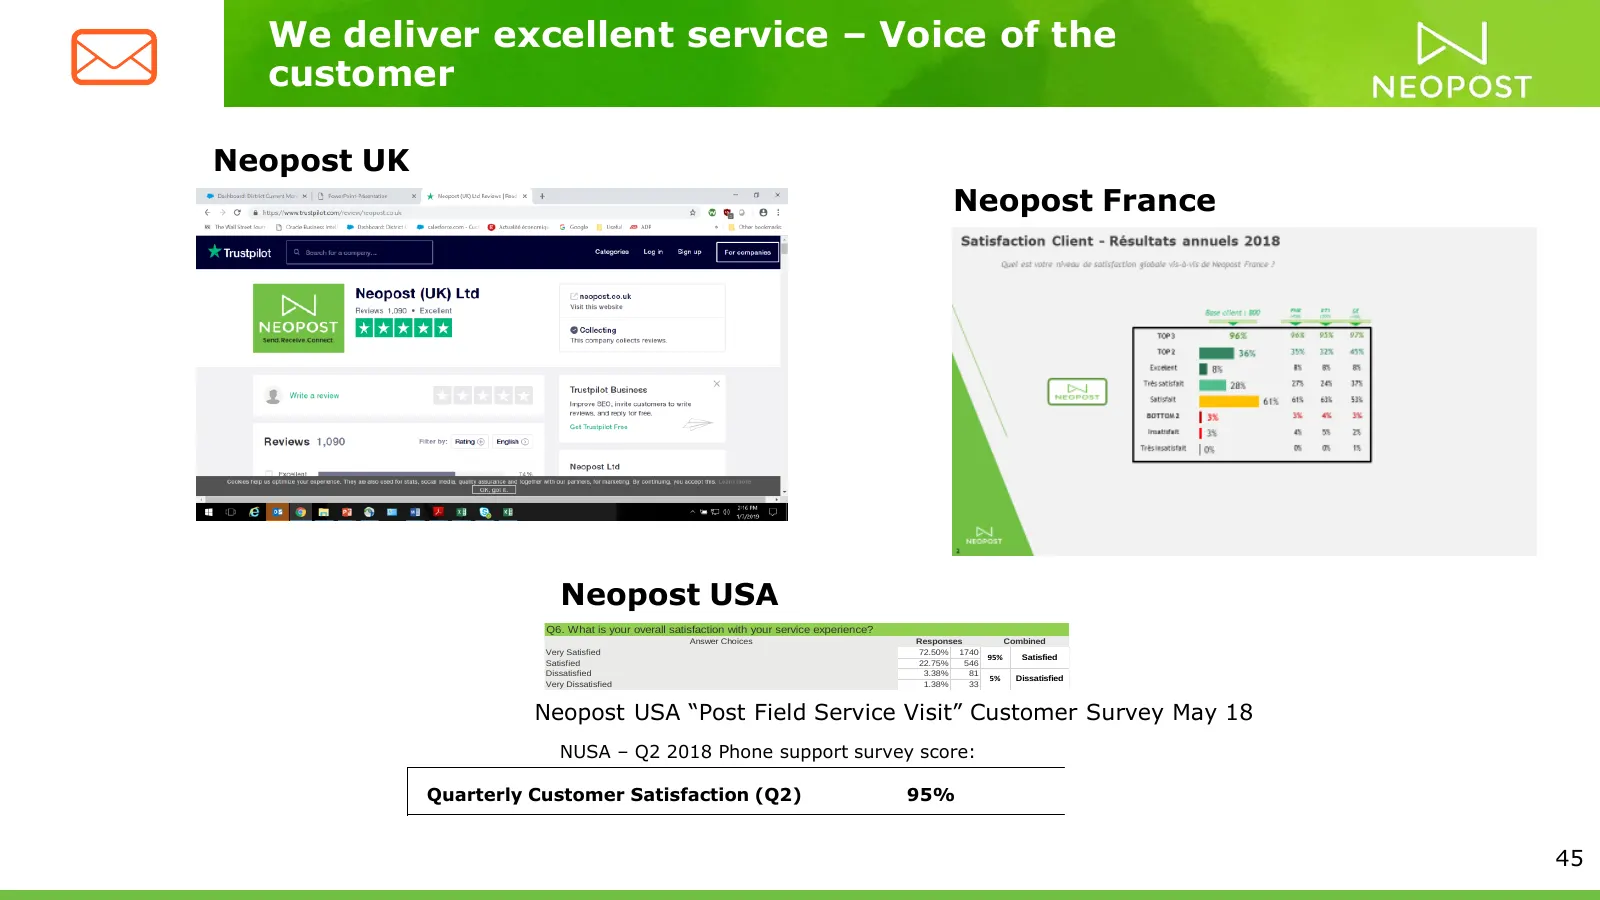
Slide 45: We deliver excellent service – Voice of the customer
We deliver excellent service – Voice of the customer Neopost UK Neopost France Neopost USA Q6. What is your overall satisfaction with your service experience? Answer Choices Responses Combined Very Satisfied 72.50% 1740 95% Satisfied Satisfied 22.75% 546 Dissatisfied 3.38% 81 5% Dissatisfied Very Di
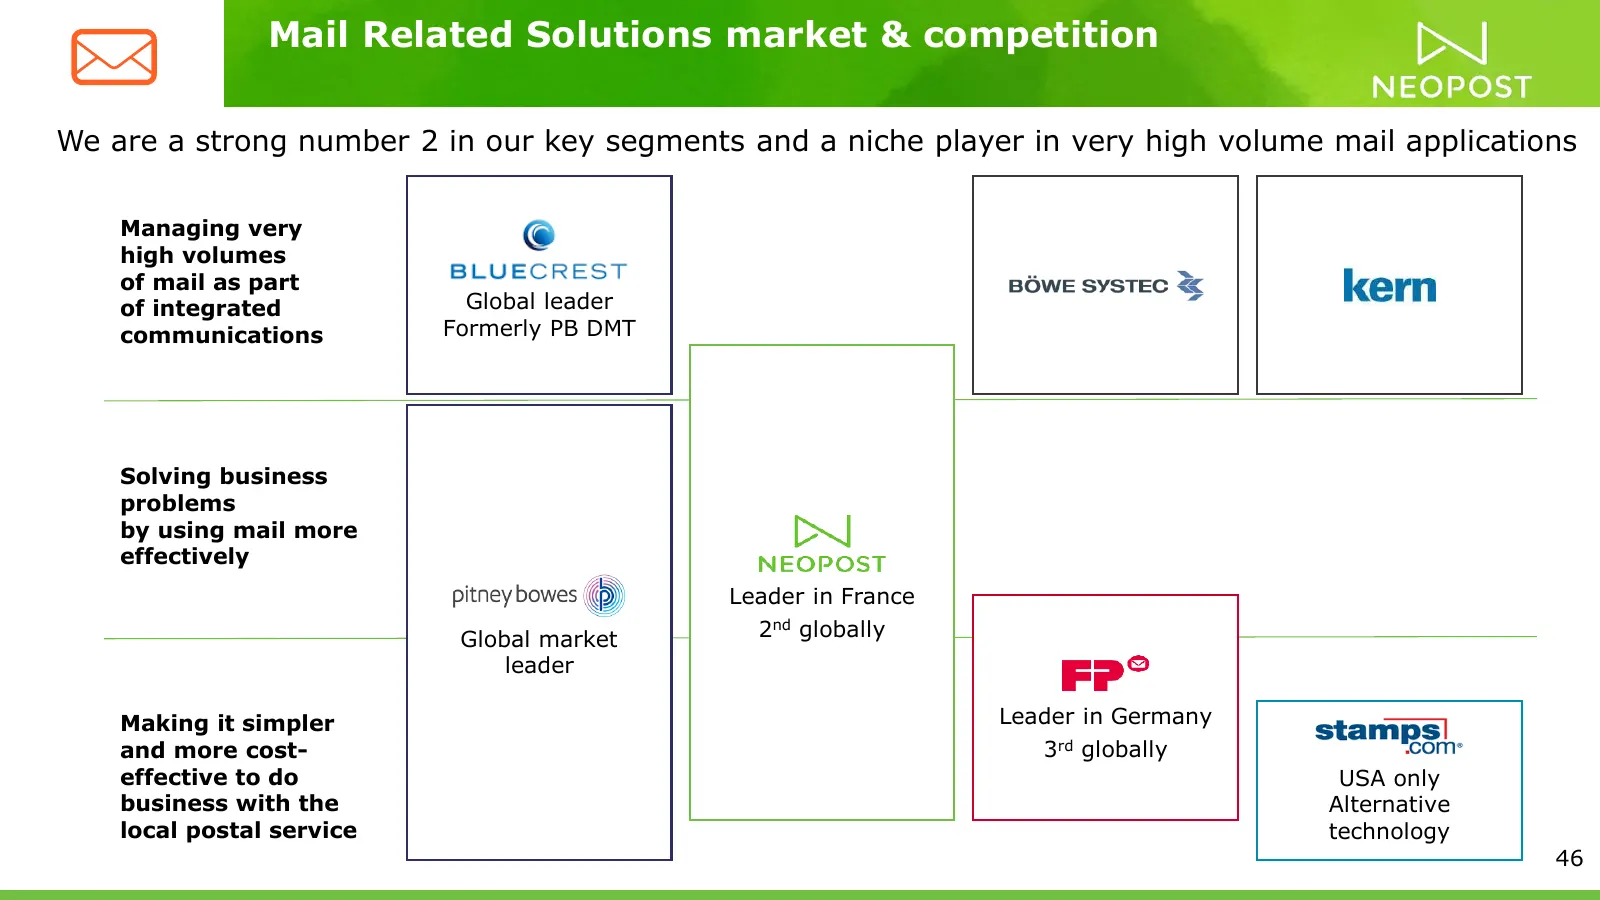
Slide 46: Mail Related Solutions market & competition
Mail Related Solutions market & competition We are a strong number 2 in our key segments and a niche player in very high volume mail applications Managing very high volumes of mail as part of integrated Global leader communications Formerly PB DMT Solving business problems by using mail more effecti
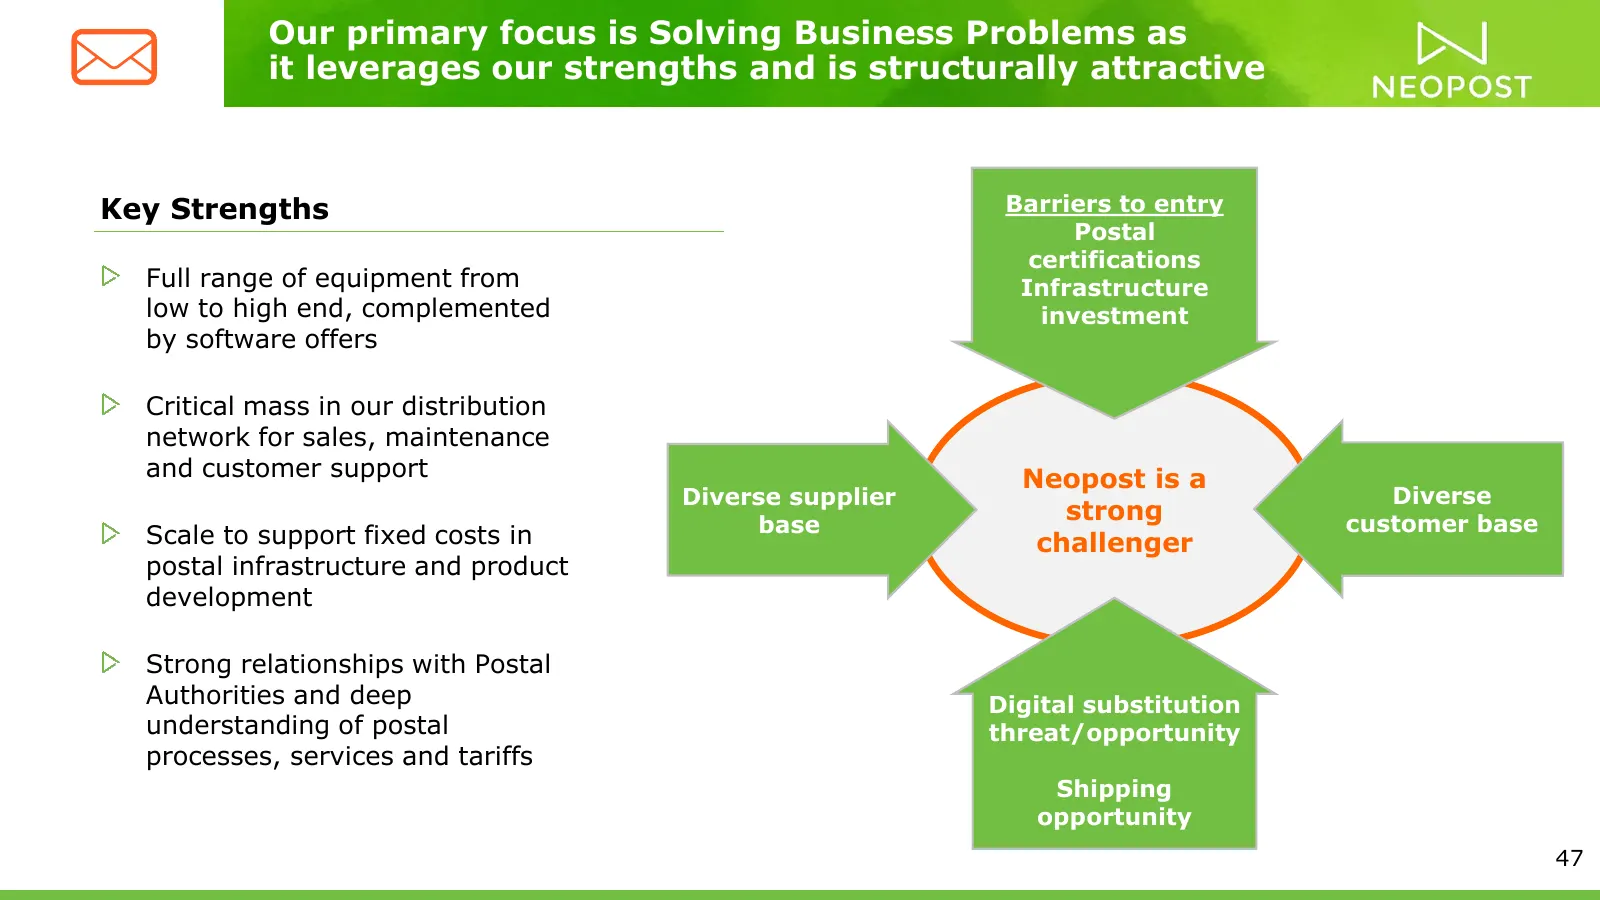
Slide 47: Focus on Solving Business Problems leverages our strengths
Our primary focus is Solving Business Problems as it leverages our strengths and is structurally attractive Key Strengths Barriers to entry Postal certifications Full range of equipment from Infrastructure low to high end, complemented investment by software offers Critical mass in our distribution
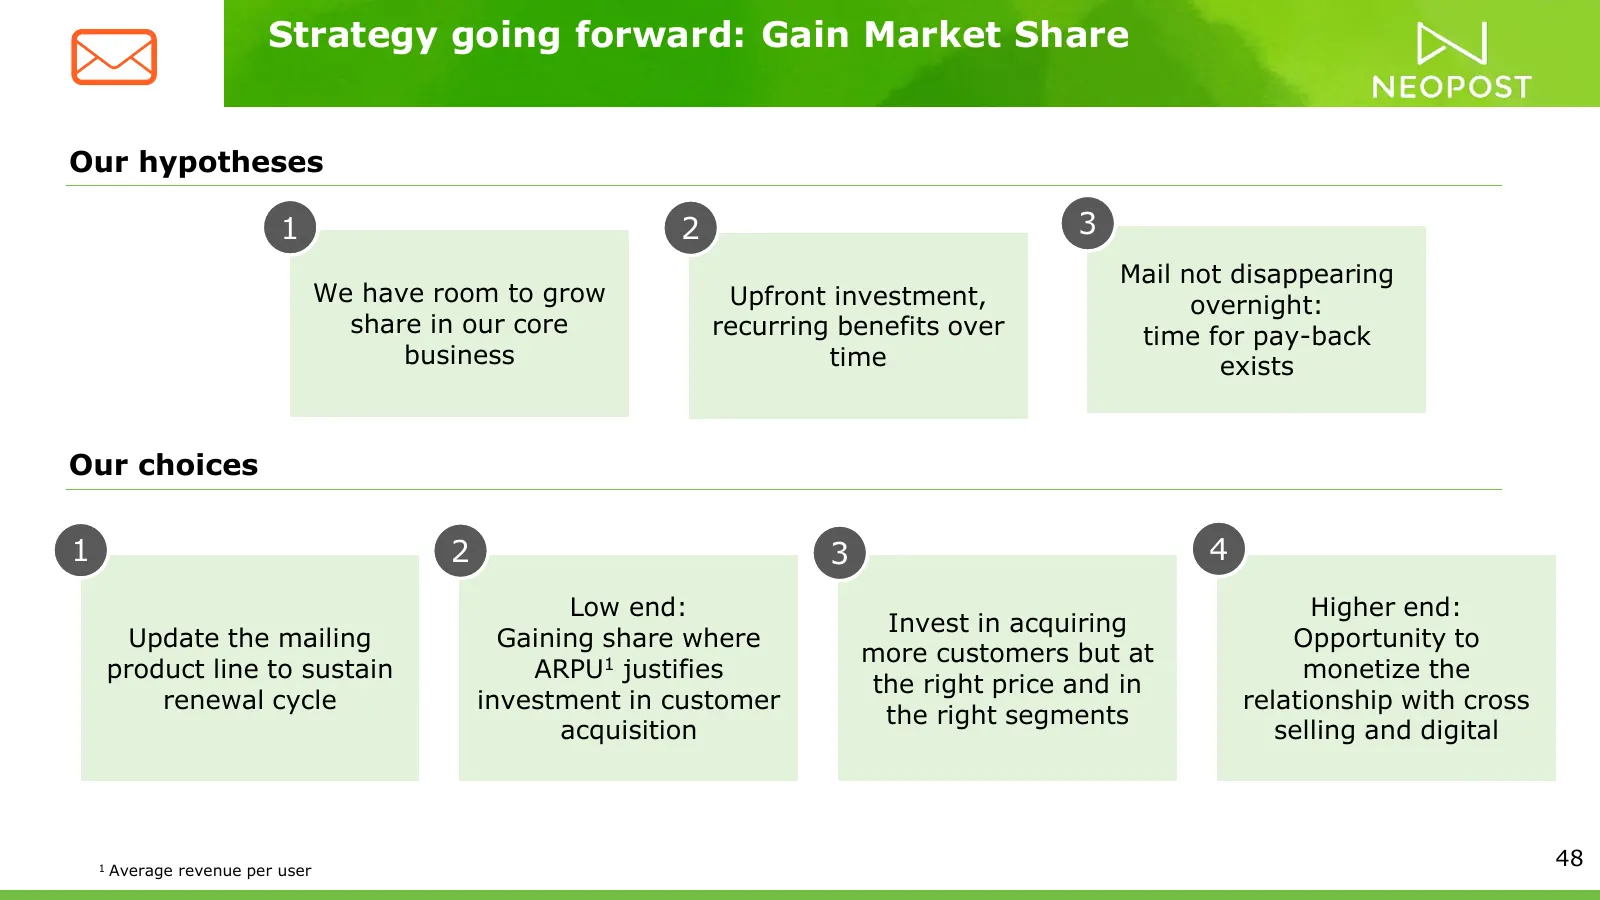
Slide 48: Strategy going forward: Gain Market Share
Strategy going forward: Gain Market Share Our hypotheses 1 2 3 Mail not disappearing We have room to grow Upfront investment, overnight: share in our core recurring benefits over time for pay-back business time exists Our choices 1 2 3 4 Low end: Higher end: Invest in acquiring Update the mailing Ga
Slide 49: Market Evolution and Neopost's Share Gain Opportunity
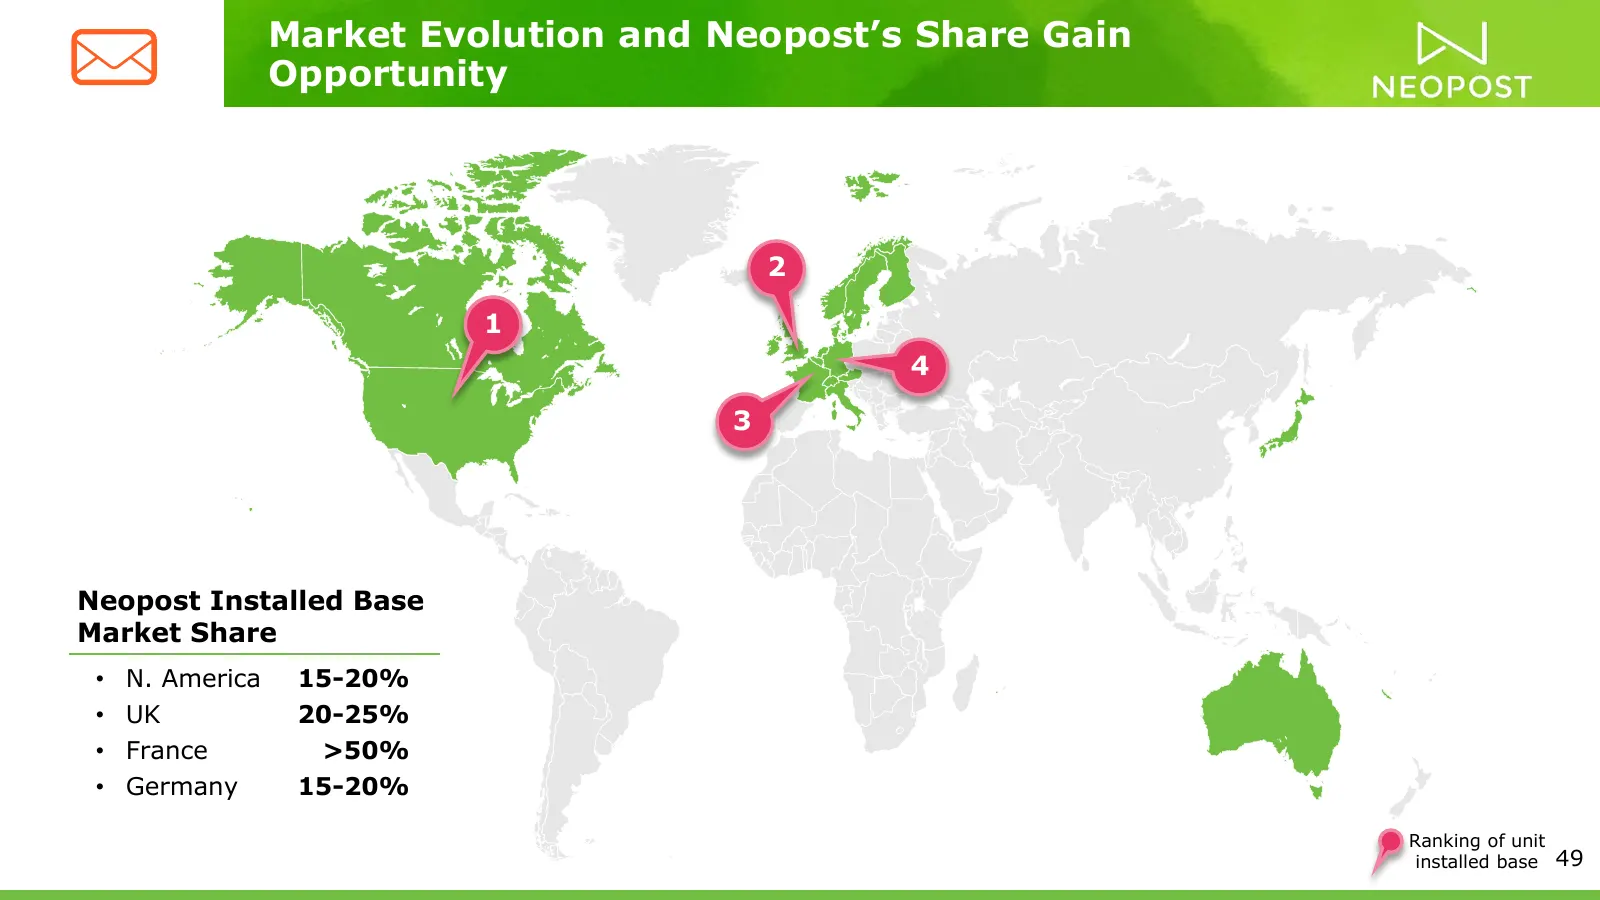
Market Evolution and Neopost’s Share Gain Opportunity 2 1 4 3 Neopost Installed Base Market Share • N. America 15-20% • UK 20-25% • France >50% • Germany 15-20% Ranking of unit installed base 49
Slide 50: Conclusion
Conclusion Maximize value over long term from Mail Related Solutions by: - Reinvesting in the offering and extend it - Keeping differentiated customer servicing - Gaining market shares - Focusing on main geographies: North America & Main European markets - Optimising local distribution footprint
Slide 51: Business Process Automation
Business Process Automation • Henri Dura
Slide 52: Automating business processes is crucial
Automating business processes is crucial to master customer experience, costs and regulation Digitalization is at the heart of back office cost optimization programs Regulation is encouraging process automation and digitalization Increasing willingness to improve customer experience 52
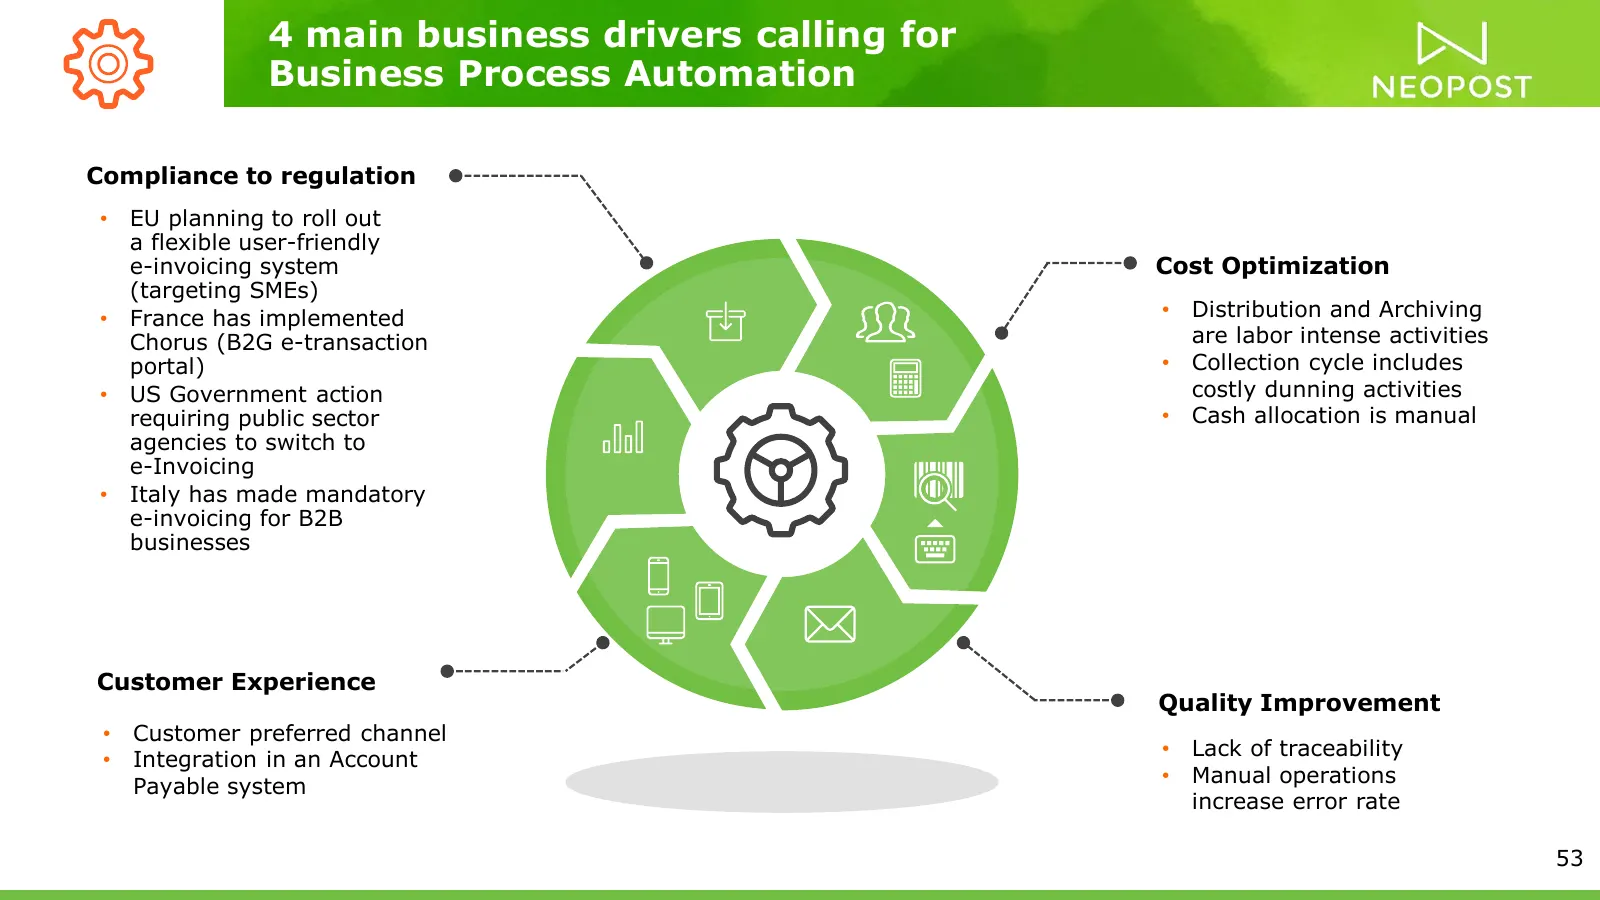
Slide 53: 4 main business drivers for Business Process Automation
4 main business drivers calling for Business Process Automation Compliance to regulation • EU planning to roll out a flexible user-friendly e-invoicing system Cost Optimization (targeting SMEs) • France has implemented • Distribution and Archiving Chorus (B2G e-transaction are labor intense activiti
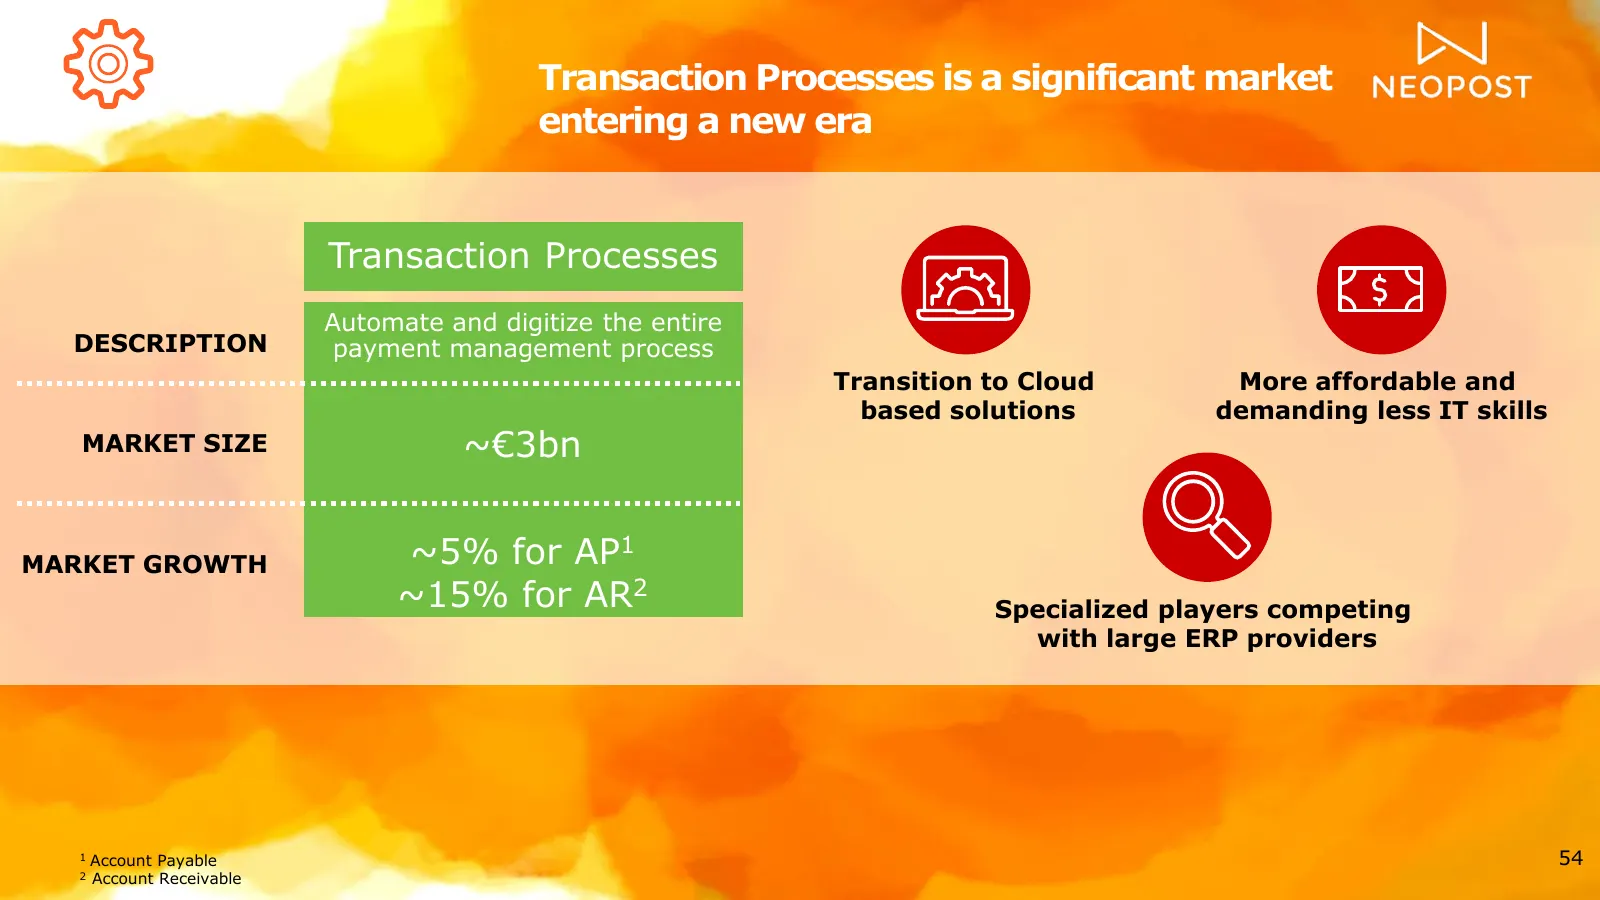
Slide 54: Transaction Processes is a significant market entering a new era
Transaction Processes is a significant market entering a new era Transaction Processes Automate and digitize the entire DESCRIPTION payment management process Transition to Cloud More affordable and based solutions demanding less IT skills MARKET SIZE ~€3bn MARKET GROWTH ~5% for AP1 ~15% for AR2 Spe
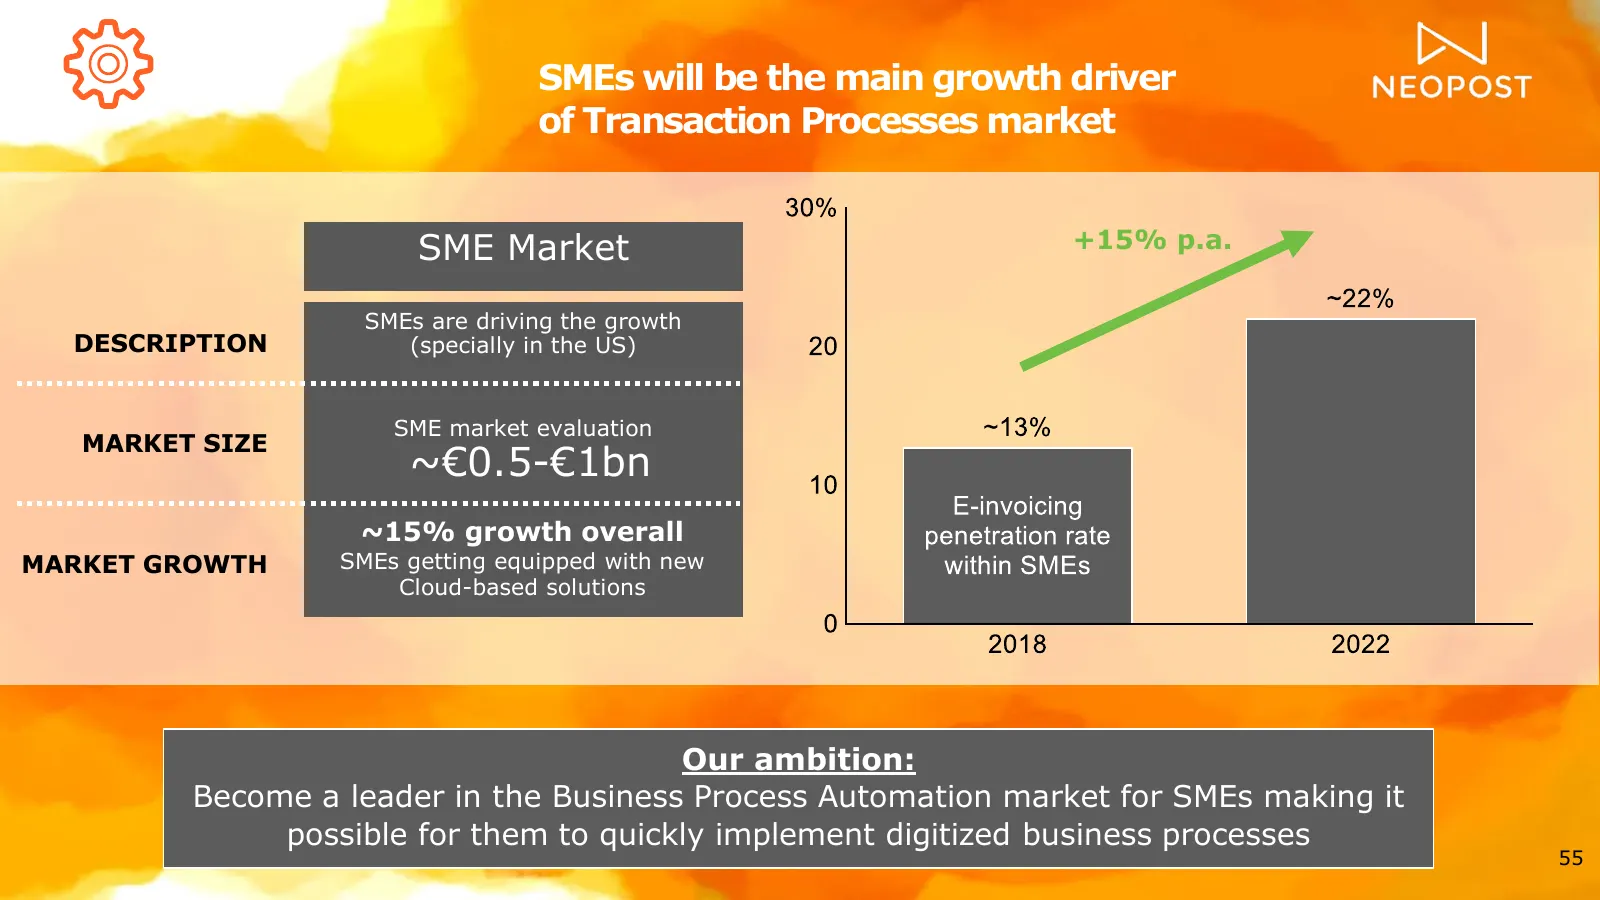
Slide 55: SMEs will be the main growth driver
SMEs will be the main growth driver of Transaction Processes market SME Market +15% p.a. SMEs are driving the growth DESCRIPTION (specially in the US) SME market evaluation MARKET SIZE ~€0.5-€1bn ~15% growth overall MARKET GROWTH SMEs getting equipped with new Cloud-based solutions Our ambition: Bec
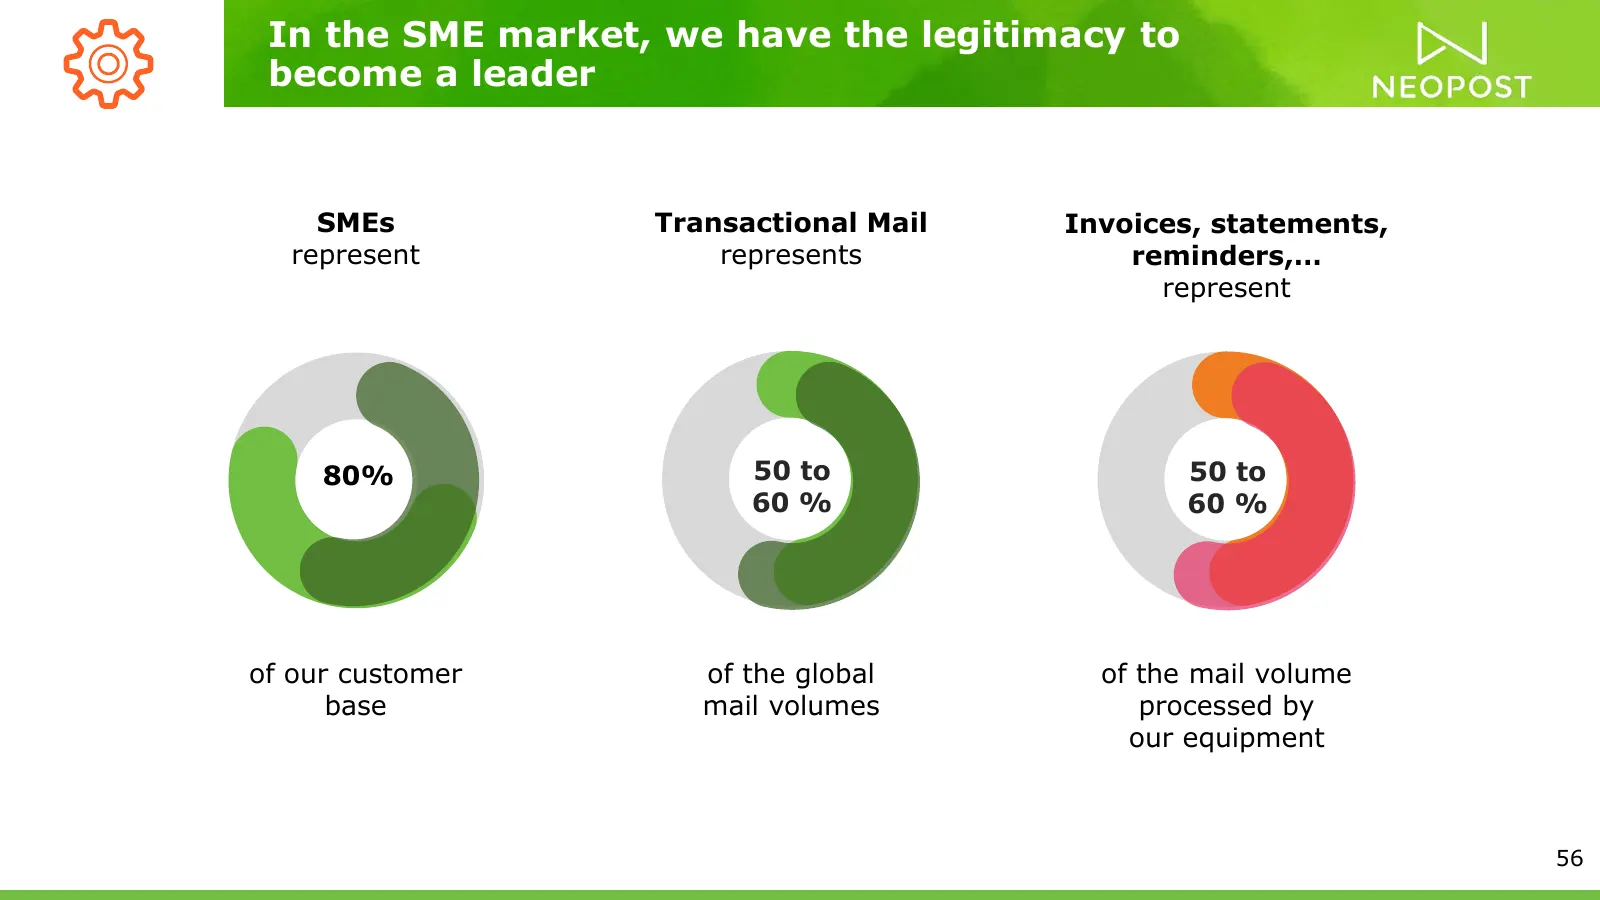
Slide 56: In the SME market, we have the legitimacy to become a leader
In the SME market, we have the legitimacy to become a leader SMEs Transactional Mail Invoices, statements, represent represents reminders,… represent 80% 50 to 50 to 60 % 60 % of our customer of the global of the mail volume base mail volumes processed by our equipment 56
Slide 57: We will build on our current solutions
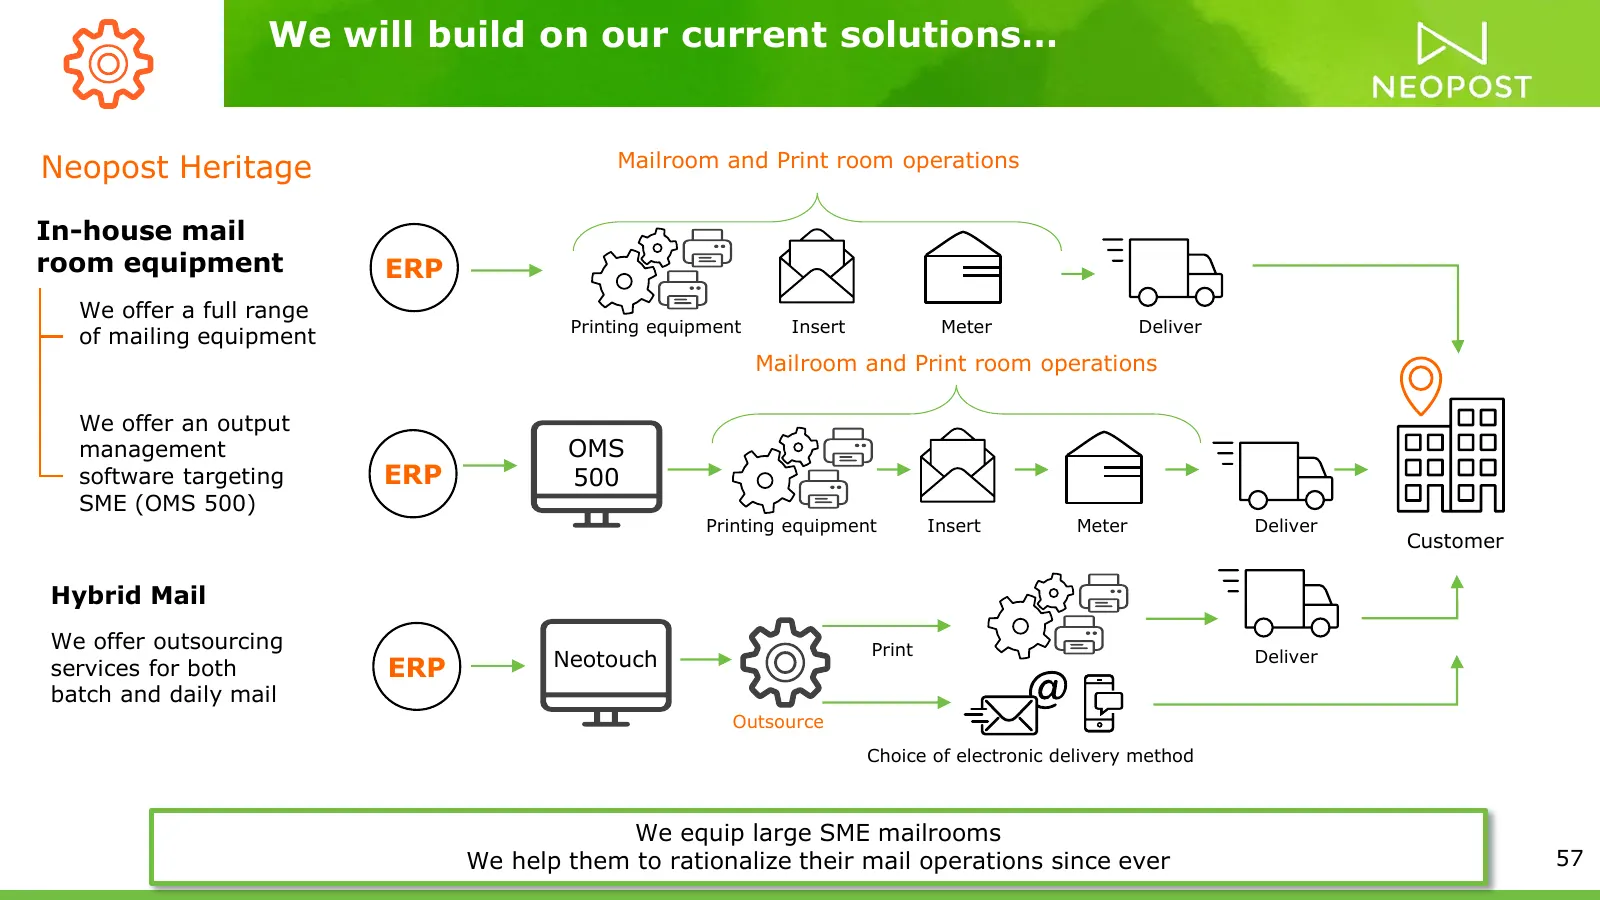
We will build on our current solutions… Neopost Heritage Mailroom and Print room operations In-house mail room equipment ERP We offer a full range Printing equipment Insert Meter Deliver of mailing equipment Mailroom and Print room operations We offer an output management OMS software targeting ERP
Slide 58: Develop new Accounts Payable and Receivable offers
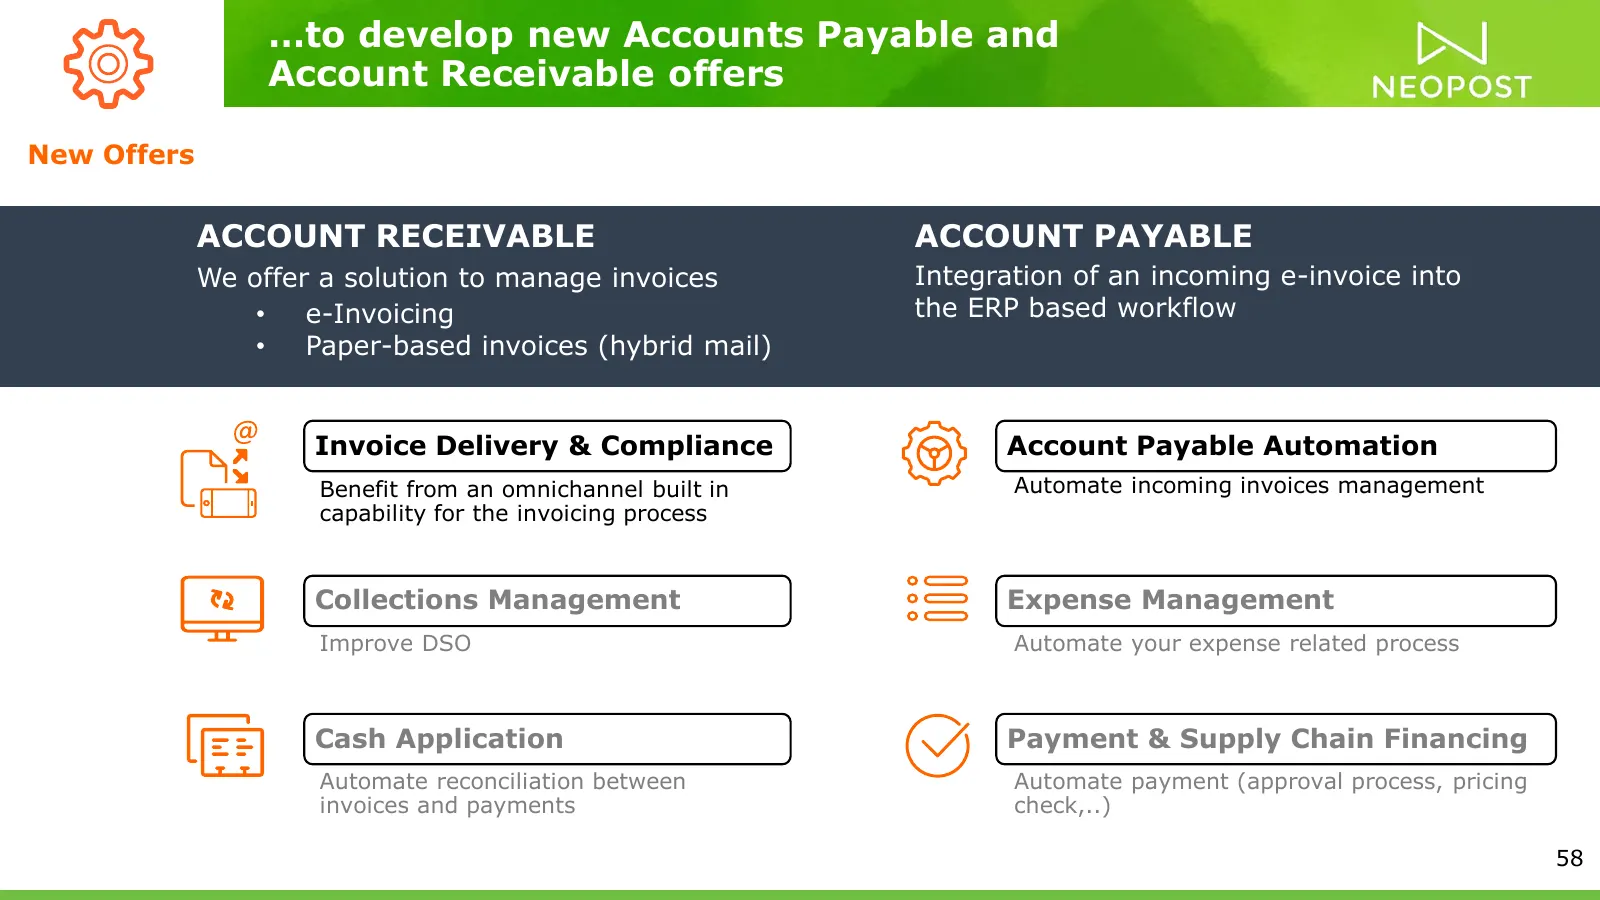
…to develop new Accounts Payable and Account Receivable offers New Offers ACCOUNT RECEIVABLE ACCOUNT PAYABLE We offer a solution to manage invoices Integration of an incoming e-invoice into • e-Invoicing the ERP based workflow • Paper-based invoices (hybrid mail) Invoice Delivery & Compliance Accoun
Slide 59: Expand offer within ERP related processes
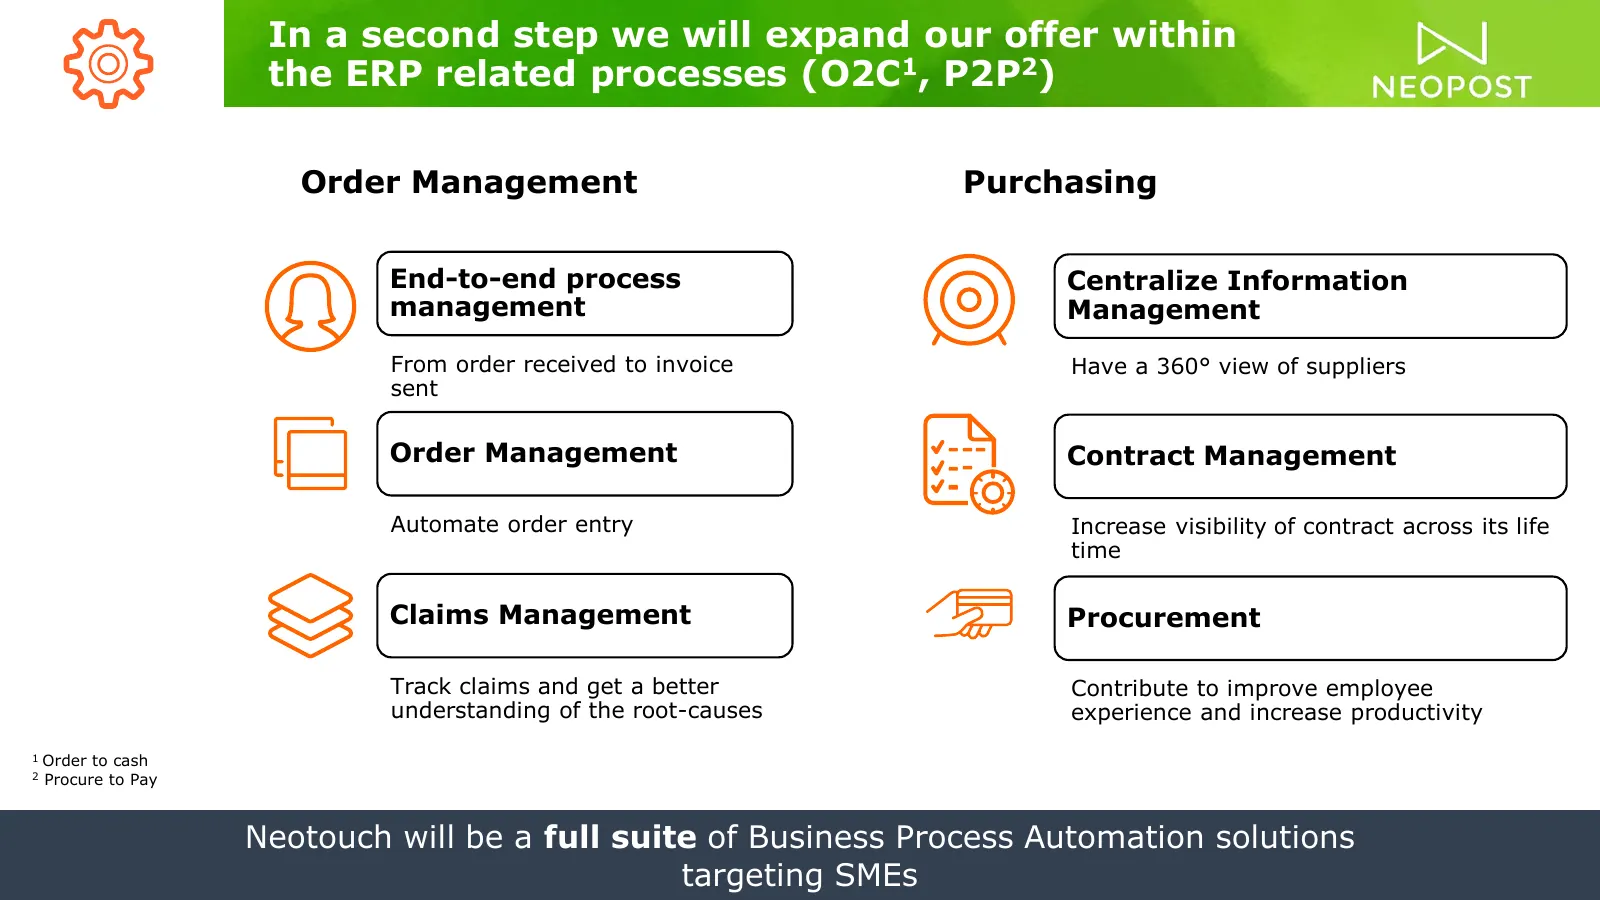
In a second step we will expand our offer within the ERP related processes (O2C1, P2P2) Order Management Purchasing End-to-end process Centralize Information management Management From order received to invoice Have a 360° view of suppliers sent Order Management Contract Management Automate order en
Slide 60: Room for specialized players, especially to serve SMEs
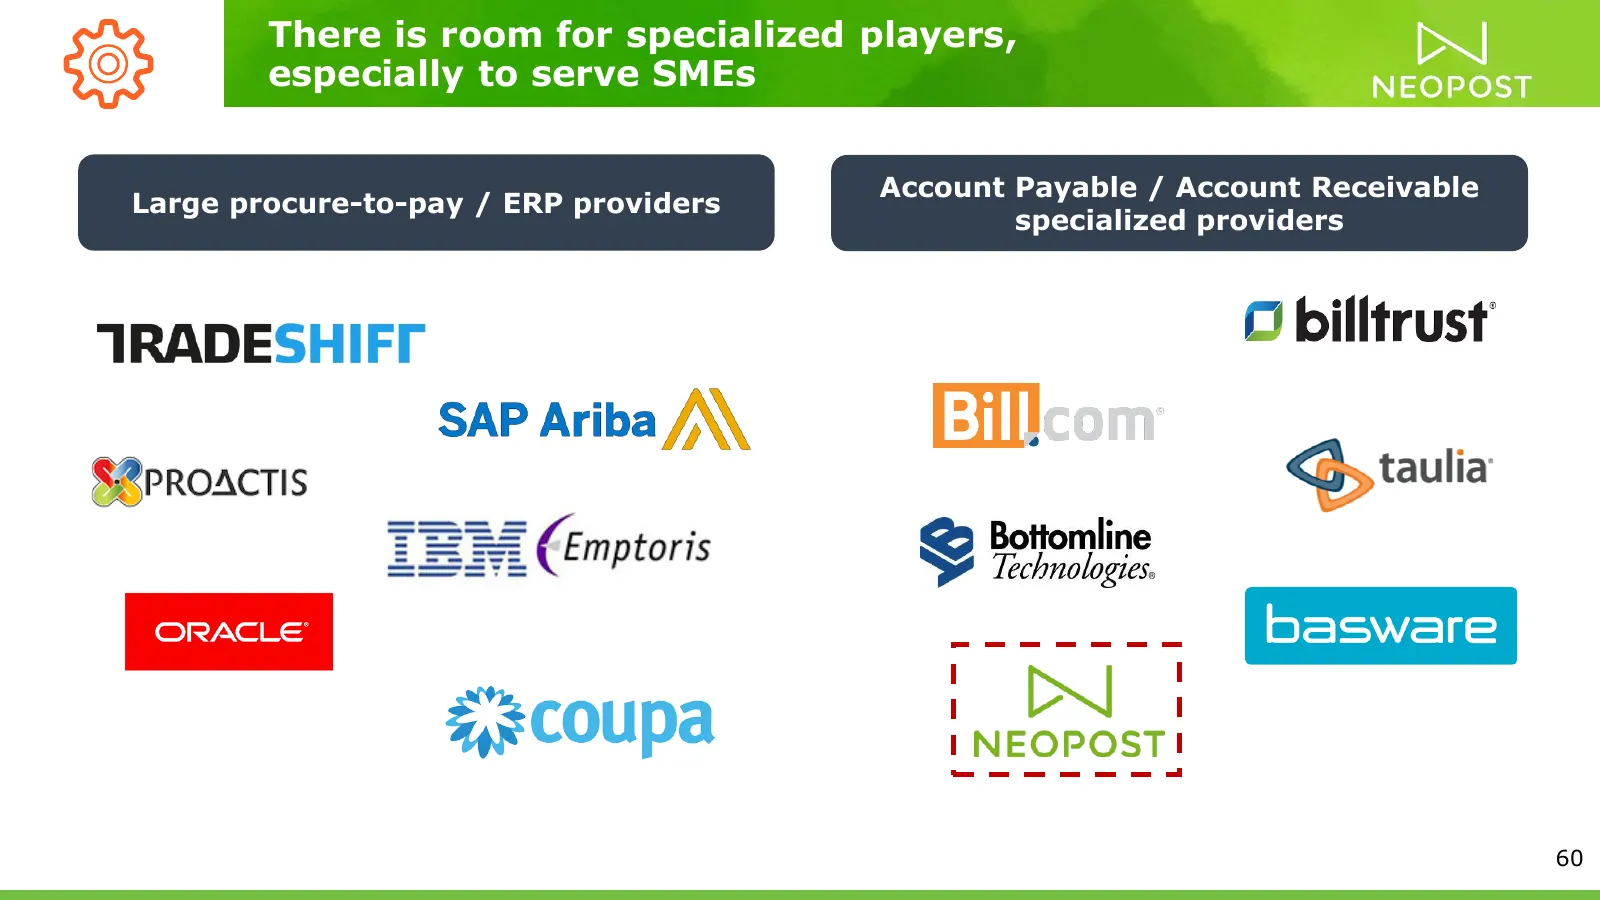
There is room for specialized players, especially to serve SMEs Account Payable / Account Receivable Large procure-to-pay / ERP providers specialized providers 60
Slide 61: Customer Experience Management
Customer Experience Management • Chris Hartigan
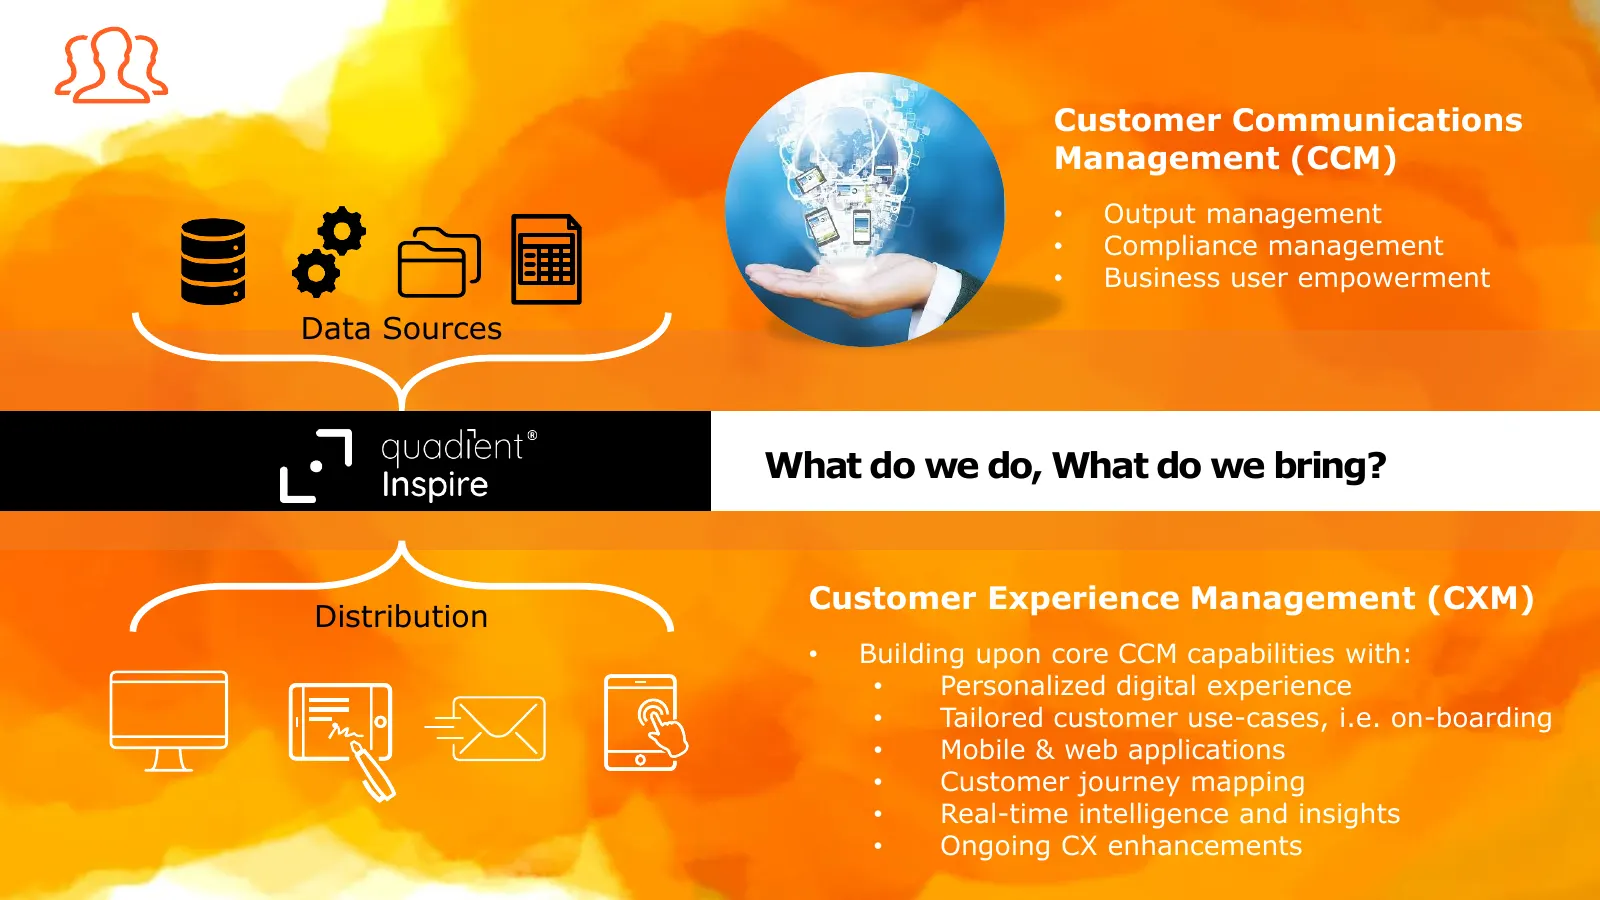
Slide 62: What do we do, What do we bring?
Customer Communications Management (CCM) • Output management • Compliance management • Business user empowerment Data Sources What do we do, What do we bring? Customer Experience Management (CXM) Distribution • Building upon core CCM capabilities with: • Personalized digital experience • Tailored cu
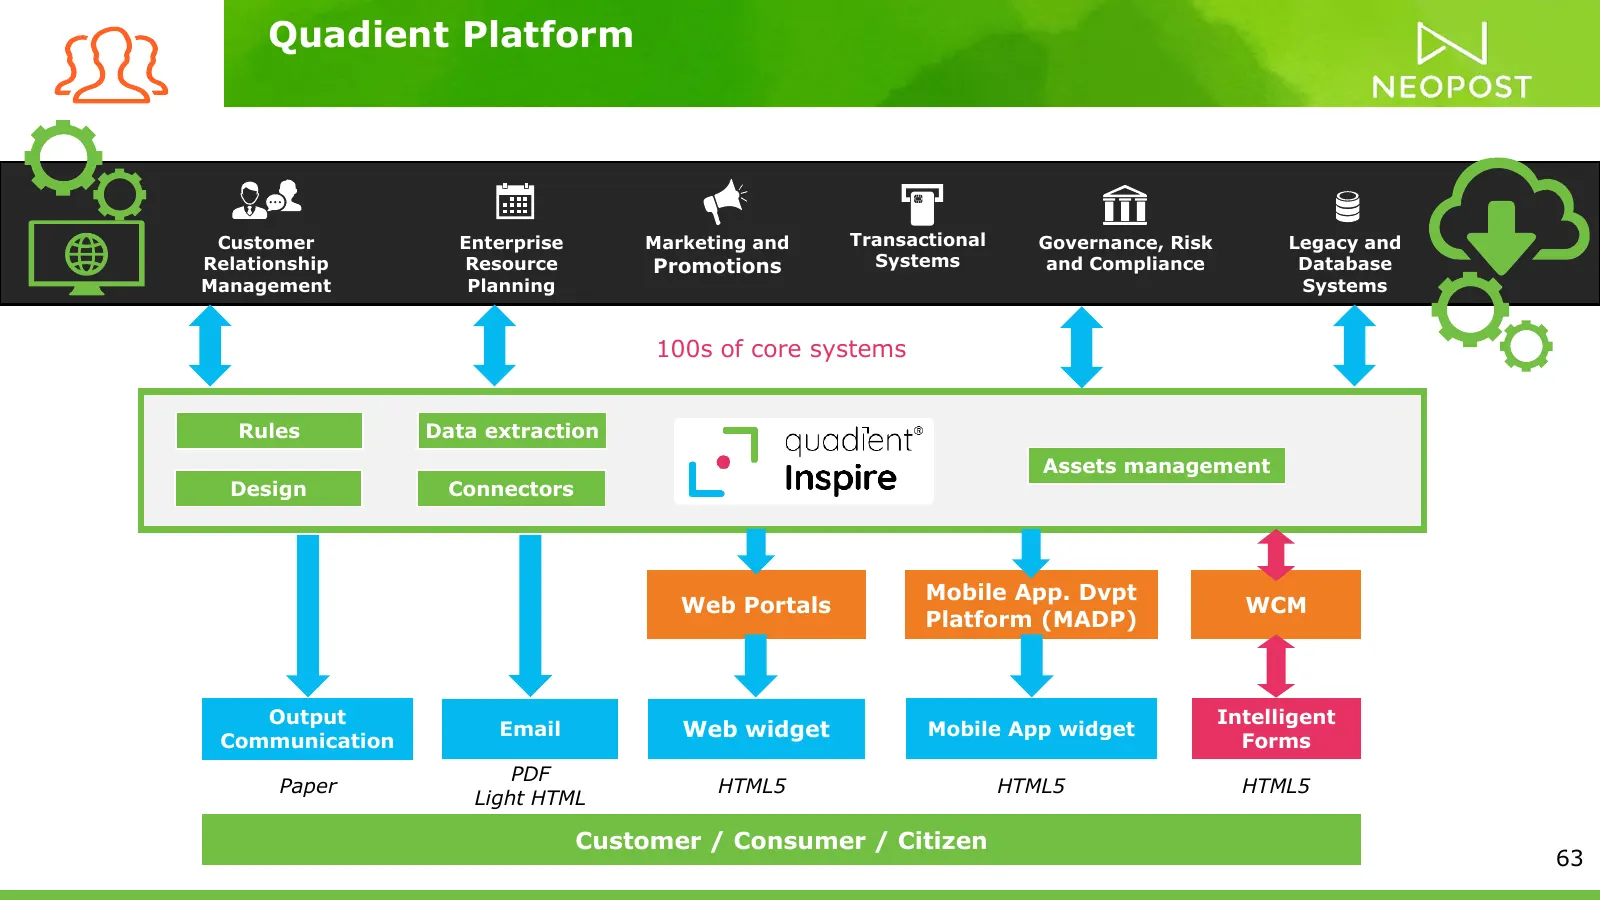
Slide 63: Quadient Platform
Quadient Platform Customer Enterprise Marketing and Transactional Governance, Risk Legacy and Relationship Resource Promotions Systems and Compliance Database Management Planning Systems 100s of core systems Rules Data extraction Assets management Design Connectors Mobile App. Dvpt Web Portals WCM P
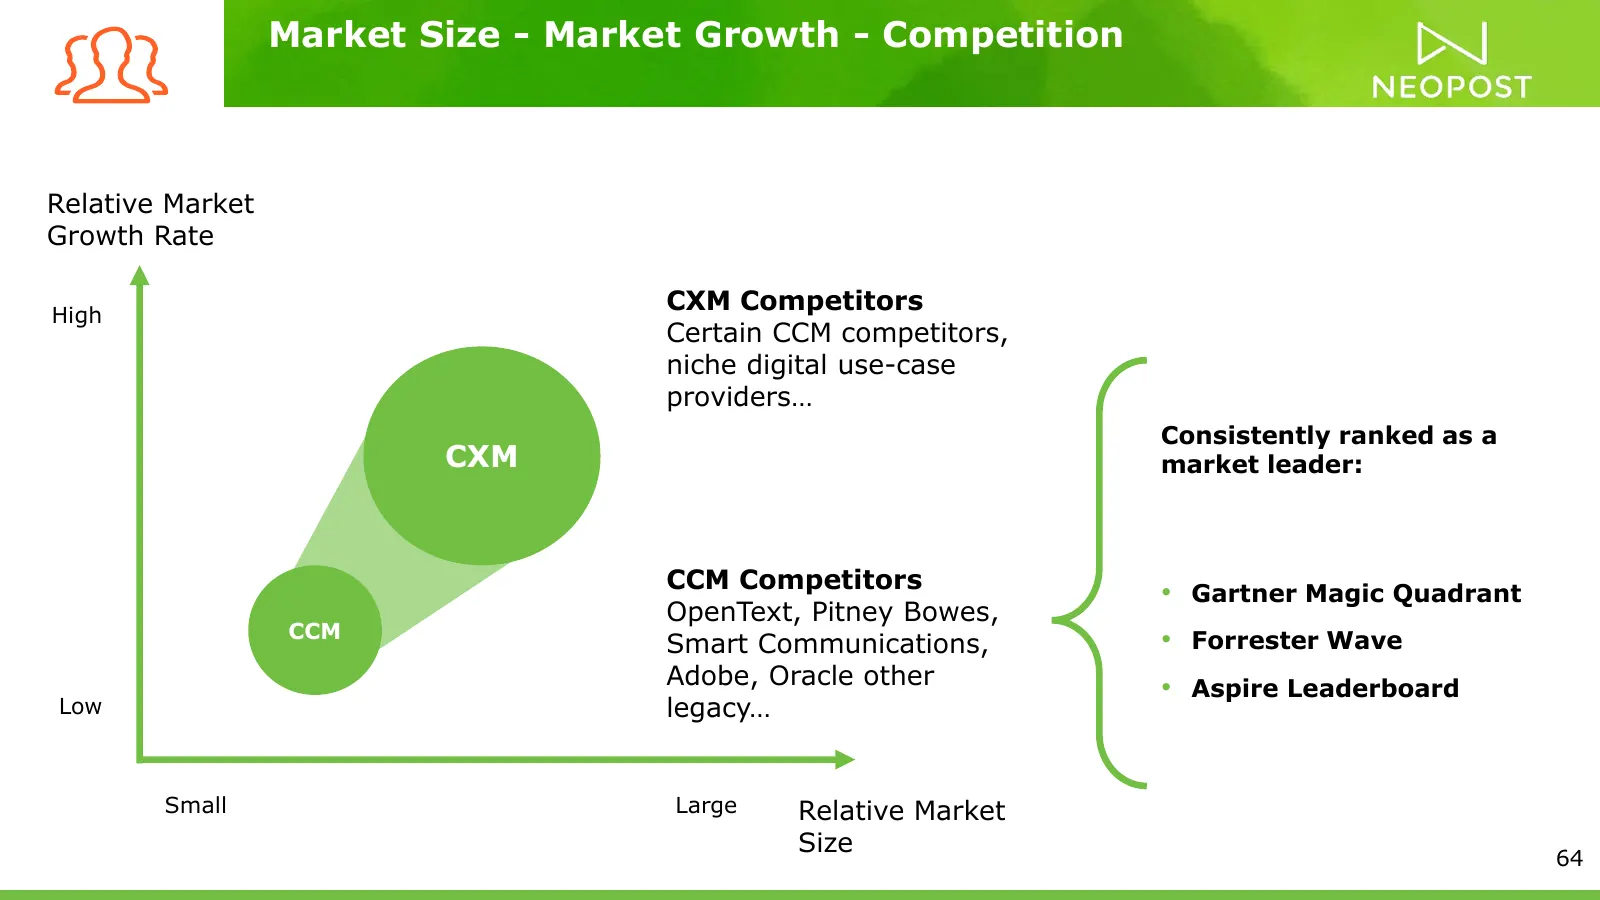
Slide 64: Market Size - Market Growth - Competition
Market Size - Market Growth - Competition Relative Market Growth Rate CXM Competitors High Certain CCM competitors, niche digital use-case providers… Consistently ranked as a CXM market leader: CCM Competitors • Gartner Magic Quadrant OpenText, Pitney Bowes, CCM • Forrester Wave Smart Communications
Slide 65: Leverage our N°1 position in Customer Communication Management
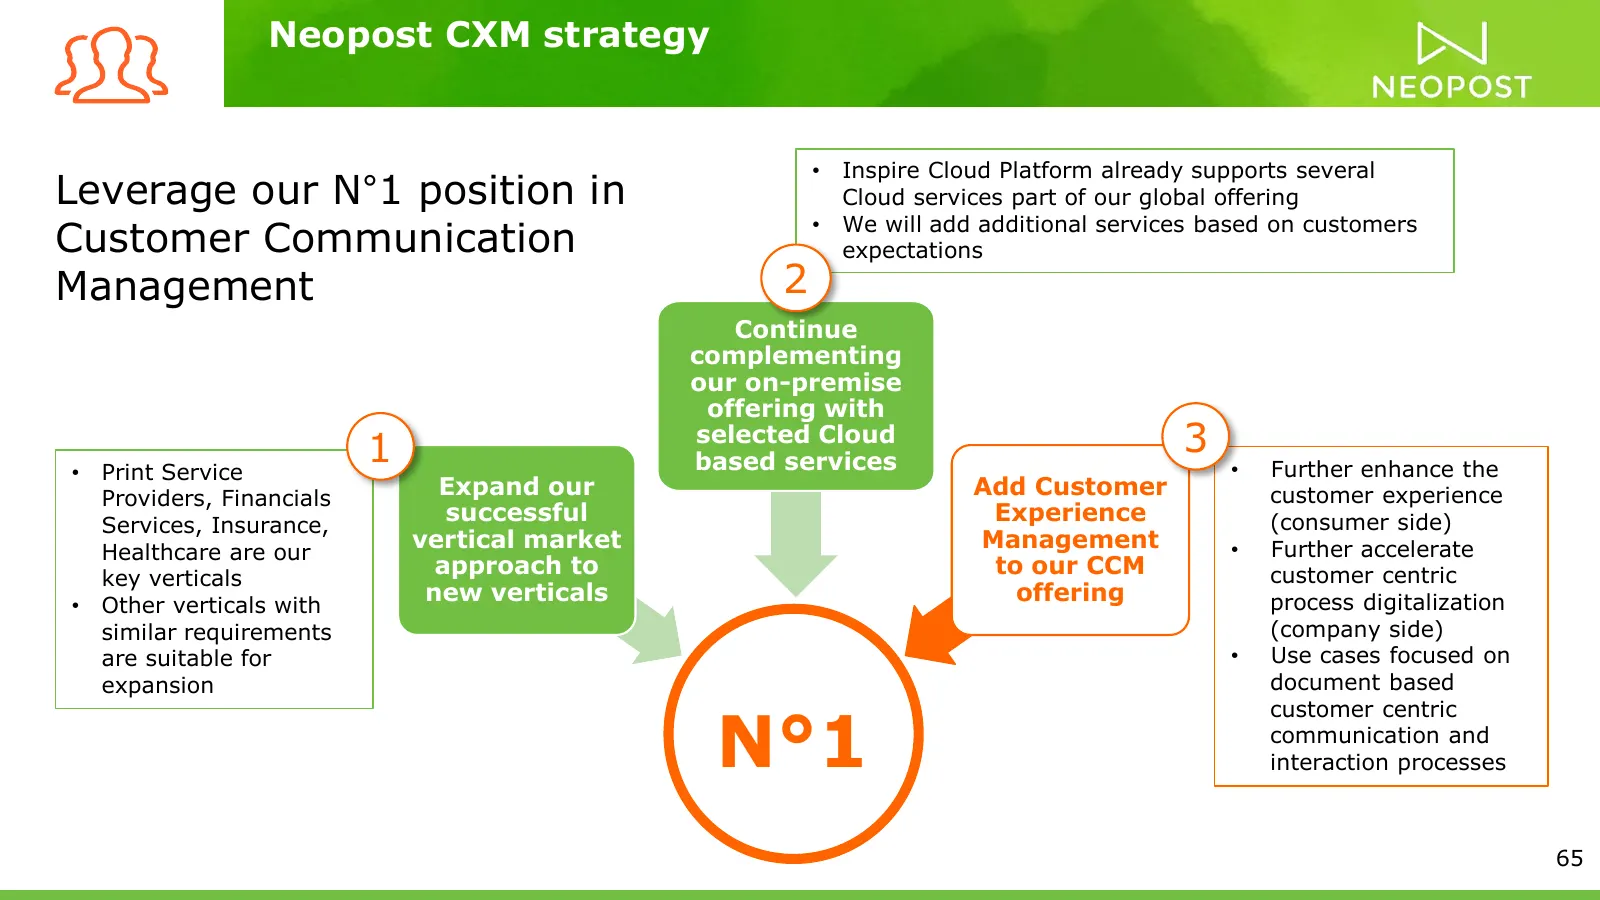
Neopost CXM strategy • Inspire Cloud Platform already supports several Leverage our N°1 position in Cloud services part of our global offering • We will add additional services based on customers Customer Communication expectations Management 2 Continue complementing our on-premise offering with 1 s
Slide 66: Expand to new verticals
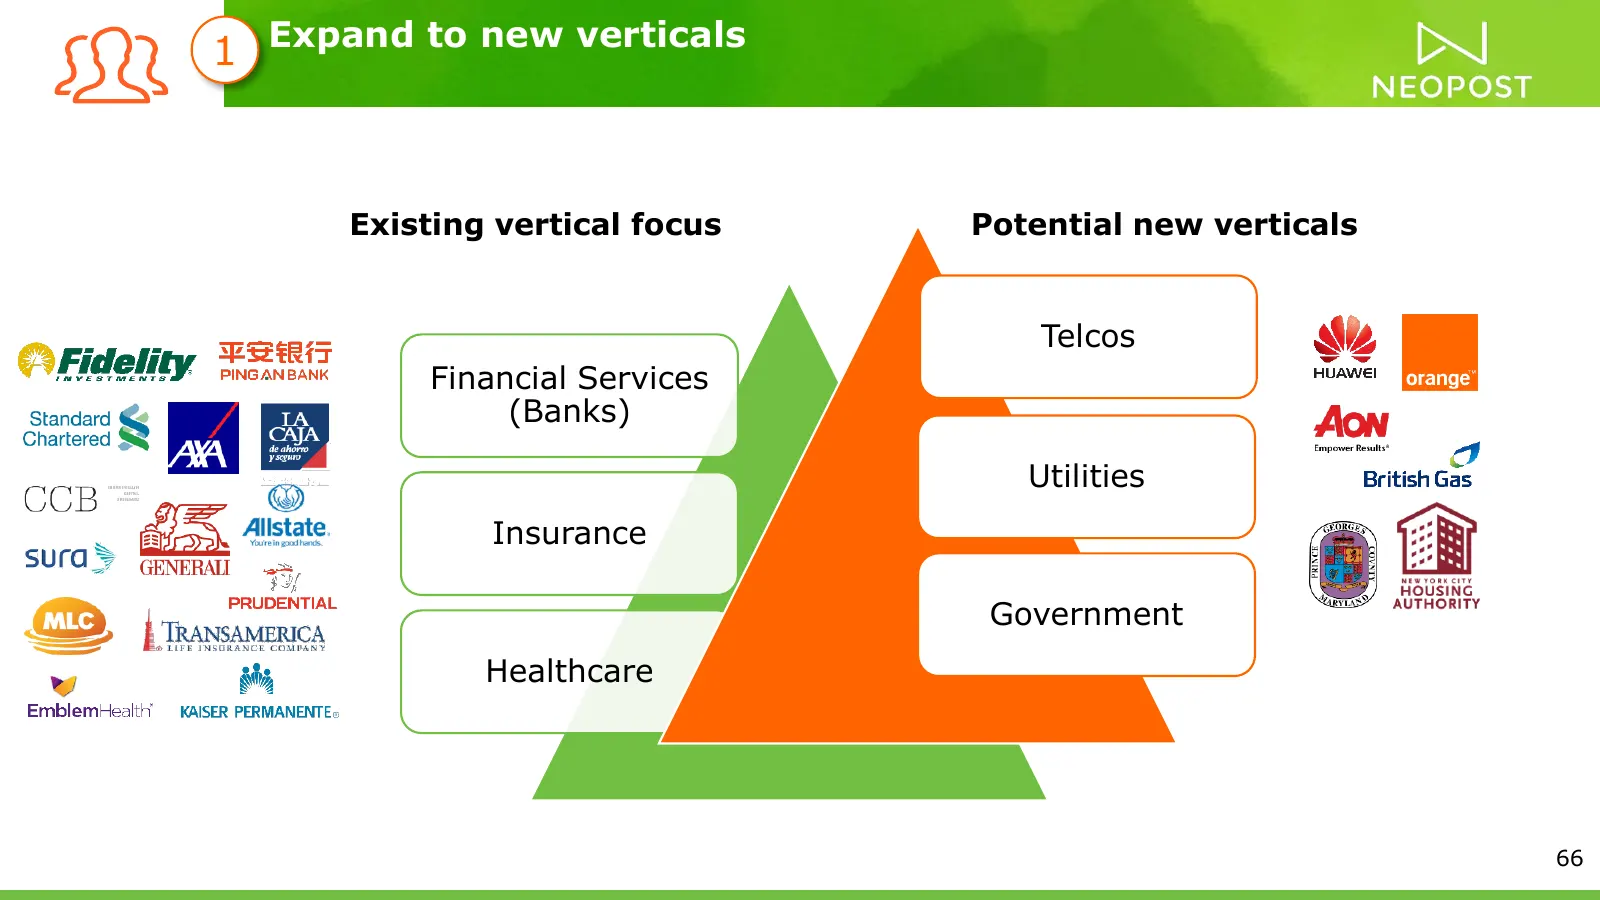
1 Expand to new verticals Existing vertical focus Potential new verticals Telcos Financial Services (Banks) Utilities Insurance Government Healthcare 66
Slide 67: Continue adding Cloud-based services
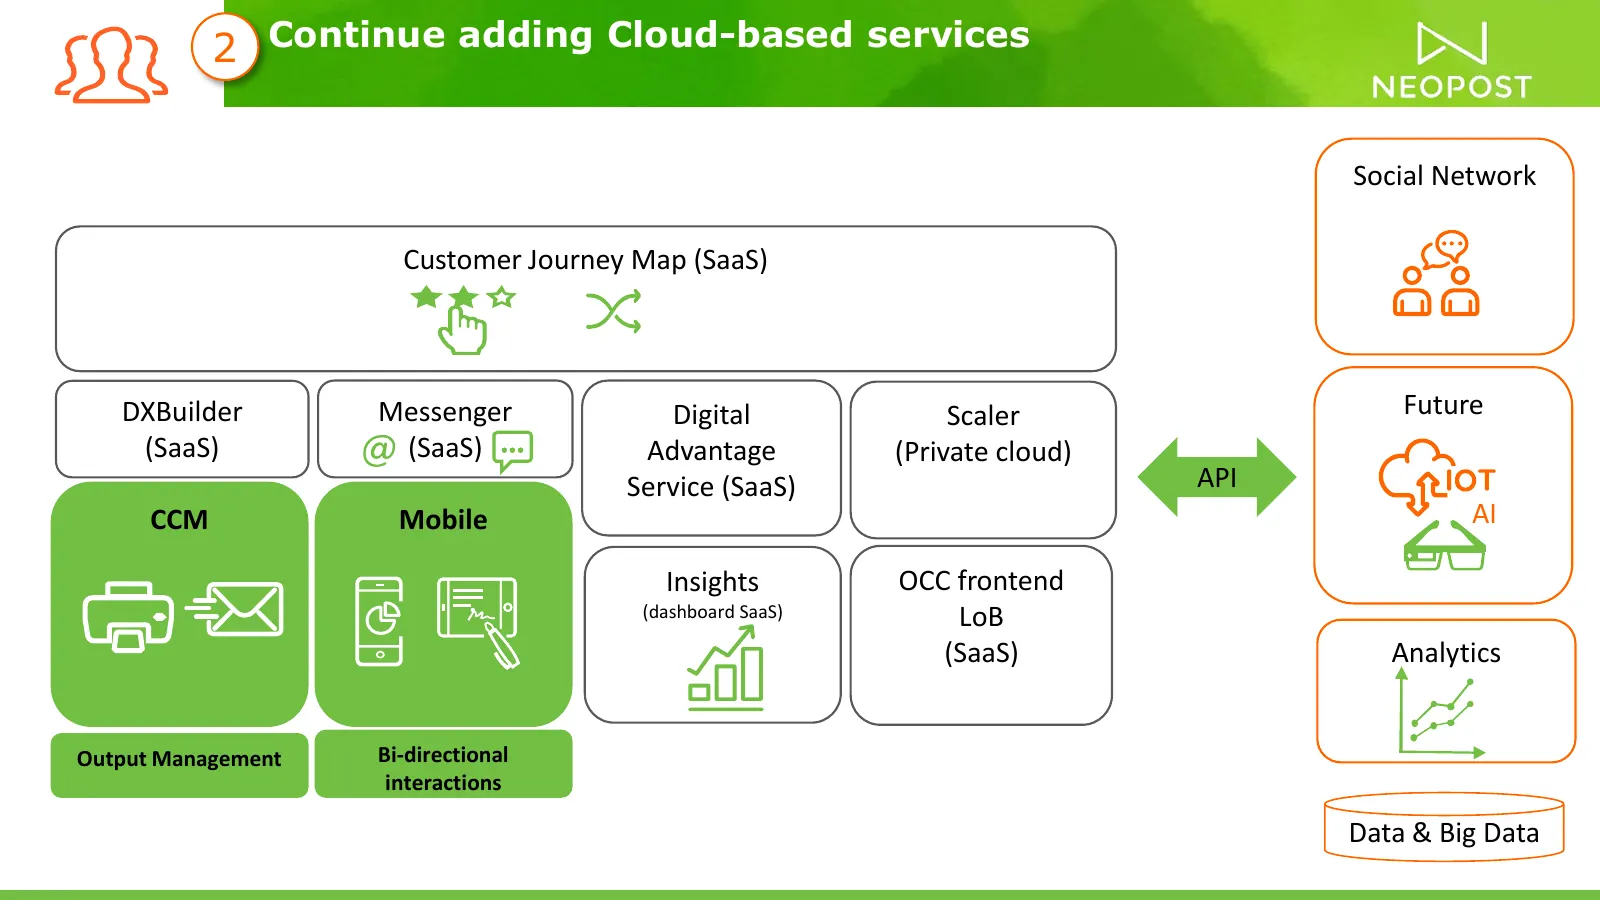
2 Continue adding Cloud-based services Social Network Customer Journey Map (SaaS) DXBuilder Messenger Digital Scaler Future (SaaS) (SaaS) Advantage (Private cloud) Service (SaaS) API CCM Mobile AI Insights OCC frontend (dashboard SaaS) LoB (SaaS) Analytics Output Management Bi-directional interactio
Slide 68: Bring customer experience to the next level
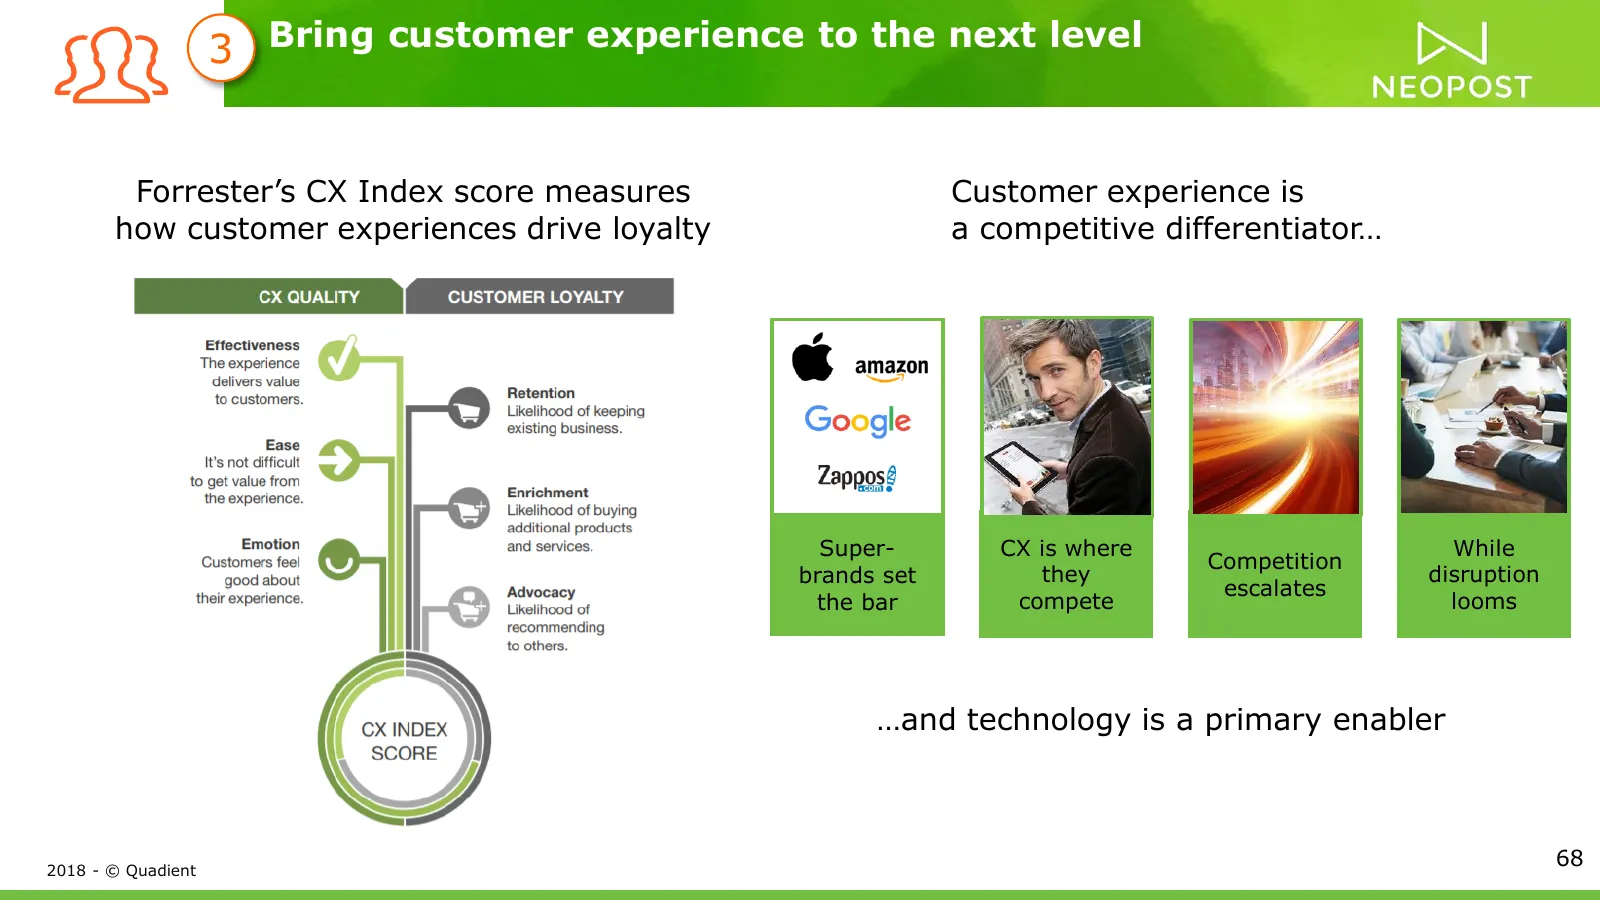
3 Bring customer experience to the next level Forrester’s CX Index score measures Customer experience is how customer experiences drive loyalty a competitive differentiator… Super- CX is where While Competition brands set they disruption escalates the bar compete looms …and technology is a primary e
Slide 69: Top global banking company
• Top global banking company with trillions of dollars of assets and tens of billions of dollars of revenue • Over 10 million customers worldwide Strategic Priority #1: “Grow Customer Loyalty and Market Share”
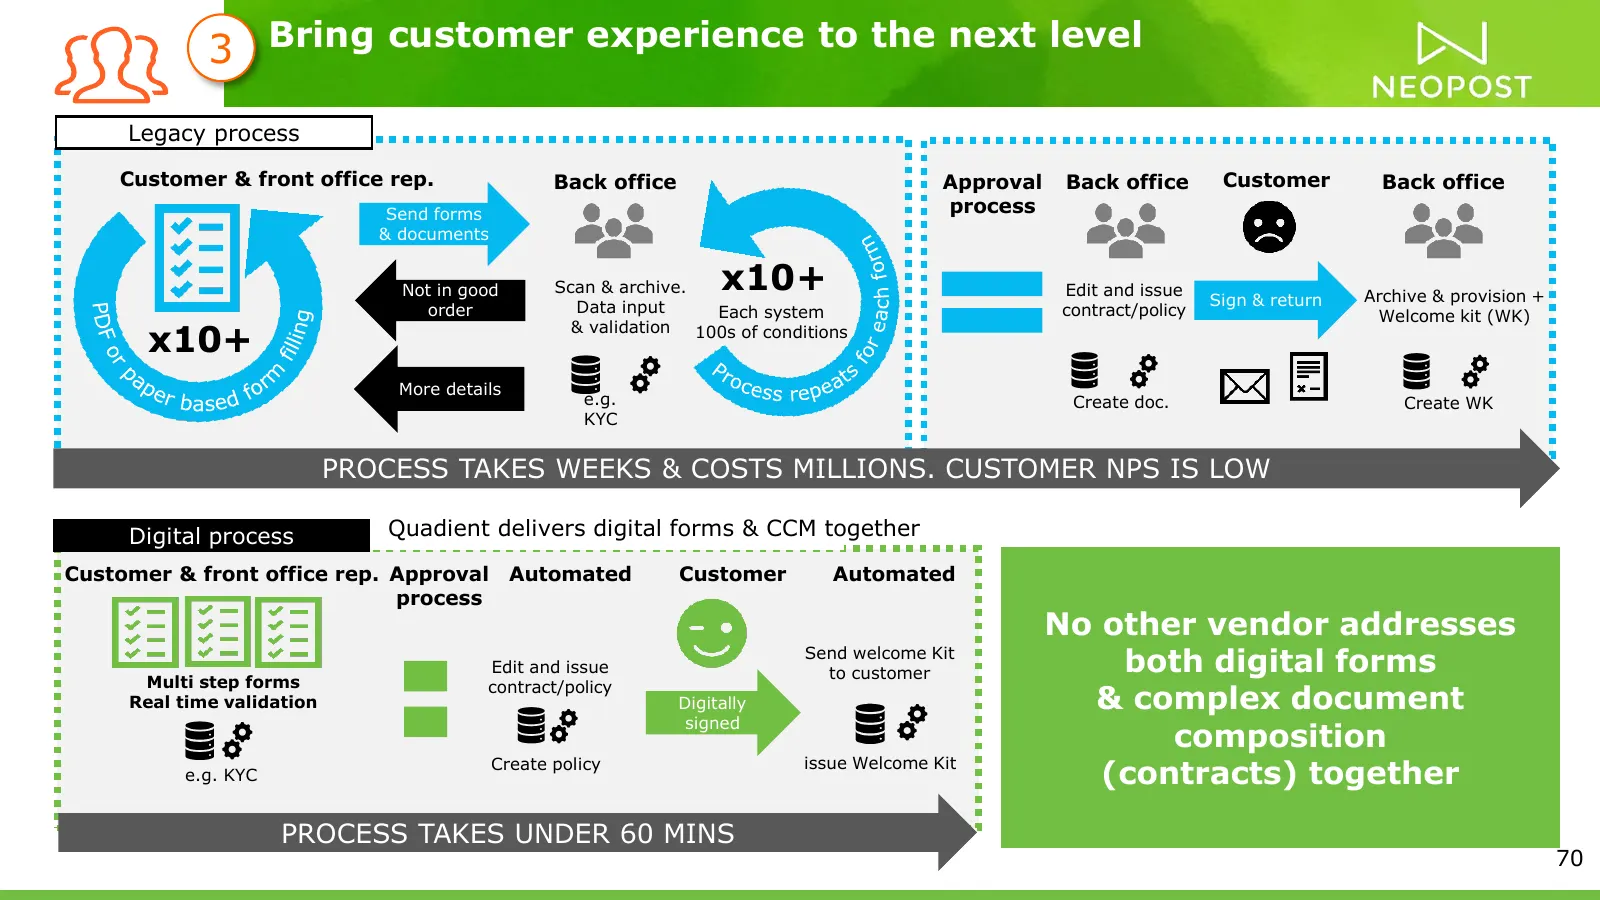
Slide 70: Bring customer experience to the next level: legacy vs digital process
3 Bring customer experience to the next level Legacy process Customer & front office rep. Back office Approval Back office Customer Back office Send forms process & documents Not in good Scan & archive. x10+ Edit and issue Sign & return Archive & provision + order Data input Each system contract/pol
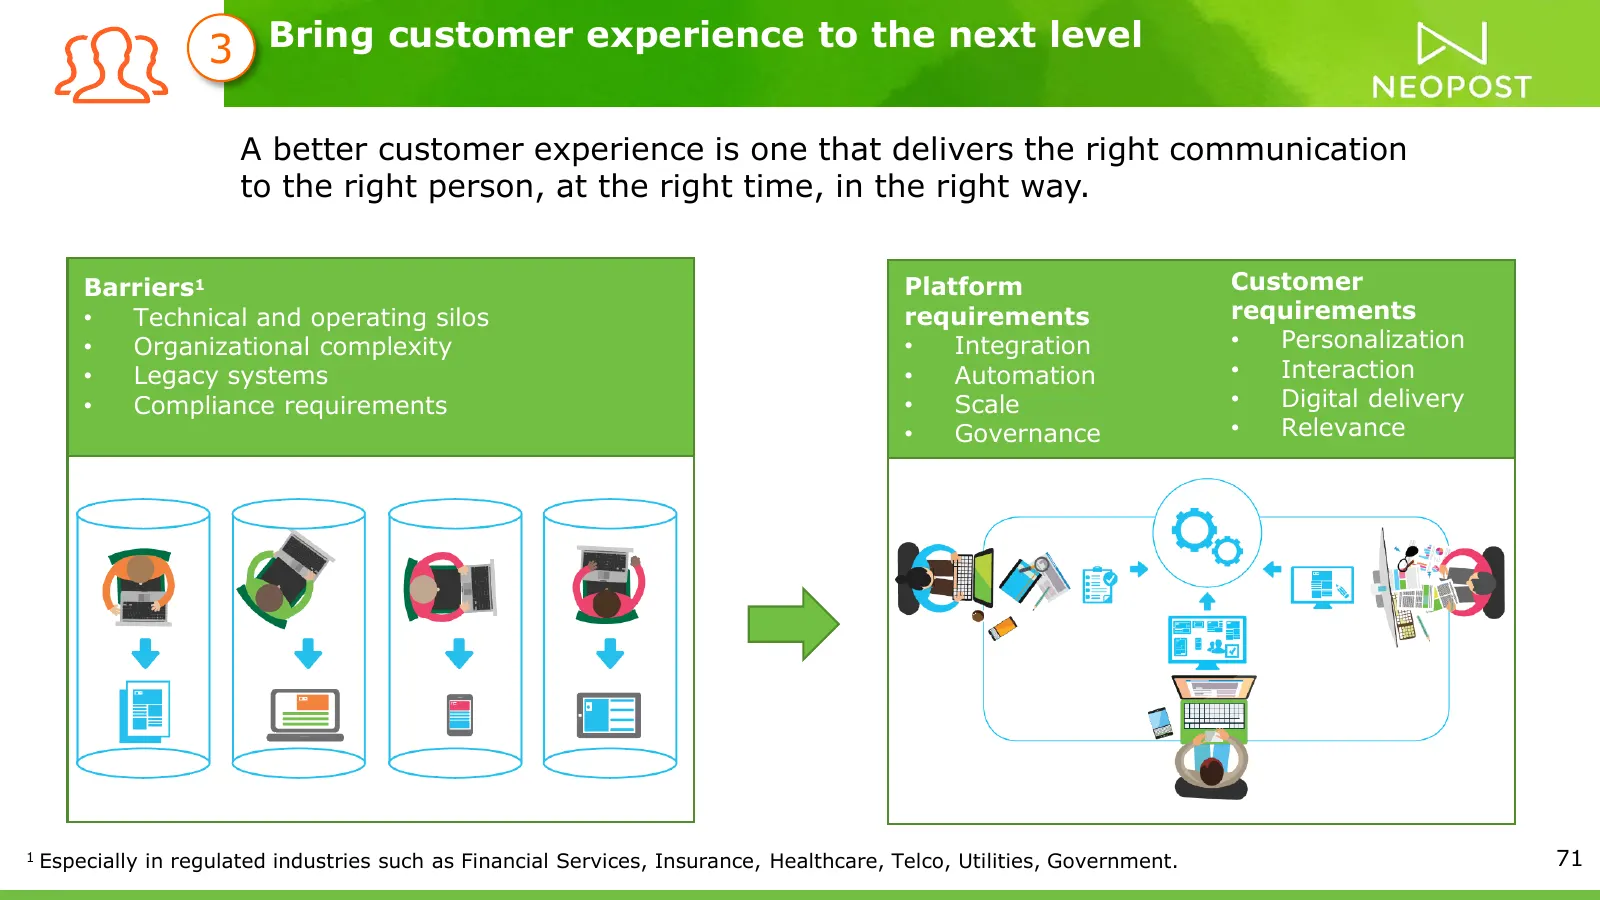
Slide 71: Bring customer experience to the next level
3 Bring customer experience to the next level A better customer experience is one that delivers the right communication to the right person, at the right time, in the right way. Barriers1 But this can be difficult Customer Platform and expensive to • Technical and operating silos achieve: requiremen
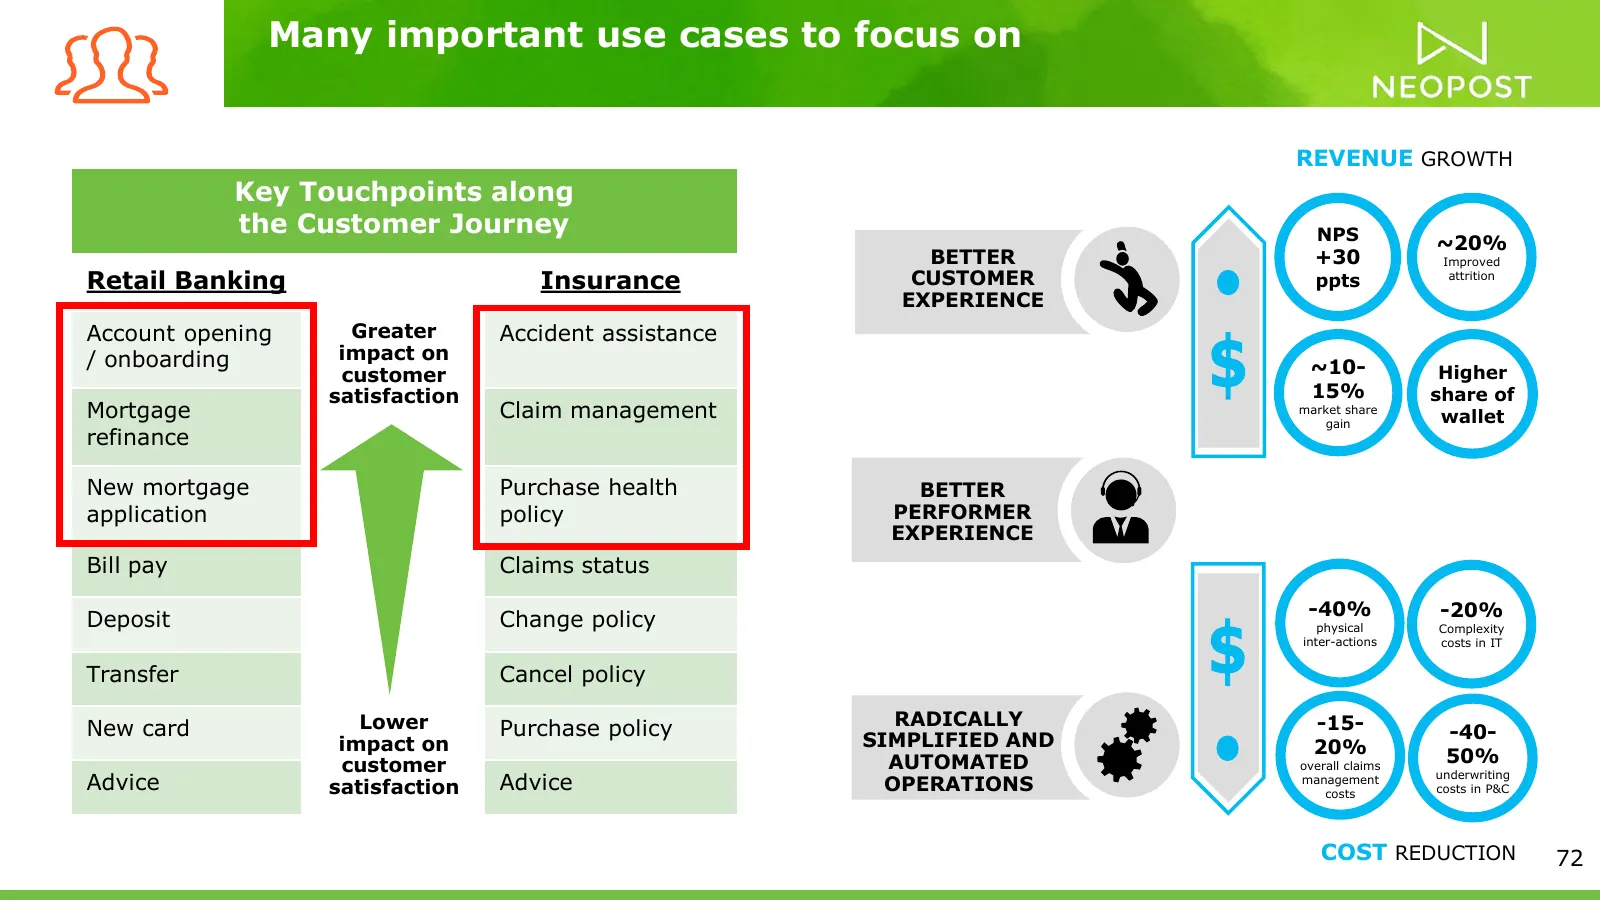
Slide 72: Many important use cases to focus on
Many important use cases to focus on REVENUE GROWTH Key Touchpoints along the Customer Journey NPS ~20% BETTER +30 Improved Retail Banking Insurance CUSTOMER ppts attrition EXPERIENCE Account opening Greater Accident assistance / onboarding impact on customer ~10- Higher satisfaction 15% share of Mo
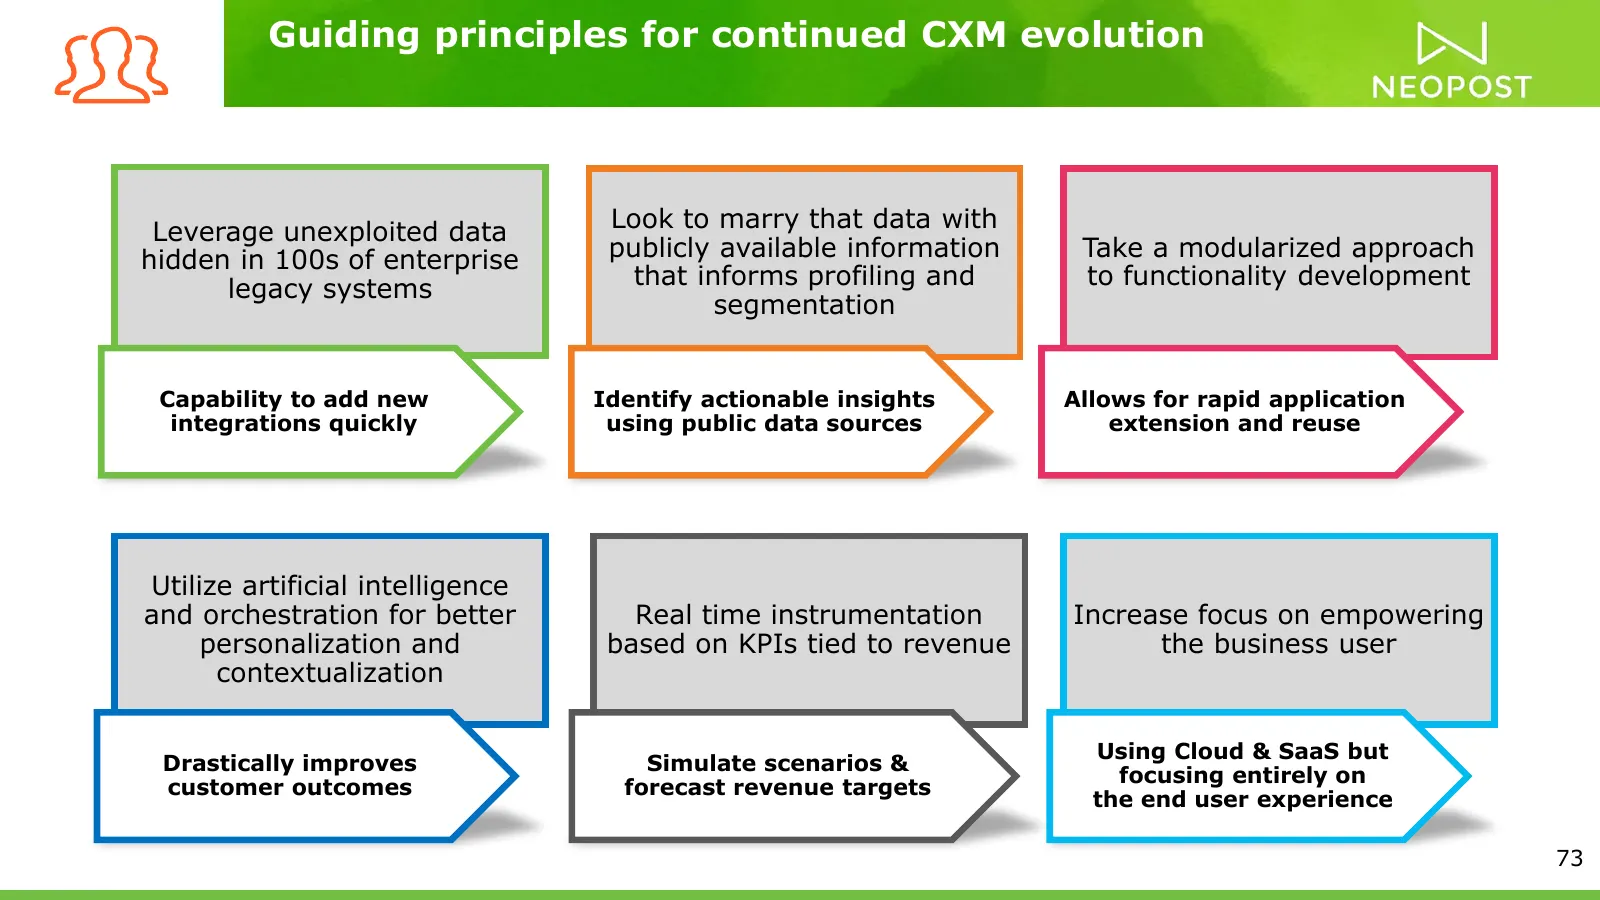
Slide 73: Guiding principles for continued CXM evolution
Guiding principles for continued CXM evolution Leverage unexploited data Look to marry that data with hidden in 100s of enterprise publicly available information Take a modularized approach legacy systems that informs profiling and to functionality development segmentation Capability to add new Iden
Slide 74: Demo
Demo
Slide 75: Summary
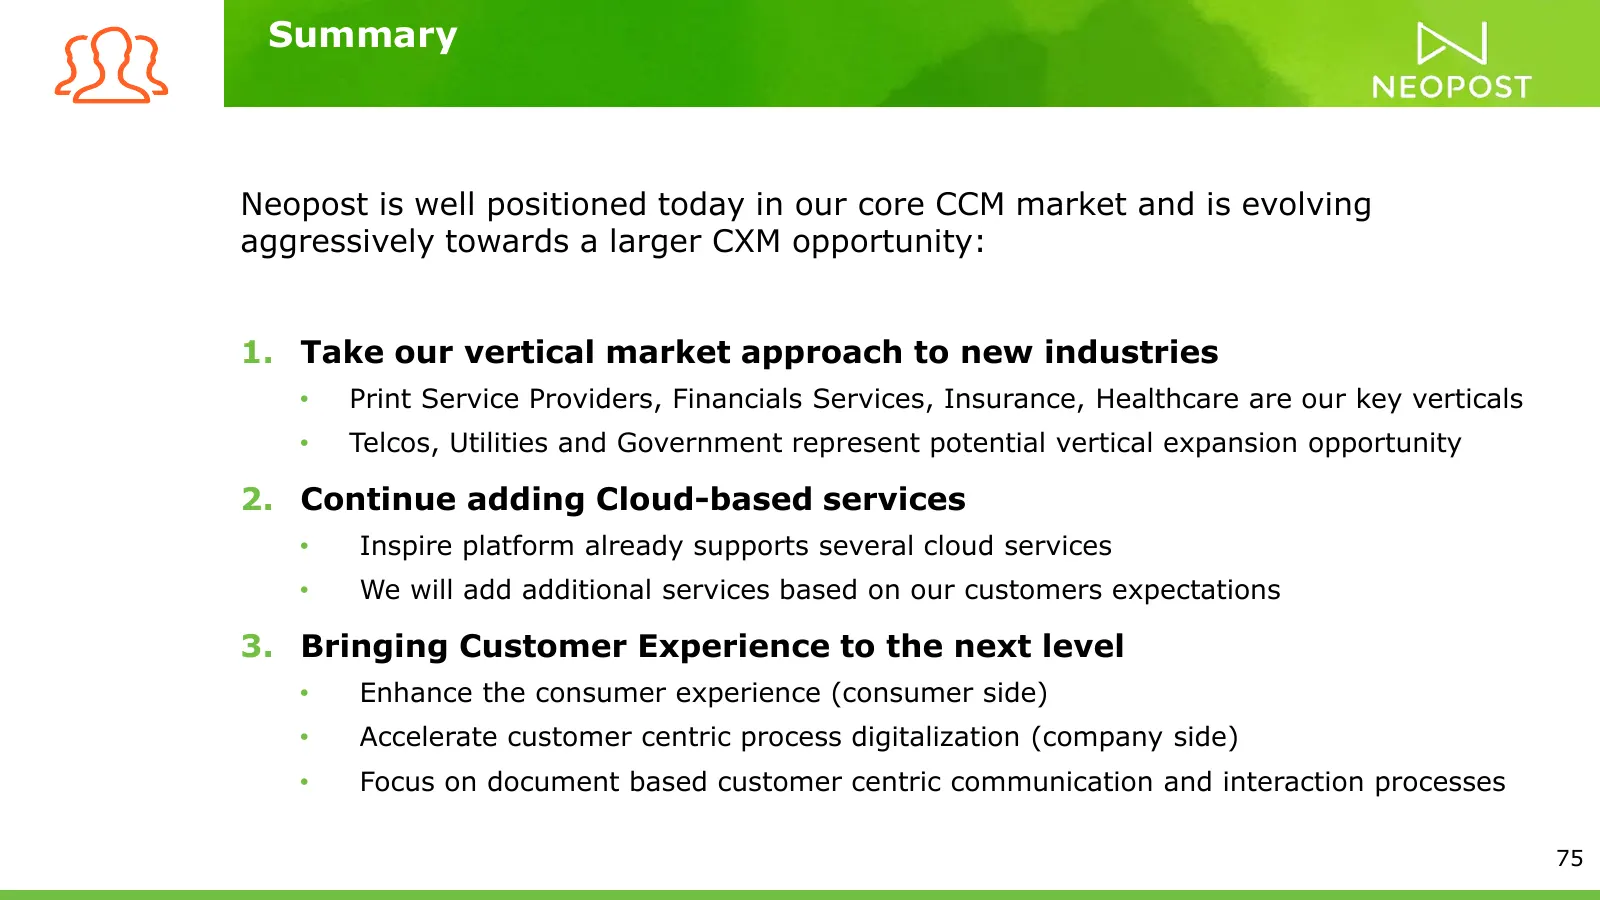
Summary Neopost is well positioned today in our core CCM market and is evolving aggressively towards a larger CXM opportunity: 1. Take our vertical market approach to new industries • Print Service Providers, Financials Services, Insurance, Healthcare are our key verticals • Telcos, Utilities and Go
Slide 76: Parcel Locker Solutions
Parcel Locker Solutions • Daniel Malouf
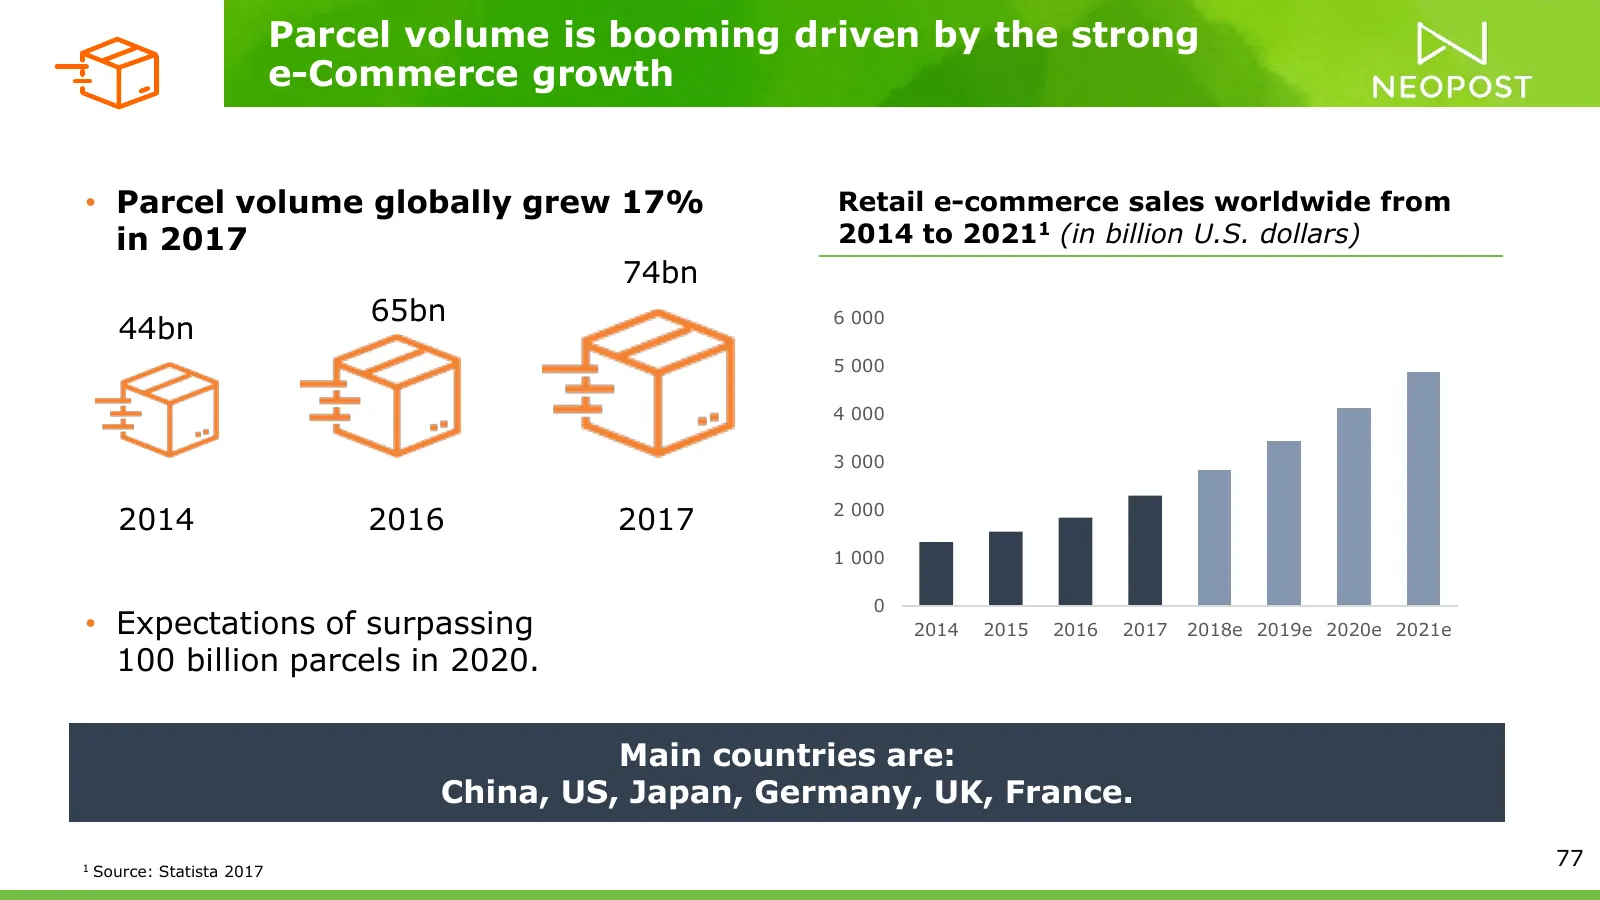
Slide 77: Parcel volume is booming driven by e-Commerce growth
Parcel volume is booming driven by the strong e-Commerce growth • Parcel volume globally grew 17% Retail e-commerce sales worldwide from in 2017 2014 to 20211 (in billion U.S. dollars) 74bn 65bn 6 000 44bn 5 000 4 000 3 000 2 000 2014 2016 2017 1 000 0 • Expectations of surpassing 2014 2015 2016 201
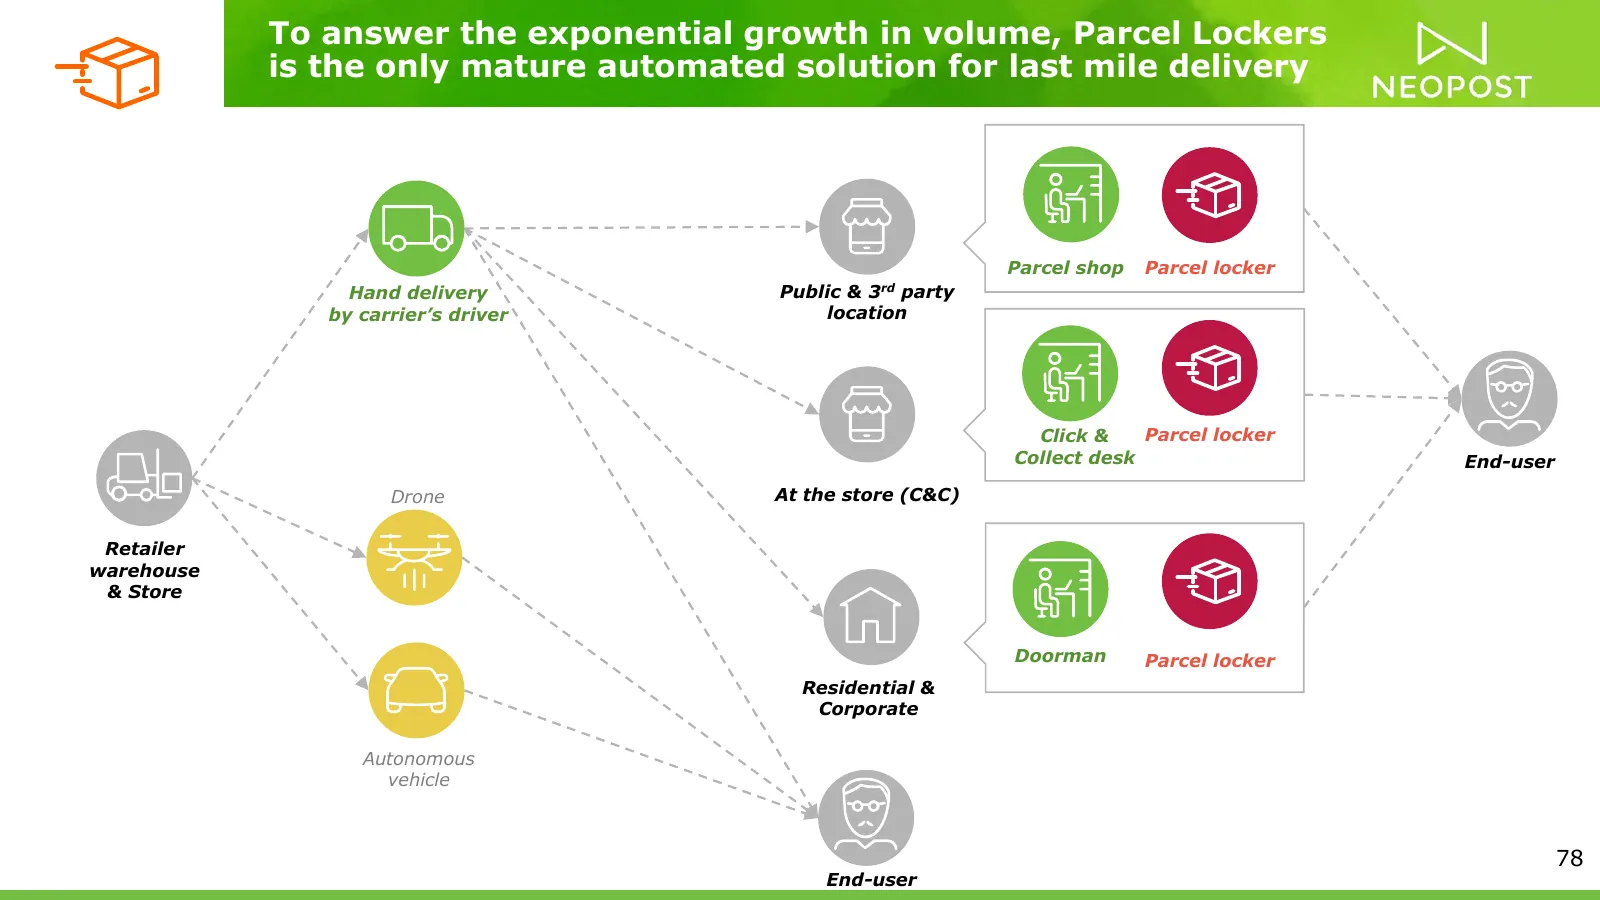
Slide 78: Parcel Lockers: the only mature automated last mile solution
To answer the exponential growth in volume, Parcel Lockers is the only mature automated solution for last mile delivery Parcel shop Parcel locker Hand delivery Public & 3rd party by carrier’s driver location Click & Parcel locker Collect desk End-user Drone At the store (C&C) Retailer warehouse & St
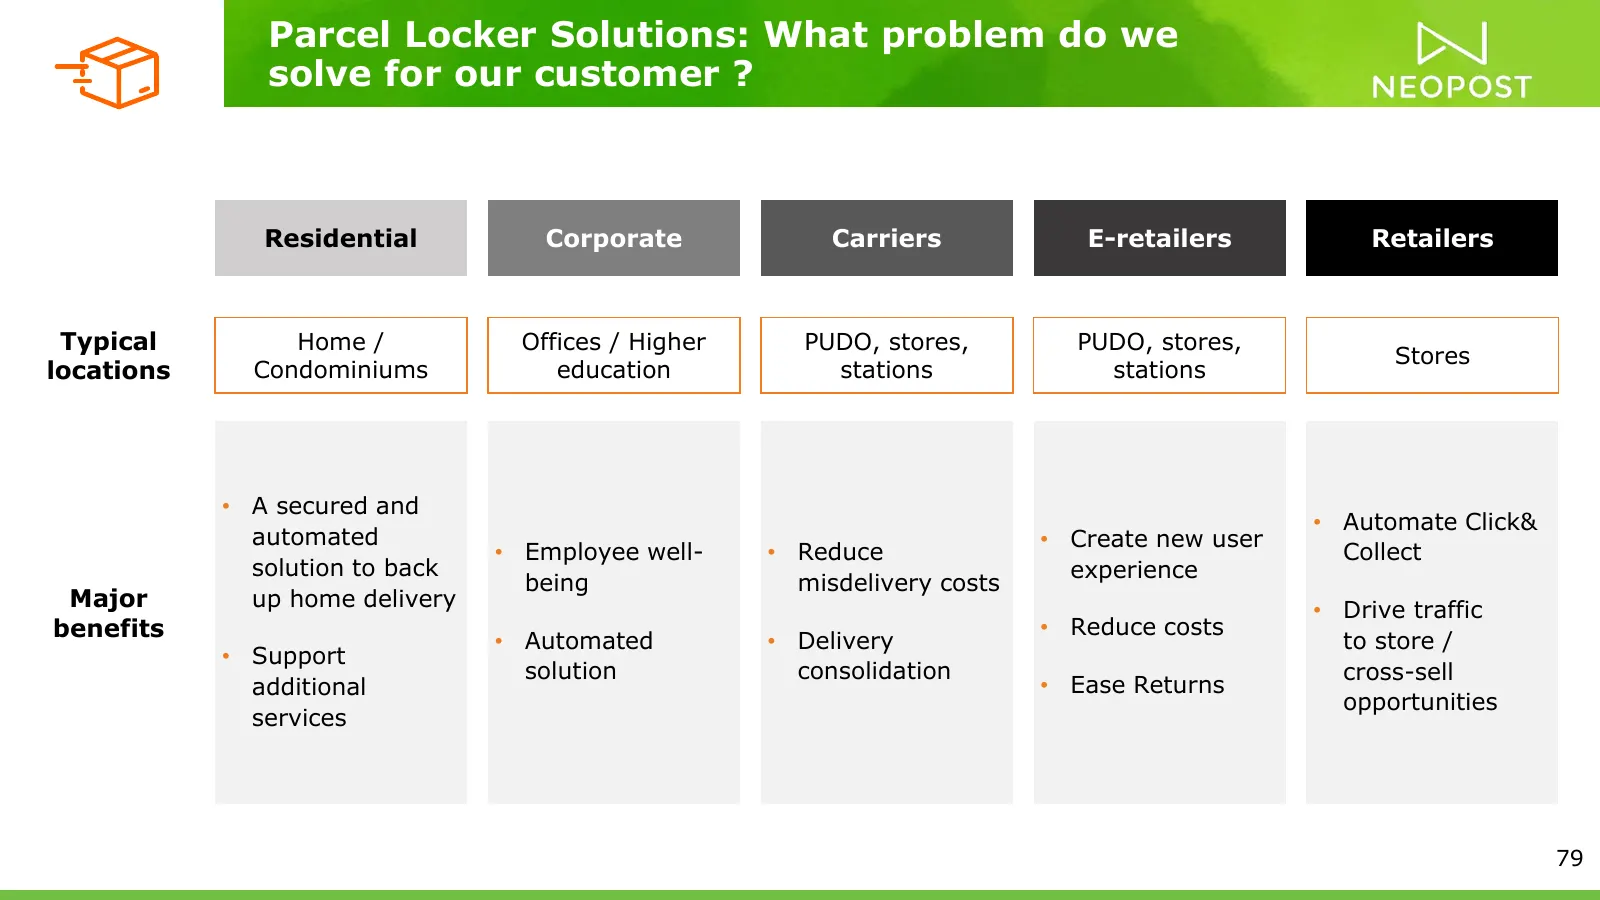
Slide 79: What problem do we solve for our customer?
Parcel Locker Solutions: What problem do we solve for our customer ? Residential Corporate Carriers E-retailers Retailers Typical Home / Offices / Higher PUDO, stores, PUDO, stores, Stores locations Condominiums education stations stations • A secured and • Automate Click& automated • Create new use
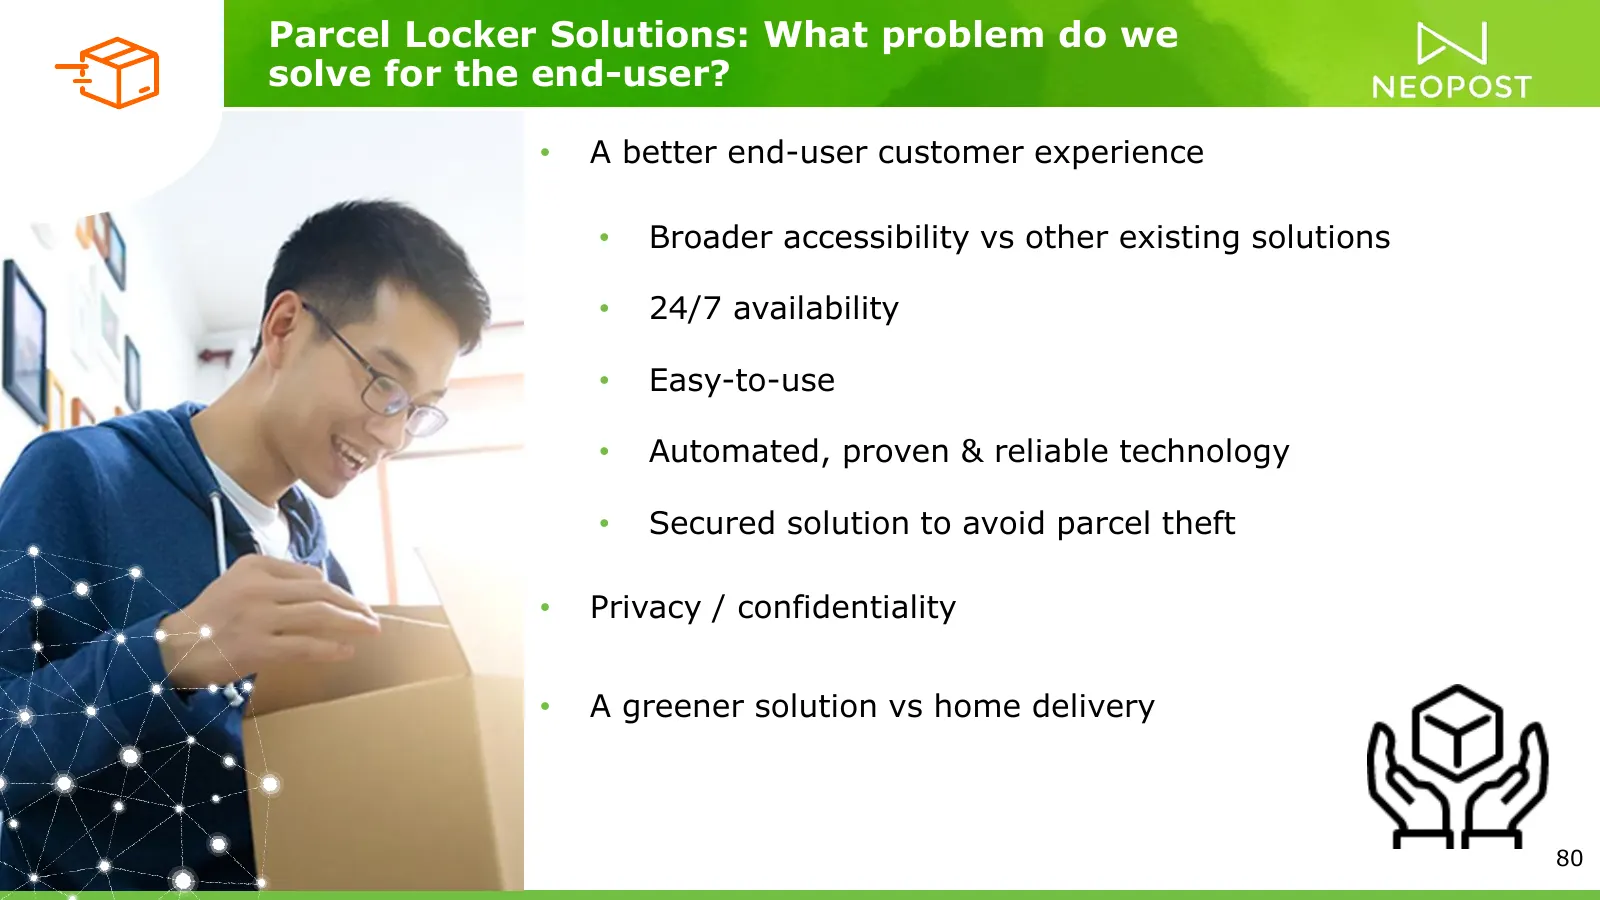
Slide 80: What problem do we solve for the end-user?
Parcel Locker Solutions: What problem do we solve for the end-user? • A better end-user customer experience • Broader accessibility vs other existing solutions • 24/7 availability • Easy-to-use • Automated, proven & reliable technology • Secured solution to avoid parcel theft • Privacy / confidentia
Slide 81: Packcity, our Parcel Locker brand
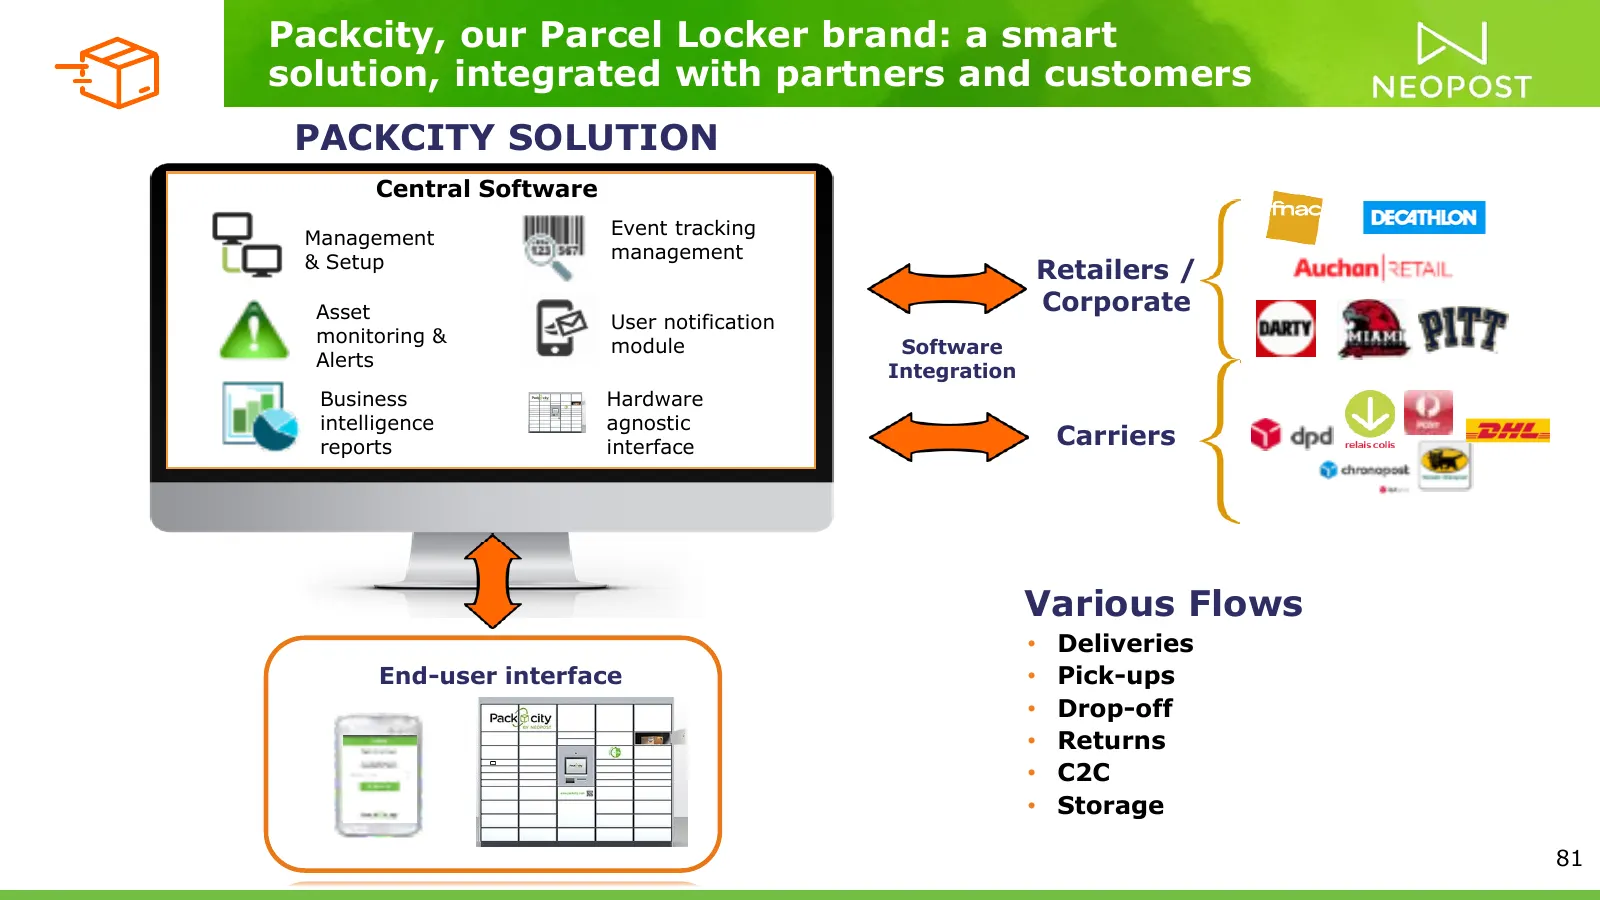
Packcity, our Parcel Locker brand: a smart solution, integrated with partners and customers PACKCITY SOLUTION Central Software Management Event tracking & Setup management Retailers / Asset Corporate User notification monitoring & module Software Alerts Integration Business Hardware intelligence agn
Slide 82: Multi-type of locations
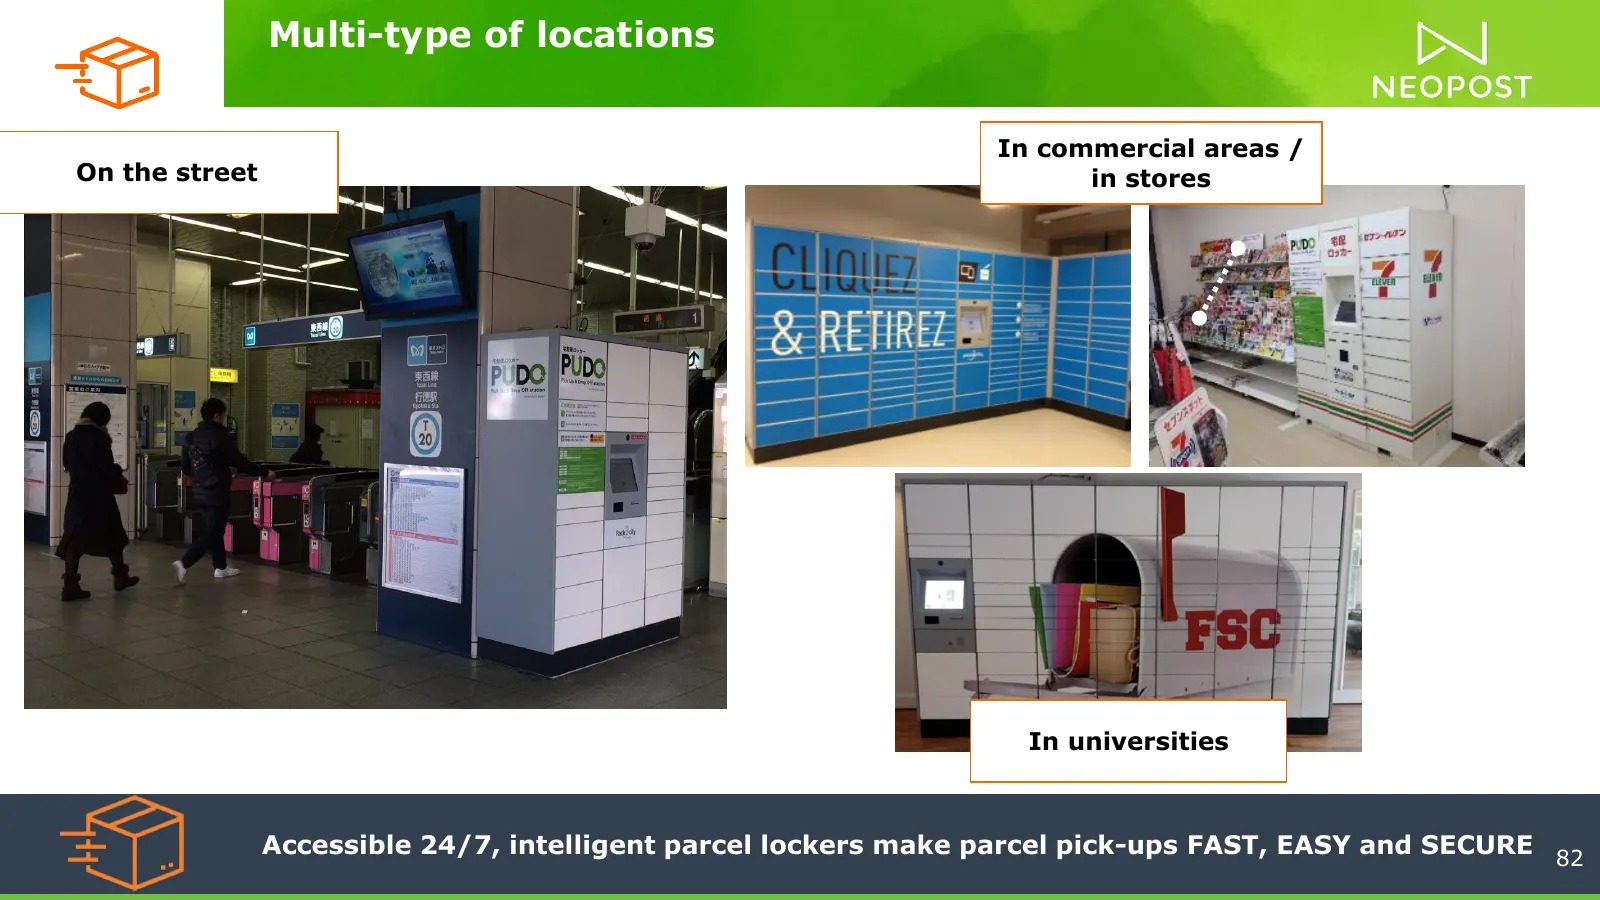
Multi-type of locations In commercial areas / On the street in stores Electronic system to open relevant locker In universities In the office / in Accessible 24/7, intelligent parcel lockers make parcel pick-ups FAST, EASY and SECURE 82 universities
Slide 83: Operating parcel lockers: a multi local business
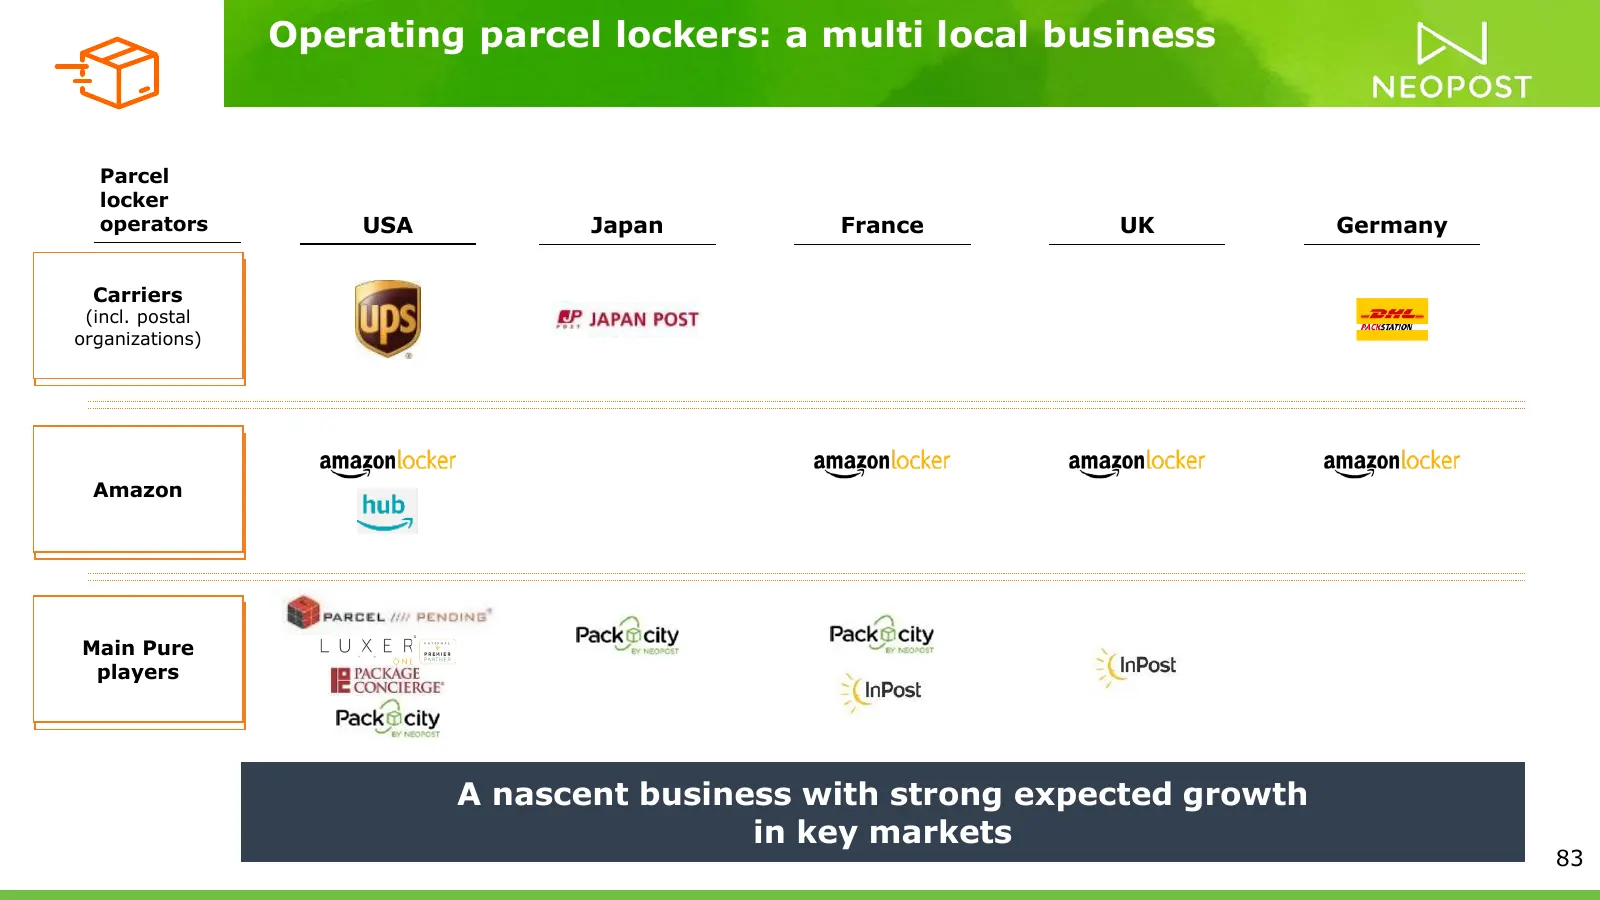
Operating parcel lockers: a multi local business Parcel locker operators USA Japan France UK Germany Carriers Carriers (incl. (incl. postal postal organizations) organizations) Amazon E-commerce Main Pure Pure players players A nascent business with strong expected growth in key markets 83
Slide 84: Parcel Locker Solutions: various business models
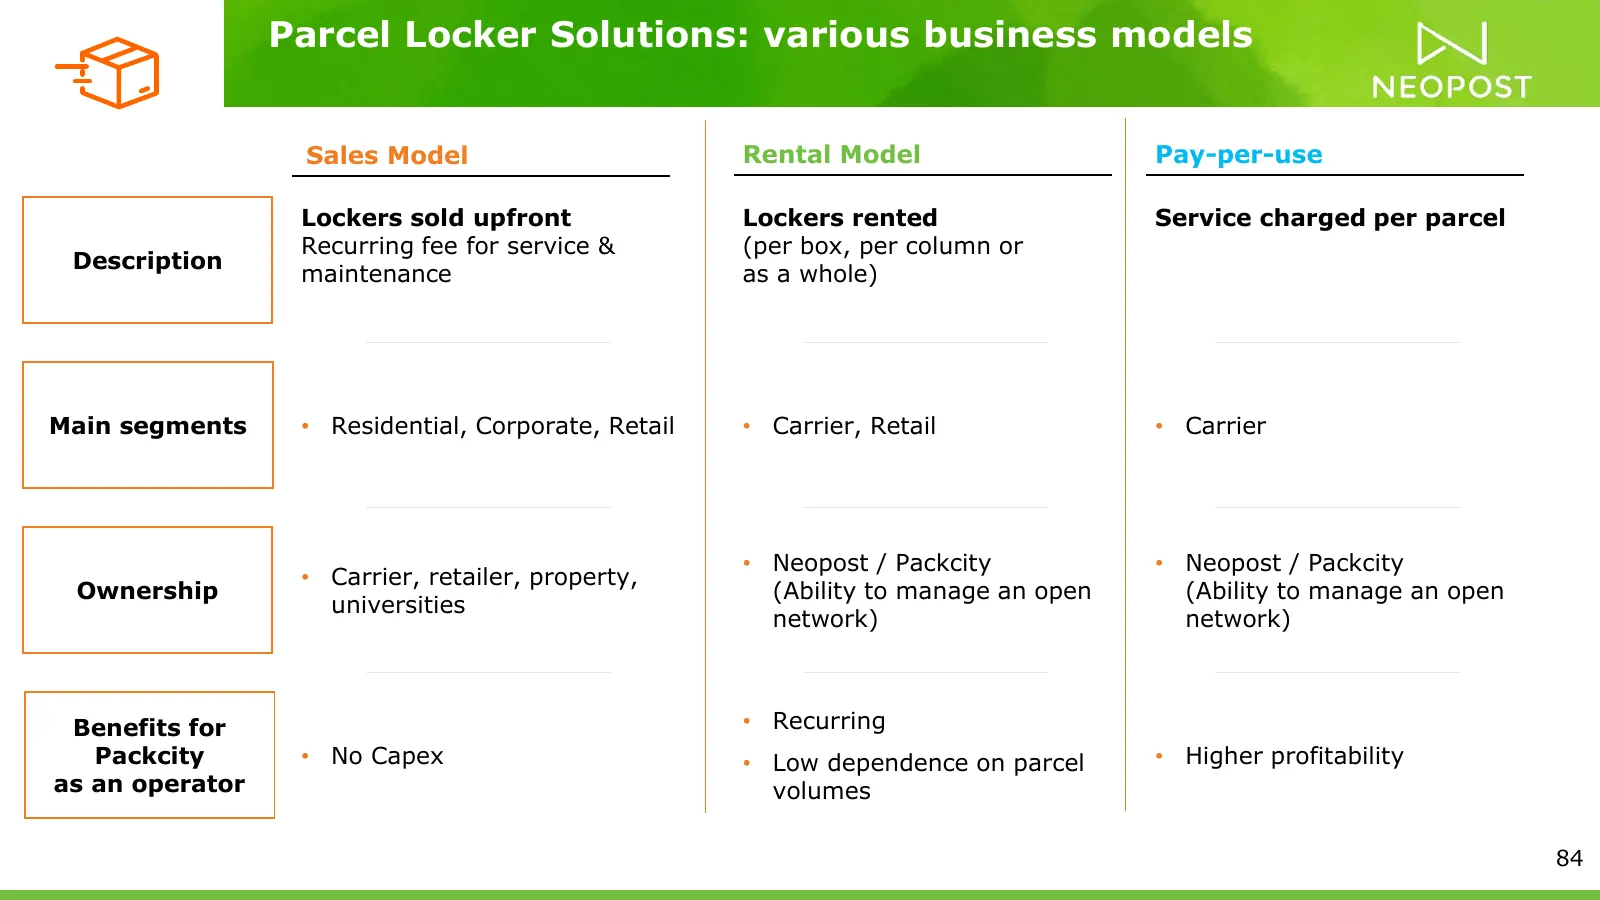
Parcel Locker Solutions: various business models Sales Model Rental Model Pay-per-use Lockers sold upfront Lockers rented Service charged per parcel Recurring fee for service & (per box, per column or Description maintenance as a whole) Main segments • Residential, Corporate, Retail • Carrier, Retai
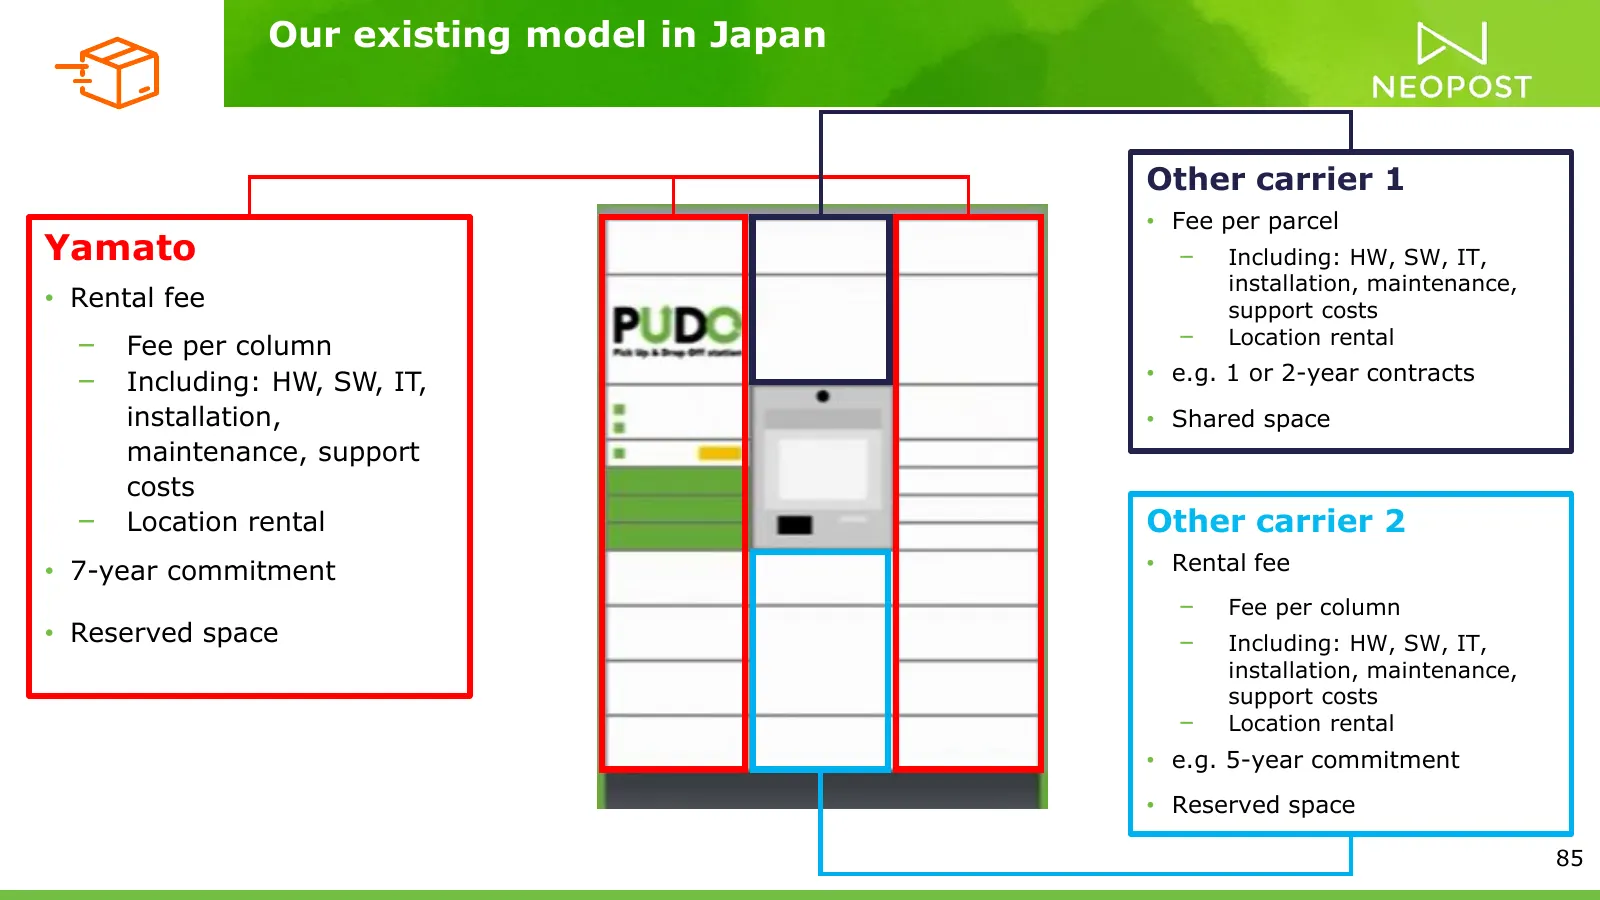
Slide 85: Our existing model in Japan
Our existing model in Japan Other carrier 1 • Fee per parcel Yamato – Including: HW, SW, IT, installation, maintenance, • Rental fee support costs – Fee per column – Location rental – Including: HW, SW, IT, • e.g. 1 or 2-year contracts installation, • Shared space maintenance, support costs – Locati
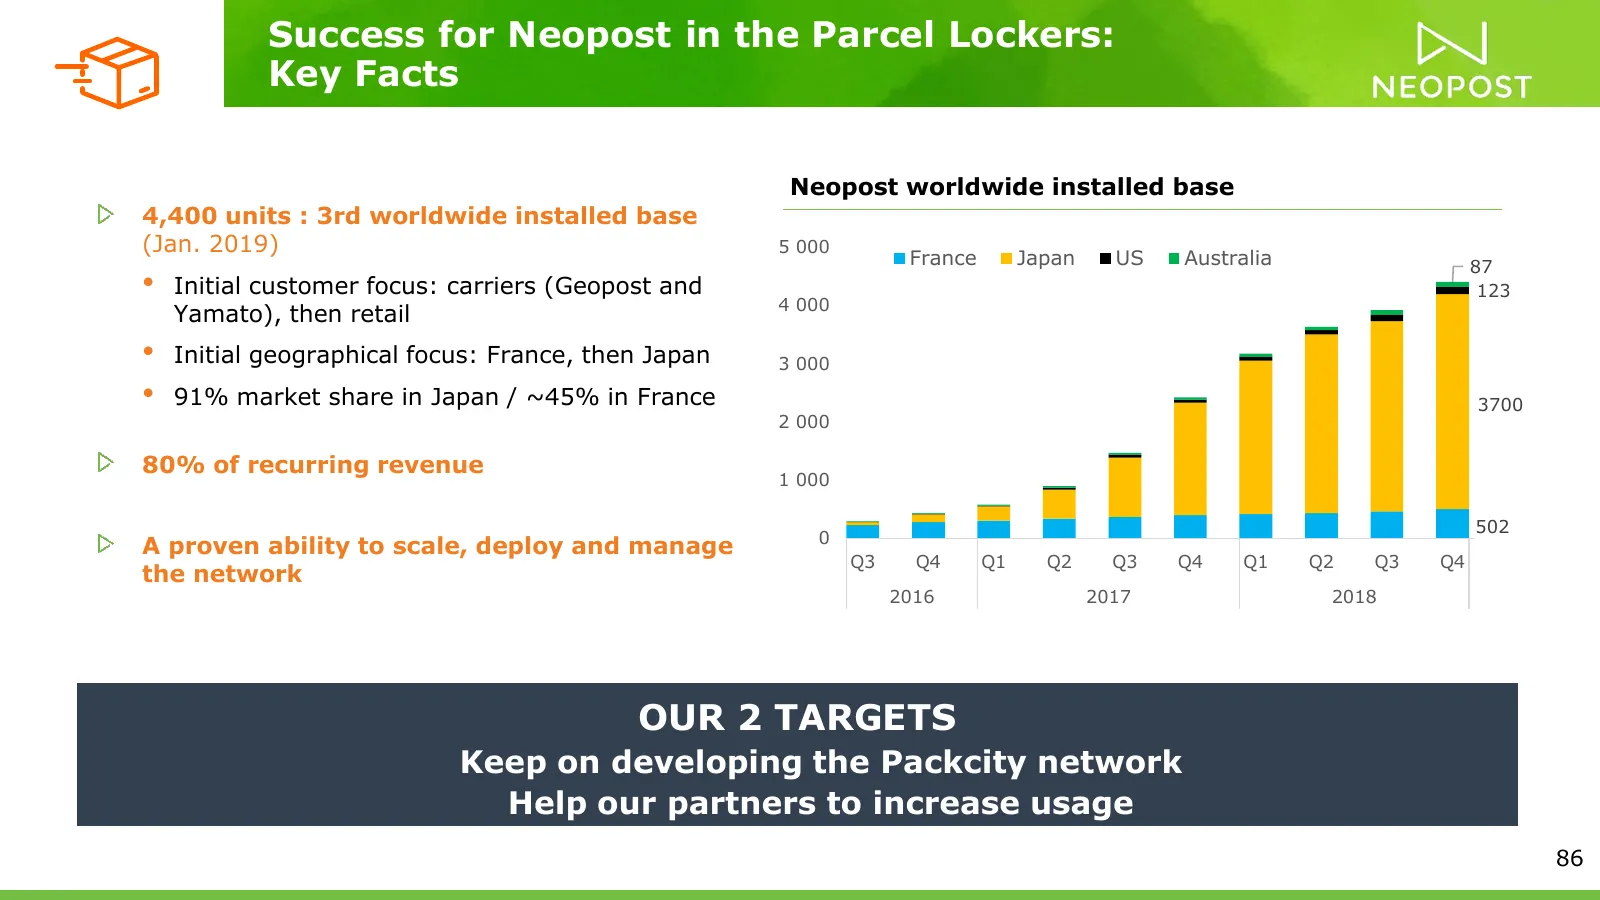
Slide 86: Success for Neopost in Parcel Lockers: Key Facts
Success for Neopost in the Parcel Lockers: Key Facts Neopost worldwide installed base 4,400 units : 3rd worldwide installed base (Jan. 2019) 5 000 France Japan US Australia 87 • Initial customer focus: carriers (Geopost and 123 4 000 Yamato), then retail • Initial geographical focus: France, then Ja
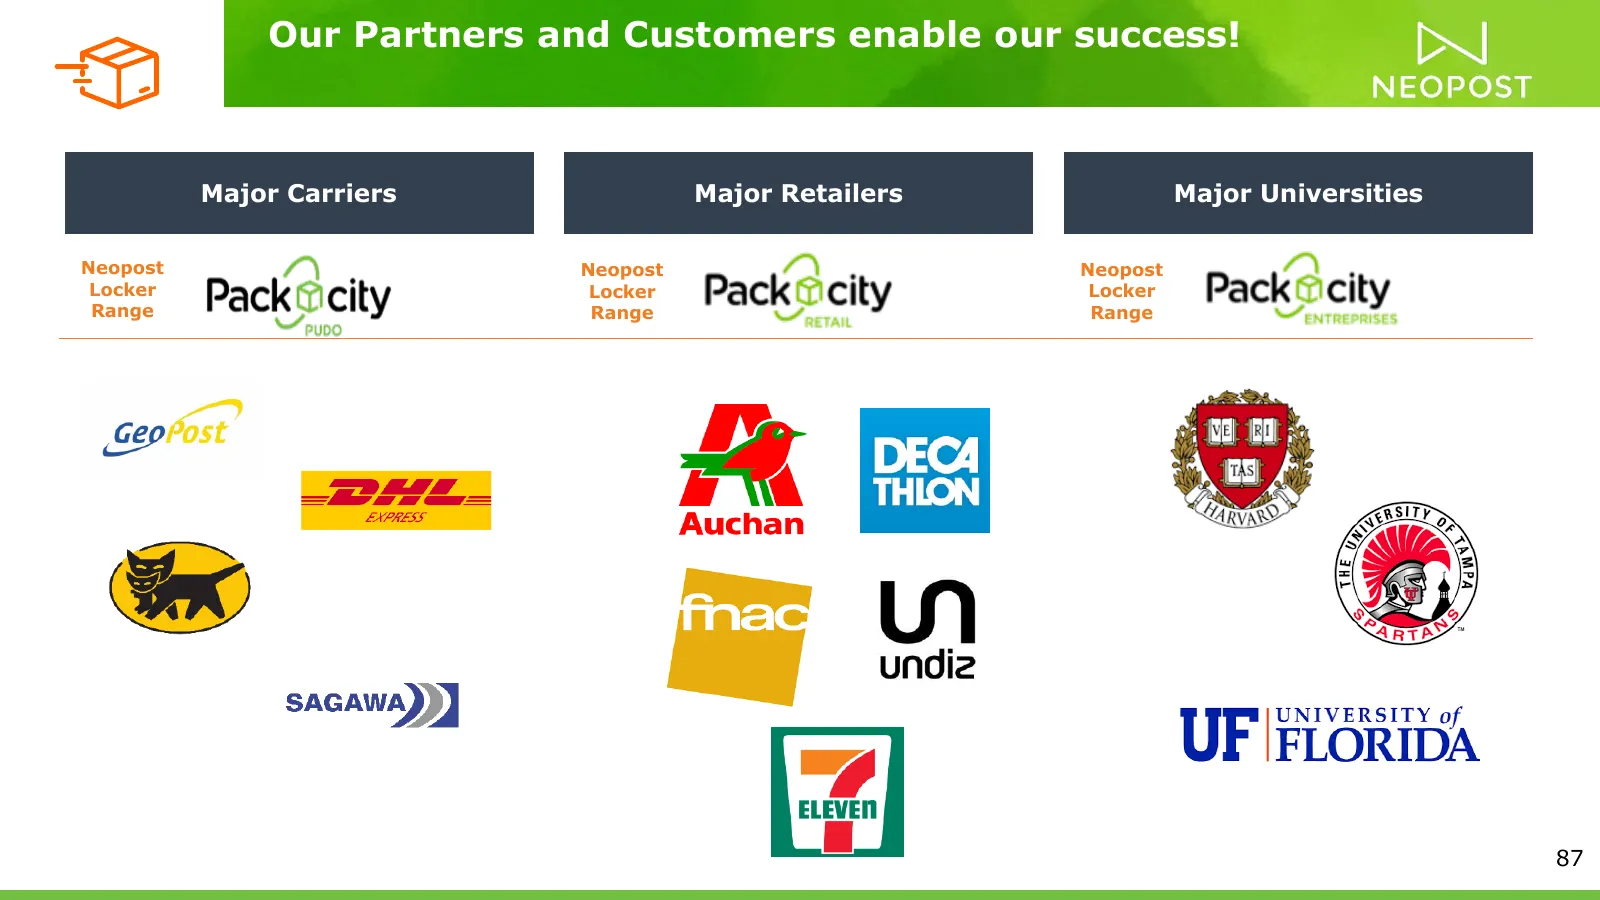
Slide 87: Our Partners and Customers enable our success
Our Partners and Customers enable our success! Major Carriers Major Retailers Major Universities Neopost Neopost Neopost Locker Locker Locker Range Range Range 87
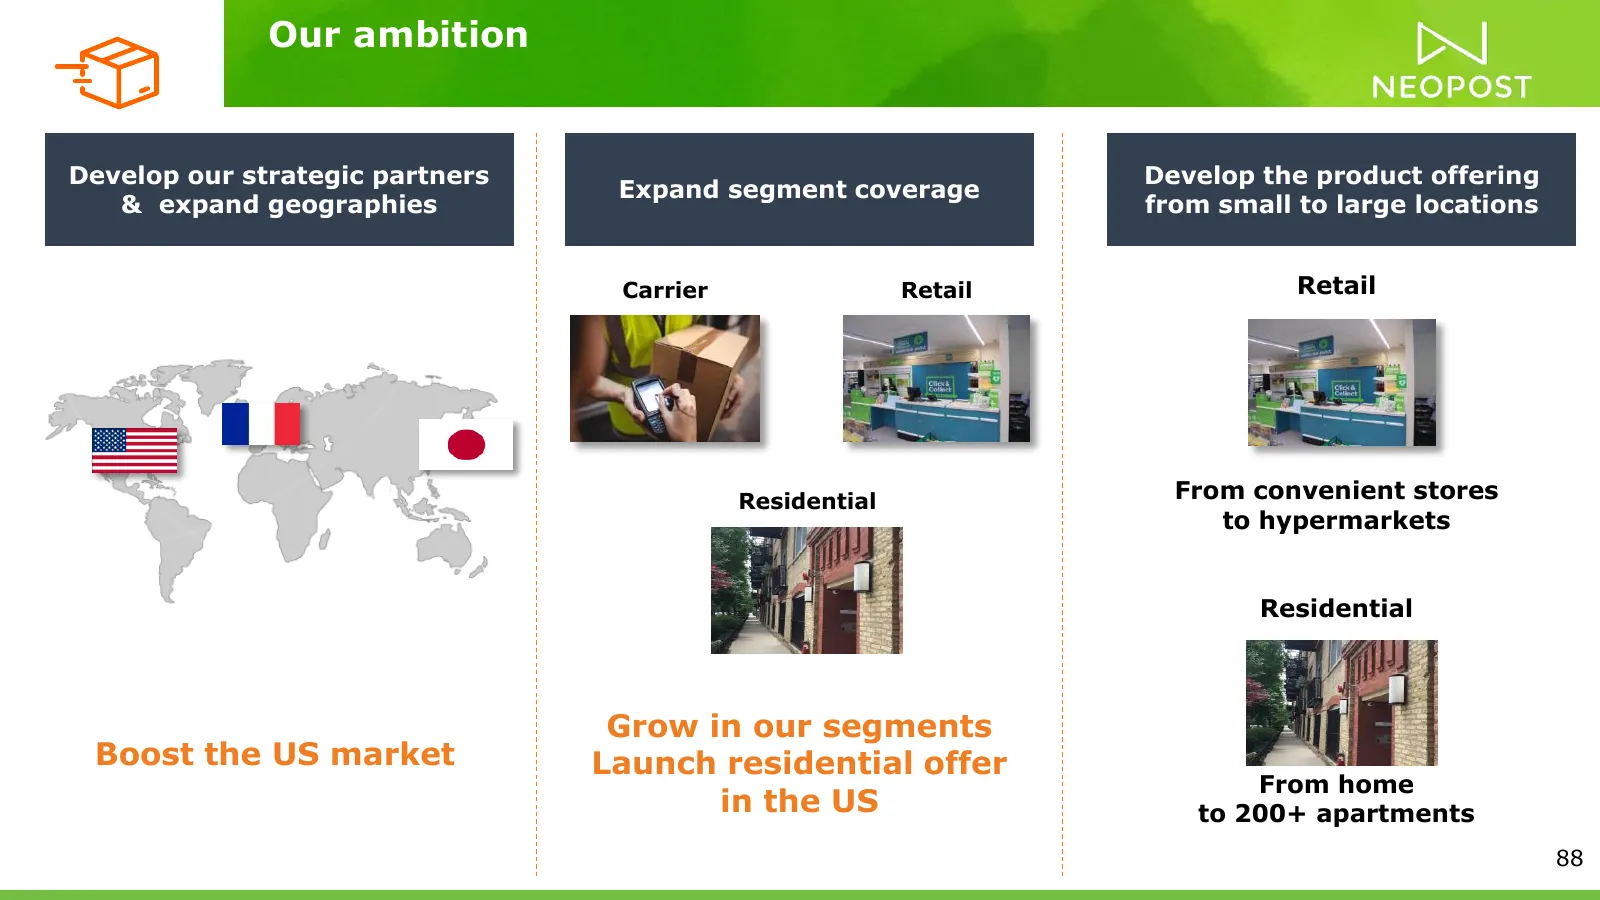
Slide 88: Our ambition
Our ambition Develop our strategic partners Develop the product offering Expand segment coverage & expand geographies from small to large locations Carrier Retail Retail Residential From convenient stores to hypermarkets Residential Grow in our segments Boost the US market Launch residential offer F
Slide 89: US Overview: Neopost's perspective
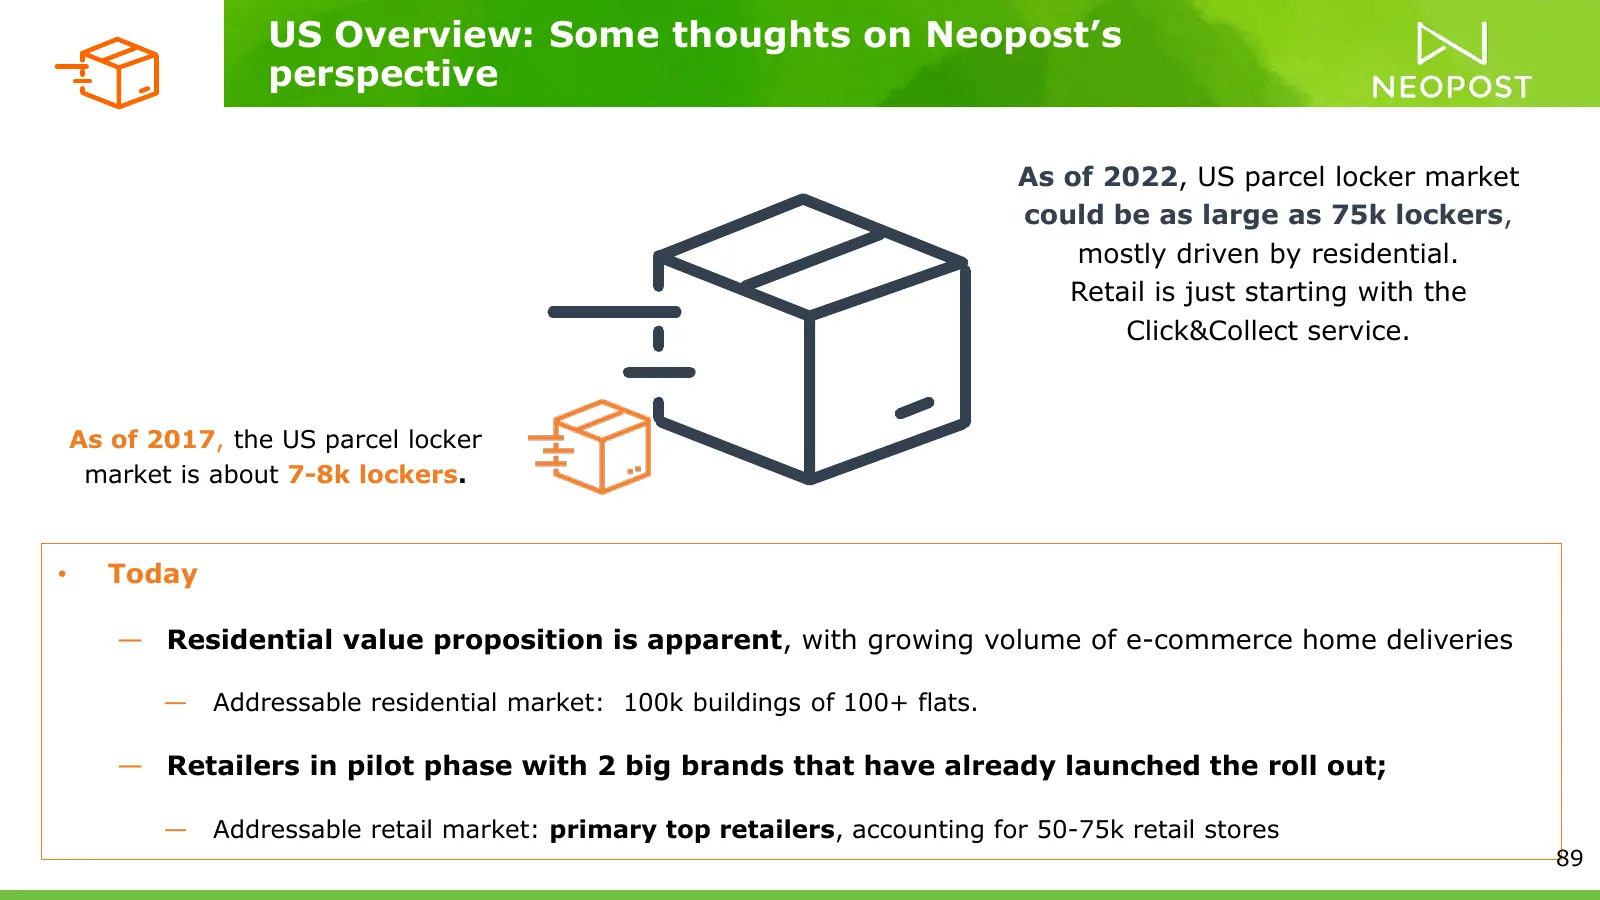
US Overview: Some thoughts on Neopost’s perspective As of 2022, US parcel locker market could be as large as 75k lockers, mostly driven by residential. Retail is just starting with the Click&Collect service. As of 2017, the US parcel locker market is about 7-8k lockers. • Today — Residential value p
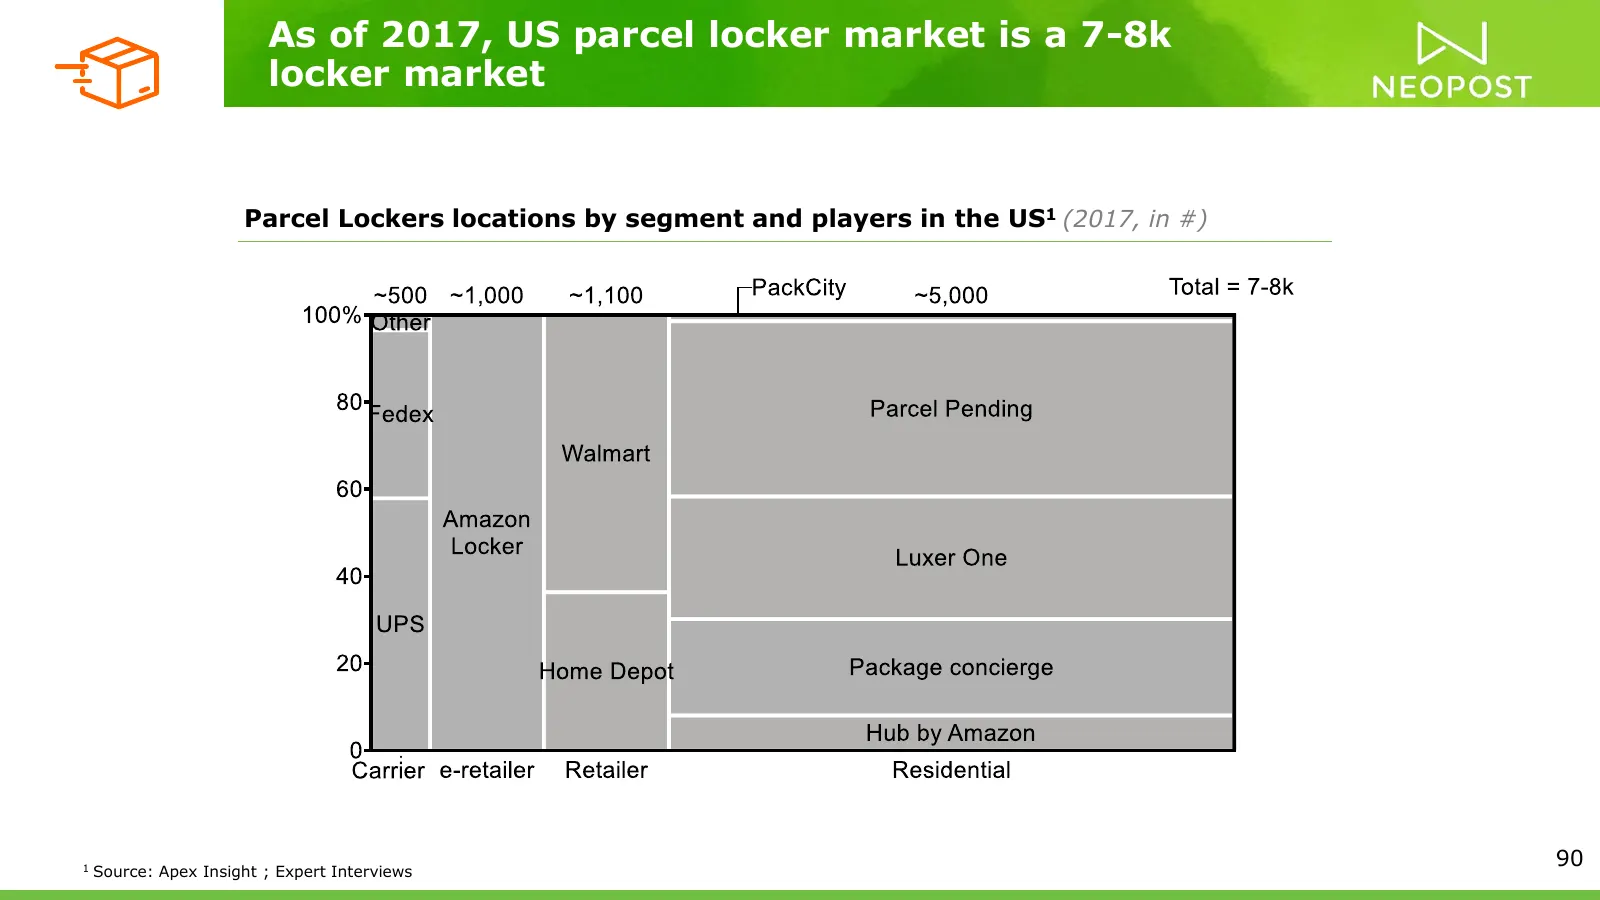
Slide 90: US parcel locker market is a 7-8k locker market
As of 2017, US parcel locker market is a 7-8k locker market Parcel Lockers locations by segment and players in the US1 (2017, in #) 1 Source: Apex Insight ; Expert Interviews 90
Slide 91: Acquisition of Parcel Pending
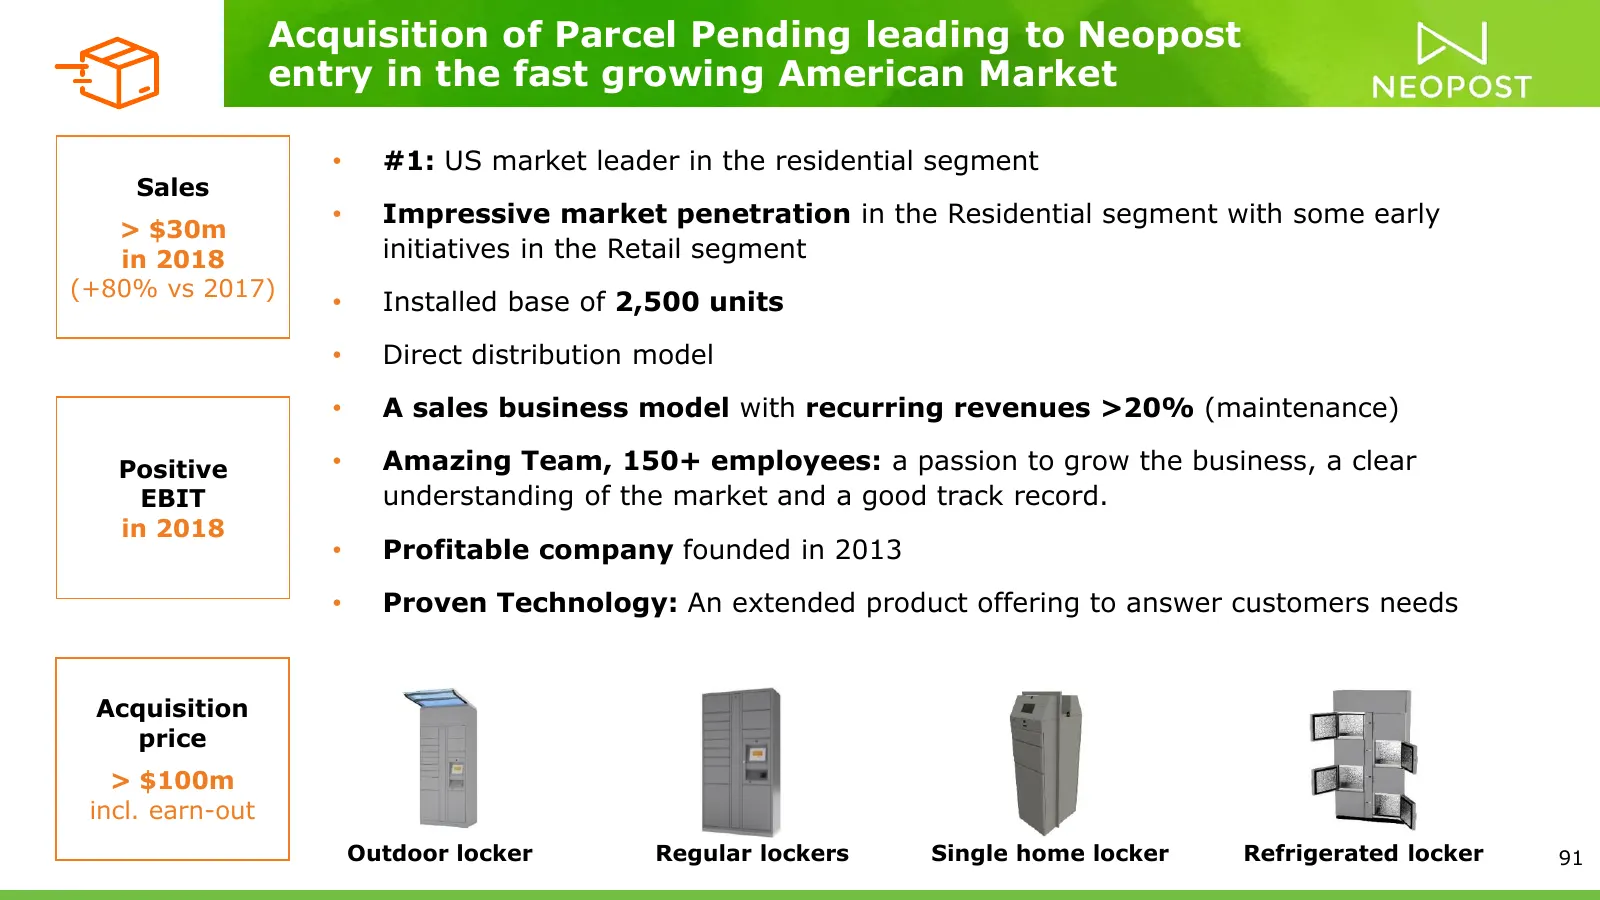
Acquisition of Parcel Pending leading to Neopost entry in the fast growing American Market • #1: US market leader in the residential segment Sales • Impressive market penetration in the Residential segment with some early > $30m in 2018 initiatives in the Retail segment (+80% vs 2017) • Installed ba
Slide 92: Parcel Pending, a perfect fit with the strategy
Parcel Pending, a perfect fit with the strategy Build a US market leader on a fast growing segment Strong growth expected over 2019-2022 A sizeable platform to address new verticals Synergies with Neopost in the United States 92
Slide 93: Our ambition
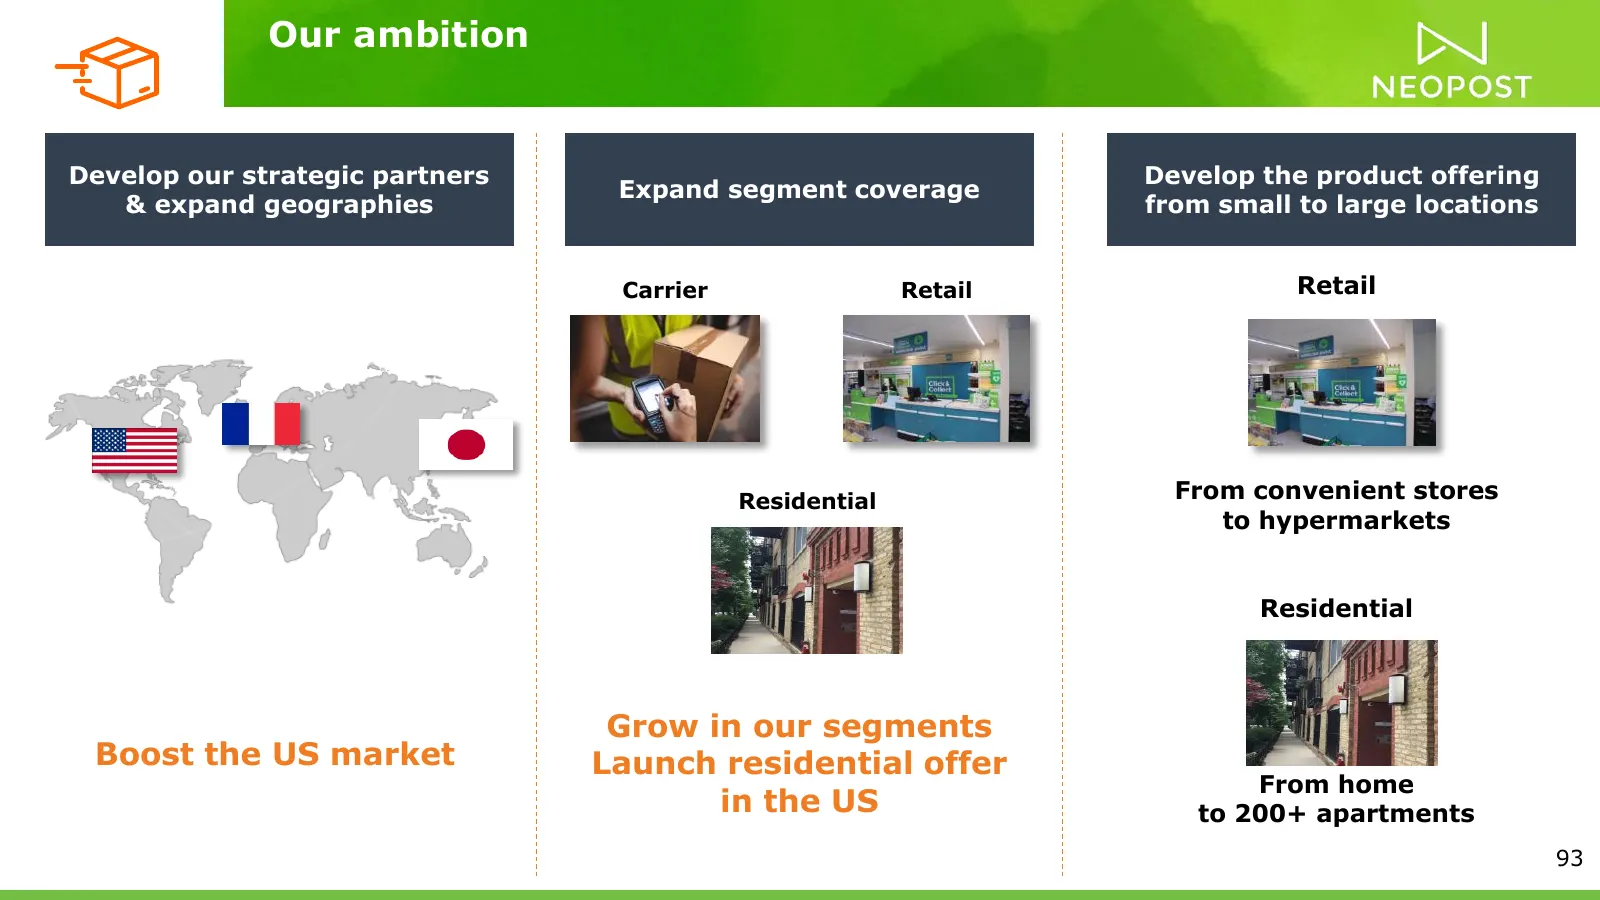
Our ambition Develop our strategic partners Develop the product offering Expand segment coverage & expand geographies from small to large locations Carrier Retail Retail Residential From convenient stores to hypermarkets Residential Grow in our segments Boost the US market Launch residential offer F
Slide 94: Unlocking Synergies
Unlocking Synergies • Henri Dura
Slide 95: From independent entities to One Company
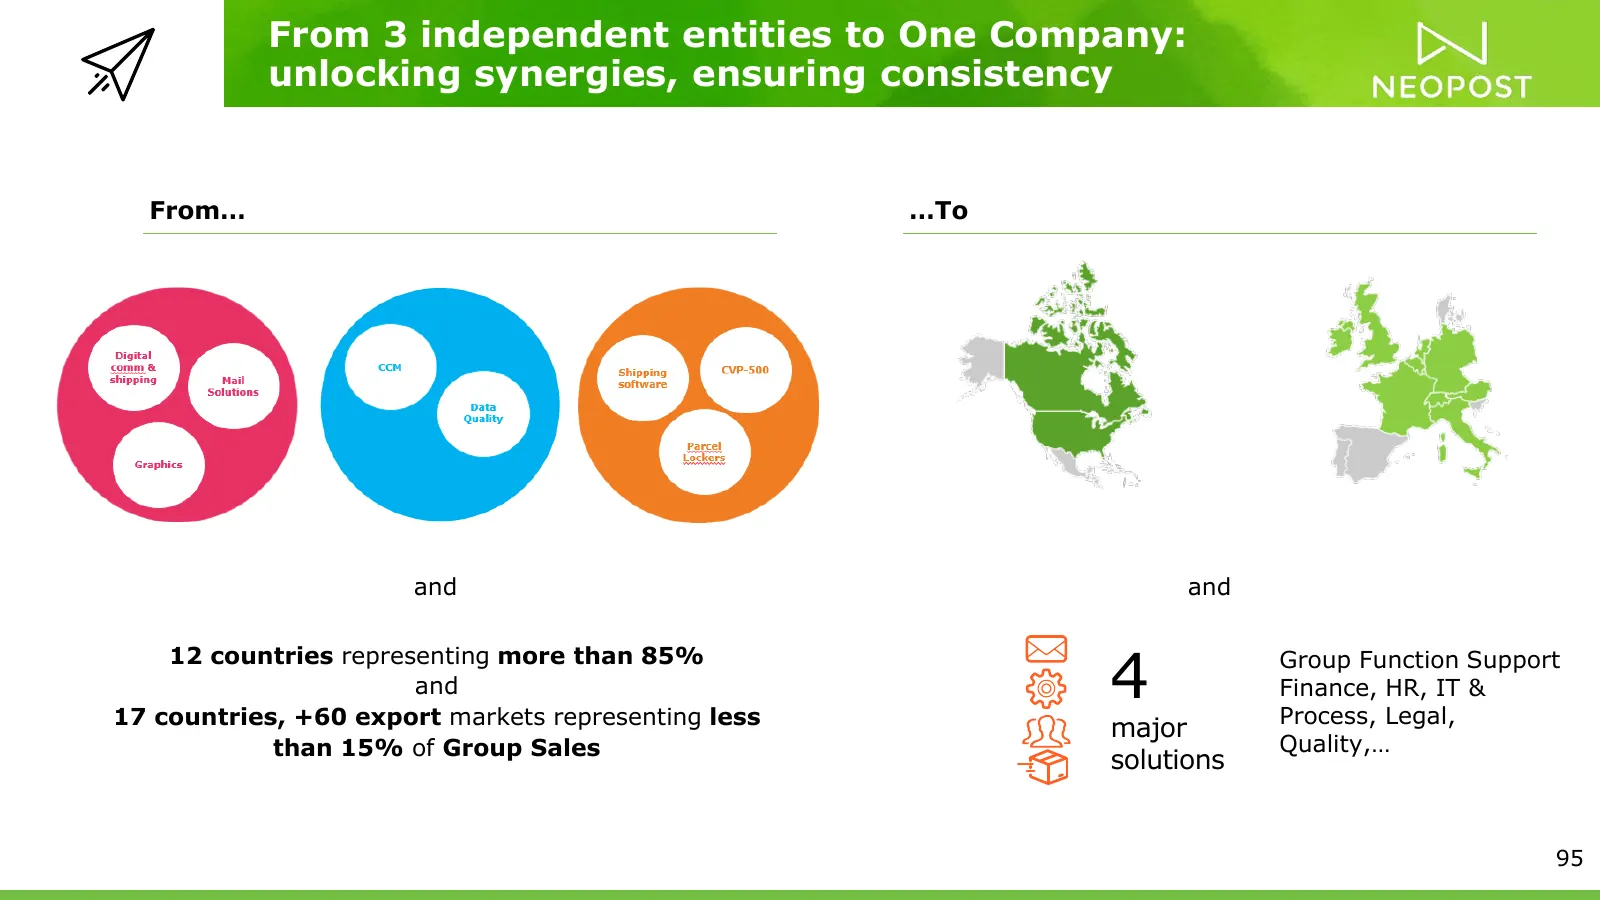
From 3 independent entities to One Company: unlocking synergies, ensuring consistency From… …To and and 4 12 countries representing more than 85% Group Function Support and Finance, HR, IT & 17 countries, +60 export markets representing less Process, Legal, major than 15% of Group Sales Quality,… so
Slide 96: Group Solutions will drive synergies
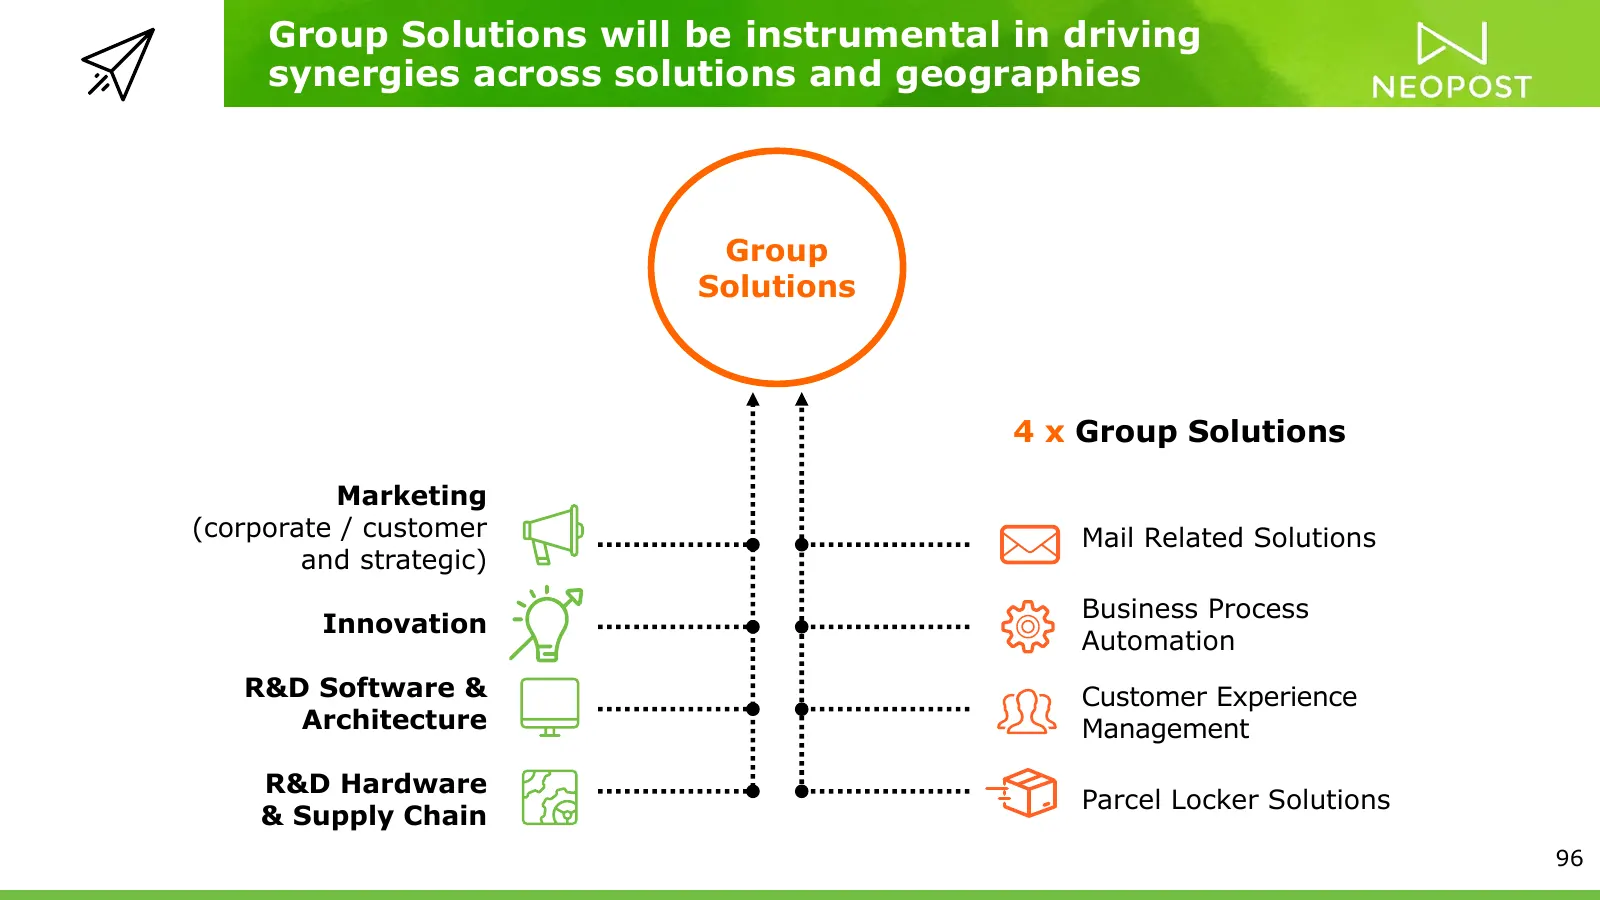
Group Solutions will be instrumental in driving synergies across solutions and geographies Group Solutions 4 x Group Solutions Marketing (corporate / customer Mail Related Solutions and strategic) Business Process Innovation Automation R&D Software & Customer Experience Architecture Management R&D H
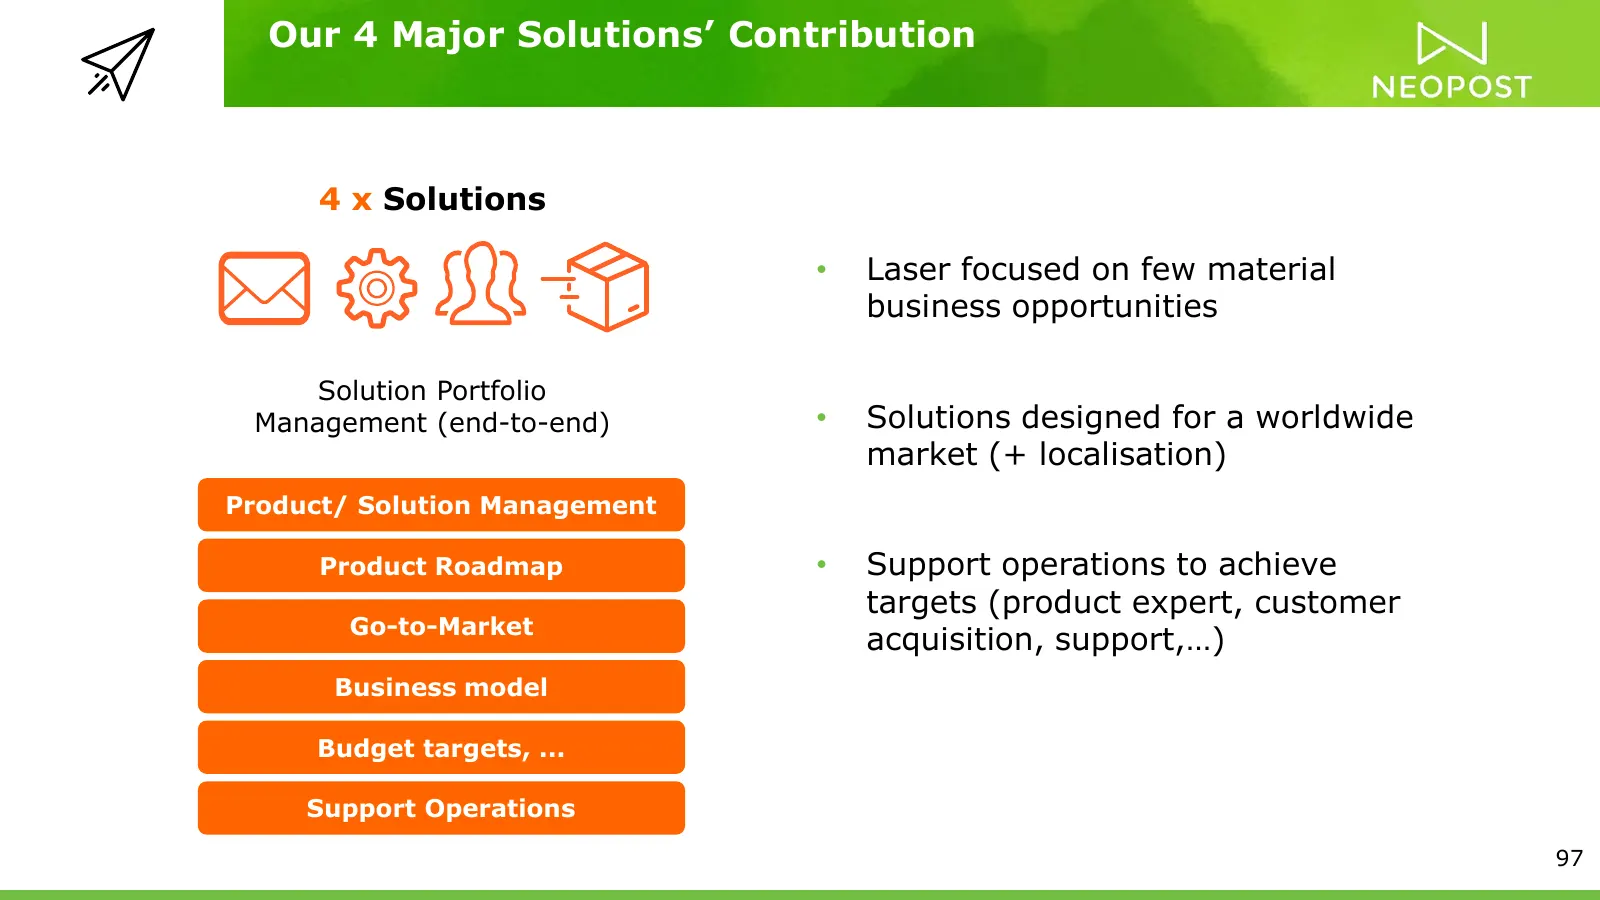
Slide 97: Our 4 Major Solutions' Contribution
Our 4 Major Solutions’ Contribution 4 x Solutions • Laser focused on few material business opportunities Solution Portfolio Management (end-to-end) • Solutions designed for a worldwide market (+ localisation) Product/ Solution Management Product Roadmap • Support operations to achieve targets (produ
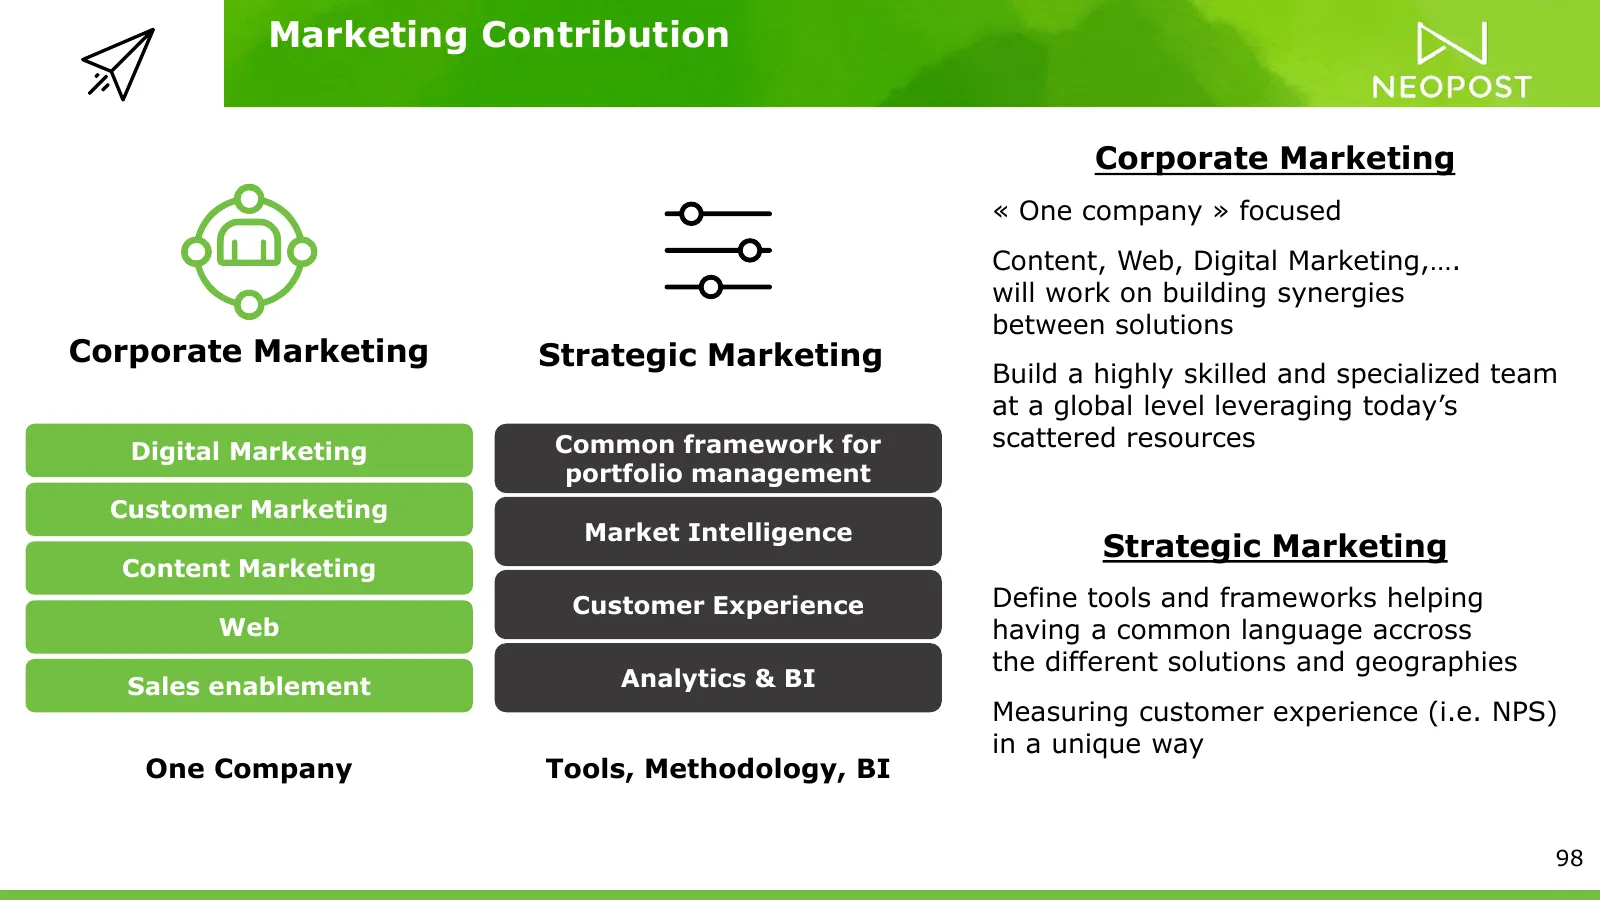
Slide 98: Marketing Contribution
Marketing Contribution Corporate Marketing « One company » focused Content, Web, Digital Marketing,…. will work on building synergies between solutions Corporate Marketing Strategic Marketing Build a highly skilled and specialized team at a global level leveraging today’s Digital Marketing Common fr
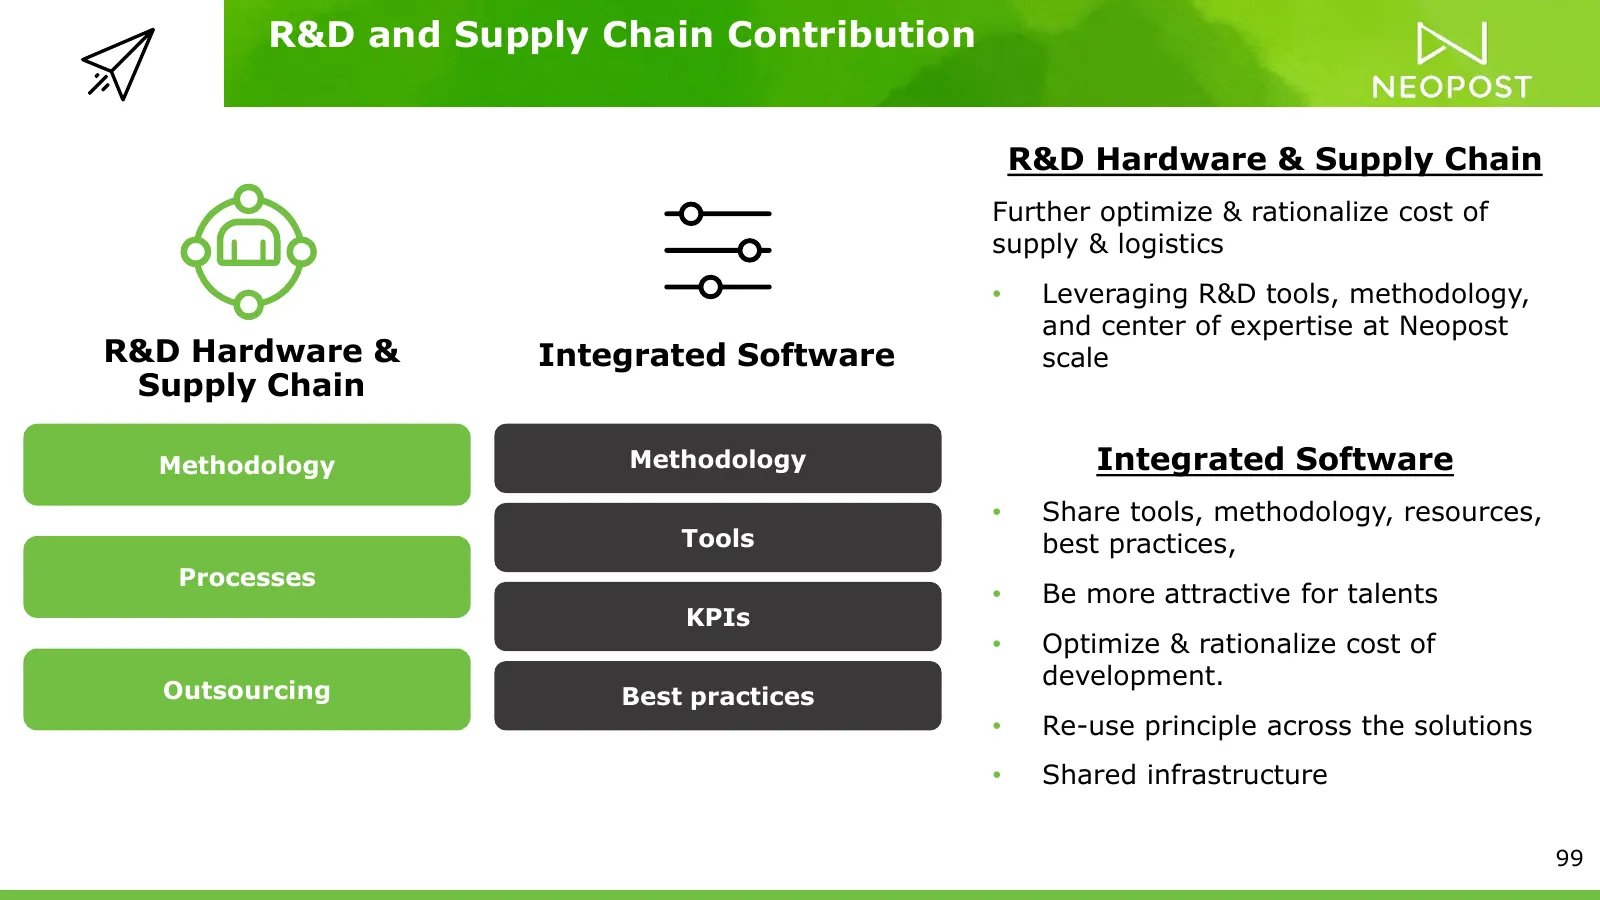
Slide 99: R&D and Supply Chain Contribution
R&D and Supply Chain Contribution R&D Hardware & Supply Chain Further optimize & rationalize cost of supply & logistics • Leveraging R&D tools, methodology, and center of expertise at Neopost R&D Hardware & Integrated Software scale Supply Chain Methodology Methodology Integrated Software • Share to
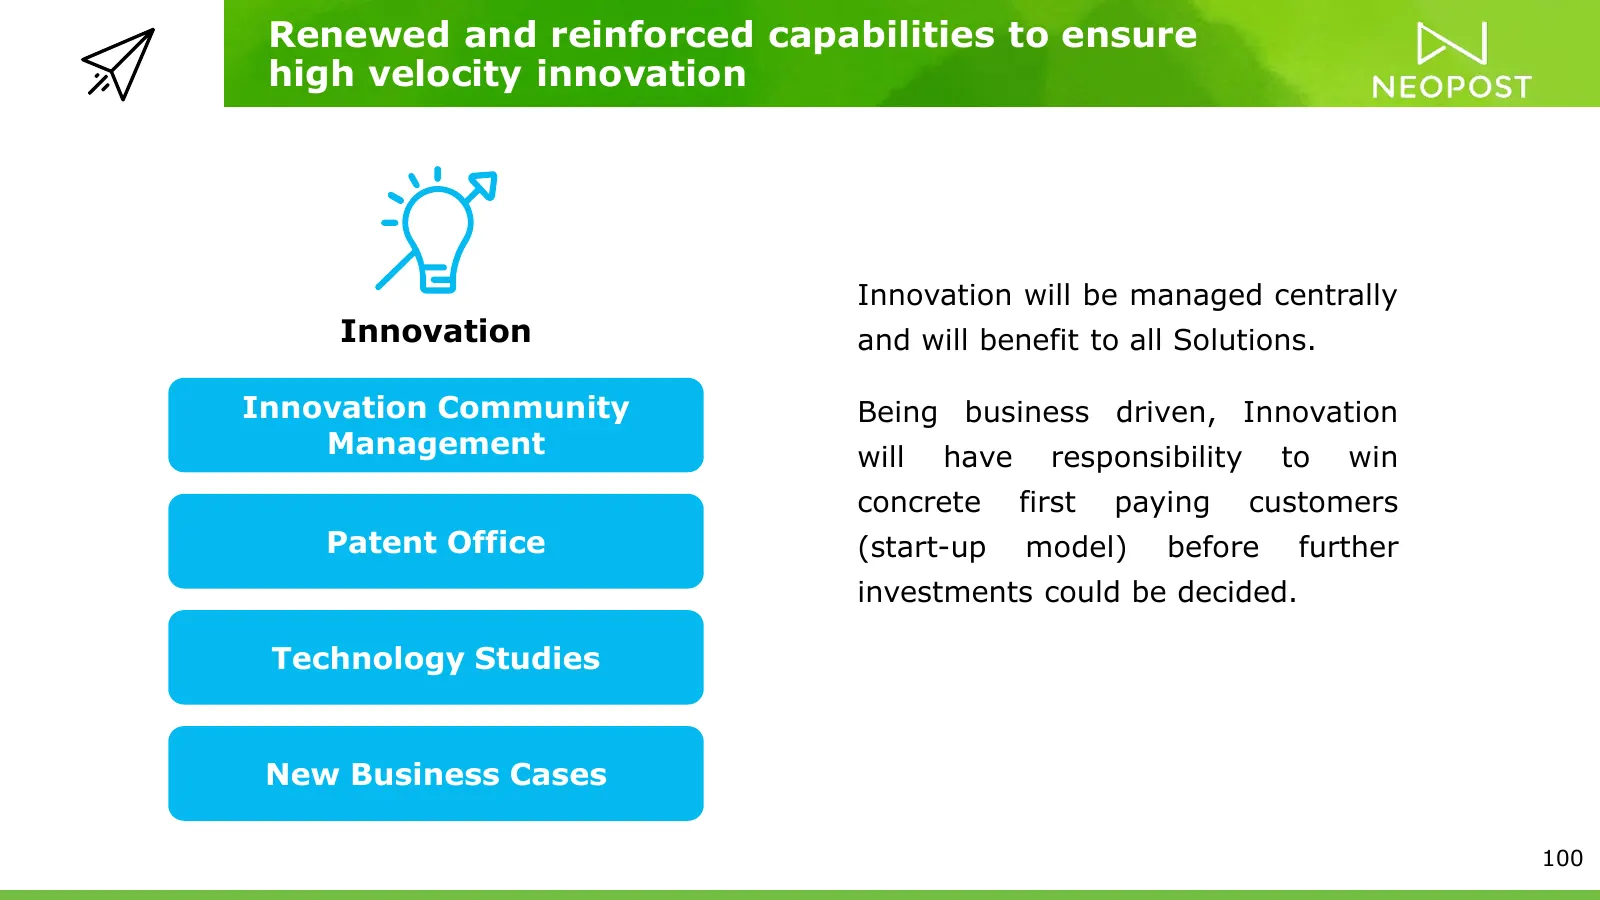
Slide 100: Capabilities to ensure high velocity innovation
Renewed and reinforced capabilities to ensure high velocity innovation Innovation will be managed centrally Innovation and will benefit to all Solutions. Innovation Community Being business driven, Innovation Management will have responsibility to win concrete first paying customers Patent Office (s
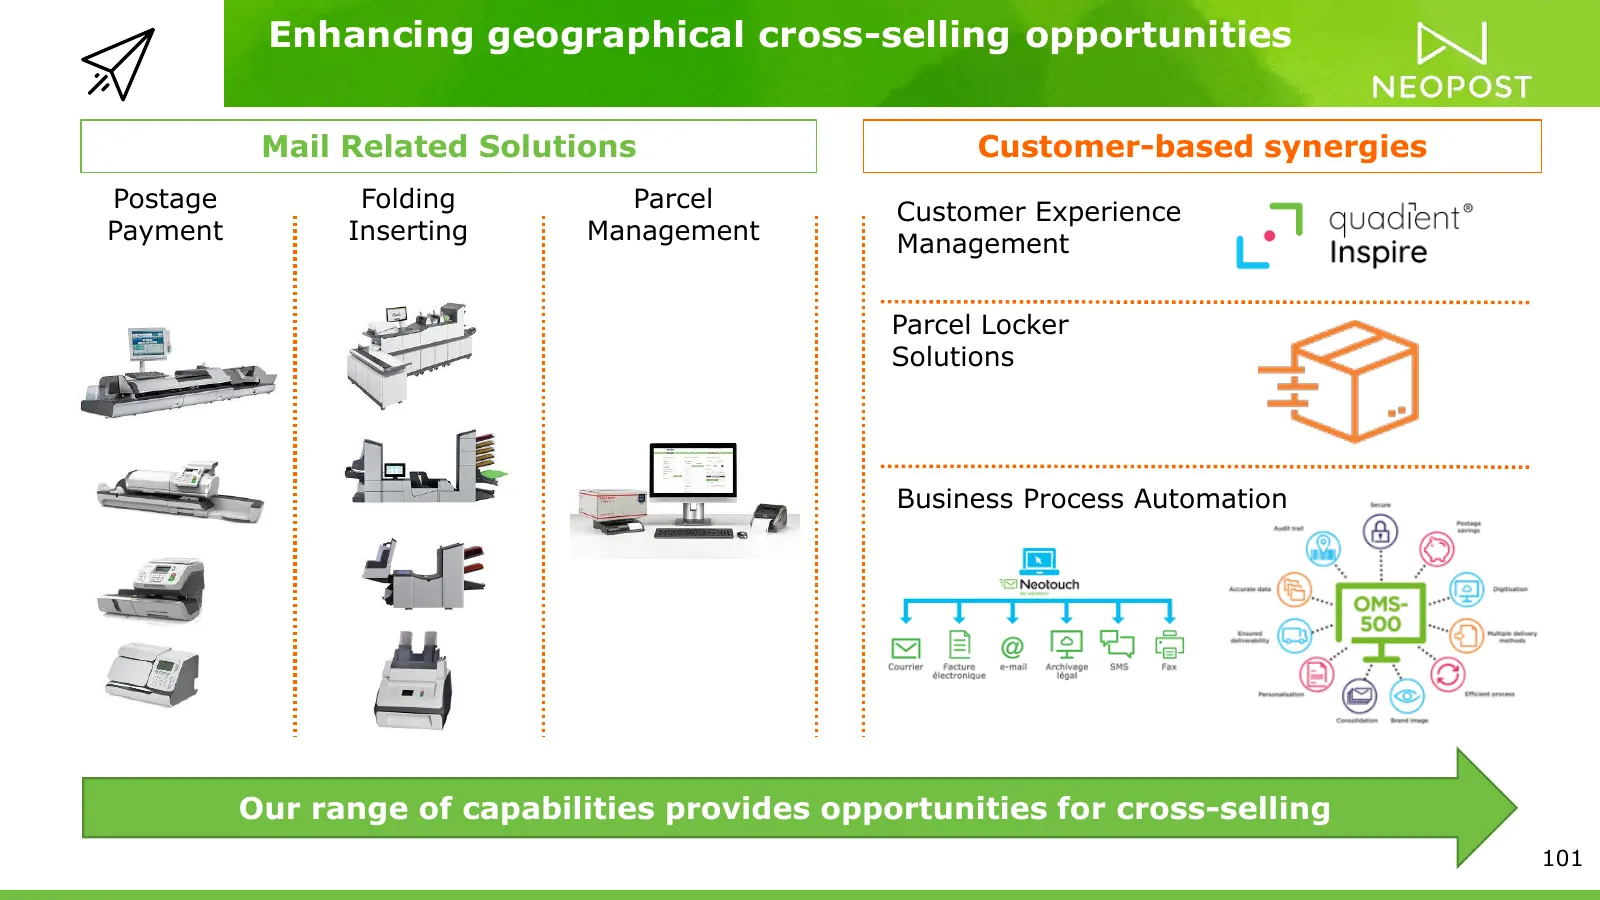
Slide 101: Enhancing geographical cross-selling opportunities
Enhancing geographical cross-selling opportunities Mail Related Solutions Customer-based synergies Postage Folding Parcel Customer Experience Payment Inserting Management Management Parcel Locker Solutions Business Process Automation Our range of capabilities provides opportunities for cross-selling
Slide 102: Financial Model and Capital Allocation
Financial Model and Capital Allocation • Jean-François Labadie • Chief Financial Officer
Slide 103: Agenda
Agenda 1 Financial track record 2 Focus on leasing and rental 3 Business model portfolio 4 Capital allocation policy 103
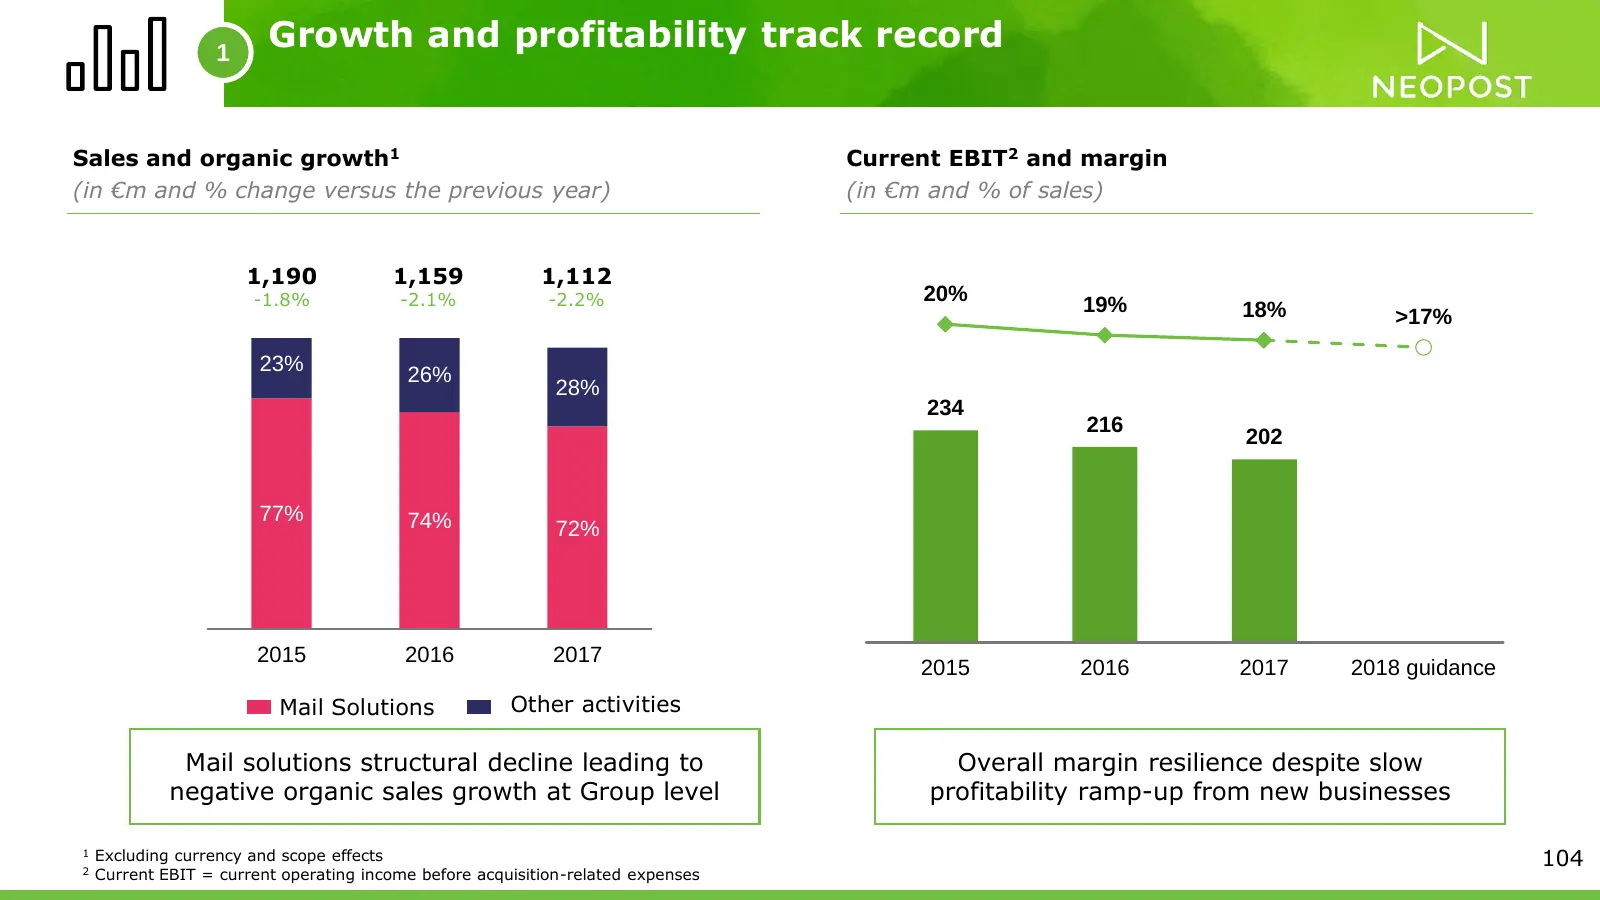
Slide 104: Growth and profitability track record
1 Growth and profitability track record Sales and organic growth1 Current EBIT2 and margin (in €m and % change versus the previous year) (in €m and % of sales) 1,190 1,159 1,112 -1.8% 1,190 -2.1% -2.2% 20% 19% 1,159 18% >17% 1,112 23% 26% 28% 234 216 202 77% 74% 72% 2015 2016 2017 2015 2016 2017 201
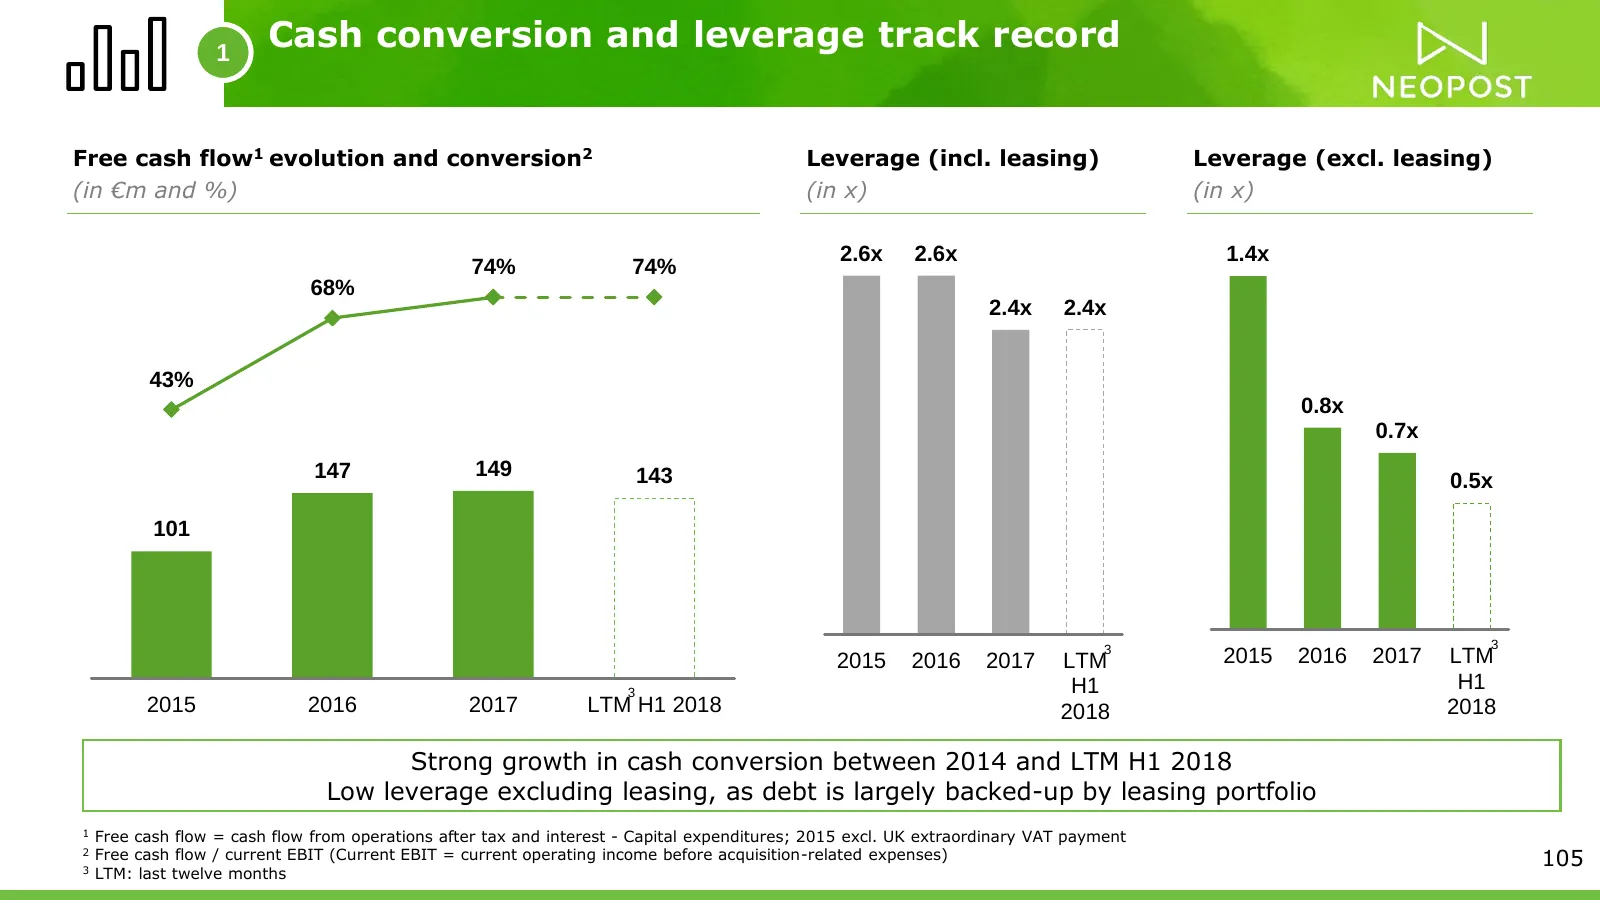
Slide 105: Cash conversion and leverage track record
1 Cash conversion and leverage track record Free cash flow1 evolution and conversion2 Leverage (incl. leasing) Leverage (excl. leasing) (in €m and %) (in x) (in x) 2.6x 2.6x 1.4x 74% 74% 68% 2.4x 2.4x 43% 0.8x 0.7x 147 149 143 0.5x 101 3 3 2015 2016 2017 LTM 2015 2016 2017 LTM 3 H1 H1 2015 2016 2017
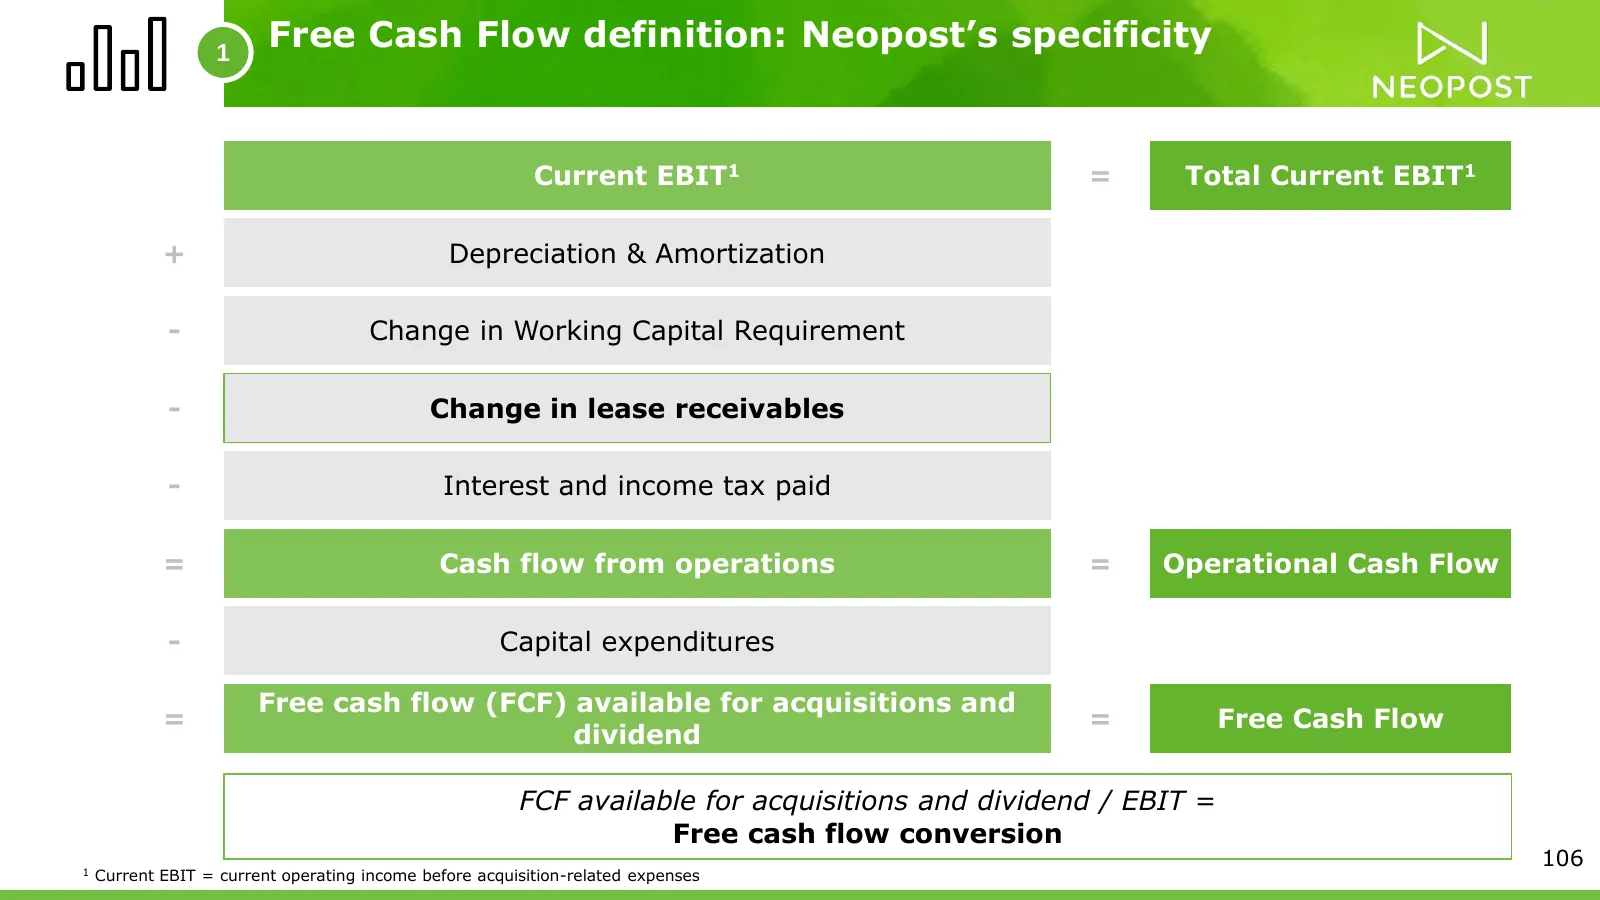
Slide 106: Free Cash Flow definition
1 Free Cash Flow definition: Neopost’s specificity Current EBIT1 = Total Current EBIT1 + Depreciation & Amortization - Change in Working Capital Requirement - Change in lease receivables - Interest and income tax paid = Cash flow from operations = Operational Cash Flow - Capital expenditures Free ca
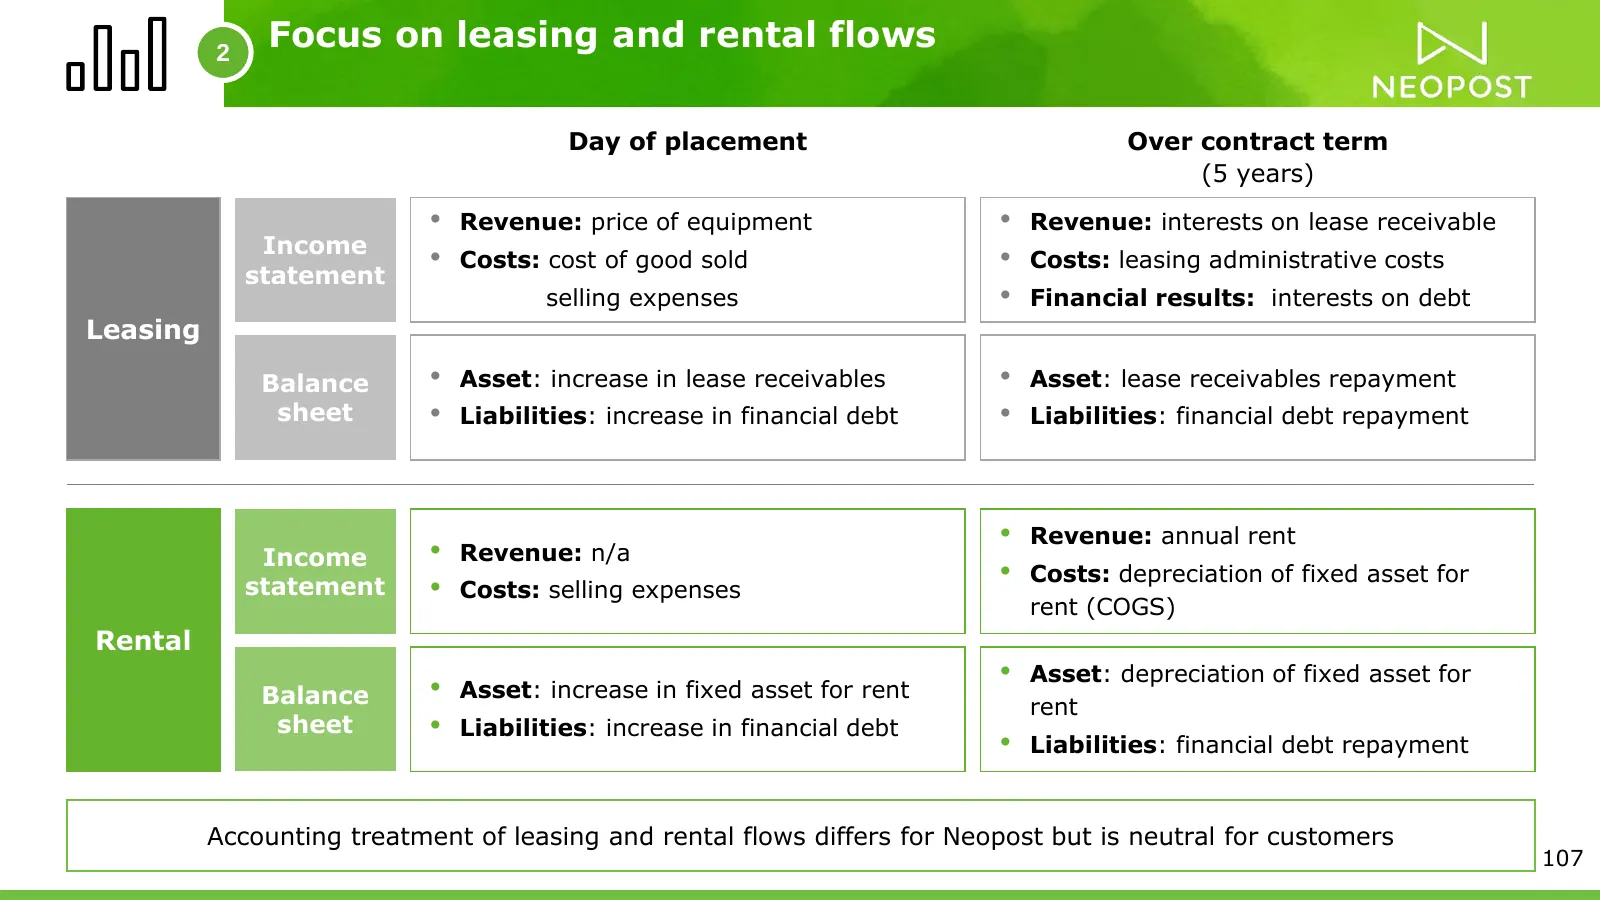
Slide 107: Focus on leasing and rental flows
2 Focus on leasing and rental flows Day of placement Over contract term (5 years) • Revenue: price of equipment • Revenue: interests on lease receivable Income statement • Costs: cost of good sold • Costs: leasing administrative costs selling expenses • Financial results: interests on debt Leasing B
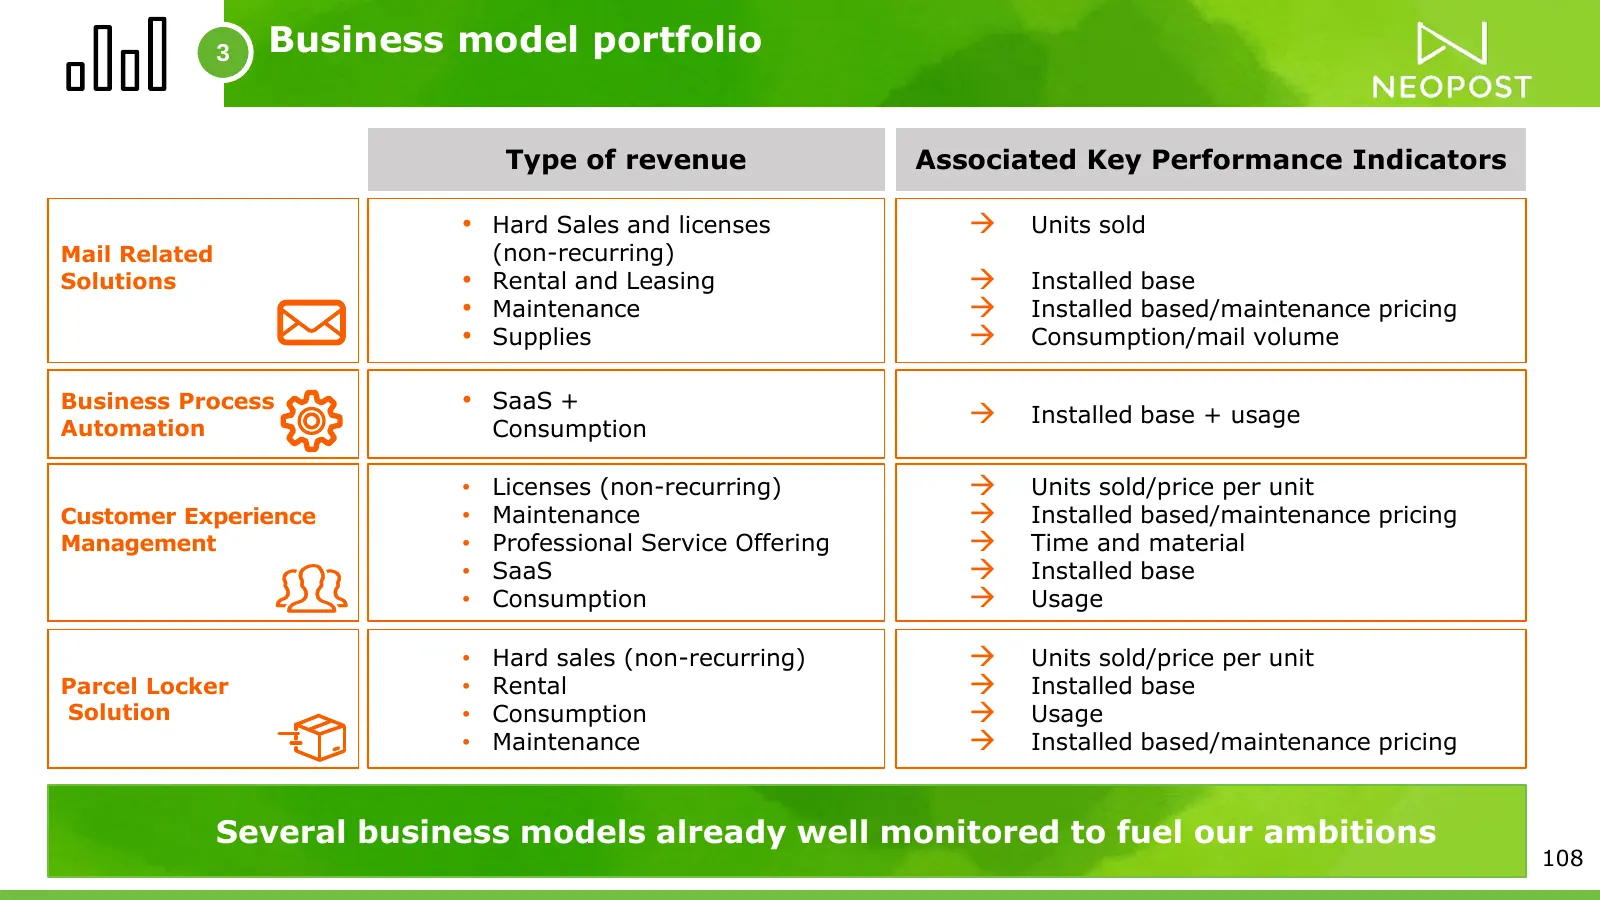
Slide 108: Business model portfolio
3 Business model portfolio Type of revenue Associated Key Performance Indicators • Hard Sales and licenses Units sold Mail Related (non-recurring) Solutions • Rental and Leasing Installed base • Maintenance Installed based/maintenance pricing • Supplies Consumption/mail volume Business Proce
Slide 109: Capital allocation priorities
4 Capital allocation priorities 1 Pursue targeted acquisitions 2 Maintain debt flexibility 3 Adapt shareholder return policy 4 Back to profitable growth 109
Slide 110: Pursue targeted acquisitions
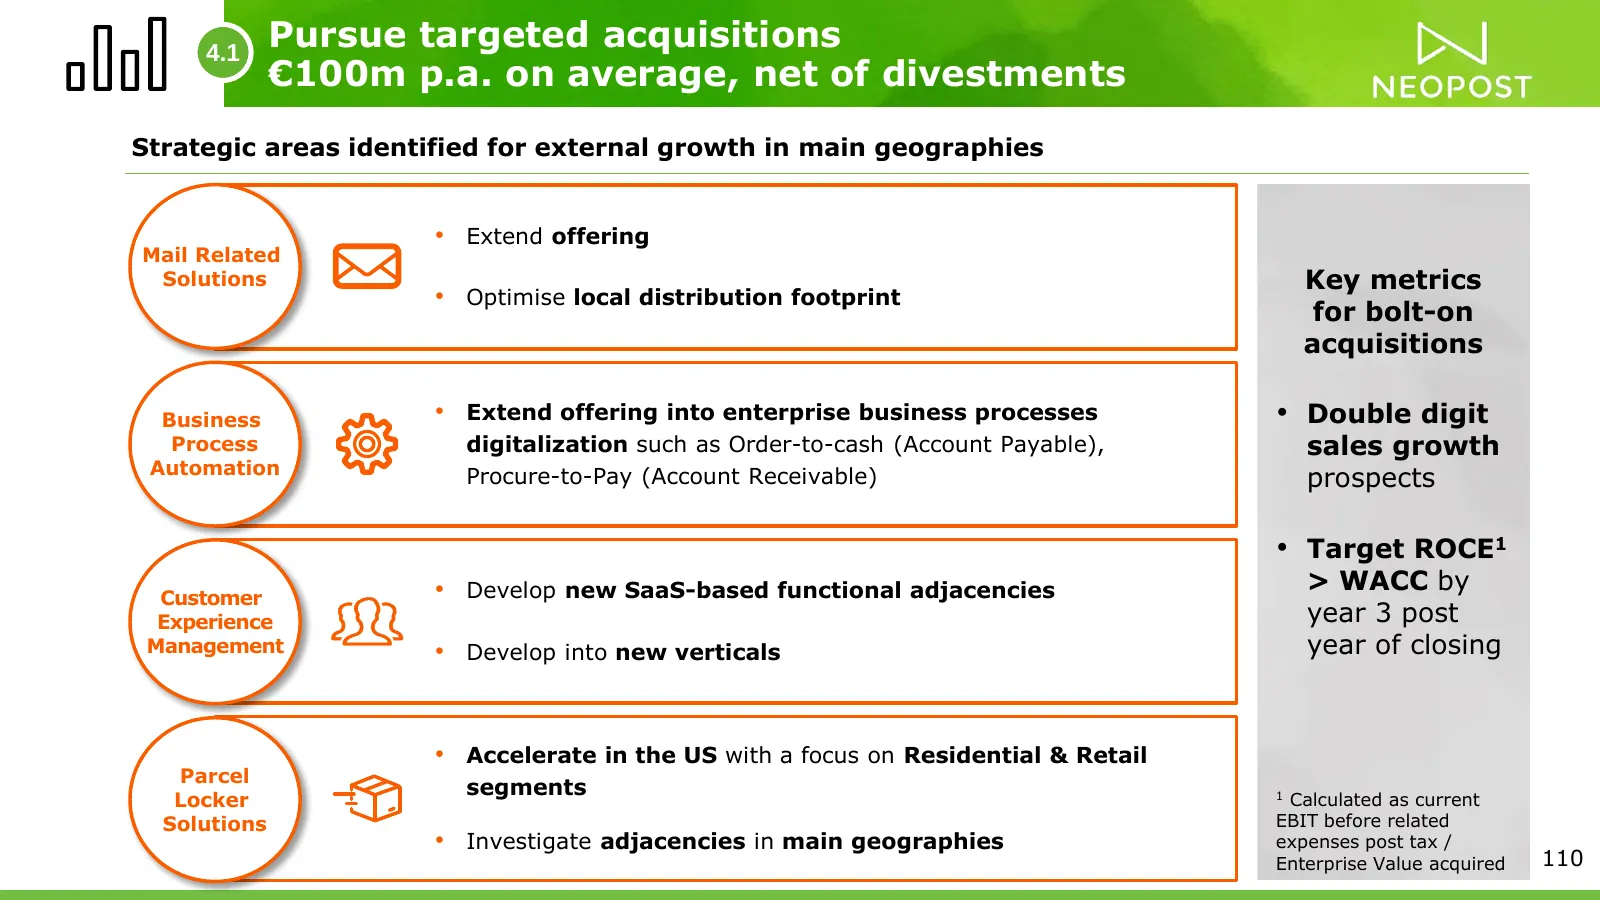
4.1 Pursue targeted acquisitions €100m p.a. on average, net of divestments Strategic areas identified for external growth in main geographies • Extend offering Mail Related Solutions Key metrics • Optimise local distribution footprint for bolt-on acquisitions Business • Extend offering into enterpri
Slide 111: Focus on GMC acquisition
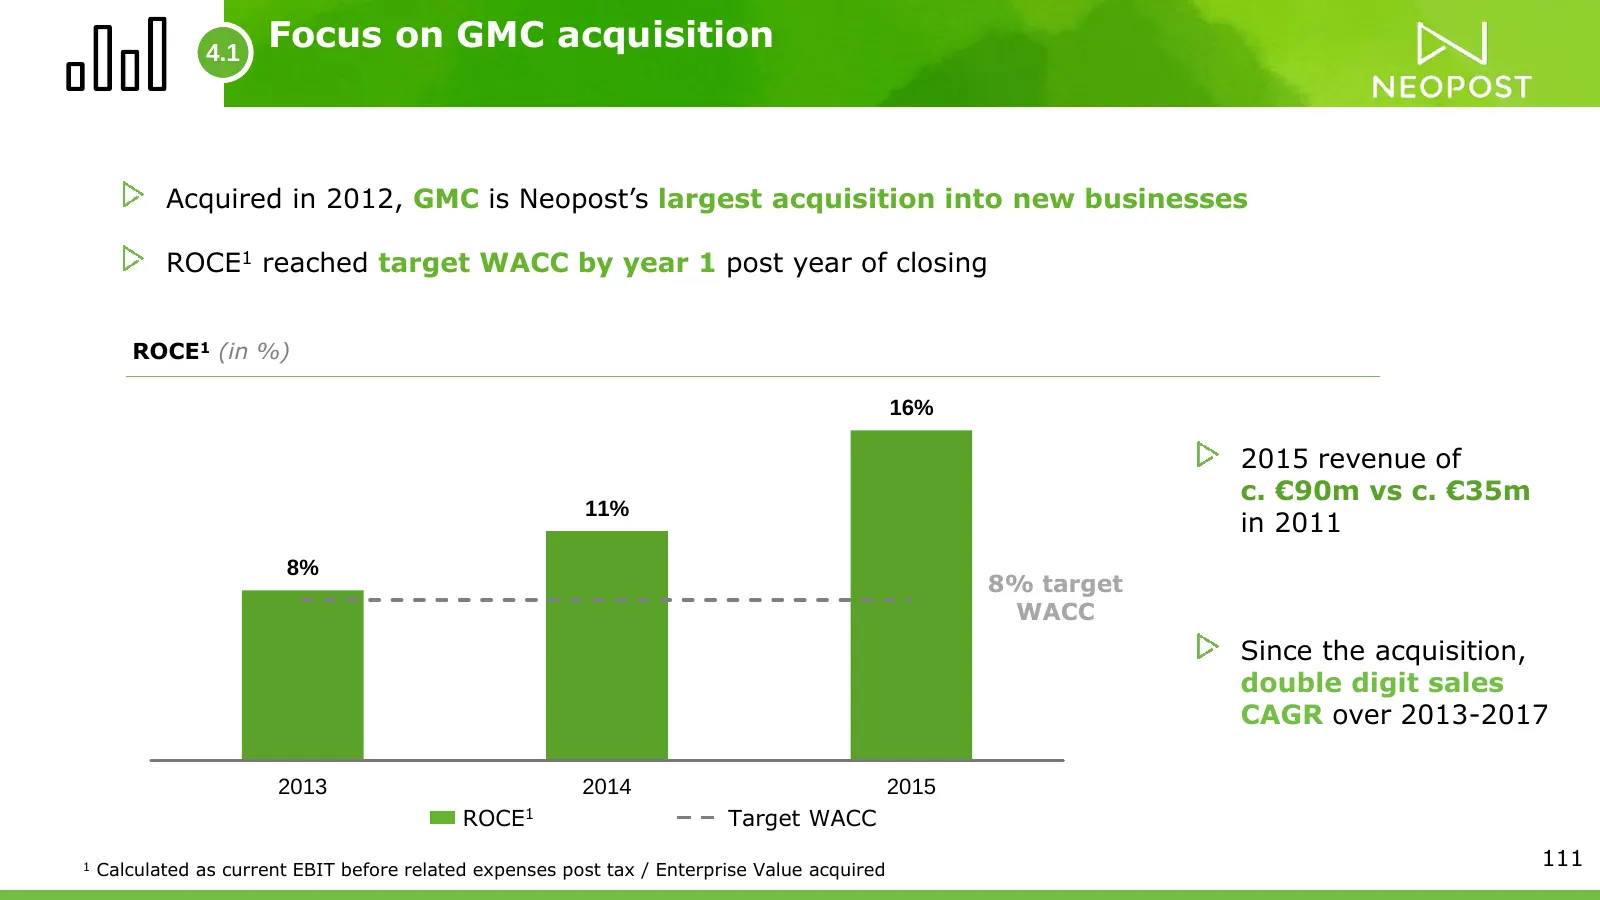
4.1 Focus on GMC acquisition Acquired in 2012, GMC is Neopost’s largest acquisition into new businesses ROCE1 reached target WACC by year 1 post year of closing ROCE1 (in %) 16% 2015 revenue of c. €90m vs c. €35m 11% in 2011 8% 8% target WACC Since the acquisition, double digit sales CAGR over 2013-
Slide 112: Parcel Pending, a perfect fit with the strategy
4.1 Parcel Pending, a perfect fit with the strategy A US market leader on a fast growing segment A strong double digit sales growth expected over 2019-2022 An already profitable company Expecting ROCE1 > WACC by year 3 post year of closing 1 Calculated as current EBIT before related expenses post ta
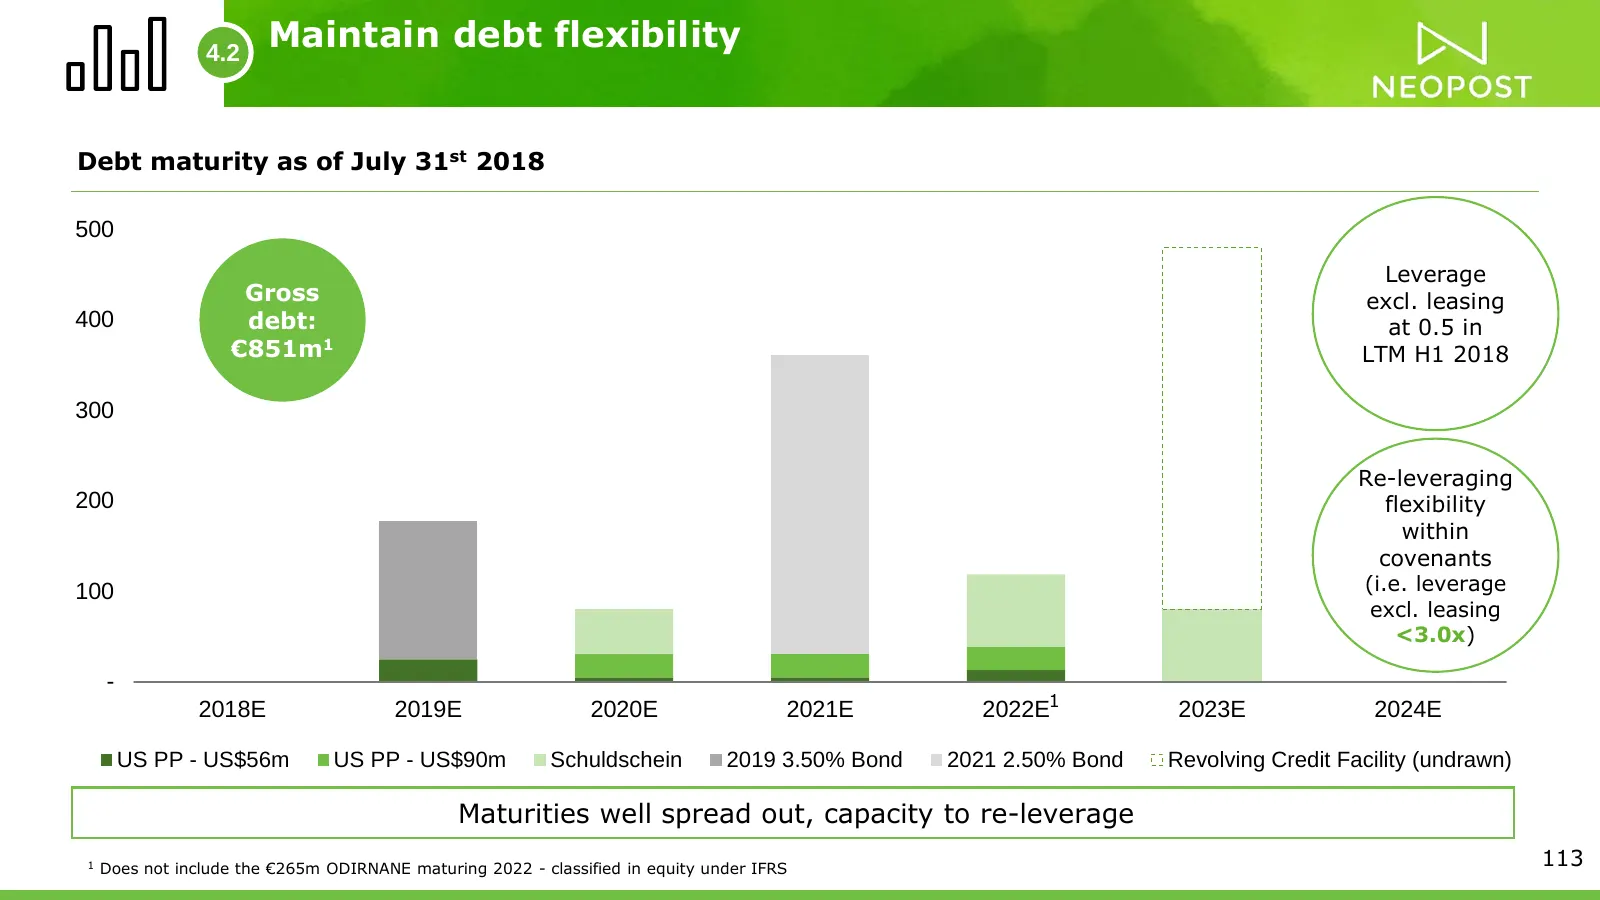
Slide 113: Maintain debt flexibility
4.2 Maintain debt flexibility Debt maturity as of July 31st 2018 500 Leverage Gross excl. leasing 400 debt: at 0.5 in €851m1 LTM H1 2018 300 Re-leveraging 200 flexibility within covenants 100 (i.e. leverage excl. leasing <3.0x) - 2018E 2019E 2020E 2021E 2022E1 2023E 2024E US PP - US$56m US PP - US$9
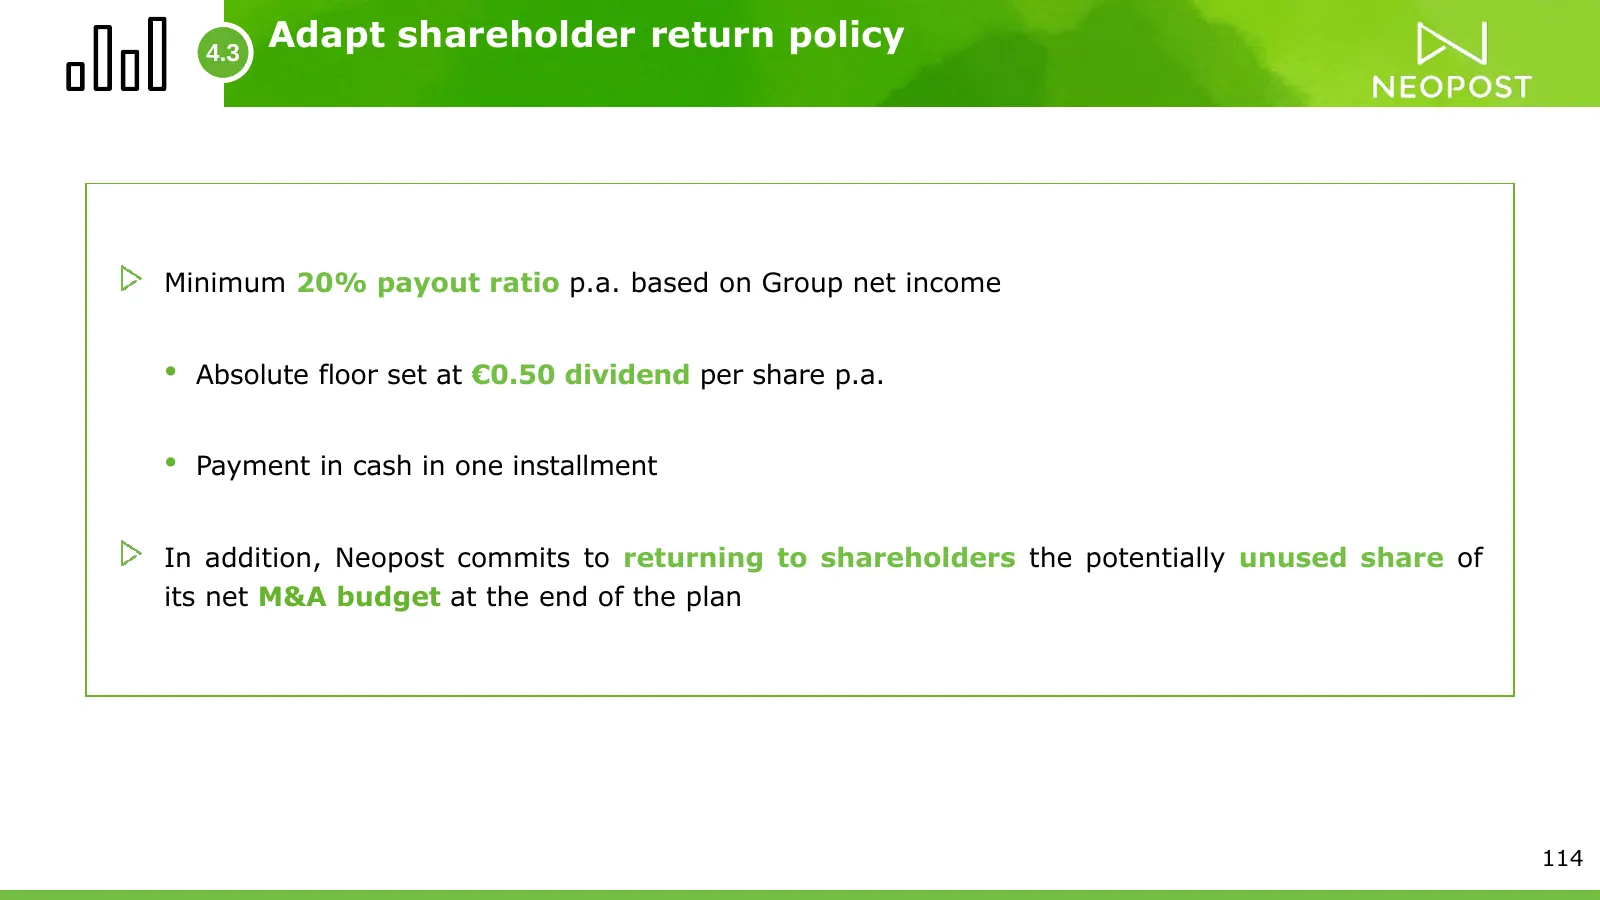
Slide 114: Adapt shareholder return policy
4.3 Adapt shareholder return policy Minimum 20% payout ratio p.a. based on Group net income • Absolute floor set at €0.50 dividend per share p.a. • Payment in cash in one installment In addition, Neopost commits to returning to shareholders the potentially unused share of its net M&A budget at the e
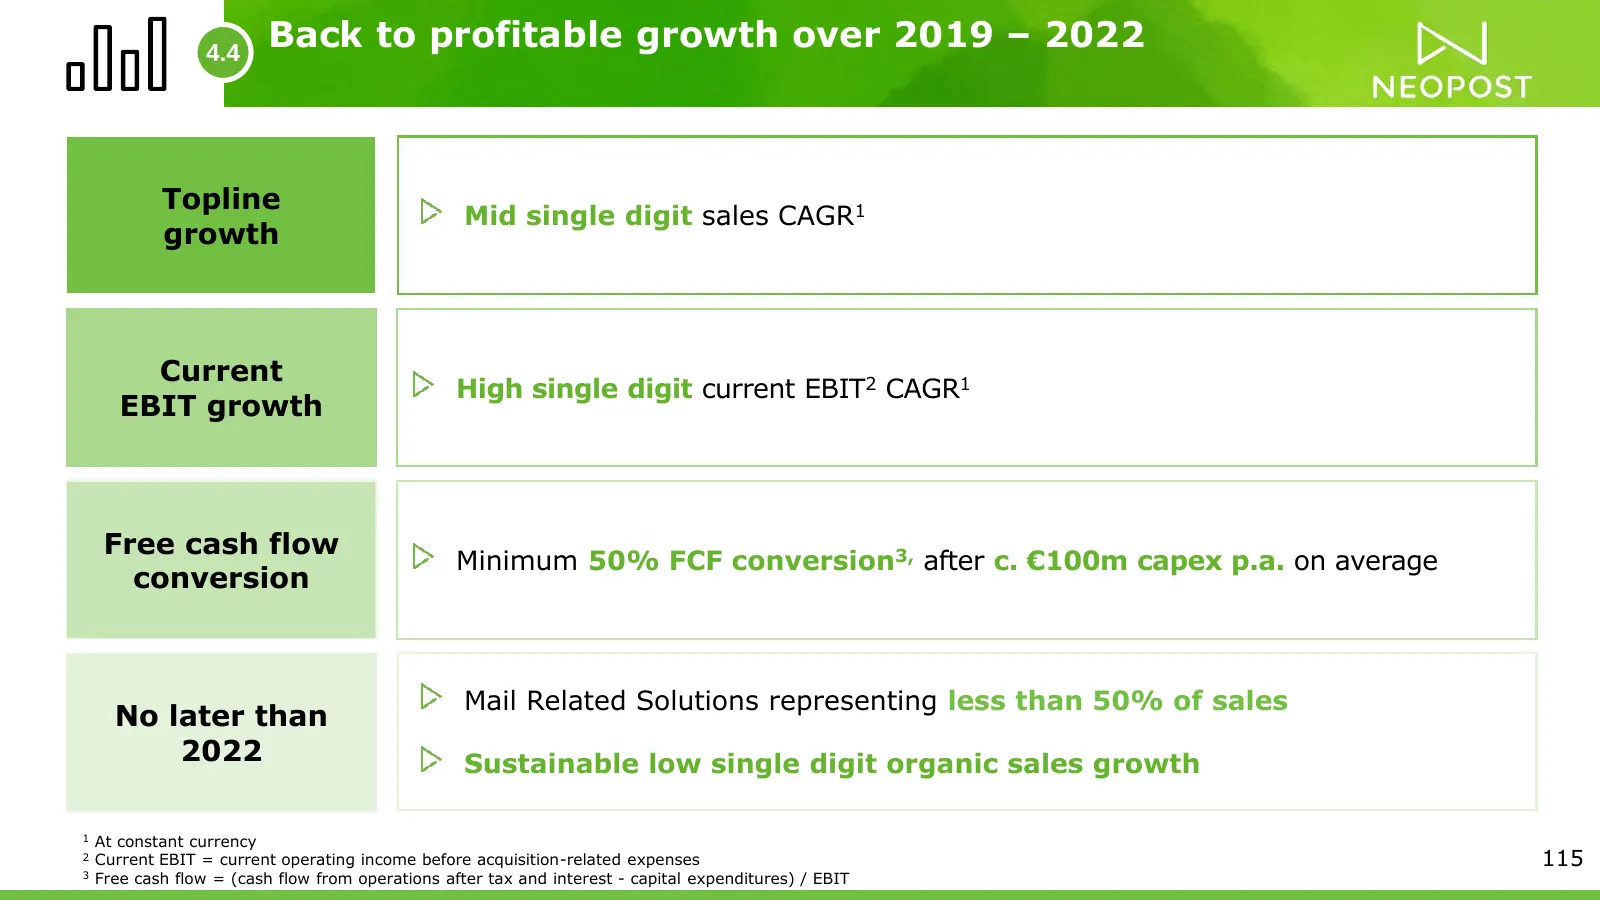
Slide 115: Back to profitable growth over 2019–2022
4.4 Back to profitable growth over 2019 – 2022 Topline Mid single digit sales CAGR1 growth Current High single digit current EBIT2 CAGR1 EBIT growth Free cash flow Minimum 50% FCF conversion3, after c. €100m capex p.a. on average conversion Mail Related Solutions representing less than 50% of sales
Slide 116: Back to Growth Wrap-up
Back to Growth Wrap-up • Geoffrey Godet • Chief Executive Officer
Slide 117: Executive Summary – Back to Growth
Executive Summary – Back to Growth Be one company: focus on 2 main geographies and 4 major solutions Grow, improve or exit Additional Operations Unlock synergies Seize opportunity to grow through bolt-on acquisitions, applying strict financial criteria No later than 2022, be positioned to grow organ
Slide 118: _———————=$9
_———————=$9
Slide 119: Thank you
Thank you
Slide 120: Investor Relations Team
INVESTOR RELATIONS TEAM financial-communication@neopost.com www.neopost-group.com/finance
Source: Internet Archive copy of resources.quadient.com
More decks from Quadient SA
 H1 2026 Earnings Presentation43 slides · Sep 23, 2026
 Shareholder Meeting (June 2026)41 slides · Jun 18, 2026
 FY2025 Earnings Presentation52 slides · Mar 25, 2026
 Q3 2025 Earnings Presentation31 slides · Dec 2, 2025
 H1 2025 Earnings Presentation40 slides · Sep 24, 2025
 Shareholder Meeting (June 2025)35 slides · Jun 13, 2025