Bravura Solutions Limited · ASX:BVS
Bravura Solutions — Shareholder Meeting (November 2010)
17 slides from Bravura Solutions's shareholder meeting presentation, November 2010
Slide 1: AGM speech FY2010 - Simon Woodfull, Group CEO
AGM speech FY2010 Simon Woodfull - Group CEO Thank you Brian. [Introduction] Having taken over the role of sole Group CEO in February this year, I am extremely pleased to be presenting to you today. As one of the co-founding partners of Bravura Solutions, it is a great honour and a wonderful opportu
Slide 2: Revenue by type and region; market dynamics
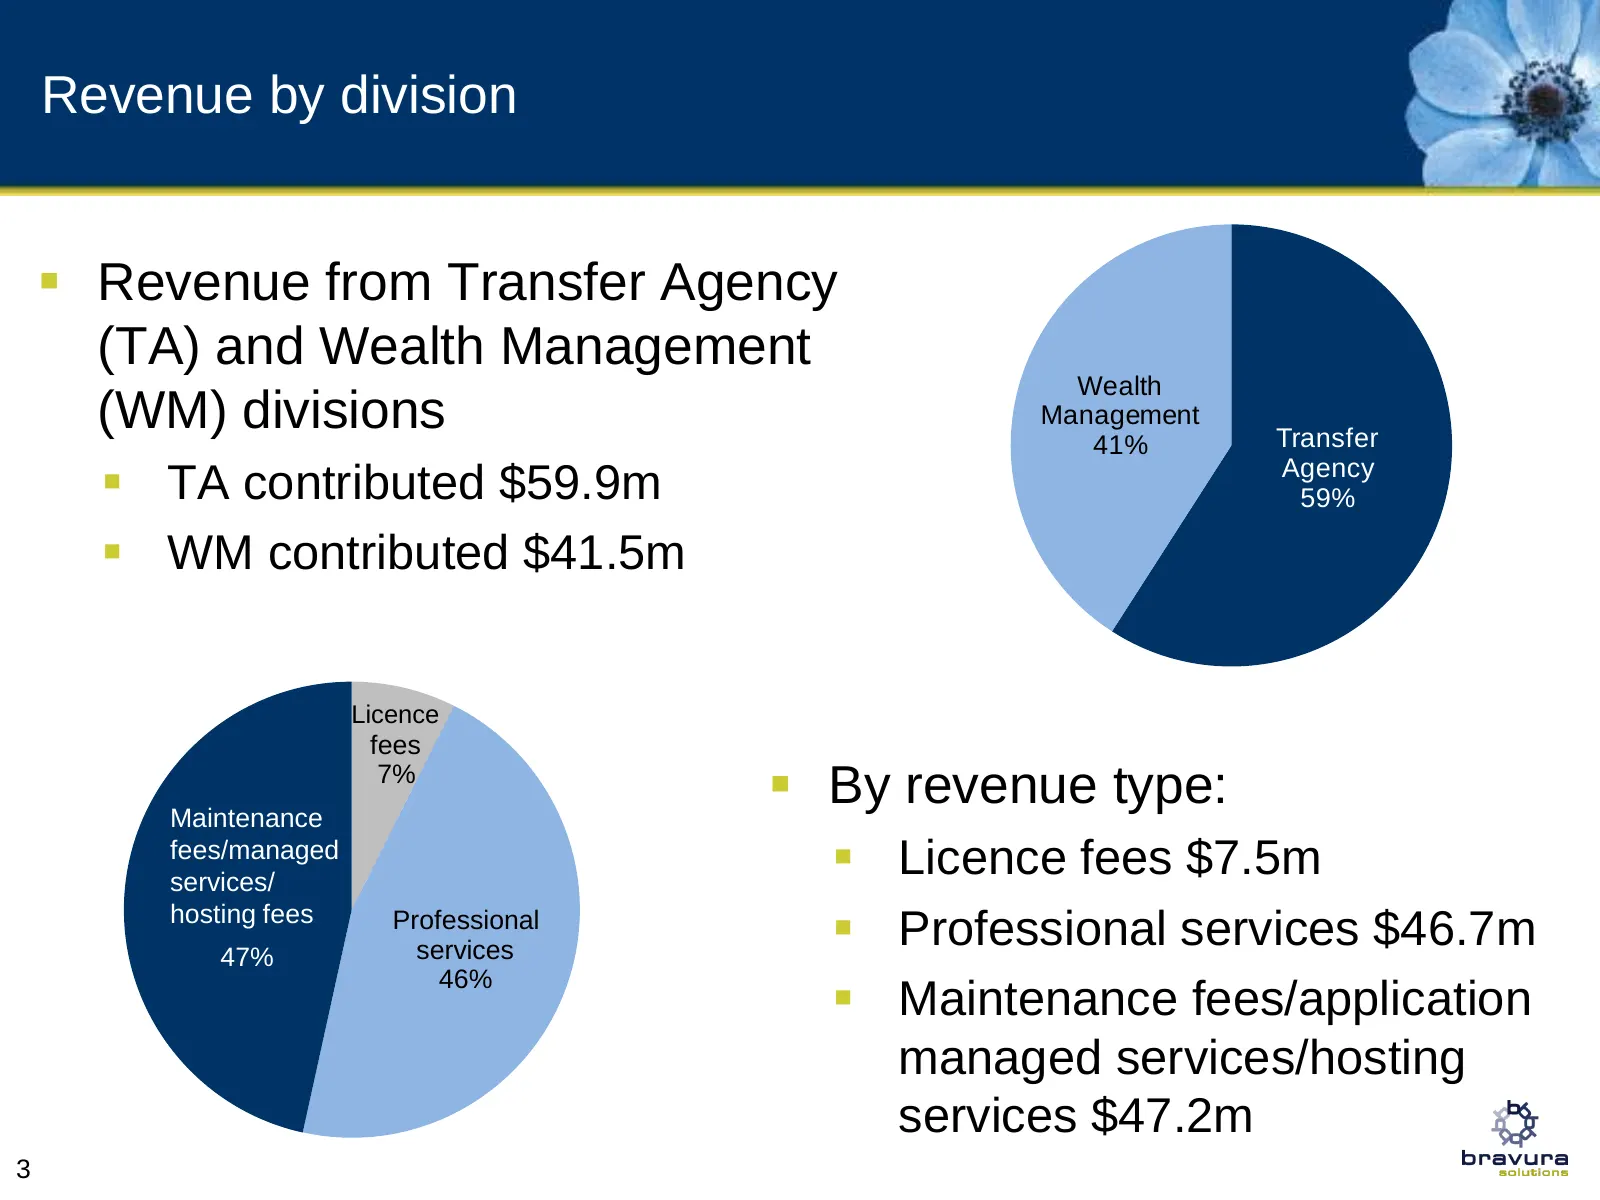
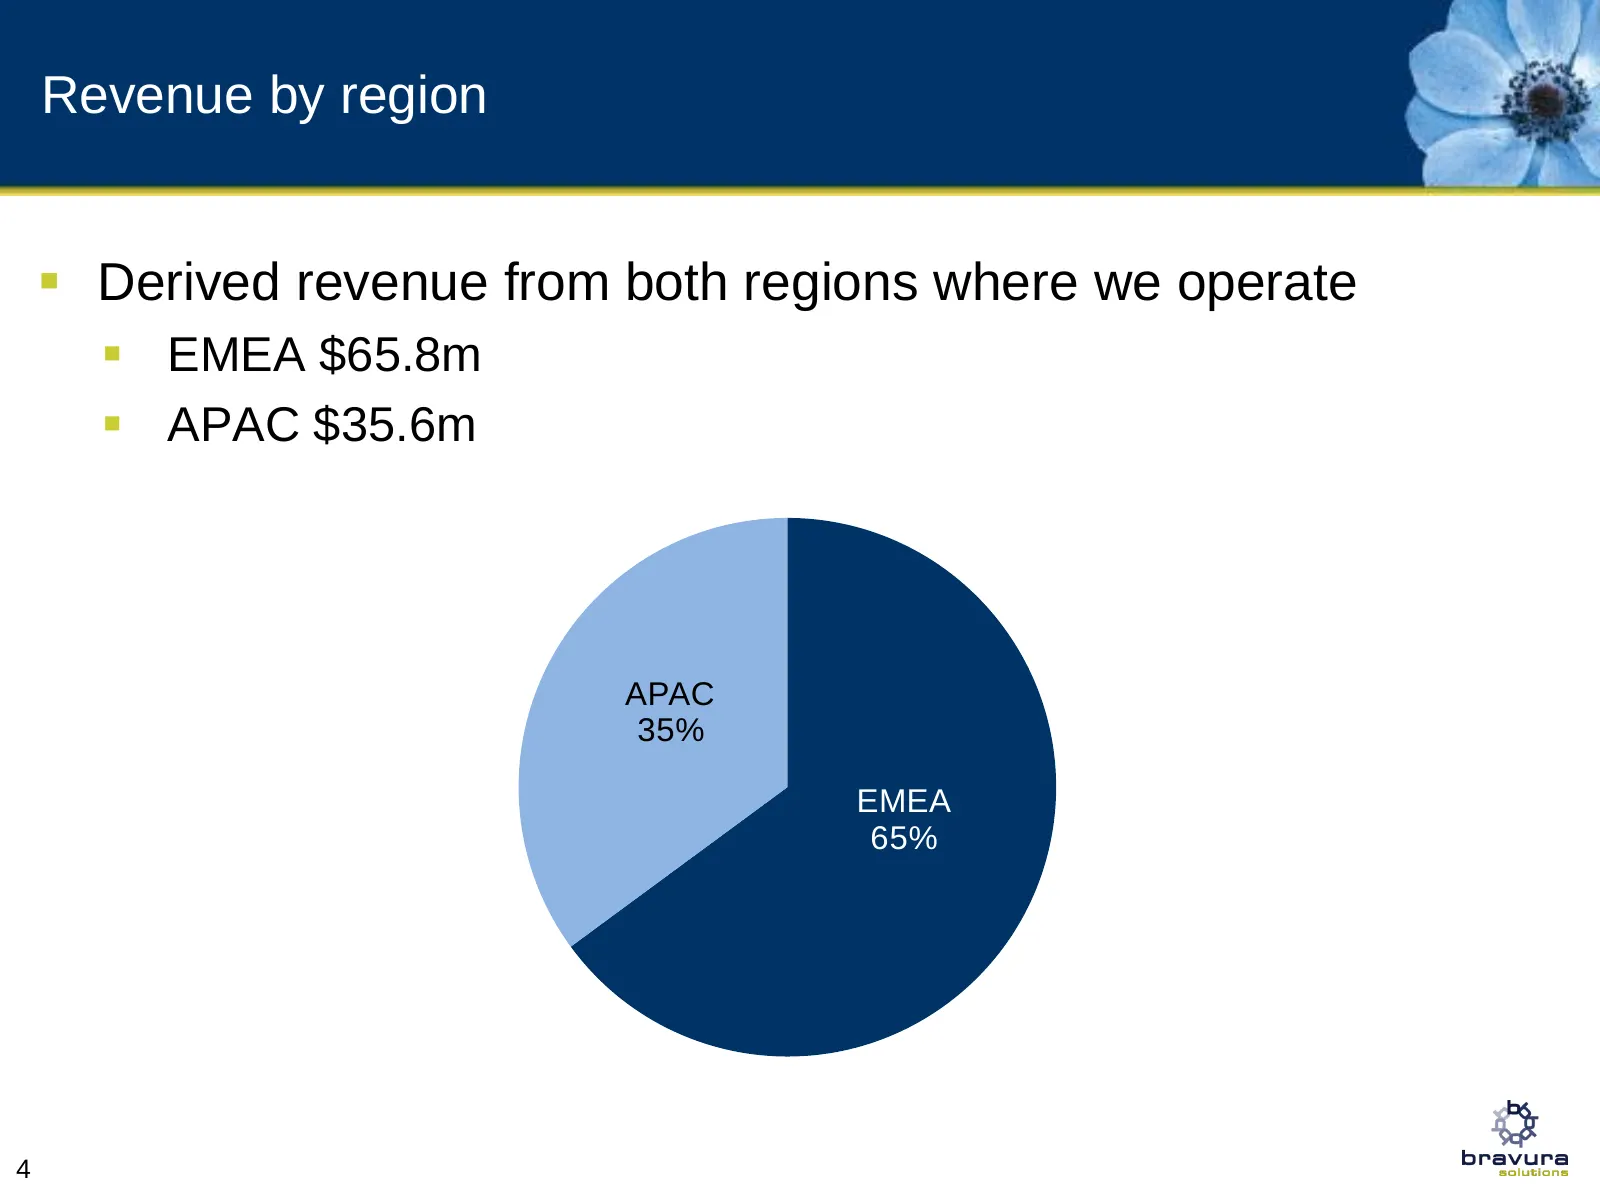
Breaking overall revenue down further by type, $7.5 million or seven per cent was from licence fees and other, $46.7 million or 46 per cent was from professional services and $47.2 million or 47 per cent was from maintenance fees, application managed services and hosting services. From a geographica
Slide 3: Emerging markets and Transfer Agency leadership in Europe
reviewing possibilities to partner with strategic clients as our method of market entry. As this exciting opportunity progresses, we will be sure to keep our shareholders updated. We are also extremely excited about the opportunities in wealth management across Australia, New Zealand, Asia, South Af
Slide 4: Sonata and product range
Our enterprise eBusiness application, ePASS, is used by over 20 clients in Australia and we are currently in the process of developing the solution to be rolled out in the United Kingdom to support group pension products. Over the past 12 months, we have invested heavily in extending functional cove
Slide 5: People and Performance strategy
Over the past year, we have signed a number of new contracts with both existing and new clients. In what remained a challenging operating landscape, we were extremely pleased with the positive relationships we developed and fostered with all of our clients. [The importance of people] We have dedicat
Slide 6: 2010 AGM – CEO’s address
2010 AGM – CEO’s address Presented by Simon Woodfull 19 November 2010
Slide 7: Vision
Vision “To be one of the world’s leading global software partners to financial services companies; the first choice for clients to work with and where exceptional people choose to work.” 2
Slide 8: Revenue by division
Revenue by division Revenue from Transfer Agency (TA) and Wealth Management Wealth (WM) divisions Management 41% Transfer TA contributed $59.9m Agency 59% WM contributed $41.5m Licence fees Maintenance 7% By revenue type: fees/managed services/ Licence fees $7.5m hosting fees 47% Professio
Slide 9: Revenue by region
Revenue by region Derived revenue from both regions where we operate EMEA $65.8m APAC $35.6m APAC 35% EMEA 65% 4
Slide 10: Market dynamics
Market dynamics Key market trends that have shaped our strategic plans and product direction Regulatory update Economic environment Social and environmental Technology Market growth 5
Slide 11: Emerging markets and opportunities
Emerging markets and opportunities New market opportunities for transfer agency in Brazil, Canada and Mexico Opportunities in wealth management across Australia, New Zealand, Asia, South Africa and the United Kingdom Asian life insurance UK wrap platform Lower cost of development and suppo
Slide 12: Transfer agency leadership in Europe
Transfer agency leadership in Europe Strengthen core business in European transfer agency market has been a priority Focus maintained on existing Rufus and GTAS clients that account for the majority of revenue generation Now with addition of MFT’s GFAS clients, 3 of the top 5 UK fund managers
Slide 13: A broad range of products
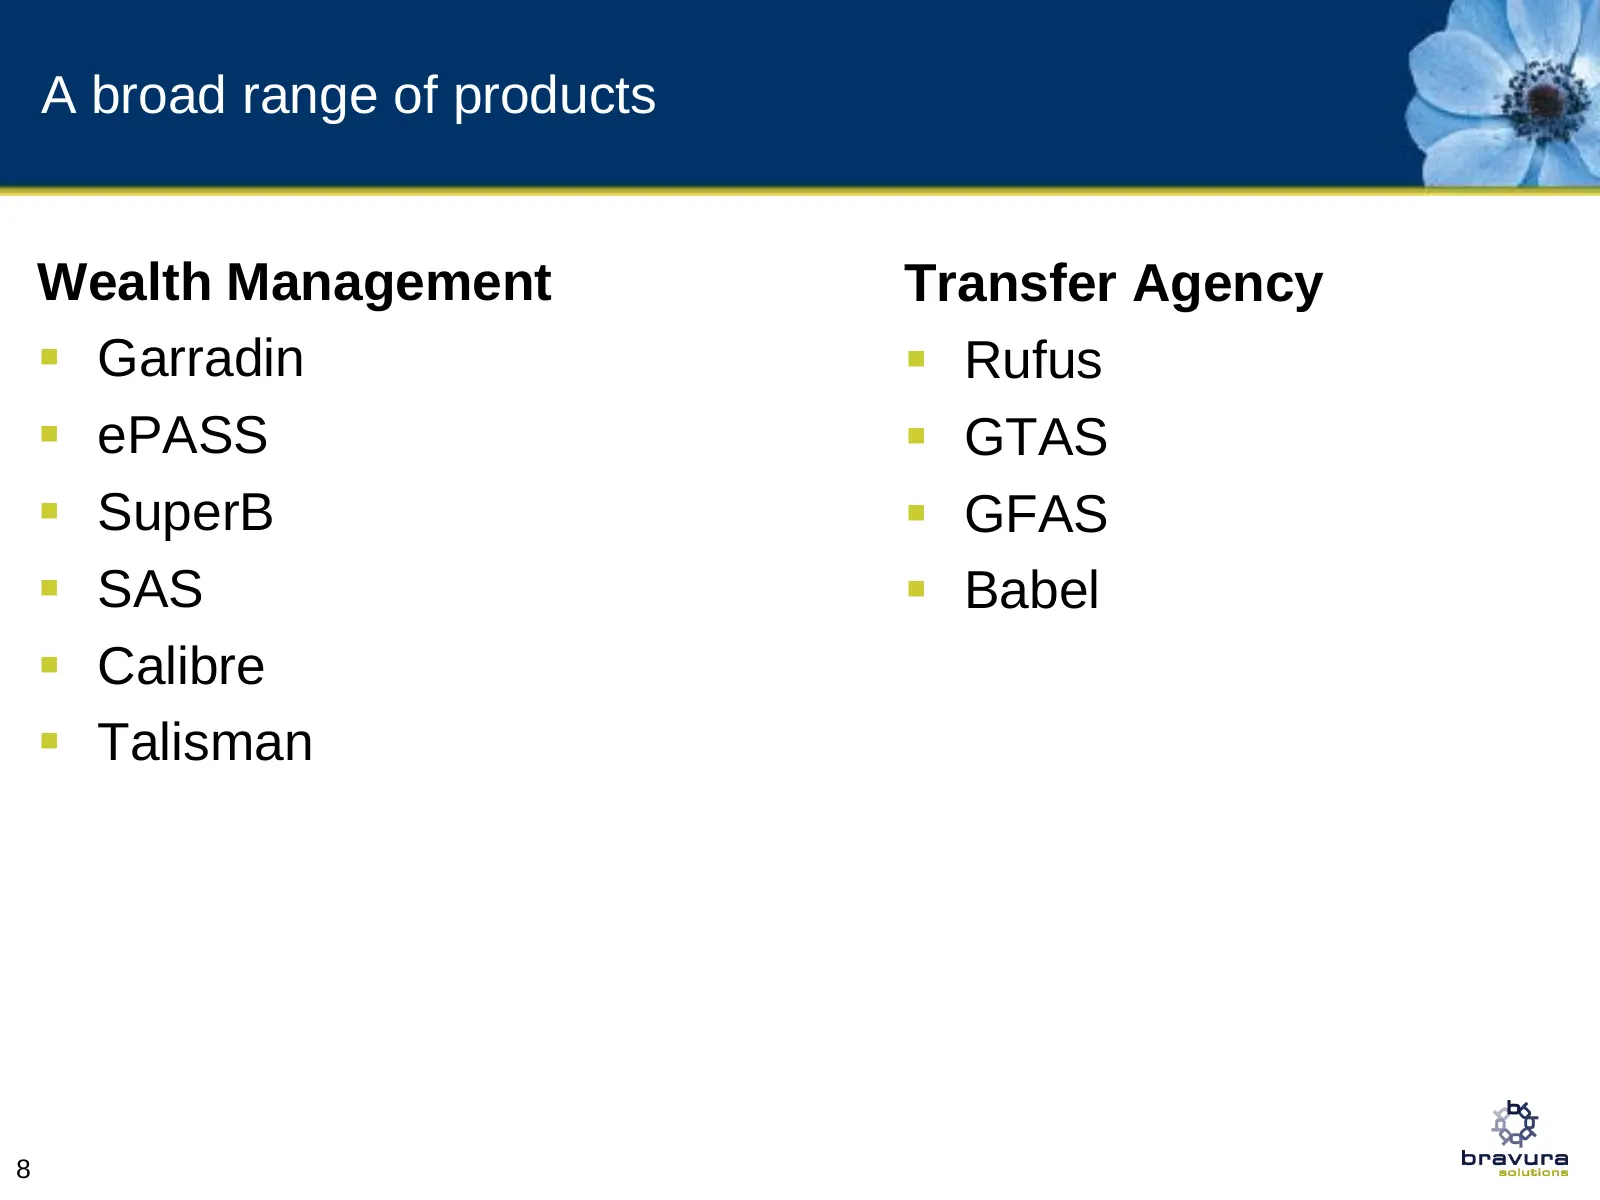
A broad range of products Wealth Management Transfer Agency Garradin Rufus ePASS GTAS SuperB GFAS SAS Babel Calibre Talisman 8
Slide 14: Sonata - next generation wealth management platform
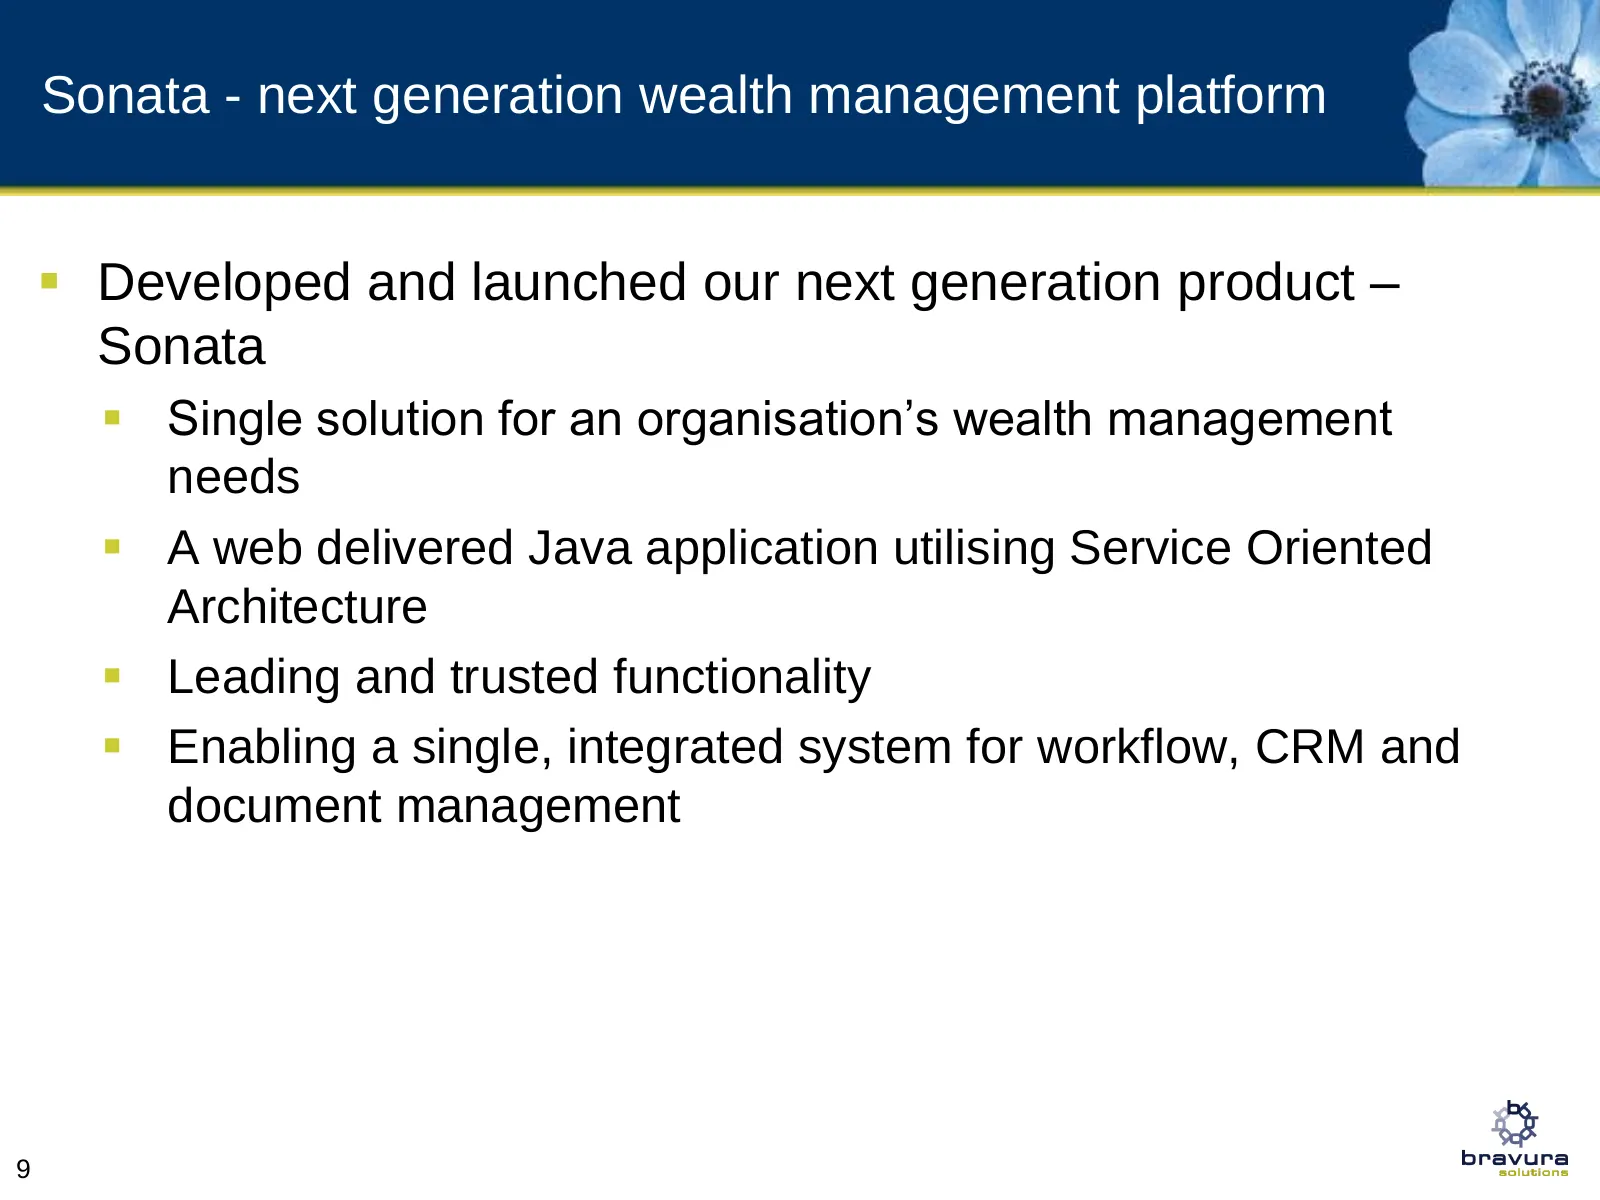
Sonata - next generation wealth management platform Developed and launched our next generation product – Sonata Single solution for an organisation’s wealth management needs A web delivered Java application utilising Service Oriented Architecture Leading and trusted functionality Enabling
Slide 15: The importance of people
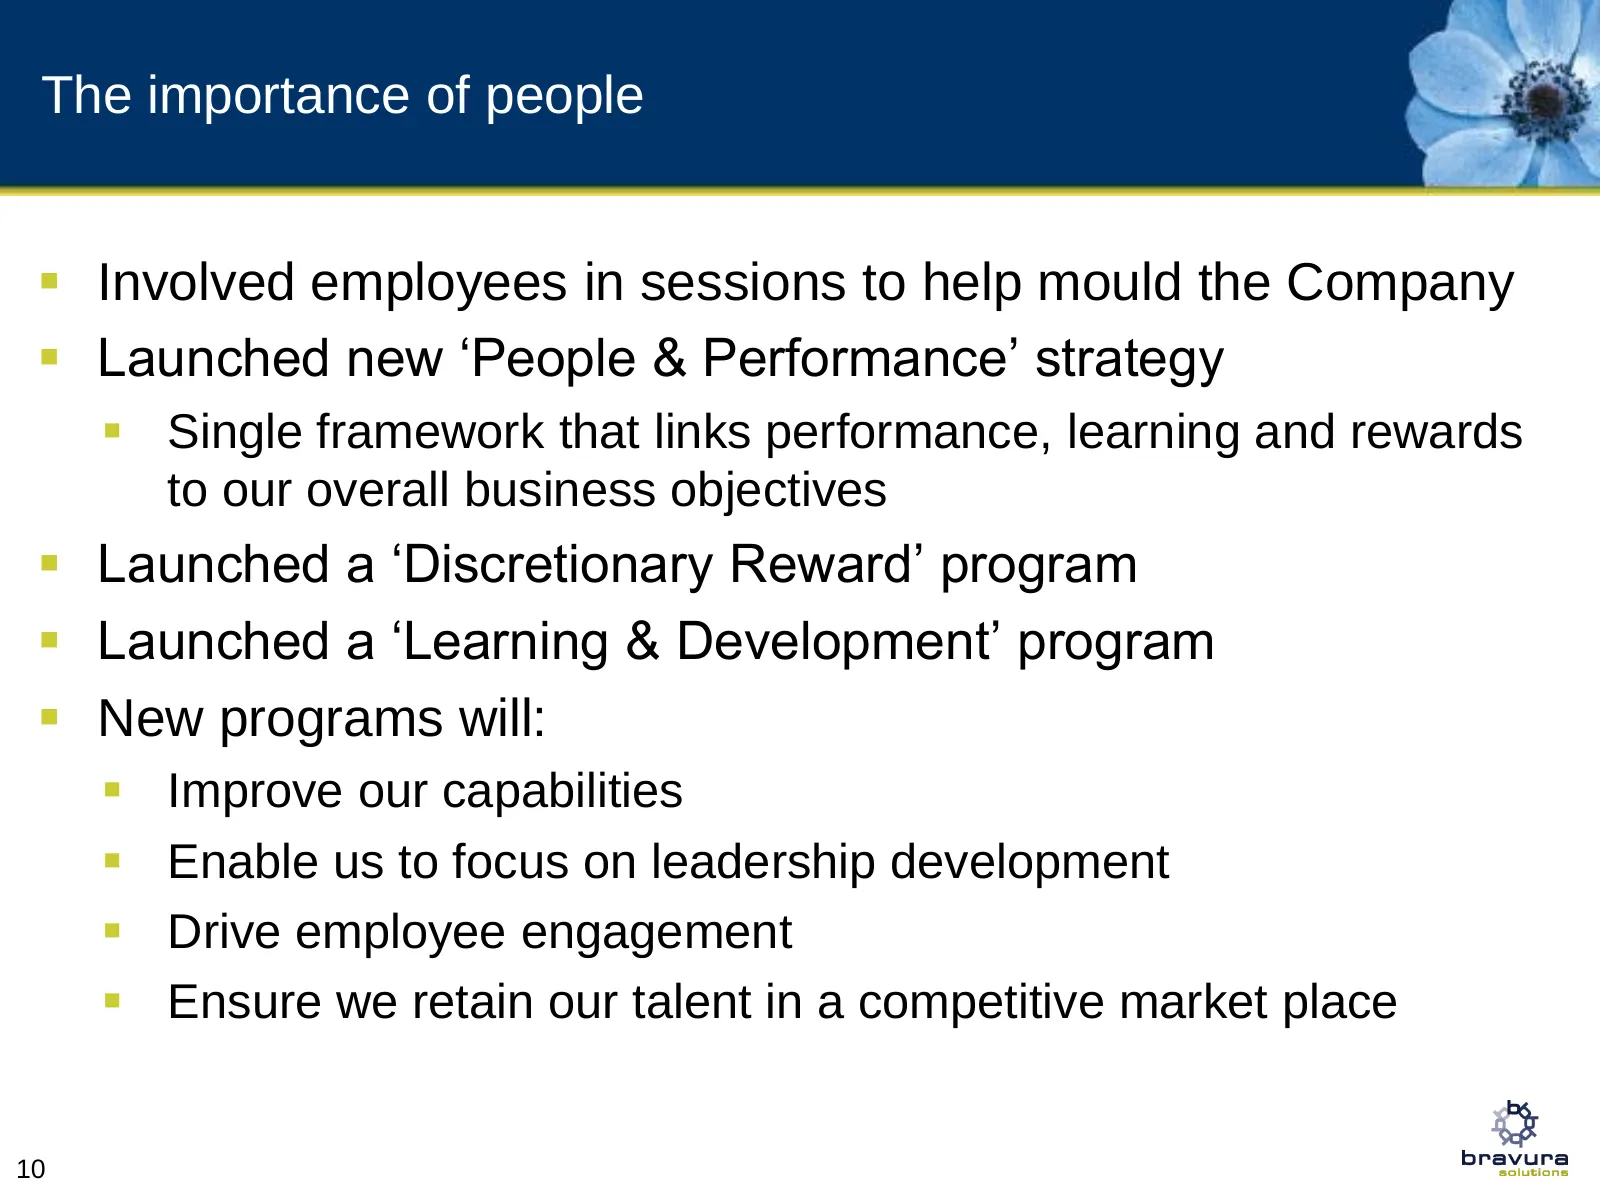
The importance of people Involved employees in sessions to help mould the Company Launched new ‘People & Performance’ strategy Single framework that links performance, learning and rewards to our overall business objectives Launched a ‘Discretionary Reward’ program Launched a ‘Learning & D
Slide 16: Well positioned to drive success
Well positioned to drive success “To be one of the world’s leading global software partners to financial services companies; the first choice for clients to work with and where exceptional people choose to work.” 11
Slide 17: Thank you
°: = yh. . »y bravura - solutions aa ‘ )
Source: Internet Archive copy of bravurasolutions.com
More decks from Bravura Solutions Limited
 FY2026 Earnings Presentation25 slides · Aug 12, 2026
 H1 2026 Earnings Presentation24 slides · Feb 11, 2026
 Shareholder Meeting (October 2025)13 slides · Oct 15, 2025
 FY2025 Earnings Presentation25 slides · Aug 13, 2025
 H1 2025 Earnings Presentation28 slides · Feb 12, 2025
 Shareholder Meeting (October 2024)18 slides · Oct 30, 2024