Infrastructure and Energy Alternatives Inc
Infrastructure and Energy Alternatives — Merger or Acquisition (October 2018)
23 slides from Infrastructure and Energy Alternatives's merger presentation, Oct 15, 2018
Slide 1: Acquisition of William Charles Construction Group, including Ragnar Benson
Acquisition of William Charles Construction Group, including Ragnar Benson October 15, 2018
Slide 2: Disclaimer
Disclaimer This presentation includes “forward looking statements” (within the meaning of the “safe harbor” provisions of the United States Private Securities Litigation Reform Act of 1995), including but not limited to those regarding the proposed acquisition by Infrastructure and Energy Alternativ
Slide 3: Conference Call Hosts and Agenda
Conference Call Hosts and Agenda Conference Call Hosts J.P. Roehm CEO and President Andrew Layman CFO Conference Call Agenda • William Charles Overview • Strategic Rational and Transaction Overview • Key Investment Highlights • Industry Overview 3
Slide 4: William Charles Overview
QDIEA William Charles Overview
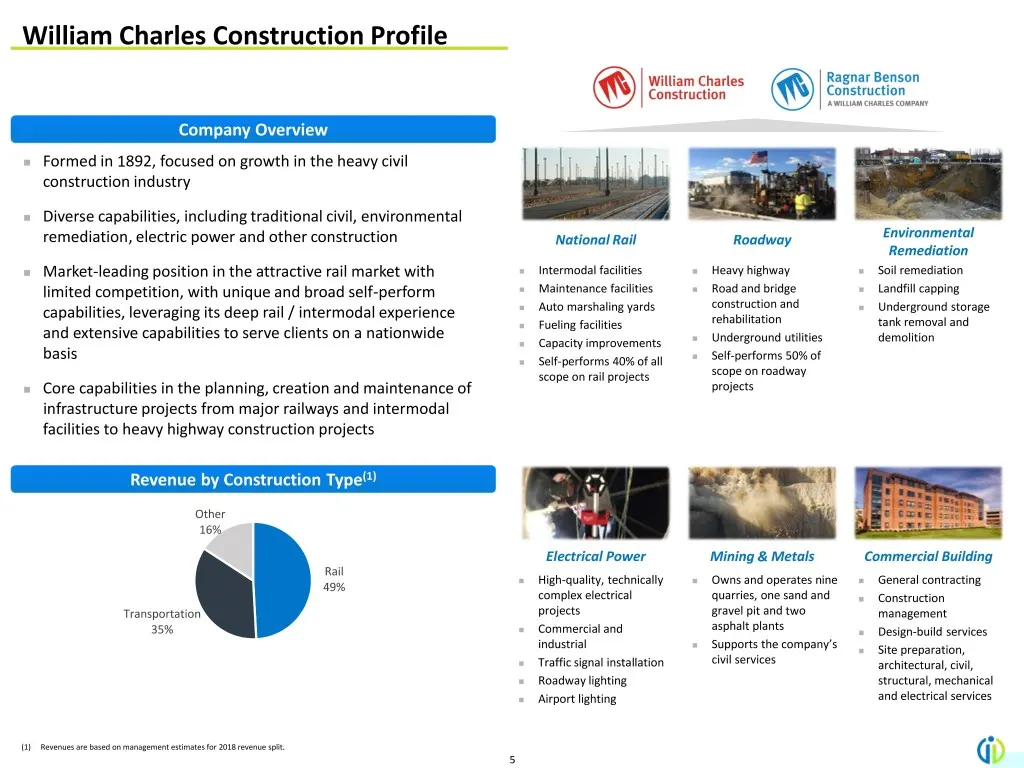
Slide 5: William Charles Construction Profile
William Charles Construction Profile Company Overview ◼ Formed in 1892, focused on growth in the heavy civil construction industry ◼ Diverse capabilities, including traditional civil, environmental remediation, electric power and other construction National Rail Roadway Environmental Remediation ◼ M
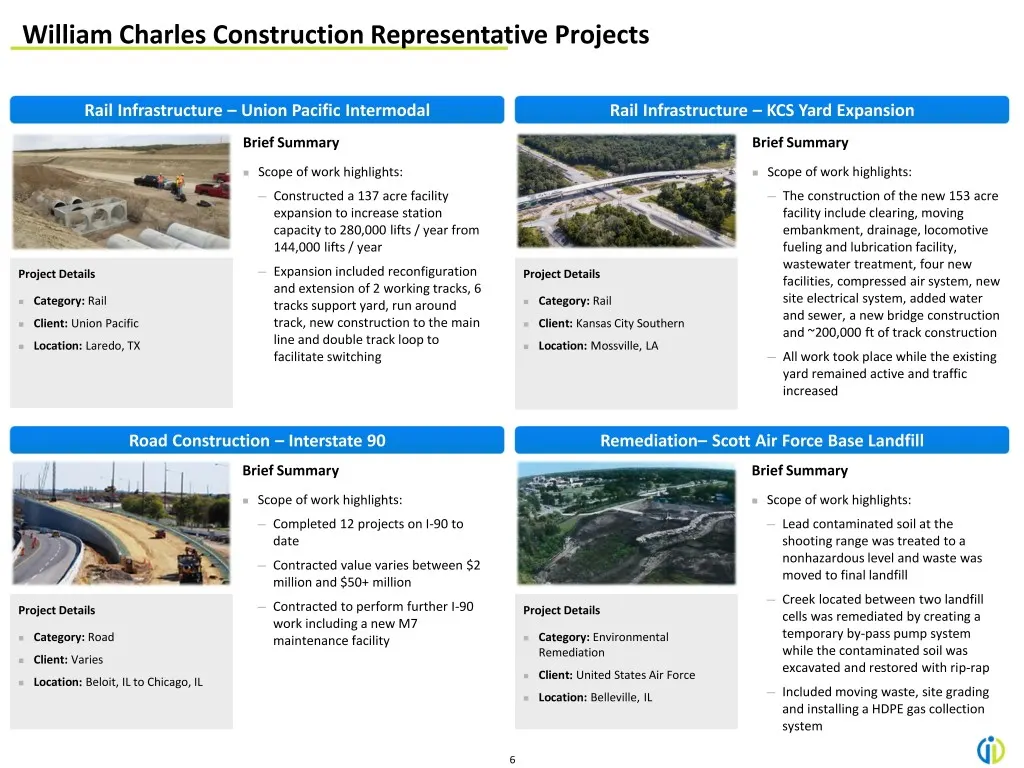
Slide 6: William Charles Construction Representative Projects
William Charles Construction Representative Projects Rail Infrastructure – Union Pacific Intermodal Rail Infrastructure – KCS Yard Expansion Brief Summary Brief Summary ◼ Scope of work highlights: ◼ Scope of work highlights: ─ Constructed a 137 acre facility ─ The construction of the new 153 acre ex
Slide 7: Strategic Rationale and Transaction Overview
Strategic Rationale and Transaction Overview
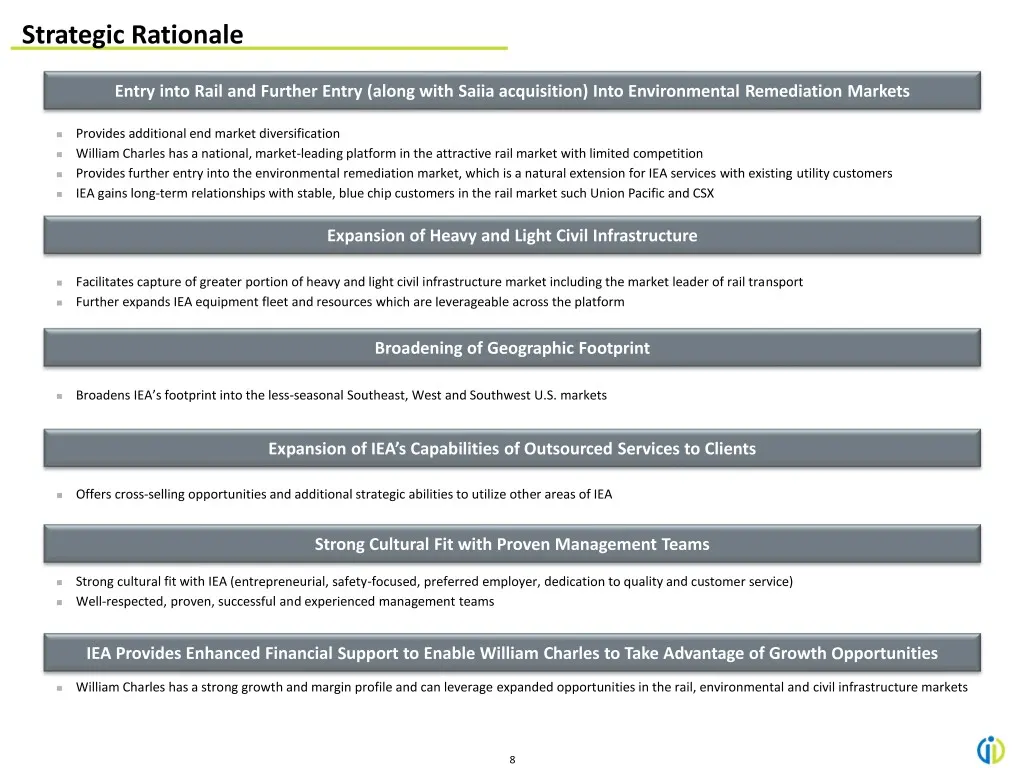
Slide 8: Strategic Rationale
Strategic Rationale Entry into Rail and Further Entry (along with Saiia acquisition) Into Environmental Remediation Markets ◼ Provides additional end market diversification ◼ William Charles has a national, market-leading platform in the attractive rail market with limited competition ◼ Provides fur
Slide 9: Transaction Overview
Transaction Overview ◼ Effective purchase price of approx. $90 million, subject to customary closing adjustments ◼ 4.5x multiple of Adjusted EBITDA(1) ◼ Closed system as of 4/30 enhancing transaction by $5 - $7 million ◼ Purchase price and related fees and expenses funded through: ➢ $75 million dela
Slide 10: Acquisition Delivers Significant Financial Benefits
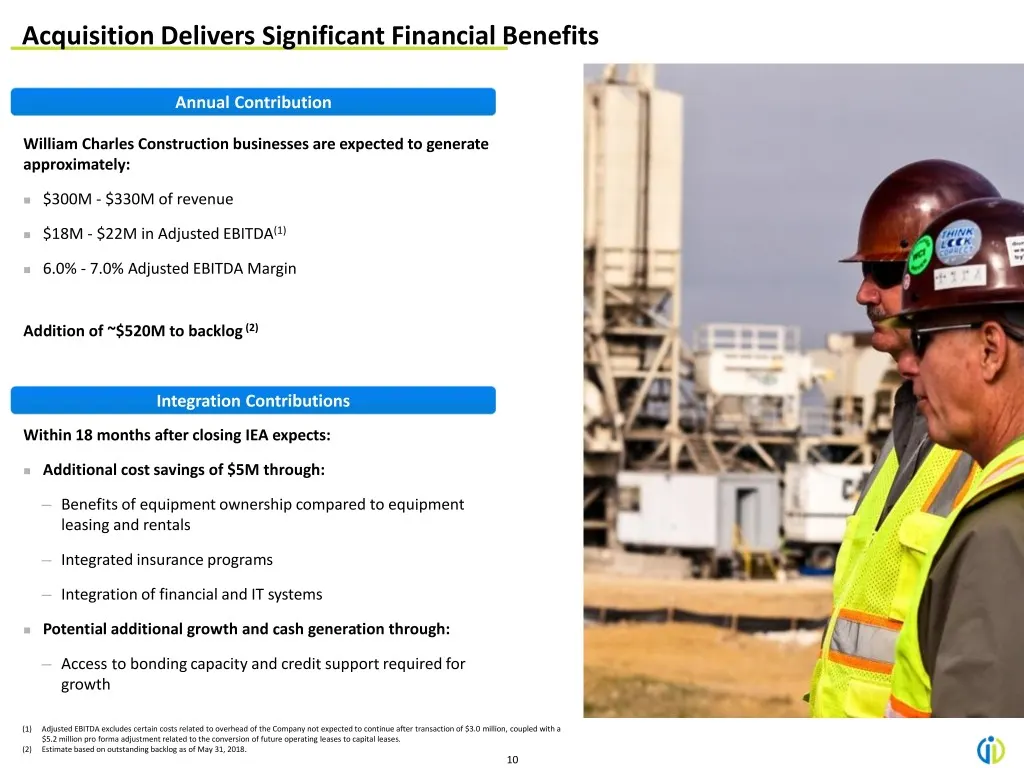
Acquisition Delivers Significant Financial Benefits Annual Contribution William Charles Construction businesses are expected to generate approximately: ◼ $300M - $330M of revenue ◼ $18M - $22M in Adjusted EBITDA(1) ◼ 6.0% - 7.0% Adjusted EBITDA Margin Addition of ~$520M to backlog (2) Integration Co
Slide 11: Combined Business Overview
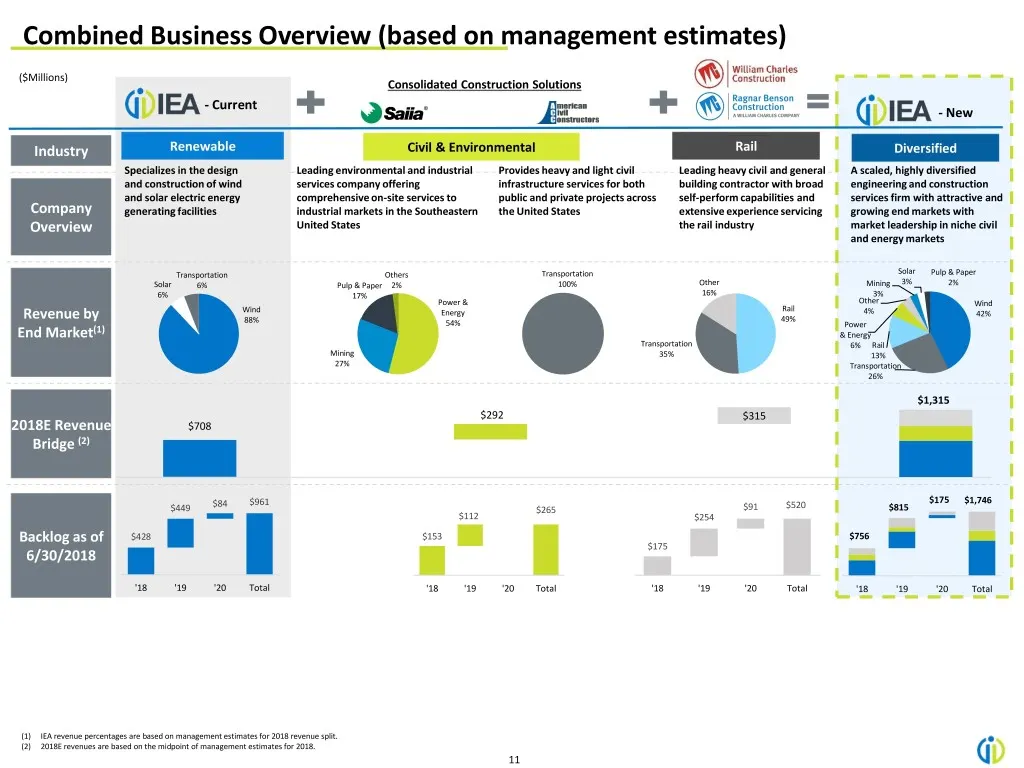
Combined Business Overview (based on management estimates) ($Millions) Consolidated Construction Solutions - Current - New Industry RenewableRenewable EnvironmentalCivil & Environmental / Power RailRail DiversifiedDiversified Specializes in the design Leading environmental and industrial Provides he
Slide 12: Combined Business Operational Overview
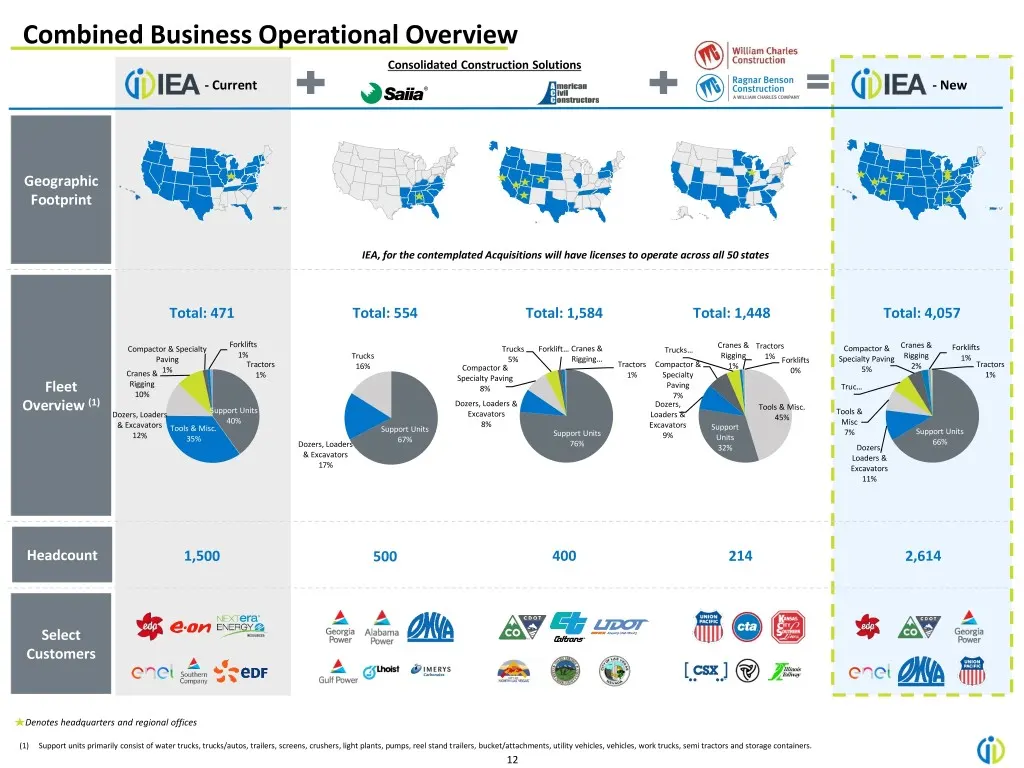
Combined Business Operational Overview Consolidated Construction Solutions - Current - New Geographic Footprint IEA, for the contemplated Acquisitions will have licenses to operate across all 50 states Total: 471 Total: 554 Total: 1,584 Total: 1,448 Total: 4,057 Forklifts Cranes & Cranes & Compactor
Slide 13: Key Investment Highlights
QDIEA Key Investment Highlights
Slide 14: IEA Key Investment Highlights Overview
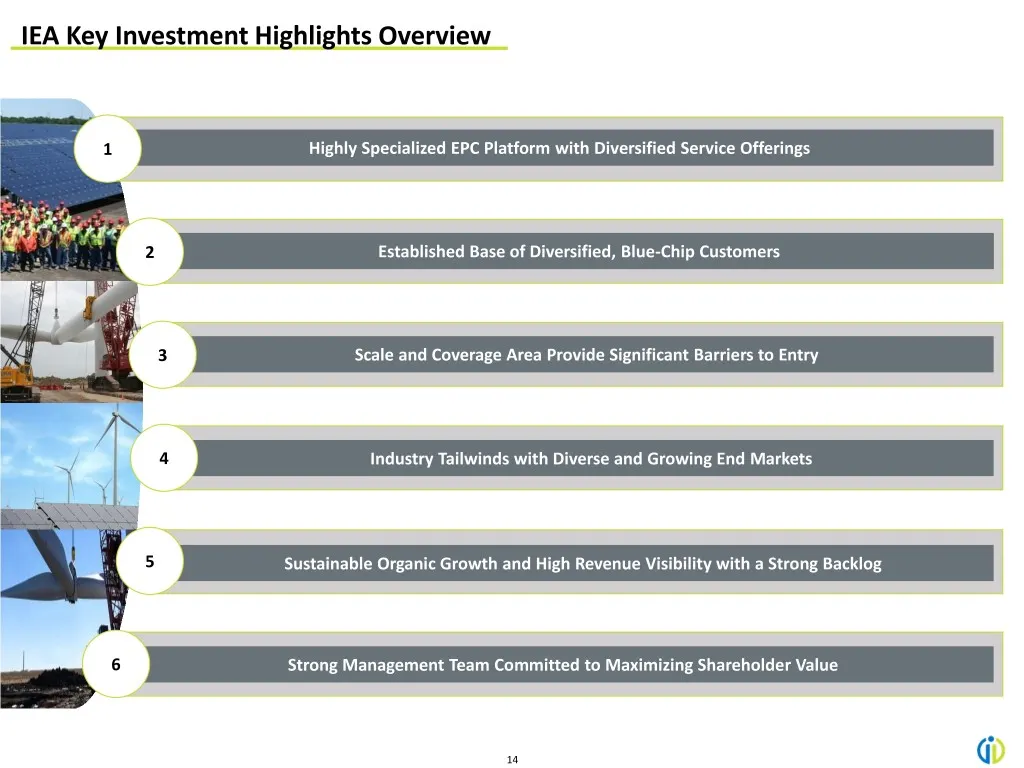
IEA Key Investment Highlights Overview 1 Highly Specialized EPC Platform with Diversified Service Offerings 2 Established Base of Diversified, Blue-Chip Customers 3 Scale and Coverage Area Provide Significant Barriers to Entry 4 Industry Tailwinds with Diverse and Growing End Markets 5 Sustainable O
Slide 15: Highly Specialized EPC Platform with Diversified Service Offerings
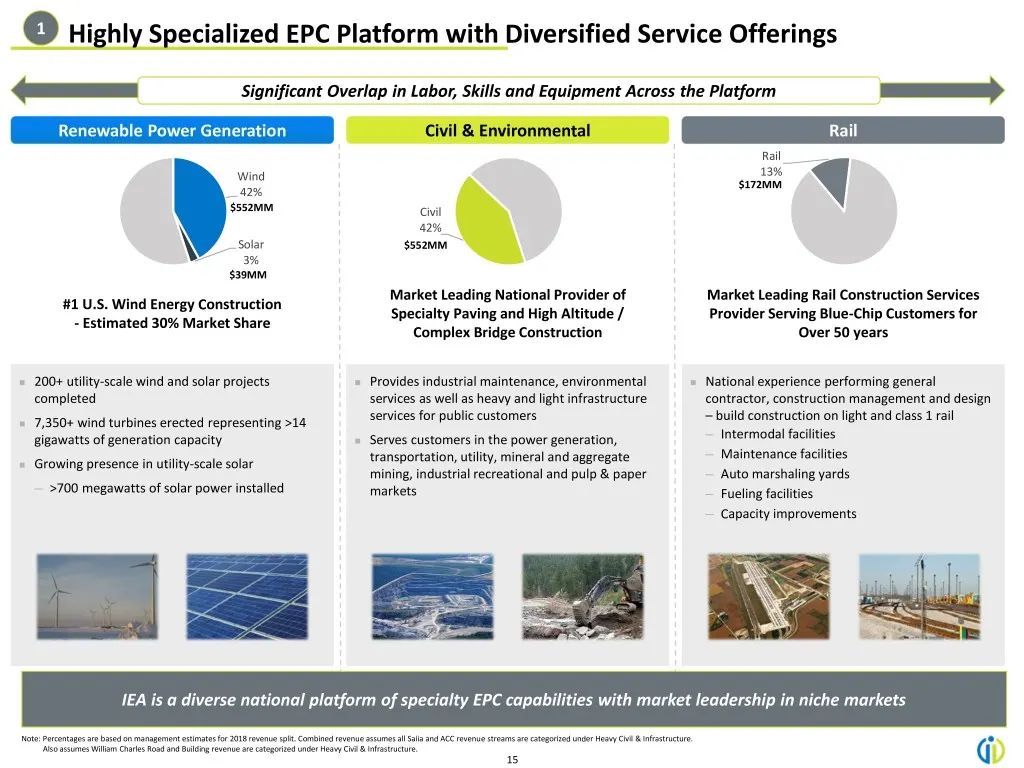
1 Highly Specialized EPC Platform with Diversified Service Offerings Significant Overlap in Labor, Skills and Equipment Across the Platform Renewable Power Generation Civil & Environmental Rail Rail Wind 13% $172MM 42% $552MM Civil 42% Solar $552MM 3% $39MM Market Leading National Provider of Market
Slide 16: Established Base of Diversified, Blue-Chip Customers
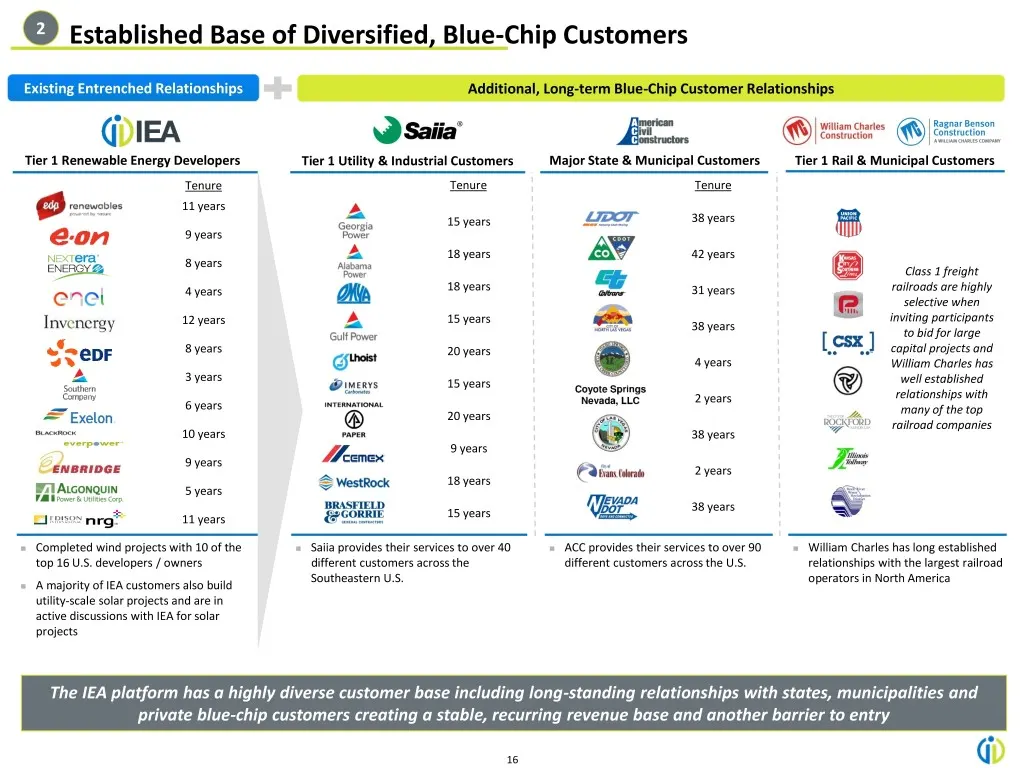
2 Established Base of Diversified, Blue-Chip Customers Existing Entrenched Relationships Additional, Long-term Blue-Chip Customer Relationships Tier 1 Renewable Energy Developers Tier 1 Utility & Industrial Customers Major State & Municipal Customers Tier 1 Rail & Municipal Customers Tenure Tenure T
Slide 17: Scale and Coverage Area Provide Significant Barriers to Entry
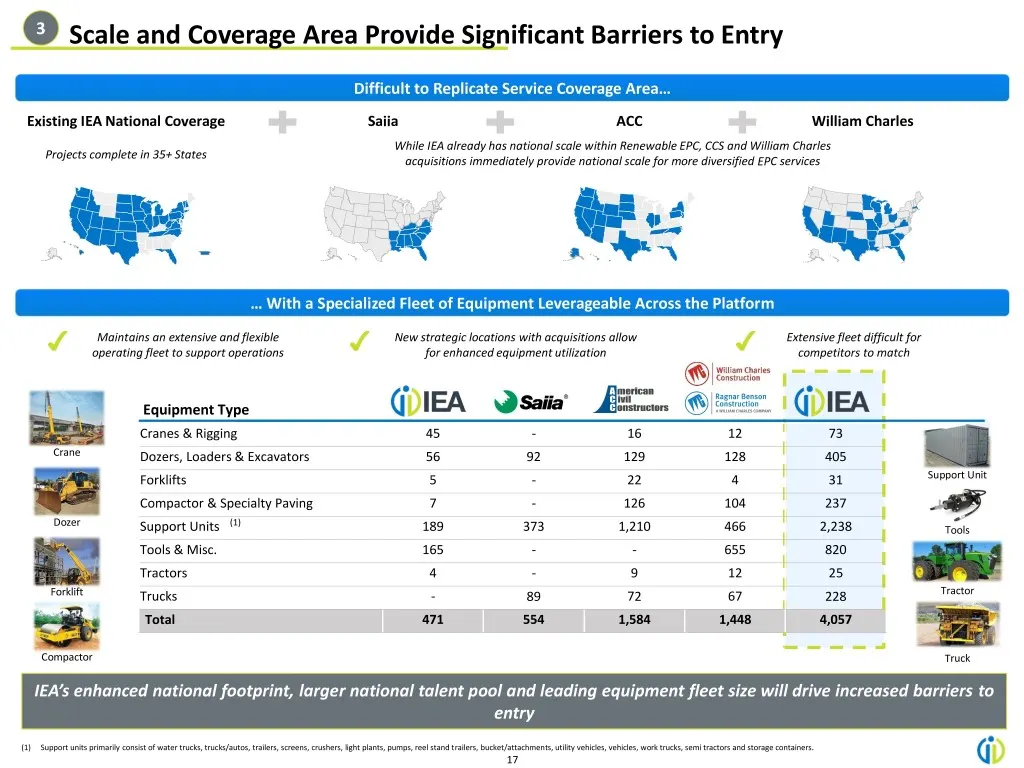
3 Scale and Coverage Area Provide Significant Barriers to Entry Difficult to Replicate Service Coverage Area… Existing IEA National Coverage Saiia ACC William Charles While IEA already has national scale within Renewable EPC, CCS and William Charles Projects complete in 35+ States acquisitions immed
Slide 18: Industry Tailwinds with Diverse and Growing End Markets
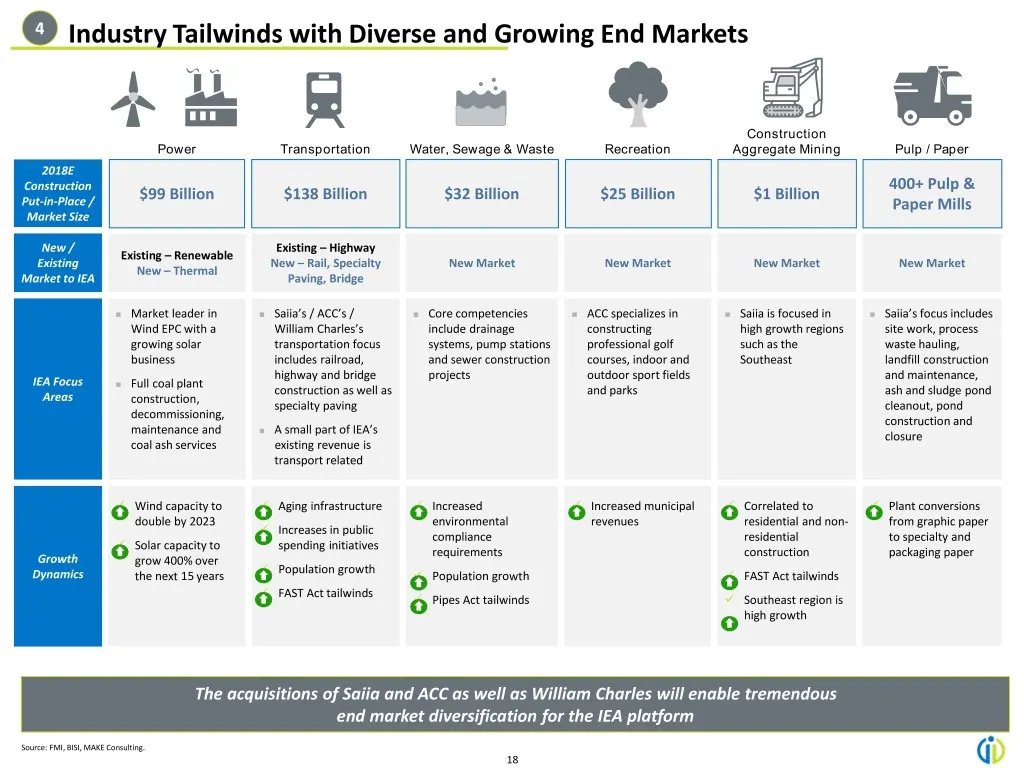
4 Industry Tailwinds with Diverse and Growing End Markets Construction Power Transportation Water, Sewage & Waste Recreation Aggregate Mining Pulp / Paper 2018E Construction 400+ Pulp & $99 Billion $138 Billion $32 Billion $25 Billion $1 Billion Put-in-Place / Paper Mills Market Size New / Existing
Slide 19: Sustainable Organic Growth & High Revenue Visibility with a Strong Backlog
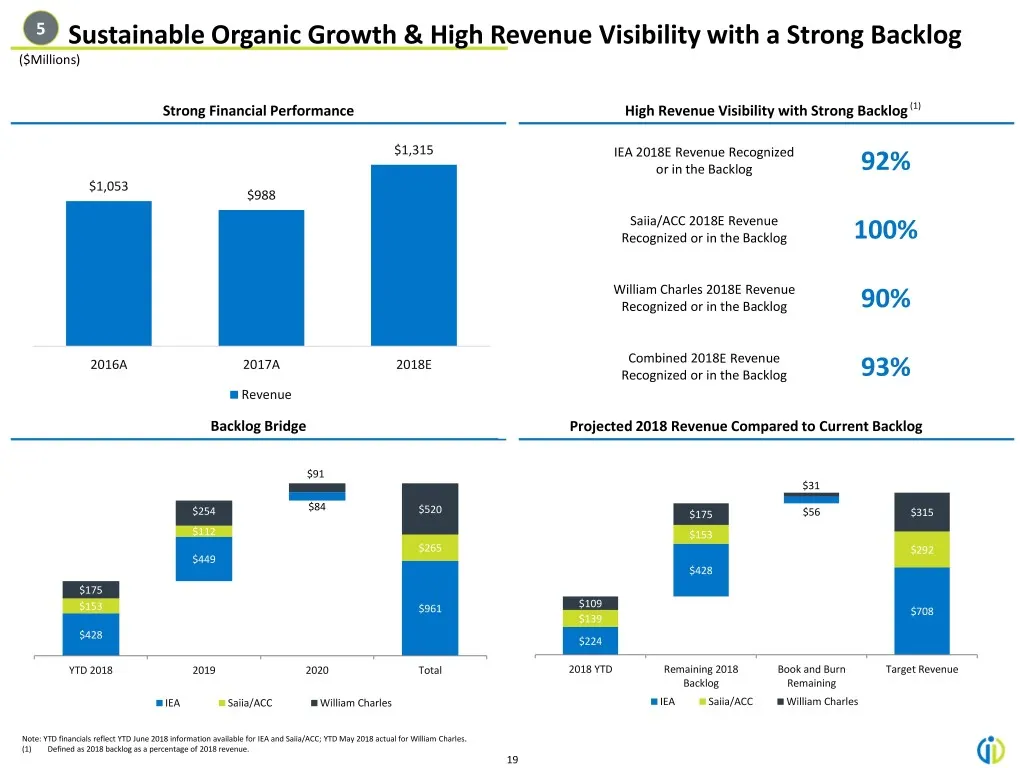
5 Sustainable Organic Growth & High Revenue Visibility with a Strong Backlog ($Millions) Strong Financial Performance High Revenue Visibility with Strong Backlog (1) 1400 $1,315 IEA 2018E Revenue Recognized or in the Backlog 92% 1200 $1,053 $988 1000 Saiia/ACC 2018E Revenue 800 Recognized or in the
Slide 20: Strong Management Team Committed to Maximizing Shareholder Value
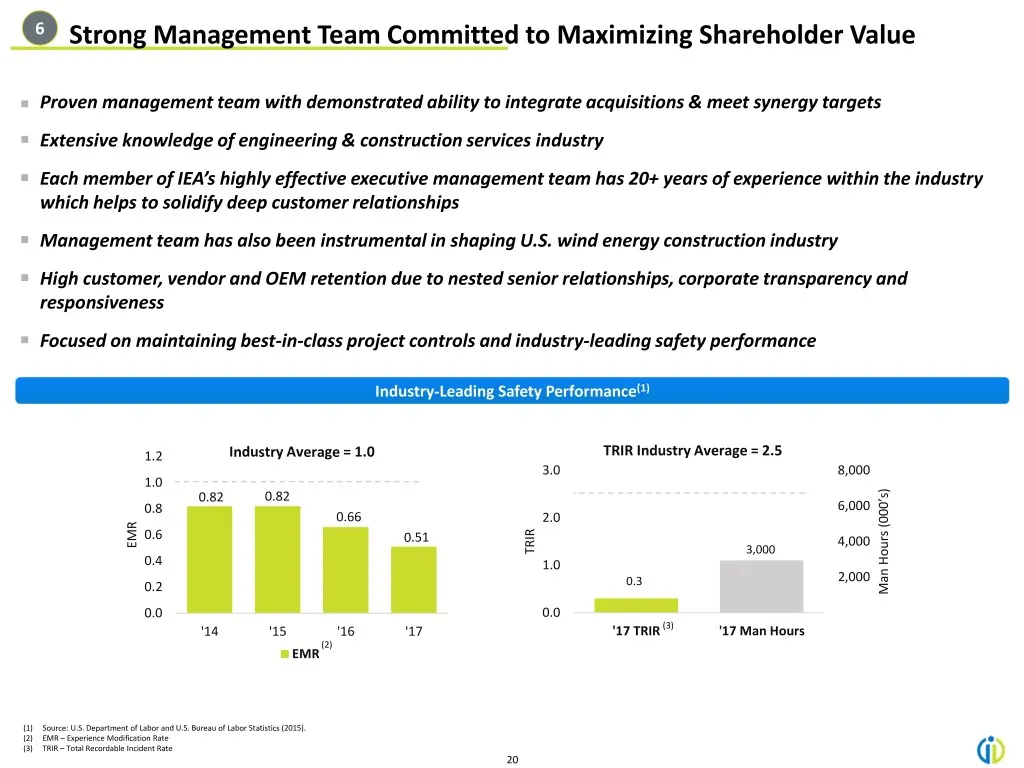
6 Strong Management Team Committed to Maximizing Shareholder Value ◼ Proven management team with demonstrated ability to integrate acquisitions & meet synergy targets ◼ Extensive knowledge of engineering & construction services industry ◼ Each member of IEA’s highly effective executive management te
Slide 21: Industry Overview
QDIEA Industry Overview
Slide 22: U.S. Construction Market Overview
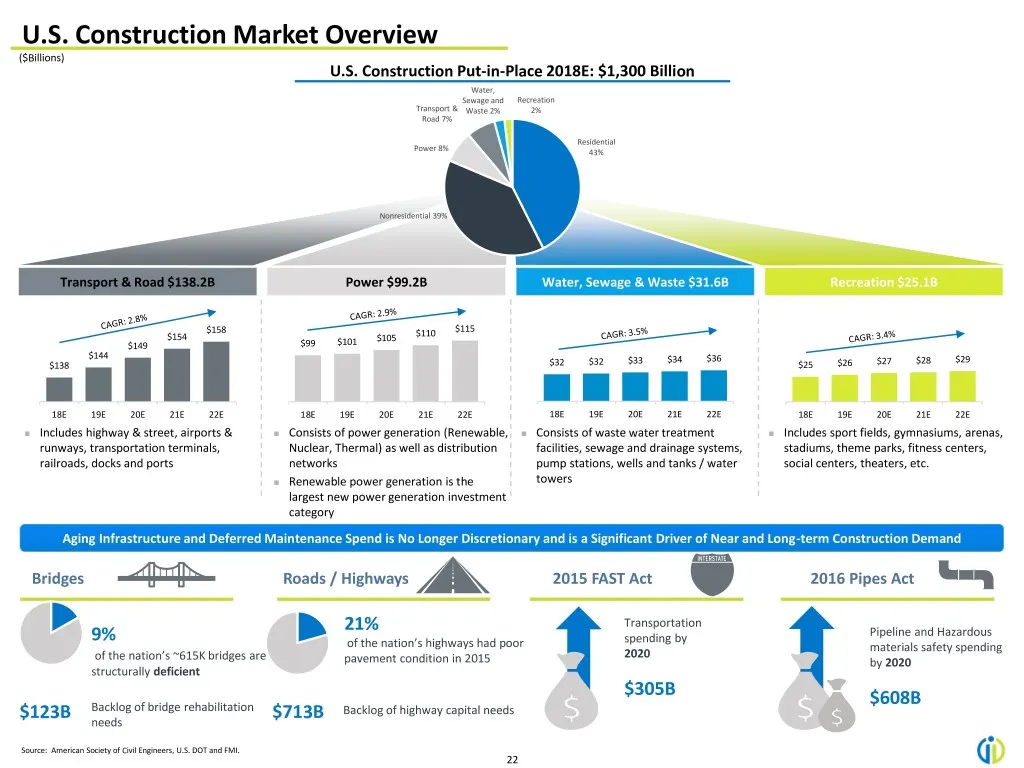
U.S. Construction Market Overview ($Billions) U.S. Construction Put-in-Place 2018E: $1,300 Billion Water, Sewage and Recreation Transport & Waste 2% 2% Road 7% Residential Power 8% 43% Nonresidential 39% Transport & Road $138.2B Power $99.2B Water, Sewage & Waste $31.6B Recreation $25.1B $158 $115 $
Slide 23: Thank You
THANK YOU Investor Relations Contact: Financial Profiles Kimberly Esterkin, Senior Vice President kesterkin@finprofiles.com 310.622.8235
Source: SEC EDGAR · 8-K/A filed Oct 15, 2018
More decks from Infrastructure and Energy Alternatives Inc
 Q1 2022 Earnings Presentation23 slides · May 9, 2022
 Q4 2021 Earnings Presentation24 slides · Mar 7, 2022
 FY2020 Earnings Presentation20 slides · Mar 8, 2021
 Q4 2019 Earnings Presentation23 slides · Mar 10, 2020
 Q3 2019 Earnings Presentation19 slides · Nov 12, 2019
 Investor Presentation (October 2019)15 slides · Oct 30, 2019