South Financial — Investor Presentation (December 2008)
30 slides from South Financial's investor presentation, Dec 3, 2008
Slide 1: Investor Presentation Fourth Quarter 2008
Investor Presentation Fourth Quarter 2008
Slide 2: Forward-Looking Statements and Non-GAAP Financial Information
Forward-Looking Statements and Non-GAAP Financial Information The forward-looking statements, as defined in the applicable federal securities laws, being made today are subject to risks and uncertainties. TSFG’s actual results may differ materially from those set forth in such forward-looking statem
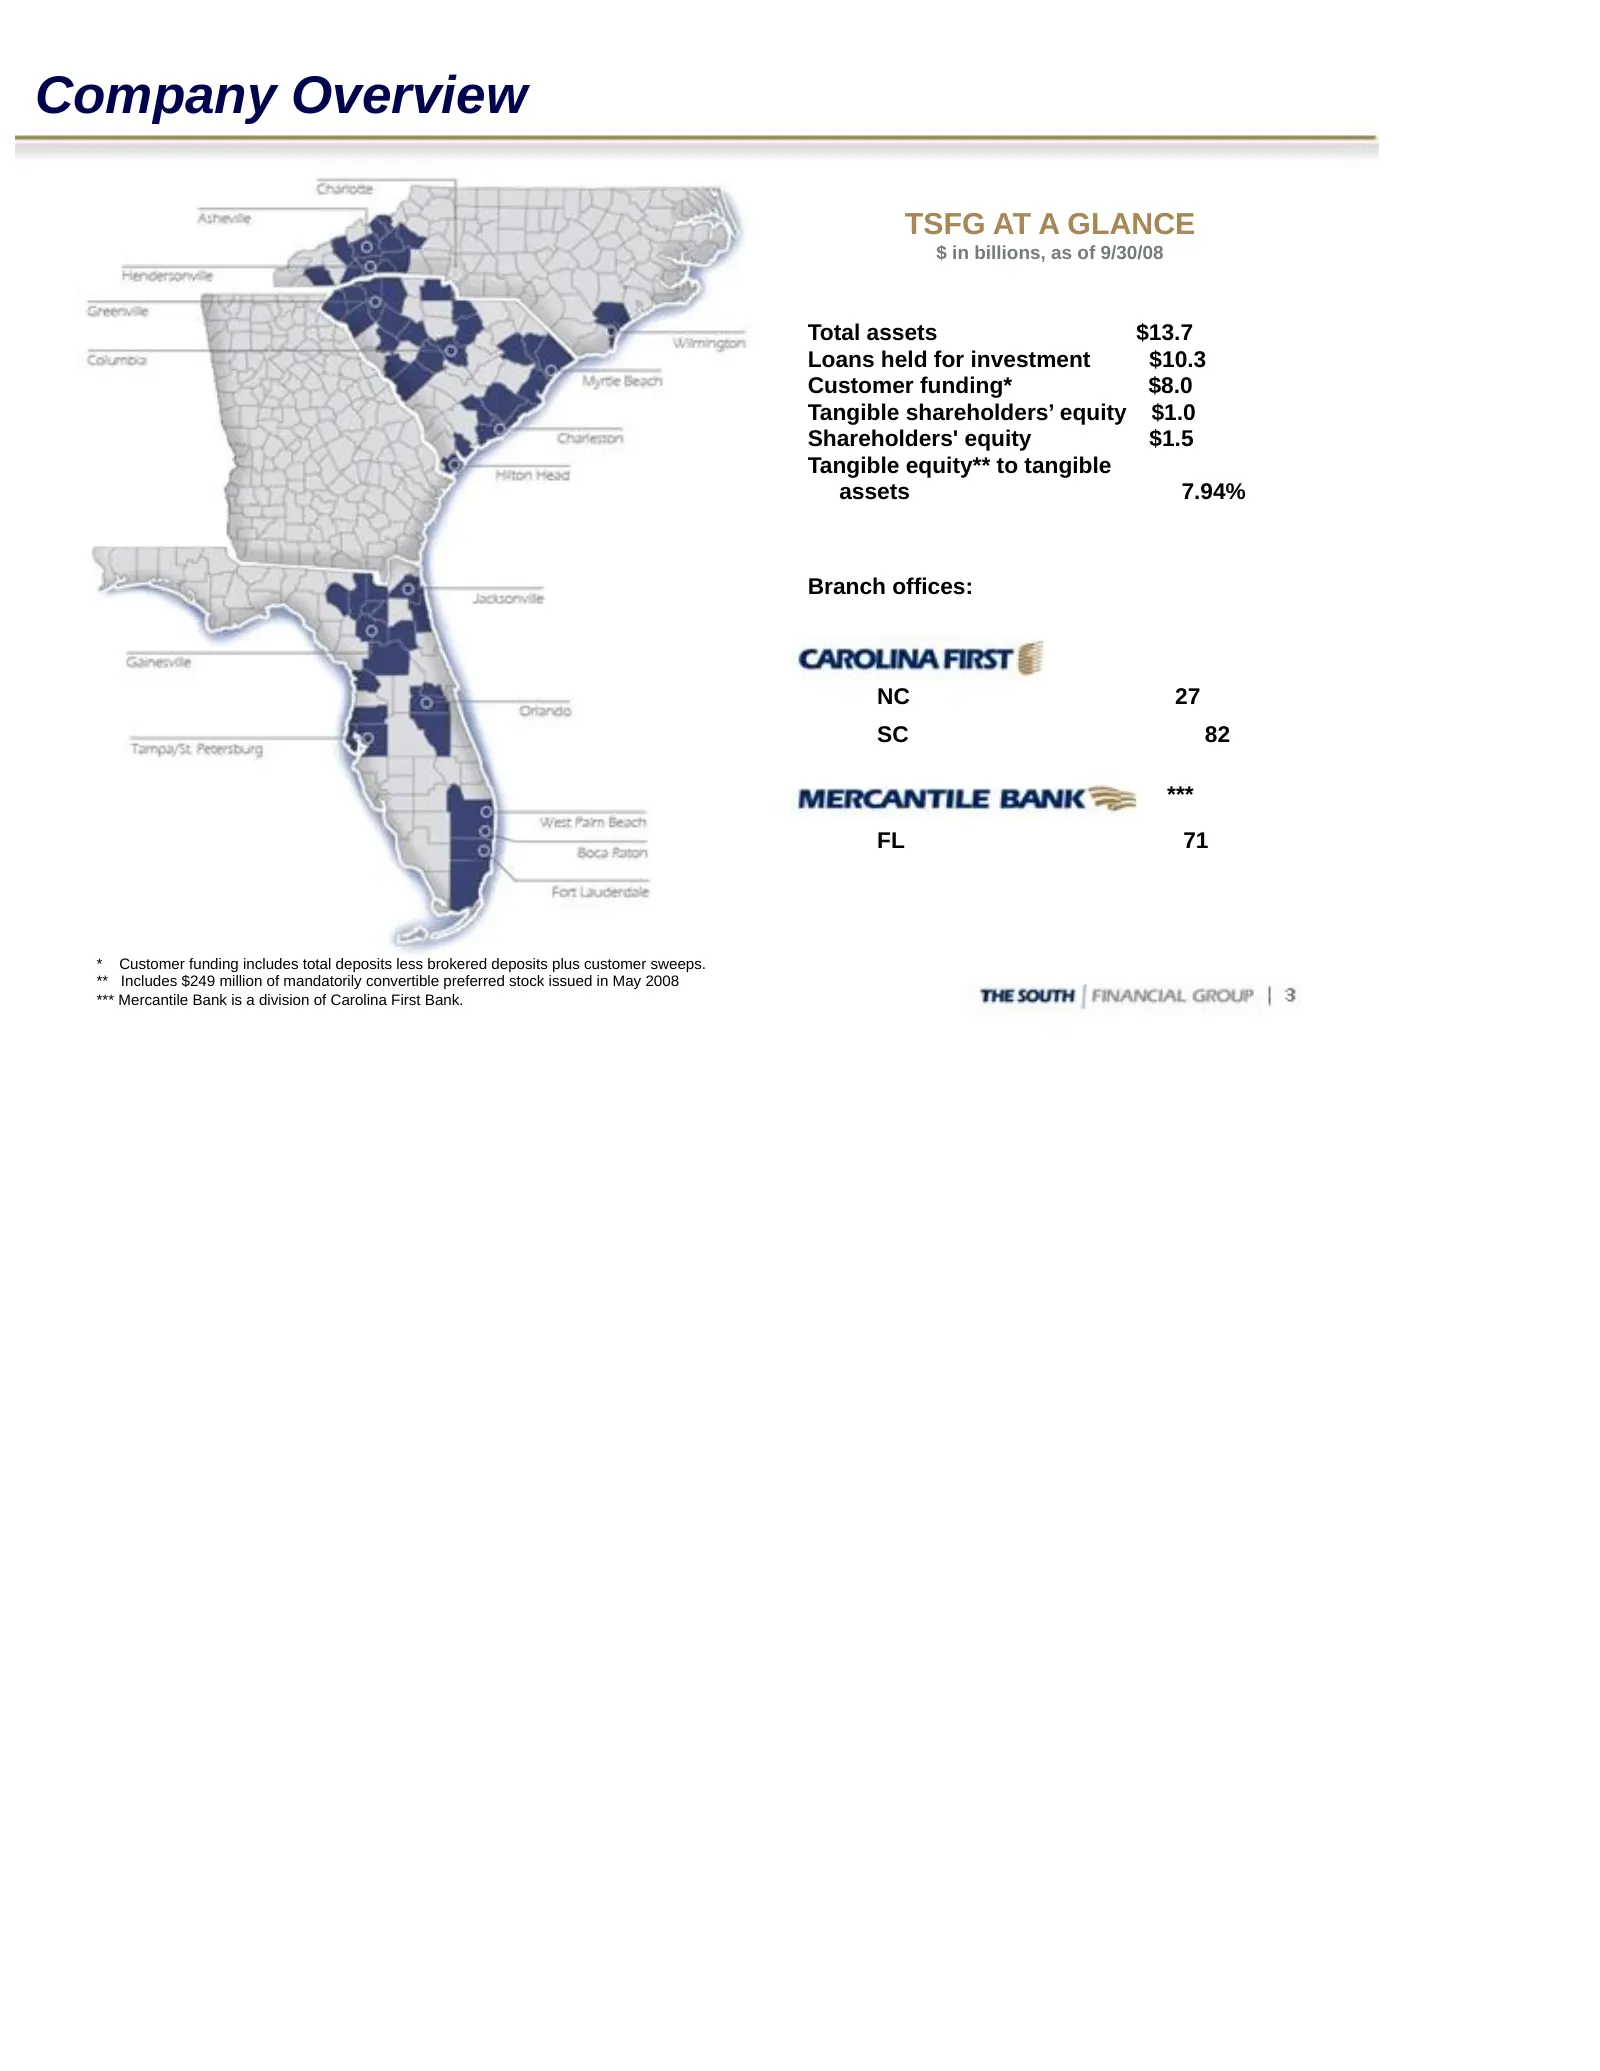
Slide 3: Company Overview
Company Overview TSFG AT A GLANCE $ in billions, as of 9/30/08 Total assets $13.7 Loans held for investment $10.3 Customer funding* $8.0 Tangible shareholders’ equity $1.0 Shareholders' equity $1.5 Tangible equity** to tangible assets 7.94% Branch offices: NC 27 SC 82 *** FL 71 * Customer funding in
Slide 4: Super-Community Bank Model
Super-Community Bank Model Community banking is the core strength of TSFG Focused on customer relationships with local decision-making Accessible and responsive Involved in our communities Target middle-market and small businesses and retail customers Built through multi-product relationships Locate
Slide 5: Footprint: Long-term Growth Potential
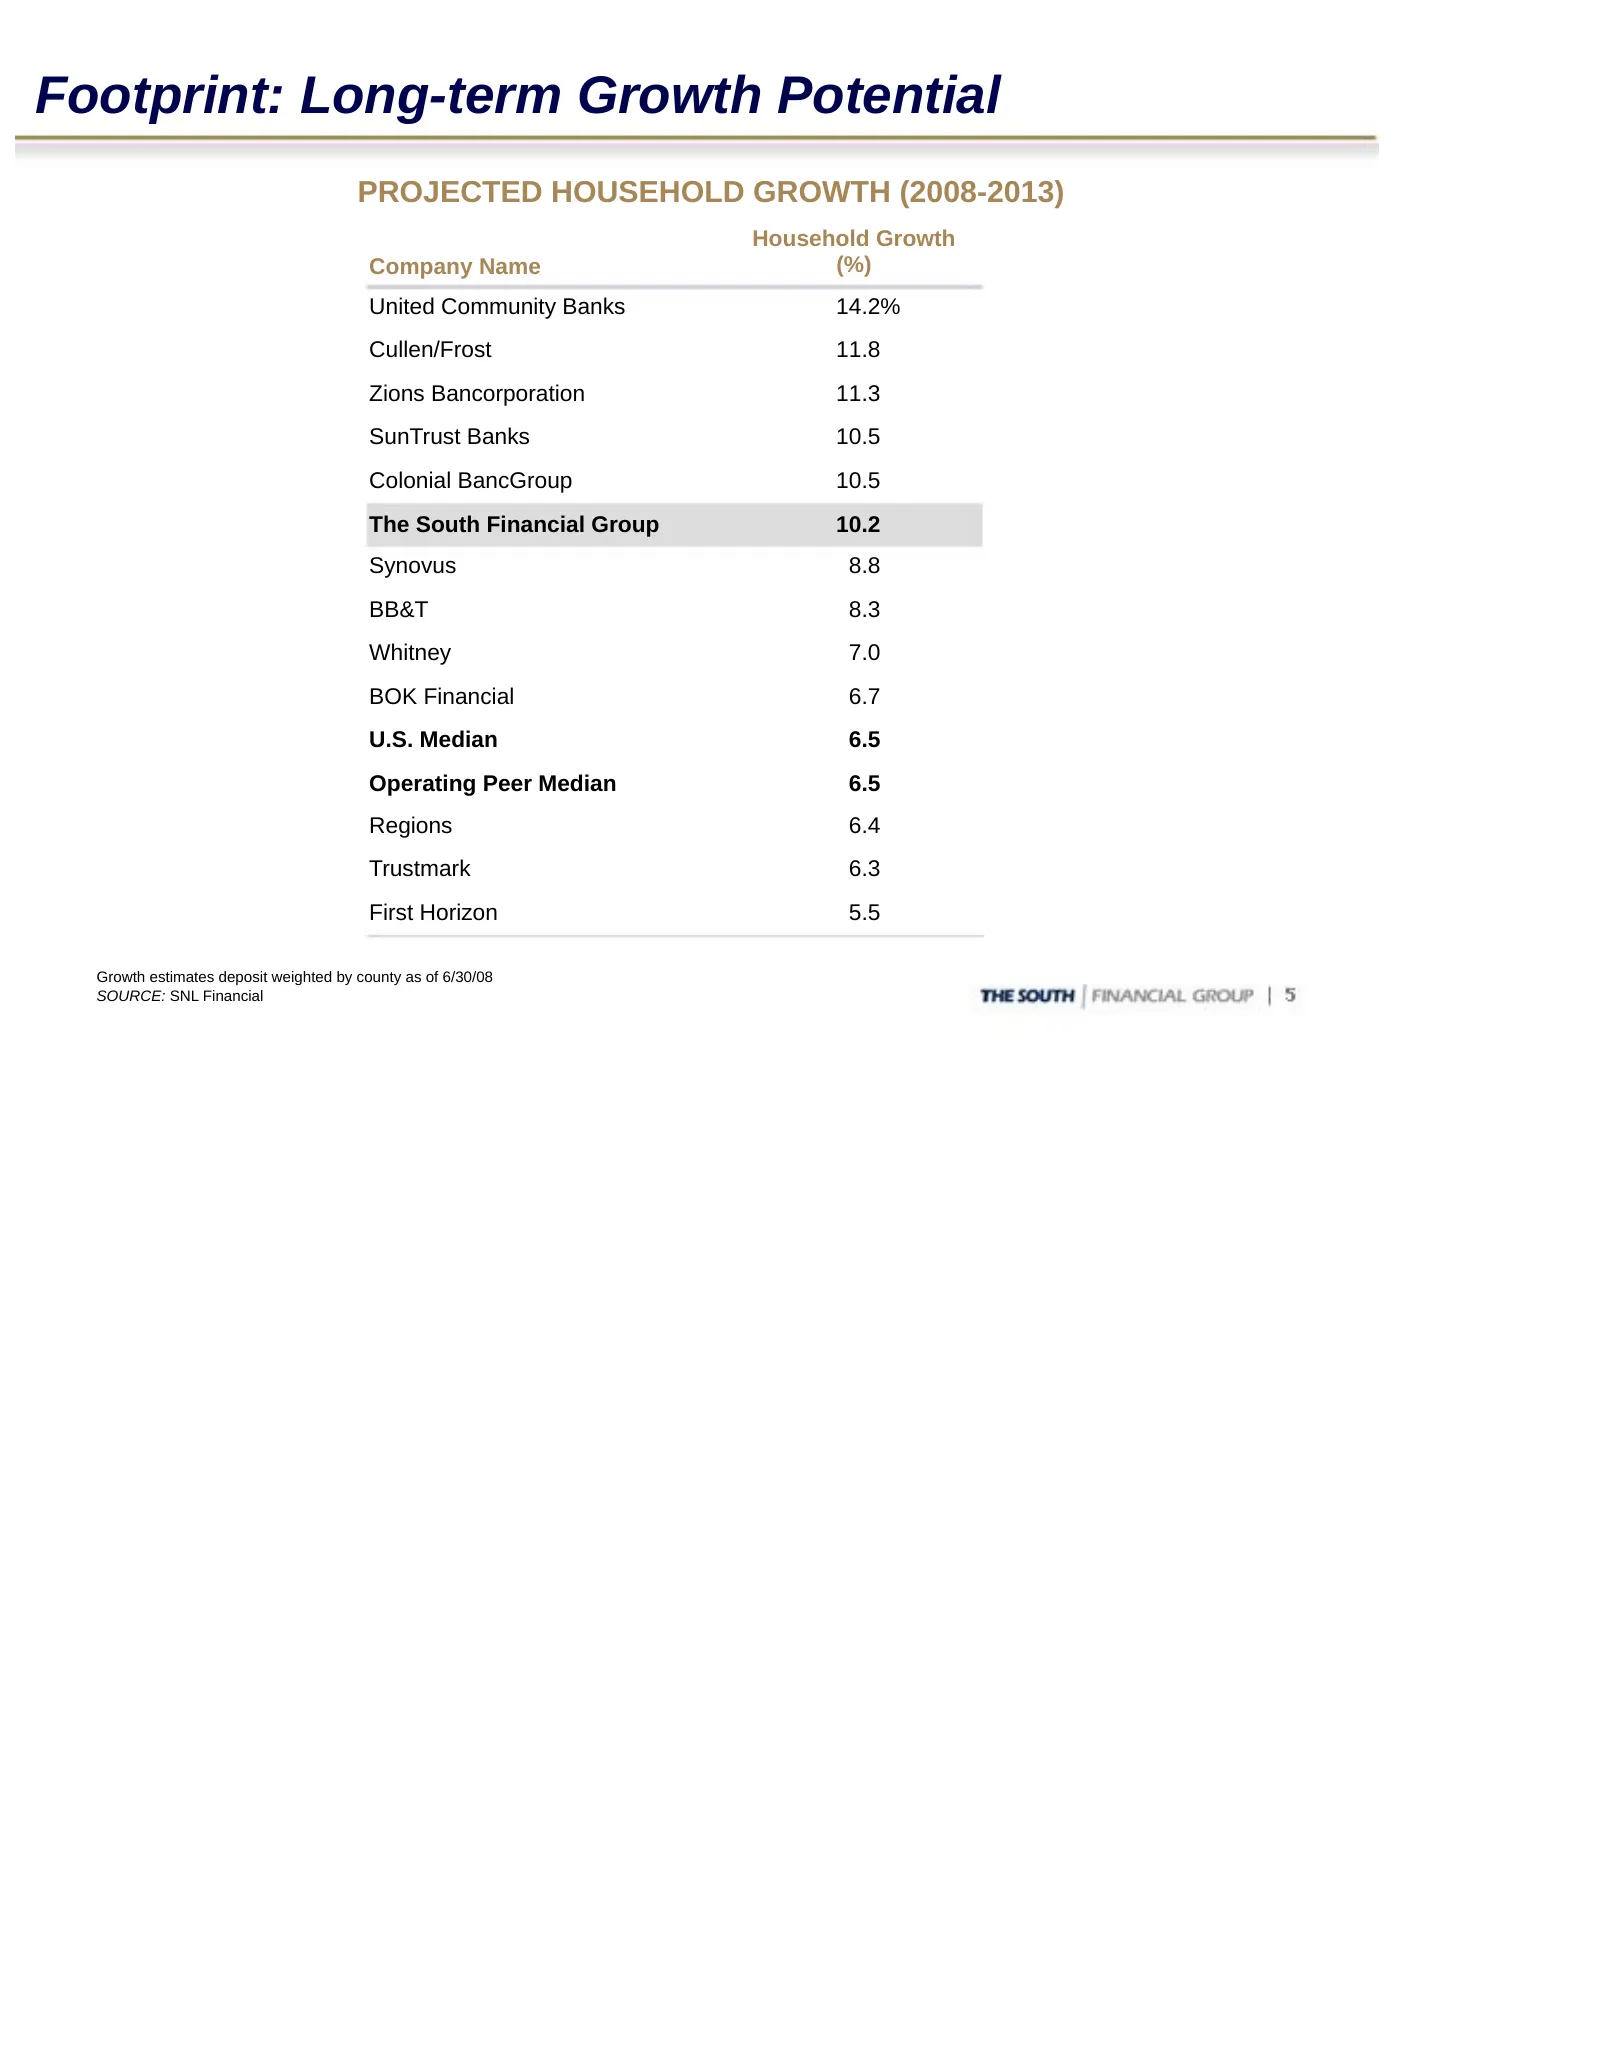
Footprint: Long-term Growth Potential PROJECTED HOUSEHOLD GROWTH (2008-2013) Household Growth Company Name (%) United Community Banks 14.2% Cullen/Frost 11.8 Zions Bancorporation 11.3 SunTrust Banks 10.5 Colonial BancGroup 10.5 The South Financial Group 10.2 Synovus 8.8 BB&T 8.3 Whitney 7.0 BOK Fina
Slide 6: Footprint: Geographic Diversification
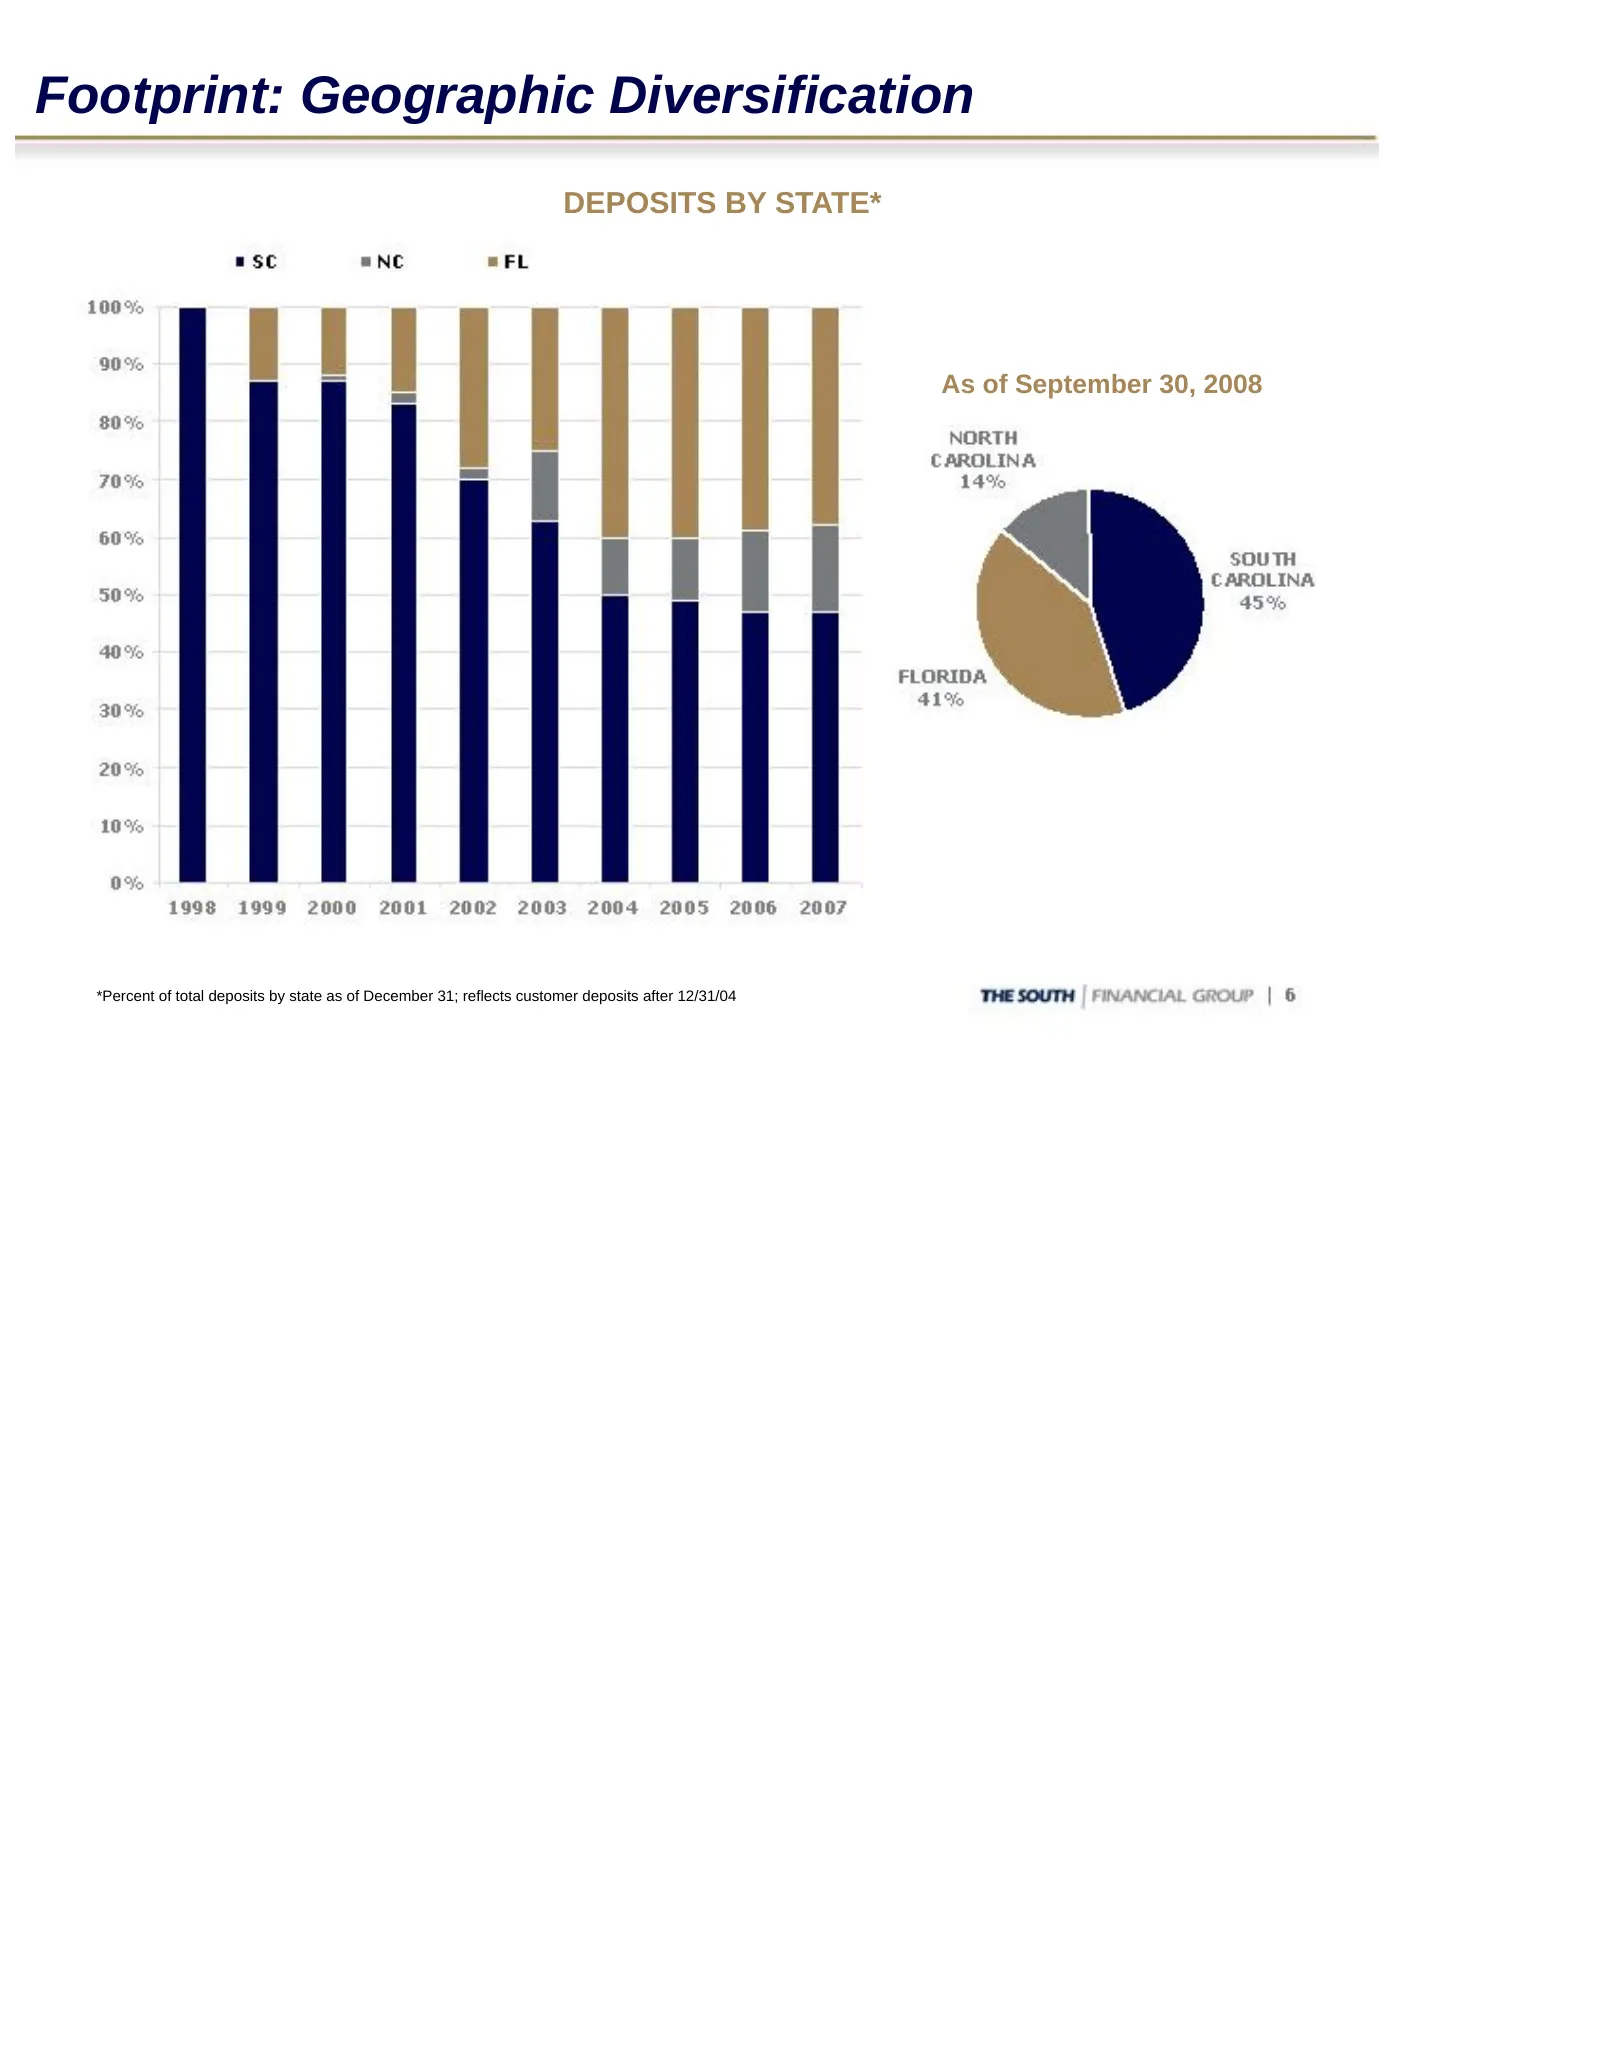
Footprint: Geographic Diversification DEPOSITS BY STATE* As of September 30, 2008 *Percent of total deposits by state as of December 31; reflects customer deposits after 12/31/04
Slide 7: Proactive and Realistic Approach to Cycle
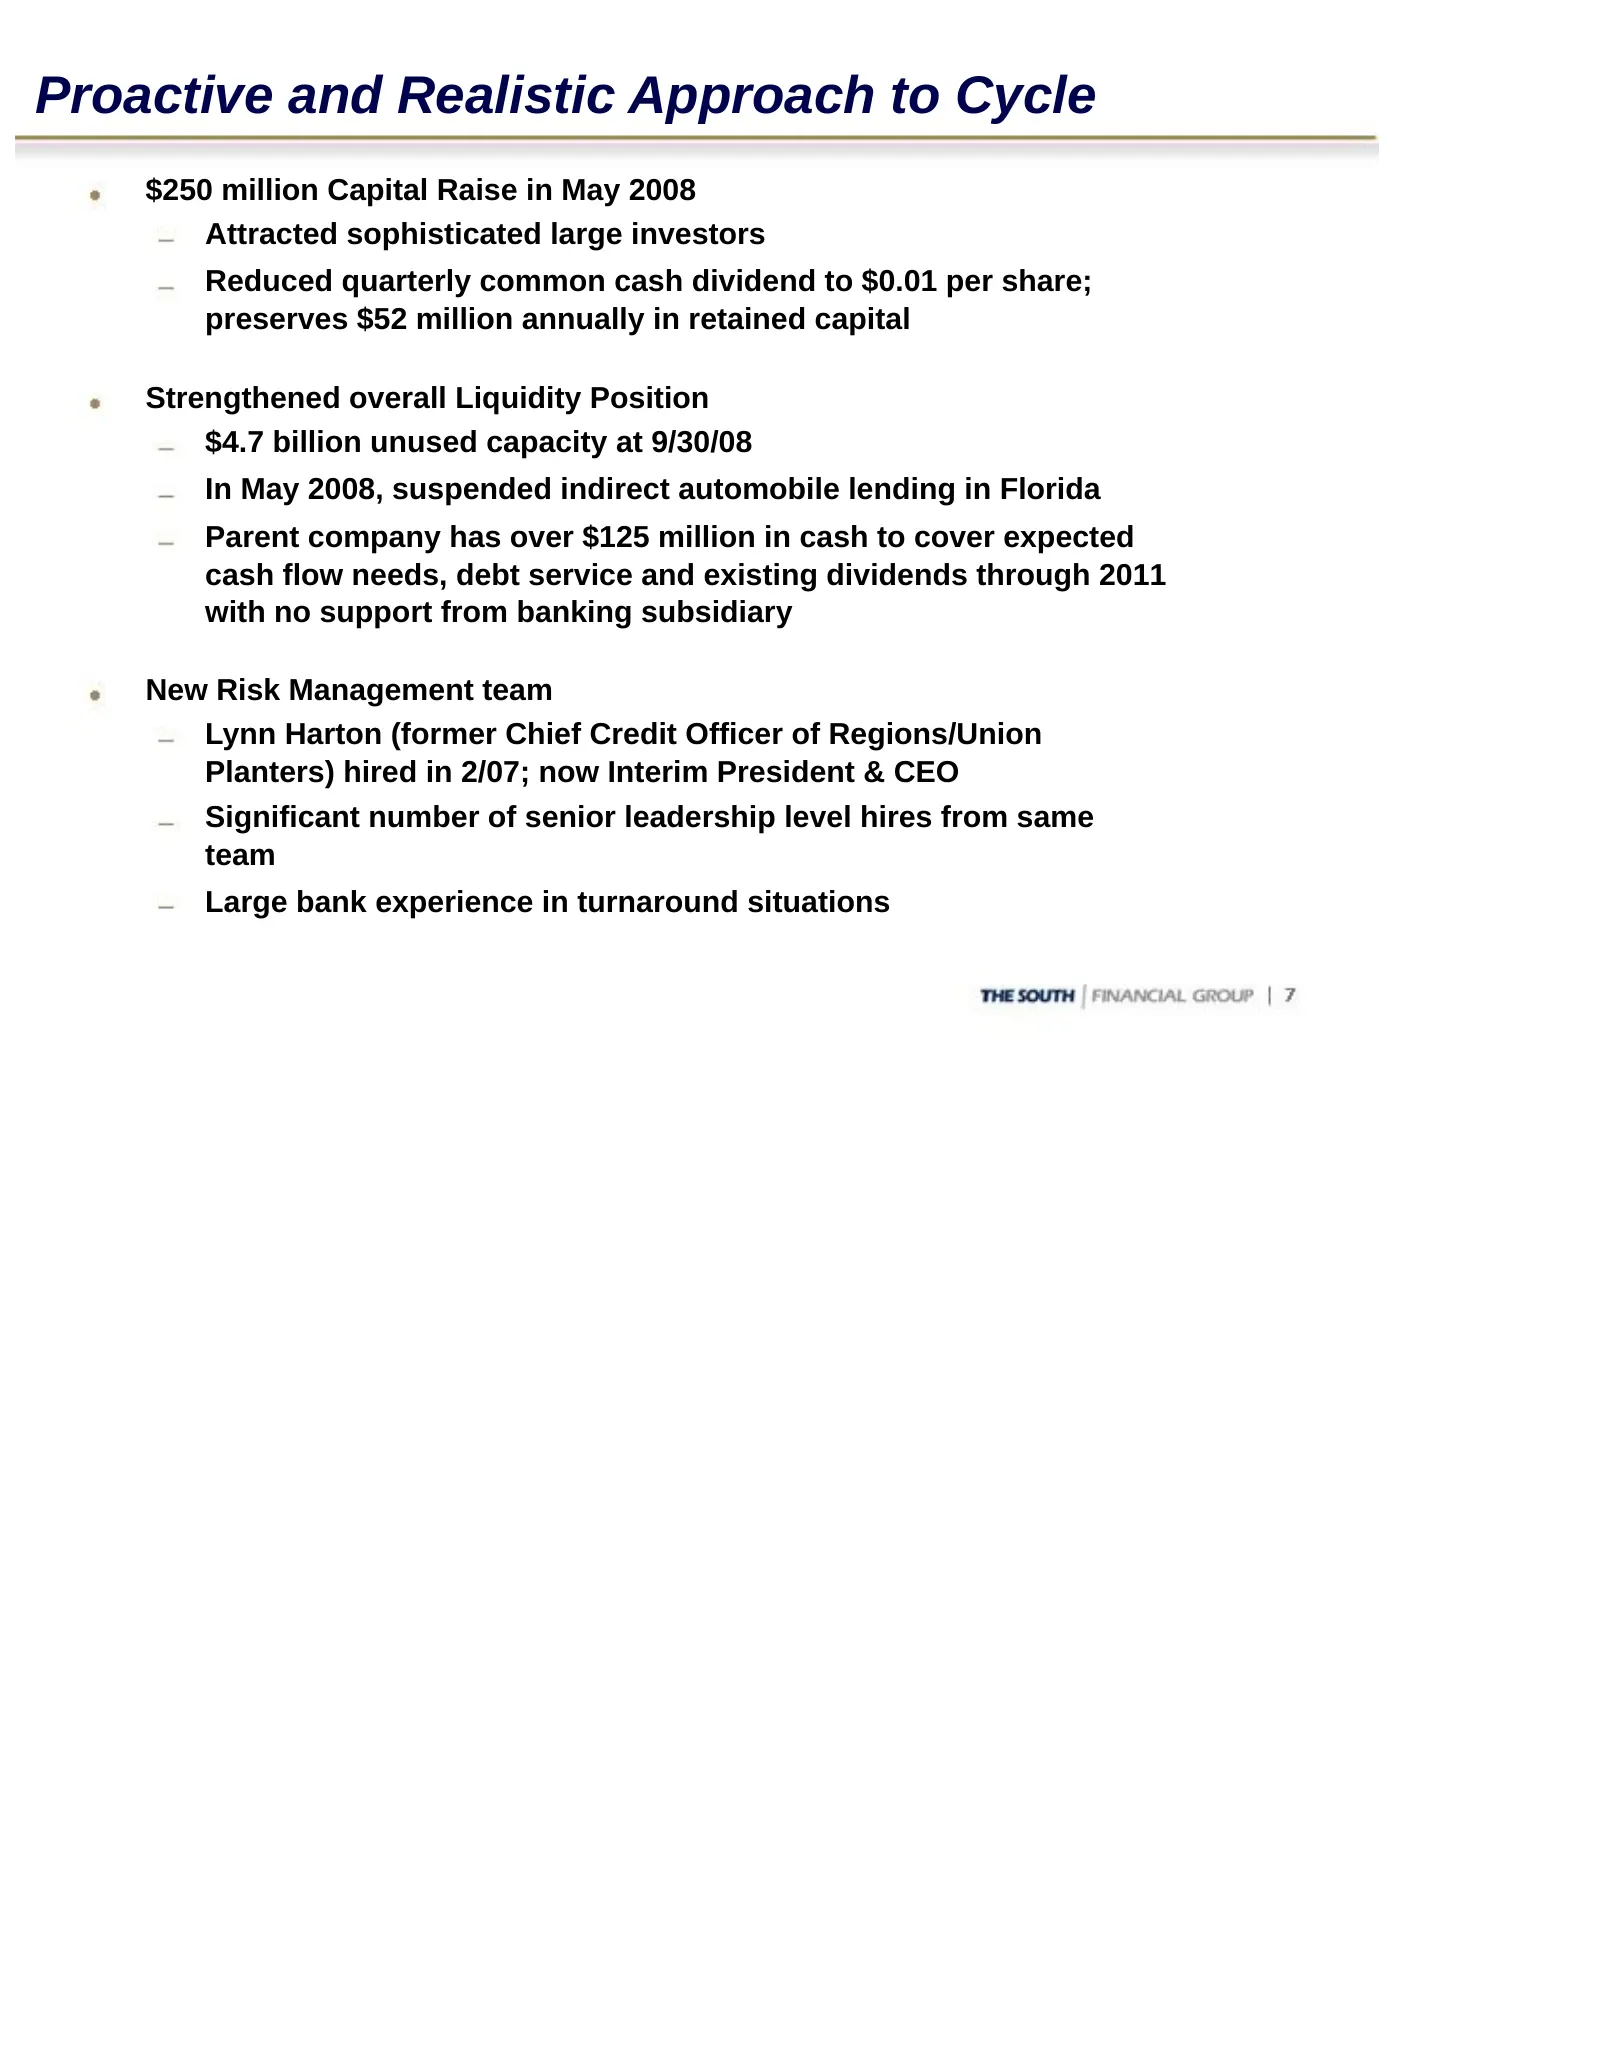
Proactive and Realistic Approach to Cycle $250 million Capital Raise in May 2008 Attracted sophisticated large investors Reduced quarterly common cash dividend to $0.01 per share; preserves $52 million annually in retained capital Strengthened overall Liquidity Position $4.7 billion unused capacity
Slide 8: Proactive and Realistic Approach (continued)
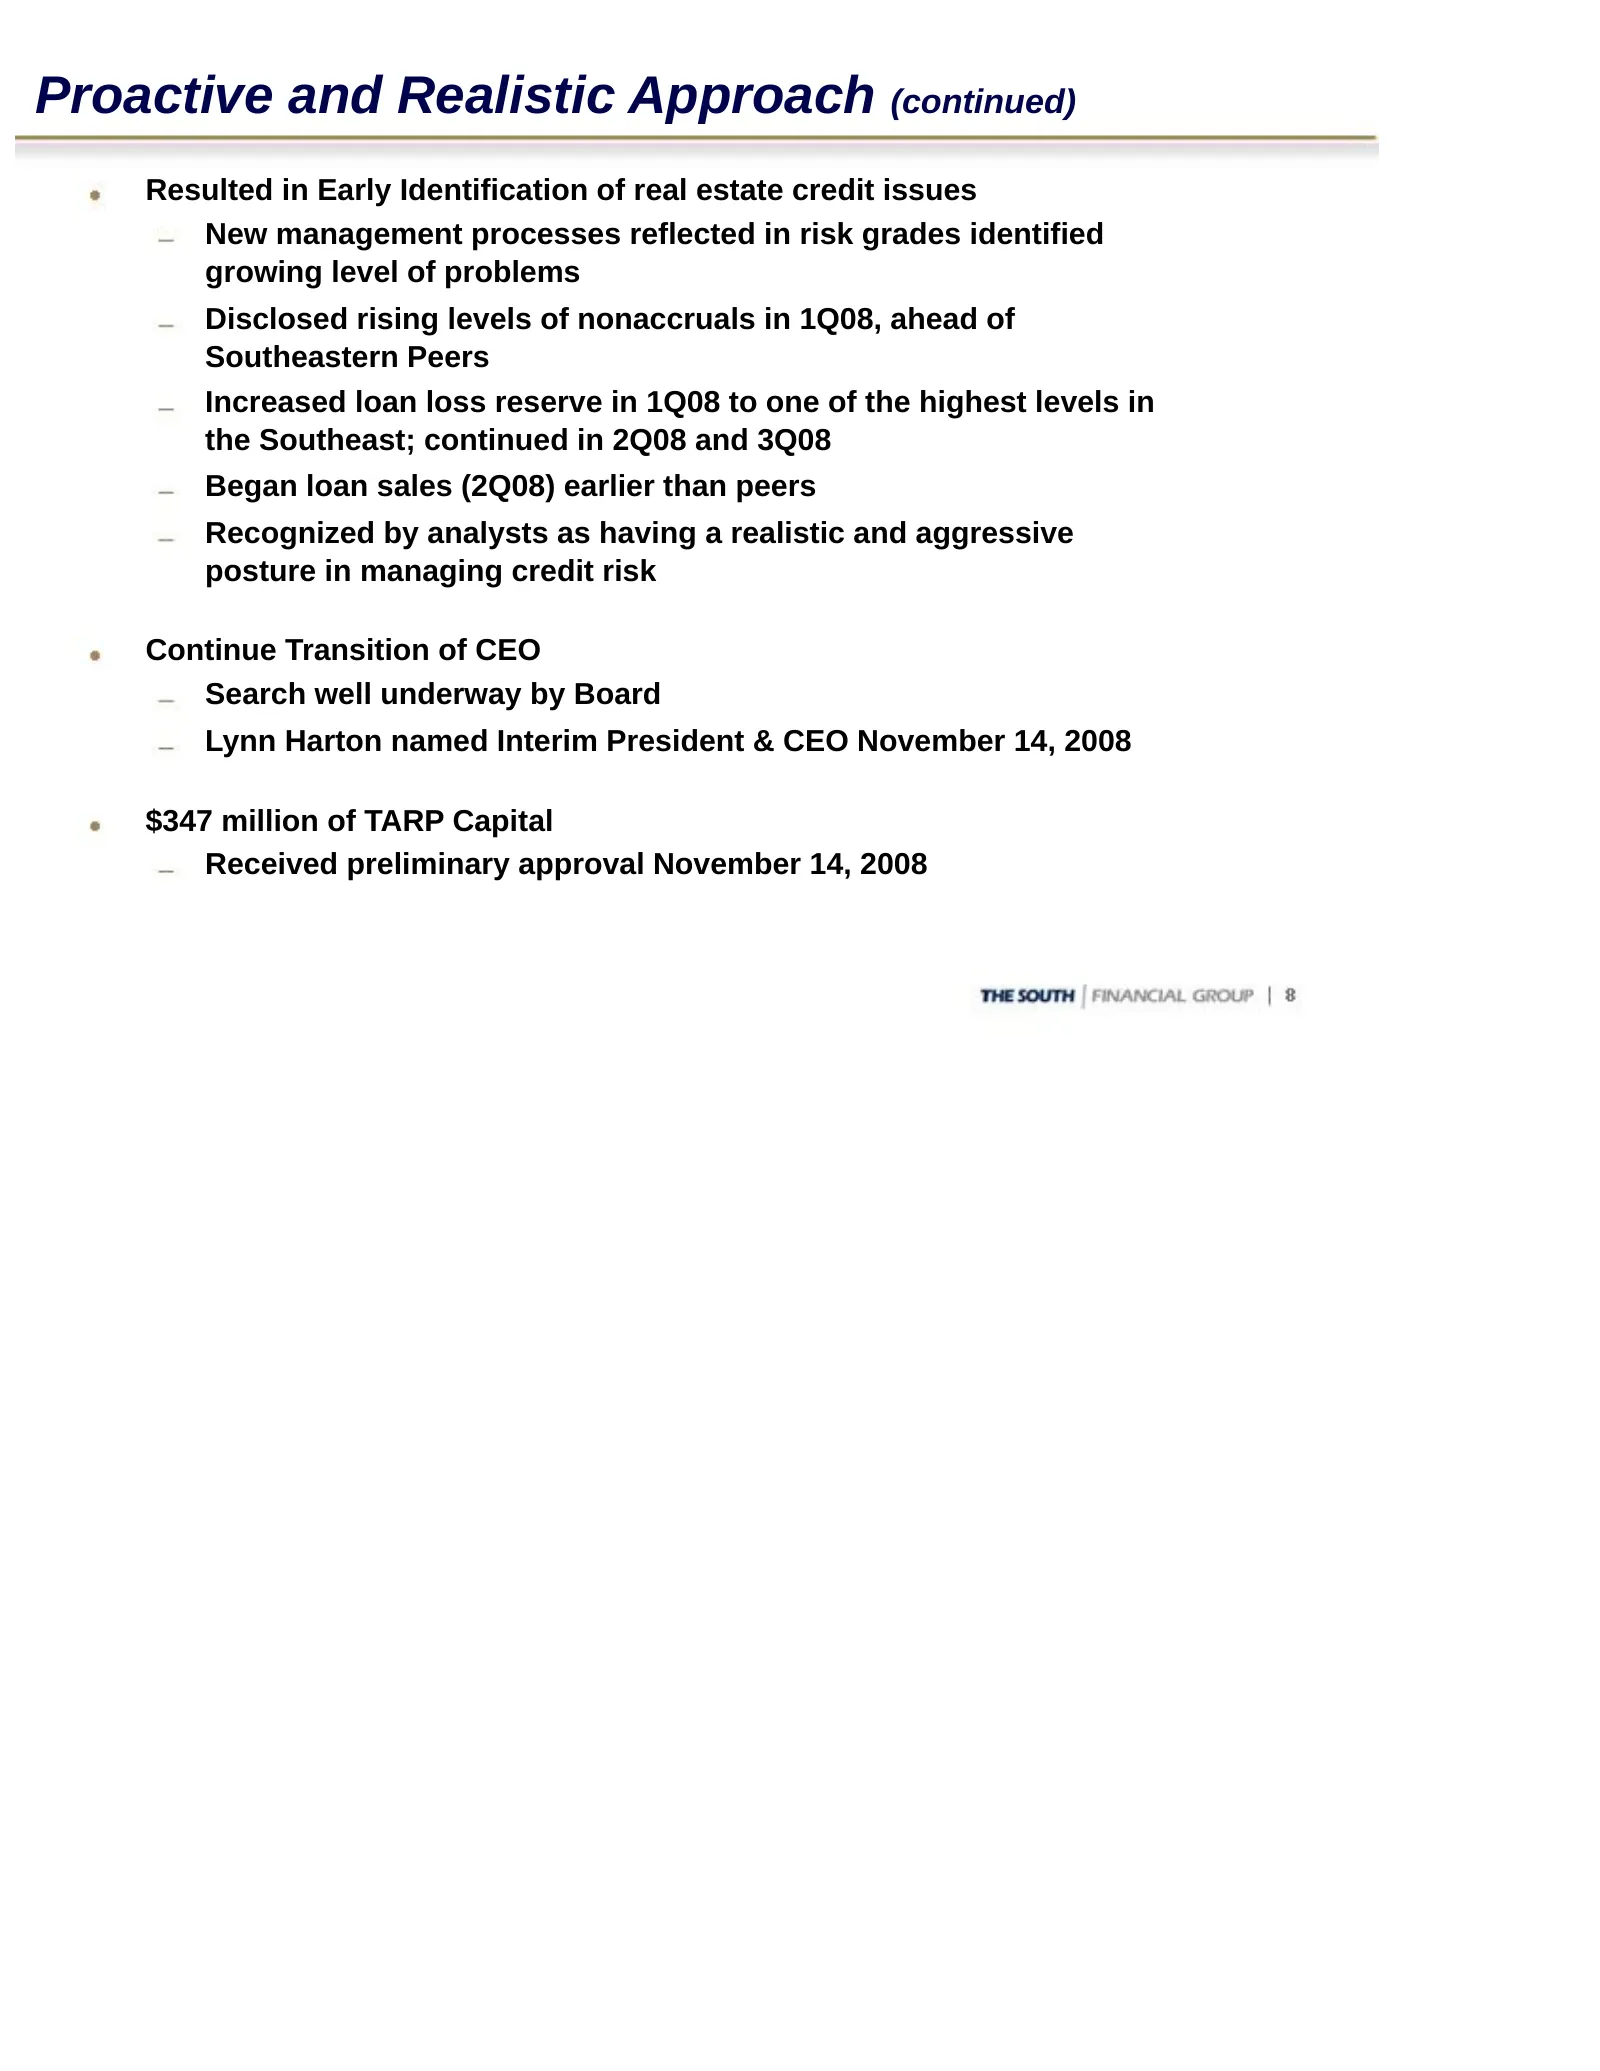
Proactive and Realistic Approach (continued) Resulted in Early Identification of real estate credit issues New management processes reflected in risk grades identified growing level of problems Disclosed rising levels of nonaccruals in 1Q08, ahead of Southeastern Peers Increased loan loss reserve in
Slide 9: Strategic Objectives
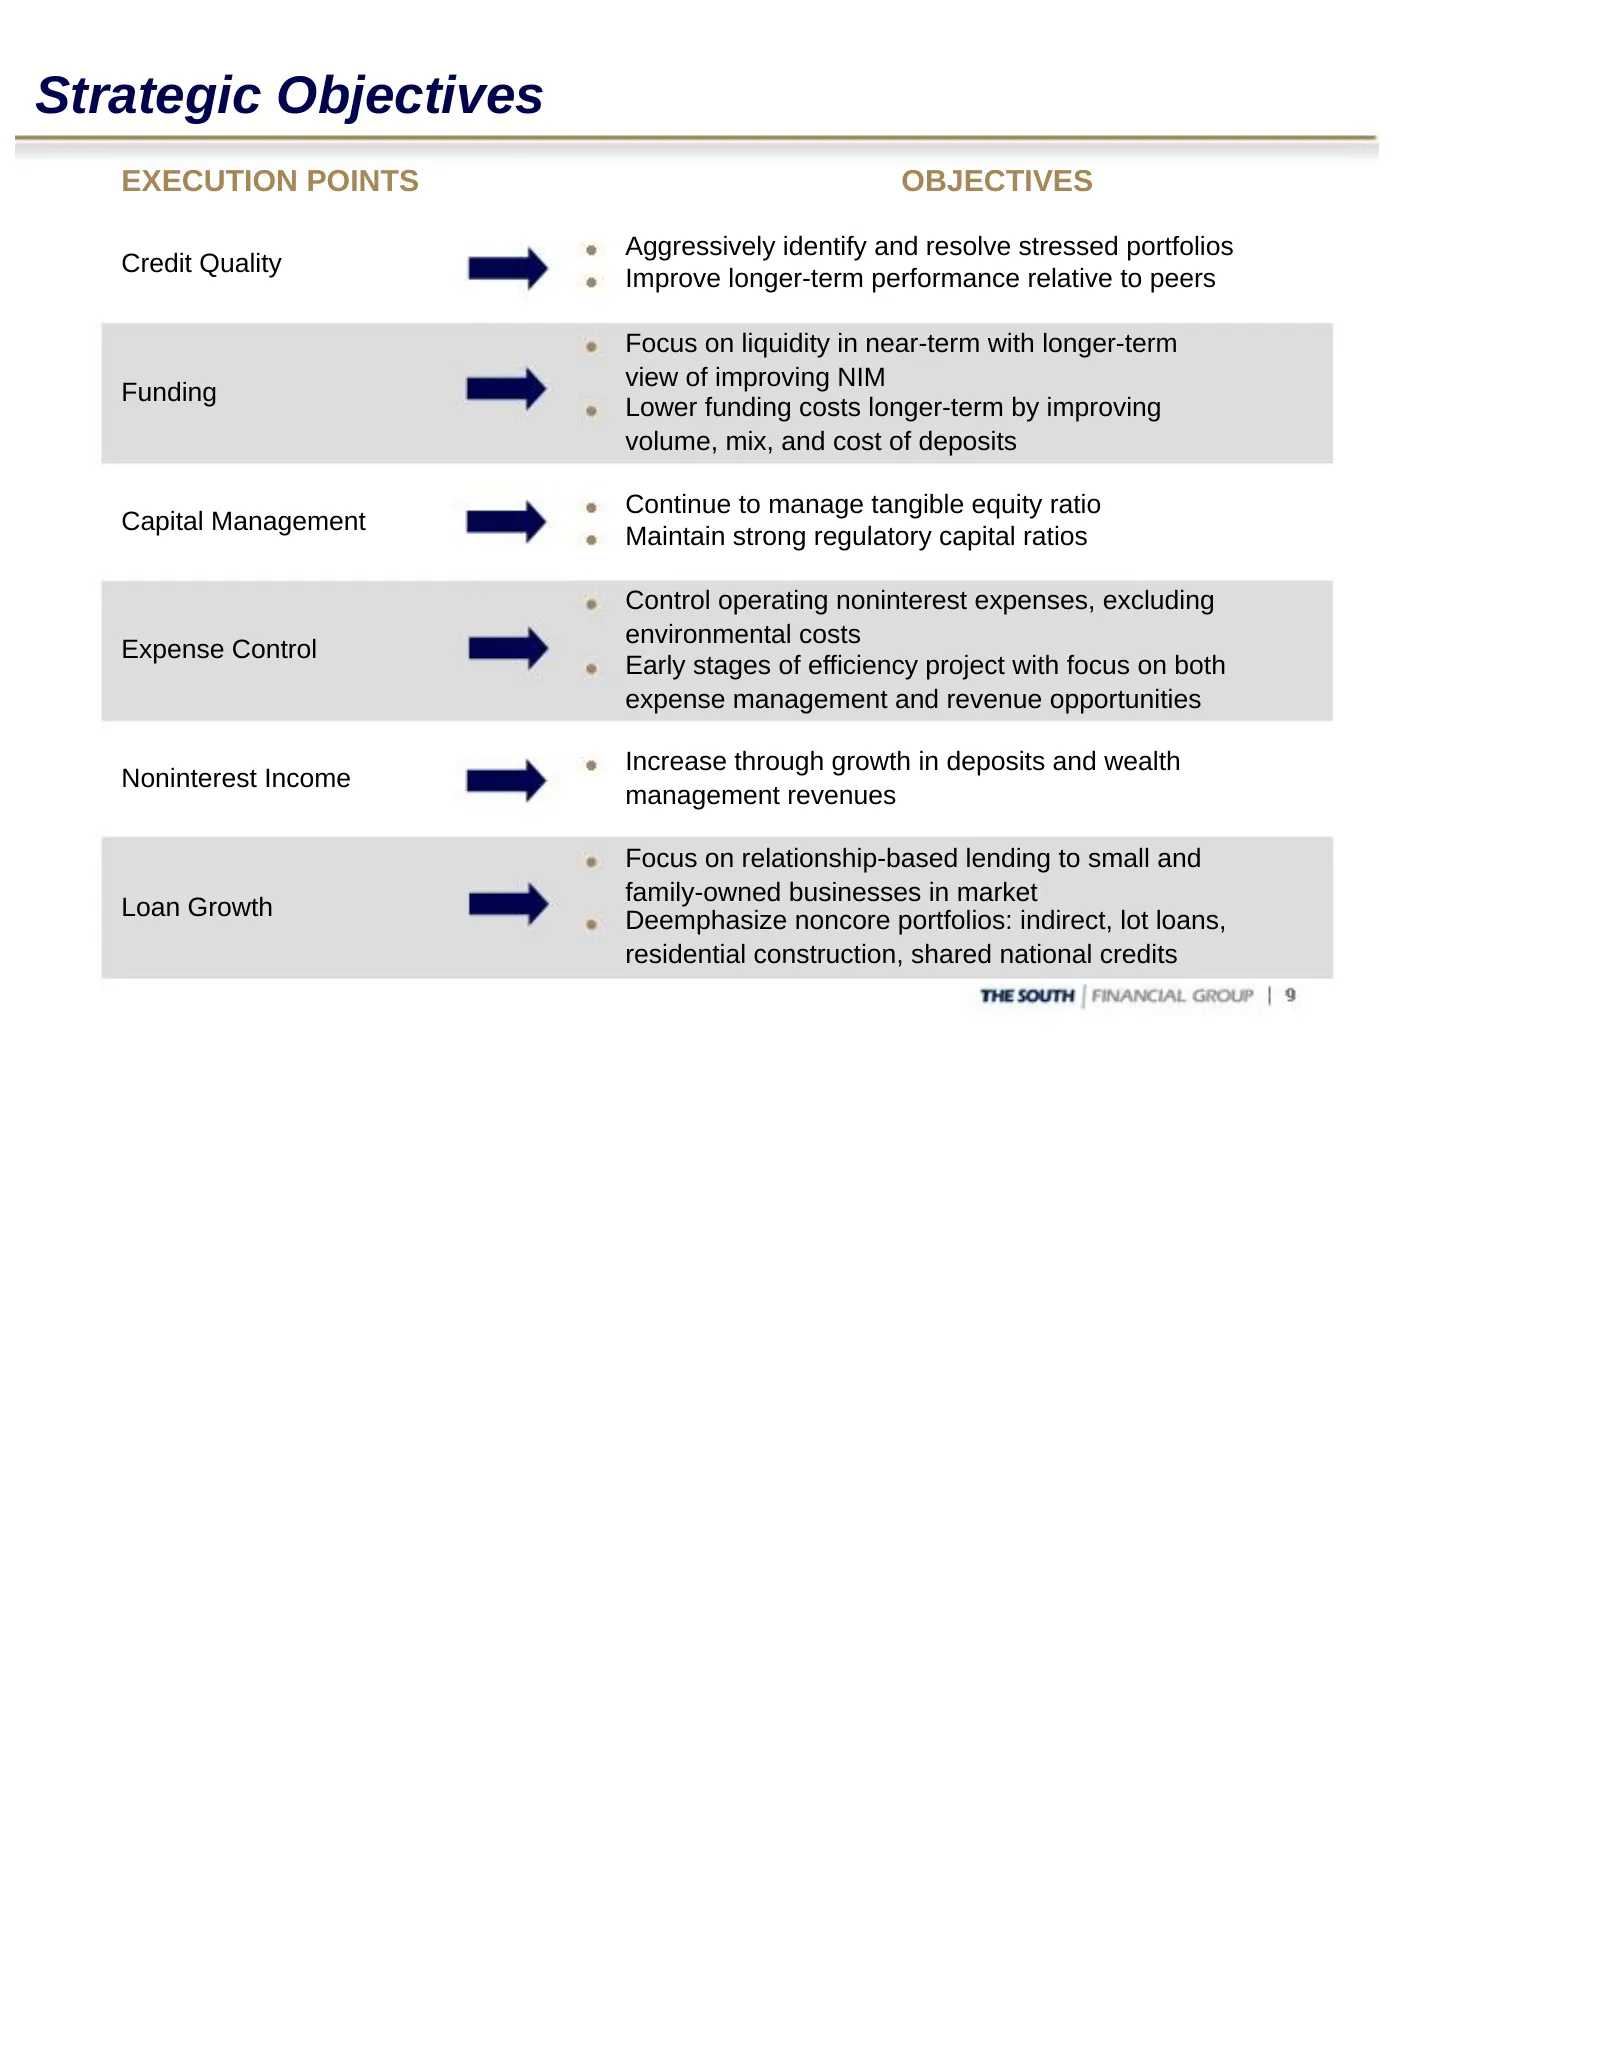
Strategic Objectives EXECUTION POINTS OBJECTIVES Aggressively identify and resolve stressed portfolios Credit Quality Improve longer-term performance relative to peers Focus on liquidity in near-term with longer-term view of improving NIM Funding Lower funding costs longer-term by improving volume,
Slide 10: Diversified Loan Portfolio
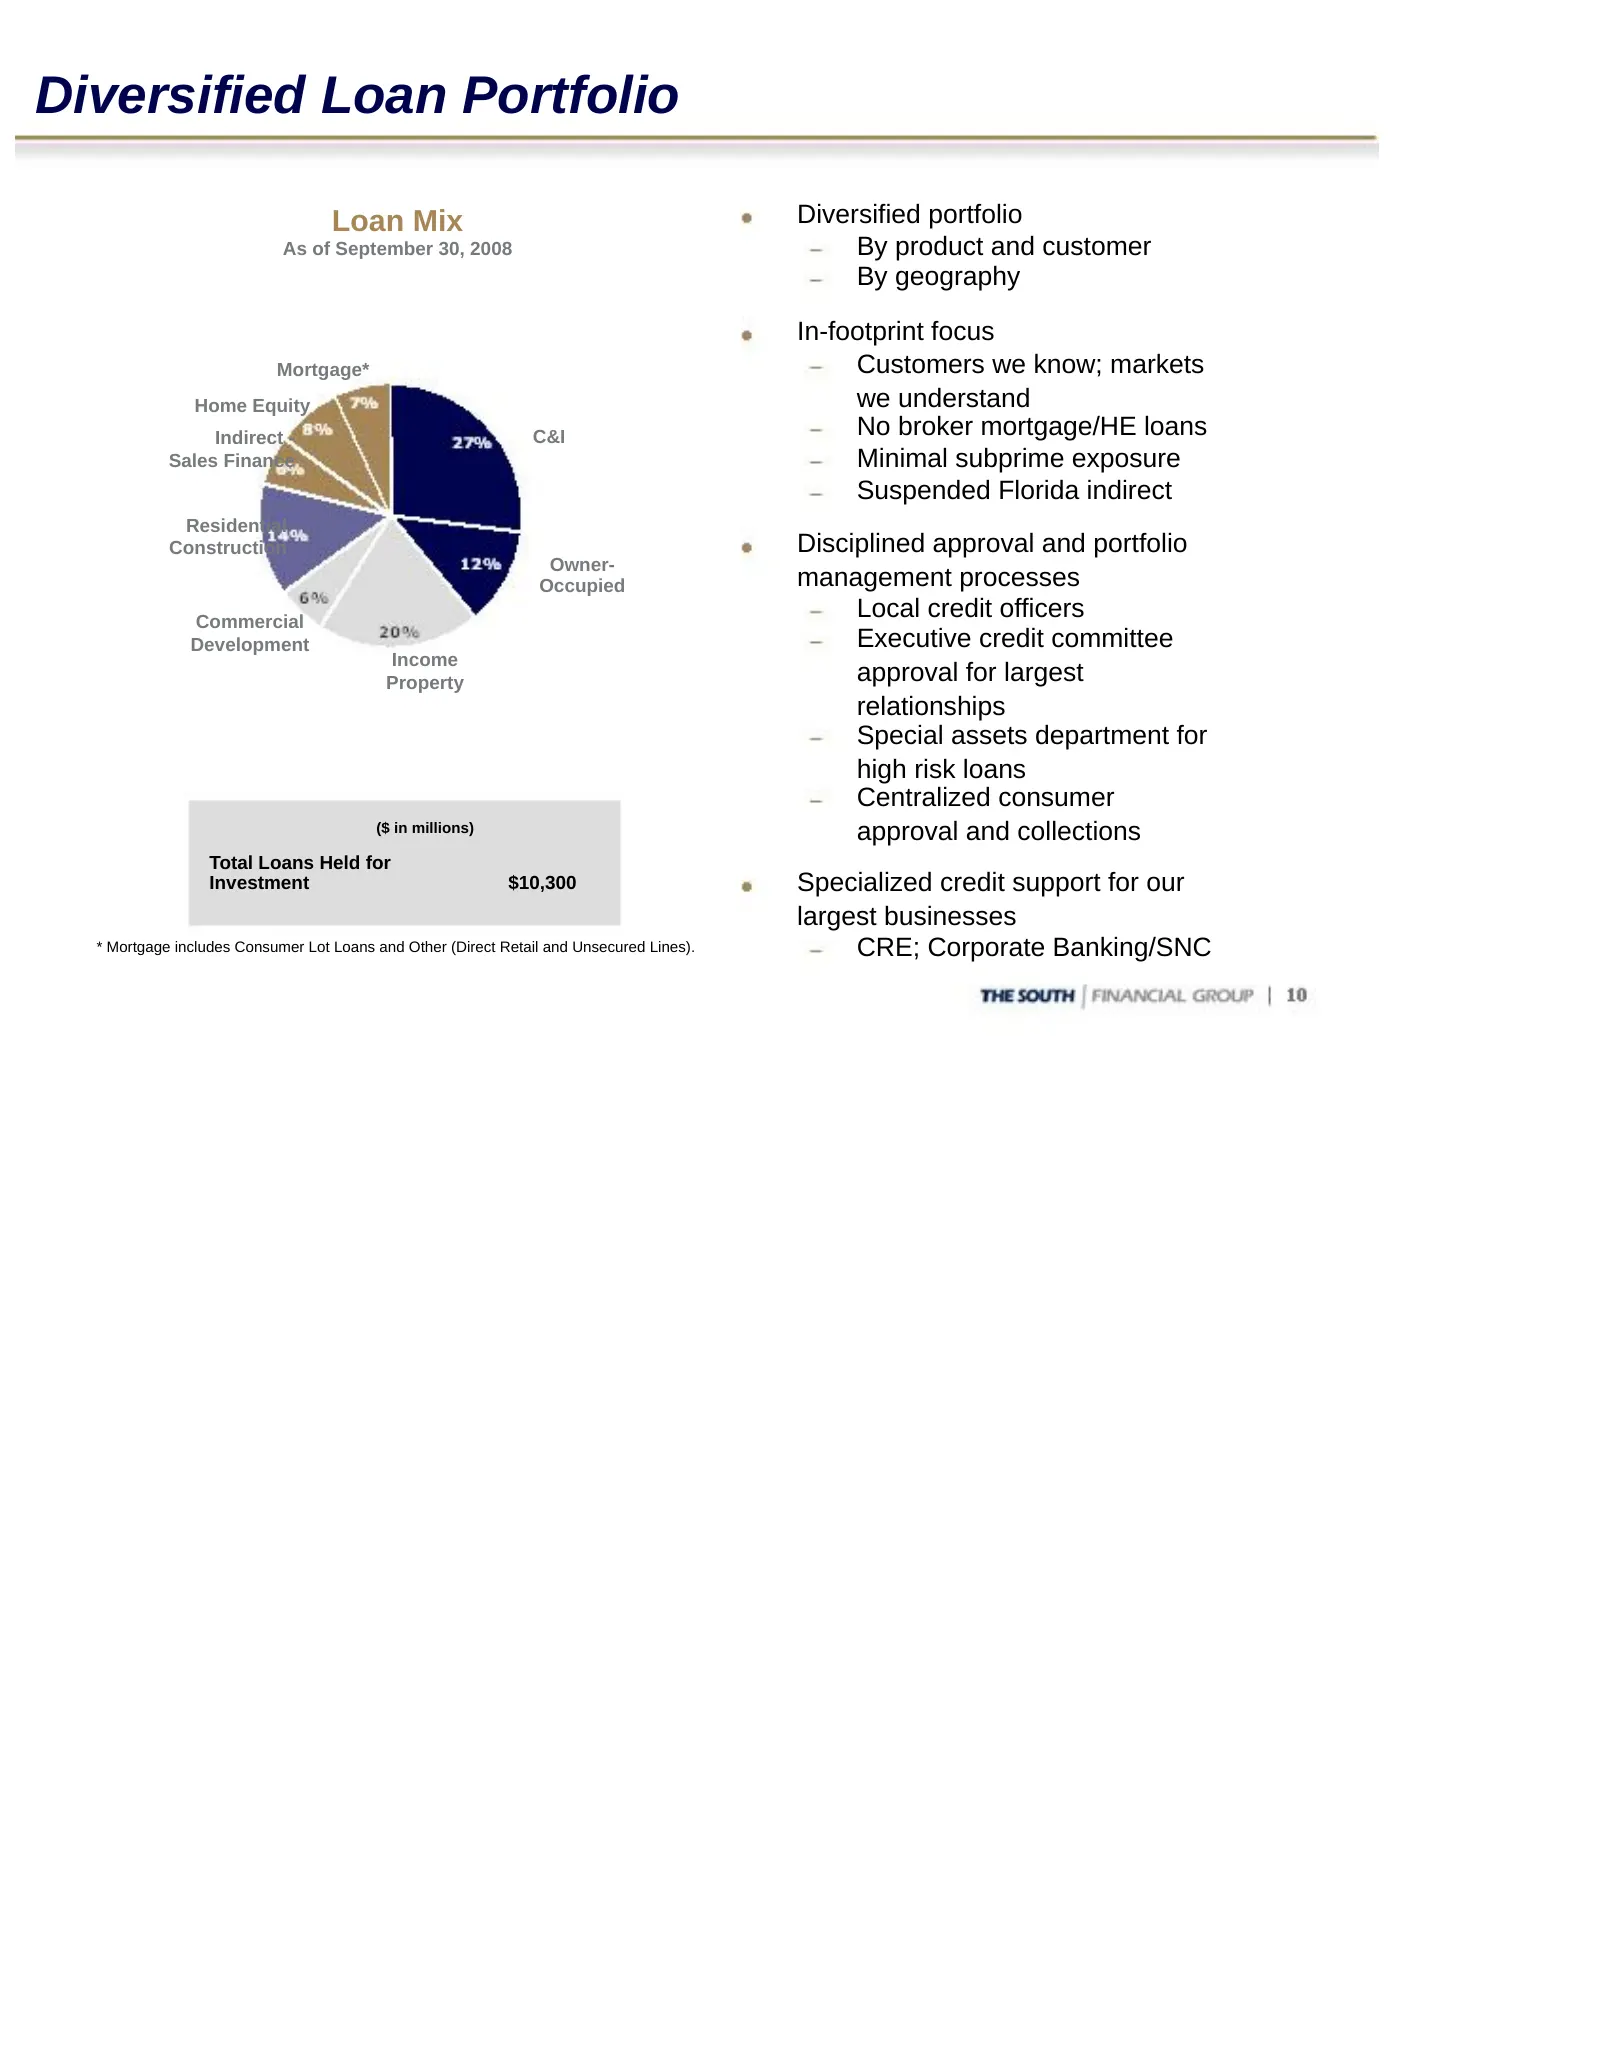
Diversified Loan Portfolio Loan Mix Diversified portfolio As of September 30, 2008 By product and customer By geography In-footprint focus Mortgage* Customers we know; markets Home Equity we understand Indirect - C&I No broker mortgage/HE loans Sales Finance Minimal subprime exposure Suspended Flori
Slide 11: Credit Quality Results – 3Q08
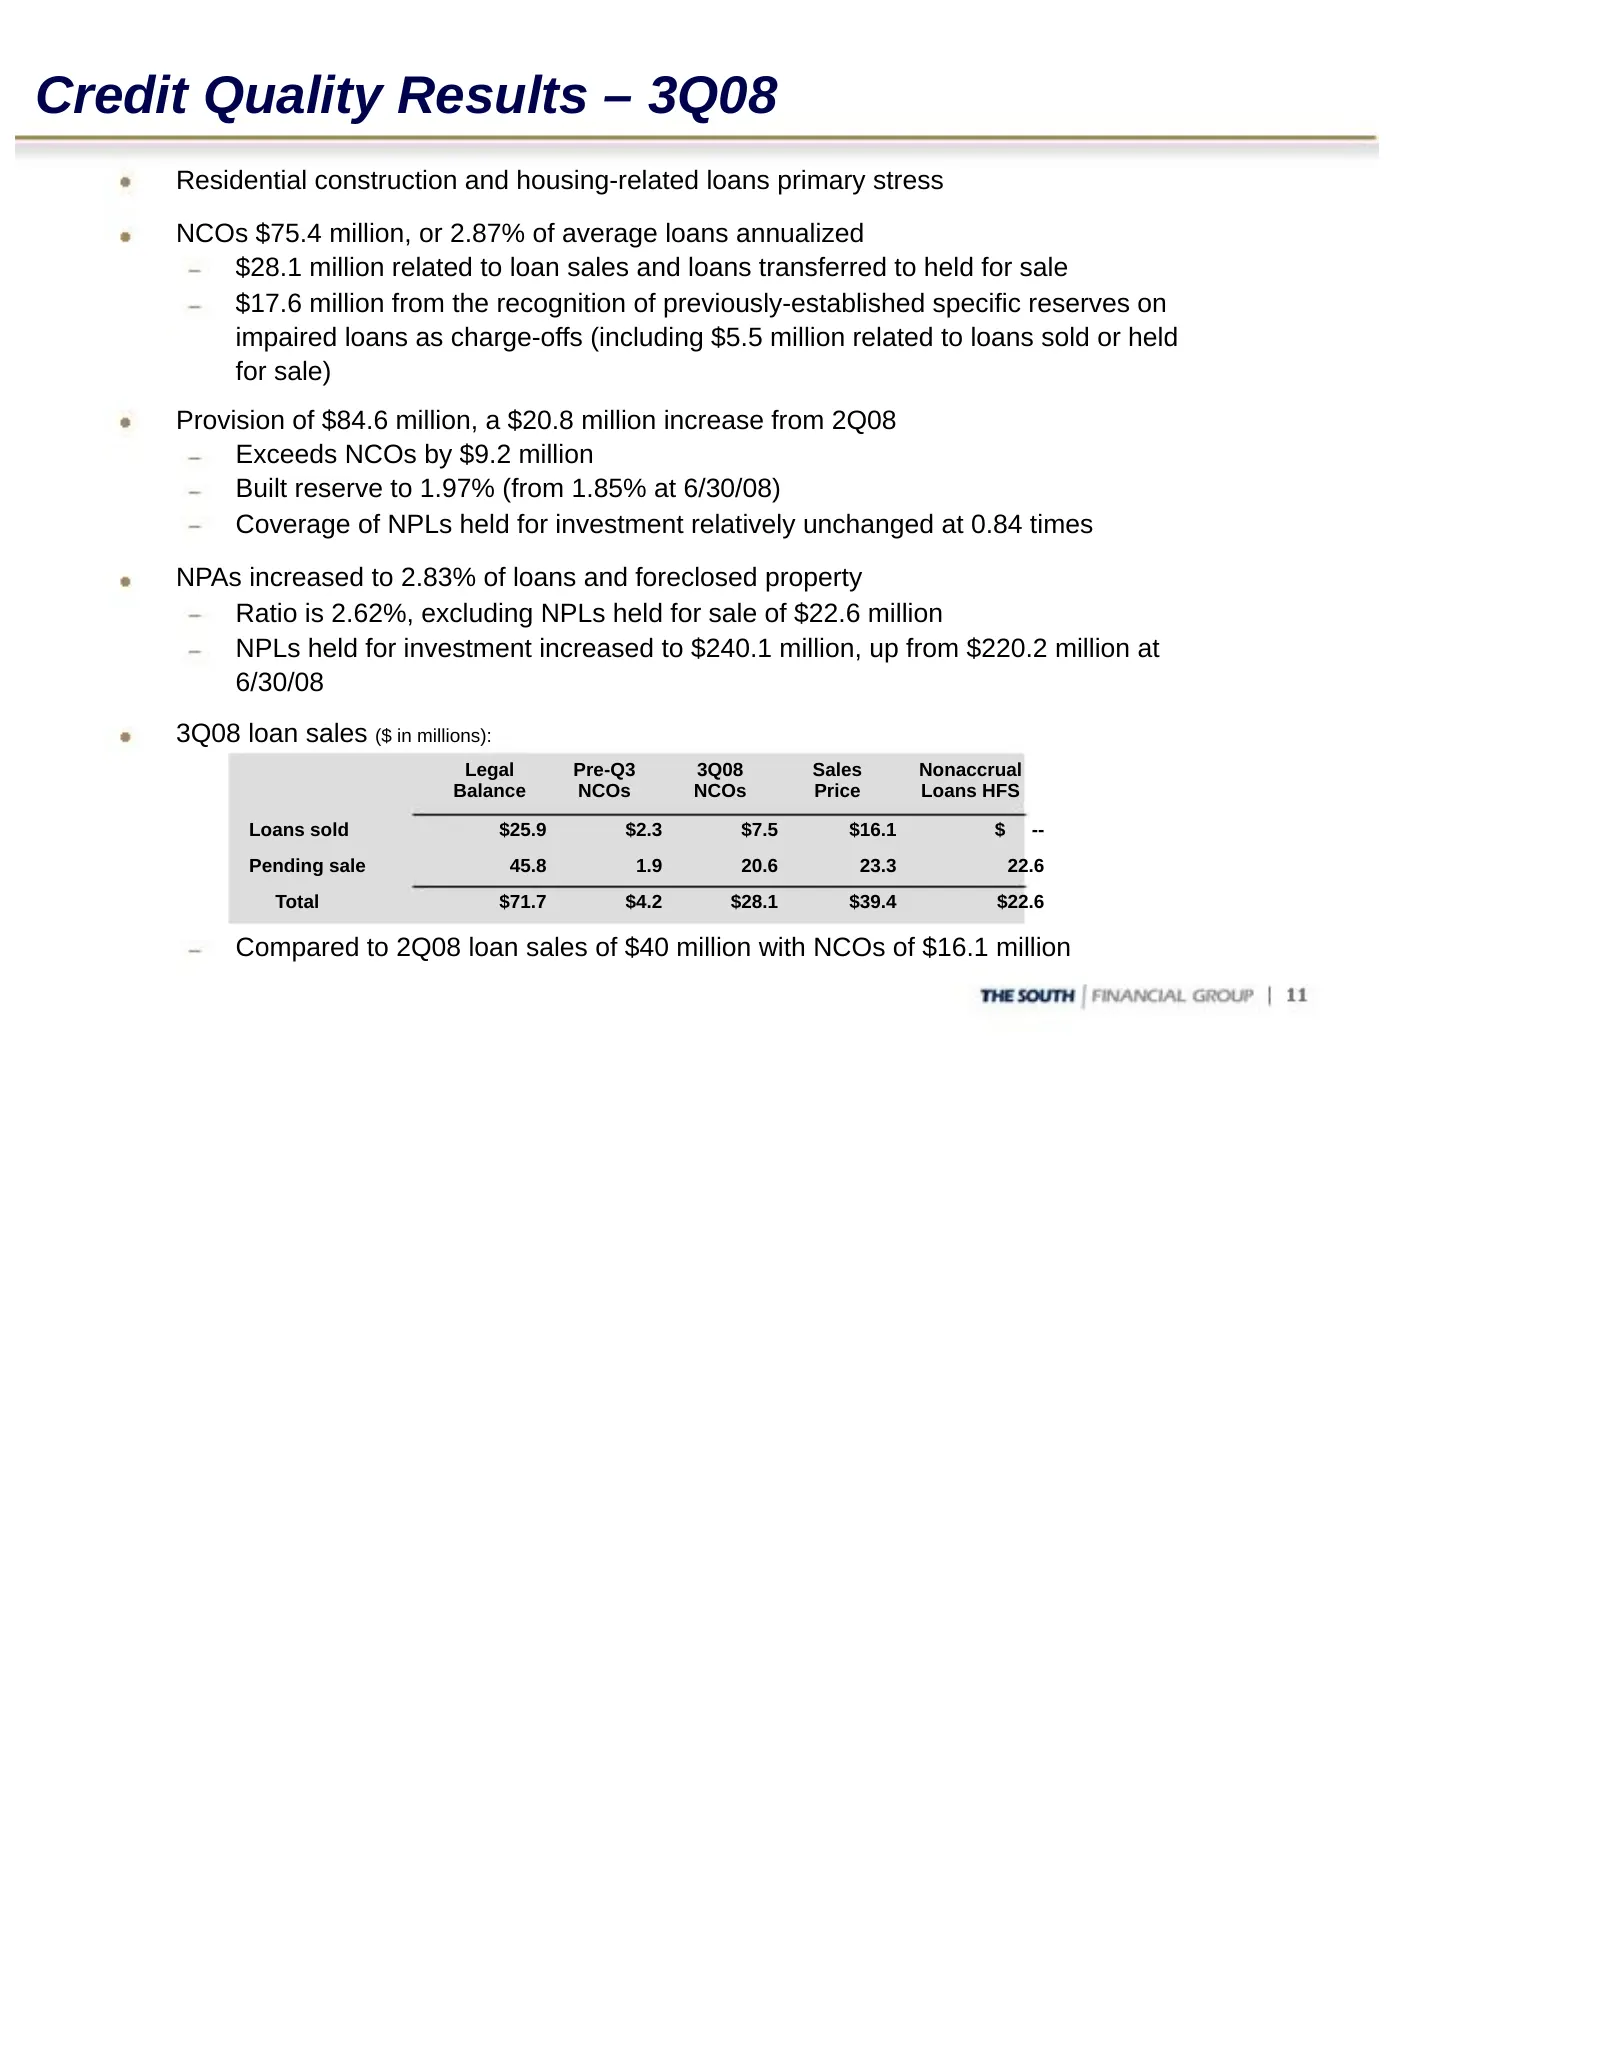
Credit Quality Results – 3Q08 Residential construction and housing-related loans primary stress NCOs $75.4 million, or 2.87% of average loans annualized $28.1 million related to loan sales and loans transferred to held for sale $17.6 million from the recognition of previously-established specific re
Slide 12: Loan and Credit Quality Stress is Housing-Related
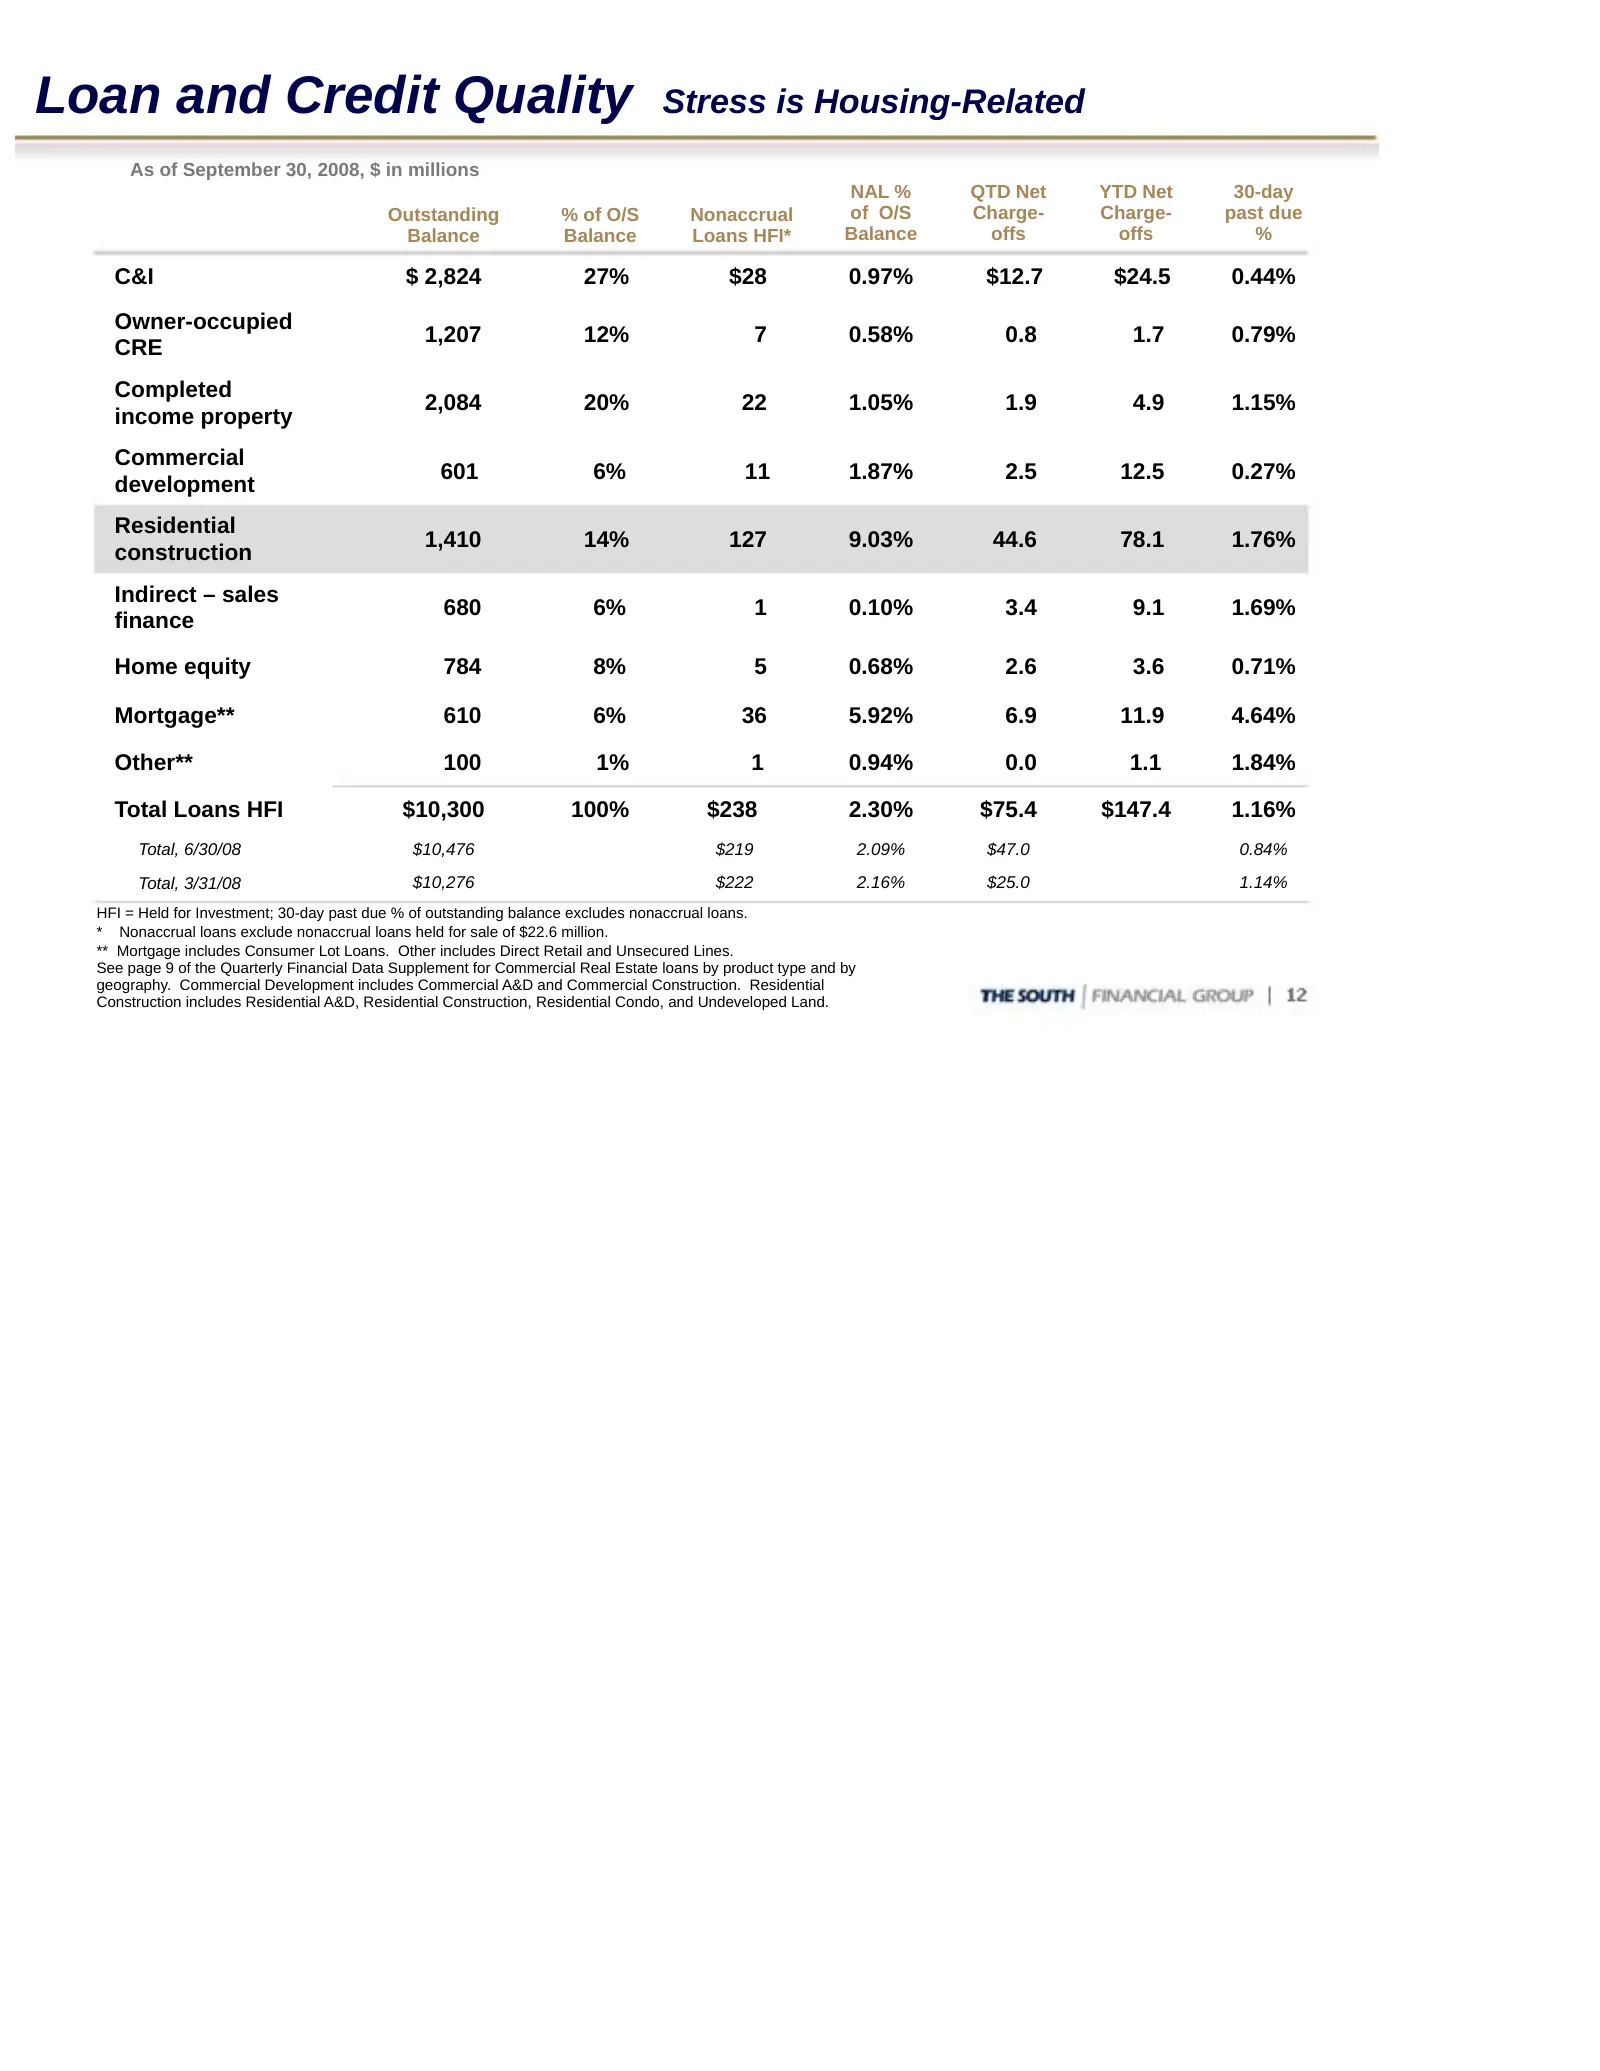
Loan and Credit Quality Stress is Housing-Related As of September 30, 2008, $ in millions NAL % QTD Net YTD Net 30-day Outstanding % of O/S Nonaccrual of O/S Charge- Charge- past due Balance Balance Loans HFI* Balance offs offs % C&I $ 2,824 27% $28 0.97% $12.7 $24.5 0.44% Owner-occupied 1,207 12% 7
Slide 13: Residential Construction Performing Differently
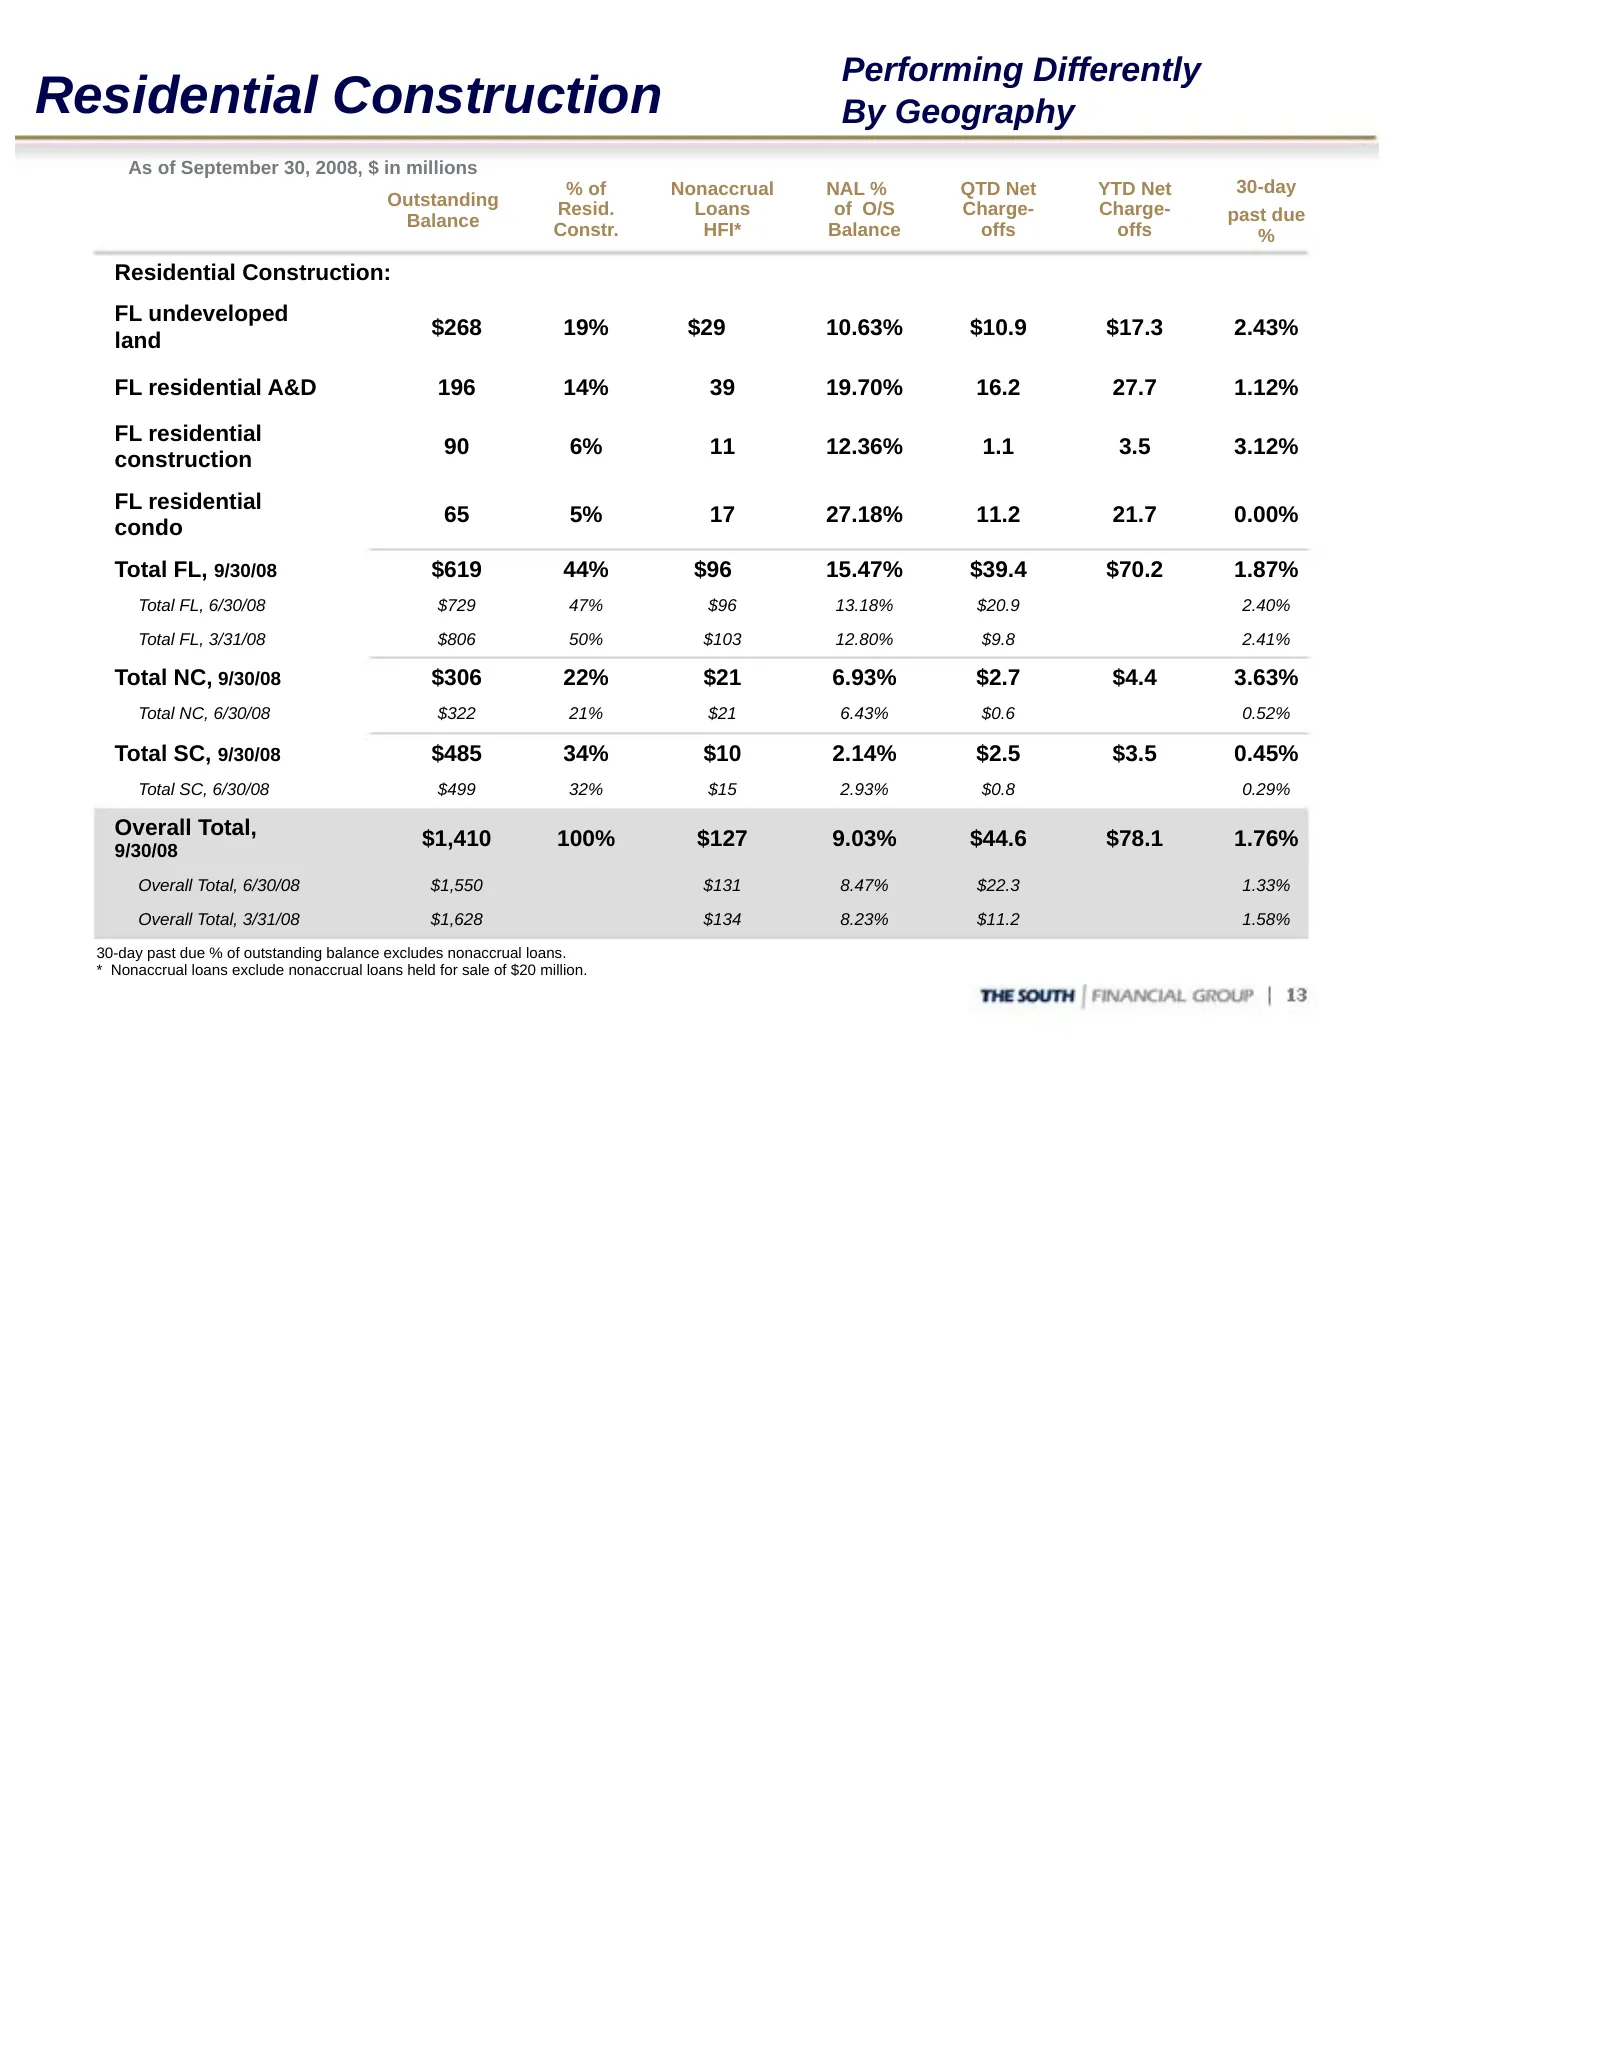
Performing Differently Residential Construction By Geography As of September 30, 2008, $ in millions % of Nonaccrual NAL % QTD Net YTD Net 30-day Outstanding Resid. Loans of O/S Charge- Charge- Balance past due Constr. HFI* Balance offs offs % Residential Construction: FL undeveloped $268 19% $29 10
Slide 14: Commercial Nonaccruals – Net Balance
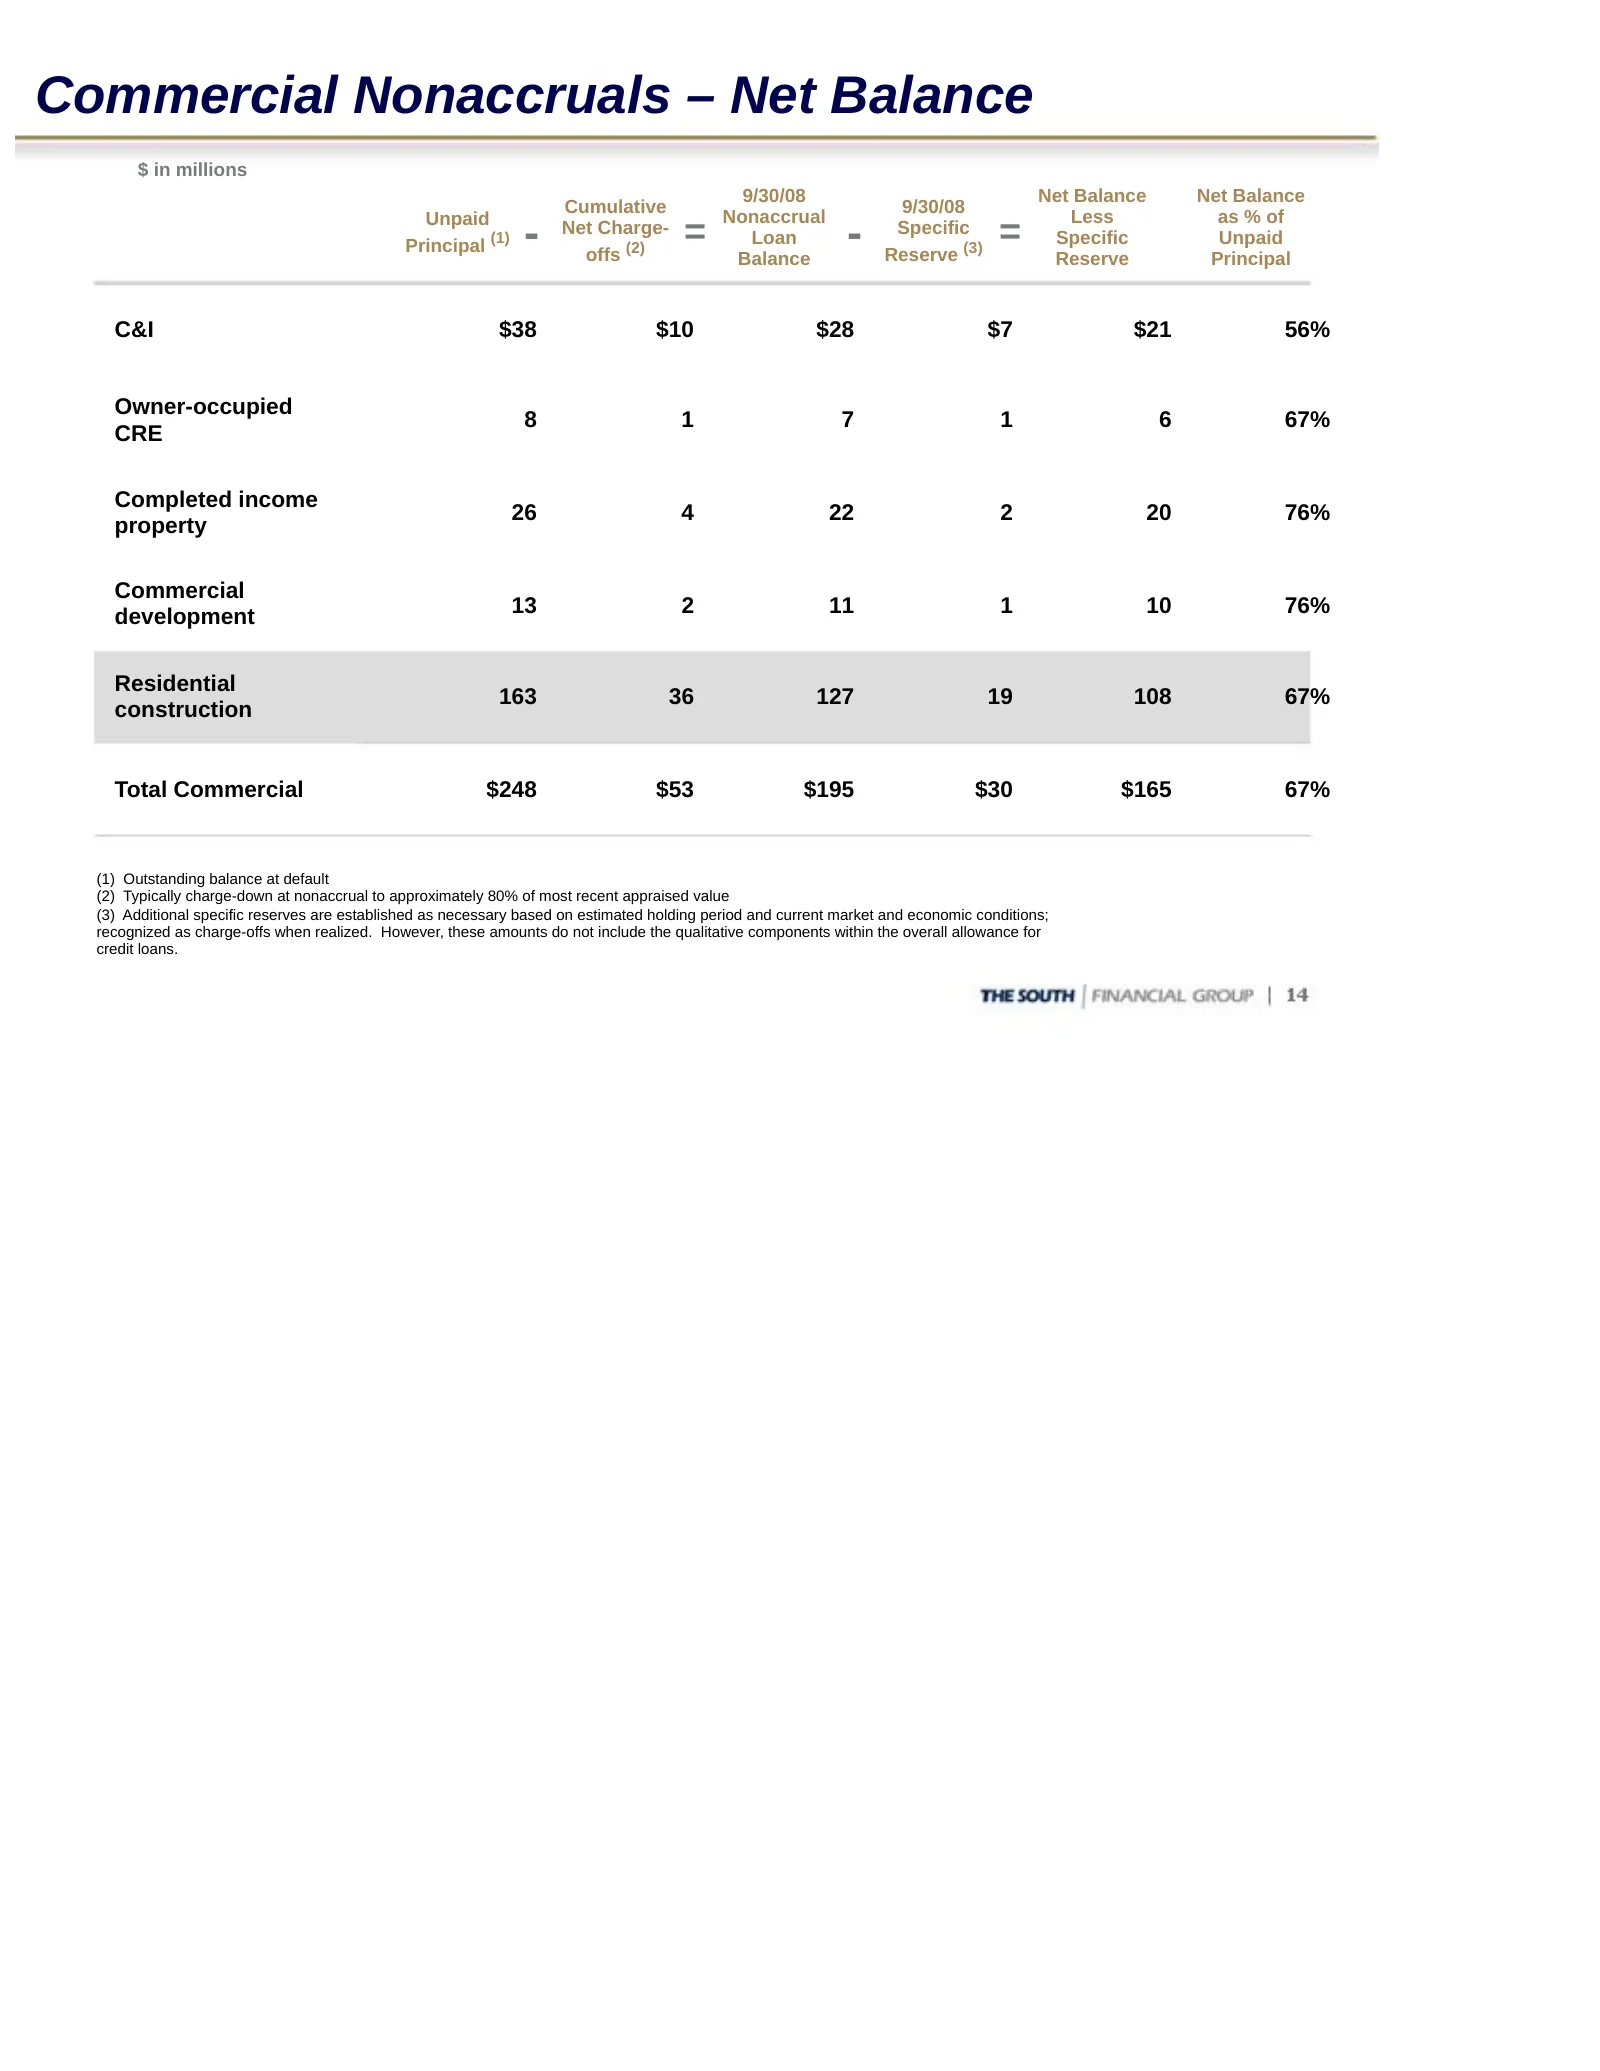
Commercial Nonaccruals – Net Balance $ in millions 9/30/08 Net Balance Net Balance Cumulative Nonaccrual 9/30/08 Less as % of - - Unpaid Principal (1) Net Charge- offs (2) = Loan Specific Reserve (3) = Specific Unpaid Balance Reserve Principal C&I $38 $10 $28 $7 $21 56% Owner-occupied 8 1 7 1 6 67%
Slide 15: Home Equity Lines/Loans
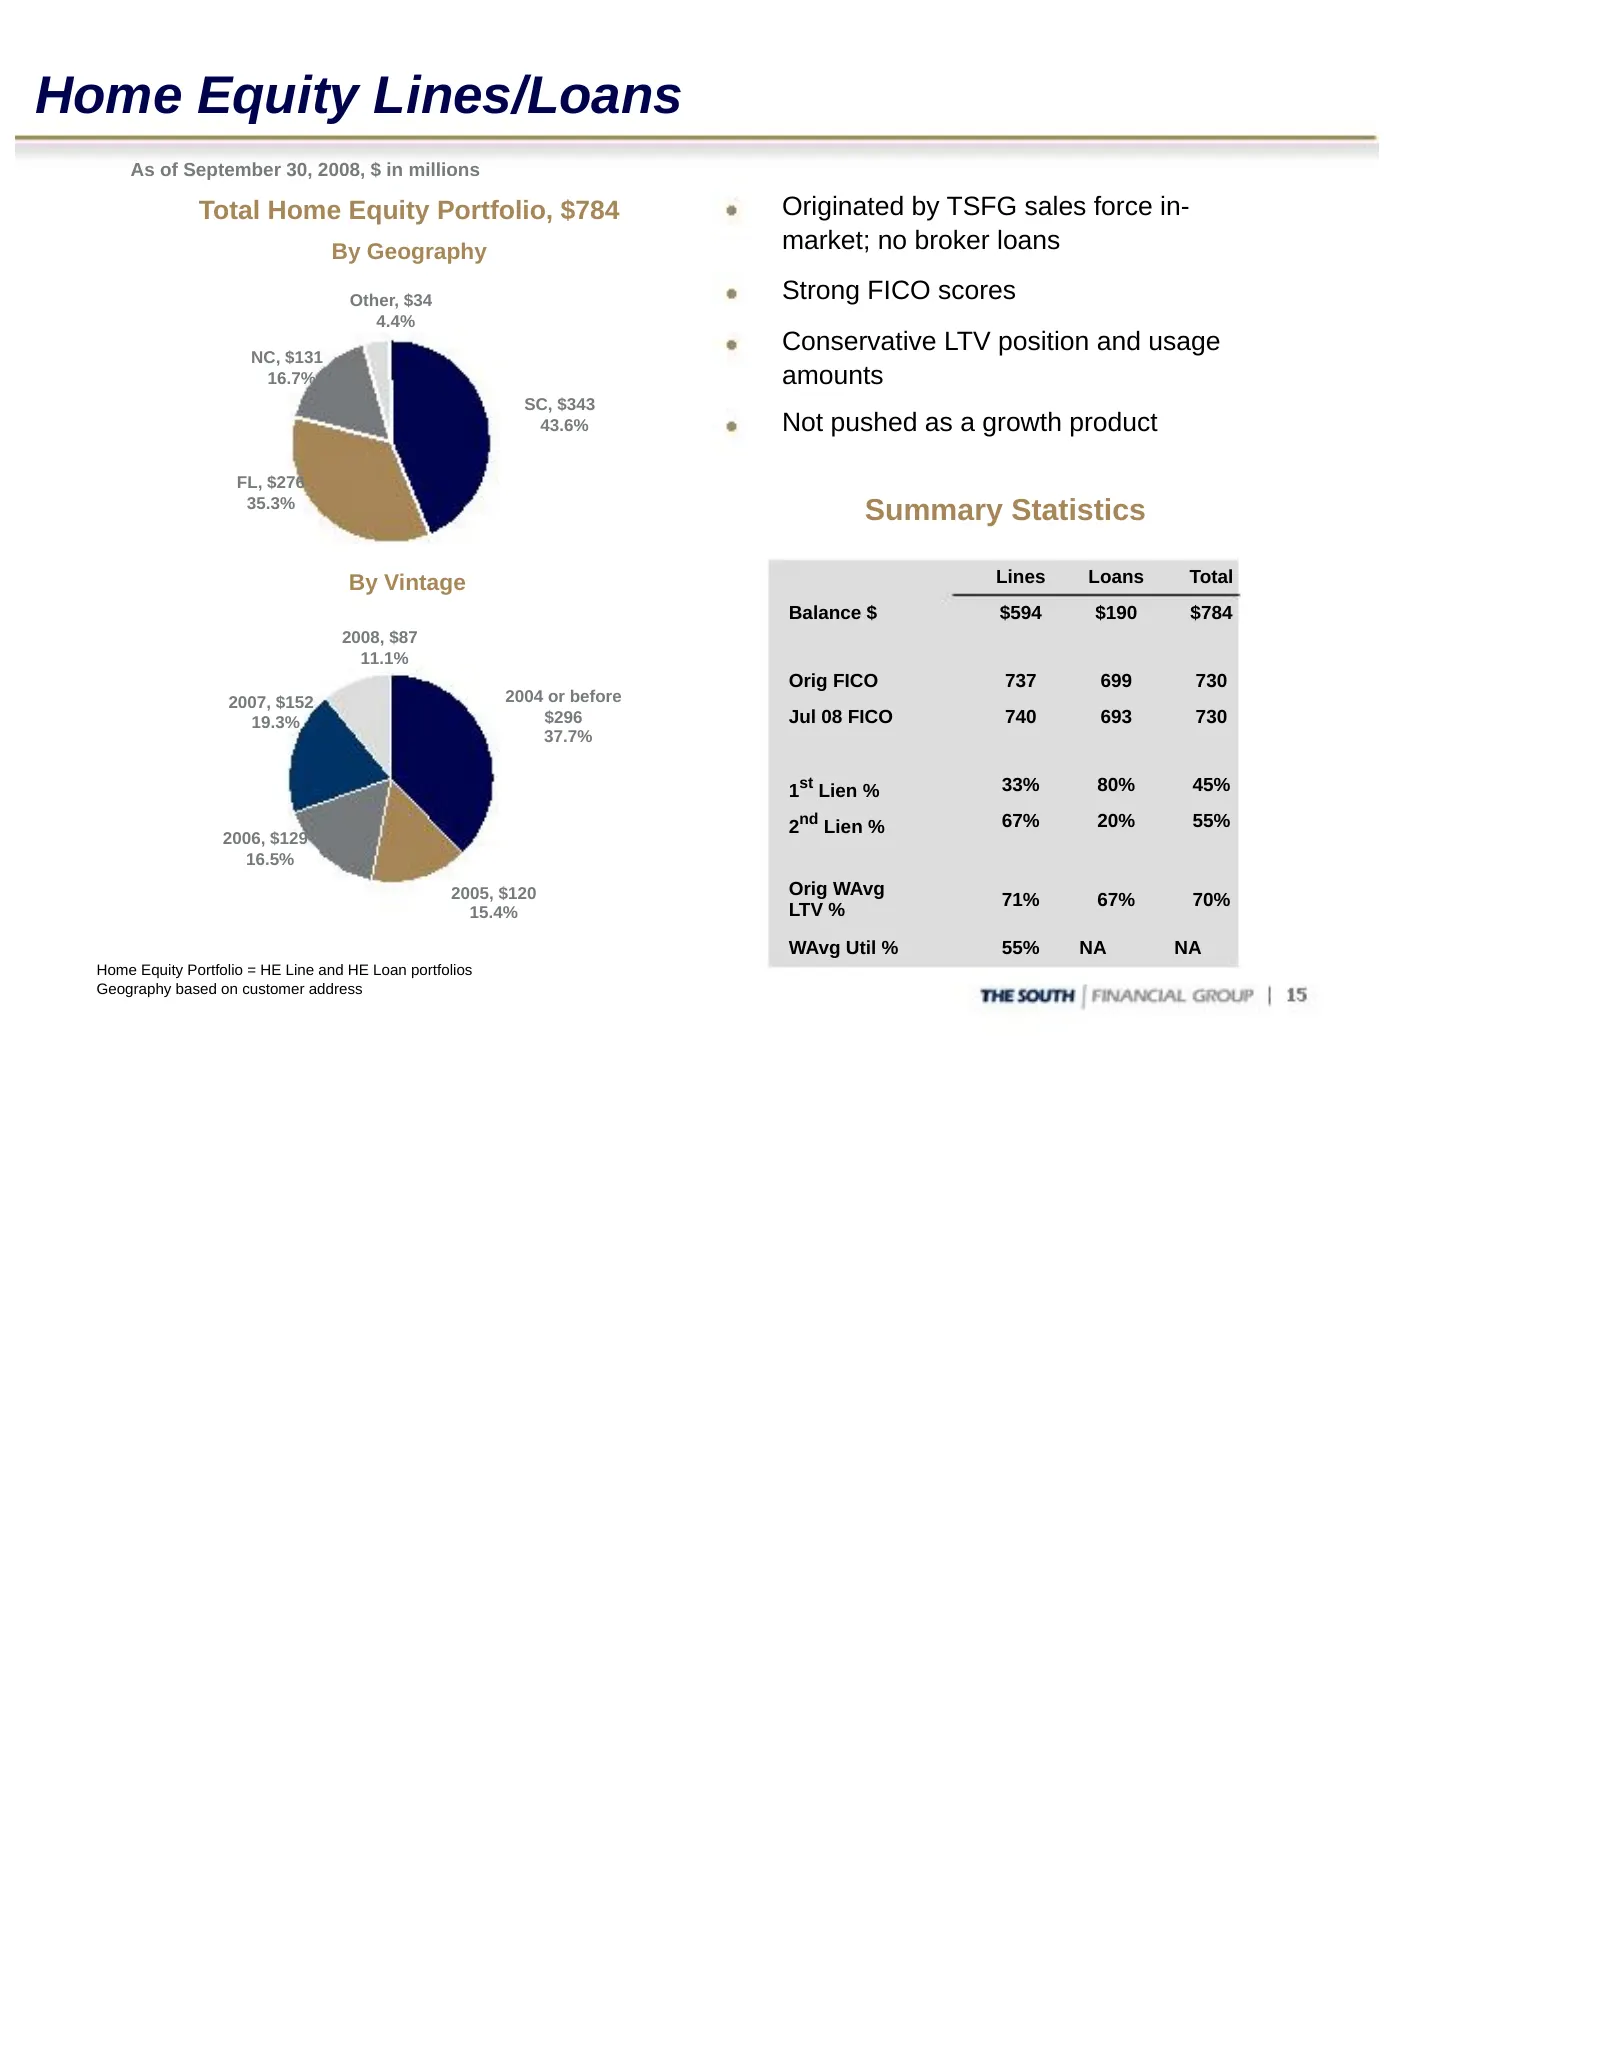
Home Equity Lines/Loans As of September 30, 2008, $ in millions Total Home Equity Portfolio, $784 Originated by TSFG sales force in- By Geography market; no broker loans Other, $34 Strong FICO scores 4.4% NC, $131 Conservative LTV position and usage 16.7% amounts SC, $343 43.6% Not pushed as a growt
Slide 16: Mortgage Banking Portfolio
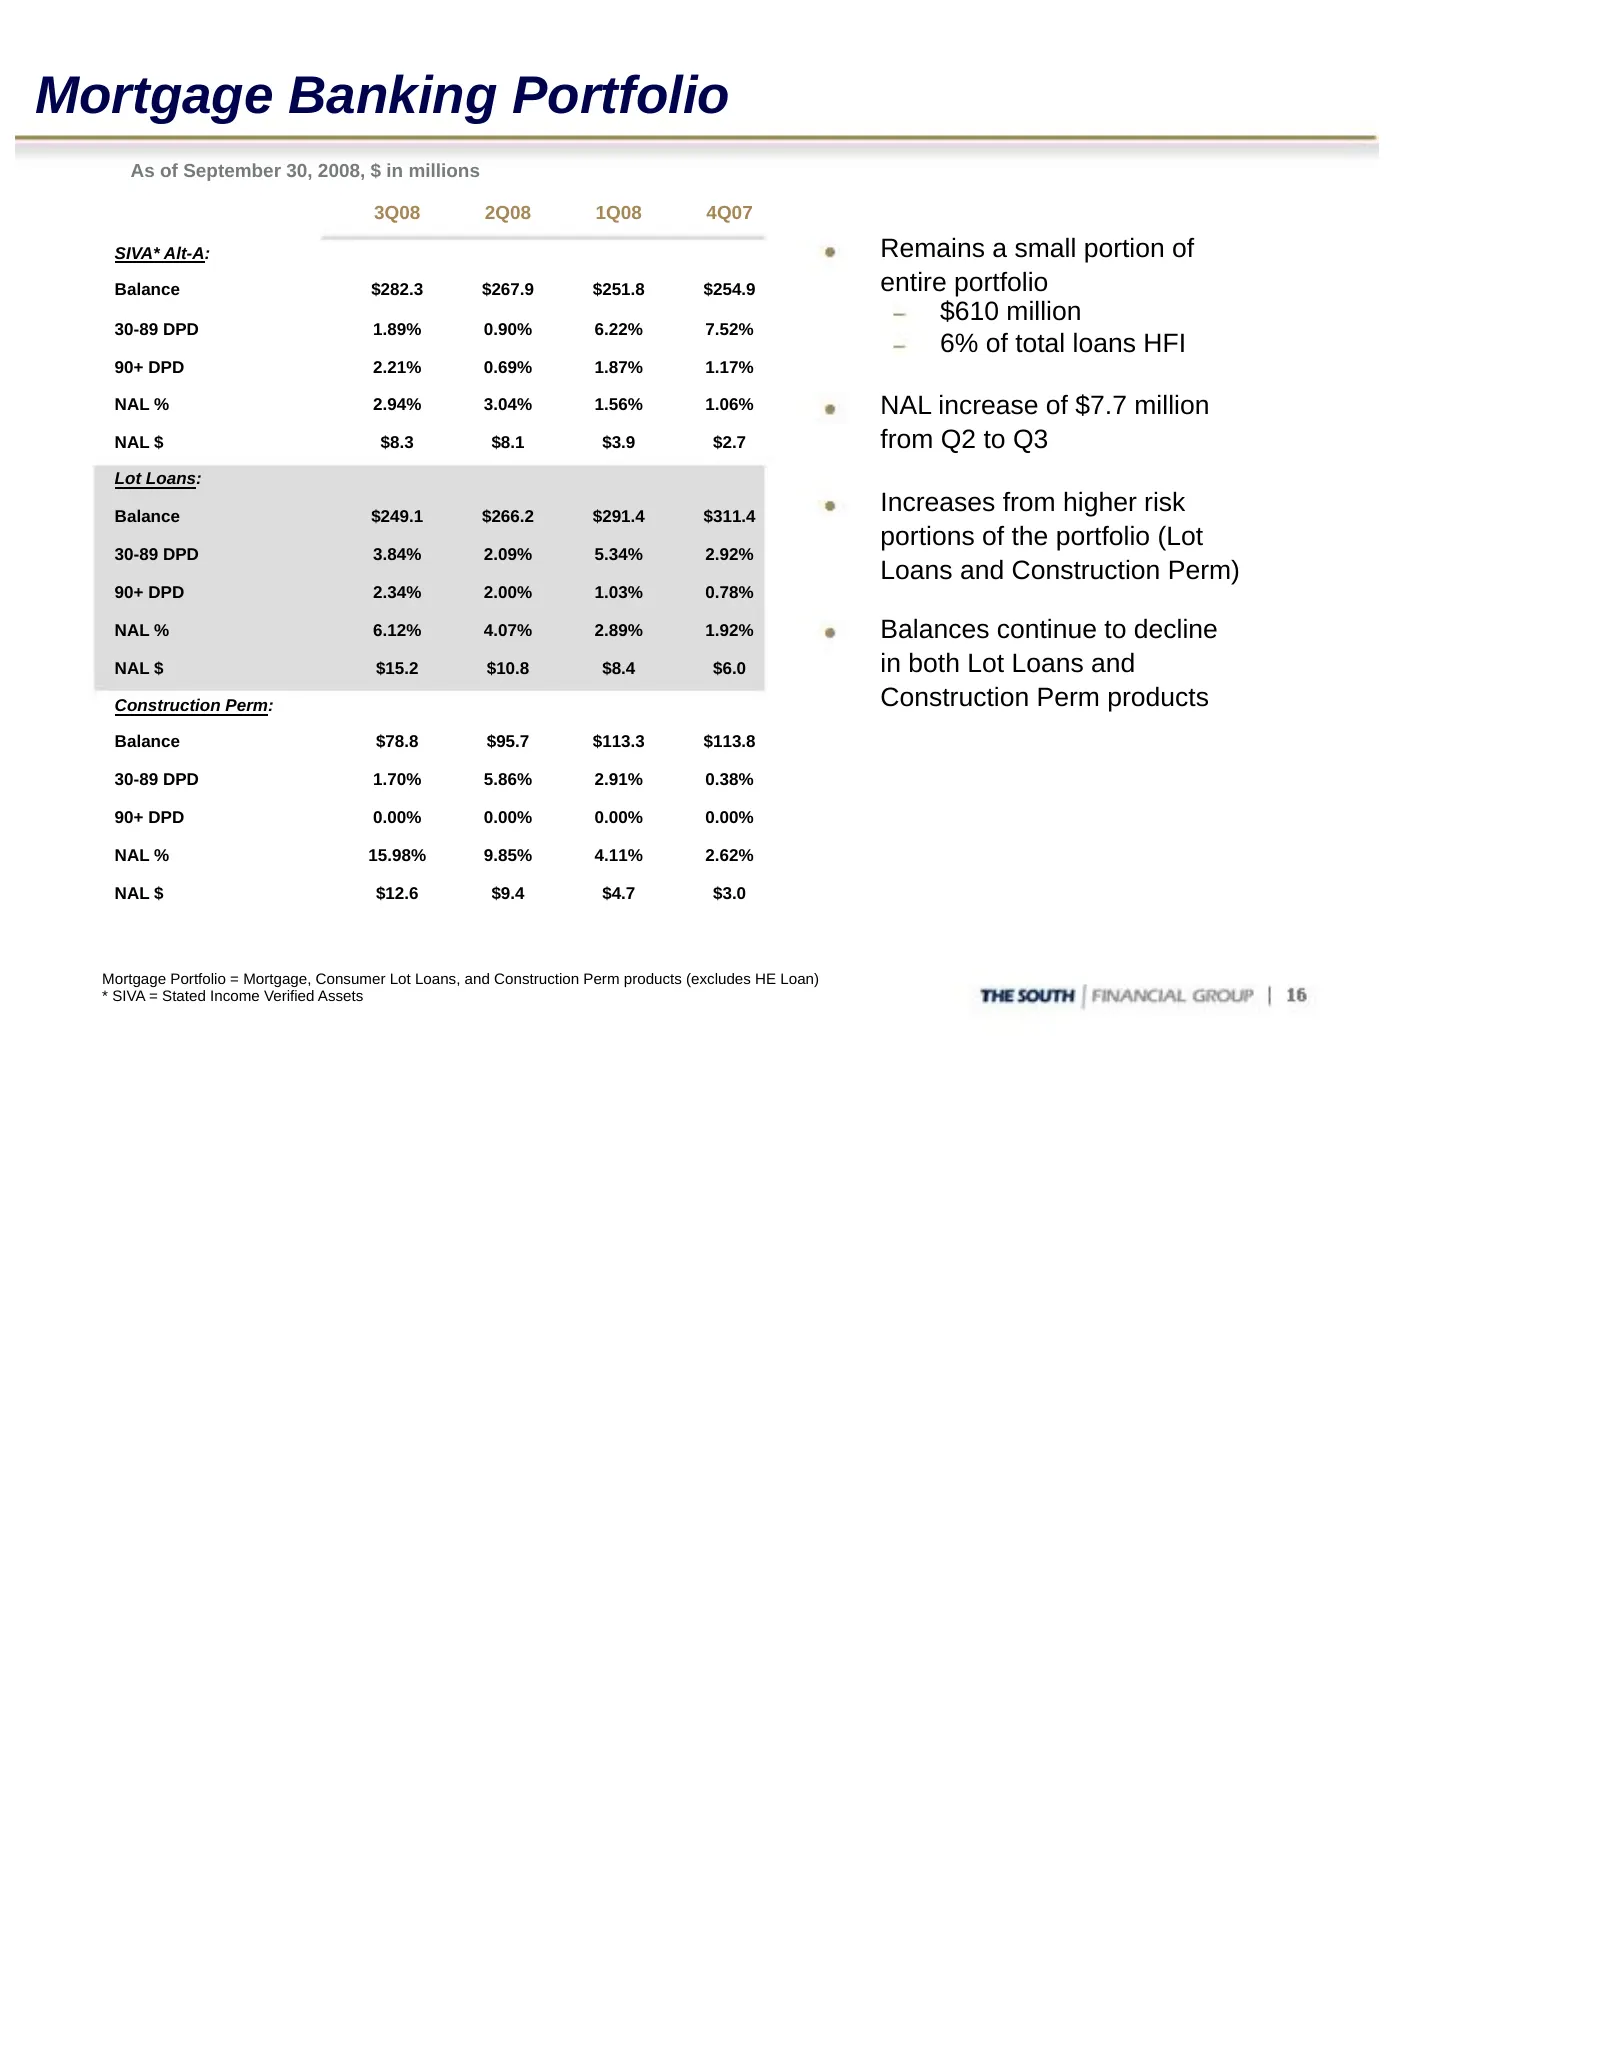
Mortgage Banking Portfolio As of September 30, 2008, $ in millions 3Q08 2Q08 1Q08 4Q07 SIVA* Alt-A: Remains a small portion of Balance $282.3 $267.9 $251.8 $254.9 entire portfolio $610 million 30-89 DPD 1.89% 0.90% 6.22% 7.52% 6% of total loans HFI 90+ DPD 2.21% 0.69% 1.87% 1.17% NAL % 2.94% 3.04% 1
Slide 17: Net Interest Margin
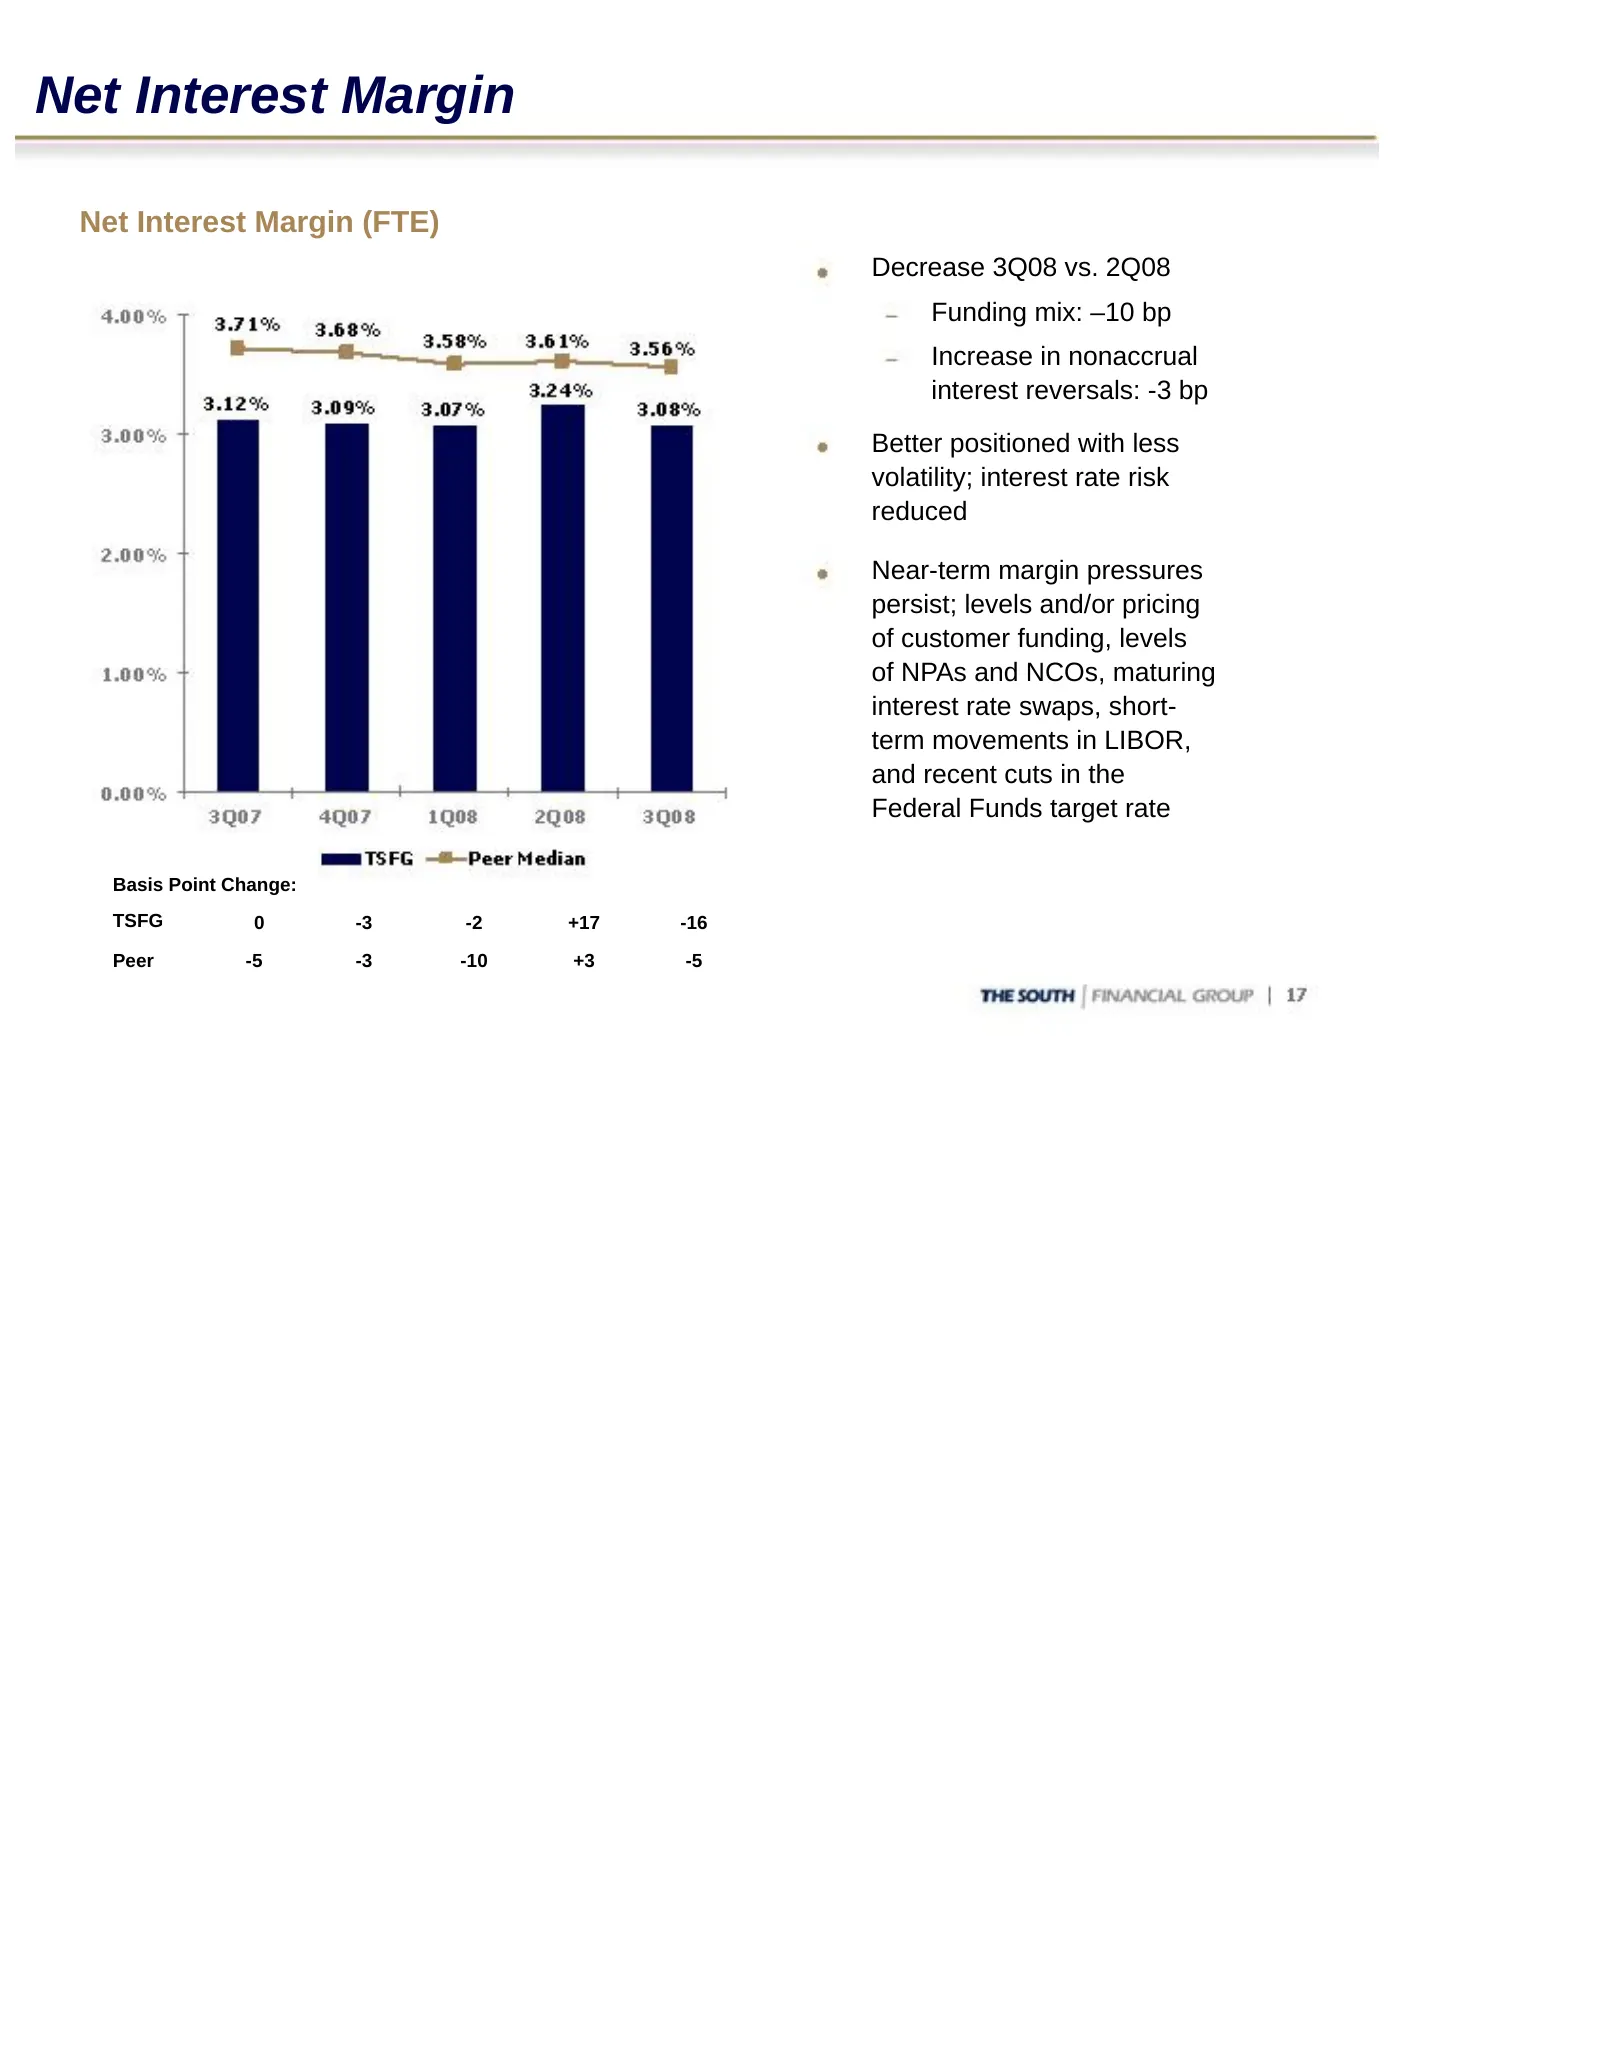
Net Interest Margin Net Interest Margin (FTE) Decrease 3Q08 vs. 2Q08 Funding mix: –10 bp Increase in nonaccrual interest reversals: -3 bp Better positioned with less volatility; interest rate risk reduced Near-term margin pressures persist; levels and/or pricing of customer funding, levels of NPAs a
Slide 18: Customer Funding
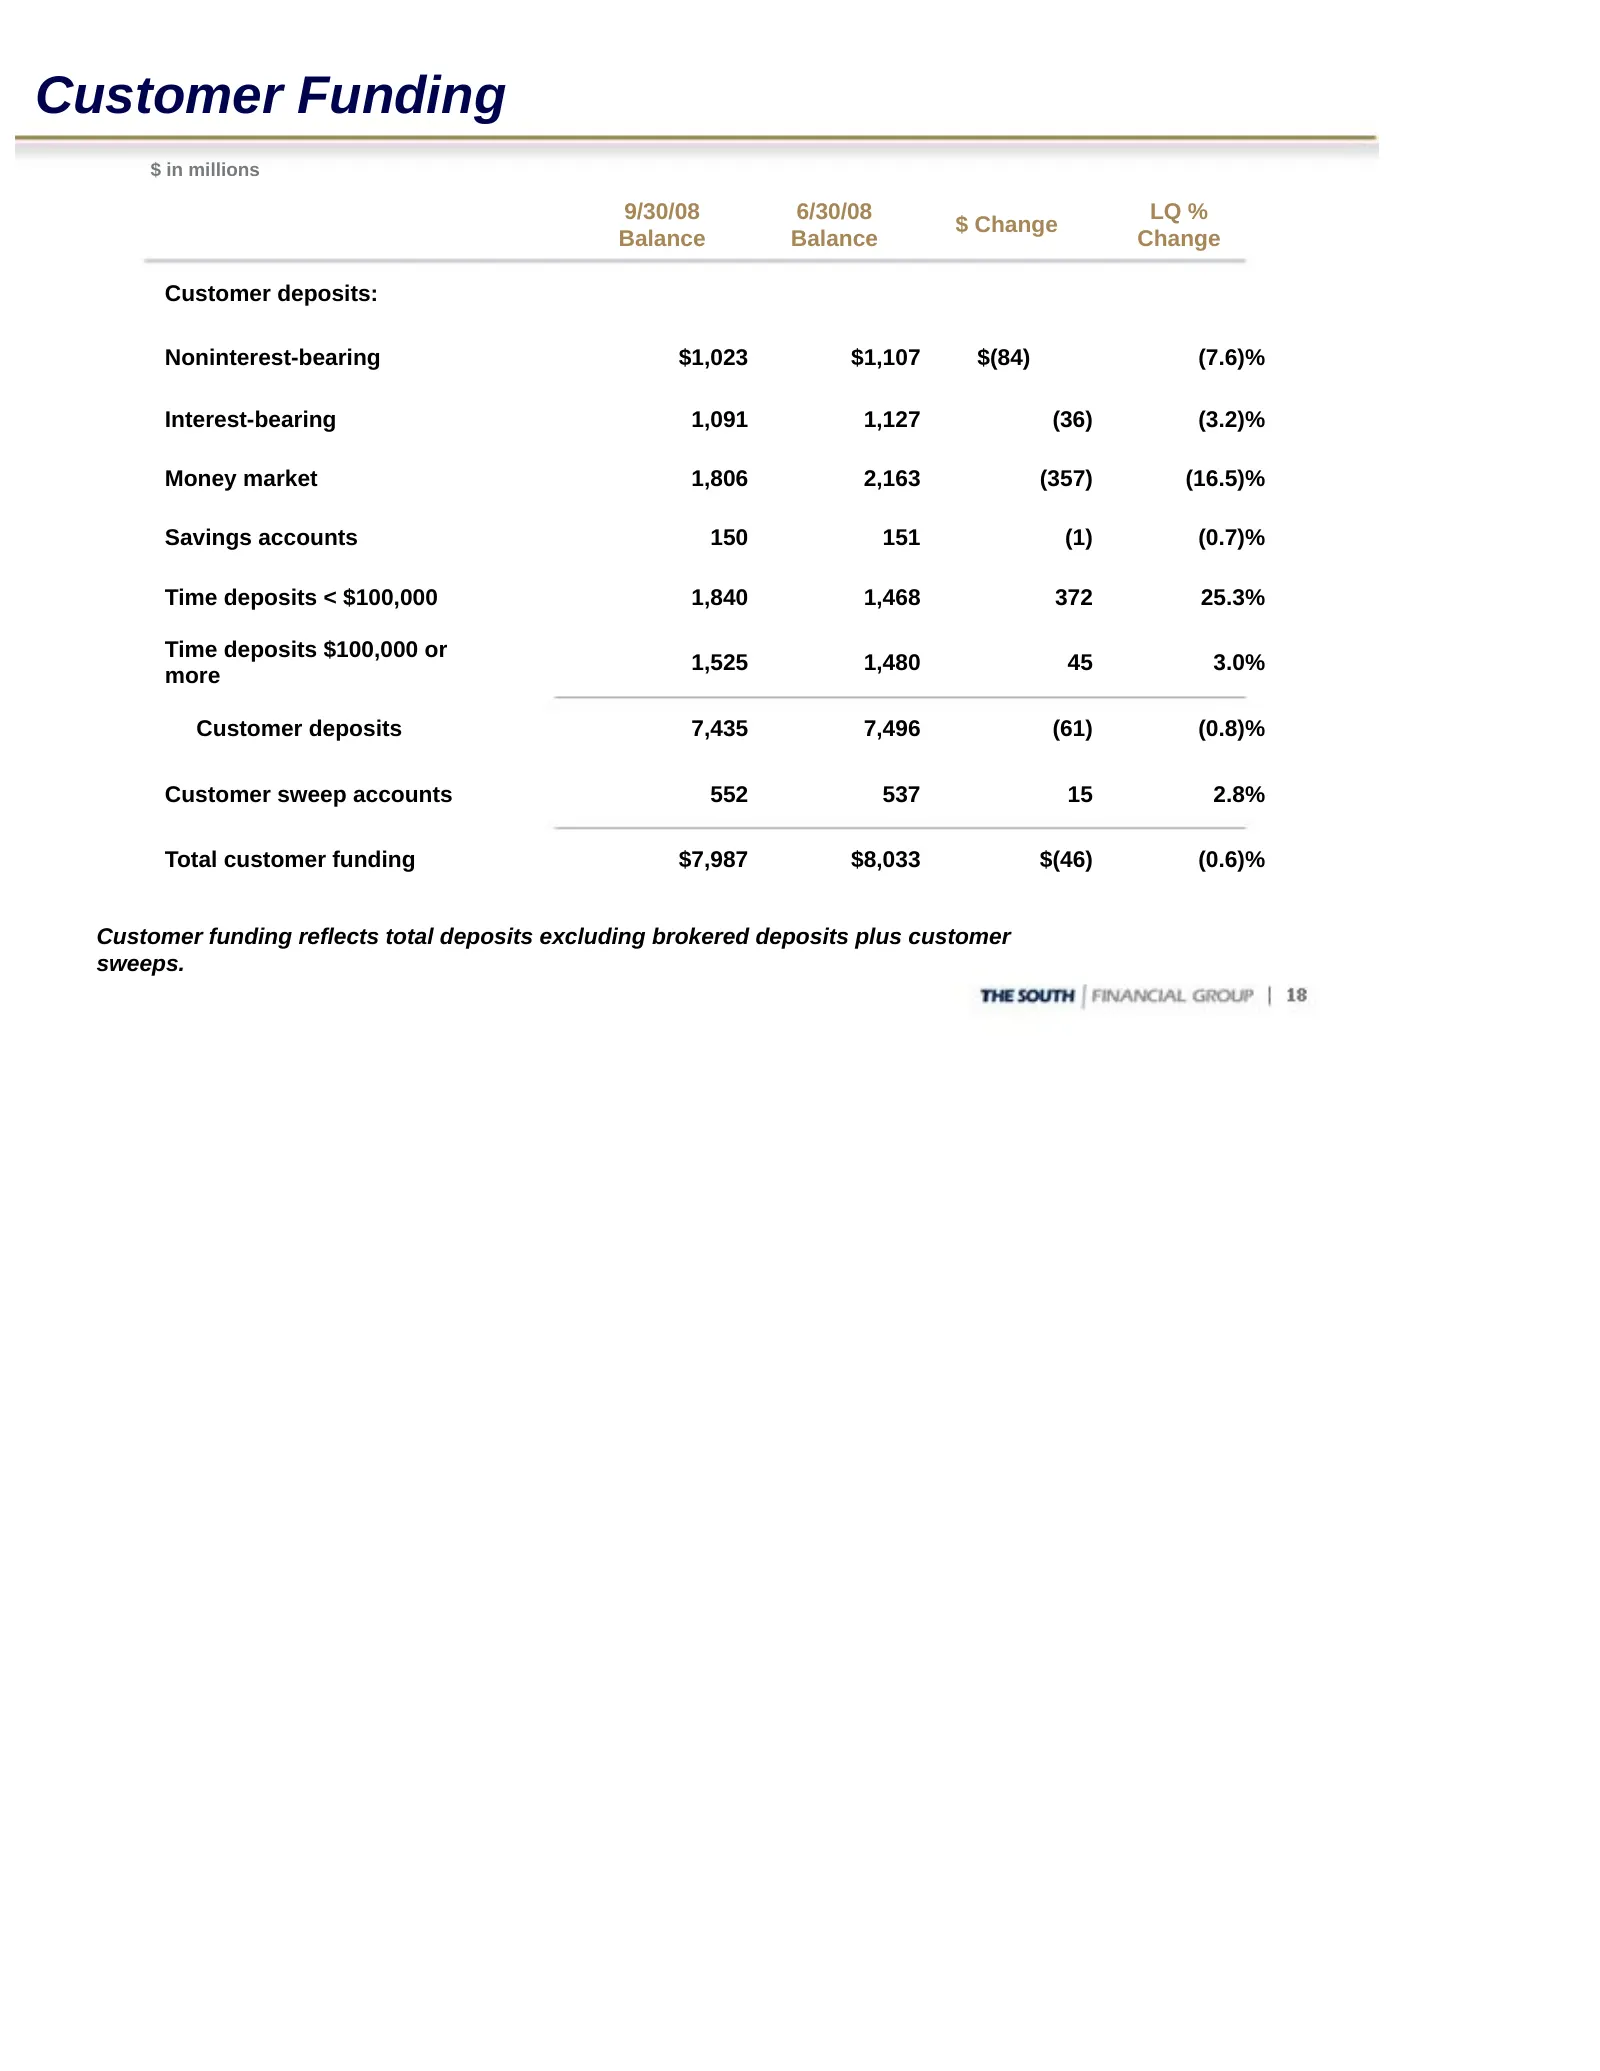
Customer Funding $ in millions 9/30/08 6/30/08 LQ % $ Change Balance Balance Change Customer deposits: Noninterest-bearing $1,023 $1,107 $(84) (7.6)% Interest-bearing 1,091 1,127 (36) (3.2)% Money market 1,806 2,163 (357) (16.5)% Savings accounts 150 151 (1) (0.7)% Time deposits < $100,000 1,840 1,4
Slide 19: Wholesale Borrowings
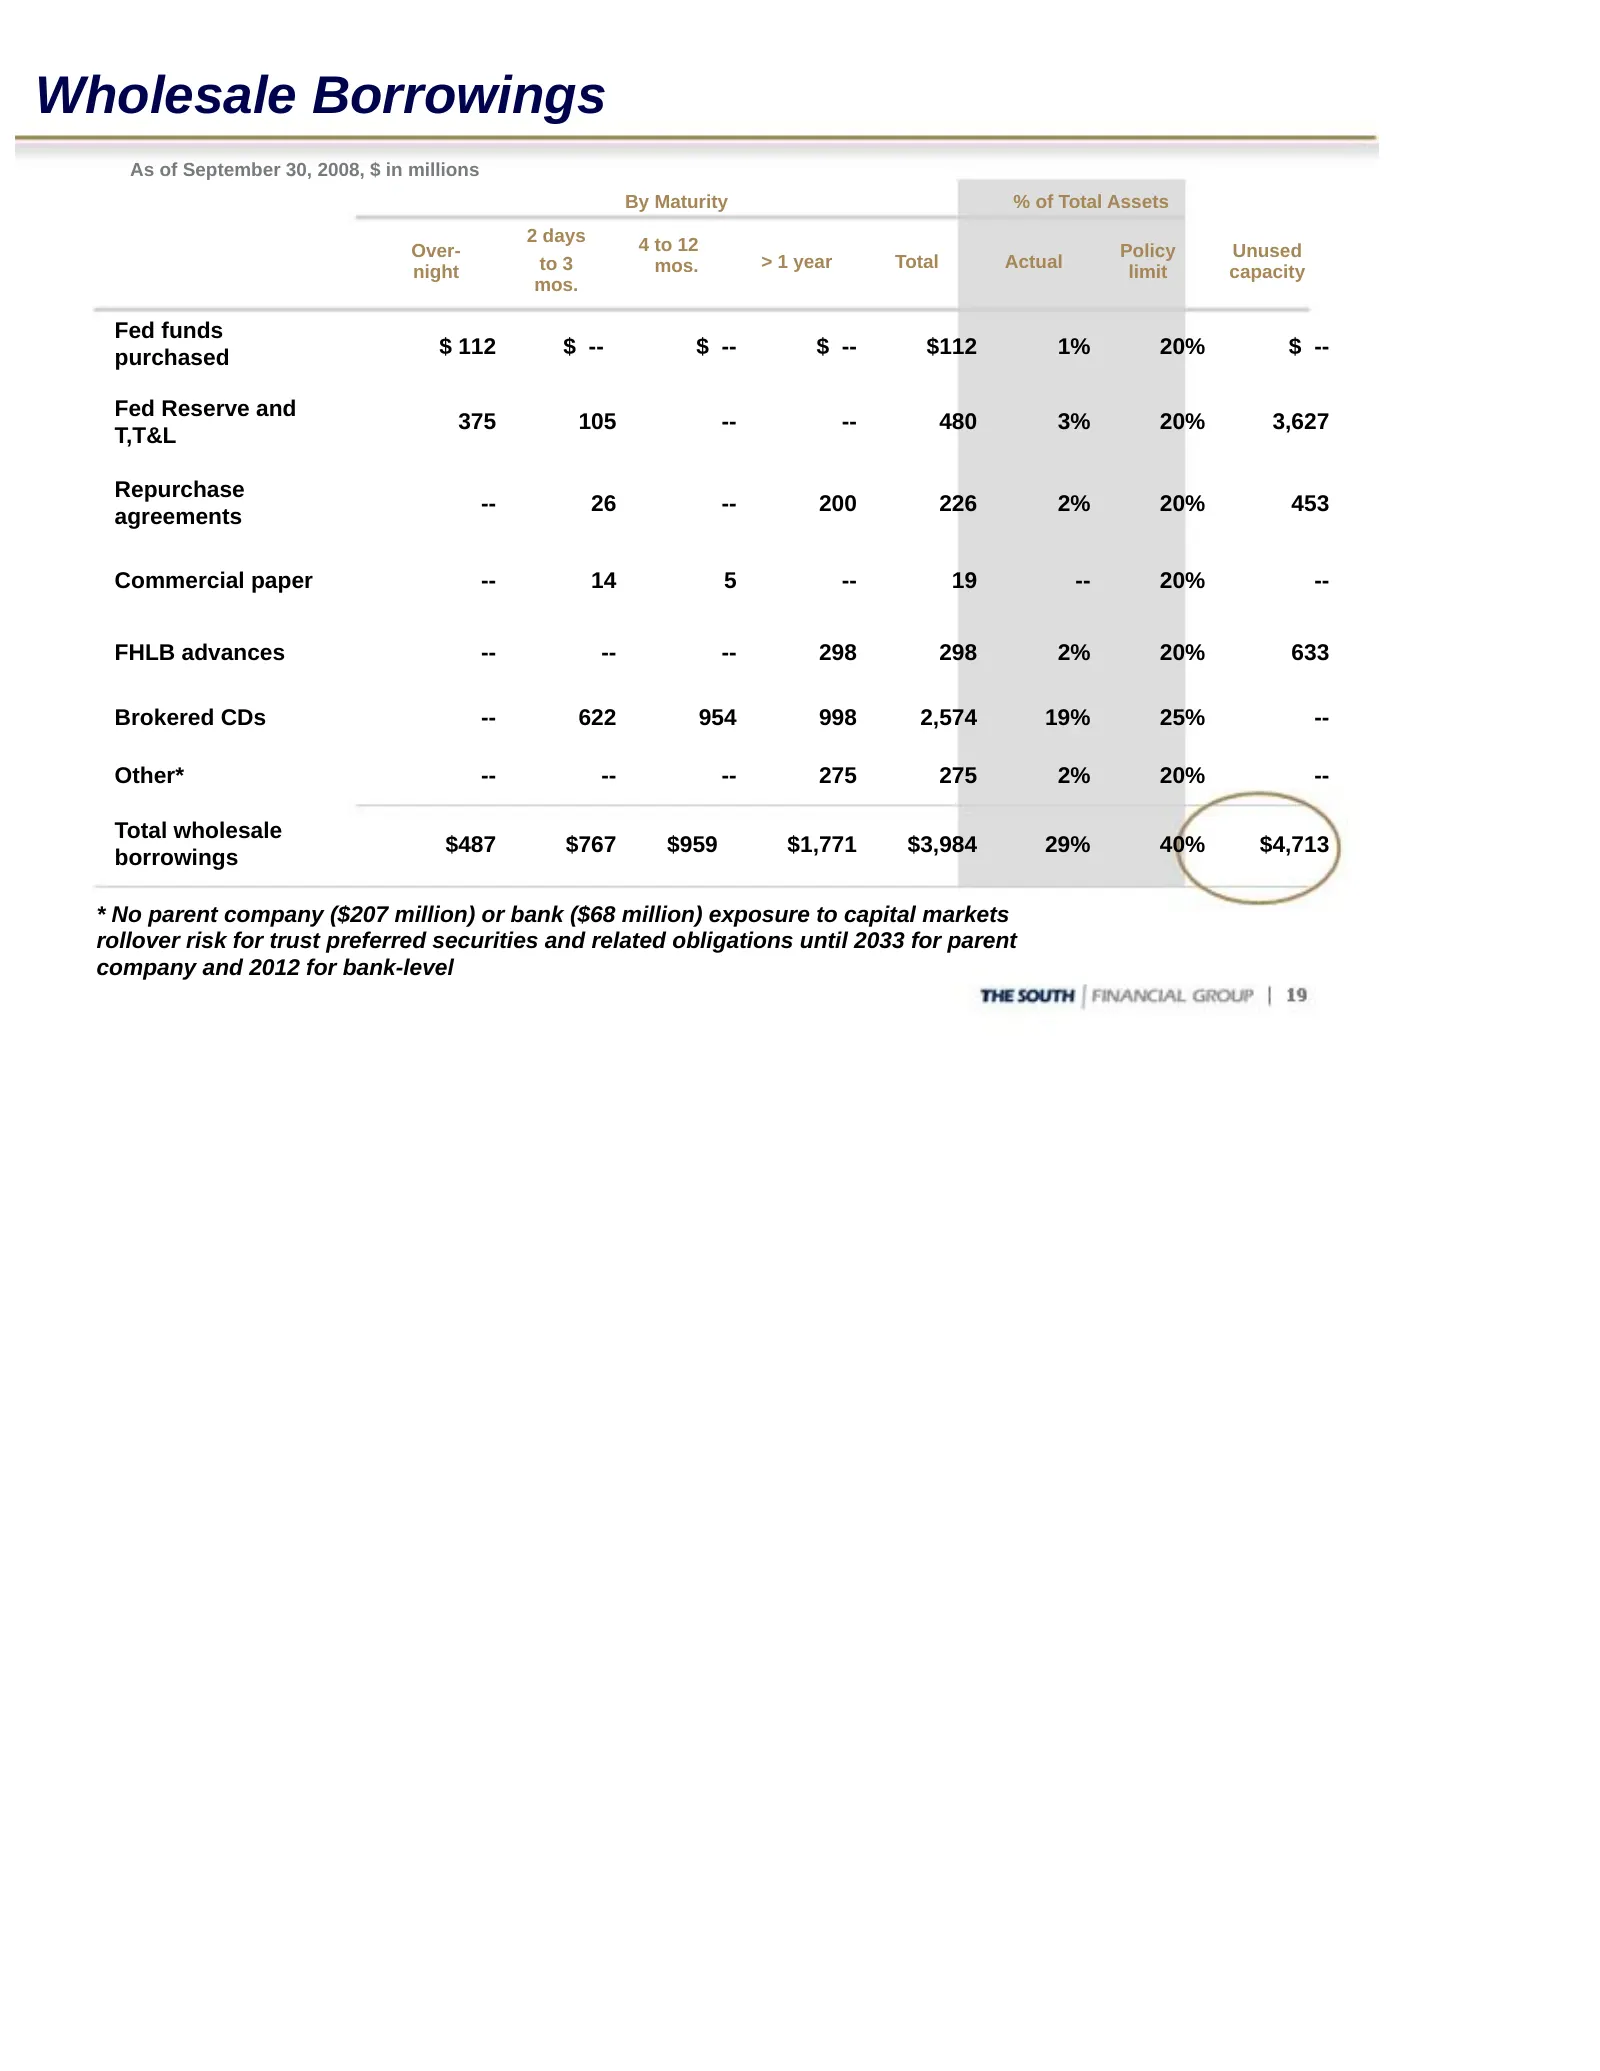
Wholesale Borrowings As of September 30, 2008, $ in millions By Maturity % of Total Assets 2 days 4 to 12 Over- Policy Unused night to 3 mos. > 1 year Total Actual limit capacity mos. Fed funds purchased $ 112 $ -- $ -- $ -- $112 1% 20% $ -- Fed Reserve and 375 105 -- -- 480 3% 20% 3,627 T,T&L Repur
Slide 20: Capital Position
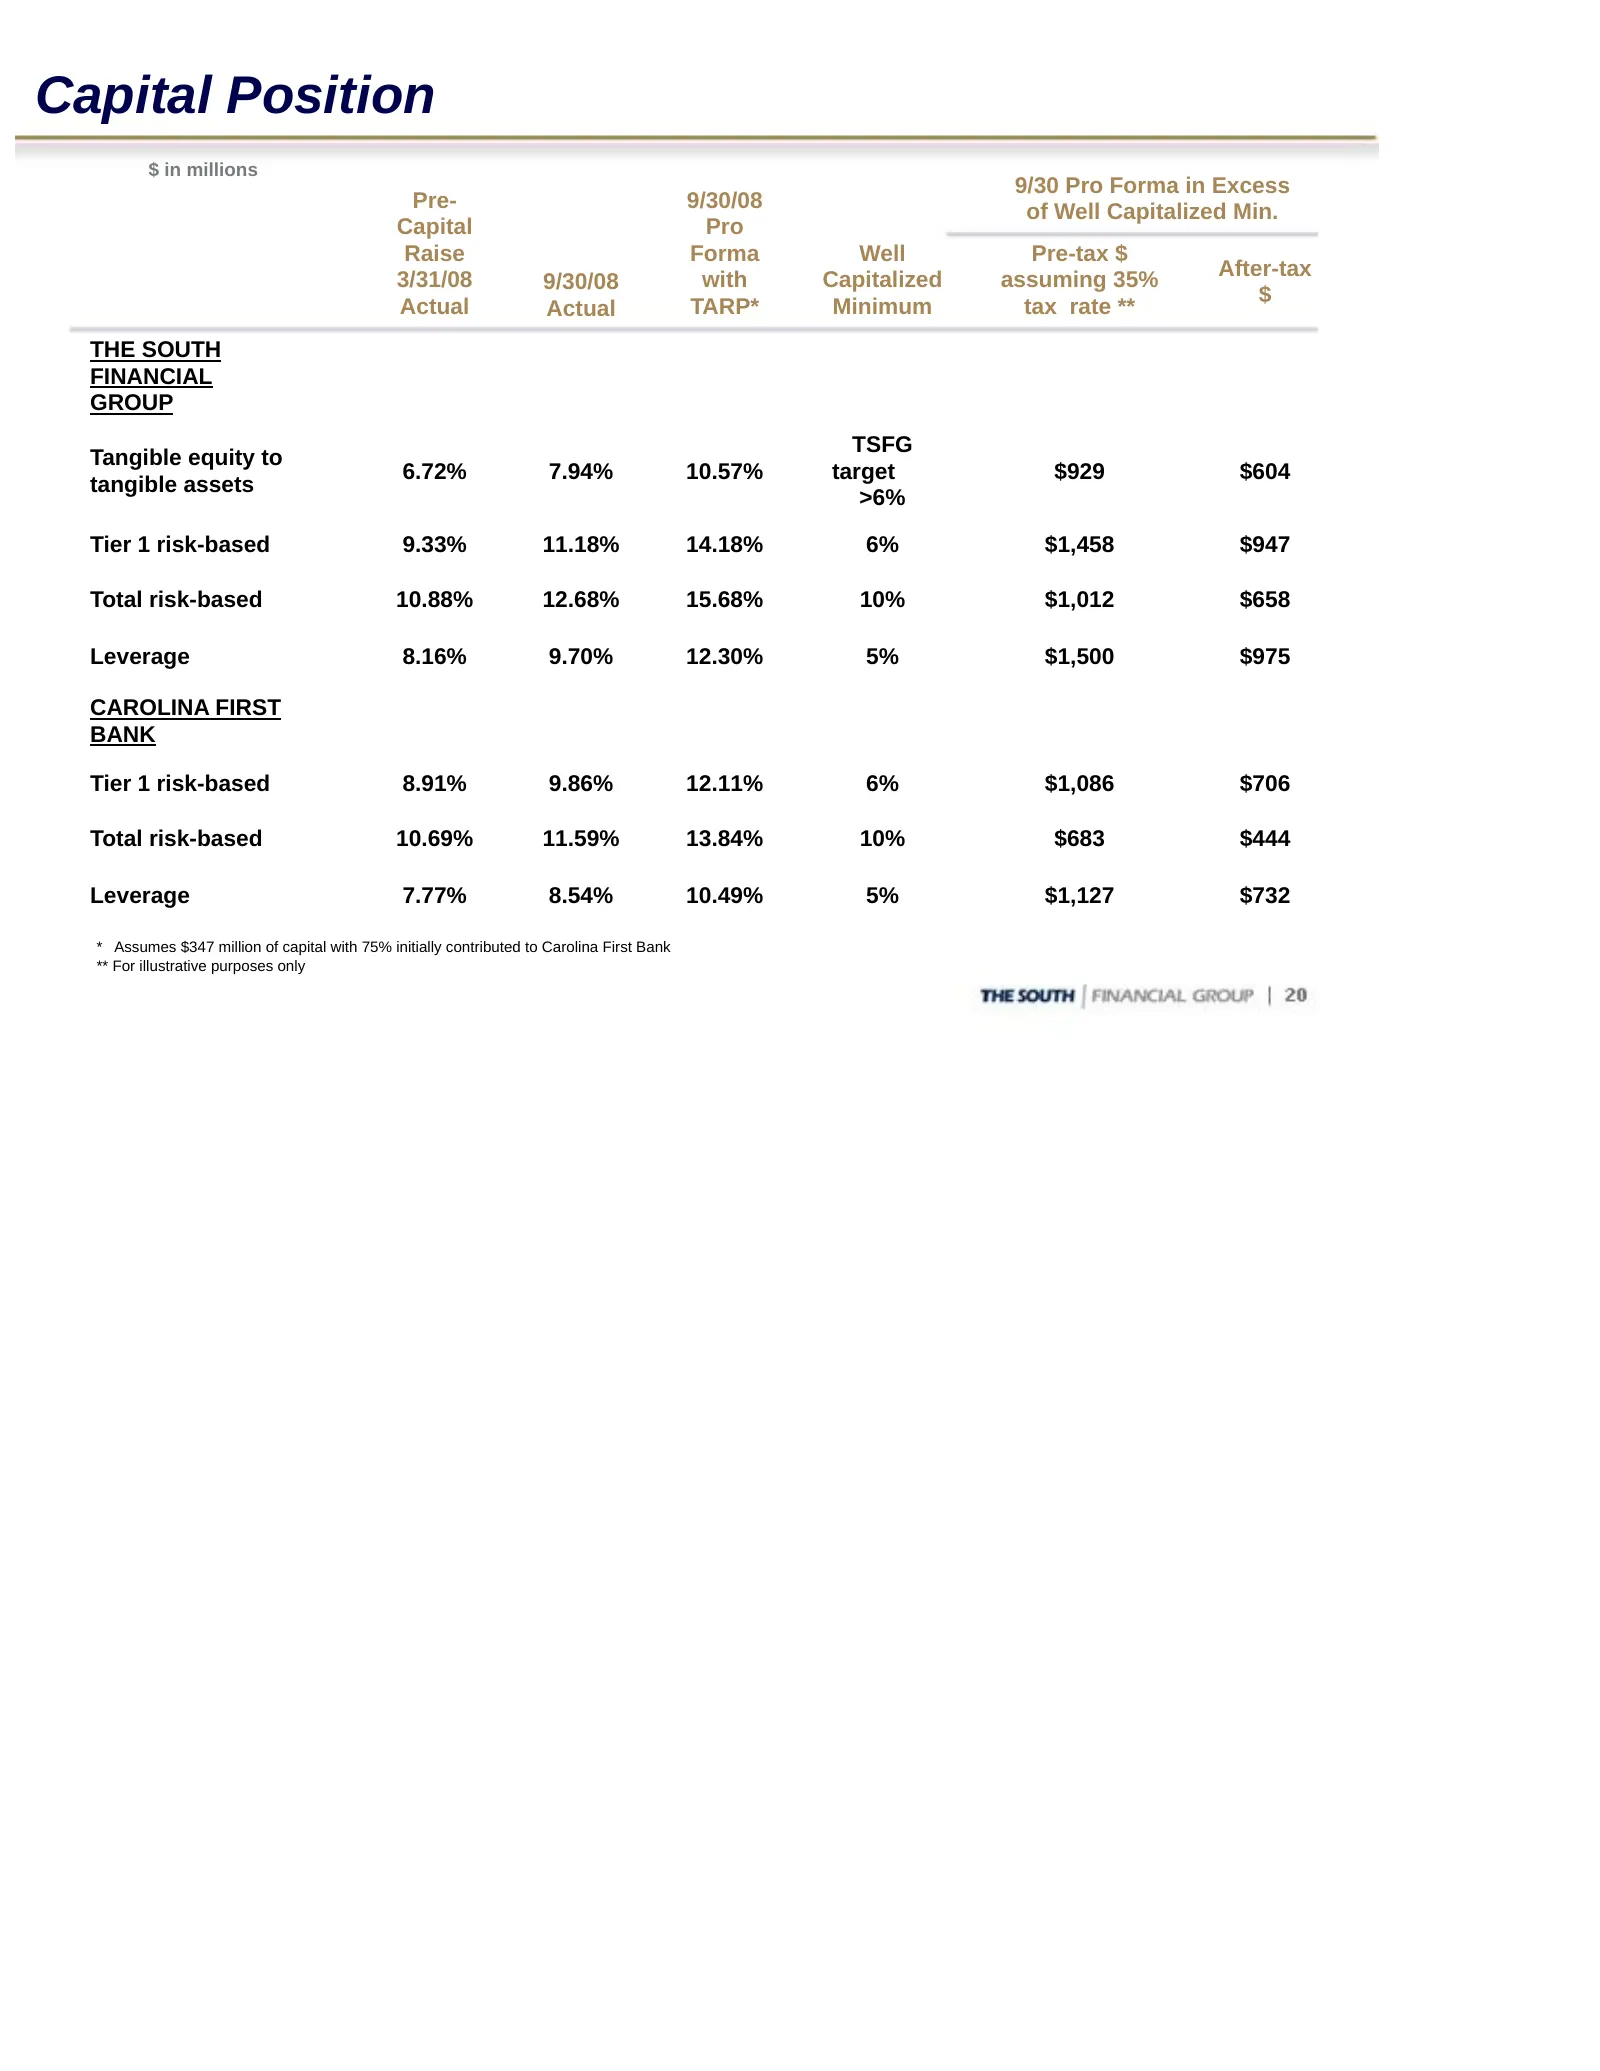
Capital Position $ in millions 9/30 Pro Forma in Excess Pre- 9/30/08 of Well Capitalized Min. Capital Pro Raise Forma Well Pre-tax $ After-tax 3/31/08 9/30/08 with Capitalized assuming 35% $ Actual Actual TARP* Minimum tax rate ** THE SOUTH FINANCIAL GROUP TSFG Tangible equity to 6.72% 7.94% 10.57%
Slide 21: Noninterest Expenses
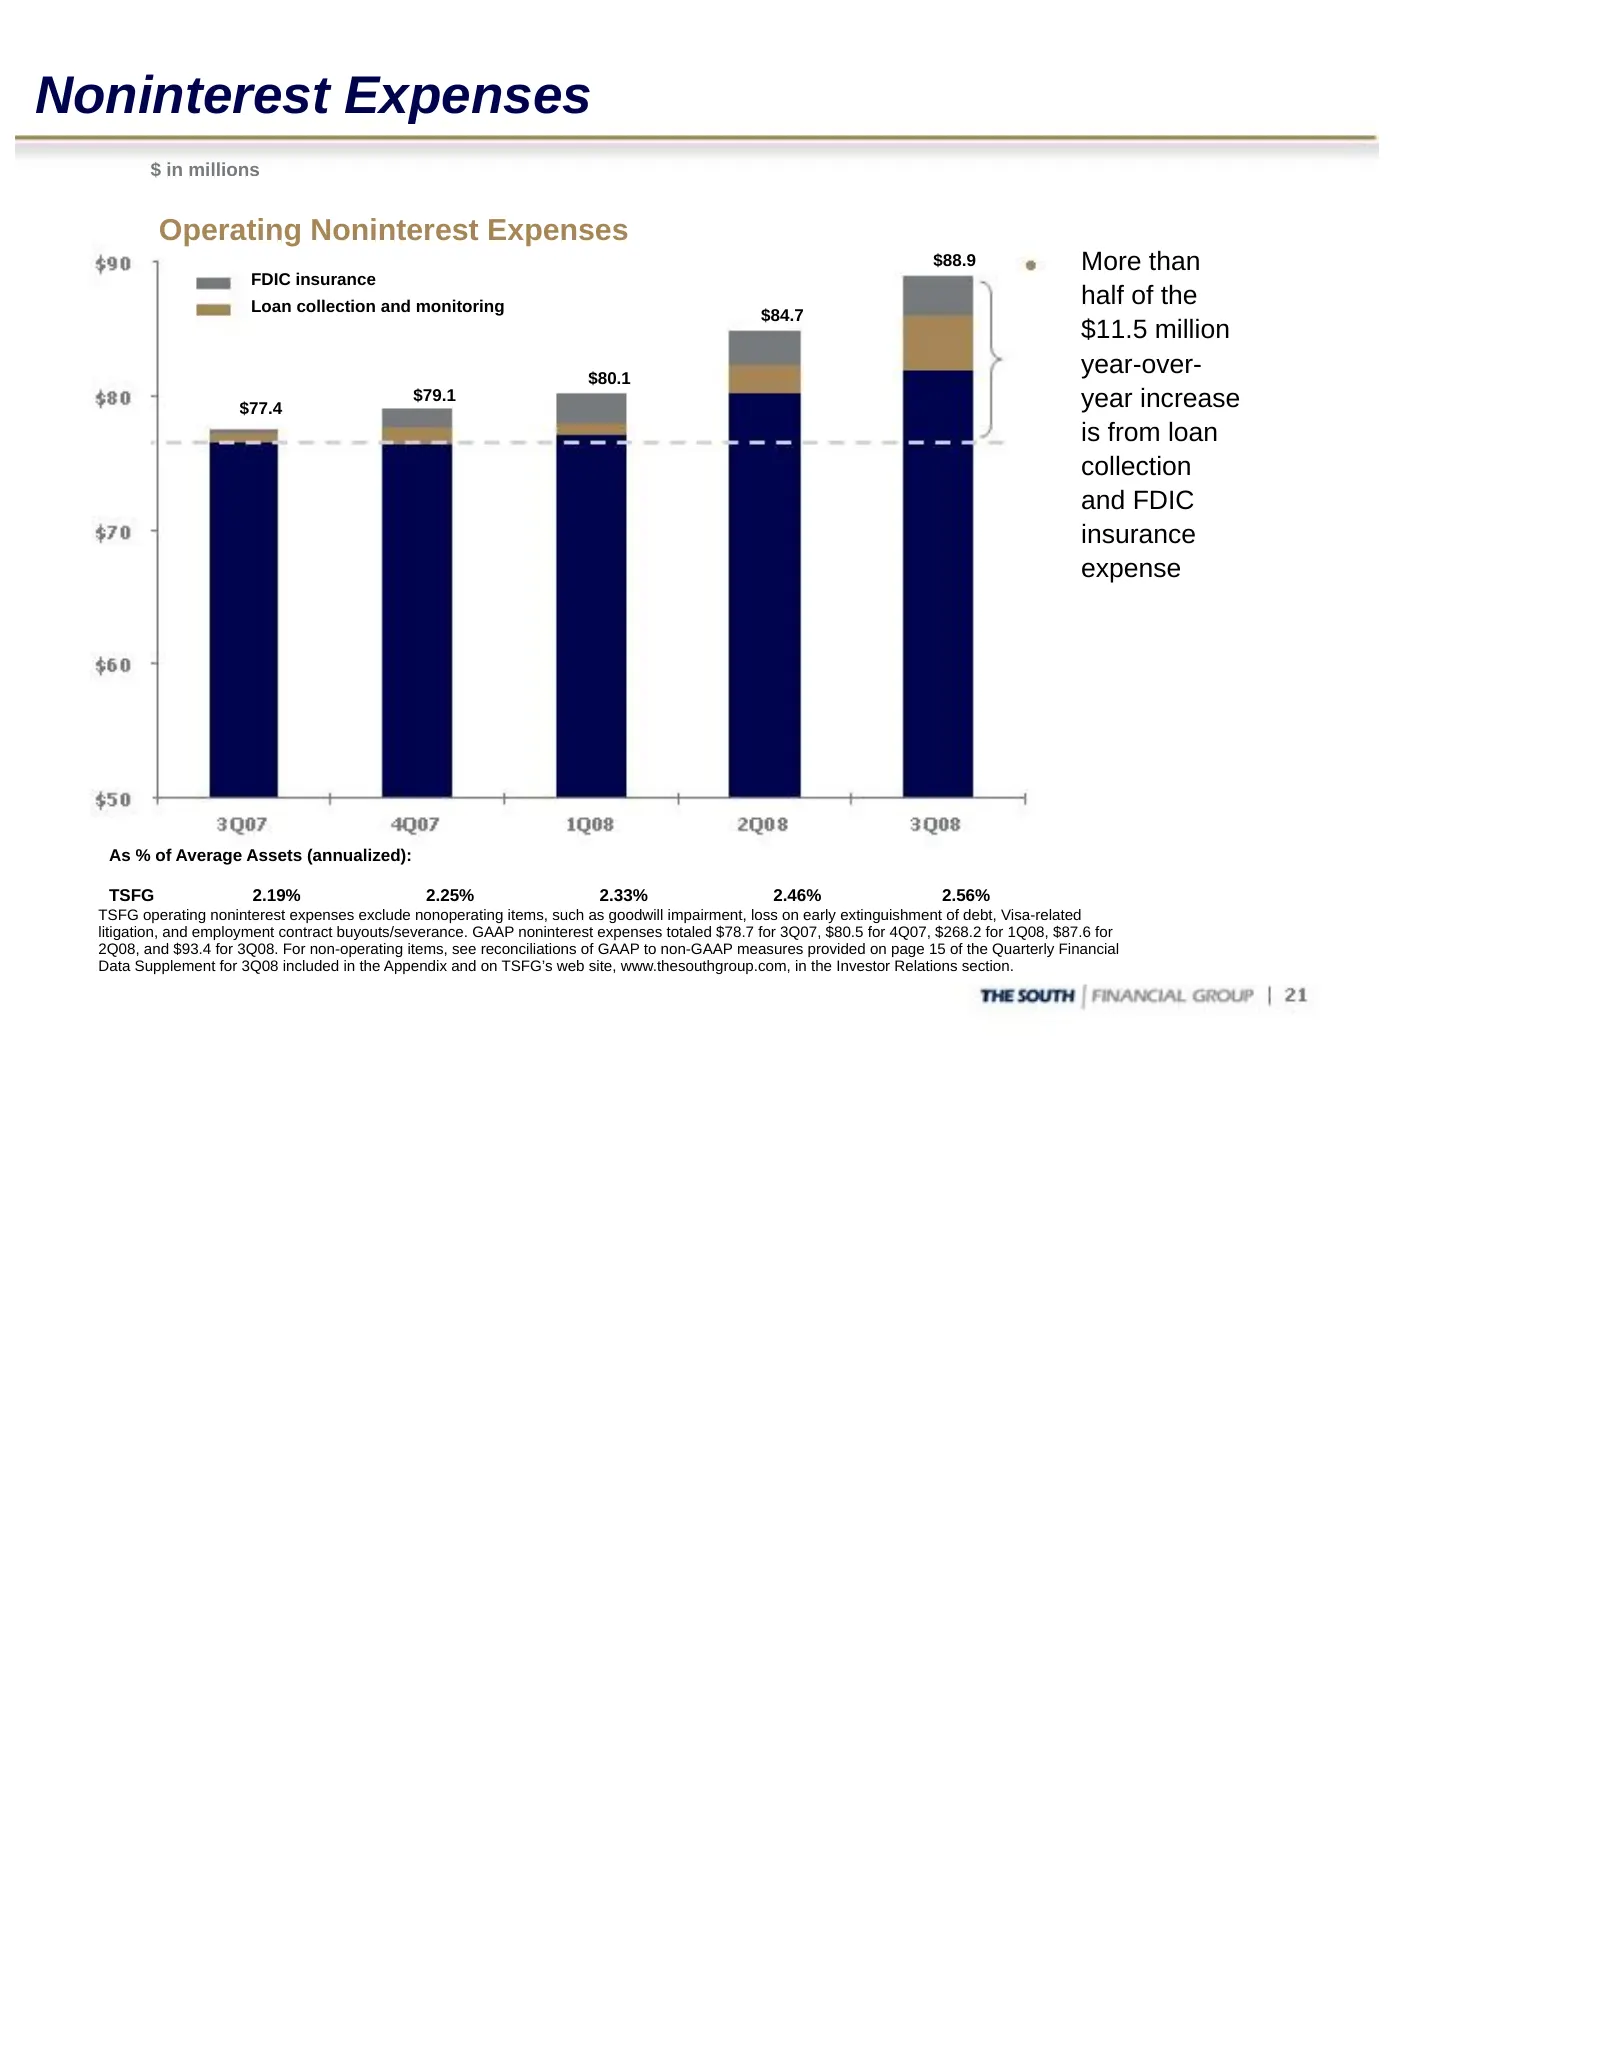
Noninterest Expenses $ in millions Operating Noninterest Expenses $88.9 More than FDIC insurance Loan collection and monitoring half of the $84.7 $11.5 million $80.1 year-over- $77.4 $79.1 year increase is from loan collection and FDIC insurance expense As % of Average Assets (annualized): TSFG 2.19
Slide 22: Efficiency Improvement Project
Efficiency Improvement Project Three fundamental objectives: Increase revenue Improve our customers’ experience Manage expenses Emphasis on improving the customer experience by improving workflows, policies, and procedures Specific examples include back office branch operations, lending process rede
Slide 23: Noninterest Income
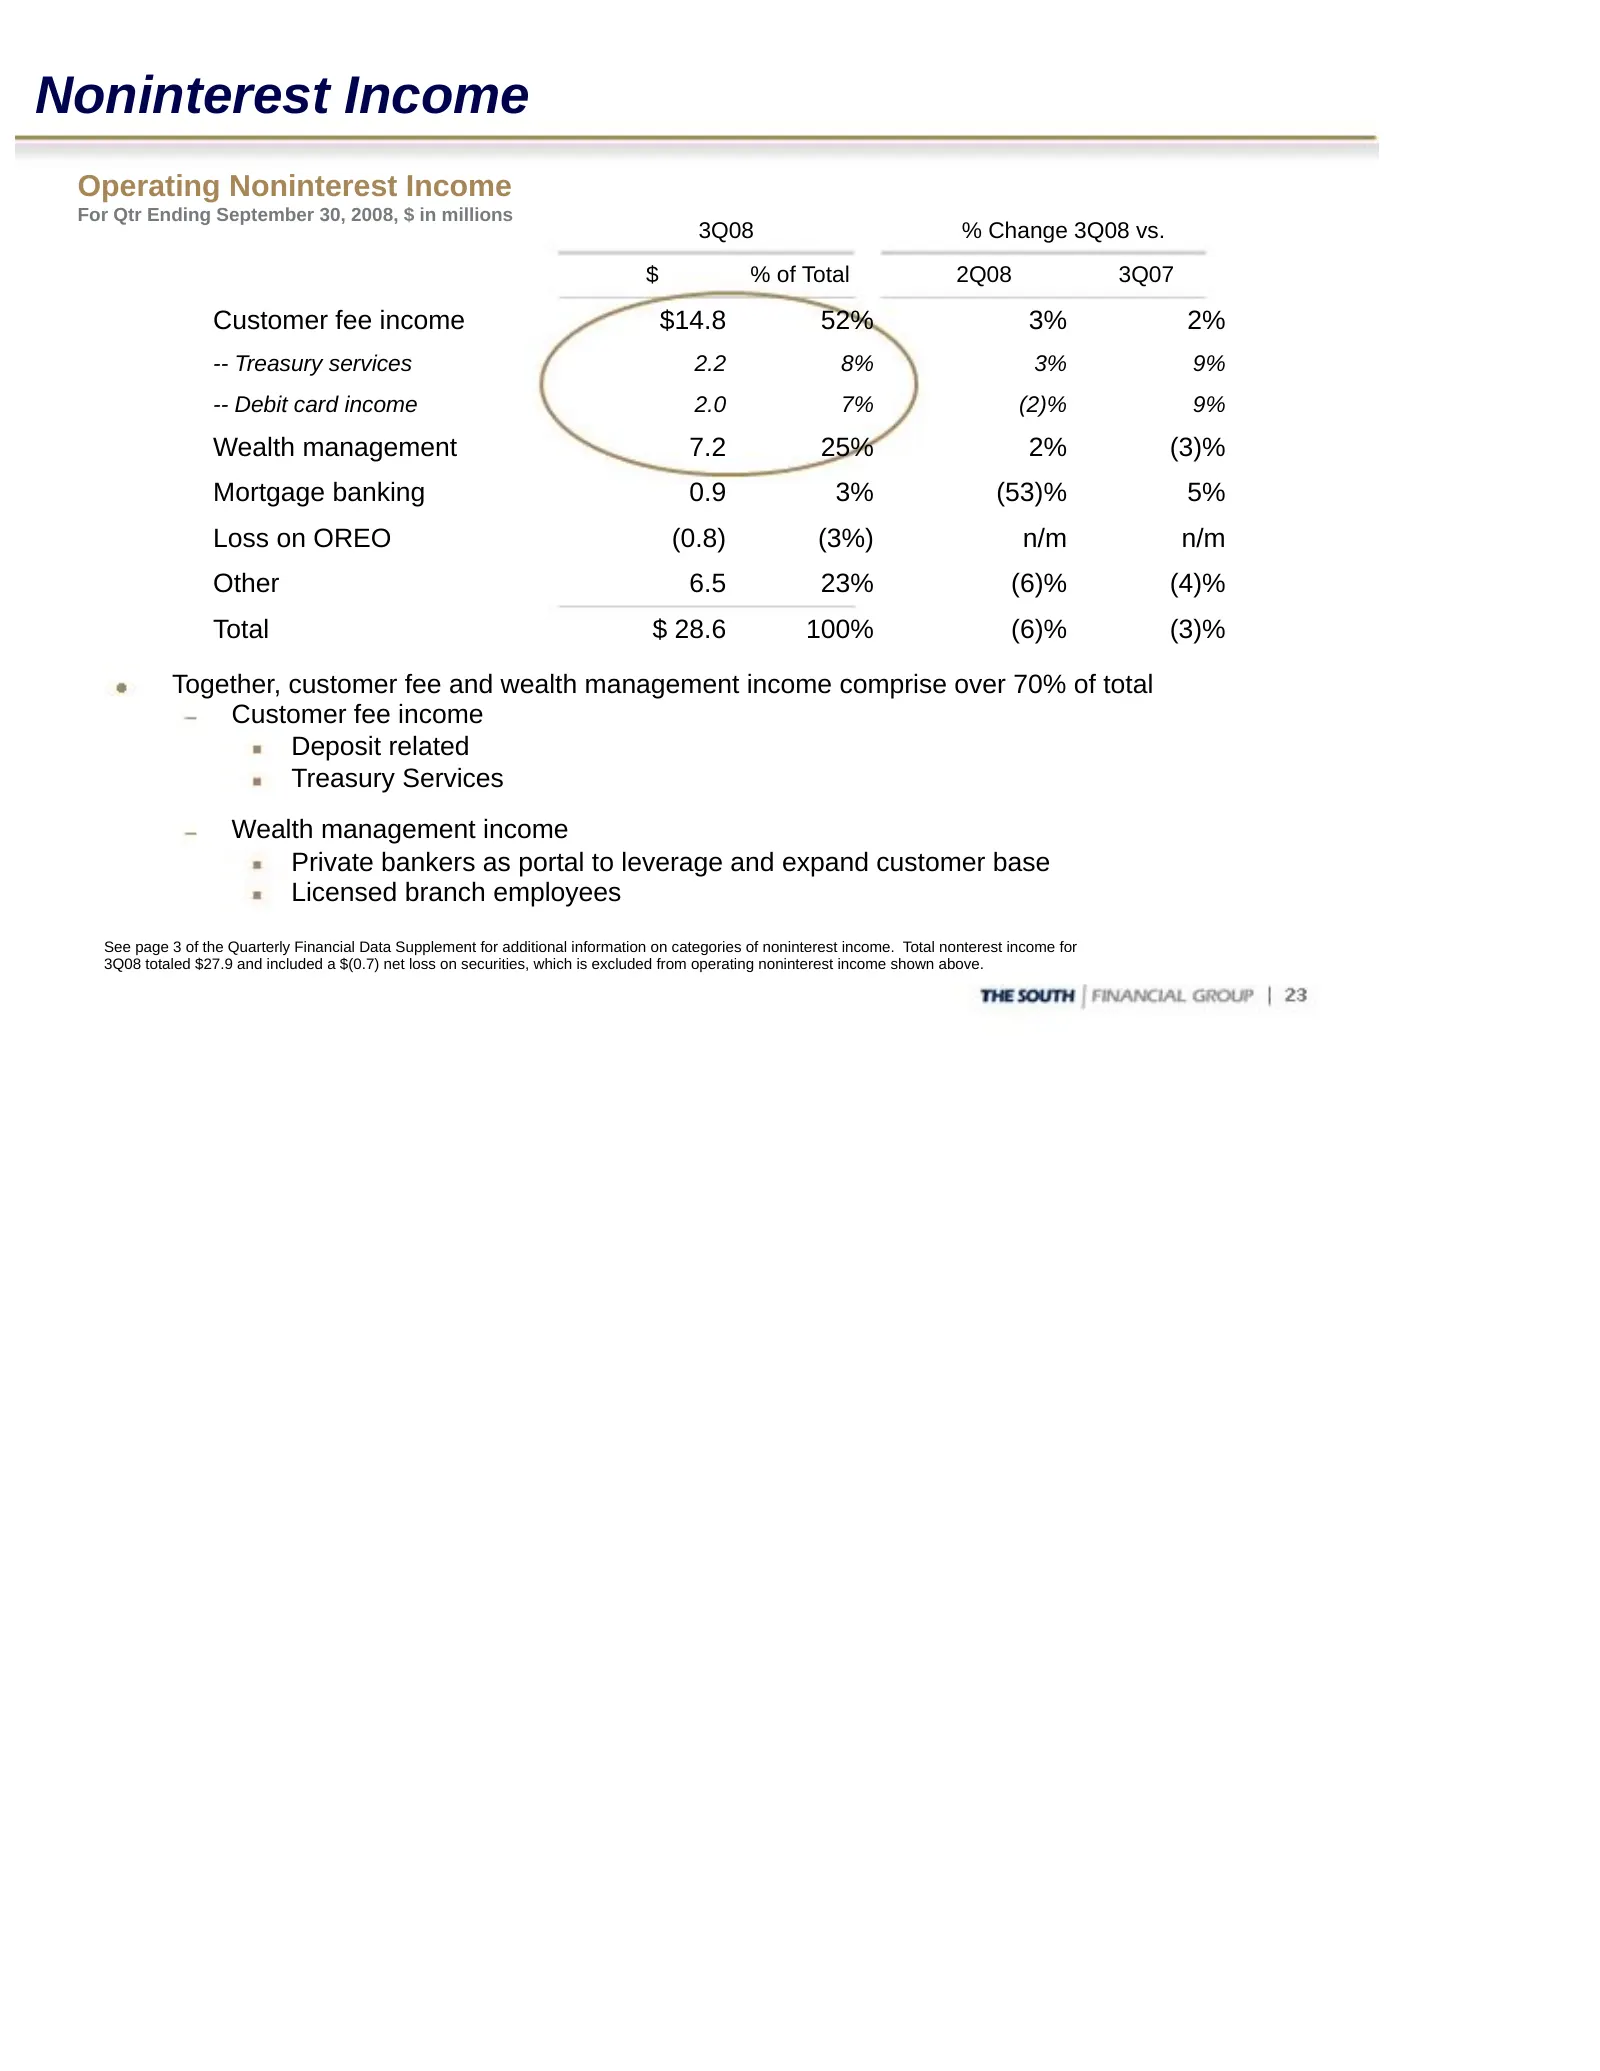
Noninterest Income Operating Noninterest Income For Qtr Ending September 30, 2008, $ in millions 3Q08 % Change 3Q08 vs. $ % of Total 2Q08 3Q07 Customer fee income $14.8 52% 3% 2% -- Treasury services 2.2 8% 3% 9% -- Debit card income 2.0 7% (2)% 9% Wealth management 7.2 25% 2% (3)% Mortgage banking
Slide 24: Positioned to Emerge Stronger
Positioned to Emerge Stronger Operate as Super-Community Bank Leverage strategic footprint and its long-term growth potential Deep and experienced management team Risk management talent and processes Maintain strong balance sheet throughout credit environment Capital strength Liquidity management Hi
Slide 25: Appendix
va “is ans, eT ee MS. rq —\ \Y "i —_— 4 5 . To | THE SOUTH mi FINANCIAL |GROUP APPENDIX
Slide 26: Appendix – List of Operating Peers
Appendix – List of Operating Peers Associated (ASBC) BOK Financial (BOKF) Colonial (CNB) Commerce (CBSH) Cullen/Frost (CFR) Fulton (FULT) Synovus (SNV) Trustmark (TRMK) United Community (UCBI) Valley National (VLY)
Slide 27: TSFG’s Footprint: Household Growth
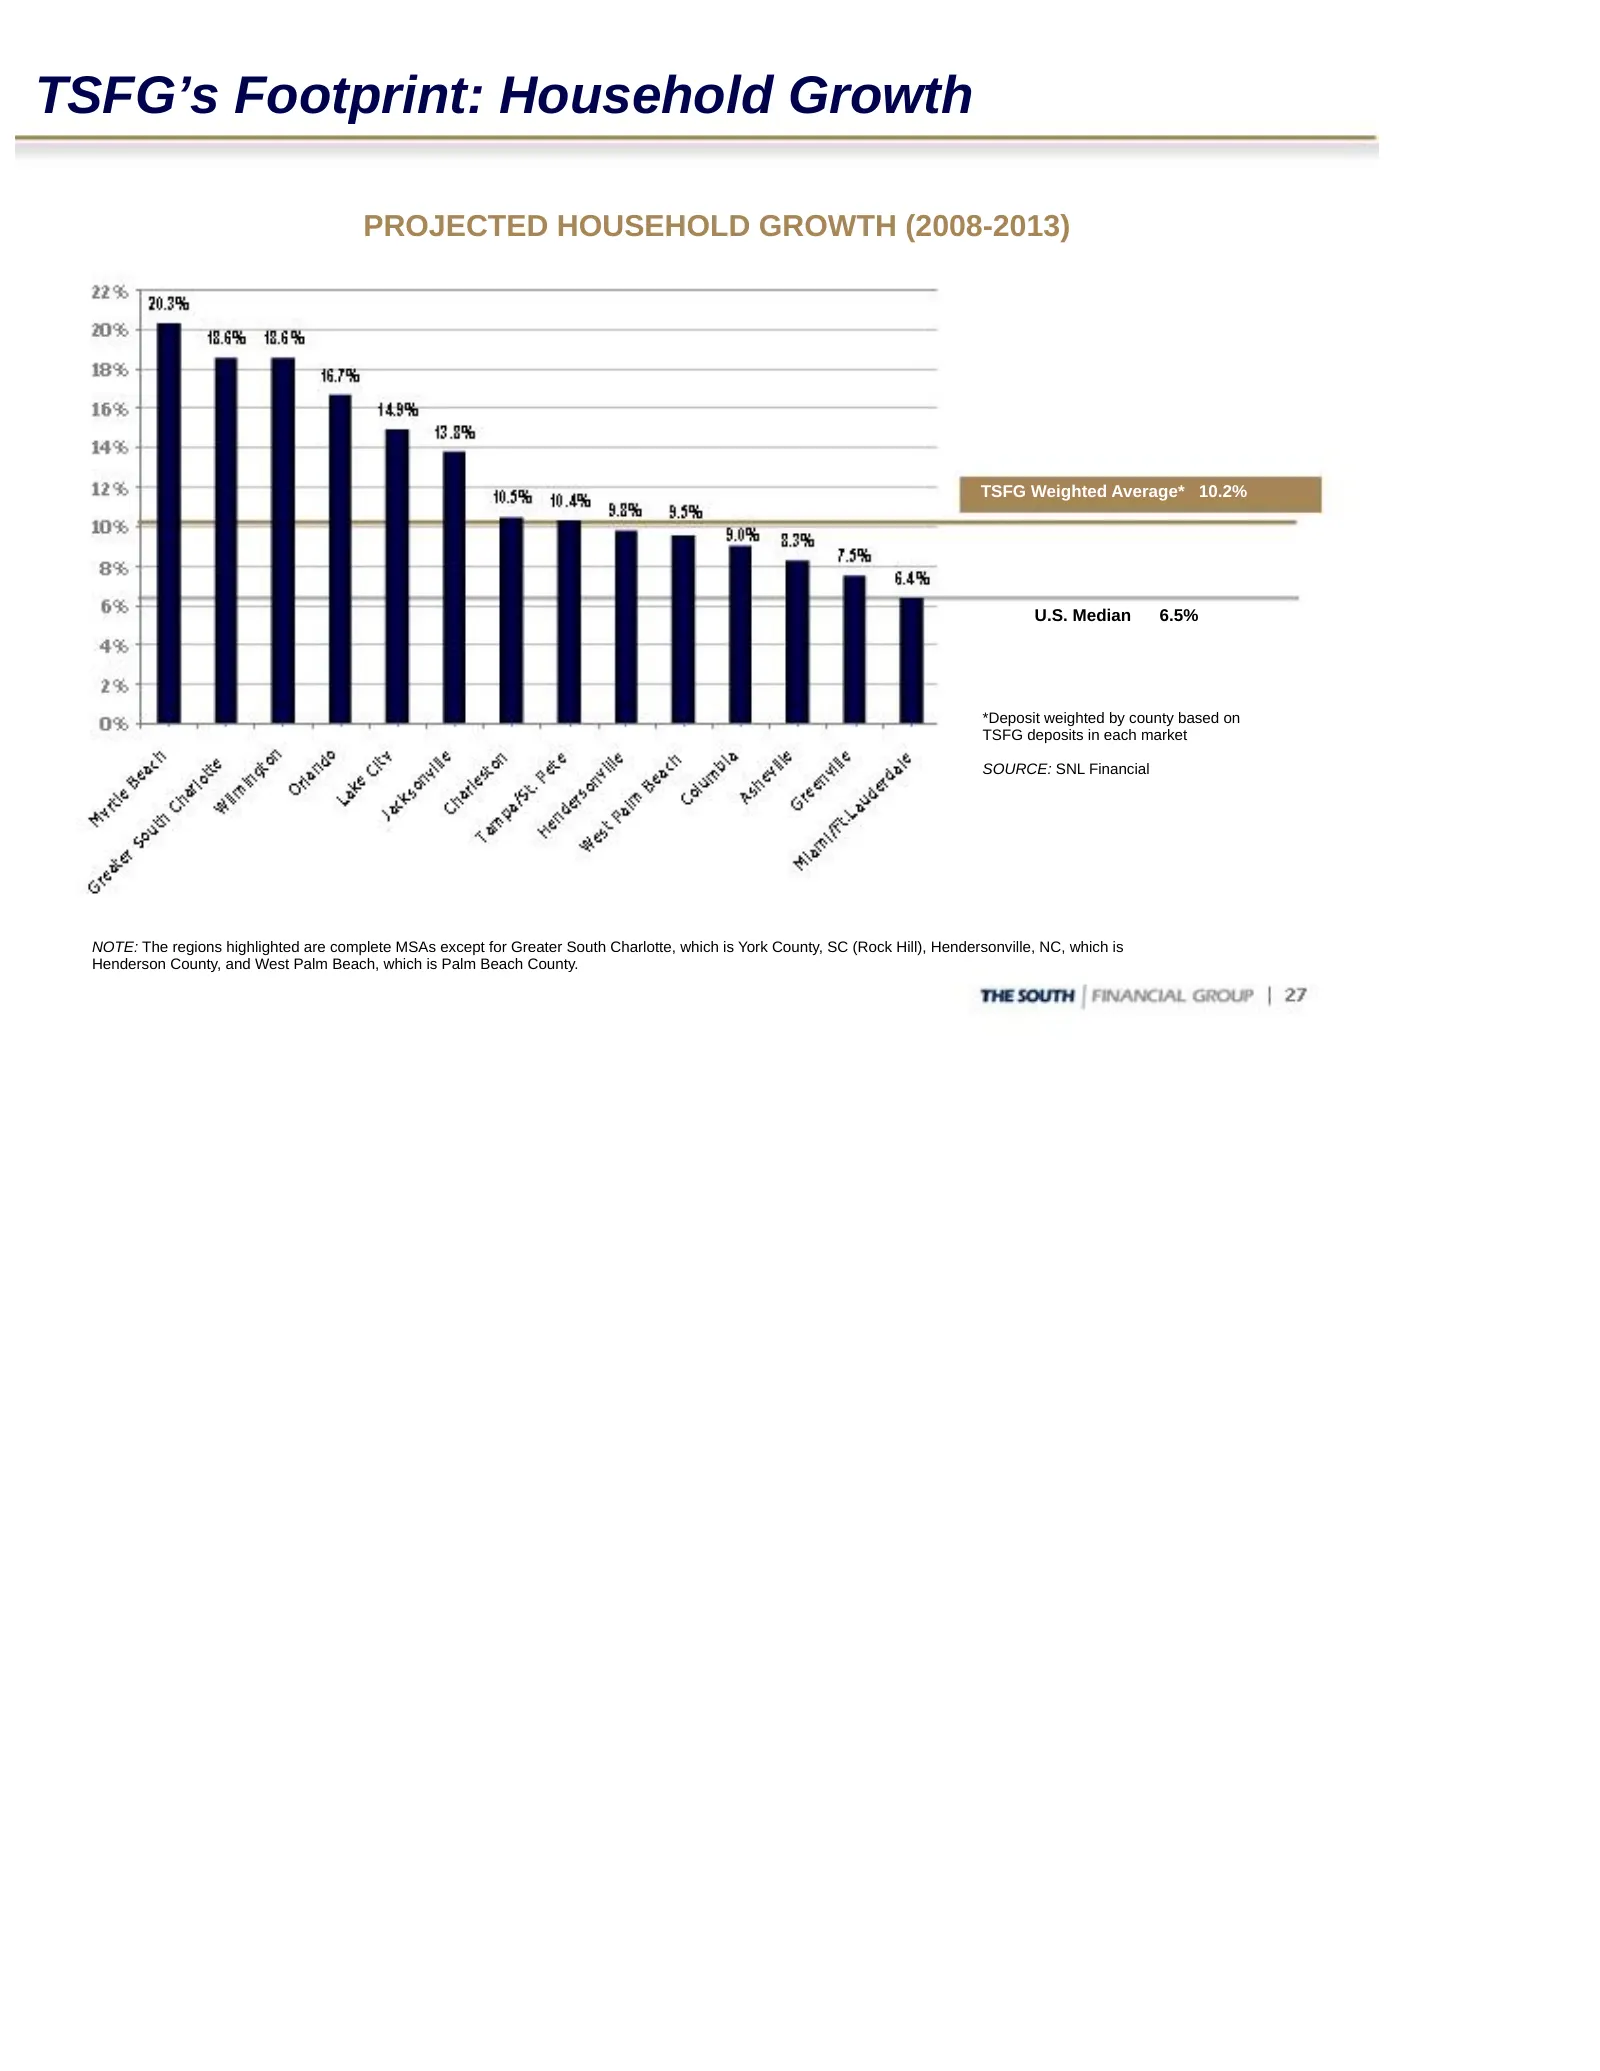
TSFG’s Footprint: Household Growth PROJECTED HOUSEHOLD GROWTH (2008-2013) TSFG Weighted Average* 10.2% U.S. Median 6.5% *Deposit weighted by county based on TSFG deposits in each market SOURCE: SNL Financial NOTE: The regions highlighted are complete MSAs except for Greater South Charlotte, which is
Slide 28: Loan and Credit Quality Composition, 6/30/08
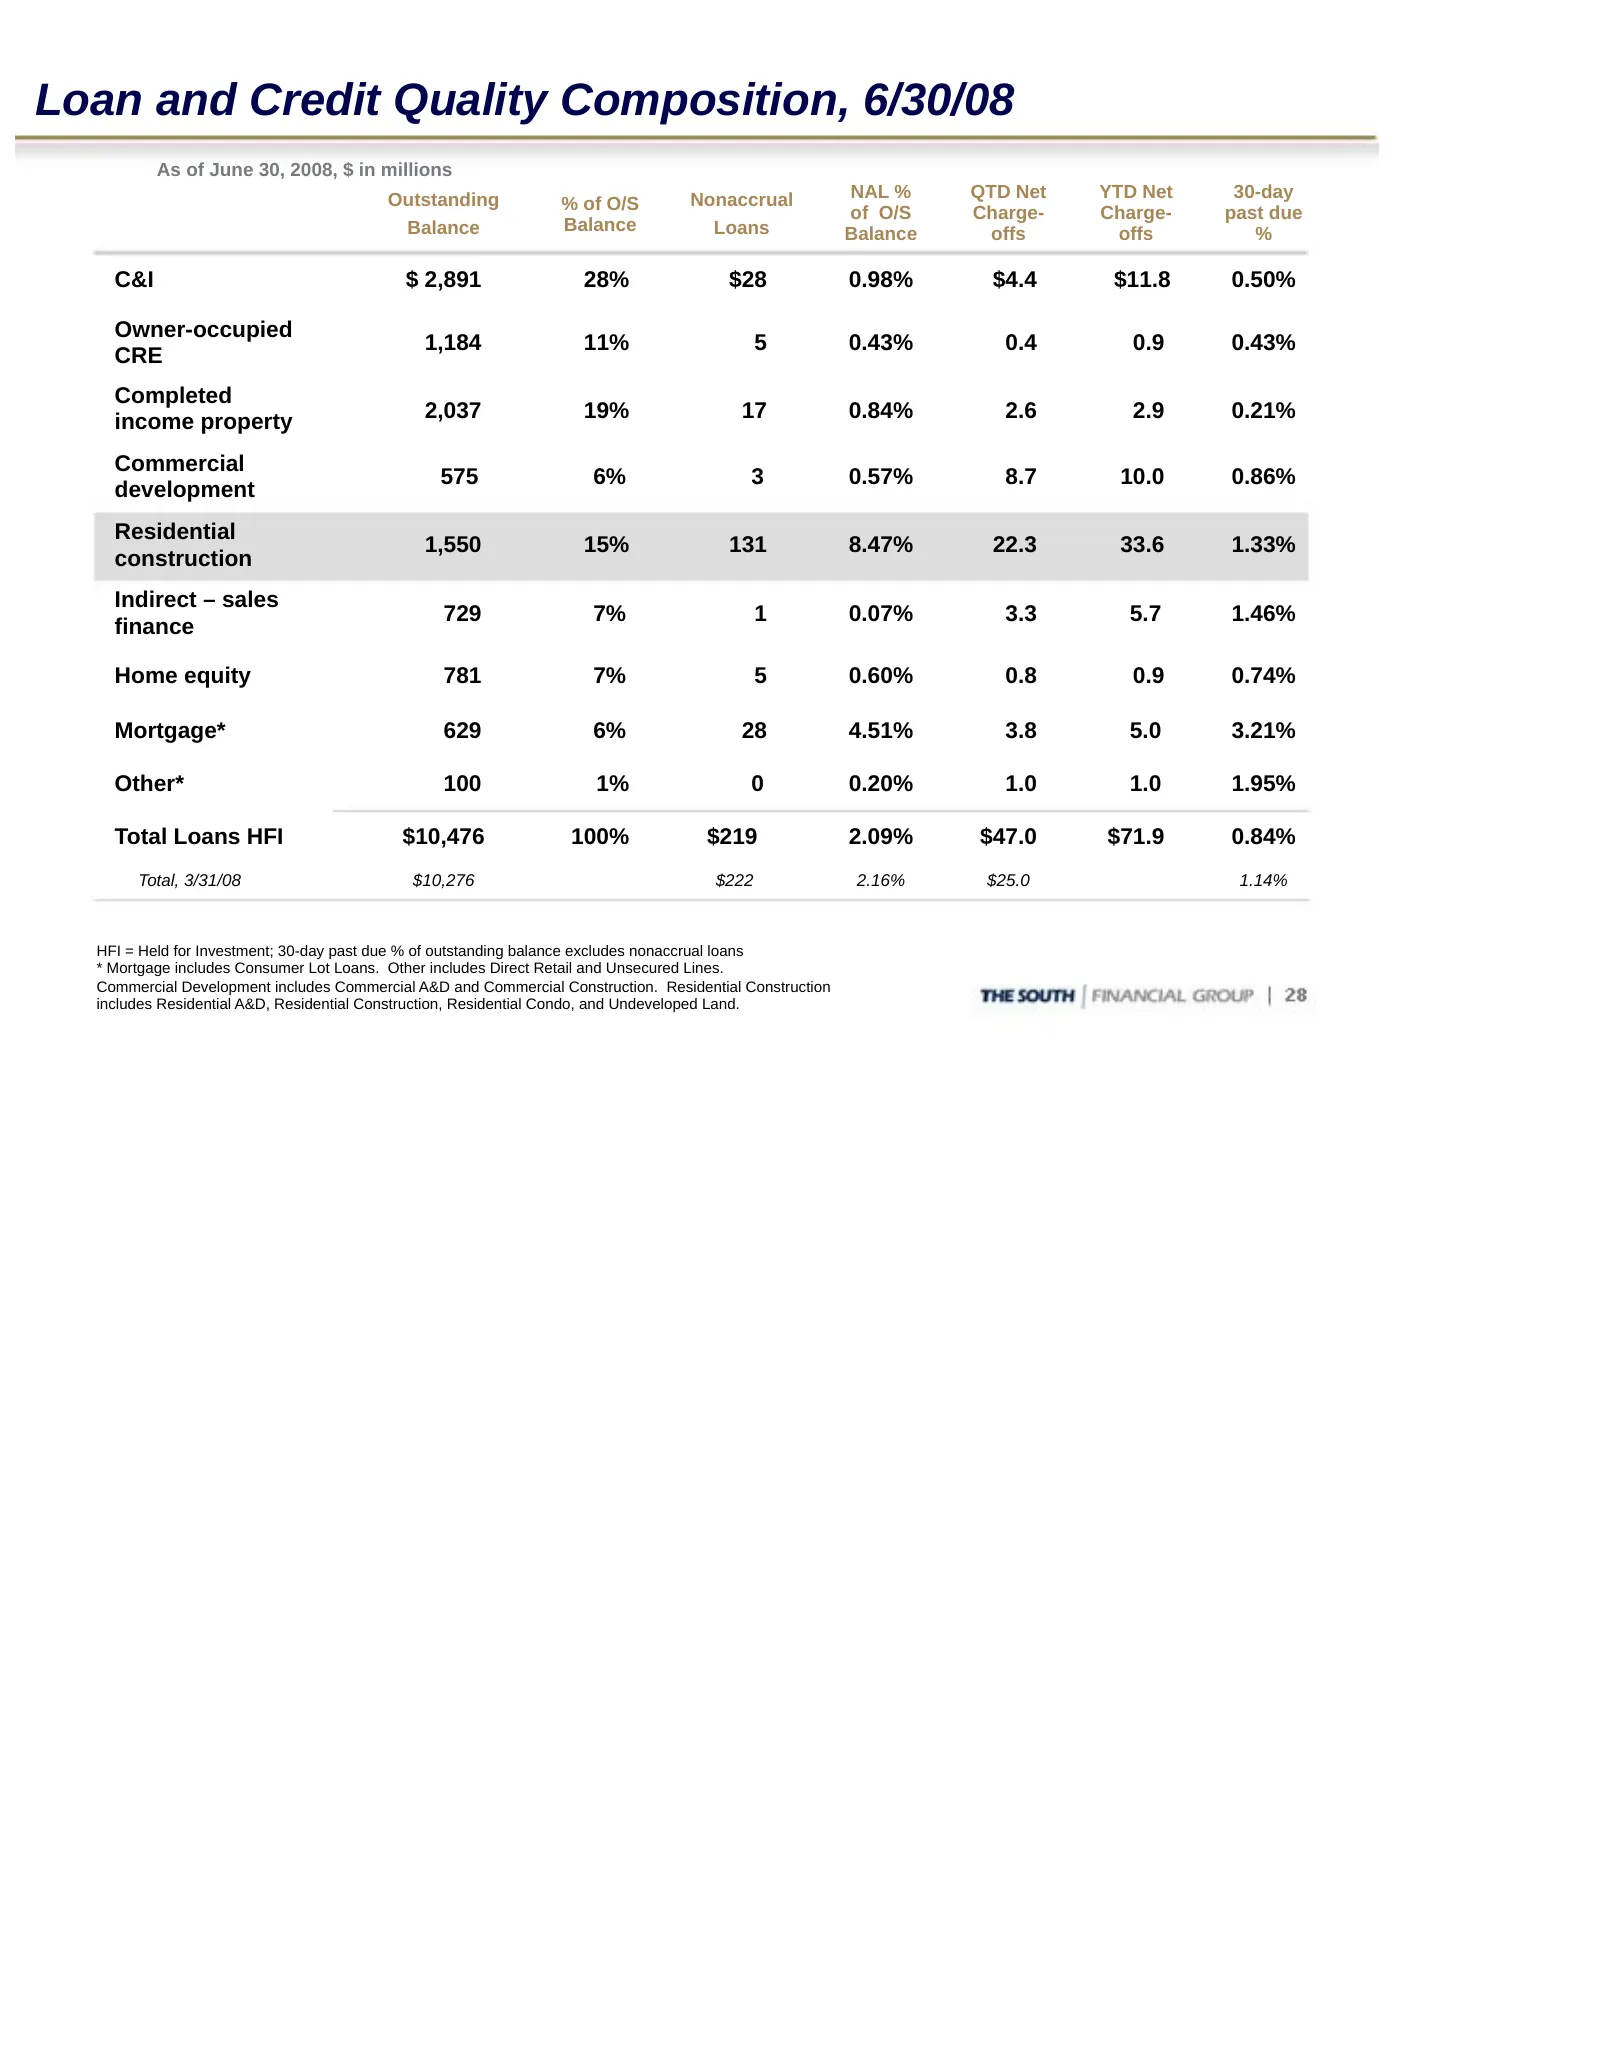
Loan and Credit Quality Composition, 6/30/08 As of June 30, 2008, $ in millions Outstanding Nonaccrual NAL % QTD Net YTD Net 30-day % of O/S of O/S Charge- Charge- past due Balance Balance Loans Balance offs offs % C&I $ 2,891 28% $28 0.98% $4.4 $11.8 0.50% Owner-occupied 1,184 11% 5 0.43% 0.4 0.9 0
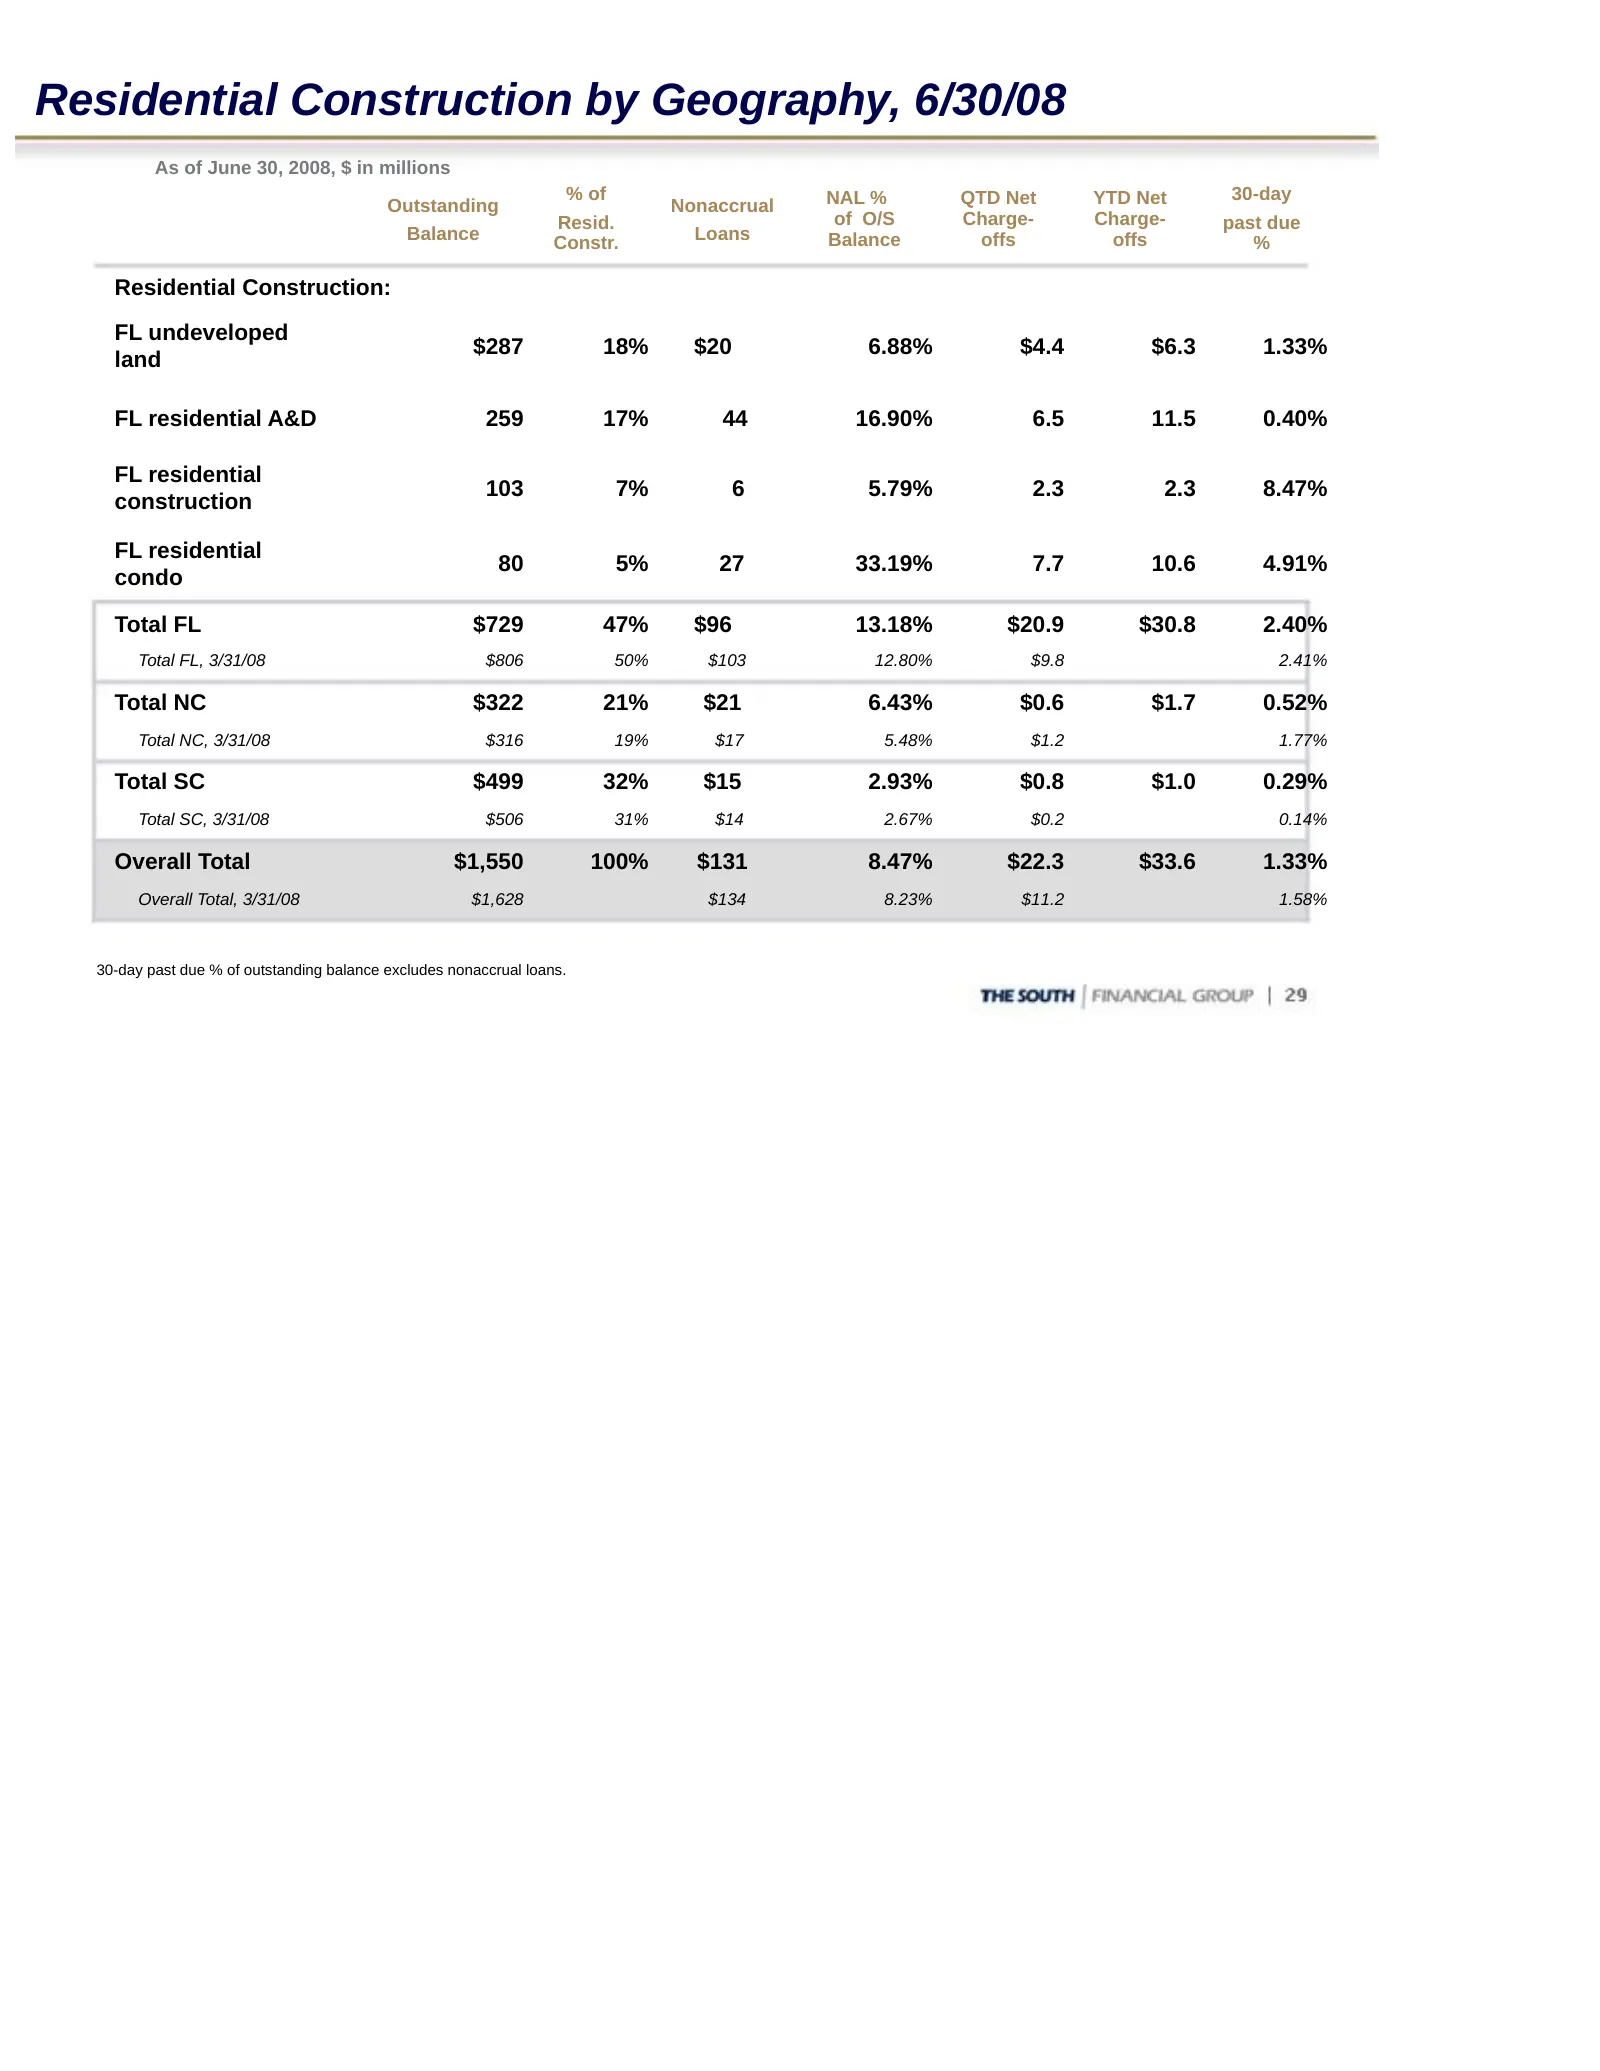
Slide 29: Residential Construction by Geography, 6/30/08
Residential Construction by Geography, 6/30/08 As of June 30, 2008, $ in millions % of NAL % QTD Net YTD Net 30-day Outstanding Nonaccrual Resid. of O/S Charge- Charge- past due Balance Constr. Loans Balance offs offs % Residential Construction: FL undeveloped $287 18% $20 6.88% $4.4 $6.3 1.33% land
Slide 30: Current as of 12/1/08
THE:SOUTH — oi FINANCIAL | GROUP Si, “an | ~ a, \ > For more information: > 7 INVESTOR RELATIONS ~ investor@thesouthgroup.com > www.thesouthgroup.com ~ Current as of 12/1/08
Source: SEC EDGAR · 8-K filed Dec 3, 2008
More decks from South Financial Group Inc
 Merger or Acquisition (June 2010)15 slides · Jun 29, 2010
 Debt Investor Presentation (June 2010)84 slides · Jun 18, 2010
 Merger or Acquisition (June 2010)43 slides · Jun 4, 2010
 Merger or Acquisition (May 2010)15 slides · May 17, 2010
 Q1 2010 Earnings Presentation30 slides · Apr 20, 2010
 Q4 2009 Earnings Presentation30 slides · Jan 26, 2010