INFICON Holding AG · SIX:IFCN
INFICON — Q2 2013 Earnings Presentation
21 slides from INFICON's earnings presentation, Aug 8, 2013
Slide 1: Q2 2013 Earnings Conference Call
Q2 2013 EARNINGS CONFERENCE CALL August 8, 2013 Bad Ragaz, Switzerland
Slide 2: Speakers
Speakers Lukas Winkler, President and CEO Key figures Q2 2013 Target market business review 2013 Expectations Matthias Tröndle, Vice President and CFO Financials Q2 2013 Outlook Q2 2013 Earnings Conference Call August 8, 2013 2
Slide 3: Lukas Winkler, President and CEO
Lukas Winkler INFICON President and Chief Executive Officer
Slide 4: Q2 2013 – Key Figures
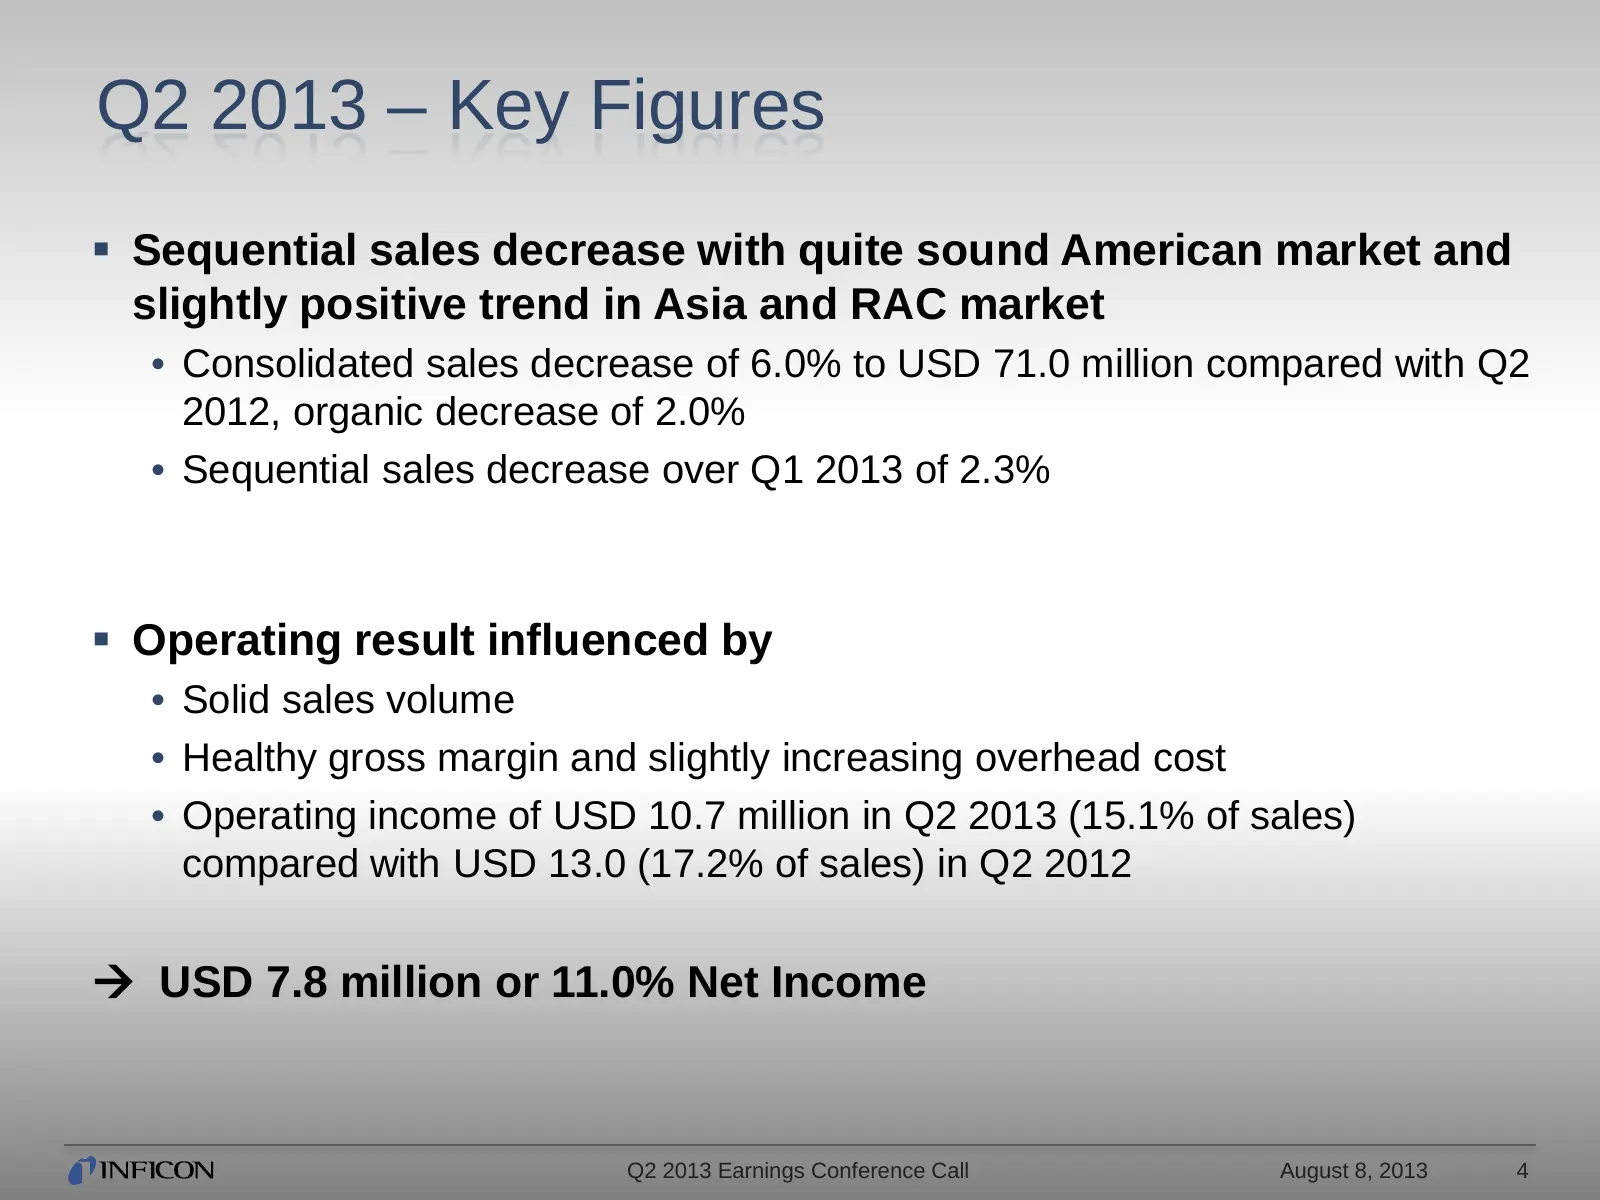
Q2 2013 – Key Figures Sequential sales decrease with quite sound American market and slightly positive trend in Asia and RAC market • Consolidated sales decrease of 6.0% to USD 71.0 million compared with Q2 2012, organic decrease of 2.0% • Sequential sales decrease over Q1 2013 of 2.3% Operating
Slide 5: Net Sales by End Market
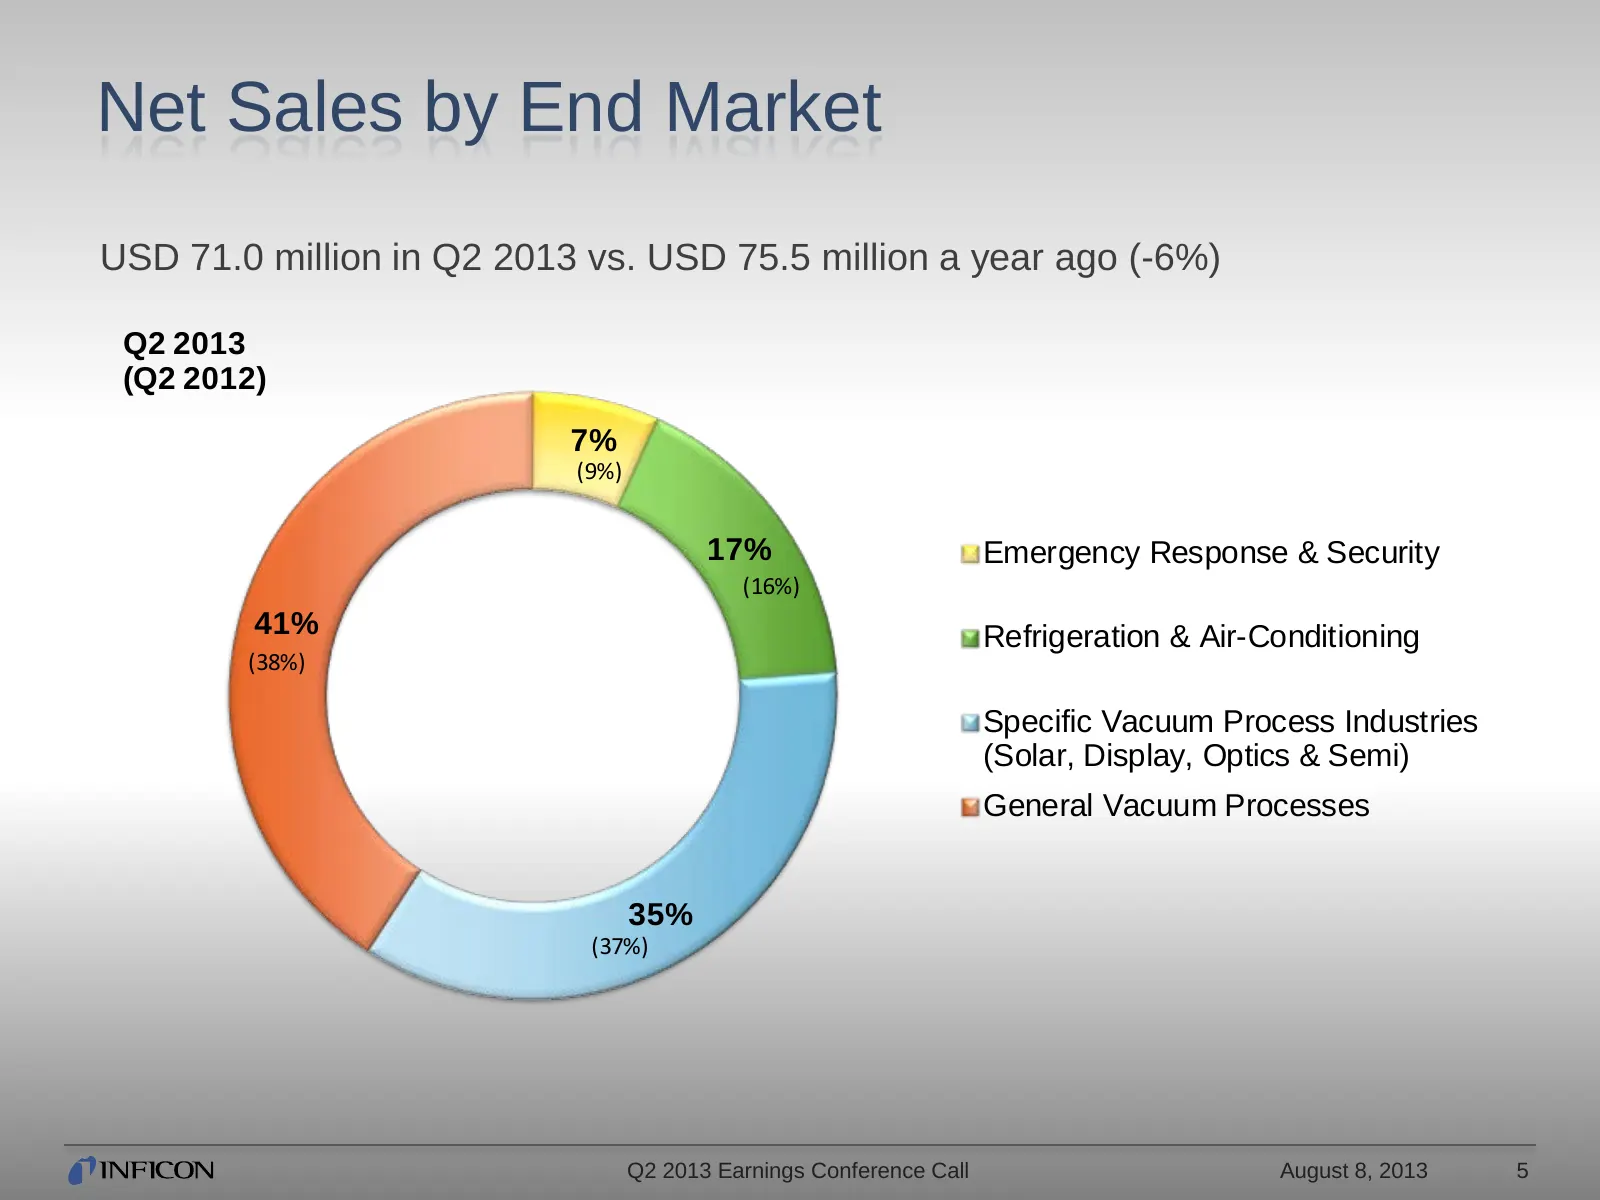
Net Sales by End Market USD 71.0 million in Q2 2013 vs. USD 75.5 million a year ago (-6%) Q2 2013 (Q2 2012) 7% (9%) 17% Emergency Response & Security (16%) 41% Refrigeration & Air-Conditioning (38%) Specific Vacuum Process Industries (Solar, Display, Optics & Semi) General Vacuum Processes 35% (37%)
Slide 6: Emergency Response & Security
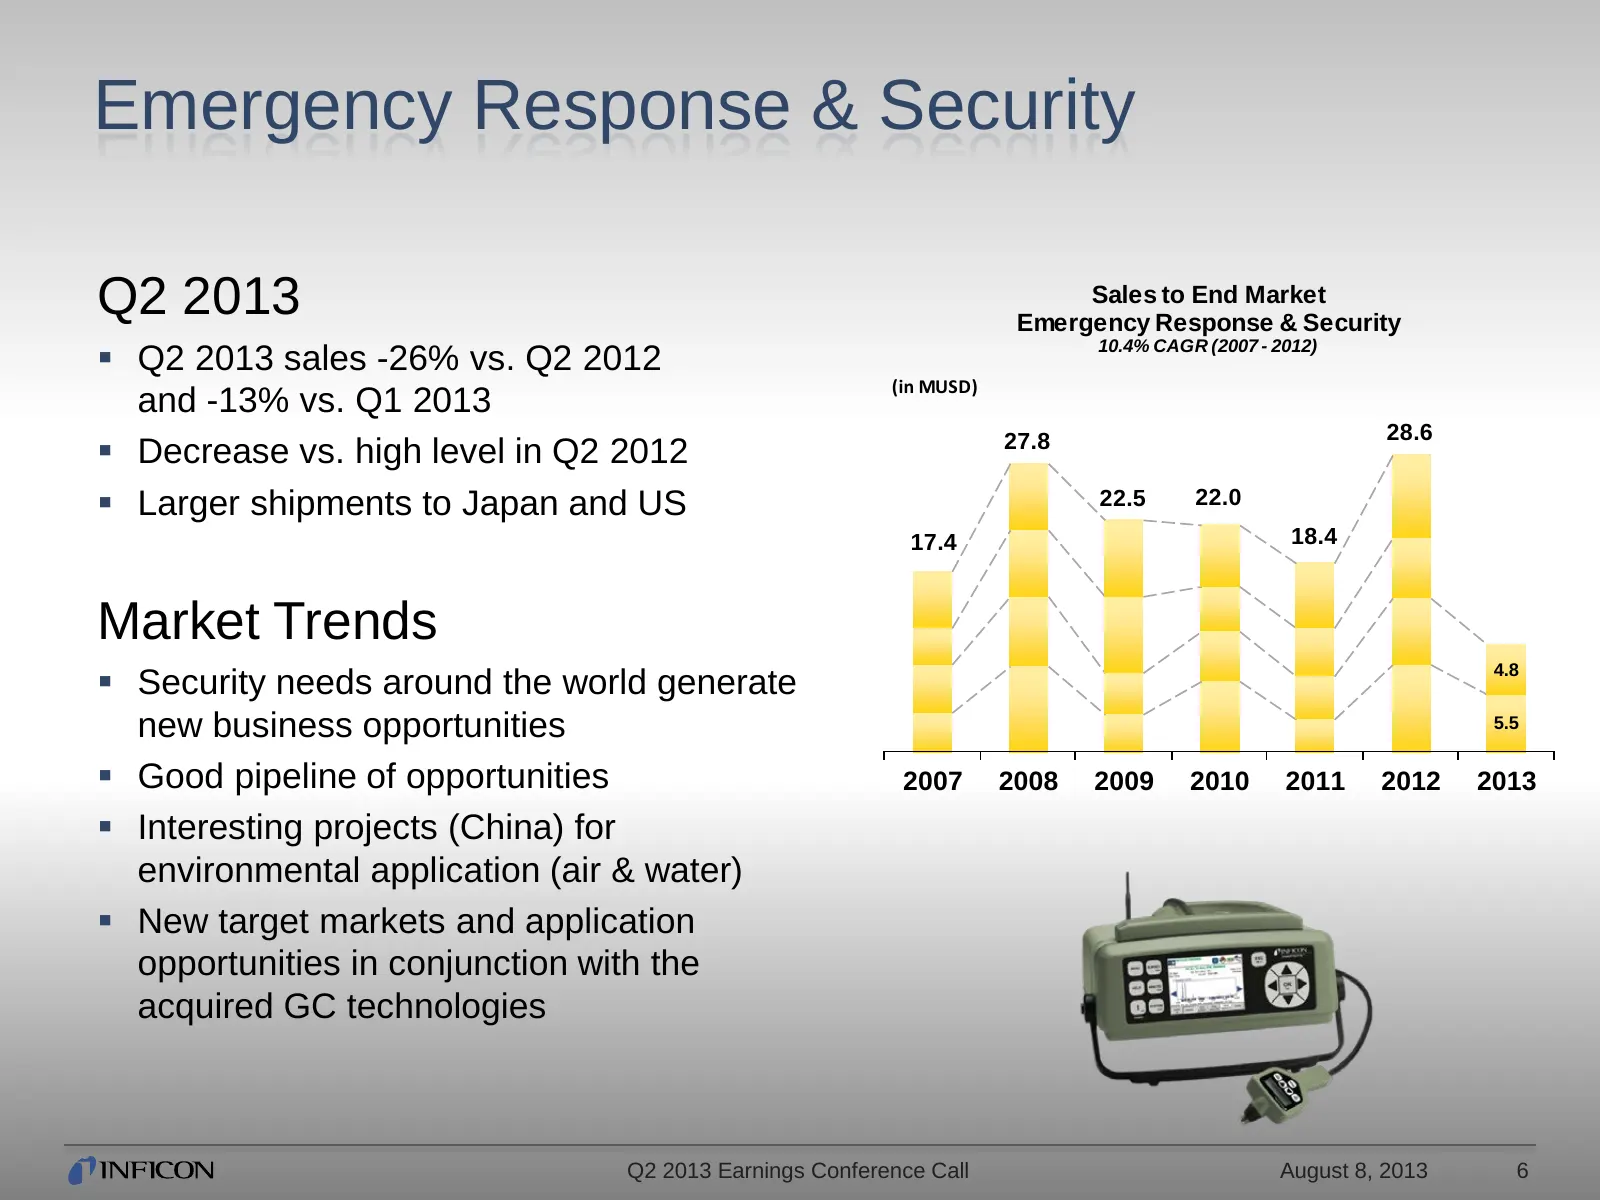
Emergency Response & Security Q2 2013 Sales to End Market Emergency Response & Security Q2 2013 sales -26% vs. Q2 2012 10.4% CAGR (2007 - 2012) (in MUSD) and -13% vs. Q1 2013 28.6 Decrease vs. high level in Q2 2012 27.8 Larger shipments to Japan and US 22.5 22.0 17.4 18.4 Market Trends Secur
Slide 7: Refrigeration & Air Conditioning
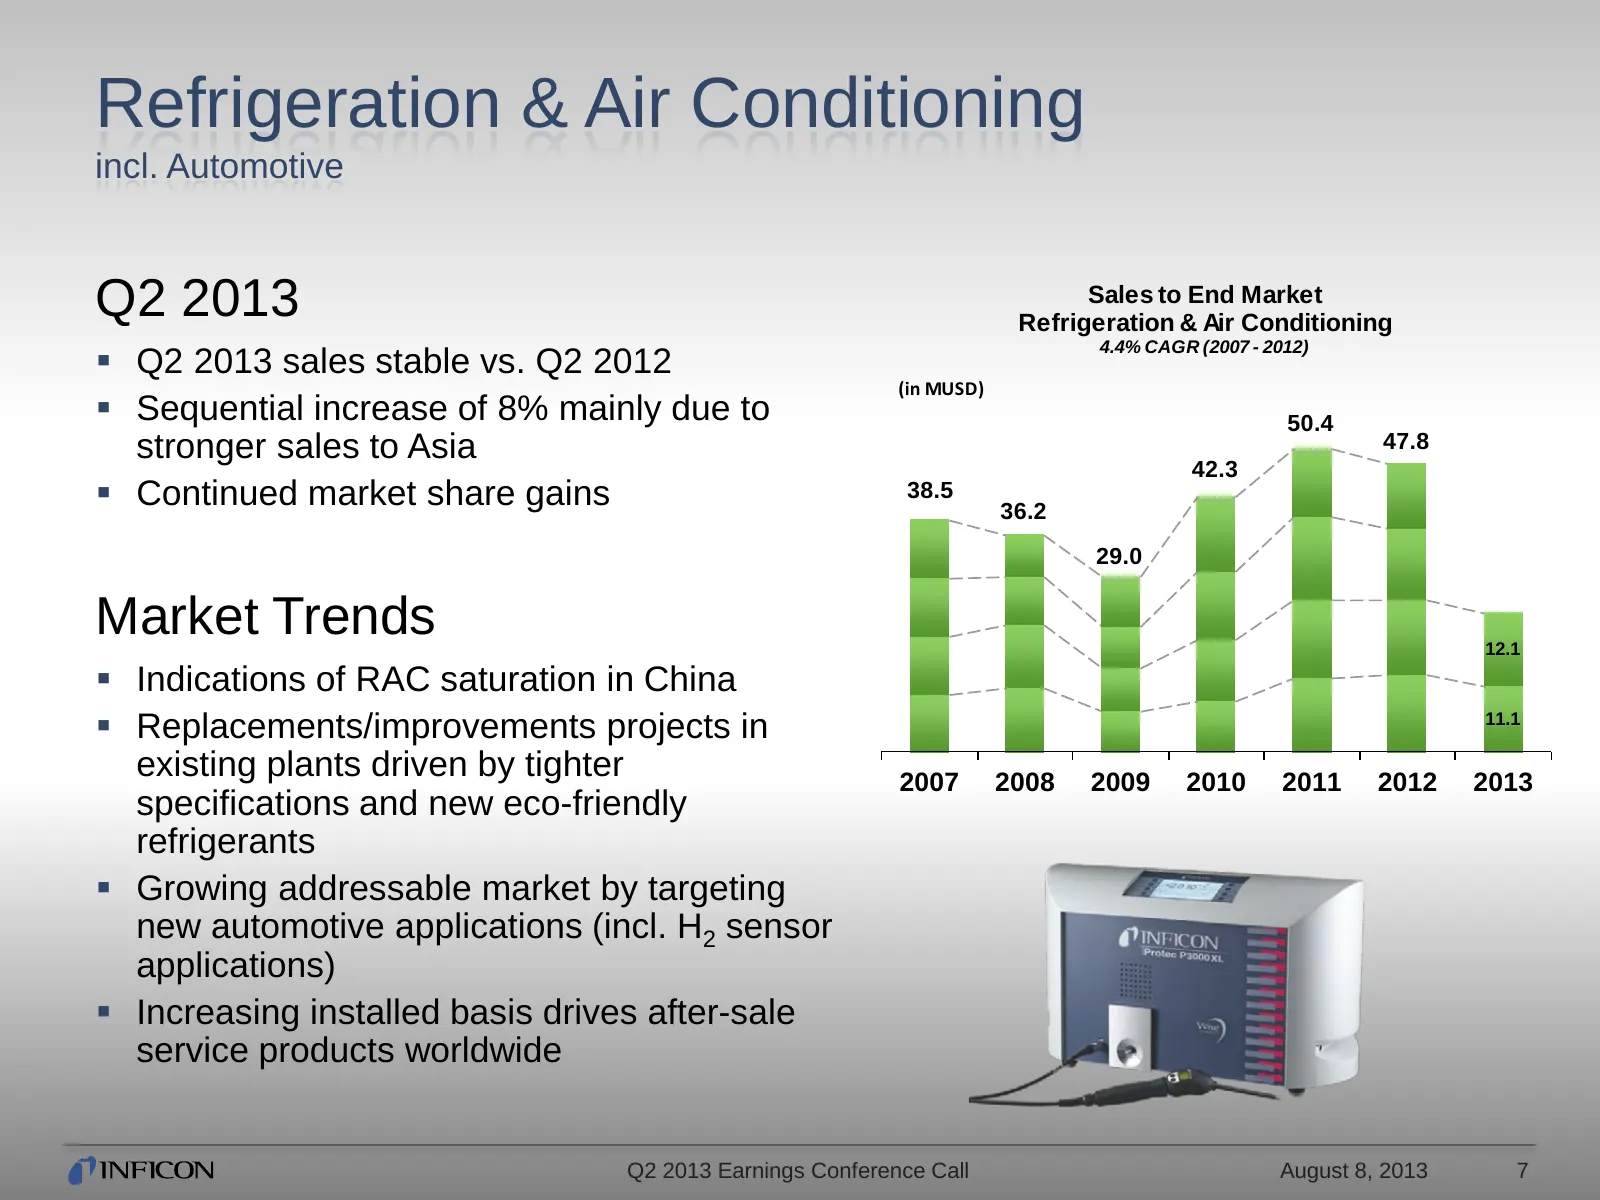
Refrigeration & Air Conditioning incl. Automotive Q2 2013 Sales to End Market Refrigeration & Air Conditioning 4.4% CAGR (2007 - 2012) Q2 2013 sales stable vs. Q2 2012 (in MUSD) Sequential increase of 8% mainly due to 50.4 stronger sales to Asia 47.8 42.3 Continued market share gains 38.5 36.2
Slide 8: Specific Vacuum Process Industries
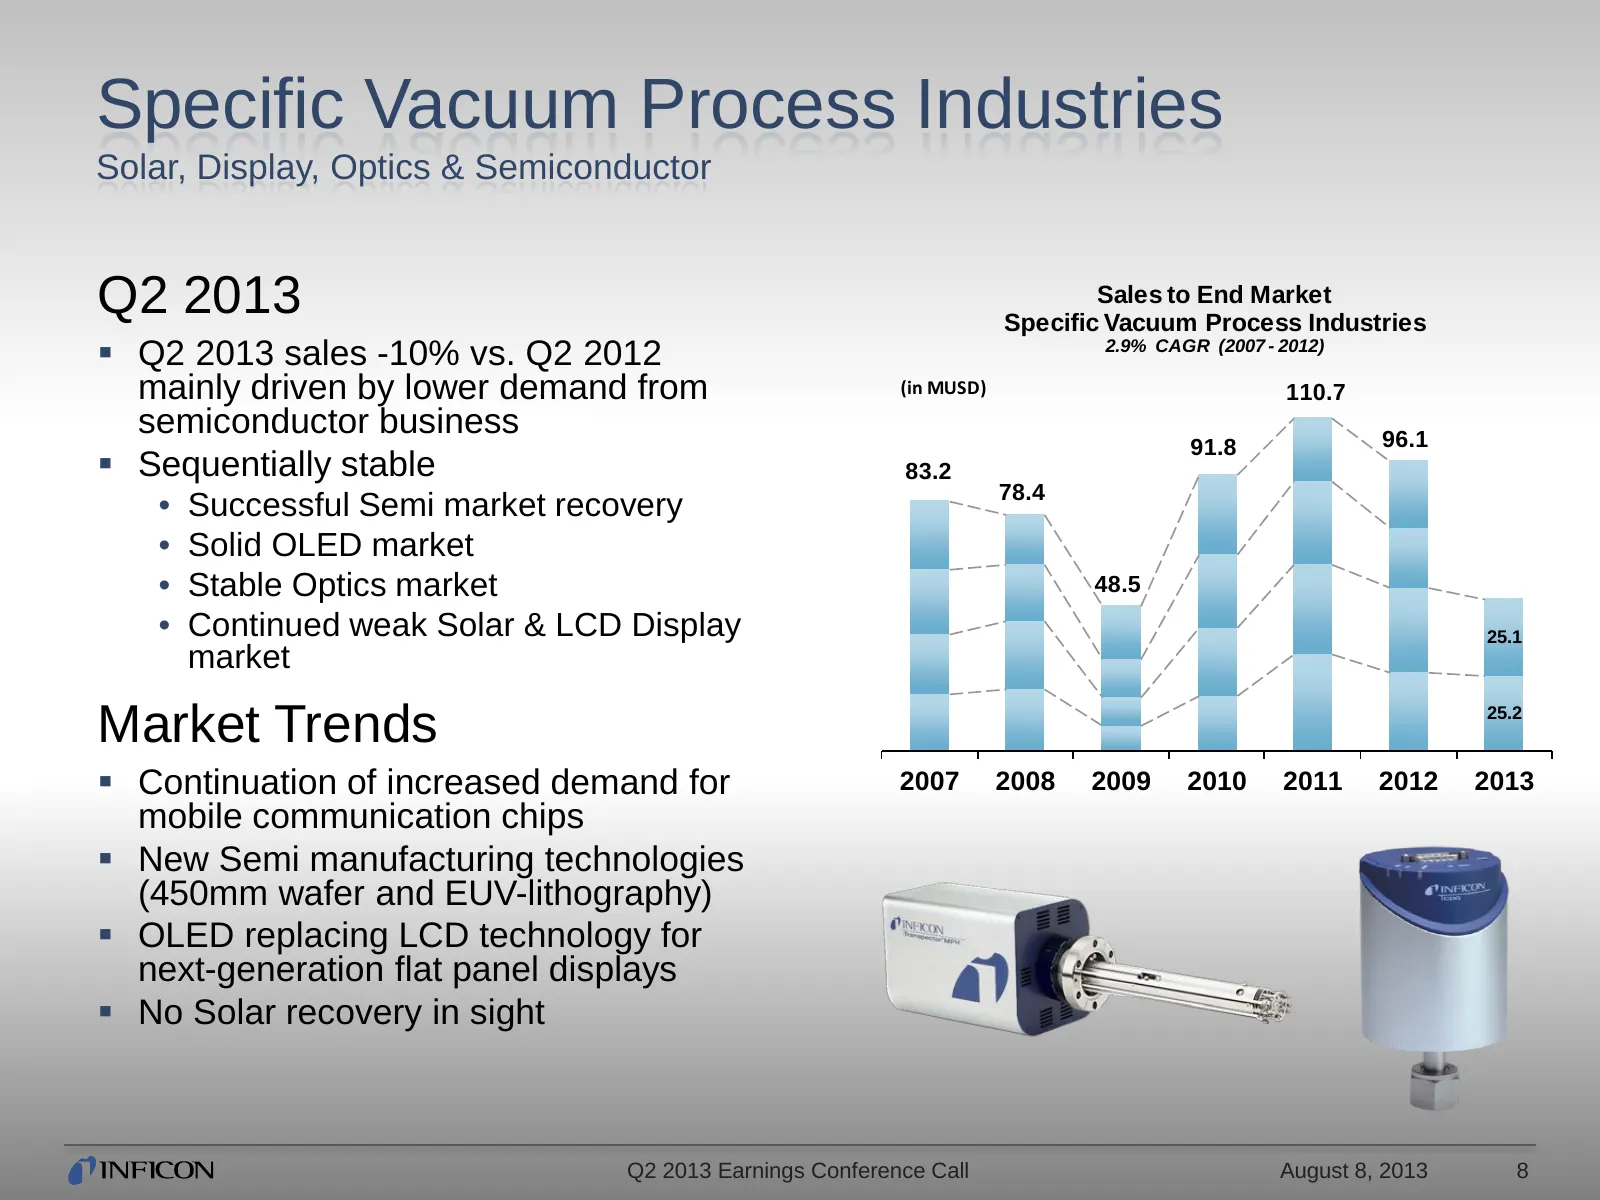
Specific Vacuum Process Industries Solar, Display, Optics & Semiconductor Q2 2013 Sales to End Market Specific Vacuum Process Industries Q2 2013 sales -10% vs. Q2 2012 2.9% CAGR (2007 - 2012) mainly driven by lower demand from (in MUSD) 110.7 semiconductor business 96.1 91.8 Sequentially stable
Slide 9: General Vacuum Processes
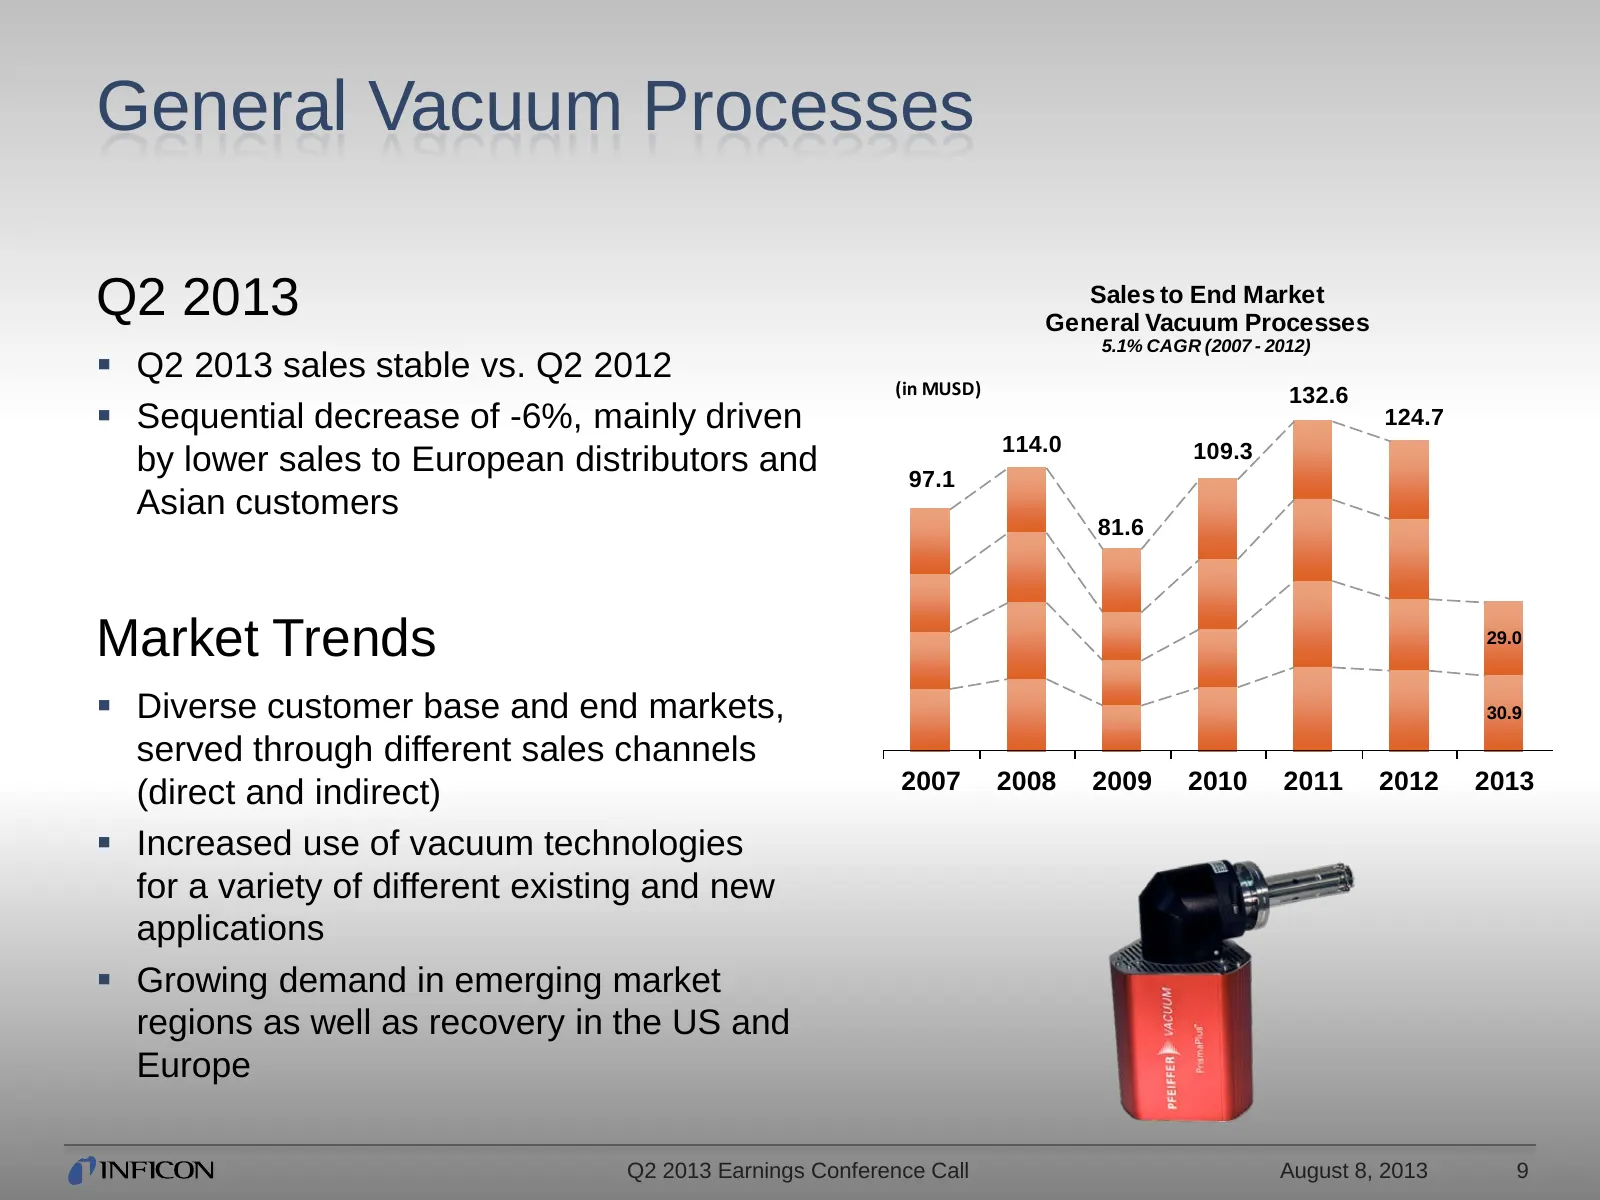
General Vacuum Processes Q2 2013 Sales to End Market General Vacuum Processes 5.1% CAGR (2007 - 2012) Q2 2013 sales stable vs. Q2 2012 (in MUSD) 132.6 Sequential decrease of -6%, mainly driven 124.7 114.0 109.3 by lower sales to European distributors and 97.1 Asian customers 81.6 Market Trends 2
Slide 10: Outlook 2013 and beyond
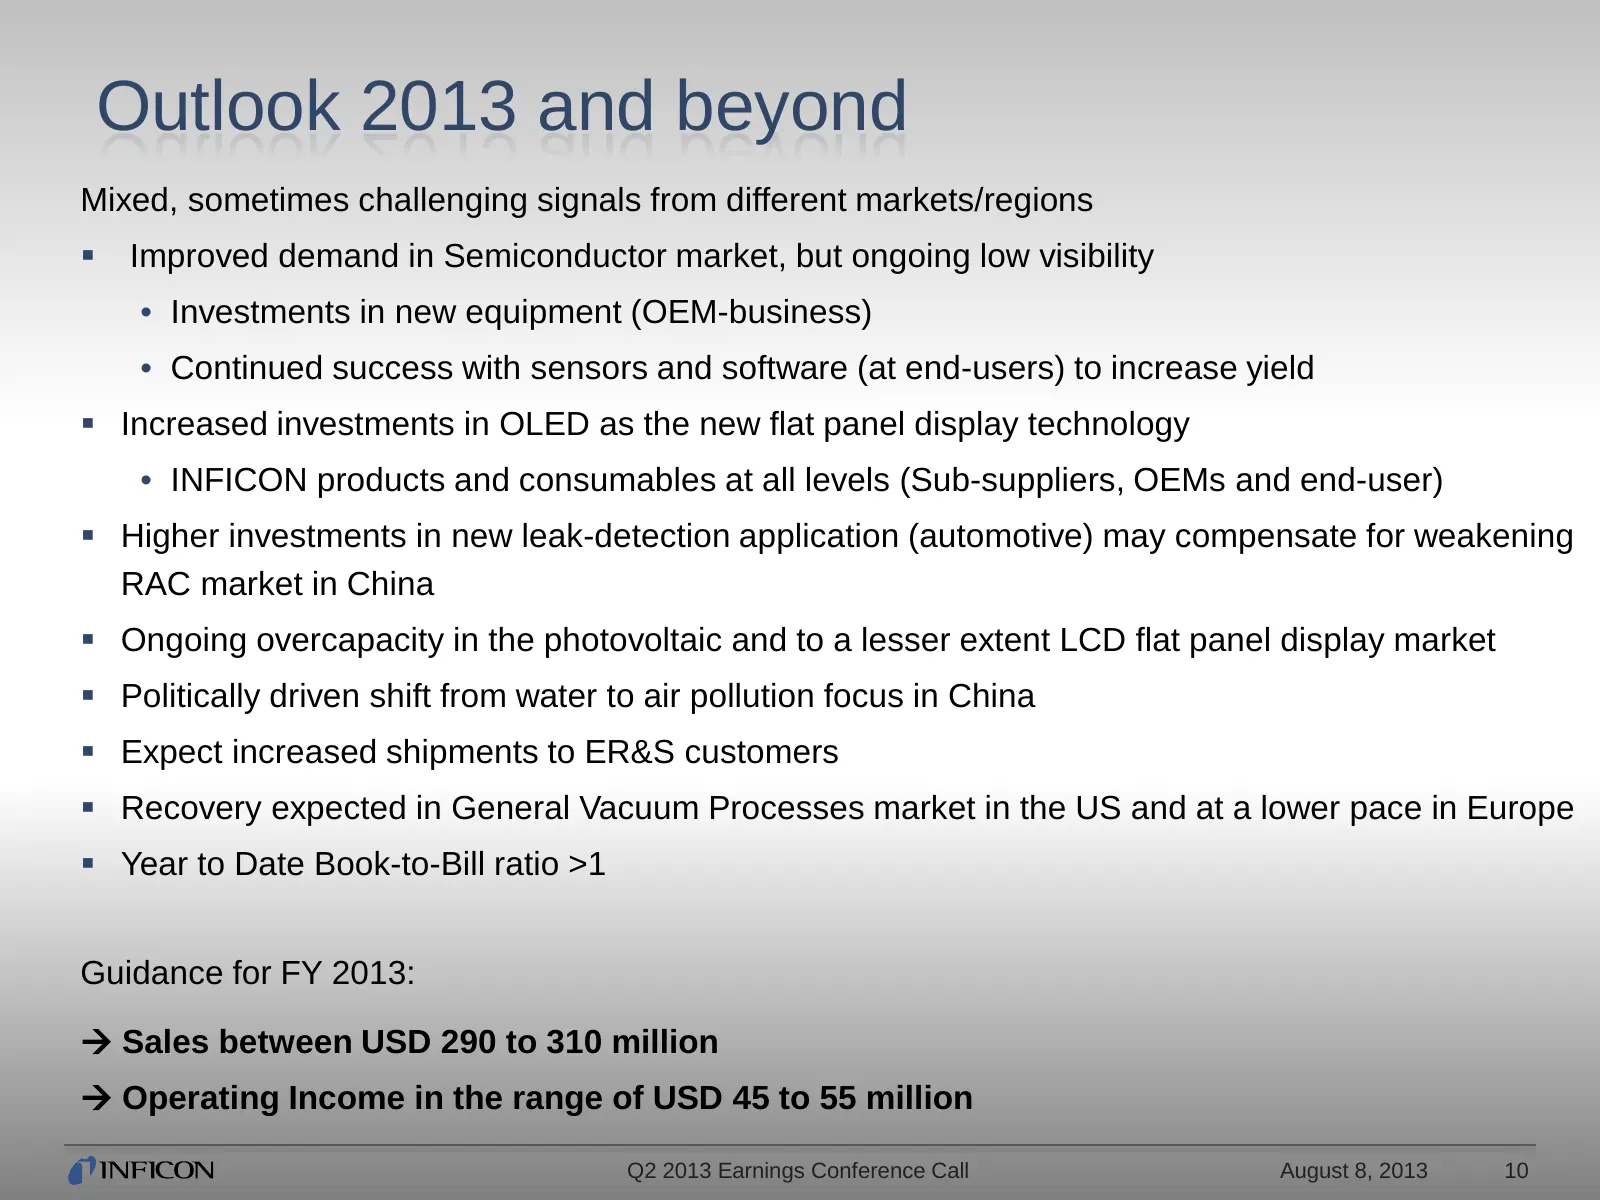
Outlook 2013 and beyond Mixed, sometimes challenging signals from different markets/regions Improved demand in Semiconductor market, but ongoing low visibility • Investments in new equipment (OEM-business) • Continued success with sensors and software (at end-users) to increase yield Increased i
Slide 11: Matthias Tröndle, Vice President and CFO
Matthias Tröndle INFICON Vice President and Chief Financial Officer
Slide 12: Sales (in USD million)
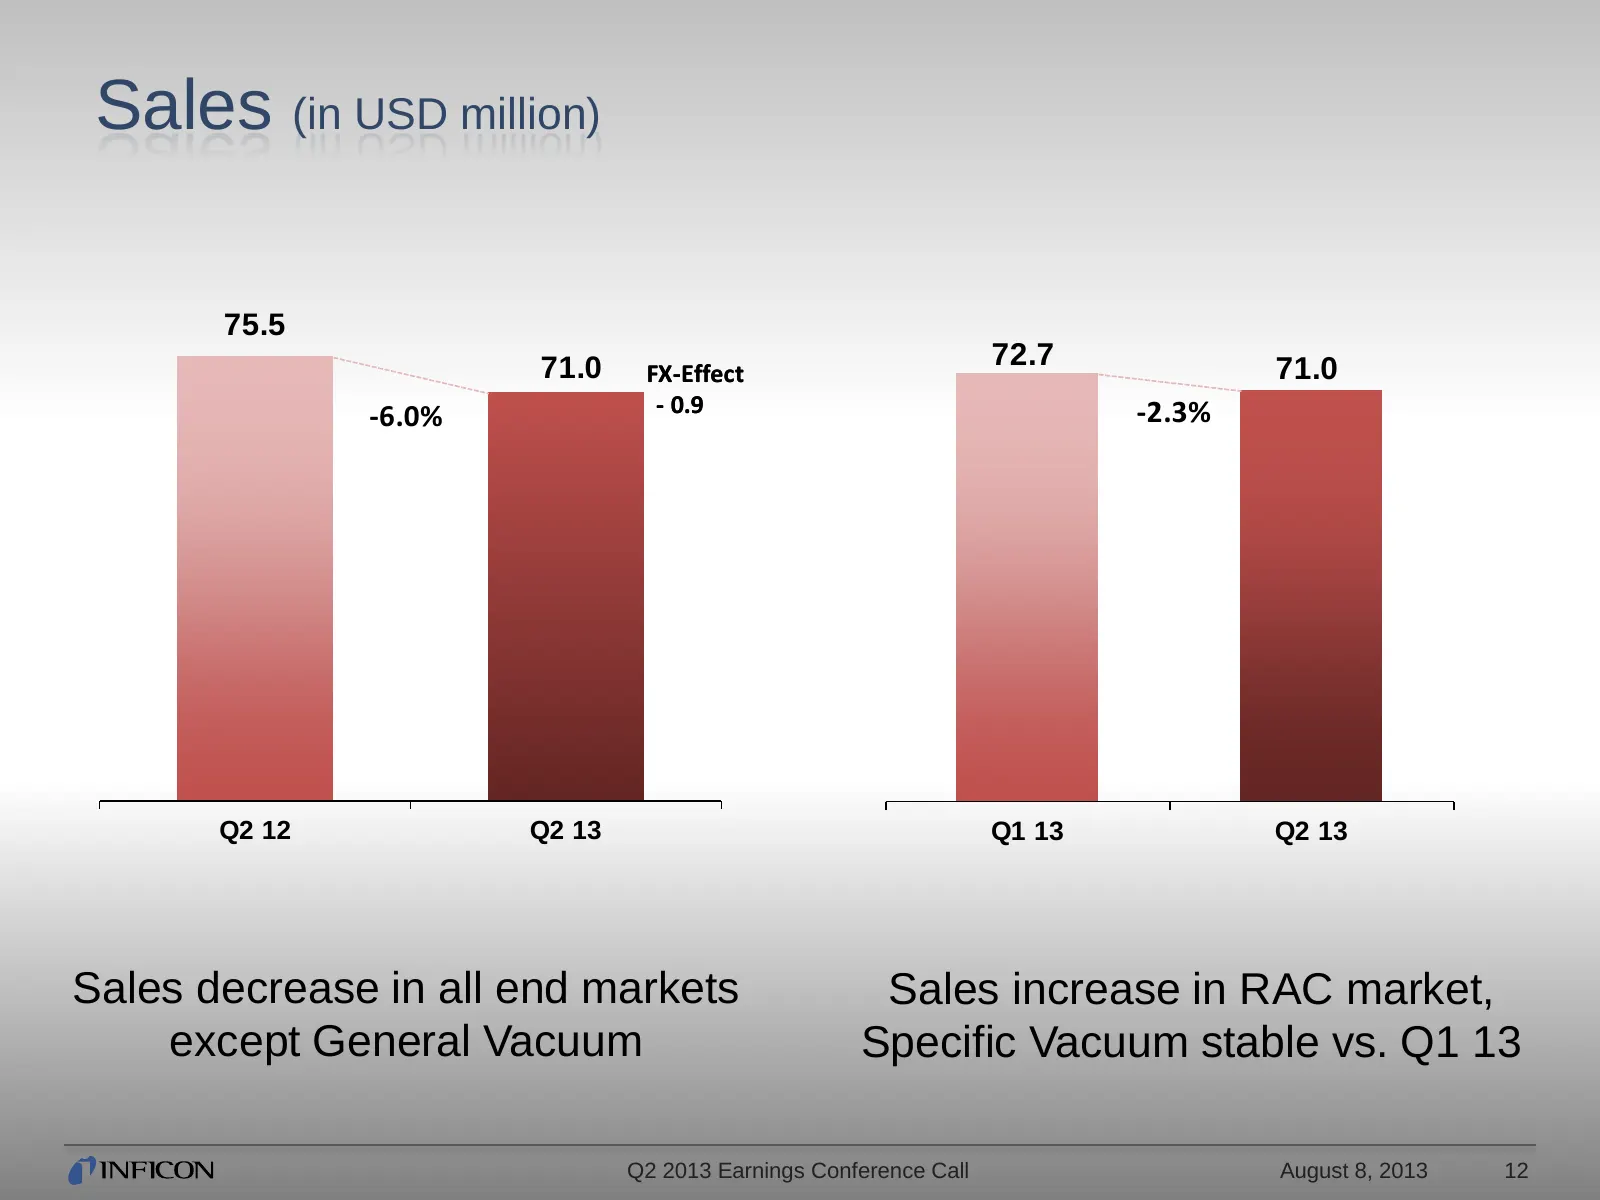
Sales (in USD million) 75.5 71.0 72.7 71.0 FX-Effect - 0.9 -2.3% -6.0% Q2 12 Q2 13 Q1 13 Q2 13 Sales decrease in all end markets Sales increase in RAC market, except General Vacuum Specific Vacuum stable vs. Q1 13 Q2 2013 Earnings Conference Call August 8, 2013 12
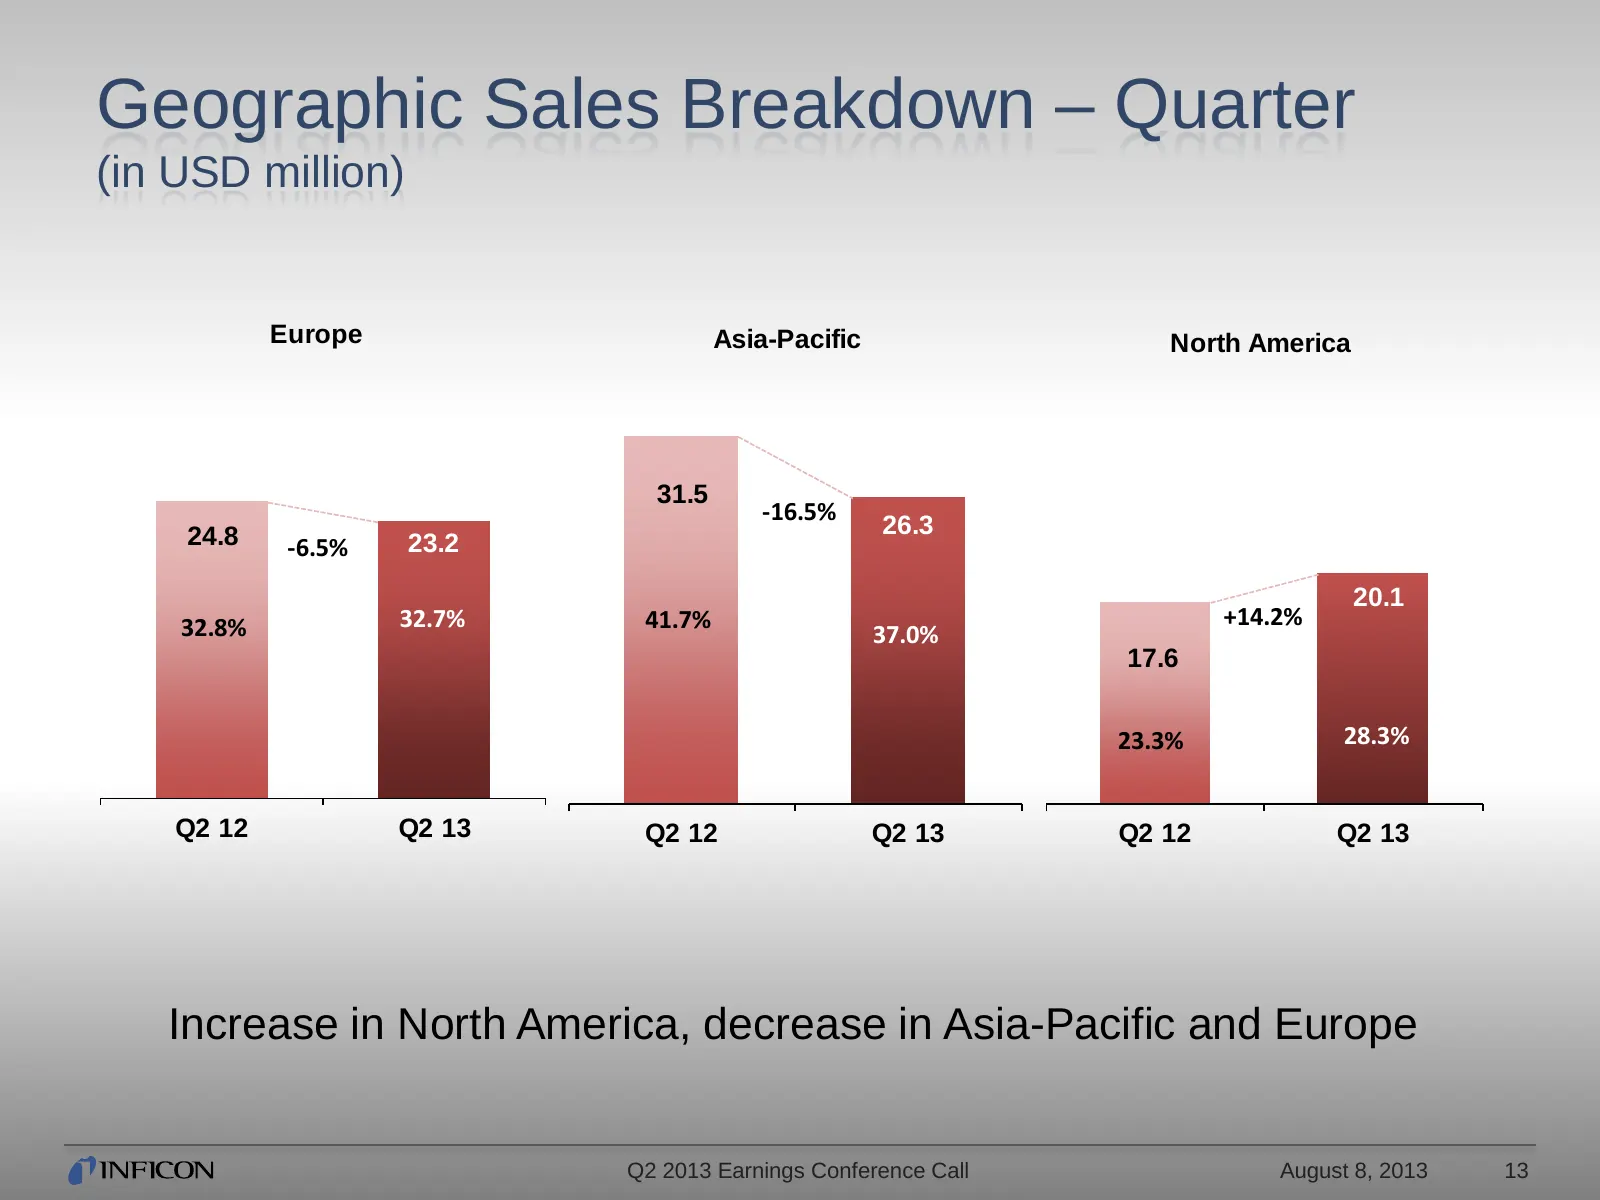
Slide 13: Geographic Sales Breakdown – Quarter
Geographic Sales Breakdown – Quarter (in USD million) Europe Asia-Pacific North America 31.5 -16.5% 24.8 26.3 -6.5% 23.2 20.1 32.8% 32.7% 41.7% +14.2% 37.0% 17.6 23.3% 28.3% Q2 12 Q2 13 Q2 12 Q2 13 Q2 12 Q2 13 Increase in North America, decrease in Asia-Pacific and Europe Q2 2013 Earnings Conference
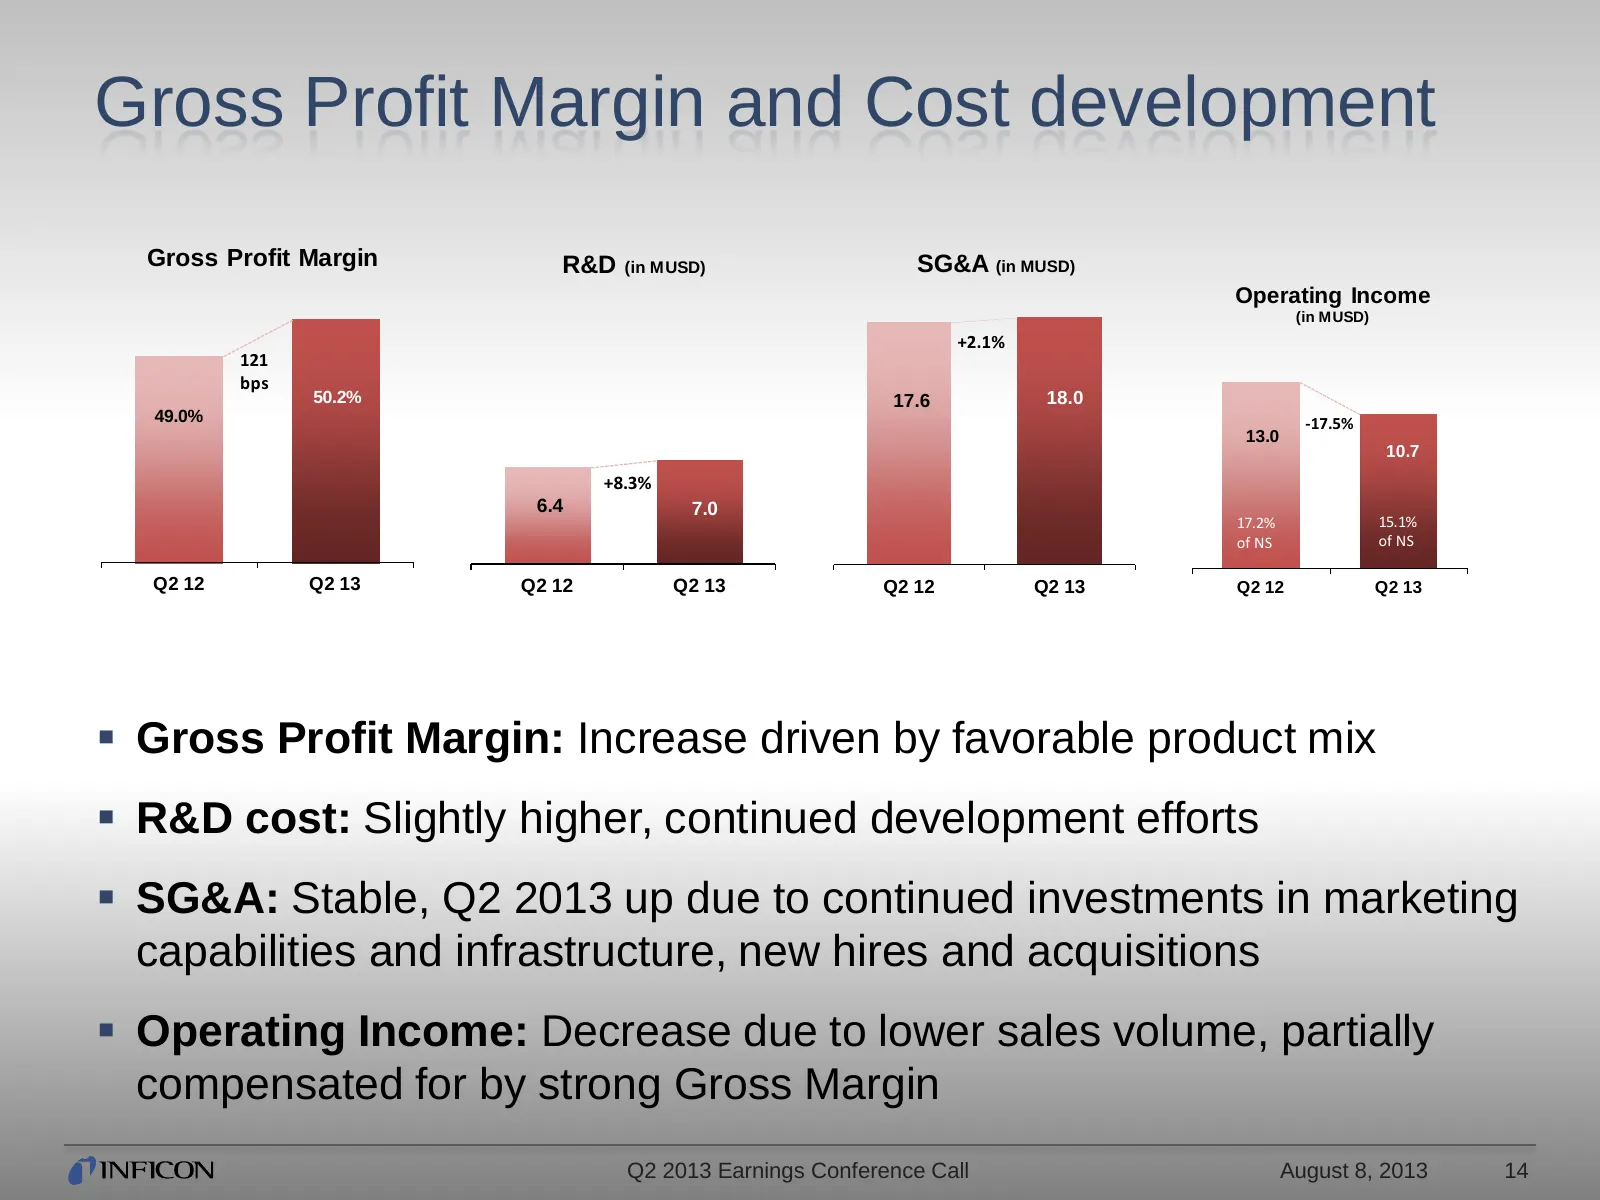
Slide 14: Gross Profit Margin and Cost development
Gross Profit Margin and Cost development Gross Profit Margin R&D (in MUSD) SG&A (in MUSD) Operating Income (in MUSD) +2.1% 121 bps 50.2% 17.6 18.0 49.0% -17.5% 13.0 10.7 +8.3% 6.4 7.0 17.2% 15.1% of NS of NS Q2 12 Q2 13 Q2 12 Q2 13 Q2 12 Q2 13 Q2 12 Q2 13 Gross Profit Margin: Increase driven by fa
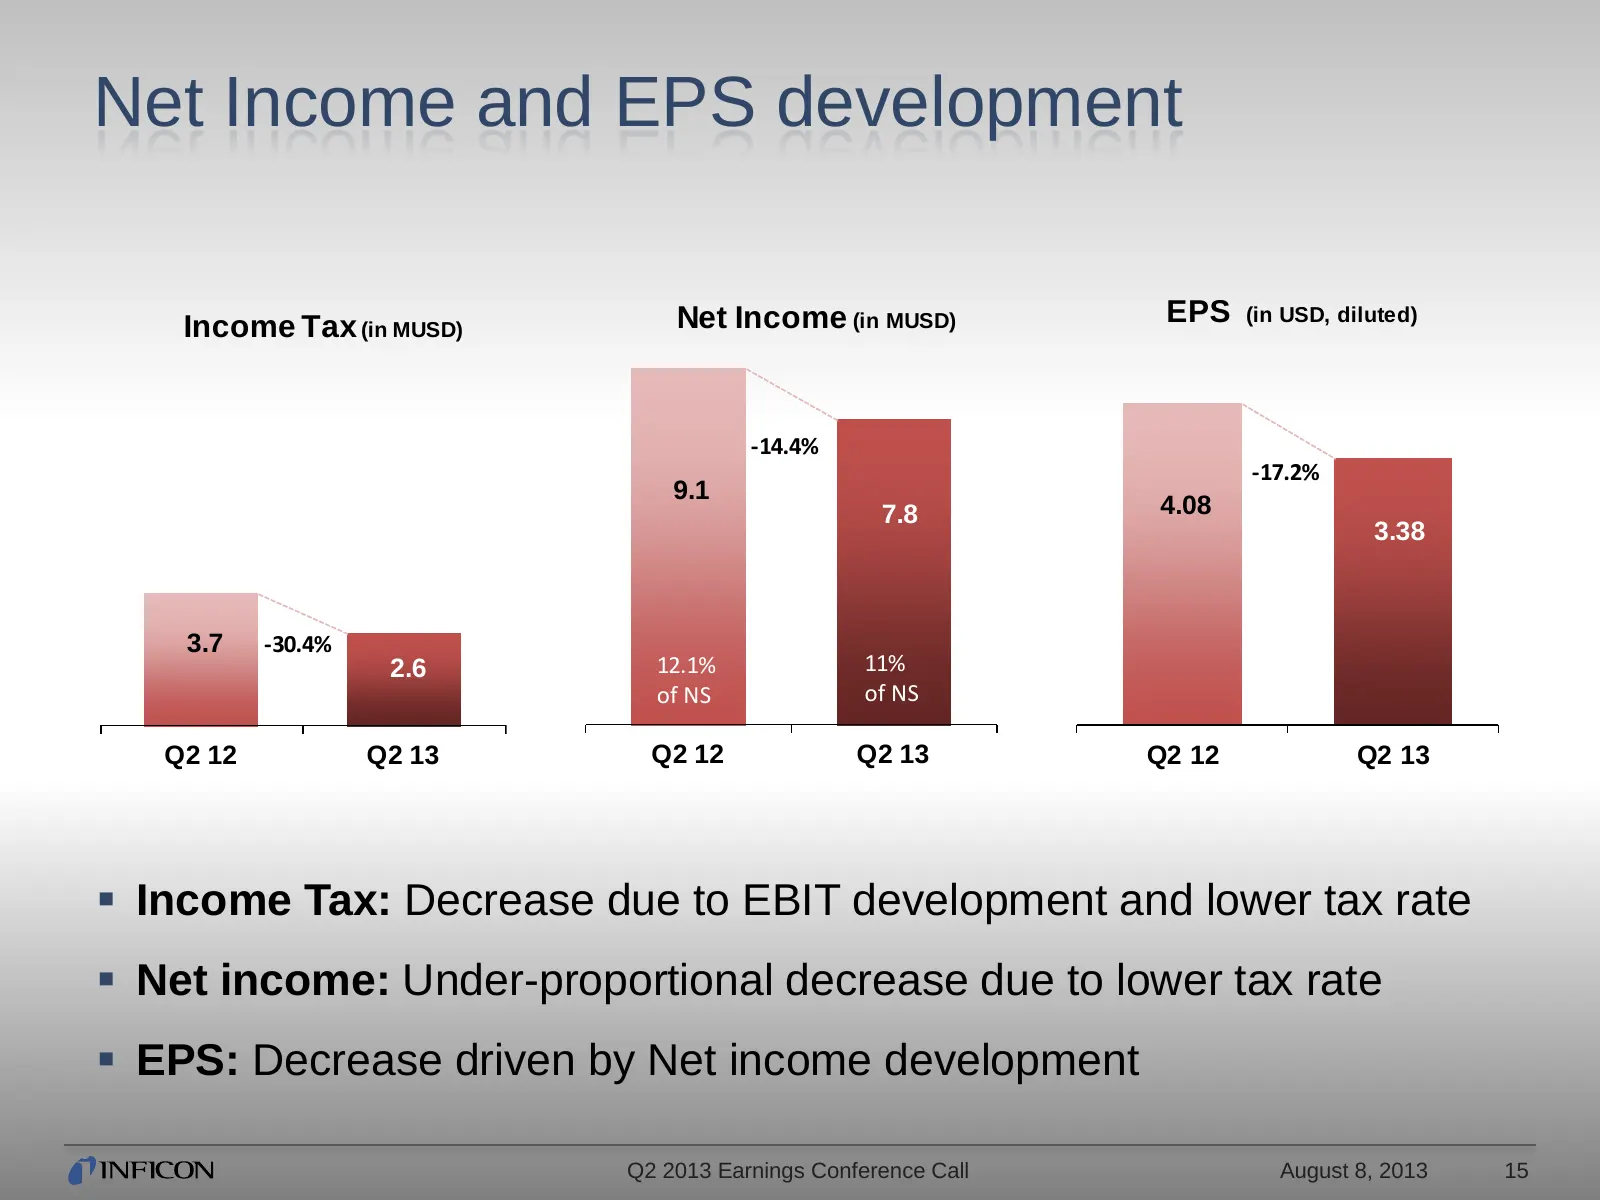
Slide 15: Net Income and EPS development
Net Income and EPS development Net Income (in MUSD) EPS (in USD, diluted) Income Tax (in MUSD) -14.4% -17.2% 9.1 7.8 4.08 3.38 3.7 -30.4% 2.6 12.1% 11% of NS of NS Q2 12 Q2 13 Q2 12 Q2 13 Q2 12 Q2 13 Income Tax: Decrease due to EBIT development and lower tax rate Net income: Under-proportional d
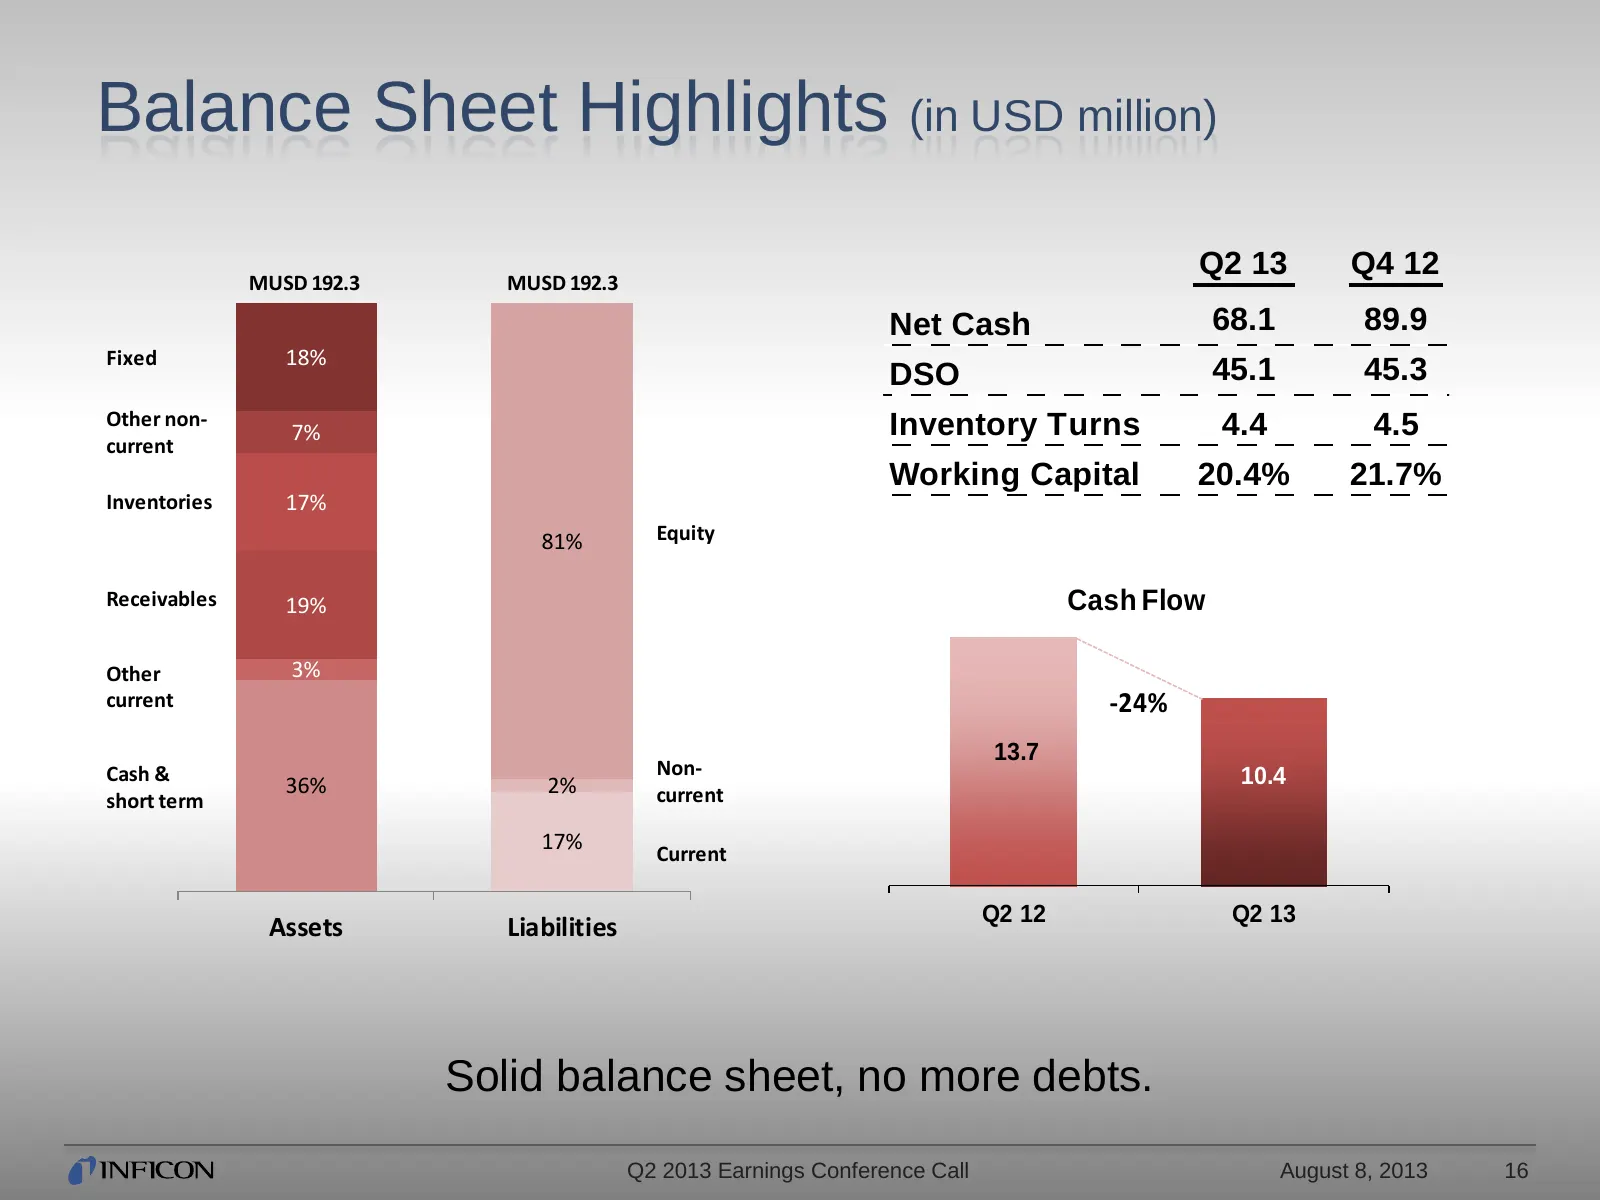
Slide 16: Balance Sheet Highlights (in USD million)
Balance Sheet Highlights (in USD million) MUSD 192.3 MUSD 192.3 Q2 13 Q4 12 Net Cash 68.1 89.9 Fixed 18% DSO 45.1 45.3 Other non- Inventory Turns 4.4 4.5 7% current Working Capital 20.4% 21.7% Inventories 17% 81% Equity Receivables 19% Cash Flow Other 3% current -24% 13.7 Cash & Non- 10.4 36% 2% cur
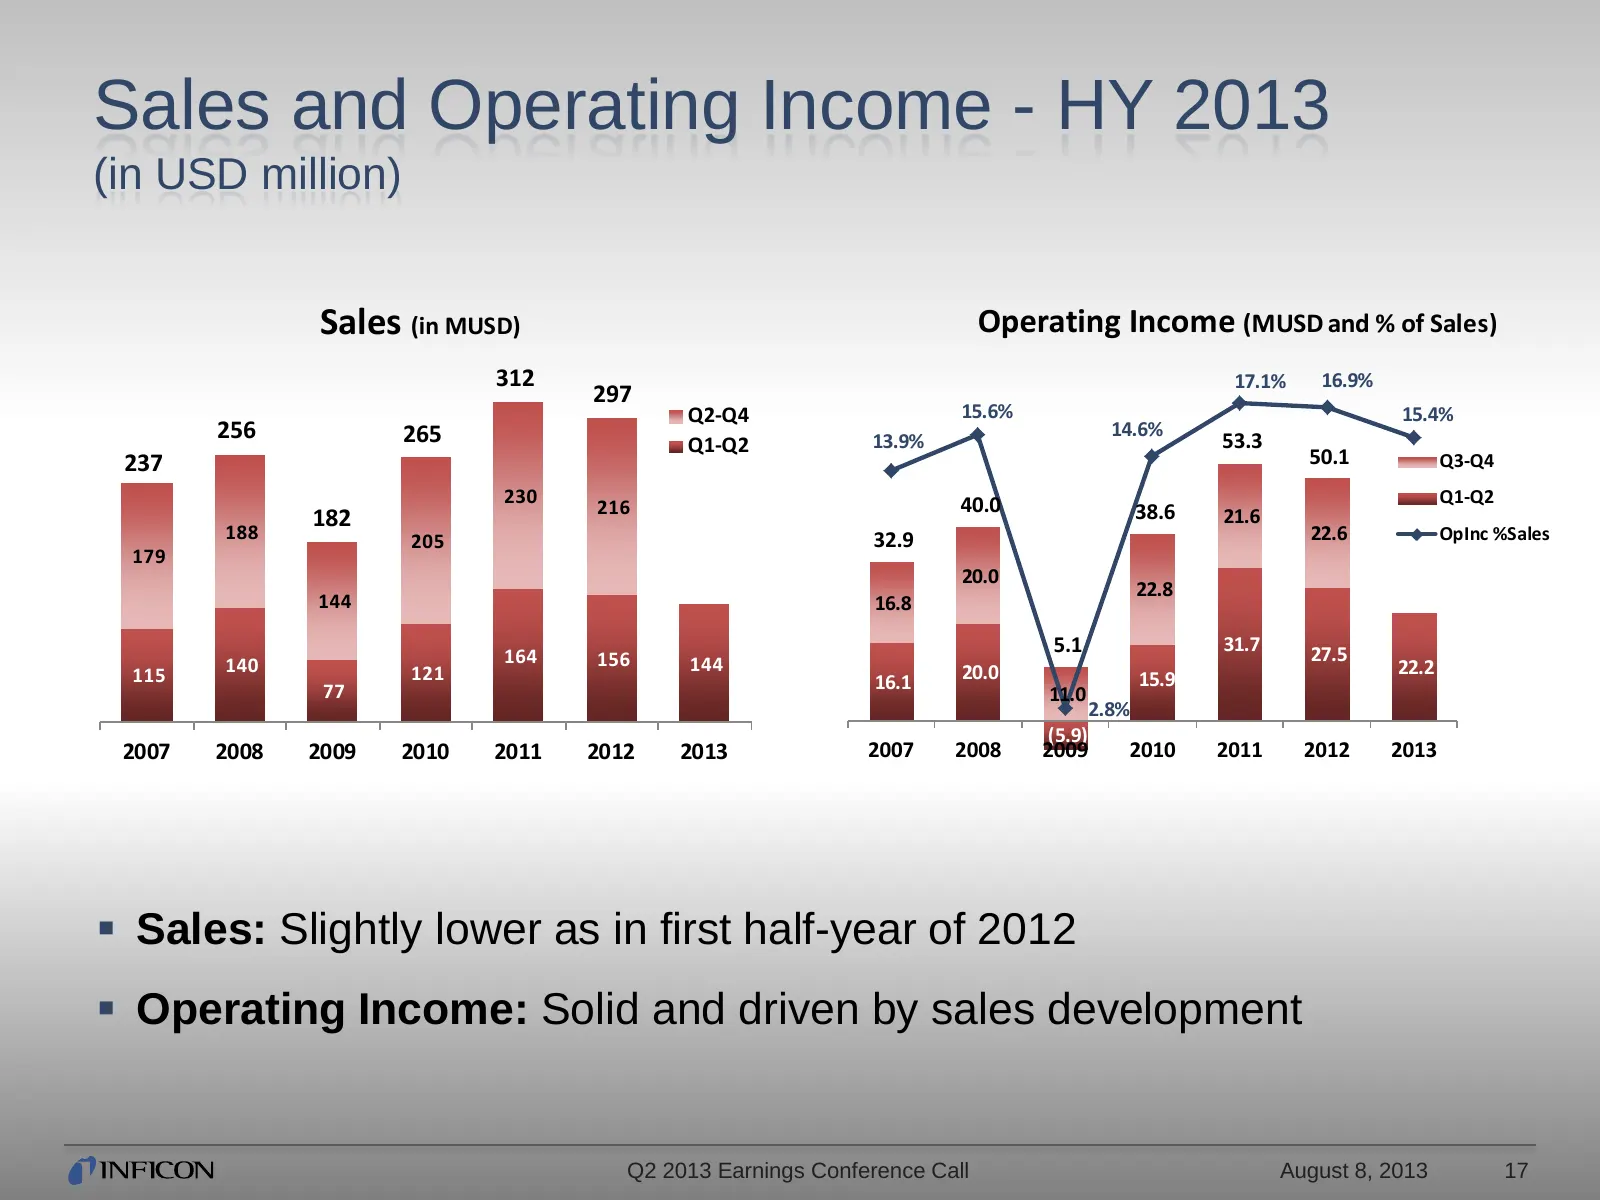
Slide 17: Sales and Operating Income - HY 2013
Sales and Operating Income - HY 2013 (in USD million) Sales (in MUSD) Operating Income (MUSD and % of Sales) 312 17.1% 16.9% 297 Q2-Q4 15.6% 15.4% 256 265 13.9% 14.6% 53.3 Q1-Q2 50.1 237 Q3-Q4 230 40.0 Q1-Q2 216 38.6 182 21.6 188 205 32.9 22.6 OpInc %Sales 179 20.0 22.8 144 16.8 164 5.1 31.7 27.5 14
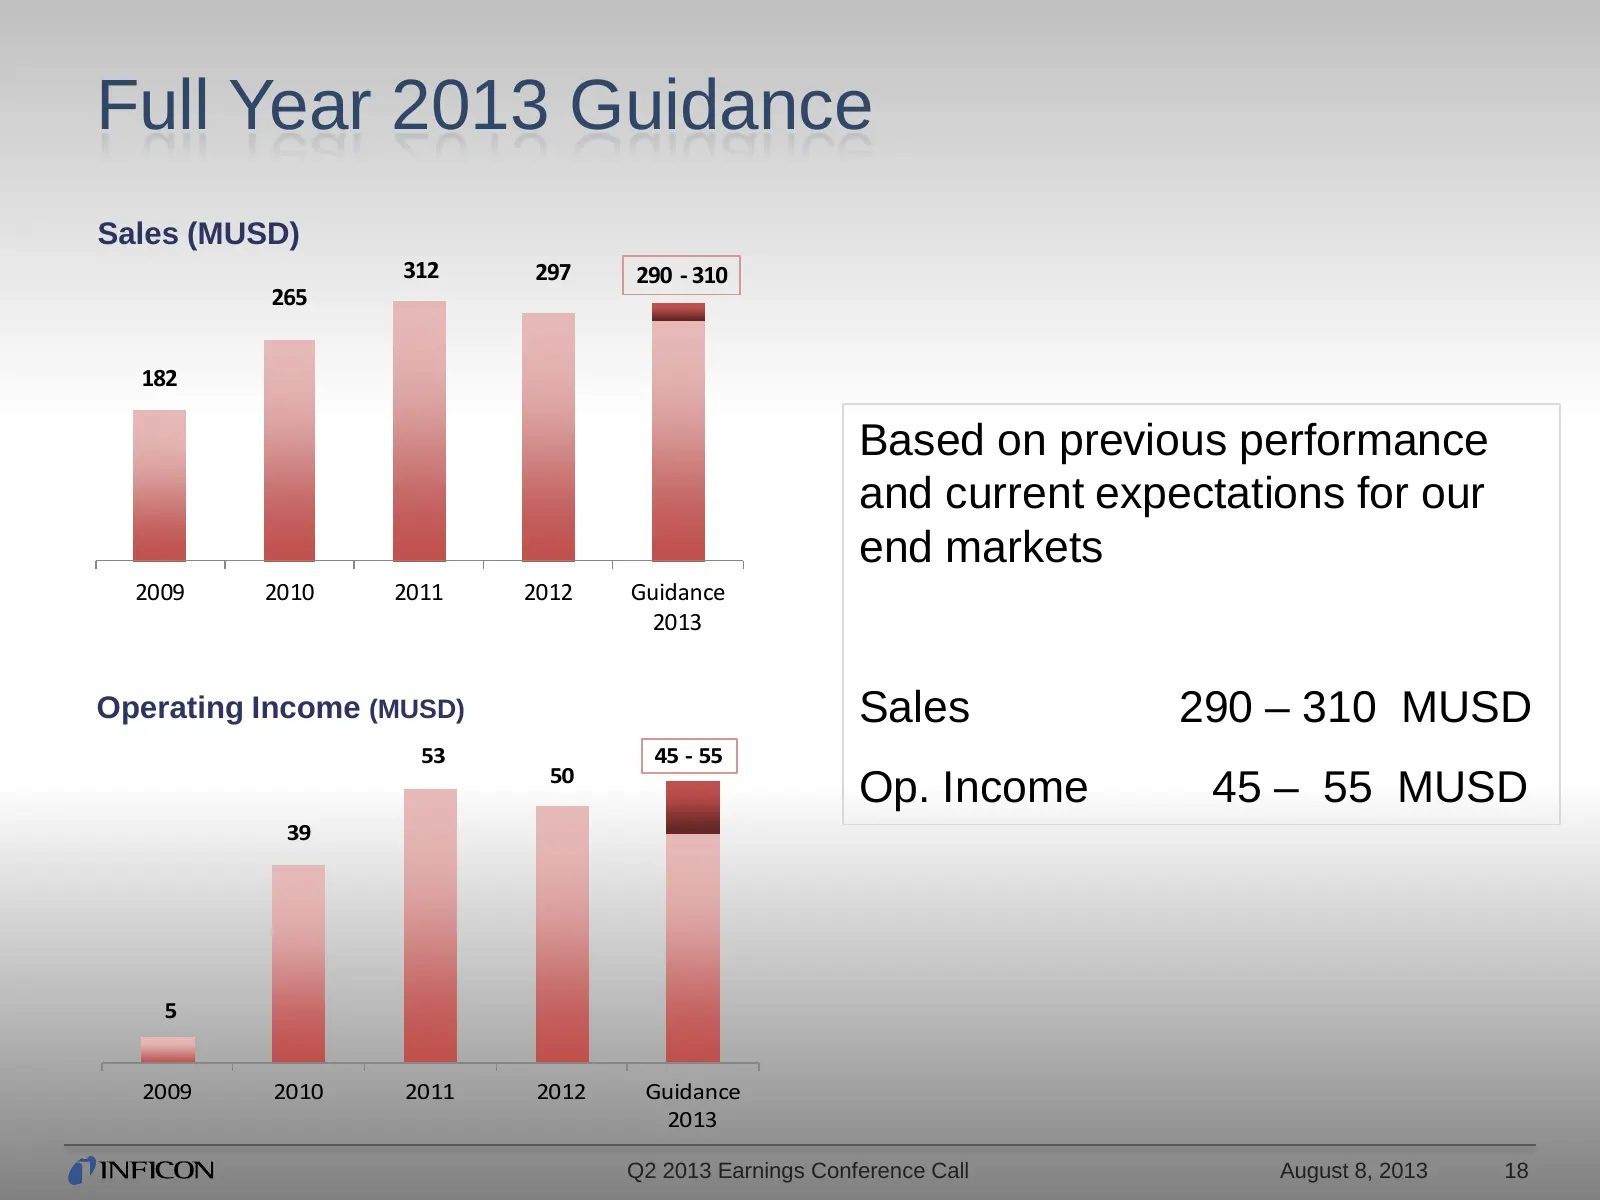
Slide 18: Full Year 2013 Guidance
Full Year 2013 Guidance Sales (MUSD) 312 297 290 - 310 265 182 Based on previous performance and current expectations for our end markets 2009 2010 2011 2012 Guidance 2013 Operating Income (MUSD) Sales 290 – 310 MUSD 53 45 - 55 50 Op. Income 45 – 55 MUSD 39 5 2009 2010 2011 2012 Guidance 2013 Q2 201
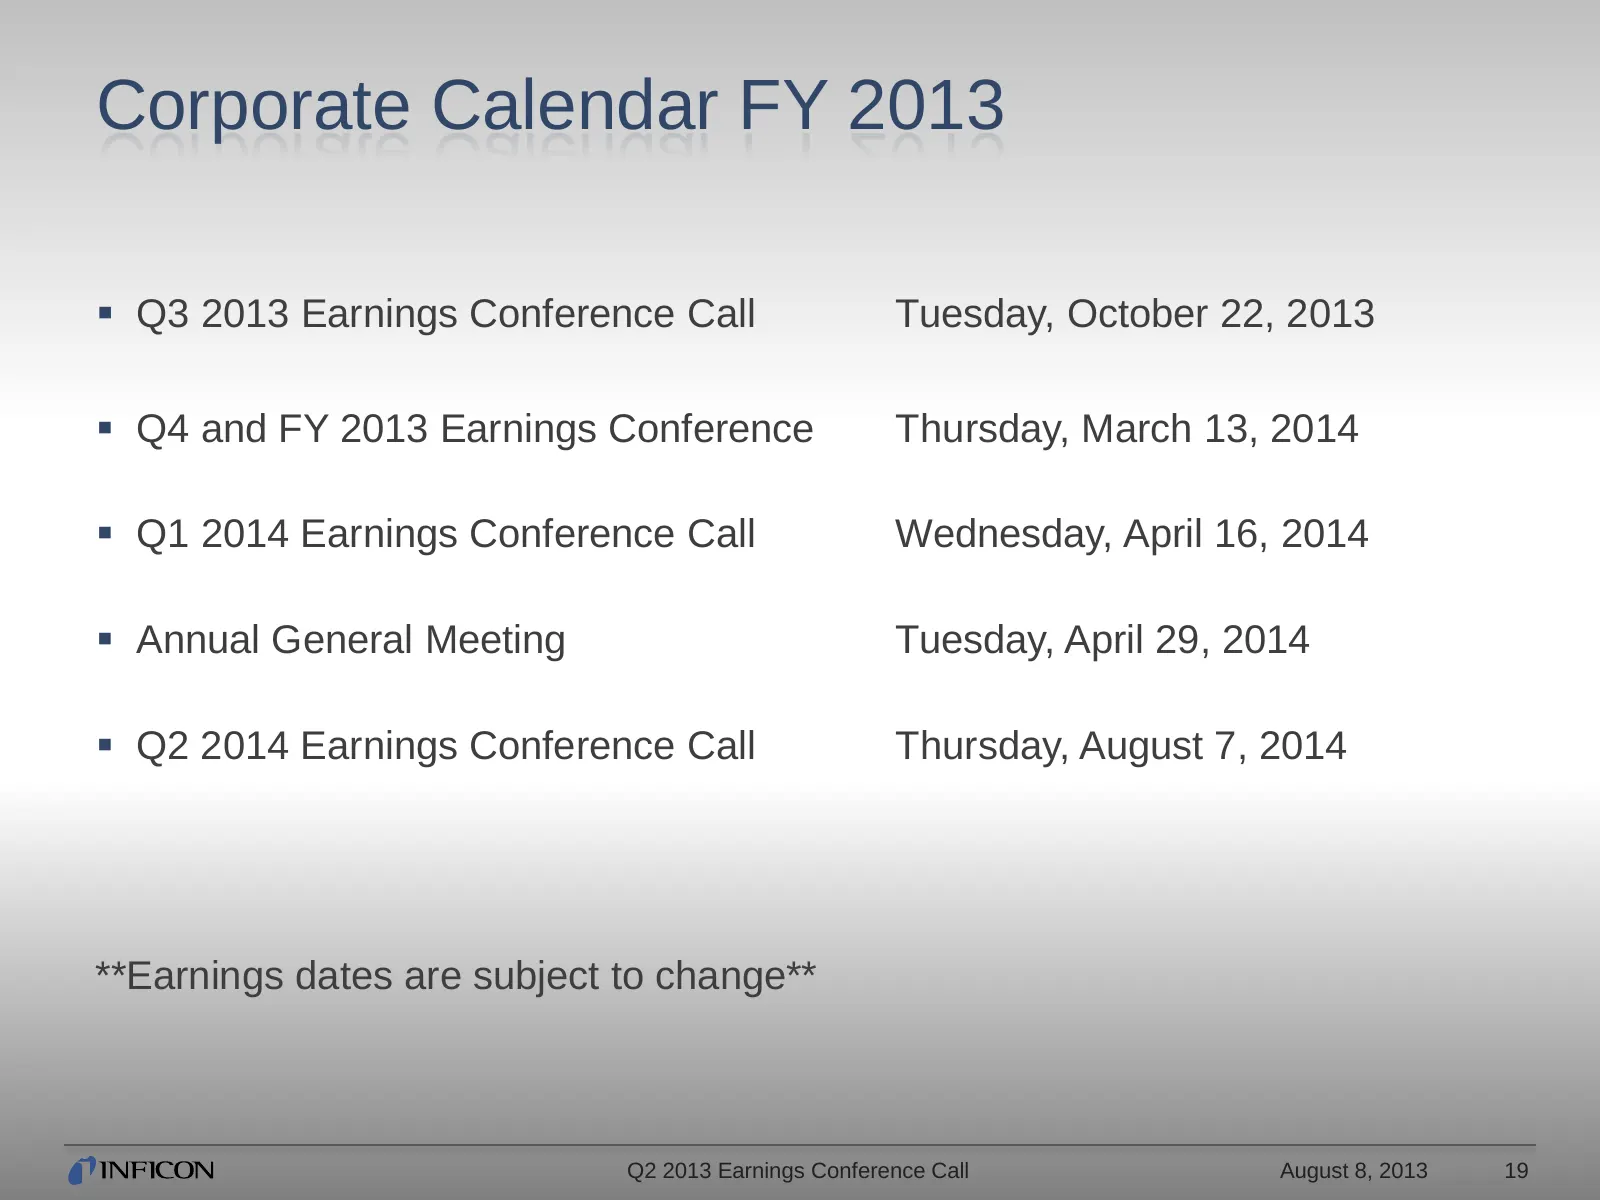
Slide 19: Corporate Calendar FY 2013
Corporate Calendar FY 2013 Q3 2013 Earnings Conference Call Tuesday, October 22, 2013 Q4 and FY 2013 Earnings Conference Thursday, March 13, 2014 Q1 2014 Earnings Conference Call Wednesday, April 16, 2014 Annual General Meeting Tuesday, April 29, 2014 Q2 2014 Earnings Conference Call Thurs
Slide 20: Thank You! Q&A
THANK YOU ! Q&A Q2 2013 Earnings Conference Call August 8, 2013 20
Slide 21: INFICON
6) INFICON Instruments for Intelligent Control™
Source: Internet Archive copy of ir.inficon.com
More decks from INFICON Holding AG
 Q3 2026 Earnings Presentation18 slides · Oct 27, 2026
 Q2 2026 Earnings Presentation20 slides · Jul 30, 2026
 Q1 2026 Earnings Presentation20 slides · Apr 24, 2026
 Q4 2025 Earnings Presentation32 slides · Mar 24, 2026
 Q1 2025 Earnings Presentation20 slides · Apr 24, 2025
 Technical Presentation (September 2024)44 slides · September 2024