SunCoke Energy Partners L.P — 2013 Citi MLP / Midstream Infrastructure One-on-One Conference
34 slides from SunCoke Energy Partners L.P's conference presentation, Aug 22, 2013
Slide 1: 2013 Citi MLP / Midstream One-on-One Conference
Exhibit 99.1 2013 Citi MLP Infrastructure August/ Midstream 21-22, One-on-One Conference 2013
Slide 2: Forward-Looking Statements
Forward-Looking Some 1934, Energy, beliefs competitive statements “continue,” Although plans, SunCoke the results All caution obligation applicable This are 22013 provided Securities forward-looking presentation Citi as of intentions to and should Inc. amended. the differ and One-on-One management t
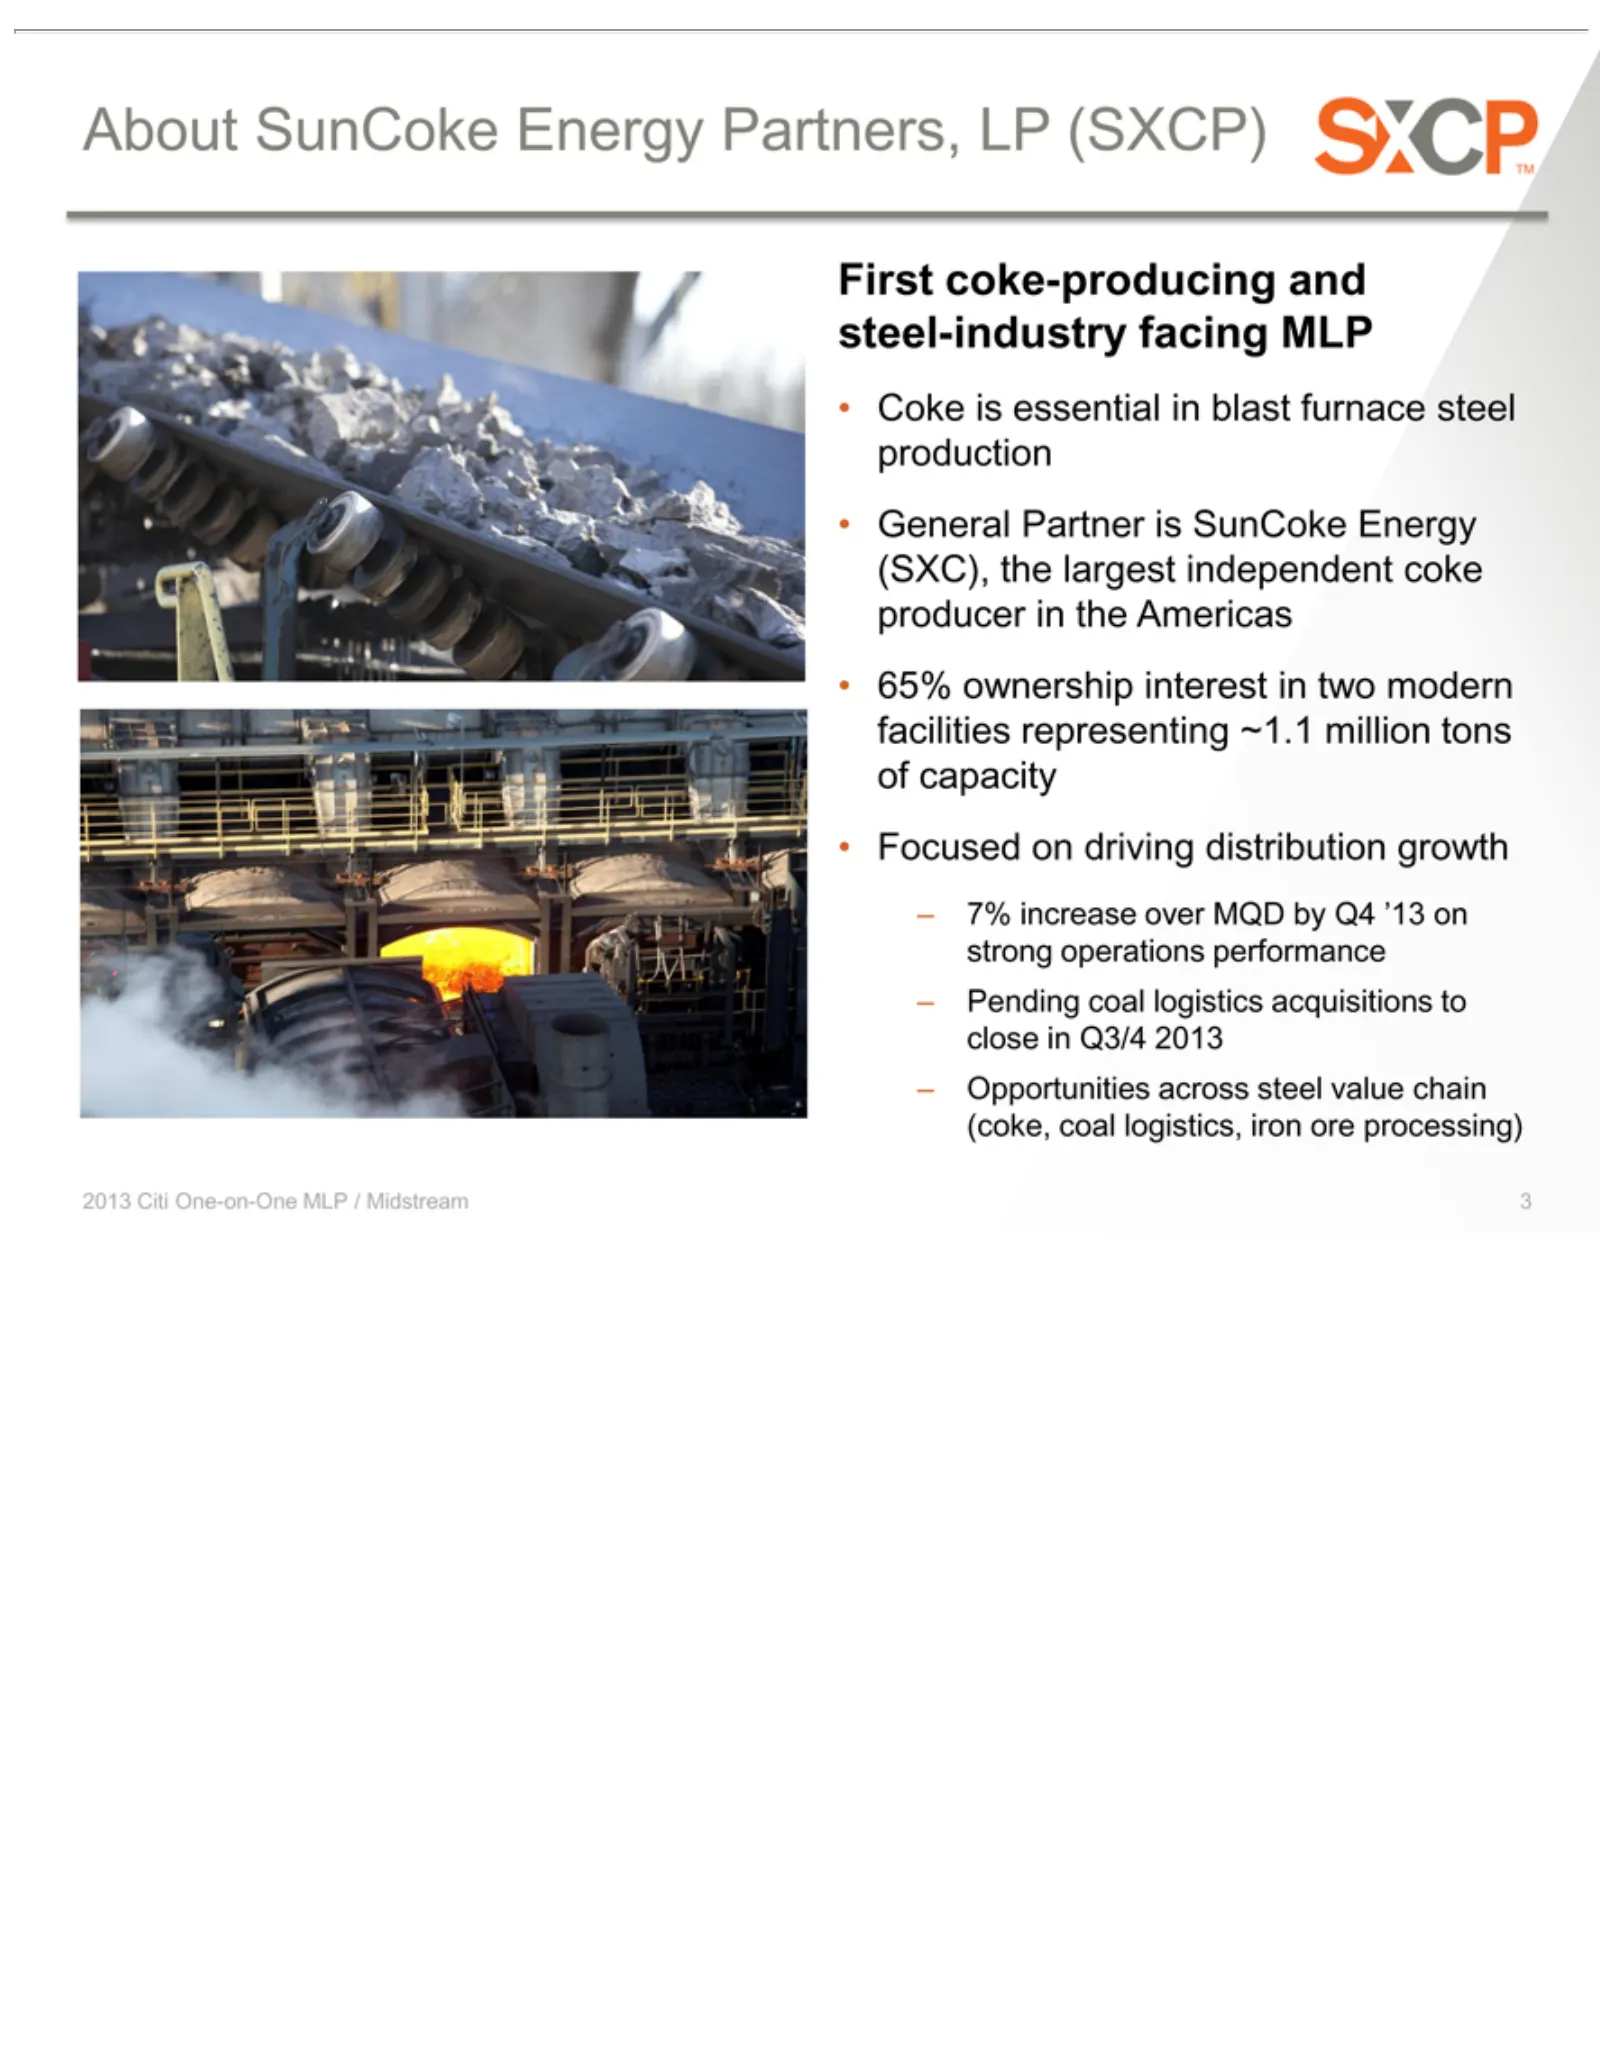
Slide 3: About SunCoke Energy Partners
About First steel-industry Coke General 65% Focused 7% Pending Opportunities 32013 increase ownership coke-producing Citi isSunCoke essential Partner coal on One-on-One driving over logistics facing across interest is Energy in MQD SunCoke distribution blast MLP steel and acquisitions MLP in by Part
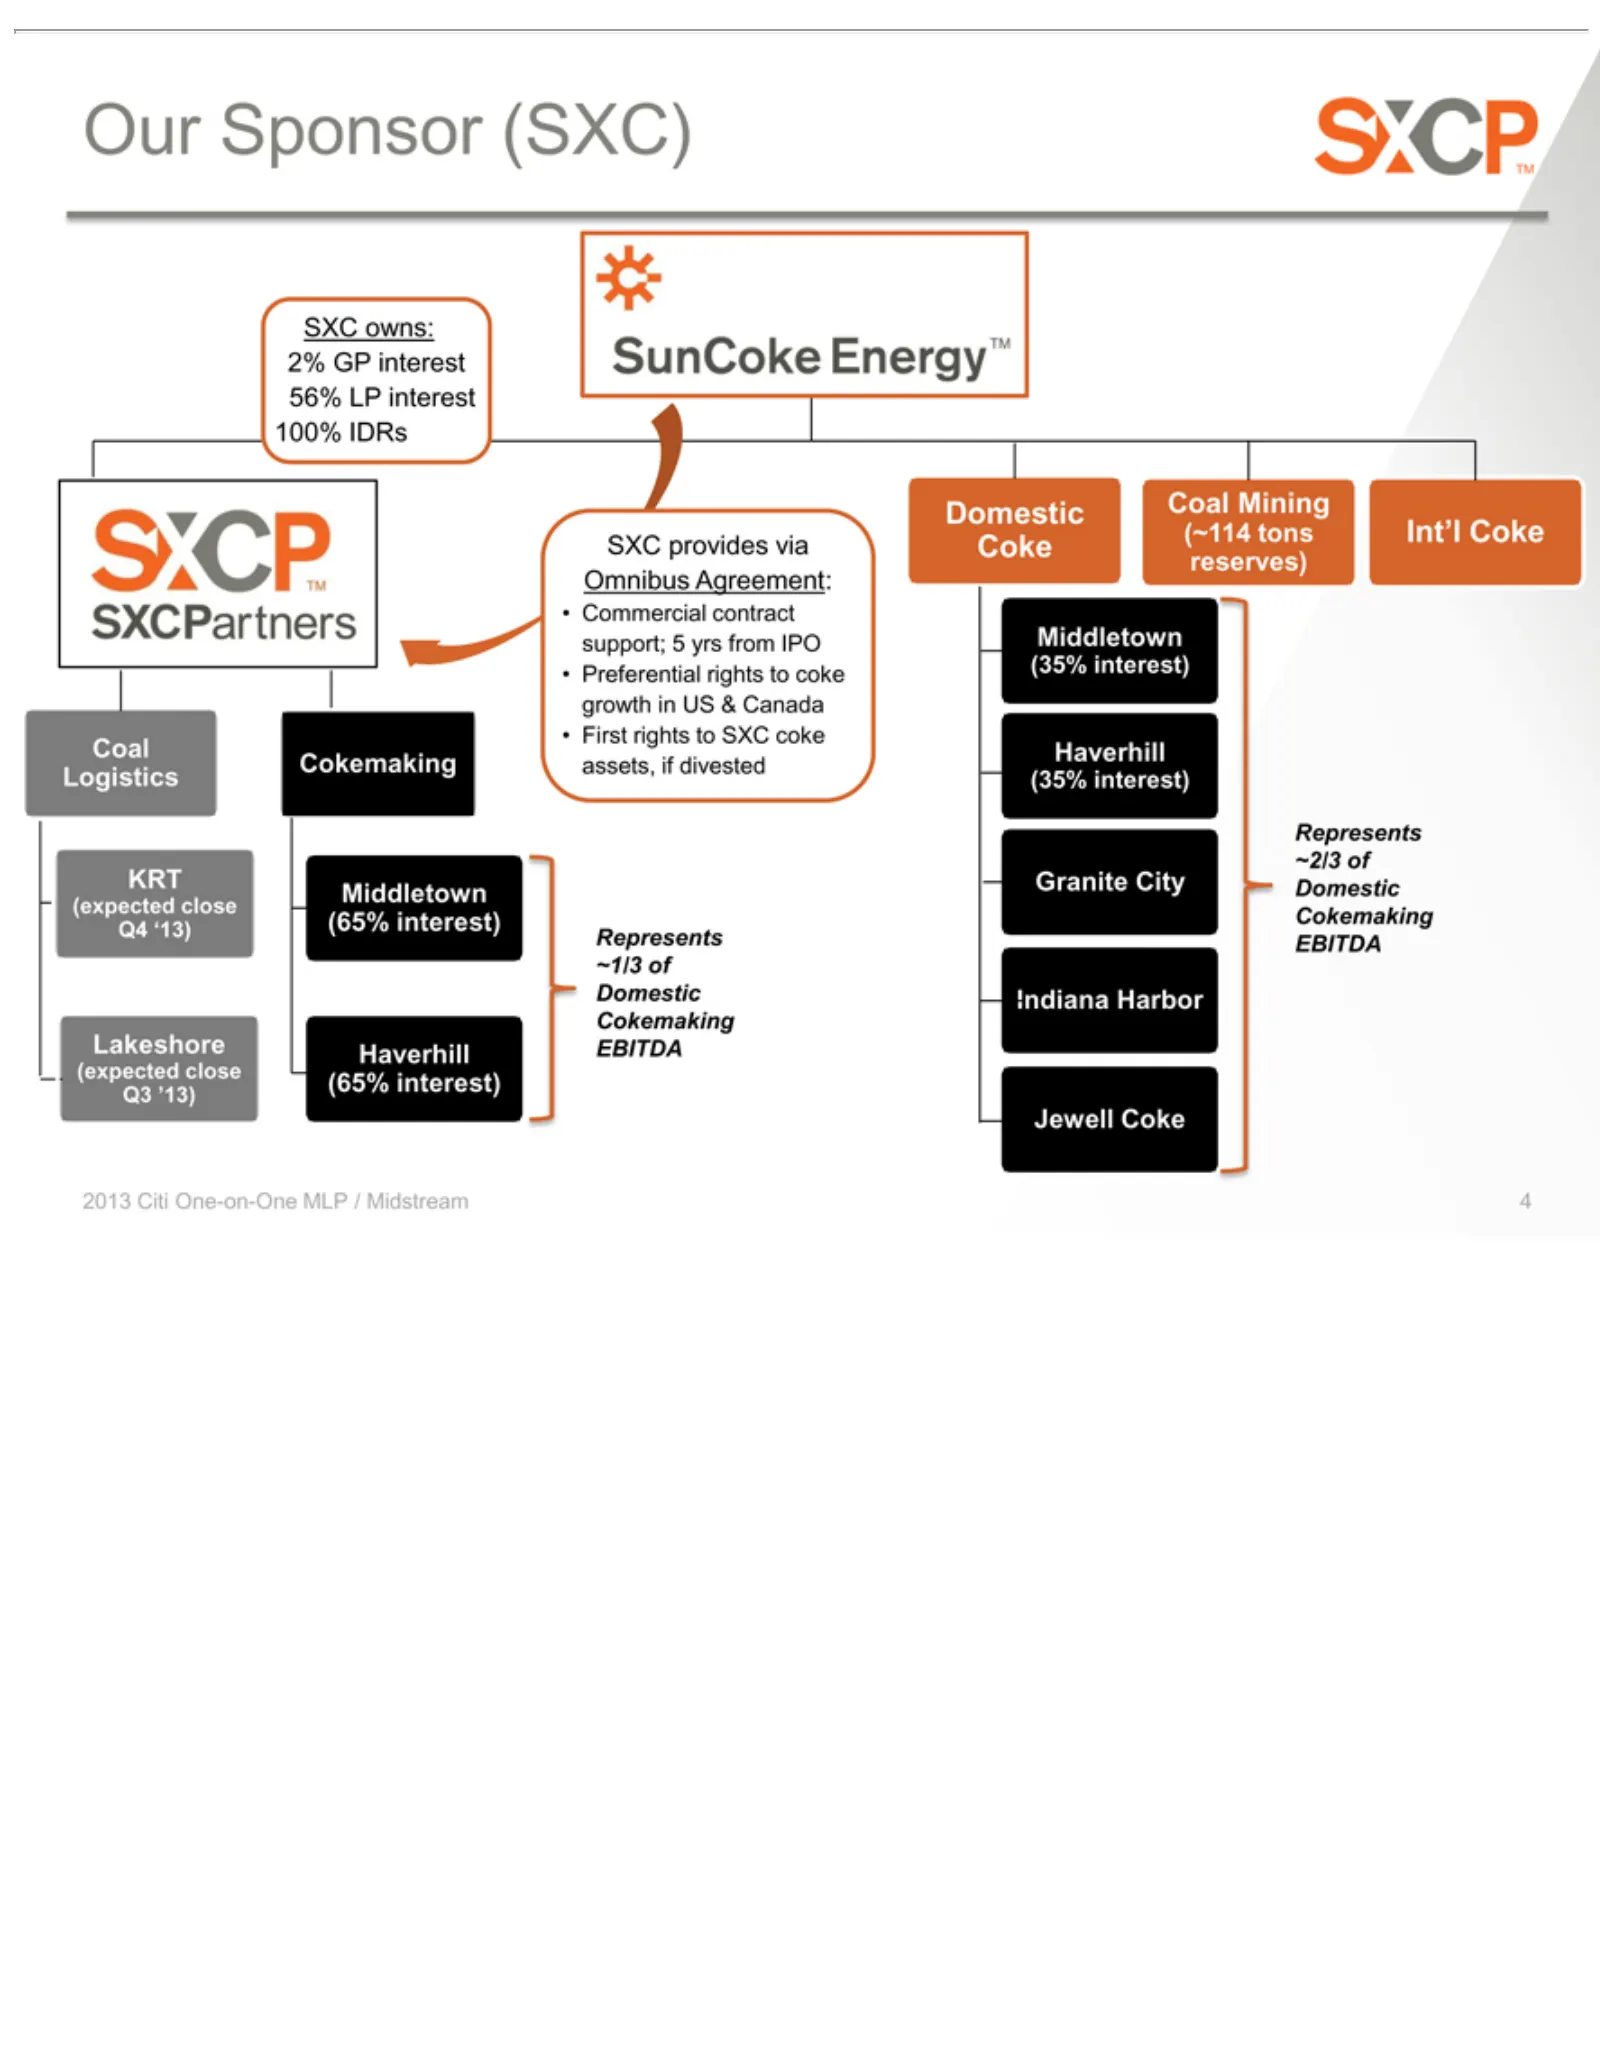
Slide 4: Our Sponsor and Asset Structure
Our’13) 2% Domestic (~114 SXC Omnibus Commercial Preferential First Coal Logistics KRT Q4 Represents Lakeshore Cokemaking (expected Q3 Jewell 2013‘13) GP Sponsor rights Haverhill Granite owns: provides Citi tons Coke interest (65% Agreement: (35% One-on-One Coal close Haverhill Int’l to ~2/3 EBITDA
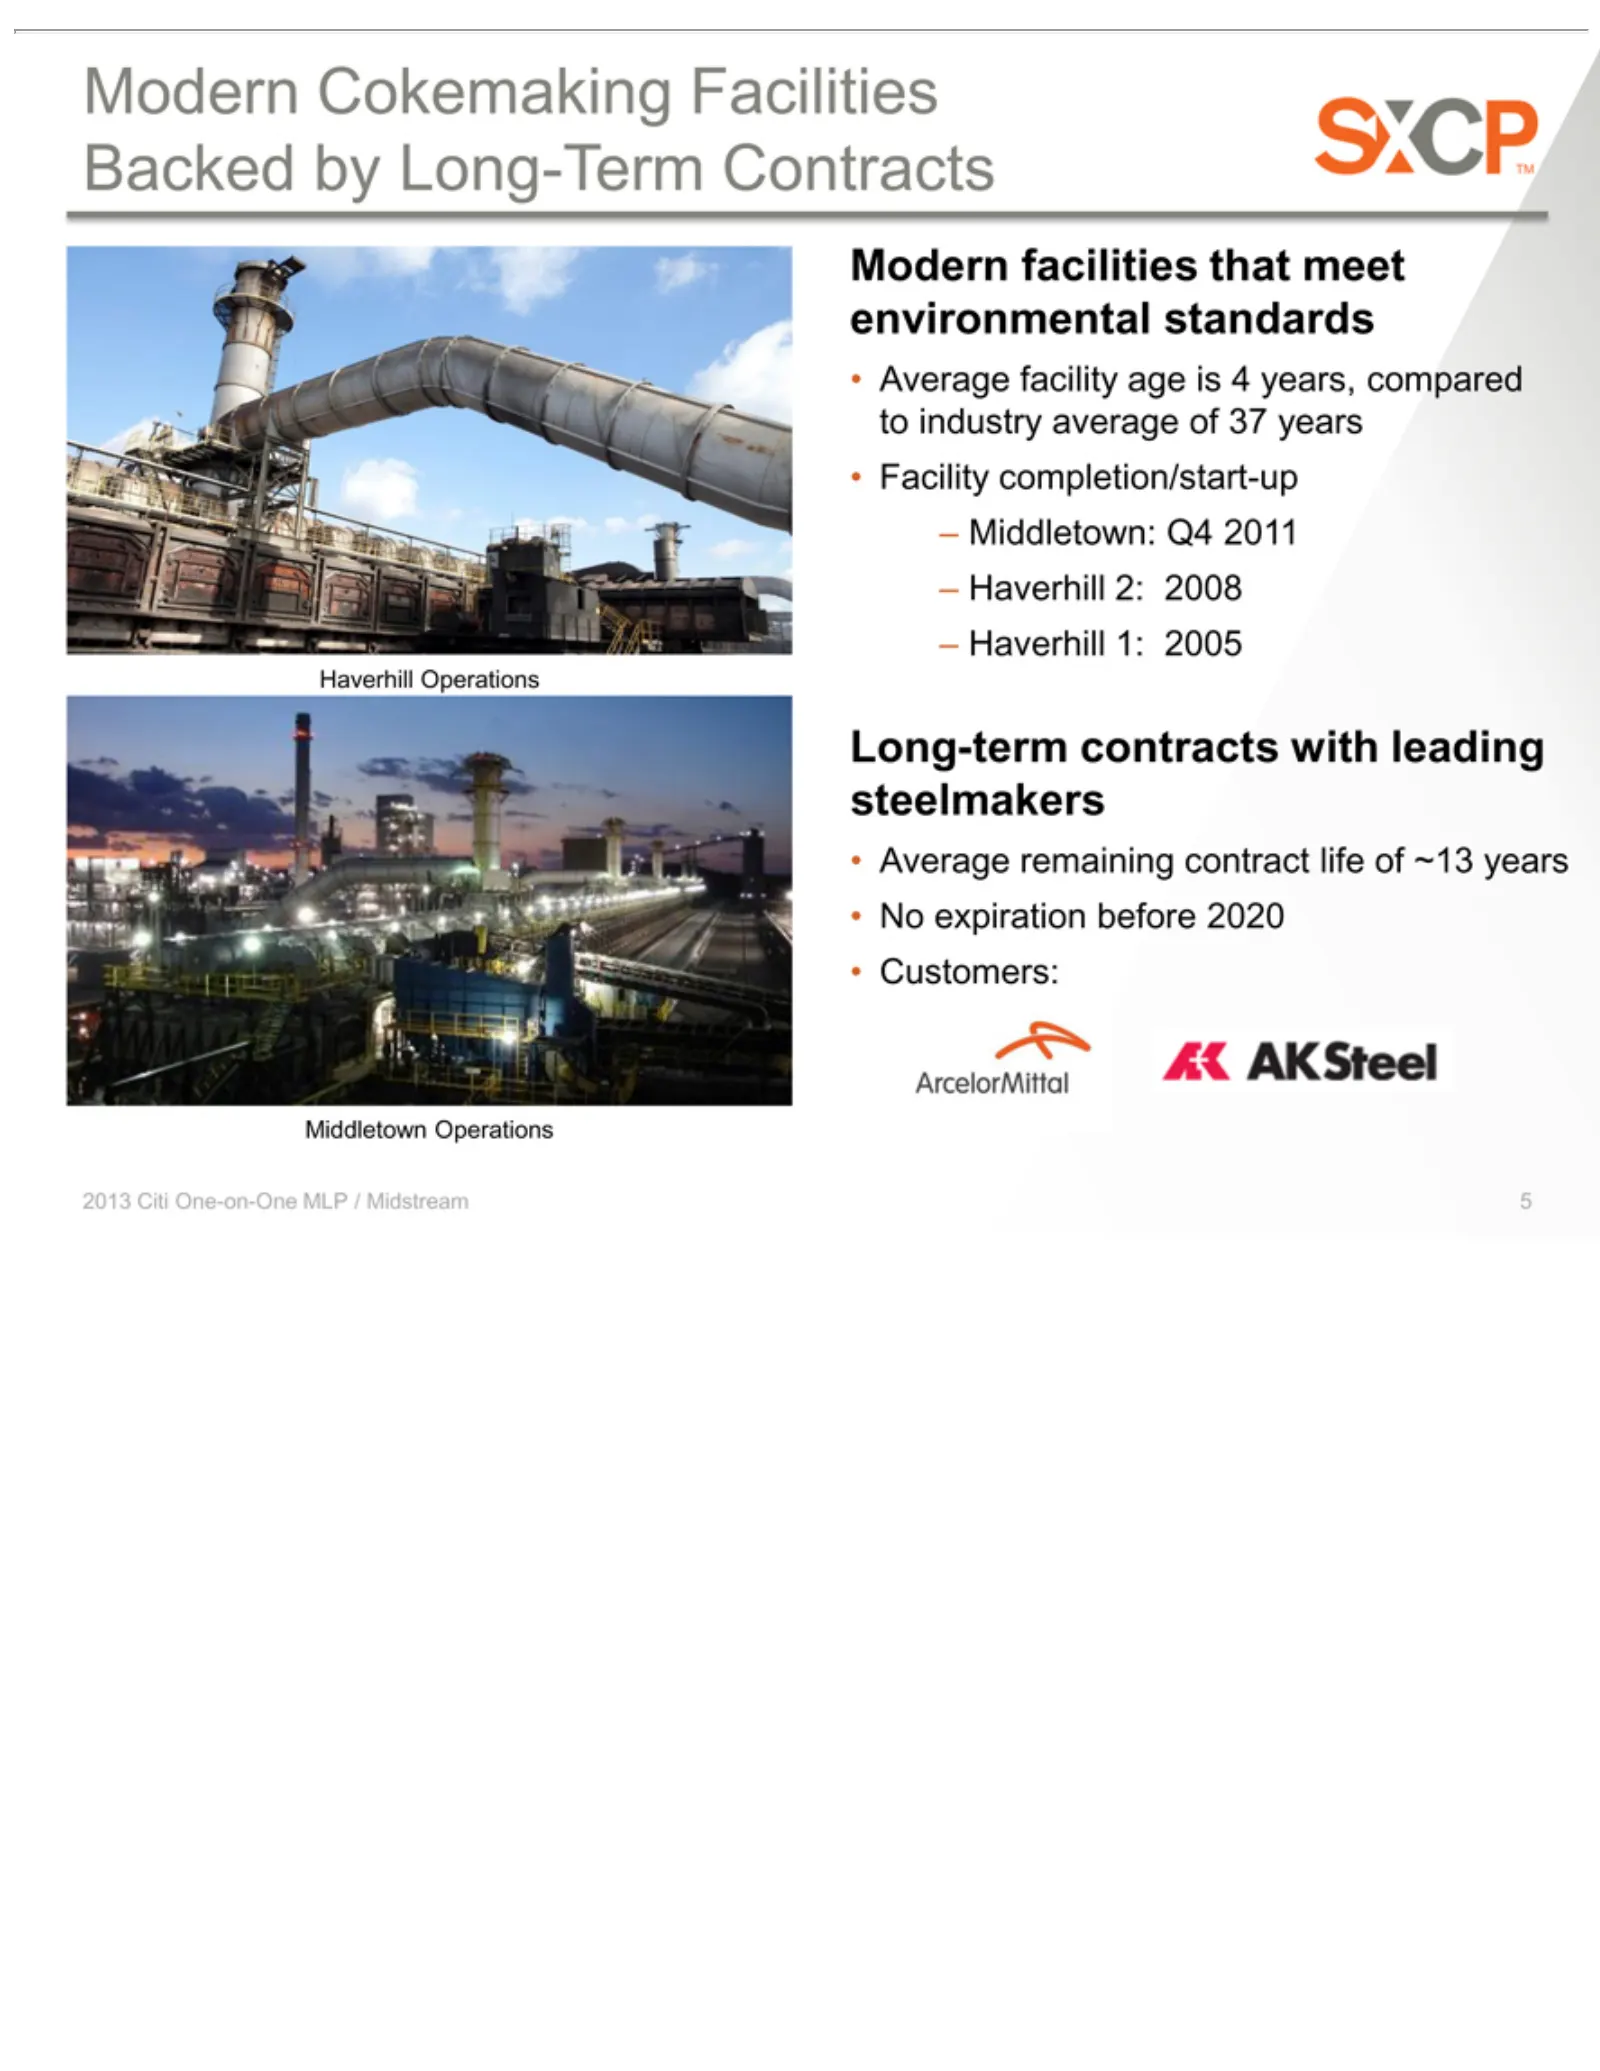
Slide 5: Modern Facilities Backed by Long-Term Contracts
Backed Modern environmental Facility Middletown: Haverhill Long-term Average steelmakers No Middletown Customers: 2013expiration Citi by completion/start-up Cokemaking facilities facility remaining One-on-One 2:Long-Term 1:contracts 2008 2005 Operations Q4before standards age 2011 that contract is w
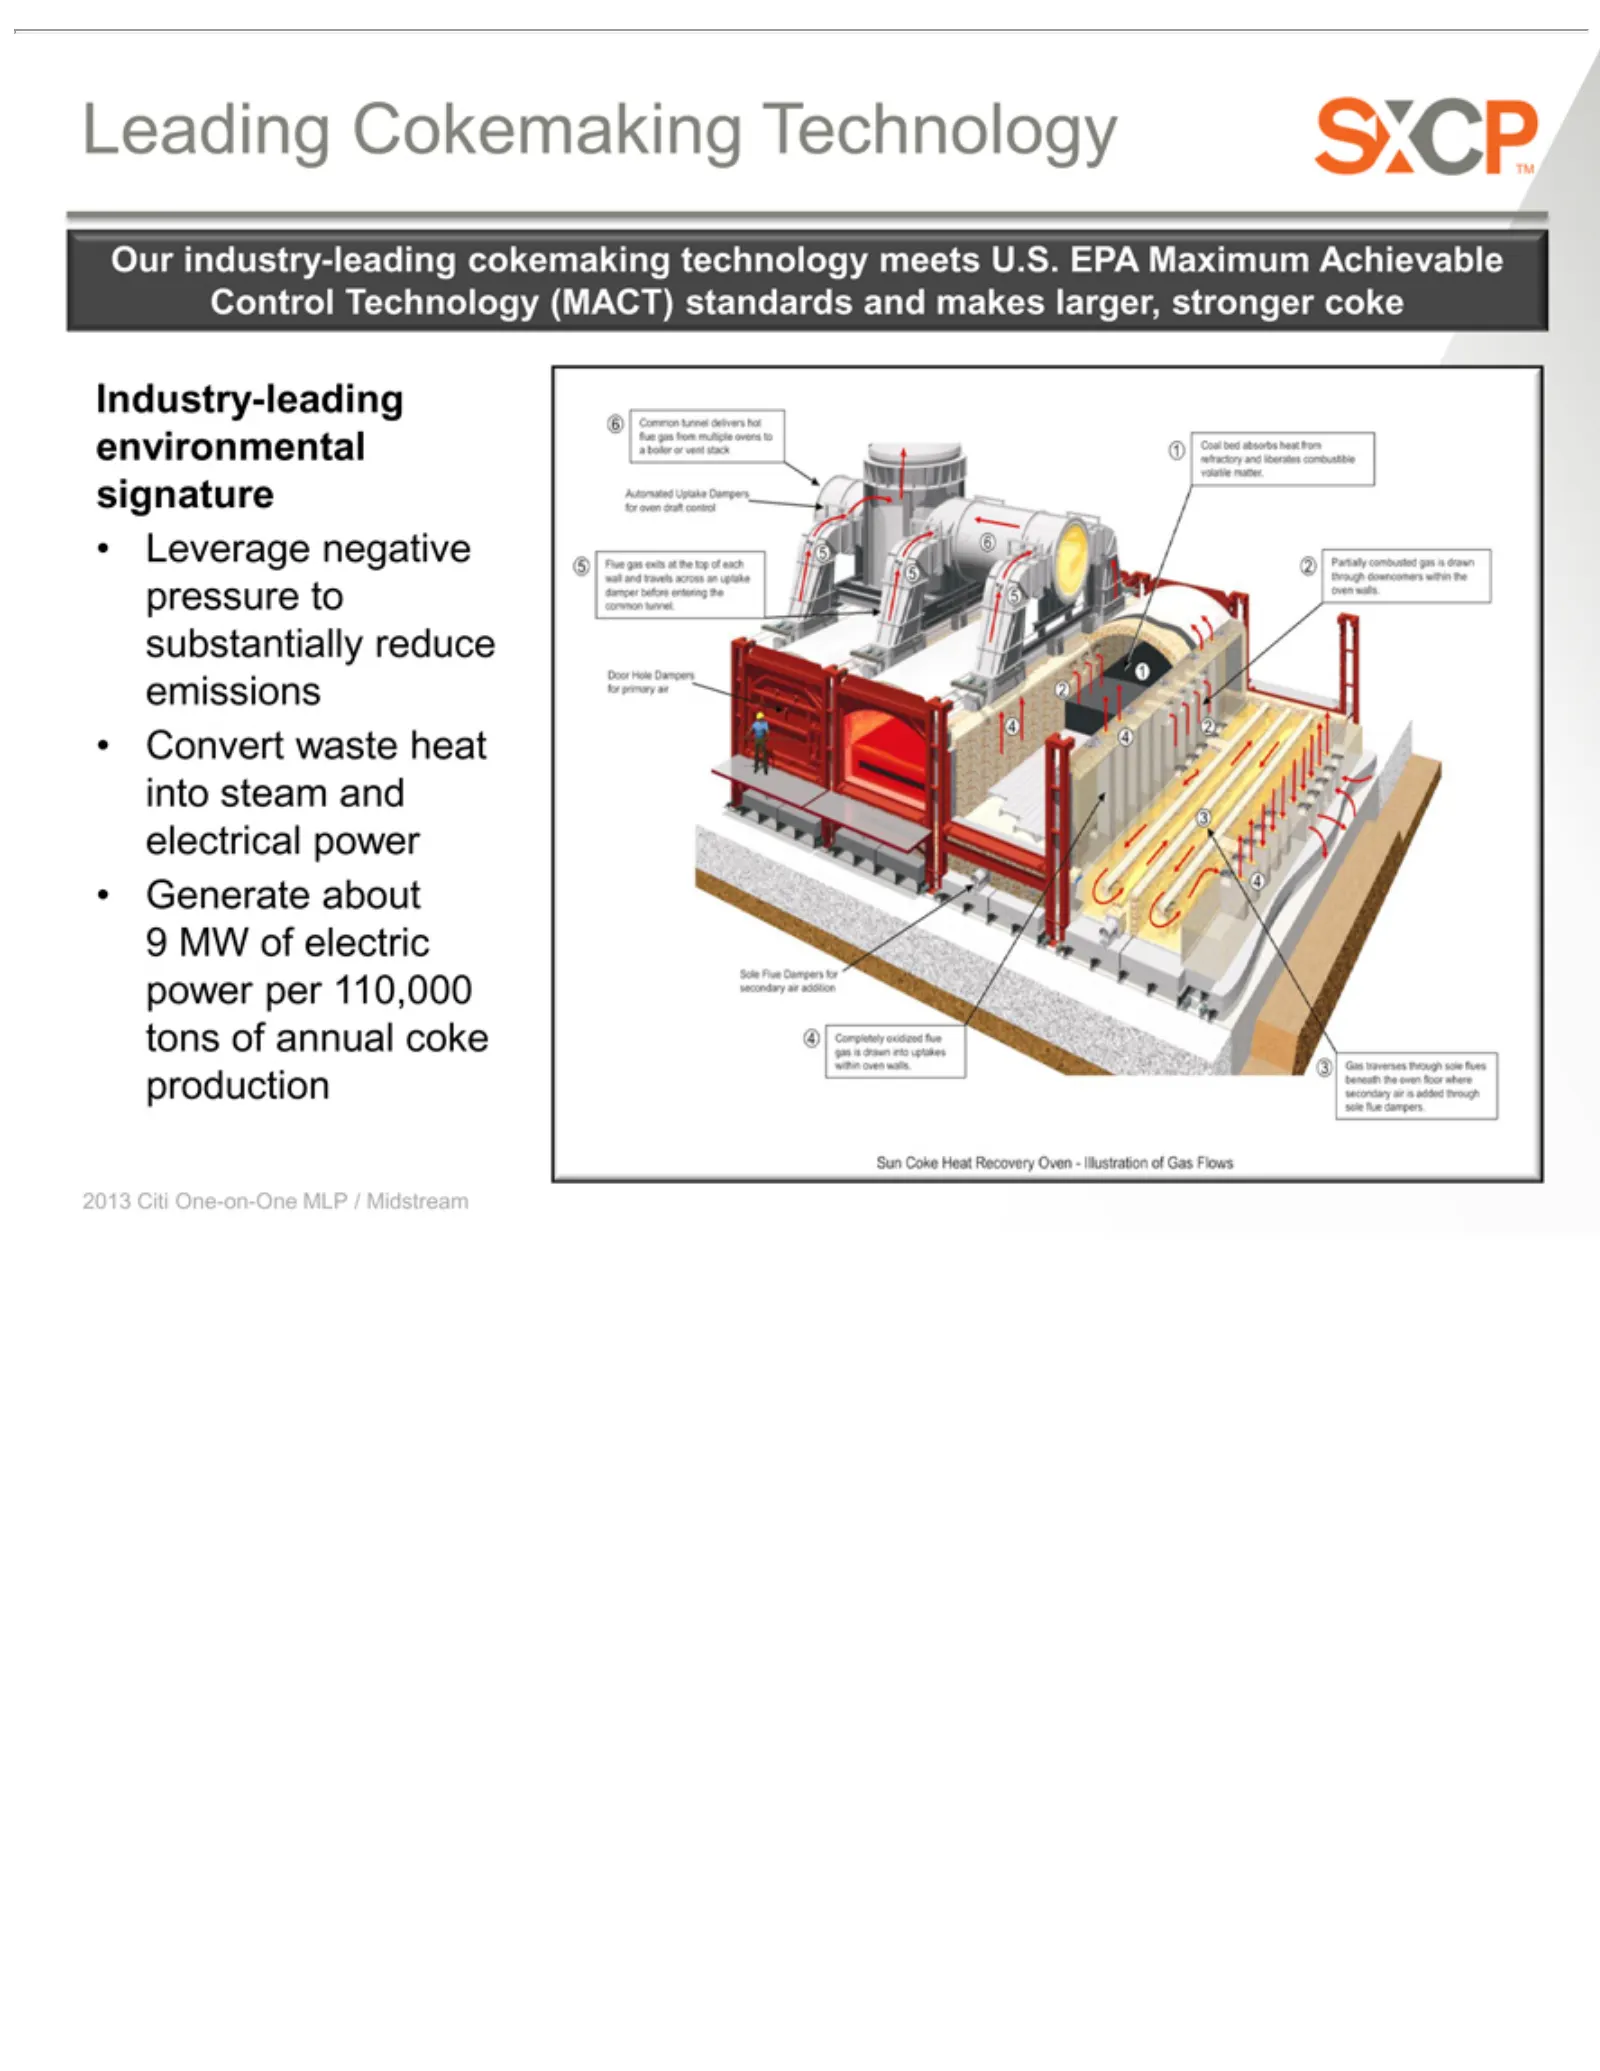
Slide 6: Leading Environmental Cokemaking Technology
Leading Our Control Leverage signature environmental Industry-leading Convert Generate 2013industry-leading CitiTechnology waste Cokemaking about negative One-on-One heat 9 MW pressure into (MACT) cokemaking Technology of MLP steam electric to/ Midstream standards substantially andpower technology e
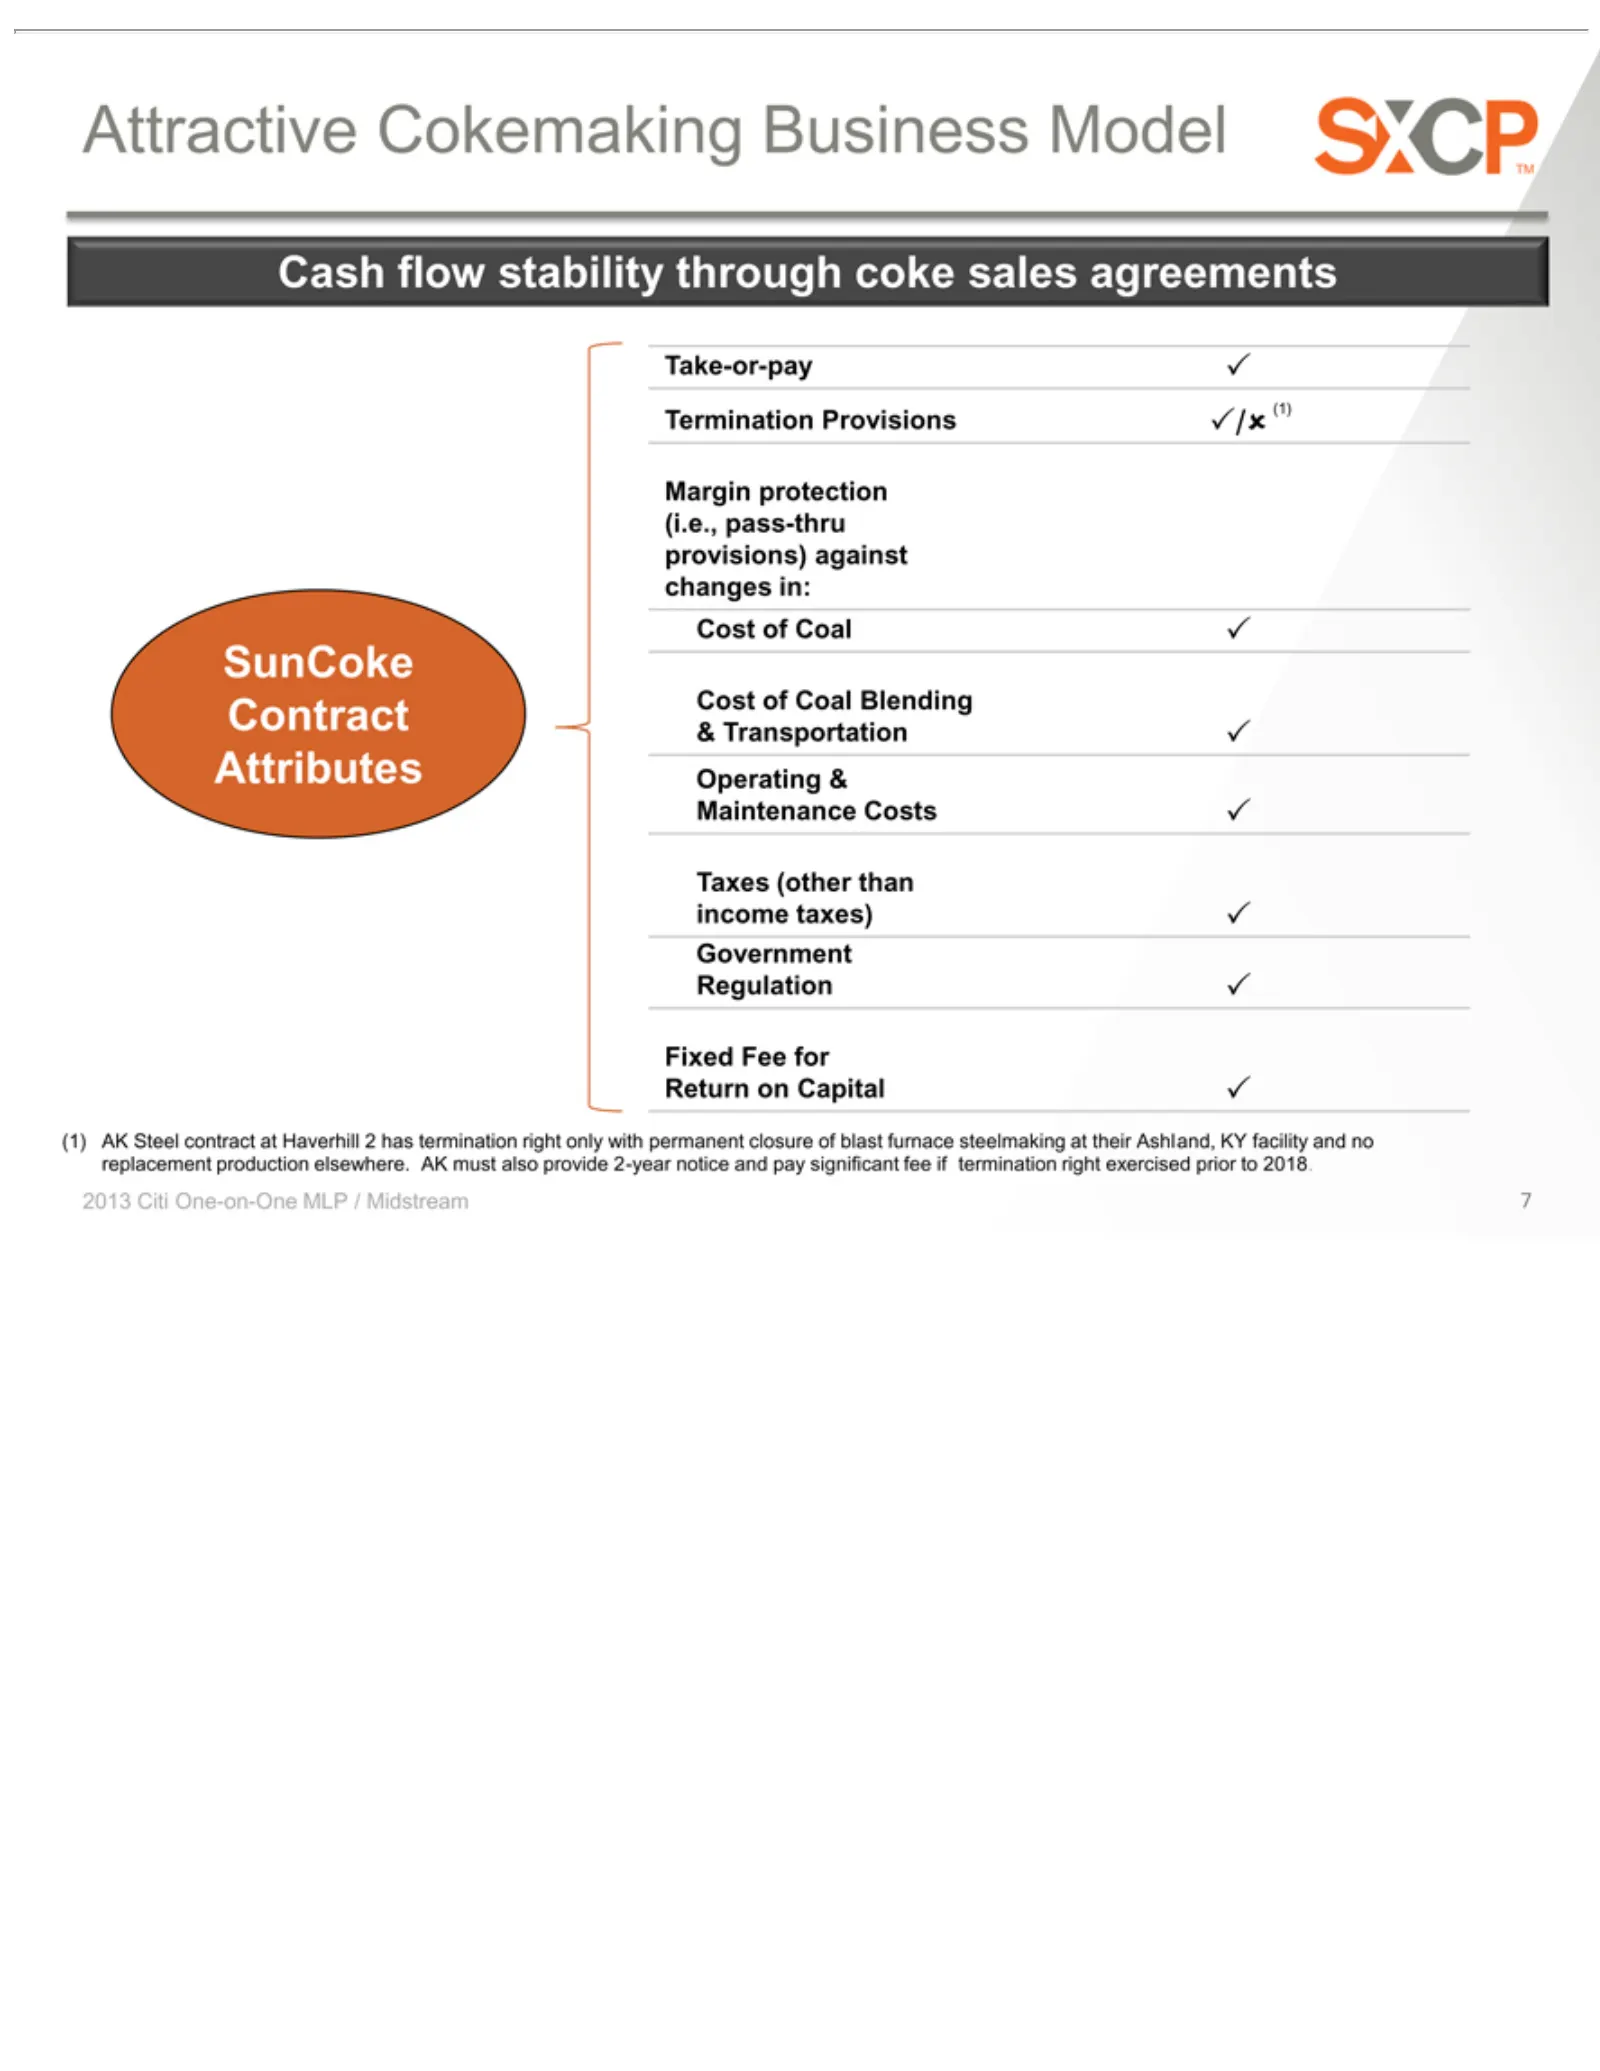
Slide 7: Attractive Cash Flow Business Model
Attractive Cash Termination Take-or-pay Margin (i.e., provisions) changes Cost Contract SunCoke & Attributes Maintenance Taxes income Fixed Regulation Government Return (1) replacement 2013 Transportation AK pass-thru of Citi flow Fee (other on Steel Coal protection taxes) in: Cost One-on-One for Ca
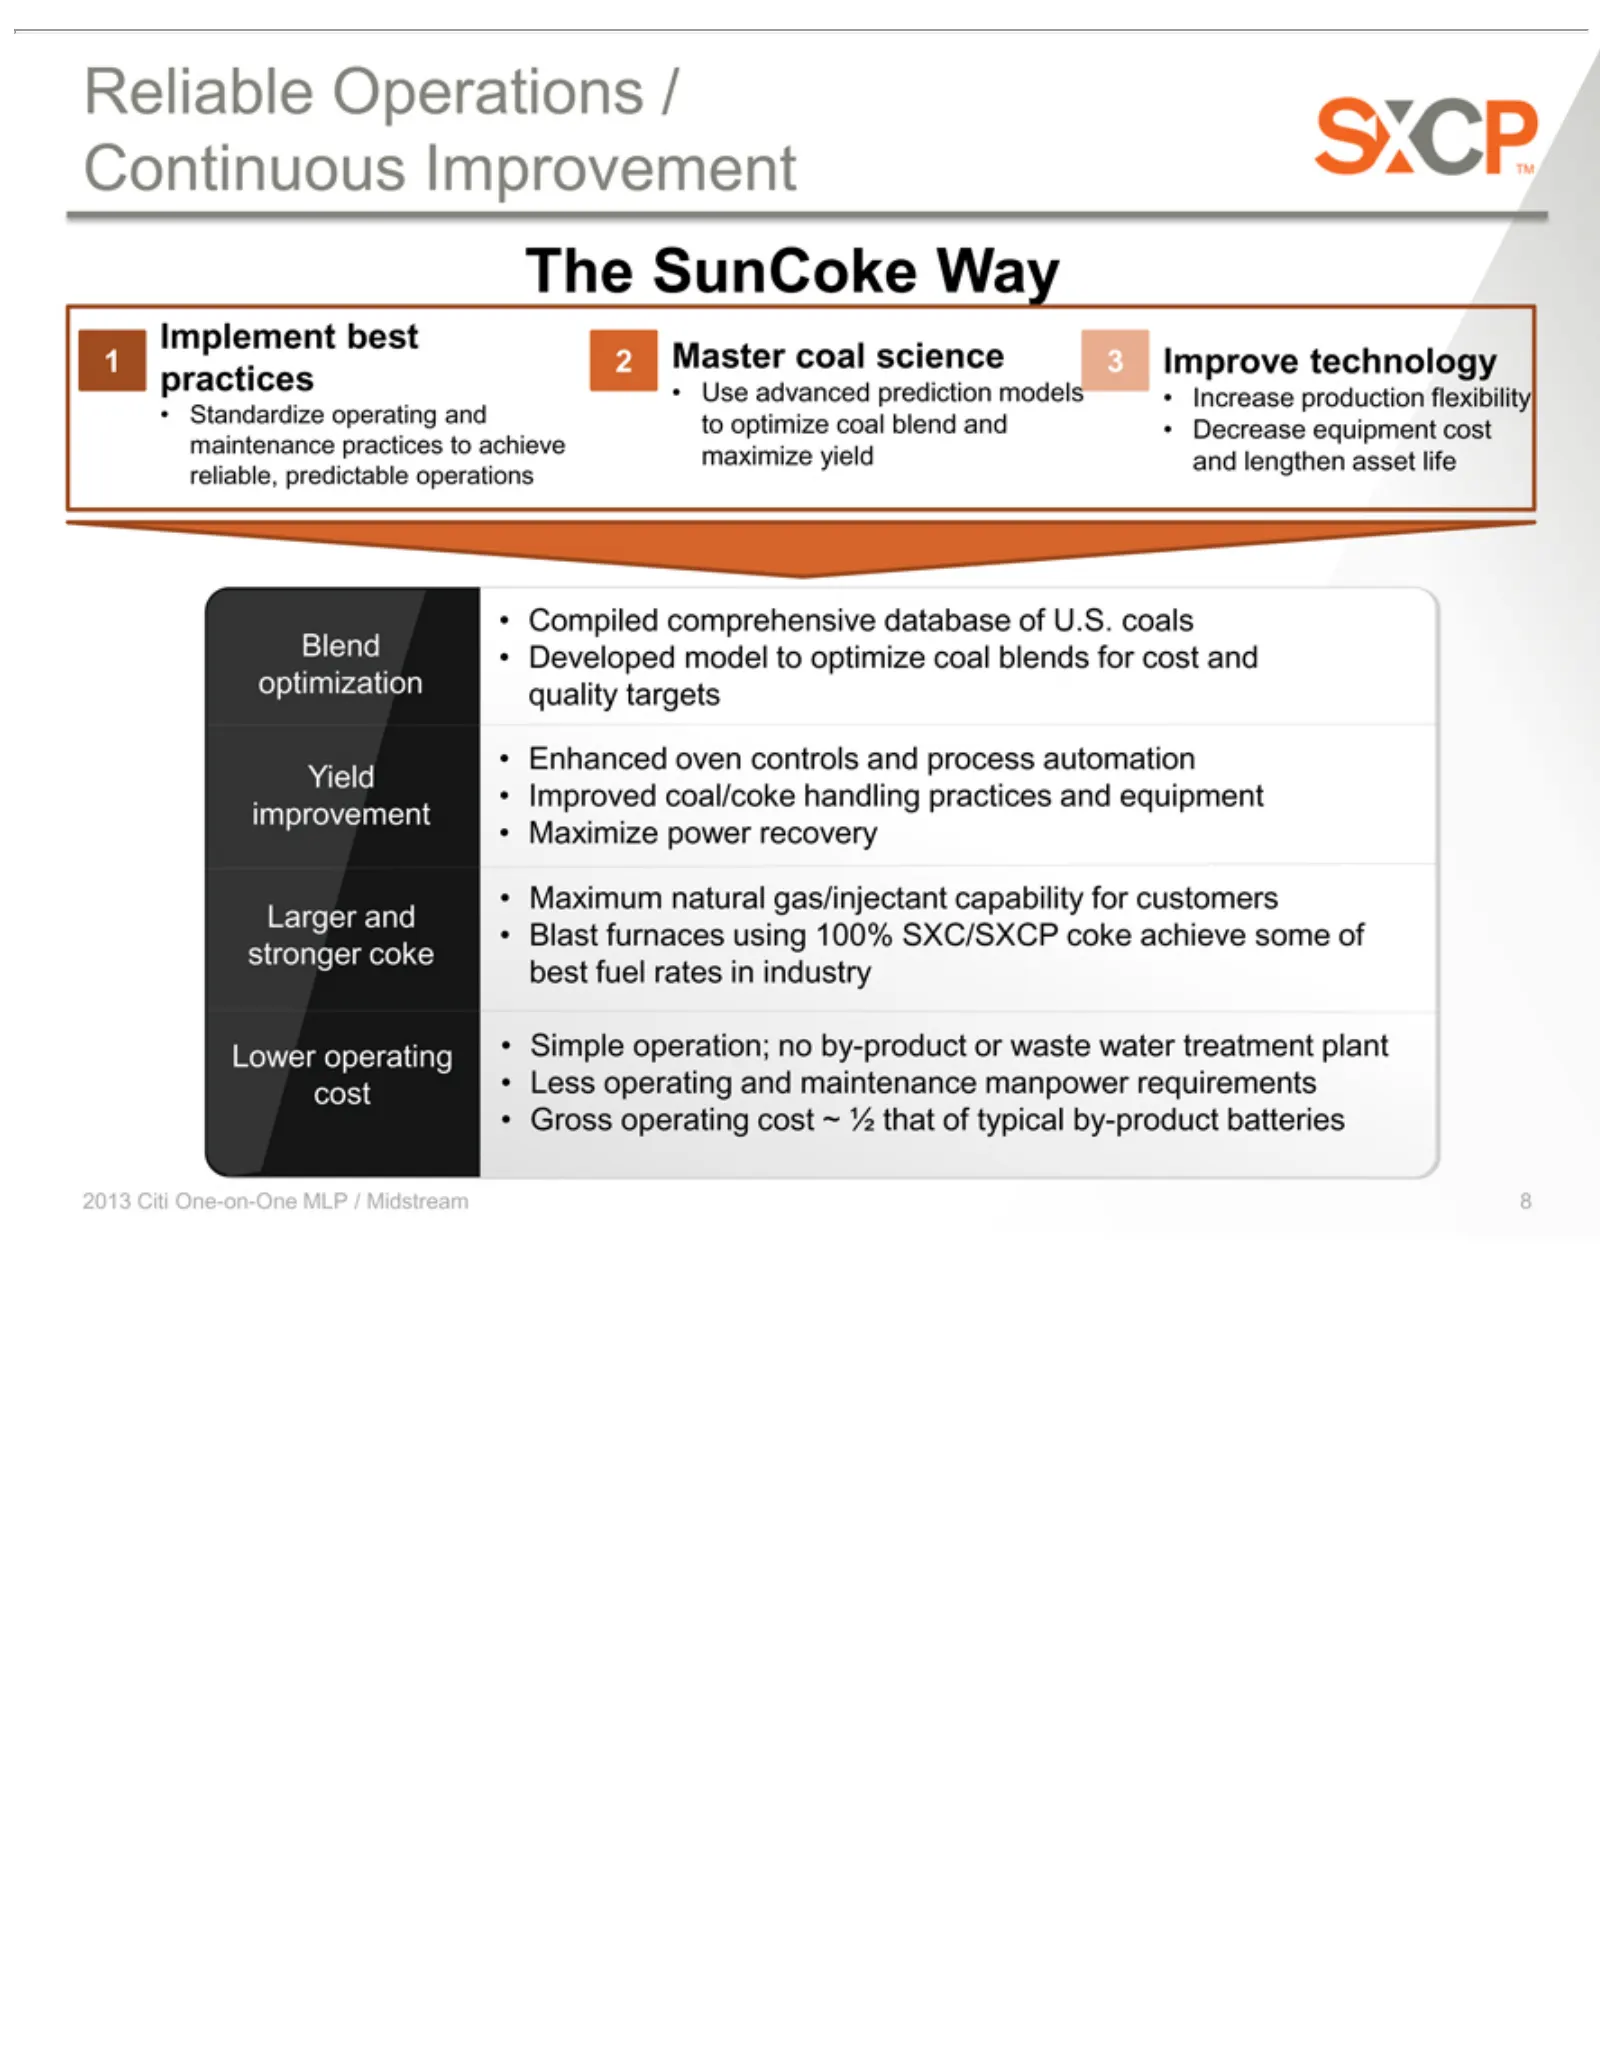
Slide 8: Reliable, Continuous Operations
Reliable Continuous The 1Implement practices maintenance reliable, Blend optimization Yield improvement Larger stronger Lower •cost Standardize Compiled Maximize Maximum 2 Master SunCoke • Citi Gross 82013 •Less •operating and Enhanced Developed predictable coke Operations •One-on-One Use coal opera
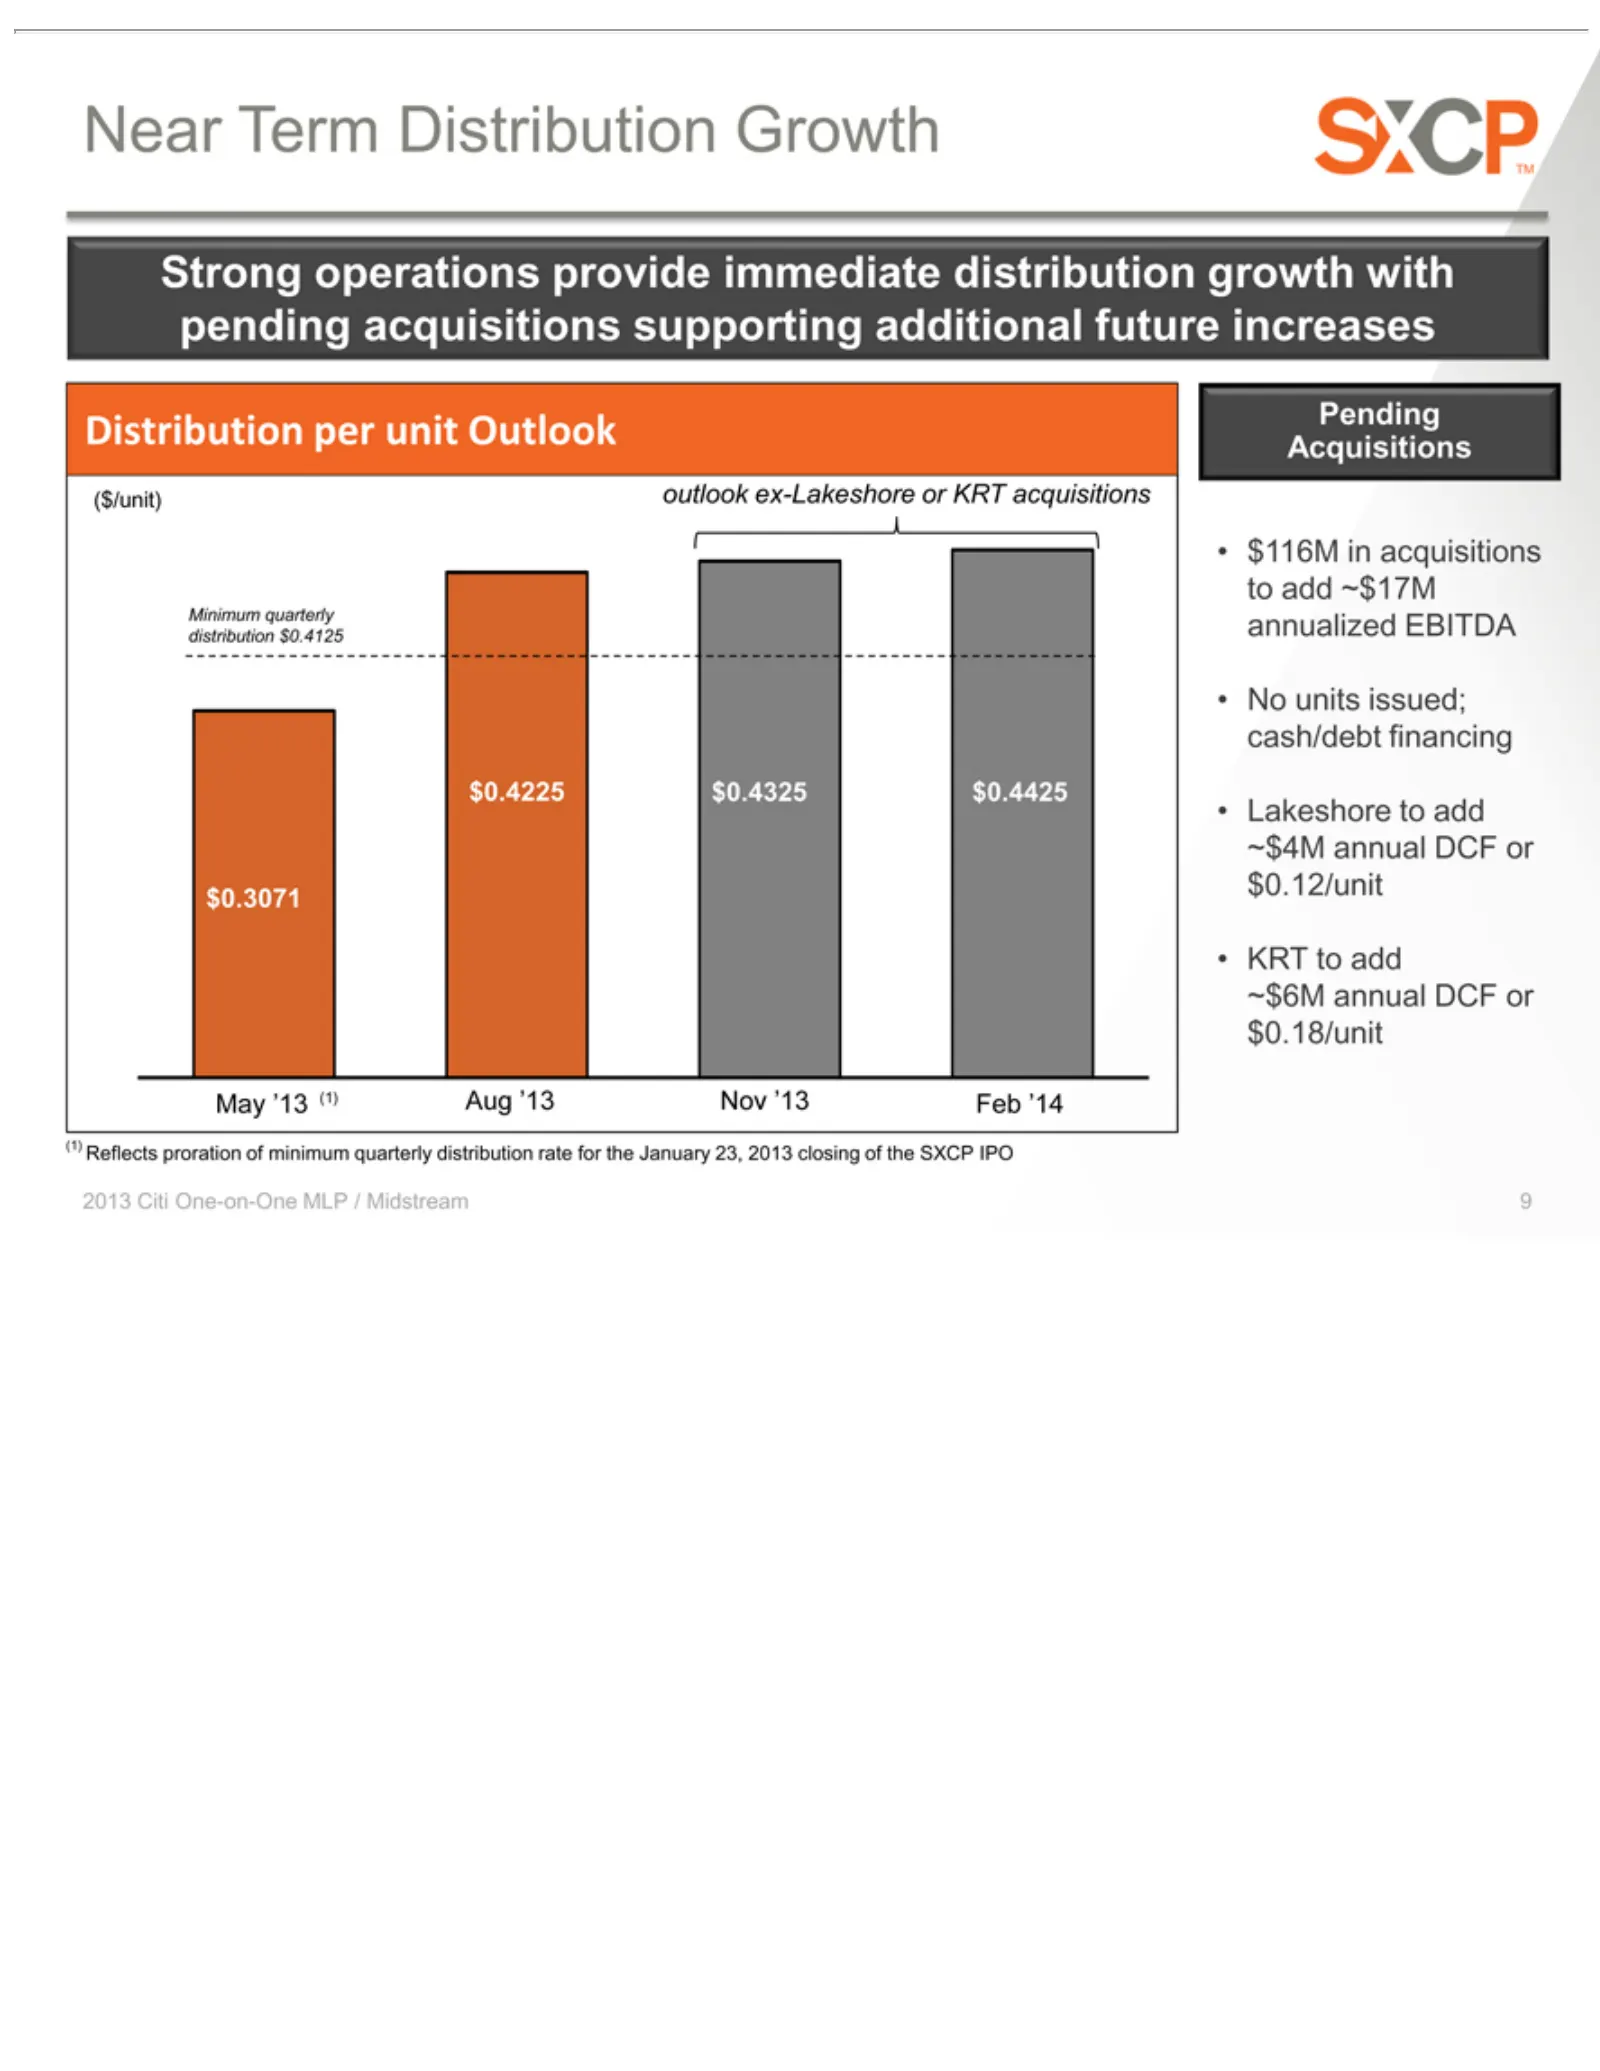
Slide 9: Near-Term Distribution Growth Outlook
Near Strong Distribution outlook ($/unit) [Graphic Minimum distribution May $0.3071 $0.4425 $0.4325 $0.4225 (1) 2013 Pending $116M No Lakeshore $4M KRT $0.12/unit 9$6M $0.18/unit Reflects units ’13 annual to Term Citi operations in add ex-Lakeshore Acquisitions (1) issued; Appears One-on-One acquisi
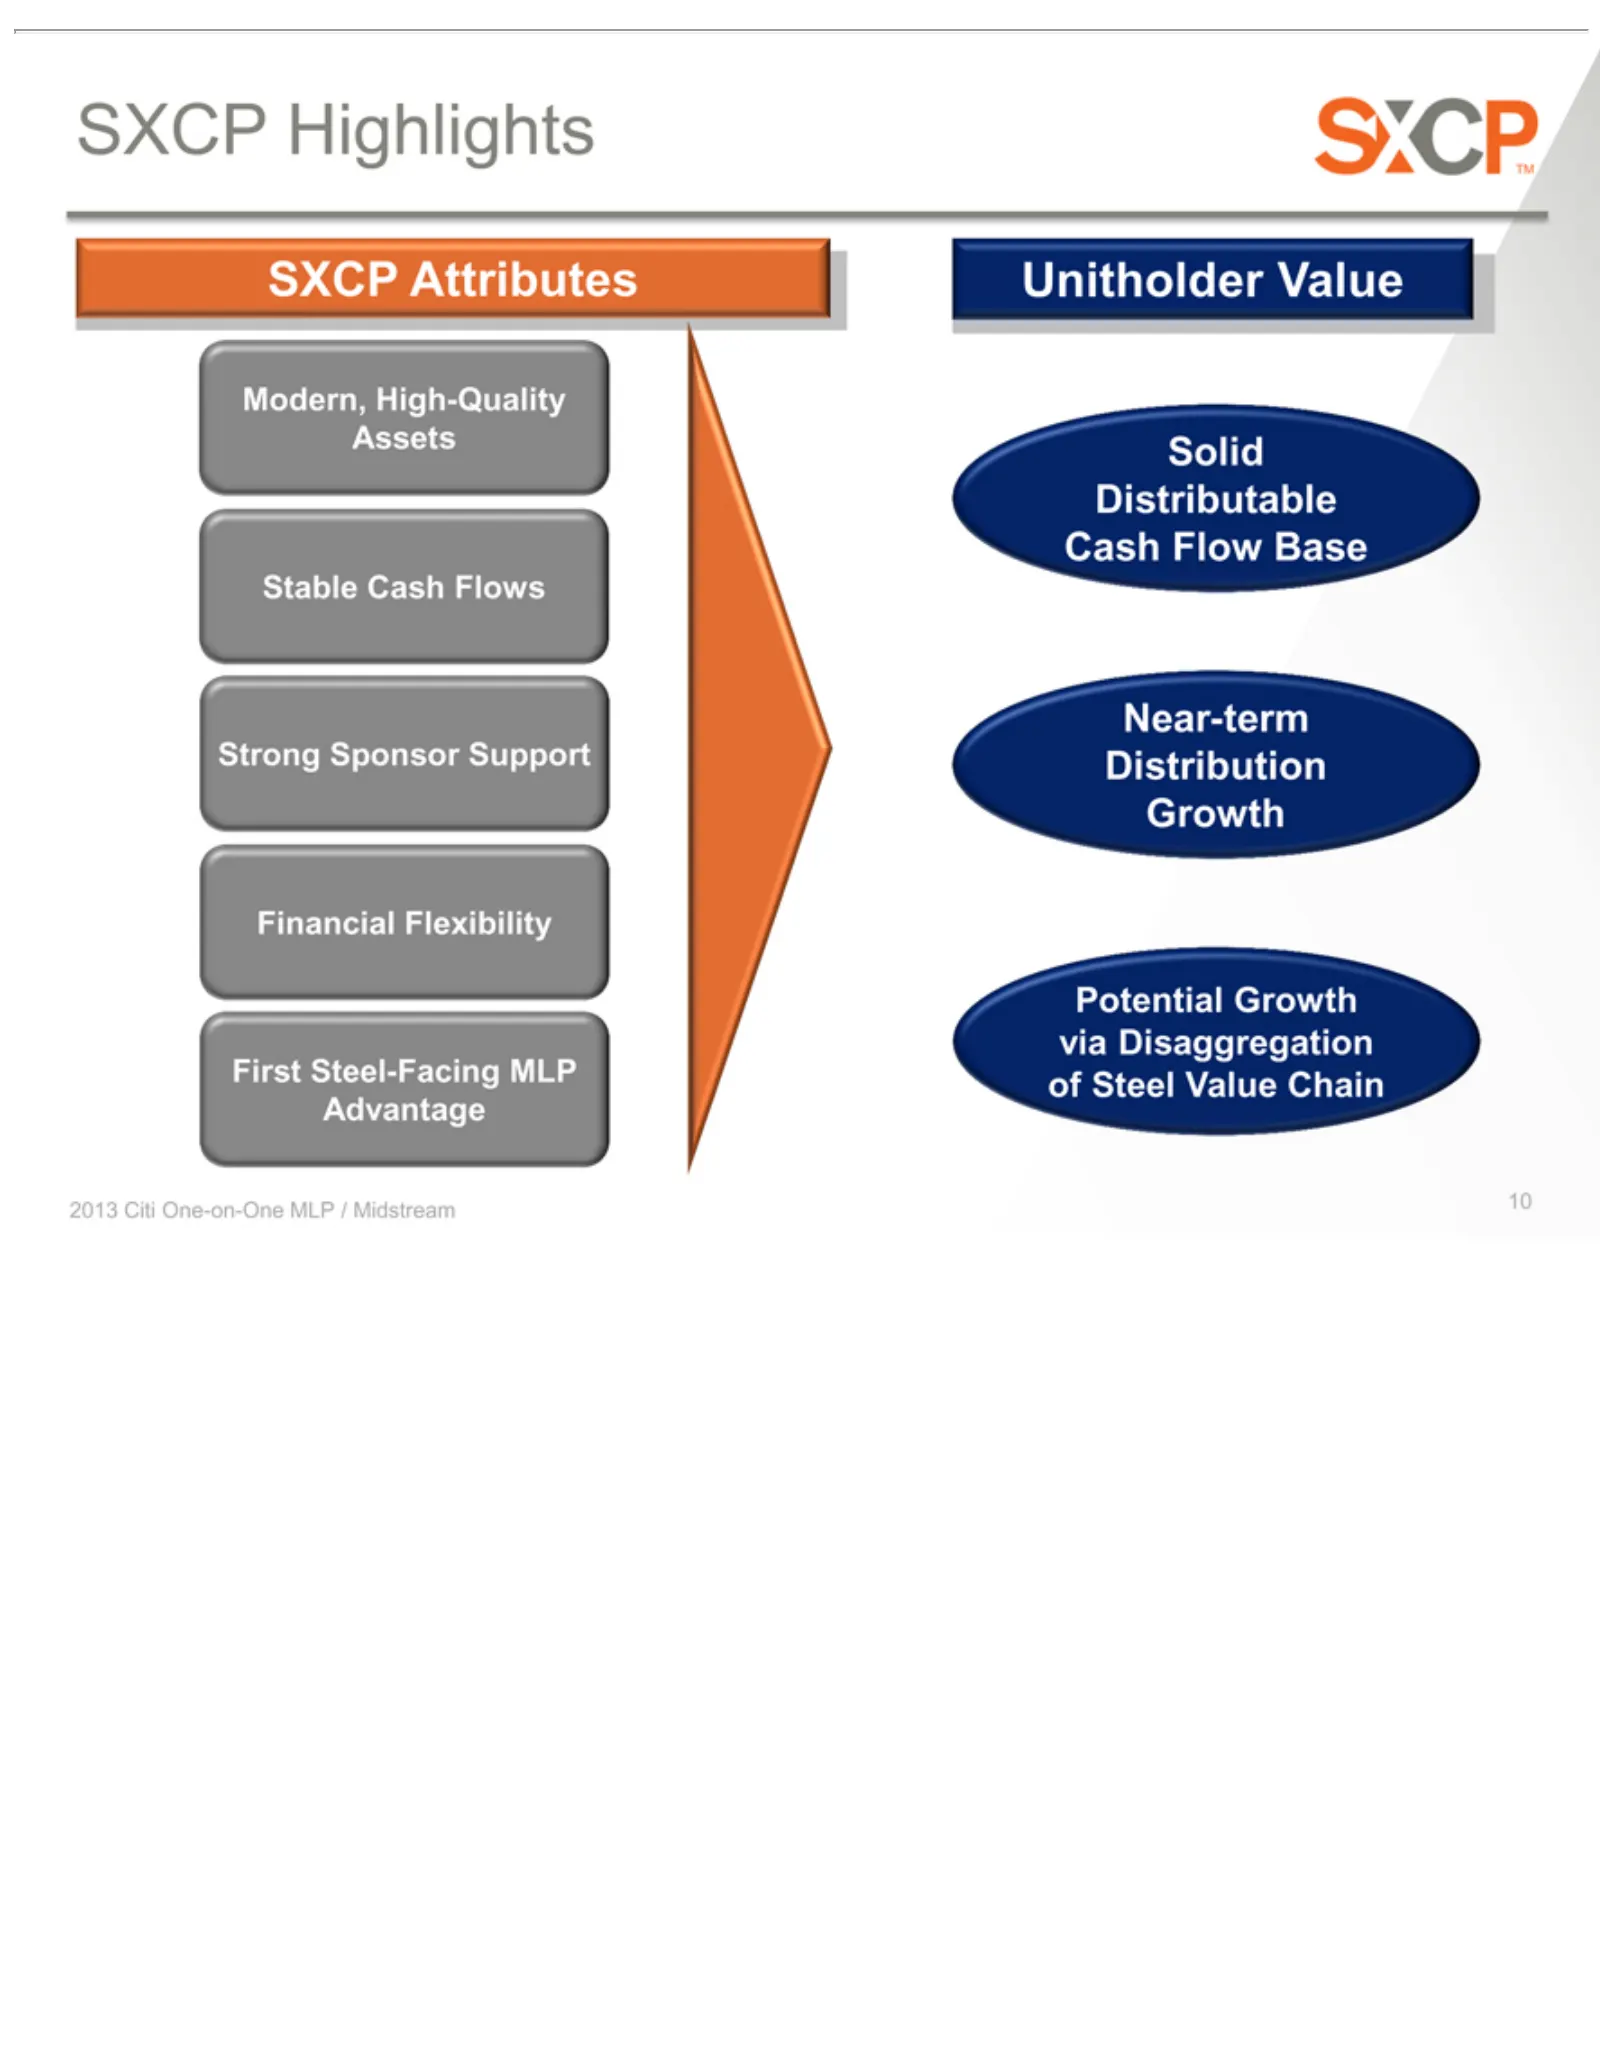
Slide 10: SXCP Investment Highlights
SXCP Modern, Assets Cash Distributable Stable Strong Near-term Financial Growth Potential via First 2013 Advantage Disaggregation Steel-Facing Citi Flow Attributes Highlights Cash Solid Sponsor High-Quality Growth Flexibility One-on-One Base Flows Support Unitholder MLPMLP of Distribution Steel Valu
Slide 11: Our Market Opportunity
OUR Citi 2013 11 MARKET One-on-One OPPORTUNITY MLP / Midstream
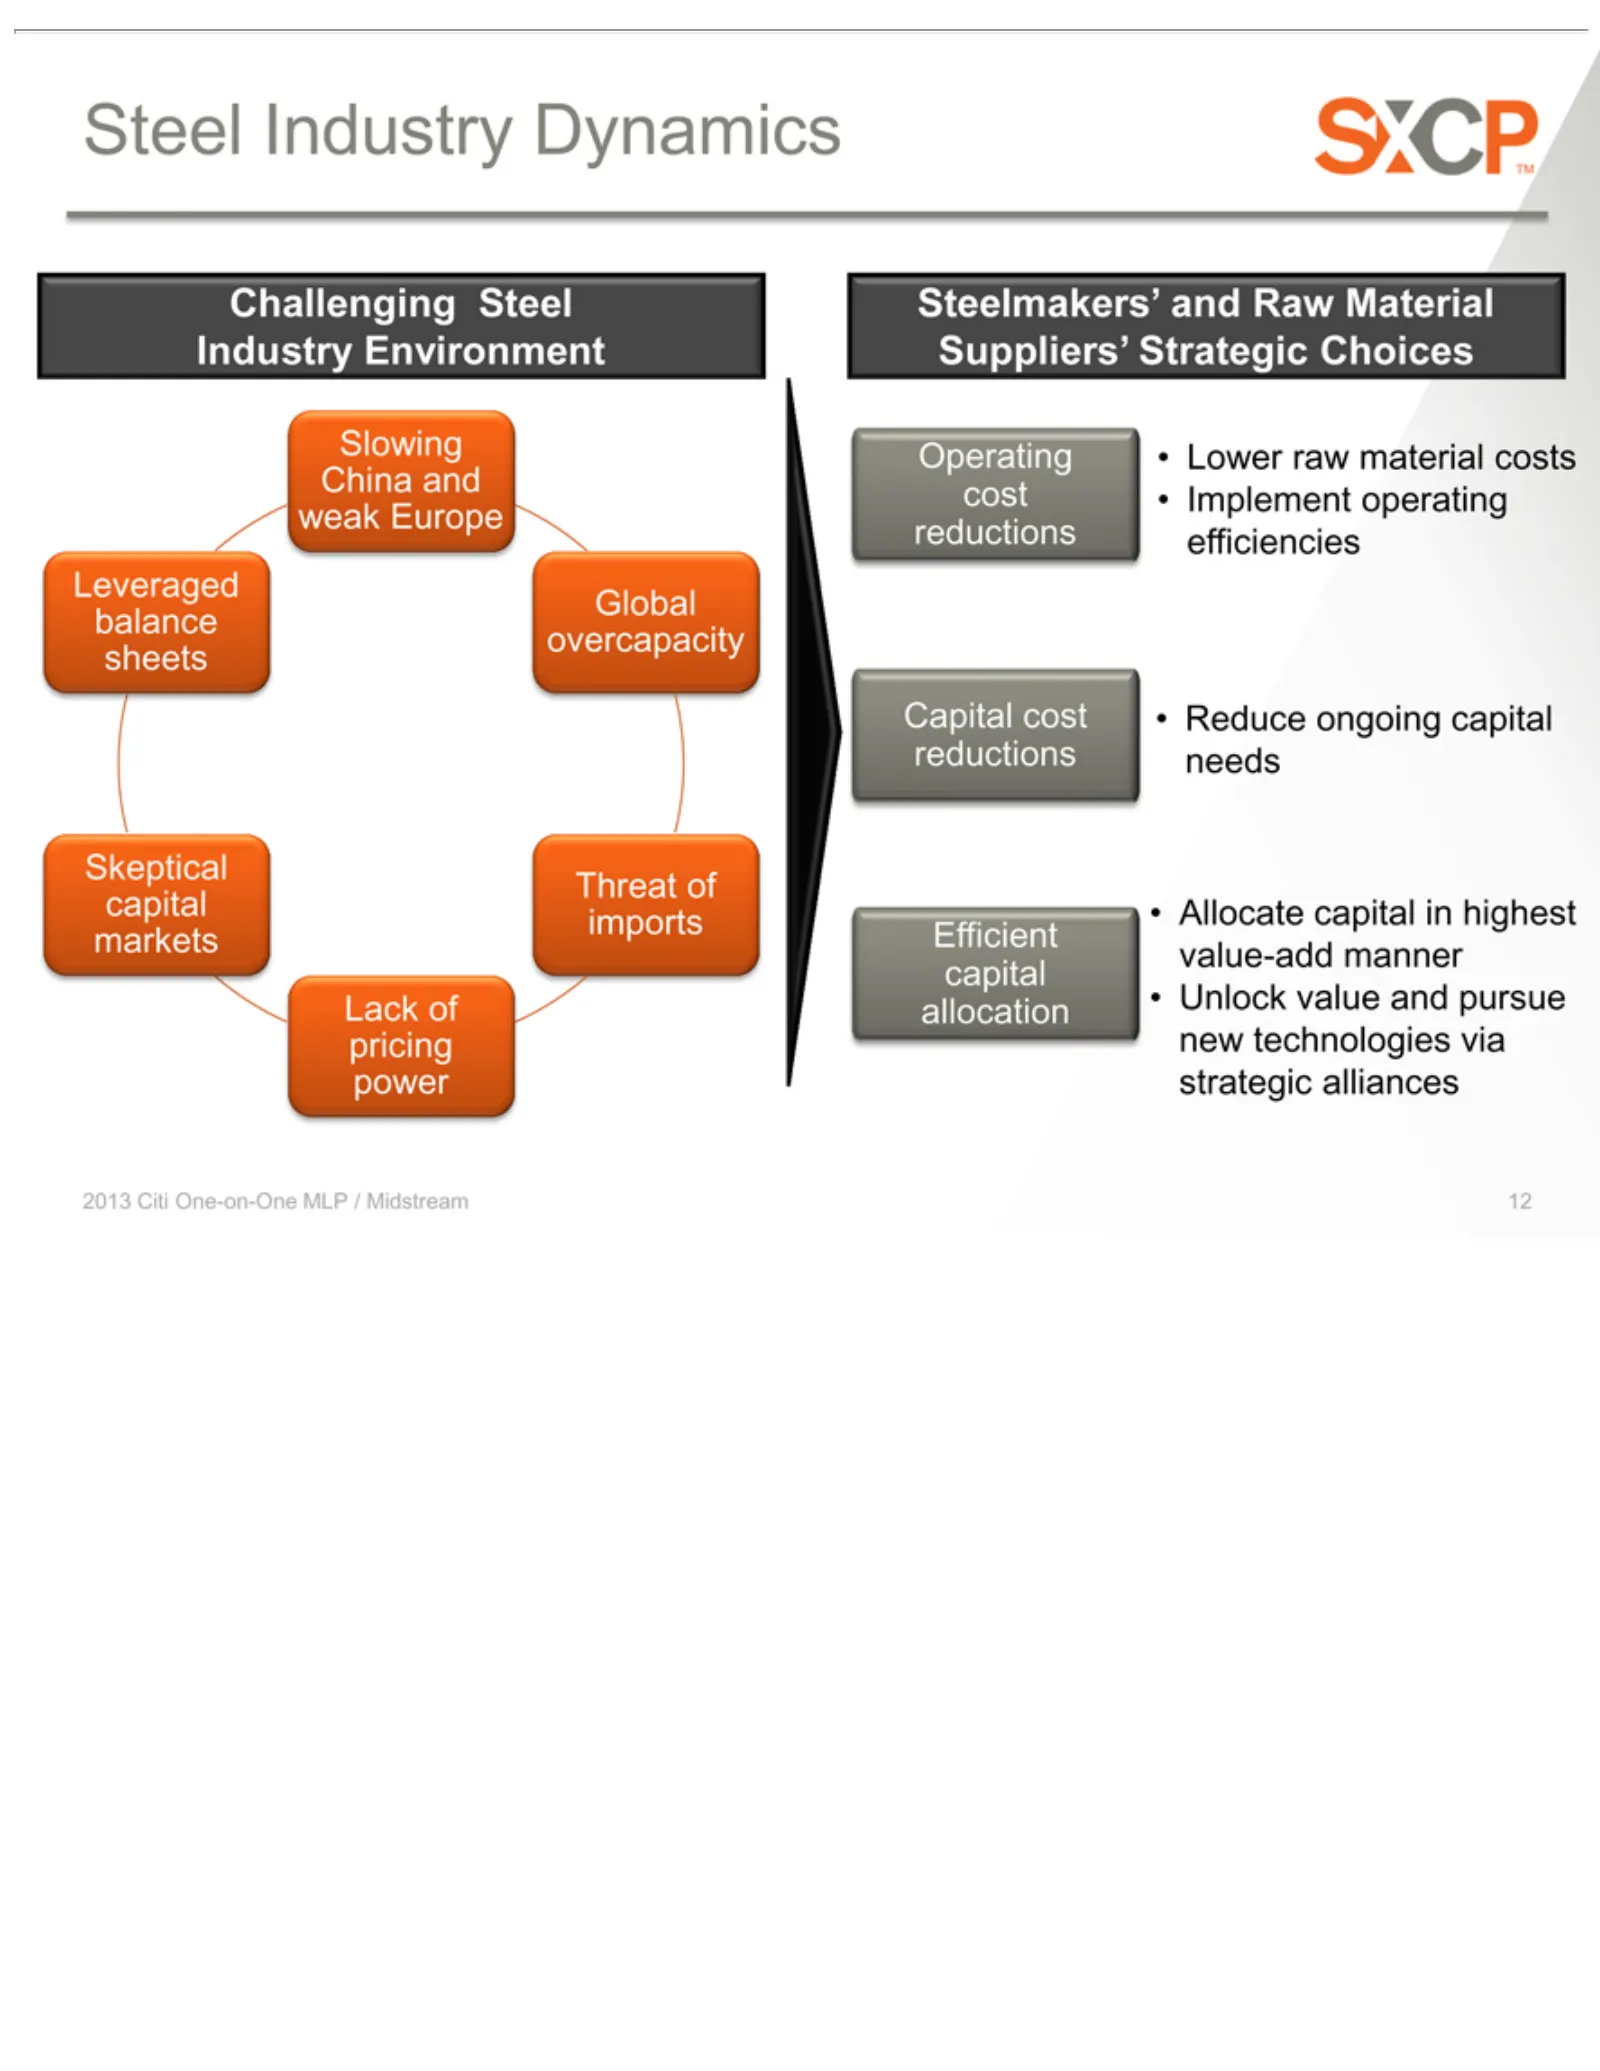
Slide 12: Challenging Steel Industry Environment
Steel of Challenging Industry Slowing China weak balance Leveraged sheets Capital Skeptical reductions markets Lack capital Lower power pricing Implement Reduce Allocate Unlock 2013 12 Industry Citi Europe and overcapacity raw Threat cost value ongoing Global allocation imports Environment Operating
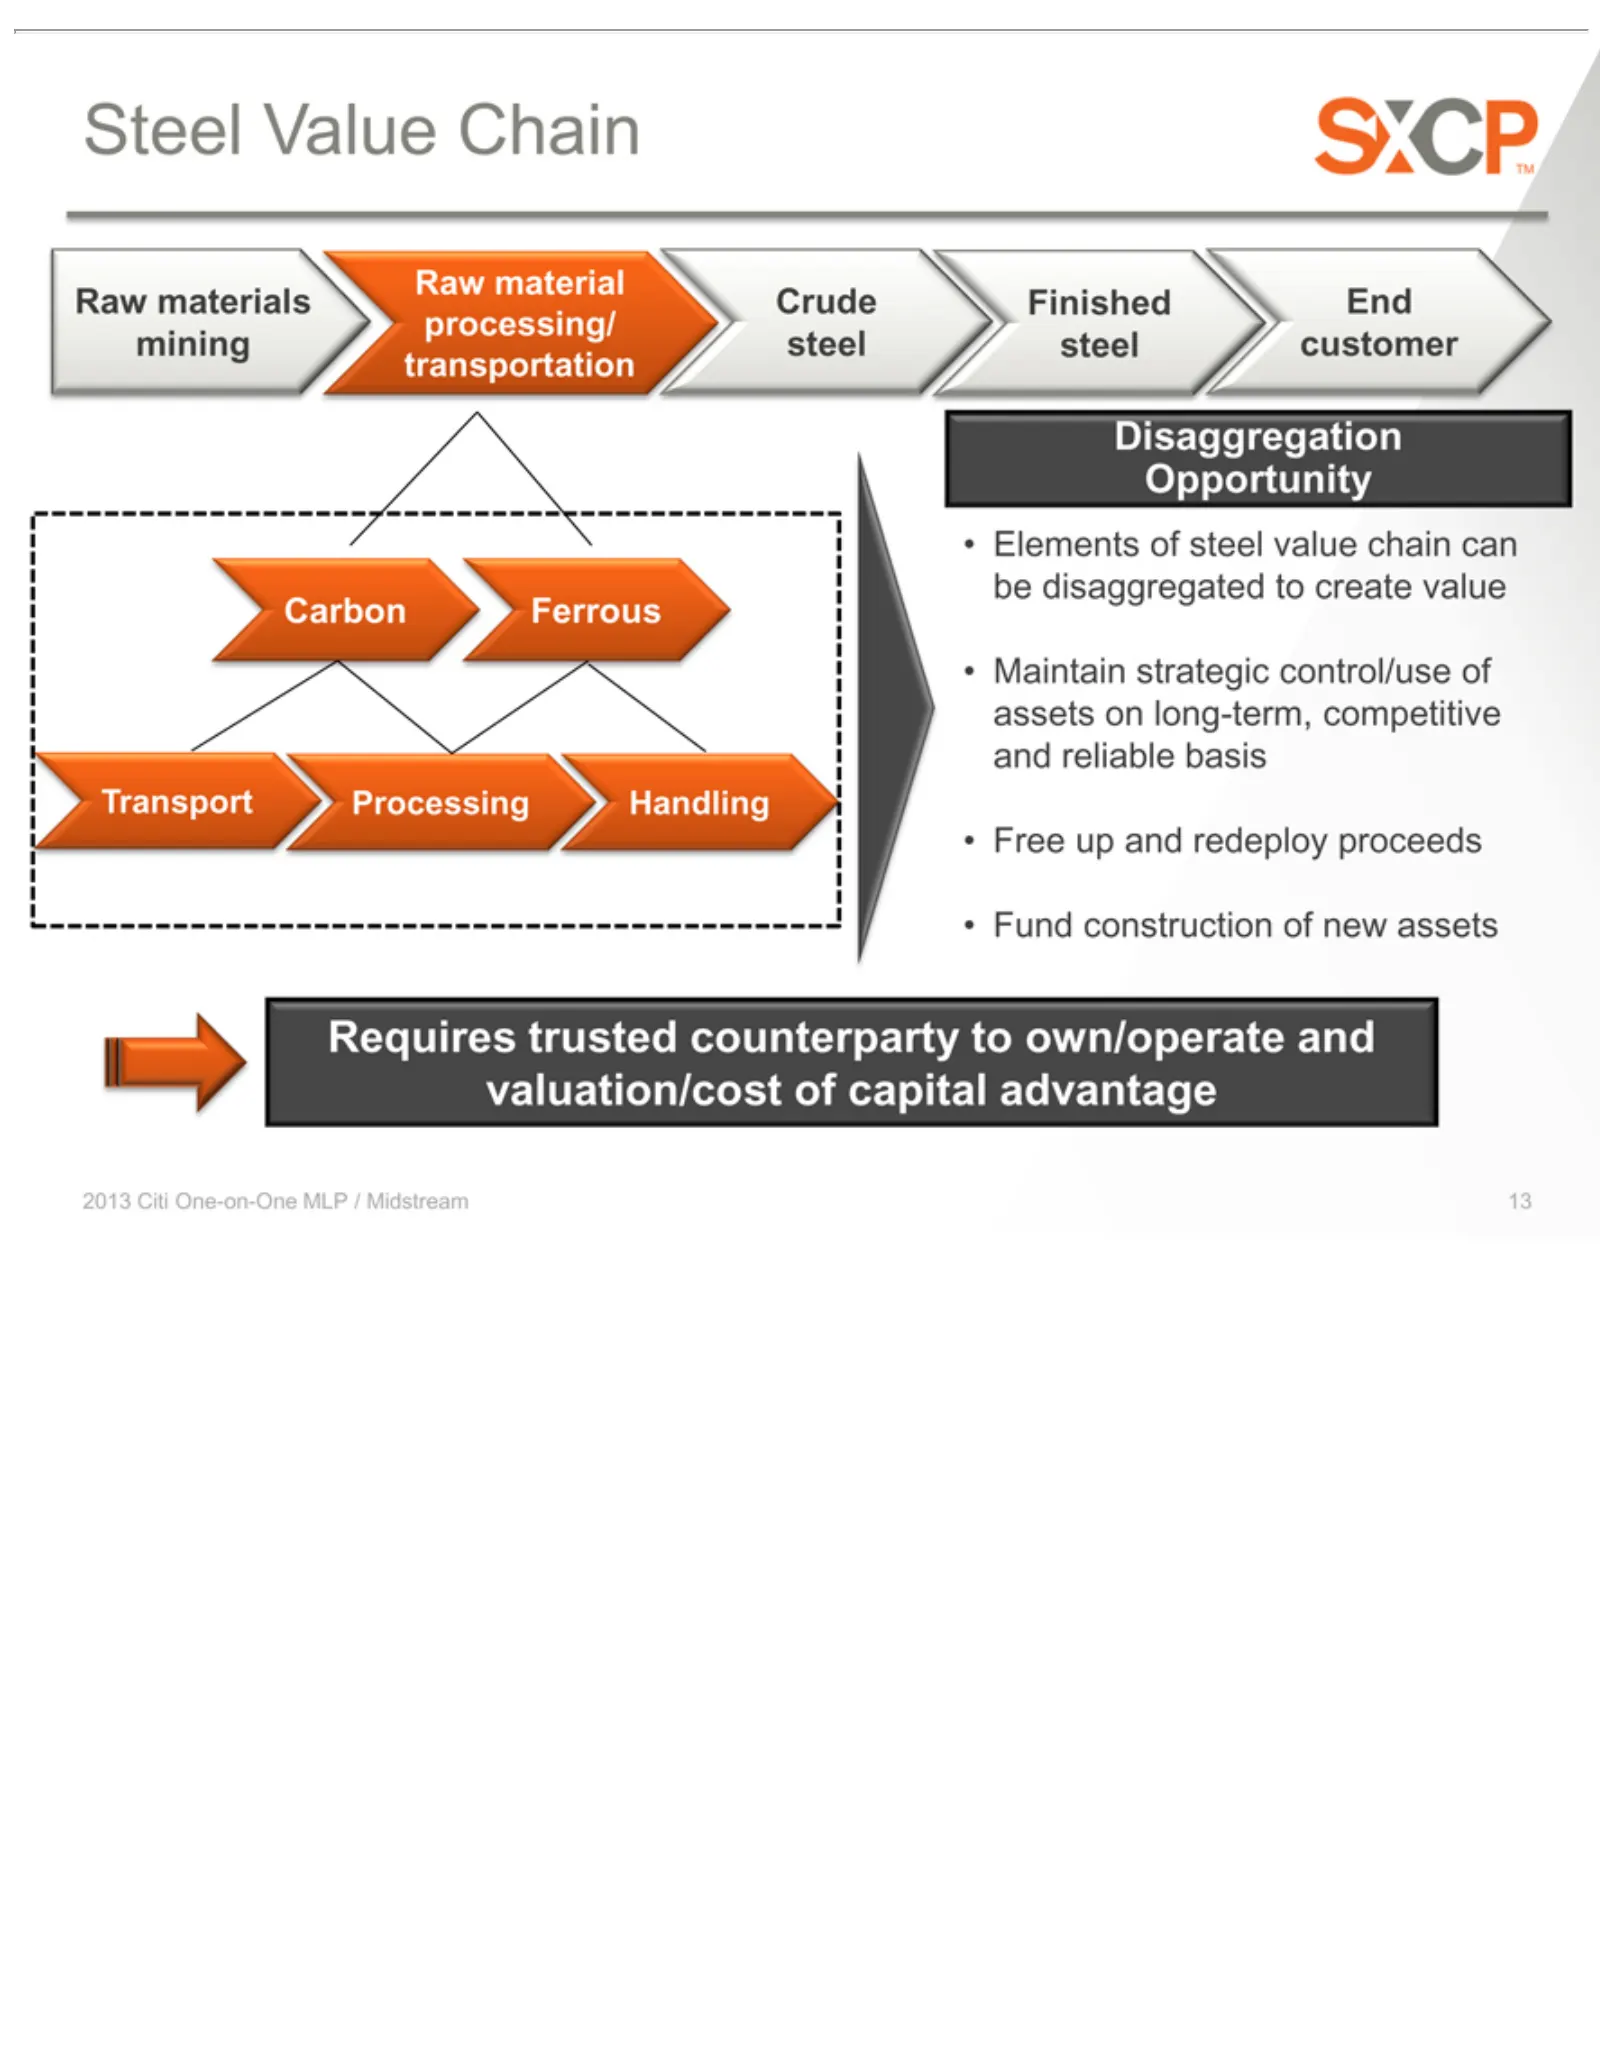
Slide 13: Steel Value Chain Disaggregation Opportunity
Steel Raw mining processing/ Carbon Opportunity Disaggregation transportation Transport Elements be Maintain assets and Free Fund Requires 2013 13 disaggregated reliable up material materials Value Citi construction onsteel Ferrous and trusted long-term, strategic of One-on-One Processing Chain basi
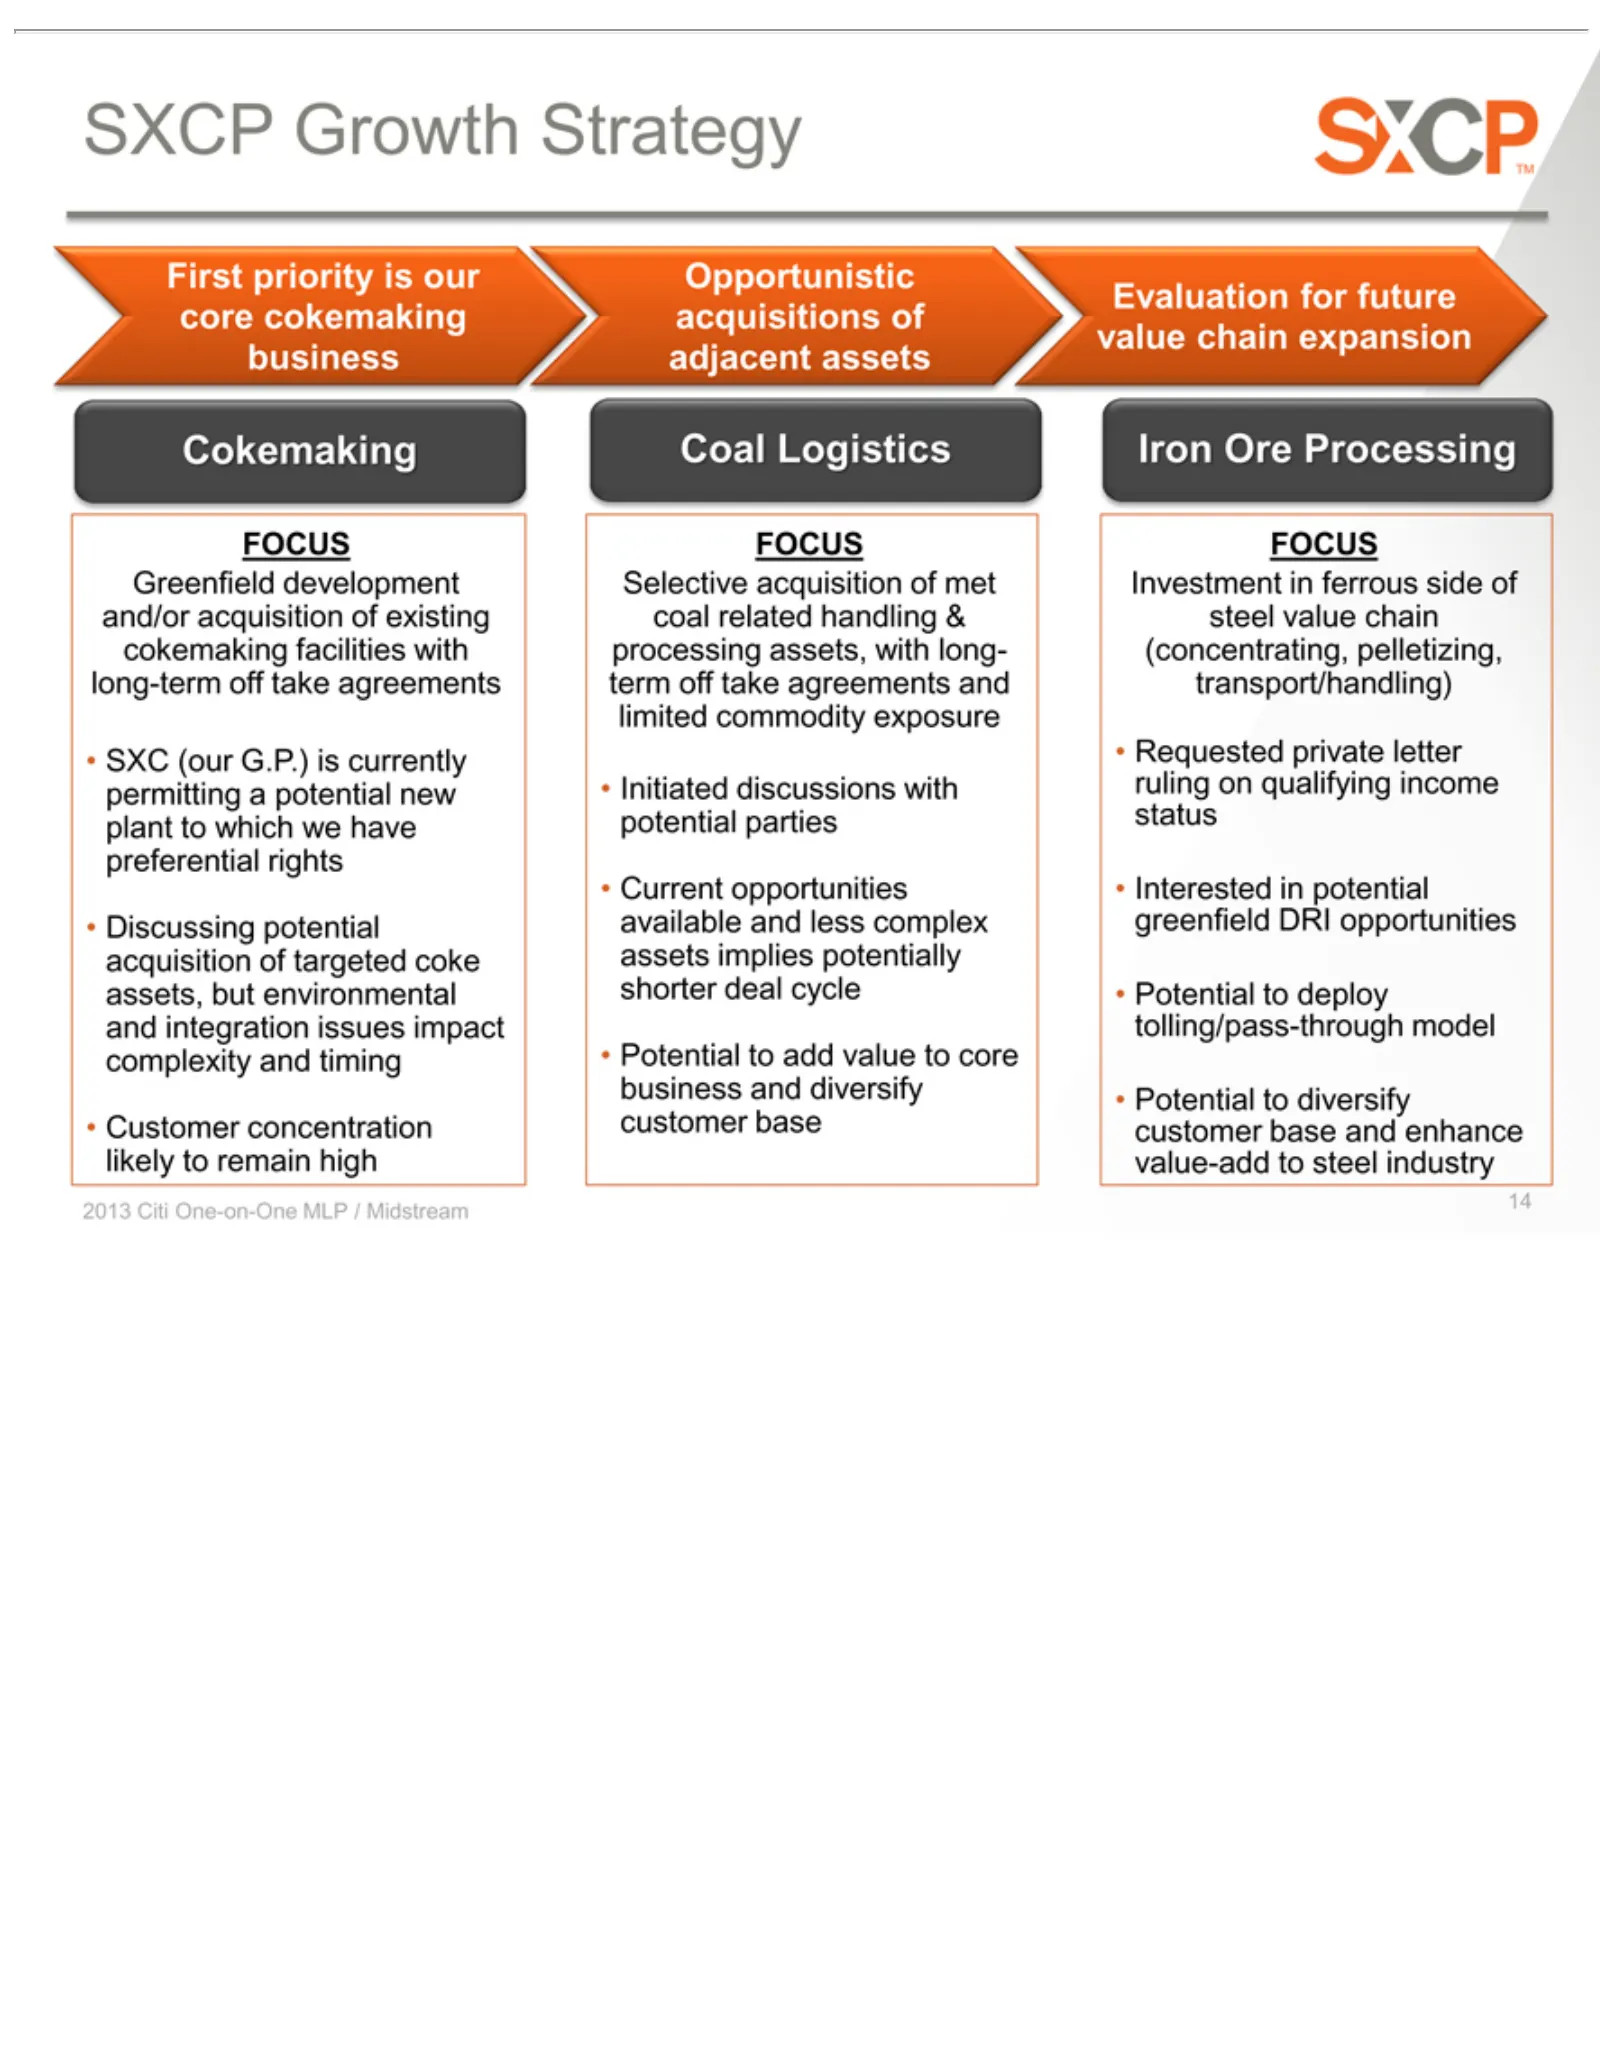
Slide 14: SXCP Growth Strategy and Focus
SXCP First Greenfield Cokemaking SXC Discussing Customer 2013 Opportunistic Coal Selective Initiated Current Evaluation Iron Investment FOCUS Requested Interested Potential 14 Ore priority Logistics (our Citi Growth opportunities discussions Processin to acquisition One-on-One G.P.) concentration in
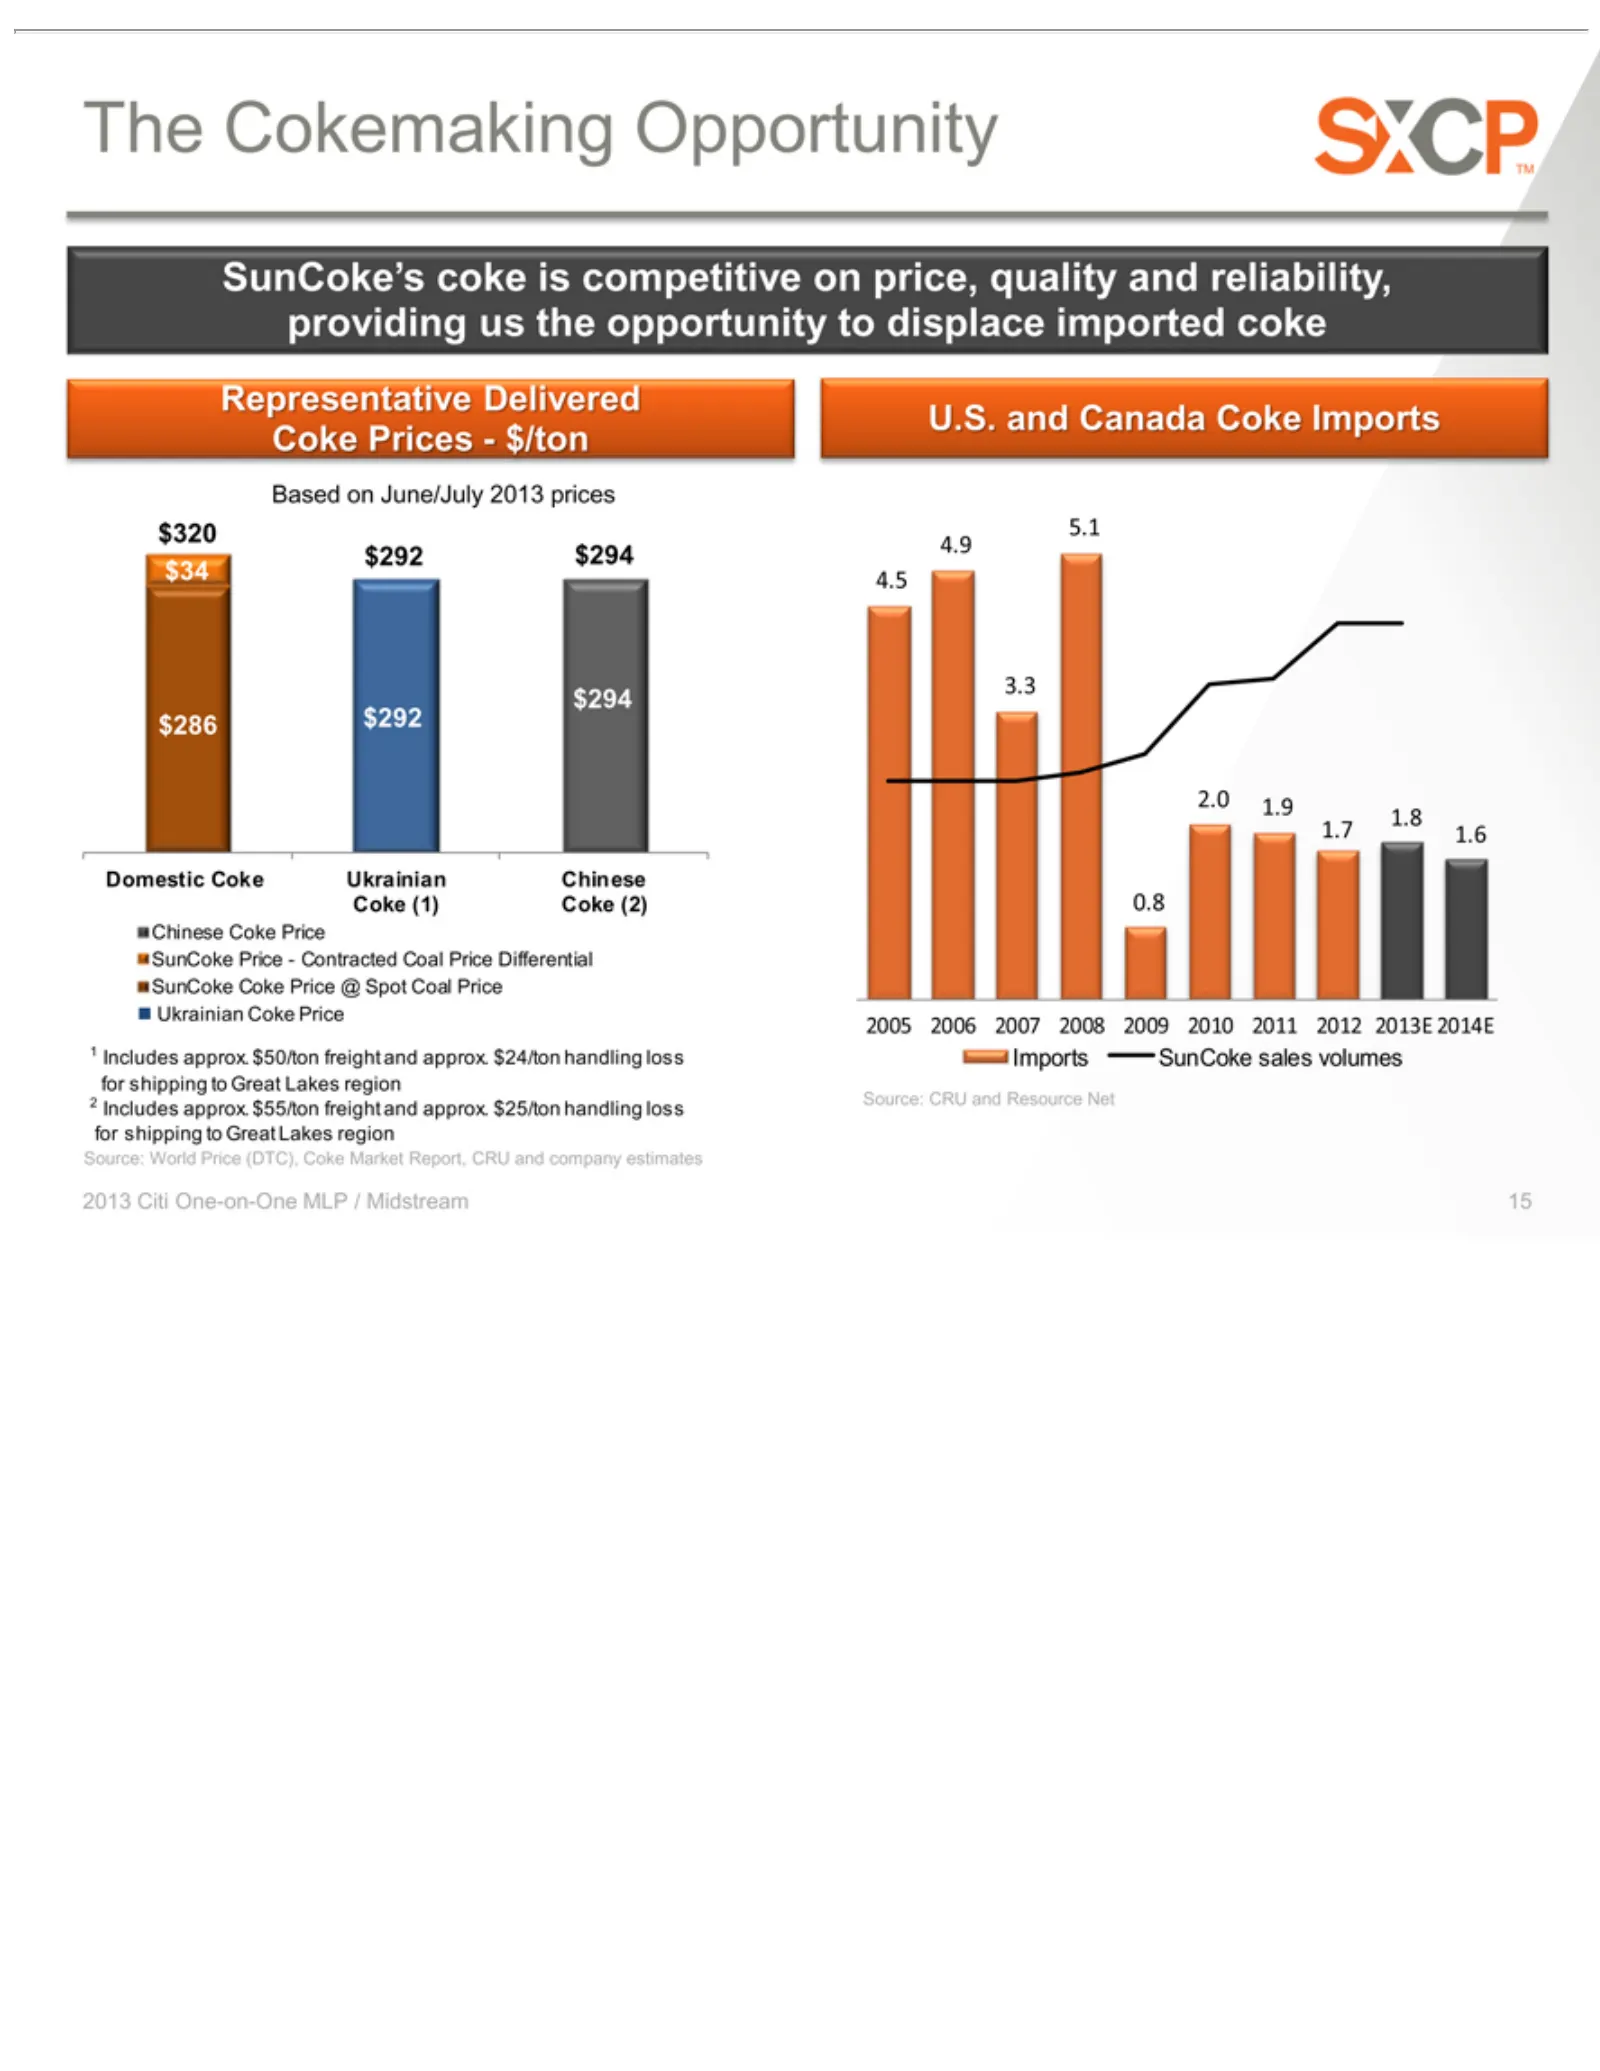
Slide 15: Cokemaking Opportunity: Coke Imports and Prices
The SunCoke’s providing Representative Coke $320 $34 $294 2.0 $292 1.7 1.8 2005 0.8 ss Source: 2013 Imports Source: 1.9 1.6 4.5 Cokemaking 5.1 $294 3.3 2006 Ci Prices World ne-on-One us CRU SunCoke 4.9 2007 coke $/ton thePrice Delivered and is opportunity 2008 Opportunity competitive MLP sales (DTC)
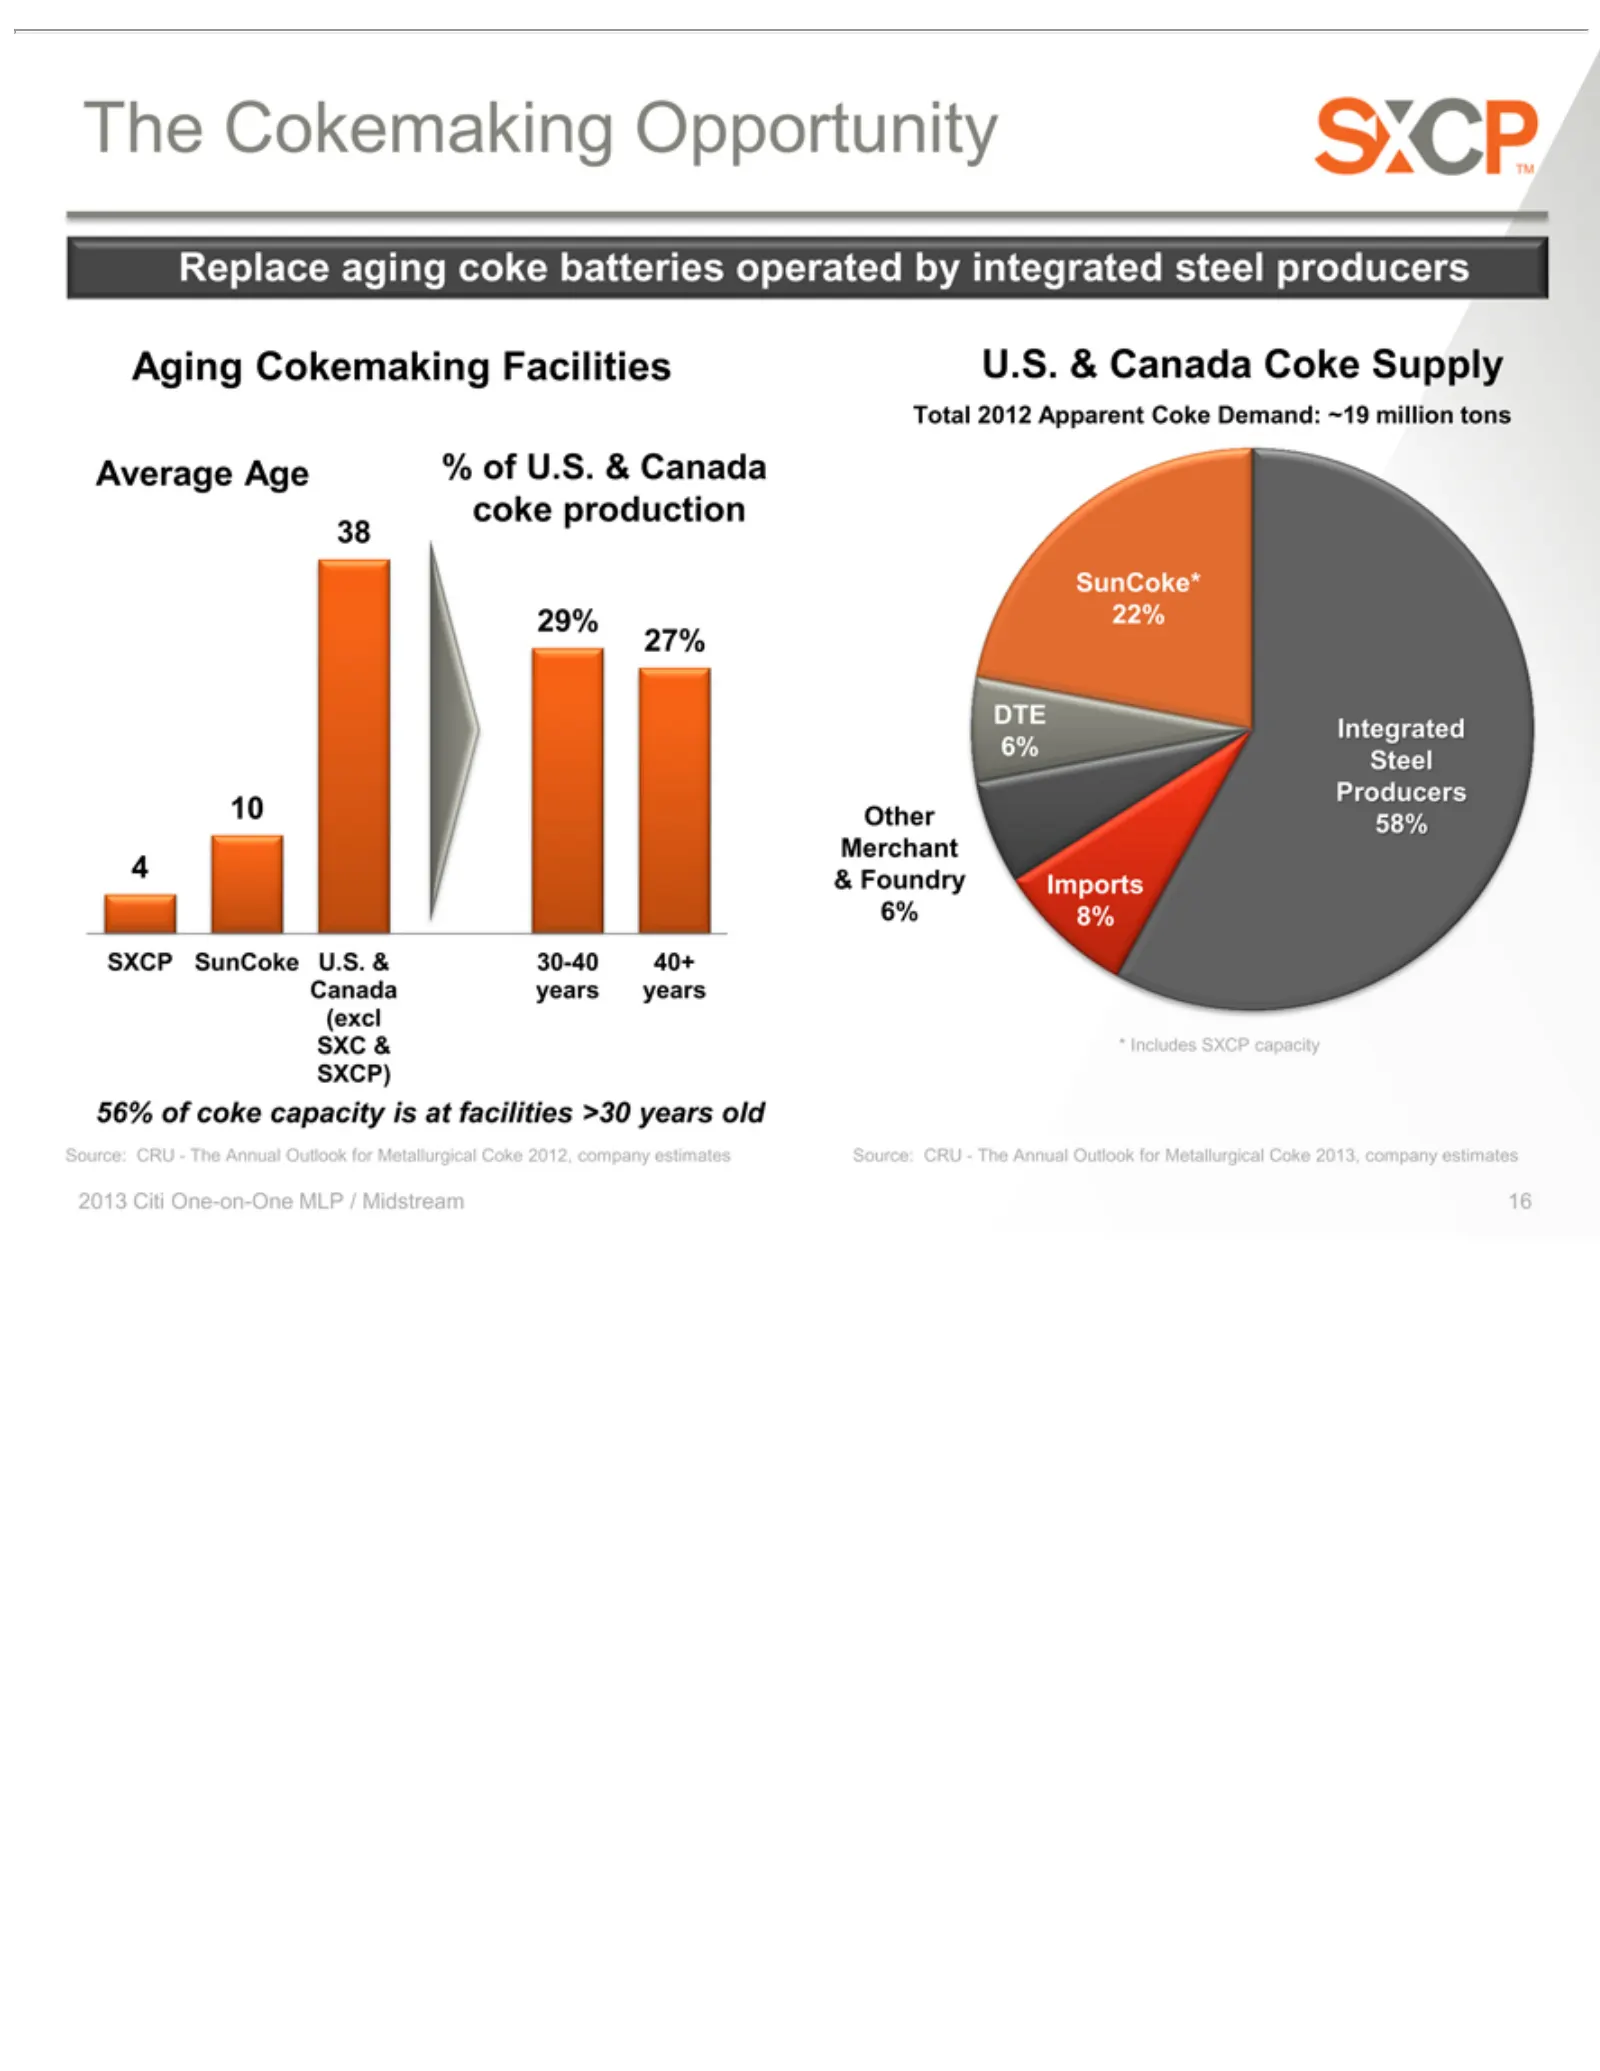
Slide 16: Replace Aging U.S. Coke Capacity
The Replace Aging Average [Graphic 27% 29% 38 SXCP Canada SXC (excl 56% SXCP) 2013 U.S. Total DTE 22% SunCoke* Other Producers & Merchant *6% Source: 16Includes Foundry Steel 8% Cokemaking & of Integrated & Citi 2012 58% SunCoke Cokemaking Canada coke years CRU—The aging Age Appears One-on-One SXCP
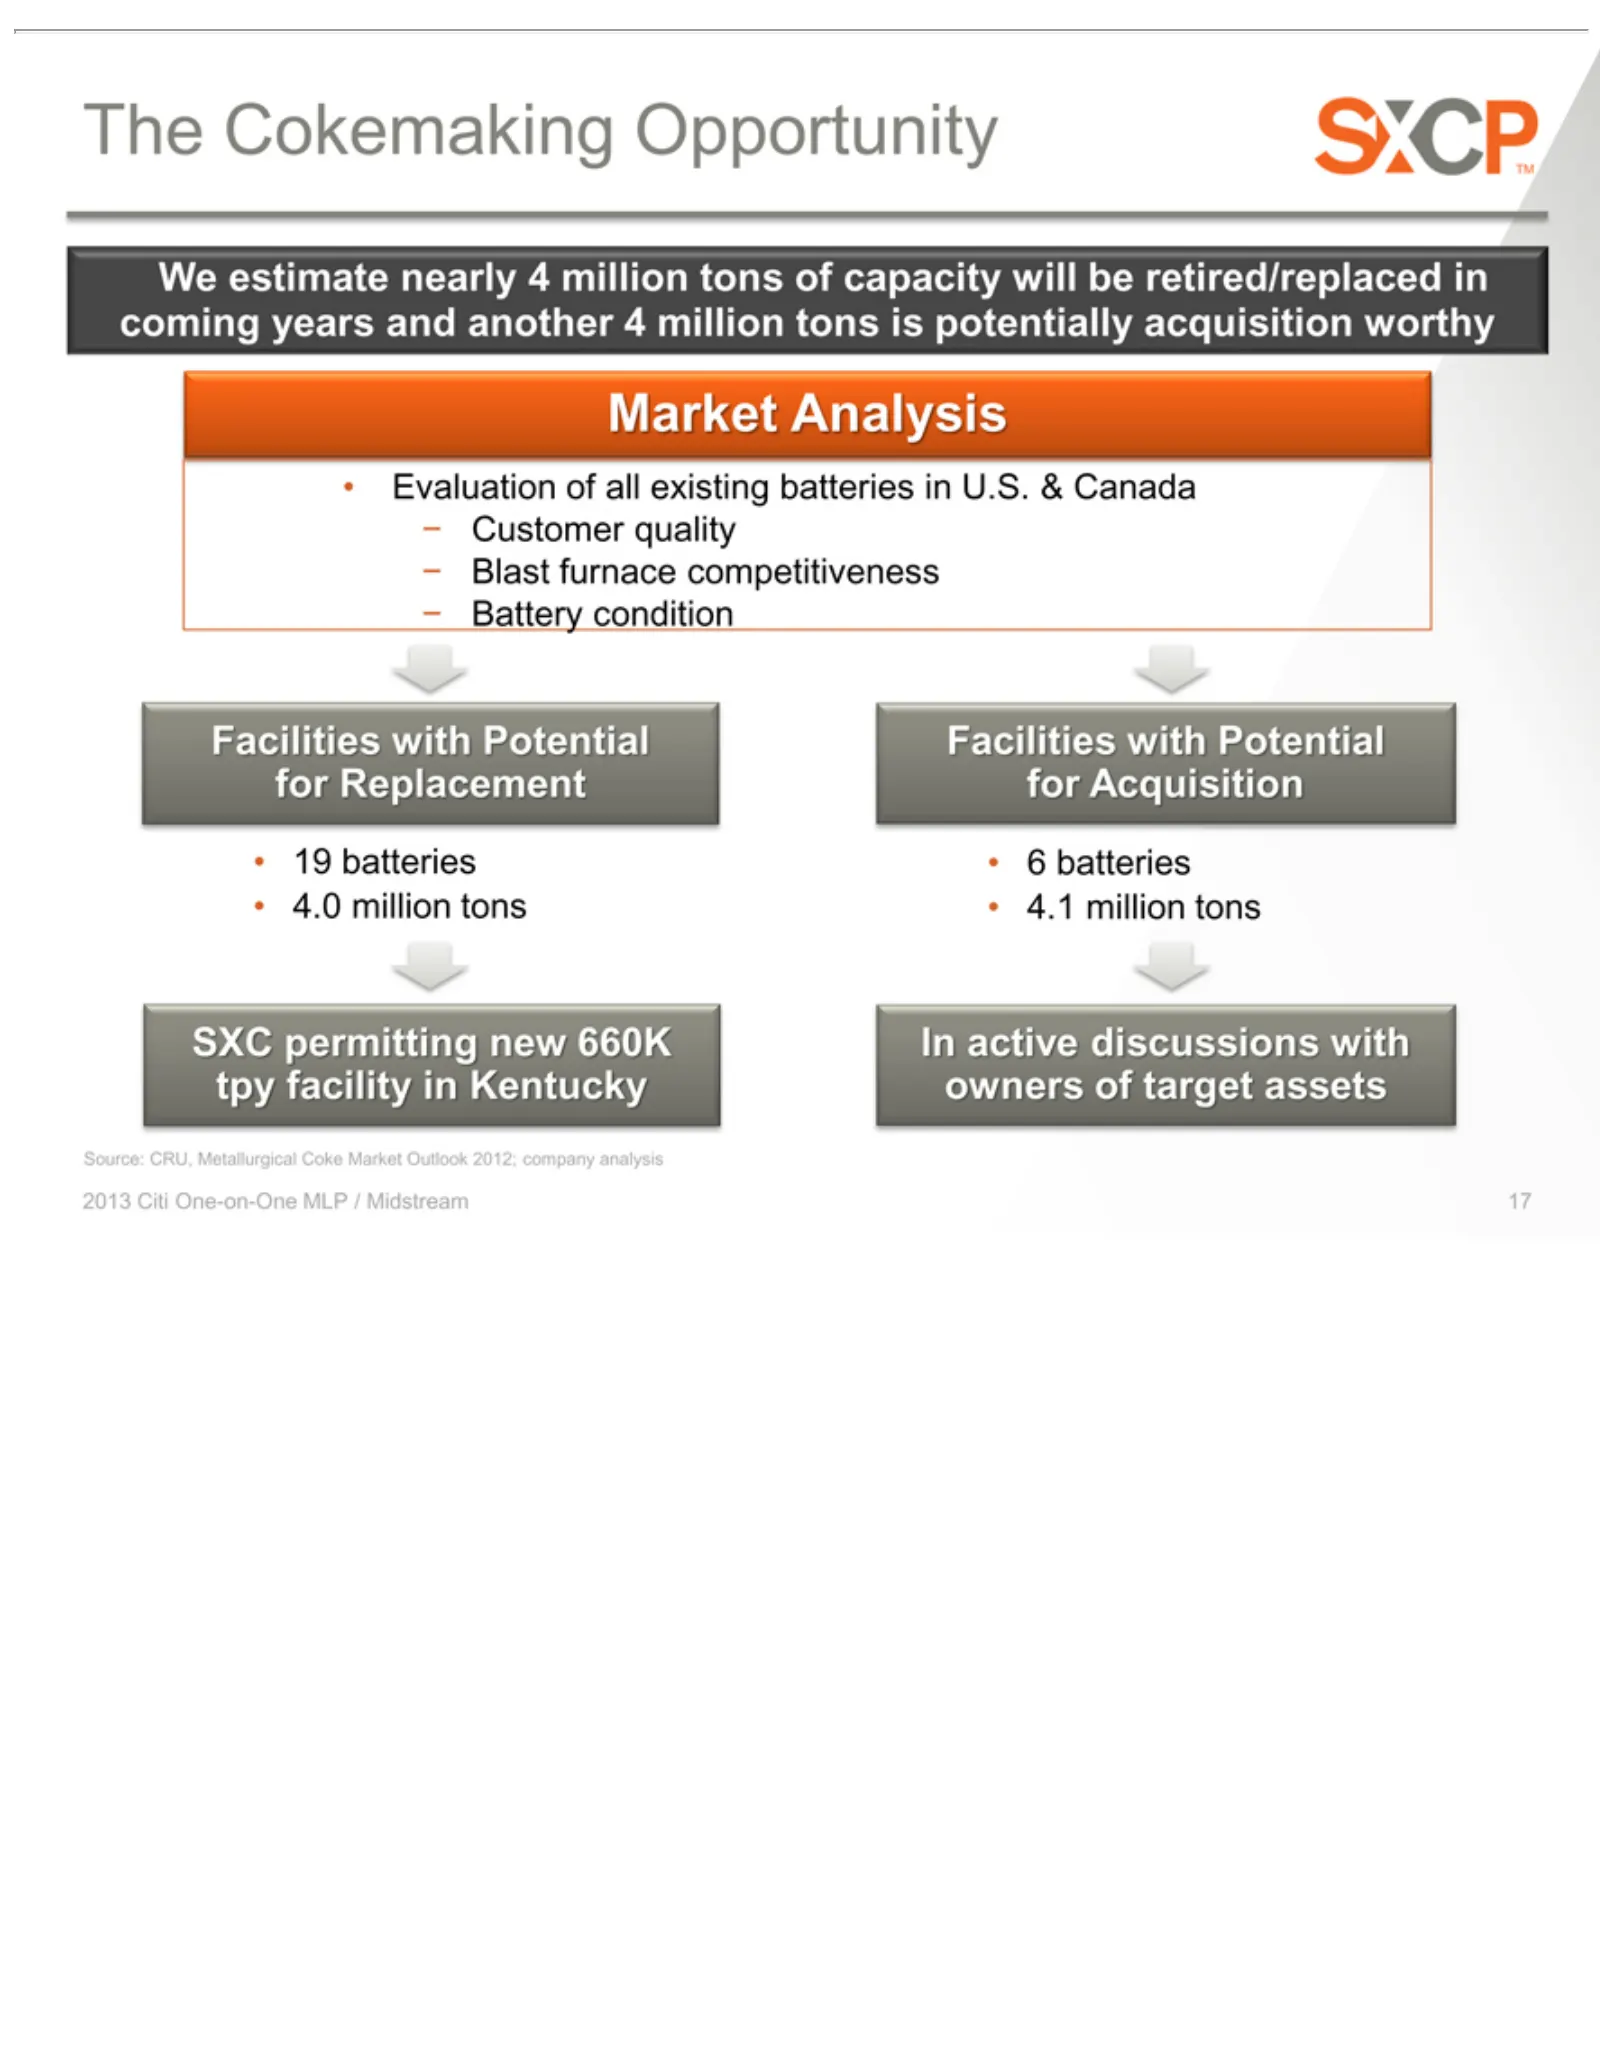
Slide 17: The Cokemaking Market Opportunity
Thebatteries We Market Evaluation Customer Blast Battery Facilities for 19 4.0 SXC tpy Source: 2013Replacement million facility estimate Cokemaking permitting Citi furnace Analysis condition CRU, with One-on-One quality of in tons 6nearly competitiveness batteries Kentucky all Metallurgical Potent 4
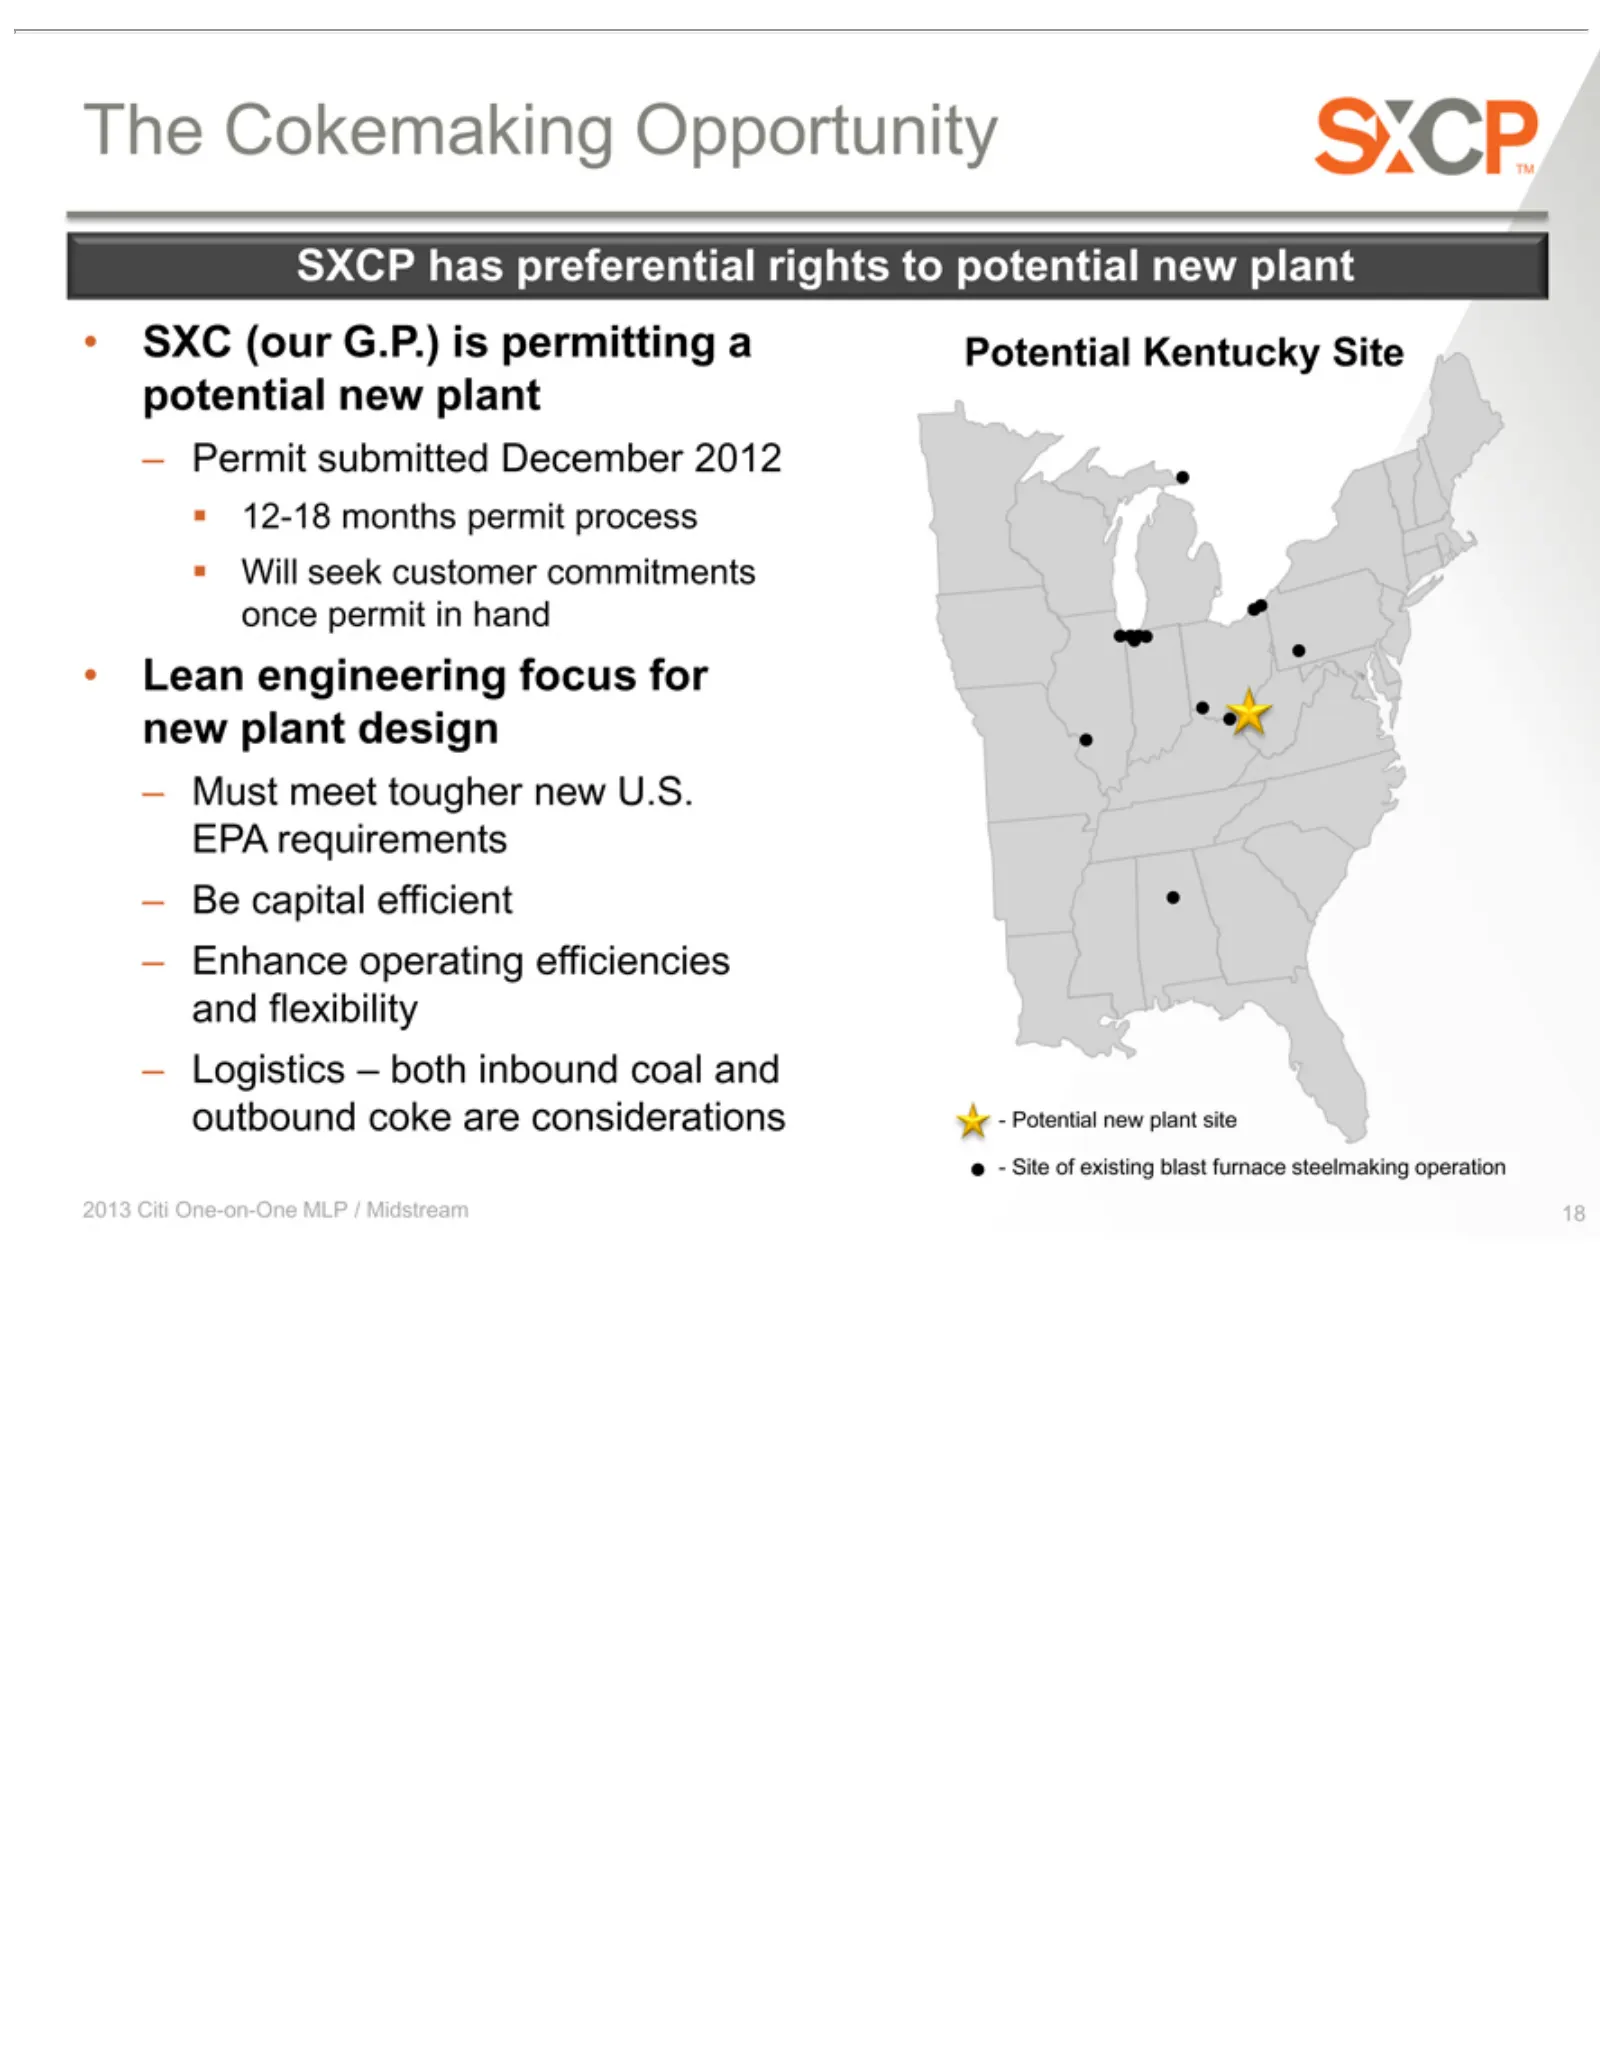
Slide 18: Greenfield Cokemaking Opportunity in Kentucky
Thecapital SXCP SXC Permit 12-18 Will Lean Must Be Enhance Logistics 2013 Potential Site 18 Cokemaking of seek (our engineering Citi meet months has existing submitted operating Kentucky new –One-on-One customer G.P.) efficient preferential tougher both plant permit blast isinbound December Opportun
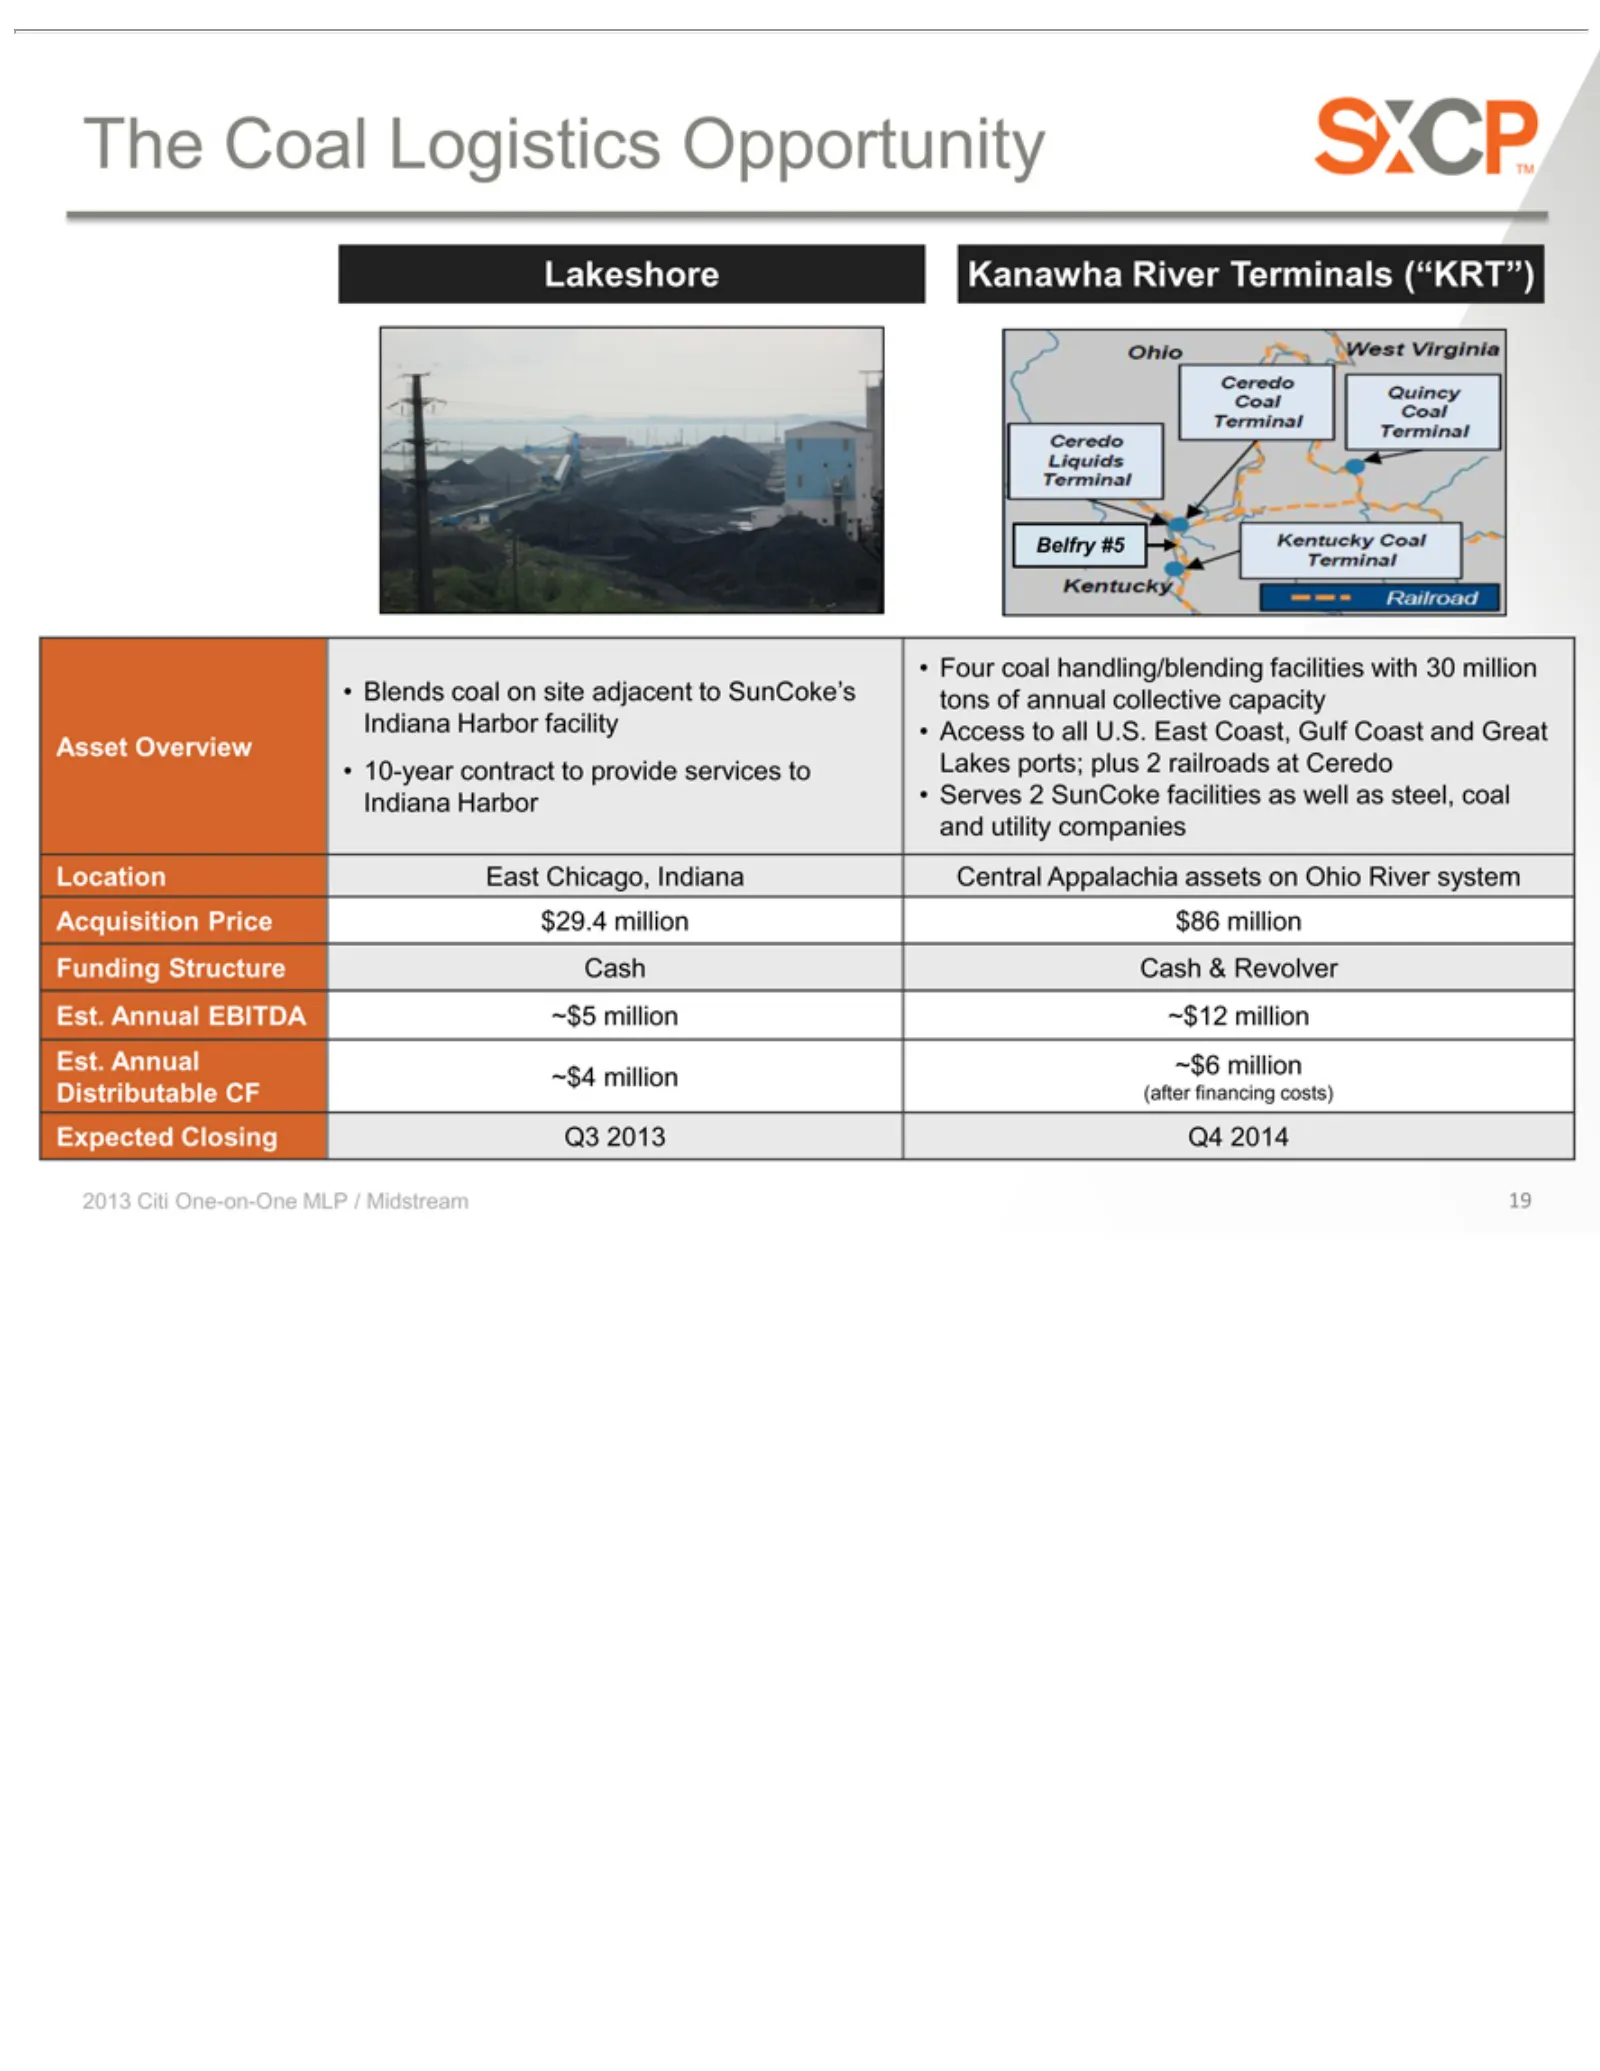
Slide 19: Lakeshore and KRT Acquisitions
The Lakeshore •Belfry Blends Asset 10-year Indiana and Location Acquisition Funding Est. ~$4 Distributable Expected 2013 Four utility Annual million Coal Citi Overview coal #5 coal Harbor contract Structure East Logistics Closing One-on-One companies Kanawha handling/blending Price EBITDA ~$6 onCF(a
Slide 20: Q2 Financial Performance & Position
Q2FINANCIAL & 2013 20 2013 CitiPERFORMANCE One-on-One POSITION MLP / Midstream
Slide 21: SXCP Q2 Results Highlights
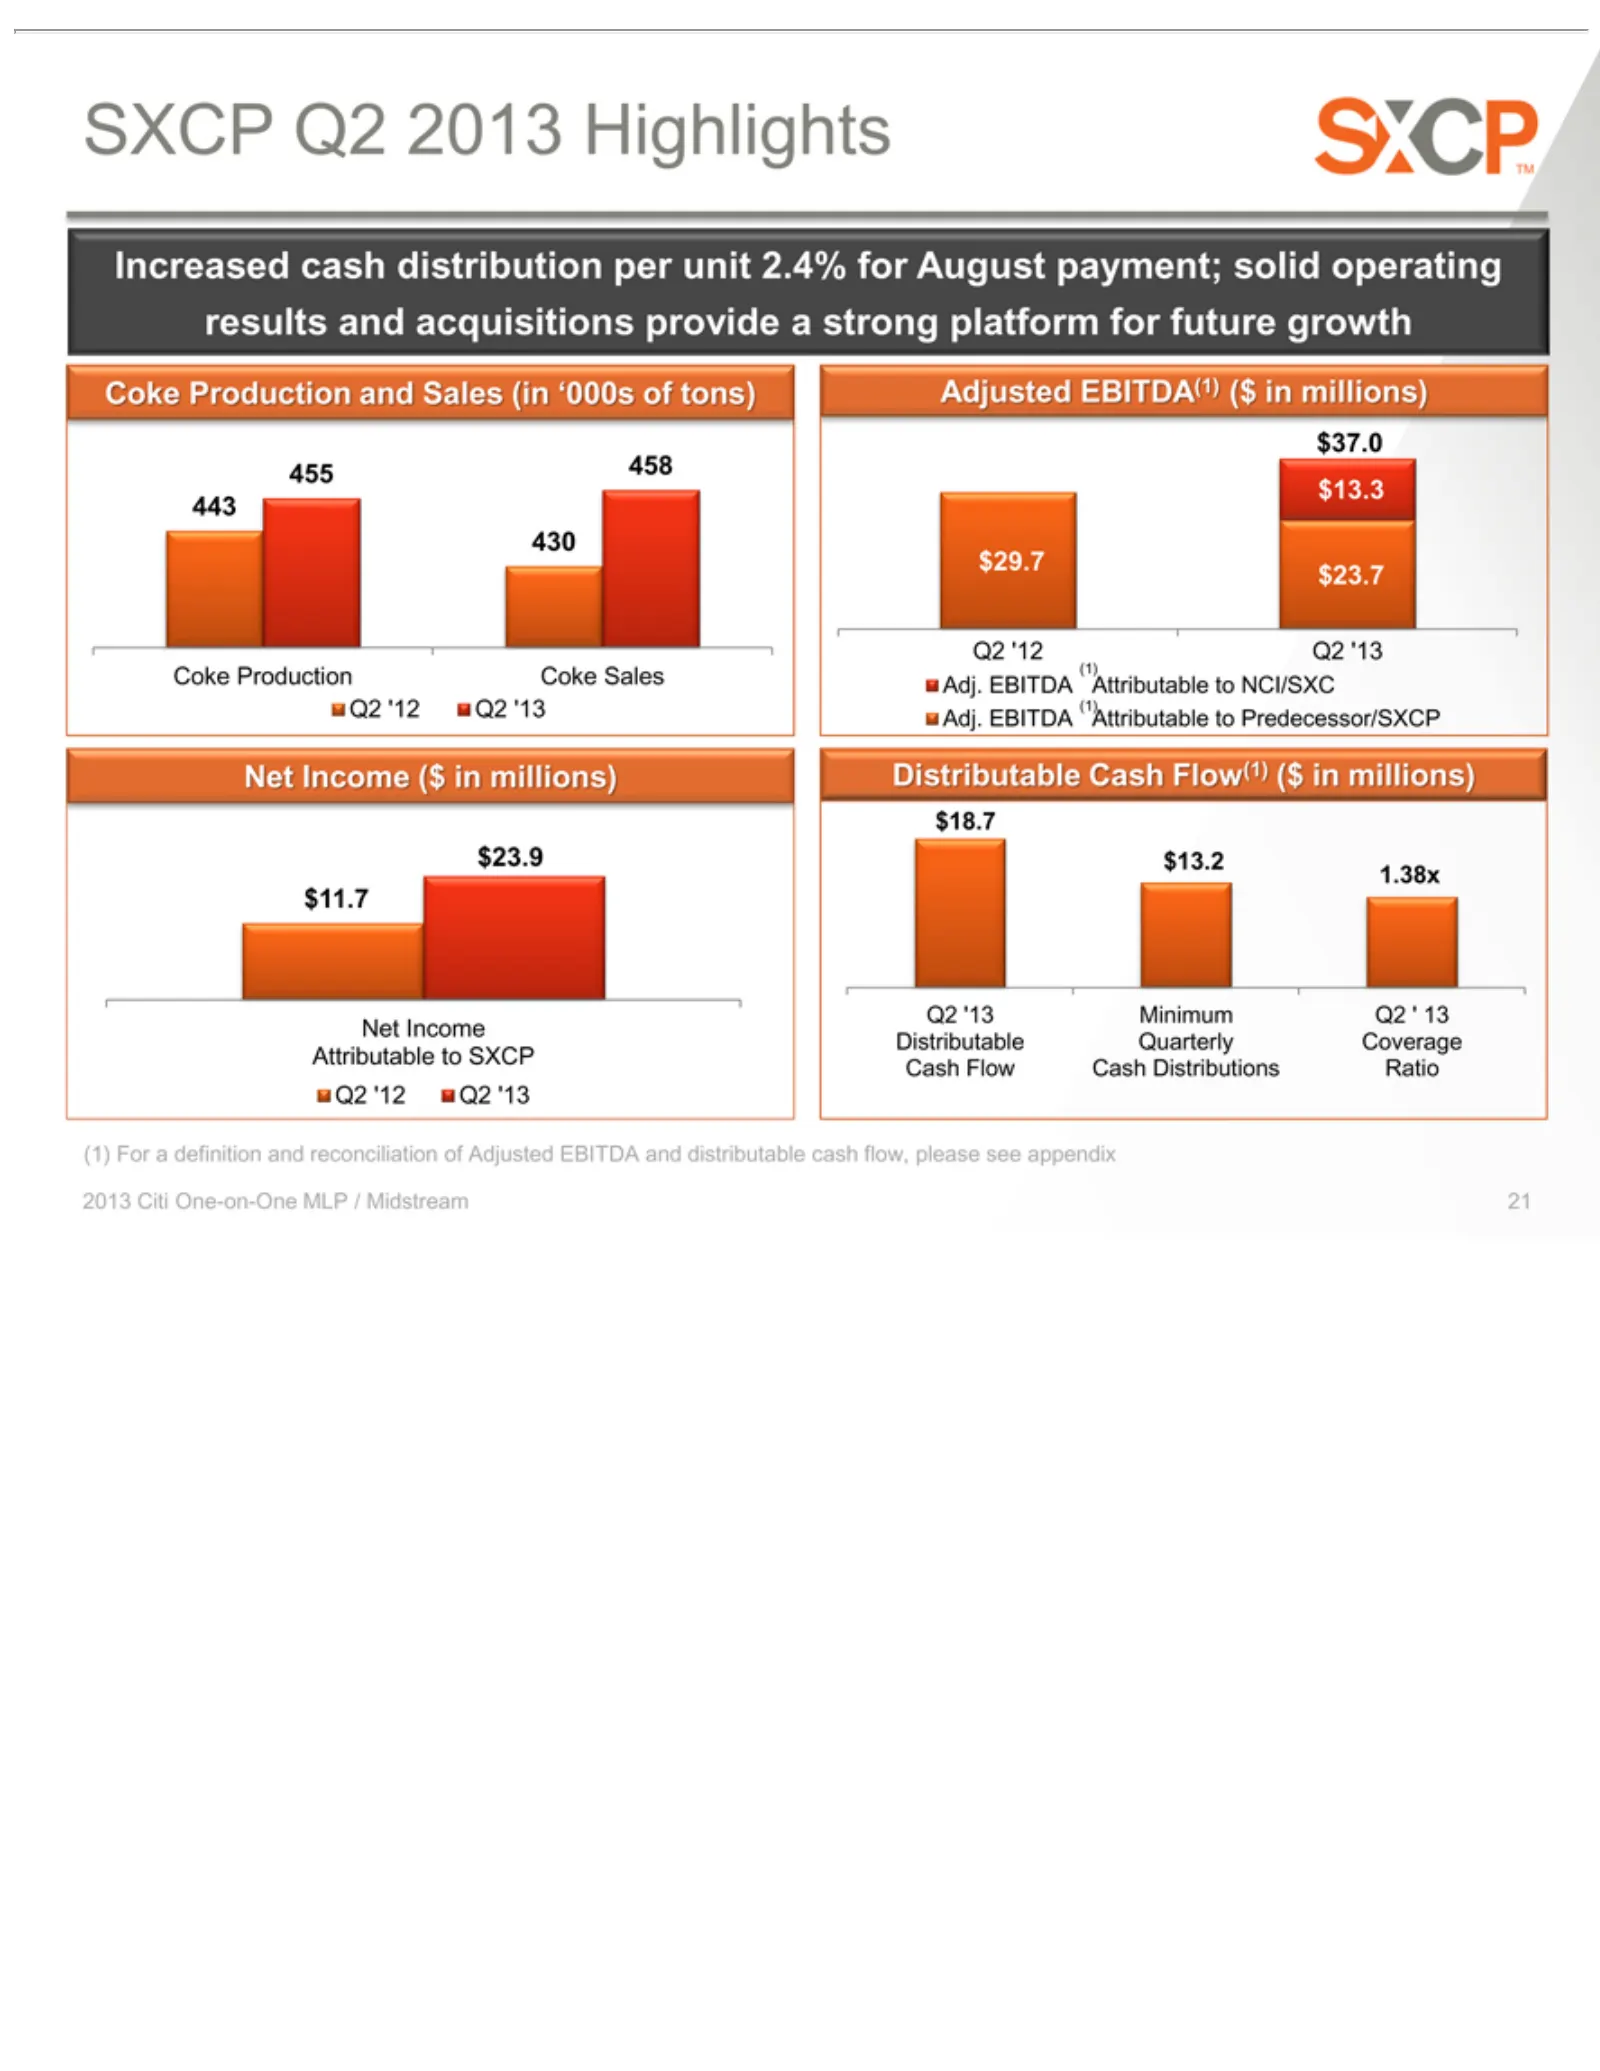
SXCP Increased $results 455 443 $29.7 430 Coke $23.9 $18.7 $11.7 Net Attributable Q2 (1) 2013 37.0 For ‘13 ‘12 Income 458 $13.3 Citi Production $23.7 $13.2 Q2 and aQ2 Minimum definition One-on-One cash 2013 ‘13 acquisitions ($ Distributable 1.38x to in Adj. distribution SXCP Highlights and Coke mill
Slide 22: Cash Position and Pre-funded Growth
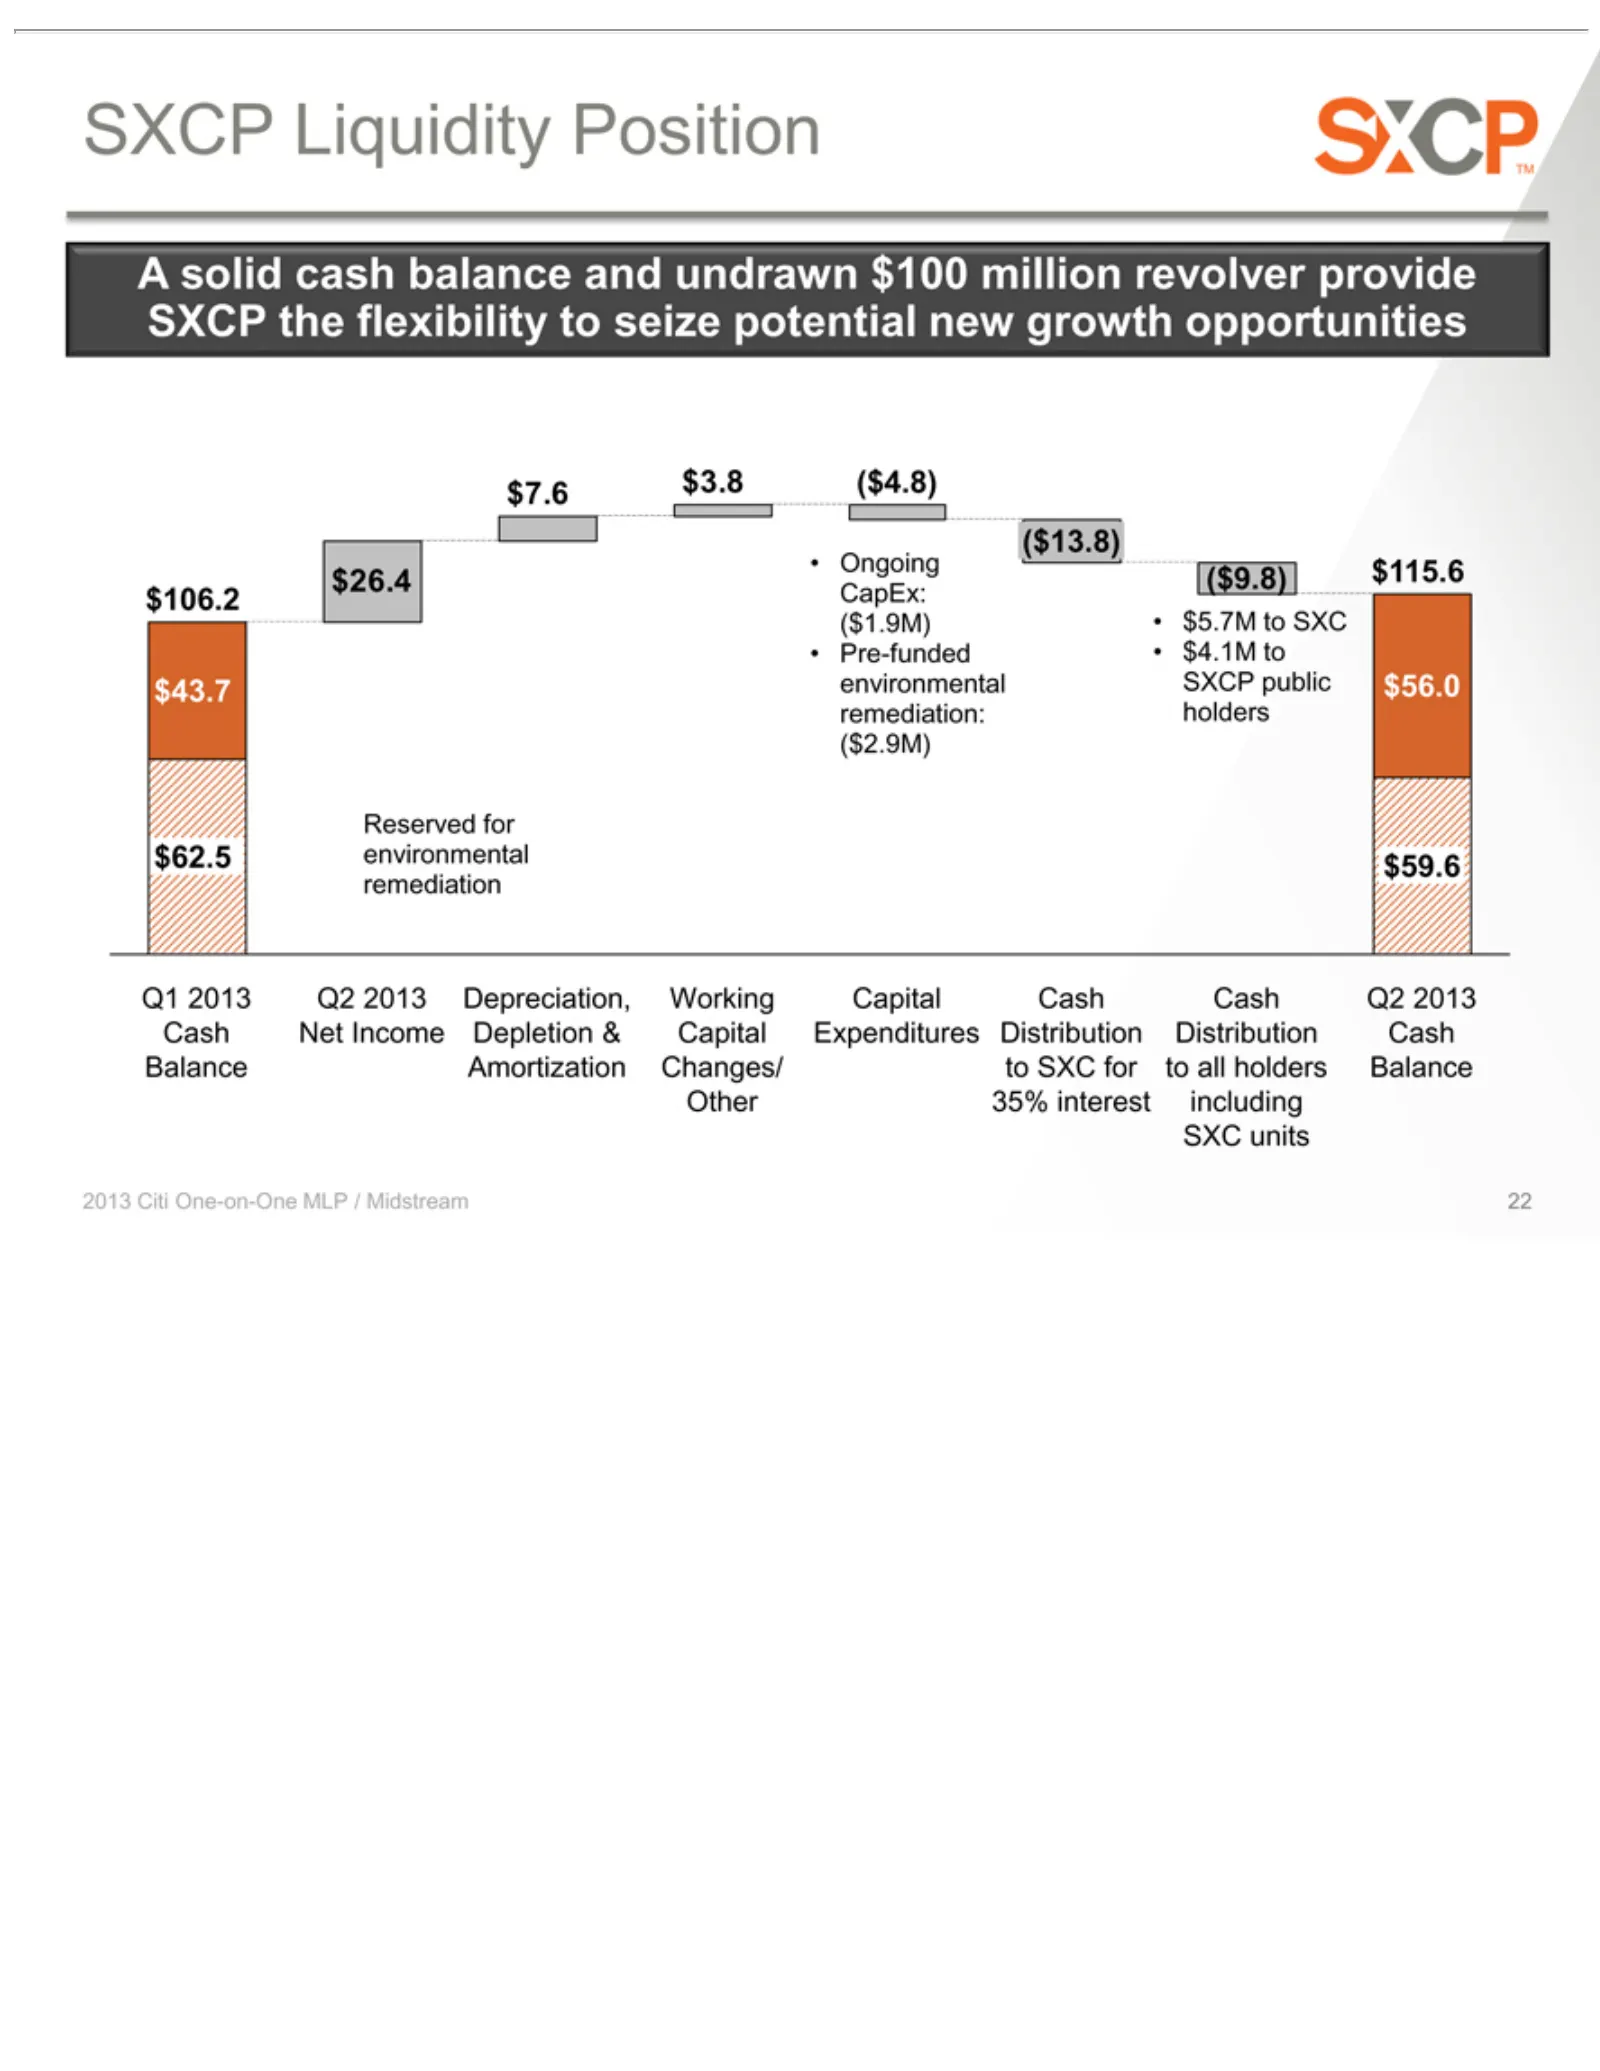
APre-funded SXCP $7.6 ($ $26.4 $106.2 •($1.9M) $43.7 remediation: Reserved ($2.9M) $62.5 Q1 remediation Cash Balance Other SXC 2013 solid 13.8) 2013 $3.8($4.8) units Citi Net •35% environmental Liquidity the CapEx: Ongoing($ cash Amortization •Q2 Income for One-on-One $flexibility interest 5.7M bala
Slide 23: Liquidity Position
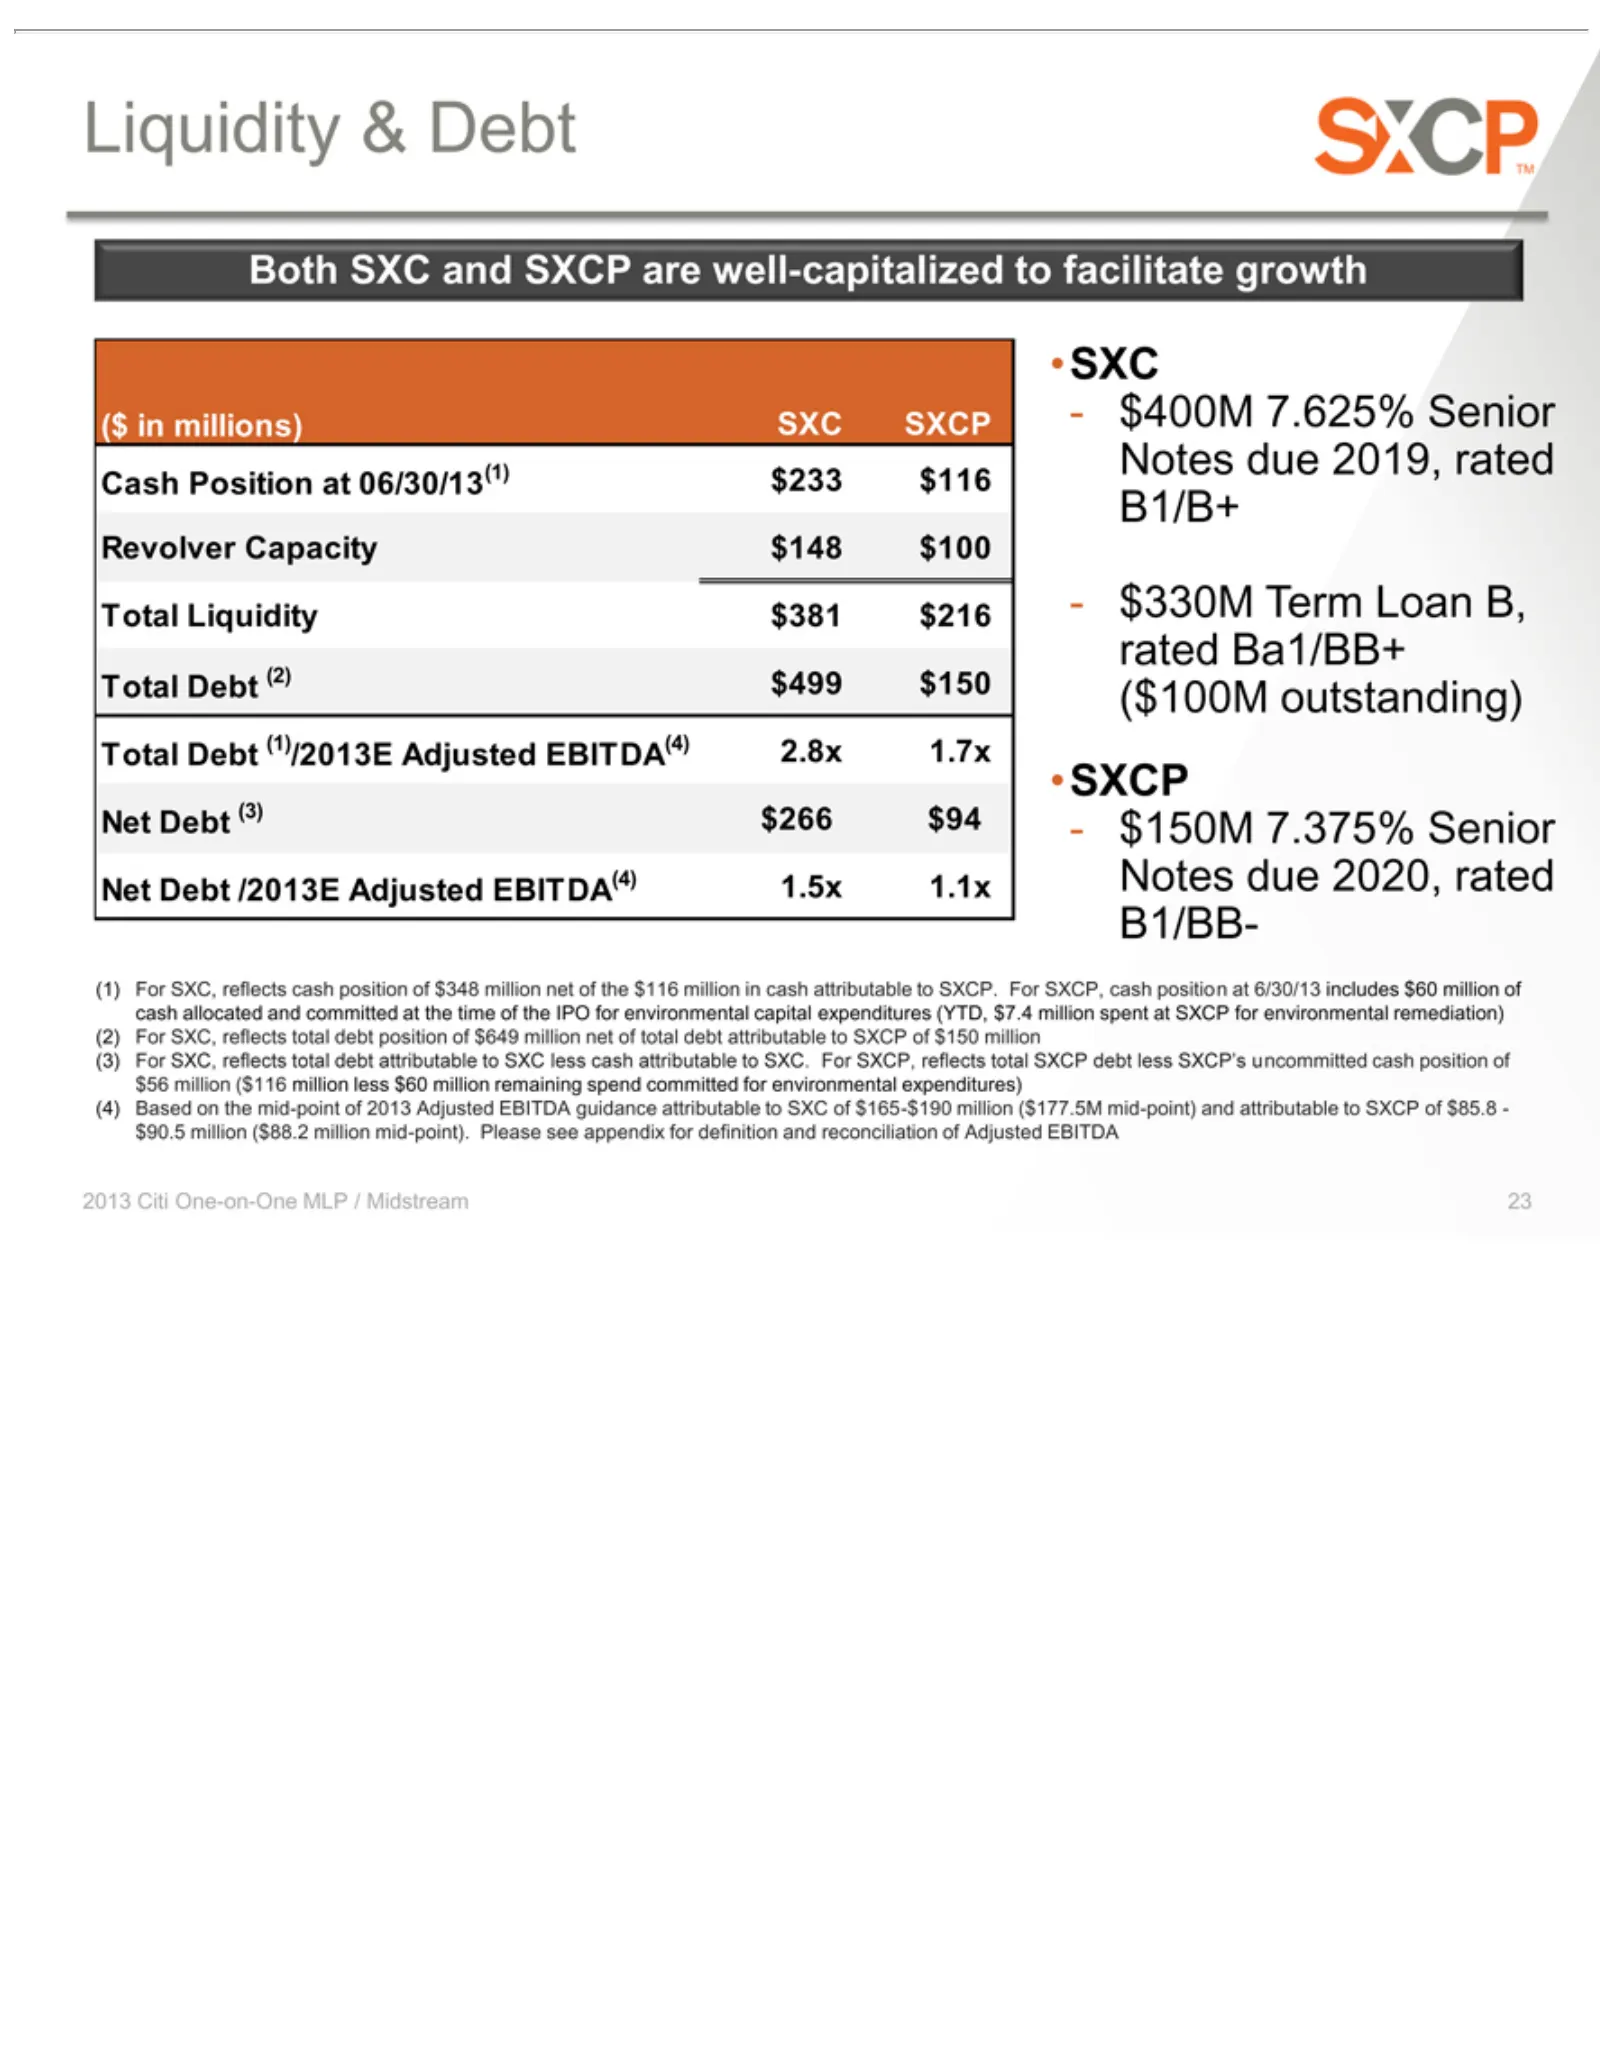
Liquidity Both ($ Cash Revolver B1/B+ rated •Total Net B1/BB- environmental For committed Based appendix 2013 23 SXC SXCP inSXC, Debt millions) SXC Ba1/BB+ Citi Position Liquidity Debt on /2013E (3) Capacity for the & One-on-One reflects and (2) (1) for Debt $266 definition mid-point at $499 /2013E
Slide 24: SXCP 2013 Guidance Outlook
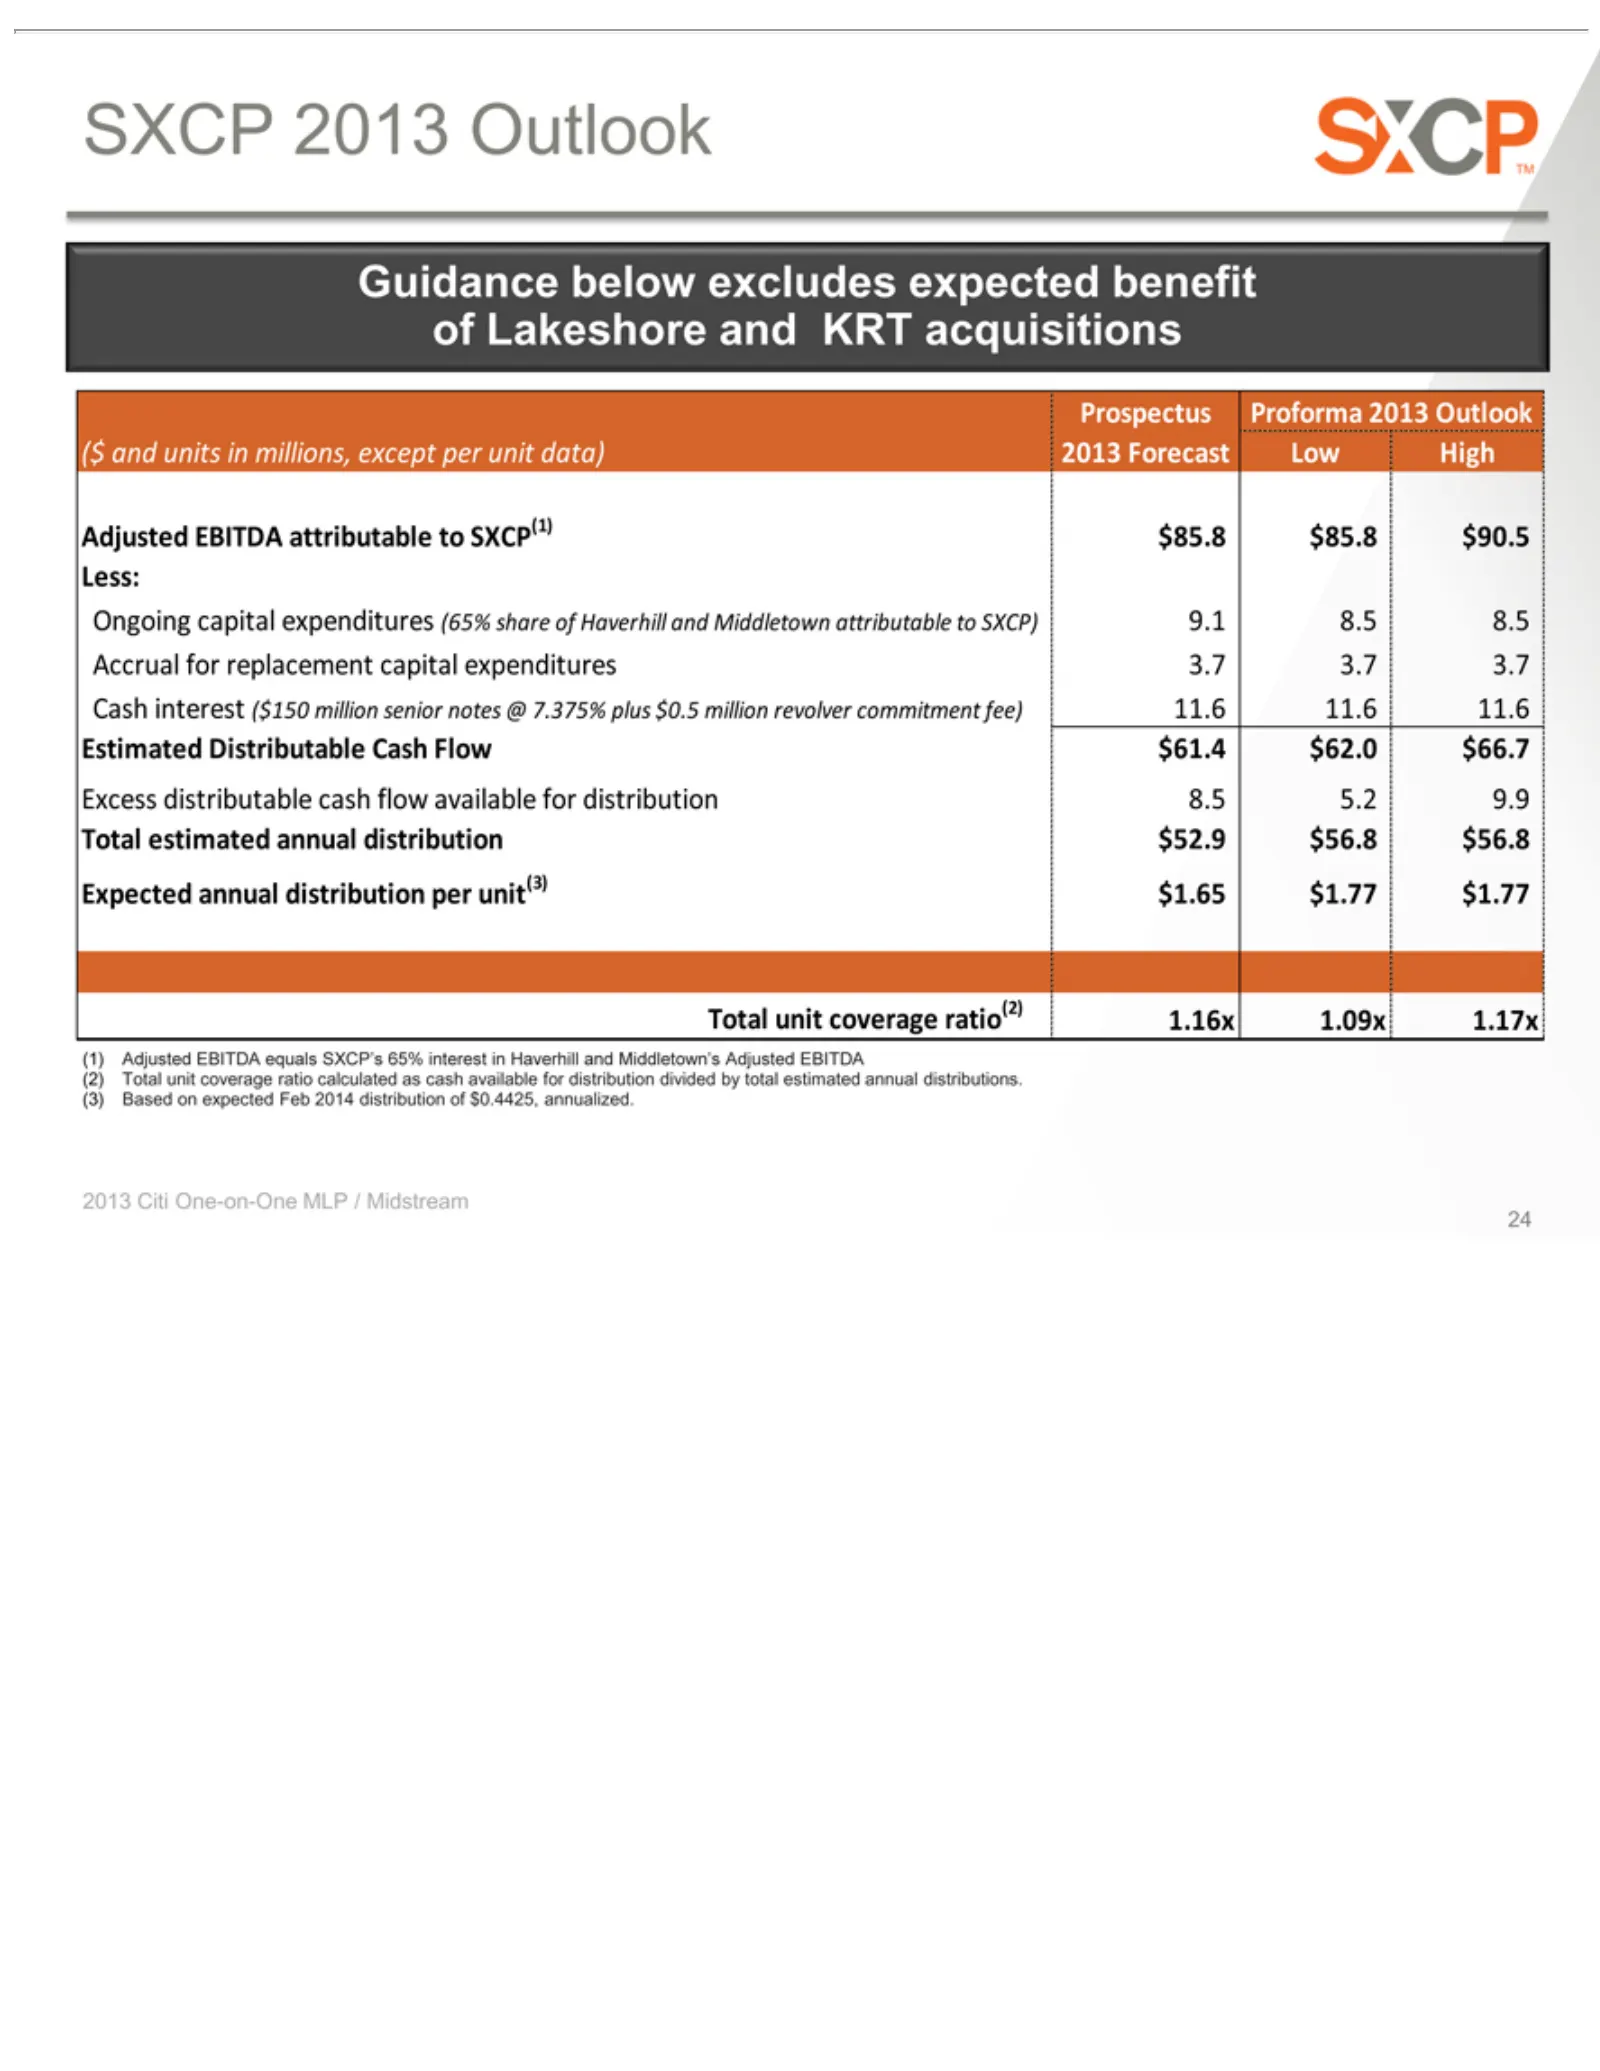
SXCP Guidance of Prospectus ($ Ongoing Less: Accrual Cash Estimated Excess Expected Adjusted Total Based 2013 24 Lakeshore andCiti interest estimated unit on 2013 units distributable for capital EBITDA expected annual One-on-One below coverage Distributable Proforma replacement Outlook in($150 and m
Slide 25: Investor Relations
Investor Relations: www.suncoke.com 630-824-1987
Slide 26: Appendix
2013 Citi One-on-One MLP / Midstream APPENDIX 26
Slide 27: Definitions
Definitions attributable income included and Management provides our accordance EBITDA Adjusted SXC 2013 27 operating Adjusted or Citi tax SXCP in useful reflects represents EBITDA EBITDA/Ton One-on-One expense. EBITDA. with tobelieves EBITDA performance. our asinformation GAAP. sales applicable. eq
Slide 28: Definitions: Distributable Cash Flow
Definitions Distributable use the The considered principles investing Additionally, Ongoing improves of Replacement estimated estimate approved 2013 28 other calculating ability Partnership’s viability to Partnership Citi assess: companies, will capital activities. by the One-on-One based (GAAP). of
Slide 29: SXCP Reconciliations
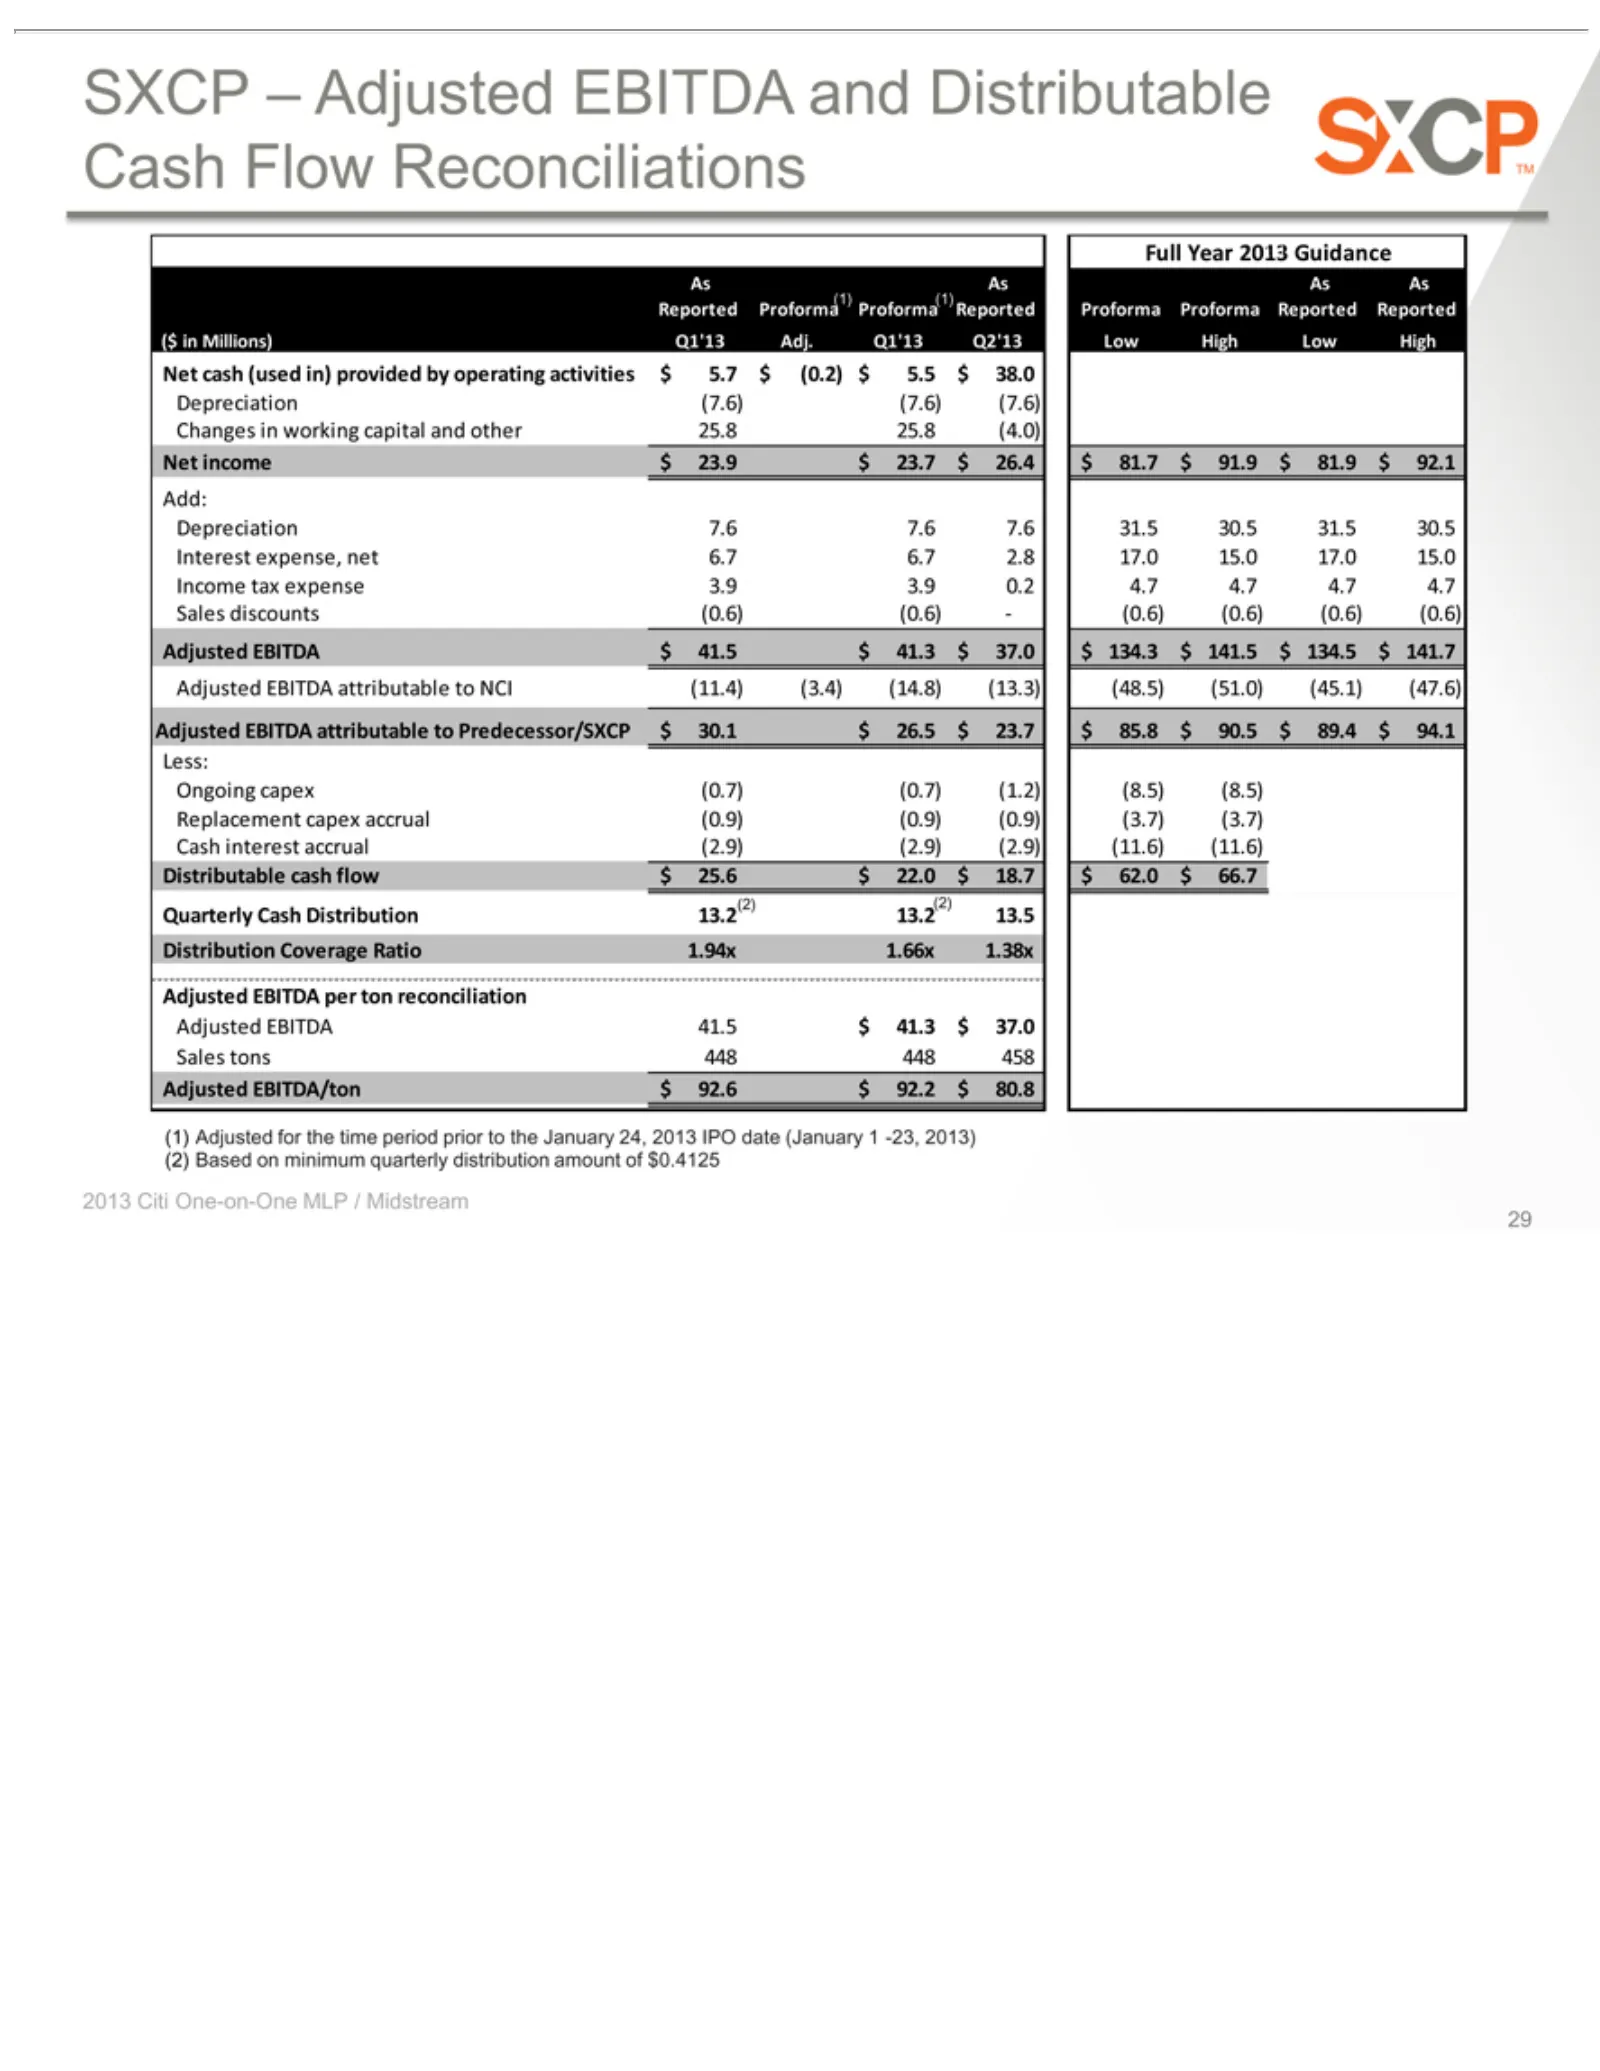
SXCP Full As Reported ($ Changes Depreciation(7.6)(7.6)(7.6) Net Depreciation Add: Interest Income Ongoing Less: Replacement Cash Distributable Quarterly Distribution Sales Adjusted Based 2013 29 in As cash income Year Millions) Citi Flow interest discounts(0.6)(0.6) tons As on – tax expense, Adjust
Slide 30: Reference
2013 Citi One-on-One MLP / Midstream REFERENCE 30
Slide 31: Blast Furnace and Coke
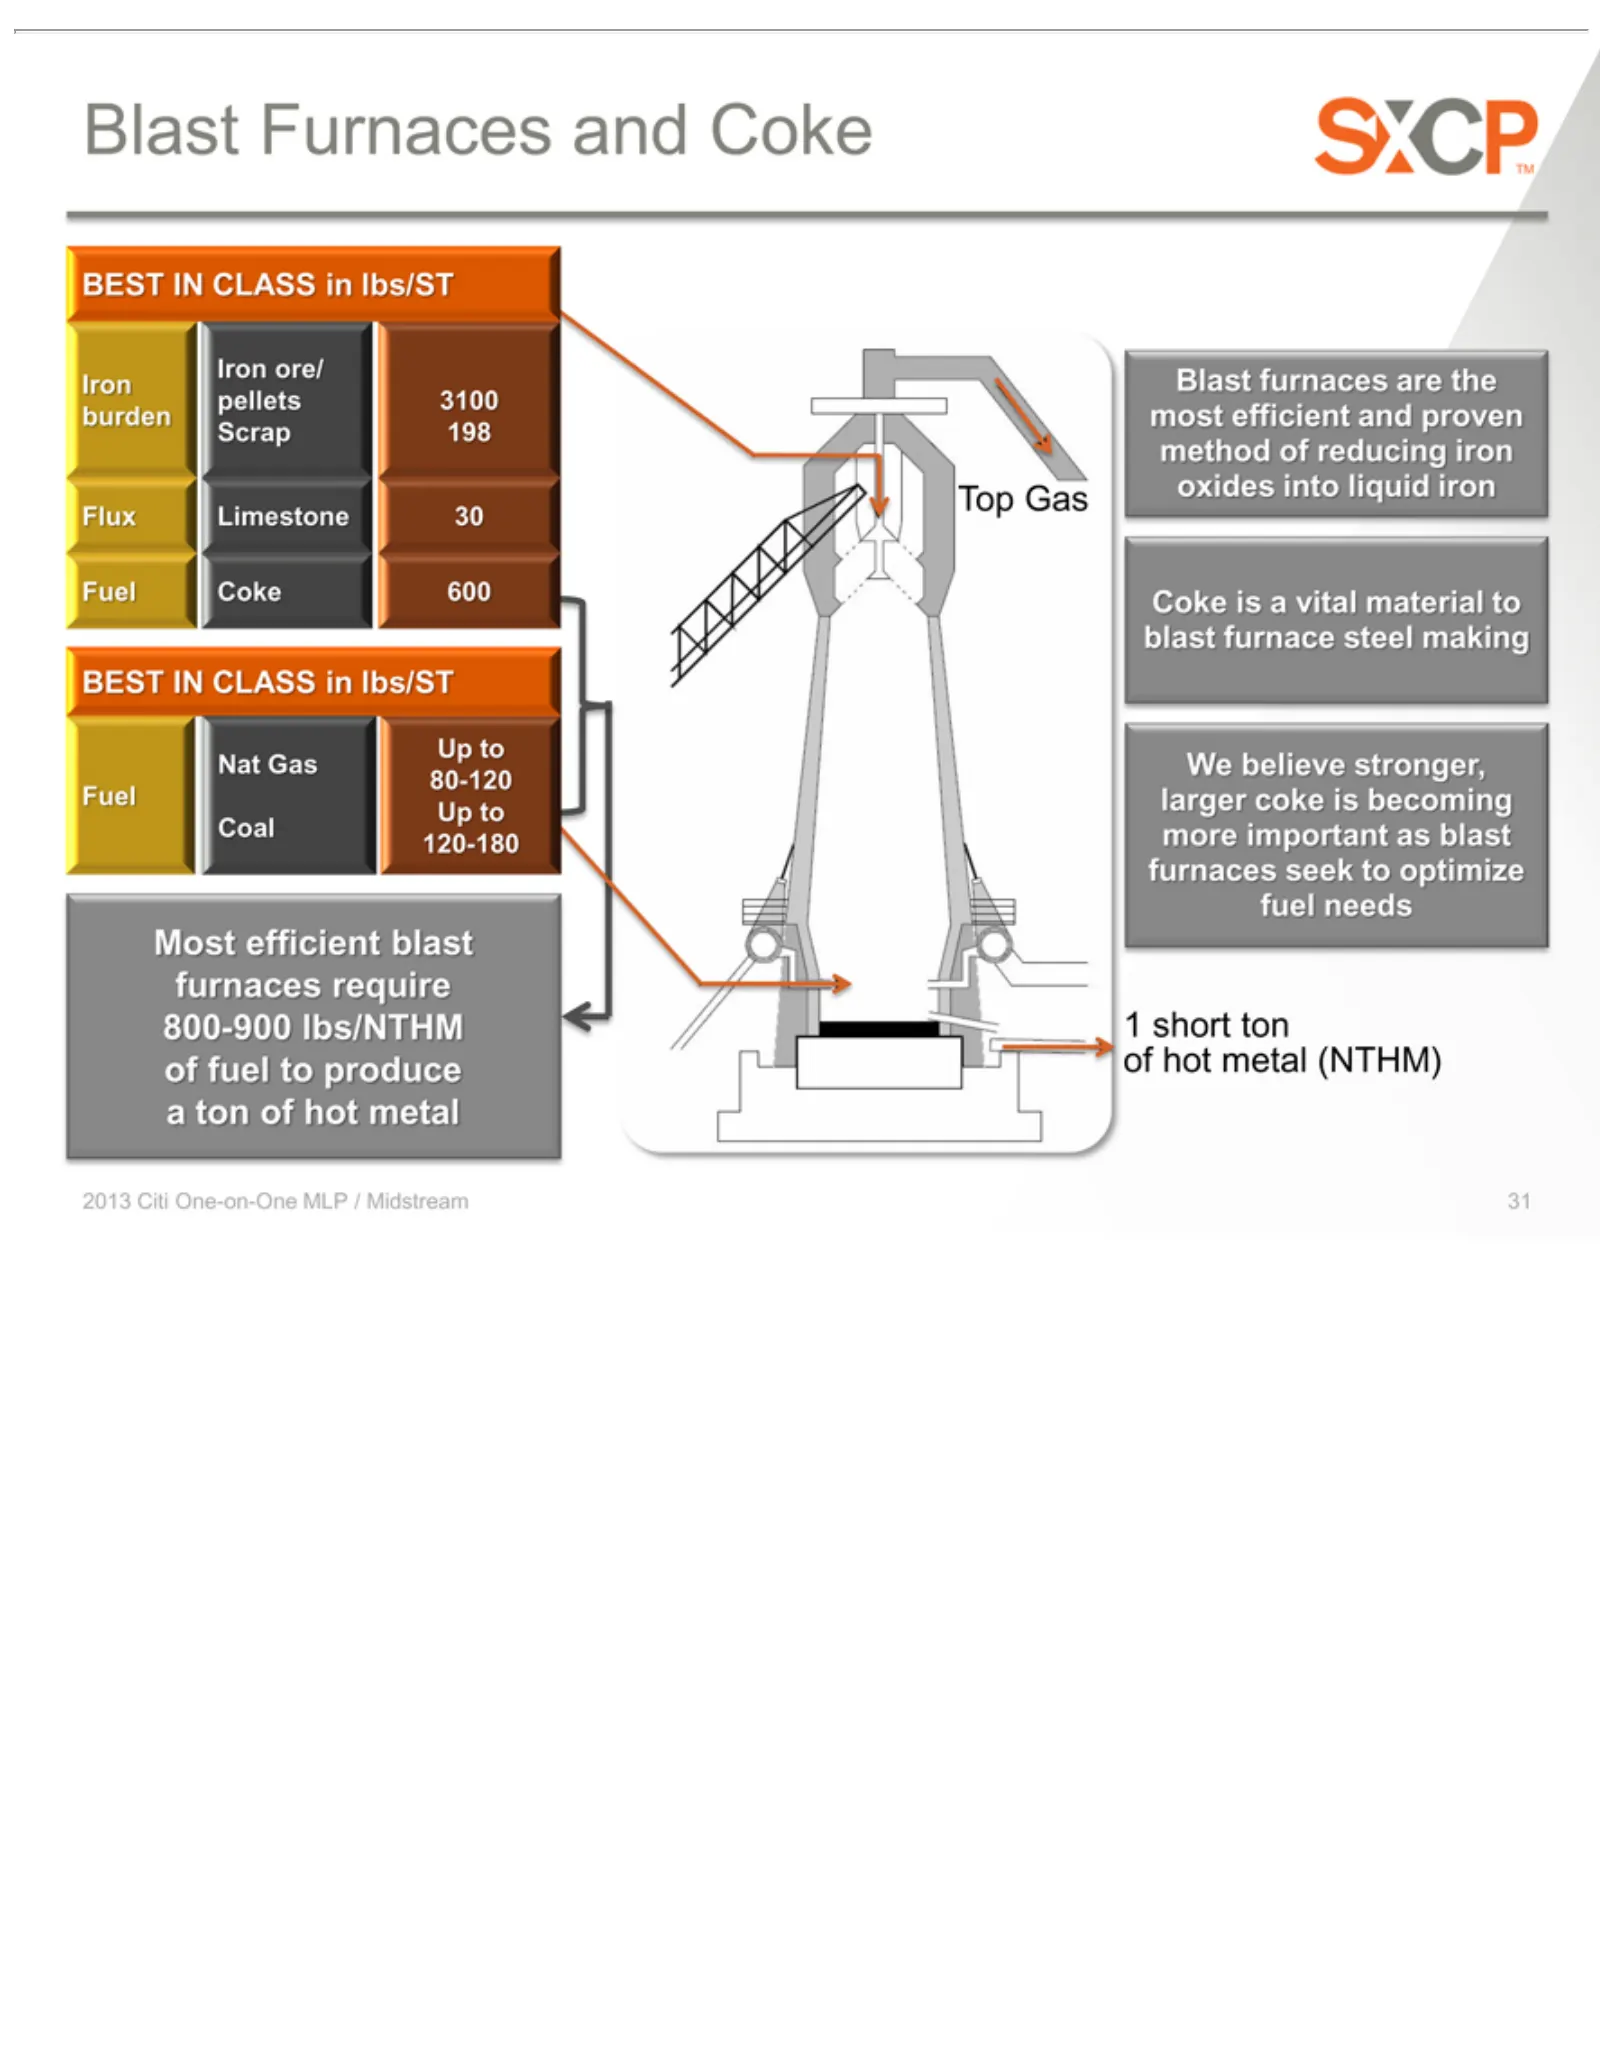
Blast Iron pellets burden Scrap Top Flux blast BEST Up Nat Fuel 80-120 Coal fuel Most furnaces 800 aof 2013 31ton fuel to Gas 900 need Iron Coke Up Limestone 120-180 furnace of Citi Furnaces efficient 198 IN 3100 to most hot We to lbs/NTHM oxides seek requ ore/ produce CLASS One-on-One method 600 la
Slide 32: Heat Recovery Cokemaking Advantages
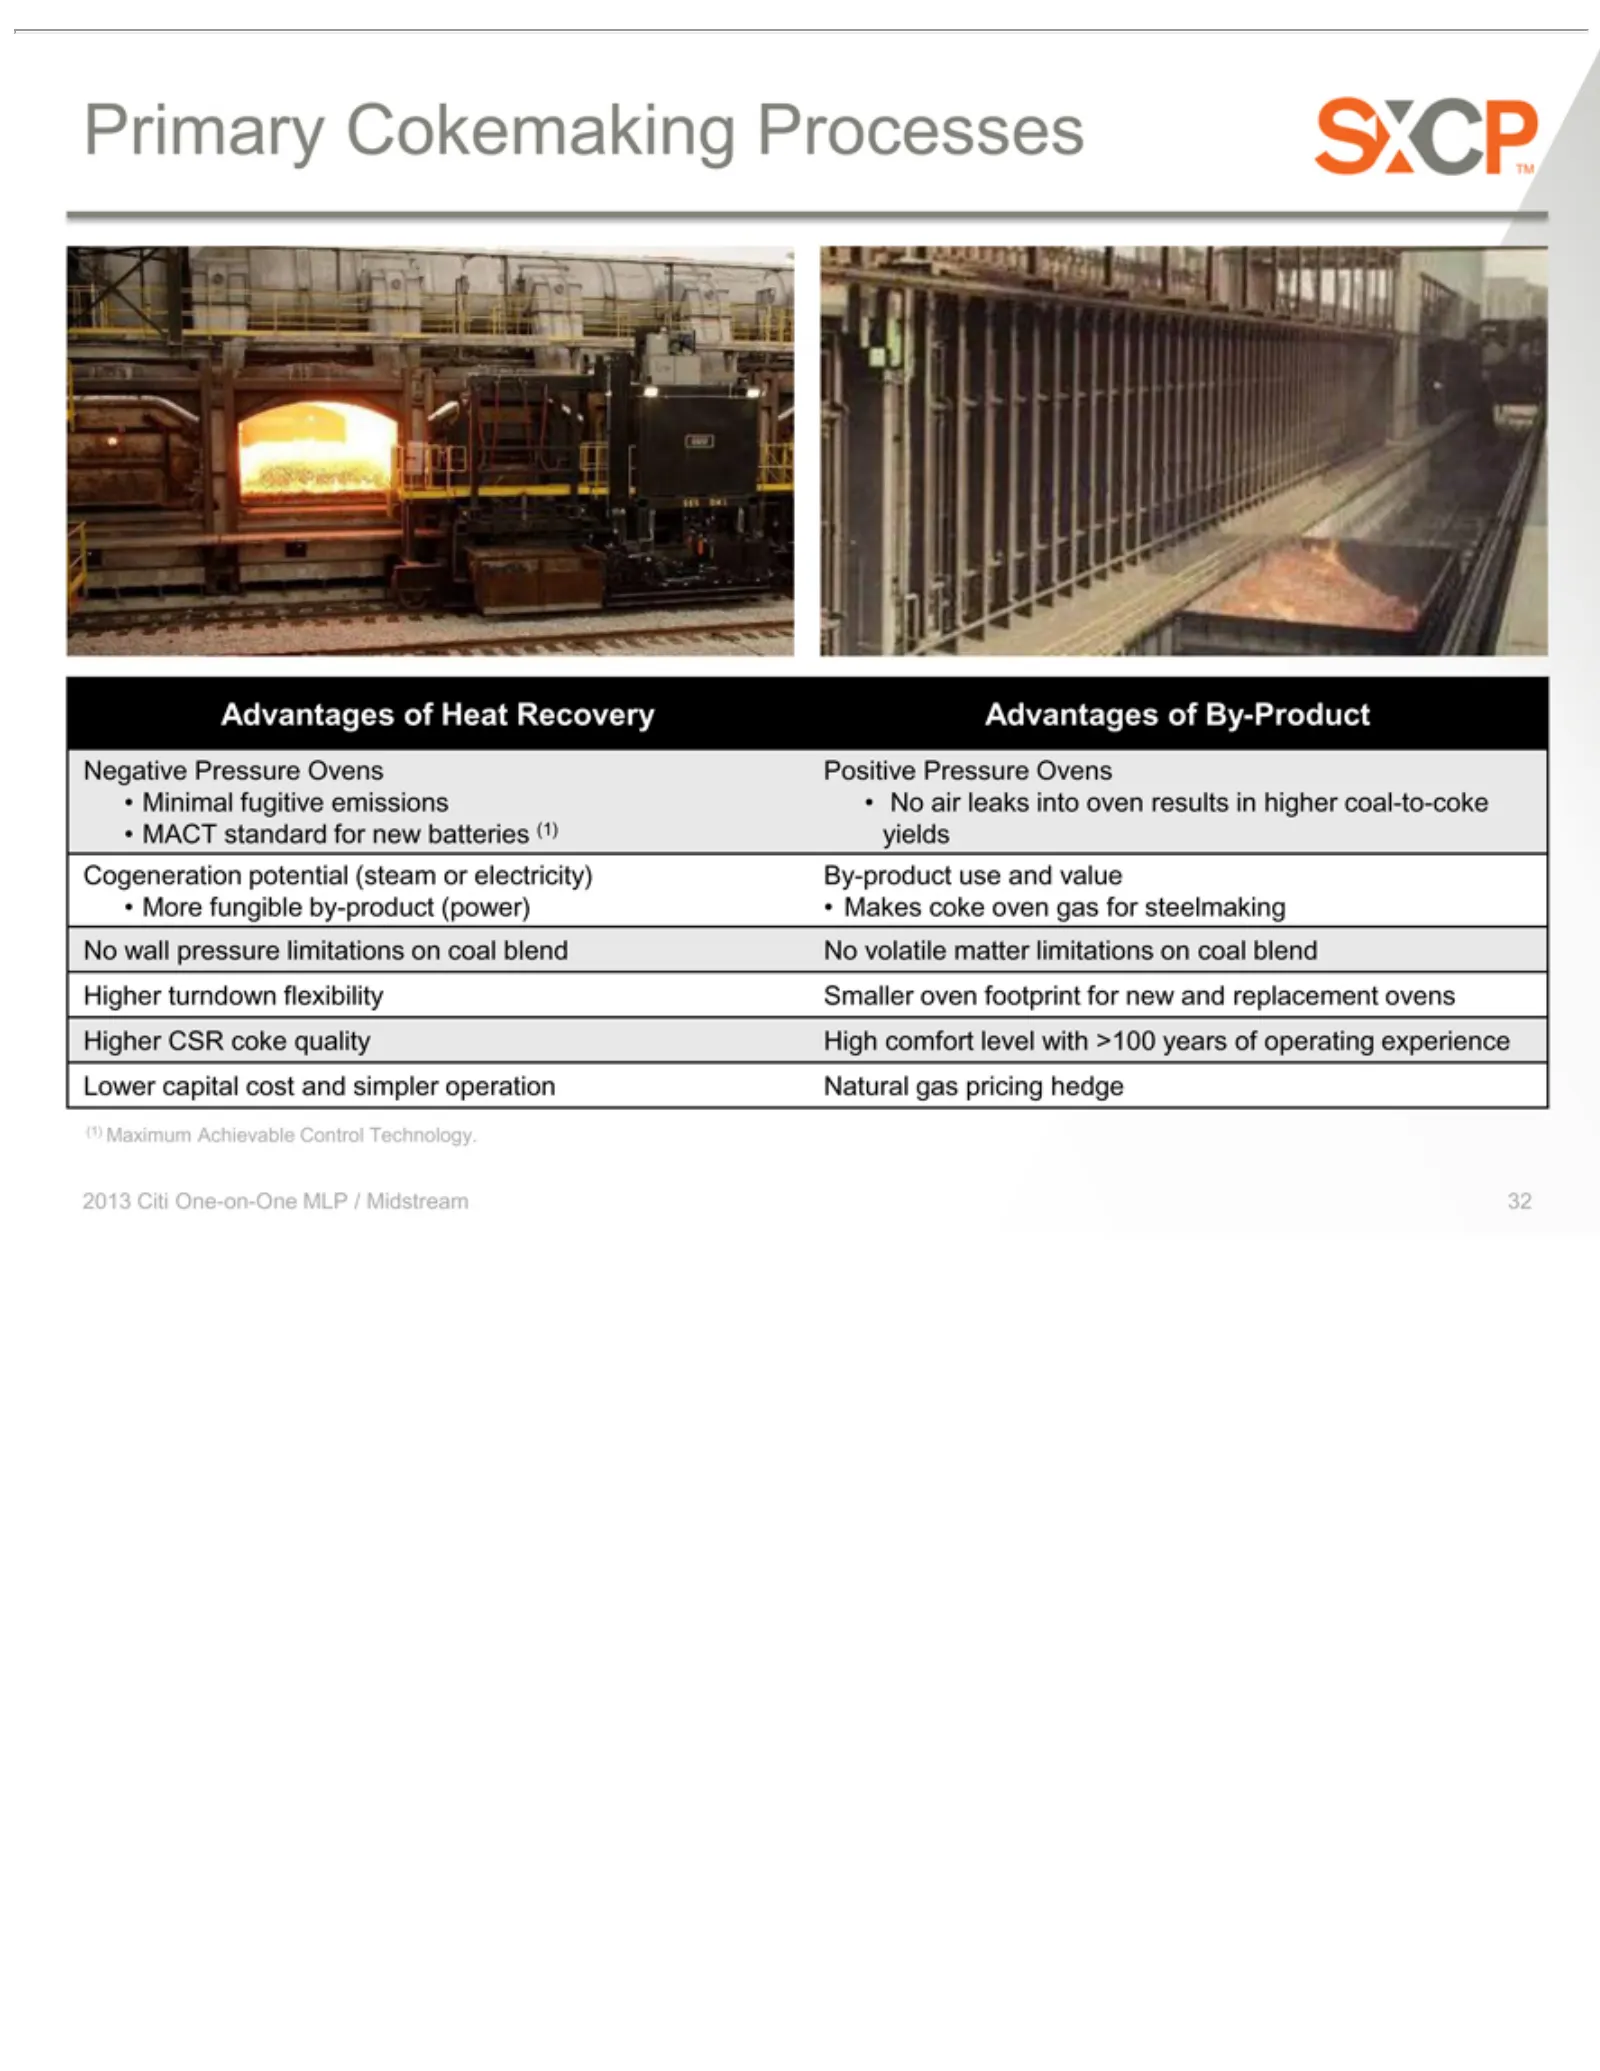
Primary Advantages Negative Minimal MACT Cogeneration More No Higher Lower (1) 2013Maximum wall Citi fungible capital turndown CSR standard pressure Cokemaking fugitive Pressure One-on-One of coke potential cost Achievable by-product Heat for limitations emissions flexibility quality Ovens and new R
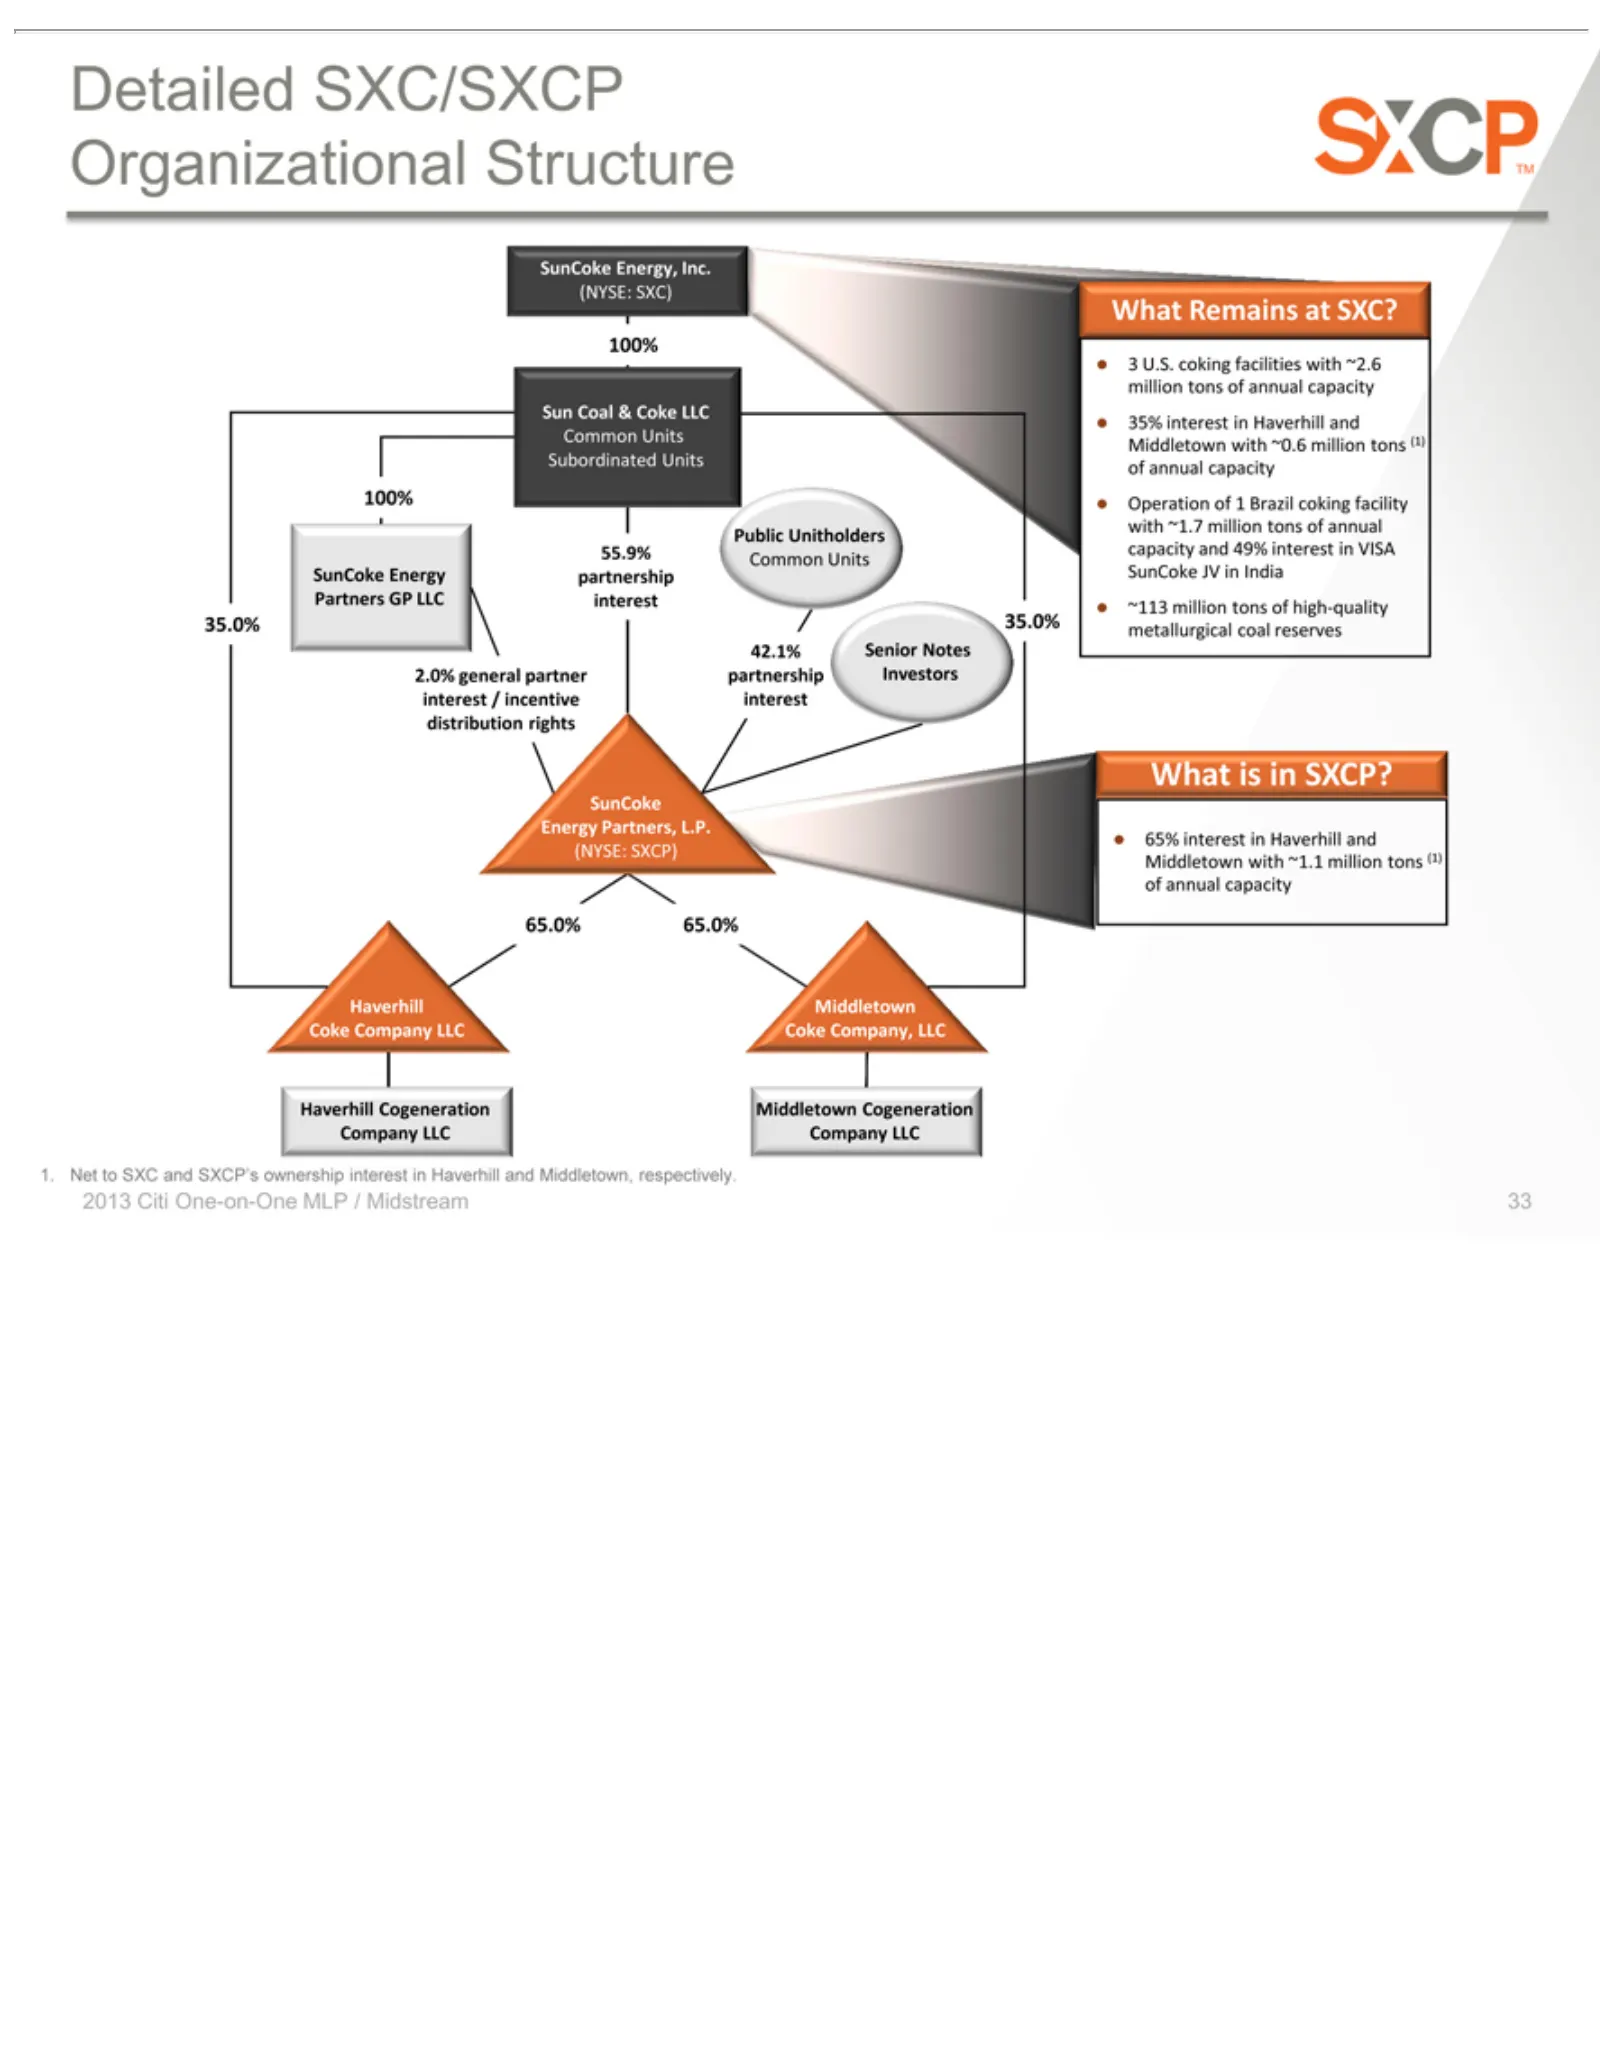
Slide 33: Detailed Organizational Structure
Detailed Organizational Sun Common 55.9% 100% 35.0% Senior (NYSE: 65.0% Haverhill Net 32013 35% Operation SunCoke ~113 What 65% 33U.S. to Coal interest Citi million Remains is SXC coking partnership 35.0% 65.0% Notes in SXC) SXCP) SXC/SXCP Energy, Energy JV & Units One-on-One Middletown Cogeneration
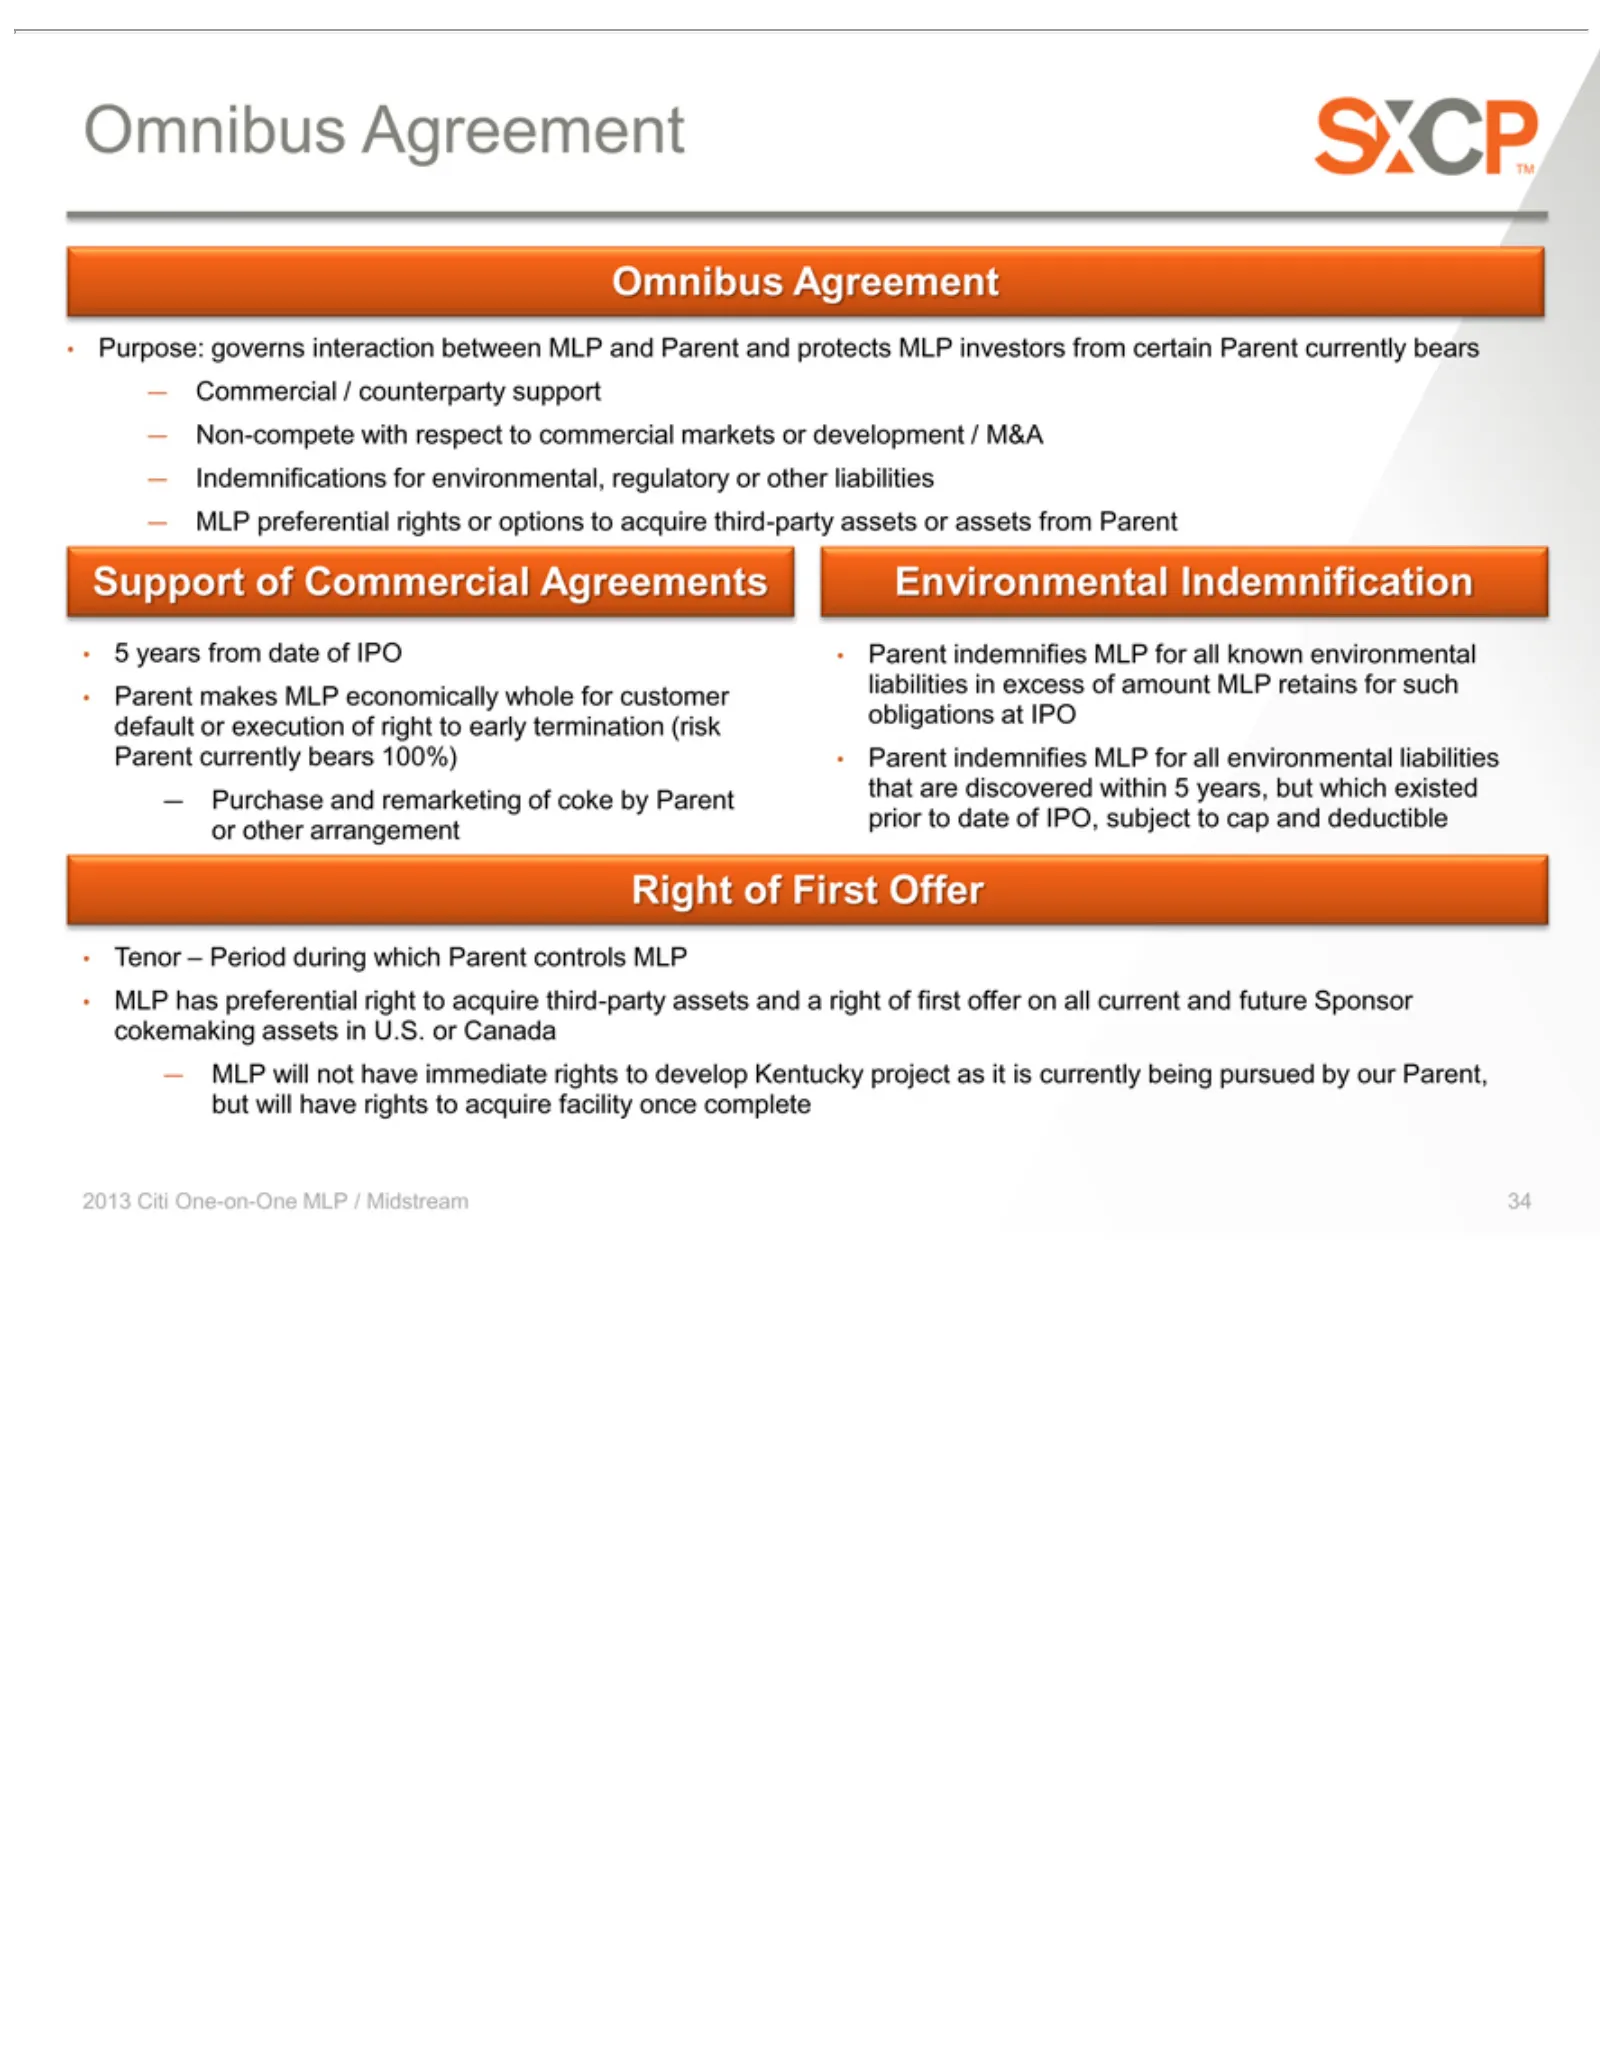
Slide 34: Omnibus and Commercial Agreements
Omnibus Purpose: Commercial Non-compete Indemnifications 5Support Purchase Environmental Parent Tenor MLP 2013 34years Citi preferential has will –indemnifies makes from Period ofgoverns preferential and Agreement One-on-One not Commercial /date remarketing have MLP with counterparty during Indemnif
Source: SEC EDGAR · 8-K filed Aug 22, 2013
More decks from SunCoke Energy Partners L.P
 Merger or Acquisition (May 2019)42 slides · May 22, 2019
 Q1 2019 Earnings Presentation26 slides · Apr 24, 2019
 Merger or Acquisition (February 2019)41 slides · Feb 26, 2019
 FY2018 Earnings Presentation37 slides · Feb 5, 2019
 FY2018 Earnings Presentation36 slides · Feb 5, 2019
 Q3 2018 Earnings Presentation25 slides · Oct 25, 2018