Temple-Inland — Investor Presentation (February 2010)
36 slides from Temple-Inland's investor presentation, Feb 9, 2010
Slide 1: Our job is to be the best - Investor Presentation
43 Our job is to be the best Investor Presentation
Slide 2: Forward Looking Statements
44 Forward Looking Statements This presentation contains “forward-looking statements” within the meaning of the federal securities laws. These statements reflect management’s current views with respect to future events and are subject to risk and uncertainties. We note that a variety of factors and
Slide 3: Create Superior and Sustainable Value
45 Create Superior and Sustainable Value • Maximize ROI • Profitably grow our business
Slide 4: 2009 Scorecard
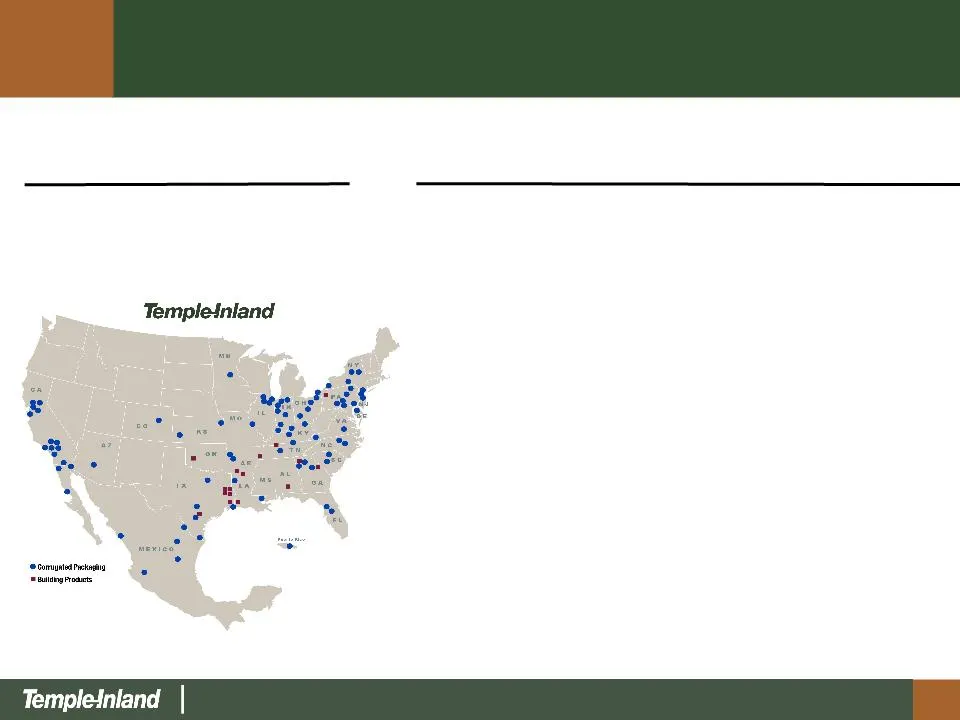
46 2009 Scorecard • Maximize ROI — » 7.0% ROI – Corrugated Packaging — » 16.5% ROI • Record earnings of $347 million • Highest ROI in peer group • Fourth consecutive year of above cost of capital returns – Building Products — » (5.0)% ROI • Generated positive EBITDA of $17 million, a $9 million impr
Slide 5: 2009 Scorecard
47 2009 Scorecard • Profitably grow our company – PBL acquisition • $20 million of synergies • $30 million from white-top • 60% ROI
Slide 6: 2009 Long-Term Debt Reduction
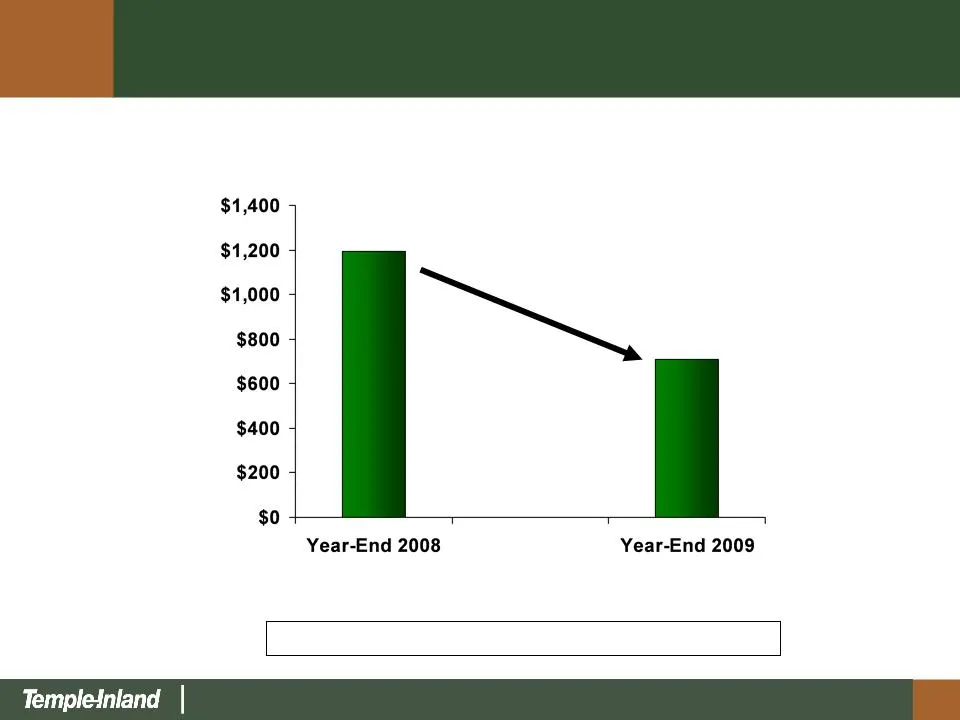
48 2009 Long-Term Debt Reduction $482 $710 $1,192 Long-term debt reduced by $482 million in 2009
Slide 7: Temple-Inland Financial Highlights
49 ($ in Millions) 2004 2005 2006 2007 2008 2009 Revenue $3,587 $3,723 $4,096 $3,850 $3,884 $3,577 EBIT $134 $133 $331 $161 $111 $192 Investment $2,370 $2,431 $2,620 $2,570 $2,484 $2,762 ROI 5.7% 5.5% 12.6% 6.3% 4.5% 7.0% EBITDA $340 $339 $542 $364 $317 $392 Temple-Inland • Corrugated Packaging • Bu
Slide 8: Corrugated Packaging Segment Highlights
50 ($ in Millions) 2003 2004 2005 2006 2007 2008 2009 Revenue $2,700 $2,736 $2,825 $2,977 $3,044 $3,190 $3,001 EBIT $18 $96 $120 $255 $287 $225 $347 Investment $2,237 $2,042 $2,125 $2,039 $2,004 $1,990 $2,109 ROI 0.8% 4.7% 5.6% 12.5% 14.3% 11.3% 16.5% EBITDA $185 $255 $280 $408 $429 $371 $492 Corrug
Slide 9: Corrugated Packaging Strategic Initiatives
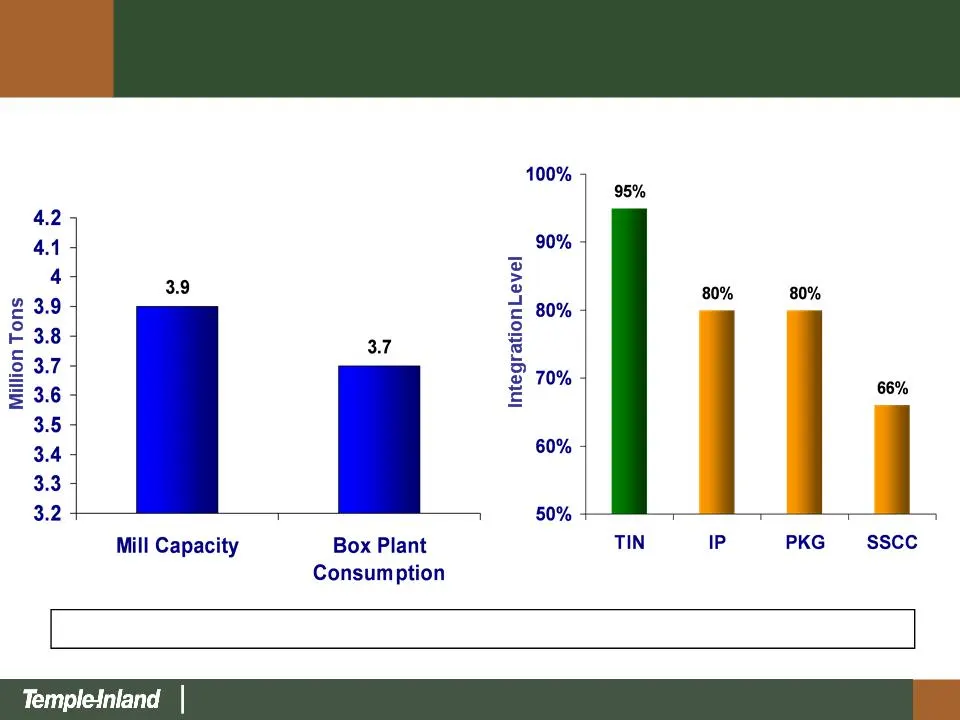
51 Corrugated Packaging Strategic Initiatives • Maintain high integration level - Box plant consumption = mill capacity • Drive for low cost - Asset utilization and manufacturing excellence • Improve mix and margins - Sales excellence • Profitably grow business - Organically / Acquisition Lowering C
Slide 10: Integration Level - Highest in the Industry
52 Integration Level - Highest in the Industry Source: Company reports Temple-Inland is the most integrated producer of corrugated containers
Slide 11: Drive For Low Cost
53 Drive For Low Cost • Lower mill costs – Enhanced reliability – Targeted investments to reduce energy consumption and enhance mix flexibility • Lower box plant costs – Box plant transformation • Cultural change to lower costs by driving asset utilization • Fewer plants, fewer machines, fewer peopl
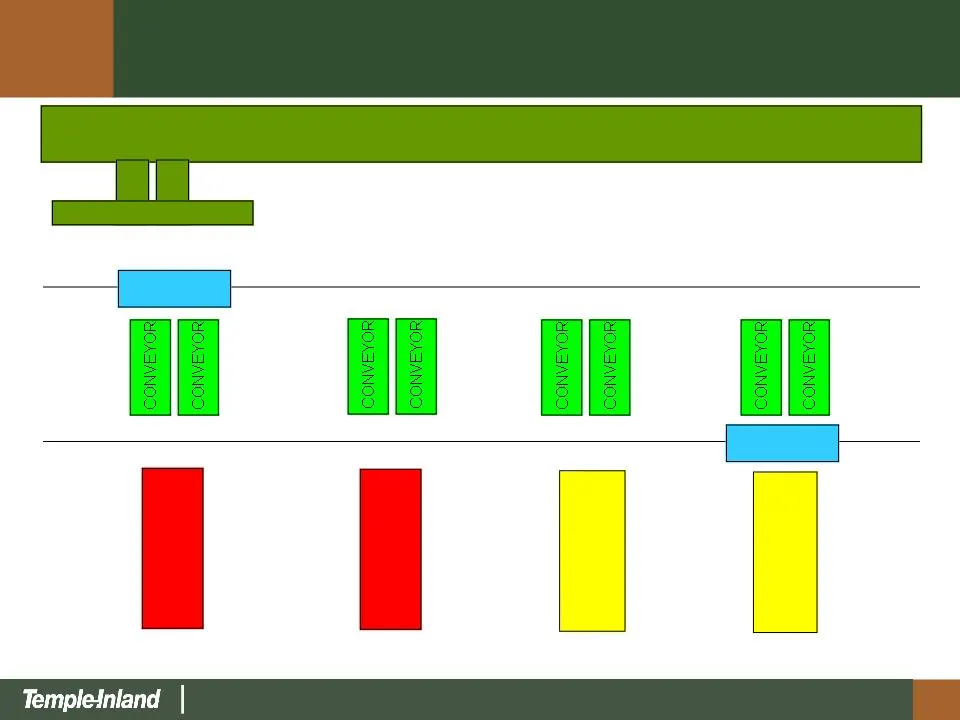
Slide 12: Asset Utilization Lexington Plant - Old Layout
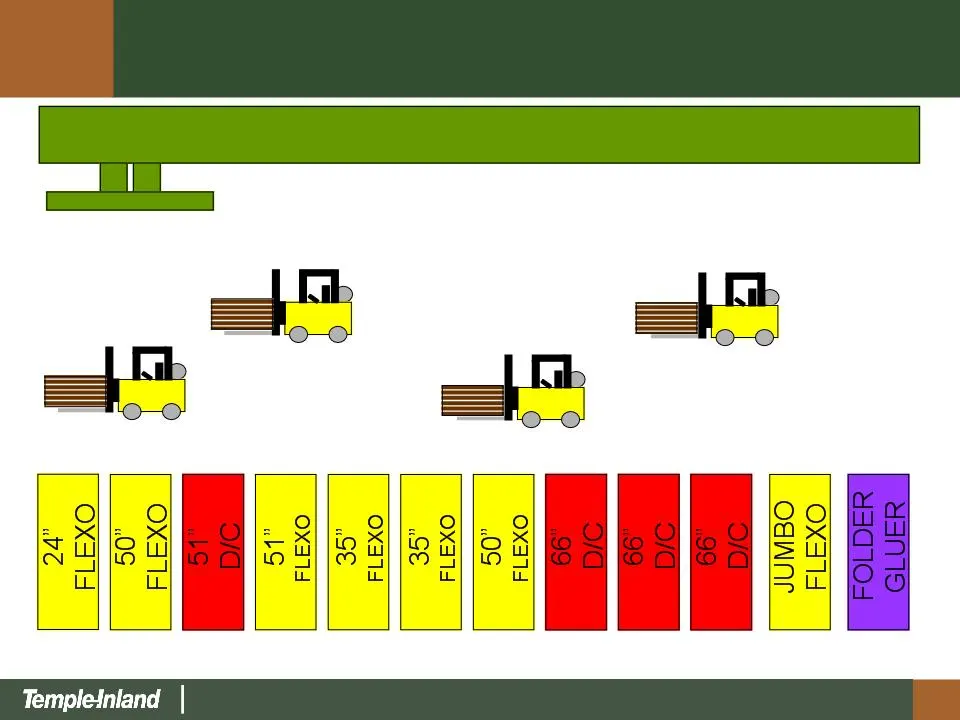
54 Asset Utilization Lexington Plant - Old Layout 98” CORRUGATOR Machines
Slide 13: Asset Utilization Lexington Plant - New Layout
55 Asset Utilization Lexington Plant - New Layout 98” CORRUGATOR T-CART T-CART 66” D/C 35” EVOL 66” D/C Machines 35” EVOL
Slide 14: Box Plant Transformation I (2006-2010)
56 Box Plant Transformation I (2006-2010) • EBIT (Lower Costs) $80MM/Year – Fewer Plants – Fewer Machines – Fewer People 1,157 • Investment $174MM • ROI 46%
Slide 15: Box Plant Transformation II (2010-2013)
57 Box Plant Transformation II (2010-2013) • EBIT (Lower Costs) $100MM/Year – Fewer Plants – Fewer Machines – Fewer People • Investment $250MM • ROI 40%
Slide 16: Improve Mix and Margins
58 Improve Mix and Margins • Centralized pricing decision making • Structured and disciplined approach to market • Target customers where we can create value
Slide 17: Shipments by End-Use Industry
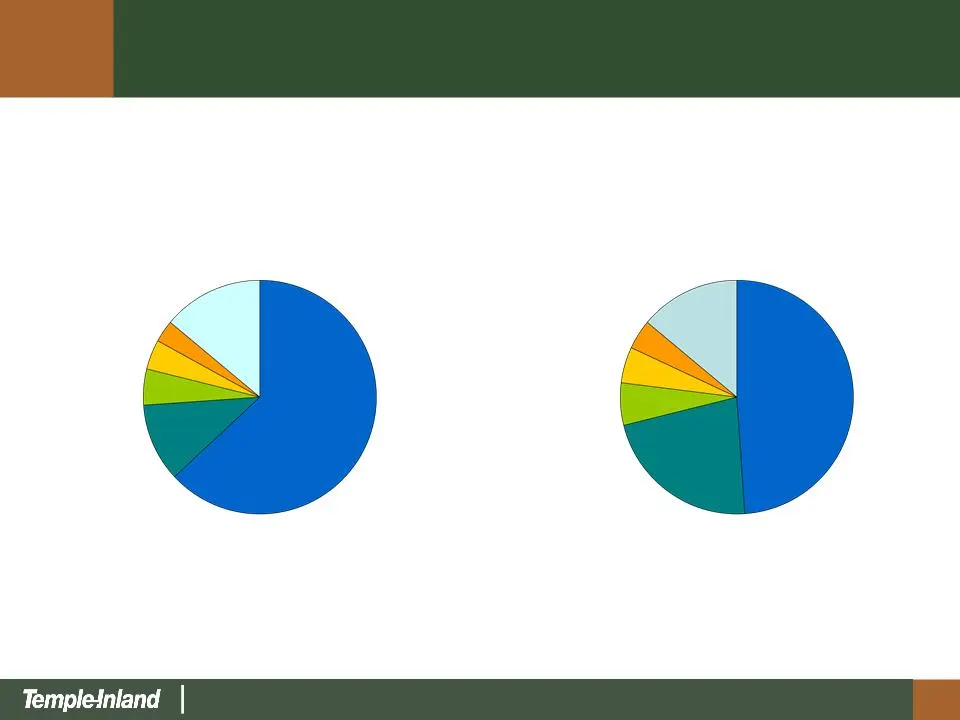
59 Shipments by End-Use Industry Food & Beverage 63% Misc. Mfg. 3% Other 14% Chemicals 4% Rubber & Plastics 5% Paper & Allied 11% Food & Beverage 49% Paper & Allied 22% Rubber & Plastics 6% Chemicals 5% Misc. Nondurables 4% Misc. Durable Goods 14% Temple-Inland Industry* *Source: Fibre Box Associati
Slide 18: Corrugated Packaging - Highest ROA in Peer Group
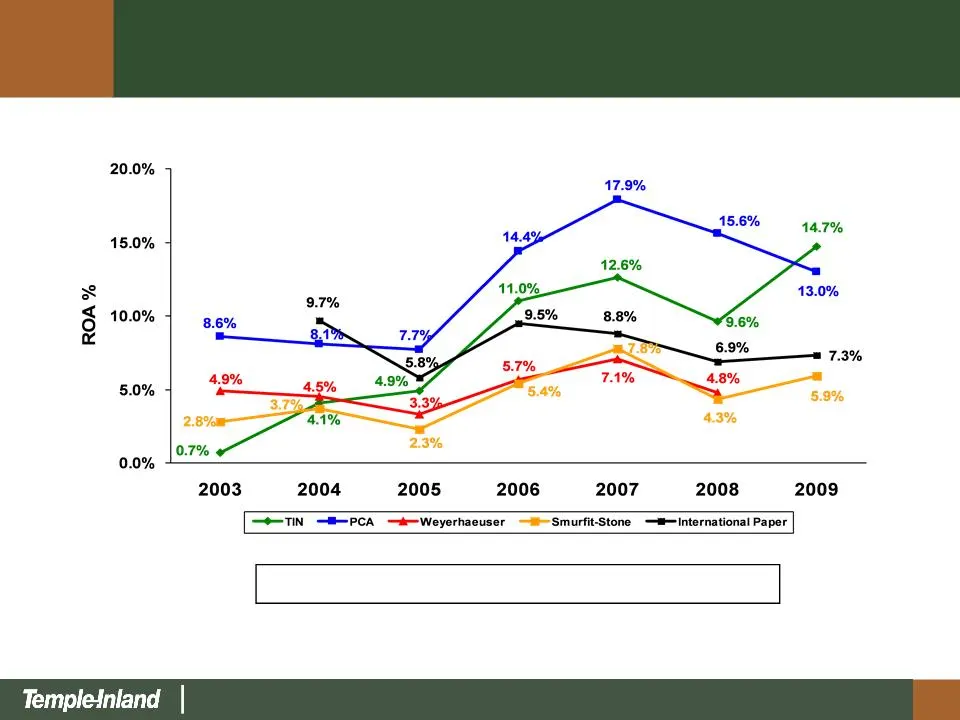
60 Corrugated Packaging - - Highest ROA in Peer Group TIN has highest ROA in the Peer Group Notes: (1) As reported by segment excluding special items for TIN, IP and Weyerhaeuser. For TIN and IP, the asset base was adjusted to include acquisitions made in Q3 2008. (2) For PCA, EBIT = Gross profit-se
Slide 19: North American Corrugated Packaging Industry Fundamentals
61 North American Corrugated Packaging Industry Fundamentals • Consolidating industry • Significant capacity rationalization and downtime • Lower inventories • Improved pricing
Slide 20: North American Containerboard Market Share 1998 vs. Today
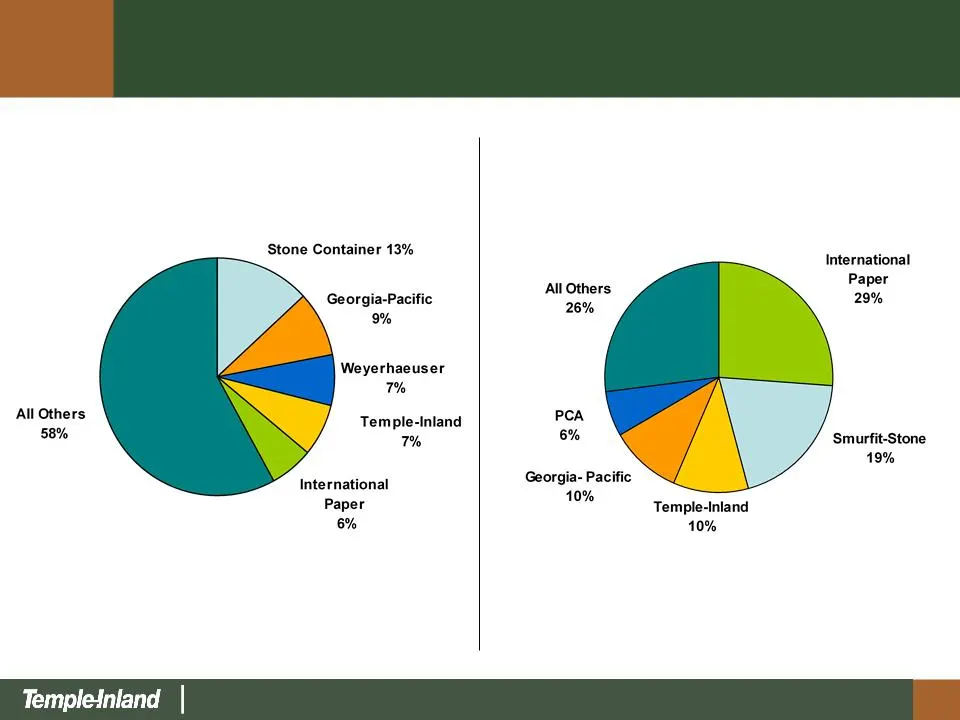
62 North American Containerboard Market Share 1998 vs. Today Top 5 Producers= 42% 1998 2010 Top 5 Producers= 74%
Slide 21: Containerboard Capacity Changes and Operating Rate
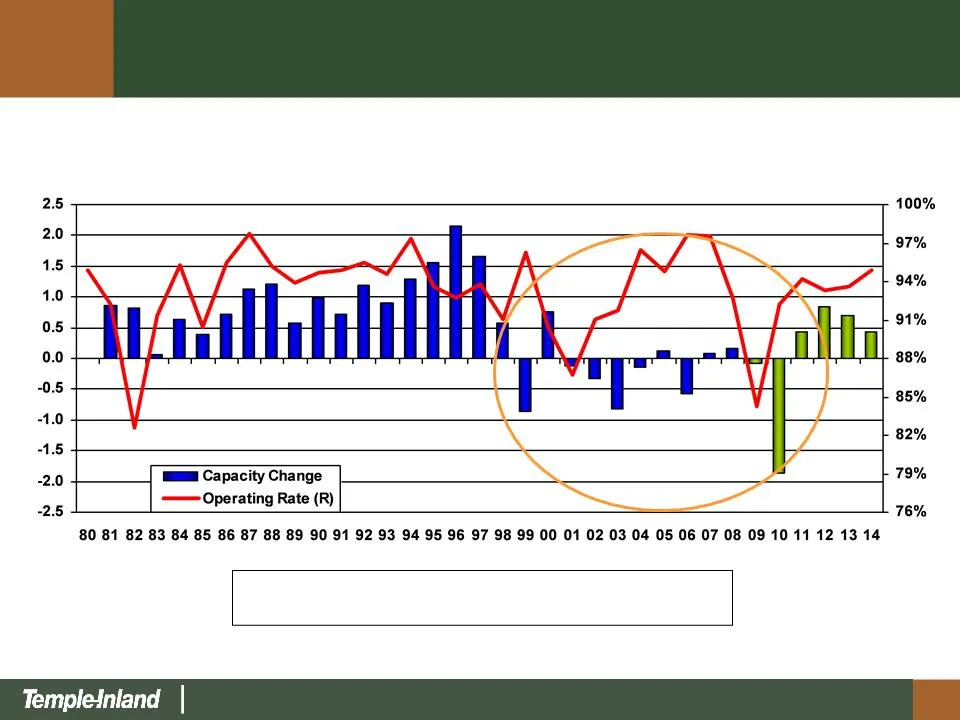
63 Corrugated Packaging Industry Containerboard Capacity Changes and Operating Rate (Million Short Tons) Source: RISI and Company reports Permanent closure announcements of 2.9 million tons, 7% of North American capacity, since Q4 2008
Slide 22: Inventory Levels Continue to Decline
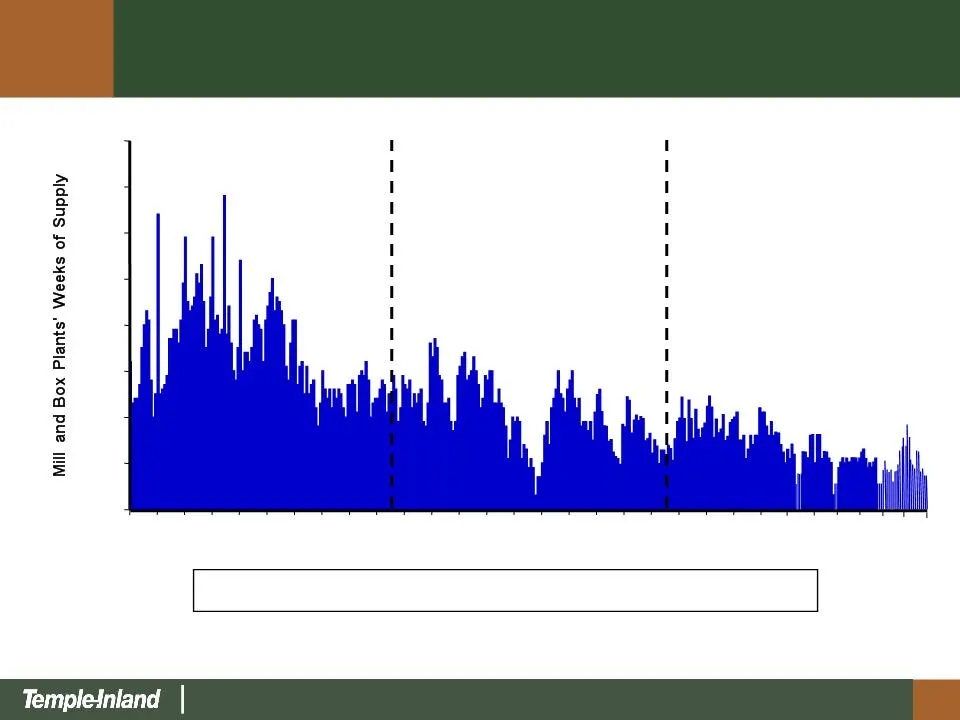
64 Inventory Levels Continue to Decline 3.0 4.0 5.0 6.0 7.0 8.0 9.0 10.0 11.0 1980 - - 1989 Average: 6.4 Weeks 1990 - - 1999 Average: 5.1 Weeks 2000 - - 2009 Average: 4.3 Weeks Source: Fibre Box Association Inventory levels are at lowest levels since 1994
Slide 23: Linerboard Pricing Trends
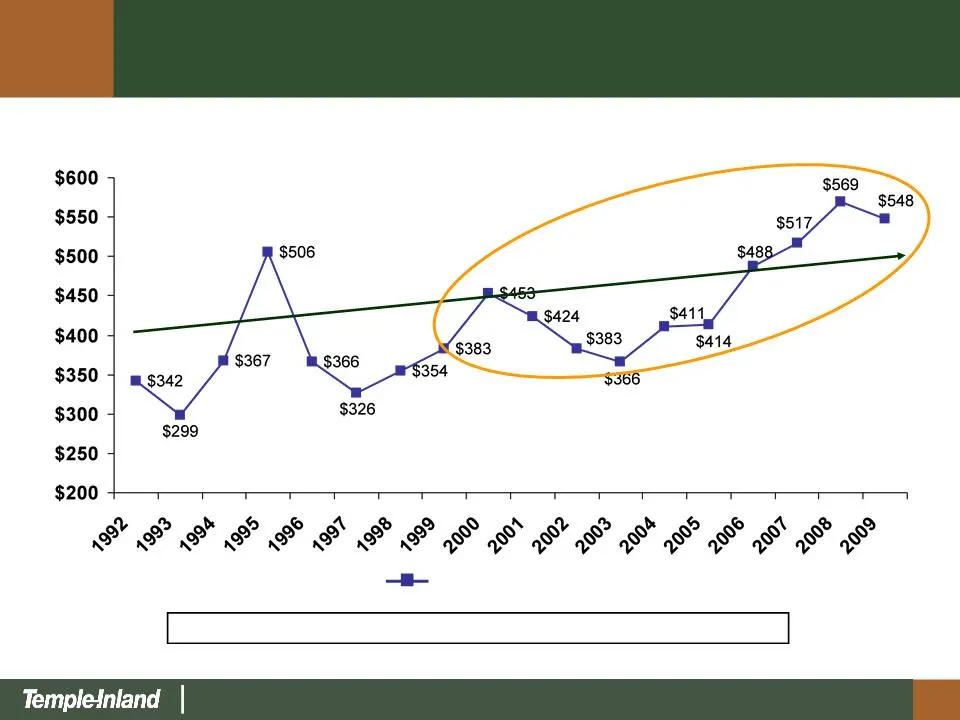
65 Linerboard Pricing Trends Source: RISI Linerboard ($/ton) Improved Linerboard Pricing Average annual linerboard price declined only modestly in 2009
Slide 24: Corrugated Packaging Summary
66 Corrugated Packaging Summary • Simple, effective strategy…execution = results • Track record of success • Improving industry fundamentals
Slide 25: Building Products Financial Highlights
67 ($ in Millions) 2004 2005 2006 2007 2008 2009 Revenue $851 $898 $1,119 $806 $694 $576 EBIT $129 $125 $221 $8 ($40) ($27) Investment $396 $361 $586 $562 $560 $535 ROI 32.6% 34.6% 37.7% 1.4% (7.1%) (5.0%) EBITDA $167 $160 $265 $53 $8 $17 Building Products • Portfolio of Products – Lumber – Gypsum –
Slide 26: Building Products Strategic Initiatives
68 Building Products Strategic Initiatives • Deliver tailored portfolio of building products – Products for new home, repair and remodeling and commercial markets • Drive low cost – Manufacturing excellence • Serve preferred markets – Favorable demographics • Profitably grow business
Slide 27: Lumber
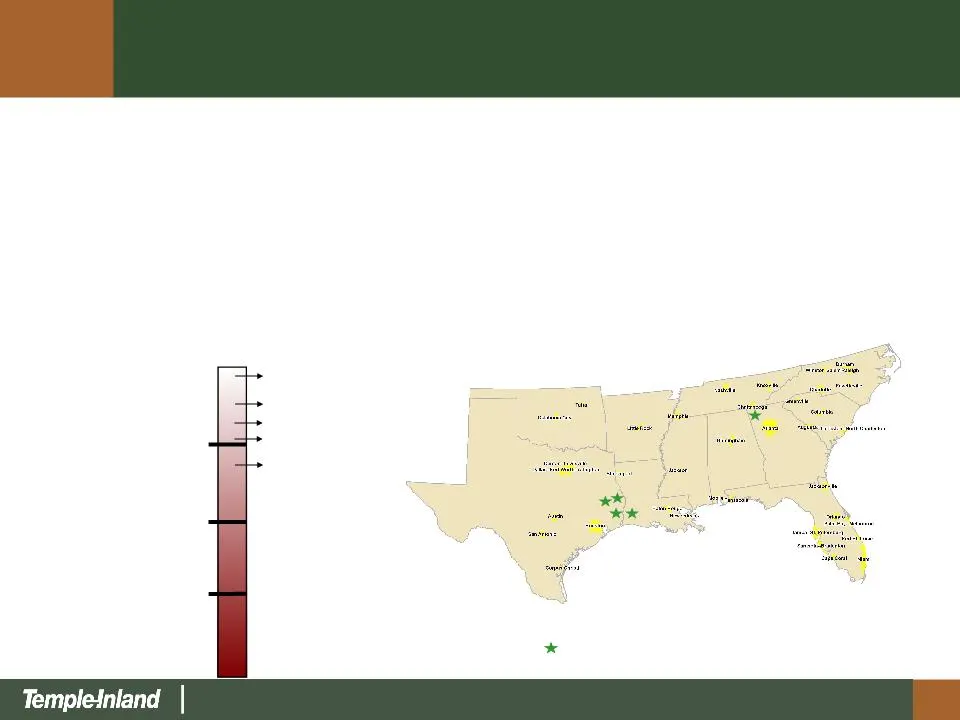
69 Lumber Buna Pineland Diboll Rome DeQuincy Lumber Competitive Position Temple-Inland Sawmills 1st Quartile 2nd Quartile 3rd Quartile 4th Quartile Source: Beck & RISI Studies Temple-Inland Sawmills Sawmill Locations • Low cost, state of art manufacturing system • Logistically advantaged to large gr
Slide 28: Gypsum
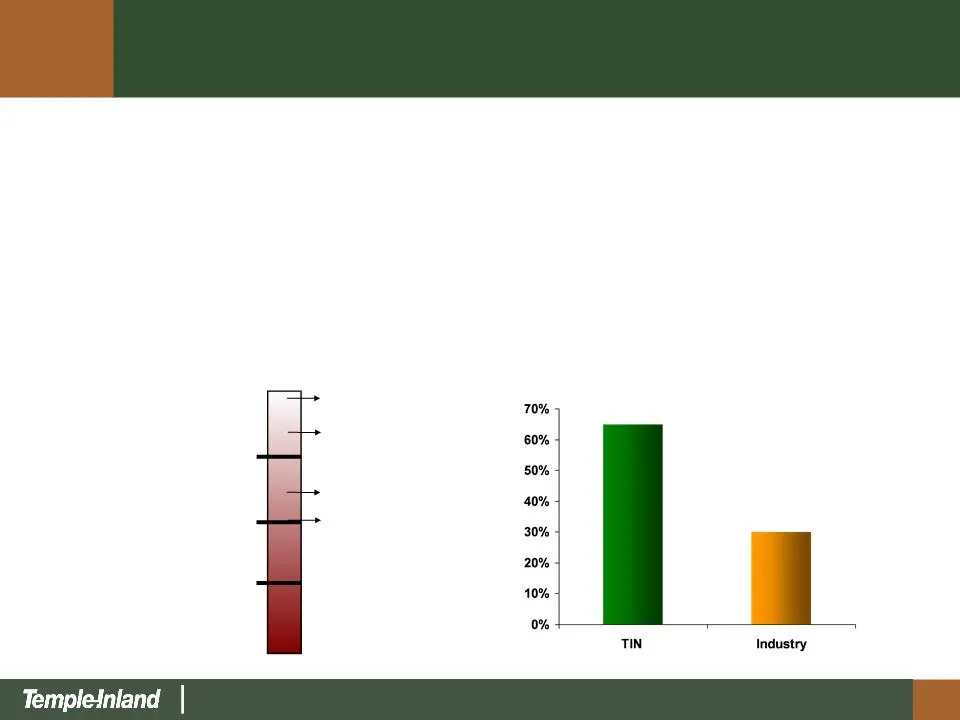
70 Gypsum Synthetic Gypsum Furnish Gypsum Competitive Position Cumberland Fletcher W. Memphis McQueeney 1st Quartile 2nd Quartile 3rd Quartile 4th Quartile Source: Internal Analysis • Low-cost manufacturing system • Synthetic gypsum furnish 65% vs. 30% for industry
Slide 29: Industrial Panels - Particleboard & MDF
71 Industrial Panels - Particleboard & MDF Panels Competitive Position Monroeville Hope Diboll Thomson 1st Quartile 2nd Quartile 3rd Quartile 4th Quartile Source: Beck Study PB MDF El Dorado Mt. Jewett • Lowest cost system • High-value engineered family of products • Targeted markets – Kitchen cabin
Slide 30: Housing
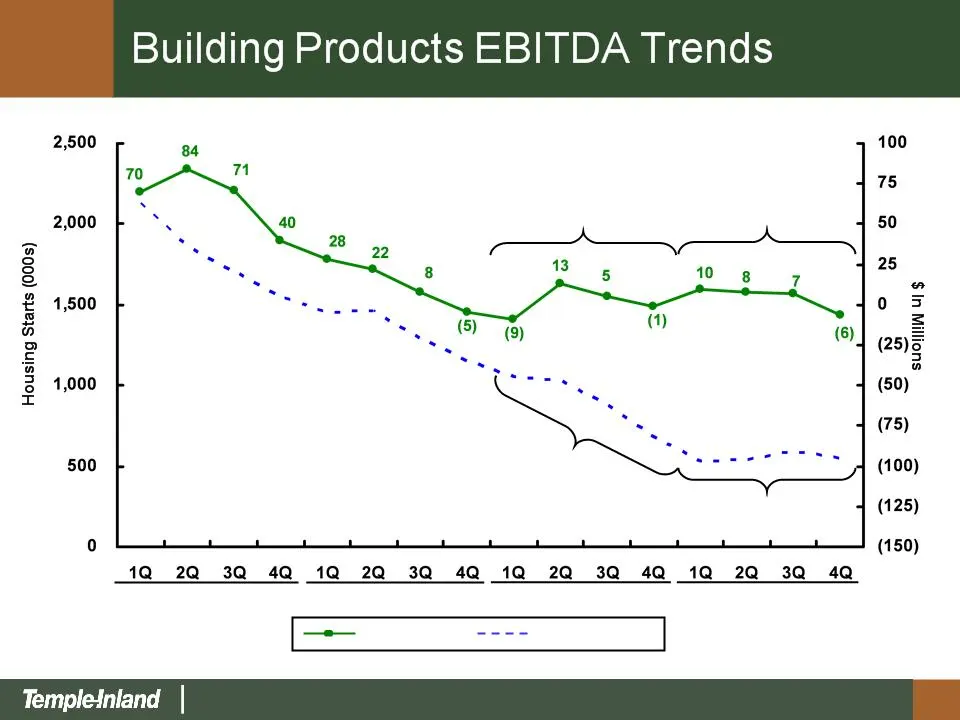
72 Housing Starts TIN EBITDA 2006 2007 2008 2,127 2009 $8 $17
Slide 31: 2010 Financial Priorities
73 2010 Financial Priorities • Return cash to shareholders – Maintained dividend during 2009 – Q1 2010 dividend increased 10% to annual rate of $0.44 per share • Reduce debt • Invest in our business • Grow
Slide 32: Create Superior and Sustainable Value
74 Feb 2010 Create Superior and Sustainable Value • Maximize ROI • Profitably grow our business
Slide 33: Temple-Inland
Templeiniand |
Slide 34: Year-End 2009 Debt Structure
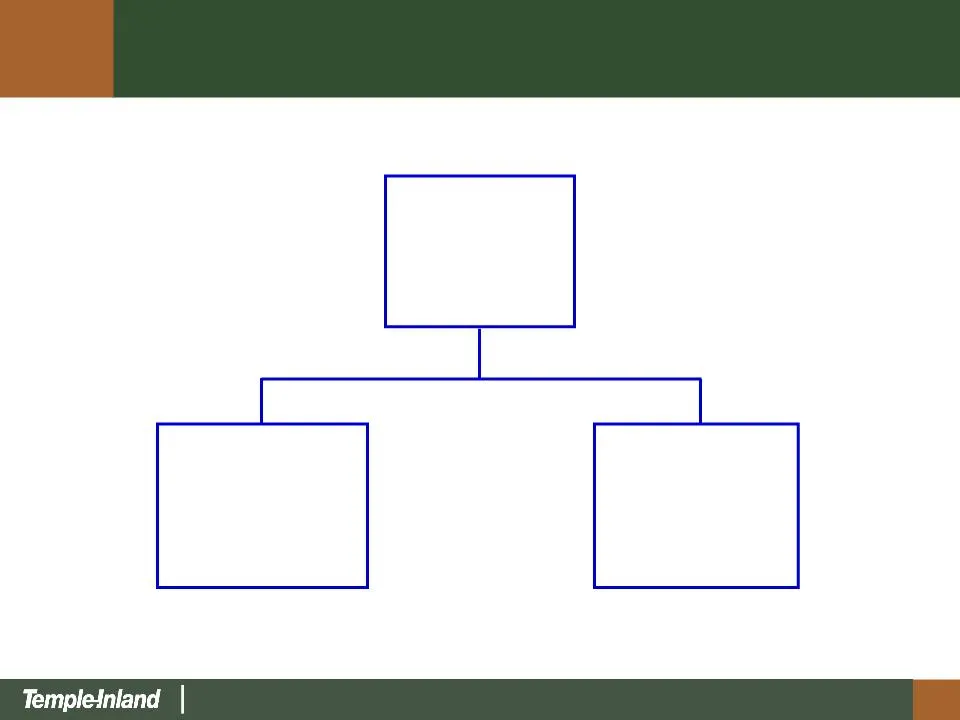
76 Year-End 2009 Debt Structure Total Debt $710 Borrowings Under Committed Credit Facilities $155 Term Debt $555 ($ In Millions)
Slide 35: Term Debt Maturity Profile as of Year-End 2009
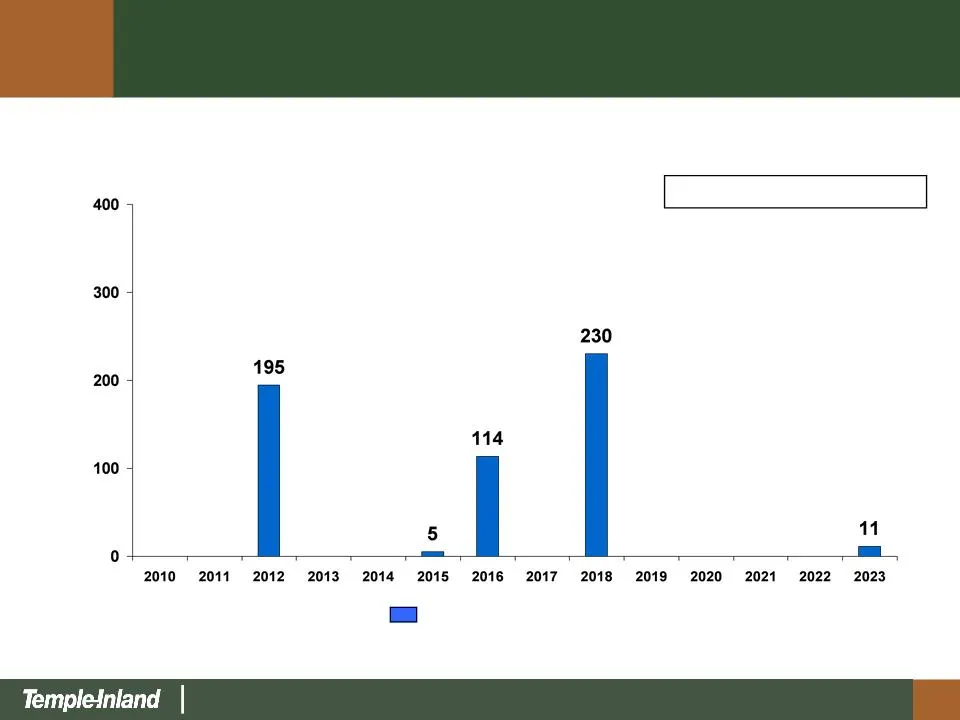
77 Term Debt Maturity Profile as of Year-End 2009 Term debt ($ In Millions) Total Term Debt = $555MM
Slide 36: Year-End 2009 Committed Credit Facilities
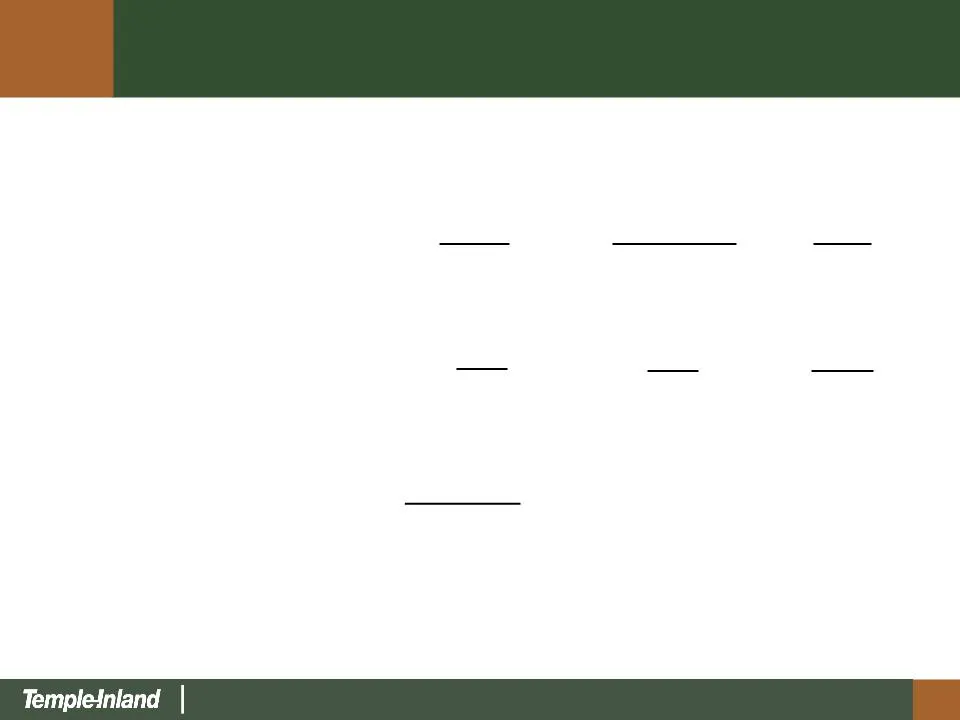
78 Year-End, 2009 Committed Credit Facilities Accounts Receivable Committed Securitization Credit Facility Agreements Total ($ In Millions) Committed $ 250 $ 825 $1,075 Less: Borrowings (130) (25) (155) Letters of credit - (30) (30) Unused borrowing capacity $ 120 $ 770 $ 890 Facility Maturities Oct
Source: SEC EDGAR · 8-K filed Feb 9, 2010
More decks from Temple-Inland Inc
 Q2 2011 Earnings Presentation17 slides · Jul 21, 2011
 Proxy Contest (June 2011)43 slides · Jun 20, 2011
 Merger or Acquisition (June 2011)38 slides · Jun 6, 2011
 Q1 2011 Earnings Presentation16 slides · Apr 20, 2011
 Investor Presentation (February 2011)35 slides · Feb 14, 2011
 Q4 2010 Earnings Presentation28 slides · Feb 8, 2011