Strategic Hotels and Resorts Inc
Strategic Hotels and Resorts — Investor Presentation (August 2014)
50 slides from Strategic Hotels and Resorts's investor presentation, Aug 25, 2014
Slide 1: Investor Presentation August 2014
Investor Presentation August 2014 Exhibit 99.1
Slide 2: Forward-looking statements
Except for historical information, the matters discussed in this presentation are forward-looking statements subject to certain risks and uncertainties. Forward-looking statements relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends, and similar exp
Slide 3: Strategic Hotels: An Overview
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Strategic Hotels: An Overview 2
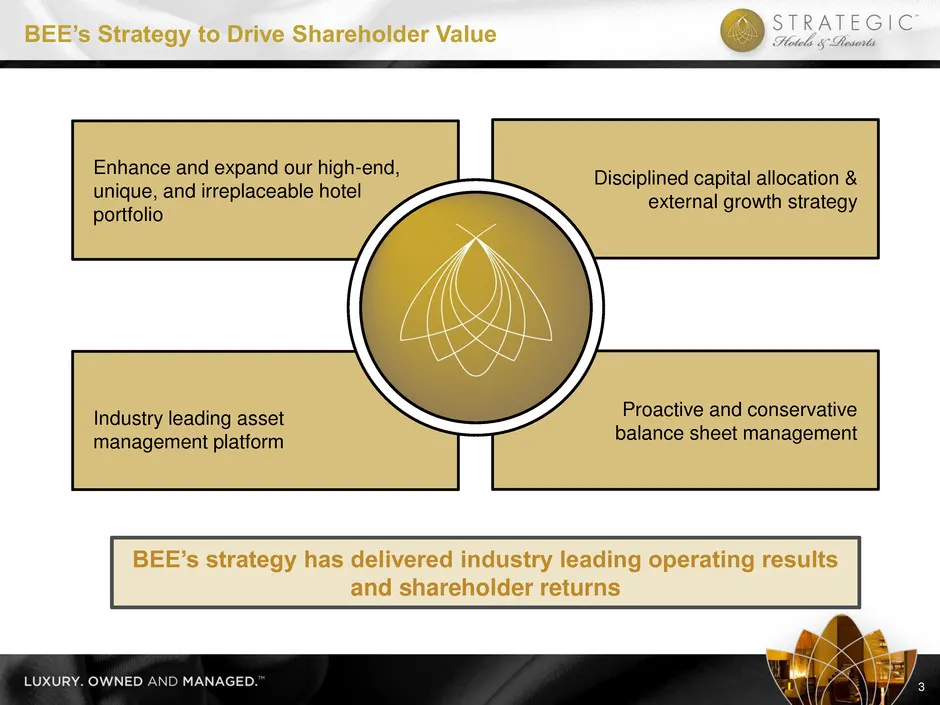
Slide 4: BEE's Strategy to Drive Shareholder Value
3 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform BEE’s strategy has delivered
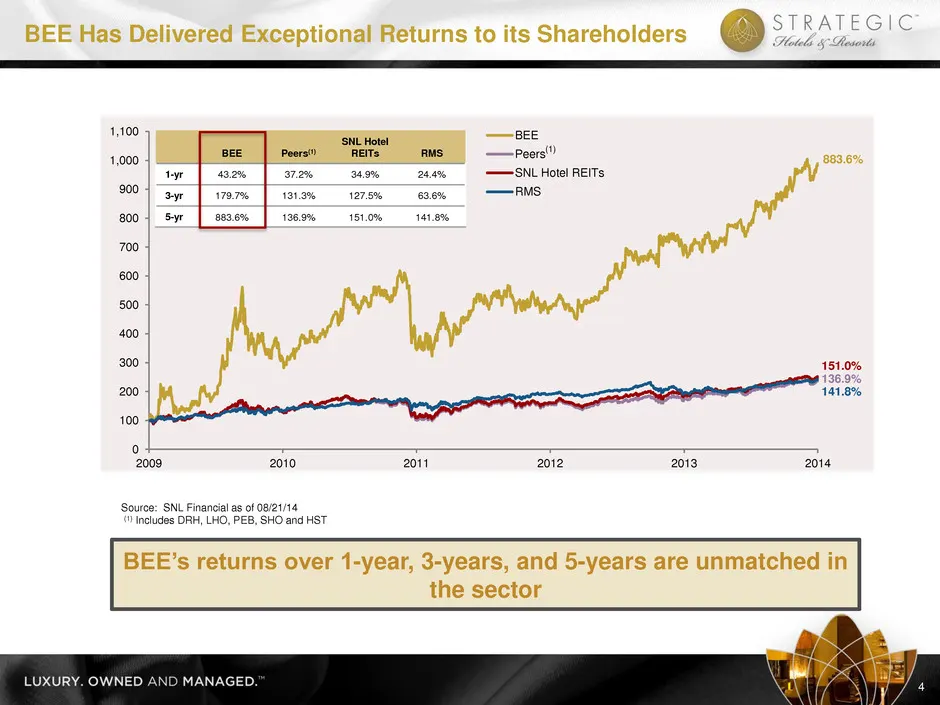
Slide 5: BEE Has Delivered Exceptional Returns to its Shareholders
4 BEE Has Delivered Exceptional Returns to its Shareholders Source: SNL Financial as of 08/21/14 (1) Includes DRH, LHO, PEB, SHO and HST BEE Peers(1) SNL Hotel REITs RMS 1-yr 43.2% 37.2% 34.9% 24.4% 3-yr 179.7% 131.3% 127.5% 63.6% 5-yr 883.6% 136.9% 151.0% 141.8% (1) BEE’s returns over 1-year, 3-yea
Slide 6: Financial Overview
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Financial Overview
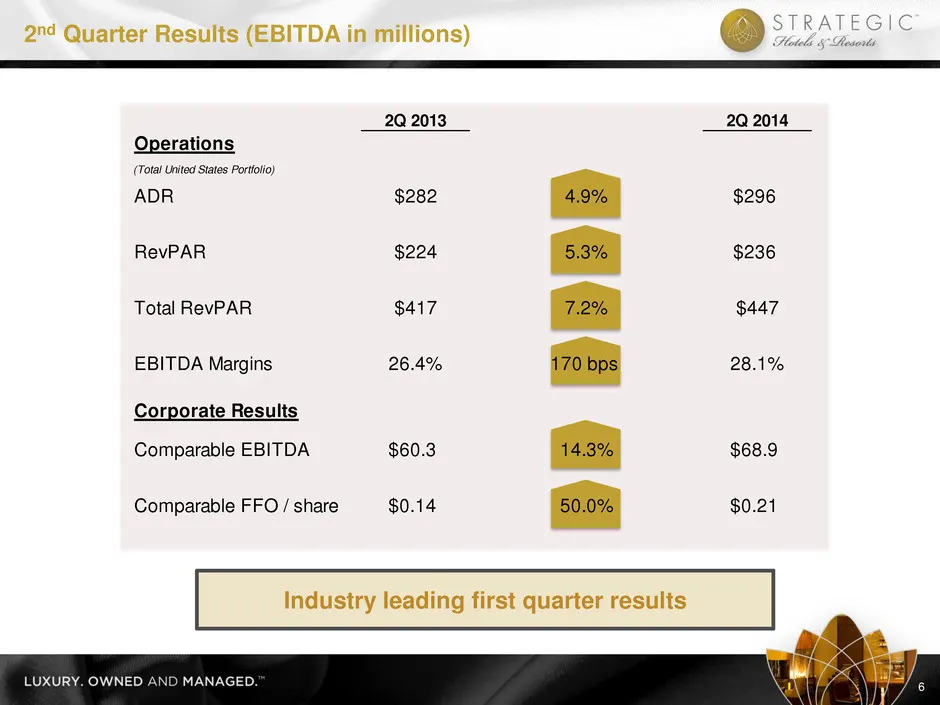
Slide 7: 2nd Quarter Results
2nd Quarter Results (EBITDA in millions) 6 Industry leading first quarter results 2Q 2013 2Q 2014 Operations (Total United States Portfolio) ADR $282 4.9% $296 RevPAR $224 5.3% $236 Total RevPAR $417 7.2% $447 EBITDA Margins 26.4% 170 bps 28.1% Corporate Results Comparable EBITDA $60.3 14.3% $68.9 C
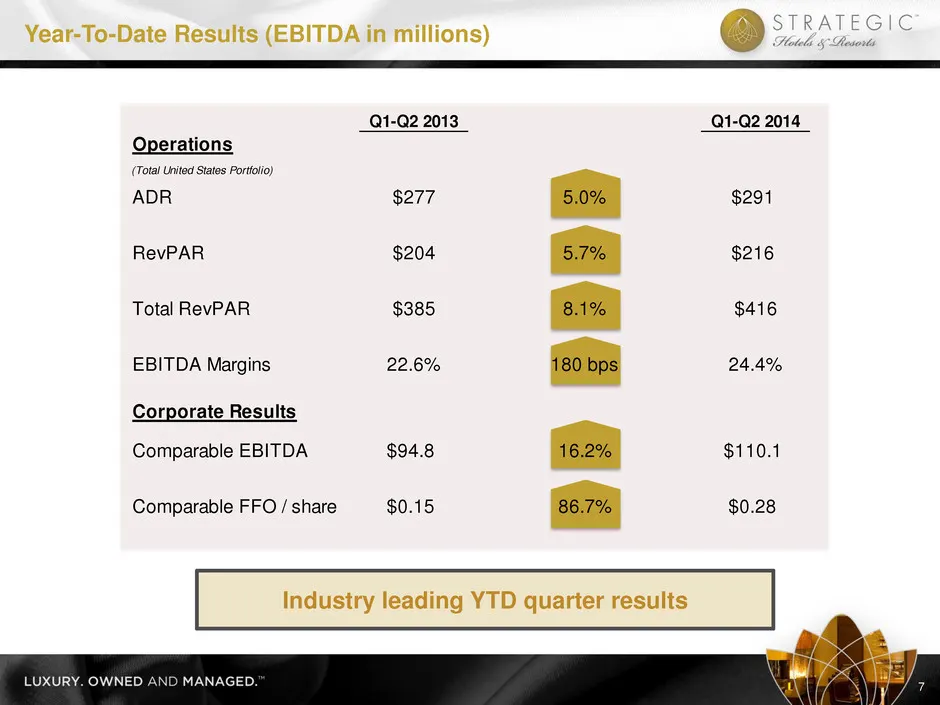
Slide 8: Year-To-Date Results
Year-To-Date Results (EBITDA in millions) 7 Industry leading YTD quarter results Q1-Q2 2013 Q1-Q2 2014 Operations (Total United States Portfolio) ADR $277 5.0% $291 RevPAR $204 5.7% $216 Total RevPAR $385 8.1% $416 EBITDA Margins 22.6% 180 bps 24.4% Corporate Results Comparable EBITDA $94.8 16.2% $1
Slide 9: 2014 Guidance
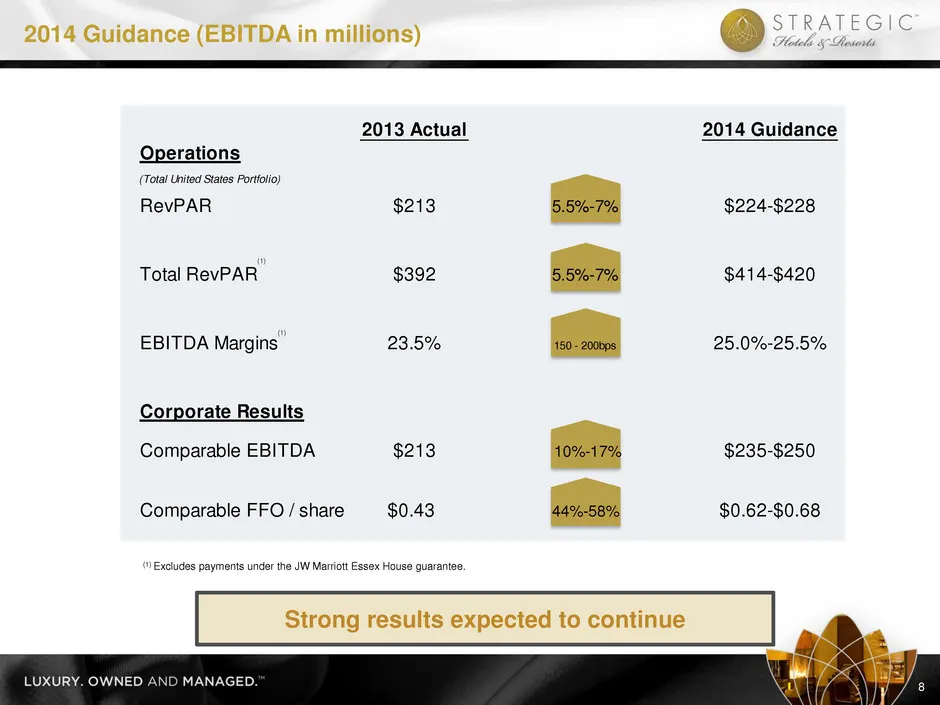
(1) Excludes payments under the JW Marriott Essex House guarantee. 2014 Guidance (EBITDA in millions) 8 Strong results expected to continue (1) (1) 2013 Actual 2014 Guidance Operations (Total United States Portfolio) RevPAR $213 5.5%-7% $224-$228 Total RevPAR $392 5.5%-7% $414-$420 EBITDA Margins 23
Slide 10: Strategic Plan
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Strategic Plan
Slide 11: BEE's Strategy to Drive Shareholder Value
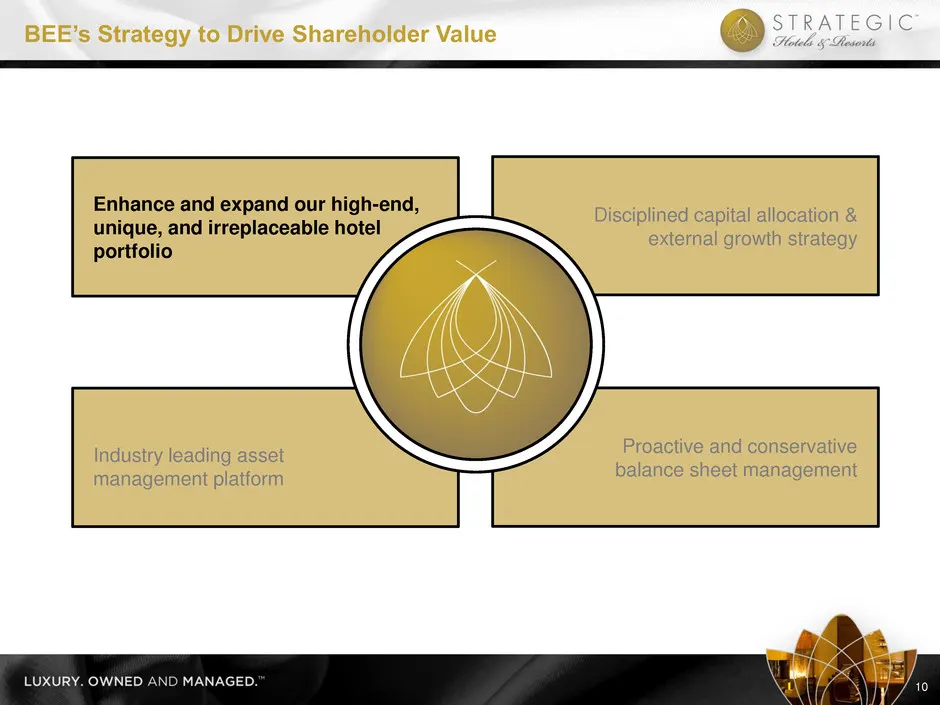
10 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform
Slide 12: High-End, Unique & Irreplaceable Portfolio
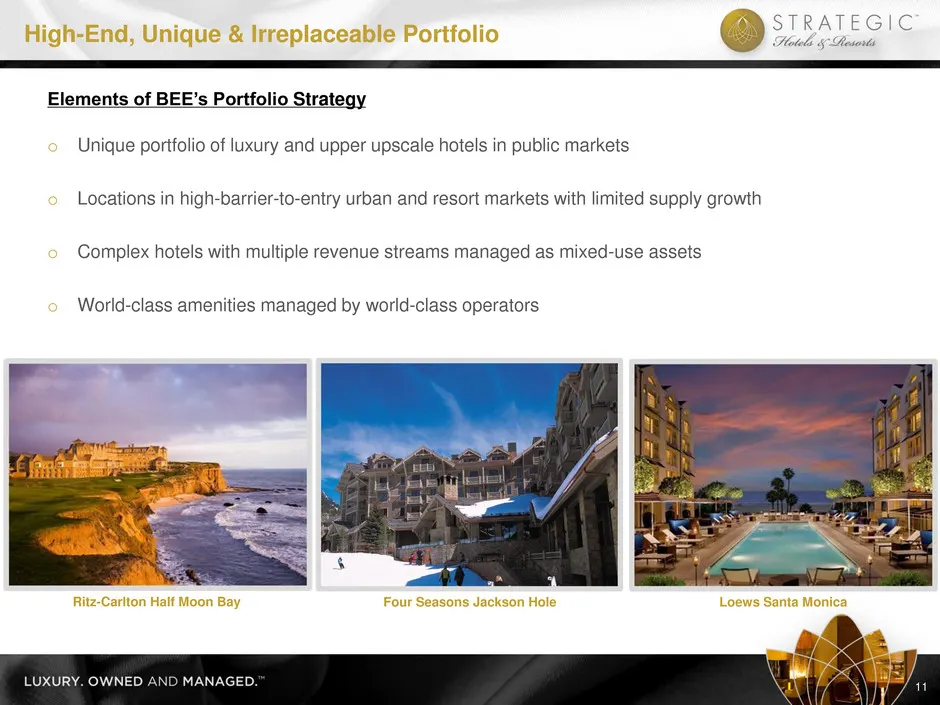
o Unique portfolio of luxury and upper upscale hotels in public markets o Locations in high-barrier-to-entry urban and resort markets with limited supply growth o Complex hotels with multiple revenue streams managed as mixed-use assets o World-class amenities managed by world-class operators High-En
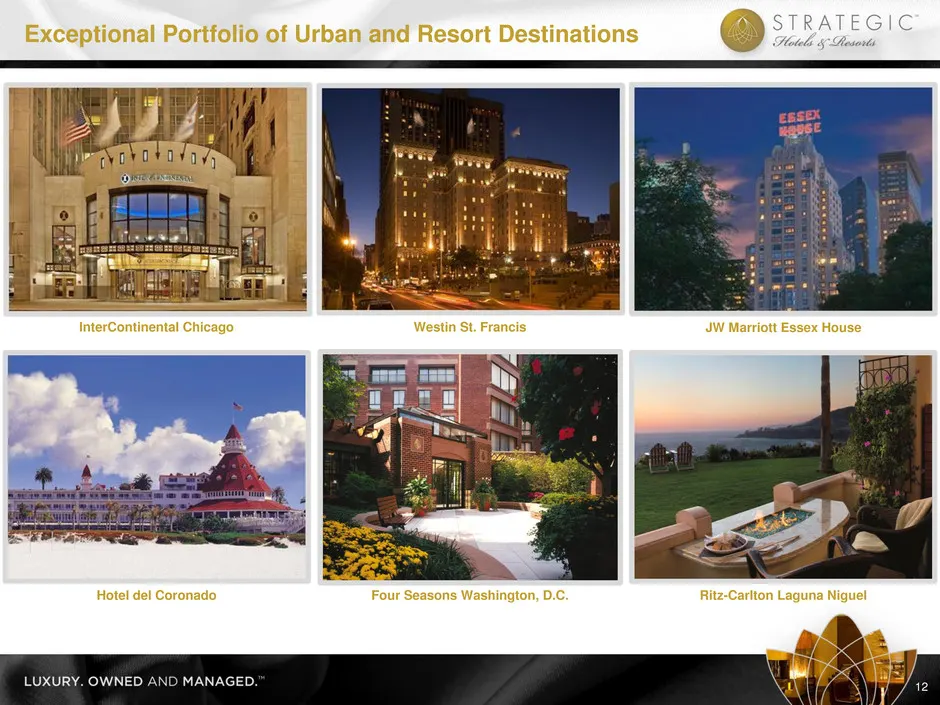
Slide 13: Exceptional Portfolio of Urban and Resort Destinations
JW Marriott Essex House InterContinental Chicago Westin St. Francis Exceptional Portfolio of Urban and Resort Destinations 12 Ritz-Carlton Laguna Niguel Hotel del Coronado Four Seasons Washington, D.C.
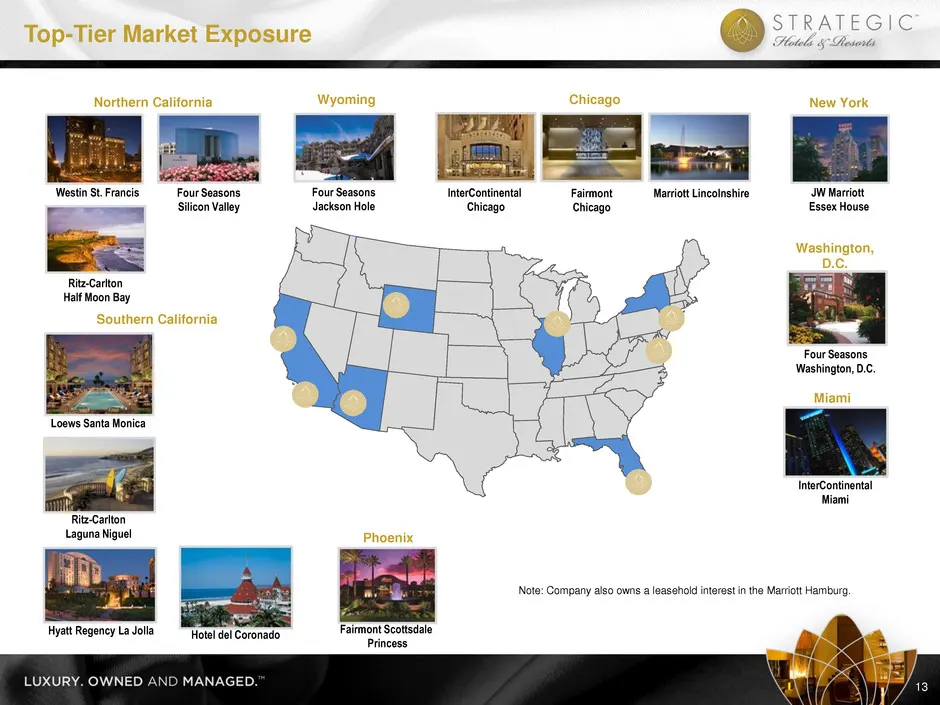
Slide 14: Top-Tier Market Exposure
Top-Tier Market Exposure 13 Northern California Westin St. Francis Ritz-Carlton Half Moon Bay Four Seasons Silicon Valley Southern California Loews Santa Monica Ritz-Carlton Laguna Niguel Hyatt Regency La Jolla Hotel del Coronado Chicago InterContinental Chicago Fairmont Chicago Marriott Lincolnshir
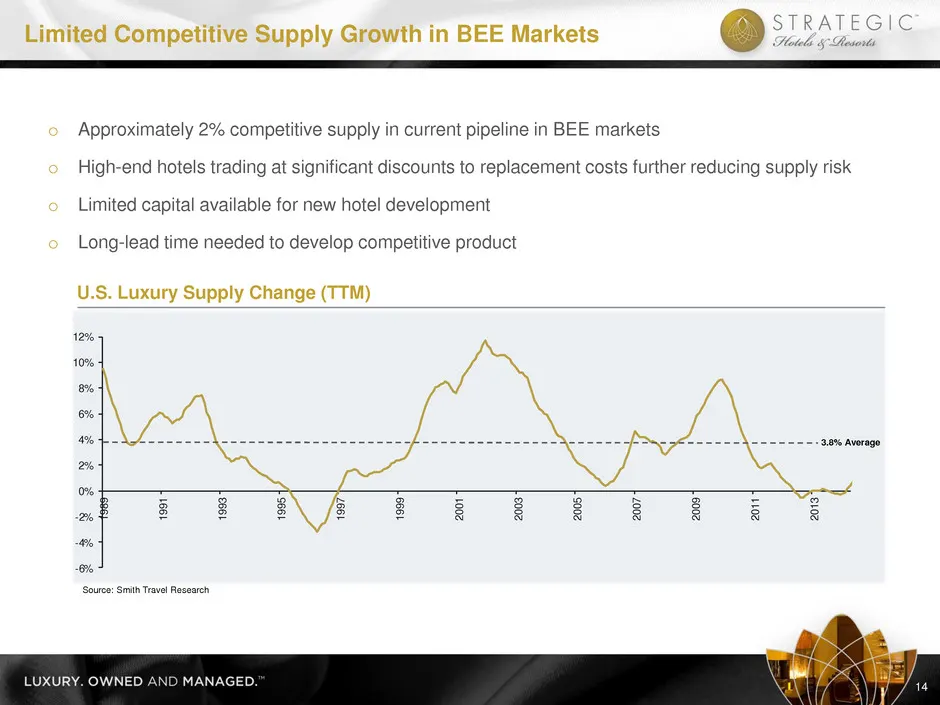
Slide 15: Limited Competitive Supply Growth in BEE Markets
-6% -4% -2% 0% 2% 4% 6% 8% 10% 12% 198 9 199 1 199 3 199 5 199 7 199 9 200 1 200 3 200 5 200 7 200 9 201 1 201 3 o Approximately 2% competitive supply in current pipeline in BEE markets o High-end hotels trading at significant discounts to replacement costs further reducing supply risk o Limited cap
Slide 16: BEE's Strategy to Drive Shareholder Value
15 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform
Slide 17: Industry Leading Asset Management Platform
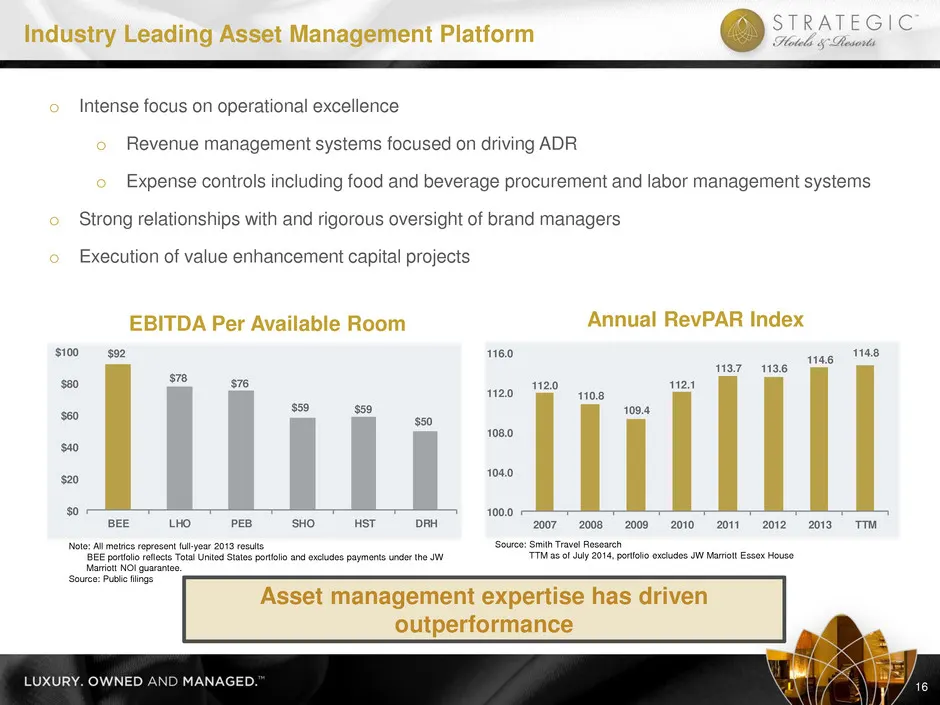
112.0 110.8 109.4 112.1 113.7 113.6 114.6 114.8 100.0 104.0 108.0 112.0 116.0 2007 2008 2009 2010 2011 2012 2013 TTM $92 $78 $76 $59 $59 $50 $0 $20 $40 $60 $80 $100 BEE LHO PEB SHO HST DRH o Intense focus on operational excellence o Revenue management systems focused on driving ADR o Expense control
Slide 18: BEE's Operating Metrics Lead the Sector
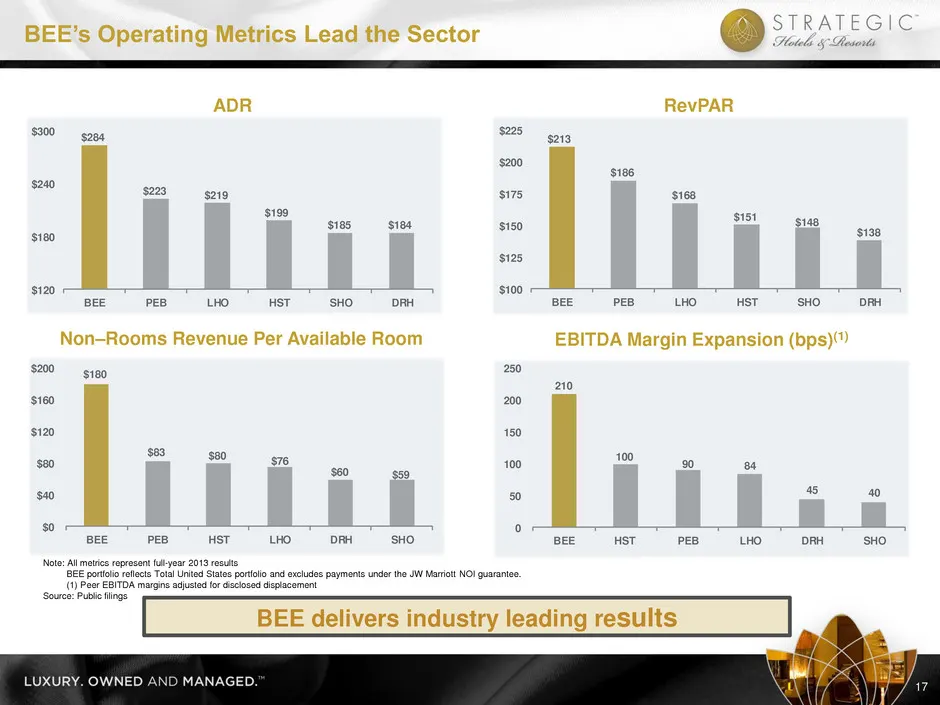
$180 $83 $80 $76 $60 $59 $0 $40 $80 $120 $160 $200 BEE PEB HST LHO DRH SHO $213 $186 $168 $151 $148 $138 $100 $125 $150 $175 $200 $225 BEE PEB LHO HST SHO DRH $284 $223 $219 $199 $185 $184 $120 $180 $240 $300 BEE PEB LHO HST SHO DRH 210 100 90 84 45 40 0 50 100 150 200 250 BEE HST PEB LHO DRH SHO AD
Slide 19: Significant Outperformance Throughout the Recovery
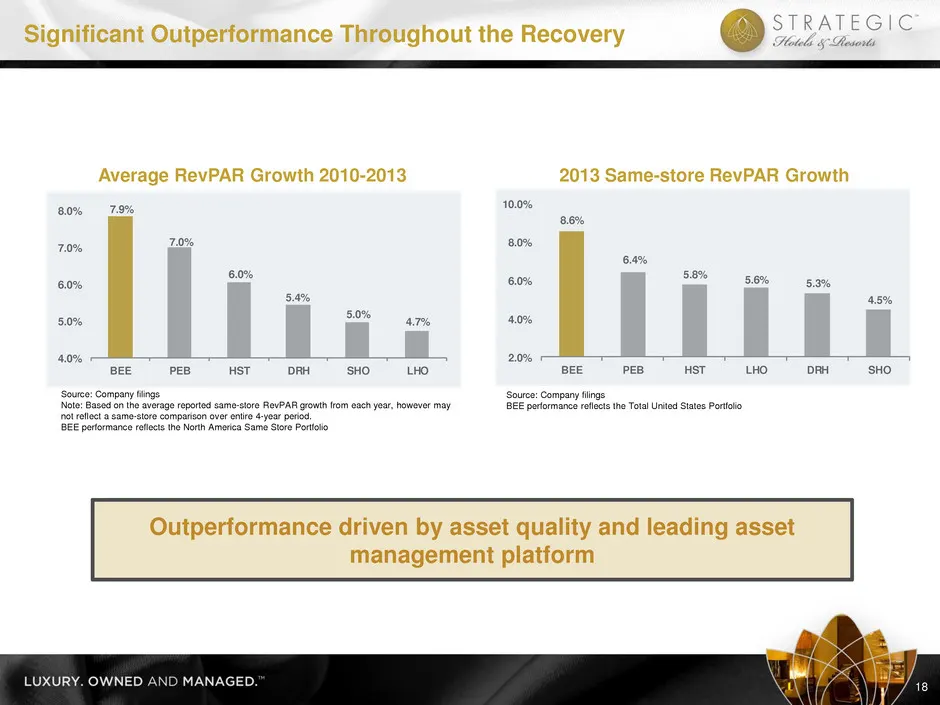
8.6% 6.4% 5.8% 5.6% 5.3% 4.5% 2.0% 4.0% 6.0% 8.0% 10.0% BEE PEB HST LHO DRH SHO 7.9% 7.0 6.0% 5.4% 5.0% 4.7% 4.0% 5.0% 6.0% 7.0% 8.0% BEE PEB HST DRH SHO LHO 18 Significant Outperformance Throughout the Recovery Source: Company filings Note: Based on the average reported same-store RevPAR growth fro
Slide 20: 2014 Group Booking Outlook
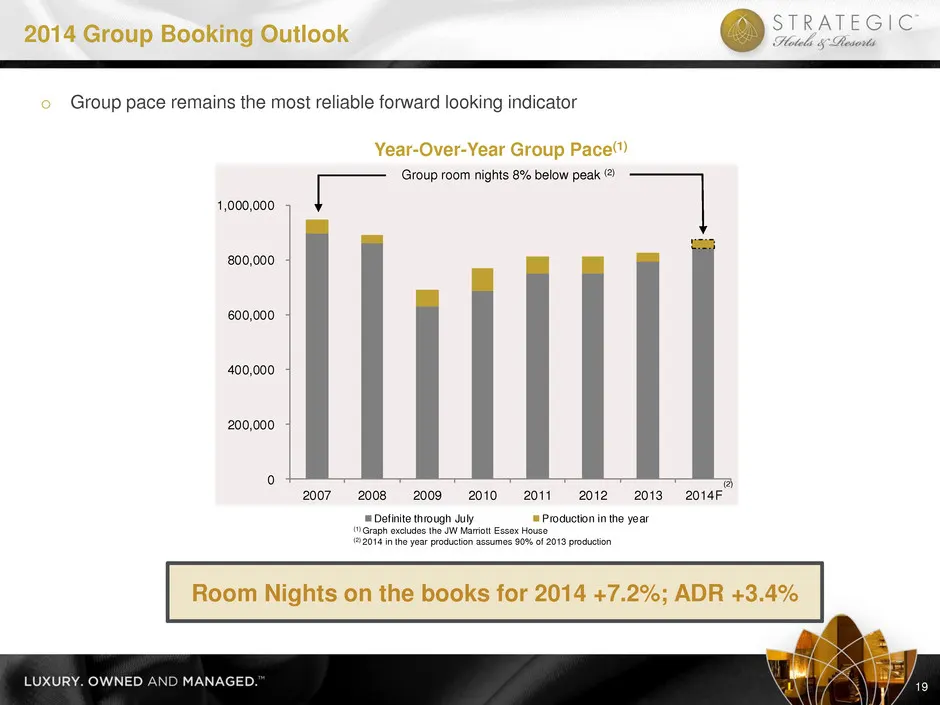
o Group pace remains the most reliable forward looking indicator Year-Over-Year Group Pace(1) Group room nights 8% below peak (2) (1) Graph excludes the JW Marriott Essex House (2) 2014 in the year production assumes 90% of 2013 production 2014 Group Booking Outlook 19 (2) Room Nights on the books f
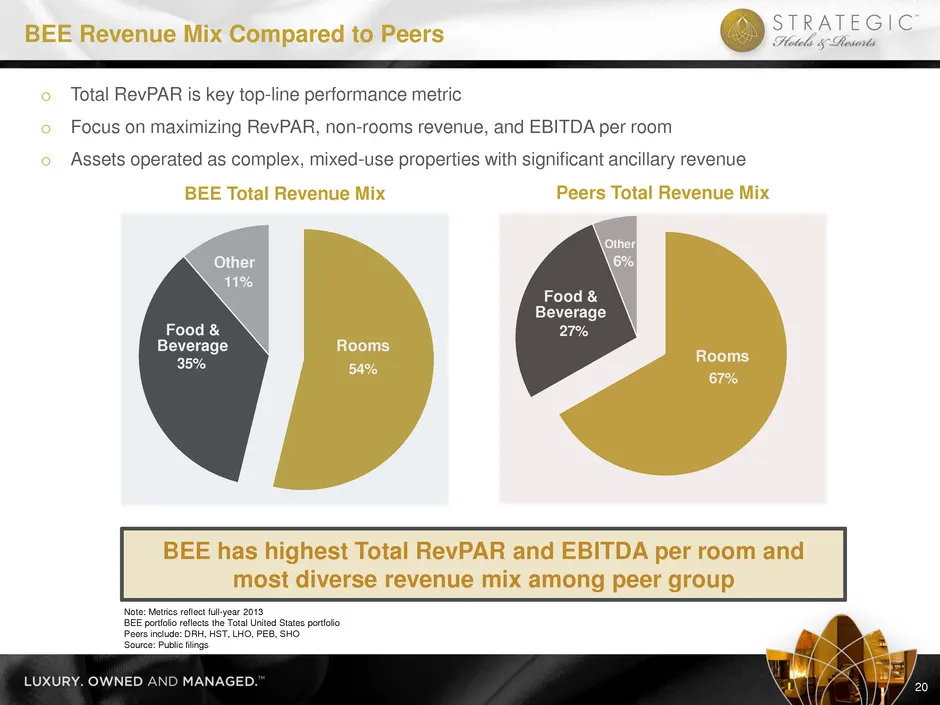
Slide 21: BEE Revenue Mix Compared to Peers
54%35% 11% Rooms Other Food & Beverage 67% 27% 6% Food & Beverage Other Rooms o Total RevPAR is key top-line performance metric o Focus on maximizing RevPAR, non-rooms revenue, and EBITDA per room o Assets operated as complex, mixed-use properties with significant ancillary revenue BEE Total Revenue
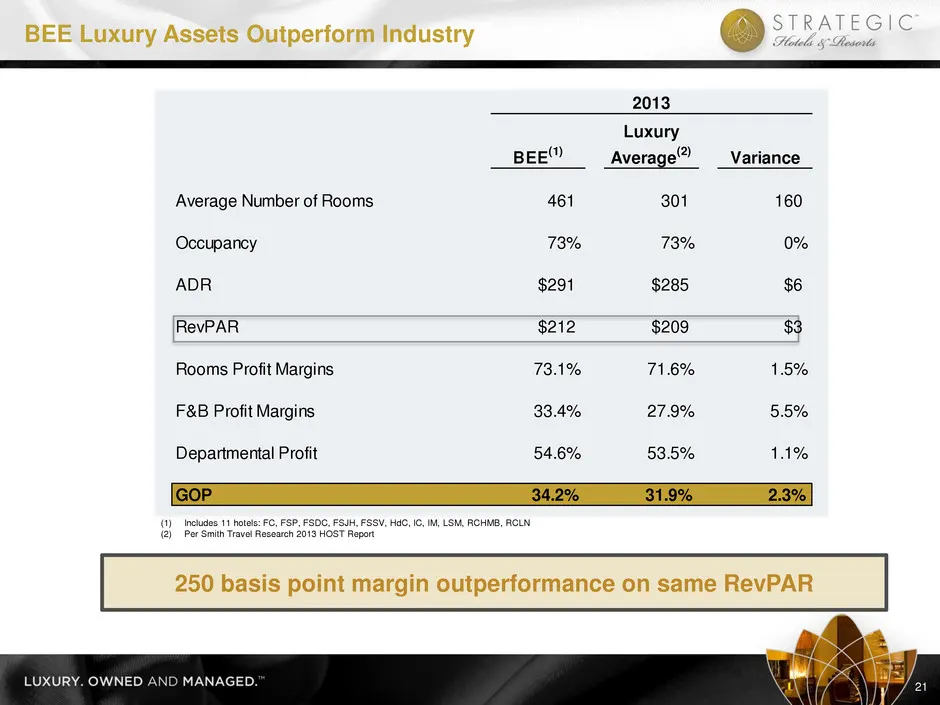
Slide 22: BEE Luxury Assets Outperform Industry
BEE Luxury Assets Outperform Industry 21 (1) Includes 11 hotels: FC, FSP, FSDC, FSJH, FSSV, HdC, IC, IM, LSM, RCHMB, RCLN (2) Per Smith Travel Research 2013 HOST Report 250 basis point margin outperformance on same RevPAR 2013 BEE (1) Luxury Average (2) Variance Average Number of Rooms 461 301 160 O
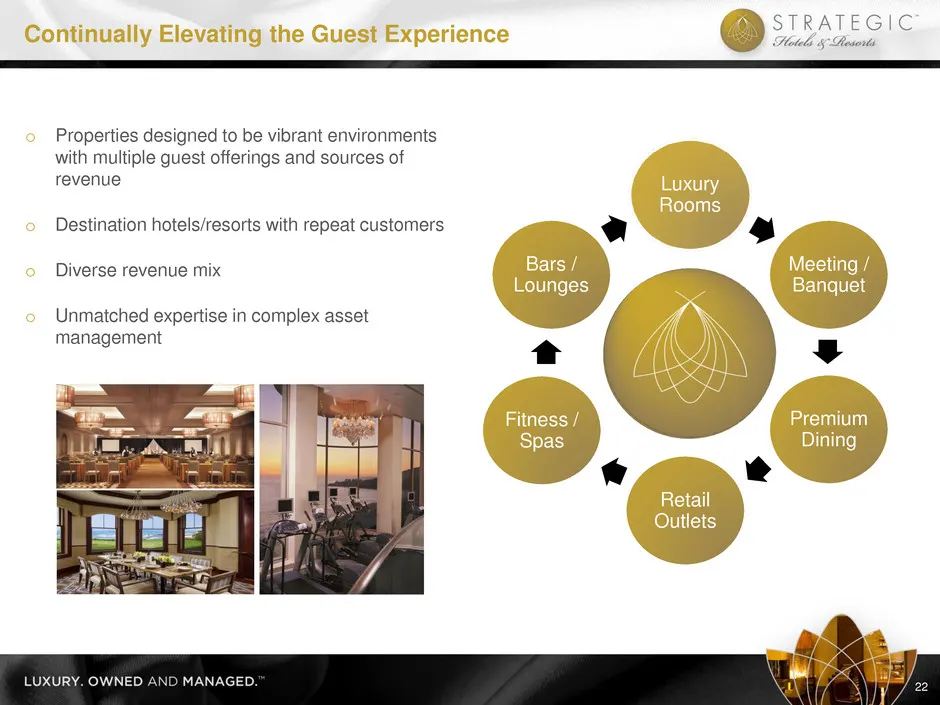
Slide 23: Continually Elevating the Guest Experience
22 Continually Elevating the Guest Experience Luxury Rooms Meeting / Banquet Premium Dining Retail Outlets Fitness / Spas Bars / Lounges o Properties designed to be vibrant environments with multiple guest offerings and sources of revenue o Destination hotels/resorts with repeat customers o Diverse
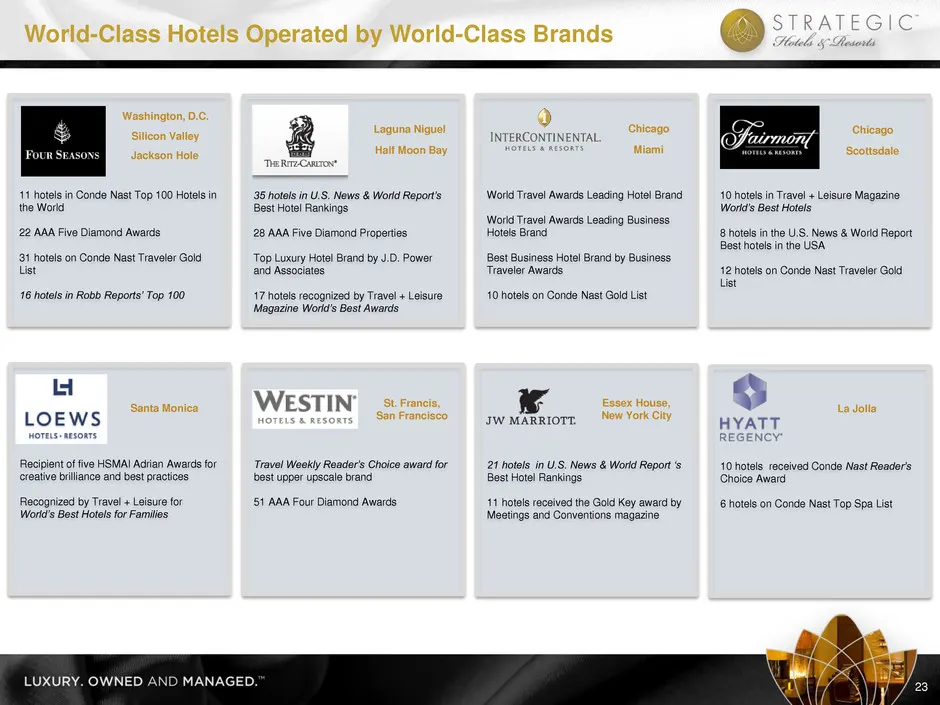
Slide 24: World-Class Hotels Operated by World-Class Brands
World-Class Hotels Operated by World-Class Brands 23 11 hotels in Conde Nast Top 100 Hotels in the World 22 AAA Five Diamond Awards 31 hotels on Conde Nast Traveler Gold List 16 hotels in Robb Reports’ Top 100 35 hotels in U.S. News & World Report’s Best Hotel Rankings 28 AAA Five Diamond Properties
Slide 25: BEE's Strategy to Drive Shareholder Value
24 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform
Slide 26: Proactive and Conservative Balance Sheet Management
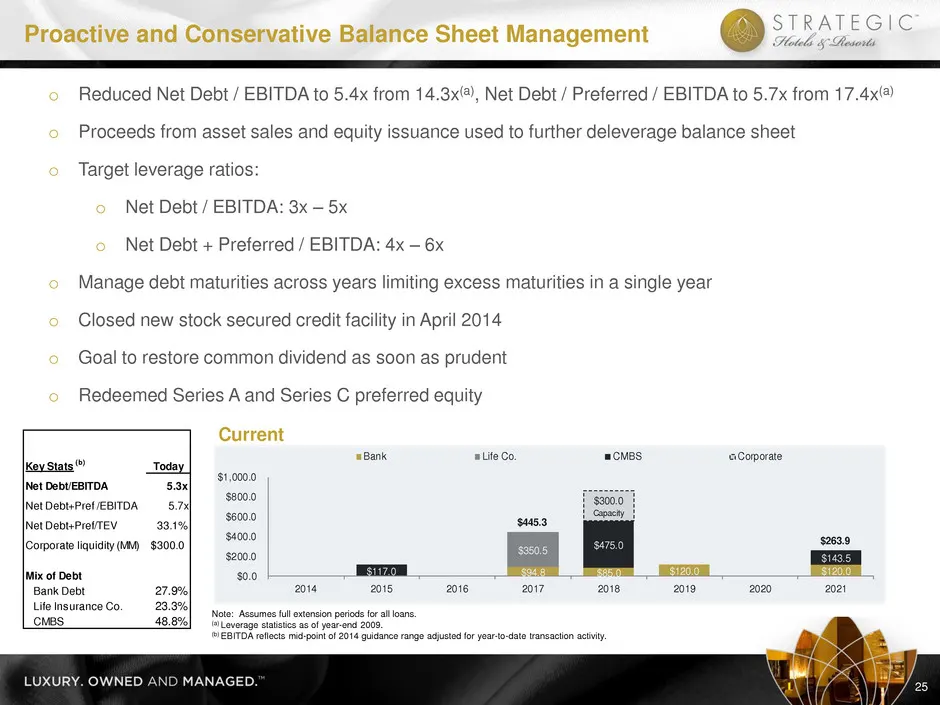
Key Stats (b) Today Net Debt/EBITDA 5.3x Net Debt+Pref /EBITDA 5.7x Net Debt+Pref/TEV 33.1% Corporate liquidity (MM) $300.0 Mix of Debt Bank Debt 27.9% Life Insurance Co. 23.3% CMBS 48.8% $94.8 $85.0 $120.0 $120.0 $350.5 $117.0 $475.0 $143.5 $300.0 Capacity $0.0 $200.0 $400.0 $600.0 $800.0 $1,000.0
Slide 27: BEE's Strategy to Drive Shareholder Value
26 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform
Slide 28: Disciplined Capital Allocation
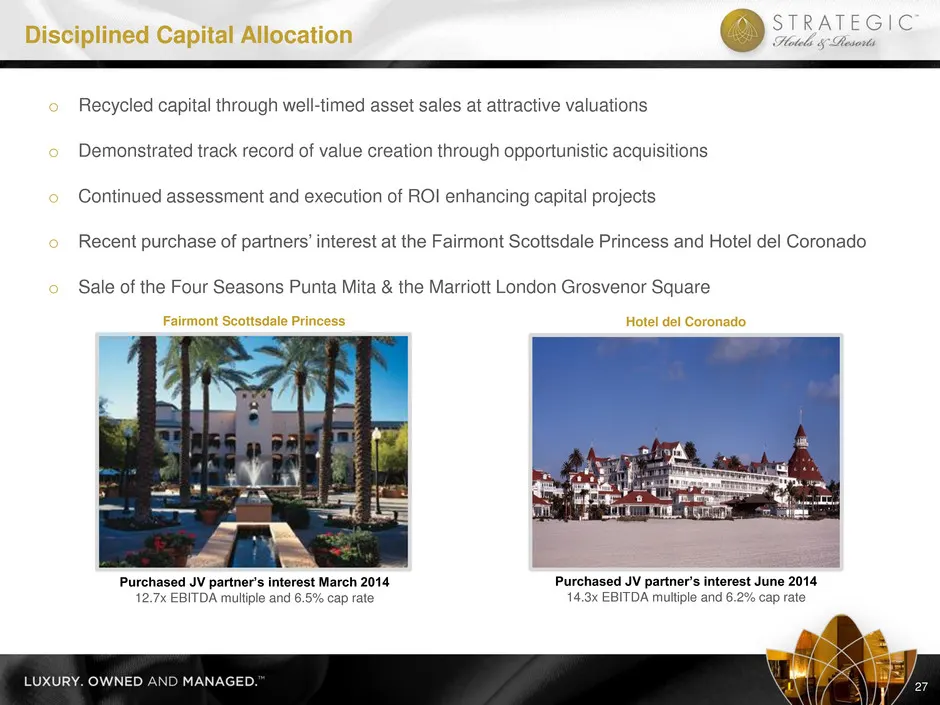
o Recycled capital through well-timed asset sales at attractive valuations o Demonstrated track record of value creation through opportunistic acquisitions o Continued assessment and execution of ROI enhancing capital projects o Recent purchase of partners’ interest at the Fairmont Scottsdale Prince
Slide 29: External Growth Strategy
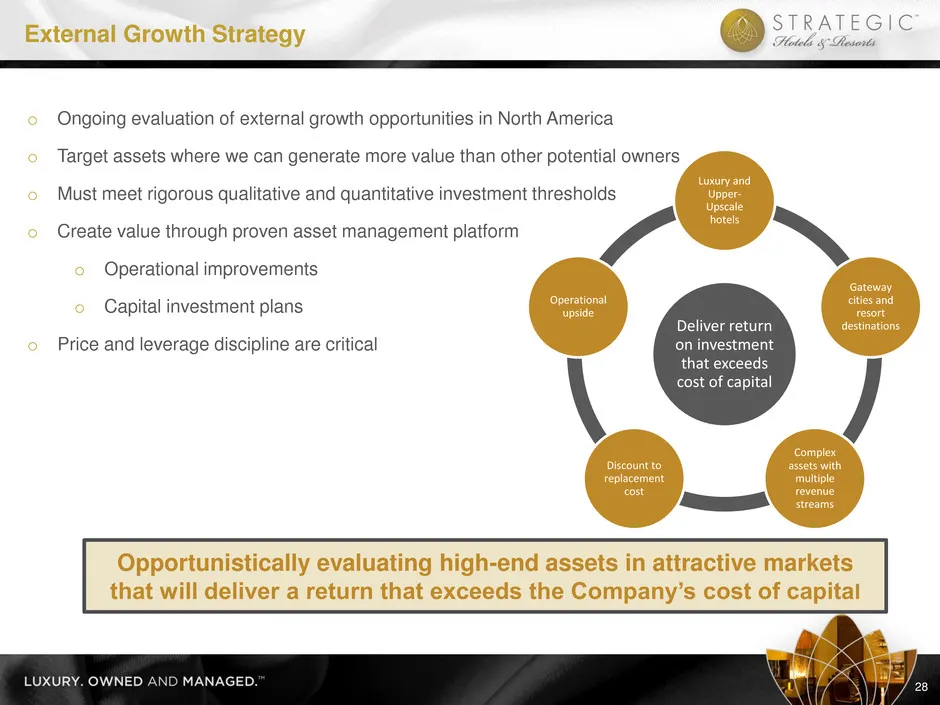
External Growth Strategy 28 Deliver return on investment that exceeds cost of capital Luxury and Upper- Upscale hotels Gateway cities and resort destinations Complex assets with multiple revenue streams Discount to replacement cost Operational upside o Ongoing evaluation of external growth opportuni
Slide 30: Industry Update & Operating Trends
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Industry Update & Operating Trends
Slide 31: Favorable Luxury Lodging Supply & Demand Dynamics
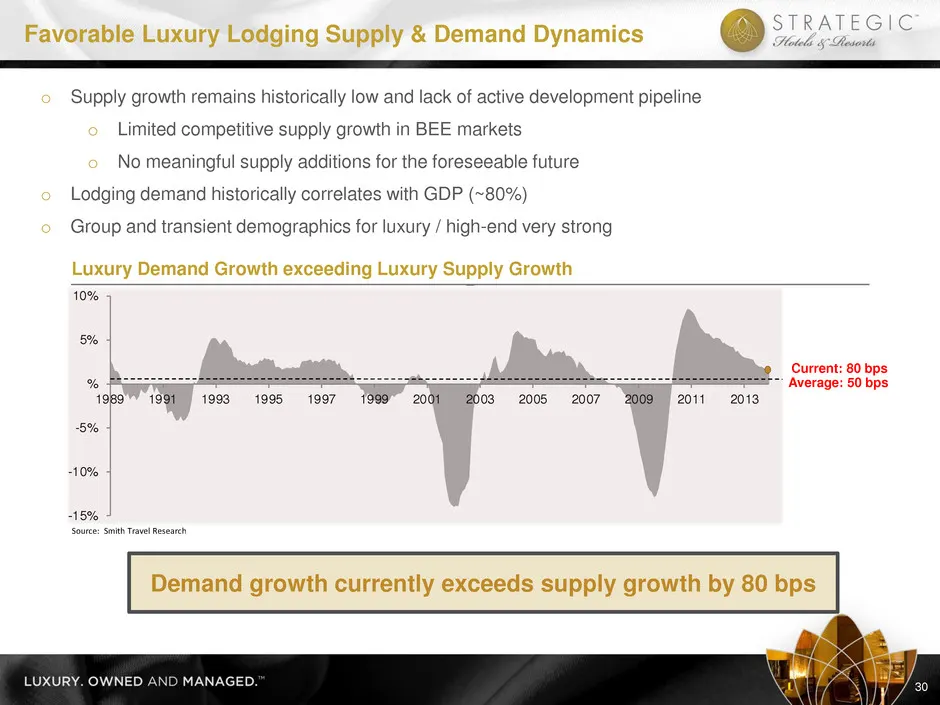
-15% -10% -5% % 5% 10% 1989 1991 1993 1995 1997 1999 2001 2003 2005 2007 2009 2011 2013 o Supply growth remains historically low and lack of active development pipeline o Limited competitive supply growth in BEE markets o No meaningful supply additions for the foreseeable future o Lodging demand his
Slide 32: Luxury Hotels Outperform in a Recovery
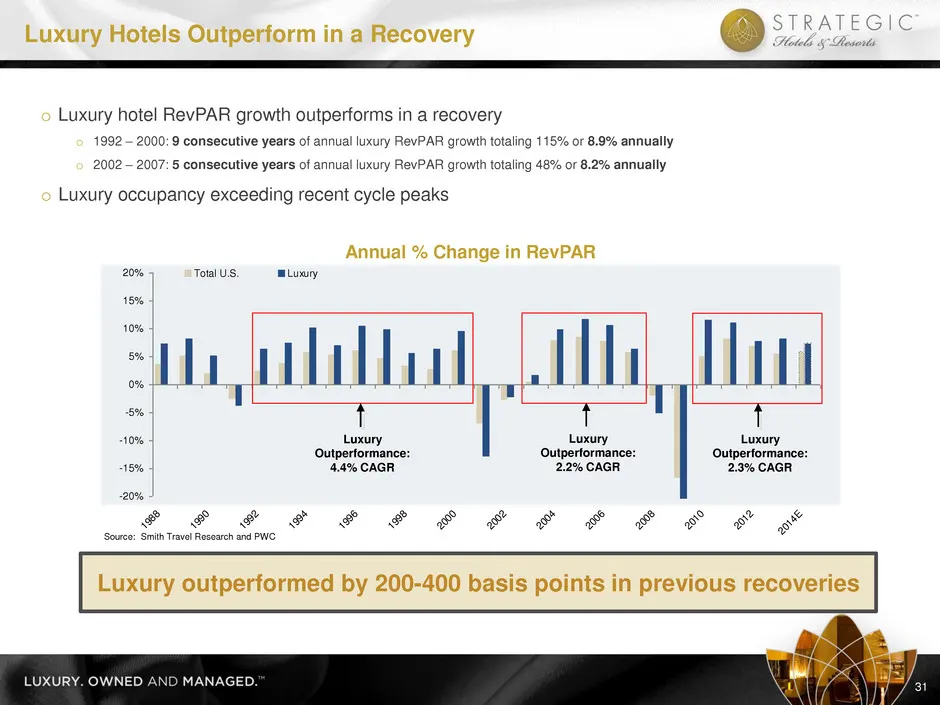
-20% -15% -10% -5% 0% 5% 10% 15% 20% 198 8 199 0 199 2 199 4 199 6 199 8 200 0 200 2 200 4 200 6 200 8 201 0 201 2 201 4E Total U.S. Luxury Source: Smith Travel Research and PWC Annual % Change in RevPAR o Luxury hotel RevPAR growth outperforms in a recovery o 1992 – 2000: 9 consecutive years of ann
Slide 33: BEE's Strategy to Drive Shareholder Value
32 BEE’s Strategy to Drive Shareholder Value Disciplined capital allocation & external growth strategy Enhance and expand our high-end, unique, and irreplaceable hotel portfolio Proactive and conservative balance sheet management Industry leading asset management platform BEE’s strategy has delivere
Slide 34: Case Studies
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Case Studies
Slide 35: JW Marriott New York Essex House – Case Study
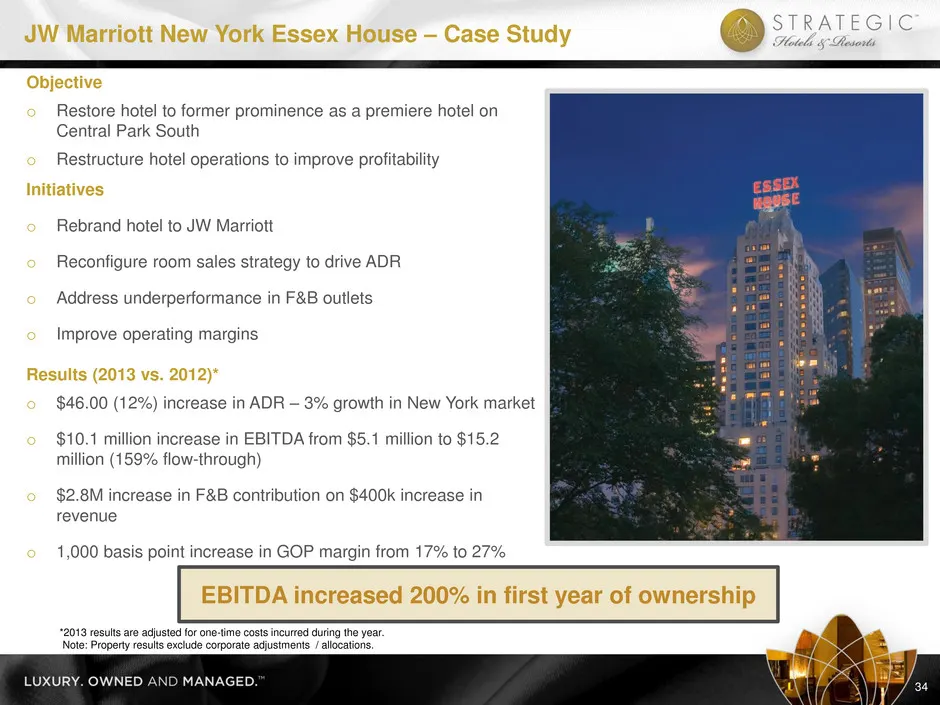
JW Marriott New York Essex House – Case Study Objective o Restore hotel to former prominence as a premiere hotel on Central Park South o Restructure hotel operations to improve profitability Initiatives o Rebrand hotel to JW Marriott o Reconfigure room sales strategy to drive ADR o Address underperf
Slide 36: Four Seasons Jackson Hole & Silicon Valley – Case Study
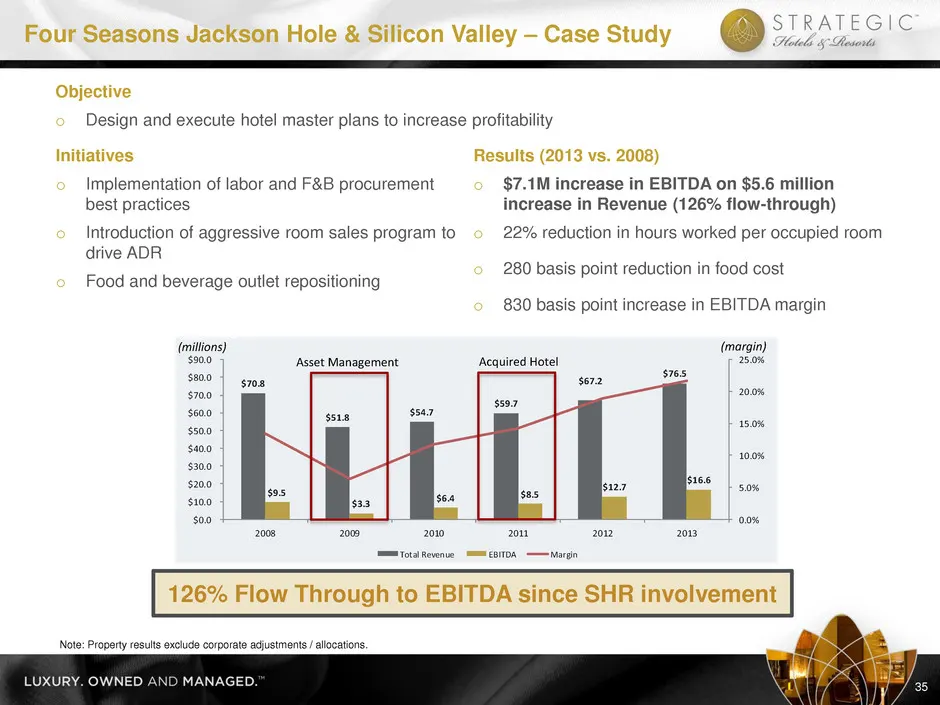
$70.8 $51.8 $54.7 $59.7 $67.2 $76.5 $9.5 $3.3 $6.4 $8.5 $12.7 $16.6 0.0% 5.0% 10.0% 15.0% 20.0% 25.0% $0.0 $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 $70.0 $80.0 $90.0 2008 2009 2010 2011 2012 2013 Total Revenue EBITDA Margin Four Seasons Jackson Hole & Silicon Valley – Case Study Initiatives o Implementat
Slide 37: Fairmont Scottsdale Princess – Case Study
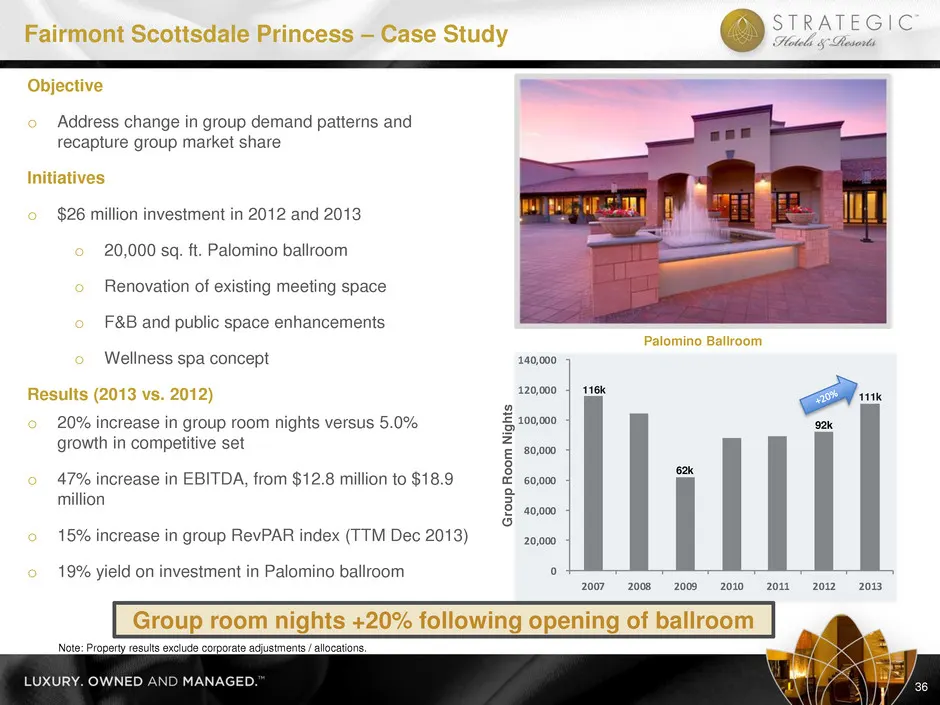
0 20,000 40,000 60,000 80,000 100,000 120,000 140,000 2007 2008 2009 2010 2011 2012 2013 Gr ou p R oo m Ni gh tsFairmont Scottsdale Princess – Case Study 36 Objective o Address change in group demand patterns and recapture group market share Initiatives o $26 million investment in 2012 and 2013 o 20
Slide 38: InterContinental Miami – Case Study
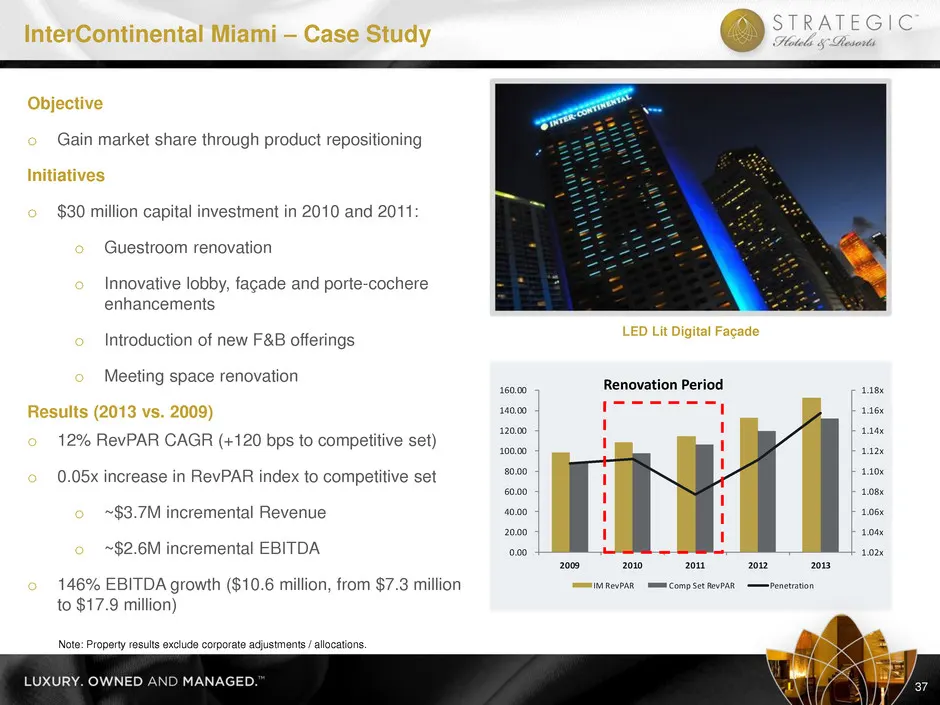
1.02x 1.04x 1.06x 1.08x 1.10x 1.12x 1.14x 1.16x 1.18x 0.00 20.00 40.00 60.00 80.00 100.00 120.00 140.00 160.00 2009 2010 2011 2012 2013 IM RevPAR Comp Set RevPAR Penetration InterContinental Miami – Case Study 37 Objective o Gain market share through product repositioning Initiatives o $30 million c
Slide 39: Four Seasons Washington, D.C. – Case Study
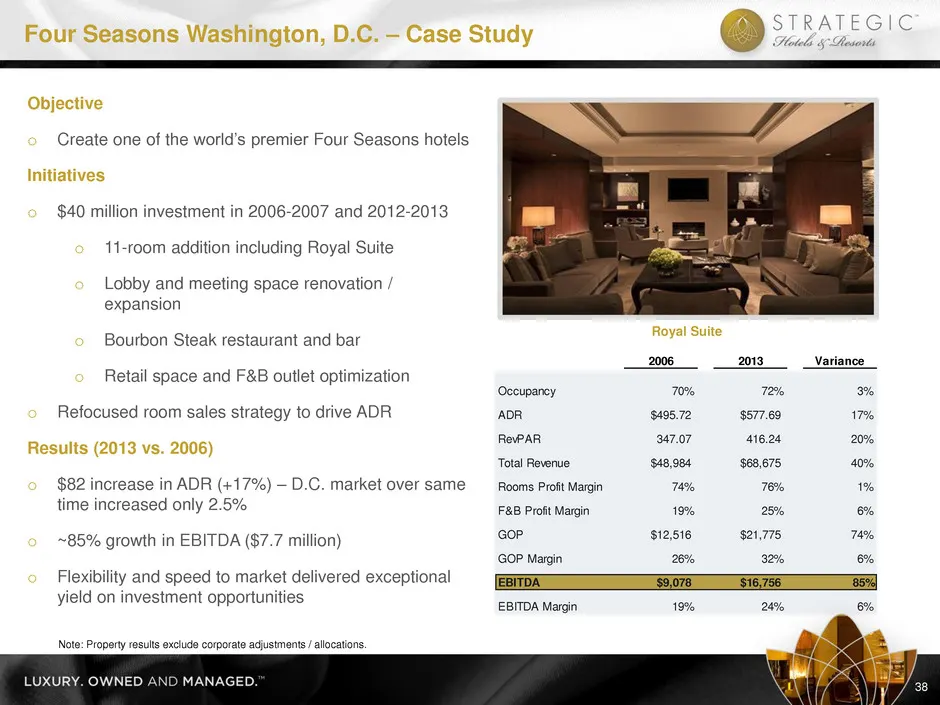
2006 2013 Variance Occupancy 70% 72% 3% ADR $495.72 $577.69 17% RevPAR 347.07 416.24 20% Total Revenue $48,984 $68,675 40% Rooms Profit Margin 74% 76% 1% F&B Profit Margin 19% 25% 6% GOP $12,516 $21,775 74% GOP Margin 26% 32% 6% EBITDA $9,078 $16,756 85% EBITDA Margin 19% 24% 6% Four Seasons Washing
Slide 40: Corporate Governance
I. Strategic Hotels: An Overview II. Financial Overview III. Strategic Plan IV. Industry Update & Operating Trends V. Appendix I. Case Studies II. Corporate Governance Corporate Governance
Slide 41: Corporate Governance Initiatives
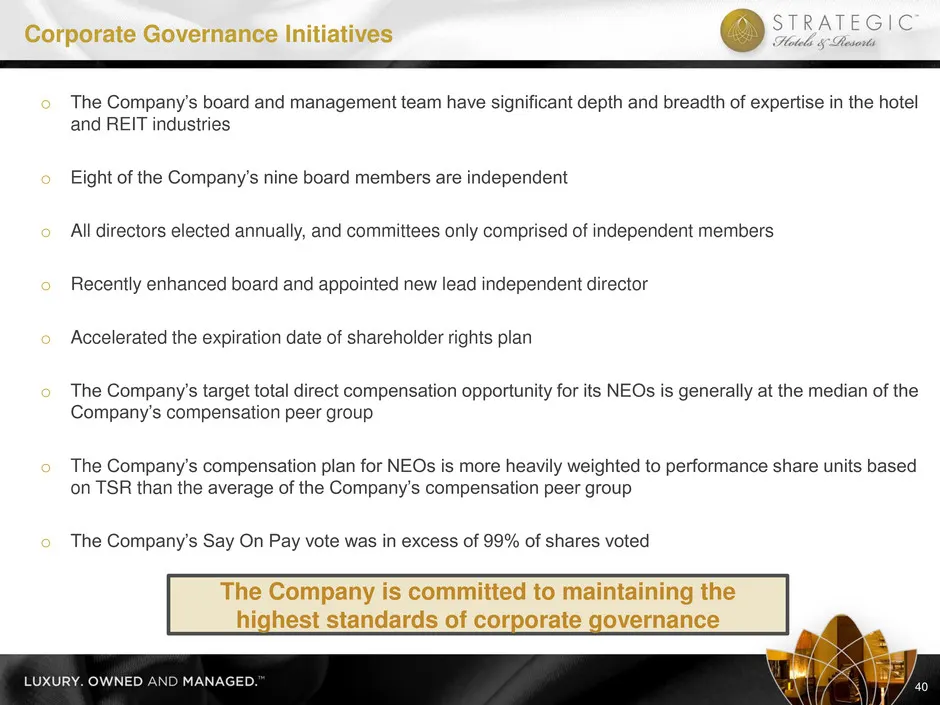
o The Company’s board and management team have significant depth and breadth of expertise in the hotel and REIT industries o Eight of the Company’s nine board members are independent o All directors elected annually, and committees only comprised of independent members o Recently enhanced board and
Slide 42: BEE's Strong Leadership Team
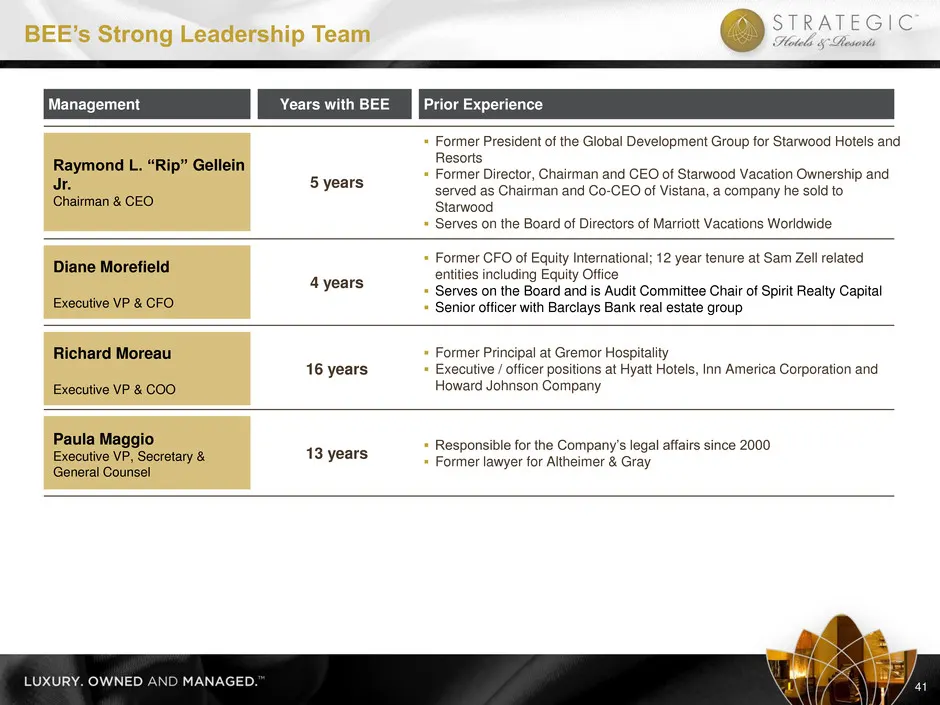
41 BEE’s Strong Leadership Team Prior Experience Management Years with BEE Former President of the Global Development Group for Starwood Hotels and Resorts Former Director, Chairman and CEO of Starwood Vacation Ownership and served as Chairman and Co-CEO of Vistana, a company he sold to Starwood
Slide 43: BEE's Highly Qualified & Independent Board of Directors
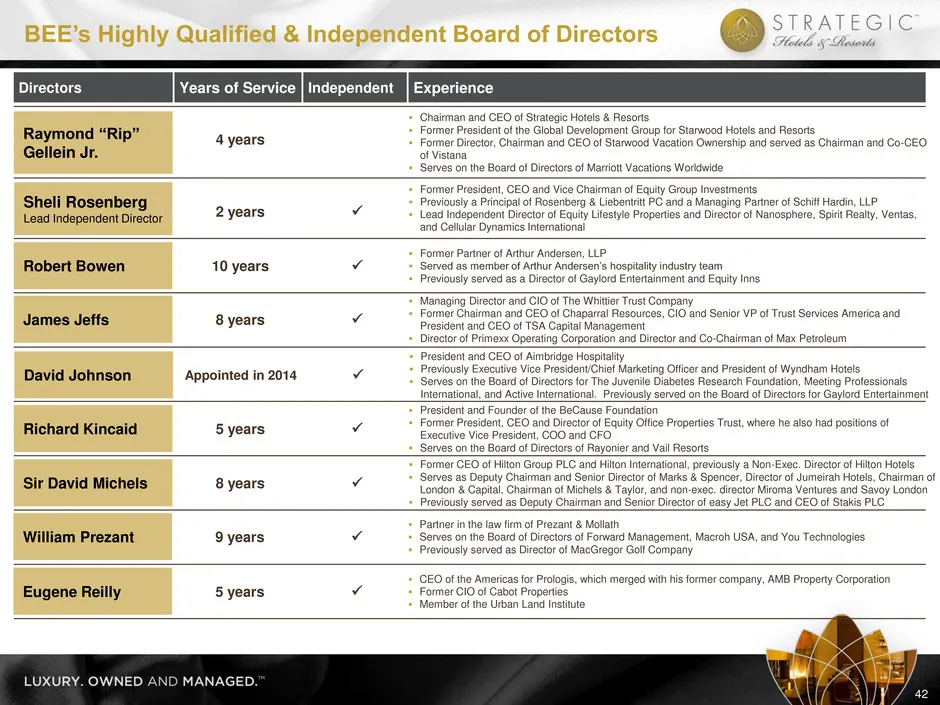
42 BEE’s Highly Qualified & Independent Board of Directors Experience Chairman and CEO of Strategic Hotels & Resorts Former President of the Global Development Group for Starwood Hotels and Resorts Former Director, Chairman and CEO of Starwood Vacation Ownership and served as Chairman and Co-C
Slide 44: Non-GAAP to GAAP Reconciliations
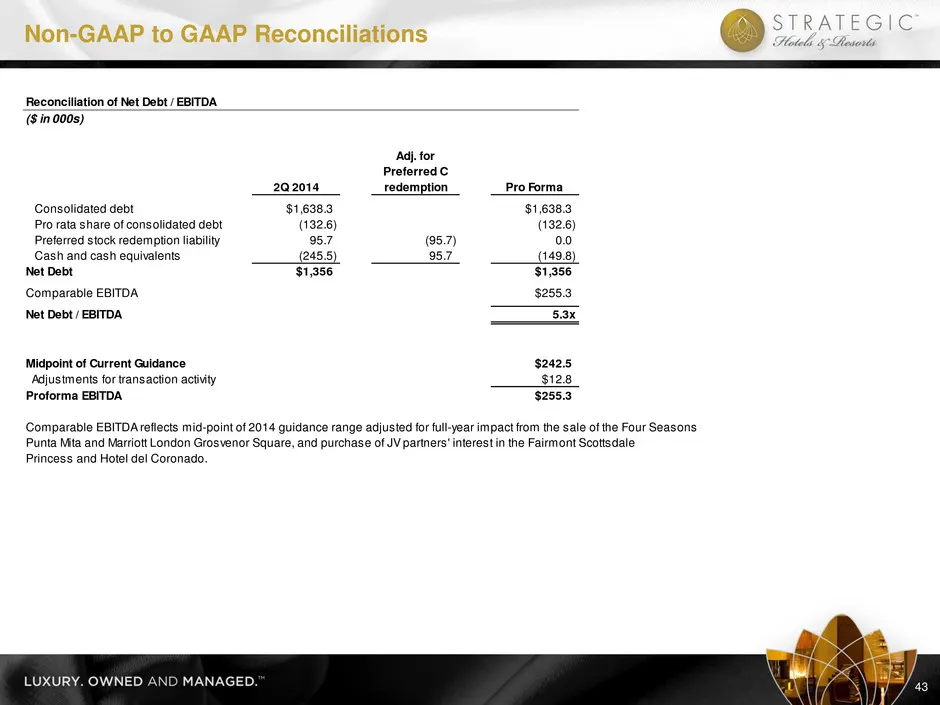
Non-GAAP to GAAP Reconciliations 43 Reconciliation of Net Debt / EBITDA ($ in 000s) 2Q 2014 Adj. for Preferred C redemption Pro Forma Consolidated debt $1,638.3 $1,638.3 Pro rata share of consolidated debt (132.6) (132.6) Preferred stock redemption liability 95.7 (95.7) 0.0 Cash and cash equivalents
Slide 45: Non-GAAP to GAAP Reconciliations
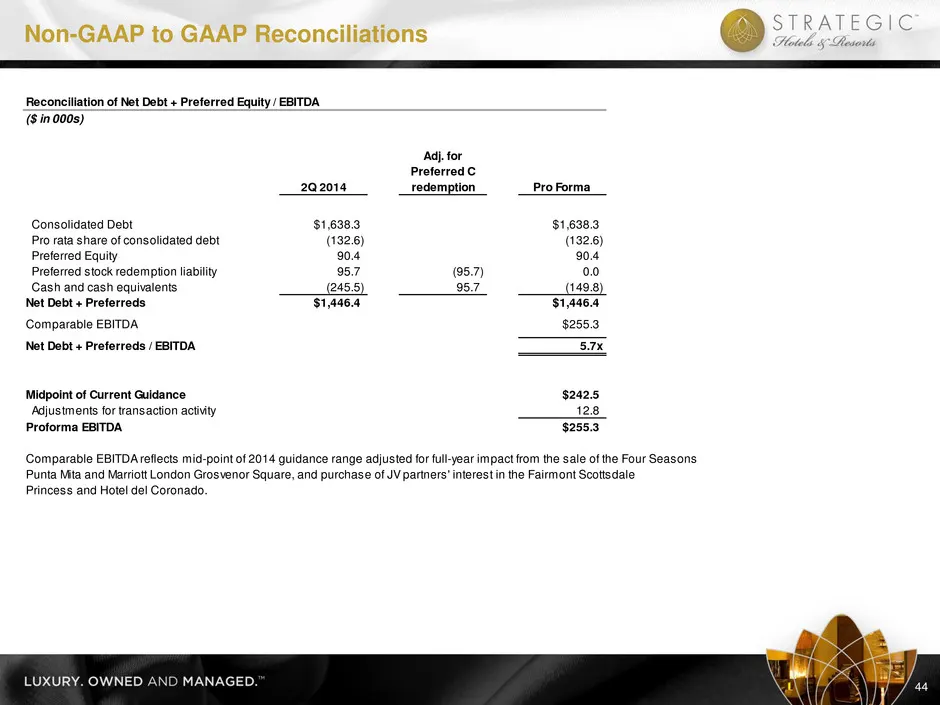
Non-GAAP to GAAP Reconciliations 44 Reconciliation of Net Debt + Preferred Equity / EBITDA ($ in 000s) 2Q 2014 Adj. for Preferred C redemption Pro Forma Consolidated Debt $1,638.3 $1,638.3 Pro rata share of consolidated debt (132.6) (132.6) Preferred Equity 90.4 90.4 Preferred stock redemption liabi
Slide 46: Non-GAAP to GAAP Reconciliations
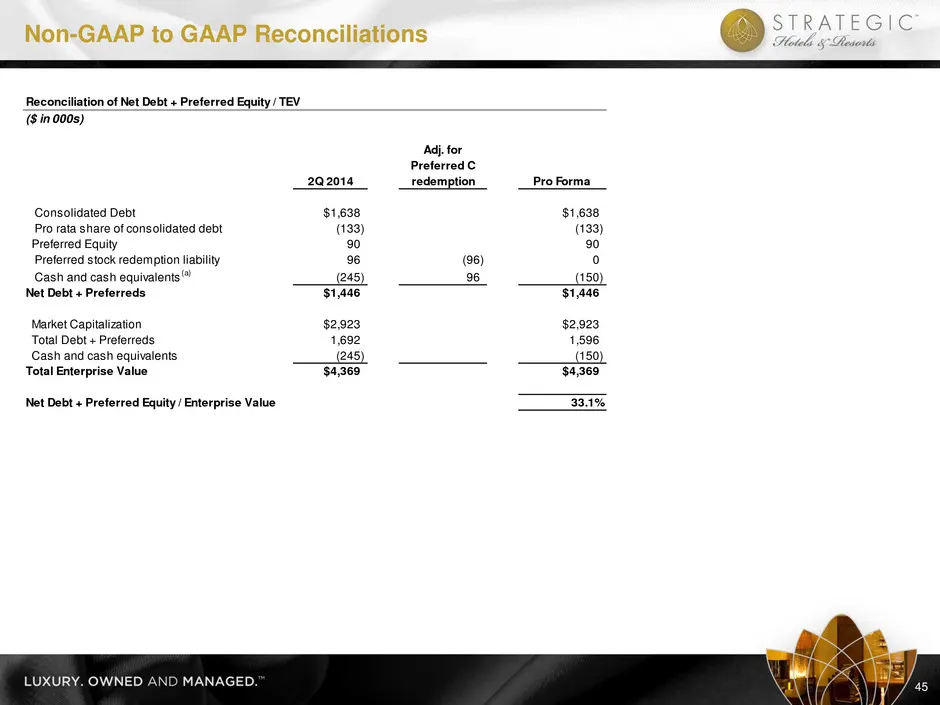
Non-GAAP to GAAP Reconciliations 45 Reconciliation of Net Debt + Preferred Equity / TEV ($ in 000s) 2Q 2014 Adj. for Preferred C redemption Pro Forma Consolidated Debt $1,638 $1,638 Pro rata share of consolidated debt (133) (133) Preferred Equity 90 90 Preferred stock redemption liability 96 (96) 0
Slide 47: Non-GAAP to GAAP Reconciliations
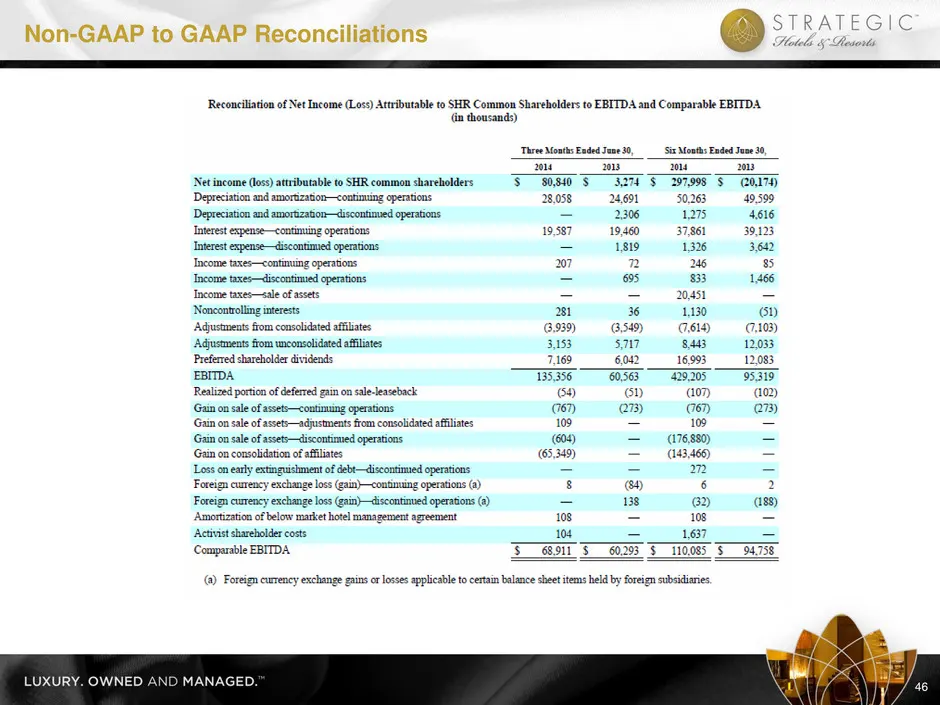
Non-GAAP to GAAP Reconciliations 46
Slide 48: Non-GAAP to GAAP Reconciliations
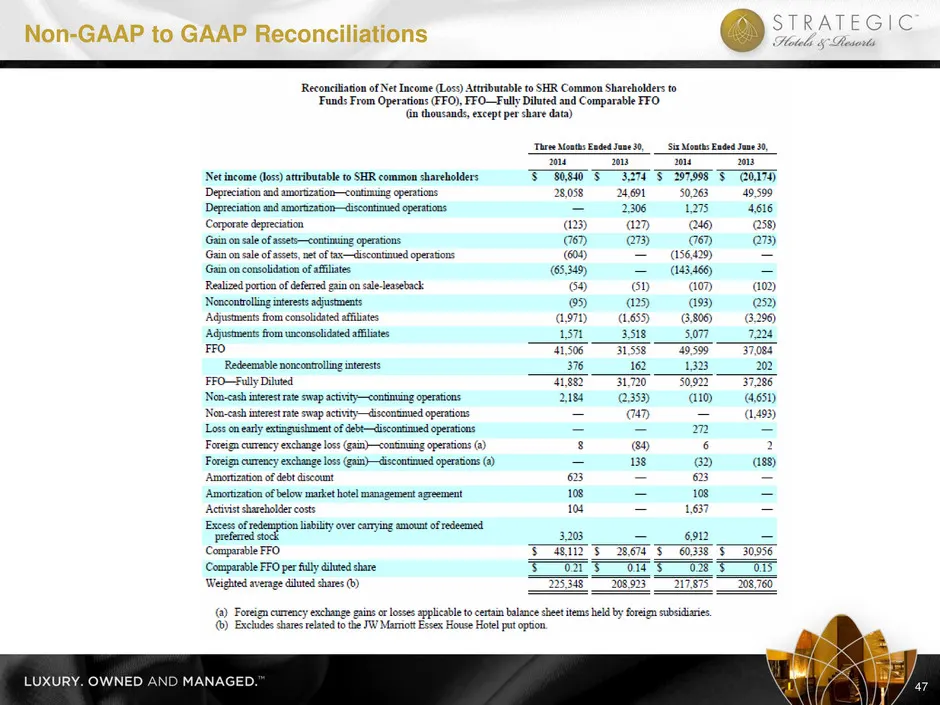
Non-GAAP to GAAP Reconciliations 47
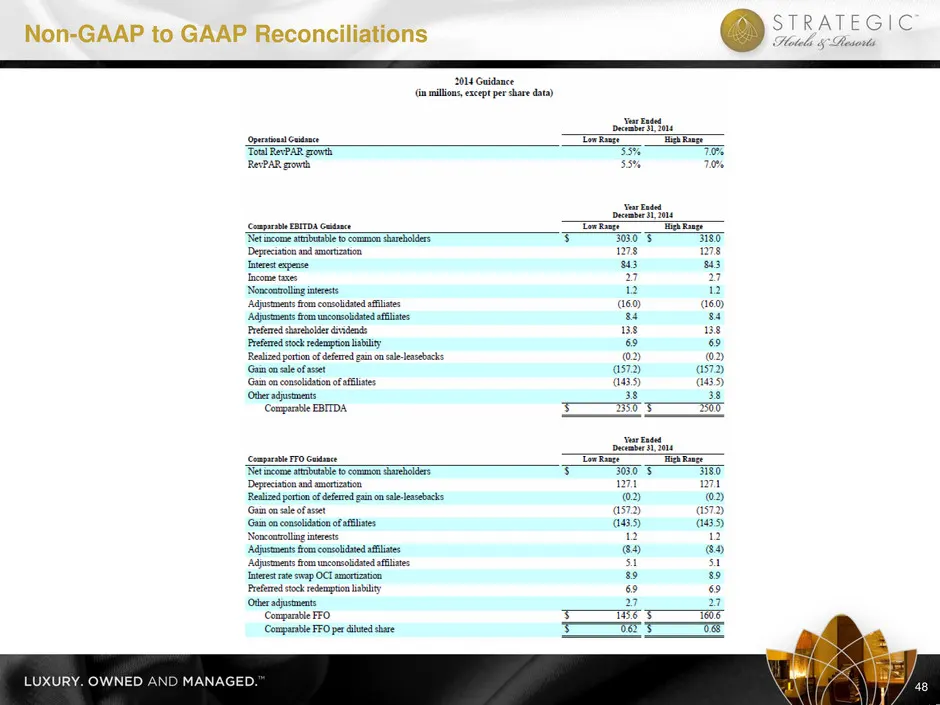
Slide 49: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations 48
Slide 50: Non-GAAP to GAAP Reconciliations
Non-GAAP to GAAP Reconciliations 49 Update when Guidance ranges available
Source: SEC EDGAR · 8-K filed Aug 25, 2014
More decks from Strategic Hotels and Resorts Inc
 Investor Presentation (June 2015)43 slides · Jun 1, 2015
 Investor Presentation (February 2015)43 slides · Feb 24, 2015
 Investor Presentation (January 2015)44 slides · Jan 26, 2015
 Investor Presentation (November 2014)50 slides · Nov 5, 2014
 Investor Presentation (October 2014)50 slides · Oct 3, 2014
 Investor Day (September 2014)67 slides · Sep 22, 2014