Carolina Financial Corporation
Carolina Financial — Merger or Acquisition (November 2016)
14 slides from Carolina Financial's merger presentation, Nov 8, 2016
Slide 1: Acquisition of Greer Bancshares Incorporated by Carolina Financial Corporation
Investor Presentation N A S D A Q : C A RO November 8, 201 6 Acquisition of Greer Bancshares Incorporated by Carolina Financial Corporation (CARO)
Slide 2: Disclaimer
2 Disclaimer Certain statements in this presentation contain “forward - looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995 , such as statements relating to future plans and expectations, and are thus prospective . Such forward - looking statements include
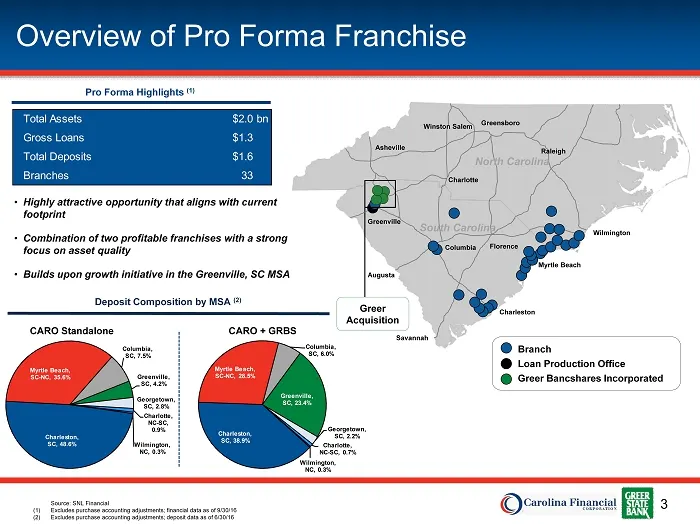
Slide 3: Overview of Pro Forma Franchise
3 Augusta Savannah Overview of Pro Forma Franchise Branch Loan Production Office Greer Bancshares Incorporated Greer Acquisition Source: SNL Financial (1) Excludes purchase accounting adjustments; financial data as of 9/30/16 (2) Excludes purchase accounting adjustments; deposit data as of 6/30/16 P
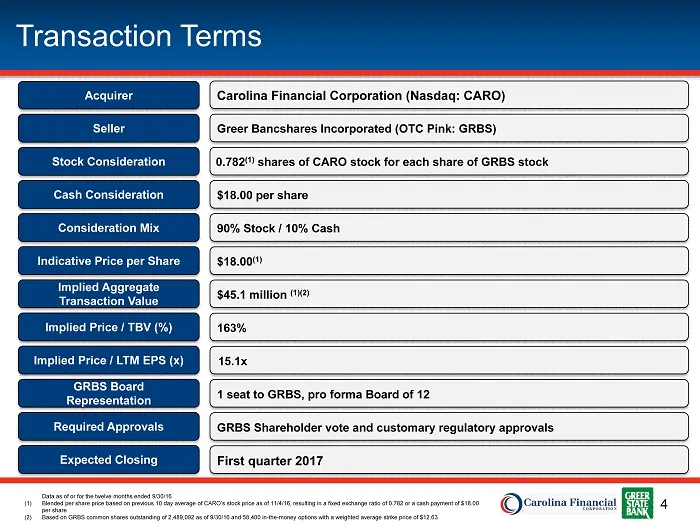
Slide 4: Transaction Terms
4 1 1 1 1 1 1 1 1 1 1 Transaction Terms Consideration Mix Implied Price / TBV (%) Required Approvals $45.1 million (1)(2) 90% Stock / 10% Cash GRBS Shareholder vote and customary regulatory approvals Implied Aggregate Transaction Value GRBS Board Representation Expected Closing First quarter 2017 1
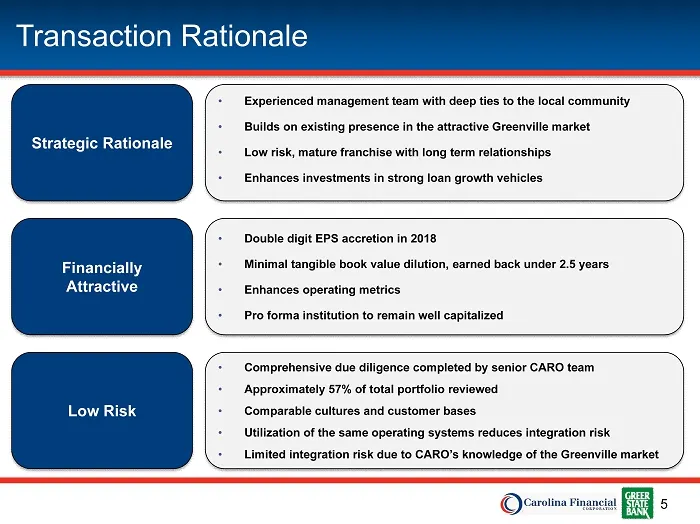
Slide 5: Transaction Rationale
5 • Double digit EPS accretion in 2018 • Minimal tangible book value dilution, earned back under 2.5 years • Enhances operating metrics • Pro forma institution to remain well capitalized • Comprehensive due diligence completed by senior CARO team • Approximately 57% of total portfolio reviewed • Com
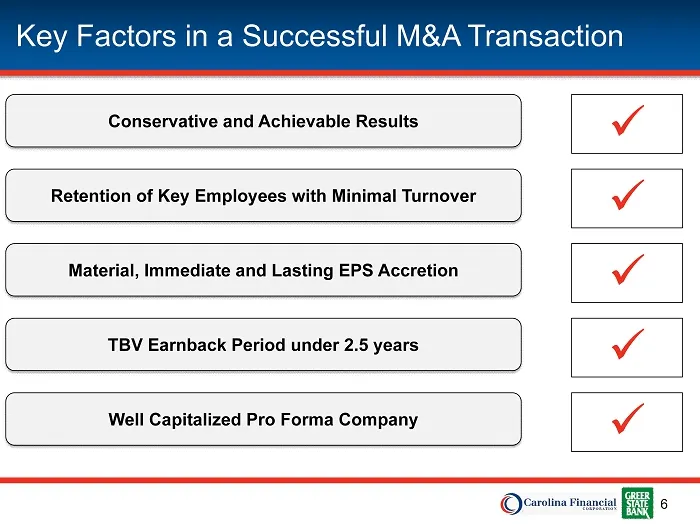
Slide 6: Key Factors in a Successful M&A Transaction
6 Key Factors in a Successful M&A Transaction Conservative and Achievable Results Retention of Key Employees with Minimal Turnover Material, Immediate and Lasting EPS Accretion TBV Earnback Period under 2.5 years x x x x Well Capitalized Pro Forma Company x
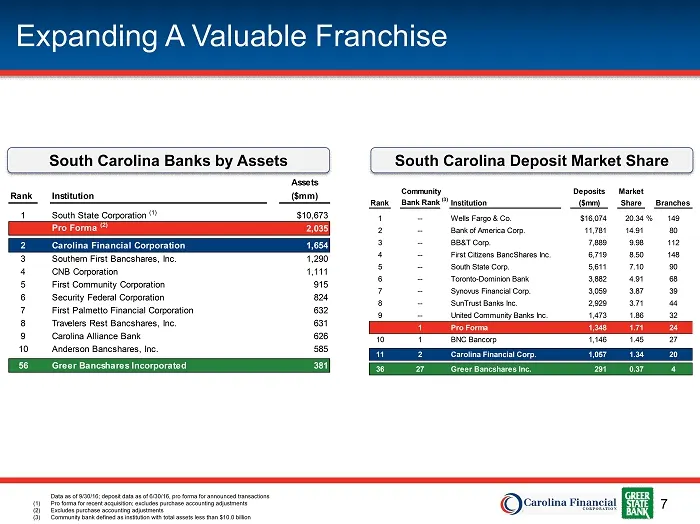
Slide 7: Expanding A Valuable Franchise
7 Expanding A Valuable Franchise Data as of 9/30/16; deposit data as of 6/30/16, pro forma for announced transactions (1) Pro forma for recent acquisition; excludes purchase accounting adjustments (2) Excludes purchase accounting adjustments (3) Community bank defined as institution with total asset
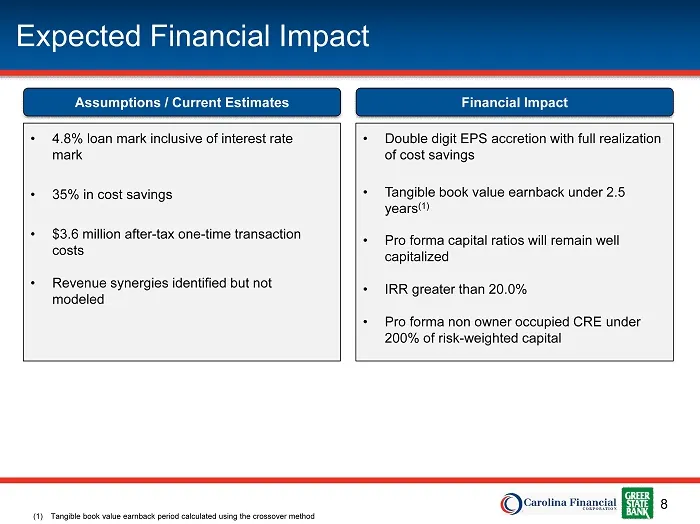
Slide 8: Expected Financial Impact
8 Expected Financial Impact (1) Tangible book value earnback period calculated using the crossover method Assumptions / Current Estimates Financial Impact • 4.8% loan mark inclusive of interest rate mark • 35% in cost savings • $3.6 million after - tax one - time transaction costs • Revenue synergie
Slide 9: Credit Due Diligence
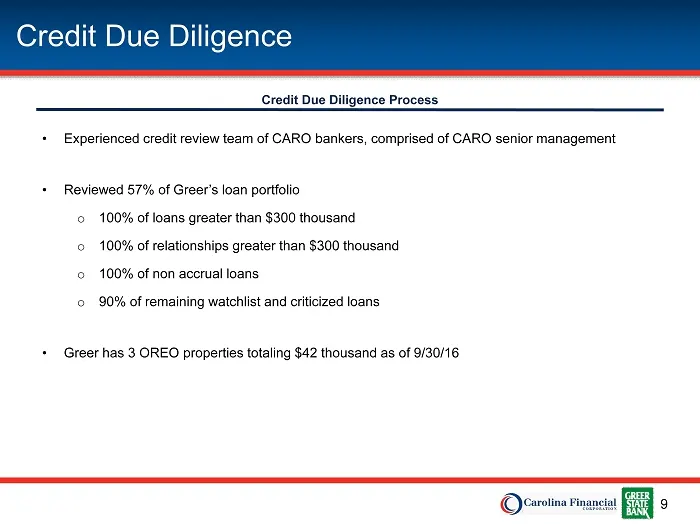
9 Credit Due Diligence Credit Due Diligence Process • Experienced credit review team of CARO bankers, comprised of CARO senior management • Reviewed 57% of Greer’s loan portfolio o 100% of loans greater than $300 thousand o 100% of relationships greater than $300 thousand o 100% of non accrual loans
Slide 10: Summary
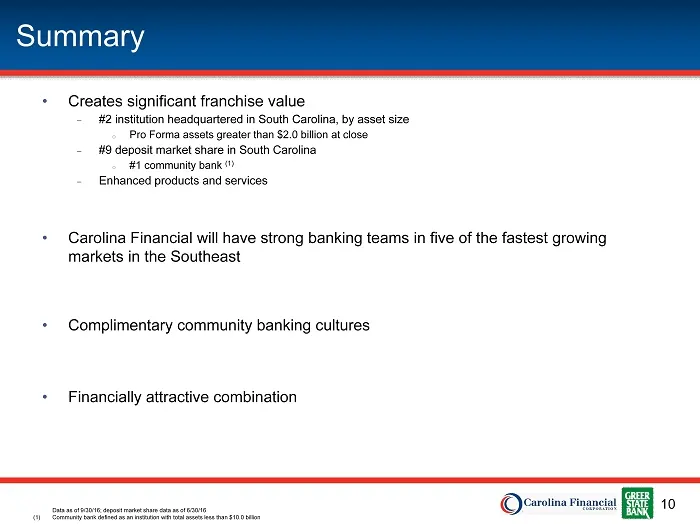
10 Summary Data as of 9/30/16; deposit market share data as of 6/30/16 (1) Community bank defined as an institution with total assets less than $10.0 billion • Creates significant franchise value – #2 institution headquartered in South Carolina, by asset size o Pro Forma assets greater than $2.0 bil
Slide 11: Appendix
Appendix ‘CORPORATION C Carolina Financial
Slide 12: Overview of Greer Bancshares, Inc.
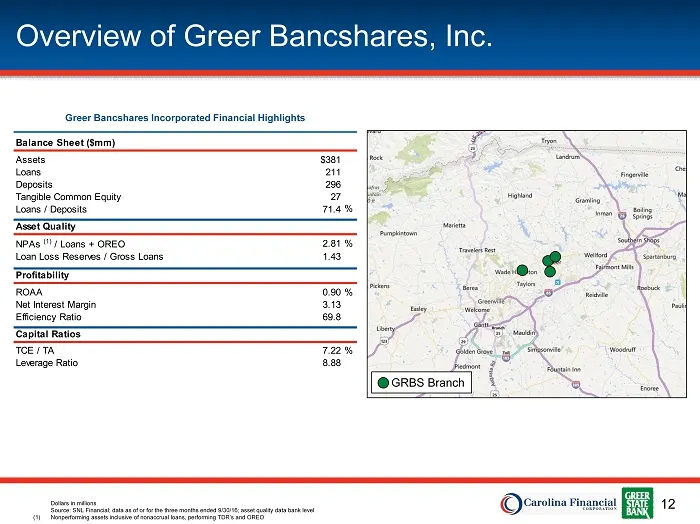
12 Overview of Greer Bancshares, Inc. Balance Sheet ($mm) Assets $381 Loans 211 Deposits 296 Tangible Common Equity 27 Loans / Deposits 71.4 % Asset Quality NPAs (1) / Loans + OREO 2.81% Loan Loss Reserves / Gross Loans 1.43 Profitability ROAA 0.90% Net Interest Margin 3.13 Efficiency Ratio 69.8 Cap
Slide 13: Market Highlights – Greenville
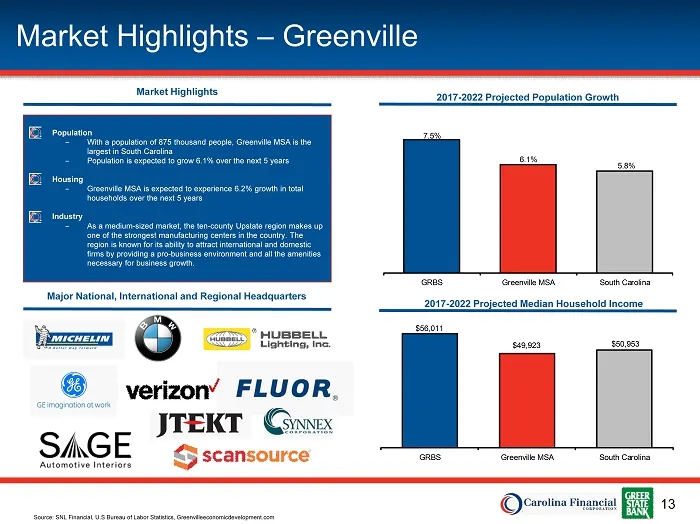
13 Market Highlights – Greenville Market Highlights Population ‒ With a population of 875 thousand people, Greenville MSA is the largest in South Carolina ‒ Population is expected to grow 6.1% over the next 5 years Housing ‒ Greenville MSA is expected to experience 6.2% growth in total households ov
Slide 14: Pro forma Loan and Deposit Composition
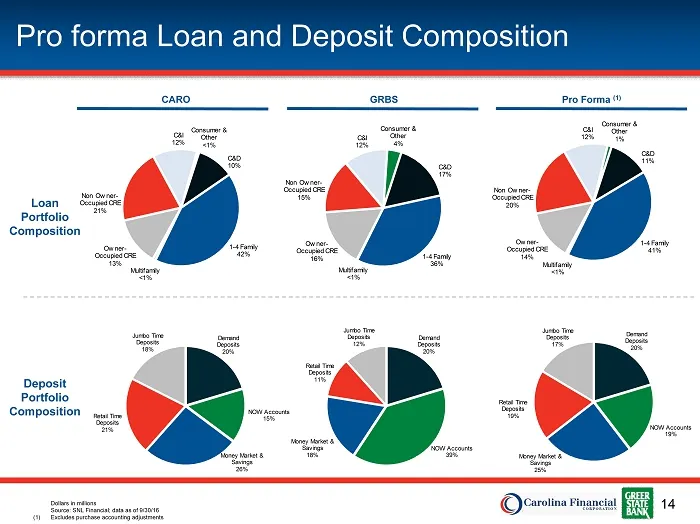
14 C&D 10% 1 - 4 Family 42% Multifamily <1% Owner - Occupied CRE 13% Non Owner - Occupied CRE 21% C&I 12% Consumer & Other <1% C&D 17% 1 - 4 Family 36% Multifamily <1% Owner - Occupied CRE 16% Non Owner - Occupied CRE 15% C&I 12% Consumer & Other 4% C&D 11% 1 - 4 Family 41% Multifamily <1% Owner - O
Source: SEC EDGAR · 8-K filed Nov 8, 2016
More decks from Carolina Financial Corporation
 Q4 2019 Earnings Presentation19 slides · Jan 29, 2020
 Merger or Acquisition (November 2019)13 slides · Nov 18, 2019
 Q3 2019 Earnings Presentation15 slides · Oct 24, 2019
 Q2 2019 Earnings Presentation18 slides · Jul 25, 2019
 Q1 2019 Earnings Presentation15 slides · Apr 24, 2019
 Q4 2018 Earnings Presentation13 slides · Jan 24, 2019