Northern Tier Energy LP — Merger or Acquisition (December 2015)
23 slides from Northern Tier Energy LP's merger presentation, Dec 22, 2015
Slide 1: Merger of Western Refining and Northern Tier
Merger of Western Refining and Northern Tier December 22, 2015 Exhibit 99.2
Slide 2: Cautionary Statements
Cautionary Statements This presentation includes “forward-looking statements” by Western Refining, Inc. (“Western” or “WNR”) (which are protected as forward-looking statements under the Private Securities Litigation Reform Act of 1995) and by Northern Tier Energy LP (“Northern Tier” or “NTI”). The f
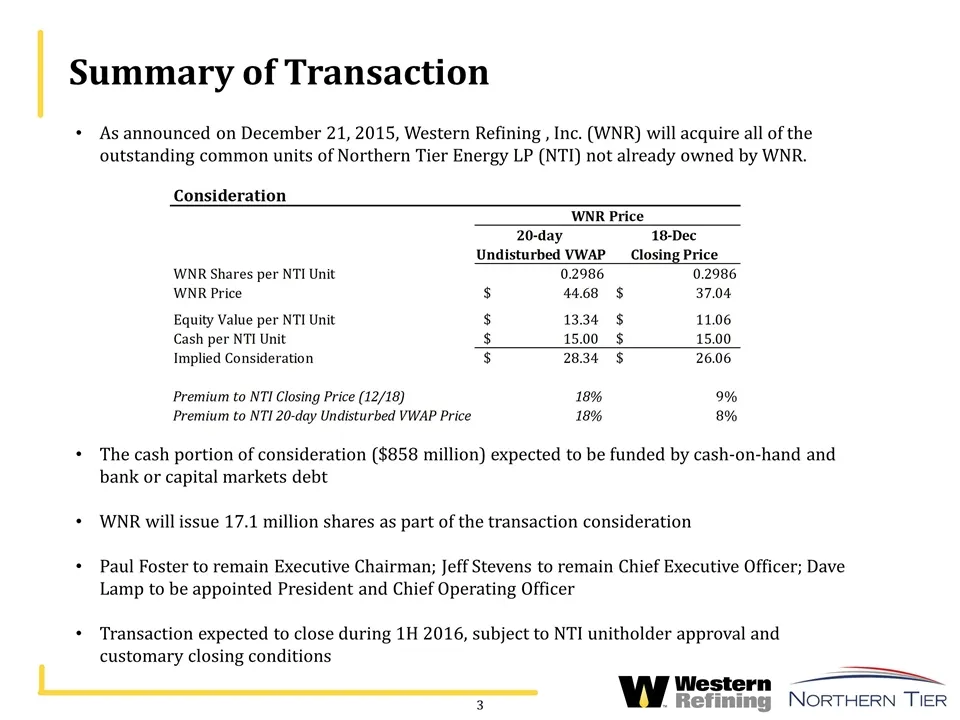
Slide 3: Summary of Transaction
As announced on December 21, 2015, Western Refining , Inc. (WNR) will acquire all of the outstanding common units of Northern Tier Energy LP (NTI) not already owned by WNR. The cash portion of consideration ($858 million) expected to be funded by cash-on-hand and bank or capital markets debt WNR wil
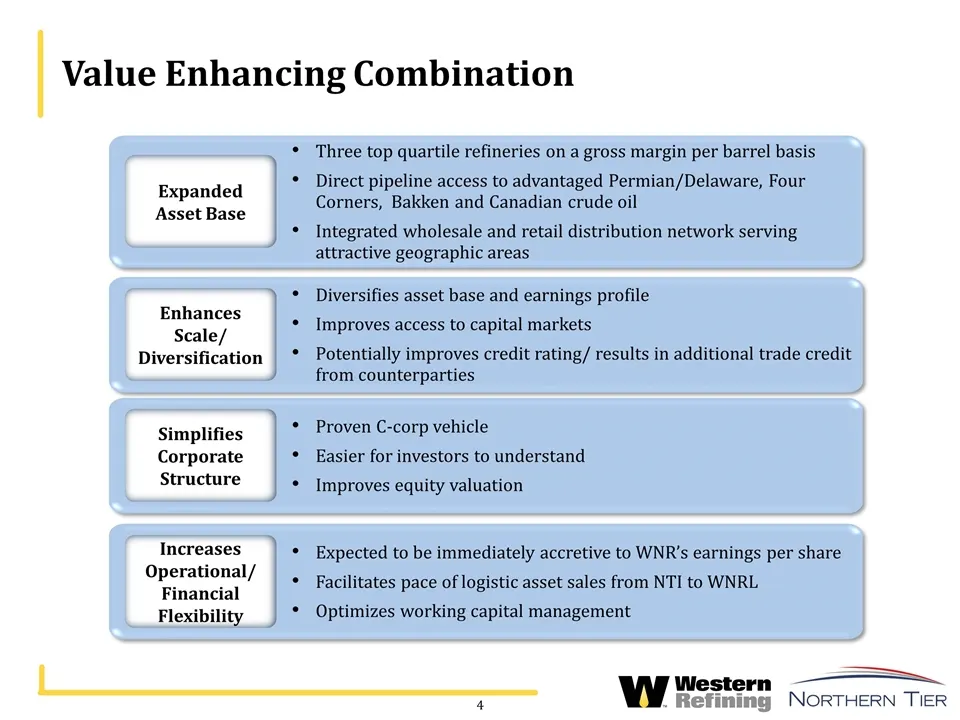
Slide 4: Value Enhancing Combination
Value Enhancing Combination Three top quartile refineries on a gross margin per barrel basis Direct pipeline access to advantaged Permian/Delaware, Four Corners, Bakken and Canadian crude oil Integrated wholesale and retail distribution network serving attractive geographic areas Expanded Asset Base
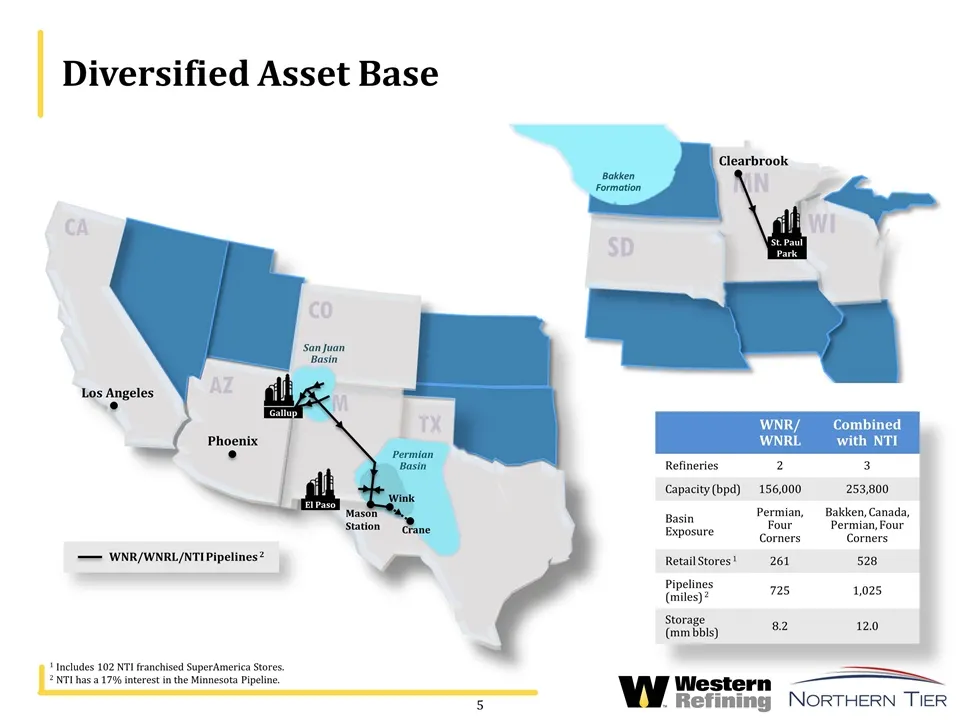
Slide 5: Diversified Asset Base
Diversified Asset Base WNR/ WNRL Combined with NTI Refineries 2 3 Capacity (bpd) 156,000 253,800 Basin Exposure Permian, Four Corners Bakken, Canada, Permian, Four Corners Retail Stores 1 261 528 Pipelines (miles) 2 725 1,025 Storage (mm bbls) 8.2 12.0 1 Includes 102 NTI franchised SuperAmerica Stor
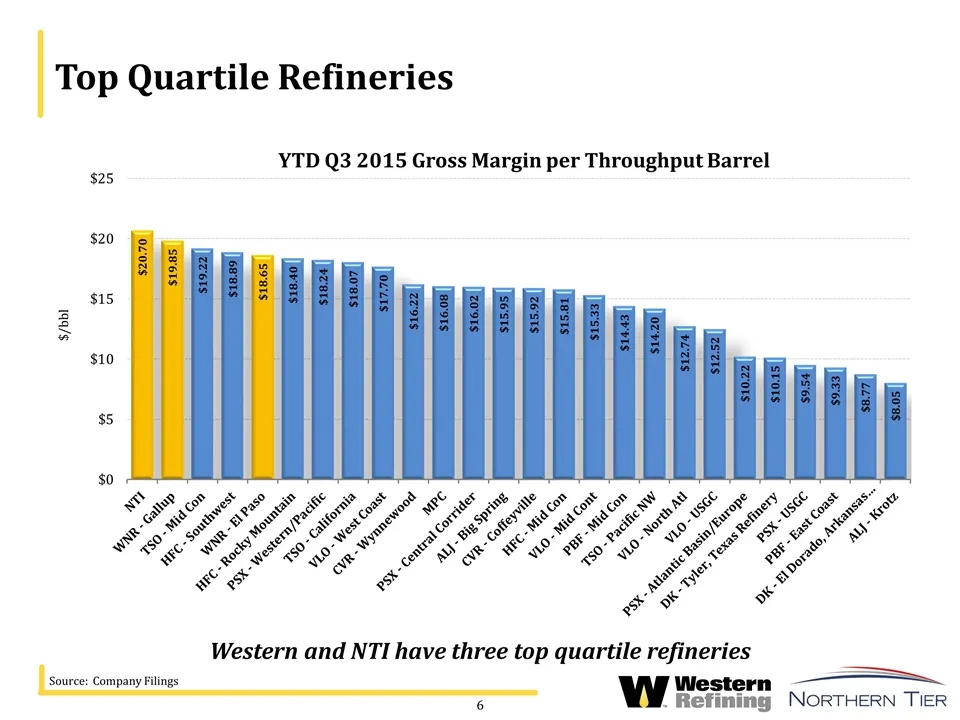
Slide 6: Top Quartile Refineries
Top Quartile Refineries Source: Company Filings Western and NTI have three top quartile refineries
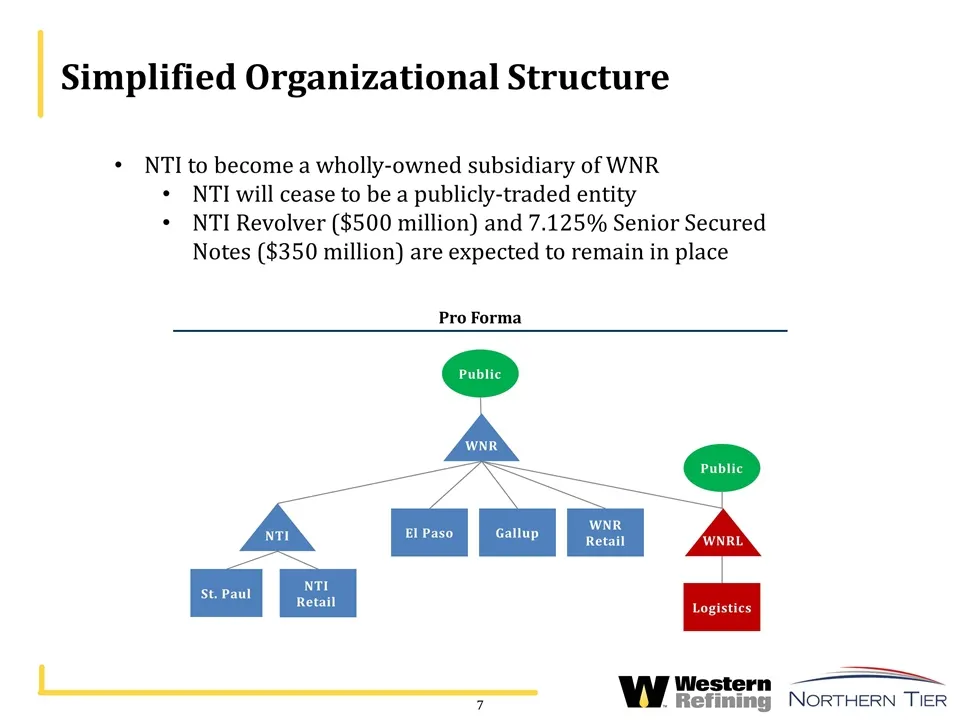
Slide 7: Simplified Organizational Structure
Simplified Organizational Structure NTI to become a wholly-owned subsidiary of WNR NTI will cease to be a publicly-traded entity NTI Revolver ($500 million) and 7.125% Senior Secured Notes ($350 million) are expected to remain in place Pro Forma Gallup WNR Retail WNRL St. Paul Logistics NTI Retail P
Slide 8: Benefits of Combining Under a Single C-Corp
Benefits of Combining Under a Single C-Corp Proven vehicle for operating and growing refining platform Broader pool of investor capital Expected to lower cost of capital and create a more competitive acquisition currency Improves ability to efficiently manage working capital and growth capital proje
Slide 9: Operational/Financial Synergy Opportunities
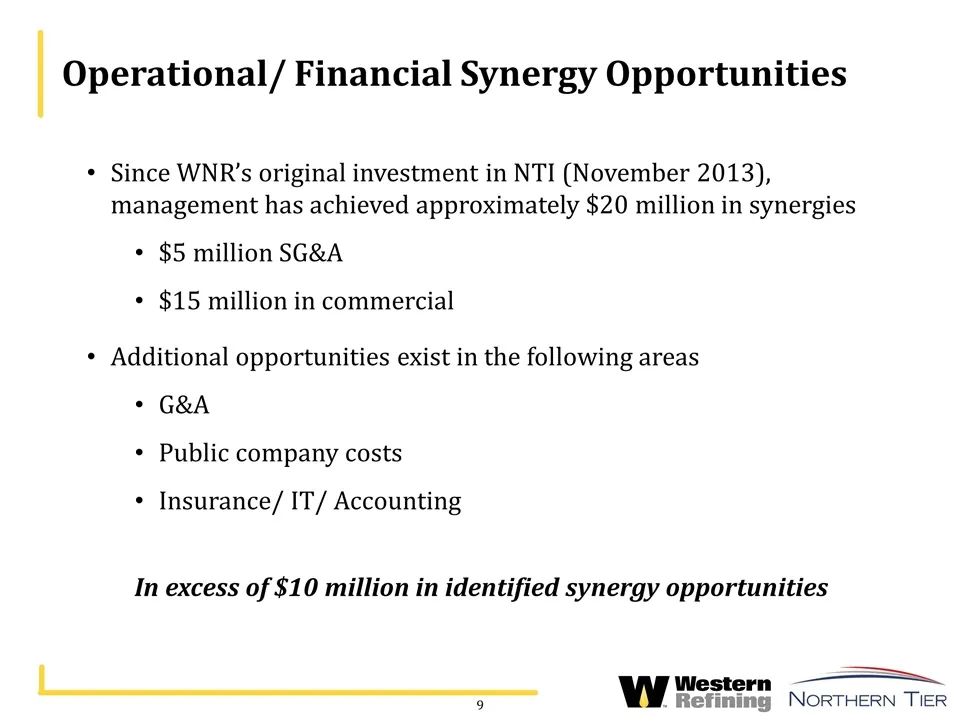
Operational/ Financial Synergy Opportunities Since WNR’s original investment in NTI (November 2013), management has achieved approximately $20 million in synergies $5 million SG&A $15 million in commercial Additional opportunities exist in the following areas G&A Public company costs Insurance/ IT/
Slide 10: Immediately Accretive to WNR EPS
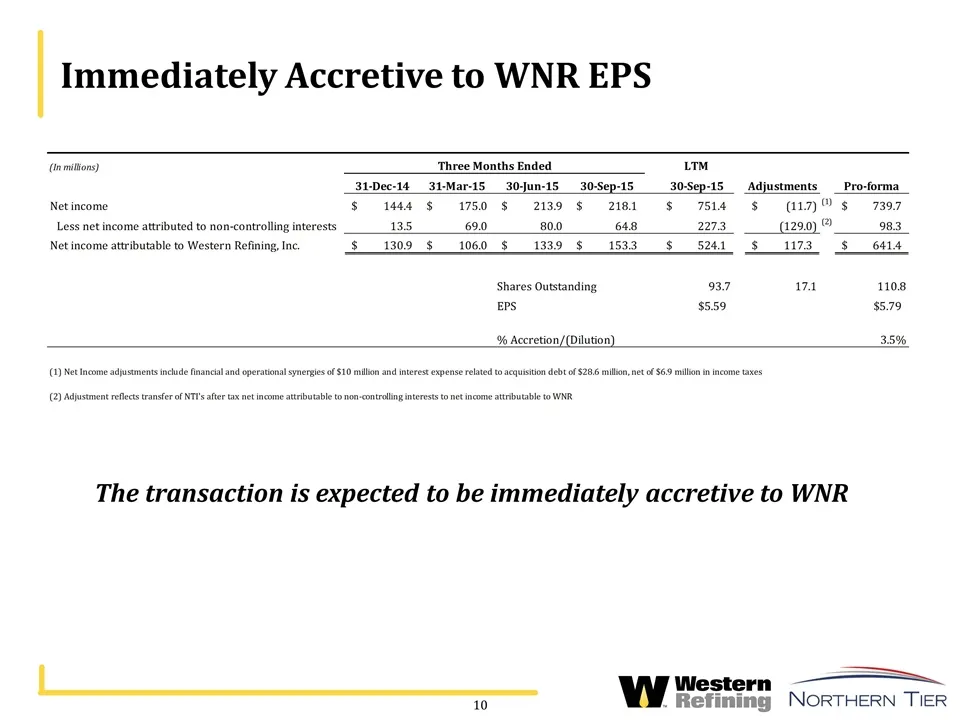
Immediately Accretive to WNR EPS The transaction is expected to be immediately accretive to WNR
Slide 11: Significant Upside Potential
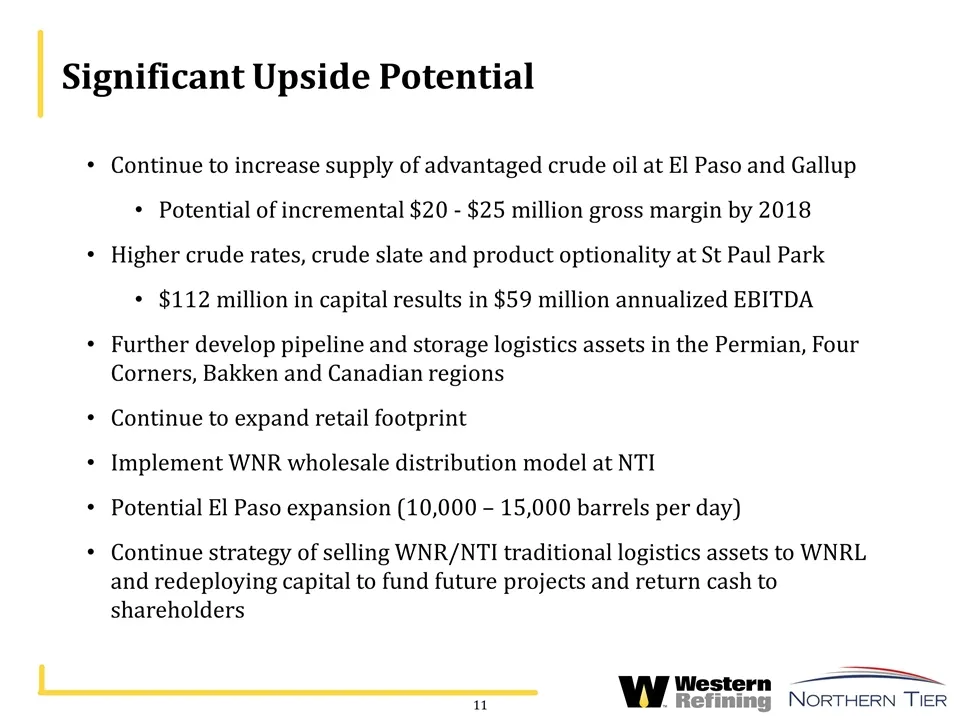
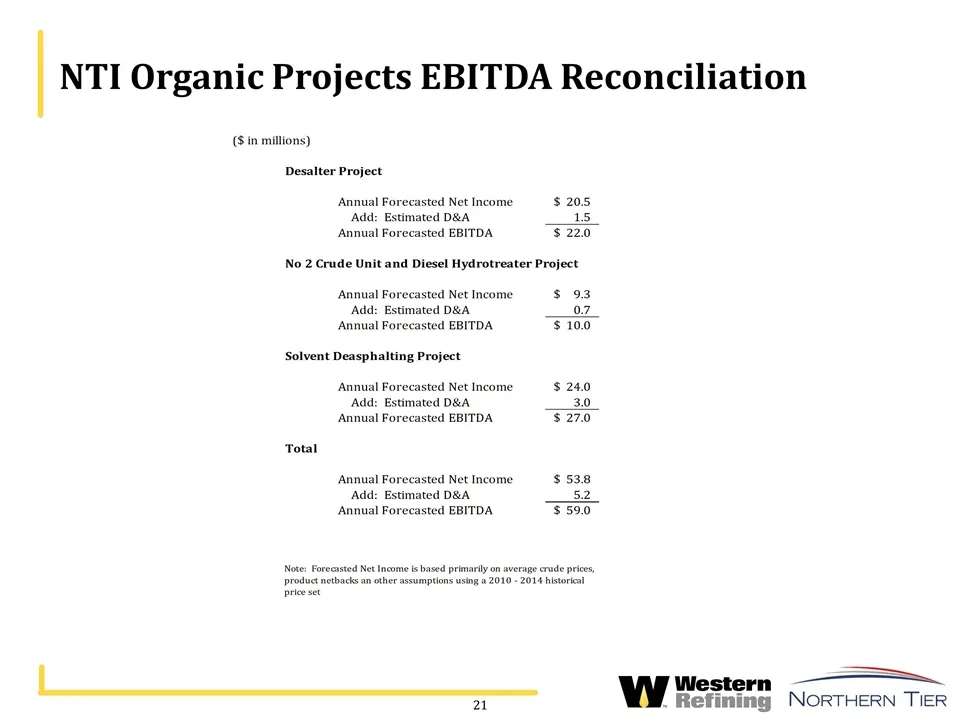
Significant Upside Potential Continue to increase supply of advantaged crude oil at El Paso and Gallup Potential of incremental $20 - $25 million gross margin by 2018 Higher crude rates, crude slate and product optionality at St Paul Park $112 million in capital results in $59 million annualized EBI
Slide 12: Proforma Capital Structure
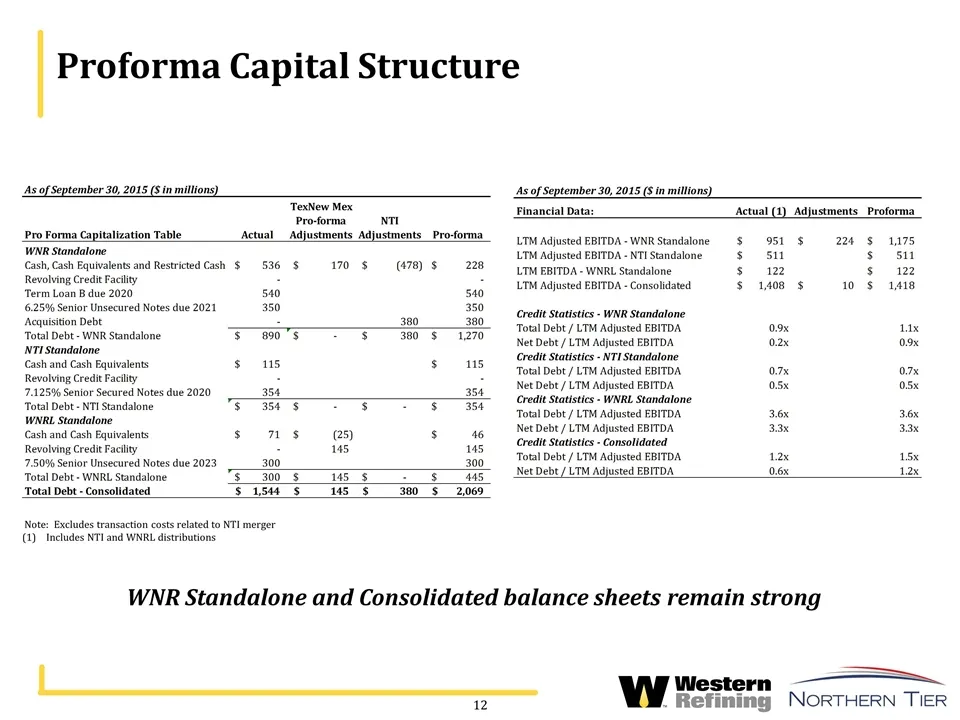
Proforma Capital Structure WNR Standalone and Consolidated balance sheets remain strong Note: Excludes transaction costs related to NTI merger Includes NTI and WNRL distributions
Slide 13: Governance Highlights
Governance Highlights Paul Foster to remain Executive Chairman Jeff Stevens to remain Chief Executive Officer Dave Lamp to be named President and Chief Operating Officer of Western WNR Board of Directors is not impacted; composition of NTI GP Board to change
Slide 14: Summary
Summary Combines three of the most profitable independent refineries (on a gross margin per barrel basis) 254,000 barrels per day crude oil capacity Diversified asset base with direct pipeline access to advantaged crude oil in the Permian/ Delaware, Four Corners, Bakken and Western Canada areas 528
Slide 15: Appendix
Appendix 15 wists: NORTHERN TIER
Slide 16: WNR Consolidated Adjusted EBITDA Reconciliation
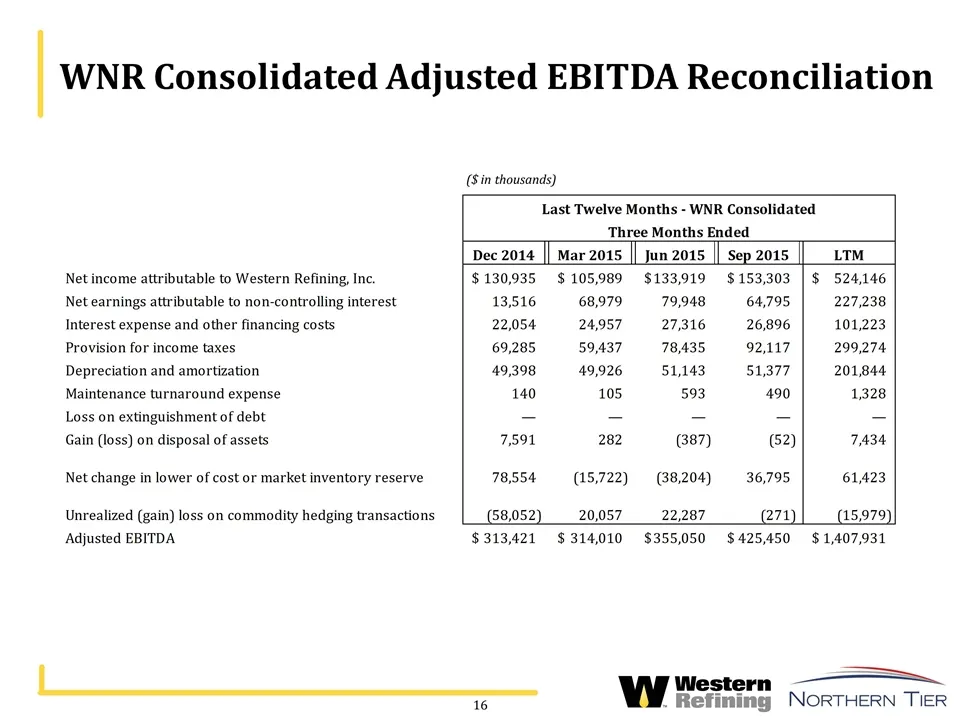
WNR Consolidated Adjusted EBITDA Reconciliation ($ in thousands)
Slide 17: WNR Standalone Adjusted EBITDA Reconciliation
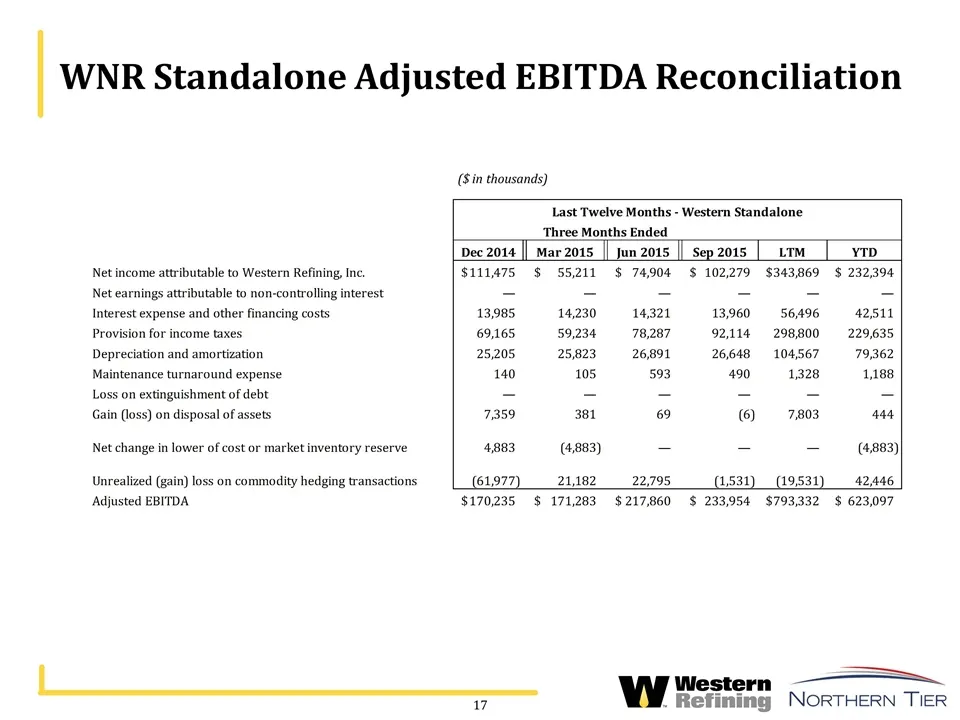
WNR Standalone Adjusted EBITDA Reconciliation ($ in thousands)
Slide 18: WNRL Standalone EBITDA Reconciliation
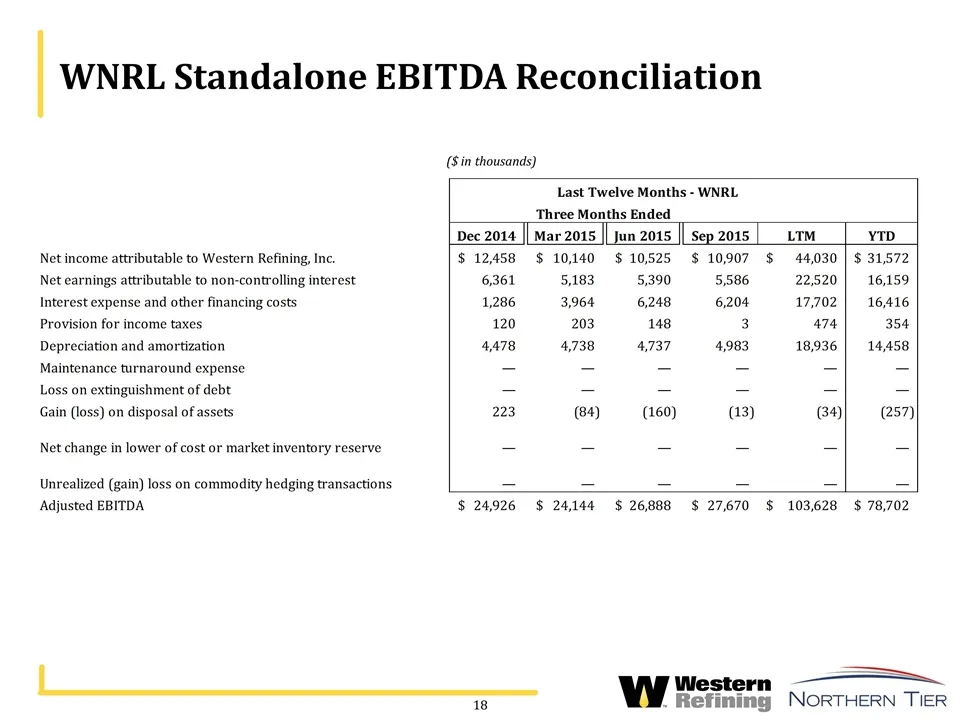
WNRL Standalone EBITDA Reconciliation ($ in thousands)
Slide 19: NTI Standalone Adjusted EBITDA Reconciliation
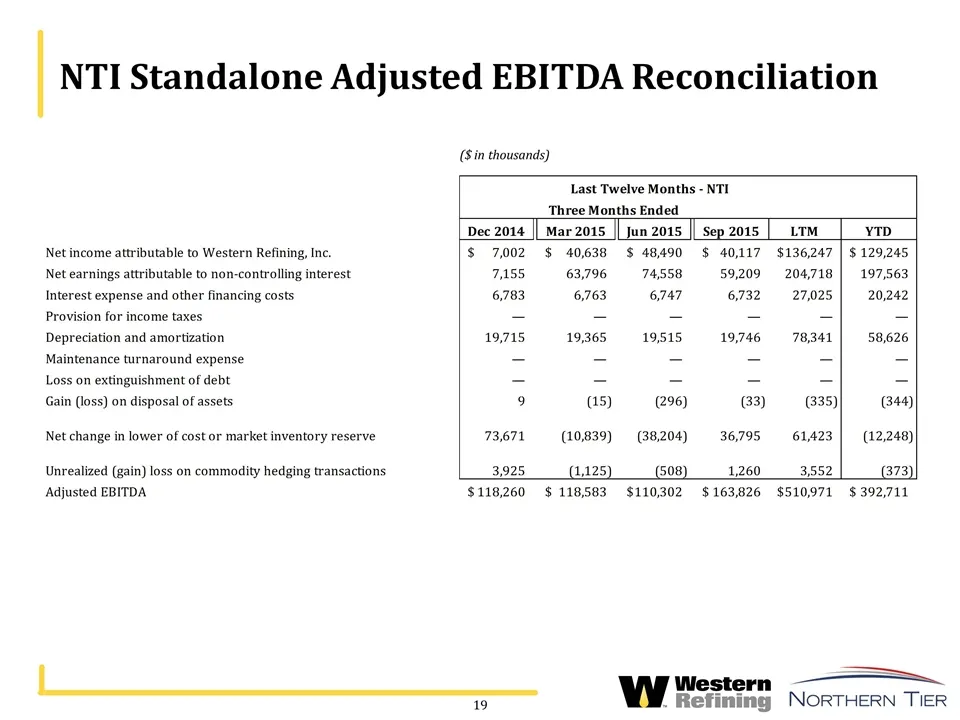
NTI Standalone Adjusted EBITDA Reconciliation ($ in thousands)
Slide 20: Pro-forma Reconciliation
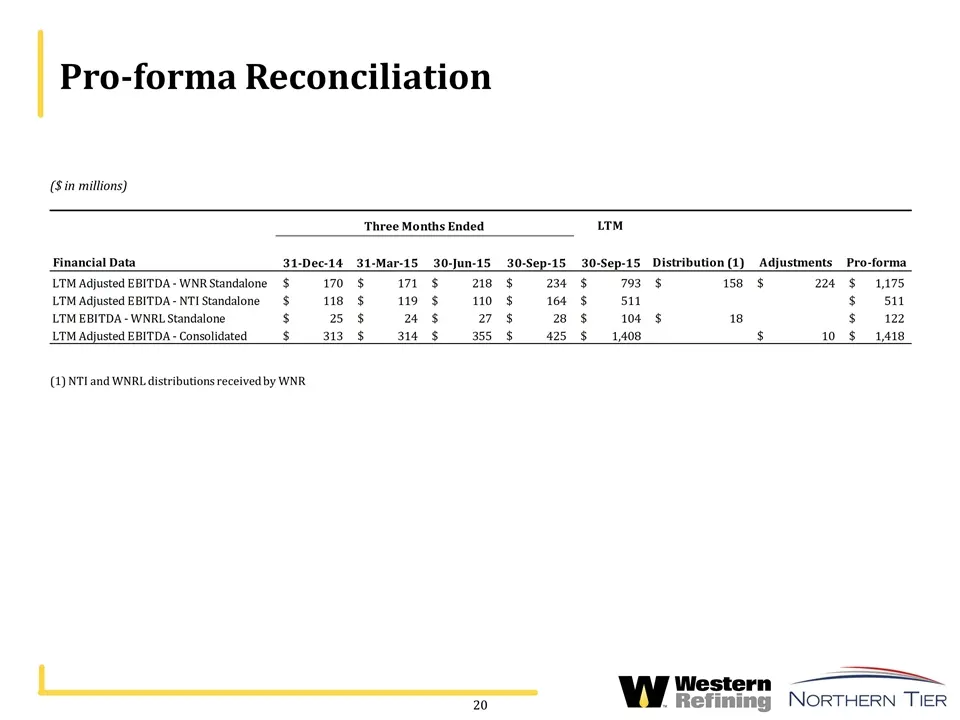
Pro-forma Reconciliation ($ in millions) (1) NTI and WNRL distributions received by WNR
Slide 21: NTI Organic Projects EBITDA Reconciliation
NTI Organic Projects EBITDA Reconciliation
Slide 22: WNR/NTI Adjusted EBITDA
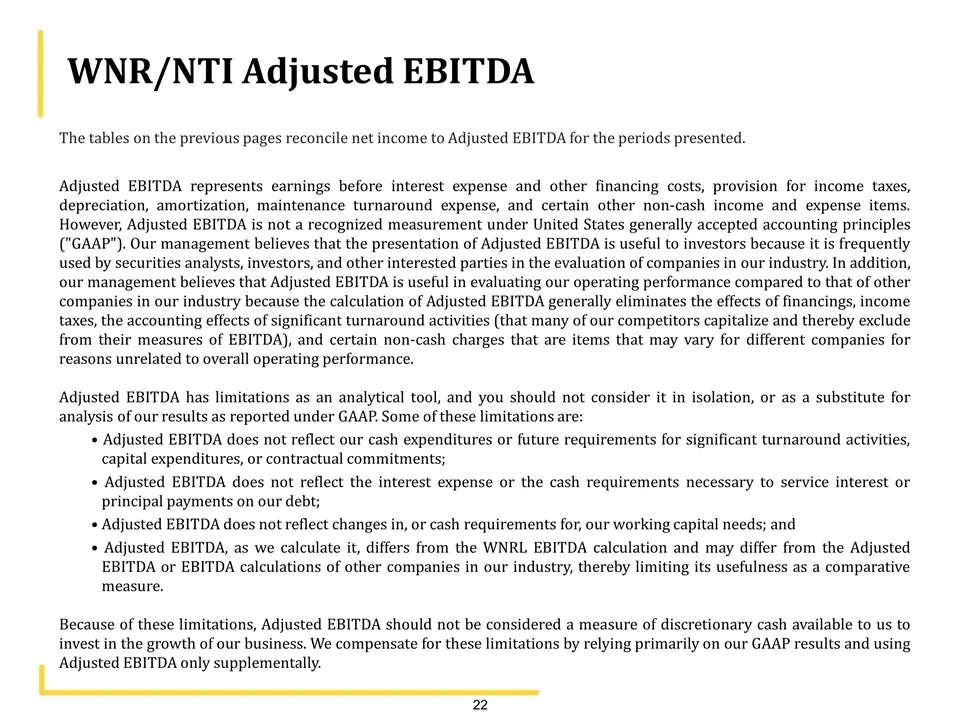
WNR/NTI Adjusted EBITDA The tables on the previous pages reconcile net income to Adjusted EBITDA for the periods presented. Adjusted EBITDA represents earnings before interest expense and other financing costs, provision for income taxes, depreciation, amortization, maintenance turnaround expense, a
Slide 23: WNRL EBITDA
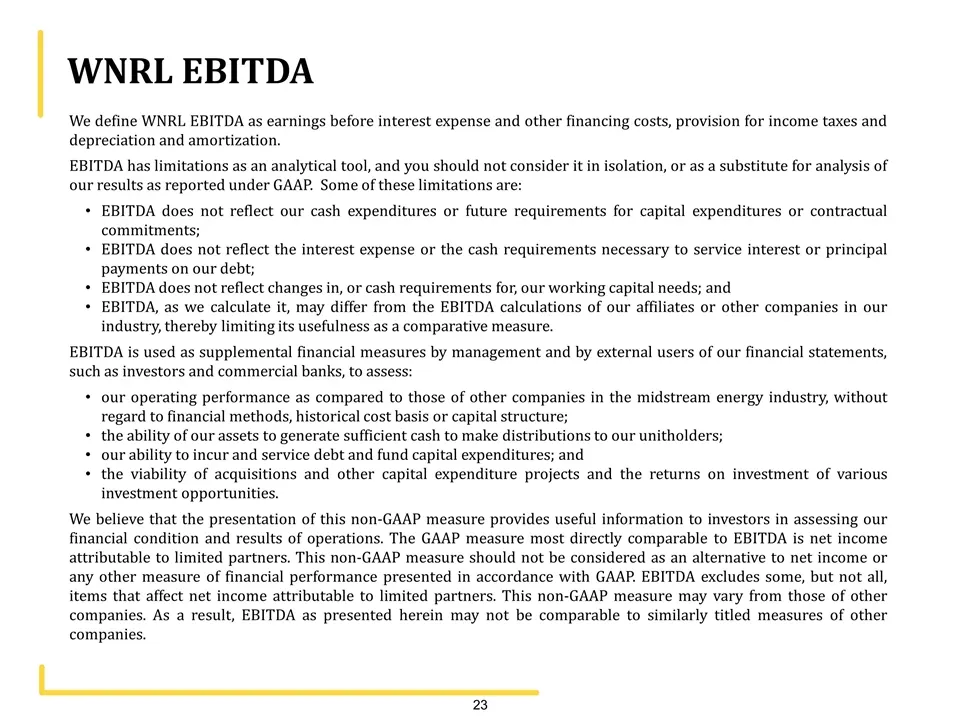
WNRL EBITDA We define WNRL EBITDA as earnings before interest expense and other financing costs, provision for income taxes and depreciation and amortization. EBITDA has limitations as an analytical tool, and you should not consider it in isolation, or as a substitute for analysis of our results as
Source: SEC EDGAR · 425 filed Dec 22, 2015
More decks from Northern Tier Energy LP
 2016 Wells Fargo West Coast Energy Conference21 slides · Jun 20, 2016
 Bank of America Merrill Lynch 2016 Energy Credit Conference21 slides · Jun 8, 2016
 RBC 2016 Global Energy and Power Executive Conference20 slides · Jun 7, 2016
 Morgan Stanley Refining Corporate Access Day 201622 slides · May 12, 2016
 Citi 2016 Global Energy & Utilities Conference21 slides · May 11, 2016
 Q1 2016 Earnings Presentation13 slides · May 3, 2016