Evoke plc · LSE:EVOK
Evoke — 888 Holdings — FY2017 Earnings Presentation
36 slides from Evoke's earnings presentation, Mar 20, 2018
Slide 1: Results for the Year Ended 31 December 2017
RESULTS FOR THE YEAR ENDED 31 DECEMBER 2017
Slide 2: Agenda
AGENDA Itai Frieberger | Strategic Review Aviad Kobrine | Financial Review Itai Pazner | Operational Review Itai Frieberger | Summary Q&A 2
Slide 3: Itai Frieberger, CEO | Strategic Review
ITAI FRIEBERGER, CEO | STRATEGIC REVIEW
Slide 4: 2017 – Resilience Through Diversification
2017 – RESILIENCE THROUGH DIVERSIFICATION
Slide 5: Aviad Kobrine, CFO | Financial Review
AVIAD KOBRINE, CFO | FINANCIAL REVIEW
Slide 6: 2017 Highlights
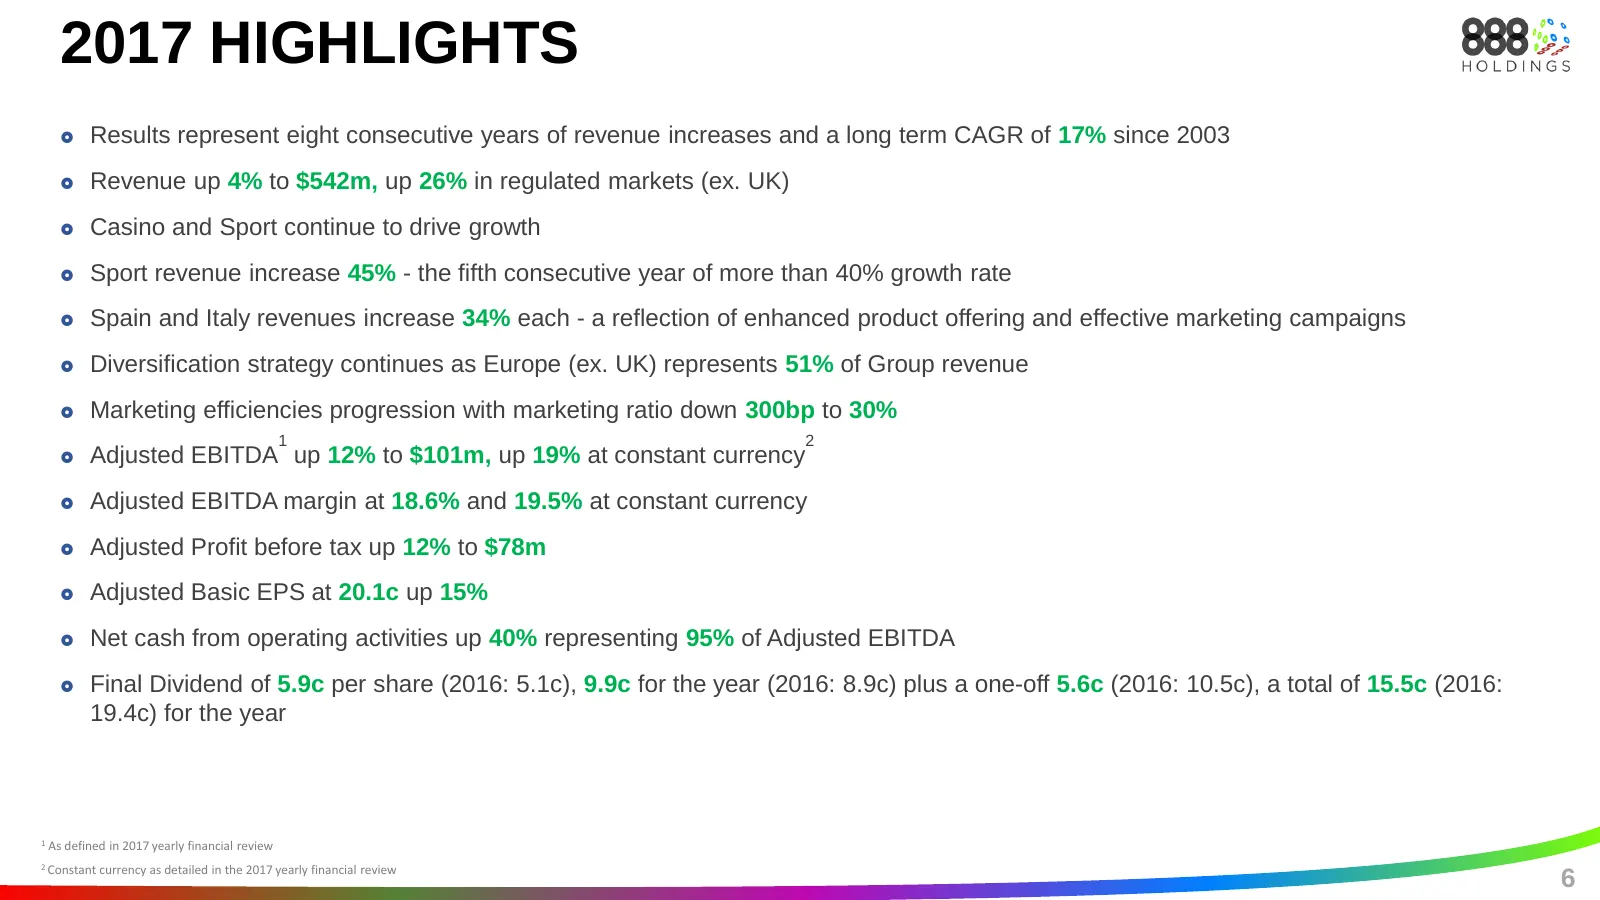
2017 HIGHLIGHTS Results represent eight consecutive years of revenue increases and a long term CAGR of 17% since 2003 Revenue up 4% to $542m, up 26% in regulated markets (ex. UK) Casino and Sport continue to drive growth Sport revenue increase 45% - the fifth consecutive year of more than 40
Slide 7: Profit and Loss Account
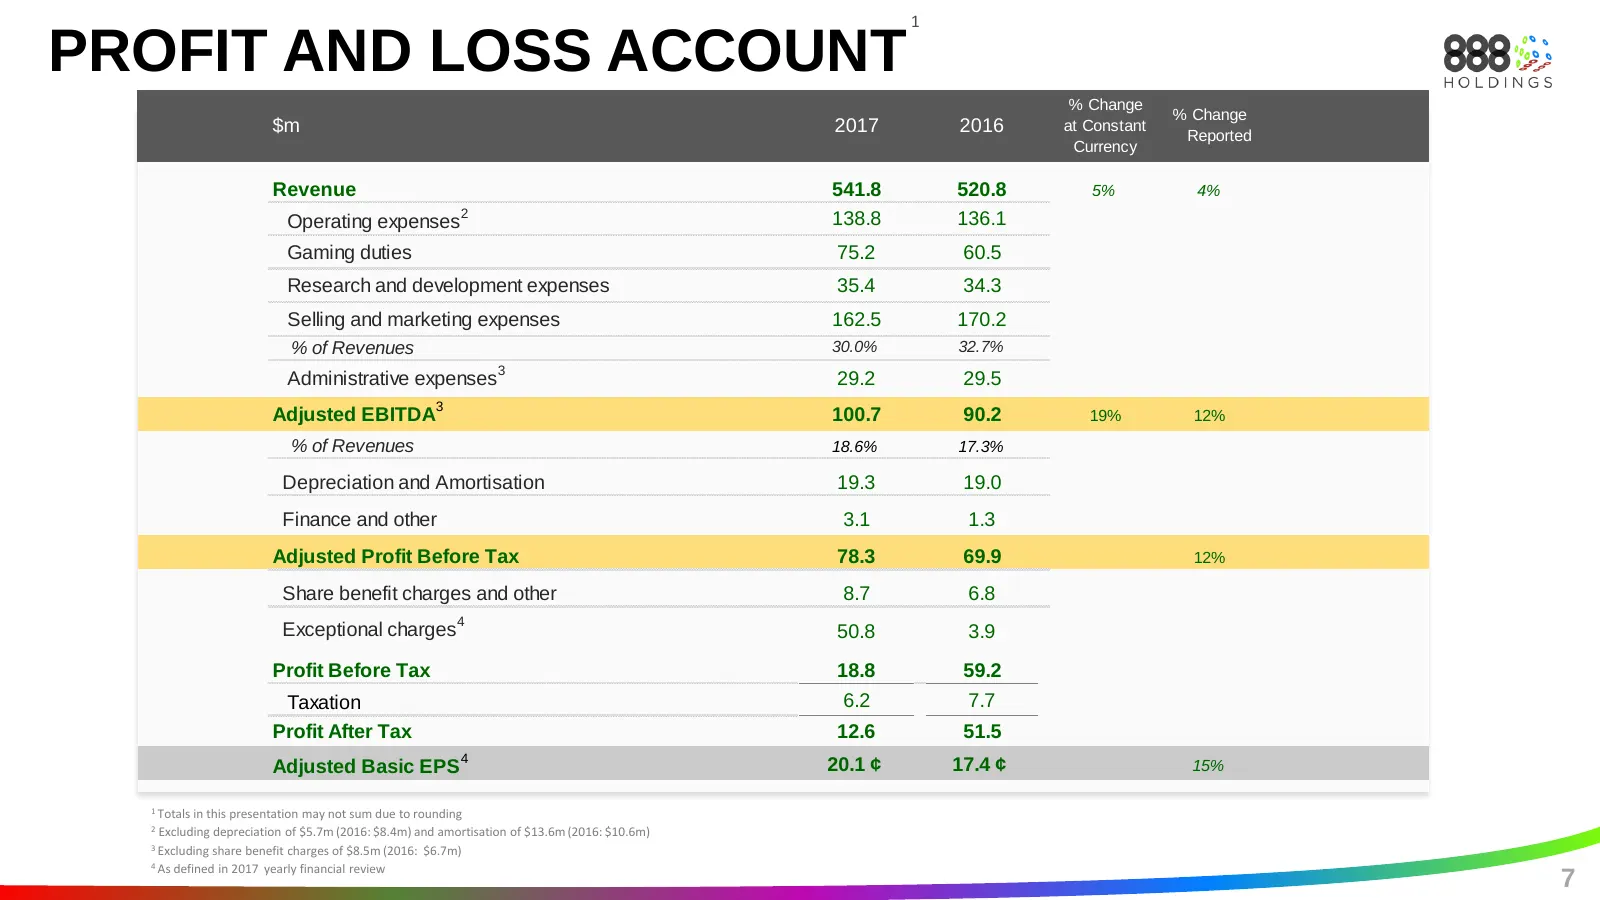
1 PROFIT AND LOSS ACCOUNT % Change % Change $m 2017 2016 at Constant Reported Currency Revenue 541.8 520.8 5% 4% 2 Operating expenses 138.8 136.1 Gaming duties 75.2 60.5 Research and development expenses 35.4 34.3 Selling and marketing expenses 162.5 170.2 % of Revenues 30.0% 32.7% Administrative ex
Slide 8: Group Revenue
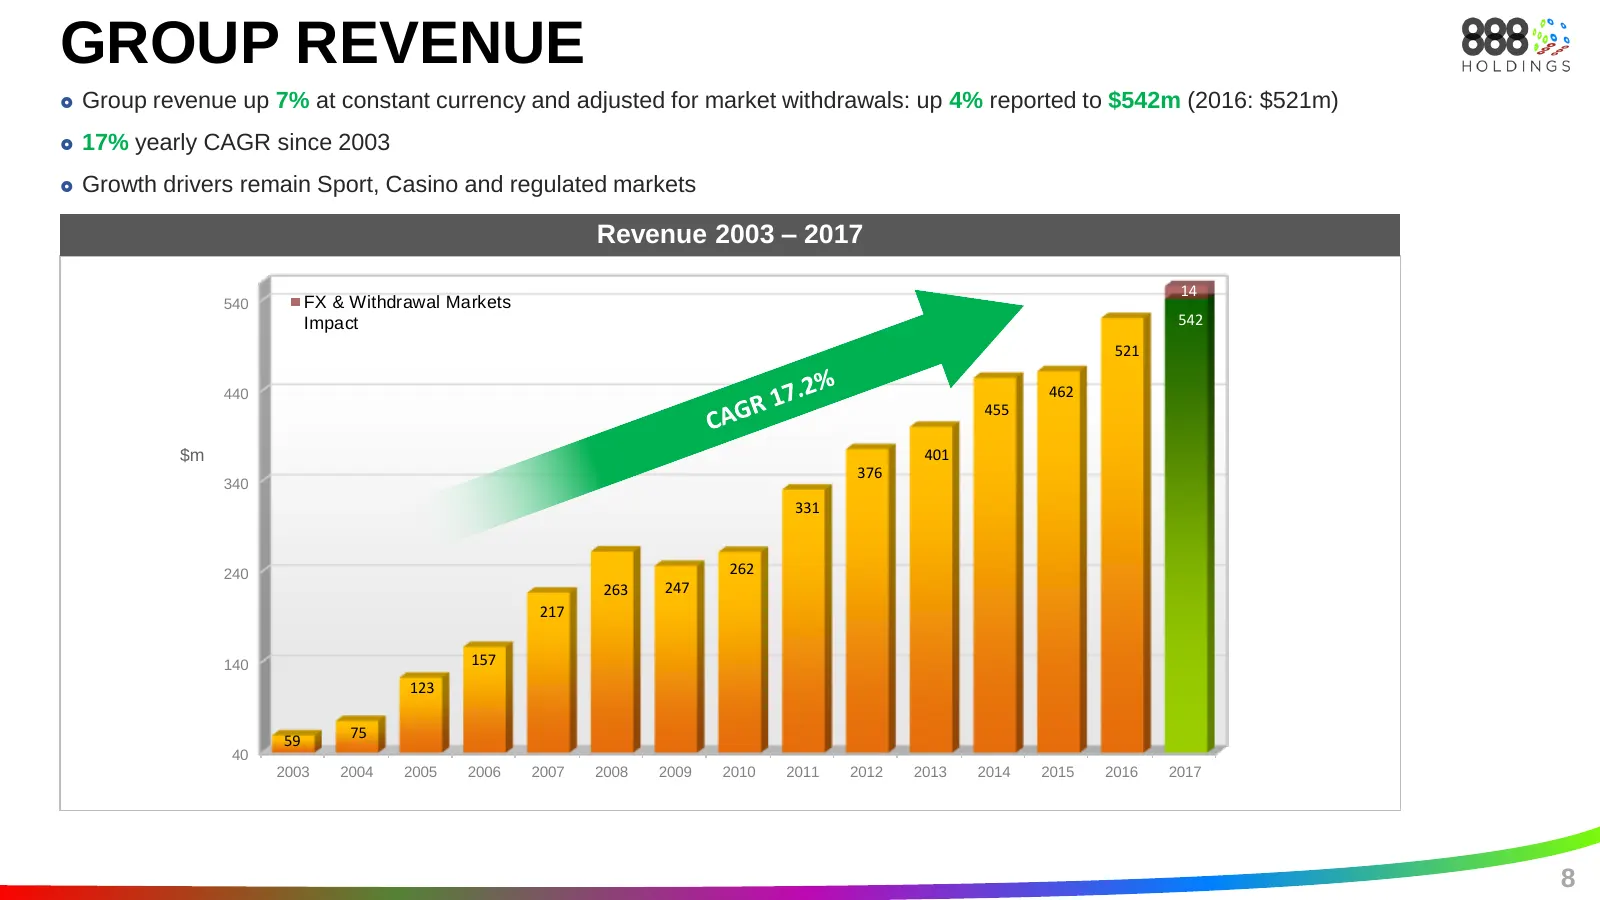
GROUP REVENUE Group revenue up 7% at constant currency and adjusted for market withdrawals: up 4% reported to $542m (2016: $521m) 17% yearly CAGR since 2003 Growth drivers remain Sport, Casino and regulated markets 12% half yearly CAGR since H1 2009 Revenue 2003 – 2017 14 540 FX & Withdrawal
Slide 9: Group Revenue
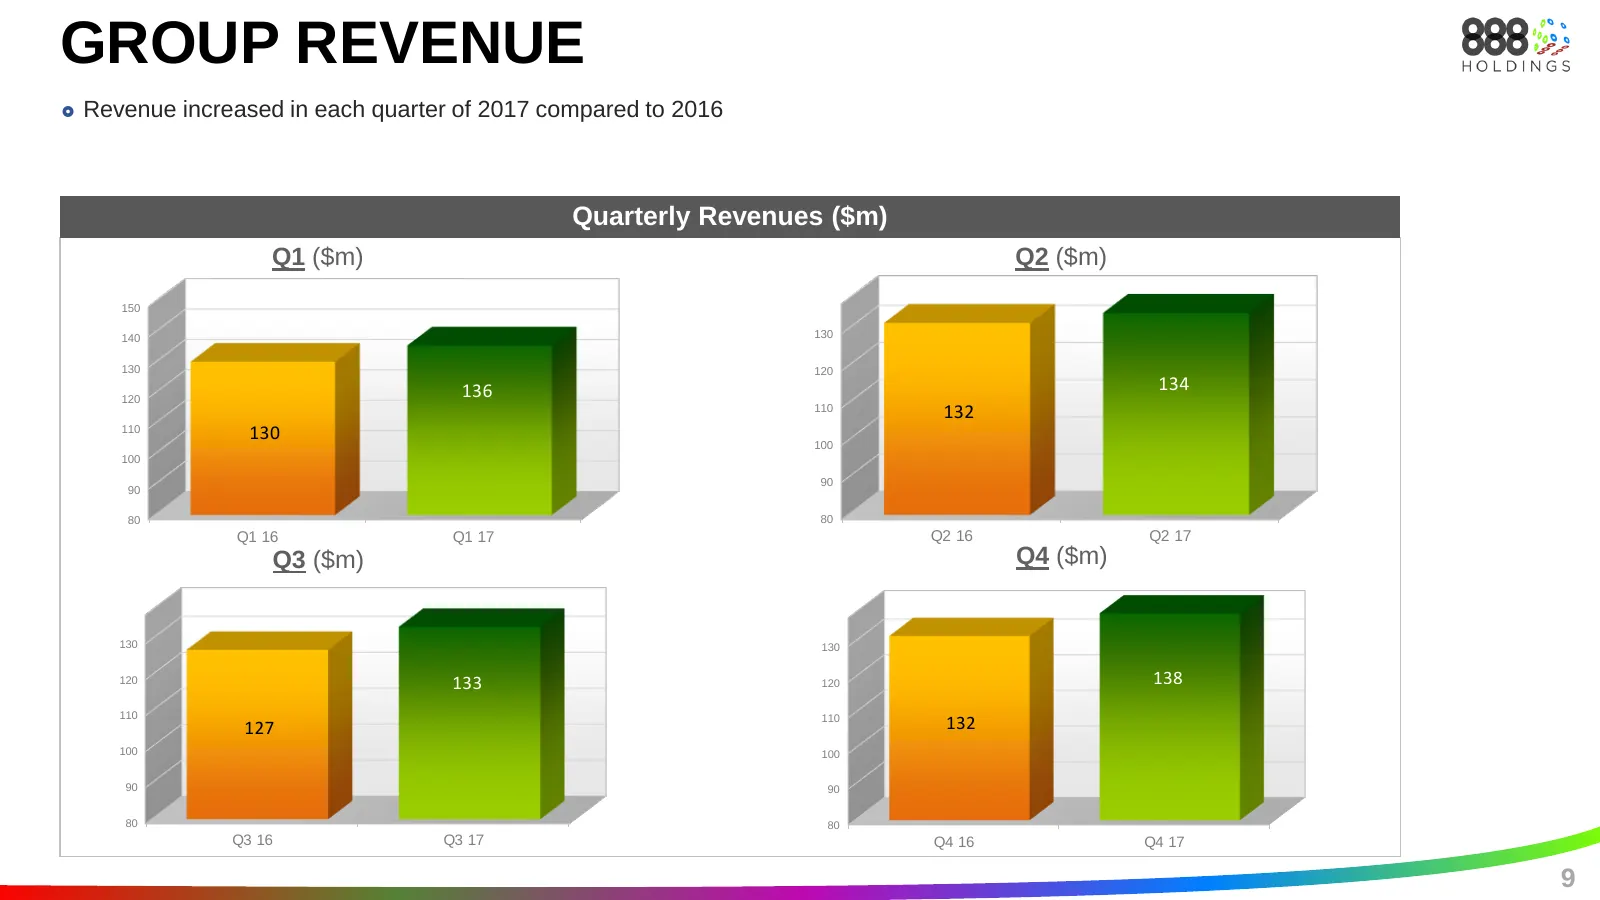
GROUP REVENUE Revenue increased in each quarter of 2017 compared to 2016 Quarterly Revenues ($m) Q1 ($m) Q2 ($m) 150 140 130 130 120 136 134 120 110 132 110 130 100 100 90 90 80 80 Q1 16 Q1 17 Q2 16 Q2 17 Q3 ($m) Q4 ($m) 130 130 120 133 120 138 110 127 110 132 100 100 90 90 80 80 Q3 16 Q3 17 Q4 16
Slide 10: Geographical Segmentation
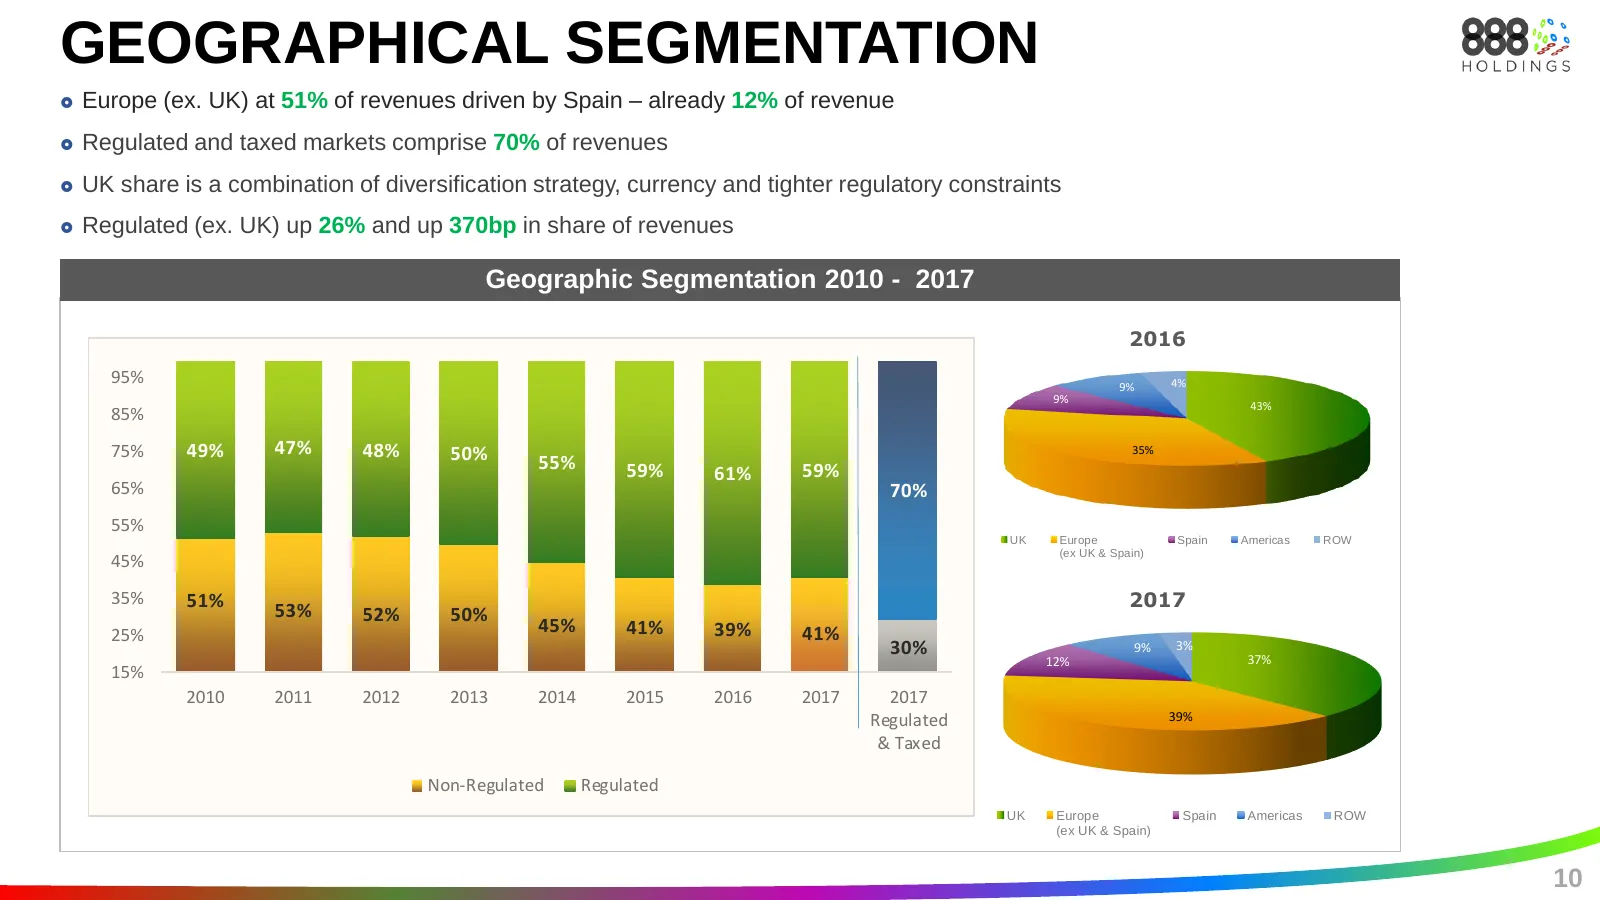
GEOGRAPHICAL SEGMENTATION Europe (ex. UK) at 51% of revenues driven by Spain – already 12% of revenue Regulated and taxed markets comprise 70% of revenues UK share is a combination of diversification strategy, currency and tighter regulatory constraints Regulated (ex. UK) up 26% and up 370bp
Slide 11: Revenue B2C
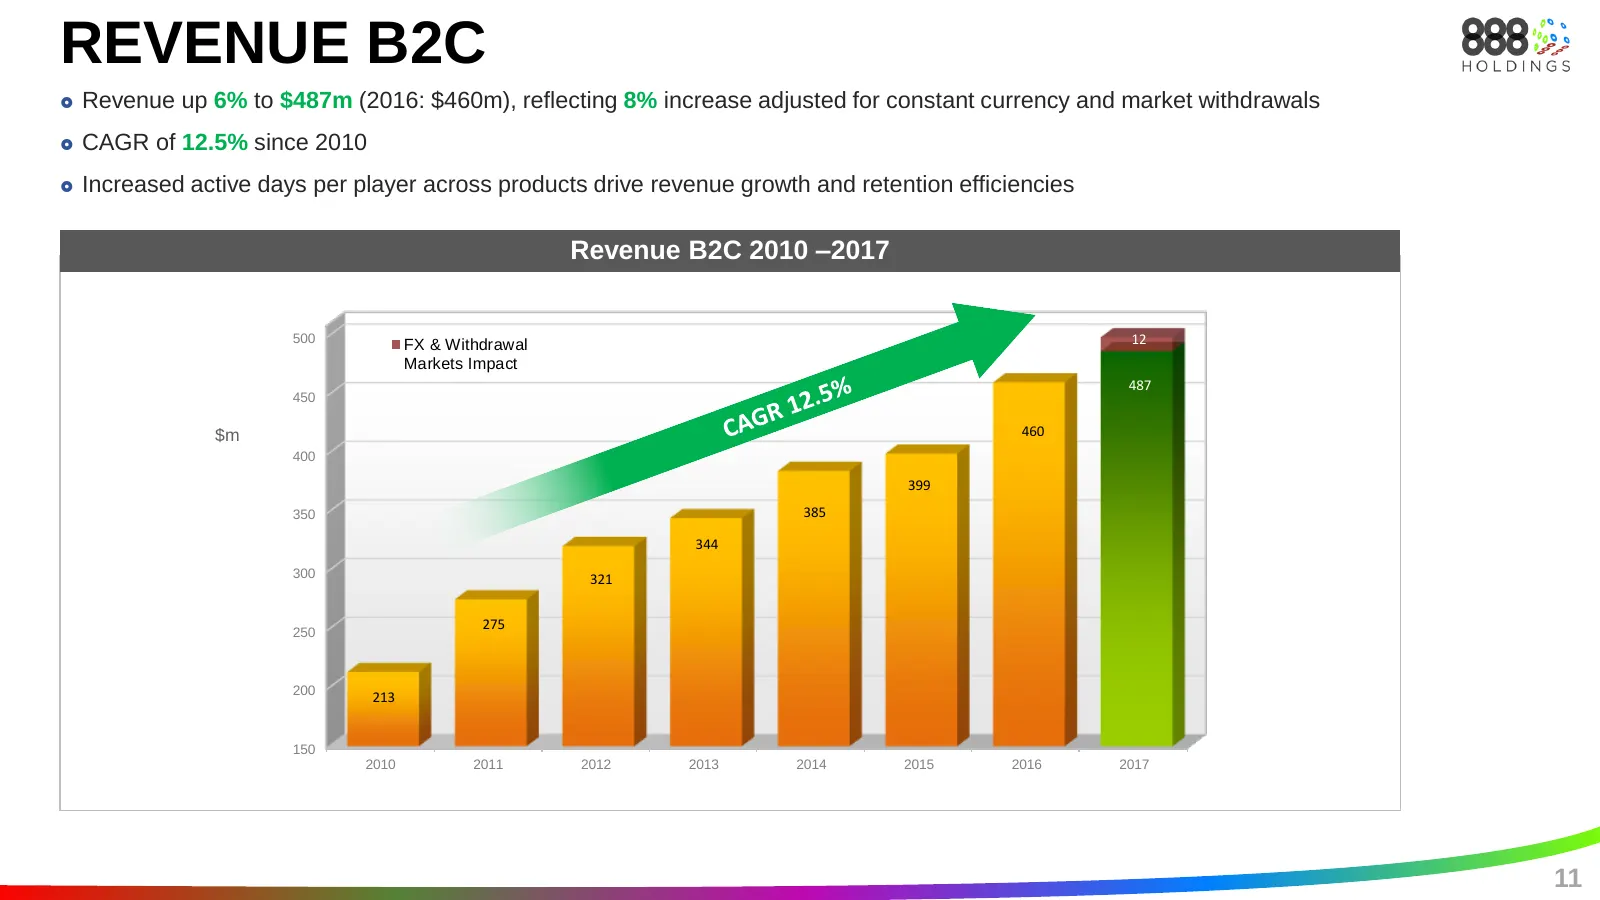
REVENUE B2C Revenue up 6% to $487m (2016: $460m), reflecting 8% increase adjusted for constant currency and market withdrawals CAGR of 12.5% since 2010 Increased active days per player across products drive revenue growth and retention efficiencies Revenue B2C 2010 –2017 500 FX & Withdrawal 12
Slide 12: Revenue Casino B2C
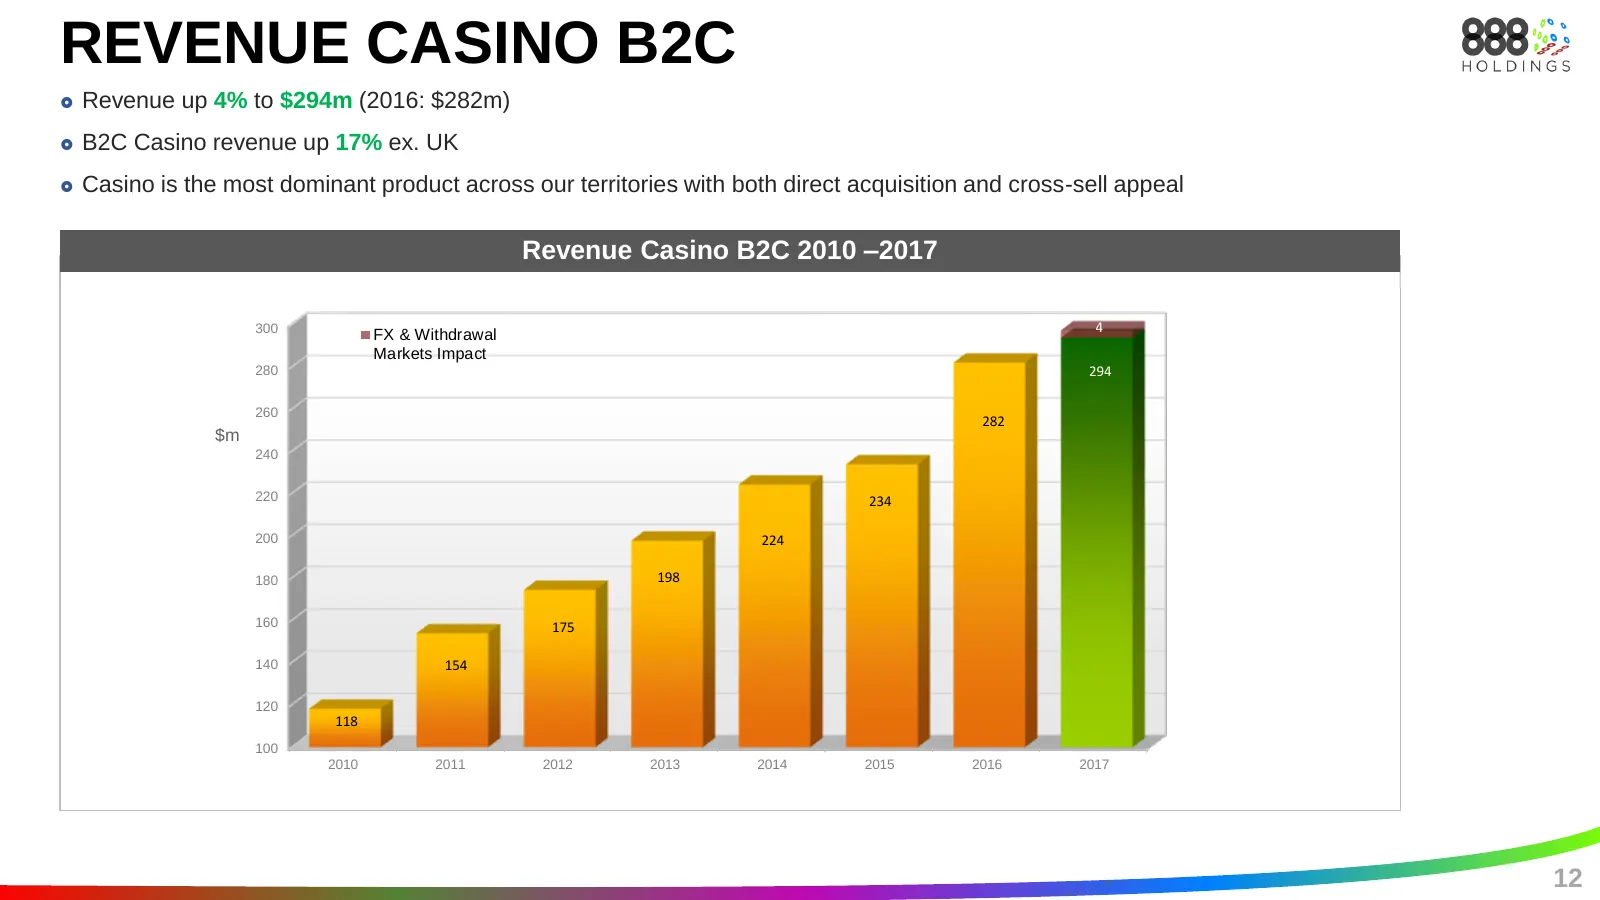
REVENUE CASINO B2C Revenue up 4% to $294m (2016: $282m) B2C Casino revenue up 17% ex. UK Casino is the most dominant product across our territories with both direct acquisition and cross-sell appeal Revenue Casino B2C 2010 –2017 300 4 FX & Withdrawal Markets Impact 280 294 260 282 $m 240 220 2
Slide 13: Revenue Sport B2C
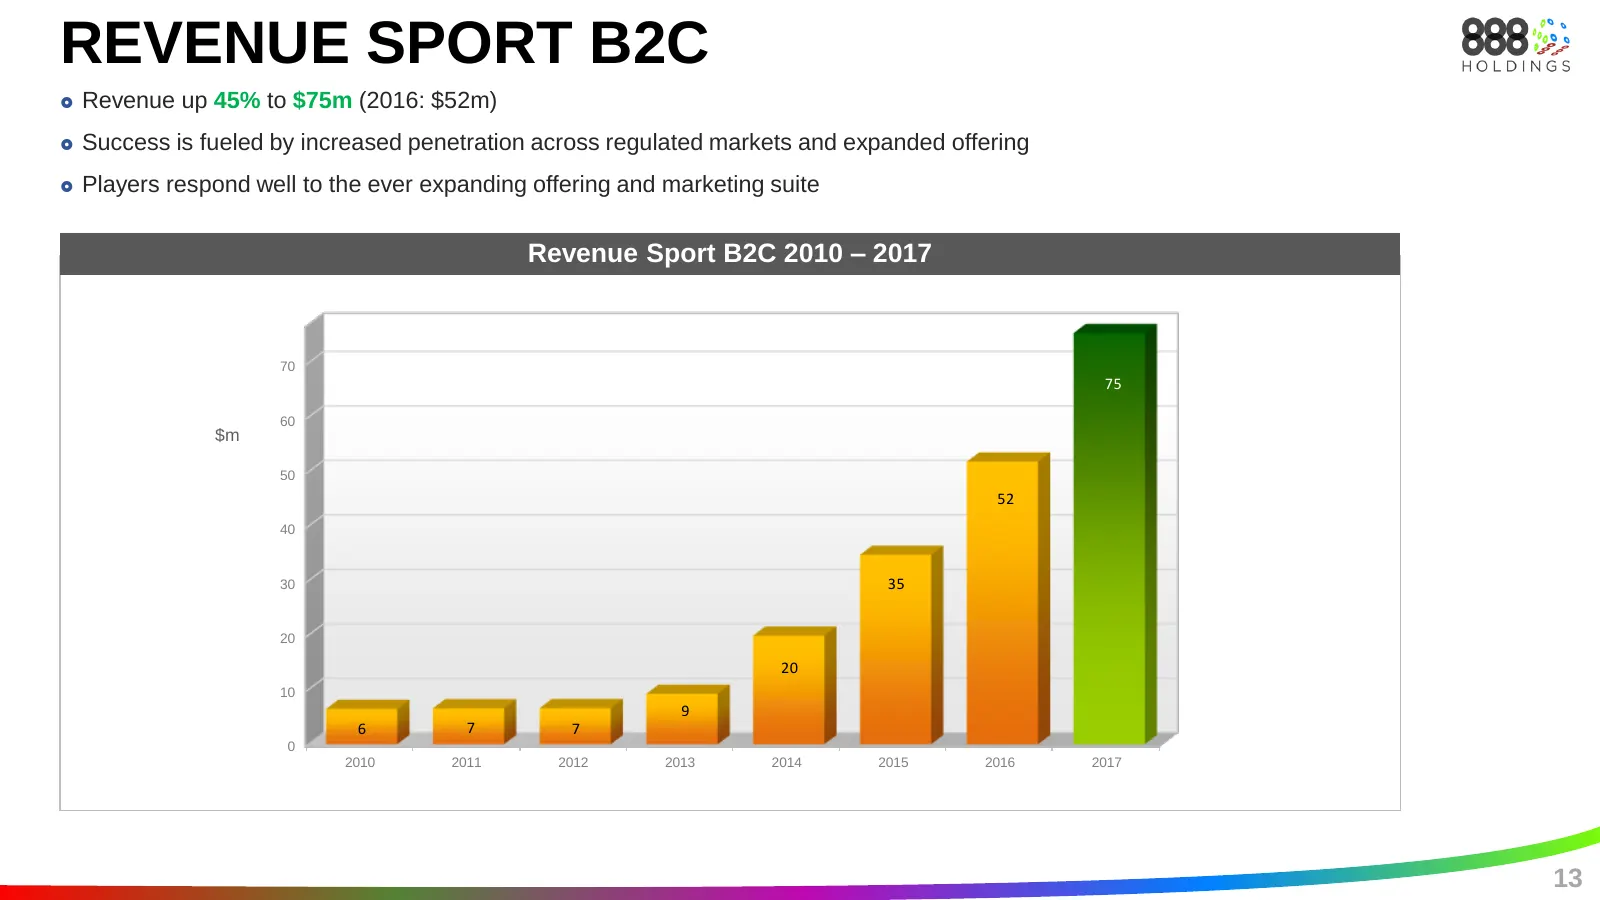
REVENUE SPORT B2C Revenue up 45% to $75m (2016: $52m) Success is fueled by increased penetration across regulated markets and expanded offering Players respond well to the ever expanding offering and marketing suite Revenue Sport B2C 2010 – 2017 70 75 60 $m 50 52 40 30 35 20 20 10 9 6 7 7 0 20
Slide 14: Revenue Poker B2C
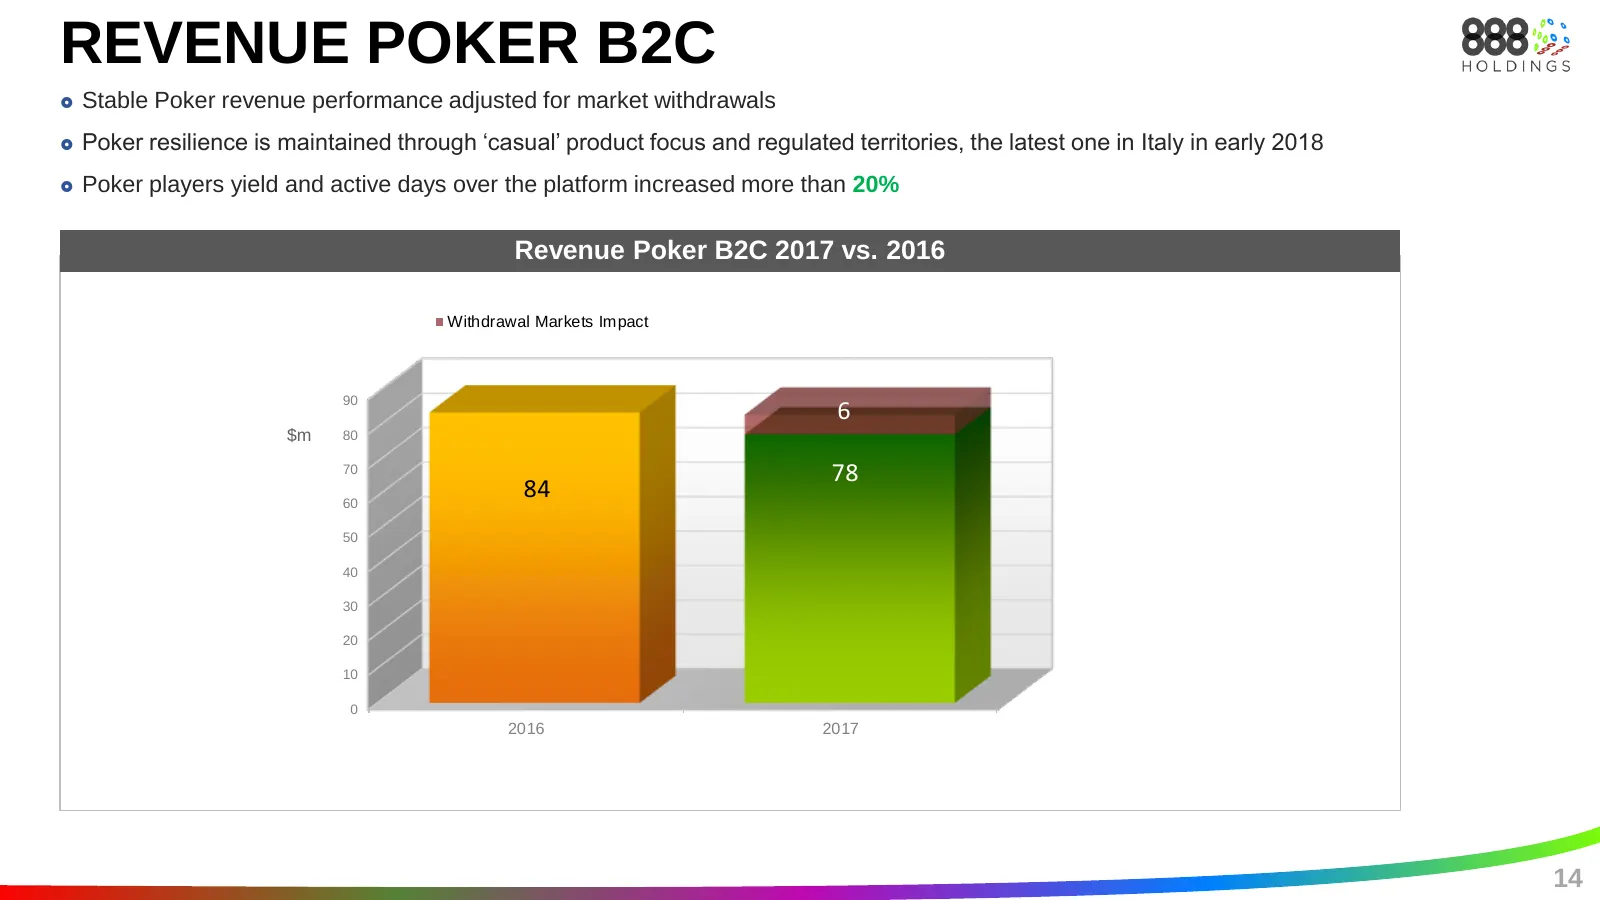
REVENUE POKER B2C Stable Poker revenue performance adjusted for market withdrawals Poker resilience is maintained through ‘casual’ product focus and regulated territories, the latest one in Italy in early 2018 Poker players yield and active days over the platform increased more than 20% Revenu
Slide 15: Revenue Bingo B2C
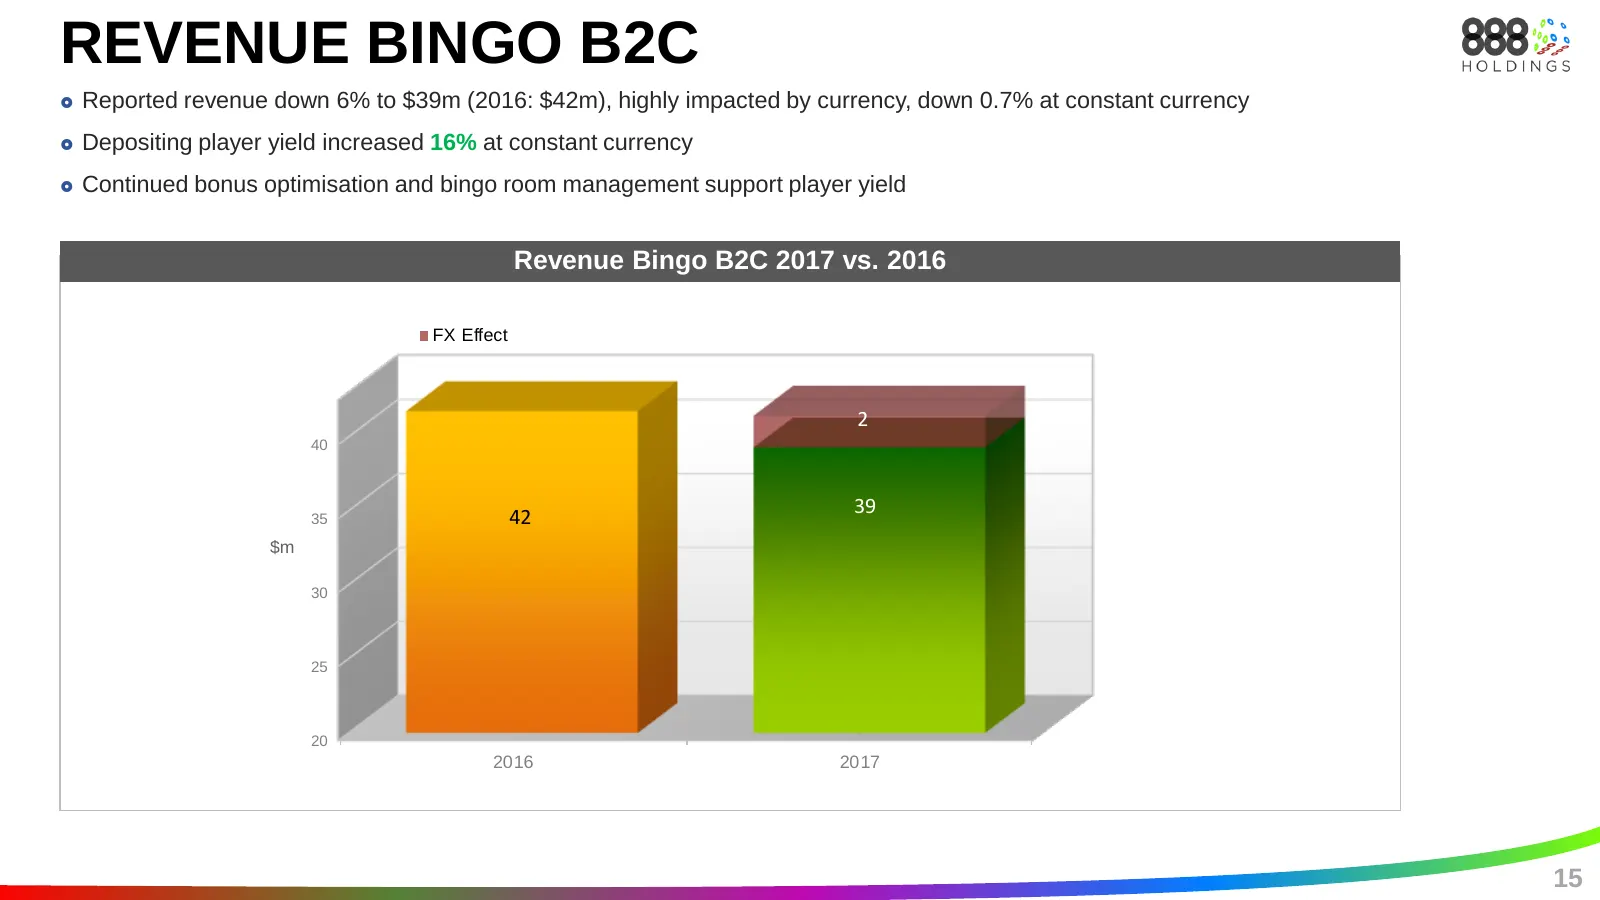
REVENUE BINGO B2C Reported revenue down 6% to $39m (2016: $42m), highly impacted by currency, down 0.7% at constant currency Depositing player yield increased 16% at constant currency Continued bonus optimisation and bingo room management support player yield Revenue Bingo B2C 2017 vs. 2016 FX
Slide 16: Marketing Cost
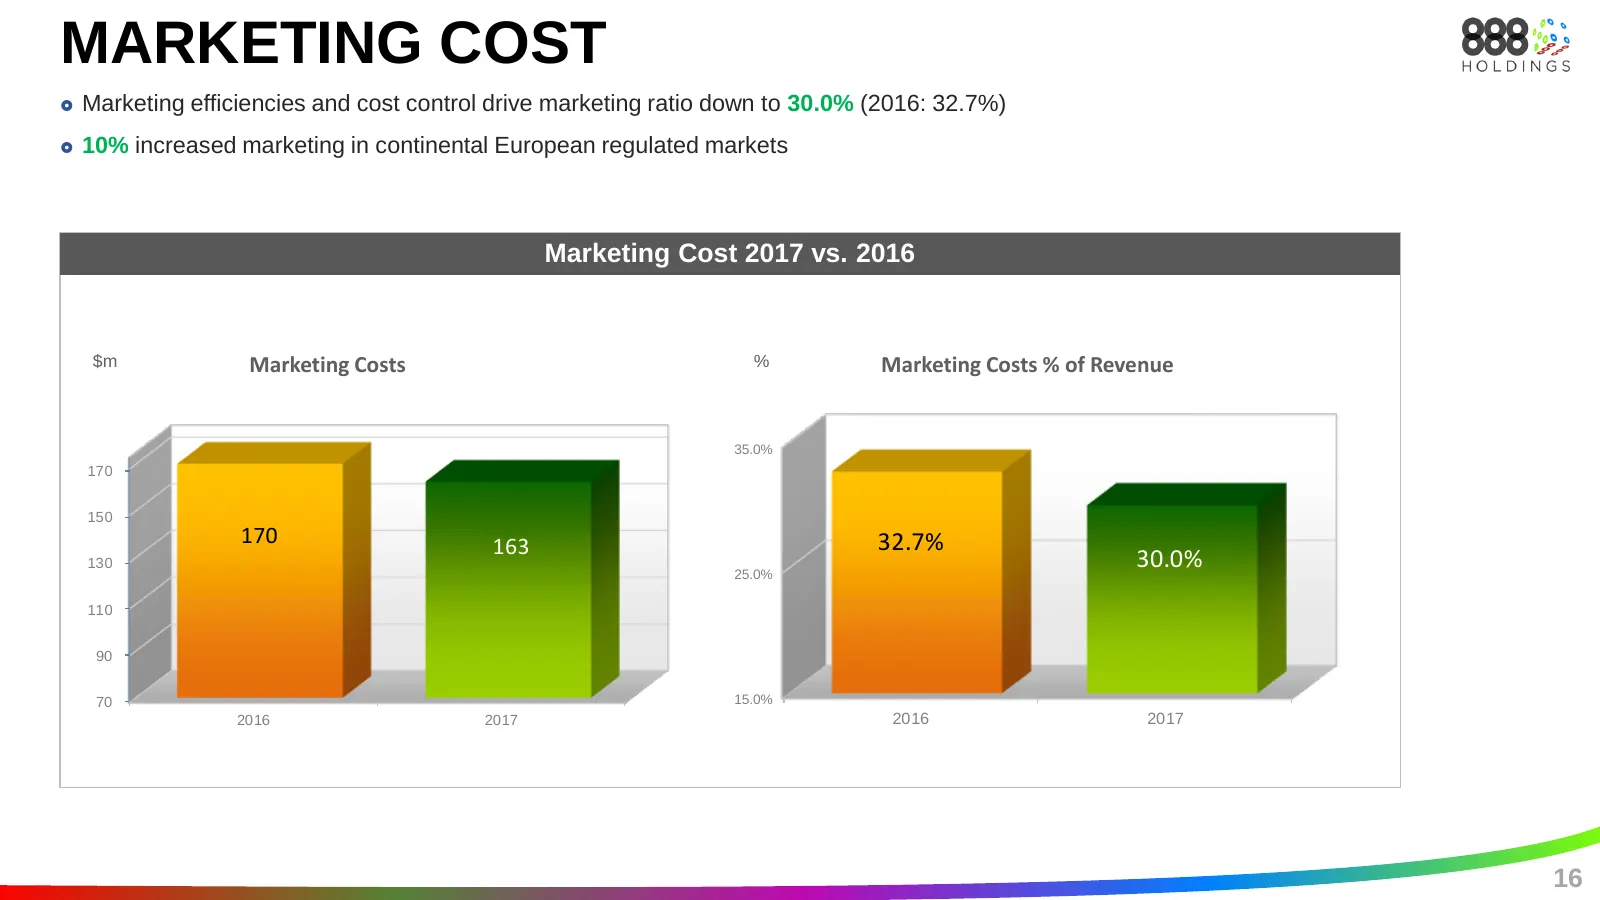
MARKETING COST Marketing efficiencies and cost control drive marketing ratio down to 30.0% (2016: 32.7%) 10% increased marketing in continental European regulated markets Marketing Cost 2017 vs. 2016 $m Marketing Costs % Marketing Costs % of Revenue 35.0% 170 150 170 163 32.7% 130 25.0% 30.0% 11
Slide 17: Cost Structure
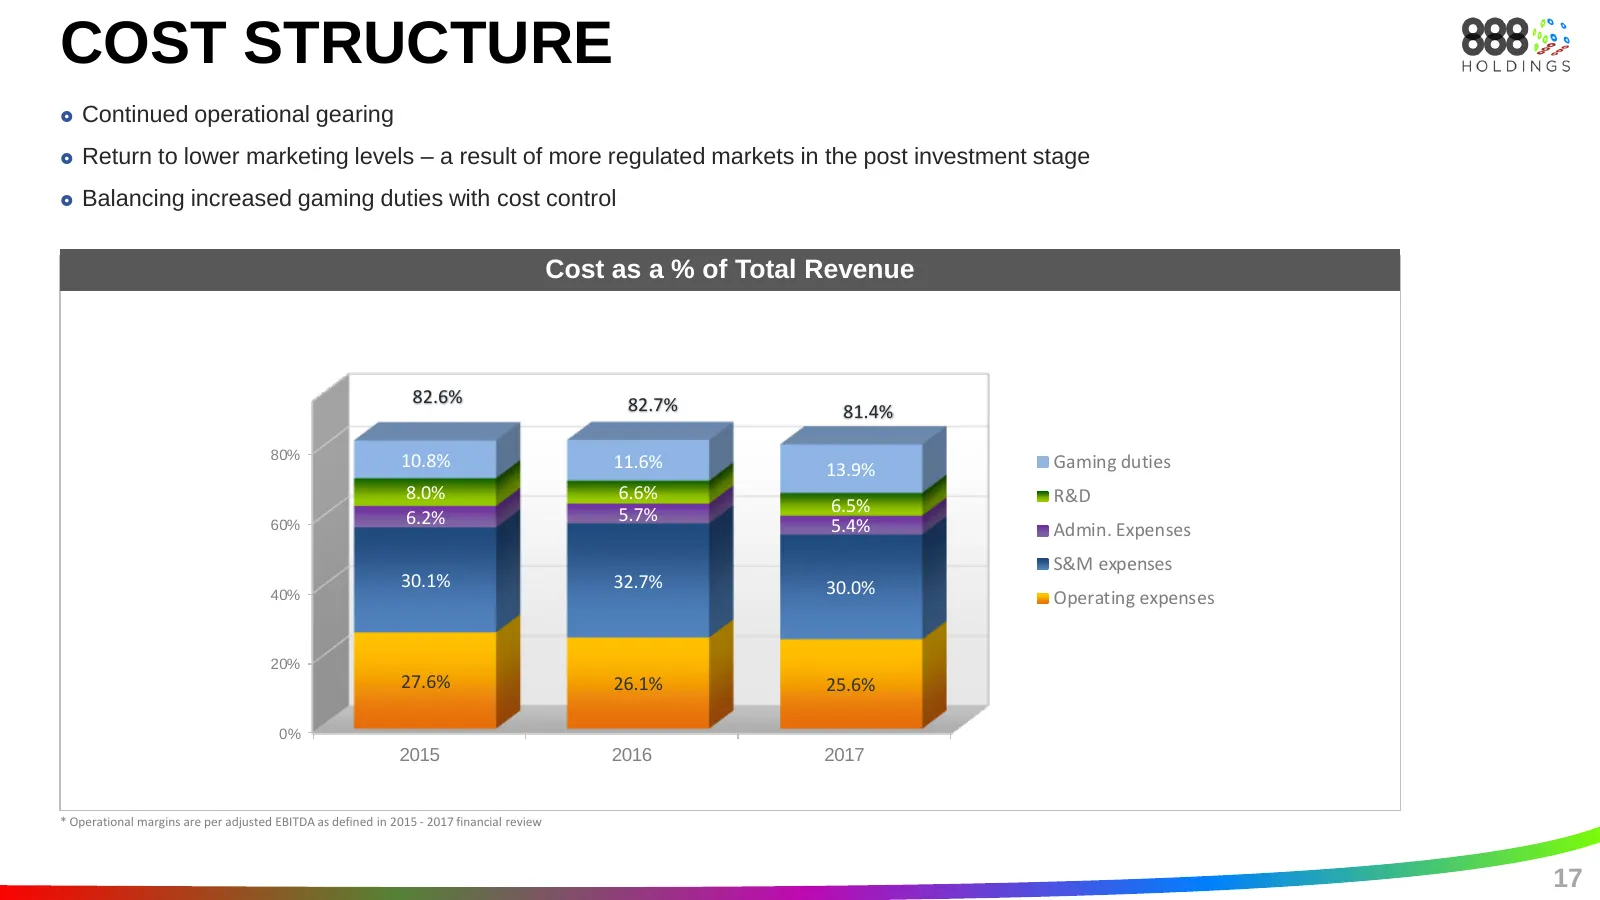
COST STRUCTURE Continued operational gearing Return to lower marketing levels – a result of more regulated markets in the post investment stage Balancing increased gaming duties with cost control Cost as a % of Total Revenue 82.6% 82.7% 81.4% 80% 10.8% 11.6% 13.9% Gaming duties 8.0% 6.6% R&D 5
Slide 18: Adjusted EBITDA and Margin
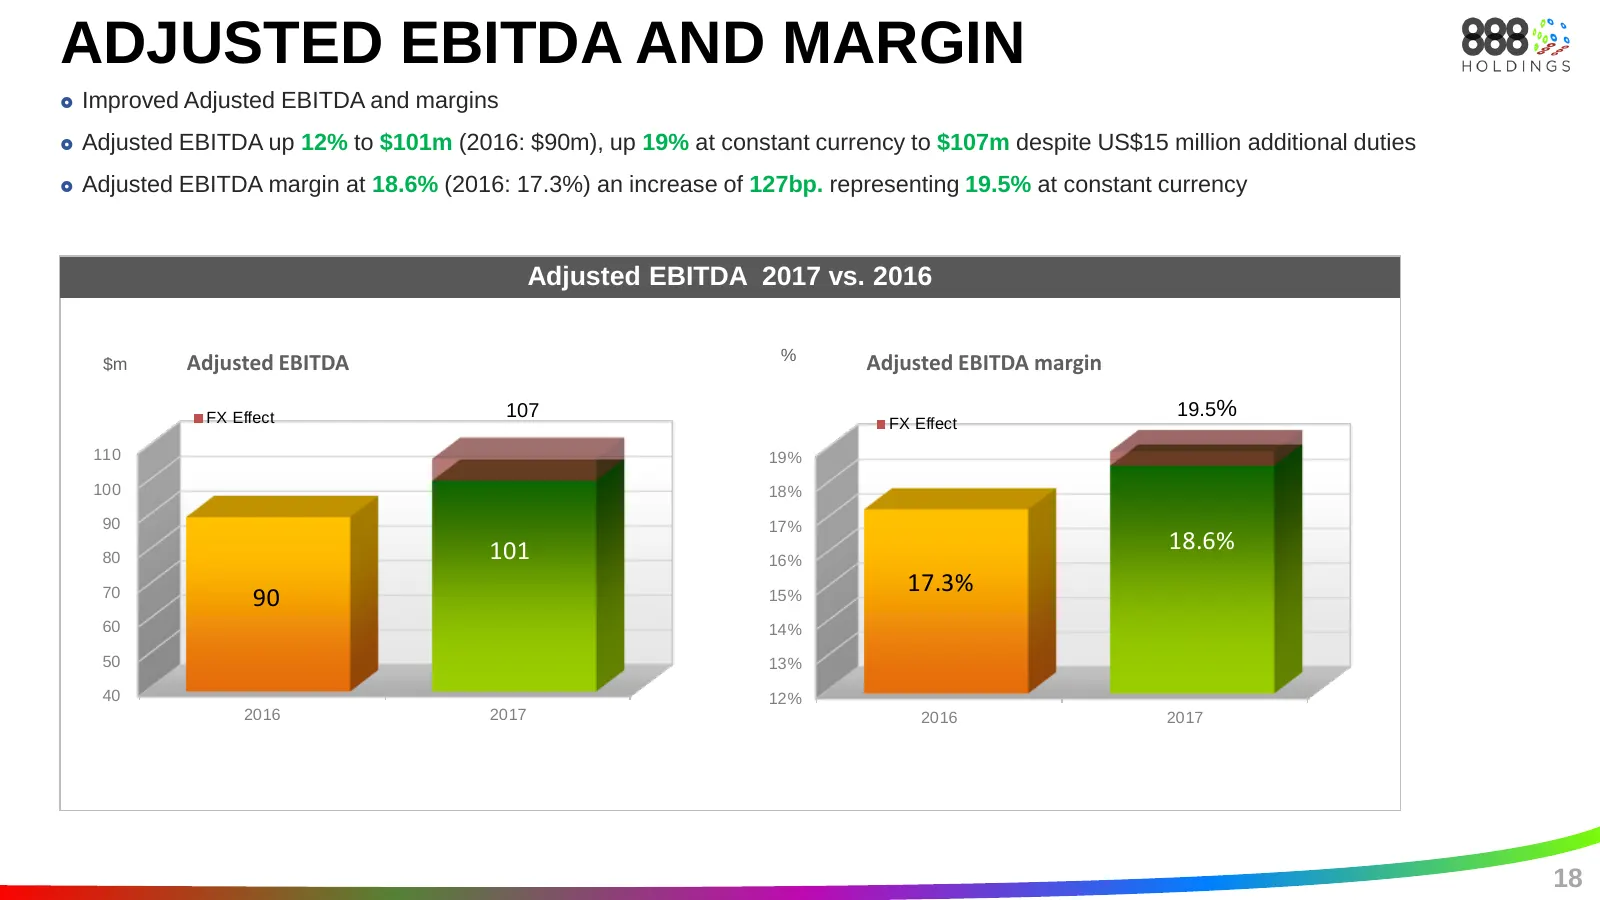
ADJUSTED EBITDA AND MARGIN Improved Adjusted EBITDA and margins Adjusted EBITDA up 12% to $101m (2016: $90m), up 19% at constant currency to $107m despite US$15 million additional duties Adjusted EBITDA margin at 18.6% (2016: 17.3%) an increase of 127bp. representing 19.5% at constant currency
Slide 19: Cash
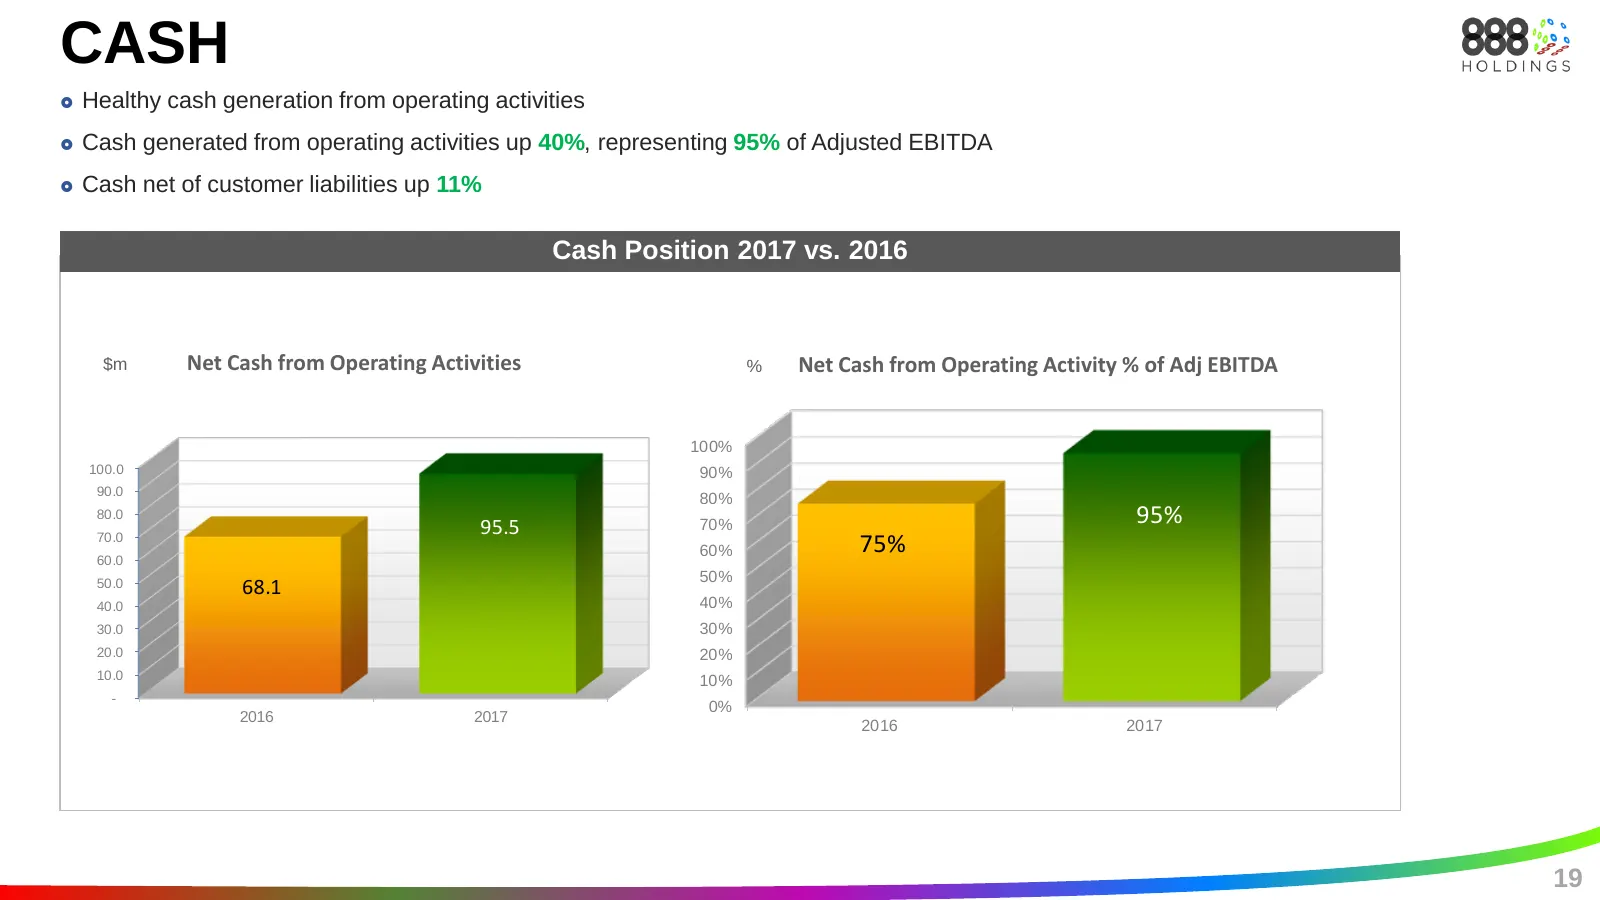
CASH Healthy cash generation from operating activities Cash generated from operating activities up 40%, representing 95% of Adjusted EBITDA Cash net of customer liabilities up 11% Cash Position 2017 vs. 2016 $m Net Cash from Operating Activities % Net Cash from Operating Activity % of Adj EBIT
Slide 20: Dividend
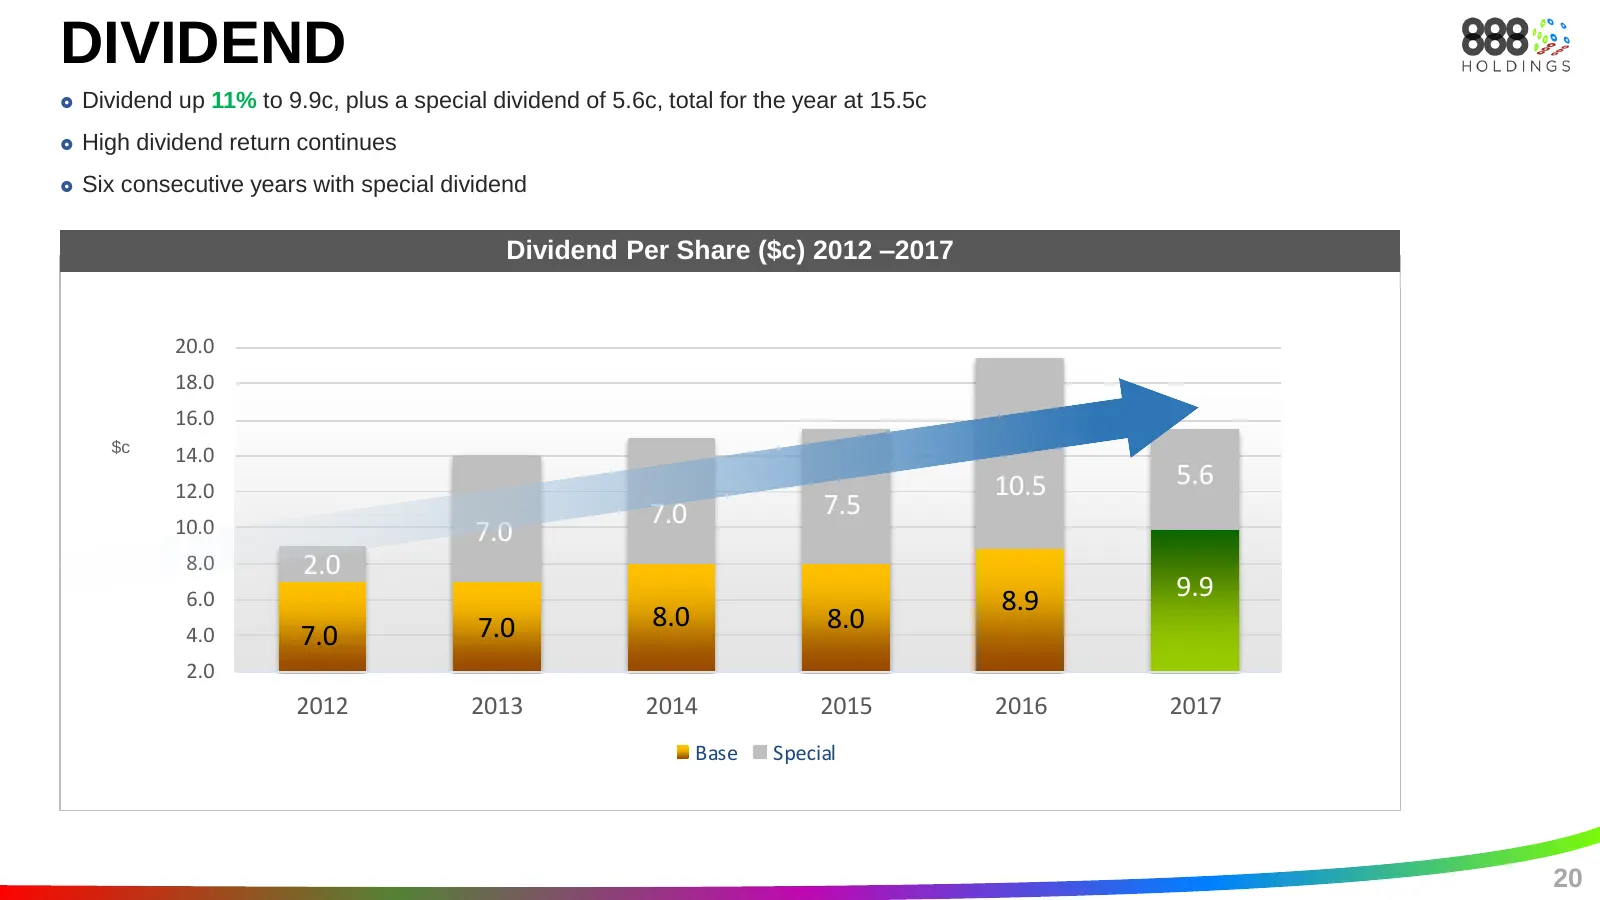
DIVIDEND Dividend up 11% to 9.9c, plus a special dividend of 5.6c, total for the year at 15.5c High dividend return continues Six consecutive years with special dividend Dividend Per Share ($c) 2012 –2017 20.0 18.0 16.0 $c 14.0 12.0 10.5 5.6 7.0 7.5 10.0 7.0 8.0 2.0 6.0 8.9 9.9 7.0 8.0 8.0 4.0
Slide 21: Balance Sheet
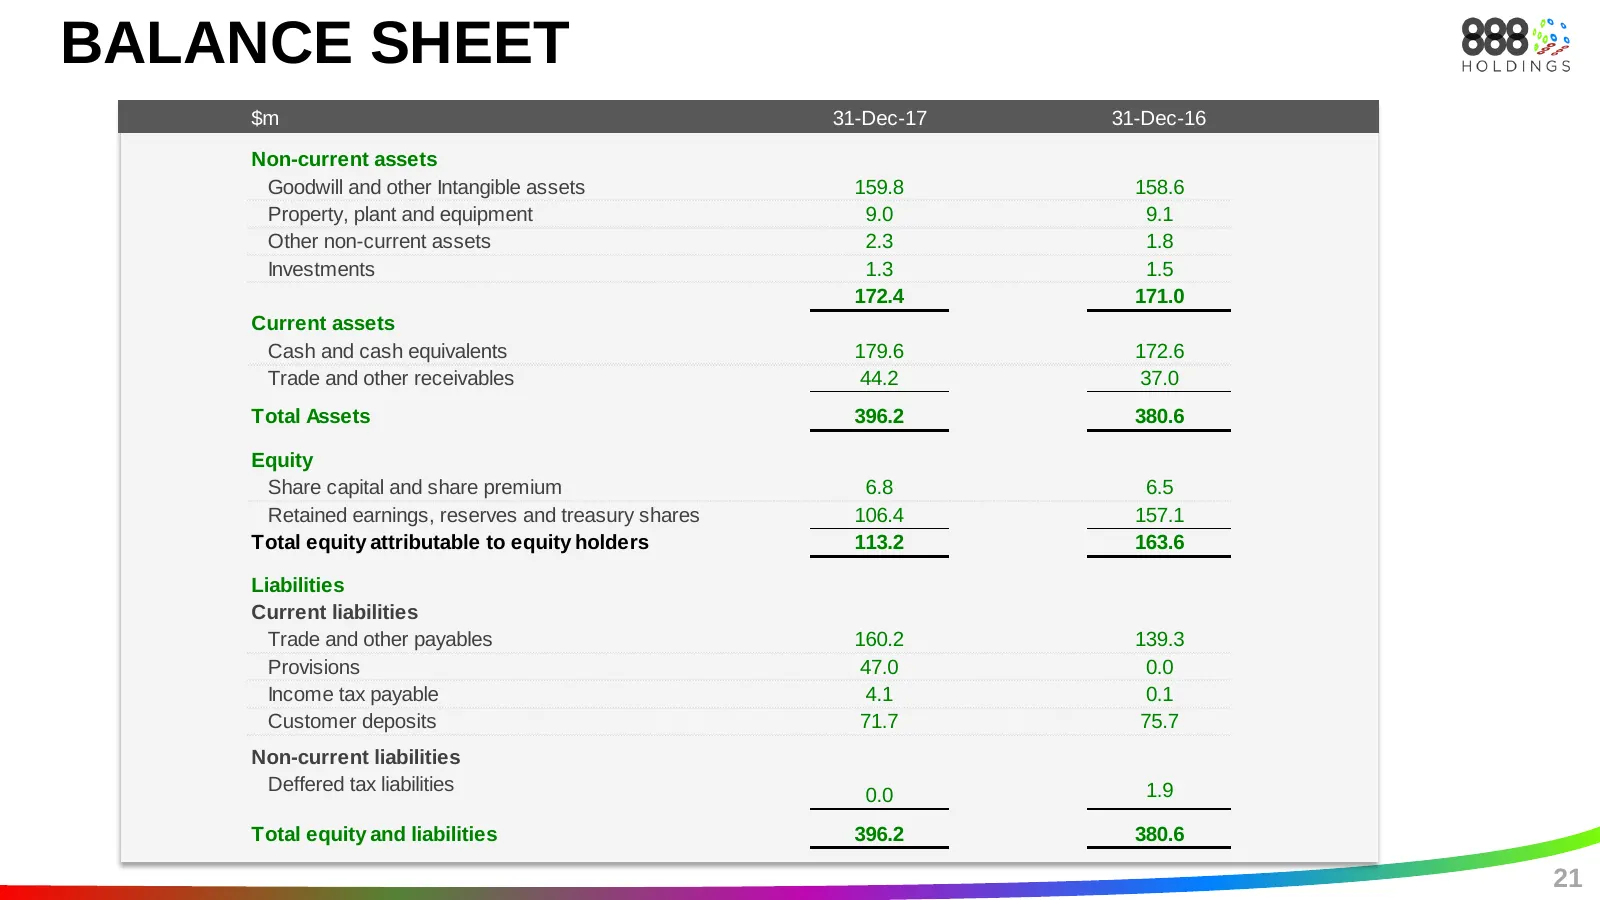
BALANCE SHEET $m 31-Dec-17 31-Dec-16 Non-current assets Goodwill and other Intangible assets 159.8 158.6 Property, plant and equipment 9.0 9.1 Other non-current assets 2.3 1.8 Investments 1.3 1.5 172.4 171.0 Current assets Cash and cash equivalents 179.6 172.6 Trade and other receivables 44.2 37.0 T
Slide 22: Cash Flow
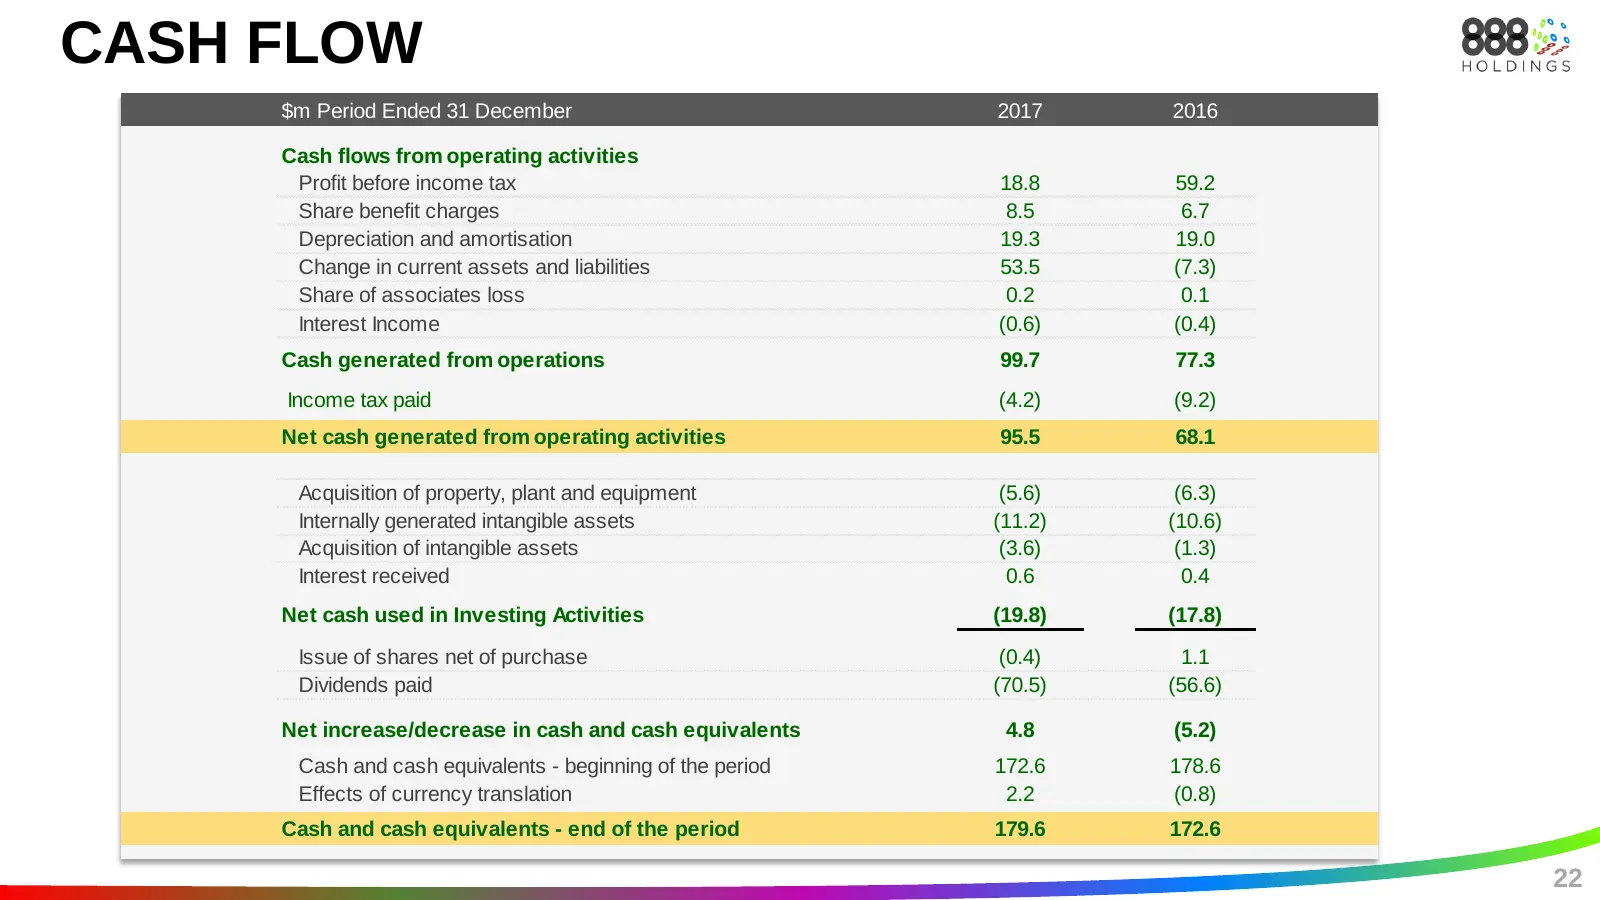
CASH FLOW $m Period Ended 31 December 2017 2016 Cash flows from operating activities Profit before income tax 18.8 59.2 Share benefit charges 8.5 6.7 Depreciation and amortisation 19.3 19.0 Change in current assets and liabilities 53.5 (7.3) Share of associates loss 0.2 0.1 Interest Income (0.6) (0.
Slide 23: Itai Pazner, COO | Operational Review
ITAI PAZNER, COO | OPERATIONAL REVIEW
Slide 24: European Regulated Markets (ex. UK)
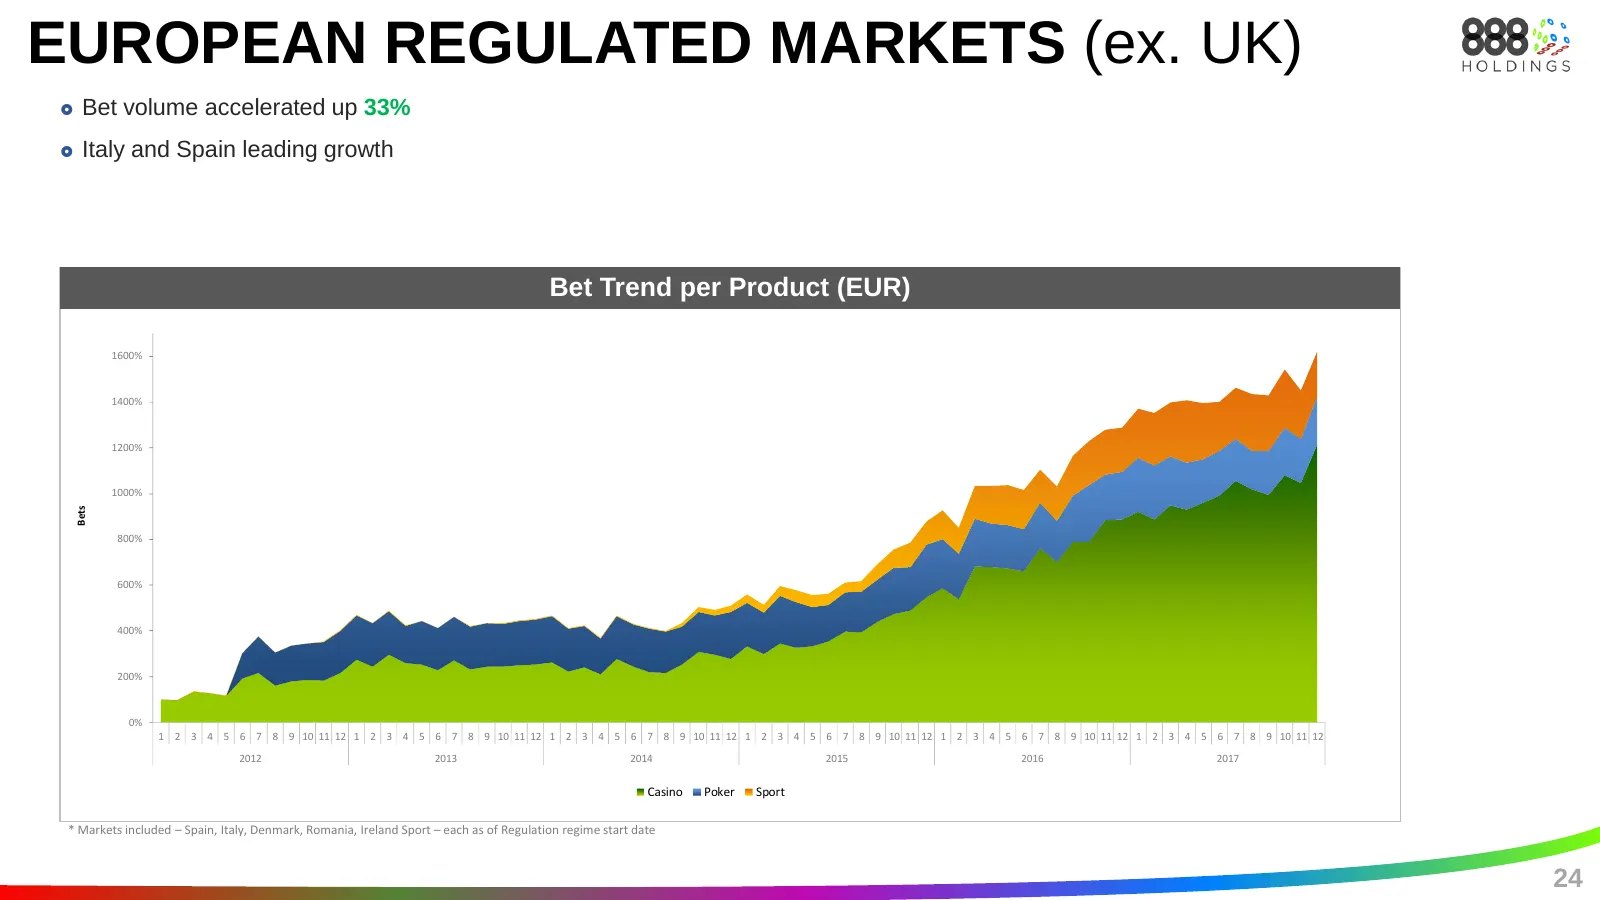
EUROPEAN REGULATED MARKETS (ex. UK) Bet volume accelerated up 33% Italy and Spain leading growth Bet Trend per Product (EUR) 1600% 1400% 1200% 1000% Bets 800% 600% 400% 200% 0% 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6
Slide 25: Deposit Trend Spain & Italy
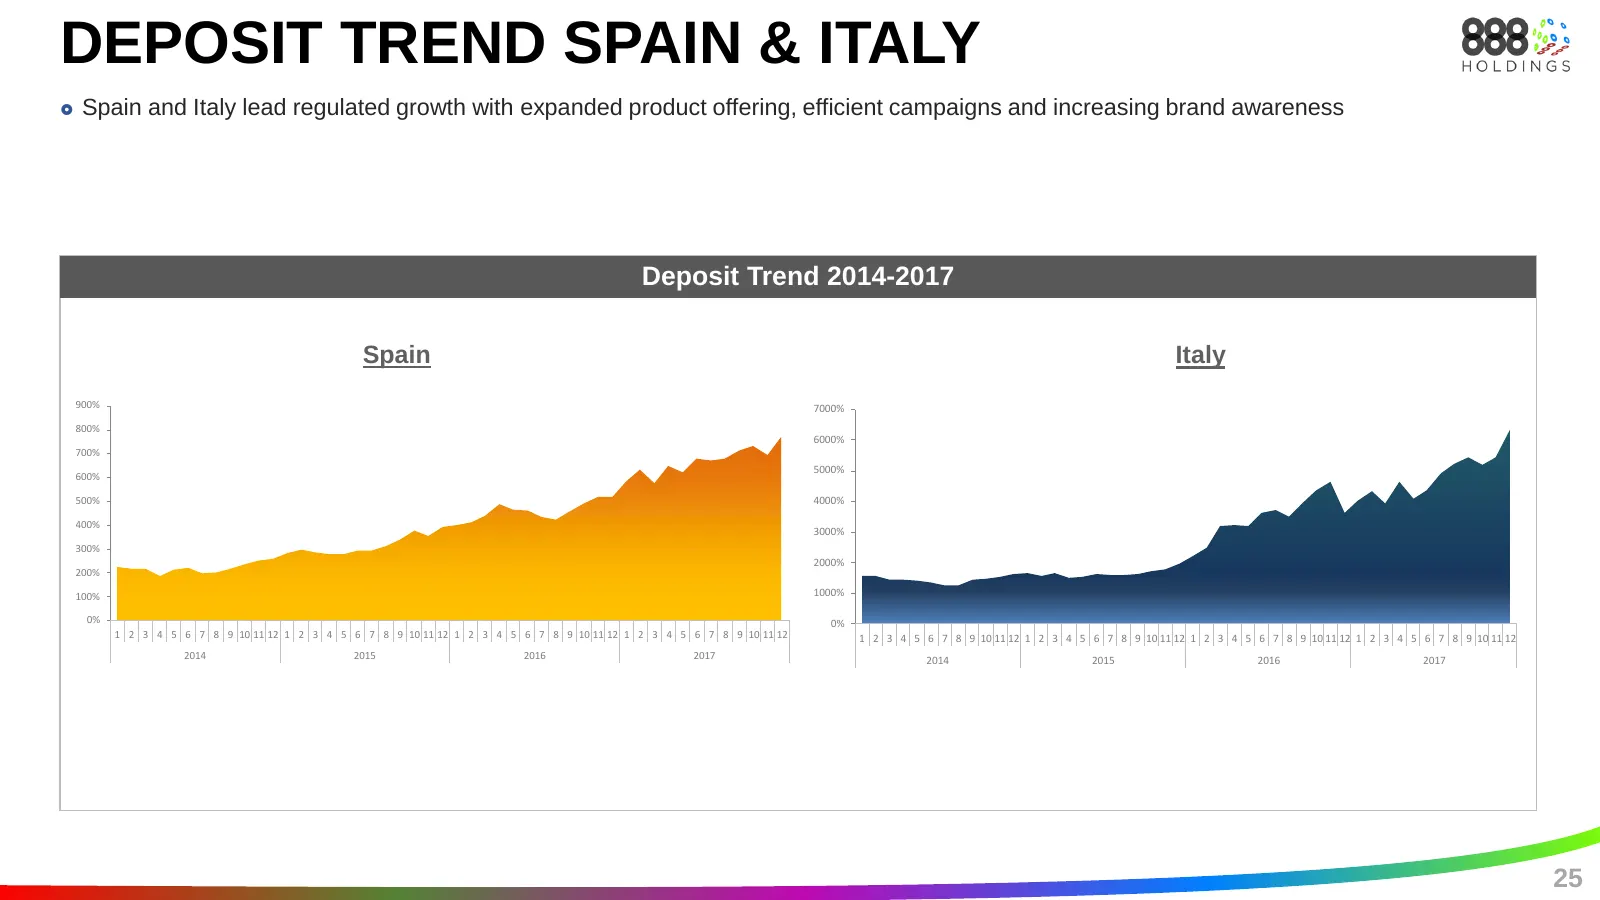
DEPOSIT TREND SPAIN & ITALY Spain and Italy lead regulated growth with expanded product offering, efficient campaigns and increasing brand awareness Deposit Trend 2014-2017 Spain Italy 900% 7000% 800% 6000% 700% 5000% 600% 500% 4000% 400% 3000% 300% 2000% 200% 100% 1000% 0% 0% 1 2 3 4 5 6 7 8 9 10
Slide 26: Compliance
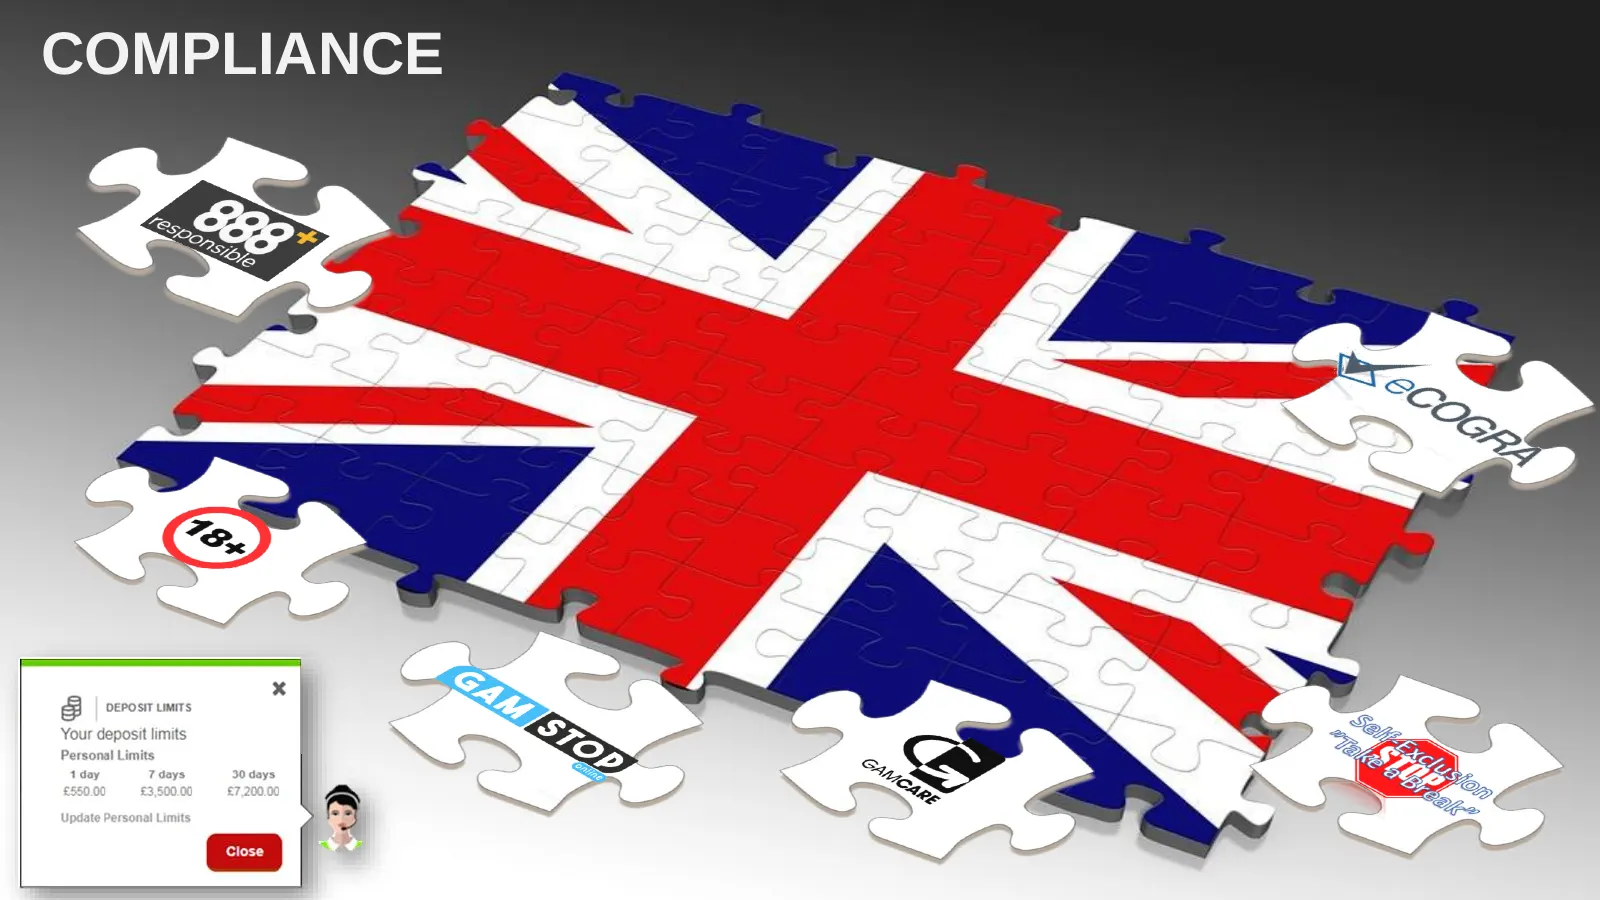
COMPLIANCE
Slide 27: Sport Bet
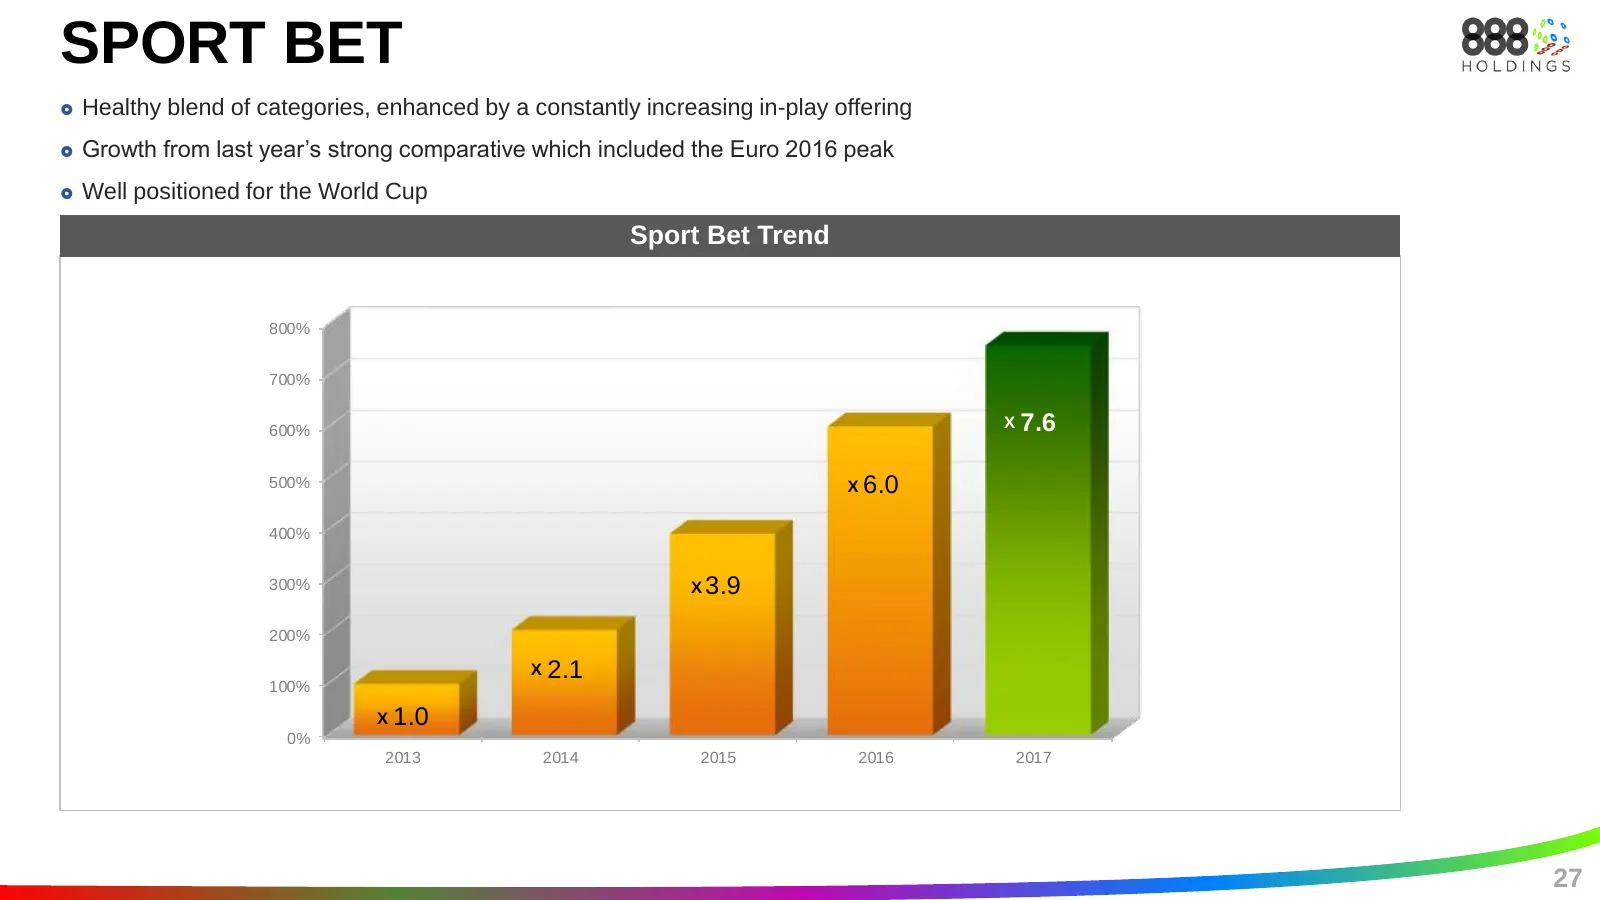
SPORT BET Healthy blend of categories, enhanced by a constantly increasing in-play offering Growth from last year’s strong comparative which included the Euro 2016 peak Well positioned for the World Cup Sport Bet Trend 800% 700% 600% X 7.6 500% X 6.0 400% 300% X 3.9 200% X 2.1 100% X 1.0 0% 20
Slide 28: Casino
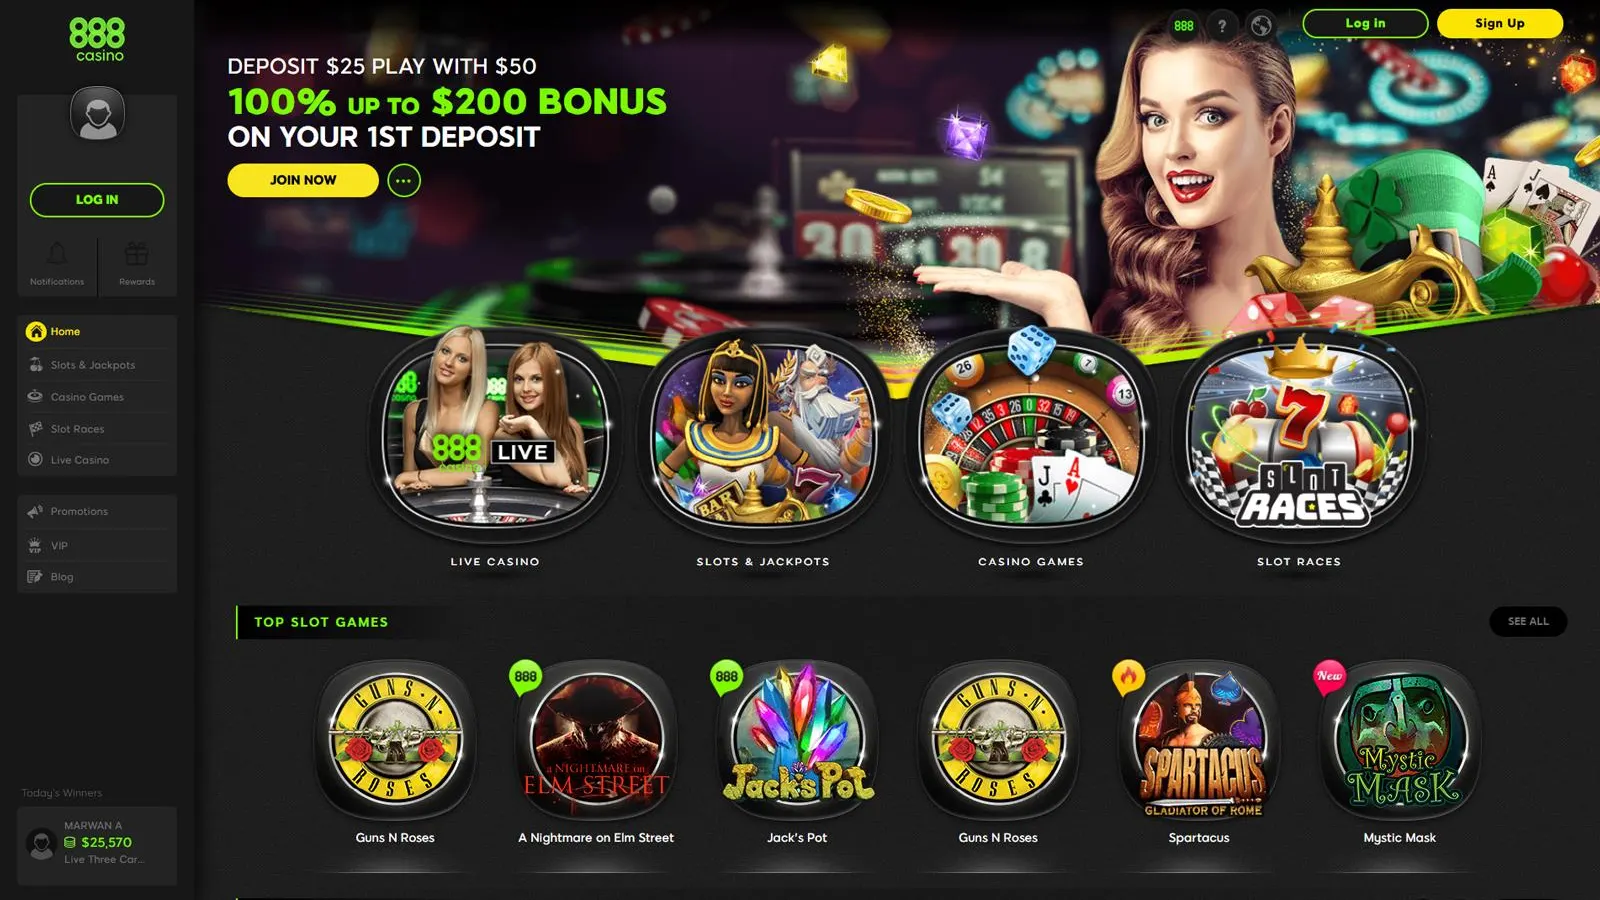
cosine DEPOSIT $25 PLAY WITH $50 Ged 100% up to $200 BONUS @ ON YOUR 1ST DEPOSIT eax © ~ LIVE CASINO SLOTS @ JACKPOTS CASINO GAMES | TOP SLOT GAMES MARWAN A & $25,570
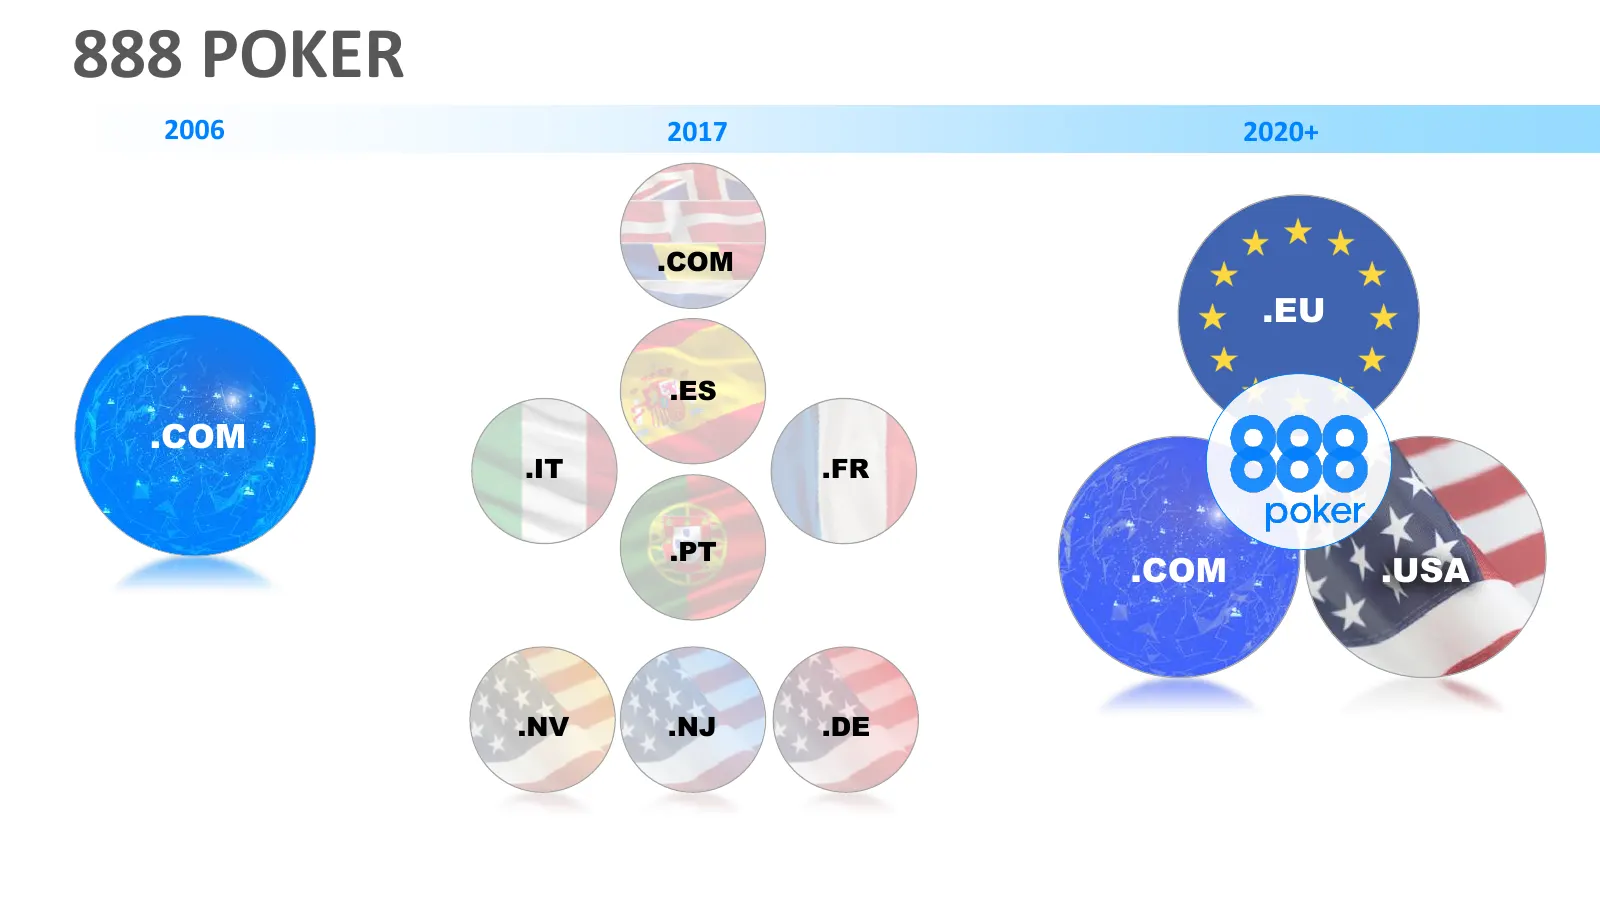
Slide 29: 888 Poker
888 POKER 2006 2017 2020+ .COM .EU .ES .COM .IT .FR .PT .COM .USA .NV .NJ .DE
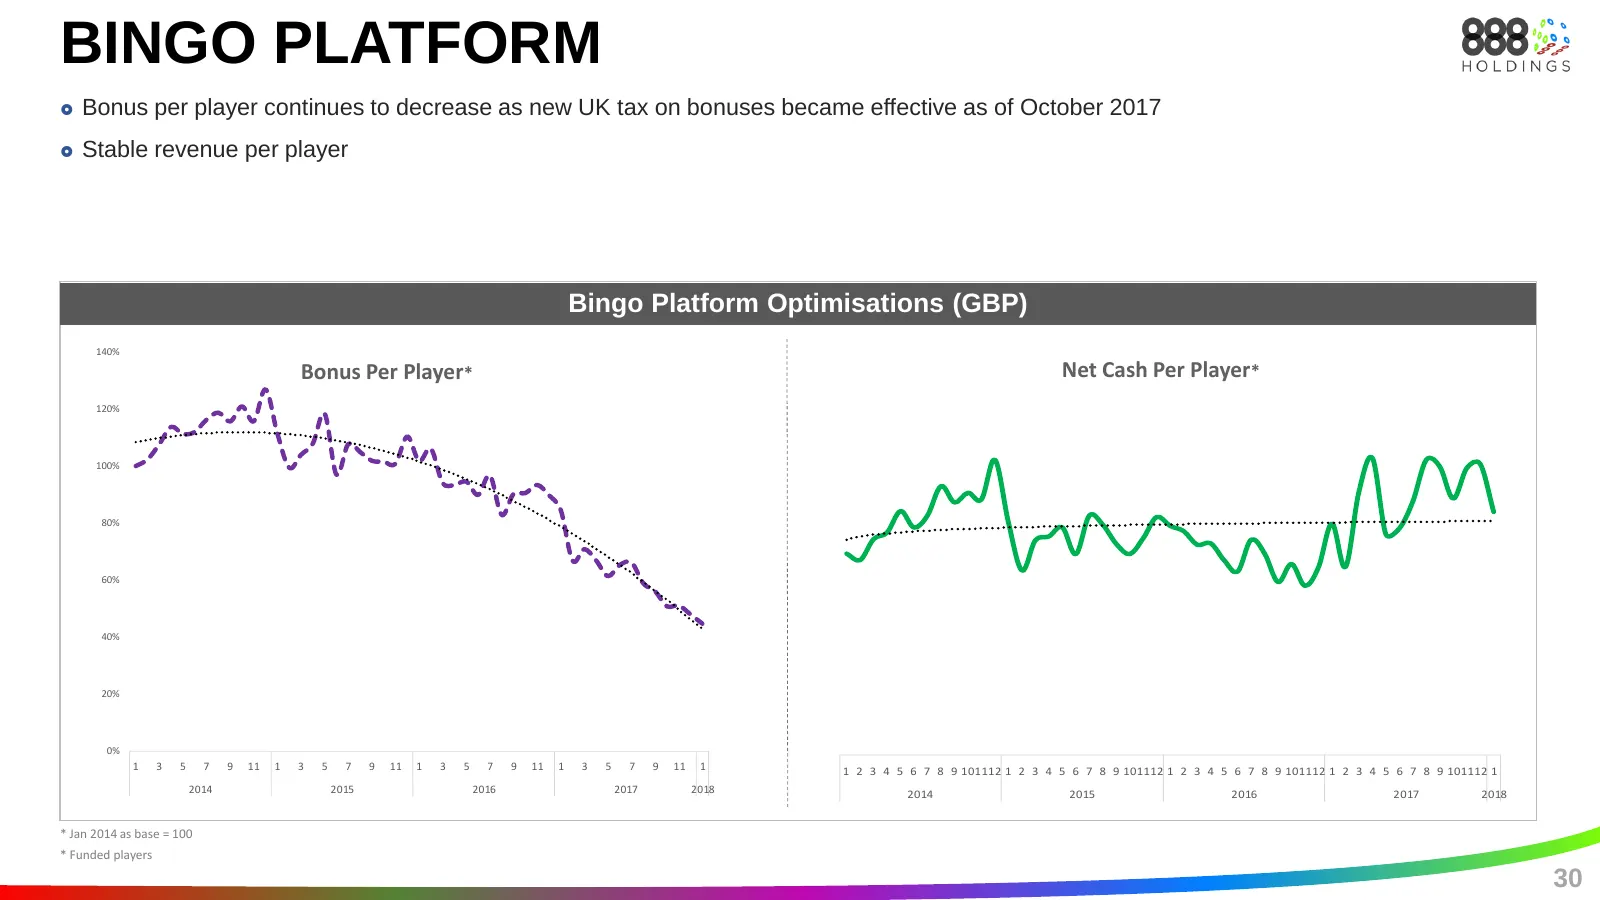
Slide 30: Bingo Platform
BINGO PLATFORM Bonus per player continues to decrease as new UK tax on bonuses became effective as of October 2017 Stable revenue per player Bingo Platform Optimisations (GBP) 140% Bonus Per Player* Net Cash Per Player* 120% 100% 80% 60% 40% 20% 0% 1 3 5 7 9 11 1 3 5 7 9 11 1 3 5 7 9 11 1 3 5 7
Slide 31: Wink Bingo
Slide 32: Looking Ahead
LOOKING AHEAD 32
Slide 33: Itai Frieberger, CEO | Summary
ITAI FRIEBERGER, CEO | SUMMARY
Slide 34: Consistent Progress
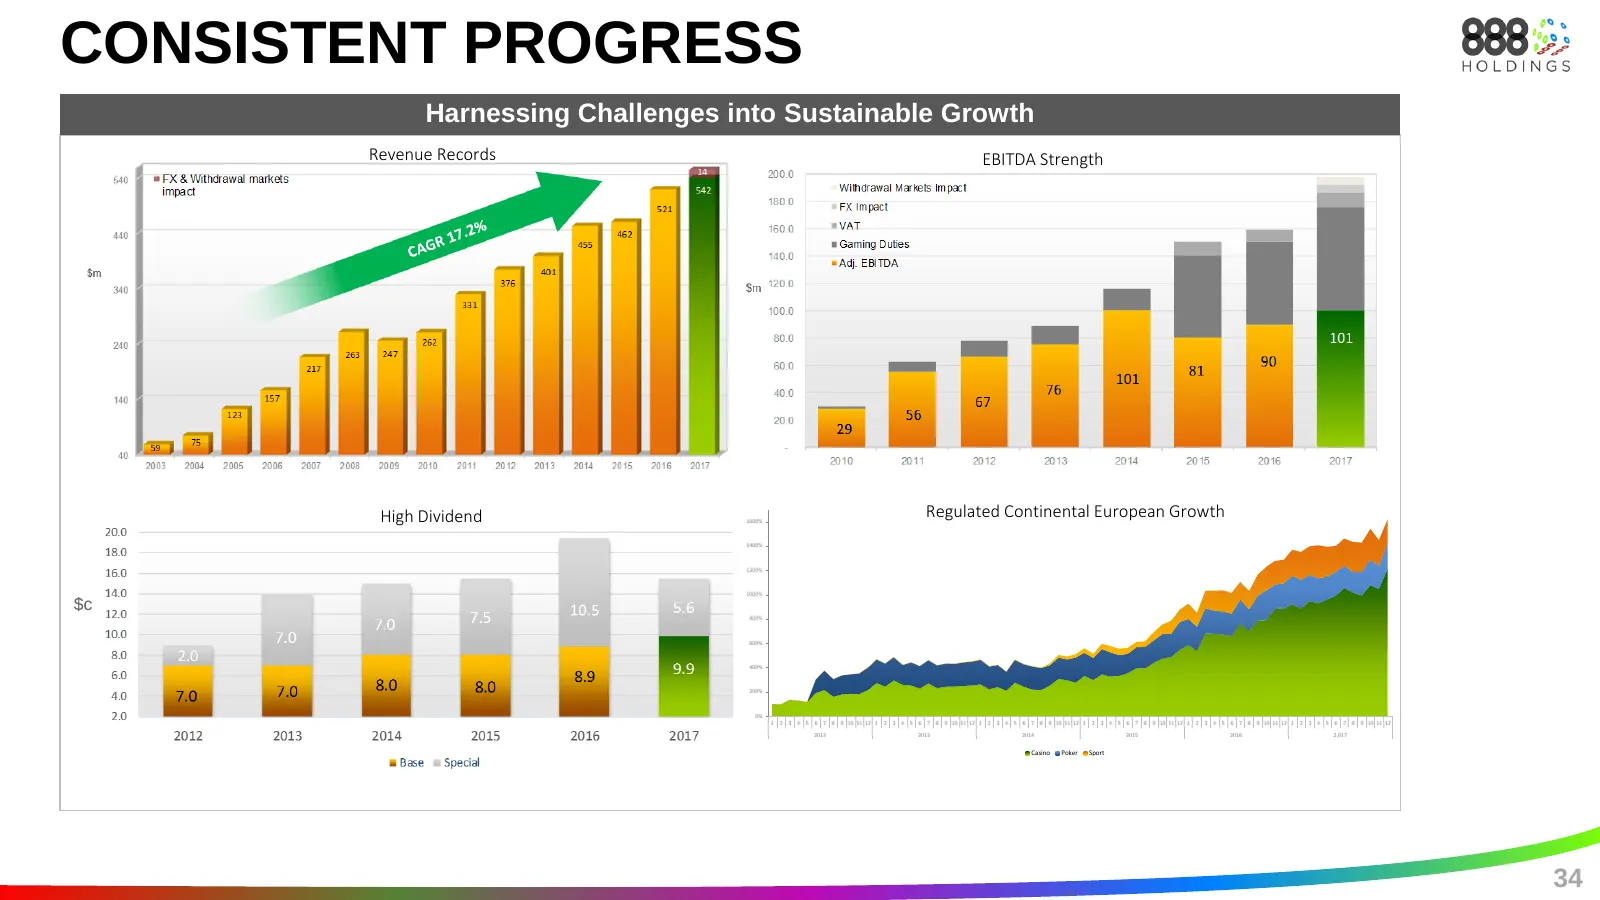
CONSISTENT PROGRESS Harnessing Challenges into Sustainable Growth Revenue Records EBITDA Strength High Dividend 1600% Regulated Continental European Growth 1400% 1200% 1000% $c Bets 800% 600% 400% 200% 0% 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7 8 9 10 11 12 1 2 3 4 5 6 7
Slide 35: Summary
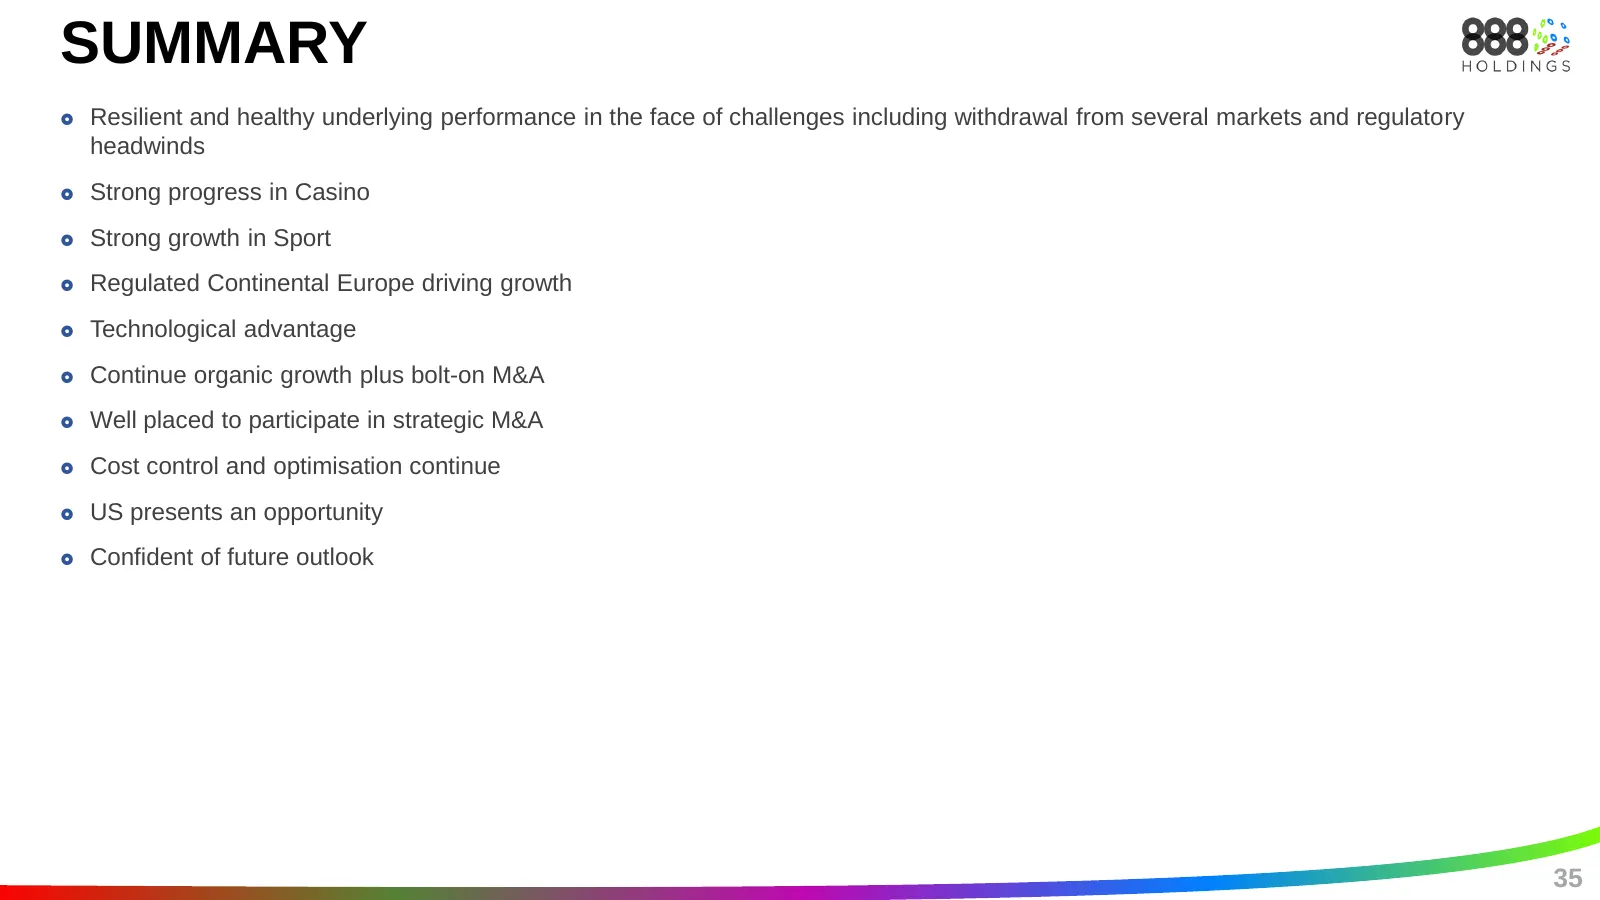
SUMMARY Resilient and healthy underlying performance in the face of challenges including withdrawal from several markets and regulatory headwinds Strong progress in Casino Strong growth in Sport Regulated Continental Europe driving growth Technological advantage Continue organic growth p
Slide 36: Q&A
HOLDINGS Q&A
Source: company website
More decks from Evoke plc
 H1 2026 Earnings Presentation15 slides · Aug 12, 2026
 H1 2025 Earnings Presentation17 slides · Aug 13, 2025
 H1 2025 Earnings Presentation29 slides · Aug 13, 2025
 FY2024 Earnings Presentation33 slides · Mar 26, 2025
 H1 2024 Earnings Presentation25 slides · Aug 15, 2024
 H1 2024 Earnings Presentation10 slides · Jul 18, 2024