Gen Digital Inc. · NASDAQ:GEN
Gen Digital — Veritas Software — Merger or Acquisition (June 2005)
37 slides from Gen Digital's merger presentation, Jun 7, 2005
Slide 1: Delivering Information Security and Availability
Delivering Information Security and Availability
Slide 2: Forward-Looking Statement
Forward-Looking Statement This presentation contains forward-looking statements, including forecasts of market growth, future revenue, benefits of the proposed merger, and expectations that the merger will be accretive to Symantec's results and other matters that involve known and unknown risks, unc
Slide 3: Where to Find Additional Information
Where to Find Additional Information Symantec Corporation has filed a registration statement on Form S-4 containing a definitive joint proxy statement/prospectus in connection with the merger transaction involving Symantec and VERITAS Software Corporation. We urge investors and security holders to r
Slide 4: Strategic Rationale
Strategic Rationale
Slide 5: i) symantec. Access
i) symantec. Access
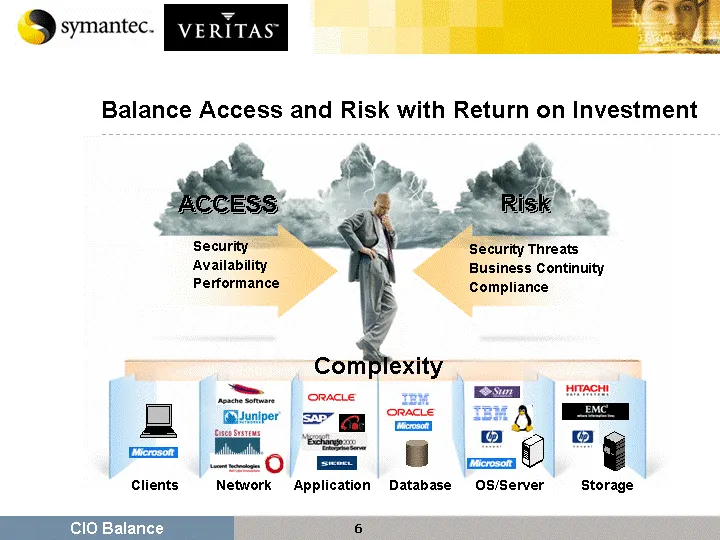
Slide 6: Balance Access and Risk with Return on Investment
Balance Access and Risk with Return on Investment Network Application Database OS/Server Storage ACCESS Complexity Risk Availability CIO Balance Security Threats Compliance Business Continuity Performance Security Clients
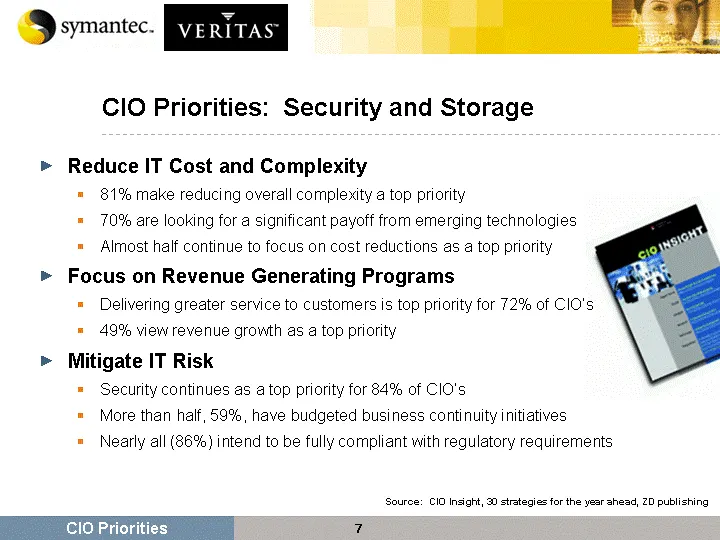
Slide 7: CIO Priorities: Security and Storage
CIO Priorities: Security and Storage CIO Priorities Reduce IT Cost and Complexity 81% make reducing overall complexity a top priority 70% are looking for a significant payoff from emerging technologies Almost half continue to focus on cost reductions as a top priority Focus on Revenue Generating Pro
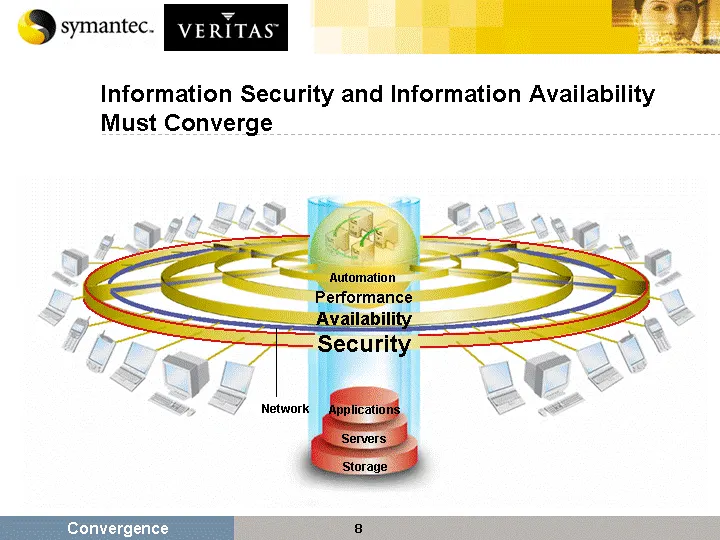
Slide 8: Information Security and Information Availability Must Converge
Information Security and Information Availability Must Converge Automation Performance Availability Applications Servers Storage Security Convergence Network
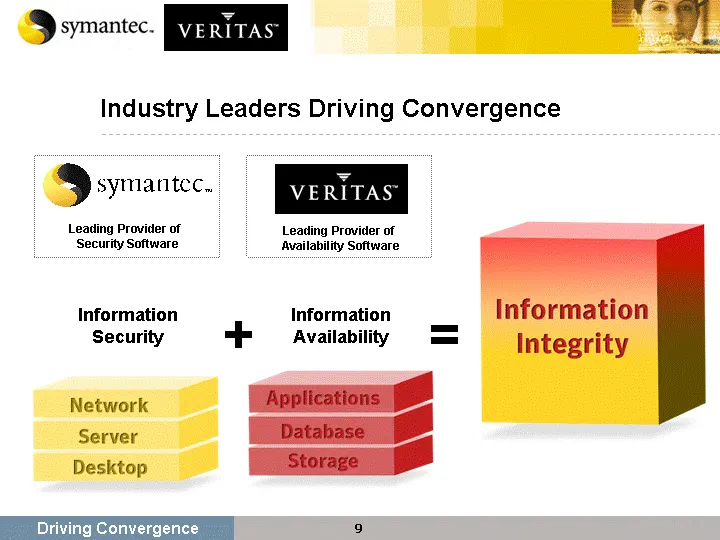
Slide 9: Industry Leaders Driving Convergence
Industry Leaders Driving Convergence Driving Convergence Leading Provider of Availability Software Information Availability + = Information Security Leading Provider of Security Software
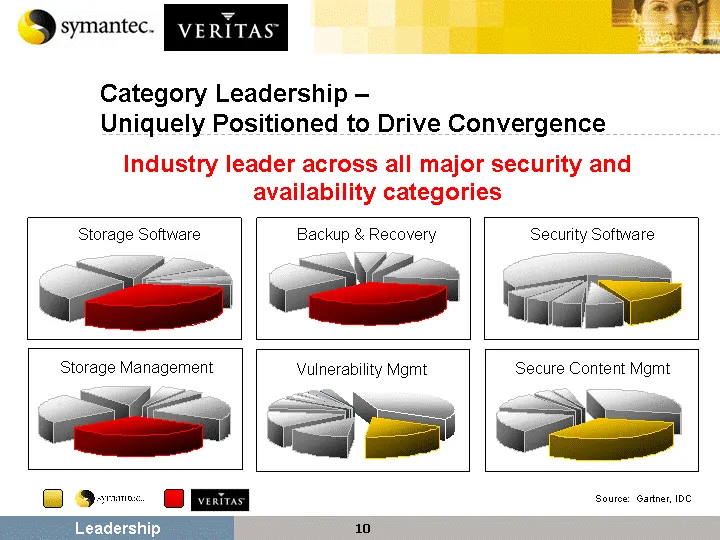
Slide 10: Category Leadership - Uniquely Positioned to Drive Convergence
Category Leadership - Uniquely Positioned to Drive Convergence Storage Software Backup & Recovery Storage Management Vulnerability Mgmt Secure Content Mgmt Security Software Leadership Source: Gartner, IDC Industry leader across all major security and availability categories
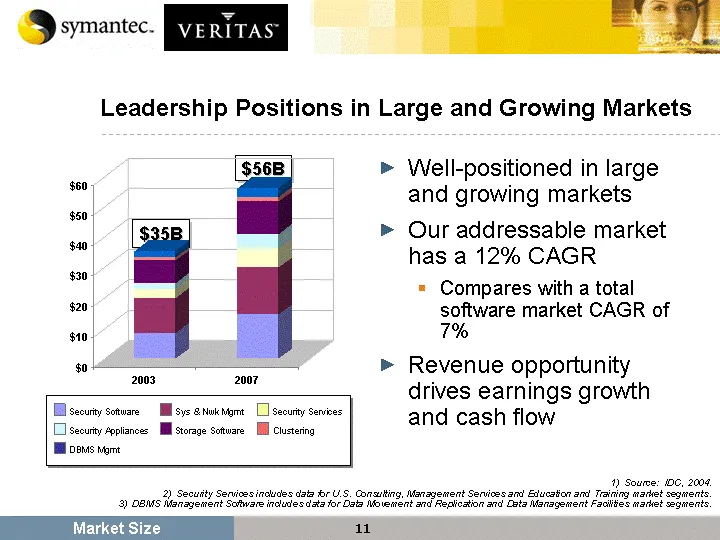
Slide 11: Leadership Positions in Large and Growing Markets
1) Source: IDC, 2004. 2) Security Services includes data for U.S. Consulting, Management Services and Education and Training market segments. 3) DBMS Management Software includes data for Data Movement and Replication and Data Management Facilities market segments. Leadership Positions in Large and
Slide 12: Competitive Advantages
Competitive Advantages Broad category leadership #1 market share in 6 market segments Unique scale and scope No hardware agenda Strong financial position Large and growing addressable markets Uniquely positioned to drive convergence Competitive Advantage
Slide 13: Integration Update
Integration Update
Slide 14: Integration Priorities
Integration Priorities Sustain business momentum Deliver on cost synergies Facilities Procurement Headcount redundancies Seize near-term revenue opportunities Communicate product strategy and roadmap to customers Priorities
Slide 15: Product Integration Plans
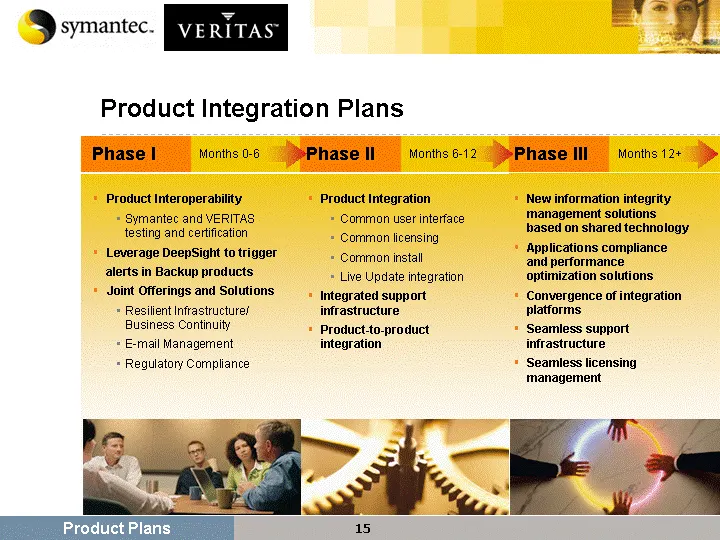
Phase III Months 12+ New information integrity management solutions based on shared technology Applications compliance and performance optimization solutions Convergence of integration platforms Seamless support infrastructure Seamless licensing management Product Integration Plans Product Plans Pha
Slide 16: Sales and Channel Integration Planning
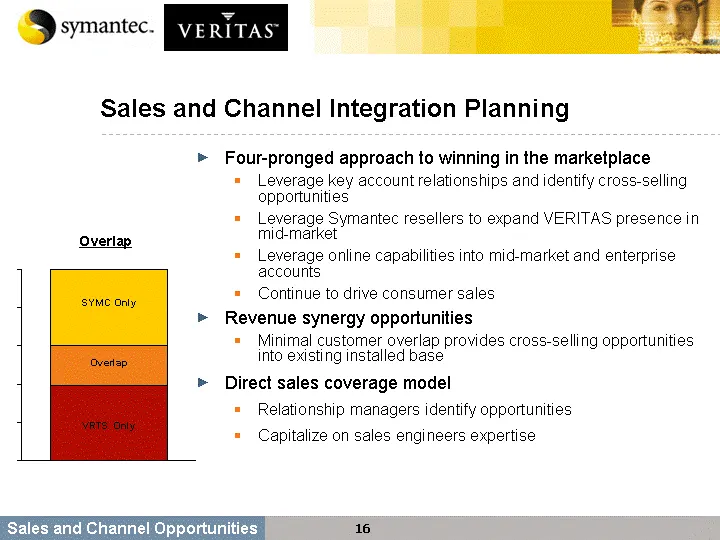
Sales and Channel Integration Planning Four-pronged approach to winning in the marketplace Leverage key account relationships and identify cross-selling opportunities Leverage Symantec resellers to expand VERITAS presence in mid-market Leverage online capabilities into mid-market and enterprise acco
Slide 17: Integration Summary
Integration Summary Infrastructure integration plans People Process Systems Announced leadership in every area of the organization Cost synergies identified Outlined product plans Identified early sales opportunities Finalized sales coverage model Integration Summary Ready to Go, Day 1!
Slide 18: Market Reaction
Market Reaction
Slide 19: Market Reaction to Transaction
Market Trends Market Reaction to Transaction Technology sector in general has been weak Software sector has been the hardest hit Typical of calendar first half seasonality Microsoft activity continues to pressure the security sector Market is discounting the inevitable consolidation of the software
Slide 20: Symantec Outperforms Security Peer Group
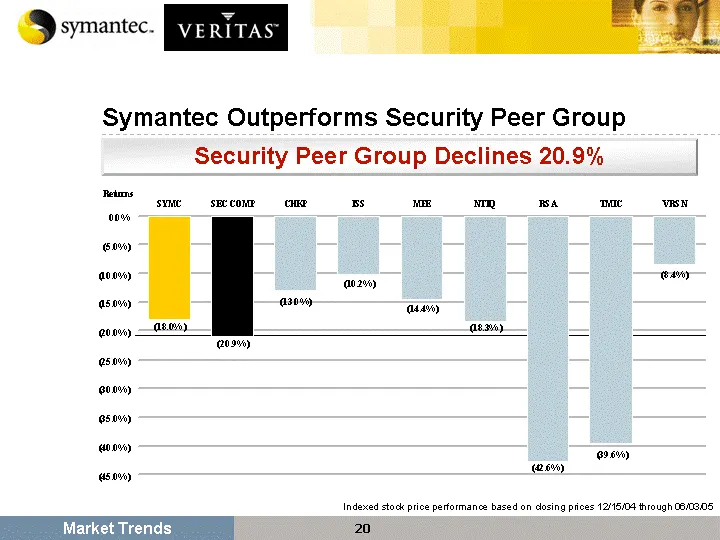
Market Trends Symantec Outperforms Security Peer Group Security Peer Group Declines 20.9% Indexed stock price performance based on closing prices 12/15/04 through 06/03/05
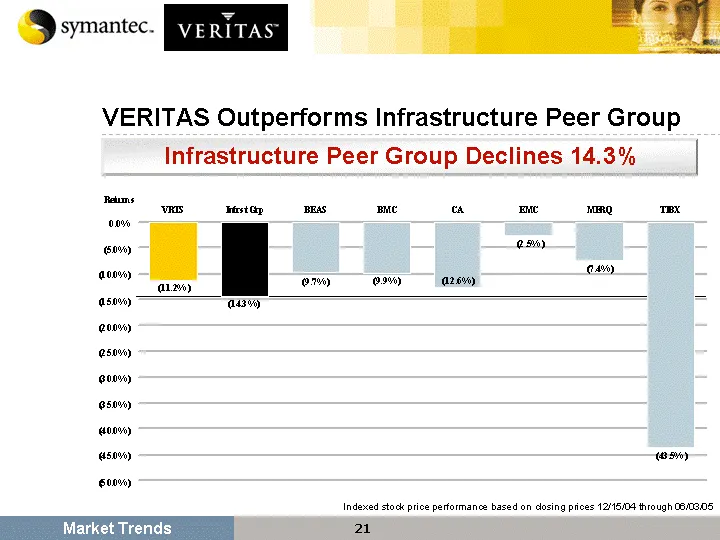
Slide 21: VERITAS Outperforms Infrastructure Peer Group
Market Trends VERITAS Outperforms Infrastructure Peer Group Indexed stock price performance based on closing prices 12/15/04 through 06/03/05 Infrastructure Peer Group Declines 14.3%
Slide 22: Financials
Financials
Slide 23: Financial Metrics
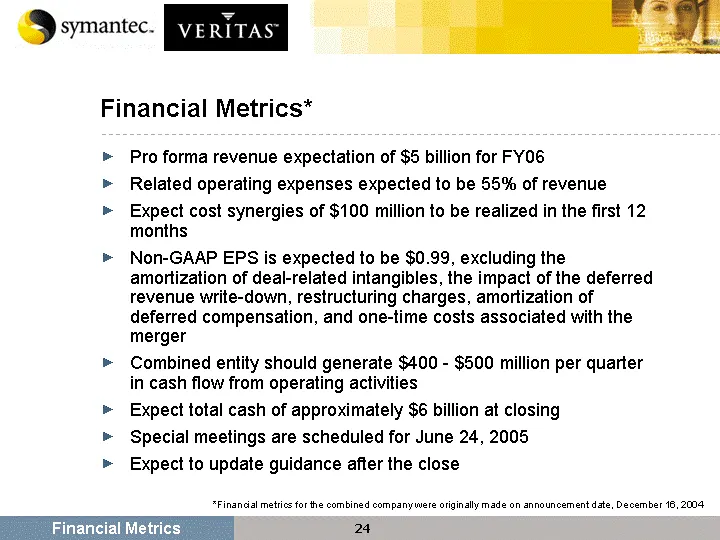
Financial Metrics* Pro forma revenue expectation of $5 billion for FY06 Related operating expenses expected to be 55% of revenue Expect cost synergies of $100 million to be realized in the first 12 months Non-GAAP EPS is expected to be $0.99, excluding the amortization of deal-related intangibles, t
Slide 24: Recent Announcements
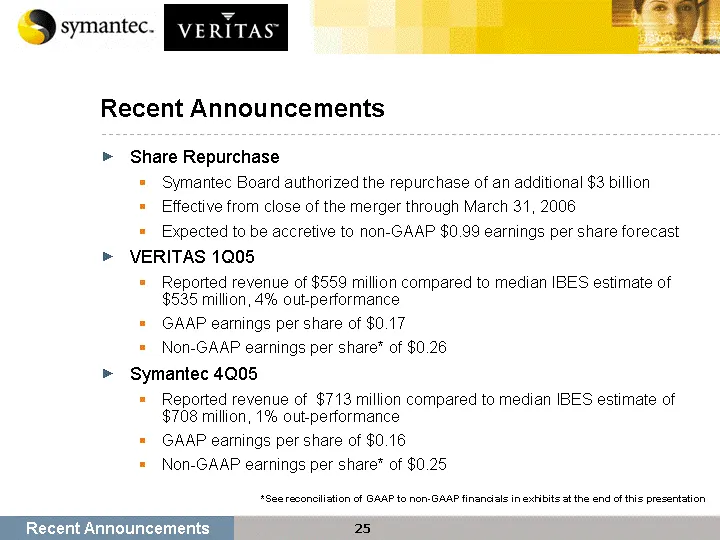
Recent Announcements Share Repurchase Symantec Board authorized the repurchase of an additional $3 billion Effective from close of the merger through March 31, 2006 Expected to be accretive to non-GAAP $0.99 earnings per share forecast VERITAS 1Q05 Reported revenue of $559 million compared to median
Slide 25: June Quarter Guidance
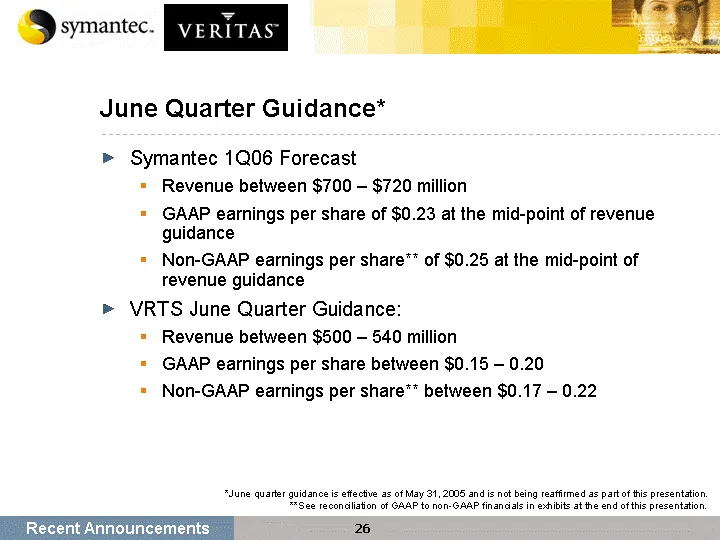
June Quarter Guidance* Symantec 1Q06 Forecast Revenue between $700 - $720 million GAAP earnings per share of $0.23 at the mid-point of revenue guidance Non-GAAP earnings per share** of $0.25 at the mid-point of revenue guidance VRTS June Quarter Guidance: Revenue between $500 - 540 million GAAP earn
Slide 26: Process & Governance
Process & Governance
Slide 27: Process Reflects "Best Practices" for Merger
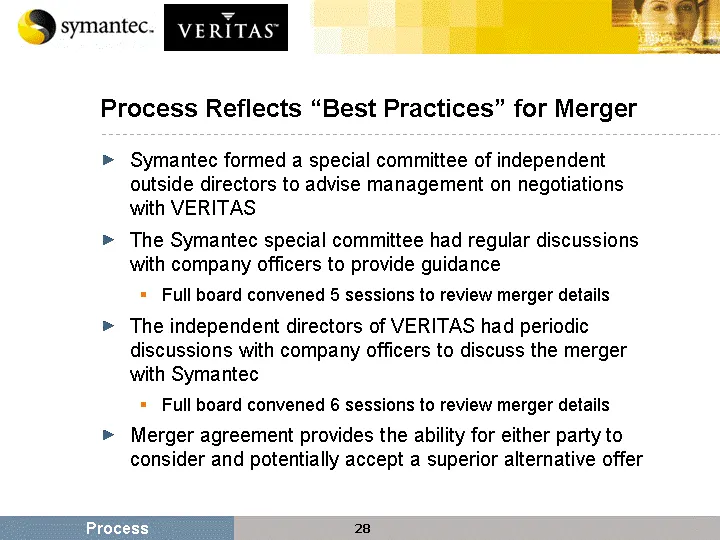
Process Reflects "Best Practices" for Merger Symantec formed a special committee of independent outside directors to advise management on negotiations with VERITAS The Symantec special committee had regular discussions with company officers to provide guidance Full board convened 5 sessions to revie
Slide 28: VERITAS Change-in-Control Provisions
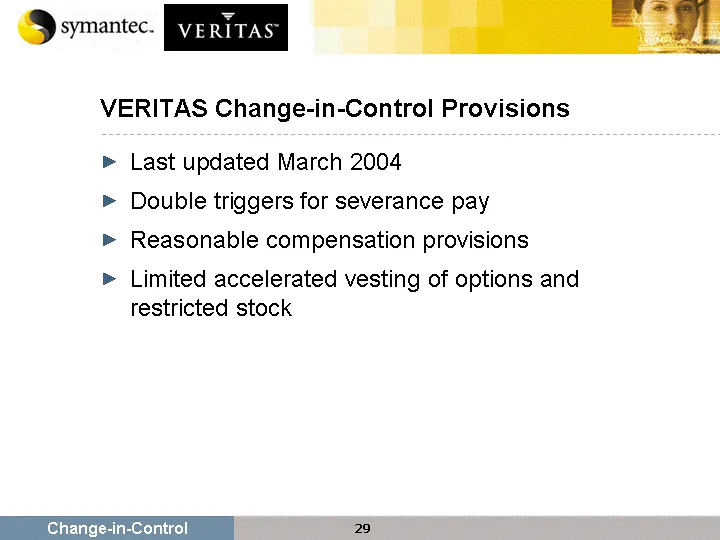
VERITAS Change-in-Control Provisions Last updated March 2004 Double triggers for severance pay Reasonable compensation provisions Limited accelerated vesting of options and restricted stock Change-in-Control
Slide 29: Best-in-Class Corporate Governance
Best-in-Class Corporate Governance No changes are being made to Symantec's "best-in-class" governance structure Majority independent board Annual elections of full board Fully independent key committees Executive stock ownership guidelines Symantec's ISS Corporate Governance Quotient: outperforms 96
Slide 30: Support for the Merger
Support for the Merger
Slide 31: Wall Street Sentiment Rising for Symantec
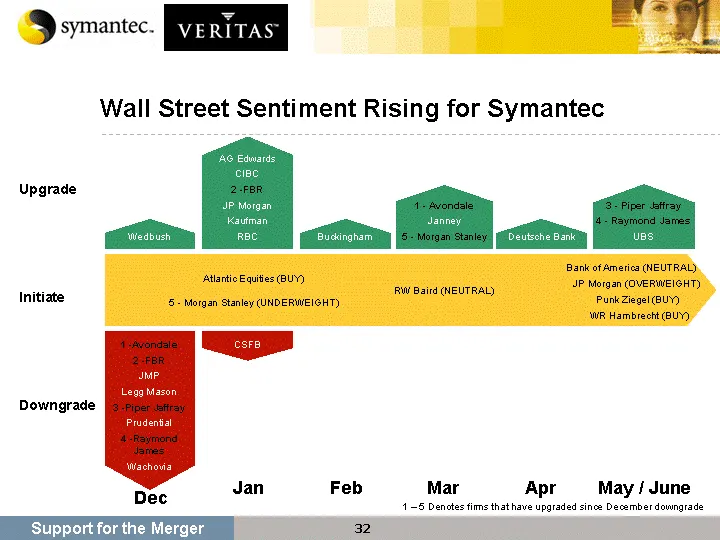
Wall Street Sentiment Rising for Symantec Support for the Merger Dec Jan Feb Mar Apr May / June 1 -Avondale 2 -FBR JMP Legg Mason 3 -Piper Jaffray Prudential 4 -Raymond James Wachovia Downgrade AG Edwards CIBC 2 -FBR JP Morgan Kaufman RBC Upgrade CSFB Buckingham 1 - Avondale Janney 5 - Morgan Stanle
Slide 32: Wall Street Sentiment Rising for Symantec
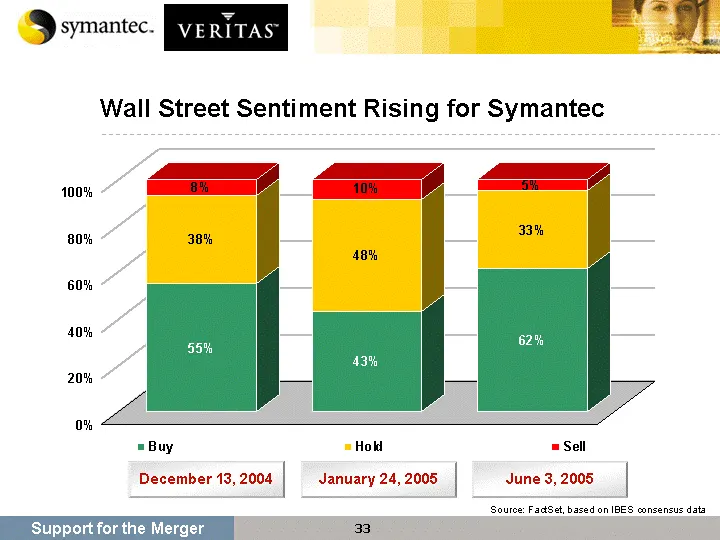
Wall Street Sentiment Rising for Symantec Support for the Merger December 13, 2004 January 24, 2005 June 3, 2005 Source: FactSet, based on IBES consensus data
Slide 33: Financial Analyst Support for the Merger
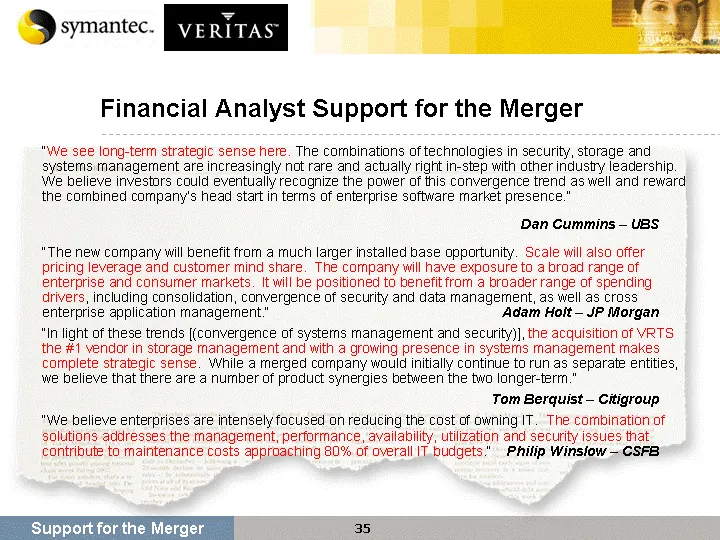
Support for the Merger Financial Analyst Support for the Merger "We see long-term strategic sense here. The combinations of technologies in security, storage and systems management are increasingly not rare and actually right in-step with other industry leadership. We believe investors could eventua
Slide 34: Symantec and VERITAS - Driving Long-term Value
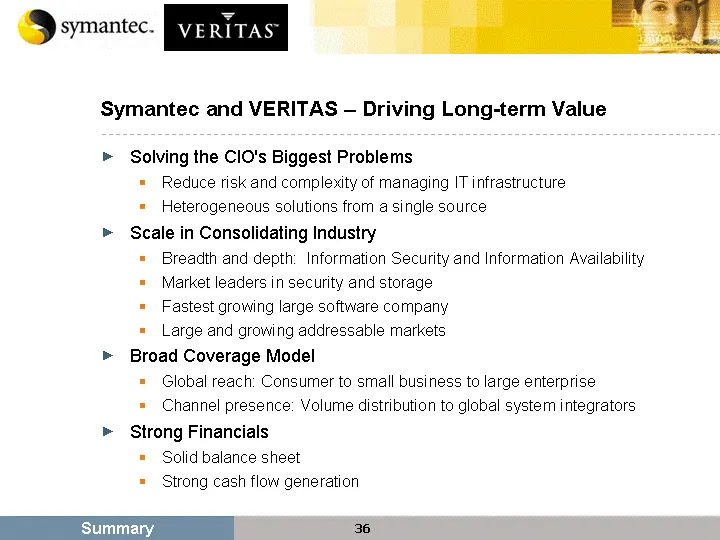
Symantec and VERITAS - Driving Long-term Value Solving the CIO's Biggest Problems Reduce risk and complexity of managing IT infrastructure Heterogeneous solutions from a single source Scale in Consolidating Industry Breadth and depth: Information Security and Information Availability Market leaders
Slide 35: Thank You
Thank You
Slide 36: Symantec's Reconciliation of non-GAAP to GAAP: Quarter View
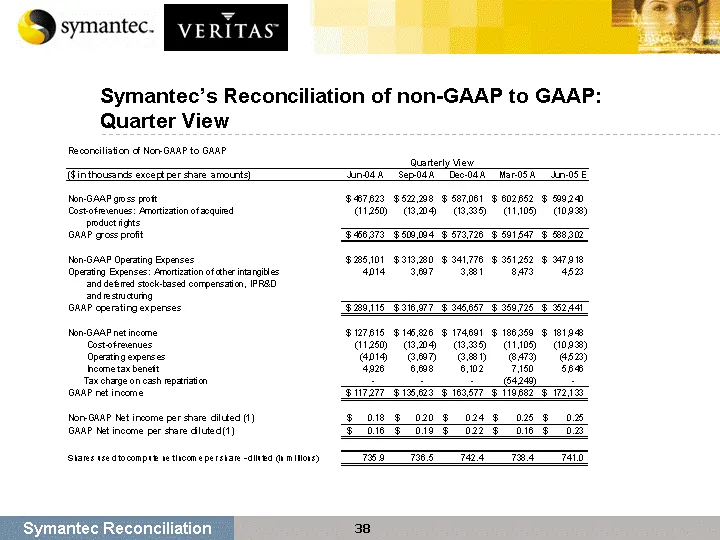
Symantec's Reconciliation of non-GAAP to GAAP: Quarter View Symantec Reconciliation
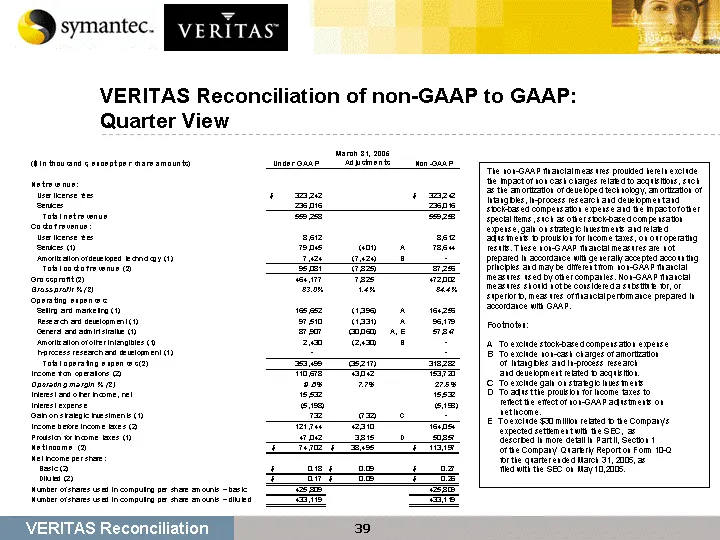
Slide 37: VERITAS Reconciliation of non-GAAP to GAAP: Quarter View
VERITAS Reconciliation of non-GAAP to GAAP: Quarter View VERITAS Reconciliation The non-GAAP financial measures provided herein exclude the impact of non cash charges related to acquisitions, such as the amortization of developed technology, amortization of intangibles, in-process research and devel
Source: SEC EDGAR · 425 filed Jun 7, 2005
More decks from Gen Digital Inc.
 Q2 FY2027 Earnings Presentation38 slides · Oct 28, 2026
 Q1 2027 Earnings Presentation40 slides · Aug 6, 2026
 Q4 2026 Earnings Presentation36 slides · May 7, 2026
 Q3 2026 Earnings Presentation34 slides · Feb 5, 2026
 Q2 2026 Earnings Presentation36 slides · Nov 6, 2025
 Investor Day (September 2025)76 slides · Sep 8, 2025