Williams Partners L.P — 2014 Barclays Capital CEO Energy-Power Conference
23 slides from Williams Partners L.P's conference presentation, Sep 2, 2014
Slide 1: Rule 425 filing legend
Filed by The Williams Companies, Inc. Pursuant to Rule 425 under the Securities Act of 1933 Subject Company: Williams Partners L.P. Commission File No.: 001-32599 The following is a slide presentation made available on the websites of The Williams Companies, Inc. and Williams Partners L.P. on Septem
Slide 2: Barclays CEO Energy-Power Conference – Alan Armstrong
Barclays Alan September Armstrong, CEO 3, 2014 Energy-Power Chief Executive Conference Officer
Slide 3: Important Information
Important This combination with STATEMENT, INFORMATION. 2by © Barclays 2014 thethe document SEC The SEC. Information CEO atWilliams transaction http://www.sec.gov. INVESTORS AND does Energy-Power Investors not OTHER Companies, constitute of Williams and ARE DOCUMENTS Conference security URGED Inc. a
Slide 4: Forward Looking Statements
Forward exclusively 1934, statements “targets,” and Expected Amounts Expansion Financial Business Cash Seasonality Natural Demand Forward-looking factors others, The Whether 3Availability ©Barclays 2014 assumptions reports, levels proposed structure, flow asthe that The gas, amended. for Looking WPZ
Slide 5: Forward Looking Statements (continued)
Forward Inflation, and Whether Our Development Costs Williams’ WPZ’s Changes Exposure The Risks Acts Additional Given statements. In cause Investors 4available © Barclays 2014 addition suppliers); strength impact ability amount ofour of, related associated the allocated terrorism, The Looking we in
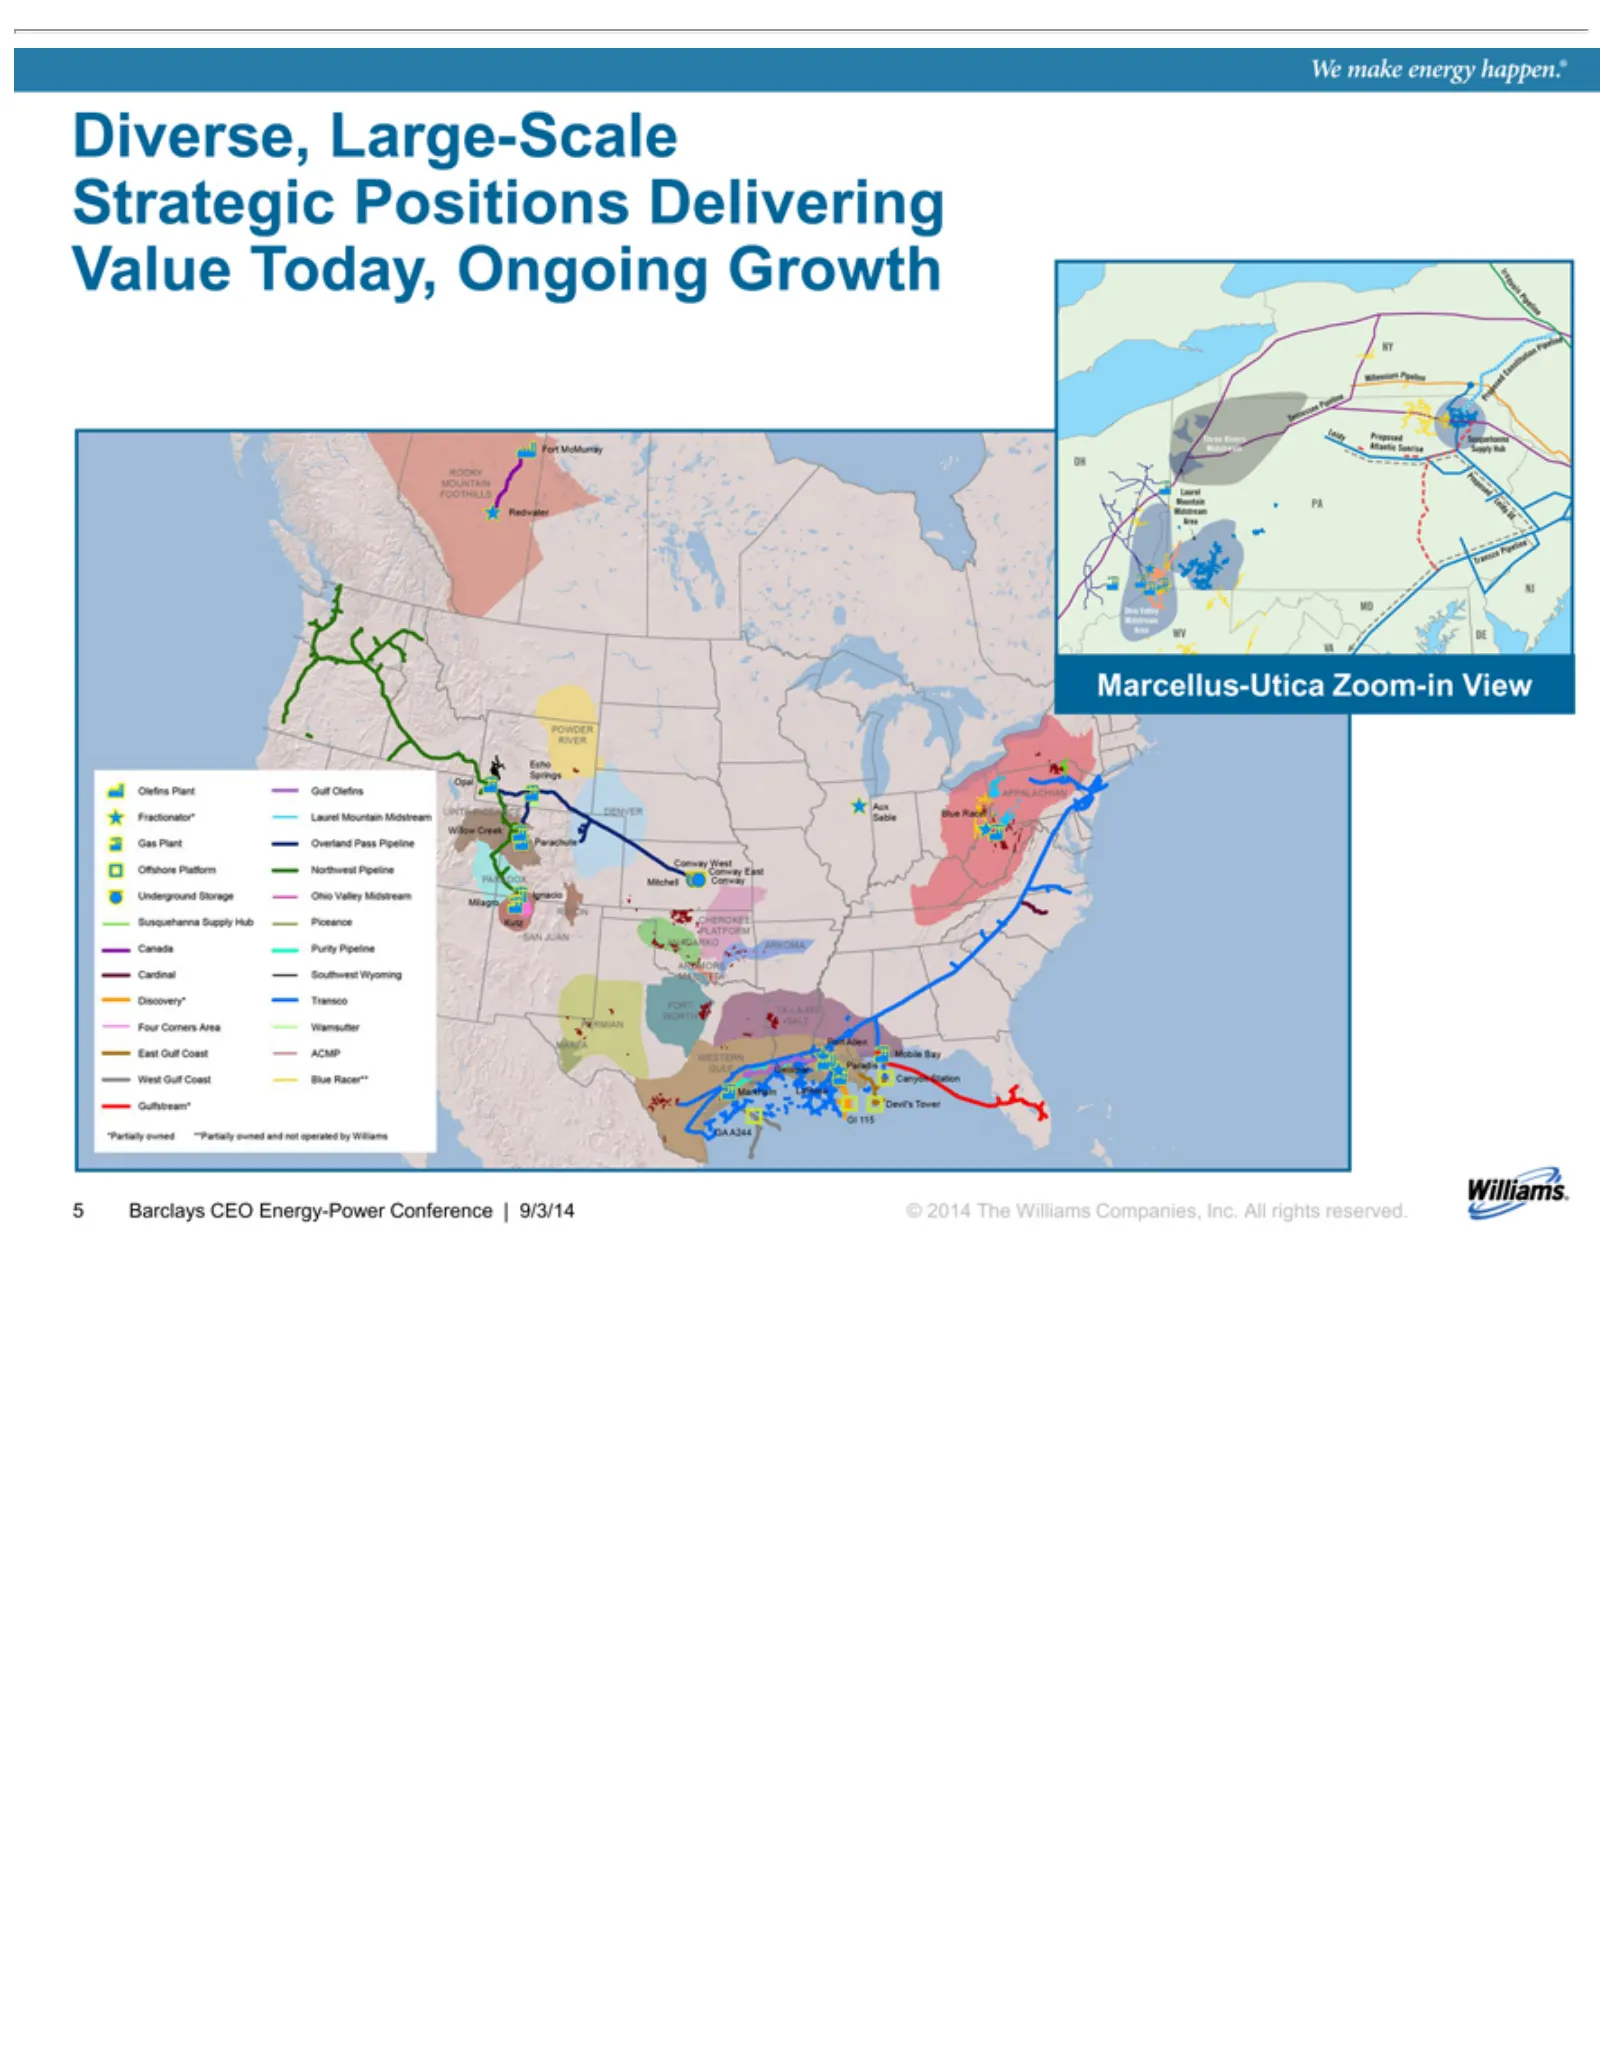
Slide 6: Diverse, Large-Scale Strategic Positions
Diverse, Large-Scale Strategic Barclays 5Marcellus-Utica CEO Positions Energy-Power Zoom-in Delivering View Conference Value Today, | 9/3/14 Ongoing © 2014 Growth The Williams Companies, Inc. All rights reserved.
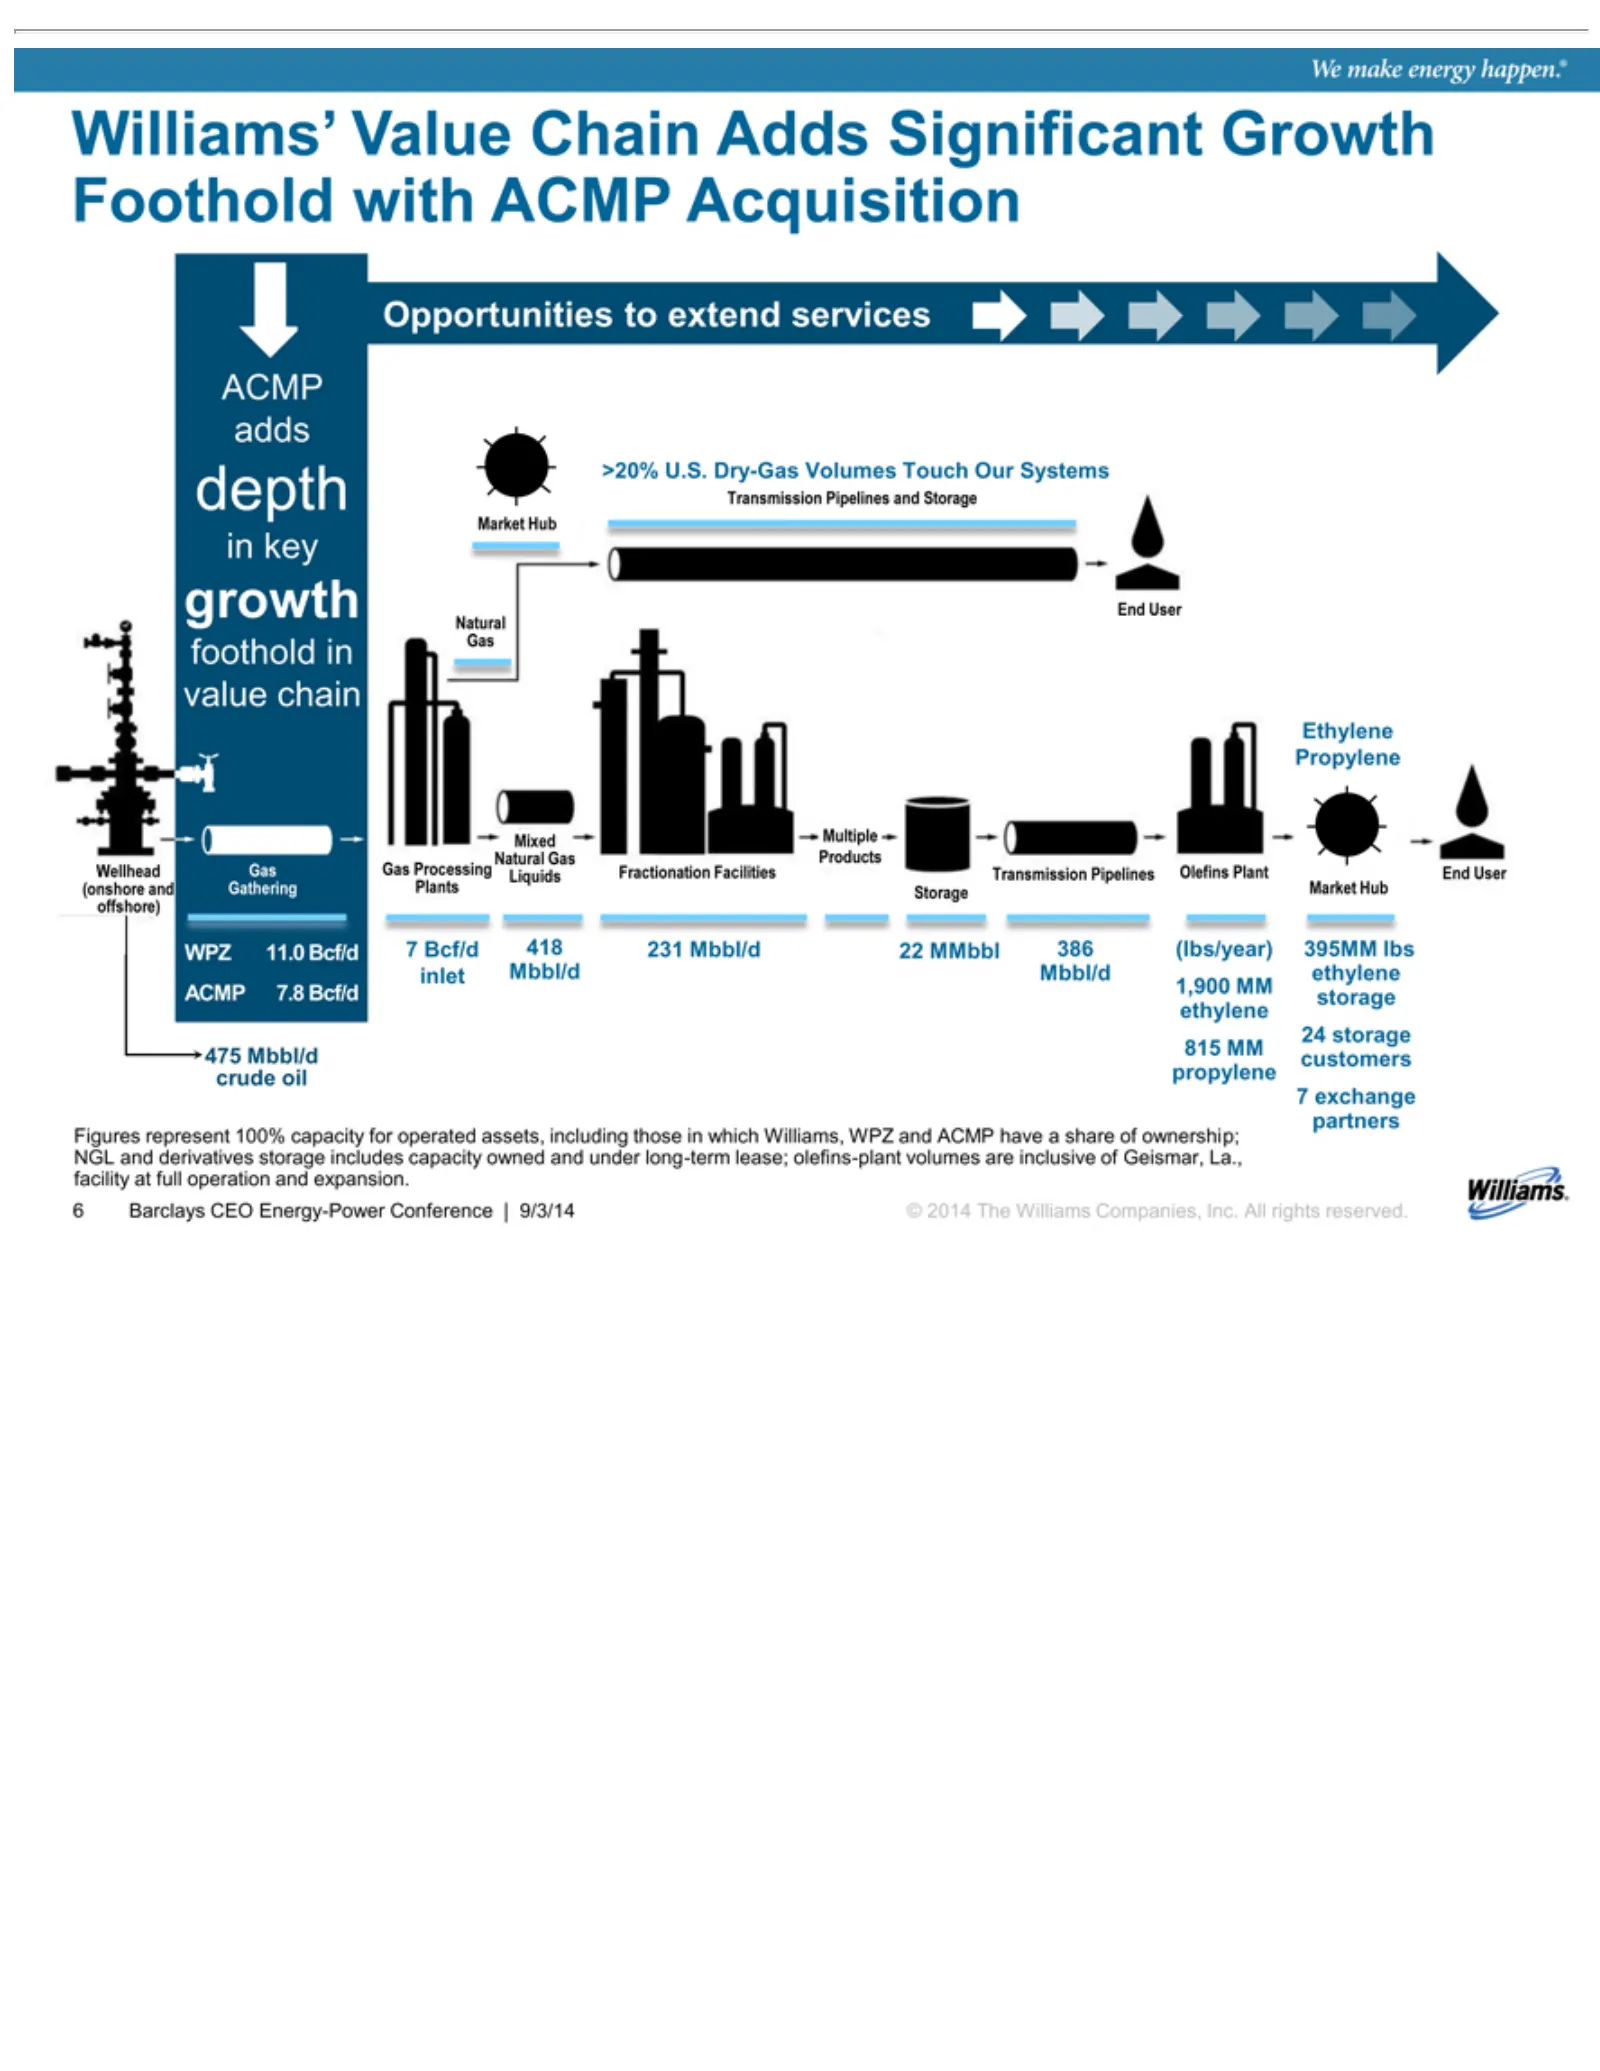
Slide 7: Williams' Foothold Opportunities
Williams’ Foothold Opportunities >20% adds Transmission Market End Mixed Propylene Ethylene Gas Natural Wellhead (onshore WPZ offshore) inlet ACMP 815 ethylene 475 7crude Figures partners NGL 6facility exchange Barclays MM Mbbl/d User Mbbl/d and 11.0 oil U.S. Multiple 7.8 at Hub Gas represent and pr
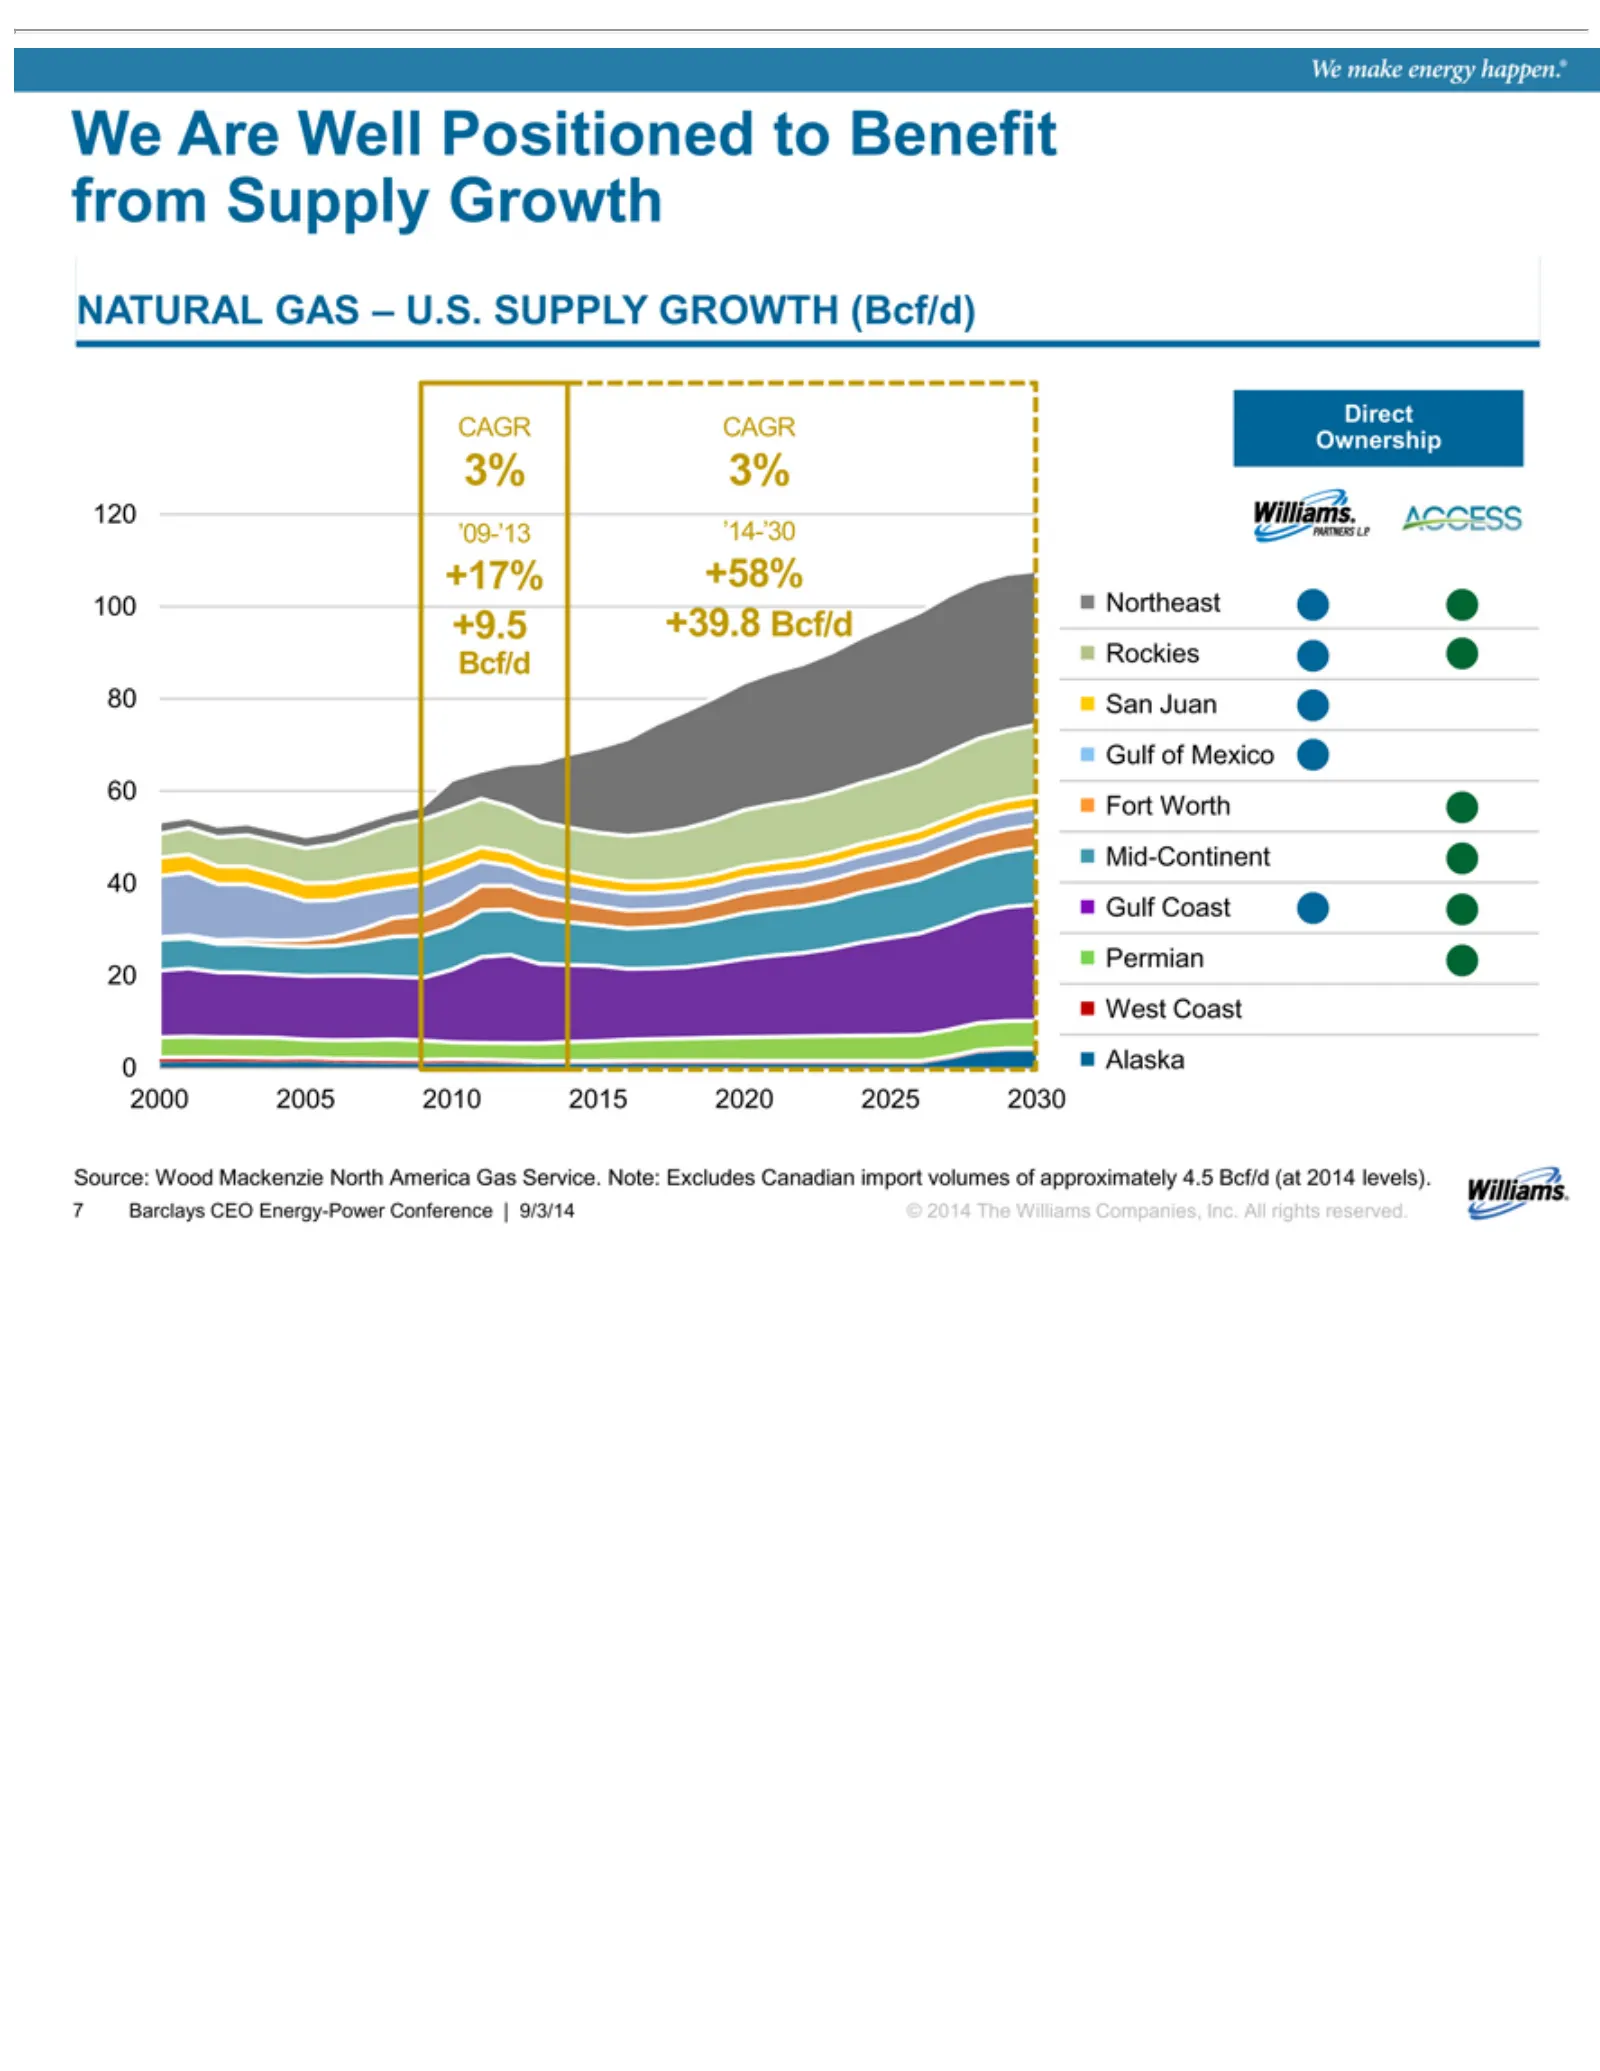
Slide 8: Natural Gas Supply Growth
We from NATURAL CAGR Direct 3% ’09-’13 120 +17% 100 Bcf/d 80 60 Gulf 40 Mid-Continent 20 0West 2000 7Source: Alaska Barclays San Fort Permian Are 3% +9.5 of Coast Supply Coast 2005 Rockies +58% Juan CAGR Worth Mexico Well ’14-’30 Wood +39.8 CEO 2010 GAS Growth Positioned Mackenzie Ownership Bcf/d En
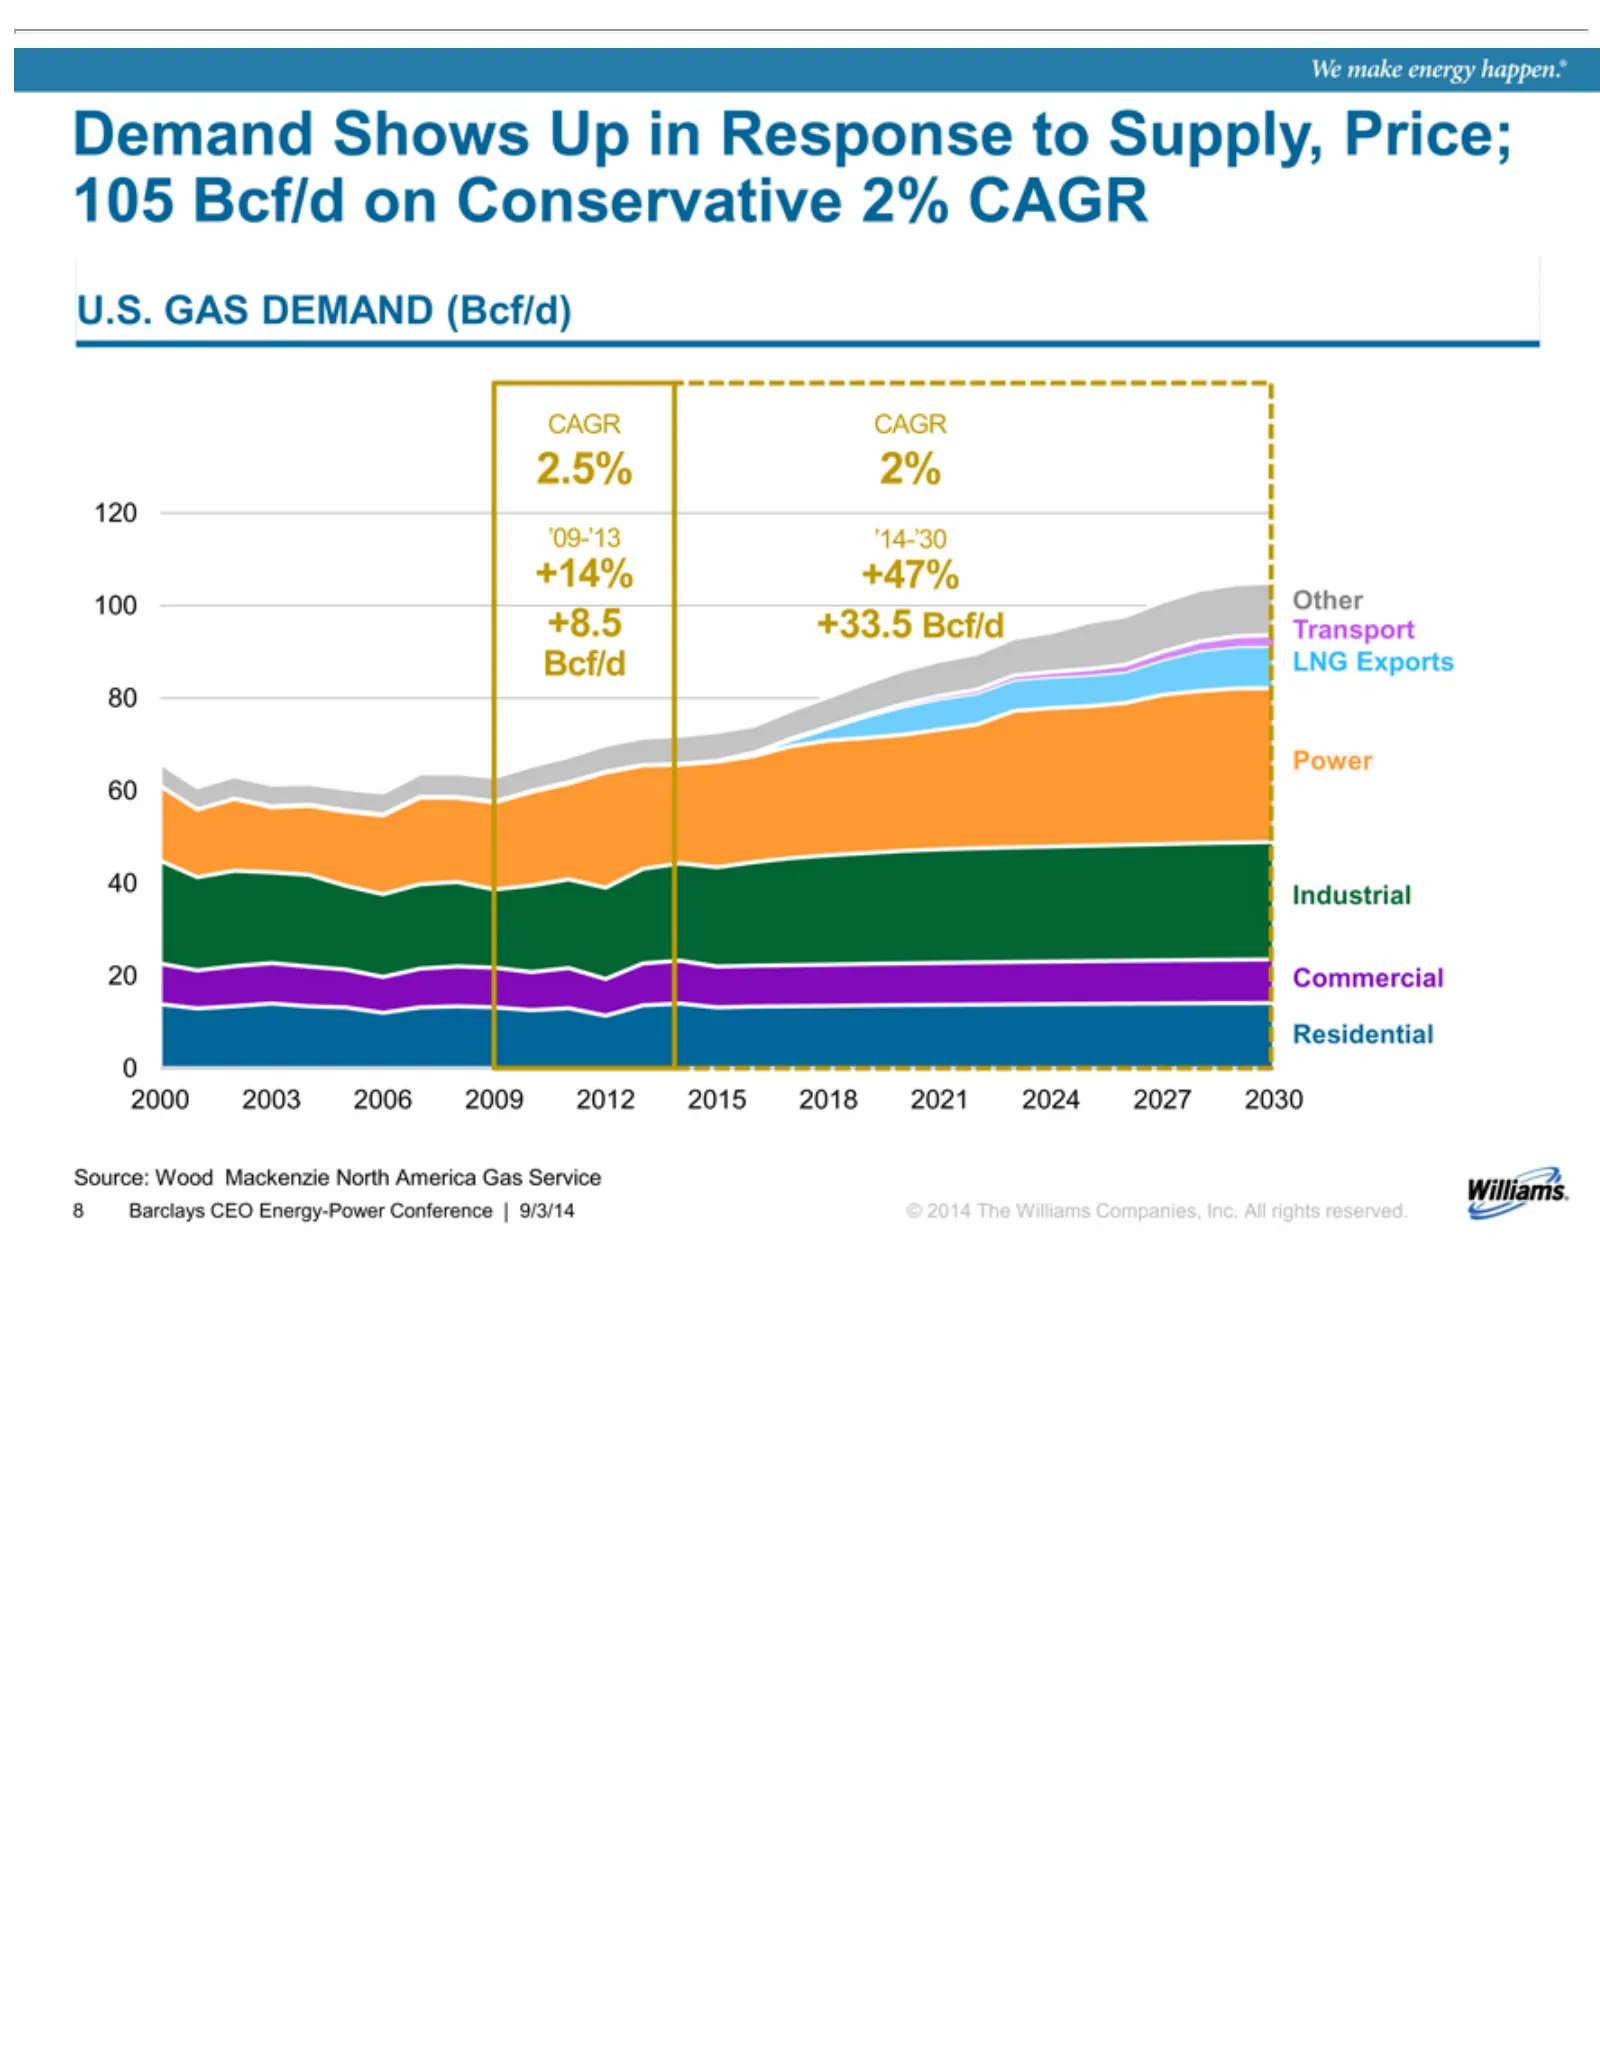
Slide 9: Natural Gas Demand Growth
Demand 105 Conservative U.S. +33.5 +8.5 Other 100 +47% +14% ’14-’30 ’09-’13 120 2% 2.5% CAGR (Bcf/d) LNG Bcf/d Transport 40 60 Power 80 0220 Residential 8Source: 000 Barclays Industrial Commercial Bcf/d GAS 2003 Exports Bcf/d Wood Shows on DEMAND CEO 2006 2% Mackenzie Up Energy-Power 2009 CAGR in 20
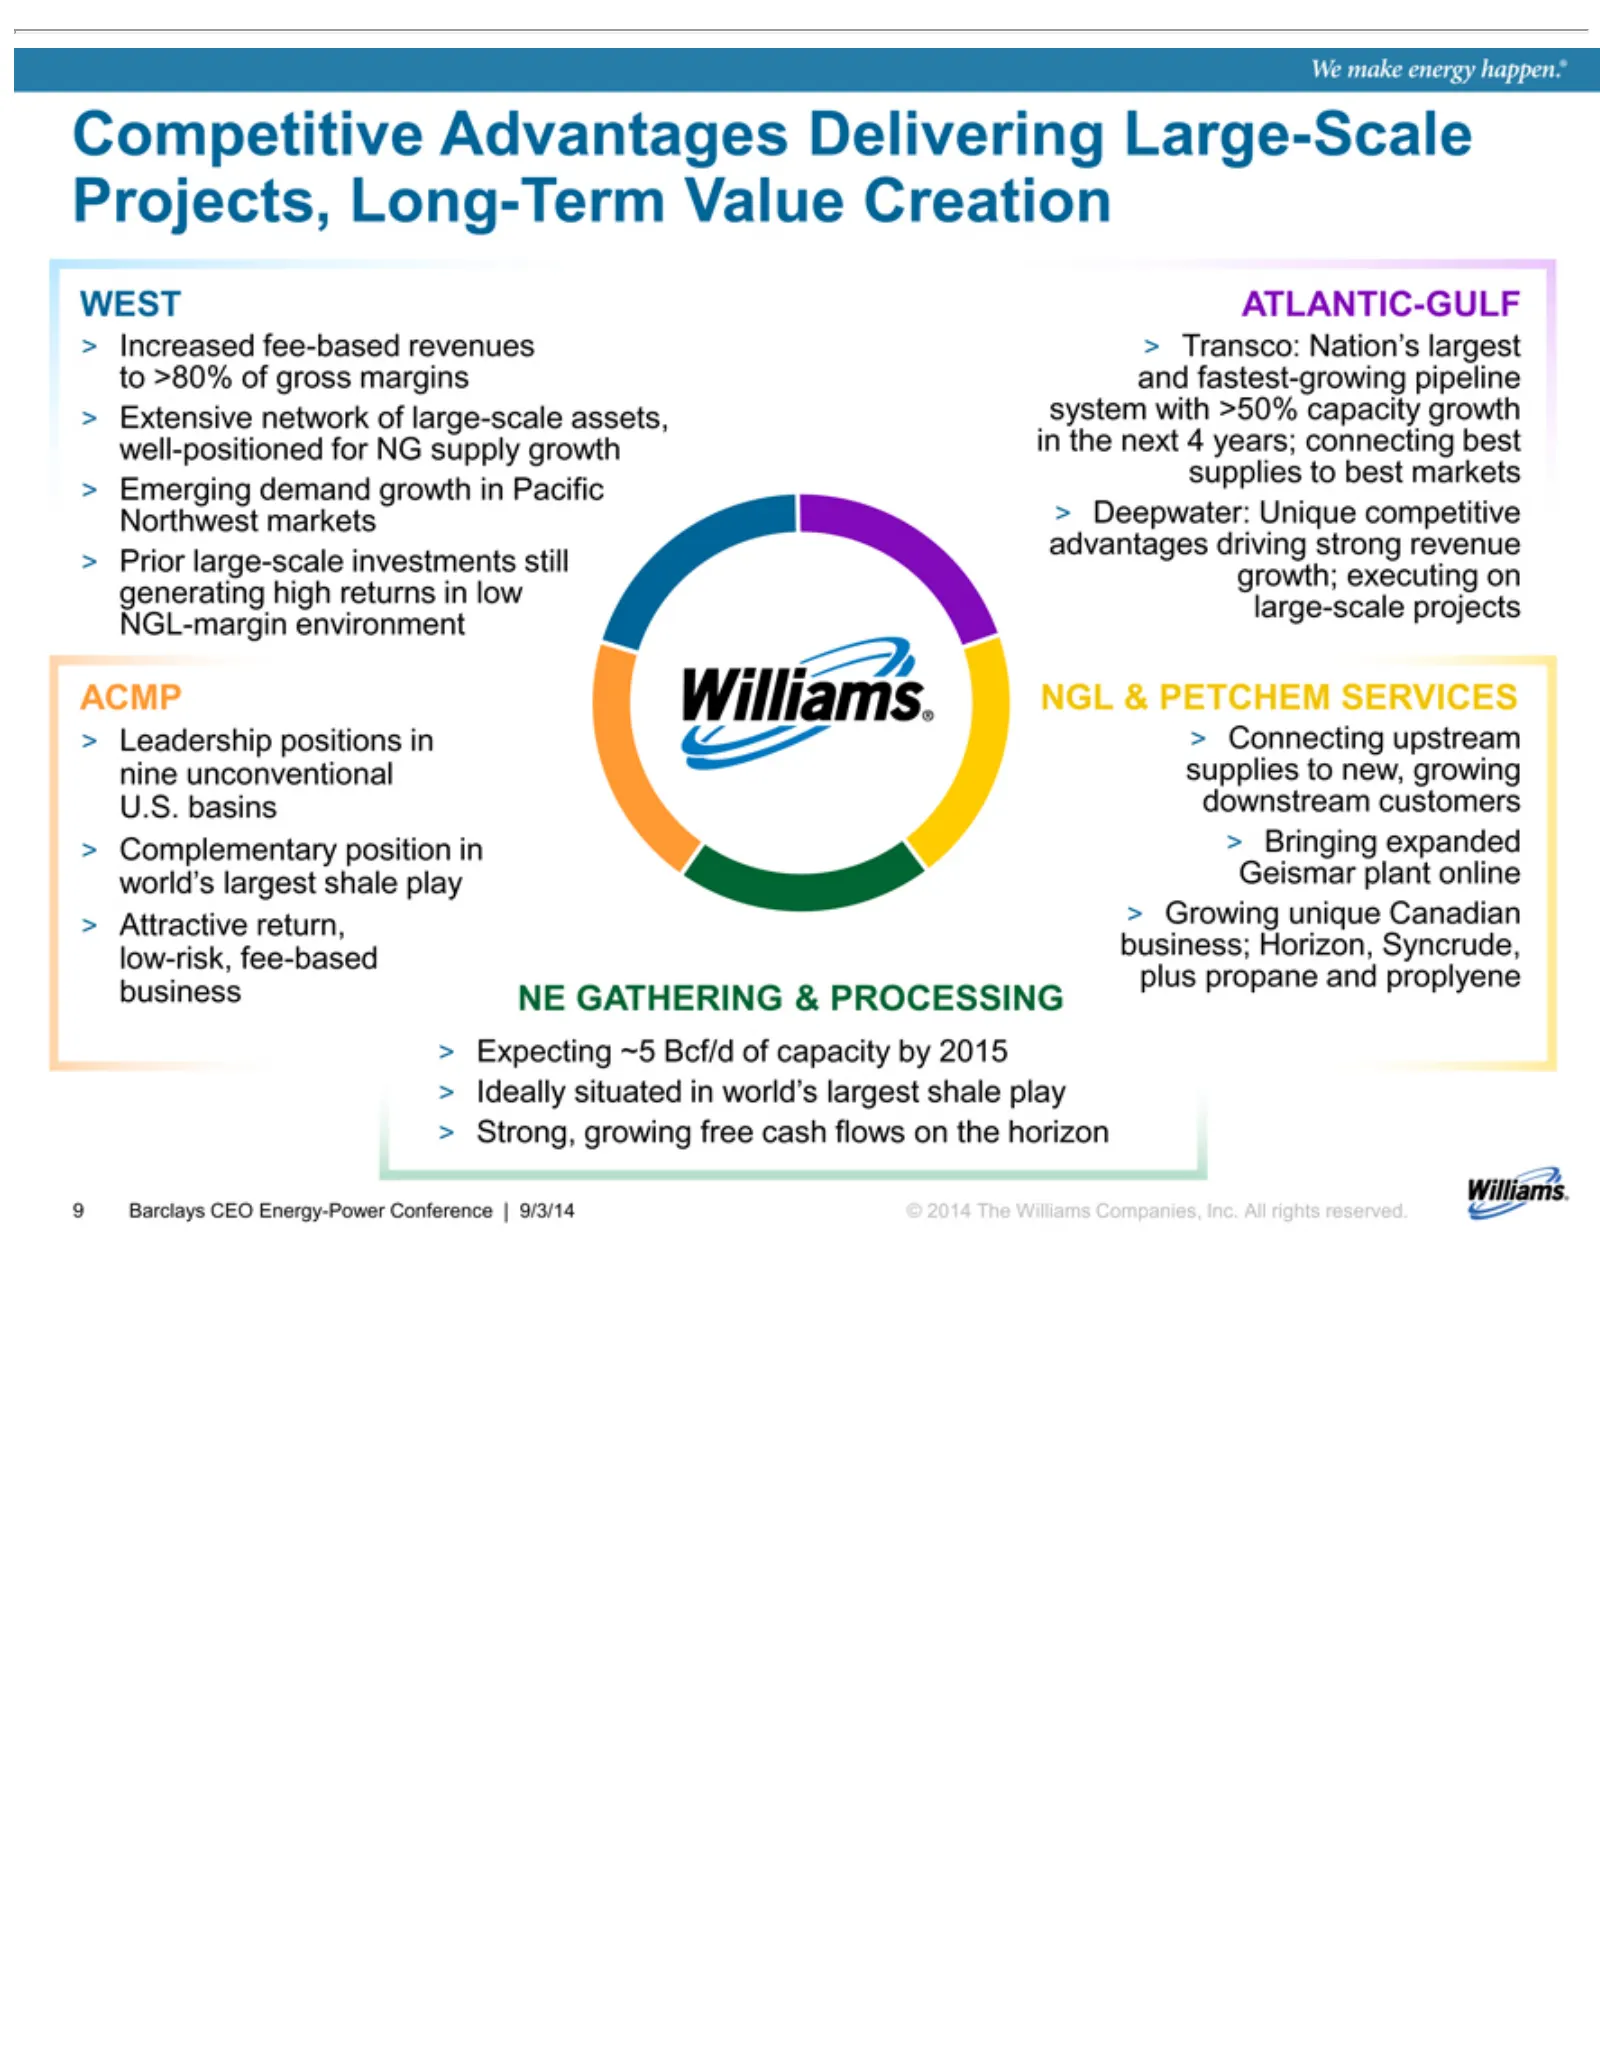
Slide 10: Competitive Advantages
Competitive WEST to well-positioned Northwest advantages generating NGL-margin ACMP nine U.S. world’s > low-risk, business Expecting Ideally 9Strong, © Barclays Attractive Increased Extensive Emerging Prior Leadership Complementary 2014 >80% unconventional basins ATLANTIC-GULF situated NGL large-sca
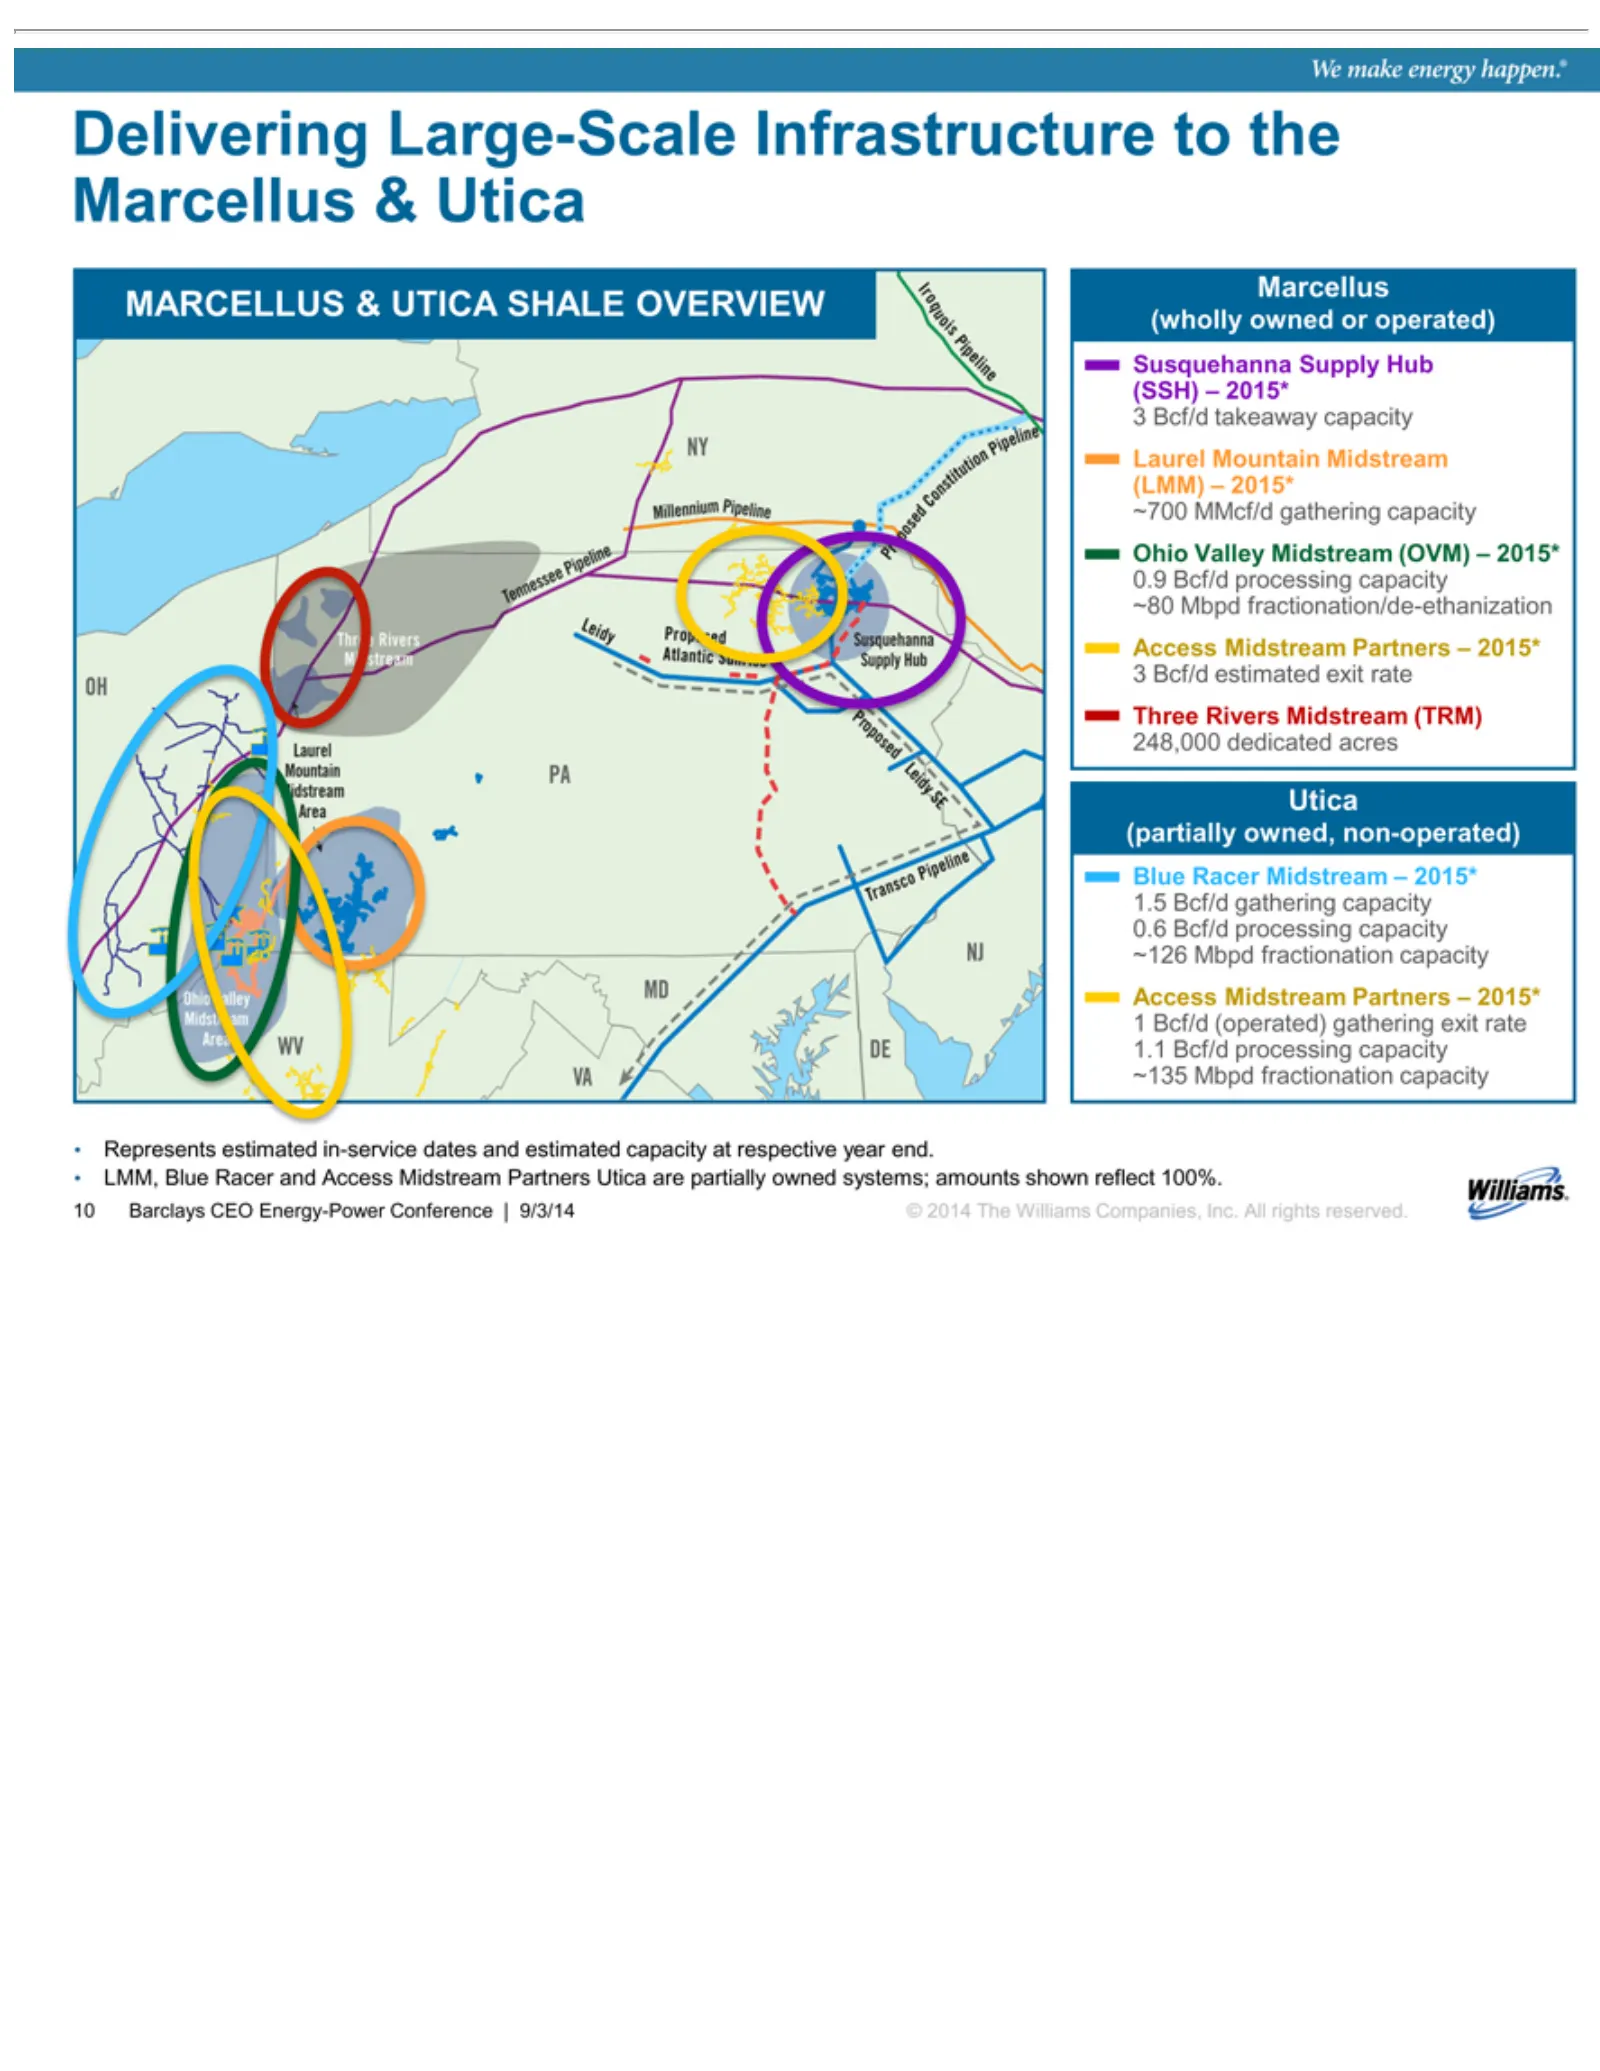
Slide 11: Delivering Marcellus and Utica Shale Value
Delivering Marcellus MARCELLUS (wholly Susquehanna (SSH) Laurel (LMM) ~700 Ohio 0.9 3~80 Three 248,000 (partially Utica Blue Bcf/d ~126 1Access 1.1 ~135 Represents LMM, 10 © Bcf/d 2014 Barclays Bcf/d Mbpd Racer Valley MMcf/d Mbpd gathering processing Rivers –Mountain Blue Midstream takeaway estimate
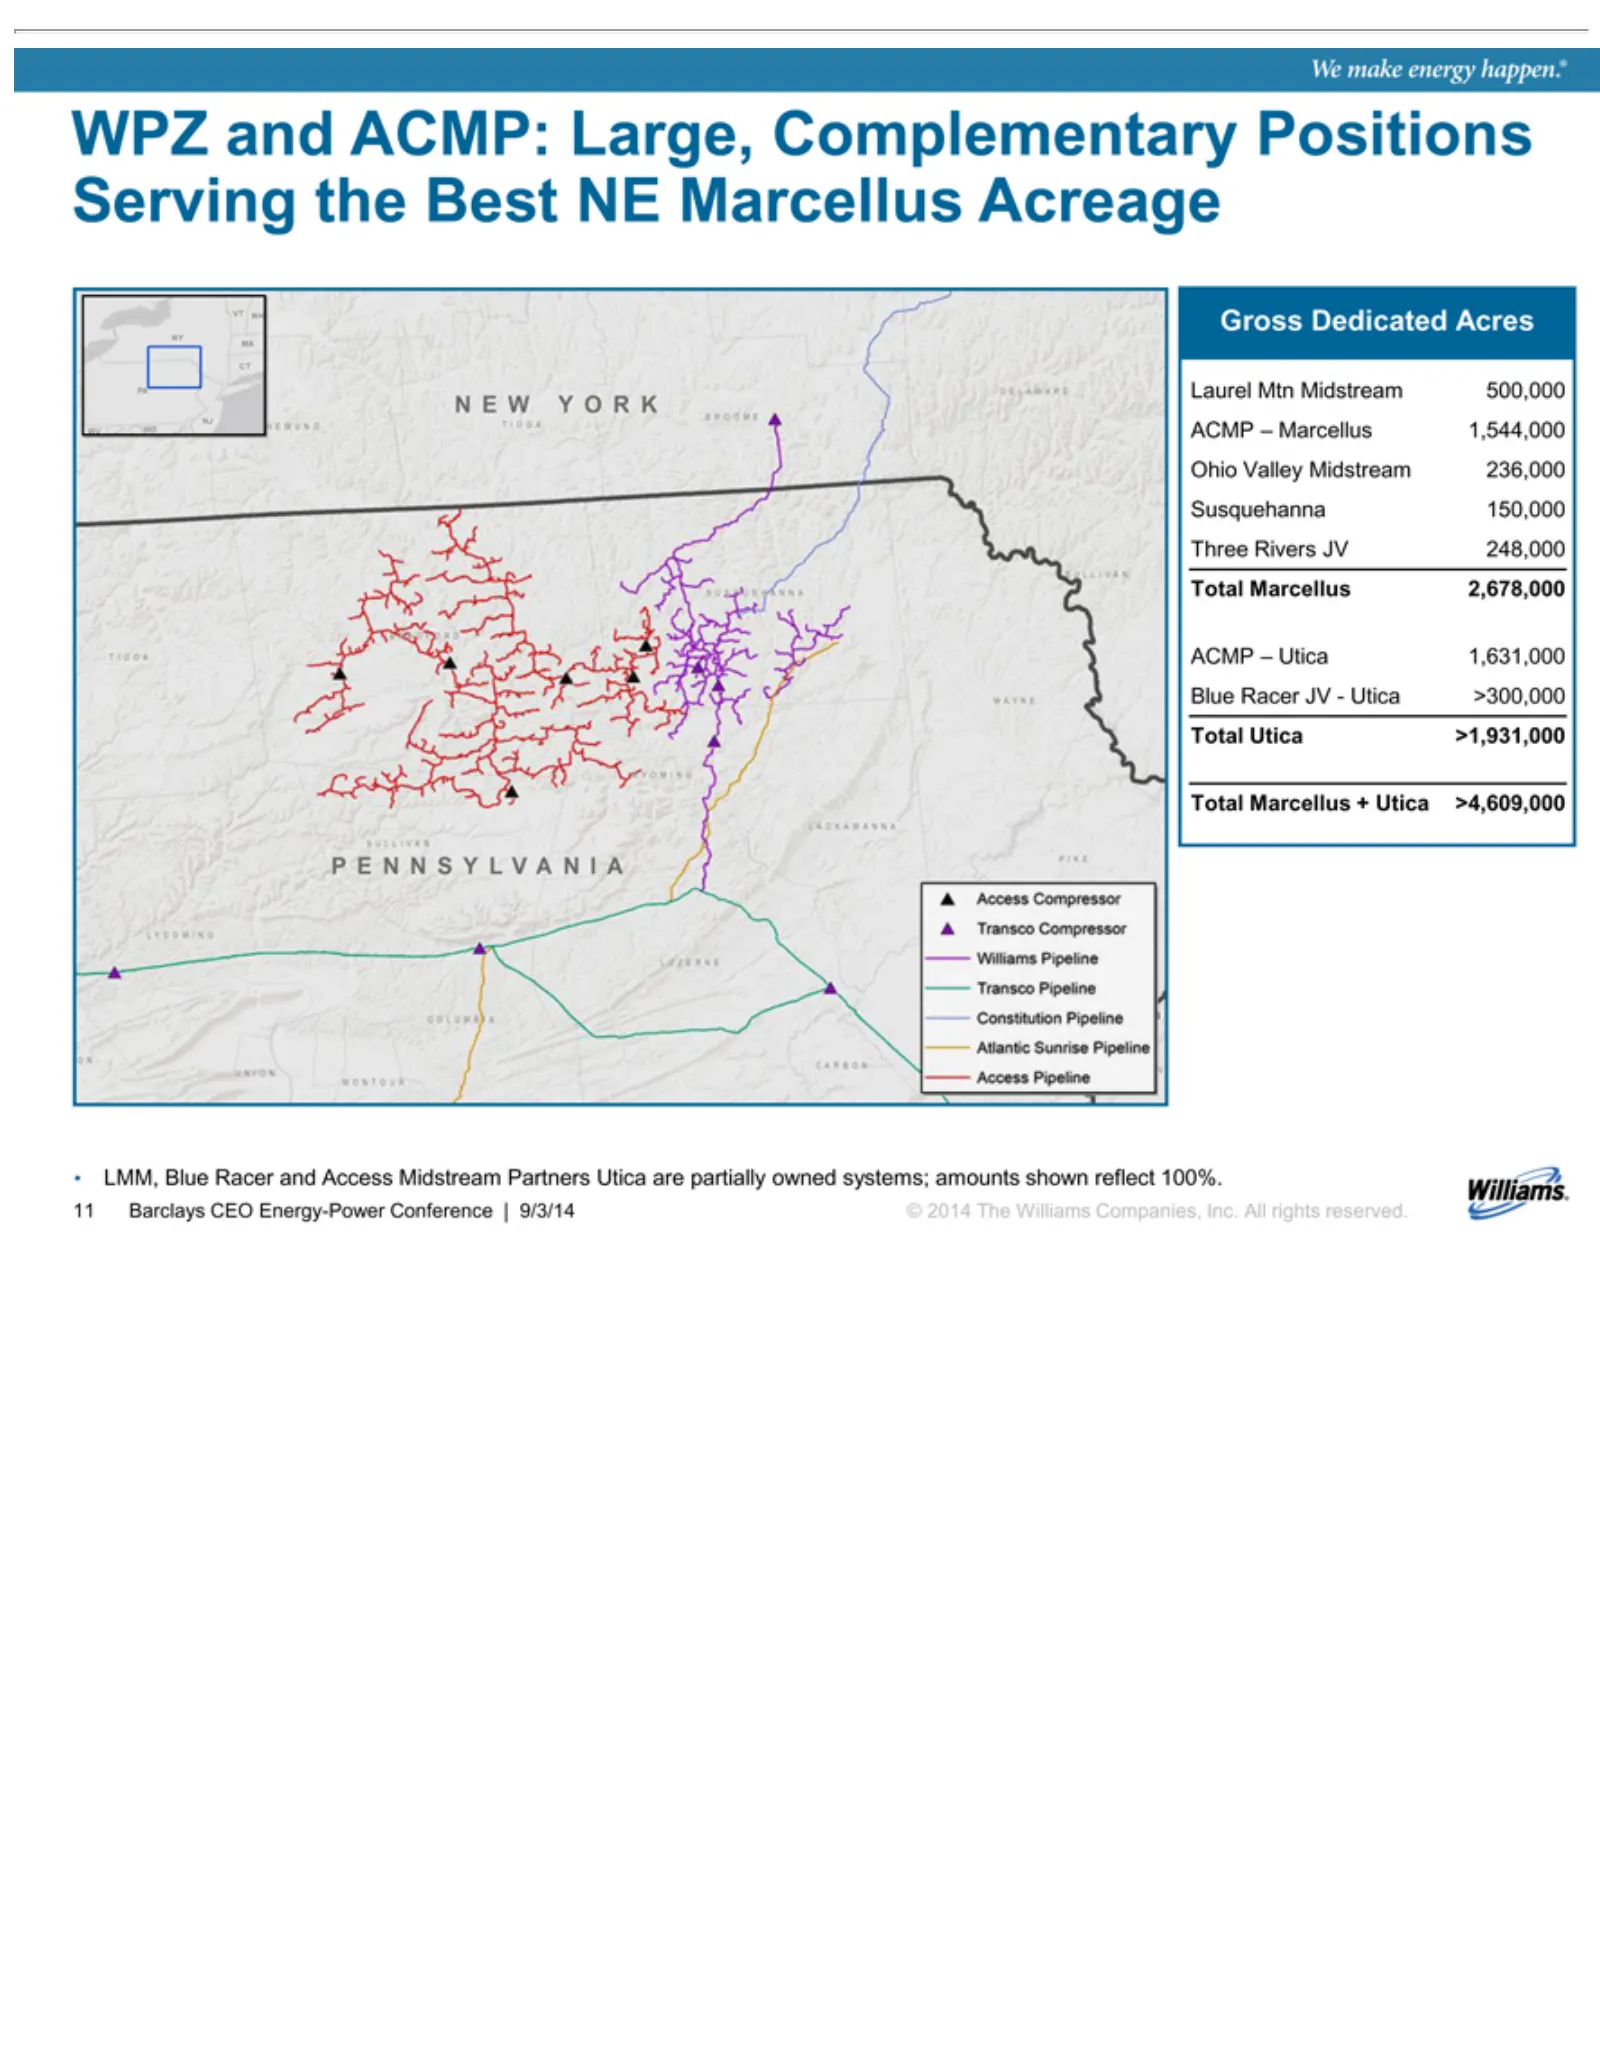
Slide 12: Large, Complementary Positions in Marcellus/Utica
WPZ Gross Laurel Ohio Susquehanna Three ACMP Blue Total LMM, 11 Barclays Racer Valley Utica Marcellus and Rivers Dedicated Mtn Blue – Utica Marcellus ACMP: >1,931,000 JV—Utica Midstream CEO Racer Midstream JV 150,000 1,631,000 2,678,000 + 248,000 Acres Energy-Power Utica Large, and 1,544,000 >300,00
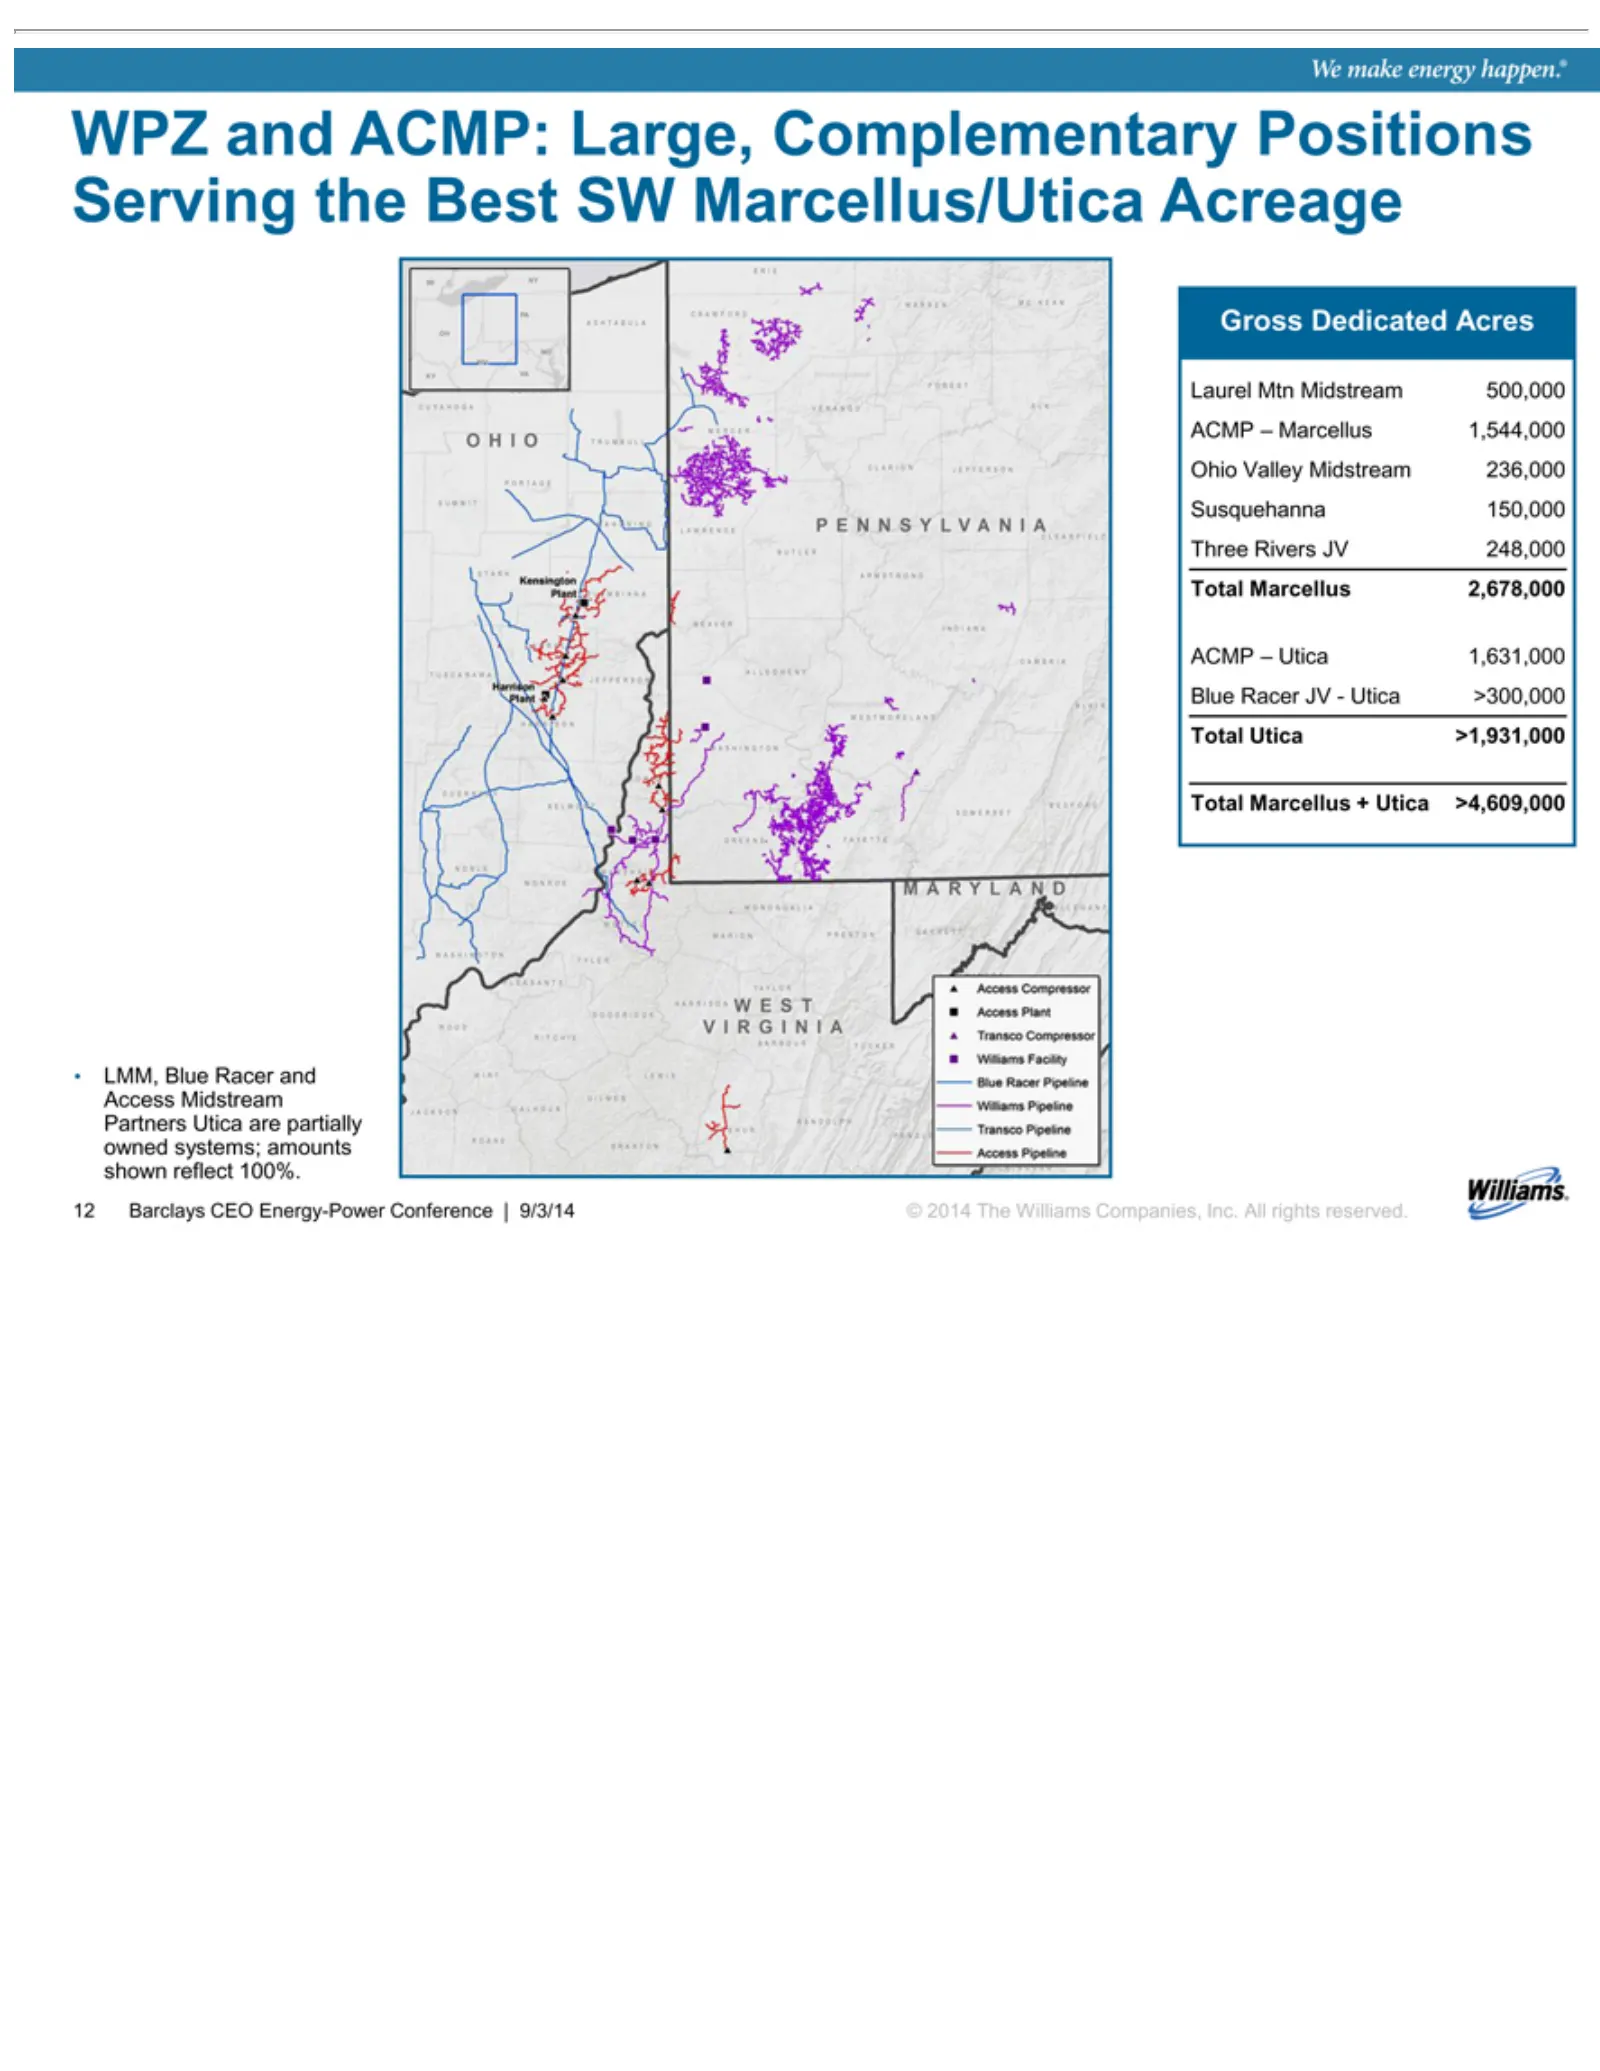
Slide 13: Large, Complementary Positions in Marcellus/Utica
WPZ LMM, Gross Laurel Ohio Susquehanna Three ACMP Blue Total 12 © 2014 Barclays Racer Valley Utica Marcellus and Rivers Dedicated Mtn Blue –The Marcellus Utica ACMP: >1,931,000 JV Midstream CEO Racer Williams Midstream JV 150,000 -1,631,000 2,678,000 + Utica 248,000 Acres Energy-Power Utica Large, a
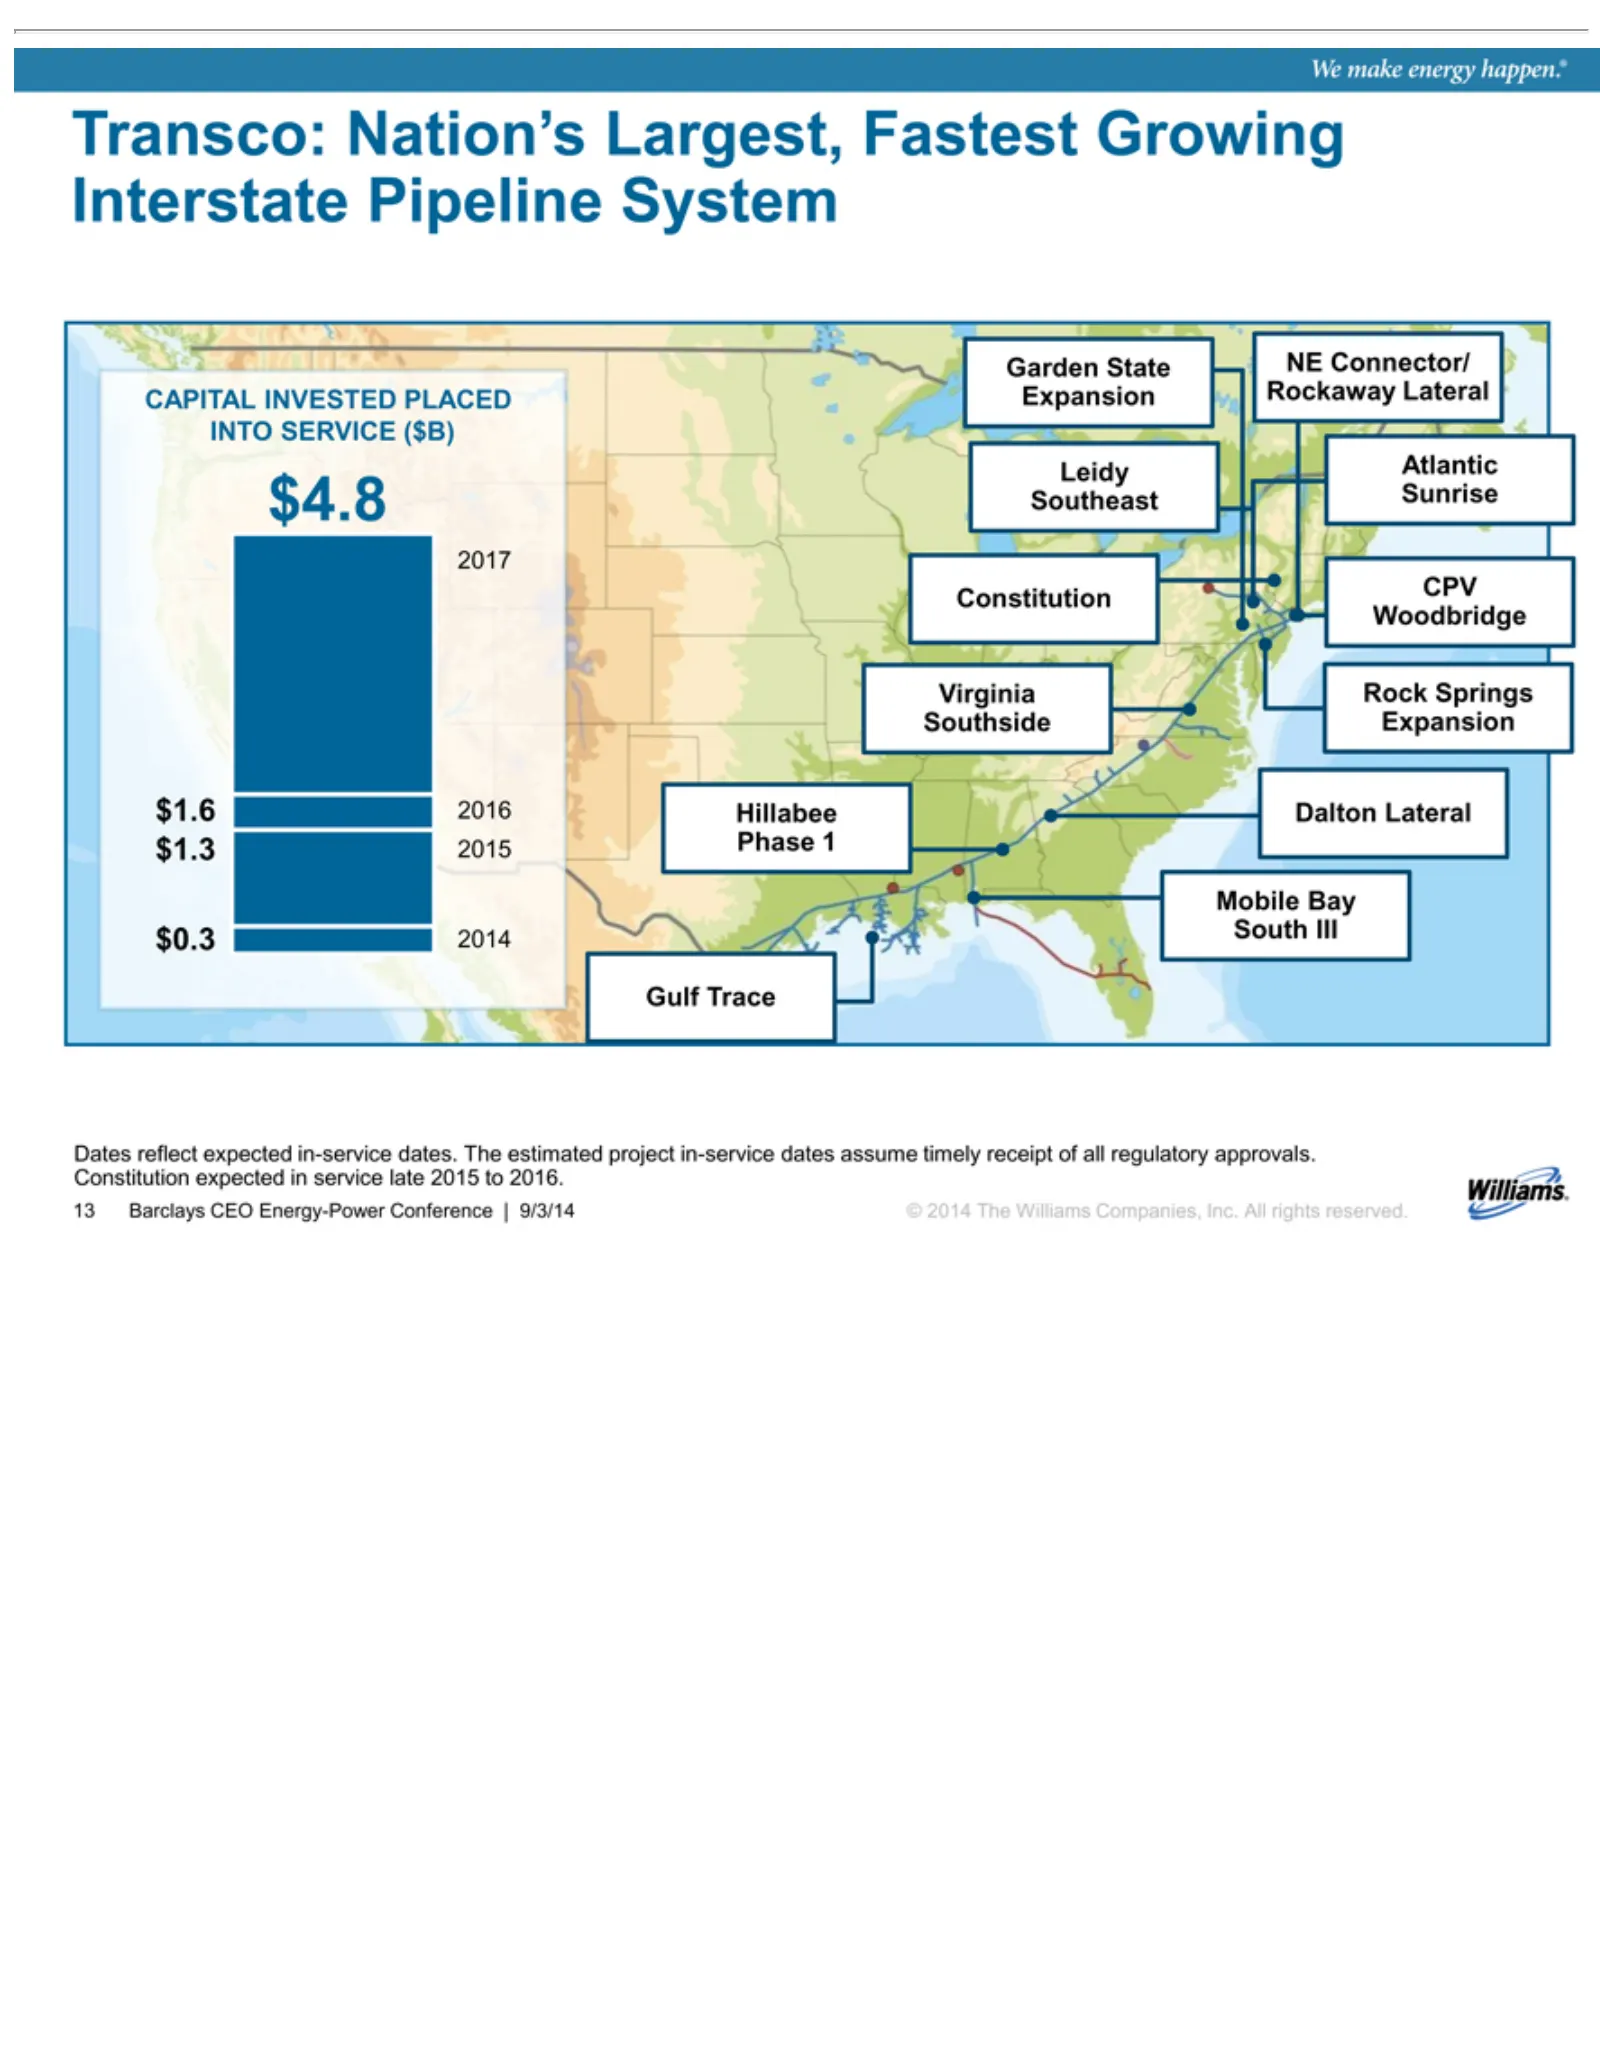
Slide 14: Transco: Nation's Largest, Fastest Growing Pipeline System
Transco: Interstate Garden NE CAPITAL INTO Leidy $4.8 2017 Virginia Woodbridge Southside $1.6 $1.3 Mobile $0.3 Gulf Dates Constitution 13 Barclays Connector/ Southeast 2016 2015 2014 Trace reflect Atlantic SERVICE Bay State Rock Nation’s Pipeline Expansion Hillabee Phase South INVESTED CEO CPV expec
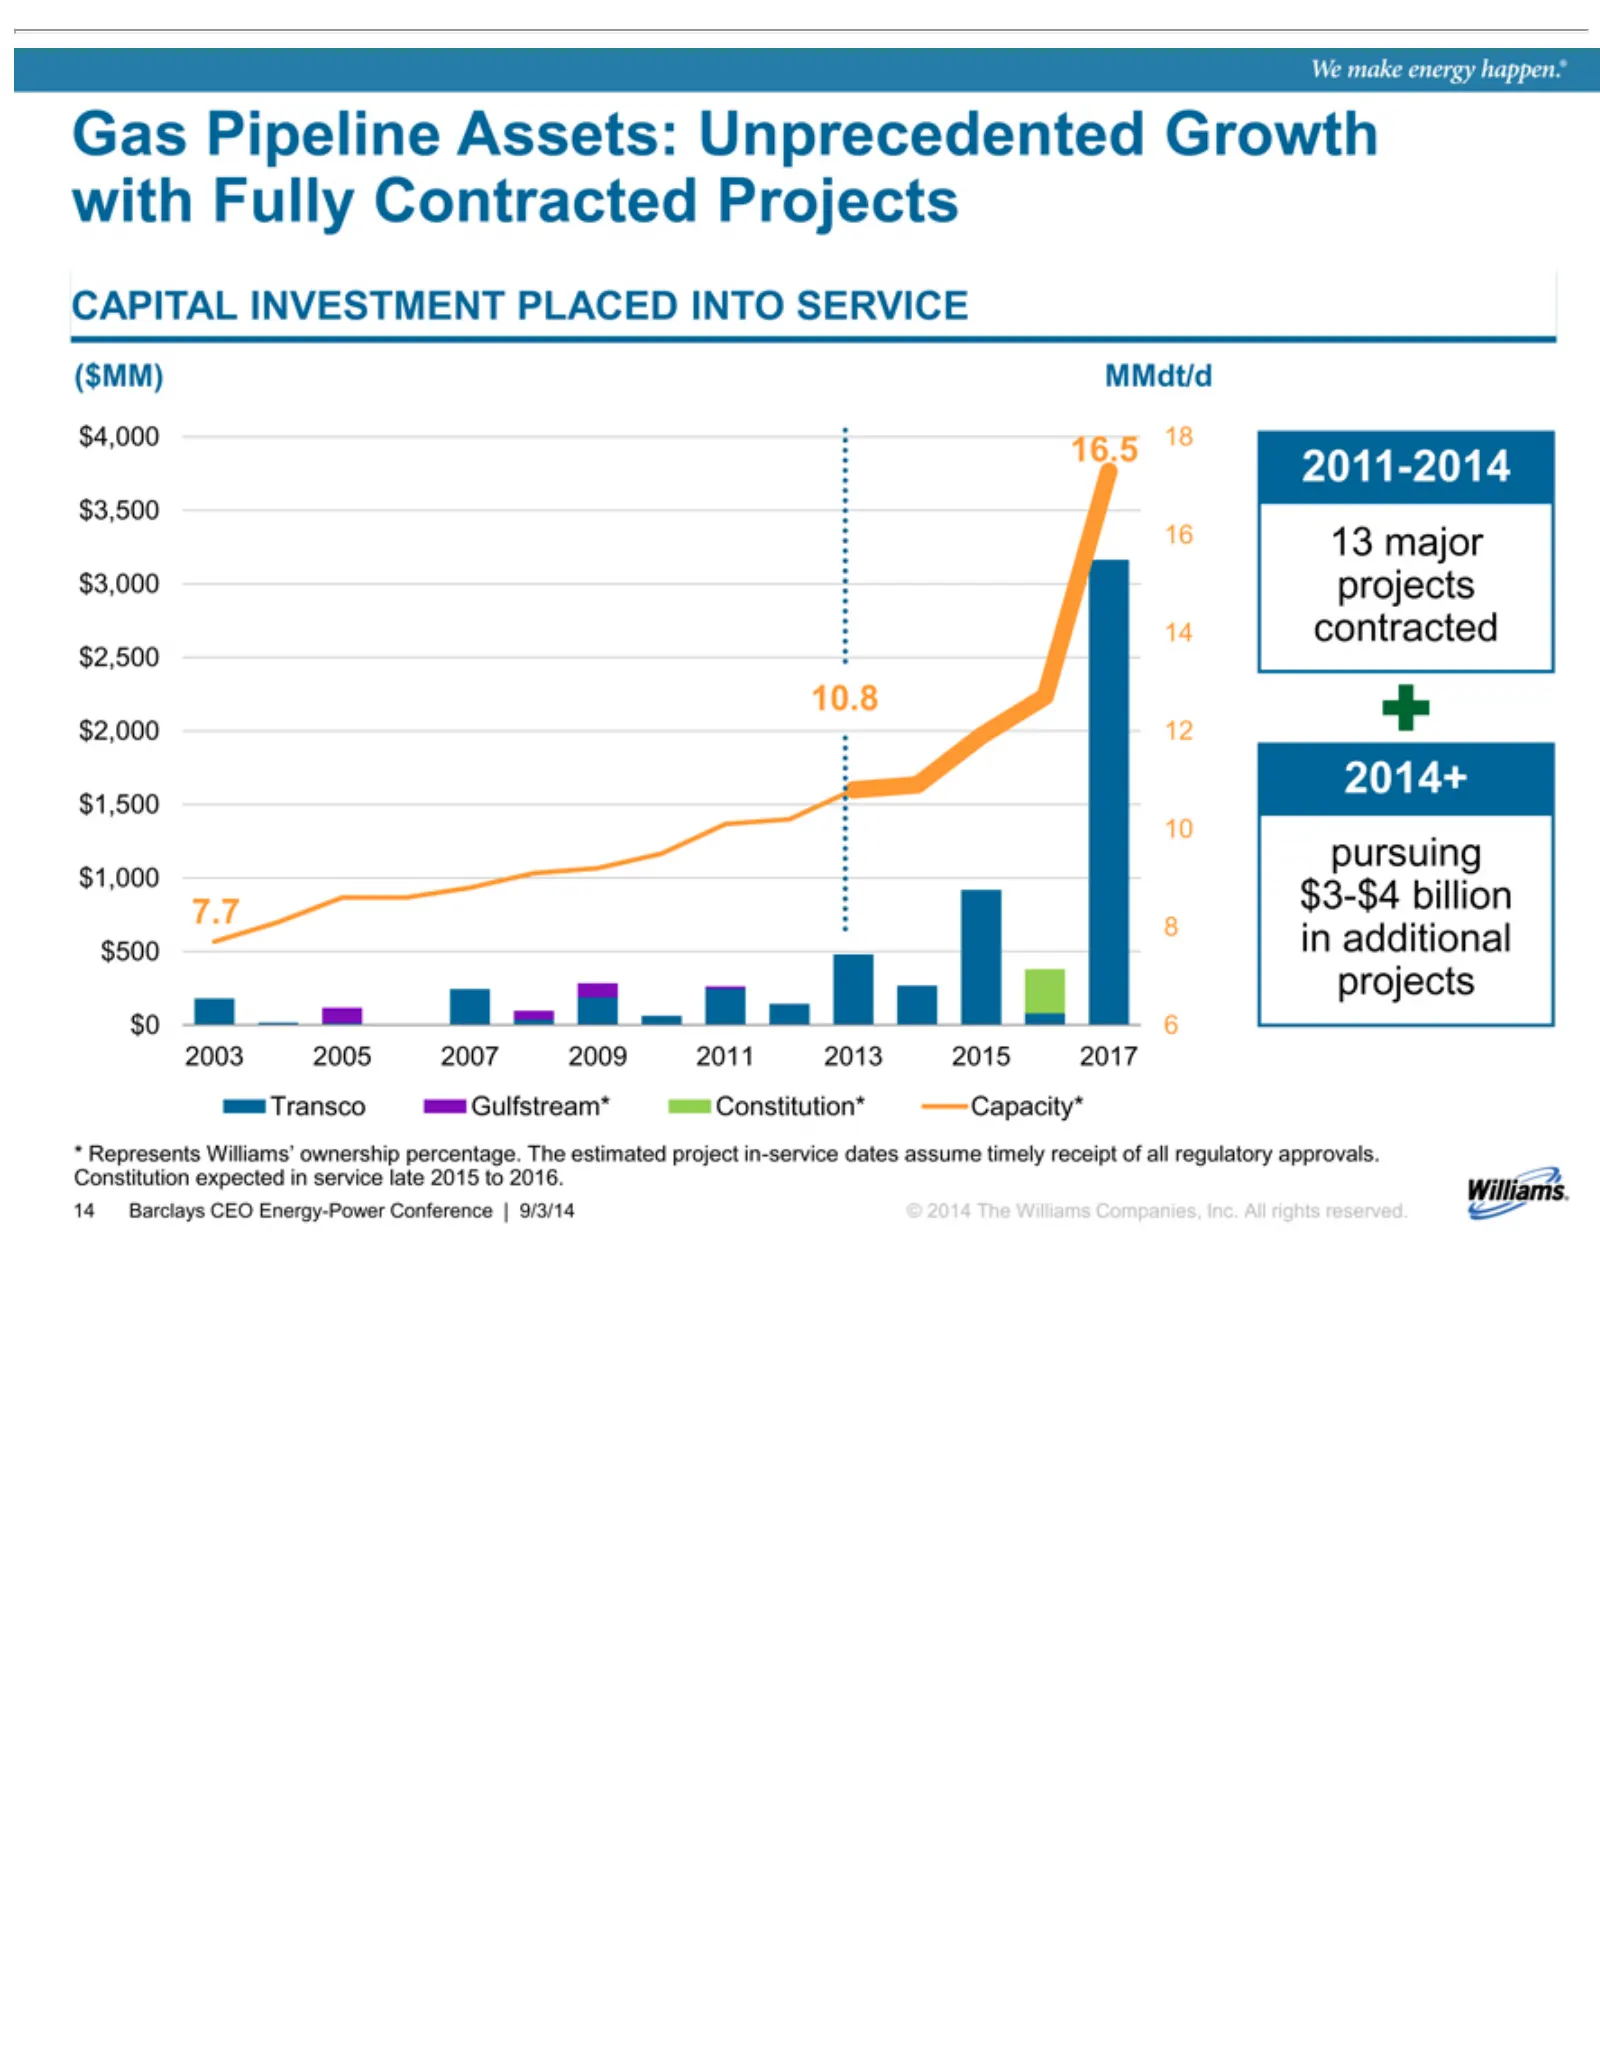
Slide 15: Gas Pipelines with Unprecedented Capital Investment
Gas with CAPITAL ($MM) $4,000 16 $3,500 2011-2014 $3,000 $2,000 10.8 $2,500 7.7 $1,000 pursuing 10 $1,500 82014+ $0 projects $500 2003 *Transco Constitution Barclays 14 © in Represents 2014 13 6contracted $3-$4 additional Pipeline Fully 2005 major 16.5 projects 12 MMdt/d The Gulfstream* CEO billion
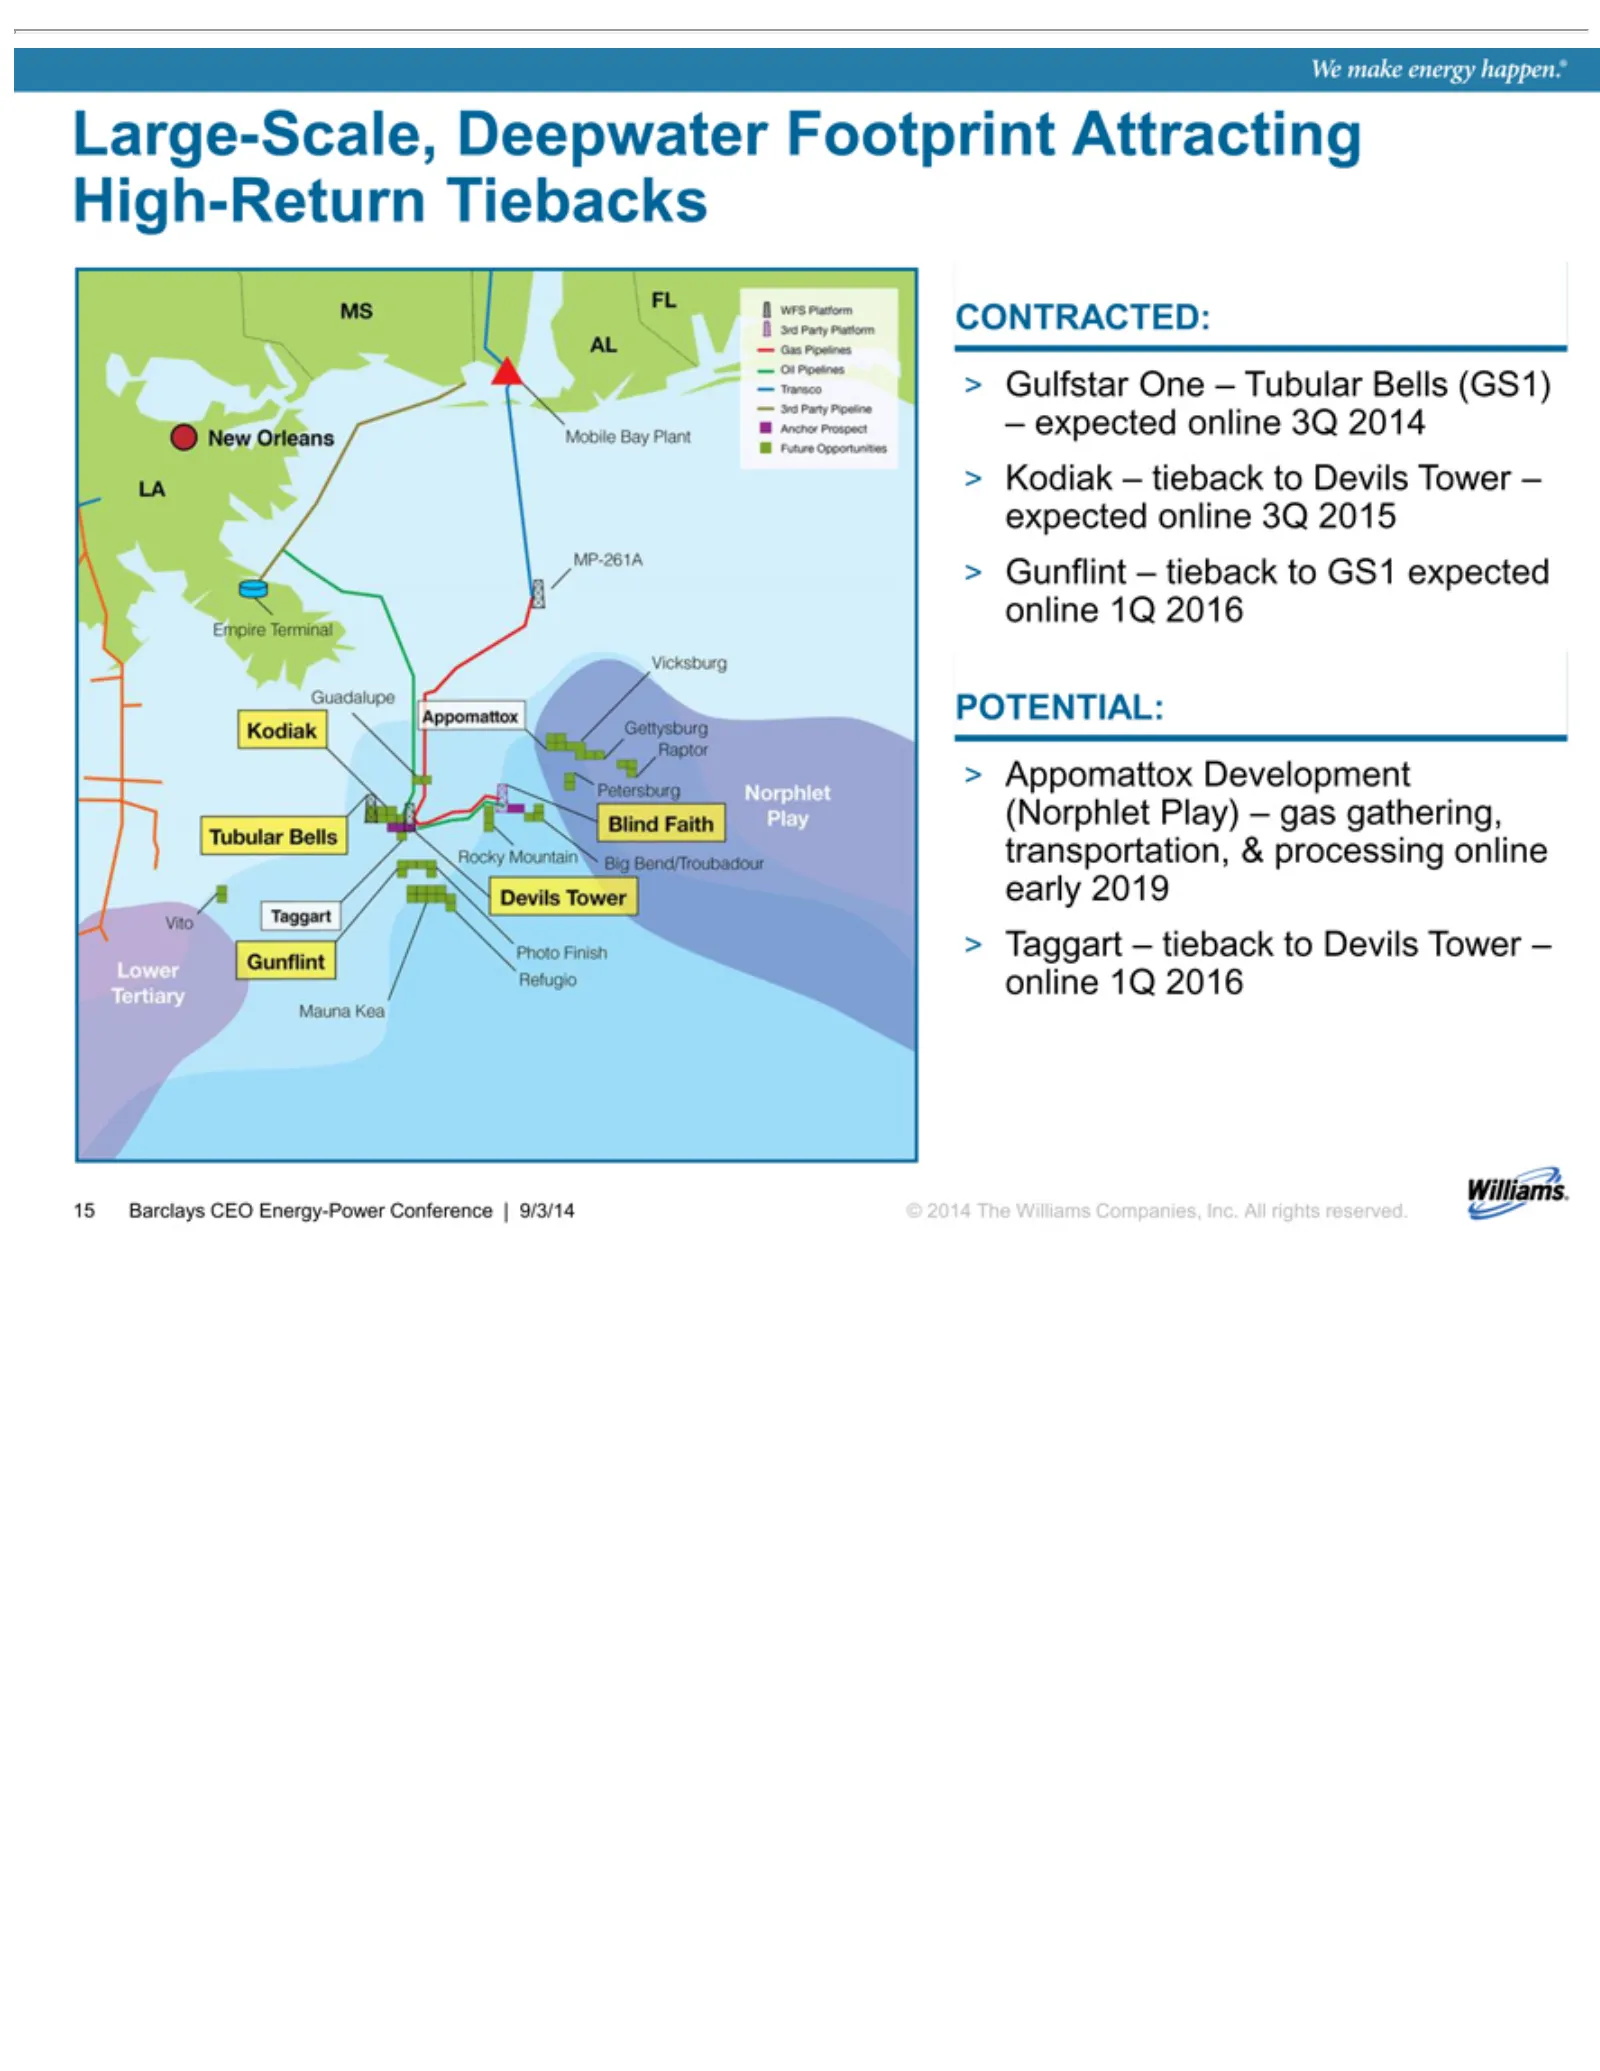
Slide 16: Large-Scale Deepwater Footprint
Large-Scale, Gulfstar CONTRACTED: Kodiak Gunflint Appomattox POTENTIAL: Taggart 15 © 2014 Barclays –The One –tieback tieback CEO Williams Development Deepwater – Tubular to Energy-Power toDevils GS1 Companies, Bells Footprint expected (Norphlet Tower (GS1) Conference –Attracting Inc. online expected
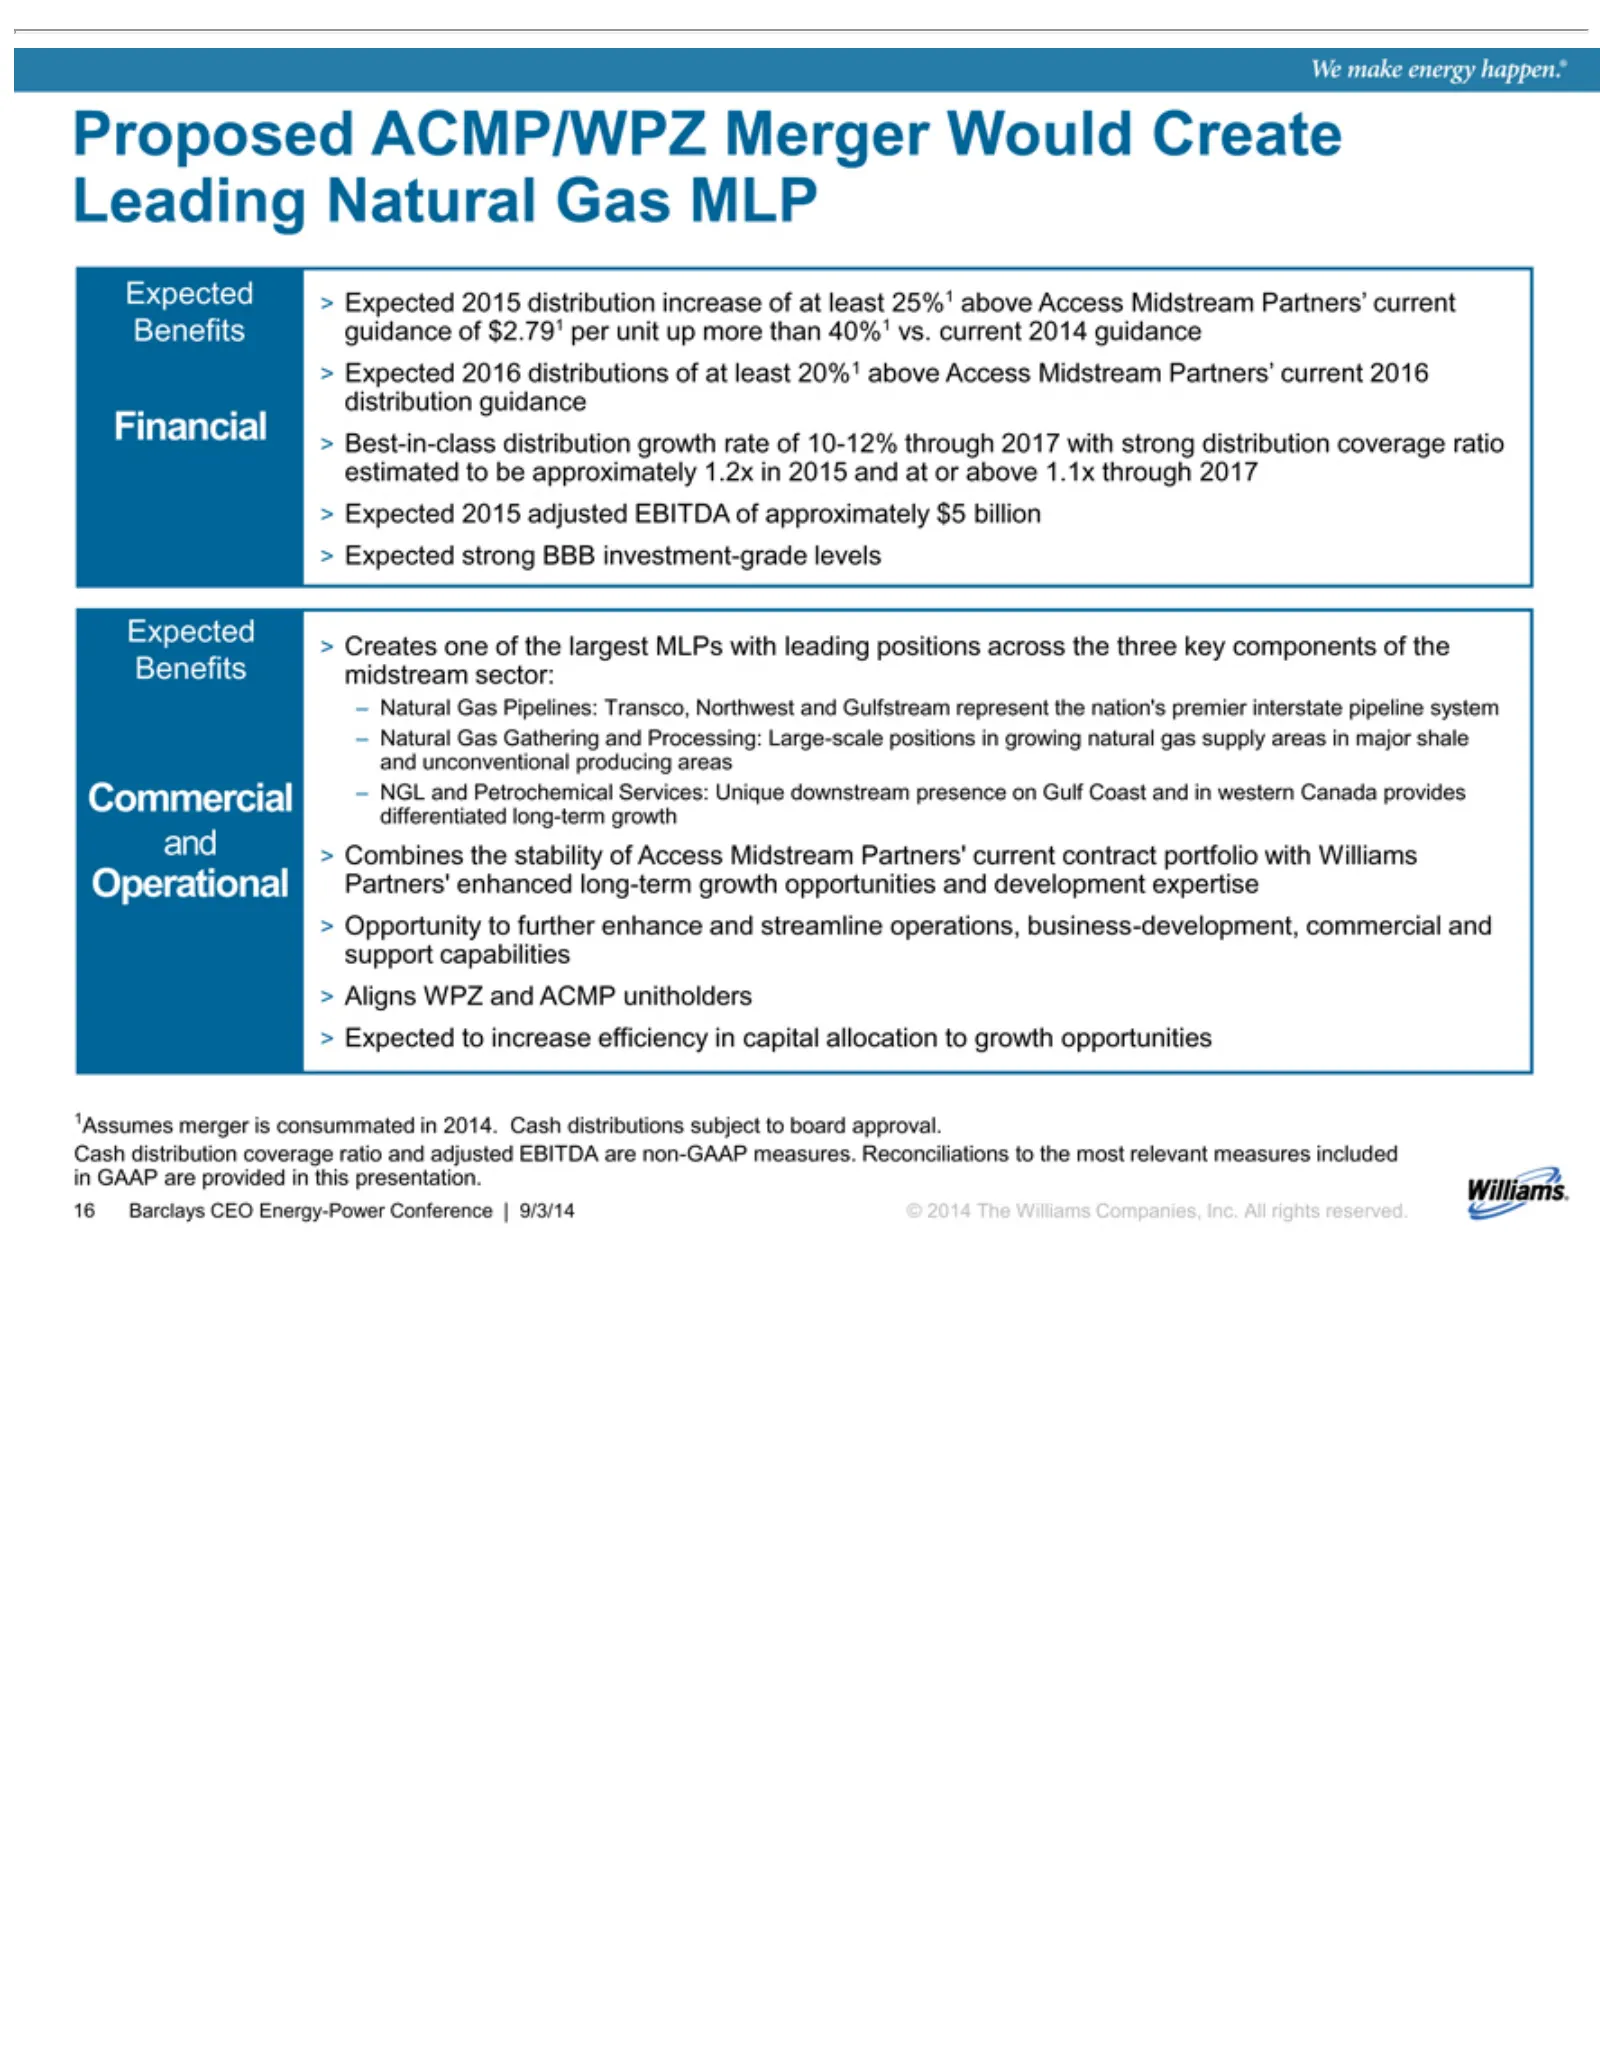
Slide 17: Proposed ACMP/WPZ Merger Benefits
Proposed distribution Financial estimated Expected –Benefits Commercial differentiated and Operational support > 1Assumes Cash 16 © Natural Aligns Opportunity Expected 2014 Barclays unconventional >distribution Combines The capabilities guidance midstream WPZ ACMP/WPZ > Gas tomerger Expected 2016 20
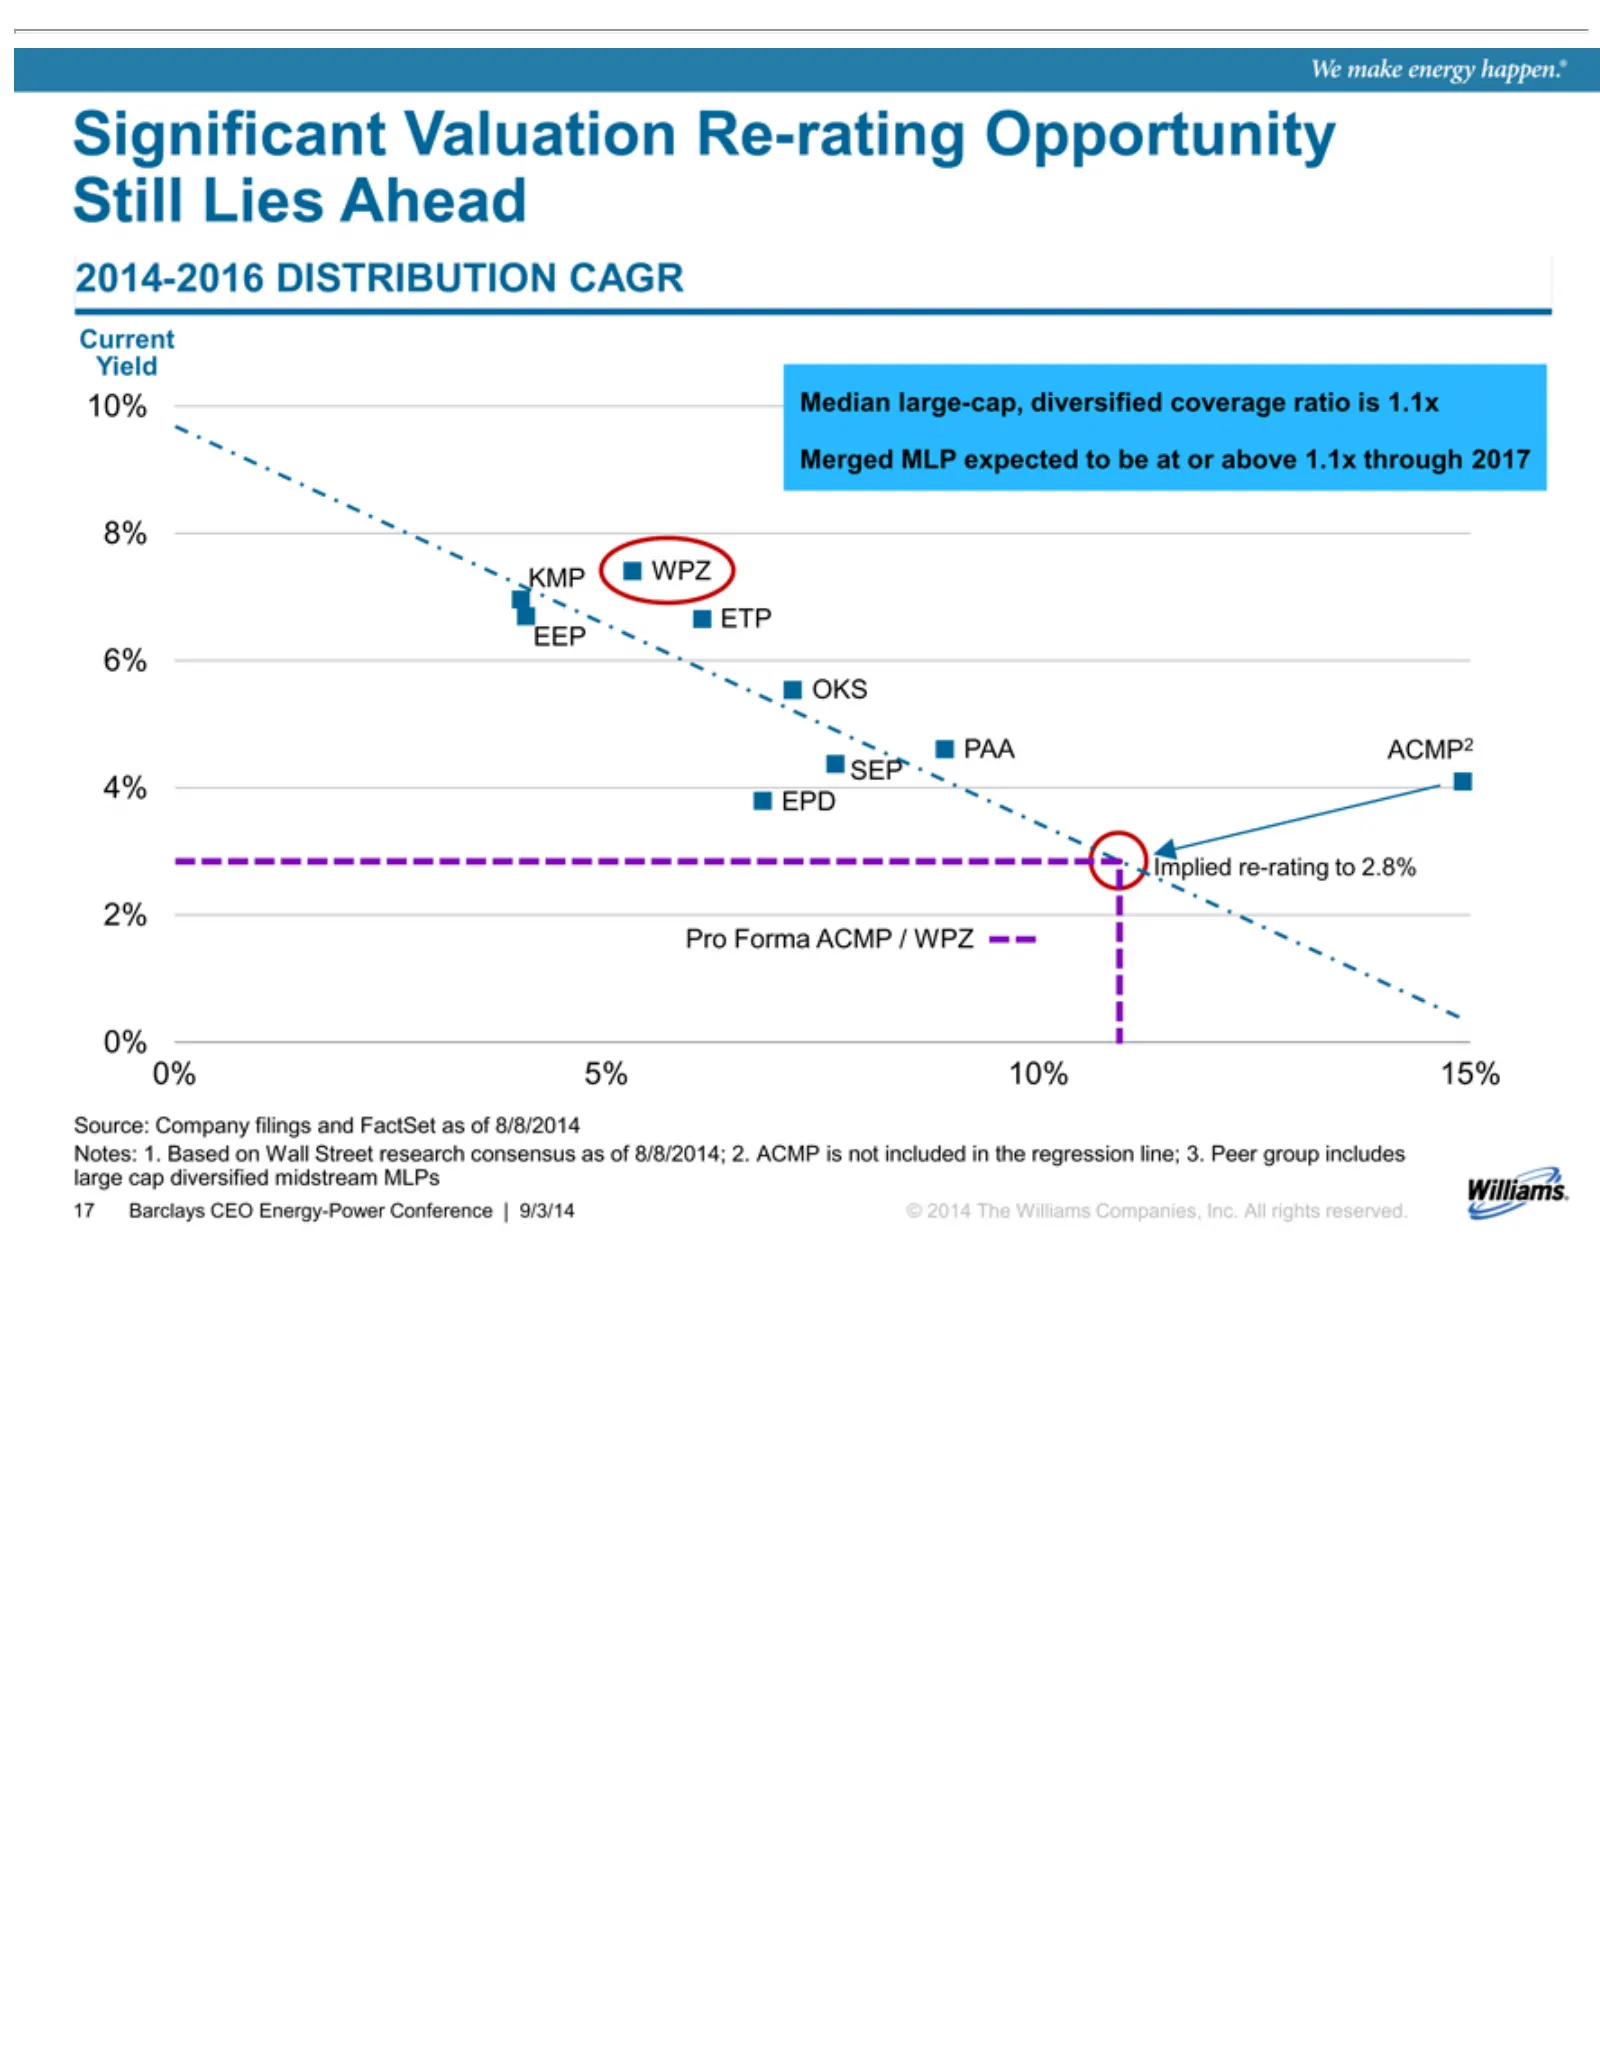
Slide 18: Significant MLP Re-rating Opportunity
Significant Still DISTRIBUTION 2014-2016 Median 10% Yield Current Merged KMP 8% PAA OKS 6% EEP ETP 4% SEP Implied Pro 2% 0% Source: Notes: 17 © 2014 Barclays EPD 5% Forma Lies ACMP2 WPZ 1.10% The Company large-cap, MLP re-rating Ahead Based ACMP Valuation CEO Williams 15% expected on to Energy-Power
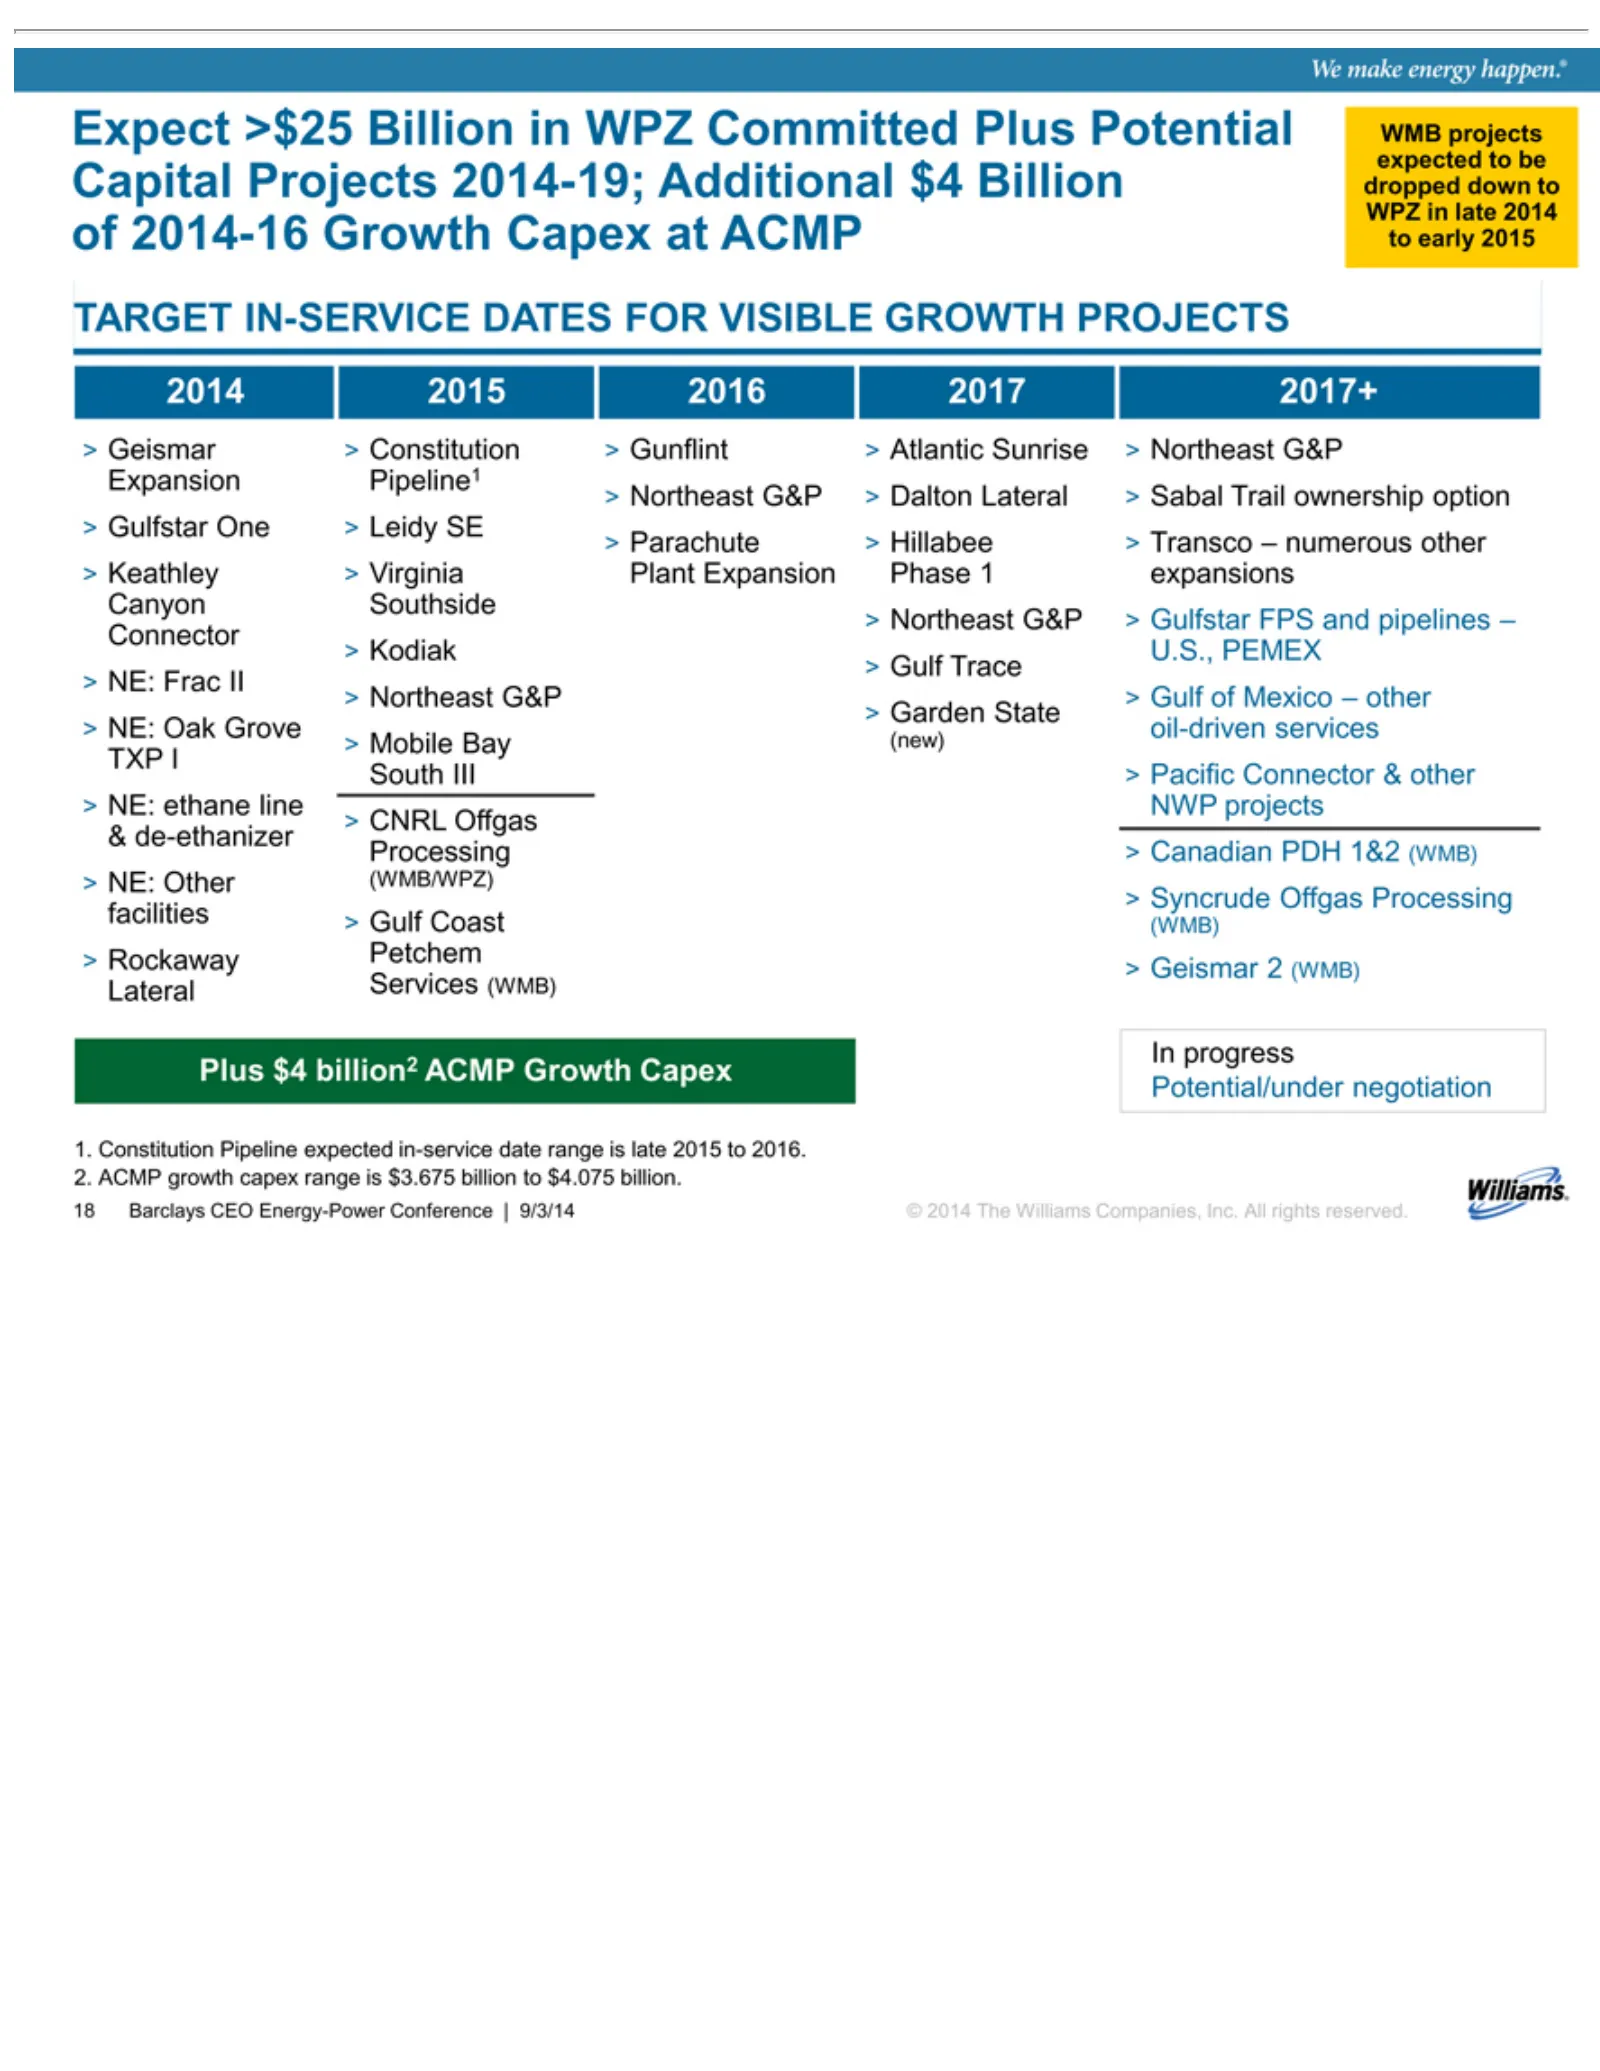
Slide 19: Expected Capital Projects and In-Service Dates
Expect expected Capital WPZ of TARGET 2014 Expansion Canyon Connector TXP & facilities > Lateral In Plus 1. 2. 18 Geismar Gulfstar Keathley Northeast Garden Mobile CNRL NE: Rockaway ACMP Constitution de-ethanizer 2014-16 progress Barclays $4 I2015 inOther Frac Oak ethane South >$25 Services Projects
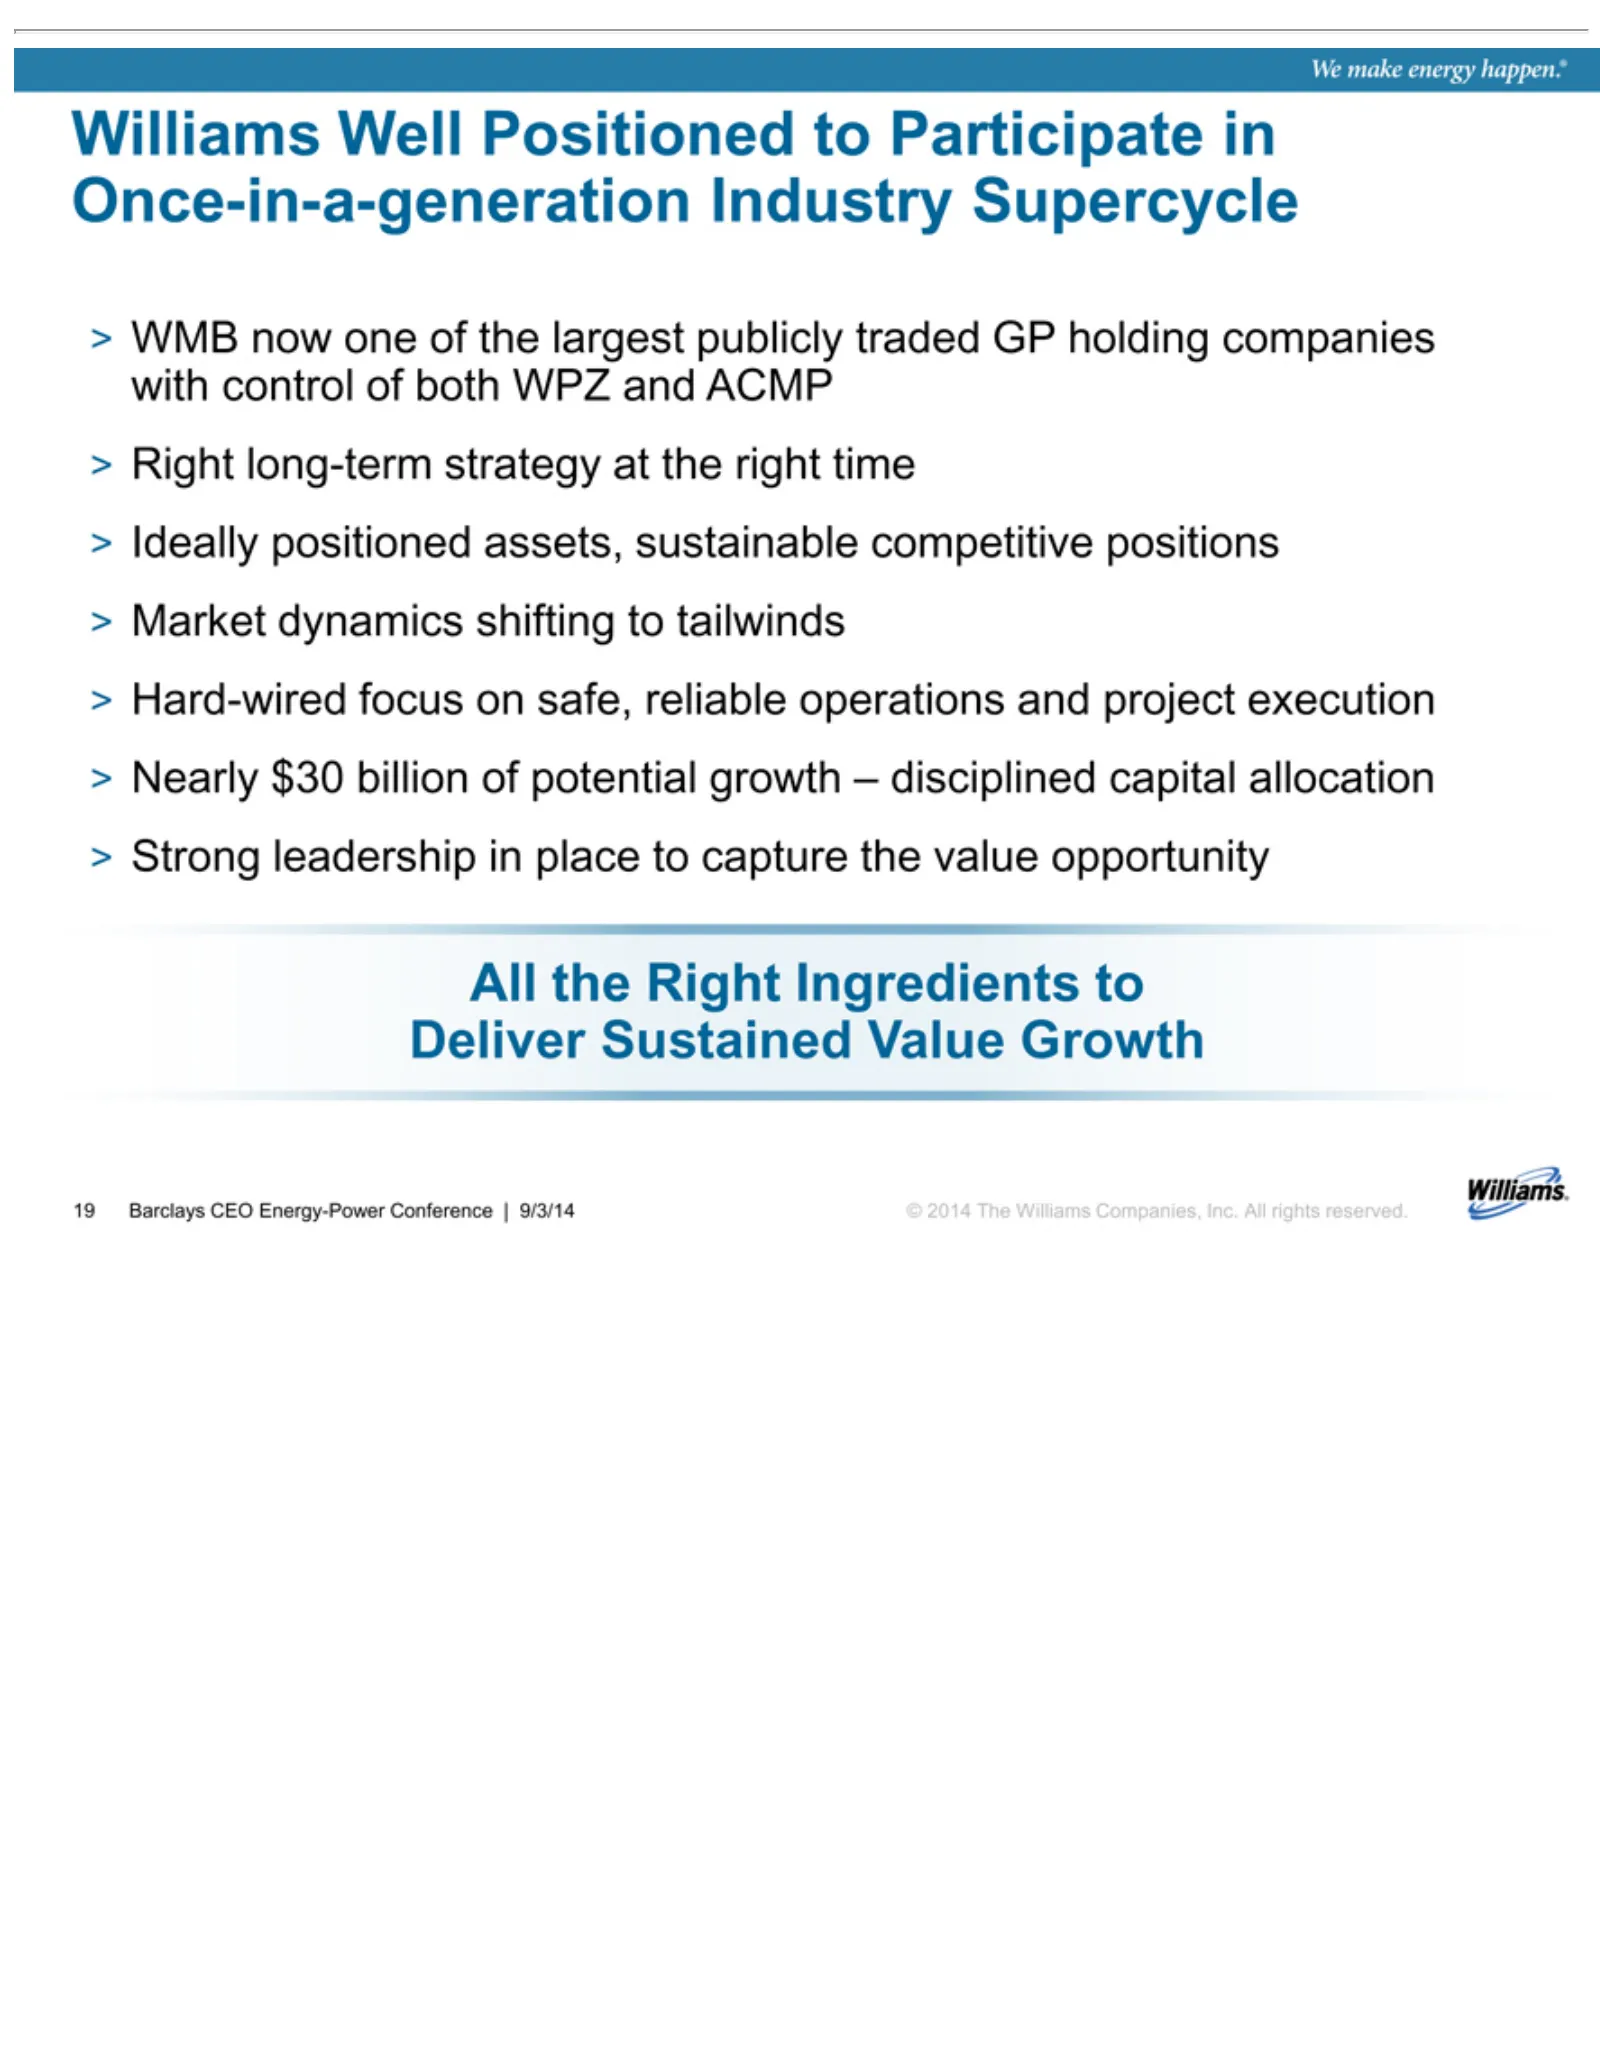
Slide 20: Williams: Right Ingredients at the Right Time
Williams WMB Right Ideally Market Hard-wired Nearly Strong All Deliver 19 © 2014 Barclays thelong-term now leadership $30 Right positioned dynamics The Sustained Well billion one focus CEO Williams Ingredients Positioned of strategy shifting Energy-Power on in Value assets, the ofplace safe, potenti
Slide 21: Non-GAAP Disclaimer
Non-GAAP Disclaimer
Slide 22: Non-GAAP Disclaimer
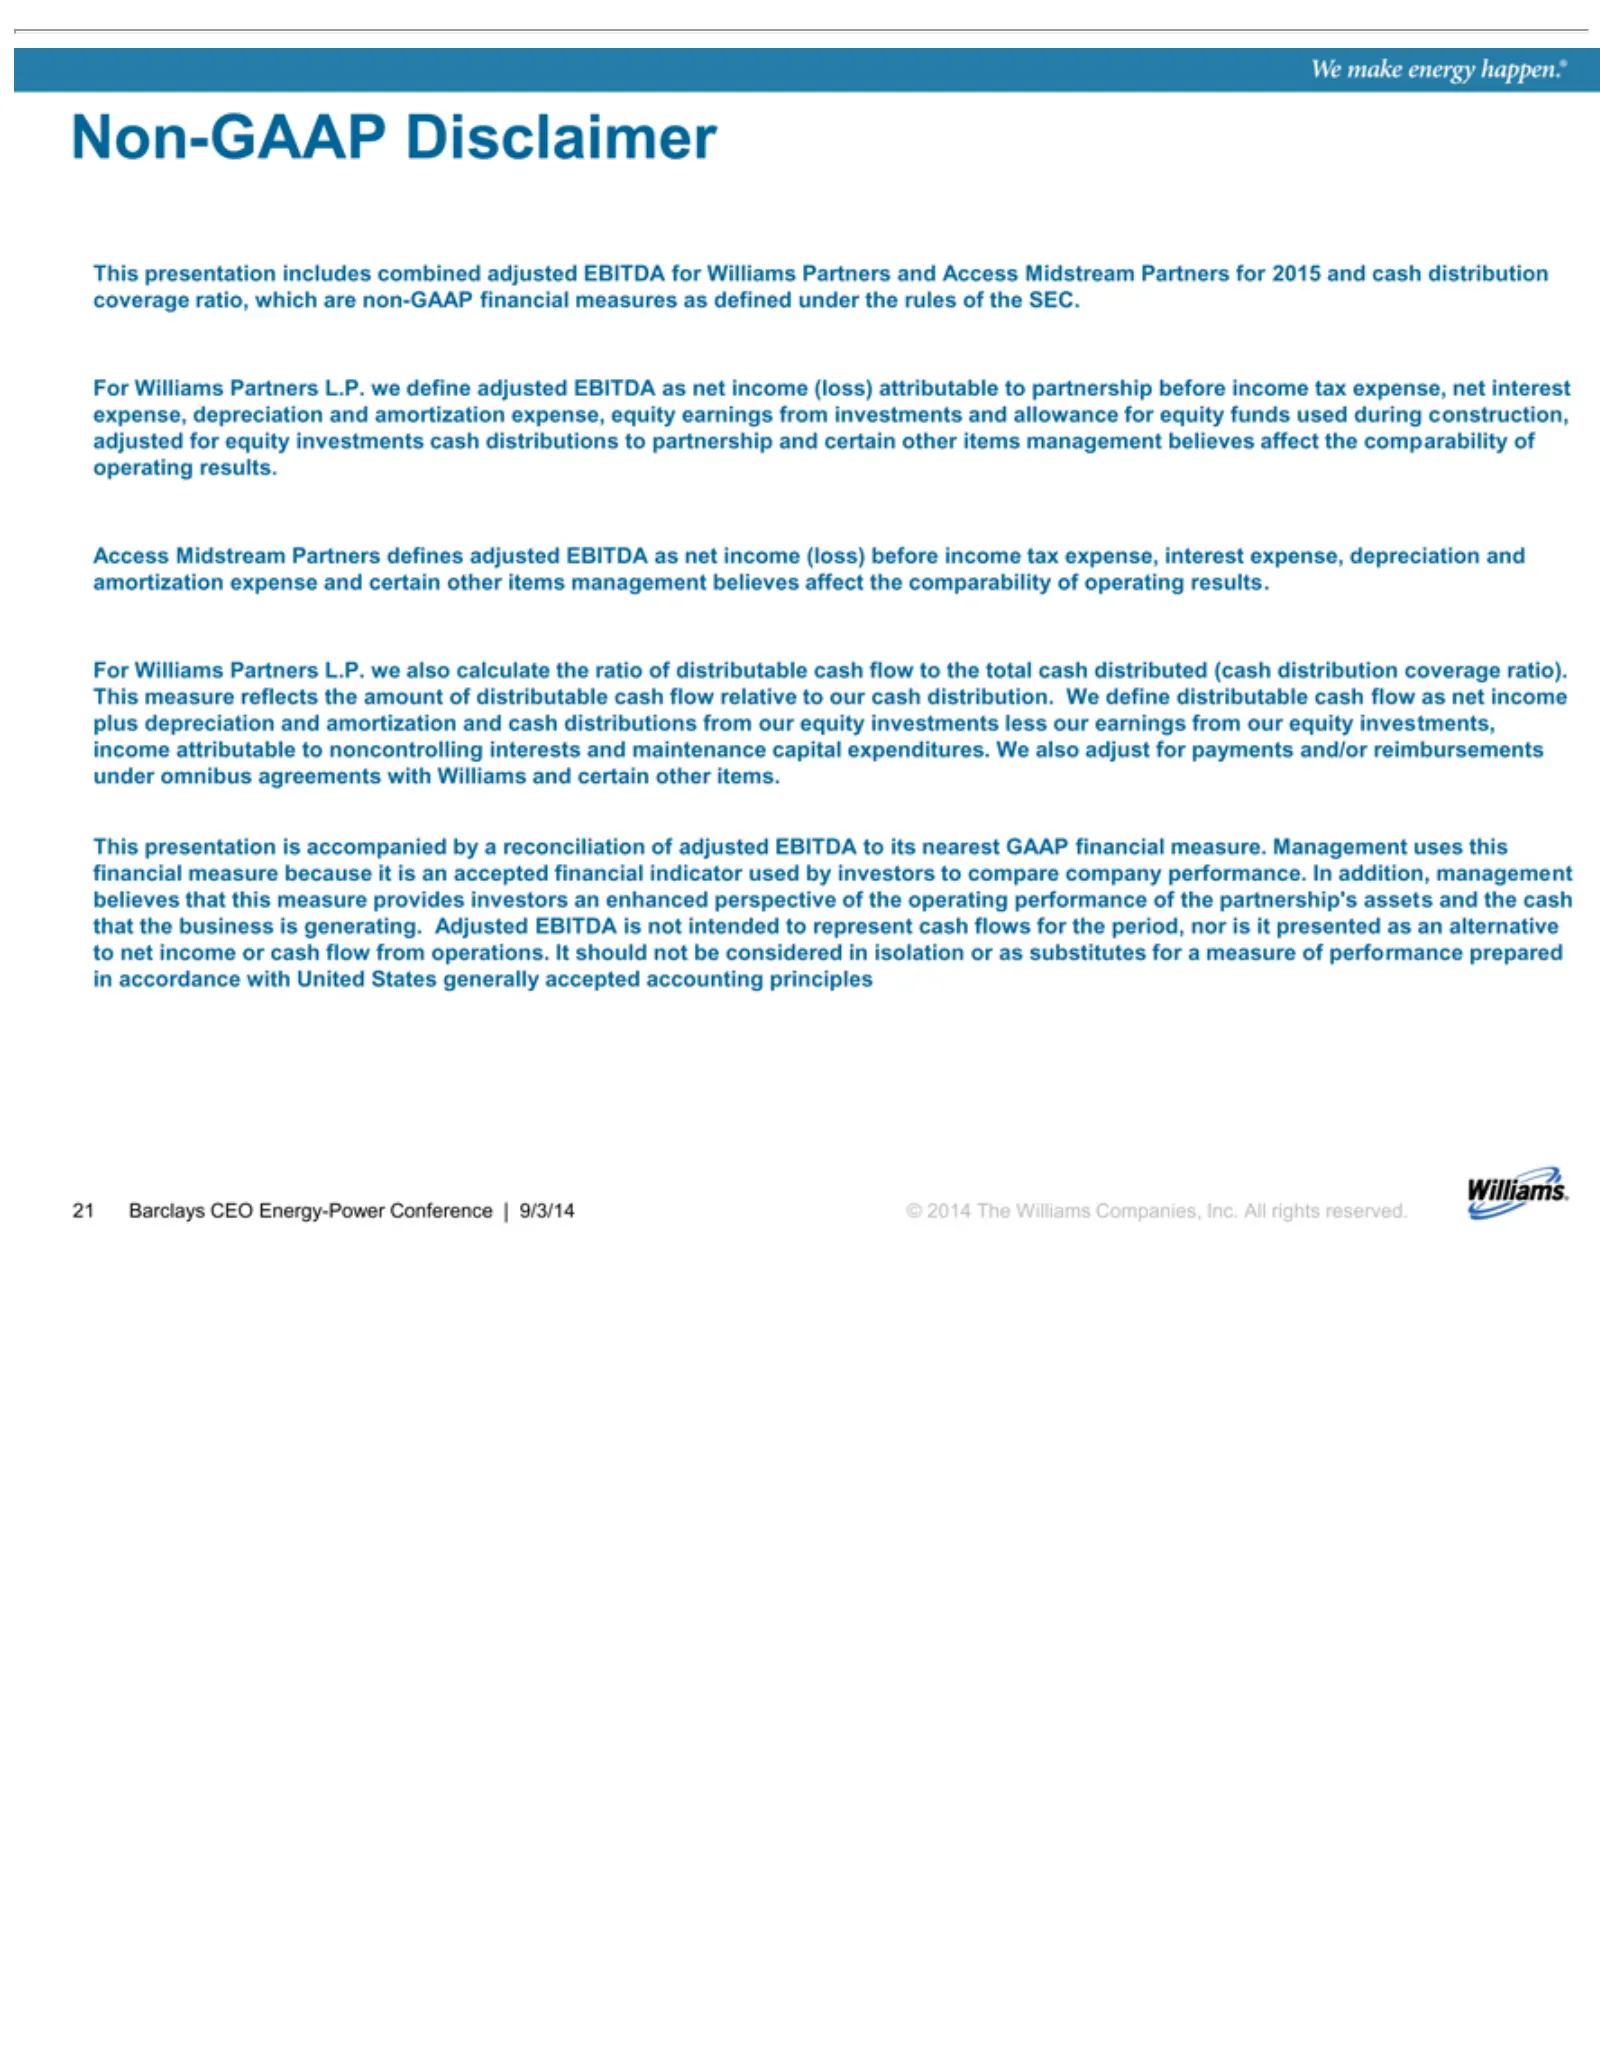
Non-GAAP rules investments Access results. comparability For cash attributable This to is substitutes 21 © generating. 2014 compare Barclays Williams distribution. presentation of Midstream The thefor company SEC. to Disclaimer CEO and Williams Partners Adjusted of noncontrolling a measure allowance
Slide 23: Williams Partners and Access Midstream Combined Adjusted EBITDA Reconciliation
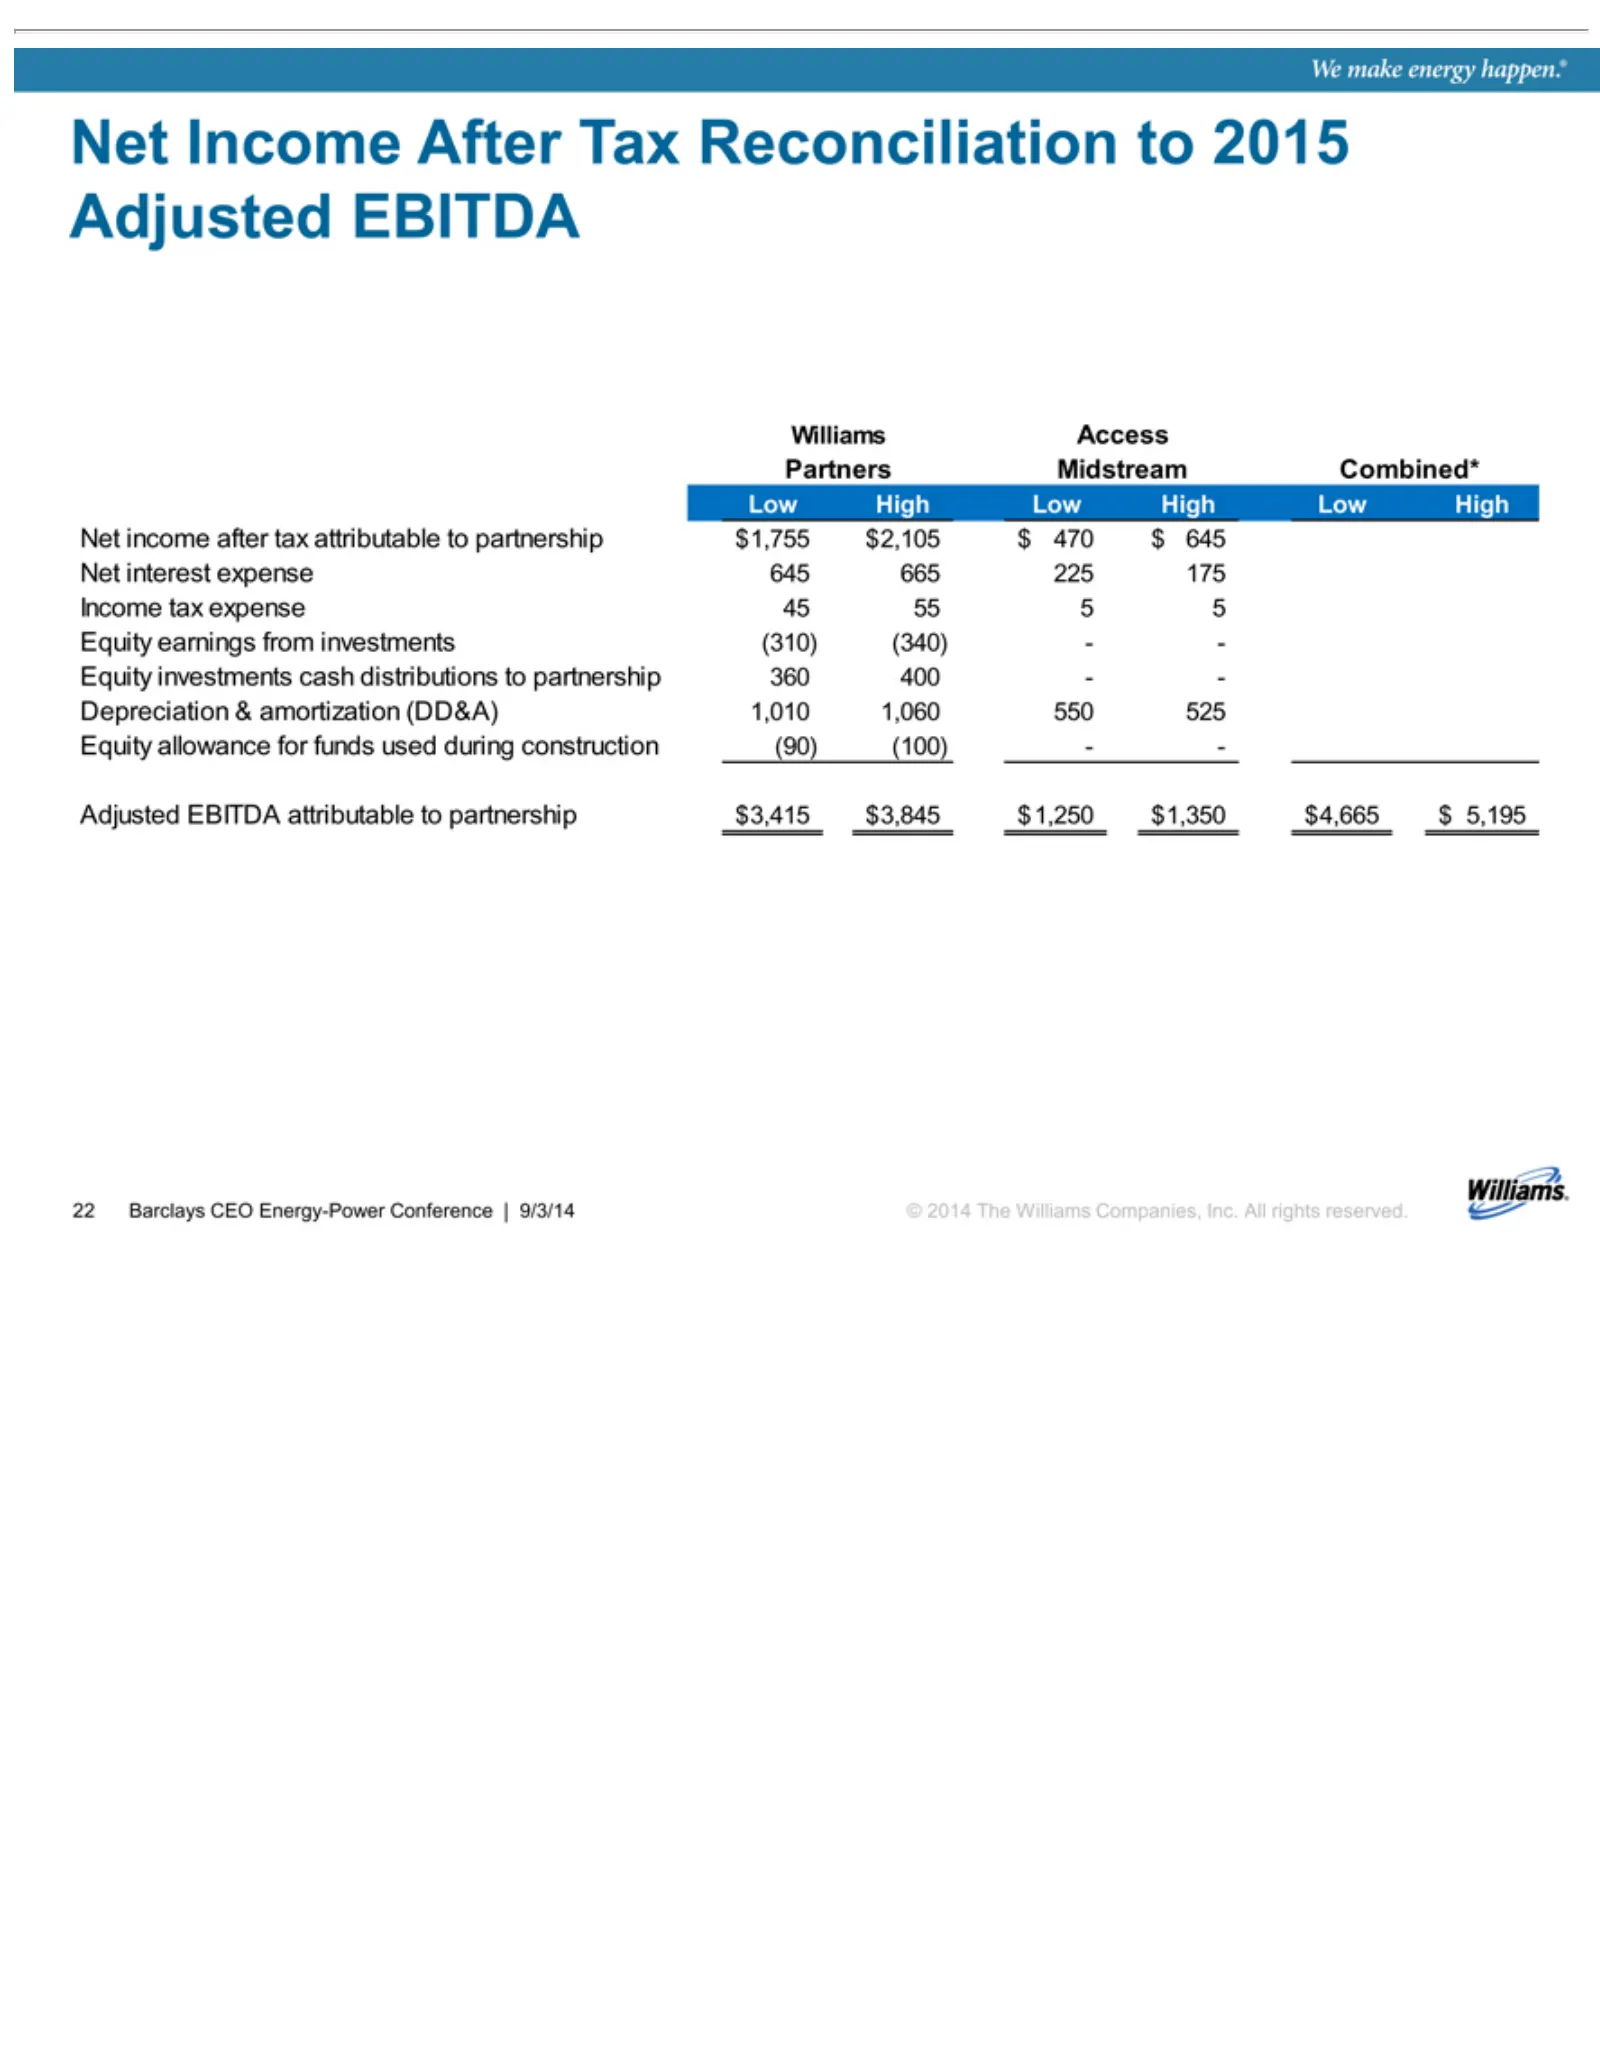
Williams Partners Low Net Income Depreciation Equity Adjusted 22 © 2014 Barclays Income income interest High earnings investments allowance The tax Midstream Access EBITDA Low expense After after expense CEO Williams & High amortization from tax for Tax Energy-Power attributable cash Combined* 45 64
Source: SEC EDGAR · 425 filed Sep 2, 2014
More decks from Williams Partners L.P
 Jefferies 2014 Global Energy Conference22 slides · Nov 12, 2014
 Howard Weil Energy Conference 201425 slides · Mar 24, 2014
 Investor Day (May 2009)29 slides · May 12, 2009
 Investor Presentation (April 2009)9 slides · Apr 16, 2009
 Q4 2006 Earnings Presentation29 slides · Feb 22, 2007
 Q3 2006 Earnings Presentation29 slides · Nov 2, 2006