Durr AG · XETR:DUE
Durr — Investor Presentation (February 2013)
39 slides from Durr's investor presentation, February 2013
Slide 1: Welcome Presentation Dürr Investor Relations
WELCOME PRESENTATION DÜRR INVESTOR RELATIONS www.durr.com
Slide 2: Disclaimer
DISCLAIMER This investor presentation has been prepared independently by Dürr AG (“Dürr”). The presentation contains statements which address such key issues as Dürr’s strategy, future financial results, market positions and product development. Such statements should be carefully considered, and it
Slide 3: Agenda
AGENDA 1. Dürr: global leader with strong competitive position 2. Markets 3. Strategy 4. Financial overview, outlook and summary © Dürr AG, CCI, Investor Relations 2013 3
Slide 4: Dürr – Global leader with strong competitive position
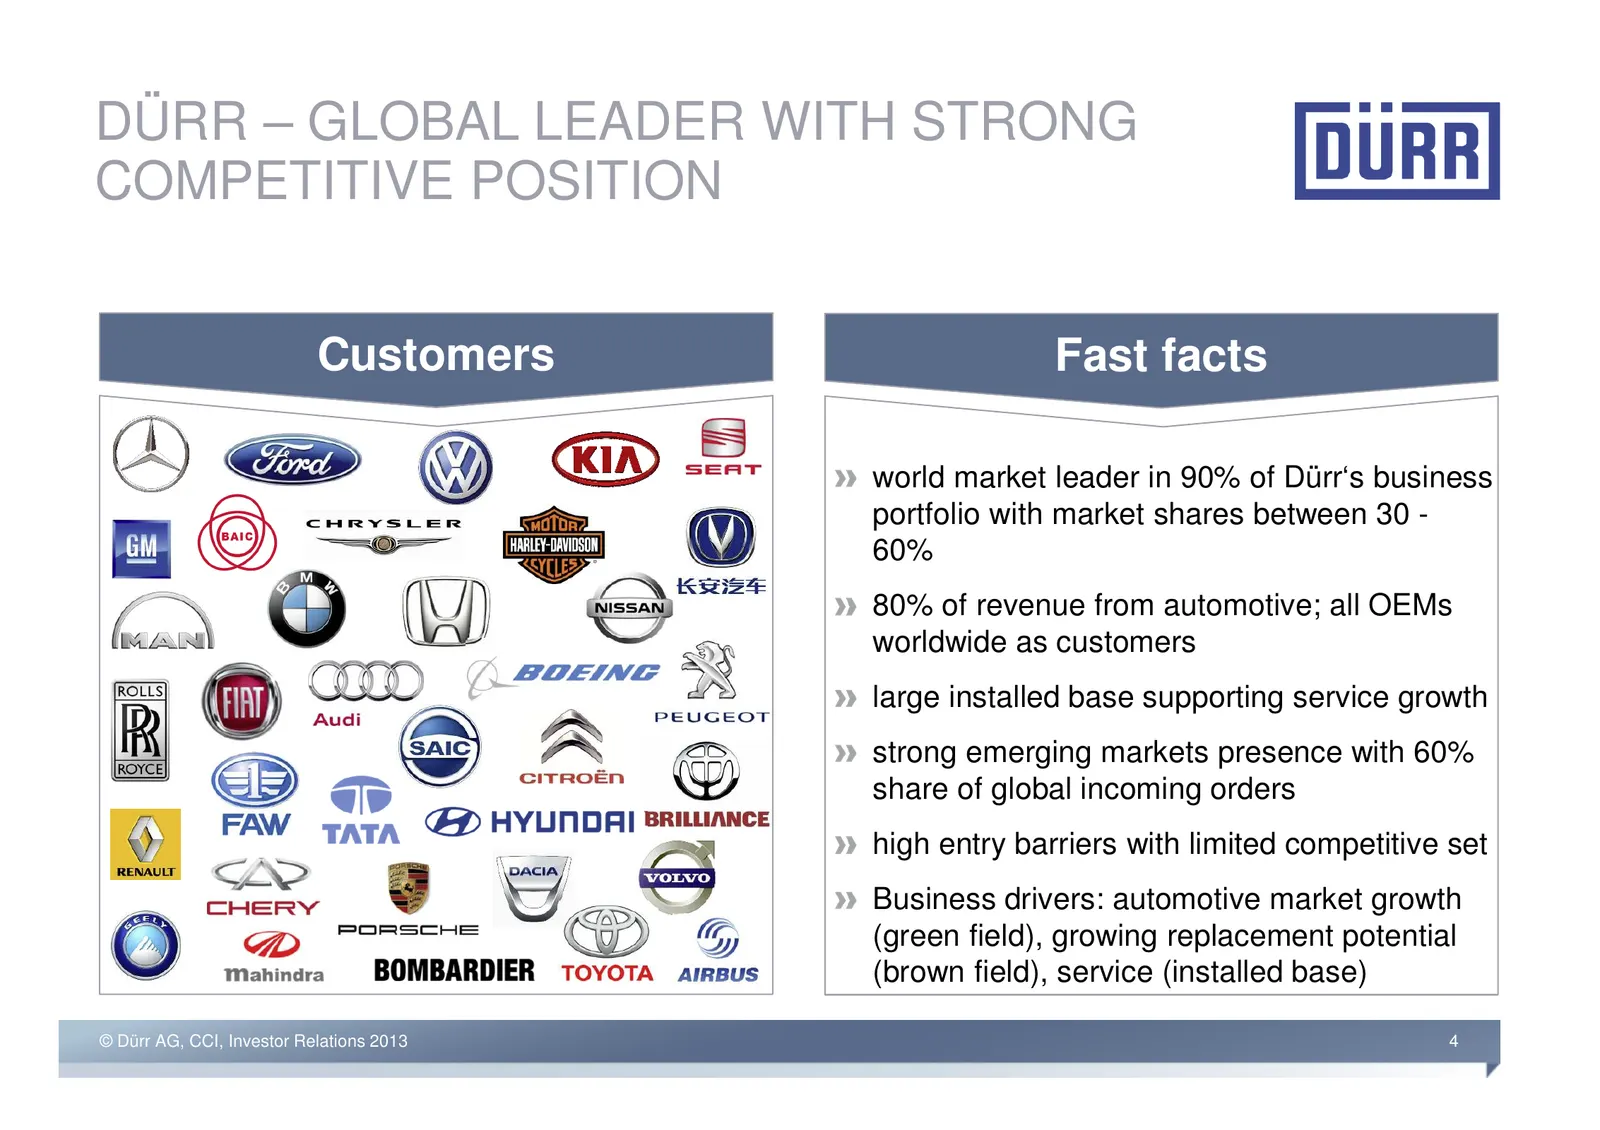
DÜRR – GLOBAL LEADER WITH STRONG COMPETITIVE POSITION Customers Fast facts world market leader in 90% of Dürr‘s business portfolio with market shares between 30 - 60% 80% of revenue from automotive; all OEMs worldwide as customers large installed base supporting service growth strong emerging market
Slide 5: Businesses at the Dürr Group
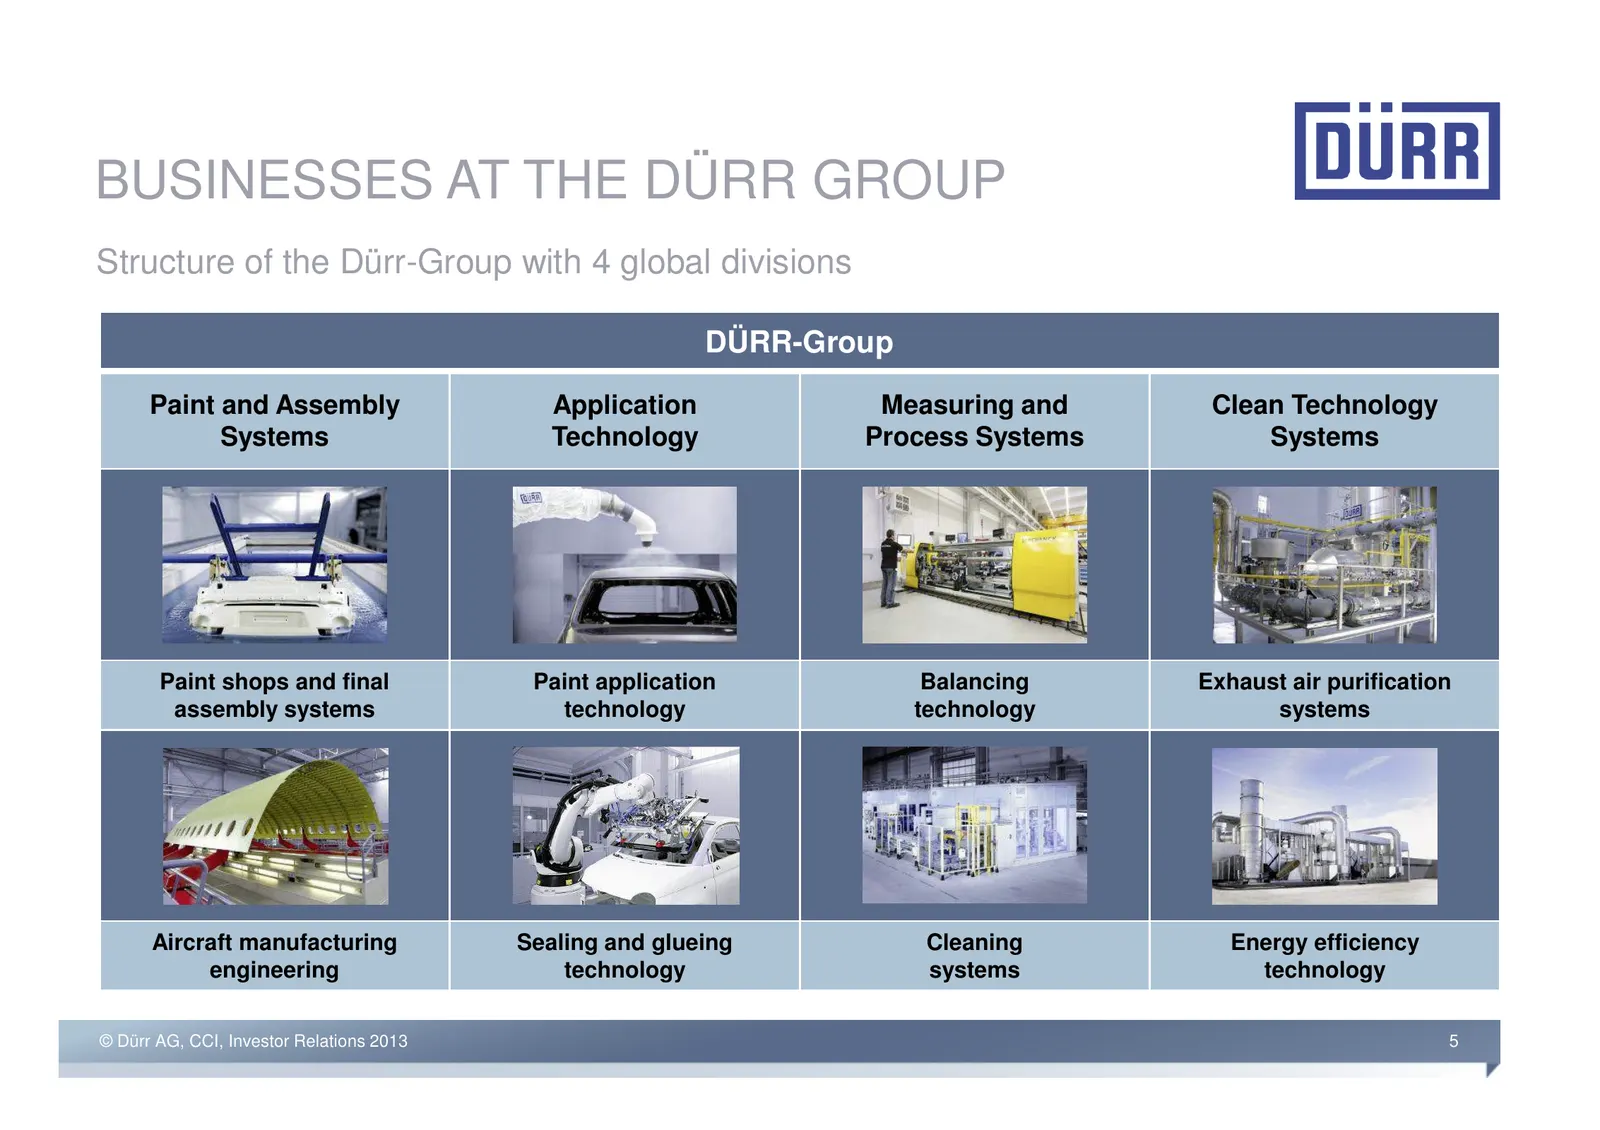
BUSINESSES AT THE DÜRR GROUP Structure of the Dürr-Group with 4 global divisions DÜRR-Group Paint and Assembly Application Measuring and Clean Technology Systems Technology Process Systems Systems Paint shops and final Paint application Balancing Exhaust air purification assembly systems technology
Slide 6: Overview divisions
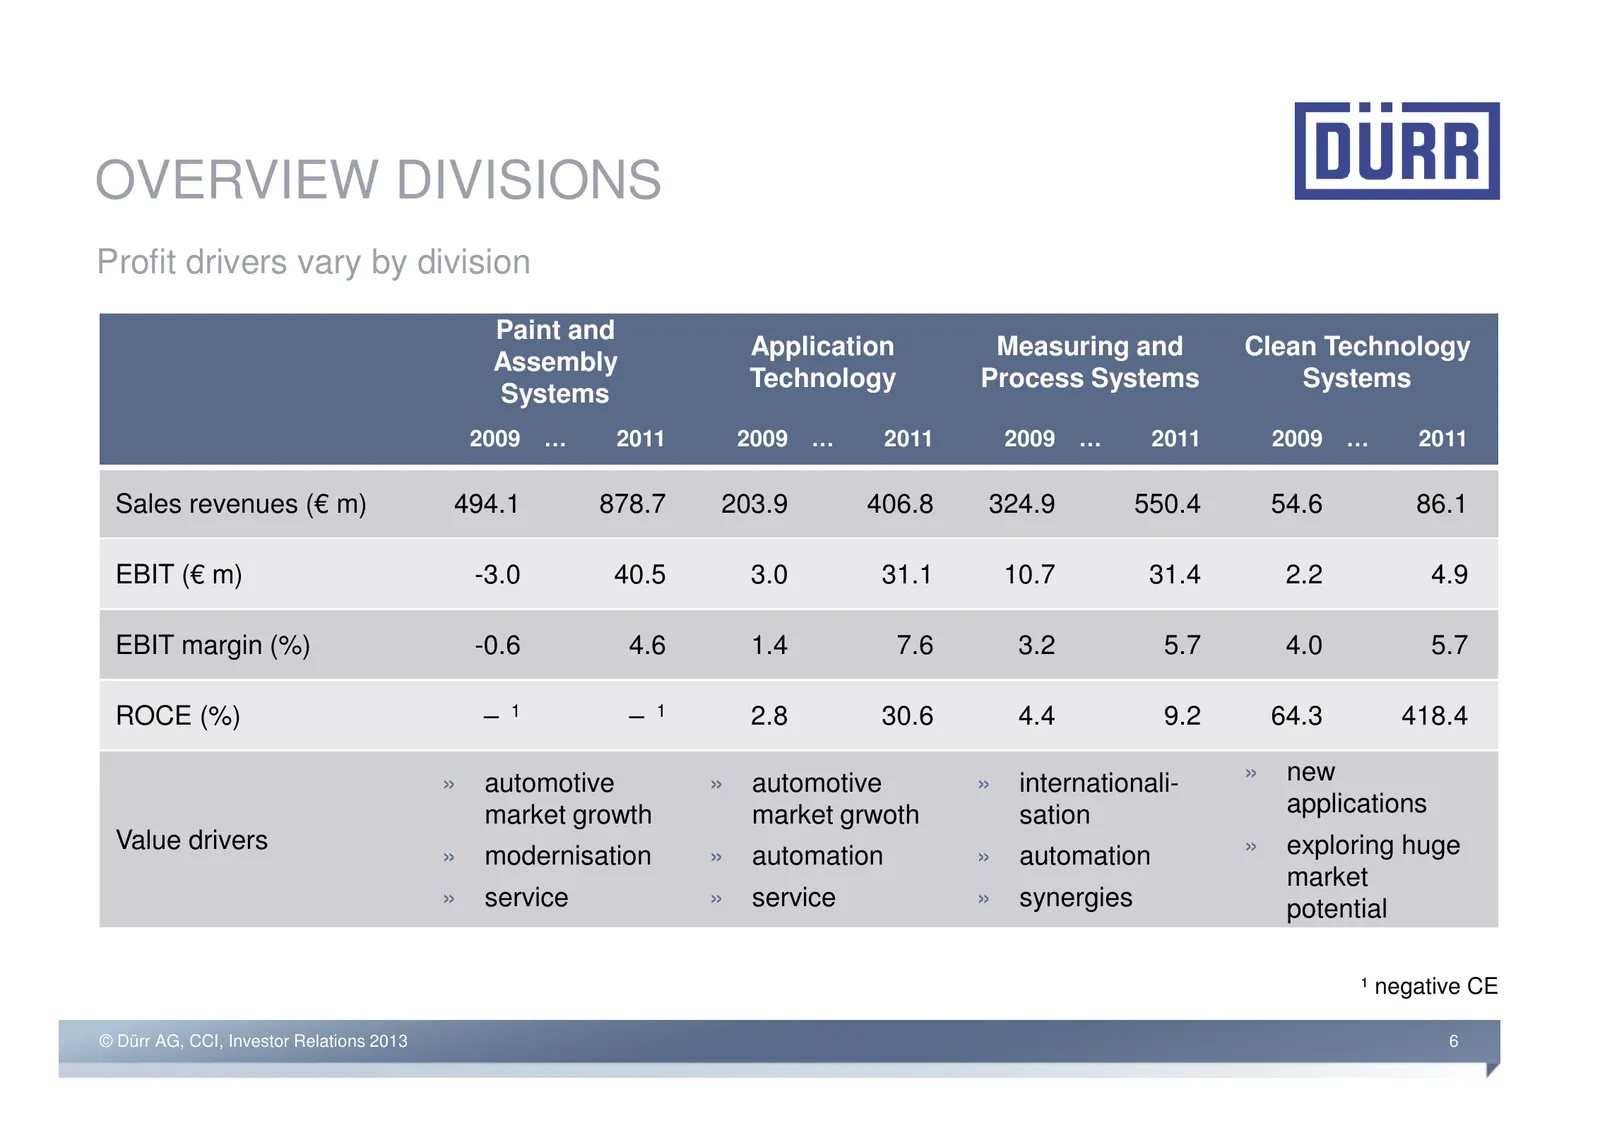
OVERVIEW DIVISIONS Profit drivers vary by division Paint and Application Measuring and Clean Technology Assembly Technology Process Systems Systems Systems 2009 … 2011 2009 … 2011 2009 … 2011 2009 … 2011 Sales revenues (€ m) 494.1 878.7 203.9 406.8 324.9 550.4 54.6 86.1 EBIT (€ m) -3.0 40.5 3.0 31.1
Slide 7: Order intake: healthy regional split
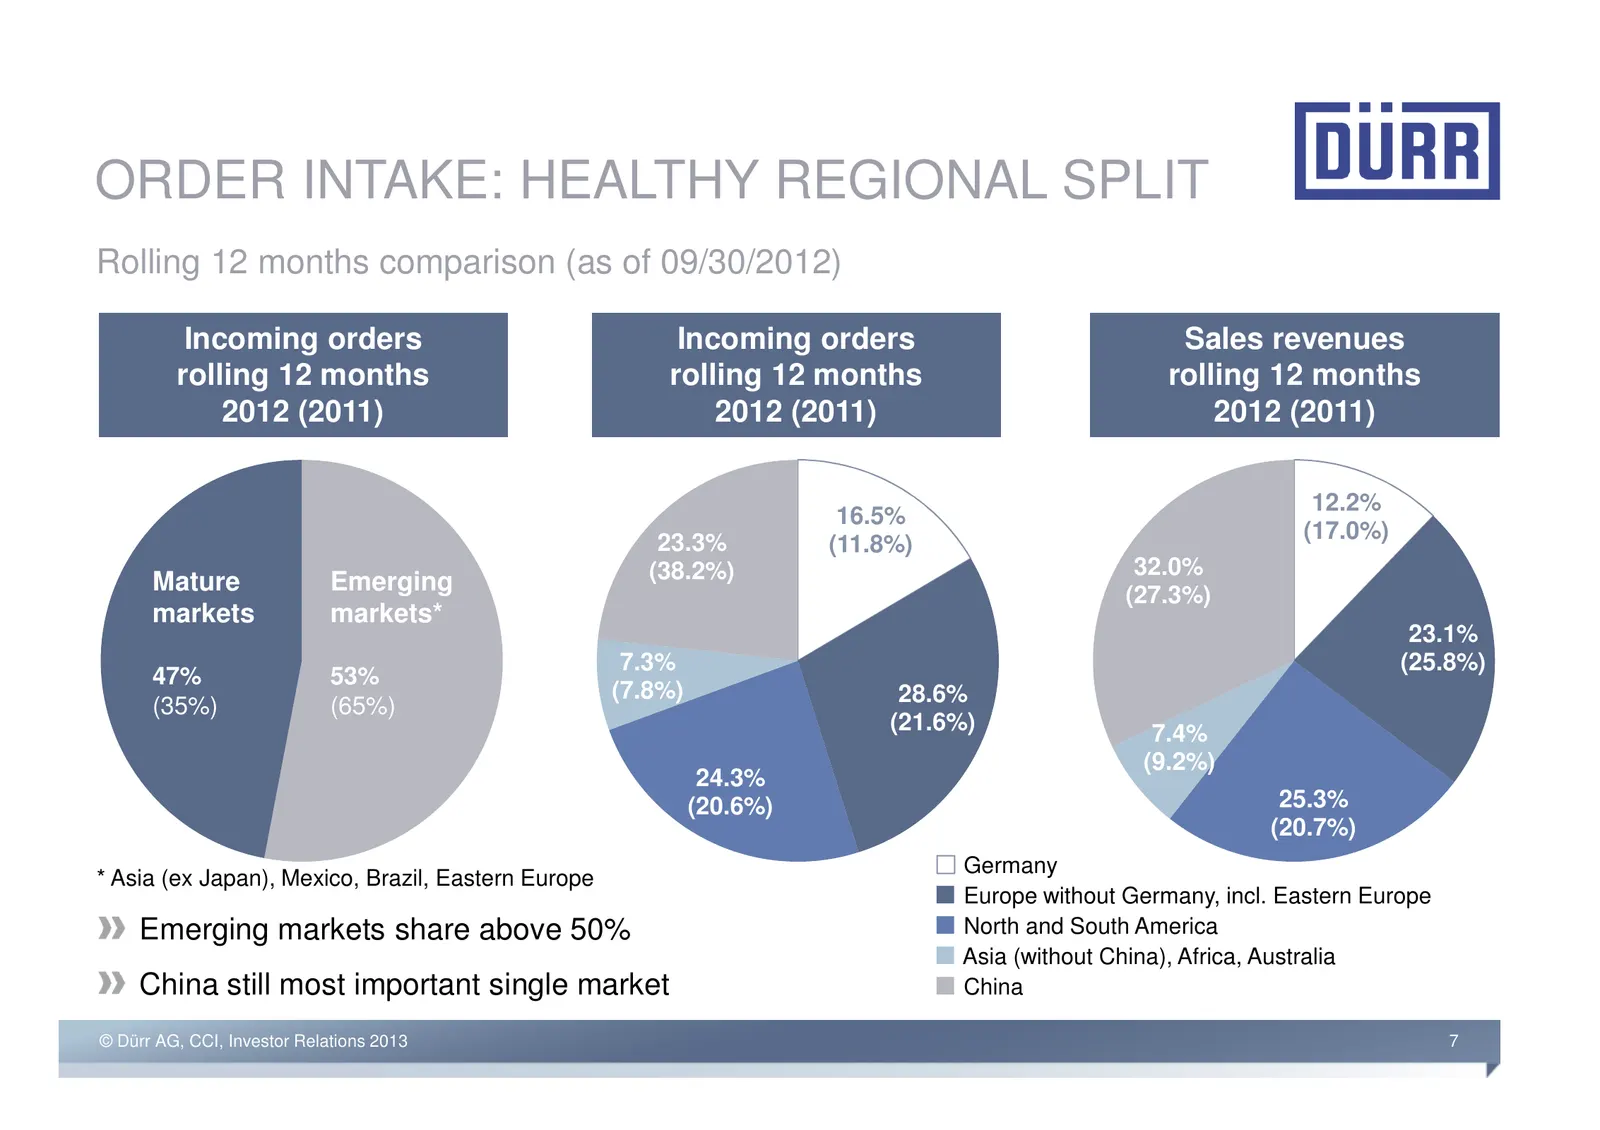
ORDER INTAKE: HEALTHY REGIONAL SPLIT Rolling 12 months comparison (as of 09/30/2012) Incoming orders Incoming orders Sales revenues rolling 12 months rolling 12 months rolling 12 months 2012 (2011) 2012 (2011) 2012 (2011) 12.2% 16.5% 23.3% (17.0%) (11.8%) (38.2%) 32.0% Mature Emerging (27.3%) market
Slide 8: Agenda
AGENDA 1. Dürr: global leader with strong competitive position 2. Markets 3. Strategy 4. Financial overview, outlook and summary © Dürr AG, CCI, Investor Relations 2013 8
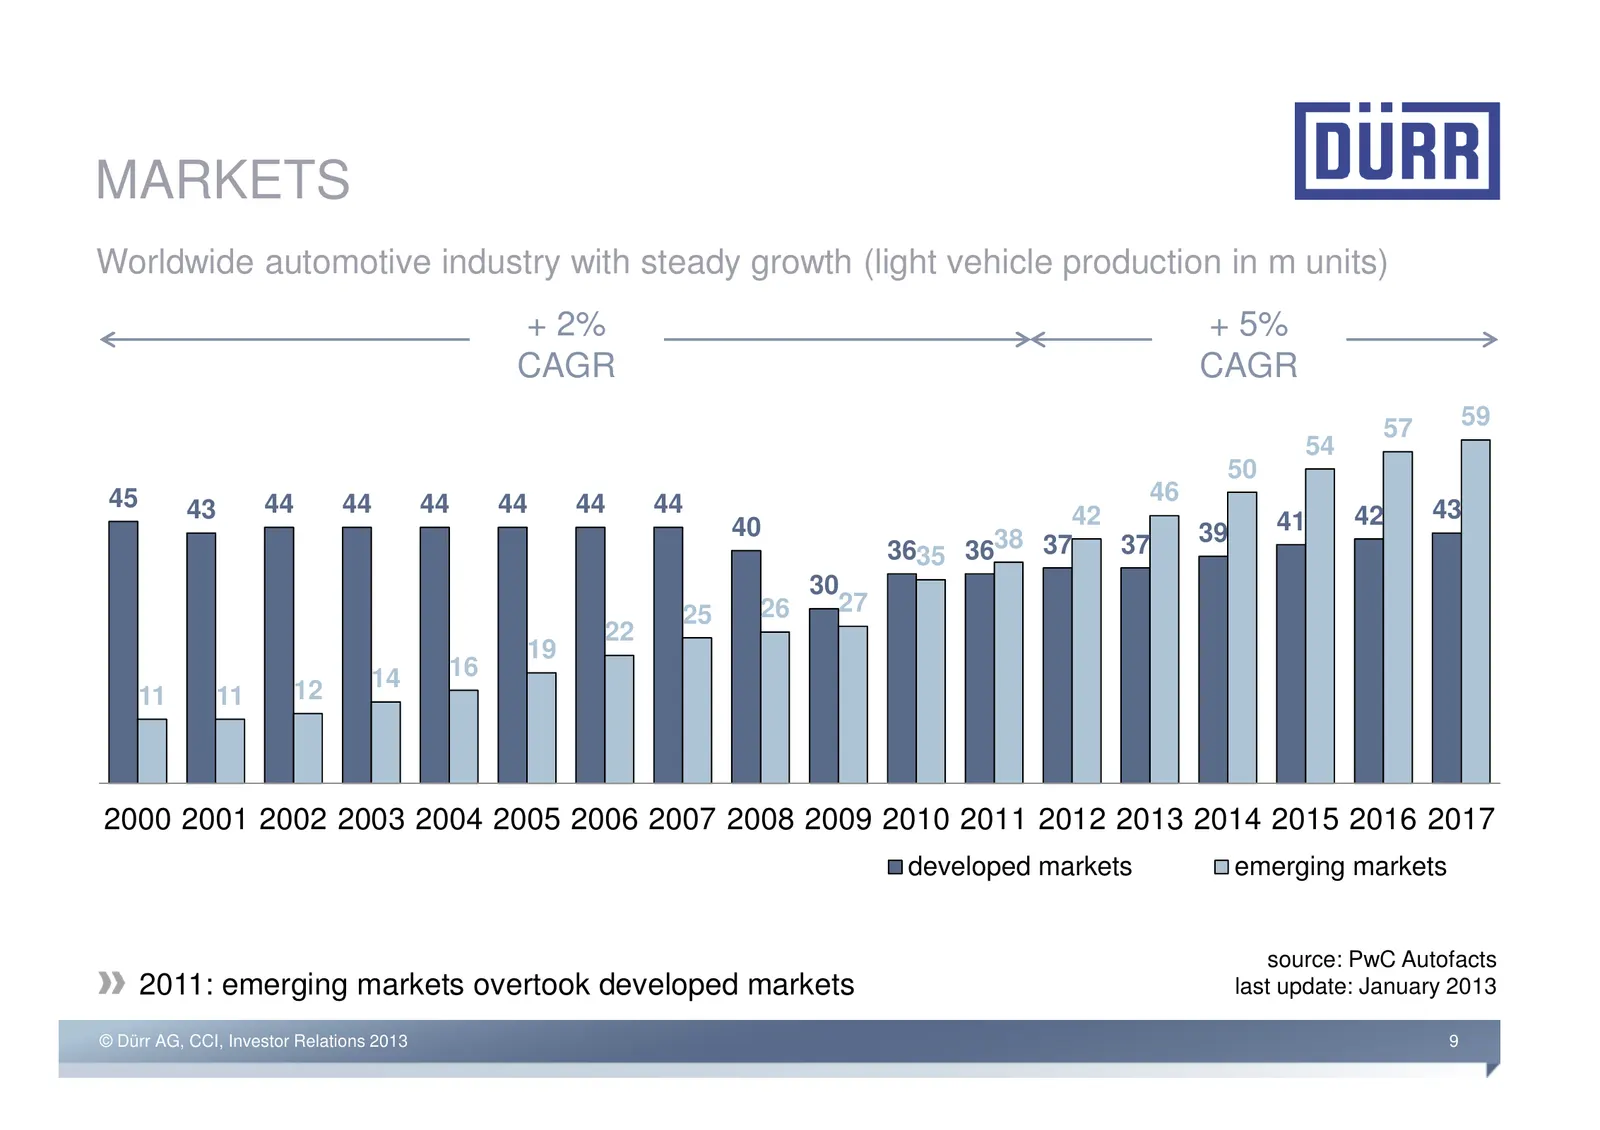
Slide 9: Markets
MARKETS Worldwide automotive industry with steady growth (light vehicle production in m units) + 2% + 5% CAGR CAGR 57 59 54 50 45 44 44 44 44 44 44 46 43 42 41 42 43 40 38 39 3635 36 37 37 30 25 26 27 22 19 14 16 11 11 12 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012 2013 2014 201
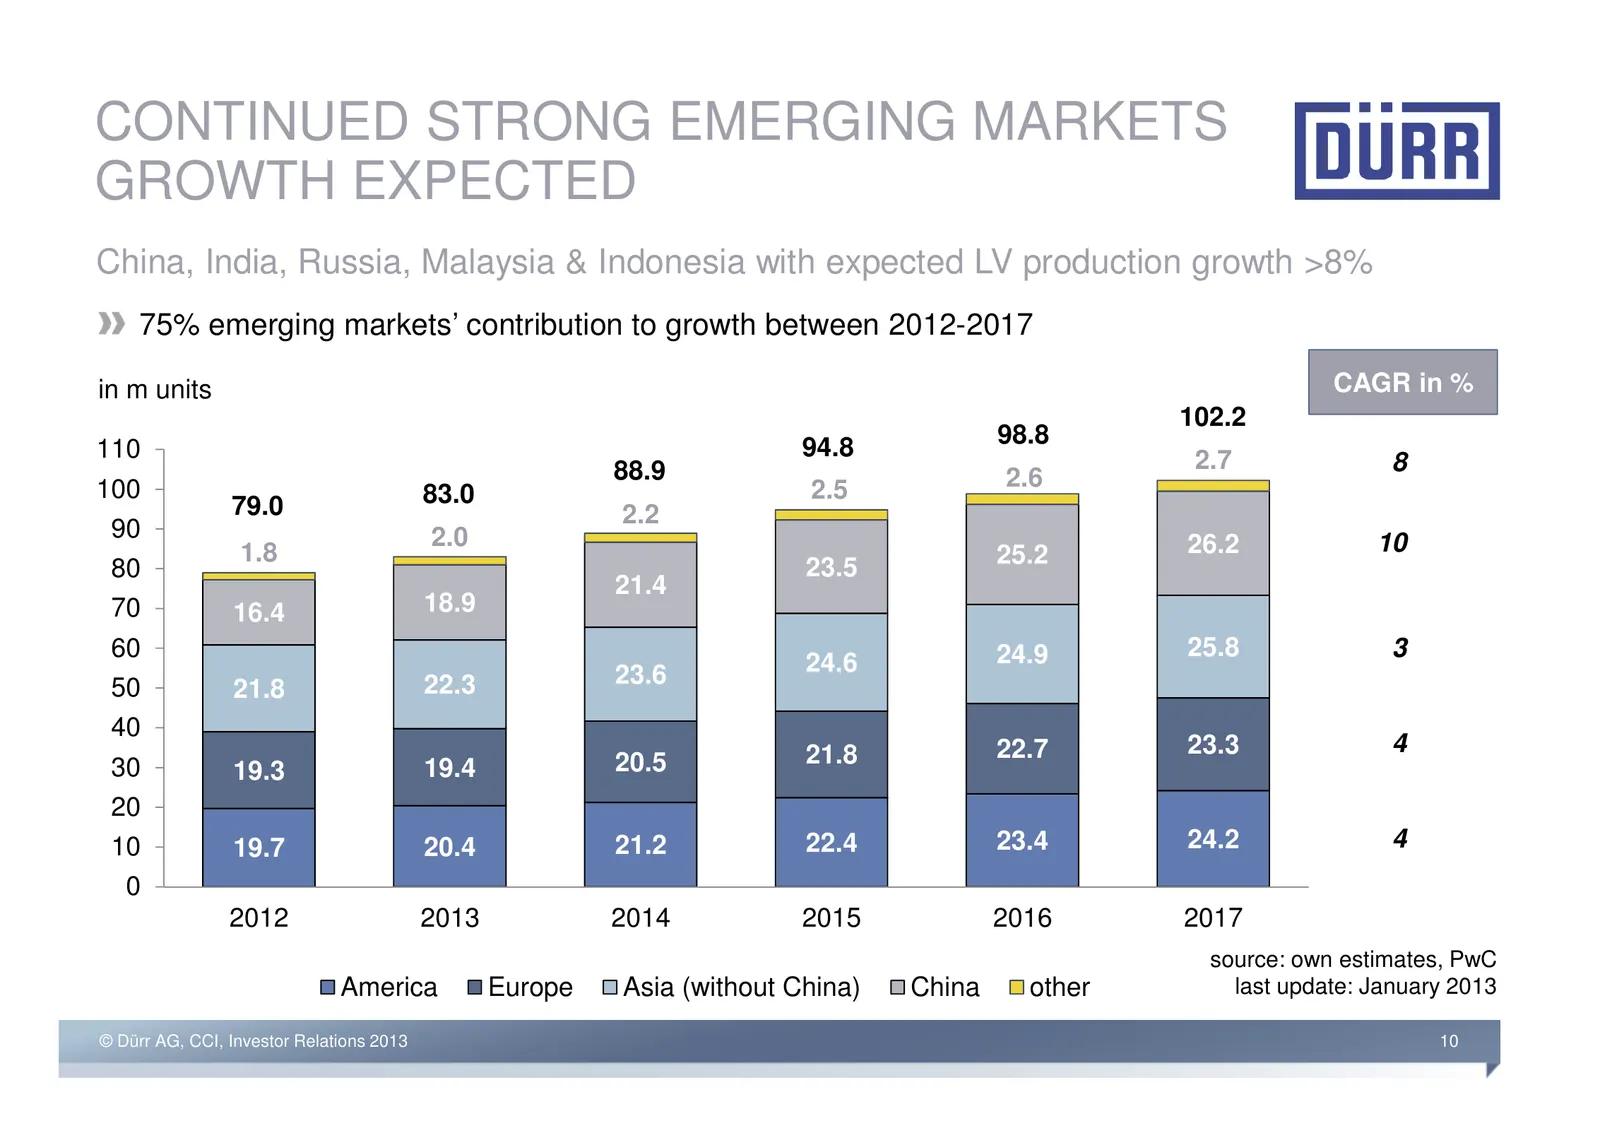
Slide 10: Continued strong emerging markets growth expected
CONTINUED STRONG EMERGING MARKETS GROWTH EXPECTED China, India, Russia, Malaysia & Indonesia with expected LV production growth >8% 75% emerging markets’ contribution to growth between 2012-2017 in m units CAGR in % 102.2 94.8 98.8 110 2.7 8 88.9 2.6 100 83.0 2.5 79.0 2.2 90 2.0 1.8 25.2 26.2 10 80
Slide 11: Agenda
AGENDA 1. Dürr: global leader with strong competitive position 2. Markets 3. Strategy 4. Financial overview, outlook and summary © Dürr AG, CCI, Investor Relations 2013 11
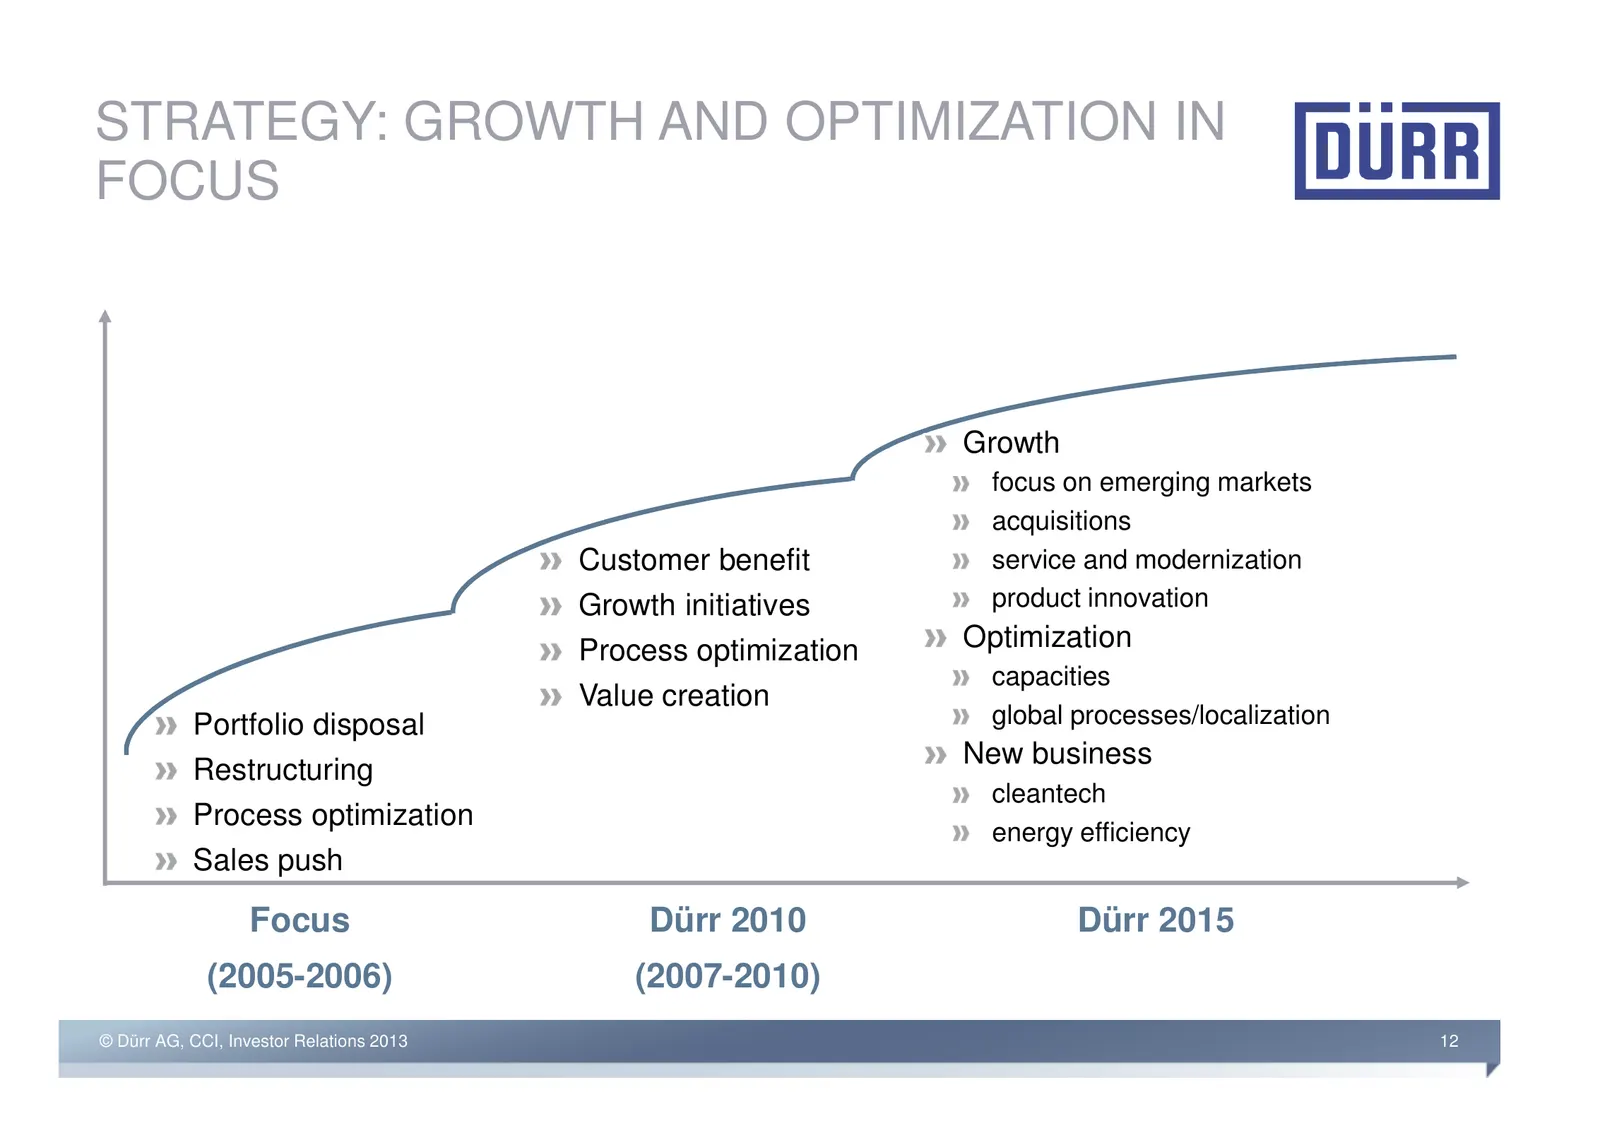
Slide 12: Strategy: growth and optimization in focus
STRATEGY: GROWTH AND OPTIMIZATION IN FOCUS Growth focus on emerging markets acquisitions Customer benefit service and modernization Growth initiatives product innovation Process optimization Optimization capacities Value creation Portfolio disposal global processes/localization New business Restruct
Slide 13: Strategy: Growth – Dürr China expansion
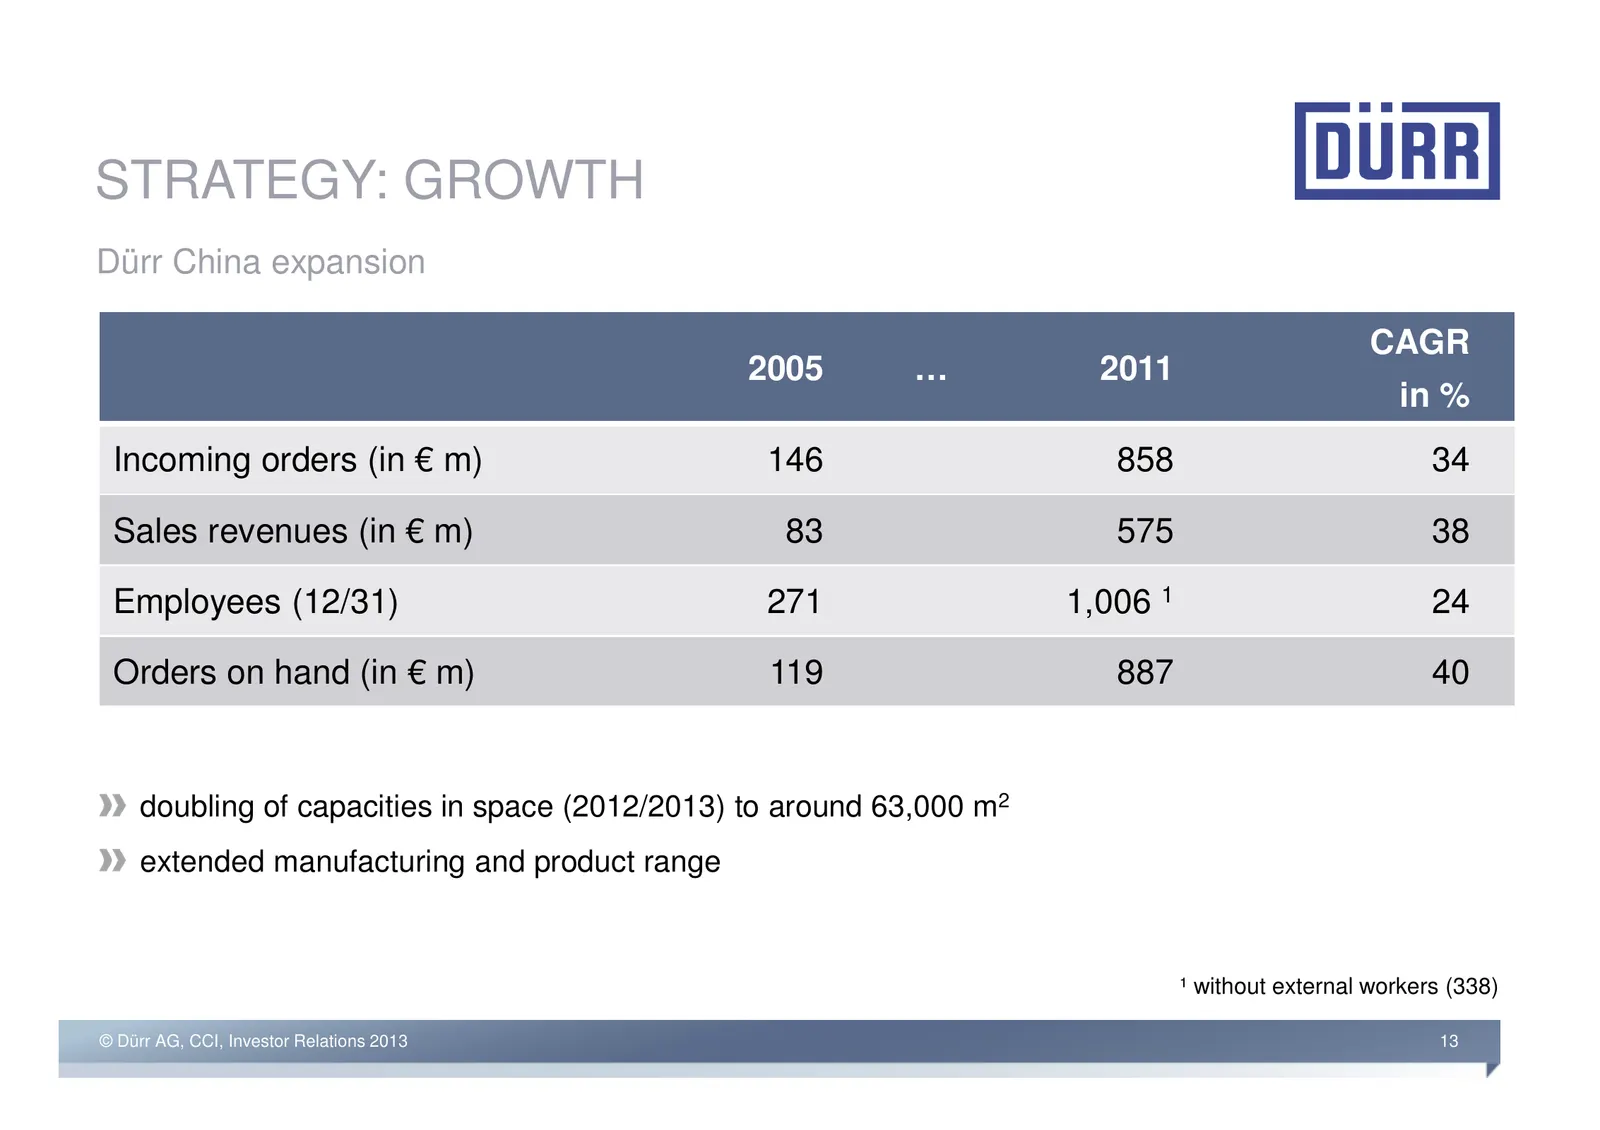
STRATEGY: GROWTH Dürr China expansion CAGR 2005 … 2011 in % Incoming orders (in € m) 146 858 34 Sales revenues (in € m) 83 575 38 Employees (12/31) 271 1,006 1 24 Orders on hand (in € m) 119 887 40 doubling of capacities in space (2012/2013) to around 63,000 m2 extended manufacturing and product ran
Slide 14: Strategy: Growth – early presence in growth markets
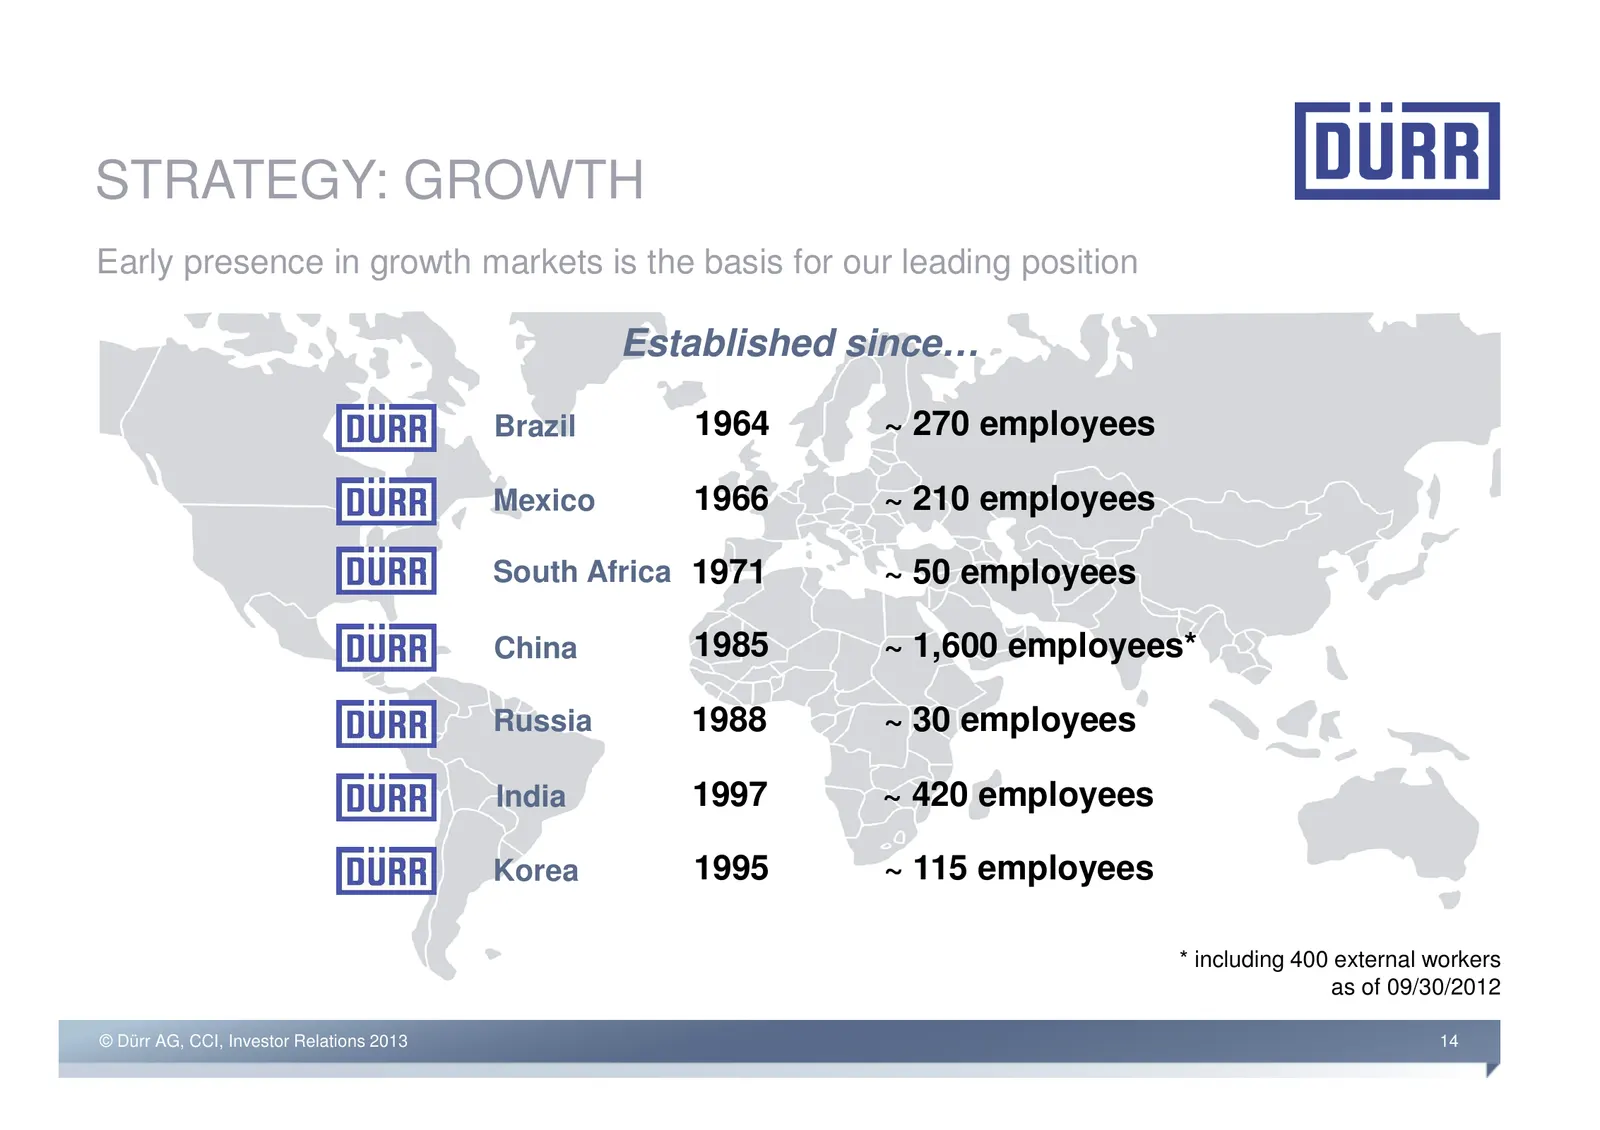
STRATEGY: GROWTH Early presence in growth markets is the basis for our leading position Established since… Brazil 1964 ~ 270 employees Mexico 1966 ~ 210 employees South Africa 1971 ~ 50 employees China 1985 ~ 1,600 employees* Russia 1988 ~ 30 employees India 1997 ~ 420 employees Korea 1995 ~ 115 emp
Slide 15: Strategy: Growth – Acquisitions
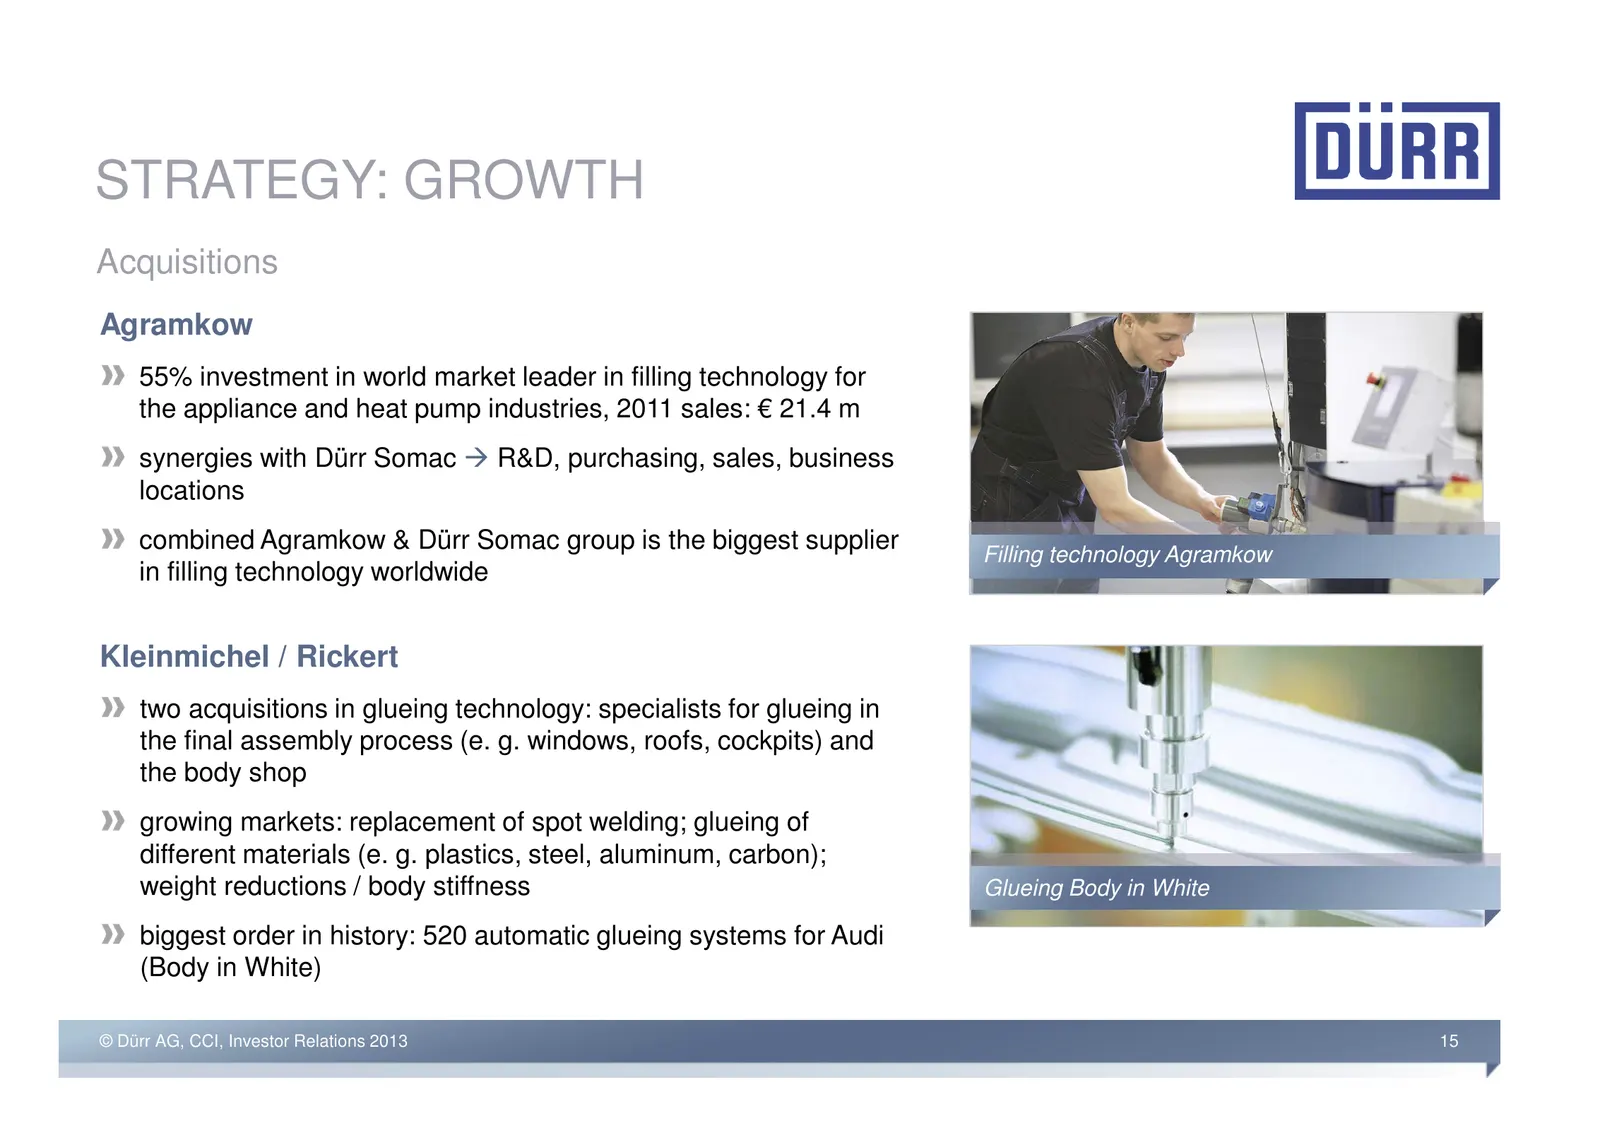
STRATEGY: GROWTH Acquisitions Agramkow 55% investment in world market leader in filling technology for the appliance and heat pump industries, 2011 sales: € 21.4 m synergies with Dürr Somac R&D, purchasing, sales, business locations combined Agramkow & Dürr Somac group is the biggest supplier Fillin
Slide 16: Strategy: Leading in production efficiency – cost per unit
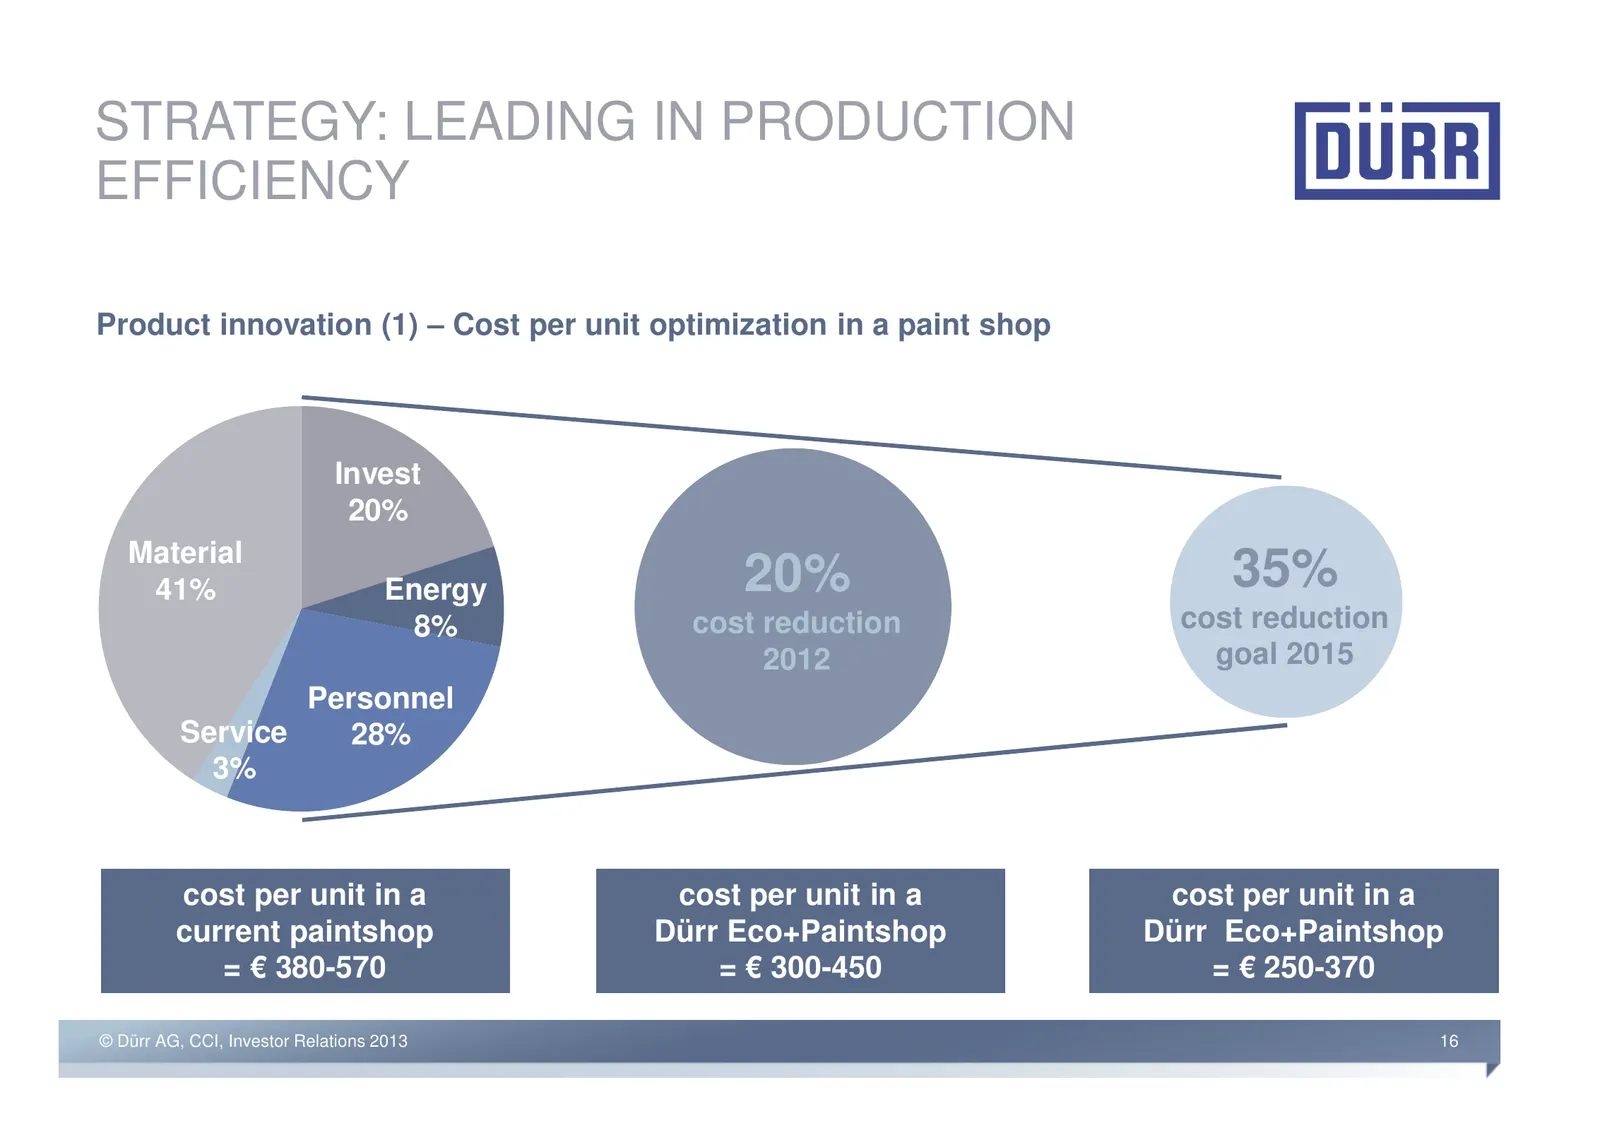
STRATEGY: LEADING IN PRODUCTION EFFICIENCY Product innovation (1) – Cost per unit optimization in a paint shop Invest 20% Material 41% Energy 20% 35% 8% cost reduction cost reduction 2012 goal 2015 Personnel Service 28% 3% cost per unit in a cost per unit in a cost per unit in a current paintshop Dü
Slide 17: Product innovation – EcoDryScrubber
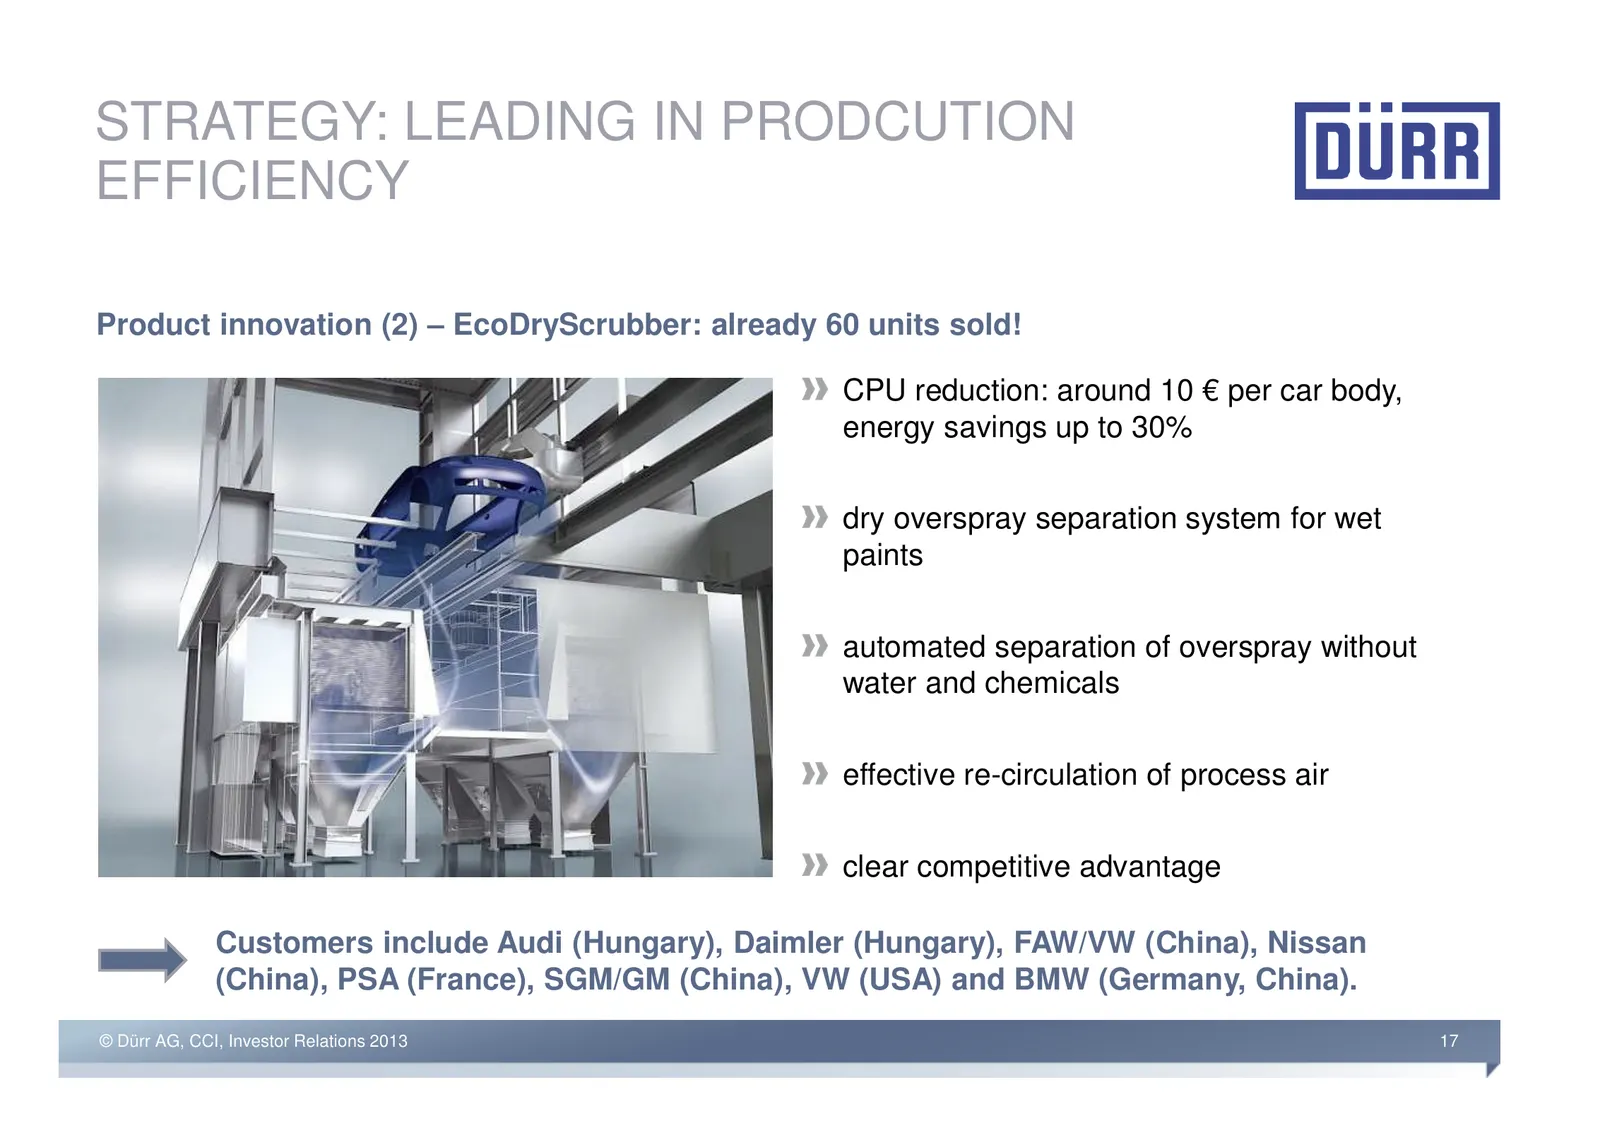
STRATEGY: LEADING IN PRODCUTION EFFICIENCY Product innovation (2) – EcoDryScrubber: already 60 units sold! CPU reduction: around 10 € per car body, energy savings up to 30% dry overspray separation system for wet paints automated separation of overspray without water and chemicals effective re-circu
Slide 18: Product innovation – EcoReBooth
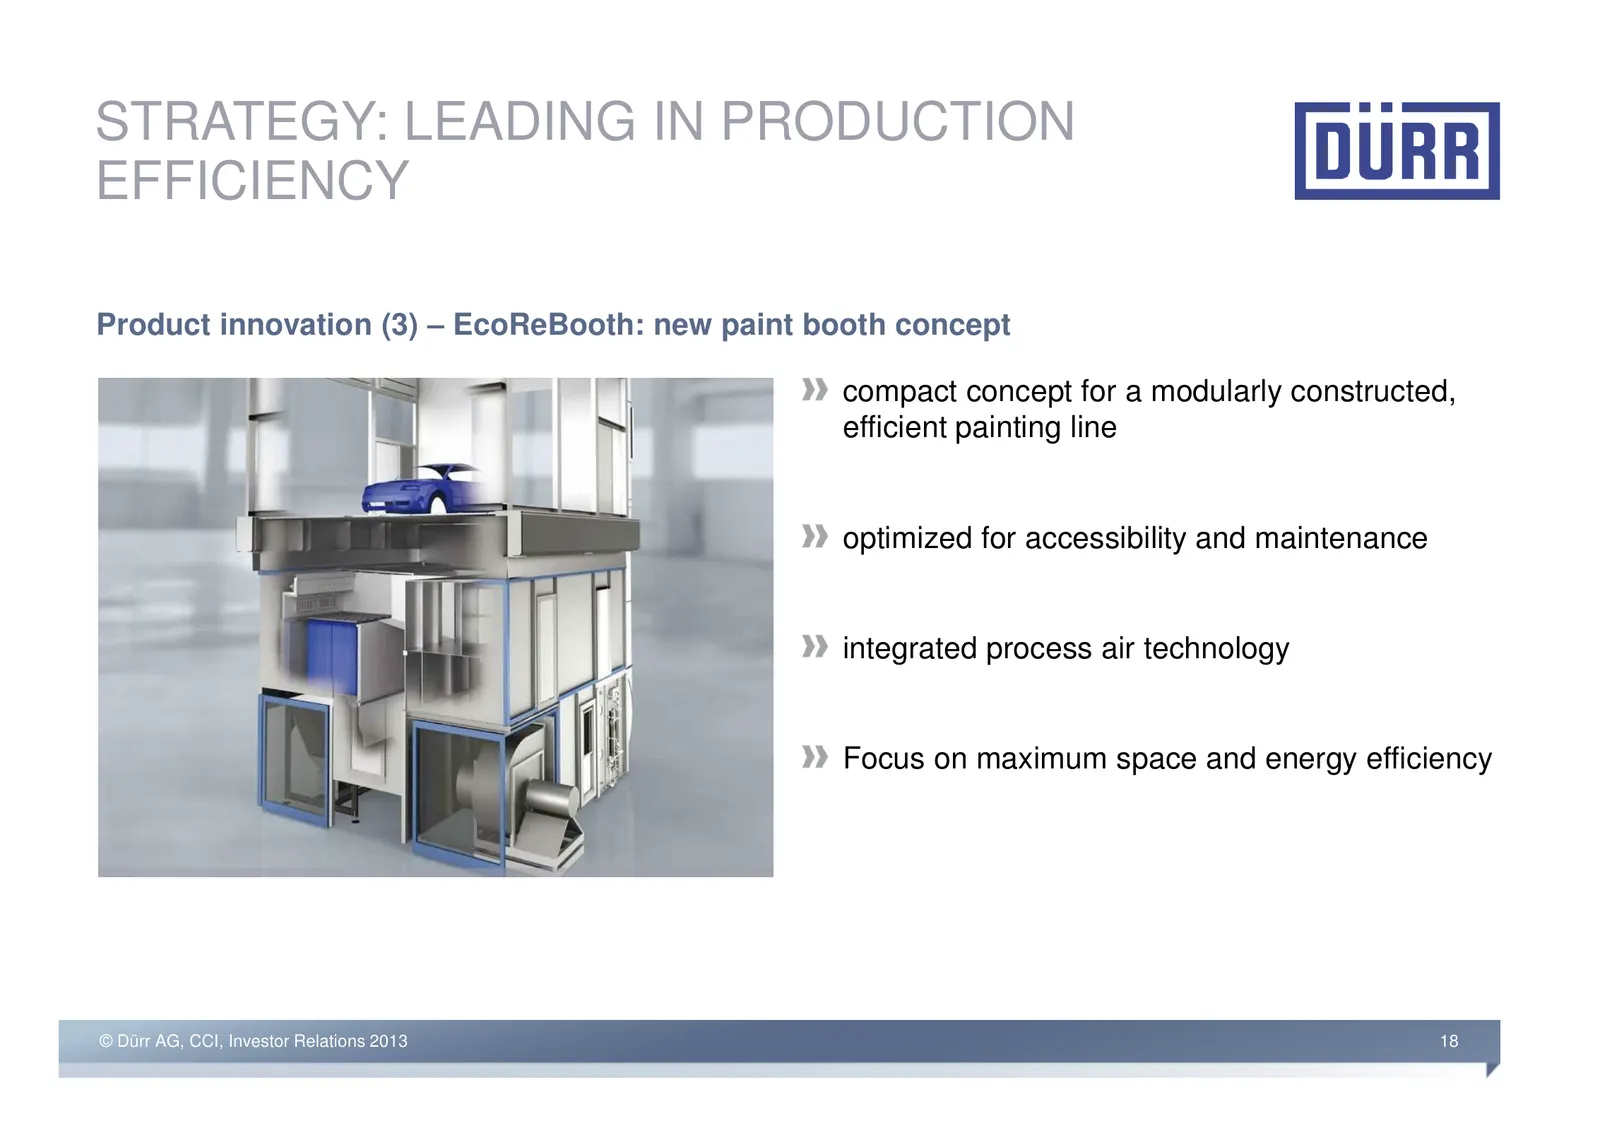
STRATEGY: LEADING IN PRODUCTION EFFICIENCY Product innovation (3) – EcoReBooth: new paint booth concept compact concept for a modularly constructed, efficient painting line optimized for accessibility and maintenance integrated process air technology Focus on maximum space and energy efficiency © Dü
Slide 19: Product innovation – EcoBell 3
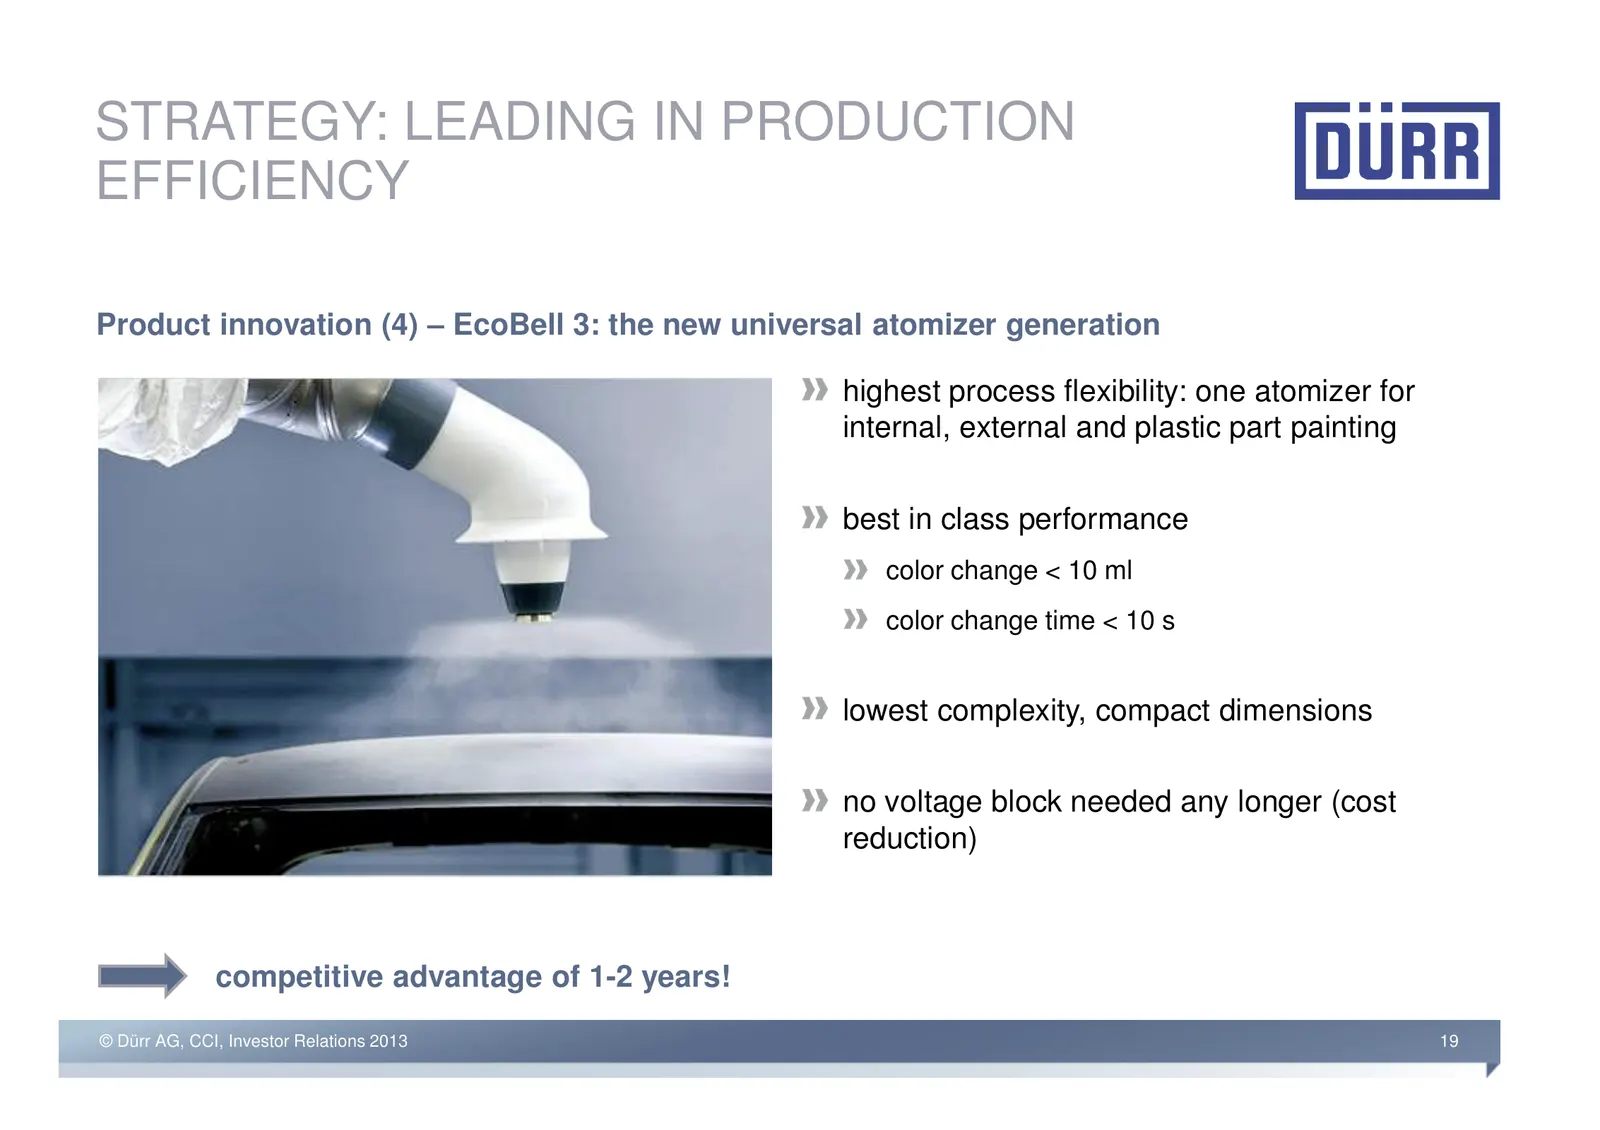
STRATEGY: LEADING IN PRODUCTION EFFICIENCY Product innovation (4) – EcoBell 3: the new universal atomizer generation highest process flexibility: one atomizer for internal, external and plastic part painting best in class performance color change < 10 ml color change time < 10 s lowest complexity, c
Slide 20: Strategy: Growth – Expanding the service business
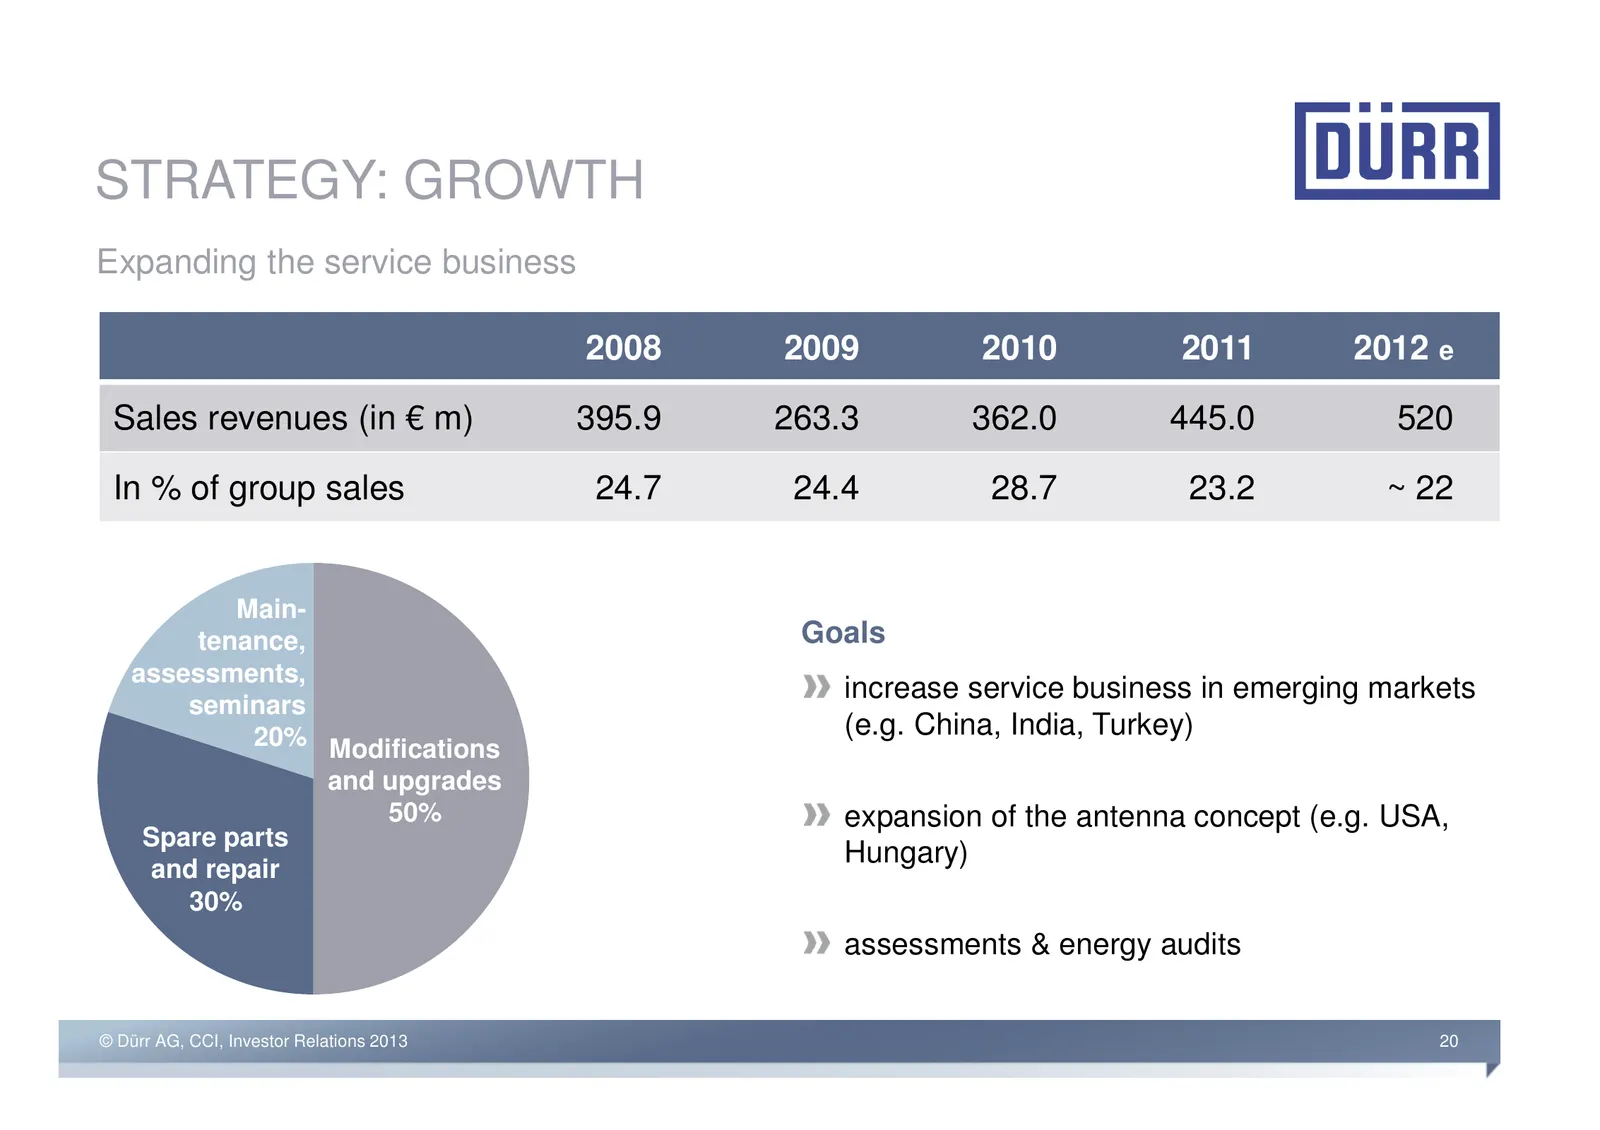
STRATEGY: GROWTH Expanding the service business 2008 2009 2010 2011 2012 e Sales revenues (in € m) 395.9 263.3 362.0 445.0 520 In % of group sales 24.7 24.4 28.7 23.2 ~ 22 Main- tenance, Goals assessments, increase service business in emerging markets seminars 20% Modifications (e.g. China, India, T
Slide 21: Expanding service business – potential in emerging markets
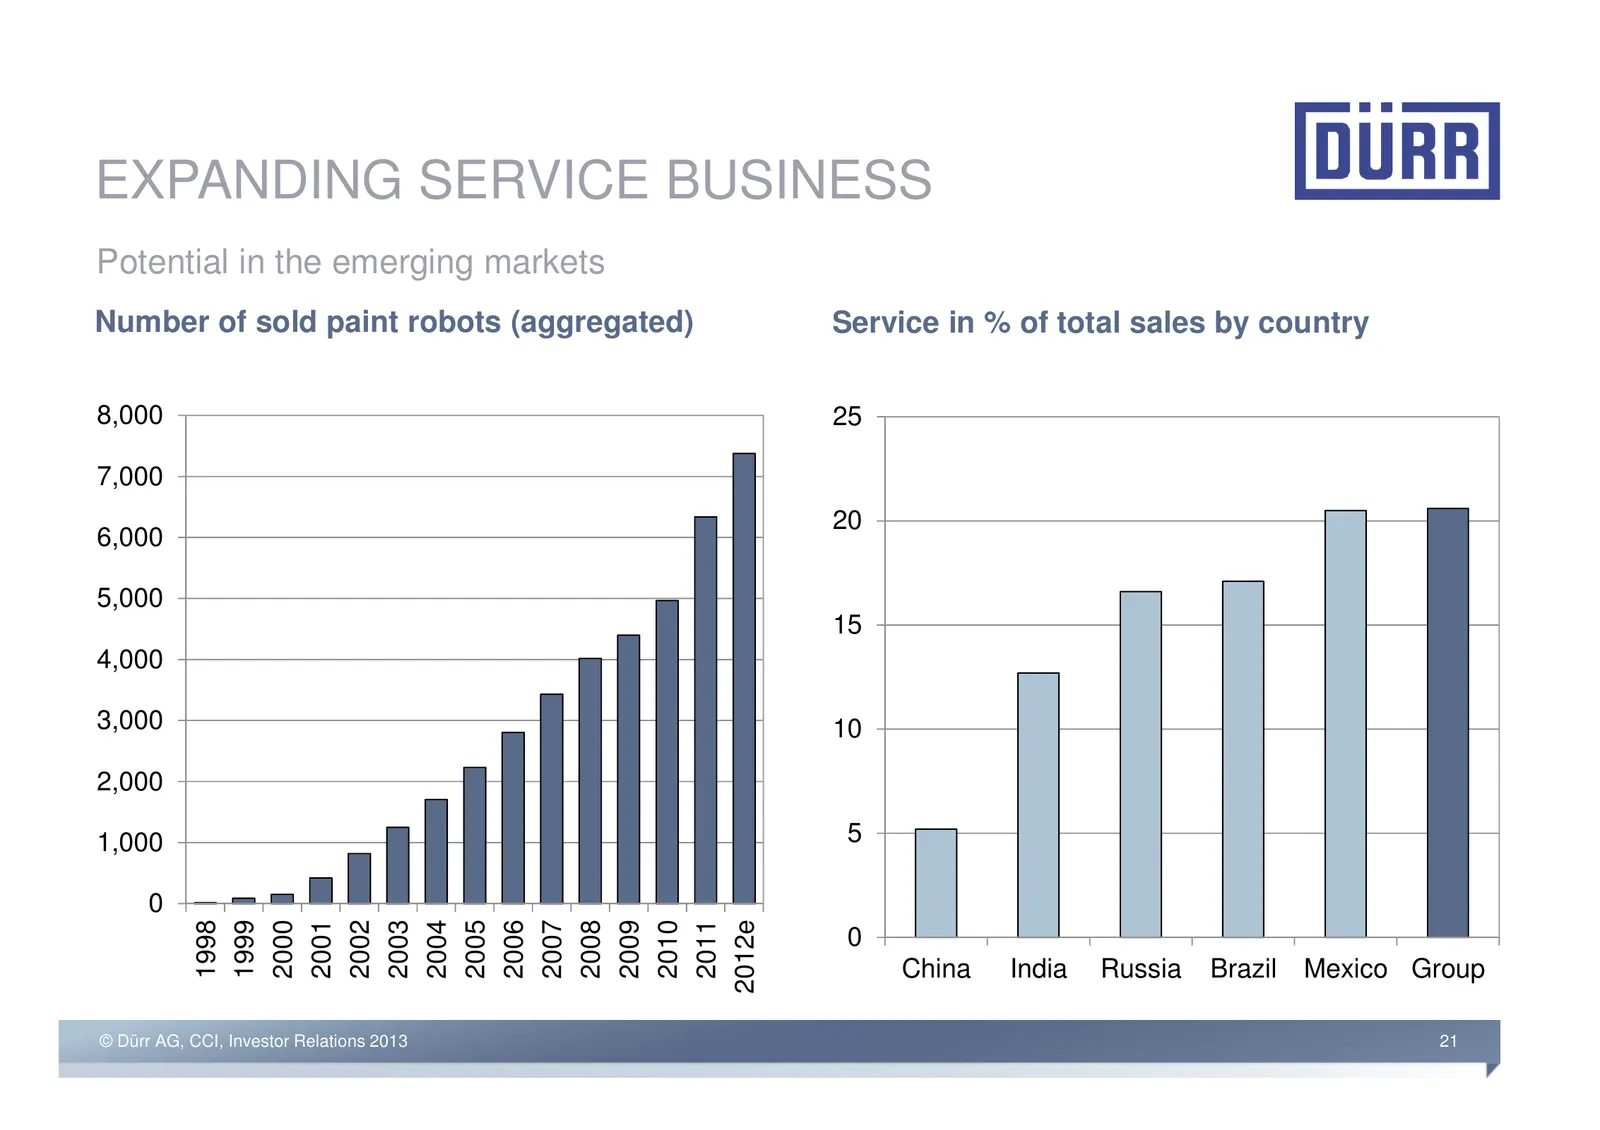
EXPANDING SERVICE BUSINESS Potential in the emerging markets Number of sold paint robots (aggregated) Service in % of total sales by country 8,000 25 7,000 20 6,000 5,000 15 4,000 3,000 10 2,000 1,000 5 0 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 2009 2010 2011 2012e 0 China India Russi
Slide 22: Strategy: Expanding modernisation business
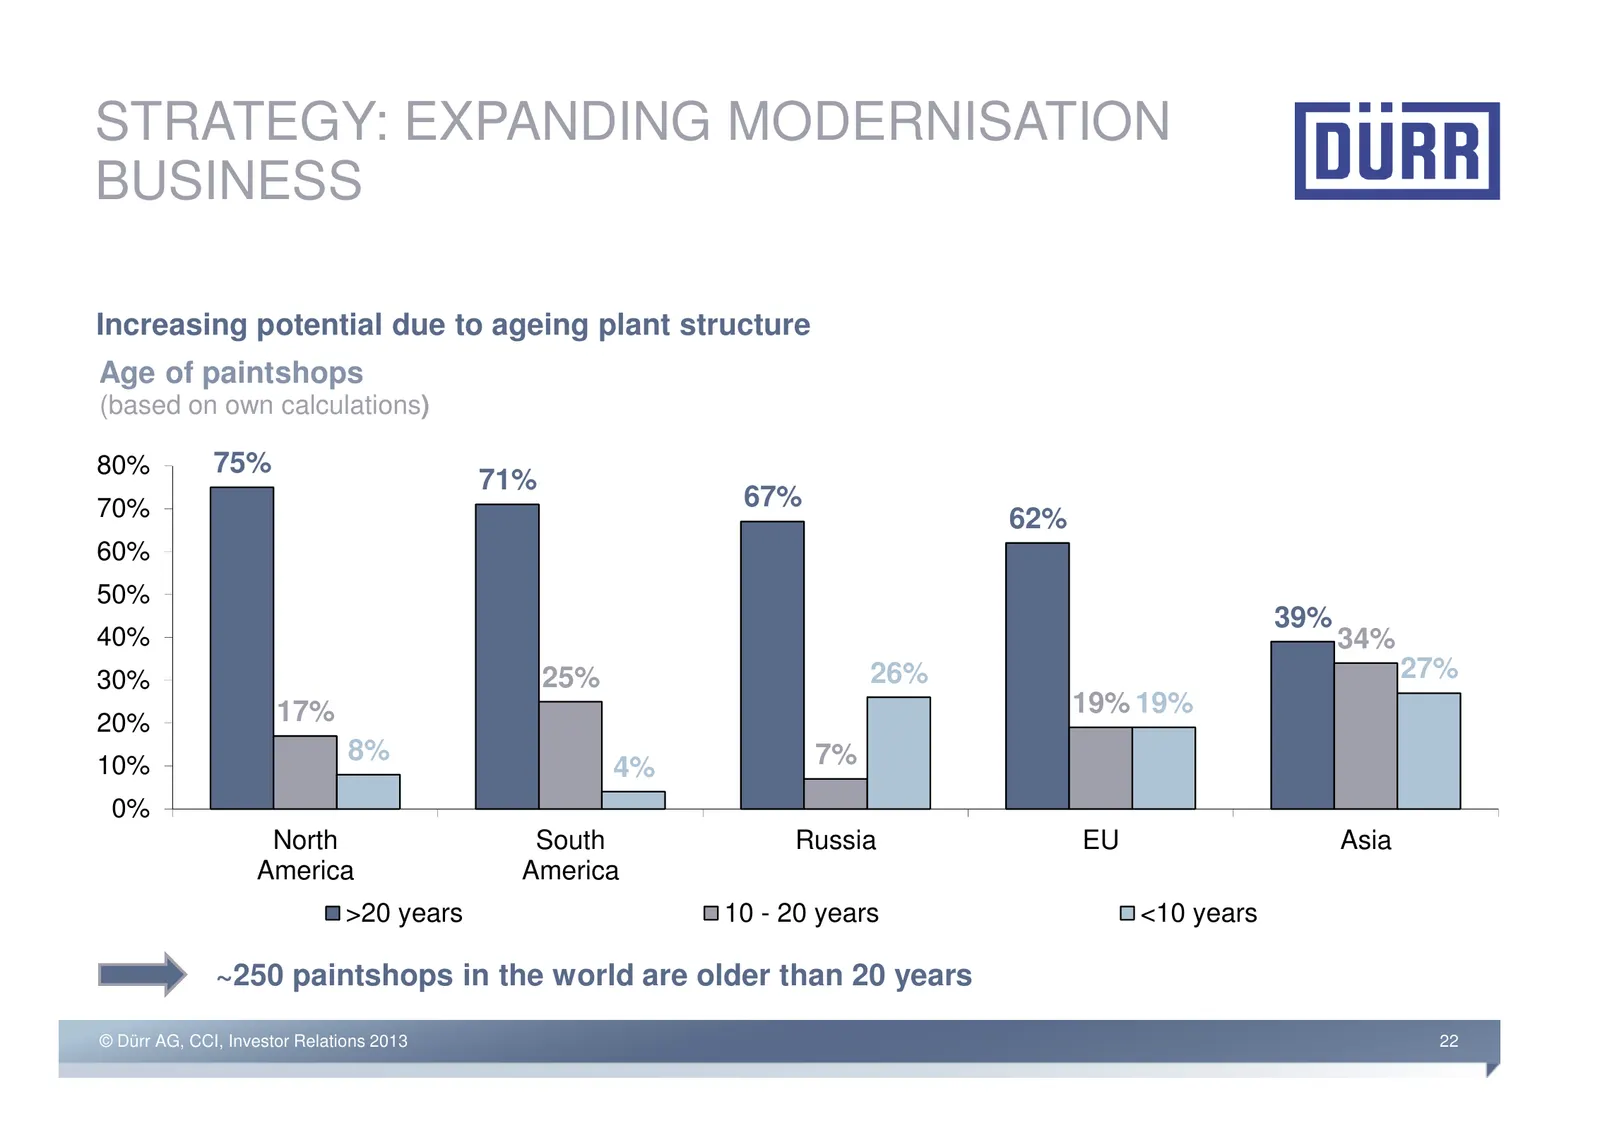
STRATEGY: EXPANDING MODERNISATION BUSINESS Increasing potential due to ageing plant structure Age of paintshops (based on own calculations) 80% 75% 71% 70% 67% 62% 60% 50% 39% 40% 34% 30% 25% 26% 27% 17% 19% 19% 20% 10% 8% 7% 4% 0% North South Russia EU Asia America America >20 years 10 - 20 years <
Slide 23: Strategy: Optimization – ongoing optimization process
STRATEGY: OPTIMIZATION Ongoing optimization process Global processes / localization further globalization of Dürr processes global processes with full utilization of SAP/CAX strengthening of engineering center in India expansion of sourcing offices in China, India, Mexico, Brazil expansion of manufa
Slide 24: Strategy: New business – Clean Technology Systems
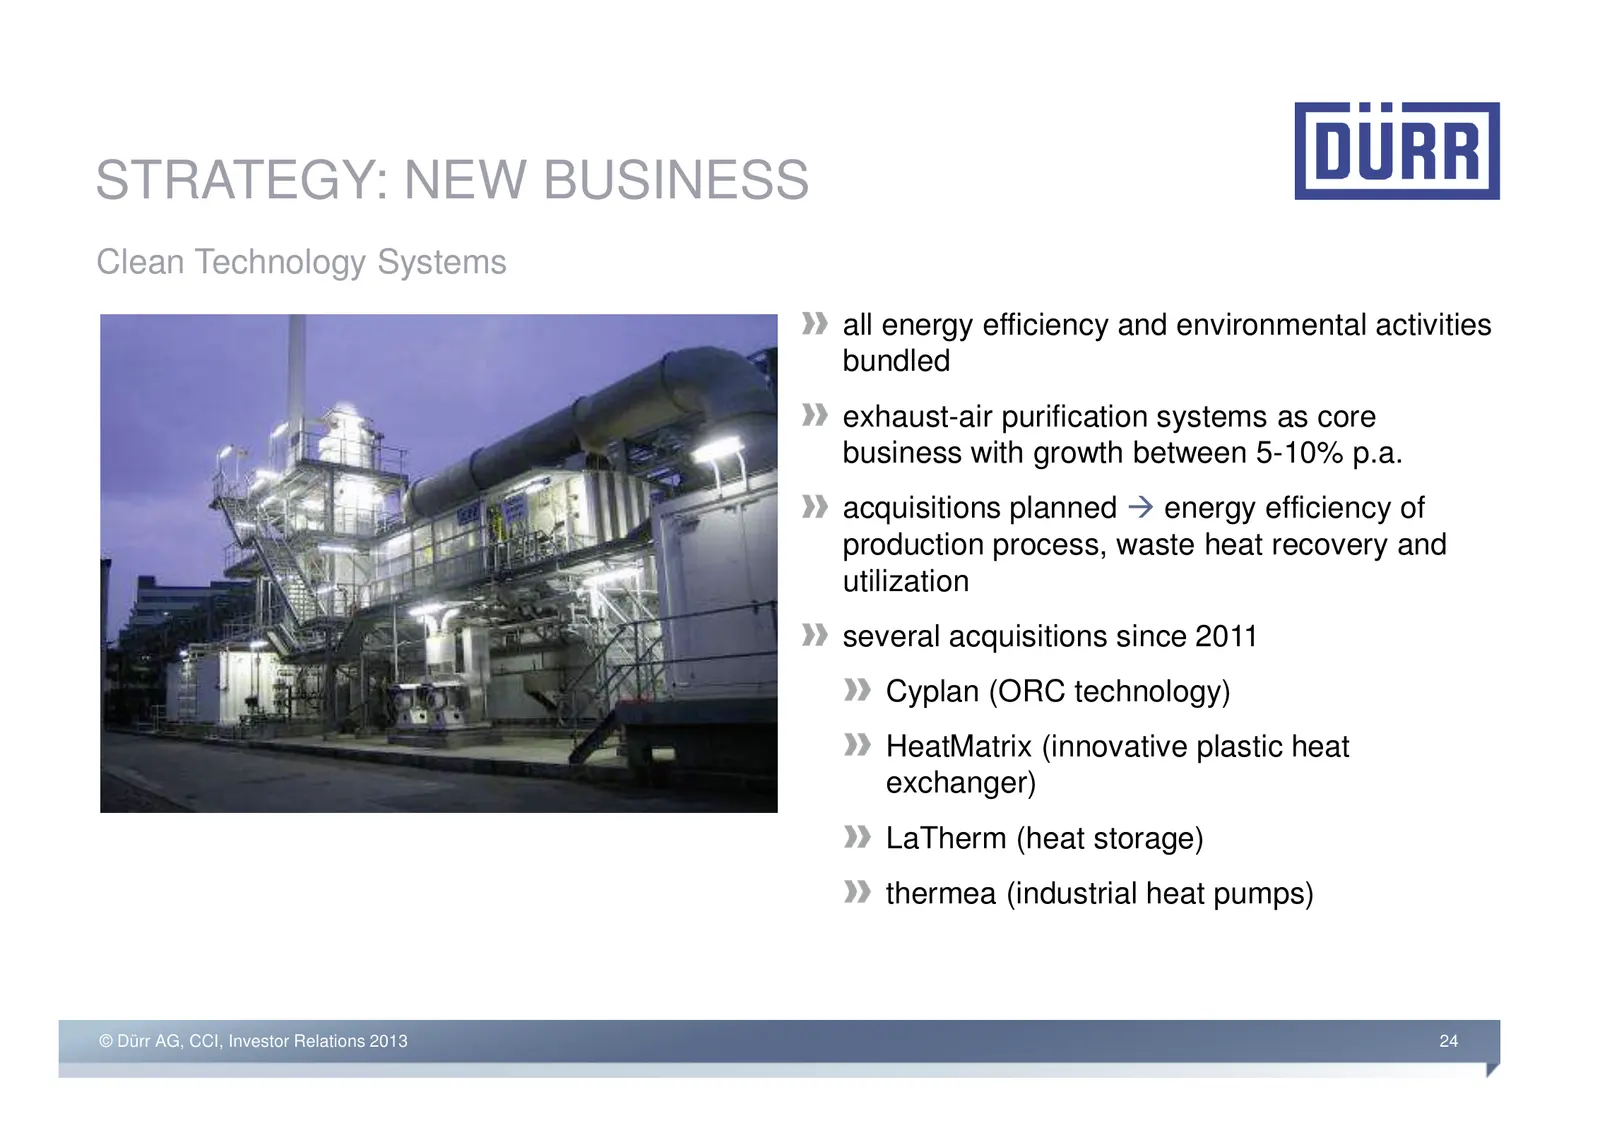
STRATEGY: NEW BUSINESS Clean Technology Systems all energy efficiency and environmental activities bundled exhaust-air purification systems as core business with growth between 5-10% p.a. acquisitions planned energy efficiency of production process, waste heat recovery and utilization several acquis
Slide 25: Energy efficiency: efficient use of heat energy/waste heat
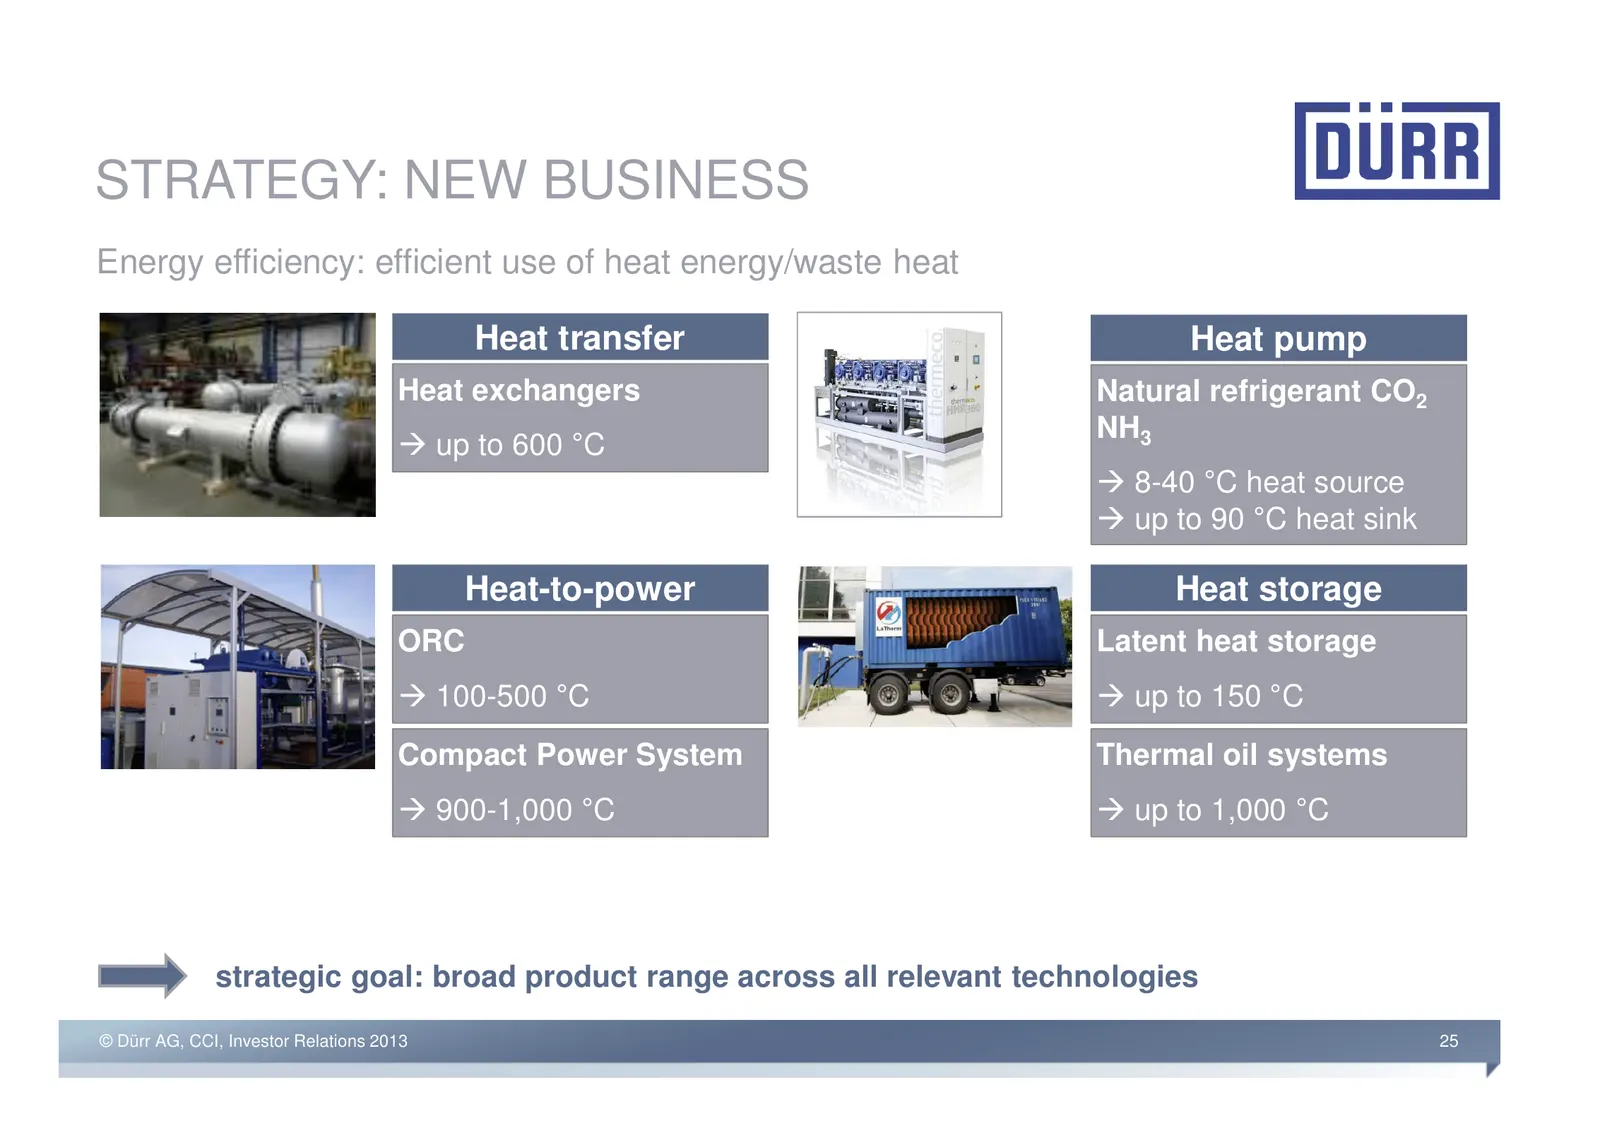
STRATEGY: NEW BUSINESS Energy efficiency: efficient use of heat energy/waste heat Heat transfer Heat pump Heat exchangers Natural refrigerant CO2 NH3 up to 600 °C 8-40 °C heat source up to 90 °C heat sink Heat-to-power Heat storage ORC Latent heat storage 100-500 °C up to 150 °C Compact Power System
Slide 26: Agenda
AGENDA 1. Dürr: global leader with strong competitive position 2. Markets 3. Strategy 4. Financial overview, outlook and summary © Dürr AG, CCI, Investor Relations 2013 26
Slide 27: Order backlog at record high
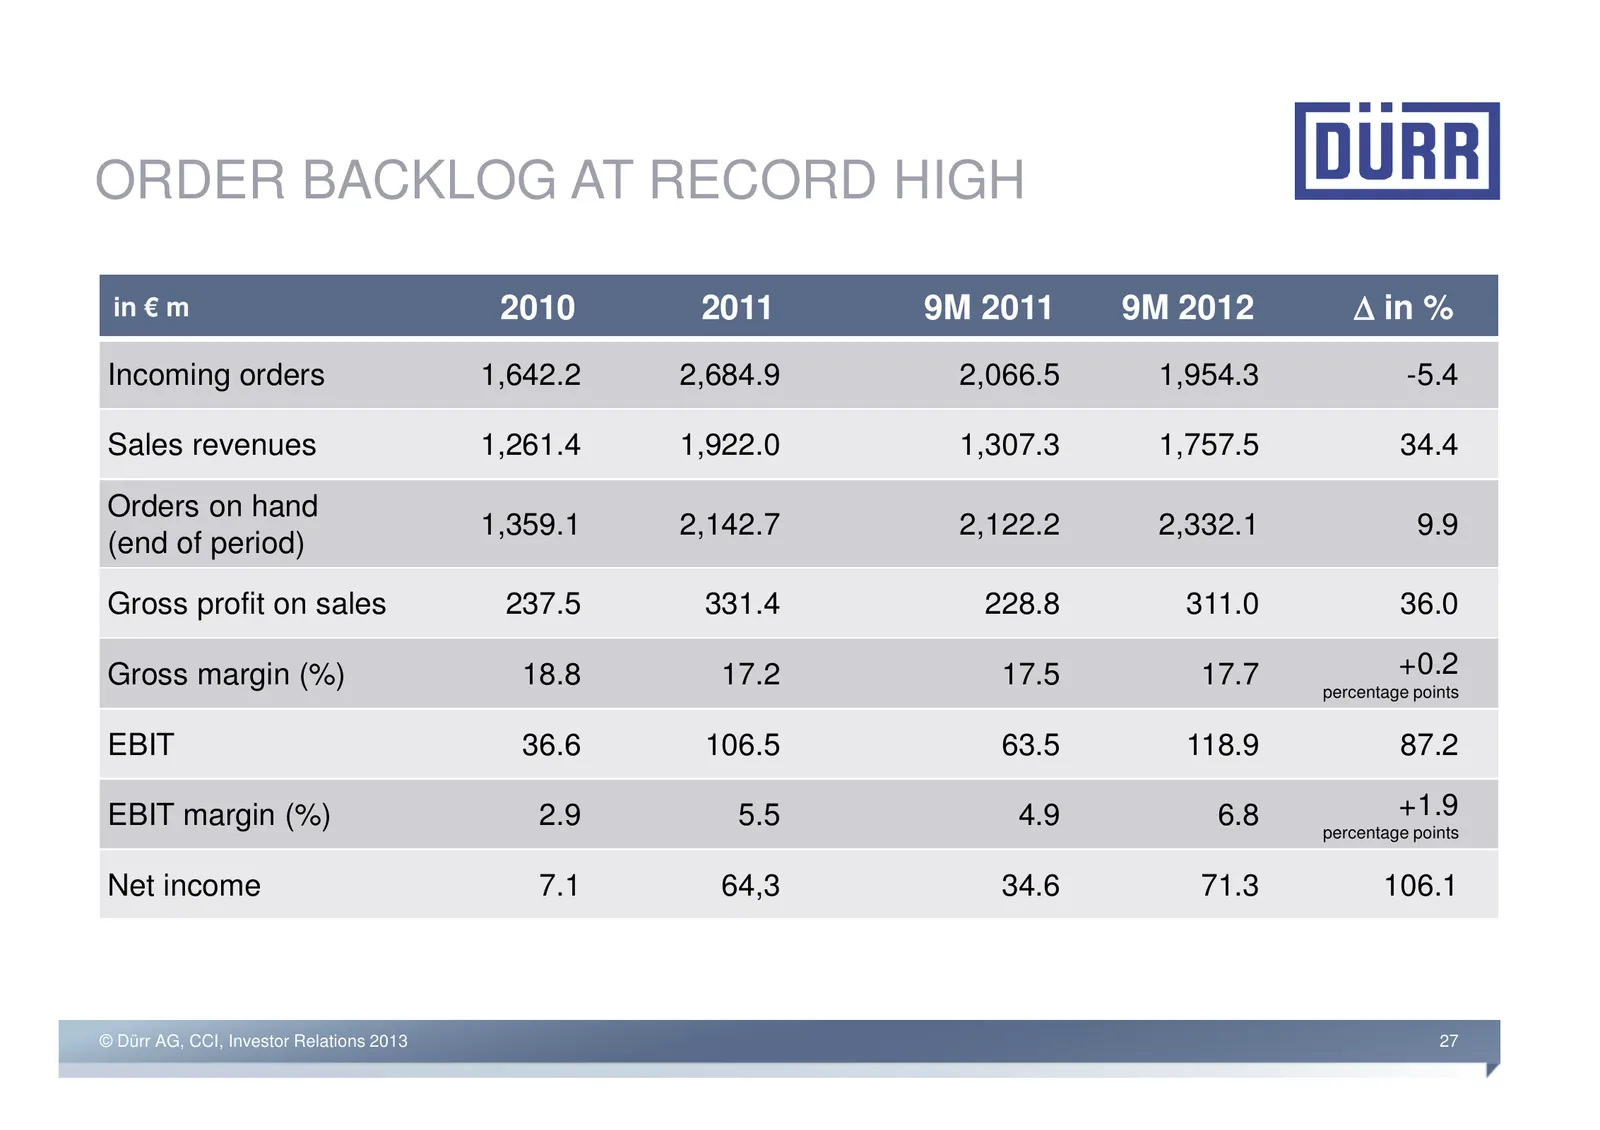
ORDER BACKLOG AT RECORD HIGH in € m 2010 2011 9M 2011 9M 2012 ∆ in % Incoming orders 1,642.2 2,684.9 2,066.5 1,954.3 -5.4 Sales revenues 1,261.4 1,922.0 1,307.3 1,757.5 34.4 Orders on hand 1,359.1 2,142.7 2,122.2 2,332.1 9.9 (end of period) Gross profit on sales 237.5 331.4 228.8 311.0 36.0 Gross ma
Slide 28: Q3 order intake level according to plan
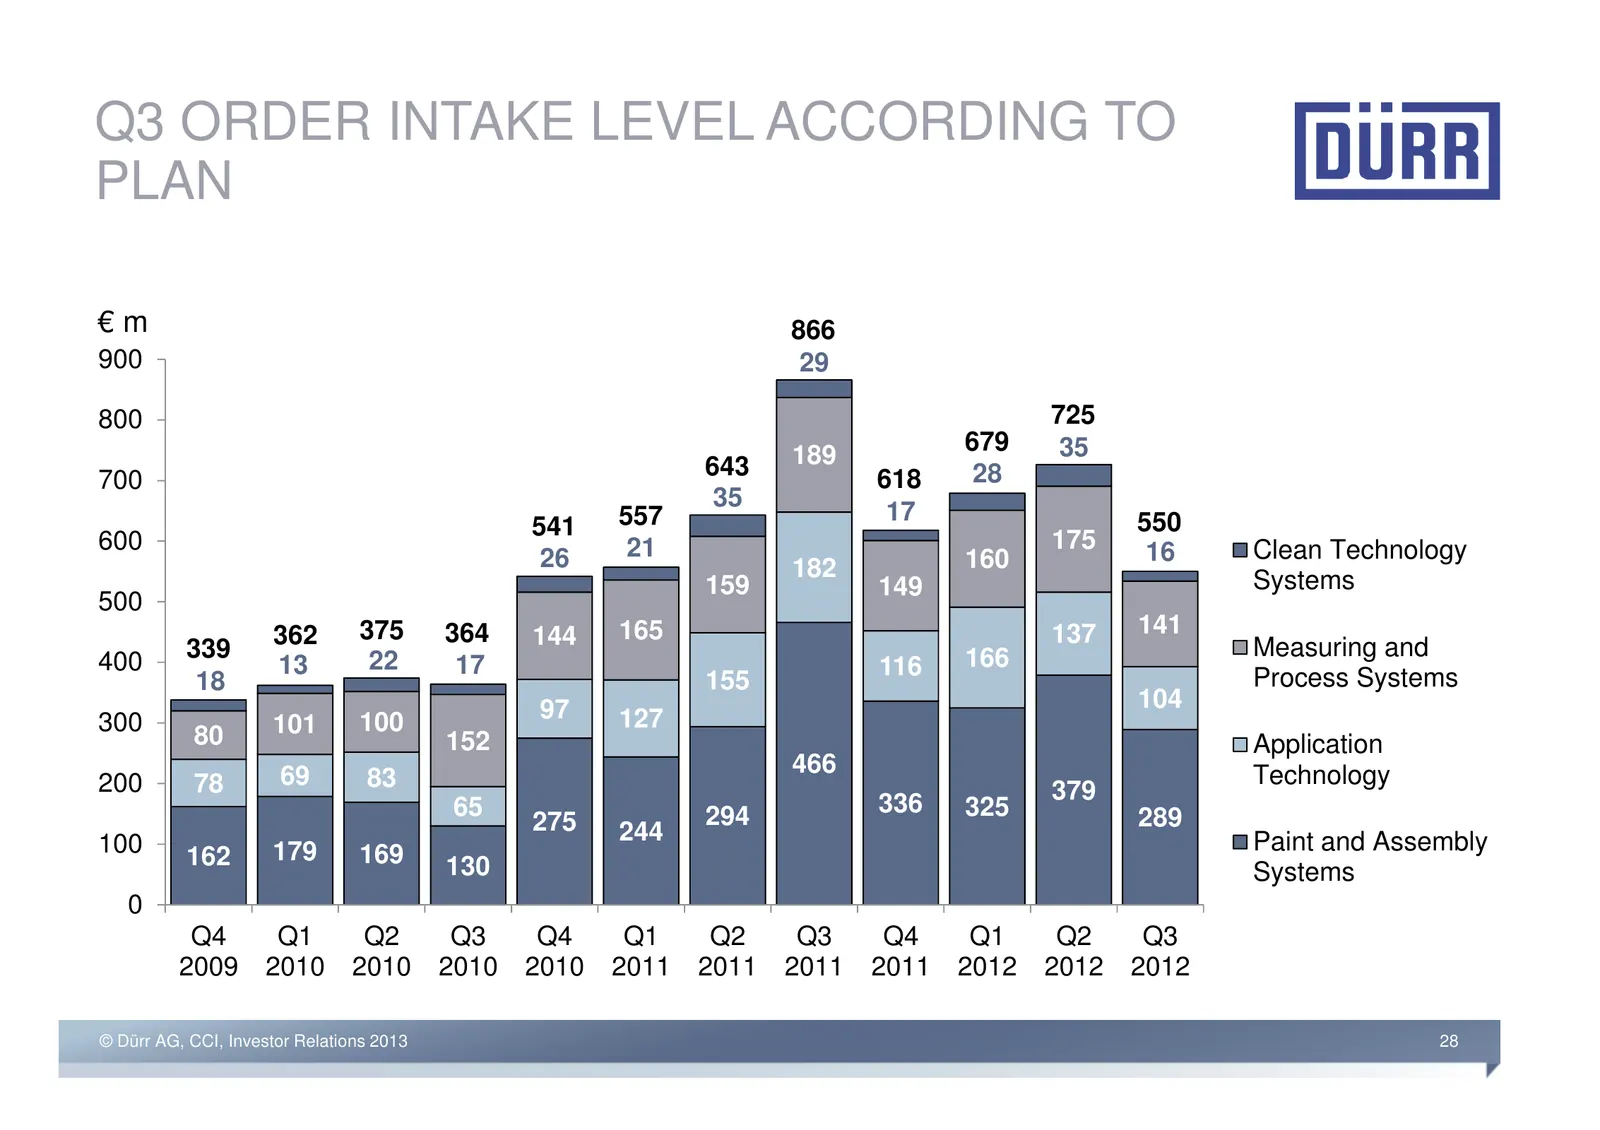
Q3 ORDER INTAKE LEVEL ACCORDING TO PLAN €m 866 900 29 800 725 679 35 643 189 700 618 28 35 557 17 550 541 175 600 21 16 Clean Technology 26 182 160 159 149 Systems 500 362 375 364 144 165 137 141 339 166 Measuring and 400 13 22 17 116 18 155 Process Systems 97 104 300 101 100 127 80 152 Application
Slide 29: Cash flow
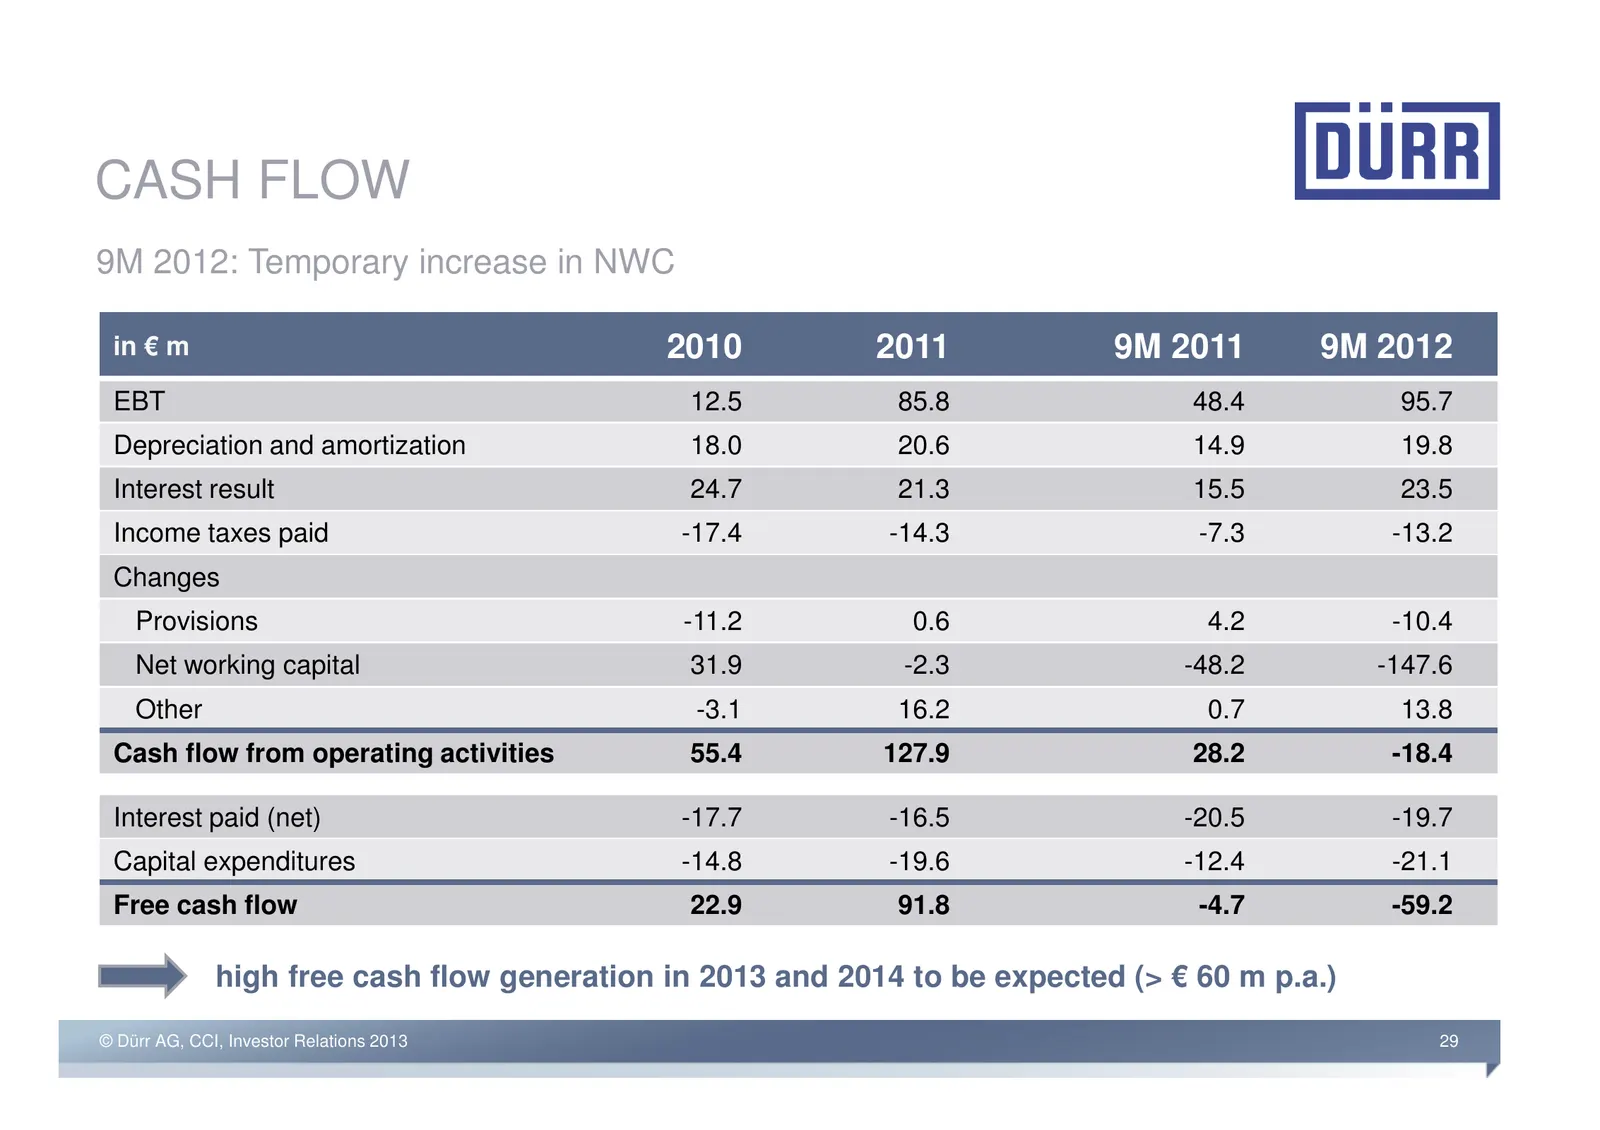
CASH FLOW 9M 2012: Temporary increase in NWC in € m 2010 2011 9M 2011 9M 2012 EBT 12.5 85.8 48.4 95.7 Depreciation and amortization 18.0 20.6 14.9 19.8 Interest result 24.7 21.3 15.5 23.5 Income taxes paid -17.4 -14.3 -7.3 -13.2 Changes Provisions -11.2 0.6 4.2 -10.4 Net working capital 31.9 -2.3 -4
Slide 30: Solid financial structure
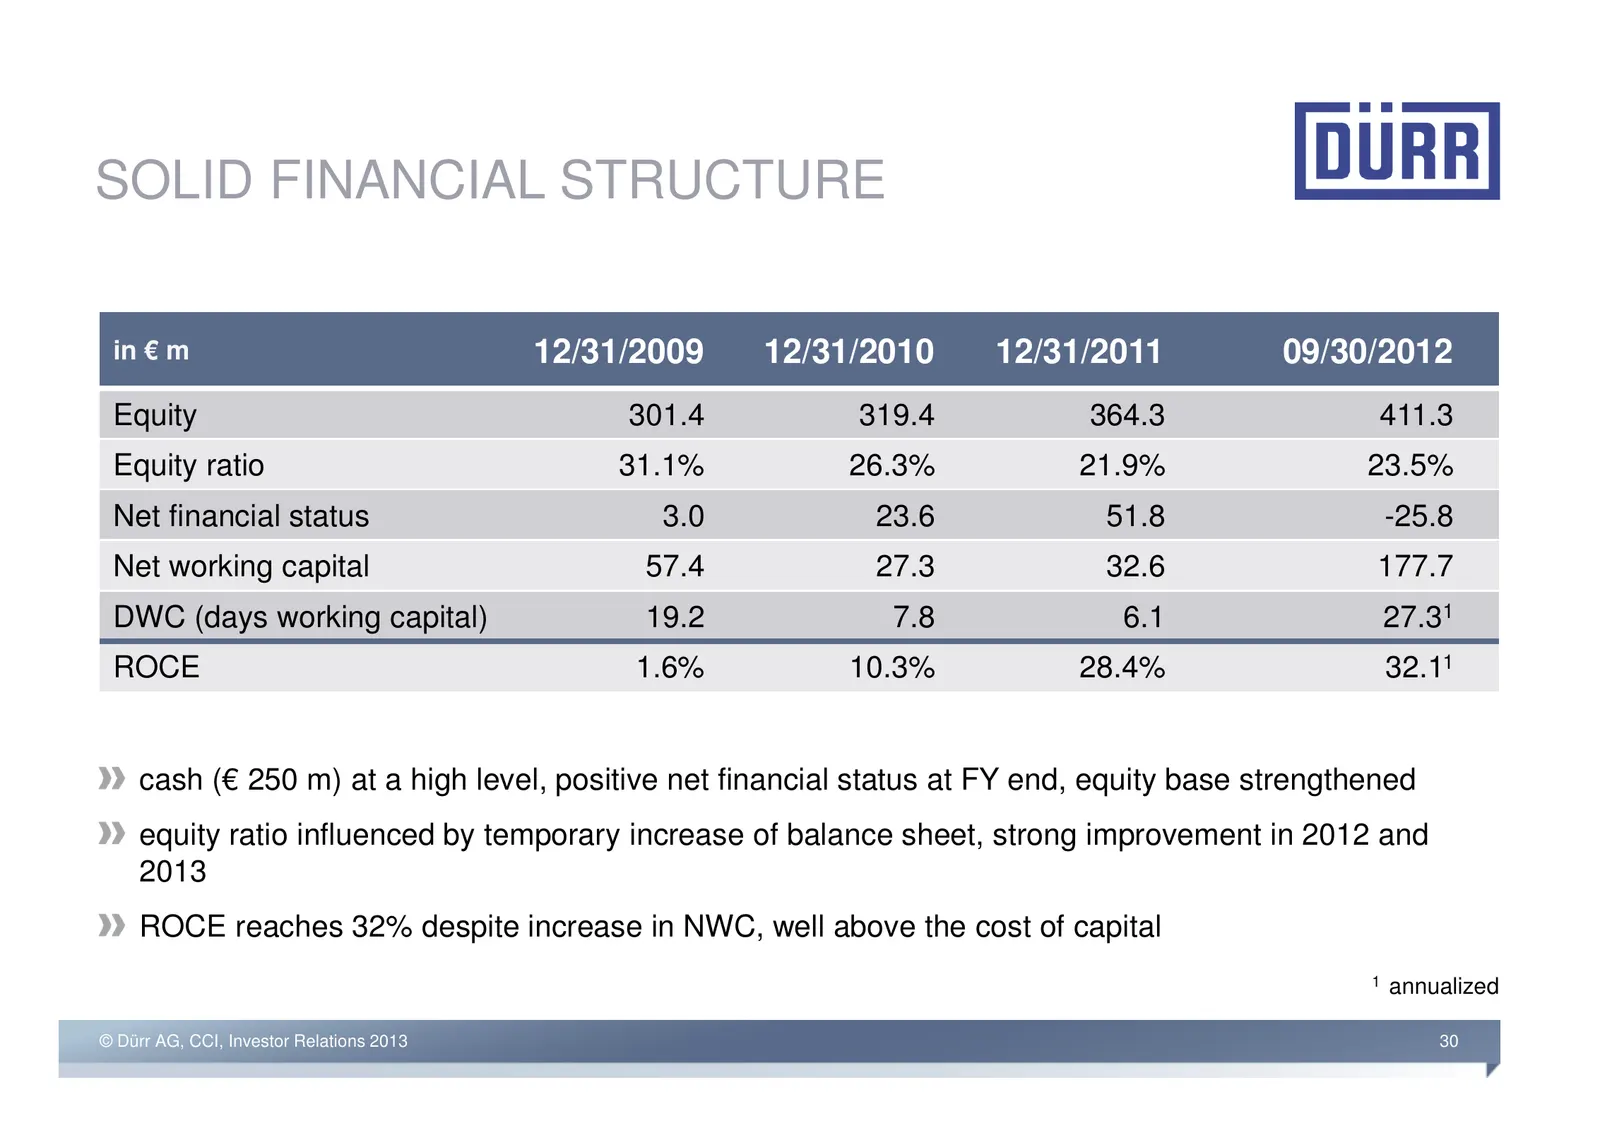
SOLID FINANCIAL STRUCTURE in € m 12/31/2009 12/31/2010 12/31/2011 09/30/2012 Equity 301.4 319.4 364.3 411.3 Equity ratio 31.1% 26.3% 21.9% 23.5% Net financial status 3.0 23.6 51.8 -25.8 Net working capital 57.4 27.3 32.6 177.7 DWC (days working capital) 19.2 7.8 6.1 27.31 ROCE 1.6% 10.3% 28.4% 32.11
Slide 31: ROCE clearly above cost of capital
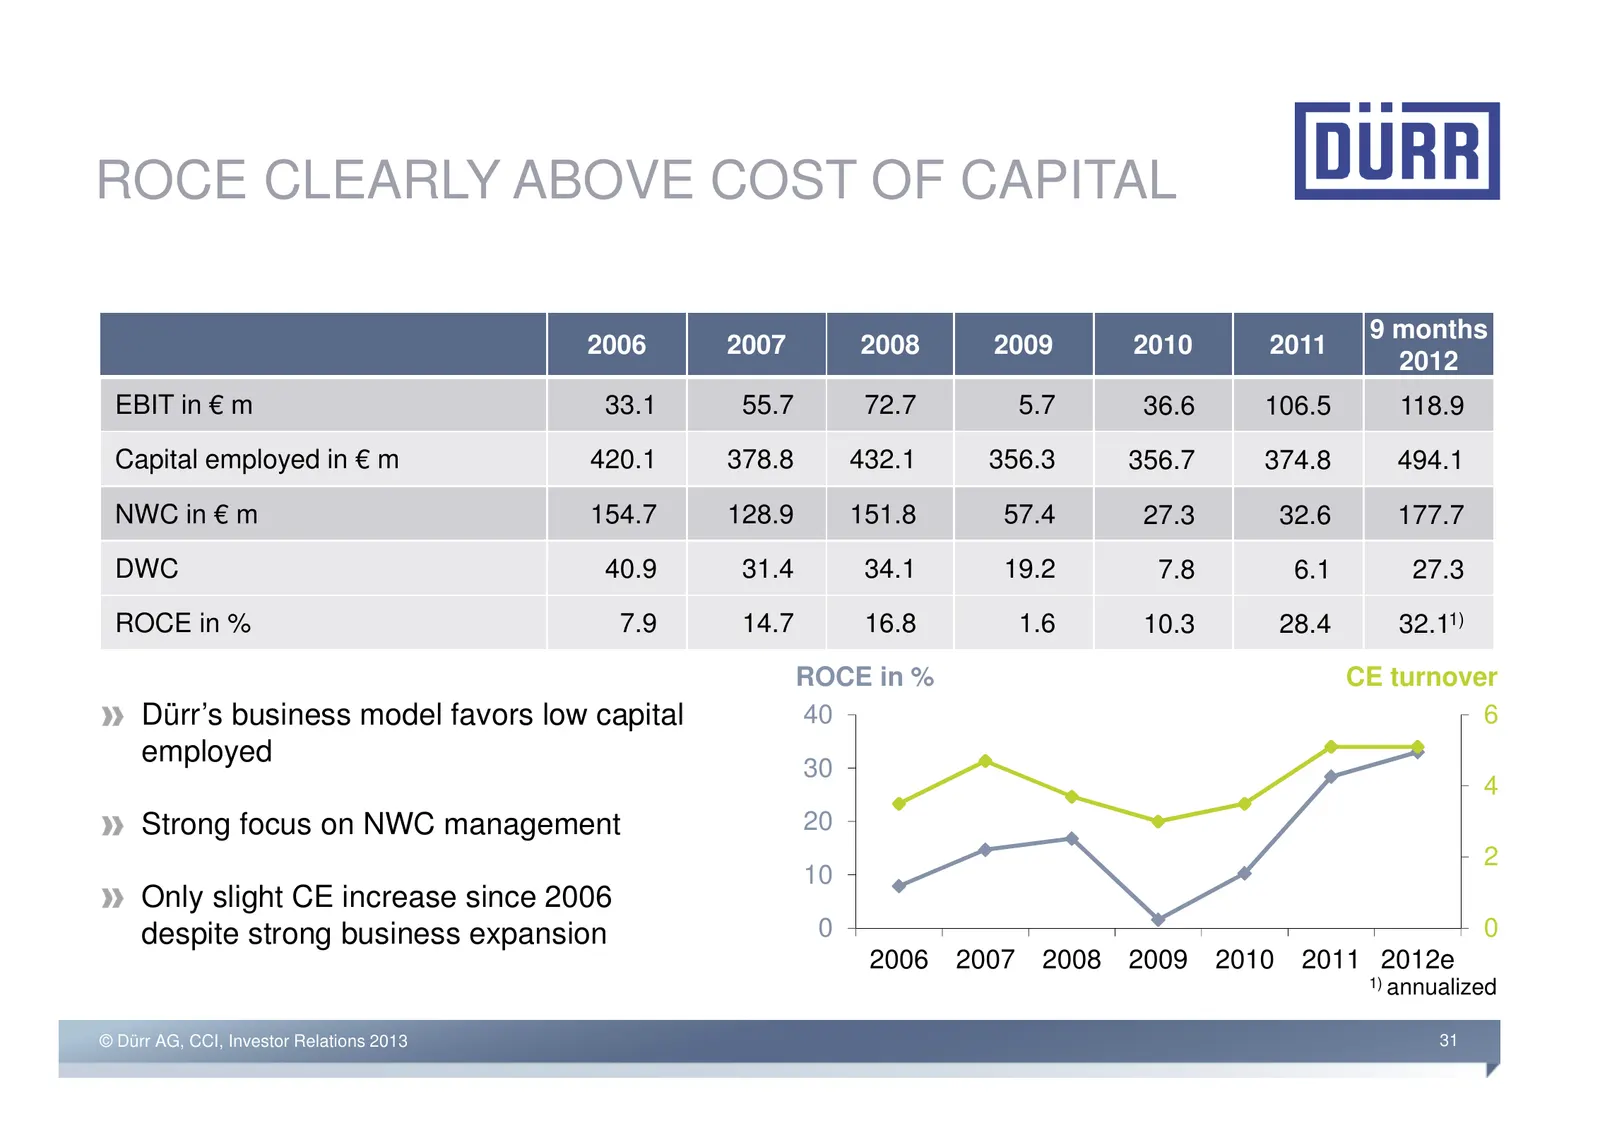
ROCE CLEARLY ABOVE COST OF CAPITAL 9 months 2006 2007 2008 2009 2010 2011 2012 EBIT in € m 33.1 55.7 72.7 5.7 36.6 106.5 118.9 Capital employed in € m 420.1 378.8 432.1 356.3 356.7 374.8 494.1 NWC in € m 154.7 128.9 151.8 57.4 27.3 32.6 177.7 DWC 40.9 31.4 34.1 19.2 7.8 6.1 27.3 ROCE in % 7.9 14.7 1
Slide 32: Outlook
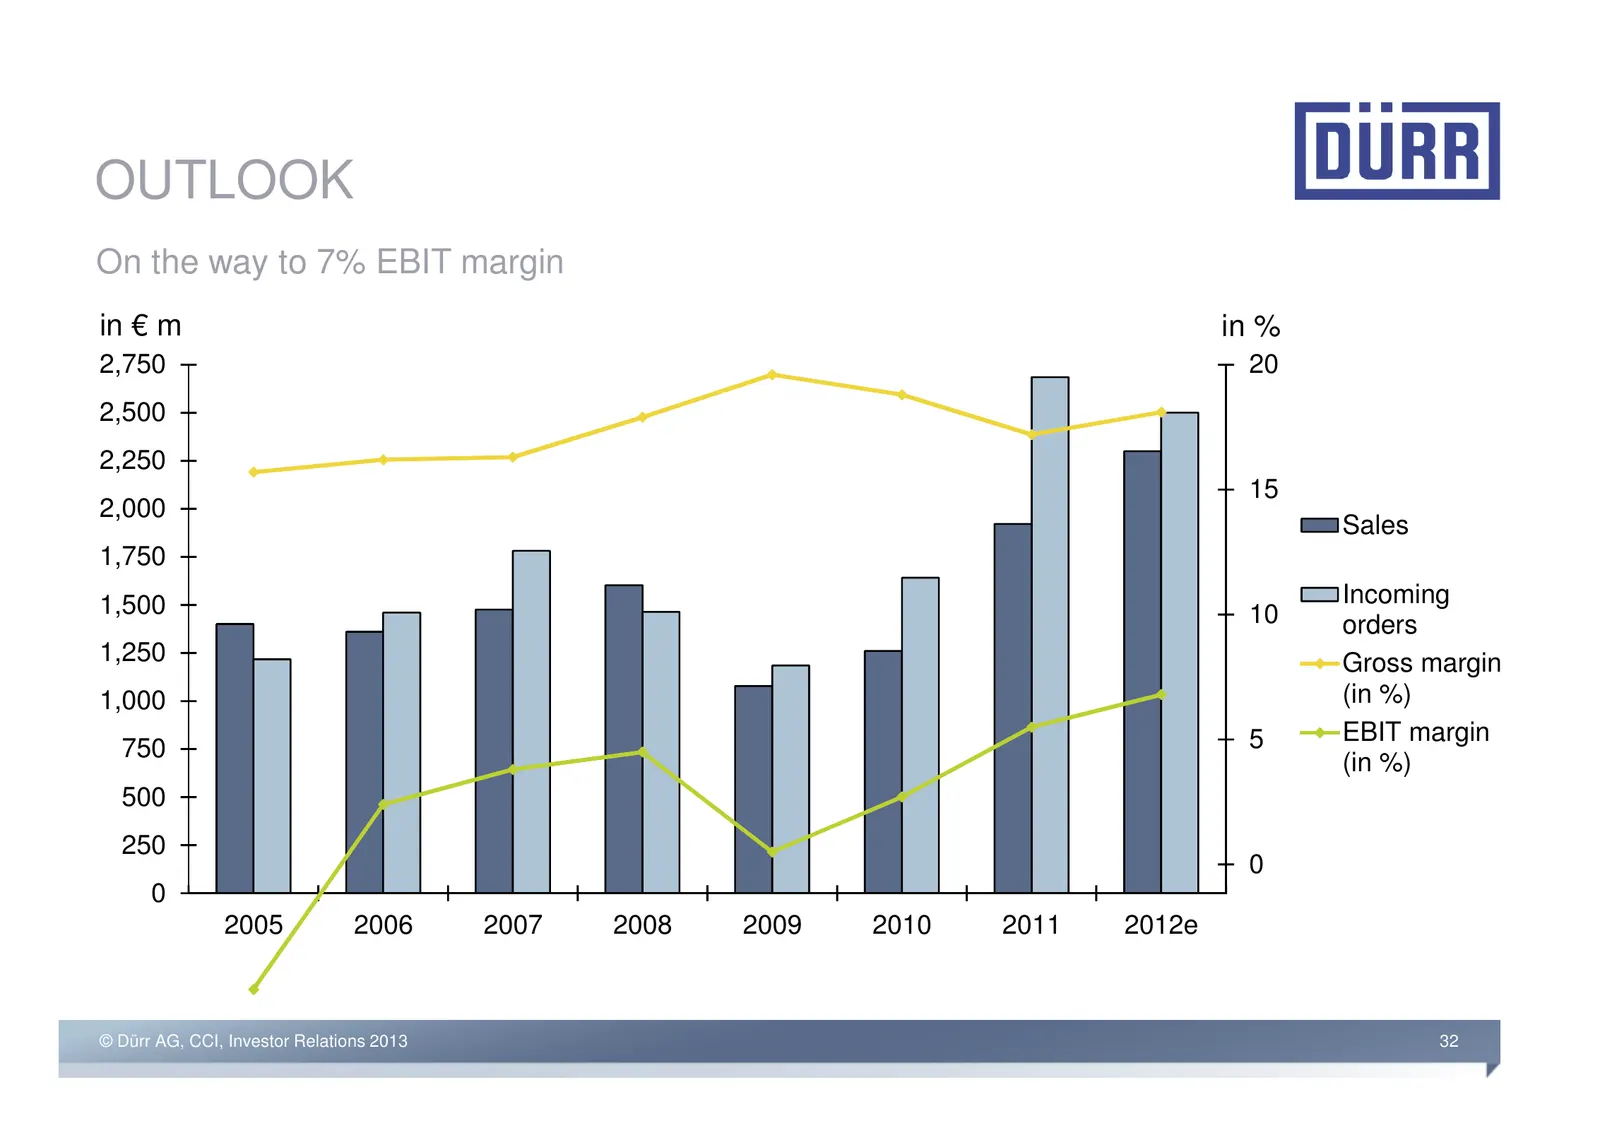
OUTLOOK On the way to 7% EBIT margin in € m in % 2,750 20 2,500 2,250 15 2,000 Sales 1,750 1,500 Incoming 10 orders 1,250 Gross margin 1,000 (in %) 5 EBIT margin 750 (in %) 500 250 0 0 2005 2006 2007 2008 2009 2010 2011 2012e -250 -500 -5 © Dürr AG, CCI, Investor Relations 2013 32
Slide 33: Shareholder structure / dividend policy
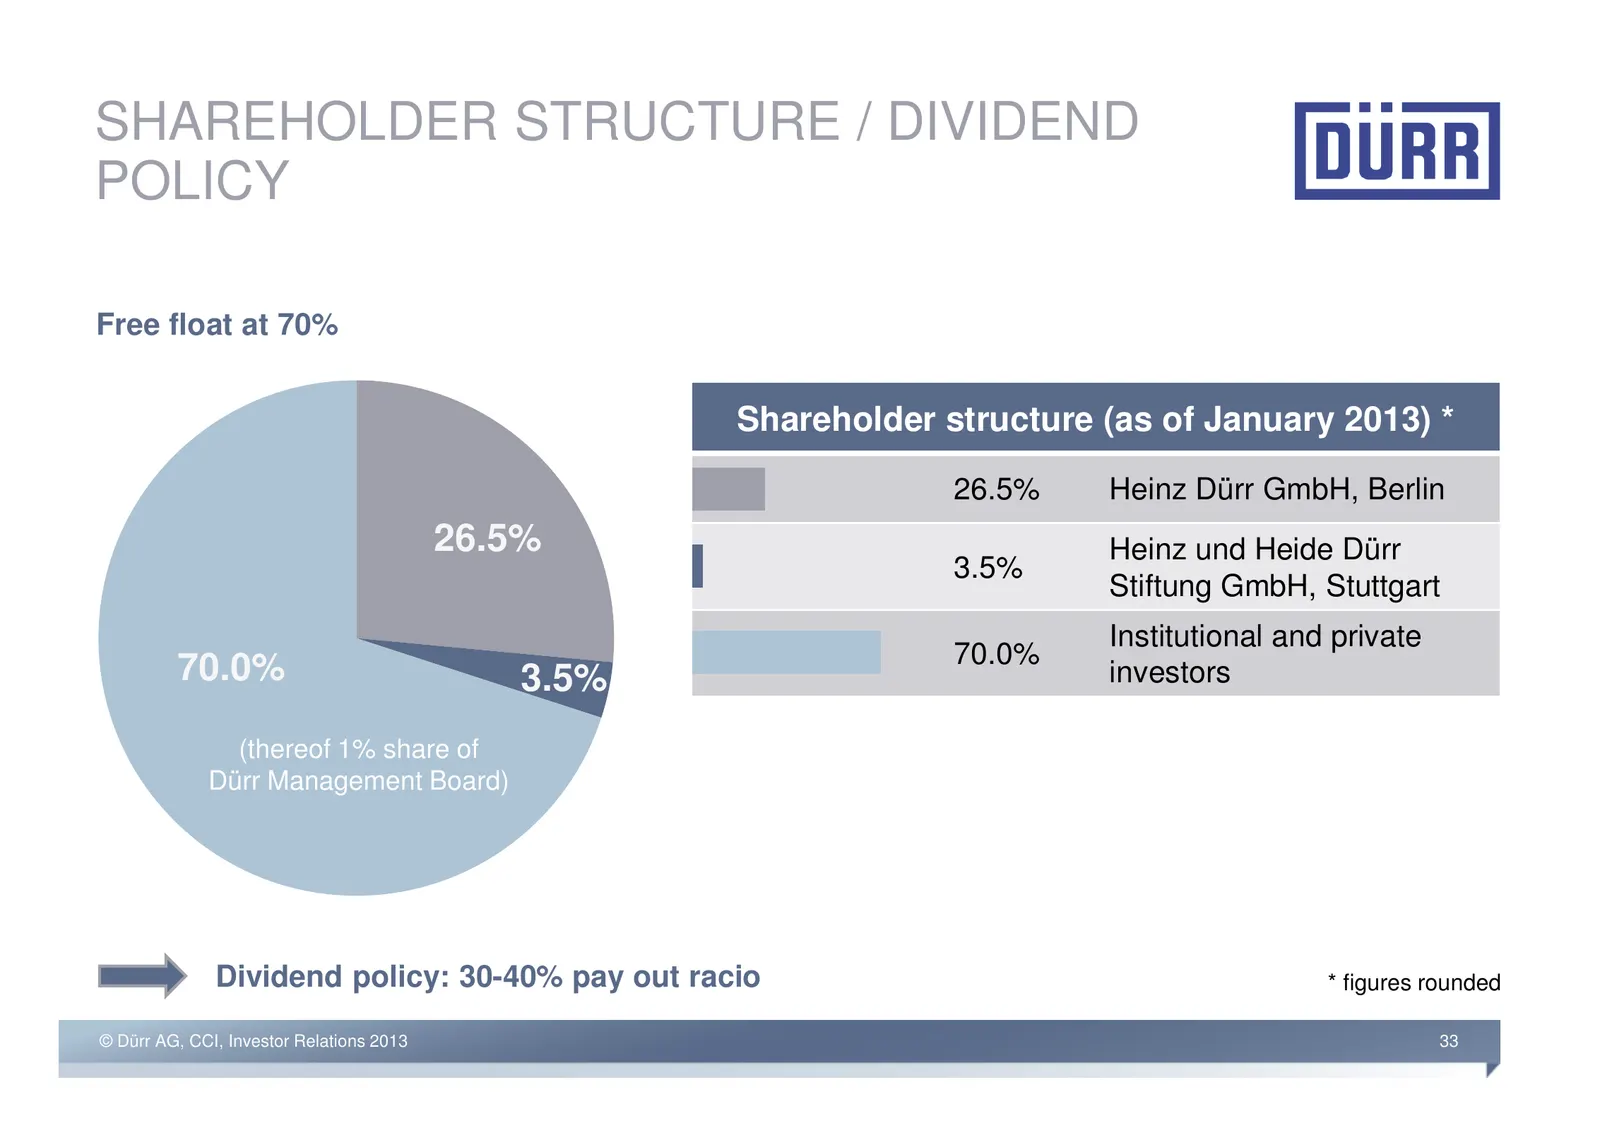
SHAREHOLDER STRUCTURE / DIVIDEND POLICY Free float at 70% Shareholder structure (as of January 2013) * 26.5% Heinz Dürr GmbH, Berlin 26.5% Heinz und Heide Dürr 3.5% Stiftung GmbH, Stuttgart Institutional and private 70.0% 70.0% 3.5% investors (thereof 1% share of Dürr Management Board) Dividend poli
Slide 34: Summary
SUMMARY Strong market conditions, positioning for further growth ongoing demand, full order pipeline, a lot of new projects are coming to the market (e.g. China, Brazil, USA) positioning for further growth: focus on emerging markets, product innovation and new business segments (environmental & ener
Slide 35: Financial calendar
FINANCIAL CALENDAR 02/19/2013 Preliminary figures 2012: Press conference 03/13/2013 Publication annual financial report of the Dürr Group 2012 04/26/2013 Annual general meeting, Bietigheim-Bissingen 05/08/2013 Interim report for the first quarter of 2013 08/01/2013 Interim financial report for the f
Slide 36: Appendix
Appendix © Dürr AG, CCI, Investor Relations 2013 36
Slide 37: Business units
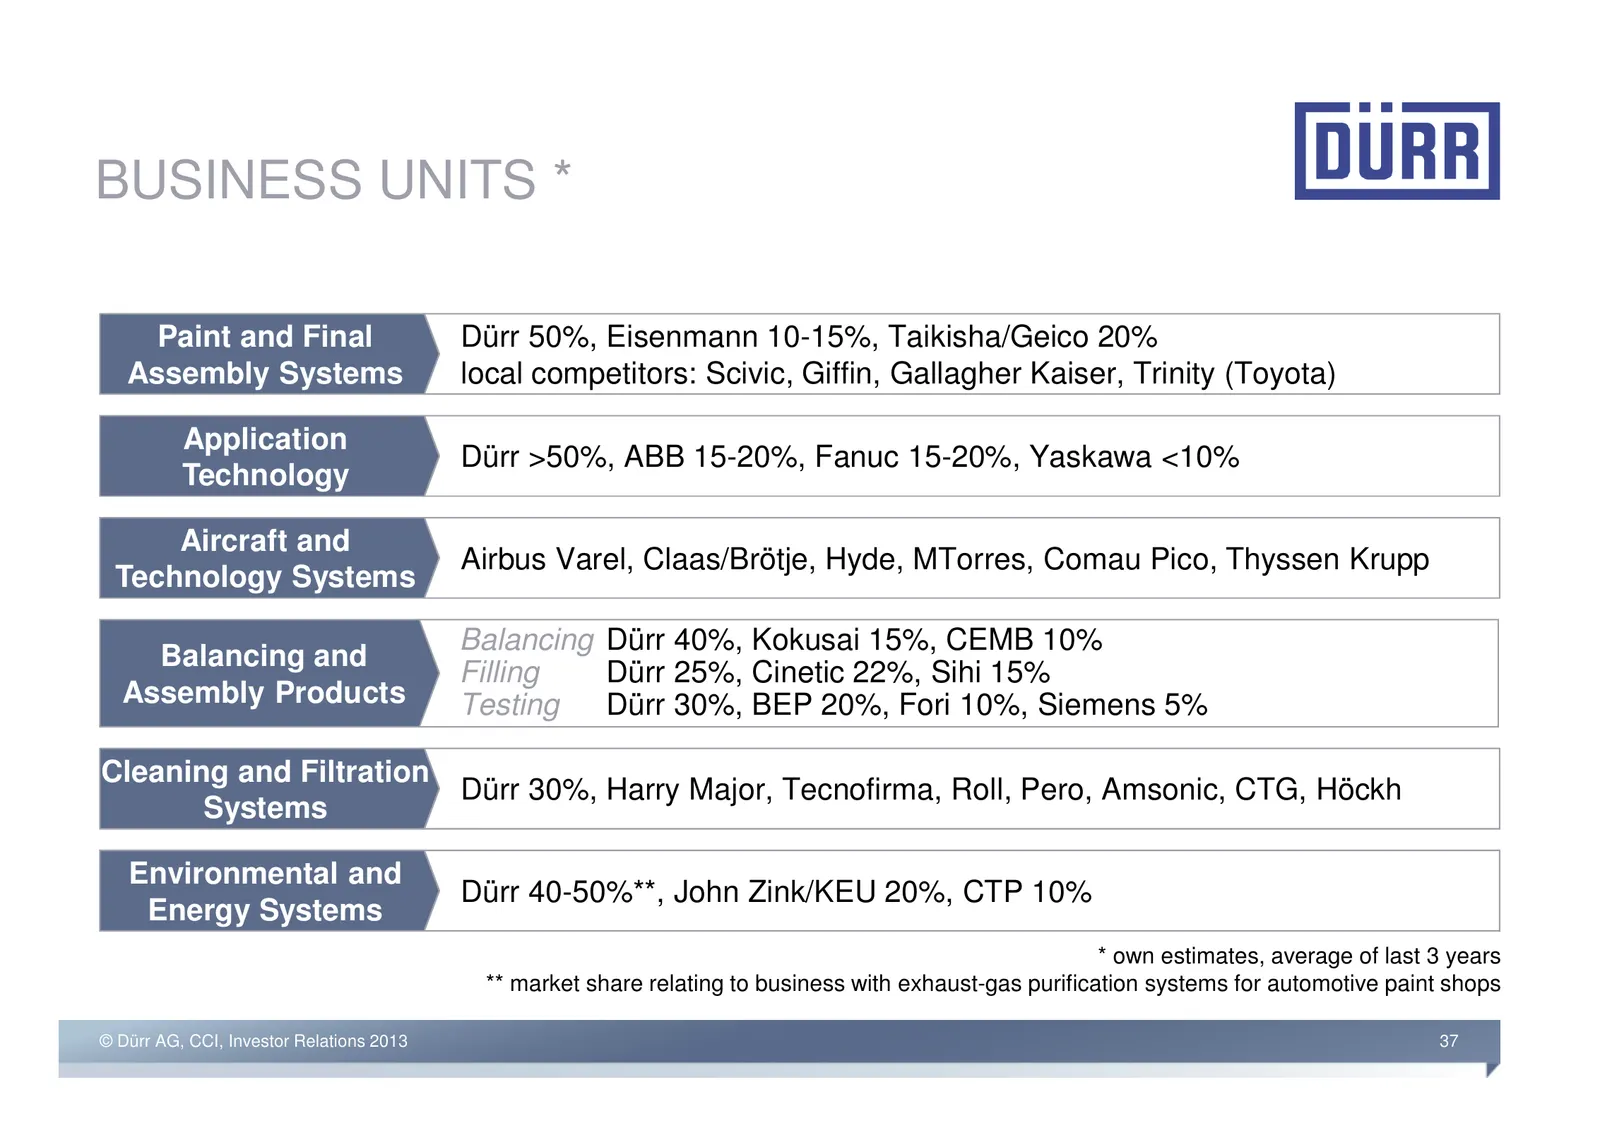
BUSINESS UNITS * Paint and Final Dürr 50%, Eisenmann 10-15%, Taikisha/Geico 20% Assembly Systems local competitors: Scivic, Giffin, Gallagher Kaiser, Trinity (Toyota) Application Dürr >50%, ABB 15-20%, Fanuc 15-20%, Yaskawa <10% Technology Aircraft and Airbus Varel, Claas/Brötje, Hyde, MTorres, Coma
Slide 38: Global car density
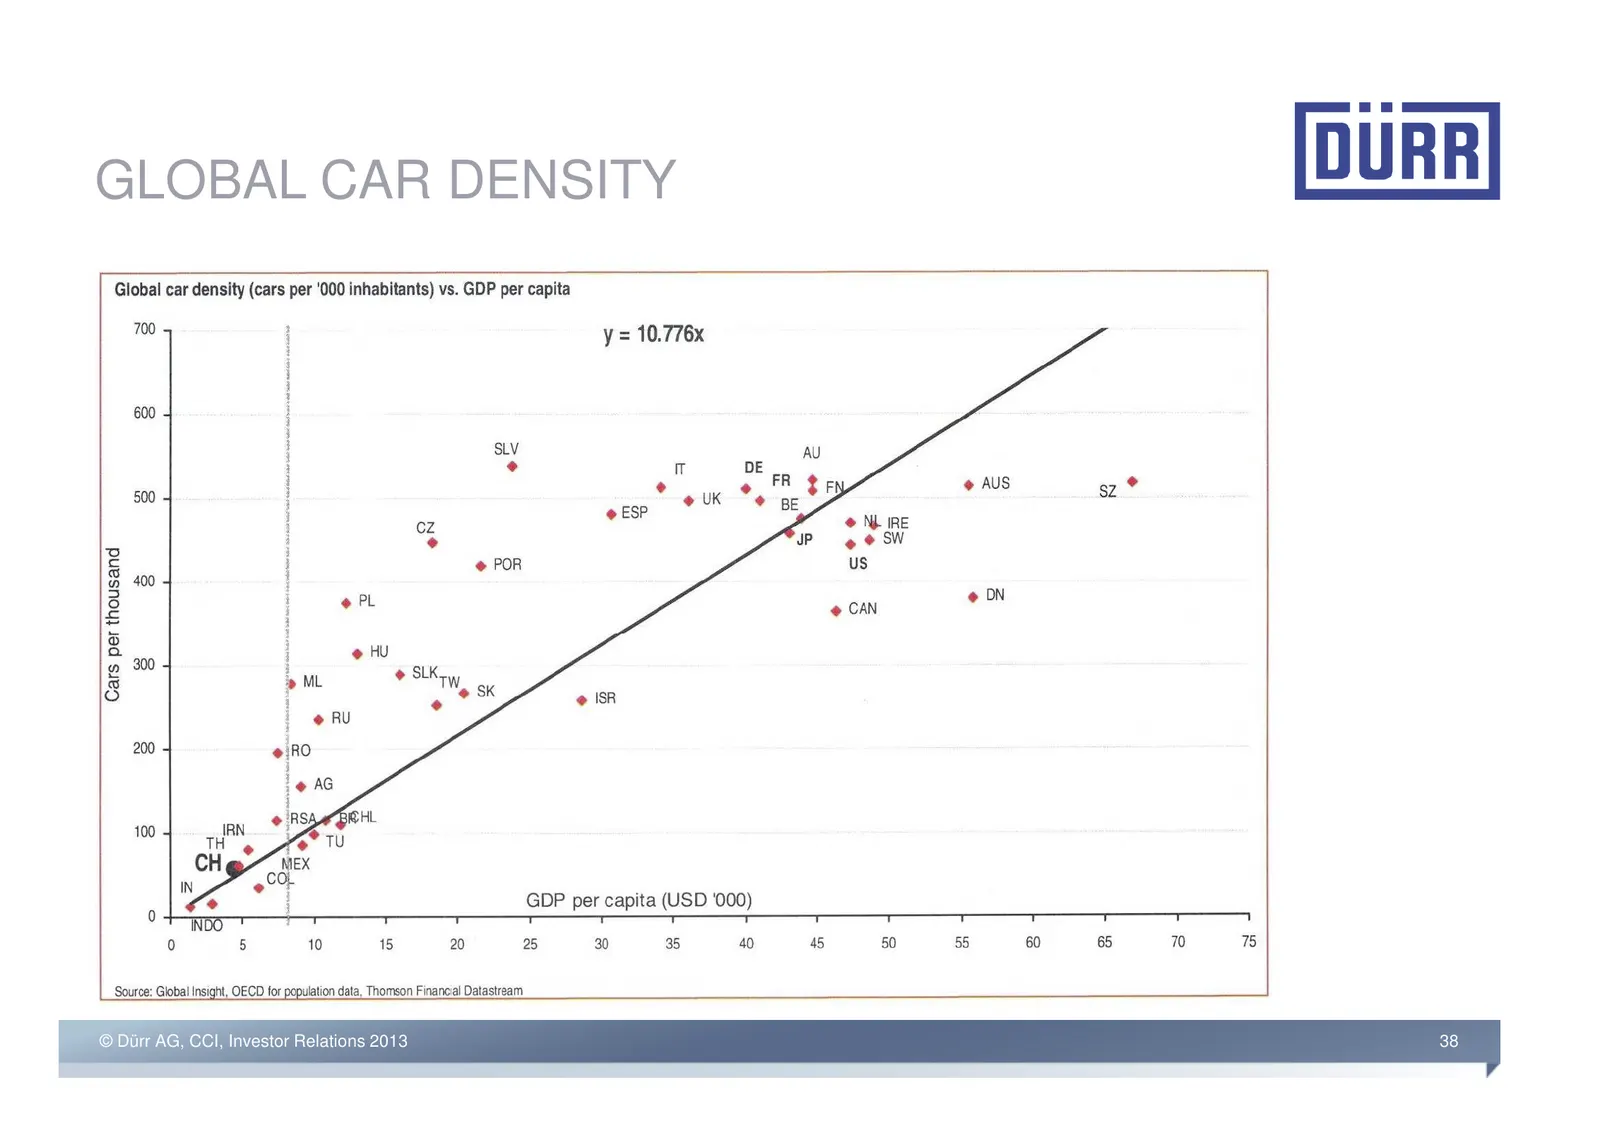
GLOBAL CAR DENSITY © Dürr AG, CCI, Investor Relations 2013 38
Slide 39: Sales development passenger cars December 2012/11
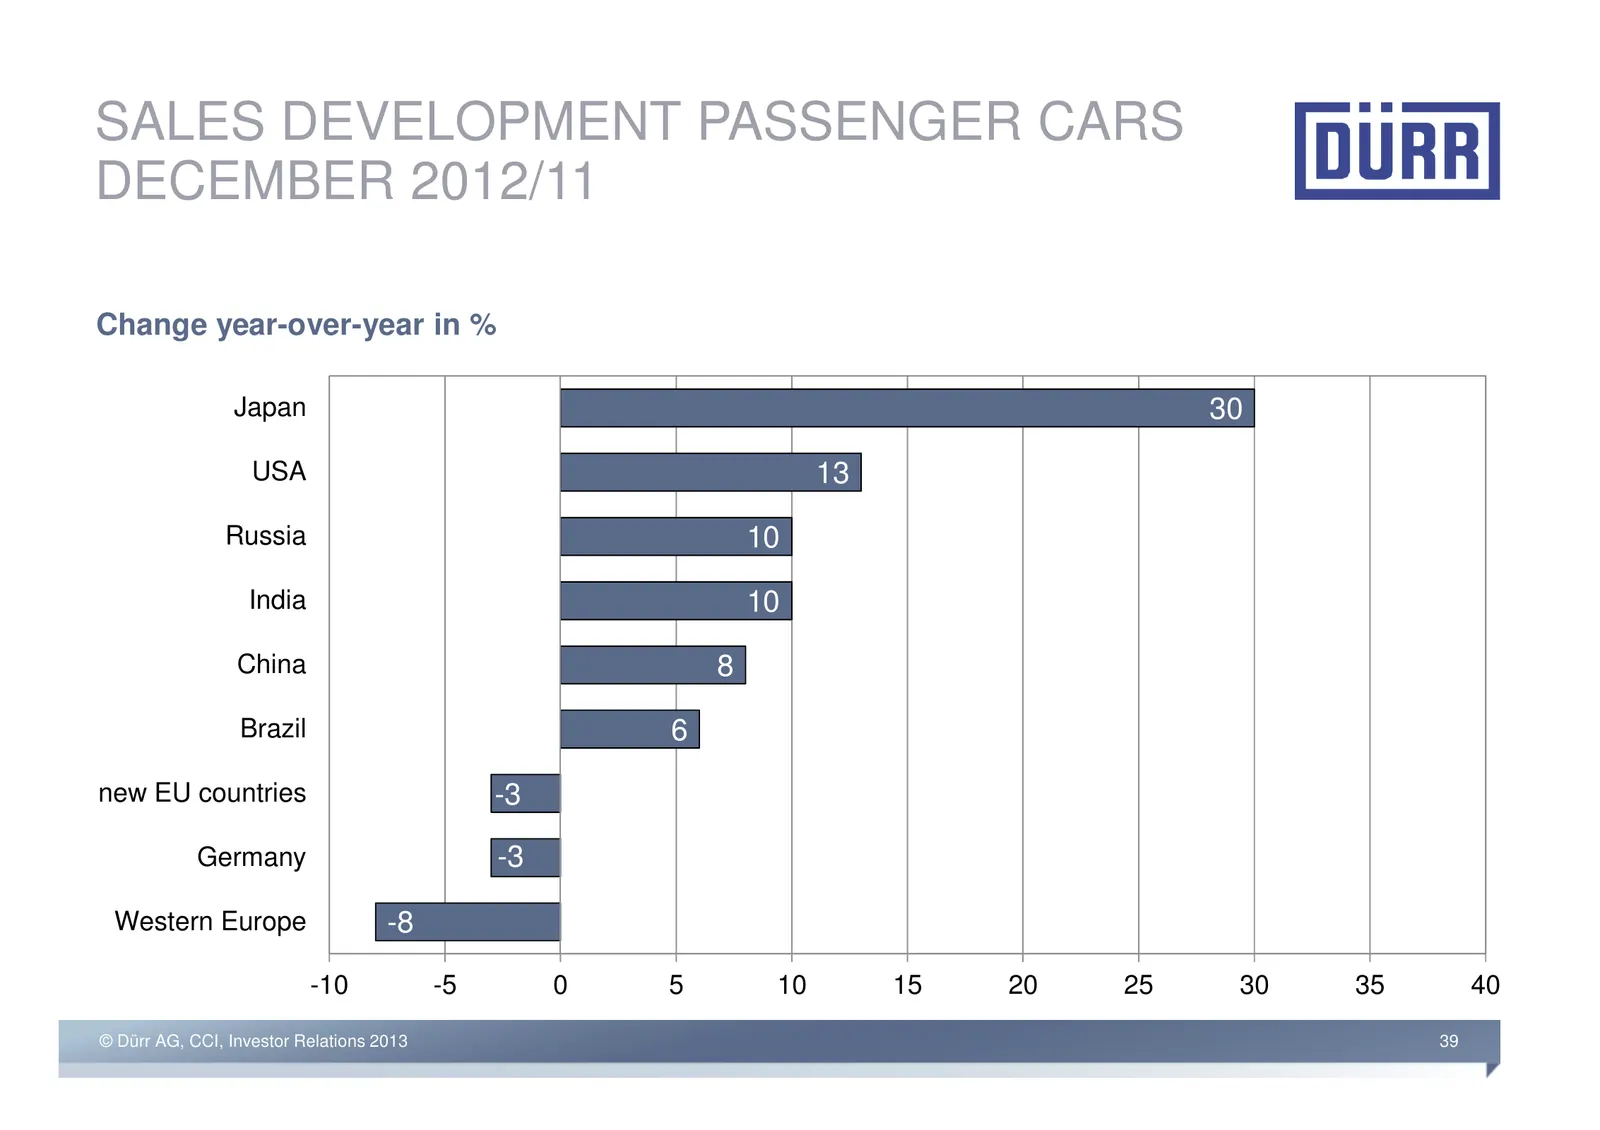
SALES DEVELOPMENT PASSENGER CARS DECEMBER 2012/11 Change year-over-year in % Japan 30 USA 13 Russia 10 India 10 China 8 Brazil 6 new EU countries -3 Germany -3 Western Europe -8 -10 -5 0 5 10 15 20 25 30 35 40 © Dürr AG, CCI, Investor Relations 2013 39
Source: Internet Archive copy of durr.com
More decks from Durr AG
 Q3 2026 Earnings Presentation33 slides · Nov 12, 2026
 Q2 2026 Earnings Presentation39 slides · Aug 6, 2026
 Q1 2026 Earnings Presentation35 slides · May 12, 2026
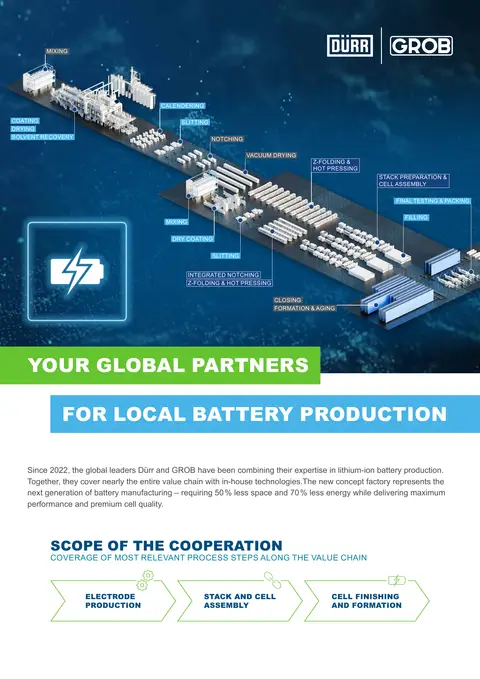 Fact Sheet (2025)2 slides · Dec 2, 2025
 Q3 2025 Earnings Presentation46 slides · Nov 13, 2025
 Q2 2025 Earnings Presentation31 slides · Jul 24, 2025