Discover Financial Services — Barclays 2015 Global Financial Services Conference
25 slides from Discover Financial Services's conference presentation, Sep 17, 2015
Slide 1: Barclays 2015 Global Financial Services Conference
Exhibit 99.1 Barclays 2015 Global Financial Services Conference Mark Graf EVP & Chief Financial Officer September 17, 2015 ©2015 DISCOVER FINANCIAL SERVICES
Slide 2: Notice
Notice The following slides are part of a presentation by Discover Financial Services (the "Company") and are intended to be viewed as part of that presentation. No representation is made that the information in these slides is complete. Throughout these materials, direct-to-consumer deposits are re
Slide 3: Executive Summary
Executive Summary Attractive business model with a solid record of success • Delivering solid card growth Driven by more new accounts, wallet share gain, low attrition rate and great credit results Aided by proprietary network impact on brand, acceptance and rewards • Utilizing consumer unsecured le
Slide 4: Positioned as the leading U.S. direct bank & payments partner
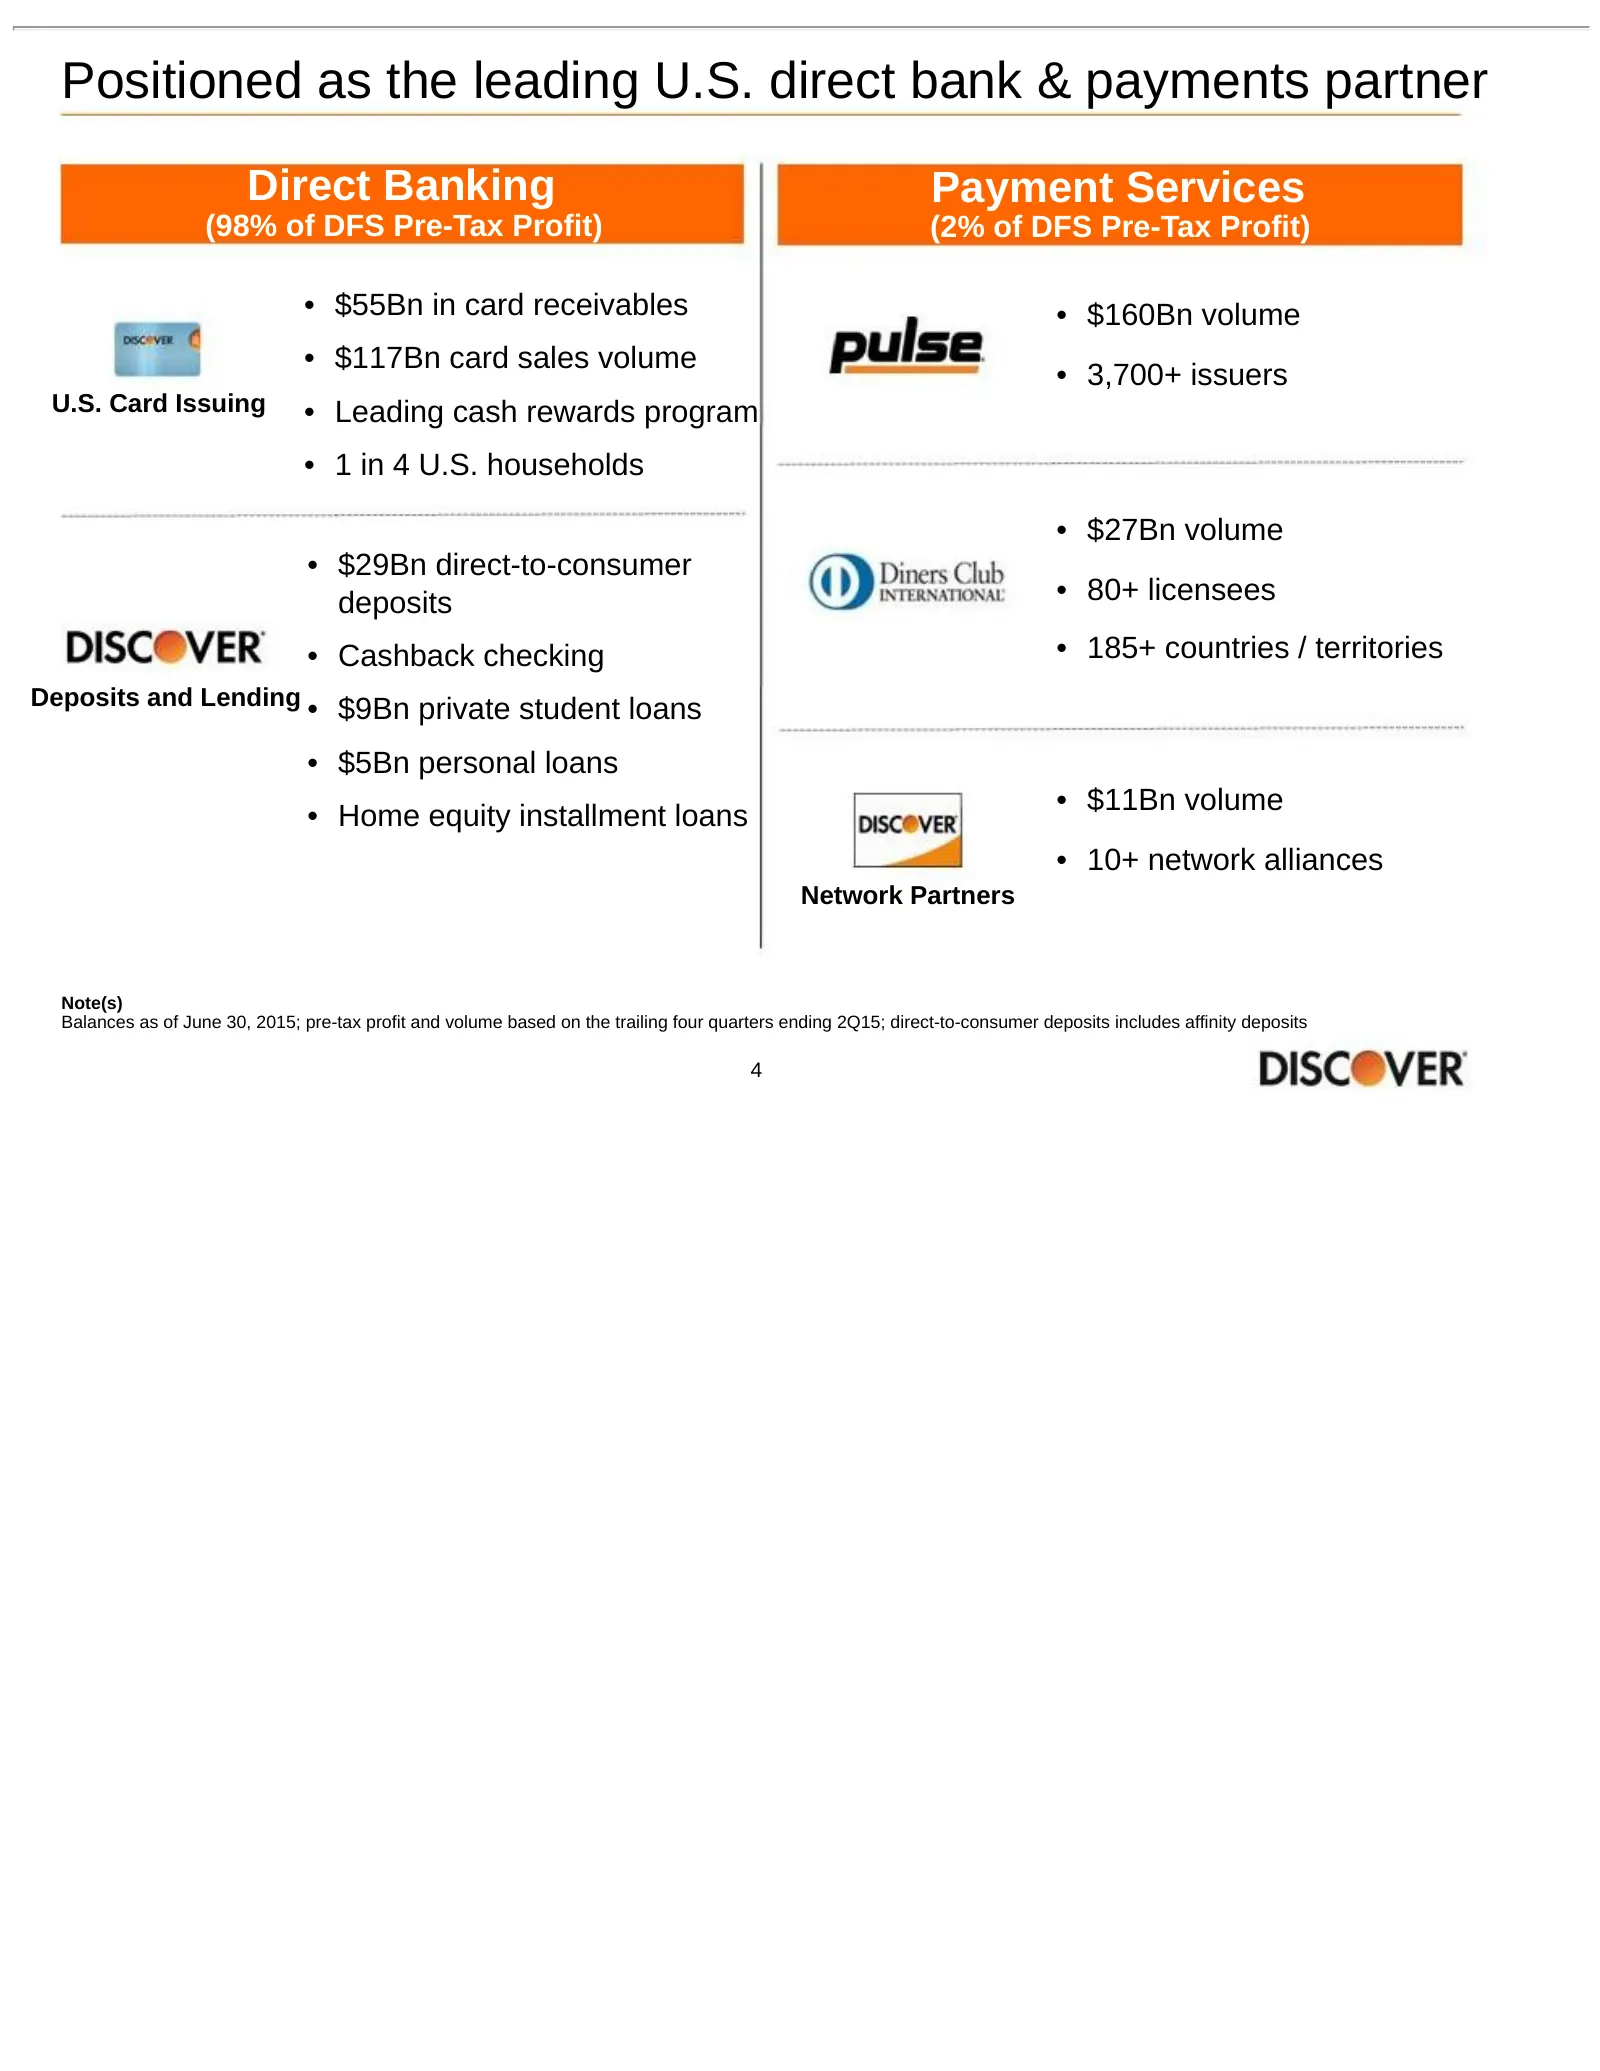
Positioned as the leading U.S. direct bank & payments partner Direct Banking Payment Services (98% of DFS Pre-Tax Profit) (2% of DFS Pre-Tax Profit) • $55Bn in card receivables • $160Bn volume • $117Bn card sales volume • 3,700+ issuers U.S. Card Issuing • Leading cash rewards program • 1 in 4 U.S.
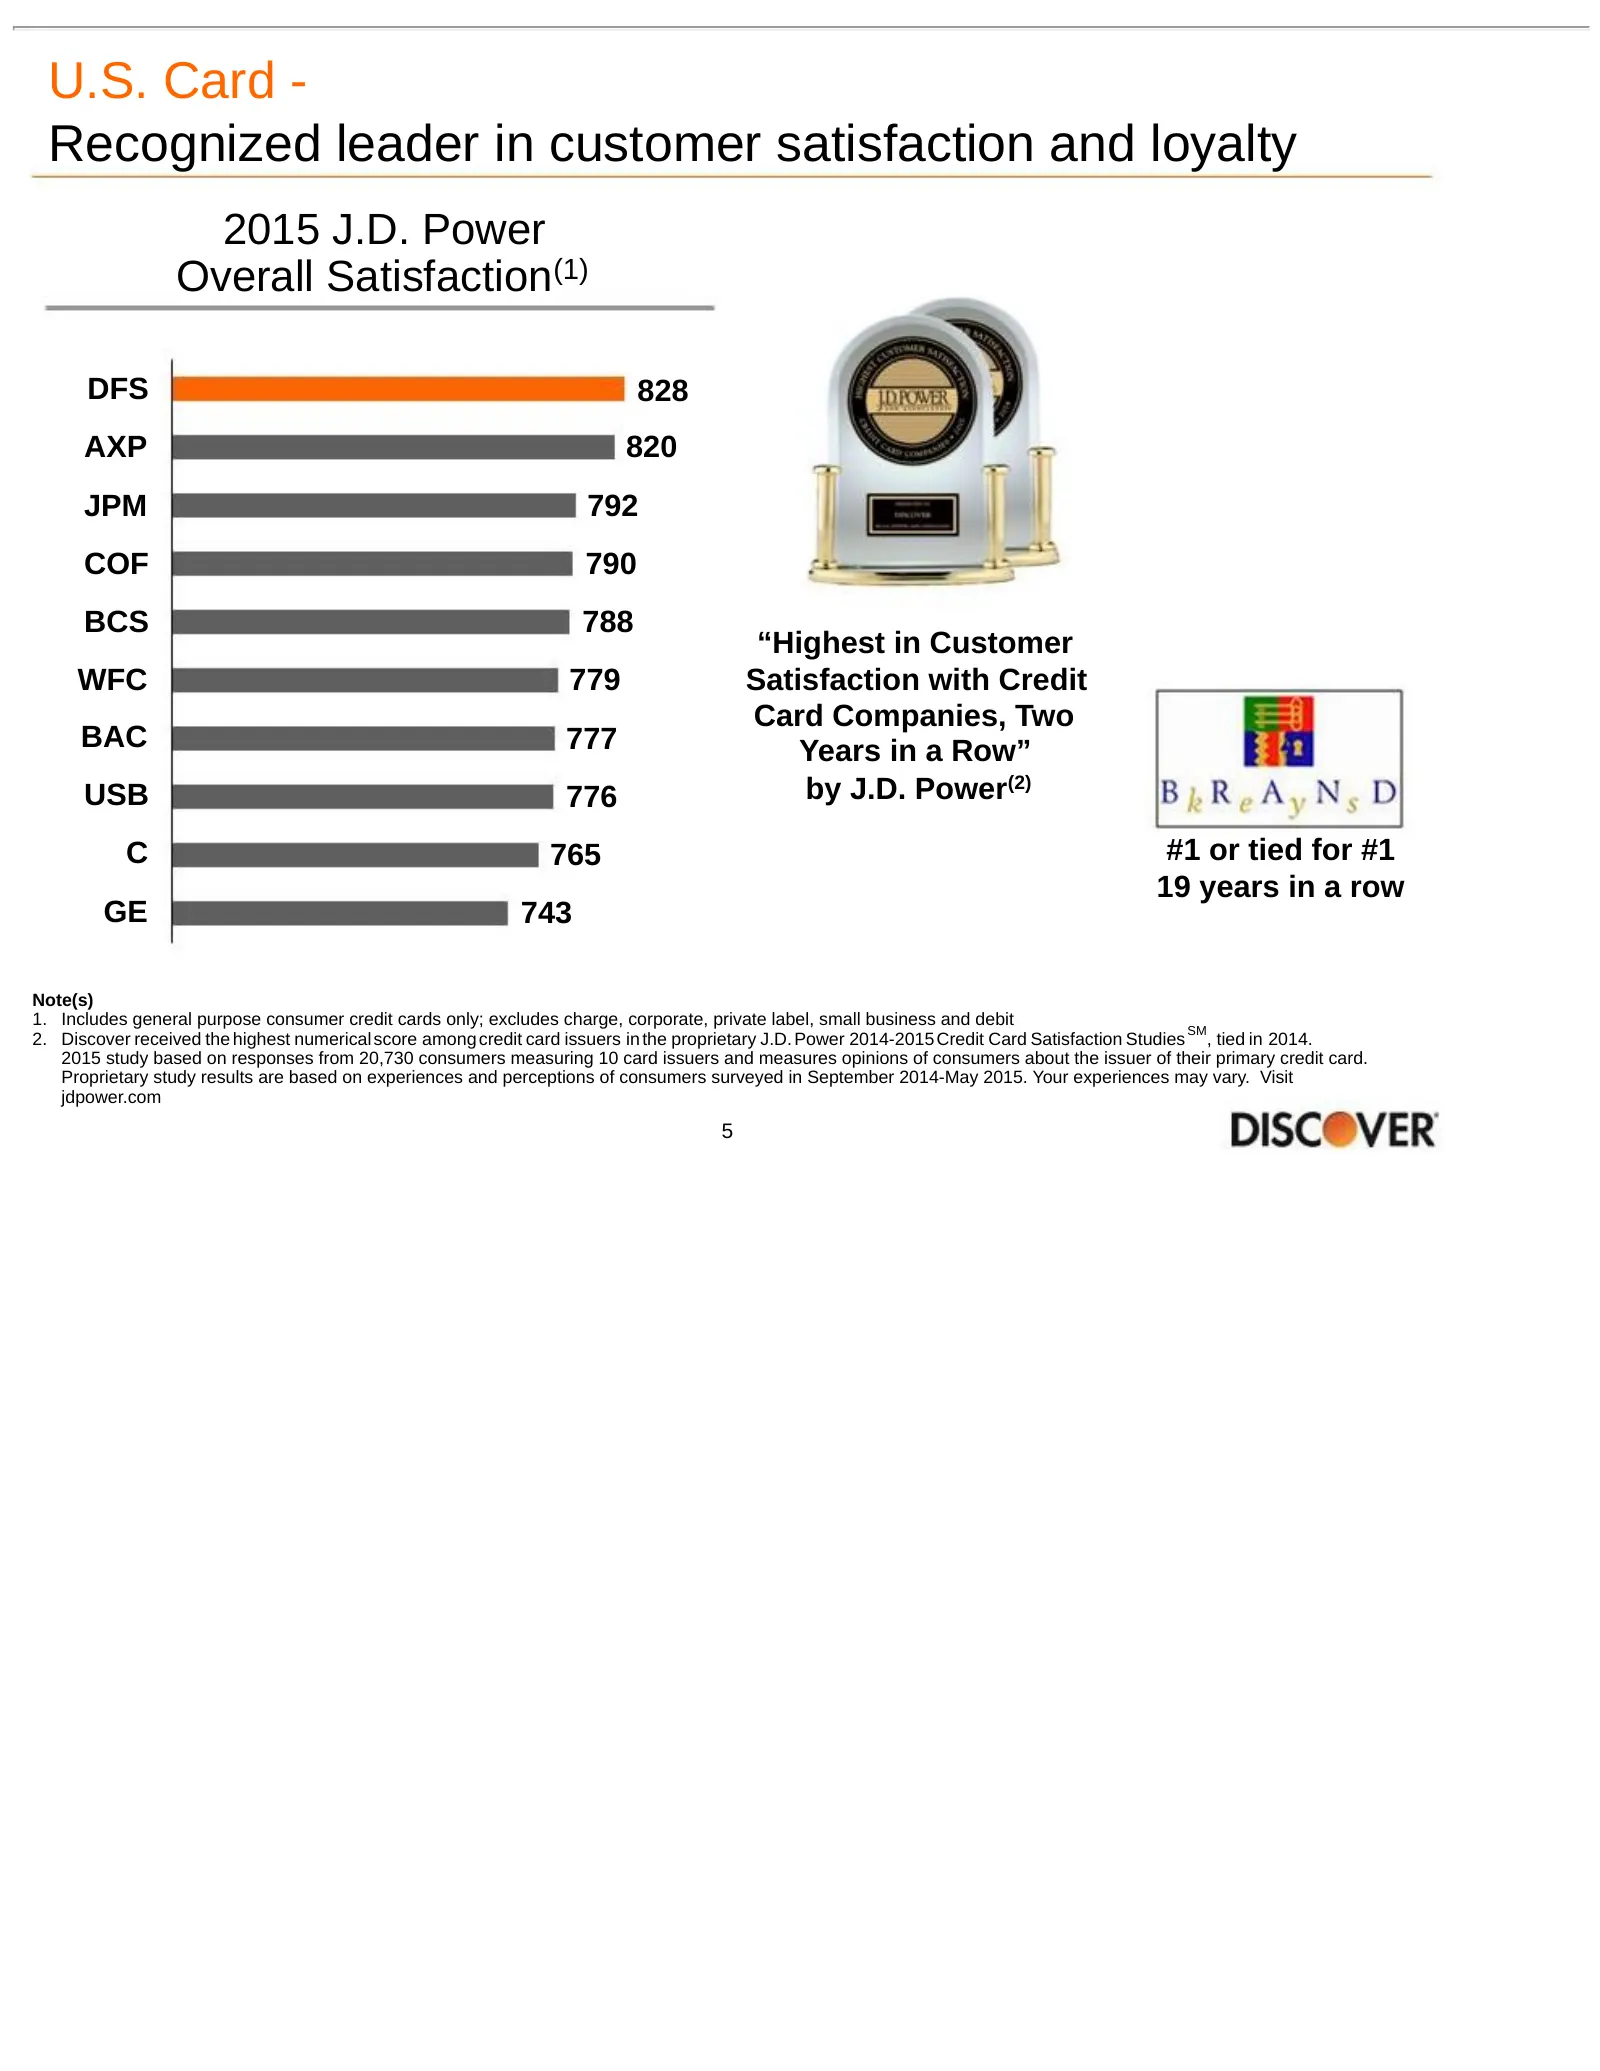
Slide 5: U.S. Card - Recognized leader in customer satisfaction and loyalty
U.S. Card - Recognized leader in customer satisfaction and loyalty 2015 J.D. Power Overall Satisfaction(1) DFS 828 AXP 820 JPM 792 COF 790 BCS 788 “Highest in Customer WFC 779 Satisfaction with Credit Card Companies, Two BAC 777 Years in a Row” USB 776 by J.D. Power(2) C 765 #1 or tied for #1 19 yea
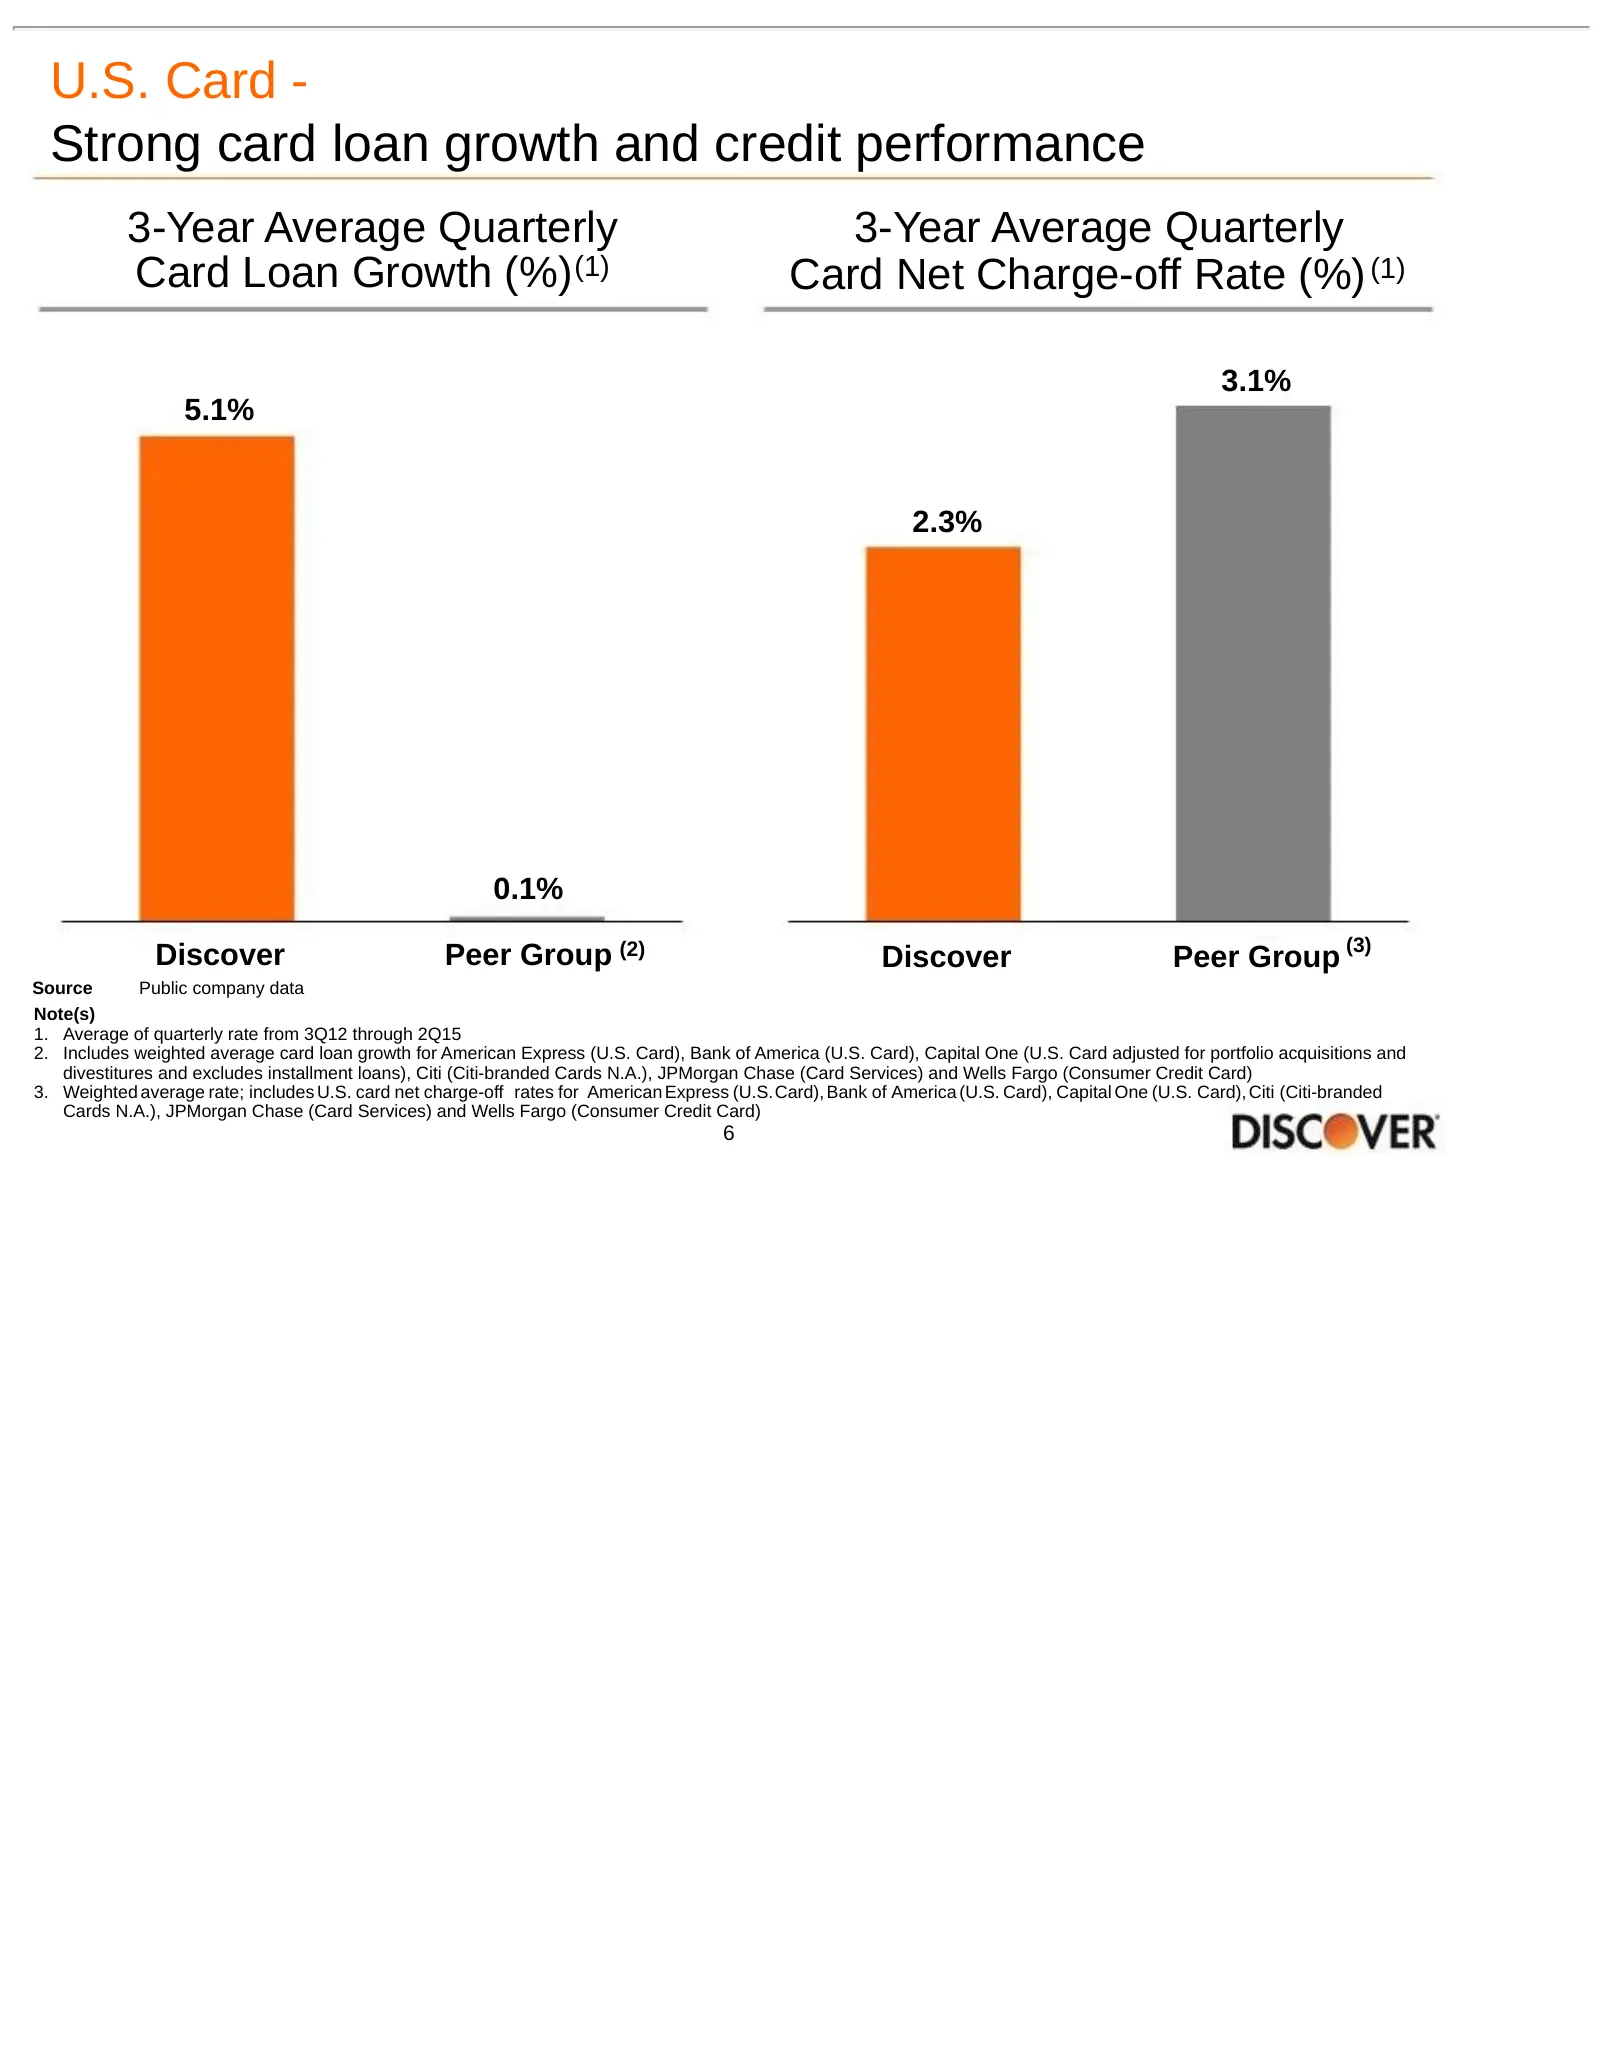
Slide 6: U.S. Card - Strong card loan growth and credit performance
U.S. Card - Strong card loan growth and credit performance 3-Year Average Quarterly 3-Year Average Quarterly Card Loan Growth (%) (1) Card Net Charge-off Rate (%) (1) 3.1% 5.1% 2.3% 0.1% Discover Peer Group (2) Discover Peer Group (3) Source Public company data Note(s) 1. Average of quarterly rate f
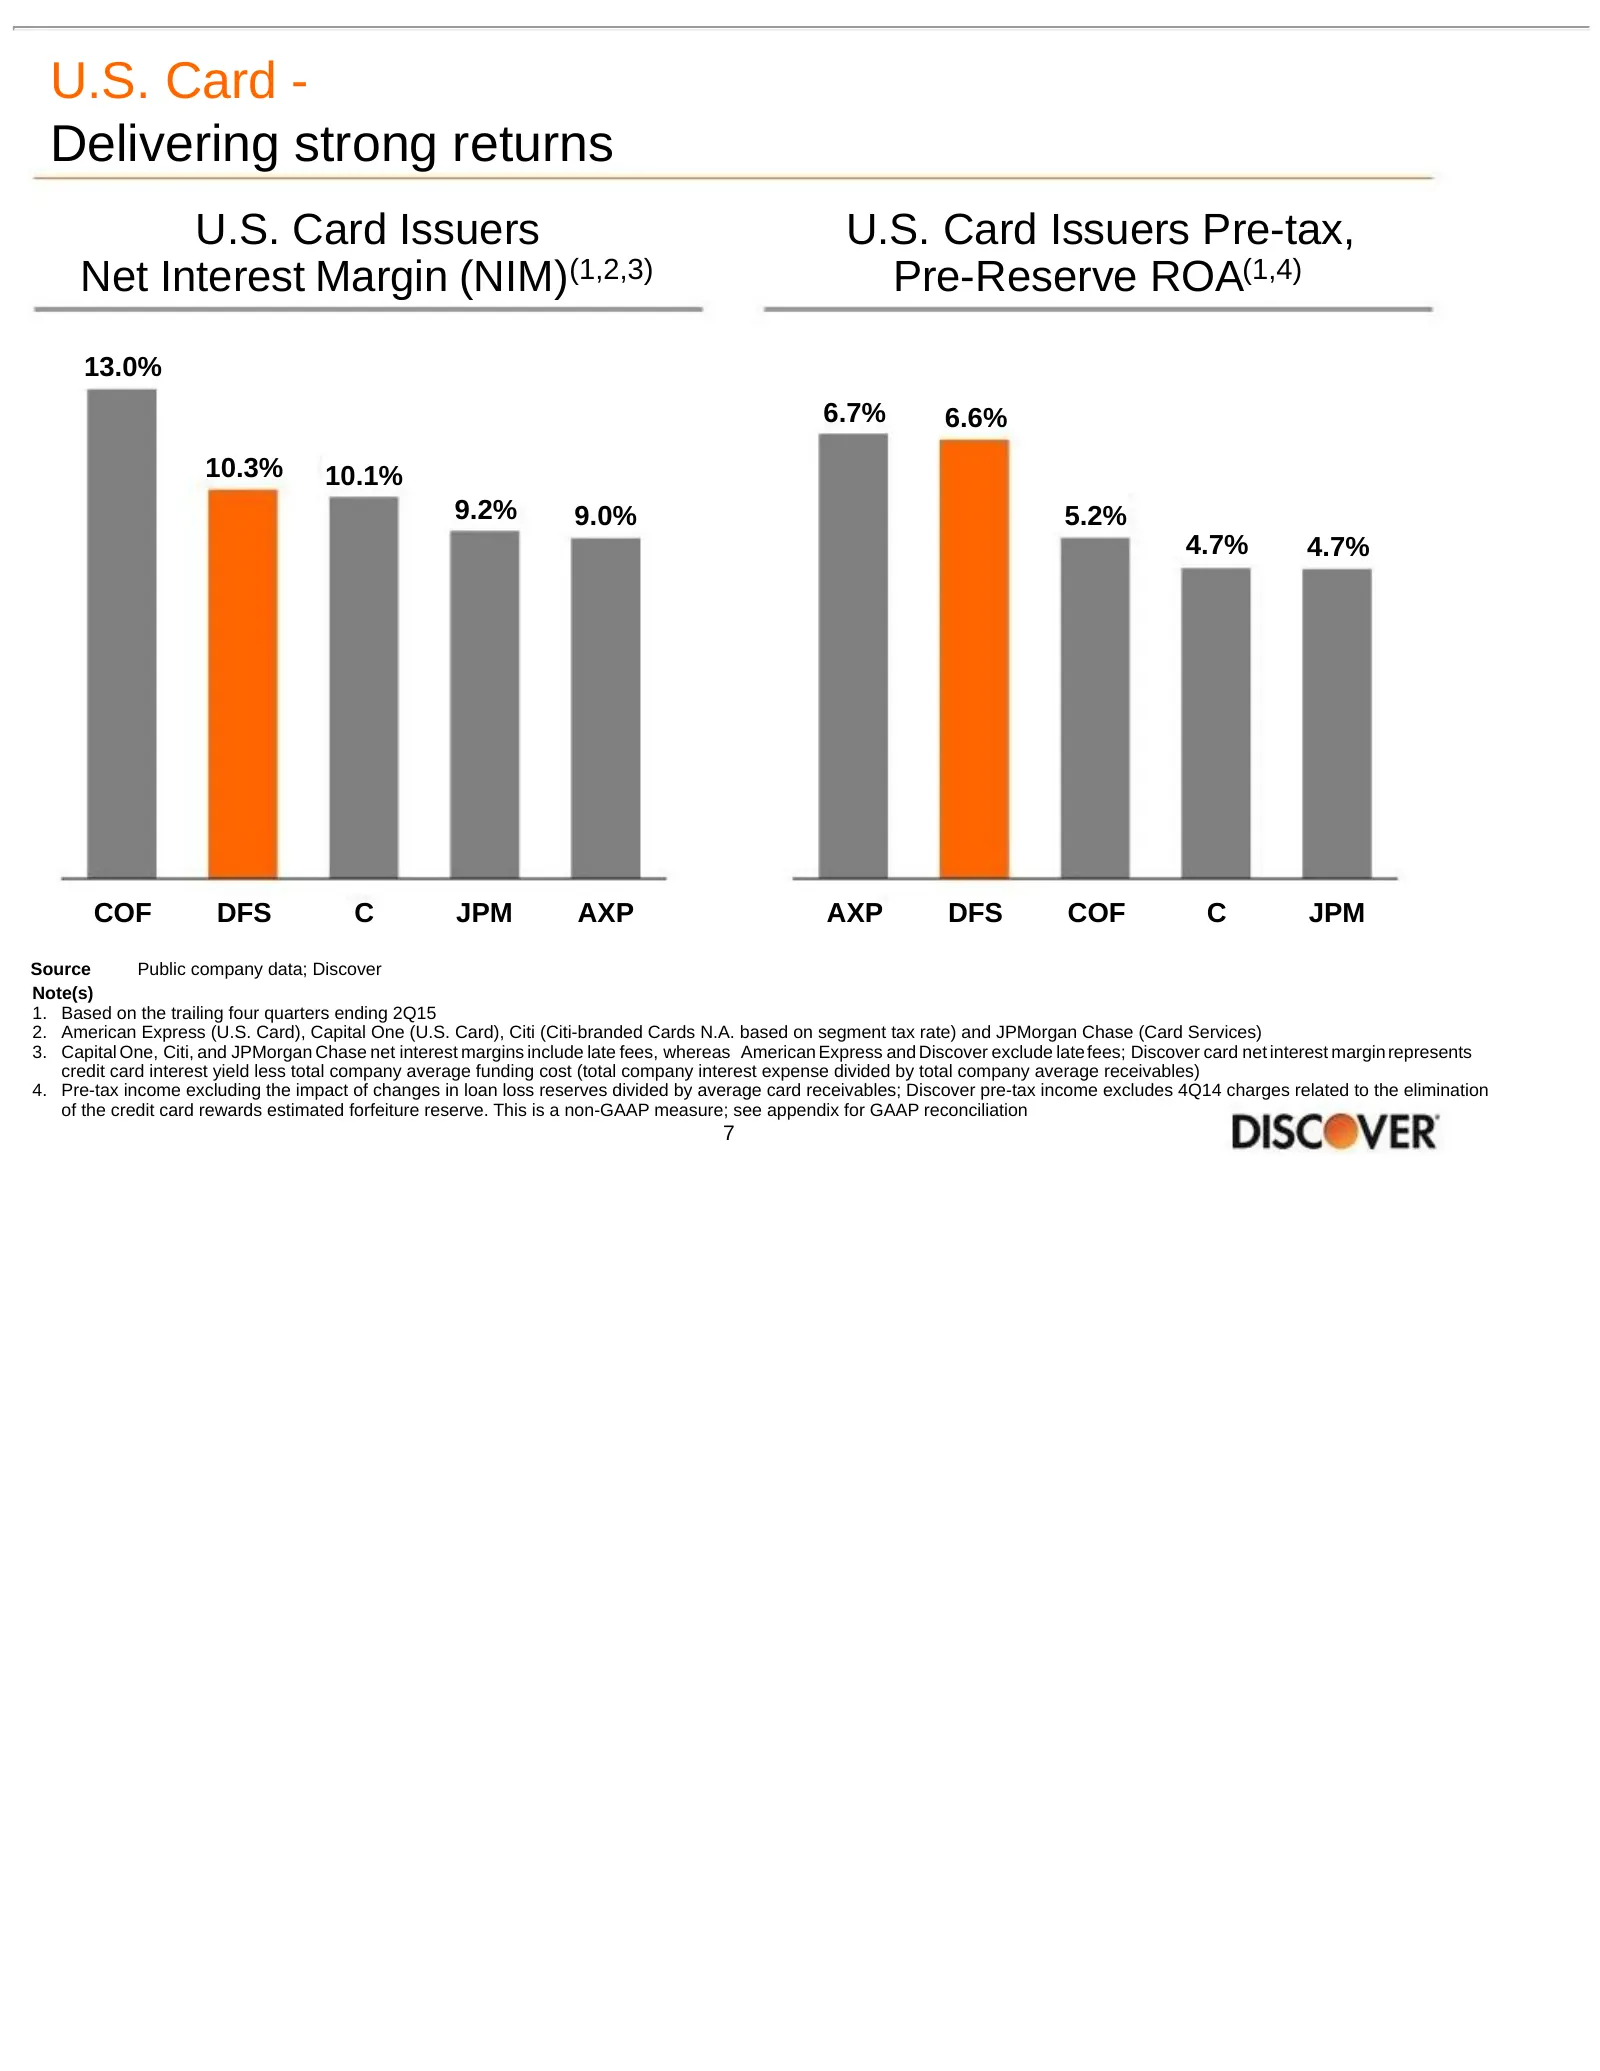
Slide 7: U.S. Card - Delivering strong returns
U.S. Card - Delivering strong returns U.S. Card Issuers U.S. Card Issuers Pre-tax, Net Interest Margin (NIM)(1,2,3) Pre-Reserve ROA(1,4) 13.0% 6.7% 6.6% 10.3% 10.1% 9.2% 9.0% 5.2% 4.7% 4.7% COF DFS C JPM AXP AXP DFS COF C JPM Source Public company data; Discover Note(s) 1. Based on the trailing four
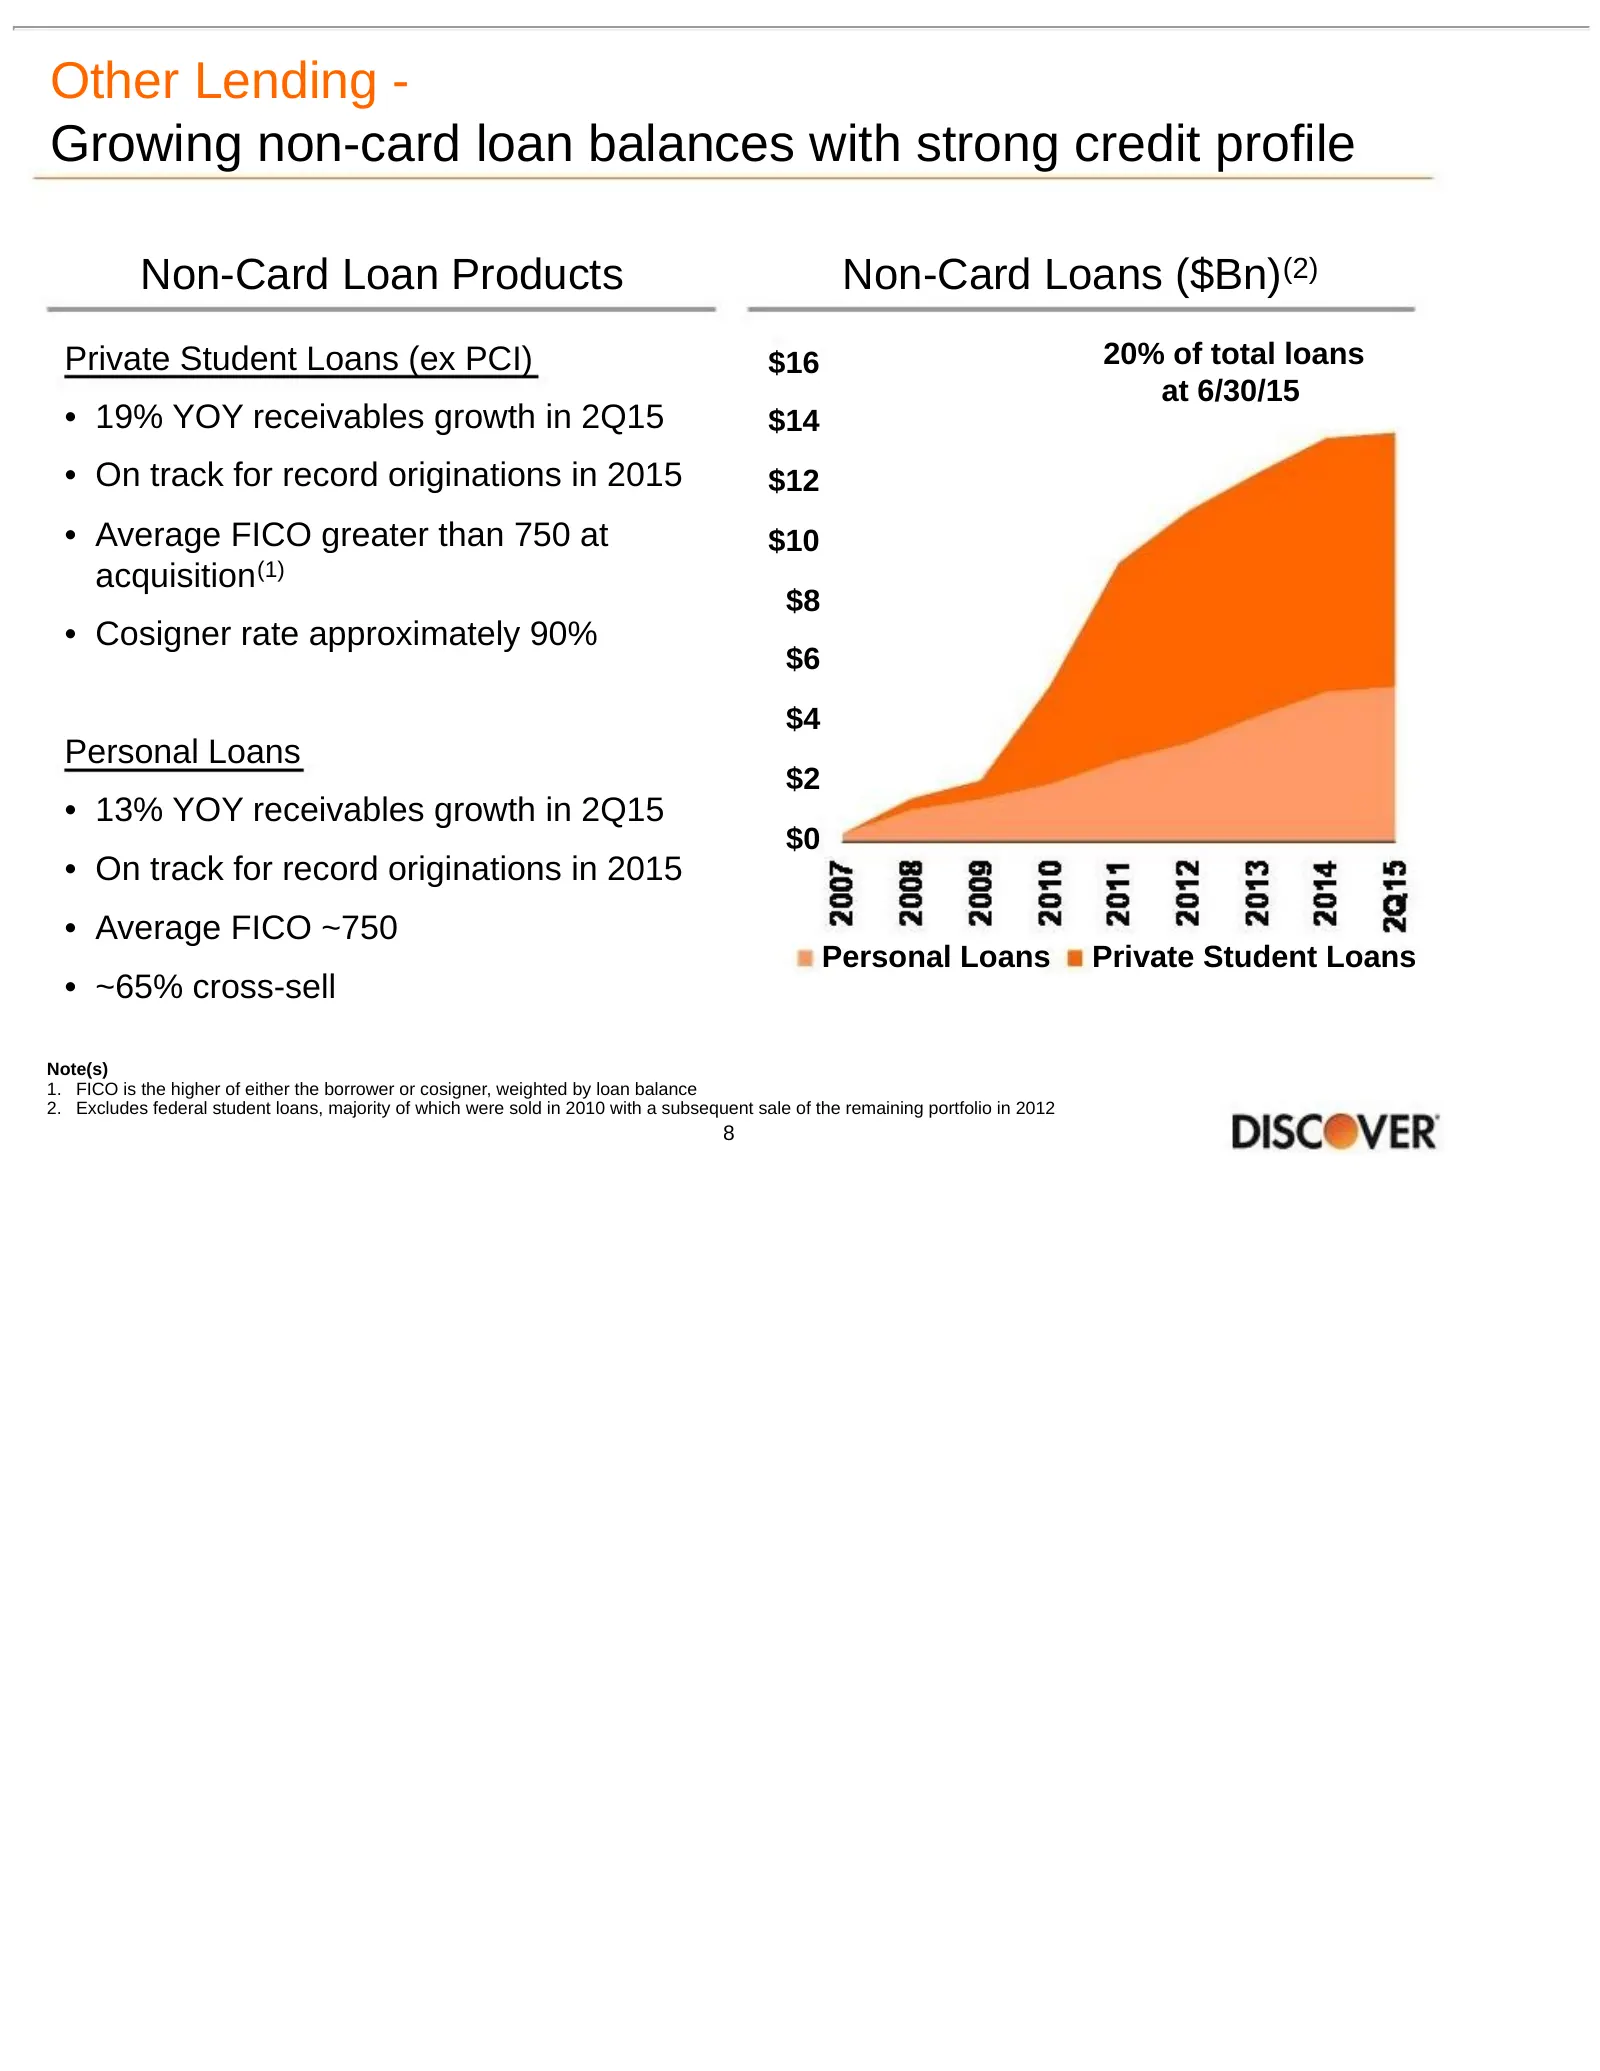
Slide 8: Other Lending - Growing non-card loan balances with strong credit profile
Other Lending - Growing non-card loan balances with strong credit profile Non-Card Loan Products Non-Card Loans ($Bn)(2) Private Student Loans (ex PCI) $16 20% of total loans at 6/30/15 • 19% YOY receivables growth in 2Q15 $14 • On track for record originations in 2015 $12 • Average FICO greater tha
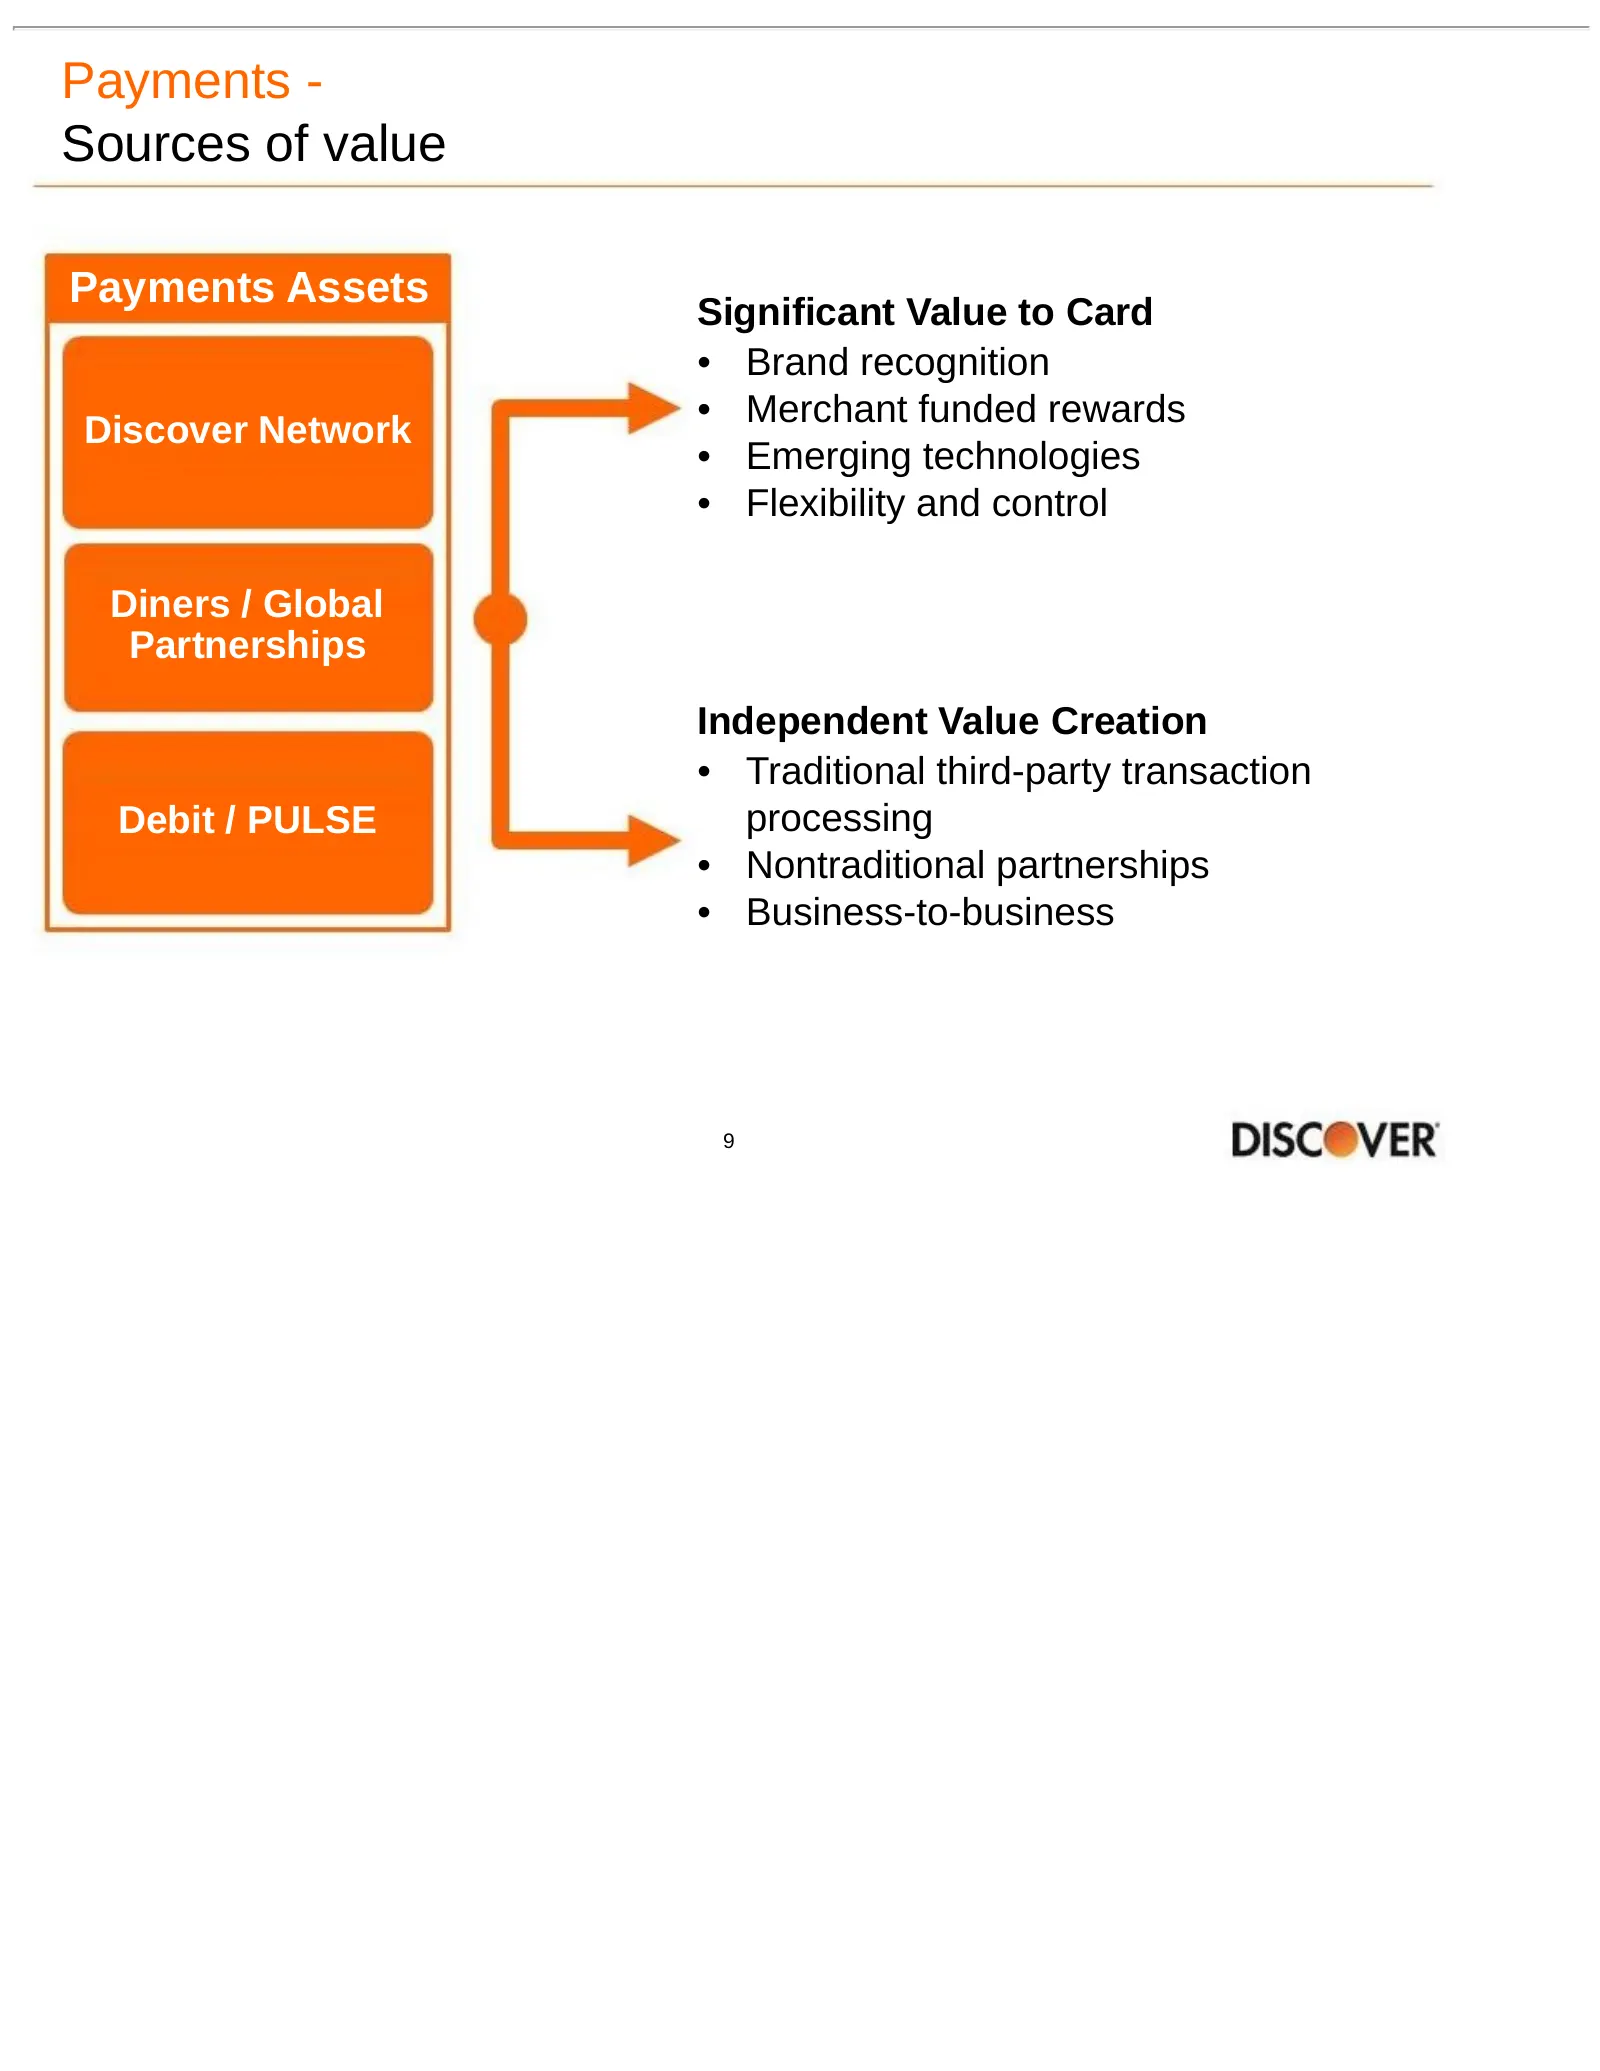
Slide 9: Payments - Sources of value
Payments - Sources of value Payments Assets Significant Value to Card • Brand recognition • Merchant funded rewards Discover Network • Emerging technologies • Flexibility and control Diners / Global Partnerships Independent Value Creation • Traditional third-party transaction Debit / PULSE processin
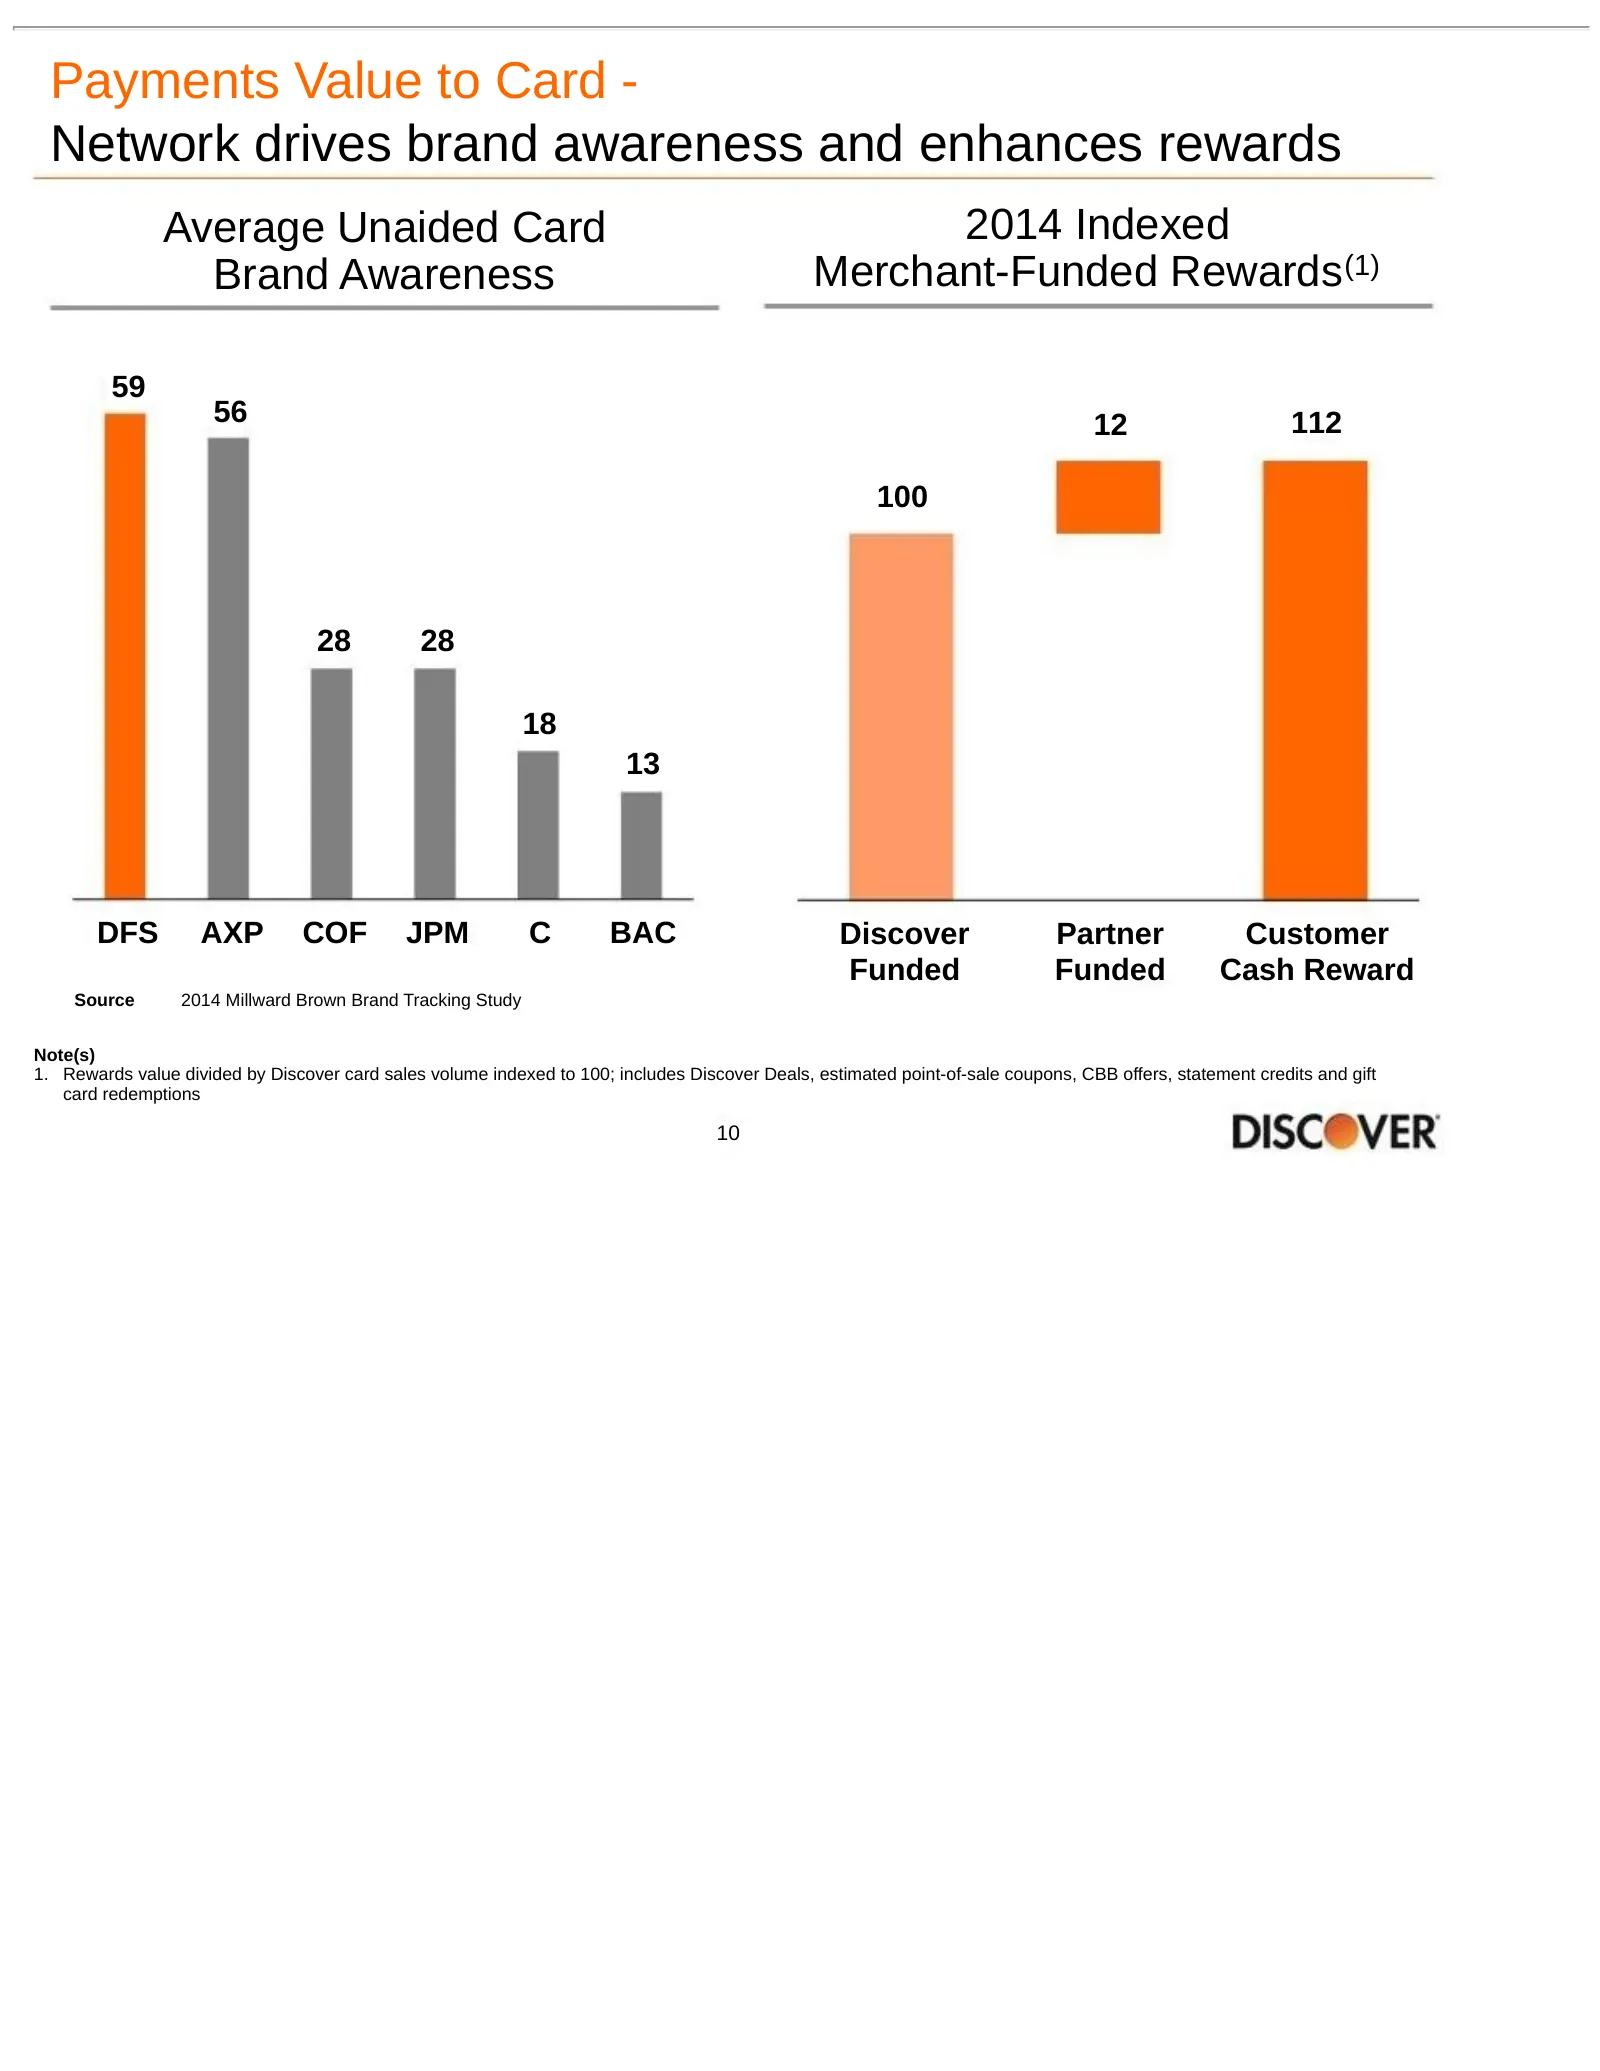
Slide 10: Payments Value to Card - Network drives brand awareness and enhances rewards
Payments Value to Card - Network drives brand awareness and enhances rewards Average Unaided Card 2014 Indexed Brand Awareness Merchant-Funded Rewards (1) 59 56 12 112 100 28 28 18 13 DFS AXP COF JPM C BAC Discover Partner Customer Funded Funded Cash Reward Source 2014 Millward Brown Brand Tracking
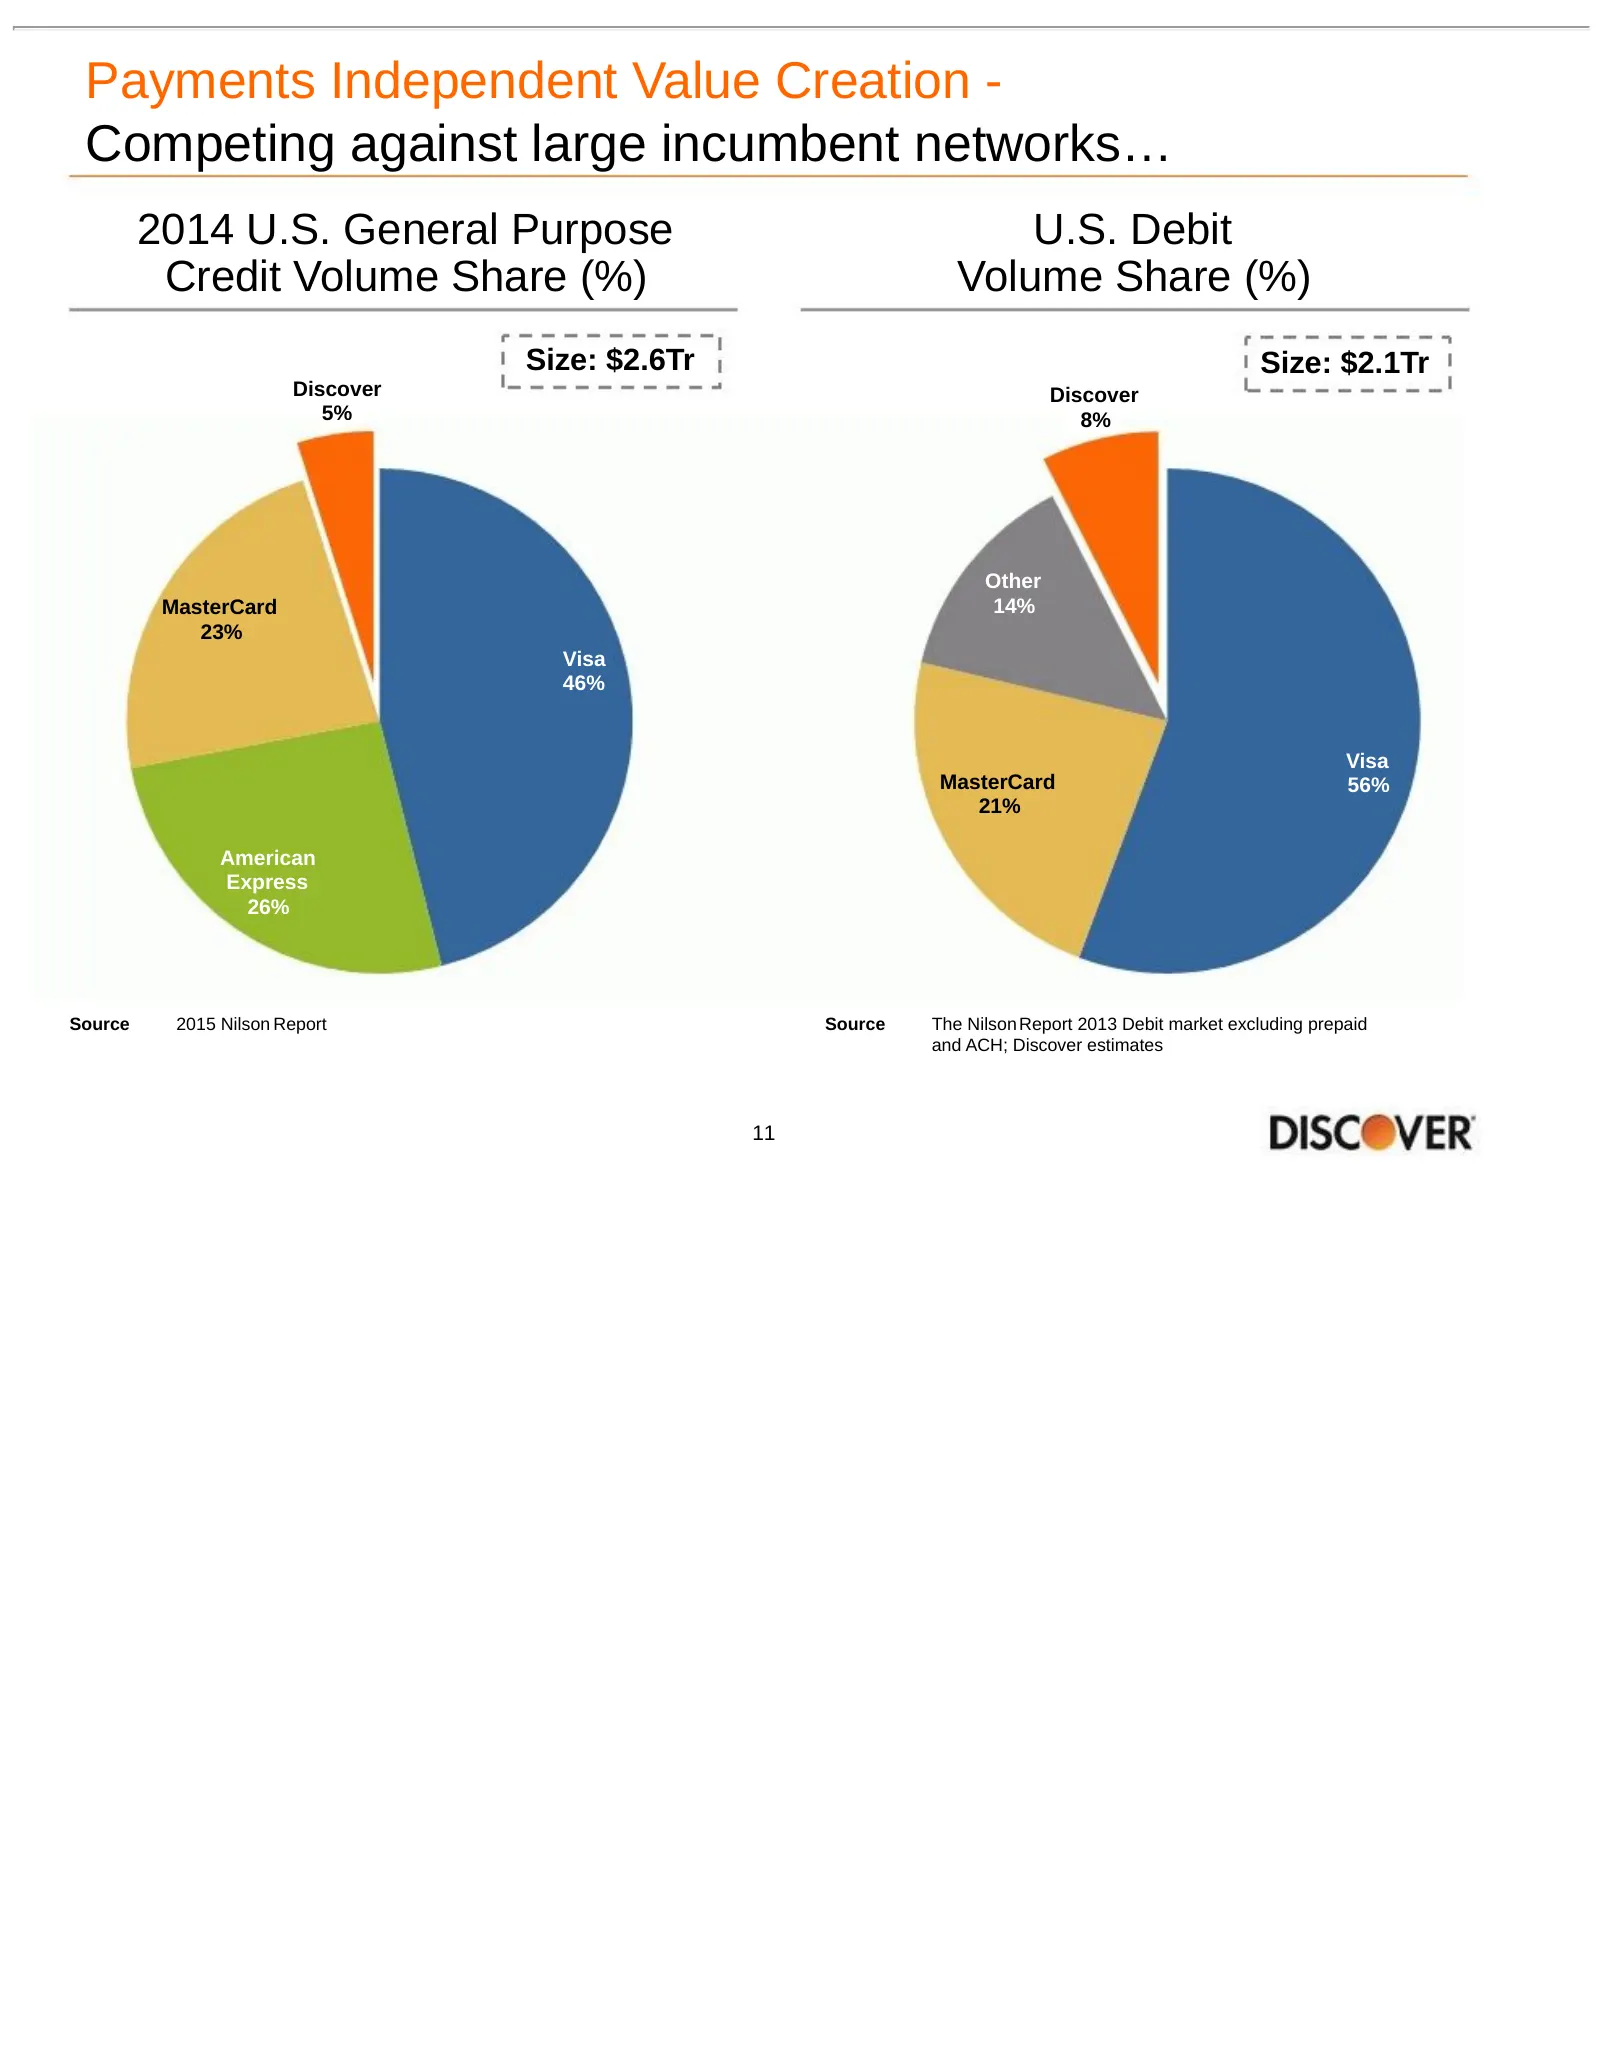
Slide 11: Payments Independent Value Creation - Competing against large incumbent networks
Payments Independent Value Creation - Competing against large incumbent networks… 2014 U.S. General Purpose U.S. Debit Credit Volume Share (%) Volume Share (%) Size: $2.6Tr Size: $2.1Tr Discover Discover 5% 8% Other MasterCard 14% 23% Visa 46% Visa MasterCard 56% 21% American Express 26% Source 2015
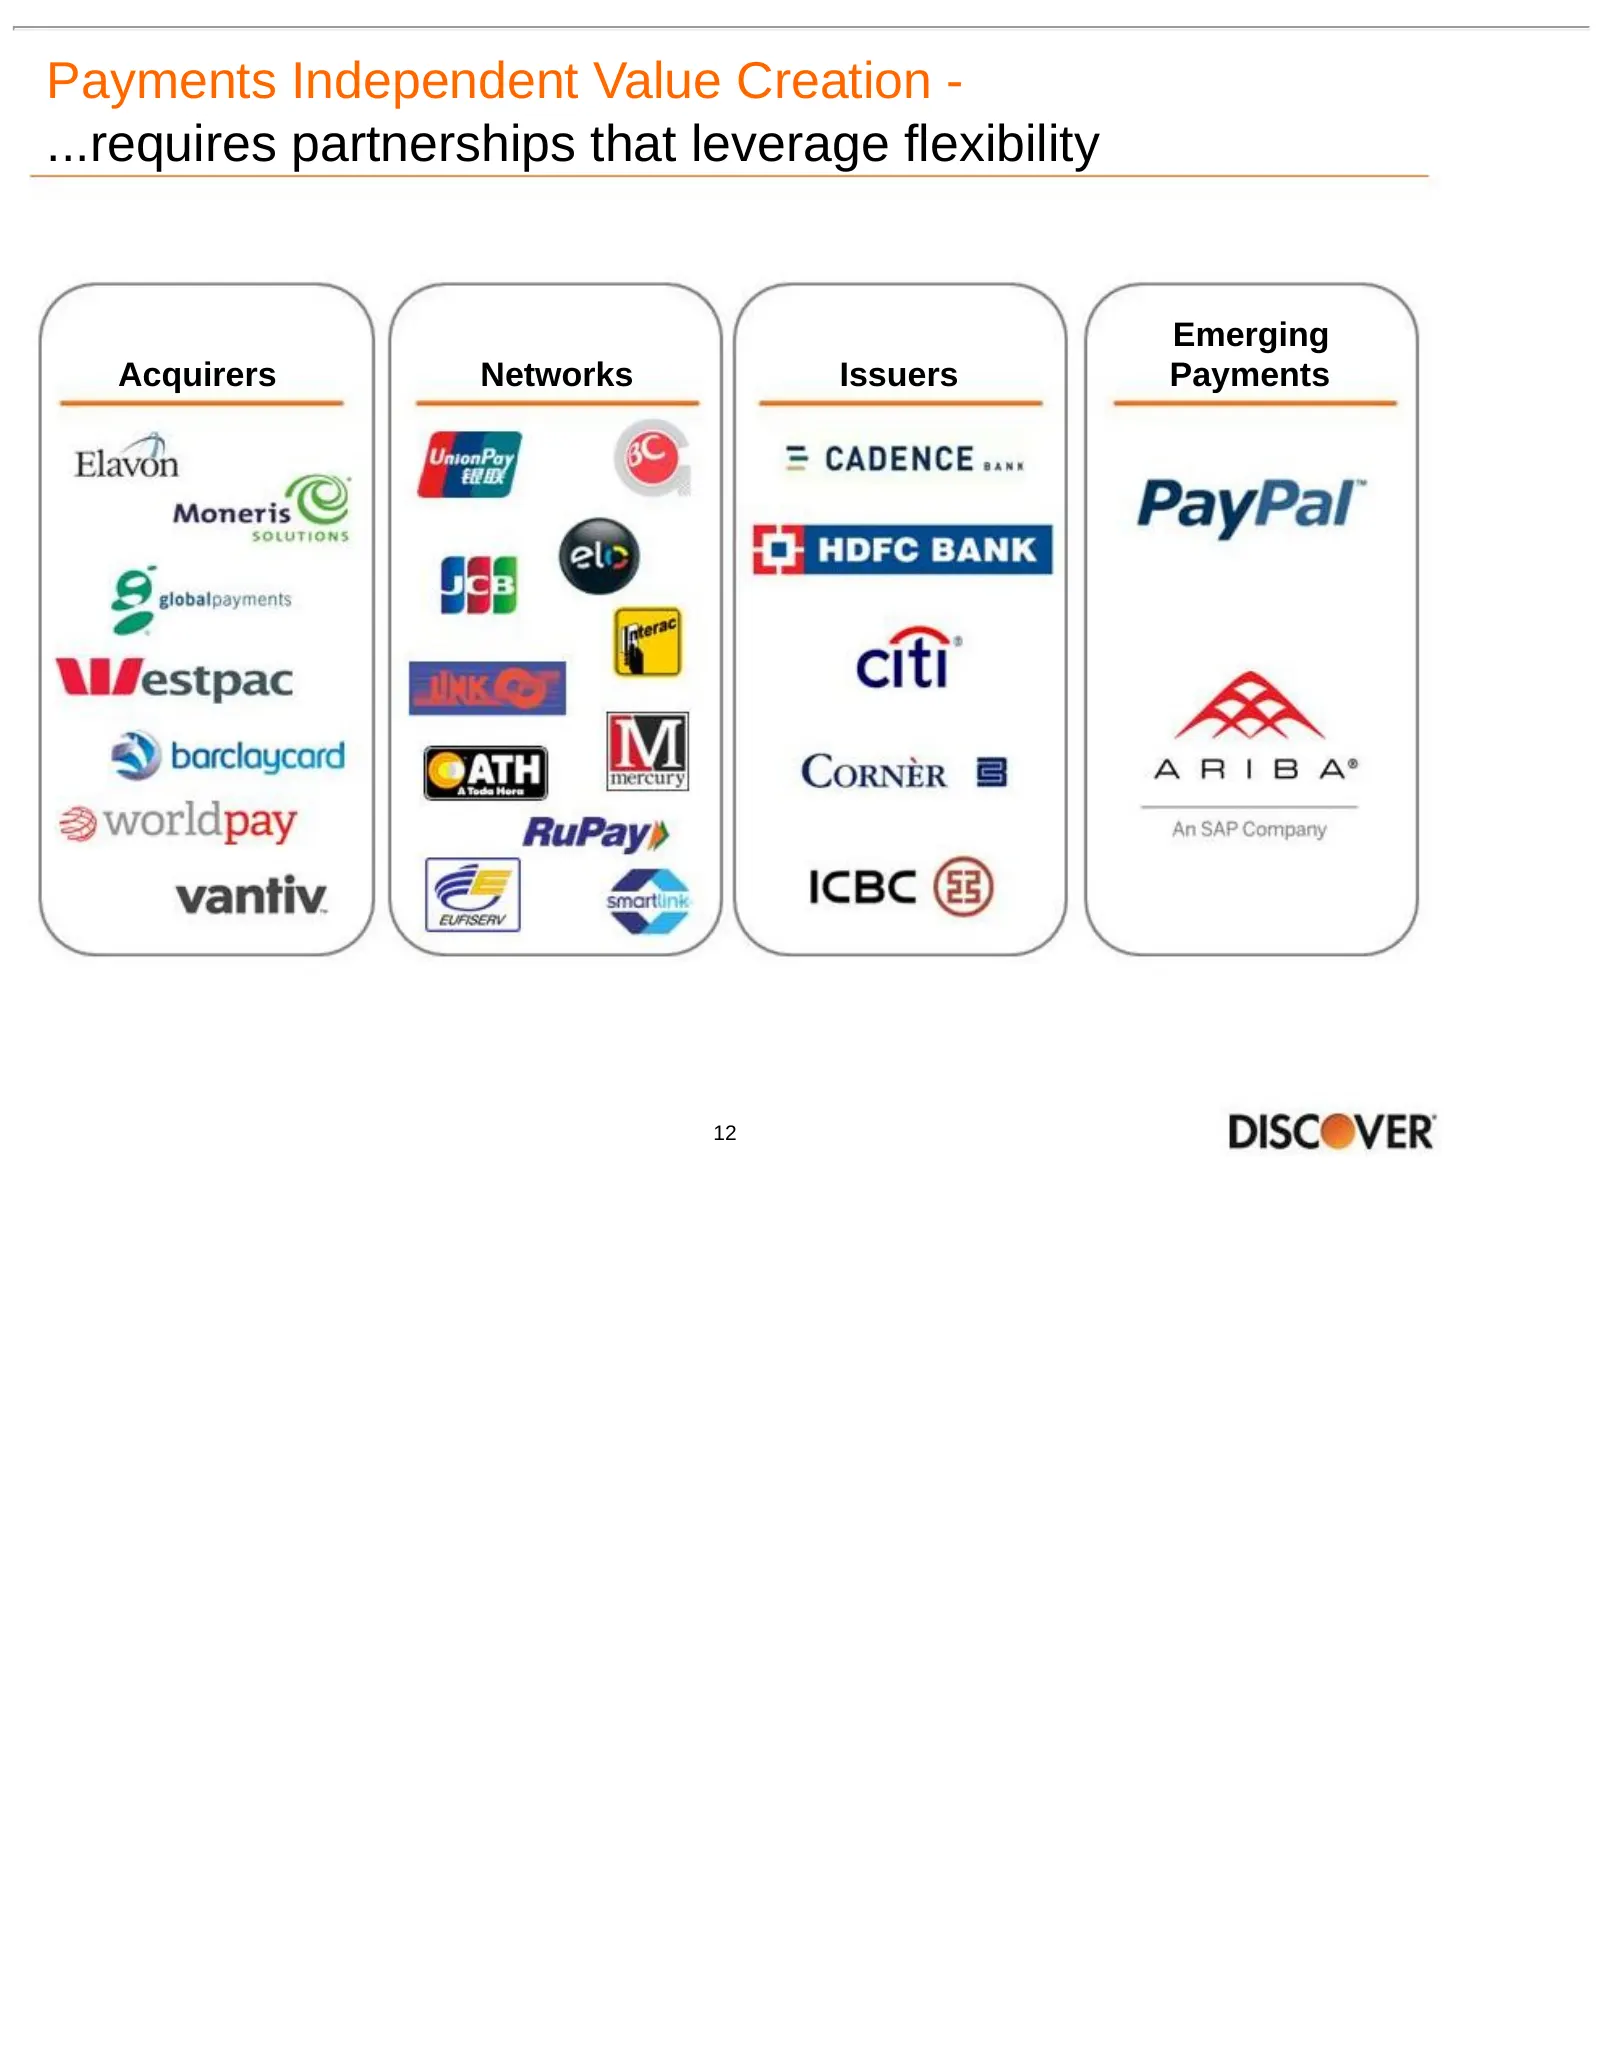
Slide 12: Payments Independent Value Creation - requires partnerships that leverage flexibility
Payments Independent Value Creation - ...requires partnerships that leverage flexibility Emerging Acquirers Networks Issuers Payments 12
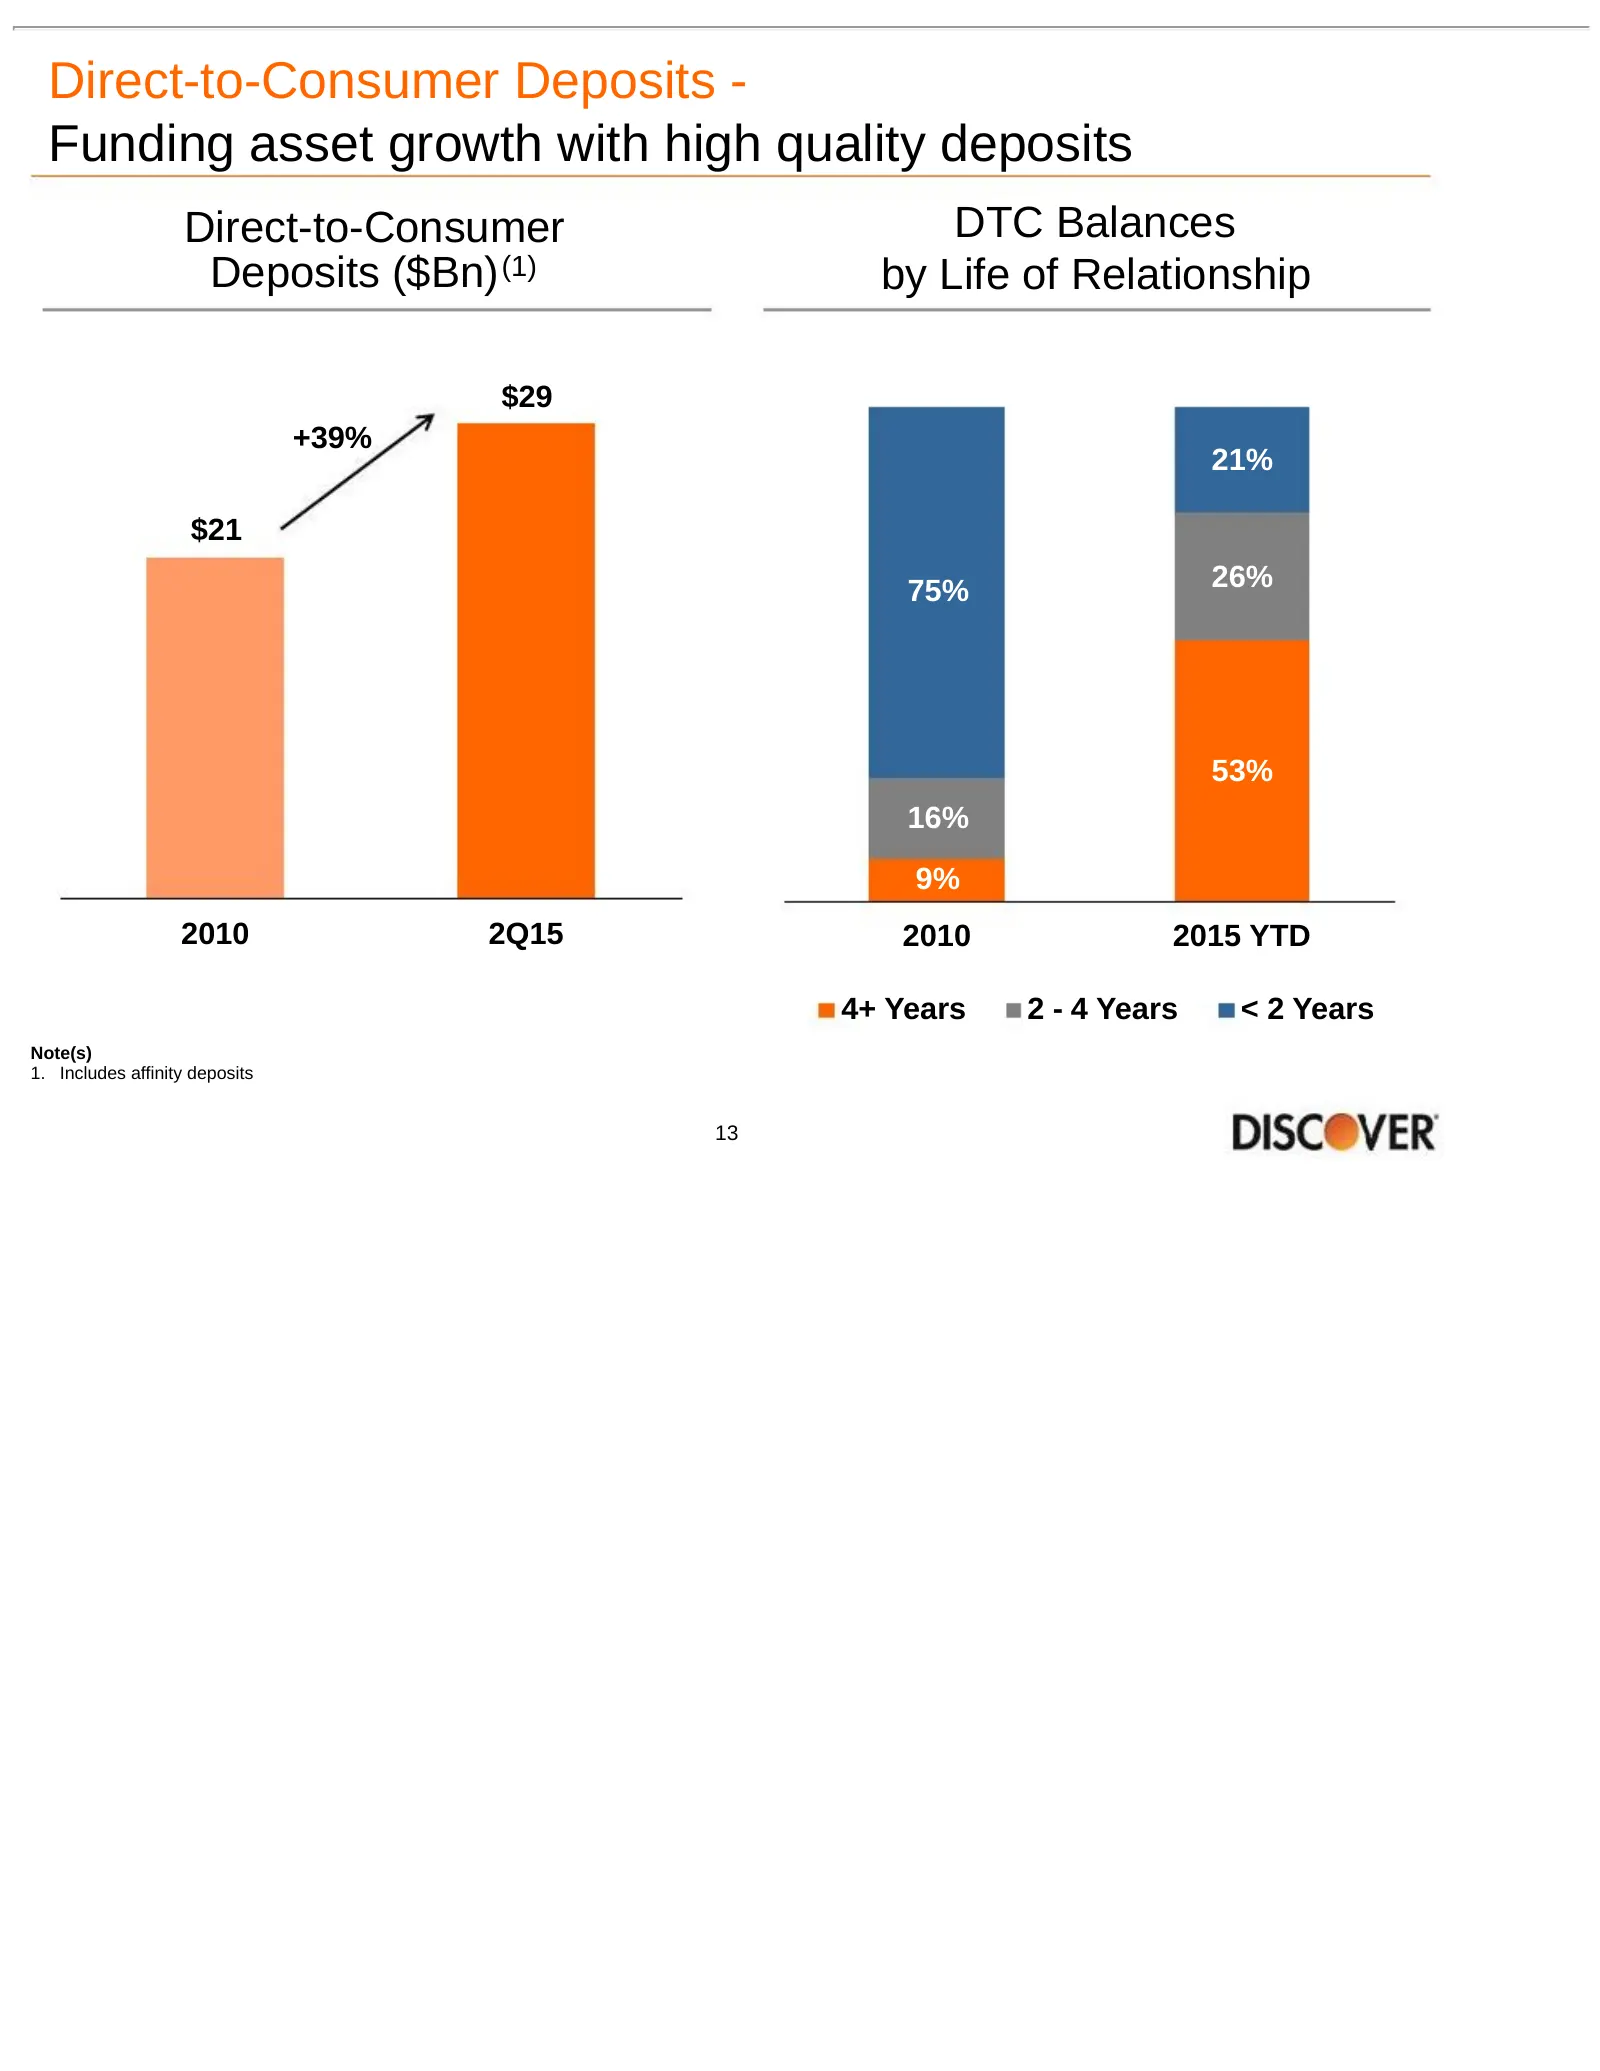
Slide 13: Direct-to-Consumer Deposits - Funding asset growth with high quality deposits
Direct-to-Consumer Deposits - Funding asset growth with high quality deposits Direct-to-Consumer DTC Balances Deposits ($Bn) (1) by Life of Relationship $29 +39% 21% $21 75% 26% 53% 16% 9% 2010 2Q15 2010 2015 YTD 4+ Years 2 - 4 Years < 2 Years Note(s) 1. Includes affinity deposits 13
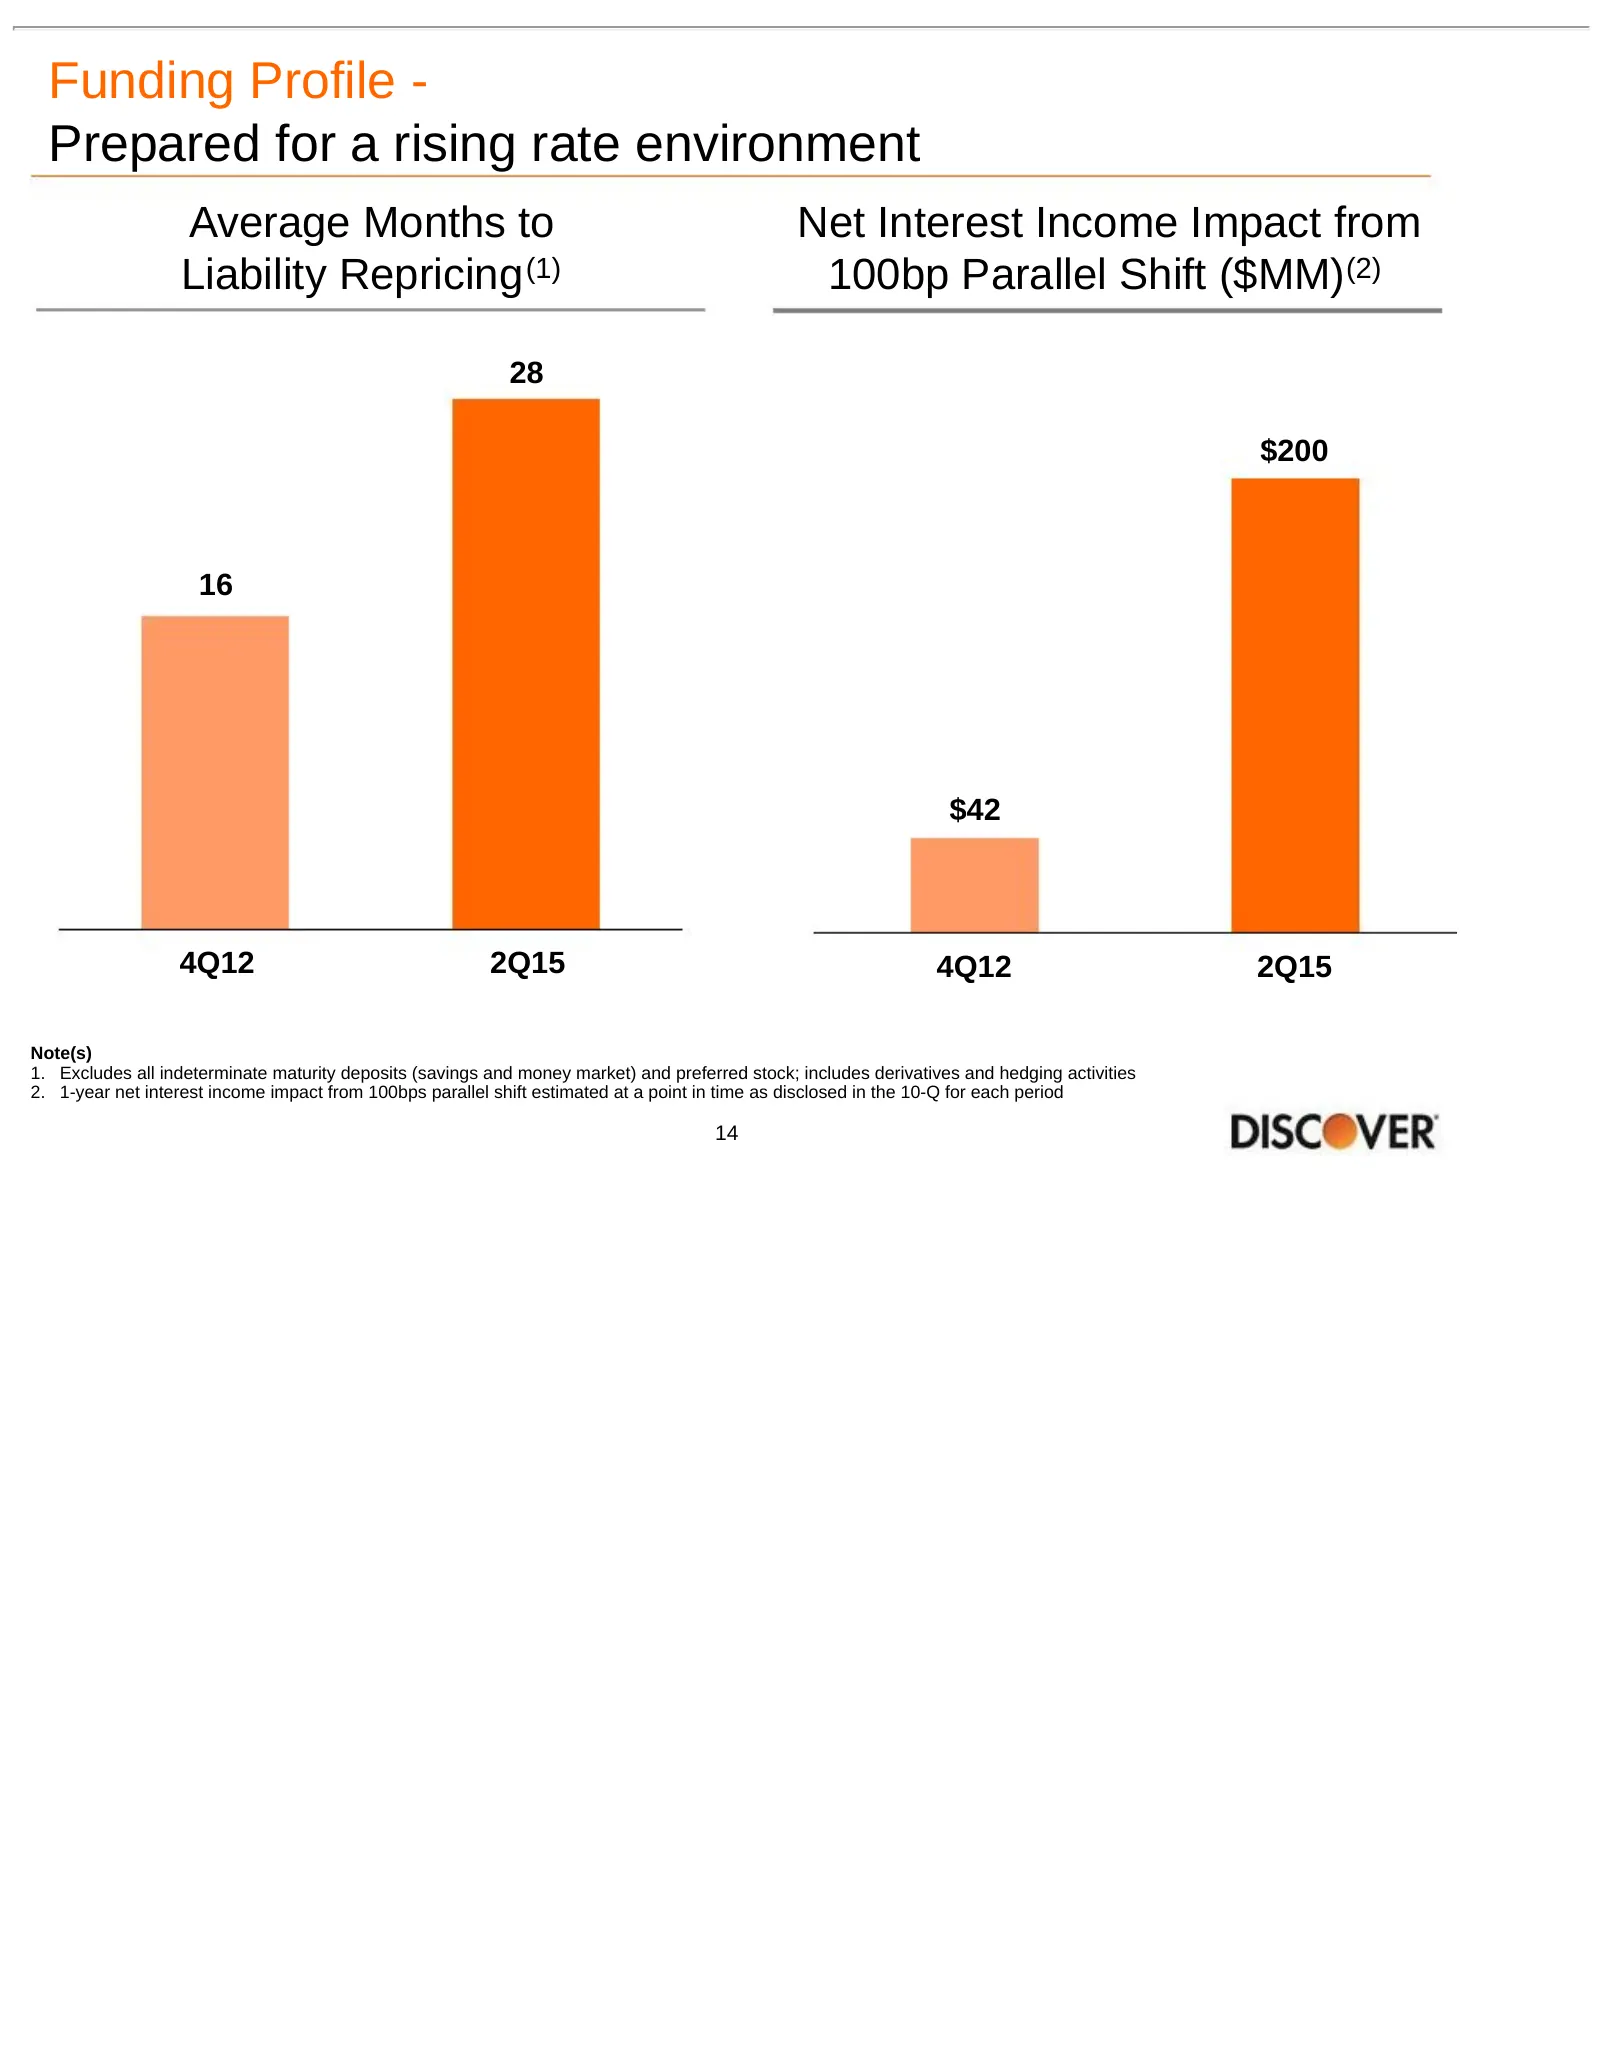
Slide 14: Funding Profile - Prepared for a rising rate environment
Funding Profile - Prepared for a rising rate environment Average Months to Net Interest Income Impact from Liability Repricing (1) 100bp Parallel Shift ($MM)(2) 28 $200 16 $42 4Q12 2Q15 4Q12 2Q15 Note(s) 1. Excludes all indeterminate maturity deposits (savings and money market) and preferred stock;
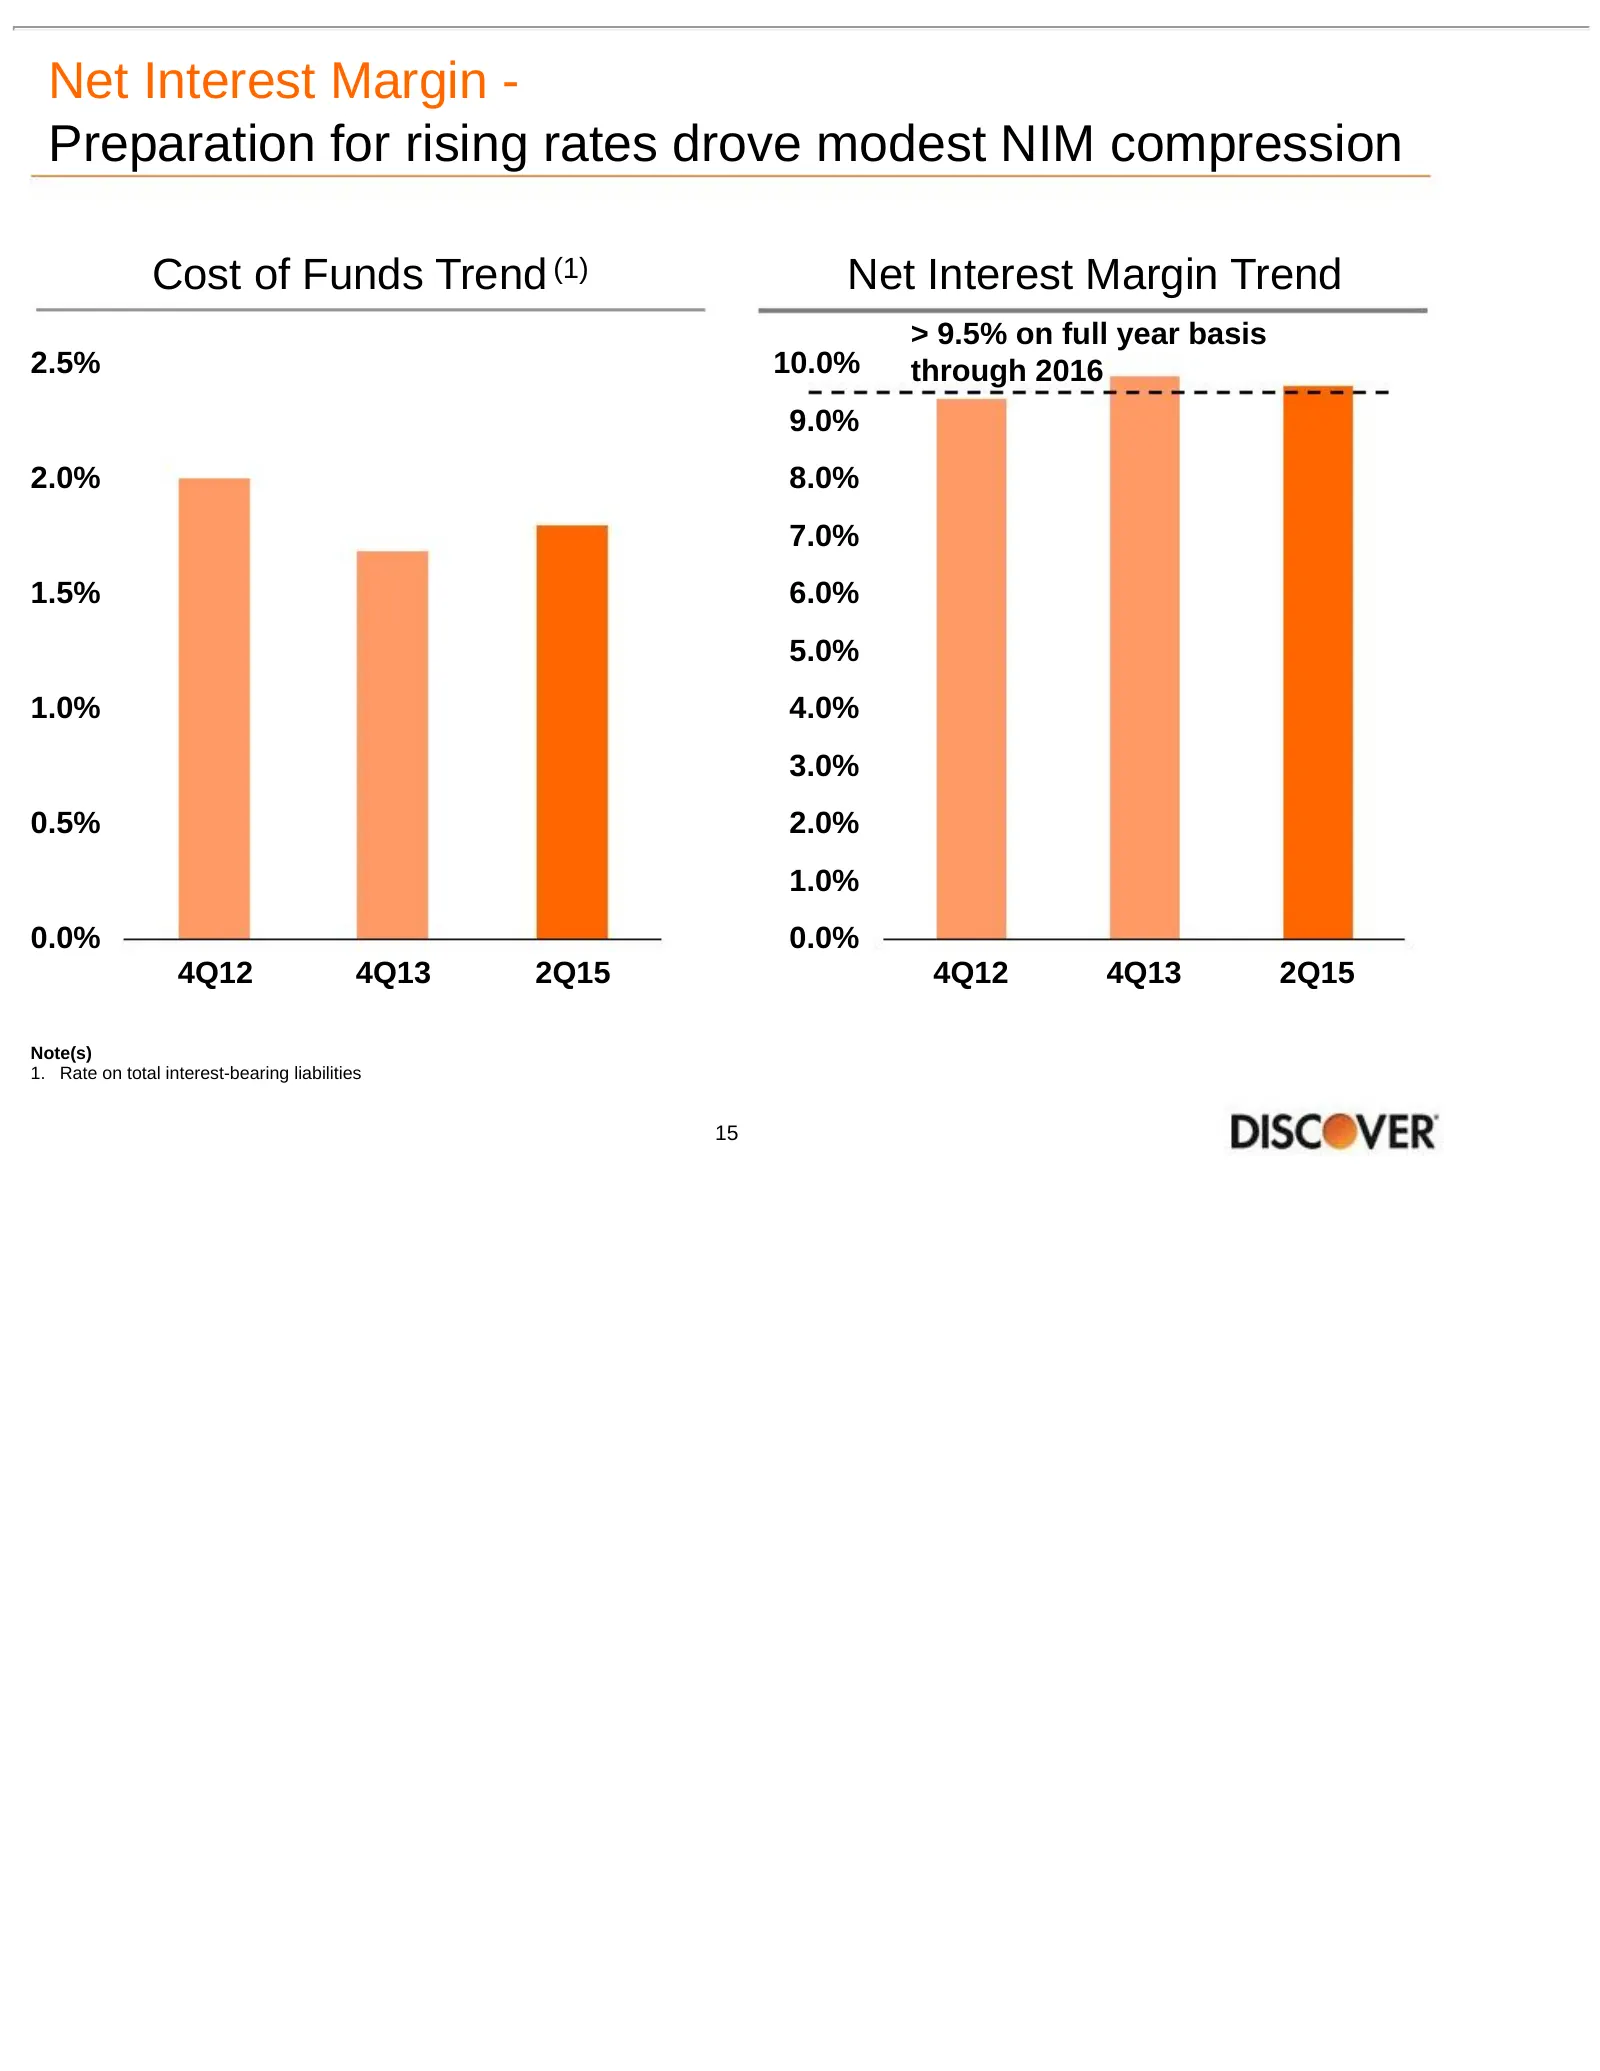
Slide 15: Net Interest Margin - Preparation for rising rates drove modest NIM compression
Net Interest Margin - Preparation for rising rates drove modest NIM compression Cost of Funds Trend (1) Net Interest Margin Trend > 9.5% on full year basis 2.5% 10.0% through 2016 9.0% 2.0% 8.0% 7.0% 1.5% 6.0% 5.0% 1.0% 4.0% 3.0% 0.5% 2.0% 1.0% 0.0% 0.0% 4Q12 4Q13 2Q15 4Q12 4Q13 2Q15 Note(s) 1. Rate
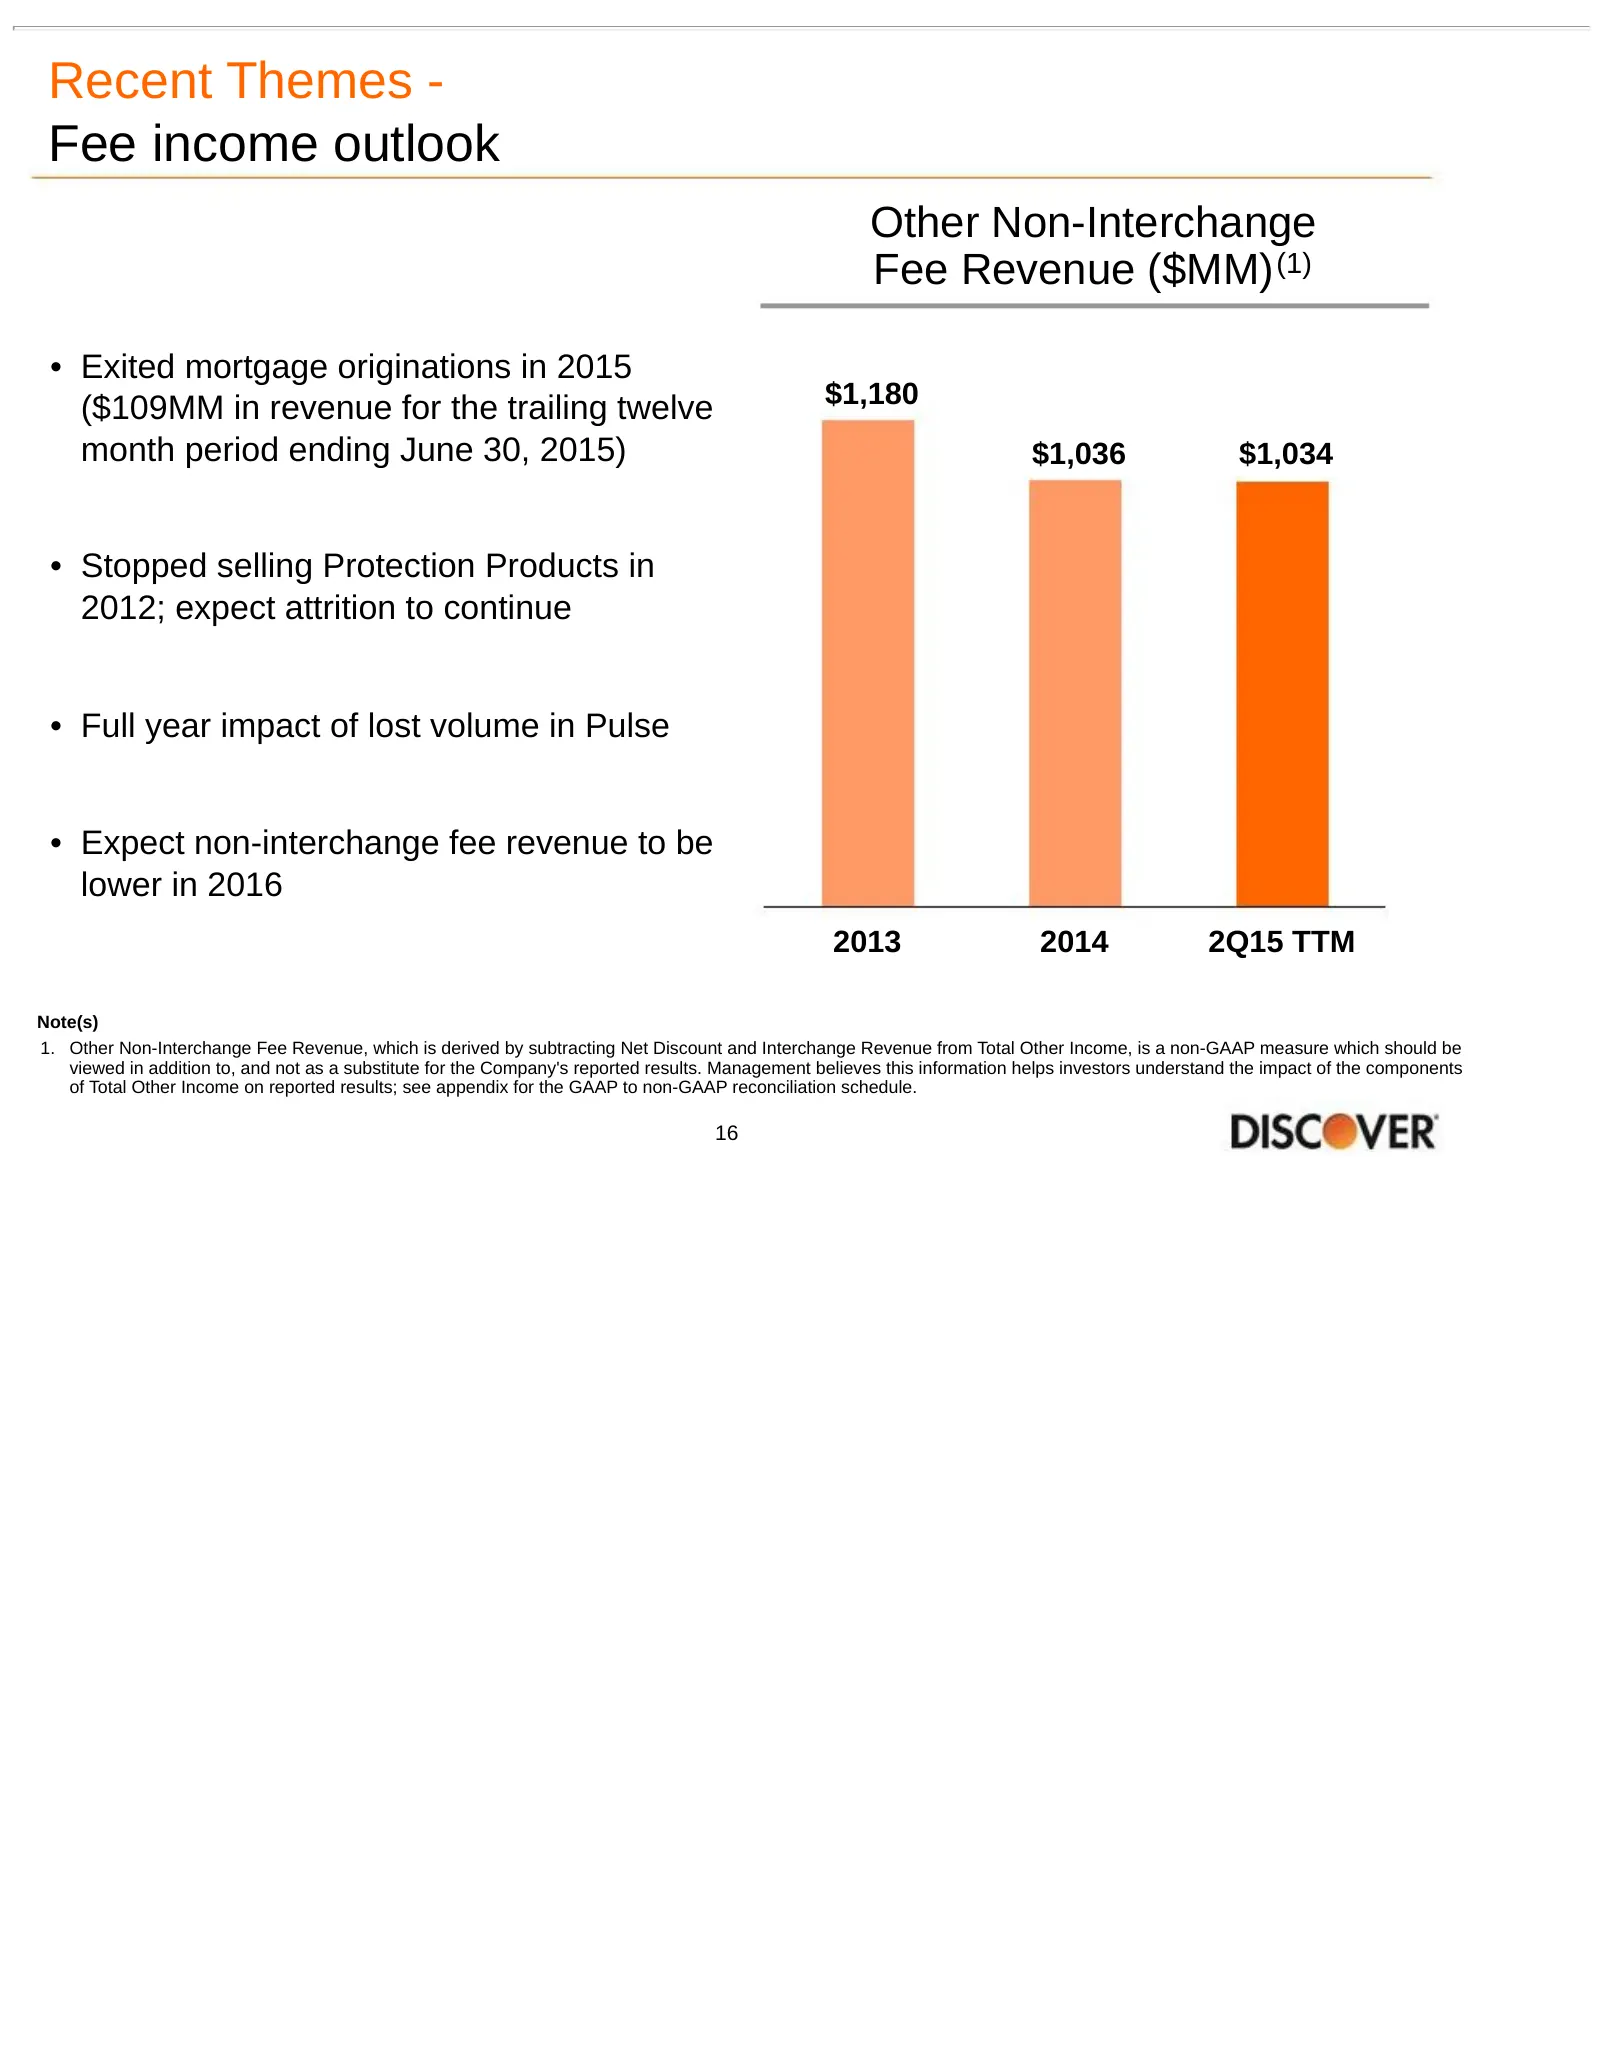
Slide 16: Recent Themes - Fee income outlook
Recent Themes - Fee income outlook Other Non-Interchange Fee Revenue ($MM) (1) • Exited mortgage originations in 2015 ($109MM in revenue for the trailing twelve $1,180 month period ending June 30, 2015) $1,036 $1,034 • Stopped selling Protection Products in 2012; expect attrition to continue • Full
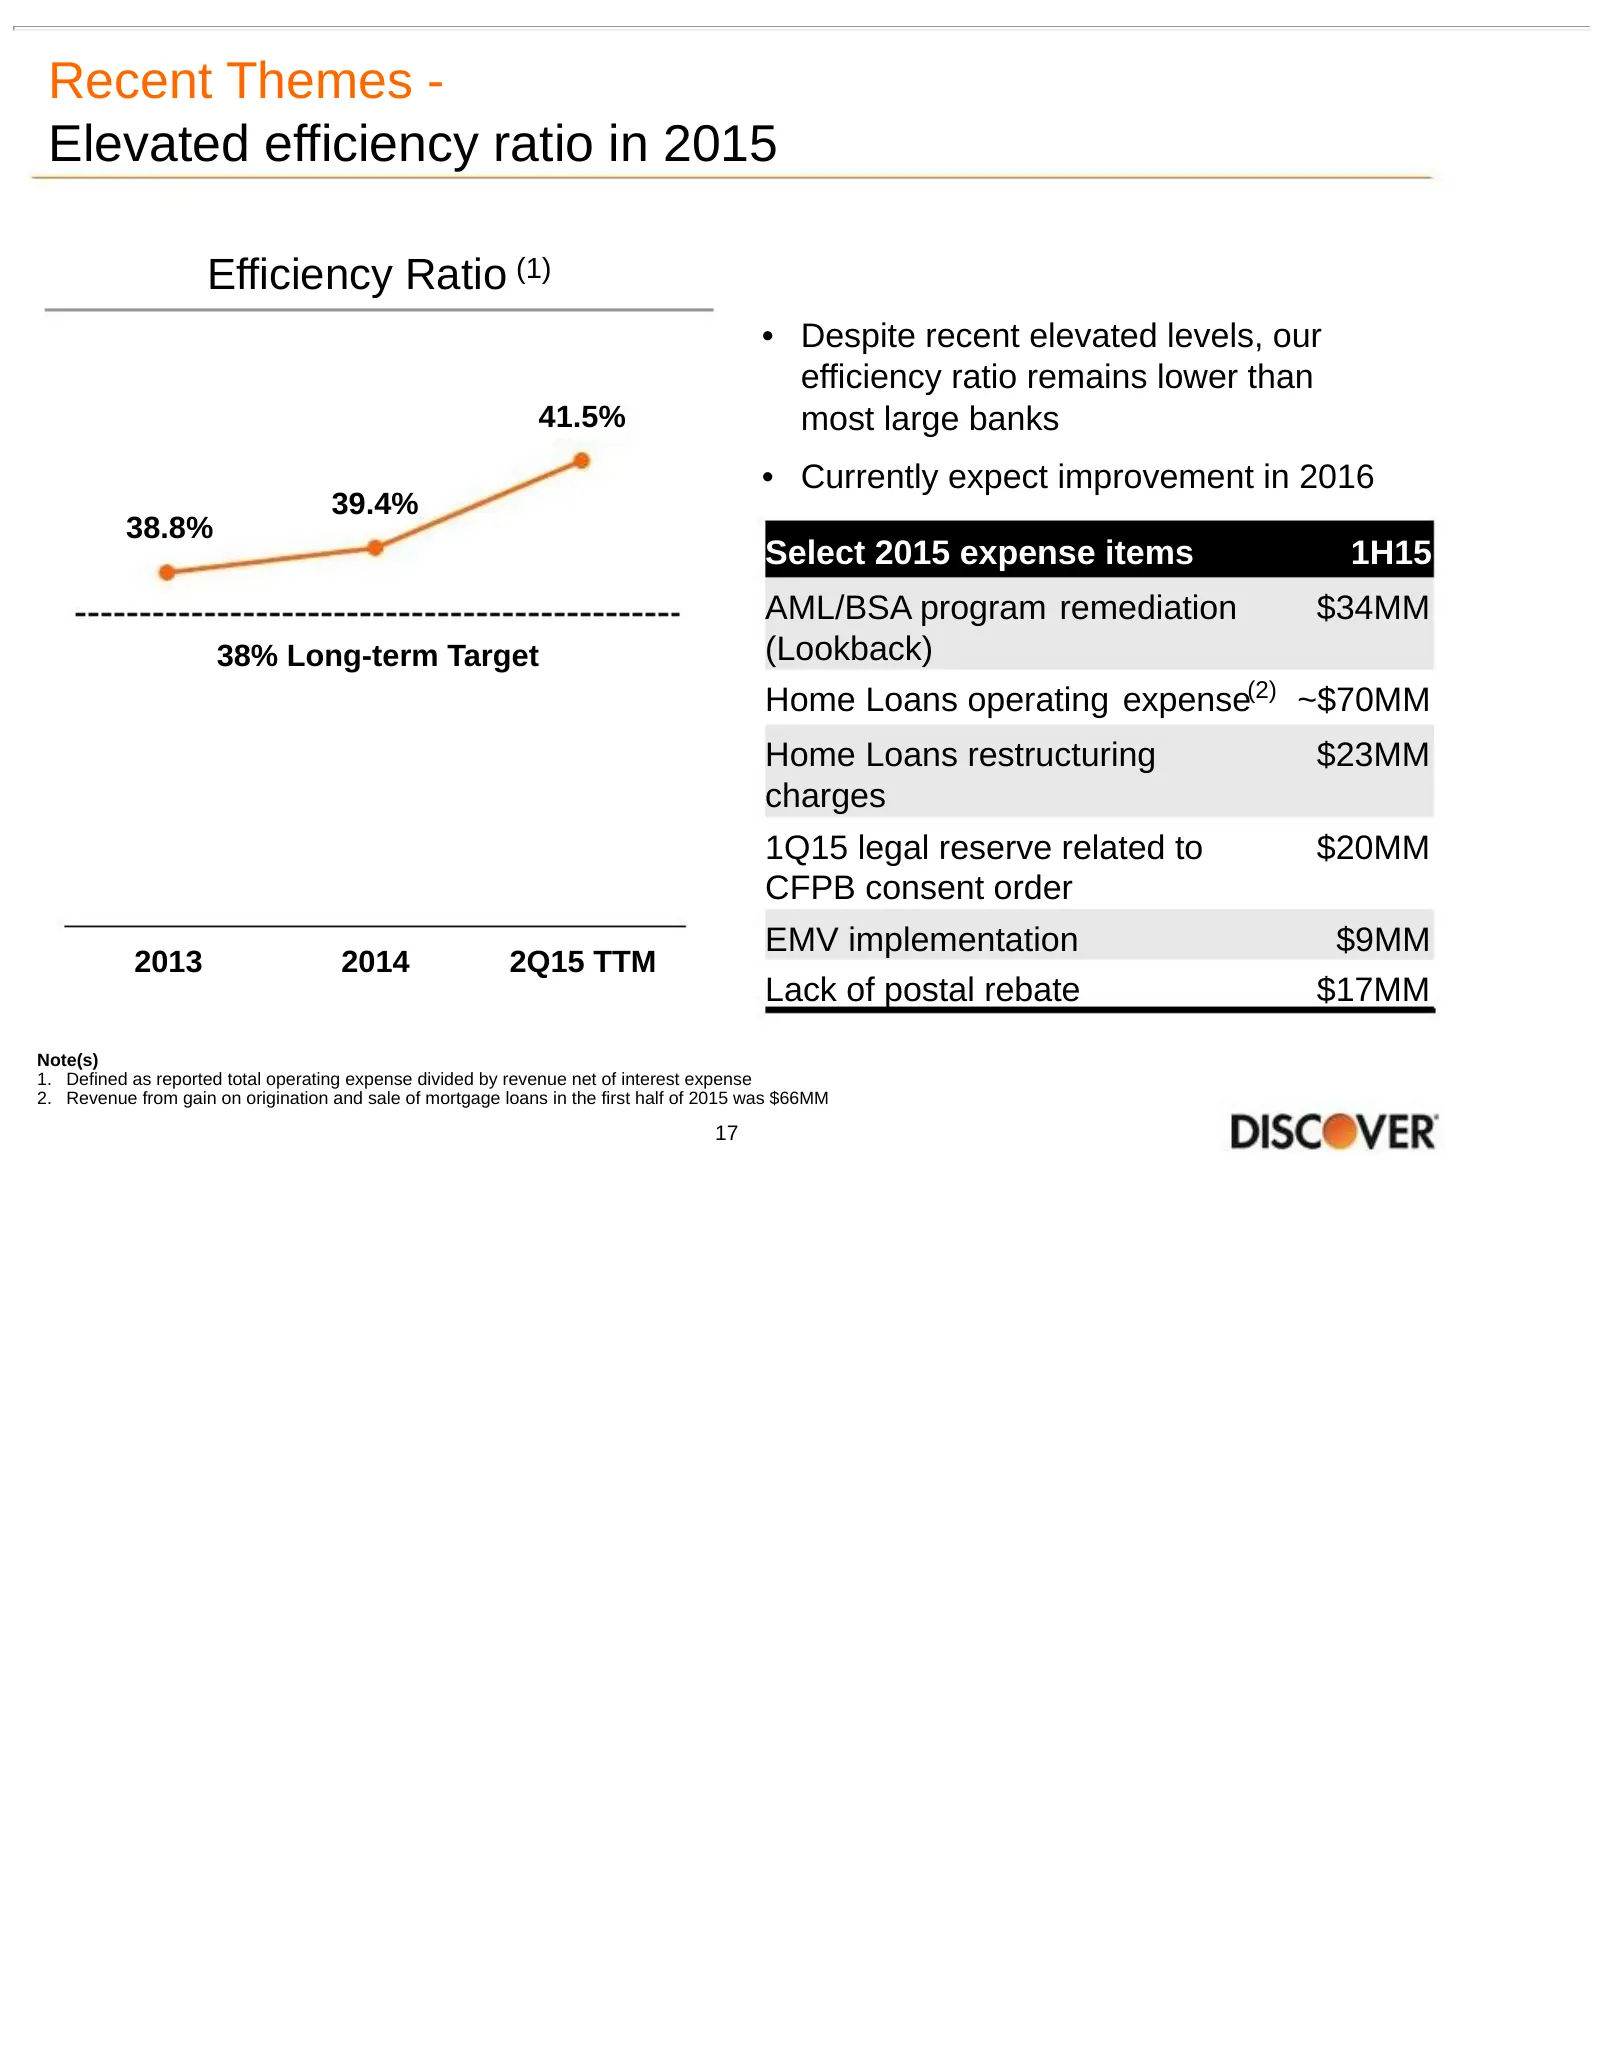
Slide 17: Recent Themes - Elevated efficiency ratio in 2015
Recent Themes - Elevated efficiency ratio in 2015 Efficiency Ratio (1) • Despite recent elevated levels, our efficiency ratio remains lower than 41.5% most large banks • Currently expect improvement in 2016 39.4% 38.8% Select 2015 expense items 1H15 AML/BSA program remediation $34MM 38% Long-term Ta
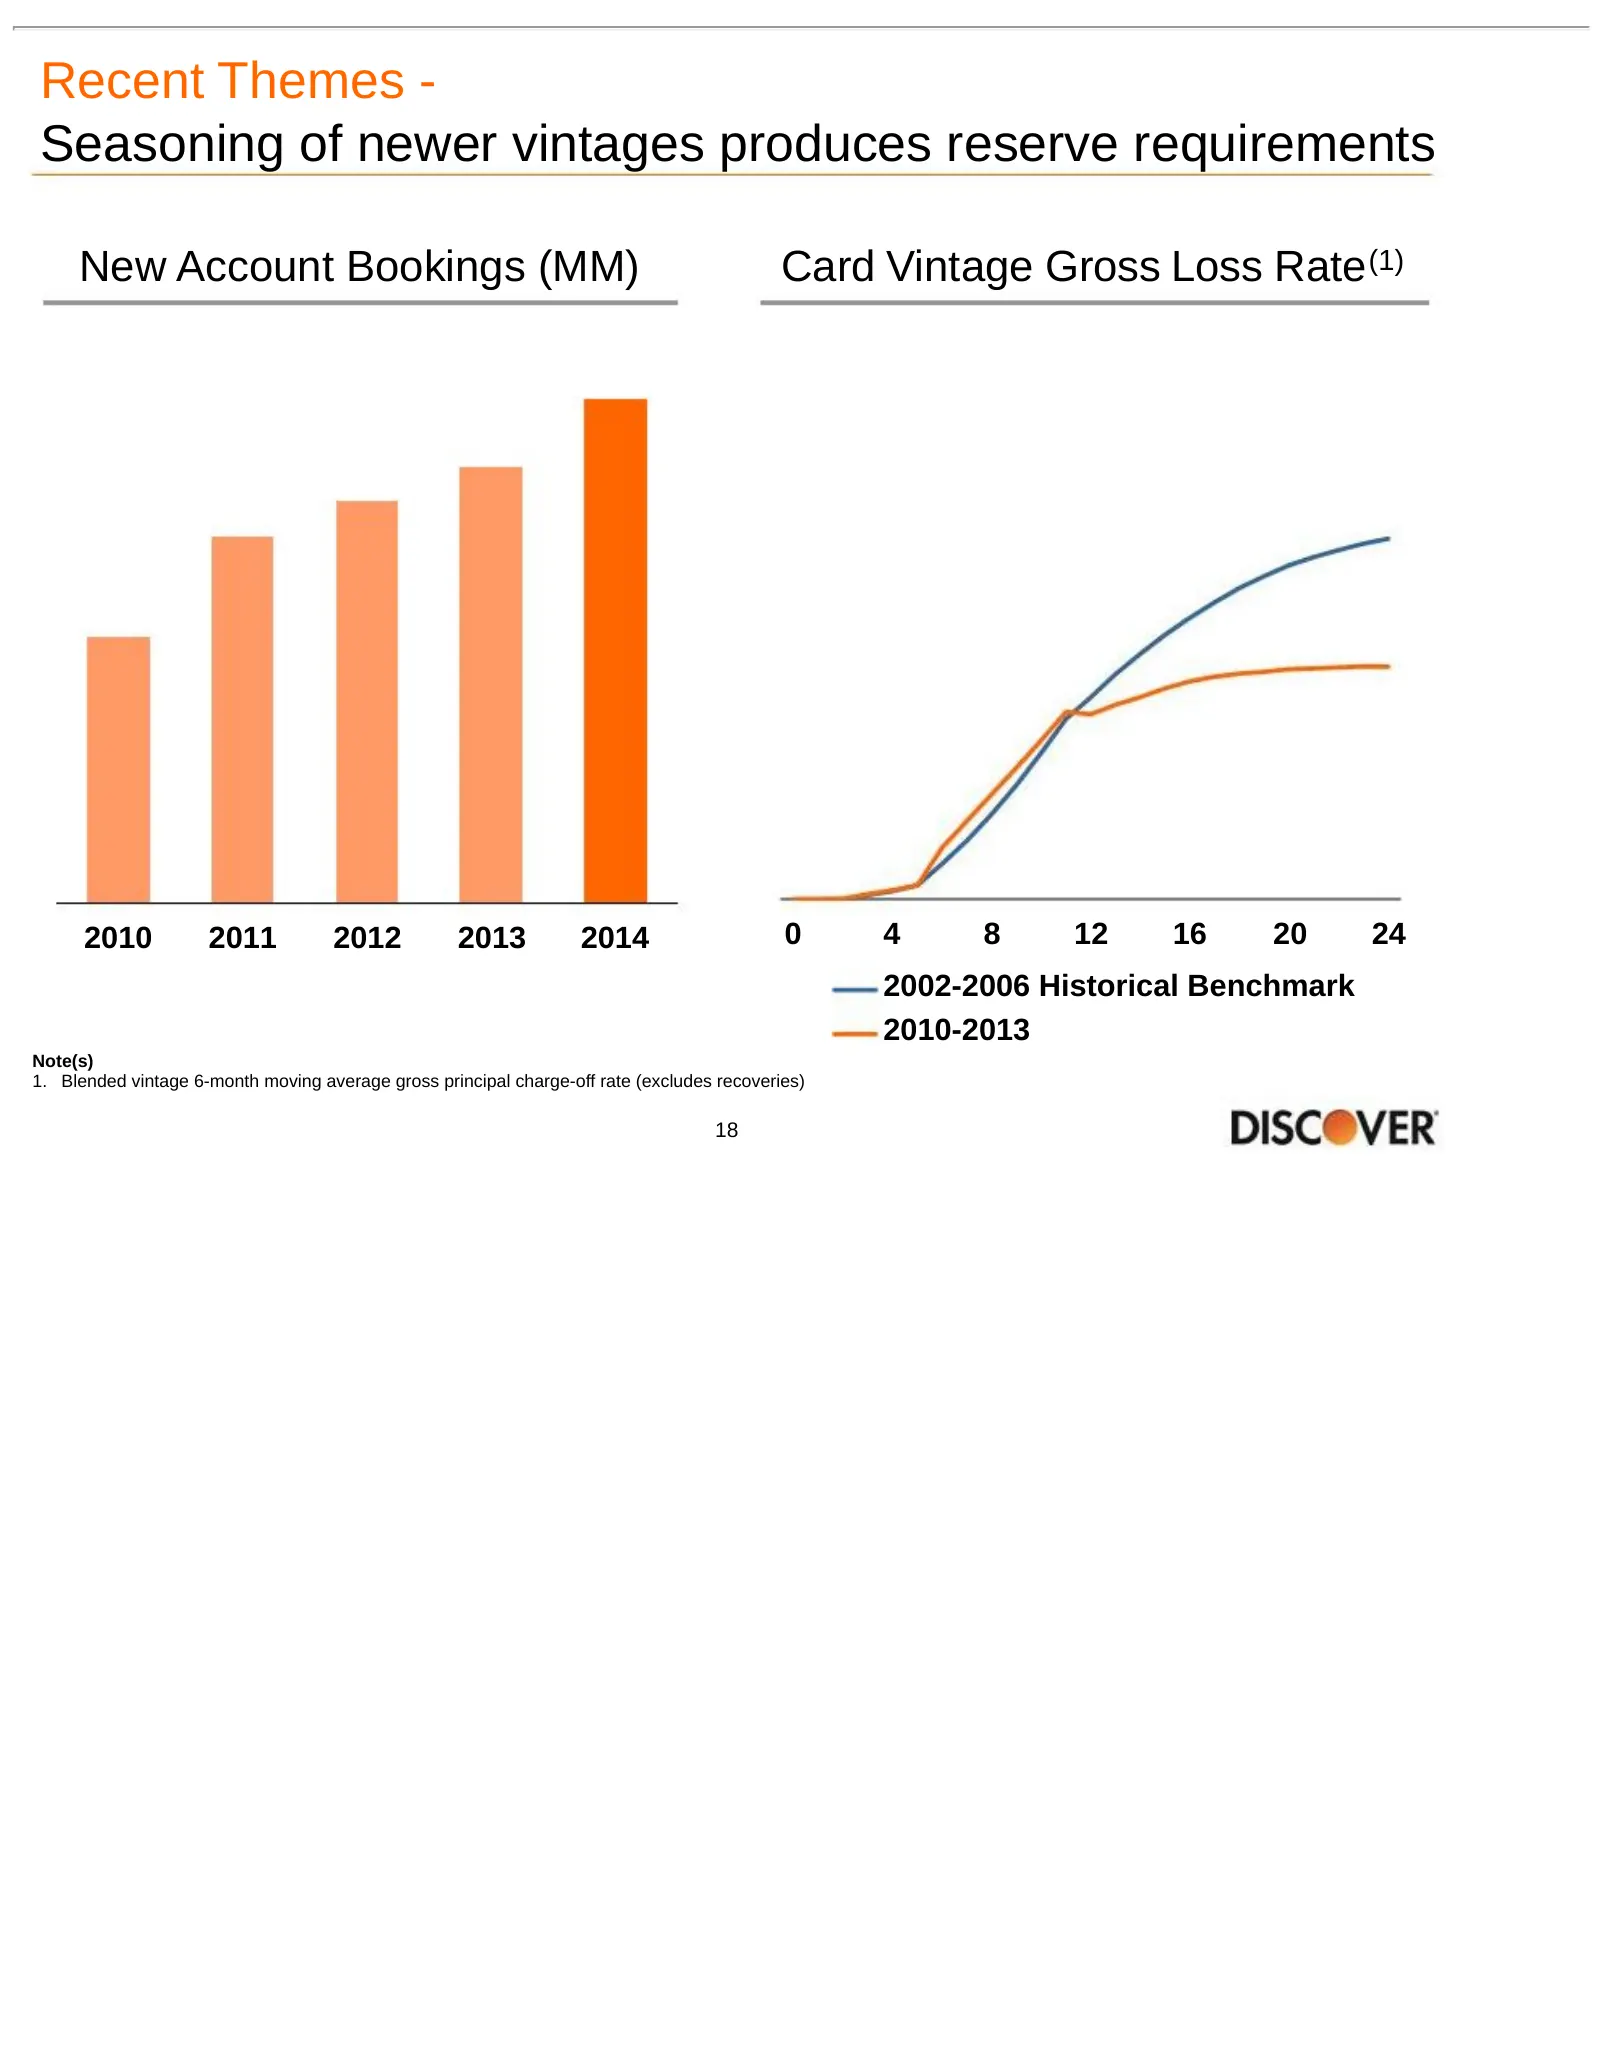
Slide 18: Recent Themes - Seasoning of newer vintages produces reserve requirements
Recent Themes - Seasoning of newer vintages produces reserve requirements New Account Bookings (MM) Card Vintage Gross Loss Rate (1) 2010 2011 2012 2013 2014 0 4 8 12 16 20 24 2002-2006 Historical Benchmark 2010-2013 Note(s) 1. Blended vintage 6-month moving average gross principal charge-off rate (
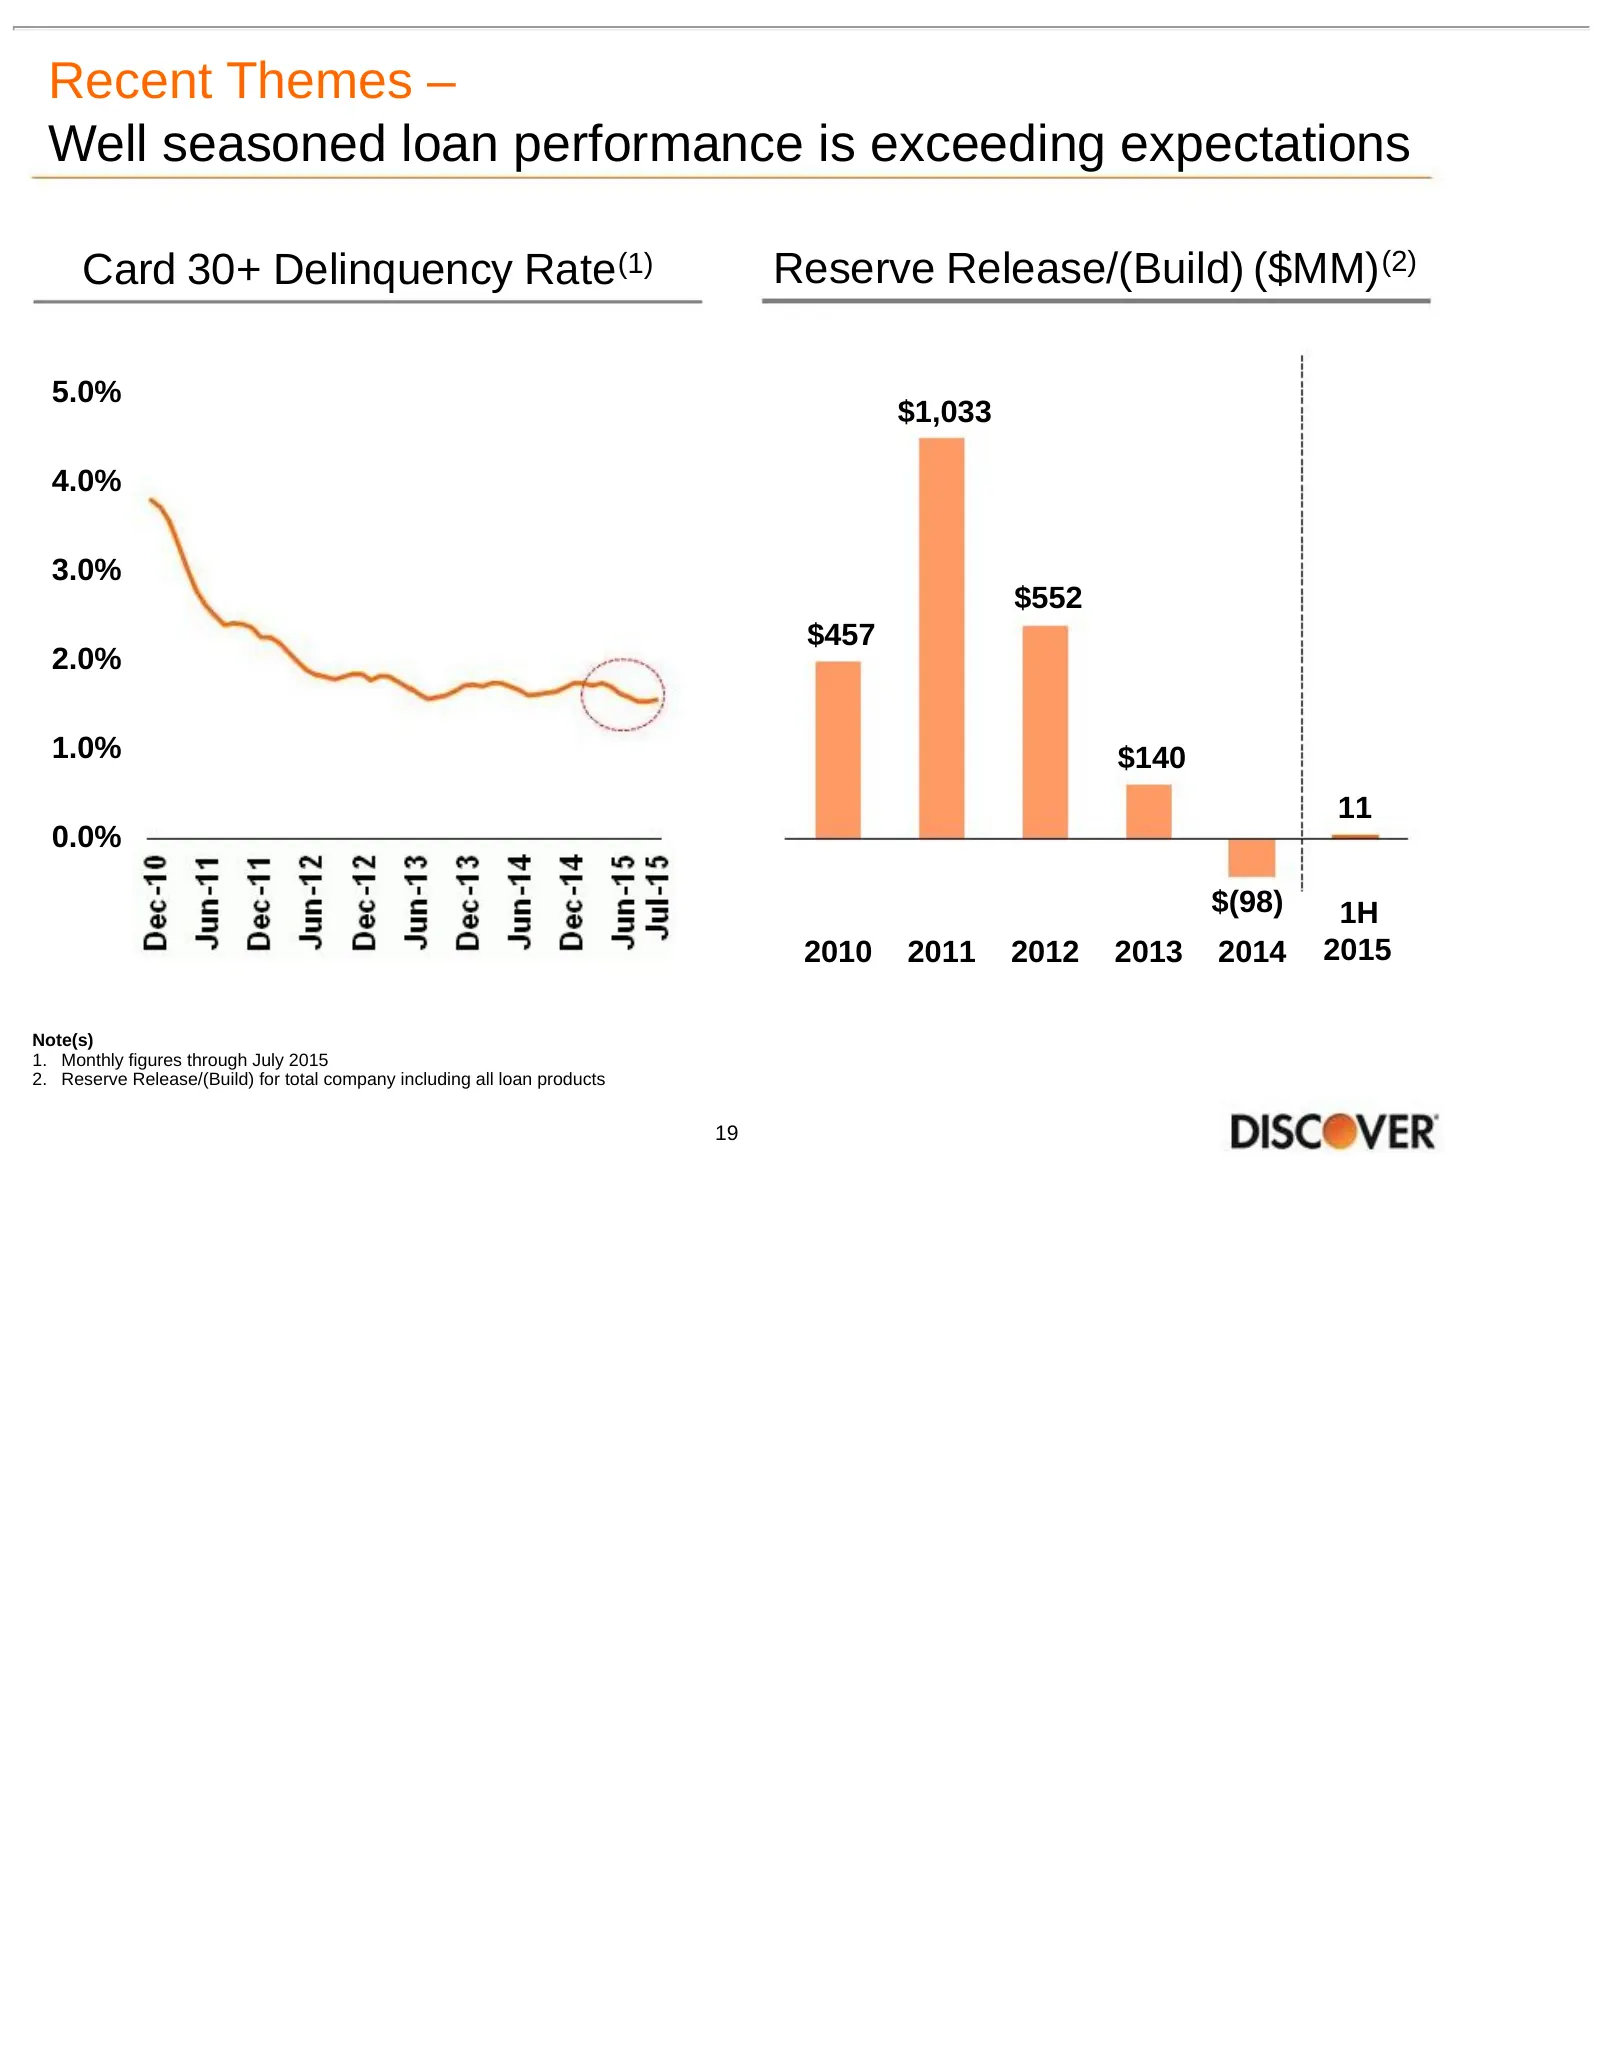
Slide 19: Recent Themes – Well seasoned loan performance is exceeding expectations
Recent Themes – Well seasoned loan performance is exceeding expectations Card 30+ Delinquency Rate (1) Reserve Release/(Build) ($MM) (2) 5.0% $1,033 4.0% 3.0% $552 $457 2.0% 1.0% $140 11 0.0% $(98) 1H 2010 2011 2012 2013 2014 2015 Note(s) 1. Monthly figures through July 2015 2. Reserve Release/(Buil
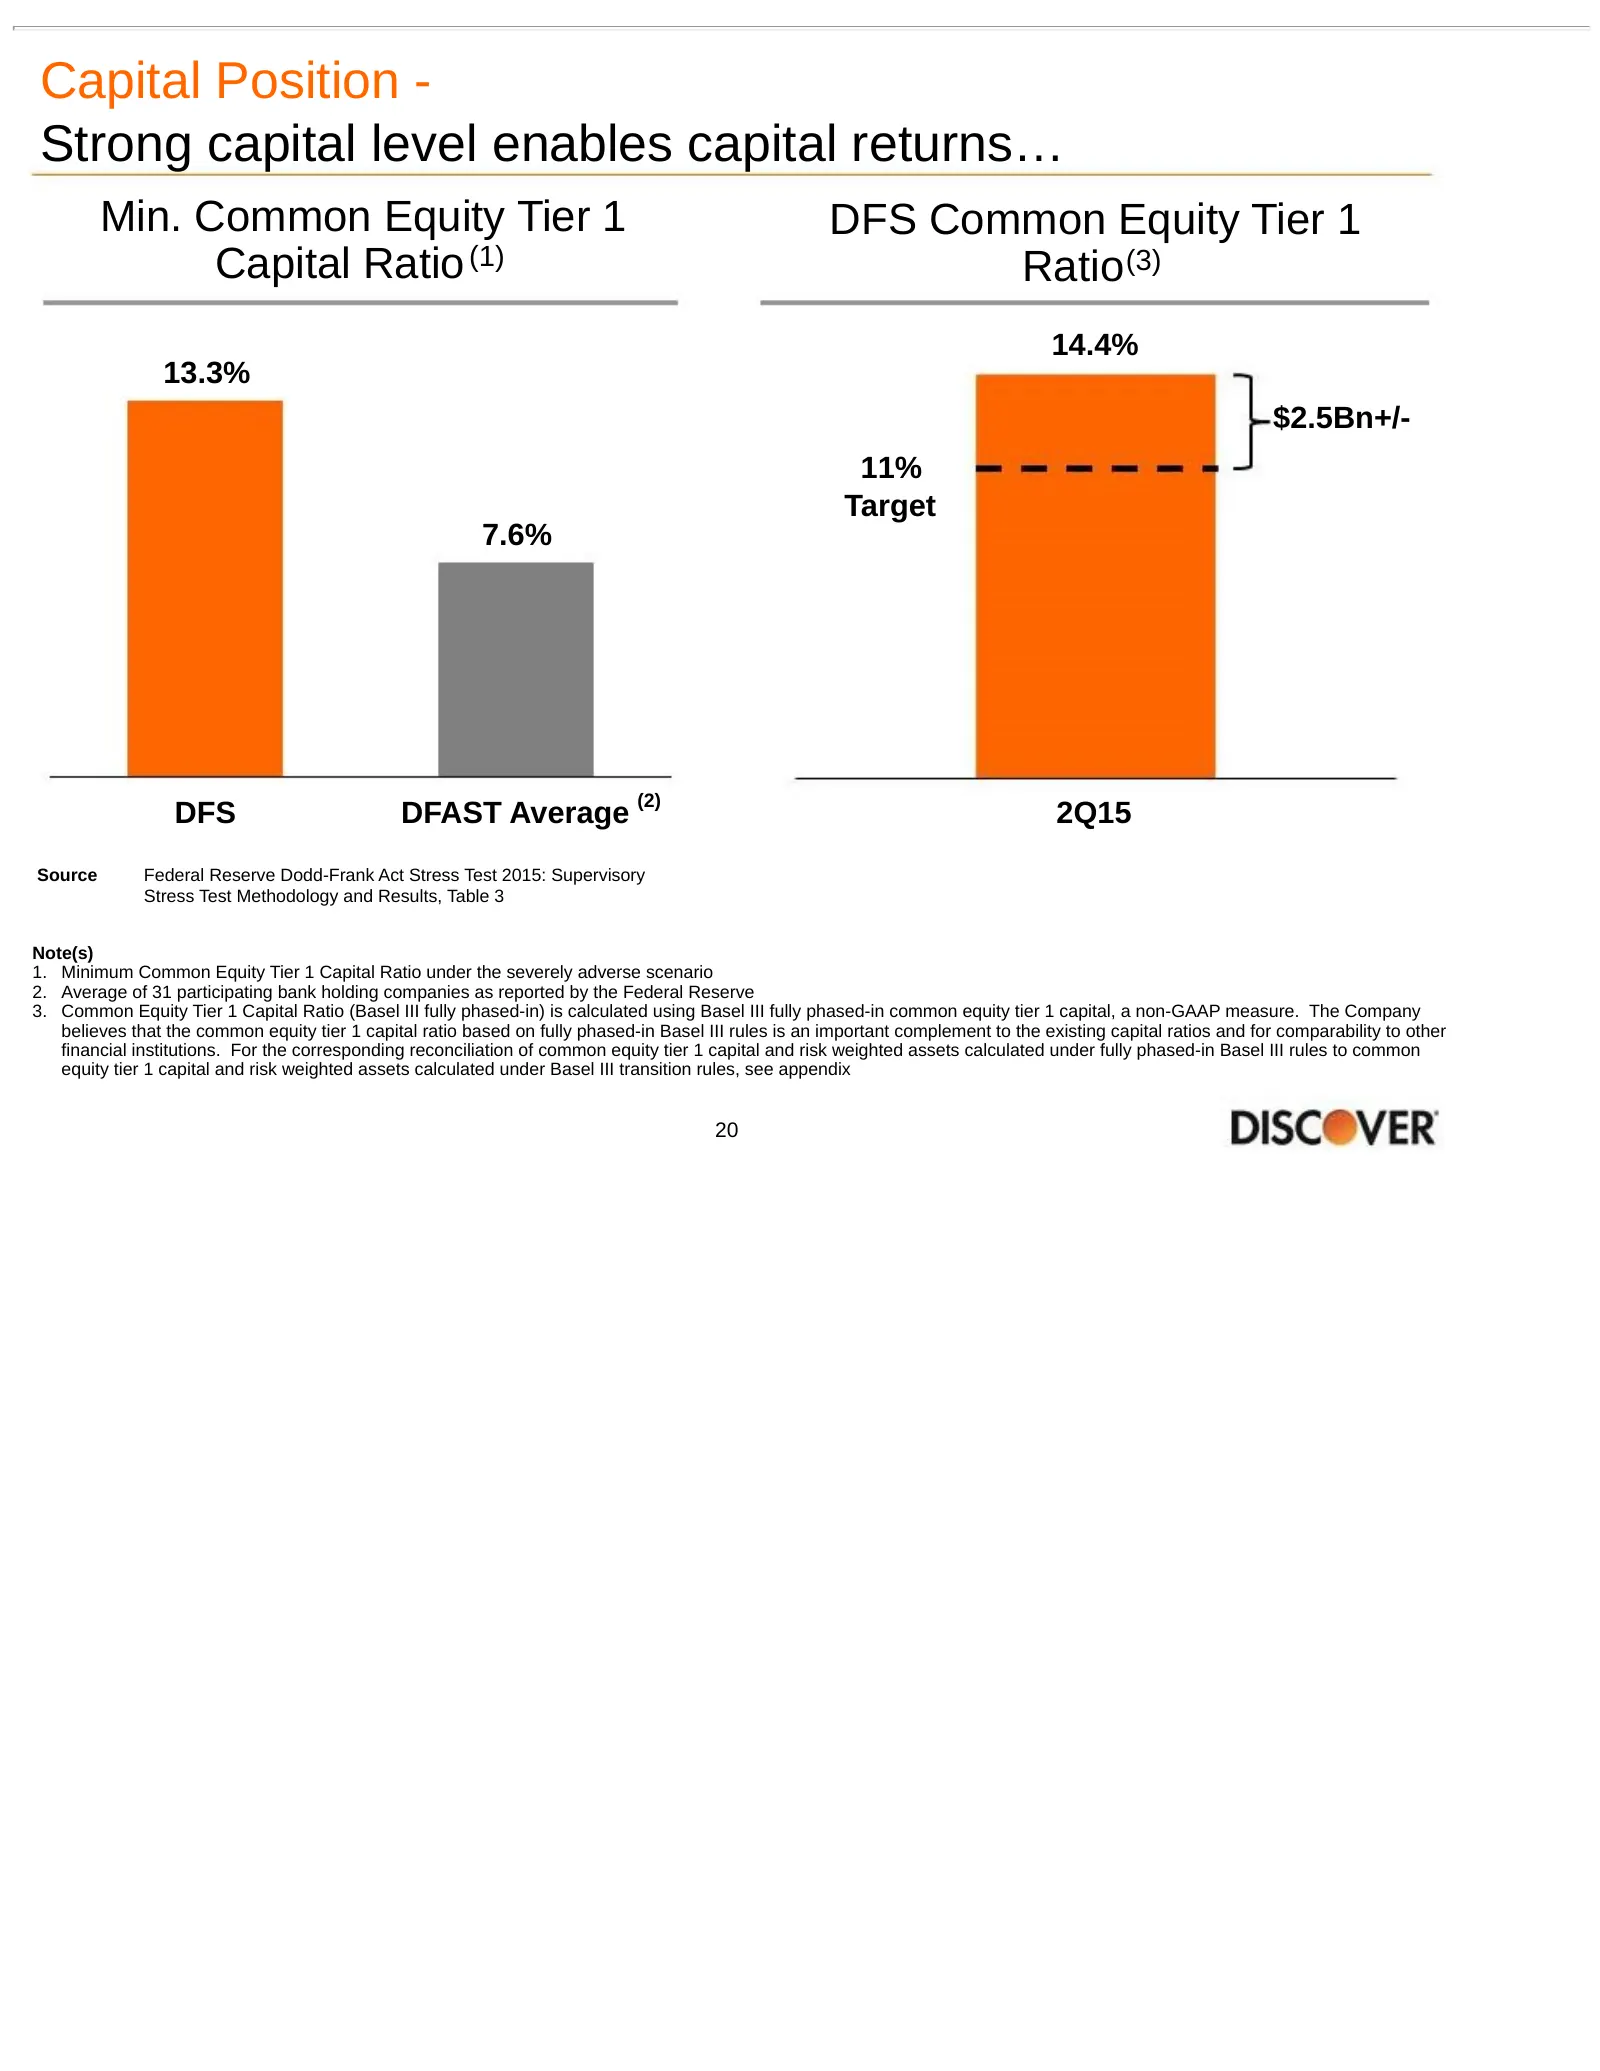
Slide 20: Capital Position - Strong capital level enables capital returns
Capital Position - Strong capital level enables capital returns… Min. Common Equity Tier 1 DFS Common Equity Tier 1 Capital Ratio (1) Ratio (3) 14.4% 13.3% $2.5Bn+/- 11% Target 7.6% (2) DFS DFAST Average 2Q15 Source Federal Reserve Dodd-Frank Act Stress Test 2015: Supervisory Stress Test Methodology
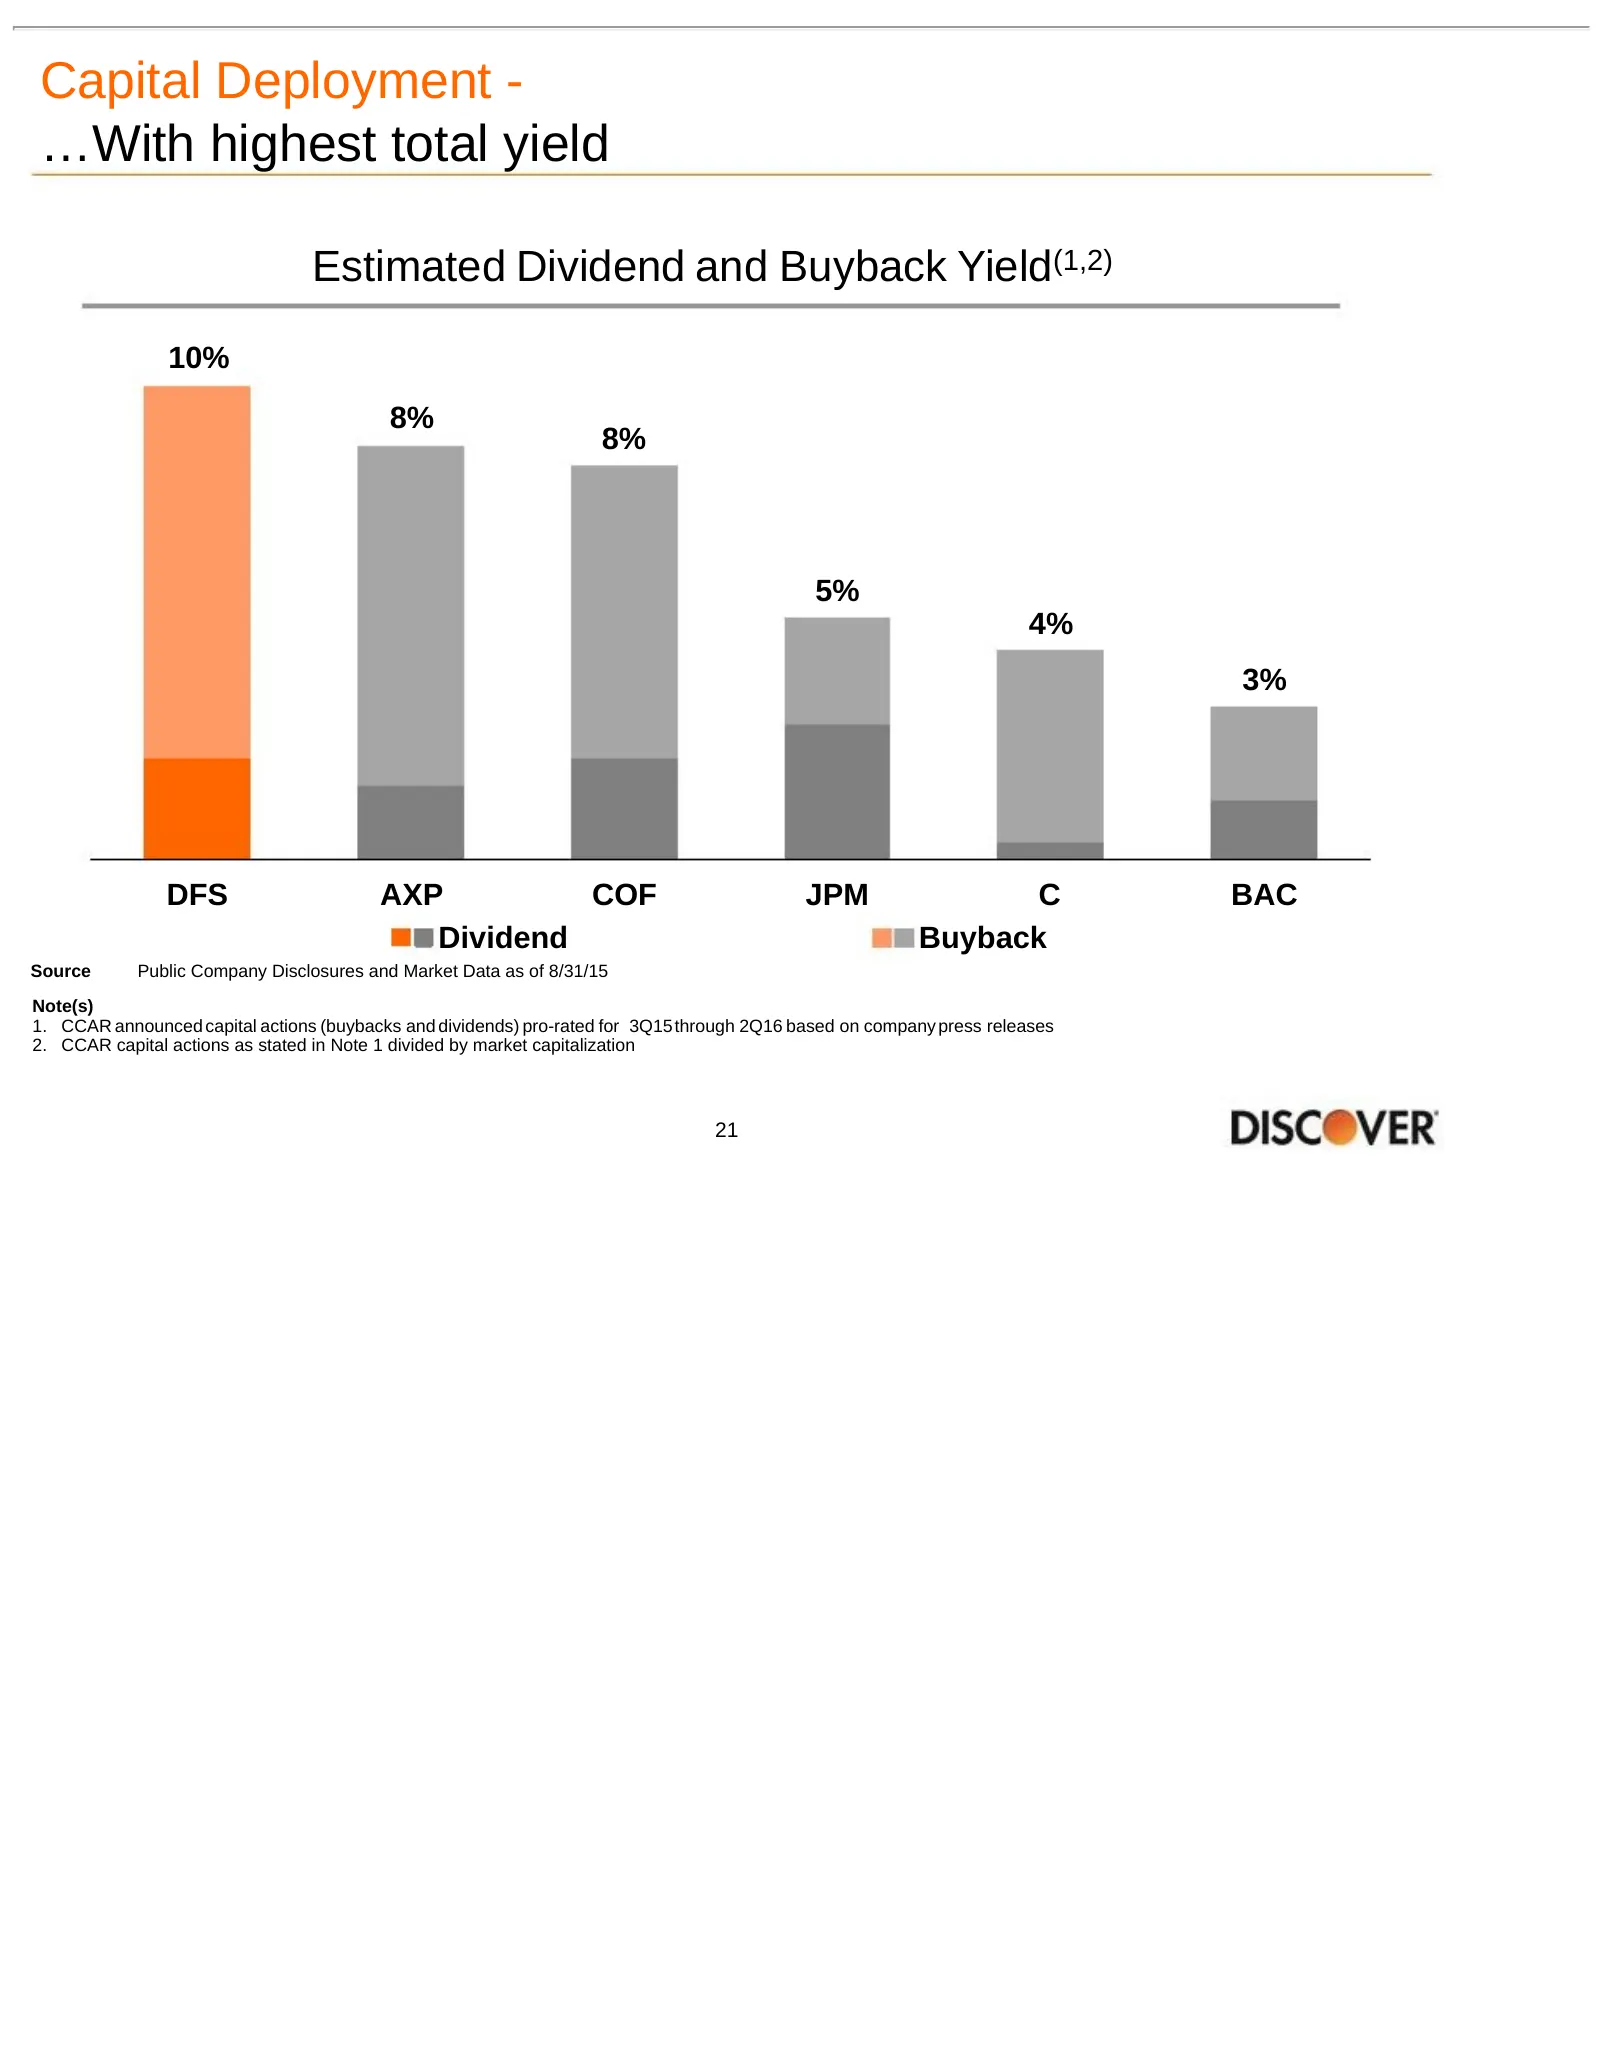
Slide 21: Capital Deployment - With highest total yield
Capital Deployment - …With highest total yield Estimated Dividend and Buyback Yield(1,2) 10% 8% 8% 5% 4% 3% DFS AXP COF JPM C BAC Dividend Buyback Source Public Company Disclosures and Market Data as of 8/31/15 Note(s) 1. CCAR announced capital actions (buybacks and dividends) pro-rated for 3Q15thro
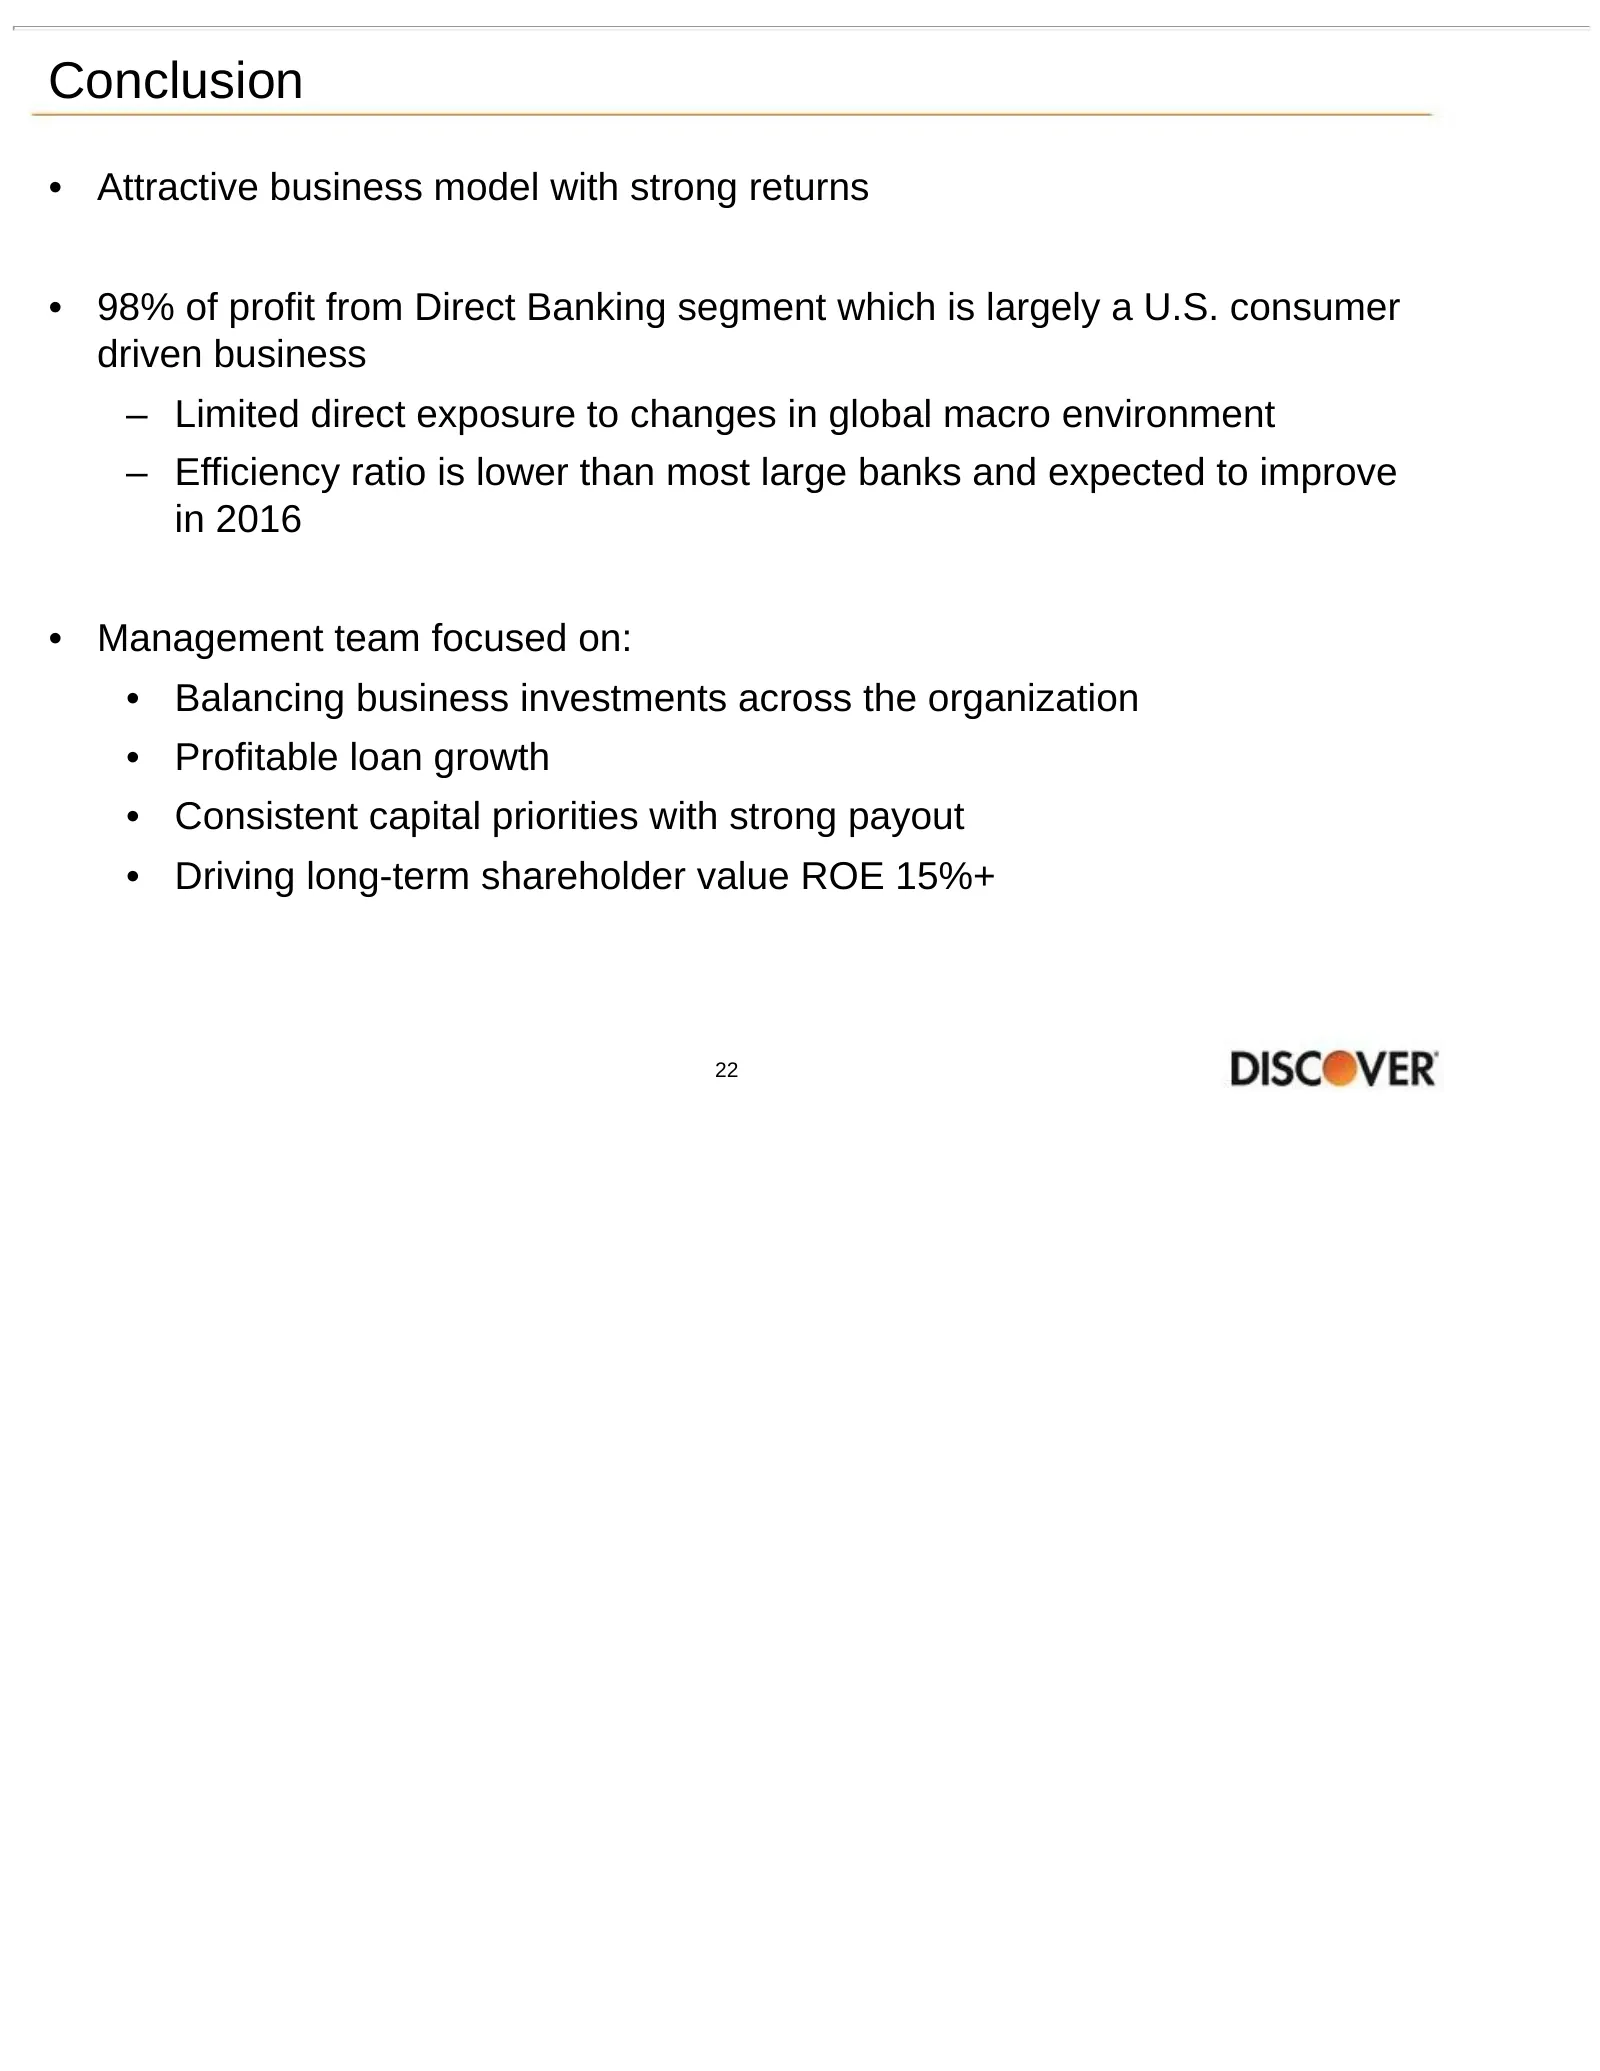
Slide 22: Conclusion
Conclusion • Attractive business model with strong returns • 98% of profit from Direct Banking segment which is largely a U.S. consumer driven business – Limited direct exposure to changes in global macro environment – Efficiency ratio is lower than most large banks and expected to improve in 2016 •
Slide 23: Appendix
Appendix DISC@®VER
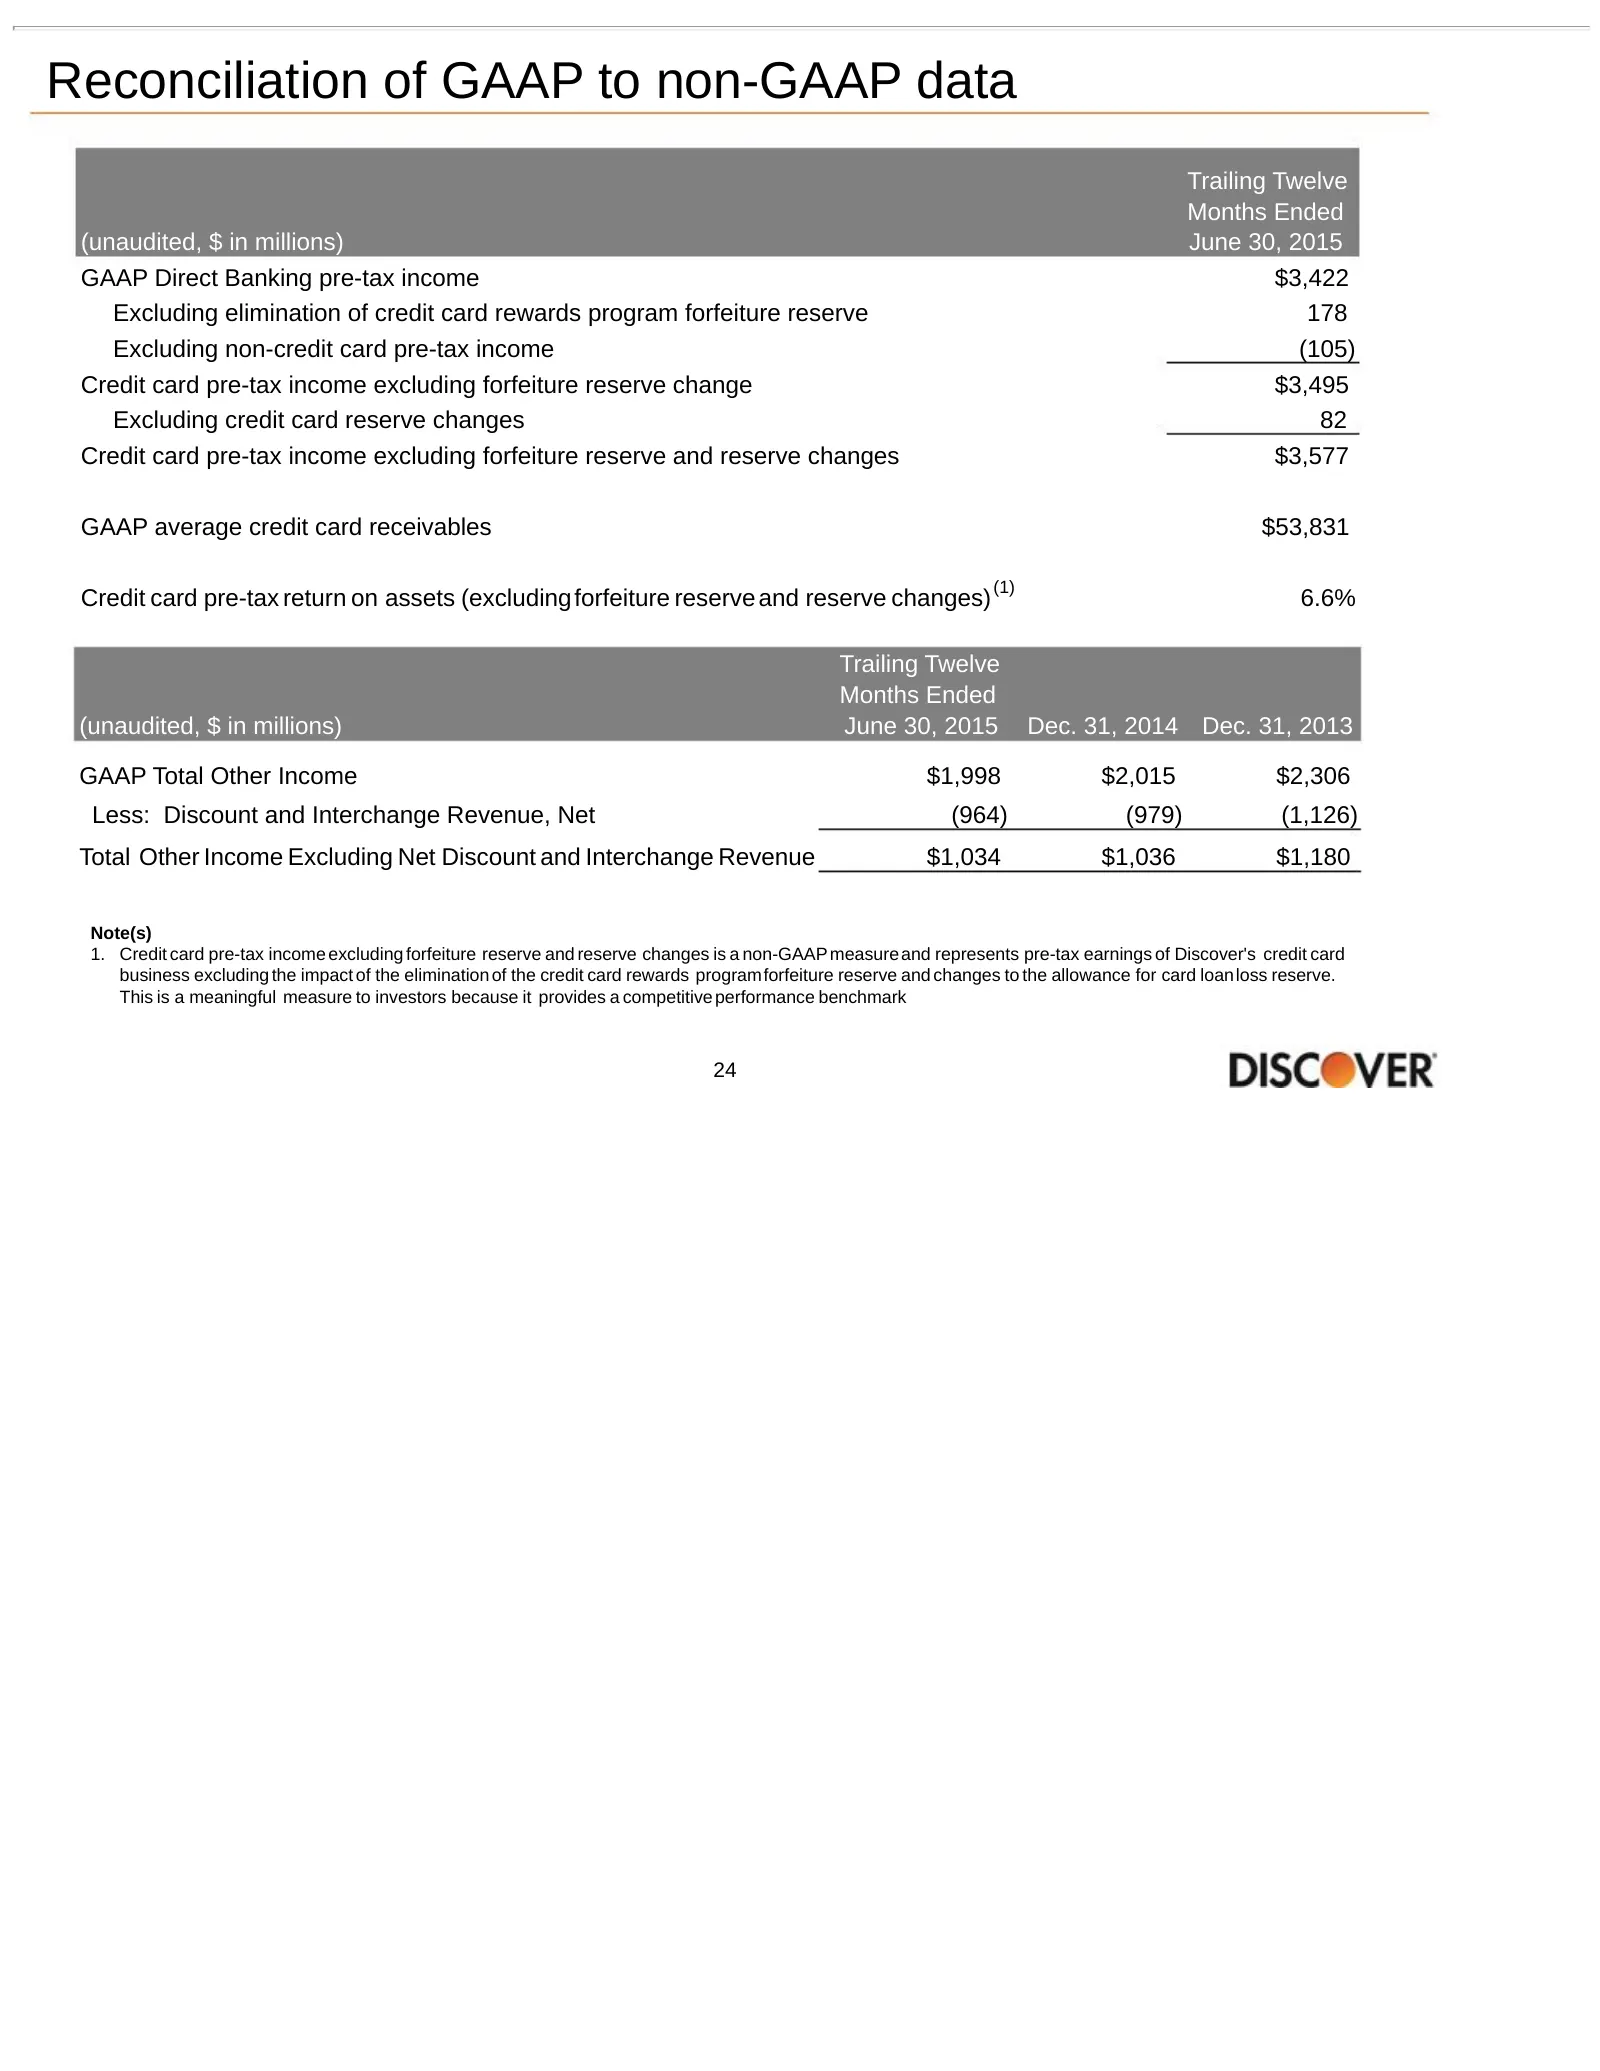
Slide 24: Reconciliation of GAAP to non-GAAP data
Reconciliation of GAAP to non-GAAP data Trailing Twelve Months Ended (unaudited, $ in millions) June 30, 2015 GAAP Direct Banking pre-tax income $3,422 Excluding elimination of credit card rewards program forfeiture reserve 178 Excluding non-credit card pre-tax income (105) Credit card pre-tax incom
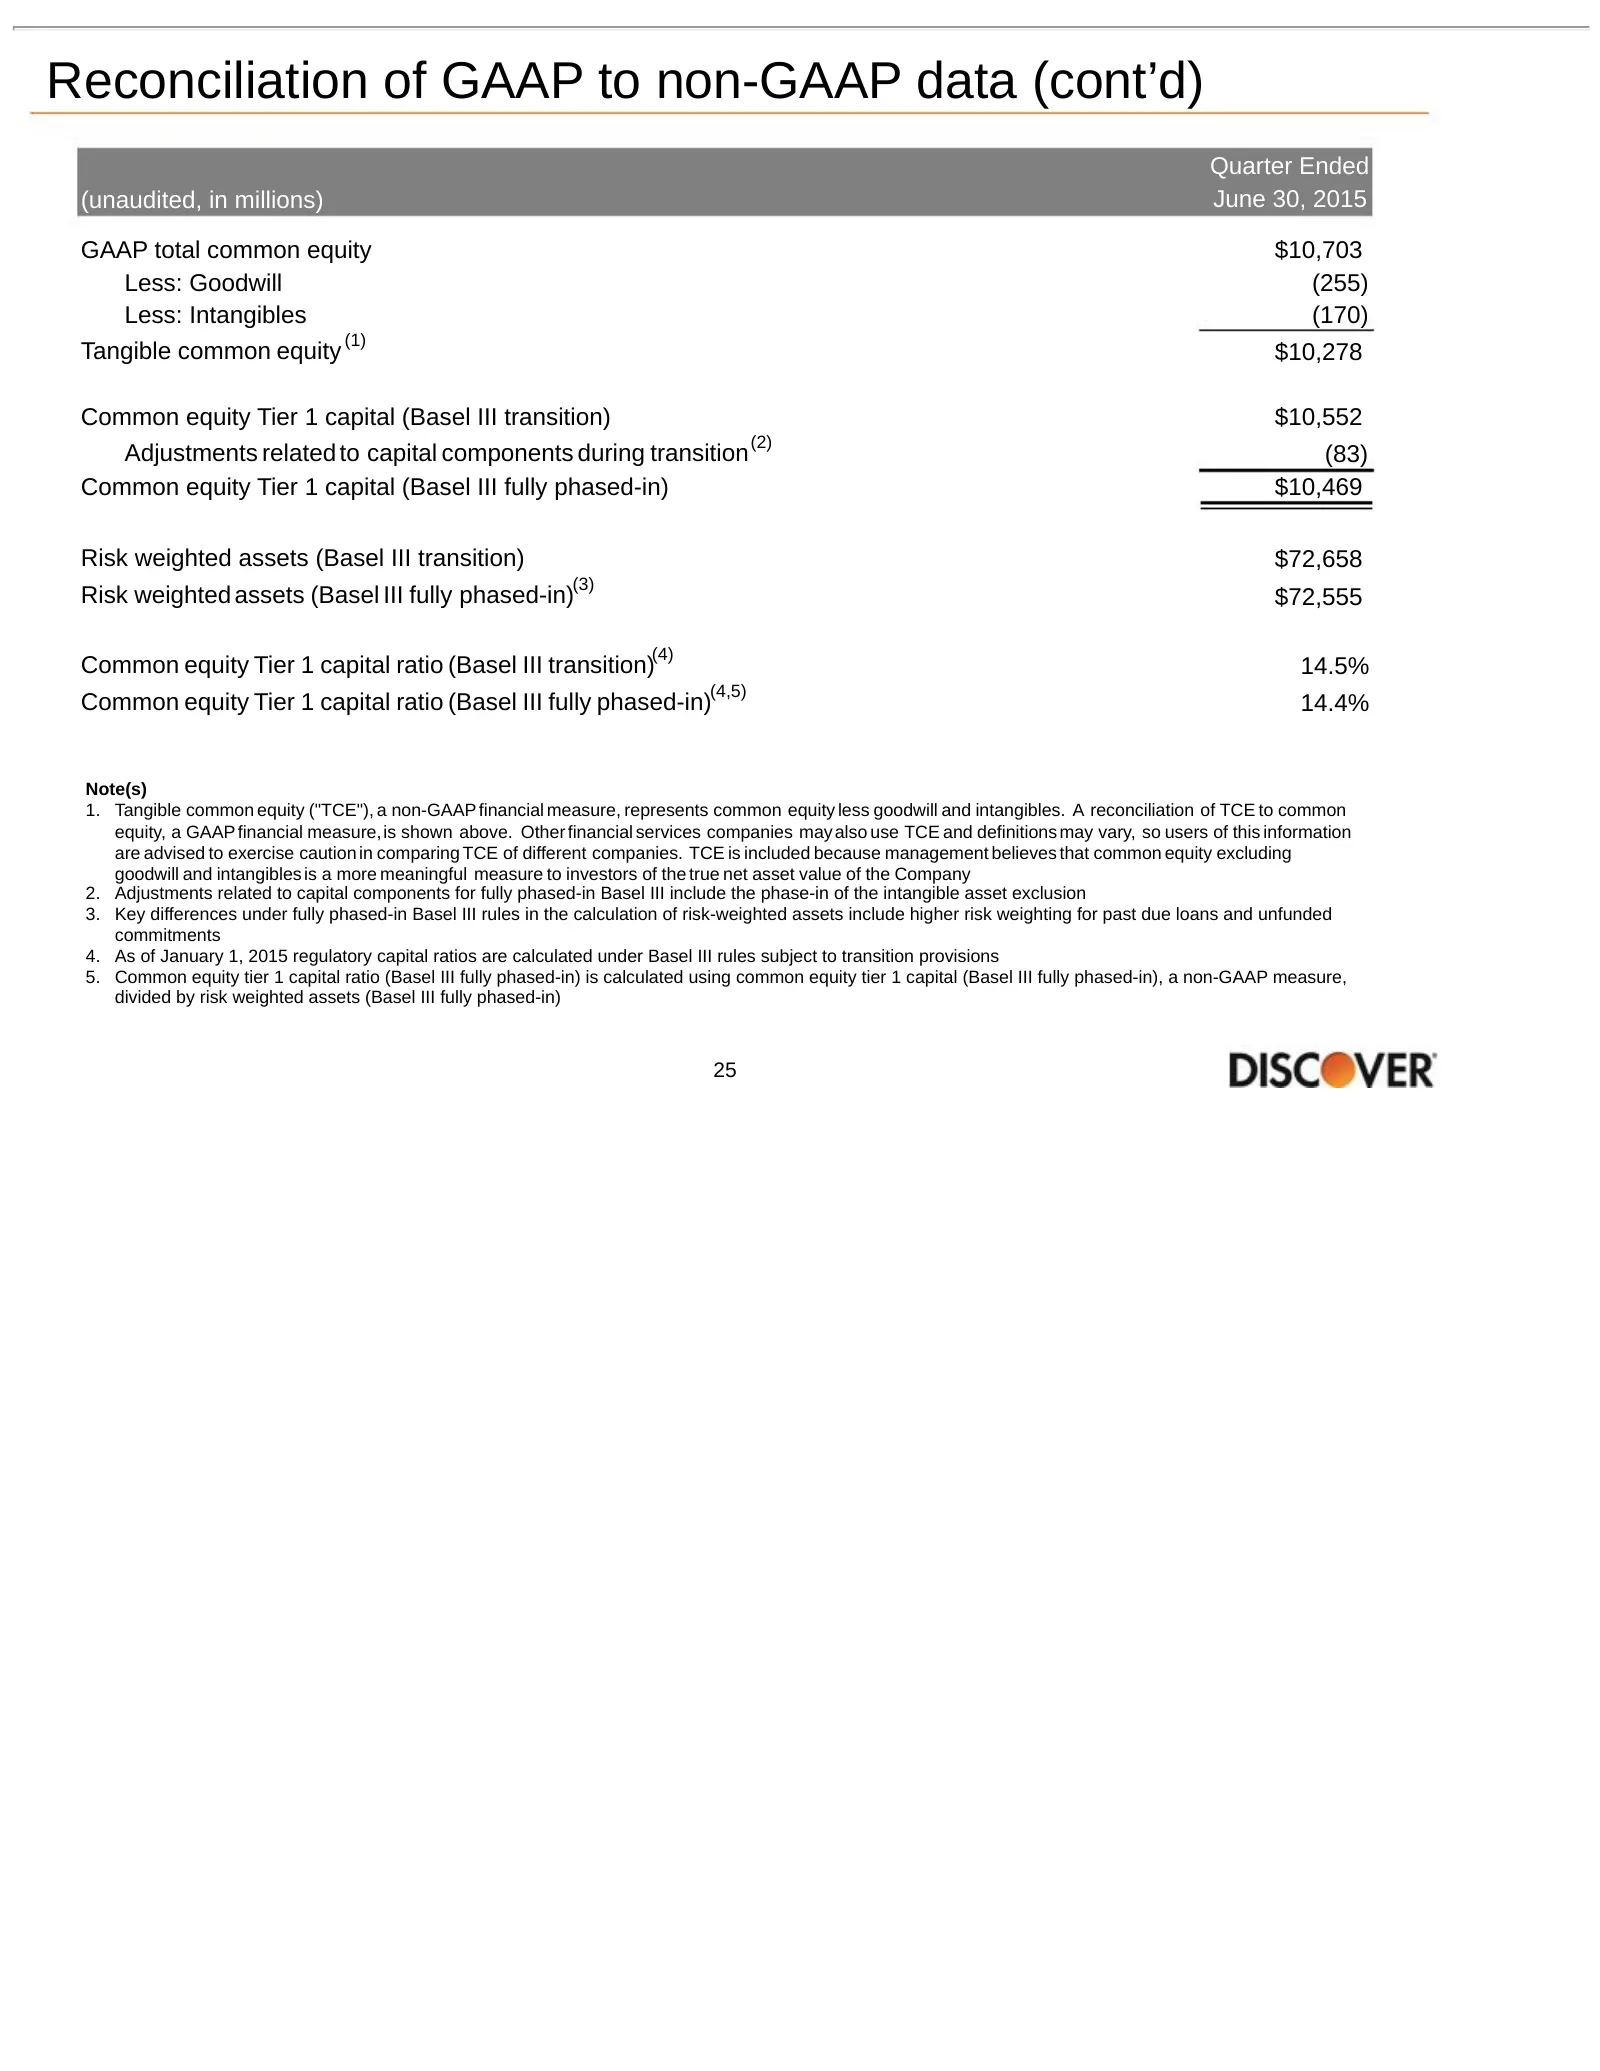
Slide 25: Reconciliation of GAAP to non-GAAP data (cont’d)
Reconciliation of GAAP to non-GAAP data (cont’d) Quarter Ended (unaudited, in millions) June 30, 2015 GAAP total common equity $10,703 Less: Goodwill (255) Less: Intangibles (170) (1) Tangible common equity $10,278 Common equity Tier 1 capital (Basel III transition) $10,552 (2) Adjustments related t
Source: SEC EDGAR · 8-K filed Sep 17, 2015
More decks from Discover Financial Services
 Q1 2025 Earnings Presentation15 slides · Apr 23, 2025
 Q4 2024 Earnings Presentation17 slides · Jan 22, 2025
 Q3 2024 Earnings Presentation17 slides · Oct 16, 2024
 Q2 2024 Earnings Presentation17 slides · Jul 17, 2024
 Q1 2024 Earnings Presentation17 slides · Apr 17, 2024
 Merger or Acquisition (February 2024)27 slides · Feb 20, 2024