Independence Contract Drilling Inc
Independence Contract Drilling — Evercore ISI Oilfield Services Tour & Growth Company 1x1 Forum (March 2015)
26 slides from Independence Contract Drilling's conference presentation, Mar 11, 2015
Slide 1: Independence Contract Drilling – Evercore ISI Oilfield Services Tour & Growth Company 1x1 Forum
Exhibit 99.1 Exhibit11, Independence Evercore March 99.1 ISI 2015 Oilfield ContractTour Drilling & Growth Company 1x1 Forum
Slide 2: Our Vision
Customer Our VISION HSE customers’ Fiancial Integrity People vision stewardship focus is expectations to be the premier and in US so doing, land drilling maximizecompany value for whoallprovides stakeholders. best in class drilling services with a focus on our employees, technology and HSE. We will
Slide 3: Forward-Looking Statements
Forward-Looking Various looking accompanied forward-looking unduly. are and Securities performance decline fluctuation inability delays an our overcapacity new labor increased the lack uncertainties All undue as unanticipated Each rating derivative Management period these aindicator EBITDA 3comparab
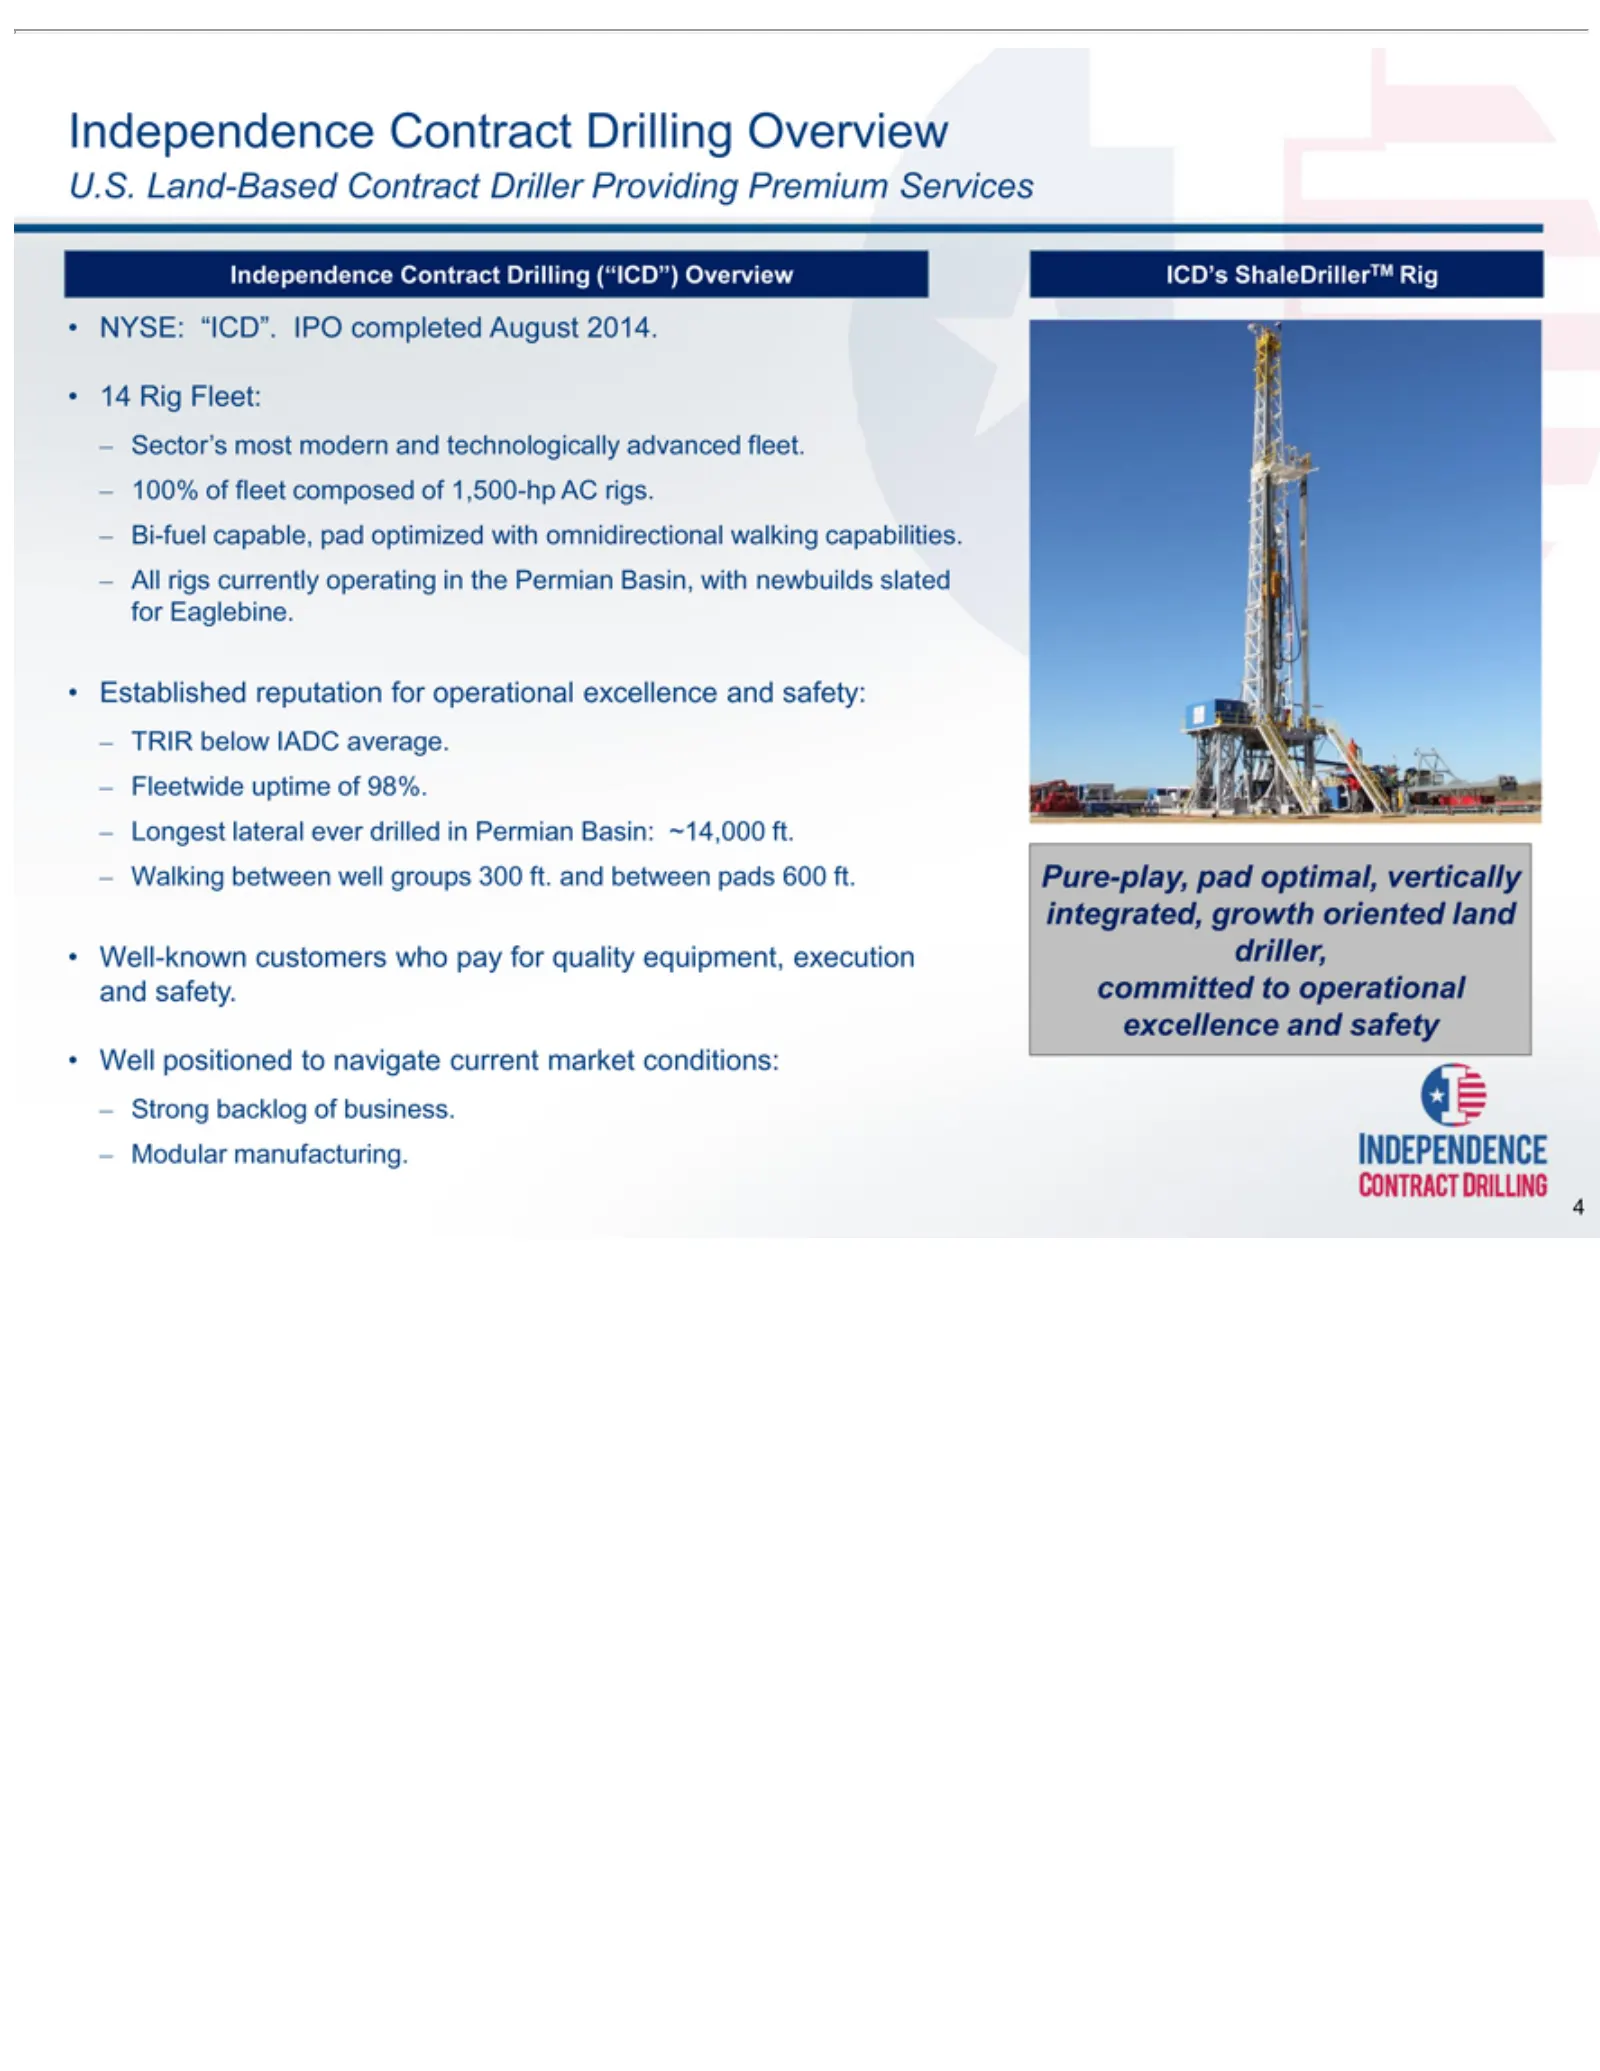
Slide 4: ICD Overview
U.S. Independence NYSE: 14 Sector’s 100% Bi-fuel All Established TRIR Fleetwide Longest Walking Well-known Well Strong Modular ICD’s 4Pure-play, Rig rigs Land-Based positioned below of ShaleDrillerTM backlog Fleet: capable, “ICD”. currently lateral most between fleet manufacturing. uptime pad reputa
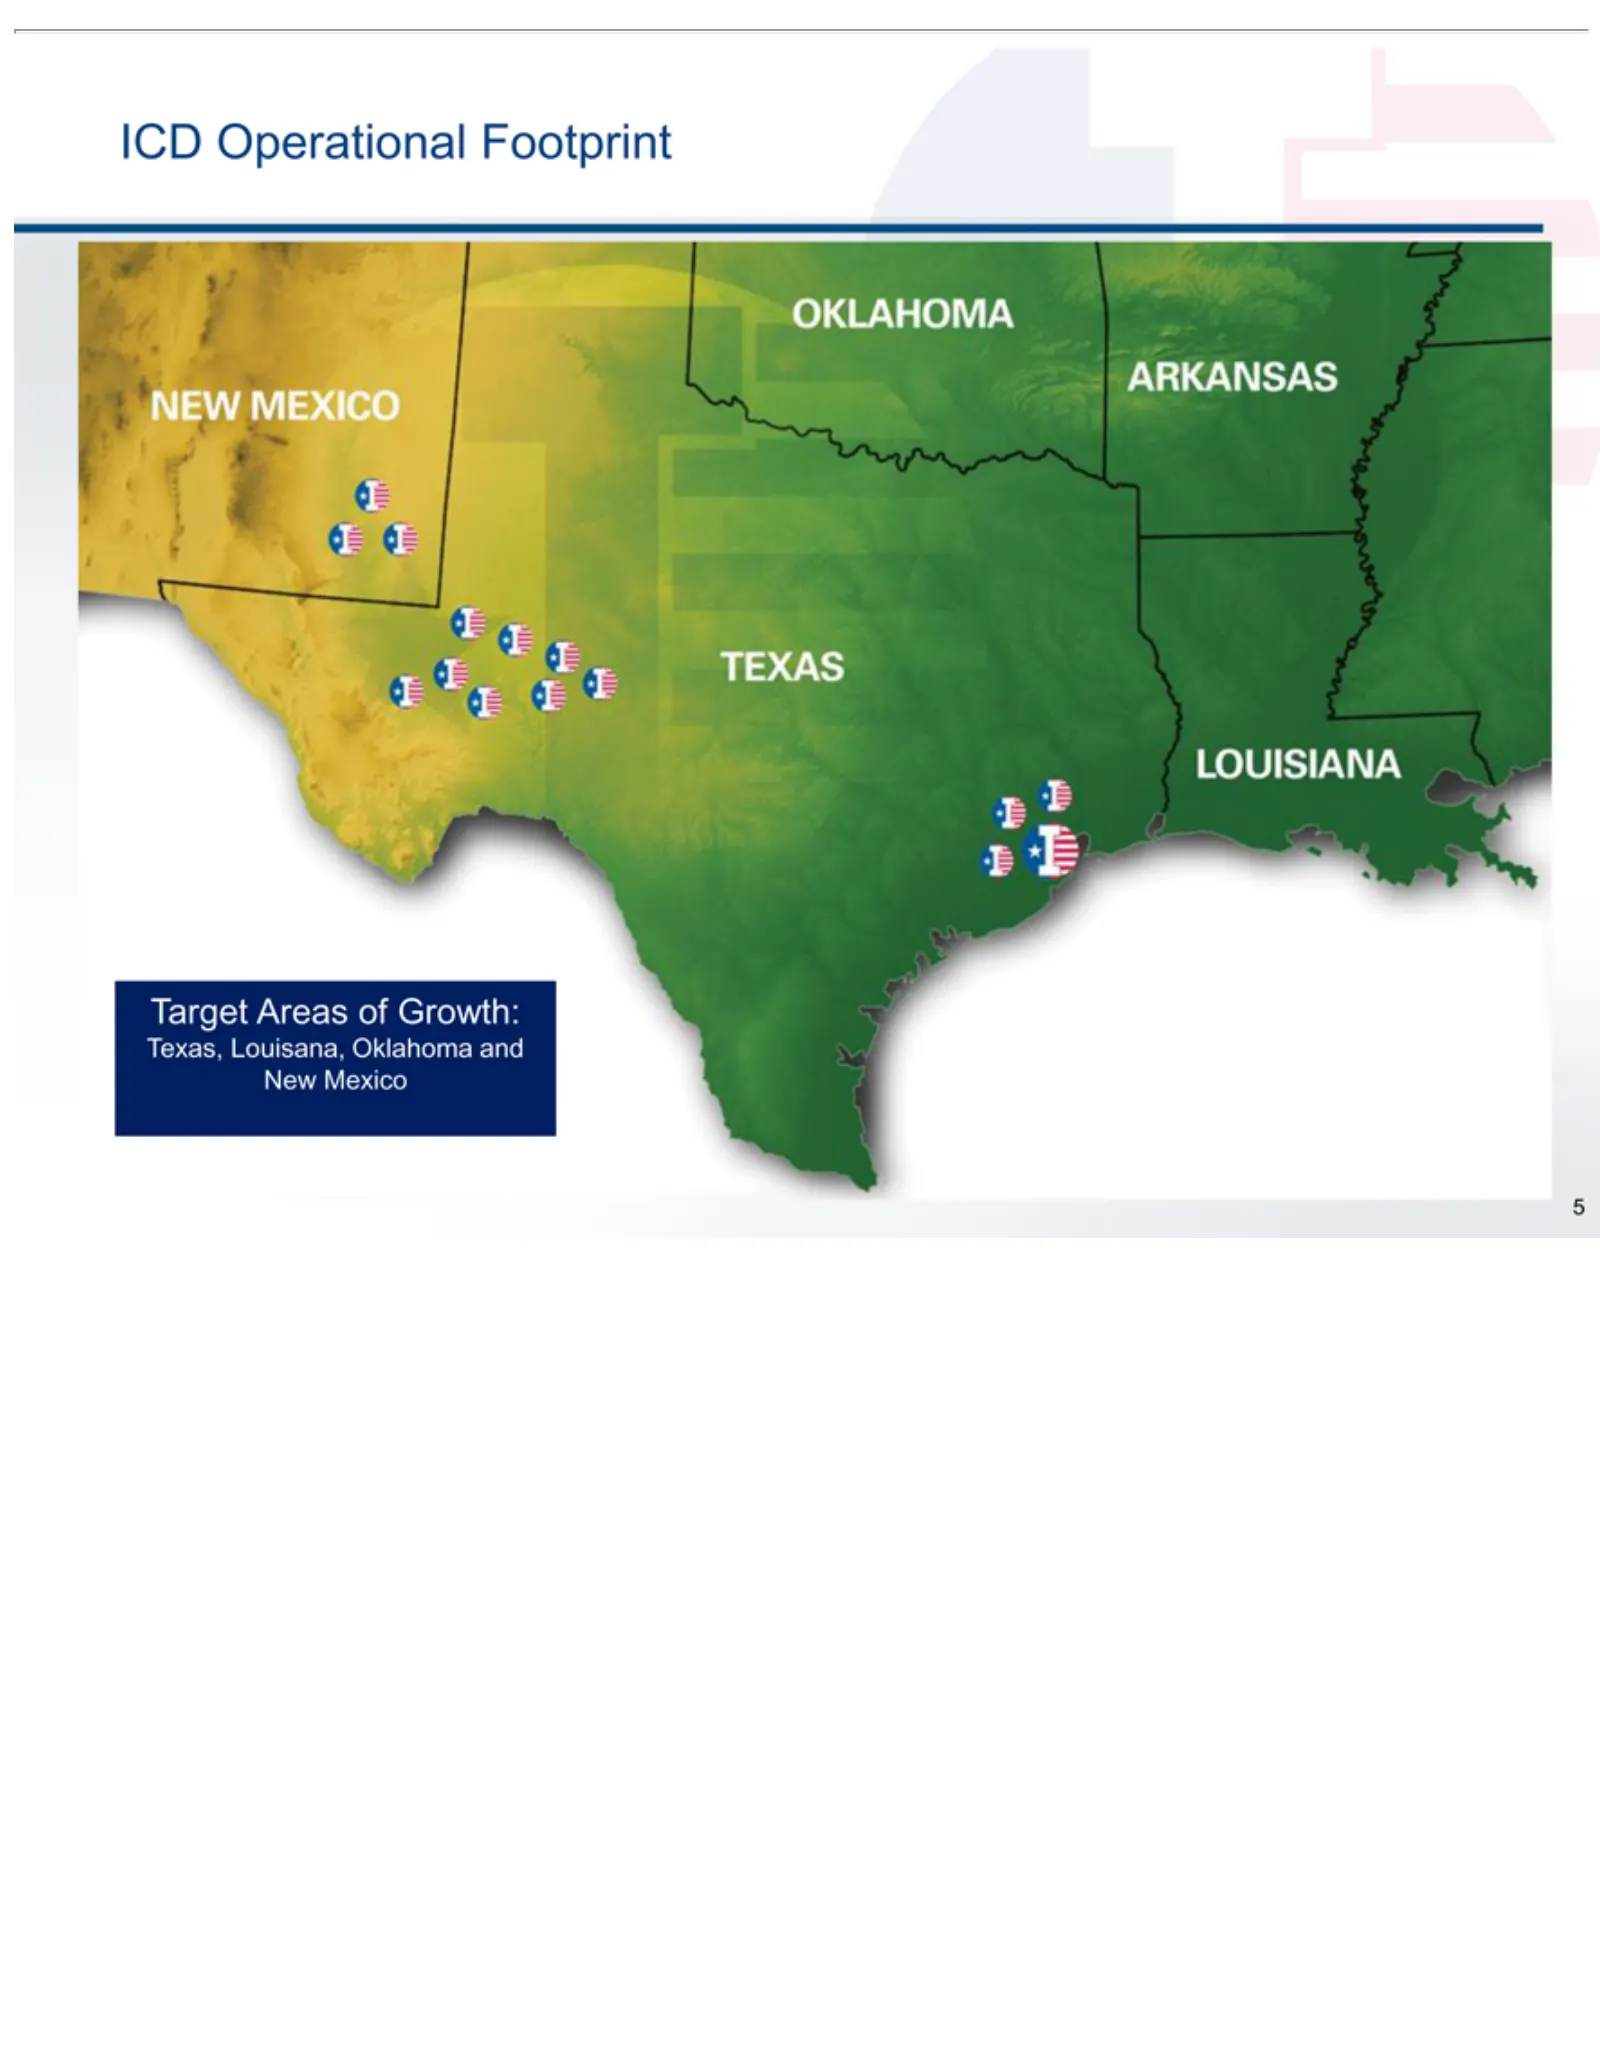
Slide 5: ICD Operational Footprint and Target Areas of Growth
ICD Operational Target 5Texas, Areas Louisana, of Growth: Footprint Oklahoma and New Mexico
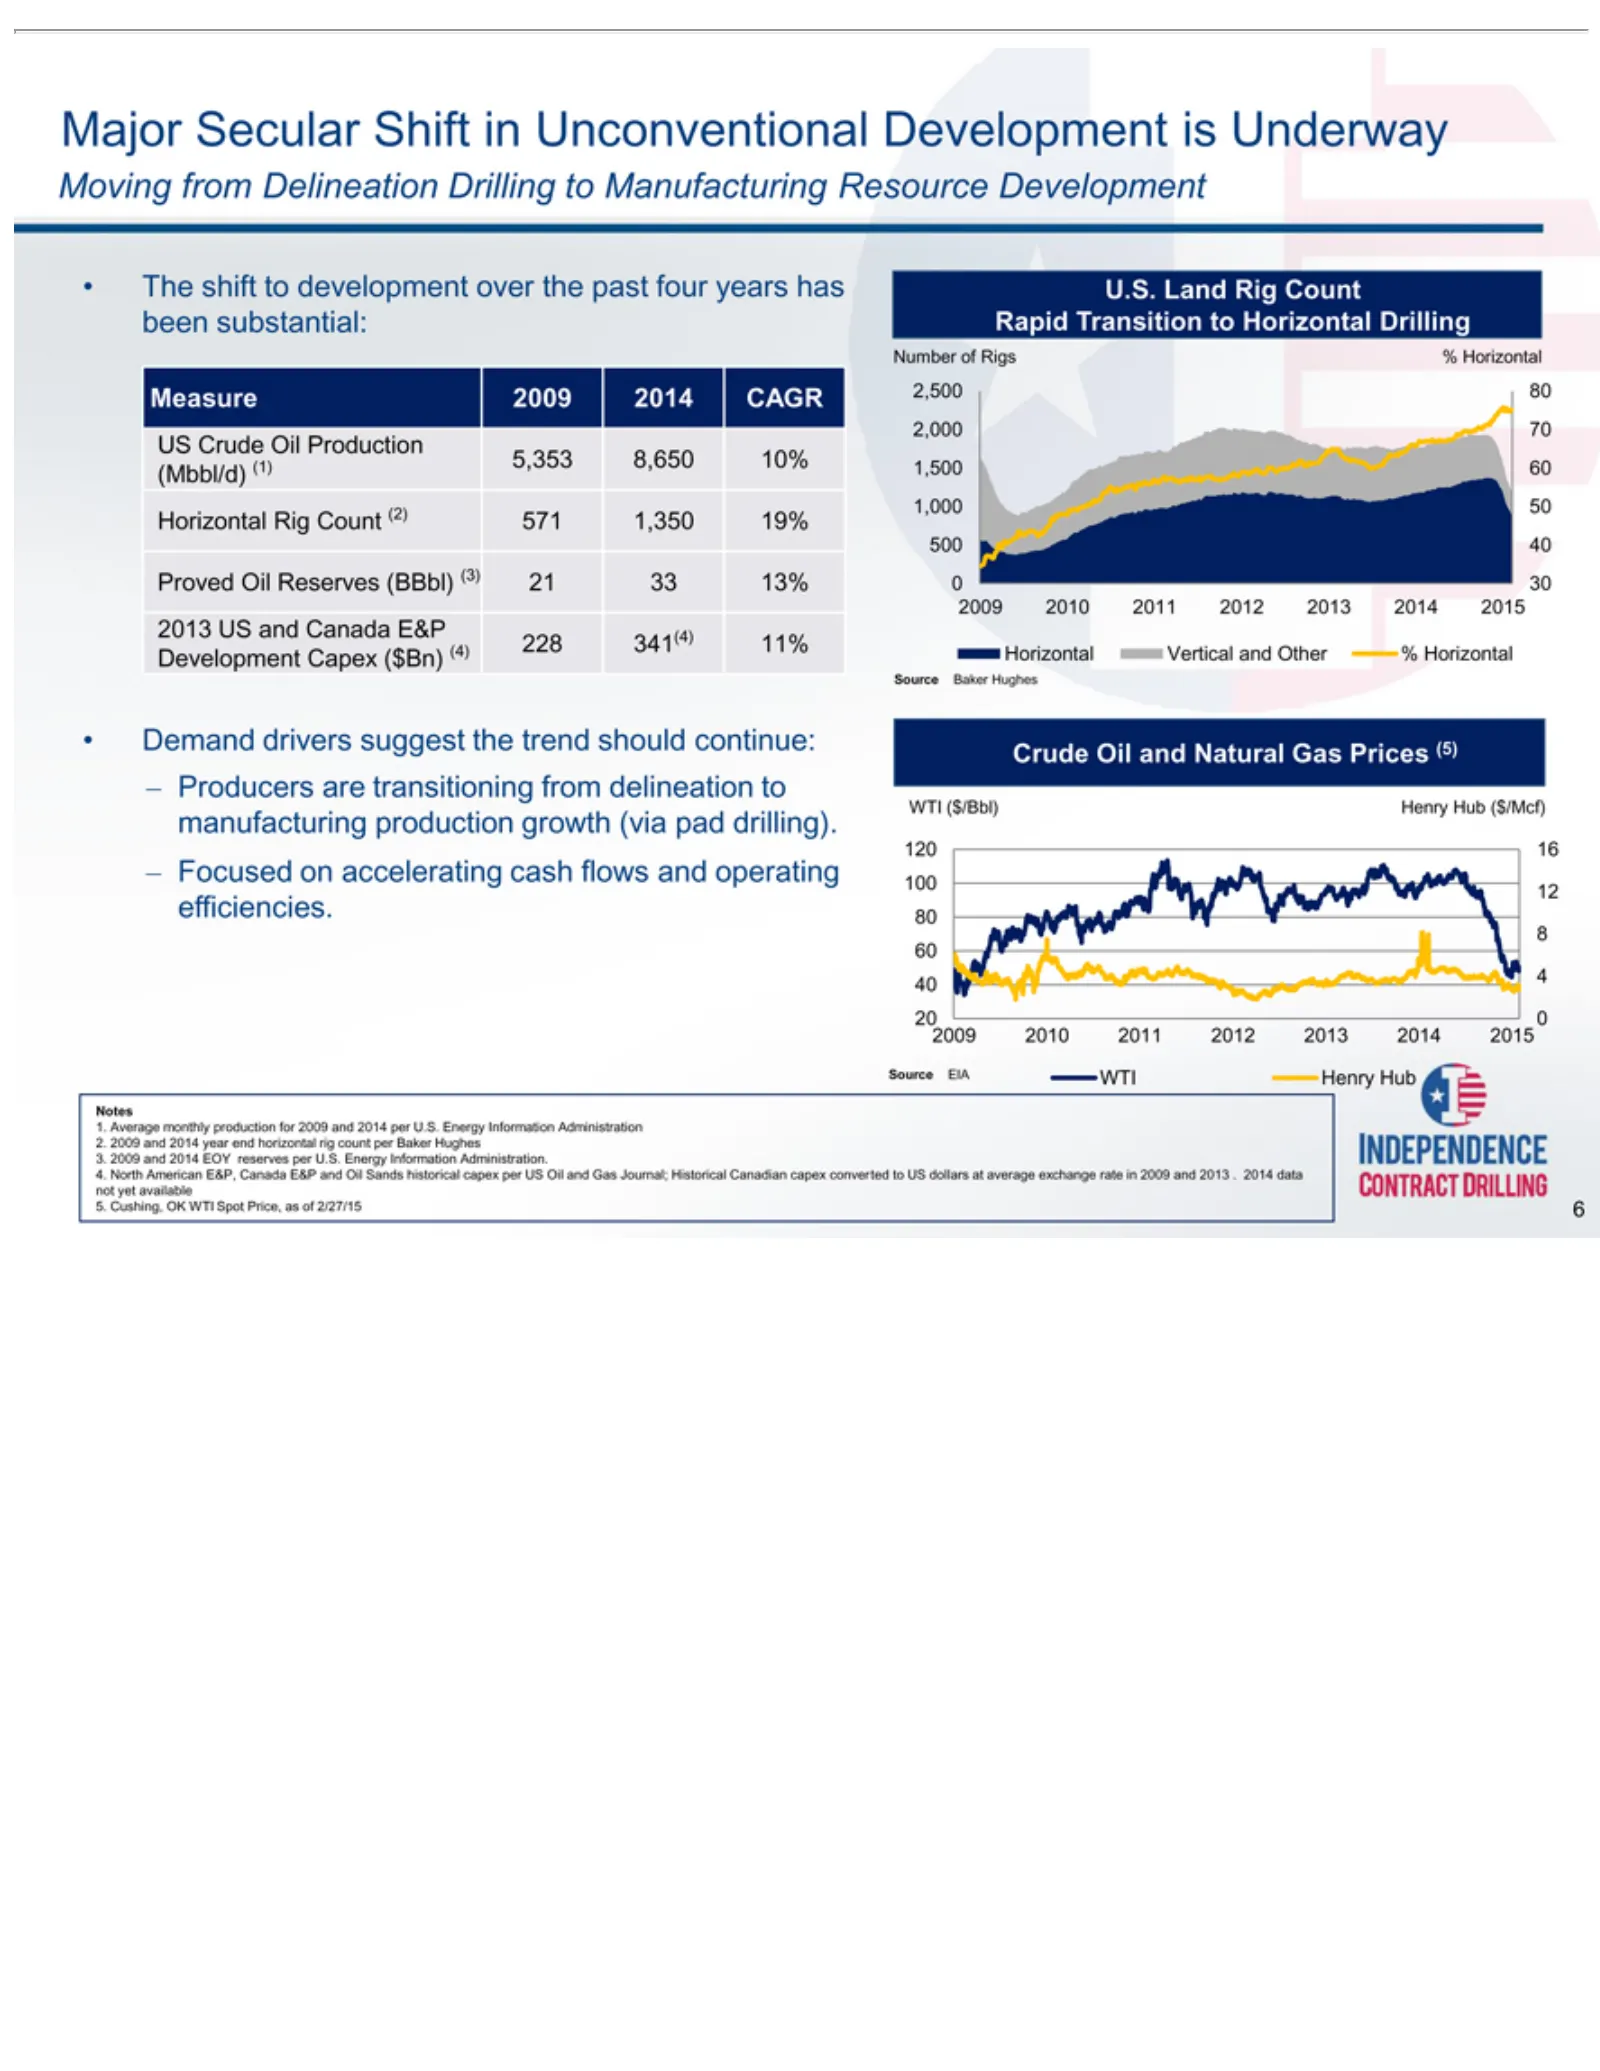
Slide 6: Major Secular Shift Moving Drilling to Horizontal Unconventional
Major Moving The U.S. been Rapid Number Measure 2,000 US (Mbbl/d) Horizontal 500 Proved 2013 Development Demand Producers Focused Crude WTI 120 86100 80 40 20 Source Average Notes 2009 North not 5. 0Cushing, 04yet Crude 40 16 12 shift Land ($/Bbl) substantial: US 2010 and 70 American Transition Secu
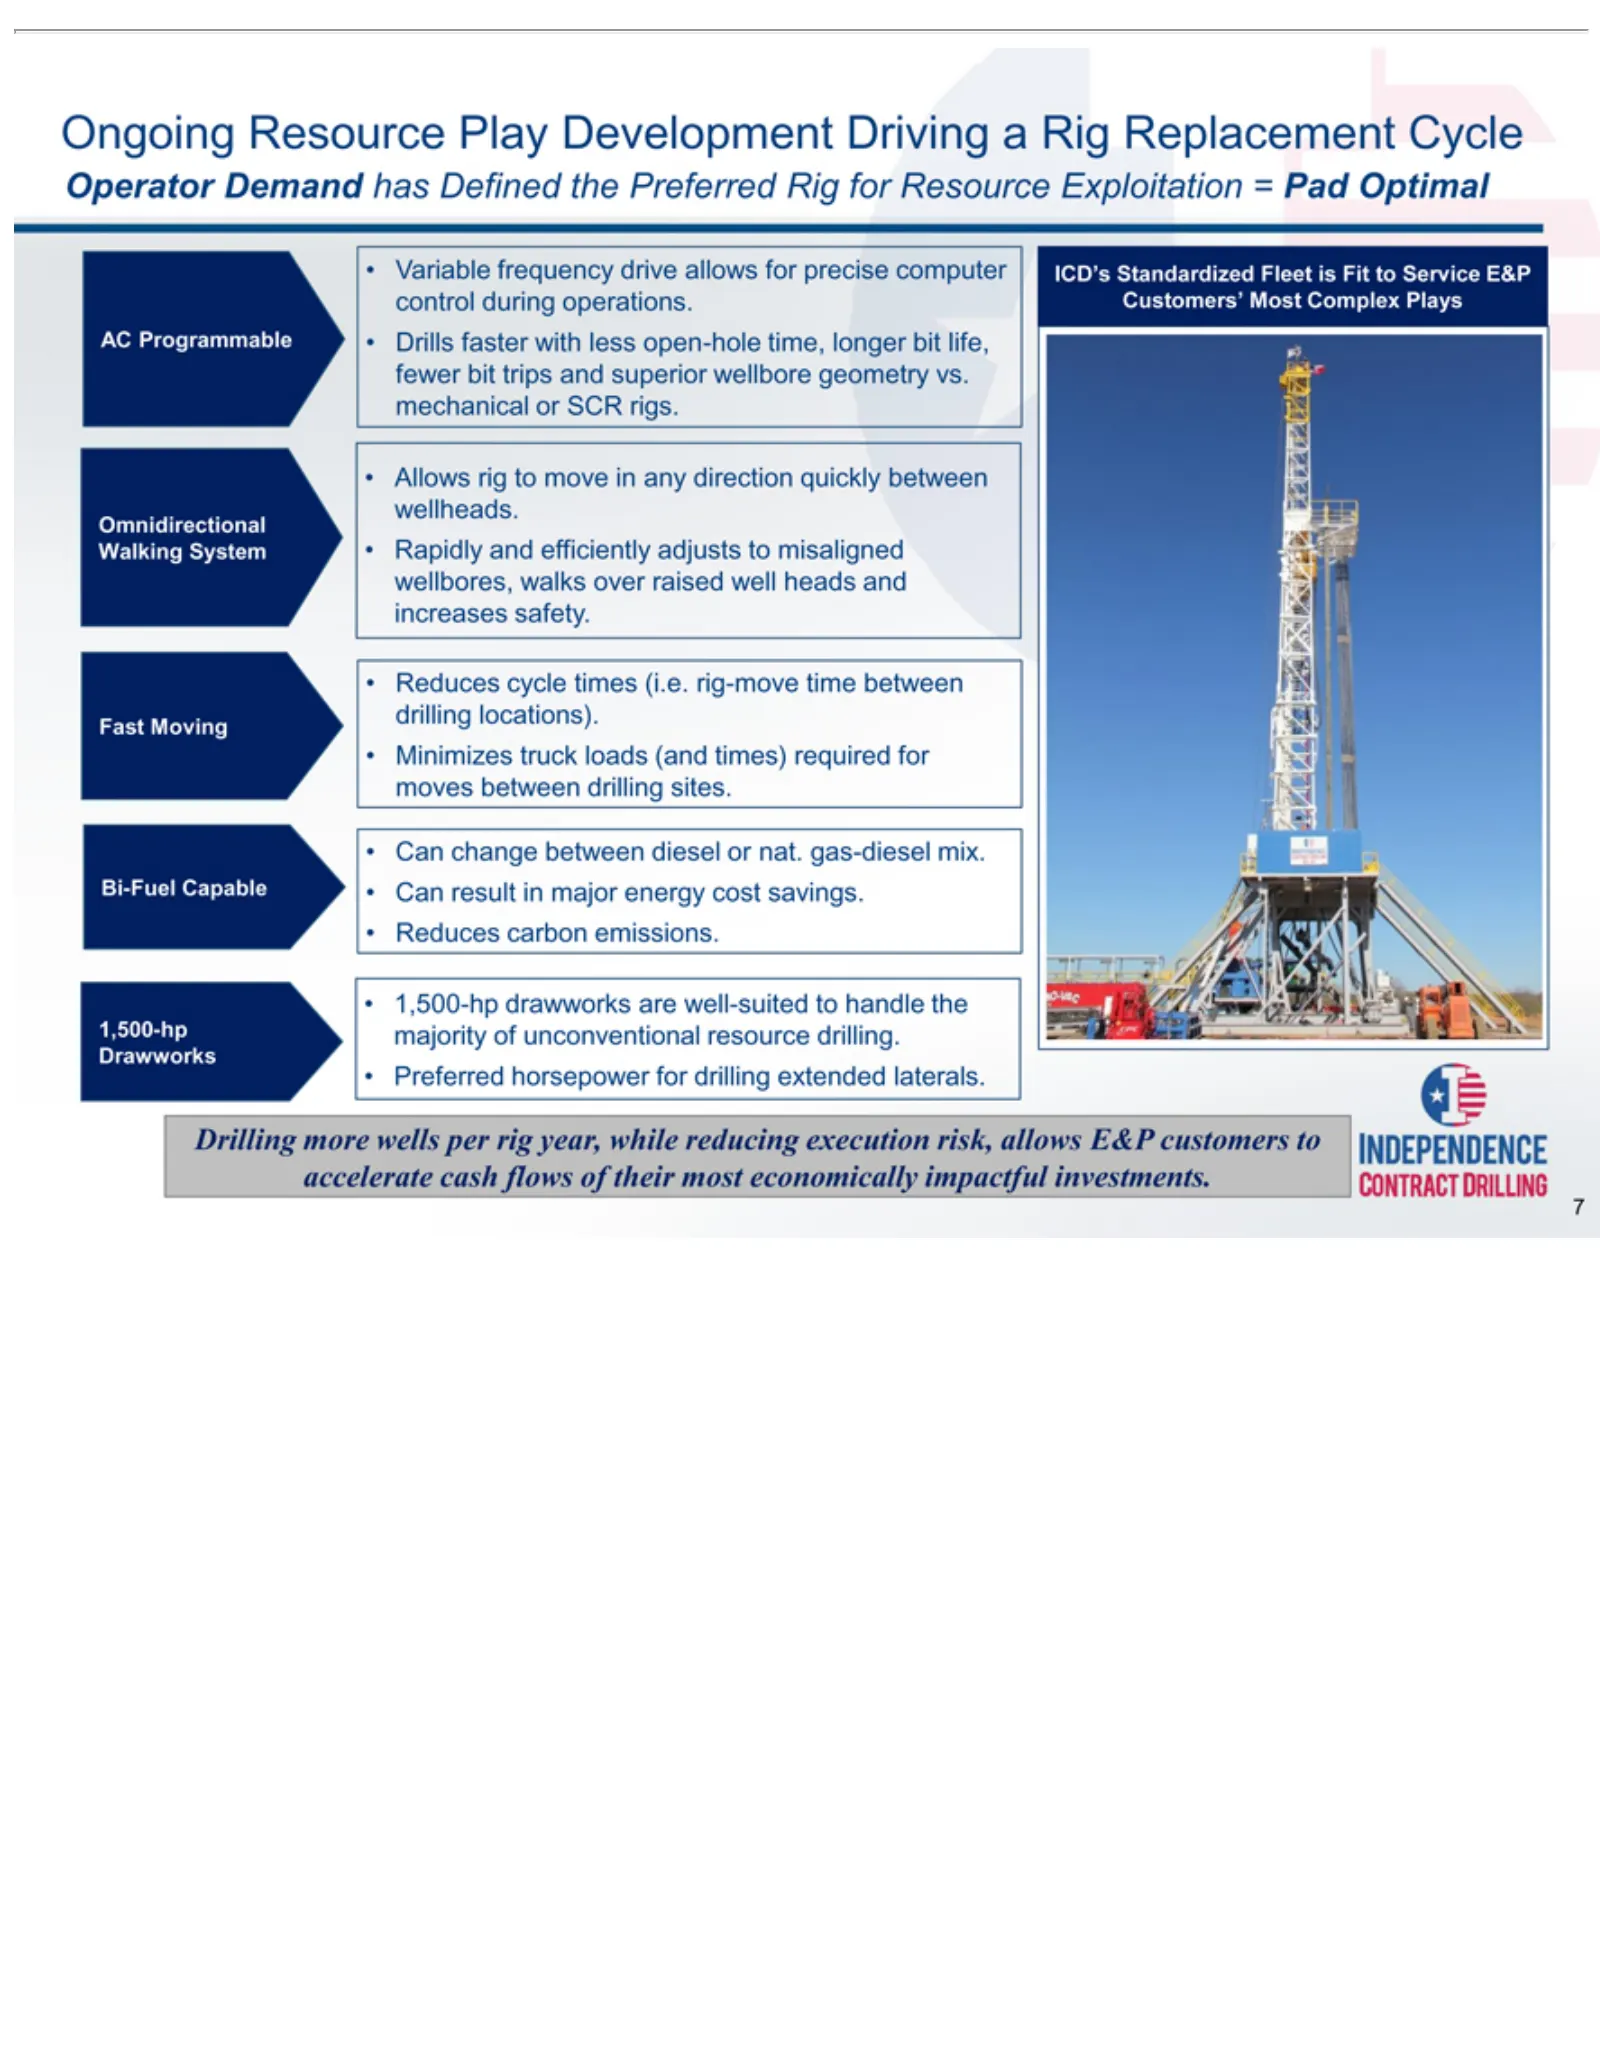
Slide 7: Ongoing Operator Demand for AC Walking Rigs
Ongoing Operator AC Walking Omnidirectional Fast Bi-Fuel Variable Drawworks 1,500-hp control Drills fewer mechanical wellheads. wellbores, increases drilling moves •majority 7Drilling Allows Rapidly Minimizes Can Reduces 1,500-hp Preferred Programmable Moving change result bit faster between during
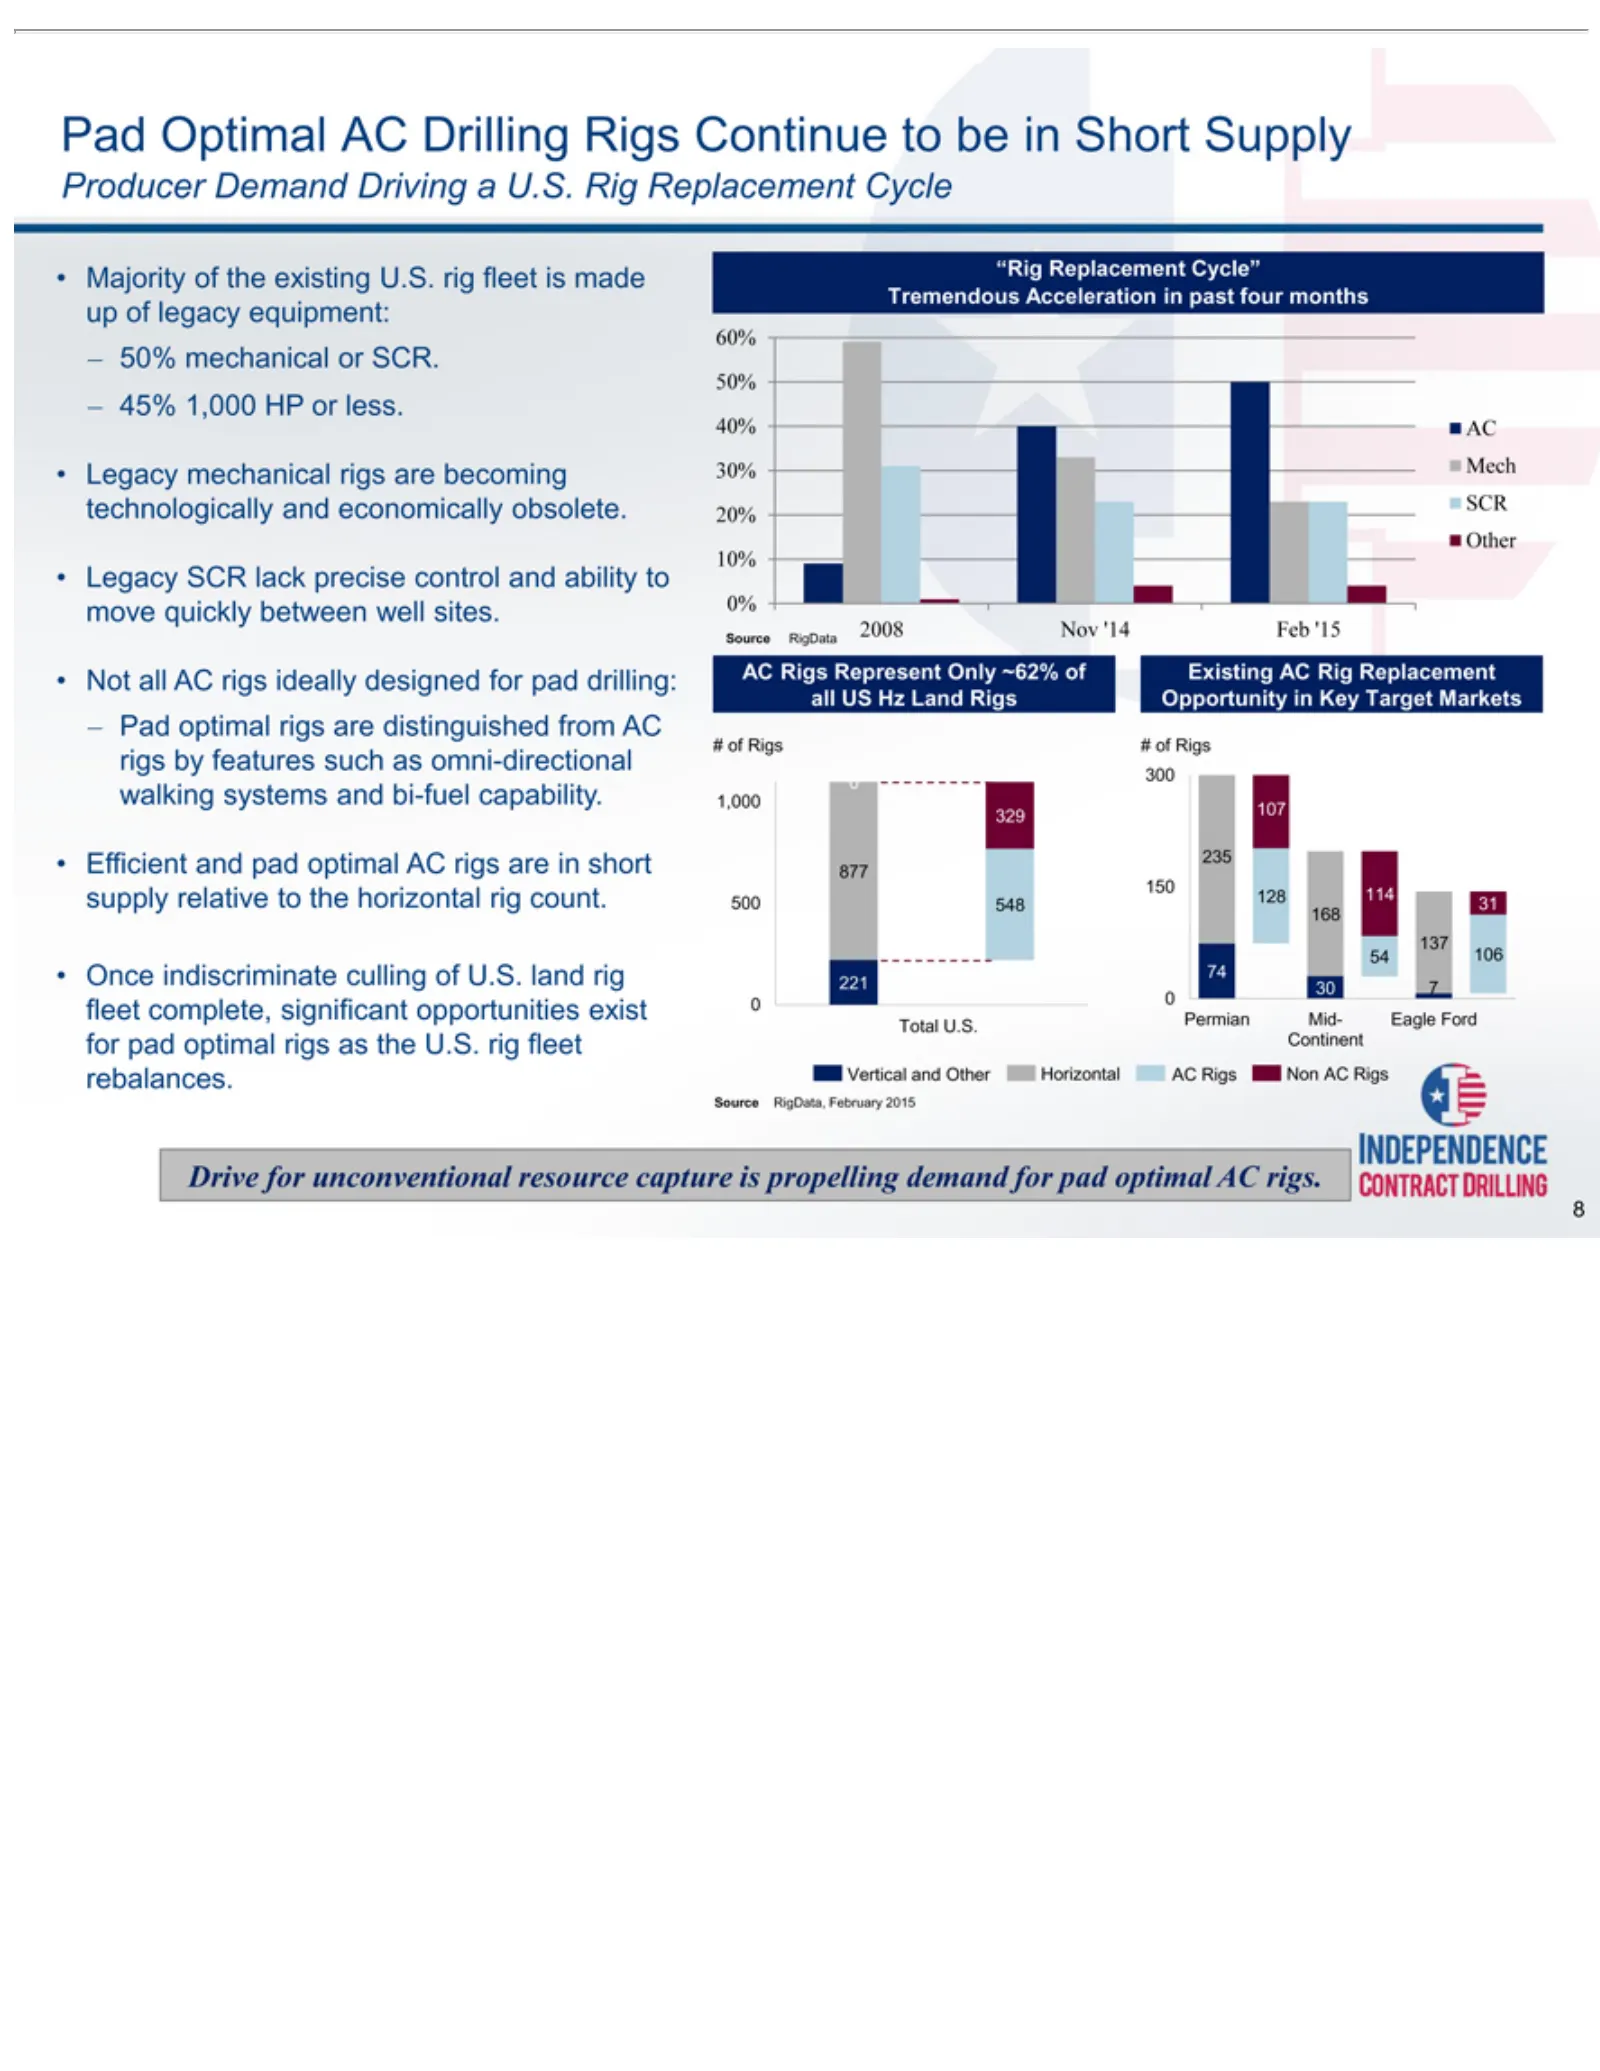
Slide 8: Rig Replacement Cycle Driving Demand for Pad-Optimal Rigs
Producer Majority 45% Legacy Not Pad Efficient Once “Rig Tremendous 40% 50% 60% 30% 20% 0% 10% Other AC #all 329 1,000 150 877 235 500 54 137 168 221 074 Total Vertical Continent Source 8Drive ofUS 0300 106 Rigs Optimal all optimal 107 128 548 30 Rigs AC mechanical 1,000 Mech SCR Replacement U.S. in
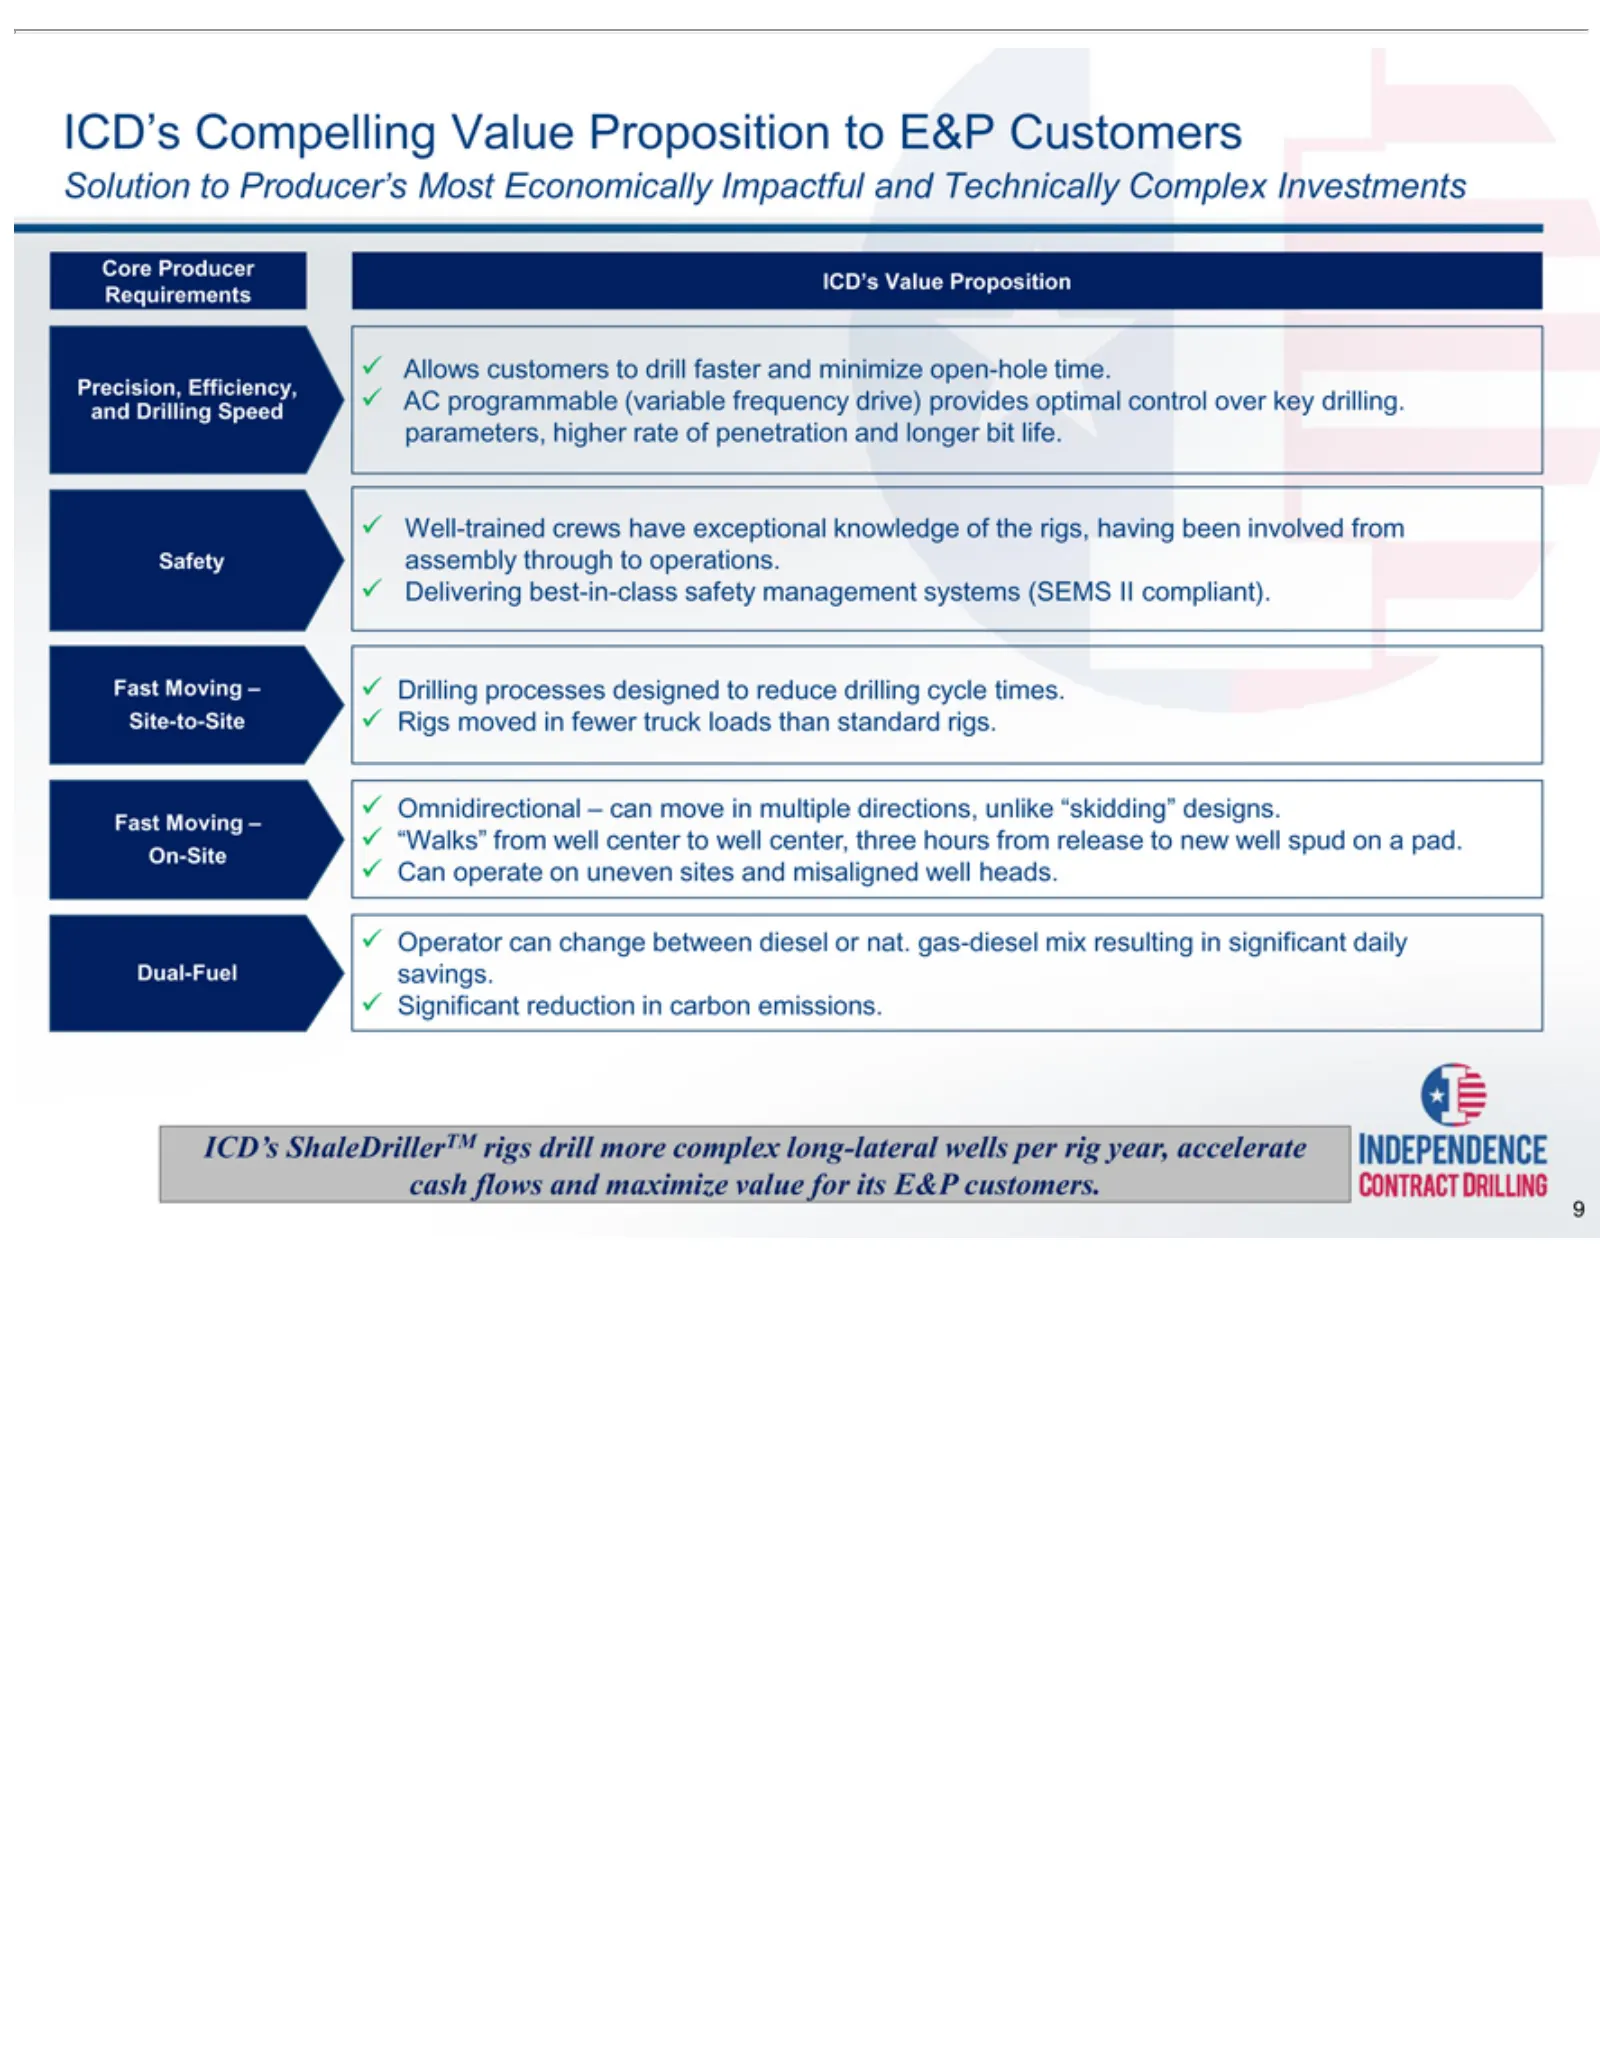
Slide 9: ICD's ShaleDriller Solution and Value Proposition
Solution Core Precision, Safety Fast Dual-Fuel Allows AC Well-trained Delivering Drilling Rigs Omnidirectional “Walks” Can Operator Significant 9ICD’s programmable operate Moving moved Producer Value Compelling ShaleDrillerTM customers processes from to can Efficiency, best-in-class reduction Produc
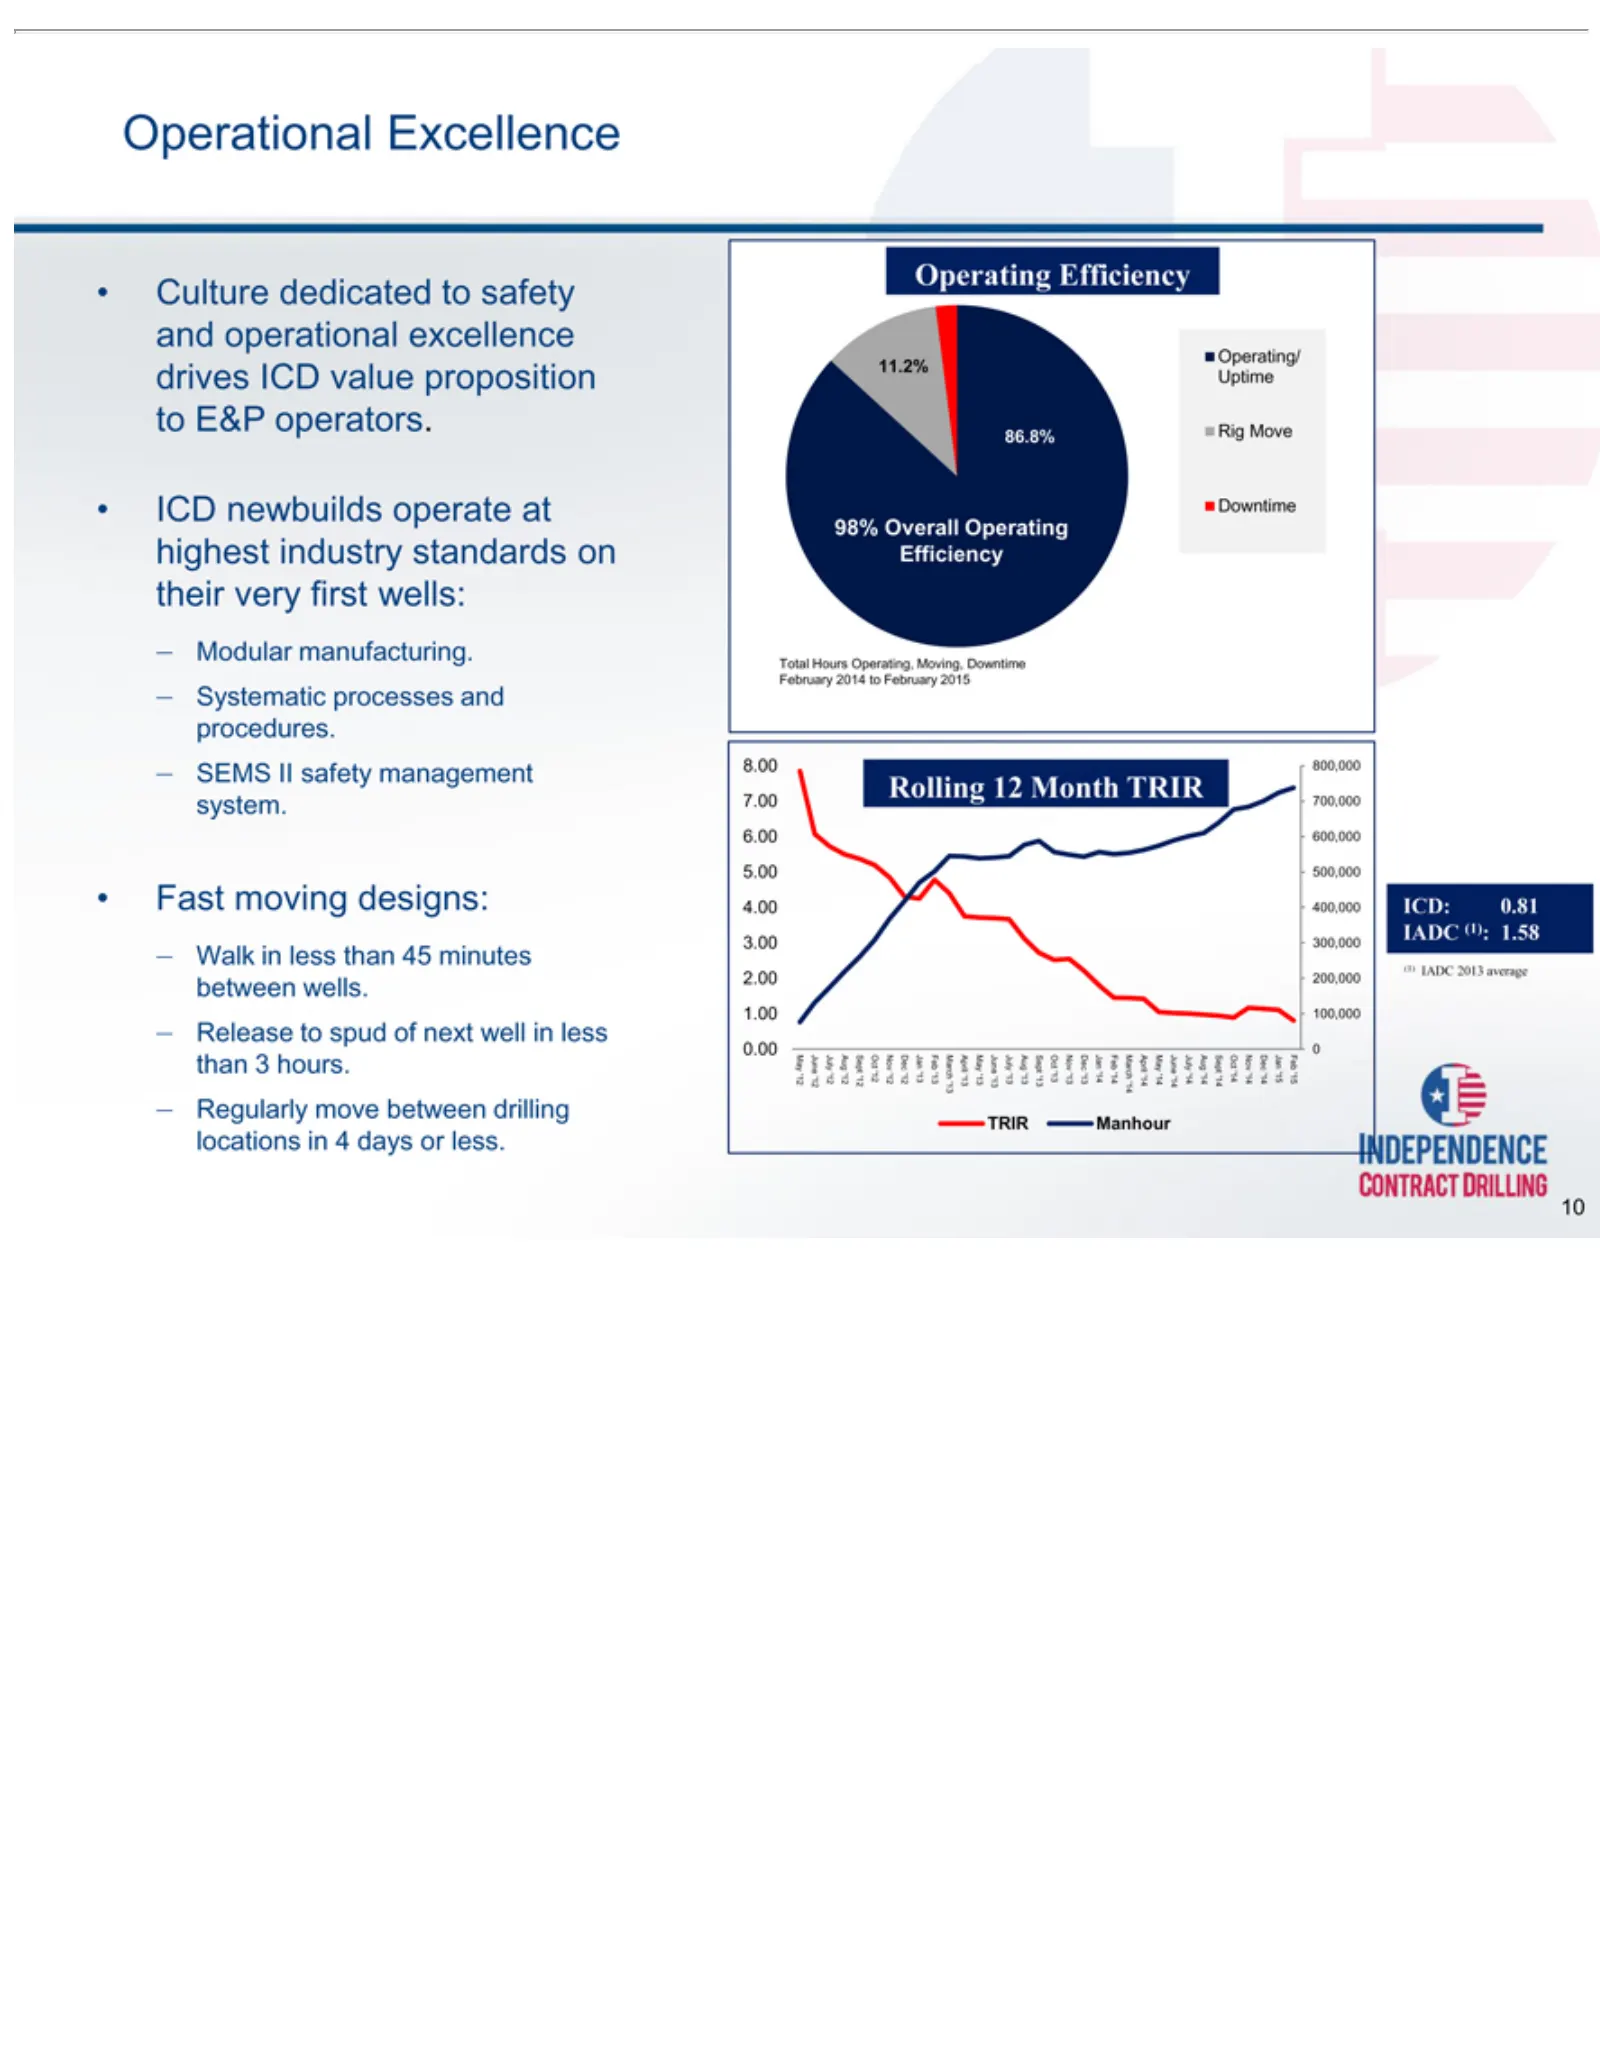
Slide 10: ICD Operational and Safety Excellence Culture
Operational Culture ICD Modular Systematic SEMS Fast Walk Release Regularly Operating 11.2% 86.8% Uptime 98% Downtime Total Efficiency February 081 (1) ICD: 800,000 TRIR Dec Month 12 April March Feb Jan Rolling Nov Oct Sept Aug July June May 800 107100 58 June :6 average ‘15 ‘14 ‘13 ‘14 ‘13 ‘12 ‘15
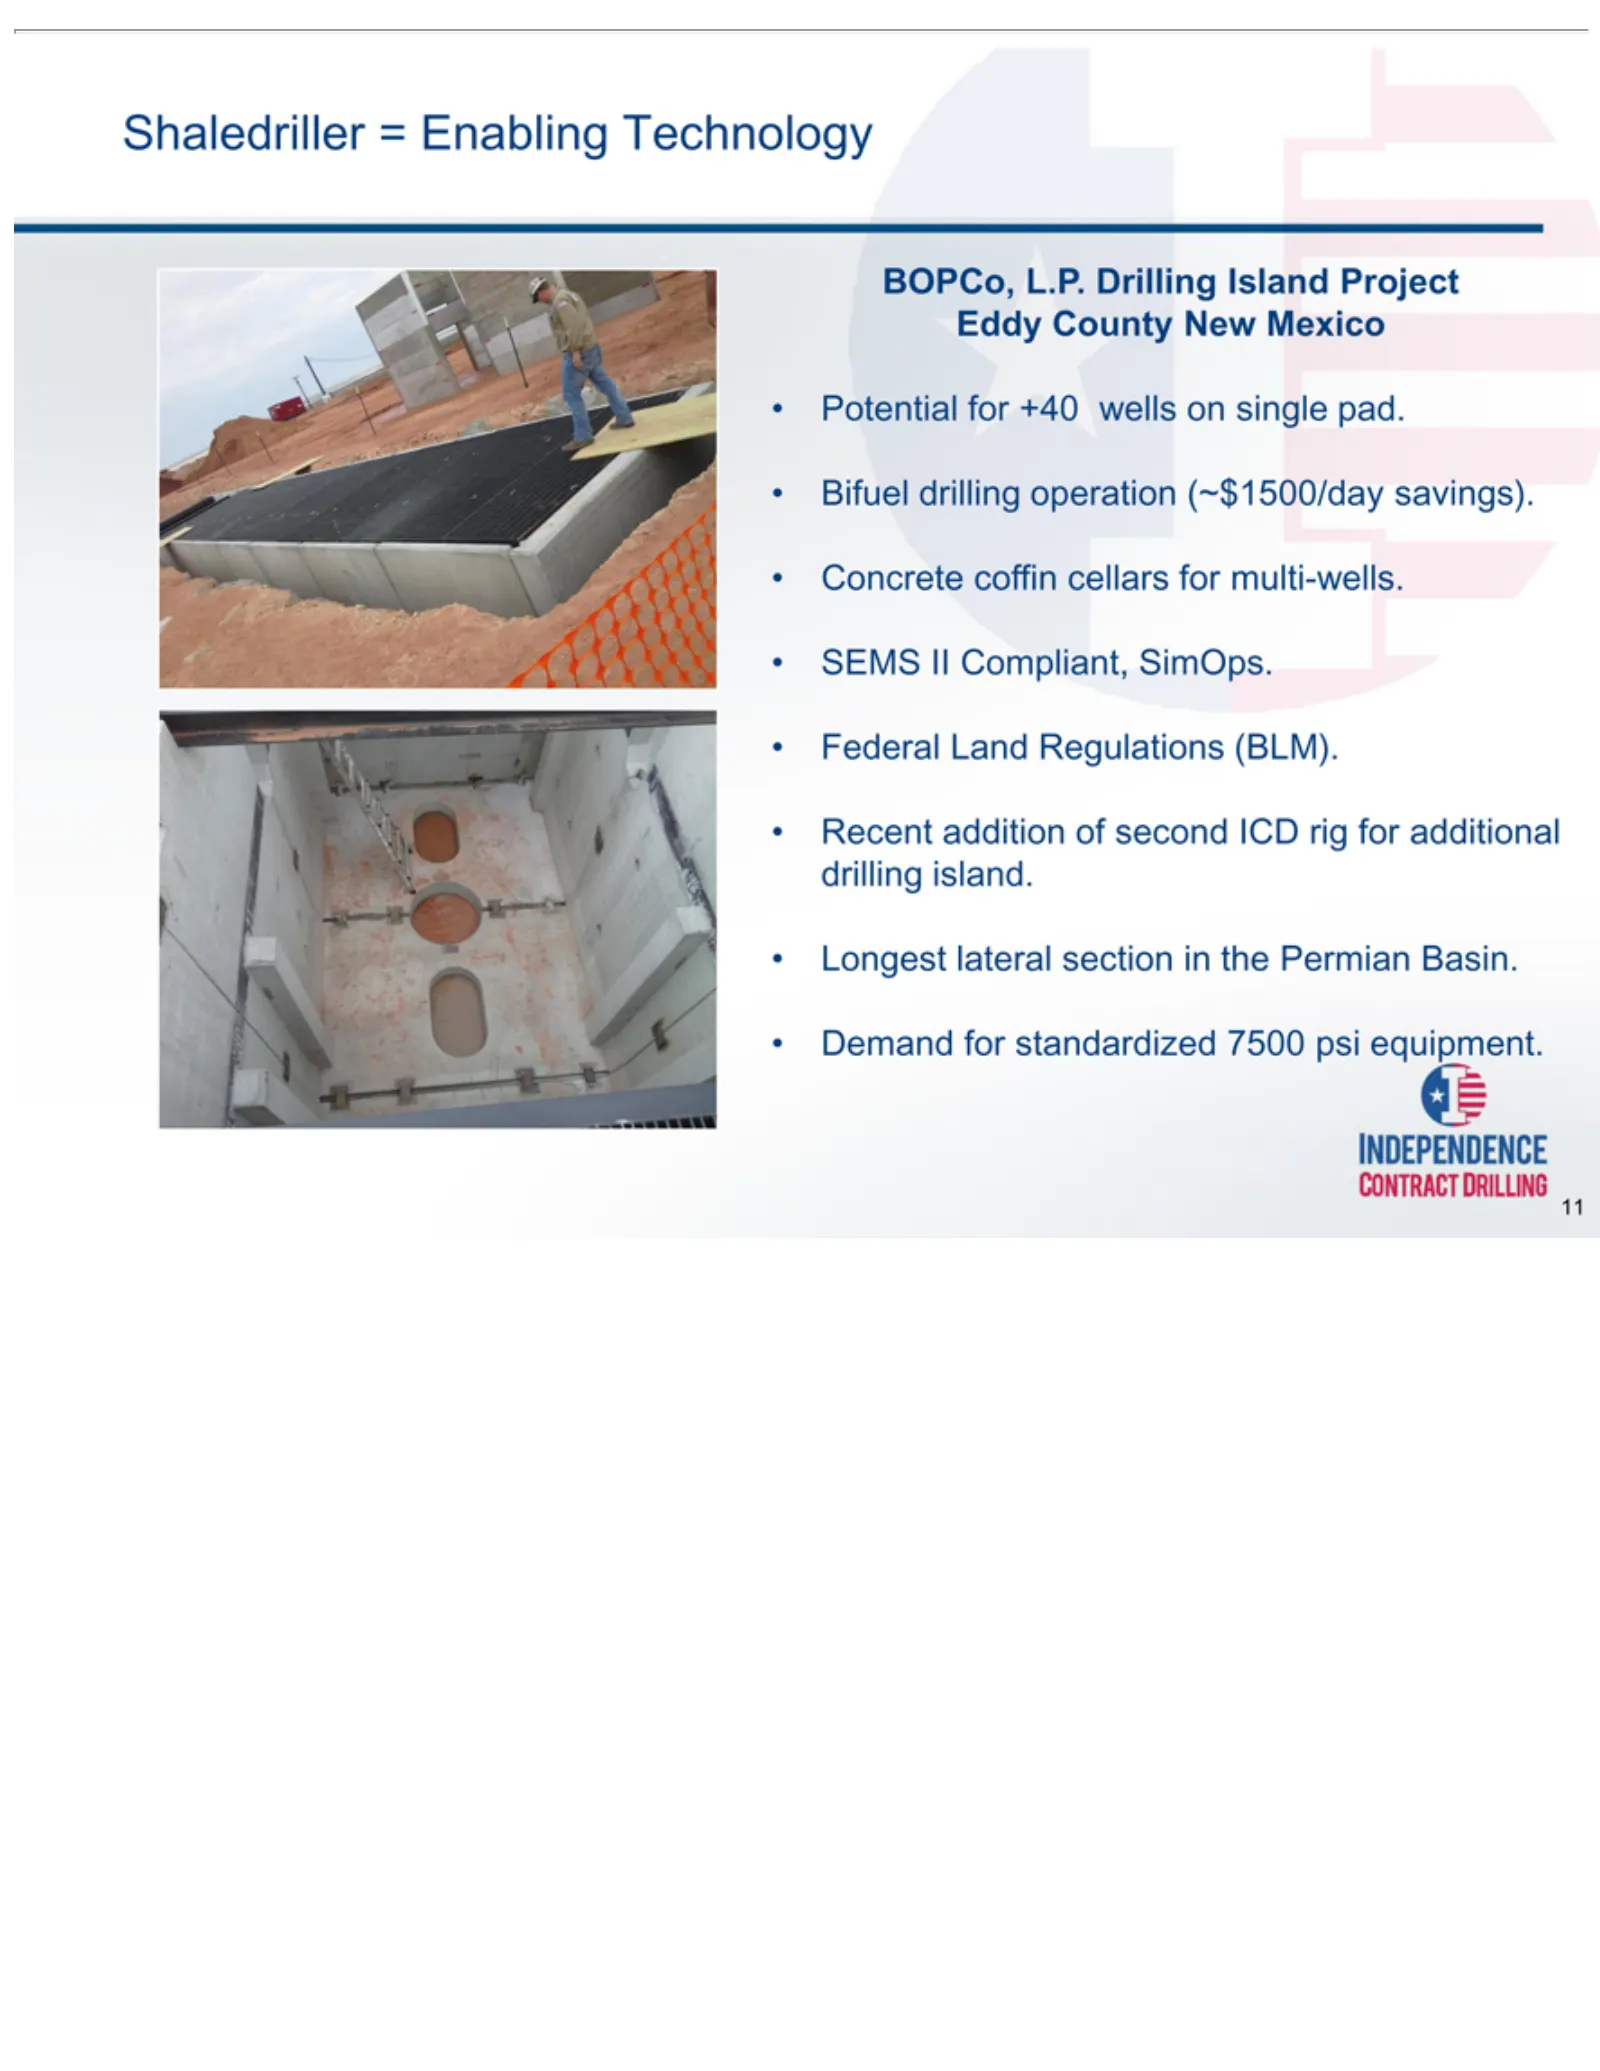
Slide 11: ShaleDriller Project, Eddy County, New Mexico
Shaledriller BOPCo, Eddy Potential Bifuel Concrete SEMS Federal Recent Longest Demand 11 County drilling II addition Land lateral L.P. for Compliant, for coffin =standardized +40 Drilling Regulations New Enabling operation section cellars ofwells second Mexico SimOps. Island in for on Technology (~$
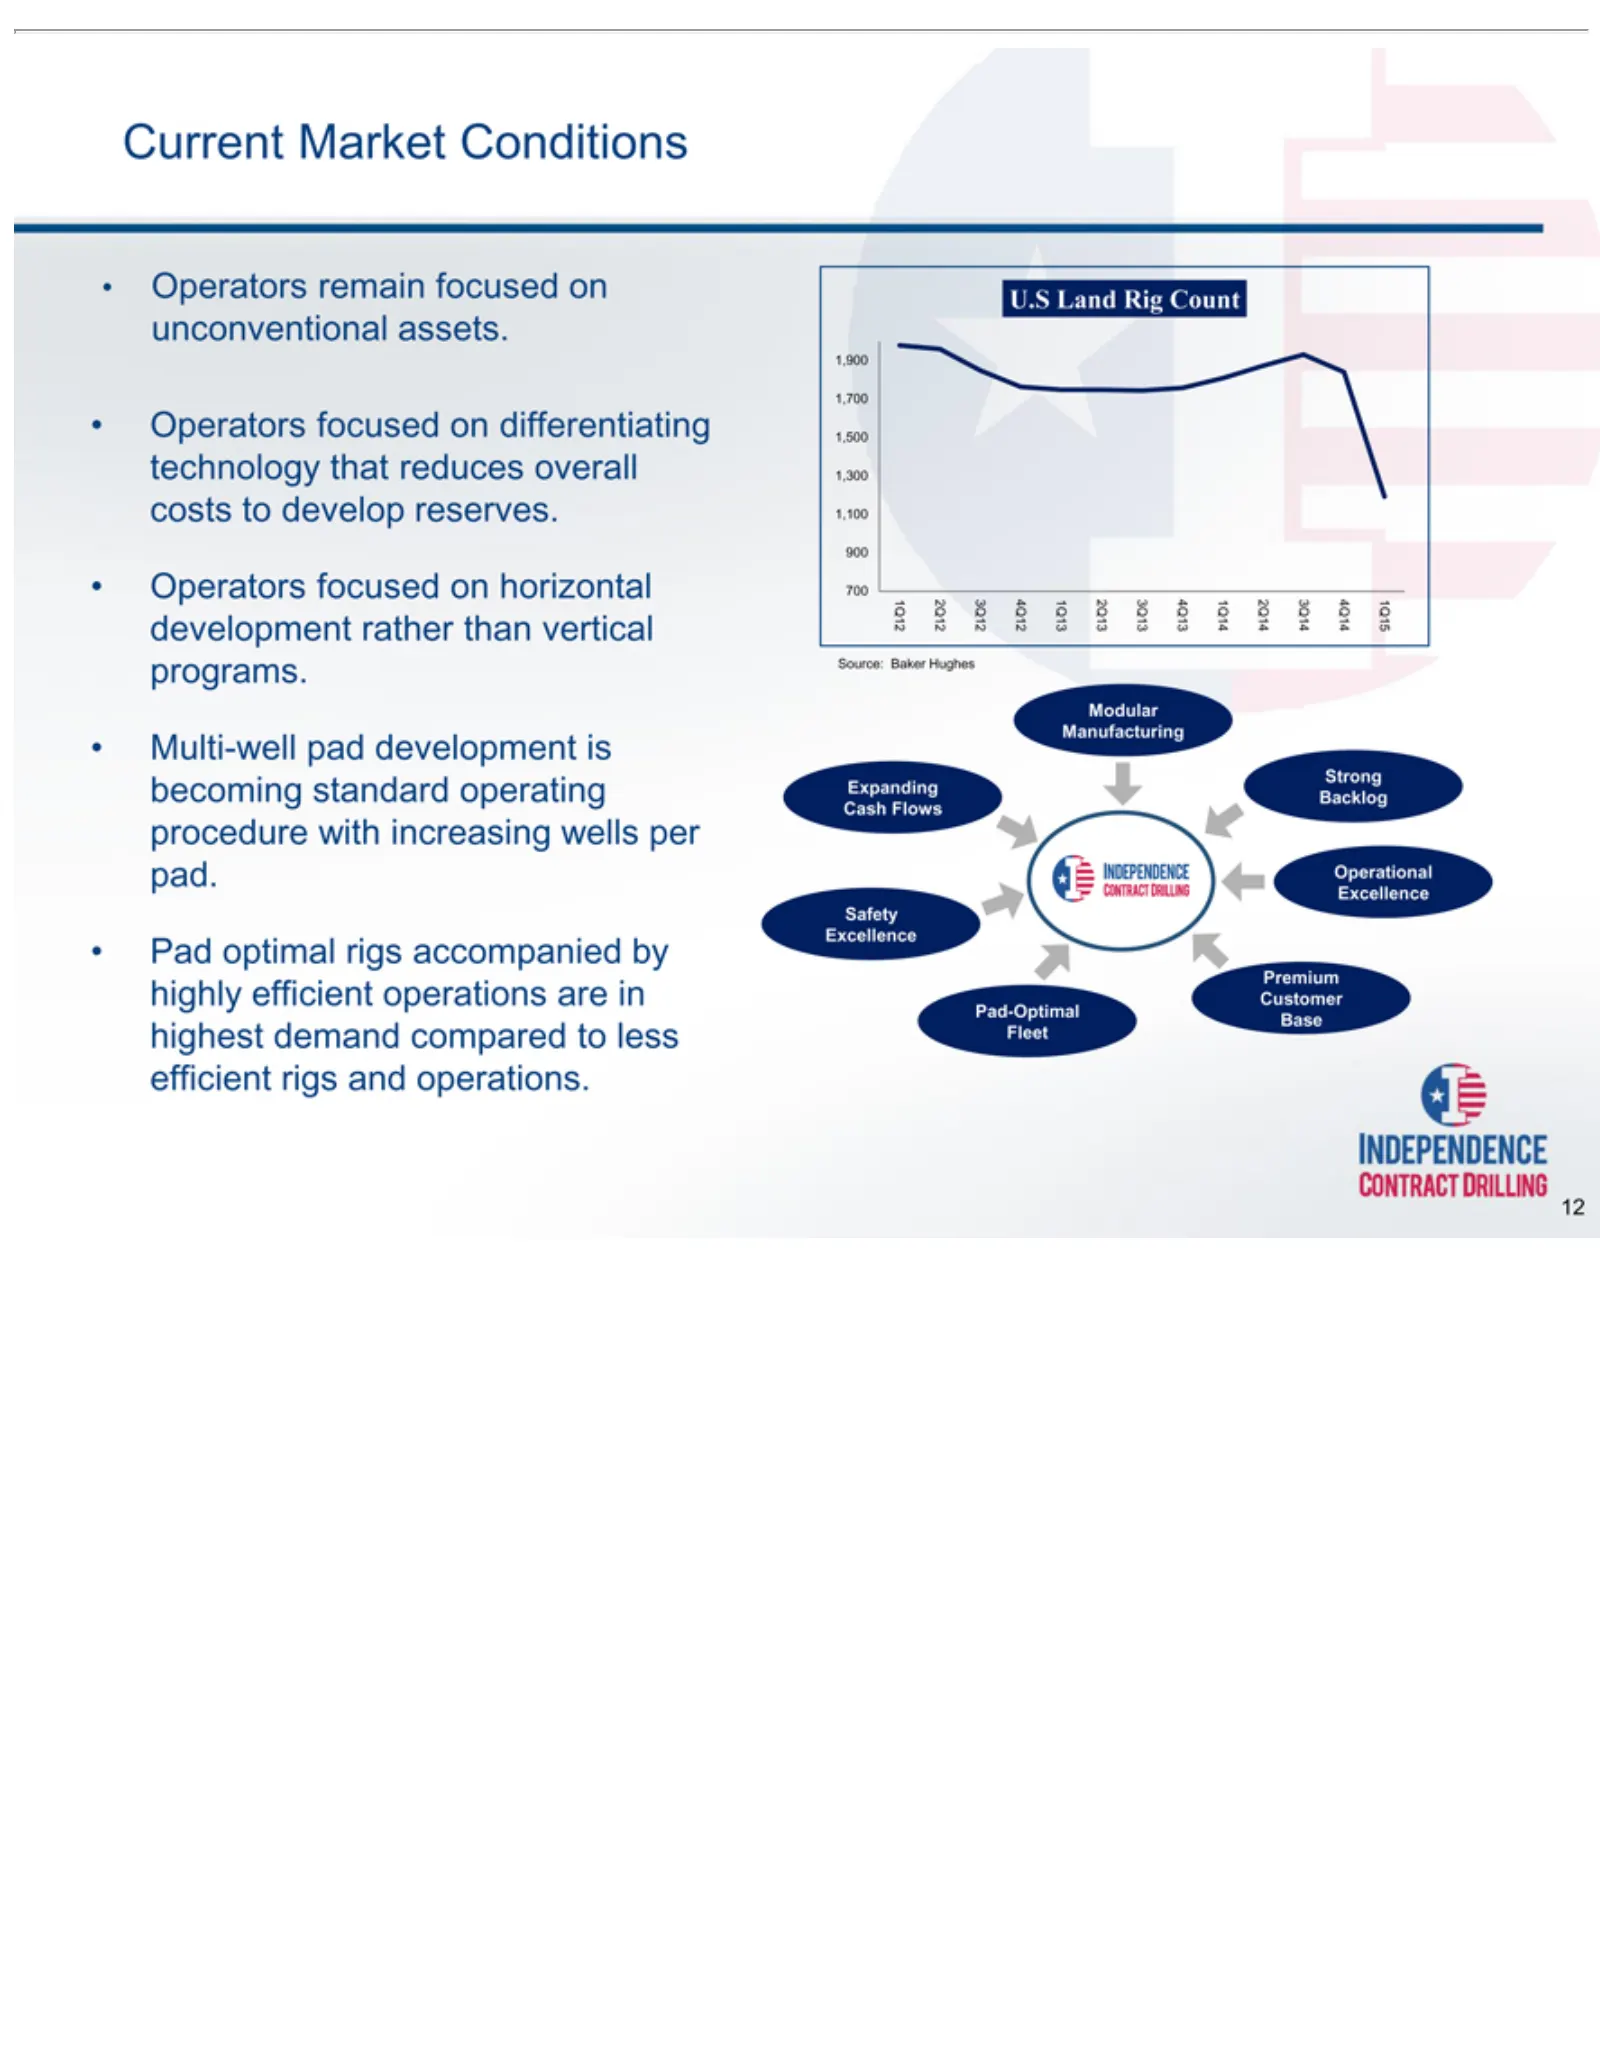
Slide 12: Current Operators Focus on Multi-well Pad Development
Current Operators Multi-well Pad U.S 1Q12 700 900 1,100 1,300 1,500 1,700 1,900 Source: Expanding Strong Manufacturing Modular Cash Pad-Optimal Customer Premium Safety Excellence Operational 12 Fleet optimal Land Flows 2Q12 Market Baker Rig remain focused pad Backlog 3Q12 rigs Base Count Hughes deve
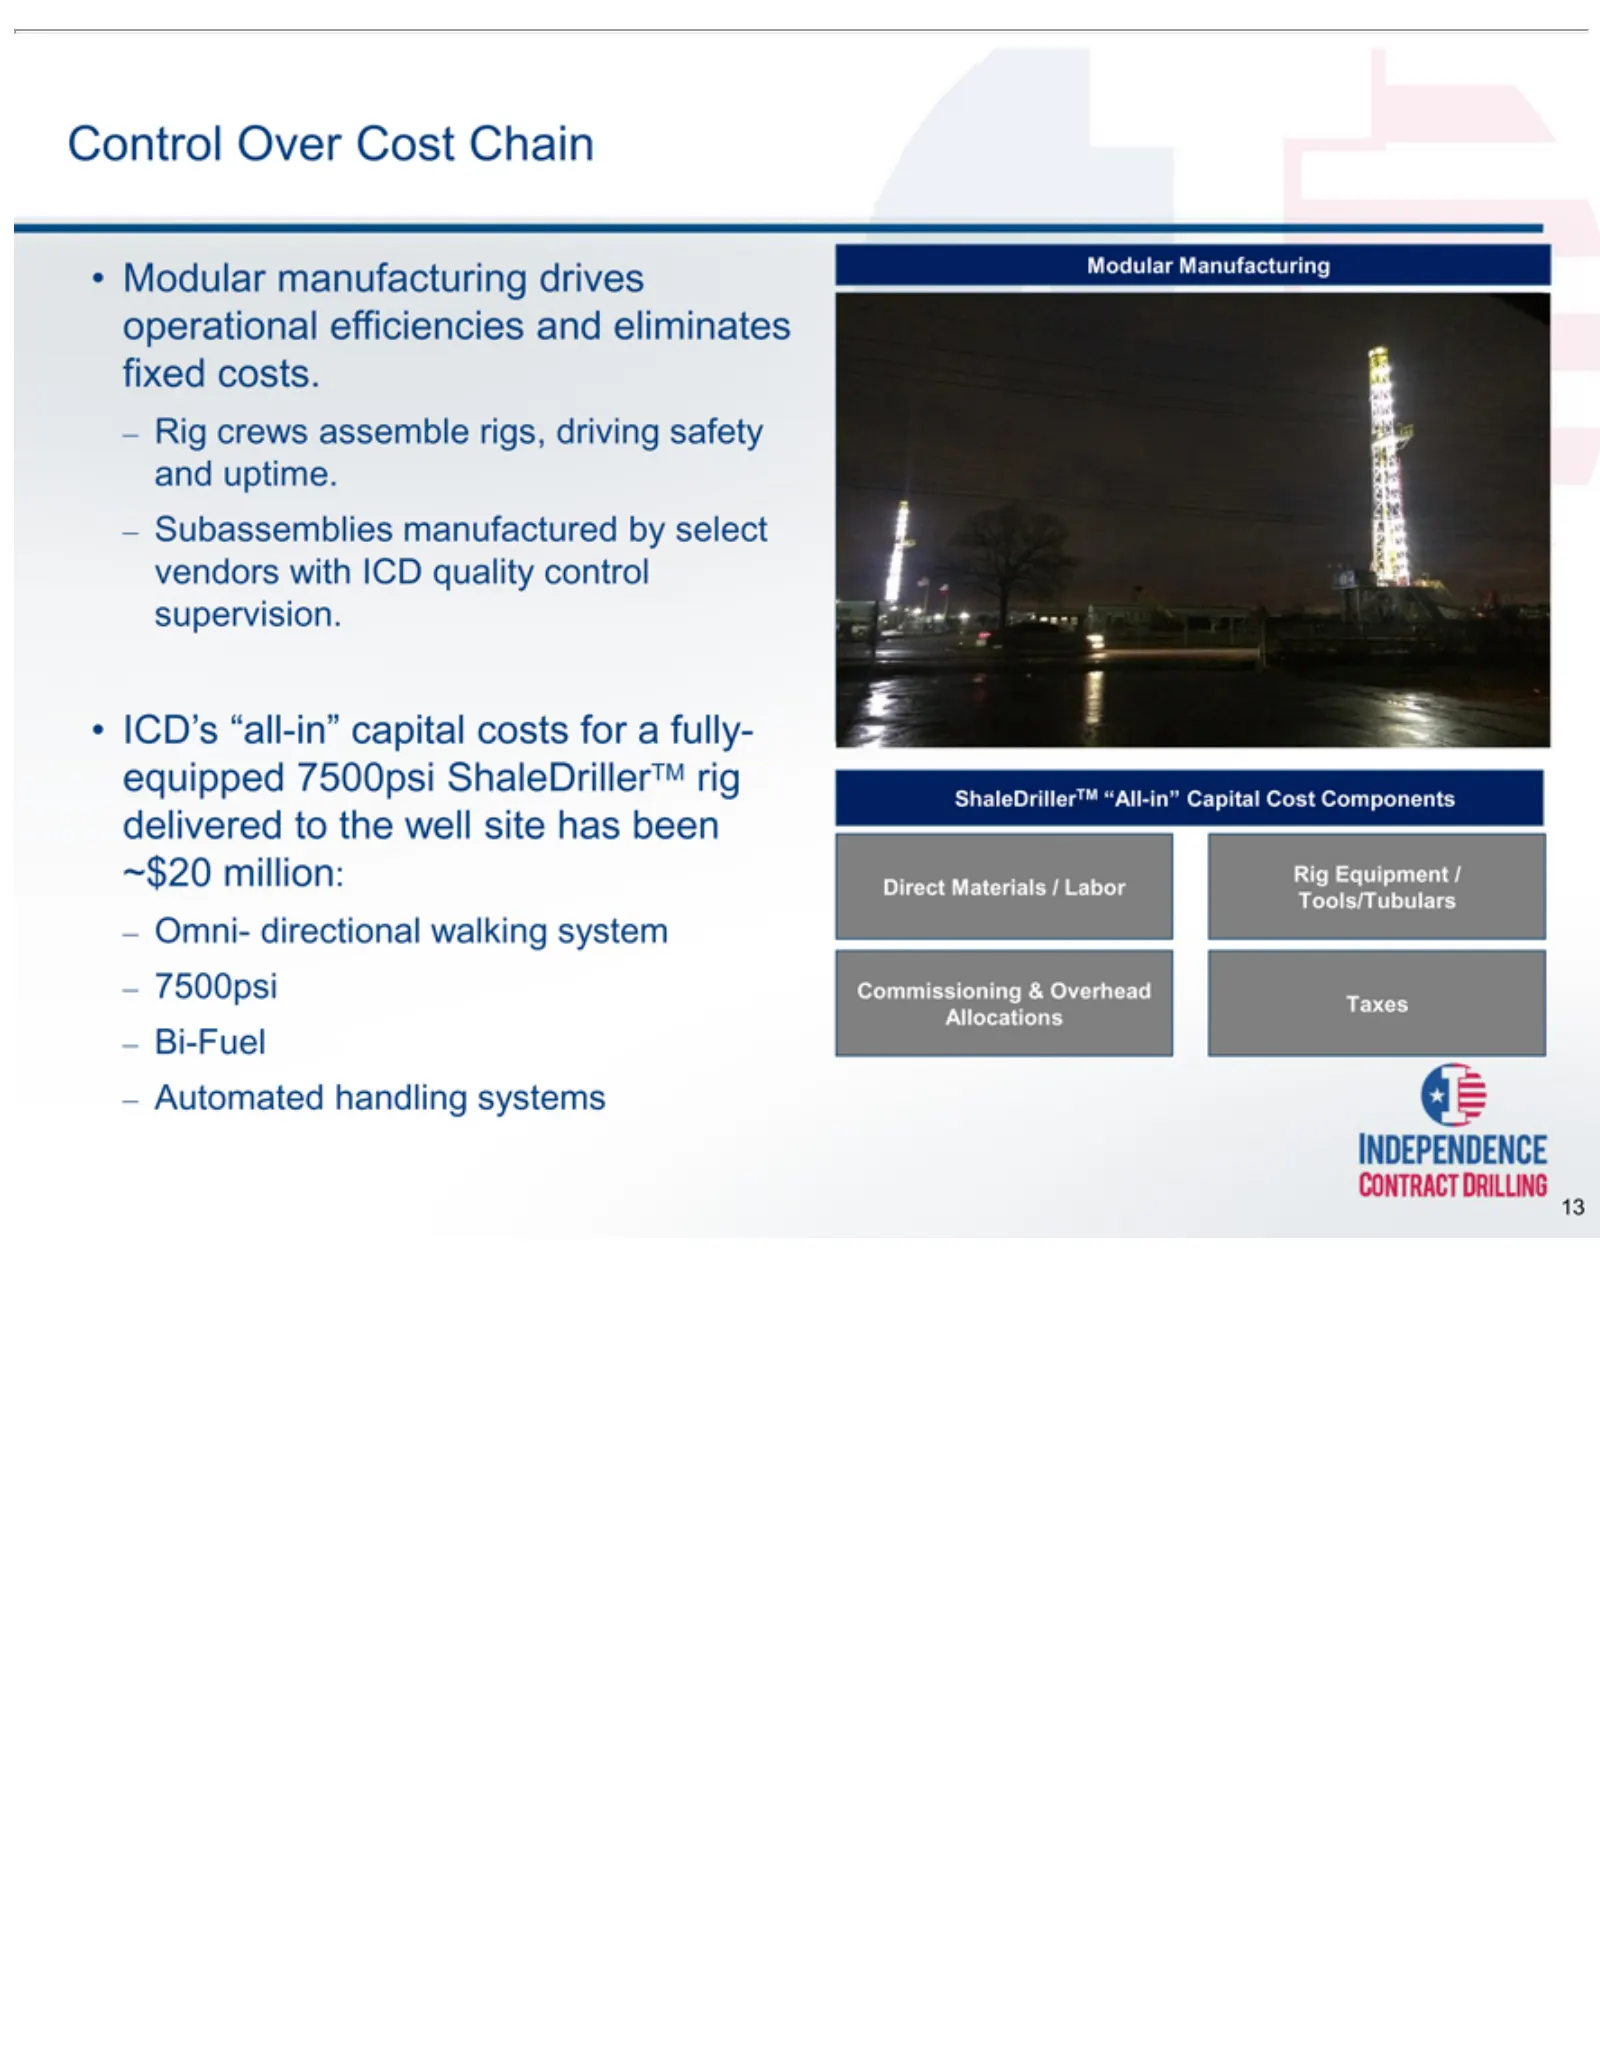
Slide 13: Modular Manufacturing Controls Rig Costs
Control Rig Subassemblies ICD’s Omni- Automated Bi-Fuel 7500psi Modular ShaleDrillerTM Direct Commissioning Tools/Tubulars Allocations 13 crews “all-in” Materials directional Over manufacturing Manufacturing assemble handling Taxes Cost capital manufactured & “All-in” / Labor walking Overhead Chain
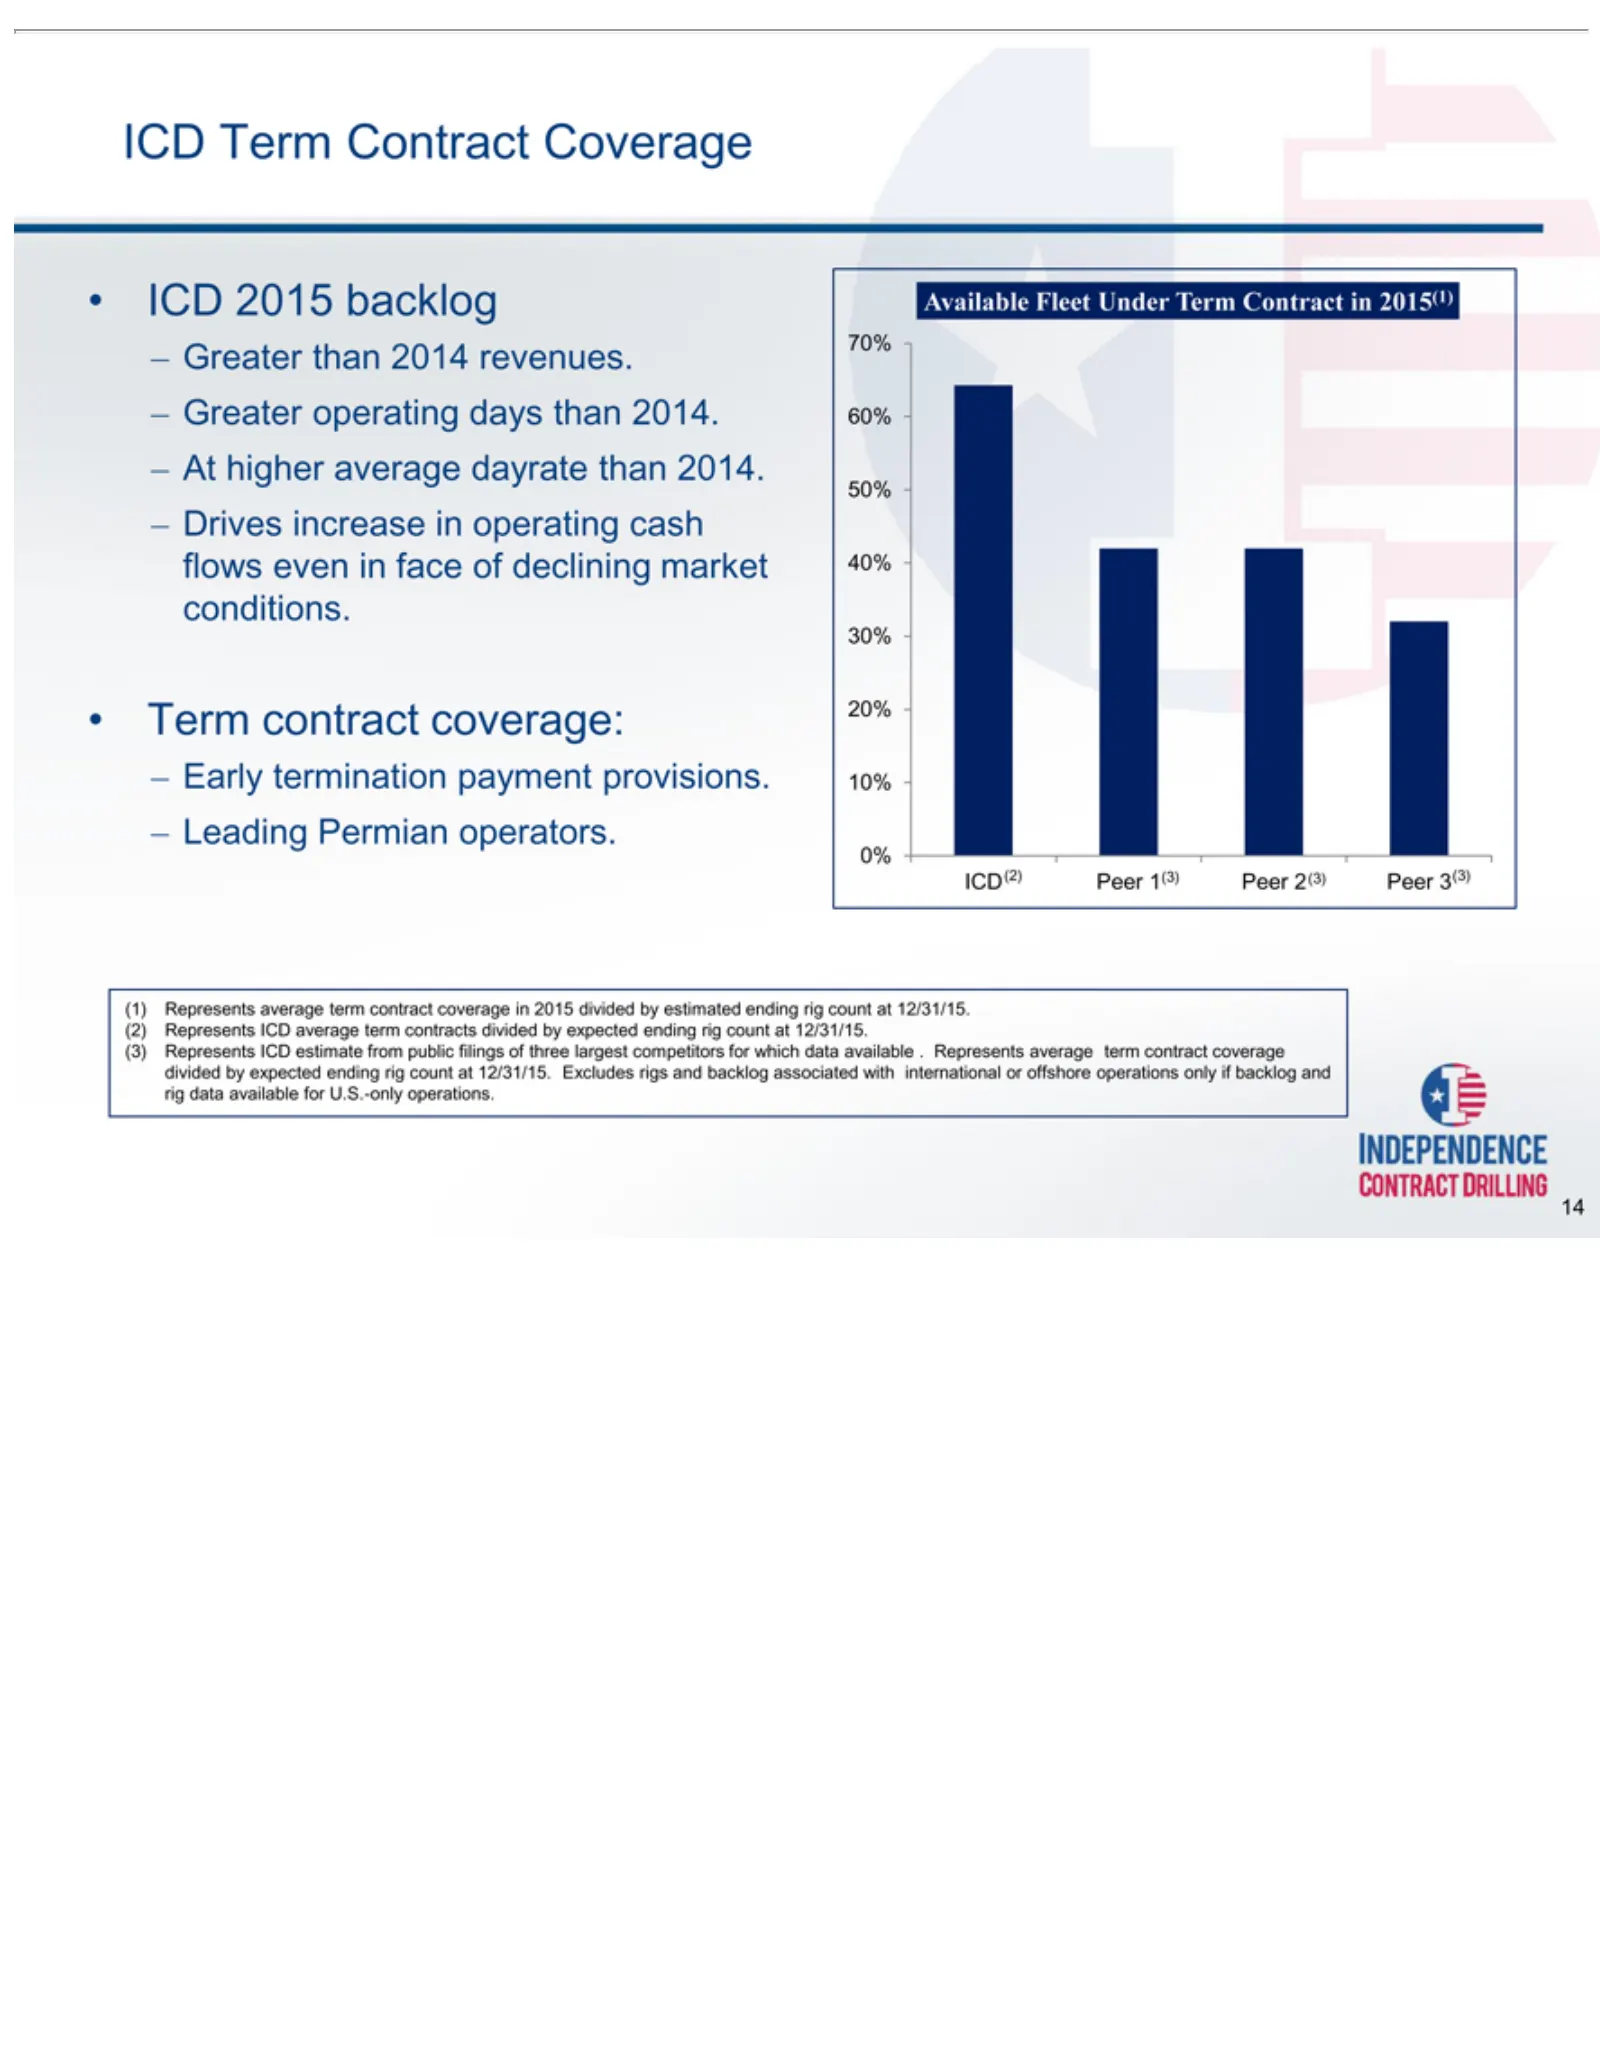
Slide 14: Contract Backlog and Term Coverage
ICDhigher Greater At Drives Term Early Leading Available ICD(2) 0% 10% 20% 30% 40% 50% 60% 70% Peer Represents backlog 14 Term 2015 1(3) 2(3) 3(3) contract termination increase than operating associated Permian average Fleet backlog Contract average ICD 2014 coverage: Under in average estimate opera
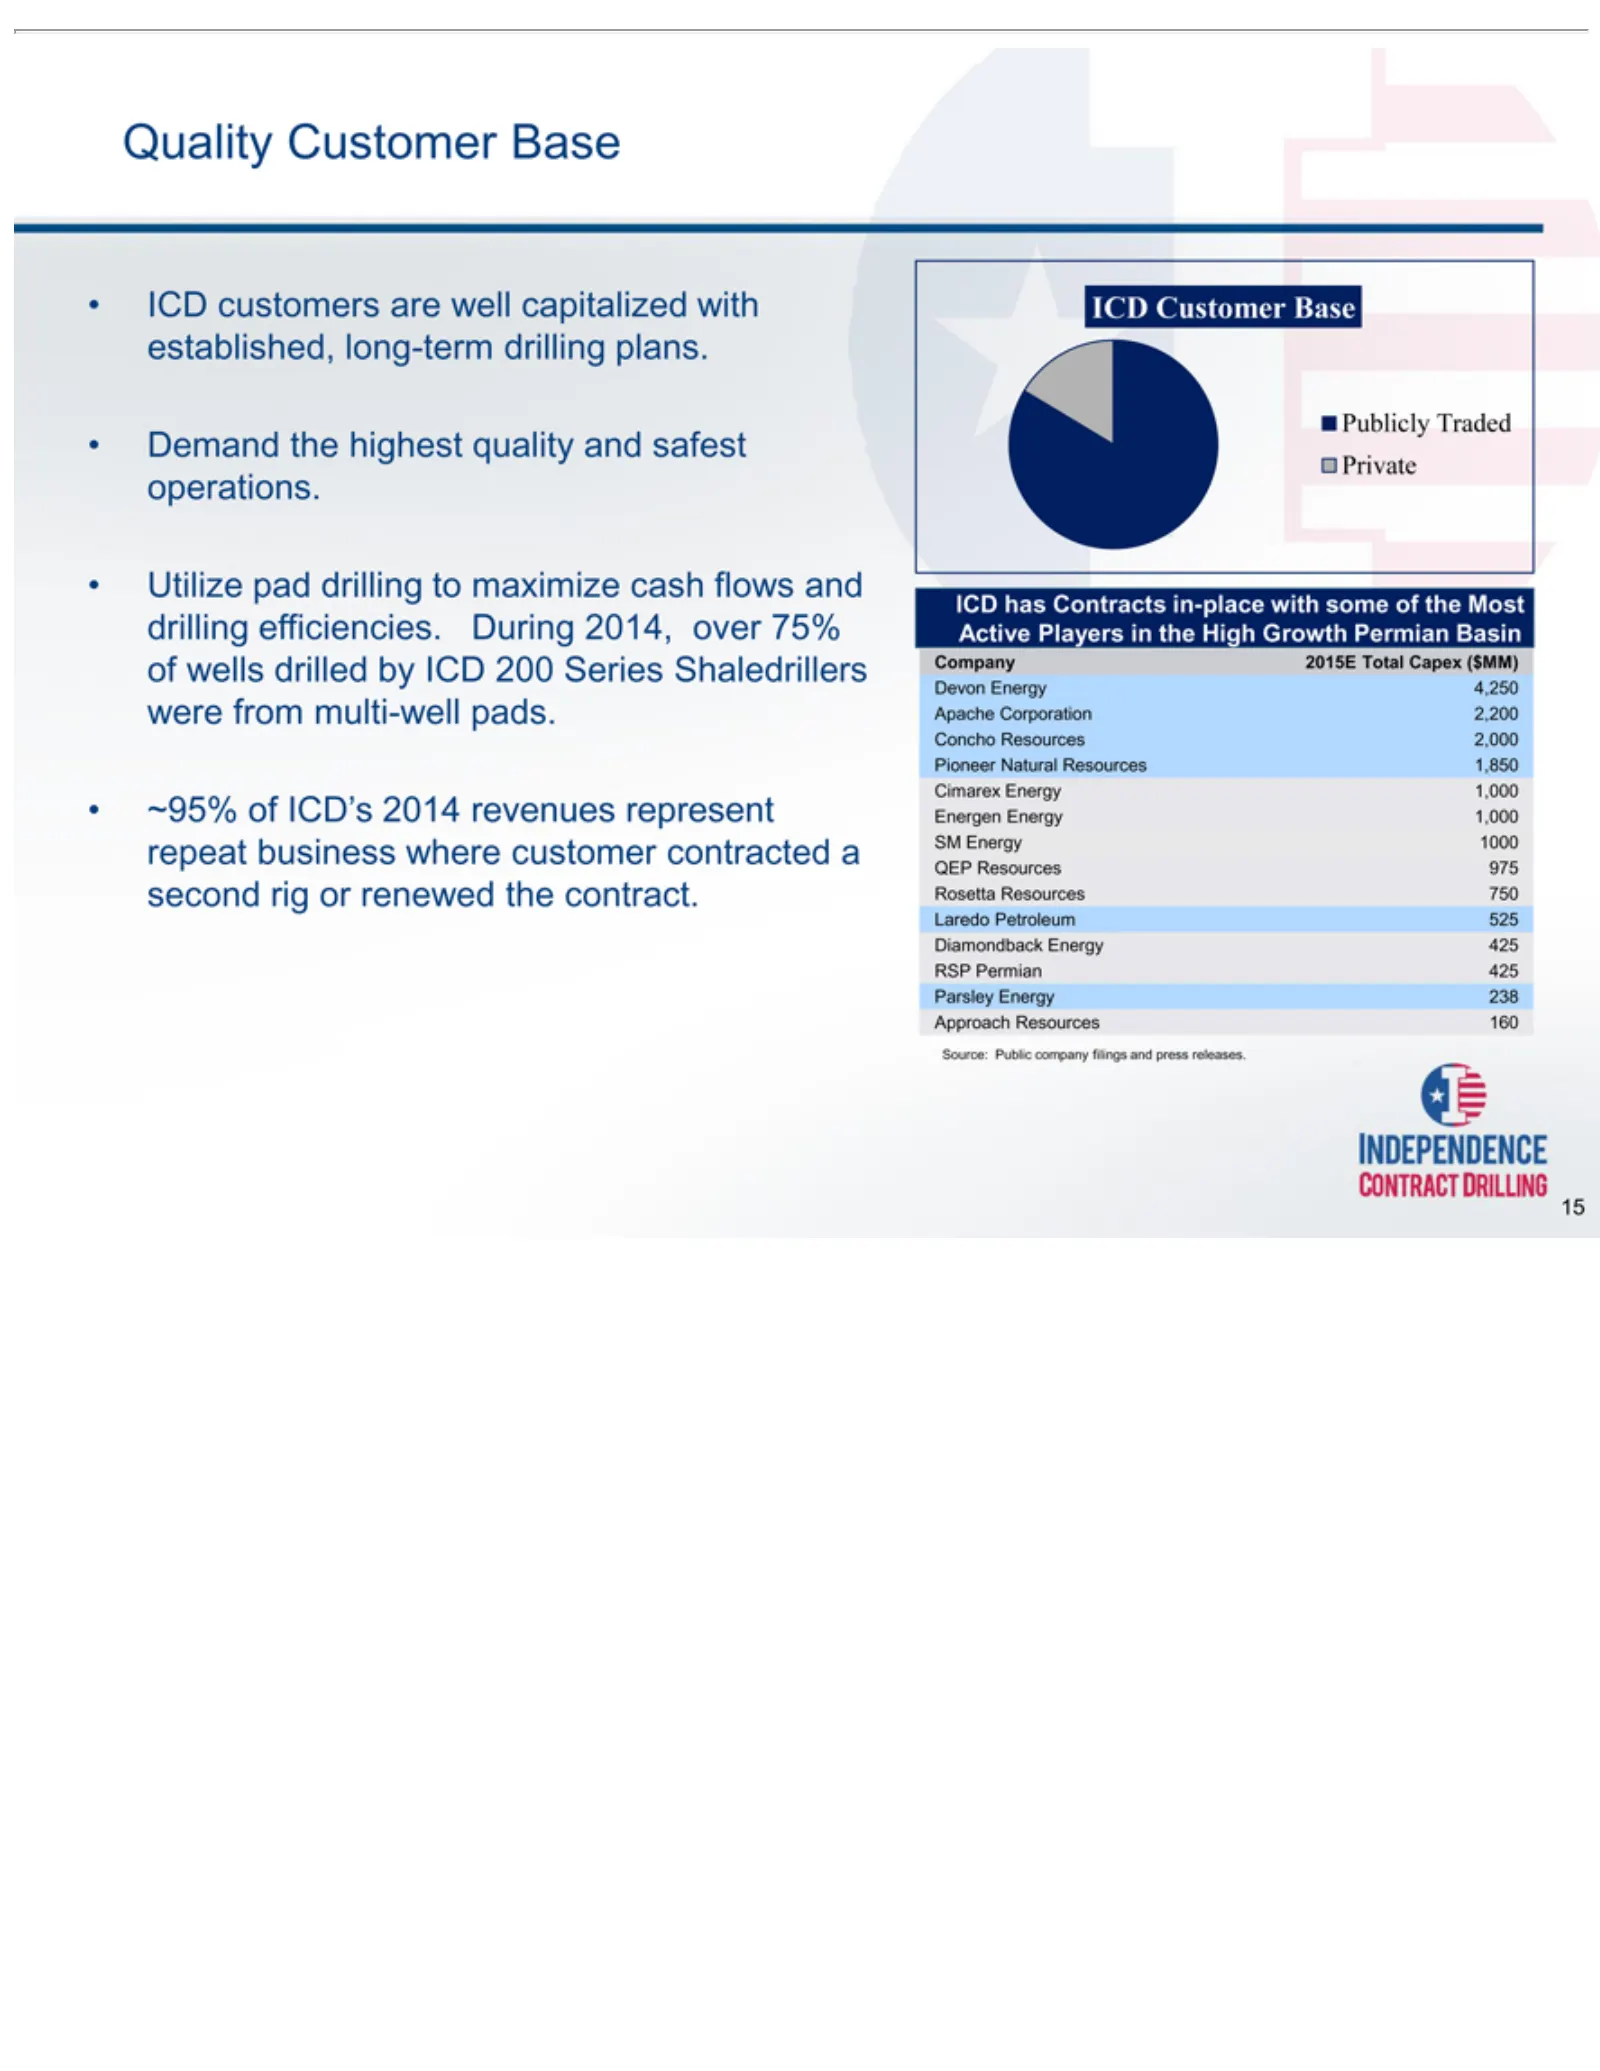
Slide 15: High Quality Customer Base
Quality Demand Utilize ~95% Publicly ICD Private Company Devon Apache Concho Pioneer Cimarex Energen SM QEP Rosetta Laredo Diamondback RSP Parsley Approach Source: 15 Energy customers Customer has Permian Resources of Energy pad Petroleum Energy Customer Resources Corporation Public Natural Resource
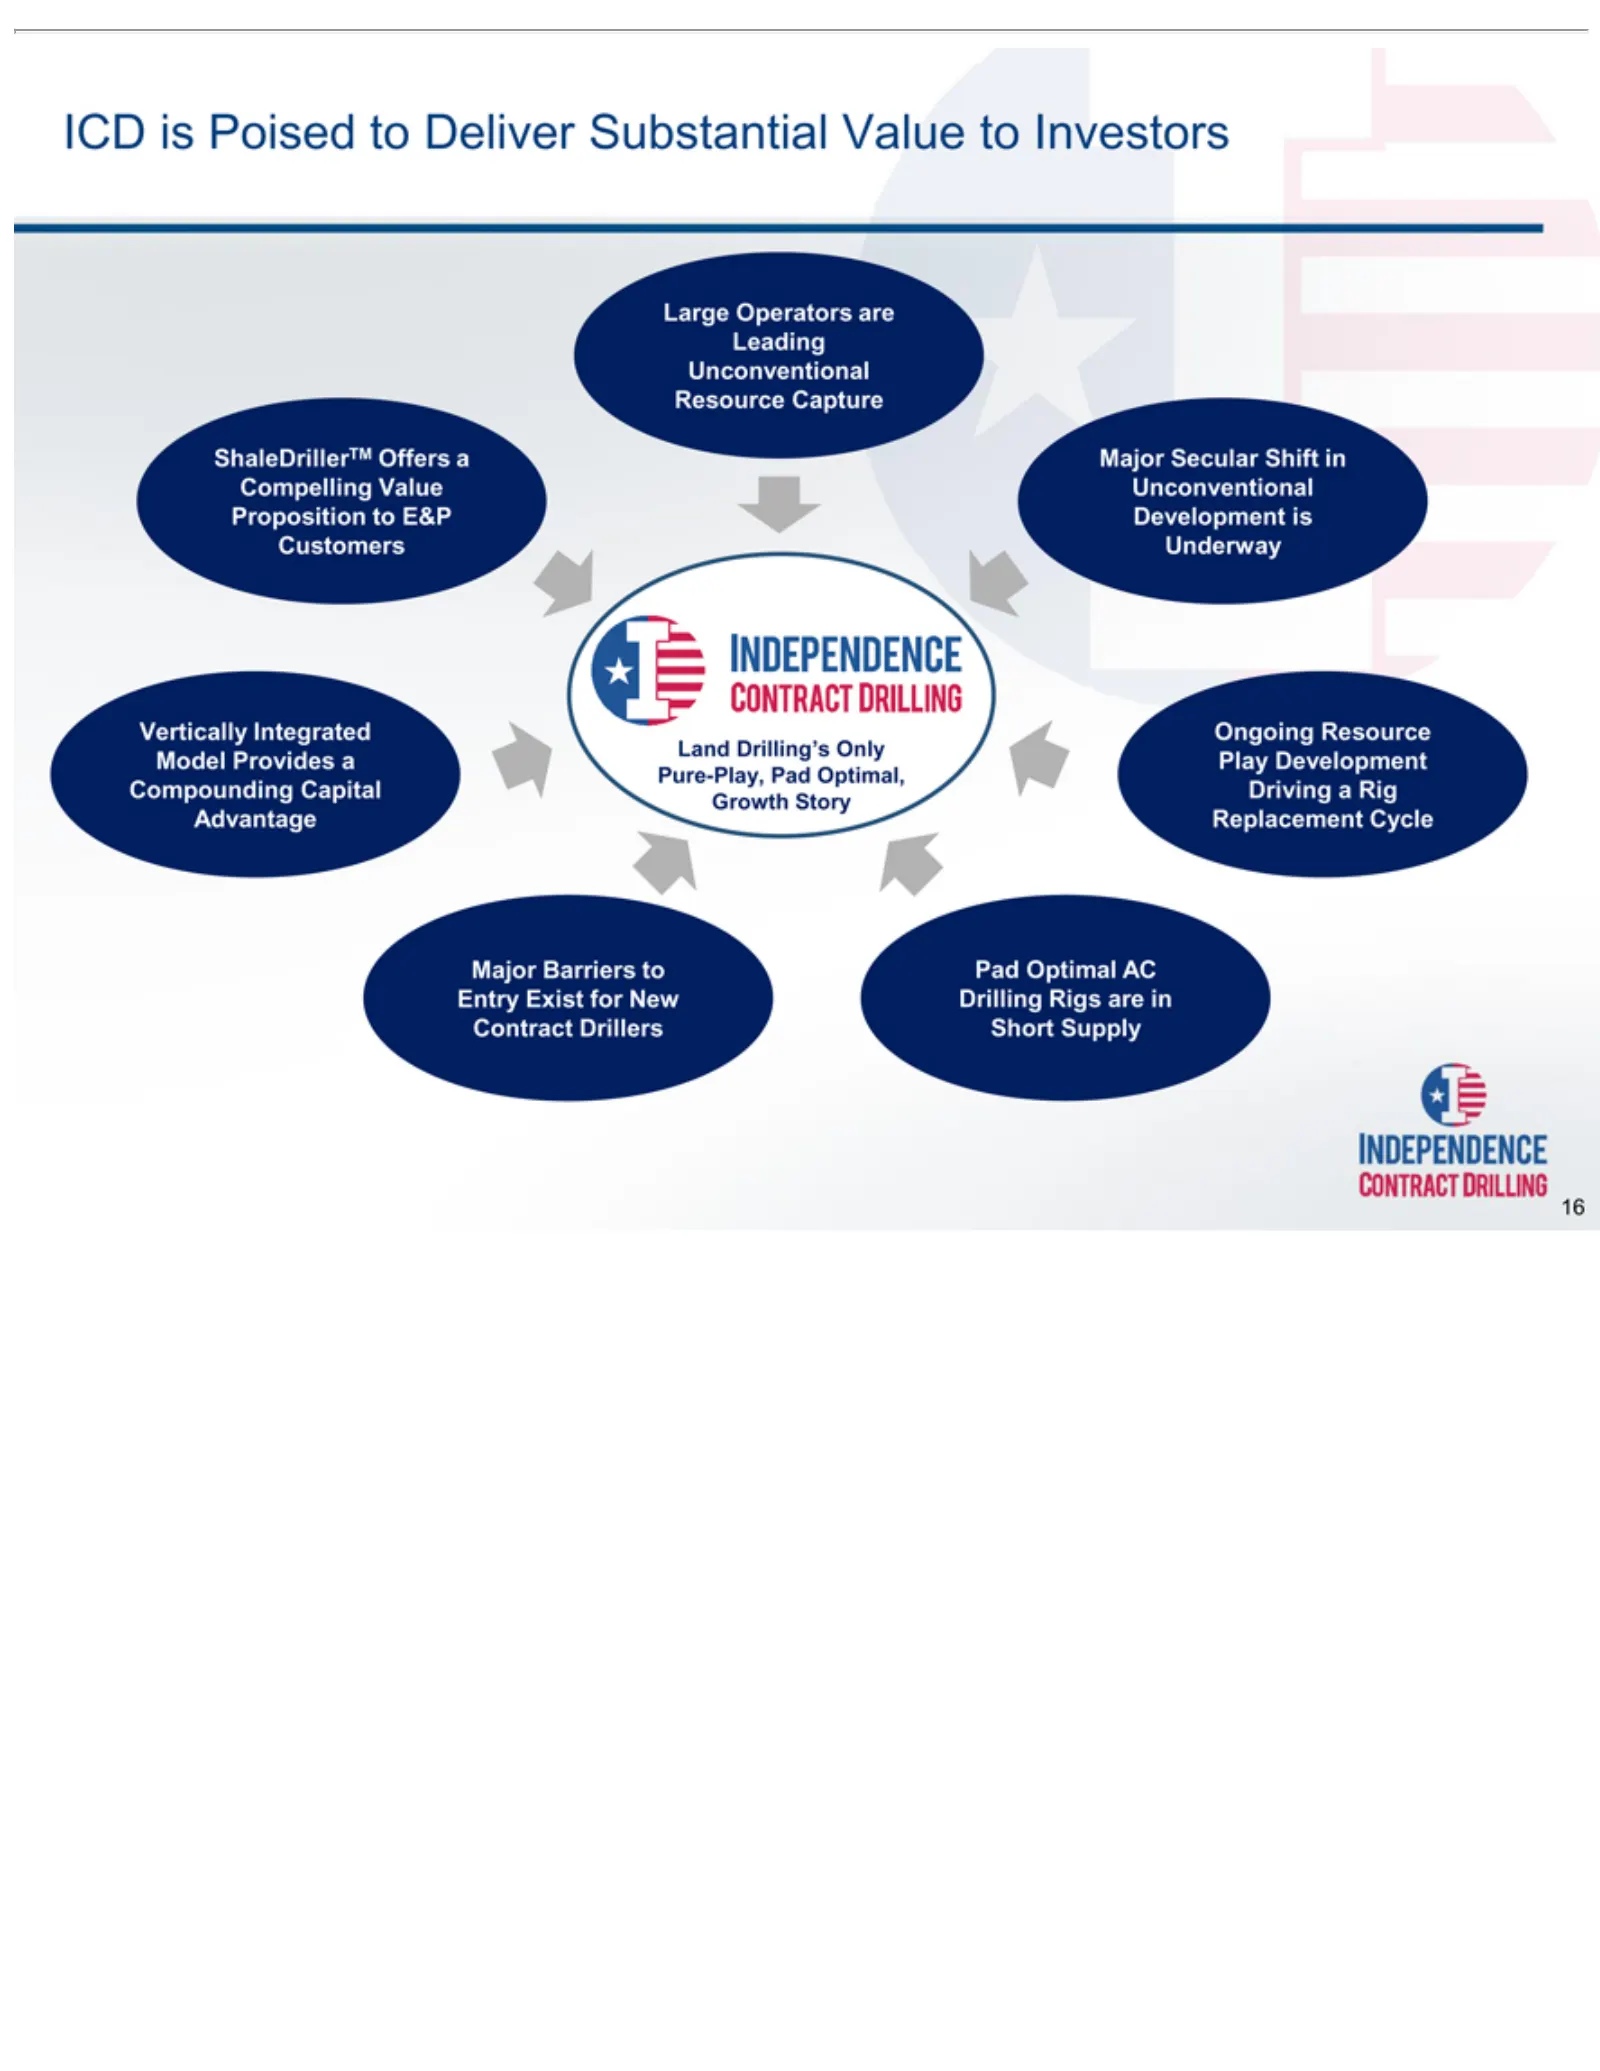
Slide 16: ICD is a Compelling Value Proposition for Investors
ICD isDrilling’s Large Resource Unconventional Leading ShaleDrillerTM Compelling Proposition Customers Vertically Land Model Pure-Play, Compounding Growth Advantage Major 16 Operators Barriers Provides Poised Story Capture Integrated Pad Underway Replacement to Value to E&P Capital Optimal, to Only
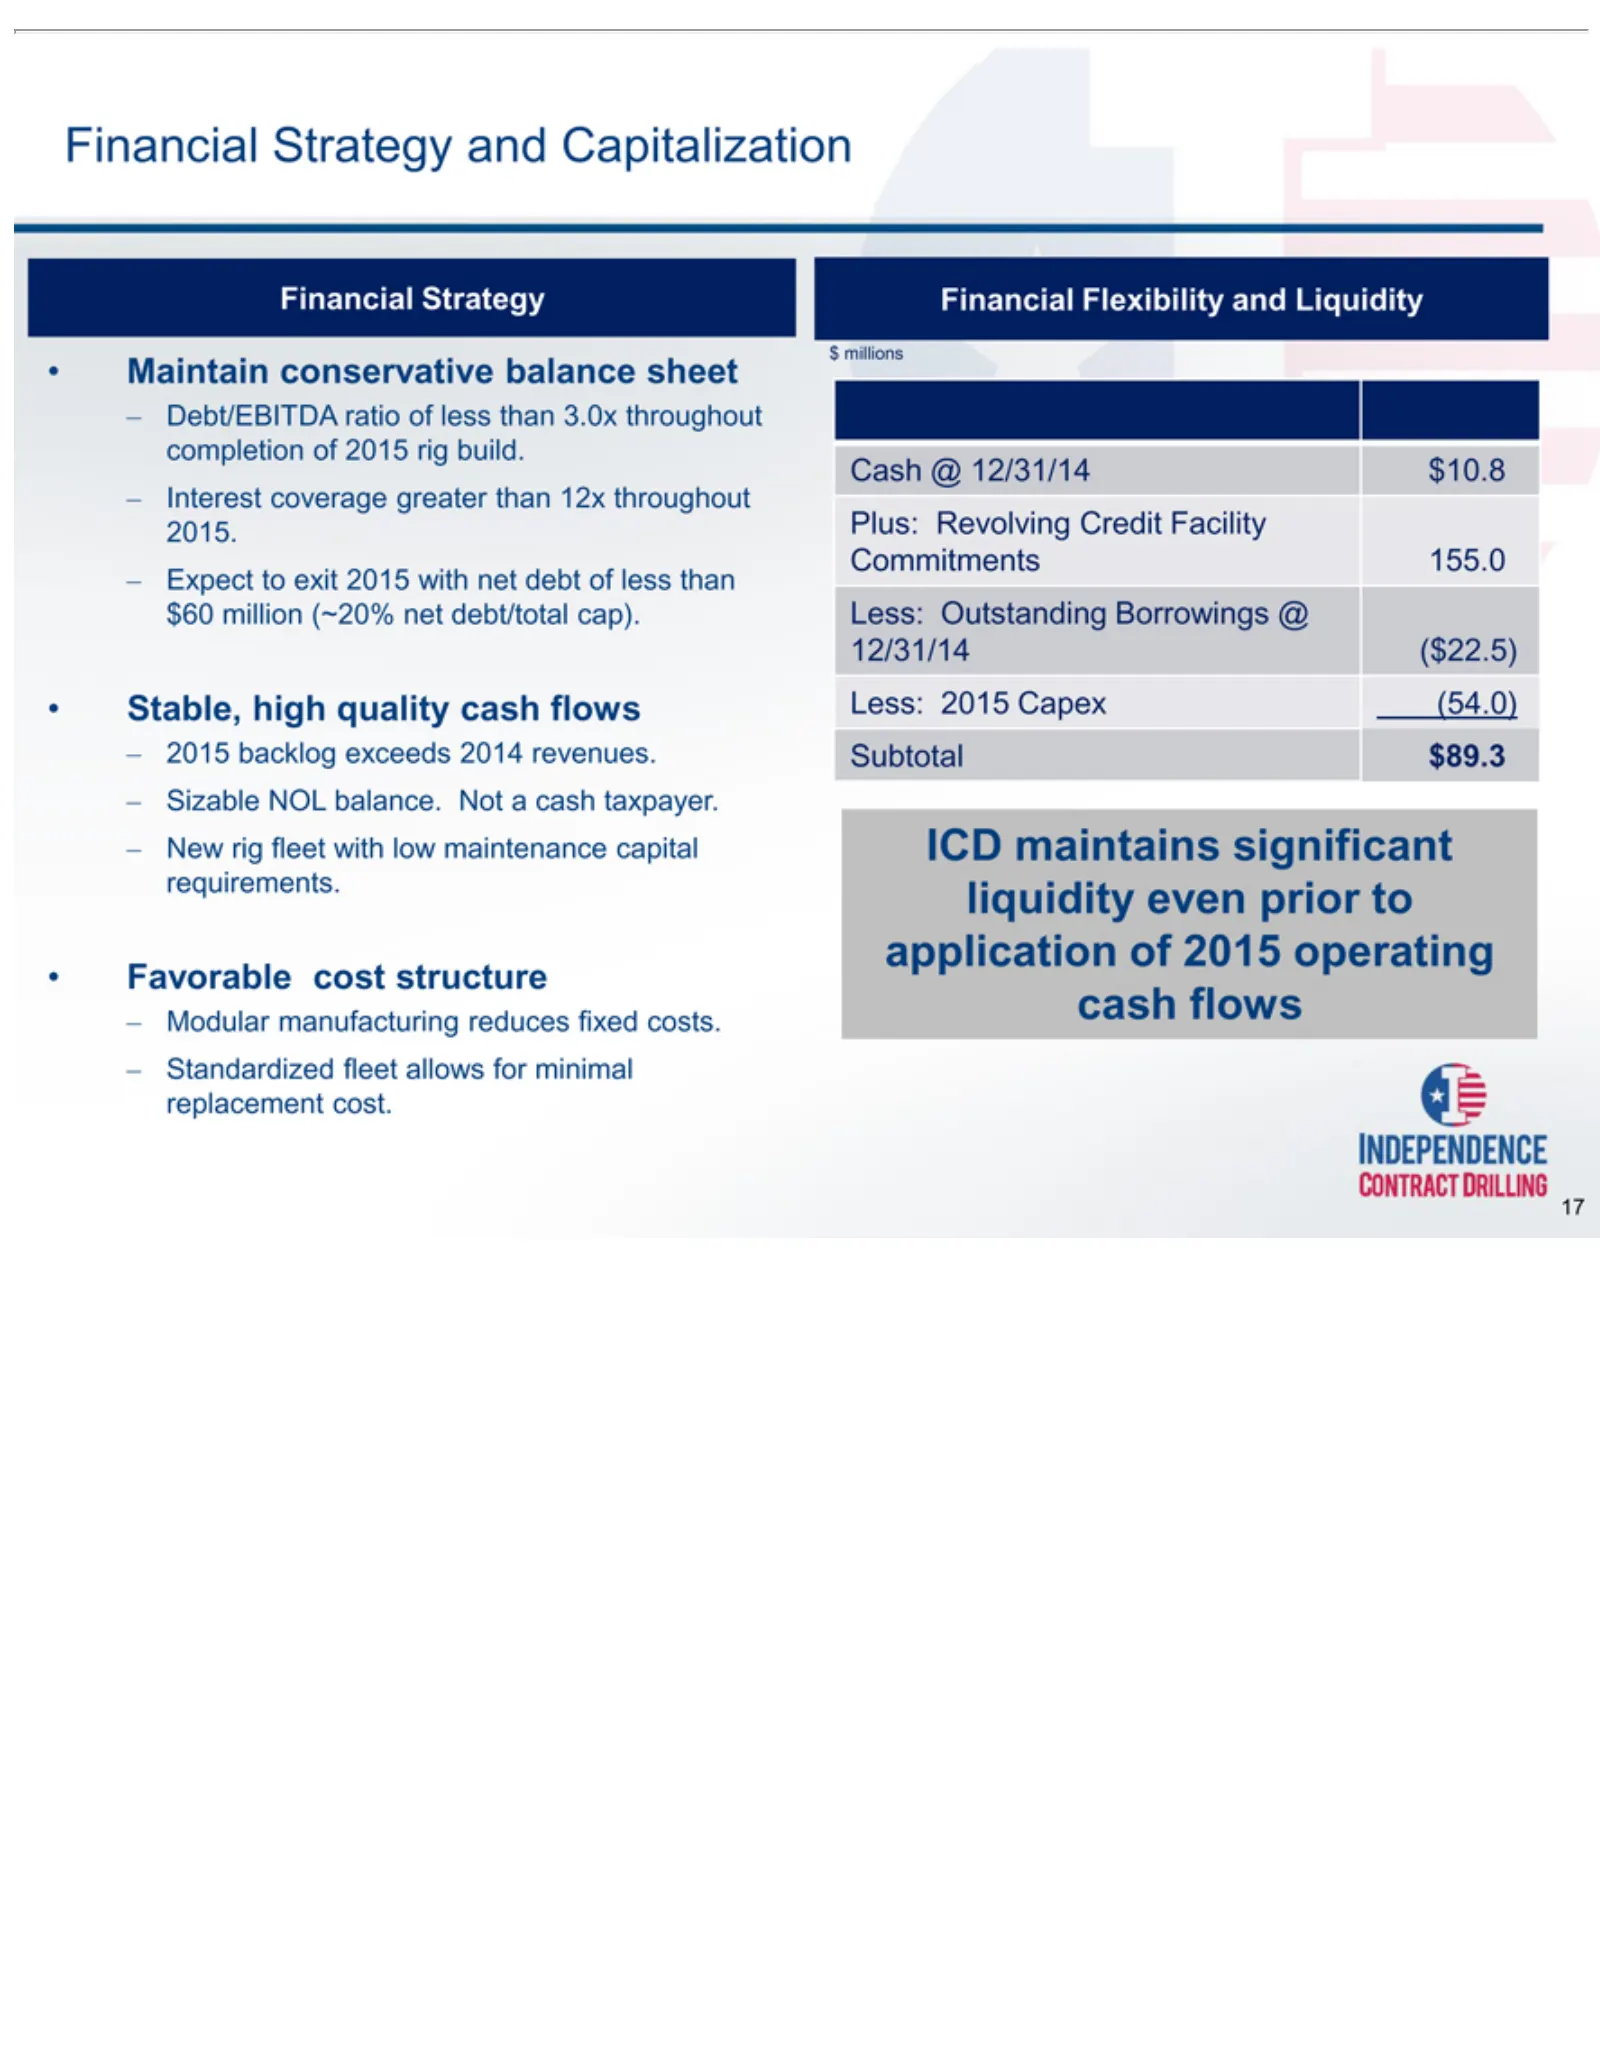
Slide 17: Maintaining Conservative Financial Structure and Liquidity
Maintain Debt/EBITDA Interest Expect Stable, 2015 Sizable New Favorable Modular Standardized $Financial Cash Plus: Commitments Less: 12/31/14($22.5) Subtotal ICD 17millions maintains rig backlog @ Revolving Outstanding 2015 high to NOL coverage 12/31/14 fleet $89.3 manufacturing conservative Strateg
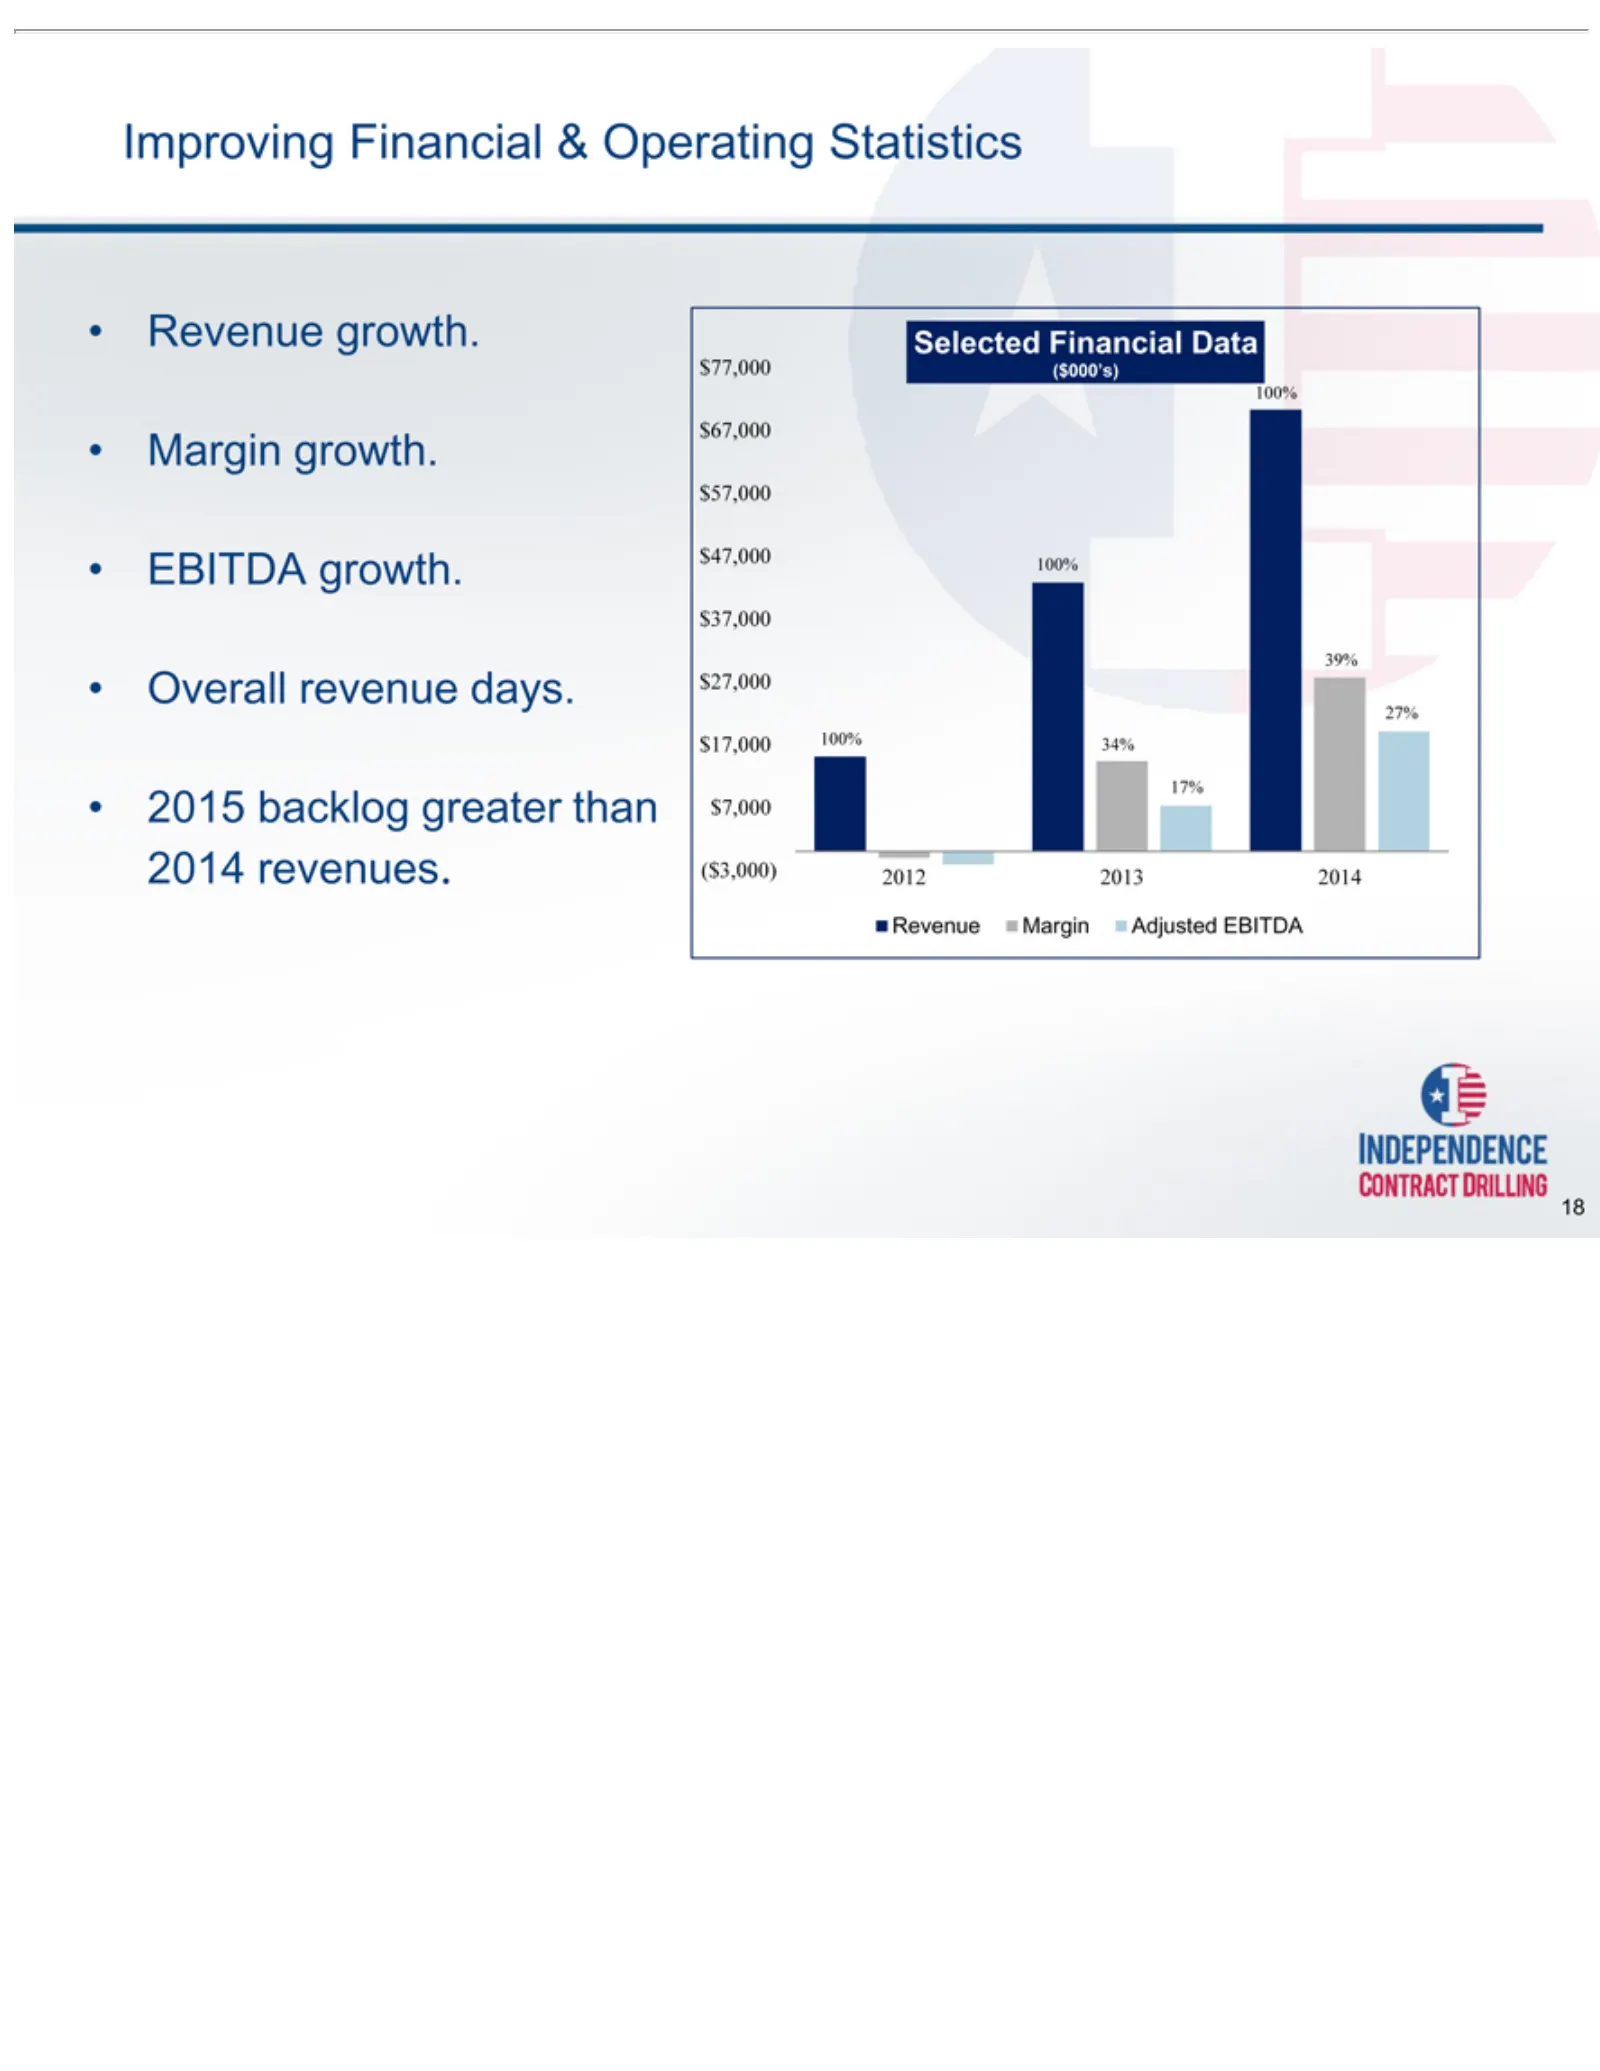
Slide 18: Improving Margin and EBITDA Growth
Improving Margin EBITDA Overall 2015 Selected $47,000 $57,000 $67,000 100% $77,000($000’s) $17,000 27% $27,000 39% $37,000 ($3,000) $7,000 17% Revenue 18 backlog growth. revenue 100% Financial 2012 growth. Margin growth. Financial greater 2013 34% days. Adjusted Data 2014 & than Operating 2014 EBITD
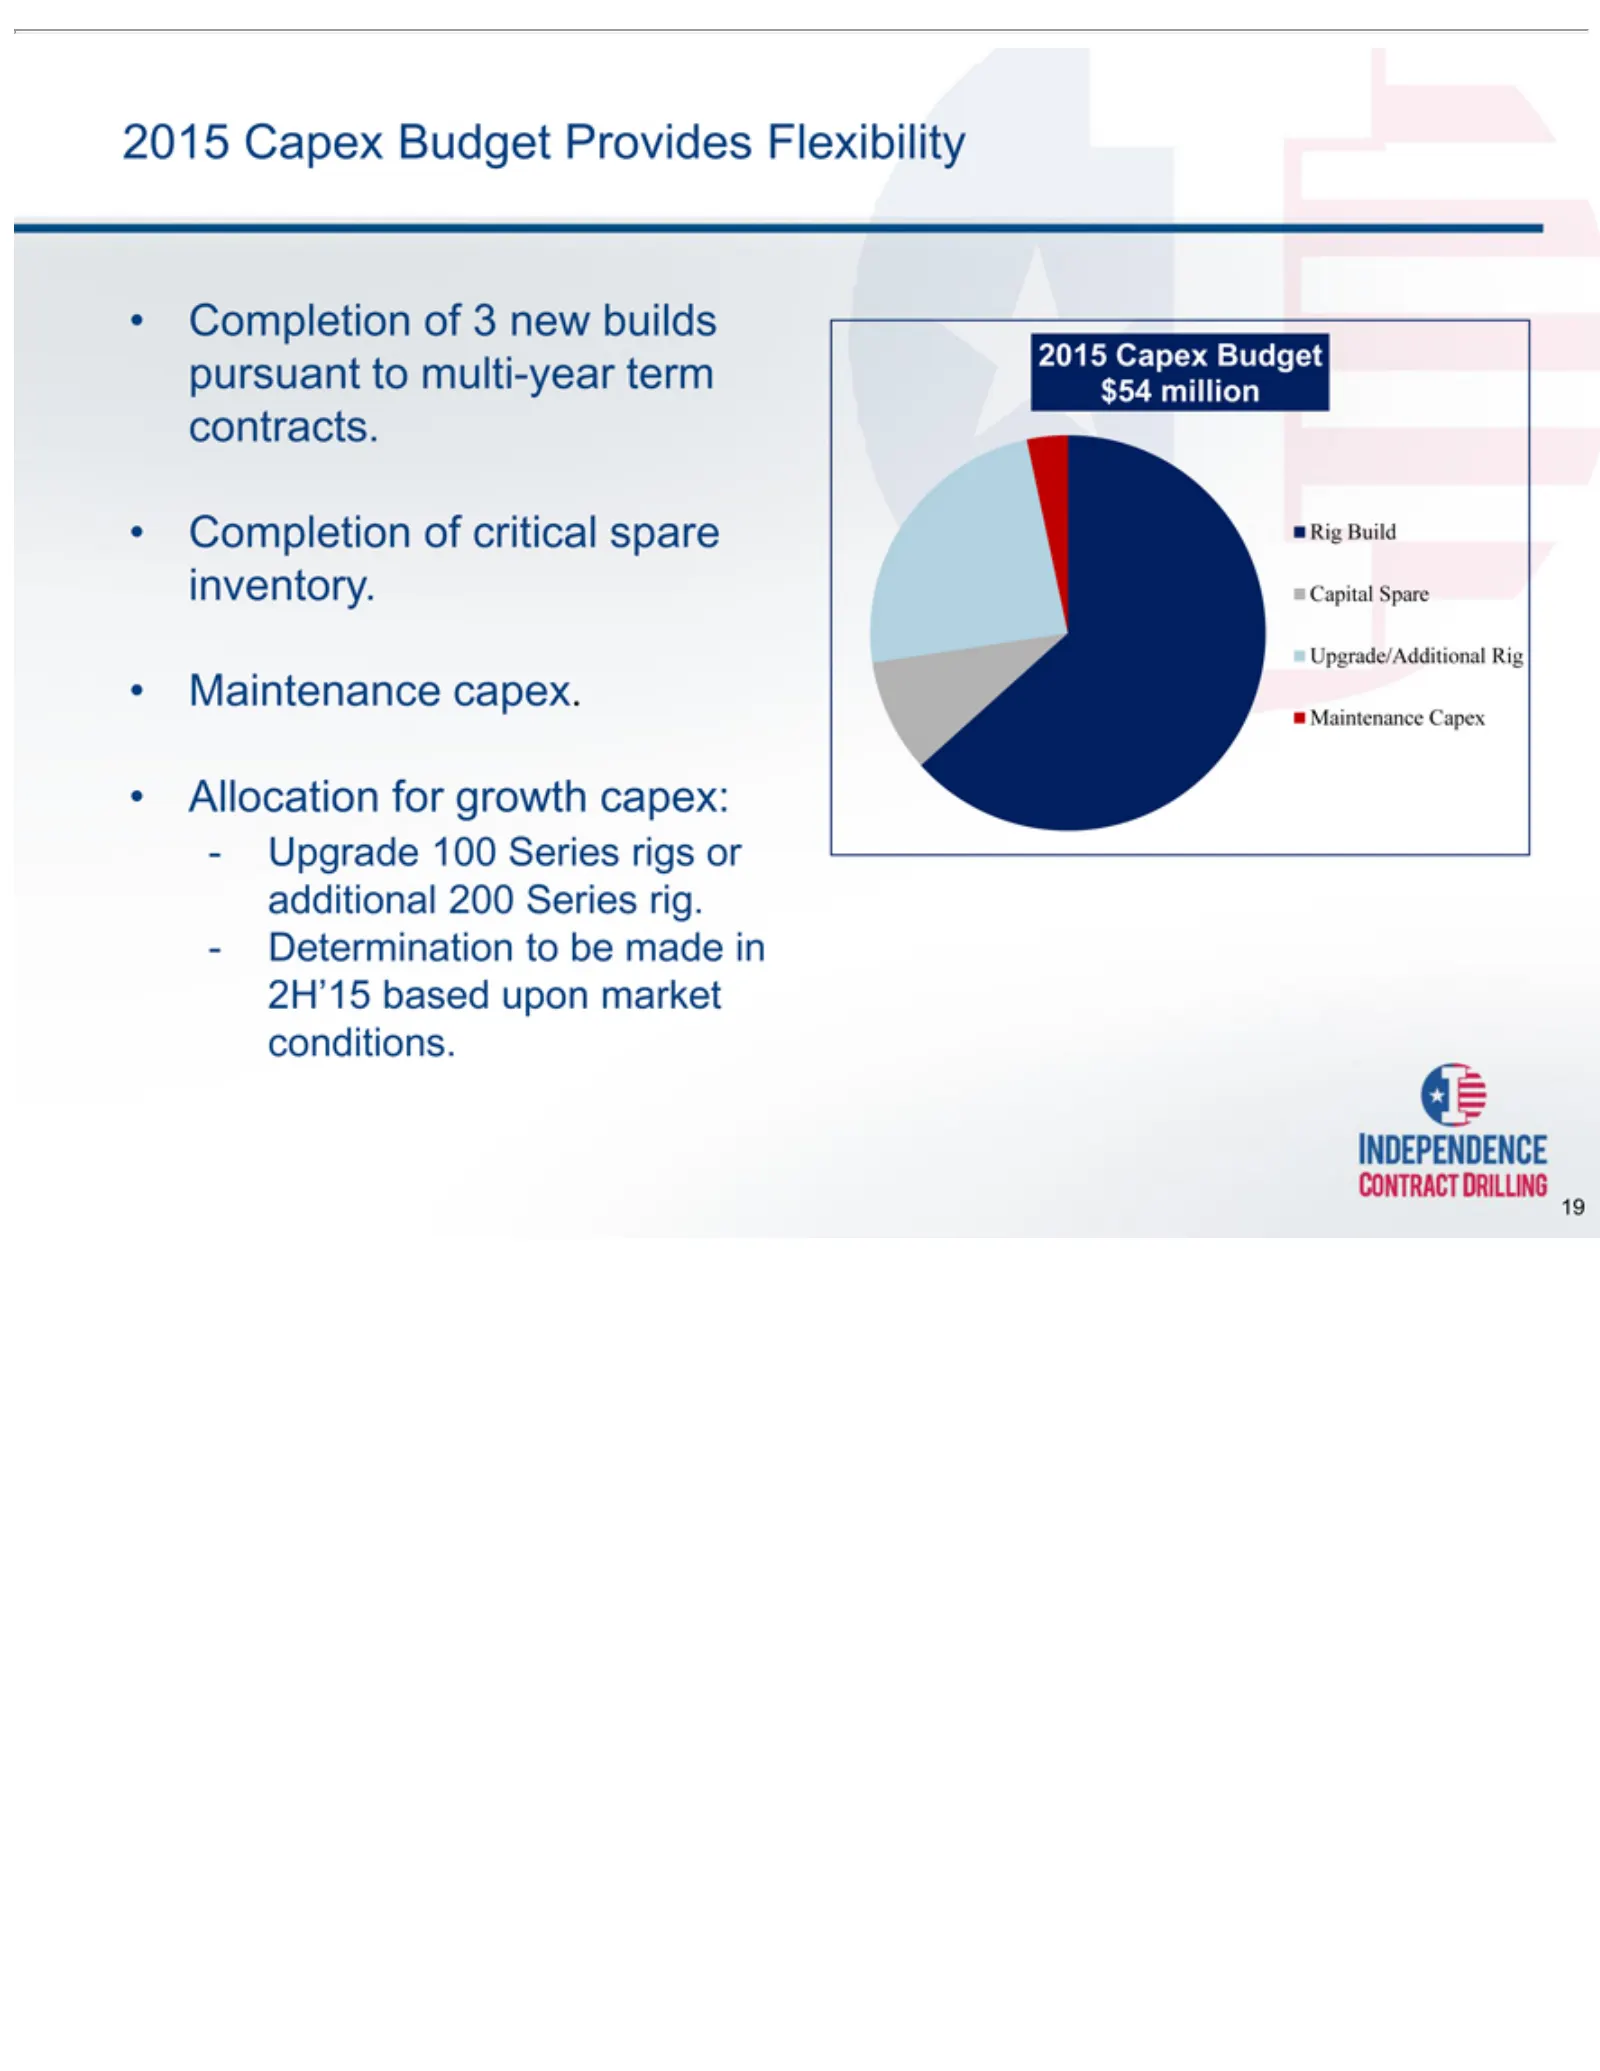
Slide 19: 2015 Capital Budget and Allocation
Completion Allocation Upgrade Determination 2H’15 2015 $54 Rig Capital Upgrade/Additional Maintenance 19 Build million Capex based Spare 100 for of Budget upon capex. Capex Series growth to 3 new critical bemarket rigs Provides made Rig builds capex: spare orconditions. inadditional pursuant invento
Slide 20: Appendices
APPENDICES INDEPENDENCE CONTRACT DRILLING oa
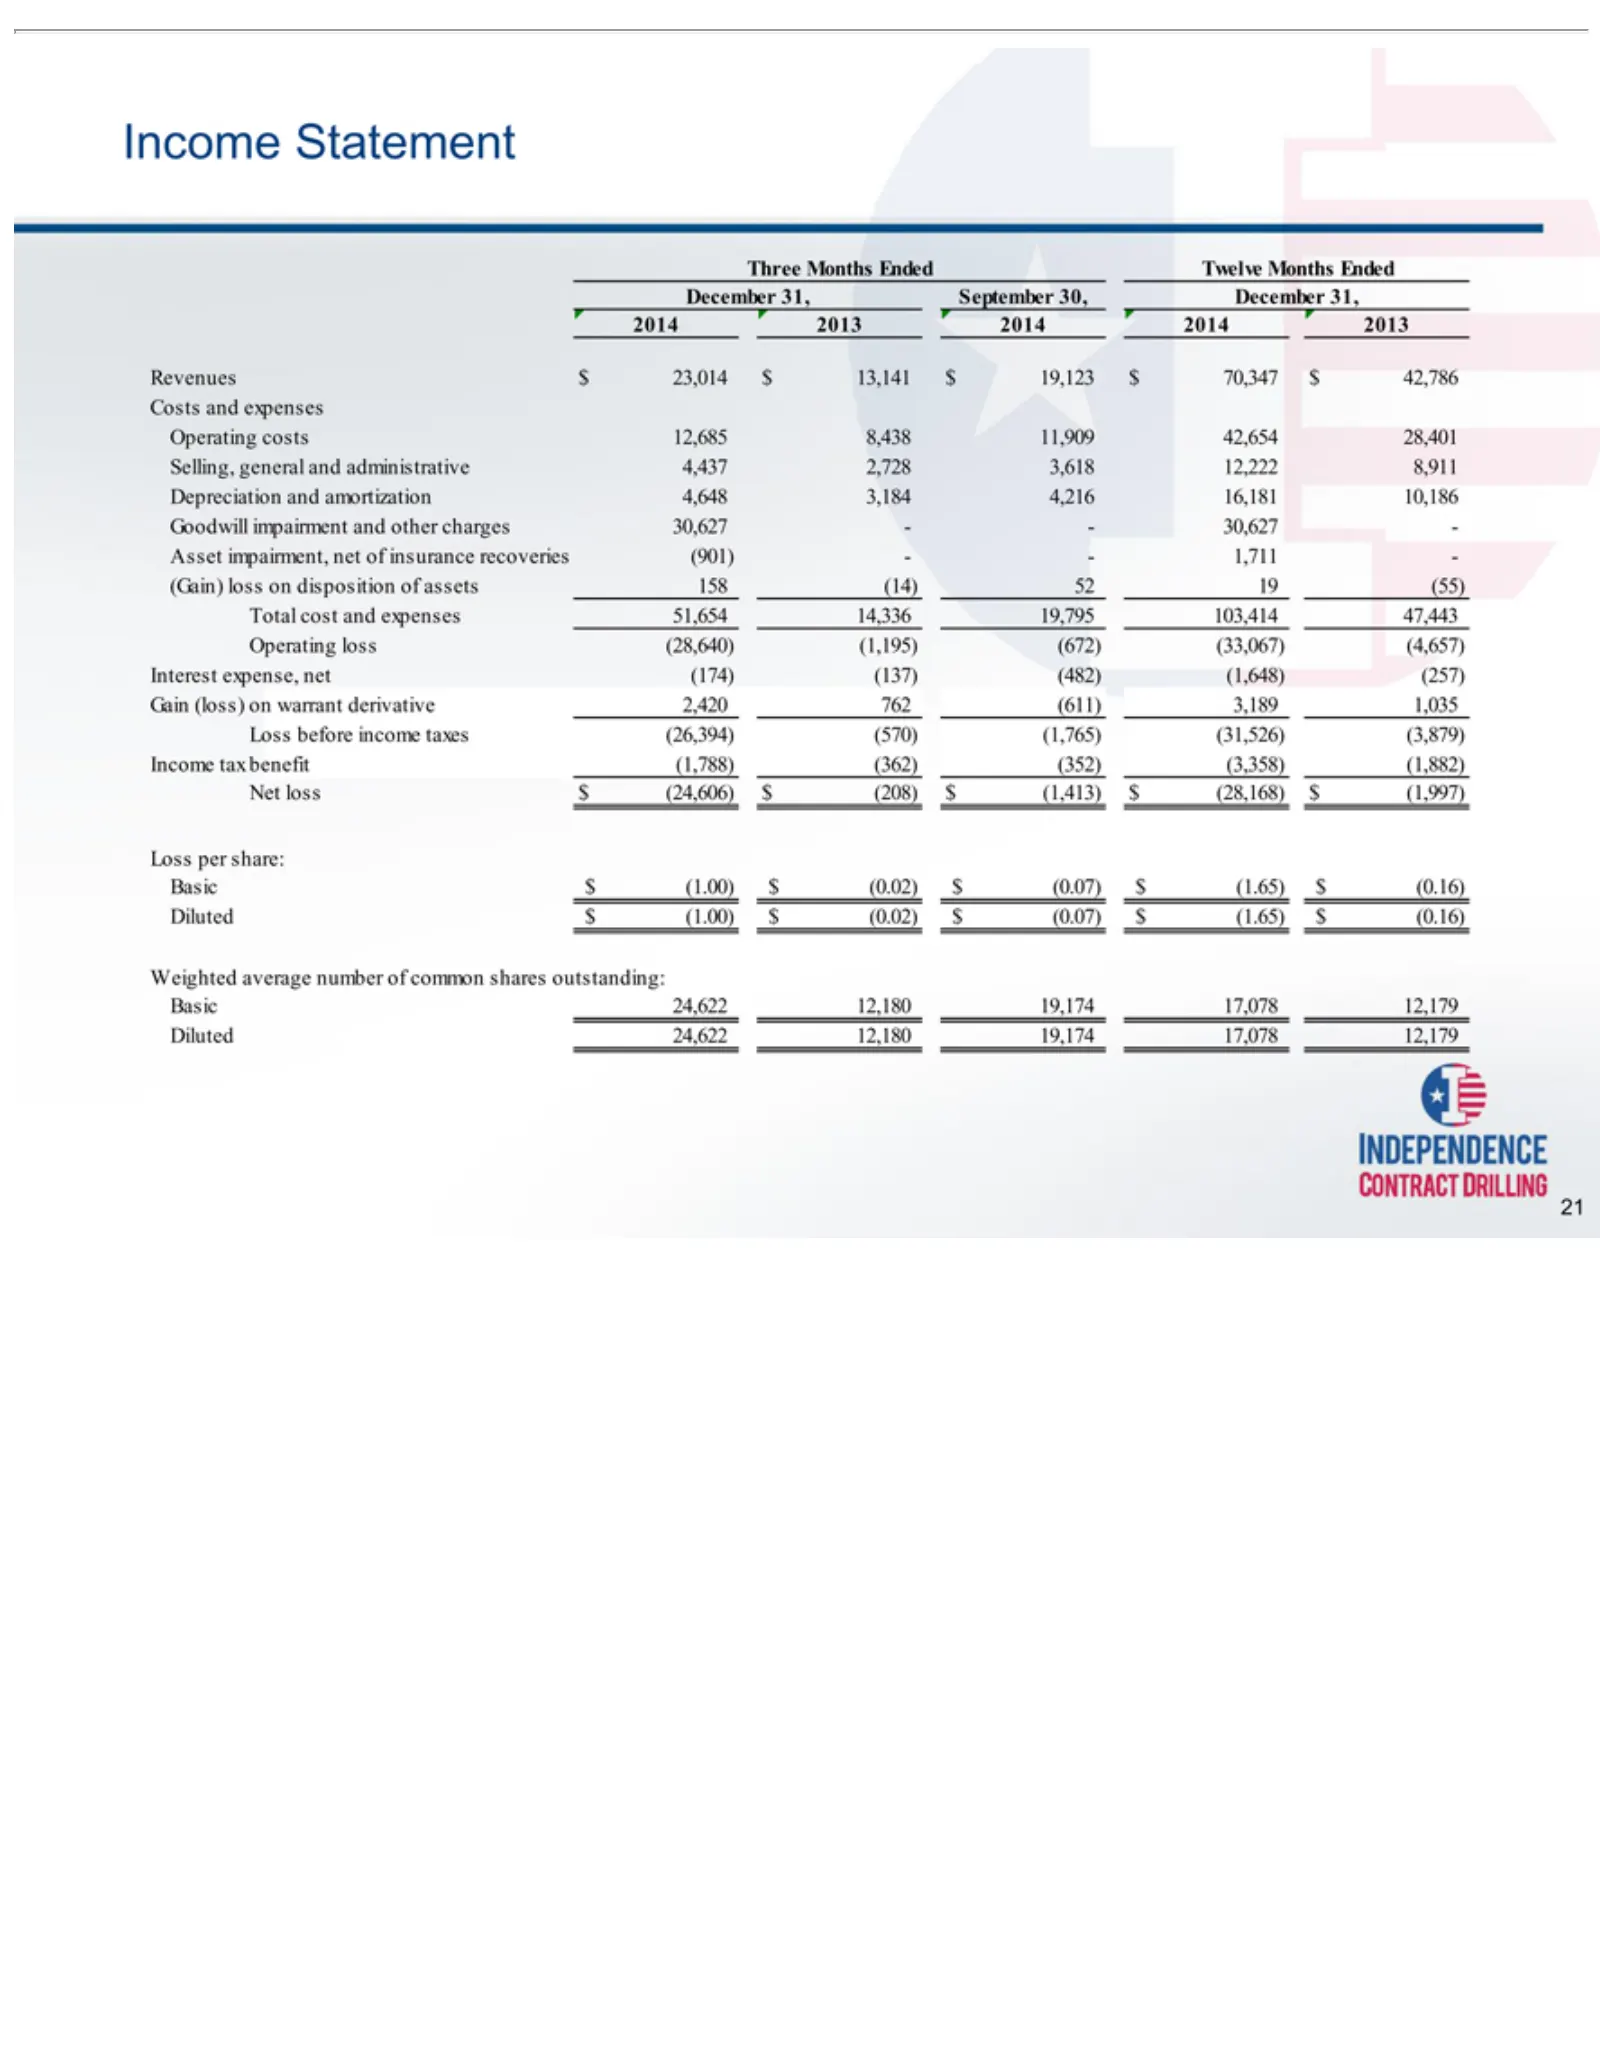
Slide 21: Statement of Operations
Three December 2014 Revenues Costs Selling, Depreciation Goodwill Asset (Gain) Total Operating Interest Gain Income Net Loss Weighted Basic Diluted 21 loss before per (loss) 2013 cost $(1.00) 24,622 impairment, and Months loss Statement expense, tax $(1.00) 24,622 general $(24,606) share: impairment
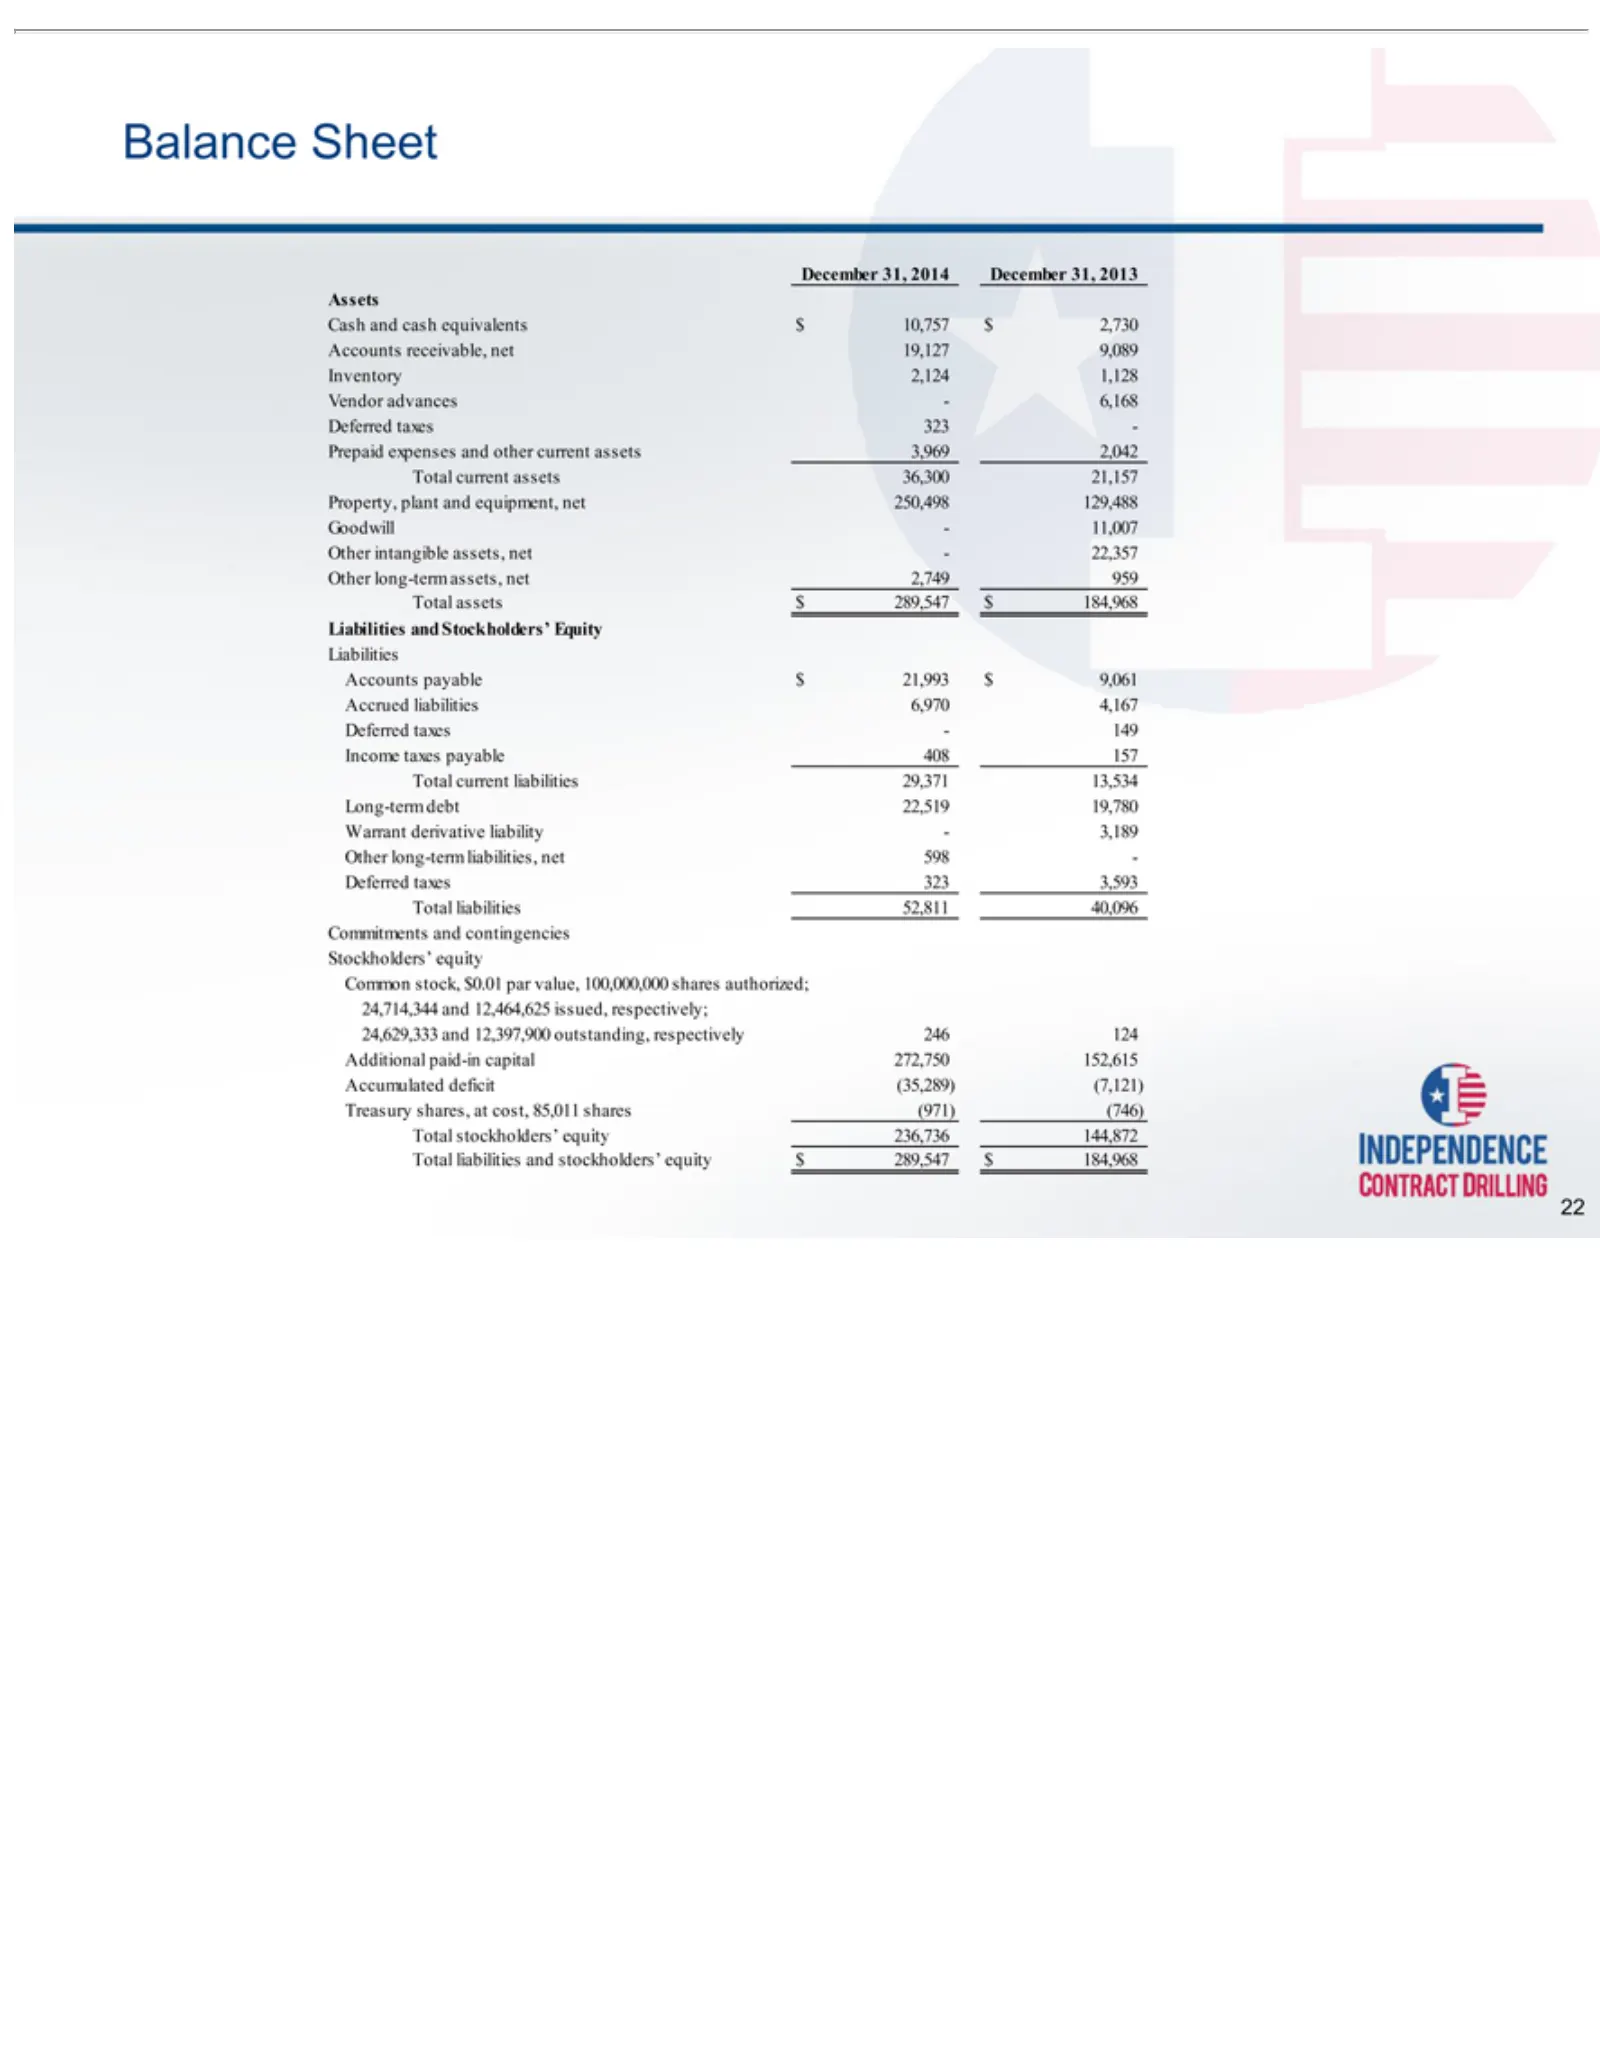
Slide 22: Balance Sheet
Balance December Cash Assets Inventory Vendor Prepaid Property, Goodwill—11,007 Accounts Liabilities Accrued Income Long-term Warrant Other Deferred Commitments Stockholders’ Common 24,714,344 24,629,333 Additional Accumulated Treasury Total 22 and assets current stockholders’ liabilities intangible
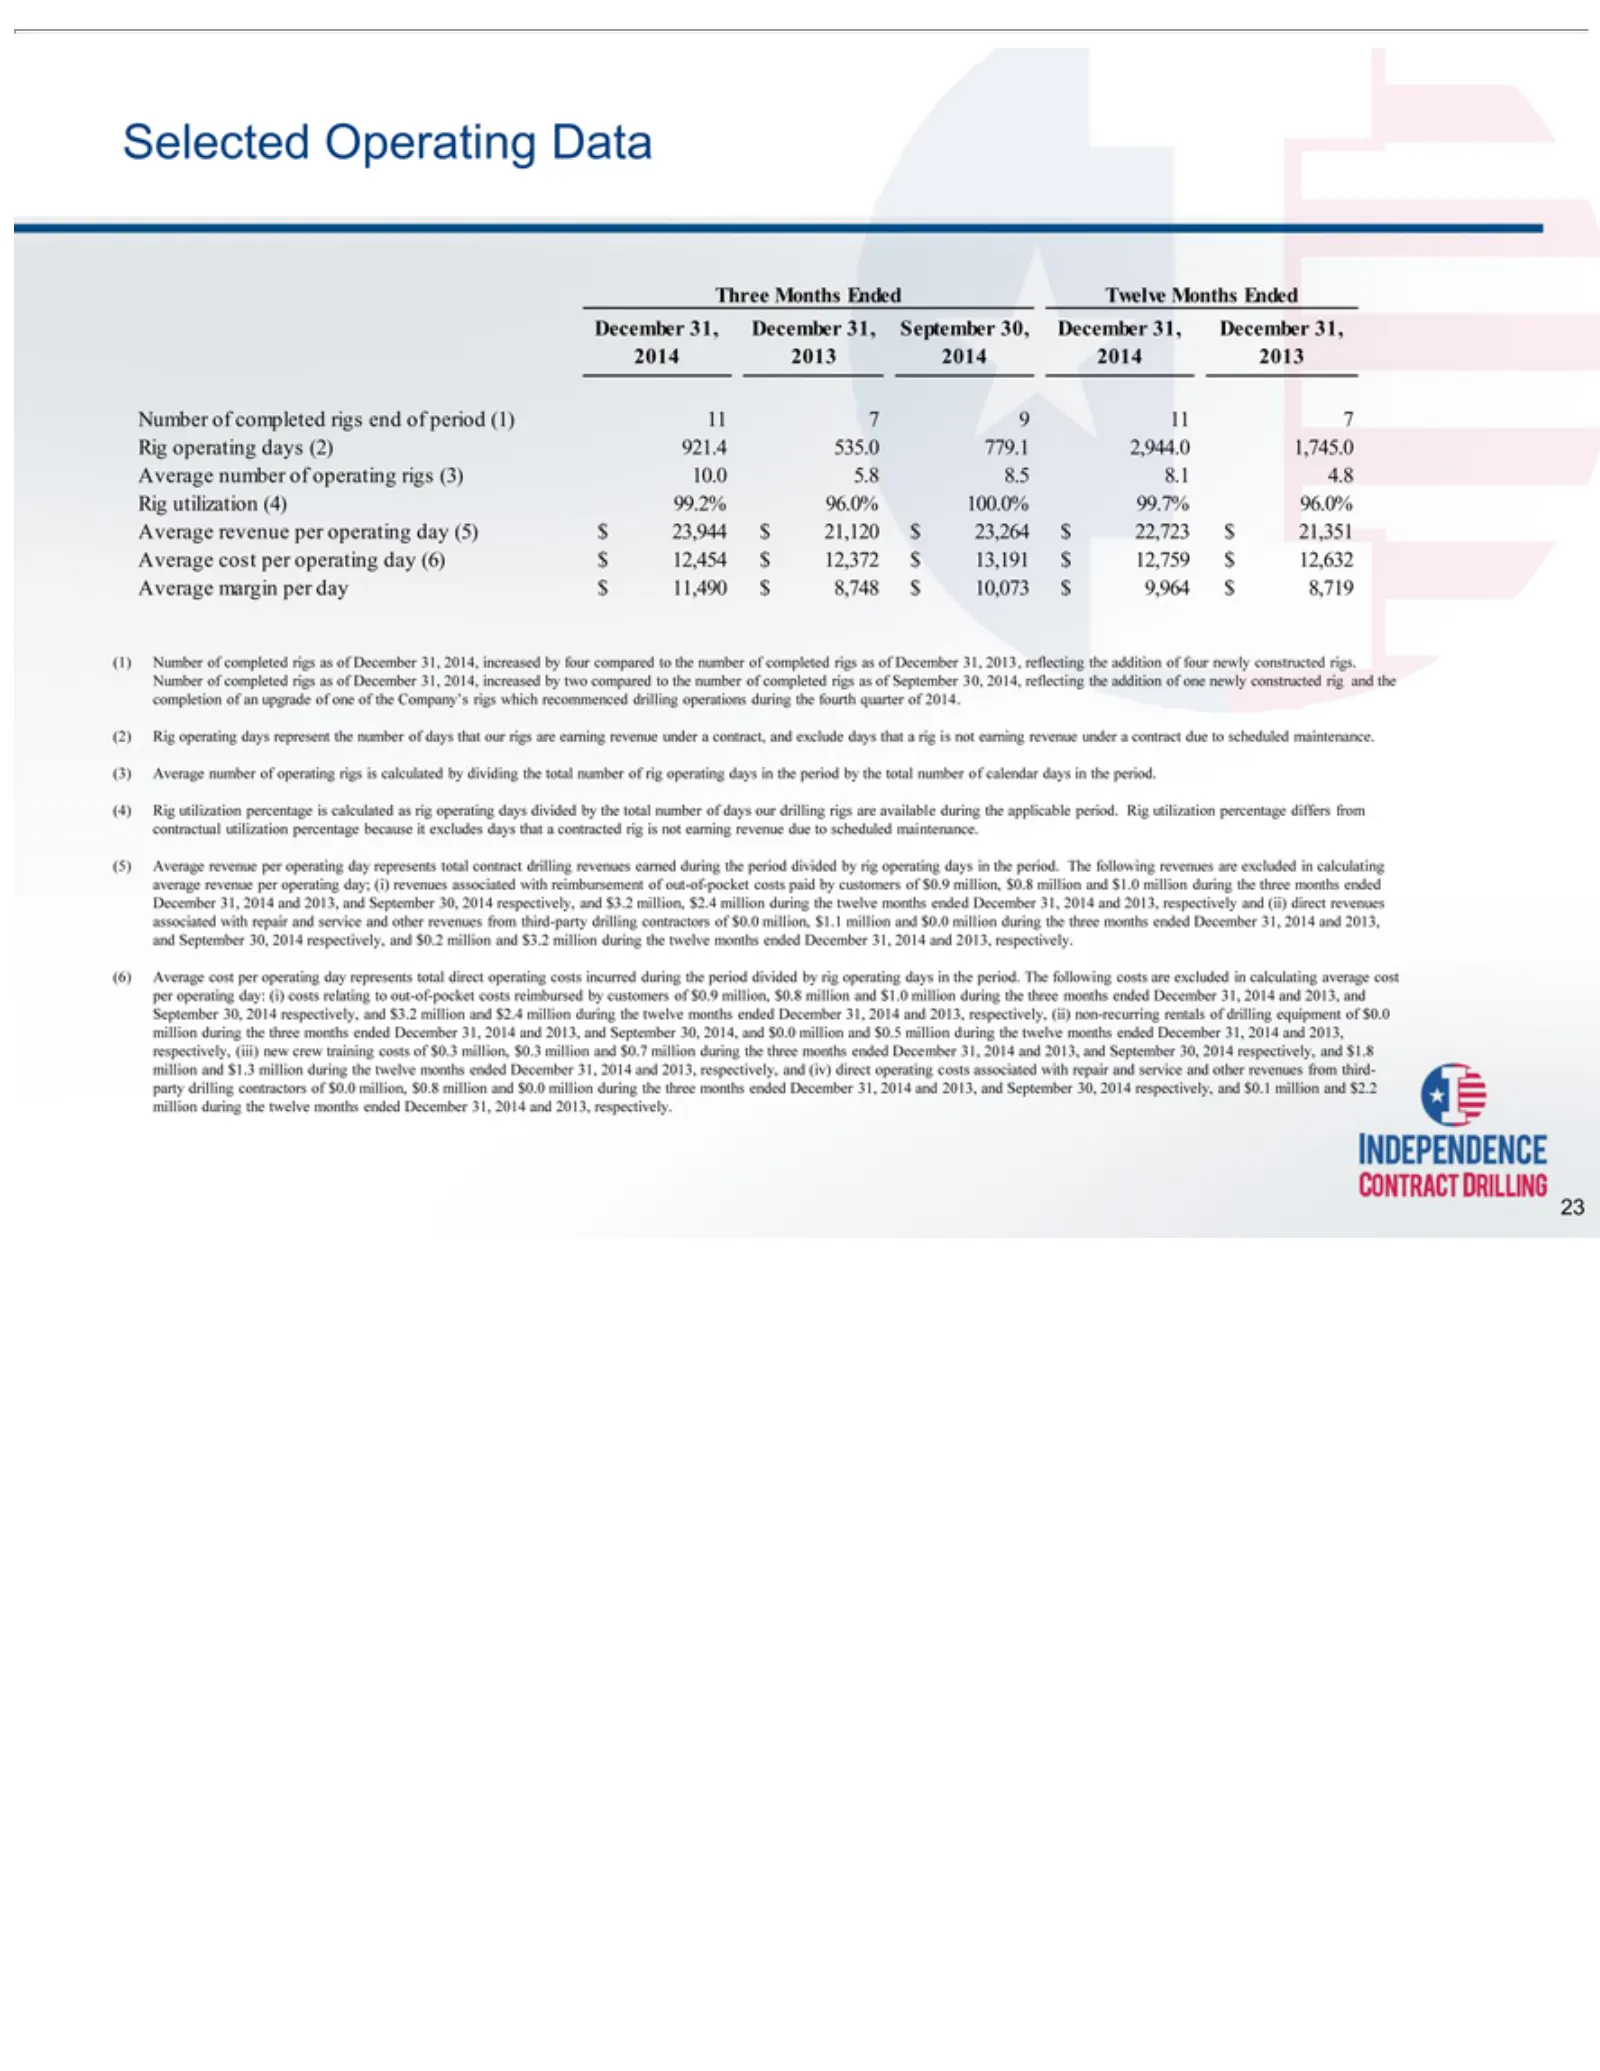
Slide 23: Selected Operating Data
Selected Three 2014 Number rigs Company’s Rig percentage per September from during Average day: and million 2013, December 23 operating $3.2 operating utilization as (i) third-party 2013 respectively, Months of the and costs of margin number revenue cost Operating million December twelve 31, 2014 30
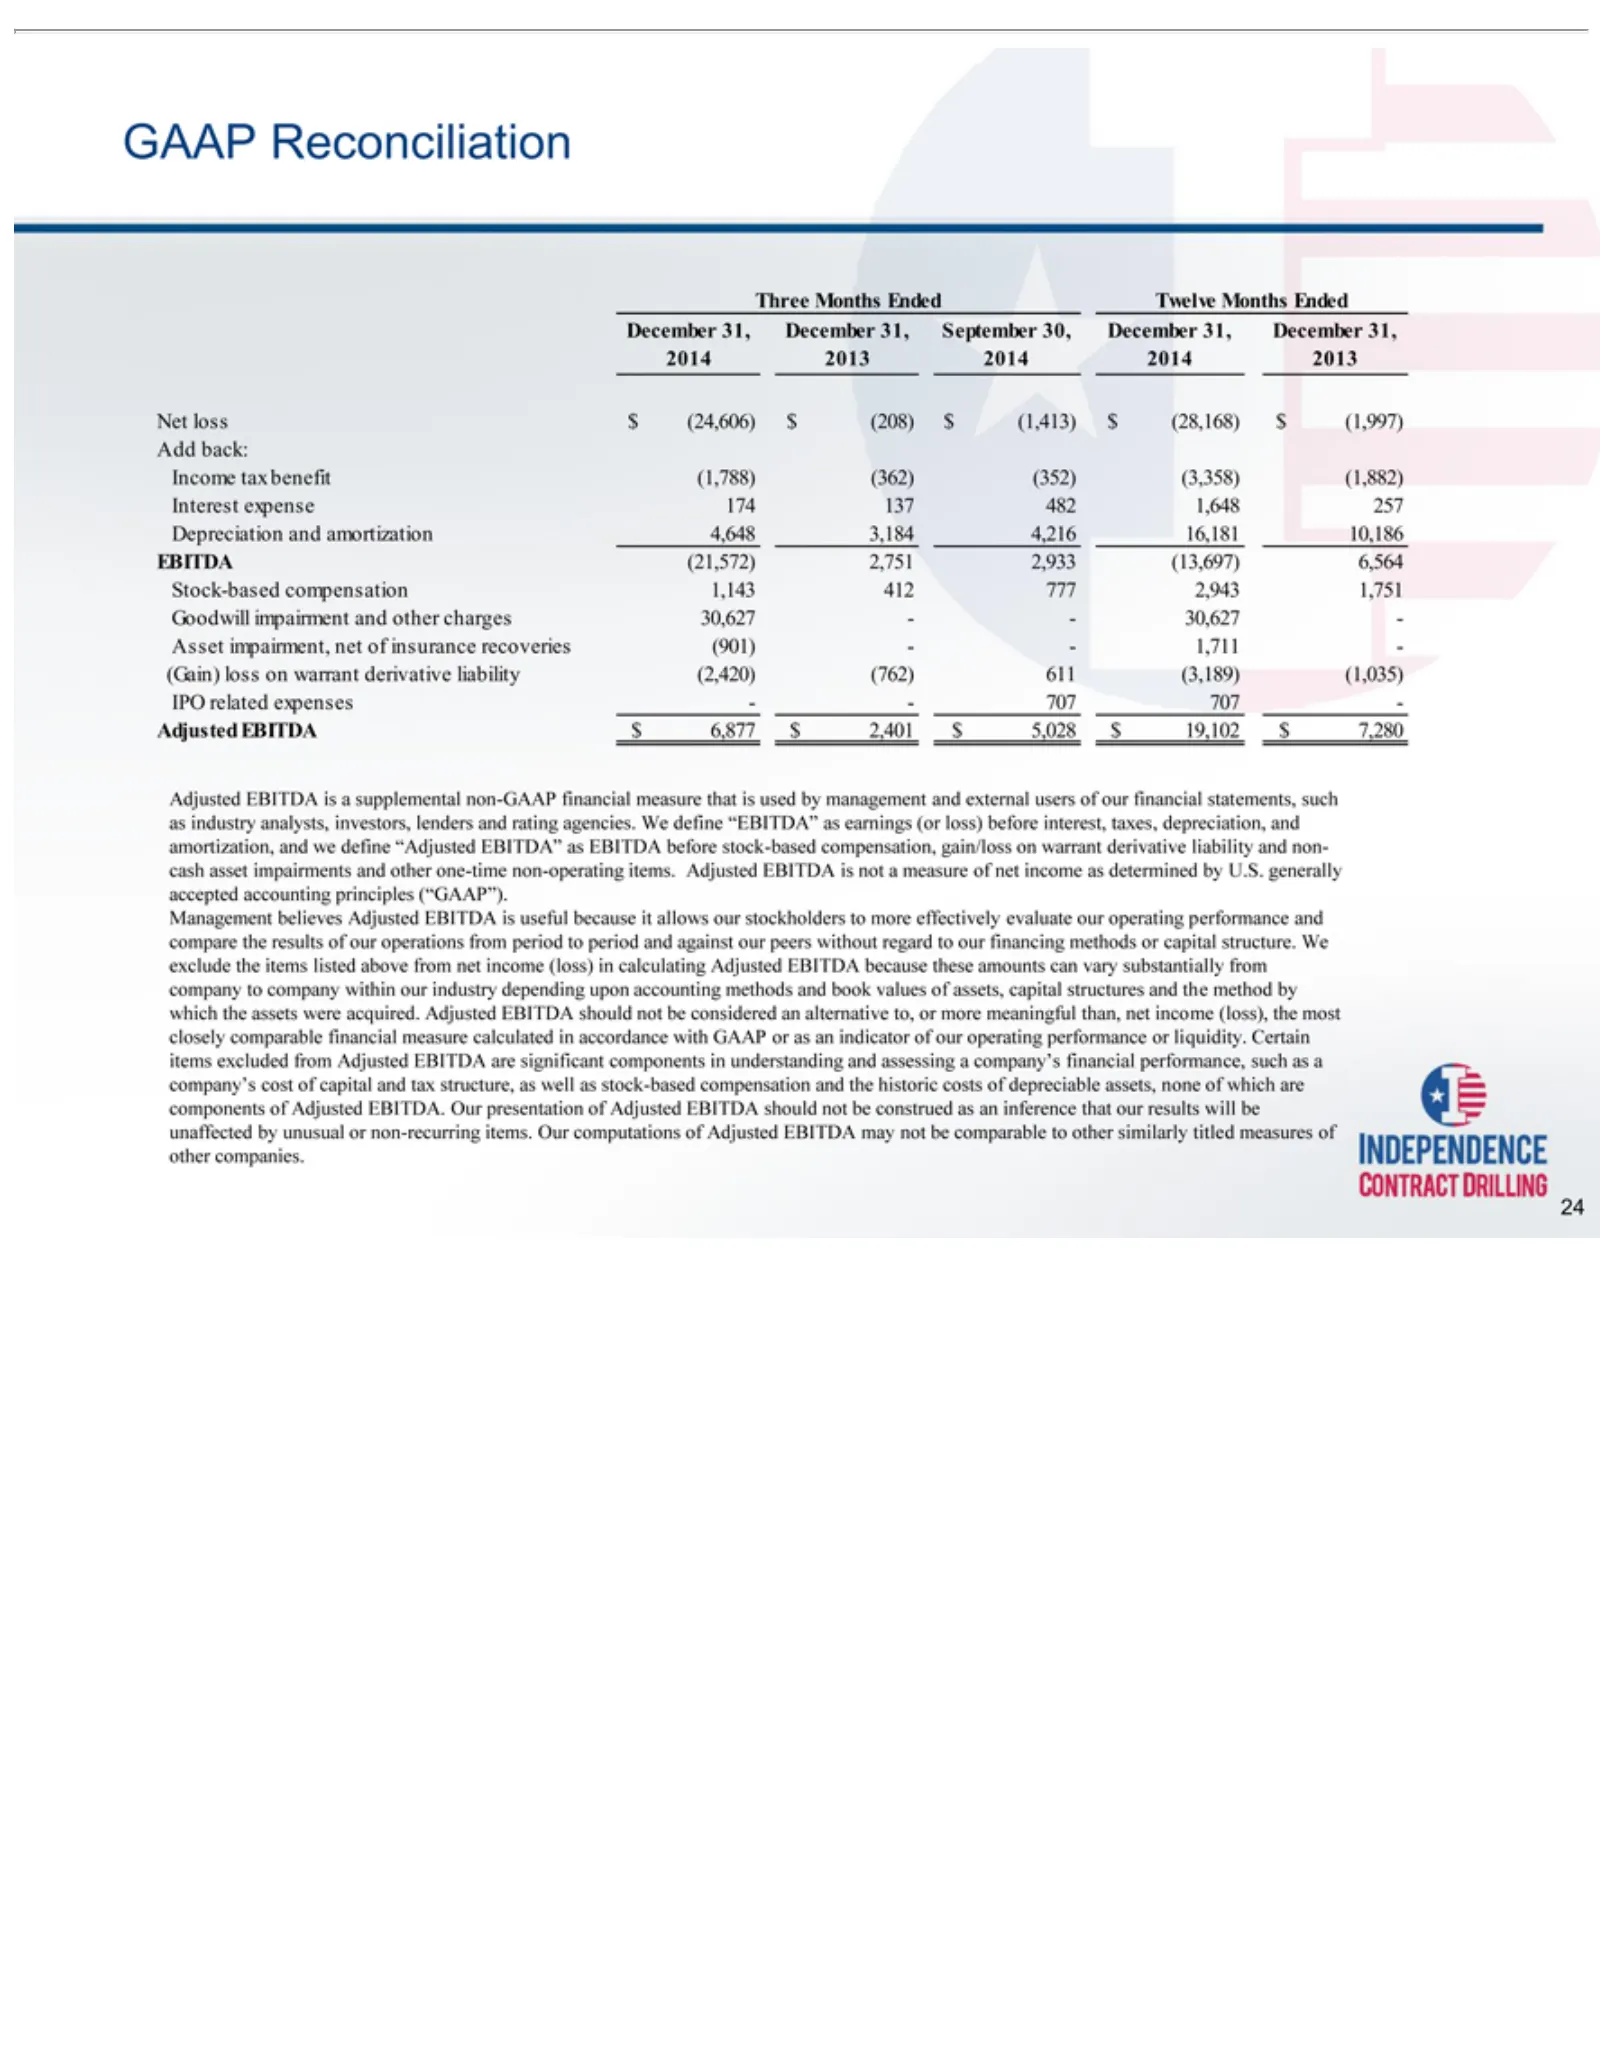
Slide 24: GAAP to Adjusted EBITDA Reconciliation
GAAP Three December 2014 Net Add Income Interest Depreciation EBITDA(21,572) Stock-based Goodwill Asset (Gain) IPO Adjusted “EBITDA” non-cash Management our company considered Certain based be 24 unaffected peers loss related back: 2013 impairment, compensation Months loss Reconciliation items tax e
Slide 25: [Graphic Appears Here]
[Graphic Appears Here]
Slide 26: [Graphic Appears Here]
[Graphic Appears Here]
Source: SEC EDGAR · 8-K filed Mar 11, 2015
More decks from Independence Contract Drilling Inc
 Presentation (December 2024)15 slides · Dec 3, 2024
 Emerging Growth Conference (November 2023)31 slides · Nov 2, 2023
 Sidoti MicroCap Conference (August 2023)32 slides · Aug 16, 2023
 Emerging Growth Conference (June 2023)38 slides · Jun 14, 2023
 Investor Presentation (March 2023)41 slides · Mar 2, 2023
 Investor Presentation (November 2022)47 slides · Nov 1, 2022